Cryptocurrency Posts
Crypto Briefing
The repricing of AI financing risks signals a shift towards more sustainable investment practices, potentially weeding out weaker market players.
The post DBS CEO Tan Su Shan says the market is repricing AI financing risks appeared first on Crypto Briefing.
TSMC's sustained profit growth underscores the transformative impact of AI on the semiconductor industry, driving global tech advancements.
The post TSMC expects record profit for sixth consecutive quarter amid AI boom appeared first on Crypto Briefing.
The shift to Sui could enhance DATA's scalability and integration, potentially setting a precedent for blockchain migrations in the industry.
The post Sui Foundation commits $30 million as DATA Network retires its own chain for Sui appeared first on Crypto Briefing.
Market confidence in Anthropic's AI leadership wanes, highlighting the critical need for robust oversight in AI deployment and testing.
The post Anthropic AI files false police tip, market confidence dips appeared first on Crypto Briefing.
Starknet's potential shift to a Layer 1 blockchain could redefine Ethereum's scaling model, impacting security dynamics and market strategies.
The post STRK surges 322% in four weeks, outpacing Bitcoin and Ether appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Bitcoin Life Insurer Meanwhile Raises $37.5M as Wealthy Families Look to Pass On Their BTC
Meanwhile, the first life insurer licensed to operate entirely in Bitcoin, has raised $37.5 million in new funding from its existing investors, the company announced.
Bain Capital Crypto led the round, with participation from Haun Ventures, Framework Ventures, Pantera Capital, Apollo, Northwestern Mutual Future Ventures and Morgan Creek Digital. The raise brings Meanwhile’s total funding to more than $180 million. Sam Altman is also among its backers.
The company said the round follows a surge in demand for its Bitcoin life insurance policies outside the US, particularly in Asia, Europe and the Middle East, amid broader macroeconomic instability.
“Wealthy families around the world already hold Bitcoin. What they haven’t had is a regulated way to pass it on,” Zac Townsend, Meanwhile’s co-founder and CEO, said in a statement.
“Brokers came to us because their clients kept asking. This round lets us keep up with them.”
In early 2026, Meanwhile launched BTC Life 1-Pay, a single-premium whole life policy aimed at high-net-worth clients outside the US. It is the company’s second product line, after BTC 10-Pay, which is designed for US taxpayers.
Under BTC Life 1-Pay, a client pays one premium in Bitcoin and receives a guaranteed death benefit in Bitcoin for life. The policy’s value grows in Bitcoin, and after the first year the owner can borrow up to 90% of it, with no repayment schedule and no margin calls.
Policies can be owned by individuals, trusts or companies, which the company says makes them suited to succession and estate planning.
Since launch, Meanwhile has signed 15 brokers serving wealthy families, including in Singapore, Hong Kong, the UAE and Switzerland. Partners include Lioner, an insurance, trust and family office group with offices in Hong Kong, Singapore and Zurich, and Apeiron Group, a marketplace for high-net-worth life insurance.
“We’re reaching a turning point where more high-net-worth clients are asking not just how to hold Bitcoin and digital assets, but how to plan around them and ultimately transfer that wealth to the next generation,” said Justin Man, CEO of Apeiron Group. Digital assets.
Meanwhile said its net long-term underwriting income has already passed last year’s total and is on track to more than double in 2026. The company did not disclose specific figures.
“Meanwhile owns every layer of a regulated life insurer and builds it like an AI-enabled startup,” said Stefan Cohen, partner at Bain Capital Crypto. “The growth this year proves the model, and we’re glad to back them again.”
The company’s operating entity, Meanwhile Insurance Bitcoin (Bermuda) Limited, holds the first Class IILT license granted by the Bermuda Monetary Authority. It received the license in July 2024 after two years in the regulator’s sandbox.
The insurer’s balance sheet, reserves and audited financial statements are all denominated in Bitcoin. Policyholder Bitcoin is held with regulated institutional custodians.
This post Bitcoin Life Insurer Meanwhile Raises $37.5M as Wealthy Families Look to Pass On Their BTC first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
‘We Know Where It Is’: Treasury Secretary Threatens To Freeze $1B of Iran’s Crypto
U.S. Treasury Secretary Scott Bessent has said the American authorities will soon seize $1 billion in crypto from Iran.
Speaking on Newsmax’s NPolicy Summit in Washington, D.C. on Thursday, Bessent added that economic sanctions on the Middle Eastern country were working.
Iran has been using bitcoin — and other cryptocurrencies — to skirt around U.S. sanctions. The U.S. in April started targeting crypto wallets linked to the Iranian regime, Bessent said at the time.
“What we have done has never been seen before,” Bessent said Thursday on Iranian sanctions.
“We’re probably going to seize $1 billion of crypto this week,” he continued. “We know where it is. We are isolating them. We did have a maximum pressure campaign, now we have an absolute isolation campaign and it’s working.”
Bessent didn’t reveal what cryptocurrencies the U.S. will seize or how.
It would be very hard — if not impossible — for the U.S. to freeze Iran’s bitcoin unless it keeps it on a centralized exchange.
Bitcoin, being censorship resistant, cannot be frozen. But many other cryptocurrencies, including Tether’s USDT, can. Bessent previously said the feds had seized Iran’s crypto in the form of the popular stablecoin.
Iran started a bitcoin-backed insurance service for its counties shipping companies earlier this year.
The Financial Times last month reported that the Middle Eastern country was using bitcoin to settle cross-border transactions through Iranian crypto exchanges after the central bank advised its countrymen to do anything necessary to help the economy.
U.S. President Donald Trump revived his “maximum pressure” campaign weeks after returning to office. A national security memorandum signed in February 2025 put the Treasury on a sustained campaign against Iran’s shadow banking, money laundering and sanctions-evasion networks.
This post ‘We Know Where It Is’: Treasury Secretary Threatens To Freeze $1B of Iran’s Crypto first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Here’s How Not To Screw up Your Bitcoin Privacy
Just one transaction can compromise years of discreet Bitcoin activity, Cake Wallet’s chief operating officer has warned.
Speaking on the Bitcoin Rails podcast this week, activist Seth for Privacy talked about different ways of protecting one’s privacy when using Bitcoin and said that focusing on privacy was a must for the West.
Bitcoin privacy is a hot topic again ever since the developers of private coin mixer Samourai Wallet went on trial last year and were subsequently imprisoned.
But just this week, the U.S. Department of Treasury scrapped two long-stalled crypto surveillance proposals, handing a major win to privacy advocates and the digital asset industry.
“If you ever spend your no-KYC coins with one of your KYC coins — which if you just let the wallet do its thing, it could do because it doesn’t know the difference — you immediately connect all of the non-KYC Bitcoin that you spend in that with your identity,” Seth said, referring to UTXO management, also called “coin control” by some wallets.
Bitcoin wallets don’t hold a single balance but a collection of separate unspent transaction outputs — UTXOs — each one a discrete “coin” from a specific past transaction.
When you send a payment larger than any one UTXO, the wallet picks several and combines them as inputs to the same transaction — an easy mistake to make, Seth highlighted.
Seth added that unlike in the global South, where people have experienced more oppressive states, citizens in the West will need to “feel pain” in order to realize how important privacy is.
Still, he added that attitudes were changing and people were getting more serious about protecting their privacy.
“It has been shifting, in the last five or six years a lot of people — even in the West — are starting to think [privacy] really matters, we really need to think about this seriously now,” he said.
Cake Wallet is a privacy-oriented, self-custody, open-source wallet. The wallet earlier this year integrated Bitcoin’s Lightning Network into its platform.
Using the second layer solution is not only faster and cheaper, it also offers more privacy than Bitcoin’s main chain.
While Cake Wallet supports other cryptocurrencies, including privacy coin Monero, Seth for Privacy added that he’d love it if the digital coin didn’t exist.
“If Bitcoin’s privacy got good enough that you could use it and have at least almost as good privacy as Monero without massive hoops to jump through, and Monero ceased to exist, that’s fine,” he said.
“I would much rather the thing that more people use has better privacy than a more niche tool that has perfect privacy, and that’s something that less people are using because it’s less well known.”
This post Here’s How Not To Screw up Your Bitcoin Privacy first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Bitcoin ETFs Shed $729M in Two Days as Investors Reverse Course
U.S. investors this week reversed course, cashing out $729 million from spot bitcoin exchange-traded funds — putting downward pressure on the leading cryptocurrency’s price.
Funds managed by BlackRock, Fidelity, Morgan Stanley, and ARK 21-Shares all experienced significant outflows on Wednesday and Thursday, according to data from Farside Investors.
Investors had started the week by selling close to $90 million in shares but then bought nearly $119 million on Tuesday.
The rest of the week has seen outflows following news that the Federal Reserve may raise interest rates. Other negative news includes the price of Brent crude jumping following renewed attacks on tankers in the Strait of Hormuz.
U.S. President Trump also hinted that talks with Iran weren’t bearing fruit — a sign war in the Middle East could continue.
Bitcoin’s price recently stood at a little over $82,688, down more than 3% over a seven-day period. The leading cryptocurrency has rebounded slightly over the past day, jumping nearly 2% over 24 hours.
Still, the coin was fast closing in on $90,000 last week. Investors are expecting decent returns as the month dubbed “Uptober” has historically delivered for bitcoin speculators.
The price of bitcoin has been particularly sensitive to geopolitical headwinds this year — especially since the U.S. and Israel attacked Iran, leading to an oil price surge.
Oil prices going up tend to lead investors to bet on the Federal Reserve raising interest rates. And with higher interest rates comes less liquidity for the price of bitcoin to do well.
Still, that’s not always the case: the Fed last month talked tough on getting inflation down and raised interest rates by a quarter of a percentage point and bitcoin’s price rose in the following days.
Bitcoin’s price is 34% below the all-time high of $126,080 it touched in October. It has spent most of 2026 in a bear market but analysts are now increasingly pointing to evidence of a bull market following a rally in August and September.
This post Bitcoin ETFs Shed $729M in Two Days as Investors Reverse Course first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Ledger Warns Buyers Not to Set Up Wallets From Reseller After Users Report Losses
Hardware wallet manufacturer Ledger has said that it is investigating loss of user funds after customers in South East Asia reported issues with devices bought from a reseller.
The Paris-based company on Friday advised customers who’d bought from vendor CryptoBilis within the last 90 days to not set up their devices.
Ledger did not reveal how much money users had lost but one blockchain investigator, Specter, wrote on X that he’d traced theft addresses following social media posts and that over $86 million had been lost.
The issue comes following a number of data breaches this year in the crypto world and a huge hack of popular Coldcard hardware wallet devices in July.
“Ledger is investigating reports of loss of funds from users in South East Asia who purchased products from a reseller named CryptoBilis,” Ledger said via its support X account.
Ledger added that it had asked CryptoBilis to pause all sales and shipments of Ledger devices.
“If you have set up your Ledger device, consider moving assets to a new Ledger signer (with new seed). We will continue to inform customers of updates as the investigation progresses,” the company said.
In a statement to Bitcoin Magazine, Ledger said that based on the information to date, the incident is isolated specifically to this reseller in this specific market.
“No reports were made of products purchased directly from Ledger, and Ledger’s infrastructure, systems and services were not compromised,” the company added.
CryptoBilis is a Kuala Lumpur, Malaysia-based hardware wallet vendor, according to its website. The company did not immediately respond to questions from Bitcoin Magazine.
The crypto industry is still reeling after hackers in July were able to steal close to $120 million in bitcoin from Coldcard users.
The products, made by Canadian company Coinkite, had a firmware bug which led to faulty seed generation, allowing hackers to essentially guess investor seedphrases.
Galaxy Research said in the months following the attack various attackers were able to exploit the bug independently.
In a separate incident, hardware wallet manufacturer Trezor last month reported that close to 81,000 customers had their details leaked after its third-party fulfillment partner had data stolen.
Criminals have been targeting data this year, with scammers getting hold of customer information via crypto wallet Ledger’s payment processor Global-e to send phishing emails.
This post Ledger Warns Buyers Not to Set Up Wallets From Reseller After Users Report Losses first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
CryptoSlate
Aave’s proposed USDG rollover would let borrowers carry their stablecoin debt into a new fixed-yield USDG position, but the replacement collateral currently yields less than three quoted borrowing rates. That leaves leverage and separately administered rewards central to whether extending the trade makes financial sense.
The proposal concerns Pendle principal tokens, or PTs, on the X Layer network: holders of the token maturing Oct. 29 would move into a replacement maturing Feb. 25, 2027. In its Oct. 8 assessment, risk provider LlamaRisk said the February token’s on-chain yield alone fell short of USDT0, USDC and USDG borrowing costs. GHO was the cheaper exception in that assessment’s Oct. 7 snapshot.
TokenLogic’s proposal would enable a flash-loan transaction that temporarily repays debt, replaces the old PT collateral, borrows again and repays the flash loan. OKX would develop that integration separately. The Aave listing and separate OKX integration would both need to be implemented.
An Oct. 10 refresh preserves the gap. Pendle’s market API reported a February PT implied annual percentage yield of about 2.98%, with data updated at 21:09 UTC. Aave’s X Layer market display, retrieved at 21:11 UTC, showed variable borrowing APYs of 4.12% for USDT0, 5.87% for USDC and 3.75% for USDG.
The readings show why transaction convenience and investment profitability are separate questions: a rollover can preserve access to borrowing while resetting the collateral’s yield at the new purchase price.
A Pendle PT is a discounted claim on an accounting asset at maturity. For this USDG market, LlamaRisk describes redemption as one PT for one USDG. The purchase discount determines the return from holding to maturity, while ordinary PT holders give up the underlying variable yield and points to the corresponding yield token, or YT, under Pendle’s mechanics.
Borrowing to buy more PT increases exposure to that discount. The strategy earns positive incremental carry when the acquired PT return exceeds its financing cost. When borrowing costs exceed the asset’s return, each additional borrowed increment reduces the position’s return before rewards and costs.
That relationship looked different in LlamaRisk’s August review. Using Aug. 18 data for the October maturity, it quoted a 3.19% PT yield against borrowing rates of 0.45% for GHO, 1.37% for USDT0 and 2.69% for USDG. The review described positive carry.
The Oct. 7 snapshot for the February replacement quoted a 2.79% PT yield against 4.48% USDT0, 4.10% USDC and 3.67% USDG borrowing rates. GHO, at 0.93%, still borrowed below the PT yield. The comparisons span different maturities; existing October PT holders retain their original purchase yield.
There is also a distinction between a quoted funding comparison and an allowed borrowing route. LlamaRisk’s recommended new Aave borrowing category, E-Mode 9, lists USDT0, GHO and USDC as borrowable assets. USDG is absent from that proposed list, so its rate provides a cost comparison rather than proof of eligibility for the February configuration.
How leverage and rewards change returns
The 2.98% annualized PT yield corresponds to about 1.11% gross appreciation over the roughly 137.1 days from the Oct. 10 snapshot to Feb. 25. The annual figure should not be mistaken for the cash return available over that shorter holding period.
A standalone PT-and-debt illustration shows how leverage changes the outcome. It holds the displayed borrowing APYs constant through maturity, excludes rewards, transaction costs and retained YT, and assumes no rebalancing. Two times exposure means assets equal twice starting equity and debt equals that equity; five times exposure means debt equals four times starting equity.
Using the APY convention in Pendle’s calculation documentation, the illustration converts each annualized rate into a return over the same holding period. It then subtracts the debt’s interest cost from the PT position’s appreciation.
| Funding comparison | Borrow APY, Oct. 10 | Return on equity at 2x exposure | Return on equity at 5x exposure |
|---|---|---|---|
| USDT0 | 4.12% | +0.69% | -0.56% |
| USDC | 5.87% | +0.05% | -3.11% |
| USDG, comparator only | 3.75% | +0.83% | -0.02% |
The table shows illustrative total returns through Feb. 25. Without borrowing, the same PT position earns about 1.11% before costs. At two times exposure, the return on the investor’s own capital can still cover the negative spread on the borrowed portion. At five times exposure, financing consumes more than the gross PT gain in all three examples.
Actual borrowing rates can change throughout the holding period. Actual purchase prices also determine effective PT yield, and the Oct. 8 assessment listed 0.05% taker fees for the February pool’s AMM and orderbook. Slippage, network fees and any applicable flash-loan charge further affect the transaction. A thin positive result can disappear after execution costs.
LlamaRisk attributes participating loop users’ profitability to external OKX Exchange Earn incentives. It also says an end to those incentives would likely encourage users to unwind.
The public OKX Wallet bonus announcement describes a separate program. It names USDG Loop or PT-USDG-29OCT2026 supplied to Aave through the designated Wallet campaign page, with bonus APY capped at 2%. Transactions through Aave or other third-party websites do not qualify.
The Wallet campaign ends Oct. 28 at 15:00 UTC+8, or 07:00 UTC, with rewards claimable afterward. Distribution depends on eligible participants’ deposit shares, and the actual payout may be below the announced 490,000 USDT reward pool.
Those terms cover the October token. February reward eligibility and the separate Exchange Earn expiry require their own terms.
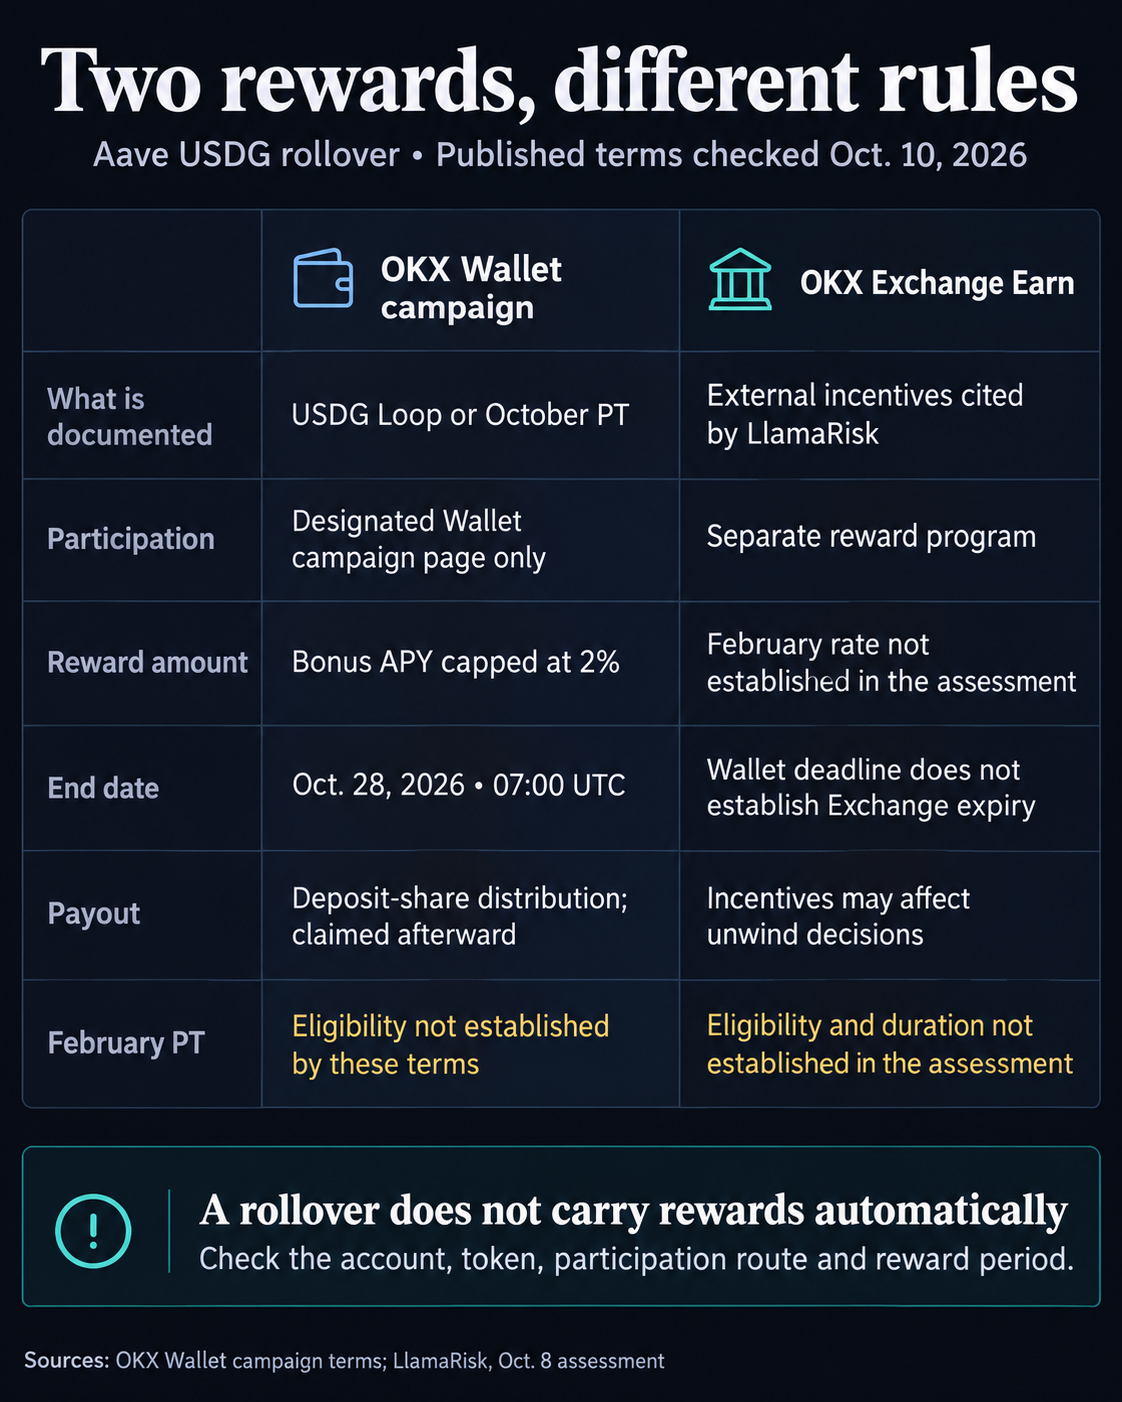
The standalone illustration also differs from an actual OKX Wallet product. Its Loop FAQ says PT Loop can leave YT separately in the user’s wallet, outside the displayed Loop position value. Those retained tokens, product rewards and execution costs must be included when assessing the wallet’s total return.
OKX Wallet’s FAQ also says a PT position does not automatically redeem, unwind, renew or roll over at maturity. PT promotional rewards stop then under those Wallet rules, and a new-term subscription depends on product availability.
Rollover limits and the October exit
LlamaRisk’s Oct. 8 recommendation also differs from the initial plan. It calls for new E-Mode 9, with a 91.48% loan-to-value limit, a 93.48% liquidation threshold and a 35 million PT supply cap. The existing E-Mode 7 threshold cited in the assessment is 94.66%. A position carried into the replacement configuration would therefore need to fit its recommended borrowing and liquidation limits if those parameters are implemented.
LlamaRisk reported 66.03 million October PT units supplied as collateral in its Oct. 8 review. The Aave display retrieved Oct. 10 showed 59.79 million October PT units supplied and $61.12 million of borrowing across the entire X Layer market. The borrowing figure covers the entire market, while the collateral figures cover October PT only.
A Sept. 9 borrower review reported 55.1 million USDT0 debt, representing 98.7% of the reviewed PT cohort’s debt, and a median health factor of 1.03 among top suppliers. That September snapshot shows how heavily the reviewed cohort relied on USDT0 and how little room its top suppliers had before liquidation.
The February pool had approximately $1.42 million of reported liquidity. A migration’s executable size depends on available quotes and acceptable slippage.
The proposed October PT loan-to-value reduction to zero after maturity concerns borrowing headroom. Under Aave’s liquidation mechanics, eligibility depends on health factor falling below one, with collateral value, debt and liquidation thresholds determining that factor.
The choice at the October maturity is consequently an economic one as well as an operational one. A borrower can preserve debt exposure through a supported migration only if the configuration and integration are available. Whether extending the position pays depends on the new entry price, actual funding costs, leverage and reward eligibility, rather than the ability to move collateral in one transaction.
The post Aave’s USDG rollover plan has a yield below most quoted borrowing rates appeared first on CryptoSlate.
Starknet's STRK token more than doubled over seven days while developers considered leaving Ethereum to build an independent Layer 1 blockchain.
A CoinGlass snapshot checked at 20:28 UTC on Oct. 11 showed STRK at $0.1190, up 17.7% over 24 hours and 116.7% over seven days.
On Oct. 8, Starknet said it was actively considering becoming an L1, with 2027 as its target for what it described as the first fully quantum-resistant network. The proposed move would replace its dependence on Ethereum's underlying security infrastructure.
Starknet considers Ethereum independence to accelerate quantum protection
StarkWare CEO Eli Ben-Sasson has framed the potential transition as a response to growing concerns that advances in quantum computing and artificial intelligence could undermine existing blockchain cryptography.
In an X post, Ben-Sasson argued that the quantum threat could arrive sooner than expected and that increasingly powerful AI added urgency to preparations. The debate follows recent AI-assisted advances in mathematical research.
His argument concerns preparing for a cryptographically relevant quantum computer; it does not demonstrate that AI can already break deployed blockchain signatures.
Starknet's ZK-STARK proof system relies on hash-based cryptographic assumptions rather than the elliptic-curve mechanisms vulnerable to sufficiently powerful quantum computers.
The network also supports programmable accounts, letting users adopt alternative signature schemes without a network-wide upgrade.
In June, StarkWare published a three-phase roadmap covering vulnerable hashing mechanisms, legacy smart contracts and dependencies inherited from Ethereum. The first two phases are within Starknet's control; the third depends on Ethereum's migration.
Starknet currently operates as an Ethereum Layer 2, processing transactions separately while relying on Ethereum for settlement and data availability. Its bridge infrastructure and Ethereum-based data commitments therefore remain exposed to cryptographic dependencies outside Starknet's direct control.
In September, the Ethereum Foundation's Protocol cluster set a December 2029 target for quantum resistance across Ethereum's execution, consensus and data layers.
An independent Starknet would need its own security and settlement model to replace the protections Ethereum provides. The Oct. 8 announcement expresses consideration and a quantum-resistance target, rather than an approved migration timetable.
STRK futures turnover reaches $3.5 billion in 24 hours
In the same Oct. 11 snapshot, CoinGlass data showed approximately $258.5 million in futures open interest and $3.5 billion in 24-hour futures volume. It also reported about $14.8 million in total futures liquidations over 24 hours.
CoinMarketCap data checked on Oct. 11 showed approximately $720 million in 24-hour trading volume against a market capitalization of about $892 million.
The rally comes ahead of an Oct. 15 token unlock. Tokenomist data lists the date, while Starknet's published vesting schedule allows up to 127 million STRK to unlock each month for early contributors and investors through March 2027.
At the Oct. 11 CoinGlass price, the maximum tranche would be worth about $15.1 million and equal 1.27% of Starknet's original 10 billion-token supply. The unlock makes previously restricted tokens transferable; it does not establish how many recipients will sell.
The post Starknet considers leaving Ethereum for a quantum-resistant Layer 1 appeared first on CryptoSlate.
Optimism is expanding its role as the operator of Ethereum-based chains for other brands. Unichain, Uniswap Labs' Ethereum layer-2 chain, plans to transfer its production sequencing, public node access, monitoring and incident response to Optimism under its October 9 migration announcement.
The planned testnet move on Oct. 13 and mainnet move on Oct. 29 extend the operating strategy set out by Jing Wang in Optimism's Ink announcement: product teams build their applications and ecosystems while Optimism runs the infrastructure beneath them. Soneium's September agreement follows the same division of labor as Ink's earlier June plan; both chains use the OP Stack.
For users, the consequence reaches beyond who answers an outage call. A common provider can bring protocol expertise and coordinated maintenance, but it also becomes a common organizational dependency. Each chain's deployed contracts determine whether users can get a transaction included and recover funds during a provider failure.
Unichain moves from support toward operations
Unichain already had an OP Enterprise relationship. Optimism's enterprise introduction, in its version updated July 31, says Uniswap Labs operates Unichain with the Mission Critical add-on. Read alongside the October announcement, the change is an expansion from support into responsibility for production operations.
Uniswap Labs says the migration preserves the chain ID, contracts, balances, applications and Uniswap v2, v3 and v4 deployments. It also says Unichain remains a Stage 1 rollup with permissionless fault proofs and its existing contract-upgrade governance. The production operator changes while the chain and its upgrade authorities remain in place.
Soneium's Sept. 30 announcement assigns the Optimism Foundation and OP Labs support for deployment, sequencer operations, node infrastructure, upgrades, monitoring and incident response. Soneium keeps its roadmap and engineering involvement, including ongoing work on the chain itself and its Tokenized IP products. The announcement does not specify a cutover date.
Ink offers an earlier version of the same strategy. In her June 23 announcement, Wang described an arrangement in which the Ink Foundation could concentrate on ecosystem growth while Optimism operated and improved the network. The plan targeted an August cutover and included mainnet and testnet sequencers, RPC, the explorer, monitoring and incident response.
A later Optimism guide published Sept. 7 describes Ink's infrastructure as operated by the Foundation through OP Labs.
The reliability promise has an operational price
OP Enterprise is Optimism's chain infrastructure and support service. Its tier definitions explain why the operating model matters. Under Self Managed, the customer runs the infrastructure and controls its sequencer and nodes; Optimism supplies support and monitoring. Under Fully Managed, OP Labs runs the sequencer, batcher, proposer and chain infrastructure, and handles security patching.
Those components perform different jobs. The sequencer orders transactions, the batcher submits transaction data to Ethereum, and the proposer submits claims about the resulting chain state. Moving those day-to-day roles to the protocol developer can reduce the work a partner coordinates internally. Sequencing, data submission and state proposals become provider responsibilities; Ethereum settlement and the contracts that accept proofs remain separate.
Soneium's agreement promises a 99.9% monthly uptime target and around-the-clock on-call incident response. The Mission Critical add-on advertises a 99.95% uptime SLA, a 15-minute initial response to the most serious incidents and status updates every 30 minutes. Unichain's earlier relationship explicitly included that add-on.
These are service commitments, not measured improvements in uptime. The 15-minute target covers an initial response; recovery can take longer.
The rationale is a direct organizational path between operating a chain, identifying a protocol problem and applying a patch. The trade-off is that distinct branded chains increasingly rely on the same organization for sequencing, maintenance and incident handling.
A provider-wide process problem could affect several customers. The announcements establish a shared operator but do not disclose whether cloud regions, signing keys or other infrastructure are shared, so correlated technical failures remain a possibility rather than an observed outcome.
Inclusion survives sequencing failure; exits differ
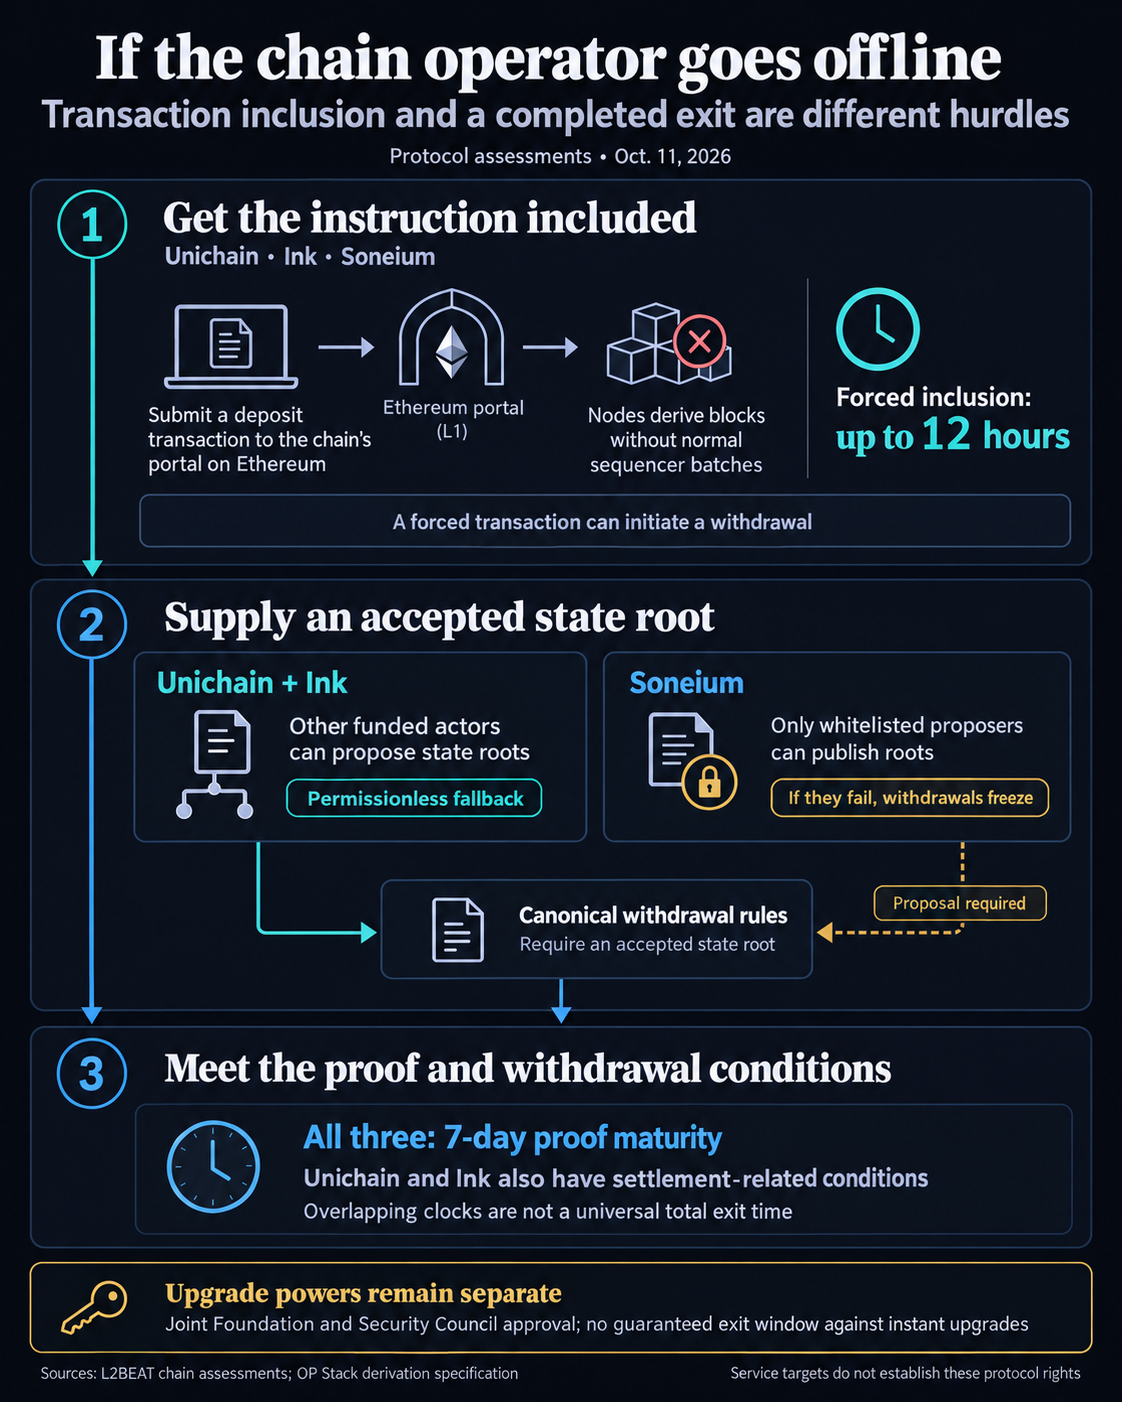
Ethereum supplies a fallback below the managed service. Current L2BEAT assessments separately list forced transaction inclusion through Ethereum for Unichain, Soneium and Ink, with up to a 12-hour delay.
The OP Stack derivation specification and forced-transaction guide describe how it works: a user submits a deposit transaction to the chain's portal contract on Ethereum. When the sequencing window expires, nodes can derive blocks containing those transactions without normal sequencer batches. A forced transaction can initiate a withdrawal.
That preserves a route around an unavailable or censoring sequencer. Money becomes available on Ethereum only after the withdrawal's separate proposal and proof conditions are met, with permissioned dependencies still possible along the way.
| Chain | Managed-operations disclosure | If the usual proposer fails |
|---|---|---|
| Unichain | Oct. 9 plan; testnet Oct. 13, mainnet Oct. 29 | Permissionless state-root proposals provide a fallback |
| Ink | June plan targeted August; September vendor guide describes managed operation | Permissionless state-root proposals provide a fallback |
| Soneium | Sept. 30 Fully Managed adoption; no precise completed cutover date | Whitelisted-proposer failure freezes withdrawals |
L2BEAT rates Unichain and Ink as Stage 1 and says other actors with sufficient funds can propose state roots. Their canonical exit paths permit others to do the usual proposer's work, provided funded actors submit accepted roots and the applicable proof and withdrawal conditions are met.
Soneium has a different dependency. Its currently respected super permissioned game has no functional onchain dispute process, according to L2BEAT, and only whitelisted proposers can publish roots. If those proposers fail, withdrawals freeze. Forced inclusion can get a transaction into the derived chain; it cannot supply the missing withdrawal proposal authority.
The withdrawal assessments for Unichain, Ink and Soneium also retain a seven-day proof-maturity period for all three chains. Unichain and Ink have additional settlement-related conditions: at least three-and-a-half days for root settlement and three-and-a-half days after settlement. Proof inclusion can precede settlement, so those clocks should not be mechanically added into a universal withdrawal time. Soneium retains withdrawal delays despite its respected game lacking an onchain challenge process.
Optimism operations do not erase upgrade powers
Production operations, contract-upgrade authority and asset custody are separate questions. Uniswap says its governance arrangement persists. L2BEAT's current assessments show joint Foundation and Security Council approval for upgrades on all three chains, with no delay on regular upgrades and no guaranteed exit window against those instant powers.
An Ethereum fallback during sequencer failure therefore does not guarantee an opportunity to leave before an unwanted contract change. Stage 1 preserves meaningful operator-independent paths, but retains powerful upgrade authorities.
Unichain's promised native interoperability remains a future feature. Soneium's announcement expressly excludes interoperability. Ink's June plan describes one-day withdrawals as a proof-system rollout, while its current withdrawal assessment still retains seven-day proof maturity.
CryptoSlate's September Upgrade 20 coverage examined the technical preparation for future interoperability. Outsourcing production operations is a separate development, with its own question of who maintains the chain and handles failures.
The next dated milestones are Unichain's Oct. 13 testnet and Oct. 29 mainnet migrations. Their completion would extend Optimism's strategy from selling protocol support to operating another established production chain. The reliability case will then depend on performance in service, while users' recourse will continue to depend on the specific inclusion, proposal and upgrade rules beneath each brand.
The post Optimism’s Unichain deal will put more chains under one operator appeared first on CryptoSlate.
Some Aave loans backed by yield-bearing collateral had narrow liquidation buffers in LlamaRisk’s Oct. 9 snapshots. Every top PT-AUSD supplier on Monad carried debt, while two syrupUSDC positions accounted for about 97% of supplied syrupUSDC on Arc. Cashing out the collateral involves a market sale or, for Arc holders choosing Ethereum redemption, a withdrawal queue that can take hours.
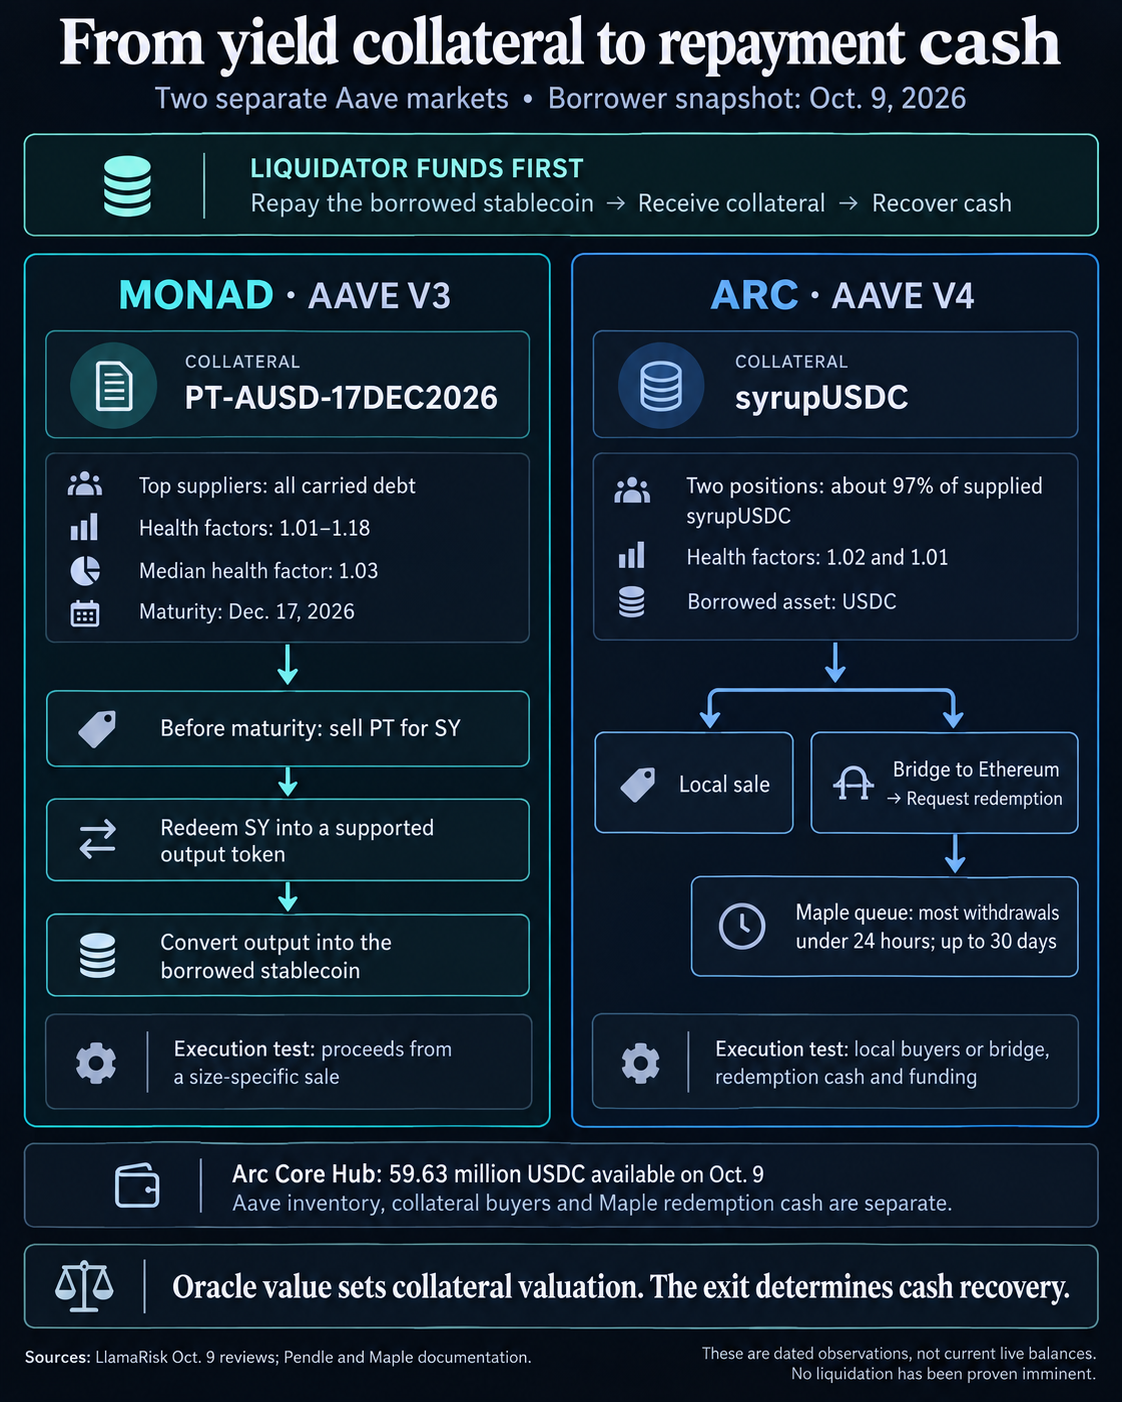
The two markets present separate versions of the same cash-flow problem. If a borrower becomes eligible for liquidation, a liquidator supplies the borrowed stablecoin, receives collateral and then recovers cash from it. December PT-AUSD requires a sale before maturity. Arc syrupUSDC offers a local sale or a bridge to Ethereum for redemption. An oracle valuation establishes collateral value within Aave; the exit determines what the liquidator can recover.
The Oct. 9 reviews of Monad and Arc recommend larger caps, making the economics of those exits consequential as borrowers seek room to grow.
Aave’s health factor compares collateral value, adjusted for liquidation thresholds, with debt. A position becomes eligible for liquidation below 1. The top Monad PT suppliers had health factors between 1.01 and 1.18, with a median of 1.03, in the Oct. 9 snapshot. USDC was their dominant debt asset, followed by USDT0.
Those readings leave a narrow valuation cushion for part of the cohort. They also reflect why borrowers pair correlated collateral and debt: smaller relative price changes can support higher leverage. Aave notes that lower health factors may be appropriate for correlated assets.
During liquidation, someone repays the borrower’s debt and receives collateral plus an incentive. The liquidator weighs the collateral’s realizable proceeds against the debt repaid, transaction and conversion costs, and the cost of financing any redemption wait. The health factor measures proximity to eligibility; a sale quote measures the exit.
Monad’s PT-AUSD Aave loans need a sale before maturity
The Monad collateral is PT-AUSD-17DEC2026, a Pendle principal token representing a claim on AUSD at its Dec. 17 maturity. The redemption entitlement is in the accounting asset. Receiving one AUSD still requires any conversion needed to obtain the USDC or USDT0 borrowed against it.
LlamaRisk reported that the reserve’s 30 million PT supply cap was fully utilized on Oct. 9 and recommended increasing it to 60 million PT. These limits measure token capacity. A larger cap would allow more collateral into Aave; its successful exit would still depend on buyers or redemption.
Before maturity, Pendle’s documented liquidation route sells PT into SY, its standardized yield wrapper, then redeems SY into a supported output token. After maturity, PT can be redeemed into SY without that market sale. Any further conversion into the borrowed stablecoin remains part of the route.
The Oct. 9 review describes the Pendle pool as 47% PT and 53% SY. A large PT sale draws from the opposite side of the pool, so a useful exit estimate needs the intended sale size, output and price impact across the full conversion.
Pricing adds another constraint. LlamaRisk says the December PT uses a linear discount oracle on AUSD/USD. Pendle’s linear-discount documentation describes a predictable path toward maturity independent of AMM prices. That valuation can follow its curve while a liquidator’s sale price depends on the market’s willingness to absorb seized PT.
LlamaRisk’s Oct. 2 launch recommendation specified a 95% liquidation threshold and a 2.62% bonus for the stablecoin E-mode, alongside a 93% borrowing limit. A liquidator has to compare the incentive applicable at execution with the actual cost of turning PT into the debt token.
Arc’s syrupUSDC Aave loans rely on buyers or a redemption queue
The Arc comparison concerns syrupUSDC, a bridged share in Maple’s Ethereum yield-bearing vault. In the Oct. 9 Arc review, the two largest positions held approximately 97% of the supplied syrupUSDC at health factors of 1.02 and 1.01. All outstanding debt among syrupUSDC suppliers was USDC.
A few positions can therefore dominate demand for that collateral’s exit. The concentration refers to supplied syrupUSDC, while the stablecoin available to Aave lenders sits in a separate reserve.
Arc had substantial Aave liquidity at the snapshot: 143.45 million USDC added to the Core Hub, 83.82 million drawn and 59.63 million available. That available balance is debt-token inventory in Aave. Buyers of syrupUSDC and cash available for Maple redemptions determine other parts of the unwind.
LlamaRisk’s September Arc assessment, using Sept. 23 liquidity data, found one local Uniswap V4 syrupUSDC/USDC venue whose proceeds saturated near $500,000 as its USDC side was exhausted. The sale ran into the venue’s available cash inventory.
The same assessment described no native Arc redemption. A holder could sell locally or bridge to Ethereum and then request redemption. It estimated the bridge transfer alone at two to five minutes under normal conditions, with throughput around $10 million an hour. Maple’s withdrawal queue adds a separate wait.
Maple’s withdrawal terms make the timing constraint explicit: requests enter a first-in, first-out queue and are processed as liquidity becomes available. Most withdrawals take under 24 hours, but they can take up to 30 days. Its contract architecture explains why entitlement to a pool’s value can exceed immediately available withdrawal cash.
For a liquidator using that route, Ethereum redemption and Arc debt repayment are separate stages. The funder needs USDC to repay the Aave loan before the collateral’s later exit pays them back. Bridge capacity, redemption cash and financing duration each affect whether the unwind is economical.
Arc’s shared Hub connects lender exposure with cap growth
LlamaRisk’s Arc onboarding recommendation values syrupUSDC through Chainlink’s syrupUSDC/USDC exchange rate and capped USDC/USD using a CAPO adapter. The exchange-rate input follows the Ethereum vault’s exit value. Local trading depth determines how much of that value a sale can realize.
The recommendation also specifies a 92% collateral factor and a dynamic liquidation bonus capped at 4%. The applicable bonus varies with the liquidation conditions. Its maximum provides a ceiling on the incentive against which a liquidator weighs exit costs.
The Maple Spoke draws from the same Arc Core Hub USDC reserve as the Main Spoke. Aave’s earlier Hub design discussion explains shared solvency inside a Hub: Spoke-level limits constrain exposure, while the Hub remains the common liquidity and accounting venue. Applied to the described Arc arrangement, that architecture places Maple Spoke exposure within the Core Hub’s shared solvency. Monad’s V3 market and Ethereum’s separate Hub configurations have different boundaries.
LlamaRisk’s Oct. 9 Arc proposal would increase the Maple Spoke’s USDC draw cap from 23 million to 46 million USDC and its syrupUSDC add cap from 25 million to 50 million shares. The draw cap was fully utilized and the add cap 87.8% utilized in that review. Share-token capacity requires its own valuation before comparison with dollar debt.
Those caps set maximum collateral or borrowing capacity; additional exposure depends on subsequent deposits and borrowing.
For lenders assessing these Aave loans, the test is concrete: compare recoverable collateral proceeds at the relevant liquidation size with the debt repaid and total exit costs, then identify who funds any redemption delay. The liquidation incentive affects how much collateral the liquidator receives. Monad’s PT requires a market sale before December maturity. Arc requires local buyers or an Ethereum exit with sufficient bridge capacity, redemption cash and financing.
The post Some Aave loans sit near liquidation with collateral that can take hours to cash out appeared first on CryptoSlate.
Evernorth is preparing to begin trading on Nasdaq on Monday, bringing approximately 473 million XRP into a publicly traded treasury company.
The company completed its merger with Armada Acquisition Corp. II on Oct. 9 and expects its shares to trade under the ticker XRPN on Oct. 12. It also reported approximately $300 million in gross cash proceeds before transaction expenses, backed by investors including Ripple, SBI Group, Pantera Capital, Kraken, and GSR.
The listing gives stock-market investors access to one of the largest corporate XRP treasuries while establishing a new source of capital for the XRP Ledger's expanding financial ecosystem.
Evernorth targets XRP liquidity and institutional finance
Evernorth intends to distinguish itself from traditional crypto treasury companies that primarily accumulate digital assets and rely on price appreciation to generate shareholder returns.
Instead, Chief Executive Officer Asheesh Birla said the company would actively deploy capital across the XRP ecosystem, supporting infrastructure and financial applications while pursuing strategies designed to increase XRP holdings per share.
The strategy includes institutional and decentralized finance yield opportunities, ecosystem participation, and capital markets activities intended to put the company's assets to productive use.
In an October 9 shareholder letter, Birla outlined a vision of financial markets moving toward blockchain-based infrastructure capable of operating continuously rather than within traditional banking and exchange hours.
He argued that tokenization could transform how securities, credit and other financial assets are traded, settled and used as collateral.
Under that model, assets could carry programmable conditions governing interest payments, lending arrangements and transfers, potentially reducing the delays associated with traditional financial intermediaries.
However, Birla identified market liquidity as an essential requirement for these applications to become commercially viable.
Tokenized assets may technically trade around the clock, but their usefulness depends on sufficient capital and market participation to support transactions whenever investors need to enter or exit positions.
Evernorth intends to help address this constraint by deploying capital on the XRP Ledger, supporting liquidity and working with developers building financial infrastructure for institutional users.
The approach could expand XRP's role beyond payments by supporting applications involving tokenized securities, lending and collateral management.
It could also create additional economic activity around the token, though any direct increase in XRP demand will depend on how Evernorth deploys its resources and whether those applications require XRP rather than other assets.
For shareholders, the company aims to combine cryptocurrency exposure with potential returns from actively managing its holdings.
That creates an additional performance measure beyond XRP's market price: whether Evernorth can generate sufficient income and accumulate additional tokens to increase the amount of XRP backing each share.
Ripple ties could complicate Evernorth's XRP earnings
The company's financial ambitions face an unusual reporting constraint stemming from its relationship with Ripple.
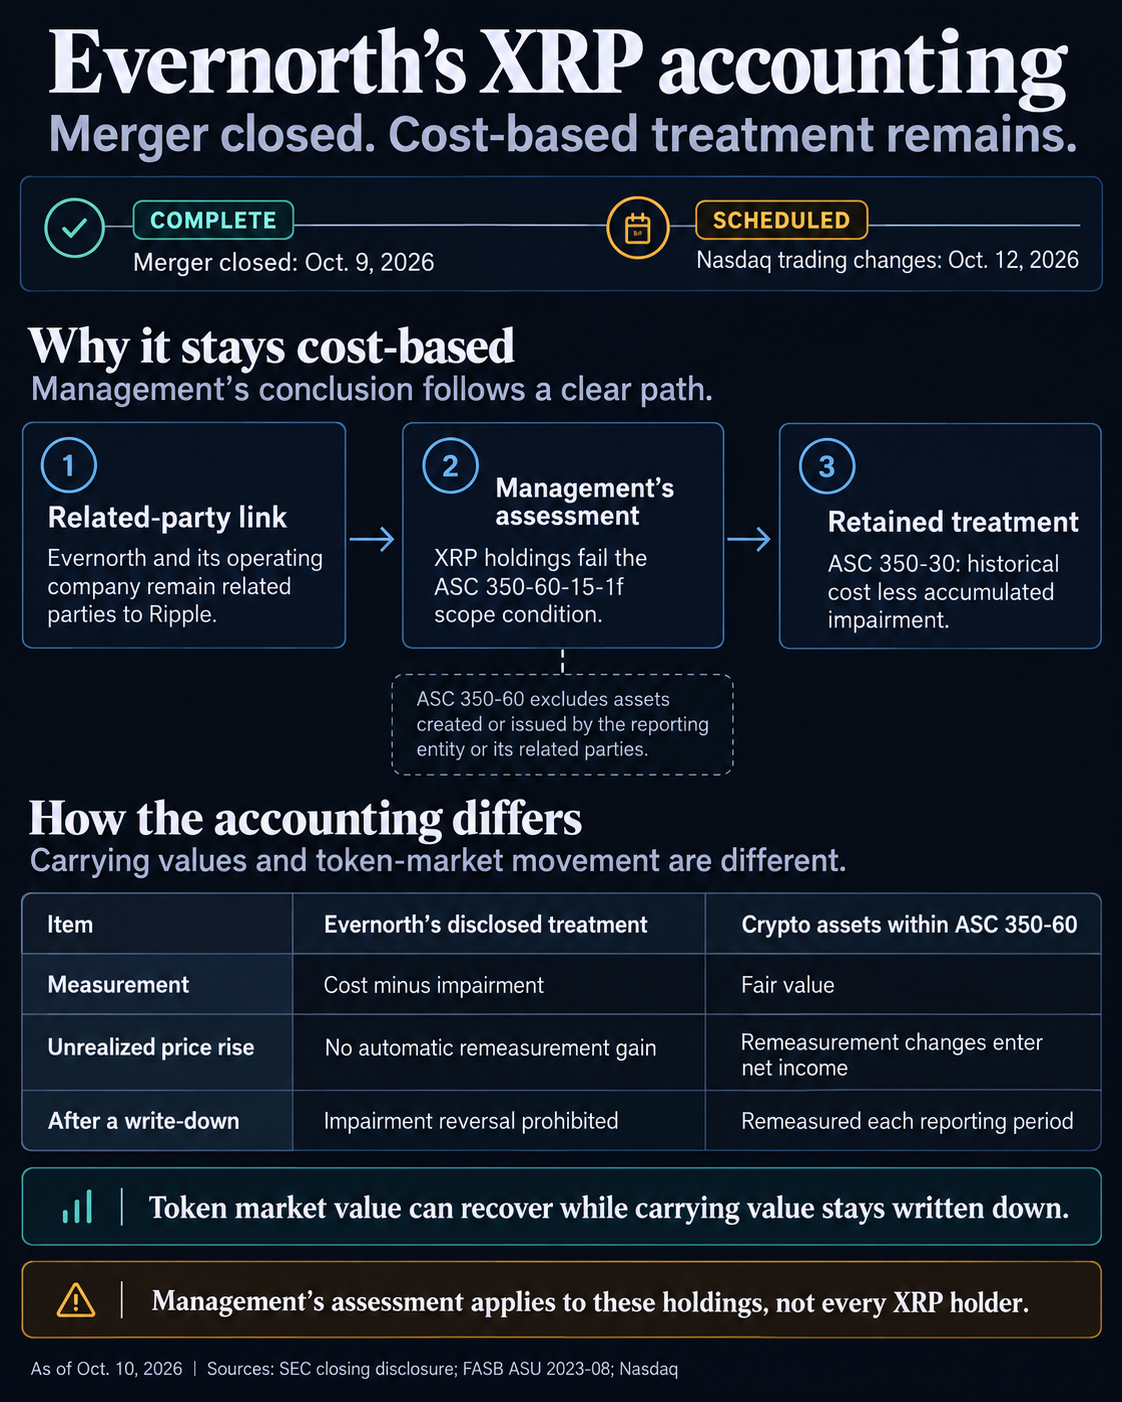
In financial disclosures accompanying the completed merger, Evernorth said it would continue to account for its XRP holdings at historical cost, reduced by accumulated impairment losses.
That differs from the fair-value accounting treatment available to many other corporate cryptocurrency holders.
Under rules introduced by the Financial Accounting Standards Board in 2023, qualifying crypto assets must be valued at prevailing market prices, with unrealized gains and losses reflected in reported earnings.
However, the standard excludes certain digital assets created or issued by a reporting company or its related parties.
Although Evernorth ceased being a wholly owned or consolidated Ripple subsidiary following its merger, management determined that the companies remained related parties.
Consequently, Evernorth concluded that its XRP holdings remained outside the newer fair-value standard and must continue under the older cost-minus-impairment model.
This distinction creates an asymmetry in its financial results.
When XRP prices decline sufficiently, Evernorth may have to recognize impairment losses that reduce the carrying value of its holdings.
However, subsequent price recoveries cannot reverse those write-downs while the assets remain under that accounting treatment.
For example, if a $100 million XRP position is written down to $70 million, a subsequent recovery to $150 million would not automatically restore its accounting value or produce an $80 million unrealized gain in earnings.
That could leave a substantial difference between the market value of Evernorth's treasury and the asset values reflected in its financial statements.
The merger disclosure already illustrates the potential consequences.
Management said XRP's lowest observable Coinbase price between July 1 and the Oct. 9 closing was $0.99, a level that would have produced an additional $6.9 million impairment after June 30. The filing did not confirm whether it ultimately recognized that amount.
Still, the accounting treatment does not prevent Evernorth from profiting economically from higher XRP prices, realizing gains through sales or recognizing income generated by its investment strategies.
However, it could make the company's reported earnings and book value harder to compare with crypto treasury businesses eligible for fair-value accounting.
That distinction becomes particularly relevant to Evernorth's promise of growing XRP per share, because changes in token holdings, market valuation, and reported accounting income may tell different stories about performance.
Investors will therefore need to distinguish returns from active treasury management from changes in XRP's market value, especially when evaluating the company's ability to finance further expansion.
Evernorth's first post-merger financial statements will initially test that distinction, showing how much its treasury activities contribute to reported results even as its accounting treatment continues to exclude unrealized XRP price recoveries.
The post XRP’s next Wall Street expansion comes with an unexpected complication from Ripple appeared first on CryptoSlate.
CryptoTicker.io
The Bitget Wallet and the Bitget exchange are two different products with two different custody models. The attack Bitget disclosed on September 24, 2026 hit the exchange's systems. Anyone holding crypto-assets in the Bitget Wallet was not automatically affected, because a different mechanism decides access there. That mechanism is precisely the point most users have never looked up: in the keyless version of the wallet, one of three key shares sits on a Bitget server, and without that share no signature comes about.
This text pulls the two apart. First the situation at the exchange, then the technology of the wallet, after that the consequences for custody, supervisory law and tax in Germany.
Bitget Wallet and Bitget exchange: two products, two custody models
The shared name misleads. The exchange is a centralised trading venue. You pay money in, the balances sit in a database held by the operator, and the private keys to the addresses where the coins actually sit are managed by the company. That is custody by a third party, custodial in the jargon. You hold a claim against the exchange, not immediate control over the coins.
The wallet works differently. It is an app that generates and keeps keys on your device, and it is therefore called self-custody. The wallet's product page frames this as a property of the product and cites the protection of balances through encryption and self-custody. It also advertises access to tokens on more than 130 blockchains and a protection fund of $300 million.
A protection fund, however, is a promise from the provider and not a property of self-custody. With genuine self-custody you need no fund in the event of damage, because nobody but you reaches the keys. The more prominent a fund becomes in the advertising, the more closely it pays to look at who actually signs alongside. We come to that further down.
$387.5 million: the attack on the exchange of September 24, 2026
On September 24, 2026, Bitget disclosed that attackers had drained balances from the exchange's hot and warm wallets through unauthorised transfers, and temporarily suspended withdrawals. The sum cited moved upwards over the course of the investigation: initial reports named $351.6 million, while the later account puts it at $387.5 million. Both figures come from the communications around the same incident, and as long as no conclusive audit exists, the range is the more honest statement.
On the cause, Bitget explained that it had identified malicious activity connected to third-party security products, including a previously unknown vulnerability, a so-called zero-day. The security firm SlowMist dates the earliest suspicious activity to August 31, 2026. Mandiant describes the attackers gaining access to third-party security appliances and moving on from there into the exchange's wallet environment. Around $1.1 million was frozen or recovered through Circle, Tether and NEAR Intents.
Important for placing this: what was affected were the exchange's hot and warm wallets, meaning the systems with which a trading venue settles ongoing deposits and withdrawals. Those are corporate systems. A key that sits only on your own phone is not deposited there. Withdrawals at the exchange reopened in stages from September 28, and in the weeks that followed customers pulled out balances on a large scale.
Custodial against self-custody: control over the private key
The private key is the number with which a transfer out of a blockchain address is signed. Whoever has it can dispose. Whoever does not have it cannot, regardless of what an app displays. The only question that counts with any provider is therefore: who can sign?
At the exchange the answer is clear. The company signs and you submit an instruction. That has advantages, for instance if you lose a password, and it has the drawback that an attack on the corporate systems can reach your balances. At the wallet the answer in the keyless version is not simply "you" but "your device together with a server". Which forms exist for this and how they differ in cost and access separates out on exactly that question.
The keyless wallet: three key shares and a 2-of-3 signature
The Bitget Wallet offers two ways to set up an account. One is the classic mnemonic wallet with a word sequence. The other is the keyless wallet, which does without a word sequence and relies instead on multi-party computation, abbreviated MPC. No single key arises that is stored somewhere. Several shares arise instead, and several parties jointly compute a valid signature without ever assembling the complete key.
Bitget describes its own implementation in the announcement of the MPC wallet with three shares. One sits on the device you are currently using. A second sits on the platform's server. The third sits as a backup in a cloud, iCloud or Google Drive for example, and takes no part in the signature. Signing requires two of the three shares, and on this account they are the share on the device and the share on the server.
When setting up, according to the provider's own guide, you first choose "Create Wallet" in the app and then "Keyless Wallet". You set a six-digit transaction password that applies exclusively to this type of wallet, while access to the account itself runs through a sign-in procedure such as email with a confirmation code. The app then prompts a backup to the cloud, and the status switches to "Backed Up". For cases where shares have to be redistributed, the documentation names a reshare mechanism without setting it out in detail.
Bitget's server share: the quiet dependency of the keyless wallet
Here lies the core of the matter. If signing requires the share on the device and the share on the server to come together, then every transfer out of a keyless wallet depends on Bitget's server joining in. Bitget places this expressly on the record and writes that the share held on the server may take part in the signing process only with the user's explicit consent and approval. The announcement simultaneously sets this against third-party custody, where the platform could access user balances unilaterally.
That is a different statement from the one many readers turn it into. It says that, on Bitget's own account, the company does not deploy the server share without your approval. It does not say that you could sign without the server share. What happens if that server is permanently unreachable or a company discontinues the service is something the announcement does not set out. In practice that means the keyless wallet takes the burden of the word sequence off you and puts an ongoing dependency on a service in its place.
Technically that is a deliberate trade and not a flaw. A word sequence on paper is the most common reason for final losses, because it gets lost, photographed or disappears in a house fire. A procedure that replaces it solves a real problem. Only the result is then a hybrid between self-custody and a service, and anyone taking the advertising for self-custody literally underestimates the role the provider retains in the chain.
Mnemonic wallet with 12 or 24 words: the second variant in the same app
The alternative is available in the same app. A mnemonic wallet generates a word sequence that represents the seed of the key, and Bitget offers it, by its own documentation, with 12 or with 24 words. Choosing it gets you a wallet whose key can be restored from those words alone, on any compatible device and without the provider's involvement.
With that the risk reverses. Nobody can lock you out, and nobody has to sign alongside. In exchange you carry the burden of safekeeping entirely yourself, and the documentation points to exactly that: the word sequence can be stolen or forgotten and has to be stored securely. For amounts that would hurt you, this is the variant that earns the term self-custody without a footnote.
Which of the two types is running in an existing account can be checked in the app. The distinction is not cosmetic: it decides whether you can act alone when it matters.
The cloud backup on iCloud and Google Drive does not sign
The third share, which the app stores in iCloud or Google Drive, is a backup on Bitget's account and takes no part in signing. Two things follow from this. First, access to your cloud account alone is not enough to transfer in your name, because two signing-capable shares are needed for that. Second, this backup is nonetheless a sensitive point in your security chain, because it exists so that a lost device can be replaced.
The account holding this backup therefore deserves the same care as access to the wallet itself, so two-factor sign-in and a password used nowhere else. A cloud account reachable through a recovery email with weak protection undoes good procedures in the app.
MiCA and crypto custody: self-custody sits outside the licensing requirement
The European MiCA regulation governs service providers that hold crypto-assets for others or trade in them. Anyone offering software with which users keep their own keys, by contrast, provides no custody within the meaning of the regulation, as long as the provider cannot dispose of the balances. Pure self-custody wallets therefore do not appear in the registers of authorised service providers, and their absence there is no shortcoming but a consequence of that boundary.
For users that produces a clear split in the questions to ask. At the trading venue the authorisation is relevant, because other people's money and other people's coins sit there. At the wallet the authorisation says less than the question of who signs. A wallet whose provider is needed for signing moves back towards a service in that one respect, even if it does not present itself as a custodian. What matters is that you know which of the two worlds your holding currently sits in.
Hardware wallet as a third tier: keys without a server and without an app provider
If the point that bothers you about the keyless version is the dependency on someone else's server, the route leads to a device that generates keys offline and performs signatures itself. A hardware wallet holds the private key in a chip that does not release it. For signing, the unfinished transfer travels into the device, is confirmed there, and only the signature comes back. Neither an app nor a provider's server is involved.
This tier costs money and a moment of familiarisation, and it shifts the risk once again, namely onto the safekeeping of the word sequence and onto buying from a source you trust. For long-term holdings it is the most sober answer to the question of access. The differences between the devices, from the form factor to the supported networks, are set out in our hardware wallet comparison.
An intermediate solution that often gets overlooked: you do not have to decide on one form. Amounts you trade with can sit at a trading venue or in an app wallet, while the holding you intend to keep for years sits on a device without a network connection. Splitting by purpose is the part of security work that takes the least effort and delivers the most.
Tax and the holding period: a transfer into your own wallet is not a sale
Anyone moving balances from an exchange to their own wallet after the incident often wonders whether that creates a taxable event. Under the German finance ministry's circular on individual questions of the income tax treatment of crypto-assets of March 6, 2025, which replaces the 2022 version, a transfer between wallets of the same owner changes nothing in the attribution: nothing is disposed of, and a running holding period continues. What remains decisive for tax is the one-year period under section 23 of the Income Tax Act and the attribution under the first in, first out method.
What does increase is the documentation work. Every transfer has to remain traceable later so that the attribution of acquisition dates holds, and self-custody does not release you from the record-keeping duty. Anyone using several wallets and trading venues quickly reaches the limit of a spreadsheet; which tools bring the transactions together is shown by our overview of crypto tax tools and portfolio trackers. For an individual case, especially with staking or lending running in the background, a visit to a tax adviser remains more reliable guidance than any how-to.
Open is the announced reform that would remove the holding period for crypto-assets acquired in future. So far it is a draft and not a law, and it changes nothing about the treatment of transfers between your own wallets.
Bitget Wallet: without the server share the keyless version does not sign
The Bitget Wallet is not the Bitget exchange, and the attack of September 2026 ran through the trading venue's systems. Users of the wallet should therefore not be reassured because nothing happened, but because they know which variant they are running. In the keyless wallet every signature needs the share on the provider's server; in the mnemonic wallet it does not. On that hangs whether you can act alone when it matters.
- Establish the variant. Look in the app to see whether your account was set up as a keyless wallet or with a word sequence, and note the result. What separates the common app wallets on this point is set out in the software wallet comparison.
- Split the holding by purpose. What you intend to keep for years belongs on a device that signs offline; the selection for that is in the hardware wallet comparison.
- Assess the trading venue separately. For balances that have to sit at an exchange, the operator's authorisation is what counts; which providers operate under regulation in the EU is shown by the overview of regulated crypto exchanges.
(As of October 11, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Buying an NFT in 2026 means facing fewer doors than a year ago. An NFT marketplace is the venue where digital collectibles are offered, auctioned and sold. Three large providers wound this business down wholly or in part over the course of the year: Binance's NFT trading, the art platform Nifty Gateway and Magic Eden's non-Solana markets. Still open are OpenSea, Blur, Tensor, Rarible and SuperRare. Since those closures, which marketplace comes into question for you is decided above all by one question: which blockchain your desired NFT sits on.
What an NFT marketplace is and where it differs from a crypto exchange
An NFT marketplace is a trading platform for non-fungible tokens, meaning tokens that cannot be swapped against one another like coins, because each of them designates its own unique piece. A crypto exchange matches buy and sell orders for mutually interchangeable cryptocurrencies; a marketplace for NFTs works more like an auction house with a shop window.
The practical difference lies in custody. At an exchange your coins generally sit in an account held by the provider. On an NFT marketplace you connect your own crypto wallet, and the NFT stays there the whole time. The marketplace only displays what is in your wallet and settles the trade through smart contracts, meaning programs that run on the blockchain itself and automatically execute the swap of tokens for payment.
That is precisely why a closure is less dramatic for collectors than it sounds. If the marketplace disappears, the shop window disappears, not the ownership.
Binance: NFT trading ended on July 3, 2026
Binance shut down the NFT section of its central trading platform as of July 3, 2026. The announcement is dated June 3, 2026, giving users a month. Transferable NFTs had to be moved into the in-house wallet or another compatible external wallet by 23:59 UTC on the cut-off date.
The handling of the non-transferable pieces is notable. Certificates from the in-house learning platform, for example, could not technically be moved out at all; they became inaccessible after the cut-off date, and the credentials were supplied as PDFs instead. A standalone NFT marketplace at Binance had in any case already closed in 2023, and the 2026 step concerned the remainder.
For German users this was above all a question of deadlines. Those who missed the notification and moved no balance lost nothing on transferable pieces, but had to go through customer service afterwards.
Nifty Gateway has been closed since April 23, 2026
Nifty Gateway was one of the oldest venues for digital art and one of the few where artworks could be bought with a credit card instead of with cryptocurrencies. Its own site today carries the notice that the platform was officially closed on April 23, 2026 and that the deadline for moving holdings expired that day.
Two commitments still stand there: by its own account the operator helps customers move their NFTs into a wallet of their choice even after the cut-off date, and it intends to keep metadata and images on its own servers permanently. For larger collections there is a tool that withdraws many pieces at once.
Anyone with something still sitting there should get in touch rather than write the matter off. The notice on the home page sets out the route via sign-in.
Magic Eden trades only on Solana now
Magic Eden announced at the end of February 2026 that it would close its markets for Bitcoin-based pieces and for EVM chains. EVM stands for the Ethereum Virtual Machine, Ethereum's execution environment; EVM chains are therefore networks that use the same technology, Polygon and Avalanche among them. According to the industry outlet Decrypt, trading there ended barely two weeks after the announcement, and support for the company's own multi-chain wallet ran out at the start of April.
What remains is the Solana market, and there Magic Eden is still a first address. Co-founder and chief executive Jack Lu justified the pivot with what he called the large opportunity in the gambling business; with Dicey the company runs a betting and casino platform of its own. How the retreat unfolded in detail is set out in our analysis of the discontinuation of the Magic Eden services.
What $576 million against $121,000 reveals about the retreat
Behind the closures sits a calculation that rarely becomes this publicly clear. Citing an analysis by the data service Dune, Decrypt reported that in the month before the announcement Magic Eden generated around $576 million of trading volume in digital collectibles, by far the greater part of it on Solana. Of that, roughly $121,000 fell to Bitcoin-based pieces.
The ratio explains the mechanism better than any statement of intent. Every additional blockchain served costs a marketplace its own indexing, its own smart contracts, its own customer service and its own security audits, and those costs arise regardless of whether much or little is traded on the chain. Once a branch's volume falls below the threshold at which it carries itself, it is switched off, and that hits the smaller chains first.
The implication: the narrower the market for a collection, the greater the danger that the venue for it will eventually disappear. Ownership stays, liquidity does not.
OpenSea, Blur and Tensor: where trading still happens today
OpenSea remains the broadest venue and, with the second version of its interface, reaches a whole series of networks, Ethereum, Polygon and Solana among them. For newcomers it is usually the obvious starting point, because its supply, collections and payment routes demand the least prior knowledge.
Blur is aimed at high-frequency traders on Ethereum. The interface shows bids and fixed prices for several collections side by side and bundles orders, which looks rather cluttered to collectors holding individual pieces. Tensor plays the same role on Solana. Both platforms are built for speed and volume, not for browsing.
All three require your own wallet and a matching cryptocurrency. Without ether on Ethereum or SOL on Solana no purchase comes about, and you obtain both beforehand on a regulated crypto exchange. How the prices of the two network tokens have developed lately is set out in our Ethereum price prediction and in the Solana price prediction.
Rarible after the brand sale to IMPOSSIBLE
Rarible has remained a multi-chain marketplace and shows collections on Ethereum, Solana and further chains. By its own account the company IMPOSSIBLE has taken over the Rarible brand and substantial parts of the platform technology, the RaribleX infrastructure business among them, and intends to continue along the course set.
Excluded from the sale is the governance token RARI, which remains with the associated foundation. For users of the marketplace the change of owner alters little day to day at first; those trading there should follow the new owner's announcements all the same, because closures in this market have recently come with short notice.
SuperRare and curated art in the niche market
SuperRare pursues the opposite approach to the mass market: artists are selected, the number of works stays small, and every artwork exists as a single piece. This part of the market lives less on trading volume than on collectors looking for a particular work.
For the choice of marketplace that is a category of its own. Collectors of digital art find a different offering on a curated venue than on an open platform where anyone can list their collection. Both routes have their justification, they simply serve different buyers.
Which wallet you need for which marketplace
The wallet decides which marketplaces are open to you at all. For Ethereum and the EVM chains you need a wallet that supports these networks; for Solana one that handles the Solana format. A multi-chain wallet covers both, a wallet limited to one chain does not.
Two points matter more here than the choice of provider. First, the recovery phrase never belongs in a photo, a notes app or a cloud. Second, before every connection you check whether the address called up is really the marketplace's, because faked interfaces are among the most common attacks in this market. How quickly real value drains away in the process was shown by the exploit around granted approvals at Magic Eden: old permissions there were enough to move other people's holdings. Granted approvals can be revoked, and that is exactly what belongs on the list after every change of marketplace. Which devices come into question for it is shown by our comparison of hardware wallets.
Fees in NFT trading: marketplace fee, royalty and network costs
The cost of a purchase is made up of three parts that are rarely shown together on the listing side. The marketplace fee is deducted from the sale proceeds by the venue. The licence fee, often called a royalty, goes to the artist or the project and is collected by the smart contract or by the marketplace; whether it is enforced is handled differently from platform to platform. Added to that are the blockchain's network costs, which on Ethereum fluctuate noticeably with load and on Solana are usually small.
Never reckon with the displayed price alone, therefore. In practice the difference between two venues lies less often in the marketplace fee than in the chain on which trading happens, and with it in the network costs.
What is left of a closed marketplace: metadata, images and the smart contract
For most collections, what sits on the blockchain is not the image but a reference to it. The metadata, meaning name, attributes and the path to the image file, often sit on the project's servers or in a distributed file system. The token itself stays in your wallet as long as the chain runs.
That is what creates the real risk of a closure. If a project switches off its servers, your NFT may show nothing but an empty surface although the entry on the blockchain is unchanged. That Nifty Gateway explicitly promises to keep hosting metadata and images is therefore more than a courtesy.
This can be checked before buying: if the collection shows where its files sit, and if they are stored in a distributed file system, the dependence on a single provider is smaller.
MiCA and NFTs: the regulation's protection does not apply here
German investors have grown used to the European MiCA regulation at crypto exchanges, which requires providers to be licensed. For NFTs it generally does not apply: article 2 paragraph 3 of the regulation excludes unique and non-fungible crypto-assets from its scope. A pure NFT marketplace therefore usually needs no authorisation from BaFin, and the duties on information sheets, complaints procedures and segregation of client assets do not bite there.
The exemption is narrower than it sounds, though. Recital 11 of the regulation expressly brings pieces from large series and collections back in, because their uniqueness is doubtful. Fractions of an NFT also fall under the rules. Whether a specific piece is exempt remains a case-by-case question, and the classification is made not by the marketplace but by the supervisor.
In practice that means buying an NFT leaves you legally worse off than buying bitcoin or ether from a licensed provider. There is no deposit protection, no regulatory minimum capital and, in a dispute, no route of complaint to the supervisor.
Tax in Germany: the one-year holding period
Under practice so far, German tax law treats NFTs like other assets held privately. Sell at a profit within a year of buying and that is a private disposal under section 23 of the Income Tax Act. After a year has passed the gain remains tax-free. An exemption threshold of 1,000 euros applies to the sum of all private disposals in a calendar year; once it is reached, the entire gain is taxable, not merely the excess.
Documentation matters, and from the outset. Time of purchase, purchase price in euros, fees and the wallet address belong on the record, because a closed marketplace will issue you no statement afterwards. What the European reporting duties mean for Ethereum-based collectibles is something we have written up in our article on NFT taxes and DAC8.
The editorial view: the chain decides the marketplace
Our assessment: choosing the venue is no longer a matter of taste in 2026 but follows the blockchain. The figures from the Magic Eden retreat argue for that, where a monthly volume of around $576 million on the strong chain stood against roughly $121,000 on the weak one, along with the closures at Binance and Nifty Gateway inside half a year. Against it stands the point that with OpenSea and Rarible two providers continue to serve several chains, so the market is not falling apart completely. Buyers today should nonetheless reckon with the marketplace for their piece being a different one in two years. A total loss of the money committed is possible at any time with NFTs, because for many collections simply no buyer comes forward any more.
NFT marketplaces: without MiCA protection only your own wallet counts
Three closures in one year have made the market easier to survey, but have also shown how quickly a shop window shuts. Your ownership hangs on the wallet and on the chain, not on the provider. Here is the order to work in:
- Determine the chain first. Establish which blockchain the collection that interests you sits on, and choose the venue accordingly. An overview of the open platforms is given by our comparison of NFT marketplaces.
- Obtain the cryptocurrency beforehand. Buy ether or SOL on a licensed platform and then transfer them into your own wallet; the terms are set out in our comparison of crypto exchanges.
- Put custody and approvals in order. Place valuable pieces on a device that keeps the keys offline, and revoke old permissions after every change of marketplace; suitable devices are shown by the hardware wallet comparison.
(As of October 11, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Shibarium processed 2,438 transactions on October 9, after 970 the day before. Several crypto outlets turned that into a gain of 151 percent and spoke of a recovery for the Shiba Inu chain. One day later the same statistic shows 1,142 transactions. The recovery therefore held for exactly 24 hours.
This article takes the figures behind the story and checks the arithmetic. All network values come from our own query of the Shibariumscan API on the evening of October 11. The price of Shiba Inu stood at $0.00000549 at the same moment, 0.12 percent above the previous day and 5.58 percent down over seven days.
What actually happened on Shibarium: 5,711, then 970, then 2,438, then 1,142
The series of daily transactions gives a different picture from the snapshot of October 9. On October 6 Shibarium processed 5,711 transactions, the highest reading since the start of September. October 7 brought 1,323, October 8 brought 970, October 9 then 2,438 again and October 10 brought 1,142. The jump the 151 percent refers to starts from one of the weakest days of the month. Measured against the October 6 peak, the current level sits 80 percent lower.
The average of the past 31 days is 1,928 transactions a day, 59,776 in total. At 1,142, the most recent fully recorded day sits 40.8 percent below that mean. The low of the period was 794 transactions on September 20. Shibarium therefore moves in a band between roughly 800 and roughly 5,700 transactions a day, and inside that band a single day-on-day comparison says little.
Investors who bought in on October 9 because the chain was supposedly running again mistook a daily swing for a trend. With percentages quoted without a baseline, that is the most common trap: 151 percent sounds like a fresh start but here means the move from 970 to 2,438, to a level that one day later was back below the monthly average.
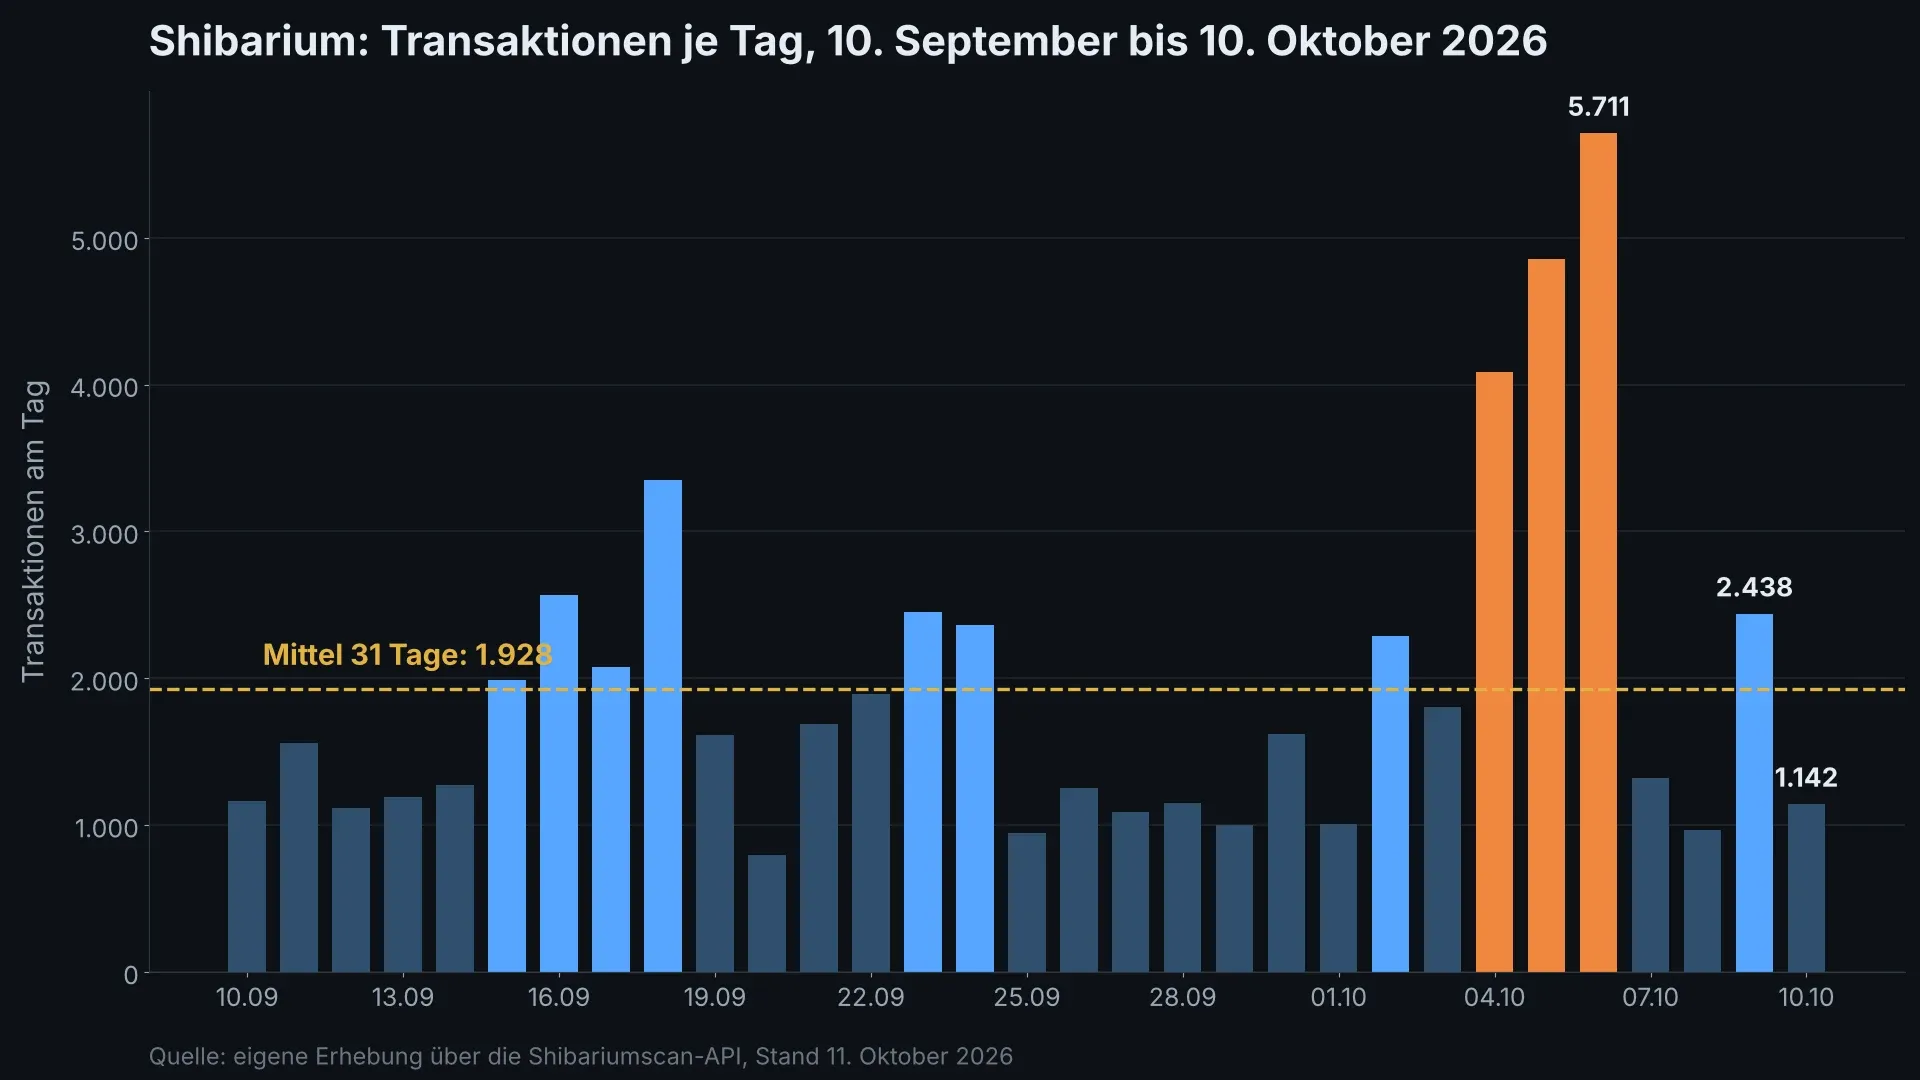
Network utilisation of 0.027 percent: only every 15th block carries a transaction
The transaction count alone says nothing about how full a chain is. Network utilisation covers that, meaning the share of available block space actually taken up. Shibariumscan puts it at 0.026787 percent, or 0.027 percent rounded.
Block time makes it more tangible. Shibarium produces a block every 5.02 seconds on average, which comes to roughly 17,211 blocks in a day. Spread 1,142 transactions across those blocks and every 15th block carries a single transaction on average. The other 14 are empty. At the monthly mean of 1,928 transactions it would still be only every ninth block.
Empty blocks are no technical defect. A chain that produces blocks on a fixed cadence turns them out without demand as well, and Shibarium ran without interruption throughout. The blocks do show how much capacity goes unused, though, and they explain why the next figure looks the way it does.
A fee market without demand: slow, average and fast all sit at 0.03
Shibariumscan reports three fee tiers: slow, average and fast. On October 11 all three sit at 0.03 gwei in BONE, the chain's fee currency. One gwei is a billionth of a BONE unit.
That the three tiers are identical is the real finding. A fee market only forms once more transactions want into a block than will fit, and senders then push ahead of each other by paying more. Without that crush there is no premium, and whoever wants to get through quickly pays the same rate as someone content to wait.
That has two implications. A transfer on Shibarium currently costs next to nothing and is confirmed immediately. At the same time, the low rate is the sign that little is happening on this chain.
How Shibarium's throughput drives the SHIB burn
The link between chain activity and token supply is where the figures become interesting for investors. Shibarium is built so that part of the fees accruing on the chain flows into the burning of SHIB. Burning means tokens are sent to an address from which nobody can retrieve them, because no private key exists for it. The tokens remain visible on the blockchain but are permanently out of circulation.
On the day under review the chain consumed 166,869,016 units of gas. At a rate of 0.03 gwei that works out to fee income of roughly 0.005 BONE for the entire day. That is the pool feeding the fee-driven part of the burn. Waiting for Shibarium to tighten the supply of SHIB noticeably means waiting for a mechanism that lacks its basis at this throughput.
None of this is a charge against the technology. A layer-2 chain is built to make transactions cheap, and that is precisely what Shibarium does. The burn depends on the product of fee rate and volume, though, and both factors are currently small. Being cheap and financing a strong burn at the same time is possible for a chain only at high throughput.
Since the Shibariumscan reindex on October 6: 80 percent fewer transactions
On October 6 we reported here that only 55 percent of Shibarium blocks were indexed in the explorer and that the displayed figures should therefore be read with care. That point has since been settled: the API now delivers a continuous series across 31 days without gaps, and the explorer counts 11,185,007 blocks and 749,707,890 transactions since the chain launched. The data situation has improved, then. The throughput has not.
October 6 was also the month's day with the most transactions. Of those 5,711, four days later 1,142 are left, a drop of 80 percent. Our article of October 10 dealt with the other side of the same coin, namely that the capital locked in Shibarium had fallen by 68 percent and that a single pool explained most of it. Less locked capital and fewer transactions belong together: where no capital sits, nothing gets swapped either.
On price the comparison comes out milder. In our article of October 6, SHIB stood at €0.00000514; on the evening of October 11 it is €0.00000491. That is 4.5 percent less in five days, while throughput on its own chain collapsed by 80 percent. The price does not follow the network one for one, and with a token whose trading takes place overwhelmingly on centralised exchanges, that is not to be expected either.
41.05 percent of the original supply has been burned: the sum with two figures
Very different burn figures circulate around SHIB, depending on which tracker happens to be measuring which period. You can work out the overall balance yourself with two publicly available figures, without having to trust any tracker.
The original supply of Shiba Inu stood at one quadrillion tokens, that is 1,000,000,000,000,000 units. As total supply, CoinGecko reports 589,495,745,532,498 SHIB on October 11. The difference of 410,504,254,467,502 tokens is the quantity burned since launch, and that is 41.05 percent of the original supply. Of that, 589,238,379,798,174 SHIB are in circulation; the remaining roughly 257 billion tokens are listed as non-circulating.
Those 41 percent sound like a lot and they are, except that they stem almost entirely from a single action in May 2021, when half the supply went to an address without a key. The running burn from chain operations, by contrast, moves in an order of magnitude that barely changes the total. Throwing both figures into one pot is the most common error in reporting on the subject, and it makes a one-off decision from five years ago look like a running supply squeeze.
SHIB at $0.00000549: daily range, monthly balance and the distance to the high
On the evening of October 11, SHIB is quoted at $0.00000549 or €0.00000491. The daily range ran from $0.00000537 to $0.00000553, a shade under three percent between low and high. Over 30 days there is a gain of 6.18 percent, over seven days a loss of 5.58 percent, over twelve months a loss of 44.74 percent. Market value stands at $3.24 billion, which means 37th place, and daily turnover at $52.1 million.
From the all-time high of $0.00008616 on October 27, 2021, SHIB is 93.6 percent away. The levels the current day provides are the daily low at $0.00000537 on the downside and the daily high at $0.00000553 on the upside. Both lie less than two percent from the current level, which explains the slight movement of the past 24 hours.
For a sense of scale: at €0.00000491 one euro buys roughly 203,700 SHIB, so a hundred euros buys a good 20.3 million tokens. The many zeros are a question of unit count and say nothing about whether the token is expensively or cheaply valued. Market value counts for that, and at $3.24 billion SHIB sits clearly behind Dogecoin, which comes to around $13.6 billion on the same evening.
Holding period and allowance: what to check before selling SHIB
Anyone holding SHIB as private assets in Germany falls under the rules for private disposals set out in section 23 of the German Income Tax Act. The gain from a sale is tax-free if more than a year lies between purchase and sale. Within the year it is taxable at the personal income tax rate as soon as the sum of all private disposal gains in a calendar year reaches 1,000 euros.
Three points are regularly overlooked here. The limit is an exemption threshold, not an allowance: at 999 euros of gain you pay nothing, at 1,001 euros the entire amount is taxable. The calculation also runs across all private disposals of a year together, gold or collectibles included. And the burning of other people's tokens changes nothing in your own holding, while a swap between two tokens is very much a taxable event.
In practice that means looking at the purchase date of each individual tranche before you unwind a position, rather than at the average. Holdings from the start of 2025 are past the one-year mark and sell tax-free. A tranche bought in the summer of 2026 is still inside the taxable window. A tax tool with a portfolio tracker handles this more reliably than a spreadsheet kept by hand, because it carries the order of acquisitions with it.
BONE staking on Shibarium: the yield hangs on the chain's throughput
On Shibarium, tokens can be deposited to share in the chain's fees. The calculation further up shows what that share currently amounts to. With fee income of roughly 0.005 BONE a day, little remains on paper once it is spread across all depositors. On a chain like this, an advertised annual yield is no promise but an extrapolation from a period when more was going on.
For tax there is the added point that income from staking and lending does not fall under the one-year rule but counts as other income under section 22 number 3 of the German Income Tax Act. A separate and considerably lower exemption threshold of 256 euros a year applies to it. Yield drawn on several platforms is added together. A look at a comparison of staking providers pays off above all on the question of who documents the income traceably, because reporting it is down to you.
Our assessment: the chain works, the burn stays small
In the editorial view, the story of the 151 percent recovery is an artefact of arithmetic and not a finding. The evidence stands further up: the jump starts from the month's second-weakest day, 53 percent of it was given back one day later, and against the monthly average of 1,928 transactions the current level lags by 40.8 percent. Claiming a turnaround takes several weeks above that average, not one day.
Against that stands the point that the chain runs technically without fault and that data quality has improved since the reindex. The infrastructure is in place, then; the demand is missing. What that means for the price is open: SHIB has added 6.18 percent over 30 days although throughput on its own chain collapsed. The price is currently carried by the general market, not by Shibarium. No recommendation to buy or sell follows from that, and with a memecoin a total loss remains possible at any time.
Shibarium: below 1,900 transactions a day the burn stays small
The threshold against which the coming weeks can be measured is the monthly average of 1,928 transactions a day. As long as Shibarium stays below it, fee income and with it the fee-driven burn stay in the order of magnitude set out above.
- Look up the figure yourself. The daily series is public at shibariumscan.io in the statistics section. No tracker and no newsletter are needed for it, and you see immediately whether a reported percentage jump was calculated from a weak or a strong previous day.
- Record the purchase date of every tranche. Tax turns on the one-year rule, not on the average price. If you hold SHIB through an exchange, export the transaction list now rather than in March. Which venues deliver that export cleanly is set out in the comparison of crypto exchanges.
- Hold yield promises against throughput. An advertised annual yield on Shibarium staking presupposes fee income. Set it against the roughly 0.005 BONE that accrued in total on the day under review before you tie up capital.
(As of October 11, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
A cryptocurrency can sit ninth among the largest coins and still have almost no trading. Figure Heloc carries a market capitalisation of $25.09 billion, and over 24 hours holdings worth $106,017 changed hands. That is 0.0004 percent. Bitcoin managed 0.89 percent over the same period, Ethereum 2.79 percent.
We therefore ran the numbers on all 25 largest cryptocurrencies, setting daily turnover against market capitalisation in each case. Four of them stay below 0.32 percent. Buy one of these assets and you own something that sits beside Bitcoin in the ranking and behaves entirely differently on the way out. cryptoticker.io collected this data itself on October 11, 2026.
Market capitalisation and trading volume measure two different things
Market capitalisation is the last traded price multiplied by the number of units in circulation. The figure states what a holding would be worth if valued at the current price. On whether that price holds for anything larger than a small order, it says nothing.
Trading volume is the cross-check. It names the sum actually traded over 24 hours. Put the two figures into a ratio and a metric appears that is shown nowhere in the ranking: the share of market capitalisation that changes hands in a day. For the large assets it runs in the low single-digit percentages, for four of the top 25 in the per-mille range.
The difference is no cosmetic flaw in the statistics. It decides whether you can sell at the price your app shows you.
Figure Heloc at number nine: not a single listed trading venue
The most striking case goes by the name Figure Heloc and sits at $25.09 billion in ninth place, between Tron and Zcash. For this token CoinGecko lists not a single trading pair on any exchange. Zero. The $106,017 of daily turnover therefore arises outside the venues that the price pages track.
For an investor in Germany that means something very practical to begin with: there is no way to buy or sell this token through one of the common crypto exchanges. In the ranking the token has climbed over recent weeks. In trading it has not.
The measurement at a glance: 0.0004 to 0.32 percent against a median of 2.23 percent
The median across all 25 assets excluding stablecoins is 2.23 percent. Measured against that benchmark, four assets stand clearly apart:
| Rank | Asset | Market capitalisation | Turnover over 24 hours | Share |
|---|---|---|---|---|
| 9 | Figure Heloc | $25.09bn | $0.11m | 0.0004 percent |
| 18 | LEO Token | $8.20bn | $0.27m | 0.0033 percent |
| 20 | Rain | $7.17bn | $13.04m | 0.18 percent |
| 23 | Canton | $5.02bn | $15.84m | 0.32 percent |
| 1 | Bitcoin | $1,678.61bn | $14,925.94m | 0.89 percent |
| 2 | Ethereum | $308.90bn | $8,609.41m | 2.79 percent |
Just above them sits WhiteBIT Coin in 16th place at 0.34 percent. At the other end of the scale stands NEAR Protocol at 11.85 percent, where almost an eighth of the market capitalisation changes hands in a day. Between Figure Heloc and NEAR, in the same list, lies a factor of roughly 30,000.
Why a high ranking can arise alongside thin trading
The mechanism is simpler than it sounds. Market capitalisation counts the entire circulating supply, including the part that has lain untouched for years or is not freely tradable at all. Figure Heloc has 23.76 billion units in circulation, Rain as many as 709.25 billion. A price of one dollar, or of one cent, is then enough for a valuation in the billions.
If a small trade moves that price, it moves the whole valuation with it. Figure Heloc's price rose 5.49 percent over 24 hours, which would lift market capitalisation by a good billion dollars. Carrying that move is a turnover smaller than a bakery's annual revenue.
The same holds in reverse on the way down, and that is the side that costs money.
LEO Token: four fifths of turnover runs through a single exchange
At LEO Token, 18th place with $8.20 billion, turnover of $271,272 is spread across seven listed trading venues. That sounds like choice. Broken down, roughly four fifths falls to a single small venue, a further slim remainder to Bitfinex, and on OKX a good $4,800 is left. One trading pair on a decentralised exchange contributes $43.
Place an order worth a few thousand euros in LEO and you are already a substantial part of the day's activity at that venue. The order book, meaning the list of all open buy and sell orders with their prices, is only a few lines deep in such cases.
Rain before the token unlock: $785.5 million against $13 million of daily turnover
Rain sits 20th with $7.17 billion and $13.04 million of daily turnover. The price gave way by 15.34 percent over 24 hours, the sharpest downward move in the top 25 that day.
A date fits that picture. The trade publication Cryptobriefing named $785.5 million of previously locked Rain tokens for October on July 2, 2026, around 73 percent of the month's seven largest unlocks. A token unlock is the point at which contractually locked holdings become tradable. Whether the holders sell, nobody knows beforehand. Only the ratio is certain: the sum named is sixty times what this token turns over in a day. CoinMarketCap's price page reports turnover for Rain in the same order of magnitude.
By our breakdown, Rain trades at twelve venues, led by BingX, HTX, MEXC and BloFin, plus one trading pair on Uniswap. Missing from that line-up is any exchange an investor in Germany would normally use as a first address. Getting in and out here means landing with providers whose EU authorisation has yet to be checked.
Canton as a counter-test: thin trading, but 18 trading venues
Canton shows that a low turnover share is no verdict on its own. The asset sits at 0.32 percent, just above the group, and added 6.75 percent over 24 hours. Its $15.84 million of turnover is spread across 18 trading venues, though, and among them are Bybit, OKX, Kraken, Upbit, Bitget, KuCoin and Gate.
What separates it from Rain and LEO is therefore less the depth of the market than its reachability. Through Kraken, Canton is open to investors in Germany by a familiar route. The trading stays thin all the same, and for the order the same applies as with the other three assets.
Spread, slippage and partial fills in a thin order book
Three things happen when the market is narrow. The spread, meaning the gap between the best bid and the best offer, widens. For the large assets it runs in hundredths of a percent, while for a token with $271,272 of daily turnover it can be a multiple of that. You pay that gap on the way in and again on the way out.
There is also slippage. The term covers the deviation between the price you saw and the price at which your order is actually filled. A market order takes what the order book holds, and in thin depth it works its way through ever worse prices. That is precisely what produces price jumps of several percent in such assets without any news at all.
If not enough is left in the order book, the order is only partly filled. The remainder then sits in the market while the price moves on. On a sale during a falling phase, that is the most uncomfortable of the three cases.
The route to Germany: MiCA authorisation and the custody question
Since the EU's MiCA regulation took full effect, providers of crypto services in the EU need a licence and can work across borders with it. For buyers that is the first filter: if a token stands only at venues without that licence, the purchase turns not merely expensive but also legally murky.
The second point is custody. If a token is held exclusively at an exchange without an EU licence, your units sit there too, and a retreat to your own wallet presupposes that the token is supported there at all.
For tax, the one-year holding period for private disposals still applies in Germany: hold for more than a year and no income tax falls due on the gain. In practice that period helps little if, at the end of the year, you find no buyer to take the position at the quoted price. The holding period solves no liquidity problem.
Our assessment: the ranking says nothing about the exit door
In the editorial view, the market capitalisation ranking is the industry figure most often misread by investors. The evidence lies in our measurement: Figure Heloc in ninth place without a single listed trading venue, LEO in 18th with four fifths of turnover at one small house, a ratio of 0.0004 percent against a median of 2.23 percent. A list that files these cases beside Bitcoin sorts by a quantity that is the wrong one for a buying decision.
Against that stands the point that a thin market does not automatically mean a weak project. Canton trades at 18 venues, Kraken among them, and a token aimed at institutions needs no high retail turnover. The metric therefore replaces no examination of the project, but answers the single question of the price at which you get back out. That question arises first on the sale, and by then it is no longer negotiable.
Thin trading: below 0.32 percent the exit turns into the problem
- Before buying, run daily turnover against market capitalisation. Below half a percent the asset belongs in a different risk class from a standard one. Which houses carry which assets at all is shown by the comparison of the best crypto exchanges.
- Study the list of trading venues, not merely how many there are. If turnover is spread across a few names without EU authorisation, the way back is missing. The licensed houses appear in the overview of regulated crypto exchanges.
- With thin assets, work with limit orders instead of market orders and cap position size at a fraction of daily turnover. Which providers map limit orders and partial fills cleanly is visible in the comparison of crypto brokers.
(As of October 11, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
You can buy Dogecoin in Europe on any exchange holding MiCA authorisation, and the price difference between the routes is larger than the difference between the exchanges. Put €100 to work on Sunday evening and Kraken, Bitvavo and Coinbase gave you, on paper, between 1,294.78 and 1,295.67 DOGE. The gap is therefore under a euro. Take the convenient instant buy at the same provider instead of the order book, though, and Kraken charges one percent rather than 0.8 percent, and 1.5 percent on a custom order. Choosing the button costs more than choosing the exchange.
Dogecoin stood at €0.077267 and $0.086534 on Sunday evening and is, at around €12.08 billion in market capitalisation, the twelfth-largest crypto asset. Where things could go from here is set out in our Dogecoin price prediction. For the purchase itself, however, the price is the least important number: what counts are the three costs sitting between your euro and your DOGE, namely the trading fee, the spread between bid and ask, and later the network fee for withdrawing to a wallet of your own.
Buying Dogecoin in Europe: these three exchanges hold authorisation in the register
Since the European crypto regulation MiCA took full effect, only a party holding authorisation as a crypto asset service provider may operate a trading venue in the EU. The European securities regulator ESMA collects these authorisations in a public register. As of October 7, 2026 it lists 370 entries. The largest home state is Germany itself: 103 entries name BaFin as the competent authority, followed by France with 36 and the Netherlands with 29.
Crypto asset service provider is a collective term here. The regulation recognises ten individual services, from custody through operating a trading platform to transfers, and every authorisation states expressly which of them a provider may deliver. For the three trading venues most frequently used in Germany to buy DOGE in euros, the register says:
- Bitvavo B.V., authorised by the Dutch regulator AFM on June 26, 2025, for custody, operating a trading platform and transfer services.
- Payward Europe Solutions Limited and Payward Global Solutions Limited, both authorised by the Central Bank of Ireland on June 25, 2025. Kraken stands behind those names; the second company holds the authorisation for operating the trading platform.
- Coinbase Luxembourg S.A., authorised by Luxembourg's CSSF on June 20, 2025, for custody, exchange against funds and the execution of orders, among others.
None of the three authorisations carries an end date. Which other providers may trade with authorisation in Germany is shown in our overview of the best crypto exchanges; the obligations MiCA imposes on companies are set out in our overview of the MiCA licence and its duties.
What €100 buys in DOGE at three trading venues
For this article we queried the order books of the three exchanges in the same minute on Sunday evening and calculated from them how much DOGE a €100 purchase yields at the respective best ask, still before any trading fee:
- Bitvavo: best ask €0.077180, bid €0.077156. €100 yields 1,295.67 DOGE.
- Kraken: best ask €0.0772332, bid €0.0772085. €100 yields 1,294.78 DOGE.
- Coinbase: best ask €0.07723, bid €0.07719. €100 yields 1,294.83 DOGE.
Between the cheapest and the most expensive venue lie 0.89 DOGE, which converts to barely seven cents. Comparing therefore pays off little at this point. The difference only matters once you buy regularly and in larger sums, because the fee accrues as a percentage and grows with the stake.
The spread between bid and ask is the price no fee table discloses
The spread is the gap between the highest price at which somebody wants to buy and the lowest at which somebody wants to sell. That difference is a genuine cost item: buy immediately and sell again immediately and you would lose precisely that gap, even without any fee. It does not appear in the exchanges' fee tables, because it is no price set by the provider but a result of the market.
Measured on Sunday evening it was small at all three venues: 0.0311 percent at Bitvavo, 0.0320 percent at Kraken and 0.0518 percent at Coinbase. On €100 that is three to five cents. With daily turnover of around $396 million, DOGE is liquid enough that the spread carries no weight on small orders. With the thin markets of smaller tokens it looks different, as we described when looking at the order book after the large transfer of October 11.
Since our report of October 10, which had Dogecoin at $0.0862, little has moved on the price: $0.086534 on Sunday evening means a gain of 0.6 percent within a day. The nine-cent level, at which the price turned several times in early October, has still not been reclaimed.
Instant buy or order book: at Kraken a whole percent lies between them
Every larger exchange offers two routes to the same coin. One is a button showing you a price that you accept. The other is the order book, where you place an order with a limit of your own. Both lead to DOGE in the account, but they cost different amounts.
Kraken discloses the rates separately in its fee schedule. In the order book you pay, on the lowest volume tier, meaning from a 30-day turnover of zero, 0.40 percent as maker and 0.80 percent as taker. Maker means your order sits in the book and waits; taker means you accept an existing order immediately. On the instant buy, by contrast, Kraken charges one percent, and 1.5 percent on a custom order, with the spread already included in the price shown. On €100, 20 cents therefore separate the taker in the order book from the instant buy, and 70 cents separate it from the custom order.
The difference looks small and grows large as soon as it repeats. Put €100 through the instant buy every month for twelve months and you pay €12 in fees; via a limit order as maker it would be €4.80. On a savings plan running over several years that adds up to an amount clearly visible in relation to the investment.
Bitvavo charges 0.25 percent as taker and 0.15 percent as maker
Bitvavo assigns every trading pair to a fee category. DOGE against the euro runs in category A there, and for that category Bitvavo's fee table names 0.15 percent for makers and 0.25 percent for takers on the entry tier. The rates fall as 30-day volume rises, which stays irrelevant for private purchases: the entry tier is the tier on which practically all retail investors trade.
That places Bitvavo below Kraken's lowest tier in the order book. On €100, the gap between 0.25 and 0.80 percent means 55 cents. That is more than eight times the difference we measured above between the best asks. For the question of what a DOGE purchase costs, the provider's fee tier is therefore the first lever and the spread the last.
We have deliberately left Coinbase out here. The provider runs several products with different fee models, and the fee page was not readily readable at the time of research. A number we cannot evidence at source is one we do not write down. Check the rates in your account before buying, then; the rate that applies to you is shown there.
Minimum order: 50 DOGE at Kraken, five euros at Bitvavo
Both exchanges set lower limits that become practical for newcomers with small amounts. In the DOGE against euro pair, Kraken requires a minimum quantity of 50 DOGE, converting to around €3.86, and a minimum value of €0.45. Bitvavo requires at least €5.00 in value, which corresponds to about 65.70 DOGE. Start with two euros and you get through at neither venue.
The price increments differ as well. Kraken calculates the pair to seven decimal places and allows price steps of €0.0000001, while Bitvavo works with steps of €0.000001. On a coin costing seven cents, that detail decides how precisely you can set a limit.
What do the service codes in the register say about your trading venue?
The most interesting part of the register sits here, and it is rarely read. Bitvavo holds the authorisation for custody, for operating a trading platform and for transfer services. Kraken and Coinbase hold, in addition, the authorisation for the exchange of crypto assets against funds. Those are not the same activity: in operating a trading platform the provider brings buyers and sellers together and you trade against other customers. In an exchange against funds the provider itself acts as the counterparty and sells you the coin from its own holdings.
For a buyer, that means the convenient instant buy is usually business against the house, while the order book is business against other customers. It also explains why the instant buy is more expensive. The provider takes on the risk of holding the coin and charges for it. Which providers hold which authorisation you can look up yourself in ESMA's MiCA section; the register is available there as a downloadable file. A pre-selection of authorised houses is in our comparison of the best regulated crypto exchanges.
Leverage up to a factor of ten: the trading pair can do more than you need
For DOGE against the euro, Kraken permits leverage tiers from two to ten, along with position limits of 14 million DOGE on the buy side and 6.3 million on the sell side. A margin call falls due at 80 percent, and at 40 percent the position is closed. These numbers are openly stated in the pair's data sheet.
For a purchase where you want to own coins, none of that is needed. Leverage turns the purchase into a forward transaction: you borrow money, and a price decline that merely annoys you without leverage ends the position with it. On a coin that has lost around 88 percent since its high of $0.731578 on May 7, 2021, that is no abstract danger. A total loss is possible at any time with crypto assets, and faster with leverage.
After buying: the transfer to a wallet of your own and what it costs
As long as your DOGE sits in the exchange's account, the exchange holds the keys. A wallet of your own is a program or a device that keeps the private key with you, so that nobody but you can dispose of the coins. The price for that is responsibility: lost access means lost coins, because there is no office that resets it.
Technically the withdrawal is an ordinary transfer in the Dogecoin network. You pay the network fee in DOGE, and it depends not on the amount but on the size of the transaction in bytes. With a small holding the fee can therefore become noticeable in proportion, while with a large one it goes unnoticed. If you buy small amounts monthly, you are better off collecting several months and transferring once. Which devices are suitable and what they cost is set out in our hardware wallet comparison.
Holding period and exemption threshold: the tax rules when selling DOGE
For tax purposes, Dogecoin belongs to the other assets within the meaning of section 23 of the German Income Tax Act. A gain from a sale is taxable only where no more than a year lies between acquisition and sale. After a year the gain is tax-free, whatever its size.
Inside the year an exemption threshold applies: where the sum of all gains from private sales in a calendar year stays below €1,000, it remains tax-free. An exemption threshold is not an allowance. Realise €1,000 or more and you pay tax on the entire gain, not merely the part above the line. Important for buyers who switch between coins: a swap of DOGE into another crypto asset counts as a sale, and the one-year period starts afresh for the new coin.
Our assessment: the instant-buy premium weighs more heavily than any spread
From the editorial team's point of view, the widespread hunt for the cheapest exchange for DOGE is the wrong question. The evidence is above: seven cents per €100 separated the best asks of the three trading venues on Sunday evening, while 75 cents separated Kraken's instant buy from Bitvavo's taker fee. The route inside the provider therefore decides costs roughly ten times more strongly than the choice of provider.
One practical objection runs the other way, and it is not a small one: a limit order wants setting and watching, and an order that never executes saves no fee but misses the purchase. Invest a small amount once and you may fare better with the instant buy, because 20 cents of difference is not worth the effort. From regular purchases or three-figure amounts upwards, the arithmetic tips. This is expressly not a recommendation to buy Dogecoin: the coin has no supply cap, mining adds around 5.26 billion DOGE a year, which is about 3.4 percent of today's circulating 156.28 billion units. Our earlier appraisal of that is at Should you buy Dogecoin now?.
Buying Dogecoin: a one percent premium costs one euro on €100
- Choose a venue by authorisation, not by advertising. Look in the ESMA register to see whether your provider holds authorisation and for which services. A pre-selection is in our comparison of the best crypto exchanges.
- Buy in the order book instead of through the instant buy. Place a limit order and check in your account which maker and taker rate applies to you. Whether you then hold the coins yourself is the second cost question; the devices for it are in our hardware wallet comparison.
- With regular purchases, work the fee out over the year. Twelve monthly purchases of €100 each cost €12 through the instant buy, and €4.80 as maker. How a savings plan is set up in practice is shown in our savings plan comparison.
(As of October 11, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
An IMF analysis found that more than half of tokenized stock trading happens outside U.S. market hours, though the roughly $2.3 billion market remains more volatile and less liquid than traditional equities.
Bitcoin ETFs have seen $386.3 million in net outflows through the first seven trading days of October, while Ethereum funds have now posted nine straight days of losses.
Zakura, a Zcash full node developer, says it expects hash-based signatures to land in Zcash in January, and is rolling out a privacy tool for rotating transparent addresses this week.
A proposed rule would expressly fold event contracts tied to sports, politics, culture and weather into the “swap” definition, while an interim rule excludes casino-style gambling—sharpening the agency’s claim to exclusive jurisdiction.
The Bermuda-based insurer, which runs entirely on Bitcoin, drew the funding from existing backers led by Bain Capital Crypto after a record year driven by demand from wealthy families in Asia, Europe and the Middle East.
U.Today - IT, AI and Fintech Daily News for You Today
The current state of the market is far from bullish as the momentary correction might turn into a full-blow trend reversal.
Cryptocurrency hardware wallet manufacturer Ledger has provided a new update on the ongoing wallet-draining scandal.
Saylor teases upcoming Bitcoin purchases at a historic $70 billion milestone for world's largest cryptocurrency treasury firm.
XRP Ledger upgrade countdown begins with key fixes for Lending, DEXs and Permission Delegation set to go live.
XRP Kuwait slams centralized control claims after a 2015 currency-minting bug forced an emergency XRP Ledger patch.
Blockonomi
TLDR:
- Ledger found an unauthorized hardware implant in one device linked to the CryptoBilis investigation.
- Blockchain investigators estimate crypto losses above $86 million, but Ledger has not confirmed the total.
- Bitquery estimates $93.2 million was taken from 315 wallets across five blockchain networks.
- CryptoBilis halted wallet sales as Ledger reviews reseller controls and strengthens hardware security measures.
Ledger has confirmed an unauthorized hardware implant in a device linked to the CryptoBilis incident, as blockchain investigators estimate cryptocurrency losses exceeding $86 million.
The October 9 incident involved devices sold through CryptoBilis, a reseller operating in Indonesia, Malaysia and the Philippines. Ledger’s October 11 update identified the reseller as the source of all confirmed cases while investigations continued.
72 hour update on reseller CryptoBilis incident
As the investigation continues, we are working with relevant authorities. The volume of impacted devices is limited. We know this is concerning, especially for those directly affected, and we are reaching out to impacted users.…
— Ledger (@Ledger) October 11, 2026

The company said its internal systems and direct sales channels remain unaffected. However, the discovery of tampered hardware has introduced a physical security concern alongside the reported thefts, with investigators still working to establish the full extent of the incident.
The number of affected devices remains undisclosed, and the manufacturer has not confirmed the total financial losses. Meanwhile, CryptoBilis has stopped selling hardware wallets as the investigation proceeds with relevant authorities.
Blockchain Analysis Estimates $93.2M Taken From 315 Wallets
Blockchain intelligence firm Bitquery estimated that approximately $93.2 million was taken from 315 wallets across Bitcoin, Ethereum, TRON, BNB Chain and Polygon. Its analysis also found that some stolen funds moved through additional addresses after the initial thefts.
The estimate exceeds separate reports placing the suspected losses above $86 million. However, neither figure represents an official loss assessment from Ledger, which has not confirmed the total amount stolen.
Reports of missing cryptocurrency emerged on October 9, when users linked disappearing funds to wallets associated with devices purchased through CryptoBilis. Investigators subsequently identified an unauthorized hardware component inside one affected device.
Hardware wallets typically isolate private keys from internet-connected devices to reduce exposure to online attacks. However, physical modifications can undermine those protections if malicious components compromise sensitive information.
Investigators have not publicly established how the affected devices were compromised or whether the hardware implant caused every reported loss. Therefore, the connection between the discovered component and the broader thefts remains under investigation.
Ledger Issues Security Guidance and Reviews Reseller Controls
Ledger has advised customers who purchased devices through CryptoBilis to take precautions based on their devices’ initialization status. Besides, buyers who have not initialized their devices should not set them up.
On the other hand, customers who have already initialized their wallets should transfer their assets to a new Ledger device using a newly generated recovery phrase. The company has also directed affected users to its official support website for assistance.
The incident has prompted a review of authorized reseller controls, hardware protections and distribution procedures. Ledger has also warned distributors against restocking returned devices, which could introduce modified products into the supply chain.
Customers have therefore been urged to avoid unauthorized sellers as hardware wallets could be counterfeit, modified or outside manufacturer security guidelines. The company also warned about follow-up scams targeting people affected by the incident.
Ledger said it will never call customers, send direct messages or request their 24-word recovery phrases. Users should therefore avoid sharing recovery information with anyone claiming to provide technical support. The investigation remains ongoing, with the number of affected customers, the confirmed financial impact and the precise compromise method still unresolved.
The post Ledger Confirms Tampered Hardware in CryptoBilis Case Amid Reports of $86M in Crypto Losses appeared first on Blockonomi.
TLDR:
- Brian Armstrong backed the SEC’s proposal on October 11 to broaden retail access to private markets.
- The SEC is considering professional credentials and FINRA exams as alternative routes to accredited investor status.
- Current eligibility generally requires $200,000 in annual income or $1 million in net worth, excluding a primary residence.
- The proposal covers regulated funds, adviser compensation disclosures and interval fund rules, but changes are not final.
Coinbase CEO Brian Armstrong has backed a U.S. Securities and Exchange Commission (SEC) proposal to broaden retail investors’ access to private markets. His support comes as regulators consider alternative ways for ordinary Americans to qualify for investments traditionally reserved for wealthier individuals.
In an October 11 post on X, Armstrong argued that everyday investors have missed opportunities as companies increasingly remain private for longer. This trend can leave early shareholders with years of access to private-company growth before ordinary investors can participate through public markets.
Armstrong also warned that late entrants could become exit liquidity for earlier shareholders. This occurs when investors buy into an opportunity while existing holders sell their positions, potentially leaving newcomers exposed to unfavorable valuations.
SEC Weighs Professional Credentials and Exams for Accredited Investor Status
The proposal follows the regulator’s September 30 announcement of potential changes affecting private-market investments and regulated funds. These measures aim to broaden participation while retaining investor protections.
Among the proposed changes, registered investment advisers could receive performance-based compensation from additional client categories, including certain regulated funds. The regulator also plans to require further disclosures about this compensation and modernize rules governing interval funds. Separately, the agency is seeking public feedback on alternative ways to qualify as an accredited investor.
Options under consideration include professional credentials, examinations and certain financial industry licenses. The qualifications being considered include the Chartered Financial Analyst (CFA) charter, Certified Public Accountant (CPA) license and Certified Financial Planner (CFP) certification. Certain Financial Industry Regulatory Authority licenses and an accredited investor examination developed by FINRA are also under consideration.
These alternatives could give individuals another way to demonstrate financial knowledge without meeting existing income or wealth requirements. However, the proposals remain under consideration and have not become established rules.
Under current requirements, individuals generally qualify through annual income exceeding $200,000 for each of the previous two years. Alternatively, joint income exceeding $300,000 or net worth above $1 million, excluding a primary residence, can establish eligibility.
Longer Private Company Lifecycles Raise Concerns About Late-Stage Access
The debate reflects a changing fundraising environment in which businesses can secure successive private funding rounds without listing shares publicly. Consequently, founders and early shareholders can retain control while delaying public disclosure requirements and listing costs.
For retail investors, this can mean waiting until an initial public offering (IPO) to access publicly traded shares. By then, early investors may have participated in private funding rounds and transactions unavailable to the wider market.
Armstrong’s warning about exit liquidity centers on this timing gap. Investors entering later could face elevated valuations while earlier shareholders sell, although outcomes depend on individual companies, investment terms and pricing.
Broader access through regulated funds would not eliminate investment risks. Private-market assets can involve limited liquidity, uncertain valuations, fees and potential losses. Interval funds also typically offer repurchases at scheduled intervals rather than unrestricted daily withdrawals.
The regulatory process will determine which proposed changes proceed and what safeguards accompany them. Until then, the proposal signals a possible change in access to private markets, not an immediate opening of every private investment to retail investors.
The post Coinbase CEO Backs SEC Proposal to Expand Retail Access to Private Markets appeared first on Blockonomi.
TLDR:
- 42 AI stocks generated 67% of S&P 500 price returns since January 2024, according to reported figures.
- AI companies accounted for 58% of S&P 500 earnings growth over the reported period, according to data.
- AI-related companies drove 81% of combined capital expenditure and R&D growth across the S&P 500.
- Only 29% of stocks outperformed the S&P 500 over the previous three years, indicating narrow market breadth.
A group of 42 artificial intelligence (AI) stocks generated 67% of the S&P 500’s price returns since January 2024, exposing the index’s growing dependence on a relatively small group of companies.
Figures shared by The Kobeissi Letter on October 11, 2026, and attributed to Bloomberg and JPMorgan, show that these companies also accounted for 58% of earnings growth and 81% of combined capital expenditure (CapEx) and research and development (R&D) growth.
The remaining 458 companies contributed 11 percentage points to the index’s price returns, compared with 22 percentage points from the AI group. The figures reveal how market performance and corporate spending have become increasingly concentrated among technology-related businesses.
AI Stocks Dominate Returns and Corporate Spending
The concentration extends beyond share prices. The 42 companies accounted for more than half of earnings growth and over four-fifths of additional spending growth across the index. Much of this spending supports data centers, advanced semiconductors and computing infrastructure required to develop and operate AI systems.
Research and development commitments also contribute to the gap between these companies and the broader market. A separate report from JPMorgan Private Bank’s Eye on the Market Outlook 2026 found that 42 AI-related companies represented approximately 65% to 75% of S&P 500 earnings, revenues and capital spending since ChatGPT launched in November 2022.
However, that analysis covers a longer period and uses different measurements from the figures shared by The Kobeissi Letter. Both sets of data point to the substantial role these companies play in corporate performance. Recent earnings figures further illustrate the concentration.
JPMorgan Asset Management reported in August 2026 that just 10 companies accounted for 77% of expected second-quarter earnings growth. Semiconductor companies drove much of that growth, while heavy infrastructure spending continued to pressure profitability at some major cloud and technology businesses.
Narrow Market Breadth Leaves the S&P 500 Dependent on AI Leaders
The concentration matters as the S&P 500 represents hundreds of companies, yet its overall performance can rely heavily on a limited number of large constituents. Reuters reported on October 9, 2026, that the U.S. bull market remained largely driven by AI-related investments.
The index had gained 117% since its October 2022 low, although rising Treasury yields, interest rates and concentration concerns threatened the rally. The Kobeissi Letter also reported that only 29% of stocks had outperformed the benchmark over the previous three years.
This limited market breadth indicates that index gains have not translated into comparable performance across most constituents. The figures do not establish whether current valuations are justified or predict future returns.
However, they identify a measurable dependence on a narrow group of companies for price performance, earnings expansion and corporate spending. The central issue remains whether continued AI investment will translate into sufficient revenue and productivity gains to support sustained business performance across the sector.
The post 42 AI Stocks Drive 67% of S&P 500 Returns as Market Concentration Deepens appeared first on Blockonomi.
TLDR
- Tether USDT worth approximately $1.45 million became accessible after restrictions on four THORChain vaults were reversed within three hours.
- THORChain resumed TRON trading, deposits, and transaction signing, while 19 other addresses in the same freezing operation remained restricted.
- Co-founder Chad Barraford said the protocol received no advance communication explaining the freeze and sought clarification from Tether.
- Restoring access to existing tokens resolved an operational disruption, but it did not establish fresh capital inflows or stronger crypto demand.
Tether USDT worth approximately $1.45 million became accessible again after the issuer reversed restrictions on four THORChain vaults on TRON. The reversal followed a roughly three-hour freeze on October 9, allowing disrupted network operations to resume.
The incident briefly interrupted a stablecoin route used for cross-chain trading. Reports said the four vault balances remained intact after their addresses were removed from the blacklist.
Tether USDT Restrictions Lifted as Vault Services Resume
THORChain technical co-founder Chad Barraford said the project received no advance communication explaining the restrictions. Before the reversal, he said the team was seeking contact with Tether and hoped a misunderstanding caused the action.
As reported, Barraford subsequently confirmed the addresses were unfrozen and trading would resume. The publication said neither company immediately responded to its requests for further details.
The four addresses reportedly left the blacklist at 15:30 UTC. THORChain then restarted TRON trading, deposits, and transaction signing. Another 19 wallets included in the same freezing operation remained blacklisted.
That distinction limits the scope of the announcement. Tether USDT access returned for the affected protocol vaults, while restrictions continued elsewhere. The reversal did not represent a general removal of wallet controls.
For traders, the operational impact concerned whether transactions could proceed through the affected route. For liquidity providers, restored services reopened access to functions interrupted during the freeze.
The incident illustrates an external dependency for protocols using centrally issued stablecoins. Decentralized infrastructure does not remove the issuer controls attached to those tokens.
Tether USDT operates within an established framework that permits wallet restrictions. In December 2023, the issuer announced expanded secondary-market freezing measures covering wallets associated with sanctioned persons.
TRON Supply Growth Puts the Liquidity Impact in Context
The wider liquidity discussion centers on TRON’s growing stablecoin supply.Lookonchain figures show an annual increase of $18.67 billion, bringing USDT supply on TRON to $94.25 billion.
Those figures imply growth of approximately 24.7%. They help explain why interruptions involving TRON can matter to traders using its stablecoin infrastructure.
However, the $1.45 million release represents approximately 0.0015% of that reported network supply. Its significance lies mainly in restoring a specific service, rather than changing marketwide buying capacity.
Tether USDT already held in the vaults remained part of the existing supply during the freeze. Removing restrictions made those balances usable again without demonstrating fresh investor deposits or new token issuance.
The USDT dominance retreated from a September resistance area near 6.7%. A lower dominance reading alone cannot confirm that holders are buying Bitcoin or altcoins.
The ratio compares the stablecoin’s market value with the broader cryptocurrency market. It can decline when other assets appreciate, even without a corresponding reduction in stablecoin holdings.
Similarly, higher stablecoin supply does not establish where holders intend to deploy their funds. Balances can support payments, transfers, collateral, or trading activity.
Any claim that Tether USDT will drive a rebound therefore requires additional evidence of actual buying. The vault reopening itself provides no measurement of subsequent Bitcoin or altcoin purchases.
At the time of reporting, the other 19 addresses remained restricted.
The post Tether USDT Unfreeze Restores $1.45M Across Four THORChain Vaults appeared first on Blockonomi.
TLDR:
- Peter Brandt favors Monero among the altcoin charts he compared, saying its previous overhead supply has already been absorbed.
- XRP faces potential selling from investors who bought at higher prices, creating resistance that could interrupt a recovery toward $2.16.
- The developing XRP reversal pattern has a short, poorly formed right shoulder, although Brandt says further development is not required.
- The $2.16 daily chart objective and earlier $5.40 monthly projection reflect separate patterns, rather than a revised single forecast.
Peter Brandt favors Monero over XRP, despite identifying a potential XRP advance toward $2.16. The veteran trader says XRP faces substantial overhead supply that could interrupt a recovery. Monero, by comparison, has absorbed the comparable supply in his chart assessment. His preference reflects trading patterns rather than an evaluation of either cryptocurrency’s underlying technology.
Brandt also compared Solana, Ethereum, and Stellar over the same period, highlighting differences in resistance and chart structure. For XRP, the bullish objective remains conditional. Its developing pattern could change, while investors who bought at higher prices may sell as the market approaches their entry levels.
Peter Brandt Favors Monero as XRP Faces Supply Barriers
Peter Brandt described Monero as his strongest choice among the altcoin charts under review. He argued that its previous overhead supply had already been absorbed, leaving a clearer technical path.
“Of these, my favorite by far is XMR,” he wrote.
That assessment explains why a bullish XRP price target did not make XRP his preferred trade. A chart can suggest potential gains while still showing barriers along the route.
Overhead supply refers to potential selling from holders who purchased above the current market price. When prices recover, some may exit near their original purchase levels, limiting further progress.
Brandt identified that issue as a significant negative for XRP. His comparison focused on the relative burden visible across charts covering the same period.
Solana received a more favorable assessment for its cup and handle formation. He considered that structure stronger than the corresponding pattern developing in XRP.
Ethereum showed considerable congestion, reflecting trading concentrated within a crowded range. However, Brandt distinguished that congestion from the overhead supply he identified in XRP.
Stellar also faced overhead supply, although he considered its burden smaller. These distinctions shaped his preference for Monero without establishing guaranteed outcomes for any asset.
For Peter Brandt, the distinction concerns both the potential move and the resistance that could delay it. His favorable reading of Monero addresses the latter issue, while XRP’s measured objective describes a possible destination without resolving the supply problem along the way.
Peter Brandt said he did not need to understand Monero’s fundamental narrative to assess its chart. His stated approach prioritizes price behavior, with Bitcoin an exception to his broader indifference toward cryptocurrency fundamentals.
Daily XRP Target Differs From Earlier Monthly Projection
Peter Brandt derived the $2.16 objective from a possible inverse head and shoulders pattern. He used daily closing prices to measure the formation, rather than intraday highs and lows.

The setup features three troughs, with the central trough deeper than the surrounding two. Projecting the pattern’s height upward produces a measured objective, subject to the structure developing as anticipated.
His earlier daily XRP chart highlighted a cup and handle formation. He suggested that smaller pattern could become the right shoulder of the larger reversal structure.
However, the shoulder remained short and poorly developed in his assessment. More formation appeared likely, although he explicitly stopped short of calling further development necessary.
Peter Brandt cautioned that chart patterns can evolve into different configurations as trading continues. A projected destination therefore does not establish that the market will reach it.
“Targets or objectives are not sacred,” he wrote.
The XRP price objective also differs from his earlier $5.40 projection, shared on September 21. That assessment came from a monthly chart and addressed a separate, longer term structure.
He did not describe $2.16 as a replacement for $5.40. Nor did he identify the lower figure as a required intermediate stop toward the higher objective.
In a September 26 comment, Brandt said XRP’s chart alone could justify considering a trade. He later asked XRP supporters not to interpret his technical criticism as a personal offense.
The post Peter Brandt Prefers Monero as XRP Rally Faces Selling Pressure appeared first on Blockonomi.
CryptoPotato
A 25-year-old man has been jailed for two and a half years for his involvement in SIM-swap fraud, which saw four people lose £200,000 worth of crypto in November 2021.
According to the City of London Police, Ajay Shinjin, also known as AJ Marley Cruz, received more than £44,000 from the proceeds of crime and used the money on luxurious vacations to Dubai, an expensive apartment, and gold-plated dental grills.
How the Swap Worked and Where the Money Went
It began in early November 2021, when BT spotted unauthorized activity on its systems. Customer phone numbers were being moved onto SIM cards controlled by criminals, a practice known as SIM swapping.
With a number under their control, the fraudsters could receive one-time passcodes by text and use them to get into a victim’s bank account or crypto wallet.
BT then identified the devices receiving the transferred numbers. Each was eSIM-enabled and had two IMEI numbers, the serial codes that identify a handset. Data from the telecommunications company led to several suspects, and Shinjin, aka AJ Marley Cruz, was attributed to four of the devices.
All the victims reported their crimes in the first week of November 2021, and police detailed four thefts, with the first seeing about £40,000 in crypto taken from a victim on November 2, and roughly £27,000 of it landed in Shinjin’s personal crypto account. A second victim lost around £17,000 between November 5 and 7, and all of which was later found in the defendant’s own wallet. The two sums made up the £44,000 he received.
In the other two cases, he helped to carry out the thefts while the money went elsewhere. Some £8,000 left a third victim’s Coinbase account on November 3, and another £130,000 was stolen from a fourth victim on the 6th and 7th of the same month.
Shinjin was arrested in October 2023 at Heathrow Airport when coming from Dubai, with prosecutors then charging him with one count of conspiracy to commit fraud by false representation and one of transferring criminal property. He entered a guilty plea in late September 2026.
“This was a complex and calculated fraud that caused significant financial harm to a number of victims,” said Detective Constable Simon Ardeman of the City of London Police.
He also called SIM-swap fraud “a sophisticated and increasingly concerning form of offending.” The detective constable added:
“This conviction sends a clear message that those who use technology to commit fraud will be brought to justice.”
An Earlier UK Case
A much larger UK crypto case reached a courtroom roughly a year ago, when Zhimin Qian, a Chinese national, pleaded guilty in late September 2025 to acquiring criminal property in the form of crypto. That case was tied to what is believed to be the world’s largest cryptocurrency seizure: more than 61,000 BTC, worth over £5.5 billion ($7.43 billion).
Qian had defrauded over 128,000 victims in China between 2014 and 2017 before converting the proceeds into BTC. Will Lyne, the Metropolitan Police’s head of economic and cybercrime command, called it one of the largest money laundering cases in UK history.
The post London Man Gets 2.5 Years for SIM-Swap Crypto Theft appeared first on CryptoPotato.
After reports emerged of a potential theft of over $80 million in crypto from its devices, Ledger confirmed over the weekend that at least one wallet tied to the ongoing CryptoBilis investigation contained an unauthorized hardware implant.
Meanwhile, a new community report on X claimed a suspicious Ledger device bought from MediaMarkt in Europe may also have been compromised, which would widen the scope well beyond Southeast Asia.
Ledger Confirms
In the latest update published on Saturday evening, the hardware wallet manufacturer said it had examined one device belonging to an impacted user and found an “unauthorized hardware implant” inside. The team said they have contacted affected users and have started working with authorities.
CryptoBilis has also responded to Ledger’s plea to stop sales of all hardware-wallet inventory, not merely Ledger products, until the investigation is concluded. The company behind devices such as Nano X said it has no indication that its own security infrastructure, systems, or services were compromised. It has also yet to determine how many affected devices contain implants or confirm that the discovered implant is responsible for all reported wallet drains.
The initial report, which we published yesterday, stated that customers who bought through CryptoBilis in Indonesia, Malaysia, and the Philippines were impacted. Initial investigations claimed the suspected losses exceed $86 million, but a new report from Bitquery puts that estimate closer to $93 million across 311 wallets on five chains.
Europe, Too?
A post from one X user claimed that a Ledger purchased through MediaMarkt in Europe also showed signs of possible hardware manipulation. The report quickly circulated through the vast crypto community, prompting warnings that the incident may no longer be geographically isolated to Southeast Asia.
However, the European situation has not been confirmed as compromised by the wallet manufacturer, and users examining the published images disagree about what they actually show. Some argued that the hardware appears inconsistent with a genuine Ledger board, while others said they could not see the same type of additional implant identified in the Southeast Asian case.
Nevertheless, MediaMarkt is an official reseller for Ledger in several European markets, including Germany and Austria. For now, though, this unconfirmed part of the story remains uncertain, while the original case in Asia continues to take new victims, according to reports on X.
The post Ledger Confirms Hardware Implant as Tampered Wallet Reports Allegedly Spread to Europe appeared first on CryptoPotato.
The spot exchange-traded funds tracking bitcoin experienced their worst week in terms of outflows since the end of June, which became one of the reasons behind the underlying asset’s major correction.
Although the net outflows from the spot Ethereum ETFs were slightly less, the overall ETH picture is worse given the lack of any green days.
BTC ETFs Bleed Heavily
The business week began on the wrong foot for the ETFs, with almost $90 million in net outflows. Coincidentally, BTC’s price was rejected at $87,000 and dropped by over a couple of grand on the same day. It recovered some ground on Tuesday when the ETF flows turned positive, and investors poured in $118.86 million.
However, the trend changed for the worse on Wednesday and Thursday, with the net outflows skyrocketing to $487.07 million and $244.13 million, respectively. As expected, BTC tumbled hard during those two days, with the culmination taking place on Thursday, with a nosedive to a 2-week low of $80,400.
The inflows returned on Friday, but they were quite modest, with just $21.13 million entering the funds. This wasn’t nearly enough to offset the major losses experienced during the previous two trading days. As such, the week ended with $681.10 million in net outflows – the most since the last full week of June, when investors pulled out $1.79 billion. The cumulative total net inflows dropped from $57.79 billion to $57.11 billion.
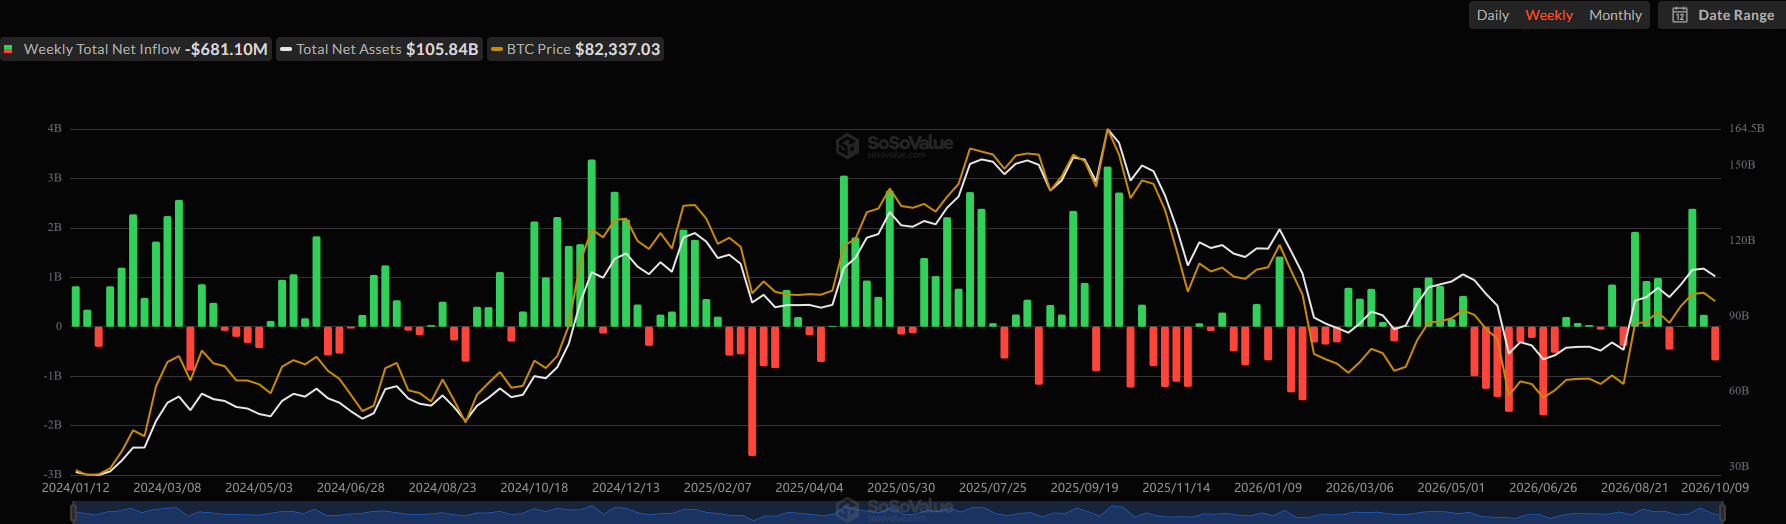
ETH ETFs Fare Even Worse
The Ethereum ETFs began the week with $50.76 million in net outflows. The pace of withdrawals accelerated on Tuesday, with $201.89 million leaving the funds, and $160.77 million on Wednesday. The red streak continued by the end of the week, with another $72.54 million taken out on Thursday and $56.10 million on Friday.
Worse still, these five consecutive red days only built on the previous four. Overall, the funds haven’t been in the green since September 28. Within this timeframe, the cumulative net totals dropped from $13.95 billion to $13.26 billion.
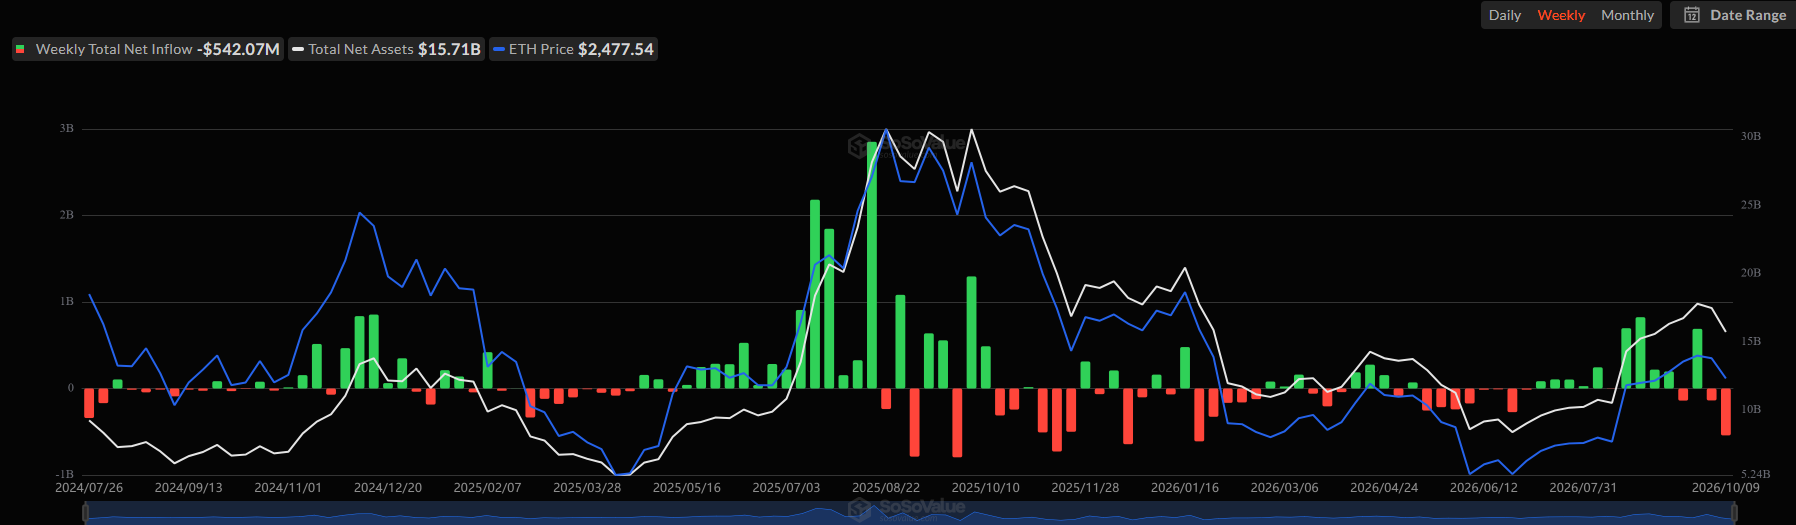
The underlying asset was halted at $2,800 a few weeks ago, but it managed to remain above $2,700 until the mid-week crash, which took it south to $2,400. It has recovered some ground since then and now trades above $2,500.
The post Bitcoin ETF Weekly Outflows Hit 3-Month High, Ethereum Funds Extend Losing Streak appeared first on CryptoPotato.
The past week didn’t go well for the entire cryptocurrency market, with prices falling to local lows after BTC was rejected at $87,000 and dragged most altcoins with it.
The ETF flows were among the reasons behind the market-wide correction, as almost all exchange-traded funds tracking crypto assets were in the red. Almost all.
XRP ETFs Defy the Trend
We will discuss in detail the major outflows from the spot BTC and ETH ETFs in another article, but we will just mention the end results here: $681 million in net outflows from the former, and $542 million from the latter. The funds tracking SOL bled out as well, with nearly $25 million taken out.
And then there were the XRP ETFs. Not only were they not in the red last week, but they actually performed better than the previous five-day trading period. Although there were three (out of five) trading days with no reportable action, which obviously is not ideal, they still attracted $3.14 million on October 6 and $8.17 million on October 8, ending the week with $11.31 million in net inflows.
Once again, the cumulative total net inflows hit a new all-time high of $1.8 billion. The week wasn’t perfect, as mentioned above, but it still extended the green-only streak to 13 consecutive weeks. It started in mid-July, and the financial vehicles have attracted over $300 million since then.
Bitwise’s XRP ETF remains the undisputed market leader, with cumulative net inflows of almost $688 million. Franklin Templeton’s XRPZ follows with $509 million, while Canary Capital’s XRPC is third with $487 million.

XRP Still Suffers
The ETF demand for Ripple’s cross-border token failed to prevent a price crash. The entire market unraveled in the past week, especially on Thursday, and XRP joined the ride south. The asset traded above $1.51 on Monday and Tuesday as analysts outlined the next major targets above $1.60 if it managed to break past that level, but the reality was different.
XRP was rejected immediately, and the market-wide pullback drove it south hard to $1.32 on Thursday evening. This became a three-week low for the token, which finally rebounded after this calamity and currently stands at $1.40. Despite this recovery, XRP is still 7% down weekly, and analysts are still bullish even if it falls to $1.20 next.

The post Ripple ETFs Defy Crypto Slump With Another Green Week but XRP Price Sinks appeared first on CryptoPotato.
Let’s start with a quick disclaimer – we used to write a lot of similar articles several years ago. The reason was simple: searches on Google typically show the demand for the cryptocurrency industry among retail investors. After all, institutions don’t go to the world’s largest search engine to ask about buying BTC or altcoins. They have their own methods.
However, the tide has turned since then, as retail investors have shown a different attitude. The charts we will display in this article prove that the actual Google queries about BTC or crypto as a whole plummeted, especially during bear market years. Now, though, there’s an interesting change.
Buy Crypto Is Back
The first chart below shows that ‘buy crypto’ searches plummeted at the end of 2021 – right at the time when BTC and the alts were charting then-ATHs, and went below 20 for over a year; yes, it coincided with the bear market. They picked up slightly in May 2024 (as prices soared), dropped again as the market cooled, and jumped high at year-end when BTC and the alts were booming after the US presidential elections.
Another decline followed in mid-2025 as the market experienced a fresh drop, and it surged to a five-year high in August. Shortly after, bitcoin marked a new (and its latest) all-time high of just over $126,000. After the October 2025 crash, the leading cryptocurrency went into a 10-11-month-long bear market, in which searches for ‘buy crypto’ decreased significantly.
The yearly bottom came in July when BTC slumped to under $58,000, and most alts struggled just as much. Since then, though, the searches have risen sharply and are projected to beat the 2026 record in October. Needless to say, prices have recovered, and we are far from the recent lows. In other words: the retail pattern has repeated perfectly again.

What About Bitcoin?
The landscape around BTC itself is less straightforward. The ‘buy bitcoin’ searches were below 40 on average for four straight years – from late 2021 to late 2025. Even the US elections couldn’t really break that negative streak. They finally picked up in August 2025, just a few months before BTC’s rise to $126,000, dipped again by January, before suddenly soaring to a new multi-year peak in February.
That was a one-month thing, as the queries quickly dropped to 40-50 for the next few months. Although they jumped again in September, the October projections are quite different than those for ‘buy crypto,’ as current Google Trends data shows a massive decline toward 20. As such, it’s somewhat safe to determine that even if retail is indeed coming back, they are not looking specifically for BTC.

The post ‘Buy Crypto’ Google Searches Hit Yearly Highs: Is Retail Coming Back? appeared first on CryptoPotato.


