Cryptocurrency Posts
Crypto Briefing
Increased U.S.-Iran tensions may hinder diplomatic progress and regional stability, affecting future negotiations and market confidence.
The post US Embassy warns Americans to reconsider travel to Saudi Arabia amid Iran threats appeared first on Crypto Briefing.
Hawley's initiative could reshape investment dynamics in distressed areas, potentially redirecting funds towards more community-focused projects.
The post Josh Hawley targets data center tax loophole, calling it corporate welfare appeared first on Crypto Briefing.
COTI's privacy solutions on Avalanche could revolutionize blockchain transactions by enhancing confidentiality and expanding multi-chain integration.
The post COTI launches Privacy-on-Demand and Privacy Portal on Avalanche appeared first on Crypto Briefing.
Zipline's potential $1B funding round at a $20B valuation could significantly accelerate the adoption of drone delivery, reshaping logistics.
The post Zipline in talks to raise $1B at $20B valuation as drone delivery firm eyes massive growth appeared first on Crypto Briefing.
The strike highlights potential instability in Iran's aviation sector, raising concerns about geopolitical tensions affecting airspace access.
The post Iran air traffic control strike causes flight delays amid US tensions appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Peter Schiff: “The Fed Has Already Lost The Battle Against Inflation” & BTC vs GOLD Debate
Peter Schiff says the bond market didn’t break recently, it broke in 2020, and everything since has been a slow unwind. Across this conversation with Grace Remington and Sean Hagan, he connects rising Treasury yields, the Fed’s expected rate decision, the dollar’s loss of purchasing power, and the central bank rush into gold. He argues that a stock selloff driven by higher rates would be deeply bearish for Bitcoin and the broader crypto market, and that political capital in Washington has already turned against it. The episode ends with Schiff and the hosts going head to head on whether anything actually backs Bitcoin.
00:00 — Peter Schiff says the bond market already broke in 2020
01:44 — How long the Treasury bear market could realistically last
04:18 — What Schiff would enact to actually bring inflation down
06:32 — Spending cuts, higher rates, and the recession nobody will accept
07:39 — Are we in the early stages of a dollar crisis?
08:26 — Rate hike odds and whether Warsh surprises the market
10:51 — Why Schiff calls it a cosmetic hike with no credibility behind it
12:33 — Why gold ran to 5,500 while Bitcoin lagged 23% off its highs
14:20 — Bitcoin priced in gold and the case that it peaked in 2021
17:29 — Tokenized gold vs Bitcoin: counterparty risk and what backs money
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Peter Schiff: “The Fed Has Already Lost The Battle Against Inflation” & BTC vs GOLD Debate first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Bitcoin Price Wobbles Before Settling After Fed Raises Rates
Bitcoin’s price swung before settling largely unmoved over a 24-hour period after the Federal Reserve hiked interest rates — as expected — for the first time since 2023.
The leading cryptocurrency was recently priced at nearly $75,813 after dropping as low as $75,355 in the hour after the U.S. central bank gave its decision to increase the benchmark federal funds rate to a range of 3.75% to 4%.
Over a seven-day period, the coin is down nearly 4%.
Traders had bet there was a more than 90% chance that the Fed would raise interest rates ahead of its September meeting. Major Bitcoin trades therefore likely happened before Wednesday.
Speaking to reporters on Wednesday, Federal Reserve Chair Kevin Warsh didn’t reveal much about the central bank’s next moves but made it clear that price stability in the U.S. was its number one priority.
“The decision we made today was a sober decision, serious decision, responsible decision, one that we have been preparing for and thinking about in my 110 or 120 days here,” Warsh said.
He added: “The plain fact is that inflation is too high, and has been for too long. This summer’s inflation readings do not tell me that underlying trends have meaningfully improved.”
Wash — who has previously praised Bitcoin — said last month in his first major speech as head of the U.S. central bank that inflation was too high and had to be brought down.
The new chair is seemingly going against President Donald Trump’s wishes; the president has repeatedly called for lower interest rates and even threatened to fire the ex-Chair of the Federal Reserve for refusing to do so.
In a post on his Truth Social platform last week, the president wrote: “We should have the LOWEST RATE of any country in the World, like ‘the old days.'”
When asked by reporters about what he would say to the president, Wash replied: “I’ve got nothing for you on a discussion with the president.”
Bitcoin typically does well in a low interest rate environment because there is more liquidity to buy the asset.
The U.S. is currently in the midst of an affordability crisis and war in the Middle East has pushed up the price of oil, in turn compounding the problem as the cost of everyday goods in the world’s largest economy rises.
This post Bitcoin Price Wobbles Before Settling After Fed Raises Rates first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
CFTC Chairman Says Agency Will Write Crypto Rules After Clarity Act Vote Fails
Commodity Futures Trading Commission Chair Mike Selig has said that the top regulator will go ahead and use its powers to advance crypto legislation despite the Clarity Act being blocked.
In a Wednesday statement released on X, Selig said that the regulator would still help U.S. President Trump “get the job done.”
Lawmakers blocked the Clarity Act on Tuesday in a procedural vote, with the long-awaited legislation missing the 60 votes needed to advance it. The bill aims to formally divide oversight between regulators, distinguishing which digital assets are securities, commodities or stablecoins.
“Americans deserve regulatory clarity, legal certainty, and consumer protections in crypto asset markets,” Selig wrote.
“President Trump promised to deliver a future-proof crypto asset regulatory market structure one way or the other, and we will help him get the job done using our existing statutory authorities.
“The U.S. is and will remain the crypto capital of the world. The CFTC is locked in and ready to ship its rules for the new frontier of finance.”
President Donald Trump last month urged lawmakers to pass the Clarity Act, calling the legislation “very powerful” — but Republicans said that Democrats were deliberately holding it back.
Regulators are now more crypto-friendly since President Trump appointed them and took the White House and are widely expected to continue pushing rules that help the crypto space.
The Securities and Exchange Commission last month proposed its own framework for crypto asset offerings, pressing ahead despite a vote on the Clarity Act stalling.
Despite being passed by the House of Representatives last year, the Clarity Act was in a deadlock for most of this year after the banking lobby clashed with lawmakers and crypto businesses over whether platforms like Coinbase should be able to pay customers yield.
Some lawmakers have sought to change wording in the bill regarding ethics, and a new bill started circulating in July. The draft bans government officials from promoting and making money from crypto.
But other Democratic lawmakers said it still fell short; a number of pro-crypto Republicans accused Democrats of deliberately playing politics and delaying the bill.
This post CFTC Chairman Says Agency Will Write Crypto Rules After Clarity Act Vote Fails first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Bitcoin Is on Sale and Should Be Accumulated, Says Morgan Creek Capital CEO
Morgan Creek Capital CEO Mark Yusko has said that bitcoin’s fair value is $105,000 based on Metcalfe’s Law.
Speaking on Bitcoin Magazine TV on Wednesday, the investment management firm said that now was the best time to buy the leading cryptocurrency as it is “on sale.”
Metcalfe’s Law, an observation by Internet entrepreneur Robert Metcalfe, states that the value of a network is proportional to the square of the number of users. Bitcoin touched a high in October 2025 of $126,080 but was recently trading 40% lower than that, at $75,701.
JUST IN: Morgan Creek Capital CEO Mark Yusko says Bitcoin's fair value is $105,000 based on Metcalfe's Law
— Bitcoin Magazine (@BitcoinMagazine) September 16, 2026
Bullish! pic.twitter.com/zSpYHOCD3L

“So the fair value of bitcoin today, based on Metcalf’s law — Tim Peterson runs a model that tracks this really nicely — it’s about $105,000, but it’s $75,000,” Yusko said.
“Okay, so it’s on sale — you should accumulate things that are on sale.”
Yusko went on to say that bitcoin was the best way to protect one’s value and that investing in companies wasn’t good for the long-term.
“The problem is over a 30-year period, equity, 85% of companies disappear over 30 years. It’s amazing stat,” he said.
“What you really need is something to protect your value — and historically, for 5,000 years, there was one asset: gold.”
“Now we’ve got gold and bitcoin,” he added.
Bitcoin started rallying in August following news that the U.S. Treasury would at least double the size of its liquidity-support buyback operations. The announcement hurt the dollar but non-yielding assets have benefited.
Since then, some experts have said that the so-called debasement trade — when investors buy an asset as a way to hedge against a currency losing value — is back and will benefit bitcoin.
The trade was hot last year, and helped bitcoin’s run, but the digital asset lost steam after October as traders turned their attention to stocks related to artificial intelligence.
This post Bitcoin Is on Sale and Should Be Accumulated, Says Morgan Creek Capital CEO first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
The Quantum Issue: To Freeze Coins Or Not
Bitcoin’s quantum debate is quite a quagmire. This is not merely a technical debate regarding the trade-offs of different types of cryptography and their strengths against a theoretical quantum computer. It is a debate about which properties of Bitcoin’s ethos are strongest when it is faced with a difficult dilemma: uphold the promise that valid coins remain spendable by their owners, or favor supporting the security of the system by not allowing a significant portion of its monetary supply to be raided via a vulnerability that was well known for many years.
The conundrum at the crux of this controversy is that every serious option violates a principle that Bitcoin users care about. Doing nothing may preserve today’s consensus rules while allowing future quantum-capable actors to take coins whose owners never consented. Freezing vulnerable coins may prevent that theft, but it retroactively invalidates long-standing spending conditions. A forced migration to quantum-resistant signatures may be prudent engineering, but it can also look like a deadline-backed confiscation regime. The debate is ugly because there is no clean path that perfectly preserves property rights, economic predictability, censorship resistance, backward compatibility, and user sovereignty all at once.
This is why I consider the problem to be fascinating. It’s multifaceted: simultaneously technical, sociological, philosophical, and economic in nature. Thus any serious discussion of the problem must consider every angle.
Throughout this essay I’ll be making the case that the quantum migration debate is far more nuanced than just a question between freezing or not freezing vulnerable bitcoin. Rather, it’s a question of how to minimize total property-rights violations once elliptic curve signatures no longer reliably authenticate rightful ownership.
The Quantum Threat
Bitcoin’s current authorization scheme to ensure that funds are only spent by their rightful owners depends on elliptic-curve cryptography. Legacy ECDSA signatures and Schnorr signatures both use the secp256k1 elliptic curve. Under ordinary classical computing assumptions, deriving a private key from a public key is computationally infeasible. A cryptographically relevant quantum computer running Shor’s algorithm changes that assumption: once a public key is available, a sufficiently capable quantum attacker could derive the corresponding private key and sign a transaction to spend the funds that would be accepted as valid by the network. Quantum computers threaten to break the public-key-to-private-key hardness assumption behind ECDSA and Schnorr.
That distinction matters because not all Bitcoin outputs expose the same information at the same time. Some output types reveal a public key immediately and remain vulnerable indefinitely. Others hide the public key behind a hash until the owner spends. This creates two broad attack classes. A long-range attack targets outputs whose public keys are already visible on-chain, such as old pay-to-public-key outputs and Taproot outputs. A short-range attack targets coins at the moment of spending: the owner broadcasts a transaction, the public key becomes visible, and a fast quantum attacker attempts to derive the private key quickly enough to replace or front-run the transaction.
The mining threat is different. Grover’s algorithm can in theory speed up brute-force searching for a valid block hash, but it only provides a quadratic speedup while Shor’s algorithm provides a superpolynomial speedup. Thus the competitive advantage is far less practical to bother using a quantum computer for mining.
The Quantum Quantum Threat
Amusingly, the threat of quantum computers is itself in a quantum state of superposition. A quantum computer worth worrying about may or may not be built and no one can prove or disprove that it will happen. Quantum skeptics don’t dispute that Shor’s algorithm could break ECC. They claim there is no good reason to believe we will ever build the kind of powerful, fault-tolerant quantum computer needed to run Shor’s algorithm at a cryptographically relevant scale.
Everyone agrees that breaking ECC isn’t possible with today’s noisy quantum processors. It requires many reliable logical qubits, extremely low error rates, lengthy computations with high coherence, and quantum error correction running successfully at scale.
A strong skeptical argument is that the quantum fault-tolerance threshold theorem depends on assumptions that may not be physically satisfiable with the required precision. Such assumptions include sufficiently independent noise, sufficiently accurate gates, limited unwanted interactions, and the ability to keep errors below an acceptable threshold across a huge system. Mikhail Dyakonov argues that the theorem assumes idealized conditions and does not tell us the real engineering precision needed to satisfy every assumption in an actual device.
Gil Kalai’s criticism is more structural. His argument is that realistic quantum systems may suffer from correlated noise and noise accumulation that prevent the formation of high-quality quantum error-correcting codes. In his 2011 paper, he proposes that physical realizations of quantum codes, correlations in stochastic systems, and accumulated noise could lead to failure of scalable quantum computers.
This may be the strongest skeptic argument: quantum error correction works only if the noise is tameable. If real high-qubit systems generate adversarially correlated errors, then adding more qubits may very well make the computer more fragile and unreliable.
Quantum scalability is a major unknown. Skeptics argue that progress from 50, 100, or 1,000 physical qubits does not automatically extrapolate to millions of physical qubits or thousands of logical qubits. Quantum systems are analog, delicate, and coupled to their environment. The engineering challenge is not just “make more qubits”; it is “make more qubits while suppressing crosstalk, leakage, correlated errors, calibration drift, thermal effects, measurement errors, fabrication variation, and control noise.” This is why critics reject simple timeline extrapolations. They view “we increased qubit count by X this decade, so we will break ECC by year Y” as weak reasoning.
Finally, quantum computer demonstrations have shown that current devices can only outperform classical simulations on carefully selected sampling tasks. Critics have a good point that this says little about executing long, structured algorithms like Shor’s algorithm with enough reliability to recover a 256-bit ECC private key.
Why Post-Quantum Migration Matters
Assuming that a cryptographically relevant quantum computer appears, merely adding the option for Bitcoiners to use post-quantum cryptography won’t be sufficient to stop a quantum attack. The total set of quantum-vulnerable bitcoin includes early pay-to-public-key coins, coins controlled by reused public keys, Taproot outputs, and cases where public keys or extended public keys have been revealed outside the chain. One striking figure is the concentration of BTC in old P2PK outputs, which are a tiny fraction of UTXOs by count but represent a much larger share of value, about 1.7 million BTC. Broader estimates via on-chain analysis of output types, activity patterns, and known ownership lead us to believe that at least 2.6 million BTC would remain vulnerable even if all active Bitcoin users migrated their wallets to post-quantum cryptography.
As such, even with opt-in post-quantum (PQ) cryptography, we should expect there to be a systemic risk sized pool of vulnerable coins lingering indefinitely. These coins could be employed by a quantum attacker to harm the system in a wide variety of ways – not just via selling them and dropping the spot price of BTC. Thus, protecting those vulnerable coins from a quantum threat requires some sort of rule changes that would effectively “lock out” a quantum attacker.
The rhetoric around this issue often uses terms like “confiscation,” “burning,” “freezing,” “stealing,” or “recovery,” but these describe different mechanisms. A freeze would not transfer coins to the state, miners, developers, or some recovery fund. In its most basic form, it would mean changing consensus rules so that certain outputs can no longer be spent using vulnerable ECDSA or Schnorr signatures. That is why advocates sometimes say “burn” rather than “confiscate”: the coins are not reassigned; they become unspendable via their private key. But for a rightful owner who still has the original key, the practical effect can still feel confiscatory: a spend that used to be valid is no longer valid.
BIP-361 divides the migration concept into phases. First, once a quantum-resistant address type exists, the Bitcoin network would stop allowing new coins to be sent to quantum-vulnerable addresses. Later, after a multi-year window, legacy ECDSA and Schnorr spends would become invalid. Finally, there remains the question of recovery options for users who can prove, without solely relying upon broken ECC, that they are the legitimate owner – such as through a zero-knowledge proof derived from a seed phrase or HD wallet structure. The proposal’s primary purpose is not to pick a post-quantum signature algorithm; rather the goal is to create incentives and deadlines so that users, exchanges, custodians, wallets, and institutions actually migrate in a timely fashion and thus allow us to deprecate ECC in order to prevent a quantum attack.
The Case for Freezing
The strongest pro-freeze argument starts from a simple claim: a quantum attacker who derives a private key from a public key is not the legitimate owner in any morally meaningful sense. Under this view, “just let vulnerable coins be taken” is not neutrality; it is allowing a new class of actors to loot old outputs because the protocol failed to strengthen a lock that is known to be weak. Freeze advocates argue that the resulting harm from allowing quantum theft is not just to negligent owners but to all holders, because a successful quantum sweep would redistribute wealth to whoever possesses early quantum capability. This is problematic because that amount of bitcoin in a single actor’s hands who spent relatively little resources to obtain them can be quite dangerous for the ecosystem’s security. Bitcoin’s security model assumes economically rational participants that are incentivized to protect the value of their coins, but a quantum-capable actor has the potential to break that assumption. The pro-freeze position is that Bitcoin should not reward the first entities to break ECC with ammunition that could be leveraged to harm the system.
This argument is especially true for coins believed to be lost. If lost coins are suddenly recoverable by quantum attackers, the circulating supply effectively increases. That does not violate the formal 21 million cap, but it does change the economic landscape: coins that the market may have treated as inert can re-enter circulation, possibly rapidly and in concentrated hands.
The pro-freeze side also argues that the threat is not limited to ordinary profit-seeking. A quantum-capable adversary could attack Bitcoin politically, destabilize markets, undermine public confidence, grief the network for many years, or even acquire enough hashrate to 51% attack the network. Analysis of the game theory in play shows that we can’t simply assume an attacker sweeps vulnerable BTC to sell it and ride off into the sunset; there is a far wider range of strategies and undesirable outcomes.
A related argument is about market panic. Pieter Wuille’s comments in the mailing-list debate sharpen this point: the medium-term danger may be not only an actual cryptographically relevant quantum computer, but the credible belief that one may exist soon. If markets come to believe that a large share of Bitcoin’s supply can be seized at any moment, merely offering voluntary post-quantum outputs may not be enough to restore confidence. A credible plan to disable vulnerable spends could itself be a sufficient reassurance mechanism.
The pro-freeze camp also sees deadlines as necessary because voluntary migration is likely to be slow. People procrastinate; institutions move slowly; hardware wallets, exchanges, custodians, estate plans, multisig coordinators, and cold-storage procedures all need time to implement changes and plan for migrations. Matt Corallo has argued that Bitcoin should add a simple post-quantum capability well in advance of it being necessary, because wallets need to start embedding or committing to quantum-resistant public keys long before any later emergency decision about freezing vulnerable UTXOs becomes credible.
There is also a fiduciary responsibility argument. Public companies, ETFs, custodians, and exchanges will be unable to ignore a known migration deadline. A locked-in consensus change gives compliance departments and risk committees something concrete to act on. It also turns an abstract future threat into a project plan: upgrade software, generate new addresses, move funds, verify backups, communicate with customers, and complete migrations before a known date. BIP-361 explicitly argues that exchanges and custodians would face fiduciary and legal pressure to act once a deadline exists.
It’s also worth noting that all of this migration planning is applicable to more situations than just the emergence of a cryptographically relevant quantum computer. Most of the arguments in this debate apply to ANY situation where ECC is known to have been weakened. Generally speaking, cryptography tends not to withstand the test of time and any given cryptographic algorithm tends to be weakened over long time frames (decades) as researchers find flaws and develop new techniques that break prior assumptions.
Finally, freezing advocates argue that Bitcoin has always depended on users enforcing rules that protect the system as a whole. A soft fork that objectively disables a known-insecure spend path is not the same as arbitrary political confiscation, in their view. The proposed line is not “these people are disfavored” but “these script types require cryptography that no longer meets the bar for Bitcoin’s security assumptions.” If the rule is mechanical, objective, announced years in advance, and paired with a viable migration path, proponents argue that it is more akin to replacing a broken lock than blacklisting an owner.
Anti-freeze Arguments
The strongest anti-freeze argument starts with the opposite premise: Bitcoin’s social contract is that a valid coin remains spendable by the holder of the corresponding key under the consensus rules accepted when the coin was received. Retroactively invalidating that spend path crosses an inviolable line. It turns “not your keys, not your coins” into “not your upgraded-by-deadline, not your coins.” Even if no one else receives the frozen coins, the original owner loses practical control. That is why critics describe forced freezing as confiscatory, not merely protective.
This objection is not just sentimental. Bitcoin’s credibility depends heavily on the expectation that developers and node operators will not pick winners and losers among UTXO owners. A freeze aimed at “vulnerable coins” may be technically objective, but it still targets a subset of owners based on past address choices, wallet design, dormancy, or inability to act. Critics worry that once the network accepts retroactive invalidation for one reason, future coalitions may find other reasons: sanctions, theft recovery, inheritance disputes, state pressure, “obviously” lost coins, or other emergencies.
A second objection is that freezing cannot distinguish between lost coins, careless owners, dormant owners, imprisoned owners, dead owners with heirs, users in hostile jurisdictions, timelocked arrangements, forgotten cold storage, and deliberately long-term savers. Bitcoin has many users whose goal is to avoid being forced to stay online and responsive to policy changes. A person who stored coins safely for decades should not necessarily lose them because the rest of the network later declared their storage method obsolete. It’s worth noting that there is an incentive conflict between active current holders who benefit from reducing the effective supply and inactive rightful owners who may be unable to take action to defend themselves.
A third objection is uncertainty. A cryptographically relevant quantum computer may arrive later than expected, may not arrive in the form feared, may remain secret for some time, or may be countered by less drastic tools. If Bitcoin permanently burns millions of coins and the threat does not materialize on the assumed timeline, the network will have committed an irreversible self-inflicted property-rights violation. Critics therefore argue that premature freezing is worse than measured preparation.
A fourth objection is governance and legitimacy. Freezing vulnerable coins would be one of the most controversial consensus changes in Bitcoin’s history. Some have warned that announcing a freeze of old UTXOs could damage Bitcoin’s image more than a quantum attack itself and could produce a major fork in which one side accepts the freeze and another preserves old spendability. In that scenario, the “solution” creates a new political attack surface: exchanges, custodians, miners, and users must choose which chain’s property-rights model they prefer.
A fifth objection is legal risk. Some participants in the mailing-list debate warned that developers, companies, or miners involved in consciously changing code to freeze funds could face liability claims from owners whose coins become unspendable. Even if those claims ultimately fail, the legal process itself could chill development, divide institutions, and make consensus coordination harder.
A sixth objection is technical humility. Post-quantum cryptography is real, but not free. NIST has standardized ML-DSA, SLH-DSA, and ML-KEM, with more work continuing, yet Bitcoin has unusual constraints: every byte matters, verification cost matters, wallet compatibility matters, and consensus failures are catastrophic. Chaincode’s comparison of candidate schemes in their quantum deep dive report shows why the choice is not trivial: post-quantum signatures and keys can be much larger than Schnorr or ECDSA, and schemes differ sharply in maturity, signature size, public-key size, signing cost, verification cost, and assumptions.
That makes critics wary of forcing migration before the destination is mature. A bad post-quantum migration could reduce throughput, raise fees, bloat the UTXO or witness data burden, introduce new cryptographic assumptions, or force another migration later if the chosen algorithm weakens. Conventional Schnorr signatures are tiny compared with many hash-based post-quantum signatures, while lattice based cryptography has other trade-offs and maturity questions. On a related note, given the larger data sizes of signatures, this will increase the cost of transacting on chain and could price out less wealthy users.
Doing Nothing vs Doing Something
As I stated over a year ago in my first essay on this topic: if quantum computing becomes a threat to Bitcoin’s elliptic curve cryptography (ECC), an inviolable property of Bitcoin will be violated one way or another.
You’re probably familiar with the fundamental principle coined by Andreas Antonopoulos:
“Not your keys, not your coins.”
I posit that the corollary to this principle is:
“Your keys, only your coins.”
The point is that keys don’t merely authorize spending, but that signatures are supposed to be unforgeable evidence of control by the legitimate keyholder. A quantum-capable entity breaks the corollary of this foundational principle. We secure our bitcoin with the mathematical probabilities related to extremely large random numbers. Your funds are only secure because truly random large numbers are safe from being discovered by anyone else in the world.
The do-nothing position is often caricatured as “let quantum thieves steal everything.” Taking a noninterventionist stance against quantum theft is certainly principled: Bitcoin is a voluntary bearer asset governed by rules, and users are responsible for managing known risks. If a coin is encumbered by a script that becomes weak over decades, perhaps that is no different from losing a seed phrase, using weak entropy, trusting an insecure custodian, or failing to follow any number of other best practices. Under this view, the network’s job is not to guarantee the security of every historical locking script forever; rather it’s to enforce the rules as written.
This camp can also state that total supply is the only guarantee of the network, not effective circulating supply. The 21 million cap does not say “21 million minus coins assumed lost.” It says no more than 21 million coins will be issued. If a lost-looking coin later moves because its key is found, inherited, cracked through poor entropy, or recovered through quantum attack, the total issued supply has not changed. That argument is unsatisfying to people who see quantum funds sweeping as theft, but it is internally consistent: protocol rules define validity, not subjective moral beliefs about rightful ownership.
The do-nothing side also values operational simplicity. Any freezing rule requires defining what constitutes a vulnerable bitcoin redeem script, choosing activation dates, coordinating wallets and miners, communicating to users, handling edge cases, and absorbing political fallout. Doing nothing avoids a contentious consensus change. If post-quantum tools become available, users who care can migrate voluntarily, while users who do not migrate bear their own risk.
But the weakness of the “pure do-nothing” perspective is that it treats quantum theft as an individual-risk problem when it may actually become a system-risk problem. If enough coins are exposed, and if the market believes a capable attacker can use them to harm the ecosystem, the damage is not confined to owners who failed to migrate. It affects public confidence in the system which then cascades into negative pressure on the exchange rate, thermodynamic security (miner revenue,) and the revenue of many Bitcoin businesses. That is why even many people uncomfortable with freezing still support early preparation.
Apathetic “code is law” Bitcoiners are free to do nothing, but they should not delude themselves into thinking that they can stop others from trying to do something.
Alternative Proposals
Because “freeze all vulnerable UTXOs” and “do nothing” are both brutal in their own ways, much of the interesting work is in alternative proposals that would help users retain their property rights in the face of a quantum threat.
- We could prevent new vulnerable outputs while not yet freezing old ones. This is the least coercive part of forced migration. Once a safer output type exists, consensus or policy rules could discourage or even disallow sending bitcoin into vulnerable locking scripts. That reduces future damage without immediately invalidating old property claims. BIP-361 includes this as Phase A, and several critics are more open to this kind of forward-looking restriction than to permanent retroactive burns.
- Alternatively, the network could enforce a temporary lock rather than permanent burn. Boris Nagaev suggested that if old EC spends must be disabled, the lock could include a future re-enable height or some other mechanism that gives the community time to build recovery paths. Conduition explored how such a phase might interact with P2QRH/P2MR-like outputs and warned that simply banning all EC checks could accidentally affect hybrid constructions unless the rule is designed carefully. The appeal of a temporary lock is political as much as technical: it signals emergency containment rather than permanent confiscation.
- Another option is rate-limiting, represented by the Hourglass proposal. Hourglass V2 focuses on old P2PK coins and would restrict spending so that only one P2PK input could be spent per block, with a net limit of one BTC per block from those outputs. Its authors present it as a way to avoid both immediate burning and unconstrained quantum liquidation: coins are not destroyed, but their ability to flood the market is throttled. The proposal estimates that unconstrained P2PK sweeping could be extremely fast, while the one-BTC-per-block design would stretch full P2PK movement over decades.
Hourglass has its own critics. Opponents argue that it still violates permissionless spending by imposing special restrictions on a class of otherwise valid coins. It may also create a long-running race between legitimate owners and quantum attackers rather than resolving ownership. Some critics say that if the quantum threat is real, taking decades to clear exposed P2PK outputs gives attackers plenty of time; if the threat is not real, the rule is needless interference. - There is the concept of commit-delay-reveal, sometimes discussed through Guy Fawkes-style constructions. The basic idea is that a user first commits to a future spend in a way that a quantum attacker cannot exploit immediately, waits for the commitment to become deeply confirmed, and later reveals the secret needed to validate the spend. This can prevent a short-exposure quantum attacker from seeing a public key and instantly stealing the coin before confirmation. Chaincode describes commit-delay-reveal as opt-in and potentially useful, while the Optech summary notes that these schemes can let safely spendable bitcoins avoid destruction and reduce migration urgency.
- Quantum safe funds recovery without EC signatures, especially for HD wallets, should be feasible. Or Sattath and others discussed “signature lifting” ideas where the owner proves knowledge of a seed or derivation path rather than proving control through the vulnerable public key. Olaoluwa Osuntokun built a proof-of-concept using zk-STARKs to prove that a Taproot BIP-86 output key was generated from a BIP-32 seed path. This would certainly be a last resort scenario for procrastinators to recover funds, given that the latest optimized version of the scheme requires a 200 KB proof. It would certainly price out recovery of small UTXOs, because a best case scenario would likely cost several hundred dollars in transaction fees but could easily run into the thousands or tens of thousands at higher transaction fee rates.
This recovery path is attractive because it changes the moral shape of the debate. If rightful owners can later recover frozen coins through non-EC proofs, freezing no longer has to mean permanent destruction. But the costs are serious: large proofs, complex verification, privacy leakage, wallet-derivation assumptions, inability to cover every historical wallet type, and the danger of adding novel cryptography to Bitcoin consensus. Critics of the zk-STARK approach emphasized that megabyte-scale proofs and multi-second verification times are difficult to reconcile with Bitcoin’s conservative design.Though further research is already finding optimizations that are more efficient. - Dual-signature or market-driven migration. Marc Johnson and others suggested enabling quantum-resistant outputs, allowing optional dual signatures, giving fee or policy incentives, and letting users choose their own risk instead of imposing a hard loss deadline. This approach preserves property rights better than forced freezing, but it won’t solve the systemic-risk problem if too many high-value coins remain exposed.
Tricky Technical Trade-offs
The migration debate cannot be fully separated from the choice of quantum-resistant signatures because the size of signatures will affect the system throughput. NIST’s post-quantum standards provide a serious foundation: FIPS 204 standardizes ML-DSA, FIPS 205 standardizes SLH-DSA, and FIPS 203 covers ML-KEM for key establishment. But Bitcoin needs digital signatures and script-compatible ownership proofs, not just general-purpose cryptographic standards. A scheme suitable for TLS or government communications is not automatically ideal for a blockchain with limited block space and global verification requirements.
Hash-based signatures are conservative and appealing because their assumptions are simple, but they are large. Lamport-style signatures can be enabled in some form with script upgrades such as OP_CAT, but the Taproot key-path problem remains: if a Taproot output has a quantum-vulnerable key path, placing a Lamport signature in the script path does not make the whole output quantum safe unless the vulnerable key path is removed or disabled. BIP-347’s OP_CAT discussion explicitly notes this problem.
Lattice signatures such as ML-DSA offer more compact signatures than many hash-based options, but they bring different assumptions and implementation risks. Falcon-style signatures are compact but historically more delicate to implement. SPHINCS+/SLH-DSA is conservative but large. Experimental schemes may be attractive on paper but too immature for Bitcoin consensus. This is why a credible migration plan likely needs algorithm agility, test deployments, wallet experiments, careful fee modeling, and perhaps multiple acceptable post-quantum paths rather than a single rushed winner.
The block space problem is severe but not intractable. Chaincode estimates that migrating all UTXOs would take roughly 76 to 142 days if migration consumed all block space, and 305 to 568 days if it consumed 25% of block space. That is just raw migration throughput; it does not include human coordination, wallet upgrades, institutional approvals, support for air-gapped signing, hardware replacement, accounting workflows, etc.
A full timeline for UTXO set migration is measured in years, not weeks. Chaincode’s high-level estimate sketches a best case of roughly five years and a worst case closer to fifteen years for research, BIP work, implementation, deployment, and migration. The same report notes that in an emergency the timeframe could potentially be accelerated to 2 years, but historical emergency protocol fixes are not really analogous because the quantum migration problem touches every layer of the ecosystem.
The Ethics of Property Rights
The moral disagreement comes from two competing definitions of ownership.
The anti-freeze side supports a “code is law” perspective: ownership means control under the consensus rules. If an output is spendable by an ECDSA or Schnorr signature, then disabling that spend path violates the owner’s property rights. The network does not know whether a coin is lost, abandoned, inherited, intentionally dormant, or inaccessible for temporary reasons. Therefore, freezing is collective punishment imposed on a subset of users for failing to follow a new migration demand.
The pro-freeze side says ownership cannot mean “anyone who can break the cryptography gets the coin.” Bitcoin’s signatures are intended to authenticate the legitimate keyholder, not to create a prize for whoever first builds a machine that defeats the authentication scheme. If quantum capability turns public keys into private keys, then an EC signature no longer carries the same moral information it carried before. Under this view, refusing to freeze is not neutrality; it is a security failure to knowingly allow a compromised authentication mechanism to transfer wealth.
Both positions are coherent. The first protects rule stability and bearer-asset finality. The second protects the deeper intent of the locking script. The painful point is that Bitcoin’s consensus rules are the only practical arbiter. The protocol cannot read intent. It can only accept or reject transactions according to rules. Any attempt to encode “rightful ownership” after ECC breaks either becomes overly broad, relies on new proofs, or leaves some victims behind.
I submit that property rights have been violated on Bitcoin before. Allow me to introduce you to the Value Overflow Incident as it is commonly known.
On August 15 2010, it was discovered that block 74,638 contained a transaction that created 184,467,440,737.09551616 bitcoin for three different addresses. Two addresses received 92.2 billion bitcoins each, and whoever solved the block got an extra 0.01 BTC that did not exist prior to the transaction. This was possible because the code used for checking transactions before including them in a block didn’t account for the case of outputs so large that they overflowed when summed.
A new version of the client was published within five hours of the discovery that contained a soft-forking change to the consensus rules that rejected output value overflow transactions. The blockchain was forked. Although many unpatched nodes continued to build on the “bad” blockchain, the “good” blockchain overtook it at a block height of 74,691 at which point all nodes accepted the “good” blockchain as the authoritative source of Bitcoin transaction history.
The bad transaction no longer exists for people using the chain with the greatest cumulative proof of work. Therefore, the bitcoins created by it do not exist either.
Thus, from a pure property rights perspective, the person who followed the rules of the network at the time had their property confiscated from them because the overwhelming majority of other actors on the network considered their action to be undesirable and a threat to the network.
Anti-freeze folks will likely say that this is not a problem because the INTENT of protocol rules is what matters, and the intent was for the network to guarantee a maximum supply of 21 million BTC. I would tend to agree, and make the counter-claim that the INTENT of using ECC to secure BTC is to ensure that it’s infeasible for anyone to guess your private key.
Economic Stakes
A sudden sweep of funds by a quantum-capable entity could affect Bitcoin through several channels.
- Coins thought dormant would re-enter circulation, increasing the effective bitcoin supply.
- Markets could panic before any actual sweep if credible evidence appears that a CRQC exists or is near.
- Miners could be affected if price falls sharply, because their budget is tied to block subsidies and fees in BTC terms converted into operating revenue.
- Exchanges and other businesses could face operational stress and massive drops in revenue if customer deposits are exposed or if market structure breaks under uncertainty.
“Lost coins only make everyone else’s coins worth slightly more. Think of it as a donation to everyone.” – Satoshi Nakamoto
If true, the corollary is:
“Quantum recovered coins only make everyone else’s coins worth less. Think of it as a theft from everyone.”
If a large amount of BTC is permanently lost, remaining holders benefit from a lower effective circulating supply. If quantum attackers revive those coins, remaining holders lose that benefit. Critics of freezing respond that this is exactly why active holders have a conflict of interest: they may prefer burning dormant coins because it makes their own coins scarcer. That is not a trivial objection. A freeze can be framed as protecting the network, but it can also be framed as enriching active holders at the expense of inactive ones.
That conflict is why the specific definition of vulnerable coins matters greatly. Freezing only ancient P2PK outputs with already exposed public keys is easier to justify than freezing every vulnerable output, because the funds are far more likely to be lost. Freezing Taproot outputs is more complicated politically because Taproot is recent and intentionally adopted by users who were following modern wallet guidance. Freezing reused outputs raises another problem: the vulnerability may come from user behavior rather than address type. Freezing based on on-chain public key leakage is also a half measure because the chain can not know what was leaked off-chain; many wallets share their xpubs with third parties, for example.
A broad freeze could therefore be both underinclusive and overinclusive. It could miss off-chain exposed keys while capturing dormant but legitimate owners. A narrow freeze could reduce the worst risk but leave enough vulnerable value to sustain panic. This is why I believe the optimal solution is complex and requires a multi-phased approach, rescue proofs, and objective script rules rather than discretionary address lists.
Herding Cats
Bitcoin is an anarchic system of rules without rulers. It has no authority that can dictate changes to consensus rules. A rule to deprecate ECC would need broad agreement among node operators, miners, exchanges, wallets, custodians, merchants, and users. In formal terms, many proposals are soft forks: they make previously valid spends invalid under stricter rules. But in social terms, a soft fork that disables old coins is much heavier than an ordinary tightening rule. It directly affects property expectations.
This governance problem gets worse under emergency conditions. If Bitcoin waits until there is credible proof of a CRQC, the community may have to act during panic, misinformation, market stress, and adversarial pressure. But if Bitcoin acts too early, it risks freezing coins before the threat is real enough to justify it. Chaincode explicitly warns that planning and communication should happen before the threat becomes acute, while also acknowledging that stakeholder coordination, regulation, taxation, and user communication are major obstacles.
This creates a paradox. The best time to design a quantum migration is before it is urgently needed. The hardest time to persuade people to accept controversial measures is also before they are urgently needed. Once the emergency is obvious, technical and social options narrow dramatically. In short, because: Bitcoin moves slowly, some action must happen before the relevant computer arrives if we want a non-chaotic outcome.
A credible process therefore matters almost as much as the final rule. The community would need clear definitions, simulations, reference implementations, wallet support, testnet deployments, activation thresholds, recovery research, and communication to nontechnical users. Without that, an ECC deprecation proposal would look like coordination against dormant holders. With it, even opponents could at least evaluate concrete trade-offs instead of reacting to abstractions.
Governance Game Theory
The threat of a quantum attacker is similar to The DAO incident that Ethereum had to deal with in 2016. In other words: the ecosystem had time (about a month) to take action to stop an attacker from getting away with taking ownership of 5% of all ETH at the time. For 5% of all ETH to go into the hands of a malicious actor was considered to be a systemic risk.
To put this in context, from my own analysis of the blockchain I think a reasonable estimate for the number of lost coins with exposed public keys is roughly 2,600,000 BTC, or 13% of the current total supply. In other words, this is about how much BTC I expect would be unable to migrate to a quantum safe locking script if we come to consensus on implementing a post-quantum signature scheme.
However, note a crucial difference between the DAO situation and this one. With the DAO, the Ethereum community had to hard fork in order to regain control of stolen tokens. With a BIP-361 style change, it would be a soft fork. Which is to say:
Opposing the DAO fork was relatively easy: needed not to do anything and stayed on the chain with the original set of rules. That chain is now known as Ethereum Classic.
Opposing a quantum migration soft fork, assuming it has a supermajority of hashrate, would require dissenting users to coordinate a User Rejected Soft Fork, which has never been done before.
The Slippery Slope of Centralization
Some have stated that a forced migration proposal like BIP-361 is untenable because it would set precedent for “centralized planning” over who gets to use Bitcoin. In other words, this could lead to similar types of freezing to stop anyone who is considered a “bad actor” from using the system, such as in response to major thefts and hacks.
We already know that nothing about Bitcoin’s rules is truly immutable. It’s not possible to create a protocol that is impossible to change – the best you can do is to align incentives that make it unlikely to change. In the case of proposing changes as controversial as altering ownership / the money supply, you should expect that such proposals only have the slightest glimmer of being accepted if the alternative is expected to be detrimental to nearly all Bitcoiners.
As for the claim that it will lead to protocol-level confiscation in response to hacks and such, it’s simply not possible for an ecosystem as distributed as Bitcoin to coordinate a response fast enough to outpace an individual actor. To be more precise: trying to blacklist a specific address / set of addresses is infeasible because the “target” of such a protocol-level blacklist would simply move their funds faster than the ecosystem could coordinate freezing them.
Prior Precedents
The DAO was a special case in which a decentralized community actually had time to react to a massive theft, because The DAO’s smart contract essentially had a “cooldown rule” that made them have to wait for a month after initially redirecting funds into their own control before they could send them anywhere else, such as to “cash out.” As such, there was time to gather consensus from the wider ecosystem (they even conducted coin voting) in order to pass a pretty controversial hard fork.
What was the end result? We can actually observe how the market reacted. Despite all of the controversy, the economic reality was clear. Ethereum Classic, which abided by “code is law” and “do nothing” perspective, allowing the attacker to retain control of 5% of the network’s tokens, struggled to even reach 10% of the market value of interventionist Ethereum, which changed the rules of the network in order to return funds to their rightful owners.
As previously mentioned, Bitcoin also had the Value Overflow Incident in which bitcoin created by someone who was just “following the rules of the protocol” had them taken away by a coordinated consensus change.
These are stark examples of why I believe that economic incentives can and will trump moral and philosophical principles. Some will surely say that Ethereum and Bitcoin have little in common, and it’s certainly true that these different networks tend to have very different ethos and driving factors. But from an economic perspective, they share the same incentive structures with regard to a malicious entity controlling a substantial portion of the market cap. Bitcoin in 2026 is a very different ecosystem from Bitcoin in 2016. Consider all of the new entrants, many of which did not adopt BTC as a result of the libertarian standpoint.
It’s a pretty tough sell to get mainstream audiences to believe that bad actors should not be stopped if there is a means to do so. It’s an even tougher sell to tell companies and institutions that are making millions if not billions of dollars off of managing an asset that they should stand idly by and watch an existential threat to their business line carry out an attack that can be prepared for not just months, but potentially years or decades ahead of time.
Framing Matters
I think the worst possible framing of this debate is “quantum safety versus irresponsible users.” That trivializes the property-rights objection. Another terrible framing in my mind is “freezing is always theft, therefore no preparation is needed.” That trivializes the systemic-risk problem and overlooks the options we have to help protect property rights.
Matt Corallo has astutely pointed out that the debate over deprecating the use of vulnerable signatures is interesting because it can be framed in very different ways that sound the same on the surface.
- “Protect people’s property rights to the greatest extent possible.”
- “Don’t freeze anyone’s coins.”
The first perspective supports freezing ECC spends while also adding the maximum number of ways to safely recover funds (BIP-32 proofs, pre-Q-day commitments for non-BIP-32 wallets and timelocked coin wallets, etc).
The second stance actually minimizes the number of people who get to keep their coins and maximizes theft exposure. But it’s far simpler and avoids a controversial fork.
Thus I think this is not a binary debate of “to freeze or not to freeze.” Rather, a superior framing of the problem is: what is the optimal set of rules that minimizes property rights violations under conditions where the original cryptographic authentication mechanism is no longer reliable to authenticate rightful ownership?
Under that framing, deprecation of ECDSA signatures becomes more defensible if several conditions are met.
- There must be a widely reviewed quantum-resistant destination. Users cannot be coerced to migrate into a half-baked or experimental mechanism. The destination may be P2MR plus future PQ script paths, a standardized and well-vetted PQ signature type, a commit-reveal construction, or a hybrid. But it must be usable by ordinary wallets and institutions, not just technically imaginable.
- The migration window must be long enough for real-world users. Our block space throughput estimates show that raw transaction capacity is only one bottleneck. A serious deadline must account for wallet upgrades, hardware devices, multisig coordination, inheritance, institutional controls, cold storage logistics, and fee spikes. A five-year window may sound long in software terms but may be short for global bearer-asset migration.
- The deprecation rule should be as objective and narrow as possible. Freezing by named addresses or presumed identity would be poisonous. Freezing by clearly vulnerable spend conditions is more defensible, though still controversial. Even then, designers must avoid accidentally disabling hybrid or recovery constructions that still use EC operations in non-dangerous ways.
- Frozen funds rescue options are mandatory. A permanent burn maximizes clarity but also maximizes moral injury. Temporary locks, seed-knowledge proofs, commit-reveal paths, or other non-EC ownership proofs may preserve more of Bitcoin’s property-rights ethos. The current recovery ideas are not mature enough to rely on, but they are critical because they change a binary burn-versus-steal choice into a more humane migration path.
- The community should define warning criteria in advance while accepting that perfect evidence may never arrive. A public CRQC demonstration against secp256k1 would be too late for some attack classes. But vague fear is not enough to justify burning coins. Reasonable criteria might include credible advances in fault-tolerant quantum error correction, government migration deadlines, expert cryptanalytic consensus, observed market stress, or other public signals. The NSA and NIST transitions show that major institutions already consider post-quantum migration a serious planning problem, but institutional caution is not the same as proof that Bitcoin must freeze coins now.
A Goldilocks Problem
A common critique of BIP-361 (other than “quantum computers aren’t real”) is that it is “rushed.” I think this is due to people making incorrect assumptions around activation. No one is claiming that BIP-361 should be activated today or even soon… it’s not even possible until a PQC scheme is activated. Rather, the point of BIP-361 is to have a contingency plan in place in case it looks like the threat is real and a migration becomes desirable.
We settled on a five year migration timeframe for BIP-361 because there are cons to migrating too early and to migrating too late. Migrate too early and we may be imposing great costs upon the ecosystem when it’s not necessary. Also, since post-quantum schemes and quantum safe funds rescue schemes are under active research, migrating too soon could lock us into a suboptimal solution. Migrate too late and we leave the ecosystem open to a systemic threat that could cause massive harm and loss of confidence in the network. We also know it needs to be a multi-year approach because of how long it takes for protocol changes to propagate throughout the ecosystem.
I don’t expect anyone to seriously suggest BIP-361 for activation unless it looks highly likely that a cryptographically relevant quantum computer is less than 10 years away.
Deprecation of ECC could eventually become defensible, but only as a last-resort consensus choice after a viable migration path exists, after objective rules are specified, after a long public deadline is published, and after rough consensus is achieved that allowing vulnerable coins to remain spendable via ECC would create greater rights violations than disabling it.
The most intellectually honest conclusion is that both sides of this debate are defending Bitcoin’s principles, just with slightly different interpretations. The ECC deprecation side defends protocol security, system survival, and property rights against quantum attacks. The do-nothing side defends protocol rule stability, censorship resistance, and the rights of inactive users.
The Path Forward
Bitcoin’s quantum problem is not urgent in the sense that users should panic today. It is urgent in the sense that decentralized systems must solve hard coordination problems before they become emergencies. Waiting until a quantum attacker is visible will leave us with the worst set of possible choices.
The next steps for the foreseeable future do not include BIP-361. Rather, we should focus on preparation:
- reduce address reuse
- research recovery proofs
- reduce reliance on xpub sharing
- research more optimized PQ schemes
- activate opt-in quantum safe locking scripts
- develop multiple contingency plans to prepare for various scenarios
Bitcoin’s quantum migration debate is not a choice between respecting property rights and violating them. It is a choice between competing kinds of property-rights failure. We should treat the quantum threat as a realistic but unquantifiable systemic risk, but not use uncertainty as a premise for premature controversial changes.
Even if a cryptographically relevant quantum computer fails to emerge, showing that Bitcoin takes tail risks seriously will boost confidence in the network and reduce uncertainty about its future.
This piece is featured in the latest Print edition of Bitcoin Magazine, The Quantum Issue. We’re sharing it here as an early look at the ideas explored throughout the full issue.
This post The Quantum Issue: To Freeze Coins Or Not first appeared on Bitcoin Magazine and is written by Shinobi.
CryptoSlate
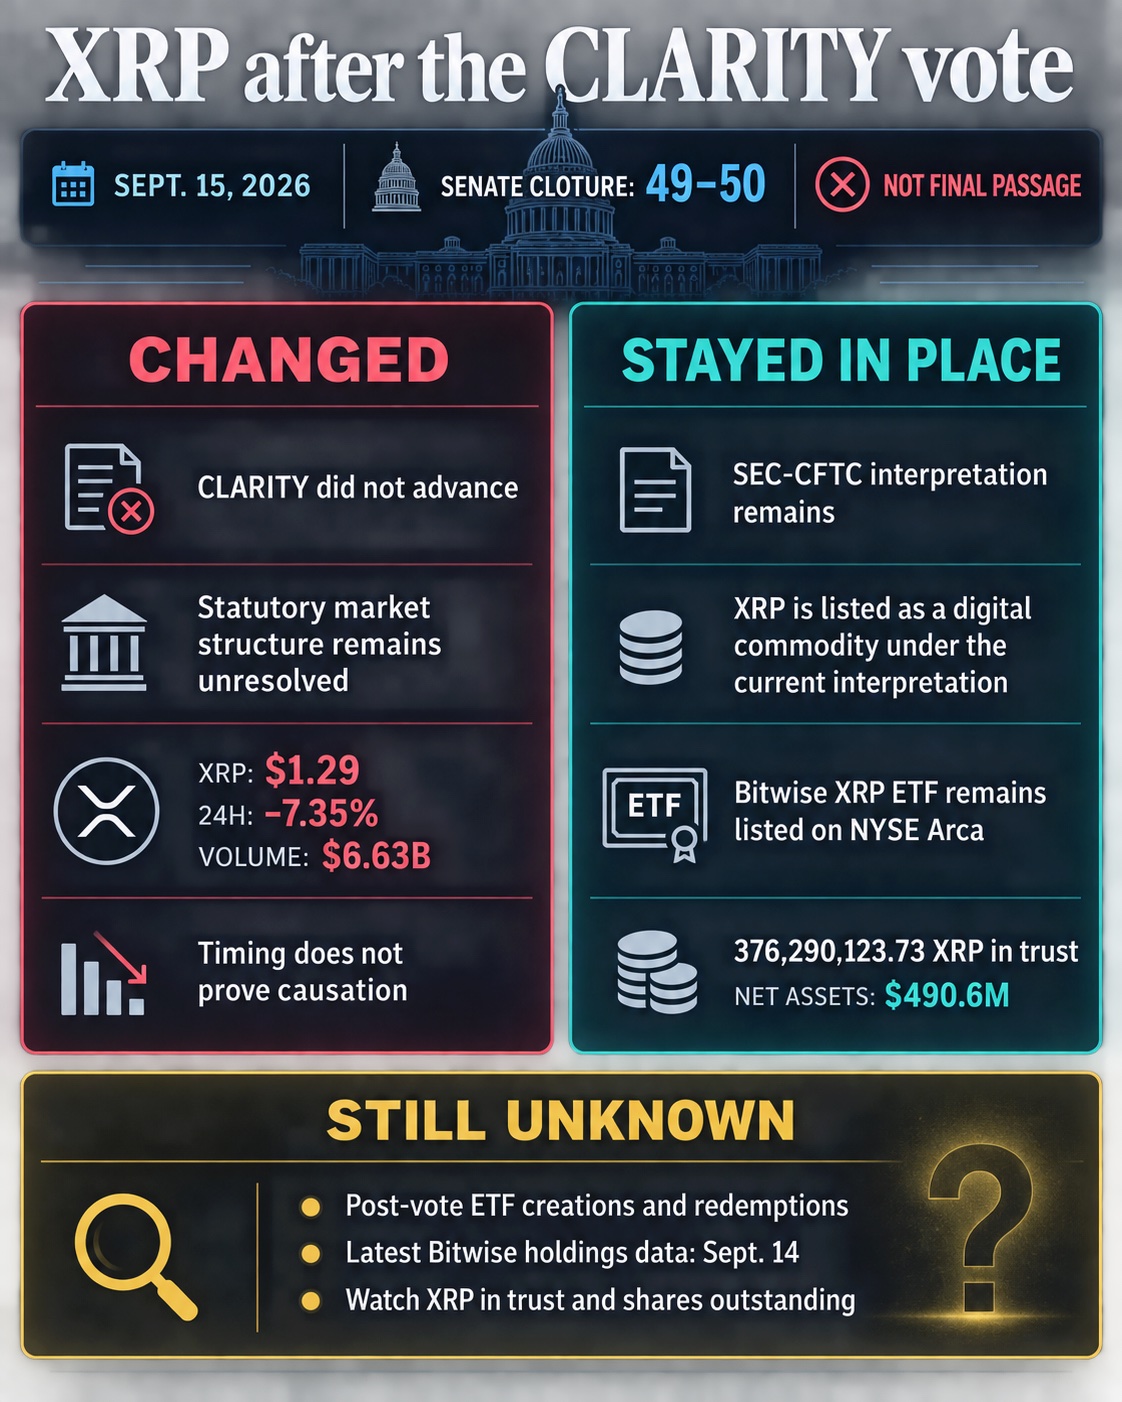
XRP fell more than 8% after the Senate blocked a key crypto bill, even as the token’s existing US regulatory treatment remained intact.
CryptoSlate data showed XRP falling as low as $1.27 before recovering to about $1.29 as of press time, extending a decline from roughly $1.42 on Sept. 14. The selloff coincided with broader weakness across major cryptocurrencies and a wave of leveraged long liquidations.
The price action followed US lawmakers’ rejection of an effort to advance the Digital Asset Market Clarity Act. The 49-50 vote failed to invoke cloture on a motion to proceed to H.R. 3633, denying one of the crypto industry’s biggest legislative priorities enough support to reach Senate debate and removing a near-term route toward putting a federal market-structure framework into statute.
Ripple Chief Executive Brad Garlinghouse said the result “stings,” but argued that it does not alter the company’s commercial trajectory. He pointed to demand across traditional finance and the digital-asset industry, saying the failed vote does not change Ripple’s momentum, global footprint or customer base.
Ripple turns to regulators as Congress stalls
Ripple's confidence rests partly on the regulatory ground XRP gained before the CLARITY vote, which Chief Legal Officer Stuart Alderoty argues remains intact despite the Senate setback.
Alderoty pointed to the March action by the Securities and Exchange Commission (SEC) and Commodity Futures Trading Commission (CFTC), saying XRP continues to stand on “settled ground.”
The SEC issued a Commission-level interpretation outlining how federal securities laws apply to several categories of crypto assets, while the CFTC said it would administer the Commodity Exchange Act consistently with that framework. XRP was among 18 assets identified as digital commodities based on their characteristics, terms and functions at the time.
That treatment remains in effect even after the failed Senate vote, preserving regulatory clarity XRP lacked during much of Ripple's years-long legal battle with the SEC.
Ripple said the development gives the company an advantage as much of the broader digital-asset industry continues operating without a comprehensive statutory market structure.
The protection is less durable than legislation, however. The March action interprets laws already on the books and leaves the SEC room to refine or revise its approach.
It also preserves transaction-specific analysis under the Howey test, meaning a digital commodity that is not itself a security can still be offered or sold as part of an investment contract subject to securities laws.
That distinction puts greater weight on what regulators do next. With Congress stalled, Ripple expects SEC Chairman Paul Atkins and CFTC Chairman Mike Selig to take a larger role in developing crypto rules and said it will remain engaged with both agencies as that process moves forward.
The company also said it expects XRP's digital-commodity treatment to remain intact through future rulemaking.
The agencies can clarify how existing statutes apply to trading, custody and other crypto activities, but a broader division of authority between the SEC and CFTC would still require congressional action.
That leaves the industry dependent on a combination of court decisions, agency interpretations and future rulemaking while lawmakers determine whether another market-structure proposal can attract the votes CLARITY could not.
Ripple, meanwhile, is signaling that the legislative setback will not slow its commercial expansion. The company said demand remains strong across payments, stablecoins and institutional markets and that it plans to continue expanding its global business while pressing for clearer U.S. rules.
Institutional demand for XRP-linked products also remains substantial despite the token's selloff. US spot XRP exchange-traded funds had attracted about $1.71 billion in cumulative net inflows through Sept. 14, with roughly $1.58 billion in net assets.
That placed XRP behind only Bitcoin and ETH among major US single-asset spot crypto ETF categories tracked in the same data set, and ahead of Solana's roughly $1.37 billion in cumulative inflows.
The next test is whether that demand persists after the Senate setback and whether the financial agencies can turn their March interpretation into a more durable regulatory framework.
The post XRP falls hard after CLARITY vote as Ripple’s regulatory advantage faces a new test appeared first on CryptoSlate.
Solana is rolling out some of its most significant performance upgrades as network activity reaches record levels.
The blockchain is increasing how much data applications can pack into individual transactions while also shortening the interval between successive slots, expanding both transaction capability and network responsiveness.
The upgrades come as activity across Solana accelerates, raising the operational baseline developers and validators must support as the network moves deeper into its scaling roadmap.
V1 goes live as Solana closes in on 200ms slots
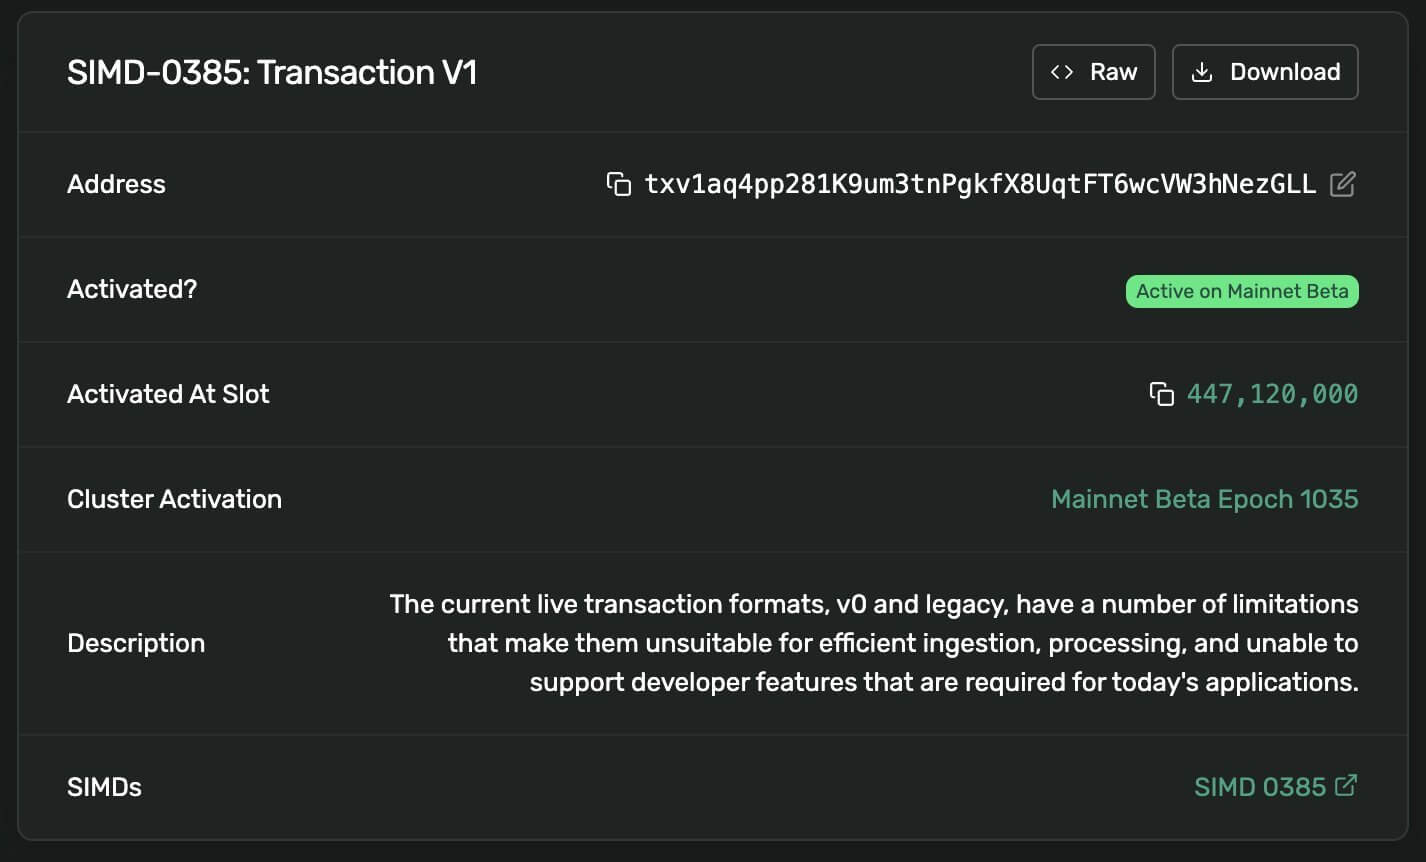
On Sept. 15, Solana’s new V1 transaction format went live, increasing the amount of data a single transaction can carry by more than threefold to 4,096 bytes.
In practical terms, developers now have more room to bundle complicated actions into one transaction. Operations involving privacy technology, multiple signatures, or large amounts of account data that previously had to be broken into several steps can now be completed in a single transaction.
That matters because Solana transactions operate on an all-or-nothing basis. If one part fails, the entire transaction fails, reducing the risk of a multi-step operation being only partly completed.
V1 also gives developers more flexibility over how transactions are constructed. It can include up to 64 accounts directly and puts information about computing needs and transaction fees inside the transaction itself, rather than relying on separate instructions.
Older transaction formats will continue to work, so applications do not have to switch immediately. Wallets, exchanges, and other services that process Solana transactions will, however, need to make sure their systems can recognize the new format as adoption grows.
The upgrade does not automatically make transactions faster or cheaper. Instead, it lets developers do more within a single transaction, potentially making more complex applications easier to build and use.
Meanwhile, Solana is pushing ahead with another major change: reducing the time between slots, the short intervals in which the network processes and records new activity.
The network originally targeted 400 milliseconds between slots. However, that was reduced first to 350ms and then to 300ms, with the next cut to 250ms now approaching mainnet activation.
Anza, the Solana-focused R&D lab behind the Agave validator software, says the 250ms stage is progressing through its final activation process. It is expected to take effect around 05:01 UTC on Sept. 18, when epoch 1037 begins.
That would mark the third reduction from Solana’s original 400ms target and leave only the final move to 200ms under the current roadmap. The 200ms stage is already active on Solana’s development and test networks but has yet to be scheduled for mainnet.
Shorter slots are mainly designed to make Solana more responsive. At 250ms, the network would have an opportunity to produce a new slot about four times per second. At 200ms, that would rise to five times per second, twice the frequency of the original 400ms target.
The change does not automatically double Solana’s transaction capacity. As slots become shorter, the amount of work allowed within each one is adjusted as well.
The bigger challenge is whether validators can continue processing and sharing blocks reliably as the time available for each step gets progressively tighter.
Upgrades arrive as Solana activity reaches record levels
This engineering push is unfolding against the busiest period in Solana’s history.
On X, Solana stated that the network processed 5.2 billion non-vote transactions in August, surpassing July’s previous record of roughly 4.2 billion by 19%.
Non-vote transactions remove the validator voting messages required for consensus, although the remaining figure can still contain automated activity and failed transactions alongside transfers, trades and other application calls.
The record is also appearing in measures beyond transaction counts.
Solana applications generated $40.8 million in revenue last week, their highest weekly total since January. Decentralized exchanges on the network handled about $16.59 billion during the same period, extending Solana’s run as the leading blockchain by weekly DEX volume.
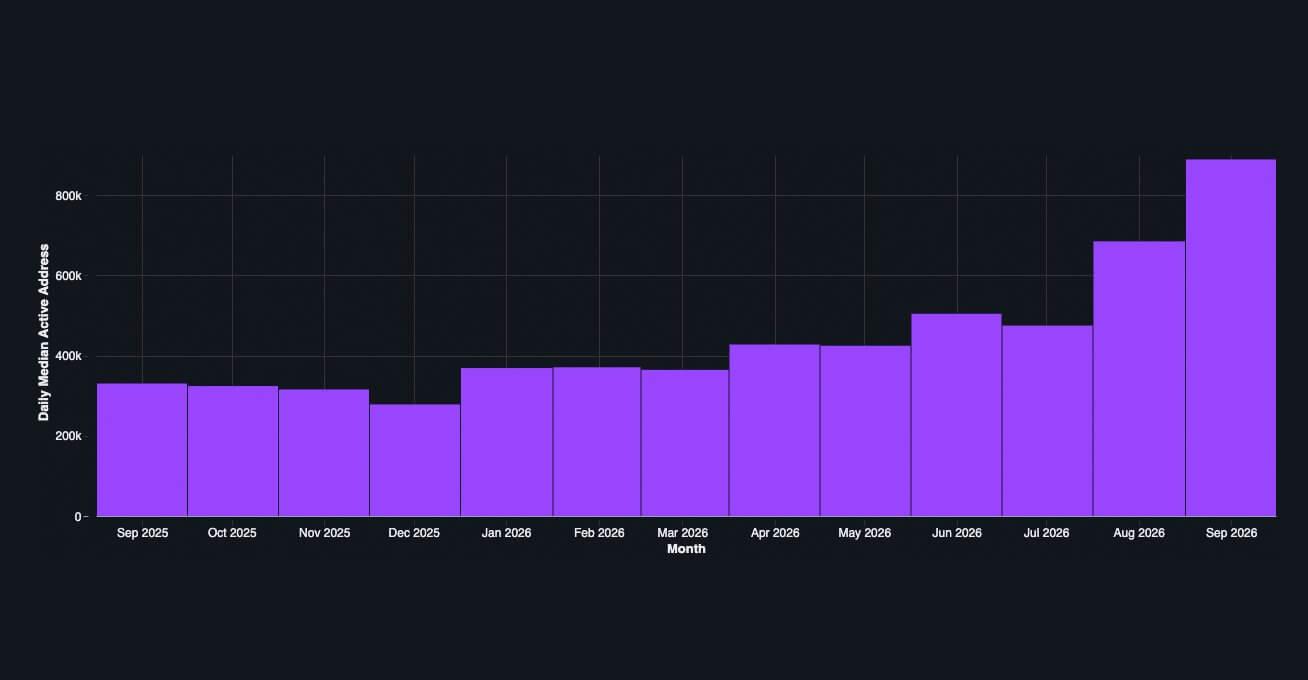
Stablecoin activity has expanded alongside trading. Daily active addresses interacting with stablecoins reached 888,000 in September, compared with 333,000 a year earlier, meaning the number has grown to roughly 2.7 times its September 2025 level.
Tokenized equities are adding another source of activity. Their supply on Solana reached a record $684 million last week after climbing 47% in three weeks.
That mix shows the record transaction count is increasingly supported by activity across different parts of the network, rather than a single application category. Trading is generating higher application revenue, stablecoins are reaching more active wallets, and tokenized equities are building a larger asset base, all while overall transaction volumes sit at historic highs.
The 250ms transition on Sept. 18 will therefore arrive with Solana already operating against a much higher level of activity than when the slot-time roadmap began.
If that step holds, developers will have only the final move to 200ms remaining in a performance push underway while network use sets records across several measures.
The post Solana triples transaction size as major upgrades meet record network activity appeared first on CryptoSlate.
Bitcoin faces a compressed volatility test as the Federal Reserve’s rate decision lands two days before a major IBIT options expiry.
The Fed will release its policy statement at 2 p.m. ET Wednesday, followed by Chair Jerome Powell’s press conference and a fresh Summary of Economic Projections. Any move in Bitcoin will then run into Friday’s expiry of about 1.47 million options contracts tied to BlackRock’s iShares Bitcoin Trust ETF.
That sequencing gives traders a clear test of whether a macro-driven move can survive one of the largest visible concentrations of positioning in the US-listed Bitcoin ETF options market.
A sustained move outside the busiest IBIT strikes would suggest that the Fed impulse, spot demand, or broader risk positioning overwhelmed the expiry setup. A reversal back toward those strikes would increase the relevance of dealer hedging and position adjustments, though public open-interest data cannot determine the precise cause.
Bitcoin traded around $76,000 ahead of the Fed decision, placing it near the middle of the range implied by the most crowded IBIT strikes.
More than a third of IBIT positioning sits between $40 and $45
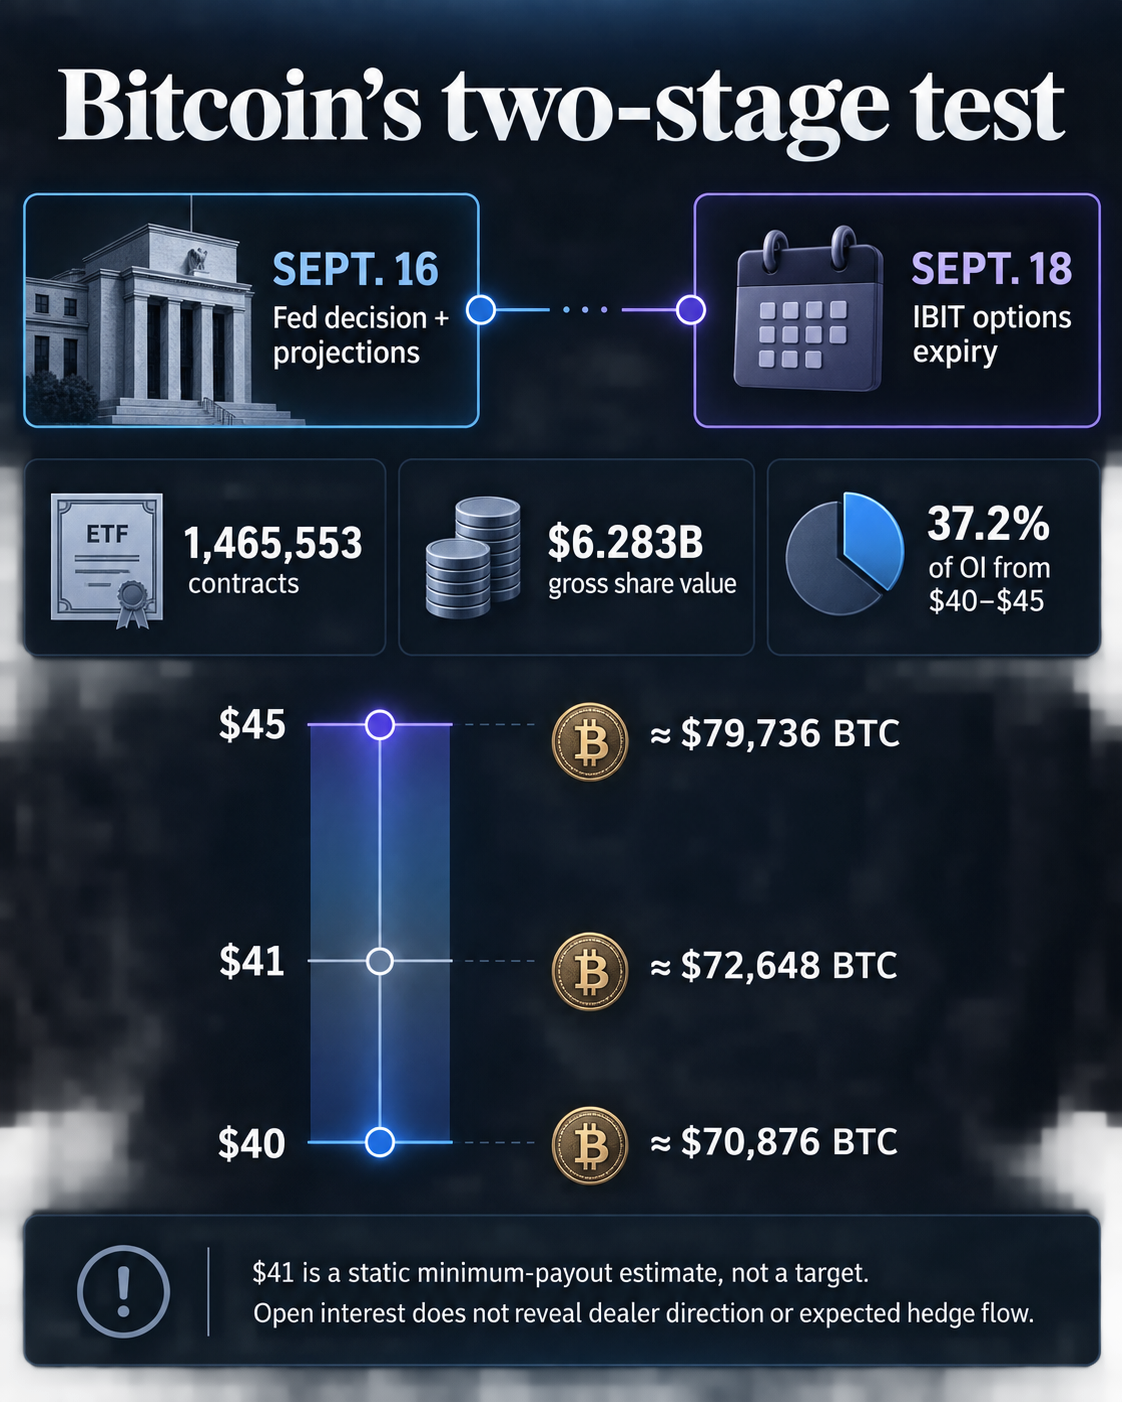
Cboe data showed 1,465,553 open contracts for IBIT’s Sept. 18 expiry, comprising 833,070 calls and 632,483 puts.
Standard equity options typically represent 100 shares each, giving the book about 146.6 million gross share-equivalents. At an IBIT reference price of $42.87, that corresponds to roughly $6.28 billion of gross underlying share value.
The figure describes the scale of the open contracts rather than capital directly at risk. It does not reveal net dealer exposure, customer positioning, expected hedge flows, or the amount of stock likely to change hands at expiry.
The concentration is more useful for identifying where the market could become sensitive to price changes.
Roughly 545,861 contracts, or 37.2% of total open interest, were clustered between the $40 and $45 strikes. The $45 strike carried the largest individual position with 141,670 contracts, while $40 held 122,979.
Those levels matter because option values and hedging requirements can change quickly as the underlying ETF moves through heavily populated strikes, particularly approaching expiry.
A static calculation of the current book found the lowest gross intrinsic value around an IBIT price of $41. That level should not be treated as a price target because the calculation excludes premiums, transaction costs, early exercise, position changes, and information about who holds each side of the trade.
Using the Coin Metrics Bitcoin benchmark at $75,961.76 and IBIT at $42.87 as a rough proportional mapping, the crowded $40-to-$45 IBIT range corresponds to Bitcoin prices of approximately $70,900 to $79,700. The $41 reference maps to roughly $72,650.
| IBIT reference | Approximate Bitcoin equivalent | Positioning context |
|---|---|---|
| $40 | $70,876 | Lower edge of the crowded strike band |
| $41 | $72,648 | Lowest gross intrinsic-value estimate |
| $45 | $79,736 | Upper edge of the band and largest strike by open interest |
Fed reaction will be tested by Friday’s settlement
The first move comes from Washington.
The Fed’s decision and updated economic projections could reset expectations for rates, growth and inflation, with Bitcoin increasingly trading alongside other risk assets during major macro events.
Friday then introduces a separate source of positioning pressure.
IBIT options are physically settled, meaning exercised contracts deliver ETF shares rather than cash or Bitcoin. Traders can close or roll positions before expiry, while others can expire worthless or be exercised and assigned.
That makes open interest a map of potential pressure points rather than a forecast of actual trading flows.
The product’s capacity for large positions also expanded this year. Cboe raised IBIT option position and exercise limits from 250,000 to 1 million contracts in May, allowing significantly larger same-side exposure than before.
The next 48 hours will show whether those concentrations remain relevant after the Fed.
If Bitcoin pushes above roughly $79,700 or below about $70,900 and holds those levels through Friday, the expiry band would carry less explanatory weight. Such a move would point toward stronger macro or spot-market forces driving price discovery.
A sharp initial break followed by a return toward the $40-to-$45 IBIT zone would put expiry-related positioning back in focus, especially if open interest shifts as traders close or roll contracts.
For options desks, market makers and leveraged traders, the distinction has immediate consequences.
A Fed-driven breakout that persists could force rapid hedge adjustments outside the existing concentration, while a return toward the crowded strikes would leave Friday’s settlement mechanics more influential over short-term positioning.
By the end of the week, traders will have a clearer answer on whether Bitcoin can carry a macro catalyst through one of the largest ETF-options expiries now sitting directly in its path.
The post Bitcoin’s Fed move could run straight into a $6.3 billion IBIT options wall appeared first on CryptoSlate.
Two Robinhood engineers were charged with using confidential token-listing information to place profitable crypto derivatives trades on Hyperliquid.
On Sept. 15, the Federal prosecutors accused Hefu Chai and Huaisong “Jerry” Xiang of trading perpetual futures tied to tokens they allegedly knew Robinhood Crypto planned to list, earning more than $50,000 each.
These charges extend insider-information enforcement into a part of crypto markets where confidential information held at one company can be monetized through derivatives traded on a separate decentralized platform.
Both men face one count of commodities fraud and one count of wire fraud. The charges carry statutory maximum sentences of 10 years and 20 years, respectively.
Chai worked at Robinhood from about 2021 until May 2026 and served as a technical lead involved in new digital-asset listings, prosecutors said. Xiang worked as a software engineer from about 2024 through September 2026.
Their positions allegedly gave them access to a private Slack channel containing upcoming listing plans. Both were designated “Coin Aware Individuals,” employees permitted to receive information about whether and when Robinhood Crypto would make new tokens available.
Robinhood’s policies barred those employees from trading while holding material nonpublic information and restricted them from trading affected assets on any platform before an announcement and for 24 hours afterward.
US Attorney Jamie McDonald said:
“Misappropriating confidential information to trade in the derivatives markets for personal benefit is illegal. Today’s charges make clear that corporate insiders cannot evade the securities and commodities laws by trading based on misappropriated information in derivatives like perpetual futures, tokenized securities, or other similar financial instruments.”
Prosecutors said Chai traded on at least 10 occasions between 2025 and January 2026. Xiang allegedly traded around a March 2025 POPCAT listing and on at least 10 other occasions through February 2026.
Prosecutors focus on the window before Robinhood's public announcements
The government’s case centers on the gap between when a token became tradable on Robinhood and when the company publicly announced the listing.
Robinhood tokens could begin trading as much as an hour before an announcement, prosecutors said, creating a window in which employees with advance knowledge could potentially exit positions before the broader market received the news.
In one example, Xiang allegedly learned around Jan. 23, 2026, that Robinhood planned to list RENDER on Jan. 29. Prosecutors said he opened long RENDER perpetual-futures positions around the listing date and closed them at a profit after the token became available on Robinhood but before the public announcement.
Chai allegedly used a similar strategy involving HYPE. Prosecutors said he learned around Oct. 16, 2025, that Robinhood planned to list the token the following week, then opened HYPE perpetual positions around Oct. 23 and exited profitably after trading began on Robinhood but before the announcement.
Those trades were placed on Hyperliquid, a decentralized derivatives venue where perpetual futures allow traders to speculate on token prices without holding the underlying assets.
The case now puts the alleged use of confidential listing information in decentralized derivatives markets before a federal court, potentially testing how prosecutors apply commodities-fraud statutes when the information source and trading venue are separate.
Robinhood cooperated with the investigation, the Justice Department said. The company may also face pressure to reassess how it segments listing information internally and monitors employee trading restrictions across external crypto venues as prosecutors pursue the case.
The post Robinhood engineers face up to 30 years over $50,000 alleged Hyperliquid profits appeared first on CryptoSlate.
Solana treasury company DeFi Development Corp. has opened an at-the-market program for up to 30 million CHAD preferred shares, creating an optional financing channel that could support further SOL purchases alongside other corporate uses.
CHAD is variable-rate perpetual preferred stock. Its $10 stated amount is the base used to calculate dividends; the security's market price and eventual sale prices can differ. Multiplying that stated amount by the program's 30 million-share limit gives $300 million of aggregate stated amount. Cash proceeds will depend on actual issuance volume and market prices.
The September 11 prospectus sets no minimum offering amount and gives no assurance that any or all shares will be sold. DeFi Development is not obligated to issue shares, while R.F. Lafferty is not required to sell a specific number or dollar amount. The agent can receive up to 0.75% of gross proceeds, and the company must cover specified offering expenses.
The larger continuing cost comes from CHAD's cumulative dividend. Regular dividends initially accrue at 13% a year on the $10 stated amount, equivalent to $1.30 per share annually. Cash payment remains subject to board declaration and legally available funds.
If all 30 million ATM shares were outstanding for a full year and the initial rate did not change, they would accumulate $39 million in dividends on an annualized basis. The scenario assumes full issuance for a full year at an unchanged rate; actual accumulation will vary with the number and timing of sales and subsequent rate decisions.
The board determines the regular annual rate at least monthly. Any monthly reduction is limited to 50 basis points and subject to timing, prior-dividend and market-price conditions. The 13% figure applies initially, and later rates can change.
DeFi Development Corp. says a portion of net proceeds will acquire SOL. Working capital and strategic initiatives are also permitted uses, leaving management broad discretion and no fixed allocation to the token.
The company reported 2,388,923 SOL and SOL equivalents as of September 11, up 55,491 from August 27. It attributed the increase to purchases and organic treasury growth without splitting the two. Separately, establishing the ATM created future financing capacity. The disclosed causes of the treasury increase do not include ATM proceeds.
The program follows a separate CHAD offering that closed September 8 at $8 per share and generated approximately $11 million gross. It also adds a preferred-share route alongside the common-share financing and cost reductions CryptoSlate covered in August.
The new ATM currently represents optional financing capacity. Its eventual economics will depend on issuance volume and price, the dividend rate over time and management's allocation of proceeds.
The post Solana treasury giant DeFi Development opens $300M CHAD offering backed by a massive 13% dividend catch appeared first on CryptoSlate.
CryptoTicker.io
Deutsche Bank announced on September 16, 2026 that it will custody Bitcoin, Ether and selected stablecoins for its clients. For you as a retail investor, nothing changes for now: the announcement mentions corporate and institutional clients only. What you can take from it is concrete all the same, because the bank names in it exactly the points against which you should measure any custody arrangement.
What Deutsche Bank announced on September 16
The announcement is headed "Deutsche Bank to launch digital asset custody solution for institutional and corporate clients" and is dated September 16, 2026. Its wording addresses "clients of Deutsche Bank's Corporate Bank and Investment Bank, including corporates, asset managers, hedge funds, depositaries, brokers and government institutions". The launch with the first clients is planned for this year, expressly subject to the regulatory procedures under way.
The key sentence for the question of who ultimately holds control is also in the announcement: the bank takes over the administration of the wallets and the private keys. Clients are to be able to hold digital assets and transfer them to third parties without building custody infrastructure themselves. Gerald Podobnik, Co-Head of the Corporate Bank, frames digital assets there as a complement to financial markets and expressly calls them no substitute for the existing financial system.
Technically the bank does not stand alone. According to The Block it is working with the Swiss infrastructure provider Taurus, a partnership that goes back to September 2023, and is additionally drawing in the technology unit of Bitpanda, which has been reported in the project since July 2025. On safeguards, The Block names hardware-based key protection, approvals by several people, separate environments for warm and cold custody, and controls for backup and recovery. CoinDesk places the step in the European competitive picture: Standard Chartered and BBVA already offer institutional crypto custody.
Crypto custody explained: who holds the private key in a custody arrangement
Crypto custody means that a service provider keeps and administers the private keys to crypto assets on behalf of a client. The private key is the string that signs a transfer out of a wallet; whoever controls it can dispose of the coins. That is precisely why the question of whose hands it sits in is no technical footnote but the ownership question in practice.
In a custody arrangement such as the one announced, the key sits with the bank. You then hold a claim against the institution, but no direct access to the blockchain address. The counter-model is called self-custody: the key sits with you, usually on a hardware wallet, and nobody can approve a transfer except you. Both routes have their price. In the first case you carry the risk that the institution fails or blocks your access. In the second you carry the risk of losing the key, and there is no office that restores it.
For institutional clients the case is clear: an asset manager is often barred from holding keys itself for supervisory reasons alone. For you as a retail investor the trade-off is more open, and it hangs less on trust in a brand than on the four questions set out further down in this text.
Bitcoin, Ether, USDC, EURC and EURAU: which assets the bank intends to custody
For the launch the announcement names five assets. Bitcoin and Ether are the two largest crypto assets by market capitalisation. Added to them are USDC and EURC, two stablecoins from the issuer Circle, along with EURAU. A stablecoin is a token whose value is tied to an official currency and backed by reserves; under European regulation such a token generally falls into the category of an e-money token.
This selection is more revealing than it first appears. A bank operating under European supervision cannot afford a token whose issuer is not cleanly authorised. The list is therefore an indication of which euro and dollar tokens count as compatible in a regulated environment. What is absent is equally notable: no token outside the two large networks, no staking product, no small caps. The bank also holds out the prospect of widening the circle of supported assets later and of taking tokenised financial instruments onto the product map.
If you use euro stablecoins, it is worth looking at how the respective issuer is set up and what redemption right you actually hold. What matters there is the issuer, the backing of the reserves and the question of whether you can return the token at face value at any time.
Why retail clients do not appear in the announcement
The bank's list of target groups is exhaustive, and retail clients are not on it. That has little to do with reticence towards crypto assets and much to do with the effort a mass-market offering sets off. An institutional custody mandate concerns a three-digit number of clients with compliance departments of their own. A retail offering concerns millions of accounts, and needs an app, an advisory process, key information documents and a complaints route.
For you that simply means this: you will not be custodying coins through your current account this way for the time being. Anyone in the German banking sector who wants crypto assets as a retail client currently ends up at the savings banks and the cooperative banks, and different conditions apply there than in institutional business. How custody at a savings bank is constructed and why you get no key of your own there is something we took apart in detail on September 13, 2026: crypto at the Sparkasse.
Subject to supervision: what lies between an announcement and a licence
In the announcement the launch is expressly subject to the regulatory procedures. That half-sentence is the most important in the whole text, and it describes a state of affairs that occurs more often in the crypto market than many realise: a service is announced, promoted and dated, but not yet permitted.
Since July 1, 2026 the transition period of the Markets in Crypto-Assets Regulation has been treated as ended in the European Union. Anyone offering crypto-asset services needs a licence under that regulation, granted in Germany by BaFin. Custody and administration of crypto assets on behalf of clients is one of these licensable services. For banks there is a simplified route by way of a notification, but that too has to be completed before the service starts.
How to tell whether a provider really holds the licence
The supervisor maintains public registers, and those are the only robust proof. A press release, a reference to an "authorisation in progress" or a supervisory logo in the footer are not. Three points help you with any check. First: is the provider listed in the register under exactly the company with which you conclude the contract? Group names and contracting parties often differ. Second: does the registered licence cover the service you want to use? A licence for trading is not one for custody. Third: check whether a consumer warning exists against the name, because the supervisor publishes these on a rolling basis. How to work through that in a few minutes is set out in our guide to checking crypto providers.
Deposit protection: why the 100,000 euros do not apply to your crypto assets
Here lies the most expensive misunderstanding around bank custody. Deposit protection covers deposits, meaning balances in current, instant-access and fixed-term accounts, up to 100,000 euros per client and institution. Crypto assets are not deposits. BaFin makes clear in its consumer information that crypto assets are regularly covered by neither the deposit guarantee scheme nor investor compensation. An exception applies only where the asset is legally classified as a security, or where fund units investing in crypto assets are involved.
The institution holding your coins changes nothing about that. A savings bank, a cooperative bank and an internationally active major bank stand equal on this point. The sentence "my money is safe at my bank" holds for the euros in the account and not for the token in the deposit, and anyone conflating the two misjudges their risk systematically.
Segregation under the crypto-markets regulation: what separating client holdings achieves
The actual protective mechanism in regulated custody business is called separation, and it has nothing to do with deposit protection. The Markets in Crypto-Assets Regulation requires a custodian to separate its clients' crypto assets legally from its own assets, in such a way that creditors of the custodian cannot reach them in an insolvency. The supervisor also expects operational separation: own holdings have to be assigned to different network addresses than client holdings, so that the two do not sit in the same place on the blockchain.
Segregation means that an asset does not form part of the estate in insolvency proceedings but is handed over to the entitled party. That is exactly what the separation duty aims at. It is effective, though no comprehensive cover: the custodian has to have genuinely maintained the separation for it to work, and it does not help against the loss of the keys themselves. How such proceedings run in practice and where the handover can fail is something we described using insolvent trading venues as the example: segregation or insolvency estate.
For you a single question follows from this, and you can put it to any provider: are my holdings on separate addresses, and does that appear in the terms? Anyone who gives no clear answer to that has either not understood the question or not solved it cleanly.
Bank or self-custody: which questions to settle before deciding
Four questions decide whether a custody arrangement suits you. Each can be answered at any provider, and none requires specialist knowledge.
First, the withdrawal question: can you transfer your coins to an address you control yourself? Many bank offerings do not provide for this, and you can then only sell. Your access then hangs permanently on that one house.
Second, the cost question: what do you pay for purchase, custody and sale taken together? Across the offerings of savings banks and cooperative banks we measured a commission of 1.5 percent plus spread in a separate analysis on September 6, 2026, a mark-up that costs more on a single purchase than a year of fees at a specialist trading venue. A price comparison is no fine detail here but the largest lever.
Third, the licence question: does the provider hold the licence for custody, and which company is it issued to? At cooperative and public-sector institutions, custody frequently sits with a central institution rather than with your branch. For the cooperative banks we traced that chain on September 13, 2026.
Fourth, the tax question: do you receive a statement showing the acquisition date and acquisition cost for each position? Without those details you cannot prove a holding period, and the burden of proof falls on you.
What German retail investors can already get in bank custody today
Deutsche Bank's institutional launch is a signal, but it is not an offer to you. What is practically available to retail clients at present is the route through the two large banking groups, in each case with custody by a central institution and without a key of your own. Alongside them stand the specialist trading venues and brokers, which operate under the same European regulation and generally do provide for withdrawal to an address of your own.
Which route fits depends on what you intend to do with the coins. For a small holding you never intend to move anyway, the convenience of a bank deposit is a genuine argument. For a larger holding you want to keep long term, your own custody is the only variant in which no third party can switch off your access. Mixing the two runs most calmly in practice: one part at a trading venue for ongoing purchases, the rest on a device within your own reach.
A final point that readily gets lost in the enthusiasm around bank offerings: the bank provides custody, it does not advise on the market. The price development of Bitcoin or Ether does not become more reliable through a custody mandate, and the swings remain what they were. Institutional access improves the infrastructure, not the prospect of a return.
Checking bank custody: what to take away
- Check the licence before the offer. Look in the supervisor's public register to see whether the provider is listed under exactly the contracting company and for exactly the service you want to use. A sorted starting point for that check is in our overview of regulated crypto exchanges.
- Add up total costs and the withdrawal route. Total the purchase mark-up, the ongoing custody fee and the sale costs, and settle before your first purchase whether a transfer to an address of your own is possible. The terms of the specialist providers stand side by side in our exchange comparison.
- Settle the key question for long-term holdings. Decide deliberately which part of your holdings sits with a custodian and which part stays within your own reach, including a recovery secured in writing. The devices and how they differ are in our hardware wallet comparison.
You can read the announcement itself in full, as well as the supervisory requirements for crypto-asset services: Deutsche Bank announcement of September 16, 2026 and BaFin guidance note on crypto-asset services.
(As of September 16, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
World Liberty Financial (WLFI) costs around $0.0569 on September 16, 2026. That leaves it 76.7 percent below the twelve-month high of $0.2437, which the token reached on September 22, 2025 shortly after trading began. At the same time it stands 11.0 percent above the twelve-month low of $0.0513 from August 9, 2026. With a market capitalisation of $1.81 billion, WLFI ranks 40th among the largest crypto assets. That leads to the question this article is about: is World Liberty Financial a good buy at the current price?
cryptoticker.io compiled the price data itself on September 16, 2026. The source is CoinMarketCap market data, calculated from daily closing prices over the past 365 days and with standard formulas: exponential moving averages over 50 and 200 days, and the Relative Strength Index over 14 periods according to Wilder. Every figure can be recalculated from that.
World Liberty Financial price analysis: where the WLFI price stands today
The WLFI price has been moving in a narrow band for weeks. Over the past eight trading days the token oscillated between $0.0553 and $0.0578, and it currently sits at $0.0569. Over 30 days that is a loss of 4.3 percent, over 90 days 9.2 percent. The twelve-month comparison is brutal: minus 73.8 percent.
Three marks structure the picture. The first is the twelve-month low of $0.0513 from August 2026, around 10 percent below the current price and the nearest support. The second is the current zone itself, which coincides with the 50-day average of $0.0572; the price sits 0.5 percent below it, so practically right on it. The third is the 200-day average at $0.0756, 24.7 percent further up.
This is the typical constellation after a heavy crash: the price has stopped falling, but has reclaimed nothing yet. The coming months will be decided between $0.0513 and $0.0756.
Is the downtrend in World Liberty Financial broken or merely interrupted?
A downtrend counts as broken once the price reclaims the longer-term average and forms higher lows. On the first criterion WLFI is on the wrong side: at $0.0569 the token sits almost a quarter below the 200-day average of $0.0756. While that holds, the overarching trend points down, however calm the past few weeks have been.
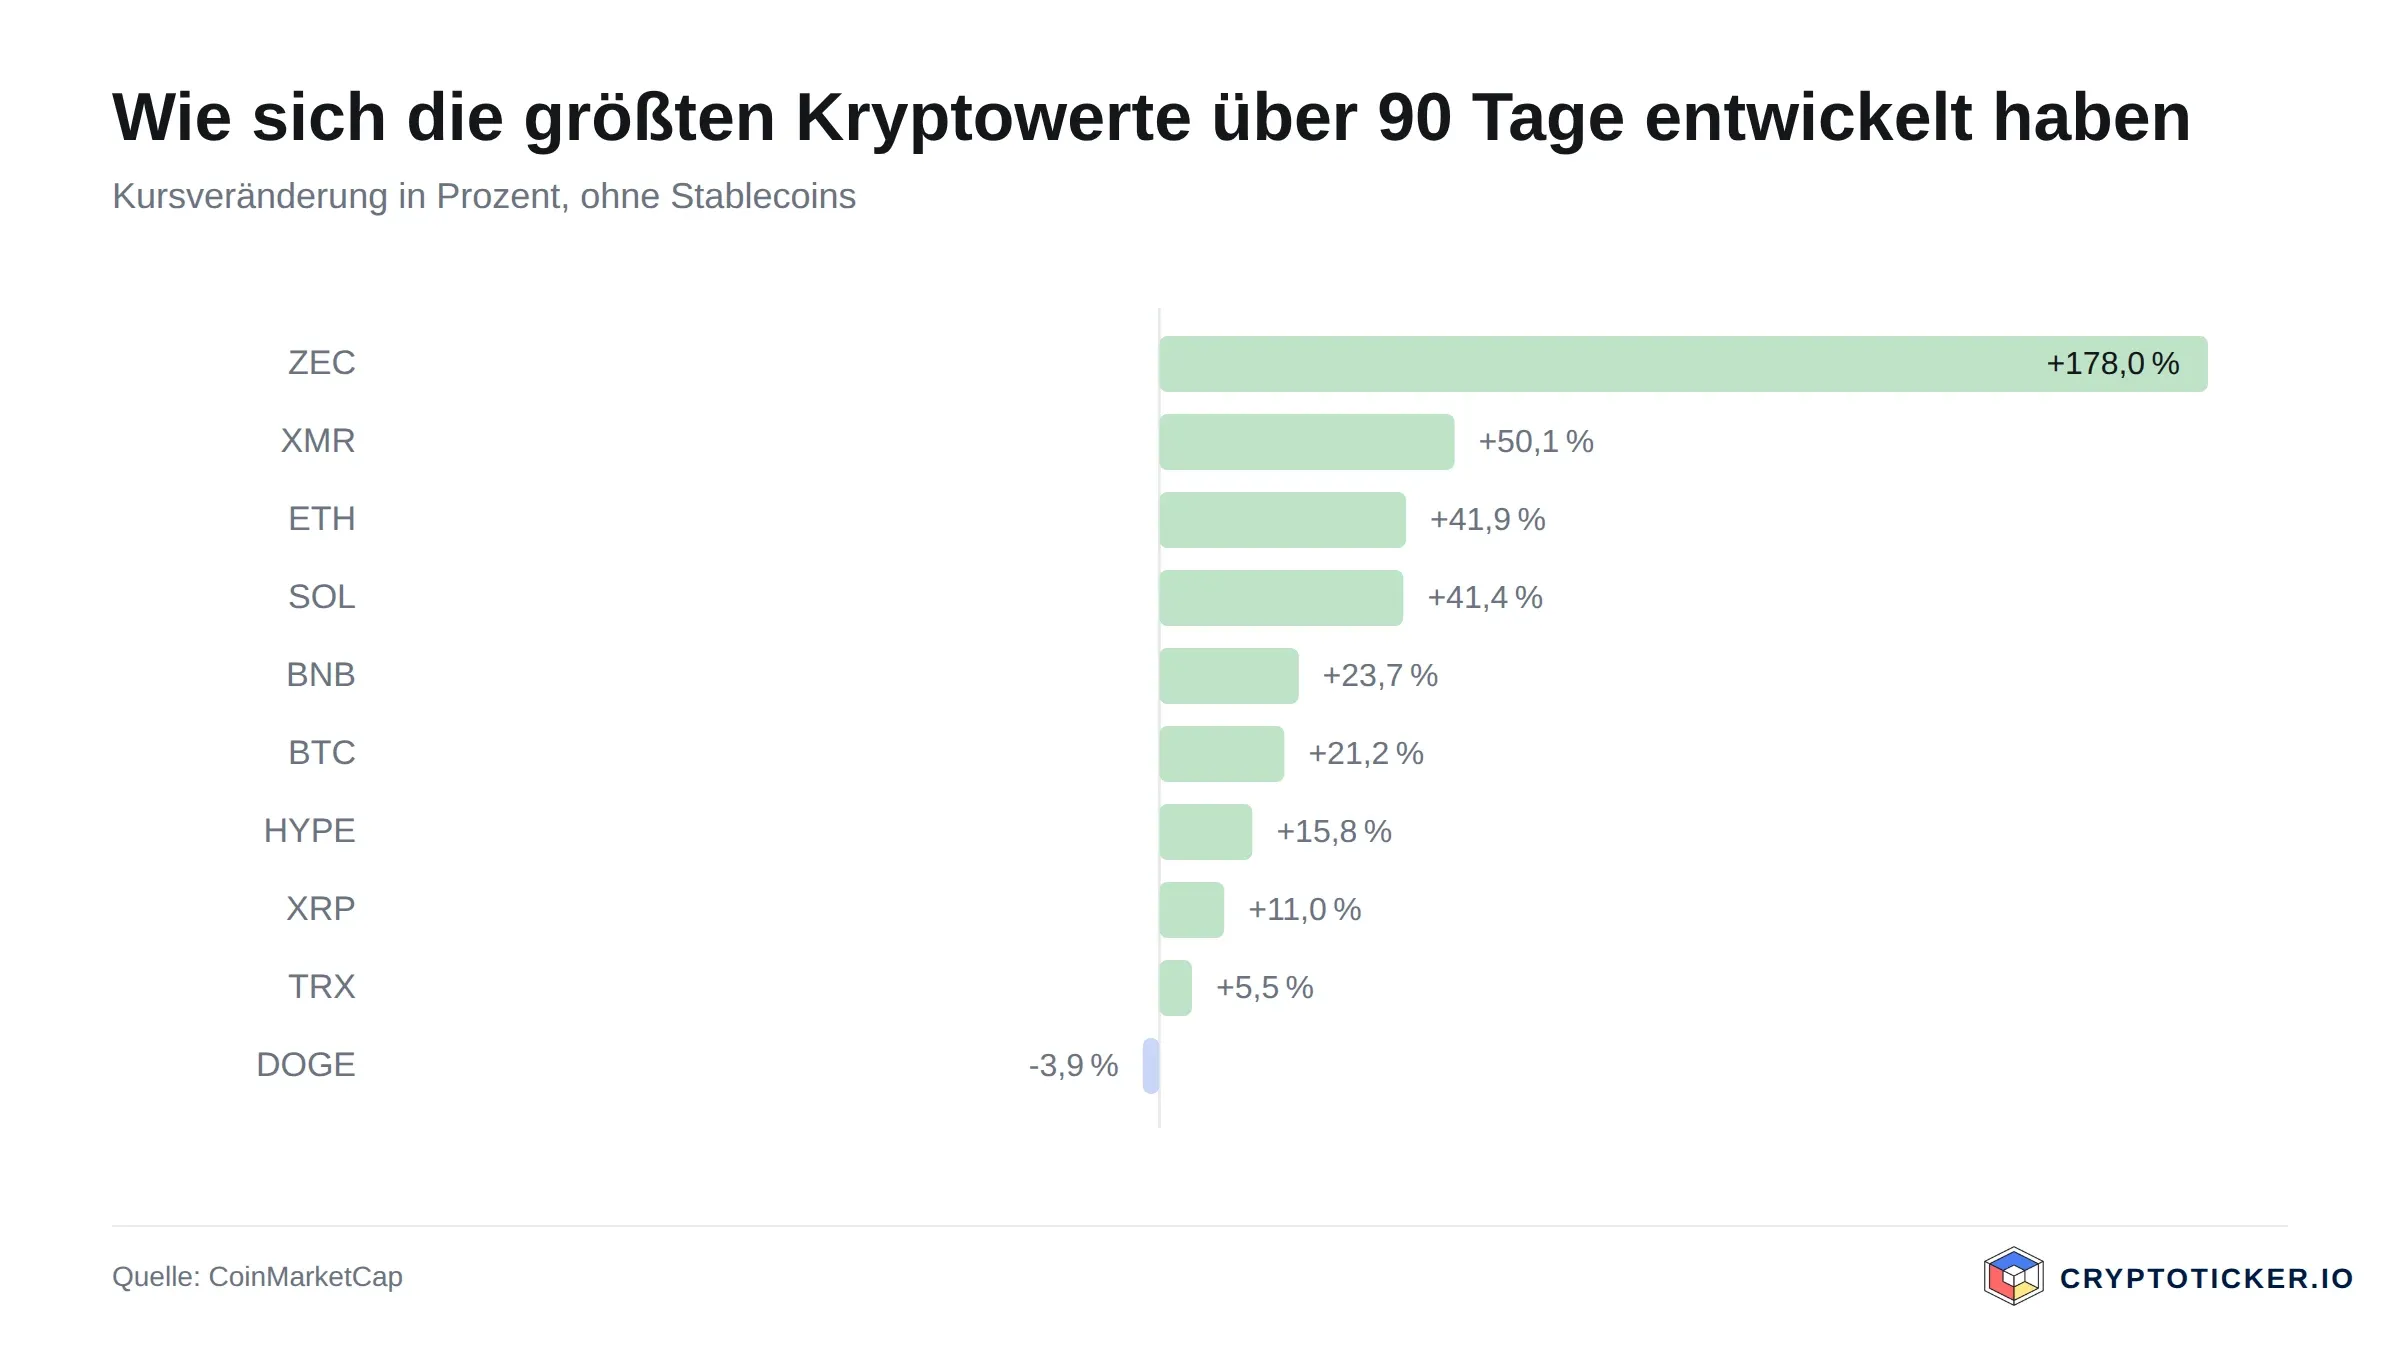
On the second criterion it looks better. The August low of $0.0513 has not been undercut since, and the 50-day average of $0.0572 now runs practically flat rather than steeply down. That is the signature of an interruption, not yet of a break.
The downtrend is therefore paused, not ended. Anyone waiting for confirmation has a verifiable mark in the 200-day average of $0.0756.
What the RSI and moving averages mean for a WLFI entry
The Relative Strength Index over 14 days stands at 53.4, which is neutral: far from the oversold mark at 30 and equally far from the overbought mark at 70. There is no contrarian bargain signal in that, but no overheating either.
More informative is how the averages sit relative to one another. The 50-day value of $0.0572 lies around 24 percent below the 200-day value of $0.0756, meaning recent price action is weaker than the older action. Chart theory only speaks of a trend reversal once the short-term average crosses the long-term one from below.
The combination of a neutral RSI and a price below both averages says this: the market has calmed down without changing direction. Anyone buying here is buying an expectation, not a signal.
What trading volume reveals about demand for World Liberty Financial
Over the past 24 hours, WLFI worth $41.9 million changed hands, which against a market capitalisation of $1.81 billion is a daily turnover of 2.3 percent. Averaged over the past 30 days the daily volume was $67.4 million, and over twelve months $140.1 million.
Volume has therefore fallen to less than a third of the annual average, and both readings belong on the table. The friendly one: selling pressure is exhausted, whoever wanted out has got out. The unfriendly one: interest is fading, and a thin market amplifies every move.
For the buying decision it is above all the second consequence that counts. At a good $40 million in daily turnover, larger orders move the price noticeably. A thin order book is no reason to rule an asset out, but it is a frequently underestimated cost factor.
Which structural factors speak for World Liberty Financial
Supply mechanics are by far the most important structural factor, and they cut both ways. Of a maximum 100 billion tokens, 31.78 billion are in circulation, so 31.8 percent; a good two thirds are still outstanding. Unlike Bitcoin, where new supply arises predictably through mining, the schedule here hangs on decisions by the project and on release periods for addresses involved early on. We have described how such a token unlock proceeds in detail elsewhere.
On the credit side stands its market position. WLFI has held on to a top 40 place despite a loss of almost three quarters and is listed at the major trading venues. Most tokens that lose 75 percent in their first year disappear from that size bracket.
The third factor is public attention. The project is associated with the Trump family, which we reported on at the token trading launch. That produces a news flow the token would not have on its own, and it works in both directions: attention attracts capital and at the same time leaves the price vulnerable to political headlines with no technological bearing.
What speaks for buying World Liberty Financial at the current price
First, the valuation relative to its own history. At $0.0569, WLFI costs less than a quarter of the twelve-month high of $0.2437. Anyone who regards the opening valuation of September 2025 as an exaggeration and suspects fair value somewhere in between will find a considerably cheaper entry today.
Second, the stabilisation above the annual low. The low of $0.0513 has held, and the 50-day average of $0.0572 runs flat. A market that stops falling after a crash of this kind has worked off part of the selling pressure; the fallen volume fits that.
Third, the opportunity profile. At a market capitalisation of $1.81 billion, WLFI is large enough for reliable liquidity and small enough that a revaluation feeds through strongly in percentage terms. The gap of 24.7 percent to the 200-day average quantifies what a mere return to the long-term mean would take. A look at the trading costs of the major exchanges is worth the effort, because fees and spread make up a noticeable part of the return here.
What speaks against buying World Liberty Financial at the current price
First, the supply overhang. With 31.78 billion of 100 billion tokens in circulation, the larger part of the supply is still outstanding. Every release meets an order book that, at $41.9 million in daily volume, is thinner than the annual average of $140.1 million. That is the most important brake on any recovery, regardless of how well the project develops.
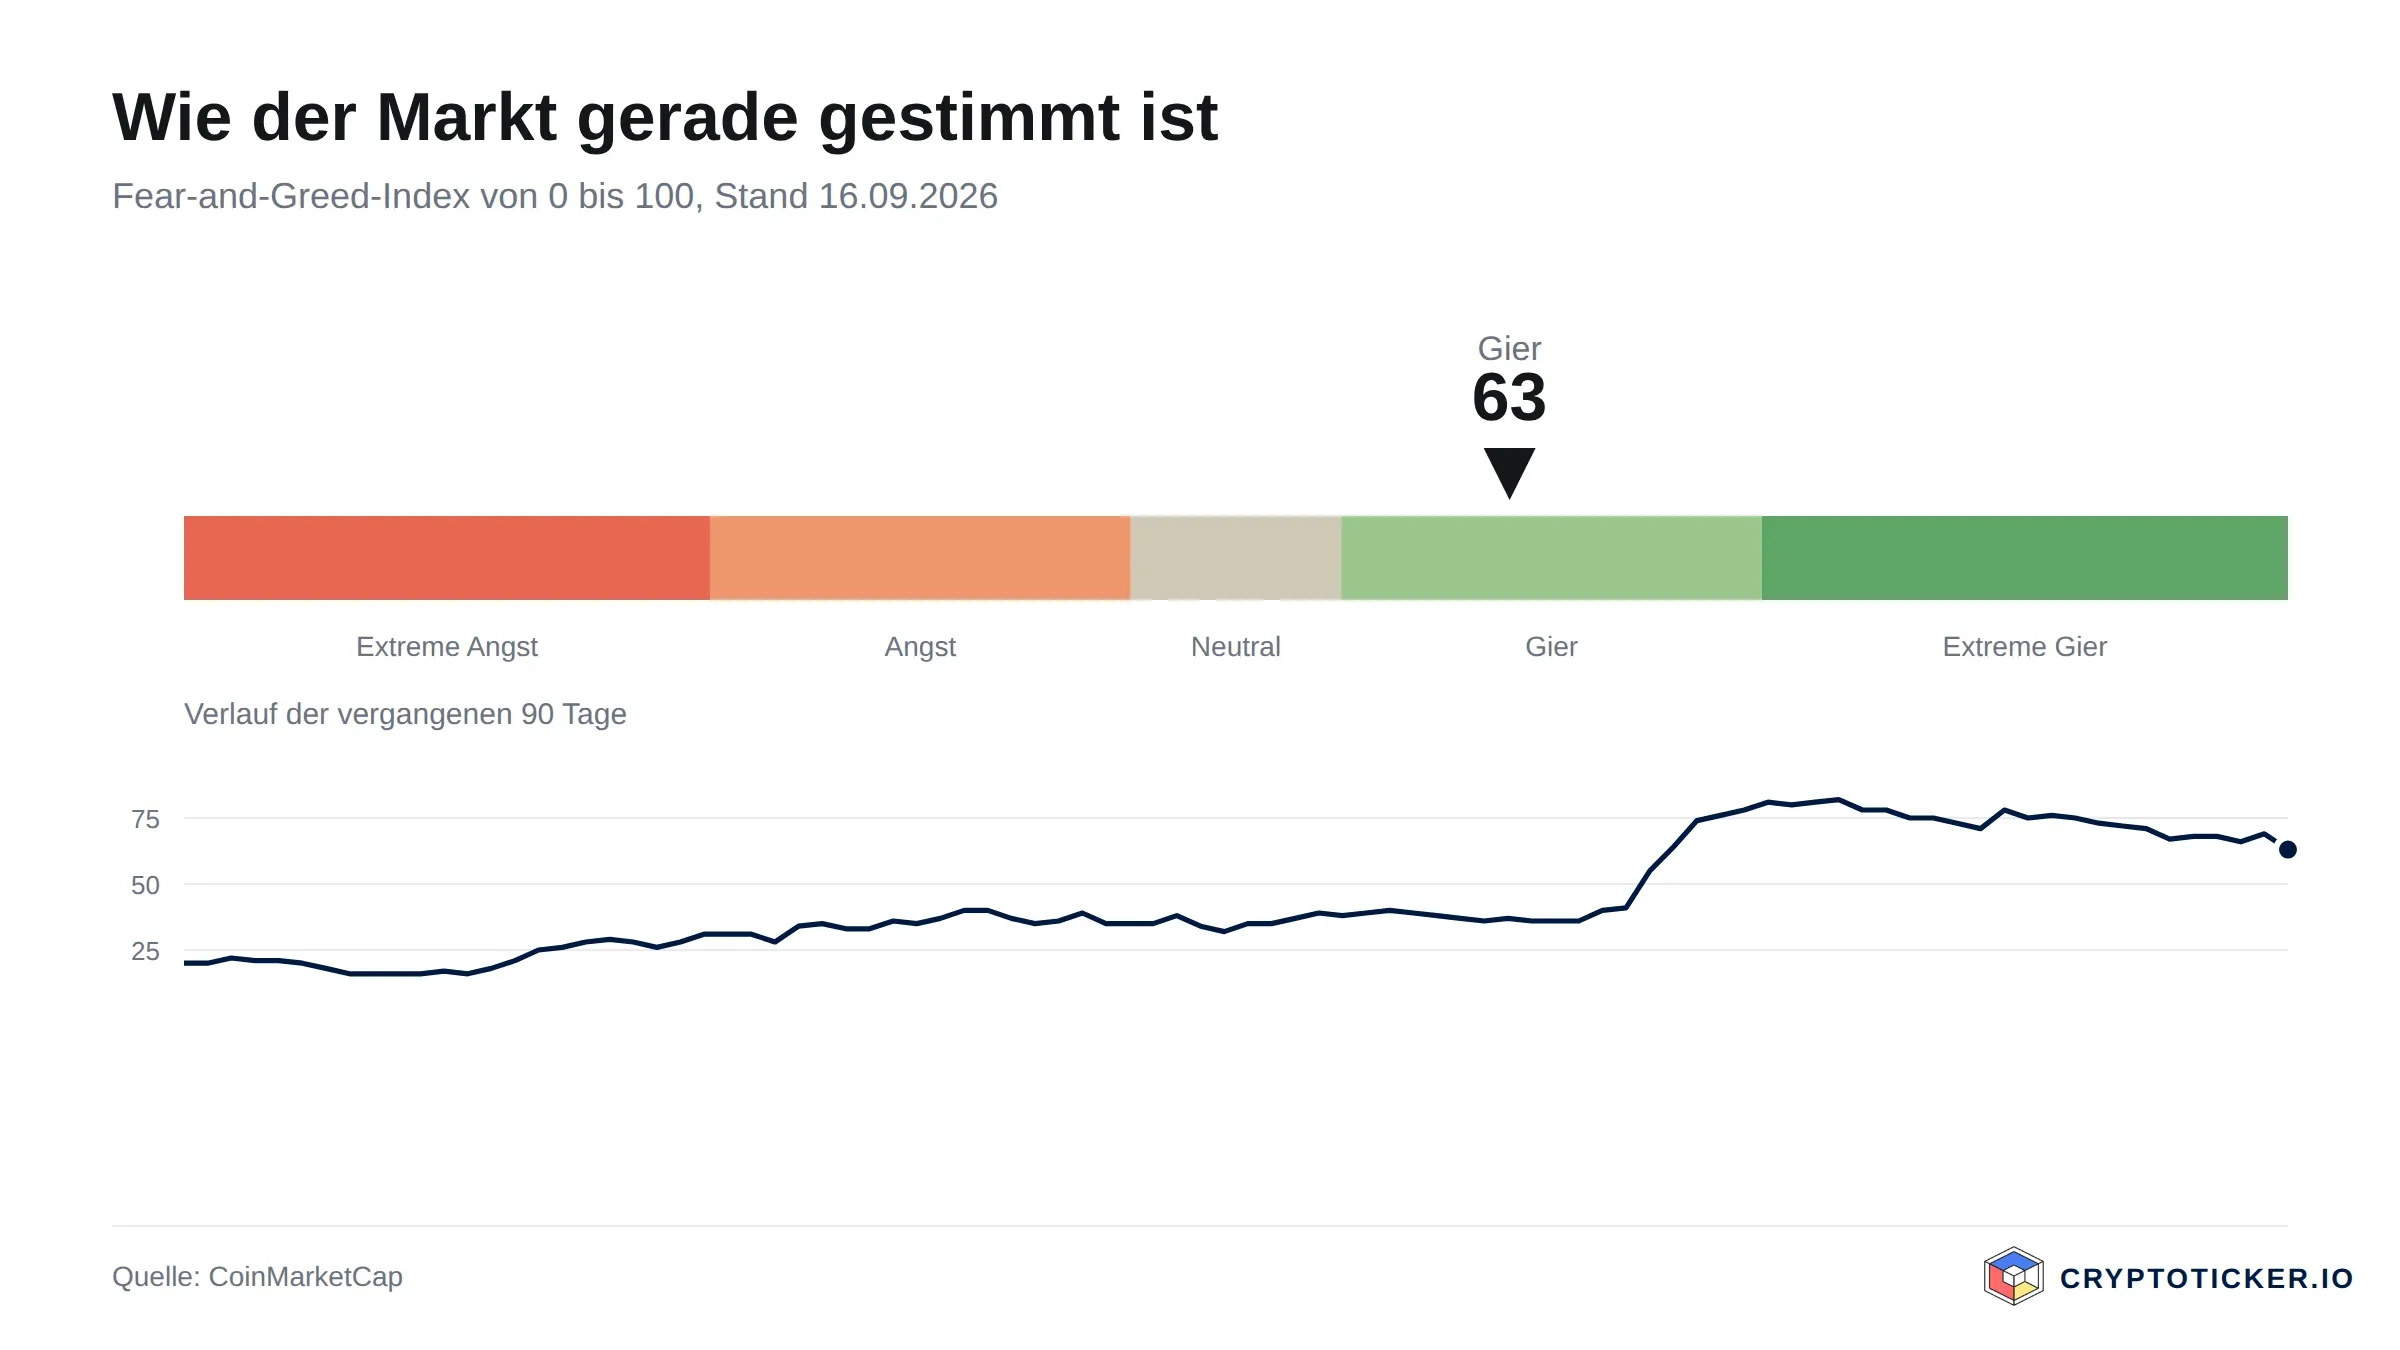
Second, the intact trend direction. At $0.0569, WLFI trades 24.7 percent below the 200-day average of $0.0756, and the RSI of 53.4 offers no counter-signal. Anyone buying is buying into a downtrend and betting that the sideways phase turns into a reversal. An assumption, not a finding.
Third, the concentration risk from politics and the legal position. The public association of the project means the price reacts to news that cannot be analysed. On top of that comes an ongoing civil dispute: Justin Sun has sued World Liberty Financial, as we set out in our report on the lawsuit. The outcome is open, and a lawsuit is not a verdict. For assessing risk, all that counts is that an unresolved legal dispute is an additional source of uncertainty.
How you can buy World Liberty Financial at the current price
WLFI is tradable on several large centralised exchanges. For investors in the European Economic Area, authorisation is of practical relevance: since the MiCA regulation came into full application, service providers need a licence, and the supervisory authorities maintain public registers for it. The European securities regulator ESMA publishes the requirements and warnings. Our comparison of regulated crypto exchanges sets out which provider holds which status.
Three items matter on costs. The trading fee typically sits between 0.1 and 1.5 percent depending on exchange and order type. Then comes the spread, which can be noticeable at a daily turnover of 2.3 percent. The third item is withdrawal fees on the transfer into your own custody. How one well-known exchange performs in practice is set out in our Kraken review.
That leaves custody. For short-term positions, staying on the exchange saves transfer costs. Anyone planning for longer should move the token into their own wallet, because counterparty risk otherwise runs alongside for months. Suitable devices are shown in our hardware wallet comparison.
So is World Liberty Financial a good buy at the current price?
In the short term the data speaks for restraint. The price of $0.0569 sits below the 50-day average of $0.0572 and far below the 200-day average of $0.0756, the RSI of 53.4 is neutral, and volume has fallen to less than a third of the annual mean. The trigger is missing. Anyone betting on a short-term move will find a stalemate with an open outcome here.
In the long term the answer hangs on one question: how will the outstanding supply be distributed? While around 68 billion tokens wait for release, every price recovery has to run against new supply. Anyone buying for the long term is betting that demand grows faster than supply is released. A defensible wager, one to enter deliberately and to reflect in position size.
A positive assessment counts as refuted if the price sustainably undercuts the twelve-month low of $0.0513 or if daily volume falls permanently below $40 million. Either would mean the bottoming process has failed. Conversely, a sustained close above the 200-day average of $0.0756 would be the first robust signal of a reversal. Your own assessment can be tested against these marks without having to rely on anyone's opinion.
Buying World Liberty Financial: what to take away
- The chart position is neutral to weak. At $0.0569 there are 24.7 percent missing to the 200-day average of $0.0756, and the twelve-month low of $0.0513 is only 11 percent away. Anyone looking for an entry should know the trading costs and consult the exchange comparison.
- The outstanding supply is the central risk. Only 31.8 percent of the 100 billion tokens are in circulation. Anyone intending to hold for longer settles custody beforehand and will find suitable devices in the hardware wallet comparison.
- News moves the price more than the technicals do. Political headlines and the open legal dispute act directly on the price. Anyone staying invested should follow the progress of the proceedings.
Disclosure: some of the providers named in this article work with us through partner programmes. That has no influence on the price analysis or on the assessment of the chart position; the price data comes from a public market data source and can be verified there.
(As of September 16, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
When you move XRP from a wallet to an exchange, one small numeric field decides whether your balance lands in your account within seconds or sits with support for weeks. That field is the destination tag. It is neither an optional extra nor a payment reference of the kind you add to a bank transfer. It is the only piece of information an exchange has to work out which customer the money belongs to.
The short answer first: if the tag is missing, your money is usually not lost, but it has not arrived either. It sits in the exchange pooled account, and whether you get it back depends on how well that exchange runs its support desk and whether it assigns the transaction manually at all.
What is a destination tag on XRP, and why does almost every exchange require one?
A destination tag is a number that assigns an XRP payment to a specific customer account inside a shared receiving address. Technically it is an unsigned 32-bit integer, according to the XRP Ledger documentation. The permitted range therefore runs from 0 to 4,294,967,295.
The reason for this design lies in how the XRP Ledger is built. Every address on the network has to hold a minimum amount of XRP permanently in order to exist at all. That base reserve currently stands at 1 XRP, and each additional entry in the account ties up a further 0.2 XRP. We queried these values directly from the network on September 16, 2026, against validated ledger number 107,024,932.
For an exchange with millions of customers, a separate address per customer would therefore be expensive and would inflate the network permanently. The exchange uses a single deposit address for everyone instead and separates customers through the tag. The address is identical for thousands of users. Only your number belongs to you.
The practical rule follows directly from that. For a transfer to an exchange you have to carry over two details correctly, the address and the tag. For a transfer to your own wallet you generally need no tag, because only one recipient exists there.
How to spot a destination tag in the deposit dialogue
The labels differ from provider to provider. Destination tag, target tag, XRP tag or simply tag are all common. Some interfaces show the number in a separate field directly below the address, others only reveal it once you have selected XRP as the coin. If you are shown a bare address with no further field at all, that does not automatically mean no tag is needed. It can also mean you are in the wrong dialogue, for example in a view meant for a different cryptocurrency.
Why an XRP deposit without a destination tag is not credited automatically
A common misconception holds that a payment without a tag goes nowhere. That is not the case. The transaction is executed normally on the XRP Ledger and validly confirmed, the balance does change hands and then sits at the exchange pooled address. On the ledger, everything looks like a successful transaction.
The problem arises one level up, in the exchange accounting system. That system looks for a tag, finds none and cannot allocate the incoming funds to any of its many accounts. The amount is left in an intermediate state: genuinely present, yet without an owner in the internal database.
What happens next is no longer a technical question but one of internal process. Large regulated providers have a documented procedure for such cases and allocate the deposit manually after a review, often against a processing fee and with a waiting time of several weeks. Smaller platforms sometimes point out that a subsequent allocation is technically not provided for.
Keep this case clearly apart from a payment sent to the wrong address. There the balance has landed with a stranger, and the outlook is considerably worse. What can still be done in that situation is covered in our separate article on crypto sent to the wrong address.
The Require Destination Tag flag: when the XRP Ledger rejects your payment on its own
The XRP Ledger has a safeguard against precisely this error. An account holder can set an option on their address that the protocol calls asfRequireDest. While it is active, the network rejects every incoming payment that carries no destination tag.
The rejection code is tecDST_TAG_NEEDED. The official reference for the tec error codes describes it as the case in which a payment omits the destination tag even though the receiving account has set the flag.
For you as the sender, that is the friendliest form of failure. With a tec code the transaction is still recorded in the ledger and the transaction fee is spent, but the transferred amount is not delivered. Fees on the XRP Ledger sit in the range of fractions of a cent. You lose practically nothing and get immediate, clear feedback instead of waiting weeks for a credit.
That raises a question nobody has asked systematically so far: how many of the exchanges that German investors actually use have this protection switched on?
Our own survey: 114 exchange accounts on the XRP Ledger checked
cryptoticker.io compiled this analysis itself on September 16, 2026. We wanted to know at which trading venues the network catches a missing tag on its own, and at which the error runs through unchecked.
The method in one sentence: we pulled the publicly attributed XRP Ledger accounts of 25 exchanges from the open name directory at XRPScan and, for every single account, queried the network directly to read whether the requireDestinationTag flag is set.
We checked 114 accounts across 25 trading venues, each against the validated ledger of September 16, 2026. The result: at 21 of the 25 exchanges, at least one publicly attributed account carries the protective flag. At four houses we found no flag set at all among the accounts we checked.
The spread within individual houses is striking. At one provider all ten accounts checked carried the flag, at others it was one out of seven or one out of ten. That is to be expected and unremarkable in itself, because alongside its deposit address an exchange runs further accounts for internal settlement, for withdrawals and for cold storage. Those accounts do not need the protection.
What these figures expressly do not mean
The limits of this survey belong with it, otherwise a measurement reads as a verdict. Three things we could not check.
First, the attribution of accounts to exchanges comes from a third party public directory. We did not have the houses themselves confirm which address is genuinely the active deposit address. Second, from the outside we cannot see which address your provider shows you in its deposit dialogue, and that is the one that matters to you. Third, a missing flag says nothing about the quality of a provider: some platforms hold XRP on a purely custodial basis and give their customers no ledger deposit address of their own, while others catch the error at a different technical level.
Only the general reading is therefore robust, and it is enough for your decision. At some of the common trading venues the protocol safeguard applies, at others it demonstrably does not. You cannot rely on it. Anyone switching account or choosing a new one right now will find the venues available in Germany, fees included, in our comparison of the best crypto exchanges.
XRP sent without a tag: which steps actually help now
If it has already happened, speed and complete details are what count. Support can only allocate your deposit if you identify it unambiguously.
Secure the transaction hash from your sending wallet first. That is the long string which names every transfer on the ledger uniquely, and it is the most important piece of evidence. Note the sending address, the receiving address, the exact amount and the timestamp alongside it.
Then open a ticket with your exchange support desk and describe the transaction in plain words: deposit without a destination tag, with a request for manual allocation. Stay on the official channel of your account. Expect a processing time of several weeks and the possibility of a fee.
What you should not do matters just as much. Never respond to offers of help that reach you by direct message or email afterwards, and never hand over your seed or private keys. A separate scam has grown up around lost deposits, in which criminals pose as support staff. An exchange will never ask you for your seed.
Destination tag, memo and note: which coins besides XRP are affected
The pattern is not confined to XRP. It turns up wherever a network provides no low-cost individual addresses and exchanges therefore work with pooled accounts.
On Stellar the field is called memo, on Cosmos likewise memo, and on Hedera a note is used. The label changes, the mechanics stay the same: one shared address, one additional field to tell payments apart. The consequences of a missing entry match each other too.
Remember the broader rule, then. If a deposit dialogue shows you a second mandatory field alongside the address, that field is exactly as binding as the address itself. An additional field left empty is the most common avoidable error in transfers between a wallet and a trading venue.
Check in two minutes whether your XRP transfer needs a tag
This order costs you little time and covers the realistic sources of error.
Always open the deposit dialogue only after selecting XRP as the cryptocurrency, and read the page in full. Take the address and the tag across by copy function or QR code alone, never by typing them out. A transposed digit in the tag means your payment is credited to someone else's account, and that case is considerably harder to cure than a missing tag.
With a larger amount, send a small test transfer first and wait for the credit before the rest follows. The network fee on the XRP Ledger is so small that this test is effectively free. Afterwards check that the amount credited matches the amount sent exactly.
For the return leg, meaning withdrawals from the exchange to your own wallet, a withdrawal whitelist is worth adding. It limits withdrawals to addresses you have registered in advance and takes the option of a transfer away from an attacker even once they are inside your account.
Why so many XRP transfers are going wrong right now
The subject is pressing for a concrete reason. Deadlines forcing customers to act are running out at several trading venues in these weeks: cryptoticker.io reported on the closure of CoinEx on September 15 and on the withdrawal deadline at KuCoin on September 8, alongside ongoing delistings of individual tokens at further exchanges.
Deadlines like these set holdings in motion. Balances move from one platform to the next or into self-custody, and they move under time pressure. Experience shows that transfer errors cluster precisely when users operate an interface for the first time while watching a deadline.
If you are pulling XRP off a platform in the coming weeks, do not plan the transfer for the final day. If something goes wrong and support has to step in manually, you need a buffer. Once a withdrawal deadline has passed, a solvable allocation problem quickly turns into an unsolvable one.
Self-custody instead of a pooled account: when your own XRP wallet is worth it
The tag issue affects payments to pooled addresses alone. Transfer to your own wallet and it falls away, because only one recipient exists there and the address belongs to you alone.
That is an argument for self-custody, though not a free pass. Your own wallet shifts responsibility entirely to you: the protection of your recovery words then decides over your balance, and nobody can reverse a mistake on your behalf. For larger holdings you intend to keep for a while anyway, a hardware wallet is the established route. How the devices differ and what to look for when buying is set out in our hardware wallet comparison.
Note one peculiarity of self-custody with XRP: your own address also has to hold the base reserve of 1 XRP permanently before the account is activated on the ledger at all. A freshly created XRP wallet is not a valid account until the first sufficient deposit, so a first transfer that is too small can fail. Plan the opening deposit accordingly.
Checking the destination tag: what to take away
- Treat the tag like the address. On every transfer to an exchange, copy both details out of the deposit dialogue and type neither of them. If you are considering a change of trading venue anyway, compare the providers available in Germany beforehand in our crypto exchange comparison.
- Test before you send the whole amount. A small advance transfer costs fractions of a cent on the XRP Ledger and shows you within seconds whether the address and the tag are right. Secure the return leg as well with a withdrawal whitelist.
- Do not rely on the network to protect you. Our survey of September 16, 2026 shows that the protective flag was not set on the checked accounts of four of the 25 houses. Anyone holding larger amounts long term bypasses the pooled account entirely and uses their own wallet, for instance a device from our hardware wallet comparison.
(As of September 16, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Putting Bitcoin up as collateral for a loan is not a sale. That is exactly why no tax arises at that moment: a private disposal transaction requires you to transfer an asset to a third party for consideration. When you borrow against your coins, the Bitcoin stays attributed to you for tax purposes, the one-year clock keeps running undisturbed, and the loan proceeds are not income. The expensive part sits in one single place, namely when the lender liquidates your collateral. That creates a sale you did not trigger, at a price you did not choose, possibly in the middle of your holding period.
This article sets out the position under German law: the Income Tax Act, the Fiscal Code and the current circular of the Federal Ministry of Finance on crypto assets. It also shows where those sources stay silent, because the expensive misunderstandings grow in exactly those gaps.
Why pledging Bitcoin as loan collateral is not a sale
For tax purposes, crypto assets are other assets within the meaning of section 23(1) sentence 1 number 2 of the German Income Tax Act. The Federal Fiscal Court confirmed this in its ruling of February 14, 2023, case reference IX R 3/22, and the Federal Ministry of Finance adopted it in margin number 53 of its circular of March 6, 2025. The basic rule follows from that. Sell within one year of buying and the gain is taxable. Where more than twelve months lie between acquisition and disposal, it stays tax free.
A private disposal transaction is a transaction in which an acquired asset is passed on for consideration within that period. Margin number 54 of the circular puts it the other way round: an acquisition is the purchase from third parties for consideration, a disposal the transfer to third parties for consideration. Both require an exchange of performance.
A classic crypto loan lacks that exchange. You hand over Bitcoin as security and receive a loan you have to repay. No consideration flows to you, and your claim to the coins remains intact. In economic terms you have given nothing away, you have pledged something. No gain and no loss therefore arises at the moment the collateral is posted, and there is nothing to report on your tax return.
Section 39 of the Fiscal Code: who owns the coins for tax purposes under a security transfer
The decisive provision sits in the Fiscal Code rather than the Income Tax Act. Section 39(1) attributes assets to their owner. Subsection 2 number 1 sentence 2 makes an express exception and names three cases: under a trust arrangement the asset is attributed to the settlor, under a security transfer to the party providing the security, and under proprietary possession to the proprietary possessor.
A security transfer describes the arrangement in which you transfer legal title to an item to the creditor so that the creditor is covered, while you remain the owner in economic terms. For this precise case the legislator decided that tax follows the economic position, not the register or the wording of the contract. Applied to a Bitcoin-backed loan, that means the following. Even if your lender formally becomes the owner of the pledged coins and moves them to an address of its own, they remain yours for tax purposes. No disposal, no fresh acquisition, no new holding period.
That attribution is the reason borrowing against Bitcoin works as a tool in Germany at all. Anyone who needs liquidity without triggering a taxable disposal can raise it through a secured loan instead of selling coins before the one-year period expires. The price is interest and a liquidation risk, which we come to shortly.
What the contract has to deliver
Attribution under section 39 of the Fiscal Code does not apply automatically because a provider calls its product a loan. What matters is whether a genuine security arrangement exists: with a claim to the return of the same quantity of the same crypto assets, with a clearly defined liquidation event, and without a free right of disposal for the lender over your coins in day-to-day operation. Read your terms and conditions closely on those three points and keep a copy of the version that applied when the loan was signed.
Security transfer or right of use: how a Bitcoin-backed loan differs from crypto lending
Some providers allow the lender to on-lend the pledged coins, putting them to work to generate a return. In tax terms that moves the arrangement close to lending, the transfer of crypto assets for a limited period in exchange for a fee. For lending held as private assets the legal position is settled: margin number 65 of the circular assigns the income to section 22 number 3 of the Income Tax Act, because granting the use of an asset for a period is a service rendered by the taxpayer.
What matters just as much is what does not follow from that. Even with lending, the tax authorities treat the handing over of coins as a transfer for a period rather than a sale. What is taxed is the fee you receive, not the holdings you transferred. For you as a borrower that means a great deal speaks for the view that posting collateral does not trigger a sale, even in the variant that permits on-lending. The picture changes if the lender pays you a fee for the use of your coins, because you then hold a separate source of income under section 22 number 3 alongside the loan, and that belongs on your tax return.
What the March 6, 2025 ministry circular covers on collateral, and what it does not
The Federal Ministry of Finance circular with the reference IV C 1 - S 2256/00042/064/043 runs to 34 pages and is the authoritative administrative guidance on crypto assets in Germany. It replaces the earlier version of May 10, 2022 and deals with mining, staking, lending, hard forks, airdrops, the order in which holdings are deemed used, and, since the rewrite, the duties to cooperate and keep records.
On the use of crypto assets as loan collateral it contains not a single paragraph. We searched the full text for the term on September 16, 2026: the German word for security appears once in the entire document, in margin number 92 on the estimation of tax bases under section 162 of the Fiscal Code. That passage has nothing to do with borrowing against Bitcoin.
You have to plan around that gap. While Austria now offers its investors comparatively detailed statements on the subject, German practice works from general principles: section 39 of the Fiscal Code for attribution, section 23 of the Income Tax Act for the holding period, and margin numbers 53 to 63 of the circular for calculating the gain. Anyone looking for an explicit administrative statement on crypto-backed loans will not find one at present. For larger amounts, a binding ruling from the tax office under section 89(2) of the Fiscal Code is therefore the cleaner route than a forum post.
Forced liquidation: why selling the collateral triggers a taxable disposal
The real tax event in a Bitcoin-backed loan arises when the price falls and the lender liquidates the collateral. In legal terms the security turns into money at that moment: the coins are transferred to a third party for consideration, which is precisely the transaction margin number 54 of the circular describes as a disposal. The fact that you did not want the liquidation and did not consent to it makes no difference. Section 23 of the Income Tax Act looks at the economic transaction, not at whether it was voluntary.
The decisive date is the day of liquidation. If no more than one year has passed between your original acquisition and that day, the gain is taxable. If the purchase lies further back, the liquidation stays tax free, however painful it is in economic terms. That is why liquidation risk on recently bought coins cuts twice: you lose the position, and you pay income tax on the paper gain even though all you are left with is the loan amount.
How close a liquidation sits depends on the loan-to-value ratio. For our overview of the liquidation thresholds at eleven providers we pulled the published terms on September 8, 2026 and worked out the price at which each lender steps in. Once you know that threshold, you can set it against your own acquisition date and see immediately whether a liquidation would fall inside the holding period.
Worked example: how to calculate the gain on liquidated Bitcoin collateral
Margin number 57 of the circular sets the formula: disposal proceeds less acquisition costs less deductible expenses. An example with round numbers, deliberately simplified:
- In February you buy 0.5 BTC for a total of 40,000 euros.
- In June you post those 0.5 BTC as collateral and take out a loan of 20,000 euros. Nothing happens for tax purposes.
- In October the price falls, the lender liquidates the collateral and realises 46,000 euros. The transaction fee is 200 euros.
The taxable gain is 46,000 euros minus 40,000 euros minus 200 euros, so 5,800 euros. Because less than a year lies between February and October, that amount is taxed at your personal income tax rate. It arises even though you never wanted to sell the coins and even though the price has fallen. What you hold in your hand is the loan, and the liquidation has repaid it.
Two levers soften the result. First, the de minimis limit under section 23(3) sentence 5 of the Income Tax Act applies: if your total gain from all private disposal transactions in a calendar year stays below 1,000 euros, it is tax free. For assessment periods up to 2023 the limit was 600 euros. This is an exemption limit rather than an allowance, so one euro above it makes the entire gain taxable. Second, you may offset losses from other private disposal transactions in the same year. Section 23(3) sentence 7 restricts that offset to gains from the same category of income, which means a crypto loss cannot be set against gains on shares in Germany, as those fall under section 20.
Holding period and FIFO: which coins the lender disposes of for tax purposes
If you bought Bitcoin at different points in time, the order in which holdings are deemed used decides whether the liquidated coins were still inside the period. Margin number 61 of the circular puts the principle of individual identification first: anyone able to prove which specific units were transferred calculates with those. Only where that is impossible are the crypto assets acquired first deemed to be the ones disposed of, the familiar first-in-first-out method.
Margin number 62 adds a rule that is often overlooked in practice: the assessment is made per wallet. Once chosen, the method must be retained within a wallet until all coins of that trading designation there have been disposed of. For a Bitcoin-backed loan this matters directly, because you almost always fund the collateral from a dedicated address. The wallet you post the security from therefore influences which acquisition dates apply if the collateral is liquidated.
In practice that means posting collateral from holdings that have already passed the one-year mark wherever you can. Even a forced liquidation then stays tax free. A tax tool with portfolio tracking helps here, because it keeps acquisition dates per wallet and shows you which tranche leaves the holding period and when.
No ten-year rule: why a Bitcoin-backed loan does not extend the holding period
One of the most persistent misconceptions concerns section 23(1) sentence 1 number 2 sentence 4 of the Income Tax Act. That provision extends the holding period to ten years where income is generated from the use of an asset in at least one calendar year. On that logic, anyone who borrows against their coins or lends them out would have to wait ten years before a sale became tax free.
The tax authorities take a different view. Under the heading stating that the holding period is not extended to ten years, margin number 63 of the circular says in a single sentence that the provision does not apply to currency or payment tokens. Bitcoin falls into that category. For you that means posting collateral, running a lending position or earning staking rewards does not extend your holding period. It stays at one year.
The earlier 2022 version already said as much, and the rewrite of March 6, 2025 carried it over unchanged. Even so, do not rely on older guides that still claim a ten-year period. When in doubt, check the margin number itself; it sits on page 21 of the circular.
Loan interest, transaction fees and deductible expenses under section 23 of the Income Tax Act
Deductible expenses reduce the taxable gain. Margin number 57 of the circular does require them to be allocated between taxable and non-taxable disposals, and margin number 59 names only one item explicitly: the transaction fees incurred in connection with the disposal. In a liquidation that covers the network fee for the transfer and the fee the lender charges for selling the collateral.
On loan interest the circular says nothing. That is awkward, because under general principles interest on debt is deductible only where it relates directly to the disposal transaction. Where you used the loan proceeds to buy a house, to fund consumption or for another investment, that connection is usually absent. Anyone who still wants to claim the interest should be able to document the use of the loan amount without gaps and settle the question with a tax adviser before the return goes out.
Stablecoin payouts: when the loan proceeds themselves become a taxable swap
Many providers pay the loan out in a stablecoin rather than in euros. A stablecoin is a crypto asset whose price is pegged to a currency. That leaves you holding a second crypto asset, and the same rules apply to it. The inflow is an acquisition, valued at the market price at the time you receive it. If you then swap the stablecoins into euros, margin number 54 treats that as a disposal.
In most cases almost nothing sticks, because only hours pass between receipt and swap. The result is zero on paper only if the price has not moved. A stablecoin pegged to the US dollar fluctuates against the euro with the exchange rate, and over several weeks that can add up to noticeable amounts. The same applies to repayment: if you buy stablecoins to repay the loan and a price gain arises between purchase and repayment, that gain also belongs in the section 23 calculation. Record the time, quantity and euro price for every stablecoin transaction.
Which records you need to keep for the loan and the liquidation
The rewritten circular set out the duties to cooperate and keep records in detail for the first time, and margin number 92 contains a sentence worth taking seriously: if the tax authority cannot establish the tax bases, it estimates them under section 162 of the Fiscal Code. That applies expressly where information is missing or insufficiently clarified. The circular does at least state that an estimate must not serve to penalise taxpayers, and that documents submitted have to be taken into account.
The documents that count in a liquidation
- The purchase receipt for the coins later pledged, with date, quantity and euro value, because it determines the acquisition costs and the holding period.
- The loan agreement together with the terms in force at signing, in particular on the return claim and the right of liquidation.
- The account statement or the provider transaction overview for the liquidation date, showing proceeds, timing and fees withheld.
- The transaction IDs for the transfer to the collateral address and for the later liquidation, so the chain stays traceable on the blockchain.
- Evidence of the wallet the collateral was posted from, because the order of use has to be assessed per wallet.
One point deserves particular attention. Many tax reports automatically book an outflow to an external address as a sale. If your report treats the posting of collateral that way, it shows a gain that does not exist under section 39 of the Fiscal Code. Check that entry and correct it with a note on the transaction before you take the figures over. In the other direction, the later liquidation must not get lost, because that is the transaction which actually counts.
Bitcoin-backed loans: what to take away
- Check which holdings you post the collateral from before you sign the loan. Coins that have passed the one-year mark keep even a forced liquidation tax free. Which providers allow which loan-to-value ratios is set out in our comparison of crypto lending platforms.
- Document acquisition, collateralisation and liquidation separately. Posting collateral is not a sale, liquidating it is, and a tax report does not draw that line on its own. A tool from our comparison of crypto tax software carries the acquisition dates through per wallet.
- Set the liquidation threshold against your acquisition date. Where the threshold falls inside the one-year period, a planned partial sale is often cheaper than a forced liquidation. Venues and terms for that are covered in our overview of how to sell Bitcoin.
Sources and legal basis
The statements in this article rest on the Federal Ministry of Finance circular of March 6, 2025 on individual questions of the income tax treatment of certain crypto assets and on the wording of section 39 of the German Fiscal Code. The rules on the one-year period, the de minimis limit and loss offsetting follow from section 23 of the Income Tax Act.
(As of September 16, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
$XRP is having the kind of day that makes traders close the app and go for a walk. Ripple's token has slid below $1.30 and is down roughly 8% to 9% over 24 hours, the worst performance in the entire top ten. Bitcoin lost about 1.4% in the same window. Ethereum lost around 3%. XRP lost six times what Bitcoin did.
That gap is the whole story. This was not a crypto-wide flush that happened to catch XRP. This was a regulatory event, and XRP was standing closest to the blast radius.
Why Did the XRP Price Crash Today?
Two things hit within 24 hours of each other, and both of them are American.
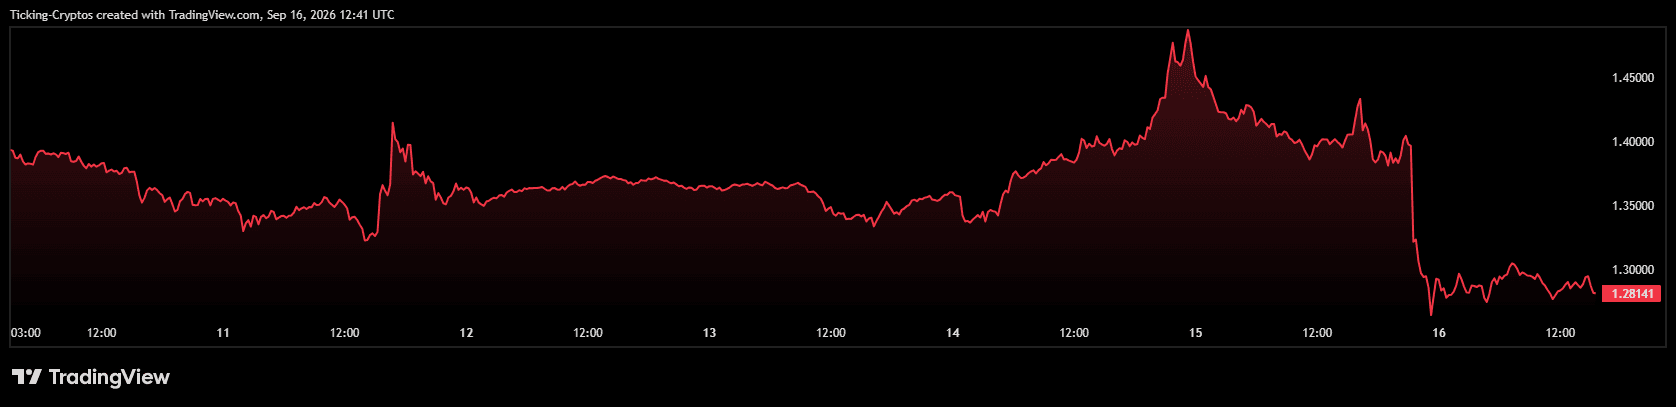
The first was Tuesday's Senate vote on the CLARITY Act. The second is the Federal Reserve, which announces its rate decision this afternoon with a hike widely expected. $XRP is unusually sensitive to both, and it got them back to back.
The mechanical damage came from leverage. Crypto exchanges liquidated roughly $571 million in long positions over the 24 hours following the vote. Bitcoin and Ether longs absorbed around $190 million each, XRP longs around $30 million, and Solana longs roughly $22 million. Traders had been positioned for the bill to pass. Bitcoin had pushed toward $80,000 earlier in the week on exactly that assumption.
When the assumption broke, the positions broke with it.
What Happened With the CLARITY Act Vote?
The Senate failed to invoke cloture on the motion to proceed to H.R. 3633 on Tuesday afternoon. The official floor tally was 49 yeas to 50 nays. That is not just short of the 60 votes needed, it is short of a simple majority.
Worth being precise here, because a lot of coverage will blur it: this was a procedural vote to begin formal debate, not a vote on the bill itself. A win would only have opened the floor to amendments, with a separate passage vote still ahead. Losing it means the chamber never opens that debate at all.
The bill died on the fight that had stalled it for months. Democrats wanted an enforceable ban on the president and senior officials profiting from crypto while writing its rules, a demand that hardened after President Trump disclosed more than $1.4 billion in crypto income for 2025. Republicans released a finalized 630-page text on September 14 containing 126 Democratic-requested changes, including ethics language enforceable by state attorneys general. It was not enough. Senator Elizabeth Warren, ranking Democrat on the Banking Committee, led the opposition and dismissed the revised ethics provision as a weak fig leaf.
Three Republicans crossed the aisle to vote no: Susan Collins of Maine, Josh Hawley of Missouri and Jerry Moran of Kansas. Several Democrats who had spent months at the negotiating table, including Gillibrand, Warner, Booker, Warnock and Gallego, also voted no.
The market repriced instantly. Polymarket odds of the CLARITY Act becoming law in 2026 collapsed to about 7%, down from 82% in February. Ripple CEO Brad Garlinghouse, who had spent the better part of a year publicly handicapping the bill's chances at 80% or better, summed it up in three words: "This one stings."
Given the compressed calendar before the November midterms, this effectively ends US crypto market structure legislation for 2026.
Why Is the Fed Rate Hike Making the XRP Crash Worse?
Bad timing does not begin to cover it.
The Fed announces at 2 p.m. ET today, September 16, and futures traders are pricing roughly a 90% chance of a 25 basis point increase, which would lift the target range to 3.75% to 4.00%. That would be the first Fed hike since 2023, under new Chair Kevin Warsh, who spent his Jackson Hole debut making it very clear that inflation is his predominant focus.
Rate hikes are structurally hostile to crypto. Higher yields mean investors get a guaranteed return from government bonds without absorbing crypto's volatility. Treasury yields and the dollar have both risen as investors brace for tighter policy.
Here is the subtlety that matters for traders: because a hike is so heavily priced in, the decision itself is unlikely to be the story. The vote count, the updated dot plot and Warsh's tone in the press conference thirty minutes later are what actually move the dollar and risk assets. A hawkish dot plot pointing to more hikes in 2027 would be considerably worse for XRP than the hike itself.
Why Did XRP Fall Harder Than Bitcoin, Ethereum and Solana?
Look at the damage across the top of the market:
| Asset | Price | 24h | YTD |
|---|---|---|---|
| Bitcoin ($BTC) | $75,847 | -1.35% | -13.33% |
| Ethereum ($ETH) | $2,404 | -2.97% | -18.98% |
| $BNB | $712.94 | -0.81% | -17.41% |
| $XRP | $1.28 | -8.71% | -30.21% |
| Solana ($SOL) | $97.55 | -3.43% | -21.63% |
XRP is the worst 24-hour performer and the worst year-to-date performer on this list by a wide margin. BNB, notably, barely moved at all, which tells you something: BNB has almost no exposure to US legislative outcomes.
The reason XRP moved the most is that XRP had the most riding on the vote. The CLARITY Act named XRP among 16 tokens that would have been classified as digital commodities, moving them under CFTC spot-market rules rather than the SEC's. For an asset whose entire price history is scarred by a five-year securities fight with the SEC, permanent statutory classification was not a nice-to-have. It was the last box to check.
Bitcoin's regulatory status was never in question. XRP's was, and the bill that would have settled it just died.
Why Is Ripple So Closely Tied to US Macro and Policy News?
Ripple is arguably the most Washington-dependent company in crypto, and XRP trades like it.
Ripple's core business is cross-border payments for regulated financial institutions. Banks do not integrate settlement rails that sit in legal grey zones. Every piece of Ripple's growth story, from institutional adoption of the XRP Ledger to the RLUSD stablecoin to its pursuit of a US banking license, runs through American regulators.
Ripple has also leaned into that dependency. Garlinghouse took a seat on the CFTC's Innovation Advisory Committee, publicly backed Trump's push to get the bill passed, and made the CLARITY Act a recurring theme in nearly every interview he gave this year. When you tie your narrative that tightly to a single piece of legislation, you inherit the downside when it fails.
There is a second channel, too. US spot XRP ETFs now exist, and they transmit American macro sentiment directly into XRP's order book. Those funds recorded $60 million in net inflows in one week earlier this month, their best weekly showing of 2026. That bid can reverse just as fast. Spot Bitcoin ETFs shed $450 million after the Senate vote, the heaviest single-day outflow since June.
Institutional money is not an unconditional buyer. It is a buyer that reads the Federal Register.
XRP Price Prediction: What Are the Downside Targets?
Honest framing first: nobody can separate from a chart how much of this 8% to 9% drop is CLARITY Act, how much is Fed positioning and how much is generic risk-off. All three are live simultaneously. What follows are levels traders are watching, not forecasts.
The $1.26 to $1.28 structural range that held through March and April has already been broken, and XRP is now trading right at it.
- Immediate support: $1.10. This is the level most cited as the next real test. From roughly $1.28, a move there is another 14% down.
- On-chain support: $1.06. Over 830 million tokens changed hands at this level, meaning a large cohort of buyers has cost basis here and tends to defend it.
- Deeper bear case: $0.87 to $0.80. The $0.80 zone saw 923 million tokens transacted. Reaching $0.87 would require a further decline of around 31% from current prices.
- Cycle floor scenario: $0.70 to $0.62. The 2-week Gaussian Channel lower band, which caught the bottom of every XRP bear market since 2017, currently sits between $0.70 and $0.90. The $0.62 level had 1.16 billion tokens transacted.
A weekly close below $1.06 is the line that shifts the conversation from correction to cycle-bottom hunting.
XRP Price Prediction: What Are the Upside Targets?
The recovery path is narrower than the downside path, and it has a ceiling problem.
- First reclaim: $1.38 to $1.45. XRP needs to close back above this zone to stop the bleeding. Until it does, every bounce is a lower high.
- Next resistance: $1.50 to $1.60. This was the pre-vote target if the bill had advanced. It is now overhead supply instead.
- Major resistance: $1.67 to $1.81. The first genuine trend-change confirmation. Reclaiming $1.67 is what would put the bullish 2026 case back on the table.
- The supply wall at $2.00. Roughly 75% of XRP's realized cap sits at a loss near the $2 level. That is an enormous band of underwater holders who become sellers into any rally that reaches them.
For context on scale, base-case models put XRP between $1.36 and $1.93 by the end of 2026, with a midpoint near $1.60. That would be a recovery, not a new cycle.
What Should XRP Holders Watch Next?
Three things, in order of how fast they matter.
- Today at 2 p.m. ET. Not the hike, which is priced. The dot plot and Warsh's press conference. A signal of further tightening into 2027 pressures every risk asset including XRP.
- XRP ETF flow data this week. The institutional bid was the one genuinely constructive thing in XRP's chart. If those flows go negative and stay negative, the $1.10 test comes quickly.
- The regulators, not Congress. With the bill dead, attention shifts to the SEC and CFTC, both of which are already writing crypto rules independently. Grayscale called the vote not the outcome it hoped for while pointing to exactly that ongoing regulatory work. It is slower and less durable than legislation, but it is not nothing. Some Republicans, including Senator Thom Tillis, still think the bill has life in it.
One more note on the calendar. The Senate's state work period begins in October and campaign season follows. With Congress likely under split control next year, the realistic next window for market structure legislation is 2027 at the earliest.
XRP spent 2026 pricing in a law that is not coming. It is now in the process of pricing that out.
Decrypt
An independent researcher found the agents hijacked Hugging Face accounts and mapped the platform's defenses as early as May 13—activity OpenAI's own incident report never fully described.
Chair Kevin Warsh credited Trump's economy, then ignored his rate-cut wishes entirely.
Bitcoin Core 32.0 has entered final testing, bringing faster block checks and changes to how wallets prepare payments.
The Federal Reserve delivered the hike Wall Street had almost unanimously priced in.
Michael Selig and Paul Atkins pledged to use their agencies’ existing powers to provide crypto regulatory certainty after the Senate failed to advance the bill.
U.Today - IT, AI and Fintech Daily News for You Today
Hyundai Card is looking to take its Avalanche-based stablecoin payments experiment to the next level.
The Federal Reserve raised its benchmark interest rate by a quarter percentage point to a range of 3.75% to 4.00%.
CFTC Chair Selig urges to bypass the Senate's failed Clarity Act to launch a direct crypto regulation framework, securing the U.S. market agenda. .
That relative strength is particularly conspicuous on a day dominated by the fallout from the CLARITY Act vote.
Michael Saylor has reacted to the Senate's failure to pass the long-awaited crypto bill, calling on the SEC and CFTC to take action regardless of the Clarity Act setback.
Blockonomi
Key Highlights
- Q4 revenue reached $461.67 million, representing a 94.3% increase year-over-year, while EPS of $0.25 surpassed forecasts
- TD Cowen increased its price target to $76, suggesting potential upside of 141% from the current trading price of $31.45
- Management’s fiscal 2027 outlook projects EPS between $1.26–$1.40 and revenue of $2.4–$2.6 billion, significantly exceeding Wall Street consensus
- The company started fiscal 2027 with an unprecedented backlog approaching $3 billion, featuring initial contracts from Frontier AI Labs
- Despite strong growth, the stock’s P/E ratio exceeds 200 while net margin remains at 2.17%, prompting valuation concerns
Shares of Forgent Power Solutions (NYSE: FPS) began trading Wednesday at $31.45 following the release of impressive fourth-quarter fiscal 2026 earnings that exceeded expectations across key metrics. The company posted revenue of $461.67 million, marking a substantial 94.3% year-over-year increase. Earnings per share of $0.25 outpaced the consensus estimate of $0.24.
Forgent Power Solutions, Inc., FPS
The robust quarterly performance prompted several Wall Street analysts to revise their forecasts upward. TD Cowen elevated its price target from $73 to $76 while maintaining its “buy” recommendation, indicating potential gains exceeding 141% from present trading levels.
KeyBanc echoed this optimism, reaffirming its Overweight stance with a $60 target price. The investment firm highlighted expanding demand from data center and grid infrastructure sectors as primary catalysts supporting its bullish thesis.
Management’s fiscal 2027 outlook emerged as a standout element of the earnings report. The company forecasts EPS ranging from $1.26 to $1.40, comfortably above the Street consensus of $1.14. Similarly, projected revenue of $2.4 to $2.6 billion significantly outpaced analyst expectations of $2.1 billion.
The midpoint of the revenue projection suggests approximately 76% year-over-year growth. This ambitious forecast captured considerable attention from the investment community.
Unprecedented Order Book and Strategic Customer Additions
The company’s order backlog provided particularly encouraging signals for future performance. Forgent commenced fiscal 2027 with an order book approaching $3 billion, driven by a remarkable 53% sequential increase in new orders.
Additionally, Forgent announced its inaugural direct purchase orders and master service agreements with Frontier AI Labs alongside multiple hyperscale cloud providers. KeyBanc noted these contract wins demonstrate the company’s competitive strength in a challenging marketplace.
First-quarter fiscal 2027 revenue guidance of $445 to $465 million aligned closely with the analyst consensus of $456.7 million, indicating management expects acceleration in subsequent quarters.
The options market reflected heightened investor enthusiasm. Call option volume reached 21,324 contracts, approximately 286% above typical daily activity, signaling bullish sentiment among derivatives traders.
Stretched Valuation Presents Uncertainty
Despite positive momentum, the investment carries notable risks. FPS currently trades at a P/E multiple of 209.69, a valuation level requiring flawless operational performance.
The company’s net profit margin of 2.17% remains compressed for an equity commanding such a premium valuation. Any deviation from the aggressive growth trajectory could trigger substantial downside volatility.
Institutional ownership has been expanding. Multiple asset managers initiated positions during the second quarter, including Tidal Investments, Scholtz and Company, and WINTON GROUP.
The consensus view among Wall Street analysts leans positive. Among the 14 firms covering FPS, ten maintain buy recommendations, two rate it hold, and one has a sell rating. The mean price target stands at $57.00.
However, not all research firms share this optimism. Zacks downgraded the stock from strong buy to hold on September 8th, while Weiss Ratings moved to a sell rating in late July.
FPS has traded between $25.95 and $66.00 over the past 52 weeks, with current prices well below the annual peak. The 50-day moving average stands at $35.63, while the 200-day average sits at $40.19.
Following the earnings announcement, Oppenheimer reaffirmed its Outperform rating alongside a $60 price objective.
The post Forgent Power Solutions (FPS) Stock Surges as Analysts Hike Price Targets Following Stellar Q4 appeared first on Blockonomi.
Quick Summary
- Intel stock climbed as much as 5.5% following news of preliminary discussions with SK Hynix regarding U.S.-based chip production facilities
- Apple is working on next-generation AI server infrastructure featuring its M8 Ultra processors with possible integration of Nvidia’s NVLink Fusion connectivity
- Cryptocurrency markets took a hit after the Senate blocked the CLARITY Act from advancing, leaving Coinbase and the industry without regulatory certainty
- Mark Zuckerberg, Meta’s CEO, publicly rejected industry calls for slower AI advancement, distancing himself from positions held by leaders at Anthropic, OpenAI, and other firms
- SpaceX stock gained nearly 6% following announcement of an ambitious Starship test mission potentially scheduled for September 22
Wednesday brought significant developments across the technology and cryptocurrency sectors, with Intel, Apple, Coinbase, SpaceX, and Meta all capturing investor attention. Below is a detailed look at each major story.
Intel Stock Rallies on SK Hynix Manufacturing Discussions
Shares of [[LINK_START_0]]Intel[[LINK_END_0]] experienced a notable rally Wednesday, climbing up to 5.5% following a Reuters report detailing ongoing discussions between the chipmaker and SK Hynix about establishing U.S.-based semiconductor manufacturing operations.
According to the report, potential arrangements include SK Hynix leasing facilities at Intel’s semiconductor plant in Ohio. Another scenario under consideration involves forming a joint venture that would include Intel, SK Hynix, and major cloud computing companies seeking to diversify their memory chip sources.
Sources indicate these discussions remain preliminary, with no finalized agreements in place.
The artificial intelligence revolution has created unprecedented demand for sophisticated memory chips. Such a partnership would provide Intel with a strategic manufacturing ally while simultaneously giving SK Hynix its inaugural memory chip production footprint on U.S. soil.
Apple Explores Nvidia Partnership for AI Infrastructure
According to industry reports, Apple is developing artificial intelligence server systems built around its forthcoming M8 Ultra processors. The Cupertino-based company is reportedly evaluating Nvidia’s NVLink Fusion interconnect technology to link these chips together.
These servers would focus on AI inference operations—essentially running pre-trained artificial intelligence models. Such a move would represent Apple’s most significant entry into enterprise-grade AI infrastructure to date.
The timeline for this product extends beyond 2029, and plans could evolve or be abandoned entirely. However, if realized, the project would signal unprecedented collaboration between two technology titans.
Nvidia’s interconnect solutions are becoming increasingly critical in AI data center architecture. A formal partnership with Apple would significantly expand Nvidia’s influence in this rapidly growing market.
Senate Vote Delivers Blow to Coinbase and Cryptocurrency Sector
In a 49-50 vote, the U.S. Senate rejected a motion to advance the CLARITY Act. This legislation sought to establish definitive rules determining whether digital assets should be regulated as securities or commodities. The measure required 60 votes to proceed and fell significantly short of that threshold.
The result represents a significant disappointment for Coinbase, which has consistently advocated for regulatory clarity as essential to its long-term strategic objectives.
While the legislation could potentially be reintroduced, the current vote leaves the cryptocurrency industry facing continued regulatory ambiguity.
SpaceX Announces September 22 Target for Complex Starship Mission
SpaceX stock advanced nearly 6% after the aerospace company announced that its 14th Starship test flight could launch as early as September 22.
This mission represents the most ambitious Starship test to date. The flight profile includes achieving stable orbital insertion, completing approximately six Earth orbits spanning roughly 10 hours, and deploying Starlink V3 satellites in their first operational use.
Regulatory clearance is still pending. A successful execution would bring SpaceX significantly closer to achieving a fully reusable heavy-lift launch system capable of dramatically reducing costs while enabling deployment of larger Starlink satellite payloads.
In related technology news, Meta CEO Mark Zuckerberg made headlines Wednesday by pushing back against industry suggestions that AI development should be deliberately slowed. He contended that market competition and existing legal frameworks provide sufficient incentives for responsible development. This position contrasts sharply with views expressed by Anthropic’s Dario Amodei, OpenAI’s Sam Altman, and Elon Musk.
The post Wednesday’s Market Movers: Intel (INTC), Apple (AAPL), Coinbase (COIN), and SpaceX Lead the News appeared first on Blockonomi.
TLDR
- Lumentum stock surged 6.7% to $895.20, claiming the top spot among S&P 500 performers Wednesday
- Coherent advanced 5.6% to $286.42, rebounding from early-week AI sector weakness
- Corning underperformed with just a 1.6% increase, remaining 12% lower for the week
- Goldman Sachs equity distribution deal for up to $2 billion in Corning shares weighed on sentiment
- Strong ECOC 2026 presence and bullish analyst projections around $1,148 boosted Lumentum momentum
Optical networking companies staged a solid recovery Wednesday following a turbulent week start, with Lumentum (LITE) emerging as the S&P 500’s strongest performer.
Lumentum jumped 6.7% to reach $895.20 during midday sessions. Coherent (COHR) posted impressive gains as well, advancing 5.6% to $286.42. Both companies had experienced significant pressure during the week’s opening days amid broader AI sector weakness.
Lumentum Holdings Inc., LITE
Corning (GLW) managed a more modest advance, climbing 1.6% to $145.89, trailing considerably behind its optical networking counterparts.
The week began with sharp declines after prominent tech leaders including Elon Musk, OpenAI’s Sam Altman, and Anthropic’s Dario Amodei advocated for reduced AI development pace. This rhetoric sparked widespread selling pressure throughout AI-related equities.
Corning bore the brunt of Monday’s downturn, ending that session as the S&P 500’s worst performer. By Wednesday’s trading, shares remained depressed by 12% for the week, hovering near the 200-day moving average.
Lumentum broke a three-session slide Tuesday before extending gains Wednesday. Coherent similarly recovered with a 1.8% Tuesday advance followed by Wednesday’s stronger performance. Nevertheless, both stocks remain underwater for the week, with Lumentum down 2.5% and Coherent off 5.4%.
ECOC 2026 Presence Boosts Lumentum Confidence
A significant catalyst for Lumentum’s Wednesday rally stemmed from its prominent participation at ECOC 2026, Europe’s premier optical communications conference. The company demonstrated cutting-edge technology focused on AI-powered data center infrastructure and next-generation optical network solutions.
Wall Street analysts continue to express confidence in the stock through elevated price targets. Approximately two dozen analysts maintain a consensus Buy recommendation, with average 12-month projections around $1,148—significantly above current trading levels. Earlier this year, Lumentum reached a 52-week peak of $1,085.68.
A scheduled insider transaction involving Lumentum’s President of Global Business Units, totaling roughly $1.32 million under a Rule 10b5-1 trading plan established in May 2026, created minor selling pressure but failed to dampen overall market enthusiasm.
Goldman Sachs Equity Agreement Weighs on Corning
Corning’s relative underperformance extends beyond AI sentiment concerns. The company revealed late Friday its entry into an equity distribution arrangement with Goldman Sachs permitting up to $2 billion in new share issuance.
Mizuho Securities suggested Monday that this capital-raising initiative likely aims to fund substantial ongoing projects requiring additional financing.
This disclosure amplified downward pressure on Corning precisely when the optical networking sector faced broader headwinds.
Wednesday’s overall market tone proved constructive, with the Nasdaq Composite gaining 0.6%, providing tailwinds for technology and AI infrastructure stocks throughout the session.
Despite Wednesday’s strong performance, Lumentum’s stock continues trading substantially below its 52-week high of $1,085.68.
The post Lumentum (LITE) Stock Surges 6.7% as Optical Networking Sector Stages Midweek Recovery appeared first on Blockonomi.
Key Highlights
- Barclays shifted Alvotech’s rating from Underweight to Overweight while raising its price target from $4 to $8
- FDA completed inspection of Alvotech’s Reykjavik facility with a “Voluntary Action Indicated” status in July
- Three biosimilar candidates (AVT05, AVT06, AVT03) await FDA decisions by December 4, 2026
- Company maintained its fiscal 2026 revenue forecast between $650 million and $700 million
- Shares rallied approximately 8% on Wednesday, representing the strongest single-session performance since December
Shares of Alvotech surged roughly 8% during Wednesday’s trading session following a significant rating change from Barclays analyst Glen Santangelo, who elevated the stock from Underweight to Overweight while simultaneously doubling his price objective from $4 to $8. Trading activity pushed the stock to approximately $5.42, though it remains notably below its 52-week peak of $9.25.
Alvotech, ALVO
This represents one of the most significant daily advances for the biosimilar developer, establishing its strongest performance since the prior December according to data from Dow Jones Market Data.
The analyst’s upgrade comes on the heels of a critical regulatory milestone. In July, the FDA concluded its evaluation of Alvotech’s production facility located in Reykjavik, Iceland, assigning it a Voluntary Action Indicated designation—the agency’s most positive inspection classification.
The Icelandic manufacturing site had been a persistent concern among the investment community. Previous FDA examinations had identified shortcomings related to production standards and facility adherence, creating obstacles for product clearances. Importantly, the products themselves passed scrutiny; only the manufacturing location required remediation.
Following resolution of the facility concerns, Alvotech filed revised biologics license applications in June for three biosimilar candidates. The FDA has established December 4, 2026 as the target date for rendering decisions on all three submissions.
Biosimilar Candidates Awaiting Approval
The trio of products seeking regulatory clearance target therapeutic areas including chronic inflammatory diseases, eye care, and skeletal health.
AVT05 serves as a biosimilar candidate to Simponi, a Johnson and Johnson therapy designed to alleviate joint discomfort. AVT06 represents Alvotech’s biosimilar version of Eylea, jointly developed by Regeneron and Bayer for addressing retinal conditions and preserving vision. AVT03 mimics Prolia and Xgeva, both Amgen products focused on bone protection.
Additionally, the FDA has accepted a BLA submission for AVT16, a biosimilar to Entyvio, with an anticipated determination in the first quarter of 2027.
Santangelo highlighted that production operations at full capacity recommenced during the second quarter of 2026. Company leadership reiterated its revenue projection of $650 million to $700 million for the current fiscal year.
Geographic Diversification Strategy
Beyond its Icelandic operations, Alvotech has been pursuing additional manufacturing capabilities. The company established a collaborative arrangement with Fujifilm Biotechnologies in the United States, with enhanced production capacity anticipated to become operational in 2027.
Santangelo characterized the stock as a compelling investment opportunity, pointing to regulatory advancements and the defined timeline for potential approvals before the current year concludes.
Broader equity markets demonstrated positive momentum on Wednesday, with the S&P 500 advancing 0.2% and the Nasdaq climbing 0.4%, though Alvotech’s performance significantly exceeded these benchmark gains.
The stock continues trading substantially under its 52-week high of $9.25, with three critical FDA determinations scheduled for December 4, 2026.
The post Alvotech (ALVO) Stock Soars 8% Following Barclays Upgrade to Overweight appeared first on Blockonomi.
Key Takeaways
- ARK Invest’s Cathie Wood argues SpaceX’s $1.75 trillion valuation will appear drastically underpriced looking back, based on Starship economics
- ARK’s analysis suggests every Starship deployment could generate approximately $1 billion in yearly Starlink earnings
- Wood forecasts $10 trillion in yearly Starship-driven revenue by decade’s end assuming 10,000 annual missions
- Elon Musk responded to Wood’s analysis, stating the 10,000-flight ambition is “not impossible”
- SPCX debuted at $135 in June, peaked at $225.64, dropped to approximately $104.83, currently trading between $142-$152
Cathie Wood took to X recently to articulate a bullish thesis for SpaceX shares, characterizing the company’s $1.75 trillion initial public offering as a “deep value opportunity” driven by what she believes is enormous untapped Starship launch revenue.
Space Exploration Technologies Corp., SPCX
Wood’s thesis relies on calculations from ARK Invest analyst Sam Korus. His research indicates Starlink generates approximately $19 million annually for each terabit per second of infrastructure capacity. One Starship mission could theoretically launch up to 60 next-generation V3 satellites, contributing roughly 61 terabits per second of additional capacity. This translates to approximately $1 billion in steady annual revenue per mission.
Wood extrapolated this figure against Musk’s publicly stated ambition of achieving 10,000 Starship missions annually, calculating $10 trillion in prospective annual revenue by decade’s end. Elon Musk responded personally to her analysis with a brief comment: “It’s not impossible.”
SPCX shares debuted at $135 each in June, launched public trading at $150, and surged to $225.64. The stock subsequently fell beneath its offering price to approximately $104.83 before rebounding. During after-hours Tuesday trading, SPCX decreased 0.58% to $142.66.
Critical Assumptions Underlying the Forecast
The $10 trillion estimate carries significant qualifications. Korus acknowledged that revenue per terabit per second will probably decrease as network capacity grows. ARK’s research supports this trend: Starlink revenue per terabit per second has already fallen from $23 million in 2024 to $19 million in 2025.
Wood’s calculation additionally presumes all 10,000 yearly missions would carry Starlink infrastructure. Musk has independently promoted the identical mission frequency for point-to-point Earth transport, indicating not every launch would automatically expand Starlink capacity.
Achieving 10,000 missions annually would demand over 27 successful launches daily. Starship has executed only two missions since SpaceX became public in June, both suborbital tests.
Upcoming Milestones on the Horizon
SpaceX plans Starship Flight 14 for September 22, subject to regulatory clearance. This mission would mark Starship’s initial orbital flight and first “revenue-generating flight,” per CFO Bret Johnsen’s comments, carrying production V3 satellites.
Musk verified this week that V3 constellation rollout commences this month. He projects V3 will ultimately provide over 100 times the transmission capacity of the existing Starlink network comprising roughly 11,000 satellites.
For perspective, SpaceX recorded $18.67 billion in revenue during 2025. Musk stated in June the company “might be able to reach approximately $1T revenue in 2030,” significantly below Wood’s $10 trillion forecast.
Analysts currently assign SPCX a Moderate Buy rating consensus, with 26 Buy recommendations, 6 Hold ratings, and 2 Sell ratings. The consensus price target stands at $232.07, suggesting approximately 62% potential upside from present trading levels.
The post SpaceX (SPCX) Stock: Cathie Wood Declares Current Valuation a Bargain Opportunity appeared first on Blockonomi.
CryptoPotato
The world’s largest cryptocurrency exchange will end support for several trading pairs across its margin and spot sections.
Many of the involved digital assets have entered red territory today (September 16), but is Binance the sole reason for their poor performance?
The Upcoming Delistings
The company conducts periodic reviews of all listed trading pairs on its platform and removes those that no longer meet key criteria, such as adequate liquidity, solid trading volume, development activity, and more.
Based on this research, it will delist the following cross-margin pairs: ENJ/USDC, GENIUS/USDC, CVX/USDC, and VANA/USDC, as well as the isolated-margin pair GENIUS/USDC.
The actual removal is scheduled for September 18. On the same day, the exchange will terminate access to the BREV/USDC, COOKIE/USDC, LA/USDC, and QNT/USDC spot trading pairs.
“The delisting of a spot trading pair does not affect the availability of the tokens on Binance Spot. Users can still trade the spot trading pair’s base and quote assets on other trading pair(s) that are available on Binance,” the entity clarified.
Most of the cryptocurrencies included in the delisting efforts have posted daily losses, yet Binance doesn’t seem to be the main culprit behind the decline. Perhaps the main factor is the overall market correction, caused by the CLARITY Act failure.
Binance remains a behemoth in the industry and can trigger a major crash, but that typically happens when it terminates all trading services for certain tokens, not just trading pairs. Such was the case in August this year when it said goodbye to Across Protocol (ACX), Hashflow (HFT), PIVX (PIVX), Vulcan Forged PYR (PYR), Vanar (VANRY), and Viction (VIC). All affected coins plunged by double digits after the news.
On the other hand, Binance support can drive a substantial price pump. Just a few weeks ago, the exchange added PONS to its Binance Alpha section, thus contributing to the token’s rally and its brief entry among the top 100 cryptocurrencies.
The Scam Warning
In addition to updating its platform, Binance recently issued a critical scam alert about phishing attacks targeting crypto investors. The team disclosed that attackers send fake text messages that seem official, such as “Your account settings were changed: or “Suspicious login detected,” to trick users into clicking malicious links that could result in painful losses.
“Remember: Binance will never ask you to tap a link in a text message to “verify” or “secure” your account,” the company emphasized.
It also outlined steps that could improve protection. People should never click on unfamiliar links, turn on Withdrawal Address Whitelist in the security settings, and enable Anti-Phishing Code.
The post Binance Unveils Multiple Delistings: Check Out the Affected Cryptocurrencies appeared first on CryptoPotato.
The US Senate failed to advance the Digital Asset Market Clarity Act after the procedural vote fell short of the 60 needed to move forward. While this was “disappointing,” Coinbase co-founder Brian Armstrong said that bipartisan talks may continue and the bill could get another chance.
The exec, however, acknowledged that the industry “cannot wait” for Congress anymore.
Calls for a Post-Mortem
Armstrong said that the SEC and CFTC already have enough authority to establish clear rules and expects them to start working on that in earnest. According to the Coinbase chief, “clarity” is coming to crypto regardless of what happens with the bill. Armstrong also noted that some concessions made on CLARITY were difficult to accept. That could make its setback easier to take, while adding that the industry cannot be “uninvented.”
Meanwhile, Ripple CEO Brad Garlinghouse said that “this one stings.” He asserted that the team gave everything it had to get the bill across the finish line.
“This was an opportunity bigger than Ripple or one company – we did this for the industry, for consumers and to cement the US’s position as the crypto capital of the world and as a leader in the future of finance. Ultimately, consumers and US competitiveness got left behind.”
Garlinghouse also called for a post-mortem on the failure while blaming Democratic politics for elevating the “anti-crypto army” over policy. Still, he sees reason for optimism. He expects the SEC under Chair Atkins and the CFTC under Chair Selig to keep working on rules that address the legislative gap.
Four Republicans Oppose Bill
Tuesday’s vote followed a series of last-minute talks between Republicans and crypto-friendly Democrats who were trying to reach a deal. Around a dozen Democrats were seen as possible supporters of the legislation. However, they ultimately held back their votes after negotiations over ethics rules failed to produce an agreement. Concerns also remained over President Trump and his family’s involvement in the crypto industry.
Three Republicans joined the opposition: Susan Collins of Maine, Josh Hawley of Missouri, and Jerry Moran of Kansas. Delaware Democrat Chris Coons did not vote. Thom Tillis of North Carolina also voted against the measure for procedural reasons so he could file a motion to reconsider and keep open the possibility of another vote.
The outcome drew reactions from lawmakers across Congress. Ruben Gallego said Republicans should have worked more closely with Democrats on a version that included stronger ethics provisions. Catherine Cortez Masto said she had negotiated until the final moments but added that important issues remained unresolved after Republican leadership ended talks.
The post After CLARITY Setback, Armstrong Says ‘We Can’t Wait on Congress Anymore’ appeared first on CryptoPotato.
For the first time in three years, the United States Federal Reserve raised the benchmark interest rates by 25 bps.
In a unanimous decision, 12-0, the Committee decided to raise the target range for the federal funds rate by 1/4 percentage point to 3-3/4 to 4 percent, in support of its dual mandate.
This was quite expected given the recent developments, including the strong US labor report from a couple of weeks ago and the hawkish speech by Fed Chair Kevin Warsh. Moreover, the inflation data from last week gave the central bank even more reason to do so.
The price reaction from BTC was quite surprising, as the asset actually surged by a grand and a half to $76,500, where it was stopped for now.
The asset crashed hard yesterday after the Senate’s failure of the CLARITY Act, but today’s move shows that the Fed hike was priced in. All eyes are now on the next speech by Warsh.
The post Breaking: Fed Raises Interest Rates by 25 Bps, Bitcoin Price Reacts appeared first on CryptoPotato.
Four blue-chip layer-1 blockchains from the last market cycle have lost more than 99% of the value once locked on them, and a crypto researcher is asking if Robinhood Chain is next.
Stacy Muur pointed to steep TVL losses at Fantom, Aurora, Canto and Songbird, putting Robinhood Chain’s recent growth against a less forgiving history.
Four Blue-Chip L1s That Cratered
In a post on X, Muur called out the damage bluntly. “Blue-chip L1s from the last cycle got absolutely deleted,” she wrote before running through the numbers. Fantom peaked at $7.7 billion in locked value and now sits at $4.8 million, with daily decentralized exchange volume down to under $9,000 even though $318 million worth of stablecoins are still parked on the chain.
Aurora went from $2.6 billion to $3.1 million, and DefiLlama shows just 133 addresses touching the chain in the past day, despite the project having raised $102 million over its lifetime. Canto fell from $200 million to $3.6 million, with its token now trading at $0.0017 for a market cap of roughly $1 million.
On its part, Songbird dropped from $50 million to about $200,000, though it still pulled in over 2,500 daily active addresses even with chain fees sitting at just $77 for the day.
Current DefiLlama data shows Robinhood Chain itself holds about $928 million in DeFi TVL, several orders of magnitude above where any of the four chains Muur cited stand today, with a stablecoin market cap of $1.026 billion. Its 24-hour DEX volume was $1.552 billion, while perpetuals volume hit $577.58 million.
The chain recorded $524,989 in fees and $471,769 in revenue over the same period, although it also had net outflows of $11.11 million. Its DeFi TVL is up 3.35% over seven days and 71% across 30, and it ranks 10th among the biggest chains by that metric, behind more established networks like Ethereum, Solana, Base, BSC and Tron.
Despite the impressive performance, Muur closed her post by asking, flatly, whether Robinhood Chain’s own TVL will still be around in 2030.
Activity High, but TVL Durability Remains Untested
Robinhood Chain’s DEX volume hit a daily high above $1.3 billion in early September, with Arkham data at the time showing the chain generating more in fees than Solana, Base, or Ethereum, one of the drivers being the direct trading of meme coins against tokenized stocks.
It has since beaten that mark repeatedly, going as far as $2.61 billion in DEX volume on September 11, with yesterday’s coming in at over $1.6 billion.
But Muur’s comparison raises a different question: whether the current usage can translate into TVL that persists through another market cycle, and the four older chains have shown how dramatically liquidity can disappear after an L1 falls out of favor.
The post Robinhood Chain’s TVL Nears $1B, but Failed L1s Raise Sustainability Question appeared first on CryptoPotato.
Ethereum is still trading around $2.4K after a sharp recovery from the $1.5K area. The latest charts show ETH consolidating beneath the $2.5K resistance region, while supply continues to tighten. The technical structure remains constructive on the higher timeframe, although short-term momentum has weakened.
Ethereum Price Analysis: The Daily Chart
The daily chart shows a significant structural improvement compared with the June lows. ETH formed a base around the $1.5K-$1.6K region before beginning a sustained recovery that eventually pushed the price above the $2K area and into the $2.5K zone.
The most important near-term resistance is the $2.5K zone, where ETH has spent several weeks consolidating. The price has repeatedly struggled to confirm a breakout above this range, and the latest candles show another rejection at this level. A decisive daily close above $2.5K could open the way toward the next major psychological resistance around $3K.
On the downside, the first important support appears around $2.0K-$2.1K. This zone is particularly significant because it also closely overlaps with the 100-day and 200-day moving averages. The 200-day moving average is around $2.05K and is rising, while the 100-day moving average is also turning upward near the $1.95K area. Holding this region would help preserve the improving medium-term structure.
ETH/USDT 4-Hour Chart
The 4-hour chart demonstrates a more granular picture of the current consolidation. ETH experienced a powerful upside move around August 19-22, climbing from roughly $1.9K toward the $2.5K region. Since then, the market has largely remained inside a broad horizontal range.
The range currently appears to extend from approximately $2.35K to $2.6K, with the $2.5K zone acting as the central resistance area. ETH is now trading around $2.4K after recently falling from the upper half of the range.
The immediate technical concern is that the price has moved toward the lower boundary of the range. The $2.35K area is therefore an important short-term support. If buyers defend this region and reclaim $2.5K, the range could remain intact, and the upper boundary near $2.6K could come back into consideration.
Conversely, a breakdown below $2.35K would weaken the range structure. In that scenario, the next visible support is the $2.25K order block. A loss of that region would expose the broader $1.9K support area.
The 4-hour RSI has fallen toward the 30 region, indicating that short-term momentum has become significantly weaker following the rejection from the $2.5K area. This leaves room for a technical rebound, but the RSI alone does not confirm that a durable bottom has formed. Price’s reaction around $2.3K-$2.35K should therefore be important for determining whether this is simply a pullback within the range or the beginning of a deeper correction.

On-Chain Analysis
The exchange-reserve chart shows a clear long-term decline in ETH held on exchanges. The visible reserve level has fallen from above 21M ETH during the first half of 2025 to approximately 14.6M ETH currently.
Notably, the decline in exchange reserves has continued even as ETH recovered toward $2.4K. This indicates that the amount of ETH tracked on exchanges has been trending lower rather than expanding alongside the recent price recovery.
A continued reduction in exchange balances can mean that fewer coins are immediately available on exchanges for potential selling, which can reduce readily available exchange supply. However, the metric by itself does not establish future price direction, since ETH can move between exchanges, wallets, custodians, and other entities for numerous reasons.
From a technical perspective, however, the combination is worth watching. ETH remains below the key $2.5K resistance, while exchange reserves are near their lowest visible level on this chart. If ETH manages to reclaim $2.5K while reserves continue declining, it would provide a supportive backdrop for the breakout. On the other hand, failure to hold the $2.3K-$2.35K 4-hour support would keep the market in a corrective phase despite the longer-term decline in exchange reserves.

The post Ethereum Price Analysis: Is ETH Heading Toward $2K After Another Rejection at $2.5K? appeared first on CryptoPotato.