Cryptocurrency Posts
Crypto Briefing
Rhilech's rise and NAVI's potential Worlds qualification could redefine the team's legacy and inspire future talent in competitive gaming.
The post NAVI’s Rhilech vows to prove doubters wrong ahead of Worlds appeared first on Crypto Briefing.
JDG's victory revives their World Championship dreams, highlighting the high stakes and intense competition in the LPL Regional Finals.
The post JD Gaming defeats Team WE 3-1, advances to LPL Regional Finals lower bracket final appeared first on Crypto Briefing.
Anthropic's expansion in AI compute capacity could intensify competition, potentially reshaping market dynamics and influencing AI innovation.
The post Anthropic reportedly told investors it is targeting a doubling of its AI compute capacity in 2027 appeared first on Crypto Briefing.
The US's space weapons deployment escalates global tensions, potentially triggering an arms race and redefining space as a war domain.
The post US confirms space weapons deployment in direct warning to China and Russia appeared first on Crypto Briefing.
Penders' call-up signals a generational shift in Belgian football, highlighting the need for fresh talent as the Golden Generation phases out.
The post Mike Penders called up to Belgian national team for Nations League matches against Italy, France, and Turkey appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Dan Hillery: Digital Credit Could Rival BTC’s $1.5 Trillion Market Cap
Two years ago, Bitcoin-backed digital credit barely existed. Today it’s a roughly $16 billion market and Dan Hillery of UXTO thinks the financialization layer on top of Bitcoin could one day rival the network itself. In the debut episode of The Allocators Edge, Hillery breaks down how variable-rate preferred securities like STRC and SATA are priced, why buybacks keep them anchored near $100 par, and what separates digital credit risk from digital equity risk. He also walks through the structured credit fund he’s building, including its senior and junior tranches.
0:00 — Digital Credit Is the Fastest-Growing Part of Bitcoin’s Capital Structure
1:18 — Why STRC’s Variable Rate Design Has No Precedent in Market History
2:59 — What Flat or Falling Bitcoin Prices Mean for Strategy and Strive
4:17 — Short-Duration Bitcoin-Backed Notes and the Next Five Years of Products
5:45 — The Biggest Misconceptions Investors Have About Preferred Securities
6:58 — How Buybacks and Capital Markets Activity Anchor STRC Near $100 Par
8:09 — Why Major Fund Classes Still Can’t Touch Digital Credit Today
9:10 — Inside the UXTO Credit Fund: Senior and Junior Tranche Structure
10:35 — Where the Leverage Comes From and How Volatility Risk Gets Transferred
11:50 — Liquidity, Redemptions, and Digital Credit in a 60/40 Portfolio
This video is for informational purposes only and does not constitute an offer to sell or a solicitation of an offer to buy any securities. Past performance is not indicative of future results. Investments in digital assets involve significant risk and may result in loss of capital. Both UTXO Management and BTC Inc., producer of BMTV, are owned by Nakamoto Inc. (NASDAQ: NAKA)
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Dan Hillery: Digital Credit Could Rival BTC’s $1.5 Trillion Market Cap first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Treasury Sanctions Iranian Crypto Exchange BitBank Over Bitcoin Transfers to IRGC
The U.S. is continuing to target Iran’s use of bitcoin.
In a Thursday statement, the U.S. Department of the Treasury designated BitBank, an Iranian crypto exchange, as part of Operation Economic Outcast — the Trump Administration’s whole-of-government economic campaign against the Islamic Republic of Iran and its enablers.
The U.S. has sanctioned Iran for decades. This year, the Middle Eastern country has stepped up its use of cryptocurrencies — including bitcoin — in order to skirt around economic penalties.
“Today’s designations of Iranian digital asset infrastructure make perfectly clear that efforts to finance the Iranian regime using cryptocurrencies are not beyond OFAC’s reach,” Secretary of the Treasury Scott Bessent said in a statement.
“If you support the Iranian regime, the Department of the Treasury will sanction you.”
The sanctions target designated Iranian financier Babak Zanjani, along with its software developer, Pishtaz Simorgh Electronic Trade Company, and three of Zanjani’s associates: Hossein Ali Zaker Hossein, Mohammad Mahdi Zaker Hossein, and Seyed Adel Heidari.
Since June, the Iranian Hormuz Safe Marine Services Authority has used BitBank to move bitcoin to the Iranian regime, according to the Treasury.
Thursday’s sanctions aim to hit the “architecture Zanjani built to launder funds,” it added.
“The Department of the Treasury will continue to not only target the Iranian digital asset ecosystem, but also international entities and actors which help facilitate it,” the statement continued.
Iran started a bitcoin-backed insurance service for its counties shipping companies earlier this year.
The U.S. in July said that it had frozen crypto linked to the Iranian regime, mostly in the form of Tether’s stablecoin.
Stablecoins like Tether’s USDT can be frozen by the company that issues the asset. But bitcoin, being decentralized and having no single issuer, cannot.
The U.S. Treasury’s Office of Foreign Assets Control in July said Iran had been dodging sanctions by accepting pay in bitcoin from ships passing through the Strait of Hormuz.
OFAC said at the time that Hormuz Safe, developed by Iran’s Ministry of Economy, “accepts payment in Bitcoin and other digital assets” so it can bypass sanctions.
This post Treasury Sanctions Iranian Crypto Exchange BitBank Over Bitcoin Transfers to IRGC first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Bitcoin Price Unlikely To Be Bothered by Interest Rate Hike: Grayscale
The Federal Reserve hiked interest rates for the first time since 2023 on Wednesday and it sent the bitcoin price — briefly — all over the place.
But then it settled and currently sits a modest 1% higher over a 24-hour period.
And according to asset manager Grayscale’s crypto research team, bitcoin is unlikely to be bothered by the Fed’s decision.
“We believe yesterday’s move was a mid-cycle adjustment, not a cyclical change,” wrote the firm’s head of research, Zach Pandl, in a Thursday note.
“And we doubt the one or two rate hikes expected for 2026 will lead to much change in capital allocation.”
Bitcoin has — in the past but not always — done well in a low interest rate environment. And when the Federal Reserve has in the past increased borrowing costs, the price of the leading digital asset has slid.
That’s because low interest rates means more liquidity for investors to take risks and buy assets like bitcoin.
Pandl added that when the Fed in 2022 started ramping up interest rates to contain inflation, it “probably weighed on the price of bitcoin” because it “meaningfully affected the opportunity cost of holding non-interest-bearing assets.”
But this time feels more like 1997, argued Pandl, when the Federal Reserve did a one off hike and the Nasdaq kept moving higher.
Bitcoin’s price recently stood at close to $76,581, up 18% over the past 30 days. The coin in August benefited from news that the U.S. Treasury would at least double the size of its liquidity-support buyback operations.
The U.S. is currently in the grips of an affordability crisis and inflation is hurting households as oil prices surge.
Federal Reserve Chair Kevin Warsh said the central bank was focused on bringing down inflation.
“The plain fact is that inflation is too high, and has been for too long,” he said on Wednesday.
U.S. President Donald Trump has repeatedly said that he wants interest rates to be lower. Writing on his Truth Social platform on Wednesday, he said: “Interest Rates in the United States should be 1%, or less, because we are the Best Credit in the World — BY FAR.”
This post Bitcoin Price Unlikely To Be Bothered by Interest Rate Hike: Grayscale first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
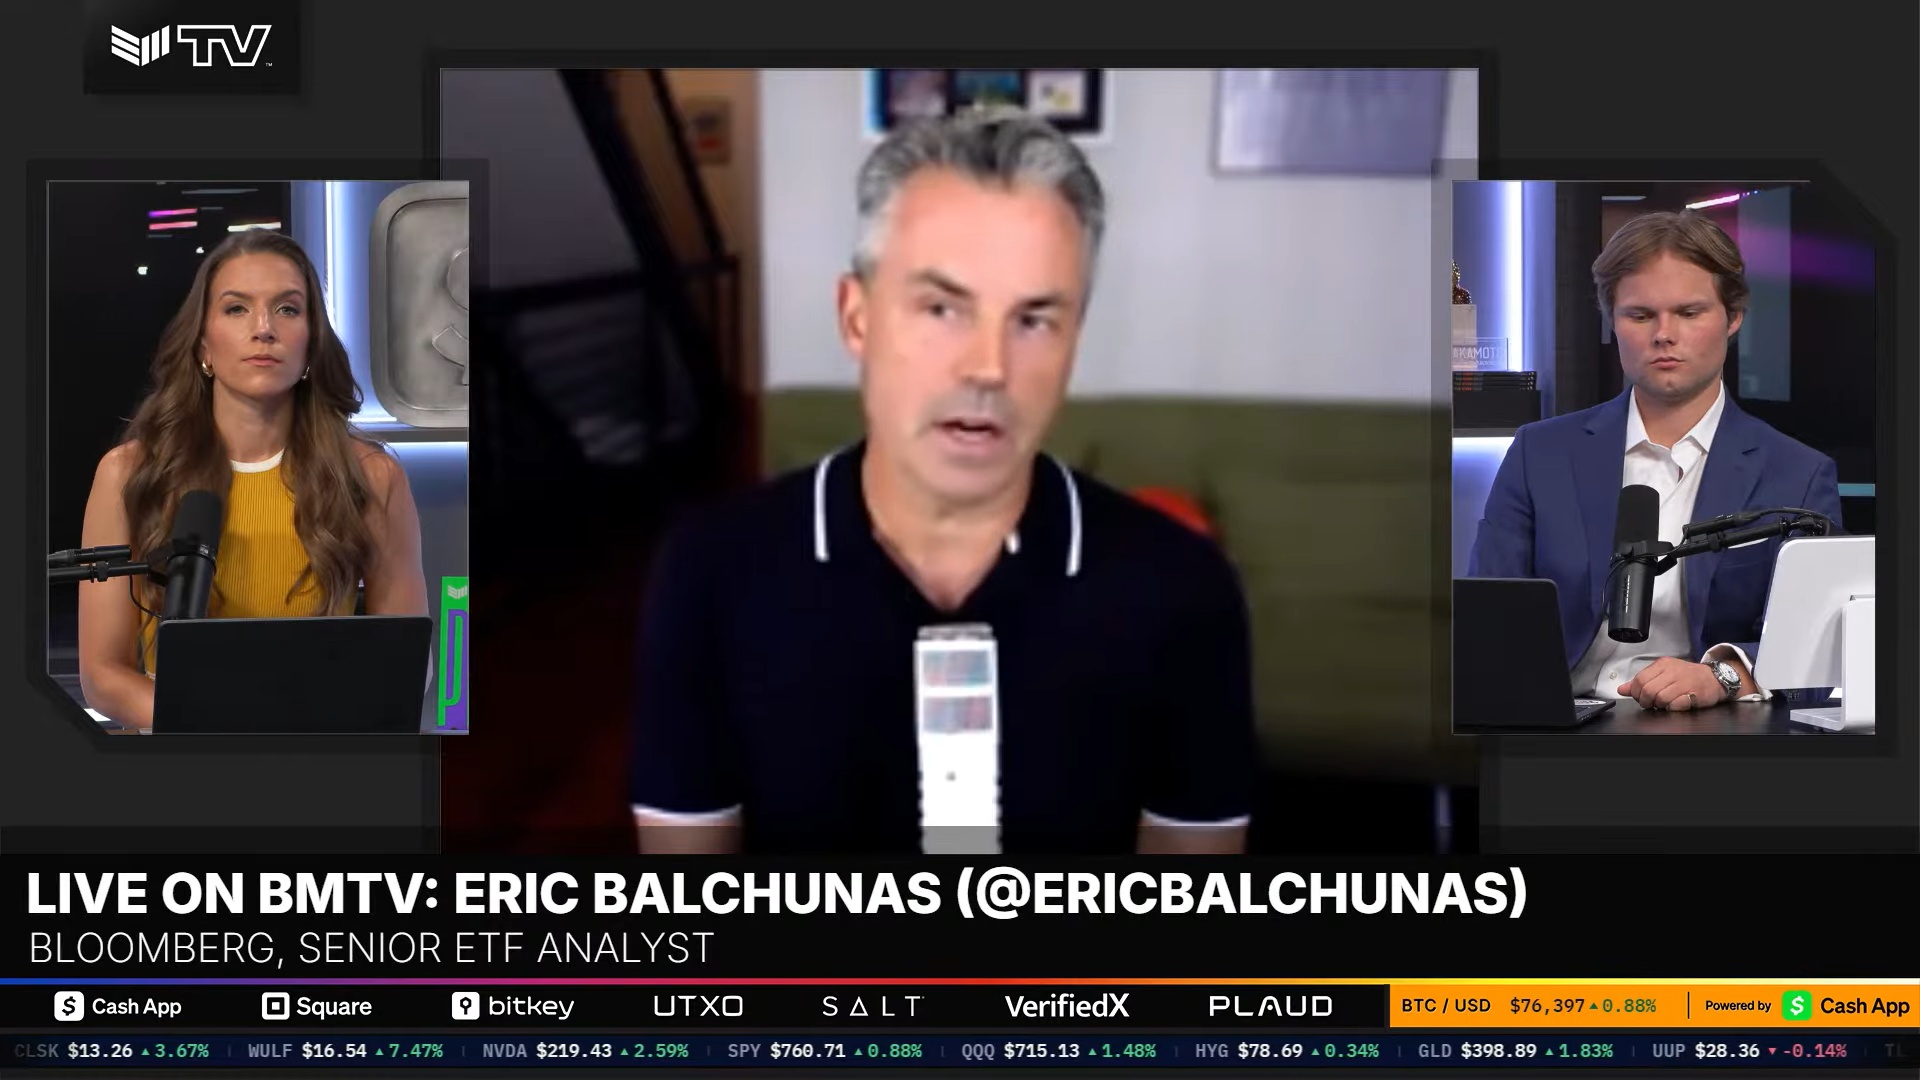
Bitcoin ETFs Could Triple Gold Counterparts as Asset Matures: Expert
Bitcoin exchange-traded funds could be three times bigger than their gold counterparts as younger investors grow up, an ETF expert has said.
Speaking to Bitcoin Magazine TV on Thursday, Bloomberg senior ETF analyst, Eric Balchunas, said that while bitcoin’s price is currently volatile, things would change in the future.
Bitcoin ETFs debuted in 2024 after a decade of denials from the U.S. Securities and Exchange Commission. The ETFs had the most successful launch in the history of the products and currently manage nearly $100 billion in assets, according to Coinglass data.
JUST IN: Bloomberg Senior ETF Analyst Eric Balchunas says Bitcoin ETFs will ultimately triple gold
— Bitcoin Magazine (@BitcoinMagazine) September 17, 2026
"I think as the younger investors get more money and grow up with Bitcoin as their store of value, I do believe that Bitcoin ETFs will triple gold in assets." pic.twitter.com/GU3lp3KIuf
“I do believe the Bitcoin ETFs will triple gold in assets,” said Balchunas.
“I always say Bitcoin is like gold as a teenager — you know, gold is 5,000 years old, it was mentioned 450 times in the Bible. I mean that’s old, and Bitcoin is 17 years old.”
Balchunas went on to say that younger generations could end up being drawn to Bitcoin as the government continues to spend wildly and things become to expensive.
He said that right now, Generation Z is rebelling against government deficits and inflation by voting for socialist politicians, but Bitcoin might be a better bet — because the government can’t confiscate it.
One of Bitcoin’s selling points is its censorship resistance but investors appear to be more focused on buying the asset as a way of hedging against currency debasement.
The so-called debasement trade was hot last year and is becoming popular again in 2026 as investors buy non-yielding assets like gold and bitcoin while the dollar becomes weaker.
Balchunas added that as bitcoin’s price becomes less volatile, big institutions will be more interested in buying the asset as a store of value.
Bitcoin in 2025 has its least volatile year in its short history.
“As that volatility and correlation get closer to gold — look out,” he said.
“I think that’s when you have the inflection moment where even the big institutions are like, okay, it’s finally ready for me to use as a sort of reliable store of value, possibly even a safe haven and an alternative.”
This post Bitcoin ETFs Could Triple Gold Counterparts as Asset Matures: Expert first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
SEC Green Lights Tokenized Stock Trading Despite Clarity Act Fail
The U.S. Securities and Exchange Commission has approved tokenized stocks trading in a move indicating that the regulator will push ahead with rulemaking despite the Clarity Act not moving forward.
Wall Street’s top regulator said Thursday that it was offering a five-year exemption to platforms that facilitate trading of tokenized stocks. Major crypto companies have long wanted to get such assets on the blockchain.
Lawmakers blocked the Clarity Act in a procedural vote on Tuesday. Regulators had said before the vote that regardless of whether the landmark legislation passed, they’d still start regulating the crypto industry.
Today, we are taking a significant step forward, within our statutory authority, to bring America’s capital markets into the digital age by facilitating onchain trading of certain tokenized stocks through the "Innovation Exemption."
— Paul Atkins (@SECPaulSAtkins) September 17, 2026https://t.co/BQK0cS70lH
“Congress was unsuccessful in advancing the Clarity Act despite the tireless efforts of many,” SEC Chairman Paul Atkins said in a statement.
“So today, the Securities and Exchange Commission is taking a significant step forward, within its statutory authority, to bring America’s capital markets into the digital age by facilitating onchain trading of certain tokenized stocks.”
Jamie Selway, Director of the SEC Division of Trading and Markets, added: “Today’s approval of exemptive relief for on-chain secondary trading on a TSV–known as the ‘Innovation Exemption’–marks an important milestone for the Commission’s work to open our capital markets for tokenized securities.”
The SEC’s move is the latest by regulators pushing ahead despite major crypto legislation stalling. The Commodity Futures Trading Commission Chair Mike Selig on Wednesday said that the top regulator would use its powers to advance crypto legislation despite the Clarity Act being blocked.
The Clarity Act aims to formally divide oversight between regulators, distinguishing which digital assets are securities, commodities or stablecoins.
President Donald Trump last month urged lawmakers to pass it but senators mostly voted against advancing the legislation — 49 for and 50 against — that the digital asset industry has long called for.
Republicans for months have accused Democrats of deliberately holding back the bill. Some lawmakers had issues with Trump’s family making money from crypto ventures. Trump and the White House have always denied any conflicts of interest.
This post SEC Green Lights Tokenized Stock Trading Despite Clarity Act Fail first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
HTTP error 429 on https://cryptoslate.com/feed/
Failed to fetch feed: https://cryptoslate.com/feed/
Failed to fetch feed.
CryptoTicker.io
Ethereum spent most of this year looking like the coin everybody had given up on. Then one candle in August changed the entire picture, and ETH has been quietly building a launchpad ever since. The $3,000 level is no longer a fantasy number. It is roughly 19% away, and the chart is doing exactly what it needs to do to get there.
Where Is the ETH Price Right Now?
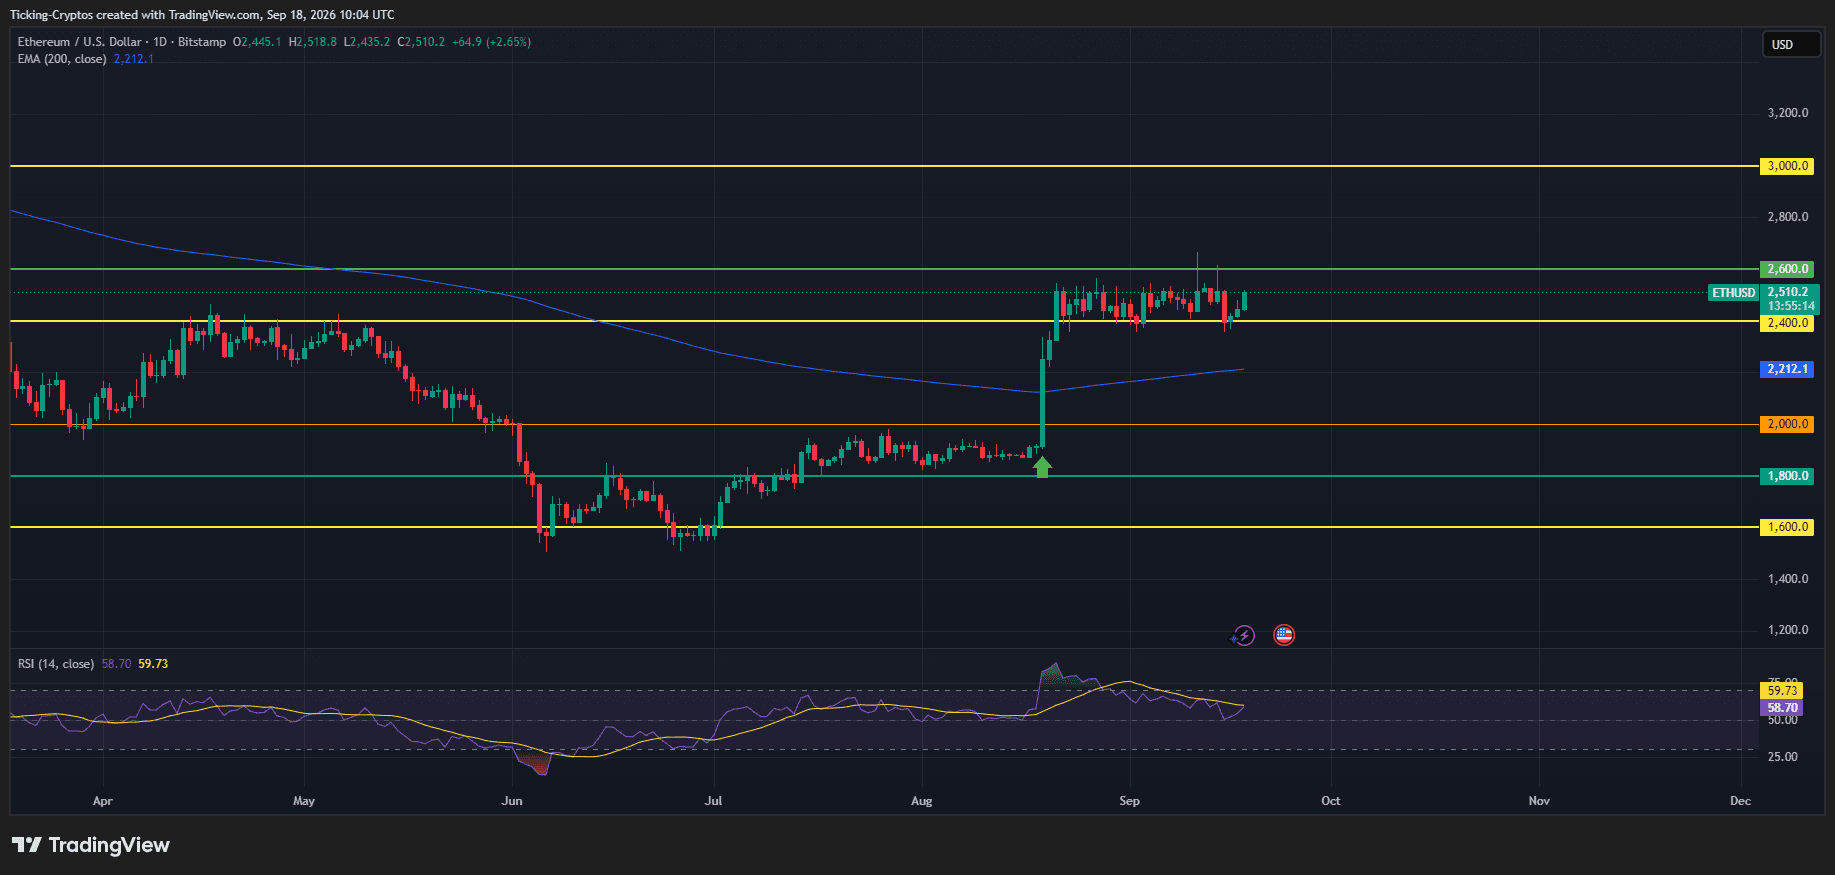
$Ethereum is trading at $2,510 on the daily, up 2.65% on the session, after opening at $2,445 and tagging $2,518 intraday. The low of the day was $2,435, which is the important part, because that is the third time in a month buyers have shown up in that exact zone.
Step back and the year looks brutal. ETH ground sideways through April near $2,400, rolled over in May, and collapsed through June into a low around $1,550. That is a drawdown of more than 65% from the August 2025 all-time high near $4,946. July was a slow repair job above $1,600. August was a boring drift between $1,900 and $2,050.
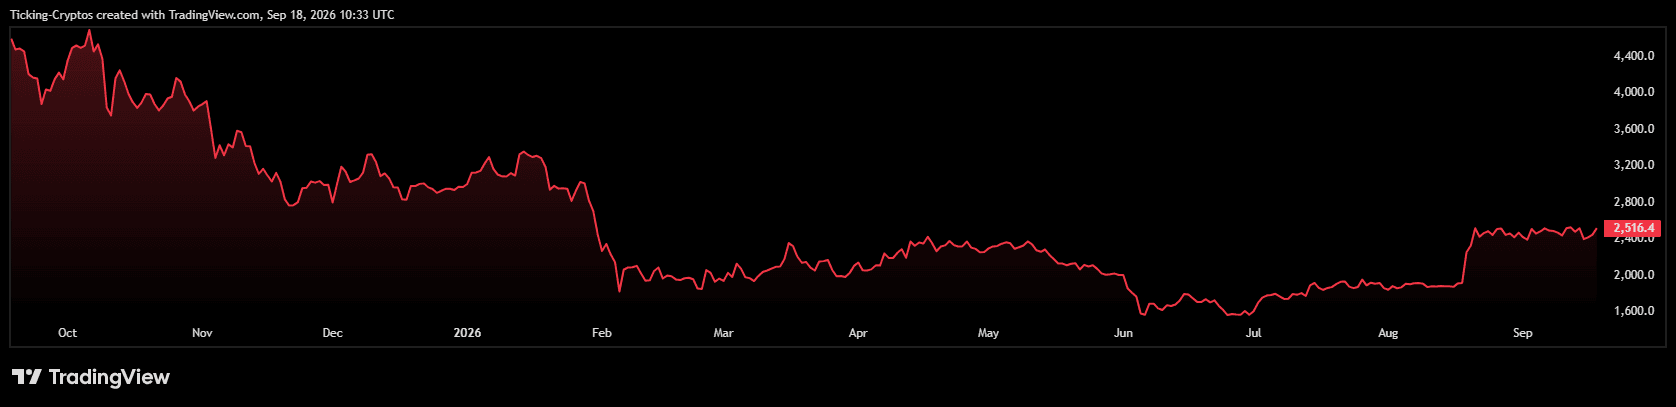
Then came the candle. In mid-August, Ethereum went vertical in a single daily session, ripping from roughly $1,950 through $2,000, through the 200 EMA, through $2,400, and closing near $2,500. That is a 28% expansion move in one bar, and it did not retrace. Everything since has been consolidation, not distribution.
What Does the ETH Chart Say About $3,000?
The structure right now is a textbook range. $2,400 is the floor. $2,600 is the ceiling. Ethereum has been locked between them for a full month, and neither side has broken.
That matters more than it sounds. When a market makes a violent vertical move and then goes sideways at the highs instead of giving the move back, it is usually absorbing supply rather than topping out. Sellers who wanted out at $2,400 have been getting filled for four weeks, and price has not cracked.
The measured move math is clean. The $1,600 to $2,000 base was 400 points wide, and the breakout above $2,000 projected $2,400. That target was hit almost exactly. The current $2,400 to $2,600 range is 200 points wide, so a clean daily close above $2,600 projects $2,800. From there, $3,000 is the next horizontal level on the chart, and it is the level that was acting as resistance through the entire first half of the year.
So the path is not a single leap. It is two steps: reclaim and hold $2,600, then run the gap to $2,800 where there is almost no historical resistance, then attack $3,000.
Is the 200 EMA Turning Bullish for Ethereum?
The 200-day EMA sits at $2,212. For eight straight months it pointed down, and every rally in spring and summer died against it. Ethereum is now trading roughly 13% above it, and more importantly, the line itself has flattened and hooked upward for the first time this year.
A rising 200 EMA underneath price is what separates a dead-cat bounce from a trend reversal. As long as ETH stays above it, the medium-term bias flips from bearish to constructive, and pullbacks become buyable instead of terrifying.
RSI backs this up without screaming. The 14-period reading is 59.73, sitting just above its own signal line at 58.70. That is the bullish half of the range with no overbought condition anywhere in sight. Ethereum can rally another 15% before RSI even starts flashing warnings, which is exactly the kind of fuel tank you want before a breakout attempt.
Are ETF Inflows Strong Enough to Push ETH to $3,000?
The chart is not moving in a vacuum. Institutional flow has flipped hard in Ethereum's favor.
US spot Ethereum ETFs pulled in roughly $1.75 billion to $1.85 billion in August 2026, their best month since August 2025, after more than $1 billion had left the funds in May and June. The week ending September 11 added another $197 million, a fourth consecutive positive week, while Bitcoin ETFs bled $463 million over the same stretch. A single session on September 11 brought in $216 million, the largest daily total of that week.
That divergence is the story. Money is not leaving crypto, it is rotating from Bitcoin into Ethereum, and the staking yield inside the newer ETH products is a large part of why. Ethereum spot ETFs now hold $16.31 billion in total net assets, around 5.28% of Ethereum's entire market capitalization.
One caveat worth being honest about: the buying is heavily concentrated, with BlackRock's ETHA accounting for roughly 72% of the inflow streak that began in mid-August. A trend carried by one issuer is a trend with a single point of failure.
The other catalyst is on the roadmap. The Glamsterdam upgrade has slipped to Q4 2026, with the Sepolia testnet fork scheduled for 28 September. A delayed catalyst is still a catalyst, and it lands right in the seasonal window where crypto tends to get interesting.
What Would Invalidate This Ethereum Price Prediction?
$2,400 is the line. It is the breakout level, it is the range floor, and it has now been defended three separate times. Bitfinex analysts also flagged the September 11 daily low near $2,432 as the level to watch on pullbacks.
A daily close below $2,400 kills the range and puts the $2,212 EMA directly in play. Lose that, and the August candle starts looking like a liquidity event rather than a trend change, with $2,000 the next real shelf underneath.
The bearish case is not just technical. ETF flows can stop as fast as they started, and the macro backdrop around Fed policy has been the single biggest driver of crypto beta all year.
Ethereum Price Prediction: How Soon Can ETH Hit $3,000?
Analyst targets are scattered across a wide band, which tells you the market genuinely does not know. CoinDCX puts September at a $2,800 target with a $2,405 to $2,950 range. LongForecast is far more aggressive, modelling a September close near $2,959 and October at $3,432. Messari's base case is $3,200 to $3,800 by December, with VanEck pointing to $4,500 if macro conditions improve. Prediction markets are more sober, giving roughly a 31% chance of a $3,500 touch before year end.
Strip out the noise and the chart gives a cleaner answer. Ethereum does not need a miracle to see $3,000. It needs one daily close above $2,600 with volume, and the structure opens up. Given the range has already compressed for four weeks with a rising 200 EMA underneath and RSI holding the bullish band, a breakout attempt in October is the base case, not the moonshot case.
Fail at $2,600 again and $ETH simply keeps grinding between $2,400 and $2,600 until something forces a decision. Ranges do not last forever.
This week was supposed to be the one that ended the rally. The Senate killed the crypto industry's biggest legislative push in years on Tuesday. The Federal Reserve raised interest rates for the first time since 2023 on Wednesday. Two catalysts, 24 hours apart, both pointing down.
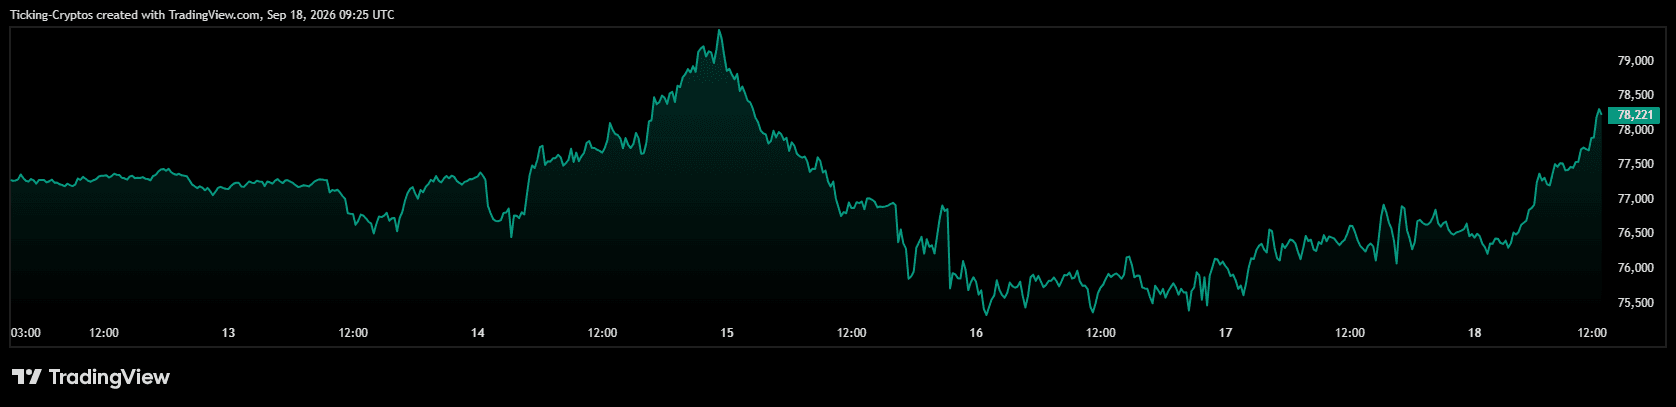
$Bitcoin is trading near $77,900 as of Friday, after a previous close of $76,559 and a day range between $76,289 and $78,051. It gave up ground, took it back, and is now sitting almost exactly where it started the week. That is not weakness. That is consolidation, and there are three solid reasons behind it.
What Is Actually Happening in the Crypto Market Right Now?
Over the past 30 days Bitcoin is up 20.5%, having run from roughly $64,000 in mid-August to the high $70,000s, with an average price of $77,286 across the period. August alone delivered a 25% gain.
A market that has just added a fifth of its value in a month does not usually push straight through. It ranges, it shakes out leverage, and it waits for the next input. That is exactly what the $75,000 to $78,000 band has been doing.
Reason 1: The Bad News Was Already in the Price
The Fed hike was priced at roughly 93% odds in futures markets going into the meeting. When the 12-0 decision landed, Bitcoin spiked to about $76,500 within five minutes and gave the move back within half an hour. A market that barely reacts to a confirmed hawkish event has already absorbed it.
The CLARITY Act was a similar story. Bitwise's CIO had already revised his outlook on the bill and argued the bull market can continue without legislation, pointing out that Bitcoin climbed above $80,000 in early September even as the odds of passage were falling. Traders had been repricing the legislative path for weeks before the vote.
Reason 2: Institutional Demand Has Not Left the Table
This is the strongest leg of the argument. Total Bitcoin ETF assets sit above $103 billion after August pulled in $3.52 billion, the best month of 2026.
The altcoin funds tell the same story. On days when spot prices fell, $Ethereum, $Solana and XRP ETFs still posted net inflows of $10.95 million, $10.19 million and $14.38 million, and $XRP funds ran 11 consecutive days of net buying worth roughly $170 million. Nasdaq put $100 million into Payward, Kraken's parent, on September 10 at a $21 billion valuation, and the Canary staked TRX ETF launched on September 9 as the first spot staked crypto fund in the US.
Positioning adds to the case. JPMorgan noted on September 16 that gold ETFs have recovered all of their 2026 outflows while Bitcoin ETFs have recovered only about half, and that short interest in BlackRock's IBIT remains near its highest level of the year. If that hedging pressure unwinds, it becomes fuel rather than drag.
Reason 3: Regulation Is Moving Without Congress
The CLARITY Act failing 49-50 looked like a wall. It is closer to a detour.
The SEC put Regulation Crypto Assets out for comment in August and has since opened a five-year pathway for tokenized US stock trading. The CFTC chair had already instructed staff to build a market-structure regime under existing Commodity Exchange Act authority. Neither depended on the Senate.
Congress has not gone quiet either. The House Financial Services Committee advanced the American Reserve Modernization Act, H.R. 8957, by 28-21, keeping the US Bitcoin reserve idea alive. Outside the US, Canada's financial regulator clarified that tokenized bank deposits are legally equivalent to traditional deposits. The direction of travel has not reversed, only the vehicle has changed.
What Could Still Break the Bull Case?
Being honest about the other side matters. Bitcoin remains roughly 39% below its October 2025 all-time high of $128,198, and the 52-week range runs from $57,833 to $126,186, so this is still a recovery, not a breakout.
The Fed is the real risk. Sixteen of eighteen officials project at least one more hike this year and four expect two, which puts December in play. With the 10-year Treasury yield near 5% and Bitcoin carrying a 0.89 correlation to the S&P 500 and 0.91 to the Nasdaq, crypto is trading as a risk asset right now, not as a hedge. If equities crack, crypto follows.
The short answer first: if you hold Bitcoin privately and move away from Germany, the move itself triggers no tax on your capital gains. There is no deemed sale on the day you deregister and no taxation of unrealised gains on your wallet balance. The exit tax that so many emigrants warn about catches something other than crypto assets.
The move can still become expensive if you overlook the four places where German tax law reaches you even after departure: the moment your tax residence genuinely ends, the one-year holding period that keeps running when you sell, the legal form of your crypto investment, and the question of what your tax office will learn automatically from the 2026 reporting year onwards. This article works through those points in order, under German law, with the statutory references you can put in front of your tax adviser if in doubt.
Does the exit tax under Section 6 AStG apply to Bitcoin held privately?
Exit taxation means the state treats an asset as if you had sold it on the day you left and taxes the increase in value, although not a single euro has reached you. That is a hard intervention, and it is precisely why the legislator drew the scope narrowly.
Section 6 of the Foreign Transactions Tax Act attaches to shareholdings within the meaning of Section 17(1) sentence 1 EStG, meaning holdings in corporations from a stake of one percent upwards. Shares in a German GmbH fall under it, and so do equity blocks above that threshold. A Bitcoin, an Ether or a stablecoin in your own wallet is not a holding in a corporation. The wording of the provision leaves no room here, and that is why there is no German exit tax on directly held crypto assets in private hands. You can read the statute yourself if you want to: Section 6 AStG on the portal of the Federal Ministry of Justice.
The distinction matters in both directions. Anyone holding their coins through their own GmbH is not safe merely because the underlying asset is crypto. In that case the GmbH share is the asset that triggers the exit tax, and the value of the coins inside it helps determine how much tax falls due. The structure is widespread among German investors, and it turns the outcome on its head. Readers interested in the motives behind such departures will find the reasons and the destination countries set out in our survey of why crypto investors emigrate.
When does your unlimited tax liability end: residence under Section 8 AO and habitual abode under Section 9 AO
The decisive question when you leave is not when you boarded the plane but when your unlimited tax liability ends. You are subject to unlimited tax liability for as long as you have a residence or your habitual abode in Germany. The German tax authorities then capture your worldwide income, including gains made on a crypto exchange in Singapore.
Residence: the key counts, not the deregistration certificate
Section 8 of the Fiscal Code defines residence by the facts on the ground: you keep a dwelling under circumstances suggesting that you will retain and use it. Deregistering at the residents' registration office is evidence of that and nothing more. Anyone who leaves the old flat standing empty, who keeps a room in the family home available at any time, or who has held on to the key to a shared flat risks the tax office treating the residence, and with it full tax liability, as continuing. A genuine tenancy agreement solves the problem. An accommodation arranged as a favour among relatives usually does not.
Habitual abode: the six-month line
Section 9 of the Fiscal Code adds the habitual abode: anyone staying in Germany for more than six consecutive months is subject to unlimited tax liability even without a dwelling, and short interruptions count towards the period. For emigrants with a German client base this is the most common trap. Spend every summer in Germany without ever documenting the days and you will have nothing to set against a tax audit later. Keep a plain travel log from day one, with dates, border crossings and evidence.
If your unlimited tax liability ends mid-year, you also need a tax report that separates the periods cleanly. Many portfolio tools default to full calendar years. Which programs handle partial periods and several tax jurisdictions is set out in our comparison of crypto tax software and portfolio trackers.
The one-year holding period under Section 23 EStG keeps running when you leave
For as long as you are subject to unlimited tax liability in Germany, gains on the sale of crypto assets are private disposal transactions under Section 23(1) sentence 1 no. 2 EStG. If more than a year lies between acquisition and sale, the gain stays tax-free. Below that it counts as taxable income and is charged at your personal rate. An exemption limit of 1,000 euros applies to all private disposal transactions of a year taken together. An exemption limit is not an allowance: one euro above it makes the entire gain taxable.
Leaving the country does not interrupt that period, it only shifts who taxes at the end. What counts is the actual sale or swap, and where you are tax resident at that moment. From this follows the most practical rule in this article: do not sell while your change of residence is still incomplete. Cash in coins inside the one-year period two weeks before you deregister and you pay the full German rate on the entire gain.
The reverse holds as well. Your acquisition data does not disappear because you leave the country. Your new country of residence will ask, by its own rules, when you bought and at what price, and some states use the value at the time of arrival. Which records support a German holding period is something we have written up in detail elsewhere, and the same paperwork will serve you abroad.
Crypto ETPs, ETFs and fund units: where the exit tax under Section 19 InvStG does bite
This is where matters turn unexpectedly serious for many German investors. Since 1 January 2025 the Investment Tax Act has had its own exit tax for fund units held privately. Under Section 19(3) InvStG, the end of unlimited tax liability through giving up a residence or a habitual abode is treated as a disposal at fair market value. The tax authorities therefore act as though you had sold your fund units on the day you left.
That is triggered only above two thresholds, either of which suffices: you held at least one percent of a fund's issued units at some point in the past five years, or your units in that fund carry acquisition costs of at least 500,000 euros. Anyone with a larger portfolio of broad equity ETFs alongside a crypto allocation breaches the second threshold sooner than they would like.
Whether your crypto position itself falls under this depends purely on the legal form of the product. An investment unit is a unit in an investment fund within the meaning of the Investment Tax Act. The crypto ETPs common in Europe, by contrast, are mostly structured as debt securities, meaning ETNs, and therefore precisely not fund units. A US spot ETF on Bitcoin, on the other hand, is a fund. Check each position individually for what you actually hold, and use the terms of issue or the key information document for that, not the product name on your brokerage statement. On departure this distinction decides a five-figure tax bill.
Extended limited tax liability under Section 2 AStG: when a low-tax country holds you for ten years
Extended limited tax liability is a run-on. Germany continues to tax you after you leave, though only on certain categories of income and only under narrow conditions. It is governed by Section 2 AStG and catches only those who meet every criterion at once.
First, in the ten years before the end of your unlimited tax liability you must have been subject to unlimited income tax as a German national for at least five years in total. Second, you must be resident in a low-tax territory or in no state at all; the law measures this against a comparative income of 77,000 euros and a burden of less than two thirds of the German income tax. Third, you need substantial economic interests in Germany, which Section 2(3) AStG assumes among other things where domestic income exceeds 62,000 euros or domestic assets exceed 154,000 euros. Where all of that applies, the run-on lasts until ten years after the end of the year of departure, and it takes effect only above 16,500 euros of income subject to limited tax liability in an assessment period.
For crypto investors the point is delicate, because Section 2 AStG captures all income that does not constitute foreign income within the meaning of Section 34d EStG. A gain on the sale of coins can be allocated neither to foreign real estate nor to a foreign permanent establishment, so the classification has to be settled case by case. Anyone moving to Dubai, Paraguay or a similarly taxing country while keeping German rental income or a stake in a German company should settle that question with a tax adviser before the move rather than after it.
Commercial trading and business assets: deemed disposal instead of exit tax
If you hold your crypto assets as business assets, a different system applies. Deemed disposal means that Germany treats an asset as withdrawn as soon as the German right of taxation over it is excluded or restricted; the legal basis is Section 4(1) sentence 3 EStG. Move your business abroad and cessation of business under Section 16(3a) EStG comes into play on top.
So anyone trading commercially, mining commercially or running a trading structure can well trigger taxation of unrealised gains on departure, and that without Section 6 AStG being needed at all. The line between private asset management and a trade depends on scale, external financing, organisation and outward appearance. If that question gives you pause, that in itself is a sign that a case-by-case review is needed.
Double tax treaties: who taxes when both states see you as resident
In the first months after a move it often happens that two states treat you as tax resident at the same time. German double tax treaties provide an order of precedence for this, modelled on Article 4 of the OECD Model Convention: first the permanent home, then the centre of vital interests, then the habitual abode, and finally nationality.
The centre of vital interests is where most emigrants come unstuck, and it is measured by mundane things. Where does your family live, where is your doctor, where is the sports club, where is the current account that pays the running costs. You do not change country with a passport alone. Most treaties, incidentally, allocate gains on the sale of crypto assets to the state of residence, because they fall under the catch-all clause for other property. That too is what makes a clean determination of residence so important.
Where your coins sit: self-custody, exchange accounts and the duty to cooperate under Section 90 AO
The location of your coins is irrelevant for tax purposes; the location of your records is not. The Federal Ministry of Finance circular of 6 March 2025 on individual questions of the income tax treatment of certain crypto assets regulated the duties to cooperate and to keep records explicitly for the first time, and it replaces the older circular of 10 May 2022. Anyone buying or selling through centralised trading platforms run by foreign operators is subject to the extended duty to cooperate in cross-border matters under Section 90(2) AO. In plain terms, you have to establish the facts and obtain the evidence yourself, and the tax office may estimate if you cannot. The full text is available as a PDF from the Federal Ministry of Finance.
That creates a practical difference between the forms of custody. An exchange account is tied to an identity and to a country: many providers block or restrict accounts when the registered address changes to a country they do not serve, and exporting the trading history then becomes difficult. A self-custody wallet moves with you and needs nobody's consent. The price is that nobody else keeps your records. If you are switching to self-custody, do it before you leave rather than after, and download every transaction history first. Which device suits you is covered in our hardware wallet comparison.
What the tax office learns about your crypto accounts from 2026: DAC8 and the KStTG
DAC8 is EU Directive 2023/2226 on cooperation between tax administrations, which obliges providers of crypto services to report on their customers. Germany implemented it through the Crypto Asset Tax Transparency Act, which came into force on 1 January 2026. The first reporting period is the 2026 calendar year; providers transmit the data by 31 July 2027 to the Federal Central Tax Office, which exchanges it with partner states.
For a departure that has two consequences. First, your master data and aggregated transactions for 2026 are reported even if you move away in the course of that year, and the comparison with your final German tax return does take place. Second, the report follows the country of residence that you give your provider. An out-of-date address in your customer account therefore generates reports to the wrong country, and untangling that costs more time than updating it in good time. How the reported amount is arrived at, and why it does not correspond to your gain, is explained in our piece on crypto reporting duties and the difference between the gross amount and the gain.
The misconceptions that get expensive when you emigrate with Bitcoin
“I have deregistered, so I am out.” Deregistration is registration law, not tax law. What counts is dwelling and abode under Sections 8 and 9 AO.
“Crypto falls under the exit tax.” For directly held coins in private assets it does not arise. For fund units above the thresholds of Section 19 InvStG, and for shares in corporations, the picture is different.
“After the move I can sell tax-free.” That holds only if your unlimited tax liability had genuinely ended at the time of sale, no run-on under Section 2 AStG applies, and your new country of residence does not tax the transaction itself.
“My exchange is abroad, so nobody finds out.” Since the 2026 reporting year that is a mistaken assumption made with fair warning, and the cross-border element triggers the stricter duty to cooperate on top.
“I will sort that out after the move.” Almost every planning option in this article requires you to use it before the cut-off date. After that, all you are doing is documenting.
Which records to secure before you move
The burden of proof for the date and the cost of acquisition lies with you, and it does not lapse with your residence. Before you leave, download the complete transaction export as a CSV from every platform, along with the annual statements, the bank's deposit and withdrawal receipts, and the account statements showing the euro inflows.
What is usually missing once it is needed
Records from trading venues that have since closed. Wallet addresses you never wrote down and whose link to you only you know. Documentation of swaps between two coins that never touched a euro account and are therefore absent from the bank statement. Evidence of staking and lending income, which many platforms keep for only twelve months. And the record of which units were disposed of in a partial sale, which you have to keep per wallet anyway once you use more than one.
Put the export on a medium that survives the move and keep a second copy separately. A tax report that cleanly closes out your German period is the best investment of this move.
Bitcoin and moving abroad: what to take away
- Settle the cut-off date first, not the tax. Determine the date on which your dwelling and abode in Germany demonstrably end, and place every sale deliberately before or after it. Keep your position data cleanly separated as you go; the tools that handle partial periods are in the comparison of crypto tax software.
- Check every position for its legal form. Directly held coins are not caught by the exit tax, while fund units from 500,000 euros of acquisition costs and holdings in corporations are. At the same time, move your custody into a form that travels with you: the options are in the hardware wallet comparison.
- Secure the records before you go. Complete transaction export, bank records, wallet addresses and a closing report for your German period. If you notice that a year has gaps, close it now with one of the portfolio trackers and not when the tax office asks.
This article sets out the legal position and does not replace tax advice in an individual case. On departure in particular the outcome turns on details that only someone who knows your paperwork can judge.
(As of September 18, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
On September 29, 2026 at 14:06:41 UTC, a protocol upgrade on the XRP Ledger arms itself: the batch amendment carrying the internal name BatchV1_1. If you hold XRP on an exchange or in a custodial wallet, there is nothing for you to do. If you run a node of your own, or run a service against a node of your own, this date is a hard deadline, after which your server drops out of the network.
This article explains what the amendment changes, where the date comes from, how to check the status yourself and which caveats are attached to the date. Every figure in this article comes from the validated ledger and from the protocol documentation, not from announcements.
What an amendment on the XRP Ledger is and why it needs no shutdown date
An amendment is a change to the rules of the XRP Ledger protocol that the network's trusted validators vote on, rather than a company scheduling it. That is what separates the process from a classic hard fork with an announced block height: there is no calendar entry that somebody sets, only a condition that the network either meets or does not.
The rule behind it is written into the protocol documentation and it is short. An amendment needs the approval of more than 80 percent of the trusted validators, and it has to hold that approval continuously for two weeks. Only then is it activated. Should approval slip below the threshold at any point during those two weeks, even briefly, the count starts again from the beginning.
For you as a reader that means two things. First, a date of this kind can be verified, because it sits in the ledger and not in a press release. Second, it is not immovable while the two weeks are still running. Both points are the heart of the matter for the date at issue here.
What the BatchV1_1 batch amendment changes technically
Batch is a new transaction type that bundles several individual transactions into one package processed together. According to the protocol reference, a package holds at least two and at most eight inner transactions, which may also come from different accounts. Until now the XRP Ledger required you to submit every step on its own and to hope, with each one, that it went through.
The practical gain lies in the certainty. Anyone submitting two steps one after the other today, say an approval and then a swap, carries the risk that the first step succeeds and the second fails. A package closes that gap, because the network knows the processing rule and enforces it.
Do I have to do anything if my XRP sits on an exchange?
No. That is the most common situation, and the least dramatic one. If your XRP sits with a trading platform or in a custodial wallet, the provider runs the infrastructure and the duty to upgrade is theirs. You do not have to move holdings, sell, or change an address. Shuffling balances in a hurry because of a protocol date mainly produces fees and, in case of doubt, a taxable event that was never needed.
The occasion is still worth a calm inventory that has nothing to do with the date. Do you know which provider holds which part of your balance, how high the withdrawal fee is there, and whether the provider is supervised in the EU? Regardless of the protocol date, those are the more important questions.
What to check if you hold your XRP in self-custody
Even in self-custody the case is usually a simple one. A hardware wallet stores your private key and signs transactions with it; as a rule it reaches the network through the servers of the wallet provider. The keys themselves are never affected by an amendment, because an amendment changes the rules of the chain, not your address and not your access.
What you can do is keep the software you use to reach the wallet up to date, and check once before the date that your recovery words are where you believe them to be. That is basic hygiene and it is right independently of September 29. If you are still undecided about which device to pick, our hardware wallet comparison helps.
Amendment-blocked: what happens to an outdated xrpld node on September 29
Amendment-blocked is the state a server falls into when it does not know an activated protocol rule. The protocol documentation describes the consequences unambiguously: a blocked server can no longer validate ledgers, can no longer submit or process transactions, can no longer take part in consensus and can no longer vote on future amendments.
The decisive sentence stands right beside it: a server's voting configuration has no bearing on this. Anyone who has set their xrpld to vote against the amendment is just as blocked after activation as someone who voted in favour. What gets a server blocked is the missing code that understands the new rule. There is no carrying on against an activated majority decision.
The server does not crash while this happens, and it throws no conspicuous error message on the wall. It keeps answering, only no longer with valid data from the running chain. That is exactly what makes the state dangerous for services that query a node of their own in the background: the application looks healthy and serves a data state that has stopped moving.
Where the September 29, 2026 date comes from and how it is arrived at
The date is calculated, neither derived nor estimated. The validated ledger holds an object that tracks the state of every amendment. It contains a field called Majorities, and for every amendment that has reached the threshold, that field records the point in time from which the two-week period runs.
This editorial team queried the object on September 18, 2026 at around 00:35 UTC through a public XRP Ledger node (ledger index 107058182, response HTTP 200). The Majorities field held exactly one entry: the amendment with the identifier 9F287AED3CDB50A7BD1ACEC24296A30C9B5230CCD136219317AC790E3B884377 and the CloseTime value 842796401.
The XRP Ledger counts time from January 1, 2000. Converting that value gives September 15, 2026, 14:06:41 UTC as the start of the period. Two weeks later falls September 29, 2026, 14:06:41 UTC. The cross-check through the feature query on the same node returned the name BatchV1_1 for the same identifier, along with the values enabled: false and supported: true. The amendment is therefore known to the network and supported, but not yet active.
How to check the status of the amendment yourself
You do not need a node of your own for this. A public XRP Ledger endpoint answers the question with a single request. Anyone comfortable with the command line sends a feature request carrying the identifier above to a public node and reads three fields out of the answer:
enabled: if this readsfalse, the amendment is not yet active. Once the value flips totrue, activation has taken place.supported: if this readstrue, the software of the node you asked already knows the rule. If it readsfalse, that very node will be blocked at activation.majority: the timestamp from which the two-week period runs. Should this field disappear again, the majority has slipped and the countdown has been reset.
That third point is precisely why you should look at the status once more shortly before the date, instead of writing the date down and ticking it off. The same route applies to a node of your own, with one important difference: send the feature query to your server, not to somebody else's. Only the answer of your own node tells you anything about your own node.
Which software version brings the new rule with it
The server software of the XRP Ledger is called xrpld and is published as open software. The current release is 3.4.0, published on September 17, 2026; before that came 3.3.0 of August 6, 2026 (both dates taken from the release dates of the official source code archive, retrieved on September 18, 2026).
Copying a version number out of an article is still the weaker route. The reliable answer comes from your own server through the supported field: it answers the question of whether the running software actually knows the rule. Which version you believe you are running plays no part in it. If false stands there, only an update helps, and it has to happen before September 29.
Why the date carries a caveat
The two-week period runs for as long as approval stays above 80 percent. Should it fall below, the counter is reset and September 29 lapses. That clause is no theoretical footnote; it is the safety mechanism built into the procedure. It leaves the validators the option, right up to the last moment, of stopping a change if a problem surfaces in the meantime.
For your planning, one simple stance follows from this. Treat September 29 as the deadline you prepare for, and treat its arrival as unsettled. Anyone who updates a node loses nothing if the countdown is reset. Anyone who postpones the update because the date might still fall through ends up, in the opposite case, with a system cut off from the chain.
The four modes of a batch package and what they mean in daily use
A package is given a mode when it is submitted, and that mode determines how the network deals with failures. The protocol reference names four:
- AllOrNothing: every single transaction in the package has to succeed. If one fails, the whole package fails. This is the mode for sequences that only make sense in full.
- OnlyOne: as soon as the first transaction has succeeded, the remaining ones are skipped. It allows alternatives to be submitted of which exactly one should take effect.
- UntilFailure: the transactions run in order until one fails; everything after that is dropped. This suits sequences that build on one another.
- Independent: all transactions are processed independently of one another, regardless of whether individual ones fail. This is pure bundling without chaining.
As a holder you will rarely set these modes yourself. The difference becomes visible where applications make use of it: in wallet interfaces that gather several steps into one confirmation, and in trading applications, where a half-executed sequence has so far been the most awkward case of all.
What services, wallet providers and payment processors should clarify now
Anyone who reaches the XRP Ledger through infrastructure of their own rather than through an outside provider is affected. That includes payment services, trading applications, accounting tools with their own data feed and every wallet whose provider runs a node. For this group, three questions need answering before the date.
- Does the feed run against a node of your own or against an outside endpoint? With an outside endpoint the duty lies with its operator, and you should ask there instead of acting yourself.
- Does your own node report the value
supported: truefor BatchV1_1? If not, an update is due, with the usual lead time for testing and a maintenance window. - Would a data state that has stopped moving show up in your monitoring at all? A blocked node keeps answering. Monitoring that only checks reachability notices nothing of it. Whoever monitors the gap between the last validated ledger and the current time notices it immediately.
Experience says the third question is the one on which everything hangs. An outage that disguises itself as normal operation is discovered late, and in the meantime bookings and displays carry on working with old data.
How this date fits into the run of amendments so far
The procedure is routine on the XRP Ledger and runs several times a year. Most recently, on September 9, 2026, we described the activation of the previous amendment; anyone who wants to read the sequence through from the start again will find it in our article on which points to check on wallet, node and position. The mechanics are the same, only this time a concrete date and an open condition hang on it.
For placing the network as a whole, a look at what is being built on it remains more telling than any single protocol step. One example from February 2026 is the euro stablecoin of Société Générale, which is issued on the XRP Ledger. Applications of that kind are the reason binding transaction packages are in demand at all: anyone automating payment sequences wants no half-executed chains.
XRP Ledger batch amendment: what you take away from it
- If your XRP sits with a provider, you do nothing. Use the date at most for a calm check on whether the provider still suits you: the overview of the best crypto exchanges puts fees and withdrawal routes side by side.
- If you hold your own coins, check access and recovery, not the protocol. Your keys are not affected by an amendment. Which device is up to the job is shown by the hardware wallet comparison.
- If you run a node of your own, send the
featurequery before September 29. Ifsupported: falsestands there, update the software. Anyone who also needs an overview of their holdings and how they are recorded for tax will find the tools for it under crypto tax software and portfolio trackers.
The primary sources for this article: the description of the amendment procedure and the protocol reference for the batch transaction, both in the official documentation of the XRP Ledger.
(As of September 18, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Anyone who sells a bitcoin position at a loss in order to use that loss for tax purposes, and buys the same quantity back shortly afterwards, triggers two things at once in Germany. The loss is realized and remains deductible. At the same time, the one-year holding period starts again from scratch for the quantity bought back. That is the price of the decision, and it hangs on a single date: the acquisition date of the new units.
The occasion is this week's slide. On September 17, 2026, Bitcoin stood at $76,555, or €66,712, and Ethereum at $2,453 and €2,138. Cryptoticker.io retrieved these figures on the same day through CoinGecko's public price interface. Many positions opened over the past year are therefore under water, and the question of whether to take the loss and get straight back in is coming up in a great many German portfolios at the same time.
Selling at a loss and buying back: what really happens for tax
In Germany, crypto assets count as other economic assets. Selling them therefore falls under private disposal transactions in section 23 of the Income Tax Act, not under the flat withholding tax. That sounds like a technicality, but it determines everything that follows.
A private disposal transaction is a sale within one year of acquisition. The gain from it is taxed at your personal income tax rate, and in return the loss from it can be offset. Anyone who sells after the year has elapsed stays tax-free, and that cuts both ways: the gain goes untaxed, but the loss is equally without effect.
That second half is routinely overlooked. A position bought eighteen months ago and sitting 30 percent under water today no longer carries any usable tax loss. That position is outside the period. Selling it brings nothing except liquidity.
The three figures you need for every lot
For each individual lot in your holdings, three pieces of information count: the acquisition date, the acquisition cost and the quantity. The acquisition date tells you whether the one-year period is still running. The acquisition cost tells you whether there is a loss at all. The quantity tells you how much of it you can move without touching other lots. Crypto tax software with portfolio tracking shows you these three values separately for each purchase, and without them the decision about a loss sale cannot be taken cleanly.
The one-year period in section 23: why a buyback starts a new clock
The holding period is the time between the acquisition and the disposal of a particular unit. That period attaches to the unit, not to the coin and not to the account. Every purchase starts its own clock.
From this follows the central point of this article. If you sell 0.3 bitcoin today that you bought in January 2026, and buy 0.3 bitcoin again ten minutes later, you have not restored the same position. You have a new position with a new acquisition date. The old eight months of holding time are not transferable; they were used up by the sale. The new unit does not become tax-free until September 2027.
On a position that is only a few weeks old anyway, this costs almost nothing. On a position that would have reached the one-year mark in three months, it costs those three months plus another twelve. That is the real calculation, and it comes out differently for every lot.
Is there a wash sale rule in Germany as there is in the US?
No. Under US tax law, a wash sale is a loss-making sale in which the same or a substantially identical security is bought back within thirty days before or after the sale. Section 1091 of the Internal Revenue Code denies the deduction of the loss in that case; it is added to the cost basis of the new position instead.
German income tax law has no equivalent for private disposal transactions. Section 23 contains no blocking period for re-entry, and there is no provision that shifts the loss into the new acquisition cost. The loss stays where it arose, in the year of the sale.
Anyone reading American guides or using an international tax tool should know this difference before deriving rules for the German tax office from them. The thirty-day window that regularly appears in such texts has no bearing on a German tax return.
Section 42 of the Fiscal Code and the same-day buyback: what the Federal Fiscal Court decided
That leaves the objection tax offices occasionally raise in such cases: abuse of legal structuring. Under section 42 of the German Fiscal Code, this exists where a legal arrangement essentially serves to obtain a tax advantage not provided for by law.
There is a decision directly on point, and it concerns precisely the provision discussed here. In a judgment of August 25, 2009, case reference IX R 60/07, the Federal Fiscal Court held that there is no abuse of structuring where a taxpayer sells securities at a loss within the one-year period and buys back securities of the same type and number at a different price on the same day. Sale and buyback, the court held, are to be assessed as separate transactions. The matter in dispute was a private disposal transaction under section 23, that is, the same provision crypto assets fall under today.
The judgment was handed down on shares and not on crypto assets, and it is not a blank cheque. It is, however, the closest thing to a supreme court statement on this constellation, and it supports the view that re-entry as such does not endanger the loss. Anyone wanting full certainty should have the case reviewed by a tax adviser before filing; a binding ruling from the tax office is the only route to genuine legal certainty in an individual case.
FIFO: why the bitcoin you buy back joins the back of the queue
FIFO stands for first in, first out and means that the unit acquired first counts as the one disposed of first. For crypto assets, the German Federal Ministry of Finance set out this consumption order in more detail in its circular of March 6, 2025, together with the record-keeping and cooperation duties attached to it. The circular carries the file number IV C 1 - S 2256/00042/064/043 and replaces the version from May 2022. It is publicly available from the Federal Ministry of Finance.
In practice that means your purchases stand in a line, ordered by date. When you sell, the line is cleared from the front. The buyback joins the end of that line.
This creates a trap that springs particularly often in a drawdown. The units at the front of the line are the oldest, and therefore often the ones with the longest holding time and the best tax position. Anyone triggering a partial sale in order to realize a loss reaches, under FIFO, for exactly those old units first, and those may well not be under water at all. A loss sale that hits the wrong lot produces a taxable gain instead of a usable loss.
How to keep them apart in practice
The wording of the law can be read in the full text of section 23 of the Income Tax Act. The consumption order can only be controlled cleanly if holdings are kept separately per wallet and per exchange account, because under the ministry circular the assessment is made in principle per individual wallet or per individual account. Anyone holding the same coin on three platforms has three separate lines and not one shared one. Which exchange gives you which export formats differs considerably; a look at our crypto exchange comparison is worth the time before you plan a loss sale spanning several accounts.
The price of the buyback: when you trade an almost tax-free lot for a loss
The decision can be boiled down to one question: which is worth more, the loss today or the remaining holding time?
On a lot that is only two months old, the answer is usually clear. Ten months of remaining period is a manageable stake, and the loss takes effect immediately. On a lot that is eleven months old, the picture flips. One month separates it from tax exemption; a buyback resets it to twelve months and extends the window in which a later gain would be taxable by eleven months.
On top of that comes a point easily lost in the arithmetic: a loss is only worth something if a gain from a private disposal transaction stands against it in the same year or in a later one. Losses under section 23 land in their own offsetting pot. They cannot be set against employment income, rental income or investment income from shares. Anyone not expecting corresponding gains realizes a loss that sits unused for years. We set out the mechanics of this offsetting and the deadlines in detail in our article on crypto losses before the one-year period expires of September 9, 2026.
The 1,000 euro exemption threshold: when a loss sale is worth it at all
An exemption threshold is a limit at which the entire amount becomes taxable once it is exceeded, not just the excess. For private disposal transactions it stands at €1,000 of total gains in a calendar year.
For the buyback decision this means two things. If your annual gain from private disposal transactions stays below the threshold anyway, an additionally realized loss is worthless for tax, because there is nothing to reduce. And conversely: if you are just above the threshold, a targeted loss sale can push the total gain below €1,000 and thereby make the entire amount tax-free. That is the only case in which a loss sale pays off in a jump rather than proportionally.
Grandfathering at December 31, 2026: what a buyback next year could change
A draft bill on the future taxation of crypto assets is on the table, providing for a switch to the flat withholding tax from 2027 and for grandfathering of holdings acquired before then. It is a draft and not applicable law; none of it has been adopted, and the cut-off date may move or disappear entirely.
But if it does come to pass, the acquisition date takes on a second meaning beyond the one-year period. Units you buy back today would have been acquired before the cut-off date. Units you only buy back in January would not. Anyone already weighing a loss sale with a subsequent buyback therefore has an argument for not pushing it into next year. We gathered the state of the draft and the open questions in our piece on the holding period and grandfathering of September 8, 2026.
What matters is the order of certainty: the one-year period applies today and is law. Grandfathering is an expectation. A decision resting on the expectation alone stands on one leg.
What proof the tax office wants for the loss and the buyback
The ministry circular of March 6, 2025 framed the record-keeping and cooperation duties considerably more sharply than its predecessor. For a loss sale with a buyback this means, concretely: both transactions must be individually documented, with time, quantity, price and platform.
In practice you need the exchange's transaction export for the sale and for the buyback, each with a timestamp. If the position came from your own wallet, proof of origin is required on top. A statement showing the holding only as a total is not enough, because the one-year period attaches to the individual lot.
The mistake that is hardest to correct
Export the data promptly. Anyone who discovers after a delisting, an account closure or a change of provider that the history is no longer retrievable has lost the proof and with it the loss. That is not a theoretical risk: in the past few weeks alone, several trading venues have set deadlines for withdrawing balances, after which the account interface was no longer reachable.
Three cases from the current drawdown worked through
The amounts below are freely chosen worked examples and not a price forecast. The cases only show how the variables interact.
Case one, a young lot at a loss. Bought in July 2026 for €8,000, current value €6,400. Loss €1,600, remaining period around ten months. A sale with an immediate buyback realizes the loss and resets the clock to twelve months. Anyone with gains from other crypto sales in the same year comes out clearly ahead here.
Case two, an old lot just short of the finish line. Bought in October 2025 for €10,000, current value €8,500. The loss of €1,500 is real, but the period runs out in a few weeks. A buyback trades an almost achieved tax exemption for a loss that is only worth something if there are enough offsettable gains. In most portfolios, waiting is the calmer option here.
Case three, a lot outside the period. Bought in February 2025, current value well below. Nothing happens for tax on a sale, neither a gain nor a usable loss. A sale here is a pure investment decision with no tax effect. We worked through a similar constellation on the gains side for Ethereum profits and the holding period on September 14, 2026.
Bitcoin losses and buybacks: what to take away
- Sort by acquisition date first, not by price. Check for each lot whether the one-year period is still running. Only within the period is a loss worth anything at all, and only there does a buyback cost you holding time. Tax software with portfolio tracking compiles this list automatically for each purchase.
- Weigh the loss against the remaining period. Young lots at a loss are the obvious candidates, lots just short of the anniversary the most expensive. And check beforehand whether you have any gains from private disposal transactions in the same year for the loss to be offset against.
- Secure the records the same day. Export the sale and the buyback with timestamps, separated by wallet and account. Which exports your exchange offers is shown in our crypto exchange comparison; if the proof is missing later, the loss goes with it.
(As of September 17, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
It came just hours after S&P Global announced its acquisition of OpenZeppelin, as everything TradFi moves onchain.
Investigators say tracing the network's crypto transactions exposed links to organized crime and murder-for-hire.
OFAC says hundreds of millions of dollars in Bitcoin moved through BitBank to the Revolutionary Guards in two months.
OpenAI's new transparency framework reveals AI models that invented fake "breach alerts," coached themselves to hide mistakes, and smuggled a file onto the public internet to talk to each other.
Brookings researchers in the US and China are urging Washington and Beijing to agree to keep humans in control of nuclear weapons.
U.Today - IT, AI and Fintech Daily News for You Today
Bloomberg strategist Mike McGlone reveals why 5% US Treasuries are now worth selling Bitcoin and gold for.
Ripple CTO Emeritus David Schwartz suggests reasons why exchanges are holding back from listing a Bitcoin-split asset, while they had previously supported other Bitcoin forks.
$0 Shiba Inu removed from its supply in hours, with SHIB community paying close attention to what comes next.
Popular market trader and technical analyst Will Meade has predicted that Bitcoin could return to $100,000 before the U.S. midterm elections.
NEAR’s biggest rally in months is being fueled by more than speculation as the protocol’s evolving cross-chain trading strategy gains traction.
Blockonomi
Quick Summary
- Nasdaq-100 futures gained 0.3% during Friday’s pre-market session while Dow futures edged lower and S&P 500 futures remained relatively unchanged
- Federal Reserve officials raised interest rates by a quarter point and indicated at least one additional increase is likely in 2024
- The dollar index climbed to its strongest position in seven weeks as traders anticipated continued monetary tightening
- Crude oil retreated to approximately $100 per barrel, providing market relief despite persistent supply disruptions from Iran tensions
- Semiconductor equities rebounded following earlier declines sparked by major AI companies advocating for development restrictions
US stock futures presented a mixed picture Friday morning as market participants processed the Federal Reserve’s latest interest rate decision and evaluated evolving concerns surrounding artificial intelligence development.
Futures tied to the Nasdaq-100 advanced 0.3%, contrasting with a 0.1% decline in Dow Jones futures. S&P 500 futures hovered near unchanged territory as trading commenced.
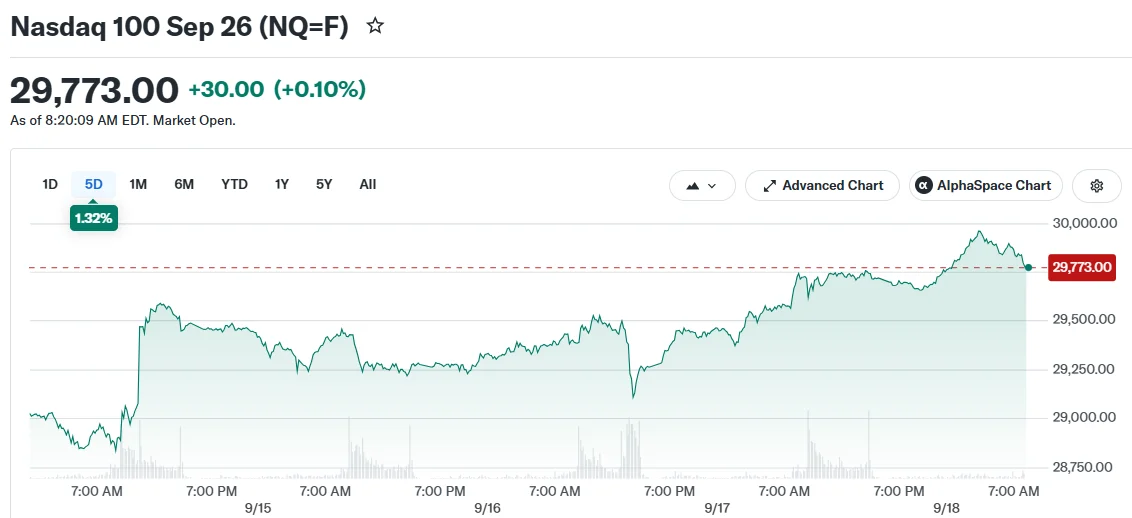
Thursday’s trading session saw equities rally back, with technology shares leading the charge. Declining crude oil prices combined with softening bond yields helped restore investor confidence following Wednesday’s anticipated 25 basis point rate adjustment from the Federal Reserve.
Financial markets quickly absorbed the Fed’s policy decision. The rate adjustment had been widely anticipated and incorporated into pricing by most market participants well in advance.
Additional Monetary Tightening on the Horizon
Federal Reserve policymakers indicated that at least one more rate adjustment is probable before 2024 concludes. Research analysts at ING noted that the central bank has “given the green light to markets to fully price in a hike in October” contingent upon inflation metrics and energy sector data.
Skepticism about inflation control remains among some financial leaders. JPMorgan Chase CEO Jamie Dimon remarked to Yahoo Finance recently: “It’s not clear to me we’ve slayed inflation.”
The US dollar index surged to 100.448, marking its most robust performance in seven weeks. This appreciation stemmed from market expectations of continued Federal Reserve rate increases.
Currency strength also benefited from weakness in the Japanese yen. Japan’s central bank implemented a 25 basis point rate increase Friday, though its future policy guidance disappointed market expectations.
Energy Markets Cool While Semiconductor Sector Rebounds
Oil prices drifted back toward the $100 benchmark, offering markets some breathing room. Crude prices have remained elevated due to ongoing disruptions affecting the Strait of Hormuz as Iran-related conflicts continue into their seventh month.
This energy market volatility has sustained inflationary pressures and created challenges for central bank policymakers globally.
Semiconductor stocks mounted a significant recovery following turbulence earlier in the week. The sector downturn had been initiated by statements from Anthropic and OpenAI advocating for reduced pace in artificial intelligence advancement.
The PHLX Semiconductor index showed only modest weekly losses entering Friday’s trading session.
US index futures extended their gains following the Bank of Japan’s monetary policy announcement, which pushed Japanese interest rates to their most elevated position in over three decades.
Market participants are now evaluating whether the Federal Reserve’s policy adjustments, coupled with moderating energy costs, will successfully curtail inflation without precipitating broader economic deceleration.
Upcoming economic releases will prove crucial, potentially determining whether the Fed proceeds with another rate increase during the October policy meeting.
The post Nasdaq Futures Gain Ground as Federal Reserve Eyes Additional Rate Increases and Crude Oil Retreats appeared first on Blockonomi.
Key Highlights
- Hyperliquid Strategies (PURR) shares climbed approximately 8% following the SEC’s release of its “Innovation Exemption” framework enabling tokenized U.S. equity trading on public blockchain networks
- The regulatory relief permits Tokenized Securities Venues to facilitate tokenized stock transactions via automated market makers for a five-year duration
- Tokenized equities are required to maintain identical shareholder privileges as conventional shares, encompassing dividend distributions and voting capabilities
- Smart contract code must be publicly accessible, auditable, and launched on permissionless blockchain platforms
- Wall Street analysts maintain a Buy rating consensus on PURR with a mean price objective of $19.80
Hyperliquid Strategies (PURR) was exchanging hands up approximately 8% at $13.82 during premarket activity Friday, continuing momentum from a comparable advance Thursday following the SEC’s Innovation Exemption announcement.
Hyperliquid Strategies Inc Common Stock, PURR
The Securities and Exchange Commission revealed Thursday it is providing temporary regulatory relief to Tokenized Securities Venues, enabling them to facilitate tokenized U.S. equity trading on public blockchain infrastructure through automated market makers. The relief framework extends to liquidity providers participating in these pools under securities-law dealer classifications.
SEC Chairman Paul Atkins characterized the initiative as an effort to transition U.S. capital markets “into the digital age.” He positioned it as a strategic response following the CLARITY Act’s failure to progress through the Senate earlier in the week.
The exemption period spans five years and includes rigorous compliance requirements.
TSVs must confirm that tokenized securities maintain equivalent rights as traditional equity instruments, including dividend entitlements and voting privileges. Smart contract infrastructure must be transparent, auditable, and established on permissionless blockchain networks. Corporate issuers retain the authority to oppose and prevent their securities from trading on any TSV platform.
Trading suspensions on the principal exchange automatically extend to the tokenized equivalent. TSVs must maintain U.S. person status and adhere to OFAC sanctions compliance standards.
Bernstein research analysts had forecasted the SEC and CFTC would pursue “aggressive and swift” regulatory action following the CLARITY Act’s collapse. Thursday’s exemption represents the initial tangible evidence of this prediction materializing.
Market Interpretation of PURR’s Position
PURR is being interpreted by market participants as a primary beneficiary. The SEC directive mandates trading on public permissionless blockchain infrastructure with auditable smart contract systems, which aligns substantially with Hyperliquid’s decentralized exchange architecture.
The firm’s investment approach focuses on accumulating HYPE, Hyperliquid’s native digital asset, and leveraging staking mechanisms and yield optimization strategies to enhance returns. Regulatory developments supporting on-chain financial infrastructure typically boost investor sentiment for companies operating in this sector.
PURR is currently trading approximately 18.6% above its 20-day simple moving average and 57.2% above its 50-day simple moving average. This stretched technical positioning indicates potential for abrupt corrections if purchasing momentum weakens.
The critical technical threshold to monitor is $14.00. A decisive breakthrough above this level would reestablish the $14.14 52-week peak as an achievable target. Rejection at that resistance could trigger a retreat toward shorter-term moving averages. The MACD indicator currently sits below its signal line, indicating upward momentum has moderated somewhat.
Wall Street Price Targets and Fund Holdings
Nine Wall Street analysts provide coverage on PURR with a unanimous Buy rating consensus and a mean price objective of $19.80. Cantor Fitzgerald elevated its target to $34.20 on September 10. Compass Point launched coverage with a Buy recommendation and $18.00 target on September 15. Chardan Capital increased its target to $17.00 on August 28.
PURR represents 100% of holdings in both the Bitwise Hyperliquid ETF (BHYP) and the Grayscale Hyperliquid Staking ETF (HYPG). This concentrated allocation means fund flows directly translate into buying and selling activity in the underlying stock.
The upcoming earnings announcement is projected for November 12, 2026. Analysts anticipate earnings per share of 12 cents and revenue of $9.78 million, with the stock currently trading at a price-to-earnings multiple of 4.0x.
The post Hyperliquid Strategies (PURR) Stock Surges 8% Following SEC’s Blockchain Trading Approval appeared first on Blockonomi.
Key Highlights
- MSTR shares climbed more than 3% during Friday’s premarket session, touching $136.60
- The SEC unveiled a five-year exemption related to tokenized stock trading, improving crypto market sentiment
- Bitcoin gained 2.3% to reach $78,112 even as the Clarity Act was rejected in the Senate and the Fed raised rates
- Coinbase shares increased 3.1% while Robinhood gained 3.5% in premarket activity
- MSTR is positioned above its 20-day and 50-day SMAs, though still hovering beneath its 200-day SMA at $137.13
Shares of Strategy experienced an upward surge exceeding 3% during Friday’s premarket session, climbing to $136.60, as favorable regulatory developments provided a boost to cryptocurrency-related equities throughout the sector.
Strategy Inc, MSTR
The advance occurred following the Securities and Exchange Commission’s announcement of a five-year exemption concerning tokenized stock trading. Additionally, the Commodity Futures Trading Commission released a no-action stance for certain passive software providers working alongside regulated entities.
These two regulatory announcements worked in tandem to enhance optimism surrounding cryptocurrency-focused firms. Strategy, whose treasury is primarily composed of Bitcoin holdings, typically mirrors broader cryptocurrency market movements.
Bitcoin increased 2.3% to $78,112 during the previous 24-hour period. The digital currency has gained approximately 1.3% since Monday’s opening, although it remains roughly 38% beneath its all-time peak established last October.
Minimal Impact from Clarity Act Setback
The upward movement occurred despite what appeared to be challenging developments for cryptocurrency markets this week. The Clarity Act, a significant piece of crypto regulation legislation, was defeated in the Senate on Tuesday. One day later, the Federal Reserve implemented an interest rate increase for the first time in over three years.
Both events failed to generate the anticipated negative market reaction. Market participants had widely anticipated that the Clarity Act would not secure passage this year, making the Senate’s decision relatively unsurprising.
Following the legislation’s defeat, both the SEC and CFTC affirmed their commitment to developing crypto regulations independently of new legislation. This assurance helped stabilize market confidence.
Regarding the interest rate increase, declining oil prices in recent sessions may alleviate pressure for additional Fed tightening measures. Markets had already incorporated expectations of a tightening cycle, minimizing negative reactions.
Additional cryptocurrency-related stocks mirrored Strategy’s upward trajectory. Coinbase advanced 3.1% during premarket hours, while Robinhood registered a 3.5% gain.
Key Technical Indicators
Examining technical analysis, Strategy is currently positioned approximately 5.2% above its 20-day simple moving average of $129.57 and 24.3% above its 50-day SMA of $109.61.
The notable resistance point it hasn’t surpassed is the 200-day SMA, currently positioned at $137.13. Trading at $136.60, the stock sits marginally below this critical level.
Technical momentum indicators present a varied picture. The MACD indicator sits beneath its signal line with a negative histogram reading. Additionally, the 50-day SMA continues trading below the 200-day SMA, a configuration that certain technical analysts interpret as a cautionary signal.
Notwithstanding these mixed technical readings, the stock maintains a Buy consensus among analysts. The average price target from analysts stands at $232.82, significantly exceeding current trading levels.
The regulatory transparency delivered by the SEC and CFTC, despite the Clarity Act’s failure, seems to have provided the catalyst cryptocurrency stocks required to advance into the weekend trading session.
The post Strategy (MSTR) Stock Surges Over 3% in Premarket on SEC Crypto Exemption News appeared first on Blockonomi.
TLDR
- COIN shares dropped 10.1% following the Senate’s rejection of the CLARITY Act on September 15
- A 25 basis point interest rate hike by the Federal Reserve on September 16 increased market pressure
- On September 17, the SEC introduced a framework enabling tokenized U.S. stock trading on blockchain platforms
- Coinbase stock recovered 3.74%, closing at $170.40 on Thursday after the regulatory announcement
- Wall Street analysts maintain an average price target of $201.31 for COIN, suggesting 16% potential upside
Coinbase (COIN) experienced significant volatility this week, oscillating between double-digit gains and losses as regulatory developments shaped investor sentiment.
Coinbase Global, Inc., COIN
Shares of COIN closed Thursday at $170.40, posting a 3.74% increase. The cryptocurrency exchange has witnessed a steep decline of approximately 50% over the past year, mirroring a broader downturn in digital asset markets where Bitcoin has tumbled roughly 34% during the same timeframe.
September 14 brought significant optimism to COIN investors, with shares surging over 10% amid expectations that the Senate would pass the CLARITY Act—proposed legislation designed to establish comprehensive regulatory guidelines for the cryptocurrency sector.
However, that enthusiasm evaporated rapidly. The CLARITY Act failed to advance past a procedural hurdle in the Senate on September 15, triggering a 10.1% plunge in COIN. Other crypto-related stocks suffered similarly: Circle tumbled 11.5%, Robinhood declined 3.4%, and Strategy fell 5.4%. Bitcoin dropped beneath the $76,000 threshold.
Market conditions worsened the next day when the Federal Reserve announced a 25 basis point interest rate increase on September 16.
SEC Introduces Alternative Regulatory Pathway
Just 48 hours after the CLARITY Act stalled in Congress, the Securities and Exchange Commission leveraged its existing regulatory powers to move forward with crypto market innovation.
The SEC announced on September 17 that it had granted two conditional exemptions, each lasting five years, permitting specific blockchain-based trading platforms and liquidity providers to facilitate transactions involving tokenized versions of U.S. equities.
According to the new guidelines, tokenized securities must maintain identical rights to their underlying shares, encompassing dividend distributions and shareholder voting privileges. Additionally, corporations will receive 30-day advance notification and retain the right to oppose tokenization of their securities.
The regulatory framework became effective immediately and may ultimately enable extended trading sessions and blockchain-powered settlement systems—capabilities already standard in cryptocurrency markets.
SEC Chair Paul Atkins stated the exemption is “designed to resolve challenges that have prevented responsible innovation from taking root in the United States while providing investor protections and market integrity standards.”
Financial markets reacted favorably to the announcement. Beyond COIN’s 3.74% advance, Circle increased 4.2%, Robinhood advanced 3.25%, and Strategy gained 5.22%. Bitcoin rebounded to approximately $76,560, up 1.1%, while Ether appreciated 2.6% and Solana climbed 3.2%.
Operational Performance Remains Strong for Coinbase
Notwithstanding the stock’s volatility, Coinbase has demonstrated meaningful operational improvements.
During the second quarter, the platform’s share of worldwide cryptocurrency trading volume expanded to 10.3% from 9.1% in the first quarter, representing the third consecutive quarter of market share expansion and reaching a company record.
The prediction markets segment has also become a rapidly expanding revenue stream. Trading volume and revenue from prediction market products increased 106% year-over-year in Q2, exceeding $100 million on an annualized basis.
The company also implemented a 14% workforce reduction in May 2026 and tightened its adjusted expense forecast for the full year to a range of $4.2 billion to $4.45 billion, down from prior guidance of $4.25 billion to $4.6 billion.
The consensus price target among 28 Wall Street analysts stands at $201.31, representing potential upside of approximately 16% from Thursday’s closing price of $170.40.
The post Coinbase (COIN) Stock Jumps 3.74% After SEC Unveils Tokenized Securities Framework appeared first on Blockonomi.
Key Takeaways
- Oklo shares climbed more than 11% Thursday following a 417-3 House vote approving the Ratepayer Protection Act
- The legislation mandates that data centers consuming over 100 megawatts bear their own grid infrastructure and electricity expenses instead of transferring them to residential customers
- X-Energy topped the nuclear sector gains with a 12.08% surge to $16.33, followed by NuScale Power’s 8.92% advance
- Wall Street analysts maintain a Buy rating on Oklo with a consensus price target of $85.46
- Technical indicators show Oklo trading beneath its 20, 50, 100, and 200-day moving averages following the rally
Oklo (OKLO) stock experienced an 11.31% jump Thursday after the U.S. House of Representatives approved the Ratepayer Protection Act with overwhelming bipartisan support in a 417-3 vote. Premarket trading Friday showed the stock hovering around $39.90, reflecting a 0.63% increase.
Oklo Inc., OKLO
The new legislation mandates that data centers drawing more than 100 megawatts of power must shoulder the additional grid infrastructure and energy supply expenses. This measure aims to shield residential consumers and small enterprises from absorbing these costs through elevated utility rates.
According to Brett Guthrie, who chairs the U.S. House Committee on Energy and Commerce, the Act guarantees that “the companies who are building data centers and not American families and small businesses are paying for the electricity they use.”
The legislation has positioned nuclear and next-generation reactor companies as potential beneficiaries. With data centers potentially facing increased grid connection expenses, operators may increasingly explore on-site energy alternatives such as small modular reactors.
This scenario creates opportunities for Oklo. The firm is advancing its Aurora powerhouse technology, which utilizes liquid-metal fast-reactor design capable of producing up to 15 megawatts using either fresh or recycled nuclear fuel.
Thursday’s gains extended beyond Oklo. X-Energy posted the strongest performance with a 12.08% rally to $16.33, topping the sector. NuScale Power advanced 8.92%. Fuel cell companies also benefited from the legislative development.
Among these three companies, X-Energy presents the highest potential upside according to analysts, with a consensus price target of $33.71, suggesting approximately 106% appreciation from present levels. The stock holds a Moderate Buy recommendation from Wall Street.
Wall Street’s Perspective on Oklo
Oklo maintains a Buy consensus among analysts with a mean price target of $85.46. Piper Sandler initiated coverage September 9 with an Overweight designation and $55 target. Truist Securities maintained its Hold stance while reducing its target to $51 on August 10. Citigroup preserved its Neutral rating and lowered its objective to $57.50 on the identical date.
Notwithstanding Thursday’s surge, Oklo’s technical positioning shows continued weakness. The shares trade 5.1% beneath the 50-day moving average and 36.3% under the 200-day moving average of $62.74. The relative strength index registers 48.04, indicating neutral momentum conditions.
Exchange-Traded Fund Holdings
Oklo maintains significant representation in nuclear-oriented ETFs. The Global X Uranium ETF allocates a 5.37% position to Oklo. The Themes Uranium and Nuclear ETF maintains a 6.09% allocation.
Market participants are monitoring $45 as the subsequent resistance threshold, while support appears established near $39.50.
The company’s Benzinga Momentum score registers a modest 2.6, indicating its position under multiple critical moving averages entering the weekend session.
The post Oklo (OKLO) Stock Surges 11% as House Passes Data Center Energy Bill appeared first on Blockonomi.
HTTP error 429 on https://cryptopotato.com/feed/
Failed to fetch feed: https://cryptopotato.com/feed/
Failed to fetch feed.