Cryptocurrency Posts
Crypto Briefing
The deal highlights strategic Arctic maneuvering, potentially altering geopolitical dynamics, but its practical impact remains uncertain.
The post US, Denmark, Greenland deal expands military access, awaits approval appeared first on Crypto Briefing.
Iran's warning could destabilize regional security, complicate U.S.-Iran negotiations, and impact future diplomatic and economic engagements.
The post Iran warns of attacks on US bases if military actions resume appeared first on Crypto Briefing.
Celtic's derby clash with Rangers could redefine the Premiership title race dynamics, impacting both teams' momentum and psychological edge.
The post Celtic aims to regain momentum against Rangers in derby clash appeared first on Crypto Briefing.
Trump's second-term stock market underperformance may erode voter confidence and encourage speculative behavior, impacting economic perceptions.
The post Trump 2.0 stock market performance lags behind predecessors appeared first on Crypto Briefing.
ZetaChain's migration to Solana could streamline operations but raises concerns about governance participation and potential token liquidity issues.
The post ZetaChain proposes shutting down its L1, migrating ZETA token to Solana appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
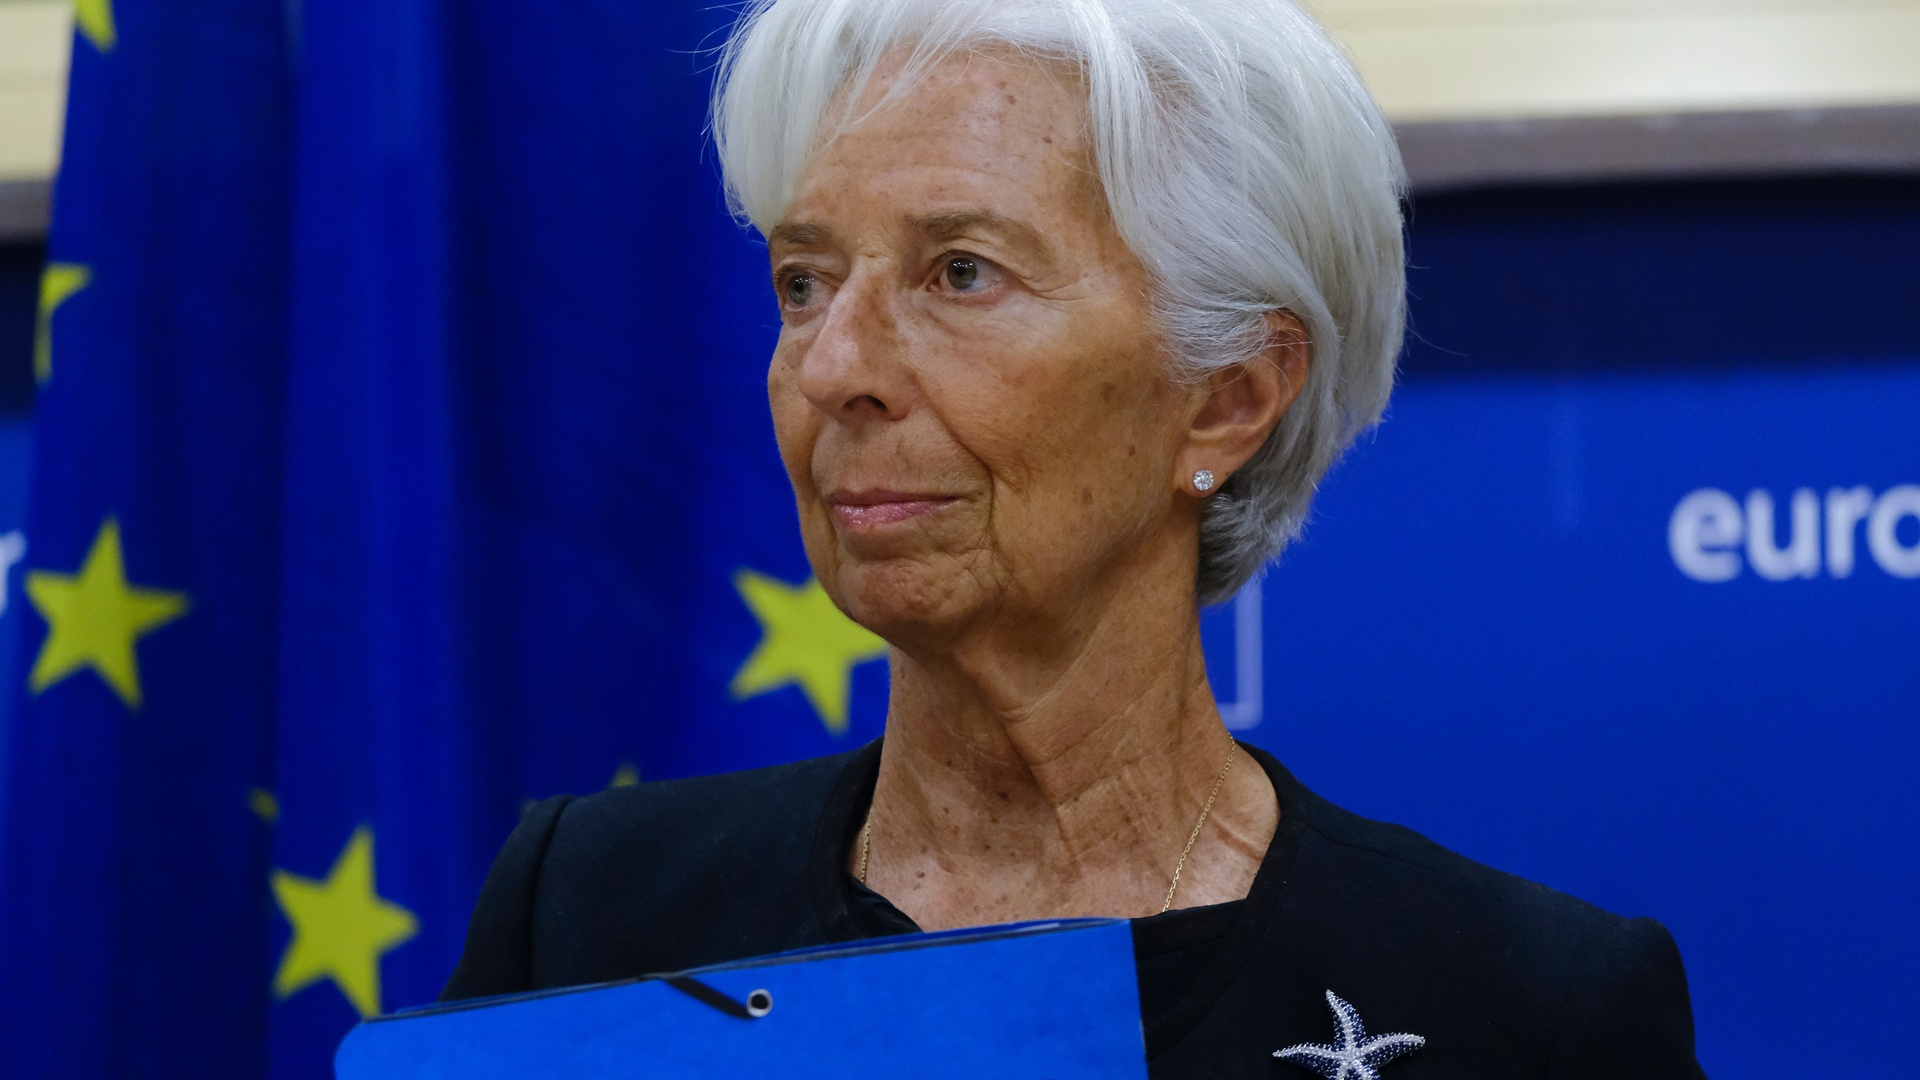
European Central Bank President Blocked Binance’s EU Entry: Report
European Central Bank President Christine Lagarde stopped Binance from operating in the European Union, according to a Wall Street Journal report.
The newspaper on Thursday reported that the top crypto exchange was on the cusp of operating in the trading bloc but then was told it couldn’t after the central bank chief waded in.
EU law requires that local Crypto-Asset Service Providers (CASP) have a MiCA license. Binance does not. Binance in June withdrew its MiCA application in Greece.
“Lagarde wanted to keep the controversial crypto exchange, which pleaded guilty to financial-crime violations in the U.S., out of the European Union,” the newspaper report said, citing interviews with officials.
Lagarde has long been anti-Bitcoin and pro-central bank digital currencies. Back in 2021, Lagarde said that the leading cryptocurrency was “a highly speculative asset” used for money laundering. She also criticized cryptocurrencies as a whole and said central banks would never hold bitcoin.
On CBDCs, though, Lagarde takes a different approach. A CBDC is a digital form of fiat money, like the US dollar or euro; nations around the world are in different stages of researching and releasing them.
The EU under Lagarde is fast moving forward with a digital euro. Lagarde has described the digital euro as key to Europe’s financial autonomy while taking aim at privately issued stablecoins.
CBDCs have been criticized by bitcoiners and others in the crypto industry who think they could be used to surveil citizens. U.S. President Donald Trump signed an executive order banning CBDCs when he took office.
The WSJ report added, citing various interviews, that Lagarde was worried Binance would embed the dominance of dollar-based stablecoins in Europe, instead of encouraging euro counterparts.
Binance is the world’s biggest crypto exchange and billions of dollars in stablecoins are traded on its platform daily.
A controversial company, Binance and its CEO, Chanpeng Zhao, in 2023 pleaded guilty to anti-money-laundering violations and paid a record $4.3 billion fine.
Binance in June said it was still working to pursue MiCA authorization in another EU Member State.
This post European Central Bank President Blocked Binance’s EU Entry: Report first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
CFTC Sends Proposal To Regulate Crypto Transactions Following Clarity Act Fail
The Commodity Futures Trading Commission on Thursday sent a proposal to the White House to regulate crypto transactions and markets.
It isn’t clear what the regulations will look like from the post on the Office of Management and Budget’s website. The proposal is titled “Regulation Crypto Asset Transactions and Regulation Crypto Asset Markets.”
The CFTC’s move comes after lawmakers blocked the long-awaited crypto legislation Clarity Act on Tuesday. Despite the law not advancing, both the CFTC and Securities and Exchange Commission have said they would go ahead with crypto rulemaking anyway.
CFTC Chair Mike Selig said on Wednesday that while the Clarity Act didn’t move forward, the watchdog would still help U.S. President Trump “get the job done” in regulating the crypto space.
“The outcome of yesterday’s Senate vote was unfortunate,” Selig wrote on X, adding that the CFTC was “locked in and ready to ship its rules for the new frontier of finance.”
Before the procedural vote on the legislation this week, Selig had said would proceed with rulemaking whether or not the Clarity Act is enacted — with the aim of finalizing rules before the administration’s term is out.
Senators last year approved Selig as the regulator’s chair. Formerly chief counsel at the SEC’s Crypto Task Force, Selig was described by White House’s Crypto and AI Tsar, David Sacks, as “instrumental in driving forward the President’s crypto agenda”
President Trump campaigned on a ticket to help the crypto space after regulators under the previous administration hit digital asset businesses with lawsuits — mostly for allegedly selling unregistered securities.
Since Trump became president, the SEC and CFTC have taken a much friendlier approach to watchdogging the space.
The CFTC isn’t the only regulator going ahead with rulemaking: the SEC earlier this week approved tokenized stocks trading. In August, it also proposed its own framework for crypto asset offerings, pressing ahead while the landmark legislation stalled.
President Trump last month urged lawmakers to pass the Clarity Act, calling the legislation “very powerful” — but Republicans said that Democrats were deliberately holding it back.
Democrats mainly took issue with the ethics side of the bill. Trump received backing from major industry players while campaigning and since becoming president, his family has made money from digital asset ventures.
Some lawmakers have alleged conflicts of interest. The White House has always denied any wrongdoing.
A new draft of the bill started circulating in July tackling the issue of ethics and banning officials from making money from crypto. But some Democrats said it didn’t go far enough.
The Clarity Act wants to formally divide oversight between regulators, distinguishing which digital assets are securities, commodities or stablecoins.
This post CFTC Sends Proposal To Regulate Crypto Transactions Following Clarity Act Fail first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Bitcoin Price Surges Over $81,000 Despite Clarity Act Fail and Interest Rate Hike
Bitcoin’s price on Friday shot above $81,000 — despite a week of setbacks for the crypto industry.
The biggest coin was recently trading for $80,982, after jumping as high as $81,055 at one point Friday morning in New York. Over the past 24 hours, it has risen by nearly 6%.
Its surge comes after lawmakers on Tuesday blocked long-awaited crypto legislation, the Clarity Act, and the Federal Reserve on Wednesday hiked interest rates.
JUST IN: Bitcoin surges to $81,000
— Bitcoin Magazine (@BitcoinMagazine) September 18, 2026pic.twitter.com/EQi5apUlxU
Digital asset industry bigwigs had long called for clear rules to regulate the crypto space and the Clarity Act — which wants to divide oversight between regulators — aimed to do that. But lawmakers blocked the landmark digital asset market structure bill in a procedural vote.
And the Federal Reserve increased borrowing costs for the first time due to skyrocketing inflation in the U.S. The central bank’s chair, Kevin Warsh, said that price stability in the U.S. was the Fed’s number one priority.
“The plain fact is that inflation is too high, and has been for too long,” Warsh said. “This summer’s inflation readings do not tell me that underlying trends have meaningfully improved.”
Bitcoin has in the past done well in a low interest rate environment because it means there is more liquidity to trade the asset.
While Bitcoin’s price dipped initially news of the Clarity Act blockage and Fed’s move, it shot up on Friday.
Bitcoin exchange-traded funds in the U.S. have so far this week experienced net negative flows, with investors cashing out nearly $427 million from the vehicles, according to Farside Investors data.
Flows on Thursday turned positive, with investors chucking nearly $160 million at the funds following two days of consecutive outflows.
In a research note Thursday, asset manager Grayscale said that it didn’t expect bitcoin’s price to be hurt by the Fed’s decision because the move reflects a mid-cycle adjustment, not a cyclical change.
And despite lawmakers blocking the Clarity Act, regulators like the SEC are already pushing ahead with pro-crypto regulation.
This post Bitcoin Price Surges Over $81,000 Despite Clarity Act Fail and Interest Rate Hike first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Bitcoin Community Recognizes Quantum Computing Risk: VanEck
Quantum computing is a risk to Bitcoin but the community recognizes the issue, according to asset manager VanEck’s Head of Digital Assets Research.
Speaking to CNBC on Friday, Matthew Sigel said that while progress on addressing the issue may be slow because of the crypto network’s decentralized nature, the community was working on it.
The crypto community has sounded the alarm about hypothetical advancements in quantum computers that could in the future be able to break Bitcoin’s cryptography.
Some in the space — including Bitcoin developers — have started preparing for a post-quantum future by testing quantum-resistant signatures on live sidechains.
“It’s a risk,” he said. “But the community has recognized the scope of the issue. There’s a lot of talent that’s now come together with a framework of how to upgrade the system.”
He added: “The upgrades don’t happen as fast because there’s no CEO who can tell the devs, ‘hey, do it now.’ There’s a governance process — it takes more time, it’s a little bit messier, but there are technological paths for quantum resistance, and I think you’ll see more of that over the next couple of years.”
Quantum computers do exist but make mistakes and a machine that can break Bitcoin’s cryptography currently does not exist. Bitcoin currently is the biggest computer network in existence.
Major companies in the space — including America’s biggest crypto exchange, Coinbase, and Bitcoin infrastructure firm, Blockstream — are already working on solutions.
Back in July, Coinbase said it plans to deliver a post-quantum signing pipeline using secure enclaves and threshold cryptography.
A Bitcoin Security Consortium — made up of BlackRock, Fidelity Digital Assets, Block, and others — formed in July and donates funds and dedicates engineers to open-source work supporting proposals like BIP-360, which aims to introduce a new transaction output type to reduce long-exposure quantum computing risks.
This post Bitcoin Community Recognizes Quantum Computing Risk: VanEck first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
The Next 3-5 Years of Bitcoin Lending
SALT Lending CRO Hunter Albright says a growing number of Bitcoin holders may eventually borrow against their bitcoin rather than sell it, creating a new relationship between bitcoin, credit and stablecoins.
Bitcoin-backed lending could become an increasingly important part of how holders access the value of their bitcoin without selling it, according to Hunter Albright, Chief Revenue Officer of SALT Lending.
Speaking on BMTV, Albright said he expects borrowing against bitcoin to become more common as the market matures and holders become more comfortable using bitcoin as collateral.
“I’d like to think we will see a growing percentage of the population of bitcoin holders borrow against it,” Albright said.
For Albright, that shift could also change how bitcoin and stablecoins function alongside one another.
“I do believe people borrowing against their bitcoin and leveraging stables is the difference between money in motion and money at rest,” he said. “The speed of conversion really creates a utility and advantage for people willing to operate in that ecosystem.”
In that framework, bitcoin increasingly becomes “money at rest” – an asset held for the long term – while stablecoins serve as “money in motion,” providing liquidity that can be transferred and used more easily without requiring holders to sell their bitcoin.
A Behavioral Shift for Bitcoin Holders
Getting there, however, will require more than simply building lending products.
Albright said greater education around both Bitcoin itself and the mechanics of borrowing against bitcoin will be necessary before the behavior becomes mainstream – something SALT Lending has made part of its own efforts in the market.
It also requires a change in how Bitcoin holders think about the value stored in their assets.
Instead of viewing bitcoin only as something to accumulate and eventually sell, holders can potentially use it as collateral to access liquidity while maintaining their bitcoin exposure.
That model is already common elsewhere in finance, where owners of real estate, equities and other assets regularly borrow against their holdings rather than liquidating them.
For Bitcoin holders, there can also be tax advantages. In the U.S., borrowing against an asset generally does not itself constitute a taxable sale, whereas selling appreciated bitcoin can trigger capital gains taxes. Individual tax consequences depend on the structure of the transaction and the borrower’s circumstances, readers should consult a tax advisor.
Albright sees that combination – long-term bitcoin holdings, growing stablecoin adoption and easier access to credit – as part of a broader shift in how Bitcoin holders may eventually use their wealth.
Rather than bitcoin needing to move every time its value is put to use, bitcoin can remain at rest while liquidity moves around it.
SALT Lending is the Official Liquidity Sponsor of BMTV. Learn more about borrowing against your bitcoin and explore SALT’s BMTV offer at https://saltlending.com/bmtv/?utm_source=bmtv&utm_medium=article&utm_campaign=52783658-BMTV%20article&utm_term=BMTV
Disclaimer: SALT Lending is a paid sponsor of BMTV and serves as BMTV’s Official Liquidity Sponsor. This article is sponsored content and does not necessarily reflect the views or opinions of Bitcoin Magazine. The information provided is for promotional purposes and should not be considered financial advice. Readers are encouraged to conduct their own research before making any investment decisions related to Bitcoin or other financial products mentioned herein.
This post The Next 3-5 Years of Bitcoin Lending first appeared on Bitcoin Magazine and is written by Josh Plischke.
HTTP error 429 on https://cryptoslate.com/feed/
Failed to fetch feed: https://cryptoslate.com/feed/
Failed to fetch feed.
CryptoTicker.io
The XRP Ledger is the blockchain that the cryptocurrency XRP runs on. It is a public network without mining: instead of pitting computing power against each other, servers vote by fixed rules on which transactions are valid. A payment is final after three to five seconds, and it costs a fraction of a cent.
Search the web for the XRP Ledger and you usually end up with a report on a protocol update or a price page. This article does something else. It explains how the ledger works technically, which of its quirks affect you as a holder in practice, and what applies when you buy, when you self-custody and when you file your taxes in Germany. You will not find a price forecast here, and there is a reason for that further down.
Are XRP and the XRP Ledger the same thing? Network, cryptocurrency and Ripple kept apart
Three terms are almost always mixed up, although they denote three different things.
The XRP Ledger (XRPL for short) is the blockchain itself, meaning the jointly maintained database together with the software that keeps writing it forward. XRP is the native cryptocurrency of that network: the only unit that fees are paid in and that exists on the ledger without any third party. Ripple, in turn, is a private company based in the United States that builds payment software and holds a large stock of XRP.
The distinction is not hair-splitting. It determines who owns what. The ledger belongs to nobody, the software is open source, and anyone may run a server. XRP belongs to whoever holds the matching cryptographic keys. Ripple is one user and contributor among many, with considerable economic weight but no special rights in the protocol.
Short definition: a blockchain is a record of transactions that many mutually independent computers keep in identical form, so that no single operator can alter entries after the fact.
Where the XRP Ledger came from: why three developers looked for an alternative to mining in 2011
The project's own documentation dates the beginning to 2011. The developers David Schwartz, Jed McCaleb and Arthur Britto were working on Bitcoin and took issue with the energy cost of mining. Their goal was a procedure that solves the same problem, namely establishing the order of payments without a central authority, without burning computing power to do so.
The XRP Ledger went live in June 2012. Chris Larsen joined shortly afterwards, and in September 2012 the group founded a company called NewCoin, quickly renamed OpenCoin and then, in 2013, Ripple Labs. The founders gifted that company 80 billion XRP. Ripple later placed most of it in escrow accounts that are released in stages.
In the early years the name Ripple stood for everything at once: for the open-source project, for the consensus procedure, for the transaction protocol under the label Ripple Transaction Protocol, RTXP for short, for the network, and for the digital unit itself, which was still called ripples back then. Because that caused confusion time and again, the currency code XRP established itself in the community as the name. Today's three-way split into ledger, coin and company is therefore the result of that clarification.
This prehistory explains two things that still matter today. There was never any mining that creates new units, and the entire supply was fixed from the outset. Both set the XRPL fundamentally apart from Bitcoin.
The XRP Ledger consensus protocol: how validators decide without mining
Instead of a race for computing power, the XRPL uses a voting procedure that the documentation calls the XRP Ledger Consensus Protocol. Every three to five seconds, specially configured servers known as validators agree on the next version of the record.
Short definition: a validator is a server that actively submits proposals for the next ledger version and checks the proposals of others. Anyone may run one; no permission and no minimum capital are required.
The sequence is the same in every round. Each validator collects the transactions it has received, proposes a selection, listens to the proposals of the servers it trusts, and adjusts its own proposal until a sufficiently large majority is proposing the same thing. After that, every server applies the same rules to the same list and must arrive at the same result. If the results match, the new ledger version counts as validated and is final.
Unlike Bitcoin, there is therefore no waiting for additional confirmations. A payment is either included in the validated version or it is not. The protocol is also designed so that, in case of doubt, the network would rather come to a standstill than let an invalid transaction through.
Not every machine on the XRPL is a validator. The large majority of servers are plain nodes. They hold a copy of the record, pass transactions on and answer queries from wallets and applications, but submit no proposals of their own. Exchanges, wallet providers and analytics platforms run such nodes, because it gives them access to the blockchain's data independently of third parties. A user needs to do nothing for this; their wallet queries one of these servers in the background.
One pointer for anyone who wants to go deeper: the English-language documentation calls this procedure the consensus protocol or consensus mechanism. Search under German terms such as Konsensverfahren and you will find considerably less material than under either of the two English labels.
Unique Node List: why every server keeps its own trust list
The decisive building block of the procedure is called the Unique Node List, UNL for short. It is the list of validators that an individual server believes. Every operator compiles it themselves, and most adopt a recommended default list.
The thresholds are named explicitly in the documentation. If fewer than 20 percent of the trusted validators behave incorrectly, operation continues undisturbed. If the share lies between 20 and 80 percent, the network stops making progress and comes to a halt. Validating an invalid transaction would require collusion among more than 80 percent of the trusted validators.
On the scale involved, the project cites on its own overview page more than 120 active validators, run among others by universities, exchanges and companies, as well as over 150 validators in total, of which more than 35 sit on the default list. Ripple, by its own account, runs exactly one of them.
This is precisely where the most common criticism of the XRPL comes in. Whoever maintains the default list has influence over whom the majority of servers trust. That is a different form of decentralisation from a mining network, and whether it is sufficient is a matter of judgement, not a matter of fact.
Account reserve on the XRP Ledger: why an account may never be emptied completely
You notice the first practical quirk as soon as you send XRP to an address of your own. The XRPL requires a reserve that must remain on the account permanently and cannot be spent. This reserve keeps the shared record small and makes creating throwaway accounts expensive.
For the main network, the technical documentation names two figures: a base reserve of 1 XRP per account and an additional reserve of 0.2 XRP for every further object your account occupies in the record, such as a trust line or an open trading offer. The first two trust lines are exempt.
For you this means two things. First, an account holding less than the base reserve does not technically exist, so a deposit below that amount will not arrive. Second, you never get your reserve back in full as long as the account remains in place. Anyone taking XRP into self-custody should plan for this floor rather than book it as an error.
Destination tag: the most common expensive mistake when depositing to an exchange
Exchanges often maintain only a single XRP address for many customers. To make sure an incoming payment is credited to the right customer, there is the destination tag, a number you supply in addition to the address.
Short definition: the destination tag is a 32-bit integer attached to the payment. On the ledger itself it does nothing; it merely tells the receiving system which internal account the amount belongs to.
If the tag is missing on a deposit to a pooled address, the money is not lost, but it sits with the operator and has to be assigned manually by their support team. That takes time, costs a processing fee at some providers and occasionally fails altogether. Checking before you hit send is therefore mandatory. How to do it is set out in detail in our article on the destination tag in XRP transfers.
The built-in marketplace: DEX, trust lines and tokens on the XRP Ledger
The XRPL has been more than a payment network from the start. A decentralised exchange is built into the protocol, with offers held directly in the record. No additional program on a second layer is needed for it.
Alongside XRP, further tokens and therefore other crypto assets can be issued on the ledger, for instance units pegged to a euro or a dollar. Such tokens are always a claim against their issuer. To be able to hold them, you set up a trust line.
Short definition: a trust line is a declaration by your account stating up to which amount it accepts tokens from a particular issuer. Without one, nobody can send you such a token.
Important for context: only XRP itself has no issuer. Every other token on the ledger stands or falls with the company behind it, however solidly the technology underneath performs. Ripple also markets a procedure under the name On-Demand Liquidity in which XRP serves as a bridge currency for cross-border payments. Whether financial institutions and payment providers use it to any significant extent is one of the core questions for the entire ecosystem.
Amendments: how the XRP Ledger changes without a hard fork
New features enter the XRPL protocol through what are called amendments. An amendment is a clearly delimited rule proposal that the validators vote on. If it reaches approval of at least 80 percent for two weeks, it takes effect automatically.
This procedure replaces the hard split that other networks need for such changes. For you as a holder it is usually invisible, but occasionally relevant: a new feature can touch fees, reserves or the use of a wallet. We follow these votes continuously, for example at the activation of an XRPL amendment and most recently at the Batch amendment XLS-56, which allows several transactions to be bundled.
Anyone running their own wallet or their own server should keep the software up to date. A server that does not know an activated amendment loses its connection to the network.
Transaction costs and the XRP supply: why every payment destroys a fraction
Every transaction on the XRP Ledger must destroy a small amount of XRP. The documentation names 10 drops, or 0.00001 XRP, as the current minimum for a standard transaction. Under heavy load that figure rises temporarily.
The difference from almost every other network lies in the recipient: there is none. Transaction fees do not go to miners or operators, they disappear. That makes spam expensive and shrinks the total supply slowly.
How slowly can be worked out. 100 billion XRP were created. CoinGecko reports a total supply of 99,985,622,230 XRP at 06:36 UTC on September 20, 2026. The difference of roughly 14.4 million XRP has been destroyed by transaction fees since the launch in June 2012, which is well under a tenth of a percent of the stock. Market capitalisation at the same moment stood at around 75.6 billion euros, and according to this source about 62.9 billion XRP were in circulation. The gap to the total supply sits mostly in Ripple's escrow accounts.
The figures are a snapshot and change daily. As an order of magnitude they still serve: fee burning is a protective mechanism against mass requests, not a meaningful scarcity factor.
Buying XRP in Germany: exchange, licence and fees
XRP is listed on practically every larger trading venue available in Germany. Your choice therefore turns on the provider rather than on the coin. Three points can be verified before you transfer any money.
First, the licence. Since the European regulation on markets in crypto assets, MiCA for short, providers of crypto asset services need authorisation from a supervisory authority in the EU. Whether your provider holds such authorisation is stated in its legal notice and can be checked against the competent authority.
Second, the actual cost. The order fee on display is rarely the whole price. Added to it is the spread, meaning the gap between the buying and selling price, and on a withdrawal to a wallet of your own often a fixed network fee that can sit far above the actual 0.00001 XRP. Comparing the terms is worth the effort, and we keep ours up to date in our crypto exchange comparison.
Third, whether you can get your money out. Before your first purchase, check whether the provider offers euro withdrawals to a German account and whether XRP can be transferred to an external address. Neither can be taken for granted.
Holding XRP: wallet, keys and the difference from an exchange
If your XRP sits on a trading venue, you hold no keys. What you hold is a claim against that company. For small amounts and active trading that is defensible. For a longer investment horizon, self-custody is the more robust option.
Technically you need a wallet that supports the XRPL and the willingness to store the seed safely. The seed is the character string from which the private keys of your account are derived. Lose it and you lose access for good, because there is no authority that can reset it.
Two peculiarities of the ledger interlock here. You need the base reserve of 1 XRP for the account to exist at all, and when withdrawing from a trading venue to your own address you should leave the destination tag out, because a personal wallet does not need one. Which devices and programs are suitable for self-custody is covered in our hardware wallet comparison.
XRP and taxes in Germany: holding period, exemption limit and record-keeping
In Germany, cryptocurrencies held as private assets count as other economic goods. Gains on their sale fall under private disposal transactions pursuant to section 23 of the Income Tax Act. Three points follow from that, and they are no different for XRP than for other coins.
Between purchase and sale there is a period of one year. Sell after it and the gain remains tax free. Sell within it and the gain counts as other income and is taxed at your personal rate. For all private disposal transactions in a given year taken together there is an exemption limit of 1,000 euros. Exceed it and the entire amount is taxable, not merely the excess.
What matters in practice is that swapping XRP for another coin is also a sale. Using the ledger's built-in marketplace therefore triggers the same events for tax purposes as trading on an exchange. A tool that collects your transactions and tracks the holding periods saves a great deal of work here; which ones are worth using is set out in our overview of crypto tax tools and portfolio trackers. The information here is no substitute for tax advice in an individual case.
Limits of the XRP Ledger: what critics hold against its distribution and control
An explanatory piece that names only the strengths is a brochure. Three objections are substantive and belong here.
The first concerns distribution. The entire supply came into being at the start, and a large part of it went to a single company. The escrow accounts make the releases predictable, but they do not change the fact that one market participant commands a considerable stock.
The second concerns the trust lists. A network in which most servers follow a recommended default list distributes power differently from one in which computing power decides. Supporters counter that anyone can change their own list and that Ripple provides only one of more than 35 entries on it.
The third concerns usage. The technology has been running for more than a decade without a major outage. How much payment traffic actually runs over the XRPL rather than through conventional channels is not answered by that, and reliable public figures are hard to come by.
XRP forecasts: why this article contains no price target
Few cryptocurrencies attract as many price targets as XRP. We deliberately name none here. A price forecast spanning years is not analysis. Whoever makes one asserts something about the future that nobody is liable for.
What can be examined instead are the drivers behind it: the number of active validators, the size of the releases from the escrow accounts, actual usage by payment providers, and the regulatory situation in the EU and the United States. If you want to read up on expectations, the documented assessments are on our XRP price prediction page, each with a name and a date attached. A price target that arrives without an author and without a date is worthless.
XRP Ledger: what to take away
- Keep network, coin and company apart. The XRP Ledger is the open blockchain, XRP the cryptocurrency on it, Ripple a company with a large stock. If you want to buy, your first decision is a trading venue licensed in the EU: the terms are in our crypto exchange comparison.
- Plan for the ledger's quirks. The base reserve of 1 XRP stays on the account, and the destination tag belongs with every deposit to a pooled address. If you want to self-custody, pick a suitable device beforehand from our hardware wallet comparison.
- Keep records of your transactions from day one. The one-year period and the 1,000 euro exemption limit decide your tax burden, and every swap counts as a sale. A tracker from our overview of crypto tax tools takes the arithmetic off your hands.
(As of September 20, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
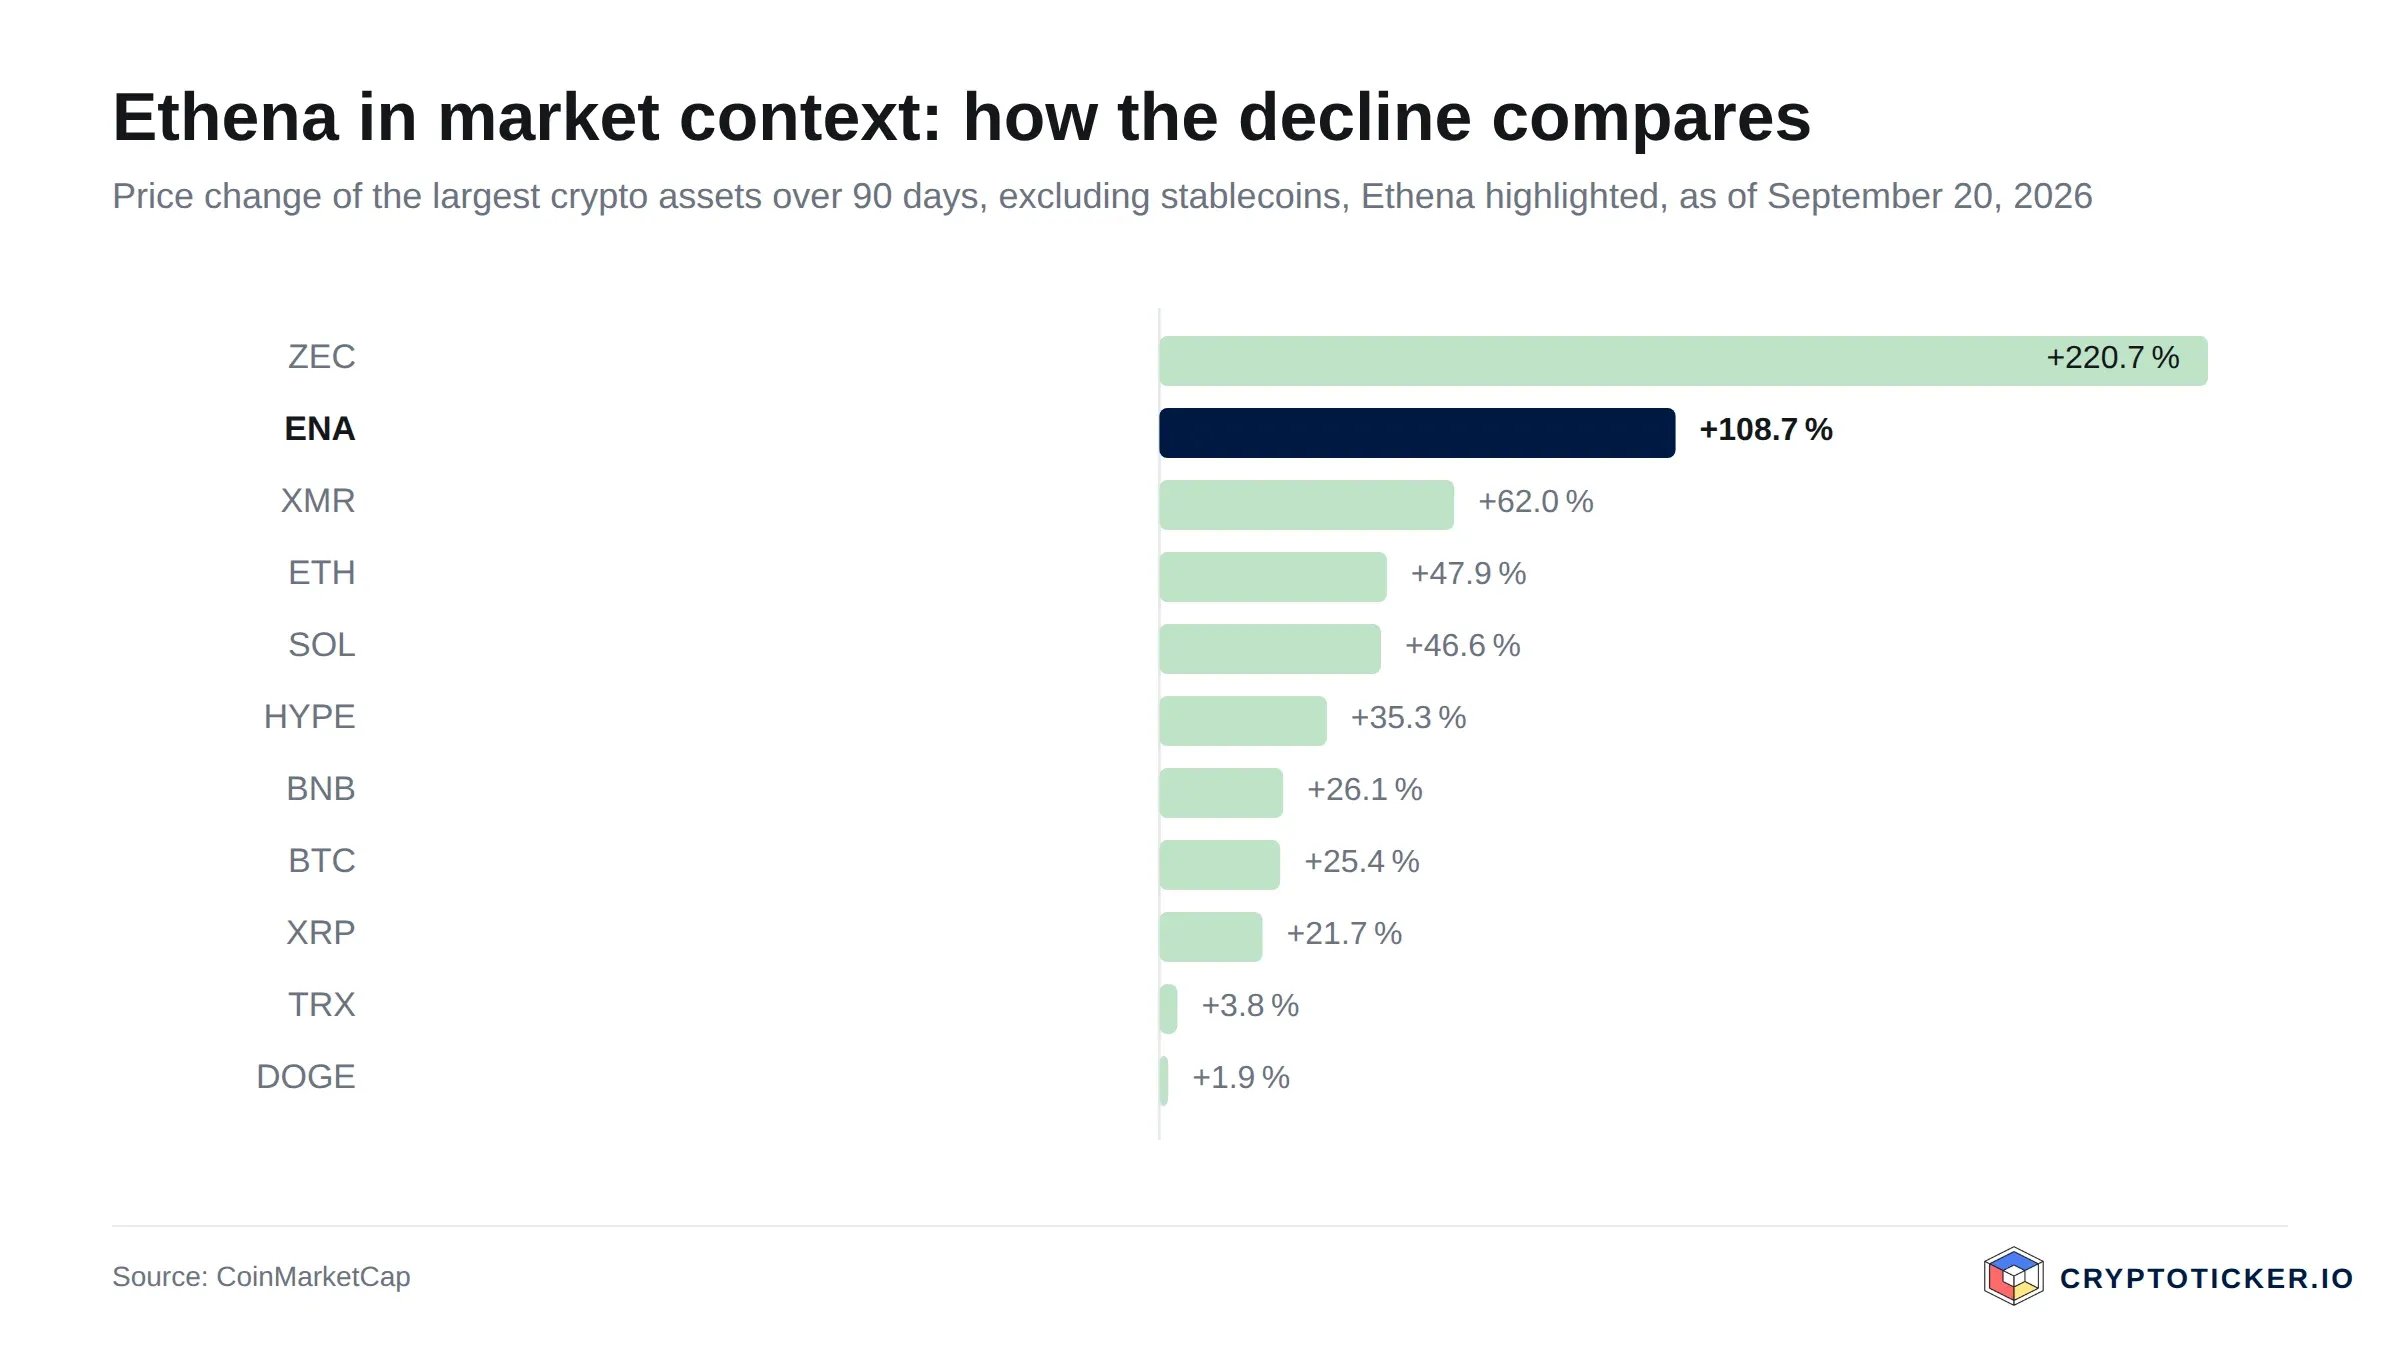
Ethena's governance token ENA trades at 0.1927 US dollars on 20 September 2026, roughly 71.4 percent below its twelve-month high of 0.6729 dollars from 20 September 2025, and about 170.4 percent above its twelve-month low of 0.0713 dollars from 2 July 2026. That spread frames the question this article sets out to answer: is Ethena a good buy at current prices, or has the easy part of the recovery already happened?
cryptoticker.io collected the price data behind this analysis on 20 September 2026. The market data comes from CoinMarketCap, the calculations use daily closing prices over the past 365 days and standard formulas: exponential moving averages over 200 and 50 days, and a 14-period RSI following Wilder's method.
Ethena price analysis: where the ENA price stands right now
The current ENA price of 0.1927 dollars sits well above both of the moving averages that matter for trend assessment. The 200-day exponential moving average stands at 0.1387 dollars, the 50-day exponential moving average at 0.1328 dollars. The token trades about 38.9 percent above its 200-day line and about 45.1 percent above its 50-day line, an unusually wide gap and a sign of how fast the move off the July low has been.
The zone that now matters most is the one between 0.13 and 0.14 dollars, where the two averages sit almost on top of each other. That is the first serious support below the market: a pullback into that band would leave the recovery intact, while a daily close underneath both lines would undo the technical improvement of the past three months. Above the current price, the twelve-month high of 0.6729 dollars remains far out of reach.
The shorter-term picture is equally stretched. ENA has gained 8.78 percent in 24 hours, 36.71 percent over seven days, 57.93 percent over 30 days and 106.93 percent over 90 days, while over the full twelve months it is still down 71.4 percent. Both statements are true at once, and which of the two an investor weighs more heavily largely determines how the current price looks to them.
Is the Ethena downtrend broken or only interrupted?
A downtrend is usually considered broken when price reclaims its long-term average and holds it, and when successive lows stop falling. ENA meets the first half of that test: the token has moved from 0.0713 dollars in early July to 0.1927 dollars today and has pulled the 50-day average back above the 200-day average, a crossover trend followers read as confirmation rather than as a signal in itself.
The second half is unfinished. A twelve-month chart that still shows a 71.4 percent drawdown describes a market that has rallied inside a larger decline. What would settle the question is a pullback that stops above the 0.13 to 0.14 dollar band and turns higher from there. Until such a retest happens, the honest reading is that the downtrend is interrupted and not yet demonstrably broken. That is an assumption about market structure, and a close back below the 200-day line at 0.1387 dollars would be the cleanest evidence against it.
What RSI and moving averages mean for an ENA entry
The 14-day RSI for ENA stands at 61.9, in the upper half of the neutral range and below the 70 mark conventionally treated as overbought. Momentum is firm without being extreme. For an entry decision that matters in a specific way: a reading near 62 after a 106.93 percent run over 90 days suggests the rally has cooled from its sharpest phase rather than exhausted itself.
The moving averages carry the more cautionary part of the story. Buying 45.1 percent above the 50-day average of 0.1328 dollars means paying for a move that has already happened. Prices that far from their medium-term average tend to consolidate or correct back towards it. The 0.1387 dollar level is the number to watch, because that is where a mechanical trend signal would flip.
What trading volume reveals about demand for Ethena
ENA turned over about 1.05 billion dollars in the past 24 hours against a market capitalisation of roughly 1.95 billion dollars. That ratio of about 54 percent is high by any standard: large-cap tokens typically trade between 3 and 15 percent of their market capitalisation in a day. Turnover of this size confirms that real order flow is meeting the move, and it also reflects short-term traders whose positioning can be unwound as quickly as it was built.
Ethena's ranking gives a sense of scale: ENA currently sits at rank 42 by market capitalisation. The broader backdrop is firm, with CoinMarketCap's Fear and Greed Index at 70, in greed territory. A sentiment reading that high is a reminder that the current price already contains a good deal of optimism.
Which structural factors speak for Ethena as an investment
Ethena's economics rest on a synthetic dollar, USDe, whose stability mechanism differs fundamentally from a reserve-backed stablecoin. Rather than holding fiat deposits, the protocol pairs spot collateral with short perpetual futures positions, so that gains and losses offset one another and the yield comes from funding rates plus staking income on the collateral. The mechanism and its risk parameters are set out in Ethena's own technical documentation, and we have explained how the yield is produced in our guide to the USDe yield.
That design creates a direct link between protocol revenue and the ENA token, which is the investment case in its simplest form. When funding rates are positive and USDe supply is large, the protocol earns; how much of that reaches token holders is the subject of the fee switch and buyback discussion we covered earlier this year.
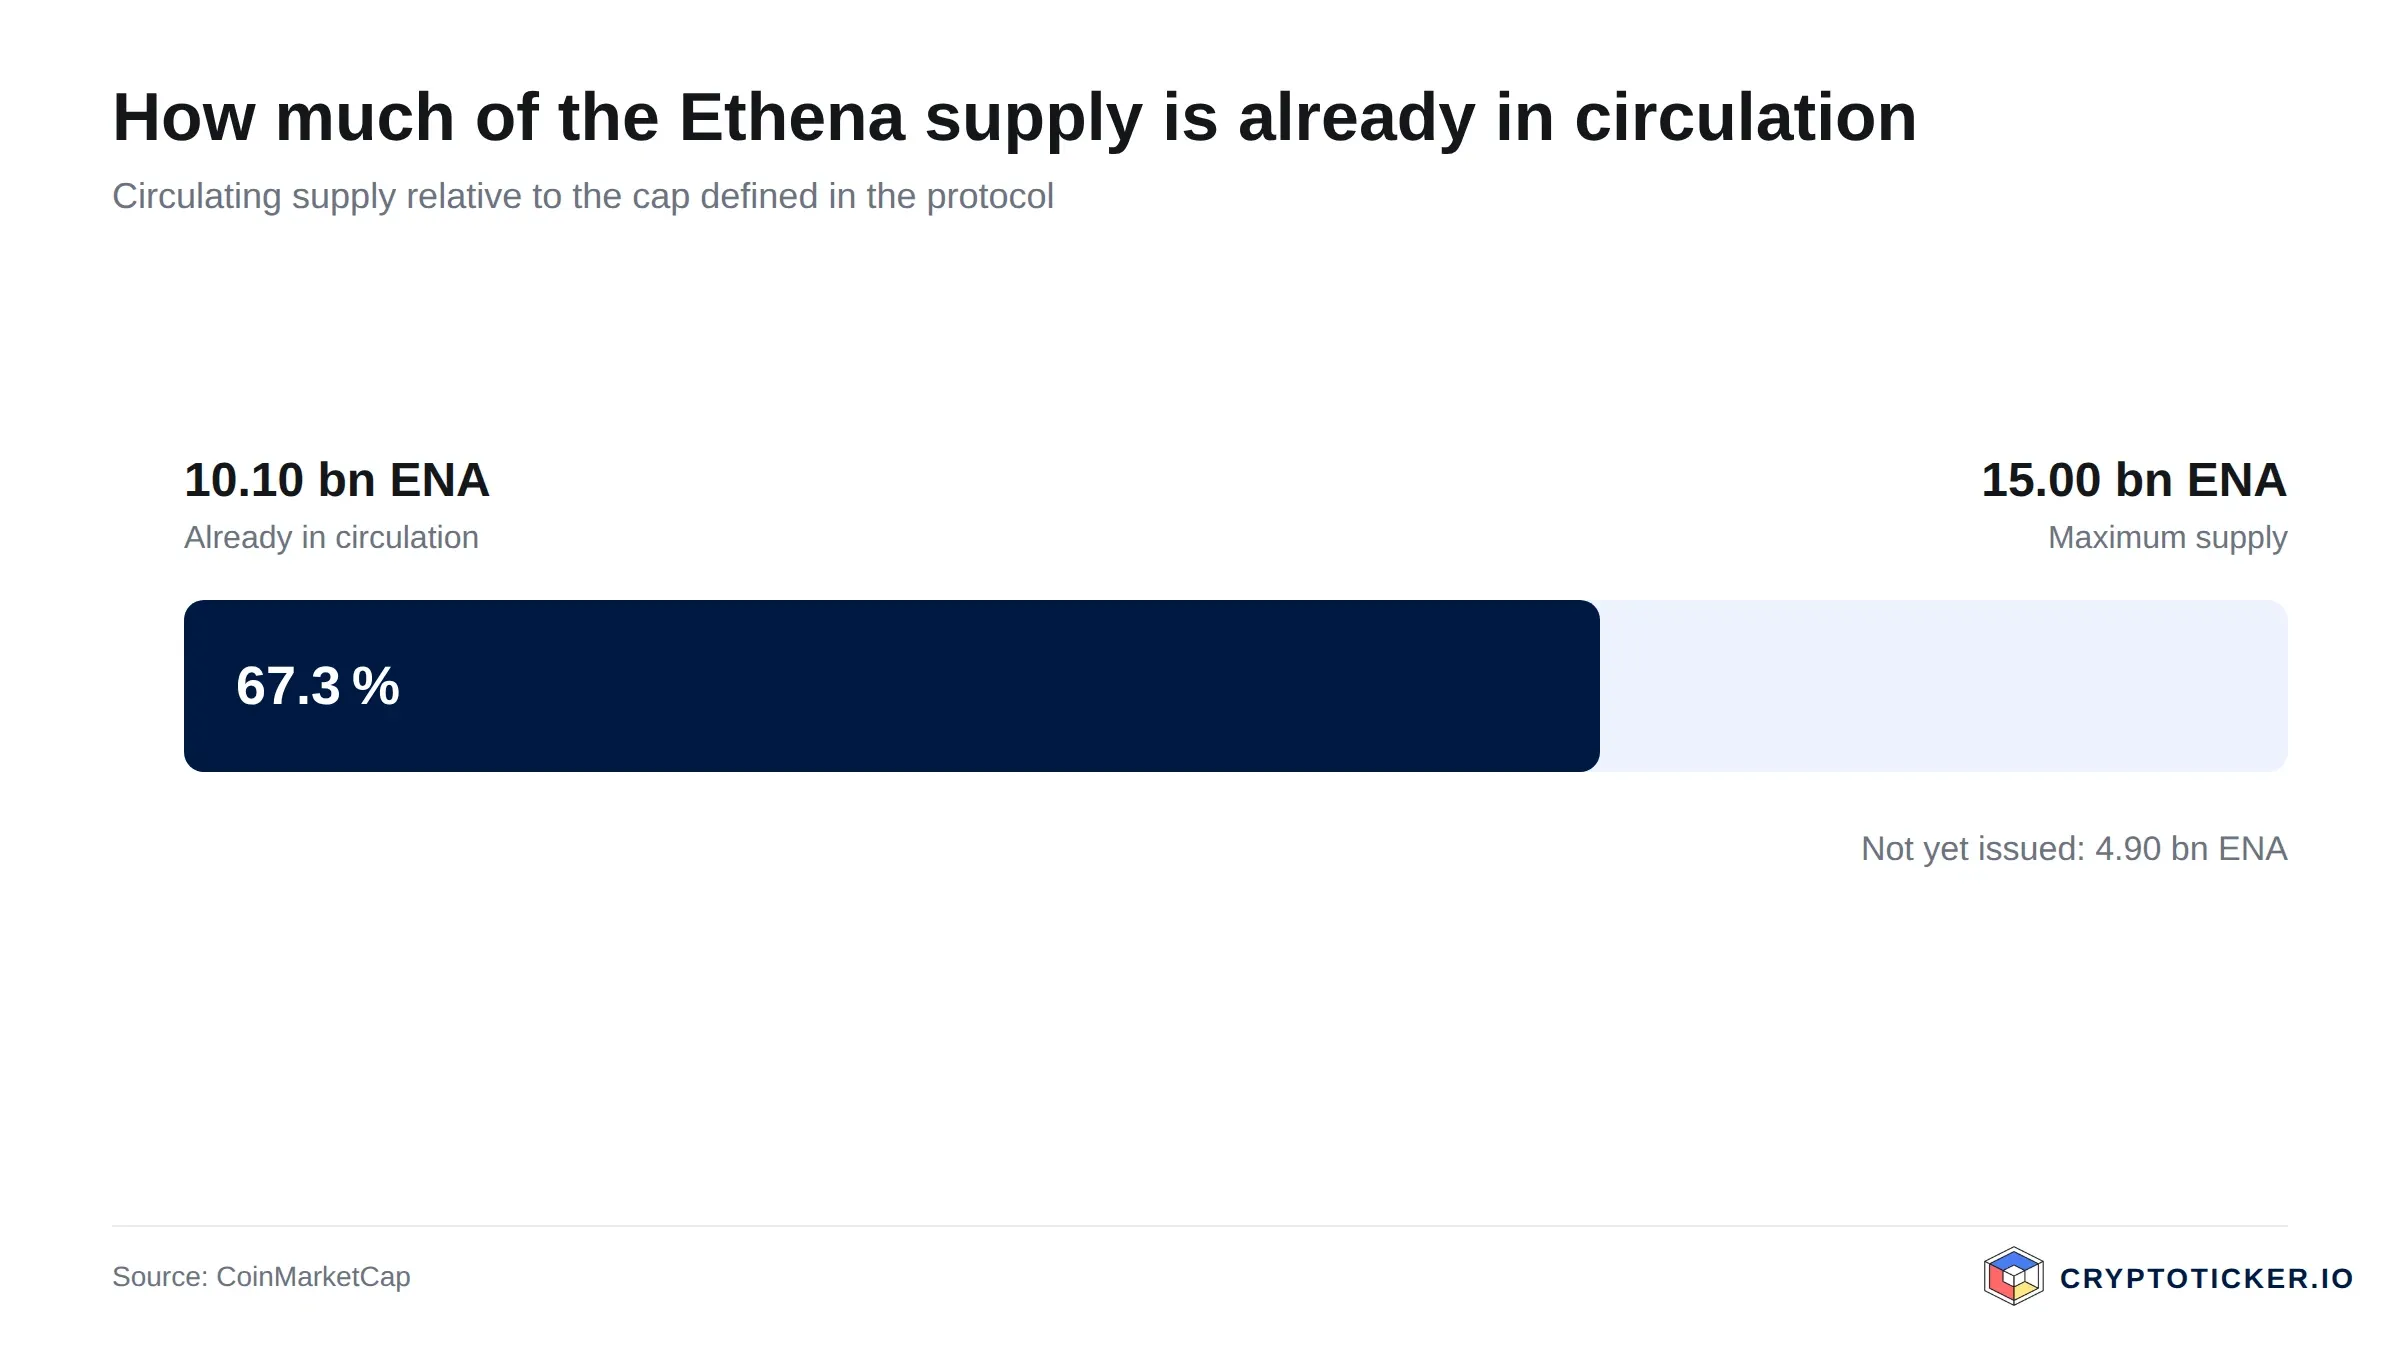
The supply mechanics cut the other way. Of a maximum supply of 15 billion ENA, about 10.1 billion are in circulation, or roughly 67 percent. The remaining third is scheduled to enter the market over time, and unlock schedules have moved this token's price before, as our reporting on the investor unlock described. Dilution of that magnitude is a structural headwind that a rising price does not remove.
Regulation is the third structural variable. In the European Union, ESMA and the national supervisors apply the MiCA framework, which sets authorisation requirements for asset-referenced and e-money tokens. Synthetic dollar designs that are not backed one for one by fiat reserves sit awkwardly against those categories, and how that is resolved will shape where USDe can be distributed in Europe. That is an open question rather than a settled fact, and one of the larger uncertainties in the investment case.
What speaks for buying Ethena at current prices
First, the trend has turned on the measures trend followers use. ENA trades above its 200-day average of 0.1387 dollars and above its 50-day average of 0.1328 dollars, with the shorter average back above the longer one. For a systematic approach, that combination is the entry condition, and it is currently met.
Second, the price is still 71.4 percent below the twelve-month high of 0.6729 dollars. Investors who believe the protocol's revenue model will survive a full funding-rate cycle are paying roughly a third of what the market paid a year ago for the same claim on that revenue.
Third, liquidity is not a constraint. Daily turnover of about 1.05 billion dollars against a 1.95 billion dollar market capitalisation means positions of retail size can be built and exited without moving the price, which is not true of every token in this size bracket.
What speaks against buying Ethena at current prices
First, the entry is extended. At 45.1 percent above the 50-day average and 38.9 percent above the 200-day average, a buyer at 0.1927 dollars pays a premium to the market's own medium-term reference price, and a mean reversion towards 0.13 to 0.14 dollars would represent a decline of roughly 28 to 32 percent without anything changing about the protocol.
Second, the supply overhang has not been worked through. With about 10.1 billion of a maximum 15 billion ENA circulating, the remaining tokens arrive against a market capitalisation of under 2 billion dollars. Absorbing them requires demand that grows at least as fast as supply, and that has not been the pattern over the past twelve months, during which the token lost 71.4 percent.
Third, the revenue model is cyclical by construction. USDe's yield depends on perpetual funding rates staying positive, which they tend to do in bullish markets and not in sustained bear phases. A token whose value case rests on protocol revenue inherits that cyclicality, and the current Fear and Greed reading of 70 suggests the market is pricing the favourable half of the cycle.
How to buy Ethena at current prices: costs, custody and providers
ENA is listed on most large centralised exchanges, so the practical differences between them are fees, regulatory status and withdrawal terms rather than access. Spot trading fees at the major venues typically run between 0.1 and 0.5 percent per trade for retail volumes, and on a token of this liquidity the spread is usually the smaller cost. Our exchange comparison sets the current conditions side by side, and our Bitpanda review goes through one European provider's fee structure in detail. Check fees at the provider before you trade: they change, and this article is a snapshot.
On custody, the choice is between leaving tokens with the exchange and withdrawing them to a wallet you control. Exchange custody is simpler and exposes you to the provider's solvency and security; self-custody removes that exposure and hands you responsibility for key management. Holders who intend to put ENA or USDe to work rather than hold it passively should read the terms first, and our staking platform comparison covers what the various providers charge and what lock-up periods apply.
Is Ethena a good buy at current prices, short term and long term?
For the short term, the setup is mixed and the price level is the reason. Momentum is intact, with an RSI of 61.9 and both moving averages beneath the market, but the distance to those averages is wide enough that a consolidation would be the normal outcome rather than a surprise. A buyer at 0.1927 dollars accepts a drawdown risk towards 0.1387 dollars as the cost of participating in a trend that is currently working.
For the long term, the question is not the chart but the revenue model and the supply schedule. The case holds if USDe supply grows, if funding rates average positive across a full cycle, if the fee mechanism directs a meaningful share of revenue to token holders, and if the European regulatory treatment of synthetic dollars settles in a workable form. The case is refuted if funding rates turn persistently negative, if the remaining 4.9 billion ENA enter the market faster than demand grows, or if MiCA implementation effectively closes the European distribution route.
Those conditions are testable, and this article issues no recommendation on how they will resolve. At 0.1927 dollars the market is no longer pricing Ethena for failure, as it arguably was at 0.0713 dollars in July, and the margin of safety has narrowed accordingly.
Buying Ethena: what to take away
- The trend has turned but the entry is expensive. ENA at 0.1927 dollars trades 38.9 percent above its 200-day average of 0.1387 dollars and 45.1 percent above its 50-day average of 0.1328 dollars. The 0.13 to 0.14 dollar band is where the technical case would break. For a comparable analysis of another protocol token, see our assessment of Aave at current prices.
- The investment case is a bet on protocol revenue rather than on a network. Yield comes from funding rates and staking income, which makes it cyclical; how much of it reaches token holders is the open question we examined in our report on the fee switch and buyback debate.
- Supply and regulation are the two structural risks. Roughly a third of the maximum 15 billion ENA has yet to enter circulation, and the European treatment of synthetic dollars is unresolved. Before choosing where to buy or hold, compare the conditions in our exchange comparison.
Disclosure: Some of the providers mentioned in this article work with us through partner programmes. This has no influence on the price analysis or on the assessment of the chart situation; the price data comes from a public market data source and can be verified there.
(As of 20 September 2026. This article is not investment advice. Prices, fees and conditions change; check them with the provider yourself before any purchase. Crypto assets are subject to high price volatility, and a total loss is possible.)
On October 18, 2026 the US administration has to set how high the new tariffs against Russia will be. The law permits up to 500 percent; it prescribes not a single figure. The act behind that deadline is H.R. 5334, and it bundles sanctions, tariffs and prohibitions against Russia into one package. For you as a crypto investor, October 18 is neither a buy nor a sell signal but a date in the calendar: that is the day it is decided whether a sanctions act turns into a macro event or stays a narrowly drawn measure. This article explains what the law actually says, by what route Russia sanctions reach Bitcoin at all, and what you can check until then without touching a single position.
What H.R. 5334 says and why October 18, 2026 counts
The White House reports the president's signature under H.R. 5334, the Lindsey O. Graham Sanctioning Russia and Iran Act of 2026, for Friday, September 18, 2026. The official statement says the act authorizes sanctions, tariffs and prohibitions against Russia, expands them and at the same time extends existing sanctions against Iran.
What matters is the difference between two things that headlines tend to merge. A sanctions act is not itself a tariff: it creates the legal basis and instructs the administration to set concrete rates within a deadline. A tariff, in turn, is a duty on imported goods that the importer pays in the destination country and as a rule passes on in its prices.
The signature starts a 30-day clock. Trade outlet CryptoSlate extrapolates it to October 18, 2026 in its analysis of September 19, 2026: by that day the administration has to determine which rates actually apply. That is exactly why the date is of any interest to the crypto market. Before it there is an authorization with a very wide frame; after it there is a number you can work with.
Up to 500 percent on Russian goods: a ceiling, not a mandatory rate
According to CryptoSlate, the act obliges the president to raise duties on all Russian goods imported into the United States. Oil, natural gas and petroleum products are named explicitly. The rate may reach up to 500 percent.
That figure is a ceiling and not a prescribed rate. A ceiling means the administration may go that far but does not have to. The room between a symbolic surcharge and the full level is therefore wider than the distance between most realistic market scenarios. Anyone reading the 500 percent as a decided measure is reading the law wrong.
For the market it is therefore not the headline that decides but the implementation. Which level is chosen, which goods are covered and from when the rates apply: those three points are not fixed before October 18, and without them no transmission route can be quantified seriously.
The third-country clause: when other countries risk tariffs of up to 100 percent
The second provision weighs more heavily in economic terms than the first. This clause is aimed at third countries, meaning countries that are not sanctioned themselves but continue to trade with Russia. Anyone making new purchases of Russian crude oil or natural gas after the 30-day deadline expires, and ranking among the five largest buyers, can be hit with tariffs of up to 100 percent on all goods that country exports to the United States, according to CryptoSlate's analysis.
The same ceiling applies to the five countries that the US administration considers most helpful in circumventing the oil sanctions. Sanctions circumvention here means any route by which sanctioned goods or sanctioned money still reach their destination via an unsuspicious third party, for instance through intermediaries, reflagging or layered companies in a third country.
The decisive point: the act names none of these countries, and it prescribes no minimum rate. Who gets hit is therefore an administrative decision, not a consequence of the statutory text. That very uncertainty makes October 18 the test of whether the package becomes a broad trade shock or a narrowly framed sanctions measure.
Ten days' warning: the first solid signal comes from Congress
The act contains a reporting duty that is more practical for you than any forecast. Before the administration imposes or changes tariffs under the third-country clause, the president or the US trade representative has to submit a written justification to six congressional committees, at least ten days in advance. According to CryptoSlate, that justification must state both the tariff rate and the methodology by which the affected country was selected.
Something concrete follows from that: the first solid signal can become public well before October 18. Anyone with the date in the calendar should therefore also keep an eye on the congressional notices of the preceding days and not only on the deadline itself. That is where it first appears how close the rates come to the ceilings and which countries are in the crosshairs.
Exemptions and waivers: why the ceiling is rarely the outcome
The act contains two built-in valves. An exemption applies to certain natural gas purchases. And the president can suspend tariffs if he certifies to Congress that doing so serves the national interests of the United States.
Such a waiver is a formal decision not to apply a rule that otherwise holds. In sanctions practice it is the norm rather than the exception, because it allows the administration to build pressure without damaging its own supply or important trading partners. For your assessment that means the range of possible outcomes runs from a decision with almost no consequences to a tangible intervention in energy flows, and both ends are covered by the act.
What the Fed decided on September 16 and why it narrows the room
The date meets a monetary policy that has just turned the other way. On September 16, 2026 the US central bank raised the policy rate by a quarter of a percentage point to a range of 3.75 to 4.00 percent and justified the increase with still elevated inflation. It was the first hike since July 2023; German business media report consistently on a unanimous decision and a further step signaled before year-end.
Why that counts here: a central bank already acting restrictively has little room to respond to an additional price push in energy with easing. An energy shock in a phase of falling rates works differently from the same shock in a phase of rising rates. The second case is the one we are in.
The transmission route to the crypto market: energy, inflation, rates, dollar
CryptoSlate describes the route from tariff to price in four links, and that description is the outlet's assessment, not this newsroom's expectation. Energy first: high tariffs on countries that keep buying Russian oil or gas can shift trade flows once further purchases become economically or politically expensive. Whether world market prices respond depends on which countries are hit, how high the rates turn out and whether Russian volumes are merely redirected rather than taken off the market.
The second link is inflation. According to CryptoSlate's account, Fed governor Christopher Waller pointed out this year that persistently higher energy costs feed through to the prices of other goods and services, because companies pass on their increased input costs. Repeated energy and tariff shocks could also raise inflation expectations.
The third link is rates and the dollar: rising inflation expectations push government bond yields up and support the dollar, which makes capital more expensive and reduces liquidity for risk assets. The fourth link is the crypto market itself. A study by the Bank for International Settlements, which CryptoSlate cites, links tighter US monetary policy to falling crypto prices and weaker demand for stablecoins.
This chain is a mechanism, not a timetable. Every link can hold or break, and nobody can say seriously where Bitcoin stands on October 19. How sensitively the market can react to tariff news was described by cryptoticker.io on February 23, 2026 in its analysis of volatility around earlier tariff plans; the route via the oil price was worked through by the newsroom on March 28, 2026 using the example of the Russian export ban.
The counter-argument: why the effect may fail to materialize
A date with an open outcome has two sides. Three things speak against a tangible market shock, all of them built into the act itself: a mild implementation with rates well below the ceilings, generous use of the waivers, and the possibility that Moscow simply redirects its volumes to other buyers rather than taking them off the market. If energy prices stay stable, nothing arrives at the end of the chain.
Three points speak for a tangible effect as well: aggressive rates against the largest buyers of Russian energy, sustained pressure on oil and gas prices, and a central bank that wants to tighten anyway because of elevated inflation. If all of that comes together, the sanctions package becomes one more brake on financing conditions. Which of the two descriptions applies cannot be settled before the rates are published, and anyone selling a direction today is selling a supposition.
Why the US act is something different from the EU crypto sanctions
A distinction is worth drawing here, because both topics end up under the same search term. Anyone searching for crypto sanctions almost always lands on the European measures and not on this American act. H.R. 5334 is a trade and sanctions law addressing flows of goods. On cryptocurrencies, crypto exchanges or crypto service providers it contains nothing, as far as the available sources report.
The European Union takes a different route and hits crypto infrastructure directly. On August 21, 2026 cryptoticker.io set out in detail which fourteen crypto platforms were blocked by the EU transaction ban from August 23 and what that means for incoming transfers. What stands there is a sanctions list, a ban on certain services for Russian actors, and a rule allowing the EU to cover entire third countries in future.
A rule of thumb for placing this: the American act affects the crypto market only indirectly, through macro channels. The European measures act directly on individual platforms, wallets and transactions. For your portfolio those are two entirely different risks, and only one of them has a date on October 18.
Why cryptocurrencies feature in sanctions debates at all
Since the war in Ukraine began, financial sanctions against banks and other financial institutions have been part of the West's standard toolkit. A financial sanction is the order to deny certain people, companies or states access to the financial system, and it works through the institutions that provide that access. That is exactly where cryptocurrencies come into view: payments can be settled without a bank, which is why many supervisors regard the crypto sector as a possible route around them.
The other side of that concern is rarely voiced. A public blockchain is a permanent cash book that anyone can inspect. Authorities and specialist analytics firms trace addresses back over years, assets on listed addresses can be frozen, and supervised crypto firms run anti-money-laundering and sanctions screening in the same working step. For the crypto sector as a whole that means regulated trading is transparent rather than anonymous, and that is the reason sanctions can be enforced there at all.
Sanctions risk in your portfolio: what happens if your exchange has a listed counterparty
The concrete, non-macroeconomic risk lies in your provider's sanctions screening. Crypto service providers in the EU have to check customers, wallet addresses and incoming transactions against sanctions lists. If that screening triggers, the amount is frozen and reported instead of processed, regardless of whether you knew anything about the origin of the funds.
If it happens to you, it runs in this order: the provider blocks the amount, informs the competent supervisor and often may not even tell you the reason. In Germany, BaFin is the authority where that route ends. Release follows only after an official review, and that takes time. Customers without complete evidence of the origin of their funds wait longest.
For you that means two things. First: a balance held with a provider without solid supervision is harder to reach in a sanctions case than a balance at a supervised exchange. Which obligations now apply to supervised providers is set out in the overview of MiCA licensing requirements for crypto firms. Second, it is worth looking at the comparison of regulated crypto exchanges before a date with an unclear outcome draws closer, not afterwards.
What you can check before October 18 without trading
The most useful preparation for a macro date consists of homework that makes sense regardless of the outcome. Buying and selling are not part of it.
- Note the date and the lead time. October 18, 2026 is the deadline; the congressional notices under the ten-day rule are the earlier signal. Both belong in the same calendar entry.
- Go through your counterparties. Where does which holding sit, which provider is under which supervisor, and how long does a payout take if it comes to that?
- Recalculate leverage and liquidation levels. Anyone working with borrowed capital should know before a window of volatility at what price a position closes automatically. That number is best known while things are calm.
- Check your access. Do two-factor methods, recovery codes and access to your own wallet work? A date with heightened attention is also a date with heightened fraud.
None of this is a bet on a direction, and all of it keeps its value if October 18 passes without consequence.
Tax: why a panic sale costs more than the price drop
A date with an unclear outcome tempts people into quick sales, and in Germany that is often the most expensive part. For private disposal transactions under Section 23 of the Income Tax Act the rule is: hold a cryptocurrency for more than a year and the gain is sold tax-free. Sell within the one-year period and the gain is taxed at your personal rate as soon as the exemption limit of 1,000 euros in the calendar year is exceeded; that limit has applied since the 2024 assessment period.
So if you sell holdings in October out of nervousness whose one-year period would have expired in December, the nervousness may cost you more than the feared price decline. On top of that comes the documentation duty: acquisition date, acquisition cost and the allocation method you chose have to be evidenced, and that is hard to do retroactively. How to keep that evidence cleanly is shown by the comparison of crypto tax software and portfolio trackers. For assessing an individual case, tax advice remains the place to go; this section does not replace it.
What this act does not say
Honest treatment of an open situation includes the list of what stays open. The act names no affected countries. It prescribes no minimum rate. According to the available sources it contains no crypto-specific provision. And it says nothing about how quickly the rates once set are actually levied.
Nor can the statutory text tell you how large direct trade between the United States and Russia even is today. Anyone wanting to estimate the effect needs that order of magnitude, and it is one of the points to be re-examined once the rates are published. As long as those figures are missing, any concrete price expectation for this date is an assertion without a basis.
Russia sanctions and crypto: what to take away
- Treat October 18, 2026 as a date, not as a signal. What will matter is the level of the rates and the list of affected countries, and a first signal can come from Congress ten days earlier. Anyone planning an entry in this phase anyway should settle the provider question first: the crypto exchange comparison takes it off the table before things get hectic.
- Check your tax position before a possible swing, not after. Holding periods and evidence often decide the net return more clearly than the price itself; the tax tools in comparison keep the history while it is still complete.
- Separate macro risk from provider risk. The US act works through energy, inflation and rates; the European sanctions hit individual platforms directly. Against the second risk, the choice of a supervised counterparty helps, as broken down in the comparison of regulated crypto exchanges.
Primary sources for this article: the White House statement on the signing of H.R. 5334 of September 18, 2026 and the assessment by CryptoSlate on the October 18 date of September 19, 2026.
(As of September 20, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Zcash traded above $1,500 for the first time since its launch in 2016 on September 19, 2026. If you hold ZEC, the most important question this weekend is neither the next price target nor whether the rally continues. It is this: when does your gain become tax-free in Germany, where will you still be allowed to trade the coin eighteen months from now, and is it sitting somewhere you can still move it from? This article works through those three points in turn and names the source and the measurement time behind every figure.
Zcash price today: $1,473.77 after an intraday high of $1,590.80
The reading everything else refers to: Zcash traded at $1,473.77 on September 20, 2026 at 00:49 UTC. That is 6.41 percent below the previous day. Within the preceding 24 hours the high was $1,590.80 and the low $1,466.66. The price therefore sits closer to the daily low than to the daily high.
Over longer periods the picture differs. Over seven days Zcash is up 31.38 percent, over 30 days 159.02 percent, over twelve months 2,913.12 percent. Market capitalization stands at $24.97 billion, which places Zcash ninth among all crypto assets. Trading volume over the past 24 hours was $1.15 billion. There are 16,940,252 ZEC in circulation out of a maximum of 21,000,000.
cryptoticker.io collected these values itself on September 20, 2026 at 00:49 UTC, through CoinGecko's public market data endpoint for the Zcash asset. A single asset was checked. What we could not check is how the quotes at individual venues differ from this aggregated average price; anyone trading on a particular exchange will see a slightly different number there.
Record or not? Why the figures for the Zcash all-time high diverge
A clarification is worth making here, because the reports over this weekend refer throughout to an all-time high. Industry outlet The Coin Republic reported a record of $1,535 on September 19 and said Zcash had risen above $1,500 for the first time ever.
CoinGecko's database, by contrast, lists an all-time high of $3,191.93, set on October 28, 2016. Both figures are correct within their own frame and cannot be merged into a single number. The October 2016 value comes from Zcash's first days of trading, when only a tiny number of coins had been issued and individual trades cleared at four-digit prices. Count that phase in, and what you see today is not an all-time high but the highest level in almost ten years. Exclude it as a distortion, and you get a record.
For your own decision the difference is less academic than it sounds. A price running into a known high meets sellers there who have been waiting years for that exit. A price in unknown territory does not face that resistance. Which of the two pictures applies depends entirely on how you rate the 2016 number.
Open interest and short liquidations: what pushed the ZEC price up
Open interest is the total of all outstanding derivatives contracts on an asset, meaning the money betting on rising or falling prices through leveraged products. For Zcash that total stood at $3.47 billion on September 19 according to The Coin Republic, higher than ever before for this coin.
A second mechanism comes on top. A liquidation is the forced closure of a leveraged position by the exchange as soon as the posted collateral no longer suffices. When a short position is force-closed, the exchange has to buy in the market, and that purchase pushes the price further up, which unwinds the next position. In the 24 hours before the report, short positions worth $26.5 million were closed this way; on the Wednesday of the same week it was $48.9 million. According to the report, a single trader lost a short position of $18.3 million after winning 26 trades in a row.
A sober reading follows from that: a substantial share of the past few days' move came from forced buying, not from fresh capital looking to position for the long term. Buying of that kind stops once the affected positions are cleared out. Seen in that light, the 6.41 percent pullback from the daily high is not a break in the move but what regularly happens once a liquidation chain ends. On its own it says nothing about the coming weeks.
The German one-year holding period under Section 23 EStG: when your Zcash gain stays tax-free
For investors with unlimited tax liability in Germany the current rule is this: crypto assets held as private assets fall under private disposal transactions in Section 23 of the Income Tax Act. Sell within a year of buying and the gain is taxed at your personal income tax rate. If more than a year lies between acquisition and sale, the gain is tax-free, regardless of its size.
Within the one-year period there is an exemption limit of 1,000 euros for the sum of all private disposal transactions in a calendar year. The word limit is to be taken literally: stay below it with a gain of 999 euros and you pay nothing; land at 1,001 euros and you are taxed on the full amount, not just on the excess euro.
If your Zcash position has gained 159 percent over the past few weeks, the purchase date decides a considerable sum. On a position acquired more than a year ago, the entire gain is tax-free under the law as it stands. On a position you bought in August of this year, the exemption is zero and the full rate applies. So check first which tranche carries which acquisition date before you think about a partial sale. Where there are several purchases, the order you base your documentation on applies; the German finance ministry accepts per-wallet treatment for crypto assets.
The draft bill and December 31, 2026: what is meant to change for the holding period
That legal position is up for revision. A draft bill from the German finance ministry names December 31, 2026 as the cut-off: crypto assets acquired after that date would fall under the flat-rate withholding tax, which would remove the one-year holding period for them. We worked through the draft in a separate article on September 8, 2026.
Two things need to be kept apart. A draft bill is a working document from the ministry and not applicable law; nothing has been decided so far, and the draft can be amended or dropped as the process continues. At the same time, that cut-off date is why the acquisition date of your ZEC is gaining importance right now: holdings you still acquire this year would not be covered by the new rule as the draft text stands.
So keep a clean record of the acquisition dates of your tranches, whatever the outcome of the process. Documentation you have to reconstruct in January is the most expensive version.
The EU anti-money-laundering regulation from July 10, 2027: what is coming for privacy coins
The second date is further away and firm in return. Regulation (EU) 2024/1624, the European Union's anti-money-laundering regulation, applies from July 10, 2027 according to the official summary on the EU law portal. It bars credit institutions, financial institutions and crypto-asset service providers from keeping anonymous accounts, explicitly including anonymous crypto accounts.
The decisive point for Zcash is the provision on anonymity-enhancing crypto assets. The industry reading is predominantly that licensed providers in the EU will no longer be allowed to offer such assets from that date, which would amount to a delisting. Whether supervisors will treat Zcash as fully covered has not been settled, and that is exactly where the coin differs from other candidates. So do not rely on a figure or a date at second hand: the text of the regulation is publicly available on EUR-Lex, and we have covered the consequences for Zcash buyers in more detail in a separate article on the EU trading ban.
What follows in practice is manageable. The regulation addresses companies, not you as a private individual. It prohibits neither holding nor transferring ZEC from your own wallet. What it changes is where you trade: if European providers delist, trading moves to platforms outside the licensed framework, and with it your risk profile moves too.
MiCA-licensed exchanges: where you can still trade Zcash in Germany today
MiCA is the EU regulation on markets in crypto assets. It governs who may offer crypto services in the EU and requires authorization for that, granted and supervised in Germany by BaFin. Since the EU-wide transition period ended on July 1, 2026, supervisors have become noticeably stricter towards providers without a license. We have set out what obligations that brings for companies in our overview of MiCA licensing requirements.
Two checks follow from that for you as a holder. First: is your trading venue on the list of authorized providers? A regulated provider may delist Zcash sooner, but it gives you an enforceable legal framework and a payout that works. You will find the selection in our comparison of regulated crypto exchanges.
Second: do you know which address types your provider supports for withdrawals? Some platforms have listed Zcash but settle deposits and withdrawals exclusively over transparent addresses. That is irrelevant for the payout itself, but it becomes a problem the moment you want to withdraw a larger holding at short notice and the receiving end does not accept the format. Better to settle that question before the cut-off date than on the day a delisting is announced.
Shielded pool and viewing key: why Zcash sits differently from Monero in technical terms
Zcash knows two kinds of address. Transparent addresses work as they do on Bitcoin: sender, recipient and amount are openly visible on the blockchain. Shielded addresses, the so-called shielded pool in technical language, hide those details using a cryptographic method known as a zero-knowledge proof. A zero-knowledge proof is a mathematical demonstration that a statement is true without disclosing the underlying data.
The difference from a fully anonymous coin lies in the viewing key. A viewing key is a separate key that lets you grant a third party sight of your shielded transactions without handing them control of the coins. You can use it to disclose to your tax adviser or an authority, selectively, what has happened on your addresses.
That mechanism is precisely why the regulatory classification of Zcash is more open than for coins without such an option. A provider can argue that selective disclosure meets anti-money-laundering requirements and keep the coin listed, possibly restricted to transparent addresses. Whether European supervisors follow that reading has not been decided. For you that means: treat the question as open and make your custody decision so that neither outcome catches you off guard.
Self-custody for Zcash: what a wallet has to do for shielded addresses
If you take your ZEC off the exchange, the choice of wallet is narrower than for Bitcoin or Ethereum. Look for three properties. The wallet has to be able to generate shielded addresses and send from them, not merely receive on transparent ones. It has to support the current address standard, because Zcash has developed its shielded addresses across several generations and older pools are being retired step by step. And it has to give you a recovery phrase that you store separately from the device.
The second point is in practice the most common stumbling block. A balance still sitting in an older pool has to be moved actively, and that does not happen by itself. We have described how to check whether your holding is affected and how the migration works. The upcoming network upgrade is also worth keeping an eye on if you hold your coins yourself: the NU7 upgrade is due on November 5, 2026, and we have written up what holders should take care of beforehand.
Hardware devices support Zcash to differing extents depending on manufacturer and firmware. Some handle transparent addresses only, which is sufficient for long-term storage but takes shielded use away from you. Clarify that before the purchase, not after.
Grayscale ZCSH and the September 30 share split: why you cannot reach it from Germany
Grayscale's Zcash fund has traded on NYSE Arca under the ticker ZCSH since August 25, 2026. The provider has announced a three-for-one share split for September 30, 2026, with the split shares tradable from that day. A split changes only the denomination and not the value of your holding; three shares at a third of the price are the same assets.
For investors resident in Germany the product remains uninteresting for a different reason. US funds built this way do not meet European requirements for distribution to retail investors, and in particular the mandatory key information document is missing. German brokers therefore regularly do not make such securities available to retail clients. We have written up the details in our article on the Zcash ETF.
The fund remains relevant nonetheless, because it shows institutional capital in the US gaining regulated access to Zcash while the European framework moves in the opposite direction. That divergence is one of the reasons the price has moved so markedly over the past 30 days.
Putting the Zcash pullback in context: what to take away
The price jump is the event, the deadlines are the work. Three steps that can be done today:
- Gather the acquisition dates of your tranches. Note the date, quantity and price for each purchase and work out which part of your holding already meets the one-year period under Section 23 EStG. That is the basis for every further decision and at the same time the documentation you would need if the draft bill goes through. Tools that pull this automatically from your exchange data can be found in the comparison of crypto tax software and portfolio trackers.
- Check your custody for shielded addresses. Establish whether your wallet supports the current address standard and whether any balance sits in an older pool. If you have held exclusively on the exchange so far, decide deliberately whether that should stay the case until July 2027. Suitable applications are shown in the software wallet comparison.
- Fix your exit route in advance. If you want to sell in full or in part before the cut-off date, check now which provider that should run through and whether euro payouts work reliably there. You will find an overview of the routes in our guide to selling crypto assets.
One thing does not follow from this weekend's numbers: any statement about where Zcash will stand in a month. Record open interest and a chain of forced purchases describe how the price got to where it is. About the direction of the next move they say nothing.
(As of September 20, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
If you still hold Stargate tokens (STG), you now have an expiry date in the calendar: after December 15, 2026, STG can no longer be converted into ZRO. LayerZero announced this in its ecosystem update on September 15, 2026, and it is the first time an end date has been named for this swap at all. Until now it ran indefinitely.
For most holders, however, an earlier deadline bites first. On September 18, Binance announced that it will carry out the swap for its own customers — and will halt trading in STG on October 6, 2026 at 03:00 UTC for that purpose. Half an hour later, at 03:30 UTC, STG deposits and withdrawals will be suspended and, according to the announcement, no longer supported. If you still want to send your tokens to the exchange, the deposit has to be fully completed before then.
And then there is the figure that nobody has written about so far. The swap runs at a fixed ratio of 1 STG = 0.08634 ZRO. That ratio comes from the acquisition proposal of August 2025. Recalculate it with today's prices and you receive considerably less for your STG than the same tokens still cost on the open market. How much less is set out below, with the arithmetic.
Until when can you swap STG for ZRO? Two deadlines, not one
The two dates belong to different houses and apply to different people. It is worth keeping them apart, because whether you have to do anything at all hangs on the distinction.
October 6, 2026 applies to you if your STG sit at Binance. The exchange states verbatim in its announcement that it will handle all technical requirements for the users involved. So you do not have to click anything. But trading ends on that day, open orders are deleted, and the route for deposits and withdrawals closes half an hour later.
December 15, 2026 applies to you if your STG sit in your own wallet. LayerZero puts it this way: the swap will remain available until December 15, after which conversions will no longer be supported. Until then the project says it is working with exchanges, market makers, custodians and ecosystem partners to accompany the transition.
A token merge is simply the consolidation of two tokens into one: one is withdrawn, the other remains, and a rate fixed in advance governs how many new units you receive for your old ones. Here STG is withdrawn and ZRO remains.
The 1 STG = 0.08634 ZRO ratio is fixed, the value it delivers is not
The ratio has been settled for more than a year. The LayerZero Foundation's acquisition proposal of August 10, 2025 states verbatim that all STG in circulation — staked and vote-escrowed included — would be swapped at a ratio of 1 STG to 0.08634 ZRO, corresponding to a value of $1.94 per ZRO and $0.1675 per STG. The same proposal names, as comparison figures, backing of $0.14444 per circulating STG and a market price at the time of $0.1637.
This is exactly where the catch lies. The ratio is a fixed number, but it connects two prices that have both moved since. ZRO stood at $1.12 on September 19, 2026 at 18:34 UTC (CoinGecko), while the exchange OKX showed $1.127 at the same moment. Against the $1.94 used in the 2025 calculation, that is around 42 percent lower.
Worked example: what 1,000 STG yield on the swap and on a sale today
Run the arithmetic on a round number and the gap is immediately visible. All prices in this section were retrieved from CoinGecko on September 19, 2026 at around 18:34 UTC.
- Swap route: 1,000 STG give you 86.34 ZRO. At a ZRO price of $1.12 that comes to $96.70, or, converted at the euro rate of 0.979998 euros per ZRO, around 84.61 euros.
- Sale route: the same 1,000 STG cost $0.142838 each on the market, so $142.84 in total, or roughly 124.43 euros.
- Gap: on this day the swap yields around 32 percent less than a sale on the market. Calculated with the OKX price for ZRO it is 31.9 percent, with the CoinGecko price 32.3 percent.
The STG price is no outlier from a single thin exchange. Within a daily volume of around $22 million, Binance showed $0.1428, Coinbase $0.1431, Kraken $0.1428 and KuCoin $0.1429. The prices sit closely together.
What you make of that is your decision and hangs on things this text does not know: your entry price, your holding period, fees, and whether you want to hold ZRO at all. What matters is only that you do the arithmetic yourself before you click, rather than taking the fixed rate for a fair price. Both prices move daily, and the figures above are a snapshot of a single afternoon. If you do not yet have an exchange on which both tokens can even be viewed, our comparison of the best crypto exchanges lists the venues that are regularly accessible in the EU.
Why the fixed 2025 swap rate sits so far from today's market price
The gap does not arise from an arithmetic error. It arises from the passage of time. The rate was fixed on a day in August 2025 when ZRO was worth almost $1.94. ZRO has given ground since, while STG holds up at a good $0.14. An offer that meant a premium on the STG market price in 2025 is therefore a discount on it today.
Why this gap has not closed by itself cannot be answered cleanly from the outside, and this text therefore makes no such claim. Only the observation itself can be verified: the fixed rate and the market price lie far apart today, and whoever swaps realises that distance. We described how strongly individual dates in the LayerZero ecosystem act on the ZRO price back in August, looking at the monthly unlocking of new tokens — read it in our analysis of the ZRO unlock and its monthly dilution.
If your STG sit at Binance: what the exchange handles automatically
For customers of the largest exchange the process is convenient, and still not without consequences. Binance announces that it will carry out the swap technically itself and refers to the project team's announcement for further detail. In practice that means your STG are converted into ZRO at the ratio of 1 to 0.08634 without you having to sign a transaction.
Three things are still worth keeping in view. First, trading ends on October 6 at 03:00 UTC, after which you can neither buy nor sell STG there. Second, open orders are deleted automatically at that moment, including limit orders you set months ago and forgot. Third, the deposit window closes at 03:30 UTC, and Binance explicitly advises allowing enough time for a deposit to be fully processed beforehand.
The Binance timetable in detail: margin, futures and spot fall away in stages
The exchange withdraws STG from circulation over a good two weeks and across several products. All times come from the Binance announcement of September 18, 2026 and are given in UTC.
- September 19, 06:00 UTC: Binance Margin suspends borrowing on the affected pairs in cross and isolated margin.
- September 24, 08:30 UTC: no new positions may be opened on the STG futures.
- September 24, 09:00 UTC: Binance Futures closes all open positions and settles them automatically. A forced settlement is a closure of a position triggered by the exchange, without you selling it yourself.
- September 24, 10:00 UTC: STG disappears from cross and isolated margin.
- October 5, 03:00 UTC: Spot Copy Trading removes the STG pairs from portfolios.
- October 6, 03:00 UTC: spot trading for STG/USDT ends, and trading bot services for this pair fall away.
- October 6, 03:30 UTC: STG deposits and withdrawals are suspended.
Nothing changes for ZRO: Binance writes that trading on the existing ZRO pairs is unaffected. Anyone who was in STG with leverage or through automated strategies therefore already has the tighter dates behind them, while the plain spot holder still has until October.
If your STG sit in your own wallet: the redemption site and its terms
Here things get less clear, and this is precisely where most guides on the internet fall down. According to the ZRO Foundation's terms of use, the official swap page is the address stargate.finance/bridge. The terms refer to it verbatim as the “STG Redemption Site” and name the ZRO Association together with the Stargate Foundation as operators. Redemption here means cashing in: you hand over STG and receive ZRO for it.
What is missing on the Stargate home page itself is striking. The navigation leads to Bridge, Earn, Stake, Pool and Overview. The addresses stargate.finance/redeem, /convert and /merge answer with a 404 error, and neither layerzero.network nor layerzero.foundation hosts a swap page of its own. The pointer to how the swap actually runs sits in a post on X that the LayerZero update links to.
This article therefore deliberately gives no click-by-click instructions. What is established: the terms name stargate.finance/bridge as the official address, and they have been unchanged since August 23, 2025. Everything beyond that you should look at on the site itself before you connect a wallet.
Why the swap is irreversible: STG are burned on redemption
This point is stated explicitly in the terms of use and belongs to the few things that leave no room for interpretation. All redemptions of STG into ZRO through the website are, accordingly, final, non-refundable and irreversible. All submitted STG are permanently and irrevocably destroyed on receipt, automatically and immediately, as part of the process via a smart contract.
This destruction is called a burn: the tokens are sent to an address from which nobody can retrieve them, and they thereby vanish from circulation. There is no way back afterwards, no cancellation and no support case that undoes the process. The terms also record that the foundation assumes no fiduciary duties and that actions you approve through your wallet are final.
Stargate switches off the bus on October 1: what that costs for bridge transfers
The same update contains a second dated change that concerns an entirely different readership: everyone who uses Stargate as a bridge between blockchains. Stargate has so far delivered transactions in two ways. Taxi delivers the value on the destination chain immediately. Bus bundles several transactions into one trip and pushes down gas costs that way.
From October 1, 2026, according to LayerZero, all Stargate transactions will be delivered via Taxi. The cheaper pooled route falls away with it. Anyone regularly moving smaller amounts between chains should recheck the costs afterwards before letting their routine run on.
Dates in the LayerZero ecosystem creating concrete deadlines for action is nothing new. In August, balances on 15 shut-down chains expired — how that played out at the time and how short the window was is in our report on the shutdown of the 15 chains.
Is swapping STG for ZRO taxable in Germany?
This question cannot be answered conclusively here, and any site claiming otherwise is overstepping its competence. What can be said is the framework within which you ask it.
A swap of one token for another typically counts, for German tax purposes, as a process in which one asset is given up and another obtained. It is therefore more than a mere renaming. Whether that becomes a taxable private disposal transaction under Section 23 of the Income Tax Act depends, among other things, on the holding period and on whether a gain arises at all. Section 23 (3) sentence 5 of the Income Tax Act provides an exemption threshold of 1,000 euros per calendar year for the sum of all private disposal transactions.
It gets particularly tricky with the Binance variant, because you do not trigger the process yourself there. Whether an automatically executed swap is to be treated differently for tax purposes than a self-initiated one is not something an article can decide for your individual case. The swap site's terms of use make clear, for their part, that you alone are responsible for determining, calculating, reporting and paying all taxes due, and that the foundation provides no tax advice.
In practice that means two things. Secure your records while you can still get them: swap date, number of STG, ZRO received, prices at the time of the transaction. At Binance that means exporting the transaction history before October 6, because after the delisting it gets more laborious. And settle your individual case with a tax adviser familiar with crypto matters.
How to spot a fake swap site
Every migration with a deadline attracts imitations, and this case is particularly vulnerable because the route is unclear. When the official path is not on the home page, people search for it, and search ads pointing at fake addresses are cheap.
Three checks that cost little time. First: type the address yourself or follow it from a source you know, instead of from a search ad or a direct message. Second: a genuine swap site never asks for your seed phrase or your private key. Anyone who does is after your balance. Third: check in your wallet's approval dialogue which contract receives which permission, and distrust unlimited approvals for tokens you have no intention of swapping.
And the sentence that always applies: there is no urgency that justifies an unchecked click. Even the tighter of the two deadlines is still a good two weeks away.
What happens if you miss the December 15 deadline?
LayerZero writes only one sentence about it, and it is unambiguous: after this date, conversions would no longer be supported. What happens to unswapped STG after that is not in the announcement. Whether a route through exchanges, custodians or a later individual arrangement stays open is therefore open, and will not be painted in here.
Only the opposite can be planned for: assume that no regular swap is possible after December 15, 2026, and organise your actions accordingly. Anyone holding at Binance has the earlier marker on October 6 anyway and has to do nothing for it — except decide beforehand whether an automatic swap at a fixed rate is what they want.
Swapping STG for ZRO: your takeaways
- Find out where your STG actually sit. At an exchange, that venue's own timetable applies, and at Binance that is October 6, 2026. In your own wallet, December 15, 2026 applies, and then you have to act yourself. Our comparison of the best crypto exchanges shows which venues are regularly accessible.
- Weigh the fixed swap rate against the market price before you do anything. Multiply your quantity by 0.08634 and that figure by the current ZRO price. Compare the result with what your STG cost on the market. On September 19, 2026 the swap route came out around 32 percent below. If you trigger the process yourself from a wallet, look first at how you store your holdings securely — the options are in the hardware wallet comparison.
- Secure the records while you can get them. Export your transaction history before the delisting and record the date, the quantity and the prices. For sorting and evaluating it, the programmes in our comparison of crypto tax tools are suitable.
Sources and status of the figures
The deadlines and the wording on the swap come from the LayerZero ecosystem update of September 15, 2026. The terms on irreversibility, the official address of the swap site and the responsibility for taxes are in the terms of use of the STG redemption site. The staggered timetable and the swap ratio for exchange customers come from the Binance announcement “Binance Will Support the Stargate Finance (STG) Token Merge to LayerZero (ZRO)” of September 18, 2026. The ratio of 1 to 0.08634 and the valuation of $0.1675 per STG are in the LayerZero Foundation's acquisition proposal of August 10, 2025. All prices were retrieved from CoinGecko on September 19, 2026 at around 18:34 UTC and cross-checked against OKX and CoinGecko's exchange overview.
(As of September 19, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
The Clarity Act failed to advance in the Senate, shifting the industry’s focus to a new wave of action from the SEC and CFTC.
A Glassnode and Bybit report found Bitcoin climbed 24.6% in five August days even as active leverage fell, with short positions supplying 89% of every liquidated dollar.
The Zcash ETF is splitting its shares three ways after pulling in more than $233 million in under a month, as Wall Street piles into crypto's hottest privacy trade.
The network's clock just sped up again, but the extra speed goes to freshness, not capacity.
The filing seeks CFTC approval for contracts giving US traders 24/5 leveraged exposure to individual stocks without ownership.
U.Today - IT, AI and Fintech Daily News for You Today
The coins had remained untouched since 2011, when Bitcoin was trading at around $3.
ARK Invest CEO Cathie Wood pushed back against Jason Calacanis after the venture capitalist dismissed Bitcoin’s latest rebound as a "dead cat bounce" and argued that the cryptocurrency has lost its technological edge.
Vitalik Buterin says he is "doubling down" on privacy as Ethereum developers work on private reads, private transactions, and stronger censorship resistance across the network.
A massive $2.2 billion whale buying spree drains XRP from exchanges, setting the stage for a breakout toward $2.
Shiba Inu builds a rare weekly 'Bull Combo' to delete a zero, but a major chart barrier stands in the way.
Blockonomi
TLDR:
- Binance Wallet’s Pre-Access uses PancakeSwap campaigns to offer tokenized exposure to private companies.
- About 1,300 private firms valued above $1B represent roughly $4.7T collectively, Binance Research estimates.
- Users can raise subscription quotas through Binance Alpha Points plus bStocks trading volume and holdings.
- Tokenized pre-IPO claims across Republic and PreStocks had reached about $41M, Binance Research said.
Binance Wallet is expanding its on-chain finance offering with a Pre-Access program that gives eligible users tokenized exposure to private companies before possible listings. Announced on September 20, the program will run limited subscription campaigns through PancakeSwap.
However, participants will not receive private-company shares directly. Instead, each campaign will provide tokenized exposure arranged by a third-party service provider. Nonetheless, Binance Wallet has not yet identified the first company entering the program.
Introducing Pre-Access campaigns, hosted by @PancakeSwap.
Get indirect exposure to popular companies before they potentially go public.
Available through Binance Wallet.
First project revealed soon.
FAQ: https://t.co/p6diDxmnm1
Keep reading
pic.twitter.com/M075rA03QV
— Binance Wallet (@BinanceWallet) September 20, 2026

The structure moves private-market access onto self-custody rails while preserving campaign-specific restrictions. It also separates the product from a traditional initial public offering allocation. This means participation depends on campaign eligibility and allocation rules, rather than holding a Binance Wallet or accessing PancakeSwap.
Alpha Points and bStocks Shape Private-Market Allocation
Eligible users can increase subscription quotas through Binance Alpha Points, alongside their on-chain bStocks trading volume and token holdings. That mechanism extends Binance Wallet’s existing reward framework into private-market products.
At the same time, the subscriptions will operate through self-custody wallets. PancakeSwap will host campaign pages showing the company, token details, subscription asset, issue price, implied valuation, timeline, claim arrangements, and risk disclosures.
Users must complete eligibility checks and accept the relevant terms before participating. Meanwhile, allocation methods, subscription limits, and eligibility standards will vary by campaign. After a campaign closes, qualifying participants can claim the tokenized exposure during the specified claim window.
Others may receive refunds under the campaign’s rules. The model therefore functions more like a tokenized private-market subscription than a conventional pre-IPO share sale. That distinction shapes what participants actually receive.
Tokenized Securities Anchor Binance’s Private-Market Expansion
The launch follows Binance Wallet’s June introduction of bStocks, tokenized U.S. securities issued as BEP-20 tokens on BNB Chain. PancakeSwap already supports on-chain bStocks trading, while eligible holders can keep those assets in compatible self-custody wallets.
The products carry transfer and geographic restrictions. The broader market for private-company exposure has also grown. Binance Research estimated about 1,300 private companies hold valuations above $1 billion.
Together, those companies represent roughly $4.7 trillion in value. Separately, tokenized pre-IPO claims across Republic and PreStocks had reached about $41 million. Still, tokenized private-market products do not always equal direct ownership of company shares.
Binance Research said some structures can instead represent contractual claims. Those claims may trade at discounts because of fees, dilution, limited liquidity, and lockup periods. Consequently, the legal structure remains central to each campaign.
Campaign disclosures therefore remain important for distinguishing economic exposure from direct equity ownership. For Binance Wallet’s Pre-Access program, the first campaign will clarify the issuer, eligible jurisdictions, redemption terms, and exact rights attached to the tokenized exposure.
The post Binance Wallet Opens Pre-IPO Access Through PancakeSwap Campaigns appeared first on Blockonomi.
TLDR:
- Ethereum staking demand exceeded exit demand by 13.6 times on September 20, with about 2.48 million ETH waiting to enter the validator set.
- Roughly 41 million ETH was locked in staking, equal to about 33.5% to 34% of supply, while the validator count approached 900,000.
- The entry queue created estimated activation waits of 43 to 45 days, as Ethereum processed validator changes at roughly 256 ETH per epoch.
- ETH technical commentary placed $2,089 as a possible pullback level, while a weekly close above $2,550 would put higher targets in focus.
Ethereum news today reveals Ethereum staking demand outpaced exit requests by 13.6 times on September 20. Around 2.48 million ETH awaited activation, while the withdrawal queue held a much smaller balance. New validators faced waits exceeding 40 days as entries moved through protocol limits.
The gap follows an earlier September peak for pending deposits and contrasts sharply with quiet exit conditions. It shows more ETH had been submitted for validation than removal at the measured time. It does not confirm why each holder chose to stake or withdraw.
Ethereum staking had already locked roughly 41 million ETH, or about 33.5% to 34% of supply. The network supported an estimated 885,000 to 900,000 validators. Those figures place the entry queue within a broader trend of increased validator participation. Large operators, including BitMine, contributed to new staking demand. Pectra also gave users more flexibility to consolidate their stake.
Ethereum Staking Queue Shows 13.6 Times More Entries
Ethereum staking entries reached about 2.48 million ETH during September. The backlog translated into an estimated 43 to 45-day wait for activation. Earlier in the year, the queue reached about 3.4 million ETH in May. By late September, it stood near 1.8 million ETH, implying an estimated 32-day wait.

The exit queue showed the opposite pattern. It fell to zero ETH at one point in July. In September 2025, exits had totaled roughly 2.67 million ETH. By early January 2026, exit demand had declined more than 99.9%, reflecting the reported queue trend. The comparison highlights how quickly pending validator activity can change.
Ethereum staking entries and exits must pass through a churn mechanism. The network permits roughly 256 ETH of validator changes per epoch, or close to 57,600 ETH daily. The limit slows rapid changes in either direction. The Validator Queue tracker describes churn as a consensus protection measure, rather than a market control.
The rate limit means a sharp rise in exit requests cannot immediately unlock all deposited ETH. Validators must clear the exit queue before their balances become withdrawable. The withdrawal process also includes a sweep period. The final timing varies as the network processes available balances.
Pectra raised the maximum balance for a compounding validator from 32 ETH to 2,048 ETH. It also allowed exits through withdrawal credentials. These changes can help operators consolidate validators, although they do not remove the queue. Validator totals therefore do not necessarily equal the number of separate staking entities. It also complicates comparisons across monthly network snapshots.
ETH Price Levels Track Support After Validator Queue Expansion
Ethereum staking removes ETH from direct validator balances but does not erase all trading liquidity. Liquid-staking tokens and exchange products can still give holders market exposure. However, a growing validator share changes the immediately accessible supply profile. The queue imbalance alone does not guarantee a price move.
Trader Tardigrade says ETH formed a local top after bouncing from the $1,510 area. He identified the 0.5 Fibonacci retracement near $2,089 as a possible pullback level. The view presents a technical scenario, not a confirmed market outcome. It also depends on the price retaining its wider recovery structure.

Another market commentator, Ted, said ETH needs a weekly close above $2,550. He said that level could place the $2,900 to $3,000 range in focus. The market still needs to establish a close above that zone. A rejection below it would leave the stated upside levels unconfirmed.
Staked ETH cannot enter or exit the validator set immediately. New staking demand also takes time to activate. With limits applying to both directions, validator supply changes tend to unfold across days or weeks rather than sessions.
The post Ethereum Staking Demand Outpaces Exits as Entry Queue Surges appeared first on Blockonomi.
TLDR:
- XLM price rose 3.79% to $0.1985 on September 19, after Stellar activated Protocol 28 and recorded 211 transactions per second across 100 blocks.
- Stellar reports about $3.3 billion in tokenized real-world assets, nearly $884 million in stablecoins, and around $294 million in decentralized-finance value.
- The $0.197 level and the middle Bollinger Band near $0.19277 form the immediate support areas in the current short-term XLM trading structure.
- XLM trades above its middle Bollinger Band, while the $0.21832 upper band and $0.21 to $0.22 range mark higher technical areas.
XLM price moved back toward $0.20 on September 19 after Stellar activated Protocol 28 two days earlier. The token traded at $0.1985, gaining 3.79% over 24 hours. Trading volume reached about $568.96 million, while market capitalization stood near $6.99 billion.
The move followed a rebound from lower September levels and put $0.20 in focus. Protocol 28 introduced consensus tooling and contract-migration capabilities. It also recorded 211 transactions per second across 100 blocks.
Traders also closely tracked a possible pullback toward $0.197. Holding that region could clarify whether short-term buyers retain control. Total crypto capitalization rose 1.6%, while altcoin capitalization increased 1.2%. XLM outperformed the broader market during that period.
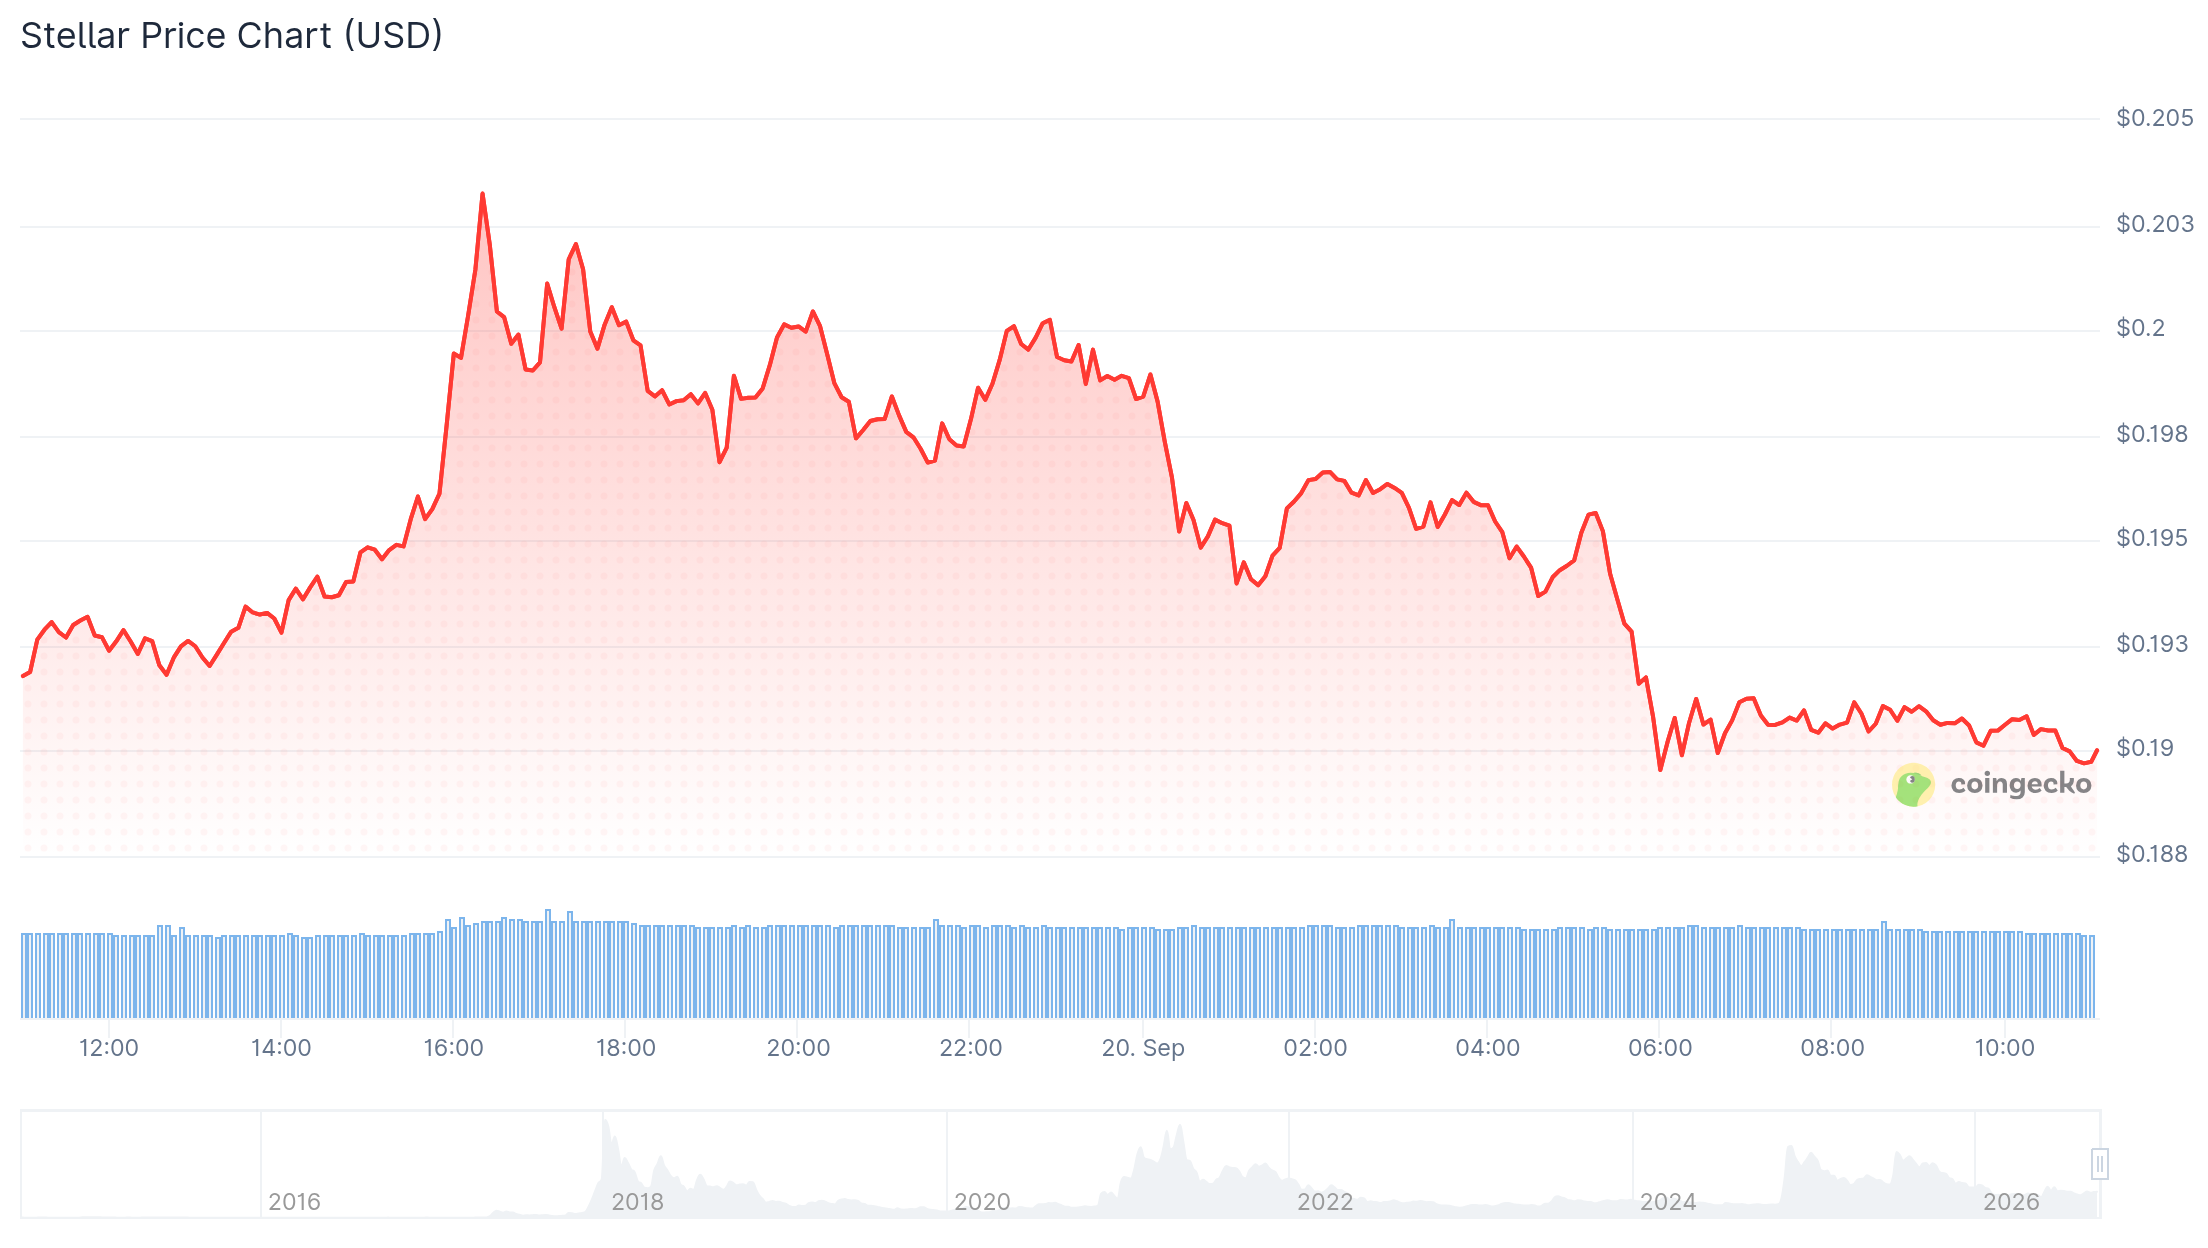
XLM Price Gains Focus After Stellar Protocol 28 Activation
Stellar activated the upgrade on September 17, adding consensus changes and contract-migration tools. The network recorded 211 transactions per second through a 100-block test period. XLM Price gained roughly 4% around activation and traded near $0.186. The timing aligns with the upgrade, though several factors can influence price action.
Protocol 28 supports Soroban development as projects prepare contracts for newer network functions. It gives developers a clearer route for moving existing contracts. Stellar processes payment and asset-issuance activity alongside token trading. Later phases could target throughput above 3,000 transactions per second.
Stellar supports about $3.3 billion in tokenized real-world assets. It also carries nearly $884 million in stablecoins and roughly $294 million in decentralized-finance value. Those measures place the upgrade within broader infrastructure activity. Franklin Templeton and Ondo have used Stellar for tokenized asset initiatives. This activity feeds the network’s real-world asset narrative.
XLM and XRP moved more than 8% during earlier positioning around US crypto market-structure legislation. The advance showed sensitivity to policy developments. Still, legislation does not set the token’s immediate technical direction.
The International Monetary Fund has published 2026 research on tokenized finance, stablecoins, and tokenized money. Its work identifies faster settlement and lower reconciliation costs as possible benefits. It also flags liquidity, interoperability, and financial-stability risks. The research does not endorse individual networks or tokens.
Bollinger Bands Define Key XLM Support and Resistance Levels
Before the recent rebound, the token traded in the mid-$0.15 range. Its return toward the 200-day moving average put the $0.188 to $0.190 zone under scrutiny. A hold above that range would keep attention on the $0.20 threshold. XLM Price now depends on buyers defending nearby levels after the breakout.
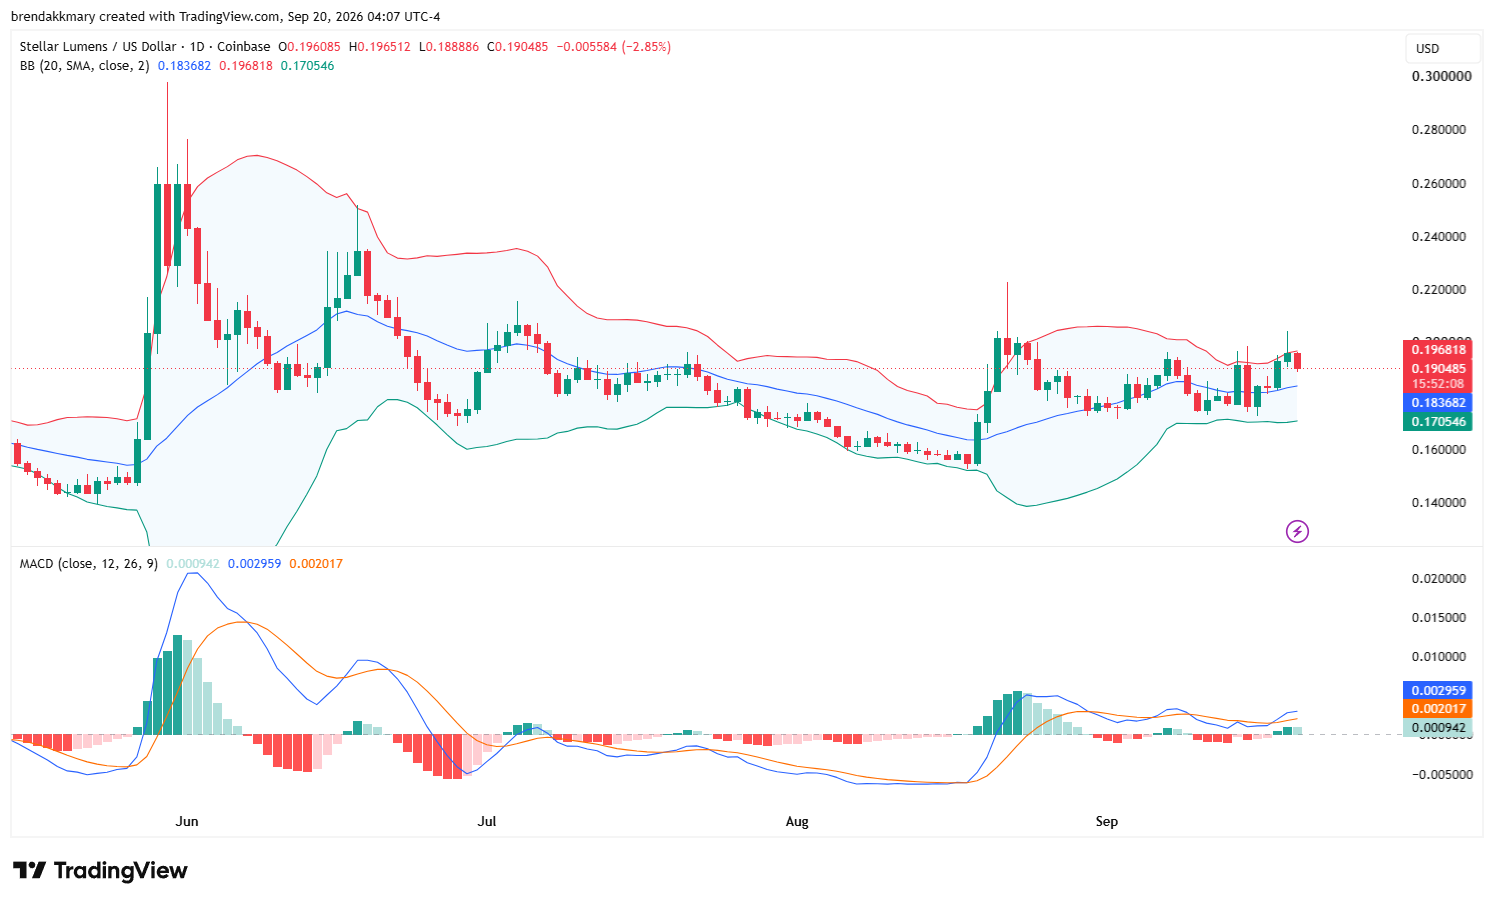
XLM price traded above the middle Bollinger Band near $0.19277. That positioning places the recent range midpoint in focus as potential support. The upper Bollinger Band stands near $0.21832, while the lower band sits around $0.16922. A move toward the upper band would extend the recovery from earlier September weakness.
Momentum indicators also show a firmer short-term structure. The MACD line stood at 0.00313, above its 0.00185 signal line. Its positive 0.00128 histogram shows buying pressure improved from weaker prior sessions. Momentum can change quickly if price returns below the middle band.
The $0.197 level features prominently in the immediate setup. Market commentator Udy Highs identified it as a possible long-entry area after a retracement. A retest that firmly holds could keep buyers focused on $0.20 and the upper band. XLM Price faces a separate test if it loses the midpoint near $0.19277.
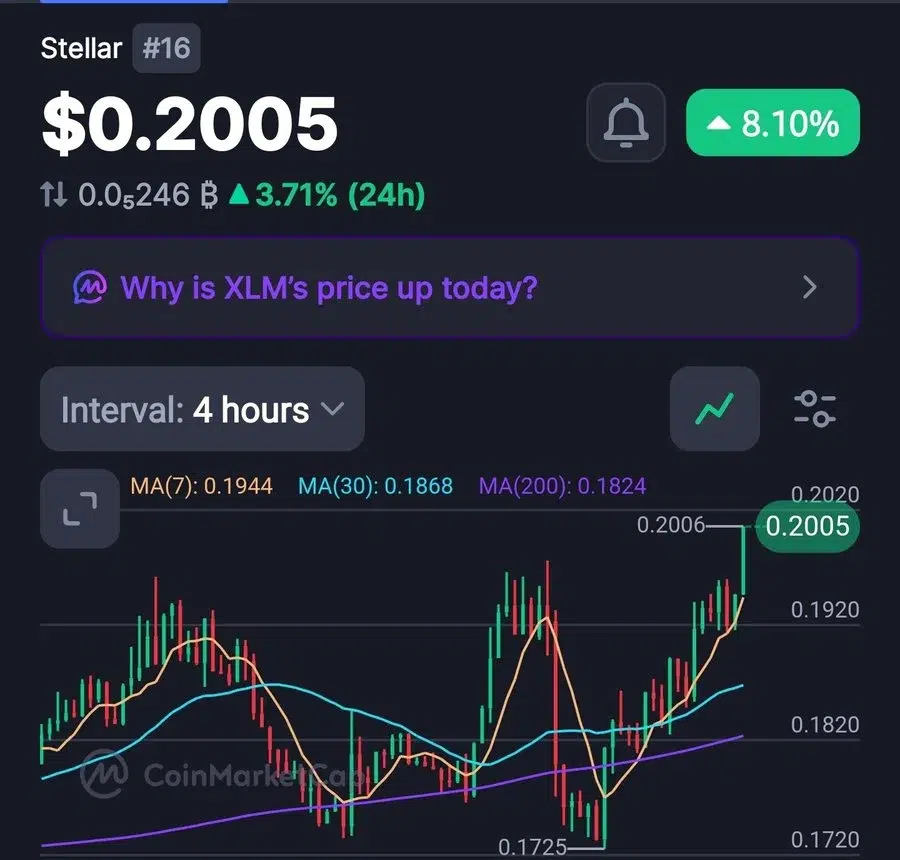
That break could shift attention toward support between $0.176 and $0.182. A sustained move through $0.20 instead puts the $0.21 to $0.22 zone in focus. Derivatives positioning adds another layer to the near-term move. Long-to-short ratios near 1.15 and positive funding rates show growing long exposure. That positioning can amplify sharp moves after network news or broad market shifts.
The post XLM Price Gains as Stellar Protocol 28 Upgrade Draws Market Focus appeared first on Blockonomi.
TLDR:
- FCA crypto authorisation applications open September 30, 2026, and firms seeking transitional arrangements must apply by February 28, 2027.
- The new UK regime covers stablecoin issuance, trading platforms, dealing, arranging, safeguarding, and cryptoasset staking activities.
- Existing registration under the Money Laundering Regulations does not provide automatic permission under the future FSMA framework.
- The FCA plans an October consultation on stablecoins, market-making, technology providers, decentralised protocols, safeguarding, and promotions.
FCA crypto authorisation applications officially open on September 30, 2026, for UK firms. UK firms can enter the approval process before new rules start. The Financial Conduct Authority published final perimeter guidance on September 16. The guidance identifies activities requiring permission under the Financial Services and Markets Act.
The framework covers stablecoin issuance, trading platforms, transaction dealing, safeguarding, and staking arrangements. The FCA says the new rules take effect on October 25, 2027. Firms that want to use transitional arrangements must apply during the designated window. Existing registration under money-laundering rules does not automatically provide permission under the new framework.
FCA Crypto Authorisation Opens Before the UK Regime Begins
The FCA guidance defines activities that fall within the regulator’s perimeter. Firms may need authorisation for qualifying stablecoin issuance or cryptoasset trading platforms. They may also need permission for dealing, arranging transactions, safeguarding assets, or arranging staking services. The list gives companies a basis for mapping their business models against the new rules.
Parliament introduced the framework through the Financial Services and Markets Act 2000 (Cryptoassets) Regulations 2026. The regulations bring specified cryptoasset activities into the FCA’s remit from October 25, 2027. The perimeter policy statement helps firms determine whether they need direct permission, an additional permission, or an exemption.
FCA crypto authorisation applications will open on September 30 and close on February 28, 2027. The FCA says firms should use this period to rely on saving or transitional provisions. The authority will assess their submissions during the process. The regulator offers pre-application support meetings and webinars for applicants.
The gateway date creates a fixed preparation timetable. Businesses must review governance, senior management, customer treatment, market conduct, systems, and controls before submitting applications. The FCA expects firms to identify UK consumer services and assess whether overseas operations fall within its perimeter.
Applicants also need to identify senior managers, document risk controls, and explain customer protection measures. The FCA will assess each submission against its standards before granting permission. Gateway access does not equal approval. Firms cannot treat it as an authorisation decision under the new rules.
UK Crypto Regime Sets Separate Duties for Existing Companies
MLR registration does not equal FCA crypto authorisation. Firms that hold Money Laundering Regulations registration must seek authorisation for covered activities. The UK crypto regime sets this requirement. Existing FCA permissions also do not convert automatically, so firms may need a variation or separate approval.
That distinction affects exchanges, custodians, brokers, stablecoin issuers, and staking providers. Companies must review each service rather than rely on their current regulatory status. The FCA crypto authorisation guidance covers firms entering UK markets. It also covers traditional finance businesses exploring crypto services and overseas firms serving UK consumers.
The application window supports transitional arrangements, but eligibility depends on meeting the relevant conditions. Firms that miss the deadline may lose access to those provisions. The FCA directs firms to its guidance, webinars, and pre-application support service when they assess their obligations.
The regulator plans an October consultation on targeted changes. Topics include UK qualifying stablecoins, proprietary trading, market-making, and certain technology providers. The list also covers decentralised protocols, safeguarding involving central securities depositories, and financial promotions. The FCA plans to publish updated perimeter guidance in early 2027 after considering those changes.
FCA crypto authorisation will operate within wider cryptoasset regulation. That framework covers market conduct, disclosures, market abuse, prudential requirements, and the FCA Handbook. The regulator has already published final rules for several parts of that framework. The regime begins on October 25, 2027. Covered firms must hold required permission under cryptoasset regulation to conduct business in the UK.
The post FCA Crypto Authorisation Gateway Opens September 30 for UK Firms appeared first on Blockonomi.
TLDR:
- Strategy stock gained 47.7% over the past month, making it the Nasdaq-100 top performer and more than doubling Meta’s 21.9% advance.
- SpaceX’s projected Nasdaq-100 weighting will rise from 1.28% to 2.82%, potentially driving $15.5 billion to $22 billion in passive buying.
- Healthcare and technology gained during the week, while utilities, financials, value stocks and small caps recorded losses across the market.
- MSTR stock benefits from concentrated Bitcoin exposure, while higher Treasury yields and sector rotation shape the wider equity backdrop.
Strategy stock has become the Nasdaq-100’s strongest performer over the past month after gaining 47.7%. The move more than doubled Meta’s 21.9% advance. It placed MSTR stock at the center of a rotation toward Bitcoin-linked equities.
The gain came as investors sought companies with direct digital asset exposure. Strategy’s corporate model gives shareholders an equity route to Bitcoin performance, while technology and healthcare posted smaller gains.
The Nasdaq-100 also faces a September 21 rebalance. SpaceX’s projected weighting will rise from 1.28% to 2.82%, creating an estimated $15.5 billion to $22 billion in passive buying. The change may affect index members.
Strategy Stock Outperformance Reflects Bitcoin Exposure and Flows
Strategy stock’s 47.7% monthly gain separates it from most Nasdaq-100 constituents. Meta’s 21.9% advance provides a comparison in performance. The gap shows stronger demand for Bitcoin-linked equity exposure during the period.

MSTR stock became a liquidity magnet as investors rotated from traditional sectors. Strategy’s concentrated Bitcoin exposure offers a different risk profile from diversified technology companies. That concentration can amplify gains when Bitcoin-linked sentiment strengthens.
Bitcoin-linked equities can attract capital when investors seek listed exposure rather than direct token ownership. This channel also allows digital asset sentiment to appear inside traditional equity benchmarks. The result is a market where thematic demand can outrun broad sector performance.
Strategy stock’s ranking does not show that every Nasdaq-100 constituent weakened. Healthcare and technology both gained, but their advances were smaller. The difference instead highlights how concentrated narratives can dominate short-term index performance.
The Strategy stock move also stands apart from the wider index. The Nasdaq-100 rose 0.72% during the week, while the S&P 500 slipped 0.08%. Value stocks fell 1.28%, and small-cap stocks declined 1.38%.
Healthcare gained 1.56%, and technology advanced 1.03%. Utilities fell 2.95%, while financial services dropped 2.29%. The figures show selective growth demand rather than broad market participation.
The performance gap leaves Strategy stock tied closely to Bitcoin sentiment and liquidity conditions. It also makes the company sensitive to changes in digital asset prices and investor appetite for thematic equities.
Nasdaq-100 Rebalancing Meets Mixed Market Breadth and Yields
SpaceX shares rose 2.6% to $154.81 and gained more than 4% for the week. Its Nasdaq-100 weighting is projected to increase from 1.28% to 2.82% on September 21.
The change follows higher free float availability after lockup expirations. Assets tracking the index total $1.7 trillion. Passive funds may need to buy $15.5 billion to $22 billion during the closing auction.
Index changes can create forced demand without changing a company’s underlying operations. The buying reflects fund mandates, not necessarily a new view of future earnings. Prices can therefore react sharply near rebalancing dates as passive and active investors adjust together. Flows can distort short-term rankings.
That demand could influence other constituents as funds adjust positions. SpaceX fell nearly 6% during its July inclusion despite $4.3 billion in passive inflows. The reaction shows that index buying does not guarantee sustained price gains.
Market breadth also reflects higher borrowing costs. The 10-year Treasury yield increased to 5.01% from 4.96%. Higher yields can pressure companies that depend on distant future earnings.
Commodities weakened during the period. West Texas Intermediate crude fell 0.50% to $99.49, while Comex gold declined 1.22% to $4,325.30. These moves accompanied weaker performance across utilities, financials and smaller companies.
Growth stocks still attracted selective buying. Zscaler gained 19.76% for the week, while Tenable and Qualys also advanced. The gains show that investors continued to target technology names despite broader market pressure.
Strategy stock therefore sits within two overlapping flows. Bitcoin exposure supports its company-specific demand, while Nasdaq-100 positioning shapes the capital backdrop. MSTR stock’s next performance will depend on both forces as index allocations change and digital asset sentiment develops.
The post Strategy Stock Leads Nasdaq-100 as Bitcoin Exposure Drives Gains appeared first on Blockonomi.
HTTP error 429 on https://cryptopotato.com/feed/
Failed to fetch feed: https://cryptopotato.com/feed/
Failed to fetch feed.