Cryptocurrency Posts
Crypto Briefing
The intensified attacks on infrastructure heighten market concerns over potential Russian territorial advances, impacting geopolitical stability.
The post Russia targets Kyiv gas stations, transport; 8 injured in Kharkiv region appeared first on Crypto Briefing.
Iran's conditions for ending hostilities could reshape U.S.-Iran relations, with Qatar's mediation highlighting potential diplomatic breakthroughs.
The post Iran sets conditions for ending US hostilities, Qatar mediates appeared first on Crypto Briefing.
The restart of Saudi pipelines reduces oil price surge risks, impacting market expectations and potentially stabilizing global economic conditions.
The post Oil prices fall as Saudi pipeline restart eases supply concerns appeared first on Crypto Briefing.
The UK's military support to Saudi Arabia highlights the strategic importance of securing global trade routes amid regional instability.
The post UK deploys RAF tanker to aid Saudi Arabia amid Houthi tensions appeared first on Crypto Briefing.
Russia's crypto regulations could centralize control, limit investor freedom, and expose users to geopolitical risks from foreign asset freezes.
The post Russia mandates investors report foreign crypto transactions, warns of losses from stablecoin freezes appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Bitcoin Investors Buy Nearly $1B in BTC ETFs as Bull Market Returns
The Bitcoin bulls are back — if ETF flows are to be believed.
U.S. bitcoin exchange-traded funds received $999 million in new investment on Monday, according to Farside Investors data.
That’s the most in one day since October 6, when the funds received over $1.2 billion and the price of the leading cryptocurrency hit a new all-time high of $126,080.
Bitcoin’s price recently stood at $86,552 after scraping $87,330 on Monday. Over the past seven days, the coin’s price has surged by nearly 13%.
Bitcoin ETFs in the U.S. — approved by the SEC in 2024 — have helped investors get exposure when they couldn’t before. Now, Wall Street firms can quickly buy shares of funds managed by the likes of BlackRock, Fidelity, Morgan Stanley, and others.
When big investment hits the funds, the price often moves significantly — as what happened on Monday.
Bloomberg ETF analyst James Seyffart on Monday said that the average ETF buyer is now in profit after the estimated ETF cost basis surged above $81,72 for the first time since January.
The ETF to receive the most of Monday’s investment — $381.4 million — was BlackRock’s iShares Bitcoin trust. The ARK 21Shares Bitcoin ETF received $289.1 million; Fidelity’s Wise Origin Bitcoin Fund took in $238.8 million.
Investors have a renewed interest in Bitcoin after the artificial intelligence stock rally cooled and the U.S. Department of the Treasury in August said it would at least double the size of its liquidity-support buyback operations.
Analysts said the move pushed 30-year Treasury yields down, weakened the dollar, and made assets like bitcoin more attractive. Following the announcement, the bitcoin price had its best run in years.
A Tuesday report from crypto market data firm CryptoQuant said that the leading cryptocurrency crossed above its 365-day moving average, a signal that the asset has finished being in a bear market.
This post Bitcoin Investors Buy Nearly $1B in BTC ETFs as Bull Market Returns first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Bitcoin’s Bull Run Is Back — and the Data Agrees
Bitcoin’s run this weekend would have observers believing that the bull market is back. But the data also backs it up.
A new report from data firm CryptoQuant shows that the leading cryptocurrency crossed above its 365-day moving average — a signal that the asset has finished being in a bear market.
Bitcoin’s price surged in August and had its best run in years, spurred by an announcement from the U.S. Treasury saying it would at least double the size of its liquidity-support buyback operations. Its run cooled but then last week shot up again and was recently trading for $86,598 after trading as high as nearly $87,330 on Monday.
JUST IN: $87,000 Bitcoin
— Bitcoin Magazine (@BitcoinMagazine) September 21, 2026pic.twitter.com/Vgl0wCA7uY
“This crossover is the definitive technical signal that has marked the start of Bitcoin’s bull markets in past cycles, and it is the first time price has reclaimed the 365-day moving average since March 2023,” the report read.
It added that the moving average is a “cycle-defining” line and confirmed the start of bull runs in previous years.
“Its track record across cycles is why this reclaim carries real weight rather than being a routine bounce,” the report added.
The report continued that long-term holders appear to have finished selling, making the way for new investors to enter the market.
Bitcoin notched a record of $126,080 in October of last year but then began to sink later that month after the biggest liquidation event in crypto history saw over $19 billion in bets closed.
In the first half of this year it continued its plunge after the Federal Reserve made it clear it was in no hurry to lower interest rates and investors increasingly threw money at artificial intelligence-related stocks to get returns.
But the so-called debasement trade — where investors throw money at an asset to hedge against a currency losing its value — is hot again. Bitcoin and precious metals like gold have done well when the dollar has weakened.
And the Federal Reserve last week raised interest rates to get sky-high inflation in the U.S. under control. Investors shrugged the central bank’s move off and bought up the asset.
Now, people seem more interested in buying an asset that can protect them from government debt and deficit. In August, total U.S. debt topped $40 trillion for the first time.
This post Bitcoin’s Bull Run Is Back — and the Data Agrees first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
White Hats Move Over $4.5 in Bitcoins From Coldcard to Recovery Trust
White hats have moved bitcoin from the hacked Coldcard signing devices to a trust for would-be victims to reclaim, Galaxy Digital’s Alex Thorn has said.
Writing on X on Monday, Thorn said that the funds were taken by white hats to protect potential victims. They are now apparently sitting in an address controlled by Crypto Recovery Trust, a Wyoming Trust created to help white hats return funds to victims.
A total of 52.37 of the bitcoins — worth over $4.5 million at today’s prices — were moved. Thorn added that the funds represented 2.8% of the coldcard exploit.
Criminals started taking bitcoin stored using Coinkite’s popular Coldcard hardware wallet on July 31.
Canadian company Coinkite said that a firmware bug in Coldcard devices caused seed generation to fall back to a weak software Pseudorandom Number Generator instead of the hardware true random number generator, allowing hackers to essentially guess investor seedphrases.
Galaxy Digital tracked the movement of funds and said 1,789.28 bitcoins were lost in the attacks. That’s $154.1 million in bitcoin at today’s prices.
Earlier this month, Nick Bax of universal market protocol Ump Labs said that he was involved in helping recover the funds.
“Finally able to say that at the end of July, I was involved in the rescue of ~50 BTC which were “imminently going to be stolen due to the COLDCARD entropy flaw,” Bax wrote on X.
He added: “The funds are currently held by a Wyoming trust, which will ensure that funds are returned to their rightful owners.”
Since the attack, cautious investors have been moving their coins to other storage solutions — including exchanges.
Coinkite said in a statement that the bug in its software “silently went unnoticed” and “its potential impact grew with every release” of its products.
Days after the first hack, the company urged investors to update their software or move their funds off the popular hardware wallet.
This post White Hats Move Over $4.5 in Bitcoins From Coldcard to Recovery Trust first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Feds Probing Binance Over Iran’s Bitcoin Use: Report
Federal prosecutors — including the U.S. Department of Justice — are investigating whether Binance has allowed Iran to dodge sanctions by using its platform, according to a report from Bloomberg.
The outlet, citing people familiar with the matter, reported Tuesday that feds were investigating whether Binance Holdings Ltd., which operates the world’s biggest crypto exchange, knowingly allowed Iran-linked entities to trade.
It comes after the U.S. Department of Justice last week said it is seizing and seeking to forfeit $61 million in cryptocurrency that it alleges came from black-market sales of sanctioned Iranian oil. The funds, according to the DOJ, were laundered through Binance by Chinese entities.
Iran has been using bitcoin — and other cryptocurrencies — to skirt around U.S. sanctions. The U.S. in April started targeting crypto wallets linked to the Iranian regime, Treasury Secretary Scott Bessent said in a statement.
Bessent went on to say that the Iranian regime’s crypto had been frozen — mostly in the form of Tether’s USDT stablecoin.
And last week, the Treasury designated BitBank, an Iranian crypto exchange, as part of Operation Economic Outcast — the Trump Administration’s whole-of-government economic campaign against the Islamic Republic of Iran and its enablers.
Iran started a bitcoin-backed insurance service for its counties shipping companies earlier this year. Bitcoin cannot be frozen, unlike many other cryptocurrencies.
The Financial Times this month reported that the Middle Eastern country was using bitcoin to settle cross-border transactions through Iranian crypto exchanges after the central bank advised its countrymen to do anything necessary to help the economy.
Binance, which has no headquarters but is incorporated in the Cayman Islands, ran into trouble with U.S. authorities after it allegedly allowed funds linked to virtual theft and terrorism to flow through its exchange undetected.
It exited the U.S. market and agreed to pay $4.3 billion. Its CEO and founder Changpeng Zhao stepped down after pleading guilty to anti-money laundering violations but was later pardoned by President Trump.
This post Feds Probing Binance Over Iran’s Bitcoin Use: Report first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
No Bitcoin Payments in Russia — But the Digital Ruble Is Open for Business
While bitcoin is banned for making payments in Russia, the government is keen on one type of digital money: its own central bank digital currency.
The digital ruble has been available for transactions in the country since September 1, according to a Tuesday report from Tass.
Citing a talk given by Prime Minister Mikhail Mishustin, the news agency said that it was all part of “developing a convenient, fast, and independent payment infrastructure” in Russia.
JUST IN:
— Bitcoin Magazine (@BitcoinMagazine) September 22, 2026Russian Prime Minister Mikhail Mishustin says:
"The circulation of cryptocurrencies has also become legal in the country starting from September 1. The relevant law was signed by the president."

Russia has been fast regulating digital assets this year. President Vladimir Putin in August signed a law regulating the circulation of digital currencies and digital rights in the country.
The law states that only registered entities can operate as exchanges, and puts limits on the amount of crypto retail investors can use.
But what about Bitcoin?
President Putin in 2024 seemed to praise the OG cryptocurrency. “For example, Bitcoin, who can ban it? Nobody,” he said at a forum at the time.
“And who can prohibit the use of other electronic payment instruments? Nobody, because these are new technologies.”
The president has also spoken about how the country has “competitive advantages” when it comes to Bitcoin mining due to the abundance of cheap energy in Russia.
Though the Kremlin still has a tight grip on what its citizens can do with it: Retail investors are limited to trading bitcoin and other liquid cryptocurrencies, capped at 300,000 rubles ($3,556) per year, according to the August law. Qualified investors have no restrictions.
And using crypto as a form of payment has been illegal in Russia since 2022.
Central bank digital currencies — or CBDCs — are a centralized form of digital money, issued by a central bank. Bitcoiners have long criticized the idea of such a product because it can be used by governments to surveil its citizens and ultimately even control their spending.
U.S. President Donald Trump even signed an executive order in 2025 prohibiting federal agencies from establishing, issuing, or promoting a CBDC.
But in Russia, a digital ruble is the best way for keeping citizens in check. The Bank of Russia settled early on an architecture that mixes a centralized ledger it controls with distributed-ledger components. The 2021 concept described the preferred model as hybrid — distributed ledgers combined with centralized components — and the full technical details have never been published.
Bitcoin payments, on the other hand, are being used by companies in international payments to counter Western sanctions, Finance Minister Anton Siluanov admitted in 2024.
This post No Bitcoin Payments in Russia — But the Digital Ruble Is Open for Business first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
CryptoSlate
Solana generated more user fees than Ethereum in data provider DefiLlama's Sept. 22 dashboard snapshot, while Ethereum burned more fees. The split shows that users' spending can reach validators and applications without producing an equivalent benefit for someone simply holding the network's coin.
The data provider's Solana overview showed about $1.1 million in chain fees over 24 hours and $117,138 in reported chain revenue. Ethereum's overview showed $649,423 in fees and $226,298 in revenue.
For these two networks, the revenue measure tracks fees reported as burned, removing tokens from supply without paying holders cash.
Solana also led on displayed seven-day and 30-day fees, while Ethereum retained a smaller lead in reported burns. Yet the dollar ranking does not settle which token offers better economics: new issuance, network value, and the share of validator income reaching stakers all change the comparison.
DefiLlama's chain fee table put Solana at $23.6 million over 30 days, compared with Ethereum's $12 million. Its chain revenue table showed a burn comparison of $2.66 million for Solana and $2.8 million for Ethereum.
| Displayed metric | Solana | Ethereum |
|---|---|---|
| 24-hour chain fees | About $1.10 million | $649,423 |
| 24-hour reported burns | $117,138 | $226,298 |
| 7-day chain fees | $5.93 million | $3.09 million |
| 7-day reported burns | $698,884 | $761,849 |
| 30-day chain fees | $23.58 million | $12.04 million |
| 30-day reported burns | $2.66 million | $2.80 million |
Exact window endpoints were not disclosed, and Ethereum's shared revenue table showed a different daily figure of $229,846. The comparison consequently applies to the displayed aggregates, with synchronization limits.
The longer windows also temper the daily headline. Ethereum's 30-day reported burn was only slightly larger than Solana's, even though its daily overview showed a much wider gap. Aggregate leadership over seven or 30 days does not mean either network led every individual day.
How fees reach validators, stakers and apps
Under Solana's fee rules, the base charge is 5,000 lamports per signature. Half of that base fee is burned, and half goes to the validator producing the block. The validator receives all priority fees, which users pay for transaction priority.
That allocation makes fee composition important. A rise in priority fees increases validator receipts without directing that stream to burning, so higher total fees can coexist with a comparatively small burn figure.
Ethereum burns execution base fees, while priority tips go to validators. DefiLlama's Ethereum data-collection code also includes blob fees in both total fees and reported burns. Two similar totals for user spending could affect supply differently, depending on the kinds of fees paid.
The data-collection programs, known as adapters, estimate parts of these reported burns. DefiLlama's Solana adapter estimates base fees by multiplying transaction count by 5,000 lamports, although the protocol charges by signature.
Ethereum's adapter uses each block's minimum effective transaction gas price as a proxy for its execution base fee and obtains blob fees separately from Dune. Neither estimate should be presented as a fully reconciled measurement of tokens destroyed.
Burning reduces supply relative to what it would otherwise have been, and it does not credit a holder's wallet, establish that total supply is falling, or guarantee a price gain. Those are separate questions from how much users paid to transact.
A validator's receipts are not automatically everyone's receipts when staking through it. Solana's staking documentation describes inflationary rewards distributed to validators and delegated stake accounts, with commissions affecting what delegators receive.
The yield also depends on total stake and validator performance. These newly issued rewards are separate from user fees.
On July 2, 2025, Solana staking infrastructure project Jito announced a live upgrade that lets validators distribute priority fees to their stakers. Validators' choices and commissions determine the distribution, and a sharing mechanism does not turn all chain fees into a uniform return for SOL stakers.
For an ordinary holder, the relevant distinction is between owning the asset and participating in a particular reward arrangement.
A passive holder receives no validator payment merely because chain fees rise, while a staker needs to know which rewards are included and what deductions apply before treating a quoted yield as fee income.
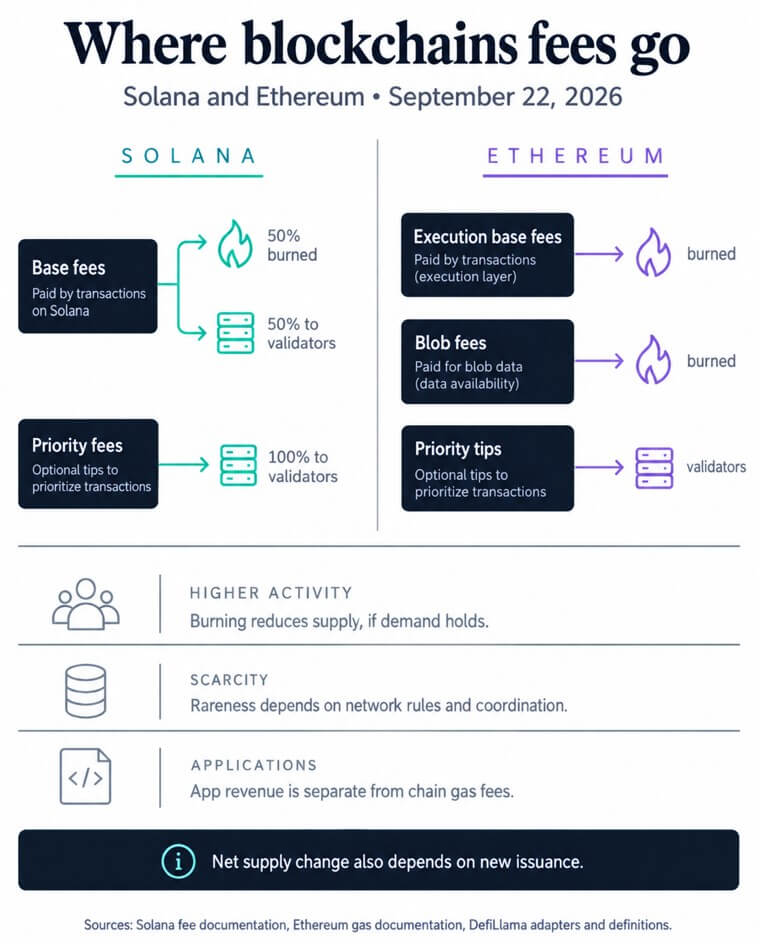
Applications represent another destination for economic activity. The Sept. 22 overviews showed $7.7 million in 24-hour app revenue on Solana versus $1.9 million on Ethereum. App fees were $18.2 million and $8.5 million, respectively.
DefiLlama's definitions separate app metrics from gas fees. They also define chain REV as chain fees plus maximum extractable value (MEV) tips. REV can describe a broader stream of transaction-related spending, but adding it to chain fees would count those fees twice.
Valuation and issuance change the investment question
Ethereum's larger dollar burn sits against a much larger token valuation. The same Sept. 22 overview snapshots displayed market capitalizations of $335 billion for ETH and $69 billion for SOL. Nearly comparable 30-day reported burns represent a larger fraction of Solana's displayed market capitalization.
A holder's yield requires a separate calculation. It compares a period's estimated burning with a valuation at one moment, and it says nothing by itself about tokens created during that period. A larger gross burn relative to market value can coexist with issuance that more than offsets it.
Ethereum's supply mechanics make that distinction explicit: net supply depends on issuance and burning. Its Merge explainer's roughly 1,700 ETH-per-day example assumes about 14 million ETH staked, so it cannot serve as a current September 2026 issuance measurement.
Without matched-period issuance for both networks, these fee tables cannot establish either a net supply advantage or a superior investment return.
Solana's accepted SGP-0002 proposal calls for increasing annual disinflation from 15% to 30%, but explicitly depends on SIMD-0550 acceptance and activation. Its current monetary effect depends on implementation.
For holders comparing SOL and ETH, the decisive missing evidence is a matched-period account of tokens issued and burned, alongside the fees actually distributed after commissions.
The September snapshot shows stronger fee generation on Solana and a larger reported dollar burn on Ethereum. Turning either observation into a return claim requires knowing how much reaches the holder, how much supply is added, and what valuation the buyer pays.
The post Solana flips Ethereum in fees, while ETH holds the burn lead appeared first on CryptoSlate.
XRP Ledger (XRPL) validators have put BatchV1_1 on a conditional path to activate at 14:06:41 UTC on Sept. 29, turning a security near-miss into a live test of the network's amendment process and its surrounding software.
On Sept. 22, xrpldashboard showed 30 of 35 trusted validators supporting the amendment, above its displayed 28-vote threshold. The majority first appeared on-ledger on Sept. 15.
Under XRPL's amendment rules, support must remain above 80% for two weeks. A fall to 80% or less ends the majority period, so the activation date remains conditional.
Sept. 29 is the first production test of whether XRPL's validator process, reference implementation, and client ecosystem converted a dangerous pre-mainnet flaw into usable atomic transaction infrastructure.
The validator firewall worked before mainnet
The original Batch amendment never activated on the XRP Ledger mainnet. In February, researchers found a critical authorization flaw while the amendment was still in its voting phase, and validators were advised to vote it down.
XRPL Labs' official vulnerability disclosure states that no funds were at risk.
The flaw sat in the loop that checked the accounts authorizing a batch. If the code encountered a signer for a newly created account whose key matched that account, it returned success immediately instead of continuing through the remaining signers.
An attacker could place that valid signer first, then add a forged entry purporting to authorize a victim account. If the amendment had gone live, the unchecked victim transaction could have executed without the victim's keys.
XRPL's response came in two stages. Version 3.1.1 marked the original Batch and fixBatchInnerSigs amendments unsupported, blocking their activation. BatchV1_1 later replaced them with a rewritten authorization path and additional defenses.
The episode was a failure caught at the boundary between software release and protocol activation.
The XRPL Foundation's final XLS-56 specification now requires a multi-account batch to contain the exact, complete set of BatchSigners whose authorization the inner transactions would ordinarily need, apart from the account whose normal signature authorizes the outer transaction.
Missing, extra, duplicate, or incorrectly ordered entries cause rejection.
Each BatchSigner also signs more than a loose collection of inner transactions. The payload binds the signature to the outer account, its sequence number or ticket, the selected batch mode, the ordered hashes of every inner transaction, and the BatchSigner account.
A multi-signed entry also binds each nested signer account. That prevents a valid signature from being lifted into a different outer transaction or reassigned to another participant.
The merged reference implementation adds enforcement around that design, including signer ordering and uniqueness checks, transaction-count bounds, rejection of directly submitted inner transactions, and protections for ledger replay.
Together, those changes address both the disclosed premature-success bug and adjacent ways that malformed or replayed batch data could cross authorization boundaries.
A Batch contains two to eight inner transactions. Each inner transaction carries no signature or fee and is marked so it cannot be submitted independently. The outer Batch selects exactly one of four modes:
- ALLORNOTHING: every inner transaction must succeed or none of their state changes commit.
- ONLYONE: the first successful inner transaction is the only one applied.
- UNTILFAILURE: transactions apply in order until one fails.
- INDEPENDENT: every inner transaction is attempted regardless of the others' results.
BatchV1_1 can support atomic all-or-nothing flows, but not every batch is atomic in that narrow sense. Developers can also use it for ordered fallbacks or independent bundles.
Activation shifts risk to implementation
The most immediate integration trap is that an outer Batch can return tesSUCCESS even when one or more inner transactions fail. Clients must inspect each inner transaction's metadata and result code to determine what happened.
That distinction is important outside ALLORNOTHING mode, where partial or independent execution is intentional.
BatchV1_1 support shipped in xrpld 3.3.0 on Aug. 6. Once the amendment activates, a server that does not understand the new rules becomes amendment-blocked. It can no longer reliably validate the ledger or participate in consensus until it upgrades.
An issue filed against xrpl.js documented that version 5.0.0 built Batch signatures using the older payload, omitting the outer account, sequence, and participant binding. BatchV1_1-enabled nodes rejected those signatures with temBAD_SIGNATURE.
The xrpl.js release history records compatible support in version 5.1.0.
| Component | Readiness point | Risk if outdated |
|---|---|---|
| xrpld | BatchV1_1 support shipped in 3.3.0 | An incompatible server can become amendment-blocked after activation |
| xrpl.js | Version 5.1.0 added the revised signing format | Version 5.0.0 can produce signatures rejected by BatchV1_1 nodes |
| Wallets | Display every inner action and the selected mode | A user may approve a bundle without understanding its full effect |
| Explorers and indexers | Preserve the relationship between outer and inner transactions | Interfaces can misreport or fragment the outcome of a batch |
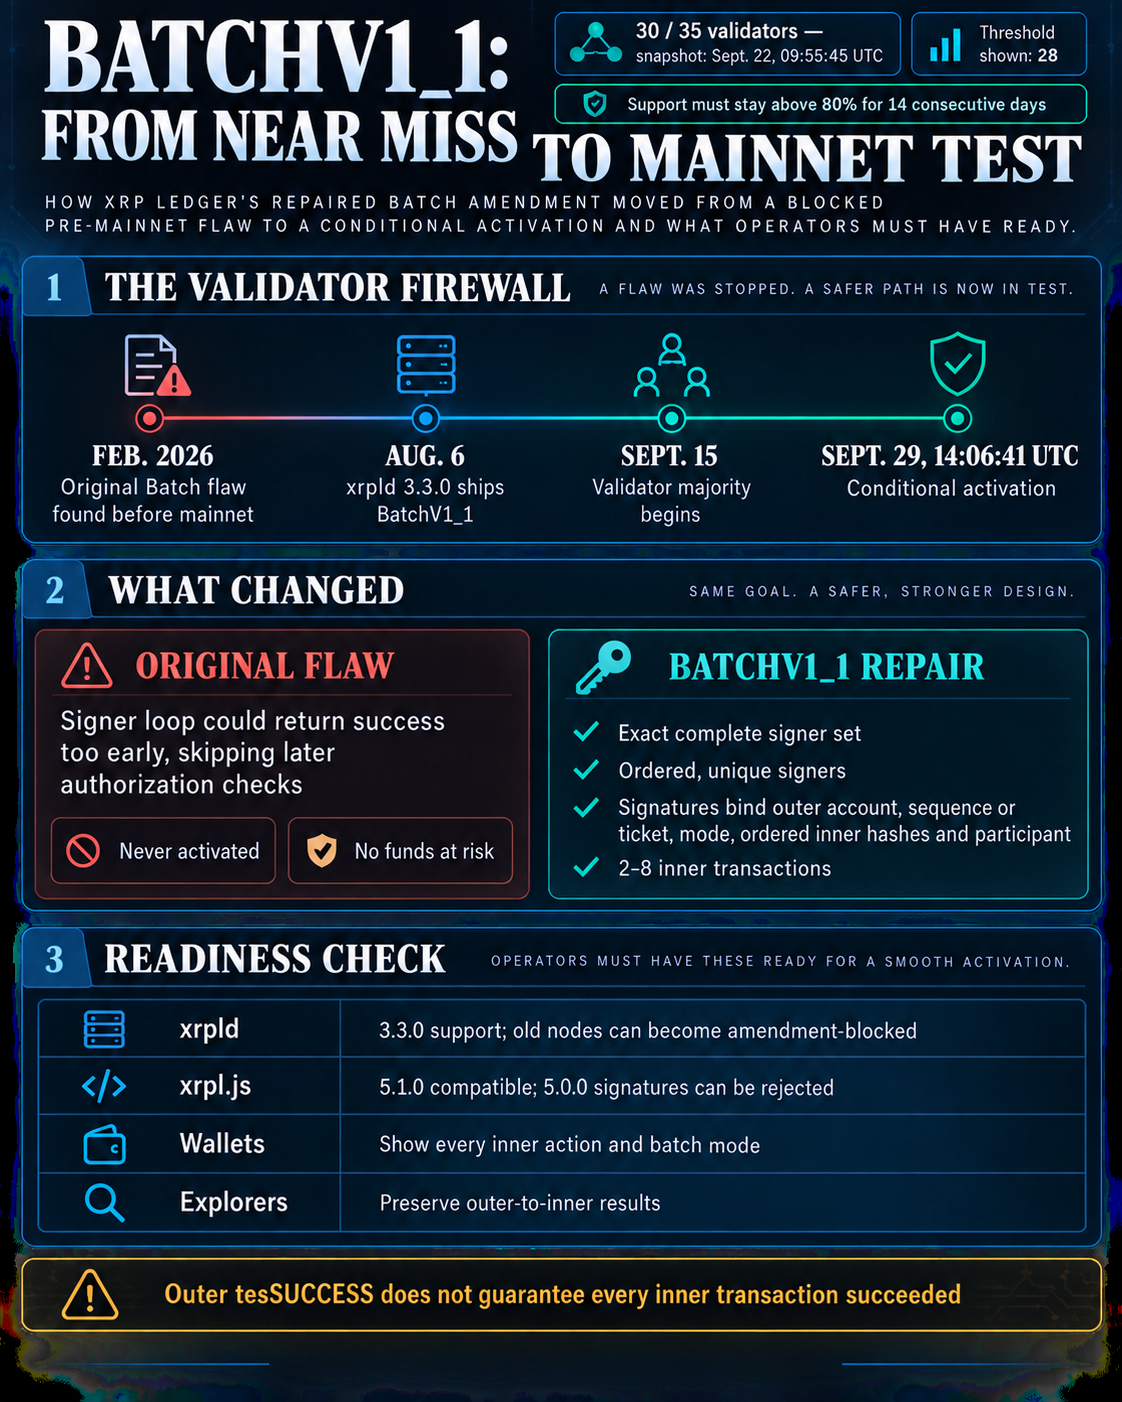
The wallet and indexer rows reflect integration guidance in the detailed XLS-56 rules. The protocol can reject a malformed signature, but it cannot force a wallet to explain a complex bundle clearly or an explorer to present every inner result in context.
The specification also flags front-running as an area still under investigation. Stronger authorization prevents a party from forging another account's approval, but it does not eliminate every risk created by packaging several market-facing actions into one ordered submission.
What Sept. 29 will prove
If the majority holds, activation will show that XRPL's validator process can stop a dangerous amendment, route operators to a disabled release and later move a repaired replacement through the same governance machinery.
It will also begin a real-world test of whether servers, signing libraries, wallets and data infrastructure agree on the new transaction format and its results.
It will not prove that applications have adopted BatchV1_1, that users want the feature, or that network transaction demand will increase. The amendment vote and software releases establish protocol availability, but they don't provide evidence of additional XRP buying.
The useful signals will come after activation: whether outdated nodes become blocked, whether signing failures cluster around old client versions, whether wallets present multi-account batches intelligibly, and whether explorers report inner outcomes without mistaking outer success for complete execution.
XRPL's validators passed the first test by preventing the original Batch flaw from reaching mainnet. The conditional Sept. 29 activation asks whether the ecosystem learned enough from that near miss to operate the replacement safely.
The post XRPL fixes critical pre-mainnet flaw, but client apps remain at risk appeared first on CryptoSlate.
Circle is doubling down on Binance after USD Coin (USDC) stablecoin customer balances on the exchange nearly quintupled since their first agreement.
On Sept. 22, the companies announced a new five-year commercial agreement alongside Binance’s $100 million equity investment in Circle, extending a relationship that has turned the world’s largest crypto exchange into one of USDC’s most important distribution channels.
The agreement focuses on expanding USDC access, particularly in emerging markets, and replaces arrangements signed in November 2024 and August 2025.
Binance bought 1.237 million Circle Class A shares at $80.84 each, a 5% discount to Circle’s Sept. 17 closing price, and agreed to a two-year restriction on selling, pledging, or hedging the shares. The commercial agreement runs through September 2031, although either company can terminate it earlier under specified circumstances.
The longer commitment follows a sharp expansion in USDC’s presence on Binance. Customers held about $1.5 billion of USDC on Oct. 1, 2024, shortly before Circle entered into its original Binance agreement in November.
Binance’s latest Sept. 1 Proof-of-Reserves snapshot shows customer USDC balances at about $7.1 billion, up roughly 376%, or almost fivefold.
USDC itself has not grown nearly as quickly. Circle reported $39.7 billion of USDC in circulation on Nov. 29, 2024, around the time it struck the first Binance agreement. DeFiLlama currently puts circulating USDC at roughly $74.4 billion, up about 87%.
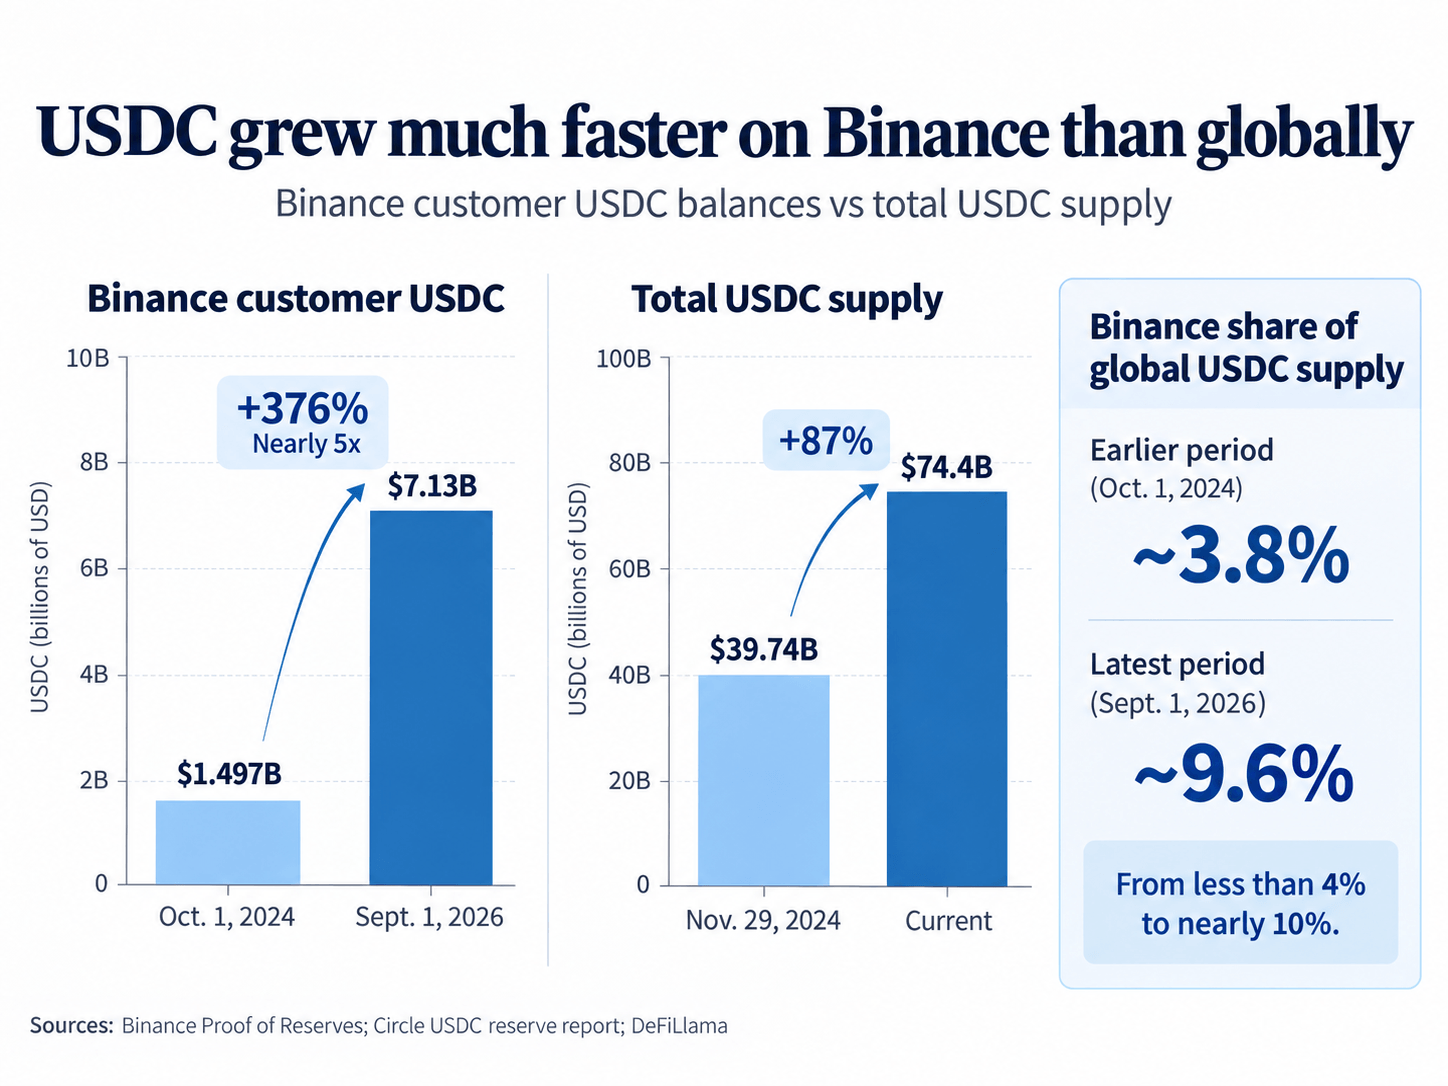
That means Binance customer balances have grown from the equivalent of less than 4% of global USDC supply at the start of the partnership to almost 10% today.
USDC closes part of Tether’s Binance lead
USDC’s expansion on Binance has also substantially outpaced Tether’s growth on the platform.
Binance customers held $21.4 billion of USDT in the Oct. 1, 2024 reserve snapshot, compared with $1.5 billion of USDC. That left roughly $14.30 of USDT on Binance for every dollar of USDC.
By Sept. 1 this year, customer USDT balances had risen to $32.3 billion, while USDC reached about $7.1 billion. The ratio had narrowed to approximately 4.5-to-1. USDT customer balances increased about 51% over the period, compared with USDC’s roughly 376% increase.
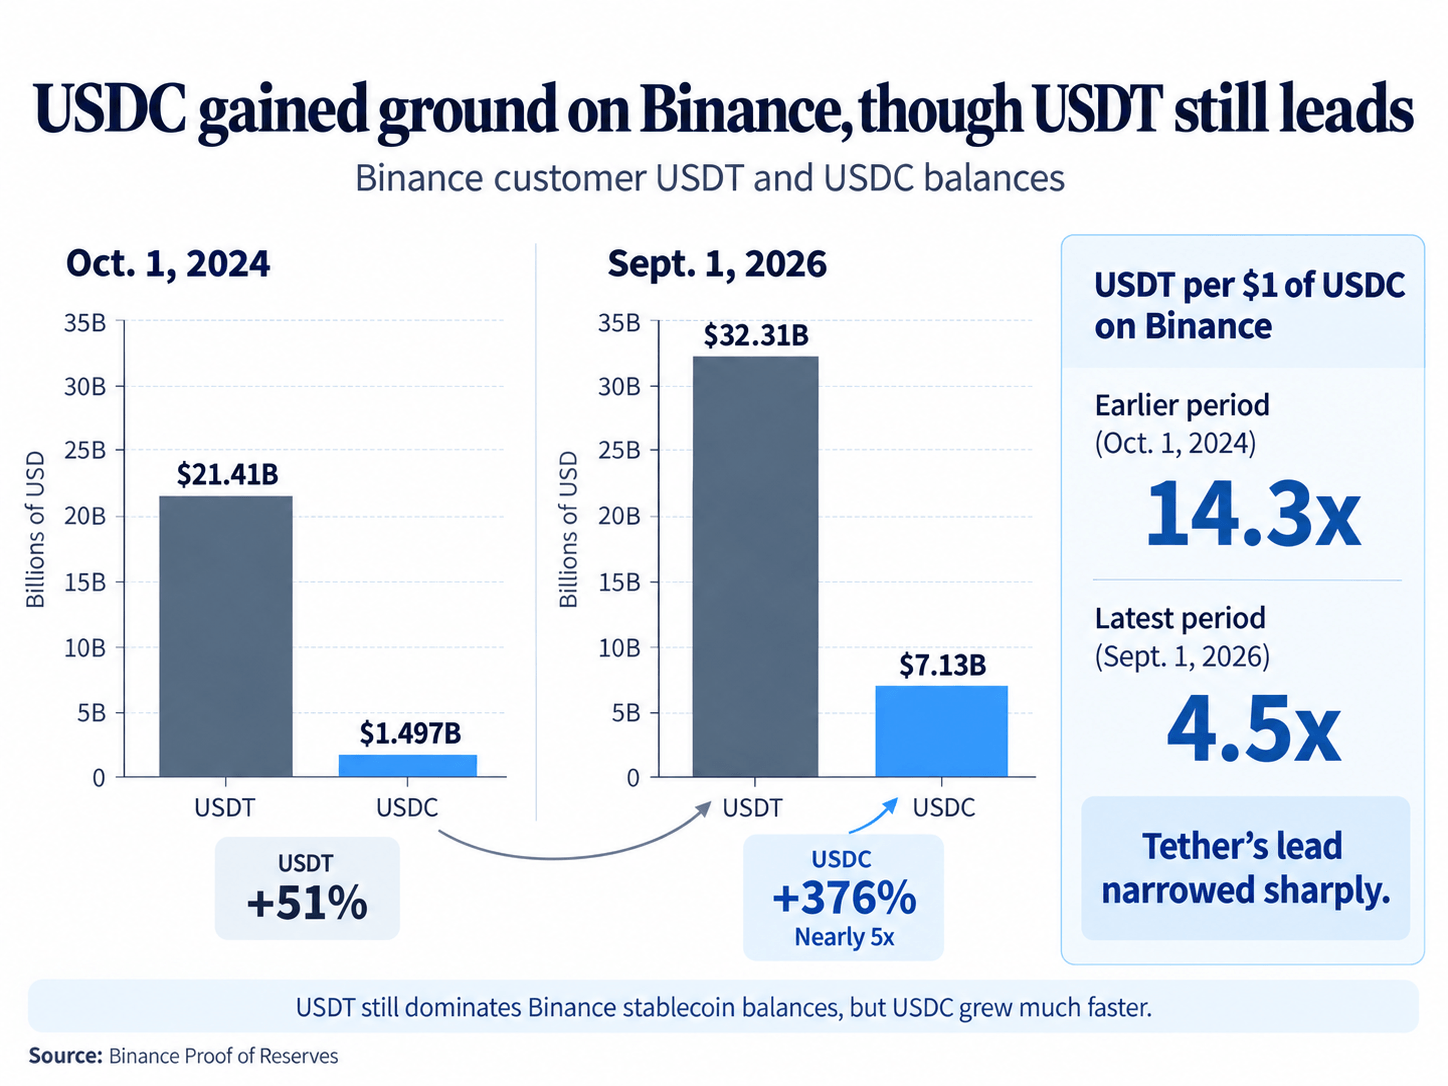
Circle’s regulatory filings show the shift gathering pace after the original deal. USDC represented 5% of stablecoins held on Binance on July 1, 2024, 10% by Jan. 1, 2025, and 22% by July 1, 2025.
The figures show that Binance became a substantially larger USDC distribution channel during the partnership, even as Tether remained the dominant dollar token on the exchange.
Circle CEO Jeremy Allaire said the latest agreement was designed to push that distribution further.
He wrote on X:
“As the world’s largest and most widely used wallet for stablecoins and onchain finance, the partnership will accelerate global and emerging market preference and adoption of USDC. The internet financial system is expanding everywhere and this partnership will help to expand access to this new financial system to hundreds of millions of people and businesses around the world.”
Circle has paid heavily for that distribution
The growth on Binance has come at a high cost, leaving the economics behind the renewed partnership as the bigger unanswered question.
Under the November 2024 agreement, Circle paid Binance a $60.25 million upfront fee and agreed to monthly incentive payments based on USDC held on the platform and in Binance’s treasury.
Those payments ranged from an annualized mid-double-digit to high-double-digit percentage of a fixed rate reset quarterly at a discount to three-month SOFR. Binance also agreed, subject to certain exceptions, to keep $3 billion of USDC in its treasury, with treasury incentive payments requiring at least $1.5 billion to remain there.
Circle expanded the relationship again in August 2025 around USDC held through its Modular Smart Contract Wallet infrastructure. The agreement provided for incentives equal to a high-double-digit percentage of a fixed rate tied to three-month SOFR.
The new five-year contract consolidates and replaces both previous arrangements, with Circle continuing to pay Binance a monthly incentive tied to USDC held in the wallet. Neither the new fee rate nor any minimum balance commitments have been disclosed.
In a note shared with CryptoSlate, Clear Street analysts Owen Lau and Nikhil Vijay said the agreement improves Circle’s visibility over one of its largest distribution channels outside Coinbase but leaves its net economics unclear.
An additional $1 billion of USDC at a 3.5% reserve return would produce about $35 million in gross annual reserve income. If Binance receives a high-double-digit share, as in earlier terms, Clear Street estimates Circle could retain only about $4 million to $7 million.
The issue is increasingly important for Circle’s margins. The company generated about $668 million of reserve income in the second quarter while reporting roughly $410 million of distribution and transaction costs, equivalent to about 61% of reserve income. Non-Coinbase distribution costs also increased as activity expanded across new and existing partnerships.
Binance was already a significant contributor to that bill. Circle said distribution costs specifically related to Binance increased by $152.1 million in 2025 as the relationship expanded.
Binance becomes a shareholder
The latest agreement changes the relationship again by making Binance an investor in the company whose stablecoin it is paid to distribute.
The $100 million investment gives Binance an equity interest in Circle while preserving the balance-linked incentive structure. Clear Street compared the arrangement with Circle’s distributor-shareholder relationship with Coinbase, although Binance’s roughly 0.5% stake is much smaller.
Meanwhile, Binance CEO Richard Teng framed the investment as a longer-term commitment to the stablecoin. He noted:
“Trust in this industry is earned through regulation, transparency, and delivery. Today, in recognition of all three, Binance commits $100M to Circle and extends our partnership for five years. This partnership is about bringing a stable, reliable digital dollar within reach of anyone with a phone.”
The next test will come from the balances and costs behind those ambitions. Clear Street said it will watch reported Binance USDC holdings and Circle’s non-Coinbase distribution expenses when third-quarter results arrive.
With Binance customers now holding more than $7 billion of USDC, those disclosures could show how much Circle is paying to preserve a channel that has grown from less than 4% of global USDC circulation to almost 10% in under two years.
The post Circle pays millions for Binance distribution while its margins collapse appeared first on CryptoSlate.
XRP registered an intraday high of $1.60 on Sept. 22, with roughly $7.4 billion in reported volume. The move was strong, but the latest public data on regulated futures showed different positioning shifts across venues.
The Commodity Futures Trading Commission's Sept. 15 snapshot showed leveraged funds cutting their net short in CME futures by the equivalent of 46.3 million XRP in one week. Net short means reported short contracts exceeded reported long contracts.
Across three separately reported Coinbase Derivatives products, adjusted for each contract's unit, the same trader category reduced its combined net short by only 2.452 million XRP and remained short about 141.6 million XRP.
That disconnect points to a concentrated positioning reset. The dates also block a causal conclusion: the positions were observed Sept. 15 and released Sept. 18, before the Sept. 22 price snapshot.
CME's reset dwarfed the Coinbase shift
CME's standard future represents 50,000 XRP per contract. Leveraged funds held 1,585 long contracts and 2,304 short contracts on Sept. 15, leaving a 719-contract net short equal to 35.95 million XRP.
A week earlier, their reported position was 1,280 longs against 2,925 shorts, or 1,645 contracts net short, equivalent to 82.25 million XRP. The change between reports reduced the net short by 926 contracts, or 46.3 million XRP.
The shift came from both higher longs and lower shorts. Leveraged-fund longs rose by 305 contracts while shorts fell by 621. Short reductions drove most of the improvement, but some new long exposure also appeared.
Open interest fell by 509 contracts over the same week, equal to 25.45 million XRP. The decline is compatible with traders closing positions even as the category added longs.
Coinbase posted a smaller change after converting its three reported products into XRP-equivalent amounts. The standard Coinbase future represents 10,000 XRP per contract. The products labeled NANO XRP and NANO XRP PERP STYLE in the CFTC table each represent 500 XRP per contract.
| Reported market | Sept. 8 leveraged-fund net short XRP | Sept. 15 leveraged-fund net short XRP | Weekly change |
|---|---|---|---|
| CME, 50,000 XRP per contract | 82.25 million | 35.95 million | 46.30 million XRP less short |
| Coinbase standard, 10,000 XRP per contract | 132.17 million | 128.52 million | 3.65 million XRP less short |
| Coinbase nano, 500 XRP per contract | 0.9945 million | 0.9025 million | 0.092 million XRP less short |
| Coinbase nano perpetual-style, 500 XRP per contract | 10.902 million | 12.192 million | 1.290 million XRP more short |
| Coinbase three-product total | 144.0665 million | 141.6145 million | 2.452 million XRP less short |
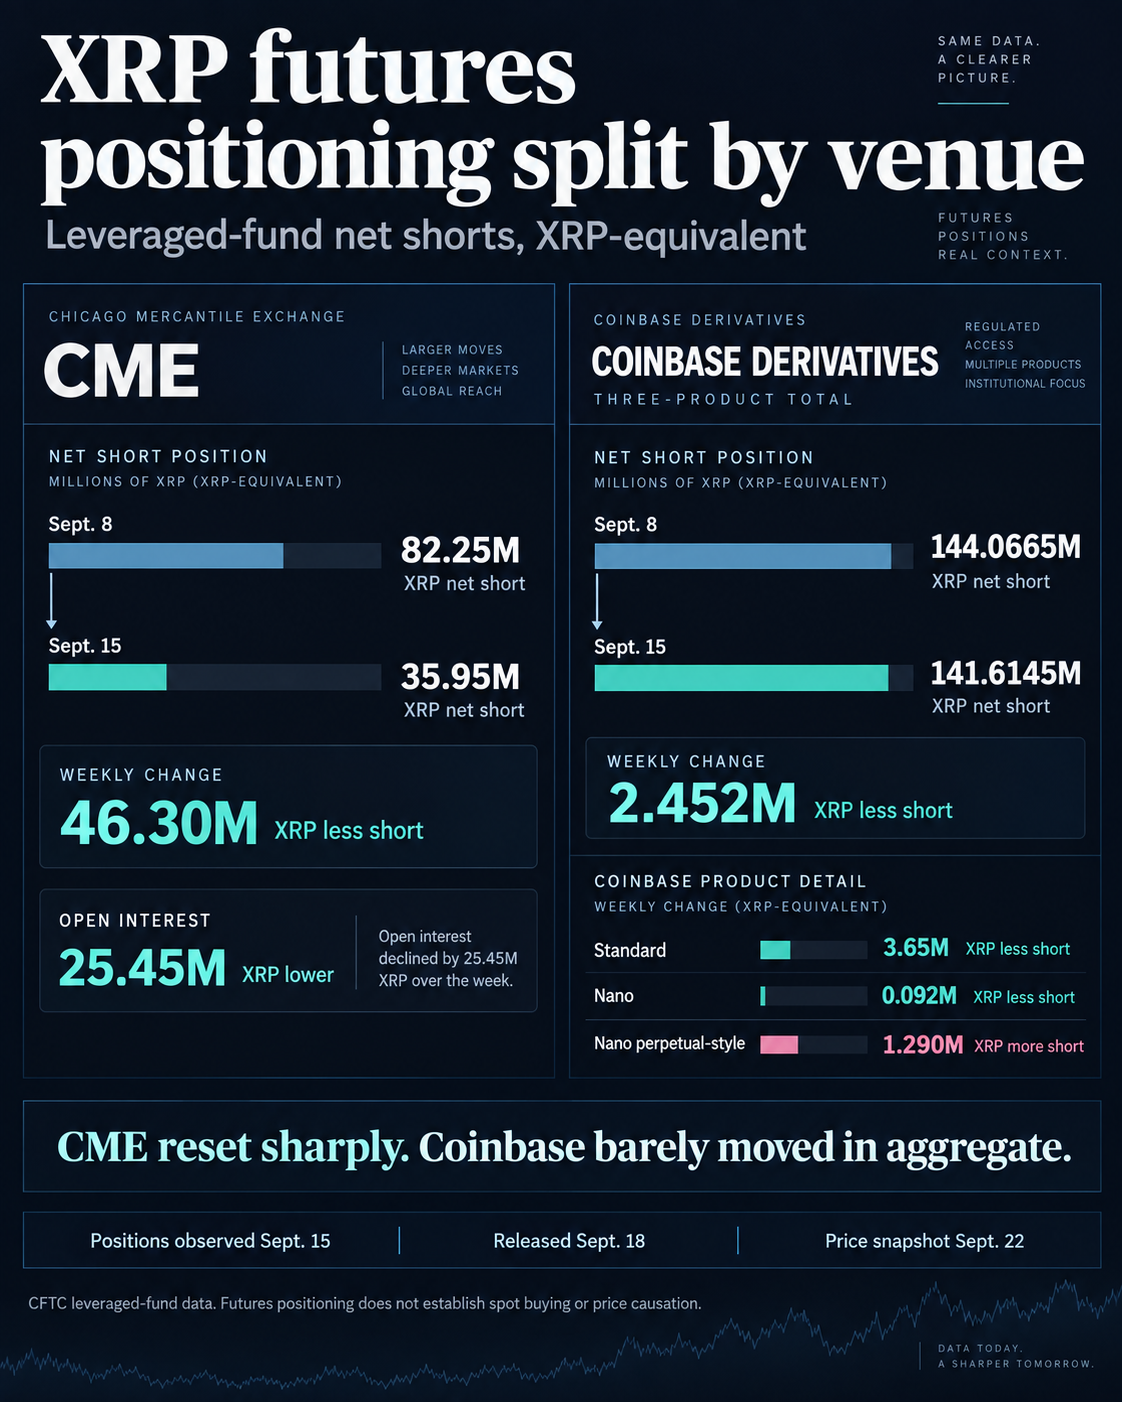
The standard contract accounted for most of Coinbase's modest improvement, while the nano contract contributed another 92,000 XRP. The perpetual-style contract went the opposite way: leveraged funds became 1.29 million XRP more net short.
That increase offset part of the reduction in the other two products. The resulting Coinbase aggregate was still nearly four times the CME net short on Sept. 15 and had moved only a fraction as much over the week.
The Coinbase perpetual-style product is structurally distinct from the unexpiring swaps common on offshore exchanges. It is a regulated, five-year cash-settled future that uses funding adjustments. Its positioning can reflect a different mix of participants and strategies, which is one reason the separate product rows matter.
CME changed far more than Coinbase overall, and Coinbase's products moved in opposing directions. The combined evidence offers weak support for a market-wide directional turn.
What the XRP positioning can and cannot show
The CFTC's leveraged-funds category covers traders whose predominant self-reported business activity fits that classification. The report also has a separate field for mechanical spreading positions, but neither feature establishes the motive behind every long or short.
A short position can express a bearish view, hedge spot exposure, offset another derivative or form one side of a basis trade. Reducing it can reflect a bullish change, a hedge adjustment, a relative-value unwind or a broader cut in risk. Public aggregates leave individual firms and each contract's economic purpose unidentified.
Those limits are key because the headline CME move combines rising longs, falling shorts and lower total open interest. The supported conclusion is that leveraged-fund positioning on CME became much less short. Labeling the full change as fresh directional buying, or as the cause of XRP's later gain, would exceed the evidence.
The comparison is also limited to the four contract families in the dated CFTC query, since CME lists Micro XRP as a distinct product. Under CFTC rules, a market is included in Commitments of Traders reports only when at least 20 traders hold positions at or above reporting levels.
A missing row leaves activity in another product unknown, and the reporting threshold is only a possible explanation for a specific absence.
The reporting lag now provides the next test. CFTC reports generally reflect Tuesday positions and are usually released Friday at 3:30 p.m. Eastern time. The agency's tentative 2026 schedule lists Sept. 25 for the report normally covering Sept. 22.
That snapshot can show whether the cross-venue split persisted during the rally, while price causation remains outside what weekly positioning data can resolve.
A broader directional shift would gain support if Coinbase's combined net short also fell materially, particularly alongside expanding open interest. If Coinbase remains heavily short while CME stays much less short, the data would continue to favor a venue-specific reset.
For now, three observations can stand together without being forced into one causal story: XRP rallied, CME leveraged funds had already reduced a large net short, and comparable Coinbase positioning had barely changed in aggregate.
The divergence is the signal, while the reason behind it remains outside what weekly category data can establish.
The post XRP volume explodes to $7.4B, and a massive CME short squeeze is blamed appeared first on CryptoSlate.
Fomopeek, a malicious iPhone app distributed through Apple’s App Store, has been linked to nearly $580,000 in stolen USDT.
Blockchain security firm SlowMist began investigating the app over the weekend after receiving reports of stolen assets linked to exposed private keys.
Some victims had previously installed versions 1.1 or 1.2 of the Fomopeek app, which was marketed as a read-only tool for tracking large cryptocurrency transactions across Ethereum, Solana and Tron.
What is Fomopeek?
Working with security researchers at crypto exchange OKX, SlowMist found two modules embedded in those versions that had no connection to FomoPeek’s advertised monitoring functions.
One communicated with external command-and-control infrastructure, while the other contained a kernel exploitation framework with eight attack methods that could adjust to the victim’s iPhone model and operating-system version.
A successful exploit could escape Apple’s application sandbox and reach Keychain information and files belonging to other apps. That created a route to locally stored private keys, seed phrases, and login credentials without requiring users to connect a wallet or enter those details into FomoPeek.
SlowMist founder Yu Xian said the risk extended to passwords stored in Apple’s Keychain and encrypted files held by other applications. An attacker who obtained both could potentially unlock wallet credentials and other sensitive information stored on the device.
He explained:
“After a successful attack, the app can break through the iOS sandbox isolation mechanism, then read and decrypt the system keychain (Keychain), and access data files from other apps on the device. Private keys, mnemonic phrases, login credentials, chat histories, files, and other user data stored on the device may all face the risk of leakage as a result. Additionally, the app connects to covert servers unrelated to its public business functions to receive remote instructions.”
The malicious components were not present in FomoPeek’s original release. SlowMist found them in version 1.1, released Sept. 9, and version 1.2 on Sept. 12, before removing them in version 1.3 on Sept. 17.
Researchers also found that the framework could receive instructions from a remote server, including settings that governed whether exploitation was enabled and how often it would run.
Nearly $580,000 stolen
The technical findings were followed by an on-chain trail showing that attackers had already converted that access into losses.
Blockchain analysis firm Salus identified 0x6d37f2C5e8F8546b648D317295565dA95975f4BB as the attacker address and estimated proceeds from the incident at about 579,900 USDT.
Salus traced 401,028 USDT through three intermediary addresses to FixedFloat. Another 20,000 USDT moved in two transactions through deposit addresses before being consolidated into a KuCoin hot wallet.
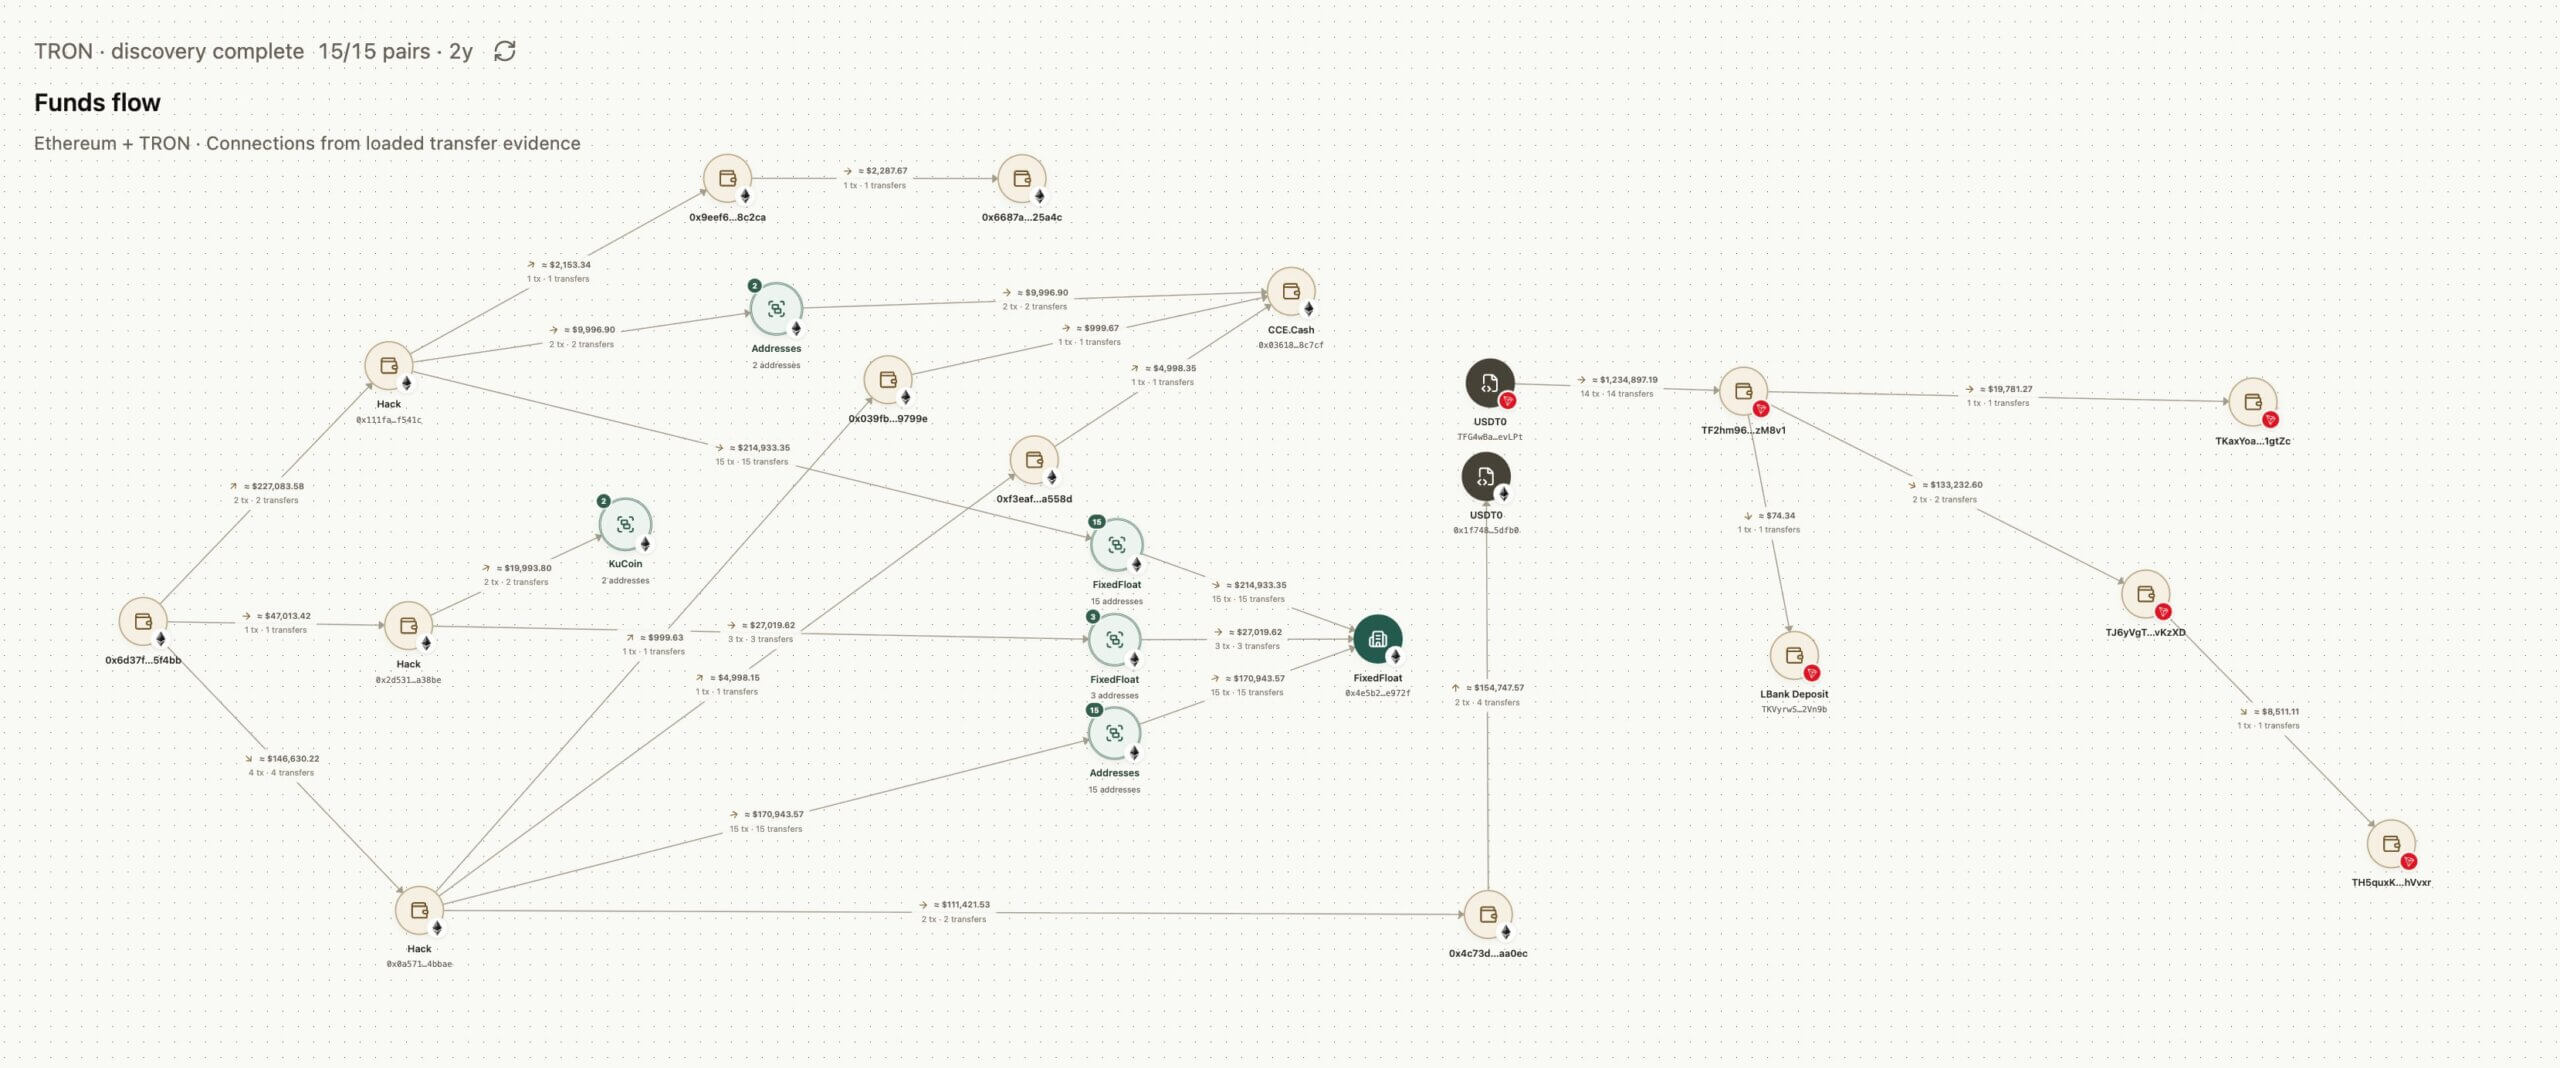
A further 111,458 USDT was routed through an address Salus associated with an escrow platform, while another 10,000 USDT passed through the CCE mixing service before reaching addresses linked to an escrow service.
Salus said its analysis also indicated that the group behind the FomoPeek incident had been involved in a separate private-key theft in June. Investigators are still determining whether the same technique was used in that attack.
Crypto platforms warn users as custody debate returns
The losses and the potential reach of the exploit have prompted warnings from several crypto platforms, including Binance, OKX, Gate, Bitget Wallet and Rabby.
Binance warned:
“The third-party app FomoPeek (versions 1.1–1.2) contains malicious code that can exploit iOS system vulnerabilities to gain the highest level of device privileges, potentially accessing sensitive data stored on the device, including private keys, seed phrases, login credentials, chat history, files, and more. Please note that this type of malware targets the device itself. If an attack succeeds, data from all apps on the affected device may be accessed.”
In light of this, the crypto firms have broadly issued the same guidance, urging crypto users to remove FomoPeek, update iOS, and move assets to newly created wallets on devices where the compromised app was never installed.
These fresh credentials are necessary because deleting the app or patching the operating system cannot invalidate a private key that may already have been copied.
Meanwhile, the incident also comes two months after on-chain investigator ZachXBT argued that a separate iPhone dedicated to crypto could be preferable to existing hardware wallets for storing funds and signing transactions.
His recommendation relied on keeping the device isolated from everyday browsing, messaging, and other activity that could expand the attack surface.
FomoPeek exposes a different weakness in that model. The app was itself built for crypto users and distributed through Apple’s official marketplace, yet researchers say it contained tooling capable of breaching the barriers separating applications on the device.
That does not establish that dedicated crypto iPhones are inherently less secure than hardware wallets. However, it shows that isolation offers limited protection if software installed on the device can compromise the operating system itself.
For affected users, the immediate focus is now on containing further losses and tracing the stolen funds.
Salus continues to follow addresses linked to the remaining proceeds, while Binance and other platforms monitor for deposits that could give investigators another opportunity to track or restrict the movement of the stolen USDT.
The post Rogue iPhone app escapes iOS sandbox to hijack $580,000 in USDT appeared first on CryptoSlate.
CryptoTicker.io
Since September 22, 2026, the US bank SoFi has settled its entire card business through a stablecoin it issues itself, across Mastercard's global network. Nobody notices anything at the checkout, and nothing about your card in Germany changes on that day. The move matters for a different reason: for the first time, the settlement of a card programme of this size runs in production through a stablecoin issued by a licensed bank. That raises the question of when a European provider will attempt the same thing, and what would apply to you if one did.
This article sets out what exactly went live, where the stablecoin actually sits in the card process, and which rules would bite in Germany. The legal framework for that is not American but European: what a nationally chartered bank may do in the United States is, in the EU, an e-money token with a licensing requirement of its own.
What SoFi and Mastercard switched on for stablecoin settlement on September 22, 2026
SoFi has put stablecoin settlement into operation for SoFi Bank's debit and credit card business. Settlement runs on SoFiUSD, a stablecoin pegged to the US dollar that the bank issues itself. According to the company, this makes SoFi the first nationally chartered US bank to use stablecoin settlement in production on Mastercard's network.
The card programme being moved onto this rail processes an annualised volume of more than 25 billion US dollars, on the company's own figures. What is being converted is the running business, not a ring-fenced pilot.
Merchants do not have to hold SoFiUSD or change their point-of-sale systems. Anthony Noto, SoFi's chief executive, describes the merchant-side benefit this way: through the bank's business platform, any merchant can receive settlement amounts immediately in a SoFi bank account and convert them into cash around the clock at no cost. Sherri Haymond, who is responsible for digital commercialisation at Mastercard, frames the step as a move from trials into production.
The two companies announced the partnership in March 2026. As the next stages they name cross-border payments and remittances by migrant workers, along with talks with larger US merchants. No date for a European launch appears in the announcement.
Settlement, not the payment itself: where the stablecoin really sits in the card process
Settlement is the step at which money actually moves between the banks involved after a card payment. It has little to do with the moment at the till.
A card payment runs through three separate stages. First authorisation: within seconds, the terminal asks whether the card is valid and has funds. Then clearing, in which the transaction data are reconciled between the acquiring bank and the card issuer. Only after that comes settlement, where amounts are bundled and balances squared, traditionally through central bank money and correspondent banks, often with a day or more of delay.
It is precisely this third stage that SoFi replaces with a stablecoin. The customer at the till still pays in dollars, the merchant is still credited in dollars, and no token appears on any statement. What changes is the transport layer behind it: it runs over a blockchain instead of the classic banking route, which means it is no longer tied to banking days.
That distinction matters because it separates the process cleanly from what is sold in Europe as a crypto credit card. There, crypto assets sit with the provider, and at the moment of payment they are sold and converted into euros. With SoFi it is the other way round: the customer has nothing to do with crypto, while the bank switches to tokens in the background.
SoFiUSD: what makes a stablecoin issued by a licensed bank different
A stablecoin is a token that pegs its value to a reference, usually a sovereign currency, and is meant to hold that peg through backing reserves. The decisive difference between individual stablecoins rarely lies in the technology. It lies in who issues them and which supervisor that issuer answers to.
With the well-known dollar tokens, the issuer is usually a specialist company that holds the reserves with custodian banks. With SoFiUSD the issuer is the bank itself. Deposit-taking, card issuing and token issuance therefore fall into one and the same supervised entity, and the reserves sit in-house rather than with a third party.
Whether that model is more robust cannot be inferred from the launch alone. All that is demonstrable is the structural difference. How strongly the coupling of issuer and trading venue, or issuer and bank, is currently reshaping the stablecoin landscape is also visible in Binance's stake in Circle, which we reported on September 22.
Why the US launch counts for your card in Germany
Directly, the move does not affect you. SoFi is a US bank, you cannot get its cards in Germany, and SoFiUSD is not an authorised e-money token in the EU.
Indirectly the matter is more interesting, because Mastercard runs a global network and explicitly talks about extending stablecoin settlement to further partners. As soon as a European bank or a European card issuer takes the same route, a rulebook applies that does not exist in that form in the United States. The questions you would then have to ask can already be answered today, and that is what the rest of this article is about.
E-money tokens under MiCA: who may issue a euro stablecoin in the EU
Under the EU Markets in Crypto-Assets Regulation, MiCA for short, an e-money token is a crypto-asset that aims to keep its value stable by referencing exactly one official currency. A euro stablecoin falls into that category, and so does a pure dollar token distributed in the EU.
The central hurdle sits in Article 48 of the regulation: as a rule, only a credit institution or an electronic money institution may issue an e-money token. A technology company without one of those authorisations is out of the running as an issuer. On top of that come requirements for the reserve and a right of redemption: as a holder, you can redeem your tokens with the issuer at par at any time. The full text of the regulation is freely available via EUR-Lex.
The reserve is subject to a split: part of the funds received must sit in segregated bank accounts, while the rest may be invested in safe, liquid financial instruments. Exactly how that split should look in future is currently in flux; the debate about the obligation to hold bank deposits in the reserve continues at European level.
Which MiCA obligations beyond issuance apply to companies working with crypto-assets in Germany is something we have pulled together in our overview of the MiCA licensing duties.
The interest ban under Article 50 MiCAR: why an e-money token pays nothing
Article 50 of the regulation prohibits issuers of e-money tokens from granting interest on those tokens. What is meant is not only classic interest. Other forms of remuneration and benefits that depend on how long and how much you hold are caught as well.
That is why stablecoin yields advertised in the EU regularly disappear or get restructured. If a provider promises you an ongoing payment on a stablecoin balance, it is worth looking closely at who is actually paying here and for what. We covered the line between a prohibited holding reward and a permissible transaction reward in detail, using the example of a stablecoin-based cashback card.
For settlement on card rails the interest ban plays a subordinate role, because nobody there holds the token any longer than necessary. But as soon as a provider offers to let you hold stablecoins yourself, it is the first rule against which you should measure their promises.
Authorised euro stablecoins: what is already being issued in the EU
The German case that comes closest to the SoFi model is EURAU. The issuer is AllUnity GmbH, a joint venture of DWS, Deutsche Bank's fund arm, the trading house Flow Traders and Galaxy Digital. BaFin granted AllUnity an electronic money institution licence on July 1, 2025, and the token went live on Ethereum in late July 2025. The company's announcement of the licence sets out the details.
Alongside it, EURC from issuer Circle and EURCV from Société Générale are among those in the market. We deliberately refrain from quoting a reliable, up-to-the-day figure for the number of authorised issuers: the tallies from different providers diverge considerably depending on the cut-off date and the counting method, and the only authoritative source is the register kept by ESMA, the European securities supervisor. You will find our own analysis of that register in the article on authorised stablecoin issuers; it reflects the state of play on the date it was compiled and is no substitute for looking at the register yourself.
In practical terms that means: before you use a euro stablecoin, check whether its issuer is actually listed there. A token distributed in the EU without authorisation can be pulled from trading venues at any time, and then all you have left is redemption or withdrawal.
Check the settlement currency: what a dollar token has to do with your foreign exchange fee
SoFiUSD is pegged to the dollar. For a US card programme with US merchants that follows logically. As soon as a card issuer in Europe were to move to dollar settlement, a currency conversion would sit there that today arises elsewhere.
On your card, what governs this is the billing currency of your card account, not the currency of settlement between the banks. If you pay in euros and your account is denominated in euros, no foreign exchange fee arises, whatever the banks square up in behind the scenes. If your account is denominated in another currency, or you pay outside the euro area, most issuers charge a fee on the turnover.
That is the one point you can and should actually look up in your card terms. Which models the providers of crypto-linked cards run is broken down in the hub on crypto credit cards.
Crypto card tax: why every payment is a disposal under Section 23 EStG
This is where the difference that costs the most money in Germany lies, and it concerns what is sold there as a crypto card, while the SoFi construction remains untouched by it.
If crypto-assets are sold at the moment of the card payment in order to provide euros, that is a private disposal transaction under Section 23 of the German Income Tax Act. If less than a year lies between acquisition and that payment, the gain is taxable once the exemption threshold for other private disposal transactions in the calendar year is exceeded. Every single coffee can therefore be a tax-relevant event, and the burden of proof lies with you. We set out the mechanics and the typical pitfalls in our article on crypto credit cards and tax.
With a stablecoin the price gain is usually small, because the token trades close to its reference. The obligation does not disappear because of that: swapping a stablecoin into euros or into another crypto-asset is also a disposal, and you still have to keep the documentation. Anyone paying regularly with such cards will struggle without clean records; you will find suitable tools in the hub on crypto tax software.
Pure stablecoin settlement between banks, as SoFi runs it, triggers nothing at all for you as a customer. You never hold the token, you never swap it, and no disposal transaction arises. That is the essential reason why this model stays unremarkable for retail customers, while crypto cards do not.
Custody and issuer risk: who holds the token when things get tight
With every stablecoin, everything hangs on the issuer and the reserve. If a token loses its peg, the blockchain will not help you; what matters then is whether the issuer redeems at par and whether the reserve is sufficient for that.
The fact that the issuer is a supervised bank shifts this risk, it does not make it disappear. With a bank, deposit protection and banking supervision come into play, while at the same time more is concentrated under one roof. For you as a German investor the simple principle holds: the longer you hold a stablecoin, the more issuer risk you carry, and for amounts you do not need in the coming days, a token is not the right place.
Where you buy crypto-assets in the first place, and how the platform in question is regulated, determines a considerable part of that risk. You will find an assessment of the trading venues authorised in the EU in the hub on regulated crypto exchanges.
Three markers that will show you the next stage
So that you can follow the story without reading every press release, these are the points at which it will be decided whether the model comes to Europe.
The first is a European card issuer announcing stablecoin settlement. That requires an authorised euro token, and the candidates for it are in the ESMA register. The second is SoFi's extension into cross-border payments, which both companies name as their next step; only there does the model touch recipients outside the United States. The third is the ongoing European debate about the composition of stablecoin reserves, because it determines how attractive issuing a euro token is for a bank in the first place.
For the crypto market as a whole, the launch changes little in the short term. If you want to follow the broader market picture, you will find our current assessment in the Bitcoin price prediction.
Checking stablecoin settlement: what to take away
- Separate settlement from the payment itself. If only the settlement between banks runs through a token, nothing happens to you for tax purposes. If, by contrast, crypto is sold at the moment of payment, every payment is a disposal transaction. Which card runs which model is set out in the terms and broken down in the hub on crypto credit cards.
- Check the issuer of every euro stablecoin. Only credit institutions and electronic money institutions may issue e-money tokens in the EU, and an ongoing payment on the balance is not permitted under Article 50 MiCAR. Anyone swapping regularly should record the transactions without gaps; the crypto tax software will help with that.
- Hold stablecoins briefly. Such a token is a means of transport and not an investment, and every day in the token is a day of issuer risk. If you buy through a platform, make sure it is authorised in the EU; the overview is in the hub on regulated crypto exchanges.
(As of September 23, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
An unknown token can be put through its paces in about half an hour, and doing so requires neither programming skills nor a subscription. The core of the exercise comes down to three questions: who stands behind the project, who owns the tokens, and how much of that can be looked up independently?
This guide works through nine checkpoints in order, from the European register to how holdings are spread across a handful of addresses. What it produces at the end is not a verdict on individual projects but a procedure you can apply again to every token that follows.
Why Due Diligence on Crypto Assets Works Differently Than on Equities
With a share, the capital market supplies the homework: audited annual accounts, notification thresholds, ad hoc disclosure duties, plus a supervised trading venue. With a freely traded token, that substructure is largely absent. The figures usually come from the project itself, and the cross-check is yours to organise.
That does not mean there is nothing to check. On the contrary: a public blockchain exposes things that would never be visible at a company. How many tokens exist, where they sit and when they last moved can be looked up by anyone. The skill lies in looking in the right places.
One point up front that puts the whole exercise in perspective: even a project that passes every checkpoint can end up worthless. These checks weed out the obvious cases and make the rest comparable. A total loss remains possible with any crypto asset, including the largest ones.
Checkpoint 1: Is the Provider Listed in the European Register?
The first look is not at the token but at the place where you intend to buy it. Since 30 December 2024, a company that holds, exchanges or brokers crypto assets for clients has needed authorisation under the European regulation on markets in crypto-assets. The European securities regulator ESMA maintains a central register under MiCAR for this, listing authorised service providers alongside whitepapers and companies that have drawn attention.
For issuers themselves, the rules differ by token type. For asset-referenced tokens the regulation requires authorisation from BaFin under Article 16(1)(a) MiCAR; for e-money tokens the procedure runs via a notification. Both categories can be viewed in ESMA’s interim register. What the duties for companies cover in detail we have compiled in our overview of the MiCA licensing obligations.
The opposite direction is just as revealing: supervisory authorities keep warning lists of providers operating without authorisation. How extensive that list has become and where the entries come from is set out in our article on the EU warning list for crypto providers. A hit there ends the review immediately.
Checkpoint 2: Is There a Whitepaper, and Does It Contain Anything Verifiable?
A whitepaper is a project’s self-description. Under MiCAR it is, for publicly offered crypto assets, a formalised document with fixed mandatory disclosures, and the supervisor expressly does not approve it: responsibility for the content stays with the provider.
Read it all the same, with one simple question in mind: which statement in here could be demonstrably false in twelve months? A document consisting solely of intentions, vision and market size contains nothing anyone could be held to. Concrete details on issue volume, use of funds, lock-up periods and responsibilities are the opposite of that.
Checkpoint 3: Who Are the People, and Are There Any at All?
Names on a project page are not evidence. It becomes verifiable only once those names can be found independently: in commercial register entries, in professional networks with a history, in conference programmes, in source code contributions with a long back story. If every trace outside the project’s own channels is missing, that is a serious signal.
Anonymity alone is no disqualifier, and the industry’s history demonstrates that vividly: Bitcoin came from a pseudonym. The difference lies in whether the work can be verified. Where nobody is liable, the program code must be open and the distribution of power must be auditable. An anonymous team plus closed source plus central control over the tokens is the combination at which a review ends.
Checkpoint 4: How Many Tokens Exist, and Who Owns Them?
The decisive figure is rarely the price but the distribution. Two terms help here:
- Total supply: how many units will exist in all.
- Circulating supply: how many of those are freely tradable today.
If the two diverge widely, a large share of the supply is still waiting for the market. Every later release increases supply without anything needing to change on the demand side. A look at the release schedule therefore belongs to every review.
Concentration in a Few Addresses
Public blockchains allow something no annual report offers: you can look up how the holdings are spread. Every block explorer shows the largest holders of an address. If eighty percent of the supply sits on a handful of addresses, the price hangs on the behaviour of a few participants. Strip out addresses that clearly belong to a trading platform, because those pool the holdings of many customers. Which tools make such analyses accessible without specialist knowledge is shown in the overview of analytics platforms.
Checkpoint 5: Does the Trading Volume Hold Up, or Is It Manufactured?
A high reported volume looks reassuring and is easy to produce. Trading against yourself generates turnover with no economic substance. Three cross-checks that cost little time:
- Count the venues. If the entire volume runs through a single, unfamiliar trading venue, the figure carries little weight.
- Look at the order book. Check how far the price would move on an order the size of your intended purchase. A book that already gives way noticeably at small amounts is thin, whatever the daily statistics say.
- Check the ratio. Daily turnover on the order of the entire market value is unusual in established assets and deserves an explanation.
The practical test remains the same as with any new account: a small amount in, a small amount back out. A trading venue where the return path stalls is finished, regardless of any metric.
Checkpoint 6: What Happens Technically When You Connect?
With tokens traded on decentralised venues, a further danger arises that need have nothing to do with the project itself. Connecting a wallet to an unfamiliar application grants approvals, and some of them are unlimited. An approval once granted keeps working, long after you have closed the page.
Two rules suffice for everyday use: for such experiments connect only a separate wallet with a small balance, and read what the confirmation window actually says. What exactly is being signed there, and how an abusive approval can be recognised, we broke down in our article on wallet drainers and signature approvals.
Checkpoint 7: How Is It Being Marketed?
The marketing often reveals more than the product. Four patterns that show up regularly in supervisory practice:
- Return promises with a figure and a timeframe. Anyone guaranteeing a fixed return is making a statement about the future that nobody can keep.
- Time pressure. Countdown, limited places, bonus today only: pressure replaces the argument.
- Advertising through fame. Prominent faces and supposed media reports are interchangeable and often used without the knowledge of those concerned.
- Referral chains. When the reward depends above all on recruiting new participants, the earnings lie in the recruiting and not in the product.
None of these patterns is proof on its own. When several appear together, the probability is high enough to skip the purchase.
Checkpoint 8: Can the Token Actually Be Sold Again?
Getting in is easy with every project; getting out is not. So check before buying what the return path looks like: which venues list the pair against the euro or against an established asset? How deep is the book there? Are there lock-up periods during which a sale is ruled out? And does the platform impose conditions for withdrawal that did not apply at the time of purchase?
A common pattern with questionable offerings: deposits work smoothly, and only on withdrawal do fees, taxes or verifications appear that were nowhere to be seen beforehand. Additional demands at the moment of payout are an alarm signal, not a formality.
Checkpoint 9: What Applies for Tax If It Does Go Wrong?
This point comes last because it is readily forgotten. Crypto assets held privately fall in Germany under private disposal transactions pursuant to section 23 of the Income Tax Act. A gain is taxable if no more than a year lies between acquisition and sale, and remains tax free if the total gain from all private disposal transactions in a year stays below 1,000 euros.
What matters on the loss side is that it can be evidenced at all. So from the very first purchase, record when you bought at what price, through which platform and to which address. Anyone wanting to claim a loss later needs exactly these records, and retrospectively they are often no longer obtainable once a platform has disappeared.
A word on expectations: a token that has become worthless does not automatically disappear from your tax file, and the treatment of such cases is disputed in detail in Germany. Anyone with larger amounts at stake settles that with tax advice rather than with a forum post.
The Half Hour in the Right Order
Taken together, this yields a sequence that sticks in the mind because it works from the outside in:
- Look up the trading venue in the European register and cross-check the warning lists.
- Read through the whitepaper for verifiable commitments.
- Search for the team outside the project’s own channels.
- Compare total supply, circulating supply and the release schedule.
- Look at the distribution of the largest holdings in the block explorer.
- Cross-check trading volume and order book depth.
- Read and limit the approvals when connecting the wallet.
- Put the marketing patterns in context.
- Settle the return path and the record-keeping before any money moves.
One failed point is not yet a verdict. Three failed points give you a decision, and a reasoned one.
Checking a Crypto Project: What to Take Away
- Check the trading venue first, not the token. An authorised provider removes no price risk, but it removes the question of whether your money even arrives where it is meant to. The overview of regulated crypto exchanges is the starting point for that.
- Look at the distribution before you look at the price. Total supply, circulating supply, the release schedule and the largest holders say more about the risk than any forecast. What lets you analyse that without specialist knowledge is set out in the comparison of analytics platforms.
- Settle the return path and the custody in advance. Check trading pairs, lock-up periods and withdrawal conditions, and decide where the tokens should sit after the purchase. For longer-term holdings, the hardware wallet comparison is worth a look.
(As of September 23, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Setting up your own crypto wallet takes about twenty minutes and comes down to four moves: choose the wallet type, generate the wallet, back up the recovery words offline, and use a small test amount to check that funds travel out and back. The third move decides everything that follows, because it is the only one nobody can catch up on for you.
This guide walks through each of those steps, explains the terms at the point where you first meet them, and closes with what a self-custodied wallet means in legal and tax terms in Germany.
What a Crypto Wallet Stores, and Why Your Coins Are Never Inside It
The name is misleading. A wallet is not a purse holding coins. Germany’s Federal Ministry of Finance puts it plainly in its letter of 6 March 2025: “No crypto assets are held in the wallet itself; they always remain on the blockchain” (paragraph 17). Keyring would be the more accurate translation.
What the wallet actually manages are two kinds of keys. The public key is the receiving address; the ministry compares it to an IBAN or an email address (paragraph 18). It may be known to others, because its only job is to assign balances on the blockchain. The private key is its counterpart: it produces the digital signature under every payment and is known to the holder alone.
From that follows the sentence this whole text rests on: whoever controls the private key controls the funds. The Federal Fiscal Court took the same view for tax purposes in 2023, attributing crypto assets to whoever is able to initiate transactions (judgment of 14 February 2023, IX R 3/22).
Three Terms You Need for the Rest
- Private key: the secret number used to sign a payment. Anyone who knows it can move the funds.
- Address: the public string others use to send you funds. The private key cannot be derived back from it.
- Recovery words, also called seed or recovery phrase: a list of twelve or twenty-four words from which every private key in a wallet can be regenerated. Whoever holds that list holds the wallet, regardless of the device.
There is, incidentally, no limit on how many wallets one person may have, and each blockchain generally needs its own, because address formats differ. Anyone holding Bitcoin alongside balances on other networks will therefore usually run several wallets side by side.
Custodial or Self-Custody: The One Question That Comes First
Before you install anything, you decide how your assets are held. There are exactly two options.
In the custodial model, a company holds the private key for you. Your access runs through a username, a password and a second factor. An account at a trading platform works this way. The advantage is convenience: a forgotten password can be reset, and support is reachable. The price is counterparty risk. If the company becomes insolvent, freezes withdrawals or loses control of its own keys, your funds are tied to that fate.
In self-custody, the key sits with you. Nobody can freeze your funds, but nobody can restore them either. There is no support desk to rescue you and no reset function. The recovery words are the entire contingency plan.
Both are legitimate, and both have their place. Many investors run a split approach: whatever is actively traded stays on a licensed platform, while the long-term holding moves into their own custody. Where the dividing line falls depends entirely on how firmly you have your own backup under control.
Software Wallet, Hardware Wallet or Exchange Account: Which Type Suits You
Within self-custody there are two practical designs, plus the exchange account as a third option with no keys of your own.
Software Wallet
An application on your phone, your computer or as a browser extension. The private key sits encrypted on the device. It is quick to set up, costs nothing and suits amounts whose loss would hurt without being existential. The weak point is the device itself: malware, a tampered browser extension or one careless click all strike exactly there. Which applications are common in German-speaking markets and how they differ is set out in our software wallet comparison.
Hardware Wallet
A small dedicated device that generates the private key and never releases it. Every payment is confirmed on the device itself, usually at the press of a button and with the receiving address shown on the device’s own screen. Even an infected computer cannot trigger a payment you do not approve on the device. Cost: roughly 50 to 200 euros depending on the model.
Exchange Account
No key of your own, but no setup effort either. For small amounts, and for anything due to be sold again soon, this is a legitimate route. As a permanent solution for larger holdings it carries the counterparty risk described above.
A rough rule of thumb from practice: up to a low four-figure amount, a cleanly configured software wallet is enough. Above that the device pays off, because the surcharge becomes small relative to the amount held.
Step by Step: How to Set Up a Software Wallet
The sequence is almost identical across all common applications. Take the twenty minutes in one sitting, without interruption.
- Check the source. Download the application only from the operating system’s official app store, or from the address printed on the manufacturer’s site that you typed in yourself. Fake wallet apps are among the most common forms of fraud there are, and search results or ads are the usual entry point.
- Generate a new wallet. On first launch, choose the option for a new wallet, not the one for a recovery. The application generates the recovery words directly on the device.
- Write the words down. The application now shows twelve or twenty-four words in a fixed order. Copy them out by hand, numbered, and do not skip a single one. No screenshot, no notes app, no cloud, no email to yourself.
- Check your transcript. Most applications then quiz you on individual words. Take that seriously, and afterwards compare word for word against your transcript once more. One transposition in the order makes the backup worthless.
- Set a device lock. Assign a PIN or password for the application and switch on the device’s screen lock. That is no defence against malware, but it is one against a lost rucksack.
- Send a test amount. Transfer a small amount to the new address, then send part of it back. Only once both directions have worked is the wallet ready for use.
- Practise the recovery once. The step almost everyone skips: reset the application and restore the wallet from your handwritten list. After that you know the backup holds, rather than merely knowing it is lying around somewhere.
The Recovery Words: Twelve Words That Carry Everything
The word list follows an open standard called BIP-39. It defines a fixed vocabulary of 2,048 words that every compliant wallet draws on. That is precisely why the words are portable between manufacturers: if one provider disappears, the same wallet can be restored in a different application.
That portability is the reason the list must be treated so strictly. A password sits next to an account. This word list is the account.
Where to Keep the List
Paper is a good start and a poor finish: it burns, it yellows, and one flooded cellar is enough. Anyone securing an amount whose loss would genuinely hurt should stamp the words into a steel plate. Such plates cost a few dozen euros and survive fire and water.
For storage the rule is: at least two locations, physically separate, both under your control. A safe deposit box and your own home are a proven combination. How to put that into practice and which variants have held up is set out at length in our guide to storing your seed phrase safely.
The Passphrase as an Optional Twenty-Fifth Factor
Many wallets additionally allow a word of your own choosing, often called a passphrase. It changes the derived keys completely, is stored nowhere, and renders a found word list worthless on its own. The catch: if the passphrase is lost, the funds are lost too, even with the complete word list. For beginners that is one more source of error; for experienced users it is a sensible second wall.
Setting Up a Hardware Wallet: What Matters When You Unbox It
The sequence mirrors the software wallet, with four particulars that make the difference.
First, the source. Buy only directly from the manufacturer or from a dealer it names. Devices from the second-hand market, classified ads or third-party marketplaces are off limits, because a tampered device cannot be identified from the outside.
Second, the pre-printed card. If the device comes with a card of words already filled in, the device is compromised. A new device generates the words only during setup, and does so on the device itself. A supplied word list is the classic setup for a fraud.
Third, the display. The words appear on the device’s screen, never on the computer. If a website or a program asks you to type in your recovery words, that is an attack, without exception and no matter how genuine the page looks.
Fourth, the firmware. Install the current firmware via the manufacturer’s official application before you transfer any meaningful amount. Which models differ in German-speaking retail and what matters in the choice is summarised in the hardware wallet comparison.
After that the same rule applies as above: test amount out, part of it back, recovery practised once.
The First Transfer: Checking Test Amount, Network and Address
Most losses at the outset come not from hacks but from operating errors on the first transfer. Three checks prevent almost all of them.
The network. The same token often exists on several blockchains, and the addresses look confusingly alike. Pick the wrong network on an exchange and the funds land on a chain for which your wallet holds no key. Sometimes it can be recovered with effort, sometimes not. What remains possible in that case we wrote up in our piece on sending crypto over the wrong network.
The address. Copy the receiving address from the wallet, then compare the first and last five characters in the exchange’s input field. There is malware whose sole purpose is to swap copied addresses in the clipboard for its own. With a hardware wallet you additionally verify the address on the device’s screen.
The test amount. On the first attempt, send an amount whose loss would not trouble you, and wait for confirmation. The network fee for it is the cheapest insurance premium in the whole exercise.
What Is Permitted in Germany: BaFin, MiCAR and Self-Custody
One question comes up regularly: do you need a permit for your own wallet? No. In its guidance notice on crypto-asset services under MiCAR, the Federal Financial Supervisory Authority states clearly that “the custody and administration of one’s own crypto assets by the holder” is not covered, because such custody is not provided “for clients”. What requires authorisation is the service to third parties, not the handling of your own assets.
The flip side is this: anyone who holds assets for you has, since 30 December 2024, needed authorisation as a crypto-asset service provider under the European regulation on markets in crypto-assets. For a provider based in Germany, that status can be traced through the supervisor’s databases. It is the single most important check before funds are left sitting on a platform.
For you as a user, that yields a simple division of labour: for the custodied part of your holdings you check the provider’s authorisation, and for the self-custodied part you check your own backup. For neither is there a third party that steps in when things go wrong.
Tax: What the Tax Office Wants to Know About Your Wallet
The wallet itself triggers no tax. It becomes relevant as evidence. Crypto assets held privately count as “other economic goods”, and a gain on sale is taxable under section 22 number 2 in conjunction with section 23 paragraph 1 sentence 1 number 2 of the Income Tax Act if no more than one year lies between acquisition and disposal. The Federal Ministry of Finance letter of 6 March 2025 records this at paragraph 53 and also names the exemption threshold there: if the total gain from all private disposal transactions in a calendar year stays below 1,000 euros, it remains tax free. Until 2023 that threshold stood at 600 euros.
Three points bear directly on the wallet:
- The assessment is wallet-based. Under paragraph 62 a wallet-based view applies, and once a method for the order of use has been chosen it must be retained within a wallet until all holdings of that trading designation there have been sold. Anyone spreading holdings across several wallets must therefore track them separately.
- Reallocations belong in the records. The record-keeping duties at paragraph 103 expressly name documentation of the chosen order of use per wallet, as well as documentation of reallocations between wallets. A transfer between two of your own wallets is not in itself an acquisition, since the letter understands that term to mean acquisition for consideration from third parties (paragraph 54). It must be documented all the same, because otherwise neither the acquisition date nor the acquisition cost can be evidenced later.
- Addresses and cut-off date holdings can be requested. Paragraph 104 lists what the tax office may demand in an individual case: information on the source of funds, wallet holdings at cut-off dates such as 31 December, the wallet addresses used, and transaction hash values.
In practice that means: on the day you set it up, create a short overview listing the wallet, its purpose and the setup date, and export the transaction list once a year. That costs minutes in day-to-day running and saves days in hindsight.
Five Mistakes That Cost the Most When Setting Up
- Backing up the words digitally. Screenshot, cloud password manager, a chat message to yourself: every one of these variants shifts the security of the wallet onto someone else’s account.
- Never testing the recovery. An unverified backup is an assumption. The test takes five minutes and is the only proof.
- Sending the full amount the first time. Without a test transfer, the first attempt carries the entire risk of the wrong network and a swapped address.
- Approving permissions unread. Connecting a wallet to applications in the browser means signing permissions. Read what appears on the device screen, and abort if it says something other than what you expected.
- Putting everything in one wallet. A separate wallet for day-to-day experimenting and one for the holding limits any damage to the part that is in motion anyway.
Setting Up a Crypto Wallet: What to Take Away
- Decide on the custody model first. Work out which part of your holdings should stay custodied and which moves into your own control. For the custodied part you check the provider’s authorisation, and our overview of regulated crypto exchanges is the starting point for that.
- Back up the recovery words before any funds move. By hand, in two separate locations, and in metal for larger amounts. Anyone wanting a dedicated device for it will find the differences between models in the hardware wallet comparison.
- Test the route with a test amount and document it. Network, address, return path, plus a note recording the wallet and setup date for your tax file. Which application suits everyday use is shown in the software wallet comparison.
(As of September 23, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Since September 22, 2026, Europe has had its first exchange-traded security tracking Zcash (ZEC). Swiss issuer 21Shares AG has brought the 21shares Zcash ETP to market under the ticker ZCASH on Euronext Amsterdam and Euronext Paris; the product itself was launched on September 21. It carries the ISIN CH1608218801 and the German securities identification number (WKN) A4AXHY. You can buy it through an ordinary securities account, with no crypto exchange and no private key of your own.
That overturns a statement which was still accurate on this site yesterday: that investors in Germany cannot get hold of a Zcash security. We checked the market at the end of August and recorded in Zcash ETF: why European investors cannot reach ZCSH that no European issuer offered a Zcash product at the time. The trading debut has made that position obsolete. What counts now are four sober questions: can your broker reach the trading venues, what does the security cost per year, who owns the coins held in custody, and how is a gain taxed.
What exactly has been tradable since September 22
The product is called the 21shares Zcash ETP and is an exchange traded product, a security listed on an exchange that tracks the price of a single underlying asset. The issuer is 21Shares AG, domiciled in Switzerland, as the country code CH at the start of the ISIN shows. The Law Debenture Trust Corporation PLC is registered as trustee, while Flow Traders and Virtu Financial Ireland Limited act as authorised participants and market makers.
The figures from launch day put the scale in perspective. On the issuer's product page at 18:35 UTC on September 22 there were 5,000 securities outstanding, a net asset value of $20.04 per unit and assets under management of $100,211.59. That is an opening balance rather than an established product size. For comparison, Bitcoin ETPs from European issuers run into the billions. A freshly launched security with six-figure assets behaves differently in trading, and we come back to that further down.
On the underlying itself, because the product's classification hangs on it: Zcash is a Bitcoin fork, a cryptocurrency built on the published source code of the Bitcoin blockchain. The issuer says as much on its product page. The network is secured by proof of work, the same computational method as Bitcoin. The difference lies in the zero-knowledge proofs: cryptographic evidence that confirms a transaction is valid without disclosing sender, recipient or amount. That feature is optional in Zcash and is the reason supervisors treat the coin differently from transparent networks. Measured by market capitalisation, Zcash remains considerably smaller than the leading cryptocurrencies, which places it among the crypto assets where security and liquidity are more closely linked than they are for the big names.
Zcash itself traded at $1,521.84, or €1,330.16, at 18:39 UTC on September 22, measured through the CoinGecko price interface. The price has multiplied over the course of the year, which explains the issuers' arrival: in the United States a Grayscale Zcash ETF has recently been trading on NYSE Arca under the ticker ZCSH, and the European ETP follows that demand.
ETP, ETN or ETF: which wrapper is this?
The three abbreviations get mixed up in everyday use, and the difference decides your risk. An ETF is an investment fund whose assets are legally separated from the issuer and which, under the EU UCITS rules, has to diversify broadly. That diversification requirement is precisely what stops a fund from holding one single cryptocurrency and nothing else. This is why no Zcash ETF exists in Europe in the legal sense, however many people search for one.
An ETP or ETN, by contrast, is a debt security: a promise by the issuer to pay you the value of the underlying. The issuer normally deposits the coins to back it, in the case of the 21shares Zcash ETP fully and physically, according to the firm. 21Shares names Coinbase Custody Trust Company, Zodia Custody, Anchorage Digital Bank, BitGo Bank and Trust and BitGo Europe as custodians. The issuer itself writes on its product page that an ETP and an ETF are different legal structures, while the buying and holding experience for investors does not differ.
That assessment holds for day-to-day trading. For the worst case it does not. We worked through the questions you should put to a crypto ETN before it goes into your portfolio in Crypto ETNs in your portfolio: how to check who is liable for your Bitcoin note. Which crypto securities can end up in a German securities account at all is sorted by underlying in our overview Buying crypto ETFs in Germany.
Where the security is listed and where we could not find it
The issuer's own information and the Cointelegraph report agree on two trading venues: Euronext Amsterdam and Euronext Paris. A listing on a German exchange is not among them on day one, even though a German WKN has been assigned. The WKN on its own says nothing about whether a security can be traded here; it is an identifier, not an admission to trading.
We checked this ourselves between 18:39 and 18:41 UTC on September 22, and the result is clearer than a first glance suggests. The order book of Tradegate Exchange answered the ISIN with the statement that the instrument is not currently traded on Tradegate BSX. The master data interface of the Frankfurt Stock Exchange returned an empty record for the same ISIN, and its product page an error code 404. The Stuttgart Stock Exchange, where many crypto ETPs are listed, rejected our request with code 403 and therefore falls outside what this measurement can decide.
What follows from that in practice? A German listing may well come in the weeks ahead; that is the usual path for European crypto ETPs. You should not rely on it today. Check the position yourself before placing an order by entering the WKN A4AXHY or the ISIN into your broker's search.
Can your broker reach Euronext Amsterdam and Paris?
This is the question a purchase hangs on today, and it has no blanket answer. German neobrokers often concentrate their offering on a handful of execution venues, while traditional direct banks and online brokers provide access to foreign exchanges for an additional fee. On its product page, 21Shares refers interested investors to their own broker with a request to ask about availability there. That is a clear sign that coverage is patchy.
Three points are worth ticking off when you look into your account. First: does your broker offer the venues Euronext Amsterdam or Euronext Paris at all? Second: what third-party charge applies per order there, and how does it compare with the amount you plan to invest? Third: is the trade settled in euros or in dollars, and what conversion mark-up does your bank charge for it? On Euronext Amsterdam the security trades in dollars, in Paris in euros. If you want to compare the providers systematically, the crypto broker comparison sorts the terms by order fees and trading venues.
One detail that is easily missed: even where your broker offers the venue, it does not have to offer the individual security. Newly launched securities sometimes take days to appear in every system. If you cannot find the WKN, that is no proof that buying it will remain impossible.
What a 2.50 percent annual product fee really costs
The annual product fee is 2.50 percent, according to the issuer. It is never debited separately but taken daily, pro rata, out of the holdings in custody, and it lowers the net asset value per unit accordingly. You therefore never see it on a statement, and it works on your position every single day.
A simple calculation shows what that means. On an investment of €1,000 it comes to roughly €25 in the first year. If the Zcash price stayed unchanged for five years, around 11.9 percent of the stake would have been eaten up after those five years, because the fee applies each year to an already reduced holding. On top of that come your broker's order fees and the spread between bid and ask at the trading venue.
Cointelegraph places this rate well above what many Bitcoin and Ether products charge in Europe. We share that assessment, but it is not a verdict on the product: an issuer tracking a smaller underlying that is more demanding to keep in custody calculates differently from one holding the largest asset in the industry. What matters is that you weigh the fee against the cost of buying directly before you commit.
Physically backed: who owns the Zcash held in custody?
Physically backed means that a corresponding amount of the underlying sits with a custodian behind every security issued. It does not mean that you own those coins. You hold a claim against the issuer, and the collateral is what is meant to make that claim worth something in the worst case.
Two entries on the product page matter here. First, a trustee has been appointed for the security and holds the collateral for the benefit of holders; this is the usual construction for European crypto ETPs and the reason they do not count as plain unsecured notes. Second, the entry for lending is an explicit no: the holdings in custody are not lent out. That removes a source of risk which has already led to losses in other products.
What remains open is the question of a delivery right, and it is no side issue. As authorised participants, able to subscribe and redeem units directly with the issuer, the product page names only Flow Traders and Virtu Financial Ireland Limited. Whether a retail investor can demand delivery of the Zcash held in custody, and on what terms, is not stated there. You will find that answer only in the key information document and the final terms, which the issuer offers for download on the same page. Read them before you buy, because the next section hangs on this question.
Why this security shows no staking yield
The product page has a field for staking yield, and for this security it stays empty. That is not an oversight. Staking means locking coins into a network that awards its blocks according to the stake committed, and paying interest for it. Zcash runs on proof of work; there is nothing to lock up here and consequently nothing to distribute.
With a staking ETP on a different network the picture changes: there the yield earned flows into the net asset value and cushions part of the product fee. With the Zcash ETP that cushion is missing altogether. The 2.50 percent a year therefore stand in the calculation without an offsetting item, which is exactly why the cost comparison from the previous section weighs more heavily here than it would for a product with running income. The holdings are not lent out either, as the lending entry on the product page records.
Holding period or flat-rate tax: the open tax question
When you buy cryptocurrencies directly, the position in Germany is clear: a sale within one year is a private disposal under section 23 of the Income Tax Act, and once the twelve-month period has passed the gain remains tax free. For a security tracking a cryptocurrency this classification is contested, and you should know why.
Tax commentary argues along two lines. If the security grants a right to delivery of the underlying, it is reasonable to treat it like direct ownership; the case law of the Federal Fiscal Court on Xetra-Gold serves as the model. Where no such right exists, much speaks for another capital claim under section 20 of the Income Tax Act, meaning 25 percent flat-rate withholding tax regardless of the holding period, but with losses offsettable inside the pot for investment income.
To our knowledge there is no supreme court decision specifically on crypto ETPs, and custodian banks treat these products inconsistently. What your bank withholds is therefore not necessarily the last word as far as the tax office is concerned. Keep every statement in full, note the purchase and sale dates, and have the classification checked professionally if in doubt. Our comparison of crypto tax tools shows which software takes the collecting and evaluating off your hands. This section is no substitute for tax advice; it only tells you which question you have to ask.
The EU trading ban from July 2027 and what it means for a security
Zcash belongs to the cryptocurrencies that offer optional encryption of transaction data. The European anti-money-laundering regulation provides that supervised firms may no longer deal in anonymity-enhancing crypto assets from July 1, 2027. What that means for direct ownership we covered in detail in Buying Zcash despite the EU trading ban.
For the ETP the legal position is a different one, and in all honesty it is unanswered. A security is not a crypto asset within the meaning of these rules; it is a debt instrument that tracks a crypto asset. Whether and how the requirements feed through to a physically backed product whose issuer and custodians actually hold the coins cannot be derived from the issuer's announcement, and we do not claim otherwise. What you can take from it: this question belongs on your list before you buy a security costing 2.50 percent a year with a horizon that runs beyond 2027. It is no reason to panic, and just as little reason to look away.
Liquidity on day one: 5,000 securities and a thin balance
A freshly launched ETP trades differently from an established one. With 5,000 securities outstanding and around $100,000 in fund assets on launch day, the 21shares Zcash ETP is a small product for now. Two market makers quote bid and ask continuously, and that is the construction which secures a price even when turnover is low. The spread between those quotes, though, is typically wider for small and volatile underlyings than it is for a Bitcoin product.
In practice that means: put a limit on your order instead of buying at market, and check how far bid and ask are apart before you send it. Trade within the core hours of the venue in question, when the market makers are active. Buying at the edges of the session with thin books often costs extra, and that premium weighs more heavily on a security of this size than the order fee does.
On order types: a limit order sets the maximum price you are willing to pay and is basic equipment when books are thin. A stop loss, by contrast, triggers a sale when a level is breached and can be executed inside a brief overshoot when the underlying is volatile. Which order types your broker offers on foreign venues is set out in its schedule of prices and services. At the same time, check that your settlement account holds enough cash in the right currency, and do not rely on delayed market data: with a freshly listed security, free quotes deviate from actual trading more than they do for a blue chip.
Watch the trading activity over the first few weeks: the daily volume and the number of securities outstanding. If both rise, the product has found demand and spreads generally narrow. If they stay at their opening level, the premium on entry and exit remains a permanent cost that your returns have to earn back first.
A second point concerns the underlying itself. Zcash is considerably smaller than the major cryptocurrencies by market capitalisation and has shown extreme price swings in both directions over the past year. A security changes nothing about that: it tracks those swings, minus the fee. A total loss of the capital invested is possible.
ETP or ZEC directly: which route suits which investor?
The decision comes down to three trade-offs, and none of them has a universally valid answer.
Custody. With the ETP, responsibility for the keys sits with institutional custodians; you need no wallet and cannot lose anything you wrote down yourself. In exchange you carry the risk of the issuer and of the custody chain. With a direct purchase that relationship is reversed.
Cost. The ETP costs 2.50 percent a year plus order fees. Buying directly on an exchange costs a trading fee once and nothing running after that, though a fee applies again when you withdraw. Over a short horizon the annual fee barely registers; over a long one it is the single largest block of cost.
Tax and access. With direct ownership you know the rules, and the twelve-month period is established. With the ETP the treatment depends on how the security is constructed and is contested. In return the ETP lands in your familiar securities account, appears in your bank's annual tax statement and can be held alongside equities and funds. For many people that is the real reason to choose a security.
If you are unsure of the answer, the smaller position via the route you already handle confidently is usually the better decision than the larger one via a route you still have to learn.
Checking a Zcash ETP: what to take away
- Check tradability first, everything else second. Enter the WKN A4AXHY or the ISIN CH1608218801 into your account's search and see whether Euronext Amsterdam or Paris is offered as a venue and what an order there costs. If you cannot find the security, the broker comparison shows which providers offer foreign exchanges.
- Project the annual fee onto your holding period. Over three months, 2.50 percent a year is a footnote; over five years it is close to a tenth of your stake. Set that against the cost of buying directly; which products exist for which underlying in Germany is shown in our overview of crypto ETFs and ETPs in Germany.
- Settle the tax question before the purchase, not in the April that follows. Read the key information document to see whether a delivery right exists, keep every statement and record your purchase and sale dates. A tax tool or portfolio tracker takes the collecting off your hands; the classification itself belongs in expert hands.
Sources to read up on: the product page of the 21shares Zcash ETP with identifiers, fee, custodians and product documents, and the Cointelegraph report on the trading debut on Euronext.
(As of September 22, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Binance has taken a $100 million stake in Circle, the company behind the stablecoin USDC, and extended the cooperation between the two firms by five years. Circle announced the move on September 22, 2026 in its own pressroom. For you as an investor in Germany, this changes neither the price of your holdings nor the route by which you buy them. Something else has shifted: who earns money from stablecoins sitting idle.
Binance and Circle: what the $100 million stake actually involves
The transaction consists of two separate parts published on the same day. The first is an equity investment: Binance subscribed for Class A shares in Circle through a private placement, around 1.24 million of them at $80.84 each according to CoinDesk. Circle’s own statement puts the purchase price 5 percent below the market price of the share before completion. The sale closed on September 17, 2026, five days before the public heard about it.
The second part is a five-year supply and marketing agreement. It replaces two earlier arrangements between the two companies dating from November 2024 and August 2025. Binance may not resell, pledge or hedge its shares for up to two years; Circle cites the customary industry exceptions, such as transfers within the group.
Jeremy Allaire, co-founder and chief executive of Circle, speaks in the statement of using USDC to broaden access to the dollar and to reach people and businesses in emerging markets. Richard Teng, co-chief executive of Binance, puts it this way: a stable, reliable digital dollar should not be a privilege but should be open to anyone who owns a phone. Both sentences promote the same goal, and neither says anything about what the contract means commercially.
The monthly incentive fee: why Circle pays for USDC balances
The commercial core sits in the filing with the US Securities and Exchange Commission that CoinDesk quotes. Under it, Circle pays Binance a monthly incentive fee calculated as a percentage of the USDC held through Circle’s wallet service. The more digital dollars sit idle in that environment, the more money flows to the trading platform.
Behind this lies a business model that many stablecoin users underestimate. An issuer such as Circle holds backing for every USDC in issue in short-dated US government bonds and bank balances. The interest on that is kept by the issuer. The holder of the token receives none of it; what the holder receives is stability, not a return. Part of that interest stream is now passed on to whoever gathers the balances.
The sober conclusion for you: a stablecoin sitting in an exchange account is a source of income for the exchange. That is neither disreputable nor new, but it explains why trading venues advertise so persistently for balances to be left with them between two trades.
USDC against USDT: how market shares stand in September 2026
A look at the relative sizes puts the deal in context. According to CoinGecko data from September 22, 2026 at 19:53 UTC, USDC had a market capitalisation of around $74.8 billion on daily turnover of some $20.8 billion. At the same moment Tether stood at around $183.4 billion in market capitalisation and roughly $81.7 billion in daily turnover. USDT therefore remains a good two and a half times the size of USDC.
That gap is precisely why Circle is prepared to pay for distribution reach. Binance is the largest trading venue in the industry, and in many emerging markets access to the dollar runs through platforms of this kind rather than through banks. Whoever sets the standard there sets it for years.
For a sense of scale: Bitcoin traded at $86,263 on the same reference date and reached a market capitalisation of around $1.73 trillion. The entire USDC supply therefore amounts to roughly 4 percent of what sits in Bitcoin.
Buying USDC in Germany: which routes MiCA leaves open
This is where the news and your own reality part company. Binance has withdrawn from retail business in the European Union; the new agreement with Circle expressly targets emerging markets rather than Europe. For an investor resident in Germany, the route to a purchase therefore remains unchanged.
In practice that means you obtain USDC through trading venues and brokers authorised for the European market. The Federal Financial Supervisory Authority maintains registers of authorised providers, and authorisation under the EU regulation on markets in crypto-assets has been the entry ticket since the German transition period ended. Which firms actually hold that authorisation is shown in our comparison of regulated crypto exchanges.
Check three points before your first purchase: whether the provider appears in the register of the competent supervisor, which currency the account is settled in, and what spread between the buying and selling price you are charged when converting euros into USDC. In practice the third point often costs more than the stated trading fee.
The MiCA interest ban under Article 50: why you earn no interest on USDC
The incentive fee Circle pays Binance would not be possible in this form towards a European retail customer. EU Regulation 2023/1114 on markets in crypto-assets expressly prohibits, in Article 50, issuers of e-money tokens and crypto-asset service providers from granting interest to holders of such tokens. For asset-referenced tokens the same prohibition sits in Article 40.
E-money tokens are, under that regulation, crypto-assets intended to maintain a stable value by referencing a single official currency. USDC falls into this group because it is pegged to the US dollar.
The ban is addressed to issuers and service providers, not to a counterparty in wholesale business. A payment from Circle to a trading platform is not interest paid to a token holder. So the position for you stands: within the authorised European framework there is no stablecoin variant on which anyone may pay you a running yield. How providers try to work around this ban through reward and cashback schemes is something we took apart using the example of the USDT cashback card.
If you come across an offer quoting a fixed percentage on stablecoin balances, read up on who the counterparty is and where it is based. As a rule the service is then provided not by the issuer but by a company outside the European supervisory framework, and your balance is lent out in return.
Tax on stablecoins: what Section 23 EStG triggers when you swap USDC
A widespread misconception holds that a stablecoin is cash for tax purposes. It is not. From the perspective of German tax law, USDC is another economic asset, and every swap is a disposal within the meaning of Section 23 of the Income Tax Act.
Three things follow for your records. First: if you swap Bitcoin into USDC, you realise a gain or a loss at that point, even though you never saw a euro. Second: if more than a year lies between acquisition and disposal, the gain remains tax-free. Third: an exemption limit of 1,000 euros applies to the total of all private disposal transactions in a year; once it is exceeded, the entire amount is taxable, not merely the excess.
The dollar exchange rate against the euro runs alongside all of this. Holding USDC over months means carrying a currency risk that shows up in the euro result even though the token stays stable against the dollar. The only way to keep this clean is a gapless record of every swap.
Issuer risk and custody: what happens if the issuer fails
A stablecoin is a claim. Its value depends on the issuer maintaining the backing and redeeming the token at par at any time. In March 2023, USDC briefly lost its peg to the dollar because part of the reserves sat at a US bank in difficulty. The price recovered within days, yet the episode remains the clearest lesson available in what issuer risk means.
The MiCA regulation drew conclusions from it and requires issuers of e-money tokens to hold the backing separately and to deposit part of it with credit institutions. How contested the precise design of that reserve duty currently is can be seen in the running debate about the bank deposit requirement for stablecoin reserves.
For your own arrangements, the question that remains is where the token sits. In an exchange account you additionally carry the platform risk; in a self-managed wallet you carry responsibility for the key. Both have a price, and both should be a deliberate decision rather than a state of affairs that simply came about.
Binance without EU access: why the deal does not change how you buy
The reach Circle is buying lies outside Europe. Binance no longer serves European retail customers on the former scale, and the five-year agreement names emerging markets expressly as its target. Anyone holding USDC in Germany will notice nothing of this partnership day to day.
Indirectly the step still matters. A stablecoin lives on liquidity: on there being counterparties everywhere willing to take it at par. If USDC keeps growing through the world’s largest trading venue, it also becomes tradable in greater depth on European venues, because market participants balance globally. That is a slow effect rather than an event that shows up in the price on any single day.
Three markers that will show you what happens next
A stablecoin has no price to point the direction. The matter can still be watched, and it comes down to three figures.
The first is the market capitalisation of USDC, around $74.8 billion as of September 22, 2026. A marked rise over the coming months would mean the distribution agreement has worked. The second is the gap to Tether, currently around $183.4 billion; if it narrows, the industry is shifting. The third is the deviation from the dollar: USDC traded at $0.9999 on the reference date. A lasting discount of more than half a percent would be the signal that genuinely deserves attention.
All three figures come from CoinGecko and can be looked up there at any time. For the European part of the story, the list of authorised providers says more than any price: who gains authorisation and who loses it decides where you will still be able to buy in a year’s time.
Checking the USDC deal: what to take away
The news itself requires nothing of you. The episode does serve as an occasion to look at three things that are due anyway.
- Check where your stablecoin sits and who earns from it. If the balance sits permanently in a trading account between two trades, you carry the platform risk and the venue takes the income. Whether your provider is authorised for the European market is shown in the overview of crypto exchanges.
- Put your records for Section 23 EStG in order. Every swap into and out of USDC is a disposal with an acquisition date of its own. Reconstructing that in the spring usually costs money; a suitable tool can be found in the comparison of crypto tax software.
- Decide on custody deliberately. For amounts you will not move for some time, self-custody is the more sober choice, provided you are confident handling the key. Which devices are up to the job is set out in the hardware wallet comparison.
Sources for further reading: the Circle statement of September 22, 2026 and Regulation (EU) 2023/1114 in full text on EUR-Lex.
(As of September 22, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
DeepSeek will address the UN Security Council on AI risks this week, sharing a stage with Dario Amodei—who has spent a year calling China's government the industry's biggest threat.
Four ancient wallets moved 1,971 BTC between Sept. 6 and Sept. 22, including a 600 BTC transfer worth $51.9 million just hours ago, with three of the four carrying "Noah Doe" lawsuit tags.
The exchange operator is adding standard and micro contracts for BCH and UNI, extending a pattern of altcoin rollouts that already covers Cardano, Chainlink, Stellar, Avalanche, and Sui.
Head of cryptography Yehuda Lindell says the exchange is designing custody that can adapt to whatever post-quantum signing scheme Bitcoin adopts.
Galaxy Research says white-hat actors consolidated coins tied to the exploit into a fresh address tagged for a "Crypto Recovery Trust," though the funds represent just 2.8% of the total haul.
U.Today - IT, AI and Fintech Daily News for You Today
Dogecoin, Shiba Inu, Near Protocol and Zcash are all testing critical technical levels after strong recent moves.
Bitcoin is having its best September in 14 years, defying the cryptocurrency’s historically weak seasonal trend as its powerful recovery pushes the price toward the $90,000 level.
Elon Musk has revived one of the strangest moments of the NFT boom, laughing at a throwback to his brief 2022 stint with a Bored Ape Yacht Club profile picture that sent ApeCoin soaring.
For the first time in 3 years, Bitcoin breaks above $80,500, flashing the rare long-term on-chain signal behind the 2019 and 2023 bull markets.
XRP has recovered sharply from its September low, while renewed ETF flows and improving technical momentum have brought the "Uptober" narrative back into focus.
Blockonomi
Key Highlights
- Six major Canadian banking institutions are collaborating on a tokenized deposit infrastructure project.
- Initial implementation targets seamless transfer of tokenized deposits among consortium members.
- Future expansion plans include integration with emerging digital asset platforms and additional financial institutions.
- The system utilizes deposits maintained within regulated banking entities, distinguishing it from cryptocurrency-based stablecoins.
- Recent regulatory guidance confirmed tokenized deposits maintain the same legal status as conventional bank deposits.
A consortium of Canada’s premier financial institutions is advancing a collaborative deposit system built on tokenization technology to accelerate interbank transactions and introduce programmable functionality. The partnership includes Bank of Montreal, CIBC, National Bank of Canada, Royal Bank of Canada, Scotiabank and TD Bank Group.
JUST IN:
Canada's six biggest banks launch joint tokenized deposits project to enable 24/7 blockchain-based payments.
• Bank of Montreal
• Royal Bank of Canada
• Toronto-Dominion Bank
• The Bank of Nova Scotia
• National Bank of Canada
• Canadian Imperial Bank of…— Watcher.Guru (@WatcherGuru) September 23, 2026
The pilot phase concentrates on facilitating digital transfers of Canadian-dollar bank deposits among consortium participants. Long-range objectives include establishing connectivity with developing digital asset ecosystems.
Major Canadian Financial Institutions Pilot Digital Deposit Technology
Tokenized deposits constitute digital representations of funds held within regulated banking institutions rather than standalone digital currencies. Each token maintains its status as a liability of the originating bank.
This architecture differs fundamentally from stablecoin products like USDC or USDT, which external corporations issue with reserve backing. A bank-centered approach enables continuous deposit mobility while preserving regulatory compliance within established banking structures.
The participating institutions highlight potential benefits including accelerated settlement times, operational improvements and transaction programmability. The network may welcome additional Canadian deposit-accepting institutions in subsequent phases.
This exploratory initiative doesn’t constitute a commitment to commercial tokenized deposit offerings. Currently, the banks are evaluating shared infrastructure models and conducting interbank transfer feasibility studies.
Regulatory Framework Established for Digital Bank Deposits in Canada
This collaboration follows recent guidance from Canada’s banking oversight authority regarding tokenized deposit treatment. On September 10, the Office of the Superintendent of Financial Institutions clarified that tokenized deposits maintain identical legal standing to conventional deposits.
OSFI’s guidance emphasized that technological representation methods don’t alter fundamental legal characteristics of financial products. This regulatory certainty provides regulated institutions with clearer parameters for blockchain-based deposit experimentation.
Canada has pursued tokenized financial market testing through complementary initiatives. Project Samara, completed in March by the Bank of Canada, RBC and TD, successfully demonstrated issuance, trading and settlement of a C$100 million bond utilizing distributed-ledger technology with tokenized wholesale Canadian currency.
The current Big Six collaboration extends these advances toward routine interbank monetary transfers. This positions Canada alongside American and international banking institutions testing tokenized deposits for institutional payment applications.
Financial Institutions Challenge Stablecoin Dominance in Digital Transactions
Global banking leaders increasingly pursue tokenized deposit solutions as alternatives to privately-issued stablecoin products. JPMorgan, Citi and Wells Fargo have launched institutional digital currency initiatives, while Swift has conducted tokenized deposit trials for continuous cross-border payment processing.
Bank-issued tokenized deposits could deliver blockchain settlement advantages, including programmability and continuous availability, while maintaining customer funds within regulated financial institutions.
Canada simultaneously develops distinct regulations for fiat-backed stablecoins. The forthcoming Stablecoin Act will establish federal standards addressing reserves, registration requirements and redemption protocols for qualifying non-bank issuers.
Institutions under existing prudential regulation, including banks and credit unions, operate outside this stablecoin framework. This creates dual pathways for digital Canadian currency: one anchored in regulated bank deposits and another in privately-issued stablecoin products.
The Big Six initiative remains exploratory, yet it provides Canada’s banking sector with unified infrastructure for digital currency testing. The immediate priority involves demonstrating efficient interbank tokenized deposit transfers before pursuing broader digital asset market integration.
The post Canada’s Leading Banks Unite to Test Tokenized Deposit Infrastructure appeared first on Blockonomi.
Key Highlights
- ETH maintained support around $2,760 following a 14% weekly surge.
- Spot Ethereum ETFs in the United States captured approximately $270 million in single-day inflows, pushing the two-day total to about $413.8 million.
- On-chain analytics platform Lookonchain tracked new whale accumulation, including a 6,247 ETH acquisition financed by selling 200.71 BTC.
- BitMine reportedly purchased an additional 12,500 ETH, following its 27,562 ETH acquisition from the prior week.
- Market analyst Ted noted that a weekly close above the 100-week simple moving average could target the $3,300-$3,400 zone.
Ethereum sustained its position above the $2,700 threshold on Tuesday as its weekly rally reached approximately 14%.
The second-largest cryptocurrency by market capitalization traded around $2,760, after touching an intraday peak near $2,804.
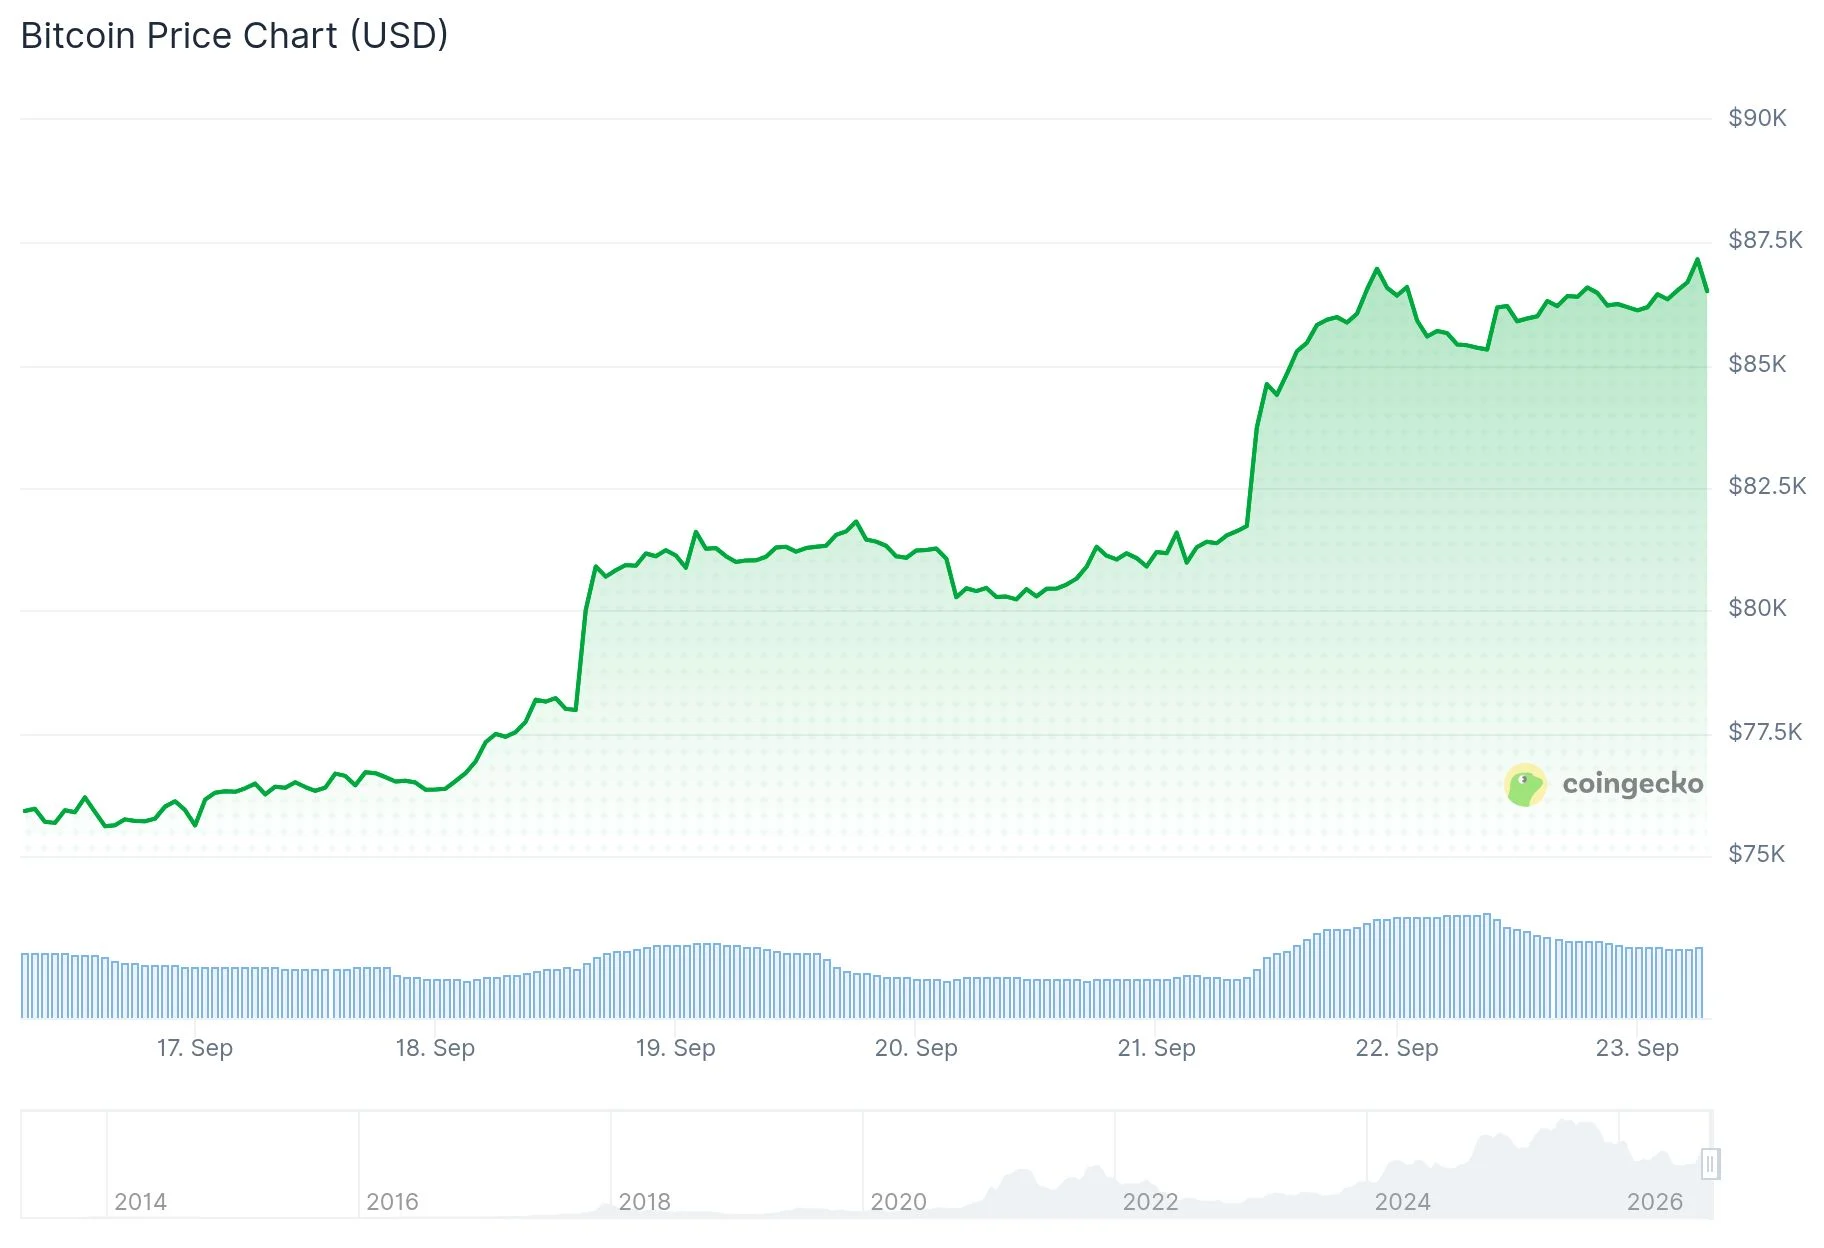
This upward momentum has been accompanied by increased capital allocation into United States-based spot Ethereum exchange-traded products.
These investment vehicles attracted roughly $270 million in net inflows during a single trading session, representing the strongest daily performance since October.
This achievement represents the second consecutive day of positive flows, bringing the cumulative two-day inflow figure to approximately $413.8 million and reversing the previous three-day outflow trend.
Major Holders and BitMine Expand ETH Holdings
According to blockchain intelligence provider Lookonchain, one over-the-counter whale acquired 4,500 ETH, increasing its total holdings to approximately 37,000 ETH.
A separate large holder converted 200.71 BTC into 6,247 ETH. Within a six-day period, this wallet has exchanged 1,308 BTC for 40,670 ETH before staking the complete allocation.
Corporate Ethereum accumulator BitMine Immersion appears to have secured another 12,500 ETH, based on Lookonchain’s tracking data.
The firm had previously acquired 27,562 ETH during the week before. Its estimated total holdings now approach 5.98 million ETH, valued at approximately $16.5 billion based on current pricing.
BitMine’s Chairman Thomas Lee stated that the organization considers Ethereum’s third-quarter price action as potentially setting up enhanced fourth-quarter momentum.
Trading activity in derivatives markets remains elevated. Aggregate ETH futures open interest reached roughly $36 billion, with CME open interest climbing more than 8%.
ETH Confronts $2,786 Barrier
Ethereum experienced a rejection around $2,786, establishing this level as the primary near-term resistance zone.
Additional resistance targets above this threshold include $2,894 and $3,177.
The cryptocurrency continues trading above its critical daily exponential moving averages, with the 20-day EMA positioned near $2,537.
The Relative Strength Index registered near 71, while the Stochastic Oscillator exceeded 90, indicating that upward momentum has entered overbought territory.
Chart analyst Ted highlighted on X that ETH has arrived at the $2,800 resistance area and is currently challenging its 100-week simple moving average.
According to Ted’s analysis, a weekly close surpassing this moving average could propel Ethereum toward the $3,300-$3,400 range, whereas rejection might trigger a pullback to approximately $2,550.
Seasoned trader Peter Brandt additionally published an extended-timeframe Ethereum futures chart on X, identifying a potential price objective near $8,674 following a decisive breakout above the $5,000 level.
Currently, ETH trades beneath the $2,786 resistance barrier, with the $2,626-$2,544 range establishing the nearest support area according to available technical analysis.
The post Ethereum (ETH) Price Surges Past $2,700 as Institutional Buying Intensifies appeared first on Blockonomi.
TLDR
- BTC is trading near $86,000 following a surge to $87,350, marking a 33-week peak.
- Energy markets saw WTI crude temporarily dip under $90, reducing inflation pressure from oil prices.
- The MVRV ratio for Bitcoin has surpassed its 365-day moving average, echoing patterns from 2019 and 2023 rallies.
- Bitcoin is poised to achieve its first consecutive July-September gains since 2012.
- Technical analyst Ted Pillows identifies $87,000-$88,000 as critical resistance, with potential support at $79,000-$80,000.
Bitcoin (BTC) maintained its position around the $86,000 level on Tuesday following a surge to its strongest price point in approximately eight months.
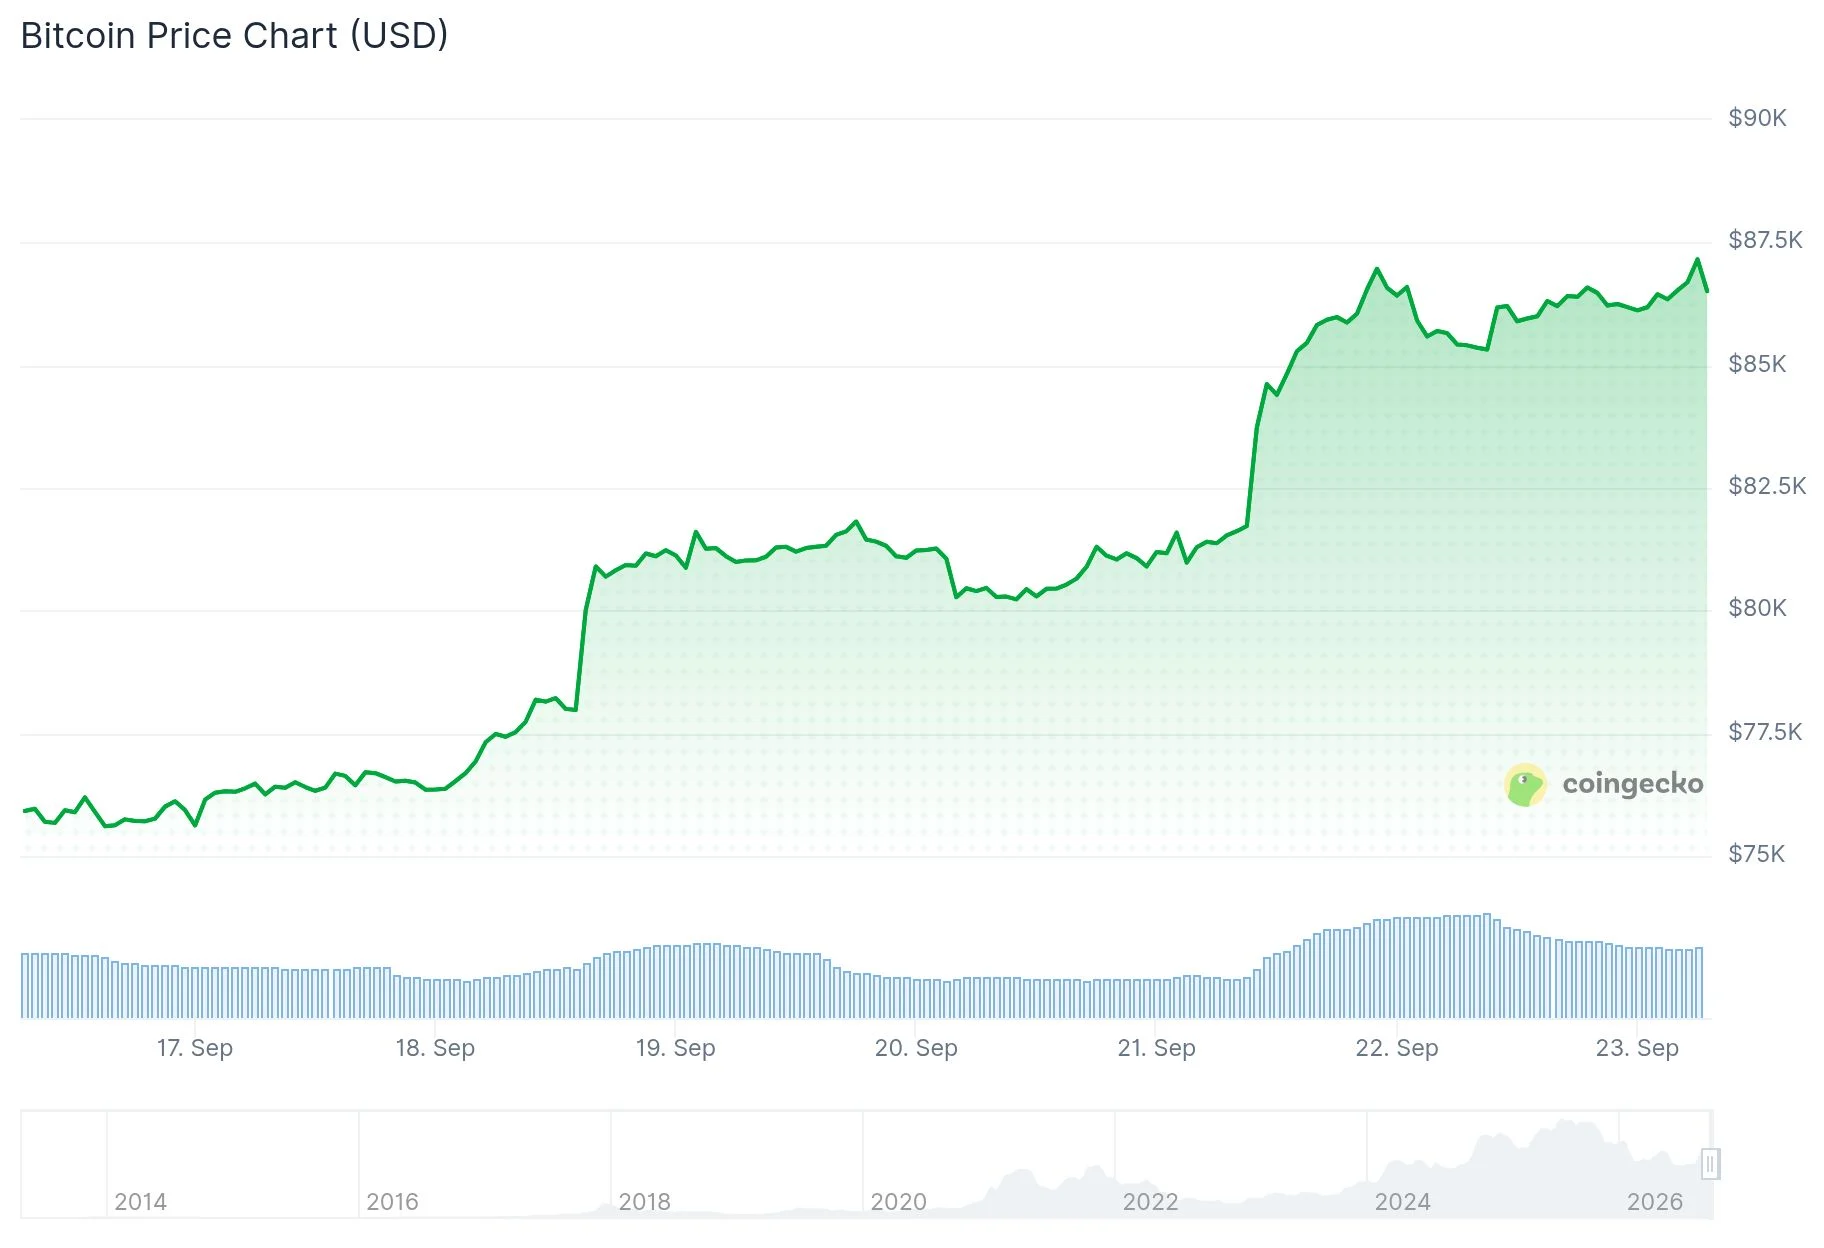
The leading cryptocurrency pushed to $87,350 during Monday’s trading session before experiencing a pullback. Support has remained robust around the $86,000 threshold, preventing any significant downward pressure.
This recent upward movement has propelled bitcoin to approximately 10.9% gains throughout September. This performance follows monthly increases of 4.8% in July and a substantial 25.2% surge in August.
Should September close in positive territory, it would mark bitcoin’s first three-month consecutive winning period from July through September since 2012.
Market participants are also monitoring activity in energy markets. WTI crude oil experienced a brief decline to $89.16 per barrel, representing its lowest point since early September.
The decline in oil prices came after news emerged that Saudi Arabia had reopened its East-West Pipeline. Subsequently, crude prices rebounded to approximately $92.
Onchain metrics signal strengthening momentum
Bitcoin’s MVRV ratio has moved above its 365-day moving average, signaling a potential shift in market dynamics.
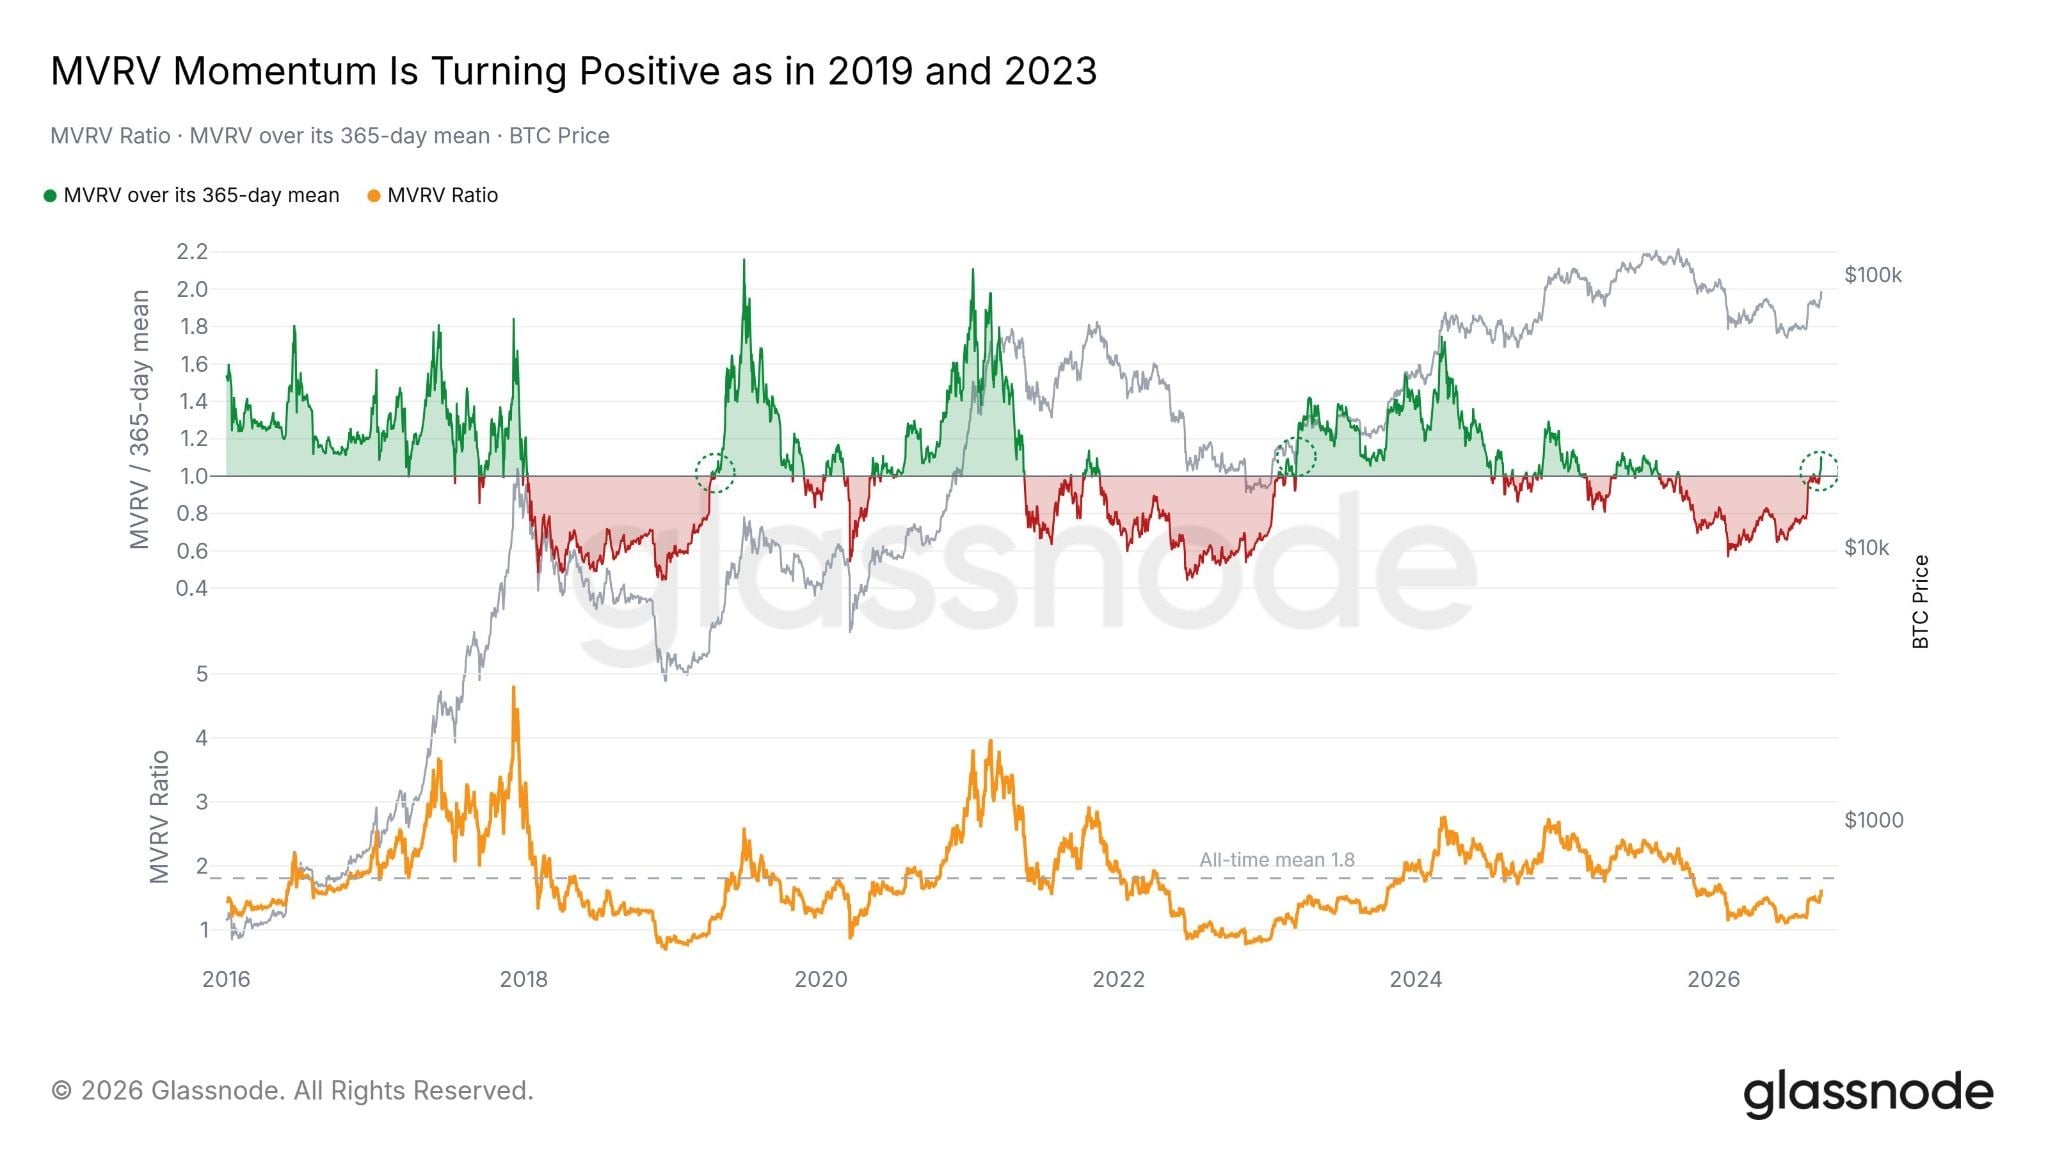
The metric currently registers at approximately 1.62, representing a significant increase from 1.19 recorded on August 16. Historical data shows similar crossovers preceded robust market rallies in 2019 and 2023.
The MVRV ratio evaluates bitcoin’s market capitalization against the average price at which coins were last transferred onchain. Elevated readings typically indicate that holders possess substantial unrealized gains.
The present 1.62 figure remains considerably beneath the 3.7 threshold that has historically coincided with previous cycle tops.
An alternative MVRV calculation utilizing the 30-day moving average is also nearing a significant threshold. A climb above 1.5 would represent the first such occurrence since January.
Key resistance zone emerges near $88,000
Market analyst Ted Pillows emphasized the importance of the $87,000-$88,000 range in a recent post on X.
Pillows noted that this zone carries significance due to its proximity to bitcoin’s yearly opening price and may function as resistance. He suggested that any pullback could redirect attention toward $79,000-$80,000 as potential support levels.
Bitcoin’s ongoing monthly winning sequence is attracting considerable interest due to its scarcity. The cryptocurrency’s only prior consecutive gains across July, August, and September occurred in 2012.
That historical precedent was succeeded by weakness in October before bitcoin eventually rallied significantly. Nevertheless, a single historical instance provides insufficient data to establish a reliable pattern.
President Donald Trump also indicated at the UN that he anticipates a resolution to the U.S.-Iran conflict, potentially following November’s midterm elections.
Currently, bitcoin continues trading in the vicinity of $86,000 after touching $87,350, with the $87,000-$88,000 range emerging as the primary resistance area under observation by traders.
The post Bitcoin (BTC) Holds Strong Above $86K Following Eight-Month Peak appeared first on Blockonomi.
Key Highlights
- Coinbase now offers fixed-rate USDC borrowing against bitcoin collateral via Morpho Midnight integration.
- Users receive predetermined interest rates and repayment schedules at loan origination.
- This offering complements Coinbase’s current variable-rate lending through Morpho Blue.
- The platform’s variable-rate lending portfolio has surpassed $1.4 billion in loans secured by approximately $3 billion in collateral.
- The service combines Coinbase’s user interface, Morpho’s protocol infrastructure, and Base network settlement.
Coinbase has introduced fixed-rate loans backed by bitcoin, offering customers an alternative method to access USDC liquidity without liquidating their cryptocurrency holdings. Operating through Morpho Midnight, this service provides borrowers with transparent interest rates and repayment timelines established at loan inception.
Introducing Borrow with @CoinbaseDev Wallets, a simple way to bring crypto-backed USDC loans directly into your app.
Browse products, open collateralized positions, and manage them over time. Starting with @Morpho Blue on @Base ↓ pic.twitter.com/8q7WzjscMx
— Coinbase Developer Platform
(@CoinbaseDev) September 22, 2026
This latest feature builds upon Coinbase’s current onchain lending infrastructure, which includes variable-rate borrowing through Morpho Blue. Customers now have the flexibility to select between fixed and variable loan structures based on their credit management preferences.
Morpho Midnight Powers New Fixed-Rate Lending Option
Morpho introduced Midnight on the Base network in July, establishing a framework for fixed interest rates and predetermined maturity dates in decentralized lending. Traditional DeFi lending platforms have primarily operated with variable interest rates subject to market fluctuations.
According to Morpho, Coinbase represents the first major consumer-facing platform to integrate Midnight loans at this scale. While market makers also utilize the protocol, Tenor Labs had previously deployed a lending service leveraging Midnight technology.
An onchain order book mechanism determines interest rates through supply and demand dynamics. Coinbase has not revealed the exact rates currently accessible to its borrowing customers.
Borrowers can presently select maturity dates corresponding to either the current month’s end or the subsequent month’s conclusion. Coinbase designates the month’s final Friday as the official end date.
Customers must satisfy their USDC debt obligations prior to the maturity deadline. Failure to repay enables lenders to exercise claims against the bitcoin collateral securing the loan.
Coinbase’s Lending Portfolio Exceeds $1.4 Billion
The platform’s existing variable-rate lending service has experienced rapid expansion. Coinbase reports that users maintain over $1.4 billion in active loans supported by approximately $3 billion in collateral assets.
These loans operate through Morpho Blue, the company’s established variable-rate lending infrastructure. According to Morpho, Blue currently facilitates roughly $5.2 billion in outstanding loans alongside approximately $16 billion in deposits across all platform integrations.
Morpho Midnight remains in earlier growth stages, with deposits totaling around $30 million as deployment continues. The Coinbase partnership could significantly expand adoption by connecting the protocol with an extensive retail user base.
The platform architecture divides responsibilities across different components. Coinbase oversees the customer-facing interface, Morpho supplies the lending technology, and Base handles transaction settlement.
Access Liquidity While Maintaining Bitcoin Exposure
The primary advantage of this service enables users to obtain liquid capital while preserving their bitcoin market position. Rather than converting bitcoin into fiat currency or stablecoins, customers can leverage their holdings as collateral to borrow USDC.
Jacob Frantz, Coinbase’s yield and investments product lead, emphasized that fixed-rate borrowing provides users with enhanced control over credit management. The fixed structure may attract borrowers who value predictable financing costs over variable rate exposure.
Morpho envisions Midnight’s expansion beyond bitcoin-collateralized lending. The protocol’s future roadmap includes potential support for structured credit instruments and loans backed by tokenized real-world assets.
Additional integrations are in development, though Morpho has not disclosed specific partners or implementation schedules. Currently, Coinbase customers benefit from an expanded onchain borrowing menu as fixed-rate DeFi lending increasingly resembles traditional financial products.
The post Coinbase Introduces Fixed-Rate Bitcoin Collateral Loans via Morpho Midnight Integration appeared first on Blockonomi.
TLDR:
- Pyth Network is now an approved external distributor of Nasdaq Basic’s real-time equity data.
- Nasdaq Basic covers best bid, offer, and last sale data for all U.S. exchange-listed securities.
- Clients must get Nasdaq’s written approval before accessing the feed through Pyth’s platform.
- The deal extends Nasdaq’s reach into software and blockchain-native financial applications.
Nasdaq Basic data is now available through Pyth Network after the oracle provider secured approval as an external distributor.
Pyth announced the news on September 22, 2026, stating it is now approved to distribute Nasdaq’s real-time quote and trade product for U.S. equities.
The move gives software and blockchain-native applications a new path to access top-of-book pricing data that brokerages, banks, and fintech platforms have relied on for over a decade.
What Nasdaq Basic Covers
Nasdaq Basic delivers real-time top-of-book data for U.S. equities. In a follow-up post, Pyth described the product as carrying the best bid and offer, with size, from liquidity in the Nasdaq market center. This gives users a live view of market depth without added cost.
The announcement noted that the product also carries the last sale price and size. This information comes from Nasdaq’s U.S. venues and from trades reported to the FINRA/Nasdaq Trade Reporting Facility. Together, these data points give a full picture of recent trading activity.
BREAKING: Pyth is now an external distributor of Nasdaq Basic.@Nasdaq's real-time quote and trade product for U.S. equities, distributed through the Pyth Data Marketplace
pic.twitter.com/1Xfg7mmYdE
— Pyth Network
(@PythNetwork) September 22, 2026
Pyth also posted that coverage is not limited to Nasdaq-listed securities. All U.S. exchange-listed securities are included, regardless of which venue a security is listed on. This broad scope makes the product useful across many types of trading desks.
Nasdaq Basic also includes the Nasdaq Official Opening and Closing Prices. These reference prices come from Nasdaq’s Opening, Closing, and IPO/Halt Crosses. Much of the industry uses them to value positions at the start and close of each trading day.
How Pyth’s Data Marketplace Fits In
Clients of the Pyth Data Marketplace can now license Nasdaq Basic directly through Nasdaq via Pyth. Prior written approval from Nasdaq is required before any client may consume the feed. This keeps distribution controlled while expanding its reach.
In one of its posts, Pyth quoted Michael Cahill, a Core Contributor to Pyth, saying that more of the market runs on software every year and that data therefore has to reach a wider and more varied set of applications. His comment points to a shift already under way across finance.
The same post quoted Cahill adding that Nasdaq has been ahead of that curve for a long time, noting that Nasdaq Basic exists because Nasdaq wanted its data in more hands. He called the addition of Pyth’s Data Marketplace a natural extension of that approach.
The Data Marketplace works as Pyth’s main channel for datasets that fall outside its other offerings. It lets institutions distribute proprietary data directly to the applications that need it. Nasdaq Basic becomes the latest addition to that growing list.
The post Pyth Network Becomes External Distributor of Nasdaq’s Real-Time Equity Data Feed appeared first on Blockonomi.
CryptoPotato
The frog-themed meme coin PEPE has emerged as one of the top-performing cryptocurrencies over the past week, with its price rising by roughly 50% to a nine-month high of $0.0000049.
The token has already demonstrated its ability to deliver triple and even quadruple gains in the past, and many analysts now believe another move of that scale could be on the horizon.
‘The Frog is Waking Up’
X user Giannis Andreou noted that PEPE’s weekly chart is holding a higher low above its 2023 base, meaning the test now comes at $0.0000048-$0.0000055.
The analyst claimed the weekly candle “is still open,” arguing that a close above the upper boundary, followed by a successful retest, could strengthen the case for $0.0000065-$0.0000075.
“Clear that, and $0.000009-$0.0000105 becomes the next zone to watch. The bigger recovery scenario reaches $0.000013–$0.000016,” he added.
At the same time, the analyst warned that a rejection may lead to a drop to the $0.0000023-$0.0000032 range.
For his part, Crypto With Gopal argued that the meme coin’s price is testing the lower trendline after a rejection near $0.0000054, showing momentum is tightening. He believes that the setup remains bullish, but buyers must defend support and reclaim the upper resistance to initiate a further upswing.
X user Plazma also chipped in, estimating that PEPE had formed a golden cross on the 50-day/200-day moving average: a setup usually considered highly positive for the price.
The Dangerous Game With Meme Coins
PEPE’s price increase is impressive and could go even higher, but traders and investors who want to hop on the bandwagon should keep in mind that tokens like this are highly volatile and often driven more by hype and speculation than fundamentals. Recently, X user Crypto Bitlord warned people to stay away from memes, claiming 99% of them are scams.
“It’s hard for me to recommend anyone play that game because the statistics are against you,” he added.
PEPE has been on the market for more than three years and has built a solid community base, but no one can say for sure whether the project has a bright future or is a time-ticking bomb.
Meanwhile, CoinGlass data shows that over the past few days, investors have moved PEPE tokens from self-custody to centralized exchanges. That reinforces the bearish scenario since it increases immediate selling pressure.

- PEPE Exchange Netflow, Source: CoinGlass
The post ‘The Frog is Waking Up!’ PEPE Explodes 50% in a Week as Golden Cross Forms appeared first on CryptoPotato.
CME Group will launch Bitcoin Cash (BCH) and Uniswap (UNI) futures on October 19, pending regulatory review, the exchange announced on Tuesday, and BCH climbed from $270 to $328 on Binance within 90 minutes of the 8:30 a.m. ET release. It kept surging in the following hours to $340, while UNI is currently up by 15% to over $10.
Each asset gets a full-size and a Micro contract: 250 BCH and 25 BCH for Bitcoin Cash, 10,000 UNI and 1,000 UNI for Uniswap.
The contracts join a single-asset lineup that already covers Bitcoin (BTC), Ether, XRP, Solana, Cardano, Chainlink, Stellar, Avalanche and Sui, and will trade on Globex, where CME began around-the-clock crypto trading on May 29.
“As crypto markets continue to mature, participants require broader, regulated tools to navigate evolving digital asset related price risk,” said Giovanni Vicioso, Global Head of Cryptocurrency Products at CME Group, adding that the contracts give clients exposure to “key crypto networks within our 24/7, regulated marketplace.”
BCH Jumps 28%, UNI Spikes
BCH is among the top performers on a 24-hour scale today, surging by 28% to a multi-month peak of $340. Bitcoin moved 1.1% over the same window on Binance, and the total crypto market cap gained 1.8% over 24 hours, per CoinGecko.
BCH closed at $216.74 on September 16 and is up 55% since then to $340, per CoinGecko, in the same stretch that took Bitcoin to an eight-month high above $87,000 on Tuesday, with BCH among the altcoins posting larger gains. The token remains 91.5% below its December 2017 peak of $3,785.82.
Uniswap’s token experienced a similar double-digit increase as well, currently showing a 15% surge since yesterday. As a result, it has topped $10.
UNI is up 64% over seven days and 105% over 30 days, per CoinGecko, after a 30% jump to a 10-month high near $9.20 on September 18, which followed the SEC’s innovation exemption for on-chain trading of tokenized stocks.
Crypto Volume Averages $8.3B a Day
CME reported first-half 2026 crypto futures and options average daily volume of 279,800 contracts, $8.3 billion in notional, with average open interest of 264,600 contracts, or $15.4 billion. The five altcoin futures added this year, Cardano, Chainlink, Stellar, Avalanche and Sui, have traded more than $1 billion in notional value year-to-date. August cryptocurrency ADV came in at 175,000 contracts, $12 billion notional, per the exchange’s September 2 volume report.
Noel Kimmel, President at Ripple Prime, said in the release that institutions managing crypto exposure “need around-the-clock access to regulated derivatives, underpinned by the clearing and financing infrastructure to match.”
The post Bitcoin Cash and Uniswap Explode by Double Digits as CME Announces Futures Launch appeared first on CryptoPotato.
XRP reserves on Binance have climbed to roughly 2.6 billion tokens, their highest level since June, with the token trading above $1.50 today.
The buildup is unfolding in the middle of a broader market rally, though a closer look at the exchange flows suggests the extra supply has more to do with trading turnover than a wave of holders lining up to sell.
Binance Reserves Climb, But Data Tells Two Slightly Different Stories
According to on-chain tracking from Arab Chain, Binance’s XRP reserves reached their highest level since June, following a period of decline and a gradual recovery in recent weeks.
The platform’s balance has risen to approximately 2.68 billion XRP, leaving a larger volume of tokens available for spot trading. But Arab Chain cautioned against treating the increase as an immediate sell signal.
“From a market dynamics perspective, a rise in reserves does not necessarily mean that XRP holders are preparing for an immediate sell-off; rather, it reflects an increase in the volume of coins held within the trading ecosystem, providing traders with greater liquidity,” the data provider wrote.
According to them, investors should watch this development alongside net flows, trading volume, and price action, particularly if reserves continue to climb.
Meanwhile, on-chain analyst Theophiluspep offered a more detailed picture of the activity. He cited CryptoQuant data showing Binance’s average daily XRP deposits running 663% above the quarterly baseline during recent sessions, with withdrawals also increasing, leaving reserves only about 0.22% above that baseline.
That combination points to substantial two-way movement, rather than a one-sided build-up of inventory on the exchange. Theophiluspep also reported that Binance netflows had turned slightly negative in the latest sessions, meaning withdrawals had begun to be more than deposits.
His focus is now on whether those outflows can become more sustained as XRP consolidates, or whether the recent activity settles back into high turnover.
XRP Reclaims $1.50
At the time of writing, XRP was at around $1.53 per CoinGecko, up more than 4% in 24 hours and about 9.5% across seven days. Still, it’s down 45% from where it was a year ago and almost 58% below its $3.65 all-time high recorded in July 2025, even though trading volume jumped 63% from yesterday to about $6.33 billion.
Meanwhile, its Relative Strength Index had moved above 70, a level commonly associated with overbought conditions. And while that does not guarantee a pullback, it should add a cautionary signal as the price continues to recover.
The post XRP Reserves on Binance Hit 3-Month High as Price Breaks $1.50 appeared first on CryptoPotato.
Animoca Brands has mutually suspended discussions with Currenc Group over a proposed reverse merger. The deal was first announced on November 3, 2025.
Both companies agreed to pause the talks after reviewing the expected timeline for completing the transaction and changes in market conditions.
Merger Talks on Hold
In its official blog post, Animoca Brands said the time needed to complete the deal does not currently fit its short- and medium-term strategic goals and added that the two sides may resume discussions if market and business conditions allow.
Despite the pause, the Web3 giant said it is currently working on its financial compliance and corporate governance plans. Animoca issued its audited financial statements for fiscal year 2023 on July 17, 2026. This was the company’s second set of audited financial statements released this year. It is now working on statements for fiscal year 2024.
According to Animoca, completing both reports is an important step in its efforts to meet the requirements for a future public listing. Meanwhile, co-founder and executive chairman Yat Siu stated,
“While we hold our proposed merger with Currenc Group in high regard, our corporate agility must take precedence. Today, we affirm our focus from a position of significant operational strength, an unmatched digital assets and AI portfolio, and a concerted drive to achieve our compliance milestones.”
Separately, Animoca Brands has also been involved in Hong Kong’s stablecoin push. In February 2025, it teamed up with Standard Chartered Bank HK and HKT to form a joint venture called “Anchorpoint Financial Limited.” In April 2026, the venture was granted one of Hong Kong’s first official stablecoin issuer licenses by the HKMA. Anchorpoint began the initial rollout of its regulated Hong Kong dollar-backed stablecoin named HKDAP for institutional investors in August.
Public-Market Push Slows
Animoca’s decision comes at a time when several major crypto firms have also slowed their listing ambitions in 2026. For instance, Kraken’s parent company, Payward, put its IPO preparations on hold in March, even after confidentially filing for a US listing in November 2025.
Crypto hardware wallet maker Ledger followed in May, after pausing its IPO plans and turning to private funding instead. Similarly, asset management giant Grayscale also delayed the process around the same time.
The post Animoca Hits Pause on Reverse Merger – But Its Public Listing Ambitions Aren’t Going Away appeared first on CryptoPotato.
Bitcoin (BTC) slipped toward $85,000 on Tuesday after briefly climbing above $87,000, putting its latest recovery under pressure. The move came after a sharp rebound from last week’s low near $75,000, when BTC fell below its September trading range.
That recovery followed a period of weakness. According to the latest Bitfinex Alpha report, Bitcoin had spent much of September between roughly $77,100 and $81,300 before breaking lower. The market then reversed sharply, with Bitcoin gaining 5.9% on September 18 as strong buying and ETF inflows pushed prices higher.
Spot Buying Supports Rally
The rebound carried BTC above the previous range and brought $85,000 into focus as an important level. Bitfinex analysts had identified that price as the first major test for the recovery.
Bitcoin later moved toward $87,000 before giving back some of its gains. Spot buying drove much of the move, but several indicators linked to sustained rallies remain weak. Trading volume has yet to show strong follow-through, while open interest remains relatively subdued.
Short covering also contributed to the rally as traders who had bet on lower prices bought Bitcoin back. Such buying can accelerate a recovery, but its effect may fade if fresh demand does not continue.
Corporate Demand Adds to Bitcoin’s Recovery
Corporate Bitcoin holdings are also receiving attention as the price moves above the estimated average purchase cost of about $80,500. Recent disclosures from Strategy and Strive showed additional Bitcoin purchases. This suggests corporate demand could become more active after slowing earlier this year.
Beyond corporate buying, investors are watching whether broader demand can support the recovery. Coin-denominated open interest remains subdued, while short-term holder exchange transfers stay below roughly 20,000 BTC daily. A sustained level below that threshold could point to lower selling pressure.
The next major test comes on September 25, when a large options expiry could add volatility and selling pressure. A sustained move above $85,000 would keep the recovery in focus, while a drop below $81,300 could return BTC to its previous range.
If selling intensifies, $77,100 remains an important lower boundary. Higher U.S. real yields also remain a challenge, with the yield recently near 2.68%. This keeps broader financial conditions relevant as the apex coin attempts to hold its recovery.
The post Bitcoin’s Rally Above $87,000 Faces Fresh Tests: Bitfinex Alpha appeared first on CryptoPotato.