Cryptocurrency Posts
Crypto Briefing
Anduril's Armory could revolutionize defense procurement, streamlining processes and potentially reshaping the defense supply chain landscape.
The post Anduril Industries launches Armory, a new defense-tech e-commerce platform appeared first on Crypto Briefing.
China's semiconductor equipment imports rose 16% in August per Jefferies, signaling a strong second-half recovery driven by AI demand and
The post China’s chip equipment imports rise 16% in August as AI demand fuels semiconductor buildout appeared first on Crypto Briefing.
Growing public dissent and memorialization efforts in Iran may signal increasing pressure on the regime, potentially leading to leadership changes.
The post Iranian families defy threats to honor protest victims amid regime tensions appeared first on Crypto Briefing.
AI agents like Muse threaten traditional financial and travel sectors by eroding consumer inertia, prompting a shift in revenue dynamics.
The post AI agents disrupt banks, brokers, and travel booking companies as Meta’s Muse reshapes consumer behavior appeared first on Crypto Briefing.
The introduction of lithium hydroxide futures could stabilize pricing and enhance market transparency, impacting global EV supply chains.
The post Guangzhou Futures Exchange plans to list lithium hydroxide futures this year appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Bitcoin Investors Buy Nearly $1B in BTC ETFs as Bull Market Returns
The Bitcoin bulls are back — if ETF flows are to be believed.
U.S. bitcoin exchange-traded funds received $999 million in new investment on Monday, according to Farside Investors data.
That’s the most in one day since October 6, when the funds received over $1.2 billion and the price of the leading cryptocurrency hit a new all-time high of $126,080.
Bitcoin’s price recently stood at $86,552 after scraping $87,330 on Monday. Over the past seven days, the coin’s price has surged by nearly 13%.
Bitcoin ETFs in the U.S. — approved by the SEC in 2024 — have helped investors get exposure when they couldn’t before. Now, Wall Street firms can quickly buy shares of funds managed by the likes of BlackRock, Fidelity, Morgan Stanley, and others.
When big investment hits the funds, the price often moves significantly — as what happened on Monday.
Bloomberg ETF analyst James Seyffart on Monday said that the average ETF buyer is now in profit after the estimated ETF cost basis surged above $81,72 for the first time since January.
The ETF to receive the most of Monday’s investment — $381.4 million — was BlackRock’s iShares Bitcoin trust. The ARK 21Shares Bitcoin ETF received $289.1 million; Fidelity’s Wise Origin Bitcoin Fund took in $238.8 million.
Investors have a renewed interest in Bitcoin after the artificial intelligence stock rally cooled and the U.S. Department of the Treasury in August said it would at least double the size of its liquidity-support buyback operations.
Analysts said the move pushed 30-year Treasury yields down, weakened the dollar, and made assets like bitcoin more attractive. Following the announcement, the bitcoin price had its best run in years.
A Tuesday report from crypto market data firm CryptoQuant said that the leading cryptocurrency crossed above its 365-day moving average, a signal that the asset has finished being in a bear market.
This post Bitcoin Investors Buy Nearly $1B in BTC ETFs as Bull Market Returns first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Bitcoin’s Bull Run Is Back — and the Data Agrees
Bitcoin’s run this weekend would have observers believing that the bull market is back. But the data also backs it up.
A new report from data firm CryptoQuant shows that the leading cryptocurrency crossed above its 365-day moving average — a signal that the asset has finished being in a bear market.
Bitcoin’s price surged in August and had its best run in years, spurred by an announcement from the U.S. Treasury saying it would at least double the size of its liquidity-support buyback operations. Its run cooled but then last week shot up again and was recently trading for $86,598 after trading as high as nearly $87,330 on Monday.
JUST IN: $87,000 Bitcoin
— Bitcoin Magazine (@BitcoinMagazine) September 21, 2026pic.twitter.com/Vgl0wCA7uY
“This crossover is the definitive technical signal that has marked the start of Bitcoin’s bull markets in past cycles, and it is the first time price has reclaimed the 365-day moving average since March 2023,” the report read.
It added that the moving average is a “cycle-defining” line and confirmed the start of bull runs in previous years.
“Its track record across cycles is why this reclaim carries real weight rather than being a routine bounce,” the report added.
The report continued that long-term holders appear to have finished selling, making the way for new investors to enter the market.
Bitcoin notched a record of $126,080 in October of last year but then began to sink later that month after the biggest liquidation event in crypto history saw over $19 billion in bets closed.
In the first half of this year it continued its plunge after the Federal Reserve made it clear it was in no hurry to lower interest rates and investors increasingly threw money at artificial intelligence-related stocks to get returns.
But the so-called debasement trade — where investors throw money at an asset to hedge against a currency losing its value — is hot again. Bitcoin and precious metals like gold have done well when the dollar has weakened.
And the Federal Reserve last week raised interest rates to get sky-high inflation in the U.S. under control. Investors shrugged the central bank’s move off and bought up the asset.
Now, people seem more interested in buying an asset that can protect them from government debt and deficit. In August, total U.S. debt topped $40 trillion for the first time.
This post Bitcoin’s Bull Run Is Back — and the Data Agrees first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
White Hats Move Over $4.5 in Bitcoins From Coldcard to Recovery Trust
White hats have moved bitcoin from the hacked Coldcard signing devices to a trust for would-be victims to reclaim, Galaxy Digital’s Alex Thorn has said.
Writing on X on Monday, Thorn said that the funds were taken by white hats to protect potential victims. They are now apparently sitting in an address controlled by Crypto Recovery Trust, a Wyoming Trust created to help white hats return funds to victims.
A total of 52.37 of the bitcoins — worth over $4.5 million at today’s prices — were moved. Thorn added that the funds represented 2.8% of the coldcard exploit.
Criminals started taking bitcoin stored using Coinkite’s popular Coldcard hardware wallet on July 31.
Canadian company Coinkite said that a firmware bug in Coldcard devices caused seed generation to fall back to a weak software Pseudorandom Number Generator instead of the hardware true random number generator, allowing hackers to essentially guess investor seedphrases.
Galaxy Digital tracked the movement of funds and said 1,789.28 bitcoins were lost in the attacks. That’s $154.1 million in bitcoin at today’s prices.
Earlier this month, Nick Bax of universal market protocol Ump Labs said that he was involved in helping recover the funds.
“Finally able to say that at the end of July, I was involved in the rescue of ~50 BTC which were “imminently going to be stolen due to the COLDCARD entropy flaw,” Bax wrote on X.
He added: “The funds are currently held by a Wyoming trust, which will ensure that funds are returned to their rightful owners.”
Since the attack, cautious investors have been moving their coins to other storage solutions — including exchanges.
Coinkite said in a statement that the bug in its software “silently went unnoticed” and “its potential impact grew with every release” of its products.
Days after the first hack, the company urged investors to update their software or move their funds off the popular hardware wallet.
This post White Hats Move Over $4.5 in Bitcoins From Coldcard to Recovery Trust first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Feds Probing Binance Over Iran’s Bitcoin Use: Report
Federal prosecutors — including the U.S. Department of Justice — are investigating whether Binance has allowed Iran to dodge sanctions by using its platform, according to a report from Bloomberg.
The outlet, citing people familiar with the matter, reported Tuesday that feds were investigating whether Binance Holdings Ltd., which operates the world’s biggest crypto exchange, knowingly allowed Iran-linked entities to trade.
It comes after the U.S. Department of Justice last week said it is seizing and seeking to forfeit $61 million in cryptocurrency that it alleges came from black-market sales of sanctioned Iranian oil. The funds, according to the DOJ, were laundered through Binance by Chinese entities.
Iran has been using bitcoin — and other cryptocurrencies — to skirt around U.S. sanctions. The U.S. in April started targeting crypto wallets linked to the Iranian regime, Treasury Secretary Scott Bessent said in a statement.
Bessent went on to say that the Iranian regime’s crypto had been frozen — mostly in the form of Tether’s USDT stablecoin.
And last week, the Treasury designated BitBank, an Iranian crypto exchange, as part of Operation Economic Outcast — the Trump Administration’s whole-of-government economic campaign against the Islamic Republic of Iran and its enablers.
Iran started a bitcoin-backed insurance service for its counties shipping companies earlier this year. Bitcoin cannot be frozen, unlike many other cryptocurrencies.
The Financial Times this month reported that the Middle Eastern country was using bitcoin to settle cross-border transactions through Iranian crypto exchanges after the central bank advised its countrymen to do anything necessary to help the economy.
Binance, which has no headquarters but is incorporated in the Cayman Islands, ran into trouble with U.S. authorities after it allegedly allowed funds linked to virtual theft and terrorism to flow through its exchange undetected.
It exited the U.S. market and agreed to pay $4.3 billion. Its CEO and founder Changpeng Zhao stepped down after pleading guilty to anti-money laundering violations but was later pardoned by President Trump.
This post Feds Probing Binance Over Iran’s Bitcoin Use: Report first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
No Bitcoin Payments in Russia — But the Digital Ruble Is Open for Business
While bitcoin is banned for making payments in Russia, the government is keen on one type of digital money: its own central bank digital currency.
The digital ruble has been available for transactions in the country since September 1, according to a Tuesday report from Tass.
Citing a talk given by Prime Minister Mikhail Mishustin, the news agency said that it was all part of “developing a convenient, fast, and independent payment infrastructure” in Russia.
JUST IN:
— Bitcoin Magazine (@BitcoinMagazine) September 22, 2026Russian Prime Minister Mikhail Mishustin says:
"The circulation of cryptocurrencies has also become legal in the country starting from September 1. The relevant law was signed by the president."
Russia has been fast regulating digital assets this year. President Vladimir Putin in August signed a law regulating the circulation of digital currencies and digital rights in the country.
The law states that only registered entities can operate as exchanges, and puts limits on the amount of crypto retail investors can use.
But what about Bitcoin?
President Putin in 2024 seemed to praise the OG cryptocurrency. “For example, Bitcoin, who can ban it? Nobody,” he said at a forum at the time.
“And who can prohibit the use of other electronic payment instruments? Nobody, because these are new technologies.”
The president has also spoken about how the country has “competitive advantages” when it comes to Bitcoin mining due to the abundance of cheap energy in Russia.
Though the Kremlin still has a tight grip on what its citizens can do with it: Retail investors are limited to trading bitcoin and other liquid cryptocurrencies, capped at 300,000 rubles ($3,556) per year, according to the August law. Qualified investors have no restrictions.
And using crypto as a form of payment has been illegal in Russia since 2022.
Central bank digital currencies — or CBDCs — are a centralized form of digital money, issued by a central bank. Bitcoiners have long criticized the idea of such a product because it can be used by governments to surveil its citizens and ultimately even control their spending.
U.S. President Donald Trump even signed an executive order in 2025 prohibiting federal agencies from establishing, issuing, or promoting a CBDC.
But in Russia, a digital ruble is the best way for keeping citizens in check. The Bank of Russia settled early on an architecture that mixes a centralized ledger it controls with distributed-ledger components. The 2021 concept described the preferred model as hybrid — distributed ledgers combined with centralized components — and the full technical details have never been published.
Bitcoin payments, on the other hand, are being used by companies in international payments to counter Western sanctions, Finance Minister Anton Siluanov admitted in 2024.
This post No Bitcoin Payments in Russia — But the Digital Ruble Is Open for Business first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
CryptoSlate
Microsoft and Coinbase helped dismantle EvilTokens, an AI phishing service tied to more than 12,000 compromised inboxes worldwide.
The operation had reached more than 10,000 organizations within months of launching, spanning financial services, real estate, healthcare, construction and other industries, Microsoft said.
The company and its partners seized 50 websites used by EvilTokens and disabled more than 150 related domains, while UK police arrested two men on Sept. 11 on suspicion of offenses connected to the alleged operation. Police later released both on conditional bail.
EvilTokens' phishing service relied on AI use
EvilTokens had packaged much of the business-email-compromise process into a subscription service sold through Telegram. Microsoft said customers paid a $1,500 initiation fee and $500 recurring subscription for tools that combined account compromise, mailbox access, reconnaissance, and AI-assisted fraud preparation in a single interface.
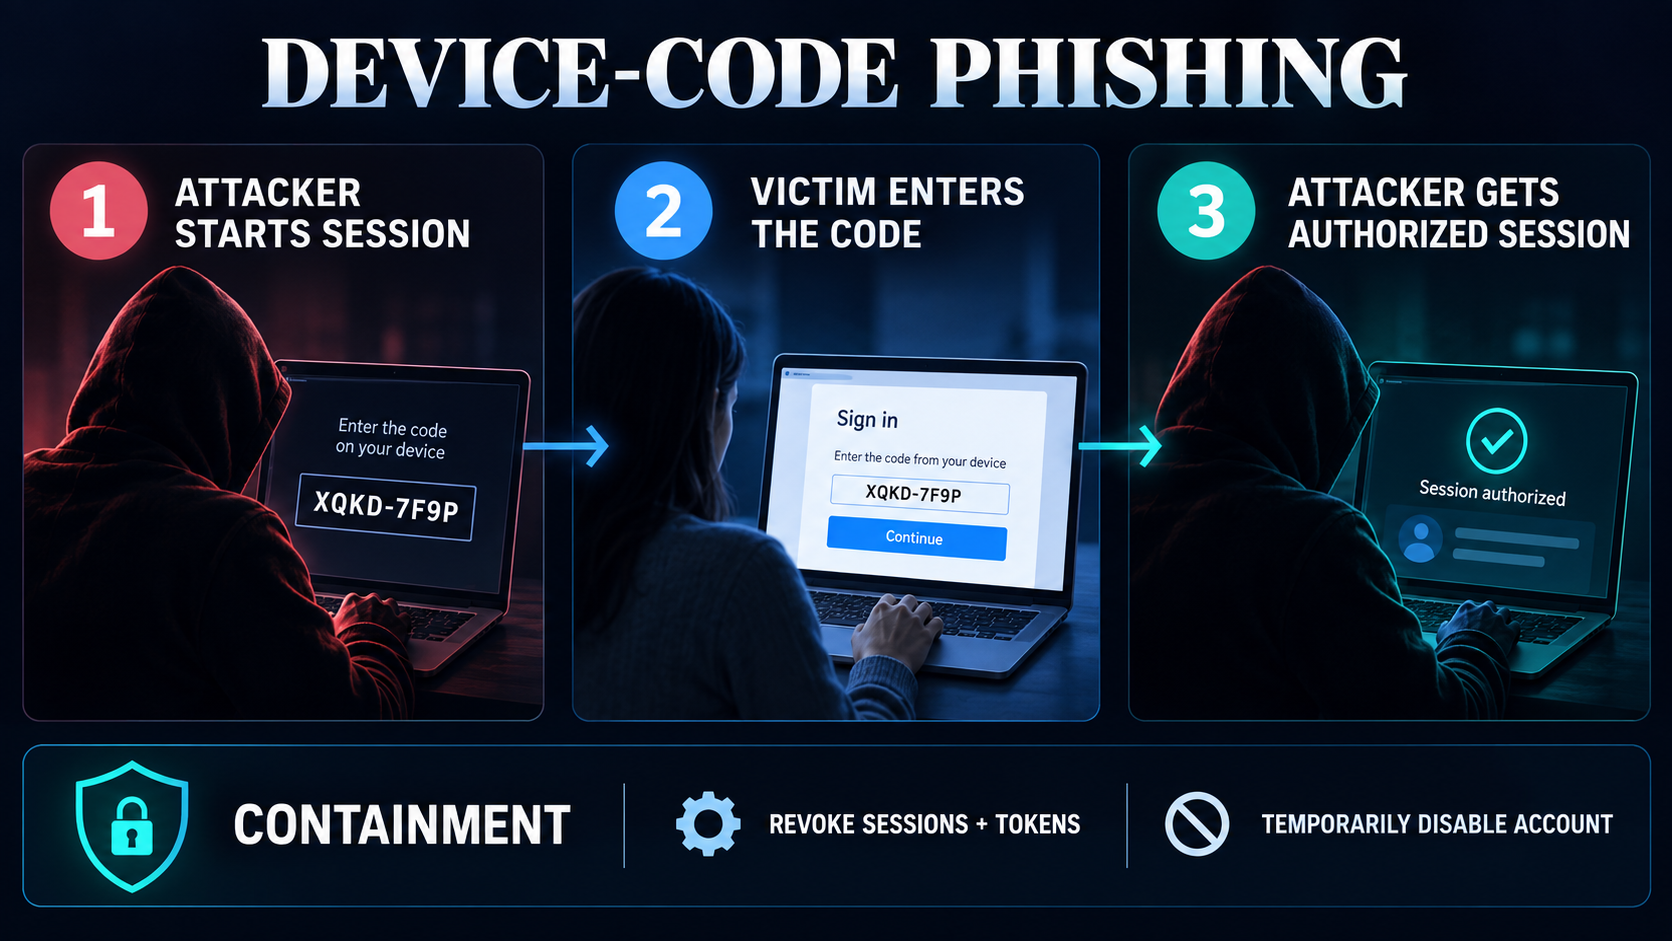
The service’s entry point relied on Microsoft’s device-code authentication, a legitimate sign-in flow designed for hardware such as smart TVs and conferencing equipment that cannot easily support standard browser logins.
Attackers initiated the authentication request themselves, then sent the resulting code to targets through phishing emails disguised as invoices, shared files, and other routine business communications.
Victims who entered that code on Microsoft’s legitimate website effectively approved the session waiting on the attacker’s device.
The process could still require a password and multifactor authentication when the user was signed out, but those credentials remained on Microsoft’s infrastructure. The process generated authorization for the attacker-initiated session.
That gave EvilTokens something more useful than a stolen password: an authenticated foothold inside the mailbox. The platform then automated work that has traditionally required attackers to spend hours reading correspondence and reconstructing how an organization moves money.
Its AI tools could translate and summarize messages, identify reporting lines and trusted contacts, surface pending invoices and wire-transfer conversations, and determine which employees had authority over payments.
Microsoft said preset prompts could identify an organization’s “money movers” and recommend people to impersonate, letting customers move from account access to targeted fraud with far less manual reconnaissance.
Investigators also found evidence that parts of EvilTokens were built with AI-assisted coding tools, lowering the technical burden on both sides of the operation.
The result was a service that could help less-skilled customers gain access to an account, understand its contents, and prepare an impersonation campaign without assembling each capability separately.
Crypto payments gave investigators a trail
The subscription model also created the financial trail Coinbase used to work backward through the operation.
Coinbase’s Global Intelligence team traced about $1.1 million in EvilTokens platform revenue across four Tron addresses between October 2025 and June 2026. It identified more than 1,000 deposits from over 700 distinct addresses and mapped flows from payments into EvilTokens through their eventual cash-out destinations. The figures represent revenue paid to the service rather than the amount ultimately stolen from phishing victims.
Coinbase said it combined transaction data with merchant records, device information and open-source intelligence to help attribute the platform to its alleged operators before referring the matter to London’s Metropolitan Police.
The exchange also investigated EvilTokens purchasers it identified on its own platform and referred those cases to law enforcement. Its evidence contributed to Microsoft’s civil action against the service.
Coinbase customers were also among those caught downstream. The exchange said some users were manipulated through compromised email conversations into sending cryptocurrency to scam-controlled addresses. Coinbase accounts and credentials were not compromised.
The disruption interrupted an operation that was already looking beyond Microsoft. Coinbase said EvilTokens’ operator had signaled plans to extend the toolkit to Gmail and Okta accounts, potentially spreading the same model across other identity platforms.
Microsoft warned that removing the service’s current infrastructure would not eliminate the method. The company recommends organizations block device-code authentication where it is unnecessary and tightly restrict it where operationally required. For accounts suspected of compromise, it advises revoking refresh tokens, forcing reauthentication and, in some cases, temporarily disabling the account.
That last step can carry a short-term operational cost, but Microsoft said standard session revocation may leave existing access tokens usable for up to an hour. Attackers have exploited that window in recent campaigns, leaving security teams to choose between brief disruption to legitimate users and continued access for someone already inside the mailbox.
The post Coinbase traced $1.1 million crypto trail behind AI phishing service EvilTokens appeared first on CryptoSlate.
Bitcoin options carrying roughly $16 billion in notional value expire on Deribit at 08:00 UTC on Friday, Sept. 25. Calls account for about $9.6 billion of that open interest and puts for about $6.4 billion.
Bitcoin trades near $86,300 heading into the settlement, after climbing above $85,000 this week. Two US economic releases and the expiry of CME's September Bitcoin futures follow within seven hours, stacking three separate tests into one trading day.
The equity side settled first
Ledn co-founder Mauricio Di Bartolomeo sees Friday as the second half of an expiry cycle that began on Wall Street.
He said in a note to CryptoSlate that quarterly expirations like September's are a two-act event. Options on BlackRock's iShares Bitcoin Trust expired last week in IBIT's largest single expiration on record, and he described the book as heavily tilted toward calls.
In his account, Bitcoin's rally through $80,000 pushed many of those calls into the money, and dealers short those contracts bought IBIT shares to stay hedged.
Di Bartolomeo argued that this demand reached Bitcoin itself once it grew large enough to require new IBIT shares, a process that pulls spot Bitcoin into the fund through authorized participants. He expects the Deribit book to inherit the same setup.
He noted:
“If the move continues, the large call blocks at $85,000 and $100,000 are where the same dynamic kicks in on the Deribit book.”
Calls make up about 60% of Friday's expiring open interest. Estimating how dealers hedge that book requires an assumption about which side of each contract they hold, since exchange data records open interest in aggregate.
ByKaranteli's open-source gamma model, which its authors present as a map of possible hedging flows under one such assumption, places the largest call wall at $95,000 and the largest put wall at $60,000. It also puts the put-to-call ratio at 0.52 and the zero-gamma level near $71,000.
That zero-gamma level sits where dealer hedging flips character.
Above it, dealers who are net long gamma sell into rallies and buy dips, absorbing moves and pulling price toward heavily populated strikes. Below it, net short gamma forces dealers to buy as price climbs and sell as it falls, amplifying whatever move is underway.
With Bitcoin trading in the $86,000 zone, the model places the market comfortably inside the zone it treats as stabilizing.
| Metric | Current reading | Why it matters |
|---|---|---|
| Total BTC options expiring | ~$16B | Large enough to affect hedging and liquidity conditions |
| Calls expiring | ~$9.6B | Calls dominate the book |
| Puts expiring | ~$6.4B | Downside hedges remain material |
| Call share of OI | ~60% | Shows upside positioning, but not dealer direction |
| BTC spot level | ~$86,300 | Near active strike zones |
| Largest call wall | $95,000 | Main upside concentration in the gamma model |
| Largest put wall | $60,000 | Main downside concentration |
| Zero-gamma level | ~$71,000 | Model’s flip point between stabilizing and amplifying hedging |
Bitcoin options markets are pricing a moderate move
Deribit's DVOL index stood at 38.1 on Sept. 22, a reading ByKaranteli classifies as very low across five years of history. Friday's at-the-money implied volatility was also 38.1%, and skew was near neutral, with 25-delta puts and calls both priced near 39.2%.
At that level, a one-standard-deviation move through Friday works out to about $2,720, or 3.15%, placing a rough band between $83,600 and $89,100. That band puts $90,000 at its outer edge and leaves the $95,000 call wall as a distant target.
Deribit sets its delivery price using a 30-minute time-weighted average of its Bitcoin index between 07:30 and 08:00 UTC.
A 2026 study published in Finance Research Letters found intraday Bitcoin price reversals around Deribit expirations that held up under statistical testing, strongest when at-the-money open interest ran high and estimated gamma exposure was negative.
The same research recorded heavier trading in Deribit perpetuals and in the spot venues feeding the settlement index during those windows.
ByKaranteli's model places the market in positive gamma at current prices, a different condition from the one where the study found the effect strongest. A sharp move that reverses within two hours of 08:00 UTC would fit that documented pattern, and a move that holds through the afternoon's events would carry broader confirmation.
| Input / Level | Value | Interpretation |
|---|---|---|
| Deribit DVOL | 38.1 | Low by five-year history, according to ByKaranteli |
| Friday ATM implied volatility | 38.1% | Moderate expected movement |
| 25-delta put IV | ~39.2% | Downside protection not heavily bid |
| 25-delta call IV | ~39.2% | Skew near neutral |
| 1-standard-deviation move | ~$2,720 | Approximate expected move through expiry |
| Lower implied band | ~$83,600 | Downside edge of the near-term range |
| Upper implied band | ~$89,100 | Upside edge of the near-term range |
| Nearby upside threshold | $90,000 | Just beyond the implied band |
| Major call wall | $95,000 | Further outside the priced move |
The afternoon handoff
US durable goods orders arrive at 12:30 UTC, four and a half hours past Deribit's settlement. The University of Michigan's final September consumer sentiment reading, which includes inflation expectations, lands at 14:00 UTC, and CME's September Bitcoin futures settle against the CME CF Bitcoin Reference Rate at 15:00 UTC.
The Fed raised its target range to 3.75% to 4.00% on Sept. 16, leaving both data points relevant to rate-sensitive assets.
Once Deribit's contracts settle, the hedges tied to them unwind or roll into October and December expiries. A macro surprise at 12:30 or 14:00 UTC then meets whatever hedging structure survives that reset.
If the expired book had been stabilizing price, the same surprise could produce a larger move than it did the day before.
US spot Bitcoin ETFs took in $159.5 million on Sept. 17, $433 million on Sept. 18 and $999 million on Sept. 21, according to Farside Investors.
Monday's rally also included about $647.9 million in short liquidations out of $746.6 million in total liquidations over 24 hours, while aggregate crypto open interest climbed 7.59% to $156 billion.
The rally is supported by spot buying through ETFs and fresh leverage on top of forced short covering.
| Time UTC | Event | Market risk |
|---|---|---|
| 07:30–08:00 | Deribit settlement-price window | Hedging, rolls, and expiry-linked flows may concentrate trading |
| 08:00 | ~$16B BTC options expire | Expiring gamma either disappears or rolls forward |
| 12:30 | US durable goods orders | First macro test after the options reset |
| 14:00 | University of Michigan sentiment | Inflation expectations may affect rate-sensitive assets |
| 15:00 | CME September Bitcoin futures settlement | Second derivatives settlement closes the sequence |
Bitcoin's rally faces three tests
The bull case has Bitcoin climbing toward $90,000 before settlement while ETF inflows continue and funding stays positive at moderate levels. Traders roll expiring calls into October and December contracts, and price holds through the durable goods, sentiment, and CME events.
Under that path, the $85,000 and $100,000 call blocks Di Bartolomeo flagged become active on the Deribit book, and buyers replace the hedging flows that expired.
The bear case has Bitcoin stalling between $88,000 and $90,000 as ETF flows slow and perpetual futures open interest stays elevated. The strength built into expiry fades once the book settles, and a firmer-than-expected durable goods or inflation-expectations reading hits a market carrying fewer hedges.
In that scenario, Bitcoin slides toward the lower edge of the implied band near $83,600, with $80,000 as the next level beneath it.
Deribit's settlement opens Friday at 08:00 UTC and CME's closes it at 15:00 UTC. Bitcoin's rally holds through that window if the buyers behind it remain in the market once every hedge tied to the expiring contracts has cleared.
The post Bitcoin faces $16 billion options expiry Friday, then two more tests hit the rally appeared first on CryptoSlate.
Europe’s central banks want the European Union to rethink a rule designed to make stablecoins safer, but that can also link a token run directly to the banking system.
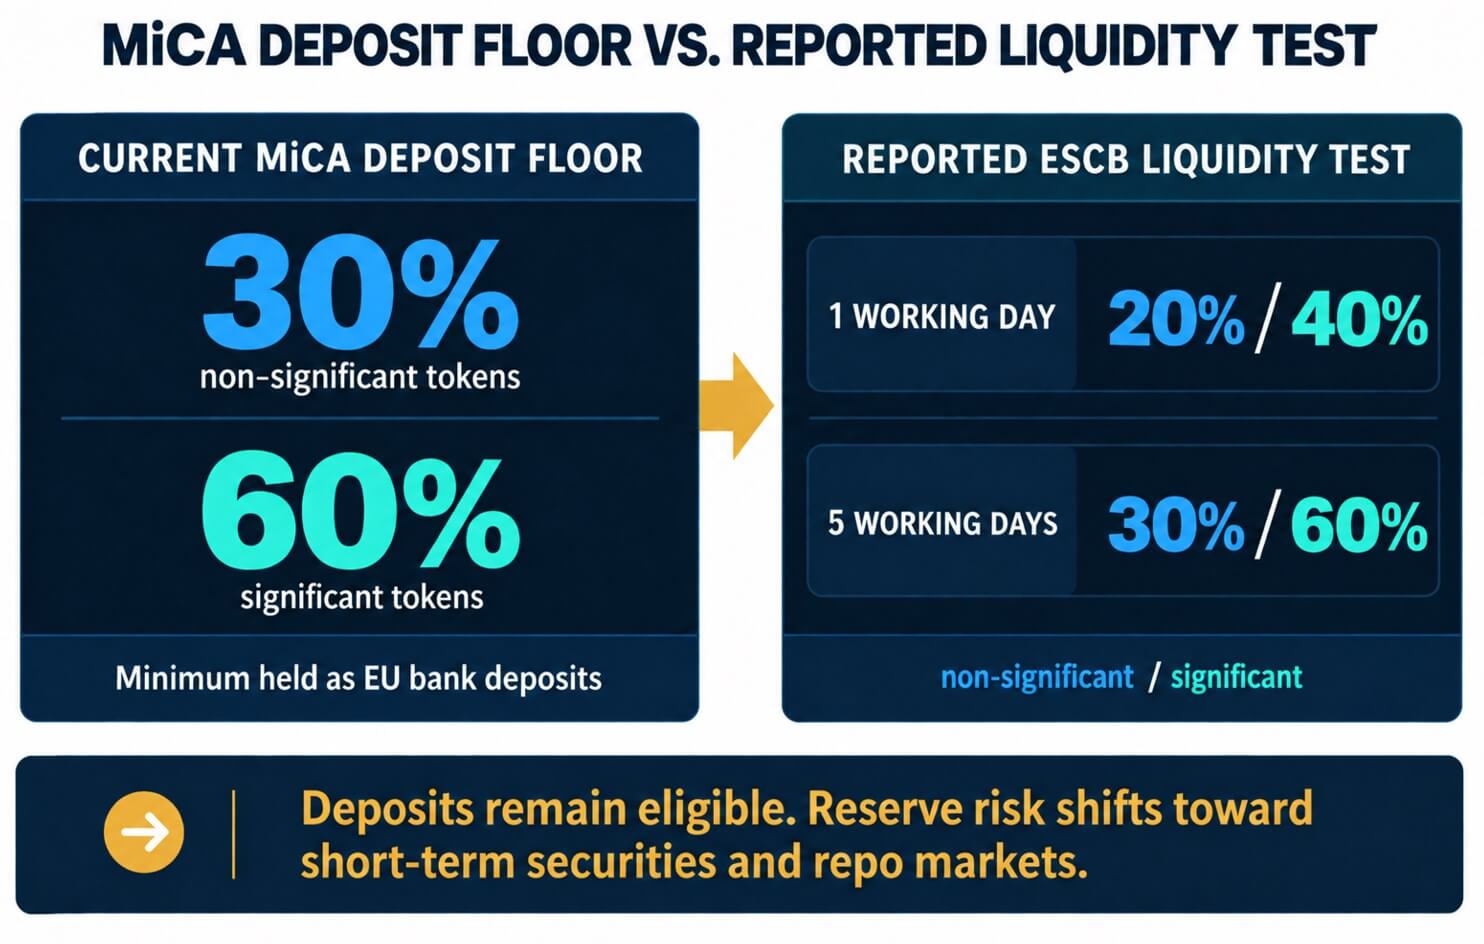
For reserve amounts tied to official currencies, MiCA currently requires issuers of non-significant tokens to keep at least 30% as deposits with EU credit institutions. The floor rises to 60% for significant tokens, according to the European Banking Authority’s technical standards.
Reuters and Cinco Días reported Sept. 22 that the European System of Central Banks wants that fixed minimum removed. Deposits would remain eligible, while reserve safety would turn on how much could become cash within one or five working days.
The position is input to the European Commission’s review of the Markets in Crypto-Assets Regulation. The consultation runs through Sept. 30, and the Commission says the responses may inform a later legislative proposal.
That leaves a policy question open: can Europe loosen the link between stablecoins and bank funding while preserving the liquidity needed for redemptions?
How MiCA’s deposit floor creates a two-way channel
Bank deposits give an issuer cash it can use when token holders redeem. Yet a deposit is also a claim on a bank, and a mandatory allocation makes the token’s reserve quality partly dependent on the condition of the institutions holding that money.
During the March 2023 banking turmoil, Circle held part of USDC’s reserves at Silicon Valley Bank, and uncertainty over access to those funds pressured the token’s peg. USDC’s market capitalization fell 26% over a month, according to an ECB analysis.
An issuer facing heavy withdrawals may pull large bank deposits at once, so stablecoin reserves that had looked like funding to a receiving bank can then behave like flighty wholesale money.
An ECB speech described how redemptions could force a stablecoin issuer to withdraw reserves and pressure a bank’s liquidity. An ECB working paper added that issuers may concentrate their deposits among a small number of banks.
Euro-denominated stablecoins had a market capitalization of about €450 million in January 2026, compared with roughly $300 billion for dollar-denominated tokens. Crypto-platform and stablecoin deposits also remain small relative to the assets of exposed euro-area banks.
The policy concern centers on the concentration and behavior of reserve deposits if adoption grows.
A fixed quota can create two reciprocal exposures. Bank distress can impair the reserves behind a token, while a token run can drain a bank's funding. The rule improves immediate access to money in ordinary conditions, but it also determines where stress first lands.
The reported ESCB alternative focuses on the redemption timetable. For official-currency tokens, it would use existing EBA liquidity buckets: at least 20% of reserves available within one working day and 30% within five days for non-significant tokens.
The thresholds rise to 40% and 60% for significant tokens. Those tests preserve a near-cash buffer while allowing issuers to meet it with a broader regulated mix of assets.
What a maturity test changes
The proposal would replace a rule about where a set share of reserves must sit with a test of how quickly the whole reserve can produce cash.
| Feature | Current MiCA framework | Reported ESCB approach | Main effect |
|---|---|---|---|
| Bank deposits | At least 30% for non-significant tokens and 60% for significant tokens | No fixed minimum deposit share | Deposits remain eligible while issuers gain allocation flexibility |
| One-day liquidity | Part of the wider reserve framework | At least 20% for non-significant tokens and 40% for significant tokens | Tests immediate redemption capacity |
| Five-day liquidity | Part of the wider reserve framework | At least 30% for non-significant tokens and 60% for significant tokens | Adds a broader near-cash buffer |
| Reserve exposure | A mandated share sits with commercial banks | More room for short-term securities and reverse repos | Bank linkage falls as market exposure rises |
Under the EBA framework, withdrawable cash and reverse repurchase agreements that can be terminated within the relevant window can count toward the thresholds. Specified highly liquid financial instruments can also qualify, while short maturity alone does not make an asset eligible.
The EBA uses Liquidity Coverage Ratio categories to identify eligible instruments. Core Level 1 sovereign and public-sector assets sit in a 0% reference-haircut category, while extremely high-quality covered bonds carry a reference haircut of at least 7%.
For reserve valuation, the rules disapply those haircuts and instead require overcollateralization to cover market-value risks.
Draft safeguards cap an issuer’s deposit at one systemically important bank at 25% of reserves and 1.5% of that bank’s total assets. Qualifying securities and money-market instruments in the 0% reference-haircut category are capped at 35% of reserves when they come from one issuer.
The change could improve issuer economics because short-term sovereign paper or repo positions may earn more than bank deposits. The result would likely shift some reserves, income, and risk toward government-debt and funding markets.
Issuers would still have to satisfy liquidity, asset-quality, concentration and overcollateralization controls.
An issuer holding short-term sovereign debt or an overnight reverse repo has less direct exposure to the failure of a particular deposit-taking bank. A redemption wave would be less likely to begin with the withdrawal of one large wholesale deposit.
Heavy redemptions can force securities sales or repo unwinds. Concentrated holdings can carry stablecoin stress into sovereign or funding markets, while falling bond prices can weaken reserve values in the opposite direction.
The ECB’s analysis of stablecoin demand for sovereign debt says the effect depends on the issuer type, its asset mix, and the sector that supplied the money used to buy the token.
Reserve design therefore allocates rather than abolishes risk. A maturity-based rule may reduce the direct bank channel, but its safety depends on the credit quality, market depth and concentration of the assets used to meet redemptions.
Tether wins one policy argument while licensing stays separate
Tether CEO Paolo Ardoino said the reported ESCB position echoed Tether’s warning about MiCA’s mandatory bank-deposit share. On that point, the company said that concentrating reserves in commercial banks can transmit distress between an issuer and a lender.
Tether’s European position includes concerns about restrictions on non-euro stablecoins and other MiCA features. The company also wound down euro-backed EURT while calling for a more risk-averse framework, and USDT remains outside the group of tokens issued under a MiCA authorization.
Removing the deposit floor would leave the broader regime in place. Issuers would still face requirements covering authorization, governance, capital, audits, reserve segregation, redemption, and prudential supervision.
The proposal would neither confer an EU authorization on USDT nor settle Tether’s broader objections to the framework.
The more consequential shift concerns control over reserve allocation. Commercial banks would lose a guaranteed share of official-currency reserves, while issuers would gain discretion within a regulated menu of deposits, short-term securities and repo arrangements.
Sovereign-debt and funding markets could receive a larger share of the assets and yield as a result.
Europe’s decision is ultimately about the architecture of redemption safety. A deposit quota emphasizes the location of reserves and anchors much of it inside banks, while a maturity test emphasizes how quickly a diversified reserve can turn into cash.
The reported ESCB position favors the second model while retaining limits on eligibility, concentration and collateral.
That framework can weaken one link in the contagion chain. Its success would depend on whether issuers can meet redemptions under stress without turning a stablecoin run into disorderly sales elsewhere in the financial system.
The post EU central banks attack MiCA rules and stablecoin runs are blamed appeared first on CryptoSlate.
Solana generated more user fees than Ethereum in data provider DefiLlama's Sept. 22 dashboard snapshot, while Ethereum burned more fees. The split shows that users' spending can reach validators and applications without producing an equivalent benefit for someone simply holding the network's coin.
The data provider's Solana overview showed about $1.1 million in chain fees over 24 hours and $117,138 in reported chain revenue. Ethereum's overview showed $649,423 in fees and $226,298 in revenue.
For these two networks, the revenue measure tracks fees reported as burned, removing tokens from supply without paying holders cash.
Solana also led on displayed seven-day and 30-day fees, while Ethereum retained a smaller lead in reported burns. Yet the dollar ranking does not settle which token offers better economics: new issuance, network value, and the share of validator income reaching stakers all change the comparison.
DefiLlama's chain fee table put Solana at $23.6 million over 30 days, compared with Ethereum's $12 million. Its chain revenue table showed a burn comparison of $2.66 million for Solana and $2.8 million for Ethereum.
| Displayed metric | Solana | Ethereum |
|---|---|---|
| 24-hour chain fees | About $1.10 million | $649,423 |
| 24-hour reported burns | $117,138 | $226,298 |
| 7-day chain fees | $5.93 million | $3.09 million |
| 7-day reported burns | $698,884 | $761,849 |
| 30-day chain fees | $23.58 million | $12.04 million |
| 30-day reported burns | $2.66 million | $2.80 million |
Exact window endpoints were not disclosed, and Ethereum's shared revenue table showed a different daily figure of $229,846. The comparison consequently applies to the displayed aggregates, with synchronization limits.
The longer windows also temper the daily headline. Ethereum's 30-day reported burn was only slightly larger than Solana's, even though its daily overview showed a much wider gap. Aggregate leadership over seven or 30 days does not mean either network led every individual day.
How fees reach validators, stakers and apps
Under Solana's fee rules, the base charge is 5,000 lamports per signature. Half of that base fee is burned, and half goes to the validator producing the block. The validator receives all priority fees, which users pay for transaction priority.
That allocation makes fee composition important. A rise in priority fees increases validator receipts without directing that stream to burning, so higher total fees can coexist with a comparatively small burn figure.
Ethereum burns execution base fees, while priority tips go to validators. DefiLlama's Ethereum data-collection code also includes blob fees in both total fees and reported burns. Two similar totals for user spending could affect supply differently, depending on the kinds of fees paid.
The data-collection programs, known as adapters, estimate parts of these reported burns. DefiLlama's Solana adapter estimates base fees by multiplying transaction count by 5,000 lamports, although the protocol charges by signature.
Ethereum's adapter uses each block's minimum effective transaction gas price as a proxy for its execution base fee and obtains blob fees separately from Dune. Neither estimate should be presented as a fully reconciled measurement of tokens destroyed.
Burning reduces supply relative to what it would otherwise have been, and it does not credit a holder's wallet, establish that total supply is falling, or guarantee a price gain. Those are separate questions from how much users paid to transact.
A validator's receipts are not automatically everyone's receipts when staking through it. Solana's staking documentation describes inflationary rewards distributed to validators and delegated stake accounts, with commissions affecting what delegators receive.
The yield also depends on total stake and validator performance. These newly issued rewards are separate from user fees.
On July 2, 2025, Solana staking infrastructure project Jito announced a live upgrade that lets validators distribute priority fees to their stakers. Validators' choices and commissions determine the distribution, and a sharing mechanism does not turn all chain fees into a uniform return for SOL stakers.
For an ordinary holder, the relevant distinction is between owning the asset and participating in a particular reward arrangement.
A passive holder receives no validator payment merely because chain fees rise, while a staker needs to know which rewards are included and what deductions apply before treating a quoted yield as fee income.
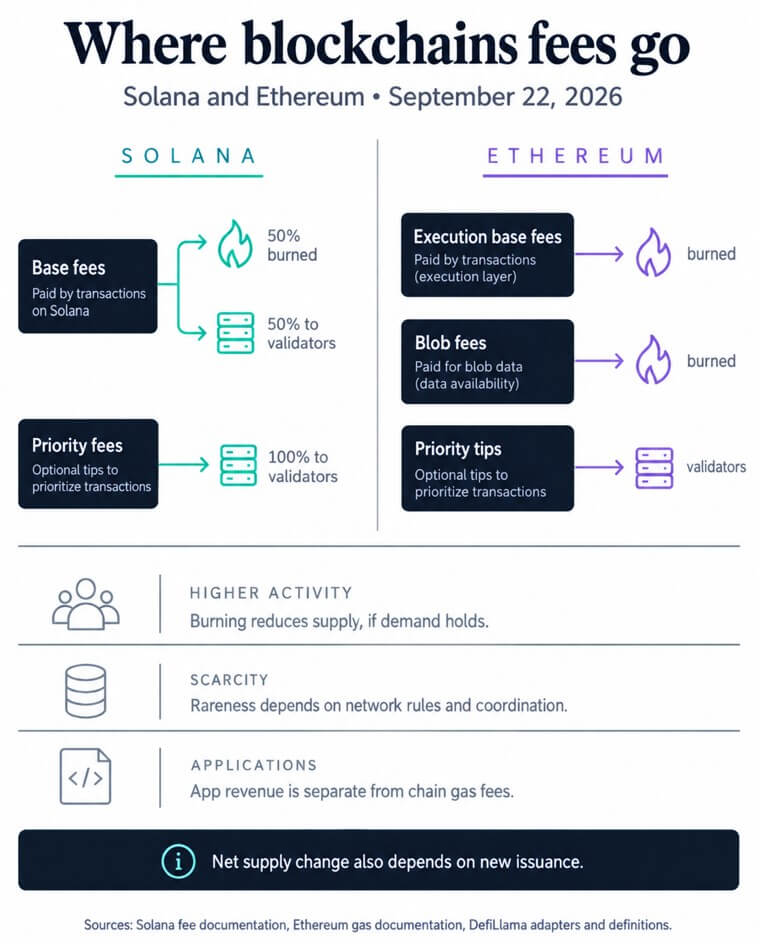
Applications represent another destination for economic activity. The Sept. 22 overviews showed $7.7 million in 24-hour app revenue on Solana versus $1.9 million on Ethereum. App fees were $18.2 million and $8.5 million, respectively.
DefiLlama's definitions separate app metrics from gas fees. They also define chain REV as chain fees plus maximum extractable value (MEV) tips. REV can describe a broader stream of transaction-related spending, but adding it to chain fees would count those fees twice.
Valuation and issuance change the investment question
Ethereum's larger dollar burn sits against a much larger token valuation. The same Sept. 22 overview snapshots displayed market capitalizations of $335 billion for ETH and $69 billion for SOL. Nearly comparable 30-day reported burns represent a larger fraction of Solana's displayed market capitalization.
A holder's yield requires a separate calculation. It compares a period's estimated burning with a valuation at one moment, and it says nothing by itself about tokens created during that period. A larger gross burn relative to market value can coexist with issuance that more than offsets it.
Ethereum's supply mechanics make that distinction explicit: net supply depends on issuance and burning. Its Merge explainer's roughly 1,700 ETH-per-day example assumes about 14 million ETH staked, so it cannot serve as a current September 2026 issuance measurement.
Without matched-period issuance for both networks, these fee tables cannot establish either a net supply advantage or a superior investment return.
Solana's accepted SGP-0002 proposal calls for increasing annual disinflation from 15% to 30%, but explicitly depends on SIMD-0550 acceptance and activation. Its current monetary effect depends on implementation.
For holders comparing SOL and ETH, the decisive missing evidence is a matched-period account of tokens issued and burned, alongside the fees actually distributed after commissions.
The September snapshot shows stronger fee generation on Solana and a larger reported dollar burn on Ethereum. Turning either observation into a return claim requires knowing how much reaches the holder, how much supply is added, and what valuation the buyer pays.
The post Solana flips Ethereum in fees, while ETH holds the burn lead appeared first on CryptoSlate.
XRP Ledger (XRPL) validators have put BatchV1_1 on a conditional path to activate at 14:06:41 UTC on Sept. 29, turning a security near-miss into a live test of the network's amendment process and its surrounding software.
On Sept. 22, xrpldashboard showed 30 of 35 trusted validators supporting the amendment, above its displayed 28-vote threshold. The majority first appeared on-ledger on Sept. 15.
Under XRPL's amendment rules, support must remain above 80% for two weeks. A fall to 80% or less ends the majority period, so the activation date remains conditional.
Sept. 29 is the first production test of whether XRPL's validator process, reference implementation, and client ecosystem converted a dangerous pre-mainnet flaw into usable atomic transaction infrastructure.
The validator firewall worked before mainnet
The original Batch amendment never activated on the XRP Ledger mainnet. In February, researchers found a critical authorization flaw while the amendment was still in its voting phase, and validators were advised to vote it down.
XRPL Labs' official vulnerability disclosure states that no funds were at risk.
The flaw sat in the loop that checked the accounts authorizing a batch. If the code encountered a signer for a newly created account whose key matched that account, it returned success immediately instead of continuing through the remaining signers.
An attacker could place that valid signer first, then add a forged entry purporting to authorize a victim account. If the amendment had gone live, the unchecked victim transaction could have executed without the victim's keys.
XRPL's response came in two stages. Version 3.1.1 marked the original Batch and fixBatchInnerSigs amendments unsupported, blocking their activation. BatchV1_1 later replaced them with a rewritten authorization path and additional defenses.
The episode was a failure caught at the boundary between software release and protocol activation.
The XRPL Foundation's final XLS-56 specification now requires a multi-account batch to contain the exact, complete set of BatchSigners whose authorization the inner transactions would ordinarily need, apart from the account whose normal signature authorizes the outer transaction.
Missing, extra, duplicate, or incorrectly ordered entries cause rejection.
Each BatchSigner also signs more than a loose collection of inner transactions. The payload binds the signature to the outer account, its sequence number or ticket, the selected batch mode, the ordered hashes of every inner transaction, and the BatchSigner account.
A multi-signed entry also binds each nested signer account. That prevents a valid signature from being lifted into a different outer transaction or reassigned to another participant.
The merged reference implementation adds enforcement around that design, including signer ordering and uniqueness checks, transaction-count bounds, rejection of directly submitted inner transactions, and protections for ledger replay.
Together, those changes address both the disclosed premature-success bug and adjacent ways that malformed or replayed batch data could cross authorization boundaries.
A Batch contains two to eight inner transactions. Each inner transaction carries no signature or fee and is marked so it cannot be submitted independently. The outer Batch selects exactly one of four modes:
- ALLORNOTHING: every inner transaction must succeed or none of their state changes commit.
- ONLYONE: the first successful inner transaction is the only one applied.
- UNTILFAILURE: transactions apply in order until one fails.
- INDEPENDENT: every inner transaction is attempted regardless of the others' results.
BatchV1_1 can support atomic all-or-nothing flows, but not every batch is atomic in that narrow sense. Developers can also use it for ordered fallbacks or independent bundles.
Activation shifts risk to implementation
The most immediate integration trap is that an outer Batch can return tesSUCCESS even when one or more inner transactions fail. Clients must inspect each inner transaction's metadata and result code to determine what happened.
That distinction is important outside ALLORNOTHING mode, where partial or independent execution is intentional.
BatchV1_1 support shipped in xrpld 3.3.0 on Aug. 6. Once the amendment activates, a server that does not understand the new rules becomes amendment-blocked. It can no longer reliably validate the ledger or participate in consensus until it upgrades.
An issue filed against xrpl.js documented that version 5.0.0 built Batch signatures using the older payload, omitting the outer account, sequence, and participant binding. BatchV1_1-enabled nodes rejected those signatures with temBAD_SIGNATURE.
The xrpl.js release history records compatible support in version 5.1.0.
| Component | Readiness point | Risk if outdated |
|---|---|---|
| xrpld | BatchV1_1 support shipped in 3.3.0 | An incompatible server can become amendment-blocked after activation |
| xrpl.js | Version 5.1.0 added the revised signing format | Version 5.0.0 can produce signatures rejected by BatchV1_1 nodes |
| Wallets | Display every inner action and the selected mode | A user may approve a bundle without understanding its full effect |
| Explorers and indexers | Preserve the relationship between outer and inner transactions | Interfaces can misreport or fragment the outcome of a batch |
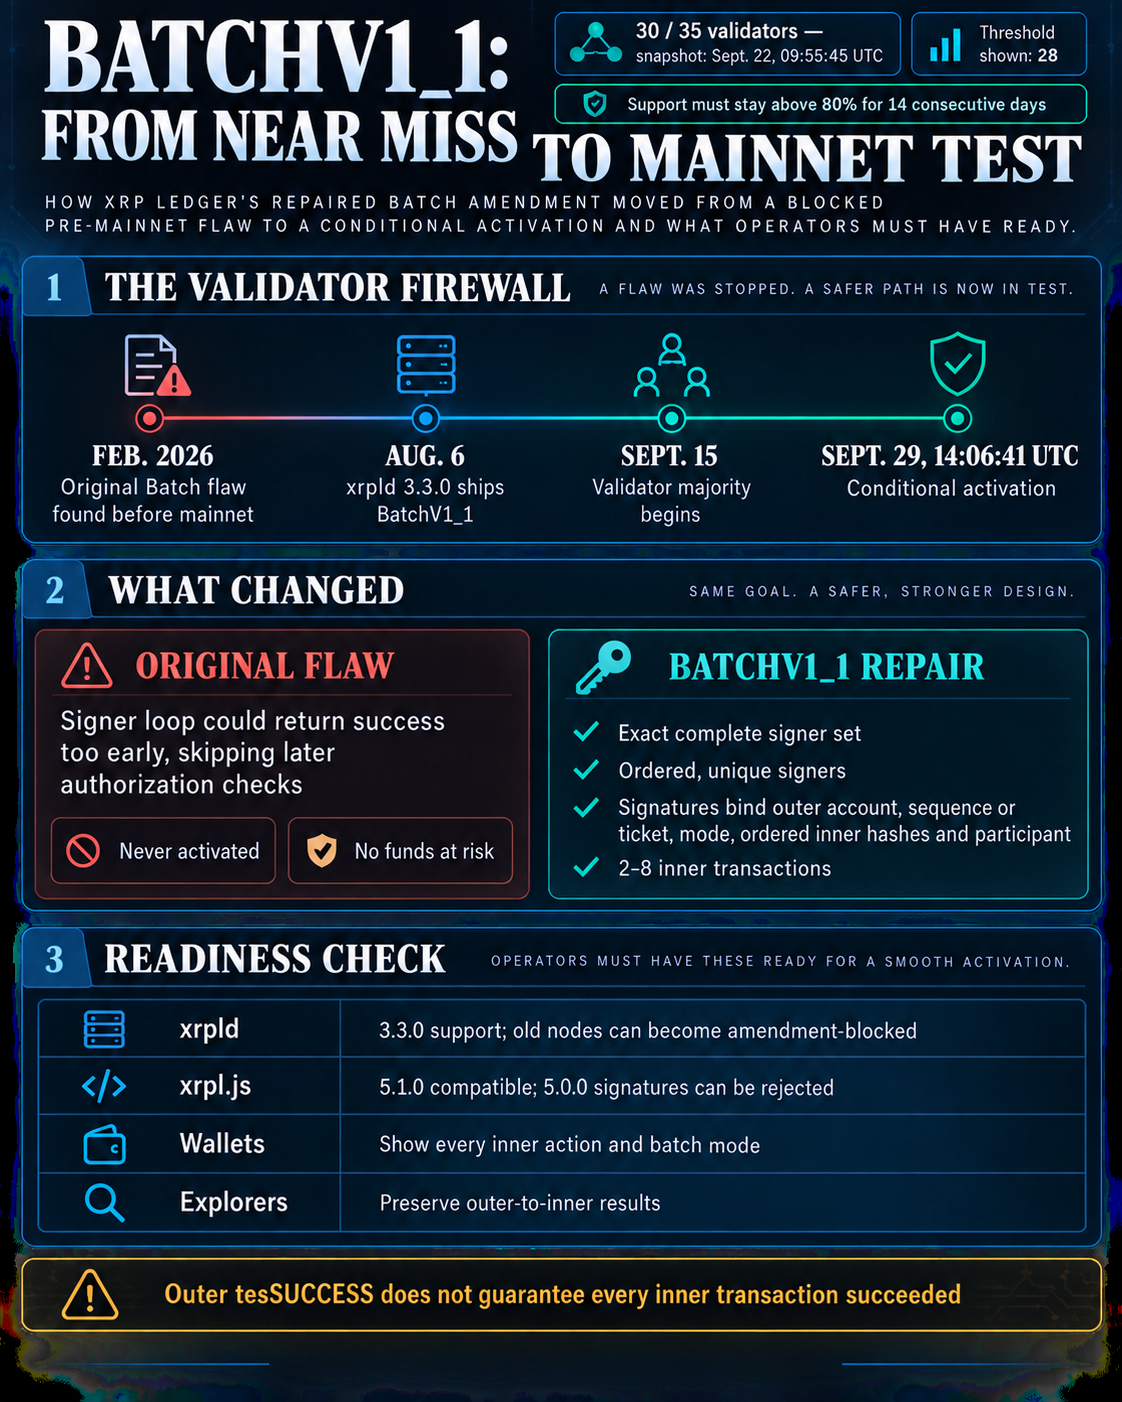
The wallet and indexer rows reflect integration guidance in the detailed XLS-56 rules. The protocol can reject a malformed signature, but it cannot force a wallet to explain a complex bundle clearly or an explorer to present every inner result in context.
The specification also flags front-running as an area still under investigation. Stronger authorization prevents a party from forging another account's approval, but it does not eliminate every risk created by packaging several market-facing actions into one ordered submission.
What Sept. 29 will prove
If the majority holds, activation will show that XRPL's validator process can stop a dangerous amendment, route operators to a disabled release and later move a repaired replacement through the same governance machinery.
It will also begin a real-world test of whether servers, signing libraries, wallets and data infrastructure agree on the new transaction format and its results.
It will not prove that applications have adopted BatchV1_1, that users want the feature, or that network transaction demand will increase. The amendment vote and software releases establish protocol availability, but they don't provide evidence of additional XRP buying.
The useful signals will come after activation: whether outdated nodes become blocked, whether signing failures cluster around old client versions, whether wallets present multi-account batches intelligibly, and whether explorers report inner outcomes without mistaking outer success for complete execution.
XRPL's validators passed the first test by preventing the original Batch flaw from reaching mainnet. The conditional Sept. 29 activation asks whether the ecosystem learned enough from that near miss to operate the replacement safely.
The post XRPL fixes critical pre-mainnet flaw, but client apps remain at risk appeared first on CryptoSlate.
CryptoTicker.io
Anyone sending their coins from one trading platform to another, or to their own wallet, loses neither the holding period nor triggers a tax. A transfer between addresses that belong to you is not a disposal, because nobody pays anything for it and the asset does not change owner. The one-year period of Section 23 of the German Income Tax Act keeps running without interruption.
The switch still gets expensive, just in a different place: the acquisition data breaks off during the transfer. The new platform does not know when you bought and at what price. Anyone not securing that beforehand faces, come the following spring, a holding with no provenance and has to explain to the tax office why the holding period is supposed to have elapsed. This article shows you what really happens for tax purposes, where the wallet-based approach bites, and which records to pull before you hit send.
Switching exchange: what the transfer triggers for tax
The short answer: nothing. Neither on sending nor on arrival does a taxable event arise, as long as sender and recipient are the same person. That follows directly from the structure of the private disposal transaction.
In its circular of March 6, 2025 on individual questions of the income tax treatment of certain crypto assets, the German Federal Ministry of Finance describes in margin number 54 what an acquisition and what a disposal is. An acquisition is the acquisition from third parties for consideration. Mirroring that, the transfer of the acquired asset to third parties for consideration constitutes a disposal. Both features are absent in a transfer to your own address: there is no third party, and no consideration flows.
Under the same margin number, a disposal arises from the exchange of crypto assets into units of a state currency such as the euro, into goods or services, and into other crypto assets. That is exactly where the distinction that matters lies. Anyone sending Bitcoin from one platform to the next has exchanged it for nothing at all. Anyone switching into a different coin along the way has sold.
Why the blockchain entry is not the moment that counts for tax
A widespread misunderstanding holds that every movement on the blockchain is relevant for tax because it is publicly visible. In margin number 20 the ministry expressly clarifies that the recorded inflow and outflow of crypto assets need not coincide with the acquisition or disposal date relevant for income tax.
The same margin number supplies the background: crypto assets are regularly traded via central trading platforms, being first transferred to the platform's personalised account and only booked back into the user's own wallet at a later point. What is then decisive is the time of the trade via the platform, not the time of the booking. The same applies where you use no wallet of your own at all and hold and trade exclusively via a platform.
For a change of platform that means: the deposit booking on the new exchange is not an acquisition date. Your acquisition date remains the day on which you originally bought the coins, and that holds even where the new platform's tax report claims otherwise.
The holding period keeps running: what that means for your year
Under Section 23 (1) sentence 1 no. 2 of the Income Tax Act, a private disposal transaction in other assets is taxable where no more than one year lies between acquisition and disposal. Once that year has elapsed, the gain remains tax free, no matter its size.
Because the transfer is not a disposal, it does not reset that period. An example makes it tangible. You buy coins on platform A on February 4. On September 20 you send them to platform B, and on December 3 onward to a hardware wallet. If you sell on February 10 of the following year, the sale falls outside the one-year period and the gain remains tax free. February 4 is the only date that counts.
Within the one-year period the threshold of Section 23 (3) sentence 5 of the Income Tax Act applies on top: gains from all private disposal transactions of a calendar year remain tax free if their total comes to less than 1,000 euros. Up to and including the 2023 assessment period this limit stood at 600 euros. Here too: once the amount is reached, the entire gain is taxable.
Ten-year holding period: why the extension does not bite with coins
A stubborn rumour says that anyone lending out their coins or earning income with them extends the holding period from one year to ten. That worry keeps many from moving their holdings at all.
Margin number 63 of the BMF circular clears it up: with currency or payment tokens, the extension of the disposal period under Section 23 (1) sentence 1 no. 2 sentence 4 of the Income Tax Act does not apply. The tax authorities took that position in the predecessor circular already and confirmed it in March 2025. For the common coins it therefore stays at one year, even where income was earned in the meantime.
The real trap: the wallet-based approach
If the transfer itself is harmless, why all the care? Because the ministry prescribes how it is to be determined which coins you actually sold. And that rule is tied to the individual wallet.
Individual identification comes first
Margin number 61 names the principle: for determining the order of use of the crypto assets disposed of, individual identification applies. So where you can attribute precisely which unit you bought when and sold again when, that is the governing route.
Where individual identification is not possible, the crypto assets of a trading designation acquired first are deemed to have been disposed of for the purposes of the holding period, and for the valuation the average method is to be applied. The ministry relies here on a judgment of the Federal Fiscal Court of November 24, 1993. For reasons of simplification it may be assumed for the valuation that the crypto assets acquired first were disposed of first, in other words the familiar FiFo method.
Where the wallet boundary runs
Then comes the sentence that becomes decisive when changing platform: a wallet-based approach applies. Within a wallet the chosen method must be retained until all crypto assets of that trading designation in that wallet have been disposed of in full. Only after a complete disposal and a subsequent fresh acquisition may the method be changed. Where crypto assets with differing trading designations are held via one wallet, a separate election exists for each.
In practice that means: spread the same coin across three addresses and you have three separate accounting circles. The order of consumption is not formed across your total holding, but per wallet. Anyone shifting holdings back and forth builds themselves a set of books that can later only be reconstructed with software and complete exports.
What really gets lost in the transfer: the acquisition data
A trading platform knows only what happened on it. When a holding arrives from outside, it sees a deposit with no prior history. Purchase price, purchase date and the order of consumption applied so far do not travel with it.
The ministry has seen this problem. On the plausibility of tax reports, margin number 90 states that adjustments and corrections do not as a rule stand in the way of plausibility where they are marked as such and substantiated comprehensibly, expressly naming as an example: because of missing acquisition costs or acquisition data on transfers to other trading platforms.
That is a relief with a condition. You may add the data later, but you have to mark the correction and be able to substantiate it. Without documents from the old platform only an estimate remains, and an estimate rarely falls in your favour. A tax tool only helps if you feed it the exports from both platforms; an overview of the providers is given by our comparison of crypto tax tools and portfolio trackers.
What to download before you send
Pull the complete transaction export from the old platform as a structured file, not as a PDF. That includes all purchases with date, quantity and price, all sales, all fees, and the withdrawal itself with transaction hash and destination address. Also secure the balance at year end: margin number 104 expressly names wallet holdings on key dates such as December 31 of the assessment period and of the previous year as details the tax authority can request.
The reason for the haste is mundane. Platforms close accounts after inactivity, withdraw from regions or disappear altogether. The export you pull today with two clicks can be a support case in a foreign language two years from now.
The special case: when the switch is a sale after all
Three variants of a platform change are taxable events after all, and to the user they look almost exactly like a harmless transfer.
The detour via a stablecoin. Anyone selling the coin on the old platform, transferring the proceeds as a stablecoin and swapping back on the new platform has triggered two disposals. Both exchanges are disposals under margin number 54, and the holding period starts afresh for the repurchased holding.
The change of wrapper. Where a coin is swapped into a wrapped variant or a network representation during the transfer, an exchange into a different crypto asset regularly exists. Whether asset identity holds in the individual case is a question of the specific design, and in case of doubt the tax authorities will assume an exchange.
The sale on delisting. Where a platform removes an asset from trading and you sell at short notice instead of transferring, that is an entirely ordinary sale with all its consequences. How tight those windows can be is something our editorial team worked through using the example of transferring delisted tokens to a fallback exchange.
Network, fees and minimum amounts: the technical part
The tax side is one half. The other is the transfer itself, and that is where the losses happen that can no longer be corrected.
The network first, then the address
The same coin often exists on several networks, and the address formats look confusingly alike. Anyone sending to the wrong network gets their balance back at best after a support case, and at worst not at all. So check first which network the destination platform supports for that asset, and select it explicitly on the sending side. Which mistakes happen most often is shown in our article on why the wrong network when sending so frequently leads to total loss.
The test transfer
Send a small amount first, wait for it to be credited, and only then send the rest. The double network fee is the cheapest insurance premium you can pay in this context. Watch the minimum withdrawal amount on the sending side and the minimum deposit amount on the receiving side, because amounts below the threshold vanish without comment into the accounting on some platforms.
What transaction fees are for tax purposes
Fees incurred on purchase form part of the incidental acquisition costs. Transaction fees expended in connection with a disposal are to be taken into account as income-related expenses under margin number 59. The plain network fee for a transfer between your own addresses, by contrast, is attributed to neither event, because nothing is bought or sold in between. Record it all the same, so that your holding adds up arithmetically after the transfer.
Where you also change the type of custody
Many change platform not because of the fees, but because they want to get their holdings off a platform altogether. That step markedly changes the legal position in the event of insolvency, because with self-custody you hold the keys yourself and depend on no segregation claim.
For tax purposes what was said above still holds: the route to a hardware wallet is also a transfer without consideration and without a third party. What changes is the evidence. On a platform the history sits in the account; with self-custody it sits with you. From that day on you are the bookkeeping yourself, and margin number 103 expressly requires documentation of reallocations within wallets for the wallet-based application of the average or FiFo method.
The checklist for the switch
Work through the points in this order and nothing gets left behind.
- Pull the complete transaction export from the old platform as a structured file and store it outside the platform.
- Note the year-end holdings of the assets concerned, for the current and the preceding year.
- Match the network on both sides and check the minimum amounts.
- Send a test transfer, wait for it to be credited, then transfer the rest.
- Record the transaction hash, destination address, date and network fee of every transfer.
- Document the chosen order of consumption for the new wallet and do not change it again while a holding of that trading designation sits there.
- Reconcile the holding after the transfer against the export before the old platform is closed.
Switching exchange and the holding period: what to take away
The transfer costs you neither tax nor holding period. It costs you traceability if you trigger it unprepared.
- Secure the history before you send. The old platform's export is the only evidence of when you bought. Without it you cannot demonstrate that the one-year period has elapsed. Which platforms deliver usable exports is shown in our exchange comparison.
- Keep the order of consumption per wallet and stick with it. The wallet-based approach is not a recommendation but the requirement from margin number 61. A tax tool calculates that cleanly if you read in both sides, see our comparison of tax tools.
- If you are moving anyway, move properly. Holdings you intend to keep for more than a year belong at an address whose keys you control yourself. Which devices are suitable for that is set out in our hardware wallet comparison.
(As of September 23, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Whether you have to pay tax on an airdrop hangs on a single question: did you do something for the coins? If you had to post on a social network, fill in a form or hand over data going beyond your wallet address, you have other income from services, and that is subject to income tax from 256 euros in a calendar year. If, by contrast, the coins landed in your wallet without any action on your part, the inflow itself is not worth any income tax, but it can fall under gift tax law. That distinction does not come from a law firm's reading, it is set out word for word in the current circular of the German Federal Ministry of Finance on crypto assets.
This article takes you through both cases, shows you which price to use for the valuation, what happens on a later sale, and which records the tax office has expected of you since the 2025 assessment period.
Airdrop and tax: the short answer first
For tax purposes an airdrop is not a category of its own. The Income Tax Act has no word for it. Instead every airdrop is sorted into one of the existing drawers, and which one it is depends solely on the relationship between you and the project handing out the coins.
Three outcomes are possible. First: you rendered a service, in which case the coins are recorded on receipt as other income under Section 22 No. 3 of the Income Tax Act, valued at the market price at the time of acquisition. Second: you did nothing, in which case a gift comes into consideration, governed by inheritance and gift tax law rather than income tax. Third: the airdrop belongs to a business, in which case it is business income. For private investors the first two cases are the rule.
The second step is the important one, and many overlook it. Selling the coins is a separate event with its own rules. Whether it becomes a taxable private disposal transaction depends on whether the inflow was an acquisition at all. That switch is thrown on receipt, not on sale.
What an airdrop is: the German finance ministry's definition
Airdrop denotes the free distribution of crypto assets to a large number of addresses. The Federal Ministry of Finance describes this in its circular of March 6, 2025 on individual questions of the income tax treatment of certain crypto assets (margin number 29) as a marketing exercise whose design can vary widely.
The circular expressly names four variants there. Participants must fill in several online forms so that customer data can be collected. Or they are meant to promote the project on social networks. With larger airdrops, sometimes only a portion of those who meet all the conditions actually receive coins, for instance after a random selection. And finally, an airdrop can take place entirely without any action by the holder of a public key.
Those four variants are not there for illustration; they form the map by which the tax office sorts your case. If you are later asked to show which variant your airdrop fell into, you will need exactly the conditions that applied at the time. This article returns to that in the section on record-keeping obligations.
The circular of March 6, 2025 replaced the older BMF circular of May 10, 2022, incidentally, and is the first to use the term crypto assets instead of virtual currencies and other tokens. Anyone still working with the 2022 version is working from a superseded text. An overview of all current airdrops and the conditions of the individual projects can be found in our airdrop overview.
The key question: did you have to do anything for the airdrop?
The term everything hangs on is service. In tax law it is drawn more widely than everyday usage suggests. Any active, passive or non-economic conduct of whatever kind can qualify as a service. A reciprocal contractual relationship between you and the project is expressly not required.
Active conduct on social media
In margin number 70 the ministry names the clearest case: where interested parties have to render a service, in particular active conduct such as naming the airdrop or the project's initiator in social media posts, other income arises. The marketing character of the exercise changes nothing about that. Anyone posting, working through a task list or recommending a project is rendering a service within the meaning of the law.
The same paragraph covers a second case that is often overlooked in practice: anyone uploading their own images, photos or videos to a platform and receiving crypto assets for it is likewise rendering a service. That applies even where ownership of those images stays with you.
Personal data beyond the public key
Margin number 71 draws a line that is easy to remember. For the mere allocation of an airdrop, your wallet's public key is technically enough. Everything beyond that is a service. If the allocation depends on you making data about yourself available that goes beyond the information required for the technical allocation, that handing over of data is your service, for which you receive crypto assets in return.
That is to be assumed at any rate where you are obliged, or have to declare yourself willing, to make personal data available. The ministry expressly distinguishes this from classic discount schemes and prize draws, where a postal address is needed for identification purposes anyway. With an airdrop it is not.
In practice that means: the email address in the sign-up form, filling in a profile, linking a social media account, stating your country and date of birth. Every one of those steps turns the supposed gift into consideration.
Airdrop in return for something: other income under Section 22 No. 3 of the Income Tax Act
Once it is established that you rendered a service, Section 22 No. 3 of the Income Tax Act applies. The coins are to be recorded in the year in which they accrued to you, in other words the moment at which you can dispose of them. The sale plays no role in this first act of taxation. That is the point at which airdrops regularly become an unpleasant surprise: the tax arises on a value that you do not yet hold in euros at that time.
The value to be applied is the market price at the time of acquisition. That amount goes into your income tax return and is charged at your personal tax rate. At the top rate that can be well over forty percent of the inflow value, while the token itself may lose value in the weeks that follow. Precisely this divergence between the moment of taxation and the moment of sale is the real risk with airdrops.
The 256 euro threshold and why it breaks sooner than you think
Section 22 No. 3 sentence 2 of the Income Tax Act contains a relief: income from services is not subject to income tax if, together with other income from services, it amounts to less than 256 euros in a calendar year.
Two features of that limit are regularly misunderstood. First, it is an exemption threshold and not an allowance. Stay below it and everything remains tax free. Reach 256 euros and the entire amount is taxable, not merely the excess. A single euro decides here whether the complete amount is taxed.
Second, it applies to all service income of a year taken together. Several airdrops add up. And they also add up with service income that has nothing to do with crypto, such as the occasional letting of movable property or other occasional intermediary services. Anyone taking part in five airdrops spread over the year and receiving coins worth sixty euros each time lands at 300 euros and is therefore fully within the scope of taxation.
Airdrop with nothing given in return: a gift rather than income tax
The second basic case is the airdrop that appears in the wallet without any action on your part. Where the allocation is not economically connected to a service, margin number 74 of the BMF circular states that a gift comes into consideration, for which the gift tax rules are to be observed.
For income tax that means: nothing happens. No inflow of service income, no 256 euro limit, no line in the annex for other income. Gift tax follows different rules with allowances of its own, which depend on the relationship between donor and recipient and apply for a period of ten years at a time. At the usual amounts of a marketing airdrop this remains practically without consequence, but the inflow has not thereby fallen into a legal vacuum.
This case is rarer than it appears in forums. The vast majority of airdrops are tied to some condition or other, even if only the linking of an account. The classic unconditional case is the token that an unrelated project distributes unprompted to a large number of active addresses without the recipients knowing about it beforehand.
Caution with tokens sent unprompted
If an unknown token turns up in your wallet with no recognisable occasion, the tax question is usually the smaller problem. Such deliveries are a common lure: the attempt to sell or swap the token leads to a doctored interface or demands an approval that makes your remaining holdings reachable. Leave tokens sent unprompted untouched and check them via a blockchain explorer first.
The element of chance: why a draw changes the calculation
Between the two basic cases lies a constellation that the ministry regulates separately. Many large airdrops work with a random selection among everyone who met the conditions. So not every participant receives coins.
On this, margin number 72 says: where the airdrop is designed so that, alongside a service, chance also decides on the receipt of crypto assets, the attribution link between service and consideration is interrupted or overlaid by the element of chance.
Translated: where chance has a say, the straight line between your conduct and the inflow that Section 22 No. 3 of the Income Tax Act presupposes is missing. That can mean that no other income arises despite a service having been rendered. Whether that holds in your case depends on how the exercise was specifically designed, which is exactly why you should secure the terms of participation while the project page is still online.
Which price to value at, and when zero euros is permissible
Where other income arises, the crypto assets are to be recognised at the market price at the time of acquisition. That is a snapshot, not an average and not a year-end closing price.
Which price source the tax office accepts
Under margin number 43, the price of a trading platform or of a web-based price list may be applied as the market price. The ministry names as examples the Börse Stuttgart Digital Exchange, Kraken, Coinbase and Bitpanda, as well as the price lists of CoinMarketCap and CoinGecko. What matters is that you document the source you choose and do not switch from one transaction to the next depending on which price happens to look more favourable.
The special case: no ascertainable market price
Freshly distributed tokens often have no tradable price at all at the moment of inflow. For that case, margin number 73 contains an express non-objection rule: where no market price can be ascertained at the time of acquisition, no objection is raised if the crypto assets received in the course of an airdrop are recognised at zero euros.
That is the most important practical relief in the whole section. Anyone receiving coins before they are listed anywhere applies a value of zero, and the later rise in value only becomes relevant on sale. The condition, however, is that you can evidence the state of affairs: the time of the inflow, the time of the first listing, a screenshot or an export file. Without that evidence, your assertion later stands against the price list the tax office calls up itself.
The sale afterwards: holding period, acquisition costs and the 1,000 euro threshold
The second moment of taxation arrives when you sell the coins, swap them into Bitcoin or another crypto asset, or pay for something with them. Each of those events is a disposal. Whether it becomes a taxable private disposal transaction is decided by a prior question: was the inflow an acquisition?
Airdrop with a service: an acquisition exists
Margin number 75 is unambiguous here. Where the allocation is made on the basis of a service within the meaning of Section 22 No. 3 of the Income Tax Act, an acquisition also exists. The acquisition costs are to be recognised at the value of the data given up or the action carried out, whereby it may be rebuttably presumed that this value corresponds to the market price of the consideration.
From the inflow onwards, the one-year holding period of Section 23 of the Income Tax Act therefore runs. Sell within a year and the gain is taxable, in other words the difference between the sale proceeds and the acquisition costs applied. Sell after the year has elapsed and the gain remains tax free. The first act of taxation under Section 22 No. 3 is unaffected by that; it already happened on inflow.
The threshold of Section 23 (3) sentence 5 of the Income Tax Act applies on top here: gains from private disposal transactions remain tax free if the total of all gains realised in the calendar year comes to less than 1,000 euros. Up to and including the 2023 assessment period this limit stood at 600 euros. This too is an exemption threshold, not an allowance.
Airdrop without a service: acquisition free of charge
Where the inflow was not consideration, you acquired the coins free of charge. In that case, under the same subsection and Section 23 (1) sentence 3 of the Income Tax Act, the acquisition by the legal predecessor is decisive. For tax purposes you step into the position of whoever acquired the coins before you, together with their acquisition date and acquisition costs.
In the practice of a marketing airdrop those details about the predecessor are next to never ascertainable. That is precisely why the question of the service is not merely a formality at the outset, but determines whether you can present a clean tax base at all when you sell. Anyone without records here ends up negotiating an estimate with the tax office.
Record-keeping obligations: what you have had to document since the 2025 assessment period
The BMF circular of March 6, 2025 contains, for the first time, a section of its own on obligations to cooperate, to keep records and to retain them. Under the application rule in margin number 106, the circular applies from its publication in the Federal Tax Gazette Part I to all open cases. Records that depart from the new requirements are no longer objected to only for assessment periods up to and including 2024. For the current year the new standard applies.
Margin number 103 lists what the tax offices can request. For airdrops there is one point there that follows directly from everything set out above: to be stated are the time of acquisition, the quantity acquired and the nature of the acquisition process, and specifically, in the case of an airdrop, expressly for the purpose of determining whether a service exists, a description of the conditions that were decisive for the allocation of the crypto assets.
The evidence list for every single airdrop
From that requirement a list can be derived which you should draw up on the day you take part, and not in the spring of the following year. The compilation comprises the name of the project and the address of the smart contract, the terms of participation in their wording as a screenshot or saved page, a note of which data or actions were demanded of you, the time of the inflow with the transaction hash, the wallet address used, and the market price together with the source, or the evidence that no price was available at that time.
In addition, margin number 103 requires documentation of the chosen order of use, in other words whether you apply individual identification, the average method or FiFo, and that for the respective wallet. Anyone who has chosen a method once should not switch it from year to year. Software takes the arithmetic off your hands; an overview of tested providers is given by our comparison of crypto tax tools and portfolio trackers. No software, however, can reconstruct the conditions of the airdrop for you once the project page has been taken down.
Where airdrop income ends up in the tax return
Other income from services under Section 22 No. 3 of the Income Tax Act belongs in Annex SO of the income tax return, in the section for services. There you enter the total of the values that accrued; you can set costs against it, such as transaction fees you incurred in collecting the coins.
Private disposal transactions from the later sale likewise belong in Annex SO, but in a different section. Both events stand side by side and concern the same holding at different points in time. A frequent error consists in forgetting the inflow and declaring only the sale, or conversely in recognising the inflow value a second time as a gain although it already forms the acquisition costs.
Losses from private disposal transactions may be offset only against gains from the same type of income, not against your employment income. Something similar applies to losses from services under Section 22 No. 3.
Four mistakes that get expensive with airdrops
The inflow is ignored because nothing was sold. The tax under Section 22 No. 3 arises at the moment of inflow. Anyone waiting until they sell declares the wrong year and risks a correction plus interest.
The terms of participation are not secured. Projects disappear, announcement pages are deleted, channels are closed. Without the conditions you can later show neither that no service was rendered nor that chance had a say.
The 256 euro limit is treated as an allowance. With 260 euros of service income it is not four euros that are taxable, but 260.
The coins are left on a trading platform with no usable export. If you cannot later pull the movements as a file, every review turns into manual work. Anyone taking part in airdrops regularly should use a platform that provides complete transaction overviews as a structured file for download, and should not try the export for the first time in the spring of the following year.
Airdrop tax: what to take away
The rules are more complicated than the picture of a gift that many projects paint. They remain manageable all the same, provided you do three things in this order.
- Settle the service question for every airdrop and put it in writing. Note on the day you take part what was demanded, and secure the conditions as a screenshot. That single note decides income tax, holding period and acquisition costs. Which trading platform will let you sell the coins at all later is best clarified beforehand, for instance via our exchange comparison.
- Record the inflow value in the year of the inflow, not in the year of the sale. Apply the market price from a source you use consistently, or document that there was no price yet. A tax tool takes over the valuation and the order of use automatically, see our comparison of tax tools.
- Move the holdings to where you can evidence them. Put coins you intend to hold for more than a year into a wallet whose keys you control yourself, and document the transfer. Which devices are suitable for that is set out in our hardware wallet comparison.
(As of September 23, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Bitcoin Cash gained around 29 percent in a single trading day on September 22, 2026, closing at 301.19 euros against 232.97 the day before on Kraken. The question everyone then asks is: buy in or wait? We did not guess at it, we recalculated it. Over the past two years there were 49 such jump days among the largest coins. Thirty days later the median case stood at minus 6.7 percent, and only 19 of 45 assessable cases were up at all. The average of plus 23.7 percent looks friendlier, but comes almost entirely from a single coin.
This analysis was compiled by cryptoticker.io on September 23, 2026. What came out of it, what the numbers do not support, and what you can actually check before buying in, is set out below.
Bitcoin Cash up 29 percent: what happened on September 22
The trigger is known. On September 22 the derivatives exchange CME Group announced that it will list futures on Bitcoin Cash and Uniswap from October 19, subject to regulatory review. Standard contracts of 250 BCH and 10,000 UNI are planned, alongside micro contracts of 25 BCH and 1,000 UNI. This follows from the CME Group announcement of September 22, 2026. We reported the announcement the same day and set out the contract details there.
A future is an exchange-traded forward contract: buyer and seller agree a price today for delivery or a cash settlement at a later date. For professional investors it is above all a hedging instrument, and that is precisely where the expectation that moved the price lies: anyone holding large positions will be able to hedge them on a regulated US exchange from October.
On the morning of September 23, Bitcoin Cash is quoted at 302.12 euros on Kraken. The range over the past 24 hours runs from 230.35 to 317.87 euros, measured at 07:20 UTC. Uniswap stands at 9.14 euros. In dollar terms, CoinGecko shows Bitcoin Cash up 30.8 percent over 24 hours at the same moment, and Uniswap up 16.8 percent. The small divergences from our figures are no contradiction: we work with daily closing prices in euros, CoinGecko with a rolling 24-hour window in dollars.
Method: where the data comes from and what was counted
The data base is the daily closing prices of the euro trading pairs on Kraken, retrieved on September 23, 2026 via the exchange's public OHLC interface. OHLC stands for open, high, low and close of a given period. The request delivers up to 721 daily candles per trading pair and therefore reaches back to October 3, 2024.
Nineteen trading pairs were examined. They cover the coins in the current top 25 by market capitalisation for which Kraken runs a euro pair, stablecoins excluded. A jump day is any day on which the closing price was at least 20 percent above the previous day's close. For each of those days we set the closing price 7 and 30 calendar days later against the close of the jump day itself.
Two things we could not check. First, coins without a euro pair on Kraken are missing, which in the current field means Dogecoin and LEO. Second, the history is not equally long everywhere: BNB reaches back to April 2025, Hyperliquid to January 2026, Whitebit Token to March 2026. A coin that only became tradable later can simply contribute fewer jump days within this window. Four of the 49 jump days sit too close to the present to have a complete 30-day window; they feed into the overview, but not into the 30-day analysis.
49 jump days in two years: which coins were affected at all
A 20 percent gain in a single day is no everyday event among the large coins, but no rarity either: 49 cases in just under 24 months works out at a good two per month, spread over 13 different coins.
The distribution is anything but even. Zcash alone accounts for 14 of the 49 jump days, Uniswap and Stellar for six each, NEAR for four, and Cardano, Bitcoin Cash, Dogecoin and XRP for three each. Ethereum, Solana and Tron come to one apiece. And six coins in the field had no jump day at all during their respective observation period: Bitcoin, BNB, Monero, Litecoin, Hyperliquid and Whitebit Token.
That is already a finding in itself. Anyone waiting for large daily moves waits in vain with Bitcoin. The jumps happen in the second tier, and there they cluster in a handful of assets that happen to have a story of their own.
Seven days after the jump: a coin toss
For 46 of the 49 jump days the price can be measured a week later. The result is remarkably unspectacular: the median stands at plus 0.1 percent. The median is the middle value of a sorted series, in other words the case where one half does better and the other worse. Unlike the average, it barely reacts to individual outliers.
In 23 of 46 cases the price stood higher seven days on than on the evening of the jump day, and lower in 23 cases. Exactly half. Anyone buying a week after a jump day in the hope of a continuation is betting on a coin toss.
Thirty days after the jump: the median case loses
After 30 days the picture turns negative. This window can be assessed for 45 jump days. The median stands at minus 6.7 percent, and only 19 of the 45 cases were up at all. In 11 cases the price had after a month fallen even below the level that applied before the jump. The whole move had therefore not merely fizzled out, but turned negative.
The spread is enormous. The bottom quarter of cases stood at minus 23.3 percent or worse after 30 days, the top quarter at plus 44.9 percent or better. The weakest single case lost 47.2 percent, the strongest gained 266.6 percent. That dispersion is precisely why an average figure misleads here.
Why the average deceives: a single coin carries the entire gain
The arithmetic mean across all 45 cases is plus 23.7 percent. That sounds like a durable continuation. Break the sample apart and little of it survives.
Excluding Zcash, 32 cases remain. Their median is minus 12.5 percent, their mean minus 0.4 percent, and only 10 of 32 stood higher after 30 days. The 13 assessable Zcash cases, by contrast, come to a median of plus 77.4 percent, 9 of them up. The reason is the coin's run in the autumn of 2025: after the jump day of October 8, 2025, Zcash stood 266.6 percent higher 30 days later, after October 1 it was 241.5 percent, and after October 4 it was 182.6 percent.
Such runs exist, and they are why the story of the jump as a starting gun survives so stubbornly. Statistically they mean the opposite of what they suggest: an average carried by a single episode describes no normal case, but an exception.
The bigger the jump, the worse the outcome
One pattern withstands the breakdown, and it is uncomfortable for anyone hunting large moves. Sort the jump days by size and the result deteriorates as the jump grows.
The 21 cases between 20 and just under 25 percent come to a median of minus 11.5 percent after 30 days, with 7 of 21 standing higher. The 12 cases at 30 percent and above sit at minus 20.8 percent in the median, 5 of 12 up. Bitcoin Cash's jump of 29.3 percent lies right on the boundary between the two groups.
Bitcoin Cash and Uniswap: what their own history shows
For the two coins at issue today, a look into their own past is worthwhile. Bitcoin Cash had two jump days in the observation period before September 22. On March 5, 2025 the price gained 20.0 percent and stood 24.2 percent lower 30 days later. On August 21, 2026 it was 29.2 percent, and a month later the price lay 10.8 percent below that. On both occasions the jump had not held after a month.
Uniswap brings six jump days with it, and here the picture is split. The jump day of November 6, 2024, at plus 31.6 percent, led to a further 92.0 percent within 30 days. The one of November 10, 2025, at plus 41.2 percent, ended 40.3 percent lower. The remaining four lay between minus 13.6 and plus 2.1 percent.
No forecast can be derived from this, and this article does not attempt one. What can be derived is the order of magnitude of the risk you have to reckon with if you buy in after a day like that.
Check the buying route: MiCA licence, euro pair and fees
If you want to buy after a jump day, the route decides the outcome first. Since January 1, 2026, providers of crypto asset services in Germany need authorisation from BaFin or a valid MiCA licence from another EU state with passporting. MiCA stands for Markets in Crypto-Assets, the EU regulation that governs trading in crypto assets on a uniform basis.
In practice that means: check whether your provider is licensed, whether it runs a euro pair for the coin in question at all, and what the purchase ends up costing. Without a euro pair the purchase runs through an intermediate step in dollars or a stablecoin, and a fee hangs on every step. Which exchanges are licensed for German customers and what they charge for trading can be found in our comparison of the best crypto exchanges.
On a day with 30 percent of movement, a second block of costs is added that many overlook: the spread, in other words the difference between the buying and selling price. It widens in fast markets. The 24-hour range for Bitcoin Cash ran from 230.35 to 317.87 euros. Anyone reaching for a market order inside a band that wide pays the price currently in the book, not the one seen on screen.
Leverage and liquidation: why a jump day shifts financing costs
Large daily moves shift the cost of leveraged positions. With perpetual futures, the perpetuals, the funding rate keeps the contract price anchored to the spot market: if there are more buyers than sellers in the market, the buyers pay the sellers on a running basis. After a jump upwards this rate is typically positive, and it runs against you for as long as you are long.
The second point is liquidation, the forced closure of a position once the margin no longer suffices. A pullback of 20 percent sits, on the numbers of this analysis, within the normal range. At fivefold leverage a counter-move of 20 percent is arithmetically enough to wipe out the deposit entirely. Anyone working with leverage should therefore know what financing costs and what liquidation thresholds their provider applies; an overview is set out in our comparison of the best perp DEX.
Holding period and tax: what a quick trade triggers in Germany
For tax purposes the difference between a quick trade and a long holding period is considerable in Germany. Gains from the sale of crypto assets fall under private disposal transactions pursuant to Section 23 of the Income Tax Act. Anyone selling within a year of buying pays tax on the gain at their personal income tax rate, provided the exemption threshold is exceeded. After twelve months of holding, the sale is tax free.
Anyone buying in after a jump day and selling again a few weeks later therefore always lands in the taxable range. That applies to a swap into another coin as well, since a swap is also a disposal. Since January 1, 2026, crypto asset service providers additionally report their customers' identity and transaction data to the Federal Central Tax Office; the first report for the 2026 period follows in 2027. Clean records of every transaction are no longer optional. Which tools automate that is shown in our comparison of crypto tax tools.
Custody after the jump: exchange account or your own wallet
A third point often gets lost in the excitement of a jump day. Coins you leave sitting in an exchange account belong to you economically, but lie within the provider's power of disposal. Anyone who wants to trade needs them there. Anyone who wants to hold a position for longer can transfer it to their own wallet and keep the keys themselves.
The transfer costs a network fee and is not a sale for tax purposes, as long as the coins continue to belong to you. For the holding period, the original acquisition date counts, not the date of the transfer. All that matters is that you carry the acquisition data with you and can evidence it.
Levels up and down: which marks now count for Bitcoin Cash
No forecast, but measured levels: on the downside, the closing price before the jump is the first relevant mark, which for Bitcoin Cash means 232.97 euros from September 21. If the price falls back there, the jump has been given up in full. That is exactly what happened within 30 days in 11 of the 45 cases assessed.
On the upside, the 24-hour high of 317.87 euros is the next mark, with the jump day's close at 301.19 euros as an intermediate level. The current price of 302.12 euros sits practically on that close. The date that actually matters lies in October in any case: the CME contracts are due to start on October 19, subject to regulatory review.
Limits of the analysis: what these numbers do not show
Honesty about the limits is part of running your own survey. Forty-five assessable cases are a small sample, and it comes almost entirely from a market phase of rising prices. A different market phase can deliver different results.
The analysis also says nothing about the cause of a jump. Whether an exchange listing, a protocol upgrade or pure positioning sits behind a given day, it does not distinguish. And it measures daily closing prices: what happened between two closes remains invisible. Anyone deriving a rule for the individual case from this overstretches the data. What the numbers deliver is a sense of the order of magnitude.
Putting a price jump in context: what to take away
- Work with the median, not the average. After 30 days the median case stood at minus 6.7 percent, and without the Zcash anomaly at minus 12.5 percent. If you still want to buy, first check your provider's licence, euro pair and fees in the comparison of the best crypto exchanges.
- Treat leverage after a jump day as its own risk class. A pullback of 20 percent is normal on this data, and at fivefold leverage it is arithmetically enough for liquidation. Which funding costs and liquidation rules apply is set out in the comparison of the best perp DEX.
- Keep the tax question clean from the outset. Buying now and selling a few weeks later is a taxable private disposal transaction in Germany. Record every transaction with date, quantity and price; that can be automated with the tools from our comparison of crypto tax tools.
(As of September 23, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
When you place a sell order on a crypto exchange and the platform rejects it without comment, the fault is rarely yours. More often the trading pair sits in a state that the exchange itself publishes, but which appears nowhere on the buy screen. The most important of these states is called cancel only, and it means this: existing orders can only be cancelled, new ones are no longer accepted. You cannot sell in that pair any more.
This analysis was compiled by cryptoticker.io on September 23, 2026. We pulled the public market directories of three trading venues and counted the status fields programmatically. The result at Kraken: 82 of 1,450 trading pairs are listed as cancel only, spread across 45 underlying assets. The delisting notice of August 27, which we reported on September 3, named 21 tickers. The remaining 24 assets appear in no announcement we could find.
What cancel only means at a crypto exchange
Every trading pair on an exchange carries an operating state. Kraken publishes it in the status field of its public market directory and lists five possible values in its own API documentation. Three of them are worth knowing.
online is the normal case: the order book accepts buy and sell orders, market and limit orders work as usual. cancel only, according to the documentation, means that only the cancellation of existing orders is permitted. A new order, in either direction, is rejected. post only allows only orders that are placed into the order book and are not executed immediately against an existing counterparty. A market order fails there, and so does a tightly set limit order.
The decisive difference from a delisting: a delisting is an announced decision with dates, which the exchange communicates to its customers. A status change to cancel only is, at first, no more than a technical state in the order book. It can be the run-up to a delisting, it can be the aftermath of a trading halt already carried out, and it can be a temporary measure. From the outside, the status field alone does not tell these apart, and that is precisely where the practical problem lies for you as a holder.
Our September 23, 2026 count: 1,450 trading pairs reviewed
The method in one sentence: on September 23, 2026, at around 4:00 UTC, we pulled the public market directories of Kraken, Bitvavo and Coinbase Exchange and counted the status fields reported by the exchanges themselves for each trading pair. All three requests returned HTTP 200.
At Kraken the directory covered 1,450 trading pairs. Of these, 1,351 were online, 82 cancel only and 17 post only. Mapping the pairs back to their underlying assets gives 623 normally tradable assets, 45 assets in the cancel only state and 11 in post only.
The 82 blocked pairs break down into 37 euro pairs, 44 dollar pairs and one pair against a stablecoin. For an investor in Germany the euro figure is the more relevant one: in 37 cases the direct route back into euros via the order book is currently shut. Anyone who bought these assets in euros cannot swap them back into euros that way.
45 underlying assets on cancel only: which tickers are affected
Kraken names the assets in the directory by ticker only. These 45 underlying assets were listed as cancel only at the time of our count, in alphabetical order: ACA, ACX, AI3, BKS, BNC, CLV, CQT, CXT, EGLD, EPT, ESX, GAIA, GHIBLI, HDX, HIPPO, HOUSE, IR, JUNO, KEY, KIN, KOBAN, KP3R, LOCKIN, M, MAT, MIR, MNGO, MULTI, NTRN, OMNI, RBC, RIZE, SBR, SCA, SIDEKICK, SLAY, TEA, TREMP, U2U, VANRY, VULT, WEN, WMTX, XTER and YALA.
Several of these tickers are short and therefore ambiguous. M, IR and KEY can hardly be identified with confidence without the full project name, and the exchange does not carry it in the directory. If you see one of these tickers in your account, match it against the project name in your portfolio view before you decide anything.
24 assets with no announcement: how our list differs from Kraken's notice
On September 3 we reported on a Kraken notice dated August 27 in which the exchange ended trading in 21 tokens as of September 11. Our article on the Kraken trading halt for 21 tokens lists the tickers in full. We set today's measurement against that list.
All 21 announced assets are on cancel only today: ACA, BKS, BNC, CQT, CXT, EPT, GAIA, HDX, IR, JUNO, M, MAT, MIR, MULTI, RBC, RIZE, SBR, SCA, VANRY, VULT and XTER. The state matches the announcement, since trading stopped on September 11 while the balances remain in the accounts.
The remaining 24 assets do not appear in that notice: ACX, AI3, CLV, EGLD, ESX, GHIBLI, HIPPO, HOUSE, KEY, KIN, KOBAN, KP3R, LOCKIN, MNGO, NTRN, OMNI, SIDEKICK, SLAY, TEA, TREMP, U2U, WEN, WMTX and YALA. Seventeen of them have a euro pair that is likewise on cancel only. Among them are assets that are no footnote in the market, such as EGLD, NTRN and KP3R.
What this means needs to be kept cleanly apart. What is documented: these 24 underlying assets carried the cancel only status at the time of our count, and we did not find them in the delisting notice cited above. What is not documented: why they carry that status. It could be a later notice that we do not have, a technical measure, or a quiet clean-up. We do not impute to the exchange an intention we cannot evidence. For you, though, the cause changes little about the practical finding: selling through the order book is currently impossible in these pairs.
post only and limit only: two further states that reject your order
Alongside cancel only there are two milder states that still cause a routine order to fail. At Kraken, 17 pairs were on post only, spread across eleven underlying assets: AIO, AKE, AUSD, BOS, EURR, GAIB, NODE, RLUSD, USDR, VELVET and XBT against USDR. It is striking that several value-referenced tokens and stablecoins are among them.
In practice, post only means this: a market order is rejected. You have to set a limit order that is not executed immediately, in other words above the best ask or below the best bid. Anyone unaware of the difference will take a rejected order for a bug in the app. At Coinbase Exchange we additionally found 23 products in the limit only state, in which nothing but limit orders is accepted.
Bitvavo and Coinbase Exchange: what halted, delisted and trading_disabled mean there
To put the Kraken figure in context, we counted two further trading venues using the same method. The states go by different names there, and the orders of magnitude are far apart.
Bitvavo listed 438 markets. Of these, 437 were on trading and a single one on halted, namely WMTX against the euro. That is the most revealing individual finding of the survey, because WMTX also appears on Kraken's list of blocked assets. Anyone holding this token currently finds no working euro order book at either venue.
Coinbase Exchange listed 838 products. Of these, 515 were online and 323 carried the delisted marker and were flagged as not tradable at the same time. Those 323 are not a snapshot of a current event, however: Coinbase keeps permanently discontinued products in the directory, so the number is an archive rather than a fresh occurrence. The meaningful slice is the euro pairs. Of 87 listed euro pairs, 54 were not tradable, leaving 33 usable euro order books.
That figure fits a survey of our own published on August 17, 2026: at that point 34 of 399 assets at Coinbase Exchange had a euro order book. The finding on euro trading pairs at four venues comes from our own house and is therefore not an independent confirmation, but a continuation of the same series of measurements. We cite it with date and origin so that you can place the numbers.
How to check your own account in five minutes
The list above is no substitute for checking your own portfolio, because status values change. Here is how to go about it.
First open the holdings overview of your account and note every asset that is not one of the large, broadly traded coins. Then, for each of those assets, try a limit sell order at a price well above the market, in other words an order that will not be executed. If it is accepted, the pair is tradable and you cancel it again. If it is rejected, the pair sits in a restricted state. The order of operations matters here: test first with an order that cannot be executed, not with a market order.
Also check whether the asset has an active euro order book at a second venue accessible to you. If it does, moving is an option. If it does not, that route falls away and only a withdrawal to your own wallet remains. If you are looking for a second venue, our overview of the best crypto exchanges helps with the choice, because it also lists euro connectivity and withdrawal routes.
Withdrawal instead of selling: which way out remains under cancel only
A blocked trading pair says nothing about whether withdrawing the balance still works. These are separate functions, and as a rule the withdrawal stays open longer than trading does. In Kraken's August 27 notice, three months lay between the trading halt on September 11 and the end of the withdrawal window on December 10.
That gap is the deadline that actually matters. Once it has passed, an exchange may liquidate a residual balance itself, and the proceeds of such a liquidation can be very low, because no liquid market need exist for it any more. For you, a clear order of operations follows: first establish whether a withdrawal window is running, then act. In the case of the stablecoin USDP being dropped by another exchange, which we reported on September 10, several weeks likewise lay between the end of trading and the end of the deadline.
If withdrawal is technically impossible because the network has been switched off on the platform, contact customer support and document the process with date and time. You may need that documentation later, in dealings with the tax office.
Self-custody after the withdrawal: what to watch with your own wallet
Withdrawing to your own wallet is often the only route left when a trading pair is blocked, and it shifts responsibility entirely onto you. Three points decide whether that goes well.
First, the wallet must support the specific network the token sits on. Many of the affected assets are not large coins with a chain of their own, but tokens on someone else's chain. Second, you need a small amount of that chain's native currency in order to be able to move the token at all later on. Anyone who withdraws only the token and keeps no fee reserve has it safely in custody but can no longer send it. Third, the recovery phrase belongs somewhere outside every device that is connected to the internet.
Which device makes sense for that depends on how many different chains you need to cover. Our hardware wallet comparison lists the supported networks per model, and with smaller tokens that is exactly the decisive point.
Tax on blocked pairs: what Section 23 of the German Income Tax Act does to the holding period
A blocked trading pair does not pause the holding period. Under Section 23 of the German Income Tax Act, the one-year period keeps running from the date of acquisition, regardless of whether you can currently sell the asset. For gains that is favourable, since after the year has elapsed a sale from private holdings is tax free.
With losses the picture reverses. A loss only takes tax effect once it is realised, and it is realised through a disposal. When the order book is closed, that is precisely what you cannot do. The loss stays on paper, and it cannot be set this year against gains from other private disposal transactions. Anyone who had counted on that should review their planning for the current year.
If the exchange liquidates a residual balance itself once the deadline has passed, that too is a disposal, only without your decision on the timing. The proceeds and the date then appear in the exchange's statement, and both belong in your records. Keep the documentation complete, because with small, illiquid assets tax tools frequently lack the price data, and then your own evidence is all that counts.
The December 31, 2026 cutoff date: why a blocked sale can get expensive
A draft bill from the German finance ministry proposes bringing crypto assets under the flat-rate withholding tax in future, while holdings acquired up to December 31, 2026 would remain under the existing rules. We have set out the details in our article on grandfathering and the December 31, 2026 cutoff date. None of it has been enacted; this is a draft.
For the case described here, a practical consideration follows all the same. Anyone wanting to reshuffle an asset before the end of the year in order to tidy up their tax position needs a functioning order book to do it. If the pair is blocked and no second venue exists, that option drops out, regardless of how the legislation ends up. That is no reason to rush, but it is a reason to look through the portfolio now rather than in December.
Limits of this analysis: what we could not check
We reviewed 1,450 trading pairs at Kraken, 438 markets at Bitvavo and 838 products at Coinbase Exchange, 2,726 entries in total, each on September 23, 2026 and each with HTTP 200.
Four things we could not check. We know the reason for not a single status value, because the directories do not supply it. We placed no test orders, but counted only the states reported by the exchanges themselves. We do not know whether a withdrawal window is running for the 24 unannounced assets, or when it ends. And we did not check whether the display in the apps and in the simplified buy screens reflects the same state as the order book, which in our experience can diverge.
Status values are snapshots, too. A pair that is on cancel only today can be online again tomorrow. The figures in this article therefore carry a date, and your own check inside the account cannot be replaced by any list.
Checking blocked trading pairs: what to take away
- Go through your holdings for small assets. For every asset outside the large coins, use a limit order that cannot be executed to test whether the order book accepts orders. If it is rejected, the pair sits in a restricted state. You will find a second venue with euro connectivity in our overview of the best crypto exchanges.
- Establish the withdrawal deadline before you do anything else. The trading halt and the end of withdrawals are two different dates, and only the second determines whether you still keep your balance in your own hands. If you are switching provider, the licensing is worth a look, which we set out in our comparison of regulated crypto exchanges.
- Prepare self-custody while the withdrawal is still running. Check in advance that your wallet supports the chain in question, and put aside a small fee reserve in the network's currency. Which devices cover which networks is set out in our hardware wallet comparison.
Anyone who checks the state of their portfolio regularly notices a status change like this while routes are still open. Anyone who only looks when trying to sell notices it on the day when none are left.
(As of September 23, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Why Is the Cardano Price Up 30% This Week?
$Cardano has woken up in a big way. On September 17, ADA was trading around $0.196. Today it's sitting at $0.258 after tagging an intraday high of $0.262, which works out to a gain of roughly 31% in just seven days. That puts ADA among the strongest large caps of the week and well ahead of Bitcoin's own rebound.
The rally didn't come out of nowhere. The broader market has turned risk-on again, with $Bitcoin climbing as much as 7.7% to above $87,000 on September 23 while several large-cap altcoins moved higher as demand returned across the market. But $ADA isn't just riding the tide. It's clearly outrunning it, and that has traders asking whether this Cardano rally is the start of something bigger.
You can follow the move live on the CryptoTicker ADA chart.
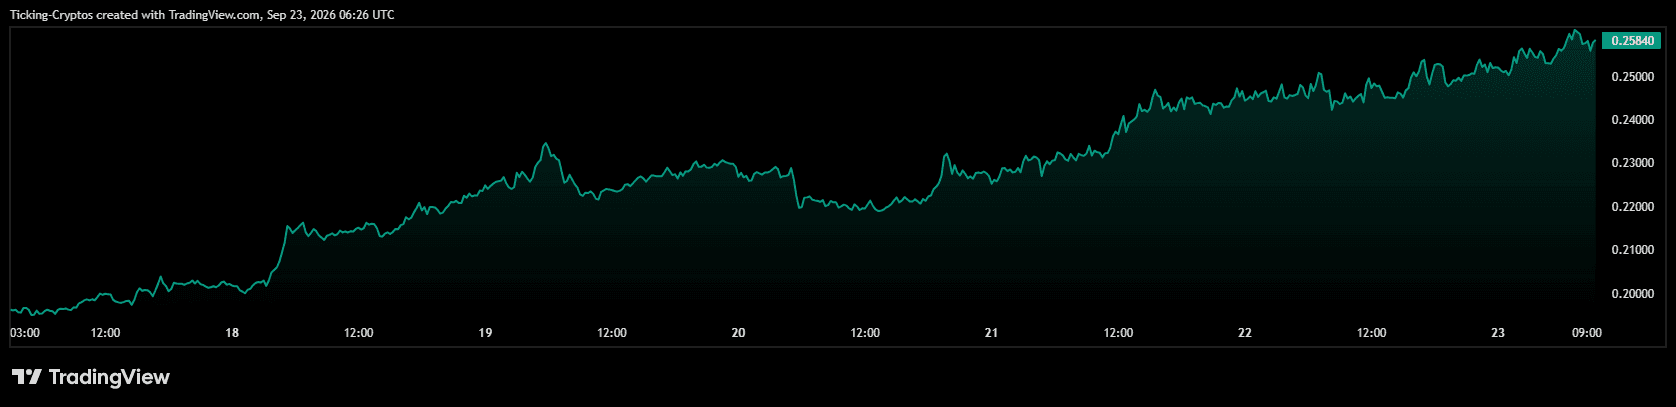
What Is Driving the Cardano Rally Behind the Scenes?
Three forces are stacking up at the same time: derivatives traders piling in, shorts getting squeezed, and a genuine uptick in network usage.
On the derivatives side, CoinGlass data shows ADA open interest across exchanges has surged since mid-September, with outstanding contracts reaching 2.37 billion ADA. Cardano's funding rate also flipped positive on September 17 and climbed to 0.010%, meaning longs are now paying to hold their positions. Rising open interest alongside rising price usually signals fresh money entering, not just old positions shuffling around.
Bears have been paying the bill too. Shorts accounted for more than 80% of liquidated ADA positions, with $2.49 million of the $3.28 million liquidated over 24 hours coming from bearish bets. Every forced short closure is a market buy, which adds fuel to an already moving price.
On-chain, the picture is also brightening. CardanoScope recorded 33,919 transactions on September 21, up 71% from the weekly low of 19,844 on September 16, while active addresses hit a weekly high of 16,388.
What Cardano News Is Fueling the Sentiment?
The biggest narrative this week is payments for AI agents. The Cardano Foundation announced on September 21 that Cardano is now part of the official x402 SDK, allowing any app or AI agent to pay for an API call in ADA or any Cardano native token over a web request, with no account, API key or checkout page needed. This builds on the earlier launch, as the x402 payment protocol went live on Cardano on September 11.
It's also worth remembering where ADA is coming from. In late June, a flaw in the third-party SecondFi wallet (formerly Yoroi) exposed private keys, compromising roughly 16 to 20 million ADA across hundreds of wallets. That headline weighed on sentiment for weeks, so this week's rally also looks like the market finally moving past that chapter.
ADA Price Analysis: Major Breakout
After bottoming near $0.139 in late June, ADA has spent three months printing higher lows: roughly $0.155 in late July, $0.175 in mid-August and $0.19 in mid-September. That's a textbook recovery structure.
This week, ADA smashed through two major barriers in one move:
The 200-day EMA at $0.239 had been sloping downward and capping every rally since spring. On August 22, ADA spiked above it intraday but got rejected hard, falling back toward $0.19. This time, price has closed several daily candles above the ADA 200 EMA, which is a much stronger signal.
The $0.245 horizontal level is just as important. It acted as support in April and May, then turned into resistance after the June breakdown. Reclaiming it flips that zone back into support.
Together, these two levels form a support cluster between $0.239 and $0.245. As long as ADA holds above it, the bulls stay firmly in control.
Is the ADA Price Overheated After the Rally?
Here's the catch. The daily RSI is sitting at 72.89, which is officially overbought territory. The last time RSI pushed this high was in late August, right when ADA spiked into the 200 EMA and then dropped nearly 25% over the following weeks.
Overbought doesn't mean the rally is over. Strong trends can stay overbought for a while. But it does mean the easy part of the move is probably behind us, and a pause or pullback toward the $0.245 zone to cool things off would be perfectly healthy. With funding turning positive and leverage building, a sharp shakeout of late longs is also on the table.
Keep an eye on the US macro calendar as well. A US economic event is flagged on the chart for later this week, and any surprise could hit risk assets across the board.
What Are the Next ADA Price Targets?
If the breakout holds, these are the levels to watch on the way up:
- $0.262: Today's high and the first hurdle. It also lines up with the top of the August 22 wick.
- $0.285: The May swing high and the last major peak before the June crash. A daily close above it would confirm ADA is back in its spring range.
- $0.30: The big psychological target and a key horizontal resistance on the chart. This is where many traders will likely take profit.
- $0.35: The extended target if momentum really takes off. It would require a sustained altcoin run and continued strength in Bitcoin.
What Is the Cardano Price Prediction for the Coming Weeks?
- Bullish scenario: ADA holds the $0.239 to $0.245 support cluster, breaks above $0.262 and pushes toward $0.285 before testing $0.30. With open interest rising and shorts still getting squeezed, this is the path of least resistance as long as Bitcoin stays firm.
- Base scenario: ADA cools off after the overbought reading and consolidates between $0.24 and $0.26 for several days. That would let RSI reset and set up a cleaner attempt at $0.30 in October.
- Bearish scenario: ADA loses the 200 EMA at $0.239 on a daily close. That would suggest another August-style fakeout, opening the door to $0.22 and possibly the $0.20 area where the September rally started. The major floor remains the June low near $0.139, but a trip that deep would need a broad market breakdown.
Our Cardano price prediction: as long as the $0.239 level holds, the structure favors a move toward $0.285 to $0.30 in the coming weeks, with a short breather along the way being the most likely path.
Decrypt
Investigators are combing the site where the exchange's founder was last seen in 2022, using experts and forensic equipment.
DeepSeek will address the UN Security Council on AI risks this week, sharing a stage with Dario Amodei—who has spent a year calling China's government the industry's biggest threat.
Four ancient wallets moved 1,971 BTC between Sept. 6 and Sept. 22, including a 600 BTC transfer worth $51.9 million just hours ago, with three of the four carrying "Noah Doe" lawsuit tags.
The exchange operator is adding standard and micro contracts for BCH and UNI, extending a pattern of altcoin rollouts that already covers Cardano, Chainlink, Stellar, Avalanche, and Sui.
Head of cryptography Yehuda Lindell says the exchange is designing custody that can adapt to whatever post-quantum signing scheme Bitcoin adopts.
U.Today - IT, AI and Fintech Daily News for You Today
Shiba Inu has finally broken through a major technical barrier that had limited its recovery for months.
BlackRock believes the artificial intelligence boom could emerge as a major new source of demand for crypto.
Ripple CTO Emeritus David Schwartz uncovers SEC-style regulatory traps in a high-profile US lawsuit outside crypto.
XRP's possibility of reaching the level we haven't seen since January just increased marginally.
XRP has reclaimed a $100 billion market capitalization after jumping more than 8%.
Blockonomi
TLDR
- KB Home shares dropped approximately 2% in extended trading despite surpassing fiscal Q3 earnings projections.
- The company posted earnings per share of $1.05 compared to analyst estimates of roughly $0.89, with revenues around $1.3 billion.
- Gross margin in housing expanded to 16.5%, supported by increased built-to-order home deliveries.
- However, management’s Q4 housing gross margin forecast of 16% to 16.6% fell short of the 17.2% analyst consensus.
- Elevated mortgage costs, declining Southern California performance, and inflationary pressures pose ongoing challenges through 2026.
Shares of KB Home (KBH) declined roughly 2% during after-hours trading Tuesday despite the homebuilder delivering fiscal third-quarter performance that exceeded Wall Street projections. The initial post-earnings rally quickly reversed as market participants digested management’s cautious margin outlook.
KB Home, KBH
The company reported earnings of $1.05 per share alongside approximately $1.3 billion in quarterly revenue. Wall Street had anticipated around $0.89 per share on comparable revenue levels, indicating the headline figures outperformed expectations.
The housing gross profit margin came in at 16.5%, surpassing analyst projections of 16.2%. Executives attributed this improvement in part to the company’s strategic emphasis on its built-to-order business model.
[[SCRIPT_0]]This approach focuses on initiating home construction after securing buyer contracts rather than building speculative inventory upfront. Roughly three-quarters of KB Home’s homes delivered during the third quarter followed this built-to-order framework.
Forward-Looking Margin Forecast Disappoints Investors
The source of investor concern centered on forward guidance. KB Home projected fourth-quarter housing gross margin ranging from 16% to 16.6%, missing the approximately 17.2% consensus estimate from analysts.
Additionally, the builder reduced its full-year gross margin outlook to a range of 16% to 16.2%. This represents a downward revision from the company’s prior forecast of 16.1% to 16.5%, which had been reiterated during the second-quarter earnings release.
Executives cited weakening sales momentum in Southern California as a contributing factor. The slowdown means fewer high-value homes from that market will be delivered during the fourth quarter than previously anticipated.
Housing revenue contracted 20% year-over-year to $1.29 billion, while home deliveries decreased 19% to 2,732 units. Net orders fell 12%, signaling persistent demand headwinds despite the quarterly earnings outperformance.
Mortgage Rate Pressure Continues to Weigh on Sector
KB Home leadership emphasized that elevated mortgage rates continue hampering affordability metrics and creating buyer hesitation. Homebuilder confidence across the industry recently touched a 12-month low in September as financing expenses and subdued demand pressured the sector.
The resale housing inventory has expanded as well, providing prospective homebuyers with additional options beyond new construction. Simultaneously, executives highlighted increasing costs related to fuel, tariffs, and general inflation as the company enters the fourth quarter.
While the built-to-order approach may provide better margin protection compared to speculative construction—since homes align more closely with committed buyers before breaking ground—this advantage cannot entirely neutralize affordability challenges and demand weakness.
Investors should recognize that KB Home maintains significant exposure to mortgage rate fluctuations and regional housing market dynamics. Should rates remain elevated or buyer caution intensify further, the company may encounter additional headwinds related to sales volume, incentive spending, and margin compression.
Currently, the market appears to be discounting the earnings beat in favor of focusing on the subdued forward outlook. KB Home’s upcoming test will be demonstrating whether its built-to-order strategy can sustain profitability throughout a challenging housing cycle.
The post KB Home (KBH) Stock Drops Despite Earnings Win on Weak Margin Forecast appeared first on Blockonomi.
Quick Summary
- In his concluding General Assembly speech, UN Secretary-General António Guterres advocated for enhanced international governance of artificial intelligence technologies.
- The outgoing UN leader pressed nations at the forefront of AI innovation to exchange critical safety data, collaborate on evaluation protocols and establish unified protective measures.
- His address additionally emphasized ending armed conflicts, accelerating climate initiatives and modernizing international organizations.
- President Donald Trump articulated an opposing viewpoint at the UN, rejecting expansive new AI regulations while maintaining government readiness to act against significant corporate-created threats.
- This policy clash emerges as the UN Security Council prepares to receive briefings from AI industry leaders regarding hazards posed by advanced systems.
United Nations Secretary-General António Guterres has advocated for establishing comprehensive international protocols to address artificial intelligence dangers, utilizing his concluding General Assembly address to caution that AI advancement outpaces institutional capacity to regulate it. His second consecutive five-year tenure concludes on December 31, marking the end of ten years at the helm of the UN.
Guterres pressed nations creating cutting-edge AI technologies to disseminate intelligence regarding emerging safety concerns and coordinate on assessment and validation efforts. He additionally advocated for autonomous monitoring mechanisms and a collaborative international framework for addressing AI-related risks.
UN Leader Advocates for International AI Governance
The Secretary-General emphasized that national governments must establish parameters for responsible AI advancement and implement protective measures capable of adapting to progressively sophisticated systems. His remarks extend a multi-year campaign to build international regulatory structures surrounding the technology.
The UN established a 39-nation AI advisory council in 2023, with the Security Council conducting its inaugural formal examination of AI threats during that same period. This week, officials from OpenAI, Anthropic and Chinese AI enterprises are scheduled to present to the council as apprehension regarding AI and global security escalates.
Guterres additionally utilized the address to advocate for conflict resolution, revitalized climate commitments and institutional restructuring that he contended increasingly mirrors an outdated distribution of global influence. He maintained that collaborative efforts and international legal frameworks remain critical amid widening geopolitical fractures.
White House Articulates Alternative Vision on AI
President Donald Trump delivered a divergent perspective during his UN remarks. Trump has resisted comprehensive new federal AI limitations and contended that the U.S. must avoid hindering innovation while competing internationally in the technology sector.
He further utilized the address to champion the terminology “Super Intelligence,” contending that artificial intelligence minimizes the technology’s capabilities. Simultaneously, Trump indicated that the Justice Department maintains authority to intervene should AI corporations generate risks necessitating governmental response.
These divergent perspectives underscore a fundamental disagreement regarding the appropriate timeline for regulating advanced AI systems. Guterres advocates for synchronized international protections, whereas the Trump administration has prioritized technological dominance and minimal regulatory constraints.
AI is anticipated to figure prominently in discussions between Trump and Chinese President Xi Jinping this week. American officials have suggested implementing a notification protocol addressing AI-related incidents with national-security ramifications as Washington and Beijing pursue expanded dialogue on AI safety matters.
The post UN Secretary-General Demands International AI Oversight Amid U.S. Deregulation Push appeared first on Blockonomi.
Quick Overview
- Bullion prices declined approximately 0.9% to reach roughly $4,318 per ounce amid dollar appreciation.
- The U.S. dollar index surged to levels not witnessed since the end of July, increasing gold’s cost for international purchasers.
- Last week’s 25 basis point rate increase by the Federal Reserve brought rates to 3.75%-4.00%, with markets anticipating additional tightening ahead.
- Declining energy costs are providing modest inflation relief, though oil prices remain significantly elevated compared to earlier in the year.
- Robust demand from China and central bank acquisitions continue to provide underlying support for gold.
Bullion experienced downward pressure on Wednesday as the appreciating U.S. dollar combined with anticipation of an extended period of elevated interest rates diminished appetite for the precious metal that generates no income.
Spot gold prices retreated approximately 0.9% to settle at $4,318 per ounce, with U.S. gold futures declining roughly 0.5%. The dollar index advanced to approximately 100.71, marking its most robust reading since July 30.
Elevated Interest Rates Weigh on Precious Metals
The Federal Reserve implemented a 25 basis point increase to its policy rate last week, establishing a new range of 3.75%-4.00% in its first rate adjustment in over three years. Central bank officials also signaled the possibility of an additional rate increase before 2026 concludes.
Elevated interest rates typically exert downward pressure on gold since the metal generates no yield. Market participants can alternatively secure superior returns through government bonds and other interest-bearing instruments.
Federal Reserve policymakers have maintained their emphasis on inflationary concerns. Susan Collins, President of the Boston Federal Reserve, noted that a moderately more restrictive policy stance might be necessary to bring inflation back to the central bank’s 2% objective on a sustainable basis.
The appreciating dollar compounds the pressure on gold prices. Since bullion is denominated in dollars, a strengthening American currency elevates costs for international buyers utilizing euros, yen, and other foreign currencies.
Energy Price Decline Provides Limited Support
Crude oil values have retreated as optimism builds regarding enhanced Middle Eastern supply conditions. Iranian authorities have suggested potential reopening of the Strait of Hormuz under specific circumstances, while Saudi Arabia has resumed operations of its East-West pipeline.
JUST IN
: Crude Oil going for 7 consecutive red days, which would be its longest losing streak since August 2021


pic.twitter.com/iNglD7iTMi
— Barchart (@Barchart) September 23, 2026
Brent crude has dropped beneath the $100 per barrel threshold, alleviating some concerns that energy costs will continue propelling inflation upward. Nevertheless, oil prices remain considerably elevated relative to early-year levels.
Reduced energy expenses could ultimately diminish pressure on monetary authorities to continue raising rates. For precious metals markets, this development provides a partial offset to dollar strength and prevailing expectations for continued monetary policy tightening.
Asian Market Demand Provides Floor for Gold
Physical purchasing and investment flows continue offering meaningful support for bullion. ANZ reported that Chinese gold imports totaled approximately 1,000 tonnes throughout the initial eight months of 2026, while exchange-traded funds focused on Chinese gold holdings increased by roughly 44 tonnes during August.
The People’s Bank of China reportedly intensified its gold acquisitions to approximately 20 tonnes in August. Central bank purchasing has emerged as a significant long-term demand source for precious metals.
Despite this support, gold has faced headwinds as market participants concentrate on real yields and currency movements. Reuters noted on Tuesday that bullion had declined more than 22% from its January peak of $5,594.82 per ounce as rising rates diminished its comparative attractiveness.
Currently, the primary market drivers remain dollar dynamics, Treasury yield movements, and speculation regarding the Federal Reserve’s next policy decision.
The post Gold Prices Tumble Under Pressure from Rising Dollar and Rate Hike Expectations appeared first on Blockonomi.
TLDR
- CME Group plans to launch Bitcoin Cash and Uniswap futures on October 19, pending regulatory review.
- Both products will come in standard and micro contract sizes.
- Bitcoin Cash rose more than 25% to $338 after the news.
- CME’s 2026 altcoin futures have produced over $1 billion in notional value this year.
- The new contracts will be CME’s tenth and eleventh single-asset crypto futures.
CME Group plans to add Bitcoin Cash and Uniswap futures to its list of regulated crypto products. The exchange said Tuesday the contracts will launch on October 19, pending regulatory review.
The new products will come in two sizes. Traders can choose between standard contracts and smaller micro contracts.
Bitcoin Cash futures will represent 250 BCH, while the micro version will cover 25 BCH. Uniswap futures will cover 10,000 UNI, and its micro contracts will cover 1,000 UNI.
Bitcoin Cash traded at $338 per coin at the time of the announcement, up more than 25% on the day. It has a market cap of about $6 billion.
Uniswap’s token traded at $9.28, up 5.5% over 24 hours. Its market cap stood at $5.75 billion.
What the Two Tokens Do
Bitcoin Cash split off from Bitcoin in 2017. It was built with a larger block size to support cheaper payments, rather than to act as a store of value.
Uniswap runs the largest decentralized exchange in crypto. Its token is used for governance, which lets holders vote on upgrades to the protocol. Holders do not collect dividends.
Giovanni Vicioso, CME’s global head of cryptocurrency products, said market participants need broader, regulated tools to manage price risk as crypto markets mature. He said the contracts offer capital efficiency and exposure to “key crypto networks” in a round-the-clock, regulated venue.
CME Continues Its Altcoin Rollout
This is not CME’s first altcoin launch this year. In February, the exchange rolled out futures for Cardano, Chainlink, and Stellar.
In April, it announced Avalanche and Sui futures, which began trading on May 4. Before Tuesday’s news, CME’s crypto lineup also included Bitcoin, Ether, XRP, and Solana.
CME said its 2026 futures for Cardano, Chainlink, Stellar, Avalanche, and Sui have produced more than $1 billion in total notional value so far this year.
Across all of its crypto products, futures and options averaged 279,800 contracts per day in the first half of 2026. That equaled $8.3 billion in daily notional volume. Average open interest reached 264,600 contracts, or $15.4 billion.
Justin Young, CEO and co-founder of Volatility Shares, called the move “another important step” in the growth of CME’s crypto futures. His firm already runs leveraged crypto ETFs tied to several of the same altcoins.
Noel Kimmel, president of Ripple Prime, said institutions “need around-the-clock access to regulated derivatives.” Ripple built the prime brokerage after buying Hidden Road in 2025. In May, the firm secured a $200 million facility to expand its lending.
If the review stays on schedule, trading will open on October 19. Bitcoin Cash and Uniswap will then become CME’s tenth and eleventh single-asset crypto futures products.
The post CME Group to Launch Bitcoin Cash and Uniswap Futures on October 19 appeared first on Blockonomi.
TLDR
- CFTC Chair Michael Selig said U.S. regulators must prepare markets for “mass tokenization.”
- He spoke Tuesday at a U.S. Treasury Market conference at the New York Fed.
- Selig named tokenization, onchain finance and 24/7 trading as major forces for the next decade.
- In February, the CFTC added stablecoins issued by national trust banks to its eligible collateral list.
- The SEC released an “innovation exemption” last week for onchain trading of tokenized stocks.
The head of the Commodity Futures Trading Commission says U.S. financial markets need to get ready for big changes. Chair Michael Selig said regulators must prepare for “mass tokenization.”
Tokenization means turning assets such as stocks or bonds into digital tokens on a blockchain. Selig also said current markets should be adjusted for new technology, including blockchain and artificial intelligence.
He made the comments on Tuesday during a U.S. Treasury Market conference at the Federal Reserve Bank of New York.
Selig Expects Major Change in the Next Decade
Selig said the coming years could reshape how markets work. “With developments like tokenization, on-chain finance, and 24/7 trading, the next decade will likely bring more change to financial markets than the previous several decades combined,” he said.
He added that the United States will continue to lead global markets.
“Across the entire Trump administration, we’ve already laid the groundwork to continue doing so by embracing innovation, encouraging competition, right-sizing regulation and maintaining the trust that has made our markets the gold standard across the world,” Selig said.
His remarks come as the Trump administration prepares for a broad update to financial markets. Tokenization, onchain finance and round-the-clock trading are all part of that effort.
CFTC Moves on 24/7 Trading and Stablecoins
The CFTC has already taken steps in these areas. Over the past year, the agency issued guidance on 24/7 trading for energy derivatives markets.
It has also asked the public to comment on round-the-clock trading. These actions reflect the agency’s growing interest in markets that never close.
In February, the CFTC expanded its list of eligible collateral. The list now includes stablecoins issued by national trust banks.
Collateral is an asset that traders post to back their positions. Adding stablecoins gives market participants another option.
Selig said the agency will look for more ways to “encourage responsible stablecoin adoption for market participants, exchanges, and clearinghouses.”
The CFTC is not the only regulator making changes. Its sister agency, the Securities and Exchange Commission, is also acting.
Last week, the SEC released its long-awaited “innovation exemption.” The exemption is designed to make room for onchain trading of tokenized stocks.
Both agencies are moving forward on their own. A bill to regulate the crypto industry as a whole has stalled in the Senate.
The post CFTC Chair Michael Selig Says Markets Must Prepare for Mass Tokenization appeared first on Blockonomi.
CryptoPotato
Solana’s native token, which plunged below $100 in mid-September, now trades near $120 after a solid 16% weekly pump. Of course, the main catalyst for that move is the broader market resurgence, with Bitcoin (BTC) briefly soaring to $87,000.
The big question now is whether SOL is gearing up for a further ascent or a short-term correction, and most analysts support the bullish scenario.
New ATH Incoming?
Earlier this month, Ali Martinez spotted a bull flag forming on SOL’s 4-hour chart and said he will watch the $105 level closely. The analyst assumed that a sustained close above (as it has happened) could confirm the bullish breakout and set the stage for a rally toward $130.
Many other analysts have also weighed in on the matter following the latest pump. X user Ash Crypto argued that SOL has one of the most bullish setups among altcoins right now. The market observer said the asset has reclaimed the weekly MA200, hit $120 for the first time in eight months, and formed a weekly golden cross, suggesting the bottom is already behind us.
Veteran trader Peter Brandt also chipped in, pointing to what he believes is a textbook cup-and-handle pattern on Solana’s chart. X user FOUR | Crypto Spaces shared the same thesis, saying:
“This is not a random pump setup. Chart is cooking like a massive cup & handle. Now we wait for the neckline because no breakout = patience. Breakout = things get very stupid. I will enter only on confirmation on retest.”
For his part, Gerla said SOL has entered the phase he has been waiting for. The analyst believes that expansion is now happening at a fast pace, setting $500 as a target.
“The only question is how long it takes to get there,” he concluded.
Overall Altcoin Season?
X user Cup, who has been quite bullish on several cryptocurrencies over the past few months, claimed that “the altcoin breakout is here” and predicted that SOL could explode to $450 amid such positive enviroinment.
As CryptoPotato recently reported, Glassnode’s Altcoin Cycle Signal flipped from Bitcoin season to altcoin season this week, thus strengthening the analyst’s prediction.
It is worth noting that the market rally came after a particularly challenging week, marked by the CLARITY Act setback, rising interest rates in the US, and escalating geopolitical tensions. Meanwhile, the crypto sector has spent much of the past several months in an evident bearish trend, suggesting it may still be too early to declare the start of a full-blown bull run or altcoin season.
The post Solana (SOL) Hits a 9-Month Peak as Analysts Project an Explosion to $500 appeared first on CryptoPotato.
Bitcoin’s price ascent drove the asset to over $87,000 once again in the past several hours, but the bears were more persistent so far, pushing it down toward $86,000.
Several altcoins have posted major gains over the past day, including Ripple’s XRP, which has soared past $1.60, and Hyperliquid’s HYPE, which tapped a new all-time high close to $100.
BTC Stopped at $87.3K Again
After last week’s failed advancement vote on the CLARITY Act and the subsequent rate hike by the US Federal Reserve, concerns emerged about BTC’s ability to sustain its August breakout. After all, the asset was rejected at $80,000 on several occasions, and both of these developments pushed it south to a three-week low at $75,000.
However, the cryptocurrency rebounded swiftly and quickly reclaimed $78,000 by Friday morning. The bulls stepped up on the gas pedal later that day, driving it past $80,000. Unlike previous occasions, though, BTC managed to continue forward and challenged $82,000 on Saturday.
The latest escalation in the Middle East conflict as well as the Ukraine-Russia war halted its progress, and bitcoin slipped to $80,300. However, it didn’t slip below $80,000. Instead, it went on a wild run on Monday, adding $7,000 in value and surging past $87,000 for the first time since late January.
It was halted there, though, and dipped to $85,000 before it tried again, only for the same scenario to repeat. As of press time, BTC has been pushed to $86,000, while its dominance over the alts remains at 59% and its total market cap is still above $1.730 trillion on CMC.

BCH, UNI, BTW Fly
ETH, BNB, SOL, DOGE, and ADA have remained at the same levels as yesterday. HYPE broke its all-time high, setting a new one at $98. Ripple’s XRP has reclaimed the key $1.60 resistance. ZEC has rocketed past $1,600 after a 7% daily surge.
Even more impressive gains are evident from BCH and UNI. Both assets benefited from this CME announcement. The former has jumped by over 33% now, while the latter is up by 16%. BTW has increased by double digits as well. AAVE and MNT are also well in the green.
The total crypto market cap has added $50 billion daily and is up to $2.950 trillion on CMC.

The post HYPE Hits New ATH Close to $100, BTC Stopped at $87K Again: Market Watch appeared first on CryptoPotato.
Bitcoin’s relationship with traditional markets has changed sharply in a matter of weeks, with Santiment data showing that its correlations with stocks, the greenback, and even gold have all weakened.
The part with gold is particularly interesting, as both assets recently moved at the same pace, but BTC now appears to be trading far more independently of all major comparison alternatives.
BTC Breaks Away
Santiment’s analysis highlighted the breakdown in bitcoin’s correlations with major assets, including the precious metal and US equities, indicating that the cryptocurrency is no longer moving closely alongside any of them. This major change materialized over the past several days, after BTC rebounded from the dip to $75,000 following the failure of the CLARITY Act vote and surged to a multi-month peak of over $87,000.
The shift is quite striking because the opposite narrative, especially when compared to gold, dominated only a few weeks ago. As reported in early September, BTC’s 90-day correlation with the precious metal had climbed above 0.50 for the first time in approximately six years. The relationship with the Nasdaq 100, though, had dropped toward the 0.30-0.33 range, prompting suggestions that investors were treating bitcoin less like a high-beta tech asset and more like a scarce monetary hedger.
That interpretation made a lot of sense at the time since BTC and gold both benefited and rallied from renewed concerns over government debt, deficits, and currency debasement, while equities struggled to keep pace. However, that relationship has proved far less durable than it initially appeared, as gold has remained at essentially the same levels, while bitcoin has posted major gains.
Bitcoin Has Completely Broken Away From Stocks & Precious Metals
Bitcoin’s market cap has grown by +36.0% since August 18, dramatically separating from the S&P 500’s +0.8% and gold’s -1.5% performances in that same time. The breakout began as smaller 0.1-10 BTC holders… pic.twitter.com/L8UaFfSsZS
— Santiment Intelligence (@SantimentData) September 23, 2026
Independent Trade?
The reversal speed is arguably more significant than the absolute correlation numbers, as BTC’s strengthening relationship with gold was one of the market’s more notable macro developments just three weeks ago. The data from this week, though, complicates that narrative, as bitcoin has continued advancing even as the precious metal has pulled back from recent highs. At the same time, US stocks have followed their separate trajectory.
The cryptocurrency also absorbed both major negative developments from last week – the Fed’s hike and the CLARITY Act setback, before it rose above $87,000.
None of this means that BTC has permanently decoupled from macro markets. Its historical correlations have repeatedly shifted depending on liquidity, monetary policy, and investor positioning, but the data now shows that it doesn’t move like digital gold, a leveraged tech stock, or an anti-dollar trade; BTC moves on its own.
The post Bitcoin Just Broke Its Correlation With Gold, Stocks, and the Dollar: What Changed? appeared first on CryptoPotato.
[PRESS RELEASE – BELIZE CITY, BELIZE, September 23rd, 2026]
Cumulative BC Engine rewards have grown more than fourfold since late May, while the average daily pace of reward accumulation has increased by approximately 46% compared with the previous period.
BC.GAME’s BC Engine has reached another major milestone, with cumulative rewards earned by eligible $BC holders surpassing 8.6 million BCD, equivalent to more than US$8.6 million.
The milestone comes just over five months after BC Engine launched and brings cumulative rewards closer to the US$10 million mark.
More importantly, the latest data highlights the growing role BC Engine is playing within the wider BC.GAME ecosystem. What began as an hourly reward mechanism for $BC holders is increasingly evolving into a core ecosystem layer that connects platform activity, users, and commercial partners through recurring and measurable value distribution.
From Launch to More Than $8.6 Million in Five Months
BC Engine launched on April 8, 2026, introducing a model in which eligible $BC holdings participate in recurring settlement rounds, with BCD rewards distributed every hour.
Since launch, cumulative rewards have grown steadily.
On May 28, BC.GAME reported that BC Engine participants had earned more than 2.1 million BCD.
By July 28, cumulative rewards had surpassed 5 million BCD, representing an increase of approximately 138% from the late-May level.
As of September 18, 2026, total BC Engine rewards have now exceeded 8.6 million BCD.
Based on these disclosed milestone figures, cumulative rewards have increased by more than 309% since late May, reaching approximately 4.1 times the level reported less than four months ago.
The pace of reward accumulation has also accelerated.
Between May 28 and July 28, BC Engine added approximately 2.9 million BCD over 61 days, equivalent to an average increase of roughly 47,500 BCD per day.
Between July 28 and September 18, BC Engine added more than 3.6 million BCD over 52 days, lifting the average daily pace to approximately 69,000 BCD or more.
Based on these disclosed milestones, the average daily pace of reward accumulation increased by approximately 46% compared with the previous period.
While individual settlement amounts vary with activity across the ecosystem, the trend is clear: an increasing amount of value is continuing to move through BC Engine.
BC Engine Is Becoming a Core Value Layer of the BC.GAME Ecosystem
The significance of the US$8.6 million milestone extends beyond the total amount distributed.
BC Engine was designed to create a closer connection between activity within BC.GAME and the value shared with participants across the ecosystem.
Eligible $BC holdings participate in recurring settlement rounds, while users can track active balances, cumulative rewards, unclaimed BCD, and settlement history directly through the BC Engine interface.
This creates an ongoing relationship between platform activity and value distribution.
Rather than relying solely on one-off promotional incentives, BC Engine keeps value circulating through repeated settlement cycles, creating a mechanism that can support longer-term participation across the ecosystem.
As the system grows, BC Engine is increasingly becoming one of the most important value layers within BC.GAME.
For users, recurring rewards provide a tangible reason to remain engaged over time.
For $BC, the Engine creates a clear and continuing source of ecosystem utility.
For products and commercial partners across BC.GAME, the Engine provides an economic layer that can connect different parts of the platform within a shared value network.
In practical terms, BC Engine creates a reinforcing cycle:
Platform activity generates value.
$BC connects users to the ecosystem.
BC Engine redistributes value through recurring rewards.
Recurring rewards support deeper and longer-term participation.
This structure brings BC.GAME, its users, and ecosystem partners into a more closely connected value network.
Building Trust Through Measurable Value Distribution
One of BC Engine’s defining characteristics is that its growth can be measured through rewards that have already been generated through completed settlement rounds.
The more than US$8.6 million disclosed to date does not represent projected future rewards, unrealised token appreciation or calculations based on movements in the market price of $BC.
Instead, it reflects BCD rewards already earned through the operation of BC Engine.
This distinction is especially important in an industry where token-based reward models are often communicated primarily through future utility or projected value.
BC Engine gives participants a visible and measurable record of value already generated within the system.
The progression from more than 2.1 million BCD in May, to 5 million BCD in July, and now to more than 8.6 million BCD in September, shows that the mechanism is operating at increasing scale.
For users, recurring and transparent rewards can strengthen trust and support longer-term engagement.
For game providers and ecosystem partners, BC Engine creates a structure in which participation can contribute to a broader economic network rather than remain an isolated commercial relationship.
For BC.GAME, the model creates stronger alignment between platform activity, token utility, partner participation, and user retention.
As a result, BC Engine is becoming an increasingly important part of BC.GAME’s differentiation within the wider online gaming market.
BC.GAME Continues Its Global Expansion
The growth of BC Engine comes alongside BC.GAME’s continued international expansion.
In 2026, BC.GAME further expanded its regulated presence in Mexico, strengthening its local operations and deepening its connection with one of Latin America’s most important gaming and sports markets.
The company also announced Mexican football icon Guillermo “Memo” Ochoa as a brand ambassador, reinforcing BC.GAME’s connection with local football culture and supporting its wider localization strategy.
The partnership reflects BC.GAME’s approach to international growth: combining regulated market access, locally relevant cultural partnerships and product-led user engagement.
BC.GAME will also attend SBC Summit 2026 in Lisbon from September 29 to October 1, continuing to expand its network of commercial, technology and gaming partners across the global industry. The event is expected to bring together around 40,000 industry professionals in Lisbon. citeturn973300search1turn973300search0
For BC.GAME, these developments represent two sides of the same strategy.
Externally, the company is expanding into new markets and strengthening its global partner network.
Internally, BC Engine is helping build the economic infrastructure that connects platform growth with users, $BC holders, and ecosystem partners.
With cumulative rewards now exceeding US$8.6 million and moving closer to the US$10 million milestone, BC Engine is increasingly demonstrating the scale and value of that model.
About BC.GAME
BC.GAME is a global online gaming and entertainment platform offering casino, sportsbook and digital asset-based products across multiple international markets.
Since its launch in 2017, BC.GAME has continued to develop a crypto-native entertainment ecosystem built around product innovation, community participation and global partnerships.
$BC is the native token of the BC.GAME ecosystem. Through BC Engine, eligible $BC holders can participate in recurring BCD reward distributions, while the Engine provides an increasingly important connection between platform activity, users and ecosystem partners.
BC.GAME continues to expand its international presence while developing new products, partnerships and technology across gaming, sports and digital entertainment.
The post BC.GAME’s BC Engine Rewards Surpass $8.6 Million as Ecosystem Growth Accelerates appeared first on CryptoPotato.
The frog-themed meme coin PEPE has emerged as one of the top-performing cryptocurrencies over the past week, with its price rising by roughly 50% to a nine-month high of $0.0000049.
The token has already demonstrated its ability to deliver triple and even quadruple gains in the past, and many analysts now believe another move of that scale could be on the horizon.
‘The Frog is Waking Up’
X user Giannis Andreou noted that PEPE’s weekly chart is holding a higher low above its 2023 base, meaning the test now comes at $0.0000048-$0.0000055.
The analyst claimed the weekly candle “is still open,” arguing that a close above the upper boundary, followed by a successful retest, could strengthen the case for $0.0000065-$0.0000075.
“Clear that, and $0.000009-$0.0000105 becomes the next zone to watch. The bigger recovery scenario reaches $0.000013–$0.000016,” he added.
At the same time, the analyst warned that a rejection may lead to a drop to the $0.0000023-$0.0000032 range.
For his part, Crypto With Gopal argued that the meme coin’s price is testing the lower trendline after a rejection near $0.0000054, showing momentum is tightening. He believes that the setup remains bullish, but buyers must defend support and reclaim the upper resistance to initiate a further upswing.
X user Plazma also chipped in, estimating that PEPE had formed a golden cross on the 50-day/200-day moving average: a setup usually considered highly positive for the price.
The Dangerous Game With Meme Coins
PEPE’s price increase is impressive and could go even higher, but traders and investors who want to hop on the bandwagon should keep in mind that tokens like this are highly volatile and often driven more by hype and speculation than fundamentals. Recently, X user Crypto Bitlord warned people to stay away from memes, claiming 99% of them are scams.
“It’s hard for me to recommend anyone play that game because the statistics are against you,” he added.
PEPE has been on the market for more than three years and has built a solid community base, but no one can say for sure whether the project has a bright future or is a time-ticking bomb.
Meanwhile, CoinGlass data shows that over the past few days, investors have moved PEPE tokens from self-custody to centralized exchanges. That reinforces the bearish scenario since it increases immediate selling pressure.

- PEPE Exchange Netflow, Source: CoinGlass
The post ‘The Frog is Waking Up!’ PEPE Explodes 50% in a Week as Golden Cross Forms appeared first on CryptoPotato.