Cryptocurrency Posts
Crypto Briefing
SpaceX's rapid AI development could intensify competition, strain resources, and shift industry dynamics, impacting innovation and talent allocation.
The post Elon Musk says SpaceX could have a Fable or GPT-6 level AI model within months appeared first on Crypto Briefing.
Lightspeed's strategic shift to early-stage AI investments in India reflects a broader industry trend prioritizing AI innovation and agility.
The post Lightspeed targets $300–$350M for new early-stage AI fund in India appeared first on Crypto Briefing.
DensityAI's rapid rise highlights the growing demand for specialized AI chips, potentially reshaping the semiconductor industry landscape.
The post DensityAI nears $10B valuation with hundreds of millions in funding and AWS deal appeared first on Crypto Briefing.
Musk's GPU expansion could redefine AI capabilities, but raises concerns over environmental impact and energy demands in tech infrastructure.
The post Elon Musk plans 660K GB300 GPUs for Colossus 2 by year-end appeared first on Crypto Briefing.
Xi Jinping's optimism may foster improved US-China relations, potentially stabilizing global markets and enhancing bilateral cooperation.
The post Xi Jinping optimistic on US-China cooperation under Trump administration appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Nearly $352M Moved From Crypto Exchange Bitget Wallets in Suspected Hack
An estimated $351.6 million in crypto has been moved from digital asset exchange Bitget’s hot wallets in a suspected hack.
The platform’s CEO said in a Thursday statement that Bitget’s security team activated an emergency response when the movements were detected. Blockchain security firms had flagged the issue earlier in the day.
“At 18:31 UTC on September 24, 2026, Bitget’s security systems detected unauthorized transfers from some of our hot wallets,” Bitget CEO Gracy Chen wrote on X. “Our security team activated emergency response protocols immediately.”
She added: “Bitget has navigated multiple market cycles. We will not run from this. Every dollar and every decision will be accounted for, transparently and in full.”
Victoria, Seychelles-based Bitget is the sixth biggest exchange, processing over $1.1 billion in trading volume per day, according to CoinGecko data.
The incident comes as crypto security is in the limelight after a string of breaches this year have the community reeling. Just in July, hackers targeted a firmware bug in the popular bitcoin hardware wallet, Coldcard, to steal nearly $120 million in user funds.
And this month, purported white-hat hackers withdrew about 4,000 bitcoins — worth about $320 million at the time — from Blockstream’s Liquid sidechain’s federation wallet.
Chen added that the exchange’s cold wallets remained fully secure and that user funds were safe.
She wrote: “Bitget operates a three-tier wallet architecture — the breach contained only a portion of the hot wallet and warm wallet layers.”
According to the statement, deposits and trading remain fully operational but withdrawals are temporarily paused until a security review is complete.
Blockchain data firm Arkham Intelligence created a dashboard soon after the unauthorized transfers showing that a number of different cryptocurrencies — including stablecoins — had been moved from the Bitget hot wallet.
While Bitcoin was not on Arkham’s list, crypto security firm Hacken later said on X that the largest cryptocurrency had been moved.
This post Nearly $352M Moved From Crypto Exchange Bitget Wallets in Suspected Hack first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
New York Sues Polymarket, Calling Prediction Market an Illegal Gambling Operation
New York Attorney General Letitia James and Governor Kathy Hochul on Thursday filed a lawsuit against crypto-based prediction market Polymarket, accusing the platform of running an unlicensed gambling operation in the state.
An investigation by the Attorney General’s office concluded that these markets meet New York’s legal definition of gambling because users stake money on uncertain outcomes they cannot control.
Polymarket never obtained a license from the New York State Gaming Commission, the suit alleges, and so avoided the taxes that licensed casinos and mobile sportsbooks pay. That revenue helps fund public schools, youth sports programs and problem gambling treatment.
The suit comes as regulators like the Securities and Exchange Commission and the Commodity Futures Trading Commission are working to regulate crypto-powered prediction markets.
Polymarket and rival Kalshi argue they aren’t gambling sites at all, but rather federally regulated exchanges offering “event contracts,” a type of derivative, which would put them under the Commodity Futures Trading Commission rather than state gaming laws.
The CFTC agrees, and it has joined the fight on the platforms’ side. In 2026 it sued nine states, arguing that it should have exclusive nationwide authority over the industry.
Thursday’s complaint also says the platform is open to users aged 18 to 20, although New York requires mobile sports bettors to be at least 21.
“By skirting New York’s laws, Polymarket is targeting the most vulnerable,” James said. Hochul added that the company had “knowingly” violated state law and put underage users at risk.
The state is asking a court to bar Polymarket from operating as an unlicensed gambling business in New York. It also wants the company to forfeit its illegal gains, repay harmed users and pay fines equal to three times those gains.
The lawsuit is the latest in a string of New York actions against gambling-adjacent platforms. James and Hochul sued rival prediction market Kalshi in July, and James sued Coinbase and Gemini in April over similar claims. Earlier this month, James secured $8 million from the leading operator of sweepstakes casinos.
Polymarket launched in the United States in December 2025, initially letting users bet on sporting events with plans to expand into markets on a wide range of topics.
This post New York Sues Polymarket, Calling Prediction Market an Illegal Gambling Operation first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
SEC Commissioner Hester ‘Crypto Mom’ Peirce Advocates Privacy-Preserving Tech
Outgoing Securities and Exchange Commission Commissioner Hester Peirce has said that regulators should rethink how they monitor the financial system, and to press for less personal data collection, not more.
In a speech Wednesday focusing on digital identity systems and decentralized networks, Peirce took aim at know-your-customer and anti-money-laundering rules.
U.S. regulators are now racing ahead with crypto rulemaking. Peirce, who earned the nickname “crypto mom” for her friendly approach to watchdogging the space, is set to leave the SEC in November.
“Today society is at a crossroads,” Peirce said at the SIFMA’s Digital Assets Conference in New York.
“Down one path lies the status quo: more data collection, more intermediary surveillance, more ‘know your customer’ requirements that turn our financial rails into a panopticon.”
“Down the other path lies an opportunity to use new technologies to improve our ability to catch criminals while collecting less personal information than ever before, and monitoring more sparingly to protect Americans’ privacy.”
Peirce argued that piling up ever more data on law-abiding customers to help find criminals doesn’t work. In her view, bigger “haystacks” make the needles harder to find, while every stored data point raises the risk of leaks or misuse.
She criticized a regulatory mindset fixated on “data go up,” comparing it to crypto enthusiasts’ obsession with rising prices.
Peirce pointed to cryptographic tools such as zero-knowledge proofs and attribute-based credentials, which can confirm facts like a person’s age, accredited-investor status, or absence from sanctions lists without revealing the underlying personal details.
She also urged the SEC to let firms rely on identity checks already performed by other regulated institutions, rather than making every firm collect and store the same sensitive information.
Under President Joe Biden, the SEC was tough on the crypto space, with its Biden-appointed former Chair Gary Gensler frequently suing major crypto companies for allegedly selling unregistered securities.
Peirce was appointed to lead the Crypto Task Force in 2025. The regulator has taken a far more friendly approach to watchdogging the space since Donald Trump became president again.
Now, regulators are saying they want to create clear rules for the fast-moving industry, despite landmark legislation, the Clarity Act, being blocked last week.
Despite Commissioner Peirce’s alias, she previously said she would not describe herself as an advocate of the industry, but rather a “freedom maximalist.”
This post SEC Commissioner Hester ‘Crypto Mom’ Peirce Advocates Privacy-Preserving Tech first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Jeff Booth: Why $1 Million BTC is Thinking too Small
Is a $1 million Bitcoin price target thinking too small? Jeff Booth thinks so, and he explains why valuing Bitcoin in dollars means pricing it from a game that’s rigged by debasement. He argues that Bitcoin isn’t just a coin or an asset, but the beginning of a decentralized, secure, and private protocol stack that will look a lot like the internet. In his view, Bitcoin is evidence of the first free market that has ever existed.
Chapters:
0:00 Jeff Booth, The Price of Tomorrow & Technological Deflation
0:30 AI Valuations & Why Free Markets Push AI Prices Toward Zero
1:29 AI Deflation vs the Debt-Based Monetary System
2:38 $40 Trillion US Debt, Bond Yields & the $350 Trillion Insolvent System
4:06 AI Singularity Claims, Fear & Monopoly Regulation
6:50 Productivity & Bitcoin’s True Value in a Deflationary Future
8:43 Why a $1 Million Bitcoin Price Target Is Thinking Too Small
10:11 Bitcoin Adoption Timeline & Why Bitcoin Isn’t Just an Asset
12:38 Bitcoin Payments & Circular Economies Scaling Worldwide
13:49 Bitcoin-Backed Private Equity & Owning Businesses Forever
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Jeff Booth: Why $1 Million BTC is Thinking too Small first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Saifedean Ammous: The Bond Crisis & Bitcoin’s Rise as a True Macro Asset
Bitcoin’s volatility is falling, and Saifedean Ammous calls that the most bullish development in Bitcoin right now. Bear-market drawdowns have shrunk from roughly 87% to 77% to about 54% this cycle, which moves Bitcoin closer to an investable asset for money managers. Saifedean explains why the halving still drives the four-year Bitcoin cycle and why fewer people are buying with leverage at the top. He also discusses how markets may eventually arbitrage these cycles away.
Chapters:
0:00 Tether, Bitcoin & the Dollar Milkshake Theory
1:45 How the US Carries $40 Trillion in Debt as the World’s Reserve Currency
4:21 Treasury Yields Hit Multi-Decade Highs & the Bond Market Bear Case
7:00 War Spending, Iran & the Collapse of Fiscal Hope
9:20 Stablecoins vs Banks & the Hidden Treasury Rollover Risk
15:11 The Longest Hash Rate Bear Market in Bitcoin History
18:47 Why Miners Are Pivoting to AI Data Centers
21:31 The Halving, Bitcoin Cycles & Shrinking Drawdowns
25:56 MicroStrategy, Strive & Bitcoin Treasury Companies
29:07 The Humble Peasant Theory of High Finance
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Saifedean Ammous: The Bond Crisis & Bitcoin’s Rise as a True Macro Asset first appeared on Bitcoin Magazine and is written by Patrick Green.
CryptoSlate
Ondo Finance launched three on-chain portfolio tokens on Sept. 24 using investment strategies BlackRock developed for the company. The tokens give buyers economic exposure to diversified baskets, but they are securities issued by Ondo, not interests in BlackRock funds.
Only eligible non-US investors who complete onboarding can redeem the tokens directly with Ondo, according to its launch release and product terms.
The first three products are Ondo High Income (BLKHIon), Ondo Diversified Growth (BLKDIGon) and Ondo High Growth (BLKGRWon). They draw on portfolio strategies BlackRock developed for Ondo, and Ondo implements the allocations using tokenized assets and rebalances the portfolios on a preset schedule, the company said in its launch explanation.
Holding a portfolio token gives economic exposure to a weighted basket that includes Ondo Stocks, which track equities and exchange-traded funds. It does not give the holder a right to the underlying funds or securities.
Ondo's legal disclosure calls each token a separate security issued by Ondo Global Markets (BVI) Limited.
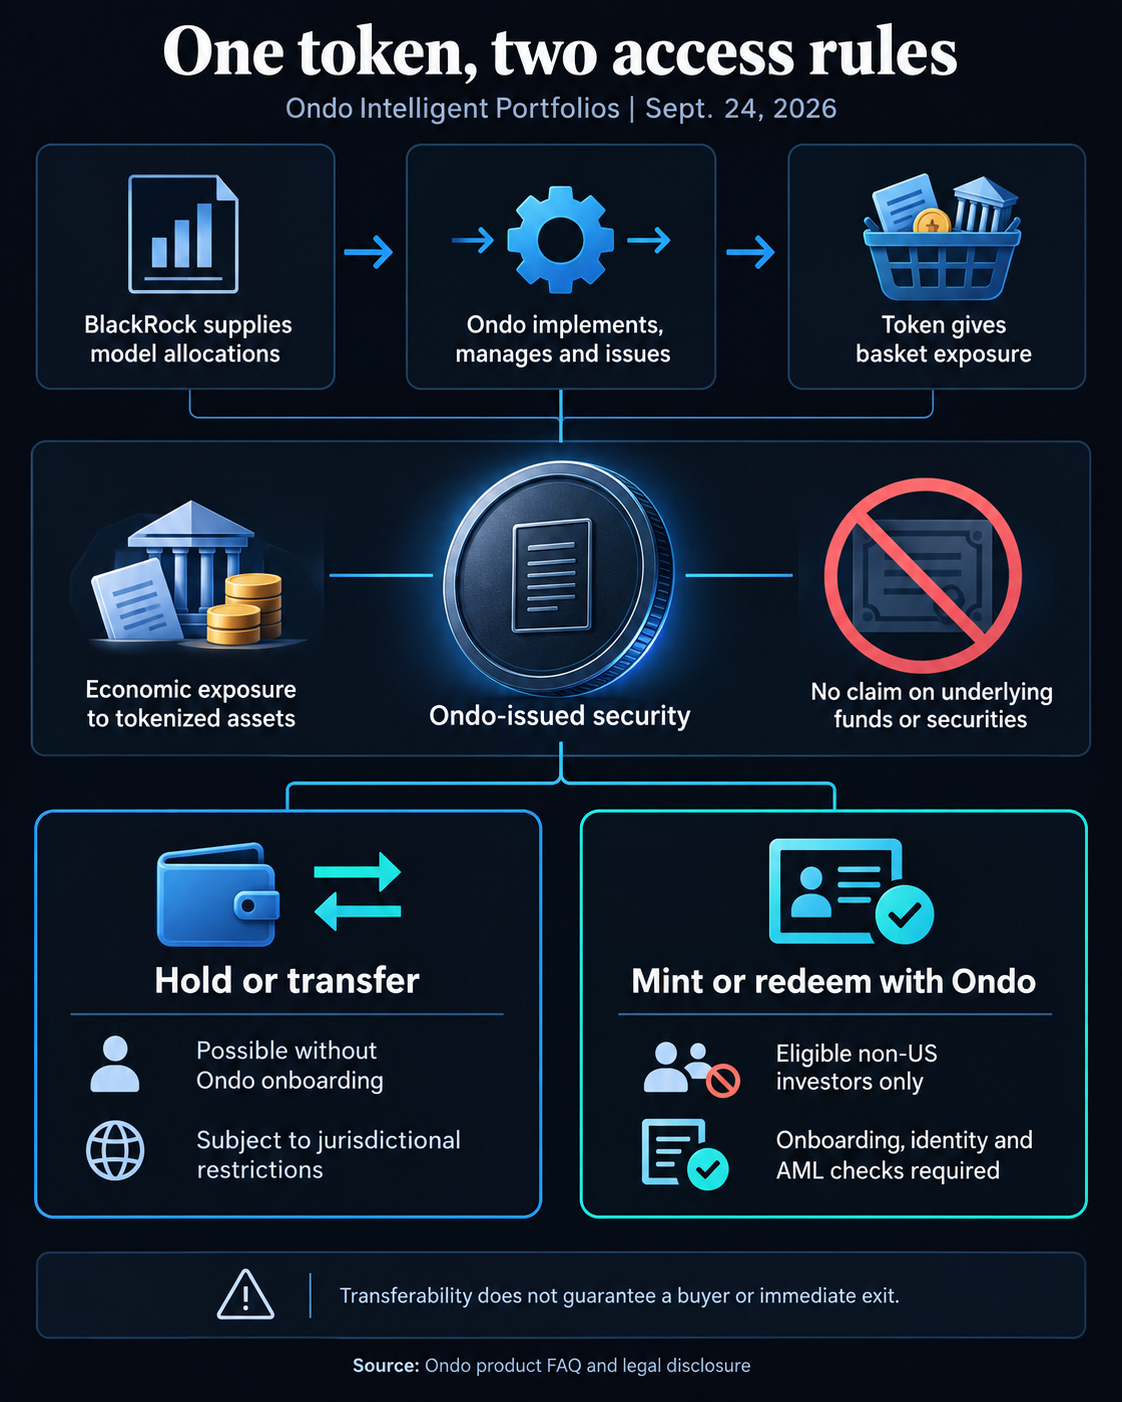
BlackRock Fund Advisors supplies model allocations to Ondo but does not make investment decisions for the on-chain portfolios. Ondo decides how to implement the models and manages, sponsors, and administers the products.
BlackRock does not manage the portfolios or owe advisory or fiduciary duties to token investors, and the company is generally not required to update its model after delivery. Ondo decides whether to apply any changes, so an on-chain portfolio may differ from the corresponding model.
Strategy for BlackRock onboarding
Ondo's FAQ says direct minting and redemption require an eligible person outside the US to complete identity and anti-money-laundering checks.
The process also screens for US-person status, restricted jurisdictions, and prohibited persons. Ondo processes redemptions only for eligible holders who have completed onboarding.
A person may still receive or hold a portfolio token without completing that process because the tokens are transferable on-chain, subject to jurisdictional and other restrictions. Possession alone does not qualify the holder to redeem with Ondo.
The ability to move a token between wallets is therefore distinct from eligibility to redeem it with the issuer.
Ondo describes peer-to-peer transfers as available around the clock, including through supported third-party platforms. That capability does not show that a buyer will be available at a given price or that a holder can exit immediately.
Anyone unable to redeem directly would depend on a third party willing to take the token, subject to that venue's rules and market conditions.
The post Ondo unlocks BlackRock portfolio strategies, but only non-US traders benefit appeared first on CryptoSlate.
Two pools that exchange TIX for other issued tokens accounted for 97.24% of the seven-day automated market maker (AMM) volume in XRP Ledger (XRPL), according to XRPL.to's Sept. 24 feed.
Neither pool contains XRP, so the outsized reading says far more about the provider's volume measure.
XRPL.to listed a 2.82069 billion seven-day volume total, including 1.68 billion for XPM/TIX and over 1 billion for RLUSD/TIX.
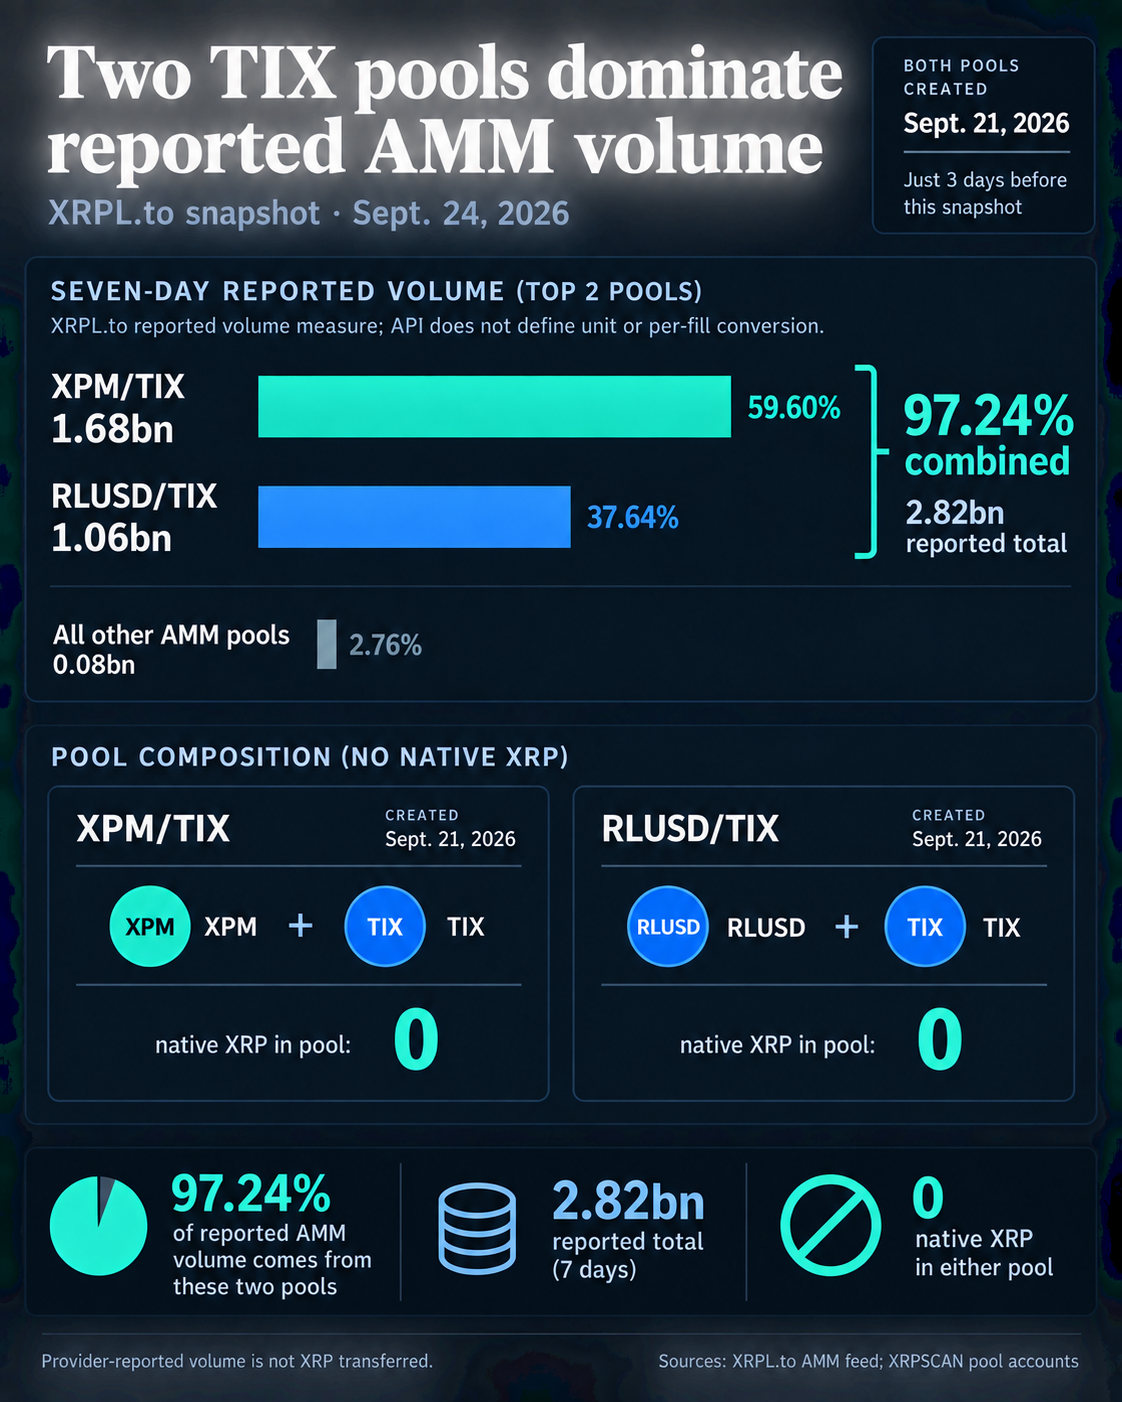
Those figures describe the provider's tally. The two pools were created Sept. 21 and list the same TIX issuer and pool creator, and XRPL.to counted 69 XPM/TIX trades and 116 RLUSD/TIX trades in its rolling seven-day window.
Neither had recorded a trade in the latest 24 hours at the Sept. 24 check. The count shows that fills occurred, but it does not establish how many independent traders took part or what those fills were worth.
A routed payment can pass through more than one pool, so pool-level counts should not be read as separate end-to-end customer payments.
What the XRPL ledger shows
A check of the XPM/TIX pool account found about 1,545 XPM and 9.69 million TIX in its reserves. The RLUSD/TIX account held only trace amounts of both assets and zero XRP.
The nearly empty account is a current liquidity warning, while the earlier trading window needs its dated balances to show what a trader could have exchanged then.
A validated payment from Sept. 22 provides one view of actual settlement. It routed through TIX and both AMM accounts, used about 5.89 XPM, and delivered 0.030177 RLUSD. Its ledger metadata shows the token balance changes at each pool.
However, it doesn't explain why an end-to-end payment and the two pool legs involved are counted differently.
The ledger's AMM rules allow pools to exchange two issued assets without an XRP trading side. Transactions still incur XRP network fees, and a longer payment route can use XRP elsewhere. Neither mechanism turns activity inside these two pools into evidence that someone bought new XRP.
To establish that demand, the trades would need to be traced through any XRP legs and separated from inventory participants already held.
XRPL dashboard leaves token-token pools out of its headline XRP-paired value locked because those reserves are harder to price in dollars. DefiLlama's XRPL DEX page showed $55.1 million in seven-day volume, while its adapter uses XRP-pair and AMM XRP-volume metrics.
Those figures cannot be set directly against XRPL.to's token-token tally as though they counted the same trades at the same prices.
The open question is the value attached to each TIX fill in XRPL.to's total. Until that conversion can be reproduced against the on-chain trades, the 97.24% concentration is best understood as a feature of one reported measure.
For XRP holders, recurring volume in pools that actually hold XRP, backed by verifiable reserves and valued fills, would be a more direct sign of trading demand. Such evidence would also distinguish a one-window spike from trading that persists after the newest pools have aged and their initial liquidity has changed.
The post Two obscure pools fuel 2.8B XRPL volume, but only 185 trades caused it appeared first on CryptoSlate.
Bitcoin researchers have proposed a system for private transfers directly on the network without requiring a soft fork or changes to its consensus rules.
The Sept. 24 paper from [[alloc] init] researchers Clara Shikhelman, Mikhail Komarov, and Aleksei Moskvin introduces Shielded Bitcoin, a metaprotocol designed to conceal transaction amounts, senders, recipients, and links between transfers while publishing its protocol data through Bitcoin mainnet.
The design adapts techniques pioneered by Zcash, including encrypted notes, public nullifiers and zero-knowledge proofs, but does not introduce a separate blockchain. Bitcoin instead provides the publication and ordering layer from which participants reconstruct the private transaction state.
That would extend Bitcoin privacy beyond existing techniques such as CoinJoin, PayJoin and Silent Payments, which can complicate transaction tracing or reduce address reuse but leave amounts and other transaction details visible.
Bitcoin would carry the transactions without validating the privacy layer
The proposal avoids waiting for a Bitcoin upgrade by moving the privacy logic above the network’s consensus rules.
Users would hold BTC-denominated value as encrypted notes. When funds are transferred, the sender would publish an envelope containing encrypted outputs, public nullifiers marking previously held notes as spent, and a zero-knowledge proof establishing ownership and value conservation.
The amount being transferred and the identities of the counterparties would remain hidden.
Bitcoin miners and nodes would not validate the shielded state themselves. Instead, implementations following the Shielded Bitcoin rules would scan BTC blocks and replay accepted transfer envelopes in their recorded order, producing a common note tree and spent-note set.
Bitcoin would therefore provide the timestamped transaction history and ordering needed to reconstruct the system, while the metaprotocol would handle encrypted balances and transfer verification.
The current implementation profile uses OP_RETURN to publish the encrypted transfer data, though the researchers leave open the possibility of other publication methods.
That architecture differs from Zcash, where the network’s consensus rules enforce shielded transaction validity directly. Shielded Bitcoin would keep BTC consensus untouched while deriving a separate private state from data anchored to the chain.
Some metadata would remain visible. Transaction timing, fees, input and output counts, and characteristics of the Bitcoin transaction carrying the encrypted data could still give observers clues.
The paper also includes viewing capabilities that could allow users to selectively disclose transaction information without surrendering control of their funds, creating a route for auditing or compliance where required.
Sam Callahan, the director of strategy and research at Bitcoin treasury company OranjeBTC, said the development fits a broader view that Bitcoin can accumulate functionality without competing with other blockchains feature by feature.
Callahan said:
“People still misunderstand Bitcoin’s moat. Bitcoin doesn’t need to win every feature race. Privacy, speed, and functionality can be built over time. The moat is its decentralization, security, and credible monetary policy,” he added. “And on those dimensions, nothing else comes close.”
The design remains incomplete at one critical boundary: moving ordinary BTC into and out of the shielded system.
Peg-in and peg-out mechanisms sit outside the current specification. Those components would need to lock Bitcoin on mainnet, represent that value inside the private note system, and later release the corresponding BTC when users exit.
[[alloc] init] expects those flows to rely on its PIPEs v2 work, but the researchers have yet to publish the detailed construction.
That leaves open questions around whether entry and exit can be made trustless, private, and resistant to transaction linkage. A distinctive deposit amount, withdrawal amount, or timing pattern could still connect activity at either end of the shielded system.
Other deployment choices also remain unresolved, including the final proof system, publication format, and how light clients can verify shielded state without replaying the full relevant Bitcoin history.
Privacy coins face fresh pressure as Zcash rally tests the thesis
The proposal comes as privacy-focused cryptocurrencies again attract investor attention, reviving a long-running debate over whether dedicated privacy networks retain an enduring technological advantage over Bitcoin.
André Dragosch, Bitwise Europe Head of Research, described Shielded Bitcoin as a “potential headwind for privacy coins,” reflecting the risk that features once associated with separate networks could increasingly be reproduced around Bitcoin without altering its monetary rules or base-layer consensus.
That argument becomes more consequential for Zcash, where privacy has become central to the token’s recent revaluation. ZEC climbed above $1,600 this week as shielded activity accelerated and investors returned to the idea that Zcash offers native transactions that can conceal senders, recipients, and amounts.
Usage has moved alongside price. Weekly shielded transactions recently reached 62,379, their highest level since 2022, while nearly 5 million ZEC were held in shielded pools this month. The network also settled more than $23 billion in transfer volume last week, its strongest weekly total since 2021.
Shielded Bitcoin pressures that narrative because it seeks to deliver comparable transaction confidentiality while keeping BTC as the underlying asset. If the system eventually works as designed, users seeking stronger privacy would have another route besides moving into a dedicated privacy coin.
The post Bitcoin researchers target privacy coins with Zcash-style shielded transfers appeared first on CryptoSlate.
A flaw in older Lightning Terminal software could mark a Bitcoin Lightning invoice paid after the payment was cancelled and returned to its sender, Lightning Labs disclosed on Sept. 21, 2026.
A merchant relying on that invoice status could release goods or credit without receiving funds. The company describes that risk but gives no tally of actual merchant losses.
The issue was a mismatch between the software's invoice record and the payment's outcome. A Lightning payment uses a hashed time-locked contract (HTLC) to carry funds.
In this case, the HTLC was canceled on the network and returned to the sender, while the receiving node still recorded the invoice as settled. The advisory does not describe a failure of Bitcoin's base chain.
Lightning Terminal bundles tapd, software for Taproot Assets, with the lnd Lightning node. In the affected setup, tapd enabled its invoice interceptor and treated any HTLC carrying custom wire records as an asset payment.
Some sender implementations added an experimental endorsement record even to ordinary BTC payments, causing tapd's strict-forwarding rule to instruct lnd to cancel the HTLC set. The trigger did not require the merchant to have any open asset channels.
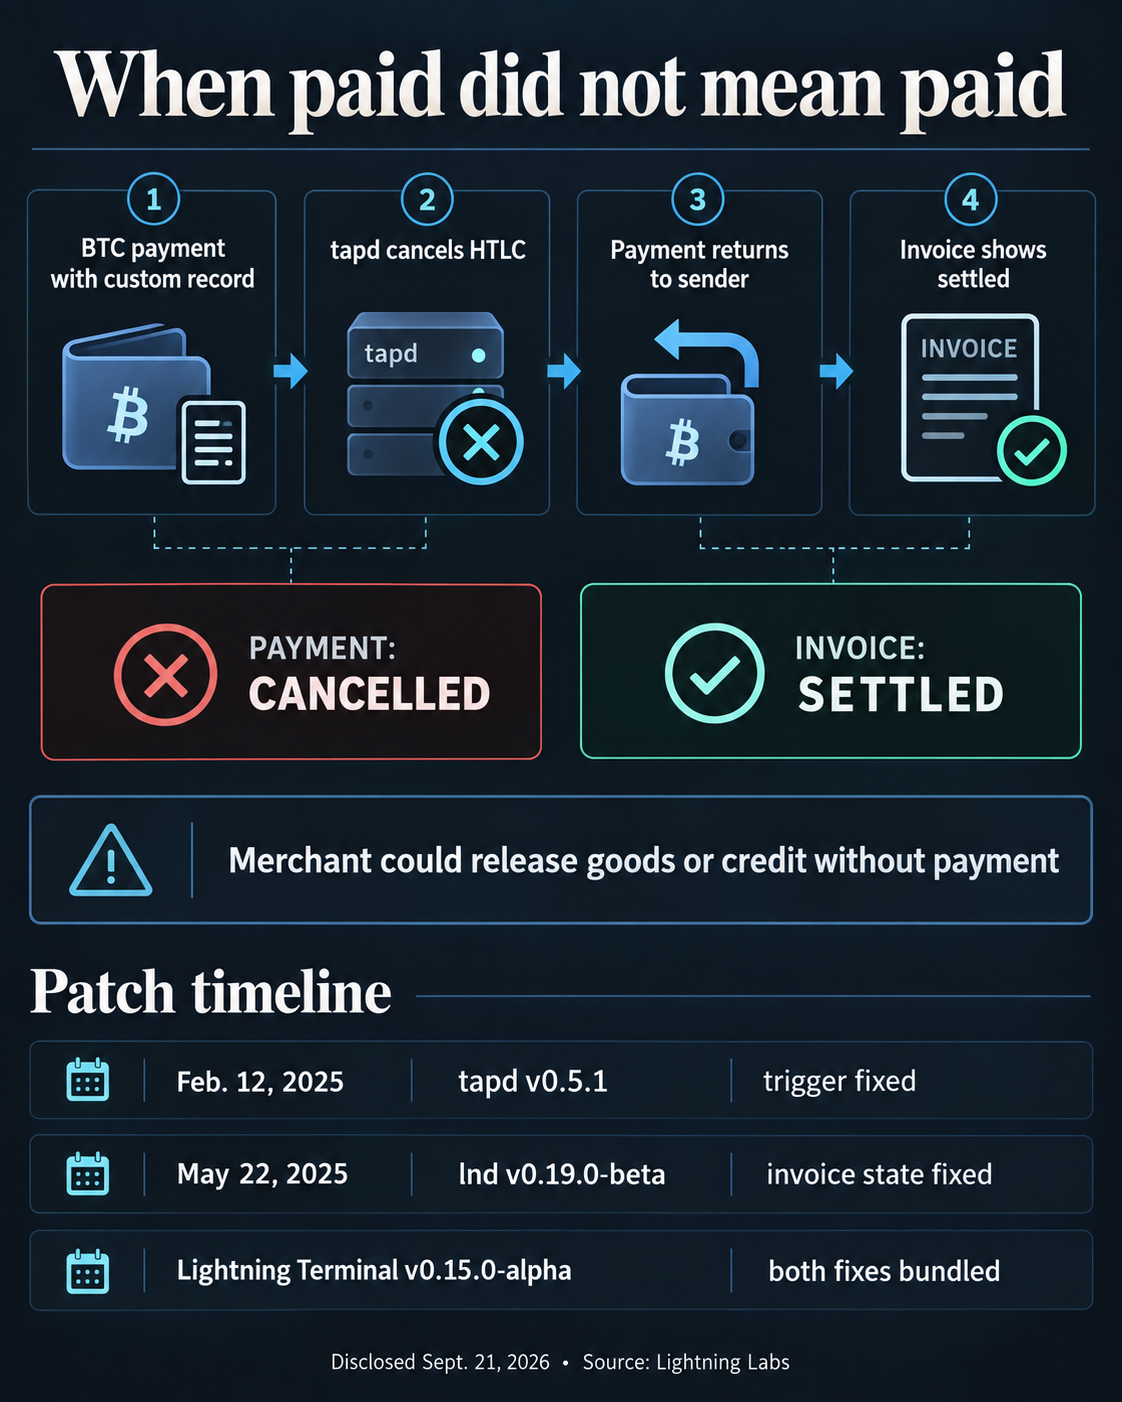
The second defect sat in lnd. When an interceptor canceled the HTLC set, affected versions canceled the payment on the wire but still marked its invoice as settled in the database.
That meant the error stood in another client of lnd's HtlcModifier interface that canceled an HTLC set could produce the same mismatch. Lightning Labs rates the vulnerability high severity because a false paid status could lead an operator or payment service to release value against a payment that never completed. According to the advisory, the sender's funds were not at risk.
Fixes shipped before disclosure
Lightning Terminal v0.15.0-alpha bundles fixes for both defects. Lightning Labs lists earlier Terminal versions as affected, along with taproot assets through v0.5.0 and lnd 0.18.4-beta through 0.18.5-beta.
The tapd trigger was fixed in v0.5.1 on Feb. 12, 2025. Terminal v0.14.1-alpha included that fix, but its bundled lnd version still had the underlying invoice-state defect.
lnd v0.19.0-beta fixed the accounting error on May 22, 2025. The September 2026 advisory therefore disclosed a vulnerability whose relevant fixes had shipped in 2025. For Terminal operators who cannot update and have no asset channels, Lightning Labs identifies --taproot-assets-mode=disable as a way to avoid the observed tapd trigger.
The post Lightning Labs discloses critical bug marking canceled invoices paid, risking free product delivery appeared first on CryptoSlate.
New York has sued Polymarket, alleging its US prediction market is an unlicensed gambling business operating across the state.
On Sept. 24, Attorney General Letitia James asked a New York state court to stop QCX LLC, which operates as Polymarket US, from offering event contracts without a state gaming license and to order restitution, disgorgement, and potentially substantial penalties. The petition covers contracts tied to sports, elections, culture, and other events.
The action targets a company that is also regulated at the federal level. QCX has been a Commodity Futures Trading Commission (CFTC)-designated contract market since July 2025, placing the lawsuit within a broader dispute over how federal derivatives oversight interacts with state gambling laws.
New York says Polymarket contracts amount to gambling
New York's case starts with the structure of Polymarket's contracts.
Users buy contracts tied to the outcome of future events, with winning positions ultimately paying according to whether the specified event occurs. The state argues that because customers risk money on outcomes outside their control, the transactions meet New York's definition of gambling.
The petition describes Polymarket as offering what is “quintessentially wagering” under the guise of event contracts and alleges that the company accepts public wagers despite having no license from the New York State Gaming Commission.
Kathy Hochul, New York's Governor, said:
“Calling it a ‘prediction market’ doesn’t change the facts. If you’re taking bets in New York, our gambling laws apply.”
The state cited Polymarket's marketing in its case. The company announced its US app in December 2025 with “sports—followed by markets on everything” and advertised itself as “legal in all 50 states.” An earlier promotion said users would be able to “TRADE EVERY FOOTBALL GAME IN ALL 50 STATES.”
Investigators said the platform offered markets involving the New York Mets, college football games, the New York governor's race and reality television show “Big Brother.” The petition also alleges Polymarket repeatedly advertised and solicited users located in New York through the internet and social media.
Sports contracts add another layer to the state's case. New York requires mobile sports wagering operators to hold a state license, while Polymarket has none, according to the filing.
The attorney general also alleges violations of the federal Wire Act through the transmission of sports wagers, information used to place them, and communications confirming payments across state lines.
Age restrictions are also central to the complaint. Polymarket allows users aged 18 and above, while New York requires mobile sports bettors to be at least 21. The state is asking the court to prohibit Polymarket from allowing people under 21 to wager on the covered event contracts.
James tied those requirements to New York's broader argument that unlicensed operators avoid safeguards and taxes imposed on licensed gaming companies.
“By skirting New York’s laws, Polymarket is targeting the most vulnerable and depriving New York families of critical services and support,” James said. New York says gambling tax revenue supports schools, youth programs and treatment for problem gambling.
State seeks triple gains and $100,000 penalties
The remedies sought by New York extend beyond shutting down Polymarket's sports contracts.
James wants a permanent injunction preventing the company from operating an unlicensed gambling business within or from New York, including by offering contracts tied to “sports, culture, elections, and other events” without obtaining the required state licenses. The requested order would also cover advertising, marketing, and soliciting participation in those contracts.
That wording would place political and cultural markets alongside sports contracts under the same requested restrictions rather than confining the case to products that resemble conventional sportsbook wagers.
New York also wants Polymarket to provide an accounting that identifies its customers and itemizes bets placed, customer losses, and gains the company received. It is seeking full restitution for customers, damages, and disgorgement of money obtained through the alleged violations.
The state is also seeking a penalty equal to three times Polymarket's gains from the alleged illegal activity.
Sports wagering carries a separate potential cost. The petition seeks $100,000 for each offering or attempt to offer unauthorized sports wagering or mobile sports wagering within or from New York. It does not specify how many offers could ultimately qualify, leaving the size of that portion of any potential penalty unresolved.
The attorney general alleges Polymarket has operated or indirectly operated a sports wagering platform in New York since at least Jan. 23, 2025, and has continued to advertise it to people in the state.
Polymarket becomes latest target of New York prediction-market push
The lawsuit follows a series of similar actions by New York against companies offering event contracts under prediction-market structures.
James sued Coinbase Financial Markets and Gemini Titan in April, alleging their prediction markets constituted unlicensed gambling because customers could bet on sports, elections and entertainment events.
Those cases also sought forfeiture of alleged illegal profits, restitution and fines equal to three times the companies' profits from the challenged activity.
New York followed in July with a lawsuit against Kalshi, another CFTC-designated contract market. That petition similarly sought to stop Kalshi from operating an unlicensed gambling business, recover alleged illegal gains, compensate users and impose fines equal to three times its gains.
The Kalshi dispute had already tested the boundary between federal derivatives regulation and state gambling enforcement.
Earlier in July, James and Hochul said Kalshi had lost a lawsuit against the New York Gaming Commission and pledged to continue applying state gambling laws to prediction markets.
The Polymarket petition now asks the same state court system for a comparable package of relief, while adding allegations tied to Polymarket's own sports promotions and New York activity.
The post New York sues Polymarket, seeks triple gains and $100,000 penalties over prediction markets appeared first on CryptoSlate.
CryptoTicker.io
The three European financial supervisory authorities added quantum risk to their official autumn risk picture on September 23, 2026. Nothing about your holdings changes today, and the paper is not a warning about an imminent attack. What changes is the expectation placed on your provider: exchanges, custodians and banks in the EU now have to plan the migration of their encryption, and you can measure them against that.
This article sets out what the document actually says, which deadlines sit behind it, where the real attack surface lies for Bitcoin and Ether, and which three things you can check about your own custody without waiting for technology that does not yet exist.
What the EU supervisors wrote about quantum risk on September 23
Behind the paper stand the three European Supervisory Authorities, the ESAs: the banking authority EBA, the insurance authority EIOPA and the markets authority ESMA. Twice a year they publish a joint risk update in which the Joint Committee names the weak points of the EU financial system. The autumn 2026 edition appeared on September 23, and its core findings had been presented on September 10 at the Financial Stability Table of the EU Economic and Financial Committee. The statement is available in full at ESMA and at the EBA.
On quantum computing the text says the technology could transform the financial sector in central areas, from process optimisation through fraud and compliance monitoring to pricing. The same paragraph carries the flip side: the technology could equally create significant risks by undermining cryptographic systems that are used at scale to secure communications, transactions, databases and blockchains. Blockchains are named explicitly there, and not as a footnote to a banking topic.
The sentence that carries the urgency is a different one: the risks could materialise faster than any commercially viable application. In other words, the supervisors expect the ability to break old encryption to arrive before the economic benefit with which quantum computers are otherwise advertised.
Three weak points in one paper
The quantum topic does not stand alone. The ESAs name three fields: dependence on providers and infrastructure outside the EU, new technologies involving artificial intelligence and quantum computing, and the rapidly grown market for private credit. For crypto investors the first two fields are relevant, and they interlock. On the same September 23 ESMA additionally declared digital innovation a new supervisory priority from 2027, which shows that this is more than a one-off remark.
“Harvest now, decrypt later”: why intercepted data becomes a problem later
Harvest now, decrypt later describes an approach in which an attacker records encrypted data today and stores it, in order to decrypt it only once the necessary computing power exists. The attack therefore happens in two steps that can lie years apart.
For banking data, health records or contract documents that is the core of the problem, because their value does not expire. With a public blockchain the case is different and in one respect more uncomfortable: there, nobody has to intercept anything. The data lies open, permanently and retrievable by anyone. Whoever stores a copy of the chain today has everything they would need in ten years.
That is precisely why the distinction in the next section matters. The transaction history is always open. What decides the question is whether the public key belonging to a particular address is open as well.
Post-quantum cryptography: the migration deadline of end-2026 and who it binds
Post-quantum cryptography, abbreviated PQC, covers encryption and signature schemes that cannot be broken even by a powerful quantum computer. It rests on different mathematical foundations, and it is not about longer passwords.
The European timetable for this was not set by the Joint Committee. It comes from the NIS Cooperation Group, in which the member states work together. In June 2025 the group adopted a roadmap that the states endorsed. It provides for three stages: by the end of 2026 all member states should have begun the migration, meaning national strategies, inventories of the schemes in use and first migration steps. High-risk applications, which expressly include the financial sector, should be protected as early as possible and by 2030 at the latest. By 2035 the migration should reach as far as is practically feasible.
One point matters for placing this correctly: these deadlines bind member states, operators of critical infrastructure and supervised financial firms. As a private individual you are bound by no deadline. That is a relief, and at the same time it is the reason you have to look for yourself, because nobody migrates your self-custody on your behalf.
Elliptic curves, public keys and Bitcoin addresses: where the attack surface sits
Bitcoin and Ethereum sign transactions with schemes based on elliptic curves. A public key is computed from a private key, and that computation is easy in one direction and practically impossible in reverse. A sufficiently large quantum computer would make the reverse direction attackable, because a known method from quantum computing solves exactly this problem.
Here is the message for holders. With the address formats common today, the chain does not hold the public key itself, only its hash. The key becomes visible only when you spend from that address for the first time. As long as an address has only received, the information needed for this attack is not public.
That leaves two groups with a clearly raised attack surface. First, very old holdings from the early days, where the public key sits directly in the chain. Second, addresses that were used again and refilled after a spend, because from the first spend onwards the key stays permanently visible.
On the question of how far the hardware is from that point there is no reliable year, and this article deliberately names none. What is documented is that the estimates are moving towards lower effort: work published by Google Quantum AI in March 2026 concluded that breaking the 256-bit curves in use should require considerably fewer physical qubits than older models had assumed, by roughly a factor of twenty according to the reporting on that work. That is a correction to an estimate, not a date.
Dependence on non-EU service providers: the second finding that hits your exchange
The finding that takes up more room in the paper than the quantum topic is dependence on providers outside Europe. The ESAs identify a persistently strong dependence on IT service providers and payment systems outside the EU, and point out that it remains visible in the financial infrastructures as well, where clearing, repo business and ratings are predominantly handled by entities outside the EU.
For you this is not an abstract subject, because a trading platform is first and foremost software. The servers, the custody system, the identity checks and often the settlement sit with service providers whose names appear in the terms and conditions rather than on the front page. When supervisors expect cryptographic migration, that whole stack has to move with it, and the migration is only as fast as the slowest supplier.
In practical terms: a platform licensed in the EU gives you a counterparty bound by European rules, and a supervisor able to ask questions. If the choice is still ahead of you, the comparison of regulated crypto exchanges breaks down the licences, the registered seat and the custody model for each provider. That does not replace reading the terms yourself, but it shortens the job considerably.
AI-assisted attacks: why phishing is the nearer risk than the quantum computer
In the same chapter the ESAs write that the rapid development of advanced AI systems could make cyberattacks more effective and harder to control, because attackers could find and exploit weaknesses at unprecedented speed. For insurers they expect more frequent and more severe claims as a result.
That ordering is worth holding on to, because public debate often runs it the other way round. Quantum risk is significant, and it has no date. Automatically generated phishing pages, convincingly written support messages and cloned voices on the phone are circulating today and cost holdings today. The same precaution works against both, and it is unspectacular: the private key never leaves the device on which it was created, and an approval is confirmed on a screen that does not belong to the sender of the message.
That is exactly the purpose of a hardware wallet: the signature is created inside the device, and the content of the transaction is displayed there. A compromised computer can then propose a false payment, but it cannot approve one unnoticed.
Exchange balance, hardware wallet or self-custody: what supervisors do not settle for you
The obligations arising from the risk picture are addressed to supervised firms. Where your coins sit therefore decides who carries the migration burden.
If the balance sits with a regulated exchange or a custodian, that provider carries the migration of its systems, and the supervisor can question it about them. In return you depend on its diligence and on its insolvency risk. If you hold the keys yourself, you carry the migration yourself, and in return nobody stands between you and your coins. A third variant is the split, in which an actively traded portion stays on the exchange while the long-term holding sits in self-custody.
What you can ask your provider
- Is there a published roadmap for post-quantum migration, and does it name years?
- Which parts of custody sit with service providers outside the EU, and who is your contact if something fails?
- Are deposit addresses generated fresh for each transaction or permanently reused?
- Can withdrawal addresses be locked and approvals tied to a second device?
- When was custody last audited, and is the result available to read?
The last three points take effect immediately, independently of any quantum debate. If the first question goes unanswered, that is no proof of negligence, but it does indicate how far the planning has got.
MiCA licence and custody duties: what you find in your provider's terms and conditions
Since the European regulation on markets in crypto-assets applies in full, service providers need an authorisation as a crypto-asset service provider, CASP in the wording of the regulation, in order to offer trading and custody. The authorisation brings duties that bite at exactly the point at issue here: client holdings have to be segregated from the firm's own funds, custody has to be documented, and there are reporting and contingency duties for outages and attacks.
These duties are the lever through which a supervisory finding reaches the provider. An ESA risk picture is not a law and sets no deadline for an individual firm. It does feed into supervisory practice, and that is where an observation turns into a question in an examination report. Which duties apply in detail and when the transitional rules run out is set out in our overview of the MiCA obligations for crypto firms.
For your own records one point matters more in practice than any debate about the regulation: write down which provider holds which assets and under which authorisation. If a provider changes its offering or leaves the market, you need that overview immediately.
Moving wallets and the holding period: why a transfer between your own wallets is not a sale
Anyone who takes this as the occasion to move holdings from an old address to a new one, or from the exchange into self-custody, rightly asks the tax question. The basic rule in Germany is clear: a transfer between two wallets that both belong to you is not a disposal. There is no sale, so no gain arises, and the one-year holding period keeps running. Only a sale, a swap into another coin or a payment made with it is a taxable event.
In practice this rarely fails on the law and often on the documentation. A portfolio tracker that does not recognise a self-transfer as such books the outgoing leg as a sale and the incoming leg as a purchase. A gain that never existed then shows up in the report, and the holding period starts again inside the software. So anyone moving holdings marks the event in their tool as an internal transfer and keeps the transaction IDs. Which programs merge self-transfers reliably is shown by the comparison of crypto tax tools.
A second point concerns the sequence. If you are consolidating several addresses anyway, it is better done calmly than under time pressure, because every move is an operation in which an address can be copied down wrongly. The most common loss in this area has nothing to do with cryptography.
“Quantum-safe” coins and wallets: how to spot dubious offers
Every supervisory announcement carrying a technical buzzword produces offers that lean on it. The pattern is predictable, and so are the markers.
- An offer promises protection and asks you to enter your existing recovery words for it, for a migration or a check, say. That is a theft attempt in every case, without exception.
- A new token is advertised as quantum-safe and is therefore supposed to rise in value. The security properties of a protocol say nothing about the price of a token.
- A year is named from which existing schemes are said to be broken. No such figure is reliable at present, including in the supervisors' papers.
- There is time pressure, a countdown or an offer valid only today. A genuine protocol migration is announced and debated over months.
The protocols themselves work on this seriously, and visibly so. Proposals for quantum-resistant signature schemes are debated in open development processes, with specifications, testnets and objections. A migration of that size will surprise nobody who follows the developer channels of their own coin.
Quantum risk and custody: what to take away
The EU supervisors have moved a long-term risk into an ongoing supervisory process. That is good news, because it creates accountability where there was only debate before. Three steps follow for you, and none of them is urgent.
- Sort your addresses. Check whether you hold balances on addresses that have already been spent from, and whether you manage very old holdings from the early days. Those are the parts that are affected at all. If everything sits with a provider, first check who holds the keys there, and compare the custody model in the overview of regulated crypto exchanges.
- Harden your approvals. The nearer risk is the attack on you rather than on the mathematics. Tie withdrawals to a second device, fix address book entries and sign larger amounts on a device kept for that purpose alone. The differences between the devices are set out in the comparison of hardware wallets.
- Book your moves cleanly. When you reorder addresses, mark every self-transfer as such and keep the transaction IDs, so that the holding period does not restart in the report. Which programs handle that reliably is shown by the comparison of crypto tax tools.
And the sentence for calm: if the ability to break elliptic curves ever exists, your wallet will not be the first target. Ahead of it stand bank connections, government communications and the signatures that hold the internet together. That is why the topic appears in the risk picture of a financial supervisor and not in a warning notice to retail investors.
(As of September 25, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
No, you cannot buy a house in Germany with Bitcoin. Since April 1, 2023, section 16a of the German Money Laundering Act has banned exactly that: the purchase price for a domestic property may not be settled in cash, nor in crypto-assets, gold, platinum or gemstones, whatever the amount involved. Your Bitcoin holdings still work as a down payment for a mortgage, but only along a single route: you sell them, have the euro amount paid into an account in your own name, and prove to the bank and the notary, without gaps, where the money came from.
That shifts the real task away from the purchase and towards the paperwork. Anyone who has moved coins across several wallets and exchanges over the years rarely fails on the value of the portfolio, and almost always on the missing proof of origin. This article sets out what German banks accept as a down payment, which documents close the chain, how the holding period changes the sum available to you, and in which order to proceed.
Can you pay for a property in Germany directly with Bitcoin?
The short answer is no. The reason lies in an explicit statutory rule, not in the convenience of the banks. The Money Laundering Act, GwG for short, is the German law that requires banks, notaries and other obliged parties to check and document the origin of the assets used. Since 2023 it has contained a prohibition of its own for property transactions.
In practice that means: even if a seller were willing to accept coins, and even if both sides recorded it in the purchase contract, the transaction could not be validly performed. The notary who applies for the transfer of title at the land registry must be shown evidence of the non-cash payment. Without that evidence the transfer cannot proceed, and without the transfer you do not become the owner.
The reverse idea does not hold either. Some buyers hope that part of the purchase price could be settled in coins at the notary's desk and only the remainder through the bank. The prohibition recognises no de minimis threshold. It applies to the obligation as a whole, and therefore to a small part-payment as well.
What section 16a of the Money Laundering Act has banned since April 1, 2023
The provision applies to legal transactions covering the purchase or exchange of domestic property, and to the acquisition of shares in companies whose assets include domestic property. The obligation owed may only be discharged by means other than cash, crypto-assets, gold, platinum or gemstones. The wording can be read at the federal justice ministry in the official text of section 16a GwG.
The consequence of a breach is more unpleasant than many expect. A prohibited payment does not render the purchase contract void, but the payment loses its discharging effect. In legal terms: the seller's claim to the purchase price continues to exist. Anyone who has paid in coins has therefore not paid the price in law and owes it again, while the transferred holdings can only be recovered under the general law of unjust enrichment. For a financing running into several hundred thousand euros, that is a risk out of all proportion to the effort of an ordinary bank transfer.
One detail often gets lost in advice: the rule applies only to legal transactions concluded on or after April 1, 2023. It does not apply to older contracts. Since the provision has now been in force for more than three years, only residual cases are affected today.
What counts as a down payment at the bank and what counts as collateral
Two terms are constantly confused in conversations with the bank, and the confusion costs negotiating position. A down payment is the freely available funds you contribute to the property financing yourself, reducing the loan amount required. Collateral, by contrast, is an asset the bank may seize in an emergency, without it reducing the loan amount. In a classic property loan the collateral is the property itself, registered by way of a land charge.
Crypto holdings can count towards the down payment once converted into euros. As collateral they are of practically no use at German banks. The building society Schwäbisch Hall puts it plainly in its guide on cryptocurrency as equity: Bitcoin as security for a loan has so far been rejected by the banks. As a source of equity, the route is open, but only through conversion into euros.
How large a down payment you need depends on the house, your income and the credit terms. Advisory practice works on the rule of thumb that the incidental purchase costs should come entirely from your own funds, plus roughly twenty percent of the purchase price. Those incidental costs are no sideshow: land transfer tax ranges from 3.5 to 6.5 percent depending on the federal state, notary and land registry account for around 1.5 to 2 percent, and where an agent is involved further percentage points are added. Together that lands at roughly 9 to 15 percent of the purchase price, depending on location and who is involved.
Why banks do not accept crypto holdings as collateral
The reason lies in the valuation logic of property financing. Banks work with the mortgage lending value, a deliberately conservative figure that should still be achievable in a weak property market. It regularly sits below the market value of the property. For a residential building, that figure can be derived plausibly through a valuation using comparable properties, replacement cost and income capitalisation.
Crypto holdings resist that logic on several counts at once. The price can move by double-digit percentages within days, which makes any valuation on a thirty-year horizon questionable. Enforcement in the event of default is legally cumbersome, because the bank can realise nothing without the private key. And any realisation would have to run through a trading venue whose liquidity is not guaranteed. A land charge has the land registry behind it; a wallet has no equivalent.
This reticence is no verdict on crypto as an asset class. Deutsche Bank announced custody of Bitcoin, Ether and selected stablecoins for institutional clients from 2026. Custody for large clients and acceptance as loan collateral in retail banking are two different things, though, and the second does not automatically follow from the first.
How crypto holdings become a recognised down payment: the route through the euro
The sequence is unspectacular, and that is precisely its strength. You sell the amount you need on an exchange or through a broker, have the euro equivalent paid out to an account in your own name, and bring that amount into the financing as your down payment. What matters is that the payout goes to your own account and not to a third party's. Every intermediate step through another person tears open the chain of evidence and creates exactly the suspicion the Money Laundering Act is aimed at.
One point deserves more attention than it usually gets: the choice of trading venue. An exchange based and authorised in the EU gives you machine-readable annual statements, trading histories and payout records in a form a bank accepts. A provider without European authorisation often does not, and a later export can turn out to be impossible if an account has been frozen or a service discontinued. So if the sale is still ahead of you, it is worth looking at our crypto exchange comparison with documentation in mind, and not only fees. The difference between two providers here is not measured in tenths of a percent, but in whether the financing goes through.
Allow time as well. Between the sell order, the credit to the reference account and the onward transfer to your own current account, several working days pass depending on provider and amount. With larger sums, checks are added that extend the process.
What proof of source of funds banks and notaries require for crypto
Proof of source of funds is the evidence showing where the money used came from. It is no formality to be dealt with by way of a screenshot. The review is risk-based: the more conspicuous a transaction looks, the deeper the bank and the notary probe. A six-figure euro amount arriving from a crypto exchange shortly before a property purchase reliably falls into the higher risk class.
What is typically required is a closed chain: wallet, then exchange, then your own bank account, then the notary's escrow account or the seller. Each transition needs its own record. Completeness is what counts, not the volume of paper. A single transfer confirmation does not answer the question of origin, because it shows only the final step.
This scrutiny does not only reach you when buying property, incidentally. In the opposite direction, when depositing funds at an exchange, a query about the source of funds can trigger a freeze. How that plays out and which documents help there is described in our article on a crypto deposit frozen over the source of funds. The logic is the same; only the direction of the money flow differs.
Which documents prove the chain from wallet to exchange to account
Gather the records before the first meeting with the bank, not after. An application that goes into a second round for want of documents loses time and often the interest rate initially offered. These are the documents asked for in practice:
- The complete trading history from the exchange as a machine-readable export, not as a screenshot. A CSV export can be checked; a photograph cannot.
- Purchase records for the original acquisition, ideally with date, quantity and euro equivalent.
- Bank statements showing the deposit made to the exchange at the time, that is, the origin of the money originally used.
- Wallet addresses and transaction identifiers for movements that ran outside an exchange.
- The exchange's payout record for the sale, together with the matching statement from your current account.
- For coins from mining, staking or airdrops, the relevant statements, because such inflows are treated differently for tax than a purchase.
A gap is not the end of the world, but it has to be explicable. A discontinued exchange, a lost login or a wallet from the early years all happen. Write such cases up in advance in a short, factual note and attach whatever still exists. A gap that is named openly and explained plausibly is usually accepted; one passed over in silence leads to a query at the worst possible moment.
How the holding period under section 23 of the Income Tax Act decides your available sum
Selling for your own home is, for tax purposes, a private disposal transaction. The governing provision is section 23 of the Income Tax Act, which can be read in the official text of section 23 EStG. The holding period is the span between the acquisition and the sale of a coin position. Where more than a year lies between the two, the gain is entirely tax-free, with no upper limit. Sell within the year and your personal income tax rate applies.
Beneath that sits an exemption limit of 1,000 euros a year. The difference from an allowance is decisive and is constantly confused: with an allowance, that amount would always stay tax-free and only the excess would be taxable. With an exemption limit, the treatment flips as soon as the limit is reached. A gain of 999 euros stays untaxed; a gain of 1,010 euros is taxable in full. For a financing where every available euro counts, that is a figure worth knowing in advance.
The calculation becomes concrete once you run it against your own holdings. Suppose you need 80,000 euros as a down payment and hold positions from two different years. The older ones are past the one-year mark and deliver their amount tax-free. The younger ones trigger a tax charge at your personal rate, falling due the following year, which you have to set aside. Sell the younger ones first and you will later be short of money you had long since earmarked. Which position was acquired when therefore helps determine your financing sum and is no mere bookkeeping question. Anyone who has accumulated many transactions over the years will not get around a clean schedule; a look at the crypto tax software and portfolio trackers saves weeks of manual work here and supplies at once the records the bank and the tax office want to see.
Why the sale belongs before the financing meeting
Banks work with euro amounts sitting in an account. A portfolio carrying price risk does not appear as a down payment in the affordability calculation, because its value on the day the loan is paid out may differ from its value on the day of the meeting. Walking into the advice session with a portfolio statement and planning the sale only after approval means negotiating over funds that do not yet exist for the bank.
The opposite mistake is just as expensive. Selling before a property is even in sight means bearing the tax consequence and giving up any price movement, without gaining planning certainty in return. The sensible moment lies between the two: once a specific property has been found and the financing request is being prepared, but before the documents are submitted. Then the amount is fixed, the records are fresh, and the bank sees a figure rather than an intention.
What the banks' three-month rule means for your bank statements
Many institutions ask for the last three months of bank statements in order to assess income, spending and the origin of the down payment. A larger inflow from a crypto exchange within that window inevitably leads to a query. That is not particular scepticism towards crypto. Every conspicuous inflow is treated this way, a gift or a severance payment included.
From that follows a practical recommendation: if you are planning the sale anyway, carry it out so that the inflow and its record are visible and explained within the review window. An inflow that disappears precisely between two statement periods strikes a case handler as more in need of explanation than a harmless one. Attach the exchange records without being asked. That shortens processing measurably, because the query falls away.
How savings banks and cooperative banks separate crypto trading from credit assessment
One observation causes many customers confusion. The same savings bank that now offers crypto-asset trading in its app still does not treat your crypto holdings as collateral in a credit assessment. What lies behind the institutions' entry into trading is described in detail in our article on the launch of crypto trading at Sparkasse.
The contradiction is only apparent, because two different departments work with two different rulebooks. The securities and custody business sells you access to an asset class and earns fees. The credit department has to secure a claim over decades and is subject to regulatory requirements on the soundness of collateral. That one house offers both says nothing about the second question. So do not count on a portfolio held at your own house bank easing the negotiation. What counts is the euro amount in the account and the quality of your records.
What is different in the United States and why it changes nothing in German practice
In the United States things are genuinely moving. On June 25, 2025, the regulator FHFA directed the two large mortgage financiers Fannie Mae and Freddie Mac to develop a proposal for how crypto holdings can be taken into account as reserves in the risk assessment of residential mortgages, without prior conversion into US dollars. The directive is confined to holdings demonstrably held on a trading platform regulated in the United States, and requires haircuts for price volatility.
Two limitations matter for you. First, the subject there was reserves in the risk assessment, meaning proof of funds held alongside the down payment, and not payment of a purchase price in coins. Second, as of mid-2026 no finally approved guideline for broad application was in place. For a property purchase in Germany it has no bearing in any case: German law applies here, and section 16a GwG rules out payment in crypto-assets. Anyone inferring from American headlines that their German bank will soon calculate along similar lines is planning on a basis that does not exist here.
Which mistakes most often sink the financing
Most refusals in this context trace back to a few readily avoidable patterns:
- Payout to someone else's account. A sale whose proceeds land in the account of a parent or partner breaks the chain. Where family funds are involved, they belong documented as a gift in their own right, not mixed in.
- Screenshots instead of exports. A photograph of an app view is not evidence. What is required is a complete, machine-readable export.
- Tax not set aside. Sell within the one-year period and you have to pay the following year. If that amount is counted into the down payment, it will be missing later for repayments.
- Incidental costs underestimated. Banks usually do not finance land transfer tax and notary fees. Allocate the entire crypto proceeds to the purchase price and you stand before the incidental costs with no funds.
- Documents left too late. Exchange exports going back years take time, and with discontinued providers they are sometimes no longer obtainable. Noticing that only after the property has been secured means losing the deadline.
A last word on expectations: even with clean documents, approval remains a decision on the individual case. Income, term, repayment rate and the valuation of the property weigh more heavily than the question of where the down payment came from. Complete proof of origin removes one obstacle; it does not replace a sound affordability calculation.
Crypto as a down payment: what to take away
- Calculate first, sell afterwards. Go through your positions by acquisition date and separate the holdings past the one-year mark from the younger ones. Only when you know which part is tax-free and what tax charge the rest triggers do you know your real down payment. The practical steps of selling, including payout routes, are set out in our overview on selling Bitcoin.
- Gather the records before you go to the bank. Trading history as an export, purchase records, bank statements for the original deposit, payout record. Check whether your trading venue supplies these documents in a usable form at all; the exchange comparison helps with that assessment, and if you are switching provider, pull the exports beforehand.
- Document the tax side in writing. A traceable schedule of all acquisitions and sales serves two purposes at once, the tax office and the credit case handler. With one of the crypto tax tools you produce it once and use it twice.
(As of September 25, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
On the evening of Thursday, September 24, 2026, the crypto exchange Bitget said it detected unauthorised outflows from part of its wallets at 18:31 UTC and suspended withdrawals in response. The figure the company itself gives is around $351.6 million. For a European investor, the most important detail is not the size of the loss but the withdrawal freeze: anyone still holding a residual balance at Bitget cannot reach it right now.
That hits a group already working against the clock. Since July 1, 2026, providers without MiCA authorisation have been barred from taking on new business in the European Economic Area. Bitget has exited the EEA market in stages and told existing customers to withdraw their balances. That single remaining route is now temporarily closed.
What happened at Bitget: hot wallets, warm wallets and $351.6 million
A hot wallet is an exchange wallet whose private key stays permanently connected to the internet. It has to be, because withdrawals are meant to settle in seconds. A cold wallet keeps the key offline instead, usually on separated hardware; it is slow, but out of reach for an attacker working over the network. Between the two sits the warm wallet, an intermediate tier with limited but real network access.
Bitget describes its custody setup as a three-tier architecture built from exactly those layers. According to chief executive Gracy Chen, quoted by CoinDesk, only part of the hot and warm wallet tier is affected and the cold wallets are intact. The amounts on-chain observers could see diverged at first: blockchain analysts reported movements of roughly $178 million to $183 million in the opening hours, while the company puts the figure at $351.6 million. A spread like that is normal in the first hours after an incident, because outside observers only see the transactions they have already been able to attribute.
The outflows were spread across fifteen transfers and seven assets on several networks, according to an analysis by CryptoSlate. The largest single block, 44.4 percent, was Ethereum; BNB, AVAX and the stablecoin USDT were among the others affected. Notably, the funds were then consolidated into a single address.
The exchange treats deposits and withdrawals differently: deposits and trading continue to run, the company says, and only withdrawals are paused for the duration of the security review. Bitget announced hourly updates and a full report on the root cause within 24 hours. Neither had appeared by the time this article went to press.
Why the withdrawal freeze hits existing European customers hardest
To a European investor the case may look remote at first, because Bitget is no longer permitted to write new business here. That is precisely what makes the situation more awkward rather than less. When a provider withdraws from the EEA in an orderly fashion, existing customers are usually left with exactly one action: withdraw. If that route is blocked for an indefinite period, the people affected lose the only option regulation had left them.
A second deadline runs alongside, unrelated to the incident. On September 18 Bitget announced it would delist the trading pairs COTI/USDT, SAGA/USDT and RVN/USDT on September 24 at 10:00 UTC. For those three assets, withdrawals run until December 24, 2026, 10:00 UTC, according to the announcement. Anyone still holding positions there has a date in the calendar and a blocked withdrawal route at the same time. That combination is why waiting does not resolve itself here.
In practice: check today whether you are affected at all. Log in, note the balance with the date and time, take a screenshot and file a withdrawal request as soon as the function reopens. A documented balance is the basis for any later claim and for your tax return. Do not respond to emails or direct messages offering help with the withdrawal in this situation: a withdrawal freeze is exactly the moment when fraudsters approach customer lists with supposed recovery services.
MiCA and the ESMA register: which exchange is allowed to serve you
The European regulation on markets in crypto-assets, MiCA for short, has since 2025 required every provider offering crypto-asset services in the EEA to hold an authorisation as a CASP (crypto-asset service provider). Authorised providers appear in a public register kept by the European securities regulator ESMA. The transitional rules for legacy providers expired on July 1, 2026.
Bitget holds no such authorisation and does not appear in that register. The company has applied for a licence in Austria and is building a European entity in Vienna; until a licence is granted, it offers no services in the EEA. What looks like a formality in hindsight is the real difference for you: with an authorised provider you would have a European supervisor to address, reporting duties and documented custody requirements. Without authorisation that whole apparatus is missing, and you depend on the company's assurances.
From that follows the first check, and it reaches beyond this one case. Find out under which company and in which country your provider is actually authorised, and compare that against the ESMA register. If you want a starting point, our overview of regulated crypto exchanges for European investors lists the providers that have cleared this hurdle. The obligations those companies face under the MiCA licensing regime are a separate subject we have set out elsewhere.
One misunderstanding comes up often: a MiCA authorisation is no shield against hacks. It obliges the provider to meet organisational requirements and to segregate client assets, and it gives you a regulated counterparty if something goes wrong. It does not prevent the technical break-in.
Three wallet tiers at an exchange: what actually protects your balance
When you hold coins in an exchange account, you do not own coins on the blockchain. You own a claim against the company. The exchange runs an internal ledger of your balance and keeps all customer holdings pooled in its own wallets. That distinction matters the moment the exchange's holdings fall below the sum of the claims against it.
Splitting funds into hot, warm and cold is the standard answer to that risk. The large majority of customer holdings is meant to sit offline, while only a working float is kept online, large enough for day-to-day withdrawals. If the split works as intended, a break-in at the hot wallet reaches only that working float. In this case, though, the sum the company names runs into the hundreds of millions, which shows how large that float gets at a major exchange.
From that you can derive a question to put to any provider: does it publish proof of reserves, and can that proof be verified independently? A meaningful attestation names addresses, a cut-off date and a method by which customers can confirm their own balance was included. A press release with a total and no verifiable addresses does not meet that bar.
The protection fund is not deposit insurance: what $464 million in cover means
Bitget points to its own protection fund, which the company says holds more than $464 million and will cover the loss in full. That is a solid commitment only within the frame in which it is meant, and that frame differs fundamentally from what you know from your bank account.
Statutory deposit insurance in the European Union protects bank balances up to 100,000 euros per customer and institution. It rests on a directive, is supervised by the state, and applies whether or not the bank wants to pay. A crypto exchange's protection fund, by contrast, is a voluntary reserve held by the company. The company itself decides on payout, priority and amount. No statutory deposit insurance exists for crypto-assets in the EU, and MiCA does not create one.
This says nothing about Bitget's willingness to pay; it describes the nature of the instrument. A protection fund can absorb a loss in full, and funds in this industry have done so before. What you cannot do is rely on it the way you rely on a bank guarantee.
Self-custody and hardware wallets: when moving off an exchange account pays
Self-custody means you hold the private key to your coins yourself and nobody else can dispose of them. A hardware wallet is a small device that generates that key and keeps it permanently separated from your computer; transfers are confirmed on the device and the key never leaves it. The seed phrase is the sequence of words from which the key can be restored, and therefore the actual access to your assets.
The advantage is obvious: a break-in at an exchange does not reach holdings that sit on your own device. The downside is often underestimated. Self-custody comes with no recovery hotline. A lost or photographed seed means permanent loss, and in August 2026 a flaw in the key generation of certain offline devices showed that this route carries risks of its own.
A workable rule of thumb separates funds by purpose. Amounts you actively trade may sit at a regulated exchange, because you need to be able to act quickly there. Anything you intend to hold for months, and whose loss would hurt, belongs on your own hardware. If you are moving funds for the first time, read up in our hardware wallet comparison first and send a small test amount before you move the rest.
One element of diligence costs nothing and is regularly forgotten: write the seed phrase down by hand, keep it separate from the device, and never store it as a photo, a text file or in cloud storage. Total losses in self-custody rarely trace back to an attack on the device. Usually a copy of the seed existed somewhere that somebody else could reach.
Tax and the holding period: what a frozen balance means for your return
A withdrawal freeze is, for tax purposes, a non-event to begin with. As long as your coins sit in the account and merely cannot be moved, you have neither sold nor swapped, and no disposal has taken place. In Germany the one-year holding period under section 23 of the Income Tax Act keeps running during this time, because it attaches to acquisition and disposal, not to availability.
It looks different once a blocked balance turns into an actual loss. Whether and how a loss from stolen or no longer withdrawable crypto-assets can be claimed for tax has not been settled in Germany and depends on the individual case. The federal finance ministry did not take a clear position on theft losses in its guidance on crypto-assets. What follows for you is above all a duty to document on your own account: secure account statements, transaction lists and the provider's notices with dates while you still have access to your account.
If you already run a portfolio tool, record the event there as a separate item rather than keeping it in your head. Our overview of crypto tax software and portfolio trackers shows which programmes produce records in a form a tax office accepts. For larger amounts a tax adviser is the cheaper option, because a wrongly stated loss position triggers questions later.
September 2026 in the hack ledger: Liquid Network, Bitget and the year's total
The incident does not stand alone. On figures CryptoSlate compiles from DeFiLlama, losses from attacks in September 2026 already stood at roughly $342 million before the Bitget incident. With the loss now reported, the month adds up to more than $684 million, surpassing the previous high for the year set in April at $646.9 million.
The largest single item before that came in early September from the Liquid Network at around $320 million, where the attackers stated they had acted as white hats. Smaller incidents followed, among them an attack on a hot wallet belonging to the provider Duelbits worth about $7 million. For context, a monthly tally depends heavily on a few large individual cases, and no trend for the coming quarter can be read from it.
For judging your own risk, another observation is more useful anyway. The large losses of this year arose overwhelmingly where assets sat pooled with a single custodian. That holds for the orderly cases too: both the shutdown of BitMEX on September 23 and the announced closure of CoinEx at the end of the year put customers in the same position, having to pull balances under time pressure off a platform they could no longer choose. Bitcoin itself barely reacted to the news that evening; the market now treats a break-in at a single exchange as an event belonging to that exchange.
Checking the Bitget hack: what to take away
- Establish today whether you are affected, and document the position. Log in, note balances with date and time, save the transaction list and the provider's notices, and file the withdrawal request as soon as the function reopens. For the three trading pairs delisted on September 24, the withdrawal window closes on December 24, 2026. Keep the records in the form a tax office will later want to see — the tools for that are in our comparison of crypto tax software.
- Check the authorisation of every exchange you use. Find out which company in which country is liable for your account, and match it against the ESMA register. A provider without CASP authorisation may not serve you in the EEA, and in a dispute you have no European supervisor to turn to. The houses that have cleared this hurdle are in our overview of regulated crypto exchanges.
- Separate trading holdings from long-term holdings. What you move around may sit at the exchange; what you hold for months belongs on your own hardware, with the seed phrase written by hand and kept apart from the device, and a small test amount sent before the first large transfer. The devices and how they differ are in our hardware wallet comparison.
A final note that applies at the time of writing: Bitget reported the incident itself, quantified the loss and promised cover from its own protection fund. Whether withdrawals reopen quickly, and whether the promised root-cause report answers the open questions, could not be foreseen as this article went to press. Until then the sober rule this evening has confirmed again applies to you: a balance at an exchange is a claim against a company, and its worth depends on that company being able and permitted to pay.
(As of September 24, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Whether a crypto gain raises your health insurance contribution hangs on a single question: how are you insured? If you are compulsorily insured as an employee, a private disposal gain has no effect on the contribution. If you are voluntarily insured, as a self-employed person or as a high earner above the compulsory insurance threshold, it counts. And if you are covered without contributions through your partner's family insurance, a single gain can tip that cover over for months.
This article sorts the three cases, gives the 2026 thresholds from the reference values ordinance, and shows which distinction moves the most money: the one between a taxable and a tax-free gain.
The decisive lever: what counts as income for social insurance purposes
Social insurance does not invent an income concept of its own; it borrows one from tax law. Under section 16 of Book Four of the German Social Code, total income is the sum of the income within the meaning of income tax law. That one sentence decides almost everything that follows.
For Bitcoin and other coins, section 23 subsection 1 sentence 1 number 2 of the Income Tax Act applies for tax purposes. If you sell within one year of buying, the gain is a private disposal and therefore taxable income. If you sell after a year has passed, the transaction is not taxable at all. It appears in no category of income, and it therefore does not raise total income within the meaning of section 16 SGB IV either.
From this follows the most important rule of thumb in this article: the holding period works twice over. That single period decides your income tax and, in many constellations, your health insurance contribution along with it. A gain of 6,000 euros after fourteen months is tax-free and, as a rule, irrelevant for social insurance. The same gain after ten months is neither.
A second point up front, because it often gets muddled: what matters is the realised gain, not the value of your holding. A portfolio that has risen in price without your having sold generates no income and moves no contribution. Health insurance contributions are assessed on receipts, not on assets. That sets them apart from procedures in which the holding itself is precisely what matters, such as the seizure of coins.
Case 1: compulsorily insured as an employee
Anyone compulsorily insured in the statutory health insurance scheme as an employee pays contributions on their employment earnings. That is the pay from the employment relationship, and only that. Income from capital, from letting property or from private disposals does not belong to it.
A crypto gain therefore does not raise your contribution in this case, not even when it is large and not even when it arises within the one-year period. You still have to declare it for tax as soon as the sum of all private disposal gains reaches the threshold in section 23 EStG. Where that belongs in the forms is set out in the article on where to enter crypto in your tax return.
Two qualifications are worth knowing. If your trading becomes a commercial activity, through its scale, its organisation and the use of borrowed capital for instance, the picture changes completely, because earned income from self-employment then arises. Where that line runs is covered in our article on the difference between private and commercial trading. And anyone who becomes self-employed on a full-time basis alongside the job may lose compulsory insurance as an employee.
Case 2: voluntarily insured, and why total economic capacity counts here
Voluntarily insured means anyone who is not subject to compulsory insurance and nevertheless stays in the statutory fund. That mainly concerns the full-time self-employed and employees whose pay exceeds the compulsory insurance threshold. Section 240 SGB V applies to this group, and its subsection 1 sets a markedly wider yardstick than employment earnings: it must be ensured that the contribution burden takes account of the member's total economic capacity.
The details are set uniformly by the National Association of Statutory Health Insurance Funds. The underlying idea: all receipts that cover the cost of living are drawn on, irrespective of their classification for tax. A taxable gain from a private disposal falls under this. With a tax-free gain after the one-year period the position is less clear-cut, because no point of connection in tax law exists there. Where in doubt, clarify this with your fund beforehand and have the answer given to you in writing rather than fighting it out afterwards.
The 2026 figures
The Social Insurance Reference Values Ordinance 2026 sets the limits between which all of this plays out:
| Figure | 2026 value |
|---|---|
| Reference value | 3,955 euros a month (47,460 euros a year) |
| Contribution assessment ceiling for health and long-term care insurance | 5,812.50 euros a month (69,750 euros a year) |
| Compulsory insurance threshold | 6,450 euros a month (77,400 euros a year) |
| Minimum assessment basis for voluntary members | around 1,318 euros a month |
The contribution assessment ceiling is the cap here. Anyone whose contributory receipts already sit above it pays not a cent more because of an additional crypto gain. The minimum assessment basis follows from section 240 subsection 4 SGB V, under which at least a ninetieth of the monthly reference value is to be applied for each calendar day.
What a gain actually costs
Reckon with the general contribution rate of 14.6 percent, the fund's own supplementary contribution and the long-term care insurance contribution. Voluntary members without an employer bear the total alone. With a taxable gain of 10,000 euros and a combined rate of roughly twenty percent, you end up in the order of some 2,000 euros in additional contributions, provided you stay below the contribution assessment ceiling with it. The exact figure depends on your fund and your other receipts, but the order of magnitude shows what is at stake.
The provisional assessment and the recalculation
For the self-employed, the fund initially assesses contributions provisionally under section 240 subsection 4a SGB V, on the basis of the most recent income tax assessment. The final calculation only happens once the assessment for the year in question is available. A crypto gain from 2026 may therefore only catch up with you in 2027 or 2028, but then retrospectively for the whole year. Anyone who has spent the gain by then faces a back payment with nothing to set against it.
Case 3: covered by family insurance, and why the smallest limit applies here
Family insurance under section 10 SGB V is free of contributions. It is open to spouses, civil partners and children, as long as several conditions are met at the same time. Crypto gains regularly breach one of them: the family member must have no total income that regularly exceeds a seventh of the monthly reference value in a month.
For 2026 that means, concretely: 3,955 euros divided by seven gives 565 euros a month. Anyone in marginal employment may instead earn up to the marginal earnings threshold. And because total income under section 16 SGB IV is the sum of income within the meaning of tax law, a taxable crypto gain counts here in full, while a tax-free gain after the one-year period stays outside the reckoning.
The word regularly is the reason so many underestimate this threshold. A one-off gain is not simply added to the month it was received and forgotten about afterwards. One-off receipts are customarily looked at spread over twelve months. A taxable gain of 8,000 euros comes to roughly 667 euros a month when apportioned, and therefore sits above the limit, even though it arose on a single day.
What happens when it falls away
If family insurance falls away, no gap in cover arises, but a liability to pay contributions does. As a rule you become a voluntary member and pay at least the contribution on the minimum assessment basis. The retrospective effect is what makes it critical: funds check the conditions on a regular cycle with a questionnaire, and if it turns out months later that the limit was exceeded, the account is settled retrospectively. That is why a larger realised gain should be reported to the fund before it asks.
What happens with staking, lending and airdrops
Income from staking and lending is for tax purposes usually other income under section 22 number 3 EStG and therefore income within the meaning of tax law. This income flows continuously rather than once, which makes it trickier for the family insurance regularity test than a single disposal gain. For voluntary members it raises contributory receipts like any other income.
A widespread misconception concerns the valuation: what is taxed, and therefore also captured for social insurance, is the inflow in euros at the price on the day of receipt, not the later sale. Anyone drawing rewards in coins and leaving them where they are has income without having seen a single euro. For airdrops it depends on whether you provided something in return. Where that is entirely absent, there is often no taxable receipt at the time of the inflow.
In all three cases you need a robust record with the date, the quantity and the euro price for each inflow. A portfolio tracker with tax reporting takes this work off your hands and supplies the statement you can put before both the tax office and the insurance fund.
Evidence: what happens if you do not supply it
Section 240 subsection 1 SGB V contains a rule that gets expensive if you overlook it. If a member does not produce the requested evidence of their contributory receipts, a thirtieth of the monthly contribution assessment ceiling counts as the contributory receipt for each calendar day. You are then classified as though you had 5,812.50 euros a month, regardless of what you actually had.
The law allows a correction. If you apply for a fresh assessment within twelve months of that assessment being notified and submit the evidence subsequently, the contributions for the periods concerned are to be recalculated. That twelve-month period works as a cut-off in everyday practice: anyone who lets it pass stays stuck with the maximum classification.
The comparison with private health insurance
Privately insured people pay risk-based premiums according to tariff, age and state of health. Income plays no part there in the size of the premium, so a crypto gain does not move it. Income is relevant at only one point, namely the employer's subsidy for employees, and when switching back to the statutory fund, which is tied to the compulsory insurance threshold of 77,400 euros in 2026.
Anyone weighing the two systems as a self-employed person should factor in that fluctuating crypto income feeds straight through to the contribution in the statutory fund and does not in the private one. That is not an argument for switching, because switching is as a rule a one-way street with considerable consequences in old age. It is an argument for building the contribution effect into the planning of a sale.
How to keep the contribution effect small before a sale
The most effective lever sits before the sale, not after it. Four points are worth a look.
Wait out the one-year period wherever you can. A sale after more than twelve months of holding is tax-free and as a rule generates no total income. If your position is just short of the period and you do not absolutely need the liquidity, waiting is by far the cheapest measure. Check the period for each tranche, because it runs separately for each acquisition.
Choose the order of the tranches. If you have to sell, dispose first of the units that already have the one-year period behind them. Which selling routes are available and what fees they carry is something you decide independently of that, but you should be able to document how the tranches were allocated.
Keep the contribution assessment ceiling in view. If as a voluntary member your other receipts already put you above 5,812.50 euros a month, the contribution effect of an additional gain is zero. That check costs five minutes and may spare you an unnecessary postponement.
With family insurance, do the arithmetic beforehand. The 565-euro monthly limit is low, and a one-off gain is apportioned. If the sale can be stretched across several years, the cover may well be preserved. Have your fund confirm the method of calculation before you rely on it.
Crypto gains and health insurance: what to take away
- Establish your insurance status first, everything else second. As a compulsorily insured employee, a private crypto gain leaves your contribution untouched. As a voluntary member it counts through section 240 SGB V; as a family member the 565-euro monthly limit decides whether contribution-free cover survives. Without that classification, every further calculation is worthless.
- Keep a complete record of your inflows and sales with the date and the euro price. You need it for your tax return and for any evidence put to the fund, and without it voluntary membership risks classification at the contribution assessment ceiling. A portfolio tracker with tax reporting handles that as you go instead of once a year under time pressure.
- Check the holding period for each tranche before any larger sale. Above the one-year mark the gain is tax-free and usually stays free of contributions; below it, it may hit you twice. If you want to keep your holdings cleanly separated for that purpose, orderly custody helps, for instance on a hardware wallet of your own with separate accounts for each acquisition period.
Sources in the text of the law: section 240 SGB V on the contributory receipts of voluntary members and the Social Insurance Reference Values Ordinance 2026.
(As of September 24, 2026. This article is not investment advice and not legal or tax advice. Contribution rates, reference values and fee structures change; check the terms with the provider before you buy, and have your individual case examined by your health insurance fund or a tax adviser.)
Yes, your crypto holdings count as assets for Bürgergeld, Germany's basic income support. They are a realisable asset within the meaning of the Social Code, they are valued at their market value, and they are set against the same allowances as an instant-access savings account or a share portfolio. What has changed since the summer of 2026: the allowances are no longer the same for everyone, and the one-year grace period at the start of a claim no longer exists for financial assets.
This article explains how much you may keep, which day decides the valuation, what you must tell the Jobcenter of your own accord, and the routes by which an authority learns of holdings you have not declared. All the figures come from the text of the law itself, not from advice portals.
Bürgergeld has become Grundsicherungsgeld: what changed on assets
The benefit that people still colloquially call Bürgergeld carries a new name in the law. Under section 19 of Book Two of the German Social Code, claimants capable of work receive Grundsicherungsgeld, basic income support. Official jargon and the search engines still lag behind; the decision letters do not. Anyone filing a claim today has the new rules applied, even if they searched for the old word.
More important than the name are two changes of substance. First, the blanket grace period for assets has gone. Assets used to be left untouched up to a high ceiling in the first year of a claim, and only then did the actual allowances bite. Under section 12 SGB II that grace period now applies only to owner-occupied residential property: a house or a flat you live in yourself stays out of the reckoning during the grace period, regardless of value and size. For portfolios, savings books and coins that buffer no longer exists. Your allowances apply from day one.
Second, the size of the allowance now depends on your age. For a crypto holder that is no marginal detail, because it can make the difference between an untouched holding and one you have to spend down, without anything about your holding having changed at all.
The asset allowances under section 12 SGB II: what your age decides
An allowance is the amount you may keep before anything at all is counted against you. Section 12 subsection 2 SGB II grades it by age, and it does so for each person in the benefit unit separately:
| Age | Allowance per person |
|---|---|
| up to the completion of age 30 | 5,000 euros |
| from age 31 | 10,000 euros |
| from age 41 | 12,500 euros |
| from age 51 | 20,000 euros |
Under the law the higher amount applies from the beginning of the month in which you reach the relevant age threshold. Someone turning 41 on the 20th of a month therefore has 12,500 euros free from the first of that same month. With a holding that sits just above a threshold, that single month can decide the outcome.
Work it through on an actual holding. Bitcoin stood at roughly 74,100 euros on September 24, 2026 (CoinGecko, retrieved 18:40 UTC). A quarter of a bitcoin is therefore about 18,500 euros. For a single person aged 35 with an allowance of 10,000 euros, some 8,500 euros sit above the line and count as assets to be spent down. The same 0.25 BTC is fully protected for a 52-year-old with a 20,000-euro allowance.
Transferable allowances: how the benefit unit adds up
In social law a benefit unit is the circle of people who are jointly responsible for their upkeep, typically partners and minor children in the household. For assets, a rule applies there that many overlook: allowances the other members have not used up are transferred under section 12 subsection 2 SGB II to the person whose assets breach their own limit.
A couple aged 34 and 52 bring 10,000 plus 20,000 euros between them, so 30,000 euros. If the entire wealth sits in the younger person's wallet alone, that does no harm as long as the total stays below 30,000 euros. The older person's unused allowance moves across in the arithmetic. Hurriedly transferring your coins to your partner before a claim therefore gains you nothing the law does not already give you, and it may well invite questions.
The second half of the calculation gets overlooked too. Alongside the allowance, section 12 subsection 1 SGB II lists items that do not count as assets in the first place. These include reasonable household effects, one reasonable motor vehicle for each employable person in the benefit unit, insurance contracts earmarked for retirement provision, and state-subsidised pension savings. A crypto holding falls under none of these exceptions, not even if you personally regard it as your retirement provision. Number 4 of that subsection does protect assets expressly designated as retirement provision, but only for periods of full-time self-employment without contributions to the state pension scheme, and only up to a statutorily calculated maximum for each year begun.
Market value on the cut-off date: why the day you file decides your entitlement
Section 12 subsection 3 SGB II contains the sentence that weighs most heavily when prices move. Assets are to be taken into account at their market value, and the decisive moment for the valuation is the point at which the claim for an award, or for a renewed award, is filed. If you acquire assets only later, the moment of acquisition counts.
Market value is the price that could be achieved on the market. For a coin with an active exchange listing, that is the price on that day, not your purchase price and not the level from the week before last. Three things follow for you, and the third is where clawbacks arise in practice.
The cut-off date is a day, not an average. A holding that sits below the allowance on a monthly average can sit above it on the day of filing and then count in full. The reverse applies in your favour. Next: every renewal claim sets a new cut-off date. A holding that raised no eyebrows on the initial claim can be above the line at renewal if the price has risen in the meantime. And finally the rule works in the other direction too. Anyone acquiring coins while receiving the benefit, from staking rewards or an airdrop for instance, has new assets at the moment of receipt, which section 60 SGB I requires them to report without delay.
If you hold your assets spread across several wallets and exchanges, have a coherent consolidated statement ready for the cut-off date. A portfolio tracker with tax reporting delivers exactly that snapshot with date, price and source, and you will need it a second time for the tax office anyway.
Which crypto holdings count as realisable and which do not
Realisable in social law means you can turn the item into money or borrow against it within a foreseeable period. For a liquid coin on a mainstream exchange that is uncontroversial. The edge cases are the interesting ones.
Locked, pledged and illiquid holdings
Coins tied up in staking for a fixed term cannot be sold immediately. That does not reduce their value, however, and a lock-up of a few weeks does not make them unrealisable. Long lock-up periods with no option to exit, or tokens without a functioning market, are a different matter. Here it comes down to the individual case, and here it pays to document the lock-up in writing rather than merely assert it.
Particular hardship
Section 12 subsection 1 number 7 SGB II exempts items and rights whose realisation would amount to particular hardship. That is a narrow exception for cases in which a sale would be economically unreasonable, for instance a sale well below value in a forced situation. As a rule it cannot be founded on a price loss since purchase. Anyone wanting to rely on it should discuss the point with an advice centre or a lawyer specialising in social law before writing it into the claim.
Debts
Assets are looked at gross as a matter of principle. An overdraft on your current account is not automatically netted off against a wallet. Anyone who has pledged coins as security for a loan should be able to document the pledge, because it genuinely does restrict realisability. How loans with coins as collateral work for tax and under civil law is set out in the article on bitcoin-backed loans, tax and the holding period.
The duty to cooperate under section 60 SGB I: what you must declare to the Jobcenter
The obligation to declare crypto is not in SGB II but one level above it. Under section 60 subsection 1 of Book One of the German Social Code, anyone who applies for or receives social benefits must state all facts that are material to the benefit. On top of that comes the duty to report changes in circumstances without delay, and the duty to name evidence and produce it on request.
That wording is deliberately broad. It does not turn on whether the claim form expressly asks about cryptocurrencies. What is material is whatever can influence the entitlement, and assets can influence it. The question about existing assets covers coins just as it covers a savings book, even if the word is missing from the form.
What changes during a claim is therefore reportable without delay as well: an inflow from staking or lending, an airdrop, an inheritance in coins, a sale that puts money in your account. Anyone who reports an inherited holding only months later also acquires an evidence problem, because they have to reconstruct the deceased's holding period and acquisition costs. How that is done is set out in our article on proving the holding period and purchase price of inherited bitcoin.
How the Jobcenter finds out about your coins
Many assume that a self-custodied wallet is invisible to an authority. That holds for the wallet itself, and it has long ceased to hold for the route that leads to it. Three channels are responsible, and they operate independently of one another.
The automated data comparison, and what it cannot do
Under section 52 SGB II, the Federal Employment Agency and the municipal bodies compare claimants' data automatically four times a year, on 1 January, 1 April, 1 July and 1 October. That comparison looks for pensions, for periods of compulsory insurance, for benefits from other institutions and for data on exemption orders reported to the Federal Central Tax Office. It does not capture crypto holdings. Anyone concluding from this that a wallet stays undetected draws the wrong conclusion, because the comparison is only the first of three routes.
The account data retrieval at the Federal Central Tax Office
Section 93 subsection 8 of the Fiscal Code expressly permits the authorities responsible for basic income support for jobseekers to retrieve account master data from the Federal Central Tax Office. The conditions are that it is necessary in order to examine the conditions of entitlement, and that a prior request for information addressed to you has not achieved its purpose or holds no promise of success. The retrieval yields no balances and no wallet addresses, but the master data of the accounts and securities accounts held in your name at German credit institutions.
For crypto it is nevertheless the most effective channel, because almost every holding came into being via a bank account. Anyone transferring euros to an exchange and later receiving euros back leaves a trail on the bank statement that leads to the exchange. From there section 60 subsection 2 SGB II carries on: anyone who holds balances or safeguards assets for a person receiving benefits must provide information to the Employment Agency on request. An exchange that holds your coins in custody falls under that provision.
The reporting duty for crypto service providers since 2026
The third channel is new. With the Crypto-Asset Tax Transparency Act, Germany implemented the EU's DAC8 directive, which builds on the international CARF framework. Since 1 January 2026, reporting crypto-asset service providers have had to collect data on their users and transmit it to the Federal Central Tax Office, which exchanges it with the tax authorities of the other member states. The first reporting period is the 2026 calendar year, with transmission in the year that follows.
What gets reported is identification data along with aggregated figures on purchases, sales and transfers for each crypto-asset. That is a tax procedure to begin with and not a social data comparison, and a Jobcenter does not receive these reports automatically. It does shift the starting point, though: a holding that is on file with the tax office is also documentable to another authority if a dispute arises. What that means for tax is described in detail in the article on where to enter crypto in your tax return.
If you have to spend down crypto: holding period, section 23 EStG and the double trap
If your holding is above the allowance, the Jobcenter will require you to spend down the excess before benefits are paid. In practice that means selling. And this is precisely where two sets of rules meet that know nothing of each other.
For tax purposes, coins count as other assets within the meaning of section 23 subsection 1 sentence 1 number 2 of the Income Tax Act. A sale within one year of acquisition is a private disposal and the gain is taxable. After a year has passed it is tax-free. Anyone selling under time pressure because the Jobcenter insists on the assets being spent down can therefore trigger a taxable gain they would not have had with a little more patience.
The second half of the trap: the sale proceeds are not income in the month of receipt but remain assets, because they derive from an asset that already existed. They are therefore not counted as income on top. The gain from them can, however, trigger a tax payment in the following year for which the money is no longer there. Anyone who has to sell should therefore set aside the likely tax out of the proceeds before spending the rest. Which routes exist for selling and where the fees sit is a topic of its own, and the differences are not incidental in a forced sale.
One point you should not overlook: within limits, you may determine the order and the timing yourself. If part of your coins has already passed the one-year mark and another part has not, it is as a rule more favourable to sell the older ones first. Social law does not prescribe which units you dispose of; it is interested only in the result.
What happens if you conceal crypto
If an undeclared holding later comes to light, the authority revokes the award decision for the periods concerned and reclaims the benefits paid. The clawback is measured by what you would have been entitled to had you declared correctly, and it can span several award periods. On top of that, incomplete statements about assets can bring administrative fine proceedings or criminal proceedings in their wake.
That is the expensive route, and it is avoidable. The cheap route is a complete declaration with clean supporting documents, in which you set out yourself, where there is doubt, why in your view a holding should not be taken into account or only in part. An authority handed a complete set of facts decides a question of law. An authority that finds a holding by itself decides on your credibility.
If a decision treats you wrongly on the substance, an objection is open to you, as a rule within one month of notification. The deadline is stated in the decision itself. Free advice is available from the social welfare associations and from independent advice centres, and with larger amounts a lawyer specialising in social law is worth the money.
Preparing your evidence: what to assemble before you file
The effort lies in the documentation, hardly at all in the form-filling. So assemble before you file what you are going to need anyway.
- A statement of all holdings by coin and by place of custody, with the position as at the day the claim is filed.
- That day's price for each coin, with the source and the time of retrieval, so that the market value applied is verifiable.
- The acquisition data, meaning date, quantity and purchase price, because they decide the one-year period for tax.
- Evidence of lock-ups, pledges or commitments that genuinely restrict realisability.
- The bank statements showing deposits to and withdrawals from exchanges, because that is the route along which questions come anyway.
Self-custodied holdings should be listed just as fully as a balance on an exchange. An authority cannot establish a wallet address by itself, and the missing declaration weighs more heavily later than the holding does. If you have kept your coins exclusively on trading platforms so far, transferring them to a hardware wallet of your own is incidentally no way to hide assets. Moving the coins changes nothing about the duty to declare and nothing about the valuation; it changes only who holds the keys.
Drawing the lines: seizure, insolvency and basic income support are three separate procedures
The allowances in SGB II apply exclusively to social benefits. When a private creditor reaches for your assets, the attachment exemption limits of the Code of Civil Procedure apply, and those amounts are different ones. A holding that is protected for basic income support can still be realised by a bailiff. How access to coins works in practice is set out in the article on whether bitcoin can be seized by creditors and insolvency administrators.
Just as non-transferable are the rules of personal insolvency and those of social assistance under Book Twelve of the Social Code, which has an asset framework of its own. Anyone facing several of these procedures at once should have them examined separately, because a statement in one procedure can have quite different consequences in another.
Crypto and Bürgergeld: what to take away
- Work out your allowance from your age, not from something you read somewhere. There are four bands between 5,000 and 20,000 euros per person, and within a benefit unit unused allowances are transferred. Then draw up a statement of holdings as at the day you intend to file, most easily with a portfolio tracker with tax reporting that supplies the price, the date and the source along with it.
- Declare all holdings in full and report every change immediately. The duty follows from section 60 SGB I, regardless of whether the form asks about cryptocurrencies. Document your figures once too often rather than once too rarely, and keep ready the bank statements showing the transfers to exchanges. Where the figures belong in your tax return is shown in the article on where to enter crypto in your tax return.
- Check the one-year period before a forced sale. Coins you have held for more than a year can be disposed of tax-free under section 23 EStG. Where in doubt, sell the oldest units first, compare the selling routes and their fees beforehand, and set aside the likely tax out of the proceeds before you spend the rest.
Sources in the text of the law: section 12 SGB II on assets to be taken into account and section 60 SGB I on the statement of facts.
(As of September 24, 2026. This article is not investment advice and not legal advice. The state of the law, prices and fee structures change; check the terms with the provider before you buy, and where in doubt have your individual case examined by an advice centre or a specialist lawyer.)
Decrypt
The central bank opened two proposals for comment under the GENIUS Act, requiring issuers it supervises to back tokens fully with safe assets and creating an application process for banks seeking to issue stablecoins.
A newly created wallet drained hot and cold reserves labeled as belonging to Bitget across multiple blockchains in under an hour.
A proposed class action accuses OpenAI of quietly routing real conversations to outside contractors through a program called Project Lily—without telling users first.
Muse Charm is Meta's palm-sized gadget for talking to its Muse AI agent on the go. It has cameras, a fingerprint sensor, and its own cell connection.
A February research paper showing AI can unmask pseudonymous internet users is freaking everyone out again this week. Here's what the paper actually says.
U.Today - IT, AI and Fintech Daily News for You Today
Bitcoin could surge to $500,000 within roughly two years, according to Volmex Labs CEO Cole Kennelly.
XRP, Dogecoin, Ethereum and Stellar are trying to preserve their recent breakouts as correction covers the market.
JPMorgan says Bitcoin’s brief move above the crucial $85,000 production-cost level could ease pressure on miners after BTC spent a staggering 280 days below it.
Solana-based stablecoins can now be used to book flights across more than 300 airlines through crypto travel platform Nomadz, expanding the network’s real-world payments footprint into global travel.
BlackRock-designed investment portfolios are officially moving onto blockchain rails.
Blockonomi
Key Highlights
- Bitcoin remained relatively stable around $84,420 following a recovery from earlier declines linked to oil price increases and Treasury yield spikes.
- U.S. 10-year Treasury yields climbed past 5%, marking the highest point since 2007 and pressuring risk-on assets including BTC.
- Brent crude oil exceeded $105 per barrel amid ongoing geopolitical tensions between the United States and Iran.
- Large-scale investors accumulated approximately 30,269 BTC during the price decline, representing around $2.57 billion in value.
- Prediction market Polymarket indicates a 62% probability that the current U.S.-Iran ceasefire remains intact until October 31.
Bitcoin maintained a relatively stable position on Thursday, clawing back a portion of earlier losses. The leading cryptocurrency was trading at $84,420.2 at 17:53 ET, based on Investing.com pricing data.
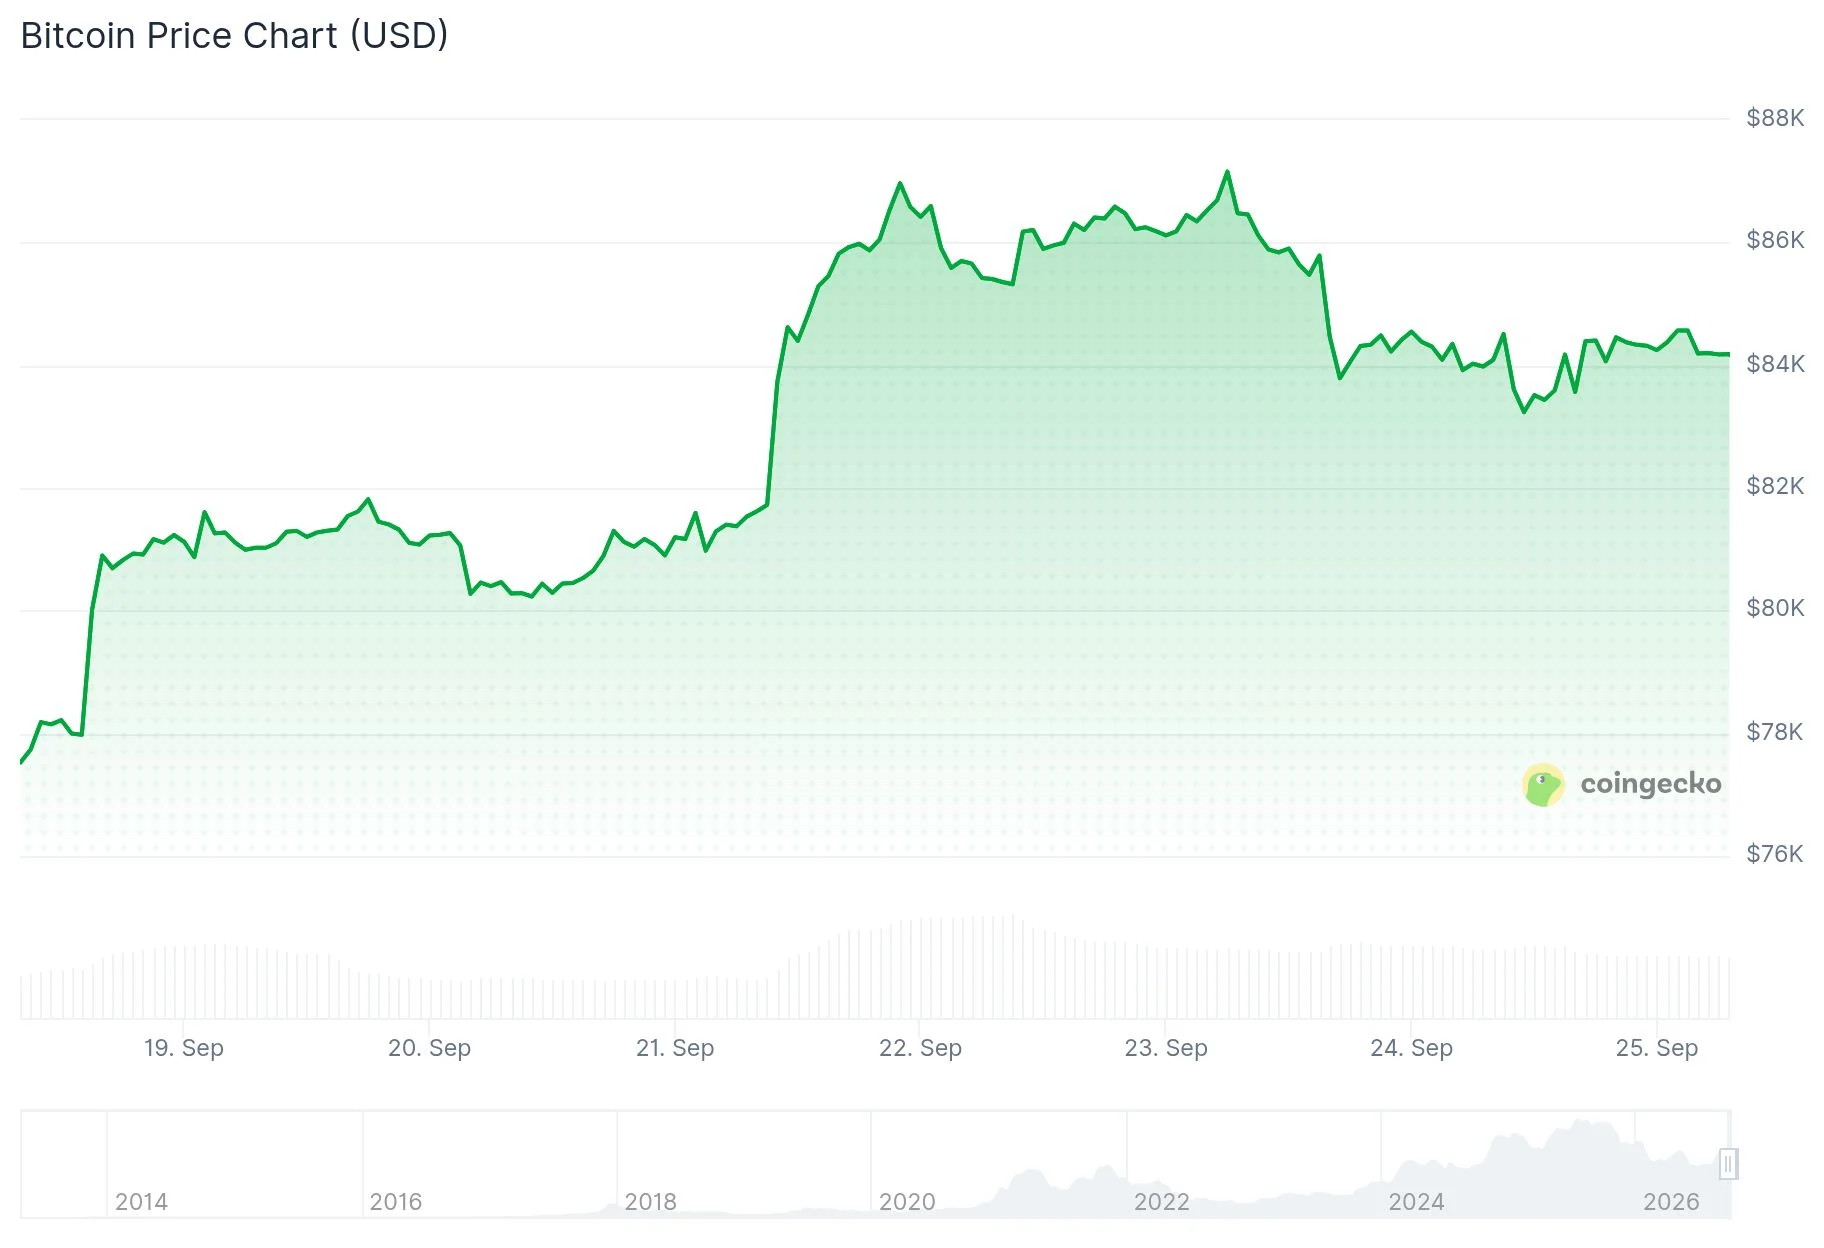
The earlier decline came as multiple headwinds converged across global markets. Energy commodities rallied, government bond yields surged higher, and market participants increased their expectations for additional Federal Reserve interest rate adjustments.
The wider cryptocurrency ecosystem similarly pared its losses. The majority of leading digital assets continued to maintain weekly gains following a strong upward movement earlier in the week on Monday.
Treasury Yields And Energy Prices Create Headwinds For Risk Assets
The benchmark U.S. 10-year Treasury yield climbed back beyond the 5% threshold. This represents the strongest level observed since 2007.
Robust U.S. purchasing managers index data combined with more aggressive rhetoric from a Federal Reserve policymaker fueled increased expectations for additional monetary tightening. The central bank had already implemented a 25 basis point rate hike during the prior week.
Elevated bond yields generally diminish appetite for speculative assets such as Bitcoin. Fixed-income securities become more attractive in such conditions, prompting certain investors to reallocate capital away from digital currencies.
The yield surge wasn’t confined to U.S. markets. Japanese 10-year government bond yields reached a three-decade peak on Thursday.
Energy markets compounded the market pressure. Brent crude climbed to $105.02 per barrel following diminished expectations for a diplomatic resolution between Washington and Tehran.
Iran’s President Masoud Pezeshkian delivered critical remarks directed at the United States and President Donald Trump during an address at the United Nations General Assembly on Wednesday. The speech timing aligned with the latest escalation in crude oil pricing.
Nevertheless, market analyst Ali Charts noted that major holders were actively accumulating during the price weakness. He highlighted that while Bitcoin declined 5.24% from $87,400 down to $82,800 starting September 21, large investors accumulated nearly 30,269 BTC—valued at approximately $2.57 billion—throughout a 96-hour period.
Meanwhile, Bitcoin bounced from an intraday bottom near $83,000 to hover around $84,300, per TradingView market data. The recovery coincided with emerging reports suggesting U.S. and Iranian representatives are considering a graduated approach to reopening the Strait of Hormuz and resolving the existing blockade situation.
Geopolitical Uncertainties Continue Influencing Inflation Expectations
Market analyst Ted Pillows drew comparisons between the current price action and historical patterns. He noted that Bitcoin experienced a 22% correction in 2023 following a comparable higher high formation, and although he’s not forecasting an identical scenario, he identified the $78,000 to $79,000 range as a potential support zone ahead of the next bullish leg.
Reuters coverage indicated that neither party in the Iran negotiations has shown willingness to relinquish strategic advantage initially, leaving the situation without definitive resolution.
The persistent conflict continues applying upward pressure to energy markets, with diesel fuel costs also reaching fresh peaks. Consumer price inflation remains elevated above the Federal Reserve’s 2% objective.
Polymarket prediction data assigns a 62% likelihood that the ceasefire arrangement persists through October 31. U.S. Secretary of State Marco Rubio characterized discussions between both nations as constructive while acknowledging that no substantial breakthrough has materialized to date.
The post Bitcoin (BTC) Whales Accumulate $2.57B Amid Market Volatility appeared first on Blockonomi.
Casper, Wyoming, USA. 25/09/2026: Moonclave, a Solana-based on-chain prediction market protocol, today announced it has surpassed 12,000 members in its loyalty and rewards program, distributing a $10,000 prize pool and over 76 million experience points (EXP) to early participants. Alongside this growth, the Moonclave team confirmed it is actively working to secure a listing on a new cryptocurrency exchange, with details to be announced in the coming weeks.
The milestone follows a recent community reactivation campaign that generated more than 427,000 impressions and added 4,400 new followers, while the project’s Discord community grew from approximately 4,000 to over 10,000 members.
Moonclave enables users to trade predictions on crypto, macroeconomic, on-chain, and real-world events, with outcomes settled directly on-chain.
The platform is live now at predictions.moonclave.fun, alongside a token, $MCV, that anchors the protocol’s rewards and community systems.
A Loyalty System Built Around Participation
At the center of Moonclave’s growth is its card-based loyalty program, accessible through the project’s rewards hub. Members earn EXP through trading activity, content creation, referrals, and community engagement across X and Discord.
As members accumulate EXP, their Moonclave Card progresses through five tiers, New Moon, Waxing Crescent, First Quarter, Waxing Gibbous, and Full Moon, with higher tiers unlocking earlier access to new features and beta releases.
“We built Moonclave around the idea that conviction outlasts noise. Crossing 12,000 members and paying out our first prize pool is proof that people are willing to show up consistently. Expanding where $MCV is accessible is the natural next step, and we’re working to get that right rather than rushing it,” said Reil Sokolaj, Founder & CEO of Moonclave.
Product Focus Over Price Speculation
Rather than positioning itself around short-term price action, Moonclave has emphasized its core product, an on-chain prediction market mechanic, as the primary draw for new users. The team describes its approach as deliberately unhurried, favoring sustained engagement over hype-driven spikes, a philosophy reflected in the project’s own messaging: the platform rewards patience and conviction rather than short-term speculation.
The project’s community is organized into five functional groups, HIVE (community and diplomacy), FORGE (technology and engineering), SCOUT (research and exploration), OATH (operations and logistics), and LABS (science and research), each contributing to different aspects of the protocol’s development and growth.
What’s Next
With its loyalty program scaling and community engagement climbing, Moonclave’s near-term roadmap includes expanding exchange access for $MCV alongside continued development of its prediction market product.
The team has not yet disclosed which exchange it is in discussions with, saying further details will be shared once confirmed.
Getting Started
New users can begin engaging with Moonclave by making their first prediction on the live app or joining the loyalty program to start earning EXP from day one, with no minimum token holding required to take part.
For those who want to stay current as the exchange listing and other updates develop, Moonclave’s X account (@themoonclave) remains the primary channel for announcements.
About Moonclave
Moonclave is an on-chain prediction market protocol built on Solana, enabling users to trade predictions on crypto, macroeconomic, and real-world events with on-chain settlement. The project is supported by an active community structure and a tiered loyalty program rewarding participation and engagement.
For more information, visit moonclave.fun or join the community on Discord and X.
Media Contact:
Reil Sokolaj, Founder & CEO of Moonclave.
info@moonclave.fun
The post Moonclave Works to Secure New Exchange Listing appeared first on Blockonomi.
TLDR
- Paramount Skydance stock climbs after launching a $7.5 billion loan plan
- New financing supports the company’s Warner Bros. Discovery acquisition deal
- Paramount prepares a broader $44.4 billion secured debt funding package
- Legal settlements help clear major hurdles for the Hollywood merger
- PSKY shares gain as investors track progress on the transaction
Paramount Skydance Corporation (PSKY) stock closed at $10.18, gaining 2.21% after recovering from early losses. The company advanced toward the $10.20 resistance zone as trading activity strengthened late in the session. The move followed Paramount’s launch of a $7.5 billion loan syndication to support its Warner Bros. Discovery acquisition.
Paramount Skydance Corporation Class B Common Stock, PSKY
Paramount Skydance Launches $7.5 Billion Debt Financing
Paramount Skydance started the senior secured term loan process as part of its broader merger funding plan. The financing supports the company’s proposed acquisition of Warner Bros. Discovery and related debt repayments. Therefore, the loan represents a major step in completing the transaction’s financial structure.
The company plans to raise about $44.4 billion in additional secured debt alongside previously announced funding arrangements. Paramount will combine the new borrowings with cash reserves and equity financing proceeds. This strategy aims to provide the capital needed for the Warner Bros. Discovery purchase.
Bank of America, Citigroup, and Apollo are leading the debt financing process for the acquisition. The wider package includes investment-grade loans, bonds, and second-lien debt structures. , the financing effort ranks among the largest entertainment industry funding deals.
Warner Bros. Discovery Deal Moves Toward Completion
Paramount Skydance’s agreement to acquire Warner Bros. Discovery gained momentum after resolving legal challenges. The company settled an antitrust case involving several state attorneys general and the Writers Guild of America. As a result, the merger moved closer to receiving final approvals.
The proposed transaction could reshape Hollywood by combining Paramount’s media assets with Warner Bros. Discovery’s entertainment portfolio. The deal would bring major brands and streaming platforms under one corporate structure. The companies continue preparing for completion after clearing key regulatory issues.
The merger remains supported by significant equity commitments from major financial backers. Larry Ellison has committed substantial equity support, while Middle Eastern sovereign wealth funds joined the financing effort. However, the combined company would carry significant debt following the transaction.
PSKY Stock Gains as Financing Supports Merger Plans
Paramount Skydance strengthened as the company advanced its acquisition funding process. The shares recovered from intraday weakness and maintained positive momentum during the closing session. Meanwhile, market activity reflected attention toward developments surrounding the Warner Bros. Discovery agreement.
The combined Paramount and Warner Bros. Discovery company is expected to carry considerable financial obligations after completion. Morgan Stanley analysts previously estimated the merged entity could hold substantial net debt. Therefore, the financing structure remains a central factor in the merger process.
Paramount Skydance continues working toward completing the Warner Bros. Discovery acquisition within the expected timeline. The company’s latest debt move marks another milestone in its strategy to finalize the transaction. Meanwhile, PSKY stock performance remains linked to progress surrounding the major entertainment merger.
The post Paramount Skydance (PSKY) Stock: Rises as $7.5B Loan Fuels WBD Deal appeared first on Blockonomi.
TLDR:
- CFTC guidance now covers tokenized permitted assets and blockchain-based regulatory recordkeeping.
- Regulation 1.25 still limits eligible customer investments despite expanded guidance on tokenized assets.
- Tokenized collateral must preserve the same legal and economic rights as its traditional equivalent.
- Blockchain records can satisfy Regulation 1.31 if they remain reliable, accessible and producible.
The U.S. Commodity Futures Trading Commission has expanded its crypto guidance to explain how regulated derivatives firms can handle tokenized investments and digital recordkeeping. The September 24 update addresses two practical questions facing regulated firms.
It covers customer funds invested in tokenized permitted assets and the use of blockchain systems for records. The revisions were issued by the agency’s Market Participants Division, Division of Market Oversight, and Division of Clearing and Risk.
However, the guidance does not change existing regulations. The underlying FAQs state that staff interpretations do not create enforceable rights, amend CFTC rules, or guarantee protection from future enforcement action.
Tokenized Assets Must Still Meet Existing Investment Rules
The latest clarification builds on guidance published in March covering the use of crypto-related infrastructure within existing derivatives regulations. A key distinction remains between tokenized assets representing permitted financial instruments and standalone cryptocurrencies that are not eligible under customer investment rules.
Earlier guidance said swap dealers may use tokenized forms of eligible collateral when those instruments satisfy existing regulatory standards. Those tokenized instruments must also provide legal and economic rights equivalent to the rights attached to their traditional versions.
However, the framework does not automatically make every cryptocurrency suitable for customer funds. The March FAQs specifically said Staff Letter 26-05 did not change the list of permitted investments under Regulation 1.25.
They also said futures commission merchants could not invest customer funds directly in payment stablecoins solely because those assets appeared within broader crypto guidance. The distinction keeps the focus on the underlying asset rather than its digital format.
As a result, tokenization can change how ownership or settlement is represented without changing whether the investment itself qualifies under existing rules.
Blockchain Records Must Still Meet Regulation 1.31 Standards
The second clarification addresses whether regulated firms can use blockchain technology to satisfy recordkeeping obligations. CFTC Regulation 1.31 already follows a technology-neutral framework for storing, retaining, and producing regulated records.
That structure was designed to accommodate changing electronic systems rather than require firms to use one specific recordkeeping technology. The updated guidance therefore gives firms a clearer compliance route for distributed ledger systems.
Records must still remain reliable, accessible, retained for the required period, and available when regulators request them. The update also aligns with Chairman Michael Selig’s recent comments about tokenization, stablecoins, and potentially continuous markets becoming more important within derivatives infrastructure.
For regulated firms, the main clarification is operational rather than expansive. Blockchain infrastructure can fit within existing CFTC compliance systems, but technology alone does not determine whether a structure is permissible.
The underlying asset, custody arrangements, accessibility of records, and existing regulatory requirements remain central to compliance.
The post CFTC Expands Crypto Guidance to Cover Tokenized Assets and Blockchain-Based Records appeared first on Blockonomi.
TLDR
- SMX stock drops as molecular marking technology gains manufacturing attention
- Company builds digital tools for material tracking and verification processes
- SMX platform connects physical materials with secure digital records
- Technology supports recycling, compliance, and supply chain transparency
- Molecular verification aims to improve trust across industrial markets
SMX (Security Matters) Public Limited Company (SMX) stock traded at $8.77, down 9.02%, after a sharp decline from the $9.60 area. The shares found support near $8.00 before recovering slightly during the afternoon session. The movement came as the company highlighted its molecular marking technology for improving manufacturing transparency.
SMX (Security Matters) Public Limited Company, SMX
SMX Stock Falls as Company Expands Material Traceability Technology
SMX develops technology that gives physical materials unique molecular identities and connects them with digital records. The system allows manufacturers to track material origin, recycled content, authenticity, and movement across supply chains. Therefore, the company aims to improve verification standards across industrial markets.
The technology focuses on replacing traditional tracking methods that depend mainly on documents and supplier information. SMX embeds markers into materials and links them with secure digital records. This approach helps companies verify product information throughout different stages of production.
Meanwhile, manufacturers face growing pressure to improve supply chain visibility and meet stricter compliance requirements. SMX positions its platform as a tool for industries seeking stronger material verification. The company’s solutions support sectors that require accurate records of production and material usage.
Molecular Technology Supports Trusted Manufacturing Processes
SMX’s Digital Material Passport Platform connects physical materials with digital information throughout their lifecycle. The platform records details from manufacturing through reuse, recycling, and resale. As a result, companies can maintain clearer records of material history and ownership.
The technology supports efforts to increase recycling efficiency by identifying materials and tracking their movement. Manufacturers can use verified information to improve resource management. This creates a system where materials maintain reliable digital identities beyond initial production.
SMX’s technology addresses challenges linked to global supply chains and sourcing verification. Companies increasingly require accurate information about materials and production methods. The platform provides a framework for improving transparency between manufacturers, regulators, and customers.
SMX Targets Greater Supply Chain Transparency With Digital Verification
The company’s molecular marking technology supports industries seeking better control over manufacturing data. SMX focuses on making material claims easier to confirm through digital verification. This creates opportunities for companies that need stronger proof of origin and compliance.
The technology can help manufacturers demonstrate domestic production standards through verifiable material records. Supply chain participants can access information about where materials originated and how they moved. This reduces reliance on traditional labeling systems alone.
SMX continues developing solutions designed for a manufacturing environment that values transparency and accountability. The company’s platform connects physical materials with digital records to strengthen industrial verification. However, SMX stock performance remains influenced by market activity and company developments as the business expands its technology adoption.
The post SMX (SMX) Stock: Drops as Molecular Technology Powers Future of Trusted Manufacturing appeared first on Blockonomi.
CryptoPotato
Bitget says its security systems flagged unauthorized transfers from a portion of its hot wallets at 18:31 UTC on September 24, with roughly $351.6 million in assets affected.
The exchange says every dollar of that loss falls under its User Protection Fund, so customers’ balances will stay intact even with withdrawals paused as it reviews the incident.
What Bitget Says Happened
According to CEO Gracy Chen, Bitget runs a three-tier wallet system, and the breach touched a slice of the hot and warm wallet layers. Cold wallets, which hold the bulk of the exchange’s assets, were not affected, and the security team’s emergency protocols kicked in within minutes of the detection, flagging and reporting the addresses tied to the abnormal transfers.
The exchange’s User Protection Fund currently holds more than $464 million, well above the $351.6 million shortfall, and Bitget plans to use it to cover the full loss.
“We will not run from this, and every dollar will be accounted for,” Chen wrote in an update posted on X. She added that a full incident report, covering root cause and corrective steps, would follow within 24 hours of the initial notice.
According to Bitget, the attacker got into a backend system inside its wallet infrastructure, used it to spoof transaction data, and tricked the exchange’s authorization process into releasing funds.
Chen ruled out a private key compromise, which narrows what went wrong, and stated that containment is confirmed, with no further unauthorized transfers possible.
Lazarus Group Could Be Responsible
On-chain investigator Specter claimed that the North Korea-linked Lazarus Group was behind the attack, a position supported by analyst Conor Grogan.
“Generally they do these on the weekends but perhaps they had a limited window for the exploit and didn’t want to risk it,” Grogan wrote.
The incident adds to what has been an eventful stretch for crypto exploits, with $1.1 billion stolen across 212 incidents in the first half of the year, and more than half of that traced back to the Lazarus Group.
The post Bitget Reports $351M Hot Wallet Breach, Says User Funds Are Covered appeared first on CryptoPotato.
Ripple’s cross-border token remains highly appealing to institutional investors, while whales have also accumulated a significant amount of tokens lately. Despite these positive factors, XRP has slipped 8% after a red wave swept through the broader market.
Meanwhile, one of the company’s top executives shared the stage at the MESA Forum with representatives from financial giants like BlackRock and HSBC to discuss stablecoins (like RLUSD), tokenized deposits, and other topics.
ETFs and Whales
Spot XRP ETFs have attracted substantial capital lately, showing that more conservative investors continue to increase their exposure to the asset. As CryptoPotato reported, these financial vehicles posted 10 consecutive green weeks, while the cumulative total net inflows reached roughly $1.75 billion. The past two days have been highly beneficial, too, signaling that the streak is likely to continue.
Companies that have launched spot XRP ETFs so far include Bitwise, Franklin Templeton, Canary Capital, 21Shares, and Grayscale. However, others are awaiting regulatory approval and may soon join the list.
Recently, T. Rowe Price updated its crypto ETF filing, which will allow exposure to multiple cryptocurrencies, with XRP sitting at a 9.15% weight. For its part, Exchange Listed Funds Trust filed the “CYBER HORNER S&P 500® and XRP 75/25 Strategy ETF” with the SEC. If it receives the necessary thumbs-up, the product will enable investors to gain exposure to both the stock market and Ripple’s native token in a 75/25 ratio.
Institutional investors are not the only ones interested in XRP lately. Last week, whales acquired over 1.54 billion units in about 96 hours. The accumulation began shortly after the CLARITY Act failed in the US, triggering a pullback and suggesting that large investors see lower prices as a buying opportunity.
Ripple, BlackRock, and More
Recently, Reece Merrick (Managing Director, Middle East & Africa at Ripple) posted a photo of himself with representatives from BlackRock, HSBC, and other financial institutions. He said the individuals were on stage at the MESA Forum discussing stablecoins, tokenized deposits, and tokenized MMFs. The topic has also moved to RLUSD (Ripple’s stablecoin), with Merrick saying:
“Stablecoins: The always-on layer moving value between institutions without existing relationships (why RLUSD was built not to replace bank money, but to let it travel).”
He also stated that the UAE is open for business, is actively building, and hinted that Ripple has already established a serious presence in the region. For instance, in summer 2025, the Dubai Financial Services Authority (DFSA) recognized RLUSD as a crypto token within the Dubai International Financial Center (DIFC).
The stablecoin officially launched in December 2024 and has since received backing from well-known exchanges and institutions. Its market capitalization has surged to the current $2.37 billion, making it the 43rd-biggest cryptocurrency and the ninth-largest stablecoin.
XRP Price Outlook
Earlier this week, Ripple’s cross-border token spiked to nearly $1.65, representing the highest level since the start of 2026. However, the broader market has corrected over the past 24 hours, and XRP has plunged to $1.47 (per CoinGecko).
X user Diana claimed the asset is now fighting to reclaim $1.50 to start a new rally. She outlined $1.61 as the major wall bulls need to attack and envisioned a rise to the $1.70-$2 range if they succeed.
For more price forecasts, read our dedicated article here.
The post Important Ripple News and XRP Price Update: September 25 appeared first on CryptoPotato.
The Trump administration is reportedly considering an initiative to promote dollar-denominated stablecoins overseas.
The goal, according to a Bloomberg report citing people familiar with the plans, is to protect the dollar’s place as the world’s reserve asset and to raise demand for US Treasuries, which stablecoin issuers typically hold as reserves.
Joint Ventures and Federal Agencies Under Discussion
Per the report, the initiative could involve several federal agencies, including the Treasury Department and the State Department. The US International Development Finance Corp. (DFC) could also be part of the plan.
One option under consideration involves creating joint ventures between the government and private-sector firms to support stablecoin projects in overseas markets.
That’s probably where the DFC would come in, as it often partners with private companies to advance US foreign policy goals, and its head is incidentally Ben Black, son of Apollo Global Management co-founder Leon Black. Apollo has reach in crypto and stablecoins, including a partnership with Coinbase Asset Management that lets users borrow against their digital assets.
Stablecoins are typically pegged to traditional currencies, with issuers generally maintaining reserves in cash and short-term government debt to back the tokens, and the US government’s proposal will focus on the dollar-backed versions, which could create a potential source of demand for US Treasuries as their circulation expands.
President Donald Trump signed the GENIUS Act into law last year, establishing a federal framework that requires stablecoin issuers to hold reserves that include the dollar and short-term Treasuries. Scott Bessent, the Treasury Secretary, has also argued that stablecoin adoption could strengthen the dollar’s position as the world’s reserve currency.
Dollar Tokens Dominate, Euro Market Is Still Small
DefiLlama data puts the total stablecoin market cap at about $306 billion, with Tether’s USDT holding nearly 60%. According to RWA.xyz, dollar-pegged stablecoins represent about $305 billion of that market cap, with their euro-backed counterparts holding nearly $805 million, and almost $81 million goes to those pegged to the Brazilian real.
The platform’s net flow data also shows positive flows for several dollar stablecoins, including $1.2 billion for USDC and $1.1 billion for USDT, followed by $819 million for Ethena’s USDe and $355 million for Ripple’s RLUSD. Meanwhile, Visa Onchain Analytics recorded $6.4 trillion in total stablecoin transaction volume over the last 30 days, with a total transaction count of 1.7 billion.
However, Washington’s plan has come at a time when other economies are developing competing payment infrastructure. For example, China’s digital yuan is already being used in Project mBridge, while the European Central Bank is advancing its digital euro project and recently launched an initiative connecting blockchain markets with existing European payment systems.
More than 12 euro stablecoins are now fully authorized under the MiCA framework, including EURR, issued by Stripe-owned Bridge, which Revolut started rolling out to select customers in Denmark, Poland, and Portugal in August.
The post Report: US Weighs Overseas Push for Dollar Stablecoins to Boost Treasury Demand appeared first on CryptoPotato.
Just a few days ago, SUI crossed the $1 psychological level and surged to a four-month high of $1.05.
Bears then stepped in and pushed the price down to $0.95 (per CoinGecko), but according to popular analyst Ali Martinez, the bull market has already begun.
Why So?
The X user said that after an 83% drop during the bear market, SUI has flashed one of its most important macro bullish signals. Specifically, the Parabolic SAR dots have flipped below price on the weekly chart, indicating a shift from a downtrend into a new uptrend.
“The indicator is designed to identify trend direction and potential reversals, with dots below the price signaling bullish momentum. After such a deep correction, this weekly flip suggests that SUI has finally entered a new bull market,” the analyst claimed.
This isn’t the first time Martinez has touched on the asset this month. Several days ago, he outlined three key reasons why the price can soon reach $1.40. Some of those include the Tom DeMark Sequential, which printed a 13th buy signal in late July, and the SuperTrend indicator, which also flipped to “buy.”
Lucky and Michael van de Poppe have also paid attention to SUI lately. The former argued that the token has been screaming NEAR vibes, highlighting its “strong development, growing ecosystem, and plenty of momentum” behind its network.
“Expecting SUI to go on a majestic run from here,” the X user added.
Michael van de Poppe warned that SUI may experience a correction (as it did), but could then jump toward $1.16 and $1.60 in the coming period.
For his part, Crypto With Gopal noted that the coin has printed a massive double bottom on its chart. He said SUI has defended the $0.55-$0.60 zone for the second time, while the neckline sits near $2.70.
“A confirmed breakout could signal a major momentum shift. The chart projects a potential move toward $5.00 if the neckline breaks convincingly. Market sentiment: Bullish setup – breakout confirmation is key,” the analyst projected.
Additional Forecasts
Earlier this week, Crypto Tony identified $1.12 as the first bullish target about to be hit, saying he plans to take some profits once the price reaches that level.
KALEO has also been quite vocal on the matter. The analyst first claimed that SUI looks like “it’s finally ready to break out.” Shortly after, they predicted a quick squeeze from $1 to $2, adding that people forget how fast the asset can run once it starts rallying.
The post SUI Flashes a Key Macro Signal: Has the Bull Market Begun? appeared first on CryptoPotato.
A clear difference has emerged in the long-term MVRV levels of major crypto assets. Bitcoin, Ethereum, and Chainlink are slightly above 0%. This means the average market participant who has held these assets over the past year is still sitting on a small profit.
XRP and Dogecoin, on the other hand, are in a different position.
Deep MVRV Discounts
According to the latest findings by Santiment, XRP’s 365-day MVRV stands at around -11.75%. DOGE is even lower at about -19.26%. The negative readings essentially mean that many long-term holders are currently holding unrealized losses. A lower MVRV can sometimes point to lower selling pressure.
Fewer traders are sitting on large profits that could lead to immediate selling. In previous instances, periods of heavy unrealized losses have also created longer-term recovery opportunities.
Santiment stated that XRP and DOGE currently stand out because their long-term holders remain deep in the red even as the market recovered.
“BTC, ETH, and LINK aren’t suddenly ‘bad buys’ just because their MVRV is slightly positive. But when comparing opportunities, assets far below 0% often deserve extra attention. The deeper the losses compared with other coins, the more interesting the setup can become.”
Fresh Selling Pressure
After a strong start to the week, the crypto market has started to cool off. XRP has been hit particularly hard in the latest pullback. Ripple’s native token dropped more than 7% over the past 24 hours and is now trading near the $1.48 level. Ali Martinez believes that “everything comes down to $1.60.” As such, a decisive break above this could confirm the pattern and trigger another 30% rally toward $2.
The OG meme coin, meanwhile, is also among the poorest performers in the past day as it shed 6.6%.
It faced a setback earlier this month when Bitwise announced that it would shut down its spot DOGE ETF, BWOW, after roughly 10 months, citing changes in investor demand and its plans to optimize its product lineup. The fund was scheduled to trade on NYSE Arca until October 14 before being liquidated.
However, investor interest in US-based spot DOGE ETFs appears to have picked up since then. These funds raked in $909,650 on Monday, and around $1.2 million on Tuesday, pushing weekly net inflows above $2 million.
The post XRP and DOGE Are Deep in the Red: Could That Be a Bullish Signal? appeared first on CryptoPotato.