Cryptocurrency Posts
Crypto Briefing
Aero's multi-chain launch could significantly enhance DeFi interoperability, potentially expanding market reach and liquidity across networks.
The post DeFi protocol Aero set to launch on Oct. 21 across seven chains appeared first on Crypto Briefing.
The increased competitiveness in Maine's Senate race highlights the volatility and unpredictability of political contests in swing states.
The post Susan Collins’ odds improve in competitive Maine Senate race against Troy Jackson appeared first on Crypto Briefing.
Jumper will launch its JUMP token sale on Legion on September 29 as the crosschain app expands into perps, RWAs, yield and advanced trading.
The post Jumper to launch JUMP token sale on Legion September 29 appeared first on Crypto Briefing.
Circle Foundation's support for onchain aid payments could revolutionize global humanitarian efforts by enhancing efficiency and transparency.
The post Circle Foundation backs UN push to move aid payments onchain appeared first on Crypto Briefing.
The incident underscores vulnerabilities in centralized exchanges, potentially affecting market confidence and prompting calls for enhanced security.
The post Bitget halts withdrawals after $351M hack, CEO assures funds safe appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Bitcoin Treasury Strategy Proposes Daily Dividends For Preferred Stocks
Bitcoin treasury company Strategy wants to pay investors daily dividends on four of its preferred stocks.
The largest corporate holder of bitcoin said Friday that it was asking shareholders to approve the move, which would pay investors dividends every calendar day — including weekends and holidays — on STRF, STRC, STRK, and STRD.
“If approved and adopted, we believe this would reduce reinvestment lag, enhance liquidity and market efficiency, and increase price stability,” Strategy said in a statement. Stockholders will attend a meeting to vote on the proposal on October 28.
Strategy slowed down with its aggressive bitcoin buys this year, as the largest cryptocurrency fell into a bear market. The Nasdaq-listed company instead focused on protecting its balance sheet and sold chunks of its bitcoin.
Friday’s announcement claimed the move would help both investors and common stockholders.
“We believe these enhancements can also benefit our common stockholders by increasing the attractiveness and utility of our Digital Credit instruments, supporting our ability to access preferred equity capital efficiently and expanding the capital markets toolkit we use to execute our Bitcoin Treasury strategy,” Strategy added in a statement.
Strategy — formerly MicroStrategy — is an enterprise software company that pivoted to buying and holding bitcoin in 2020.
It first bought the cryptocurrency to protect its shareholders from inflation. Since then, it has aggressively bought the asset and pivoted to being a bitcoin treasury.
Investors can now buy its shares to get heightened exposure to the cryptocurrency, or get paid a yield via its digital credit products.
The company would buy bitcoin every Monday but slowed down its buys after announcing a program under which it may sell BTC from time to time to generate up to $1.25 billion in proceeds for the USD reserve, additionally fund preferred stock dividends and interest expenses or fund repurchases.
Strategy said in a filing Monday that it last week bought 950 bitcoins for $75.7 million — its first buy since August.
Its Nasdaq-listed stock (MSTR) is down nearly 50% over the past year after the price of bitcoin took a hit.
But since the company started buying bitcoin in 2020, MSTR has appreciated by nearly 1,000%.
This post Bitcoin Treasury Strategy Proposes Daily Dividends For Preferred Stocks first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Is US Defence Secretary Pete Hegseth a Bitcoiner? This Is What His Accounts Say
U.S. Secretary of Defense Peter Hegseth holds more cash than he does bitcoin.
That’s according to his newly released 2025 annual financial disclosure, which shows he has between $16,000 and $65,000 in the leading cryptocurrency while a bank account holds $1 million in cash.
Hegseth, who was appointed Defense Secretary in January 2025, is part of the most crypto-friendly administration the U.S. has had.
President Donald Trump was backed by digital asset industry bigwigs and last month pushed for landmark crypto legislation, the Clarity Act, to pass.
Hegseth’s Office of Government Ethics filing also showed that he and his wife have retirement accounts containing investments worth roughly $2.05 million to $4.35 million.
Some of the investments include exchange-traded funds like the tech-heavy Invesco QQQ Trust and the closed-end fund the Apollo Diversified Real Estate Fund.
Transactions made by Hegseth including sales of Amazon, Microsoft, and Apple stock.
The bitcoin stash held by Hegseth is kept in a Coinbase wallet, the filing states.
Hegseth’s crypto holdings are modest compared to the Trump family’s, which has made billions in crypto ventures since the president took office.
President Trump personally disclosed that he’d made more than $1.4 billion from the family’s digital asset ventures, making crypto his largest income source and far ahead of real estate and legal settlements.
His family — including sons Eric and Donald Jr. — made $2.3 billion from four crypto ventures through the end of April 2026, a Reuters investigation reported this year.
Critics, including Democrats, have accused Trump of profiting from crypto while shaping policy on it. The White House has consistently denied any conflicts of interest, and Trump has pointed to stock trading by members of Congress, particularly Nancy Pelosi, calling for a ban on the practice.
This post Is US Defence Secretary Pete Hegseth a Bitcoiner? This Is What His Accounts Say first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Mitchell Askew Explains What 15M Inactive BTC Means for Bitcoin’s Next Move
Bitcoin is rallying despite a Fed rate hike and the failure of the Clarity Act, and the on-chain data suggests sellers may be nearly exhausted. Mitchell Askew, Head of Blockware Intelligence, breaks down long-term holder supply, which hit an all-time high of 15 million BTC this summer. He explains why so many coins sitting still signals more room for price to run. He also shares what Bitcoin ETF flows reveal about institutional buyers returning to the market.
Chapters:
0:00 Mitchell Askew of Blockware Intelligence on Bitcoin’s Rally
0:22 Is Bitcoin Selling Pressure Exhausted? Long-Term Holder Supply
1:36 Bitcoin ETF Flows & Returning Institutional Buyers
2:36 Why the Four-Year Halving Cycle Is Breaking
4:06 AI Data Centers Pulling Compute Away From Bitcoin Mining
5:56 The Hash Rate Bear Market: Should Bitcoiners Worry?
6:58 Stranded Energy, Global Mining & AI Data Center Arbitrage
8:12 Why Gen Z Isn’t Buying Homes
9:58 Will Gen Z Ever Save in Bitcoin?
11:26 Shallower Drawdowns & the Future of Bitcoin Cycles
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Mitchell Askew Explains What 15M Inactive BTC Means for Bitcoin’s Next Move first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Nearly $352M Moved From Crypto Exchange Bitget Wallets in Suspected Hack
An estimated $351.6 million in crypto has been moved from digital asset exchange Bitget’s hot wallets in a suspected hack.
The platform’s CEO said in a Thursday statement that Bitget’s security team activated an emergency response when the movements were detected. Blockchain security firms had flagged the issue earlier in the day.
“At 18:31 UTC on September 24, 2026, Bitget’s security systems detected unauthorized transfers from some of our hot wallets,” Bitget CEO Gracy Chen wrote on X. “Our security team activated emergency response protocols immediately.”
She added: “Bitget has navigated multiple market cycles. We will not run from this. Every dollar and every decision will be accounted for, transparently and in full.”
Victoria, Seychelles-based Bitget is the sixth biggest exchange, processing over $1.1 billion in trading volume per day, according to CoinGecko data.
The incident comes as crypto security is in the limelight after a string of breaches this year have the community reeling. Just in July, hackers targeted a firmware bug in the popular bitcoin hardware wallet, Coldcard, to steal nearly $120 million in user funds.
And this month, purported white-hat hackers withdrew about 4,000 bitcoins — worth about $320 million at the time — from Blockstream’s Liquid sidechain’s federation wallet.
Chen added that the exchange’s cold wallets remained fully secure and that user funds were safe.
She wrote: “Bitget operates a three-tier wallet architecture — the breach contained only a portion of the hot wallet and warm wallet layers.”
According to the statement, deposits and trading remain fully operational but withdrawals are temporarily paused until a security review is complete.
Blockchain data firm Arkham Intelligence created a dashboard soon after the unauthorized transfers showing that a number of different cryptocurrencies — including stablecoins — had been moved from the Bitget hot wallet.
While Bitcoin was not on Arkham’s list, crypto security firm Hacken later said on X that the largest cryptocurrency had been moved.
This post Nearly $352M Moved From Crypto Exchange Bitget Wallets in Suspected Hack first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
New York Sues Polymarket, Calling Prediction Market an Illegal Gambling Operation
New York Attorney General Letitia James and Governor Kathy Hochul on Thursday filed a lawsuit against crypto-based prediction market Polymarket, accusing the platform of running an unlicensed gambling operation in the state.
An investigation by the Attorney General’s office concluded that these markets meet New York’s legal definition of gambling because users stake money on uncertain outcomes they cannot control.
Polymarket never obtained a license from the New York State Gaming Commission, the suit alleges, and so avoided the taxes that licensed casinos and mobile sportsbooks pay. That revenue helps fund public schools, youth sports programs and problem gambling treatment.
The suit comes as regulators like the Securities and Exchange Commission and the Commodity Futures Trading Commission are working to regulate crypto-powered prediction markets.
Polymarket and rival Kalshi argue they aren’t gambling sites at all, but rather federally regulated exchanges offering “event contracts,” a type of derivative, which would put them under the Commodity Futures Trading Commission rather than state gaming laws.
The CFTC agrees, and it has joined the fight on the platforms’ side. In 2026 it sued nine states, arguing that it should have exclusive nationwide authority over the industry.
Thursday’s complaint also says the platform is open to users aged 18 to 20, although New York requires mobile sports bettors to be at least 21.
“By skirting New York’s laws, Polymarket is targeting the most vulnerable,” James said. Hochul added that the company had “knowingly” violated state law and put underage users at risk.
The state is asking a court to bar Polymarket from operating as an unlicensed gambling business in New York. It also wants the company to forfeit its illegal gains, repay harmed users and pay fines equal to three times those gains.
The lawsuit is the latest in a string of New York actions against gambling-adjacent platforms. James and Hochul sued rival prediction market Kalshi in July, and James sued Coinbase and Gemini in April over similar claims. Earlier this month, James secured $8 million from the leading operator of sweepstakes casinos.
Polymarket launched in the United States in December 2025, initially letting users bet on sporting events with plans to expand into markets on a wide range of topics.
This post New York Sues Polymarket, Calling Prediction Market an Illegal Gambling Operation first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
HTTP error 429 on https://cryptoslate.com/feed/
Failed to fetch feed: https://cryptoslate.com/feed/
Failed to fetch feed.
CryptoTicker.io
A Bitcoin forecast worth anything today does not consist of a single number, but of a range, a reason and an action. The Bitcoin price stands at $83,877 at 16:40 UTC on September 25, 2026, the equivalent of 73,605 euros (retrieved from CoinGecko, market data API). The measured volatility of the past 30 days produces a band between roughly $73,600 and $94,200 for the coming month, within which the price will stay with a probability of about two thirds. More important than that band, though, for you as a German investor is the calendar: the third quarter ends on September 30, the Crypto Asset Tax Transparency Act took effect on January 1, 2026, and Germany's transition period under MiCA expired on December 31, 2025. This article adds both sides together: the levels the market sets, and the checks you can carry out today regardless of the price.
Bitcoin forecast on September 25, 2026: what the price is currently measuring
As of 16:40 UTC, Bitcoin stands at $83,877. Over the past 24 hours the price has lost 1.1 percent, moving between $83,230 and $85,208. Over seven days it is up 3.4 percent, over 30 days up 7.6 percent. The twelve-month view looks different: there it is down 25.0 percent. Market capitalisation is $1.685 trillion, trading turnover over the past 24 hours $37.6 billion, and 20,089,253 Bitcoin are in circulation.
The all-time high of $126,080 dates from October 6, 2025. The current price sits 33.5 percent below it. Anyone reading a forecast today that names the all-time high as the next waypoint should know this figure: from $83,877 to $126,080 is a gain of 50.3 percent. That is no argument against such a target, but it frames the time horizon in which it would be reachable.
The sentiment index from alternative.me, which builds a value between 0 and 100 out of volatility, trading volume, market dominance and survey data, stands at 71 points on September 25, placing it in Greed territory. The previous day it also stood at 71. A high reading is not a sell signal; it says only that the market is pricing in little fear right now. For your planning that means one thing above all: the price of hedging is lower in such phases than it is after a slump.
The range of the past 30 days: $75,590 to $86,597 as the frame for any forecast
For this article, the daily closing prices of the past 180 days were retrieved from CoinGecko's market data API and analysed. The result is the most robust part of any forecast, because it predicts nothing but measures.
- Lowest level of the past 30 days: $75,590 on September 16, 2026.
- Highest level of the past 30 days: $86,597 on September 22, 2026.
- Lowest level of the half-year: $58,566 on July 1, 2026.
- Moving average of the past 50 days: $75,318.
- Moving average of the past 180 days: $71,007.
Two things stand out. First, Bitcoin ran through a range of 14.6 percent within six trading days between September 16 and September 22. Second, the current price sits 11.4 percent above the 50-day average and 18.1 percent above the 180-day average. Both lines are therefore below the price, and both are rising. That is the technical starting position from which forecasts for the fourth quarter are built.
How wide a month really is: volatility as a forecasting frame
Volatility is the measure of how strongly a price fluctuates around its own path. The same 180 daily data points give an annualised volatility of 42.5 percent for the past 30 days, and 38.2 percent across the full half-year. The average daily move of the past 30 days is 1.49 percent, regardless of direction.
Scaling the annual volatility of 42.5 percent down to one month produces a standard deviation of 12.3 percent. Applied to today's price, that means a band from $73,586 to $94,168 for the coming four weeks. Calculated over one week, the band shrinks to $78,934 to $88,820. On the assumption of normally distributed returns, around 68 percent of all paths lie within one standard deviation.
That assumption is deliberately conservative, because it understates the tails: crypto markets produce extreme days more often than a normal distribution expects. The band is therefore not a guarantee but a lower bound for the width you should reckon with. Anyone reading a forecast that names a single figure for four weeks rather than a range is ignoring these measured 12.3 percent.
Upside levels: the September high at $86,597 and what lies beyond it
The next level to the upside is the September high of September 22 at $86,597, 3.2 percent above the current price. That level matters because the market turned there three days ago: whoever bought at the peak is currently sitting on a small loss and tends to sell on a return to break-even. That behaviour creates supply and turns a high into a resistance.
Above $86,597 the air thins out, because not a single daily closing price of the entire half-year lies higher. The next reference point from the record is the all-time high at $126,080. A forecast expecting that leap within a few weeks demands a move of 50.3 percent, a good four monthly standard deviations. Such a path would be realistic across several quarters, not across a change of quarter.
In classical chart analysis, a breakout counts as confirmed by a daily close above the level accompanied by rising turnover. The $37.6 billion turnover of the past 24 hours is the benchmark against which you can measure that.
Downside levels: the 50-day line at $75,318
To the downside two levels lie close together, and that is precisely what makes them robust. The 30-day low of September 16 is at $75,590, 9.9 percent below the current price. The 50-day moving average is at $75,318, 10.2 percent below it. Where a trough and a closely watched average line sit at almost the same level, buy orders and hedges accumulate.
If that zone breaks, the next stop is the 180-day average at $71,007, 15.3 percent below the current price. Below that, within this half-year's data window, there is no notable zone of concentrated trading until the July low of $58,566. The distance from the current price to that point is 30.2 percent.
In practice that means: if you want to set a selling threshold, it does not belong on a round number like $80,000 but below the zone that has actually held. A threshold just above $75,318 is reached by any ordinary daily move of 1.49 percent as soon as the price so much as tests the zone.
Holding period and quarter-end: why the calendar sets your selling date
This is where the German view parts company with any international forecast. Under the Federal Ministry of Finance circular of March 6, 2025, Bitcoin counts among the other economic assets within the meaning of section 23 (1) sentence 1 no. 2 of the German Income Tax Act. If you sell privately held coins after more than twelve months, the gain is tax-free regardless of its size. If you sell within the twelve months, the gain is taxable at your personal income tax rate.
From that follows a check you can carry out today and which depends on no price forecast: look in your purchase record for the tranches bought between September 26 and December 31, 2025. Those positions cross the one-year mark in the coming quarter. For each of them the date matters more than the forecast, because selling a few days before the deadline costs you the full tax rate on the gain, while selling a few days after costs nothing.
Under the circular of March 6, 2025, the same applies to holdings you have lent out or staked in the meantime: the holding period stays at one year. The running income from staking or lending is to be considered separately and arises as other income. A detailed treatment of the German rules is in our overview of crypto tax in Germany.
The 1,000-euro exemption limit and FIFO: what to calculate before every sale
An exemption limit of 1,000 euros per calendar year applies to gains from private disposals within the one-year period. The term exemption limit is to be taken literally and differs from an allowance: if your total gain from such transactions is 999 euros, it stays tax-free. If it is 1,001 euros, the entire amount is taxable, not merely the one euro above.
Which coins you actually sell is decided by the consumption sequence. The customary method, accepted by the tax authorities, is first-in-first-out, under which the units bought first count as sold first. Where several purchases are spread across the year, that order determines whether a sale hits an old, tax-free tranche or a young, taxable one.
A worked example at today's price: you bought for 4,000 euros in February 2026 and again for 4,000 euros in July 2026. If you sell part of it now, FIFO reaches the February tranche first, which would become tax-free in February 2027. Anyone who overlooks that gives away a deadline they can hardly get back. If you use several exchanges and wallets, you need a seamless record across all accounts for this, otherwise each platform calculates only its own slice.
Crypto Asset Tax Transparency Act: what your exchange reports from 2026
Since January 1, 2026, the Crypto Asset Tax Transparency Act has applied in Germany, implementing the EU directive DAC8. According to the overview of the act by audit firm KPMG, retrieved on September 25, 2026, the current calendar year 2026 is the first reporting period. Providers must transmit the data to the Federal Central Tax Office by July 31, 2027. For breaches, section 18 of the act provides for fines of up to 50,000 euros per case.
What gets reported are trades, exchange transactions and transfers, together with details about you as the user. In practice that means: what you declare for the current year in your tax return can be reconciled from 2027 with the data from your exchange. Anyone who puts their records in order only once the report has already been filed has missed the easier route.
The check that follows from this is unspectacular and effective: before the quarter ends, export the complete transaction history of every exchange you used in 2026, and file it together with the wallet addresses through which you processed withdrawals. Exchanges change export formats, discontinue services or lose authorisations. An export you pull today is available; one you need in 2027 may no longer be.
Buying under MiCA: Germany's transition period has expired
MiCA is the EU regulation on markets in crypto-assets. It requires authorisation as a crypto-asset service provider for operating a trading platform, for exchange transactions and for custody on a client's behalf. Germany brought the national transition period forward to December 31, 2025 through its crypto markets supervision act, ending it half a year earlier than the latest EU-wide deadline of July 1, 2026. Since January 1, 2026, providers without authorisation may no longer render services in Germany.
For you that is a concrete check before your next purchase: look up whether the provider you buy through is listed in BaFin's company database or operates under an EU passport from another member state. A provider without authorisation is not automatically disreputable, but in a dispute you stand outside the supervisory framework, and deposit protection does not cover crypto-assets in any case.
If you switch providers, the switch itself becomes a tax matter: transferring your own holdings between your own wallets is not a sale and triggers no tax, but it must be documented so that the acquisition data, and with it the holding period, are preserved. Which platforms are authorised for German investors and how they differ on fees and withdrawal routes is shown by our comparison of the best crypto exchanges.
Custody: what to check before the next swing
The measured volatility of 42.5 percent has a side effect that rarely appears in forecasts: in hectic phases, load and waiting times at exchanges rise, and that is exactly when you want access. Anyone holding larger amounts therefore does well to separate the trading position from the long-term position.
Three checks are possible today without any view on the price. First: is your recovery phrase held in two physically separate places, and is at least one copy protected against fire and water? Paper in a desk drawer does not meet that. Second: have you ever tested the recovery process, meaning restoring the wallet from the phrase on a second device? An untested backup is an assumption. Third: at every exchange you still use, is two-factor sign-in set to an app or a security key rather than to SMS?
Which devices meet these requirements, and how they differ in handling and backup procedure, is a question of the backup method and of usability, not of price.
Leverage and liquidation: what a 1.49 percent daily move means for your account
Anyone trading with leverage should read the forecast not in price targets but in probabilities. From the measured monthly volatility of 12.3 percent it is possible to estimate how often an adverse move grows large enough to liquidate a leveraged position. On the simplifying assumption of normally distributed returns and disregarding financing costs, the picture for a one-month period is:
- Three times leverage, liquidation at an adverse move of around 33 percent: about 0.3 percent probability.
- Five times leverage, liquidation at around 20 percent: about 5.2 percent.
- Ten times leverage, liquidation at around 10 percent: about 20.8 percent.
- Twenty times leverage, liquidation at around 5 percent: about 34.2 percent.
The figures are a lower bound, because real price paths swing out at the tails more often than the model does, and because liquidations can be triggered before the calculated point once the margin call takes hold. At twenty times leverage, three and a half times an average daily move of 1.49 percent is arithmetically already enough to end the position.
For retail investors in the EU, leverage on crypto contracts for difference is capped at two times in any case. Anyone using higher leverage with providers outside that framework loses not only this protection but also trades products whose tax treatment departs from the simple one-year rule: gains from derivatives fall under investment income and not under section 23 of the Income Tax Act.
Fees: what one percent costs at $83,877
Fees are the only part of a forecast that is certain to materialise. On a purchase of 5,000 euros, a spread of one percent costs 50 euros; at one percent on both the buy and the sell side, 100 euros in total. By way of comparison: the average daily move of 1.49 percent amounts to 74.50 euros on the same sum. Your trading costs therefore sit in the same order of magnitude as an average trading day.
Two cost types are regularly overlooked. First, the gap between the buy and sell price at providers who advertise zero percent order fees and place the margin in the price. Compare the displayed rate at the moment of purchase against a reference rate. Second, the withdrawal fee in euros and the network fee on a transfer, which on small amounts can account for the largest share.
Anyone buying monthly should recalculate both once a quarter. On a savings plan of 200 euros a month, a one percent spread is 24 euros a year, and 1.5 percent is 36 euros. Over five years that is the equivalent of roughly two monthly instalments.
Three scenarios for the fourth quarter, each with its reasoning
Sideways within the measured band, $73,600 to $94,200. This scenario needs no new piece of news; it is the continuation of the measured volatility. It is therefore the most likely outcome for the coming four weeks, as long as neither the September high nor the zone around $75,300 is durably broken.
Upward through $86,597. A daily close above the September high with rising turnover opens the area in which the half-year record holds no further resistance. The first realistic stage is the upper edge of the monthly band at around $94,200, which is 12.3 percent above today's price. In this scenario the all-time high at $126,080 remains a target for several quarters, not for weeks.
Downward through $75,318. Should the price fall below the double zone of the 30-day low and the 50-day average, the next stop is the 180-day average at $71,007. If that break is confirmed as well, no load-bearing zone remains before the July low at $58,566. For leveraged positions this scenario is the most expensive; for investors with the one-year deadline in view it is above all a question of the selling date, not of selling as such.
None of the three scenarios is a recommendation. What they do is assign consequences to levels, so that you know in advance what you will do at which price.
Checking the Bitcoin forecast: what to take away
- Sort your purchase dates before the quarter ends. Check which tranches cross the one-year mark in the fourth quarter, and note the dates. A tool that tracks the deadlines automatically is in the comparison of crypto tax tools and portfolio trackers.
- Check your buying route and its authorisation. Look up whether your provider has been authorised since the end of the German transition period, and compare spread and withdrawal fees against the alternatives in the overview of the best crypto exchanges.
- Test your custody, do not assume it. Restore your wallet once from the recovery phrase on a second device. Which devices support that comfortably is shown by the hardware wallet comparison.
(As of September 25, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Chainlink traded at $13.86 at 14:55 UTC on September 25, 2026, 11.2 percent higher than 24 hours earlier. The break above the September high of roughly $13.70 is real, and the figure most often quoted alongside it is a rise of about 25 percent in open interest. That number is currently being read as evidence of an overheated market. We therefore queried the derivatives data ourselves, and it does not support that reading: funding sits exactly at the baseline rate on both perpetual markets we were able to check.
What that means for your leverage, your route to buying and your tax position is set out below. If you hold Chainlink in your portfolio, or are weighing an entry, these three figures from the derivatives market matter more than any price target.
Chainlink price on September 25, 2026: the numbers behind the breakout
All price figures in this section come from CoinGecko's public market interface, retrieved at 14:55 UTC on September 25, 2026. LINK stands at $13.86. Over 24 hours that is a gain of 11.2 percent, over seven days 18.5 percent and over 30 days 22.7 percent. The daily range ran from $12.46 to $14.19.
Market capitalisation is $10.36 billion, which places LINK 13th among all cryptocurrencies. Trading volume over the past 24 hours came to $1.07 billion. Circulating supply is 748.1 million LINK out of a maximum of one billion.
Why the year-on-year comparison tempers the enthusiasm
A look beyond the daily candle puts the jump in perspective. Measured against its level a year ago, LINK is still down 33.5 percent. It sits 73.7 percent below the all-time high of $52.70 set on May 9, 2021. Today's breakout is therefore a move inside a multi-year sideways and downward phase, not a return to former levels. An investor who sizes a position on that basis reaches different conclusions from one who looks only at the daily candle.
Chainlink open interest: what 25 percent more open contracts actually tells you
Open interest is the total of all derivatives contracts open at a given moment that have been neither closed nor settled. The measure captures how much capital is tied up in the futures market, and on its own says nothing about whether that capital is positioned for rising or falling prices.
Industry outlet KuCoin reported on September 25, 2026 that LINK had passed its September high of around $13.70 while open interest rose by some 25 percent; market-wide, the report puts the figure for September 24 at roughly $650.7 million, against a range of $350 million to $450 million in spring and early summer. Financial service FXStreet attributes the move on the same day to institutional demand, positioning in the derivatives market and new partnerships.
Our own measurement confirms the order of magnitude on the two markets we were able to query. At OKX, 2,143,973 LINK were open in the perpetual contract at 14:55 UTC on September 25, 2026, equivalent to $29.9 million. On Hyperliquid the figure was 7,326,573 LINK, equivalent to $102.3 million. Rising open interest alongside a rising price means, in the first instance, only that new positions are being built. Whether they are the risky kind is a question only the financing side answers.
Funding rate tested in-house: why OKX and Hyperliquid show no overheated long book
The funding rate is the periodic payment between the long and short side of a perpetual futures contract that tethers its price to the spot market. When it is clearly positive, buyers pay sellers, and that is taken as a sign of a one-sided, expensively financed long book.
That is precisely not the case here. At OKX the funding rate on the LINK-USDT contract stood at 0.0100 percent per eight-hour period at the time of retrieval. That is the baseline value the exchange applies as its starting level, and it corresponds to 0.03 percent a day, or just under 11 percent a year. On Hyperliquid the rate was 0.00125 percent per hour, which works out to the same daily figure. Two independently operated markets, one identical result.
For context, that means the eleven percent price jump was not bought by leveraged buyers who had to pay unusually heavily for their positions. Anyone trading perpetual contracts will find the fee and funding models of the individual platforms side by side in our perp DEX comparison; funding is an ongoing cost item there, not a sideshow.
Perp premium and long-short ratio: the second cross-check
The premium on a perpetual contract is the gap between its market price and the oracle price taken from the spot market. On Hyperliquid that gap stood at minus 0.007 percent and at exactly zero across our two retrievals at 14:48 and 14:55 UTC. Despite the day's gain, the contract was therefore not trading above the spot price.
The third cross-check comes from the ratio of accounts holding long to short positions at OKX. In the most recent daily slice it stood at 1.60. In the preceding days it ranged between 1.68 and 2.01. The long side is thus more thinly populated relative to the short side than it was a week ago, not more densely. Three measures from two sources point the same way, and that carries more weight than a single number.
How we measured, and what we could not measure
This analysis was carried out by cryptoticker.io itself on September 25, 2026. Method: we queried three public programming interfaces directly, namely CoinGecko's market interface for price and volume, along with the swap endpoints at OKX and the info endpoint at Hyperliquid for open interest, funding rate, premium and position ratio. That covers two perpetual markets and one spot aggregate, with every request returning HTTP status 200.
What we could not check belongs in the record too. Binance's interfaces answered from our environment with HTTP 451, those at Bybit with HTTP 403. Two of the largest perpetual markets for LINK are therefore missing from our measurement. Our funding and premium figures describe OKX and Hyperliquid, not the market as a whole. The market-wide open interest figure comes from the report linked above and is not a survey of our own.
LINK liquidation: what a daily range of $12.46 to $14.19 does to your leverage
A liquidation is the forced closure of a leveraged position by the exchange once the collateral posted no longer covers the loss. It is not an edge case but the built-in normal case of every leveraged product, and today's daily range makes that tangible.
There is $1.73 between the day's low and the day's high. Measured from the high that is 12.2 percent, from the low 13.9 percent. Anyone who had gone long near $14.19 with five times leverage would have been down roughly 61 percent on their stake at the daily low of $12.46. At ten times leverage the stake would have been wiped out on paper, meaning the position would have been force-closed before that point. This calculation leaves out fees and financing costs, which make the outcome worse still.
How to work out the distance to your liquidation price before you place the order
The rough rule of thumb is quick to form: at leverage of x, the stake is consumed on paper by an adverse move of 100 divided by x percent. Five times leverage means 20 percent, ten times leverage ten percent, twenty times leverage five percent. The trading interface shows you the actual liquidation price before you submit the order; because of the maintenance margin it always sits somewhat closer to the entry price than the rule of thumb suggests.
The practical step that follows: hold the rule of thumb against the previous day's range. Where that range was close to 14 percent, as it is here, ten times leverage is not an aggressive bet but a position that an entirely ordinary daily move would already have ended. Cutting leverage buys time, and in a sideways phase time is the scarcer commodity, not return.
Buying LINK in Germany: spot orders, MiCA authorisation and what to check beforehand
To buy LINK without leverage you need a trading venue authorised in the EU. The European regulation on markets in crypto-assets has applied in full since December 30, 2024; anyone offering crypto services in Germany requires authorisation as a crypto-asset service provider, granted and supervised in Germany by BaFin. What that authorisation demands of providers ranges from own-funds requirements through the separation of client money from the provider's own assets to ongoing reporting and disclosure duties towards the supervisor.
Three things to check before your first order. First, the provider's authorisation status, which you look up in the supervisor's public register and not on the provider's marketing page. Second, the total cost, meaning trading fee plus spread plus any withdrawal fee, because on small order sizes the spread decides the outcome more than the headline fee does. Third, the withdrawal route for moving the coins to a wallet of your own, because a balance on an exchange remains a claim against that exchange. Our crypto exchange comparison sets these points side by side for the providers available in Germany.
Chainlink tax: one-year holding period for spot, futures treatment for the perp
For tax purposes the spot purchase and leveraged trading are two different worlds, and anyone doing both is best served by keeping two separate sets of records.
Buying LINK on the spot market and selling it later counts as a private disposal under section 23 of the German Income Tax Act. If more than a year passes between purchase and sale, the gain is tax-free. Within the one-year period an exemption limit of 1,000 euros applies to the sum of all private disposals in a year. Exemption limit means that once it is exceeded, the entire gain becomes taxable and not merely the portion above it.
Gains from perpetual futures, by contrast, do not fall under the holding period. Such gains count as investment income and are treated as futures transactions, subject to 25 percent withholding tax plus the solidarity surcharge and, where applicable, church tax. There was one relief in 2024: the previous cap, under which losses from futures transactions could be offset only up to 20,000 euros a year, was abolished outright by the Annual Tax Act 2024 of December 2, 2024 and has not applied to any open case since. Law firm CMS has set out the legislative change in detail.
In practice that means documenting every transaction with its time, quantity and euro value, kept separately for spot and derivatives. Anyone who has to reconstruct that after the fact from exchange exports loses more time than the running effort would have cost. Which tools actually reflect German tax rules and which merely deliver a portfolio overview differs considerably; the relevant comparison is linked below. This section is no substitute for tax advice; for larger amounts or unclear cases the matter belongs with a tax adviser.
Staking LINK: why a running yield is no substitute for leverage
Chainlink offers staking of its own, in which LINK is locked up for a term and rewarded for it. We covered the points to check in detail on September 19, 2026 in our article on the price move above twelve dollars; the questions raised there about lock-up period, unbonding time and custody still apply unchanged.
For today's situation the distinction matters most. Staking and leveraged trading solve two different problems. Staking locks up capital you intend to hold anyway and delivers a running return on it at unchanged price risk. A leveraged contract raises price risk and delivers no running return; it costs financing instead. An investor looking for a yield finds it in the first instrument; one who wants to take a directional bet takes the second and sizes it accordingly small.
On custody, the unspectacular sentence holds, and it does not wear out: coins you intend to keep for longer than the holding period do not belong on a trading account. A hardware wallet costs a one-off sum and takes away the counterparty risk that every exchange inevitably brings with it.
Levels above and below: resistance at $14.50 and $15, support at $13.00 to $13.20
Technical levels are observations about how the market has behaved in the past, not a forecast. In its analysis of September 25, 2026, financial service FXStreet names the next notable resistance at around $14.50, followed by the round figure of $15; as the nearest support the service cites the zone between $13.00 and $13.20. The daily high of $14.19 therefore sits below the first resistance named.
What argues for a continuation and what argues against it
Arguing for a continuation is the combination of increased open interest and an unremarkable funding rate. That configuration describes a market in which new capital is arriving without the long side being financed at an inflated price. Such configurations have more room than those in which the financing costs have already run away.
Arguing against it is the wider picture. LINK is down 33.5 percent on the year, and the declining long-short ratio shows that part of the market is using the move to exit rather than to add. On top of that, the rise falls into a broadly friendly market environment; a pullback in Bitcoin would in all likelihood take LINK with it. Both readings stand alongside each other, and neither has been settled.
Checking the Chainlink breakout: what to take away
- Check your leverage against the daily range before you add to a position. Almost 14 percent between low and high means that ten times leverage would have been force-closed on paper today. Compare the funding and fee models in the perp DEX comparison before you open a leveraged position, because over a longer holding period the running costs weigh more heavily than the entry price.
- Settle your route to buying if you want in without leverage. Look up your provider's authorisation status in the supervisor's register, add the fee and the spread together, and check whether you can withdraw the coins to a wallet of your own. The side-by-side view of the trading venues available in Germany is in the crypto exchange comparison.
- Keep your records separate for spot and derivatives. The one-year holding period with its 1,000-euro exemption limit runs on the spot holding, while withholding tax on futures transactions applies to perpetual contracts. Which tools keep the two cleanly apart is shown by the crypto tax software comparison.
(As of September 25, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
The cross-chain protocol Universal is being wound down. Anyone holding uSOL, uXRP, uDOGE, uADA, uBTC or uLTC on Base can redeem these six tokens through a smart contract into the respective bridged counterpart after November 17, 2026. Anyone holding any of the other roughly 80 uAssets gets USDC. Until November 17 everything runs as normal: you can sell through the Universal app or redeem straight into the underlying asset held in reserve.
That makes the question you face clearly defined, and it has a date. Either you decide yourself by November 17 what happens to your position, or a contract decides it for you afterwards. For everything other than the six named tokens, that means a forced conversion into a dollar stablecoin, at a moment you did not choose. For holders in Germany there is also a tax question attached, which gets a section of its own further down.
What Universal announced on September 18
The team behind Universal announced the wind-down on September 18, 2026 on its own site. As its reason it states, in its own words, that adoption did not reach the scale that would have been needed to make the protocol viable in the long run. Over two years, Universal says it supported more than 80 underlying assets.
The timetable is short and unambiguously worded: "The Universal protocol will remain operational, business-as-usual, for the next 60 days, through November 17." During that period the uAssets remain backed by their underlying assets as usual, and the existing infrastructure stays in operation. After November 17 the protocol is wound down, and remaining uAssets become redeemable through a smart contract.
uAssets explained: what sits behind uSOL, uXRP and uDOGE
A uAsset is a token on one blockchain that represents an underlying asset from another blockchain and is backed one to one by that underlying asset. uSOL on Base therefore stands for Solana, uXRP for XRP and uDOGE for Dogecoin. The purpose of such constructions: an asset sitting on its home chain becomes tradable in a foreign ecosystem without having to switch chains.
From that follows the property that matters most for this deadline. A uAsset is a placeholder whose value hangs on the promise that somebody custodies the underlying asset and handles redemption. If the operator falls away, it is not the market that decides the placeholder's fate but the wind-down rule. That rule is exactly what Universal has now published.
The November 17 deadline: what stays unchanged until then
Up to and including November 17, 2026, nothing changes for you in the mechanics. Universal expressly undertakes to maintain the backing of the uAssets with their underlying assets and to provide relayer liquidity as usual. Two routes are open to you in that window.
- Selling through the Universal app. The protocol itself calls this the simplest route for most users wanting to close their position.
- Redeeming directly through the mint-and-redeem interface, if you want the underlying asset itself rather than sale proceeds.
One caveat is also in the announcement and belongs here rather than in the small print: because of the elevated number of redemptions during the wind-down, a direct redemption may take longer than usual for security reasons. So anyone waiting for the last day is planning with no buffer. For larger amounts, Universal points to contacting the team so the process can be coordinated.
After November 17: six uAssets get the original, the rest get USDC
For the period after the deadline, Universal has published a table. Six uAssets held on Base are then redeemable into their respective bridged counterpart:
| uAsset on Base | redeemable into |
|---|---|
| uSOL | SOL on Base |
| uXRP | cbXRP |
| uDOGE | cbDOGE |
| uADA | cbADA |
| uBTC | cbBTC |
| uLTC | cbLTC |
| all other uAssets | USDC |
The prefix cb stands for the bridged versions held on Base. Anyone holding one of the six tokens therefore swaps one placeholder for another and stays in the same underlying asset. Anyone holding one of the other roughly 80 uAssets leaves their underlying asset entirely and afterwards holds a dollar-pegged stablecoin.
Sell or redeem: which route is right for you
The decision comes down to a single question: do you want to stay invested in the underlying asset or not?
You want to stay invested. Then you redeem directly by November 17 and hold the underlying asset itself afterwards, or you take the bridged counterpart after the deadline if you hold one of the six named tokens. With all other uAssets that is not an option: there the link to the underlying asset ends on the deadline, and you would have to buy the asset back after the conversion with the USDC you receive, at whatever price applies then.
You want out. Then you sell through the app while the liquidity is being guaranteed. Anyone who waits meets a market everybody wants to leave at the same time, and at trading volumes that are small. How small is shown in the next section.
There is no third possibility. Doing nothing is a deferred swap for the six tokens and, for everything else, a conversion into USDC that you do not control.
Why waiting gets expensive: what market cap and daily turnover say
This is not a billion-dollar affair, and that is precisely the point. Our own query to CoinGecko on September 25, 2026 at around 12:49 UTC: uXRP shows a market capitalisation of roughly $2.95 million on daily turnover of about $279,000. uDOGE stands at around $341,000 market capitalisation and about $72,000 daily turnover.
Put those figures in proportion. With uXRP, daily turnover does not even amount to a tenth of the outstanding supply. If a meaningful share of holders wants to sell simultaneously in the last days before November 17, that supply meets a very thin market. The discount you would then accept is not market risk in the usual sense, but a consequence of the deadline.
The flip side: deciding early costs you little in this case. As long as Universal guarantees relayer liquidity and the backing is intact, you sell close to the price of the underlying asset. That is the real message in these numbers.
Is the peg still holding? Our own measurement on uXRP and uDOGE
A holder's first question is whether the placeholder still trades where its underlying asset stands. Measured at the same time, September 25, 2026 at around 12:49 UTC: uXRP trades at $1.60, XRP itself at $1.61. That is a discount of roughly 0.6 percent. uDOGE trades at $0.098152, dogecoin itself at $0.098275, so around 0.1 percent below. Solana stood at $120.40 at the same moment.
The peg is therefore holding, with a small discount that reflects the uncertainty about the wind-down. That is a snapshot and no guarantee for November 16. Anyone wanting to follow the situation themselves compares the price of the uAsset with the price of the underlying asset, ideally daily and from the same data source. If the discount widens noticeably, that is a sign the market is judging redemption less favourably than before.
What the caveat in the announcement means for you
On the published redemption table, Universal writes explicitly: "The redemption assets above reflect our current plans and are subject to change as the wind-down progresses." The mapping of which uAsset is redeemed into which asset is therefore provisional. The team says it will publish final details on redemption values, the smart contract and the exact procedure before November 17.
For you that sentence has a practical consequence. Planning around the table means planning around a statement of intent. Selling or redeeming directly before the deadline, by contrast, makes you independent of the final version. This is no reproach to the protocol, which communicates the caveat openly, but a trade-off you make for yourself.
Tax: why the forced conversion into USDC is a disposal
A private disposal transaction under section 23 of the German income tax act exists where an asset is disposed of again within one year of acquisition. A swap counts as a disposal, because you give up one asset and receive another. Anyone whose uAsset gets converted into USDC therefore has a transaction the tax office treats like a sale, even though a contract triggers it rather than you.
Three points follow that you should settle before November 17. First: if your acquisition is more than a year back, a gain is tax free under the law as it stands, and the timing of the conversion is immaterial to you. Second: if it is more recent, the gain counts among private disposal transactions, for which an exemption threshold of 1,000 euros per calendar year has applied since 2024. Third: by choosing when you sell you also decide which tax year the transaction falls into. Anyone converted only after November 17 no longer has that choice.
Unsettled is the treatment of redeeming a uAsset into its bridged counterpart, say from uXRP into cbXRP. Whether that constitutes a swap of two different assets or merely a change of technical wrapper has not been conclusively determined. Tools that carry acquisition dates and holding periods across such events are in our overview of crypto tax software and portfolio trackers. This section is not tax advice; with larger positions the individual case belongs with a tax adviser.
Where investors hold uAssets in the first place
uAssets are not tokens you find on a European-authorised trading platform. These tokens live on Base, an Ethereum layer 2, and are traded there through decentralised venues and the Universal app. Anyone holding them generally has them in a self-custodied wallet, not in an account with a provider holding European authorisation.
That has two consequences for this deadline. First, nobody will remind you. There is no provider dropping a deadline into your inbox, and no German-language outlet has picked the matter up so far. Second, the entire process is in your hands: you need access to the wallet holding the tokens, and some network fee on Base to be able to trade or redeem at all. Both are better checked now than on November 16.
Anyone wanting to carry on afterwards with the USDC received or the redeemed underlying asset will sooner or later come back to the question of where they trade and where they custody. Both are decisions in their own right, and neither should be made under time pressure.
Redeeming uAssets: what to take away
- Check by the end of October whether you hold any uAssets at all, and which. What matters is the distinction between the six tokens with a bridged counterpart and all the others, which end in USDC. If you then want to sell, you need a venue for the proceeds: our comparison of crypto exchanges shows which providers come into question.
- Decide early rather than on the deadline. Daily turnover is small, direct redemptions may take longer, and the redemption table carries a caveat. Anyone wanting to keep the underlying asset and custody it themselves will find suitable devices in our hardware wallet comparison.
- Settle the holding period before the contract decides for you. A conversion into USDC is a disposal for tax purposes. Which tools keep acquisition data and deadlines cleanly in view is set out in our overview of tax software and portfolio trackers.
The announcement in full is in Universal's wind-down notice of September 18, 2026; an independent report on it was published by PANews on September 20, 2026.
(As of September 25, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
From September 29, 2026, Binance will move its users' crypto balances out of the Funding Account and into the Spot Account. From that day the Funding Account accepts no further on-chain deposits, and in January 2027 it will be renamed "Stocks Account". You do not have to act: anything you have not moved yourself will migrate automatically, in batches, into the Spot Account from January 2027, with no change to your total holdings. Two points sit in the small print of the announcement, though, and they will cost you time or money if you miss them. First, an outdated app version will no longer show your Funding balance at all. Second, standing instructions and recurring orders stop running if they are paid exclusively out of the Funding Account.
For users in Germany the date carries extra weight. Since the MiCA transition period ended on July 1, 2026, Binance has held no European authorisation as a crypto-asset service provider. Anyone with an account here can view and withdraw their balance, but can no longer trade under regular terms. That is precisely the group holding residual balances that need to leave the account at some point, and precisely for them the question of which sub-account this money sits in is now shifting.
What Binance is doing with the Funding Account on September 29
The exchange announced the change on September 23, 2026. The stated purpose: the account structure is to become simpler, and the settlement of stocks and stock options is to get an account of its own. Binance has run a US stock trading service since 2026; its settlement will in future be separated from the crypto business.
Two things happen simultaneously on September 29. The Funding Account accepts no further on-chain deposits, and a One-Click Migration button appears in the account, with which you move your crypto holdings into the Spot Account yourself. Deposits and withdrawals for all other crypto assets run exclusively through the Spot Account from that point. The rest is a timetable that runs into January 2027.
The announcement states verbatim that Binance will move users' crypto holdings "starting from 2026-09-29 to January 2027" from Funding Accounts into Spot Accounts, with the exact dates to be announced later. One assurance is in there too: the total value and the security of holdings remain untouched, and historical transaction records keep their original Funding Account label.
Funding Account, Spot Account, Earn Account: which sub-account does what
Binance runs several sub-accounts with separate balances. The Spot Account is the trading account: whatever sits there can go straight into buy and sell orders. The Funding Account was until now the collecting account for everything alongside that, meaning P2P trades, Binance Pay, gift cards and card payments. The Earn Account holds balances tied up in interest or staking products.
This split explains an observation many users know well: a deposit has arrived, yet it does not appear in the trading window, because it sits in a different sub-account. That duplication is what Binance is now clearing away. After the migration there is only one place where crypto assets come in and go out.
One term recurs throughout the announcement: settlement assets. These are the six currencies in which Binance settles stock transactions, namely USD, USDC, USDT, USD1, U and BNB. These six remain usable in what will then be called the Stocks Account after the renaming, though with one restriction we return to below.
The timetable to January 2027: four stages worth knowing
The changeover runs over four stages. Anyone with only September 29 in the diary will miss the stages at which something actually falls away.
- September 29, 2026: No further on-chain deposits into the Funding Account. One-Click Migration is switched on. Binance Card, gift card and Binance Pay credit incoming amounts to the Spot Account from then on. New Convert limit orders freeze their funds in the Spot Account and settle there. Recurring orders settle into the Spot Account or the Earn Account.
- From December 2026: P2P advertisers get a dedicated P2P account. Anyone running adverts will be prompted to move the amounts tied to them across.
- January 2027: The Funding Account becomes the Stocks Account. Crypto holdings not moved by the user migrate automatically, in batches, into the Spot Account. Binance has not yet named an exact date.
- After January 2027: P2P adverts that have not moved to the new account are closed automatically.
In between sits a date without a fixed day that matters in practice: the Funding Account will be removed as a payment source before the renaming takes place. Until then, amounts can still be debited from it for payments.
One-Click Migration: how to move your balance into the Spot Account yourself
The button appears in the Funding Account from September 29. One press transfers the supported holdings into the Spot Account. It is an internal transfer between two sub-accounts of the same provider, not a transaction on a blockchain: there is no network fee, and there is no recipient address that could be wrong.
Whether you do it yourself or leave it to Binance from January 2027 makes no difference to the total value. It does make a difference to your room for manoeuvre. As long as your balance sits in the Funding Account, it is attached to an account that is being rebuilt and will end up reserved for stock settlement. In the Spot Account it sits where withdrawals leave from anyway. For users in Germany, who may now only withdraw, that is the shorter route.
Anyone taking the holding off the exchange entirely needs somewhere to put it. A wallet of your own removes your dependence on any account structure, but demands that you manage the key material yourself. Anyone wanting to keep trading needs an exchange with European authorisation instead.
Outdated app version: why your Funding balance suddenly disappears
This point is the quietest and the most expensive in the whole announcement. The wording: "Users will not see the 'One-Click Migration' feature on older versions of the app, including their assets in Funding Accounts." In plain terms: on an outdated app version, not only the button is missing but the display of the Funding Account holdings as well.
Anyone who has not updated their app for months may therefore see part of their balance vanish from view on September 29 and, in the worst case, assume it is gone. It is not. Binance moves such holdings automatically from January 2027, and the total value stays untouched. The route there still runs through an update: bring the app up to date, then look in the Funding Account to see what is actually in there.
That check is worth doing for a second reason. Many users have no idea they hold anything in the Funding Account at all. Residues from P2P trades, returns from card payments and old gift card amounts accumulate there without ever appearing in the trading window.
Binance Pay, Binance Card and gift cards: where payments go from September 29
From September 29, amounts you receive through Binance Card, gift cards or Binance Pay are credited to the Spot Account. Balances in the future Stocks Account will no longer be debited for payments. Payments can still be debited from the Funding Account for a transitional period, but only until Binance removes it as a payment source.
One consequence of that is spelled out in the announcement: recurring payment plans served solely from the Funding Account will stop executing afterwards. Binance writes that users have to set up new recurring plans with a different payment source. No automatic reminder is given; anyone running such a plan is better off checking it themselves.
A separate rule applies to Binance Alpha 2.0: from September 29, stablecoins for purchases and sales of Alpha tokens are debited from and credited to the Alpha Account on limit orders. Rewards from the liquidity provider programme on limit orders land there too.
Limit orders, recurring orders and API connections: where standing instructions break
With Convert limit orders, meaning conversion orders with a price limit including take-profit and stop-loss variants, amounts already frozen stay frozen in the Funding Account. After September 29, however, these orders settle into the Spot Account. Expired limit orders likewise release their funds there. New limit orders from September 29 freeze exclusively in the Spot Account and settle there.
With recurring orders, meaning repeated purchases of the savings plan type, all orders settle into the Spot Account or the Earn Account from September 29. Refunds on failed orders go to the Spot Account. Binance explicitly asks users to switch the account selection from Funding to Spot so that their plans keep running. Anyone buying regularly therefore has a setting to change.
Anyone running an API connection, whether for a portfolio tool, a tax tracker or a trading bot, has to switch the account reference from Funding to Spot. Leave it as it is and the tool reads out an account that holds nothing after the migration. With tax tools this produces gaps in the history that are laborious to close by hand later on.
Why the changeover hits German users hardest after the MiCA exit
The European regulation on markets in crypto-assets, MiCA for short, requires every crypto-asset service provider to hold an authorisation in an EU member state. Binance withdrew its application in Greece and let the transition period pass on July 1, 2026 without a valid authorisation. Existing customers in Germany have since been able to reach their account and balance and to withdraw; regular trading and new deposits are restricted. We described the situation in detail in our piece on switching to a MiCA-regulated exchange, and the obligations the regulation places on providers are set out in our overview of the MiCA duties through 2026.
What follows for you is a very practical order of operations. If your residual balance is due to leave the account anyway, the best approach is to do it in one go: update the app, check the Funding Account, move the holding into the Spot Account, withdraw. Every stage of the migration you wait out only lengthens the route. If you want to keep trading instead, you need a provider with European authorisation; which exchanges hold it and how their fees differ is shown in our comparison of regulated crypto exchanges.
A word of context: the account change is a worldwide measure and not a response to European supervision. Binance gives the separation of stock and crypto settlement as its reason. The changeover hits German users harder only because their room for manoeuvre has shrunk to withdrawal.
Stocks Account: which six settlement assets remain and why you cannot withdraw them directly
After the renaming in January 2027, the Stocks Account serves exclusively to settle stocks and stock options. The six settlement currencies USD, USDC, USDT, USD1, U and BNB can still be used there for stock purchases. Deposits and withdrawals of all other crypto assets run only through the Spot Account.
A practical note on navigating this: these accounts carry English proper names, including in the notices Binance sends to German users. So in the app you are looking for Funding Account, Spot Account, Earn Account and, from January 2027, Stocks Account. For trading between private individuals, a separate P2P Account arrives in December 2026, purchases of Alpha tokens run through the Alpha Account, and the transfer itself is called One-Click Migration. Anyone searching the interface for translated terms will find nothing.
One detail from the accompanying FAQ Binance published on the migration matters: direct deposits and withdrawals to a blockchain are not provided for out of the Stocks Account, not even for these six assets. So anyone wanting to get USDT or BNB out of the Stocks Account first transfers them internally into the Spot Account and withdraws from there. For users in Germany, who may now only withdraw anyway, that is an extra intermediate step better known before you need it.
P2P trading: what December brings for adverts
Trading between private individuals follows its own schedule. From September 29, P2P users with no advert history and no merchant status use the Spot Account as the default source of funds for buy and sell orders, as soon as their app is current. Advertisers continue working with the Funding Account until December 2026, for all P2P activity including posting adverts, merchant deposits and maker and taker orders.
From December 2026, Binance introduces a dedicated P2P account for advertisers and instructs them to move the amounts tied to their adverts there. Adverts that have not moved by January 2027 are closed automatically. Anyone based in Germany is barely affected, because P2P trading here is constrained by the missing authorisation in any case. Anyone running an account from another country has one more deadline to keep.
Tax and holding period: does the internal transfer change anything for the tax office?
A transfer between two sub-accounts of the same provider is neither a sale nor a swap. There is no disposal, so no taxable gain arises, and the one-year holding period under section 23 of the German income tax act keeps running. That holds whether you press One-Click Migration yourself or Binance moves the holding automatically from January 2027.
More important than the tax question here is the documentation. Binance writes that historical transaction records from before and after the migration keep their original Funding Account label and are not altered. That helps with reconciliation, but it replaces no record of your own. Pull an export of your transaction history before September 29, while the account structure is still the old one. Tools that read in such histories and track holding periods are in our overview of tax software. This is not tax advice; with larger holdings, settle the individual case with a tax adviser.
Binance Funding Account: what to take away
- Update the app and look inside the Funding Account before September 29 arrives. On an old app version the holdings there are no longer displayed. If you intend to take the balance off the exchange anyway, you need somewhere to put it: our hardware wallet comparison shows which devices suit which amounts.
- Switch recurring orders and API connections from Funding to Spot. Plans paid solely out of the Funding Account stop executing as soon as that account falls away as a payment source. If you want to keep trading afterwards, the route runs through an authorised provider: comparison of regulated crypto exchanges.
- Secure your transaction history while the old account structure is still standing. An export before the move saves you hunting for gaps later. Which tools track holding periods and acquisition costs is set out in our overview of crypto tax software and portfolio trackers.
The announcement in full is in the Binance notice of September 23, 2026; an independent account of the move comes from crypto.news.
(As of September 25, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Chainlink trades at $13.93 on September 25, 2026 at 13:46 UTC, putting it 12.21 percent above where it stood 24 hours earlier. Behind the rise sits a concrete product launch: on September 24, Paxos Labs brought the token PAXGy to market and made Chainlink's cross-chain rail CCIP the sole route between networks. What you can draw from that as a holder or a prospective buyer depends less on the percentage than on four things: the buying route, the holding period, custody, and whether you want staking at all.
Chainlink price at $13.93: the numbers behind the jump
The groundwork first, so you can place the move. All the figures below come from our own retrieval of CoinGecko market data on September 25, 2026 at 13:46 UTC.
- Price: $13.93
- Change over 24 hours: plus 12.21 percent
- Change over seven days: plus 19.19 percent
- Daily range: $12.41 to $14.19
- Trading volume over 24 hours: around $1.05 billion
- Market capitalisation: around $10.43 billion, rank 13
Two figures matter more for context than the daily gain. The first is the ratio of volume to market capitalisation: a good billion dollars of turnover against ten billion dollars of market value means that roughly a tenth of the stock changed hands that day. That is a day with real participation, not thin trading. The second figure is the distance to the all-time high. That sits at $52.70, set on May 9, 2021, leaving the current price about 73.6 percent below it. A twelve percent day changes little about that distance.
Of the total supply of one billion LINK, 748.1 million units are in circulation. Around a quarter of the supply is therefore not yet on the market, a point worth carrying with you whenever you look at the market capitalisation.
Why is the Chainlink price rising? The documented drivers of September 24 and 25
There is one trigger on this day that can be traced to a primary source, and a second that has been running in the background for weeks. Both feed the same narrative: Chainlink earns money not from an application of its own, but from other applications using its infrastructure.
PAXGy: what Paxos Labs launched on September 24
Paxos Labs has issued a token called PAXGy. It is backed by PAX Gold, the house's existing gold-backed token, and differs from it in one respect: the number of fine ounces attributed to a token grows over time. The yield for that comes from institutional gold lending, in which large market participants lend out physical gold for a fee.
For you as someone interested in Chainlink, the technical footnote is the heart of the news. According to the Paxos Labs announcement, PAXGy uses Chainlink's Cross-Chain Interoperability Protocol (CCIP) as the exclusive provider for messaging between blockchains, alongside Chainlink Price Feeds for price data. The token launched simultaneously on the OKX exchange and on several on-chain platforms. Anyone moving PAXGy from one network to another triggers a CCIP operation in doing so.
CCIP: what the Cross-Chain Interoperability Protocol actually does
CCIP is a transfer protocol that moves messages and tokens between different blockchains without sender and recipient having to trust each other. In practice, a network of independent nodes takes on the job of confirming that what is claimed on the destination chain really happened on the origin chain. Centralised bridges used to perform the same function, and for years those were the most vulnerable point in the crypto market.
The economic link to the token is indirect and deserves a sober look. Fees for CCIP operations can be paid in LINK, and the Chainlink Reserve collects revenue from network operations in LINK. A single product launch does not move that revenue noticeably. What it moves is the expectation of how many such launches are still to come.
Chainlink Reserve: what the accumulation says about supply
The Chainlink Reserve is a holding of LINK built up from network revenue and secured against rapid outflows by a time lock in the contract. Consistent market reports from mid-September put the holding at around 5.96 million LINK, worth roughly $68.7 million. On September 18, according to those reports, 97,500 LINK worth around $1.1 million were added, and over 30 days some 480,700 LINK worth about $5.5 million.
These figures come from reporting; we did not read them out of the contract ourselves. If the point matters to you, it is better to check it yourself: Chainlink maintains a public dashboard for the reserve showing the current holding. The same applies to the PAXGy announcement, available in full as a press release from Paxos Labs.
What that means for you: around 5.96 million LINK, measured against 748.1 million circulating units, is less than one percent of supply. As a signal about the direction of network revenue the reserve is interesting; as a supply squeeze it is currently far too small to carry a price. Anyone using it as a reason to buy is stretching the number.
The Infosys partnership: why 1.7 billion accounts are not revenue yet
On September 22, Chainlink announced a collaboration with the Indian IT services provider Infosys. According to the announcements it covers six Chainlink services: CCIP for transfers between chains, CRE for orchestrating workflows, ACE for compliance checks, Proof of Reserve for automated backing attestations, and Data Feeds and Data Streams for market data on chain. Infosys puts the reach of the systems involved at more than 1.7 billion customer accounts worldwide.
The figure sounds enormous and is given commensurate prominence in headlines. In fact it describes the reach of the systems Infosys looks after, and not the number of accounts on which Chainlink technology will run. Neither Chainlink nor Infosys has named a single bank, payment network or asset manager that will deploy the services first. Commercial terms and timelines were likewise not disclosed. On what is known so far, this is a technology partnership and not yet live operation.
The market initially read it the same way: in the first hours after the announcement, LINK gave up around four percent according to reports from several trade publications. That the price is now up twelve percent two trading days later is hard to explain by the partnership alone. The more plausible reading is the combination of the concrete PAXGy launch and a broad altcoin day on which other names in the top 25 also rose sharply.
Buying LINK in Europe: the buying route, MiCA and what to check at your provider
LINK is available on practically every major trading platform active in Europe. The difference between providers rarely lies in availability and almost always in three other places: the actual fee including the spread, whether you can withdraw the token to an address of your own afterwards, and the regulatory status of the firm.
On status: crypto service providers targeting customers in the EU need an authorisation under the European MiCA regulation. You can check that without specialist knowledge. Look for the provider in the register of authorised providers held by ESMA and in the national company register of your supervisor. If you do not find it there, that is no proof of a problem, but it is a reason to look more closely before your first deposit. An overview of the firms that can be traded with under regular terms is in our comparison of the best crypto exchanges.
On fees, a concrete calculation. On a purchase of 1,000 euros, a difference of 0.5 percentage points in the total fee comes to 5 euros. That sounds like little. Buy monthly and you pay 60 euros over a year, and at a price of around 12 euros per LINK that is about five tokens. The fee is the only part of your return you know in advance.
Holding period and tax: what section 23 of the German income tax act means for your LINK
For crypto assets held privately in Germany, section 23(1) sentence 1 no. 2 of the income tax act applies. Sell at a profit within one year of acquisition and that profit is taxable, charged at your personal income tax rate. Leave more than a year between purchase and sale and the profit stays tax free. Since the 2024 assessment period, gains within the period benefit from an exemption threshold of 1,000 euros per calendar year. An exemption threshold is not an allowance: exceed it by one euro and the entire gain is taxed.
On a day with a twelve percent gain, that is the practically most important question. If you bought LINK in the past six months and sell now, the profit falls inside the period. Which units count as sold follows the first in, first out principle per wallet or account. That is exactly why you need a clean record of your acquisition dates, and you need it before you sell rather than in May of the following year. Tools that keep that running for you are set side by side in our comparison of crypto tax software.
Staking rewards work differently for tax than capital gains
Rewards from staking are not disposal gains. For tax purposes they count as other income under section 22 no. 3 of the income tax act and must be recognised in the year of receipt at the market value at the time of receipt. There is a separate exemption threshold of 256 euros a year for them. The extension of the holding period to ten years for staking and lending, once under discussion, was ruled out by the German federal finance ministry in its circular of May 10, 2022; it does not apply to crypto assets. None of this replaces advice in an individual case, and with larger amounts the road leads to a tax adviser.
Staking LINK: what to check before the lock-up
Chainlink offers staking of its own, in which LINK is posted as economic security for the reliability of its data services. Alongside that, trading platforms advertise staking offers for LINK that are something else entirely in technical terms: there you hand your tokens to the provider and are promised a yield.
The difference decides your risk. When you stake through a platform, you no longer hold a key of your own. What remains is a claim against a company. Should that company become insolvent or fall victim to an attack, your holding takes its place in the queue of creditors. The events of recent years have shown how short that queue can turn out to be for retail customers.
Three questions to settle before the first deposit. How long is your holding tied up, and is there a cooldown period before you can dispose of it again? Is the promised yield paid out in LINK or in some other asset? And who carries the risk if the provider does not earn the promised return? If one of those answers is not in the terms, that is the answer.
Storing LINK: why the network is what counts when you send
LINK is originally an ERC-20 token on Ethereum. Through CCIP, editions now exist on further networks, and that is exactly where the most common expensive mistake when withdrawing from an exchange comes from. Addresses look identical across many networks even though they point to different chains. Send LINK on one network to an address that has no key there, and the holding is not lost in the sense of destroyed, but it is out of reach without outside help.
The routine that prevents this is unspectacular: the network on the sending side and on the receiving side have to be the same, and you check that with a small test amount before you send the rest. The fee for that test is the cheapest insurance in all of crypto.
Whether you want to self-custody at all is a question of amounts and of your own diligence. A holding you could shrug off if it were lost may sit on a regulated platform. Anything beyond that belongs on an address whose key only you know, with a backup of the recovery words that survives a house fire.
Leverage and liquidation: what the daily range says about your risk
The daily range of $12.41 to $14.19 amounts to a gap of roughly 14.3 percent between low and high. Do the arithmetic against leverage before you take any on. At ten times leverage, a move of around ten percent against your position is enough to consume the capital you put in; in practice liquidation bites before that, because fees and funding costs run alongside. A range of 14 percent in a single day is therefore no outlier for LINK. It is the environment a leveraged position lives in.
With perpetual futures, the funding rate comes on top. It is typically settled several times a day between the buy and sell sides, and after a sharp rise it regularly turns expensive for the buy side. Anyone entering with leverage on a day like this generally pays the premium for everyone else wanting to trade in the same direction. How platforms for such contracts differ is something we have prepared separately.
For investors without derivatives experience, the sober answer is this: a spot purchase without leverage turns bad timing into a bad entry, while leverage turns it into a total loss.
Levels above and below: where to anchor your next step
Price levels are not a forecast. They are useful as observation points at which you carry out a decision made beforehand. Three figures from the September 25 retrieval serve that purpose.
On the upside, the daily high of $14.19 is the first point. If the day closes above it, the move has carried beyond the day; if the price stays below, the high was a spike within the day. On the downside, the daily low of $12.41 is the counterpart. A drop below it would clear out the entire daily gain and shrink the weekly balance of plus 19.19 percent considerably. And as a long-term marker, the all-time high of $52.70 from May 9, 2021 stands: anyone buying today is buying around 73.6 percent below it.
What you do at these levels is better fixed in advance than in the moment of the move. A selling target formulated only after the rise is usually just permission to keep waiting.
Checking the Chainlink rally: what to take away
- Settle the buying route and the provider's status before you react to a rally in progress. Look for the provider in the ESMA register and in your national supervisor's register, calculate the total fee including the spread on your actual order size, and check whether a withdrawal to an address of your own is possible. For the custody side, our hardware wallet comparison shows which devices come into question.
- Assemble your acquisition dates before you sell. The one-year clock under section 23 of the German income tax act and the 1,000 euro exemption threshold decide your tax bill; staking rewards run under section 22 no. 3 with their own threshold. If you are considering staking, compare lock-up and counterparty first in our comparison of staking platforms.
- With leverage, take the daily range as your yardstick, not the daily direction. A 14.3 percent gap between low and high means a ten times leveraged position can be stopped out within a single trading day. Anyone still intent on using futures should lay the funding rates and liquidation logic of the platforms side by side in our perp DEX comparison.
(As of September 25, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
Leaked code strings and screenshots point to a new tier that would cost 25 times more than ChatGPT Plus, aimed at people who need the bot to work faster, not just longer.
An attacker faked internal transfer requests to drain $387.5 million from Bitget's hot and warm wallets, and the exchange's CEO says the fingerprints look like Pyongyang's.
A flaw in Limit Break's Payment Processor V2 put old Magic Eden Ethereum listings at risk, prompting a whitehat rescue of more than 23,000 NFTs.
Pullback or reversal? Here's what the charts suggest for BTC.
STRF, STRC, STRK and STRD would accrue dividends on weekends and holidays, in a move Strategy says will dampen volatility.
U.Today - IT, AI and Fintech Daily News for You Today
Bitcoin tests the key $83,000 level ahead of a crucial weekly close that could redefine the technical market framework for Q4 2026.
Binance has added two new crypto assets to its alpha platform, allowing its users access to exclusive investment opportunities.
CoinMarketCap has acquired CoinGlass, one of the crypto industry’s most widely used platforms for tracking Bitcoin, XRP, Shiba Inu and other tokens’ liquidations, open interest and derivatives activity.
Stellar (XLM) has overtaken Bitcoin Cash (BCH) in market capitalization as a fresh wave of buying pressure sends XLM higher over 13%.
Cardano setting up for what could become its first major golden cross of 2026.
Blockonomi
TLDR
- NetApp NTAP shares gained as PEAK:AIO acquisition plans boosted AI infrastructure focus
- PEAK:AIO technology will expand NetApp’s metadata and file system capabilities
- The deal aims to support larger data environments and advanced workloads
- NetApp combines ONTAP expertise with PEAK:AIO scalable architecture solutions
- Acquisition strengthens NetApp’s position in the evolving infrastructure market
NetApp, Inc. (NTAP) shares gained 1.48% to $200.16 as the company announced plans to acquire PEAK. The deal targets stronger AI infrastructure capabilities by adding advanced metadata architecture and parallel file system technology. NetApp expects the acquisition to improve large-scale data management for growing AI workloads.
NetApp, Inc., NTAP
NetApp Expands AI Infrastructure Strategy Through PEAK Deal
NetApp announced its agreement to acquire PEAK, a company focused on high-performance metadata systems. The transaction supports NetApp’s strategy to build infrastructure for expanding enterprise AI applications. Furthermore, the deal adds specialized technology to its existing data management portfolio.
The acquisition combines PEAK’s metadata architecture with NetApp’s ONTAP software platform. This integration aims to improve storage performance for large computing environments. Therefore, organizations can access stronger systems for handling complex and data-intensive workloads.
PEAK developed technology designed for demanding computing operations with support from research institutions. The company created solutions that improve metadata scaling and global file access. Consequently, NetApp plans to use these capabilities to support larger data environments.
NetApp Targets Scalable Storage Growth With Advanced Data Systems
NetApp stated that the combined platform will support massive file environments and multi-exabyte deployments. The architecture separates metadata services from stored data to improve scalability. In addition, the approach helps organizations manage growing infrastructure requirements.
The planned integration introduces parallel access features for large-scale workloads. NetApp will maintain its focus on security, resilience, and operational simplicity. Meanwhile, PEAK technology will expand options for customers managing advanced computing systems.
The acquisition reflects rising demand for infrastructure that supports modern data operations. Companies continue developing larger computing environments that require faster and more efficient storage solutions. As a result, NetApp aims to strengthen its position in the expanding infrastructure market.
The company expects PEAK’s technology to complement its existing product ecosystem. The integration will focus on improving performance across demanding workloads. Additionally, NetApp will provide global resources and operational expertise to expand adoption.
The acquisition adds another step in NetApp’s long-term infrastructure development strategy. The company continues adapting its offerings for changing enterprise technology needs. Through the PEAK transaction, NetApp seeks to deliver more scalable data solutions for future workloads.
The post NetApp, Inc. (NTAP) Stock: Rise as PEAK:AIO Acquisition Targets AI Infrastructure Growth appeared first on Blockonomi.
TLDR
- Microsoft stock rises as Oppenheimer lifts its price target to $570
- Copilot strategy shifts focus toward enterprise AI adoption and usage
- New billing model links AI agent revenue with customer demand growth
- Microsoft combines Copilot tools to improve workplace productivity features
- AI expansion supports Microsoft’s broader cloud and software strategy
Microsoft Corporation (MSFT) shares traded at $517.17, gaining 3.86%, after Oppenheimer raised its price target following stronger enterprise AI expectations. The analyst increased the target to $570 from $515 while maintaining a positive rating. Microsoft continues reshaping Copilot to strengthen its position in business technology.
Microsoft Corporation, MSFT
The company’s latest Copilot strategy focuses on corporate customers rather than consumer AI services. As a result, Microsoft aims to expand enterprise adoption through workplace productivity tools. The shift comes as businesses increase demand for AI-powered software solutions.
Microsoft has also introduced usage-based billing for AI agents, changing how the company generates revenue from these services. Future AI income could depend more on customer activity. The model moves beyond traditional subscription-based software structures.
Microsoft Copilot Shift Strengthens Enterprise AI Position
Oppenheimer analyst Brian Schwartz raised the Microsoft price target after identifying stronger enterprise adoption trends. The analyst noted that customers increasingly select Microsoft as their main enterprise AI platform. The research also highlighted potential challenges from changing technology demand.
Microsoft shares have gained 7% year to date, while the Technology Select Sector SPDR Fund has increased 37%. The performance gap reflects concerns surrounding Microsoft’s AI spending strategy. The Copilot update has renewed attention toward its enterprise growth plans.
The company has combined consumer and workplace Copilot services into one application. This move places greater emphasis on business users and professional workflows. Microsoft is now prioritizing productivity solutions that help organizations complete tasks more efficiently.
The redesigned Copilot application includes several workplace-focused features. Users can access conversational tools, manage tasks, and edit Microsoft Office documents through one platform. The system supports broader workplace automation.
New AI Agent Billing Model Creates Revenue Opportunities
Microsoft’s updated billing structure introduces a pay-as-you-go approach for AI agents. The model connects revenue generation with actual usage instead of relying only on fixed subscriptions. Businesses could increase spending as they expand AI adoption.
The company already supports millions of Copilot subscriptions across enterprise customers. Usage-based pricing creates another pathway for revenue growth. This approach could allow Microsoft to capture value from increased workplace automation.
Microsoft’s AI strategy remains connected to its broader cloud and software ecosystem. The company continues integrating AI features across products including Microsoft 365 and GitHub. Enterprise demand remains a major focus for future expansion.
The Copilot changes also reflect Microsoft’s decision to compete differently in the AI market. The company has shifted away from building consumer-focused personal assistants. Instead, it is concentrating on tools designed for workplace productivity and business operations.
Copilot Tools Expand Microsoft Workplace Automation
Microsoft organized the updated Copilot platform around three main capabilities. The application combines chat features, task assistance, and document editing functions. It introduces tools that allow employees to create workflows using simple instructions.
The platform also incorporates technology from GitHub Copilot for software development tasks. This feature allows non-technical employees to build applications and dashboards. Companies can maintain control through administrator-managed environments.
Microsoft continues developing AI services as competition increases across the technology sector. The company’s enterprise focus creates a different path compared with consumer-oriented AI products. As a result, Copilot remains central to Microsoft’s future software strategy.
The latest price target increase reflects expectations that enterprise AI demand could support Microsoft’s growth. The company still faces risks from higher spending and changing market conditions. Microsoft’s Copilot expansion remains a key factor shaping its long-term business direction.
The post Microsoft Corporation (MSFT) Stock: Surge as New Copilot Strategy Could Unlock AI Revenue Growth appeared first on Blockonomi.
TLDR
- Nike stock falls as analysts delay recovery expectations until fiscal 2028
- Bank cuts Nike price target after weaker sales growth forecasts emerge
- North America wholesale growth faces pressure from slowing demand trends
- China operations struggle with weak demand and excess inventory levels
- Nike shares remain under pressure after major earnings estimate cuts
NIKE, Inc. traded at $36.08, gaining 0.24%, after analysts lowered the company’s outlook and delayed expectations for a sales recovery. The downgrade reduced the price target to $30 from $47, while the firm cited weaker growth conditions. Nike faces renewed pressure as its turnaround timeline moves further into fiscal 2028.
NIKE, Inc., NKE
The sportswear company has experienced a difficult period as demand patterns continue changing across major markets. Analysts have reduced earnings expectations for the coming fiscal years. The latest outlook reflects concerns over slower sales momentum and weaker product performance.
Nike remains focused on improving product innovation and rebuilding consumer demand. Analysts expect challenges to continue as the company manages inventory levels and shifting customer preferences. The stock has already declined significantly this year compared with broader market gains.
Nike Earnings Forecasts Face Further Reductions
Analysts lowered their fiscal 2027 and fiscal 2028 earnings per share estimates by 11% and 12%, respectively. Forecasts now show negative sales growth continuing through fiscal 2027. The changes reversed earlier expectations that Nike could see a faster recovery.
The revised outlook also reduced Nike’s income rating because of concerns surrounding dividend sustainability. The analysts highlighted that the company’s dividend payout ratio exceeds current earnings levels. The valuation outlook has weakened as profit expectations decline.
The new $30 price target uses a 16 times price-to-earnings multiple. Previously, the target used a higher 22 times multiple based on stronger growth expectations. The adjustment reflects a lower valuation approach compared with earlier projections.
North America Wholesale Growth Faces Pressure
Nike’s North America wholesale business showed recent strength with 14% growth in fiscal 2026. Analysts expect this momentum to weaken as retailer demand slows. Retailers may reduce orders when new products fail to generate expected sales.
The company faces pressure because product launches and classic styles have not delivered consistent consumer interest. Analysts expect North America wholesale sales declines during fiscal 2027. The slowdown could affect Nike’s broader recovery strategy.
Nike has relied heavily on wholesale partnerships to support regional growth. Changing customer demand and cautious retail purchasing could limit future expansion. The company continues efforts to strengthen its product pipeline and brand appeal.
China Market Challenges Add Pressure on Nike Stock
Nike’s China operations face additional challenges as the company changes its online distribution strategy. The transition is expected to increase promotional pressure before the company creates a more unified online presence. As a result, short-term sales conditions remain difficult.
Analysts identified weak sports demand, slower running category growth, and excess inventory across China. Newer products have struggled to attract stronger consumer interest. These factors have created additional obstacles for Nike’s regional recovery plans.
Nike shares have fallen 44% year to date, while the S&P 500 has gained 12% during the same period. Analysts noted that earnings estimates have already declined significantly. Further reductions could continue influencing the company’s valuation.
Nike has made progress with product innovation and brand improvements. Those efforts have not fully offset weakness across larger casual product categories. The company now faces a longer path toward restoring sales growth and improving financial performance.
The post NIKE, Inc. (NKE) Stock: Price Target Slashed as Sales Recovery Faces Delays appeared first on Blockonomi.
TLDR
- Cipher Digital stock fell despite a major $5.2 billion revenue expansion deal
- Barber Lake lease extension lifts contracted revenue above $9 billion
- Cipher Digital shifts focus toward large-scale computing infrastructure growth
- Texas data center project gains longer contracts and stronger demand outlook
- ERCOT power approvals remain key for future facility expansion plans
Cipher Digital Inc. (CIFR) traded at $17.75, down 1.93%, after its shares retreated from intraday highs. The company expanded its Barber Lake data center agreement, adding $5.2 billion in contracted revenue potential. The lease extension increased the facility’s contracted period while supporting its shift toward computing infrastructure.
Cipher Mining Inc., CIFR
Cipher Digital Extends Barber Lake Contract With $9 Billion Revenue Potential
Cipher Digital secured a lease amendment with Fluidstack that extends the Barber Lake contract framework. The updated arrangement covers a 300-megawatt Texas facility and expands the contract duration up to 20 years. The agreement raises the site’s potential contracted revenue from $3.8 billion to more than $9 billion.
The company also established a separate long-term commitment with a leading artificial intelligence laboratory. The additional agreement could generate about $5.2 billion in incremental contracted revenue over ten years. However, the stock declined as the market absorbed the expanded project details and recent trading pressure.
The Barber Lake site remains scheduled for phased delivery between the fourth quarter of 2026 and first quarter of 2027. Cipher Digital expects individual data halls to begin generating rent after each delivery milestone. The company linked the updated schedule to tenant requirements and project changes.
Cipher Digital Faces Pressure After Infrastructure Expansion Update
Cipher Digital continues building its position in large-scale data center development. The company has moved its focus toward high-performance computing infrastructure and away from traditional Bitcoin mining operations. This transition has increased demand for its long-term facility agreements.
The company will cover the first $359.3 million in costs above the original Barber Lake budget. Meanwhile, the tenant will reimburse 50% of additional costs above that amount through extra rent payments. The structure aims to provide Cipher Digital with a contracted return on reimbursed expenses.
Cipher Digital has secured additional support for Fluidstack obligations through financial backing arrangements. The company expects these agreements to strengthen the project’s long-term revenue visibility. The development highlights rising demand for large-scale computing facilities across the sector.
Cipher Digital Tracks Texas Data Center Growth Challenges
Cipher Digital continues addressing power access requirements linked to expanding data center operations in Texas. The company received conditional grid-capacity designations from ERCOT for several projects. However, those designations still require final approvals before active power connections begin.
The company must complete construction, grid connections, and delivery milestones before reaching full operational capacity. Therefore, project execution remains a key factor for future revenue realization. Cipher Digital maintains that Barber Lake remains aligned with its revised delivery timeline.
The latest contract expansion strengthens Cipher Digital’s contracted infrastructure portfolio while adding new revenue opportunities. The stock performance reflected short-term market pressure despite the broader project expansion. The company remains focused on developing long-duration data center assets for growing computing demand.
The post Cipher Digital Inc. (CIFR) Stock: Slip Despite $5.2 Billion AI Revenue Expansion appeared first on Blockonomi.
TLDR:
- Solana price moved above $120 and reached $122.18 during the session, placing the $122 to $124 band at the center of the next technical test.
- The Federal Reserve opened comment on two GENIUS Act proposals covering reserves, capital, custody, risk management, and application procedures for supervised issuers.
- The Federal Reserve action does not regulate Solana or endorse SOL, although stablecoin regulation can shape how supervised issuers approach public blockchain activity.
- ETF buying and short liquidations supported the move, while a loss of $120 could bring $116 and the $108 to $110 demand zone into view.
Solana price climbed above $120 on September 25, hitting an intraday high of $122.18 after a 4.97% daily gain. The advance carried SOL into its strongest trading area in months after recovering from below $100 earlier in September. The SOL price outpaced a mostly flat Bitcoin, while renewed spot demand and liquidations supported the move.
Traders now face a narrow technical decision around the $120 breakout level. The next ceiling sits between $122 and $124, where sellers slowed the session. A durable move through that band could bring the $132 chart target into view. A reversal could return attention to $116 first.
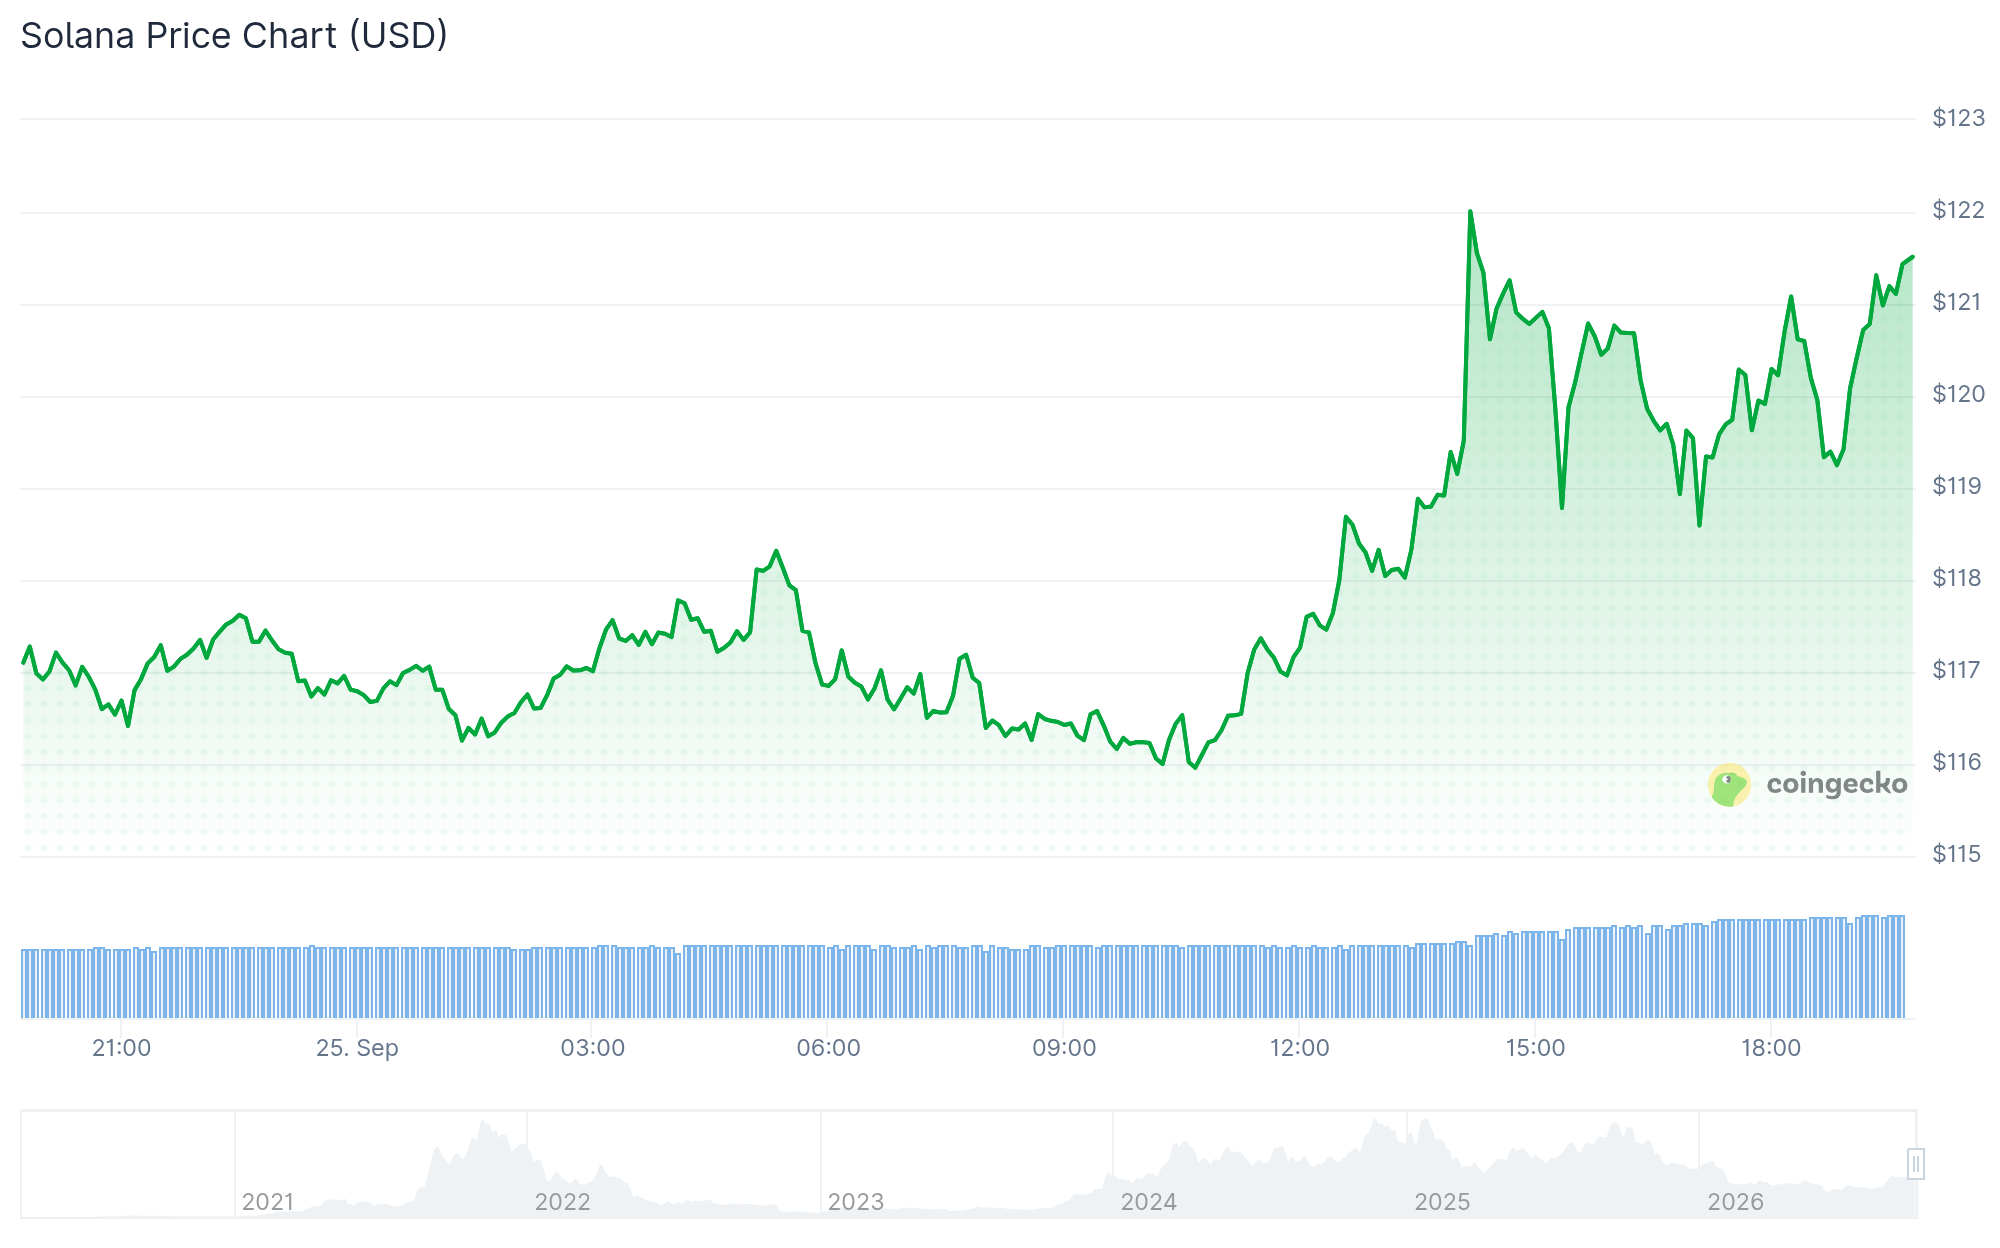
Solana Price Rises as Stablecoin Rules Enter Review
On September 24, the Federal Reserve requested comment on two payment stablecoin issuer proposals under the GENIUS Act. The first would require issuers to fully back payment stablecoins with permissible reserve assets. Short-term Treasury bills and other high-quality liquid assets appear among the listed examples.
The proposal also sets standardized capital requirements for credit and operational risks. It would establish risk management standards and rules for firms safeguarding reserve assets.
Payment stablecoins would need assets that can be converted rapidly during redemptions. Capital standards address losses from credit and operational events. The comment period closes 60 days after publication in the Federal Register. Public comments may shape final standards before they take effect. Comments are invited.
The second proposal creates a tailored application process for Board-supervised banks seeking approval to issue payment stablecoins. Applicants must submit business plans and financial information to the Federal Reserve. The rules concern supervised institutions, reserves, custody, and approval procedures. They do not regulate the Solana blockchain or endorse its token. Solana price nevertheless moved higher as traders tracked a broader rotation into large alternative coins.
Stablecoin regulation can matter to the network because digital dollars support trading, payments, and decentralized finance activity. Clearer rules may reduce uncertainty for supervised issuers without deciding which public blockchain they use.
Any issuer choosing Solana would still need to meet those institution-level standards. Network activity alone does not alter an issuer’s regulatory status. Nothing in the proposals creates a new approval for a blockchain.
Solana Price Faces $122 to $124 Test After the Rally
SOL reached $122.18 before moving back toward $120, leaving the $122 to $124 area as immediate resistance. The rally began near $115.86 and accelerated after the price moved through $118.38 on the 30-minute chart. That pattern placed $120 at the first support level to watch. The Solana price needs to hold above that former barrier to preserve the short-term breakout.
Ali Charts marked $132 as the next upside objective if buyers maintain control. The target reflects a technical scenario, not a confirmed outcome. Volume increased alongside the price climb, lending support to the recovery. Yet the intraday pullback showed active selling near the high. Buyers must still reclaim the upper range on a sustained basis.
Two-week ETF purchases exceeded 1.4 million SOL, while roughly $19.5 million in shorts were liquidated. Those flows coincided with stronger interest in other large-cap tokens. Solana price outpaced Bitcoin during the same period. Forced buying from closing short positions can accelerate an existing rise, but it can also fade quickly. This makes the next close around $120 important for the SOL price.
A rejection below that level exposes $116 as the nearest support. A wider pullback could send attention toward the $108 to $110 zone, where buyers previously appeared. The $122 to $124 range will show whether demand can absorb supply. A close above $124 would strengthen the current chart structure. It would also leave $132 as the next chart target for buyers.
The post Solana Price Faces New Test as Stablecoin Rules Enter Review appeared first on Blockonomi.
HTTP error 429 on https://cryptopotato.com/feed/
Failed to fetch feed: https://cryptopotato.com/feed/
Failed to fetch feed.