Cryptocurrency Posts
Crypto Briefing
Circle's cirBTC wrapped Bitcoin token has crossed 5,000 tokens issued, up from roughly 40 in mid-August, as institutional DeFi demand
The post Circle’s cirBTC surpasses 5,000 issued tokens appeared first on Crypto Briefing.
The incident underscores the urgent need for enhanced human-layer security measures in the crypto industry to combat sophisticated scams.
The post Bitget CEO Gracy Chen reveals $80K loss from fake interview scam tied to Lazarus Group appeared first on Crypto Briefing.
The shift to onchain trading of real-world asset perps signifies a major decentralization trend, challenging traditional financial systems.
The post 86% of real world asset perp volume now trades onchain appeared first on Crypto Briefing.
The rapid decline in token prices threatens AI infrastructure ROI, pushing tech giants to reassess strategies amid rising open-source competition.
The post Goldman warns declining token prices may hinder investment growth appeared first on Crypto Briefing.
TALIS's protocol on Robinhood Chain could democratize access to complex financial instruments, enhancing global participation in tokenized markets.
The post TALIS launches onchain structured markets protocol for tokenized stocks on Robinhood Chain appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
North Korean Hackers Linked to $388M Bitget Crypto Exchange Theft: CEO
Hackers from North Korea targeted crypto exchange Bitget on Thursday, according to an update from the CEO, making away with close to $388 million in digital assets — more than originally reported.
Bitget CEO Gracy Chen said Friday that the higher figure “reflects a more complete accounting of transfers during the incident.” Chen had first reported that over $350 million had been moved.
Security firms first flagged unauthorized transactions from the Victoria, Seychelles-based exchange’s hot wallets on Thursday before the company announced it had frozen withdrawals.
Bitget is the sixth biggest crypto exchange, processing over $1 billion in trading volume per day, according to CoinGecko data.
“Based on IP behavior patterns and on-chain analysis, the attack method in this incident is highly consistent with known patterns of North Korean hacker organizations,” Chen wrote on X on Friday.
She added: “Our goal is to complete a full recovery as soon as possible. We will announce the specific time window immediately upon confirmation.”
In a security update, the exchange said it identified the digital assets stolen, which mostly included ethereum, tron, and USDT stablecoin — and no bitcoin. But a stolen funds tracker does show that the attacker has over $28.8 million in the leading cryptocurrency.
Crypto stealing criminals — especially from North Korea — have become more sophisticated and faster since last year. Experts have said that the use of artificial intelligence tools is allowing cyber crooks to work more efficiently.
U.S. authorities have long alleged that hacking groups with ties to the North Korea’s government, such as Lazarus, steal from crypto exchanges.
Crypto security is in the limelight after a string of breaches this year have the community reeling. Just in July, hackers targeted a firmware bug in the popular bitcoin hardware wallet, Coldcard, to steal nearly $120 million in user funds.
And this month, purported white-hat hackers withdrew about 4,000 bitcoins — worth about $320 million at the time — from Blockstream’s Liquid sidechain’s federation wallet. They then returned 85% and demanded to keep the rest as ransom days later.
This post North Korean Hackers Linked to $388M Bitget Crypto Exchange Theft: CEO first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Bitcoin ETFs Extend Winning Streak With Nearly $3B in Inflows
Bitcoin exchange-traded funds are on a winning streak, with investors buying for six consecutive days.
The funds — managed by the likes of BlackRock, Fidelity, and Morgan Stanley — have received over $2.8 billion in new investment since September 17, according to Farside Investors data.
On Monday alone, investors bought nearly $1 billion in shares — the most since October 6, when the funds received over $1.2 billion and the price of the leading cryptocurrency hit a new all-time high of $126,080.
Still, Bitcoin’s price on Friday is only up modestly: it recently stood at nearly $83,975 after reaching as high as $87,330 on Monday. Over the past seven days, the coin’s price has surged by nearly 4%.
While the price of the leading cryptocurrency has since dipped from earlier this week, Bloomberg ETF analyst James Seyffart pointed out that the average ETF buyer is now in profit after the estimated ETF cost basis surged above $81,72 for the first time since January.
Investors have a renewed interest in Bitcoin since the U.S. Department of the Treasury in August said it would at least double the size of its liquidity-support buyback operations.
Bitcoin’s price rallied as the move pushed 30-year Treasury yields down and weakened the dollar. Since the August announcement, U.S. Treasury yields have surged again.
Bitcoin continued its run last week, shrugging off the fact that lawmakers had blocked landmark crypto legislation, the Clarity Act, and the Federal Reserve had hiked interest rates.
Some analysts have said that the leading cryptocurrency is now in a bull run. Crypto market data firm CryptoQuant this week wrote that the leading cryptocurrency crossed above its 365-day moving average, a signal that the asset has finished being in a bear market.
Bitcoin notched a record of $126,080 in October of last year but then began to sink later that month after the biggest liquidation event in crypto history saw over $19 billion in bets closed. But the so-called debasement trade — where investors throw money at an asset to hedge against a currency losing its value — is hot again, and bitcoin’s price has benefited as the dollar has weakened.
This post Bitcoin ETFs Extend Winning Streak With Nearly $3B in Inflows first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Bitcoin Treasury Strategy Proposes Daily Dividends For Preferred Stocks
Bitcoin treasury company Strategy wants to pay investors daily dividends on four of its preferred stocks.
The largest corporate holder of bitcoin said Friday that it was asking shareholders to approve the move, which would pay investors dividends every calendar day — including weekends and holidays — on STRF, STRC, STRK, and STRD.
“If approved and adopted, we believe this would reduce reinvestment lag, enhance liquidity and market efficiency, and increase price stability,” Strategy said in a statement. Stockholders will attend a meeting to vote on the proposal on October 28.
Strategy slowed down with its aggressive bitcoin buys this year, as the largest cryptocurrency fell into a bear market. The Nasdaq-listed company instead focused on protecting its balance sheet and sold chunks of its bitcoin.
Friday’s announcement claimed the move would help both investors and common stockholders.
“We believe these enhancements can also benefit our common stockholders by increasing the attractiveness and utility of our Digital Credit instruments, supporting our ability to access preferred equity capital efficiently and expanding the capital markets toolkit we use to execute our Bitcoin Treasury strategy,” Strategy added in a statement.
Strategy — formerly MicroStrategy — is an enterprise software company that pivoted to buying and holding bitcoin in 2020.
It first bought the cryptocurrency to protect its shareholders from inflation. Since then, it has aggressively bought the asset and pivoted to being a bitcoin treasury.
Investors can now buy its shares to get heightened exposure to the cryptocurrency, or get paid a yield via its digital credit products.
The company would buy bitcoin every Monday but slowed down its buys after announcing a program under which it may sell BTC from time to time to generate up to $1.25 billion in proceeds for the USD reserve, additionally fund preferred stock dividends and interest expenses or fund repurchases.
Strategy said in a filing Monday that it last week bought 950 bitcoins for $75.7 million — its first buy since August.
Its Nasdaq-listed stock (MSTR) is down nearly 50% over the past year after the price of bitcoin took a hit.
But since the company started buying bitcoin in 2020, MSTR has appreciated by nearly 1,000%.
This post Bitcoin Treasury Strategy Proposes Daily Dividends For Preferred Stocks first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Is US Defence Secretary Pete Hegseth a Bitcoiner? This Is What His Accounts Say
U.S. Secretary of Defense Peter Hegseth holds more cash than he does bitcoin.
That’s according to his newly released 2025 annual financial disclosure, which shows he has between $16,000 and $65,000 in the leading cryptocurrency while a bank account holds $1 million in cash.
Hegseth, who was appointed Defense Secretary in January 2025, is part of the most crypto-friendly administration the U.S. has had.
President Donald Trump was backed by digital asset industry bigwigs and last month pushed for landmark crypto legislation, the Clarity Act, to pass.
Hegseth’s Office of Government Ethics filing also showed that he and his wife have retirement accounts containing investments worth roughly $2.05 million to $4.35 million.
Some of the investments include exchange-traded funds like the tech-heavy Invesco QQQ Trust and the closed-end fund the Apollo Diversified Real Estate Fund.
Transactions made by Hegseth including sales of Amazon, Microsoft, and Apple stock.
The bitcoin stash held by Hegseth is kept in a Coinbase wallet, the filing states.
Hegseth’s crypto holdings are modest compared to the Trump family’s, which has made billions in crypto ventures since the president took office.
President Trump personally disclosed that he’d made more than $1.4 billion from the family’s digital asset ventures, making crypto his largest income source and far ahead of real estate and legal settlements.
His family — including sons Eric and Donald Jr. — made $2.3 billion from four crypto ventures through the end of April 2026, a Reuters investigation reported this year.
Critics, including Democrats, have accused Trump of profiting from crypto while shaping policy on it. The White House has consistently denied any conflicts of interest, and Trump has pointed to stock trading by members of Congress, particularly Nancy Pelosi, calling for a ban on the practice.
This post Is US Defence Secretary Pete Hegseth a Bitcoiner? This Is What His Accounts Say first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Mitchell Askew Explains What 15M Inactive BTC Means for Bitcoin’s Next Move
Bitcoin is rallying despite a Fed rate hike and the failure of the Clarity Act, and the on-chain data suggests sellers may be nearly exhausted. Mitchell Askew, Head of Blockware Intelligence, breaks down long-term holder supply, which hit an all-time high of 15 million BTC this summer. He explains why so many coins sitting still signals more room for price to run. He also shares what Bitcoin ETF flows reveal about institutional buyers returning to the market.
Chapters:
0:00 Mitchell Askew of Blockware Intelligence on Bitcoin’s Rally
0:22 Is Bitcoin Selling Pressure Exhausted? Long-Term Holder Supply
1:36 Bitcoin ETF Flows & Returning Institutional Buyers
2:36 Why the Four-Year Halving Cycle Is Breaking
4:06 AI Data Centers Pulling Compute Away From Bitcoin Mining
5:56 The Hash Rate Bear Market: Should Bitcoiners Worry?
6:58 Stranded Energy, Global Mining & AI Data Center Arbitrage
8:12 Why Gen Z Isn’t Buying Homes
9:58 Will Gen Z Ever Save in Bitcoin?
11:26 Shallower Drawdowns & the Future of Bitcoin Cycles
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Mitchell Askew Explains What 15M Inactive BTC Means for Bitcoin’s Next Move first appeared on Bitcoin Magazine and is written by Patrick Green.
CryptoSlate
A Bitcoin address sent 4,499.99987779 BTC to a single destination in a transaction confirmed at 02:30:04 UTC on Sept. 25, 2026.
The output was still unspent at a 13:33 UTC check, leaving nearly 4,500 BTC visible at one address after the move.
At Coinbase's BTC/USD low and high of $84,152.88 and $84,882.18 during the 02:00-03:00 UTC hour that included confirmation, the Bitcoin output had an estimated value of about $379 million to $382 million. That price window helps size the transfer.
The transaction spent eight outputs from the source address and created one output at the destination. Its largest input was 4,499.99986261 BTC, received on April 21, 2022. That principal output had not moved for more than four years before the Sept. 25 transaction.
The address wasn't completely inactive during that period. Its transaction history shows seven later deposits, each worth only a few hundred satoshis, between Dec. 30, 2024 and Sept. 11, 2026.
Together they totaled 2,821 satoshis (0.00002821 BTC). The nearly 4,500 BTC principal was long held, while small later Bitcoin payments still reached the address.
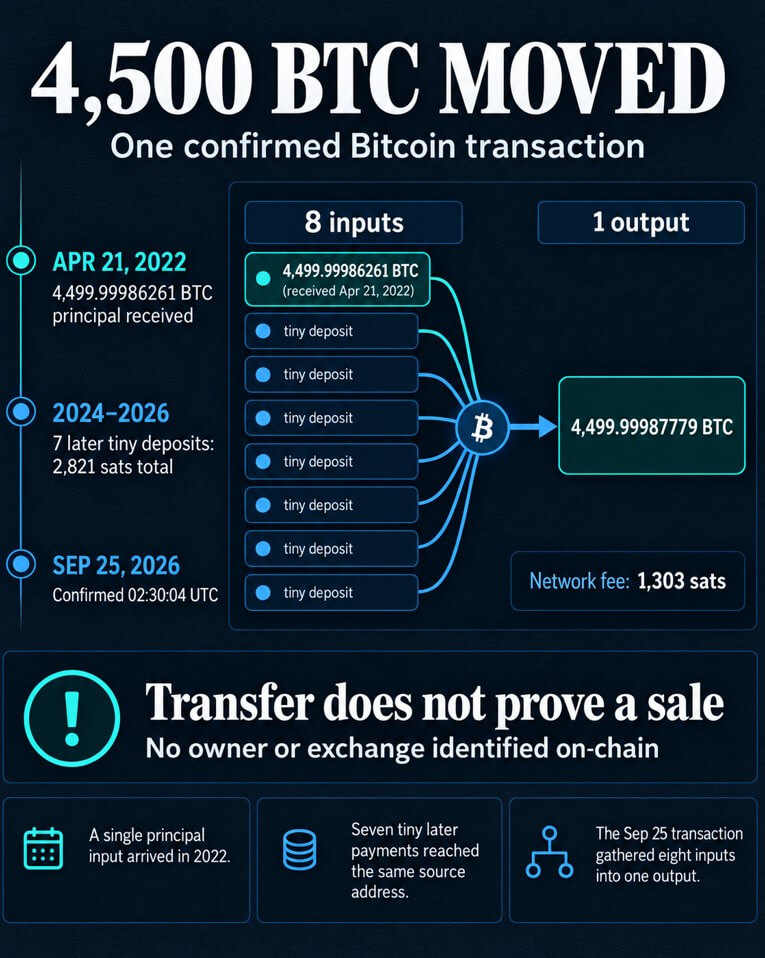
At the 13:33 UTC snapshot, the receiving address had one confirmed incoming Bitcoin output totaling 4,499.99987779 BTC, no spent output, and no mempool transaction. The source address's eight inputs were combined into that single output, with 1,303 satoshis paid as a network fee.
Those records show a confirmed on-chain transfer, but they do not identify who controls the destination. They also do not establish that the address belongs to an exchange, that Bitcoin was sold, that beneficial ownership changed or that an off-chain trade occurred.
A Bitcoin transfer can precede any of those events, yet this transaction alone follows from none.
The balance says nothing about the holder's other wallets or any trades elsewhere, and a later transaction could change it. That is why any claim about the coins' current location needs a time-stamped address check, while any claim about trading needs separate evidence.
Large movements of old coins can draw attention because traders watch for potential supply reaching exchanges. Here, the full output remained at one address at the time of the check, with no visible onward transfer.
A later spend would be observable on Bitcoin's blockchain, but its purpose would still need separate evidence.
The post Dormant whale moves $380M Bitcoin, leaving the sale question unanswered appeared first on CryptoSlate.
Bitcoin is holding near $84,000 even as a historic US bond selloff pushes Treasury yields to decades-high levels.
The benchmark 10-year Treasury yield climbed to 5.22%, extending a move that has taken borrowing costs to their highest level since 2007. The 30-year yield reached a fresh 22-year high of 5.5185% before trading around 5.511%, up nearly five basis points on the session.
The surge is raising the hurdle for Bitcoin and other risk assets by offering investors yields above 5% on US government debt while simultaneously lifting financing costs throughout the financial system.
Yet crypto has absorbed the latest leg of the bond rout relatively calmly so far. Bitcoin remained inside a roughly $83,000 to $85,000 range after retreating from this week's high near $87,000.
Camran Khosravi, an analyst at Bitwise, said Bitcoin has gained about 22% since Aug. 19 even as the 10-year real yield climbed 50 basis points. Real yields have risen steadily, while Bitcoin posted most of its gains early in the period and then held much of them.
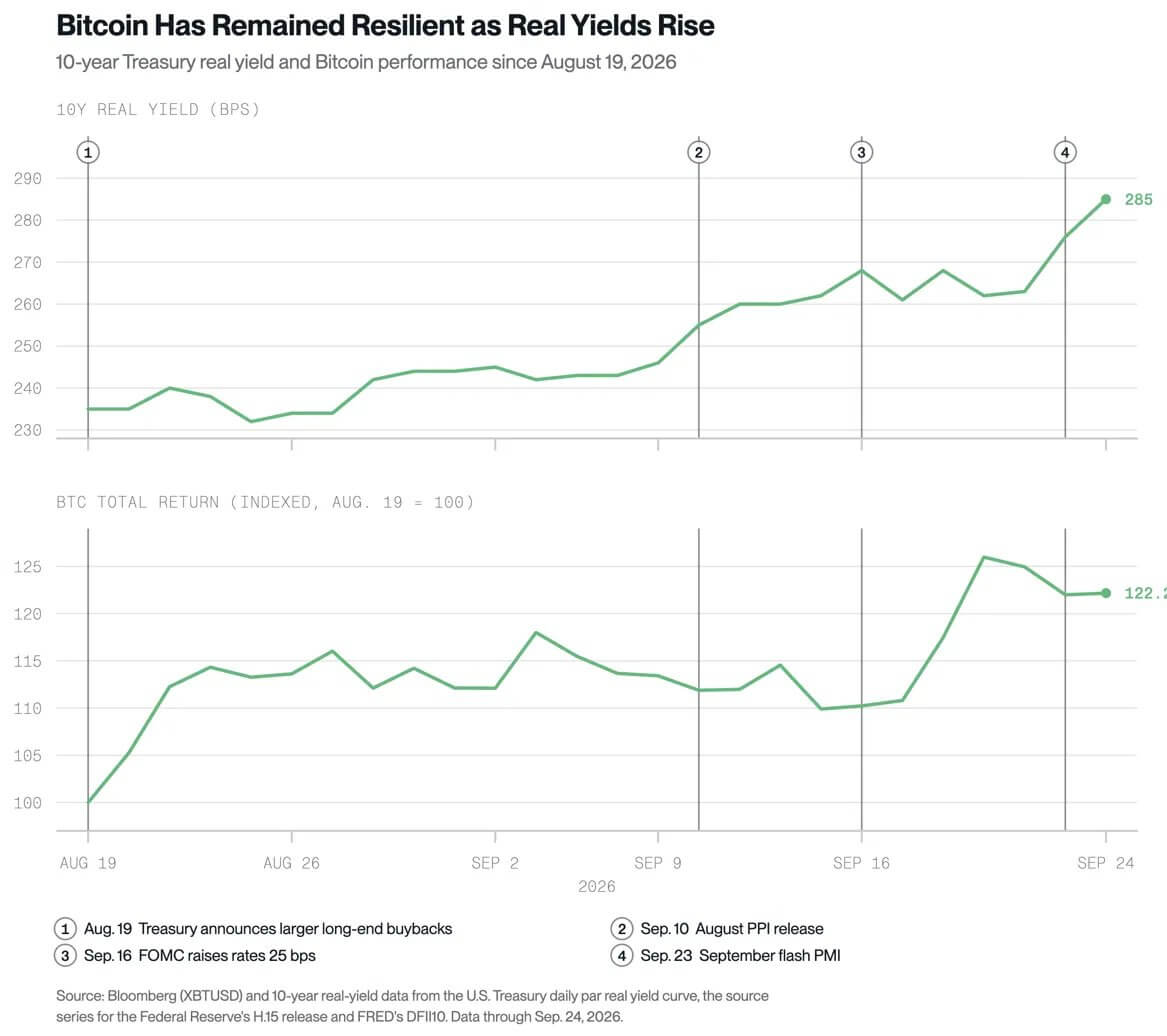
That leaves traders confronting whether Bitcoin can continue resisting one of the sharpest increases in risk-free yields in decades.
5% Treasury yields raise Bitcoin’s opportunity cost
The pressure has been building for months, with Jefferies noting that the 10-year yield is on track for a seventh consecutive monthly increase. That would tie the longest such streak in data going back to 1970.
Demand at this week's Treasury auctions has also shown signs of strain.
James Lavish, co-managing partner of Bitcoin Opportunity Fund, said a $44 billion sale of seven-year notes Thursday cleared at 5.085%, up sharply from 4.512% in August and the highest auction yield since April 1993. The auction tailed the prevailing market yield by 0.7 basis points, while its bid-to-cover ratio slipped to 2.42 from 2.50 previously.
The Treasury discontinued seven-year notes in 1993 before reintroducing the maturity in 2009, making the latest auction yield the highest in roughly 33 years.
Mohamed El-Erian, chief economic adviser at Allianz, said the selloff reflects forces visible for some time, including heavy government and corporate borrowing, strong economic activity, and reduced willingness or capacity among some traditional Treasury buyers.
He argued that investors may also remain anchored to the unusually low yields that followed the 2008 financial crisis, leaving markets less prepared for borrowing costs that stay structurally higher.
The economic data are adding to those longer-term pressures.
The Federal Reserve raised its target range by 25 basis points last week, while strong business activity, resilient employment and elevated energy costs are keeping expectations of further tightening alive.
S&P Global's preliminary September composite purchasing managers' index jumped to 58.4 from 56.0, its strongest reading since July 2021. Companies increased payrolls at the fastest pace in more than four years while input costs climbed to near a four-year high.
Those readings have reinforced concern that an economy running hotter than expected could keep inflation pressure elevated and force policymakers to maintain restrictive conditions for longer.
With yields now above 5%, that repricing is also changing the investment case for bonds themselves.
Jurrien Timmer, director of global macro at Fidelity Investments, said a 5% 10-year yield provides bond investors with a substantial cushion. By his calculation, a 100-basis-point decline in yields could generate an 11.9% return, while a rise to 6% would produce a loss of only about 1.9%.
That asymmetry raises Bitcoin's opportunity cost because the asset pays no coupon or dividend while government debt now offers nominal yields above 5%.
Timmer nevertheless said Bitcoin remained among the leading assets in his current multi-asset framework, alongside commodities, while long-duration bonds were lagging.
Bitcoin sheds leverage without a comparable price collapse
Bitcoin's adjustment to the macro shock has so far been more pronounced in derivatives positioning than in its spot price.
CryptoQuant data show combined Bitcoin open interest across Binance, Gate.io, HTX and Bybit falling to about $10.3 billion on Sept. 25 from $12 billion on Sept. 22.
The $1.7 billion decline represents a 14.3% contraction in leveraged exposure, compared with only about a 2.3% decline in Bitcoin from roughly $86,000 to $84,000 over the same period.
The reduction was broad-based, led by a roughly $710 million decline on Gate.io and a $680 million drop on Binance, while HTX and Bybit also recorded lower open interest.
Open-interest data cannot establish whether longs or shorts accounted for most of the reduction because contracts disappear when either side closes a position. The scale of the contraction relative to Bitcoin's price decline nevertheless shows that traders have substantially reduced leverage without producing a proportional break in spot.
That deleveraging can reduce the fuel available for cascading liquidations, although large pockets of leveraged positioning remain around the current market.
CoinGlass' 24-hour liquidation heatmap shows concentrations around $85,300 to $85,700 above Bitcoin, with additional liquidity near $83,000 and a larger cluster around $80,000 below.
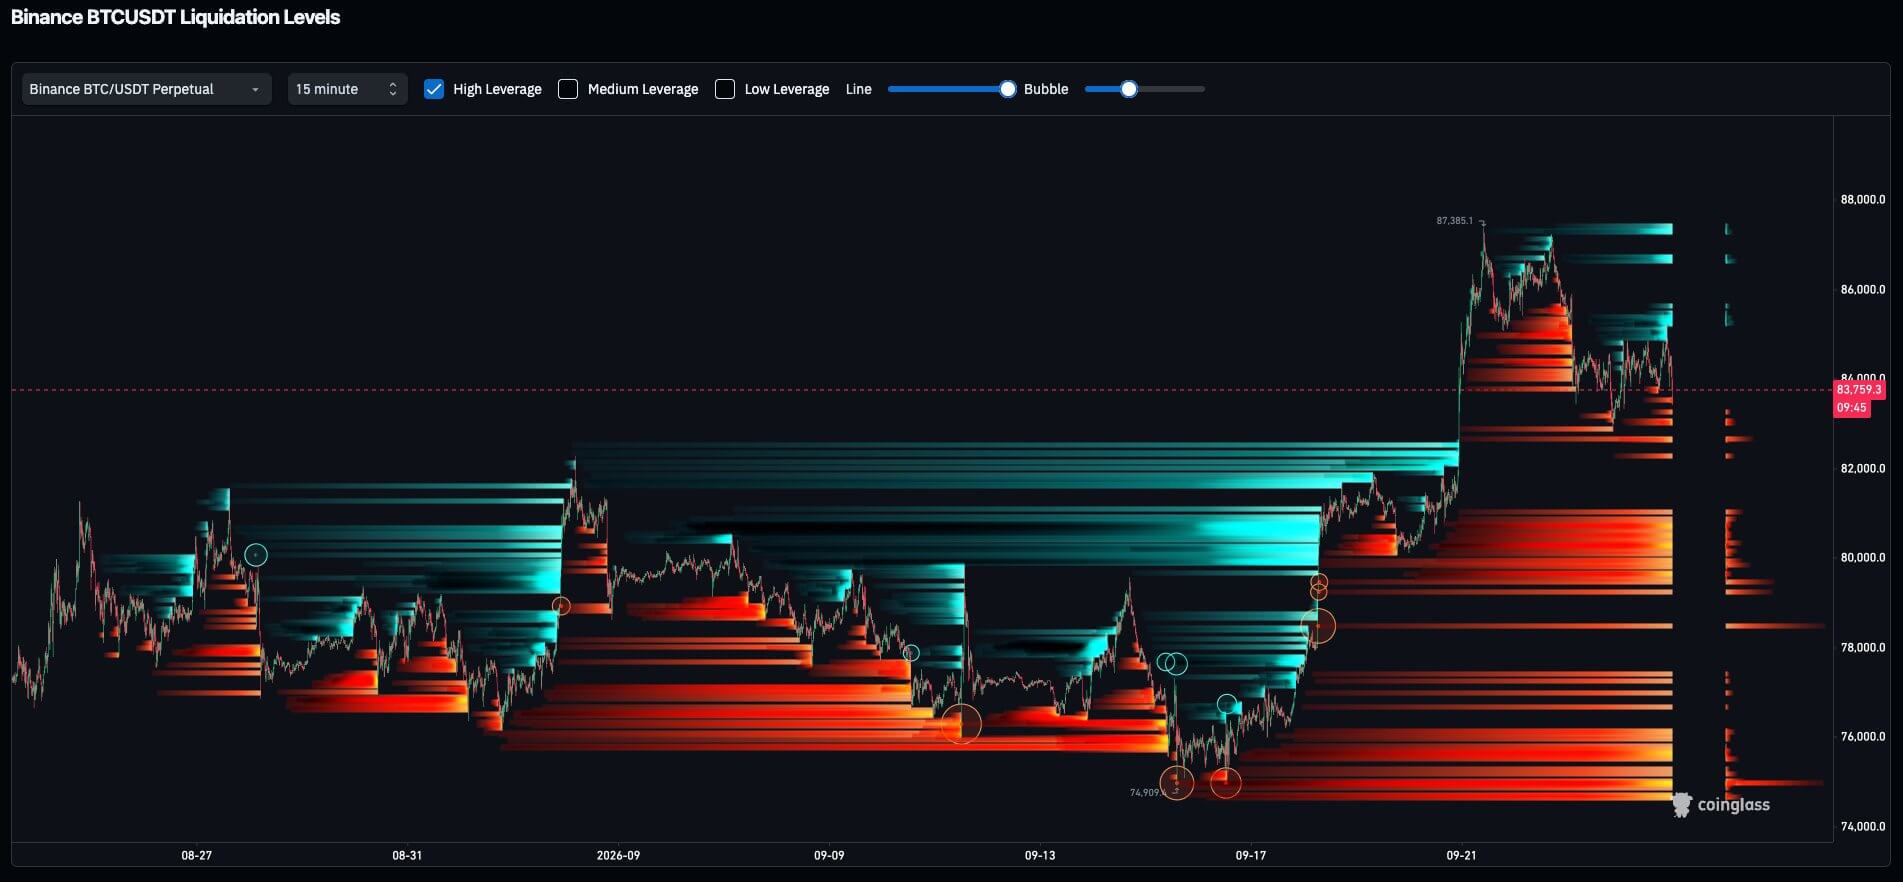
BlockScholes said the surge in long-term Treasury yields had yet to produce a comparable expansion in crypto volatility, with Bitcoin remaining inside its recent range while 30-day implied volatility stayed near the lower end of its recent range.
That leaves the Treasury market as an increasingly important test of whether Bitcoin's recent resilience can persist.
A further rise in the 10-year above 5.2%, or in the 30-year beyond 5.52%, would test whether the bond-market shock can finally break through Bitcoin's recent resistance.
Falling yields would ease that pressure after the cryptocurrency absorbed a double-digit contraction in selected-exchange leverage while largely maintaining its spot range.
The next major test comes from the Fed's preferred PCE inflation gauge on Sept. 30, followed by the September employment report on Oct. 2. Strong readings could give bond traders further reason to push long-term yields higher and subject Bitcoin's relative resilience to a more sustained macro test.
The post Bitcoin survives a 5.2% Treasury shock as traders slash $1.7 billion in leverage appeared first on CryptoSlate.
Bitget has raised the estimated value of assets taken in its Sept. 24 breach to $387.5 million as exchanges and security firms mobilize to freeze and recover the stolen funds.
The new estimate is up from $351.6 million after further on-chain tracing identified Zcash and TRON assets that were excluded from Bitget's initial accounting, Chief Executive Officer Gracy Chen said in a Sept. 25 update. She said the increase reflected transfers made during the original incident and that no additional unauthorized transactions had occurred.
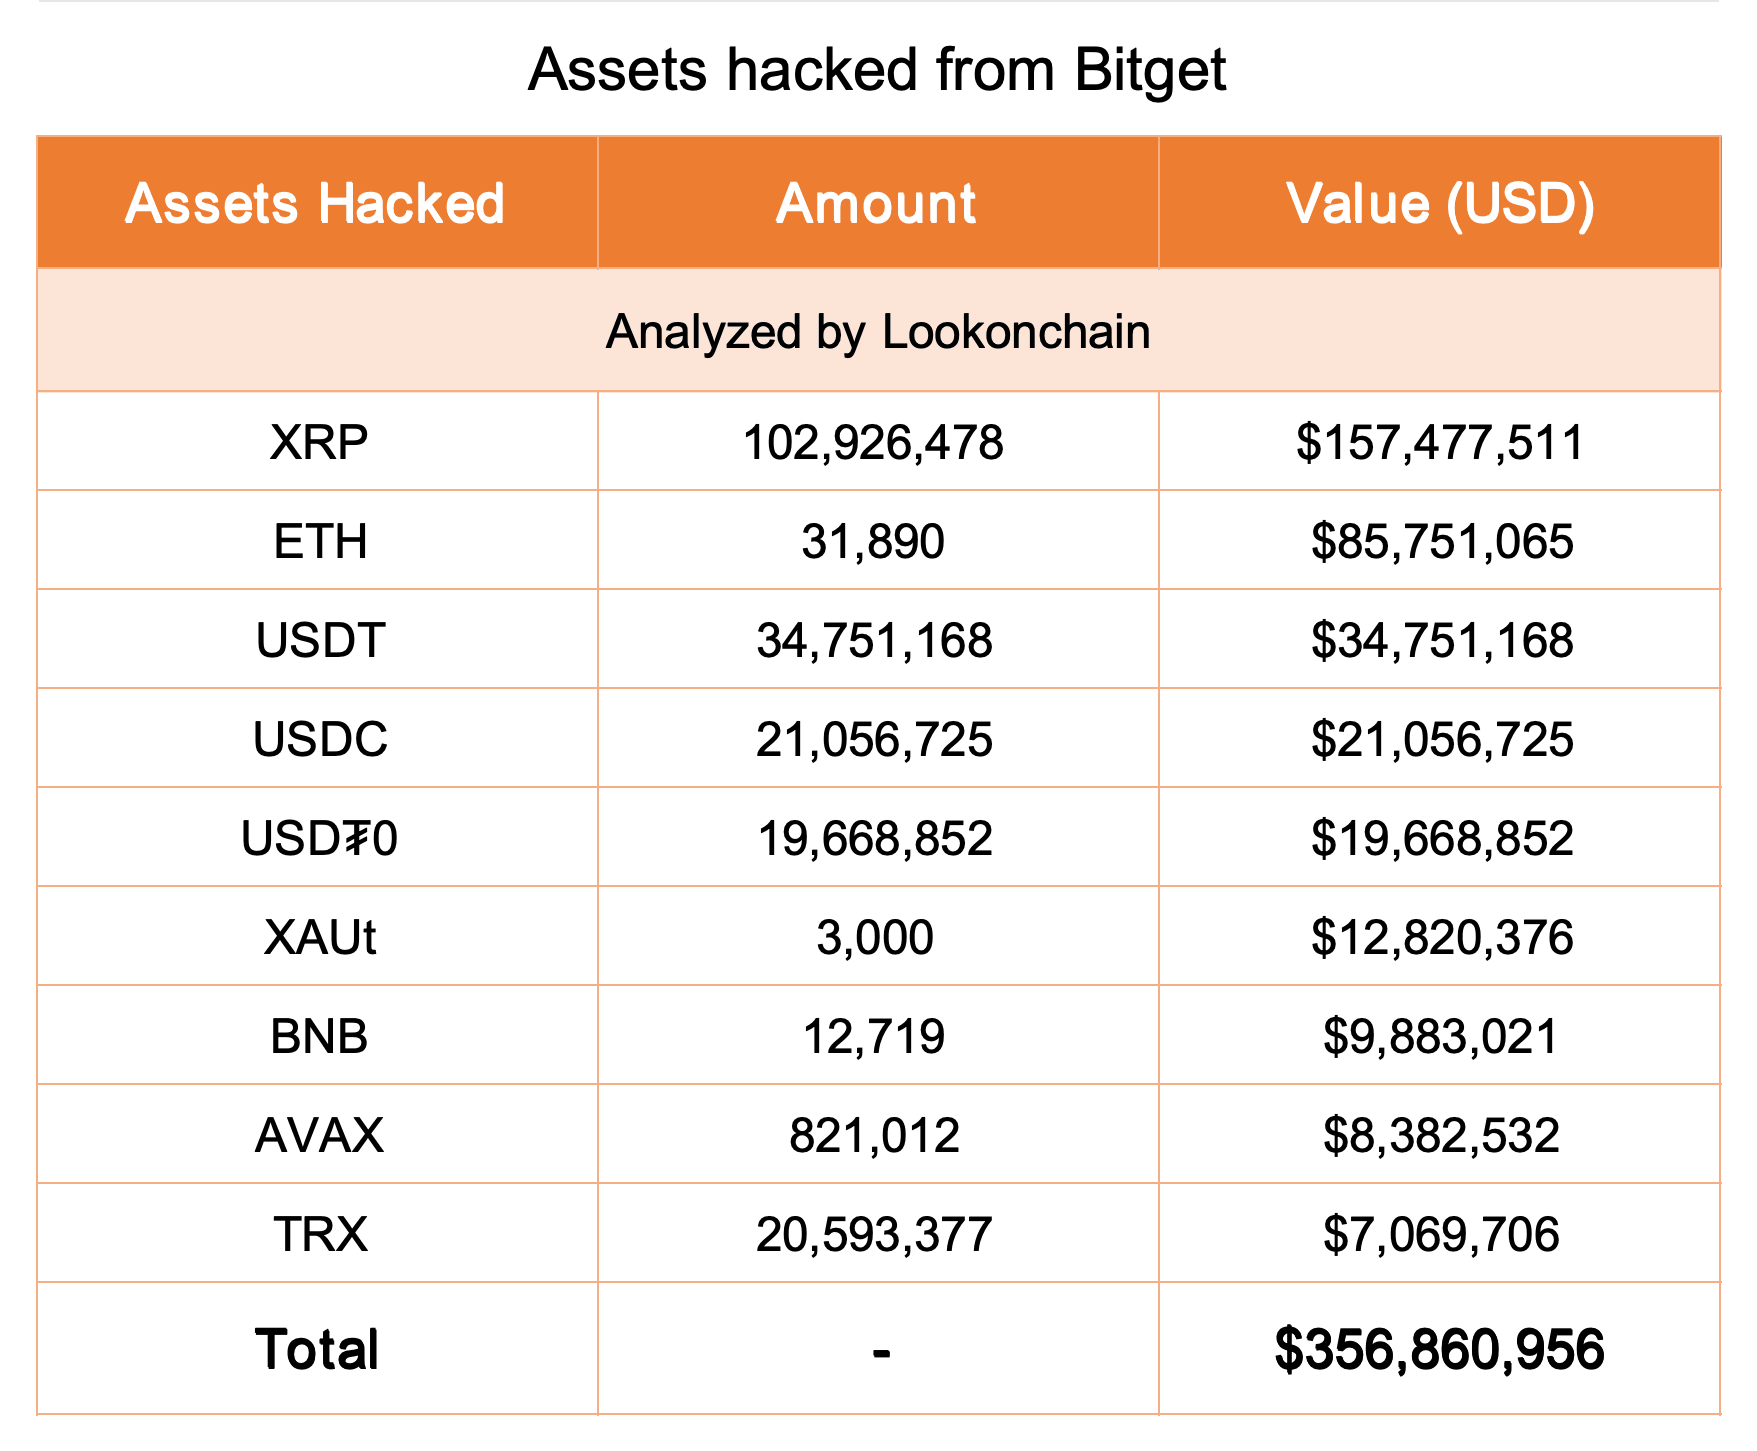
Bitget said its investigation with blockchain security firms Mandiant and SlowMist remains underway, with further forensic findings expected as investigators establish how attackers breached its systems.
The exchange first detected the unauthorized transfers from some hot wallets at 18:31 UTC on Sept. 24 and suspended withdrawals while keeping deposits and trading operational. Its security team has since identified and patched the underlying vulnerability, according to the latest update.
The higher loss estimate comes as Bitget shifts its response toward tracing and recovery, drawing support from other crypto exchanges, blockchain projects and security companies.
Exchanges join effort to freeze stolen assets
Bitget said it has already frozen some affected assets in coordination with industry partners, though it has not disclosed their value.
Binance and Bybit are among the exchanges publicly supporting the recovery. Bybit's Chief Executive Officer Ben Zhou said the company would assist Bitget and update its LazarusBounty platform to track the stolen funds, returning support Bitget provided after Bybit's own $1.5 billion breach in 2025. Bitget said it would use LazarusBounty as a main channel for its recovery campaign.
Chen said exchanges, foundations and security teams had already moved to freeze some attacker-controlled assets. Bitget has also published a real-time tracing dashboard, a reporting portal and an API containing attacker addresses to allow exchanges, stablecoin issuers, bridges and other infrastructure providers to monitor the funds.
The exchange paired those efforts with a new Recovery Bounty Program offering rewards tied directly to frozen or returned assets.
Eligible parties whose voluntary actions freeze stolen funds can receive 5% of the amount successfully frozen. Bitget is separately offering 5% of funds successfully recovered through eligible voluntary efforts.
Freezes secured before the program's announcement can also qualify.
Bitget will determine eligibility and bounty amounts, while actions carried out under court orders, law enforcement requests or other compulsory legal processes are excluded.
The program could make the recovery campaign increasingly dependent on whether stolen assets reach infrastructure that can block their movement. Stablecoin issuers and centralized exchanges can freeze certain assets or accounts, while native cryptocurrencies moved to self-custodied addresses can be harder to stop.
Withdrawals remain the next test
For customers, withdrawals remain suspended more than a day after the breach.
Chen said Bitget is working to restore the service and will announce its withdrawal plan by Sept. 26 at 04:00 UTC. The company has not said withdrawals themselves will necessarily resume at that time.
Its latest security update says technical teams are validating the remediated systems and completing required checks before withdrawals can safely resume. Deposits and trading remain available.
Bitget previously said customer balances remained accurate and that its User Protection Fund, which held more than $464 million when the incident was disclosed, covered losses.
The revised $387.5 million estimate narrows that headline cushion to about $76.5 million before accounting for any assets recovered from the attackers. The protection fund's role will depend partly on how much of the stolen crypto Bitget and its industry partners ultimately recover.
The immediate milestone is the withdrawal announcement due Sept. 26. Beyond restoring customer access, the tracing effort will determine how much of the $387.5 million Bitget ultimately has to absorb and how much it can claw back through the exchange-wide recovery campaign.
The post Bitget’s hack just got $36 million bigger, and now there’s a bounty on the stolen crypto appeared first on CryptoSlate.
Old Magic Eden NFT approvals could still put some former users at risk months after the company closed its Ethereum marketplace. A September 25 warning from wallet security service Revoke.cash says that a vulnerability in Limit Break's Payment Processor V2 affects wallets that still authorize the contract to move NFTs. Those approvals remain active until owners revoke them.
The notice says security researcher 0xQuit used the vulnerability to move 3,832 NFTs from approved wallets as zero ETH sales. He described the transfers as a whitehat rescue and said the assets were being held in a custody wallet until it was safe to return them, according to Revoke.cash. The figure counts transfers reported in the notice; the service had not established how many NFTs, if any, malicious actors took.
Magic Eden ended EVM marketplace support on March 9, 2026. Its listings and offers were offchain and ceased to be visible or actionable on the site. The operator approval users gave the processor exists onchain, however. Closing the marketplace did not cancel that separate permission, leaving people who have not traded there for months with a live exposure.
Which Magic Eden NFT approvals should users revoke?
Revoke.cash says users should revoke Payment Processor V2 approval on Ethereum. It also warns anyone who approved Payment Processor V3 on ApeChain to revoke that separate permission. An NFT operator approval lets a contract move assets on a wallet's behalf. A permission granted for marketplace trading can outlast the listing that prompted it, so former users need to check the approval itself rather than their old sale history.
Canceling a listing will not protect an exposed wallet, Revoke.cash said. Its FAQ also explains that disconnecting a wallet from a website leaves onchain approvals active. The incident page includes an exploit checker so users can inspect whether their address is affected and revoke the relevant permission. The warning applies to the named processor approvals; it does not establish that losses occurred on both Ethereum and ApeChain. Revocation is a preventive step, the FAQ says: it reduces future exposure but does not retrieve assets already taken. That distinction makes checking old permissions urgent even while the full incident outcome remains unknown.
The technical details of the flaw had not been published in Revoke.cash's September 25 notice, and the service said it remained unclear whether malicious actors had taken any NFTs. The reported rescue leaves the final loss figure unresolved. For holders with lingering approvals, the action identified in the warning is to revoke access to the affected processor contracts.
The post Old Magic Eden NFT approvals put users at risk after whitehat moves 3,832 NFTs appeared first on CryptoSlate.
The @saylor account said Friday that Strategy wants to pay dividends daily on four of the preferred shares it uses in its Bitcoin financing strategy. The proposal would put cash in holders' hands sooner without changing the securities' economics at their current rates. Its value to Strategy depends on whether investors will pay more for that timing.
The hurdle differs across the four shares. At Thursday's close, before the proposal, STRF traded above $100 and STRC was close to it, while STRK and STRD were in the low $70s. Those prices are a trading baseline, not evidence that daily payment will lift demand or that Strategy could issue new shares at the same prices.
According to the post, dividends on STRF, STRC, STRK and STRD would accrue every calendar day, including weekends and holidays, and be paid the next business day. It did not specify daily record dates, an effective date or the series-by-series approvals. Strategy's August 31 dividend declaration still sets quarterly payments for STRF, STRK and STRD and twice-monthly payments for STRC.
A faster calendar does not equal the same claim
Strategy's preferred-stock disclosure draws a sharper distinction than payment frequency. Dividends on STRF, STRC and STRK are cumulative, meaning unpaid amounts can accrue under their terms. STRD's are noncumulative: an omitted regular dividend does not become an arrears claim. Payments across the four series remain subject to board declaration and legally available funds. STRK may pay a declared dividend in cash, MSTR shares or both.
| Security | Current payment cadence | Annual dividend rate | Sept. 24 close | Sept. 24 volume |
|---|---|---|---|---|
| STRF | Quarterly | 10%; cumulative | $103.28 | 20,313 shares |
| STRC | Twice monthly | 12% at the latest declaration; variable and cumulative | $98.28 | 1,023,834 shares |
| STRK | Quarterly | 8%; cumulative | $73.59 | 69,162 shares |
| STRD | Quarterly | 10%; noncumulative | $72.10 | 93,762 shares |
The rates and rights come from Strategy's filings; its August 31 report set STRC at 12% annually for semi-monthly periods beginning September 16. The closing prices and share volumes are the September 24 regular-session figures reported by ChartExchange. A single day's volume does not establish lasting liquidity.
The $100 line is a comparison point, not a uniform legal par or guaranteed redemption price. In its June 30 filing, Strategy listed $0.001 legal par for these securities and no $100 stated amount for STRK, although it reported a $100 liquidation preference for STRK at that date. The other series also have their own preferred terms.
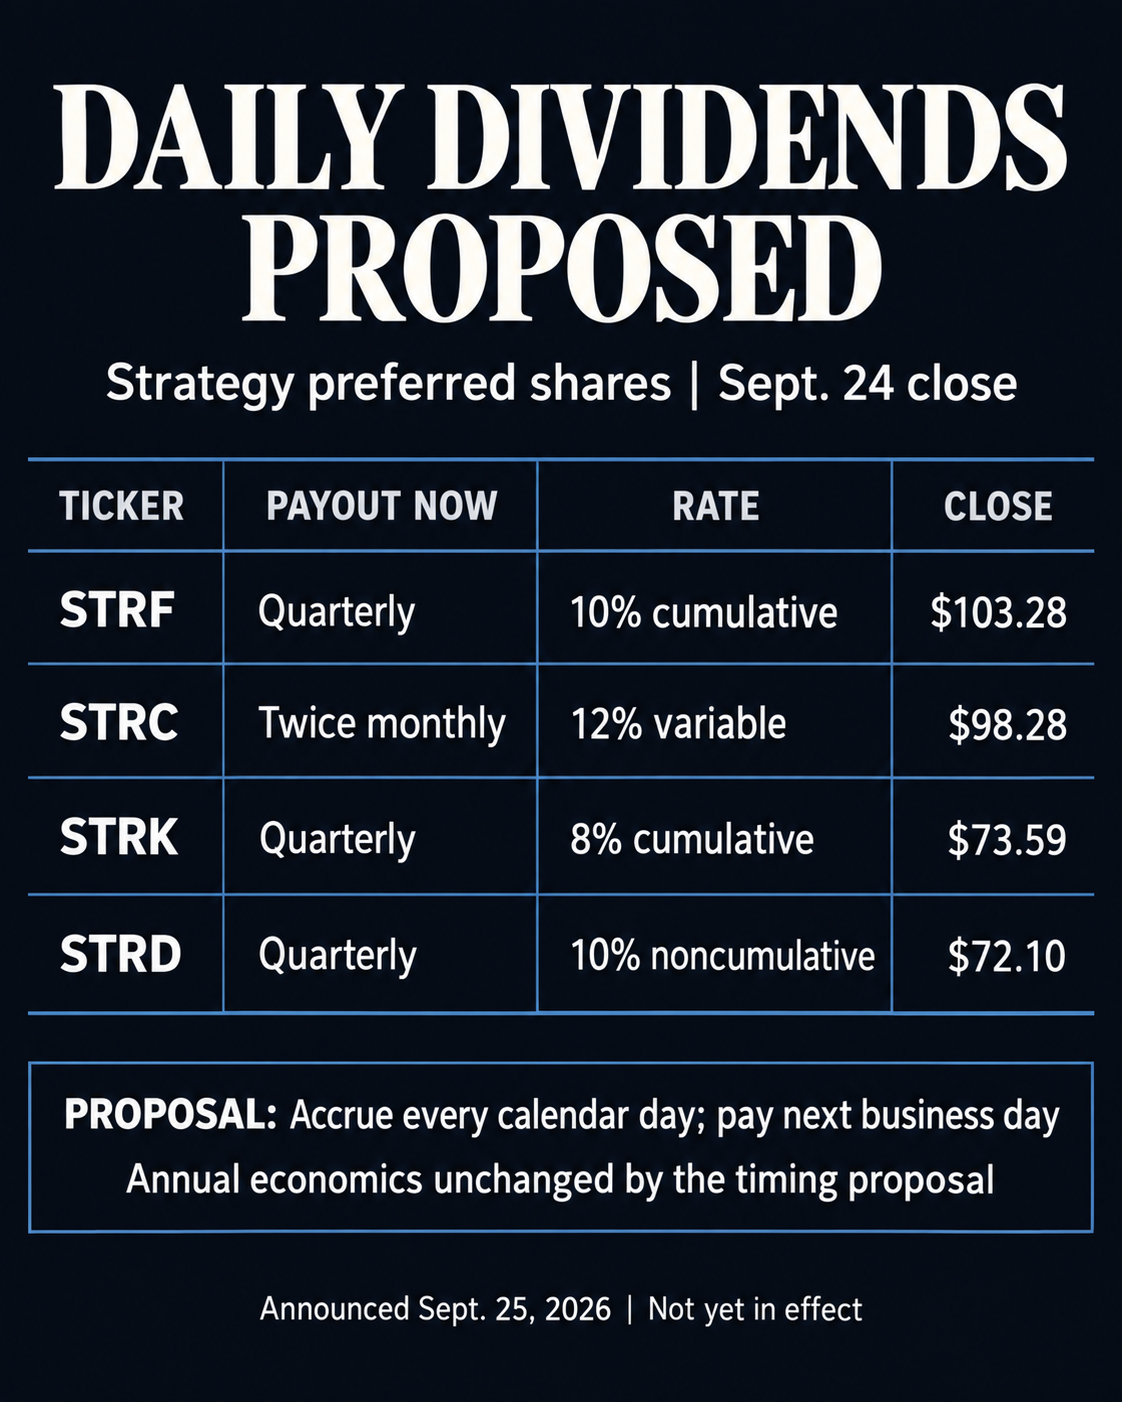
Under the August 31 declaration, holders of record on September 15 are due $2.50 per STRF share, $2 per STRK share and $2.50 per STRD share on September 30, as well as $0.50 per STRC share. Another $0.50 STRC payment is due October 15 to holders of record on September 30. The two STRC payments each represent a 12% annualized rate. The daily proposal has not replaced those declared dates.
STRC's last schedule change shows that a faster calendar can leave the dividend obligation intact. Majorities of common and STRC holders approved its move from monthly to twice-monthly record and payment dates on June 8. The June 30 filing says that change took effect that day without increasing the company's dividend obligation. That precedent does not settle what approvals or amended terms the proposed daily payments would need for all four series.
The Bitcoin financing test
More frequent cash receipt could make a preferred share more attractive. If that translates into sustained buying and firmer trading prices, new preferred issuance could become more attractive to Strategy as a way to raise capital for its Bitcoin strategy. This is a conditional market effect, not a higher annual rate or a stronger legal claim. The September 24 prices and volumes cannot show a reaction to a September 25 proposal, much less proceeds from a future offering.
Strategy's September 21 cash update shows why demand for new securities matters even with a large reserve. As of September 20, its USD Reserve, intended for preferred dividends and debt interest, stood at $5.04 billion. A separate $1.05 billion of USD Cash was available for broader treasury uses. During the previous week, $57.4 million of reserve money paid preferred dividends and interest. Strategy used USD Cash to repurchase $174 million of STRC and buy 950 Bitcoin for $75.7 million. It reported no at-the-market share sales that week and said $875.1 million of preferred-share repurchase authority remained.
The buyback supported existing STRC shares in the market; it was not new financing from investors. Daily distributions might improve demand for future preferred sales, but the next useful evidence is specific amended terms and approvals, followed by prices, sustained trading and actual issuance after any change takes effect. Until then, the proposal changes the payment timetable on paper, while the funding benefit remains unproved.
The post Strategy’s daily dividend proposal puts Bitcoin funding back in investors’ hands appeared first on CryptoSlate.
CryptoTicker.io
Selling bitcoin privately is not a special case under German tax law. The same rule applies as for a sale through a crypto exchange: if more than a year sits between purchase and sale, the gain is tax free under Section 23 of the German Income Tax Act. Sell inside the one-year window and the gain becomes taxable as soon as all private disposals in a single calendar year together exceed the threshold of 1,000 euros. Whether the money changes hands as cash across a café table, arrives by SEPA transfer or runs through the escrow of a peer-to-peer marketplace makes no difference to that calculation.
The difference from an exchange sale lies elsewhere, and it is the reason for this guide: an exchange gives you a transaction report at the end of the year showing the acquisition date, the sale price and the gain. On a direct sale of bitcoin to a private individual, that report does not exist. You build the chain of evidence for the tax office yourself, and the best day to do it is the day of the sale.
This article explains how to calculate the taxable gain on a peer-to-peer sale, which documents you need, when the threshold tips over, what anti-money-laundering law expects of you, and where the figures belong in your tax return.
What is taxed is the gain, not the sale price
A private disposal is the sale of another asset within one year of its acquisition. Under German income tax law, crypto assets such as bitcoin or ether count as these other assets, which is why Section 23 applies rather than the flat withholding tax on investment income. Only the gain is taxable.
The calculation is plain: sale price minus acquisition cost minus associated expenses. The sale price is the amount you actually receive, in euros. The acquisition cost is the purchase price of the coins sold plus the proportionate purchase fee. Associated expenses cover costs attributable to the individual sale, such as the network fee for the transfer to the buyer's wallet or a fee charged by the peer-to-peer marketplace.
Worked example: in March you bought 0.2 BTC for 16,000 euros and paid an 80 euro purchase fee. In September you sell those same 0.2 BTC privately for 19,000 euros and pay a 12 euro network fee for the transfer. Your disposal gain is 19,000 minus 16,080 minus 12, so 2,908 euros. That amount is taxable, because less than a year separated purchase from sale and the threshold has been exceeded.
The rate applied to that gain is your personal income tax rate, the same rate that applies to your salary or your business profit. Private disposals carry no flat 25 percent rate of the kind that applies to interest and dividends. The solidarity surcharge is added, as is church tax if you are liable for it. The term speculation tax, used colloquially for this charge, appears in no statute; what is always meant is income tax on a private disposal.
When is a bitcoin sale tax free? The one-year holding period under Section 23
Hold your coins for longer than a year and the gain on sale is entirely tax free, regardless of its size. A gain of 50,000 euros after fourteen months of holding triggers no tax at all. This one-year speculation period is the most effective lever a private investor has on crypto assets under German tax law. The statutory text sits in Section 23 of the German Income Tax Act.
The period runs to the exact day. What counts is the acquisition date, meaning the day you acquired the coins, and the date of disposal. A purchase on May 14 means that a sale from May 15 of the following year onwards falls outside the one-year window. Deliver one day too early on a peer-to-peer sale and you lose the tax exemption for the coins concerned in full.
What does not extend or interrupt the one-year period
A transfer between your own wallets is not a disposal and does not restart the clock. You can therefore move your coins from an exchange to a hardware wallet before selling without touching the holding period. Staking and lending are a different matter: where coins are made available to third parties for use, the treatment of the holding period was contested for a long time, and the Federal Ministry of Finance dropped the earlier extension to ten years as far back as its 2022 version. If part of your holding comes back from staking, it is worth checking your own history before you sell.
The 1,000 euro threshold is not an allowance
Gains from private disposals within the one-year window are subject to a threshold of 1,000 euros per calendar year. It has sat at this level since the 2024 assessment period, having previously been 600 euros. The distinction between a threshold and an allowance decides the entire tax charge, and the two are regularly confused.
A threshold works on an all-or-nothing basis: stay below it and the gain remains entirely tax free. Exceed it by even a single euro and the whole gain becomes taxable, not merely the part above the line. An allowance, by contrast, would always be deducted. In concrete terms: a 999 euro gain from peer-to-peer sales is tax free, while a 1,001 euro gain is taxable on the full 1,001 euros.
Important for planning: the threshold applies to all private disposals in a year taken together. If you also sell gold inside the one-year window in the same year, or a collection, or other cryptocurrencies, those gains count towards the same pot. Losses from such transactions can be offset, which may push the total below the threshold. A loss inside the one-year window is only usable for that purpose, however, if you declare it in your tax return.
Cash, bank transfer or escrow: the payment method does not change the tax liability
German tax law grants no privilege to cash payment. Anyone swapping 0.1 BTC for a bundle of notes inside the one-year window has carried out the same taxable transaction as someone selling through a regulated platform. The gain arises at the moment of disposal, and receipt of the purchase price in cash is a receipt.
The same holds for a swap. If you hand over bitcoin in a direct deal and receive another coin or a stablecoin in return, that too is a disposal. It is valued at the market value in euros at the time of the swap. For the asset received, a fresh one-year period begins at that same moment. Paying for goods with bitcoin between private individuals is likewise a sale for tax purposes.
Selling to friends and family
A sale to people you know remains a sale, even at a friendly price. Sell noticeably below market value and the tax office may treat part of the transaction as a gift. A genuine gift, on the other hand, is not a private disposal: the recipient steps into your shoes and takes over your acquisition date and your acquisition cost. For the gift itself, the rules on gift tax may apply depending on the value and the family relationship, with allowances of their own.
FIFO and acquisition costs: which coins you hand over in a peer-to-peer sale
Bitcoin is divisible and carries no individual marking. Anyone who has bought at different prices over the years therefore has to determine which acquisition costs belong to the sale. That is the purpose of the FIFO method: first in, first out means the coins bought first count as the ones sold first. The method decides two things at once, because it fixes both the gain and the holding period of the units sold.
An example: you bought 0.3 BTC in January 2024 for 18,000 euros and a further 0.3 BTC in June 2026 for 30,000 euros. If you now sell 0.3 BTC privately, first in, first out treats the January 2024 coins as disposed of. The gain comes out larger, because the older acquisition costs were lower, yet it is tax free, because those coins were held for more than a year. Anyone who does not know the sequence either gives away a tax exemption or declares too much.
The Federal Ministry of Finance set out how this applies in its circular of March 6, 2025 (file reference IV C 1 - S 2256/00042/064/043), which replaces the earlier circular of May 10, 2022. Under that circular, a wallet-based or address-based view governs crypto assets held privately, and FIFO is permitted as the consumption sequence per wallet. In practice that means you account separately for each wallet and each exchange account. How that looks with old holdings scattered across several places is covered at length in our article on calculating acquisition costs and gains on a purchase made years ago.
Are crypto gains reported to the tax office?
New reporting obligations have applied to crypto-asset service providers since January 1, 2026. The German Crypto Asset Tax Transparency Act transposes the EU directive DAC8 into German law and requires reporting providers to send user and transaction data to the Federal Central Tax Office, which passes the data on to local tax offices and to other states. The first reporting period is the 2026 calendar year, with transmission taking place the year after. The obligation falls on the provider, not on you as a user.
From that follows a particularity that is often misread in peer-to-peer trading. A deal you settle directly with another person, with no service provider involved, appears in none of these reports. That does not make the gain tax free. The tax liability arises from statute, not from a report, and your duty to declare exists regardless of what any platform reports. Anyone failing to declare a taxable gain risks a tax shortfall with the consequences that follow.
On top of that, both sides of a peer-to-peer deal leave traces. The blockchain transaction is permanently public, the counterparty may well have bought or sold through an exchange, and the arrival of the purchase price in your bank account is documented. The notion that a direct sale is an unobserved event does not hold up in practice.
Your chain of evidence on a peer-to-peer sale: which records the tax office expects
The circular of March 6, 2025 devotes its own section to the duties of declaration, cooperation and record-keeping, and makes clear that these cooperation duties apply to crypto assets held privately as well. Where a platform supplies a tax report, the tax authority examines whether it is plausible, internally consistent and not obviously incomplete, and whether the settings are apparent, such as the prices applied and the consumption sequence used. On a private sale there is no such report, so you have to produce the same traceability yourself.
A sensible approach is your own schedule, drawn up on the day of the deal and kept. It should contain:
- Date and time of the sale and of the original purchase, each with supporting documents
- Quantity in coins, to the full decimal place
- Sale price in euros and the form of payment
- The price applied and its source, where the price differs from market value
- Transaction ID of the blockchain transfer, sending and receiving address
- Network and platform fees paid, as associated expenses
- Details of the counterparty and, for a larger amount, a written agreement signed by both sides
A short sale confirmation on paper takes ten minutes and saves considerable effort in any later audit. The transaction history of the exchange where you originally bought the coins belongs in the archive too, because exchanges close, and access that works today is not guaranteed in five years. If you would rather not keep the document collection by hand, our comparison of crypto tax software and portfolio trackers covers software that can record your own transactions, including peer-to-peer deals you enter yourself, and output them as a tax report.
Anti-money-laundering law and due care when selling to strangers
Alongside tax, a private sale raises a second legal question that has nothing to do with the tax office. Anyone taking coins from an unknown person, or handing them over for cash of unclear origin, can end up in money-laundering proceedings, because negligent conduct alone can suffice where circumstances point to an illegal source. For you as the seller, the reverse applies: cash from a sale that you later deposit at a bank can prompt questions.
Questions of that kind discharge a statutory duty of the bank, which has to monitor business relationships on an ongoing basis and establish the plausibility of the origin of assets. They can be answered with exactly the documents from the previous section: purchase record, transaction history, sale confirmation. Sensible precautions during the deal itself are a public meeting place, the identity of the counterparty, a traceable payment trail, and declining any deal where the other side demands unusual haste or anonymity.
Anyone unwilling to carry that effort sells through a supervised provider. Platforms providing crypto-asset services to customers in the EU have required authorisation since the MiCA regulation took effect; which providers can show such a permission is set out in our overview of regulated crypto exchanges. The drawback is the identity check, the benefit is the report you receive at the end of the year.
Where disposal gains belong in the tax return
Gains from private disposals of crypto assets go into Anlage SO of the income tax return, in the section for private disposals. A gain exceeding the threshold must be declared, and a loss is worth declaring too, because it can be offset against other gains of the same income category and carried forward. Gains that are tax free because the one-year period has elapsed do not belong in Anlage SO, but should stay documented.
What has to be stated is the acquisition and disposal dates, the acquisition cost, the disposal price and the associated expenses. Where there are several transactions, attaching a schedule is advisable rather than entering totals with no derivation: a traceable table answers questions before they arise. The individual lines and boxes are explained in our article on where crypto gains are entered in the tax return.
Deadlines: the tax return for a calendar year is in principle due by July 31 of the following year. Anyone instructing a tax adviser or an income tax assistance association has considerably longer. Where the history across several years is hard to follow, where the trading takes on commercial features, or where the amounts are larger, tax advice is worth the money; this guide is no substitute for it.
When private trading becomes a business
The rules in this article apply to crypto assets held as private assets. Anyone trading at high frequency, working with other people's capital, presenting themselves outwardly as a dealer, or building an organisation for the purpose, can move close to a commercial activity. Different provisions then apply: the one-year period falls away, the gains become business income, and bookkeeping duties arrive along with trade tax depending on the circumstances.
A private investor selling coins a few times a year is a long way from that. Anyone regularly acting as counterparty for others, however, and earning an income from the spread between purchase and sale, should have the classification examined professionally before the tax office does it for them. Mining and commercial brokering likewise fall into a different category from the occasional private sale.
What could still change in crypto taxation
The one-year holding period is politically contested. The draft federal budget of July 3, 2026 contains a proposal to treat gains from crypto assets like investment income in future, meaning like interest, dividends and share gains. That would end the tax exemption after one year and bring a flat rate instead. As at the time of this article, the proposal is a political plan.
For your decision today, then, the law as it stands applies: for as long as Section 23 remains in its current form, a gain after more than a year of holding stays tax free. Anyone holding a larger position with unrealised gains should keep an eye on the legislation without letting a draft drive them into a hasty sale that breaks the holding period and thereby triggers exactly the tax it was meant to avoid.
Common mistakes when selling bitcoin privately
Four patterns recur in practice, and all four are avoidable:
- Selling shortly before the anniversary. A few days of patience decide whether the gain is entirely tax free. Every sale deserves a look at the purchase date of the units concerned.
- Assuming cash is invisible. The transaction is taxable, and depositing cash at the bank creates a documentation duty of its own.
- The forgotten swap. Anyone exchanging coin for coin in a direct deal has sold, even without seeing a single euro.
- Missing documentation of the purchase. Without evidence of the acquisition cost, the tax office can estimate the gain, and an estimate rarely lands in your favour.
Selling bitcoin privately: what to take away
- Check the purchase date first, then the price. Use first in, first out per wallet to work out which units you are handing over and how long they have been held. If the purchase is more than a year back, the gain is tax free; if it is less, calculate the gain and compare it with the 1,000 euro threshold. Tools for that are covered in our comparison of crypto tax software and portfolio trackers.
- Build the chain of evidence on the day of the sale. Purchase record, transaction ID, quantity, price, fees and a short written confirmation from the counterparty. If you would rather skip that effort, sell through a supervised provider from our overview of regulated crypto exchanges, which will supply you with an annual report.
- Enter the gain in Anlage SO, and a loss as well. A declared loss reduces the tax on other disposal gains in the same year. Which selling routes exist alongside a private deal, and what they cost, is shown in our comparison on how to sell bitcoin.
(As of September 25, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
A company that announced in July 2025 that it intended to hold one hundred thousand bitcoin by the end of 2030 holds not a single one today. French semiconductor maker Sequans Communications said on September 24, 2026 that it had sold the last 314 bitcoin on its balance sheet, completing its retreat from its own crypto reserve. If you hold a share like this because it promised easy access to bitcoin through your usual broker, this is the moment to open your portfolio this evening.
The case is instructive because it exposes a mechanism that nobody notices in quiet markets. A treasury stock's link to bitcoin is a board decision, and decisions can be reversed. Anyone invested here is buying corporate policy along with the price exposure.
Sequans and the last 314 bitcoin: what was announced on September 24, 2026
In a statement headed "Sequans Completes Bitcoin Treasury Exit and Emerges with a Solid Financial Foundation", the New York-listed company writes that it has sold the 314 bitcoin still carried on its books as of June 30, 2026. That completes the exit, which began with the repayment of its convertible bond in May 2026. According to the company, no crypto assets remain on the balance sheet, and no liabilities beyond state-funded research projects.
Chief executive Dr Georges Karam frames the step as a return to the core business: full strategic and financial attention now goes back to the semiconductor business supplying cellular chips for connected devices. The company points to product revenue growth of more than 80 percent in the second quarter of 2026 against the same quarter a year earlier, and a six-month order backlog that it says has more than tripled.
What the statement expressly does not name is the proceeds. No figure appears in the document, either for the final 314 bitcoin or for the sales in the months before. That gap matters for any valuation, and we return to it below.
From 3,234 bitcoin to zero: the wind-down in four stages
Measured against its own ambition, the strategy was short-lived. The sequence, according to company statements and trade press reports:
- June 2025: the bitcoin reserve begins, funded by a capital raise of roughly 377 to 384 million dollars in equity and secured convertible notes.
- July 2025: the target is set, one hundred thousand bitcoin by the end of 2030. Holdings stand above 3,000 coins at this point.
- October 3, 2025: peak holdings of about 3,234 bitcoin.
- November 2025: 970 bitcoin are sold to repay half of the convertible bond.
- May 2026: the remaining convertible is redeemed and holdings fall to around 658 bitcoin.
- June 30, 2026: 314 bitcoin remain on the balance sheet.
- September 24, 2026: those last 314 bitcoin are sold and the exit is complete.
The striking element is the role of the convertible bond, which first made the purchase possible and then forced the sale. Two of the four wind-down steps are explicitly attributed to its repayment, which means the bitcoin holding was never free capital. It was the counterweight to a debt with a due date.
What a convertible bond is
A convertible bond is a loan that the creditor can exchange for shares in the company under agreed conditions. For the company it is cheaper than a conventional bank loan, because the creditor pays for that exchange option. The cost arrives when the option is used: new shares are created, and existing shareholders hold a smaller claim on profits. If the option goes unused, the money has to be repaid, on a date that takes no interest in where bitcoin trades that day.
Cost basis of 116,643 dollars against a price of 83,935 dollars: the calculation we ran ourselves
Sequans reported a net investment of roughly 377.2 million dollars for its peak holdings and an average purchase price of 116,643 dollars per bitcoin. Those figures can be set against the current market price. cryptoticker.io collected this data itself on September 25, 2026.
Method in one sentence: a direct call to CoinGecko's public market interface on September 25, 2026 at 18:48 UTC (HTTP 200), multiplying the bitcoin price reported there by the peak holdings Sequans disclosed. One object was examined, the bitcoin spot price in US dollars as an aggregate across the venues CoinGecko covers.
The price stood at 83,935 dollars at that moment, with a daily range of 83,230 to 85,208 dollars. Against the stated average cost basis of 116,643 dollars, the market price is therefore about 28 percent lower. Applied to peak holdings of 3,234 bitcoin, an acquisition value of 377.2 million dollars stands against a present market value of roughly 271.4 million dollars, a difference of some 106 million dollars.
What we could not verify, and what this calculation therefore does not say: it says nothing about what Sequans actually realised. The sales are spread across eleven months, individual selling prices were never disclosed, and bitcoin traded both well above and well below today's level over that period. The figure is a snapshot of the gap between cost basis and current price, not a business result. Anyone looking for a result of that kind will find it only in the company's audited accounts.
Why a bitcoin treasury stock is not bitcoin: the board risk
A treasury stock is a stake in a company that, among other things, holds bitcoin. That sounds like a technicality and it is the heart of the matter. You acquire no claim on any particular quantity of bitcoin. You acquire a share of the whole company, including its debts, its operating business and its management decisions.
The Sequans case shows how that works in practice. Whoever bought the share in the summer of 2025 to gain bitcoin exposure through a familiar broker now holds a pure semiconductor company. The reasoning behind the change is commercially sound, and the decision was taken without shareholder involvement. Nobody holding bitcoin directly in their own wallet or at an exchange carries that risk.
The reverse direction applies too. A company can also add to its holdings at a point when you had no intention of adding to yours. Both directions are decisions taken by other people about the exposure you carry in your portfolio.
Dilution and maturity: how the financing feeds through to the share price
Bitcoin treasury strategies are rarely paid for out of operating cash flow. The usual route runs through new shares, through convertible bonds, or through a mixture of the two, as at Sequans with roughly 384 million dollars in June 2025. For you as a shareholder that produces two effects that sit inside the share price and nowhere in the bitcoin price.
The first is dilution. When new shares are issued, the same corporate value is spread across more of them. The second is maturity pressure. A bond has a repayment date, and if there is not enough cash on hand when that date arrives, whatever can be sold has to be sold. That is exactly what happened here twice, in November 2025 and in May 2026.
For anyone assessing a treasury stock, that leads to a sober question with no connection to the bitcoin price: which debts fall due when, and from which source are they meant to be serviced? If the answer contains the word bitcoin, the holding is tied to a calendar.
Crypto tax rules: capital gains tax on the share, Section 23 of the Income Tax Act on the coin
Here lies the distinction most often lost in debates about treasury stocks, and it hits your after-tax return directly. In Germany, two routes to the same underlying asset carry two entirely different tax regimes.
The share
Gains on the sale of shares count as investment income and fall under the flat withholding tax of 25 percent, plus the solidarity surcharge on that amount and church tax where applicable. Without church tax the combined rate comes to roughly 26.375 percent. There is no holding period after which the gain becomes tax free: hold for ten years and you pay the same tax on the gain as you would after ten days. The only exemption is the saver's allowance of 1,000 euros per person per year. With a domestic securities account the bank withholds the tax directly.
The coin
Directly held crypto assets count as other assets. A sale within one year of purchase is a private disposal under Section 23 of the German Income Tax Act, and the gain is then taxed at your personal income tax rate, which can sit above or below the flat rate. Once a year has passed, the gain is tax free regardless of its size. Inside the one-year window, total gains of less than 1,000 euros in a year remain untaxed, and that figure is a threshold rather than an allowance: exceed it and the entire amount becomes taxable, not merely the excess. Assessment runs through your own tax return, with nothing withheld automatically.
In practice that means the tax treatment of the directly held coin is considerably more favourable over a long holding horizon, while the share can have the edge over very short holding periods combined with a high personal tax rate. Bear in mind that legislation on the taxation of crypto assets from 2027 is currently in progress and its outcome is open; anyone making a decision today with the one-year window in mind should follow the state of that legislation and take tax advice in case of doubt. This article is not tax advice.
Premium to holdings value: how to see what a bitcoin costs in a share wrapper
Treasury stocks frequently trade above or below the value of their crypto holdings rather than at it. The metric for this sets the company's market capitalisation against the value of the coins it holds, adjusted for debt and the operating business.
A premium means you pay more for a bitcoin in a share wrapper than you would in the market. The justification usually offered is that the company can raise capital cheaply and keep buying. A discount means the opposite. A discount typically widens when the market starts doubting whether the financing is sustainable, and it can widen without the crypto holding itself shrinking at all.
Checking this before you buy is uncomfortably simple: multiply the number of coins held by the current price, subtract net debt and compare the result with the market capitalisation. If the market capitalisation sits well above it, you are paying a premium that can disappear again without bitcoin losing a cent. At Sequans the holding is now zero, which makes the metric moot, and the share once again values the chip business.
The three routes to bitcoin compared: treasury stock, ETN and direct purchase
Anyone who wants bitcoin exposure in a portfolio has essentially three options in Germany, and they differ in access, custody, tax and risk.
The treasury stock works through any securities broker, appears in your account statement and requires no wallet of your own. In exchange it carries corporate and financing risk, depends on board decisions, and falls under the flat withholding tax with no holding period.
Exchange-traded notes on bitcoin, usually labelled ETN or ETP, also trade through a securities account. A bitcoin spot fund under European fund law is not permitted here, which is why the exchange-listed route runs through these notes; the physically backed versions place the coins with a custodian. Their tax classification depends on the specific structure and is not clear-cut in every case, which makes this route a matter for examination where the one-year window is concerned. We have set the structures, cost ratios and custodians side by side in our overview of crypto ETFs and ETNs in Germany.
The direct purchase through a trading platform gets you the coin itself, and with it the one-year window under Section 23. Since the EU Markets in Crypto-Assets Regulation, known as MiCA, providers need authorisation to serve retail clients in the EU, and that authorisation can be checked in the supervisor's public register. Which venues hold it and what they charge in fees is shown by our crypto exchange comparison. In return, custody becomes your responsibility here.
Custody on a direct purchase: exchange, hardware wallet and the question of the keys
On a direct purchase, custody decides the largest remaining risk. Leave the coins on the trading platform and the platform holds the keys, which leaves you dependent on its solvency and its security arrangements. The breach at a major trading platform this week, with damage running into the hundreds of millions, was a reminder that this risk is not theoretical.
The alternative is self-custody through a hardware wallet, where the keys never leave a device that has no internet connection. The price is personal responsibility: lose the recovery phrase and the balance is lost, with no institution able to reset it. For amounts whose loss would hurt, this is the standard recommendation, and it holds whatever the price happens to be doing.
Levels and checkpoints: how to read the situation over the coming weeks
Three things about this story can be verified concretely, without any forecast being required.
On the upside the signal would be a company launching a treasury strategy afresh, or adding to its holdings without taking on debt. That would suggest financing conditions have turned, and it could be checked against the company's own statement.
On the downside the signal would be a second complete exit within a short span, particularly one justified as this one was by the repayment of a bond. The maturity dates of the large convertible bonds are public and appear in annual reports.
On the price itself, bitcoin moved in a daily range of 83,230 to 85,208 dollars on September 25, 2026, according to our reading at 18:48 UTC. The average cost basis of 116,643 dollars reported by Sequans sits above that range, and for as long as that remains the case, other companies with late purchases from 2025 are in the same position. Anyone setting levels for their own portfolio should write them down before buying rather than after.
Open questions: proceeds, timing of the sale and the balance sheets of other treasury companies
Three points remain unresolved after the announcement and deserve to be named rather than estimated. First the proceeds: no prices are available for the final 314 bitcoin or for the earlier sales, so the accounting effect cannot be calculated. Second the timing of the sale within the reporting period, which can account for a difference of several million dollars. Third the question of whether other companies with comparable financing will follow the same pattern; nothing can be demonstrated on that today, and speculation about other companies' balance sheets has no place in an article of this kind.
Checking bitcoin treasury stocks: what to take away
- Look at what you actually hold. Open your portfolio and check, for every position you bought because of bitcoin, whether the company still holds any coins today and how many. The figure appears in the latest quarterly report or in the announcements on the investor relations page. If you would rather track the price itself than corporate policy, you will find the authorised venues and their fees in our overview on how to buy bitcoin.
- Factor in the tax before you reshuffle. Moving from the share to the coin is a sale subject to the flat withholding tax, after which the coin starts a fresh one-year window. Keep a complete record of purchase dates and acquisition values, otherwise the tax office will end up estimating them; which programmes handle that is shown in our crypto tax software comparison.
- Settle custody before you buy, not afterwards. Decide in advance how much may sit on the trading platform and above which sum the coins move to a device of your own. The devices and their backup procedures are covered in our hardware wallet comparison.
The lesson from the Sequans exit is unspectacular and useful for that reason: a bitcoin on a company's balance sheet belongs to that company. Everything that follows from it for you depends on decisions taken somewhere else.
Sources: the statement from Sequans Communications dated September 24, 2026 and the reporting by Cointelegraph. The price data comes from our own reading of CoinGecko's market interface on September 25, 2026 at 18:48 UTC.
(As of September 25, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
A Bitcoin forecast worth anything today does not consist of a single number, but of a range, a reason and an action. The Bitcoin price stands at $83,877 at 16:40 UTC on September 25, 2026, the equivalent of 73,605 euros (retrieved from CoinGecko, market data API). The measured volatility of the past 30 days produces a band between roughly $73,600 and $94,200 for the coming month, within which the price will stay with a probability of about two thirds. More important than that band, though, for you as a German investor is the calendar: the third quarter ends on September 30, the Crypto Asset Tax Transparency Act took effect on January 1, 2026, and Germany's transition period under MiCA expired on December 31, 2025. This article adds both sides together: the levels the market sets, and the checks you can carry out today regardless of the price.
Bitcoin forecast on September 25, 2026: what the price is currently measuring
As of 16:40 UTC, Bitcoin stands at $83,877. Over the past 24 hours the price has lost 1.1 percent, moving between $83,230 and $85,208. Over seven days it is up 3.4 percent, over 30 days up 7.6 percent. The twelve-month view looks different: there it is down 25.0 percent. Market capitalisation is $1.685 trillion, trading turnover over the past 24 hours $37.6 billion, and 20,089,253 Bitcoin are in circulation.
The all-time high of $126,080 dates from October 6, 2025. The current price sits 33.5 percent below it. Anyone reading a forecast today that names the all-time high as the next waypoint should know this figure: from $83,877 to $126,080 is a gain of 50.3 percent. That is no argument against such a target, but it frames the time horizon in which it would be reachable.
The sentiment index from alternative.me, which builds a value between 0 and 100 out of volatility, trading volume, market dominance and survey data, stands at 71 points on September 25, placing it in Greed territory. The previous day it also stood at 71. A high reading is not a sell signal; it says only that the market is pricing in little fear right now. For your planning that means one thing above all: the price of hedging is lower in such phases than it is after a slump.
The range of the past 30 days: $75,590 to $86,597 as the frame for any forecast
For this article, the daily closing prices of the past 180 days were retrieved from CoinGecko's market data API and analysed. The result is the most robust part of any forecast, because it predicts nothing but measures.
- Lowest level of the past 30 days: $75,590 on September 16, 2026.
- Highest level of the past 30 days: $86,597 on September 22, 2026.
- Lowest level of the half-year: $58,566 on July 1, 2026.
- Moving average of the past 50 days: $75,318.
- Moving average of the past 180 days: $71,007.
Two things stand out. First, Bitcoin ran through a range of 14.6 percent within six trading days between September 16 and September 22. Second, the current price sits 11.4 percent above the 50-day average and 18.1 percent above the 180-day average. Both lines are therefore below the price, and both are rising. That is the technical starting position from which forecasts for the fourth quarter are built.
How wide a month really is: volatility as a forecasting frame
Volatility is the measure of how strongly a price fluctuates around its own path. The same 180 daily data points give an annualised volatility of 42.5 percent for the past 30 days, and 38.2 percent across the full half-year. The average daily move of the past 30 days is 1.49 percent, regardless of direction.
Scaling the annual volatility of 42.5 percent down to one month produces a standard deviation of 12.3 percent. Applied to today's price, that means a band from $73,586 to $94,168 for the coming four weeks. Calculated over one week, the band shrinks to $78,934 to $88,820. On the assumption of normally distributed returns, around 68 percent of all paths lie within one standard deviation.
That assumption is deliberately conservative, because it understates the tails: crypto markets produce extreme days more often than a normal distribution expects. The band is therefore not a guarantee but a lower bound for the width you should reckon with. Anyone reading a forecast that names a single figure for four weeks rather than a range is ignoring these measured 12.3 percent.
Upside levels: the September high at $86,597 and what lies beyond it
The next level to the upside is the September high of September 22 at $86,597, 3.2 percent above the current price. That level matters because the market turned there three days ago: whoever bought at the peak is currently sitting on a small loss and tends to sell on a return to break-even. That behaviour creates supply and turns a high into a resistance.
Above $86,597 the air thins out, because not a single daily closing price of the entire half-year lies higher. The next reference point from the record is the all-time high at $126,080. A forecast expecting that leap within a few weeks demands a move of 50.3 percent, a good four monthly standard deviations. Such a path would be realistic across several quarters, not across a change of quarter.
In classical chart analysis, a breakout counts as confirmed by a daily close above the level accompanied by rising turnover. The $37.6 billion turnover of the past 24 hours is the benchmark against which you can measure that.
Downside levels: the 50-day line at $75,318
To the downside two levels lie close together, and that is precisely what makes them robust. The 30-day low of September 16 is at $75,590, 9.9 percent below the current price. The 50-day moving average is at $75,318, 10.2 percent below it. Where a trough and a closely watched average line sit at almost the same level, buy orders and hedges accumulate.
If that zone breaks, the next stop is the 180-day average at $71,007, 15.3 percent below the current price. Below that, within this half-year's data window, there is no notable zone of concentrated trading until the July low of $58,566. The distance from the current price to that point is 30.2 percent.
In practice that means: if you want to set a selling threshold, it does not belong on a round number like $80,000 but below the zone that has actually held. A threshold just above $75,318 is reached by any ordinary daily move of 1.49 percent as soon as the price so much as tests the zone.
Holding period and quarter-end: why the calendar sets your selling date
This is where the German view parts company with any international forecast. Under the Federal Ministry of Finance circular of March 6, 2025, Bitcoin counts among the other economic assets within the meaning of section 23 (1) sentence 1 no. 2 of the German Income Tax Act. If you sell privately held coins after more than twelve months, the gain is tax-free regardless of its size. If you sell within the twelve months, the gain is taxable at your personal income tax rate.
From that follows a check you can carry out today and which depends on no price forecast: look in your purchase record for the tranches bought between September 26 and December 31, 2025. Those positions cross the one-year mark in the coming quarter. For each of them the date matters more than the forecast, because selling a few days before the deadline costs you the full tax rate on the gain, while selling a few days after costs nothing.
Under the circular of March 6, 2025, the same applies to holdings you have lent out or staked in the meantime: the holding period stays at one year. The running income from staking or lending is to be considered separately and arises as other income. A detailed treatment of the German rules is in our overview of crypto tax in Germany.
The 1,000-euro exemption limit and FIFO: what to calculate before every sale
An exemption limit of 1,000 euros per calendar year applies to gains from private disposals within the one-year period. The term exemption limit is to be taken literally and differs from an allowance: if your total gain from such transactions is 999 euros, it stays tax-free. If it is 1,001 euros, the entire amount is taxable, not merely the one euro above.
Which coins you actually sell is decided by the consumption sequence. The customary method, accepted by the tax authorities, is first-in-first-out, under which the units bought first count as sold first. Where several purchases are spread across the year, that order determines whether a sale hits an old, tax-free tranche or a young, taxable one.
A worked example at today's price: you bought for 4,000 euros in February 2026 and again for 4,000 euros in July 2026. If you sell part of it now, FIFO reaches the February tranche first, which would become tax-free in February 2027. Anyone who overlooks that gives away a deadline they can hardly get back. If you use several exchanges and wallets, you need a seamless record across all accounts for this, otherwise each platform calculates only its own slice.
Crypto Asset Tax Transparency Act: what your exchange reports from 2026
Since January 1, 2026, the Crypto Asset Tax Transparency Act has applied in Germany, implementing the EU directive DAC8. According to the overview of the act by audit firm KPMG, retrieved on September 25, 2026, the current calendar year 2026 is the first reporting period. Providers must transmit the data to the Federal Central Tax Office by July 31, 2027. For breaches, section 18 of the act provides for fines of up to 50,000 euros per case.
What gets reported are trades, exchange transactions and transfers, together with details about you as the user. In practice that means: what you declare for the current year in your tax return can be reconciled from 2027 with the data from your exchange. Anyone who puts their records in order only once the report has already been filed has missed the easier route.
The check that follows from this is unspectacular and effective: before the quarter ends, export the complete transaction history of every exchange you used in 2026, and file it together with the wallet addresses through which you processed withdrawals. Exchanges change export formats, discontinue services or lose authorisations. An export you pull today is available; one you need in 2027 may no longer be.
Buying under MiCA: Germany's transition period has expired
MiCA is the EU regulation on markets in crypto-assets. It requires authorisation as a crypto-asset service provider for operating a trading platform, for exchange transactions and for custody on a client's behalf. Germany brought the national transition period forward to December 31, 2025 through its crypto markets supervision act, ending it half a year earlier than the latest EU-wide deadline of July 1, 2026. Since January 1, 2026, providers without authorisation may no longer render services in Germany.
For you that is a concrete check before your next purchase: look up whether the provider you buy through is listed in BaFin's company database or operates under an EU passport from another member state. A provider without authorisation is not automatically disreputable, but in a dispute you stand outside the supervisory framework, and deposit protection does not cover crypto-assets in any case.
If you switch providers, the switch itself becomes a tax matter: transferring your own holdings between your own wallets is not a sale and triggers no tax, but it must be documented so that the acquisition data, and with it the holding period, are preserved. Which platforms are authorised for German investors and how they differ on fees and withdrawal routes is shown by our comparison of the best crypto exchanges.
Custody: what to check before the next swing
The measured volatility of 42.5 percent has a side effect that rarely appears in forecasts: in hectic phases, load and waiting times at exchanges rise, and that is exactly when you want access. Anyone holding larger amounts therefore does well to separate the trading position from the long-term position.
Three checks are possible today without any view on the price. First: is your recovery phrase held in two physically separate places, and is at least one copy protected against fire and water? Paper in a desk drawer does not meet that. Second: have you ever tested the recovery process, meaning restoring the wallet from the phrase on a second device? An untested backup is an assumption. Third: at every exchange you still use, is two-factor sign-in set to an app or a security key rather than to SMS?
Which devices meet these requirements, and how they differ in handling and backup procedure, is a question of the backup method and of usability, not of price.
Leverage and liquidation: what a 1.49 percent daily move means for your account
Anyone trading with leverage should read the forecast not in price targets but in probabilities. From the measured monthly volatility of 12.3 percent it is possible to estimate how often an adverse move grows large enough to liquidate a leveraged position. On the simplifying assumption of normally distributed returns and disregarding financing costs, the picture for a one-month period is:
- Three times leverage, liquidation at an adverse move of around 33 percent: about 0.3 percent probability.
- Five times leverage, liquidation at around 20 percent: about 5.2 percent.
- Ten times leverage, liquidation at around 10 percent: about 20.8 percent.
- Twenty times leverage, liquidation at around 5 percent: about 34.2 percent.
The figures are a lower bound, because real price paths swing out at the tails more often than the model does, and because liquidations can be triggered before the calculated point once the margin call takes hold. At twenty times leverage, three and a half times an average daily move of 1.49 percent is arithmetically already enough to end the position.
For retail investors in the EU, leverage on crypto contracts for difference is capped at two times in any case. Anyone using higher leverage with providers outside that framework loses not only this protection but also trades products whose tax treatment departs from the simple one-year rule: gains from derivatives fall under investment income and not under section 23 of the Income Tax Act.
Fees: what one percent costs at $83,877
Fees are the only part of a forecast that is certain to materialise. On a purchase of 5,000 euros, a spread of one percent costs 50 euros; at one percent on both the buy and the sell side, 100 euros in total. By way of comparison: the average daily move of 1.49 percent amounts to 74.50 euros on the same sum. Your trading costs therefore sit in the same order of magnitude as an average trading day.
Two cost types are regularly overlooked. First, the gap between the buy and sell price at providers who advertise zero percent order fees and place the margin in the price. Compare the displayed rate at the moment of purchase against a reference rate. Second, the withdrawal fee in euros and the network fee on a transfer, which on small amounts can account for the largest share.
Anyone buying monthly should recalculate both once a quarter. On a savings plan of 200 euros a month, a one percent spread is 24 euros a year, and 1.5 percent is 36 euros. Over five years that is the equivalent of roughly two monthly instalments.
Three scenarios for the fourth quarter, each with its reasoning
Sideways within the measured band, $73,600 to $94,200. This scenario needs no new piece of news; it is the continuation of the measured volatility. It is therefore the most likely outcome for the coming four weeks, as long as neither the September high nor the zone around $75,300 is durably broken.
Upward through $86,597. A daily close above the September high with rising turnover opens the area in which the half-year record holds no further resistance. The first realistic stage is the upper edge of the monthly band at around $94,200, which is 12.3 percent above today's price. In this scenario the all-time high at $126,080 remains a target for several quarters, not for weeks.
Downward through $75,318. Should the price fall below the double zone of the 30-day low and the 50-day average, the next stop is the 180-day average at $71,007. If that break is confirmed as well, no load-bearing zone remains before the July low at $58,566. For leveraged positions this scenario is the most expensive; for investors with the one-year deadline in view it is above all a question of the selling date, not of selling as such.
None of the three scenarios is a recommendation. What they do is assign consequences to levels, so that you know in advance what you will do at which price.
Checking the Bitcoin forecast: what to take away
- Sort your purchase dates before the quarter ends. Check which tranches cross the one-year mark in the fourth quarter, and note the dates. A tool that tracks the deadlines automatically is in the comparison of crypto tax tools and portfolio trackers.
- Check your buying route and its authorisation. Look up whether your provider has been authorised since the end of the German transition period, and compare spread and withdrawal fees against the alternatives in the overview of the best crypto exchanges.
- Test your custody, do not assume it. Restore your wallet once from the recovery phrase on a second device. Which devices support that comfortably is shown by the hardware wallet comparison.
(As of September 25, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Chainlink traded at $13.86 at 14:55 UTC on September 25, 2026, 11.2 percent higher than 24 hours earlier. The break above the September high of roughly $13.70 is real, and the figure most often quoted alongside it is a rise of about 25 percent in open interest. That number is currently being read as evidence of an overheated market. We therefore queried the derivatives data ourselves, and it does not support that reading: funding sits exactly at the baseline rate on both perpetual markets we were able to check.
What that means for your leverage, your route to buying and your tax position is set out below. If you hold Chainlink in your portfolio, or are weighing an entry, these three figures from the derivatives market matter more than any price target.
Chainlink price on September 25, 2026: the numbers behind the breakout
All price figures in this section come from CoinGecko's public market interface, retrieved at 14:55 UTC on September 25, 2026. LINK stands at $13.86. Over 24 hours that is a gain of 11.2 percent, over seven days 18.5 percent and over 30 days 22.7 percent. The daily range ran from $12.46 to $14.19.
Market capitalisation is $10.36 billion, which places LINK 13th among all cryptocurrencies. Trading volume over the past 24 hours came to $1.07 billion. Circulating supply is 748.1 million LINK out of a maximum of one billion.
Why the year-on-year comparison tempers the enthusiasm
A look beyond the daily candle puts the jump in perspective. Measured against its level a year ago, LINK is still down 33.5 percent. It sits 73.7 percent below the all-time high of $52.70 set on May 9, 2021. Today's breakout is therefore a move inside a multi-year sideways and downward phase, not a return to former levels. An investor who sizes a position on that basis reaches different conclusions from one who looks only at the daily candle.
Chainlink open interest: what 25 percent more open contracts actually tells you
Open interest is the total of all derivatives contracts open at a given moment that have been neither closed nor settled. The measure captures how much capital is tied up in the futures market, and on its own says nothing about whether that capital is positioned for rising or falling prices.
Industry outlet KuCoin reported on September 25, 2026 that LINK had passed its September high of around $13.70 while open interest rose by some 25 percent; market-wide, the report puts the figure for September 24 at roughly $650.7 million, against a range of $350 million to $450 million in spring and early summer. Financial service FXStreet attributes the move on the same day to institutional demand, positioning in the derivatives market and new partnerships.
Our own measurement confirms the order of magnitude on the two markets we were able to query. At OKX, 2,143,973 LINK were open in the perpetual contract at 14:55 UTC on September 25, 2026, equivalent to $29.9 million. On Hyperliquid the figure was 7,326,573 LINK, equivalent to $102.3 million. Rising open interest alongside a rising price means, in the first instance, only that new positions are being built. Whether they are the risky kind is a question only the financing side answers.
Funding rate tested in-house: why OKX and Hyperliquid show no overheated long book
The funding rate is the periodic payment between the long and short side of a perpetual futures contract that tethers its price to the spot market. When it is clearly positive, buyers pay sellers, and that is taken as a sign of a one-sided, expensively financed long book.
That is precisely not the case here. At OKX the funding rate on the LINK-USDT contract stood at 0.0100 percent per eight-hour period at the time of retrieval. That is the baseline value the exchange applies as its starting level, and it corresponds to 0.03 percent a day, or just under 11 percent a year. On Hyperliquid the rate was 0.00125 percent per hour, which works out to the same daily figure. Two independently operated markets, one identical result.
For context, that means the eleven percent price jump was not bought by leveraged buyers who had to pay unusually heavily for their positions. Anyone trading perpetual contracts will find the fee and funding models of the individual platforms side by side in our perp DEX comparison; funding is an ongoing cost item there, not a sideshow.
Perp premium and long-short ratio: the second cross-check
The premium on a perpetual contract is the gap between its market price and the oracle price taken from the spot market. On Hyperliquid that gap stood at minus 0.007 percent and at exactly zero across our two retrievals at 14:48 and 14:55 UTC. Despite the day's gain, the contract was therefore not trading above the spot price.
The third cross-check comes from the ratio of accounts holding long to short positions at OKX. In the most recent daily slice it stood at 1.60. In the preceding days it ranged between 1.68 and 2.01. The long side is thus more thinly populated relative to the short side than it was a week ago, not more densely. Three measures from two sources point the same way, and that carries more weight than a single number.
How we measured, and what we could not measure
This analysis was carried out by cryptoticker.io itself on September 25, 2026. Method: we queried three public programming interfaces directly, namely CoinGecko's market interface for price and volume, along with the swap endpoints at OKX and the info endpoint at Hyperliquid for open interest, funding rate, premium and position ratio. That covers two perpetual markets and one spot aggregate, with every request returning HTTP status 200.
What we could not check belongs in the record too. Binance's interfaces answered from our environment with HTTP 451, those at Bybit with HTTP 403. Two of the largest perpetual markets for LINK are therefore missing from our measurement. Our funding and premium figures describe OKX and Hyperliquid, not the market as a whole. The market-wide open interest figure comes from the report linked above and is not a survey of our own.
LINK liquidation: what a daily range of $12.46 to $14.19 does to your leverage
A liquidation is the forced closure of a leveraged position by the exchange once the collateral posted no longer covers the loss. It is not an edge case but the built-in normal case of every leveraged product, and today's daily range makes that tangible.
There is $1.73 between the day's low and the day's high. Measured from the high that is 12.2 percent, from the low 13.9 percent. Anyone who had gone long near $14.19 with five times leverage would have been down roughly 61 percent on their stake at the daily low of $12.46. At ten times leverage the stake would have been wiped out on paper, meaning the position would have been force-closed before that point. This calculation leaves out fees and financing costs, which make the outcome worse still.
How to work out the distance to your liquidation price before you place the order
The rough rule of thumb is quick to form: at leverage of x, the stake is consumed on paper by an adverse move of 100 divided by x percent. Five times leverage means 20 percent, ten times leverage ten percent, twenty times leverage five percent. The trading interface shows you the actual liquidation price before you submit the order; because of the maintenance margin it always sits somewhat closer to the entry price than the rule of thumb suggests.
The practical step that follows: hold the rule of thumb against the previous day's range. Where that range was close to 14 percent, as it is here, ten times leverage is not an aggressive bet but a position that an entirely ordinary daily move would already have ended. Cutting leverage buys time, and in a sideways phase time is the scarcer commodity, not return.
Buying LINK in Germany: spot orders, MiCA authorisation and what to check beforehand
To buy LINK without leverage you need a trading venue authorised in the EU. The European regulation on markets in crypto-assets has applied in full since December 30, 2024; anyone offering crypto services in Germany requires authorisation as a crypto-asset service provider, granted and supervised in Germany by BaFin. What that authorisation demands of providers ranges from own-funds requirements through the separation of client money from the provider's own assets to ongoing reporting and disclosure duties towards the supervisor.
Three things to check before your first order. First, the provider's authorisation status, which you look up in the supervisor's public register and not on the provider's marketing page. Second, the total cost, meaning trading fee plus spread plus any withdrawal fee, because on small order sizes the spread decides the outcome more than the headline fee does. Third, the withdrawal route for moving the coins to a wallet of your own, because a balance on an exchange remains a claim against that exchange. Our crypto exchange comparison sets these points side by side for the providers available in Germany.
Chainlink tax: one-year holding period for spot, futures treatment for the perp
For tax purposes the spot purchase and leveraged trading are two different worlds, and anyone doing both is best served by keeping two separate sets of records.
Buying LINK on the spot market and selling it later counts as a private disposal under section 23 of the German Income Tax Act. If more than a year passes between purchase and sale, the gain is tax-free. Within the one-year period an exemption limit of 1,000 euros applies to the sum of all private disposals in a year. Exemption limit means that once it is exceeded, the entire gain becomes taxable and not merely the portion above it.
Gains from perpetual futures, by contrast, do not fall under the holding period. Such gains count as investment income and are treated as futures transactions, subject to 25 percent withholding tax plus the solidarity surcharge and, where applicable, church tax. There was one relief in 2024: the previous cap, under which losses from futures transactions could be offset only up to 20,000 euros a year, was abolished outright by the Annual Tax Act 2024 of December 2, 2024 and has not applied to any open case since. Law firm CMS has set out the legislative change in detail.
In practice that means documenting every transaction with its time, quantity and euro value, kept separately for spot and derivatives. Anyone who has to reconstruct that after the fact from exchange exports loses more time than the running effort would have cost. Which tools actually reflect German tax rules and which merely deliver a portfolio overview differs considerably; the relevant comparison is linked below. This section is no substitute for tax advice; for larger amounts or unclear cases the matter belongs with a tax adviser.
Staking LINK: why a running yield is no substitute for leverage
Chainlink offers staking of its own, in which LINK is locked up for a term and rewarded for it. We covered the points to check in detail on September 19, 2026 in our article on the price move above twelve dollars; the questions raised there about lock-up period, unbonding time and custody still apply unchanged.
For today's situation the distinction matters most. Staking and leveraged trading solve two different problems. Staking locks up capital you intend to hold anyway and delivers a running return on it at unchanged price risk. A leveraged contract raises price risk and delivers no running return; it costs financing instead. An investor looking for a yield finds it in the first instrument; one who wants to take a directional bet takes the second and sizes it accordingly small.
On custody, the unspectacular sentence holds, and it does not wear out: coins you intend to keep for longer than the holding period do not belong on a trading account. A hardware wallet costs a one-off sum and takes away the counterparty risk that every exchange inevitably brings with it.
Levels above and below: resistance at $14.50 and $15, support at $13.00 to $13.20
Technical levels are observations about how the market has behaved in the past, not a forecast. In its analysis of September 25, 2026, financial service FXStreet names the next notable resistance at around $14.50, followed by the round figure of $15; as the nearest support the service cites the zone between $13.00 and $13.20. The daily high of $14.19 therefore sits below the first resistance named.
What argues for a continuation and what argues against it
Arguing for a continuation is the combination of increased open interest and an unremarkable funding rate. That configuration describes a market in which new capital is arriving without the long side being financed at an inflated price. Such configurations have more room than those in which the financing costs have already run away.
Arguing against it is the wider picture. LINK is down 33.5 percent on the year, and the declining long-short ratio shows that part of the market is using the move to exit rather than to add. On top of that, the rise falls into a broadly friendly market environment; a pullback in Bitcoin would in all likelihood take LINK with it. Both readings stand alongside each other, and neither has been settled.
Checking the Chainlink breakout: what to take away
- Check your leverage against the daily range before you add to a position. Almost 14 percent between low and high means that ten times leverage would have been force-closed on paper today. Compare the funding and fee models in the perp DEX comparison before you open a leveraged position, because over a longer holding period the running costs weigh more heavily than the entry price.
- Settle your route to buying if you want in without leverage. Look up your provider's authorisation status in the supervisor's register, add the fee and the spread together, and check whether you can withdraw the coins to a wallet of your own. The side-by-side view of the trading venues available in Germany is in the crypto exchange comparison.
- Keep your records separate for spot and derivatives. The one-year holding period with its 1,000-euro exemption limit runs on the spot holding, while withholding tax on futures transactions applies to perpetual contracts. Which tools keep the two cleanly apart is shown by the crypto tax software comparison.
(As of September 25, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
The cross-chain protocol Universal is being wound down. Anyone holding uSOL, uXRP, uDOGE, uADA, uBTC or uLTC on Base can redeem these six tokens through a smart contract into the respective bridged counterpart after November 17, 2026. Anyone holding any of the other roughly 80 uAssets gets USDC. Until November 17 everything runs as normal: you can sell through the Universal app or redeem straight into the underlying asset held in reserve.
That makes the question you face clearly defined, and it has a date. Either you decide yourself by November 17 what happens to your position, or a contract decides it for you afterwards. For everything other than the six named tokens, that means a forced conversion into a dollar stablecoin, at a moment you did not choose. For holders in Germany there is also a tax question attached, which gets a section of its own further down.
What Universal announced on September 18
The team behind Universal announced the wind-down on September 18, 2026 on its own site. As its reason it states, in its own words, that adoption did not reach the scale that would have been needed to make the protocol viable in the long run. Over two years, Universal says it supported more than 80 underlying assets.
The timetable is short and unambiguously worded: "The Universal protocol will remain operational, business-as-usual, for the next 60 days, through November 17." During that period the uAssets remain backed by their underlying assets as usual, and the existing infrastructure stays in operation. After November 17 the protocol is wound down, and remaining uAssets become redeemable through a smart contract.
uAssets explained: what sits behind uSOL, uXRP and uDOGE
A uAsset is a token on one blockchain that represents an underlying asset from another blockchain and is backed one to one by that underlying asset. uSOL on Base therefore stands for Solana, uXRP for XRP and uDOGE for Dogecoin. The purpose of such constructions: an asset sitting on its home chain becomes tradable in a foreign ecosystem without having to switch chains.
From that follows the property that matters most for this deadline. A uAsset is a placeholder whose value hangs on the promise that somebody custodies the underlying asset and handles redemption. If the operator falls away, it is not the market that decides the placeholder's fate but the wind-down rule. That rule is exactly what Universal has now published.
The November 17 deadline: what stays unchanged until then
Up to and including November 17, 2026, nothing changes for you in the mechanics. Universal expressly undertakes to maintain the backing of the uAssets with their underlying assets and to provide relayer liquidity as usual. Two routes are open to you in that window.
- Selling through the Universal app. The protocol itself calls this the simplest route for most users wanting to close their position.
- Redeeming directly through the mint-and-redeem interface, if you want the underlying asset itself rather than sale proceeds.
One caveat is also in the announcement and belongs here rather than in the small print: because of the elevated number of redemptions during the wind-down, a direct redemption may take longer than usual for security reasons. So anyone waiting for the last day is planning with no buffer. For larger amounts, Universal points to contacting the team so the process can be coordinated.
After November 17: six uAssets get the original, the rest get USDC
For the period after the deadline, Universal has published a table. Six uAssets held on Base are then redeemable into their respective bridged counterpart:
| uAsset on Base | redeemable into |
|---|---|
| uSOL | SOL on Base |
| uXRP | cbXRP |
| uDOGE | cbDOGE |
| uADA | cbADA |
| uBTC | cbBTC |
| uLTC | cbLTC |
| all other uAssets | USDC |
The prefix cb stands for the bridged versions held on Base. Anyone holding one of the six tokens therefore swaps one placeholder for another and stays in the same underlying asset. Anyone holding one of the other roughly 80 uAssets leaves their underlying asset entirely and afterwards holds a dollar-pegged stablecoin.
Sell or redeem: which route is right for you
The decision comes down to a single question: do you want to stay invested in the underlying asset or not?
You want to stay invested. Then you redeem directly by November 17 and hold the underlying asset itself afterwards, or you take the bridged counterpart after the deadline if you hold one of the six named tokens. With all other uAssets that is not an option: there the link to the underlying asset ends on the deadline, and you would have to buy the asset back after the conversion with the USDC you receive, at whatever price applies then.
You want out. Then you sell through the app while the liquidity is being guaranteed. Anyone who waits meets a market everybody wants to leave at the same time, and at trading volumes that are small. How small is shown in the next section.
There is no third possibility. Doing nothing is a deferred swap for the six tokens and, for everything else, a conversion into USDC that you do not control.
Why waiting gets expensive: what market cap and daily turnover say
This is not a billion-dollar affair, and that is precisely the point. Our own query to CoinGecko on September 25, 2026 at around 12:49 UTC: uXRP shows a market capitalisation of roughly $2.95 million on daily turnover of about $279,000. uDOGE stands at around $341,000 market capitalisation and about $72,000 daily turnover.
Put those figures in proportion. With uXRP, daily turnover does not even amount to a tenth of the outstanding supply. If a meaningful share of holders wants to sell simultaneously in the last days before November 17, that supply meets a very thin market. The discount you would then accept is not market risk in the usual sense, but a consequence of the deadline.
The flip side: deciding early costs you little in this case. As long as Universal guarantees relayer liquidity and the backing is intact, you sell close to the price of the underlying asset. That is the real message in these numbers.
Is the peg still holding? Our own measurement on uXRP and uDOGE
A holder's first question is whether the placeholder still trades where its underlying asset stands. Measured at the same time, September 25, 2026 at around 12:49 UTC: uXRP trades at $1.60, XRP itself at $1.61. That is a discount of roughly 0.6 percent. uDOGE trades at $0.098152, dogecoin itself at $0.098275, so around 0.1 percent below. Solana stood at $120.40 at the same moment.
The peg is therefore holding, with a small discount that reflects the uncertainty about the wind-down. That is a snapshot and no guarantee for November 16. Anyone wanting to follow the situation themselves compares the price of the uAsset with the price of the underlying asset, ideally daily and from the same data source. If the discount widens noticeably, that is a sign the market is judging redemption less favourably than before.
What the caveat in the announcement means for you
On the published redemption table, Universal writes explicitly: "The redemption assets above reflect our current plans and are subject to change as the wind-down progresses." The mapping of which uAsset is redeemed into which asset is therefore provisional. The team says it will publish final details on redemption values, the smart contract and the exact procedure before November 17.
For you that sentence has a practical consequence. Planning around the table means planning around a statement of intent. Selling or redeeming directly before the deadline, by contrast, makes you independent of the final version. This is no reproach to the protocol, which communicates the caveat openly, but a trade-off you make for yourself.
Tax: why the forced conversion into USDC is a disposal
A private disposal transaction under section 23 of the German income tax act exists where an asset is disposed of again within one year of acquisition. A swap counts as a disposal, because you give up one asset and receive another. Anyone whose uAsset gets converted into USDC therefore has a transaction the tax office treats like a sale, even though a contract triggers it rather than you.
Three points follow that you should settle before November 17. First: if your acquisition is more than a year back, a gain is tax free under the law as it stands, and the timing of the conversion is immaterial to you. Second: if it is more recent, the gain counts among private disposal transactions, for which an exemption threshold of 1,000 euros per calendar year has applied since 2024. Third: by choosing when you sell you also decide which tax year the transaction falls into. Anyone converted only after November 17 no longer has that choice.
Unsettled is the treatment of redeeming a uAsset into its bridged counterpart, say from uXRP into cbXRP. Whether that constitutes a swap of two different assets or merely a change of technical wrapper has not been conclusively determined. Tools that carry acquisition dates and holding periods across such events are in our overview of crypto tax software and portfolio trackers. This section is not tax advice; with larger positions the individual case belongs with a tax adviser.
Where investors hold uAssets in the first place
uAssets are not tokens you find on a European-authorised trading platform. These tokens live on Base, an Ethereum layer 2, and are traded there through decentralised venues and the Universal app. Anyone holding them generally has them in a self-custodied wallet, not in an account with a provider holding European authorisation.
That has two consequences for this deadline. First, nobody will remind you. There is no provider dropping a deadline into your inbox, and no German-language outlet has picked the matter up so far. Second, the entire process is in your hands: you need access to the wallet holding the tokens, and some network fee on Base to be able to trade or redeem at all. Both are better checked now than on November 16.
Anyone wanting to carry on afterwards with the USDC received or the redeemed underlying asset will sooner or later come back to the question of where they trade and where they custody. Both are decisions in their own right, and neither should be made under time pressure.
Redeeming uAssets: what to take away
- Check by the end of October whether you hold any uAssets at all, and which. What matters is the distinction between the six tokens with a bridged counterpart and all the others, which end in USDC. If you then want to sell, you need a venue for the proceeds: our comparison of crypto exchanges shows which providers come into question.
- Decide early rather than on the deadline. Daily turnover is small, direct redemptions may take longer, and the redemption table carries a caveat. Anyone wanting to keep the underlying asset and custody it themselves will find suitable devices in our hardware wallet comparison.
- Settle the holding period before the contract decides for you. A conversion into USDC is a disposal for tax purposes. Which tools keep acquisition data and deadlines cleanly in view is set out in our overview of tax software and portfolio trackers.
The announcement in full is in Universal's wind-down notice of September 18, 2026; an independent report on it was published by PANews on September 20, 2026.
(As of September 25, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
Federal prosecutors are targeting a Montana payments firm and a Caribbean bank accused of moving money without a license.
Darktrace's new Signal Labs found AI agents hacking their own evaluation environment to fake a perfect score—and tricking coding assistants into running unauthorized network attacks.
Google's PageBreak agent autonomously finds and verifies real vulnerabilities in its own web apps, cutting through the flood of noisy AI-generated security reports.
The two stablecoin issuers blacklisted a wallet labeled "Bitget Exploiter 8," locking about $318,000 in USDC and USDT—but the attacker swapped most funds into unfreezable ETH before they could act.
Leaked code strings and screenshots point to a new tier that would cost 25 times more than ChatGPT Plus, aimed at people who need the bot to work faster, not just longer.
U.Today - IT, AI and Fintech Daily News for You Today
SEC Commissioner Hester Peirce, widely known as “Crypto Mom” for her influential role in shaping U.S. cryptocurrency policy, has formally submitted her resignation.
Bitcoin tests the key $83,000 level ahead of a crucial weekly close that could redefine the technical market framework for Q4 2026.
Binance has added two new crypto assets to its alpha platform, allowing its users access to exclusive investment opportunities.
CoinMarketCap has acquired CoinGlass, one of the crypto industry’s most widely used platforms for tracking Bitcoin, XRP, Shiba Inu and other tokens’ liquidations, open interest and derivatives activity.
Stellar (XLM) has overtaken Bitcoin Cash (BCH) in market capitalization as a fresh wave of buying pressure sends XLM higher over 13%.
Blockonomi
TLDR:
- Google PageBreak found more than 500 verified XSS vulnerabilities across company web applications after testing suspected exploits in live environments.
- Dedicated validators test JavaScript payloads and other attack paths, keeping false positives close to zero before reports reach engineers.
- Two XSS flaws surfaced among hundreds of applications built with high-assurance frameworks, limited to internal applications or debug endpoints.
- Google plans a closer link between PageBreak and CodeMender so teams can review generated fixes beside confirmed security findings.
Google PageBreak has identified more than 500 cross-site scripting flaws across the company’s first-party web applications. The AI security agent tests suspected weaknesses against working services before product teams receive a report. That validation step separates usable exploits from believable but faulty model-generated attack descriptions.
Google began PageBreak as a pilot in November 2025 and made it a formal project in January 2026. Google’s Product Security team said the system found XSS flaws on sensitive company domains. Google did not name the affected applications or disclose a severity breakdown. The figure covers its web application estate.
Google PageBreak Filters XSS Flaws Before Team Review
PageBreak sends each candidate issue to a dedicated validator rather than routing every alert to engineers. For an XSS vulnerability, the validator injects JavaScript into the relevant page and observes whether it executes. Google said that process holds false positives close to zero. It prevents untested claims from reaching product teams for review.
Google PageBreak also tests whether injected inputs alter database queries, expose files through path traversal, or trigger code execution. Another validator examines requests that may reach internal services. Those checks let the system assess several attack classes. They also keep reports focused on working paths.
Most scans use Gemini 3.1 Pro or Gemini 3.5 Flash. Separate tools perform the exploit checks. The validators do not come from the AI agent itself. Google repeats attempts because models can abandon a productive route. They can also pursue an attack path that fails under actual application conditions.
Unverified results do not leave the internal security workflow as confirmed bugs. Teams can use them to refine future scans or create additional validators. This distinction matters because language models can produce detailed security narratives. Those narratives may not reproduce when tested in an application.
Google said its system validates more than browser scripts. It can check whether an injected input changes a database query. It can also identify file exposure through path traversal. Each candidate needs an independent proof before engineers treat it as a vulnerability.
Google PageBreak Extends Testing into Repair Workflows
Google PageBreak found two XSS vulnerabilities among hundreds of applications built on its high-assurance web frameworks by September 4. Both cases involved internal applications or debug endpoints with missing protections. That count applies only to the framework group. It does not cover the more than 500 findings across Google’s wider application estate.
The result tests framework protections under repeated automated scans. PageBreak can inspect code paths across services through the company repository. Security data from live web traffic can connect a requested page with relevant source code. Existing scanners also provide authenticated access to internal sites.
That environment sets PageBreak apart from a public model scan. External researchers cannot usually inspect Google code, traffic data, or protected testing systems. Google PageBreak therefore reflects an internal security workflow with deep operational access. The count does not show that another organization could get the same result by running Gemini alone.
Google plans to connect Google PageBreak more closely with CodeMender, an agent designed to generate security fixes. Product teams could then review a proposed repair beside a confirmed vulnerability. The company said the pairing could reduce work created by a large volume of verified findings. Google gave no timetable for integration.
Comparable verification problems affect crypto software, where AI tools can create many plausible reports. The Ethereum Foundation has used separate reviewers to reproduce agent-generated findings. A Bitcoin Red Team scan found only 24.7% of reported issues had reproducible proofs at the time. Google has not said it will make PageBreak available to external projects.
The post Google PageBreak Finds More Than 500 XSS Flaws Across Web Apps appeared first on Blockonomi.
TLDR:
- Buybacks on functional crypto systems don’t signal a promise of essential managerial efforts.
- Non-functional systems face stricter scrutiny if buybacks are framed as yielding returns.
- Staking Receipt Tokens may qualify as digital commodities under certain issuer structures.
- SEC staff stress these FAQs are nonbinding and carry no legal force or effect.
The U.S. Securities and Exchange Commission staff released new FAQs on September 25 clarifying how token buybacks and liquid staking fit within federal securities laws.
The guidance explains that announcing a buyback of a non-security token on a functional crypto system does not amount to a promise of essential managerial efforts.
This distinction matters for issuers navigating the Howey test and determining whether their tokens qualify as investment contracts under current SEC interpretations.
Buyback Programs and Functional Systems
The FAQs, issued by the Division of Corporation Finance, address a common industry practice. Issuers often run buyback programs for treasury management, supply reduction, or rebalancing purposes.
According to the new guidance, these announcements do not constitute a promise to undertake essential managerial efforts when the underlying crypto system is already functional.
The analysis changes for systems that are not yet functional. A buyback announcement could be treated as such a promise if the issuer frames it as “creating yield or return for token holders,” according to the FAQs.
This distinction ties directly into the Howey test, which examines whether purchasers expect profits based on the efforts of others.
Journalist Eleanor Terrett summarized the update on X, writing that the new FAQs are “clarifying how the Commission’s March interpretive release” applies to token functionality and staking receipts. She added that the guidance reflects staff views only and carries no legal force.
NEW: SEC staff has issued new FAQs clarifying how the Commission’s March interpretive release on digital assets applies to token functionality, staking receipt tokens and investment contracts.
Among the guidance: once a network is functional, services to maintain, improve or… pic.twitter.com/jxOiWGLQN9
— Eleanor Terrett (@EleanorTerrett) September 25, 2026
The FAQs also reaffirm an earlier position from the Commission’s August proposing release. Securing, maintaining, or enhancing a functional system does not involve essential managerial efforts. The same applies to funding or sponsoring development projects that support network effects.
Staking Receipt Tokens and Classification Guidance
The FAQs further address how Staking Receipt Tokens are classified under the Interpretive Release. A receipt tied to a digital commodity that is not subject to an investment contract functions as a digital tool. It evidences ownership of an underlying asset rather than creating new financial rights.
However, classification can shift depending on the issuer. A Staking Receipt Token issued by a protocol-based Liquid Staking Provider may itself qualify as a digital commodity.
Its value derives from the programmatic operation of a functional crypto system, alongside ordinary supply and demand dynamics.
The staff also clarified how promotional language factors into the analysis. Promoting a system’s current utility and capabilities likely does not, on its own, create a promise of managerial efforts. Indefinite statements about future utility receive similar treatment when profit potential is not mentioned.
Notably, the document states the answers have “no legal force or effect” and do not alter existing law. Issuers and market participants should treat the guidance as interpretive context rather than binding regulation.
The post SEC Staff Clarifies Token Buybacks and Liquid Staking in New FAQs appeared first on Blockonomi.
TLDR:
- Bybit’s Restricted Counterparty List includes Garantex, Bitzlato, EXMO, Payeer and dozens of platforms.
- The list also names Lazarus Group, Hamas, Ansarallah and ISIS-K as sanctioned organizations.
- Bybit screens transactions on an ongoing basis and may suspend accounts linked to violators.
- Huione Guarantee and Xinbi Guarantee face scrutiny over facilitating illicit fund transfers in Asia
Bybit has released a comprehensive Restricted Counterparty List identifying crypto platforms, wallets, and organizations barred from its services.
The list spans trading platforms, payment processors, mixers, darknet markets, and sanctioned entities such as Lazarus Group, Hamas, Ansarallah, and ISIS-K.
The exchange said it actively screens transactions against these names and reserves the right to suspend accounts, block funds, and report violations to regulators.
Bybit Names Dozens of Restricted Platforms and Services
The Restricted Counterparty List includes well-known names such as Garantex, Bitzlato, EXMO, Payeer, and Nobitex. Other flagged platforms include Bitpapa, Chatex, Cryptex, Grinex, and Rapira. The exchange also named WhiteBird, OMPFinex, Ramzinex, HTX, and Wallex among restricted services.
Additional entries cover Tetherland, Bit24, QvaPay, and two guarantee marketplaces, Huione Guarantee and Xinbi Guarantee. These marketplaces have drawn scrutiny for facilitating illicit fund transfers across Southeast Asia.
Mixing services Samourai Wallet, Bitcoin Fog, and ChipMixer appear on the list as well, alongside darknet markets Sinbad and Hydra Market.
Bybit cited its Platform Terms and Conditions as the basis for the restrictions. Under Section 23 of these terms, and Section 28 of the BVAPO Terms, the exchange does not offer services to entities designated under applicable sanctions frameworks.
This includes names on the U.S. Treasury’s Specially Designated Nationals list, the EU’s Consolidated Financial Sanctions List, and equivalent registries maintained by competent authorities worldwide.
The exchange said its screening process runs on an ongoing basis rather than as a one-time check. Where a connection to a prohibited entity is identified, Bybit may suspend or terminate accounts linked to that entity. It may also block related transactions, file regulatory reports, and liquidate open positions tied to the account.
Sanctioned Organizations and Compliance Obligations Outlined
Beyond crypto platforms, the list names organizations tied to security concerns, including Lazarus Group, also known as Hidden Cobra.
Hamas, referred to as the Islamic Resistance Movement, appears alongside Ansarallah, commonly known as the Houthis. ISIS-K, listed as ISIS-Khorasan, rounds out the named organizations.
Bybit outlined user obligations tied to these restrictions in its terms. Users who transact with, transfer funds to, or otherwise engage with a prohibited entity violate the platform’s terms. Users who become aware of such a transaction are required to inform Bybit immediately under the policy.
The exchange stated it reserves the right to take all necessary steps to maintain compliance with applicable laws. This includes cooperation with regulatory bodies and law enforcement authorities across relevant jurisdictions. Bybit did not specify a timeline for updates to the list.
The move reflects a broader pattern among major exchanges tightening compliance amid rising regulatory pressure. Platforms handling sanctioned counterparties face growing scrutiny from global financial watchdogs.
Bybit’s published list gives users a reference point for avoiding inadvertent violations tied to these entities.
The post Bybit Unveils Restricted Counterparty List, Blacklists Lazarus Group and Dozens of Crypto Platforms appeared first on Blockonomi.
TLDR
- Meta stock drops 3.35% as shares move toward the $750 support zone
- Meta introduces Muse AI features for its growing smart glasses lineup
- Charm device expands access to Meta’s consumer AI technology ecosystem
- The company plans over 100 AI glasses styles by year-end
- Meta continues building wearable AI products beyond smartphones
Meta Platforms (META) shares traded at $751.51, down 3.35%, after selling pressure pushed the stock lower from the $770 area toward the $750 support zone. The decline followed Meta’s announcement of new AI glasses features linked to its Muse agent and Charm device. The company continues expanding its consumer AI strategy through wearable technology and connected devices.
Meta Platforms, Inc., META
Meta Stock Falls After New AI Glasses Developments
Meta Platforms reported plans to bring Muse capabilities to its AI glasses lineup as the company expands its consumer AI products. The feature allows the glasses to respond to what users see and support tasks during ongoing conversations. Meta also introduced Charm, a smaller device designed for users to interact with Muse.
The company stated that Muse will support functions such as shopping, payments, work integrations, and daily assistance. Meanwhile, Meta plans to expand its AI glasses range to more than 100 styles by year-end. The move strengthens Meta’s focus on wearable devices beyond traditional smartphone-based experiences.
META shares fell during the trading session on September 25, 2026. Shares fell 2.8% to $755.815 at 10:13 am ET before continuing the broader intraday decline. The stock later traded near $751.51 as selling pressure remained active.
Meta Expands Muse Across Wearable Technology
Meta’s AI glasses strategy builds on the company’s efforts to combine hardware, software, and artificial intelligence features. The company aims to increase daily usage through devices that provide direct access to its AI services. The expansion adds another layer to Meta’s existing social media and technology operations.
Muse will include features that connect users with digital services while using Meta’s glasses. The system will also have its own email address, which supports broader communication features. These updates position Meta’s glasses as a central part of its consumer technology roadmap.
The company has continued investing heavily in artificial intelligence products and infrastructure. Meta has introduced several AI-focused initiatives across its platforms, including social applications and hardware products. The latest announcement highlights its effort to expand AI access through physical devices.
META Valuation Reflects AI Growth Focus
Meta’s valuation snapshot on September 25 placed the company below its GF Value estimate of $856.24. The figure showed META trading 11.73% below that estimate. The valuation data does not confirm future performance but reflects current market calculations.
The company’s future revenue opportunities from Muse depend on adoption of its AI glasses and related services. Meta has highlighted areas such as subscriptions, purchases and advertising as potential business models. However, the company has not provided confirmed revenue figures from Muse.
Meta continues to develop its AI ecosystem while maintaining its core advertising business. The company’s wearable technology expansion adds a new product category alongside its existing platforms. META shares remain focused on market reactions as the company advances its AI glasses plans.
The post Meta Platforms (META) Stock: Drops as AI Glasses Push Muse Into the Spotlight appeared first on Blockonomi.
TLDR
- NetApp NTAP shares gained as PEAK:AIO acquisition plans boosted AI infrastructure focus
- PEAK:AIO technology will expand NetApp’s metadata and file system capabilities
- The deal aims to support larger data environments and advanced workloads
- NetApp combines ONTAP expertise with PEAK:AIO scalable architecture solutions
- Acquisition strengthens NetApp’s position in the evolving infrastructure market
NetApp, Inc. (NTAP) shares gained 1.48% to $200.16 as the company announced plans to acquire PEAK. The deal targets stronger AI infrastructure capabilities by adding advanced metadata architecture and parallel file system technology. NetApp expects the acquisition to improve large-scale data management for growing AI workloads.
NetApp, Inc., NTAP
NetApp Expands AI Infrastructure Strategy Through PEAK Deal
NetApp announced its agreement to acquire PEAK, a company focused on high-performance metadata systems. The transaction supports NetApp’s strategy to build infrastructure for expanding enterprise AI applications. Furthermore, the deal adds specialized technology to its existing data management portfolio.
The acquisition combines PEAK’s metadata architecture with NetApp’s ONTAP software platform. This integration aims to improve storage performance for large computing environments. Therefore, organizations can access stronger systems for handling complex and data-intensive workloads.
PEAK developed technology designed for demanding computing operations with support from research institutions. The company created solutions that improve metadata scaling and global file access. Consequently, NetApp plans to use these capabilities to support larger data environments.
NetApp Targets Scalable Storage Growth With Advanced Data Systems
NetApp stated that the combined platform will support massive file environments and multi-exabyte deployments. The architecture separates metadata services from stored data to improve scalability. In addition, the approach helps organizations manage growing infrastructure requirements.
The planned integration introduces parallel access features for large-scale workloads. NetApp will maintain its focus on security, resilience, and operational simplicity. Meanwhile, PEAK technology will expand options for customers managing advanced computing systems.
The acquisition reflects rising demand for infrastructure that supports modern data operations. Companies continue developing larger computing environments that require faster and more efficient storage solutions. As a result, NetApp aims to strengthen its position in the expanding infrastructure market.
The company expects PEAK’s technology to complement its existing product ecosystem. The integration will focus on improving performance across demanding workloads. Additionally, NetApp will provide global resources and operational expertise to expand adoption.
The acquisition adds another step in NetApp’s long-term infrastructure development strategy. The company continues adapting its offerings for changing enterprise technology needs. Through the PEAK transaction, NetApp seeks to deliver more scalable data solutions for future workloads.
The post NetApp, Inc. (NTAP) Stock: Rise as PEAK:AIO Acquisition Targets AI Infrastructure Growth appeared first on Blockonomi.
CryptoPotato
HIFI, the New York stablecoin infrastructure company that took part in DTCC’s July tokenized securities trades, raised a $37 million Series A led by Left Lane Capital, it said on Thursday, with the money going to licenses, cards and capital markets.
Matthew Miller, Managing Partner at Left Lane Capital, joins the board. HIFI said its platform moves more than $7 billion a year and that usage among existing customers has grown more than fourfold in six months.
Companies building on it have also onboarded more than 10,000 businesses and 200,000 individuals, with payouts reaching 87 countries, the team stated.
Repo Trades and Visa Payouts
Sumitomo is rebuilding its cash management and trading operations on the platform, Dapper is building digital marketplaces on it, and Arival Bank uses it for stablecoin payments.
A Form D that HIFI Bridge, Inc. filed with the SEC on September 3 covers a $27.3 million equity offering, $21.8 million of which has been sold to 24 investors since a first sale on August 19.
DTCC ran production trades with tokenized DTC-held securities on July 15 across more than 30 firms, among them BlackRock, Goldman Sachs, J.P. Morgan and Nasdaq, covering collateral pledges, securities lending and Treasury and repo settlement, before an October launch of its tokenization service.
HIFI said it was part of the tokenized repo pilot and also supported a live tokenized repo trade on Tradeweb between DRW and Marex, settled on Canton with USDCx as the cash leg. This month HIFI launched stablecoin push-to-card payouts through Visa Direct, starting with payouts to more than 4 billion Visa cards worldwide, and has integrated with the Circle Payments Network.
Visa and DTCC are founding validators of Circle’s Arc blockchain alongside BlackRock, Mastercard and Standard Chartered.
“We think of settlement as one problem, not three,” said Zach Walsh, CEO of HIFI.
Licenses, Cards and Capital Markets
The round will pay for additional regulatory licenses so more of the stack runs under HIFI directly, a bigger team in New York and abroad, and an extension from payments into cards and capital markets, where Walsh said custody and control remain the hardest problems.
Payment stablecoins gained a federal framework under the GENIUS Act in July 2025, and stablecoin supply stands near $307 billion, per Blockworks.
On the securities side, the SEC issued an Innovation Exemption on September 17 that lets permissioned venues trade tokenized US stocks onchain.
“HIFI is building an important layer in that market, giving developers the infrastructure to create products that can operate across networks and borders,” Miller said.
The post HIFI Raises $37M Series A to Build Settlement Rails for Tokenized Money appeared first on CryptoPotato.
KelpDAO has filed a lawsuit against LayerZero and its co-founder Bryan Pellegrino, accusing the bridge provider of security failures behind the $292 million exploit of its rsETH token in April.
The suit, filed in British Columbia, is KelpDAO’s most direct attempt yet to hold LayerZero accountable after months of public disagreement over what caused the breach.
KelpDAO Accuses LayerZero of Security Failures
In a statement posted on X on September 25, KelpDAO alleged that the exploit resulted from LayerZero’s failure to disclose weaknesses in its technology and prevent an infiltration of its security infrastructure.
“Rather than take responsibility, over the last few months, LayerZero and Mr. Pellegrino publicly blamed us for their failures,” KelpDAO stated. “But the record is straightforward: LayerZero reviewed and endorsed—in writing—our deployment and configuration of LayerZero’s technology.”
That directly challenges LayerZero’s argument that the attack was isolated to KelpDAO’s rsETH configuration because the bridge used a 1-of-1 Decentralized Verifier Network, or DVN.
Under that setup, LayerZero’s own DVN was the sole verifier, meaning a forged cross-chain message could be accepted without a second independent verifier rejecting it.
LayerZero maintained that it had recommended using multiple DVNs to avoid such a single point of failure. But KelpDAO pushed back on that account in a May 6 report. The protocol argued that the 1-of-1 configuration was not an unusual setup chosen against LayerZero’s guidance. Instead, it claimed the configuration followed LayerZero’s official documentation and default deployment practices.
Up until supposed white-hat hackers drained $320 million from Liquid Network (most of which was returned) and today’s $351 million Bitget hot wallet breach, the KelpDAO incident had been the largest crypto security exploit of 2026.
Cyvers at the time estimated that about $293.7 million in rsETH was drained, with the attacker moving the assets into ETH across Ethereum and Arbitrum, while lending protocols including Aave V3, Compound V3, and Euler were also affected.
Pellegrino Ready to Defend Himself
In its own words, KelpDAO wants to set the record straight and “hold LayerZero and Mr. Pellegrino accountable for the harm they have caused.”
And the LayerZero CEO responded within hours on X, confirming that Evercrest, KelpDAO’s parent entity, had filed a notice of civil claim against him and his company in British Columbia.
“The claim continues to be meritless, will meet them in Vancouver and defend myself accordingly,” he wrote.
Also on X, Solana Foundation’s Seraphim Czecker summed up the mood around founding DeFi as something closer to a Game of Thrones plotline, where you are either at the top making hundreds of millions of dollars or your business is suffocating and dying.
“If you get hacked, you get sued into oblivion and lose years to court battles,” he added.
The post KelpDAO Sues LayerZero and CEO Bryan Pellegrino Over $292M Hack appeared first on CryptoPotato.
On September 25, a wallet linked to pseudonymous security researcher Quit pulled 3,832 NFTs out of hundreds of unrelated wallets, the first visible sign of a rescue operation built around a bug in LimitBreak’s Payment Processor V2 contract.
The operation eventually relocated 23,155 NFTs worth nearly $6 million, while a separate exploit path left 660 WETH unrecovered.
White Hat Operation Moves Thousands of NFTs
The incident first drew attention when NFT trader Cirrus reported that a wallet had drained 3,832 NFTs from more than 100 wallets. Quit, who is also the VP of Blockchain at Yuga Labs, later confirmed that the transfers were part of a white-hat operation.
“Everything in 0x71cF3f5724bD2B72Ef6464992aCd26216DE7fe33 is safe and will be returned once they are no longer at risk,” the researcher wrote.
They explained that the underlying issue involved Payment Processor V2. At 9 a.m. EST, an attacker used the bug to take 10 Meebits, 50 Otherdeeds, 10 World of Women NFTs, and 235 Despertae Apewives.
Quit then found that many other NFTs were exposed to the same vulnerability, but the situation was complicated by the fact that V2 could not be paused. LimitBreak was able to pause Payment Processor V3 after being contacted, but V3 on ApeChain also temporarily could not be paused.
“The only path towards protecting affected assets was to run a whitehat operation,” noted Quit.
In total, 23,155 NFTs were rescued, with the researcher estimating their value at approximately $6 million. Owners will later be able to claim the assets after revoking the vulnerable approvals.
However, the rescue did not recover every asset exposed to the flaw, as Quit later found that the vulnerability could also be exploited in reverse to steal WETH, putting 660WETH at risk.
“Worked through the entire night to save ~$6M worth of NFTs and all I’ll be able to think about is the $1.7M in WETH I wasn’t fast enough for,” they said on X.
A Second Breach the Same Day
The NFT incident happened nearly the same time as a breach on Bitget, where hackers moved more than $351 million from a portion of its hot and warm wallets, while cold storage, holding most of the exchange’s assets, stayed untouched.
As CryptoPotato reported earlier today, Bitget chief executive Gracy Chen attributed the loss to a compromised backend system that allowed an attacker to spoof transaction data rather than a stolen private key. She also said that affected customers will be reimbursed, with the money coming from Bitget’s $464 million user protection fund.
XRP made up the largest single share of cryptocurrency that was stolen, with over 100 million units worth upward of $158 million spread across a handful of wallets.
The post White Hat Operation Rescues 23K NFTs After Payment Processor Exploit appeared first on CryptoPotato.
The world’s largest cryptocurrency exchange announced a delisting move that will primarily affect its Ukrainian clients.
Binance has been making headlines lately amid regulatory challenges in the European Union, and reports say US prosecutors have been examining alleged Iran-linked trading on the platform.
The Latest Announcement
Binance revealed that it will close UAH deposits and withdrawals via Fiat Trade UAH and delist the USDT/UAH spot trading pair. These services will no longer be supported after September 28.
“All open orders on the USDT/UAH Spot trading pair will be automatically removed after trading ceases. Users are advised to manage their UAH balances and open orders before the above deadlines,” the company clarified.
The exchange also said it will automatically convert all remaining UAH balances to USDT by September 30. No action is required from users who choose this option.
UAH is the symbol for the Ukrainian hryvnia, the official currency of the Eastern European country. The move is likely to disappoint some of the local users, as it means one less gateway between the domestic financial system and the crypto market.
Ukraine has in fact emerged as a stronghold for Binance, with millions of Ukrainians using its services. Earlier this year, the company focused on some of its strongest markets and launched seven new official WhatsApp channels. One of those is specifically dedicated to users in Ukraine.
Binance’s Issues
The European Union’s MiCA regulatory framework took effect on July 1, and crypto platforms that couldn’t obtain the required license were not allowed to offer services to local clients. Binance, which applied through Greece, was rejected, and many users indeed reported disruptions.
Earlier this month, The Wall Street Journal disclosed that Christine Lagarde (President of the European Central Bank) has personally asked Greek Prime Minister Kyriakos Mitsotakis to block Binance’s bid for permission. According to the media outlet, the main reasons are the company’s earlier guilty plea to US money laundering and sanctions violations, and fears that allowing the entity into Europe would push more people toward dollar stablecoins just as the ECB was trying to launch its own digital euro.
Meanwhile, Binance recently faced a new investigation in the United States over potential violations of sanctions on Iran. According to Bloomberg, local authorities have been examining whether the exchange enabled certain trading activity linked to the Asian country on its platform.
Recall that in 2023, the firm agreed to plead guilty and pay $4.3 billion in penalties to resolve US anti-money-laundering, sanctions, and money-transmission violations. At the time, its former CEO, Changpeng Zhao (CZ), was sent behind bars for four months and paid a $50 million fine. Donald Trump later granted him a presidential pardon.
The post Important Binance Announcement Concerning Ukrainian Users: What’s Happening? appeared first on CryptoPotato.
DeFi protocol Ethena (ENA) announced a partnership with Binance and began backing USDe with stocks on Friday, essentially buying the exchange’s bStocks and shorting its matching equity perpetuals to earn the funding that leveraged longs pay.
Ethena is partnering with @Binance as our first venue for the extension of the basis trade into equity perpetuals, one of the most exciting updates to the USDe collateral backing since launch.
This expands the addressable market of underlying collateral from $2.5 trillion of… pic.twitter.com/be4Mz7XHk1
— Ethena (@ethena) September 25, 2026
Ethena Seeks To Break Records In Crypto Perpetuals
It is the same hedged trade that has backed the $4.9 billion synthetic dollar with crypto since launch, and also the same structure that Ethena has run on Bitcoin (BTC), Ether (ETH), and Solana (SOL).
In other words: hold the spot asset, short the perpetual, and collect the funding that leveraged longs pay. Here, the spot leg is a bStock, issued by Binance affiliate BTech Holdings Limited and backed one-for-one by custodied shares.
Ethena said in its post on X that Binance’s equity basis has averaged about 11% annualized over the past six months, and that the exchange gives eligible delta-neutral accounts (Ethena’s among them) lower priority in auto-deleveraging.
“We expect the market opportunity size for equity perpetuals to far exceed the $15b+ of crypto perpetuals captured by Ethena last cycle,” the company wrote.
Flagging bStock Terms
The allocation follows a framework Kairos Research wrote for the Ethena Risk Committee. A name qualifies on $25 million of perpetual open interest over 14 days, 30 days of funding history, and a matching tokenized stock on the same venue, among other conditions.
Seventeen of Binance’s 67 pairs passed, Nvidia, Tesla, and SpaceX among them, on a venue holding $2.14 billion of the $2.9 billion measured across four exchanges.
Across 37 earnings events, the underlying stocks gapped 9.9% on average while the hedged position moved 20.3 basis points. Carry on the approved Binance names had halved in a month to about 7%, with two names negative. The report made bStocks approval conditional on a side letter with the issuer, because holders have no proprietary interest in the backing shares and every bStock contract sits behind a single upgrade key.
CryptoQuant data showed Binance handling 76% of the $250 billion in equity perpetual volume traded in July, and its tokenized U.S. equities reached $100 million in assets within two weeks of their June launch. ENA traded at $0.24 on Friday, up 12% in 24 hours, per CoinGecko.
USDe supply peaked at $14.8 billion on October 4, 2025, per DefiLlama. Ethena last widened the collateral this way when it added Bitcoin to USDe’s backing in April 2024, with supply at $2 billion.
The post Ethena Partners With Binance to Back USDe With a Tokenized Stock Basis Trade appeared first on CryptoPotato.