Cryptocurrency Posts
Crypto Briefing
AI-driven investments may strain supply chains, potentially elevating inflation risks, while productivity gains remain uncertain in timing.
The post Fed’s Lisa Cook warns AI spending could fuel inflation into 2027 appeared first on Crypto Briefing.
Increased scrutiny on Nvidia's oversight could lead to tighter export controls, impacting global chip trade and geopolitical tech dynamics.
The post US officials question Nvidia’s oversight as restricted chips reach China appeared first on Crypto Briefing.
The exploit highlights the critical need for rigorous security audits of third-party modules in DeFi, as vulnerabilities can lead to significant financial losses.
The post Aave v3 exploit drains up to $310K after Safe module attack appeared first on Crypto Briefing.
New Zealand's policy could drive renewable energy growth, attract significant AI investment, and stabilize electricity costs for consumers.
The post New Zealand’s National Party wants data centers to bring their own power appeared first on Crypto Briefing.
The arrest highlights escalating tensions in US-China tech relations, potentially tightening export controls and scrutiny on global tech supply chains.
The post California man arrested over alleged $300 million Nvidia AI chip smuggling scheme to China appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Frank Holmes: They Will Print $100 Trillion – Why to Buy Bitcoin & Gold
Bitcoin miners already have the power, the land, and the substations that AI needs. Frank Holmes, executive chairman of HIVE Digital Technologies, explains why he calls Bitcoin mining a “tier one” data center, how GPUs that once mined Ethereum led HIVE into AI, and why he thinks the next wave of AI factories will be built on mining infrastructure from Paraguay to Canada.
Chapters:
0:00 Frank Holmes on HIVE: From Gold Investor to Bitcoin Miner to AI Compute
2:12 How ETFs Changed Bitcoin: From the Fear Trade to the Love Trade
4:20 The Binance $19 Billion Liquidation and the $350 Trillion Money Supply
5:45 Gamers, Younger Quants, and Why Bitcoin Will Keep Gaining Adoption
7:29 Covid’s $40 Trillion of Money Printing and the Global MMT Risk
9:24 China, Russia, and Why Bitcoin Is a Tier One Data Center
11:33 China’s Bitcoin Mining, $1.4 Trillion of Lending, and Central Banks Buying Gold
13:44 Paraguay’s Central Bank and Bitcoin Mining as an Export
14:57 Compute as a Commodity: Canada’s AI Push and Bitcoin Miners’ Power Advantage
20:34 Where to Find Frank Holmes’s Weekly Investor Alert Newsletter
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Frank Holmes: They Will Print $100 Trillion – Why to Buy Bitcoin & Gold first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Nico Lechuga: Bitcoin Will Revolutionize the $4T Private Equity Industry
Traditional private equity is always on a clock, says Nico Lechuga. Funds run seven to ten years, so businesses get flipped in three to five. Lechuga, a founding partner at Ego Death Capital and co-founder of ORANGE JUICE, explains how permanent capital and a Bitcoin treasury could give owner-operators another option.
Chapters:
0:00 Meet Nico Lechuga of ego death capital and ORANGE JUICE
0:31 Why Private Equity’s Fund Model Keeps Owners on a Clock
1:16 What Makes a Good Acquisition Target for a Permanent Holding Company
3:11 Bitcoin or Another Business: How Free Cash Flow Gets Allocated
4:33 Why Debt Is a Drag and How Permanent Capital Differs
7:23 Owner-Operators as Frontline Intelligence, and the Role of Roll-Ups
9:12 How to Tell a Real Bitcoin Business From a Pitch
11:30 Competing With MBA Search Funds for Small Businesses
12:29 Brand as an Edge: The People Behind ORANGE JUICE
13:34 Acquisition Currency and Crossing the Chasm
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Nico Lechuga: Bitcoin Will Revolutionize the $4T Private Equity Industry first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Darius Dale: Will Global Liquidity Send Bitcoin Higher in 2027?
Are we headed for a period of chop before a bigger move in Bitcoin? Darius Dale, founder of 42 Macro, says a decline in funding liquidity could mean near-term volatility, but that if liquidity comes back in 2027, which he sees as more likely than not, Bitcoin could resolve higher over the following 12 to 18 months. He also explains why Bitcoin deserves a portfolio allocation as a different exposure from stocks and gold.
Chapters:
0:00 Darius Dale on Who Benefits From Rising Treasury Yields
1:06 Why Higher Rates Haven’t Hit the Economy Yet: The AI Capex Boom
2:02 Default via Debasement and a Fed–Treasury Accord 2.0
4:30 Five Paths Out of the Debt Problem, and Only Three Are Acceptable
6:32 Risk Management, Asset Allocation, and Why No Bonds
8:22 Bitcoin Outlook: Near-Term Chop and the 2027 Liquidity Case
9:34 Bitcoin’s Role vs. Gold and Stocks, and Where Bond Yields Reach Fair Value
10:53 The “Wealth Pump” and Money in Politics
17:09 Why AI Is Too Big to Fail and What a Bust Would Look Like
19:11 Running for Office, Why He’s Not a Socialist, and Jackie Robinson
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Darius Dale: Will Global Liquidity Send Bitcoin Higher in 2027? first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
SEC Proposes New Rules On Crypto Custody
The U.S. Securities and Exchange Commission has proposed new rules to update how investment advisers and regulated funds hold assets, with a big focus on crypto.
In a statement Thursday, the Wall Street watchdog said it would allow advisers and funds acting through their advisers, to hold client crypto themselves, but only if no permitted custodian is available.
Regulators are pushing ahead with rulemaking for the digital asset space despite lawmakers blocking the Clarity Act last month.
JUST IN:
— Bitcoin Magazine (@BitcoinMagazine) October 1, 2026SEC Chairman Paul Atkins releases a statement to address the custody of crypto assets.
"Since the advent of Bitcoin in 2008, the crypto asset market has grown from a niche curiosity into a multi-trillion-dollar asset class"pic.twitter.com/SbLR2HAeW1

The long-awaited legislation — a framework for distinguishing between digital assets that are securities, commodities or payment stablecoins — didn’t get the votes needed to advance.
“Since the advent of Bitcoin in 2008, the crypto asset market has grown from a niche curiosity into a multi-trillion-dollar asset class to which investors actively seek exposure. Unfortunately, our rules and regulations have not kept pace,” SEC Chairman Paul S. Atkins said in a statement.
“To that end, today’s proposal would provide a clear regulatory framework for the custody of crypto assets, giving investment advisers and funds a compliant pathway where none existed before — and replacing the grey of uncertainty created by custody rules crafted for a bygone era.”
The regulator said in its proposed rules that records kept on a blockchain could count toward compliance, subject to conditions.
It added that it would allow use of state trust companies as custodians for client and regulated fund crypto assets, subject to conditions.
Lawmakers blocked the Clarity Act in a procedural vote last month. Regulators had said before the vote that regardless of whether the landmark legislation passed, they’d still start regulating the crypto industry.
The SEC before the vote sent a proposal to the White House aiming to “clarify the framework for the custody of crypto assets” for investment advisers and companies.
Pro-crypto Atkins said he would still work to make the U.S. the “crypto capital of the world” regardless of the landmark legislation getting through.
This post SEC Proposes New Rules On Crypto Custody first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Sazmining Launches the Wild Sats Club, a Loyalty Program That Discounts Mining Management Fees as Customer Hashrate Grows
Most mining customers pay the same management fee whether they run a quarter of a petahash or twenty-five. The Wild Sats Club ties that fee to the hashrate a customer already runs with Sazmining, and applies the lower rate across their entire fleet, not just to newly purchased machines.
The Phase 1 discount starts at 1.0 PH with a 1% management fee discount, rising to 3% from 2.5 PH and 6% from 5.0 PH, with the tier recalculated every month. A customer activates once with a qualifying purchase from Sazmining that meets the hashrate to activate: 0.25 PH for Bronze, 0.50 PH for Silver, or 1.0 PH for Gold, in a single order or in orders within a 30 day period. New, pre-owned, and refurbished rigs purchased from Sazmining can qualify. Full terms are at https://www.sazmining.com/wildsatsclub/terms
Customers who make a qualifying purchase during the founding-member window, September 1 to December 31, 2026, activate at their full earned tier, with the lower fee starting on their first monthly recalculation after their new hardware is energized. Every benefit at launch is a management fee discount, never cash or transferable value.
“Mining customers have been asked to accept the same fee whether they run a quarter of a petahash or twenty-five,” said Kent Halliburton, CEO and Co-Founder of Sazmining. “This program fixes that. As a customer’s hashrate grows, their cost of having us run it comes down, and it comes down on everything they already own. We are building long-term relationships with our clients, not one-off transactions, which means advising them on what fleet growth can realistically look like against the goals they are actually trying to reach. We expect this program to appeal in particular to the family offices that want Bitcoin exposure with the depreciation benefits of owning the equipment, real estate investors looking to diversify, and the customers who are simply growing one rig at a time. We are looking forward to adapting and evolving the program so that Sazmining customers keep getting the very best product we can build.”
The program is built to keep opening up as customers grow with Sazmining. Further member benefits will be announced as each becomes available.
To learn more about the Wild Sats Club, visit the program page, or book a consultation with one of Sazmining’s Bitcoin Strategy Advisors here.
Disclaimer: This is a sponsored press release. Readers are encouraged to perform their own due diligence before acting on any information presented in this article.
This post Sazmining Launches the Wild Sats Club, a Loyalty Program That Discounts Mining Management Fees as Customer Hashrate Grows first appeared on Bitcoin Magazine and is written by Bitcoin Magazine.
CryptoSlate
Bitget said on Sept. 30 that it had restored its Protection Fund to more than $300 million after absorbing the Sept. 24 security breach's financial impact. The exchange describes the fund as an additional safeguard for customers, separate from reserves backing their account balances.
In its announcement, Bitget says the fund absorbed approximately $388 million in impact from the incident, while customer balances remained accurate and unaffected. It says it fulfilled a Sept. 28 pledge to bring the fund back to at least $300 million within a week, completing the replenishment two days after that commitment.
The release does not quantify the new capital contributed, and Bitget's fund page says its displayed valuation uses prices at midnight UTC each day.
What the restored backstop covers
Under Bitget's published fund conditions, users may submit claims when accounts are compromised, or assets are stolen or lost through platform-wide events not attributable to their own actions or trading behavior.
The exchange retains the right to assess claims and investigate affected accounts or assets, with outcomes subject to its findings.
Eligibility to submit a claim does not guarantee reimbursement of a particular loss. The reported replenishment does not remove that assessment process or establish that compensation has been completed.
Bitget says customer reserves back covered account balances, while the Protection Fund adds a financial safeguard. Its separate reserve report gives an overall ratio of 131% across 19 covered assets, each above 100%, for a snapshot taken at 09:00 UTC on Sept. 29.
A 2023 advisory from the PCAOB's Office of the Investor Advocate noted that proof-of-reserves reports are not audits, may omit liabilities or borrowed assets, and cannot assure subsequent asset availability.
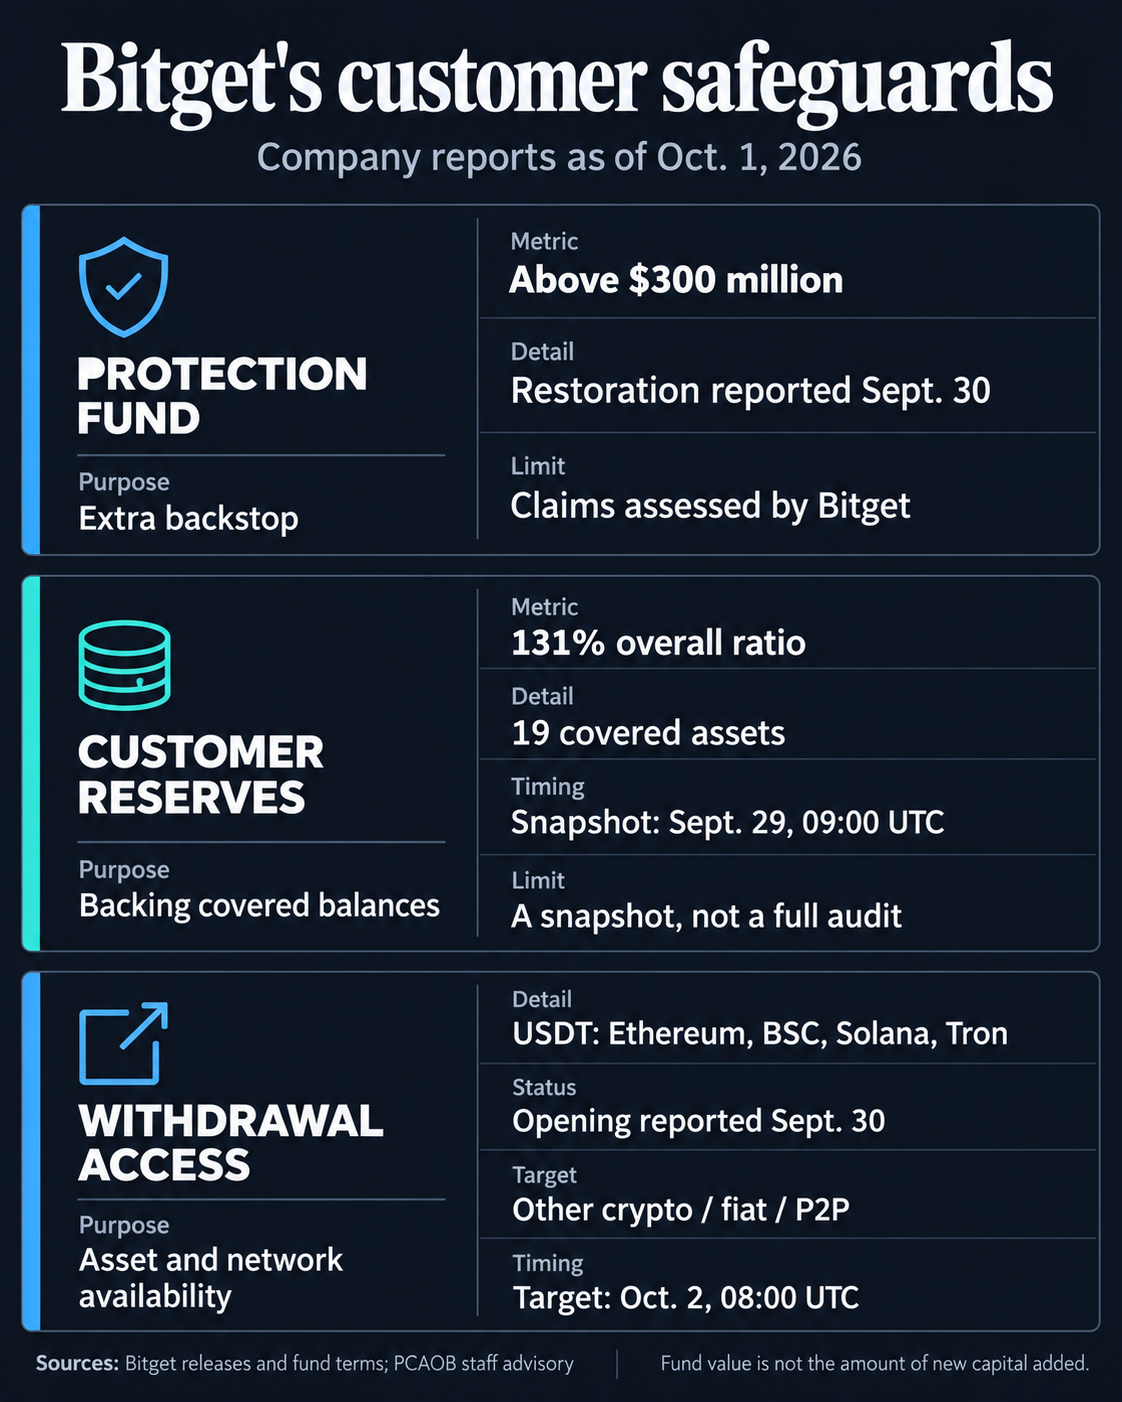
Withdrawal access continues to follow its own asset and network timetable. Bitget's Sept. 30 service notice says USDT withdrawals opened on Ethereum, BSC, Solana and Tron. A service-opening notice describes availability on those networks.
The exchange's incident timetable schedules the remaining cryptocurrencies, fiat, and peer-to-peer services for Oct. 2 at 08:00 UTC. Customers awaiting those services still face a separate milestone from the fund restoration that Bitget has reported.
The post Bitget restores $300M fund after absorbing $388M security breach appeared first on CryptoSlate.
Crypto firms and users have lost nearly $2.7 billion to security incidents this year, with North Korea-linked thefts exceeding $1 billion.
Blockchain security firm CertiK recorded 658 incidents through September, with about $420.4 million of stolen assets frozen or returned. That leaves adjusted losses of roughly $2.26 billion and an average loss of $4.1 million per incident.
September sharply altered the year's tally. Losses reached about $766.5 million, surpassing April's $651.3 million and making it the costliest month of 2026. Bitget's $387.5 million breach and the $318.7 million Liquid Network incident accounted for more than $700 million of the damage.
The surge has left the annual total increasingly dependent on a small number of outsized attacks. It has also brought state-linked theft deeper into the industry's security calculations after blockchain analytics firm Elliptic said suspected North Korean hackers have taken more than $1 billion in crypto this year.
Mega-hacks are reshaping the annual toll
September propelled Bitget and Liquid Network to the top of CertiK's 2026 incident ranking, widening the gap between the largest breaches and hundreds of smaller attacks.
Bitget alone represents about 14.4% of CertiK's year-to-date losses. Liquid Network ranks second, followed by KelpDAO at $291.3 million, Drift Protocol at $285.3 million, and an unidentified victim at $284.8 million.
Those five incidents account for about $1.57 billion, or almost 59% of the $2.68 billion recorded so far this year.
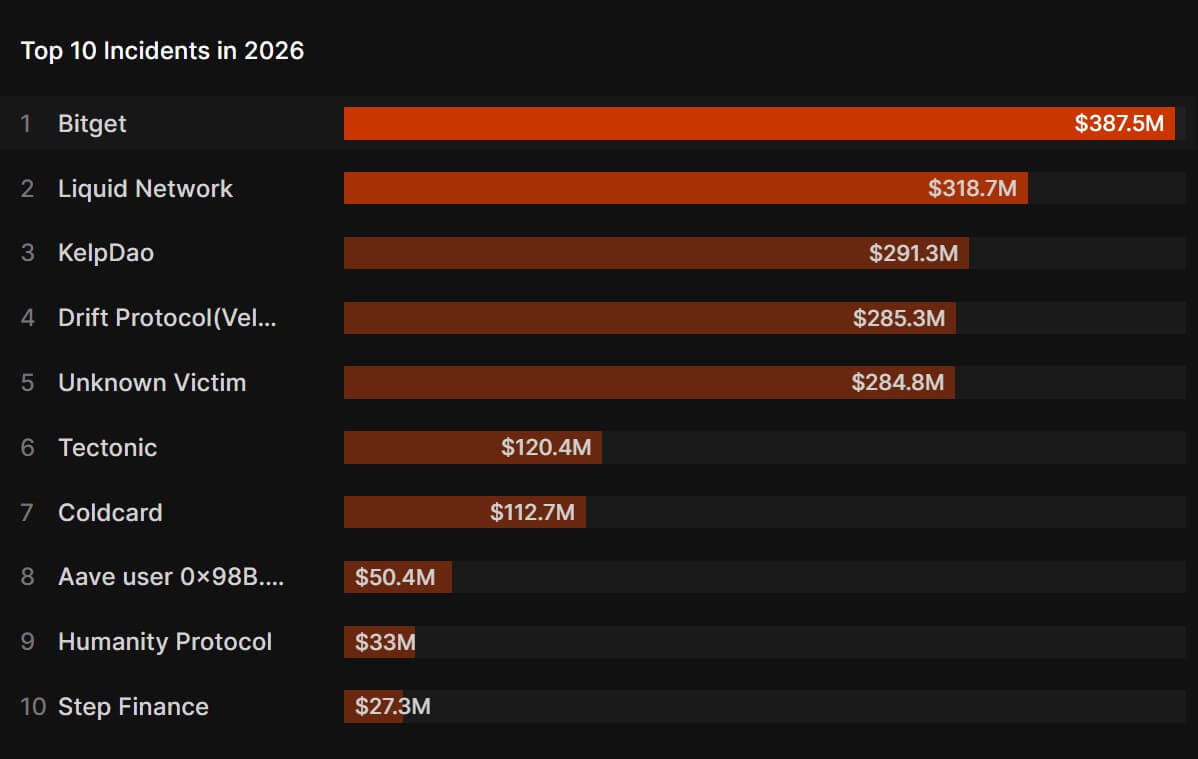
That concentration means a single compromise at a large exchange, protocol, or infrastructure provider can materially change the industry's annual loss profile. For context, Bitget and Liquid Network together contributed roughly $706 million, equivalent to more than a quarter of all gross security losses tracked by CertiK in 2026.
September's figures further illustrate the imbalance. Beyond those two attacks, the month's remaining incidents contributed only a fraction of its $766.5 million total.
Meanwhile, some of the damage from these attacks has since been reversed. CertiK counts $420.4 million of assets as frozen or returned this year, reducing its adjusted loss figure to $2.26 billion. Liquid Network recovered a large portion of the assets involved in its incident, while other attacks have also resulted in partial or full returns.
So, the gap between gross and adjusted losses has widened as exchanges, issuers, security firms and blockchain operators move faster to identify and restrict stolen funds.
However, that recovery capacity does not eliminate the immediate cost to affected businesses. Large breaches can force operators to suspend services, replenish customer balances, rebuild infrastructure and commit capital before stolen assets are recovered.
Meanwhile, the attacks are also spreading across different parts of the crypto market. CertiK's annual data show incidents involving multiple blockchains have generated the greatest dollar losses, while Ethereum has recorded the largest number of security events.
The threat has extended beyond software. CertiK recorded 52 so-called wrench attacks during the first half of 2026, up from 39 in the same period last year. Exposure from those physical attacks climbed to $124.2 million from $10.5 million, while the average amount involved increased to about $2.4 million from roughly $270,000.
North Korea’s crypto theft machine crosses $1 billion in 2026
The growing size of individual breaches has amplified the impact of one of crypto’s most persistent adversaries.
Elliptic said the Bitget incident pushed the value stolen in attacks it attributes to North Korea above $1 billion in 2026, spanning more than 51 suspected incidents. The blockchain analytics firm assessed the Bitget breach as highly likely to be linked to the Democratic People’s Republic of Korea, citing laundering behavior, infrastructure shared with earlier attacks and other indicators.
Measured against CertiK’s $2.68 billion industrywide gross-loss figure, Elliptic’s North Korea tally equals more than 37% of security losses recorded this year.
Elliptic previously linked the roughly $286 million Drift Protocol exploit to North Korean actors. Drift is also among CertiK’s five largest incidents of 2026, putting suspected DPRK operations behind more than one of the year’s biggest crypto thefts.
The concentration extends a campaign that has generated billions of dollars for North Korea over the past decade.
Elliptic estimated last year that DPRK-linked hackers had stolen more than $6 billion in crypto since 2017, with governments and international organizations saying the proceeds help finance the country’s nuclear weapons and ballistic-missile programs.
North Korean hacking groups initially built a reputation by attacking banks and conventional financial infrastructure before increasingly targeting cryptocurrency businesses, where large pools of transferable assets can move across borders without relying on the traditional banking system.
The US Treasury designated Lazarus Group and related groups in 2019, describing them as state-sponsored operations controlled by North Korea’s Reconnaissance General Bureau.
Some of crypto’s largest historical breaches have since been attributed to the country. US authorities tied Lazarus to the roughly $620 million Ronin Bridge theft in 2022, while Treasury said the group used crypto mixers to launder proceeds from the $100 million Atomic Wallet attack and other hacks.
The escalation peaked in February 2025 when attackers stole about $1.46 billion from Bybit, the largest confirmed crypto theft on record. The FBI formally attributed that breach to North Korea, while Elliptic tracked the subsequent movement of funds through thousands of addresses, cross-chain services and laundering platforms.
Those laundering techniques have become more elaborate as exchanges, stablecoin issuers and blockchain analytics firms improve their ability to freeze and trace stolen assets. Elliptic said North Korean operators increasingly use repeated cross-chain transfers, mixers and less-monitored networks to break the transaction trail.
That leaves North Korea as one of the biggest variables in crypto’s 2026 security bill as the state-backed actors increasingly threaten the emerging industry.
The post Crypto hackers have taken $2.7 billion in 2026 and the losses are alarmingly concentrated appeared first on CryptoSlate.
US manufacturers reported more widespread input-price increases in September, raising a potential financing risk for Bitcoin if investors respond by expecting higher interest rates ahead of Friday’s jobs report.
The Institute for Supply Management’s Oct. 1 release put its manufacturing prices index at 77.9, up 6.8 points from August’s 71.1. The manufacturing PMI registered 54.5, new orders 55.3 and employment 52.7.
For Bitcoin, that combination matters because resilient activity and widening cost pressures could complicate the case for lower interest rates.
The prices gauge measures how widely monthly increases are reported, and its 77.9 reading is not a 77.9% inflation rate. Higher input prices were reported by 58.6% of respondents, compared with 46.2% in August. The diffusion-index method counts higher responses plus half of unchanged responses.
The potential pressure runs through rates
The policy backdrop already includes a completed increase by the Federal Open Market Committee, which raised its target range by a quarter percentage point to 3.75% to 4% on Sept. 16.
In Sept. 29 remarks, New York Fed President John Williams said another upward adjustment might be appropriate late this year if the economy broadly followed his forecast. That was his conditional outlook, and he also said there was no evidence yet of the identified price shocks spilling into broader, more persistent inflation.
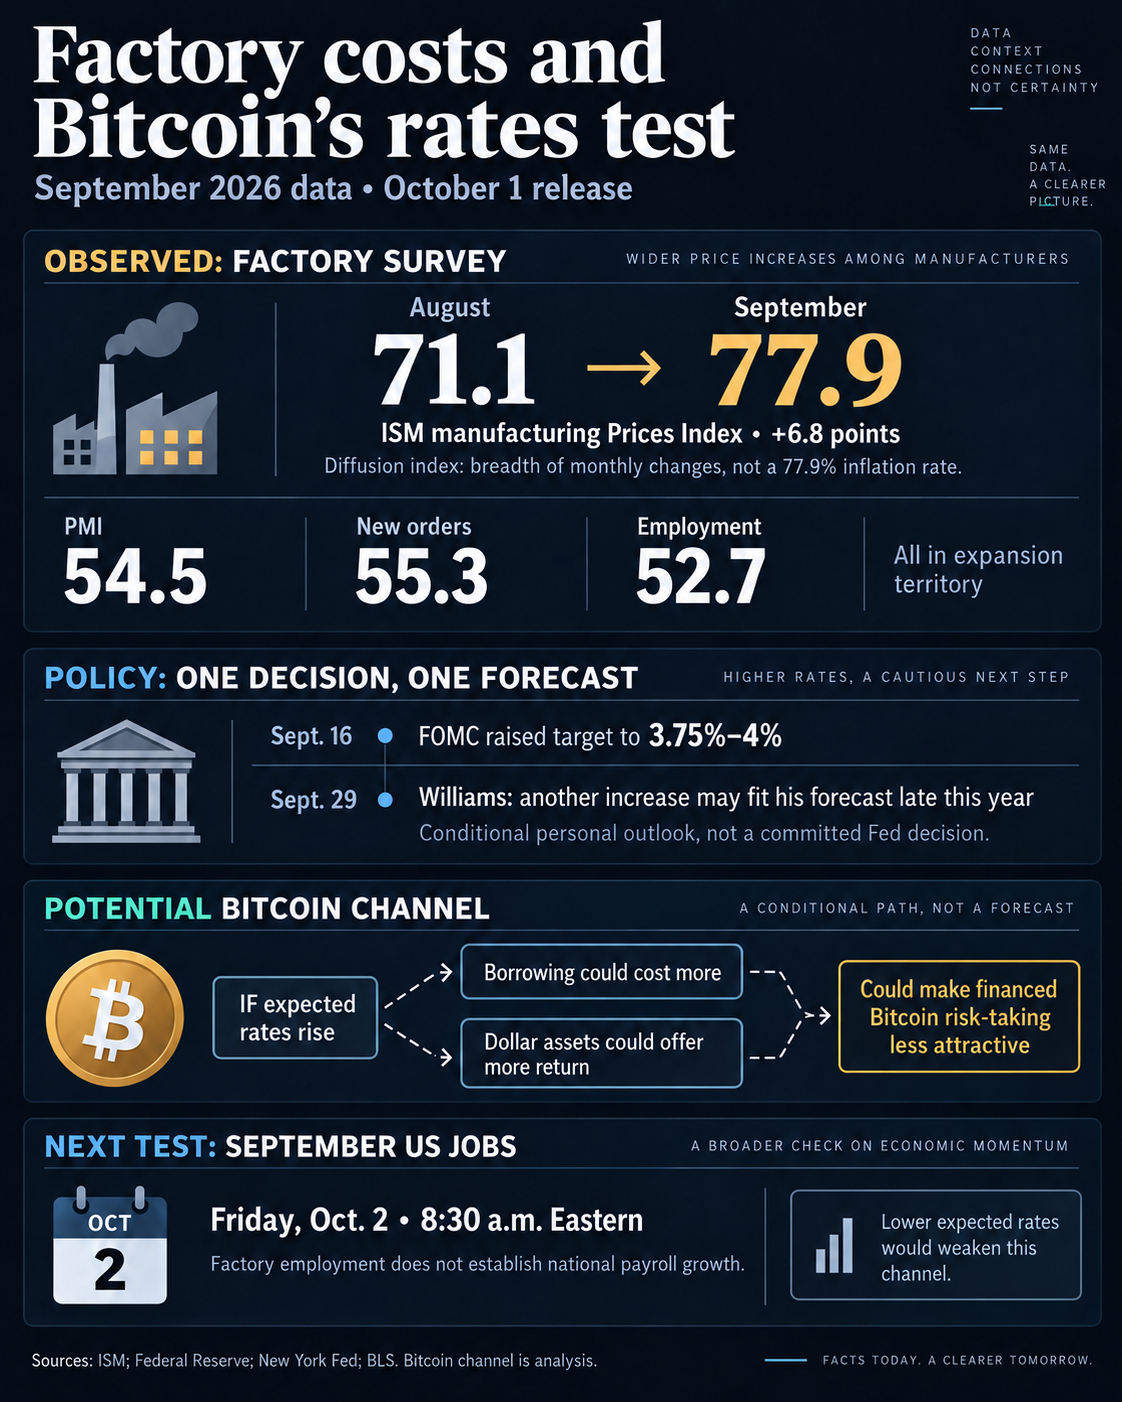
September’s factory survey adds evidence about input costs to that policy debate, and the Fed’s transmission framework explains that policy changes affect short-term borrowing costs and Treasury bill returns. Meanwhile, expectations of future policy influence longer-term rates and financial conditions.
Applied to Bitcoin, the potential pressure splits into more expensive borrowing, which could make financed risk-taking less attractive, and higher returns on interest-bearing dollar assets, which could also raise the return investors demand to hold Bitcoin.
The Bureau of Labor Statistics schedules September’s Employment Situation for Oct. 2, and the ISM’s manufacturing employment reading cannot substitute for that national report.
Bitcoin's implications depend on how investors interpret the combined data. If the jobs report strengthens expectations of higher rates, financing and competing dollar returns could become a firmer obstacle. If front-end Treasury yields or expected policy rates fall, that would weaken the proposed transmission.
A February 2023 New York Fed staff study found no systematic Bitcoin response to monetary and macroeconomic news in its historical intraday sample. The practical test is therefore whether rate expectations move and Bitcoin responds, rather than assuming a factory-cost increase guarantees a selloff.
The post US factory costs spike, threatening Bitcoin’s rally above $85,000 appeared first on CryptoSlate.
NEAR’s new US ETF is facing its first stress test days after launch as a $3.8 million ecosystem exploit hit the token.
NEAR fell about 10% to $4.86 after NEAR Intents disclosed a security incident involving its Omni deposit-and-withdrawal infrastructure. The selloff came less than two days after Bitwise opened the token to US exchange-traded fund investors through its NEAR ETF, with the ticker NRR.
The fund began trading on NYSE Arca on Sept. 29 and attracted $35.5 million of net inflows on its first day. By Sept. 30, cumulative inflows had risen to over $50 million, while total net assets reached $52.8 million, equivalent to about 0.76% of NEAR’s market capitalization, according to SoSoValue data.
That timing gives the newly launched product an unusually early test of investor conviction. The ETF protects buyers from the operational burden of wallets, private keys, and direct staking, but its value still moves with NEAR, leaving shareholders exposed when problems elsewhere in the ecosystem undermine confidence in the token.
A $3.8 million exploit hits NEAR Intents
In an X statement, NEAR Intents said it temporarily halted services after detecting what it described as a bug in the interaction between its Omni infrastructure and the Intents smart contract.
The preliminary loss was about $3.8 million, and the project said it would fully compensate affected users. The team patched the contract vulnerability, and NEAR Intents and near.com resumed operations after a temporary suspension.
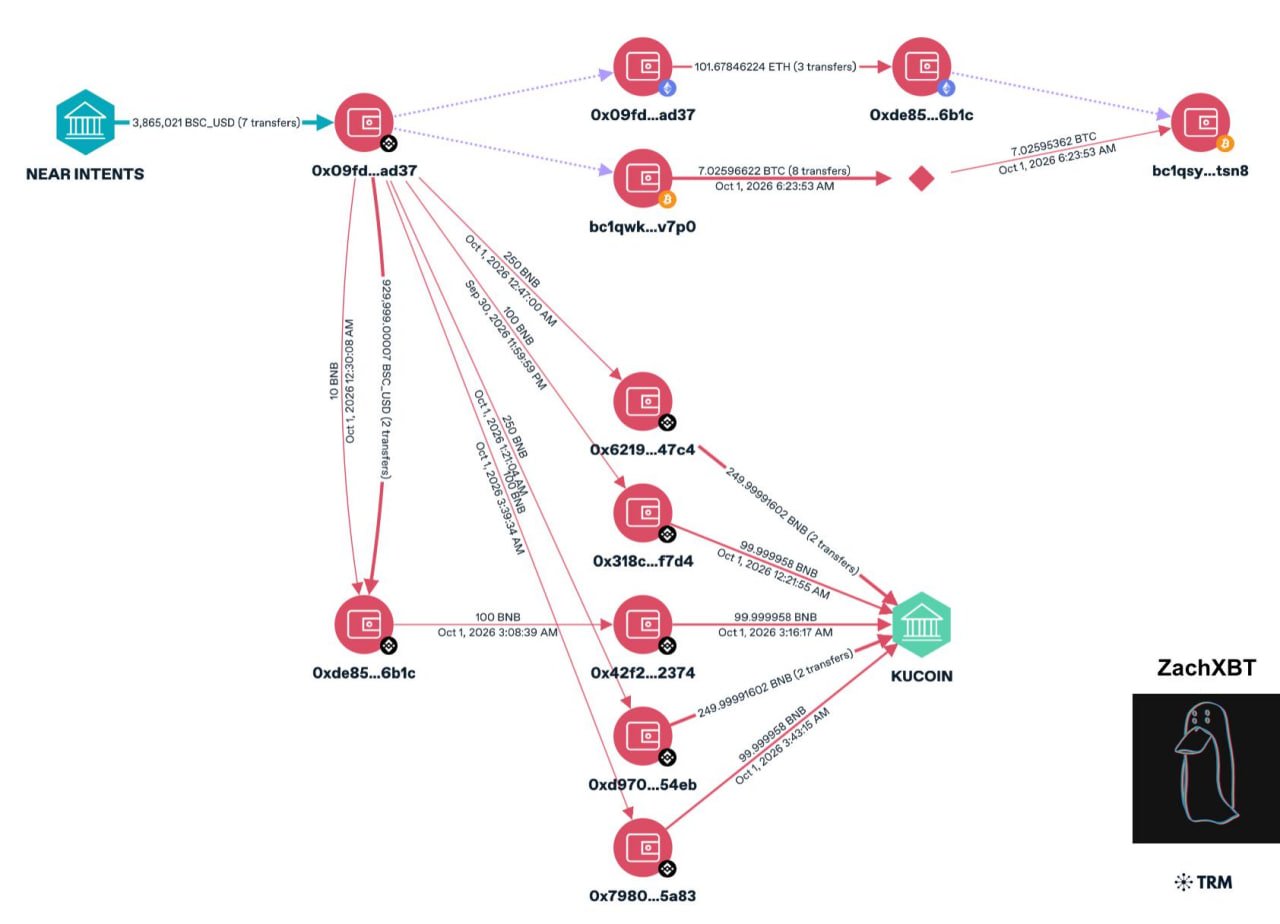
Some deposit and withdrawal routes remained unavailable for longer while the team completed fixes to Omni infrastructure covering networks including BSC, Polygon, TON, Optimism, Avalanche, Stellar and Scroll.
NEAR co-founder Illia Polosukhin said the exploit was isolated to USDT on BSC and that NEAR Intents’ SHIELD security system detected unusual activity before pausing services. He said the team identified and fixed the vulnerability within an hour.
The base NEAR blockchain continued operating throughout the incident. NEAR Protocol said the exploit did not involve a vulnerability in the network or the native NEAR token, and that block production and transaction processing continued without interruption.
That separation limits the direct operational impact on Bitwise’s ETF, which holds exposure to NEAR rather than assets deposited through NEAR Intents. The market reaction nevertheless shows how quickly application-level failures can feed through to an asset newly packaged for traditional investors.
The Intents business is also large enough to make the incident more than a peripheral ecosystem problem. Polosukhin said the service now processes more than $4 billion a month in trading and payments volume, positioning it as one of NEAR’s major connections to other chains and applications.
The team has reported the incident to law enforcement and is working with blockchain analytics and security firms to trace the stolen funds. A fuller postmortem is expected in the coming days.
Polosukhin said the ecosystem plans to expand its use of formal verification and other security tools after the breach, including work already underway on a verification system for NEAR smart contracts.
He stated:
“The crypto space is entering a new era of far more sophisticated cyber attacks. Recently, we have seen BitGet, Metamask, Lido all being targeted by criminals equipped with AI systems that are continuously trying to hack all infrastructure. As a space, we need to be far more vigilant and raise the bar on both onchain contract standards and offchain monitoring and proactive prevention.”
The ETF arrived after leverage had already started leaving
The price decline also landed in a market whose speculative positioning had already changed substantially before NRR began trading.
Blockchain analysis firm Santiment said NEAR-denominated futures open interest peaked at roughly 215 million NEAR on Sept. 21, eight days before the ETF launch. By Sept. 29, that figure had dropped about 21% to 169 million NEAR, even as the token’s price had risen roughly 86% from Sept. 16.
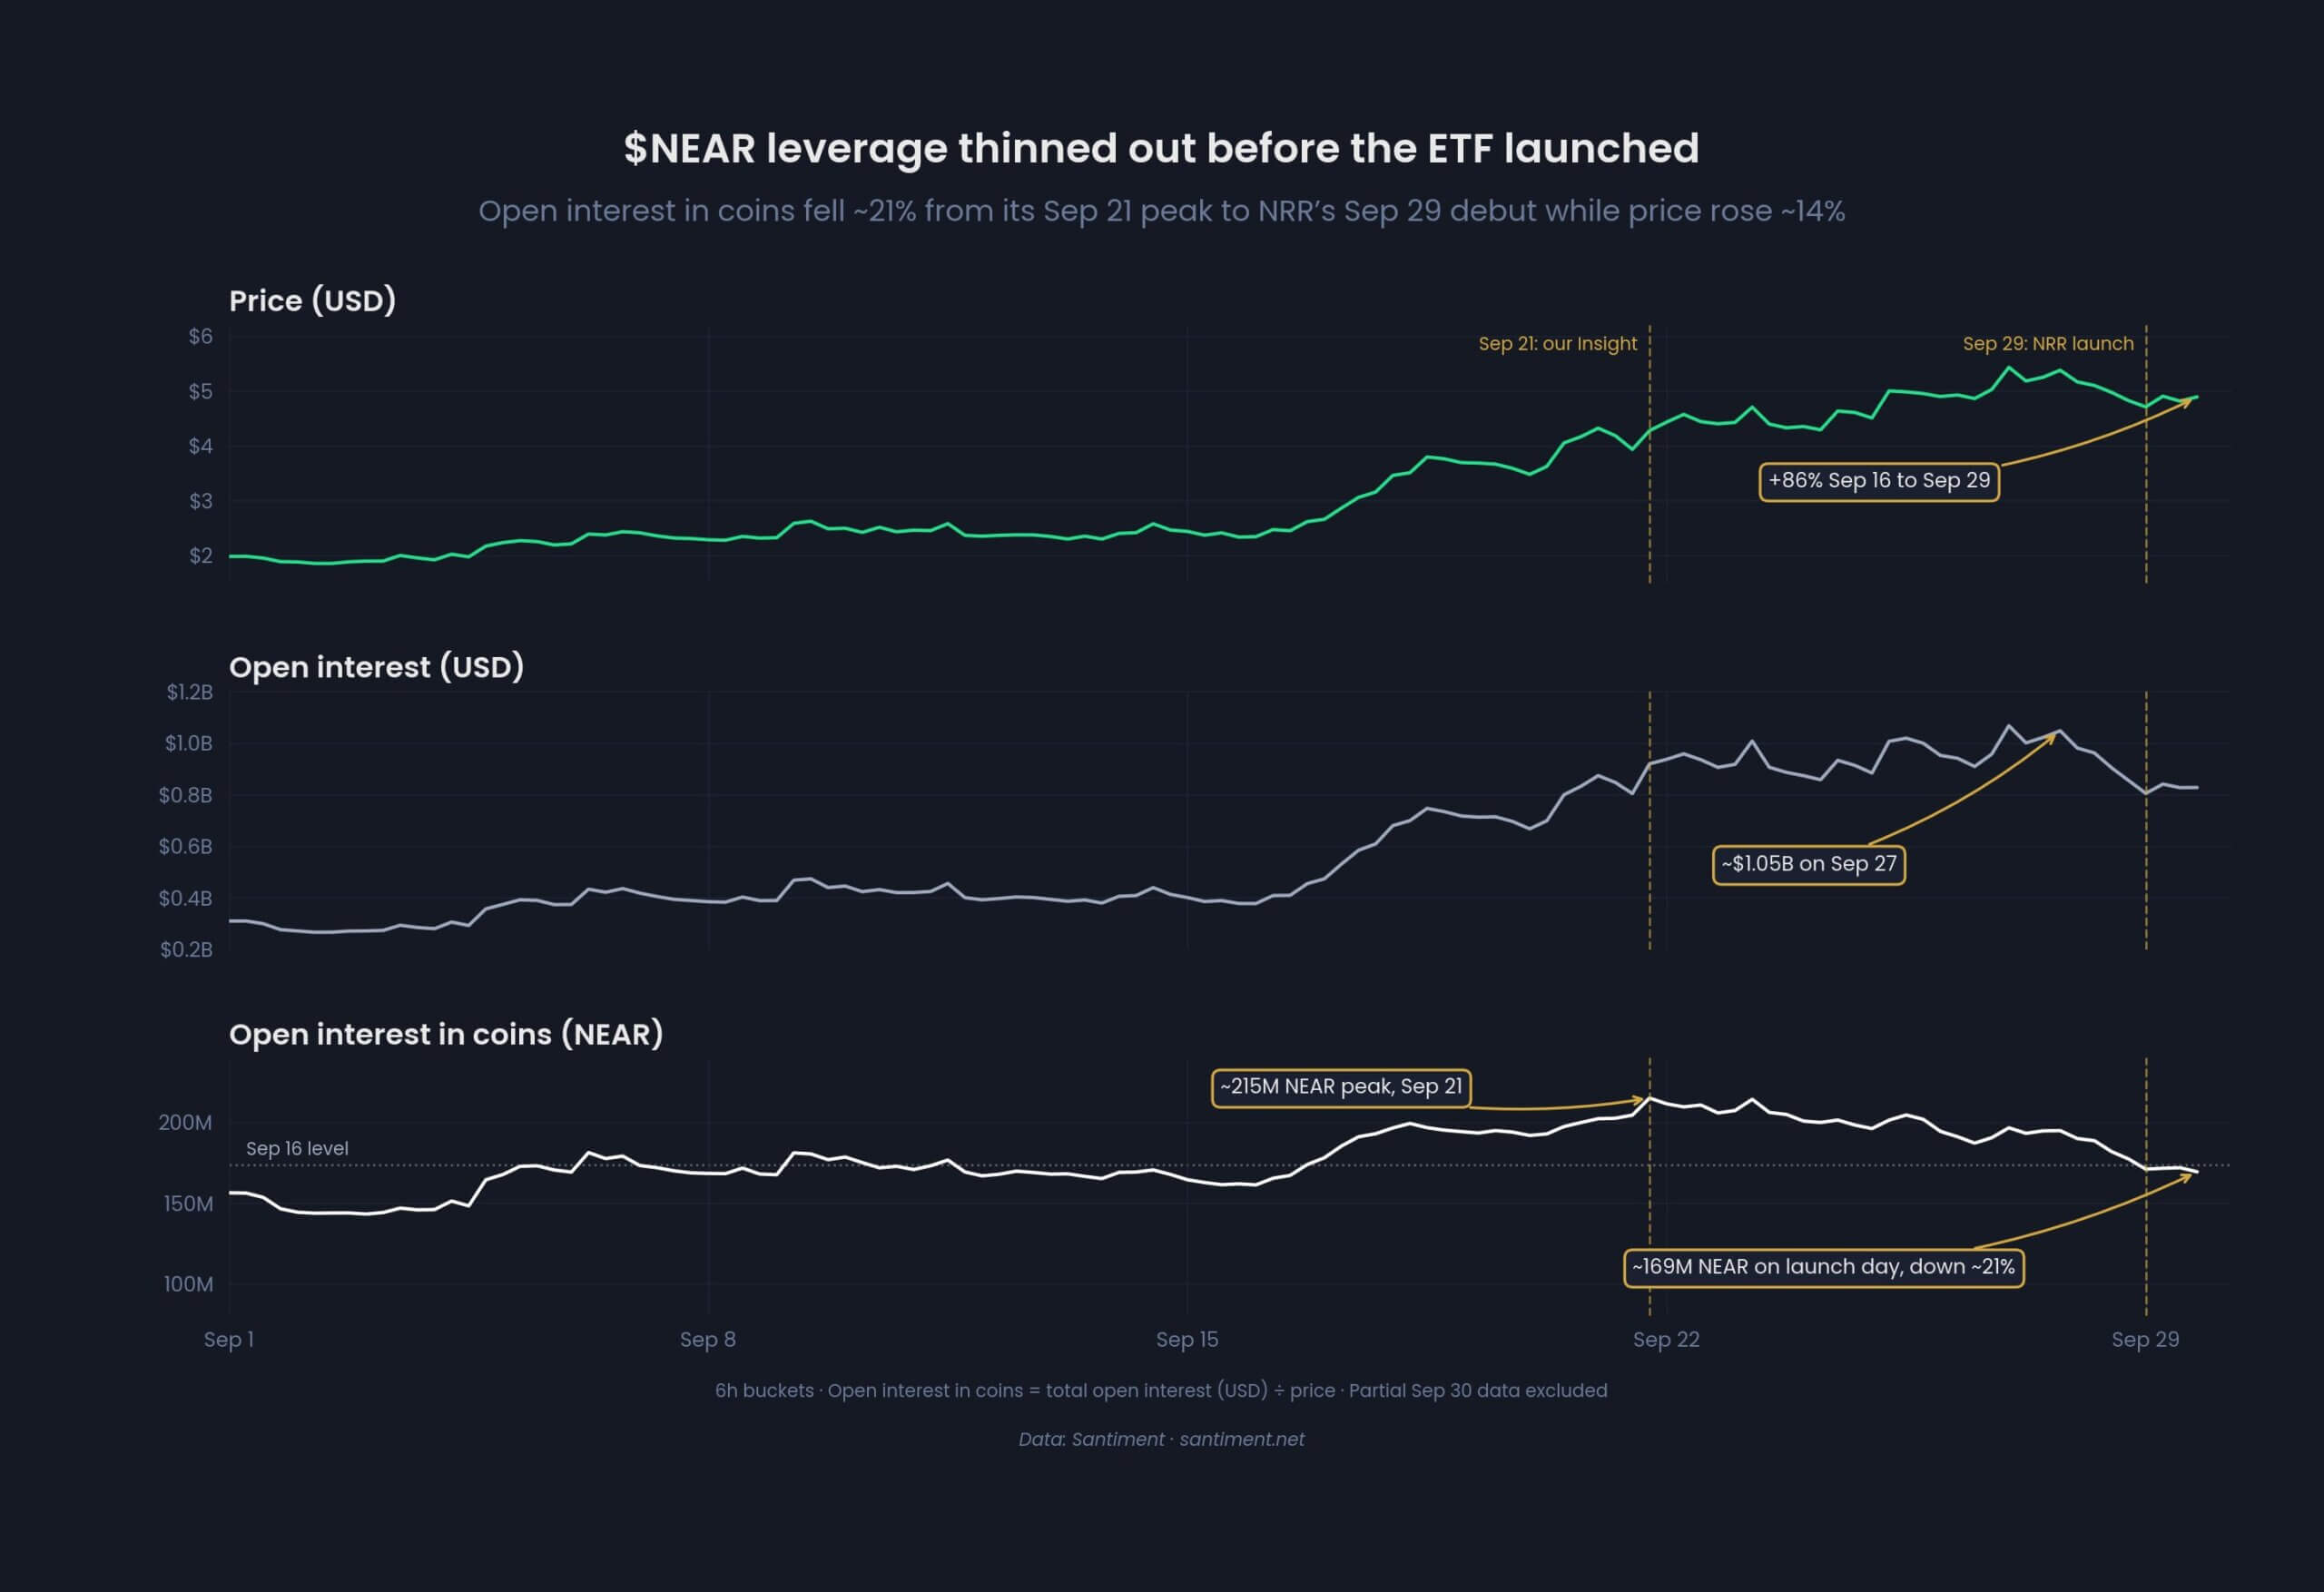
Dollar-denominated open interest continued climbing for several days, reaching about $1 billion on Sept. 27, but the declining number of NEAR committed to derivatives suggested leverage was already thinning before the ETF opened.
That makes the post-exploit move different from a straightforward leveraged unwind. Spot demand had strengthened into the launch while speculative positioning was being reduced, according to Santiment, giving the ETF inflows a more prominent role in the market structure.
NRR’s first two days showed that institutional demand was present, but the harder test begins after the breach.
If inflows continue despite the 10% drop, investors would be signaling that they are willing to separate an application-specific exploit from the investment case for the underlying network. A reversal in flows would show how quickly an ecosystem security event can interrupt demand for an ETF that has existed for only a handful of trading sessions.
The post Wall Street arrived in NEAR just as a $4 billion-a-month app got hacked appeared first on CryptoSlate.
XRP is beginning to support live dollar borrowing on Ethereum, though the market remains heavily concentrated among a handful of borrowers.
A Morpho market backed by FXRP, a tokenized representation of XRP, had about 7.18 million RLUSD in outstanding loans against 10.76 million FXRP as of Oct. 1. The three largest addresses accounted for almost all of that debt, limiting how far the activity can be read as broad adoption.
The market, launched in August through Flare, lets XRP holders mint FXRP, move it to Ethereum, and borrow Ripple's RLUSD stablecoin without immediately selling their XRP exposure.
That adds a new credit use case for XRP, but also introduces bridge, collateral, and redemption dependencies that borrowers do not face when holding native XRP directly.
Three borrowers dominate XRP’s emerging credit market
The early borrowing activity is heavily concentrated among a small number of participants.
The three largest addresses account for 93% of roughly $7.2 million in outstanding debt, giving a handful of positions outsized influence over the market's size. A large repayment could sharply shrink borrowing, while another loan from the same wallets could lift the total without bringing in many new users.
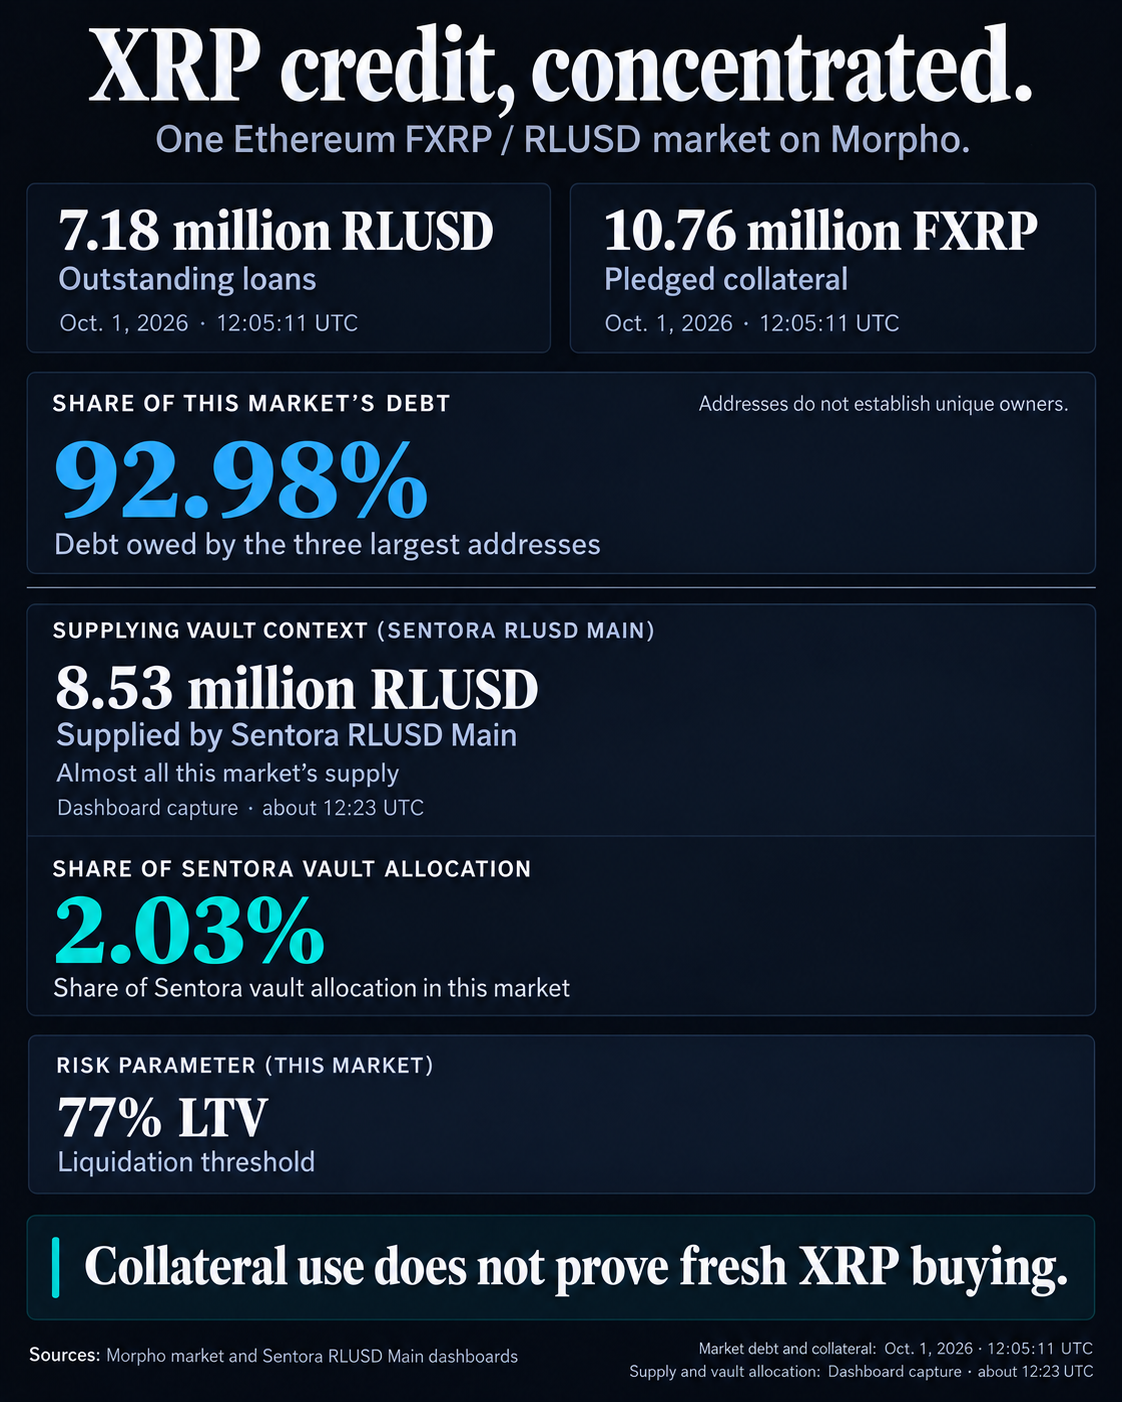
The concentration may be even greater than the address count suggests. On-chain records identify wallets rather than their owners, so several addresses could belong to the same investor or institution.
Funding is similarly concentrated. Sentora RLUSD Main supplied about 8.53 million RLUSD, providing nearly all of the liquidity available to borrowers at the time observed. Even so, the FXRP market represents only about 2.03% of Sentora's broader vault allocations, leaving room to commit more capital if demand increases.
Sentora can supply up to 10 million RLUSD under the current limit. That gives borrowers room to take on more debt, though the spare capacity says little about whether a wider group of XRP holders will actually use it.
The same concentration could become more important if XRP price weakens.
Morpho allows lenders to liquidate a position once the value of its debt rises above 77% of the collateral backing it. The three biggest borrowers remain well away from that point. Based on their current debt and collateral, the largest position could withstand roughly a 45% decline in the FXRP-to-RLUSD ratio, while the next two have buffers of about 38%.
Some smaller borrowers have less room. One position with about 121,000 RLUSD of debt against 133,000 FXRP could reach its liquidation threshold after roughly a 21% decline, assuming the position otherwise remains unchanged.
The market recorded some liquidations in September but showed no realized or unrealized bad debt as of Oct. 1. A sharper move would provide a more meaningful test because a liquidator taking over one of the largest positions would suddenly have to absorb a sizeable amount of FXRP.
That would not necessarily mean the underlying XRP is immediately sold. A liquidator could hold the FXRP, sell it, move it back toward Flare, or redeem it for native XRP.
For now, the bigger issue is how quickly a few large wallets can reshape the market. New borrowers spreading the debt across more addresses would make the $7.2 million total more representative of broader demand. If activity remains concentrated, a single large repayment, new loan, or liquidation could materially change the market almost overnight.
Native lending could broaden XRP credit without creating new buyers
The concentration in Morpho may prove temporary as developers prepare to bring lending directly onto the XRP Ledger.
XRPL’s proposed lending architecture, which is currently undergoing security reviews, would allow fixed-term credit to originate on the network rather than requiring XRP holders to mint FXRP, bridge it to Ethereum, and borrow through Morpho.
Removing those steps could make XRP-backed credit easier to access and give institutions another way to use XRPL assets for financing and liquidity management. It would also introduce a different credit model from Morpho’s overcollateralized loans, with underwriting handled before fixed-term loans are created.
More lending, however, would not necessarily translate into fresh demand for XRP. Existing holders could simply deploy XRP they already own, while institutions could recycle existing balances through lending markets. Outstanding debt could therefore rise substantially without a corresponding increase in the number of XRP owners or the amount of new capital entering the token.
That makes borrower composition as important as loan volume. A market that grows because the same large holders increase their borrowing would deepen XRP’s utility without demonstrating broader adoption. Growth spread across new borrowers, larger lending pools, and sustained activity after repayments would provide stronger evidence that credit is widening the asset’s economic use.
Native lending will provide the next test. If the amendments clear their security reviews and gain validator approval, XRP holders would have a direct lending route on XRPL alongside the existing Ethereum-based Morpho market.
The comparison will show whether reducing cross-chain friction attracts a broader borrower base or simply gives existing XRP holders another way to leverage the same capital.
The post XRP is becoming collateral for real loans and the first market is already dominated by whales appeared first on CryptoSlate.
CryptoTicker.io
A bitcoin donation to a charitable organisation is tax-deductible in Germany, and it counts as a donation in kind. How much you may deduct turns on a single question that is written into the law and that hardly anyone else mentions: would a sale of this bitcoin have been taxable at the moment of the donation?
If the answer is no, because the one-year holding period has elapsed, you may use the fair market value, that is the price on the day of the donation. If it is yes, because you bought the bitcoin only eight months ago, the deduction is capped at the carried-forward acquisition cost, meaning what you paid. On a position that has quadrupled, that is a difference of a factor of four, purely because of the date.
This rule is in section 10b paragraph 3 of the German Income Tax Act. Because the donation itself is not a sale, it also produces no taxable gain. The two together lead to a result that surprises many: donating out of an old holding sitting on a large gain is more favourable for tax than the detour through a sale.
The donation itself produces no taxable gain
Private disposals of crypto assets fall under section 23 of the Income Tax Act. What is taxable there is a gain from a disposal, and a disposal presupposes consideration. A donation is gratuitous: you give the bitcoin away and receive nothing for it. The trigger to which the tax attaches is therefore absent.
The law itself confirms this logic in a telling place. Section 10b paragraph 3 asks whether the disposal of the asset transferred "would not fulfil a taxable event at the time of the transfer". The question is put in the subjunctive, and is therefore hypothetical. If the transfer were itself already a disposal, that subjunctive would not be needed.
The same system applies to other gratuitous transfers. Anyone giving bitcoin away as a gift likewise triggers no private disposal; what comes into play there instead is gift tax and its allowances, which we have written up separately for the case of gifts to children. On a donation to a tax-privileged organisation no gift tax arises, because charitable recipients are exempt from it.
Section 10b paragraph 3: the deductible amount hangs on the holding period
The decisive mechanism in sentences 3 and 4 of the provision can be set out in two lines.
Case one, holding period elapsed. A sale would have been tax-free on the day of the donation, because more than a year lies between acquisition and donation. The amount of the transfer is then determined by the fair market value, that is the price.
Case two, holding period still running. A sale would have been taxable. In determining the amount of the transfer, the carried-forward acquisition cost may then not be exceeded. The increase in value is thus left out of the deduction.
The provision can be read in full at section 10b of the Income Tax Act, and the holding period itself at section 23. Note one subtlety here that is often overlooked: for case two it does not matter whether you would in fact have made a gain on a sale. What counts is whether the taxable event would be fulfilled, and within the year it is, regardless of the outcome.
A second subtlety concerns the 1,000-euro exemption threshold in section 23. This threshold does not undo the taxable event; it merely leaves the gain free in the result. Anyone wanting to rely on a donation within the year being treated as case one for that reason is on uncertain ground; we have collected the most common errors of reasoning around this threshold in a separate piece on the exemption threshold.
A worked example with 20,000 euros of cost and 80,000 euros of market value
Suppose you bought bitcoin for 20,000 euros, and the position stands at 80,000 euros on the day of the donation. Both figures are freely chosen, to show the mechanics.
- Donation after fourteen months: a sale would be tax-free. 80,000 euros are deductible as a donation in kind.
- Donation after eight months: a sale would be taxable. 20,000 euros are deductible.
The difference comes to 60,000 euros of special expenses, on an identical donation to an identical recipient. What that amount saves in tax depends on your personal tax rate and on the ceiling, on which more below. The direction, though, is the same in every case: six months of patience decide the order of magnitude of the deduction here.
Selling and then donating cash: this route can trigger tax
The obvious route is often the more expensive one. Anyone who first sells the bitcoin on an exchange and then transfers the euro amount has triggered two separate operations: a sale and a cash donation.
Within the one-year period that sale is a private disposal, and the gain is charged at your personal income tax rate. The cash donation that follows is deductible in the amount donated, but it works as a special expense and not as an offset against the gain. Once the one-year period has elapsed the sale is tax-free, and then both routes lead to the same result.
A plain rule of sequence follows from this: if the acquisition is less than a year back, the direct donation in kind is the cleaner route for tax, even if the deduction then covers only the acquisition cost. Anyone who sells instead pays on the gain and donates from what is left after tax.
Who qualifies as a recipient and where to check it
Deductible are transfers for the promotion of tax-privileged purposes under sections 52 to 54 of the Fiscal Code. As recipients the law names three groups: legal persons under public law and public bodies, corporations exempt from tax under section 5 paragraph 1 number 9 of the Corporation Tax Act, and corresponding institutions in another member state of the European Union or in the European Economic Area.
In practice that means the association or foundation has to be recognised as charitable. A collective appeal by a loose initiative, a project without a legal form or a wallet address in a forum post do not meet that condition, however worthwhile the cause may be. The purpose alone is not enough; what matters is the recipient's recognised status.
It can be checked with the recipient itself: a charitable organisation evidences the status on request and issues the confirmation you need for the deduction. Anyone who cannot or will not issue a confirmation cannot accept a deductible donation either.
Donation receipt on the official template, simplified proof up to 300 euros
For the deduction you need proof. Above 300 euros that is the donation receipt on the official template, issued by the recipient. Up to and including 300 euros a simplified proof suffices, if the recipient is a domestic legal person under public law, a domestic public body or a corporation exempt from tax under section 5 paragraph 1 number 9 of the Corporation Tax Act.
With a donation in kind the confirmation has a peculiarity that regularly prompts questions with crypto assets: the value of the item has to be stated in it, and that value is exactly the amount the rule in section 10b paragraph 3 prescribes. The recipient, however, does not know your acquisition data. In practice the donor therefore supplies the details on which the organisation bases its confirmation: date of acquisition, acquisition cost, quantity and the market value on the day of the transfer.
That makes your own records a precondition of the deduction. Anyone whose purchases are spread across several exchanges and wallets should pull the history together in full before donating; which programmes do that automatically and build a report for the tax office is set out in our comparison of crypto tax tools. If the purchase record is missing altogether, no evidenced deductible amount is left on a donation within the one-year period, because without acquisition cost there is no ceiling that could be substantiated. The trade statements can usually still be obtained after the fact in your trading venue's account; which providers export how far back is shown by our exchange comparison.
20 percent of total income as the ceiling
The deduction is not unlimited. Transfers are deductible in total up to 20 percent of total income, or alternatively up to 4 per mille of the sum of turnover, wages and salaries. For a private individual without a business, the first limit is as a rule the relevant one.
With a large donation in kind out of an old holding, that limit is quickly reached. Anyone donating 80,000 euros with total income of 70,000 euros can apply only 14,000 euros in that year. The remainder is not lost, though: deductible transfers above the ceilings are carried forward into the following years, the so-called donation carry-forward.
For planning purposes that means a very large donation works for tax across several years. With a gain that has accrued over years that is an important point, because unlike the increase in value the deduction is tied to your current income. How losses and other deductible items work alongside it, we have written up using the example of a total loss.
What happens if the organisation sells the bitcoin immediately?
Many recipients hold no crypto assets but convert a donation into euros straight away. For your deduction that changes nothing. What counts is the time of the transfer, that is the moment the bitcoin arrives at the organisation, and what counts is the value at that moment.
If the charitable organisation then sells, that is its operation and not yours. The proceeds it achieves may lie somewhat above or below the value on the day of transfer because of price movement. For the confirmation the value on the day of transfer applies, and you hold to that value in your tax return as well.
A clean delineation matters with donation portals and payment service providers. If the transfer runs through a service provider that accepts the crypto asset, sells it and passes on the euro amount, the question arises as to who your recipient actually was. A deductible donation in kind presupposes that the charitable organisation receives the crypto asset. If it is converted into euros first and only the euro amount is transferred, what exists economically is a cash donation, and section 23 then applies to the sale again.
Membership fees and sports clubs: where the deduction stays excluded
The law treats donations and membership fees in the same sentence, but draws a series of limits around the fees. Not deductible are membership fees to corporations that promote sport, to corporations for cultural activities that primarily serve leisure, and to corporations for the care and study of local heritage.
Genuine donations to those very same clubs, by contrast, remain deductible. Anyone transferring bitcoin to the local sports club can claim that as a donation; the annual fee for membership, on the other hand, stays out. Membership fees to corporations promoting art and culture are expressly deductible, even where members are granted benefits in return.
For a crypto donation this distinction is rarely the problem, because a membership fee is hardly ever paid in bitcoin. It becomes relevant where a club books a transfer flatly as "support". If the confirmation ends up saying membership fee instead of donation, the deduction is lost for the purposes named.
Crypto donations abroad and the limits of the European Economic Area
That a blockchain transfer does not stop at borders changes nothing about the tax border. The recipient has to be located domestically, in a member state of the European Union or in a state of the European Economic Area. A transfer to an organisation outside that area is not deductible under section 10b, however easily the transfer may be made technically.
With recipients not resident domestically a further hurdle is added: the state in question has to provide administrative assistance on the exchange of information and support with recovery. If a domestic public body pursues the privileged purposes exclusively abroad, the law additionally requires that persons resident in Germany are supported, or that the activity can also contribute to the standing of the Federal Republic.
In practice, the route through an organisation recognised in Germany that works abroad is therefore almost always the more workable one than a direct transfer to an institution in a third country. The first variant gives you a confirmation the tax office knows.
From 2027 the draft bill shifts this calculation
The rule in section 10b paragraph 3 attaches to the question of whether a sale would be taxable at the time of the transfer. That is precisely the question the federal finance ministry's draft bill on the taxation of crypto assets, due to go to cabinet on October 14, 2026, intends to answer anew.
If the one-year holding period falls away for holdings acquired after December 31, 2026, the sale of those would be taxable permanently. On the current wording of section 10b paragraph 3, the donation deduction for such holdings would then be capped at the acquisition cost, and that even after ten years of holding. For legacy holdings acquired up to the end of 2026 the existing legal position is to continue to apply; the cut-off date and its grandfathering are set out in our analysis of the draft.
This is a consequence the draft does not expressly regulate; it emerges only from the interplay with the law on donations. Whether the legislature intends it that way cannot be said today, and the draft is not yet law. Anyone planning a larger donation out of a holding they are only going to build up in future should keep this point in view.
Donating bitcoin: what to take away
Three steps lead from the intention to an evidenced deduction.
- Establish the acquisition date and purchase price for the specific quantity. That decides whether you may apply the market value or only the acquisition cost. If the purchase is less than a year back and the donation is not urgent, waiting moves the deduction markedly upwards. You get the records from your trading venue's account; which provider releases which history is set out in our overview of regulated crypto exchanges.
- Clarify the recipient's status and the confirmation in advance. Ask before the transfer whether the organisation has the status under section 5 paragraph 1 number 9 of the Corporation Tax Act and whether it issues a donation receipt for a donation in kind in crypto assets. After the transfer this can hardly be repaired. The valuation on which it bases its confirmation you supply yourself; the evidence for it is produced by the programmes in our comparison of crypto tax tools.
- Document the transfer. Transaction ID, time, quantity and market value on the day of the transfer belong together in your files. Anyone sending from their own wallet is solely responsible for that; which programmes record addresses and histories permanently is shown by our software wallet comparison.
A closing note that goes beyond tax: none of these steps is a reason to forgo or postpone a donation when the help is needed now. The holding period determines the size of the deduction, not the worth of the donation.
(As of October 1, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
NEAR Intents confirmed an exploit of more than $3.8 million on October 1, 2026, closed the vulnerability and halted deposits and withdrawals on eleven networks. Full reimbursement of all affected funds has been promised; a date for it has not. If you have used the swap layer to move balances between two blockchains, one thing now decides above all: where your balance sits at this moment, and whether it has to stay there.
The price of NEAR stood at $4.90 on the afternoon of October 1, 2026, 6.96 percent below the previous day; over the week the value is up 7.66 percent. The price here is only the visible part, though. The more important part is an infrastructure through which, according to the operators, more than $30 billion has already flowed across 35 networks, and which was only partly usable for several hours.
What happened at NEAR Intents on October 1, 2026
NEAR Intents is the cross-chain swap layer in the orbit of the NEAR protocol. This layer takes in an intention, such as swapping a token on one blockchain for a token on another, and lets service providers compete to execute it. On Thursday, irregular withdrawals flowed out through a hot wallet of this layer. The damage, as the project describes it, amounts to more than $3.8 million.
The team publicly acknowledged the incident, closed the affected point in the smart contract and suspended deposits and withdrawals on several connected networks. Core operations were, by its own account, to resume quickly, while deposits and withdrawals stay down longer. That order matters more to you than the damage figure: a service that permits swapping but not withdrawing is not usable for you.
Hot wallet: what the term means here
A hot wallet is a wallet whose keys sit on a system connected to the internet, so that a platform can execute payments automatically. That access is the reason it is fast, and at the same time the reason it remains the preferred target of an attack. Set against it is the cold wallet, whose keys stay offline.
The fault sat between the Omni bridge and the Intents contract
The project describes the cause as a fault in the way the Omni system for deposits and withdrawals interacted with the NEAR Intents smart contract. It was not a single component that was defective, but the handover between two. That is the normal case in attacks on cross-chain infrastructure, and the reason audit reports on individual contracts say only so much: what is audited is usually the building block, what is exploited is the joint.
In this architecture Omni is the layer that accepts deposits from an external blockchain and releases withdrawals back to it. The Intents level above it decides what happens to the balance. Anyone who can get the order of the two levels out of step can trigger a withdrawal for which there was no valid deposit. The contract-side gap has been closed, according to the team.
Why a patch is not yet the all-clear
A closed contract fault prevents a repeat of the same attack. It says nothing about whether the same joint is still open elsewhere, and it does not bring back any funds that have flowed out. What counts for you is therefore not the notice about the patch but the release of withdrawals on the network where your balance sits.
Eleven networks without deposits or withdrawals: BNB Smart Chain, Polygon, TON and more
Affected by the suspension, according to the CoinDesk report, were BNB Smart Chain, Polygon, TON, Optimism, Avalanche, Stellar, Monad, X Layer, ADI, Scroll and Plasma. This list is the day's actual finding. A single faulty handover point can shut down access to eleven different ecosystems at once, and the list shows at the same time how many chains now hang off a shared layer.
In practice that means a swap in progress whose counter-value was due to arrive on one of these networks could be left hanging. A balance already sitting on one of these chains was not automatically affected, as long as it was in a wallet of your own and not in the swap layer. The distinction between in my wallet and in transit within a service decides the damage in hours like these.
How ZachXBT traced the $3.8 million through KuCoin into bitcoin
The investigator ZachXBT, who publicly analyses on-chain traces, has retraced the movement: the irregular outflows began at a hot wallet on BNB Chain attributed to NEAR Intents. From there the funds went to the KuCoin exchange and were swapped into bitcoin. This chain is typical, because bitcoin offers the deepest liquidity and a move through an exchange breaks the trail as soon as accounts are interposed there.
The project says it has reported the incident to law enforcement and brought in security and analytics firms to follow the funds further. Whether an exchange freezes the amounts received is its own decision, and usually only after a formal request. There are no reliable statements about recovery on this day, and nobody should promise you any.
Full reimbursement promised, date open: what happens to your balance in the gap
The team has promised to reimburse affected funds in full. No timetable was named. This combination is the most delicate point of the incident, because it creates a claim you can neither quantify nor date: your claim is against a project, not against a supervised institution with deposit protection.
In practice that means three things. Your balance in the swap layer is unavailable until release. A promised reimbursement without a date is a declaration of intent, not a due date. And as long as you have no evidence of the state of your balance before the incident, you carry the burden of proof for your own claim. A screenshot with a date and the transaction ID of the last swap are worth more at this point than any market analysis.
Anyone holding long-term positions should take the opportunity and put them where no third-party service stands between them and the key. Which devices and programmes come into question for that and how they differ is set out in the hardware wallet comparison. A swap layer is a passage, not a warehouse.
Cross-chain swaps, intents and solvers: how the swap layer works
An intent is a declaration of intention: you set out what you want to give up and what you want to receive, and leave the route there to others. A solver is the service provider that carries out this intention and earns on the price difference. A classic bridge, by contrast, locks your token on one chain and issues a representation of it on the other.
The difference is decisive for the risk question. With a bridge, the risk lies in the locked holding that backs the representations. With an intent system it lies in the deposit and withdrawal layer and in the hands of the solvers, who temporarily have other people's balances at their disposal. That is precisely the layer affected on October 1. For you that means the question is not whether a method is safe, but how long your balance is in a third party's hands at all.
How long your balance is in transit
A swap completed in seconds exposes you briefly to a failure. A swap whose counter-value arrives only minutes or hours later exposes you for a long time. A balance you leave sitting in the service after the swap exposes you permanently. The third variant is the most expensive and at the same time the most common, because it is convenient.
$50 million blocked a week ago, now hit itself
The same platform was on the other side of events the week before: back then the service intercepted some $50 million from the Bitget hack before the money could move on. We described that on September 30, 2026, under the title "NEAR Intents blocks $50 million from the Bitget hack". Seven days later, $3.8 million is missing from the same infrastructure.
No schadenfreude follows from that, but a sober insight. A platform able to stop other people's funds has deep insight into payment flows and correspondingly many points of contact. The same reach that makes a block possible creates the attack surface. Anyone who looks only at a service's capabilities and not at the number of its handover points is pricing the risk too cheaply.
What to check now on your own cross-chain holdings
Four concrete points are at stake, and none of them takes more than a few minutes.
- Open swaps: look through your history for a swap after September 30 that still stands without a matching entry. Note the time, the network and the transaction ID.
- Residual balance in the service: a balance left sitting in the layer after a swap belongs in your own wallet as soon as withdrawals are released again.
- Approvals in your wallet: revoke permissions you once granted a contract for unlimited amounts. An old approval keeps working even if you stopped using the service long ago.
- The network your balance is on: if it sits on one of the eleven suspended chains, wait for the release and do not attempt a detour through a second unfamiliar service.
What matters is the difference between waiting and doing nothing. Waiting means watching the situation, securing evidence, putting no new funds into the affected layer. Doing nothing means leaving a balance there and being unable to show later how much it was.
MiCA, custody and holding period: the German legal framework in an exploit
Since January 1, 2026, only authorised providers may offer crypto-asset services in Germany; the national transition periods in the EU expired on July 1, 2026 at the latest. A decentralised swap layer is not a supervised custodian, and that is exactly what the legal consequence hangs on: there is no deposit protection, no supervisory complaint to BaFin over a duty to provide a service, and no body that enforces a reimbursement.
Anyone wanting to draw this line cleanly in daily use buys and sells through an authorised provider and uses cross-chain routes only for the purpose they were built for. An overview of providers with European authorisation is in the hub on regulated crypto exchanges. That replaces no judgement of your own, but it moves the part of your assets entrusted to a third party into a framework with obligations.
What a reimbursement does to your holding period
The one-year holding period under German income tax law attaches to the acquisition and disposal of the same asset. Whether a reimbursement counts for tax as a reversal or as a new acquisition depends on how it is technically executed: whether the same token comes back or a counter-value in another currency. You should document that distinction before the reimbursement happens, not after.
How NEAR reacted to the exploit: $4.90 and 6.96 percent down
The NEAR price stood at $4.90 on the afternoon of October 1, 2026, after a day's high of $5.52 and a day's low of $4.79. The loss of 6.96 percent against the previous day makes NEAR the weakest value among the 25 largest cryptocurrencies that day; the market capitalisation is around $6.4 billion, daily turnover some $1.4 billion. Over seven days a gain of 7.66 percent still stands. The figures come from CoinGecko.
These numbers describe a reaction, not a valuation. A decline of almost 7 percent on damage of $3.8 million shows that the market classes the sum itself as small and the interruption of the swap layer as the costlier part. How things go from here depends on how quickly deposits and withdrawals run again on all eleven networks.
A month of heavy losses as the backdrop
The incident does not stand alone. On September 30, 2026 we compiled the finding that crypto hacks caused losses of $766 million within a month. Against that backdrop $3.8 million is a small item, and for that very reason the lesson from it is the more important one: it is not only the large sums that are hit, and not only the unknown projects.
Tax after a hack: how to document the loss and the reimbursement
For a German tax return, what you can evidence is what counts. Secure the following now rather than later: the holding before the incident with its date, the transaction IDs of the affected operations, the project's public statement with its date, and every later credit with its amount and time. A loss that cannot be evidenced has no effect for tax, and a reimbursement whose origin you cannot explain prompts questions.
Whether a loss from a theft is deductible at all has not been conclusively settled in Germany and depends on the individual case; only a tax adviser or the tax office can give a binding answer on that. The first step is undisputed: a complete, timely record. How the basic rules on holding period, allowance and reporting obligations interact is set out in our overview of crypto tax in Germany.
The NEAR Intents exploit: what to take away
- Secure your evidence, today. The holding before the incident, the transaction IDs, the date of the project's statement. For the ongoing bookkeeping of your holdings, one of the tools from the hub on tax tools and portfolio trackers helps.
- Take long-term holdings out of the passage. What you intend to hold for longer does not belong in a swap layer. Which programmes allow self-custody on a phone or a computer is shown by the software wallet comparison.
- Separate the buying route from the swapping route. Regular purchases through an authorised provider, cross-chain routes only for the specific purpose. The selection is in the hub on the best crypto exchanges.
Sources for further reading: the report by CoinDesk of October 1, 2026 with the list of affected networks and ZachXBT's findings, and the NEAR Intents documentation on how intents and solvers work.
(As of October 1, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
A protocol extension is close to activation on the XRP Ledger that will let accounts hand individual rights to other accounts without surrendering their own master key. The amendment is called PermissionDelegationV1_1 and carries the specification number XLS-75. Numerous trade outlets have named October 5, 2026 as the date in recent days, some of them to the minute at 11:18 UTC.
The ledger itself says something different. The majority on which the two-week period rests has only been recorded there since September 24, 2026 at 21:25 UTC. The amendment can therefore take effect no earlier than October 8, 2026 at around 21:25 UTC, a good three days later than announced. Cryptoticker.io compiled this analysis itself on October 1, 2026. It rests on the XRP Ledger's amendment data, verified at two mutually independent sources. All 113 amendments the network currently carries were checked, four of them with an ongoing or still open vote.
For you as a holder of XRP this is more than a calendar question. Around protocol updates, trading venues and custodians regularly suspend deposits and withdrawals for a short period, and anyone with the wrong day in mind will schedule a transfer into the very window in which it stalls. XRP is trading at $1.48, or 1.32 euros, down almost 2 percent within a day, at a market capitalisation of some $93.5 billion.
PermissionDelegationV1_1: the amendment stands at 29 of 35 validators
Changes to the XRP Ledger are voted on by the network's validators; no company switches them on. An amendment is a protocol change that these validators vote on and that only takes effect once it has held a qualified majority behind it for long enough.
PermissionDelegationV1_1 currently reaches 29 of the 35 trusted validators, which is 82.9 percent. The threshold the network itself applies to this amendment stands at 28 votes. The margin to the threshold is therefore a single vote: if one validator drops out or changes its position, the extension is on the edge.
The extension was introduced with version 3.3.0 of the reference server software; in the network the leading nodes are meanwhile running 3.4.1. The predecessor is notable: an older amendment of the same name and with the same specification number XLS-75 is still in the register, but reaches a single vote and is marked as superseded. The first attempt at this function therefore failed, and what now stands before activation is the revised second version.
Why one vote makes the difference
The threshold of a good 80 percent is deliberately set high and is meant to prevent a narrow majority from changing the rulebook of a chain on which payments are settled. The side effect: an amendment can lose its majority again shortly before the finish line, and that is evidently what happened here.
Two dates in circulation: October 8 stands in the ledger, October 5 in the reports
The timeline named in many reports begins on September 21, when the amendment reached the two-week phase. Fourteen days later that yields October 5. The entry in the ledger, however, carries September 24 at 21:25 UTC, and that is the point from which the period is actually counted.
The network's own rule explains how both dates can arise. If an amendment loses the necessary support during the waiting period, it is provisionally rejected and the two-week period starts again. Several trade services had reported in the same week that the attempt had been restarted; the date given was in many cases not carried along. Anyone relying on October 5 is going by a clock that was put back in the meantime.
The counter-check belongs to the picture: October 8 is the earliest possible date, not a commitment. If support stays above the threshold until then, the network switches the extension on. If it falls before that, the period begins again, and the date moves out by another two weeks.
Flag ledgers and the two-week period: an amendment's path to activation
The XRP Ledger counts the votes at fixed intervals. Every 256th block is a flag ledger, a block at which the network tallies the amendment votes. This happens every few minutes, and the process spreads across four consecutive blocks: in the block before, the validators cast their votes; in the flag ledger they are counted; in the next block the enablement is recorded; and in the block after that the change takes hold.
In practice that means the following for October 8: the extension takes effect at the first flag ledger tallied after 21:25 UTC, so possibly a few minutes later. For planning purposes, the evening of October 8 is precise enough, which in central European time means the late evening of the same day.
The official description of this procedure is in the XRP Ledger documentation on amendments. It also sets out the rule that the period restarts if support falls back below the threshold.
DelegateSet: ten rights per delegate, the master key stays with the account
Technically the change works through a transaction type of its own called DelegateSet. With it, one account grants individual powers to another account, alters them later or withdraws them. Permission delegation denotes precisely this principle: one account allows another to submit certain transactions on its behalf without passing on its own signing key.
The ceiling is ten powers per delegation entry. Anyone needing more is referred in the documentation to the multi-signing that already exists. That sounds like a footnote but is the actual use case: a company can allow its payments department to initiate transfers and its compliance department to approve them, without either one getting hold of the key to the overall account.
The key itself stays with the delegating account. That is exactly why the function is of interest to custodians, payment service providers and trading venues, which today work either with omnibus accounts or with laborious multi-signature arrangements. How you keep your own keys is untouched by this; anyone wanting to compare the devices will find the overview in the hardware wallet comparison.
What changes for a private account
For an ordinary XRP account, nothing changes at first. As long as you set up no delegation yourself, your account remains as usable as before. The extension creates an option, not an obligation. It becomes relevant to you in two places: in the software you use to access the account, and at the service that holds your XRP in custody.
Non-delegable rights: key rotation and granting rights stay barred
The specification draws a line that is decisive for the security assessment. Certain powers expressly cannot be handed over, among them those with which a delegate could swap out the account's keys or grant itself further rights. If a transaction attempts it anyway, the network rejects it with a malformed-transaction error.
This line prevents the obvious attack. Without it, a partial right once granted could be built up into the complete takeover of an account, because the delegate would make itself the key holder. With it, a delegation remains revocable, and solely by the account that granted it.
The full list of excluded powers is set out in the specification XLS-75 on permission delegation. Anyone operating wallet software or planning an integration cannot get around this document.
PaymentBurn: the caveat in the XRPL documentation on newly minted tokens
The technical description of the DelegateSet transaction contains a note that is easily missed on a skim read. As long as one further amendment is not switched on, a delegate holding the narrowly drawn PaymentBurn power may under certain circumstances also create new tradable tokens. The documentation lists this as a caveat, not as a bug.
The point has practical significance for issuers of their own tokens on the XRP Ledger, not for you as a holder of XRP itself. Anyone holding tokens of an issuer that works with delegations from the activation day onwards does, however, have a question for that issuer: which powers are granted, to whom, and how are they revoked.
The caveat also shows why such extensions arrive in stages. A single protocol change intervenes in a rulebook made up of dozens of earlier changes, and the interactions are not always clear from the outset.
BatchV1_1 and LendingProtocolV1_1: the other amendments in the window
Permission delegation is not the only change in the queue. Three periods run alongside each other in October, and a fourth vote is still at the beginning. The overview reflects the position as of October 1, 2026.
| Amendment | Specification | Validators | Majority since | Earliest active |
|---|---|---|---|---|
| PermissionDelegationV1_1 | XLS-75 | 29 of 35 | Sept 24, 21:25 UTC | Oct 8, 21:25 UTC |
| BatchV1_1 | XLS-56 | 30 of 35 | Sept 25, 14:46 UTC | Oct 9, 14:46 UTC |
| fixBatchV1_2 | bug fix | 34 of 35 | Sept 25, 14:12 UTC | Oct 9, 14:12 UTC |
| LendingProtocolV1_1 | XLS-66 | 5 of 35 | no majority | open |
BatchV1_1 bundles several transactions into one package that is processed together, and reaches 30 votes. The accompanying bug fix carries the broadest support of all four at 34 of 35 votes. Both would take hold one day after permission delegation, on October 9.
The case of the lending protocol LendingProtocolV1_1, about which much has been written lately, is markedly different: it stands at 5 of 35 votes and has not reached a majority. There is no sign of an activation there in the coming weeks, and no date for one. Anyone reading reports of imminent lending on the XRP Ledger can hold this figure up against them.
Custody and exchange account: the activation day for holders in Germany
The day itself passes unspectacularly for most holders, with one exception: trading venues and custodians occasionally suspend XRP deposits and withdrawals for a few hours around protocol updates, in order to wait out the transition. That is routine and not an incident, but it affects everyone who has planned a transfer for that evening.
Anyone holding XRP with a provider will usually see an announcement in the status area or by notification, mostly one to three days beforehand. Anyone self-custodying needs wallet software that can handle the new transaction type; older versions may not display an unknown transaction type at all, or display it incorrectly. Which providers in Germany are authorised under the European regulation on markets in crypto-assets, and how they differ on fees and custody, is shown in the crypto exchange comparison.
A protocol update changes nothing for tax
An amendment activation is not an inflow, not a disposal and not a new token. Your holding period runs on unchanged, and no taxable event arises. It would be different only if a chain were to split; there is no indication of that here, because the extension is running with a broad majority and without a competing proposal.
Phishing with delegation rights: a new pattern for forged approvals
Every new permission function in a chain brings a new fraud pattern with it. On Ethereum the same pattern ran after delegated accounts were introduced: a purported approval page asks for a signature, and the signature grants not a payment but lasting rights over an account.
For the XRP Ledger that means, from the activation day onwards: a request to sign a DelegateSet transaction belongs among the operations where it pays to look twice. An account to which you grant rights can act within those rights until you revoke them. Because key rotation remains excluded from delegation, the damage is limited; that does not make it pleasant.
Such a request never reaches you from a network itself. Neither the XRP Ledger nor a wallet sends you a message saying you have to confirm rights for a protocol change to take effect. That notification is a forgery, without exception.
Permission delegation: your next three steps
- Update your wallet software before October 8 arrives. A version that knows DelegateSet shows you a delegation transaction as such instead of listing it as an unknown type. Which programmes are maintained and which have stood still for months is set out in the software wallet comparison.
- Check the window with your custodian. If you have planned an XRP deposit or withdrawal for October 8 or 9, move it to another day, or fetch your provider's status notice beforehand. Anyone thinking about switching anyway will find the authorised providers in the exchange comparison.
- Keep larger holdings out of reach of the approval function. An account that never delegates cannot be attacked by this route either. For amounts you do not move, custody on a device of your own remains the calmer solution; the devices and their differences are set out in the hardware wallet comparison.
The date stays movable to the last. As long as support lies above the threshold of 28 votes, the evening of October 8 applies; if it falls below, the two-week period begins again. This can be followed through the validators' vote count, which changes continuously in the network.
(As of October 1, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Anyone moving AVAX from an exchange into their own wallet faces a question that no other major network poses in quite this form: which chain? Avalanche consists of three blockchains that run in parallel and each use their own addresses. The Avalanche C-Chain is the only one of them where tokens, smart contracts and the entire DeFi world live. Send your balance to an address on the neighbouring chain by mistake and it will not arrive where you expect it.
This guide shows you how to identify the right address, what a transfer on the C-Chain currently costs, how to trace a transaction in the Snowtrace explorer and where an AVAX withdrawal most often goes wrong. It is the final part of our series on the major networks; the shared overview is at Adding a network, bridges and explorers.
C-Chain, X-Chain and P-Chain: what the three Avalanche chains are for
Avalanche calls its core the Primary Network. It consists of three blockchains with clearly separated jobs, and every wallet, every exchange and every explorer always refers to exactly one of them.
The C-Chain (Contract Chain) is an implementation of the Ethereum Virtual Machine, the computing environment in which smart contracts are executed. Everything an investor normally associates with Avalanche runs here: tokens, exchanges such as LFJ, lending protocols, NFTs. Because it is EVM-compatible, it works technically like Ethereum and uses the same addresses, which begin with 0x.
The X-Chain (Exchange Chain) handles the issuance and trading of what are known as Avalanche Native Tokens. This chain does not know smart contracts; its model is simpler, and its addresses carry the prefix X-avax. Historically it was the standard chain for plain AVAX transfers, and that is precisely where the risk of confusion comes from.
The P-Chain (Platform Chain) manages validators, staking and the creation of custom networks. Addresses on this chain begin with P-avax. Anyone delegating AVAX moves their balance there. For an investor's day-to-day it matters only for staking. The official description of all three chains is in the Avalanche developer documentation.
The consequence is what matters: the same AVAX can sit on three different chains. That does not make them lost, but on the wrong chain they remain invisible to smart contracts, and the way back costs an extra step.
How to recognise a C-Chain address
The distinction is simpler than it sounds once you look at the prefix. A C-Chain address looks exactly like an Ethereum address: 42 characters, beginning with 0x. An X-Chain address begins with X-avax, a P-Chain address with P-avax. So you can only confuse them if you are not looking at all, or if an exchange offers you two options and you click the wrong one.
That is exactly how a failed withdrawal unfolds: the exchange's withdrawal window has a field for the address and below it a menu for the network. For AVAX, both chains frequently appear there, sometimes with an additional entry for an Ethereum version of the token. Copy a 0x address out of your wallet but select X-Chain as the network, and in the best case the exchange rejects the withdrawal. In the worse case it sends the balance to an address your wallet cannot reach.
The rule of thumb: the chain your wallet shows you decides, not the one you are used to. Open the wallet, check whether the address begins with 0x, and then select the same network at the exchange. The same check applies on every EVM network, for instance when switching to Arbitrum One, where picking the wrong network has the same consequences.
Core Wallet and MetaMask: the Avalanche network in your own wallet
Core is the wallet developed by Ava Labs. It knows all three chains out of the box and can move funds between them. Anyone planning more with Avalanche than a single transfer is most comfortable there, because switching between C-Chain and P-Chain is a built-in operation rather than a detour.
MetaMask and most other EVM wallets do not know the C-Chain by default, but can be set up for it in one step. You need four details, all of them from the official documentation: the chain ID 43114, the RPC endpoint https://api.avax.network/ext/bc/C/rpc, the currency symbol AVAX and Snowtrace as the explorer address. Once added, Avalanche appears like any other network in the list, and your familiar 0x address applies there too.
One point is often overlooked: a browser wallet extension is convenient, but it sits on a device that is connected to the internet. For amounts you intend to hold for longer, the private key belongs on a device without an internet connection. Which models are suitable and how to spot a tampered device is set out in our hardware wallet comparison.
Whatever the wallet, one rule holds: the recovery words are written down once and never photographed, never put in a cloud and never typed into a form. No reputable provider asks for them.
Fees in AVAX: what a transfer on the C-Chain costs
Payment on the C-Chain is made exclusively in AVAX, just as it is in ETH on Ethereum. The arithmetic behind it is the same: every transaction consumes a certain number of gas units, and every unit costs a price that depends on how busy the network is. A simple transfer consumes 21,000 units, a swap on a decentralised exchange a multiple of that.
These prices have fallen sharply twice in the past two years. Until December 2024 the minimum price was 25 nAVAX per gas unit, after that 1 nAVAX, and since the Octane upgrade of April 2025 it has stood at one wei, the smallest fraction that can be represented at all. Octane replaced the fixed gas target with a mechanism in which the price adjusts continuously to actual demand.
In practice that means the following. On the evening of September 29 the base price stood at around 5 nAVAX per gas unit. A simple AVAX transfer therefore cost roughly 0.000105 AVAX. At a price of around 9.91 euros per AVAX, that is about a tenth of a cent. Even a swap on a decentralised exchange stays in single-digit cents, as long as the network is not unusually busy.
One feature sets Avalanche apart from Ethereum: both components of the fee, the base price and the voluntary tip, are burned in full. Validators receive none of it; the amount leaves circulation permanently. If you want to understand the concept of gas and its components from the ground up, the detailed explanation is in our piece on Ethereum gas and Etherscan; the mechanics are the same, only the order of magnitude differs.
What matters day to day is the consequence: you always need a small AVAX balance on the C-Chain, even if all you want to move is a stablecoin or another token. Without the fee token every transaction stalls, however large the token holding.
From the exchange straight to the network, or across a bridge
There are two ways to get AVAX or other tokens onto the C-Chain, and they differ considerably in cost and effort.
The easier route is a withdrawal from a trading platform. You buy AVAX, select the C-Chain in the withdrawal window and enter your 0x address. The exchange covers the network fee internally but usually charges a withdrawal flat fee of its own, which depending on the provider can sit well above the actual network cost. The amount is shown in the summary before you confirm, and it is worth reading: on small sums it eats a noticeable share. Which platforms in Germany operate under European supervision and what their terms look like is set out in our overview of crypto exchanges.
The second route is a bridge from another network. If your balance is already on Ethereum or another EVM network, a bridge transfers it to the C-Chain. Core includes such a function, and there are providers that connect several networks. Unlike the optimistic rollups, where bridging back to Ethereum involves a seven-day wait, Avalanche operates as an independent network and has no such lock-up period. A transfer is usually complete within minutes.
Bridges carry a different caveat, though: they are smart contracts holding large sums, and they have been among the most frequently attacked building blocks in crypto for years. For a one-off transfer of a manageable amount, the exchange route is therefore usually the calmer one.
Reading Snowtrace: following a transaction in the explorer
A block explorer is a network's public ledger. For the C-Chain it is called Snowtrace and has been run by Routescan since the previous operator handed it over. Every transaction, every address and every token balance can be looked up there, without registration and without connecting a wallet.
The explorer is useful above all in four situations. First, when a withdrawal does not arrive: you enter your address and see immediately whether a transaction came in at all. If nothing is there, the fault lies with the exchange or the chain, not with your wallet. Second, when a transaction hangs for a long time: the status reveals whether it is confirmed, still pending or failed. A failed transaction still costs fees but changes nothing about the balance.
Third, for tokens that do not show up in the wallet. The token transfers of an address list what has actually arrived. If a token is missing only from your wallet's display, you have to add it there manually using its contract address. And fourth, when checking a token before buying: the explorer shows how many addresses hold it and when the contract was created. A token that came into being three days ago and has twelve holders is not an established project.
A warning belongs with this: anyone can create a token and call it whatever they like. Counterfeit tokens bearing well-known names regularly turn up in wallets uninvited. What counts is always the contract address, taken from the project's official site or from an established price database, never the name displayed.
The most common mishaps in an AVAX withdrawal
Four patterns can be read out of the accounts that reach us, and three of them cost not the balance but only time.
The wrong network comes first. A balance that lands on the X-Chain instead of the C-Chain is not lost: a wallet that knows both chains will move it across. Anyone using only MetaMask needs Core, or a comparable wallet with the same recovery words, once for that.
The missing fee token is the second most common cause. There are tokens in the wallet but no AVAX, and so nothing can be moved. The remedy is plain: send over a small amount of AVAX before trying anything else.
The stuck transaction arises when it was sent at a very low gas price. On Avalanche this has become rare thanks to the dynamic pricing, but it still happens with manually set values. Most wallets offer to replace the same transaction at a higher price.
The fourth mishap is the only one that really costs money: a withdrawal to an address belonging to someone else. It happens through malware that swaps the address in the clipboard as you copy it. Only one thing helps against it: before sending, compare the first and last four characters of the address in the withdrawal window with the wallet. That second is the only control the process has, because a transaction once sent cannot be recalled.
Token approvals and phishing: where the biggest risks lie
The C-Chain works with the same approval model as Ethereum, and that is the most underestimated danger in daily use. When you want to swap a token on a decentralised exchange, you first grant the associated smart contract an approval. That contract may then debit the token in question from your address. Many applications request an unlimited approval by default, because it saves a confirmation on every further swap.
The approval remains in place until you withdraw it. If the contract is attacked later, or was malicious from the start, it can pull the approved token at any time, even months afterwards, without you clicking anything. That is why going through the approvals you have granted from time to time, and revoking everything you no longer need, belongs to the routine. The revocation is an ordinary transaction and costs only the fraction of a cent mentioned above on the C-Chain.
With phishing the pattern has been the same for years, only the packaging changes. A message announces a reward, an urgent verification or a network migration and leads to a cloned site. There you are asked either to enter your recovery words or to sign an approval that clears you out. Against the first variant, the rule that those words are never typed in anywhere is enough. Against the second, it helps to read what is actually being permitted in the wallet's confirmation window, instead of pressing approve.
Tax in Germany: holding period and allowance for AVAX
For private investors in Germany, the same rules apply to AVAX as to other crypto assets. A sale within one year of purchase is a private disposal; the gain from it is taxable as long as the sum of all such gains in a year exceeds the allowance of 1,000 euros. After one year has elapsed the sale remains tax-free. What counts is the date of acquisition, and that does not change because you move the balance from the exchange into your own wallet.
This is the point at which many become unsure: a withdrawal to the C-Chain is not a sale and therefore does not trigger tax. It is a movement between two places of custody belonging to the same owner. A taxable event only arises when you exchange AVAX for euros, for another coin or for goods.
With fees it gets more granular. The network fee you pay in AVAX when swapping on a decentralised exchange is itself a disposal of a fraction of your holding. At the scale of tenths of a cent this makes no practical difference, but it does for documentation: anyone making many transactions should carry the fee lines along. That is exactly what portfolio tools are for, reading transactions in automatically and tracking the holding periods per tranche; which of them support German tax offices is set out in our overview of tax tools and portfolio trackers.
A note on staking: anyone delegating AVAX and receiving rewards has income that is treated differently from a pure capital gain. Because the classification depends on the individual case, that is the point at which a visit to a tax adviser pays off more than a search in a forum.
Avalanche: the key points for your decision
Practice on Avalanche is less laborious than the three-chain structure first suggests. Once you have grasped that the C-Chain is the chain with the 0x addresses and that everything else is a special case, there is little to get wrong in a withdrawal. Fees have been so low since the Octane upgrade that they barely weigh on the decision, and with Snowtrace every operation can be traced publicly.
- Settle the purchase route. First compare the withdrawal flat fee of the platform you buy AVAX from; on small amounts it is the largest cost item. Our exchange comparison lists the terms of the providers available in Germany.
- Decide on custody. Before the first withdrawal, decide whether the balance stays in a browser wallet or moves to a device without an internet connection. For amounts meant to sit for longer, the hardware wallet comparison lists the models and their differences.
- Set up your records. Note the purchase date and quantity from the first tranche onwards, so that the one-year period can be evidenced later. A portfolio tracker does this automatically and saves reconstructing it after the fact.
(As of September 29, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
The German Federal Ministry of Finance’s draft bill on the taxation of crypto assets held privately has had a date since September 30, 2026: on October 14, 2026 the federal cabinet is due to take it up. For you, what matters about it is less the date than a figure that has barely featured in the coverage so far: January 1, 2028. From that day, crypto exchanges and other service providers are to withhold the tax on your gains directly and pass it to the tax office, the way a German bank does today with shares.
The short answer to the question of what that means for your trading account: for most purchases, nothing at all changes at first about the duty to declare for yourself. Deduction at source comes two years after the new rules, it affects only certain providers, and with self-custody it does not apply at all under the draft. Anyone who mixes that up is counting on relief that never arrives.
A note on the sources, because it counts for placing all this: the draft is not publicly available on the ministry’s pages. What is public is the covering letter, which Blocktrainer has published, and a detailed legal assessment of the draft version presented by the tax lawyer David Hötzel in the specialist portal Der Betrieb. Everything below is the state of the draft, not law in force.
Two dates the draft keeps strictly apart: January 1, 2027 and January 1, 2028
The draft works with two points in time that are often thrown together, although they govern different things.
January 1, 2027 is the start of the new substantive tax rules. Gains from crypto assets acquired or received after December 31, 2026 then fall under investment income within the meaning of Section 20 of the German Income Tax Act. For those holdings, the tax exemption after one year of holding therefore falls away. They are taxed at the rate for investment income, under the draft 25 percent plus the solidarity surcharge, and that applies after five, ten or twenty years as well.
January 1, 2028 is the start of the deduction of tax at source. Only from that day is a service provider to withhold the tax on investment income. The year 2027 is therefore a transitional year with new substantive law and old procedural practice: gains from new holdings will as a rule not yet be taxed at source and have to be entered in the tax return.
By exchange crypto assets the draft means crypto assets within the meaning of the European MiCA regulation that are accepted as a means of exchange without being issued or guaranteed by a central bank. The explanatory memorandum expressly names Bitcoin and Ether. NFTs, security tokens and e-money tokens under Title IV of the MiCA regulation are to remain excluded; for them, what follows from the right conveyed in each case continues to apply.
The timetable up to cabinet: consultation deadline October 6, deliberation on October 14
The ministry sent the draft to associations and interest groups on September 30. Comments are to be submitted by October 6, 2026. Six days is a very tight allowance for a consultation of associations on a change of system, and that is precisely the signal: the pace here is being forced.
On October 14 the cabinet is to deal with the draft. If it clears that hurdle, the ministerial draft becomes a government bill. That is more than a formality, because the content thereby moves from one ministry’s working version to the declared line of the federal government. The Bundestag and the Bundesrat follow, and amendments remain possible there.
A cabinet deliberation, incidentally, is an agenda item, not a decision on the wording. Appointments of this kind get postponed, and drafts change between consultation and cabinet, which is what the October 6 deadline is for. The sentence “from 2027 this applies” is therefore wrong today. What is right: this is how it stands in the draft the cabinet is due to deal with on October 14.
Is the December 31, 2026 cut-off date certain, then?
No, it is not certain, and for two reasons that stand independently of one another.
First, the grandfathering of existing holdings is so far only the content of a ministry draft and not a legally secured position. Cabinet, Bundestag and Bundesrat are still to come. Second, the cut-off date can shift during the procedure if the timetable shifts. Until then, only this is dependable: under the current draft, crypto assets acquired up to December 31, 2026 remain within the old regime of private disposals.
What this grandfathering concretely means under the draft: holdings that are already tax-free remain disposable tax-free. For old holdings whose one-year period is still running on January 1, 2027, the tax exemption can still arise once that year has elapsed. There is no step-up; the historical date of acquisition remains decisive. We wrote up the placing of the cut-off date in the draft at the beginning of September in a separate analysis of the grandfathering; the cabinet date has only now been added.
In practice, two regimes therefore arise permanently, hanging on the date of acquisition or receipt. For your records that means: proof of when a coin came to you becomes the most important document you hold about it.
Who is to withhold the tax from 2028: domestic crypto asset service providers
This is where it becomes concrete for your trading account. Those to be obliged to deduct tax under the draft are domestic crypto asset service providers and crypto asset operators, as well as domestic branches or permanent establishments of foreign providers, in each case to the extent that they pay out or credit the corresponding income.
The decisive term is the domestic paying agent. What is meant by it is not simply “a large, well-known exchange” but an entity that sits in Germany for tax purposes and actually credits the amount to you. A platform with a European authorisation but without a domestic branch does not automatically satisfy that criterion on the wording.
For the choice of your trading venue this becomes a hard distinguishing feature from 2028 that appears on no product page today. Anyone wanting to know which providers are authorised in the European Union at all and where they are based will find the overview in our comparison of regulated crypto exchanges. The question of whether a given provider will deduct for you cannot be answered from it today, because the law is not settled, but the question of domicile already can be.
Self-custody, DeFi and foreign platforms stay in the assessment procedure
Even from 2028, the deduction of tax will under the draft not apply across the board. Anyone who holds their coins in self-custody, who trades through decentralised applications, or who uses a foreign platform without a domestic paying agent remains obliged in principle to act for themselves: those gains still belong in the tax return.
The common line that “crypto will then run like shares” therefore covers only some of the cases. The assessment does not disappear, it becomes rarer. In practice two worlds arise side by side: domestic deduction cases, in which the provider does the arithmetic, and foreign or decentralised cases, in which you do. That both worlds together generate more administrative effort than one uniform solution has been noted expressly in the legal assessment of the draft.
From that follows an uncomfortable consequence for practice: you still need a complete record of your own, and precisely so if you move between wallets and platforms. Anyone whose purchase dates and purchase prices exist only in the interface of an exchange does not hold proof but a display.
Crypto-to-crypto swaps: the provider liquidates coins in order to pay the tax in euros
One point of the draft is usually skipped in the general coverage, although it reaches directly into your account. Swapping one crypto asset for another remains a tax-relevant transaction, because what is captured is the gain on disposal, and that term covered crypto-for-crypto swaps under the previous law too, in the view of the tax authorities and the tax courts.
From that arises a procedural problem the draft solves expressly: in a swap, no euro flows to you, yet the tax has to be paid in euros. The explanatory memorandum therefore sets out that the party obliged to deduct must be able to liquidate part of the crypto assets used in order to pay the tax in money.
The upshot is this: on a swap carried out on a platform obliged to deduct, part of the position may from 2028 be sold so that the tax can be paid. Anyone counting on a particular number of units should factor that deduction in. Exactly how the liquidation proceeds, what order applies to it and how the valuation is done is not settled in the draft down to the last question.
Missing acquisition data: 50 percent of the disposal proceeds as a substitute basis
If the platform does not know the date and the cost of acquisition, it may under the draft in principle fall back on your own particulars, as long as no contradictory data are available. Where those particulars cannot be applied, the procedure assumes the coins were acquired after December 31, 2026, and the deduction of tax is then measured on 50 percent of the entire disposal proceeds.
Two points of placing belong together here. The 50 percent are not a final fiction of profit: a deduction that is too high can be corrected in the assessment procedure. Until then, however, the money is gone, and from that arises a considerable liquidity risk. Particularly affected are transfers from a self-custodied wallet or from a foreign platform to a German platform obliged to deduct, which is precisely the route many take when selling. We worked that mechanism through in detail in a separate article on the substitute basis of assessment.
From that follows the one preparation that already helps for certain today, regardless of how the law ends up looking: a complete history of all purchases with date, quantity and price, together with the transfers between your addresses. Which tools pull that history together automatically from exchanges and wallets and build a report for the tax office out of it is in our comparison of crypto tax tools.
Loss offsetting without carryback: from 2027 there are two separate loss pools
Losses from new holdings are in future to be recognised within the system of investment income. They can therefore in principle be offset against other positive investment income and carried forward into future years. What falls away: a carryback into the immediately preceding year, as was possible in the regime of private disposals, is no longer provided for in the new system.
Old losses remain in the previous offsetting pool. The draft contains no transitional rule making losses from before the change of system offsettable, for a limited period, against gains from new crypto assets. From 2027 there are therefore two separate loss pools: one for old holdings and other private disposals, one for new crypto assets and the remaining investment income.
Anyone still holding unrealised losses in their old holdings should look at this separation before the end of the year, because under the draft it cannot be bridged after the fact. How a loss carryforward works under the law in force and which deadlines apply to it we wrote up in an article on the loss carryforward.
Crypto flat-rate tax compared with the taxation of shares from 2009
Structurally the model resembles the introduction of the flat-rate withholding tax for private share investments in 2009: a hard cut-off date, two regimes running permanently side by side, the date of acquisition as the switch. In one place, though, the draft departs from that precedent, and to your disadvantage: in 2009 there was a time-limited transitional rule for old losses, here none is provided for.
One more difference that matters for placing it: with shares, deduction by the bank came together with the new law. With crypto assets a year lies between the two, and even after that a large part of the cases stays with the taxpayer. The flat-rate tax on shares works because almost every custodian bank is a domestic paying agent. With crypto assets that is the exception.
Who gains and who loses cannot be stated across the board here. Long-term holders lose the complete tax exemption after one year. Short-term traders can come out better if their gains were previously charged at a personal marginal rate above 25 percent, and their losses become usable within a broader pool. So the model does not necessarily favour holding for a long time.
Lending and passive staking become investment income
The draft reaches beyond disposal gains to the running income as well. Receipts from making crypto assets available and from participating in transaction processing are likewise to count as investment income. What is meant by that is above all classic lending and passive staking.
One detail of this matters for old holdings and is easily read past: according to the explanatory memorandum, lending or staking rewards that flow in after December 31, 2026 out of an old holding count themselves as a new holding. The underlying old holding stays in the old regime, the reward from it does not. So anyone who lends or stakes a position held for years is, from 2027, continuously generating new holdings with their own tax consequence.
Many questions in the decentralised area remain open in the process: liquid staking, pools, wrapped tokens, the exact moment of inflow and the boundary with commercial transaction processing. Also unresolved is a point that can have considerable consequences for gifts and inheritance: crypto assets received without consideration are to be entered with acquisition costs of 0 euros. Whether that also catches the relative receiving a gift or an inheritance who gets a Bitcoin bought before 2027 cannot be taken unambiguously from the draft. That ought to be clarified in the legislative procedure.
160 million euros for 2028: the additional revenue the draft itself expects
The draft names the additional revenue expected for the state as a whole, and the series is remarkably modest: zero euros in 2027, around 160 million euros in 2028, around 305 million in 2029, around 325 million in 2030 and around 350 million euros in 2031. The zero for 2027 fits the logic of the procedure, because without deduction at source the money only flows with the assessment.
For comparison: in the budget debate of the spring, amounts in the billions per year were in circulation. Nothing of that is left in the draft’s impact assessment. The compliance cost for citizens, business and administration is so far marked “to follow” in the draft, so it has not yet been priced. The provisions are to be evaluated six years after they come into force.
For the political placing that means: by its own calculation the reform brings the state less than a medium-sized item in the federal budget, while demanding a new documentary discipline from every private holder. That discrepancy is an argument certain to turn up in the comments submitted by October 6.
Crypto tax: the key points for your decision
Three things can already be dealt with now, regardless of how the law ends up looking. None of these steps presupposes that the draft goes through unchanged.
- Secure the acquisition data in full. Date, quantity and price of every purchase, plus the transfers between your addresses. That is the proof that prevents the substitute basis of 50 percent, and it helps you in every conceivable legislative scenario. Where you made your purchases and how you export the history depends on the provider; the export routes of the common trading venues are in our exchange comparison.
- Keep custody and responsibility apart. With self-custody the duty to declare stays with you under the draft, even after 2028. Anyone considering their own custody anyway should know that no service provider will then do the tax arithmetic for them; the types of device and how they are operated are in the hardware wallet comparison.
- Go through the running income before the turn of the year. Rewards from lending and staking that flow in from 2027 out of an old holding count as a new holding under the draft. Anyone holding such positions should look at the terms and the inflow rhythms; an overview of the providers and their models is in the lending comparison.
What you should not derive from this text, by contrast, is a buying decision. That an acquisition before December 31, 2026 stays within the old regime on the current state of the draft is a tax consequence. Whether a purchase makes sense for you is an entirely different question, and no explanatory memorandum answers it.
(As of October 1, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
ZEC is 21% off its $1,698 peak after ETF outflows and a suspected North Korean heist routed money through its shielded pool. Is the run over, or will traders buy the dip?
The proposal would let advisers and funds use state trust companies as custodians and permit self-custody under certain conditions, aiming to replace years of ambiguity with a clear compliance path.
Reddit RSS dies November 13 and outside apps lose their data pipeline by March 2027. Reddit blames scraping bots, though it licenses its own content to AI companies.
OpenAI says it disrupted a campaign involving 15,000+ users and ties a core cluster to people associated with Moonshot, the startup behind Kimi.
Communications chief Andy Stone said reading Messages requires two permissions the user controls, disputing a journalist who reported Muse synced his texts despite his settings.
U.Today - IT, AI and Fintech Daily News for You Today
The crypto market is showing mixed momentum, with several assets pushing toward key resistance levels while others remain stuck in consolidation.
XRP trader sentiment has plunged to its lowest level since mid-August, with bearish commentary now overwhelmingly dominating social media despite the token’s recent rally.
A highly persistent WordPress malware strain is using Ethereum infrastructure to stay alive, with redundant copies scattered across compromised sites allowing it to rebuild itself even after attempted cleanup.
Dogecoin gains more US ground as Kalshi launches fully regulated onshore perps with strict leverage limits and Section 1256 tax perks.
Evernorth clears the final hurdle to debut the first actively managed, Ripple-backed XRP treasury on Nasdaq this October 8.
Blockonomi
TLDR
- SEC proposes a tailored crypto custody framework for investment advisers and regulated funds.
- Advisers could self-custody certain crypto assets when specified conditions are met.
- State trust companies could qualify to safeguard crypto assets for advisers and regulated funds.
- The proposal updates custody requirements under two major federal investment laws.
- Public comments will remain open for 60 days following Federal Register publication.
The U.S. Securities and Exchange Commission has proposed new rules governing how investment advisers and regulated funds can hold crypto assets. The plan would create a dedicated custody framework while updating requirements written primarily for traditional financial assets.
SEC Chairman Paul Atkins linked the proposal to the growth of crypto from a niche market into a major asset class. He argued that advisers need clearer options to safeguard digital assets while staying within federal securities laws.
SEC Proposal Opens a Path to Crypto Self-Custody
Under the proposal, registered investment advisers could self-custody crypto assets if they meet specified requirements. The framework would also cover registered investment companies and business development companies.
Atkins had previewed that approach in September because suitable third-party custodians remain unavailable for some digital assets. His earlier plan for adviser crypto self-custody also included a role for state trust companies.
The latest proposal turns those earlier policy remarks into formal rulemaking. It would amend requirements under the Investment Advisers Act of 1940 and the Investment Company Act of 1940.
The changes would also address financial statement audits for registered advisers and broker-dealer custody services used by regulated funds. The SEC has not adopted the framework, so the proposed provisions are not yet in effect.
State Trust Companies Could Expand Custody Options
The SEC would also permit advisers and regulated funds to use qualifying state trust companies for crypto custody. This could provide another option alongside banks and other permitted custodians.
The agency had already moved toward that model through 2025 staff guidance. That guidance provided conditional no-action relief involving certain state-chartered trust companies holding crypto assets.
The broader rulemaking has been developing for months. The SEC previously sent its crypto custody framework for White House review as work continued on a replacement for earlier custody proposals.
State trust custody has also drawn disagreement inside the Commission. Commissioner Caroline Crenshaw previously argued that state oversight can vary and may offer fewer safeguards than federal banking supervision.
The current effort follows an adviser custody proposal introduced under the SEC’s previous leadership that never became a final rule. The agency later revived its crypto custody rulemaking as part of its wider digital asset agenda.
Crypto Custody Joins Broader SEC Rulemaking
The custody plan arrives alongside other SEC work covering crypto offerings, tokenized securities, and market infrastructure. Atkins has presented those initiatives as connected parts of the agency’s approach to digital assets.
In August, the Commission proposed Regulation Crypto Assets, which would create tailored exemptions for some investment contracts involving digital assets. The SEC has also updated its approach to transfer agents as securities increasingly use blockchain-based records.
The new custody framework addresses how regulated firms hold crypto rather than determining whether particular tokens qualify as securities. Those classification questions remain subject to separate SEC interpretations and rules.
Public comments will remain open for 60 days after the custody proposal appears in the Federal Register. The Commission can revise the proposed requirements after reviewing feedback before considering whether to adopt final rules.
The post US SEC Proposes New Crypto Custody Rules for Investment Advisers and Funds appeared first on Blockonomi.
TLDR
- STLA stock gained 5.39% as stronger U.S. vehicle sales supported the rally.
- Ram 1500 sales surged 73% year over year, leading Stellantis U.S. sales growth.
- Jeep Cherokee hybrid retail sales climbed 53% from the prior quarter in Q3.
- Dodge sales rose 2%, while Durango posted its strongest third quarter since 2005.
- Chrysler Pacifica sales increased 6%, supporting broader U.S. sales growth.
Stellantis N.V. (STLA) stock rose 5.39% to $4.595 as stronger U.S. sales supported the afternoon rally. The automaker reported a 3% year-to-date sales increase. Third-quarter sales held steady at 324,277 vehicles, while core brands posted stronger retail demand.
Stellantis N.V., STLA
Stellantis Stock Gains as U.S. Sales Improve
Stellantis shares extended their advance through the afternoon and traded near the session high. Fresh U.S. sales data showed continued strength across major models. The company maintained stable quarterly sales despite a competitive industry environment.
Year-to-date sales rose 3% from the same period in 2025, giving the company momentum. Retail demand improved across pickup trucks, SUVs, and minivans, supporting the broader sales picture. Dealer activity supported the company’s U.S. retail performance.
The data supported STLA stock after shares gained more than 5% during the session. The rally highlighted the company’s U.S. vehicle mix and improving brand performance. Stellantis continues to expand product launches across American nameplates.
Ram Sales Surge 73% in Third Quarter
Ram delivered the strongest growth among Stellantis brands during the third quarter. Ram 1500 total sales jumped 73% from the same quarter in 2025. Total Ram pickup sales increased 34% during the period.
The Ram brand posted a 29% overall sales increase from the third quarter of 2025. Retail sales for the Ram 1500 increased 42%, showing stronger demand across the pickup lineup. The model also led its large light-duty segment in a 2026 JD Power study.
Orders opened for the 2027 Ram 1500 Rumble Bee 5.7L during the quarter. Initial allocation for the 2026 calendar year sold out within 90 minutes. Stellantis expects the Rumble Bee to reach dealerships during the fourth quarter.
Jeep Dodge and Chrysler Add Sales Support
Jeep recorded a 5% increase in Wrangler sales compared with the third quarter of 2025. Cherokee hybrid retail sales increased 53% from the second quarter of 2026. The Cherokee hybrid later posted its strongest retail month in September.
Dodge reported a 2% increase in total sales from the same quarter last year. Charger retail sales increased 22%, while Durango posted its strongest third-quarter sales result since 2005. Dodge also began production of the 2026 Durango R/T 392 Launch Edition.
Chrysler added support as Pacifica sales increased 6% from the third quarter of 2025. Total Chrysler brand sales also rose 6% during the period. Together, the results strengthened Stellantis’ U.S. sales profile and supported the STLA stock rally.
The post Stellantis N.V. (STLA) Stock: Rise 5% as Ram Sales Surge 73% and U.S. Sales Growth Fuels Rally appeared first on Blockonomi.
TLDR
- Bank of America stock trades at $53.58 after falling 1.57% on Thursday.
- Bank of America gives $10 million toward Boston Children’s Brighton campus.
- The project will combine behavioral health, outpatient and rehabilitation care.
- The Brighton expansion will create up to 200 jobs and 3,320 construction roles.
- New programs will support autism, developmental care and early intervention.
Bank of America (BAC) shares traded at $53.58, down 1.57%, as the bank announced a $10 million healthcare grant. The funding will help Boston Children’s Hospital develop a new pediatric behavioral health campus in Brighton, Massachusetts. The project will expand treatment capacity while adding inpatient, outpatient and rehabilitation services for children and adolescents.
Bank of America Corporation, BAC
$10 Million Grant Supports Brighton Expansion
Bank of America will provide $10 million to Boston Children’s Hospital for the planned behavioral health campus. The facility will rise on the Franciscan Children’s campus, which joined Boston Children’s health system in 2023. The project will create new clinical space and increase access to behavioral health services across Greater Boston.
The new campus will combine inpatient treatment, outpatient care and rehabilitation services within one integrated location. It will also include single-patient rooms and dedicated programs for children with developmental and intellectual disabilities. Boston Children’s expects the expanded capacity to improve early intervention and reduce treatment delays for families.
The hospital also plans partial hospitalization and intensive outpatient programs for pediatric and adolescent patients. Rehabilitation services will cover both post-acute care and outpatient treatment for children with different medical needs. These services will broaden the campus beyond traditional behavioral health care and create a more complete treatment network.
New Campus Adds Jobs and Specialized Services
Boston Children’s expects the Brighton project to create between 150 and 200 permanent jobs in the community. Construction work will also support more than 3,320 jobs throughout development of the new campus. That expansion adds an economic component to Bank of America’s healthcare-focused community investment.
The project will serve children with behavioral health needs and patients requiring specialized neurodevelopmental care. It will also create spaces designed for children with autism and intellectual and developmental disabilities. Families will participate more directly in care through layouts designed around long-term treatment and clinical support.
Beyond patient care, the campus will support research, workforce development and collaboration with schools and community organizations. Boston Children’s plans to use the site as a broader center for behavioral health innovation. Those programs could extend treatment and support beyond hospital walls and into surrounding communities.
Bank of America Extends Greater Boston Giving
Bank of America has built a substantial operating presence across Greater Boston through employees, branches and community programs. The company has more than 3,600 employees and nearly 130 locations serving customers throughout the region. Since 2021, it has contributed more than $53 million through philanthropic programs across Greater Boston.
Bank employees have also completed more than 216,000 volunteer hours across community programs since 2021. The bank has provided $963 million in home loans and $651 million in small business loans locally. These programs complement its financial support for healthcare, housing, economic mobility and community development.
Bank of America also marked the healthcare commitment through employee volunteer activities at Franciscan Children’s. Staff members participated in recreational and creative activities with patients across rehabilitation and behavioral health units. The grant therefore combines direct capital support with broader community participation around the planned Brighton campus.
The post Bank of America (BAC) Stock: Boston Children’s Lands $10 Million Grant for New Campus appeared first on Blockonomi.
TLDR
-
Sandisk stock gains 2.27% as Citi maintains its $2,100 price target on shares.
-
Tight NAND supply could support Sandisk pricing and margins through 2028 ahead.
-
Micron’s NAND revenue jumped 42% sequentially as selling prices strengthened.
-
AI data centers are increasing demand for SSD storage and NAND-based products.
-
Industry NAND shipments may grow at a mid-20% pace during both 2027 and 2028.
Sandisk Corporation (SNDK) stock rose 2.27% to $1,779.38 as stronger NAND pricing supported the company’s storage outlook on Thursday. Citi maintained a $2,100 price target while highlighting tighter NAND supply and stronger artificial intelligence infrastructure demand. The outlook extends through 2028, when supply growth may still trail rising storage requirements across major data center markets.
Sandisk Corporation, SNDK
Citi Sees Tight NAND Supply Supporting Sandisk
Citi’s view followed Micron Technology’s latest quarterly results, which showed a sharp improvement in its NAND business performance. Micron reported a 42% sequential increase in NAND revenue during its fourth quarter, reflecting stronger demand and pricing. Bit shipments climbed 10%, while average selling prices increased by almost 30% during the reporting period.
That pricing increase exceeded Citi’s earlier expectation for roughly 20% average NAND price growth across the market. The stronger move suggested that industry supply remains constrained even as storage demand continues expanding across enterprise applications. Sandisk could benefit because firmer pricing can support margins across flash memory and solid-state storage products over coming quarters.
Micron expects its NAND supply growth in 2026 to trail overall industry expansion as manufacturers manage production carefully. Industry NAND bit shipments could rise at a mid-20% pace during 2027 and 2028. That combination could keep market conditions tight if data center demand grows faster than new production capacity.
AI Data Centers Increase Demand for SSD Storage
Artificial intelligence infrastructure continues creating larger storage requirements across data centers and cloud computing systems worldwide. Operators need fast storage for model training, inference workloads, caching, and large-scale data movement across computing clusters. Solid-state drives are becoming more important across high-performance computing environments and modern data center architectures.
Citi analyst Atif Malik highlighted AI key-value cache workloads as another source of storage demand. Data centers can shift some of these tasks toward lower-cost SSDs instead of more expensive memory products. That approach could expand demand for NAND-based products as companies seek lower costs without sacrificing storage performance.
Sandisk sells flash-memory products and storage solutions that serve consumer, enterprise, and data center markets globally. Rising enterprise SSD demand could give the company another growth channel beyond traditional device storage. Stronger pricing would also improve revenue visibility if supply remains disciplined across the broader NAND industry through 2028.
Sandisk Outlook Strengthens Through 2028
Citi kept its buy rating and $2,100 price target for Sandisk following the updated NAND outlook. The target reflects expectations that constrained supply and higher demand could support stronger earnings conditions over several years. Sandisk stock’s 2.27% gain places shares closer to that target after recent shifts across semiconductor and storage stocks.
The wider memory industry is also recovering from an earlier downturn that pressured prices and production plans. Producers previously reduced output and capital spending after excess inventories weakened memory pricing across several technology markets. Now, stronger data center spending and tighter inventories are helping support a more favorable supply environment.
Future performance will still depend on NAND pricing, shipment growth, and the pace of capacity additions. Industry conditions could shift if producers expand output faster than expected during the next two years. Demand growth must also remain strong enough to absorb additional supply without weakening pricing across the storage market.
Sandisk’s current setup links its growth outlook directly to the broader expansion of artificial intelligence infrastructure. Data centers require more storage as models generate larger datasets and increasingly complex workloads across enterprise systems. That trend could keep NAND demand elevated through 2028 if infrastructure spending remains strong and production growth stays controlled.
The post Sandisk Corporation (SNDK) Stock: AI Storage Boom Could Keep NAND Supply Tight Through 2028 appeared first on Blockonomi.
TLDR
- Greenland Mines stock slides 13% after breaking sharply below the key $10 level.
- The Skaergaard campaign completed 4,480 meters of drilling across 17 holes.
- More than 104 tons of bulk material will support larger metallurgical tests.
- New LiDAR, magnetic, and bathymetric data strengthen future mine planning work.
- Environmental baseline work advances Skaergaard toward an Initial Assessment.
Greenland Mines Ltd fell 13.21% to $9.21 after breaking below the $10 level during Thursday trading. The decline came as the company completed its 2026 Skaergaard field program in southeast Greenland. The program now moves Skaergaard toward metallurgical studies, mine planning, environmental work, and an Initial Assessment.
Greenland Mines Ltd., GRML
Greenland Mines Completes 4,480-Meter Drilling Program
Greenland Mines completed 4,480 meters of diamond drilling across 17 holes during the field season. Global Drilling recovered both HQ and NQ core from several parts of the mineralized system. The company designed the work to support metallurgy, geotechnical studies, geochemistry, and future mine planning.
The program also produced more than 104 tons of bulk material from blasted mineralized sites. Greenland Mines mapped and sampled each site before contractors completed the blasting work. The larger samples will support more representative testing of gold, palladium, platinum, vanadium, iron, and gallium.
GTK Mintec will assess metal recovery, material variability, comminution needs, and potential by-product recovery. The company also collected large-diameter HQ core for deeper metallurgical testing. Meanwhile, NQ core will support assays and geotechnical analysis for possible open-pit and underground development.
Skaergaard Data Expands Mine Planning Work
Greenland Mines added new structural, geophysical, terrain, and hydrological data during the campaign. Teams used core photography, density measurements, point-load testing, televiewer surveys, and deviation surveys. These datasets will support future mine design, groundwater studies, and geological model updates.
The company also completed detailed drone LiDAR and photogrammetry across development areas. The surveys covered possible mine access, waste areas, tailings locations, and infrastructure zones near Miki Fjord. Greenland Mines reported LiDAR precision of about three to four centimeters across surveyed areas.
A drone aeromagnetic survey covered about 482 line-kilometers across 10.8 square kilometers. The survey focused on geological correlation, structural interpretation, drill targeting, and mine-planning applications. Greenland Mines also completed bathymetry and ground-penetrating radar work for access and infrastructure studies.
Environmental Work Supports Initial Assessment
WSP Denmark completed the first year of environmental baseline studies at Skaergaard during the 2026 campaign. The work starts a multi-year dataset for future environmental assessment and permitting requirements. Greenland Mines will combine those findings with engineering and technical studies during the next development phase.
The company also tested portable X-ray fluorescence methods against decades of historical drilling and assay data. That work identified geochemical patterns that could improve logging and mineralized-horizon targeting. Greenland Mines plans further laboratory validation before using the method more widely in project development.
Skaergaard contains gold and palladium-platinum mineralization within gabbro host rocks in East Greenland. Greenland Mines also controls the Sarfartoq project in West Greenland, which adds rare earth exposure. Together, the projects give the company exposure to precious metals and several critical mineral categories.
The post Greenland Mines Ltd (GRML) Stock: Slides 13% as 4,480-Meter Drilling Program Moves Skaergaard Toward Assessment appeared first on Blockonomi.
CryptoPotato
EU regulators are reportedly questioning Binance over its use of a legal exemption to keep serving some European customers after the exchange failed to win a MiCA license.
Enforcement action is possible if they reject its interpretation of the rule.
Regulators Weigh the Reverse Solicitation Exemption
The Financial Times, citing people familiar with the matter, reported that the European Securities and Markets Authority (ESMA) and regulators in France, Germany and Greece are reviewing whether Binance qualifies for MiCA’s “reverse solicitation” exemption.
The platform was ordered to wind down its EU business after it failed to secure a license this summer. Under the rules, unlicensed firms were supposed to take “immediate steps” to wind down from July 1 and stop serving customers, other than to help them transfer or sell their holdings.
In June, Binance had said that it had worked with regulators for about 18 months and had received no formal sign of rejection. But it later withdrew an application in Greece and stated it would pursue authorization in another member state.
Another report from the Wall Street Journal alleged that European Central Bank President Christine Lagarde personally asked Greek Prime Minister Kyriakos Mitsotakis to block Binance’s application after Greek regulators had all but approved it.
By early June, the application had cleared its technical review, and the mandatory 40-day assessment period had ended without objections. Her reasoning traced back to the exchange’s earlier guilty plea to US money-laundering and sanctions violations, and to a worry that letting it in would push more people toward dollar-denominated stablecoins while the ECB works on a digital euro.
ESMA Asks for More Enforcement Powers
A day before the FT report, ESMA stated that European regulators should get more powers to enforce MiCA. According to Reuters, it wants authority to order crypto companies to freeze assets when there are reasonable grounds to suspect links to crime, arguing that current procedures are so slow that suspicious assets have often disappeared by the time a freeze is requested.
National regulators could also be able to remove websites tied to scams or unauthorized crypto firms, and to act against non-EU companies that actively solicit EU investors without authorization.
ESMA also proposed banning certain misleading marketing techniques, adding rules for third-party marketing and requiring full cost information for customers. The proposals form part of its response to a consultation on MiCA, which is under review. A group of European central banks published its own response last week, and Reuters noted that some regulators have voiced concern about divergence and patchy enforcement of the rules.
The post Report: Binance Under EU Review Over Continued Operations After MiCA Miss appeared first on CryptoPotato.
Cardano’s native cryptocurrency posted an impressive 23% price increase over the past month and is currently trading just under $0.25.
Many analysts expect October to bring further gains, but Ali Martinez outlined several important factors that could trigger a short-term pullback.
Time to Cool Off?
The popular X user started his analysis by noting that demand for ADA in the futures market is cooling. He said open interest has declined 9% over the last week, from almost $2 billion to about $1.81 billion.
“This suggests traders are reducing leveraged exposure,” he explained.
Martinez then turned to whale activity, which should serve as a clear bearish signal. According to him, large investors have offloaded 90 million tokens (worth around $22.5 million) since September 20, adding to the recent selling pressure.
His third negative factor is the Tom DeMark Sequential indicator, which flashed a sell signal on ADA’s daily chart on September 26. Martinez noted that the asset’s valuation has plunged 10% since then and hinted that the correction may not be over yet.
Subsequently, the market observer focused on $0.24, calling it the key mid-range support. He believes that losing that level could lead to a further drop to $0.21. At the same time, holding the lower boundary could present the next buying opportunity, targeting the channel top near $0.28.
ADA’s seasonality should also be mentioned. Unlike BTC, which often thrives in October, Cardano’s native token has historically underperformed during this period, finishing in the red six times over the past nine years.

The Bullish Scenario
Recently, Brazil’s state oil giant Petrobras reportedly tapped the Cardano blockchain to verify environmental data related to low-carbon fuels.
Several popular X users quickly reposted the development, including TMA | The Money Ape. They suggested that “Cardano real-world use case is here,” reminding that ADA skyrocketed by over 17,000% during the 2021 bull run.
Another market observer who envisioned a major rally is JAVON MARKS. Earlier this month, they said that ADA appears to have “based” just like in 2020 before a massive price increase. That said, the analyst expects another “monstrous run” and set $2.90 as a target.
The post Cardano (ADA) Ends September With Massive Gains: But Major Bearish Signals Are Flashing appeared first on CryptoPotato.
Crypto may have benefited from the failure of the US CLARITY Act, according to Bitwise Chief Investment Officer Matt Hougan.
The CLARITY Act failed to get the 60 votes needed to move forward in the US Senate after years of negotiations. But instead of hurting the crypto market, its failure was followed by a strong rally across several digital assets.
Unexpected Wins in Washington
Both Bitcoin and Ethereum rose about 11% after the vote. Some other tokens posted much bigger gains. NEAR jumped 125%, Uniswap rose 49%, and Avalanche gained 44%, according to Hougan. The reaction may seem surprising because the crypto industry had strongly supported the bill. Hougan said the industry wanted the legal certainty that CLARITY promised. But added that the final version also included several compromises that could have created new restrictions for crypto companies.
One major area is stablecoins. The exec explained that the proposed legislation would have restricted platforms from paying customers interest or rewards on stablecoin balances. With the bill now stalled, existing stablecoin rules remain in place. Hougan said this could benefit companies such as Coinbase, which use stablecoin rewards to attract users.
CLARITY would have created a national licensing system for spot crypto exchanges. It also could have placed limits on the way exchanges combine trading and brokerage services. With the bill gone, established exchanges such as Coinbase and Kraken avoid those changes for now.
Instead of waiting for new legislation and lengthy studies, the SEC recently allowed certain tokenized US stocks to trade through blockchain-based systems under temporary rules, which, according to Hougan, could give tokenization companies a chance to test the technology in real markets sooner.
Revenue-generating tokens are another area that has benefited from clearer regulatory guidance. Several tokens, including NEAR and Uniswap, have gained strongly while using protocol revenue for token buybacks. The SEC has also clarified that, once a blockchain network is functional, announcing a buyback program does not by itself turn a token into a security.
There is still a major risk as regulation can change when a new administration takes office. A future SEC or CFTC leadership could take a tougher approach to crypto. Despite this, Hougan expects “crypto to be too big to crush.”
Progress Under Existing Rules
Michael Saylor, co-founder and former CEO of Strategy, also sees the failure differently. He recently argued that crypto may be better served by working with supportive regulators at the SEC, CFTC, Treasury, and banking agencies than accepting the restrictions included in the bill’s final version.
Saylor believes the sector should use the next few years to build compliant crypto products under existing rules instead of rushing to accept a compromise simply to get legislation passed. His focus is on products that can lower costs, expand access, and give users more control over their money.
The post Crypto May Be Better Off Without CLARITY Act, Says Bitwise CIO: ‘Too Big to Crush’ appeared first on CryptoPotato.
September was a strong month for many cryptocurrencies, including Bitcoin (BTC), Ethereum (ETH), and Zcash (ZEC), all of which posted significant gains.
Nonetheless, their pumps can’t be compared to what happened with Quant (QNT). The altcoin became a sensation after surging nearly 400% in a month, fueling expectations of a continued bull run among top analysts. On the other hand, traders and investors should tread lightly, as key signals suggest a short-term pullback may be coming.
Final Barrier Before the Real Boom?
As of this writing, it seems surreal that less than two weeks ago QNT was worth around $60. By the end of September, the token’s price skyrocketed to nearly $350, and now it trades just under $280.
Perhaps the biggest catalyst for the rally was the announcement that The Clearing House (which operates payment networks that process over $2 trillion each day) selected Quant to power its On-Chain Money Initiative.
One of the many analysts commenting on the token’s bull run lately is Ali Martinez. Earlier today (October 1), he set $430 as key resistance, which sits at the top of a certain channel.
In his view, a decisive break above this level could send QNT into price discovery mode, potentially triggering another parabolic expansion toward an all-time high of $2,000.
Jia Crypto also made an optimistic prediction, albeit far less bullish than Martinez’s take. She believes QNT could cross $300 “soon with big profits,” and then might rise to $400.
Beware, Bulls
Despite the overall optimism, a further price uptrend is not guaranteed. Lookonchain revealed that the Quant Network founder’s wallet has woken up after seven years of inactivity and has moved almost $7 million worth of QNT. Even if no actual sale occurs, traders may interpret the move as a sign of potential profit-taking, which can trigger uncertainty and panic selling.
Meanwhile, QNT investors have been abandoning self-custody en masse and flocking to centralized exchanges over the past several days. This in turn increases immediate selling pressure.

The token’s Relative Strength Index (RSI) should also serve as a warning. The ratio has surged past 70, suggesting that QNT has entered overbought territory and could be on the verge of a short-term correction. The index ranges from 0 to 100, where anything below 30 is considered a buying opportunity.

The post Quant (QNT) Could Explode to $2,000: Analyst Reveals the Critical Factor appeared first on CryptoPotato.
Evernorth’s merger with Armada Acquisition Corp. II won shareholder approval on Wednesday, putting its 473 million XRP treasury on course for a Nasdaq listing.
The vote passed with about 20.5 million shares in favor and 1.4 million against, according to Armada II’s filing on Thursday. It came five weeks after the SEC declared Evernorth’s registration statement effective on August 27.
Evernorth expects the deal to close on October 7. The company’s shares should start trading the next day under XRPN, the ticker the SPAC already uses.
Over $1 Billion Raised
The firm said the deal and its private placements have raised more than $1 billion, the total it first put on the merger in October 2025. Investors contributed part of that total as XRP, which the release does not value in dollars.
Evernorth’s release puts about $300 million of the total in gross cash. Private placements supply $225 million of that cash. Another $30 million comes from convertible notes the company agreed to sell in September.
Advance funding investors provided $214 million of the private placement money, according to the proxy statement. Evernorth spent it in late 2025 on 84.4 million XRP, at an average of $2.54 per token. Those tokens are already part of its holdings.
The SPAC’s trust adds about $48 million of cash. That trust held about $241.9 million on the August 20 record date. Public shareholders could redeem their shares from the trust at an estimated $10.52 each until September 28. Neither Thursday’s release nor the vote filing says how many shareholders did.
RippleWorks supplied the largest block of Evernorth’s XRP, 211.3 million tokens, by investing them in the SPAC’s sponsor, Arrington XRP Capital Fund. The sponsor must exchange those tokens for Evernorth shares at closing. It has agreed to vote the shares as RippleWorks directs. Ripple co-founder and Executive Chairman Chris Larsen co-founded RippleWorks and sits on its board.
Ripple itself contributed 126.8 million XRP when the merger agreement was signed. A further 50 million comes from the Larsen Lam Children’s Remainder Trust.
Books Carry XRP Below Cost
Evernorth Holdings’ financial statements in the proxy put the cost of 346.3 million of its XRP at $846.6 million. By June 30, 2026, the company carried those tokens at $348.8 million. It recorded impairment charges of $233.7 million in 2025 and $264.1 million in the first half of 2026.
Evernorth books XRP at cost and writes it down to the lowest intraday price seen since it acquired each lot. The written-down value is not adjusted upward when the price recovers.
The post XRP Is Coming to Nasdaq: Evernorth Clears Key Vote With 473M Treasury appeared first on CryptoPotato.