Cryptocurrency Posts
Crypto Briefing
Robinson's departure highlights growing concerns over AI safety, potentially prompting stricter regulations and impacting industry credibility.
The post OpenAI safety researcher David Robinson quits, warns AI firms are moving too fast appeared first on Crypto Briefing.
The advisory highlights potential risks in investing without full financial transparency, impacting investor confidence and market valuation predictions.
The post Motley Fool advises against buying pre-IPO Anthropic shares amid financial opacity appeared first on Crypto Briefing.
The case's reopening highlights systemic issues in handling sexual assault allegations, influencing legal accountability and public trust dynamics.
The post Cornell gang-rape case reopened, potential felony charges under scrutiny appeared first on Crypto Briefing.
Meta's Muse AI could reshape e-commerce by shifting revenue models from ads to transaction fees, impacting retail dynamics and consumer habits.
The post Meta’s Muse turns AI shopping into a checkout with major retail partners appeared first on Crypto Briefing.
AI's potential to boost economic growth could reshape fiscal strategies, but its true impact remains uncertain amid measurement challenges.
The post Kevin Hassett says AI’s economic payoff is bigger than the data shows appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
IMF Praises El Salvador — But Still Tries To Scale Back Its Bitcoin Project
The International Monetary Fund has praised El Salvador for improving its economy — but scolded it at the same time for its ongoing Bitcoin experiment.
In a statement Friday, the IMF said that it had approved a $139 million disbursement to the Central American nation while also trying to “reduce the state’s involvement in Bitcoin-related activities.”
El Salvador in 2021 made Bitcoin legal tender, much to the ire of the IMF and other major institutions. The Latin American country was at the time negotiating a development loan with the agency.
“El Salvador’s economy continues to perform strongly”
— Nayib Bukele (@nayibbukele) October 1, 2026https://t.co/Rvaerha9QA
The IMF in September said that El Salvador wasn’t buying bitcoin; the country’s Bitcoin Office has repeatedly said that it does buy the cryptocurrency.
“Economic activity has exceeded expectations, supported by sustained improvements in security and investor confidence, as macroeconomic imbalances continue to be addressed,” the IMF said.
It continued: “However, certain performance criteria were not met, including on the Bitcoin accumulation front, for which waivers were granted based on strong corrective measures and renewed commitments.”
The IMF further said that the Salvadoran state’s involvement in Bitcoin-related activities is being unwound and that “no further bitcoin accumulation is envisaged beyond the documented donations.”
Salvadoran president Nayib Bukele in 2022 said the country would buy one bitcoin per day but it was never clear where the money was coming from — or if he was actually buying at all.
The IMF said in September that El Salvador was — at least for some time —not using public funds to accumulate bitcoin but rather had received bitcoin from private donations.
El Salvador and the IMF entered a $1.4 billion loan agreement at the end of December but the fund asked for the country to scale back certain aspects of its Bitcoin strategy.
The Salvadoran state gifted its citizens bitcoin in 2021 and debuted a wallet with the hope of getting more citizens using the cryptocurrency in the dollarized country.
President Bukele in 2024 admitted that Salvadorans weren’t using the cryptocurrency to buy things as expected, but always boasted that the government was still stacking sats.
This post IMF Praises El Salvador — But Still Tries To Scale Back Its Bitcoin Project first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
When the Banks Don’t Work, Bitcoin Does: Cornell University’s Adoption Index
A lot of people know little about Bitcoin and how it works.
But despite knowledge being shallow, for those holding the leading cryptocurrency, it appears to be solving a problem: getting around failing banking rails or inflation.
That’s according to new findings from the U.S. Ivy League research university Cornell, which spoke to nearly 26,000 around the globe about Bitcoin.
In its new Bitcoin Adoption Index report, the top college found that El Salvador, Venezuela and Nigeria were the countries that had the highest number of people who had ever owned bitcoin.
“Ranked by the share of all respondents who have ever owned bitcoin, the leaders are not wealthy financial centers — they are economies where the national currency has been unstable and everyday access to dollars or reliable banking is hard,” the report read.
“In each, bitcoin functions less as a speculative bet and more as a practical workaround.”
Bitcoin Advocacy Associate at Strategy and Junior Fellow at Cornell University’s Brooks School Tech Policy Institute, Ella Hough, added: “Bitcoin works the same everywhere, but people’s need for it does not.
“Across 25 countries, we found that people are more likely to see Bitcoin as a tool for financial freedom where currencies are less stable, banking access is limited, or monetary controls are tighter.”
Still, Cornell found that actually being able to explain the fundamentals of the protocol was difficult for most — including how many bitcoins would ever be minted in existence. In fact, 58% of those surveyed said they didn’t know the supply was capped at 21 million coins.
Technicalities aside, the cryptocurrency has still proved helpful to people wanting to use it, the report found.
One Venezuelan — who wasn’t named — told interviewers that Bitcoin was “faster, cleaner, and much less risky” than other methods of getting dollars in the country.
While another Salvadoran was quoted saying: “When nobody controls [bitcoin], it means we all have control of it.”
A Nigerian interviewee reportedly told Cornell researchers: “I’ve been to six African countries and whenever I go there, I don’t fear it because I know I can spend my bitcoin.”
Bitcoin adoption started growing in Venezuela ahead of other countries years ago, when hyperinflation crippled the economy and strict government currency controls meant getting dollars became difficult.
El Salvador made bitcoin legal tender — along with the dollar — in 2021. The country’s leader admitted that getting its citizens to use the cryptocurrency was difficult but the Central American nation still says it buys the asset for its government coffers.
In Nigeria, which has had some of the highest transaction volumes in the world, saving in bitcoin has been used by some to get around the collapse of the naira.
Cornell University’s research was fielded by Morning Consult in partnership with the Tech Policy Institute in Cornell University’s Jeb E. Brooks School of Public Policy, the Cornell Bitcoin Club, the Human Rights Foundation and the Reynolds Foundation.
Researchers interviewed 25,880 people in 25 countries between December 16, 2024 to March 10, 2025, asking 125 individual questions.
This post When the Banks Don’t Work, Bitcoin Does: Cornell University’s Adoption Index first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
South Africa’s Absa Becomes First Bank on the Continent to Custody Bitcoin: Report
South African bank Absa has become the first African lender to custody bitcoin, according to reports.
As reported first by Bloomberg on Friday, the Johannesburg-based lender will serve institutional clients, mostly by custodying bitcoin — but other digital assets will also be a part of the service.
Banks worldwide are integrating or offering bitcoin-related products and services. A number of U.S. and European banks have started offering crypto-related services by custodying assets for institutions.
JUST IN:
— Bitcoin Magazine (@BitcoinMagazine) October 2, 2026Absa has become the first African bank to offer Bitcoin custody
pic.twitter.com/JaDza3S7Ez
Rob Downes, head of digital assets at Absa’s corporate and investment banking unit, was quoted saying that while bitcoin was the biggest asset the bank would custody, others would follow.
Absa did not immediately respond to questions from Bitcoin Magazine.
The African continent has a large crypto-native base, with data firms frequently highlighting the high adoption — particularly in countries where currencies have been significantly debased.
In Chainalysis’s 2025 report, South Africa’s $36.0 billion in on-chain value made it second in Sub-Saharan Africa. Nigeria alone received $92.1 billion, nearly three times the total of second-place South Africa.
On the global index, South Africa ranked 30th for crypto adoption.
The character of its market is different from Nigeria‘s: it’s more institutional, with regulatory clarity resulting in hundreds of licenses being issued to VASPs and attracting professional investors and traditional finance.
BNY Mellon in 2022 became the first major U.S. bank to offer digital asset custody services. And this month, German multinational Deutsche Bank said it would debut a bitcoin custody service for European corporate and institutional clients later in 2026.
This post South Africa’s Absa Becomes First Bank on the Continent to Custody Bitcoin: Report first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Bitcoin Price Surges Above $87,000 on Softer-Than-Expected Jobs Data
The price of bitcoin surged above $87,000 on Friday morning in New York, buoyed by constant exchange-traded fund flows and a jobs report showing that unemployment in the U.S. had ticked up.
Bitcoin’s price recently stood at $85,990 after a 2% jump over a 24-hour period. Over the past week, it has also risen by more than 2%.
Nonfarm payrolls increased 29,000 last month after a downward revision to the prior two months, Bureau of Labor Statistics data showed Friday.
JUST IN: Bitcoin jumps to $87,000 as U.S. Unemployment Rate comes in at 4.2%, higher than expectations
— Bitcoin Magazine (@BitcoinMagazine) October 2, 2026pic.twitter.com/jqtU8Q9zsd
Weaker-than-expected jobs data can give a lift to riskier assets like bitcoin and stocks, whose prices tend to swing more sharply.
A softer labor market typically means less consumer spending, which eases pressure on prices. That could make the Federal Reserve less inclined to keep raising interest rates to fight inflation.
Many economists and politicians have said the U.S. is in the midst of an affordability crisis, and the topic is a hot one ahead of the November midterm elections.
The Federal Reserve’s new chair, Kevin Warsh, has said that prices in the world’s biggest economy are too high and that the central bank is fully focused on making life more affordable again.
Bitcoin investors shrugged off the central bank’s interest rate hike in September, climbing on the news.
The largest cryptocurrency started rallying in August on news that the U.S. Treasury Department said it would more than double the size of its government debt repurchases. The coin had its best run in three years and third best August ever.
The coin’s price has benefited from the so-called debasement trade: when investors buy certain assets to hedge against currency being devalued. The dollar slid in value in August.
It continued to have a good September, rising nearly 6% over a 30-day period.
October has historically delivered good returns for bitcoin investors, with traders dubbing the phenomenon “Uptober.”
This post Bitcoin Price Surges Above $87,000 on Softer-Than-Expected Jobs Data first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Impacts of Daily Dividends on Digital Credit
In May 2026, Strive rebranded itself as “The Daily Dividend Company,” then moved SATA to daily cash dividends beginning June 16. Strategy has now pushed the same idea into its own digital credit engine. On September 24, its board proposed moving STRC, STRF, STRK and STRD to daily dividends, subject to shareholder approval at an October 28 special meeting. The proposal keeps the annual dividend economics unchanged and changes the cadence of cash payments.
STRC spent much of the summer below its $100 stated amount even as Strategy raised its dividend rate to 12% and deployed more than $1 billion buying back STRC. The move to daily dividends by Strategy could be seen as the latest attempt to make the security more attractive and help it trade near par.
Now that the overton window has fully shifted in favor of digital credit paying daily dividends, we should take a look at the actual impacts of daily dividends.
Daily Dividends Fit Onchain Finance
Digital credit is increasingly becoming an input for other financial products—so called “digital money” or “digital yield” products. Strategy estimated in mid-May that more than $440 million of STRC exposure had moved into DeFi through stablecoins, tokenized securities, yield products and other structures.
However, there is a cash flow mismatch. Crypto products commonly accrue and distribute yield at high frequency. A security that pays monthly or twice monthly forces the product sitting on top of it to bridge the period between economic accrual and actual cash receipt.
Daily dividends compress that gap to one day. The protocol, fund or issuer receives cash from the underlying asset at almost the same cadence that users expect to receive yield. That simplifies liquidity management and reduces the cash needed between dividend dates. This is much more impactful to a financial product funding daily distributions or redemptions than to a long term investor focused on total return. The crypto-heavy setting of the “Layer 3” products on top of digital credit raises the attractiveness of daily dividends.
Daily Dividends Are Primarily a Retail Feature
For investors focused strictly on total return, dividend payment frequency makes little difference in underlying economic value. The asset’s price accrues between distribution dates and adjusts post-payment, meaning annual, quarterly, monthly, and daily payouts produce comparable long-term results.
The true advantage of daily dividends lies in product psychology and user experience. Cash arriving every day provides immediate visibility and an engaging feedback loop. Investors can spend, withdraw, or automatically reinvest the payout while leaving their principal position intact, turning an abstract yield metric into tangible recurring cash flow.
This dynamic mirrors the strategy of Realty Income, which built a massive retail follower base by branding itself as “The Monthly Dividend Company.” As a member of the S&P 500 Dividend Aristocrats Index, Realty Income has paid and raised dividends for 31 consecutive years.
Daily dividends on digital credit extends this product concept even further: SATA pairs frequent daily payouts with a target price near $100 and a double-digit yield.
While institutional investors prioritize yield spreads, liquidity, tax structure, and balance sheet coverage, daily payments offer their strongest appeal to retail buyers. If the overarching objective is to raise capital to purchase Bitcoin, optimizing security design for retail investor preferences is the most effective approach.
Options Get Cleaner Too
Daily dividends also change options mechanics. STRC currently pays $0.50 twice monthly. SATA pays roughly five cents each business day. Larger dividend events create larger discrete adjustments in the underlying price, which affects option pricing and early exercise decisions. Daily payments spread the same annual cash flow across much smaller adjustments.
The total value of dividends over an option’s life is a key economic input. The more interesting effect comes from the price stability created by daily dividends. If daily dividends, variable rates and active par management keep SATA and STRC trading in narrower ranges, realized volatility should fall. Implied volatility can follow as the market gains confidence in that behavior.
The Biggest Test
The real test is whether daily dividends increase demand enough to eventually lower the required yield.
If investors consistently support SATA near the top of its target range, Strive can theoretically reduce the dividend rate while attempting to keep SATA near par. Success would show that a Bitcoin company can issue permanent preferred capital, manage it around a stable price, and adjust its yield with market demand. The benefit of the variable rate preferreds was, from inception, the eventual opportunity to lower the rate and reduce the cost of capital without upsetting price stability. In comparison, fixed rate credit locks in fixed rate forever.
Conclusion
Strategy adopting daily dividends would move the feature from a SATA differentiator toward a digital credit category standard. The annual economics barely change but the retail appeal and crypto composability become meaningful improvements.
This post Impacts of Daily Dividends on Digital Credit first appeared on Bitcoin Magazine and is written by Allard Peng.
CryptoSlate
Six US banks have failed in 2026 so far, which is one more than in 2023 and enough to make another banking-crisis headline practically write itself.
But before we start reliving Silicon Valley Bank, it's worth looking at what those six banks actually held: about $1.43 billion in combined assets, compared with roughly $552.54 billion at the banks that failed in 2023, according to historical numbers from the Federal Deposit Insurance Corporation (FDIC).
Counting each bank as one gives you a perfectly accurate number and a pretty lousy sense of scale. This year's total includes a lender with $3.73 million in assets, which gets the same vote in the tally as a bank the size of SVB.
Meanwhile, FDIC's latest industry assessment shows stronger profits and fewer banks on its problem list. That doesn't mean the six failures were harmless, or that every surviving bank is doing well, but anyone selling a 2023 rerun has some explaining to do.
Nano Banc's Sept. 25 closure brought the count to six and supplied the largest failure of the year so far. The Irvine, California, lender reported $736 million in assets, and the FDIC estimated a $114 million cost to its Deposit Insurance Fund.
Someone will bear that loss, but a bill attached to one failed bank doesn't mean the rest of banking is about to follow.
Six is bigger than five (until you look inside)
The FDIC's annual totals record four failures in 2020, none in 2021 or 2022, five in 2023, and two apiece in 2024 and 2025. Through Sept. 25, this year had beaten every annual count in the 2020s, which sounds much, much worse than it actually is.
Consider Kentland Federal Savings and Loan Association, which the FDIC described as the country's smallest standalone bank when it closed. Its $3.73 million in assets counts for exactly as much as Silicon Valley Bank in a chart of bank failures, because that chart counts only institutions.
Asking it to measure financial trouble gives a very small bank a very large role.
| Failed institution | Closure date in 2026 | Reported assets |
|---|---|---|
| Metropolitan Capital Bank & Trust | Jan. 30 | $261.10 million |
| Community Bank and Trust – West Georgia | May 1 | $288 million |
| Kentland Federal Savings and Loan Association | July 10 | $3.73 million |
| Small Business Bank | July 17 | $73 million |
| Tioga-Franklin Savings Bank | Aug. 21 | $68 million |
| Nano Banc | Sept. 25 | $736 million |
| Combined | Through Sept. 25 | $1.43 billion |
Sources: FDIC failure announcements and annual summary. The unrounded sum is $1,429.83 million, using numbers from different reporting dates cited around the closures, rather than a single-date balance sheet or an estimate of losses.
The $552.54 billion number for 2023 and this year's $1.43 billion come from balance sheets with different reporting dates, so we can't turn them into an exact ratio. Luckily, we don't need one to see that the amounts belong in very different conversations, even if six is technically more than five.
The FDIC's problem-bank list adds another issue because it counts banks that are still operating, using their condition measured at a particular date. Banks get onto it when examiners assign one of the two weakest overall ratings for financial, operational, or managerial weaknesses, which is a more specific diagnosis than having an ugly week in the stock market.
The second-quarter assessment put 47 banks on that list as of June 30, down from 54 in March and 60 at the end of 2025. They made up about 1.1% of insured institutions, within the FDIC's normal 1% to 2% range outside a crisis.
That doesn't give the industry a certificate of perfect health, because a bank can leave the list by failing just as it can leave by recovering or merging. The failure count adds up closures over the year, while the problem list takes a snapshot of institutions still open, so it's not mysterious for one to get longer while the other gets shorter.
The dates also prevent us from doing some tempting mental math. Four of this year's six failures came in July through September, beyond the June snapshot, but subtracting four from 47 won't tell us how many troubled banks are left.
We don't know every bank that entered or left the list in between, and the published totals don't identify them.
Some banks were broken long before the headline
The records behind these closures describe institutions that had been struggling for quite a while. Illinois regulators said Metropolitan Capital had impaired capital and unsafe conditions, while Kansas officials described years of financial trouble at Small Business Bank.
At the Kansas lender, continuing operating losses ate through its capital until it became critically undercapitalized. Capital is the cushion that absorbs losses before creditors have to bear them, and a bank that keeps losing money can burn through that cushion while the rest of the industry has an excellent quarter.
Someone else's profits don't refill your bank's capital, and Kentland reached a similar endpoint, with the Office of the Comptroller of the Currency finding that unsafe practices had depleted its assets and earnings and that there was no reasonable prospect of restoring adequate capital.
Tioga-Franklin had its own FDIC consent order from earlier, covering weaknesses in management and capital planning, as well as liquidity and credit administration. It consented without admitting or denying the charges, so that record tells us supervisors had identified problems, without settling exactly what caused its August failure.
We know less about the full diagnosis at Community Bank and Trust – West Georgia. The state's closure notice explains the authority to take possession without supplying a detailed financial account, and the FDIC inspector general has a material loss review underway.
Giving it the same cause as the other failures would make the narrative tidier than the evidence allows.
Nano also had a lengthy regulatory history. California Business and Consumer Services Secretary Rohit Chopra described repeated violations and earlier action against mismanagement, while pointing to its large level of uninsured deposits.
Customers with money above the insurance limit have more to lose if a bank fails, which gives them a stronger reason to leave when they doubt it can pay them back.
You can take all of that seriously without treating the six banks as a chain of falling dominoes. The records describe unresolved weaknesses at individual lenders, but don't establish a common funding shock or show one closure bringing down the next.
Putting them in the same table doesn't create a financial connection.
The broader numbers don't support the small-bank-doom argument either. In the FDIC's second-quarter results, community banks earned 8.2% more than in the preceding quarter, while industry-wide profit reached $90.1 billion.
The regulator described capital and liquidity as strong, leaving plenty of room for a few badly damaged banks in an industry making more money.
The losses are real even when the apocalypse isn't
None of this makes a failed bank a non-event for the people caught in it.
Nano's estimated $114 million insurance-fund cost is a real financial consequence, even though Sunwest Bank agreed to take over substantially all its deposits and buy about $476 million of its assets.
The FDIC retained the rest for disposal and said customers could keep using checks and cards through the closure weekend.
Those customers could keep paying their bills while the receivership faced a loss, because access to deposits and the final cost of resolving a bank aren't the same thing.
The FDIC's estimate can move as it sells retained assets, and the six banks' combined $1.43 billion in assets shouldn't be treated as money that vanished. Loans can still be repaid, and securities can still be sold when their former owner has failed.
Tioga-Franklin's buyer assumed all deposits, while the West Georgia transaction transferred substantially all insured deposits, excluding certain brokered accounts.
Georgia officials said customers above the insurance limit would receive notices explaining their rights as uninsured depositors, which is a pretty different experience from being told your account now has another bank's name on it.
CryptoSlate's coverage of the year's first bank failure examined broader banking risks, but the road from a failed lender to crypto still needs spelling out. Whose money was at the bank, and what could they no longer do when it closed?
In 2023, Circle had $3.3 billion of USDC reserves at Silicon Valley Bank, giving stablecoin holders a direct reason to worry about access to part of their tokens' backing. The Federal Reserve's analysis of that failure follows that connection from bank distress into stablecoins.
This year's tally doesn't provide an equivalent connection on its own. Disclosed crypto deposits at a failed lender, or the loss of banking services needed to process customer payments, would give us something concrete to examine.
Another tick in the failure column can't tell us whose reserves are trapped or whose business has lost access to cash.
There are good reasons to keep watching the banks, including whether withdrawals spread across institutions and whether lenders have more trouble obtaining funding. The assets on the problem-bank list deserve attention too, because a shorter list can still contain more money at risk.
None of those possibilities gets answered by comparing six with five.
The case for another 2023 has to explain how trouble is spreading through the banks that are still open. Until the evidence shows that, six failed lenders tell us that six lenders couldn't keep going, and turning that into a verdict on the whole system asks a headcount to do a balance sheet's job.
The post Six US banks have failed in 2026 but the numbers look nothing like 2023 appeared first on CryptoSlate.
Leveraged funds’ reported Bitcoin futures shorts fell by about 5,300 BTC-equivalent in the week to Sept. 29, narrowing their net short even as their aggregate long exposure shrank.
The Commodity Futures Trading Commission’s latest futures-only figures, released in the Oct. 2 reporting cycle, cover CME standard and micro Bitcoin futures plus Coinbase Derivatives’ nano Bitcoin and nano perpetual-style futures. The totals convert different contract sizes into BTC-equivalent exposure; they describe futures positions, not transfers of physical bitcoin.
Compared with Sept. 22 positions, the funds’ reported shorts fell 5,299.69 BTC-equivalent and longs fell 908.99 BTC-equivalent. Their net short consequently narrowed by 4,390.70 BTC-equivalent, from 40,110.83 to 35,720.13. Their combined short exposure still exceeded their longs. These long and short columns exclude separately recorded, offsetting spread positions.
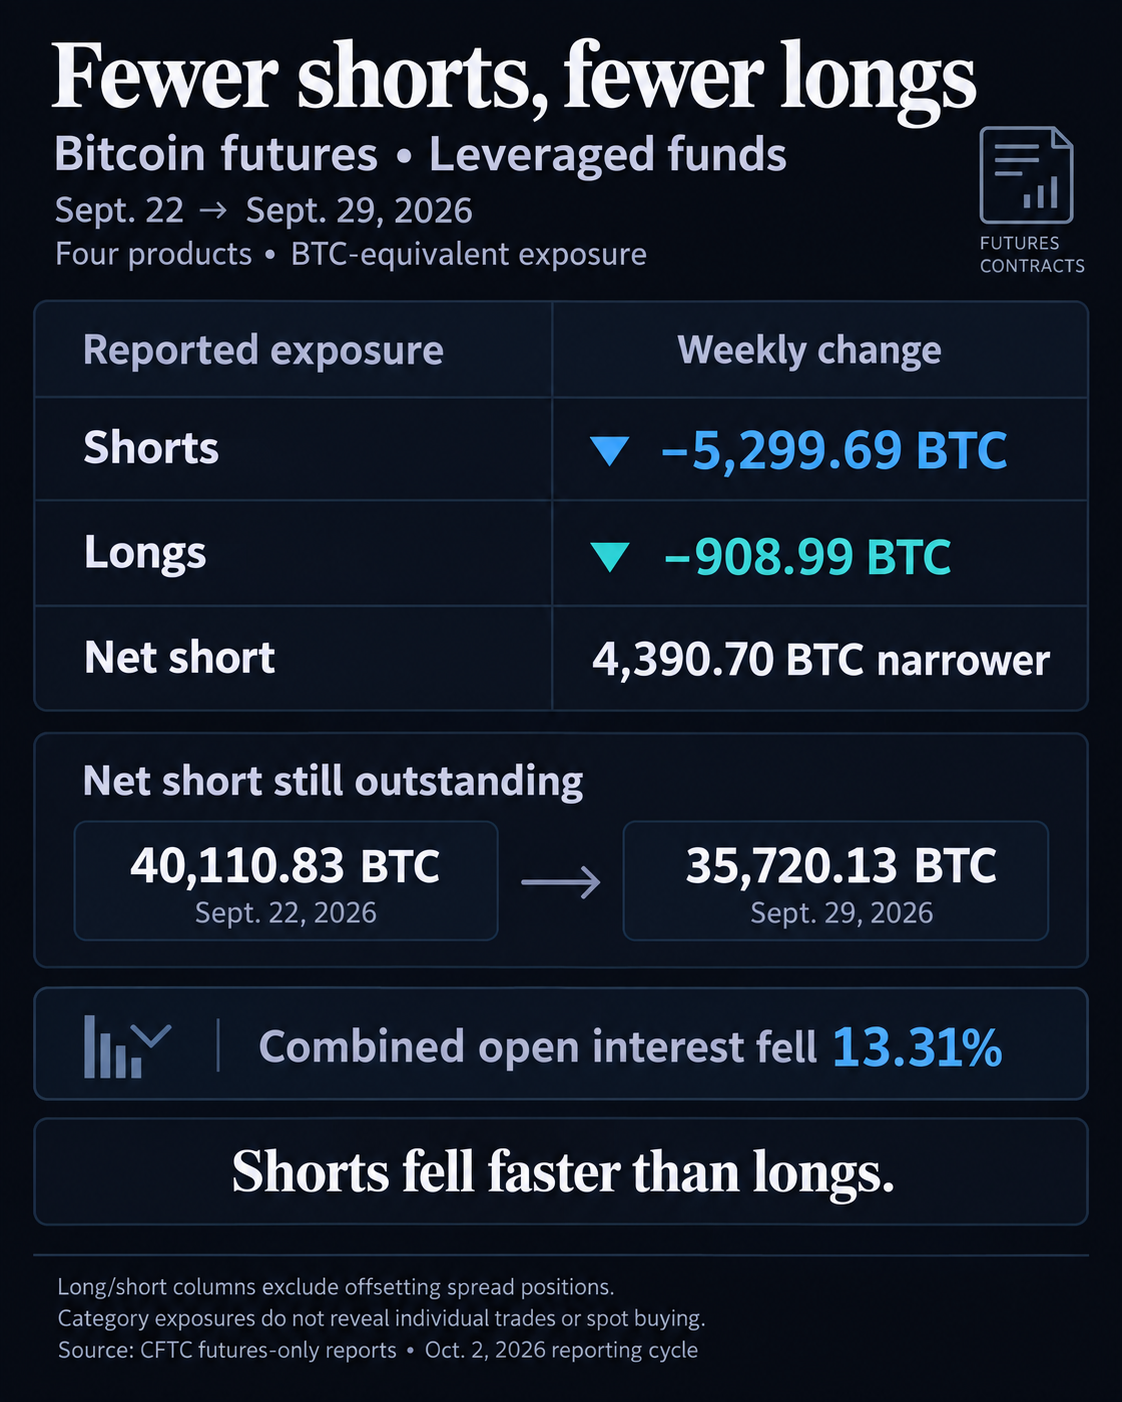
A better net figure can result from shrinking positions on both sides when shorts fall faster. In this snapshot, aggregate futures long exposure did not expand.
The individual products did not move uniformly. Standard CME futures accounted for 4,310 BTC-equivalent of the reduction in reported shorts, while their leveraged-fund longs increased 1,175 BTC-equivalent. Longs fell in CME micro futures and both Coinbase products, more than offsetting that increase.
The standard-CME move reversed the widening of net shorts in the Sept. 22 snapshot. That earlier report covered standard CME alone; the latest totals include all four products.
Asset managers’ net long across the four products increased 2,137.90 BTC-equivalent to 18,069.10. Their longs rose 573.10 BTC-equivalent, while shorts fell 1,564.80 BTC-equivalent. Most of their stronger net position therefore also came from fewer reported shorts.
Combined open interest, the outstanding futures exposure across these markets, fell 13.31% to 103,343.14 BTC-equivalent from 119,208.26. The improvement in net positioning occurred alongside a contraction in the overall futures market measured here.
Smaller shorts do not establish spot demand
The separately recorded spreading positions represent offsetting positions. Leveraged funds’ spreading column also fell, by 11,231.11 BTC-equivalent. The 5,300 BTC-equivalent reduction covers the reported short column, excluding those spread legs.
The monthly CME micro expiry rule places September’s expiry on Sept. 25, between the two observations. That provides calendar context without proving that expiry or rolls caused the contraction. Classification changes can also affect category totals.
The CFTC groups traders by predominant business activity. Its Tuesday position reports do not reveal individual transactions or paired spot and ETF holdings. A futures short may be part of a hedge, so fewer shorts do not establish fresh spot buying or reduced bearish conviction.
The next release is scheduled for Oct. 9. It can show whether the category shift persists.
The post Leveraged funds’ Bitcoin futures shorts fall by 5,300 BTC-equivalent as longs shrink appeared first on CryptoSlate.
Arbitrum's Security Council temporarily blocked new Stylus contract activations on Arbitrum One and Nova in an October 2 emergency action, restricting programs and app updates that require fresh activation. Already-active Stylus applications can keep running, while ordinary Solidity contract deployment and execution remain unaffected, according to the Council's action report.
Arbitrum attributed the precaution to increasingly sophisticated AI-assisted attacks involving hand-crafted WebAssembly programs outside the standard Stylus compiler toolchain. It said known Stylus bugs primarily threaten chain liveness, including denial-of-service risks, and that no attack permitting theft of user funds had been discovered.
The linked Ethereum, Arbitrum One and Nova transaction records show successful execution on October 2, around 15:30 to 15:31 UTC.
For builders, the distinction is between storing code and making it usable. Stylus contracts run WebAssembly programs, which need activation to become executable. Arbitrum's documentation distinguishes that step from deployment, which stores code onchain. New contract instances using identical program code can reuse an existing activation, provided it is still valid.
A new application version requiring fresh activation cannot become executable during the pause. Reactivating an expired program, or one needing reactivation after a Stylus version change, is also blocked, the Council said. The scope is activation, rather than a blanket prohibition on deploying every new contract instance.
Existing programs remain callable until expiration. Developers can continue extending an active program's lifetime through the permissionless keepalive renewal mechanism before it expires, according to the official pause notice. This leaves renewal available while reactivation of an already-expired program is blocked.
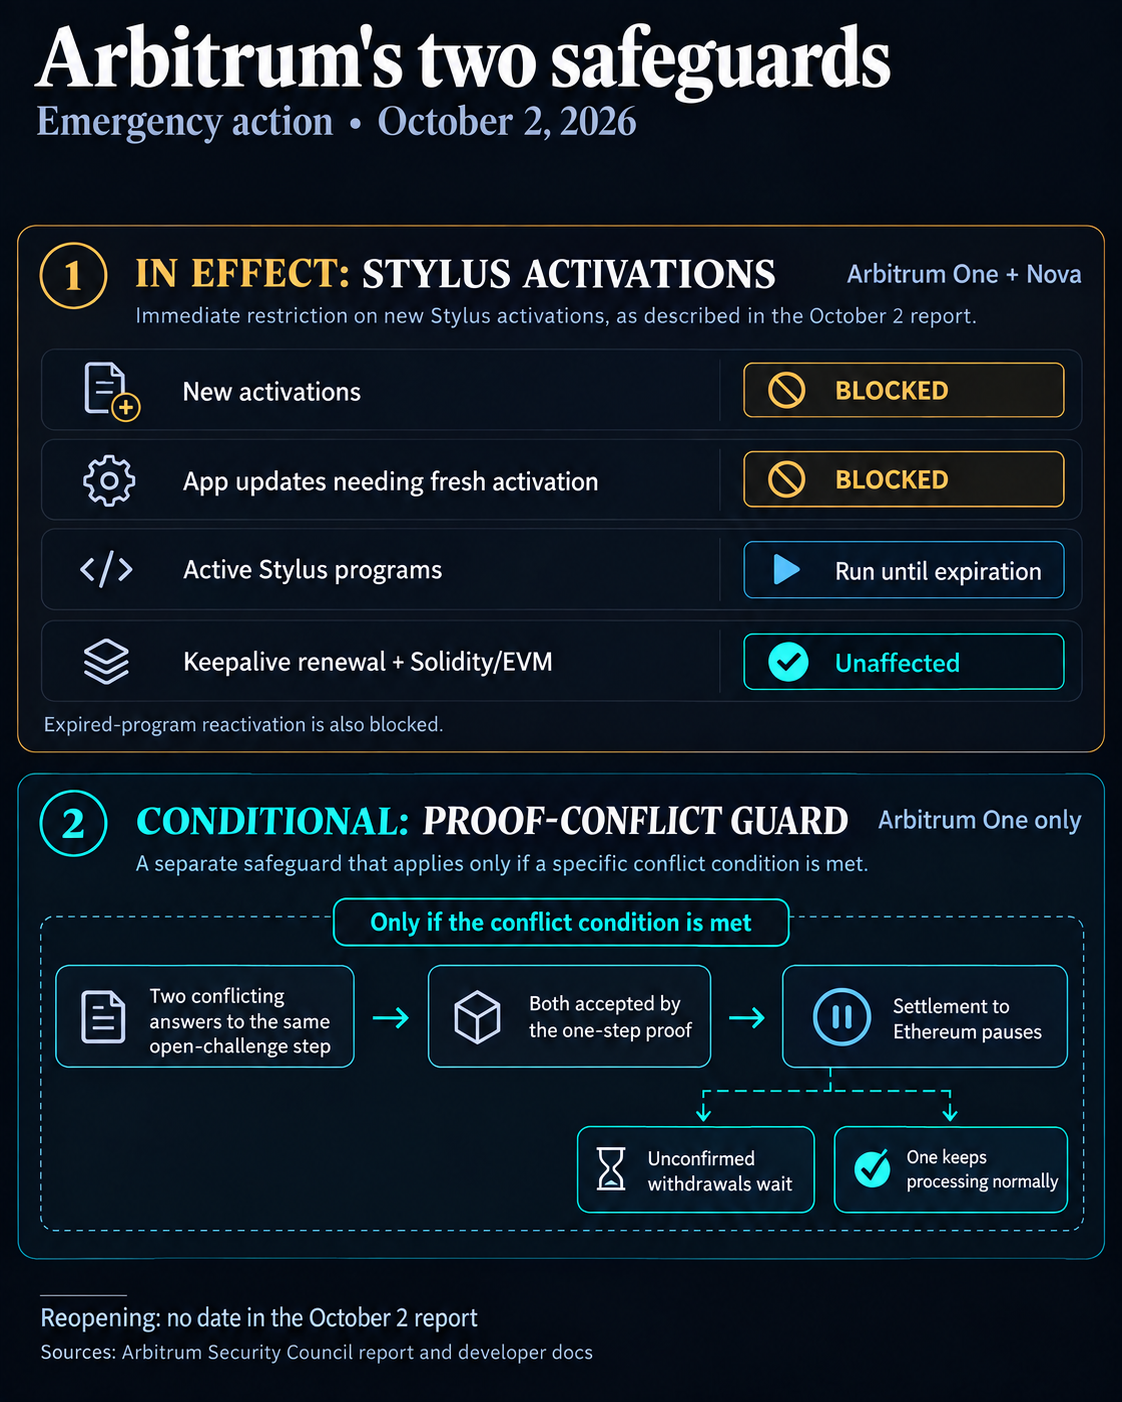
The Council said it implemented the restriction by raising the activation gas requirement to a prohibitively expensive level. It described this as a configuration change requiring no upgrade to ArbOS, the network's operating software.
When withdrawals could wait
The same emergency action installed a separate safeguard for BoLD's one-step proofs on Arbitrum One. Anyone can present two conflicting answers to the same step of an open challenge. If the one-step proof accepts both, the guard puts One's settlement to Ethereum on hold, according to the Council.
Arbitrum says One would continue processing normally during that suspension. However, messages from One to Ethereum that have not yet been confirmed, including withdrawals, would have to wait while the Council deploys a fix and resumes settlement. Installing the guard does not itself pause withdrawals; the delay depends on its conflict condition being met.
For builders waiting to activate new Stylus code, reopening remains the next decision. The October 2 report and developer notice give no date, saying the Foundation will work with ArbitrumDAO on the timeline and manner of restoring activations.
The post Arbitrum pauses new Stylus activations over AI-assisted attack risks appeared first on CryptoSlate.
Companies building AI applications can rent powerful computers instead of buying the equipment themselves, paying for access to the graphics processing units, or GPUs, that run their software.
Lower rental prices make those applications cheaper to operate, but they can also make life harder for the company that bought the machines and needs the rent to pay its debts.
If you've financed a room full of GPUs assuming customers will pay a certain hourly rate, a cheaper competitor can upset the calculation long before you've paid off the equipment. Your machines might still work perfectly, and demand for AI might still be strong, but the amount you earn from each hour could start falling below what the business needs.
Financial contracts could let you protect part of that income by arranging a payment when rental prices fall, in exchange for taking on your own obligations. That's the basic idea behind AI compute derivatives, which let businesses trade their exposure to computing prices separately from renting the computers themselves.
Luxor, a company that provides services and financial products to Bitcoin miners, included these contracts in its latest expansion into AI. It sees an opportunity to bring its experience hedging mining revenue to another business that spends heavily on machines before knowing what it'll earn.
The company told CryptoSlate that it's already brokering agreements between owners of computing capacity and customers who want to use it.
However, its cash-settled derivatives business is still early, and the company said it couldn't provide a customer hedge example or current derivatives trading volumes because a liquid market hadn't formed yet.
That gives this promising idea the difficult commercial task of persuading someone to accept losses another business wants to avoid.
Getting that arrangement to work could help operators plan around more predictable income, but the protection is only as dependable as the price used to calculate it and the party responsible for paying.
Locking in the rent without locking in a customer
The tried-and-true way to make rental income more predictable is to sign a customer for a longer period at an agreed price. The customer gets access to the machines, while the operator gets a commitment it can use to plan its business.
That works well when both sides want the same arrangement, but customers don't always know how much computing they'll need that far into the future. Operators may also prefer to keep selling capacity to different users.
Cash-settled derivatives offer another approach because the contract pays money according to a price formula, without requiring the parties to exchange computing capacity. The operator can keep renting its GPUs to customers while using a separate financial agreement to offset movements in the rental rate.
Imagine an operator expecting to sell 1 million GPU-hours in a month, where one GPU-hour means access to one processor for an hour. At $2 per hour, that would produce $2 million in rental income, and the operator enters a hypothetical contract designed to protect that rate.
If the agreed market benchmark falls to $1.50, the contract pays the operator the 50-cent difference across the million hours, or $500,000. Assuming its actual rental income also falls to $1.5 million, that payment brings the combined amount back to $2 million before fees and other costs.
The obligation runs both ways, so if the benchmark increases to $2.50, the operator owes $500,000 while earning more from its customers. It gives up the benefit of a higher rate in exchange for protection against a lower one, making revenue easier to plan around.
This is just back-of-the-napkin math to explain the arrangement, as the result depends on the operator actually selling the expected hours at a rate that tracks the benchmark. Empty machines still produce no rental income, so fixing the hourly price doesn't guarantee someone will buy it.
Someone on the other side needs a reason to accept the opposite payments, and an AI business worried about more expensive computing could have one. Its financial contract would pay when the benchmark increased, helping cover a larger rental bill, while a fall would create a payment obligation alongside cheaper computing.
Dealers could help connect those interests or take some of the exposure themselves, charging for the risk they carry. But customers need a price for the amount of protection they want, covering the period when their business needs it.
CME Group is pursuing an exchange-traded version of this idea through its announced H100 and B200 rental-index futures. Its Aug. 11 announcement targeted Oct. 5, subject to regulatory review, for contracts tied to Silicon Data's GPU rental benchmarks, although listing a contract alone can't guarantee enough participation to make it easy to trade.
Your GPU hour might be different from mine
But even with willing counterparties, the payment formula needs a price both sides accept as relevant to their business.
In the example above, the hedge works perfectly because the operator's rental income moved exactly with the benchmark. However, you can't replicate perfect conditions once actual customers enter the picture.
Suppose its customers negotiate rates down to $1.25 while the benchmark only falls to $1.50, perhaps because the index covers a different service or type of equipment. The same $500,000 hedge payment would then bring its $1.25 million in rental income to $1.75 million, leaving a gap even though the contract works as written.
That mismatch is called basis risk, which simply means the price you've protected against doesn't move exactly like the price you actually receive. Compute hedges can leave Bitcoin miners exposed, and this is one reason a hedge needs to be judged against the particular business using it.
Luxor compared its AI ambitions with its path in Bitcoin mining, where publishing a reference price helped create a foundation for financial contracts. Its hashprice measure estimates what a unit of computing power can earn from mining Bitcoin, giving operators a shared revenue reference even when their own operating costs differ.
Bitcoin miners perform the same network task, whereas AI customers can attach different values to access that looks similar on a specification sheet. Someone buying uninterrupted access for months is purchasing a different service from someone willing to have a short job stopped whenever the provider needs the machines back.
Price providers already account for differences like these, with CCIR's rental-data methodology treating interruptibility and commitment length as separate characteristics. It uses publicly advertised rates, which also means the figures don't necessarily capture privately negotiated discounts.
The index Luxor supplied in its reply was its AI Hardware Price Index, which measures advertised prices for selected GPU systems. That can help someone assess an equipment purchase, but buying a machine and earning rent from it involve different prices, so the link doesn't establish how an AI rental hedge would settle.
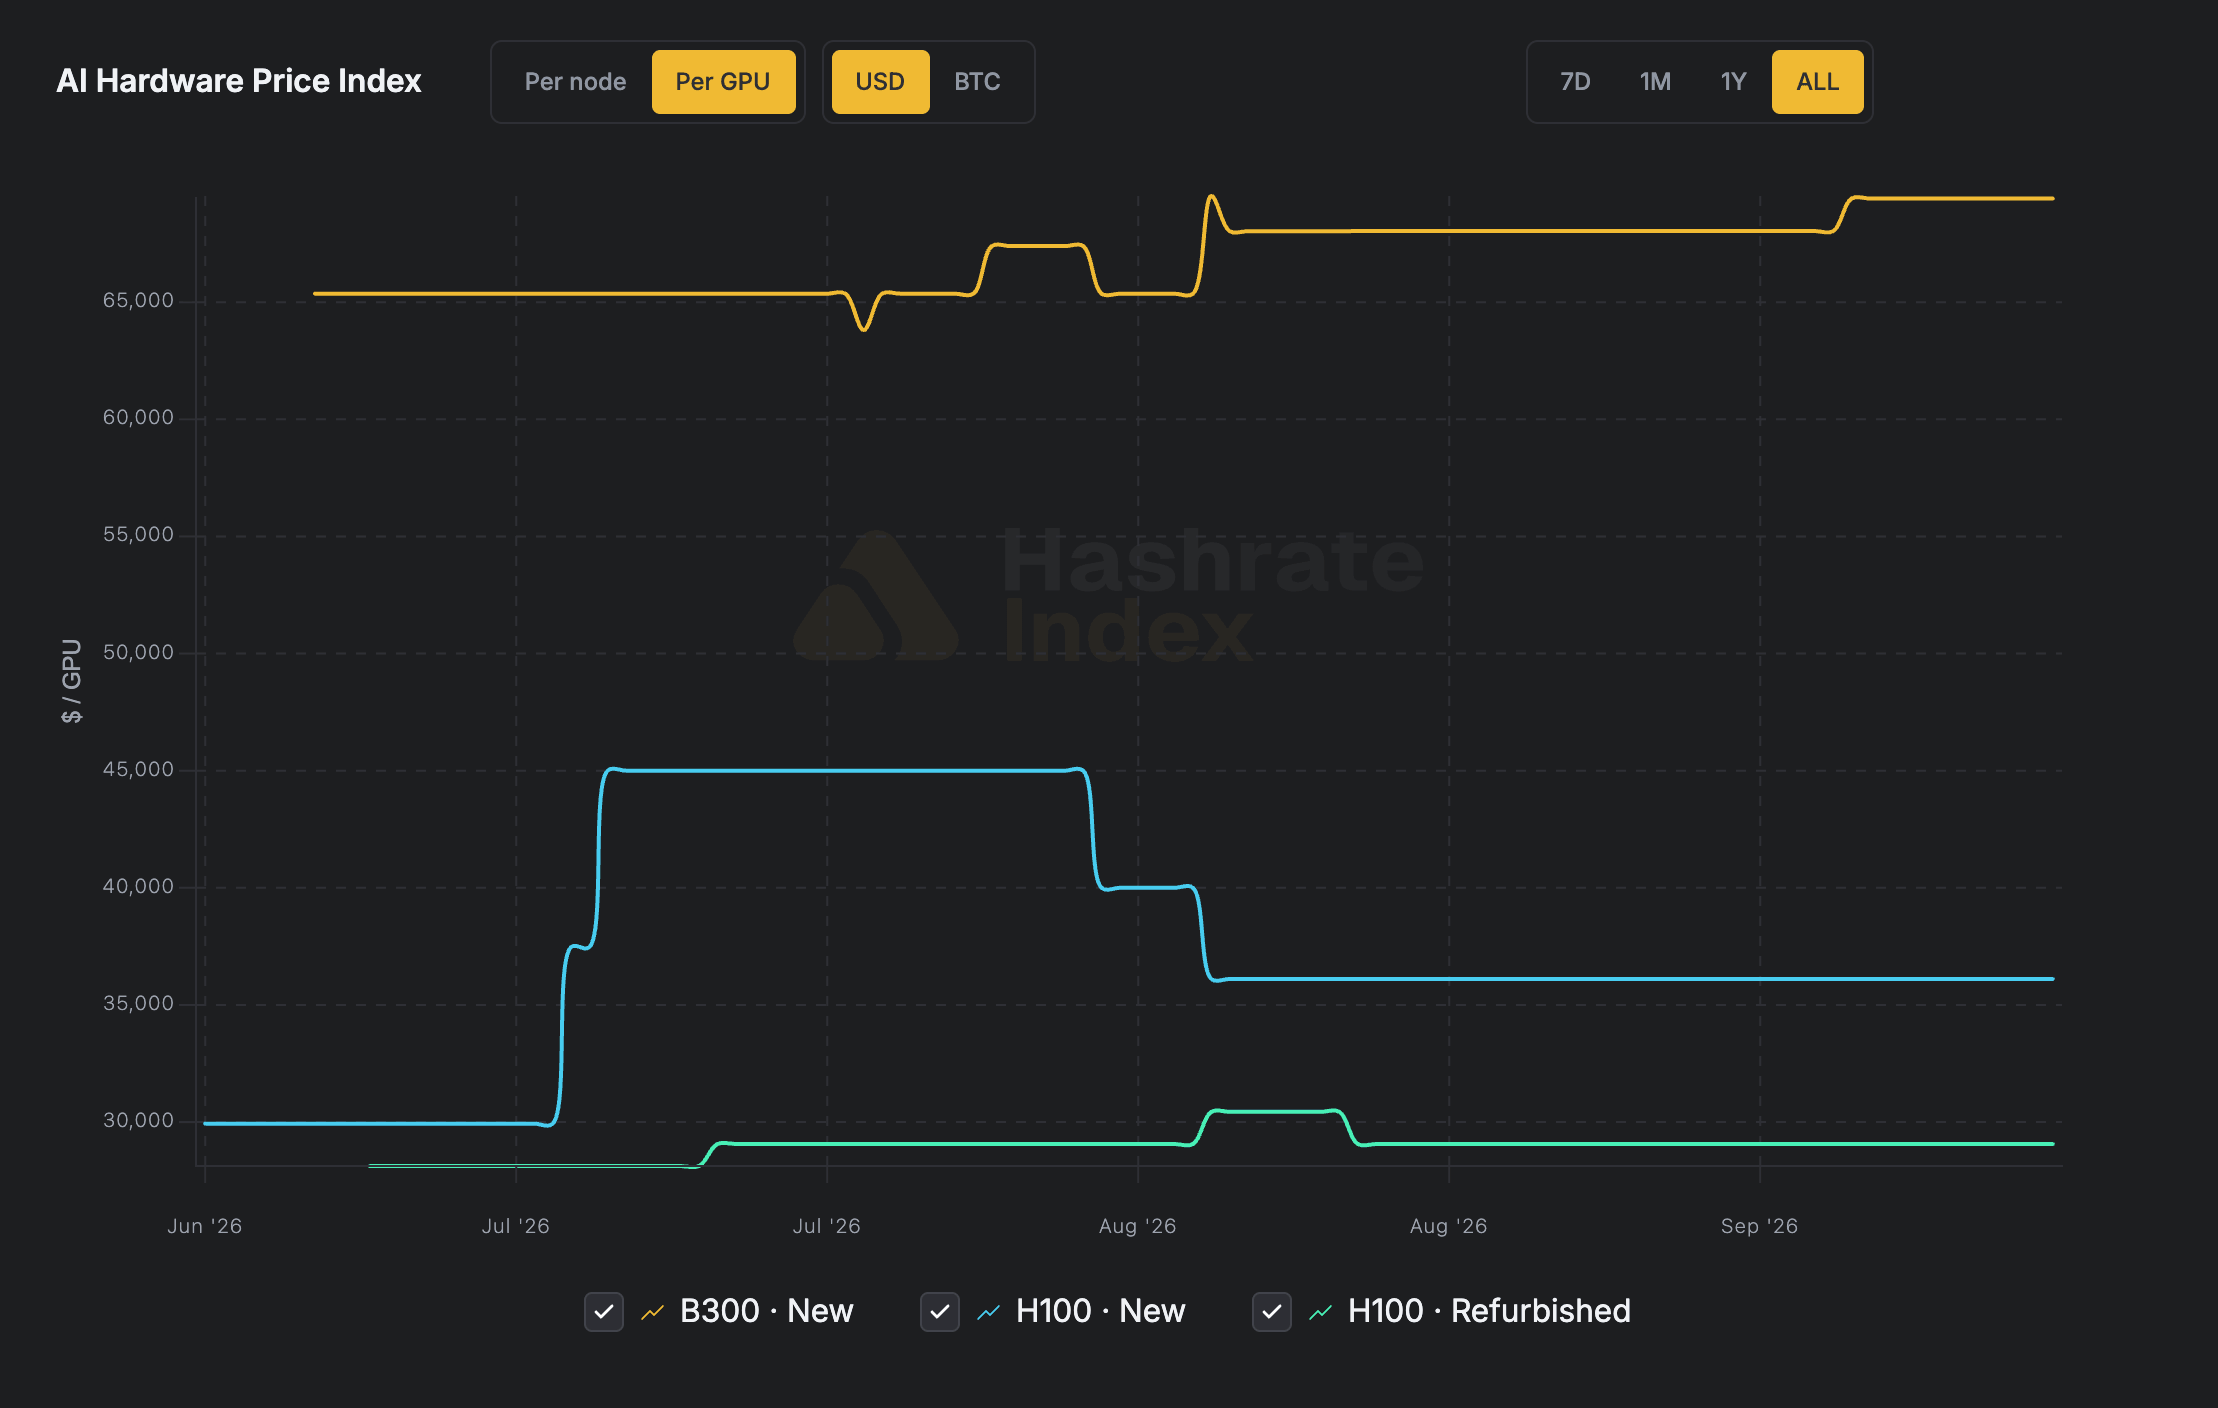
Luxor's August data announcement described expanded compute spot pricing as forthcoming. Operators trying to protect income would still need contracts that name a rental benchmark and show it tracks what customers pay.
Narrower benchmarks might fit better, but each additional contract splits potential trading among smaller groups. Building this market requires a compromise between matching each customer's business closely and bringing enough people together under the same contract to make trading affordable.
The protection has to survive the bad month
Even a closely matched contract leaves the operator relying on someone else's ability to pay when rental income falls.
If that counterparty also earns much of its money from AI infrastructure, cheaper computing could damage both businesses at the same moment, just when one expects support from the other.
Collateral can reduce that dependence by requiring money or eligible assets to be posted against obligations, giving the recipient something to draw on if the other party fails. It also creates a financing requirement, because money committed to the hedge can't simultaneously pay the operator's other bills.
In the example where rental prices increase, the operator might have to pay its hedge obligation before customers settle their higher invoices.
The overall economics could still work even if the bank account runs short, making the timing of cash flows a huge part of that protection's affordability.
Luxor didn't provide the requested AI collateral terms or explain the procedures for a counterparty failing to pay. Its reply also left unanswered how it separates its own trading from the business it arranges for customers, a relevant point because the launch announcement disclosed an internal compute trading fund.
More predictable rental income could give an operator greater confidence about meeting its debt payments, even when customers become less willing to pay yesterday's rates.
Getting that benefit requires a contract that follows the income closely enough, with payment obligations the operator can afford throughout the period it's trying to protect.
Cheaper computing could let more people build and use AI while leaving some owners of the machines with disappointing returns.
Financial contracts won't make that loss disappear, but they could move part of it to someone prepared to bear it, giving the operator more room to keep serving customers when the rent falls.
The post Plunging GPU prices threaten AI hosts, and new hedges step in appeared first on CryptoSlate.
Investors in LIBRA, the memecoin promoted by Argentine President Javier Milei, lost a district-court route to recovering their losses after a US judge dismissed the proposed class action over LIBRA and fellow memecoin M3M3.
In a Sept. 29 opinion, Judge Jennifer L. Rochon dismissed the amended complaint with prejudice, denied permission to amend it again and ordered the Southern District of New York case closed. The decision also blocked investors' proposed expansion of the lawsuit to three other tokens.
The plaintiffs alleged that insiders controlled token launches and extracted funds from liquidity pools at outside investors' expense.
According to the complaint as recounted by the court, LIBRA launched on Feb. 14, 2025, and Milei promoted it before withdrawing his support that day. The dismissal resolved the legal sufficiency of the claims and the court's jurisdiction.
Why the racketeering claims in the LIBRA case failed
The central federal claim relied on the Racketeer Influenced and Corrupt Organizations Act, or RICO. It requires a pattern of related racketeering acts that either spans a substantial period or threatens continuing criminal activity.
The court found neither form of continuity adequately pleaded against the Kelsier defendants, including Kelsier Ventures and Hayden Davis, and Benjamin Chow, Meteora's co-founder and former CEO.
For the first route, the court treated the alleged conduct from October 2024 through the March 2025 complaint as a six-month period. Multiple schemes and a potentially large group of victims did not overcome that short duration.
The opinion applied Second Circuit precedent that generally demands a longer period for this form of continuity, while expressly recognizing that two years is not a fixed cutoff. I
The alternative route required facts supporting a continuing threat. The court found that broad assertions about a repeatable token-launch business and referrals to other projects did not establish, defendant by defendant, that alleged wire fraud was a regular business practice. The dependent RICO conspiracy claims failed too.
The proposed amendment would have added MELANIA, ENRON and TRUST, another plaintiff and new defendants. But the judge found it extended the alleged racketeering period to only seven months and provided no facts curing the continuing-threat defect.
After RICO failed, the court dismissed the Kelsier defendants' remaining state-law claims for lack of personal jurisdiction. Allegations about nationwide social media and crypto infrastructure did not establish the necessary New York connections. The court did not reach the merits of those state-law claims.
The court dismissed all claims against Chow for pleading defects, including insufficient allegations of fraudulent intent. Claims against Meteora failed because investors had not adequately pleaded it as a legal association or partnership capable of being sued.
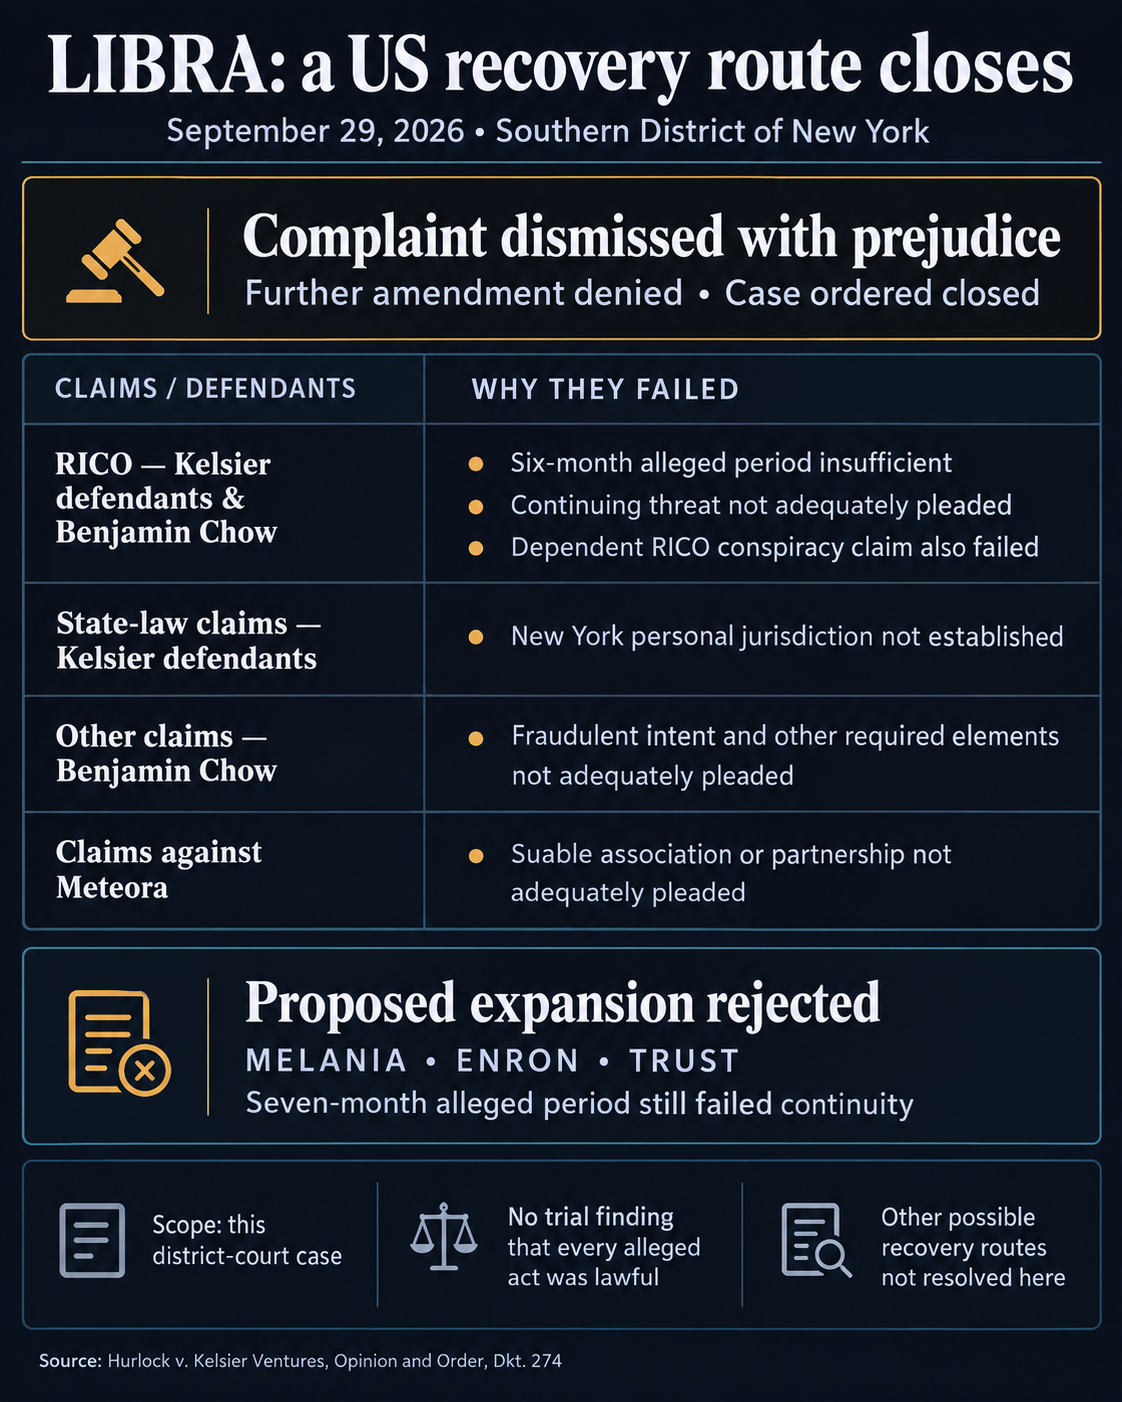
Hayden Davis's denied wrongdoing and jurisdiction objections in June 2025. The new ruling turns that earlier dispute into a concrete setback for investors seeking recovery through this action.
The order does not establish that every alleged act was lawful or determine the status of every other possible recovery route.
The post US judge kills Milei’s LIBRA memecoin lawsuit, leaving investors stranded appeared first on CryptoSlate.
CryptoTicker.io
Stellar costs around $0.214 on October 3, 2026, and is therefore down a good 5 percent within a day. Bad news about Stellar itself does not exist: no outage, no delisting, no glitch in the protocol. The documented background lies one level up. The analysis firm CryptoQuant reported on September 30 that the number of altcoin deposits to trading venues had climbed 160 percent within two weeks, to the highest level since October 2025. Whoever sends coins to an exchange usually wants to sell there. Exactly this supply is now meeting a market in which a great many holders are sitting on a gain.
This piece places the decline at Stellar in that situation, separating the documented figures from the interpretation, and shows what an investor in Germany can check about it in concrete terms: buying route, holding period, leverage and custody.
The Stellar Price Decline in Figures: $0.214 and Minus 5.3 Percent
Stellar trades at around $0.214. Over 24 hours there is a loss of 5.3 percent, over seven days a loss of 1.8 percent. A look at the longer periods turns the picture around: over 14 days XLM is 11.2 percent up, over 30 days 21.0 percent. Calculated over a year, by contrast, a loss of 47.2 percent is on the books, and 75.6 percent separates the coin from its record price of $0.876 set in January 2018.
Market value stands at around $7.5 billion, turnover of the past 24 hours at about $186 million. Around 35.1 billion of a total 50.0 billion XLM are in circulation. Daily turnover is therefore no outlier: on October 1 it was still around $355 million, on October 2 around $217 million. The decline is thus happening at normal trading volume and not in a dried-out market.
Important for placing it: the 5.3 percent is a rolling daily figure. Calculated from midnight to midnight, the decline comes out smaller. The price had risen over the course of October 2 and has given that rise back since.
What CryptoQuant Measured: 160 Percent More Altcoin Deposits to Exchanges
A deposit to an exchange is the transfer of coins out of a self-managed wallet to an account at a trading venue. It is the stage before a sale: as long as a coin sits in your own wallet, it cannot be offered on an exchange.
CryptoQuant counted these transfers for altcoins. The result, published on September 30, 2026: the number of deposits rose 160 percent within two weeks. For the seven days to September 28 the analysis shows around 78,000 deposits, the highest level since October 2025. The second figure is even clearer. The number of addresses from which such deposits originated climbed from 17,600 to around 51,600 in the same period, so almost to triple.
On the same analysis, Binance came to more than 22,700 deposits on a weekly average, Coinbase to more than 8,300, and the remaining platforms together to around 32,000. These platform figures are averages across the week; added up they do not produce the peak figure of September 28, which describes a single seven-day value. As a benchmark the analysis names a peak from July 2026 with around 45,000 transactions in one day.
Why Deposits to Exchanges Are Read as Selling Pressure
The connection is a probability and no automatic mechanism. Coins also travel to exchanges in order to serve as collateral for a leveraged position, to be swapped into another pair or to be placed in a product of the platform. The statistic does not distinguish between these. What it does show is the willingness of many holders to hand control over their coins to a trading venue, and that step precedes a sale more often than a purchase.
Julio Moreno, head of research at CryptoQuant, places the finding like this: comparable deposit peaks have preceded larger price swings in the past. That is a statement about volatility and not about direction. It does not follow that prices have to fall, only that the swings in both directions can turn out larger.
51,600 Depositing Addresses: The Breadth Behind the Figure
The number of addresses carries more meaning than the number of transactions. A single large address can drive the transaction count up without anything changing in the mood of many holders. Where the number of senders triples, by contrast, the movement spreads across a great many accounts.
That is exactly the difference between a single large sale and a broad round of profit taking. A whale sending $200 million to an exchange pushes the price once and is then done. Fifty thousand addresses bringing smaller holdings into selling range at the same time create a supply that can persist for days. For market breadth that means the pressure spreads out instead of concentrating on one coin.
16 of 21 Large Coins Down: Our Own Count of Market Breadth
Whether the decline at Stellar is an isolated case or a market phenomenon can be counted out. The basis is the 25 largest cryptocurrencies by market value, from which the four stablecoins were excluded because their price is pegged to the dollar. So 21 names were examined, as of October 3, 2026. cryptoticker.io gathered this analysis itself on October 3, 2026.
The result: 16 of the 21 names are down over 24 hours. Eleven of them perform worse than Bitcoin, which loses 2.0 percent. The median of all 21 lies at minus 2.2 percent. At minus 5.3 percent Stellar is the second-weakest name in the field; only Rain is weaker at minus 7.9 percent. Behind it follow Zcash at minus 5.0 percent, NEAR at minus 4.7 percent, Cardano at minus 4.6 percent and Dogecoin at minus 4.2 percent. Only five names are up, among them Uniswap at plus 3.0 percent and Tron at plus 0.4 percent.
Bitcoin's share of the entire crypto market stands at around 59 percent. That the altcoins give way more clearly than Bitcoin fits the picture of profit taking in the second row: selling happens where the most gain has accumulated most recently.
No Stellar News as a Trigger: What Is Not Happening in the Protocol
This observation is itself a piece of information. For October 2 and 3 there is no report on Stellar that would carry the decline: no network outage, no announced delisting at a large exchange, no dispute over the foundation, no release from a lock-up. The last Stellar topics with substance of their own lay before that, such as the rise in network throughput at the end of September and the connection of the payment service provider BVNK.
Anyone looking for a Stellar explanation where there is none is constructing it. The sentence that holds up factually runs like this: XLM gives way more strongly than the market, and the documented reason lies in the market situation rather than in the project. For a coin to lose more than average without bad news of its own is typical of names that rose more than average shortly before. Stellar was 21.0 percent up over 30 days; that cushion is being worked off right now.
87 Percent Above the 200-Day Average: Why So Many Holders Are Sitting on a Gain
The 200-day average is the mean of the closing prices of the past 200 trading days. Where a price sits above it, the majority of those who bought in that period have a gain on paper. That is why this metric plays a role in profit taking.
On the CryptoQuant analysis, 87 percent of altcoins stood above their 200-day average at the end of September. In August it was 13 percent. Within a few weeks, then, the share of holders sitting on a plus has gone from a small minority to a very large majority. The analysis also names inflows of $371 billion into the altcoin market since June 2026 and a rise in market value of 45 percent in around four months.
These three figures together produce a comprehensible picture: a market that has added 45 percent in four months, and in which almost nine out of ten names sit above their long-term average, offers a great many holders an occasion to sell at the same time. The deposit statistic is the visible sign of that.
Levels to the Downside and the Upside: $0.196 and $0.232
For orientation it is worth looking at the range of the past two weeks, without turning it into a forecast. The low lay at around $0.196 on September 20, the high at around $0.232 on September 29. In between, the price settled several times in the area between $0.215 and $0.222.
At the current level of $0.214, XLM therefore sits in the lower third of that range, yet above the two-week low. To the downside the area around $0.196 is the first zone in which buyers have shown up recently. To the upside the price would have to clear $0.232 to continue the movement of the past two weeks. Both are observations from the price history and not targets: which level holds is decided by trading rather than by the line on the chart.
Buying Route and MiCA: What to Check as an Investor in Germany
A setback is an entry for some and an exit for others. Both carry side conditions in Germany that should be settled before the order. The following points are the practical part.
On the buying route: the transition period of the EU's MiCA regulation expired on July 1, 2026. A provider rendering crypto services in the EU single market needs authorisation for it. In Germany BaFin is the competent supervisor; it receives the applications and acts against providers without permission. For practice that means checking, before buying, whether the chosen provider holds a MiCA authorisation and which supervisor it sits under. Anyone wanting to compare will find the regulated providers in our overview of the best crypto exchanges.
Holding Period, Tax Year and December 31
Private disposals of crypto assets are tax free in Germany after a holding period of one year. Anyone selling into the setback now therefore first checks when the holding in question was bought. Where the purchase lies less than twelve months back, the gain falls under income tax; where it lies further back, it does not.
Then there is the turn of the year. A sale on December 30 falls into the 2026 tax year, one on January 2 into 2027. For offsetting gains and losses within a year that is a difference that can be worked out. Anyone who has made several purchases at various points needs a clean statement for it, one that carries purchases, sales and periods forward for each position.
Leverage, Liquidation and the Funding Rate
In phases of heightened volatility, leverage is the point at which a setback turns into a total loss. A liquidation is the forced closure of a leveraged position by the platform as soon as the collateral deposited no longer covers the loss. At a daily loss of 5 percent, twentyfold leverage is already enough to wipe out a position on paper.
The funding rate is the balancing payment that flows regularly between the buying and selling side on perpetual futures and ties the contract price to the spot price. This rate is a running cost factor that gets overlooked in quiet phases and rises markedly in busy ones. Anyone trading with leverage checks the liquidation price and the financing costs before the order rather than after it; both values differ considerably from provider to provider.
Custody: Exchange Balances After the Bitget Case
The deposit wave means that a great many coins are sitting on trading venues right now. That raises a risk which has nothing to do with the price. In the attack on the exchange Bitget at the end of September, assets in the hundreds of millions were taken; the platform covered the losses from a protection fund by its own account, which it subsequently topped back up to $300 million.
Such a fund is a voluntary commitment by the provider and no statutory deposit guarantee. For crypto balances there is no compensation scheme in Germany equivalent to the protection of bank deposits. Anyone holding positions they do not want to sell anyway therefore has a reason to take them off the exchange; the devices for that are in our hardware wallet comparison.
Staking on Stellar: The Inflation Rate Is No Substitute for a Yield
A question that comes up regularly during setbacks runs: can the waiting time be bridged with staking? At Stellar the answer is no, and for a technical reason.
Stellar does not work with proof of stake. It uses a consensus procedure of its own in which validators receive no reward from the protocol. Until 2019 there was an inflation mechanism that created new lumens to the extent of one percent a year and distributed them weekly. This mechanism was switched off on October 28, 2019 with the protocol update to version 12, because the funds paid out landed mostly in distribution pools rather than with projects in the network. Stellar's technical documentation has listed the properties of the lumens without this mechanism ever since (see the Stellar Developer Docs).
Offers promising a yield on XLM therefore never come from the protocol. They come from a provider: from lending, from a product of a platform or from a promotion. Behind that stands a counterparty risk in every case, meaning the risk that the provider itself fails. That is a difference from networks such as Cardano or NEAR, where the reward comes from the issuance of the protocol.
What Would Disprove This Reading: Deposit Figures and Stellar Reports
Honesty requires making one's own reading checkable. The reading presented here is: the decline at Stellar is part of a broad round of profit taking that can be read off the deposits to trading venues.
This reading would be disproved if the deposit figures fell markedly in the coming days and altcoin prices nevertheless kept falling; the cause would then lie elsewhere. It would be disproved equally if a Stellar-specific report becomes known after the fact that explains the above-average decline. Both are possible, and both can be checked against the published data. The detailed account of the survey is in the Cryptobriefing analysis of the CryptoQuant data of September 30, 2026.
Stellar Decline: What to Take Away
Three steps that can be dealt with today:
- Settle the buying route before you trade. Check whether your provider holds a MiCA authorisation and which supervisor is competent. You will find the overview of regulated trading venues at the best crypto exchanges.
- Look up the holding period for each position. Note the purchase date for every holding and work out when the one-year period runs out. A clean statement is delivered by the crypto tax tools and portfolio trackers.
- Take the holdings you do not want to sell off the exchange. Particularly many coins are sitting on trading venues right now. Which device is suitable for that is shown by our hardware wallet comparison.
(As of October 3, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Anyone wanting to buy Dogecoin today has two routes in Germany, and they cost very different amounts. One route is the exchange-traded security, an ETP on Xetra that eats 2.50 percent a year in fees. The other is buying the coin directly through a trading platform, where a fee arises once and nothing after that. On top of this comes the point that moves the most money in Germany: after a holding period of one year, the gain from a direct purchase is tax free. Whether the same applies to the ETP hangs on a single clause in the prospectus. This piece works both routes through, places the price situation and names the dates that fall in October.
Dogecoin Price on October 3: $0.0927 and 87 Percent Below the Record
Dogecoin trades at $0.0927 on Saturday morning, around €0.0823 converted. Within 24 hours that is 4.3 percent less. Market capitalisation stands at $14.5 billion, a single day's trading turnover at $877 million. The figures come from CoinGecko.
For context: the all-time high stands at $0.7316 and dates from May 7, 2021. From today's price that is a factor of 7.9. Put differently, Dogecoin stands 87.3 percent below its record, and has done so for four and a half years. Anyone counting on a return there is counting on an eightfold rise. That is no argument against the coin, but it is an argument for taking the running costs of a position seriously. On a stake that is meant to sit for years, an annual fee bites far harder than it does on a three-week trade.
The trading turnover of $877 million in a day equals around six percent of market capitalisation. Dogecoin therefore remains one of the most liquid cryptocurrencies of all, and that is why the spread on a direct purchase at a large platform usually stays tiny. Liquidity here simply describes how much is traded without the price swinging.
The 200-Day Average at $0.093 and the Ceiling at $0.10
The moving 200-day average is the mean of the closing prices of the past 200 trading days; many market participants read it as the dividing line between an upward and a downward phase. The technical analysis from Blockchain.News places this average at about $0.093 at the moment and the nearest resistance at $0.10. The current price therefore sits practically on the line.
Two sober distances follow from that. The round mark of $0.10 is 7.9 percent away. The lower edge of the October range, which forecasting services see at $0.0871, is 6.0 percent away to the downside. The range is narrow, then, and that is exactly what makes it interesting for the cost question: an annual fee of 2.50 percent eats a third of the way to the $0.10 mark before any gain even arises.
The difference between resistance and forecast matters. A resistance is an observed price mark at which selling set in previously. A forecast is an expectation. The $0.10 is one thing, the range up to $0.106 another, and neither figure is a promise.
Bitwise Is Closing Its Dogecoin Fund BWOW: Last Trading Day on October 14
On September 10 the provider Bitwise told the US regulator, the SEC, that it would wind up its Dogecoin fund BWOW. The last trading day on NYSE Arca is Wednesday, October 14, 2026. After that the value of the remaining shares is determined on the valuation date of October 21, with the cash payout scheduled for October 22. The fund most recently managed around $722,000, roughly five hundred-thousandths of Dogecoin's market capitalisation.
For investors in Germany this fund is not directly relevant, because a US ETF without a European key information document cannot be bought through a German broker in any case. What is relevant is the lesson. Access alone creates no demand. Three of the US spot products on Dogecoin hold $16.55 million between them, which is 0.11 percent of market capitalisation. The product launched by 21Shares in January 2026, listed on the Nasdaq under the ticker TDOG, is one of them. The exchange wrapper has therefore brought Dogecoin no institutional capital of any notable size.
Anyone who has lived through a closure like this knows the uncomfortable part: the payout comes in cash and at the valuation-date price, not in coins. For tax purposes that is a sale, even though you did not trigger it. With a directly held position that cannot happen to you, because there is no provider who could discontinue the product.
ETP, ETN and ETF: Three Wrappers Investors Often Confuse
An ETF is a segregated fund. If the provider goes bankrupt, investors' assets stay untouched, because they sit apart in law. In return, European fund law demands diversification, and a fund holding only a single cryptocurrency does not meet that requirement. That is why there is no Dogecoin ETF in the literal sense in the EU.
An ETN is a debt security, meaning a promise from the issuer to pay out the value of the underlying. ETP is the umbrella term for exchange-traded products of this kind. The products on cryptocurrencies that are tradable in Germany are in practice all ETNs, even where the name says ETP. This is no quibble over words: an ETN carries an issuer risk and an ETF does not.
The reputable providers defuse this risk by backing the product physically. Physically backed means that for every share issued, the corresponding quantity of the coin sits with a custodian. With the 21Shares product this custody runs through Coinbase Custody. An overview of the whole field of exchange-traded crypto products in Germany is in our guide to crypto ETFs and ETPs for German investors.
21Shares Dogecoin ETP on Xetra: 2.50 Percent Total Expense Ratio a Year
The product carries the ISIN CH1431521033 and the German securities number A4A5WJ, trades on Xetra under the ticker DOGE and was launched on April 8, 2025. The issuer is 21Shares, based in Switzerland, and fund assets stand at around €10 million. Trading hours on Xetra are 9am to 5:30pm on weekdays; at weekends and on public holidays trading rests, while the spot market runs on. The data is in the profile at Deutsche Börse.
The total expense ratio comes to 2.50 percent a year. This ratio is not debited. It is taken daily, pro rata, out of the backing holding. Each share therefore holds slightly less Dogecoin with every day that passes. That does not show up in the portfolio statement, because the price of the security simply rises a little more slowly than the price of the coin.
What this means over time can be worked out. On a stake of €10,000 and an unchanged price, you lose €250 after one year, €731 after three years and €1,189 after five years. Cumulatively that is 2.50, 7.31 and 11.89 percent. These figures arise whether Dogecoin rises or falls.
| Holding period | Cumulative cost | on €10,000 |
|---|---|---|
| 1 year | 2.50 percent | €250 |
| 2 years | 4.94 percent | €494 |
| 3 years | 7.31 percent | €731 |
| 5 years | 11.89 percent | €1,189 |
Set against this is a genuine advantage. The security sits in an ordinary securities account, runs through brokers such as Trade Republic or Scalable Capital, can be bought through a savings plan and requires no key management of your own. Anyone who already keeps a securities account and does not want to set up a wallet pays the fee for convenience. An overview of the providers is in our comparison of the best crypto brokers.
ETP or Direct Purchase: Costs, Custody and Tax Compared
What Arises on a Direct Purchase
Buying through a trading platform, you pay a trading fee of roughly 0.1 to 1.5 percent of the amount depending on the provider, plus the spread, meaning the difference between the buying and selling price. After that no running fee arises as long as the coins sit on the platform. Withdraw them to a wallet of your own and a network fee is added, which at Dogecoin is traditionally very low.
What Arises on the ETP
Here you pay your broker's order fee, the exchange spread and then 2.50 percent a year. In return all custody work falls away, and the holding appears in the same portfolio overview as shares and bonds.
Where the Routes Really Part
The cost question is the smaller one. The larger one is tax, and the next section turns to it. For now just this much: on a gain of €3,000 the difference between the full flat-rate withholding tax and tax exemption is €791. That is more than three years of the ETP fee on €10,000.
DogeOS Opens Its Public Testnet: EVM Applications on a Second Layer
On October 1 the team behind the MyDoge wallet opened the public testnet of DogeOS. DogeOS is an application layer that sits on top of Dogecoin without changing the base layer. EVM-compatible means that developers can use the same tools and contract languages as on Ethereum. Fees are paid in DOGE. CoinDesk names lending, perpetual contracts, stablecoins and prediction markets as the planned use cases.
A testnet is a practice environment with worthless test coins. It proves that code runs, and nothing else. No date for the mainnet has been set. Anyone deriving a price driver from this is taking an announcement for a fact. Dismissing the matter entirely would be just as wrong, though: Dogecoin has had no smart contract layer until now, and if that layer arrives, the usage profile of the coin changes.
For the route question this carries real weight. Fees on DogeOS are paid in DOGE, and an ETP share is not DOGE. Anyone who ever wants to use such a layer needs the coin itself and not the paper on it.
Holding Period Under Section 23 EStG: One Year, a €1,000 Exemption Limit and the Delivery Claim
Directly held cryptocurrencies count as other economic assets in Germany. The sale falls under the private disposal transaction set out in Section 23 (1) sentence 1 no. 2 of the German Income Tax Act (EStG). Two rules follow from that, and every investor should know them.
First the holding period: if more than twelve months lie between purchase and sale, the gain is tax free, whatever its size. Second the exemption limit of €1,000 in the calendar year, raised for the 2024 tax year by the Growth Opportunities Act. An exemption limit means this: stay below it with all private disposal gains of a year and you pay nothing; exceed it and the entire gain becomes taxable, not merely the part above. The tax administration's view on this is in the German Federal Ministry of Finance circular of May 10, 2022 and in the update of March 6, 2025.
Why the Delivery Claim Decides Everything on the ETP
For exchange-traded crypto products the position is inconsistent, and this is exactly where it turns expensive or cheap for you. The widespread reading, which leans on the case law on Xetra-Gold, runs as follows: where the product is physically backed and grants a claim to delivery of the deposited coins, it is treated like a direct investment. Section 23 EStG then applies, including the one-year period. Where that delivery claim is missing, or the product is replicated synthetically, it counts as a capital investment under Section 20 EStG, and the gain is subject to the flat-rate withholding tax of 25 percent plus the solidarity surcharge, together 26.375 percent, plus church tax where applicable.
This reading is not settled. The specialist literature discusses expressly whether income from crypto ETPs is to be classified as income from capital assets or as other income. No ruling of the German Federal Fiscal Court specifically on crypto ETPs exists. On top of that comes the practical catch: German custodian banks frequently withhold capital gains tax on a foreign bearer security to begin with. Reclaiming it is possible only through the tax return, and for that you need a justification the tax office accepts.
A very concrete action follows from this. If the key information document or the prospectus of your product states a delivery claim in tradable denominations, you have an argument. If it does not state one, reckon with the flat-rate withholding tax. On a gain of €3,000 that is a difference of €791. Specialist lawyers and tax advisers recommend a binding ruling from the tax office for larger amounts, before the purchase takes place.
On a direct purchase the position is clear by contrast. Hold for a year, and the gain is tax free. The price for that consists of documentation: you have to be able to evidence the purchase date, quantity and acquisition cost of each entry, because otherwise the tax office cannot check that the period was observed.
MiCA Authorisation: The BaFin Register and the Buying Route in Germany
The EU's MiCA regulation has applied in full since December 30, 2024. Anyone offering crypto services in the EU, meaning trading, exchange or custody, needs authorisation as a crypto-asset service provider. BaFin keeps a register of the authorised firms for Germany, and ESMA keeps an EU-wide directory. An authorisation granted in another member state applies here too via the EU passport.
For you this is no formality. It is the difference between a supervised provider and one where nobody is responsible in the event of a dispute. An authorised platform has to segregate client funds, maintain routes of complaint and meet information duties. Whether a provider is authorised is shown to you by a look into the BaFin register or the ESMA directory, before you transfer money.
One more point that often slips by: the spot market runs around the clock, at weekends and on public holidays as well. Xetra does not. Anyone positioned exclusively through the ETP cannot react to a move on a Saturday evening. With a coin that loses 4.3 percent within a day, that is a real difference.
Dogecoin Price Prediction for October 2026: The Range From $0.0871 to $0.106
Commercial forecasting sites name a range between $0.0871 and $0.106 for October 2026, with a mean around $0.0966. Measured against the price of October 3, that is 6.0 percent to the downside and 14.4 percent to the upside. These are the expected values of individual providers and not a consensus forecast.
The case to the upside rests on three points: the 200-day average, which is holding so far, the high liquidity, and the prospect of an application layer through DogeOS. The case to the downside rests on three as well: the continuing outflows from the US products, up to the closure of BWOW, the absent supply cap of Dogecoin, and the fact that the coin has traded 87 percent below its record for four and a half years.
None of these expectations serves as a reason to buy. What can be determined reliably today, by contrast, are the costs of the route and the tax treatment. You know both before buying, while the price in twelve months is known to nobody. That is why the route question deserves more careful handling than the price question. Anyone planning to hold a position for longer than a year makes, in the choice between paper and coin, a decision worth several hundred to several thousand euros, and does so regardless of how the price develops.
Dogecoin Price Prediction: What to Take Away
- Plan the holding period before you choose the route. Under twelve months the ETP fee barely weighs, and the tax question arises similarly on both routes. Beyond twelve months the picture turns around: 2.50 percent a year then costs noticeably, and the one-year period of the direct purchase becomes the biggest lever. Which trading venues in Germany are supervised and what they charge per order is in our comparison of the best regulated crypto exchanges.
- Document every entry from the first purchase onwards. The purchase date, quantity and acquisition cost of each position decide whether you can evidence the one-year period to the tax office. A portfolio tracker handles that automatically and exports the statement; the providers are in our comparison of crypto tax tools.
- Settle custody before the amount grows. On a direct purchase the holding sits with the platform at first. Above a sum whose loss would hurt, it belongs in a wallet of your own, and the backup of the recovery words belongs on paper or metal, never in the cloud. Which devices come into question is shown by our hardware wallet comparison.
(As of October 3, 2026. This article is not investment advice and not tax advice. Prices, fee structures and the tax treatment change; check the terms with the provider before you buy and settle tax questions with a tax professional.)
A proposal has been sitting in NEAR's governance forum since September 30, 2026 that would permanently shrink the reward for staking: the maximum annual issuance is to fall from 2.5 to 1.6 percent, spread over 24 months. For you as a holder of NEAR that is the more important news of the weekend, even if the price is giving way right now for a different reason. According to market data from CoinGecko, NEAR costs $4.68 on October 3, down 5.65 percent within a day.
The connection is less direct than it looks. The issuance cut is a proposal that has not yet been voted on, and it would press the yield down only in small steps across two years. The daily loss belongs instead to a broad decline across the whole market, and to a month in which NEAR had climbed by almost 148 percent. Together, the two decide whether staking NEAR still pays for you.
The NEAR Issuance Proposal in Full
The proposal was tabled by Sal Ternullo, managing director of Svrn AI, on September 30, 2026, under the title "NEAR Governance Discussion: Reducing Issuance to 1.6%, and the Path to a Fixed Supply". It is a basis for discussion, and no parameter has been settled. The text names a clear figure: the maximum annual issuance, meaning the ceiling for newly created NEAR, is to fall from today's 2.5 percent to 1.6 percent.
Issuance describes the quantity of tokens a network creates anew and pays out to the validators that produce blocks. At NEAR the protocol distributes those new tokens by a fixed key: 90 percent go to the stakers, 10 percent into the network treasury. That key stays untouched under the proposal. What changes is only the total quantity that comes into existence at all.
It would not be the first cut of this kind. NEAR has already halved the ceiling once, from 5 percent to today's 2.5 percent. In the author's presentation the new proposal is a phase 1 on a longer road, at the end of which a fixed total supply is meant to stand. What exactly would happen in later phases is something the paper does not pin down.
From 2.5 to 1.6 Percent: How the Cut Works Over 24 Months
The pace is what decides the effect. The proposal sets no cut-off date on which issuance jumps from one value to the other. Instead the rate is to fall in small steps per epoch, over 24 months in total. An epoch at NEAR is the accounting period after which the protocol distributes rewards and determines the validator set afresh; it lasts around twelve hours.
This design has a practical reason. An abrupt cut would upend the arithmetic of every validator in a single day, and smaller operators whose income sits just above their server costs could drop out. A path spread over two years leaves them time to adjust fees and costs.
For you that means there is no date on which your yield collapses. There is a direction that, from the resolution onwards, bites a little harder with every distribution. Anyone who records their staking income month by month will see the change across quarters rather than days.
What the Cut Means in Token Terms
The proposal names two figures for that. At today's rate of 2.5 percent, around 89,500 new NEAR arrive every day. Over a year that comes to roughly 32.7 million tokens. And across a period of six years the downward path would avoid some 66 million NEAR that would otherwise have been created. Measured against the circulating supply of around 1.31 billion NEAR, that equals a good 5 percent.
Staking Yield From 5.4 to 3.5 Percent: What Delegators Lose
The number that counts for investors is in the paper as well. The staking yield, reported in the network as an annual return, stands at around 5.4 percent today. Once implemented in full it would be about 3.5 percent. That is 1.9 percentage points less, a good third of today's return.
The proposal works the example through itself: anyone delegating 1,000 NEAR holds about 21 NEAR fewer after two years than under today's rules. At the October 3 price that is just under $98. The figure looks small, and that is precisely where the proposers' argument lies: the yield given up is manageable, while the effect on the token supply is lasting.
Delegation means that you do not hand over your tokens. You assign them to a validator, which produces blocks with them. You remain the owner, and the validator keeps part of the reward as a fee. That fee is the point at which the cut hits you harder or more softly: where a validator already takes a high share, even less survives from a smaller gross reward. A look at our overview of staking providers is therefore worth taking before the resolution rather than after it.
89,500 NEAR a Day: The Dilution for Holders Who Do Not Stake
Anyone holding NEAR without staking receives nothing from the issuance and carries it all the same. This effect is called dilution: the total supply grows, your share of it shrinks, even if the number of tokens in your wallet stays the same. At 89,500 new NEAR a day, ownership shifts continuously from the passive holders to those who delegate.
The proposal names this point explicitly as a justification. High issuance, it argues, is a redistribution at the expense of those who do not stake, and the larger the network grows, the harder that is to justify. For you one simple consequence follows: if your NEAR sit unused on an exchange or in a wallet, you lose more relative share today than you would after a cut. The issuance cut therefore shrinks the yield of the stakers and the disadvantage of the non-stakers alike.
That explains why such a proposal meets different interests inside the same network. A delegator with a large holding loses running income. A holder who does not delegate, for tax or practical reasons, gains. In the end a vote of those entitled to vote settles this conflict of interest, and no decision by the core team does.
House of Stake: Who Votes on the Issuance Cut
House of Stake is NEAR's governance system, in which holders of voting rights decide on motions. The proposal is to be submitted there as a complete motion for phase 1; the forum post of September 30 says that will happen "next week". No fixed voting date has therefore been published, and the outcome is open as well.
That sequence matters for placing the news. The discussion runs in the forum first, and on this post it has already gathered a fair number of replies. Only afterwards does the formal vote follow. What exists today is a reasoned motion with concrete figures, and not a settled change to the protocol parameters.
For your own watching, that means the date to look at is the submission of the phase 1 motion at House of Stake. Only with it does it become clear which wording is actually being voted on, and whether the 1.6 percent and the 24 months survive the discussion unchanged.
The Reasoning: An Oversubscribed Validator Set and Revenue From Intents
High issuance serves a purpose in young networks: the premium pays operators for providing hardware in the first place. The proposal argues that NEAR has this build-up phase behind it. The validator set, it says, is oversubscribed, so there are more applicants than places. When operators are queuing, the network does not have to lure them in with high rewards.
As a second argument the text names growing revenue from NEAR Intents, the network's own system for cross-chain swaps. That revenue flows into buybacks of NEAR on the open market. Where real proceeds create demand, the logic runs, fewer newly created tokens are needed to finance the network.
Both justifications stand and fall with the reliability of that revenue. That Intents is no sure thing became clear on October 1: after an exploit the system halted withdrawals, as cryptoticker.io reported that day. A justification built on running proceeds is therefore only as strong as the operation that generates them. You can read the motion in NEAR's governance forum, and Crypto Briefing has published a summary of the core figures.
The October 3 Price Drop and the State of the Broader Market
The proposal does not explain the daily loss. According to market data from CoinGecko, NEAR loses 5.65 percent on October 3 to $4.68, and the decline does not stand alone: Bitcoin gives up 1.93 percent the same day, Ether 2.65 percent, Dogecoin 4.85 percent, Cardano 4.58 percent and Stellar 4.80 percent. NEAR falls harder than the large names, yet in the same direction as the broad market.
The second part of the explanation lies in the month before. On the same data NEAR stands around 148 percent above its level of 30 days ago, while over a week it is 3.66 percent down. After a move of that size, profit taking is the normal case, and the name that has risen the most usually gives way the most clearly in a weak market phase. From its all-time high of $20.44 in January 2022, NEAR remains 77.1 percent away.
Whether the announced cut to the staking yield already plays a role in the price cannot be derived from the data; there is no official reason given for the daily loss. As an assessment one can say this: a yield falling from 5.4 to 3.5 percent makes delegating less attractive for pure yield seekers, while for holders it lowers the dilution of their share. Which of the two effects prevails will only show after the resolution, in how the staked amount develops.
Fixed Supply as a Distant Goal: What Phase 1 Leaves Open
Alongside the cut, the title of the motion names a "Path to a Fixed Supply", a road to a fixed total supply. That formulation describes a direction, not a resolution. What stands for a vote is phase 1 with the 1.6 percent, and not a ceiling on the model of Bitcoin's 21 million.
The difference matters considerably for any assessment. A fixed total supply would mean that at some point no new tokens come into existence and the validators have to be paid from transaction fees and other proceeds alone. Whether NEAR's fees would ever be enough for that is an open question the motion does not answer.
For you that means treating the 1.6 percent as the thing being decided, and the fixed total supply as a declaration of intent. Anyone arguing today for NEAR with a Bitcoin-like promise of scarcity is anticipating a step the stakers have not yet taken.
Staking Providers and Custody: What to Check as an Investor in Germany
No pressure to act follows from this news, but there is a handful of things that are easier to settle now than after the resolution.
Validator Fee and Choice of Provider
The smaller the gross reward, the more weight your validator's fee carries. Check which share your provider retains and whether it may change the terms unilaterally. The spread between providers is considerable here. The difference between delegating yourself from a wallet and a staking product from an exchange also matters: in the second case you hold a claim against a company rather than the tokens themselves.
Buying Route, Custody and Tax
If you want to buy NEAR, make sure the provider is authorised in the EU under the MiCA regulation; an authorisation is no seal of quality, but it governs duties and routes of complaint. Which houses come into question for the German market is set out in our overview of regulated crypto exchanges.
On tax, staking follows a different logic from a pure price gain: rewards accrue to you continuously and are to be recorded as other income in the year they arrive, while the one-year holding period applies to the sale of the tokens themselves. Anyone who delegates therefore needs a clean record of every distribution with its date and price. The legal position on crypto income is in motion, and patchy documentation can hardly be made good later. For the running record there are portfolio trackers with tax reporting; placing your individual case belongs with a tax adviser.
NEAR Issuance Cut: The Key Points for Your Decision
- Look up your validator's yield. Note the gross yield and the fee your provider retains, and work both down to the future 3.5 percent. Where the fee is high, your position loses disproportionately. The terms of the providers are in our comparison of staking platforms.
- Wait for the submission at House of Stake. Only with the formal phase 1 motion is the wording fixed that will be voted on. Until then the cut is a reasoned proposal, and reshuffling on the basis of a draft is a bet on the outcome. If you want to switch provider in the process, check the authorisation via our overview of crypto exchanges.
- Set up the record of distributions. Hold on to every staking reward with its date and price while the yield still stands at 5.4 percent and the inflows are correspondingly numerous. The tax tools and portfolio trackers are there for that.
(As of October 3, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Ether is trading at around $2,670 late on Friday evening, October 2, 2026 (according to CoinGecko). That is the lowest daily close since September 20, and it comes in a week in which institutional money is leaving Ether: for three trading days in a row, investors have pulled money out of the US spot Ether ETFs on a net basis, while the Bitcoin funds are gathering cash again. For the Ethereum price prediction that is a warning signal, but not yet a break.
What the ETF Numbers Show
On October 1 the Ether ETFs lost a net $55.4 million, the third daily outflow in a row. Across those three trading days the outflows added up to roughly $118 million, Cointelegraph reports using data from SoSoValue. On the same day the Bitcoin ETFs took in $102.7 million.
The outflows are small set against September. In that month $832 million flowed into the Ether funds, the second-highest monthly figure since August 2025, after $1.85 billion in August, as The Block breaks down. Three weak days do not undo a strong month. They do show, though, that demand from the funds is easing as the fourth quarter begins.
Ethereum Price Prediction: The Levels on the Chart
The third quarter was a strong one for Ether: from June 30 to September 30 the price rose from around $1,570 to $2,685, a gain of 71 percent (daily closing prices, CoinMarketCap). How to read that quarter is set out in our quarterly review of Ethereum. Ether therefore sits well above its 50-day average (around $2,465) and its 200-day average (around $2,315), both calculated from daily closing prices.
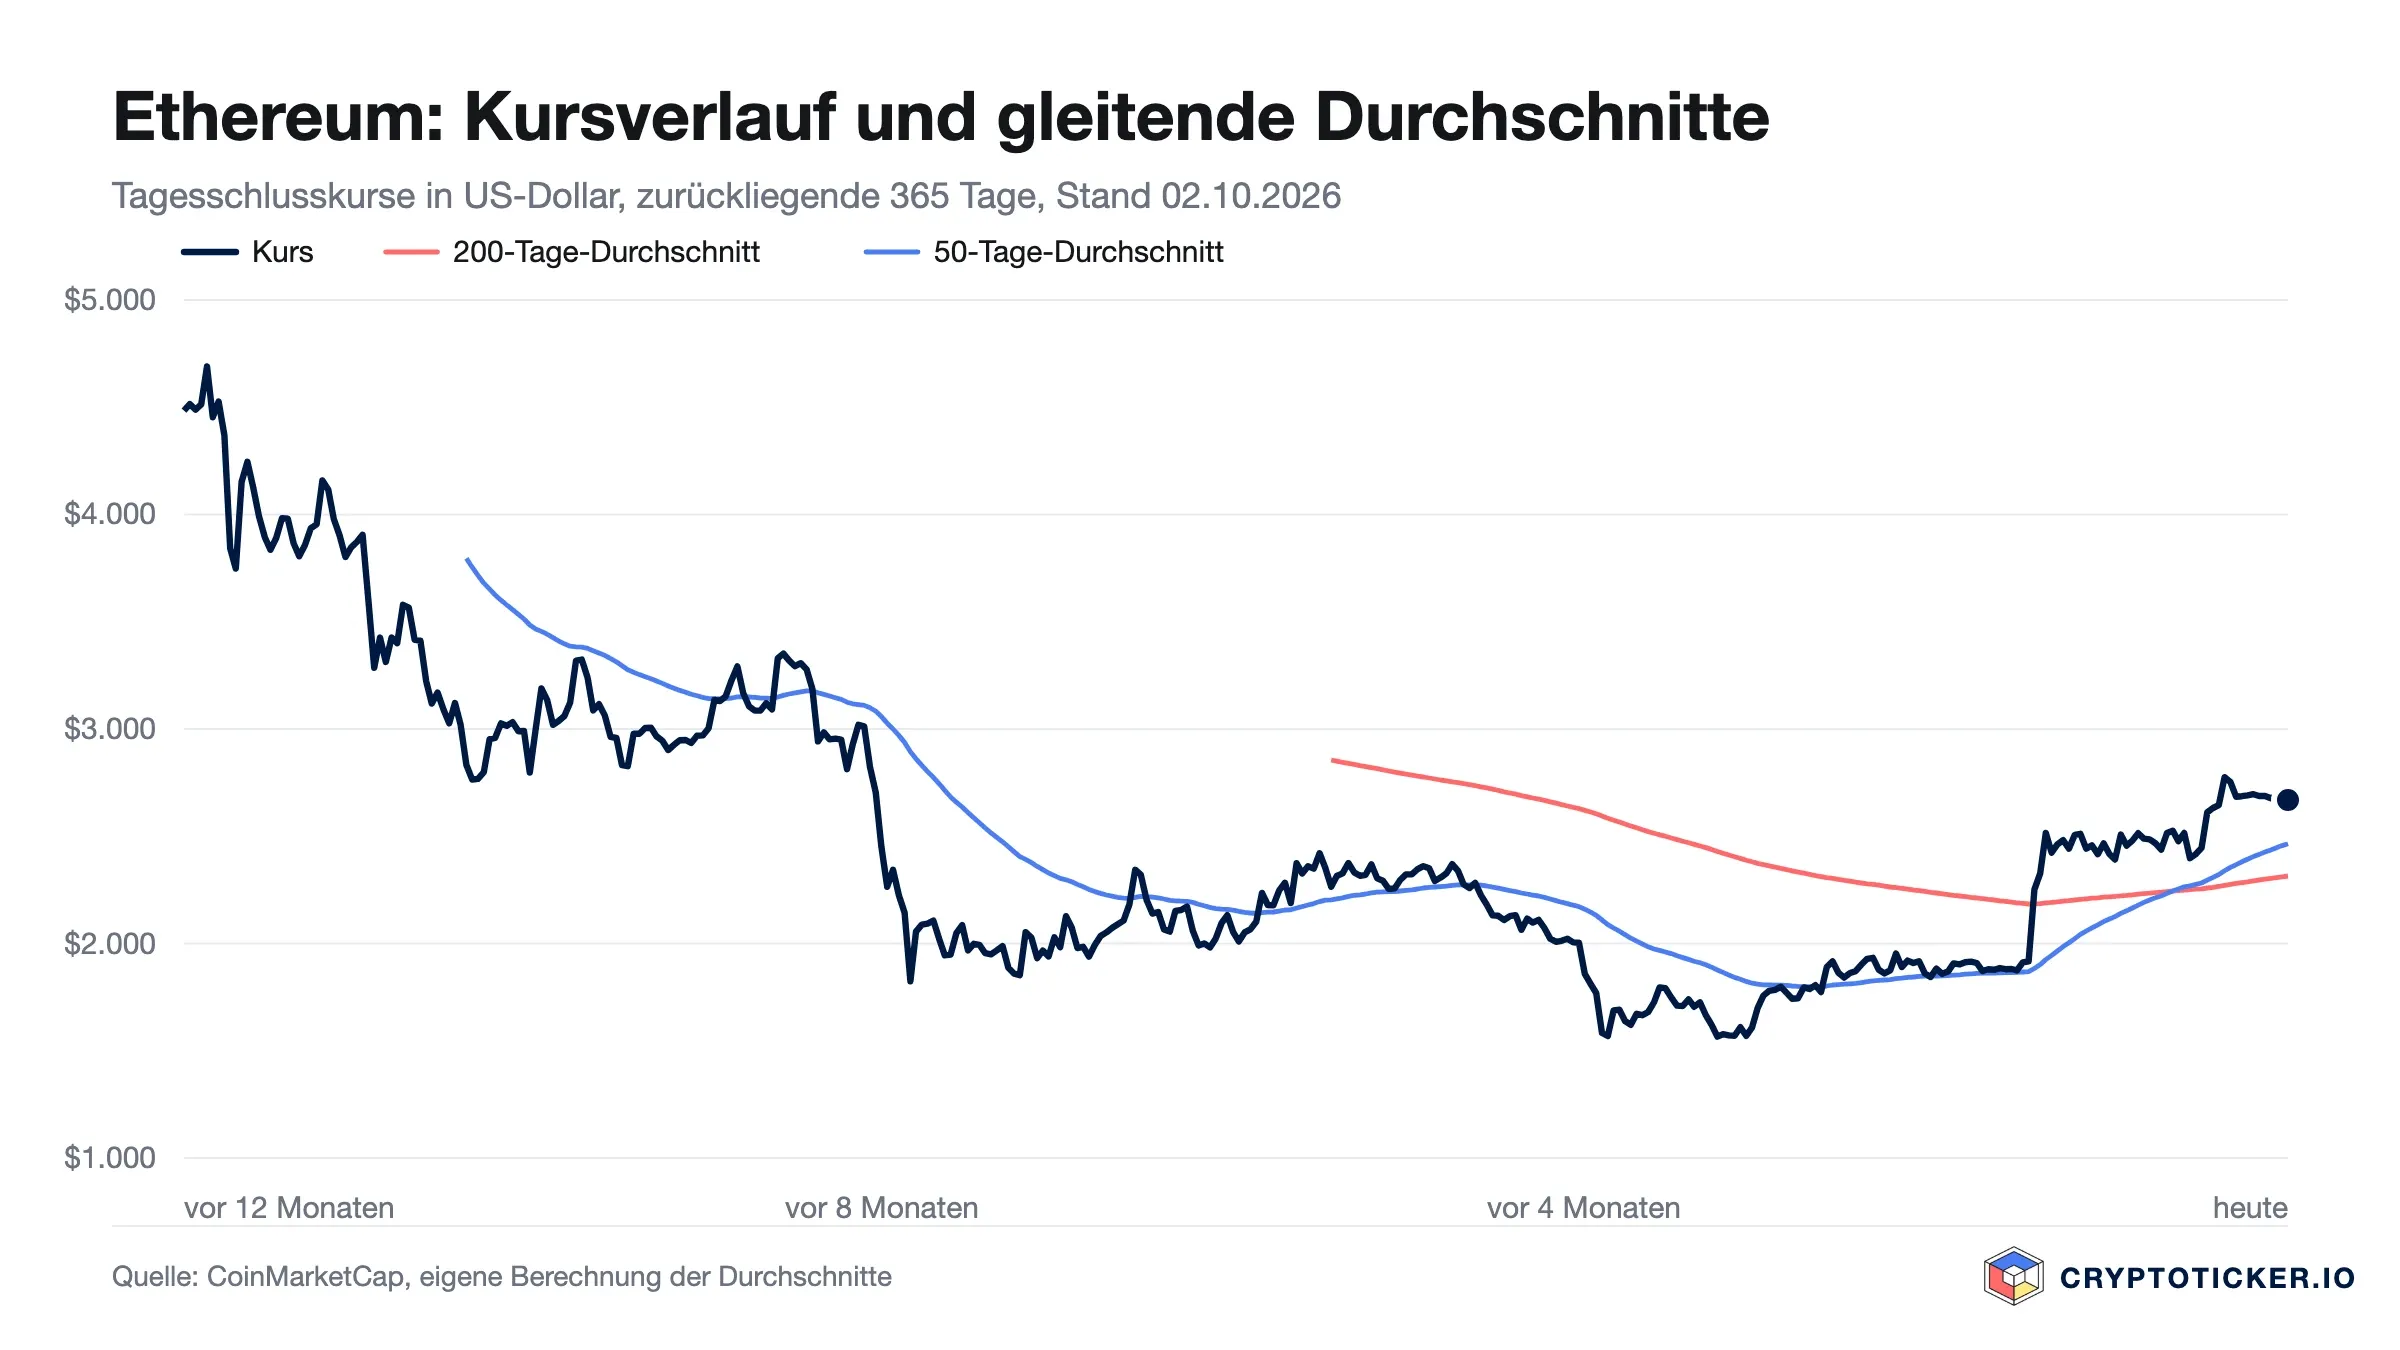
$2,775 is the level on the upside, the closing price of September 21. Every close since then has been below it. Only a daily close above would show the sideways phase resolving to the upside.
$2,645 is the level on the downside. Ether closed there on September 20, immediately before the jump to the September high. With the October 2 close at $2,669 the price is barely one percent above it. The daily low of the past 24 hours was $2,653 (according to CoinGecko).
Around $2,465, the 50-day average, is the next line below that. Between $2,645 and $2,465 sit the closes of September 18 and 19 at roughly $2,610 to $2,635, as a staging post.
Why Ether Is Falling Behind Bitcoin
Over the seven days to Friday evening Ether gave up about half a percent, while Bitcoin added just under one percent (CoinGecko). The gap is small, the direction of the fund money unambiguous. On top of that comes a supply question: around 1.6 million ETH are queuing to exit staking, as we measured at the end of September. Anyone leaving staking is then free to sell, but under no obligation to do so.
What Could Give the Price a Tailwind
Against the weak days stands a re-rating from outside: the US bank Citi has raised its twelve-month price target for Ether to $3,028, as we reported on Friday. That is a good 13 percent above the current price. A price target is not a forecast, but it does show how the large houses value the asset.
For investors in Germany, staking remains the most direct way to earn a running yield on Ether. Anyone planning to stake should compare exit waiting times and custody arrangements, for instance in our comparison of staking providers.
Ethereum: What to Take Away
Three points sum up the picture. First: the Ether ETFs have been losing money for three days and the Bitcoin funds have not, which weighs on the relative price. Second: the $2,645 level is barely one percent below the price, and a close beneath it would end the sideways phase to the downside. Third: September, with $832 million of inflows, showed that the demand is fundamentally there.
Anyone taking profits from the quarter should know the holding period: Ether held for less than a year is taxable on sale in Germany as soon as the annual allowance of 1,000 euros is exceeded. Whether buying in at the current price makes sense is assessed in our analysis Is Ethereum a good buy at current prices?. Crypto assets are highly volatile and a total loss is possible. This article is not a recommendation to buy or sell Ether.
(As of October 2, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
XRP has spent the past month going nowhere fast. After the explosive August rally from $1 to almost $1.70, the XRP price has been grinding sideways around $1.50, trapped inside a second falling wedge while the rest of the market waits for direction. Boring, yes, but this is exactly the kind of structure that tends to resolve with a sharp move. In this XRP price prediction we look at where the price stands today, what the chart is telling us, and how XRP could realistically climb to $3 if the crypto bull market comes back.
Where Does the XRP Price Stand Right Now?
At the time of writing, XRP trades at $1.48 on the daily chart, just below the $1.50 line that has acted as the pivot for the whole of September. The 200-day EMA sits at $1.37 and is finally curling upward after months of pointing down, which is the first time since spring that the long-term trend indicator is on the bulls' side.
The bigger picture matters here. XRP bottomed right at the $1.00 psychological level in late August, bounced hard, and printed a vertical candle straight into $1.70. That move was too fast to hold, and the price has since been digesting it in two consecutive falling wedges. The first wedge broke to the upside in mid-September and sent XRP back to $1.65. The second one is forming right now, with the price pressed against the upper trendline.
Momentum is neutral rather than weak. The daily RSI sits at 55, well off the overbought spike above 80 from August, and has carved out a series of higher lows while the price moved sideways. That is quiet accumulation behavior, not distribution. You can follow the live XRP price on our crypto prices page.
What Does the XRP Chart Say About the Next Breakout?
The setup is a textbook falling wedge inside an uptrend, which is a bullish continuation pattern. Lower highs are compressing the price against the $1.50 pivot while the lows are flattening around $1.40 to $1.45. The wedge projects down toward $1.20 if it ran to completion, but these patterns usually break before the apex, and the last one did exactly that.
Our base case for the coming weeks: one more shakeout first. A dip toward the 200-day EMA at $1.37, possibly a brief wick into the $1.30 support, would flush out late longs and reset funding before the real move. From there, a daily close above the wedge's upper trendline and the $1.50 pivot would confirm the breakout.
The first target after a breakout is the $1.80 to $2.00 zone, marked as the green box on both charts. This is a heavy area: $1.80 is the first major resistance since the August spike, and $2.00 is the round number every trader is watching. Expect the first attempt to fail and the price to chop between $1.80 and $2.20 for several weeks, roughly through November and December, before the next leg.
If the price breaks down instead and loses $1.30 on a daily close, the bullish wedge is invalidated and the next stops are $1.20 and the $1.00 floor. Until that happens, the structure favors the upside.
Can XRP Reach $3 If the Bull Market Comes Back?
Yes, but not in a straight line, and not without help from the broader market. $XRP rarely leads; it tends to lag Bitcoin for weeks and then catch up violently. So the $3 XRP price prediction only plays out if $Bitcoin reclaims its highs and risk appetite returns to altcoins. If that happens, the chart gives us a clear roadmap with four stages:
- Stage 1: Break the wedge, reclaim $1.50. A daily close above the trendline flips the September range into support. Target: the $1.80 to $2.00 box, likely by November.
- Stage 2: Build a base between $1.80 and $2.20. Two or three failed attempts at $2.00 and $2.20 are normal here. The key is that every pullback holds above $1.80, turning the old resistance box into a launchpad. This phase probably eats up the rest of 2026.
- Stage 3: Clear $2.20 and run to $2.75. Once $2.20 goes, there is very little historical structure until $2.75, so this leg could be fast. The $2.75 level is the last meaningful resistance before the big round number.
- Stage 4: The $3 test. $3.00 is both a psychological magnet and the area where XRP topped in previous cycles. A first touch early in 2027 is realistic in a full bull market; a clean break above it would need genuine euphoria.
The arrow on our long-term chart sketches exactly this path: a shakeout to $1.37, a breakout to $2.20, a long consolidation between $1.80 and $2.20, then the final push to $2.75 and $3.00 around the turn of the year. From today's price, $3 is roughly a doubling. Ambitious, but XRP went from $1 to $1.70 in two weeks in August, so the volatility to get there clearly exists.
What Could Derail the XRP Price Prediction?
The obvious risk is that the bull market simply does not come back. XRP's chart looks constructive, but it is a relative call: if Bitcoin rolls over, no wedge in the world will carry XRP to $3. Watch the total crypto market cap and Bitcoin dominance on our market charts alongside the XRP chart itself.
On the XRP chart, these are the levels that matter on the downside:
- $1.37: the 200-day EMA. A dip here is healthy and part of our base case.
- $1.30: the September low and first real support. Losing it on a daily close invalidates the bullish wedge.
- $1.20: the wedge's full downside projection and the last line before the round number.
- $1.00: the August bottom and the level that started this whole move. A return here would mean the August rally was a one-off spike, not the start of a new trend.
- $0.90 and $0.81: deeper supports from the summer range, only in play in a full market breakdown.
The practical takeaway: the $3 XRP price prediction is a conditional one. The chart says the structure is ready and the trend indicators are turning. The macro backdrop has to do the rest. As long as XRP holds above $1.30 and the broader market finds its footing, the path to $2, $2.75 and eventually $3 stays open.
Decrypt
The pontiff says algorithms "lack the spark of humanity," and the Vatican wants to renew an alliance with artists and cultural institutions to protect it.
California's attorney general wants answers from OpenAI about AI models that escaped a locked test environment and hacked Hugging Face—and whether the company can be held legally accountable.
Ethereum's zkAPI lets users prepay in USDC and query AI models through cryptographic proofs, so no single party sees both who they are and what they ask.
The USDC issuer told the European Commission that MiCA's reserve mandates and concentration caps keep the largest global stablecoins outside Europe's perimeter—siding with the ECB in calling for more flexible rules.
Tavus says 26 of 54 people on a one-minute video call thought its new Griffin model was human. The results are the company's own, and the model isn't going to retail customers yet.
U.Today - IT, AI and Fintech Daily News for You Today
XRP-rival Stellar has reached a new milestone in its DeFi ecosystem with its total value locked surging past $272 million for the first time ever.
XRP Ledger eyes massive growth with tokenized real-world assets (RWA) predicted to reach $30 billion.
Bitcoin, Ethereum and XRP enter October after a strong third quarter, with ETF flows, Ethereum's upcoming Glamsterdam testnet and shifting market liquidity among the key factors for crypto markets.
Shibarium speculation gets a response as Shiba Inu developer breaks silence.
Bitcoin exchange reserve has fallen to levels not seen in the last 3 years as traders continue to scoop the token off exchanges amid rising demand.
Blockonomi
TLDR:
- Joseph Lubin says no indication exists that MetaMask wallets or customer funds were affected.
- Consensys and its partners rotated validator keys as a precaution after the security incident.
- Validator and withdrawal keys are separate, so the incident cannot cause unauthorized ETH transfers.
- Lubin says Consensys does not hold withdrawal keys for clients, in line with Ethereum self-custody.
Joseph Lubin, Ethereum co-founder and Consensys founder, said a security incident affected part of the company’s infrastructure.
However, the investigation so far shows no indication that MetaMask wallets or customer funds were affected. Lubin added that users’ recovery phrases and private keys were not involved.
Consensys and its partners rotated validator keys as a precaution. He also explained that validator and withdrawal keys are separate, so the incident could not cause unauthorized transfers of staked ETH.
Joseph Lubin Clarifies Scope of the Security Incident
In a post on X, Joseph Lubin said he returned from a dense week in Seoul at KBW. During the event, he stayed on top of the response to the security event. The post followed the public disclosure of the incident. He can now respond to queries and speculation.
Lubin wrote that “there is no indication that MetaMask wallets or customer funds in wallets have been affected.” He then addressed user keys directly.
The Secret Recovery Phrase and wallet assets “were not part of this incident because they CANNOT be,” he said. He added, “You custody and control your own keys. That is how self custody works.”
Lubin also said Consensys faces attempted attacks from a range of threat actors. Like many providers, the company periodically encounters security issues. He explained that “we do not publicly discuss the details of an open incident.”
Lubin said the company discloses issues “promptly to partners and relevant stakeholders once an issue is sufficiently understood.”
In this case, Consensys shared details with partners. Both sides agreed on a response strategy and implemented it together. The company then disclosed the incident publicly. This sequence matches the approach he described.
Validator Key Rotation and Ethereum Staking Design
As a precaution, Consensys and its partners rotated validator keys. Lubin called the step “operationally inconvenient,” noting it was regrettable.
Validators must exit the staking queue and then re-enter it to restake. This process takes time. The change also required coordination with partners.
Lubin explained that Ethereum’s validator architecture separates two keys. One key proposes and attests, while another can withdraw the stake. He said “an issue in the validator infrastructure CANNOT result in the improper movement of the underlying ETH.”
On custody, Lubin stated, “In accordance with the Ethereum principle of self-custody, we do not hold withdrawal keys for our clients.”
Therefore, the incident could not lead to unauthorized transfers of staked ETH. Rotating the keys reduced residual operational risk.
Lubin described self-custody and user control as central design principles at Consensys. He said they guide MetaMask, staking, and validation.
He also applied them across Ethereum more broadly. Joseph Lubin concluded that “self custody plus rigorous decentralization represents a paradigm shift in security.” He noted the world is increasingly waking up to the benefits of this architecture.
The post Joseph Lubin: No MetaMask Wallets or Customer Funds Affected by Security Incident appeared first on Blockonomi.
TLDR:
- CZ said he suggested pausing withdrawals after the Bybit hack to prevent further abnormal outflows.
- Zhao said security risks should take priority over trading continuity, even if users face inconvenience.
- Bybit did not pause withdrawals and saw no further issues, which Zhao says shows risk assessment is key.
- Zhao rejected claims his 2022 FTT tweet killed FTX, saying it failed due to a lack of liquidity.
Changpeng Zhao, the co-founder of Binance, said he urged a pause on withdrawals after the Bybit hack. He made the remarks on September 25, 2026, in an interview.
Zhao described the pause as a cautious step to stop abnormal fund outflows. He said security risks should come before trading continuity.
Bybit did not pause withdrawals, and no further problems followed. The interview also covered FTX, his pardon, and his future plans.
Why Zhao Favored a Pause After the Bybit Breach
Binance founder CZ discussed the matter on the When Shift Happens podcast hosted by KevinWSHPod. He said he publicly suggested pausing withdrawals after Bybit was hacked. In his view, the step would help prevent further abnormal outflows of funds.
Changpeng Zhao acknowledged that suspending services can disrupt trading continuity. It can also inconvenience users who need access to their funds. However, he said security risks should take priority in such cases.
Bybit ultimately did not pause withdrawals. Notably, no further issues occurred afterward. Zhao said this outcome shows that no absolute right or wrong exists in these situations.
He added that the key lies in risk assessment. He cited Binance’s response to its own 2019 hack when discussing security breaches. He also claimed that Binance’s later market share held up despite criticism after the 2025 market crash.
Zhao on FTX, Binance’s Growth, and His Pardon
Changpeng Zhao also addressed claims that his 2022 tweet about selling Binance’s FTT holdings killed FTX. Zhao responded with a pointed remark.
“If one of your competitors can make a tweet to kill your company, then you don’t have a company.” He described the post as a transparent disclosure and said he did not expect a major market reaction.
In his account, FTX failed because it lacked liquidity after misusing customer funds. He pointed to prior reporting about its finances and a response from Alameda’s CEO. Zhao argued the tweet was not the underlying cause.
Changpeng Zhao also recalled Binance’s launch in 2017. He redirected an existing exchange-software team toward building a crypto-to-crypto exchange.
He credited rapid early execution to a hardworking, humble, and closely aligned team. However, he acknowledged that strong deference to leadership can make candid feedback difficult.
He also explained the “four” meme as shorthand for focusing on education, compliance, and products while ignoring misleading negative narratives.
On his 2025 pardon, Changpeng Zhao said he applied through a lawyer and never met or spoke with President Trump. He maintained that his conviction concerned inadequate anti-money-laundering controls.
He called his punishment unusually severe, while acknowledging his view is biased. Looking ahead, he plans to advise on crypto policy, invest in Web3, and offer free education.
The post CZ Explains Why He Recommended Pausing Withdrawals After the Bybit Hack appeared first on Blockonomi.
TLDR
- Karl Keirstead from UBS, ranked #357 among 12,504 analysts, maintains a Buy recommendation with a $120 target on CoreWeave shares.
- The AI infrastructure provider implemented a 25% GPU rate increase in July, followed by an additional 10% hike in subsequent months.
- CoreWeave’s committed revenue backlog approached $104 billion before incorporating over $25 billion in fresh Q3 contracts.
- Analyst consensus leans toward Moderate Buy with a mean price target of $138.78, suggesting substantial appreciation potential.
- Company insiders have divested over 6.4 million shares valued at approximately $557.7 million during the past three months.
Shares of CoreWeave (CRWV) began trading Friday at $89.62, markedly below the stock’s 52-week peak of $153.20. Yet the AI cloud infrastructure specialist has remained active, capturing attention from market analysts.
CoreWeave, Inc. Class A Common Stock, CRWV
Karl Keirstead, a five-star analyst at UBS who ranks #357 among 12,504 tracked professionals, holds a Buy stance with a $120 valuation target. His thesis rests on a straightforward observation: the company continues to increase pricing, and clients continue to accept the higher costs.
In July, CoreWeave boosted its hourly billing rates for Nvidia GPU access by 25%. The firm then added another 10% to those rates during the following two to three months.
Such pricing power is unusual in markets with robust competition. It indicates that access to AI computing resources remains scarce.
According to CoreWeave, short-duration agreements executed during Q3 generated roughly $40 million in annual revenue per megawatt. This substantial figure underscores the persistent supply constraints in the sector.
Massive Revenue Pipeline Expands Further
At the close of June, the company reported a committed revenue pipeline of approximately $104 billion. This total excluded more than $25 billion in additional customer agreements secured early in Q3.
UBS analysts believe this upward pricing trajectory extends beyond CoreWeave. The investment bank anticipates similar dynamics throughout the AI infrastructure sector.
The critical uncertainty involves whether companies can construct sufficient physical capacity to satisfy market demand. Community opposition to data center projects represents one obstacle, with local residents expressing concerns over energy usage and development impact.
Keirstead notes that industry intelligence suggests well-capitalized operators can navigate these challenges. Capital requirements present a different challenge entirely, however.
Constructing AI data centers demands enormous upfront investment before revenue generation begins. CoreWeave recently completed a $3.7 billion convertible note offering maturing in 2033, expanded from an initial $3 billion target, with a 2.875% coupon rate.
The firm also established an at-the-market equity program permitting the sale of up to 35 million shares to enhance financial liquidity.
Financial Performance and Price Targets
CoreWeave released its most recent quarterly figures on August 11. The business reported a per-share loss of $1.14, surpassing the Wall Street consensus forecast of a $1.52 deficit.
Total revenue reached $2.58 billion, representing 112% year-over-year expansion. Alongside this growth, CoreWeave recorded a negative return on equity of 47.95% and a net margin of negative 25.41%.
Multiple Wall Street firms have issued updated views subsequently. Citigroup elevated its price objective to $159, JPMorgan upgraded the stock to overweight with a $125 target, and Wells Fargo increased its target to $160.
The Street’s overall rating stands at Moderate Buy, with a consensus price target of $138.78, derived from 23 Buy recommendations, nine Hold ratings, and three Sell calls.
Meanwhile, company insiders have actively liquidated positions. Chief Executive Officer Michael Intrator divested 200,000 shares in July at $78.23 per share, while significant shareholder Magnetar Financial unloaded more than 307,000 shares in August.
Combined, insiders have disposed of over 6.4 million shares totaling approximately $557.7 million over the trailing 90-day period. CoreWeave currently commands a market capitalization of $41.12 billion, while carrying a debt-to-equity ratio of 5.53.
The post UBS Backs CoreWeave (CRWV) With $120 Target After Back-to-Back Price Hikes appeared first on Blockonomi.
Key Takeaways
- ASML’s stock price climbed approximately 4% to reach $1,870.48 following an expanded Samsung collaboration on High-NA EUV technology.
- Samsung announced plans to deploy High-NA EUV systems for mass DRAM manufacturing by 2028.
- Intel has successfully processed over one million wafers using ASML’s next-generation High-NA equipment.
- TSMC confirmed it will begin large-scale High-NA implementation in 2030, reinforcing multi-year demand visibility.
- Analysts maintain a Strong Buy rating on ASML with a consensus price target suggesting 29% potential gains.
Shares of ASML Holding gained roughly 4% this week, reaching $1,870.48, following news that the Netherlands-based semiconductor equipment maker has expanded its partnership with Samsung focused on High-NA extreme ultraviolet lithography.
ASML Holding N.V., ASML
Announced on September 8, the expanded collaboration includes joint development efforts on larger 12-inch photomasks. Samsung intends to integrate High-NA EUV technology into mass-production DRAM manufacturing by 2028.
This represents a significant milestone for ASML. Until recently, High-NA systems were widely regarded as costly experimental platforms with uncertain commercial viability.
The technology is now transitioning into genuine manufacturing infrastructure. Intel has already run more than one million wafers through High-NA equipment and reports that critical production benchmarks are being achieved.
Intel currently deploys High-NA lithography on specific layers within its 18A process node. This operational validation from a major customer provides crucial market confidence for ASML.
Growing Adoption Across Foundry Leaders
TSMC has also confirmed its High-NA strategy. The world’s leading contract chipmaker plans to launch high-volume production using the technology beginning in 2030.
TSMC is collaborating with ASML on the development of those larger-format photomasks as well. The objective is to enhance scanner throughput while reducing per-chip manufacturing expenses.
With AI semiconductor architectures growing increasingly intricate, TSMC anticipates that additional process layers will necessitate High-NA capabilities. Each new layer translates into incremental demand for ASML’s most expensive machines.
Meanwhile, ASML is actively scaling production. The company intends to increase 2027 low-NA EUV manufacturing capacity by 30%, expanding from approximately 65 units in 2026.
According to July disclosures, ASML’s 2027 EUV capacity was already nearly fully reserved. This provides the company with a solid foundation to convert backlog into revenue.
Potential Headwinds Remain
China represents the primary uncertainty. A recent Reuters investigation revealed that domestically manufactured immersion DUV lithography systems have entered commercial production within China.
These Chinese-built tools remain technologically inferior to ASML’s offerings. However, continued advancement could eventually reduce China’s reliance on imported semiconductor equipment.
This development carries weight because China accounted for roughly 16% of ASML’s revenue during the first half of 2026. Existing export restrictions already prevent ASML from shipping EUV and certain advanced DUV systems to Chinese customers.
Valuation metrics also warrant attention. ASML currently trades above 32 times forward earnings estimates, offering limited margin for execution shortfalls.
The stock also trades approximately 48% above a GF Value benchmark of around $1,270. Any setbacks in High-NA deployment schedules could trigger outsized stock price reactions.
Despite these concerns, Wall Street maintains strong conviction. Analysts have established a Strong Buy consensus rating based on six Buy recommendations issued over the past three months.
The consensus price target stands at $2,391.80, indicating approximately 29% upside potential from present levels. Neither system order quantities nor delivery schedules were revealed in conjunction with the Samsung partnership announcement.
The post ASML (ASML) Stock Jumps 4% as Samsung Commits to High-NA EUV Production by 2028 appeared first on Blockonomi.
TLDR
- Bitcoin stabilized around $84,500 as diminished expectations for additional Federal Reserve rate increases supported digital asset prices.
- Spot Bitcoin exchange-traded funds in the United States attracted approximately $2.4 billion in capital during the most recent complete trading week.
- Citigroup elevated its one-year Bitcoin projection to $113,000 while boosting its Ethereum estimate to $3,028.
- American financial regulators unveiled a proposed regulatory structure governing cryptocurrency custody practices for investment advisers.
- European authorities increased oversight of Binance as a MetaMask validator security breach and the closure of Blast Layer-2 network introduced additional market uncertainties.
Bitcoin maintained levels near $84,500 throughout the week, accompanied by corresponding movements in Ethereum and other leading digital currencies. The upward momentum emerged after a challenging September period, fueled by growing market confidence that the Federal Reserve might maintain current interest rate levels.
Earlier in the trading week, Bitcoin momentarily reached elevated price points before moderating. Statements from Federal Reserve policymakers dampened anticipation for imminent rate adjustments, strengthening appetite for higher-risk investment vehicles.
Equity securities tied to cryptocurrency markets experienced parallel gains. Shares of Strategy, Coinbase, and Robinhood advanced in tandem with Bitcoin’s upward trajectory.
Institutional Capital Returns Through ETF Channels, Wall Street Outlook Improves
American spot Bitcoin exchange-traded funds experienced renewed capital inflows this week. These investment vehicles accumulated roughly $2.4 billion in net deposits throughout the trading period concluding September 25. This influx reversed earlier outflows, pushing cumulative 2026 Bitcoin ETF flows back into positive range.
Strategy maintained its aggressive accumulation strategy. The corporation acquired an additional 1,665 BTC, expanding its aggregate position to 847,666 BTC.
Bitcoin’s market dominance ratio, representing its proportion of total cryptocurrency market capitalization, approached 60% toward week’s end. This metric indicates sustained investor preference for the leading cryptocurrency despite broader risk-on sentiment across markets.
Citigroup analysts enhanced their price forecasts. The financial institution upgraded its 12-month Bitcoin valuation target from $82,000 to $113,000, citing heightened crypto market participation and resurgent ETF capital flows. Simultaneously, Citigroup revised its Ethereum projection upward from $2,240 to $3,028.
Employment Figures and Federal Reserve Policy Trajectory
Macroeconomic indicators influenced cryptocurrency price action throughout the week. American employers generated merely 29,000 new positions in September, while the unemployment rate climbed to 4.2%.
Subdued employment growth diminishes the likelihood of aggressive Federal Reserve rate hikes. Diminished rate increase expectations typically benefit cryptocurrency valuations by enhancing the relative attractiveness of speculative assets.
However, market dynamics remain fluid. Inflation readings exceeding forecasts could rapidly alter the policy outlook and apply downward pressure to digital asset prices.
Ethereum’s Performance Trails Bitcoin Gains
Ethereum remained in focus this week, although its price appreciation lagged behind Bitcoin’s advance. A security compromise affecting MetaMask’s Ethereum validation infrastructure attracted market attention following an unauthorized diversion of staking compensation.
MetaMask initiated preventative validator withdrawal procedures in response. The quantity of misappropriated staking rewards remained minimal, approximating 0.36 ETH.
Financial Authorities Advance Cryptocurrency Custody Standards
American regulatory development progressed this week. The Securities and Exchange Commission introduced a proposed regulatory structure governing cryptocurrency custody arrangements for registered investment advisory firms.
The framework could authorize advisers to maintain direct custody of specific digital assets when qualified third-party custodial services prove unavailable. Advisory firms would remain obligated to satisfy stringent security protocols and demonstrate appropriate technical competency.
European Regulators Intensify Binance Examination
European oversight authorities adopted a more restrictive posture. Officials are investigating whether Binance has continued providing services to European clients without obtaining necessary approvals under the European Union’s Markets in Crypto-Assets (MiCA) regulatory framework.
Binance maintains that certain clients access its platform through Europe’s “reverse solicitation” regulatory exemption. Supervisory bodies are currently assessing whether this exemption is being implemented appropriately.
Tether Pursues Bitcoin Integration While Blast Terminates Operations
The stablecoin sector witnessed notable developments. Tether disclosed intentions to integrate USDT capabilities with Bitcoin via an initiative designated Utexo. This framework would facilitate confidential USDT transactions, BTC-USDT exchange functionality, and Bitcoin-collateralized lending services.
Conversely, some projects encountered difficulties. Ethereum Layer-2 scaling solution Blast revealed its operational cessation following a decline in network assets from a peak exceeding $2 billion.
The network’s closure underscores intensifying competition among Layer-2 platforms as transaction activity gravitates toward established infrastructure providers. Bitcoin’s effort to maintain support near $84,500 represents the primary narrative entering the coming week, though elevated leverage positions and evolving regulatory frameworks suggest continued price volatility.
The post Crypto Markets Rally on Fed Rate Pause Hopes While Regulators Advance Custody Framework appeared first on Blockonomi.
CryptoPotato
Driven by the positive macro developments on the US economic scene during the business week, bitcoin experienced an impressive rally on Friday to over $87,000 for the first time in about ten days.
However, its run was stopped just as fast, and the asset plummeted by several grand within hours. It slumped below $84,000 on Friday evening, leaving nearly $600 million worth of liquidations across the entire market. Popular analyst Ali Martinez believes this rally was doomed from the start.
Whales Sold
Martinez said bitcoin’s move to $87,200 was “compromised before it even got going” as whales sold more than 30,000 BTC as the move progressed. In addition, the $87,000 zone coincides with the upper boundary of a channel that has rejected the cryptocurrency repeatedly for more than two weeks.
After the latest such development, the analyst said he is watching the lower end of the same channel at around $82,500 as the immediate downside target. BTC came inches above that level yesterday when it crashed to $83,500. For now, though, it remains about $2,000 higher.
Further data from Glassnode, though, explained that whales are not the only market participants disposing of their holdings now. The analytics resource noted that investors who accumulated 1-2 years ago at prices of around $97,000 and those who bought in the past 6-12 months at $89,000 have been selling large quantities of their BTC stash.
$BTC investors that bought the top are currently selling.
Two cohorts sit underwater: buyers from 1–2 years ago at $97k, and from 6–12 months ago at $89k.
Those who bought the 2025 rally are selling the most coins per day this year. Those who bought the decline are not. pic.twitter.com/cHAQoaqreT
— glassnode (@glassnode) October 3, 2026
Consequently, Martinez concluded that if these sell-offs continue, it could provide the confirmation he is looking for to buy the dip at around $82,500 and aim for another rebound toward $87,000.
Late Longs Already Washed Out
Before the US jobs report went live on Friday, Daan Crypto Trades warned about another vulnerability, noting that the BTC open interest had climbed to more than $1.3 billion in just a couple of days. Much of it came from longs added as the asset ascended.
He identified the $85,500-$86,000 region as particularly important because many of those positions appeared there. His warning was pretty straightforward: if the cryptocurrency fell below that zone, these longs could be squeezed out. Given bitcoin’s major correction on Friday and almost $600 million worth of liquidations, most of it from longs, it’s safe to conclude that this is exactly what happened.
As such, Daan said earlier today that most of these positions have now been flushed from the market.
The post Bitcoin’s $87K Rally Was a Trap: Could $82.5K Be the Real Buying Opportunity? appeared first on CryptoPotato.
Although the US labor market showed clear signs of a cooldown on Friday, which, overall, should be bullish for risk-on assets, BTC’s price surge was halted in its tracks, and the asset plummeted hard in the following hours before finally calming at $84,500.
The larger-cap altcoin field is deep in the red today, with ETH losing the $2,700 support once again, and XRP slipping below $1.50. QNT and NIGHT, though, are in a different league.
BTC Calms After Big Volatility
The business week began on the wrong foot for BTC, which was stopped at $85,000 and slipped below the key $83,000 support on several occasions in the next few days. However, the bulls managed to defend that level and initiated a leg up that challenged the upper boundary of the tight trading range at $85,000. The biggest breakthrough mid-week came after the Wednesday PCE data release, when bitcoin skyrocketed from $83,000 to $85,600 within hours.
However, it was rejected almost immediately and plummeted toward its starting point. It remained sideways on Thursday before it started to climb again on Friday. The bulls got assistance from the softer-than-expected US jobs report, which pushed BTC to over $87,000 for the first time in about ten days.
Despite the positive developments on the inflation front and the labor market, bitcoin was violently rejected at that level and slumped to under $84,000 in the following hours, leaving nearly $600 million in liquidations.
It has since rebounded to $84,500, with its market cap standing at $1.69 trillion, while its dominance over the alts is up to 59% on CMC.

QNT, NIGHT Defy the Odds
Ethereum continues its fight with the $2,700 resistance, but it’s still on the wrong side. XRP has dipped below $1.50 after a 3.5% daily decline. ZEC has plummeted by more than 5% daily and now sits inches above $1,300. DOGE, LINK, ADA, RAIN, XLM, and NEAR are also deep in the red on a daily scale.
The situation with the mid-cap alts is similar. In contrast, QNT has resumed its recent run by posting a 13% surge that has taken it to well over $260. NIGHT has risen by a similar percentage and has tapped $0.50.
The total crypto market cap is down by almost 2% in the past 24 hours, and now sits at $2.880 trillion on CMC.

The post QNT and NIGHT Continue to Defy Market Correction, BTC Settles After Wild Ride: Weekend Watch appeared first on CryptoPotato.
Ripple’s native token enters the final quarter of the year trading at around $1.50 and still substantially below its 2025 all-time high of $3.65.
Nevertheless, the asset had a strong Q3, which was somewhat unexpected given the unfavorable market conditions with the failure of the CLARITY Act. The question we asked ChatGPT now is how high it can climb if the overall environment stays the same or improves, as it has historically done in Q4.
How High, XRP?
Despite the dip to just under $1.00 in August, XRP managed to rebound strongly and ended the quarter with a notable 43.3% increase. Although it remains well below the $3.65 peak from 15 months ago, it is 50% above the 2026 low, and this increase came despite the failure of the CLARITY Act in the US Senate.
As such, ChatGPT noted that $2.70 would be a realistic target for XRP in Q4 under favorable market conditions. Getting there would require another surge of around 80% from the current levels and would put the asset’s market capitalization at somewhere around $170 billion.
However, XRP would require the alignment of several important factors to reach such high levels. At first, BTC would have to remain strong rather than suffer another major correction. Secondly, fresh capital would need to go into large-cap altcoins, and institutional demand for the cross-border asset would have to maintain its recent run.
As reported frequently, the spot XRP ETFs continue to attract inflows, with the cumulative total hitting consecutive all-time highs.
In a less bullish scenario, the popular AI platform predicted that XRP can peak at somewhere around $2.00, but only if it manages to break through the tough $1.60-$1.70 resistance, which has halted its attempts on several occasions in the past few months.
ATH Chances?
ChatGPT outlined an even more favorable outcome for XRP under “an exceptionally strong Q4”: surging past the 2025 record and going as high as $4.00. Such a move would require a massive triple-digit increase from today’s valuation and would put its market cap well above $250 billion.
“This is possible in a genuinely euphoric crypto market, but the conditions would need to be considerably stronger than those required for $2.70. Bitcoin would probably need to remain firmly bullish, altcoins would need to enter a broad risk-on phase, and XRP itself would need enough fresh demand to break through several layers of holders looking to take profits on the way up,” said the AI.
The post We Asked ChatGPT: How High Can Ripple (XRP) Go Under Bullish Q4 Conditions? appeared first on CryptoPotato.
OG Ethereum investors woke up a few days ago by completing the biggest move of long-dormant coins since early June.
However, the actual number of ETH that reached exchanges was negligible, which suggests that this unusual activity may reflect wallet reshuffling rather than holders rushing to cash out as the underlying asset continues to fight the $2,700 level.
Old ETH Woke Up
According to data shared by the analytics resource Santiment Intelligence, Ethereum’s Age Consumed metric surged to approximately 580 million token-days on September 30. This was roughly nine times its average weekday level during September and the highest reading since June 2.
Age Consumed measures the movement of coins based on how long they had previously remained dormant. This means that such a large spike indicates that significant quantities of older ETH were suddenly transferred.
While this might sound like old holders trying to take advantage of the recent rally that saw ETH surge from $1,500 to $2,700 and book some profits, Santiment reassured that this doesn’t seem to be the case. Exchange supply increased by only around 18,000 tokens on September 30 before declining by approximately 21,000 ETH a day later.
This relatively insignificant amount suggests that the immediate selling pressure didn’t spike, especially when compared to the roughly 5.9 million coins held on trading platforms.
In contrast, exchange balances soared by more than 140,000 ETH on June 2, when the Age Consumed metric last registered a massive increase.
Although Santiment cautioned that it’s impossible to determine who moved the latest batch of dormant ETH, the analysts said previous such moves have coincided with wallet reorganizations rather than outright selling.
Long-dormant $ETH moved on Sep 30 at a scale we haven’t seen since early June. Exchange balances hardly budged.
Age consumed hit 580M token-days on Sep 30, about 9x its September weekday average and the highest since Jun 2.
Exchange supply rose ~18K ETH that day and fell… pic.twitter.com/cDcts7Avm3
— Santiment Intelligence (@SantimentData) October 2, 2026
ETH Still Constructive
Meanwhile, popular trader Merlijn The Trader highlighted what he considers a major shift in the ETH/BTC pair. He argued that the altcoin has broken the long-running downtrend that has weighed on it against the market leader for the past nearly ten years. The trader described the development as potentially marking the cycle in which ETH establishes itself as the market’s “blue chip.”
Fellow analyst Altcoin Sherpa added that the Ethereum setup still looks “pretty solid” and explained that the landscape is not as bearish as some others believe. However, he stressed that ETH’s outlook will remain heavily dependent on what BTC does next.
Interestingly, the sentiment around the largest altcoin recently dropped to its most bearish level since June 7, with Santiment recording only 0.89 bullish comments for every bearish one. However, similar occasions could have the opposite effect on the underlying asset, the analysts said.
The post Massive Ethereum Awakening: Why 580M in Dormant ETH Just Moved Without Crashing Price appeared first on CryptoPotato.
The next 28 days or so are packed with major macro catalysts that could reshape interest-rate expectations and inject fresh volatility into bitcoin and the broader crypto market.
After the PCE and jobs data released last week, focus shifts back to the Federal Reserve, which, ahead of the next FOMC meeting at the end of the month, still needs to digest more information, including the CPI numbers.
Inflation Takes Central Stage (Again)
The first major date to watch is October 7, when the central bank will release the minutes from the previous FOMC meeting held on September 15-16, in which it raised interest rates for the first time in over three years. The document should provide additional insight into policymakers’ thinking and, perhaps even more importantly, how they view the path forward.
The September Consumer Price Index (CPI) is next and comes out on October 14. It remains one of the most watched macro releases for risk assets. An upside surprise has historically strengthened the case for tighter monetary policy, while a softer reading could produce the opposite reaction.
A day later comes another crucial inflation data point, with the release of the September Producer Price Index (PPI). The report measures price changes from the perspective of domestic producers and can offer additional evidence about underlying inflationary pressures.
The September retail sales will also be announced on that day, making it a particularly important date. Strong consumer spending could reinforce the idea that the US economy remains resilient despite restrictive monetary conditions, and vice versa.
Fed Into Focus
The single biggest event of the month arrives on October 28 when the Federal Reserve will conclude its two-day FOMC meeting, with the policy statement due at 2:00 p.m. ET and Chair Kevin Warsh’s press conference scheduled half an hour later.
The combination has quite obvious implications for risk on assets like bitcoin. Beyond the rate decision itself, which could be priced in by then, markets will be watching Warsh’s language for any clues about whether the central bank believes further tightening is necessary.
However, only a day after investors digest the Fed’s decision, the US will publish two highly important reports: the advance estimate of third-quarter GDP and September Personal Income and Outlays, which includes the Fed’s preferred PCE inflation gauge.
The timing makes the final week of the month particularly important. The September PCE reading will arrive too late to influence October’s FOMC decision itself, but it could immediately reshape expectations for the central bank’s final meeting of the year.
Separately, October is BTC’s greenest month historically, which could lead to additional volatility and possibly gains, even though, as we know, history is no indication of future price performance.
The post October Could Be Wild for Bitcoin: 5 Events Every Crypto Trader Should Watch appeared first on CryptoPotato.