Cryptocurrency Posts
Crypto Briefing
AI-driven blockchain interactions could redefine user engagement, raising privacy and security concerns as traditional interfaces recede.
The post Vitalik Buterin: traditional on-chain apps may fade as AI agents take over appeared first on Crypto Briefing.
DLMM Pro's customizable features could enhance Solana token launches, potentially increasing protocol adoption and benefiting MET holders.
The post Meteora unveils DLMM Pro, a customizable AMM for Solana token launches appeared first on Crypto Briefing.
Backable's launch on Solana democratizes fundraising, empowering global founders and backers while shifting due diligence responsibility to investors.
The post MetaDAO launches Backable, a permissionless fundraising platform on Solana appeared first on Crypto Briefing.
The shift to cheaper Chinese AI models highlights a growing trend of cost-driven diversification, impacting US firms' market dominance.
The post AI startups shift to cheaper Chinese models as US firms face price pressure appeared first on Crypto Briefing.
Hyperscale Data holds about 220 Bitcoin worth approximately $19 million and $37.4 million in cash as it pivots from mining to AI data centers.
The post Hyperscale Data reports about 220 Bitcoin and $37.4 million in cash appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Now Accepting Bitcoin: Old Major Market Brings Artisanal Meats to 48 States
Table of Contents
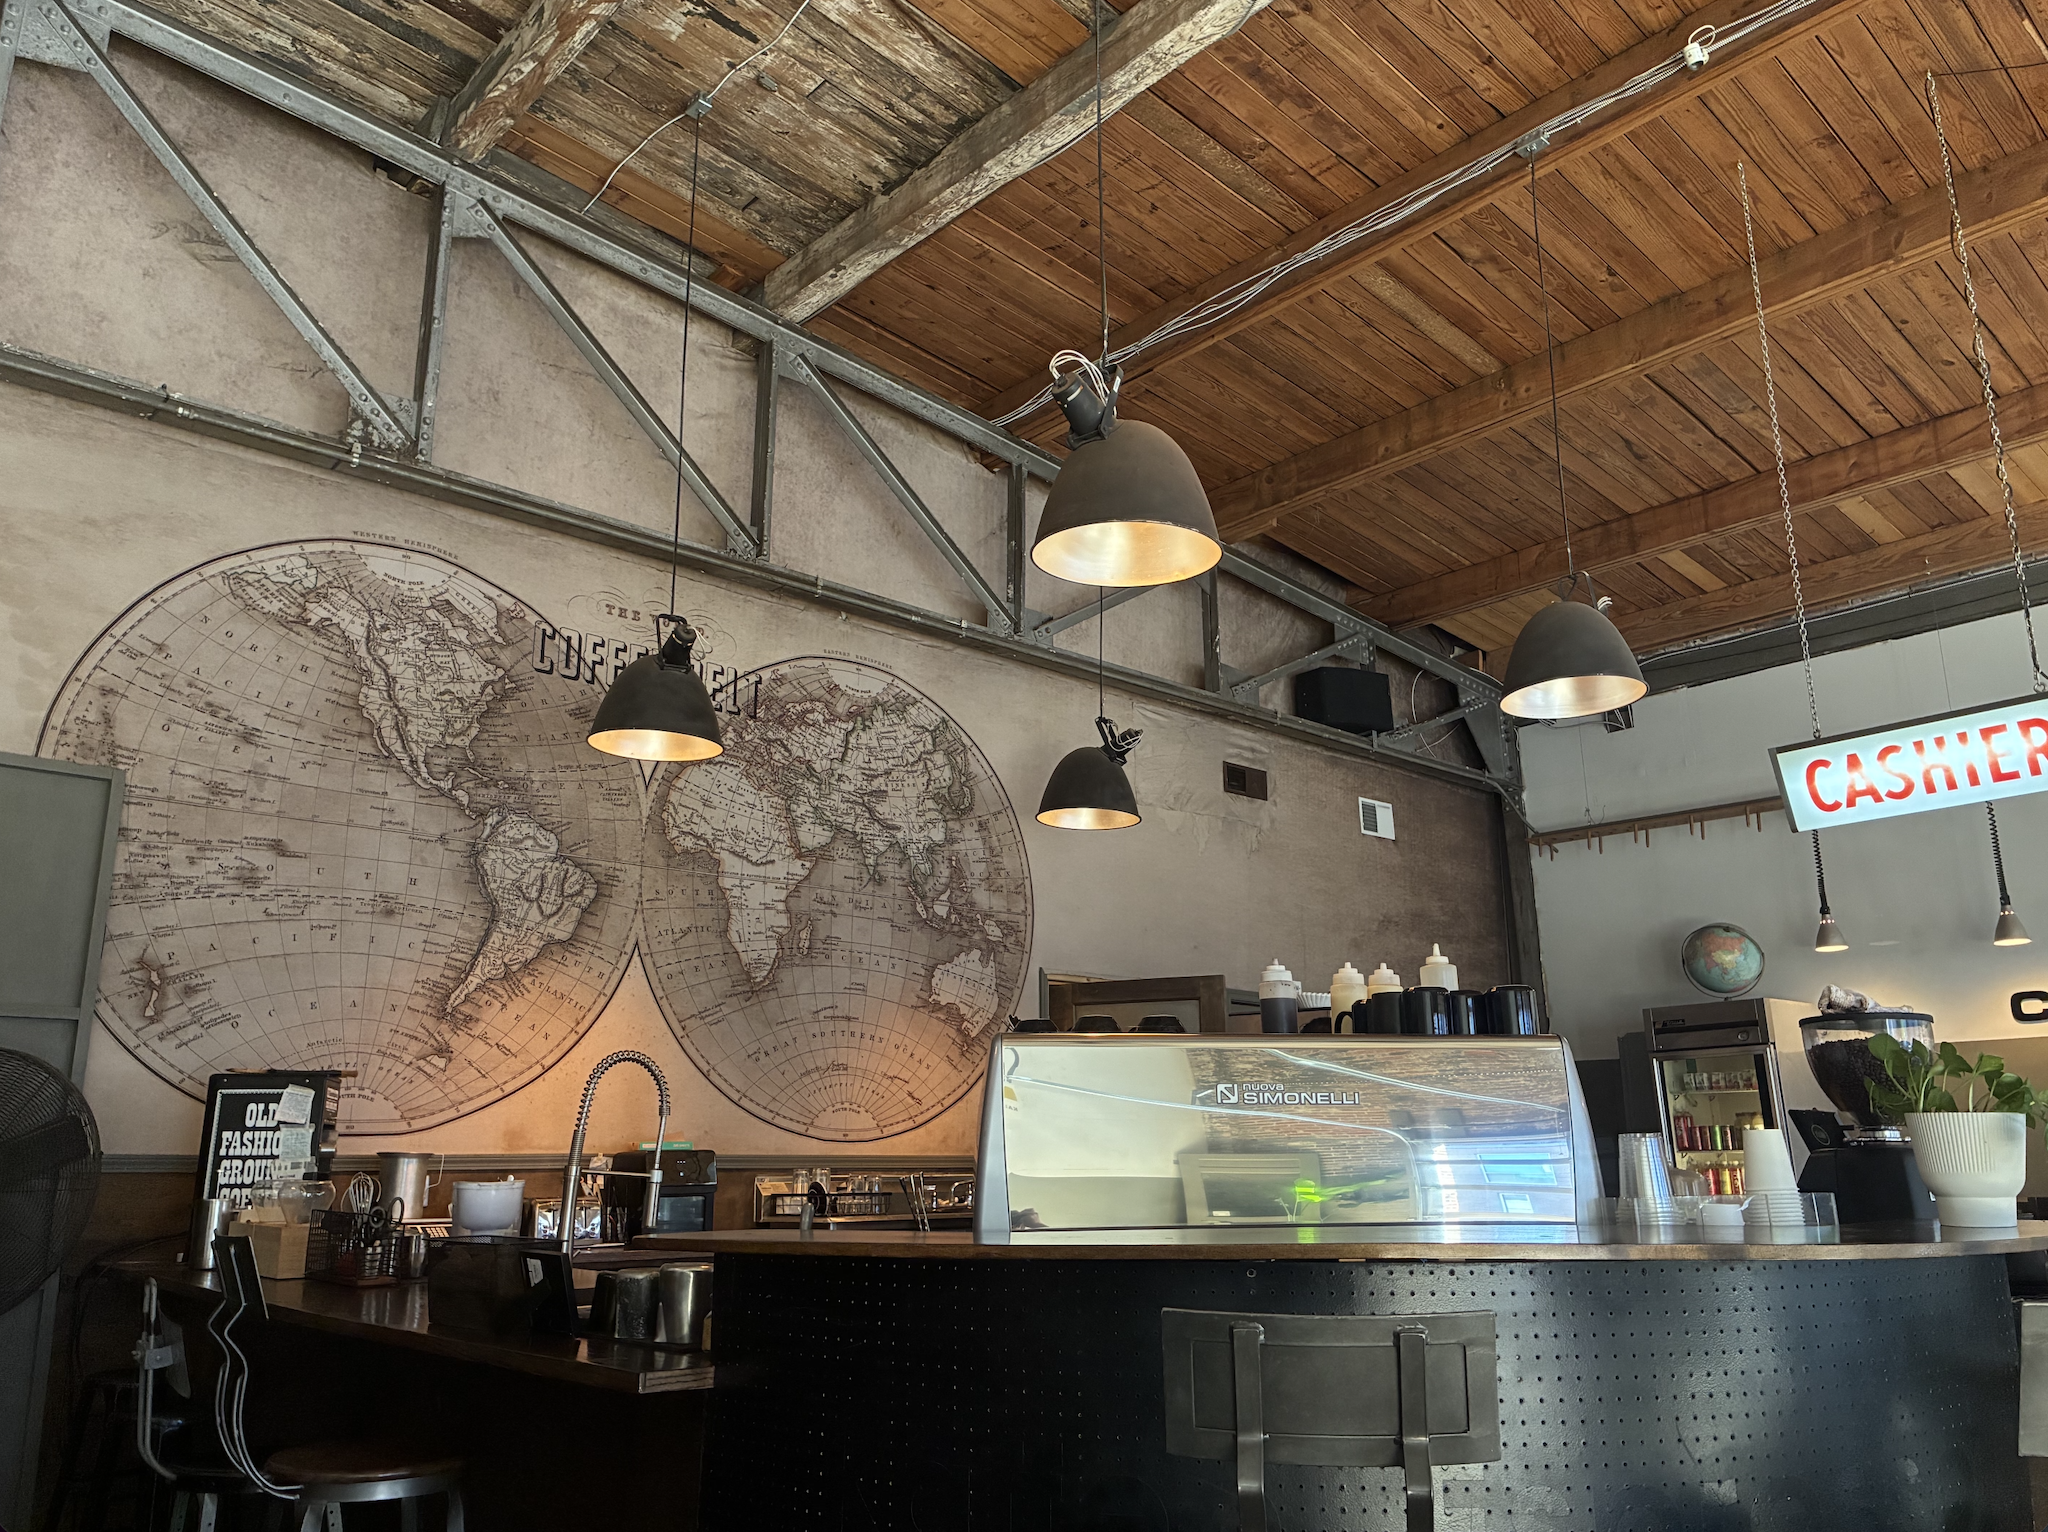
The trip to Indianapolis that introduced me to Old Major Market started at Kaffeine Coffee Co. on Fulton Street. The coffee was tasty, but my real surprise was running into a local Bitcoiner who was also paying for his order in satoshis, making me feel like not such a rare breed in this fiat world.
The friend I made shared about a network of Indiana merchants the Indianapolis local Indy Bitcoin Group has been orange pilling.
First Up: Old Major Market LLC (Artisan Meats)
A common complaint of merchant Bitcoin adoption is that the shop owners will liquidate 100% of their Bitcoin back into cash using payment processors like Square. This is true to start, but a fascinating shift occurs once a business owner reads about bitcoin. Old Major LLC, an artisan meat distributor based in Indianapolis, is a prime example of that shift.
The Big Ole Update!!
According to owner Mark LaFay, Starting in 2026, Old Major Market made a major strategic decision: they are keeping 100% of the Bitcoin they receive directly on their balance sheet. They realized that holding bitcoin opens up significant long-term upside. Old Major ships their meats to all 48 lower states. Mark says the Maple bourbon bacon is very popular!
Big shout out to the Bitcoiners in Central Indiana that have been stopping by Old Major for over a year to buy bacon, sausages, and specialty meats with sats. While the shop originally agreed to accept Bitcoin and instantly converted every transaction to cash, the steady stream of Bitcoin payments caught their attention.
The “1% Orange Pill” Math
When a dedicated community directs its routine spending toward supportive merchants, the business case for the owner becomes undeniable:
- The Baseline: A local merchant generating $1 Million in annual revenue with a 10% profit margin brings home $100,000 in net profit.
- The 1% New Customer Shift: If local Bitcoiners represent just 1% of total sales, that’s $10,000 in annual Bitcoin transactions. If the owner sells the coins, regret creeps in, “what if I held the coins?”…
- The BTC Holding Strategy: Let’s assume the store instead decides to hold that Bitcoin in 2026, and BTC doubles in value this year. A 1% shift in customer payment preference increases the owner’s total annual up 20% at $120,000.
That financial reality is the ultimate orange pill. A focused group of customers directing their commerce toward open-minded owners can move the needle for merchant adoption, whether the owner holds from day one or learns along the way that they are missing profit.
Notable Mentions: Local Indy Staples: Coffee & Wine
- Kaffeine Coffee Co. (Downtown Indy): Third Wave craft coffee meets native Bitcoin rails. Meeting fellow Bitcoiners at the counter proves how coffee hubs act as the natural gateway for real-world community building.
- The Rejoicing Vine (Northwest Indy): A mission-driven winery specializing in sparkling wines that doubles as the host spot for local “Lightning Socials”. Owner Brent Kumfer agreed to accept Bitcoin over a year ago through Square, enjoying zero processing fees and a steady stream of local Bitcoiner events. They are not yet holding bitcoin, but they are considering it.
Have a Story or a Local Merchant Network to Feature?
As always, a growing directory of verified Bitcoin-accepting merchants is listed below. If you want your business added to the map, or if you have a new city and story to feature in an upcoming column, write directly to vagabond@b.tc in the series “NOW ACCEPTING BITCOIN“.
APPENDIX – 200 Indiana Stores Accepting Bitcoin
Arts & Entertainment
- LangLab (Arts Centre) — 1302 High St, South Bend
- AMC Castleton Square 14 (Cinema) — 6020 E 82nd St, Indianapolis
- AMC Washington Square 12 (Cinema) — 10280 E Washington St, Indianapolis
- AMC CLASSIC Bloomington 12 (Cinema) — 2929 W 3rd St, Bloomington
- AMC Perry Crossing 18 (Cinema) — 380 Cinema Blvd, Plainfield
- AMC Showplace Traders Point 12 (Cinema) — 5920 W 86th St, Indianapolis
- AMC Indianapolis 17 (Cinema) — 4325 S Meridian St, Indianapolis
- AMC CLASSIC Crawfordsville 8 (Cinema) — 205 Dry Branch Rd, Crawfordsville
- Fort Wayne Improv (Theatre) — 1314 E State Blvd, Fort Wayne
- Pine Acres Miniature Farm (Zoo) — 6801 Union Chapel Rd SE, Corydon
Automotive & Repair
- 317 Auto Service — 499 Wall St, Greenwood
- Hobbs Automotive Diagnostics & Repair — 3594 SR 9, Anderson
- McIntire Auto Repair — 1927 S Curry Pike, Bloomington
- Salvadors Collision — 30841 Old US 33, Elkhart
- 2nd Chance Towing & Repair — 2252 Straight Line Pike, Richmond
- Bulls Tire Shop — 2233 E Washington St, Indianapolis
- Direct Tire — 1506 N Post Rd, Indianapolis
Bars, Breweries & Wineries
- Westfield Wine Vault — 100 N Union St, Westfield
- Mad Hyena Bar and Grill — 1538 Indiana Ave, New Castle
- Fish Moon Brewing Company — 309 N Main St, Rushville
- The Health Club Taproom & Cafe — 6420 Cornell Ave, Indianapolis
- Books & Brews — 9402 Uptown Dr, Indianapolis
- Tollys Bar and Grill — 2341 Maple Ave, Terre Haute
- Easley Winery — 205 N College Ave, Indianapolis
- The Rejoicing Vine — 8440 W 82nd St, Indianapolis
Beauty, Hair & Wellness
- Apothecary Salon & Spa — 2050 Burton Ln, Martinsville
- Allure Salon — 100 S 1st St, Zionsville
- Angel Barber Studio — 1990 Conner St, Noblesville
- B Beauty — 11717 E Washington St, Indianapolis
- Brow Ink — 5250 E US Hwy 36, Avon
- Bryans Barbershop — 224 N 12th St, Decatur
- Cutting Loose Salon — 3815 S Main St, Elkhart
- Exotic Nails — 1617 E Michigan Rd, Shelbyville
- Harmony Day Spa — 7654 N Bleck Rd, Trail Creek
- Indulge Beauty Salon — 3521 Lake Ave, Fort Wayne
- Lee’s Barber Lounge — 409 W Taylor St, Kokomo
- Lux Esthetics Lab — 1251 US-31 N, Greenwood
- Luxury Spa & Nails — 217 S Green River Rd, Evansville
- Marengo Barber Shop — 109 Main St, Marengo
- Mdg Salon — E 116th St, Carmel
- Midou Studio — 9935 E 42nd St, Indianapolis
- Modern Barbershop and Salon — 1641 N Lebanon St, Lebanon
- Naturally You — 6101 N Rural St, Indianapolis
- Sarah L Studio — 6251 Winthrop Ave, Indianapolis
- The Station Hair Parlor — 200 Byrd Way, Greenwood
- Wax that Cat — 3009 25th St & 3042 State St, Columbus
- Indy Holistic Massage — 1133 W Main St, Greenfield
- Sacred Roots Custom Massage — 26 W Broadway St, Shelbyville
Cafes, Bakeries & Desserts
- Gramz Bakey and Cafe — 409 Washington St, Columbus
- Kaffeine Coffee — 707 Fulton St, Indianapolis
- Moar Tea — 448 Massachusetts Ave, Indianapolis
- Seoul Fresh — 49 W Maryland St, Indianapolis
- The Beach Hut — 100 W Moss Pkwy, Michigan City
- The Java Bean Cafe — 151 N 2nd St, Decatur
- Cosmic Cardinal Cafe — 101 W Ohio St, Indianapolis
- Capstone Cafe & Bookstore — 6620 Northview Way, Indianapolis
- Rocky Mountain Cafe — 209 Lincolnway, La Porte
- Wildflour Bakehouse — 1012 E County Rd 750 S, Nineveh
- Brown’s Shuga Shack — 6099 State Rd 16, Monticello
- Heartland Homemade Ice Cream — 4911 S Emerson Ave, Indianapolis
- Sugar + Ice — 103 S Randolph St, Garrett
- Sugarfield Creamery — 1051 E Tabor St, Indianapolis
Contractors, Repair & Home Services
- 33 Electric — 7939 Dix Rd, Indianapolis
- AR Engineering (HVAC) — 3002 W Western Ave, South Bend
- Bravo Carpentry — 305 Railroad Ave, Wheeler
- DEG Electronic Repair Services — 3712 N Mitthoeffer Rd & 2818 Westlane Rd, Indianapolis
- Energy Efficient Replacements / 574-Sunroom — 51285 Bittersweet Rd, Granger
- KM Electronics — 8238 Madison Ave, Indianapolis
- NGR Electric — 4320 Calhoun St, Gary
- Roman Tech Computer Repair — 3611 E US Hwy 12, Michigan City
- TechBar — 4121 Cleveland St, Gary
Groceries, Specialty Foods & Farms
- Old Major (Butcher) — 4201 Millersville Rd, Indianapolis
- The Wurst (Butcher) — 130 N Broad St, Griffith
- For You Brewing Supplies — 503 Honey Creek Dr, Terre Haute
- Hidden Acres (Farm) — 10645 W 425 S, Wilkinson
- K&B Liberty Farms — 2254 Nature Ln SE, Corydon
- Binford Farmers Market — 6620 Northview Way, Indianapolis
Professional & Financial Services
- D M Property Management — 6446 Ralston Ave, Indianapolis
- Dennis Hartley & Son Monuments — 89 E Walnut St, Martinsville
- Great Lakes EV Charging — 51285 Bittersweet Rd, Granger
- Inguard Insurance — 231 W Canal St, Wabash
- Olive Tree Resources (NGO) — 110 E Market St, New Albany
- Overhauser Law Offices — 101 W Ohio St, Indianapolis & 18 E Main St, Greenfield
Restaurants, Fast Food & Delis
- Amorè Fine Italian Ristorante — 730 Highlander Point Dr, Floyds Knobs
- Food King Chinese Restaurant — 1472 E 86th St, Indianapolis
- Full Circle Grill & BBQ — 110 W Berry St, Fort Wayne
- George’s Gyros Spot #2 — 1201 W 37th Ave, Hobart
- Grateful Grubs BBQ — 5654 IN-10, DeMotte
- Guadalupe’s Mexican Grill — 2031 South Bend Ave, South Bend
- Lonestar Bar B Que — 905 N Park Dr, Evansville
- Major Munch — 101 NW 1st St, Evansville
- Oscar’s Pizza — 515 N Buckeye St, Kokomo
- Panini Panini — 1720 Franklin St, Michigan City
- Rusted Silo Southern BBQ — 411 N State St, Lizton
- Social Que BBQ and Catering — 1701 Franklin St, Michigan City
- The Lincoln Kitchen — 704 Silhavy Rd, Valparaiso
- The Owlery Restaurant — 118 W 6th St, Bloomington
- Tlaolli — 2830 E Washington St, Indianapolis
- Tsunami Sushi & Korean Wings — 700 Sagamore Pkwy N, Lafayette
- Turkuaz Cafe — 301 E 3rd St, Bloomington
- Union Jack Pub — 921 Broad Ripple Ave, Indianapolis
- Uptown Cafe — 102 E Kirkwood Ave, Bloomington
- Griller’s Restaurant — 1240 119th St, Whiting
- Oh Mamma’s On The Avenue Deli — 1202 Mishawaka Ave, South Bend
- OyVey! Bakery & Deli — 901 Lafayette Ave, Terre Haute
- Cracklin Shack — 5058 S 800 W, Swayzee
- Hoosier Spice & BBQ Company — 11622 NE Executive Dr, Edinburgh
- Las Cubanitas — 53 Valparaiso St, Valparaiso
- Los Dos Amigos by Awiwi — 202 Carrie Ln, Columbus
- Steak ‘n Shake — 30+ locations statewide (Avon, Indianapolis, Fort Wayne, Lafayette, Bloomington, Elkhart, South Bend, Terre Haute, Greenwood, Valparaiso, Columbus, Clarksville, Seymour, Merrillville, Schererville, Muncie, Bedford, Lawrenceburg, Franklin, etc.)
- Steve’s Una Pizza — 1005 S Saint James Blvd, Evansville
- Union Jack Pub Food Truck — 924 Broad Ripple Ave, Indianapolis
Retail, Apparel, Hobbies & Specialty Shops
- Above ALL Bowling Supply — Valparaiso & Hobart
- Blossom Floral Design — 615 N Michigan St, South Bend
- Geeked Out Games — 10830 Bennett Pkwy, Zionsville / Fishers
- Its Not Corn (Apparel) — 120 N Miller Ave, Marion
- Jayla’s Gifts, Plants, Flowers — 207 E Market St, Nappanee
- Jewelry Gallery — 17425 Carey Rd, Westfield
- Lake Effect Florals — 278 E 1500 N, Chesterton
- Mr. Kay’s Fashionable Shoes — 2218 Southlake Mall, Merrillville
- Nature’s Mercantile — 122 N Main St, Auburn
- Nick Nackery — 201 E Virginia St, Evansville
- Old-School Outpost (Games) — 3825 S East St, Indianapolis
- Prideland Comics & Collectibles — 5668 Crawfordsville Rd, Speedway
- Rock Bottom Resale — 11186 County Rd 34, Goshen
- Rock Daddy (Esoteric) — 418 E McGalliard Rd, Muncie
- Sewer Lair Toys — 3197 S 3rd Pl, Terre Haute
- Smoke Xpress (Tobacco) — Michigan City & Elkhart
- Svpplements — 316 W Cleveland Rd, Granger
- The Co Op Shop (Video Games) — 3540 State Rd 38 E, Lafayette
- Unique Creations by Joe — 1148 S 17th St, Kokomo
- Versed Skateboard Shop — 1006 Virginia Ave, Indianapolis
- War Room Tabletop Gaming — 10830 Bennett Pkwy, Zionsville
- 710 Lounge (Cannabis) — 3673 W 86th St, Indianapolis
- A Pooch Palace (Pet Grooming) — 3839 S Lafountain St, Kokomo
- First & Wilkerson Designs / Farmkidz Apparel — Fort Wayne & Lebanon
Second-Hand & Thrift Stores
- DTF Sales — 51 N Main St, Cloverdale
- Millie’s Thrift Store — Lafayette (2 locations) & West Lafayette
- MoJo’s Thrift-N-Collectibles Store — 527 Cass St, Wabash
- Mood — 248 Spring St, Jeffersonville
Tattoo & Piercing Studios
- A1 Art Tattoos — 4606 E Michigan St, Indianapolis
- Altered Image — 10030 E US Hwy 36, Avon
- Big Time Tattoos and Piercings — 5353 Madison Ave, Indianapolis
- Crown Point Tattoo — 114 W Hack Ct, Crown Point
- Evolution Tattoo — 2901 Mitchell Rd, Bedford
- La Familia Tattoo — 529 W Chicago Ave, East Chicago
- Resurrection Studios Tattoos & Piercing — 2200 Elmwood Ave, Lafayette
- Tracy Scott at Bankai Tattoo Collective — 421 7th St, Columbus
This post Now Accepting Bitcoin: Old Major Market Brings Artisanal Meats to 48 States first appeared on Bitcoin Magazine and is written by Vagabond.
Bitcoin Magazine
Bringin Opens Euro Business Accounts for Bitcoin Companies Across 30 European Countries
Bringin today opened an invite-only beta of euro business accounts that let companies hold, accept, and pay in Bitcoin and stablecoins, and run SEPA payments from a vIBAN in the company’s own name. The launch builds on Bringin’s consumer platform, which has processed more than €15 million according to a press release shared with Bitcoin Magazine.
More European businesses want what Bitcoin and stablecoins offer: instant settlement, global reach and lower costs. Buying Bitcoin in Europe is easy enough; the challenge is running a company on Bitcoin and stablecoin rails. Many Europeans face bank account restrictions and blocked transfers when they operate with Bitcoin or other virtual assets. Every conversion to euros adds friction, records sit across disconnected tools, and the Travel Rule requirements turn simple payments into paperwork. As a result, Bitcoin’s potential as money gets tangled up in bureaucracy.
Bringin for Business seeks to bridge Bitcoin and banking. According to the press release, companies can add Bitcoin to their treasury, accept Bitcoin, Lightning, or stablecoin payments, and pay suppliers and payroll in Bitcoin. Euro accounts and the company’s Bitcoin wallet sit in one place, with the governance and security a business needs. A dedicated virtual IBAN, a euro account number in the company’s own name, connects it to SEPA payments, with additional global payment rails planned.
Keys are generated and stored in a hardware security module rather than omnibus exchange wallets. Only designated company owners can move funds, make payments, and add approval policies, according to the press release.
Separately, Bringin plans APIs and MCP servers so companies can work with AI agents. With support for Lightning and stablecoins, companies can accept payments from artificial intelligence bots, building on Bringin’s 2025 demonstration of agent payments over the Lightning Network.
“Bitcoin is the first money native to the internet, and Lightning makes it fast enough for everyday commerce. I’ve seen that potential since I started building on it in 2018,” said Prashanth Chandrashekar, founder and CEO of Bringin. “We proved it with consumers first. Now companies can use Bringin to get paid, hold value and move money globally, with accounts designed around self-custody and a seamless payment experience.”
Built on the MiCA-authorized infrastructure of Lightspark Payments Europe AS, Bringin for Business is currently in pilot with 15 businesses, including Lightning payment tools, mining-rig sellers, and Bitcoin conferences, handling cross-border payments and instant Bitcoin-to-euro conversions. It is available to companies across 30 European countries.
This post Bringin Opens Euro Business Accounts for Bitcoin Companies Across 30 European Countries first appeared on Bitcoin Magazine and is written by Juan Galt.
Bitcoin Magazine
Coinbase’s Ryan VanGrack: CFTC Approval “Opens Many Doors” for Bitcoin
The SEC’s proposed custody rules could make it easier for investment advisors to help clients own Bitcoin directly. Coinbase’s Ryan VanGrack explains why institutional capital tends to flow where there are clearer rules, and why he sees direct ownership and ETFs as “both and, not either or.” He also shares why traditional finance is accelerating its push into Bitcoin and digital assets.
Chapters:
00:00 Coinbase Wins CFTC Approval for Its Own Clearinghouse
01:29 Can SEC Guidance Last Without the Clarity Act?
02:40 SEC Custody Proposal: Helping Advisors Hold Bitcoin Directly
04:14 Tokenization: The Biggest Upgrade Since Electronic Trading
05:41 How Tokenization Cuts Out Wall Street’s Middlemen
07:34 What Washington Still Needs to Fix for Bitcoin Holders
08:56 Institutional Adoption Accelerates After the Clarity Act Vote
11:07 How Coinbase Is Bringing Digital Asset Infrastructure to Community Banks
12:01 Sponsor: Square
12:34 Is Crypto Really a Tool for Illicit Finance?
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Coinbase’s Ryan VanGrack: CFTC Approval “Opens Many Doors” for Bitcoin first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Coinbase Business Chief: Big Banks Increasing BTC Exposure | Shan Aggarwal
New SEC rules could open the door for financial advisors to hold Bitcoin for their clients, and Coinbase is already at the center of that custody story. Shan Aggarwal, Coinbase’s first-ever Chief Business Officer, explains how Coinbase custodies most of the Bitcoin ETFs and supports the advisor community. He sees the advisor rule as expanding the pie for Bitcoin access, with Coinbase providing the infrastructure behind it.
Chapters:
00:00 How the SEC’s New Advisor Rules Could Bring Bitcoin to Wealth Managers
01:13 What BlackRock and JPMorgan Want From Bitcoin Infrastructure
02:16 What Will Drive the Next Wave of Bitcoin Adoption
03:28 Can the Coinbase One Card Turn Spenders Into Bitcoin Owners?
04:22 Coinbase’s Trillion-Dollar Stablecoin Opportunity
05:14 Coinbase and Citi Bring Stablecoin Payments to Merchants
05:56 Sponsor: SALT Lending
06:26 How Coinbase Customers Are Using Bitcoin Lightning
07:37 Will AI Agents Pay in Bitcoin or Stablecoins?
08:30 Coinbase Expands Into Collectibles and Everyday Bitcoin Rewards
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Coinbase Business Chief: Big Banks Increasing BTC Exposure | Shan Aggarwal first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
TD Cowen’s Lance Vitanza: BTC to $132k in 2027 & MSTR Price Outlook
Institutions are no longer debating whether to own Bitcoin. Now the question is how. TD Cowen Managing Director Lance Vitanza explains why Bitcoin is evolving from a standalone asset into a capital markets ecosystem of common stock, preferreds, bonds and income products. He shares what he heard at the Bitcoin Treasuries conference in New York and why institutional investors increasingly evaluate Bitcoin within a portfolio.
Chapters:
00:00 Bitcoin Is Evolving From an Asset Into a Capital Markets Ecosystem
01:36 Bitcoin Preferreds, Bonds and Dividend-Paying Instruments
03:25 How Analysts Are Evaluating Digital Credit
05:23 Which Bitcoin Treasury Companies Survive a Downturn
07:28 Strive, Metaplanet and Nakamoto: Why Operating Businesses Matter
10:24 Could MSCI Index Removal Hurt Bitcoin Treasury Companies?
12:27 Blockchain Surveillance, Front-Running and Trust in Bitcoin Prices
14:20 Sponsor: Cash App
15:01 TD Cowen’s Bitcoin Price Target for 2027
16:38 Why Well-Run Bitcoin Treasury Companies Could Outperform Bitcoin
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post TD Cowen’s Lance Vitanza: BTC to $132k in 2027 & MSTR Price Outlook first appeared on Bitcoin Magazine and is written by Patrick Green.
HTTP error 429 on https://cryptoslate.com/feed/
Failed to fetch feed: https://cryptoslate.com/feed/
Failed to fetch feed.
CryptoTicker.io
If you hold VELO, it becomes a different token in November. Velodrome and Aerodrome, the two largest decentralised exchanges on Optimism and on Base, are merging into a single protocol called Aero. At Coinbase the swap runs from November 2 to November 4, 2026; for each VELO you receive around 0.044 new AERO, and the exchange takes no fee for it. Anyone holding VELO in their own wallet, however, is not covered by this swap at all and has to act themselves.
November 2 is not actually the date on which things get tight for you. They get tight earlier: at Coinbase, VELO can already only be traded with a limit order today, and the exchange no longer accepts a plain market order. Anyone assuming there is time until November to sell the position in the normal way is therefore already wrong.
What exactly happens in the Velodrome and Aerodrome merger
Both exchanges belong to the category of decentralised exchanges, DEX for short. A DEX is a venue that works without a custodian: you swap directly out of your own wallet, and pricing is handled by a program on the blockchain instead of an order book inside a company. Velodrome is that venue on Optimism, Aerodrome the same blueprint on Base, the secondary network of Ethereum operated by Coinbase. Behind both stands the same development firm, Dromos Labs.
Both work on the so-called ve(3,3) model. That means: whoever locks their tokens for a fixed period receives voting rights in return and thereby steers which trading pairs the rewards flow into. The value of the token arises from this mechanism, and it is precisely this that is now being merged. Instead of two separate voting systems on two chains, there is to be one in future serving several networks. Among the first chains of the new protocol are OP Mainnet and Ink alongside Base.
To place the setting, it is worth a look at the ecosystem of the Coinbase chain Base, in which Aerodrome has played the largest role so far. The merger changes exactly that map: what were two regional top dogs becomes one provider across several networks.
The swap factor of 0.044 AERO per VELO and how it comes about
For holders of AERO nothing changes arithmetically; one old AERO becomes one new AERO. For VELO the factor of roughly 0.044 applies. That number derives from the announced split of the new supply: 94.5 percent of the new AERO quantity goes to the existing AERO holders, 5.5 percent to the VELO side. The basis for that split is the economic performance of both protocols in the 52 weeks before the announcement, that is essentially the trading fees and revenues each of the two exchanges earned in that period.
That split can be checked against the market, and this is the point at which the matter becomes verifiable for you. In early October, Aerodrome carries a market capitalisation of around $835.5 million, Velodrome around $48.6 million. Together that is about $884 million, and Velodrome's share of it is 5.50 percent. The announced split of 94.5 to 5.5 and what the market actually pays today therefore agree to a hundredth. The market has long since priced the merger in.
Worked through: 1,000 VELO yield 44 new AERO
Concretely, with the prices of October 6: AERO stands at $0.8355 or 0.7455 euros, VELO at $0.036265 or 0.032355 euros. A holding of 1,000 VELO is thus worth $36.26 or 32.36 euros in the market. After the swap that becomes 44 AERO, and at the same prices those are worth $36.76 or 32.80 euros.
The difference comes to 50 cents, that is 1.38 percent in favour of the swap. The market ratio of VELO to AERO stands at 0.0434, the offered factor at 0.044. For you that means one thing above all: there is no discount here that you would avoid by selling quickly beforehand, and no premium you could collect by buying in. Anyone trading hectically because of the swap factor pays trading fees for an advantage that does not exist in that order of magnitude.
One caveat belongs with it: this calculation is a still image. Prices move, and the factor of 0.044 is fixed, while the market prices of both tokens will fluctuate until the window in November. Whether the difference will then still be 1.38 percent, larger, or reversed cannot be said today and is not worth a forecast either.
At Coinbase the wind-down is already running: VELO by limit order only
Trading in VELO at Coinbase has already been switched to so-called limit-only operation. A limit order is an order with a price condition: you set the price at which you want to buy at most or sell at least, and the order waits in the order book until someone takes it at that price. A market order, by contrast, is executed immediately at the next best available price, and that option no longer exists for VELO there.
That this is not a normal state for small trading pairs is shown by the counter-check on the sister pair: AERO can still be traded at the same exchange without that restriction. Limit-only operation is the first stage of an announced two-stage wind-down path, on whose second stage VELO trading is discontinued entirely.
In practice that means three things. First, you no longer have an execution guarantee: your order sits in the book and may never be filled, or only in part. Second, the spread between bid and offer typically widens in such phases, because fewer participants are quoting. Third, exiting thereby becomes a decision with lead time rather than a click. Anyone reconsidering their choice of venue anyway will find in the crypto exchange comparison the points that matter on trading pairs, fees and authorisation in Germany.
The timetable: launch on October 21, swap from November 2 to 4
Two dates structure the process. On October 21, 2026 the unified protocol is to launch, initially on OP Mainnet and Ink among others. From November 2 to November 4, 2026 the swap window then runs at Coinbase, in which the two legacy tokens become the new AERO.
Within that window the exchange pauses deposits and withdrawals of the legacy tokens. Anyone wanting to move holdings to or from Coinbase during those three days therefore cannot. Anyone wanting to shift their holding before the window is better off doing it well in advance and not on the evening of November 1, because a withdrawal on a network can take time depending on load.
Coinbase charges no fee for taking part in the swap, according to its own announcement. That concerns the conversion itself, not the trading fees that arise on a purchase or sale as they otherwise would.
Those whose holding sits at Coinbase and those who self-custody: two different routes
Here runs the dividing line at which, in experience, money gets lost. If your VELO sits in the Coinbase account, the swap happens without any action from you. You have to click nothing, confirm nothing and apply for nothing; after the window, AERO is in the account.
If instead you hold VELO in your own wallet on Optimism, you are not covered by Coinbase's handling at all. For that case there is the protocol's own migration route, and you have to take it yourself. Anyone who misses it holds, after the swap, a token that is no longer traded at its home venue.
A precautionary rule applies here that matters more at any token migration than the migration itself: migration pages are a classic target for fraud attempts. Around every announced swap, replica pages appear demanding a wallet connection and an approval, and with it they clear out the holding. You obtain the address of the genuine migration route exclusively via the official project page, never via a link from a direct message, a comment or a search ad. How to custody holdings in general so that a single bad approval does not cost everything is set out in the hardware wallet comparison.
veVELO locks: tied positions are the least clear part
In the ve(3,3) model there are, alongside the freely tradable tokens, the locked positions, called veVELO at Velodrome. Whoever locks gives up availability for a set period and receives voting rights and a share of the protocol's revenues in return. These positions sit, by their nature, in the protocol itself and not on an exchange.
It is precisely on this that the least solid information is publicly available. The announced split of 94.5 to 5.5 percent expressly includes the locked positions on both sides, so there is no indication that they come away empty-handed. How a running lock period is treated at the transition, whether voting rights continue seamlessly, and what happens to positions whose term reaches beyond the swap cannot currently be answered conclusively from the outside. Anyone holding a locked position therefore follows the project's announcements more closely than someone who only has free tokens sitting on an exchange.
Tax on a token swap: section 23 of the Income Tax Act and the open holding-period question
In Germany, gains from the sale of crypto assets held privately fall under section 23 of the Income Tax Act, the private disposal. The basic rule is familiar: hold for more than a year and you stay tax-free; sell within the one-year period and you pay tax on the gain at your personal rate, provided the exemption threshold is exceeded. The Federal Ministry of Finance most recently set out the treatment of crypto assets in its circular of March 6, 2025.
The point of dispute in a process like this one is: is the swap of one token for another a disposal that starts a new holding period? A swap from one crypto asset into another is in principle treated like a sale for tax purposes. Whether that also applies to a conversion in which the same project replaces its token and the holder economically keeps the same thing is a question of the individual case that nobody here can answer for you across the board. This is expressly not tax advice, and with meaningful amounts the question belongs with a tax adviser.
What you can do regardless is secure the evidence. Record which VELO holding you had at which point in time, at what factor it was converted and when. Anyone recording their purchases and swaps as they happen anyway has an easier time at year end; the comparison of tax tools and portfolio trackers shows which tools map such conversions cleanly.
An older ratio of 0.55 AERO per VELO is still doing the rounds
Anyone researching the topic comes across reports from the announcement period stating an entirely different ratio: 0.55 AERO per VELO. That ratio was a proposal from an early phase and was expressly marked as non-final at the time. It is not the factor at which the swap now takes place.
What governs is the number the exchange states for the November window, and that stands at around 0.044. The best protection against an outdated search hit is the cross-check from the second section: a factor of 0.55 would assign the VELO side around 40 percent of the new supply, while its market capitalisation today sits at a good 5.5 percent of the combined total. A number that is off by a factor of seven from what the market pays is in all likelihood out of date.
What this swap does not remove in terms of risk
A swap rearranges the tokens, but it does not turn a risky asset into a safe one. Three points remain unchanged.
First, protocol risk. Decentralised exchanges run on program code, and errors in that code have repeatedly proved expensive in recent years. A merger means new, altered code, and new code is least tested in its first weeks.
Second, liquidity risk. VELO currently turns over around $2.0 million a day, on a market capitalisation of around $48.6 million. In such a market even a medium-sized order moves the price, and in the limit-only phase that applies all the more. Anyone wanting to sort out the terms around decentralised trading, fee models and settlement in general will find the basics in the explainer on what a perp DEX is.
Third, price risk. On the direction of AERO after the merger this text deliberately says nothing. The combination widens the addressable market of both protocols; that is a fact about the structure, not a statement about the price. A total loss is possible at any time with crypto assets of this size.
The announcement of the combination comes from the development firm behind both exchanges and is documented on its own project page; the details on the window at Coinbase, on the factors and on the absence of fees were compiled among others by Cryptobriefing.
The VELO swap: What to take away
The swap itself is unspectacular and for exchange holdings even convenient. The work lies beforehand, and it consists of three steps.
- Settle where your holding sits. In an exchange account the swap happens automatically; in your own wallet on Optimism nothing happens at all unless you take the project's migration route yourself. If you are thinking about the venue anyway, the crypto exchange comparison helps with the question of where trading pairs, fees and authorisation in Germany fit together.
- Secure the records before the holding is converted. Noting the holding, the date and the factor costs five minutes and spares you a reconstruction in case of doubt. Which tools capture such conversions cleanly is shown by the comparison of tax tools and portfolio trackers.
- Check your custody before you grant an approval anywhere. Around every announced swap, replica migration pages appear. How to separate holdings so that a single bad approval does not cost everything is set out in the hardware wallet comparison.
(As of October 6, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
The US financial regulator FinCEN closed two projects on October 5, 2026 that would have made transfers to self-custodied crypto wallets reportable. For you as an investor in Germany, nothing changes immediately. What happens when you withdraw to your own wallet is governed by European law, and European law is currently moving in the opposite direction.
FinCEN is the Financial Crimes Enforcement Network, the anti-money-laundering unit of the US Treasury. It prescribes which data banks and financial service providers must retain about payments and when they must file a report. Two of its proposals would have extended those duties explicitly to crypto transfers to wallets without a custodian for the first time. Both are now off the table.
What FinCEN withdrew on October 5, 2026
On Monday, October 5, 2026, the agency filed two withdrawal notices; publication in the Federal Register, the US official gazette, was scheduled for October 6. Two so-called NPRMs are affected, that is Notices of Proposed Rulemaking. An NPRM is the formal announcement of a planned rule on which anyone affected may comment before it takes effect.
The first project dates from December 23, 2020 and ran under the docket number 1506-AB47. The second was published on October 23, 2023 and carried the number 1506-AB64. The older one had thus sat unresolved for almost six years, the newer one for three. Neither was ever in force; they hung in the state in which an agency has announced a rule but not adopted it.
The $3,000 threshold and the report from $10,000
The December 2020 proposal would have required banks and payment service providers to keep records on crypto transactions involving a self-custodied wallet from $3,000 upwards, including details of the counterparty. From $10,000 a report to FinCEN would have become due. A self-custodied wallet, an unhosted wallet in the agency's English, is a wallet whose private key nobody but you holds; there is no company there that could provide information.
That was precisely where the dispute lay. Anyone sending money to an address with no service provider behind it can say about the recipient only what that recipient states themselves. The criticism of the proposal therefore came down to the duty being either impossible to fulfil or an invitation to guess. In 2021 the industry filed several thousand comments within an unusually short window.
Why the 2023 mixing special measure fell
The second project targeted mixers. A mixer is a service that pools payments from many users and pays them out in a new distribution, so that the trail between deposit and withdrawal can no longer be drawn unambiguously in the blockchain. FinCEN wanted to designate international crypto mixing under section 311 of the USA Patriot Act as a class of transactions of primary money-laundering concern. The consequence would have been a duty to report wallet addresses, transaction hashes and IP addresses.
That it comes to nothing is justified by the agency, according to Decrypt, by the reporting burden and by the objection of many commenters that the broad definition could deter lawful use. FinCEN stated verbatim that it would take no further action on this NPRM. Both withdrawals refer to the White House digital asset report of July 2025 and its sentence that lawful users of digital assets should be able to transact privately on a public blockchain.
The legal basis remains in place
A withdrawal is not a ban on the rule but the end of a single proceeding. Peter Van Valkenburgh of the advocacy group Coin Center said on that point that the underlying statutory authority to create new, similarly bad rules remains. That is the sober reading: what was withdrawn is the proposal, not the power to write a new one.
The same agency tightens the screws on the A7 network the same day
That FinCEN is pulling back across the board cannot be inferred from the day. On October 5, 2026 the same agency published a new finding together with a proposed rule in the Federal Register under the number 1506-AB77. It is directed at companies outside the US controlled by the so-called A7 network, a service for sanctions evasion and money laundering with links to Russia. The legal basis is section 9714(a) of the Combating Russian Money Laundering Act.
What is proposed is a prohibition on certain transmittals of funds by covered financial institutions. The comment period ends on November 4, 2026. The pattern is therefore recognisable: the agency is abandoning blanket capture of private transfers and working instead with targeted prohibitions against named networks.
Proof of ownership from 1,000 euros: how far the EU transfer-of-funds regulation reaches
In the European Union, Regulation (EU) 2023/1113, the transfer-of-funds regulation for crypto assets, has applied since the end of 2024. Its Article 14 requires that, for a transfer to a self-hosted address above 1,000 euros, the originator's crypto service provider take appropriate measures to establish whether that address is owned or controlled by the originator. A self-hosted address is the same thing FinCEN calls an unhosted wallet: an address with no service provider behind it.
In practice that means your exchange wants to see proof above this threshold that the destination address belongs to you. What that proof looks like we set out in a separate assessment of which providers demand which evidence from 1,000 euros. Below the threshold it stays with the details that are collected anyway. Anyone intending to self-custody permanently cannot avoid the question of which device the keys sit on; our hardware wallet comparison sorts the devices by price, handling and supported networks.
So the EU demands precisely what the US is now dropping: an attribution of transfers to wallets without a custodian. The difference is the direction of access. The American rule would have produced a report to the agency. The European one produces a duty of verification at the service provider, the result of which is documented there.
The anti-money-laundering regulation from July 10, 2027 and the end of anonymous accounts
The second building block is not yet in force. Regulation (EU) 2024/1624, the EU anti-money-laundering regulation, applies from July 10, 2027. Its Article 79 prohibits credit institutions, financial institutions and crypto service providers from keeping anonymous accounts. At the same time it prohibits dealing in anonymity-enhancing coins, that is crypto assets whose protocol systematically conceals sender, recipient or amount. Monero is the best-known case.
For regulated exchanges in the EU that means taking such coins out of their offering. What exactly this prohibition captures and what holders can do until then we treated separately in an assessment of the privacy coin ban from 2027. What stands for today's occasion is this: while surveillance of private transfers is being rolled back in Washington, a deadline is running in the EU after which a part of private transfers will not be possible at all through regulated providers.
Which provider sits under which supervision is therefore no longer a formality but decides which coins you will still be able to trade there in two years. Our overview of regulated crypto exchanges lists who holds an authorisation under the European crypto market regulation MiCA and in which member state it was granted.
What happens on a withdrawal to your own wallet in Germany
The procedure differs by provider, but the components are the same everywhere. You enter the destination address, and above the 1,000-euro threshold the provider asks for proof that it belongs to you. Common forms are a signed message from the wallet, a screenshot of the address in the wallet software, or a small test transfer. Some providers additionally work with an allowlist on which a new address only becomes usable after a waiting period.
The American withdrawal changes nothing about that, for a simple reason: the duty falls on your service provider, and your service provider is as a rule based in the EU or serves you under European supervision. A provider licensed in Germany follows the transfer-of-funds regulation, not whatever FinCEN plans or drops. Anyone trading with a provider outside the EU leaves that framework; then what applies there applies, and the way back to a German bank account runs through the European rules again.
These five details to check before your next withdrawal
Before you pull holdings off an exchange and onto your own wallet, five points are worth a look, as they cause most of the delays in practice.
- The amount threshold. If the withdrawal is above 1,000 euros, the duty of proof under Article 14 applies. Anyone staying just below it to avoid that runs into the opposite: a series of conspicuously small transfers is a pattern any money-laundering desk examines.
- The network. The same coin often exists on several networks. A withdrawal on the wrong network does not arrive and in many cases cannot be recovered.
- The form of the proof. If the provider demands a signed message, your wallet has to be able to do it. Not every app offers the function, and with a hardware wallet it sometimes sits in the companion software rather than in the device.
- The waiting period on the allowlist. If a newly entered address only becomes usable after hours, a withdrawal is not something for the evening before a deadline.
- The records. Acquisition date, acquisition cost and the transaction number belong saved before you leave the account. Anyone requesting them from the exchange later gets them in the best case; in the worst, the provider is gone.
In tax terms the withdrawal changes nothing in Germany
A transfer between two of your own wallets is not a sale and in itself produces no taxable gain. What it does produce is documentation work: after the move, the holdings sit where no service provider draws up an annual statement any more. The duty to be able to evidence the acquisition date and acquisition cost stays with you. Tools that read addresses along permanently and build a statement from that we set side by side in the crypto tax tool comparison.
That a reorganisation of crypto taxation is being negotiated in Berlin at the same time is a separate matter and has nothing to do with the American reporting duties. For the question of where your coins sit it is nonetheless not immaterial: the longer a holding sits with you yourself, the more important it becomes that the origin of every position stays traceable.
Self-custody: What to take away
The news from Washington is a relief for American financial service providers and a signal to everyone who treats self-custody as a case for suspicion. A change in your situation in Germany it is not. Three steps follow from it.
- Settle where your keys are to sit. Anyone wanting to take holdings off an exchange permanently decides on the device first and only then on the timing. Our hardware wallet comparison names the differences that matter in doing so.
- Check your provider's authorisation. From July 2027 it decides which coins remain tradable there. The overview of regulated crypto exchanges shows who holds a MiCA authorisation.
- Secure the records before you move. Acquisition data and transaction numbers are harder to obtain after leaving the account than before; a tax tool keeps them together permanently.
(As of October 6, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Sources for further reading: the withdrawn proposal of December 2020 in the Federal Register and the mixing special measure of October 2023 in the same place.
Shibarium's block explorer is showing only part of the network this Tuesday morning. Of the 10,700,889 blocks the chain has produced so far, 55 percent have been read into the index. Around 4.8 million blocks are still missing from it. For you as a holder of Shiba Inu that means every transaction figure, every address counter and every daily statistic you read there right now describes the state of the index, not the state of the network. cryptoticker.io compiled this assessment itself on October 6, 2026, on the basis of the Shibariumscan status display for indexing progress.
This is not an outage and not a fault in the chain. Shibarium keeps producing blocks, one every eight seconds on average. What is being rebuilt is the catalogue of those blocks. And as long as the catalogue is unfinished, the figures in it are incomplete. Anyone reading them as evidence of growth or contraction is drawing a conclusion the data cannot support.
Shibariumscan on October 6: 55 percent of blocks in the index
The status display at Shibariumscan gives three values that together make up the picture. The share of blocks read in stands at 0.55, that is 55 percent. The flag for whether indexing is complete reads no. And the flag for whether at least the blocks have been worked through also reads no. The home page carries a note alongside it saying the chain is currently being read in and that individual counters may be inaccurate.
The 55 percent are a snapshot. Two queries on the morning of October 6 returned the same value, so progress is moving slowly. Rebuilding an index covering 10.7 million blocks is computing work that takes days, not hours.
What a block explorer actually does
A block explorer is a searchable database covering a blockchain. The chain itself stores its data in blocks that reference one another, but it offers no search. The explorer reads each block individually, breaks it down into transactions, addresses and events, and files the result in tables that can be queried. If that database disappears, the chain carries on unchanged; only looking things up becomes laborious.
Reindexing explained: why the chain runs while its catalogue is rebuilt
Reindexing means the explorer rebuilds its database from the start, going through every block of the chain again. At Shibarium this was triggered by an infrastructure change that has been running since late summer. Part of it was a switch of the access nodes through which wallets and applications talk to the network. We reported on that change of access addresses on September 29, when the subject was the settings in your wallet.
Alongside it, a reorganisation of the chain was cleaned up, during which two variants of the same block sequence were briefly in circulation. According to the developers, that point is settled. What remains is the rebuilding of the index. The project's technical documentation describes the architecture of Shibarium and its tools.
The decisive sentence for you: the percentage measures the progress of a database, not the health of a network. A transfer that cannot currently be found in the explorer may nonetheless sit complete and final in the chain.
Internal transactions: the field with no value
The position is even clearer with internal transactions than with blocks. Their indexing share currently returns no value at all; the field is empty. Internal transactions are movements that do not originate directly from a wallet but arise inside a smart contract, for instance when a swap runs through several steps.
That hits precisely the processes that matter when retracing a swap. Anyone who has swapped on Shibarium, provided liquidity or used a bridge will not find the intermediate steps broken down in the explorer right now. The outer transaction is visible, the chain beneath it is not.
4,859 transactions in a day: this figure measures the catalogue, not the network
The daily counter stood at 4,859 transactions on the morning of October 6. In total the index reports 639,100,978 transactions and 267,880,184 addresses. Those sums sound solid; at present they are not, because they come from the same 55 percent.
How badly that can mislead is shown by an episode from September. Between September 6 and September 8 the number of daily transactions rose from 786 to 1,750, a jump of 122 percent. Several trade publications reported it as an increase in network load. In the early stages of a rebuild, however, an explorer shows markedly fewer blocks and transactions than the network has actually processed. A jump upwards can therefore simply mean that the catalogue has moved along a stretch.
From that follows a plain rule for the coming weeks: as long as the share sits below 100 percent, no change in these counters serves as proof of a change in the network. A report that claims otherwise has skipped a step.
A gas price of 0.04 Gwei at all three tiers: a pointer to real utilisation
There is one reading that the rebuilding of the index leaves untouched, because it comes from live operation: the gas price. Gas is the fee unit a network uses to charge for computing work, and Gwei is a subunit of it. On the morning of October 6, Shibarium quoted the same value for all three urgency tiers, 0.04 Gwei, once for slow, once for normal, once for fast.
That the three tiers coincide is telling. Different prices arise only when transactions compete for space in a block and whoever wants to get through faster pays more. When they coincide, that jostling does not exist. Network utilisation confirms it at 0.22 percent. For comparison: Ethereum stood at around 0.19 Gwei at the same time, roughly five times as much, and that too is historically low.
For you as a user this is the good news in the situation. A transfer on Shibarium costs very little right now, and it goes through quickly. The thin loading is pleasant from a fee perspective and, from the standpoint of network usage, a finding that leaves the question of viability open.
Records for a Shibarium transaction: the hash belongs in your own files
Here lies the practical consequence that makes work this week. Anyone who has so far produced their records by pulling up a page in the block explorer is left without a reliable basis. The transaction exists; its depiction in the explorer may be missing.
What makes you independent of that is the transaction hash. This is the unique identifier of a transaction in the chain, a long string your wallet shows you after every transfer. With it the transaction can be looked up again at any time later, even if a single explorer finds nothing today. Without it you depend on searching for your address, and that is precisely what is currently incomplete.
In practice that means noting the hash of every Shibarium movement from the wallet, together with the date, time, amount and euro value at the time of the transaction. A portfolio tool takes this bookkeeping off your hands and reads the movements along as they happen, instead of reconstructing them after the fact. Which providers cover German specifics is shown in our overview of tax tools and portfolio trackers.
Holding period and proof: what applies when the block explorer is incomplete
In Germany, gains from the sale of crypto assets count as private disposals under section 23 of the Income Tax Act. The decisive factor is the one-year holding period: sell within a year of buying and the gain is taxable; sell after that and it stays tax-free. On top of that comes an exemption threshold of 1,000 euros a year for the sum of all private disposals.
The burden of proof for the purchase date and purchase price lies with you. The tax office does not demand a block explorer, it demands a traceable record. That is exactly why an incomplete index is not a tax problem as long as you have your own documents, and a considerable one if you have relied on being able to call the data up again at any time.
One point easily lost at Shibarium: moving your own tokens between your own wallets is not a sale and does not restart the holding period. It looks different if you switch via a bridge into another representation of the same token, because views diverge there. Since October 4 SHIB has also existed on a further network; the details are in our piece on the bridge and its two contract addresses. Anyone taking that route documents it with particular care and, in case of doubt, has the classification reviewed by a tax adviser.
Two chains, one circulating supply: 589 trillion SHIB on October 6
While work goes on at the infrastructure, the market barely moves. SHIB was quoted at $0.00000585 on Tuesday morning, down 1.0 percent within a day. In euros the price sits at 0.00000522 euros, where the daily loss comes to 1.47 percent, with a range between 0.00000518 and 0.00000536 euros. The difference between the two percentages comes from the exchange rate and not from the token.
Market capitalisation stands at around $3.45 billion, roughly 3.08 billion euros. Some 589 trillion SHIB are in circulation. The price is far from the peak of October 2021 at $0.00008616. Dogecoin, the larger reference point in the same market segment, stood at $0.094382 the same morning and gave up 1.26 percent, moving very similarly.
That an additional network widens access changes nothing about the circulating supply. The bridge locks the token on the originating chain and reissues it on the destination chain; the total across both chains stays constant. New access creates demand only if buyers use it.
Levels above and below: $0.0000055 and $0.0000060
On the upside the next hurdle is the zone around $0.0000060, where the price has failed several times in recent days. Above that lies the area around $0.0000067. On the downside the zone around $0.0000055 serves as a catchment area; it held at the end of September. These levels follow from the price action of the past weeks and are not a promise.
Important for context: with a price carrying eight decimal places, the last tradable digit moves the price noticeably in percentage terms. A one percent move here corresponds to fractions of a millionth of a dollar. Anyone working with tight limits should do that arithmetic beforehand, otherwise an order triggers on a move that is barely visible on the chart.
Buying route and custody: two networks, two wallet settings
When buying, the European crypto regulation MiCA requires your provider to hold an EU authorisation. Licensed firms display their licence publicly, and a look at it before the first deposit takes two minutes. Which platforms meet that condition and what they charge is set out in our crypto exchange comparison.
With custody, this week's particularity is added on top. Anyone holding SHIB themselves and using Shibarium needs the network's current access addresses in their wallet, otherwise it shows outdated balances or none at all. Anyone additionally active on the new network runs a second wallet there with its own address format. Two networks mean two backups of your access credentials, and both belong somewhere that is not the same computer.
Shibarium reindexing: What to take away
The situation is less dramatic than half a percentage figure sounds, and it still asks something of you. The chain runs, its index does not run complete, and as long as that holds, the figures from it are not records.
- Pull your records from your own wallet. Save the transaction hash of every Shibarium movement, together with date, amount and euro value. A portfolio tracker handles that as it happens, instead of you piecing it together afterwards.
- Keep the credentials for both networks separate. Anyone operating on two chains keeps two backups. Which devices map that cleanly is shown by the hardware wallet comparison.
- Leave reports on network load unjudged for now. Rising or falling transaction figures from the explorer say nothing about the network until indexing is finished. Anyone wanting to buy or sell should instead check fees and licensing at the provider, for example via the exchange comparison.
(As of October 6, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
The attacker who drained about $3.8 million from the cross-chain service NEAR Intents on October 1 has sent the money back in full. Since then the price of NEAR Protocol has turned higher: $5.23 on Tuesday morning, October 6, 2026, a gain of 7.8 percent within a day and of 14.4 percent over the week. Those are CoinGecko's figures. That made NEAR the only coin among the 25 largest crypto assets excluding stablecoins to move more than five percent on the day that morning.
Two documented developments coincide here, and both are older than the price jump: the full return of the drained sum, and the launch of the first US spot ETF on NEAR on September 29. How much each contributes cannot be separated out. What can be said is this: the risk that sat on the token for a week, worth $3.8 million, is off the table.
The Omni flaw at NEAR Intents: $3.8 million via BNB Chain
The incident on October 1 did not hit the NEAR blockchain itself but a service running on it. The affected part was the Omni infrastructure that handles deposits and withdrawals at NEAR Intents. The flaw sat in the way that infrastructure communicated with the smart contracts. The outflow stayed confined to BNB Chain, and the bulk of the haul consisted of the stablecoin USDT.
What NEAR Intents does technically
NEAR Intents is a service for swapping crypto assets across network boundaries. An intent is a statement of purpose: you define what you want to end up with, and a network of service providers finds the route there. Unlike a classic bridge, no token is locked in a contract on one side and reissued on the other. The technical description is set out in the project's technical documentation.
That the attack hit the settlement layer and not the protocol is more than a nicety. Anyone who held NEAR in their own wallet and never used the swap service was untouched by the outflow. What was affected were funds sitting in Omni settlement. The team has pledged to compensate affected users in full.
The service's security layer flagged the access itself, after which NEAR Intents was shut down for about an hour. During that time the gap on the contract side was closed. Core functions ran again afterwards, while individual cross-chain functions stayed switched off during the repair. We described the withdrawal halt and its reasons in detail on October 1.
A 48-hour ultimatum: how the attacker was identified
Within 24 hours of the outflow the team had, by its own account, identified the person behind the access. It then set a 48-hour deadline for the return of the funds and published addresses the money was to go to. This is standard practice in the industry: it leans on the threat of prosecution while leaving the other side a way out.
The way out was taken. A few hours after the deadline was set the other side signalled willingness to talk, and the full sum came back within the time allowed. The team then closed its investigation.
A caveat belongs with that. A return after an ultimatum is no proof that the tactic works reliably. In many cases over recent years the money stayed gone. At NEAR Intents several things came together: the trail was fresh, the sum was small relative to the risk of being found, and the outflow was confined to a single chain.
Bug bounty instead of exploit: the words of Shevchenko and Polosukhin
Alex Shevchenko, general manager of NEAR Intents and co-founder of Aurora Labs, confirmed the return publicly and tied it to an appeal: “The funds from the $3.8M NEAR Intents hack were sent back in full. We are stopping the investigation. Please use bug bounties instead of disrupting the services.”
Illia Polosukhin, co-founder of NEAR Protocol, echoed that: “For security researchers looking for exploits, we encourage you to use bug bounties. They exist for a reason.” A bug bounty programme is an advertised reward for reporting a vulnerability to the operator rather than exploiting it.
For you as an investor, the admonition matters less than the fact that both statements are attributed by name and by role. In incidents of this size, figures from anonymous sources circulate routinely. Here the amount, the cause and the outcome have names behind them.
The Bitwise NRR ETF: $35.5 million of inflows on day one
The second documented reason for the demand is less than a week old. On September 29 the first US spot ETF on NEAR began trading, issued by Bitwise and listed under the ticker NRR on NYSE Arca. The management fee is 0.75 percent a year. Bitwise has said it will stake a substantial share of the tokens it holds.
The provider published the first trading day's figures itself: $36 million of assets under management, $35.5 million of net inflows, $15.1 million of trading volume. That bought roughly 7.2 million NEAR, about 0.55 percent of the circulating supply. The price rose 10.2 percent on the launch day to $5.38.
A spot ETF actually buys the underlying asset. Every inflow is therefore a purchase in the market that shrinks the circulating supply. For a token with around 1.31 billion units in circulation, 0.55 percent in a single day is a size you cannot argue away. The reverse applies just as much: outflows become sales.
The NEAR price in detail: $4.87 to $5.35 in one day
The day's range ran from $4.87 to $5.35. That is just under ten percent between low and high within 24 hours. Turnover of around $961 million stands against a market capitalisation of about $6.85 billion, which put NEAR in 21st place.
For context on the upside: the all-time high of $20.44 dates from January 16, 2022. From current levels that is around 290 percent away. Anyone reading the term all-time high in a forecast should read that date alongside it, because it is more than four years back.
The comparison with the wider market is what makes the move interesting. Bitcoin was virtually unchanged the same morning, and so was Ethereum. The rise in NEAR therefore did not come out of a general market move but out of its own news flow.
Buying NEAR in Europe: MiCA authorisation and a euro pair
If you want to buy NEAR in Germany, two practical questions decide the cost. The first is authorisation: now that the EU regulation MiCA applies in full, providers of crypto services need a licence from a European supervisor, in Germany from BaFin. Which firms hold that licence and what they charge is set out in our crypto exchange comparison.
The second question is the trading pair. If NEAR trades against the euro, you pay a trading fee once. If the route runs via the dollar or a stablecoin, conversion and spread are added on top, and for a coin showing a ten percent range in a day, the time lost between two steps weighs in as well.
A third point concerns the very subject of this article: cross-chain services are convenient, but they add a layer that can have faults of its own. If you simply want to buy NEAR and hold it, you do not need them.
Custody after a cross-chain exploit: your own keys or an exchange account
The incident is a lesson in where crypto assets sit. Three places need to be distinguished. On an exchange they sit in the provider's name; in your own wallet they are your responsibility; and in a settlement service such as the Omni layer they sit temporarily in a contract while a swap runs. The third place is the shortest-lived and the least considered.
In practice that means this: a balance caught up in a swap is not part of your holdings but part of a running process. Anyone who swaps across network boundaries regularly should keep the amounts small and not leave them sitting and waiting. For anything meant to stay longer, self-custody is the cleaner route; which devices qualify is shown by the hardware wallet comparison.
Holding period and tax: December 31, 2026 as the cut-off
A gain of 7.8 percent in a day raises the tax question immediately. In Germany, crypto assets currently fall under the one-year holding period of section 23 of the Income Tax Act: sell after more than twelve months and the gain from the private disposal is tax-free. Sell before that and it counts towards taxable income, provided the exemption threshold is exceeded.
That framework is up for change. A draft bill from the Federal Ministry of Finance provides for a flat 25 percent withholding tax regardless of the holding period. As the draft currently stands, it would apply only to crypto assets acquired after December 31, 2026; anyone buying up to and including that day keeps the old rule. The cabinet is due to take it up on October 14, 2026. We have broken down the draft and its timetable separately.
What this means for you depends on your time horizon, not on the day's move. A draft is not a law, and the Bundestag has not yet taken it up. Anyone who nonetheless wants to plan around the deadline should document the acquisition date of every purchase, because under a cut-off rule that date becomes the decisive piece of evidence.
Staking and a 0.75 percent fee: what separates the ETF from holding your own tokens
Bitwise intends to stake a substantial share of the ETF's tokens. Staking means pledging tokens in the network to help secure the blockchain and receiving a reward for doing so. For the fund that is income, set against the 0.75 percent management fee.
If you hold NEAR yourself you can stake too, but you carry the work and the risk alone: choosing a validator, lock-up periods when withdrawing, and the tax treatment of the income, which the draft bill explicitly wants to assign to investment income. Which platforms offer which terms is set out in the staking provider comparison.
The difference is not in the yield alone. With the ETF you buy a security in a brokerage account and hold no keys. With your own tokens you hold the keys and with them the duty to secure them.
Leverage and liquidation: 7.8 percent in a day is enough for a margin call
A range from $4.87 to $5.35 within a day is the real story for leveraged positions. At ten-times leverage a ten percent move against you is enough to consume the margin; in practice liquidation kicks in earlier, because the exchange holds a safety buffer. On Monday and Tuesday exactly those ten percent lay between low and high.
On top of that, perpetual futures carry a financing charge, the funding rate. It is settled several times a day between the buy and sell sides. After a fast rise it is typically positive, which means holding costs fall on the buy side for as long as the position stays open.
Levels above and below: $5.35, $4.87 and $4.70
On the upside the day's high of $5.35 is the next marker, and above it the ETF day's starting level of $5.38. On the downside sits the day's low of $4.87, and below that the zone around $4.70 where the recovery began.
These values are observation points, not a forecast. What they are useful for is settling on a decision in advance rather than in the moment of the move. Analyst opinions on price targets are plentiful; each belongs to the person or house that voiced it, not to the market.
NEAR after the exploit: How to proceed now
- Settle the buying route and the fees. Check whether your provider holds a European licence under MiCA and whether a euro pair on NEAR exists. Both are in the crypto exchange comparison, and both decide more about your outcome than an entry a few cents lower.
- Separate holdings from swap balances. What you want to hold for longer does not belong in a settlement service. The test is where the keys sit; suitable devices are in the hardware wallet comparison.
- Decide on holding period and staking in advance. Note the acquisition date and decide whether you want to lock tokens up before you pledge them. Lock-up periods and provider terms are in the staking provider comparison.
(As of October 6, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Swapping Bitcoin for a gift card is not a purchase for tax purposes, it is a sale. The moment you pay for a gift card, a good or a service with crypto assets, you hand over the coins and receive something else in return. The tax office treats that transaction exactly like a sale on an exchange: as a private disposal under section 23 of the German Income Tax Act, the EStG.
Whether tax actually falls due hangs on two numbers. If more than twelve months lie between the purchase and the gift card payment, the gain stays tax free. Below that it counts, and it counts together with every other private disposal of the year against the threshold of 1,000 euros. So if you buy Bitcoin in January and pay for a gift card with it in March, you have a tax relevant transaction on the books, even though not a single euro has landed in your account.
The gift card purchase is a disposal, not an exchange
A disposal within the meaning of section 23 EStG is any transfer of an asset for consideration. The fact that what you receive in return is a gift card rather than euros changes nothing: for consideration simply means that something flows the other way. On February 14, 2023, the Federal Fiscal Court confirmed that crypto assets are other assets in this sense and fall under the provision.
That is what sets the gift card purchase apart from a gratuitous transfer. Anyone who gives coins away or hands them to a charitable organisation is not disposing of them, because nothing flows the other way; different rules apply there, which we have written up under claiming Bitcoin donations against tax. A gift card is consideration with a quantifiable value, and the whole calculation hangs on that.
In practice that means there is no free pass for spending coins by way of a gift card in order to sidestep the tax. The opposite is true, because unlike with a sale on an exchange you are afterwards left without the exchange statement as evidence.
What counts as the disposal proceeds: the market value of the gift card
The disposal proceeds are the value of what you received for the coins. With a gift card that is its face value in euros, meaning the sum printed on the card that you can redeem with it. From that you deduct the acquisition cost, meaning the euro amount the coins you handed over cost you when you bought them, plus the incidental purchase costs at the time.
An example with round figures: you bought coins for 400 euros and eight months later pay for a gift card worth 700 euros with them. The taxable gain is 300 euros. Had you instead sold the same coins on an exchange for 700 euros, the result would be identical. The gift card merely stands in for the euro as consideration.
You need to pay attention when the provider takes a premium and you hand over coins with a market value of 730 euros for a gift card worth 700 euros. What then governs is what you actually received. The premium reduces your result, and you should be able to document it, because otherwise the higher market value of the coins can be used as the basis.
The one-year holding period decides the tax
The holding period begins on the day after the purchase and ends after twelve months. Redeem the gift card after that and the gain stays tax free, however large it is. Within the period it is taxable at your personal income tax rate.
What is decisive is the date of the payment, not the date on which you later use the gift card in a shop. The swap of coins for a gift card is the moment that counts for tax. Anyone who wants to see the mechanics of the period in context will find them in our comparison of the loss sale and buyback within the holding period.
The 1,000 euro threshold: why a gain of 1,001 euros is taxable in full
Private disposals are subject to a threshold of 1,000 euros per calendar year. A threshold is not an allowance: once it is reached or exceeded, the entire gain becomes taxable, not just the part above it. On a gain of 999 euros you pay nothing; on 1,001 euros you are taxed on 1,001 euros.
The limit applies to all private disposals of a year taken together, not per transaction and not per coin. Two gift card purchases with a gain of 600 euros each breach the limit jointly. Gains from other private disposals in the same year count towards it as well. Losses from such transactions reduce the total and therefore need documenting just as carefully as gains.
FIFO or specific identification: which coins the gift card purchase uses up
Anyone who has been adding over months holds coins with different acquisition dates. On the question of which of them the gift card purchase uses up, there are two routes. Under specific identification you demonstrate which particular coins were handed over, for instance because they sat in a wallet of their own. Where that cannot be allocated, the FIFO method comes into play: first in, first out, with the oldest holdings treated as handed over first.
FIFO often works against you when prices are rising, because the oldest holdings carry the lowest acquisition cost and therefore show the highest gain. In exchange, those holdings are also the most likely to be older than a year and therefore tax free. Which variant comes out cheaper depends on the individual case and belongs with a tax adviser, not in a rule of thumb.
Wallet separation matters here: anyone who keeps coins for everyday spending in a wallet of their own and the long term holdings separately from it can substantiate the allocation in the first place. That separation costs nothing and cannot be created after the fact.
The BMF circular of 6 March 2025 replaces the 2022 version
The tax authorities' position on the taxation of crypto assets is set out in a circular from the Federal Ministry of Finance dated March 6, 2025. It replaces the earlier circular of May 10, 2022, and classifies, among other things, airdrops, forks, transactions on decentralised platforms and the boundary between private asset management and commercial activity.
Two things about it matter for the gift card purchase. First, the classification of the payment as a disposal remains in place. Second, the circular expressly stressed the requirements for records and cooperation, and that bites precisely on transactions for which no exchange issues a statement. An administrative circular binds the tax offices, incidentally, not the courts.
Part of the legal position is also what does not currently apply: a bill to abolish the one-year tax exemption was rejected in the Bundestag. The discussion continues, but nothing has been decided. Until then the twelve-month period stands.
VAT stays out of it: the swap counts as a payment
Alongside income tax, the question of VAT comes up regularly. For private holders the answer is short: anyone using coins as a private individual to pay with is not supplying anything subject to VAT. The tax authorities treat crypto assets as equivalent to conventional means of payment for VAT purposes, in so far as they are purely means of payment.
The VAT on the good or service is still owed by the merchant, and it is already baked into the gift card value. You pay it along with everything else, just as with any other method of payment. The position is different for businesses holding crypto assets as operating assets; separate rules apply there, and this page deals with the private case.
Evidence for the tax office: price, date and gift card value
With a sale on an exchange the platform supplies a statement. With a gift card purchase nobody supplies one, and the burden of proof sits with you. So secure four details for every transaction: the date of the payment, the face value of the gift card in euros, the quantity of coins handed over, and the acquisition date together with the purchase price of those coins.
Add to that the records you do receive: the provider's confirmation, the transaction in your wallet or in the block explorer and, where there is one, the invoice for the premium. Evidence of the price on the day of the transaction belongs there too, because the market value of the coins handed over is the cross-check against the gift card value. Programs that keep track of these transactions and produce a report for the tax return are listed in our comparison of crypto tax software and portfolio trackers.
You should keep these records for as long as the tax office can examine the transaction. For private individuals that means, in practice, until the tax assessment for the year in question is final, and longer if in doubt.
Where you can pay for gift cards with Bitcoin, and what the premium costs
Gift cards against crypto assets are brokered by specialised providers, and in some cases by individual merchants directly. The process is similar everywhere: you choose the gift card, the provider quotes an amount in coins, you transfer, and the code arrives by email or in your customer account. Three items determine the price.
First, the premium on the face value, with which the provider covers its price risk and its margin. Second, the network fee for the transfer, which weighs heavily on small amounts. Third, the price the provider calculates with, and the window for which it guarantees that price. So always work the gift card out as a total price in euros and compare it with the route through a sale on an exchange and an ordinary card payment. What that detour costs on an exchange is set out in our comparison of the best crypto exchanges.
Check as well whether the provider offers returns or refunds at all. A redeemed gift card code is as a rule not revocable, and in a dispute you have no payment service provider chargeback available of the kind you know from a credit card.
The gift card itself triggers no further crypto tax later
After the swap you no longer hold a crypto asset, you hold a claim denominated in euros. When you redeem the gift card in a shop weeks later, that is not a private disposal, because no asset within the meaning of the provision is being disposed of any more. The transaction that mattered for tax was complete when the coins changed hands.
That has a practical consequence: if the price keeps rising after the gift card purchase, you have no share in it any more, and a later slide in the price does not shrink the tax that has already arisen. The gain is fixed as at the moment of the swap. Anyone planning the transaction shortly before the turn of the year should keep that in view, because the gain falls into the year of the payment.
If a gift card expires unused, the transaction still stands for tax purposes. The loss of the gift card value is a private financial loss and not a reduction of the disposal gain that arose back then.
Bitcoin for a gift card: How to proceed now
- Check the holding period before you pay. Look up when the coins you intend to hand over were bought. If the purchase is more than twelve months ago, the gain is tax free; below that you count it against the threshold of 1,000 euros. A tool from our comparison of crypto tax software carries those periods parcel by parcel.
- Work the total price out against the exchange route. Add up the premium, the network fee and the price gap and compare the sum with the route through a sale and an ordinary payment. What a sale on an exchange costs is shown by our comparison of the best crypto exchanges.
- Secure the records the same day. The date, the gift card value, the quantity of coins handed over, the price and the provider's confirmation belong together in one folder before the email sinks in your inbox. Anyone paying with crypto assets regularly will find solutions that document the transaction together with a statement in our comparison of crypto credit cards.
The legal position in this article rests on the circular of the Federal Ministry of Finance dated March 6, 2025, file reference IV C 1 - S 2256/00042/064/043, whose changes against the 2022 version are set out in detail by PwC, and on section 23 of the Income Tax Act. This article is no substitute for tax advice.
(As of October 6, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
Adam Iza used off-duty LA deputies to pull warrants and personal data on his rivals, then moved the proceeds through crypto custodians.
Built with input from J.P. Morgan, the open-source "DvP" program lets institutions settle trades atomically on Solana with finality in seconds instead of days.
The Nasdaq-listed bitcoin treasury company, co-founded by Vivek Ramaswamy, paid roughly $169 million for 2,000 coins last week and now holds 29,462 BTC.
Nasdaq-listed DeFi Development Corp's latest SEC filing shows its Solana stash grew 1%, to about 2.56 million SOL and SOL equivalents—roughly half the prior week's gain and well below mid-September's pace.
Investigators say a Bonita Springs woman's Claude "diary" tripped Anthropic's safety filters. A human review team sent it to police, and Anthropic's own terms allow exactly that.
U.Today - IT, AI and Fintech Daily News for You Today
Over 297 million SHIB permanently removed from circulation in a marked increase for Shiba Inu's burn rate.
XRP Ledger is entering a potentially cautious period as volumes are finally recovering.
With 4.9% of all ETH secured, Tom Lee spots a "coiled spring" trade as Russell 2000 shorts hit an all-time high.
Near's rally is certainly exhausted as multiple local resistances turned out to be unbreakable for it.
Cardano founder Charles Hoskinson has once again urged Gemini to list ADA, reviving a years-long dispute over the major U.S. exchange’s persistent refusal to support Cardano’s native token.
Blockonomi
TLDR
- Nike shares declined over 1% in Tuesday’s premarket session, heading toward their lowest close in 13 years.
- Berenberg slashed Nike’s rating to Sell from Hold while cutting the price target from $49 to $27.50.
- The stock has tumbled 47% year-to-date in 2026 and sits 81% beneath its November 2021 peak.
- Analyst Buy recommendations for Nike have fallen to 26%, marking the weakest support in two decades.
- Berenberg projects fiscal 2027 EPS of $1.08, sharply below consensus, citing unresolved margin pressures.
Nike stock retreated more than 1% during Tuesday’s premarket hours. The decline positioned the shares to record their weakest closing price in over a decade.
NIKE, Inc., NKE
The selloff intensified after Berenberg issued a fresh downgrade. The firm lowered its rating to Sell from Hold while reducing its price objective from $49 down to $27.50.
Berenberg analyst Nick Anderson stated that Nike has effectively acknowledged a diminished role within the athletic apparel industry. He characterized the structural market transformation as “irreversible” in Tuesday morning research commentary.
This downgrade arrived mere days following Nike’s fiscal first-quarter results released last Thursday. The company’s fiscal 2027 forecast fell short of investor expectations, with executives projecting revenue will contract by a high-single-digit percentage through May 2027.
Nike shares have endured substantial pressure throughout the current period. The stock has plummeted 47% during 2026.
A broader perspective reveals even steeper losses. Shares currently trade 81% below their all-time closing peak established in November 2021.
Athletic Performance Segment Shows Strength While Lifestyle Products Stumble
Berenberg’s research team identified several positive elements within the quarterly report. Running, soccer, North American basketball, tennis and golf categories each delivered double-digit revenue expansion during the period.
However, the general sportswear segment, representing nearly half of total company revenue, contracted by a low-double-digit percentage. Jordan brand revenue declined by a mid-teens percentage, weighing on consolidated performance.
This category weakness represents a primary driver behind Nike’s projected high-single-digit revenue contraction for fiscal 2027, Berenberg noted. The China market presents the most significant challenge.
Despite China serving as a cornerstone of Nike’s “Win Now” recovery strategy launched in December 2024, revenue in the region is anticipated to decline for at least one additional quarter. Berenberg warned that restoring brand strength in China will require years rather than quarters.
Financial Projections Slashed Dramatically
Berenberg reduced its revenue forecasts for Nike by 6.5%, 11% and 13% across fiscal years 2027 through 2029. Earnings per share projections were cut even more severely, declining 38%, 46% and 34% respectively across the same timeframe.
The firm currently anticipates fiscal 2027 EPS will reach only $1.08. Berenberg also highlighted that Nike provided no gross margin guidance for fiscal 2027, interpreting this omission as a cautionary signal.
The company’s restructuring initiative, called Pace, isn’t projected to deliver meaningful benefits until fiscal 2029. The program targets $2.5 billion in cost reductions through fiscal 2031, though the majority of savings are weighted toward 2029 and 2030.
Conversely, $1 billion in pre-tax restructuring charges will hit results in the near term, creating additional headwinds. Berenberg described this timing mismatch as a challenging environment for investors seeking rapid improvement.
The firm’s revised $27.50 price objective applies Adidas’s 20-year historical price-to-earnings ratio to Nike’s fiscal 2029 earnings forecast. Berenberg contends Nike’s valuation premium relative to competitors is no longer justified.
Analyst sentiment on Wall Street has shifted decidedly negative. Only 26% of analysts tracking Nike currently maintain Buy ratings on the shares.
This represents the smallest proportion of bullish recommendations in at least two decades, based on FactSet records. Nike did not immediately provide comment regarding the downgrade.
The post Nike (NKE) Plunges 81% From Peak as Analyst Confidence Hits 20-Year Low appeared first on Blockonomi.
TLDR
- Apogee Enterprises (APOG) delivered fiscal Q2 2027 adjusted earnings of $1.17 per share, obliterating the $0.63 Street estimate.
- Quarterly sales increased 9% year-over-year to $391.1 million, well above the $359.46 million consensus.
- The stock rallied as much as 23% during pre-market hours following the announcement.
- Full-year adjusted EPS guidance was lifted to $3.00-$3.40 from the previous $2.70-$3.25 range.
- Strategic pricing initiatives and the Kalwall acquisition bolstered both revenue and profitability during the period.
Shares of Apogee Enterprises (APOG) surged as much as 23% in pre-market activity Tuesday following a second-quarter earnings report that significantly exceeded analyst projections.
Apogee Enterprises, Inc., APOG
The architectural products manufacturer based in Minneapolis disclosed adjusted earnings of $1.17 per share for the fiscal second quarter, handily beating the Wall Street consensus estimate of $0.63.
Quarterly revenue reached $391.1 million, representing a 9% increase compared to the prior-year period. The Street had anticipated revenue of $359.46 million.
Beyond the strong quarterly performance, Apogee elevated its full-year financial expectations, a move that typically energizes investor sentiment.
Management now projects fiscal 2027 adjusted earnings per share in the $3.00 to $3.40 range. This represents an upward revision from the prior guidance of $2.70 to $3.25, with the updated midpoint comfortably exceeding the $2.87 analyst consensus.
The company also increased its revenue outlook to between $1.46 billion and $1.50 billion, up from the earlier projection of $1.38 billion to $1.43 billion.
Key Performance Drivers
Much of the quarter’s outperformance stemmed from strategic pricing actions and operational improvements the company has implemented. Apogee refers to one such initiative as “Project Fortify 2.”
Apogee Enterprises, $APOG, Q2-27.
A huge EPS beat, with stronger margins and a raised outlook.
Revenue: $391.1M | +9.2% YoY
FY27 adj. EPS guide: $3.00-$3.40, up from $2.70-$3.25
Gross margin: 24.6% | +150 bps pic.twitter.com/sJ7hoJ87uq
— EarningsTime (@Earnings_Time) October 6, 2026
The Kalwall acquisition, completed recently, contributed $16.4 million to quarterly sales. However, this benefit was partially counterbalanced by weaker volumes in what management characterized as an uneven demand backdrop.
Don Nolan, Executive Chair and CEO of Apogee, attributed the results to strong execution throughout the organization. He cited the robust first-half performance as justification for the upgraded outlook.
Operating margin widened by 110 basis points to 8.6% during the quarter. Adjusted EBITDA climbed nearly 12% to $49.5 million, with the margin expanding to 12.7% from 12.4%.
Gross margin improved by 150 basis points to 24.6%. The improvement reflected favorable pricing, productivity enhancements, and the Kalwall integration, though these positives were partially offset by elevated material and manufacturing expenses.
Business Segment Performance
Apogee operates through four distinct business segments, three of which delivered robust sales growth during the period.
The Architectural Glass segment paced the group with sales jumping 21% to $87.4 million, driven primarily by the Kalwall addition. Architectural Services revenue increased 8% to $108.5 million on stronger project activity.
Performance Surfaces posted 14% sales growth to $55.3 million, benefiting from both volume gains and pricing improvements. Architectural Metals represented the slowest-growing segment with sales rising just 2% to $143.5 million.
Net income on a GAAP basis edged down to $22.4 million from $23.6 million in the year-ago period, with diluted earnings per share declining to $1.07 from $1.10. The adjusted figures paint a more favorable picture after accounting for one-time charges.
The company completed two strategic acquisitions during the quarter: Kalwall and Groglass. Management noted that Kalwall’s early integration has exceeded expectations.
From a cash flow perspective, operating cash flow for the first half of the fiscal year improved to $43.3 million from $37.3 million. The company allocated $27.3 million to shareholders via stock repurchases and dividend payments.
Long-term debt totaled $335.5 million at the end of the quarter, resulting in a leverage ratio of 1.7x.
The post Apogee Enterprises (APOG) Crushes Q2 Estimates, Lifts Full-Year Forecast appeared first on Blockonomi.
TLDR:
- Stellar tokenized assets passed $3 billion in Q2 2026, after crossing $1 billion and $2 billion marks
- Stablecoin transfer volume on Stellar reached a record $11.4 billion in Q2 2026, per the SDF
- XLM’s smaller market capitalization means moderate inflows could produce larger percentage moves than XRP
- Network growth does not guarantee XLM price growth, as value may not flow to the native token
XLM upside potential is under review as a new analysis compares Stellar with XRP over the next six months. The author says XLM could outperform XRP between October 2026 and April 2027.
The argument rests on Stellar’s smaller market capitalization and rising tokenized asset activity. The author states the view is neither a certainty nor a buy recommendation. XRP, by comparison, still holds a stronger institutional profile in global payments and finance.
Smaller Market Capitalization Shapes XLM Upside Potential
XRP has a much larger market capitalization than XLM. That gives XRP deeper liquidity, market depth, and institutional visibility.
The analysis compares the two assets on positioning, market capitalization, and ecosystem. XRP is linked to Ripple, XRPL, and RLUSD, while XLM is linked to Stellar, Soroban, and RWAs.
However, a larger asset needs more capital to produce the same percentage gain. XLM starts from a smaller base, so moderate inflows could move its price further in percentage terms.
The view was shared on X by Stellar XLM Holder. The author adds that XLM does not need to match XRP’s valuation. A partial narrowing of the gap could still lift XLM upside potential.
XLM: Could It Have More Upside Potential Than XRP Over the Next 6 Months?
While XRP has established itself as one of the largest and most closely watched cryptocurrencies in the payments and institutional-finance space, another digital asset could offer a particularly… pic.twitter.com/jHQ6EWsM0I
— Stellar XLM Holder (@SylvianGuibal) October 6, 2026
Tokenized Assets and Stablecoins Drive Stellar’s Growth
Stellar Development Foundation data shows tokenized assets on the network passed $3 billion in the second quarter of 2026. The network had crossed the $1 billion and $2 billion marks earlier in the year.
Stablecoin transfer volume on Stellar also reached $11.4 billion in Q2 2026, a record for the network. Tokenized assets on Stellar can represent bonds, money-market funds, gold, private credit, and digital dollars. The author describes this as real financial usage rather than a theoretical payments network.
The analysis says asset tokenization has become one of the industry’s major structural narratives. Stellar is positioning itself within that market, and the author links this trend to XLM upside potential.
Soroban and Institutional Interest Support the Thesis
Stellar also runs Soroban, its smart-contract platform. The analysis says Soroban lets the network host decentralized financial applications and institutional use cases.
The author says combining fast payments, stablecoins, tokenization, smart contracts, and compliance could broaden the valuation thesis.
The Stellar Development Foundation has pointed to institutional initiatives focused on tokenized financial markets. The ecosystem is expanding across stablecoins, money-market funds, tokenized bonds, private credit, and cross-border payments.
XRP still holds an institutional edge. Ripple has expanded its European operations and its payments infrastructure, while developing the XRPL ecosystem and RLUSD. The author says this makes the comparison with XLM interesting.
Scenarios and Risks Facing XLM Upside Potential
The analysis outlines three scenarios for the October 2026 to April 2027 window. Crypto markets are narrative-driven, the author says, so catalysts may converge and trigger a repricing. In a weak market, capital favors Bitcoin and Ethereum, and XRP could keep its advantage.
In a moderate recovery, growth in RWAs and stablecoins could let XLM outperform XRP. A strong bull phase could widen that gap because of XLM’s smaller starting valuation. The author calls the catch-up effect the most speculative factor.
The author notes that network growth does not guarantee price growth. A blockchain can host more assets without value flowing to its native token.
Metrics to watch include XLM demand, liquidity, stablecoin volumes, developer activity, and institutional adoption. Under these conditions, XLM upside potential depends on whether demand reaches the token itself.
The post XLM Upside Potential: Can Stellar Outperform XRP Over the Next 6 Months? appeared first on Blockonomi.
TLDR
- Google’s parent company Alphabet is on the verge of finalizing a nuclear energy contract with Constellation Energy valued at more than $1 billion.
- Bloomberg News reports the deal announcement could come within days.
- Shares of Constellation Energy (CEG) jumped 4% during premarket hours after news broke.
- Major technology companies like Amazon and Microsoft have already secured comparable nuclear energy contracts to meet AI-driven power needs.
- Alphabet has previously entered nuclear power partnerships with NextEra Energy and Southern Company.
Shares of Constellation Energy (CEG) surged 4% in Monday’s premarket session after Bloomberg News disclosed that Alphabet (GOOGL), Google’s parent corporation, is close to finalizing a substantial nuclear power contract with the energy provider. Sources familiar with the matter say the multi-year arrangement is valued at $1 billion or higher and may be unveiled before the week ends.
Alphabet Inc., GOOGL
Both Alphabet and Constellation Energy have remained silent about the potential partnership. Google failed to respond to comment requests made outside normal business hours, while Constellation explicitly refused to provide a statement.
Specific terms of the proposed arrangement remain undisclosed. The total power capacity covered by the contract and the source facilities for the energy have not been revealed.
Why Tech Companies Want Nuclear Power
Artificial intelligence infrastructure requires enormous quantities of electricity, and consumption continues to escalate. Nuclear facilities generate consistent power without producing direct carbon emissions, making them attractive options for corporations expanding massive computing operations.
Solar and wind installations depend on environmental conditions, but nuclear reactors operate continuously day and night. For server farms requiring uninterrupted electricity supply, this dependability is critically important.
Google is far from the only technology leader pursuing nuclear energy solutions. Multiple industry competitors have already secured comparable arrangements.
Amazon (AMZN) finalized an agreement with Constellation to purchase 690 megawatts of capacity. A portion of that electricity will originate from planned expansion work at Constellation’s Calvert Cliffs facility located in Maryland.
Microsoft (MSFT) executed a comparable transaction in 2024, committing to purchase power generated by Pennsylvania’s Three Mile Island facility. Constellation intends to bring that plant back online in the coming year.
Google’s Growing List of Nuclear Partnerships
A Constellation partnership would not represent Google’s inaugural nuclear energy commitment. The technology company collaborated with NextEra Energy (NEE) in the previous year to facilitate the reactivation of Iowa’s Duane Arnold nuclear facility.
Additionally, Google executed a contract with Southern Company (SO) just last month to finance upgrades at two of the utility’s nuclear installations. A finalized Constellation arrangement would represent another significant addition to the company’s expanding energy strategy.
Should the transaction proceed, Alphabet would secure additional dedicated electricity to support its artificial intelligence infrastructure. This objective has gained prominence as the corporation continues expanding its data center network.
Financial analysts maintain positive outlooks on Alphabet stock independent of this specific deal’s outcome. TipRanks data shows GOOGL holds a Strong Buy consensus recommendation, supported by 24 Buy ratings and four Hold ratings issued over the last three months.
The consensus analyst price target stands at $427.88, suggesting potential upside of approximately 24% from present trading levels. This optimistic perspective reflects analysts’ confidence in Alphabet’s overall business operations, extending beyond its energy procurement initiatives.
Constellation has successfully established power supply relationships with three of the technology sector’s most prominent corporations: Amazon, Microsoft, and potentially Google. While each agreement features unique characteristics, the underlying trend remains consistent. Major technology firms require substantially more electricity, and nuclear generation is increasingly becoming a preferred solution.
At present, the Google-Constellation partnership remains unverified by either organization. Bloomberg’s disclosure, attributed to individuals with knowledge of the negotiations, represents the sole information source available. An official public announcement may emerge in the coming days.
The post Google Parent Alphabet (GOOGL) Closing In on $1 Billion Nuclear Energy Agreement appeared first on Blockonomi.
TLDR
- Elon Musk reclaimed trillionaire status Monday as Tesla and SpaceX stock prices surged.
- His net worth increased by approximately $65 billion during a single market session.
- SpaceX stock advanced more than 7% amid reports of potential Taiwan Semiconductor Manufacturing Company partnership discussions.
- Tesla stock rose 2.2% following positive analyst assessments of European and Chinese delivery data.
- Musk’s current wealth exceeds Taiwan’s GDP and approaches the economic output of Poland and Switzerland, according to Forbes.
Elon Musk has reclaimed his position as the world’s only trillionaire. On Monday, his net worth reached approximately $1.04 trillion, as reported by the Bloomberg Billionaires Index, following substantial increases in both Tesla and SpaceX stock valuations.
Elon Musk is a trillionaire again.
The fortune of the world’s richest person jumped by $65 billion on Monday to $1.04 trillion, according to the Bloomberg Billionaires Index, as the value of his stakes in SpaceX and Tesla rose. https://t.co/GvDSsEAFnH
: Chip Somodevilla/Getty… pic.twitter.com/XuNeyQZ3zc
— Bloomberg (@business) October 6, 2026
The single-day rally boosted his personal fortune by approximately $65 billion. His wealth portfolio remains heavily concentrated, with over 98% derived from ownership stakes in these two companies.
Recent months have seen dramatic fluctuations in Musk’s net worth. Following SpaceX’s public market debut earlier this year, his wealth peaked near $1.3 trillion. However, investor concerns about the company’s aggressive expansion pace triggered a subsequent selloff.
His fortune dipped to roughly $957 billion by June 24—merely 12 days following the company’s stock market debut. This decline temporarily pushed him beneath the trillion-dollar threshold.
Catalysts Behind Monday’s Rally
SpaceX stock climbed more than 7% during Monday’s trading session. The advance came after Musk shared updates regarding potential strategic partnerships.
Space Exploration Technologies Corp., SPCX
Industry sources indicate SpaceX has entered discussions with Taiwan Semiconductor Manufacturing Company regarding construction of a dedicated manufacturing facility. The proposed plant would potentially produce specialized chips tailored for SpaceX applications.
Musk addressed the speculation on X, characterizing the negotiations as “just discussions, but something may come of it.”
Tesla stock advanced 2.2% during the same trading session. Market analysts attributed the gain to encouraging third-quarter delivery figures across key markets.
A Deutsche Bank analyst maintained a Buy recommendation on Tesla stock, projecting approximately 11% appreciation potential from present price levels.
The analyst highlighted Tesla’s strengthening September performance across European markets. Chinese sales also exceeded forecasts, bolstered by promotional cash incentives on existing inventory vehicles.
Deutsche Bank subsequently adjusted its third-quarter revenue projection for Tesla upward. The revised estimate stands at $27.7 billion, compared to the previous $27.2 billion forecast.
Musk’s Fortune Measured Against National Economies
Forbes currently values Musk’s net worth at $1 trillion. When benchmarked against national economic output using 2025 GDP data from the International Monetary Fund, this would position him at 23rd place globally.
His wealth sits marginally below Poland’s $1.04 trillion economy. Meanwhile, he surpasses Taiwan’s $920 billion GDP.
Switzerland’s economic output also measures $1.04 trillion. Additional wealth accumulation would position Musk near the economic scale of the Netherlands and Saudi Arabia.
Meta CEO Mark Zuckerberg holds second position on Forbes’ billionaire rankings. His net worth currently stands at $254 billion.
Tesla has scheduled its third-quarter 2026 earnings release for October 21. Market participants will scrutinize updates regarding electric vehicle sales momentum and autonomous driving technology development.
SpaceX stakeholders are anticipating the fifteenth Starship test flight, currently targeted for late October or early November. A sixteenth test flight is projected before the calendar year concludes.
SpaceX has provisionally scheduled its third-quarter earnings announcement for November 5. Analysts will assess whether the company maintains trajectory toward its $100 billion annual recurring revenue objective.
SpaceX faces upcoming stock lockup expiration dates on October 9 and October 26. A more substantial lockup period concludes December 8. These milestones could introduce additional share supply to the market.
Consensus Wall Street analyst ratings assign SpaceX a Strong Buy designation. Tesla currently carries a Moderate Buy rating according to recent analyst consensus surveys.
The post $65 Billion Added to Musk’s Wealth in Single Day on Strong Tesla, SpaceX Performance appeared first on Blockonomi.
HTTP error 429 on https://cryptopotato.com/feed/
Failed to fetch feed: https://cryptopotato.com/feed/
Failed to fetch feed.