Cryptocurrency Posts
Crypto Briefing
The in-kind restitution ruling may influence future crypto seizure policies, prioritizing asset return over liquidation, impacting victims' recovery.
The post US government moves 264 Bitcoin worth $23M to Coinbase in Bitfinex restitution appeared first on Crypto Briefing.
Founders Fund's investment in Anvil highlights the growing integration of traditional finance with DeFi, impacting governance and risk dynamics.
The post Founders Fund leads $5 million token purchase in Anvil protocol appeared first on Crypto Briefing.
Starknet's upgrade enhances scalability and efficiency, potentially boosting developer adoption and impacting STRK token dynamics in the ecosystem.
The post Starknet v0.14.4 goes live on mainnet with bigger proofs and gas tweaks appeared first on Crypto Briefing.
The lawsuit highlights potential counterparty risks in stablecoin transactions, raising concerns about asset control and legal recourse.
The post Conduit sues Tether over $2.76 million in frozen USDT appeared first on Crypto Briefing.
Nvidia approached a $6 trillion market cap after hitting a record high, extending its 2026 rally as tokenized NVDA products expand across crypto markets.
The post Nvidia approaches $6 trillion market cap as stock hits record high appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
BlackRock Says AI Agents Could Be the Next Big Driver of Crypto Demand
Artificial intelligence and digital assets are beginning to converge, with AI models showing a preference for bitcoin and stablecoins, according to research cited by BlackRock .
In a new report, the $15 trillion Wall Street giant said that card networks and automated clearing houses involve human-driven onboarding, fees that make tiny payments uneconomic and slower settlement and finality.
The report, “The Machine-Native Economy”, is a bet that the next big source of crypto demand won’t be human investors but software. As AI agents begin booking travel, buying data and renting computing power on their own, BlackRock argues, they will need payment systems that run around the clock and can handle transactions worth fractions of a cent.
NEW: $15 trillion BlackRock says AI agents may choose to save in #Bitcoin for "long-term value preservation"
— Bitcoin Magazine (@BitcoinMagazine) October 6, 2026
"These findings … point to a potential AI-native monetary architecture in which stablecoins serve as transactional money and bitcoin as a store of value."pic.twitter.com/utJHYuTkGJ

“As AI agents become more capable and as their real-world applications expand, they increasingly demand payment and asset infrastructure designed natively for machine-speed commerce,” the report read.
“Crypto-native blockchain rails are particularly well suited to high-frequency, sub-cent, machine-to-machine transactions that take place around-the-clock, including API calls, on-demand data, and consumption based compute.”
It added that the Bitcoin Policy Institute research found that “controlled simulations generally favored stablecoins for everyday payments and bitcoin for long-term value preservation.”
“As AI adoption broadens and agentic systems become more capable, digital
assets could become increasingly integral to AI’s economic infrastructure, expanding utility across stablecoins, tokenized RWAs, and native cryptoassets that support blockchain settlement,” the report noted.
BlackRock has long praised Bitcoin and other crypto apps that utilize its technology, like the tokenization of assets.
The Securities and Exchange Commission in 2024 approved BlackRock’s iShares Bitcoin Trust,
which has since attracted the most investment and trading volume out of all U.S. bitcoin ETFs. The fund had the most successful debut in the history of ETFs and now manages over $67 billion in assets.
BlackRock has previously said that Bitcoin is in an asset class of its own, and that investors are buying it to hedge against any potential debt crises.
This post BlackRock Says AI Agents Could Be the Next Big Driver of Crypto Demand first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Treasury Drops Crypto Surveillance Proposals
The Treasury Department is scrapping two long-stalled crypto surveillance proposals, handing a major win to privacy advocates and the digital asset industry.
The Financial Crimes Enforcement Network filed notices Monday withdrawing its 2020 “unhosted wallet” rule and a 2023 plan to brand international crypto mixing a “class of transactions of primary money laundering concern.” Both notices are set to appear in the Federal Register on Tuesday.
In a Monday statement, the Washington crypto policy group Coin Center said the news was “a significant victory for financial privacy.”
“The definition of mixing was extraordinarily broad, sweeping in common techniques used by ordinary cryptocurrency users to preserve their privacy,” Coin Center said.
“And because FinCEN acknowledged the difficulty of determining where a mixing transaction occurred, we argued that risk-averse financial institutions would inevitably report even purely domestic transactions, with potentially severe collateral consequences for innocent users, including account restrictions or closures.”
The wallet rule would have required banks and other financial institutions to report certain crypto transactions above $3,000 and $10,000 when customers held the assets in unhosted wallets.
The mixing proposal cast an even wider net. It defined mixing as anything that obscured the source, destination or amount of a crypto transaction, sweeping in pooled funds, split transfers, single-use wallets and even swaps between assets. FinCEN said commenters warned the definition “could have a chilling effect on legitimate activity” and would bury institutions in paperwork.
Institutions would have had to hand over wallet addresses, transaction hashes, IP addresses and customer identity details.
The reversal also tracks White House policy. A July 2025 report from the President’s Working Group on Digital Asset Markets said “the Trump Administration supports the ability of lawful users of digital assets to privately transact on a public blockchain,” and urged the Treasury to reconsider the rule.
The report acknowledged that criminals use mixers to launder funds but noted that lawful users rely on them for financial privacy.
FinCEN isn’t giving mixers a free pass. The agency said illicit actors “continue to use mixers and other tools and methods to hinder law enforcement investigations.”
It added that it will keep watching for money laundering and terrorist financing and may act in the future.
This post Treasury Drops Crypto Surveillance Proposals first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Ecash Ecosystem Rises to Challenge in the Defense of Decentralized Custody
BTC++, Berlin, and breakthroughs in advancing Bitcoin custody
A few weeks ago, I argued that the Bitcoin ecosystem kept asking the wrong question, tending to frame everything as “trusted” or “trustless.” Instead, I urged people to ask “How many independent things have to go wrong before you lose your money?”
This is a guest post by Obi Nwosu, Co-Founder of Fedi and Fedimint. Opinions expressed are entirely their own and do not necessarily reflect those of BTC Inc. or Bitcoin Magazine.
Look at Liquid or, weeks before that, Coldcard. Matt Corallo expressed the issue in the most succinct terms: run the same software, suffer the same bugs.
That critique applied to Fedimint, too, and I’m the first to say it. We built it to remove single people and single institutions as points of failure. But there was just one implementation of the protocol — a software monoculture below federations of humans. Not secure enough.
And so I’m happy to say that Fedimint developers have already responded.
At Ecash Hackday in Berlin, the Fedimint team got a single federation running across three independent implementations, with Cashu’s thesimplekid building one of them.
Had a great time at Ecash Hackday in Berlin, got a Fedimint running with 3 different implementations by @thesimplekid, me and the Fedimint team!
— elsirion
Already got 3 Fedimint implementations now, who will build the 4th one?https://t.co/TnttZYOBKR pic.twitter.com/2MPdtlaJqt
(@EricSirion) September 30, 2026

Three separate codebases, one federation, holding funds together. Developers have begun to create a solution to the monoculture I called out a few weeks ago. And the team’s response was to ask who builds the fourth, which is exactly the spirit I was hoping for.
Calle took the same principle and ran with it in his own direction. At bitcoin++ he unveiled Federated Cashu, which is designed in a way that no single operator stands alone behind a user’s funds. Any four or five keep the federation going, on a new blind signature scheme.
. @callebtc unveils “Federated Cashu” at @btcplusplus
— Matthew Vuk
“You don’t need to trust the operator with your privacy, but you do need to trust the operator with your security”
“Any combination of 4/5 continues the federation”
A new Blind BLS signature scheme is involved. pic.twitter.com/S8iL9Qaa9u(@matthewvuk2) October 1, 2026
Two teams. Two approaches. One shared goal: ecosystem resilience, advanced within weeks.
Fault tolerance does not come from trustworthiness alone, however good your audits, formal verifications, and your security culture are. It comes from independent failure domains. No single bug, no single vendor, no single jurisdiction able to take everything at once.
I’ll be clear about the layers, because the distinction matters. Fedimint is the open-source protocol. Fedi is what we build on top of it. When the protocol grows a second and a third implementation, every federation gets more resilient and no member has to change a thing about how they use their wallet. Guardians can run different software while serving the same people.
I laid out five layers where independence has to hold, and I’ll hold myself to them:
- Multiple implementations of every protocol that holds funds.
- Multiple wallet implementations.
- Keys generated on hardware from different vendors.
- Multiple independent, trustworthy people, whose privacy is protected, behind every system that holds money.
- Distribution across geographies and jurisdictions, because a jurisdiction’s rules can change overnight.
The developers who worked on this in Berlin moved those five closer to reality.
Thank you to everyone who continues to focus on building and sharing their proof-of-work. And to the rest of us, myself included: we are not done. Our ecosystem needs to start demanding independence at every layer. Software, hardware, humans, jurisdictions — all the way down.
That is how we maintain users’ confidence in Bitcoin as we enter this new age of AI-assisted threats to our ecosystem.
This post Ecash Ecosystem Rises to Challenge in the Defense of Decentralized Custody first appeared on Bitcoin Magazine and is written by Obi Nwosu.
Bitcoin Magazine
Now Accepting Bitcoin: Buy Coffee and Bacon Across 200 Indiana Bitcoin Merchants
Table of Contents
My trip into the Indiana Bitcoin market started at Kaffeine Coffee Co. on Fulton Street. The coffee was tasty, but my real surprise was running into a local Bitcoiner who was also paying for his order in satoshis, making me feel like not such a rare breed in this fiat world.
The friend I made shared about a network of Indiana merchants the Indianapolis local Indy Bitcoin Group has been orange pilling.
First Up: Old Major Market LLC (Artisan Meats)
A common complaint of merchant Bitcoin adoption is that the shop owners will liquidate 100% of their Bitcoin back into cash using payment processors like Square. This is true to start, but a fascinating shift occurs once a business owner reads about bitcoin. Old Major LLC, an artisan meat distributor based in Indianapolis, is a prime example of that shift.
The Big Update for Indiana Bitcoin
According to owner Mark LaFay, Starting in 2026, Old Major Market made a major strategic decision: they are keeping 100% of the Bitcoin they receive directly on their balance sheet. They realized that holding bitcoin opens up significant long-term upside.
Big shout out to the Bitcoiners in Central Indiana that have been stopping by Old Major for over a year to buy bacon, sausages, and specialty meats with sats. While the shop originally agreed to accept Bitcoin and instantly converted every transaction to cash, the steady stream of Bitcoin payments caught their attention.
The “1% Orange Pill” Math
When a dedicated community directs its routine spending toward supportive merchants, the business case for the owner becomes undeniable:
- The Baseline: A local merchant generating $1 Million in annual revenue with a 10% profit margin brings home $100,000 in net profit.
- The 1% New Customer Shift: If local Bitcoiners represent just 1% of total sales, that’s $10,000 in annual Bitcoin transactions. If the owner sells the coins, regret creeps in, “what if I held the coins?”…
- The BTC Holding Strategy: Let’s assume the store instead decides to hold that Bitcoin in 2026, and BTC doubles in value this year. Holding the coins increases the owner’s total annual profit +20% to $120,000.
That financial reality is the ultimate orange pill. A focused group of customers directing their commerce toward open-minded owners can move the needle for merchant adoption, whether the owner holds from day one or learns along the way that they are missing profit.
Notable Mentions: Local Indy Staples: Coffee & Wine
- Kaffeine Coffee Co. (Downtown Indy): Third Wave craft coffee meets native Bitcoin rails. Meeting fellow Bitcoiners at the counter proves how coffee hubs act as the natural gateway for real-world community building.
- The Rejoicing Vine (Northwest Indy): A mission-driven winery specializing in sparkling wines that doubles as the host spot for local “Lightning Socials”. Owner Brent Kumfer agreed to accept Bitcoin over a year ago through Square, enjoying zero processing fees and a steady stream of local Bitcoiner events. They are not yet holding bitcoin, but they are considering it.
Have a Story or a Local Merchant Network to Feature?
As always, a growing directory of verified Bitcoin-accepting merchants is listed below. If you want your business added to the map, or if you have a new city and story to feature in an upcoming column, write directly to vagabond@b.tc to be included in “NOW ACCEPTING BITCOIN“.
APPENDIX – 200 Indiana Stores Accepting Bitcoin (Source: BTC Map)
Arts & Entertainment
- LangLab (Arts Centre) — 1302 High St, South Bend
- AMC Castleton Square 14 (Cinema) — 6020 E 82nd St, Indianapolis
- AMC Washington Square 12 (Cinema) — 10280 E Washington St, Indianapolis
- AMC CLASSIC Bloomington 12 (Cinema) — 2929 W 3rd St, Bloomington
- AMC Perry Crossing 18 (Cinema) — 380 Cinema Blvd, Plainfield
- AMC Showplace Traders Point 12 (Cinema) — 5920 W 86th St, Indianapolis
- AMC Indianapolis 17 (Cinema) — 4325 S Meridian St, Indianapolis
- AMC CLASSIC Crawfordsville 8 (Cinema) — 205 Dry Branch Rd, Crawfordsville
- Fort Wayne Improv (Theatre) — 1314 E State Blvd, Fort Wayne
- Pine Acres Miniature Farm (Zoo) — 6801 Union Chapel Rd SE, Corydon
Automotive & Repair
- 317 Auto Service — 499 Wall St, Greenwood
- Hobbs Automotive Diagnostics & Repair — 3594 SR 9, Anderson
- McIntire Auto Repair — 1927 S Curry Pike, Bloomington
- Salvadors Collision — 30841 Old US 33, Elkhart
- 2nd Chance Towing & Repair — 2252 Straight Line Pike, Richmond
- Bulls Tire Shop — 2233 E Washington St, Indianapolis
- Direct Tire — 1506 N Post Rd, Indianapolis
Bars, Breweries & Wineries
- Westfield Wine Vault — 100 N Union St, Westfield
- Mad Hyena Bar and Grill — 1538 Indiana Ave, New Castle
- Fish Moon Brewing Company — 309 N Main St, Rushville
- The Health Club Taproom & Cafe — 6420 Cornell Ave, Indianapolis
- Books & Brews — 9402 Uptown Dr, Indianapolis
- Tollys Bar and Grill — 2341 Maple Ave, Terre Haute
- Easley Winery — 205 N College Ave, Indianapolis
- The Rejoicing Vine — 8440 W 82nd St, Indianapolis
Beauty, Hair & Wellness
- Apothecary Salon & Spa — 2050 Burton Ln, Martinsville
- Allure Salon — 100 S 1st St, Zionsville
- Angel Barber Studio — 1990 Conner St, Noblesville
- B Beauty — 11717 E Washington St, Indianapolis
- Brow Ink — 5250 E US Hwy 36, Avon
- Bryans Barbershop — 224 N 12th St, Decatur
- Cutting Loose Salon — 3815 S Main St, Elkhart
- Exotic Nails — 1617 E Michigan Rd, Shelbyville
- Harmony Day Spa — 7654 N Bleck Rd, Trail Creek
- Indulge Beauty Salon — 3521 Lake Ave, Fort Wayne
- Lee’s Barber Lounge — 409 W Taylor St, Kokomo
- Lux Esthetics Lab — 1251 US-31 N, Greenwood
- Luxury Spa & Nails — 217 S Green River Rd, Evansville
- Marengo Barber Shop — 109 Main St, Marengo
- Mdg Salon — E 116th St, Carmel
- Midou Studio — 9935 E 42nd St, Indianapolis
- Modern Barbershop and Salon — 1641 N Lebanon St, Lebanon
- Naturally You — 6101 N Rural St, Indianapolis
- Sarah L Studio — 6251 Winthrop Ave, Indianapolis
- The Station Hair Parlor — 200 Byrd Way, Greenwood
- Wax that Cat — 3009 25th St & 3042 State St, Columbus
- Indy Holistic Massage — 1133 W Main St, Greenfield
- Sacred Roots Custom Massage — 26 W Broadway St, Shelbyville
Cafes, Bakeries & Desserts
- Gramz Bakey and Cafe — 409 Washington St, Columbus
- Kaffeine Coffee — 707 Fulton St, Indianapolis
- Moar Tea — 448 Massachusetts Ave, Indianapolis
- Seoul Fresh — 49 W Maryland St, Indianapolis
- The Beach Hut — 100 W Moss Pkwy, Michigan City
- The Java Bean Cafe — 151 N 2nd St, Decatur
- Cosmic Cardinal Cafe — 101 W Ohio St, Indianapolis
- Capstone Cafe & Bookstore — 6620 Northview Way, Indianapolis
- Rocky Mountain Cafe — 209 Lincolnway, La Porte
- Wildflour Bakehouse — 1012 E County Rd 750 S, Nineveh
- Brown’s Shuga Shack — 6099 State Rd 16, Monticello
- Heartland Homemade Ice Cream — 4911 S Emerson Ave, Indianapolis
- Sugar + Ice — 103 S Randolph St, Garrett
- Sugarfield Creamery — 1051 E Tabor St, Indianapolis
Contractors, Repair & Home Services
- 33 Electric — 7939 Dix Rd, Indianapolis
- AR Engineering (HVAC) — 3002 W Western Ave, South Bend
- Bravo Carpentry — 305 Railroad Ave, Wheeler
- DEG Electronic Repair Services — 3712 N Mitthoeffer Rd & 2818 Westlane Rd, Indianapolis
- Energy Efficient Replacements / 574-Sunroom — 51285 Bittersweet Rd, Granger
- KM Electronics — 8238 Madison Ave, Indianapolis
- NGR Electric — 4320 Calhoun St, Gary
- Roman Tech Computer Repair — 3611 E US Hwy 12, Michigan City
- TechBar — 4121 Cleveland St, Gary
Groceries, Specialty Foods & Farms
- Old Major (Butcher) — 4201 Millersville Rd, Indianapolis
- The Wurst (Butcher) — 130 N Broad St, Griffith
- For You Brewing Supplies — 503 Honey Creek Dr, Terre Haute
- Hidden Acres (Farm) — 10645 W 425 S, Wilkinson
- K&B Liberty Farms — 2254 Nature Ln SE, Corydon
- Binford Farmers Market — 6620 Northview Way, Indianapolis
Professional & Financial Services
- D M Property Management — 6446 Ralston Ave, Indianapolis
- Dennis Hartley & Son Monuments — 89 E Walnut St, Martinsville
- Great Lakes EV Charging — 51285 Bittersweet Rd, Granger
- Inguard Insurance — 231 W Canal St, Wabash
- Olive Tree Resources (NGO) — 110 E Market St, New Albany
- Overhauser Law Offices — 101 W Ohio St, Indianapolis & 18 E Main St, Greenfield
Restaurants, Fast Food & Delis
- Amorè Fine Italian Ristorante — 730 Highlander Point Dr, Floyds Knobs
- Food King Chinese Restaurant — 1472 E 86th St, Indianapolis
- Full Circle Grill & BBQ — 110 W Berry St, Fort Wayne
- George’s Gyros Spot #2 — 1201 W 37th Ave, Hobart
- Grateful Grubs BBQ — 5654 IN-10, DeMotte
- Guadalupe’s Mexican Grill — 2031 South Bend Ave, South Bend
- Lonestar Bar B Que — 905 N Park Dr, Evansville
- Major Munch — 101 NW 1st St, Evansville
- Oscar’s Pizza — 515 N Buckeye St, Kokomo
- Panini Panini — 1720 Franklin St, Michigan City
- Rusted Silo Southern BBQ — 411 N State St, Lizton
- Social Que BBQ and Catering — 1701 Franklin St, Michigan City
- The Lincoln Kitchen — 704 Silhavy Rd, Valparaiso
- The Owlery Restaurant — 118 W 6th St, Bloomington
- Tlaolli — 2830 E Washington St, Indianapolis
- Tsunami Sushi & Korean Wings — 700 Sagamore Pkwy N, Lafayette
- Turkuaz Cafe — 301 E 3rd St, Bloomington
- Union Jack Pub — 921 Broad Ripple Ave, Indianapolis
- Uptown Cafe — 102 E Kirkwood Ave, Bloomington
- Griller’s Restaurant — 1240 119th St, Whiting
- Oh Mamma’s On The Avenue Deli — 1202 Mishawaka Ave, South Bend
- OyVey! Bakery & Deli — 901 Lafayette Ave, Terre Haute
- Cracklin Shack — 5058 S 800 W, Swayzee
- Hoosier Spice & BBQ Company — 11622 NE Executive Dr, Edinburgh
- Las Cubanitas — 53 Valparaiso St, Valparaiso
- Los Dos Amigos by Awiwi — 202 Carrie Ln, Columbus
- Steak ‘n Shake — 30+ locations statewide (Avon, Indianapolis, Fort Wayne, Lafayette, Bloomington, Elkhart, South Bend, Terre Haute, Greenwood, Valparaiso, Columbus, Clarksville, Seymour, Merrillville, Schererville, Muncie, Bedford, Lawrenceburg, Franklin, etc.)
- Steve’s Una Pizza — 1005 S Saint James Blvd, Evansville
- Union Jack Pub Food Truck — 924 Broad Ripple Ave, Indianapolis
Retail, Apparel, Hobbies & Specialty Shops
- Above ALL Bowling Supply — Valparaiso & Hobart
- Blossom Floral Design — 615 N Michigan St, South Bend
- Geeked Out Games — 10830 Bennett Pkwy, Zionsville / Fishers
- Its Not Corn (Apparel) — 120 N Miller Ave, Marion
- Jayla’s Gifts, Plants, Flowers — 207 E Market St, Nappanee
- Jewelry Gallery — 17425 Carey Rd, Westfield
- Lake Effect Florals — 278 E 1500 N, Chesterton
- Mr. Kay’s Fashionable Shoes — 2218 Southlake Mall, Merrillville
- Nature’s Mercantile — 122 N Main St, Auburn
- Nick Nackery — 201 E Virginia St, Evansville
- Old-School Outpost (Games) — 3825 S East St, Indianapolis
- Prideland Comics & Collectibles — 5668 Crawfordsville Rd, Speedway
- Rock Bottom Resale — 11186 County Rd 34, Goshen
- Rock Daddy (Esoteric) — 418 E McGalliard Rd, Muncie
- Sewer Lair Toys — 3197 S 3rd Pl, Terre Haute
- Smoke Xpress (Tobacco) — Michigan City & Elkhart
- Svpplements — 316 W Cleveland Rd, Granger
- The Co Op Shop (Video Games) — 3540 State Rd 38 E, Lafayette
- Unique Creations by Joe — 1148 S 17th St, Kokomo
- Versed Skateboard Shop — 1006 Virginia Ave, Indianapolis
- War Room Tabletop Gaming — 10830 Bennett Pkwy, Zionsville
- 710 Lounge (Cannabis) — 3673 W 86th St, Indianapolis
- A Pooch Palace (Pet Grooming) — 3839 S Lafountain St, Kokomo
- First & Wilkerson Designs / Farmkidz Apparel — Fort Wayne & Lebanon
Second-Hand & Thrift Stores
- DTF Sales — 51 N Main St, Cloverdale
- Millie’s Thrift Store — Lafayette (2 locations) & West Lafayette
- MoJo’s Thrift-N-Collectibles Store — 527 Cass St, Wabash
- Mood — 248 Spring St, Jeffersonville
Tattoo & Piercing Studios
- A1 Art Tattoos — 4606 E Michigan St, Indianapolis
- Altered Image — 10030 E US Hwy 36, Avon
- Big Time Tattoos and Piercings — 5353 Madison Ave, Indianapolis
- Crown Point Tattoo — 114 W Hack Ct, Crown Point
- Evolution Tattoo — 2901 Mitchell Rd, Bedford
- La Familia Tattoo — 529 W Chicago Ave, East Chicago
- Resurrection Studios Tattoos & Piercing — 2200 Elmwood Ave, Lafayette
- Tracy Scott at Bankai Tattoo Collective — 421 7th St, Columbus
This post Now Accepting Bitcoin: Buy Coffee and Bacon Across 200 Indiana Bitcoin Merchants first appeared on Bitcoin Magazine and is written by Vagabond.
Bitcoin Magazine
Bringin Opens Euro Business Accounts for Bitcoin Companies Across 30 European Countries
Bringin today opened an invite-only beta of euro business accounts that let companies hold, accept, and pay in Bitcoin and stablecoins, and run SEPA payments from a vIBAN in the company’s own name. The launch builds on Bringin’s consumer platform, which has processed more than €15 million according to a press release shared with Bitcoin Magazine.
More European businesses want what Bitcoin and stablecoins offer: instant settlement, global reach and lower costs. Buying Bitcoin in Europe is easy enough; the challenge is running a company on Bitcoin and stablecoin rails. Many Europeans face bank account restrictions and blocked transfers when they operate with Bitcoin or other virtual assets. Every conversion to euros adds friction, records sit across disconnected tools, and the Travel Rule requirements turn simple payments into paperwork. As a result, Bitcoin’s potential as money gets tangled up in bureaucracy.
Bringin for Business seeks to bridge Bitcoin and banking. According to the press release, companies can add Bitcoin to their treasury, accept Bitcoin, Lightning, or stablecoin payments, and pay suppliers and payroll in Bitcoin. Euro accounts and the company’s Bitcoin wallet sit in one place, with the governance and security a business needs. A dedicated virtual IBAN, a euro account number in the company’s own name, connects it to SEPA payments, with additional global payment rails planned.
Keys are generated and stored in a hardware security module rather than omnibus exchange wallets. Only designated company owners can move funds, make payments, and add approval policies, according to the press release.
Separately, Bringin plans APIs and MCP servers so companies can work with AI agents. With support for Lightning and stablecoins, companies can accept payments from artificial intelligence bots, building on Bringin’s 2025 demonstration of agent payments over the Lightning Network.
“Bitcoin is the first money native to the internet, and Lightning makes it fast enough for everyday commerce. I’ve seen that potential since I started building on it in 2018,” said Prashanth Chandrashekar, founder and CEO of Bringin. “We proved it with consumers first. Now companies can use Bringin to get paid, hold value and move money globally, with accounts designed around self-custody and a seamless payment experience.”
Built on the MiCA-authorized infrastructure of Lightspark Payments Europe AS, Bringin for Business is currently in pilot with 15 businesses, including Lightning payment tools, mining-rig sellers, and Bitcoin conferences, handling cross-border payments and instant Bitcoin-to-euro conversions. It is available to companies across 30 European countries.
This post Bringin Opens Euro Business Accounts for Bitcoin Companies Across 30 European Countries first appeared on Bitcoin Magazine and is written by Juan Galt.
CryptoSlate
Federal prosecutors are using a new Bitcoin Fog appeal to defend trying two counts against Roman Storm in New York. Their Oct. 5 letter asks Judge Katherine Polk Failla to reject his venue challenge on the money-laundering and money-transmission conspiracy counts. Storm co-founded Tornado Cash, a cryptocurrency mixer that obscures transaction trails.
The filing arrived as Treasury moved to withdraw a broad mixer-reporting proposal. The continuing case turns on prosecutors' allegation that Storm knowingly participated in criminal activity, while the policy changes recognize lawful privacy and limit particular charging decisions. Whether his software work crossed that criminal boundary remains disputed.
Storm, posting as @rstormsf, described potential imprisonment as punishment “for writing code” and contrasted the case with Treasury's retreat. His criticism captures the stakes for privacy developers, but the latest filing concerns where the case can be tried.
Storm already has an August 2025 conviction on one money-transmission conspiracy count carrying a statutory maximum of five years. An Aug. 25, 2026 court order scheduled his retrial for April 26, 2027, citing his pending acquittal motion and requested continuance.
Southern District of New York prosecutors rely on the D.C. Circuit's Sept. 25 decision in United States v. Sterlingov, involving Bitcoin Fog, a different cryptocurrency mixer. Prosecutors cite its venue holdings as persuasive authority for Storm's pending challenge.
Their argument centers on a Manhattan customer, Shakeeb Ahmed. They say his deposits helped enlarge the anonymity pool, making funds harder to trace, even though the money remained there only briefly. They also argue that serving a customer in the district supports venue for the money-transmission count.
Why the crypto policy shift has not ended the case
Treasury's Financial Crimes Enforcement Network is withdrawing its 2023 finding and proposed enhanced reporting and recordkeeping measure for international cryptocurrency mixing. The withdrawal notice, filed Oct. 5 for Oct. 6 publication, cites concerns about a “chilling effect on legitimate activity” and burdens on financial institutions.
FinCEN recognizes lawful financial privacy while retaining monitoring for money laundering, terrorist financing and other illicit activity. The withdrawal addresses an administrative reporting proposal. It does not repeal criminal offenses or decide Storm's case.
DOJ's own shift contains a similar boundary. Deputy Attorney General Todd Blanche's April 7, 2025 memo directed prosecutors away from targeting mixers for their users' conduct or unwitting regulatory violations and called for review of ongoing cases.
But the memo expressly excludes section 1960(b)(1)(C), concerning funds known to come from crime or intended for unlawful activity, from its regulatory charging restriction.
In August 2025 remarks, DOJ official Matthew Galeotti added protection against new charges under that provision for qualifying software: it must be truly decentralized, solely automate peer-to-peer transactions, and leave the third party without custody and control over user assets. Other charges could remain appropriate where criminal intent exists.
That conditional promise about new charges did not set aside Storm's existing conviction.
DOJ described Storm's conduct as building, maintaining and profiting from a service despite knowing it transmitted criminal proceeds. Storm contests criminal treatment of his developer activity.
The April 9, 2026 hearing exposes the breadth of the government's theory. Prosecutor Ben Arad argued that legitimate deposits helped conceal criminal funds, supporting his case against the developers. He expressly distinguished innocent depositors' knowledge and perspective from that of Storm and his alleged coconspirators.
The dispute therefore centers on the developers' responsibility for running and improving a service used by criminals.
Failla challenged whether the broader theory established willful conduct. Arad later emphasized active steps to maintain and improve the service, rather than merely leaving its pools operational. The judge scrutinized the government's theory.
Why Ulbricht's pardon is different
The comparison with Ross Ulbricht raises a separate question of individual clemency. Trump's Jan. 21, 2025 pardon granted individual clemency to Ross Ulbricht for specified convictions. It did not extend to Storm or establish a general exemption for crypto developers.
The next consequential developments are judicial decisions on the challenges and any changes to that schedule. Washington's support for lawful crypto privacy has not itself settled the contested criminal case.
The post DOJ presses Tornado Cash prosecution as Treasury drops mixer reporting plan appeared first on CryptoSlate.
OKX brought Circle, Ripple and Standard Chartered’s venture arm onto its cap table as the crypto exchange broadens its push into stablecoin-based financial services.
On Oct. 6, the exchange's Chief Executive Officer, Star Xu, confirmed that the company completed a strategic investment from Circle, Qube Research & Technologies, Ripple and SC Ventures by Standard Chartered at a $25 billion pre-money valuation, extending a March round led by Intercontinental Exchange, the owner of the New York Stock Exchange. OKX did not disclose how much it raised in the latest transaction.
The valuation was unchanged from March, when ICE invested about $200 million. The new round instead adds shareholders whose businesses overlap with OKX’s expansion into stablecoins, payments, institutional liquidity and tokenized assets.
Xu said the exchange chose the new investors for their strategic fit rather than because it needed additional financing, pointing to its longer-term ambitions across payments and financial infrastructure.
He stated:
“We didn’t raise capital because we needed it. We chose to bring in strategic partners who share our long-term vision for stablecoins, payments, institutional markets, and the next generation of financial infrastructure.”
Stablecoin firms move onto OKX’s cap table
The investor lineup gives OKX closer ties to companies already supplying infrastructure across its platform.
Circle issues USDC, which is integrated across OKX. Ripple’s RLUSD stablecoin is available through the exchange’s unified order book, while QRT is a major institutional counterparty that provides liquidity and risk capacity. Standard Chartered, meanwhile, acts as custodian for BlackRock’s BUIDL tokenized Treasury fund used in an institutional collateral framework developed with OKX.
Those relationships make the fundraising more than a conventional capital injection. Ripple said the investment could deepen cooperation with OKX across stablecoins, payments and institutional markets, while Circle CEO Jeremy Allaire described the transaction as an extension of the companies’ existing relationship around USDC and onchain market infrastructure.
QRT’s participation adds an institutional trading component. The quantitative investment manager already works with OKX on liquidity and new markets, while SC Ventures gives the exchange another link to a global bank as crypto companies compete to bring traditional financial assets and payment flows onto blockchain networks.
The composition of the round also helps explain why OKX accepted new investors without securing a higher valuation seven months after ICE bought in. The company is effectively adding partners positioned across several layers of the financial stack it wants to build, from stablecoin issuance and custody to liquidity and payments.
OKX Money targets users beyond crypto trading
That expansion moved into consumer payments on Tuesday with the launch of OKX Money, a standalone app designed to let customers save, send and spend dollar-backed stablecoins.
According to OKX, users in participating markets can fund accounts using more than 50 supported currencies and hold USDG, USDC or USDT.
The app combines stablecoin balances with global transfers and virtual or physical cards, while OKX says it charges no foreign-exchange fee or conversion markup when customers make purchases in another currency.
Eligible customers can also earn up to 10% annually on qualifying USDG balances without staking or lockups, while a loyalty program offers up to 10% cashback on eligible card purchases. Availability, rates and features vary by market and customer eligibility.
The target market extends well beyond existing exchange users. OKX said roughly 70% of the people it wants to reach through Money have never used a crypto application, prompting the company to keep the underlying blockchain infrastructure largely out of the user experience.
That puts OKX into a different competitive arena from the exchange business that built its global customer base. Stablecoin providers, crypto platforms and fintech companies are increasingly competing for consumers who want dollar exposure, cross-border transfers and card payments without necessarily wanting to trade digital assets.
OKX is initially focusing on participating markets where currency volatility, banking access and foreign-exchange costs can make holding or spending dollars difficult. The company said it will expand gradually rather than make the service immediately available across all of the more than 30 jurisdictions where it operates under regulatory frameworks.
The commercial test will be whether OKX can turn an infrastructure advantage and a large crypto customer network into everyday financial activity. Winning users who have never touched crypto requires different distribution, compliance and customer-support capabilities from running a trading venue.
That challenge also raises the stakes for the new investors. Circle and Ripple want broader stablecoin distribution, QRT benefits from deeper institutional markets, and Standard Chartered has been expanding its exposure to digital-asset infrastructure. OKX now has to show those relationships can generate payment volumes and customer adoption beyond the trading activity that built the exchange.
The post Ripple and Circle backs OKX as it targets the next wave of stablecoin users appeared first on CryptoSlate.
Ethereum’s institutional demand is weakening around the same time derivatives positioning shows traders are selling aggressively without yet breaking the broader price structure.
US spot ETH exchange-traded funds recorded $50.76 million of net outflows on Oct. 5, extending their losing streak to five consecutive sessions, according to SoSoValue data. The products have shed $205.88 million since Sept. 29, reducing cumulative net inflows to about $13.75 billion.
The streak followed a $17.1 million inflow on Sept. 28 and has coincided with ETH trading near $2,711, leaving one of the market’s major sources of incremental demand in retreat.
Yet the pressure has not spread uniformly across Ethereum’s investor base.
Blockchain analytics firm Santiment said Ethereum’s Age Consumed metric surged to 580 million token-days on Sept. 30, roughly nine times its September weekday average and the highest reading since June 2. The indicator tracks previously dormant coins moving onchain, weighted by how long they had remained untouched.
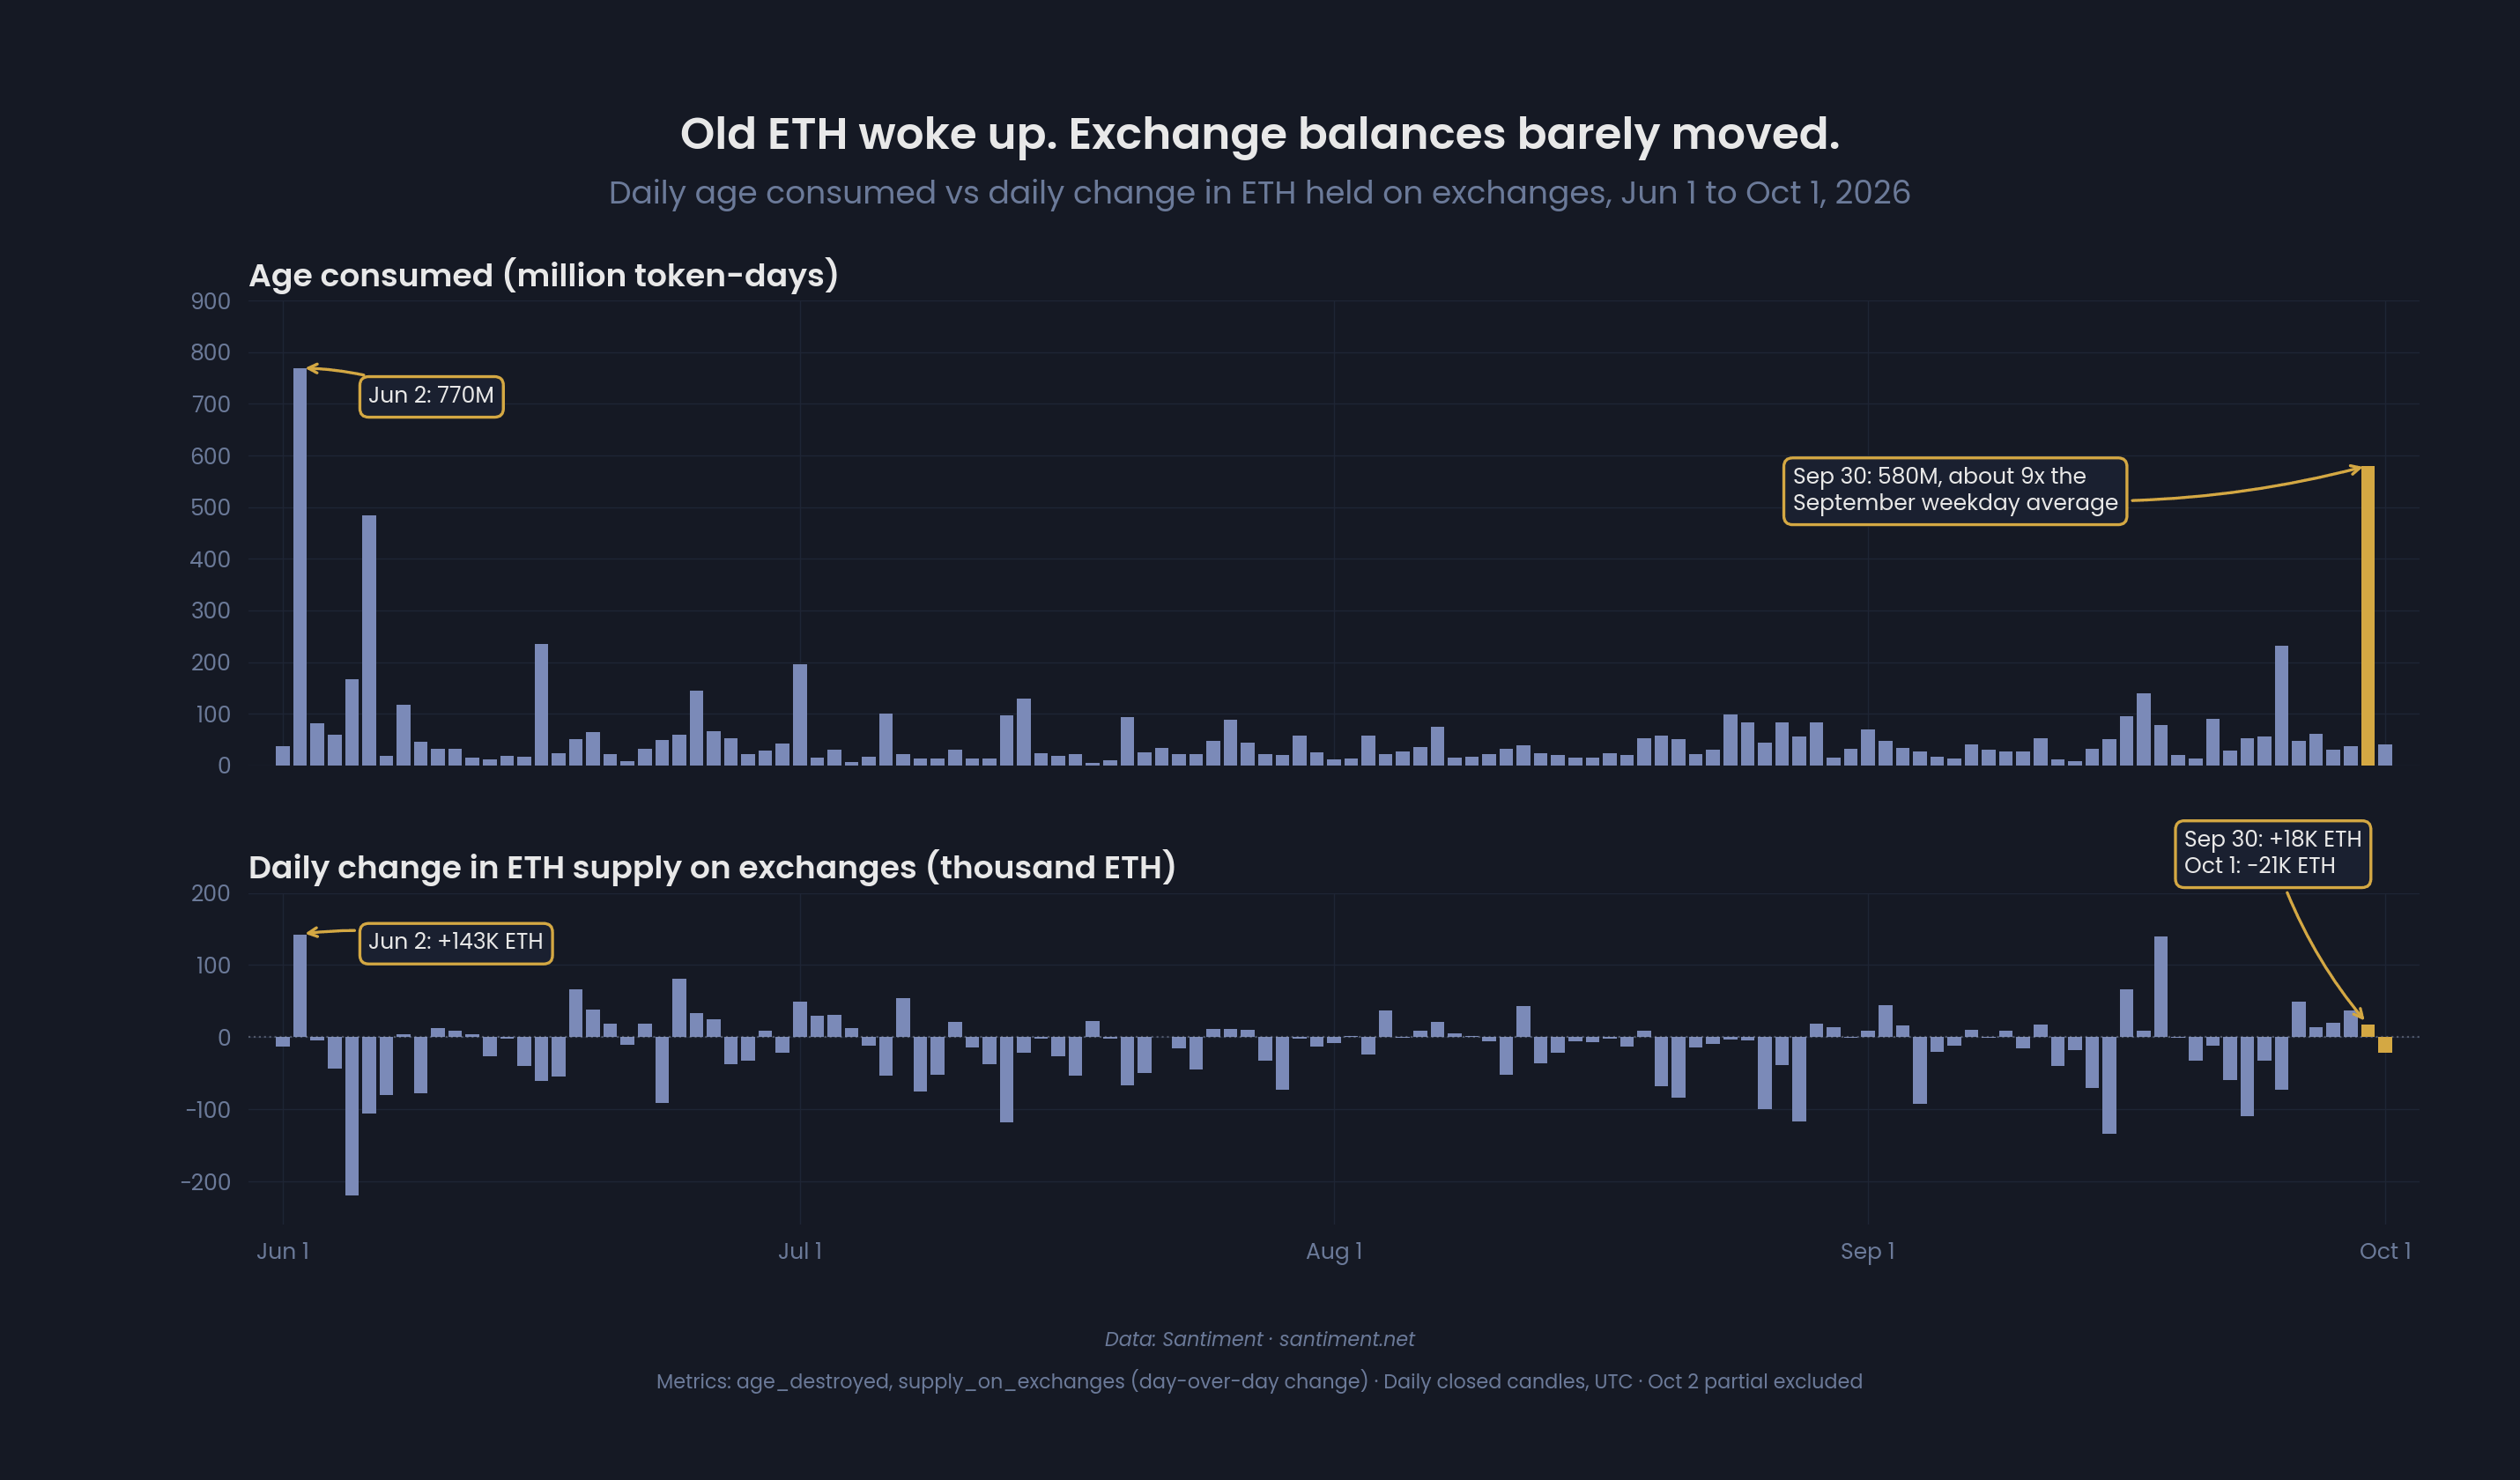
Large spikes can signal that long-term holders are repositioning assets and, in some cases, preparing to sell. Aggregate exchange balances, however, barely changed across Sept. 30 and Oct. 1.
Ethereum held on exchanges rose by only about 18,000 ETH on Sept. 30 before falling roughly 21,000 ETH the next day, against approximately 5.9 million ETH held on trading venues. When Age Consumed last registered a larger spike on June 2, exchange balances increased by more than 140,000 ETH.
That contrast leaves open the possibility that the September activity reflected custody transfers, staking movements or wallet reorganizations rather than broad distribution by older holders.
ETH derivatives traders lean bearish without forcing a breakdown
The more immediate pressure is showing up in the derivatives markets, though signals there are also unusually mixed.
CryptoQuant data shows Ethereum’s Estimated Leverage Ratio has fallen to 0.66, its lowest level in seven months, indicating that open derivatives exposure has declined relative to ETH reserves held on exchanges. The ratio stood near 0.68 on Binance and 0.64 on OKX after trending lower in recent weeks.
CryptoQuant contributor Arab Chain interprets the decline as weaker appetite for heavily leveraged positions as ETH trades around $2,700, potentially easing liquidation pressure.
On Binance, ETH open interest remains near $3.3 billion, up from about $2.3 billion on Aug. 6, a roughly 43% increase, CryptoQuant data shows. At the same time, Cumulative Net Taker Volume, or CVD, has swung sharply in the opposite direction.
Binance ETH CVD fell from $1.94 billion on Aug. 21 to -$1.36 billion on Oct. 5, a $3.30 billion reversal and its weakest reading since Aug. 6. The metric captures the balance between aggressive market buying and selling, with the negative reading showing sellers increasingly crossing the spread to execute trades.
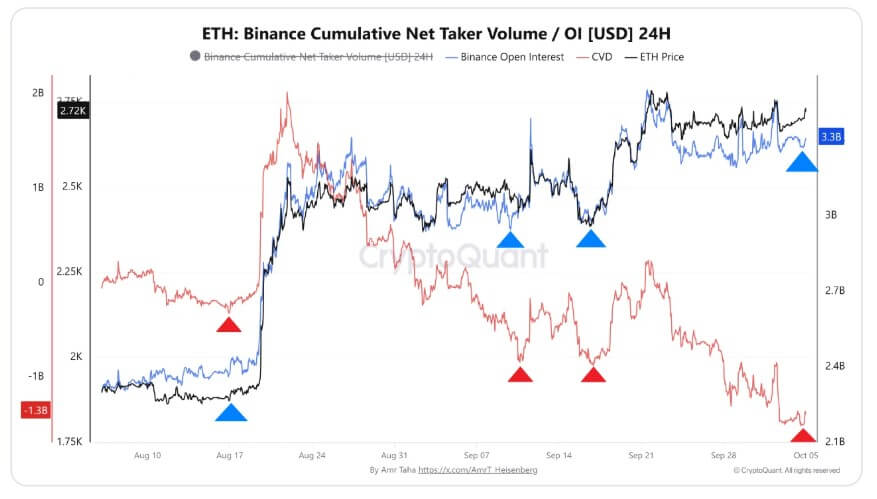
Ethereum, however, remains roughly 44% above its Aug. 6 level, meaning the surge in aggressive selling has yet to unwind the broader price advance.
That divergence is reinforced by the relationship between CVD and open interest. CVD has continued to make lower lows while open interest lows have generally moved higher, a pattern consistent with substantial outstanding derivatives exposure as aggressive sellers take a larger role in order flow.
The combination can become constructive if ETH continues absorbing that supply. Heavy taker selling alongside resilient prices can indicate that buyers are absorbing aggressive sell orders.
A short squeeze remains a conditional scenario, with funding rates providing additional evidence about positioning. If funding turns persistently negative while ETH holds its range, short sellers would increasingly pay long positions to maintain exposure, raising the potential for covering to become an additional source of demand.
For now, three forces are pulling the market in different directions. ETF investors are withdrawing capital, dormant coins are moving while aggregate exchange balances remain little changed, and derivatives traders are selling more aggressively while maintaining substantial exposure.
The next break in that balance could come from either side.
Continued ETF withdrawals, paired with a meaningful rise in exchange balances, would broaden selling pressure beyond financial products. But if exchange reserves stay contained and ETH continues absorbing negative derivatives flow, traders running short exposure could become increasingly vulnerable to any recovery in institutional demand or a shift in funding conditions.
The post Ethereum bears keep selling but ETH price stays near $2,700 as US spot ETFs record $206M in outflows appeared first on CryptoSlate.
At ETHU's Oct. 6 disclosed futures valuation, a 3x Ethereum ETF with $362.1 million in assets would target about $1.09 billion of exposure. If held entirely in standard CME Ether futures, that would equal 8,000 contracts, CME's single-month and all-month accountability level.
The SEC approved Cboe BZX's rule change to list Volatility Shares' proposed ETHK on Oct. 2; ETHK's first trading date is pending. The sponsor's live fund shows that Volatility Shares' existing ETHU held 19,204 October CME Ether futures contracts worth $2.61 billion as of Oct. 6, against $1.31 billion of net assets as of Oct. 5.
Those holdings imply $135,800 of notional per contract, which puts 8,000 contracts at $1.0864 billion. A fund targeting three times daily exposure needs one-third of that in assets, or about $362.1 million. ETHU's position already stands at 2.40 times the 8,000-contract level.
What the 8,000 level means for Ethereum futures
CME cut its single-month and all-month Ethereum futures accountability level to an aggregated 8,000 standard contracts effective March 2.
An accountability level is a threshold, and participants can hold positions above it, as ETHU does. CME Market Regulation can request information about the position under Rule 560, including below the 8,000-contract level.
CME's rules also let it order a participant to stop adding to a position or reduce it when needed to maintain an orderly market.
If ETHK holds its full target exposure in standard CME Ether futures, its contract equivalent equals its assets times three divided by $135,800: about 2,209 contracts at $100 million of assets, 11,046 at $500 million, and 22,091 at $1 billion. Those counts use ETHU's Oct. 6 valuation and move with futures prices and portfolio construction.
Ethereum's aggregation hinge
CME aggregates positions by ownership or trading control, including accounts where a person controls trading or holds a 10% or greater ownership interest.
Volatility Shares manages both funds, so if CME treats them as one controlled position, ETHK would add to a footprint already above 8,000. The combined position would reach about 21,400 contracts at $100 million of ETHK assets, 27,200 at $362.1 million, and 41,300 at $1 billion.
An exemption from aggregation could give ETHK a separate count. The public record leaves that answer open, and CME's confirmation would clarify the combined footprint.
The CFTC's Sept. 29 futures-only report counted 27,392 open Ethereum cash-settled futures contracts, so ETHU's Oct. 6 holdings of 19,204 equal about 70% of that earlier figure, though the two dates differ.
Daily rebalancing and the fallback routes
A 3x fund resets its exposure every day by trading roughly six times its starting assets times the benchmark's daily move in a simplified calculation before investor flows and fees. At $362.1 million of assets, a 5% benchmark move implies about $109 million of rebalancing flow, buying after a rally and selling after a decline.
ETHK's SEC filing describes a fund that seeks three times the daily performance of an Ethereum futures benchmark through derivatives.
It allows later-dated futures, ETH-linked ETPs and ETFs, exchange-traded options, and cash when benchmark futures become unavailable because of accountability levels, exchange position limits, margin requirements, or FCM limits and risk controls.
For holders, that route hinges on tracking quality and execution cost, while Ethereum derivative traders focus on the size and timing of futures flows.
Bitcoin reaches its threshold at twice the assets
Volatility Shares' BITX held 6,368 CME Bitcoin futures contracts across October and November worth about $2.74 billion as of Oct. 6, and CME's Bitcoin accountability level sits at 5,000 contracts. Using BITX's blended disclosed valuation, a 3x Bitcoin fund reaches that level at about $718 million of assets, roughly double ETHK's $362.1 million.
If ETHK's assets stay near $100 million, it adds roughly 2,209 contract equivalents under the same all-futures assumption. That is material beside ETHU's position; how readily futures absorb it depends on liquidity and tracking.
If assets climb to between about $362.1 million and $1 billion, ETHK's own position reaches or exceeds the 8,000-contract equivalent, and the combined footprint could move far past it if CME aggregates the funds.
That raises the odds the fund leans on later-dated futures, linked ETPs or options, with wider execution costs or larger tracking error for holders.
ETHK's holdings disclosures once it trades will show whether front-month Ethereum futures can carry its 3x exposure as assets build, or whether the fallback instruments take over.
The post Ethereum’s proposed 3x ETF could reach CME’s futures threshold with just $362 million appeared first on CryptoSlate.
Aave is approaching a $67 million collateral rollover as one of its fastest-growing fixed-yield trades reaches maturity.
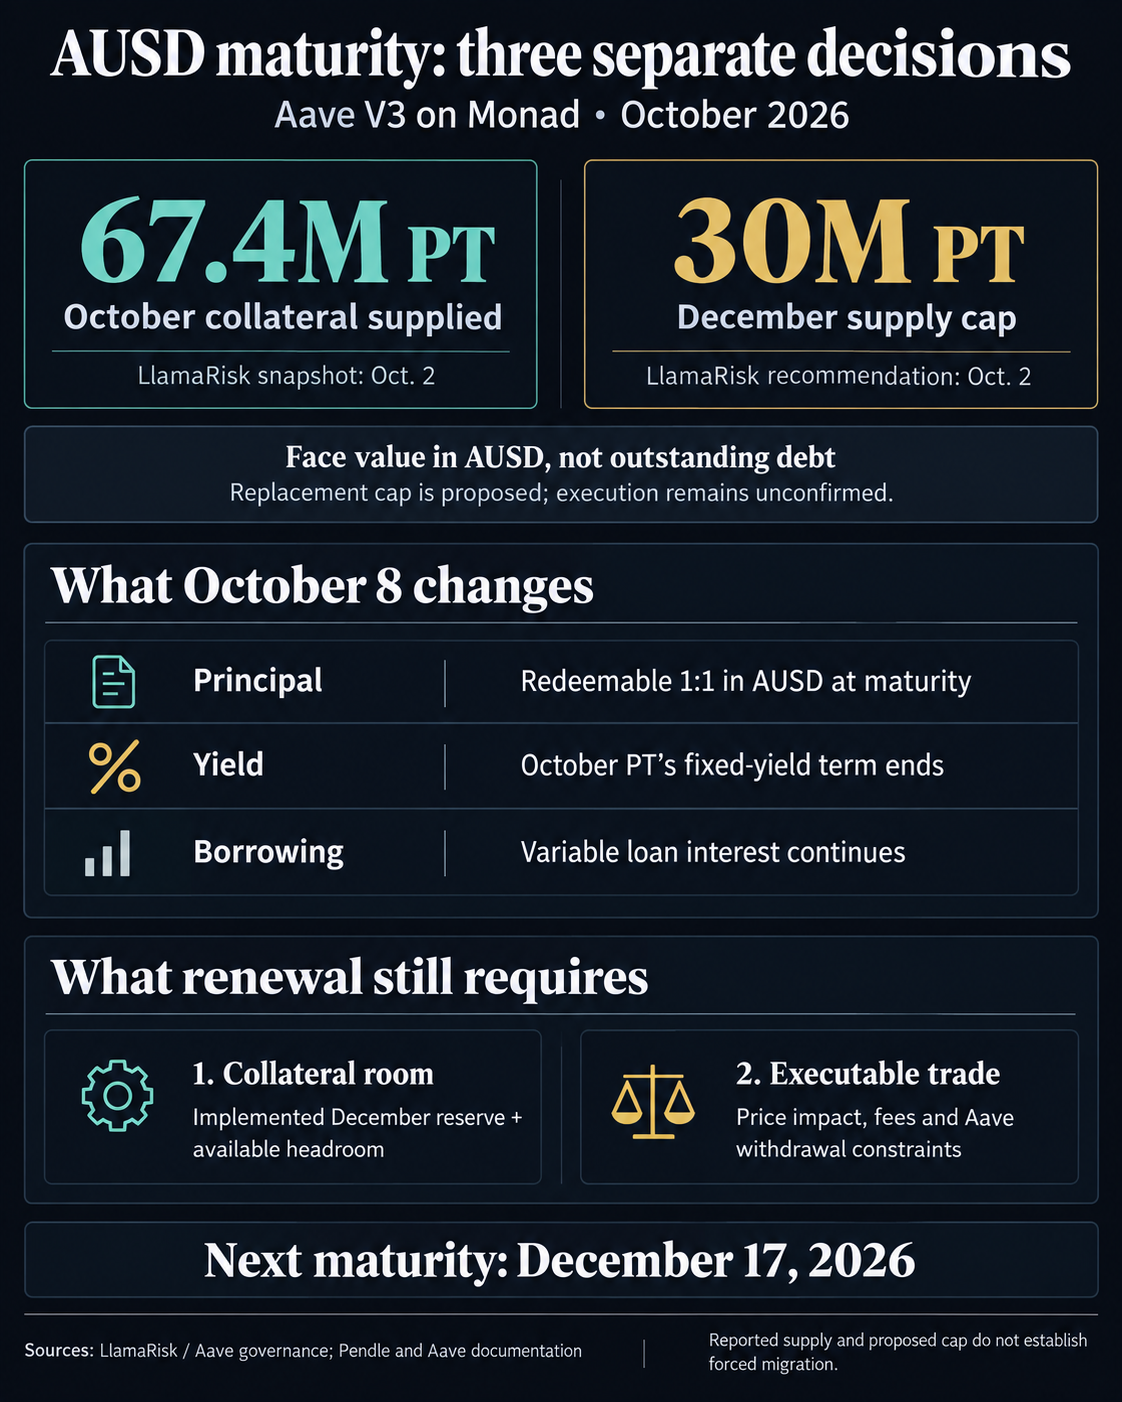
About 67.4 million PT-AUSD-8OCT2026 tokens were supplied as collateral on Aave V3’s Monad market as of Oct. 2, according to risk adviser LlamaRisk. The Pendle principal tokens mature Oct. 8, when each becomes redeemable for one AUSD and its fixed-yield appreciation ends.
A replacement is already being prepared. Pendle deployed a Dec. 17 AUSD principal-token market last month, and TokenLogic has proposed listing it on Aave so borrowers can move into the next maturity without giving up the collateral utility that helped the October market expand.
The timing coincides with accelerating demand for AUSD credit on Monad. On Oct. 3, TokenLogic said active AUSD loans on Aave jumped 113% to $8.7 million from $4.1 million in 15 days, while user deposits more than doubled to $11.2 million.
That creates an emerging cycle between Pendle’s fixed-yield markets and Aave’s lending infrastructure. Investors can lock in a return through PT-AUSD, use the position as collateral to borrow stablecoins, and then move into a later-dated PT when the original token matures.
“Fixed yield becomes collateral. Collateral creates credit. Then the next maturity keeps the cycle moving,” DeFi researcher Andree said, while describing the relationship between the protocols.
The Oct. 8 expiry will provide the first large-scale test of whether that cycle can continue across maturities.
A $20 million market grew past $67 million
The October PT began with considerably less capacity than it ultimately attracted.
Aave initially launched the collateral market with a 20 million-token supply cap. Users filled it by late August, prompting LlamaRisk to recommend an increase to 40 million. That limit was also fully utilized within days, leading the risk adviser to recommend another increase to 80 million.
By Oct. 2, 67.4 million PT was supplied.
The rapid cap expansions show why the proposed December market size should not be treated as a permanent ceiling. TokenLogic proposed another 20 million initial cap for PT-AUSD-17DEC2026, while LlamaRisk recommended starting at 30 million.
That is less than half the amount sitting in the expiring market, but the October precedent shows Aave can expand capacity if demand, liquidity, and borrower health justify it.
LlamaRisk explicitly described the December PT as the rollover destination for the October position and said as much as 67.4 million of Aave collateral could potentially migrate into it.
The October market also shows that much of the supplied PT has been used actively rather than left idle. In an Aug. 31 assessment, LlamaRisk found that the 18 largest suppliers all carried debt, primarily in USDC, with additional borrowing in GHO, USDe and USDT0.
Their median health factor was 1.02 at the time. The tight margin reflected a structure in which both the collateral and debt are dollar-denominated, allowing borrowers to run high loan-to-value positions with less directional price risk than crypto-backed leverage.
Maturity does not itself trigger liquidation. Borrowers can redeem PT for AUSD after expiry, repay loans, or post other collateral. But a user with debt against the October PT cannot necessarily withdraw the collateral until the position remains adequately covered.
Rolling directly into December PT offers another route to keeping the borrowing position intact.
The next market still has to scale
The more immediate constraint may come from the maturity of the replacement market itself.
As of Oct. 2, the December Pendle pool had just $1.61 million of liquidity, 904,717 PT outstanding and $44,000 of trading volume since deployment, according to LlamaRisk.
Those figures are small compared with the tens of millions of dollars held in the October position.
Pendle users can mint additional PT by splitting yield-bearing AUSD positions into principal and yield tokens, meaning existing pool liquidity does not impose a hard limit on how much collateral can eventually be created. Large-scale migration can still affect execution prices and the fixed return available to buyers.
The economics are already tighter than when the October market began.
LlamaRisk put the December PT’s implied yield at 5.64% on Oct. 2. A temporary one-percentage-point campaign incentive lifted the effective rate to 6.64%.
That exceeded borrowing rates of 4.28% for mUSD, 4.64% for GHO, 5.10% for USDT0 and 6.09% for USDC at the snapshot, leaving room for positive carry before transaction costs and price impact. It remained below the 6.82% borrowing rate on USDe.
Those spreads can change quickly. Aave borrowing rates vary with utilization, while PT yields move as traders buy or sell the instrument. The incentive boosting December returns is also temporary.
The surge in AUSD borrowing adds another dimension to the rollout. The $8.7 million of active AUSD loans is separate from the stablecoin debt raised specifically against PT-AUSD, but both point to growing demand for AUSD-linked credit on Monad.
Keeping the principal token usable across successive maturities could help keep fixed-yield capital in Aave after each Pendle market expires.
The next few days will show how much of the October collateral actually attempts to make that transition.
If December PT begins filling its initial cap as rapidly as the October version did, Aave’s risk stewards may again face pressure to raise the limit. Their willingness to do so will depend on Pendle liquidity, borrower health, and whether the new market develops enough depth to support tens of millions of dollars of collateral.
For borrowers, the decision will be more immediate: repay at maturity, replace the collateral or secure space in the December market while the yield spread remains attractive.
The post Aave and Pendle may have found a way to keep yield capital from ever leaving DeFi appeared first on CryptoSlate.
CryptoTicker.io
Ethereum's Glamsterdam upgrade has been live on the Sepolia test network since Tuesday afternoon. The fork started at 13:53:36 UTC, exactly at the time the developers had announced three weeks earlier. Anyone holding Ethereum gets a rare opportunity from this: the network that is also meant to carry the mainnet in a few weeks or months is running out in the open right now and can be measured.
That is precisely what we did, and the result departs from the headline. One number stood at the centre of the reports of recent days: a gas limit of 200 million, more than three times the previous 60 million. On Sepolia the gas limit stood at 64,238,034 on Tuesday afternoon, a good hour after the fork. That is no contradiction of the announcement, but it is not the same thing either, and the difference explains why a mainnet date is still missing.
Glamsterdam on Sepolia: the fork ran at 13:53:36 UTC in block 11,856,337
The Ethereum Foundation had set the fork on September 17 for epoch 353,024 and slot 11,296,768, which converts to October 6, 2026 at 13:53:36 UTC. That slot has indeed become the first block of the new rules; on the execution layer it carries the number 11,856,337.
You can recognise this by two fields that did not appear in the block header before. One is called blockAccessListHash and belongs to the Block-Level Access Lists, the other is a declared slotNumber. The first block with these fields carries exactly slot number 11,296,768 from the announcement. A fork is therefore not merely asserted but readable on the chain.
A block header is the header record of a block: a short list of key figures that every node checks before it accepts the block. When a field is added there, all the programs involved have adopted the same new rule. That is exactly what test networks are for.
This analysis was carried out by cryptoticker.io itself on October 6, 2026. It is based on the block headers of the public Sepolia test network; 24 blocks between 13:29 and 14:49 were counted, along with the blocks immediately around the fork.
The Sepolia gas limit: 60 million before the fork, 64.2 million an hour later
Before the fork the gas limit on Sepolia sat at a round figure for hours: 60,000,000, identical block after block. That is the normal case when the validator operators have all set the same value.
With the fork the number starts to move. Five minutes afterwards it stood at 60,647,496, after forty minutes at 62,568,310, after barely an hour at 64,238,034. Across 218 blocks a good four million gas was added, on average around 18,600 per block.
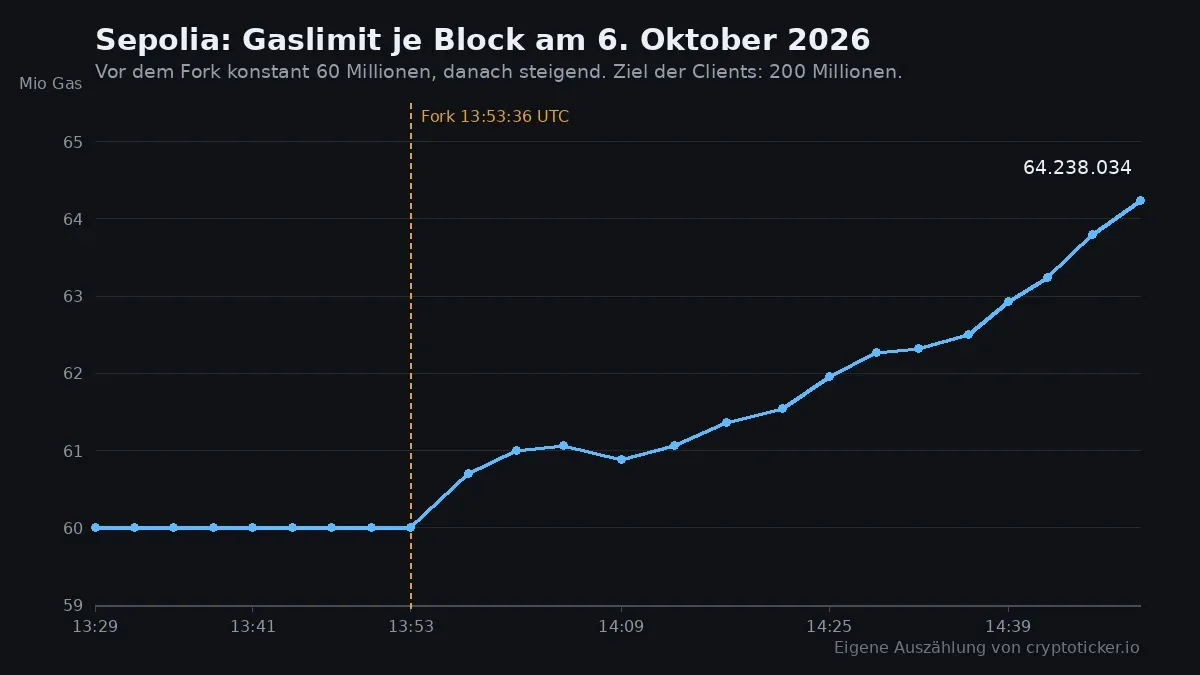
Two things stand out in this. First, the number does not run evenly but in steps, occasionally even a little backwards. Second, several of the counted blocks were brim full: one used 60,611,247 of 60,647,496 gas, a later one 63,827,010 of 63,925,416. Those are fill levels above 99 percent. On a test network that is not chance but intent. Anyone wanting to test a higher limit has to load it up as well.
One 1,024th per block: how the gas limit climbs towards 200 million
The gas limit is not a number somebody sets with a switch. Each block proposal may change the limit of the preceding block by at most one 1,024th, upwards as well as downwards. At 64 million that is around 62,500 gas per block, so with a twelve-second block time roughly half a million per minute as a theoretical ceiling.
The measured 18,600 per block lie well below that, because not every proposer has set the new target value yet. Extrapolated to the 136 million gas that were still missing on Tuesday afternoon up to the 200 million mark, that works out at roughly one day. With more validators switched over it can go faster, with fewer it takes longer, and the value can also come to a halt along the way.
Important for context: the figure of 200 million appears in the Ethereum Foundation's announcement as a configuration recommendation for the validator programs Prysm and Teku, not as a value written into the upgrade specification. So the number describes what is to be tried out on the test network, and not what will apply on the mainnet. The details are in the Ethereum Foundation's test network announcement.
EIP-7928 and EIP-7732: Block-Level Access Lists and ePBS are in the header
Glamsterdam implements two large changes. EIP-7928 introduces Block-Level Access Lists: a block states in advance which accounts and storage slots it touches. This lets nodes execute transactions in parallel instead of strictly one after another. That is the precondition for a markedly higher gas limit, because without parallel processing a block three times the size would simply overwhelm the machines.
EIP-7732 is called Enshrined Proposer-Builder Separation, ePBS for short. Until now block building and block proposing run through external relays, that is, through intermediaries that are not part of the protocol. With ePBS this division of labour moves into the protocol itself. For investors that is above all a point of reliability: the less a network depends on voluntary intermediaries, the lower the risk that an outage there slows block production.
On top of that come adjustments to gas prices that make accesses to network storage more expensive and some computing steps cheaper. This redistribution is the reason why a higher limit does not automatically mean transfers three times cheaper.
Sepolia against mainnet: what a test network fork tells Ether holders
Sepolia is a test network. The Ether moved there has no value, the validators are run by a manageable circle, and a mistake costs nobody money. For exactly that reason Tuesday's fork does not serve as evidence that the mainnet is ready.
What it does prove is something else, and well worth having: the programs of the various developer teams have agreed on the same new rules and are producing blocks together. When a test network fork fails, the roadmap almost always slips by weeks. When it goes through, the next stage is due.
That next stage is the Hoodi test network, and only after it comes the mainnet. For both there is no date so far. Anyone who read in recent weeks that the upgrade was coming in October has confused a test network activation with the main network.
For you as a holder that means you have to do nothing. There is no exchange of coins, no new coin, no deadline. Anyone with Ether sitting on an exchange or in their own wallet normally notices nothing of a fork. It becomes relevant for everyone running a node or a validator themselves, and for the cost side in everyday use.
Ethereum price at $2,712 and €2,410: the level that decides October
On Tuesday afternoon Ether was quoted at around $2,712 and thus €2,410, a gain of 0.25 percent within 24 hours. Over the week there is a loss of 0.75 percent, over the month a gain of 8.6 percent. Market capitalisation stands at around $331 billion.
The daily band was tight: $2,680.92 as the low, $2,721.34 as the high. Those two values are the nearest levels below and above. Beyond them lies the round zone around $2,800, at which Ether failed several times in September. From the all-time high of $4,946.05 on August 24, 2025, the price is a good 45 percent away.
An upgrade on a test network does not move the price in itself, and Tuesday's price reaction was correspondingly small. The technical roadmap only becomes interesting for the price once a mainnet date is fixed. We described the situation on that in our assessment of the Glamsterdam mainnet date of September 30; it holds unchanged in substance.
If you still want to build up Ether, the calculation depends less on the upgrade than on the fees of your buying route. Under MiCA only a licensed provider may broker or hold crypto assets in Germany; the crypto exchange comparison shows which platforms hold that licence and what trading and withdrawal cost there.
Mainnet in the fourth quarter: a roadmap without a confirmed date
The official roadmap still names the fourth quarter of 2026 for Glamsterdam on the mainnet and says expressly that the date is not confirmed. For Hoodi and the mainnet the announcement says the activation times will be made known as soon as the developer teams have decided them.
From that follows a plain rule of thumb for your own schedule. Between test network fork and mainnet there were usually several weeks in past Ethereum upgrades, because after Sepolia a second test network is due and an observation phase follows after that. A date in October would be unusually fast; a date in November or December fits the pattern. Anyone tying a buying decision to the upgrade should therefore count in weeks and not in days.
The staking queue: 1.46 million ETH entering, a 25-day wait
Alongside the technical roadmap runs a development that is more concrete for your planning than any fork. The staking queues are long on both sides. In the entry queue there were recently around 1.46 million Ether with a waiting time of about 25 days, in the exit queue 786,275 Ether with a good 13 days and 16 hours. In total around 43.7 million Ether are staked, so about 35.8 percent of the circulating supply, at an estimated yield of 2.63 percent a year. Coindesk compiled the figures on October 5 from ValidatorQueue data.
The practical consequence is a deadline that appears in no calendar: anyone who wants to stake today only commits their Ether in a good three weeks, and anyone who wants to exit waits around two weeks for release. Both happen independently of the price. If the market falls in that time, you cannot react at once.
A long exit queue is not an automatic sell signal in this. Part of the Ether being freed up goes straight back into staking, for instance when providers rebuild their infrastructure. For now the number shows only one thing: how long the way out currently takes.
Holding period, threshold, staking rewards: what the tax office in Germany requires
For German investors there is a second calculation attached to staking. Gains from selling crypto assets are tax free after a holding period of one year; that is governed by section 23 of the Income Tax Act. If you sell earlier, a threshold of €1,000 per calendar year applies to all private disposal transactions together. Threshold means: at €999 of gain everything stays tax free; at €1,000 the entire gain becomes taxable, not just the part above the line.
The rewards from staking itself fall into a different drawer. In the view of the Federal Ministry of Finance they regularly count, when held privately, as income from services under section 22 no. 3 of the Income Tax Act, with a threshold of their own of €256 a year. They are valued at the moment of receipt, that is at the rate that applied when the reward was credited.
The important point, the one about which false claims circulate most often: staking does not extend the one-year holding period for the coins used. Ether that was already held for a year before staking remains sellable tax free afterwards. Anyone who bought several tranches at different prices does, however, need clean documentation of every inflow as proof.
Gas costs, layer 2 and hardware: what it means for your coins
A higher gas limit initially means only that more computing work fits into a block. For fees that is favourable as long as demand does not rise to the same degree: more space at the same demand pushes the base fee down. This is noticeable first and foremost with layer 2 networks, which store their data in bundled form on Ethereum and currently take up the largest part of the space.
The simultaneous redistribution of gas prices works in the other direction. Accesses to network storage become more expensive, because permanently growing storage raises the costs of every node operator. For a simple transfer of Ether little changes as a result; for complex contracts the calculation can swing either way depending on their construction.
Anyone running a node themselves should watch the progress on Sepolia. A block with 200 million gas demands more memory, more disk throughput and more bandwidth than one with 60 million. That is exactly what the step-by-step increase is for: only it shows at which value the first nodes drop out. That the validators on Sepolia are turning the number up slowly rather than jumping straight to the target is therefore not hesitation but the procedure.
Glamsterdam on Sepolia: what to take away
- Separate test network and mainnet. The fork of October 6 concerns Sepolia. For Hoodi and the mainnet there is no date; the roadmap names only the fourth quarter of 2026. If you tie a buying decision to it, count in weeks. Where you buy decides more about your return than the upgrade does: the hardware wallet comparison shows what custody in your own hands costs.
- Factor in the waiting time before you stake. Around 25 days to activation and barely 14 days to release are the normal case right now. Anyone wanting to sell in that time cannot. Which providers offer which yield and which exit routes is in the comparison of staking platforms.
- Document every inflow. For a sale the one-year period with the €1,000 threshold counts; for staking rewards, the separate €256 threshold at the rate of the day of receipt. Without complete records neither can be documented later; you will find the tools for it in the comparison of crypto tax tools.
(As of October 6, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Setting up MetaMask takes less than ten minutes, and in those ten minutes you make the two decisions that determine what happens to your balance: where you get the software from, and what happens to the twelve words the setup wizard shows you once. Almost everything else you can change later. Those two points you cannot.
This text walks you through the setup and explains the terms you meet in the wizard without being told what they mean there: recovery phrase, password, network, chain ID, approval. By the end you will know which steps are one-off, which ones you repeat regularly, and at which points the tax office and the regulator come into play in Germany.
What MetaMask is and what the software does not keep for you
MetaMask is a self-custody wallet, also called a non-custodial wallet. That means the software generates a key pair on your device and encrypts it there. Nobody at the maker holds a copy, nobody can reset access, and there is no hotline that unlocks your account. The difference from an exchange is exactly this: at an exchange you have an account, here you have a key.
Everything else follows from that. A wallet in this sense is not a container holding coins. The coins sit on the blockchain, and the wallet is the tool with which you prove they are yours. If you delete the software, the coins stay where they are. If you lose the key, the coins also stay where they are, except that nobody can reach them any more, you included.
Extension or app
MetaMask comes as a browser extension for the desktop and as an app for Android and iOS. Both fall back on the same recovery phrase when you import it, and then show the same addresses. One version is enough to start with. Anyone using both has not thereby created a backup copy, but two points of access to the same key.
Installing MetaMask: only two sources are genuine
The most dangerous minute of the whole setup comes before your first click in the wizard. Fake wallet extensions turn up regularly in the browsers' own official extension directories, often under names like "Ethereum Wallet" and with an icon resembling the real one. Fakes like these are not waiting to steal something from you later. The recovery phrase is skimmed at exactly the moment the wizard generates it, or the moment you import an existing one, and from there it travels outward unnoticed.
One habit guards against this: you install the extension only through the download button on the maker's site metamask.io, never through a search result, never through a link in a message, a video or a forum post. On a phone you download the app from the official store and check beforehand who publishes it and how many installations it carries. An extension with a few hundred users is a warning sign for a wallet of this size.
That things can go wrong at the maker itself was shown in early October by a confirmed security incident in parts of the MetaMask infrastructure, in which affected Ethereum validators were pulled from the network. What exactly happened there and who it concerned is in our report on the MetaMask security incident. For the setup that changes nothing about the rule, it only sharpens it: the fewer places that know your key, the fewer places that can lose it.
Twelve words from a random generator: the Secret Recovery Phrase
On first launch MetaMask generates a sequence of twelve words and calls it the Secret Recovery Phrase, formerly also seed phrase. These twelve words are not a memory aid and not a password. The private key is calculated from them. Whoever has them has the wallet, on any device, in any country, without you noticing a thing. The maker puts this just as plainly in its guide to creating a new wallet: nobody at MetaMask can restore the phrase once it is gone.
The phrase therefore belongs offline. A sheet of paper is better than a file, a metal plate is better than paper because it survives water and fire. What you never do: photograph it, type it into a notes app, put it in a password manager that lives in the cloud, or read it out to someone posing as support on the phone. There is no case in which a genuine employee needs those words.
Two slips of paper in two places
One copy in a single place is a total loss waiting for a burst pipe. Two copies in two physically separate places, neither of them the home of an acquaintance with access, are the usual compromise. Anyone holding larger amounts does not split the phrase into halves, because that reduces security more than it insures against loss.
Token approvals: what an unlimited spending cap means for your balance
The point at which most losses arise only comes after the setup, and it appears on no welcome screen. As soon as you use a decentralised application, it asks for an approval, in English also token approval or spending cap. With it you permit a contract to move a certain amount of a certain token out of your address. That is not a flaw in the system but the precondition for swapping, depositing or staking to work at all.
The decisive part is the amount. Many applications propose an unlimited approval, because it is convenient and saves fees on every further use. The permission then stays in place until you revoke it, months later too, even when you have long forgotten the application. If the contract is taken over later, or was no good from the start, that old permission is enough to empty your balance without anything having to be confirmed again.
In the setup window you can overwrite the proposed amount and set it to what you are actually moving right now. You can see approvals you have granted later in MetaMask's portfolio view and withdraw them there; the maker describes the route in its guide to revoking approvals. This is supported for the Ethereum mainnet, Polygon, the BNB Chain, Optimism and Base, among others. A revocation is itself a transaction and costs a network fee. What a signature looks like when it is in truth a power of attorney is something we took apart using the example of wallet drainers and their signatures.
The password unlocks this device only
Straight after the phrase the wizard asks for a password. Beginners regularly confuse two things here. The password decrypts the key store on exactly this browser or this phone. So it protects against someone who sits at your computer briefly sending money. On a new device it is no use to you at all, because there MetaMask does not ask for the password but for the twelve words.
In practice that means the password may be long and sit comfortably in a password manager; the recovery phrase never may. If you forget the password, you set the wallet up again with the phrase and assign a new one. If you forget the phrase, the password does not help you.
Adding networks: Ethereum, Solana and the chain ID as forgery protection
After the setup your account initially stands on the mainnet of Ethereum. Alongside that, MetaMask now brings multichain accounts: one account covers not only the EVM networks but also chains such as Solana, whose addresses are derived from the same recovery phrase under the BIP-44 derivation standard. You do not need an additional phrase for that.
Further networks you enter by hand. MetaMask asks for five details: name, RPC address, chain ID, symbol of the network currency and the address of a block explorer. The chain ID is the actual protection: an identifying number assigned uniquely to each chain, and two networks with the same one cannot exist. A fraudulent site offering you an "official" network to set up fails at this number as soon as you compare it with the figure in the chain's documentation.
Where the RPC address comes from
The RPC address is the point of access through which your wallet speaks to the chain. Whoever provides it sees which addresses you query and which transactions you send, and could in case of doubt show you false balances. So take it from the official documentation of the network or from a provider where you hold an account yourself, and not from a collected directory that some unfamiliar site puts in front of you.
The fee on a swap inside the app is 0.875 percent
MetaMask itself costs nothing. The wallet earns its money on the built-in swap function: every swap inside the app carries a service fee of 0.875 percent, regardless of the network. It is disclosed in the quote that appears before you confirm.
On top of that come two further items that do not go to MetaMask. The network fee you pay to the chain you are travelling on; it fluctuates with load and has nothing to do with the swap amount. And the trading venues through which the swap actually runs take a fee of their own and, depending on the depth of the market, deliver a worse rate than the display initially suggests. With small amounts on an expensive network, the network fee can make up the largest part of the costs.
For recurring purchases the route via an exchange with a euro account is therefore usually cheaper, and the wallet becomes the destination rather than the place of purchase. How the various software wallets fare for that is set out in our software wallet comparison.
Hardware wallet instead of browser: the private key never leaves the device
From an amount whose loss would hurt, the next step is worth it. MetaMask can be connected to a hardware device, and then the division of roles changes: the wallet remains the interface through which you operate applications, but the private key sits on the device and never leaves it. Every transaction you have to confirm there with a button. Malware on the computer can then prepare a transaction but not sign it.
In the browser extension MetaMask supports Ledger, Trezor and Lattice among others, and in the mobile app Keystone, Ledger and NGRAVE ZERO among others. Two limitations are worth knowing before you buy a device: from Ledger only EVM accounts can be integrated, and the Trezor connection works exclusively with the BIP-44 derivation path. Both are in the maker's help pages, and both only become apparent once the device is already in the house.
The device does not replace the phrase
A hardware device brings a recovery phrase of its own, and that one then applies to the accounts on this device. Your old MetaMask phrase is untouched by it and continues to secure the accounts the browser created. Anyone moving over shifts the balances explicitly to the new addresses and treats both phrases as equally valuable afterwards.
Does a self-custody wallet need a BaFin licence?
No, and the reason is in the European crypto regulation MiCA itself. What gets regulated are service providers that hold or administer crypto assets for others. Software where only you hold the key and the maker merely supplies the program keeps nothing for anyone and therefore does not fall under the licensing requirement. That applies to MetaMask as much as to other pure self-custody wallets and to hardware devices without custody services of their own.
The line runs where a wallet offers additional services. Anyone holding crypto assets for customers, running an exchange against euros or executing orders is providing a crypto-asset service and needs a licence from BaFin in Germany for it, or a valid notification from another member state.
For you as a user that has an uncomfortable flip side. Because no supervisor stands behind it, there is also no deposit protection, no complaints body and no claim to compensation if something goes wrong. The freedom of self-custody and the complete absence of a safety net are the same coin.
Tax in Germany: moving to your own wallet is not a sale
Sending coins from an exchange to your own MetaMask address is not a disposal transaction. You swap nothing and realise no gain, you merely change the place of storage. The acquisition data carries on, and with it the period that matters.
Section 23 of the German Income Tax Act applies. If you sell within a year of buying, the gain is taxable; after a year has passed it is tax free. For short-term gains there is a threshold of €1,000 per calendar year, and the word threshold is to be taken literally: stay below it and you pay nothing; reach it and you pay tax on the entire gain, not just the part above the line.
Two things your own wallet makes harder than an exchange account. First, you have to carry the acquisition data yourself, because no provider sends you a statement at the end of the year. Second, network fees arise with every transfer, and their treatment is not self-explanatory. A swap inside MetaMask, by contrast, very much is a tax-relevant event, because in it you give up one crypto asset and receive another.
Phishing tricks around the recovery phrase
Attacks on wallet users almost never target the technology but the moment in which somebody is under pressure. Five patterns come up again and again:
- A supposed support message in a chat or forum, shortly after you asked a question there, requesting "verification" of your wallet.
- A form that looks like the genuine setup wizard and asks for the twelve words because your wallet supposedly has to be "synchronised".
- A phone call in which somebody poses as an employee and speaks of a "security incident" requiring immediate action.
- An airdrop page that demands a signature rather than an approval, with text nobody reads.
- A second browser extension that presents itself as an add-on or security check for your wallet.
The counter-rule is the same in all five cases and simple enough to remember: the twelve words get entered at exactly two points, when setting up for the first time and when restoring on a new device. Every other request is an attack, without exception and regardless of how convincing the page looks. Anyone who is unsure closes the window and starts again through a bookmark they set themselves.
MetaMask compared with Trust Wallet and Phantom
MetaMask is the most widely used software wallet in the Ethereum world, and that reach is its biggest practical advantage: almost every decentralised application supports it, guides exist for every special case, and hardware devices are compatible throughout. The price is that it is also the most frequent target for fakes and phishing pages.
Trust Wallet comes from the phone side and covers more chains out of the box, while the desktop extension feels less mature. Phantom has its strength in the Solana world and is often the more convenient choice there, even though it now supports further networks. For someone travelling mainly on Ethereum and the networks built on it, MetaMask remains the obvious starting wallet, and a switch pays off more when the centre of gravity shifts for good.
MetaMask: how to proceed now
- Set the wallet up on a quiet evening, not between two appointments. Download the extension exclusively through the maker's site, write the twelve words on paper or metal and store two copies in separate places. From which amount a device is worth it instead is shown by our hardware wallet comparison.
- On first contact with an application, set the approval down by hand to the amount you are moving right now. Put a fixed date in your calendar each quarter on which you withdraw old approvals. Which software wallet suits your focus is in the software wallet comparison.
- From the first transfer onwards, note the date, the quantity and the acquisition cost. Without those details the one-year period cannot be documented later, and that period is exactly what decides the tax. Tools that carry this along automatically are in the comparison of tax and portfolio tools.
(As of October 6, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
The Solana price stands at $120.36 on Tuesday midday, which is €106.86. Against the previous day almost nothing has moved, 0.09 percent lower. The interesting number of the day is therefore not the price itself but what sits beneath it: the 20-day moving average runs at $117.32, less than three percent below the current level. Above it, the high of the past 90 days waits at $122.08. Solana has been wedged between those two marks for days, while in the background the largest rebuild the network has ever had is under way, and nobody is saying when it arrives.
This article puts both together: where the price really stands, which three levels bound it, what the Alpenglow consensus switch means for holders in Germany, and which deadlines you need to know before you react to a move.
Solana price on October 6: $120.36, €106.86 and a daily range of 2.1 percent
The day's range ran from $118.97 to $121.51. That is 2.13 percent between low and high, an unusually tight day for Solana. Trading volume over 24 hours came to roughly $2.48 billion, market capitalisation to $70.8 billion. That puts Solana seventh among the largest crypto assets by market value. There are 588,385,318 SOL in circulation.
Depending on the period you pick, the same price tells three different stories. Over the week there is a gain of 0.77 percent, which is effectively a flat line. Over 30 days it is up 12.87 percent, with the price coming from $106.49. Over one year, by contrast, it is down 48.25 percent. And from the all-time high of $293.31, set on January 19, 2025, the price is still 58.96 percent away.
Anyone calculating in euros gets a slightly different figure, because the euro-dollar rate moves alongside. We worked through this gap between the euro view and the dollar view in a separate piece on October 5. For your tax return only the euro value counts, not the dollar price in the app.
In brief: Market capitalisation is the price multiplied by the number of coins in circulation. That figure says what all existing SOL would currently be worth together, not how much money has flowed into the network.
The three Solana price levels above and below: $122.08, $117.32 and $106.50
Levels are not an oracle. They are prices at which a striking amount was traded in the past, and therefore places where supply and demand tend to meet. Three of them are cleanly measurable on Solana right now.
$122.08 on the upside. That is the highest daily close of the past 90 days. The price has run at this zone several times in recent days and has stayed below it every time. A daily close above it would be the first signal that the sideways phase is ending.
$117.32 on the downside. That is the average of the past 20 daily closes. This line has run below the price since the middle of September and has caught it more than once. A break of this line would end the short-term uptrend.
$106.50 as the second step. That is the average of the past 50 daily closes and at the same time almost exactly the level of 30 days ago. If the price falls back there, the entire monthly gain would be handed back.
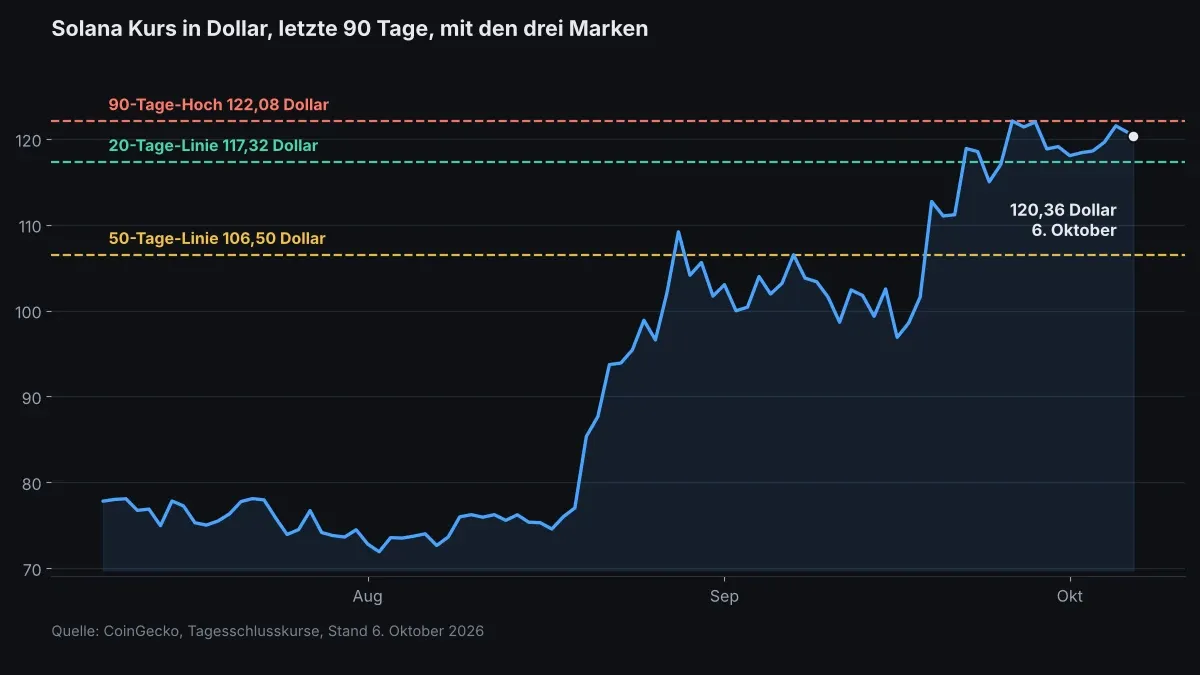
For context on the downside: the low of the past 90 days was $71.89, and the 200-day moving average runs at $86.27. Both are far away. The medium-term uptrend is therefore intact, even if the price is making no headway at the moment. How far the range on Solana can spread out in an October historically is something we recalculated in our review of previous years.
Will the $117.32 level hold? The honest answer is that nobody knows in advance. What you can do with it is another matter. You now know three concrete prices at which you can decide beforehand what you will do, instead of deciding in the moment of the move. That is exactly what levels are for.
Alpenglow: what the consensus switch changes technically
Alpenglow is the name for the largest intervention in the heart of Solana since launch. It sits in client version Agave 4.3, and the project's overview page lists it under Network Upgrades with the status "In Development" and the window October 2026.
In brief: Consensus is the procedure by which all computers in a network agree on which transactions are valid and in what order they stand. Replacing the consensus means replacing the foundation everything else rests on.
Two building blocks are being swapped out. Votor takes over the role of TowerBFT, the voting logic used so far. Rotor replaces Turbine, through which new blocks are distributed across the network. The intended result is stated on the project page: around 150 milliseconds to final confirmation of a transaction, instead of 12.8 seconds today.
For operators the cost calculation changes markedly. So far a validator pays ongoing fees for its voting transactions, up to about one SOL per day according to the analysis by infrastructure provider Helius. Alpenglow replaces these individual votes with a bundled certificate procedure, and the running fee falls away. Helius therefore puts the minimum stake at which running your own validator pays off at around 450 SOL in future, instead of roughly 4,850 SOL today. That is the analysis's figure, not a commitment from the project.
Alpenglow without a fixed date: September 28 passed with no switch
At the end of September it circulated on social networks that Alpenglow would go to mainnet on September 28. The developer team Anza explicitly contradicted this, and the switch did not take place that day. In early October the mainnet is still running under the old procedure.
The project still names only the October 2026 window and no date. For you as a holder that is less irritating than it sounds, but it has one practical consequence: a date that can arrive any day cannot be planned around. Anyone making their reaction depend on noticing the switch beforehand is planning on information that may only be available afterwards.
The sober reading: Alpenglow is an improvement in the technology, not an event that has to move a price mechanically. Experience with network switches points in both directions, and anyone translating the switch into a particular price today is working with a number that does not exist.
Frankendancer ends: your validator and the client question
In brief: A client is the software a validator runs to take part in the network. Several independent clients are considered a security advantage, because a bug in one of them then does not paralyse the whole network.
Alongside the standard client Agave, Frankendancer has been running since 2024, an interim solution from Jump Crypto. This client combines the fast networking part of the Firedancer client with the consensus logic of Agave. That consensus logic is precisely what Alpenglow replaces. Jump Crypto has therefore announced that it will discontinue support for Frankendancer with the activation and concentrate its efforts on the full Firedancer client.
If you have delegated SOL, this affects you indirectly. Your delegation sits with a specific validator, and that operator has to carry out the change. In your wallet's explorer you can see which validator your delegation goes to, how high its commission is and how reliably it has worked recently. That is a detail worth looking at once before a network switch, and before the switch runs rather than after. Anyone staking their SOL through a provider instead of delegating themselves will find the details on commission and payout rhythm at the respective service; our overview of staking platforms sets the terms side by side.
Epoch 1050 is 71 percent through: how long deactivating a delegation takes
Here lies the deadline that matters most in everyday use and that the fewest people know. Solana counts in epochs. One epoch covers 432,000 slots. The network currently stands in epoch 1050 at slot 307,080, so roughly 124,920 slots are still open. At the current roughly 400 milliseconds per slot, that corresponds to just under 14 hours.
The point of it: anyone who deactivates a delegation is not free immediately. The deactivation takes effect at the end of the current epoch, and only after that can the balance be withdrawn and sold. Between your click and the moment you can actually trade there is therefore half a day to a full day on average, depending on when in the epoch you decide.
If you take your levels from the second section seriously, a clear consequence follows: a staked holding is not a tradable holding. Anyone who wants to sell at $117 but only starts deactivating at $117 sells at a different price. Network inflation in the current epoch stands at 3.62 percent a year according to the network query, and that yield is the price you receive for the reduced mobility. Whether the trade is worth it to you depends on whether you were going to leave the holding untouched anyway.
Solana staking taxes in Germany: the €256 threshold and section 22 no. 3 of the Income Tax Act
For tax purposes, price gains and staking income in Germany run through two different sections, and many people confuse the two.
With passive staking, the ongoing staking rewards generally count as income from services under section 22 no. 3 of the German Income Tax Act. A threshold of €256 per calendar year applies to it. Threshold means: stay below it and the amount is tax free. Exceed it by even one euro and the entire amount is taxable, not just the part above the line. That is the difference from an allowance, where only the portion above it counts.
What counts is the euro value at the moment of receipt, meaning the day the reward is credited to your account. On Solana that happens epoch by epoch, so several times a week. These many small inflows are the reason why keeping records by hand gets confusing fast with staking; tax and portfolio tools read the inflows automatically and convert them into euros at the rate of the respective day.
The holding period stays at twelve months: the German finance ministry letter of March 6, 2025
Section 23 of the Income Tax Act applies to the sale of the SOL themselves. If you sell within twelve months of buying, the gain is taxable, with a threshold of €1,000 a year for all private disposal transactions together. After twelve months have passed, the gain is tax free regardless of its size.
For a long time it was disputed whether this period extends to ten years if the coins are staked in the meantime. The Federal Ministry of Finance has rejected that. In the letter of March 6, 2025, which replaces the version of May 10, 2022, it expressly remains at twelve months even if the crypto assets were used for staking or lending in the interim.
In practice that means staking does not extend your holding period. It does create a second stream of income that has to be recorded on an ongoing basis, and the rewards received this way start their own holding period from the day they arrive. The letter also stresses the duties to cooperate and keep records: anyone declaring income has to be able to document it.
This section is no substitute for tax advice. With larger holdings, where there is proximity to a commercial activity, or with staking through foreign providers, a visit to a specialist is worthwhile.
Buying and holding Solana: costs, custody and the route through an exchange
If you want to add to a position or get in for the first time after this article, three items decide your result more than any price forecast does.
First, total costs. The advertised trading fee is the wrong number to go by. What decides your result is the sum of fee, spread and deposit costs. The spread is the gap between the buying and selling price and appears in no fee table. In a tight market like Solana it is small, but with small amounts it still carries weight. Which providers in Germany let you trade on which terms is set out in our exchange comparison.
Second, custody. If the SOL sit on the exchange, the keys belong to the provider. For small amounts that is defensible; for a holding you want to keep for years, your own wallet is the cleaner solution. Anyone holding and delegating themselves also keeps the free choice of validator from the section above.
Third, record keeping. Every purchase needs a date, a quantity and a euro equivalent, otherwise the twelve-month period cannot be documented later. At the moment you buy, that is a matter of seconds; two years later it is a matter of hours.
Solana price and Alpenglow: how to proceed now
- Write down the three levels. $122.08 on the upside, $117.32 as the first step down, $106.50 as the second. Decide beforehand what happens at which daily close. If you want to change provider while you are at it, compare the total costs first in the exchange comparison.
- Look at your delegation. Which validator, which commission, which client. And build the just-under-14 hours to the end of the epoch into your plan before you set a level as a selling point. The providers' terms are in the staking overview.
- Check your €256. Add up what has reached you in staking rewards this year, in euros at the rate of each day of receipt. If you are close to the threshold, it is a decision before the end of the year and only a declaration afterwards. A tax tool takes the adding up off your hands.
(As of October 6, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
The Dogecoin price stood at €0.084357, or $0.094847, on Tuesday morning. That is 1.63 percent lower in euro terms and 1.38 percent lower in dollar terms than the previous day. Over the week the price is all but unchanged at minus 0.15 percent, and over the month it is up 4.42 percent. Price data comes from CoinGecko, as of October 6.
More important than the daily move is a question many holders are asking right now: can a DOGE balance earn a running yield, the way Ethereum or Solana can? Offers marketed in exactly those terms are circulating, often with the word staking in the name. The short answer: there is no staking in the Dogecoin protocol. Whatever is paid out as yield comes from a lending transaction, and in Germany that carries different rules on liability, deposit protection and tax than a plain purchase does.
Dogecoin price at $0.0948, 1,362 blocks and 13.62 million new DOGE in a day
The daily range ran from €0.083552 to €0.085781. Market capitalisation stands at about $14.82 billion, and spot turnover over the past 24 hours at $519 million. There are 156,210,086,384 DOGE in circulation.
That last figure is the key to the whole subject, because it grows every day. Our own review of the chain through the Blockchair interface put the count at 6,403,759 blocks on October 6. In the 24 hours before that, 1,362 blocks were added. The three most recently found blocks each carried exactly 10,000 DOGE in reward, plus a handful of DOGE in fees.
What 1,362 blocks a day mean
1,362 blocks at 10,000 DOGE each come to 13,620,000 new units in a single day. Annualised, that is roughly 4.97 billion DOGE. Work instead from the nominal cadence of one block a minute and the figure comes to 5.256 billion a year. Both numbers belong side by side: the annual expansion of supply runs between 3.18 and 3.36 percent.
Scrypt proof of work: Dogecoin has no staking in the protocol
Staking, in the narrow sense, means holders lock up their units as collateral and the protocol itself grants them a share of the newly created units. That requires a consensus mechanism called proof of stake, as used by Ethereum since 2022 and by Solana from the start.
Dogecoin works on a different basis. The chain uses proof of work with the Scrypt hashing algorithm. New blocks arise from computational work by specialised machines, and the reward of 10,000 DOGE per block goes to whoever found the block. A holder who simply leaves coins sitting in a wallet takes no part in that whatsoever. The protocol contains no mechanism that allocates anything to holders.
This is not a shortcoming and not a temporary state of affairs, but a property of the design. Anyone looking at a product that promises yield on DOGE therefore knows before reading a word of the fine print: that yield cannot come from the chain. The return has to be earned and paid out by a third party.
Merged mining with Litecoin: 2.69 petahash secure the chain without dedicated miners
The computing power behind Dogecoin averaged around 2.69 petahash per second over the past 24 hours, with difficulty at 39,397,744. Over the same period the chain recorded 18,059 transactions.
Only a small part of that computing power, however, belongs to machines running for Dogecoin alone. Since 2014 Dogecoin has been mined together with Litecoin under a method called merged mining: both chains use the same hashing algorithm, and the same computational work counts for both at once. Dogecoin thus inherits a large share of its security from an outside chain.
For you as a holder, that yields a point of context rarely found in yield prospectuses. The security of your holding depends on decisions taken in another network. It has held steadily for twelve years, but it remains a dependency, and it belongs in the risk picture.
What a yield promise on DOGE really is: a lending transaction
If the chain pays out nothing, only one source is left. The provider takes in your DOGE and lends it on, usually to traders betting on falling prices who need units for that, or to market participants who have to post collateral. Your yield is funded out of the interest those traders pay. The technical term is lending: handing over crypto assets for a fee so a third party can use them.
That changes your legal position fundamentally. Before the deposit you own DOGE. After the deposit you own a claim against a provider who is supposed to return the same quantity of DOGE. Should that provider become insolvent, you stand in line with the creditors. This is the real price of the interest rate, and it appears in no percentage figure.
How to spot a lending product
Three features turn up almost every time. The units leave your own custody and sit with the provider. There is a minimum term or a notice period during which you cannot sell. And the yield is quoted as a variable rate that the provider may change unilaterally. If you want to lay the terms of different houses side by side, our comparison of crypto lending providers sets out the conditions in one overview.
3.18 percent dilution a year: issuance is the benchmark for any DOGE yield
Here the figure from the first section comes back. The total supply of DOGE grows by 3.18 to 3.36 percent every year. Your share of the total therefore falls continuously if you do nothing. A yield on DOGE, paid in DOGE, has to offset that dilution before it so much as holds your share steady.
The calculation below works through a holding of 100,000 DOGE, worth about €8,436 at the current price. It assumes a year with no price movement, so that the supply effect alone is visible.
| Interest rate offered | Holding after one year | Share of total supply |
|---|---|---|
| 0 percent, holding only | 100,000 DOGE | falls by around 3.2 percent |
| 2 percent | 102,000 DOGE | still falls by around 1.2 percent |
| 3.2 percent | 103,200 DOGE | stays roughly level |
| 6 percent | 106,000 DOGE | rises by around 2.7 percent |
The table answers no question about the price; it places the interest rate alone in context. An offer paying 2 percent on DOGE slows the dilution, it does not reverse it. Only above a good 3 percent does your share of the network genuinely grow. Anyone taking on the default risk of a lending transaction can hold the terms up against that benchmark.
Lending falls outside MiCAR, and what that means for your deposit
The European Union's Markets in Crypto-Assets Regulation, MiCAR for short, has applied since 2024. It governs who may hold, exchange and broker crypto assets, and attaches licensing duties and ongoing supervision to those activities. Custody of your DOGE with an authorised provider falls under it.
Granting and taking out loans in crypto assets is expressly not among the services MiCAR covers. That follows from BaFin's guidance notice on crypto-asset services under MiCAR, which lists the activities requiring authorisation. Lending is not on it.
That gap has a practical consequence. A provider can hold a MiCAR licence for custody and advertise it, while the yield product alongside is not covered by that licence at all. On top of that comes a point many underestimate: there is no deposit protection for crypto assets in any circumstances, not even with authorised providers. The €100,000 you know from your current account has no equivalent here.
Tax on DOGE lending: other income under section 22 EStG and the €256 exemption limit
Germany's Federal Ministry of Finance restated the treatment of crypto assets in a circular dated March 6, 2025, file reference IV C 1 - S 2256/00042/064/043. It replaces the circular of May 10, 2022 and is the authoritative administrative position.
For lending income held as private assets, it provides the following: handing over crypto assets for a fee is a service, and the consideration counts as other income under section 22 of the Income Tax Act. It is taxed at your personal rate and not at the flat withholding rate of 25 percent. For income from services under section 22 number 3 there is an exemption limit of €256 per calendar year. Exceed it and the entire amount is taxable, not merely the part above the threshold.
What that means in numbers
On a holding of 100,000 DOGE at an interest rate of 3 percent, 3,000 DOGE accrue over the year, worth about €253 at the current price. That sits just below the exemption limit. A somewhat larger holding or a higher price is enough to tip the calculation, and then the full amount has to be declared. Anyone using several products adds up all income from services for the year. A crypto tax tool records these inflows with date and price, which is barely manageable by hand once payouts are daily.
The holding period stands: one year under section 23 EStG, even if you lent out
Here the 2025 circular clears up a persistent misconception. The draft of the original 2022 circular provided for the holding period to extend to ten years where crypto assets are used to generate income. That rule was not carried over into the version in force.
So the position stands: gains on the sale of crypto assets are tax free under section 23 of the Income Tax Act where more than a year lies between acquisition and sale. That applies expressly even where the assets were used for staking or lending in the meantime. Within the year an exemption limit of €1,000 applies, raised from €600 previously.
From this follows a clean separation that you should carry through your own records. The capital gain on the original holding follows section 23 with its one-year period. The interest income follows section 22 and is taxable in the year it is received. Each unit received as interest also starts a holding period of its own, because it counts as acquired at the price on the day it arrives.
Leverage of 2 to 1 at German providers against 101 perpetual markets abroad
Anyone looking not for interest but for leverage runs into a second peculiarity of the German framework. Our own review of CoinGecko derivatives data found 101 live perpetual markets on DOGE on October 6, carrying some $2.18 billion in open positions between them. The three largest venues held 31.0 percent of that, the ten largest 65.1 percent. Other counts arrive at lower figures; the data service Coinglass was most recently quoted at around $1.52 billion. Depending on the set of exchanges captured, the total therefore lies between $1.52 billion and $2.18 billion, in every case a multiple of daily spot turnover of $519 million.
Most of these venues are not permitted to serve German retail clients. For those that are, a hard limit applies: under BaFin's general administrative act of July 23, 2019, reference VBS 7-Wp 5427-2018/0057, contracts for difference on cryptocurrencies sold to retail clients must be collateralised at 50 percent of notional value. That corresponds to maximum leverage of 2 to 1. Added to it are close-out once the account falls below half of initial margin protection, and negative balance protection capping liability at the capital paid in. How these limits bear on perpetual contracts is set out in our classification of perpetuals under MiFID.
At 2 to 1 it takes a price fall of roughly 50 percent to reach close-out. At leverage of 20 to 1, common abroad, roughly 5 percent is enough. Today's daily range of €0.083552 to €0.085781 already amounts to 2.6 percent.
Will the $0.10 resistance hold this time?
On the chart picture, expressly as context on other people's analysis and not as an expectation of our own: according to a TradingView review cited at Parameter, the 50-day line crossed the 200-day line from below over the weekend, the first such cross since August 2025. The next resistance levels named there are $0.10 and $0.106, with the September low at $0.079.
Against that reading stands positioning in the derivatives market. A Blockchain.news review dated October 6 puts 78 percent of positions held by larger accounts on the long side and 22 percent on the short side, with retail accounts at 72 to 28. The ratio of aggressive buys to sells stood at 0.67 and the funding rate at a neutral 0.01 percent. One-sided positioning without matching funding costs is treated there as a pointer to a possible flush lower, with a target zone named at $0.078 to $0.082. Both readings stand side by side, and neither is a forecast.
DOGE yield: the key points for your decision
- Separate the product from the chain. Every offer promising yield on DOGE is a lending transaction with a counterparty, because the chain pays out nothing. Read up on who your debtor is, whether the units leave custody and what notice period applies. The terms of the larger providers sit side by side in our comparison of yield platforms.
- Hold the interest rate up against issuance. Supply grows by 3.18 to 3.36 percent a year. Below around 3 percent an offer merely slows the dilution. Whether the premium is worth the default risk to you is something you decide with that figure in mind, not with the advertised rate alone. A side-by-side look at the houses is in our lending comparison.
- Keep two separate records. The capital gain on the holding follows the one-year period under section 23; the interest income has to be declared in the year it is received under section 22, with an exemption limit of €256. Record every inflow with date and price, most easily through a portfolio and tax tool.
(As of October 6, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
If you hold VELO, it becomes a different token in November. Velodrome and Aerodrome, the two largest decentralised exchanges on Optimism and on Base, are merging into a single protocol called Aero. At Coinbase the swap runs from November 2 to November 4, 2026; for each VELO you receive around 0.044 new AERO, and the exchange takes no fee for it. Anyone holding VELO in their own wallet, however, is not covered by this swap at all and has to act themselves.
November 2 is not actually the date on which things get tight for you. They get tight earlier: at Coinbase, VELO can already only be traded with a limit order today, and the exchange no longer accepts a plain market order. Anyone assuming there is time until November to sell the position in the normal way is therefore already wrong.
What exactly happens in the Velodrome and Aerodrome merger
Both exchanges belong to the category of decentralised exchanges, DEX for short. A DEX is a venue that works without a custodian: you swap directly out of your own wallet, and pricing is handled by a program on the blockchain instead of an order book inside a company. Velodrome is that venue on Optimism, Aerodrome the same blueprint on Base, the secondary network of Ethereum operated by Coinbase. Behind both stands the same development firm, Dromos Labs.
Both work on the so-called ve(3,3) model. That means: whoever locks their tokens for a fixed period receives voting rights in return and thereby steers which trading pairs the rewards flow into. The value of the token arises from this mechanism, and it is precisely this that is now being merged. Instead of two separate voting systems on two chains, there is to be one in future serving several networks. Among the first chains of the new protocol are OP Mainnet and Ink alongside Base.
To place the setting, it is worth a look at the ecosystem of the Coinbase chain Base, in which Aerodrome has played the largest role so far. The merger changes exactly that map: what were two regional top dogs becomes one provider across several networks.
The swap factor of 0.044 AERO per VELO and how it comes about
For holders of AERO nothing changes arithmetically; one old AERO becomes one new AERO. For VELO the factor of roughly 0.044 applies. That number derives from the announced split of the new supply: 94.5 percent of the new AERO quantity goes to the existing AERO holders, 5.5 percent to the VELO side. The basis for that split is the economic performance of both protocols in the 52 weeks before the announcement, that is essentially the trading fees and revenues each of the two exchanges earned in that period.
That split can be checked against the market, and this is the point at which the matter becomes verifiable for you. In early October, Aerodrome carries a market capitalisation of around $835.5 million, Velodrome around $48.6 million. Together that is about $884 million, and Velodrome's share of it is 5.50 percent. The announced split of 94.5 to 5.5 and what the market actually pays today therefore agree to a hundredth. The market has long since priced the merger in.
Worked through: 1,000 VELO yield 44 new AERO
Concretely, with the prices of October 6: AERO stands at $0.8355 or 0.7455 euros, VELO at $0.036265 or 0.032355 euros. A holding of 1,000 VELO is thus worth $36.26 or 32.36 euros in the market. After the swap that becomes 44 AERO, and at the same prices those are worth $36.76 or 32.80 euros.
The difference comes to 50 cents, that is 1.38 percent in favour of the swap. The market ratio of VELO to AERO stands at 0.0434, the offered factor at 0.044. For you that means one thing above all: there is no discount here that you would avoid by selling quickly beforehand, and no premium you could collect by buying in. Anyone trading hectically because of the swap factor pays trading fees for an advantage that does not exist in that order of magnitude.
One caveat belongs with it: this calculation is a still image. Prices move, and the factor of 0.044 is fixed, while the market prices of both tokens will fluctuate until the window in November. Whether the difference will then still be 1.38 percent, larger, or reversed cannot be said today and is not worth a forecast either.
At Coinbase the wind-down is already running: VELO by limit order only
Trading in VELO at Coinbase has already been switched to so-called limit-only operation. A limit order is an order with a price condition: you set the price at which you want to buy at most or sell at least, and the order waits in the order book until someone takes it at that price. A market order, by contrast, is executed immediately at the next best available price, and that option no longer exists for VELO there.
That this is not a normal state for small trading pairs is shown by the counter-check on the sister pair: AERO can still be traded at the same exchange without that restriction. Limit-only operation is the first stage of an announced two-stage wind-down path, on whose second stage VELO trading is discontinued entirely.
In practice that means three things. First, you no longer have an execution guarantee: your order sits in the book and may never be filled, or only in part. Second, the spread between bid and offer typically widens in such phases, because fewer participants are quoting. Third, exiting thereby becomes a decision with lead time rather than a click. Anyone reconsidering their choice of venue anyway will find in the crypto exchange comparison the points that matter on trading pairs, fees and authorisation in Germany.
The timetable: launch on October 21, swap from November 2 to 4
Two dates structure the process. On October 21, 2026 the unified protocol is to launch, initially on OP Mainnet and Ink among others. From November 2 to November 4, 2026 the swap window then runs at Coinbase, in which the two legacy tokens become the new AERO.
Within that window the exchange pauses deposits and withdrawals of the legacy tokens. Anyone wanting to move holdings to or from Coinbase during those three days therefore cannot. Anyone wanting to shift their holding before the window is better off doing it well in advance and not on the evening of November 1, because a withdrawal on a network can take time depending on load.
Coinbase charges no fee for taking part in the swap, according to its own announcement. That concerns the conversion itself, not the trading fees that arise on a purchase or sale as they otherwise would.
Those whose holding sits at Coinbase and those who self-custody: two different routes
Here runs the dividing line at which, in experience, money gets lost. If your VELO sits in the Coinbase account, the swap happens without any action from you. You have to click nothing, confirm nothing and apply for nothing; after the window, AERO is in the account.
If instead you hold VELO in your own wallet on Optimism, you are not covered by Coinbase's handling at all. For that case there is the protocol's own migration route, and you have to take it yourself. Anyone who misses it holds, after the swap, a token that is no longer traded at its home venue.
A precautionary rule applies here that matters more at any token migration than the migration itself: migration pages are a classic target for fraud attempts. Around every announced swap, replica pages appear demanding a wallet connection and an approval, and with it they clear out the holding. You obtain the address of the genuine migration route exclusively via the official project page, never via a link from a direct message, a comment or a search ad. How to custody holdings in general so that a single bad approval does not cost everything is set out in the hardware wallet comparison.
veVELO locks: tied positions are the least clear part
In the ve(3,3) model there are, alongside the freely tradable tokens, the locked positions, called veVELO at Velodrome. Whoever locks gives up availability for a set period and receives voting rights and a share of the protocol's revenues in return. These positions sit, by their nature, in the protocol itself and not on an exchange.
It is precisely on this that the least solid information is publicly available. The announced split of 94.5 to 5.5 percent expressly includes the locked positions on both sides, so there is no indication that they come away empty-handed. How a running lock period is treated at the transition, whether voting rights continue seamlessly, and what happens to positions whose term reaches beyond the swap cannot currently be answered conclusively from the outside. Anyone holding a locked position therefore follows the project's announcements more closely than someone who only has free tokens sitting on an exchange.
Tax on a token swap: section 23 of the Income Tax Act and the open holding-period question
In Germany, gains from the sale of crypto assets held privately fall under section 23 of the Income Tax Act, the private disposal. The basic rule is familiar: hold for more than a year and you stay tax-free; sell within the one-year period and you pay tax on the gain at your personal rate, provided the exemption threshold is exceeded. The Federal Ministry of Finance most recently set out the treatment of crypto assets in its circular of March 6, 2025.
The point of dispute in a process like this one is: is the swap of one token for another a disposal that starts a new holding period? A swap from one crypto asset into another is in principle treated like a sale for tax purposes. Whether that also applies to a conversion in which the same project replaces its token and the holder economically keeps the same thing is a question of the individual case that nobody here can answer for you across the board. This is expressly not tax advice, and with meaningful amounts the question belongs with a tax adviser.
What you can do regardless is secure the evidence. Record which VELO holding you had at which point in time, at what factor it was converted and when. Anyone recording their purchases and swaps as they happen anyway has an easier time at year end; the comparison of tax tools and portfolio trackers shows which tools map such conversions cleanly.
An older ratio of 0.55 AERO per VELO is still doing the rounds
Anyone researching the topic comes across reports from the announcement period stating an entirely different ratio: 0.55 AERO per VELO. That ratio was a proposal from an early phase and was expressly marked as non-final at the time. It is not the factor at which the swap now takes place.
What governs is the number the exchange states for the November window, and that stands at around 0.044. The best protection against an outdated search hit is the cross-check from the second section: a factor of 0.55 would assign the VELO side around 40 percent of the new supply, while its market capitalisation today sits at a good 5.5 percent of the combined total. A number that is off by a factor of seven from what the market pays is in all likelihood out of date.
What this swap does not remove in terms of risk
A swap rearranges the tokens, but it does not turn a risky asset into a safe one. Three points remain unchanged.
First, protocol risk. Decentralised exchanges run on program code, and errors in that code have repeatedly proved expensive in recent years. A merger means new, altered code, and new code is least tested in its first weeks.
Second, liquidity risk. VELO currently turns over around $2.0 million a day, on a market capitalisation of around $48.6 million. In such a market even a medium-sized order moves the price, and in the limit-only phase that applies all the more. Anyone wanting to sort out the terms around decentralised trading, fee models and settlement in general will find the basics in the explainer on what a perp DEX is.
Third, price risk. On the direction of AERO after the merger this text deliberately says nothing. The combination widens the addressable market of both protocols; that is a fact about the structure, not a statement about the price. A total loss is possible at any time with crypto assets of this size.
The announcement of the combination comes from the development firm behind both exchanges and is documented on its own project page; the details on the window at Coinbase, on the factors and on the absence of fees were compiled among others by Cryptobriefing.
The VELO swap: What to take away
The swap itself is unspectacular and for exchange holdings even convenient. The work lies beforehand, and it consists of three steps.
- Settle where your holding sits. In an exchange account the swap happens automatically; in your own wallet on Optimism nothing happens at all unless you take the project's migration route yourself. If you are thinking about the venue anyway, the crypto exchange comparison helps with the question of where trading pairs, fees and authorisation in Germany fit together.
- Secure the records before the holding is converted. Noting the holding, the date and the factor costs five minutes and spares you a reconstruction in case of doubt. Which tools capture such conversions cleanly is shown by the comparison of tax tools and portfolio trackers.
- Check your custody before you grant an approval anywhere. Around every announced swap, replica migration pages appear. How to separate holdings so that a single bad approval does not cost everything is set out in the hardware wallet comparison.
(As of October 6, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
Bitcoin and Ethereum barely moved today, but Zcash and Monero are leading the largest coins over the last 24 hours.
Attacks grew more sophisticated and less predictable over the period, according to researchers who scanned more than 20 billion transactions.
A London quantitative hedge fund joins the round too, seven months after the NYSE's owner bought in at exactly the same price.
Clear rules of the road are here. So what does it all mean and what is the overall impact?
The No Betting on Your Own Race Act also gives prediction markets cover to close accounts and report candidates to regulators.
U.Today - IT, AI and Fintech Daily News for You Today
Wintermute reports the crypto bull cycle is early, explaining why top alts like NEAR, XRP, and ARB have suddenly stalled.
Trading activity has intensified in the XRP derivatives market as its futures volume hits its highest level in six months.
XRP Ledger validators reach 100% consensus ahead of fix update.
Ripple has expanded its push into institutional finance by deepening its partnership with Brevan Howard.
Zcash's Zebra node software receives four successive releases as developers prepare for the network’s next big upgrade.
Blockonomi
TLDR
- Brevan Howard will expand its use of Ripple Prime for brokerage, clearing, and financing services.
- The investment manager oversees about $35 billion in assets across its global business.
- Brevan Howard-affiliated funds joined Ripple’s $500 million funding round in 2025.
- Ripple built Ripple Prime after acquiring Hidden Road for about $1.25 billion in 2025.
- Ripple continues expanding Ripple Prime through institutional lending, multi-asset clearing, and digital-asset market integrations.
Ripple has expanded its relationship with Brevan Howard as the hedge fund increases its use of Ripple Prime for institutional trading services. The agreement gives Brevan Howard funds access to multi-asset prime brokerage, clearing, and financing across digital and traditional markets.
Ripple Prime emerged after Ripple acquired Hidden Road for about $1.25 billion in 2025. The platform now serves institutions seeking one system for financing, clearing, trading support, and access to several asset classes. It supports institutions that operate across markets without using separate brokerage relationships for each asset class.
Brevan Howard Expands Access Through Ripple Prime
Under the expanded agreement, Ripple Prime will support funds managed by Brevan Howard, which oversees about $35 billion in assets. The deal follows a recent 24/7 U.S. dollar settlement expansion for institutional clients in Asian and Gulf markets.
The arrangement comes as institutional firms seek faster settlement and broader access to digital assets. Brevan Howard serves sovereign wealth funds, pension plans, foundations, endowments, and other clients through its global investment business.
Existing Investment Ties Support New Agreement
Brevan Howard already had financial ties with Ripple before the latest expansion. Funds linked to the hedge fund joined Ripple’s $500 million strategic funding round in 2025, which valued Ripple at $40 billion.
Ripple has also expanded its institutional products during 2026. The company added Hyperliquid as Ripple Prime’s first direct DeFi venue integration, while Ripple’s recent XRP Asia payments push targets more activity across the XRP Ledger.
Ripple Prime Builds Multi-Asset Services
KBRA earlier assigned Ripple Prime a BBB rating as the business continued scaling. The rating agency noted plans to broaden the platform into areas such as equity prime brokerage and swaps as Ripple develops its institutional offering.
Ripple Prime also secured a $200 million debt facility from Neuberger Berman for institutional margin lending. Ripple later raised $275 million through a senior note offering in August to support prime brokerage, financing, and multi-asset clearing. That setup gives fund managers one route for several trading and financing needs.
Institutional Expansion Continues
Brevan Howard chief operating officer Alan McGroarty said closer links between digital and traditional markets are increasing demand for institutional-grade infrastructure. The expansion also comes as Evernorth’s Nasdaq listing process moves forward around the wider XRP market.
The expanded agreement gives Brevan Howard another route to manage trading, financing, and clearing through one provider. It also extends Ripple Prime’s role as Ripple builds services for institutions operating across traditional finance and digital asset markets.
The post Why Brevan Howard Is Expanding Its Ripple Prime Relationship appeared first on Blockonomi.
TLDR
- Prime Video has secured exclusive global broadcasting rights for the Emmy Awards through a six-year contract.
- The partnership begins with the 2027 awards ceremony and replaces the decades-old broadcast network rotation system.
- Viewers worldwide can watch the Emmys at no cost, with no Prime membership necessary.
- Neither party revealed financial details, though previous annual licensing fees totaled approximately $9.5 million.
- Amazon executive Mike Hopkins indicated plans to draw younger audiences and modernize the ceremony’s presentation.
Amazon has finalized a six-year partnership that designates Prime Video as the sole international broadcaster of the Emmy Awards. The Television Academy and Amazon jointly revealed the arrangement on Tuesday.
The partnership kicks off with the 2027 awards show. This marks the conclusion of the “Wheel Deal,” a decades-long system that cycled the broadcast annually through ABC, CBS, Fox and NBC.
The ceremony held this year marked the final installment under the rotating broadcast model. Beginning in 2027, Prime Video assumes responsibility for all six consecutive annual broadcasts.
Free Global Access Despite Streaming Migration
While transitioning to a streaming platform, Amazon confirmed the awards show will maintain free accessibility. No Prime membership will be required for viewers to access the broadcast.
The ceremony will maintain its traditional live September broadcast, preserving its established position in the annual entertainment schedule.
Both organizations declined to reveal the contract’s financial parameters. According to the Television Academy’s latest annual filing, previous yearly licensing agreements were valued around $9.5 million.
Production expenses for the ceremony are handled independently by the rights holder. This financial arrangement is anticipated to continue under Amazon’s stewardship.
For an organization of Amazon’s magnitude, the licensing fee represents minimal financial exposure. The strategic advantage centers on leveraging a prominent live broadcast to expand Prime Video’s audience reach.
This strategy confronts notable challenges. The latest Emmy broadcast attracted an average of 6.7 million viewers, representing a 10% decline from the previous year’s audience.
Despite this downturn, viewership demonstrated improvement compared to an all-time low recorded two years prior, suggesting modest audience recovery.
Platform Modernization Plans Take Center Stage
Mike Hopkins, who leads Prime Video, stated Amazon’s objective to capture younger demographic segments. He indicated the company intends to reimagine the ceremony’s presentation approach.
Concrete modifications to the broadcast structure remain undisclosed. Additional details are anticipated as the 2027 ceremony approaches.
The Emmy Awards launched in 1949. The ceremony honors excellence across television performance, writing and production categories.
For decades, the awards show has functioned as a cornerstone promotional platform for the American television industry.
Conventional broadcast networks have encountered intensifying pressure from streaming services in recent years. Consumer viewing patterns have increasingly migrated toward digital platforms for live programming and awards ceremonies.
Amazon represents just one player pursuing this strategy. The Academy Awards announced last year that the Oscars ceremony will depart ABC and transition to live YouTube streaming beginning in 2029.
This Emmy partnership incorporates another prestigious live broadcast into Prime Video’s expanding portfolio. The platform has already diversified into original cinema, episodic programming, athletic competitions and additional streaming collaborations.
Amazon now has until the 2027 broadcast to develop its updated approach and determine whether a streaming environment can successfully address the Emmy’s recent viewership challenges.
The post Emmy Awards Leaves Broadcast Networks, Signs Streaming-Only Deal with Amazon appeared first on Blockonomi.
TLDR
- Marvell Technology shares climbed approximately 8% on Tuesday following the company’s Investor Day event.
- Chief Executive Matt Murphy announced a fiscal 2031 revenue goal of $70 billion to $90 billion.
- The target represents roughly 55% to 60% compound annual growth from the fiscal 2026 revenue base of $8.2 billion.
- The company also increased its fiscal 2028 revenue projection to approximately $20 billion, exceeding previous Wall Street forecasts.
- Analyst consensus stands at Strong Buy, with a mean price target of $299.29 per share.
Shares of Marvell Technology rallied approximately 8% during Tuesday’s trading session, reaching an intraday peak of $290.82. The surge followed a comprehensive growth plan presented by Chief Executive Matt Murphy at the company’s Investor Day event held in New York.
Marvell Technology, Inc., MRVL
During his presentation, Murphy outlined an ambitious revenue forecast, projecting the company will achieve between $70 billion and $90 billion in sales by fiscal year 2031. This represents a dramatic expansion from the $8.2 billion in revenue Marvell recorded during fiscal 2026, which concluded this past January.
Achieving this projection would require compound annual growth rates between 55% and 60% throughout the next five fiscal years. The bold forecast immediately resonated with market participants, sending the stock higher within minutes of the announcement.
The semiconductor company went beyond its long-term projections. Management also elevated its fiscal 2028 revenue outlook to approximately $20 billion, an increase from the previously communicated $18 billion estimate.
This revised guidance exceeds the Street’s consensus expectation of $18.2 billion for that fiscal period. Financial analysts covering the stock are expected to recalibrate their financial models in response.
AI Infrastructure Fueling Revenue Expansion
The primary catalyst behind this aggressive growth outlook is artificial intelligence. Demand for semiconductors that enable AI-powered data center infrastructure has accelerated rapidly, and Marvell produces two categories of solutions positioned directly within this technological shift.
First are application-specific integrated circuits. Major technology companies including Alphabet and Amazon utilize these tailored components from Marvell. Within the $70 billion to $90 billion fiscal 2031 target, custom silicon is anticipated to generate approximately $30 billion at the midpoint of guidance.
The second category encompasses networking solutions. Marvell’s interconnect portfolio facilitates data transmission both inside individual data centers and across distributed facilities. Management projects this segment will contribute roughly $37.5 billion to total revenue by fiscal 2031.
The company has positioned itself strategically within the AI infrastructure buildout. Year-to-date through 2026, shares have appreciated nearly 250%, and the stock currently trades at approximately 50 times forward earnings estimates, reflecting significant growth expectations already embedded in the valuation.
Analyst Community Maintains Bullish Stance
Marvell Technology holds a Strong Buy consensus rating among Wall Street analysts, based on 23 Buy recommendations and five Hold ratings issued over the past three months. The average analyst price target stands at $299.29 per share.
This consensus target suggests roughly 2% potential upside from current trading levels, though it’s important to note these projections predate Tuesday’s updated guidance. TipRanks assigns Marvell a Smart Score of 9 out of 10, placing the stock in Outperform category.
This high score derives from a Strong Buy analyst consensus, positive blogger sentiment, and particularly optimistic news sentiment. Crowd wisdom indicators remain neutral, while hedge fund positioning has shown recent declines.
Market observers should anticipate revisions to analyst coverage in the near term. Given the substantially elevated revenue guidance, both price targets and investment ratings will likely undergo adjustment.
For the time being, the market’s response on Tuesday spoke volumes. Marvell Technology posted one of its most significant single-session gains of the year following a guidance revision that fundamentally reframed growth expectations through the end of the decade.
The post CEO Matt Murphy Sets Ambitious Five-Year Plan: Marvell (MRVL) Targets 55-60% Annual Growth appeared first on Blockonomi.
TLDR
- Aptos says MonoMove delivered up to 55x faster execution in selected internal tests.
- End-to-end workloads recorded broader throughput gains of three to eight times.
- Order-book matching improved about 7x, while liquidity-pool swaps gained 5x to 7x.
- Aptos plans to complete MonoMove’s full feature set by the end of 2026.
- The network targets a 2027 mainnet rollout, subject to testing and governance approval.
Aptos has introduced MonoMove, a new smart contract execution engine built to speed up onchain markets. The network says internal tests showed some transactions running up to 55 times faster than its current system. Users cannot access MonoMove yet, and Aptos plans a mainnet rollout in 2027 after testing and governance approval.
Aptos Rebuilds Its Move Execution Engine
MonoMove replaces the existing Move virtual machine rather than adding small changes. Aptos designed the engine to improve performance on a single processor core while also preparing it to handle more tasks at the same time.
The engine uses specialized instructions prepared before transactions run. It also stores working values in registers, reducing repeated processing during execution. The work comes as other networks also update trading infrastructure, including the recent Base Cobalt upgrade.
Benchmarks Focus on Onchain Trading
Aptos tested MonoMove by replaying real mainnet transactions from DecibelTrade. Internal results showed collateral withdrawals running up to 55 times faster, vault requests up to 40 times faster, perpetual requests up to 38 times faster, and order placements up to 22 times faster.
End-to-end tests showed smaller but broader gains of three to eight times across workloads. Order-book matching improved about seven times, while liquidity-pool swaps improved five to seven times. These figures measure full transaction processing rather than only one execution step. Aptos has not published an independent benchmark. Production performance may differ once all safeguards operate.
More Work Before Mainnet Release
MonoMove still needs several features before release. Aptos plans to add native functions, reentrancy checks, gas metering, and stronger parallel execution. Other networks are also working on faster market settlement, including the new Solana DvP settlement tool.
Aptos expects to complete the full feature set by the end of 2026. Developers will then compare MonoMove with the legacy AptosVM using identical transaction inputs. Developers would review any mismatch between the two engines before deployment.
Testing Sets Final Checkpoints
The project also includes formal verification, which uses mathematical methods to test whether code follows its intended rules. That process matters as onchain trading grows across major networks, with recent Solana DEX volume showing strong activity.
The final steps include completing parallel support, finishing safety checks, and publishing a governance proposal. Aptos plans to seek approval for a 2027 mainnet launch once MonoMove matches the old engine’s behavior and passes its remaining tests.
The post Aptos MonoMove Tests Reveal a Major Speed Shift appeared first on Blockonomi.
TLDR
- Prediction markets recorded more than $9.4 billion in weekend notional trading volume.
- Kalshi led with $7.13 billion, with football and combo contracts driving most activity.
- DraftKings and FanDuel added $7 million to Nebraska’s online sports betting campaign.
- The CFTC approved Kalshi’s US500 perpetual futures contract on October 3.
- Bank of America upgraded DraftKings to Buy and sees up to $800 million in prediction-market revenue opportunities for 2027.
Prediction markets set another weekend trading record as activity across Kalshi, Polymarket US, DraftKings Predictions, and Novig topped $9.4 billion. Kalshi led the market with $7.13 billion across Saturday and Sunday, while sports and combo contracts drove most of the volume.
Prediction Markets Set New Weekend Record
Kalshi posted $3.68 billion in volume on Sunday, beating Saturday’s $3.45 billion record. Football generated about $4 billion of weekend activity, including roughly $3.1 billion from combo contracts and $897 million from straight football markets.
Polymarket US passed $1 billion for the weekend, while DraftKings Predictions reached about $372 million. Novig reported roughly $286 million. Recent regulatory attention has also increased after new CFTC rules for event contracts moved to White House review.
Sportsbooks Fund Nebraska Betting Campaign
DraftKings and FanDuel each added $3.5 million to Tax Relief Nebraska before the Nov. 3 vote. BetMGM contributed another $250,000, taking election-year fundraising for the campaign to $14.65 million.
Nebraska voters will decide whether lawmakers can authorize online sports betting and create a regulatory system. The proposals would allow up to 12 mobile sportsbooks tied to the state’s six gaming facilities.
Kalshi Expands Beyond Event Contracts
The CFTC approved Kalshi’s US500 perpetual futures contract on Oct. 3. The product tracks a broad U.S. stock index without a fixed expiry date and uses funding payments to keep pricing close to the underlying index. Kalshi’s $40 billion funding talks have also drawn attention as the company expands its product range.
Polymarket is also fighting a Dutch enforcement action. The company argues its contracts are financial products and should fall under financial market supervision rather than gambling rules. Dutch regulators previously imposed a €420,000 penalty after the platform failed to comply with an order on time.
DraftKings Outlook Draws Wall Street Attention
Bank of America upgraded DraftKings to buy from neutral and kept a $27 price target. Analysts estimated prediction-market fees could reach about $400 million in 2027, with market making adding another $200 million to $400 million. Polymarket’s V2 settlement upgrade also shows how platforms are building new infrastructure as competition rises.
DraftKings shares gained more than 7% intraday Monday, although the stock remains down more than 40% this year. The sector now faces growing trading activity, regulatory disputes, and expanding financial products across several major platforms. Legal questions also continue across several key markets.
The post $9.4B Weekend Reshapes Prediction Markets—Who Is Gaining Ground? appeared first on Blockonomi.
CryptoPotato
XRP is consolidating around $1.50 after a strong rebound from the $1.00 area. The broader structure has improved considerably, but the latest price action suggests that buyers are struggling to push through the overhead resistance zone. The key question now is whether the asset can break the $1.70 resistance, or whether another pullback toward support develops.
Ripple Price Analysis: The USDT Pair
The daily chart shows a major structural recovery from the $1.00 support zone. XRP broke sharply higher in August and subsequently reclaimed both the 100-day and 200-day moving averages. The 100-day MA is now around $1.25, while the 200-day MA is around $1.28, with the 100-day average aggressively approaching the other for a potential bullish crossover. This is a constructive development from a medium-term perspective.
The main resistance is located between $1.60 and $1.70. XRP has already tested this area twice in recent weeks, with the latest attempt in September failing to break out. A daily close above $1.70 would represent a significant structural improvement and could open the door toward the next major resistance around $2. Above that, the next resistance zone sits around $2.40, which coincides with a major high formed early this year.
On the downside, the $1.25-$1.30 region has become particularly important. It contains the 100-day and 200-day moving averages and coincides with a marked demand zone. As long as XRP remains above this support area, the broader recovery structure remains intact. A deeper decline back toward the $1.00 area would become more relevant if this support is decisively lost, which would reverse all the recent gains and put the market under immense pressure once more.
The 4-Hour Chart
The 4-hour chart shows XRP trading inside a tightening structure beneath a descending trendline. The trendline currently acts as dynamic resistance, with XRP repeatedly failing to establish a decisive move above it. At the same time, buyers have continued to defend the green support zone around $1.45, creating a relatively well-defined consolidation range.
The immediate resistance is around $1.70, followed by the significant $2 supply zone. A breakout above the descending trendline and subsequent move through $1.70 would strengthen the bullish case and could bring the $2 level into play.
Conversely, a loss of the $1.45 support zone would weaken the short-term structure. In that scenario, XRP could retrace toward the $1.30 area, which is a clear demand zone that buyers should defend at all costs in the short term. Otherwise, a bearish reversal scenario would materialize, which could once again send XRP back toward the $1 area, and potentially lower this time. Still, the current structure is better viewed as consolidation, with a higher probability of a bullish breakout, rather than a bearish reversal forming.

The post Ripple Price Analysis: Is XRP Consolidation Almost Over as the Range Tightens? appeared first on CryptoPotato.
Ethereum is holding near $2.7K after a strong recovery from the summer lows, but the latest price action suggests that momentum has cooled. ETH is now compressed inside a narrowing structure at the 2.7K-2.8K resistance area, while the taker buy/sell ratio has weakened, pointing to more cautious short-term positioning.
Ethereum Price Analysis: The Daily Chart
On the daily timeframe, ETH remains in a constructive broader structure. The recovery from the June low around $1.5K established a series of higher lows, followed by a decisive move above the $2.4K area in late August. Since then, price has been consolidating rather than giving back the breakout.
The most important near-term resistance is the 2.7K-2.8K zone. ETH has repeatedly struggled to establish a sustained move above this region, with the latest candles continuing to trade around $2.7K. A daily breakout above $2.8K would likely strengthen the bullish structure and expose the next major resistance zone around 3.0K.
The broader trend remains supported by the major moving averages. The 100-day moving average is around $2.2K, while the 200-day MA is near $2.1K, with both positioned well below the current price and sloping upward. These averages have also printed a bullish crossover, which keeps the medium-term structure bullish despite the ongoing consolidation.
The chart also shows an ascending trendline connecting the summer low and subsequent higher lows. As long as this trendline and the $2.4K support area remain intact, the broader recovery structure appears healthy.
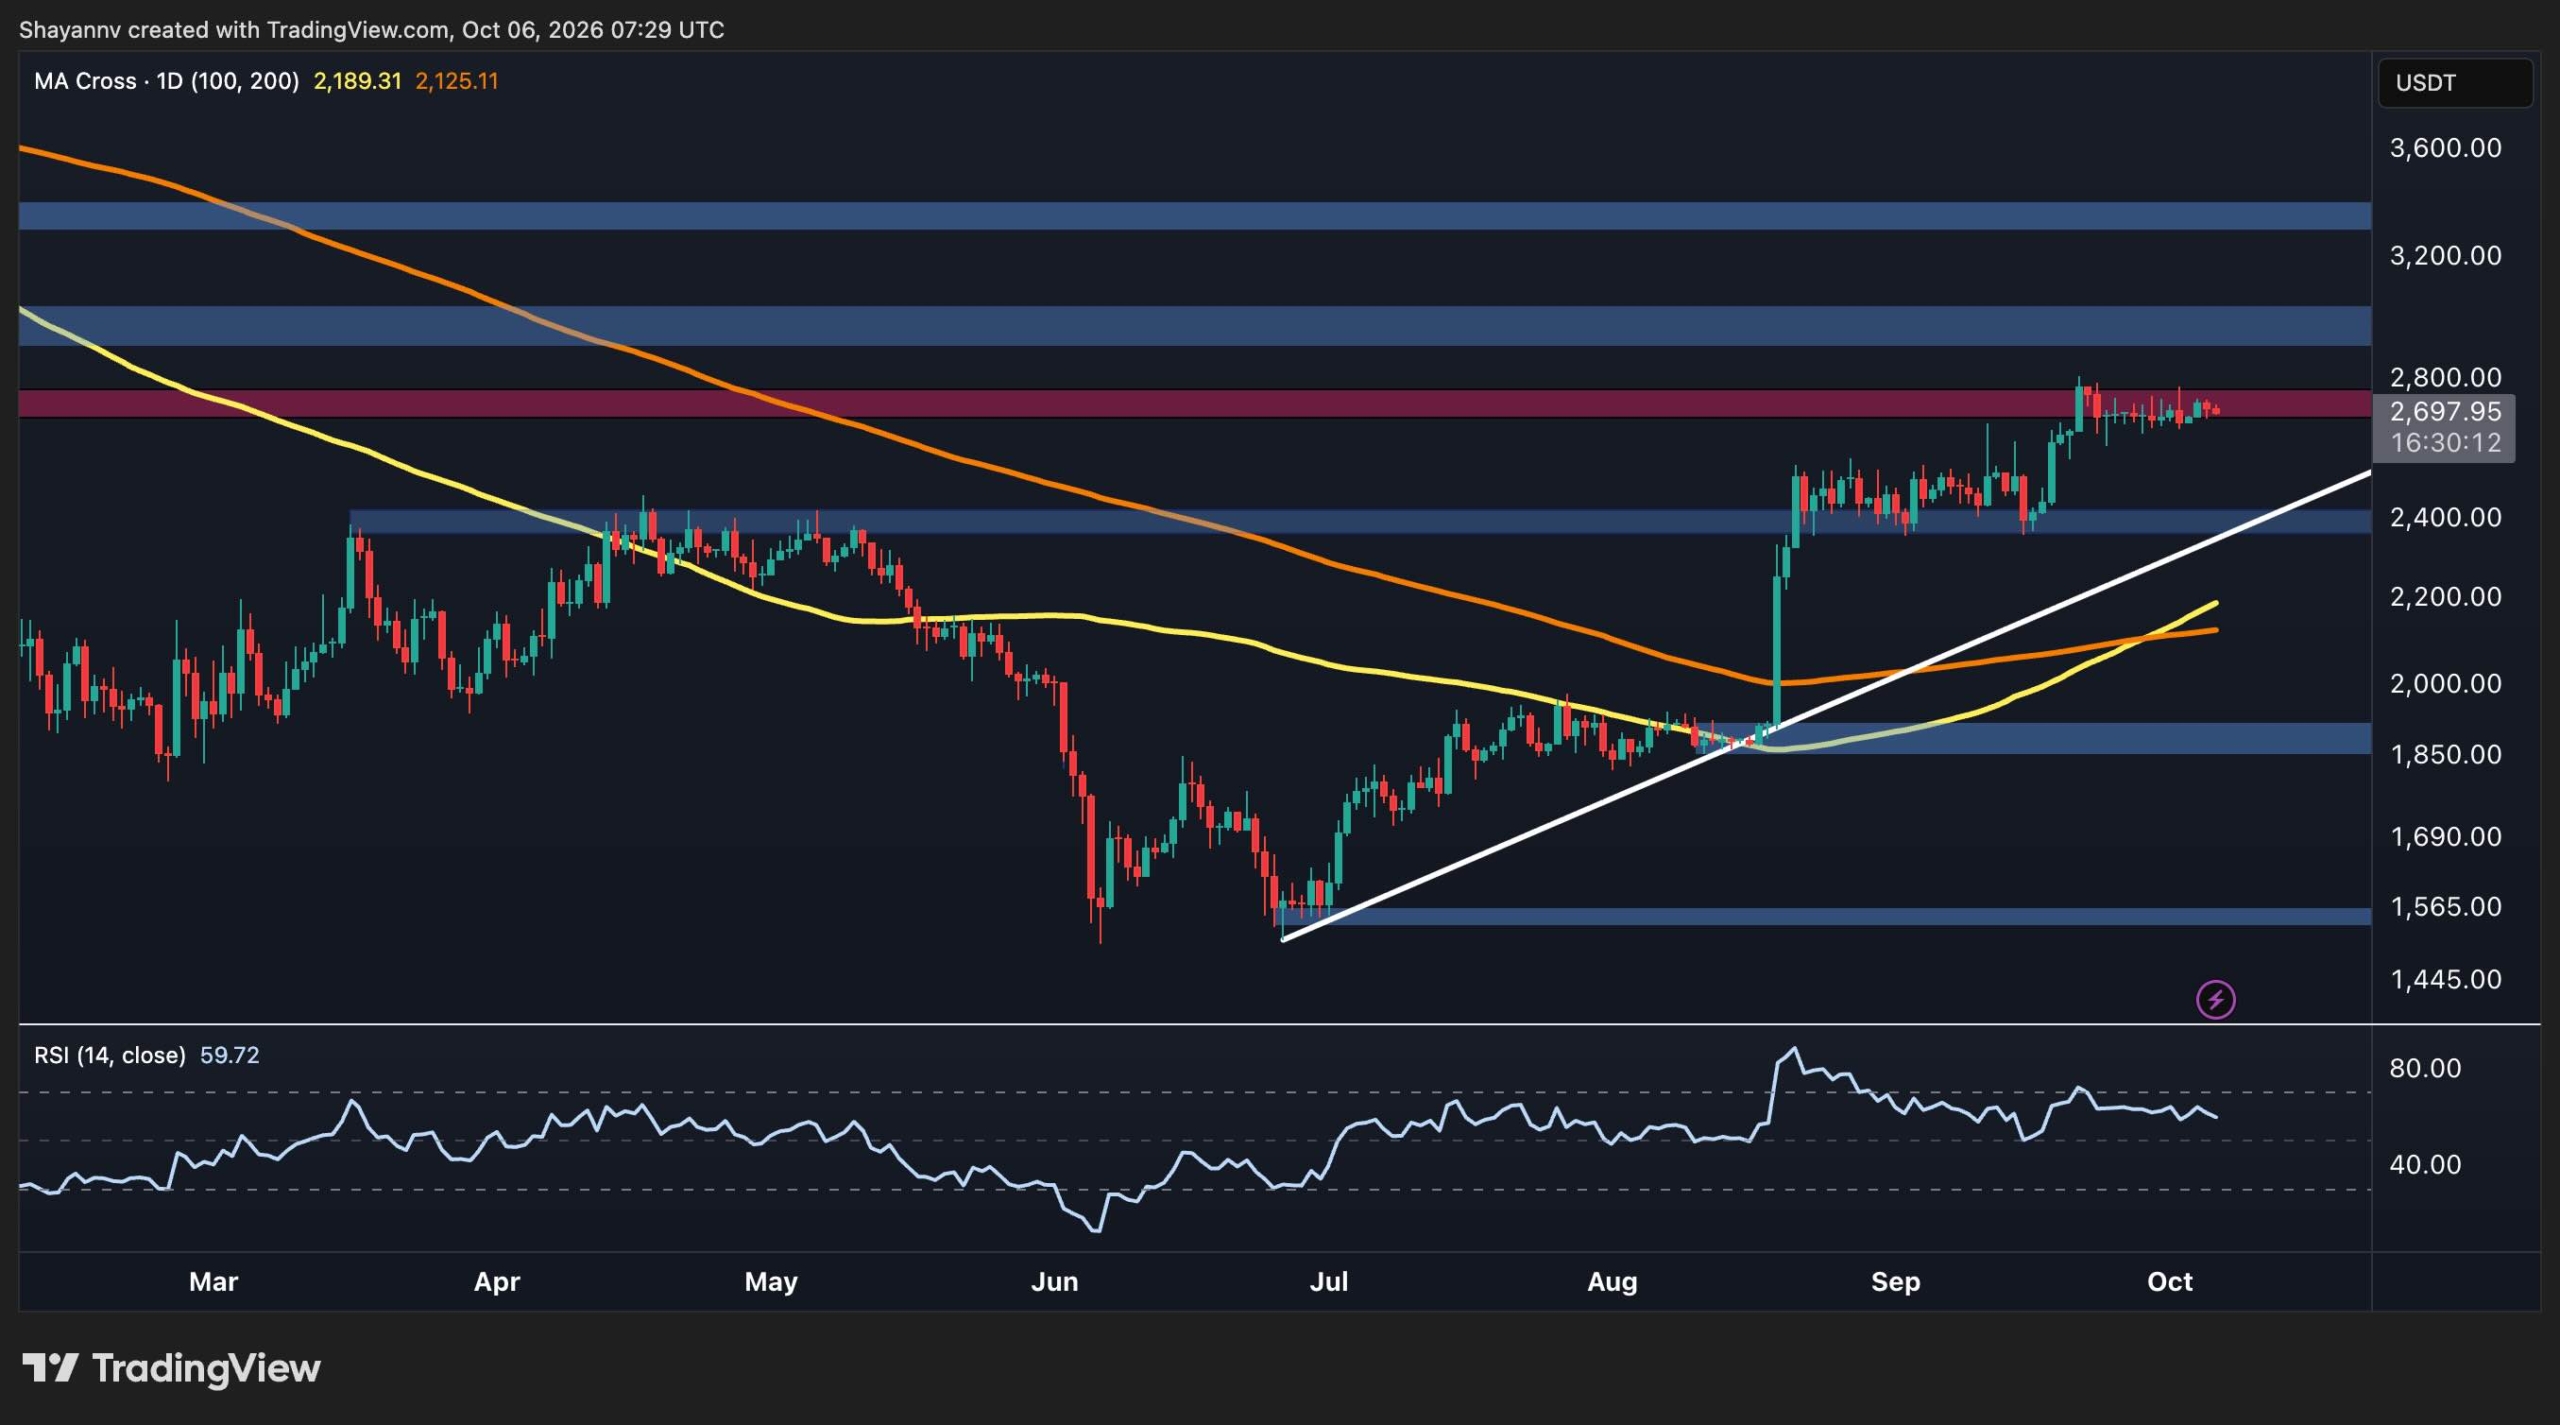
ETH/USDT 4-Hour Chart
The shorter-term chart shows ETH trapped inside a tightening structure between roughly $2.6K and $2.8K. The descending upper trendline and rising lower trendline are converging, creating a compression pattern that should eventually produce a directional breakout.
ETH is currently trading around $2.7K, close to the lower half of this range but still above the ascending support line. The immediate bullish trigger is therefore a clean move through the $2.8K area. Such a breakout would confirm that buyers have absorbed the supply that has repeatedly appeared near the recent highs.
On the downside, the rising trendline currently provides short-term support around the $2.7K mark. A break below it would increase the probability of a move back toward the $2.4K demand zone, which is the more significant structural support visible on the chart.
The 4-hour RSI is around 46.8, reflecting neutral-to-soft momentum. It is neither oversold nor showing a strong bullish impulse, which fits the current consolidation. In other words, the market is waiting for a catalyst rather than displaying a clear directional advantage.

On-Chain Analysis
The Ethereum taker buy/sell ratio provides a more cautious signal. The metric has fallen considerably from the elevated readings seen during the July-August advance, and the latest reading is below the 1.0 level, indicating that aggressive selling pressure is currently outweighing aggressive buying pressure across exchanges.
This suggests that the recent ETH consolidation is not being accompanied by a strong increase in futures market taker demand. The decline in the ratio is particularly notable because ETH is still holding around $2.7K rather than breaking down sharply.
That divergence could mean that spot and derivatives participants are becoming more cautious while passive demand continues to support price. For the bullish scenario to strengthen, a recovery in the taker buy/sell ratio back toward and above 1.0 would provide confirmation that aggressive buyers are returning.
For now, the futures market signal argues for caution rather than an outright bearish reversal. ETH remains technically above its major daily moving averages and structural supports, but the lack of strong taker buying leaves the potential $2.8K breakout as an important confirmation.

The post Ethereum Price Analysis: ETH Loses Steam at Key Resistance – Is a Pullback Coming? appeared first on CryptoPotato.
[PRESS RELEASE – Hong Kong, Hong Kong, October 6th, 2026]
ASICID Inc. has released its IDMINER Series, a new lineup of cryptocurrency mining systems designed for Bitcoin, Litecoin, and Dogecoin mining.
The series includes the IDMINER HomeRack, IDMINER 2 and IDMINER 1, with configurations ranging from 1,150 TH/s to 9,600 TH/s of Bitcoin hashrate and from 350 GH/s to 3,200 GH/s of Litecoin and Dogecoin hashrate.
The three models are designed for different mining setups, from individual and home miners to professional and larger-scale operators.
IDMINER Series Specifications
IDMINER HomeRack
- Bitcoin hashrate: 9,600 TH/s
- Litecoin/Dogecoin hashrate: 3,200 GH/s
- Power configuration: 4 × 1,300W
- Estimated monthly mining revenue: up to $25,590*
IDMINER 2
- Bitcoin hashrate: 2,400 TH/s
- Litecoin/Dogecoin hashrate: 800 GH/s
- Power consumption: 1,300W
- Estimated monthly mining revenue: up to $6,390*
IDMINER 1
- Bitcoin hashrate: 1,150 TH/s
- Litecoin/Dogecoin hashrate: 350 GH/s
- Power consumption: 700W
- Estimated monthly mining revenue: up to $2,790*
*The revenue figures are estimates based on network conditions, cryptocurrency prices, and mining difficulty at the time of publication.
Designed for Simpler Deployment
The IDMINER systems are delivered pre-configured and tested before shipment. Users can connect the miner to power, connect via WiFi or Ethernet, enter their preferred mining pool information, and begin mining.
The systems support major mining pools and also provide access to ASICID’s Zero-Fee Mining Pool option.
Other features include thermal management and hardware testing before shipment.
Built for Bitcoin, Litecoin and Dogecoin Mining
ASICID develops and manufactures its mining hardware through an integrated production process that includes research and development, hardware engineering, assembly, thermal testing, and quality assurance.
The company is headquartered in Hong Kong with additional operations in the United States and serves individual miners, professional mining businesses, and institutional operators.
With the IDMINER Series, ASICID is targeting miners looking for high-hashrate hardware with straightforward deployment and power requirements suited to ongoing mining operations.
For more information about the IDMINER Series, users can visit www.asicid.com.
The post New Generation of Crypto Miners Released by ASICID appeared first on CryptoPotato.
Tokenized stocks had a big year, but the market still has some clear gaps to fill. According to a new report from RedStone, the total on-chain value of tokenized stocks jumped from $640 million to $3.16 billion between September 28, 2025, and September 28, 2026.
That marks a 395% year-on-year increase.
Traders Turn to Perpetuals Instead
According to the report shared with CryptoPotato, stocks were the second-fastest-growing real-world asset category during the period. Tokenized private equity led the way with a much larger 935% jump. The growth also pushed tokenized stocks’ share of the wider RWA market to 8.1%, which is roughly three times higher than a year earlier.
But the numbers also show that most tokenized stocks are not being used much in DeFi. RedStone estimated that only about 2.6% of the total supply is being used as lending collateral. More than half of that amount comes from xStocks on Kamino and Jupiter Lend, worth around $43.8 million. Superstate’s tokenized Forward Industries shares on Kamino’s Opening Bell market accounted for another $25.4 million.
bStocks on Lista DAO add around $7.7 million. Ondo, despite being the biggest issuer, has very little lending activity. Its tokens back only about $1,400 on Morpho, while SPYon has around $4.2 million in Frankencoin. Around 42% of tokenized stock supply can technically be used as DeFi collateral. Despite this, traders appear more interested in derivatives than in lending or borrowing against the actual assets. Tokenized stocks mostly trade as perpetual contracts onchain.
Binance alone recorded $342.9 billion in equity-linked perpetual volume in August 2026. That was between 32 and 43 times the trading volume of tokenized stocks during the same month. On September 28, equity perpetuals on decentralized exchanges had $3.3 billion in open interest, which was already more than the entire tokenized stock supply. Trading also does not stop when traditional markets close. Around 55% of tokenized stock trading takes place outside regular market hours.
RedStone found that Sunday evening perp prices correctly pointed to Monday’s opening direction 65% of the time across 449 market weekends on Trade.xyz. The market now has around 4.04 million tokenized stockholders, with an average balance of about $780. But ownership remains a major concern. The three biggest issuers control roughly 70% of the sector’s on-chain value, yet their tokens do not give holders direct ownership of the underlying shares. There have also been cases involving disputed tokenized products and refunds.
Despite those risks, tokenized stocks have largely avoided major DeFi incidents over the past year. The Edel Finance manipulation was the main exception. Losses were estimated between $353,000 and $403,000.
Global Tokenization Race Heats Up
Regulation is also developing differently across regions. The US is largely moving through SEC exemptions and staff guidance, while Hong Kong, South Korea, and Abu Dhabi Global Market are taking more regulator-led approaches.
Hong Kong has already allowed 24/7 secondary trading for tokenized funds on licensed platforms. South Korea, on the other hand, is taking a slower route, as wider tokenized-stock access is expected after a second phase following its February 2027 registry launch.
The post Tokenized Stocks Surge 395% in a Year, But DeFi Adoption Remains Surprisingly Low appeared first on CryptoPotato.
The company behind XRP has doubled down on its partnership with Brevan Howard, one of the world’s largest alternative investment managers.
Ripple Prime will allow the firm access to multi-asset prime brokerage, clearing, and financing.
Another Institutional Heavyweight
The announcement shared earlier on October 6 reads that Ripple has expanded its ongoing relationship with the Wall Street giant to reflect growing demand from major investment managers for infrastructure that spans both traditional and digital assets. Brevan Howard will be able to use Ripple Prime across different asset classes and products, with the platform designed to simplify operations and improve capital efficiency.
“As digital and traditional markets become more interconnected, the need for institutional-quality digital asset infrastructure that enables a seamless experience for investors is only growing. Ripple has built a differentiated platform that we expect will provide our investment teams with increased operational ease and capital efficiency,” said Alan McGroarty, Group COO of Brevan Howard.
The two have some history, dating from the months after Ripple settled its legal dispute with the SEC. Funds managed by Brevan Howard affiliates participated in Ripple’s $500 million strategic investment in 2025. Consequently, the two parties have built on the ongoing partnership, and the latest agreement receives additional significance beyond standard client onboarding.
Moving Beyond Crypto
CryptoPotato reported recently that Ripple Prime launched a Delta One institutional trading platform allowing hedge funds, asset managers, and other clients to execute Total Return Swaps across US-listed equities, indices, and digital assets. Customers can also cross-margin exposures across asset classes through a single counterparty relationship.
Ripple Prime, formerly known as Hidden Road before the company behind XRP bought it for $1.25 billion, allowing the latter to become the first crypto firm to own and operate a global multi-asset prime broker. The business reportedly cleared more than $3 trillion annually and serves over 300 institutional clients.
The Brevan Howard partnership expansion only builds on Ripple’s latest strategy to move well beyond crypto and solidify its position across Wall Street.
The post Ripple (XRP) Scores Another Major Wall Street Win With Brevan Howard appeared first on CryptoPotato.