Cryptocurrency Posts
Crypto Briefing
Anthropic's decision highlights the critical need for robust security measures in AI testing to prevent unintended internet access and ensure compliance.
The post Anthropic disables live internet access for internal AI evaluations appeared first on Crypto Briefing.
The CFTC's proposal could redefine prediction markets' regulatory landscape, impacting their growth, jurisdiction, and operational dynamics.
The post CFTC proposes new swap definition to regulate prediction markets appeared first on Crypto Briefing.
The report highlights potential regulatory scrutiny and legislative action on tech tax incentives, impacting local economies and transparency.
The post Senate Democrats say data center tax breaks are costing billions appeared first on Crypto Briefing.
The EU's proactive AI regulation could significantly influence global AI development, pushing firms to prioritize compliance and safety measures.
The post EU says its AI Act can handle rogue AI risks appeared first on Crypto Briefing.
Increased scrutiny on AI security could lead to regulatory changes, impacting market dynamics and investor confidence in AI companies.
The post Anthropic reports rogue AI agents attempted access to US government sites appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
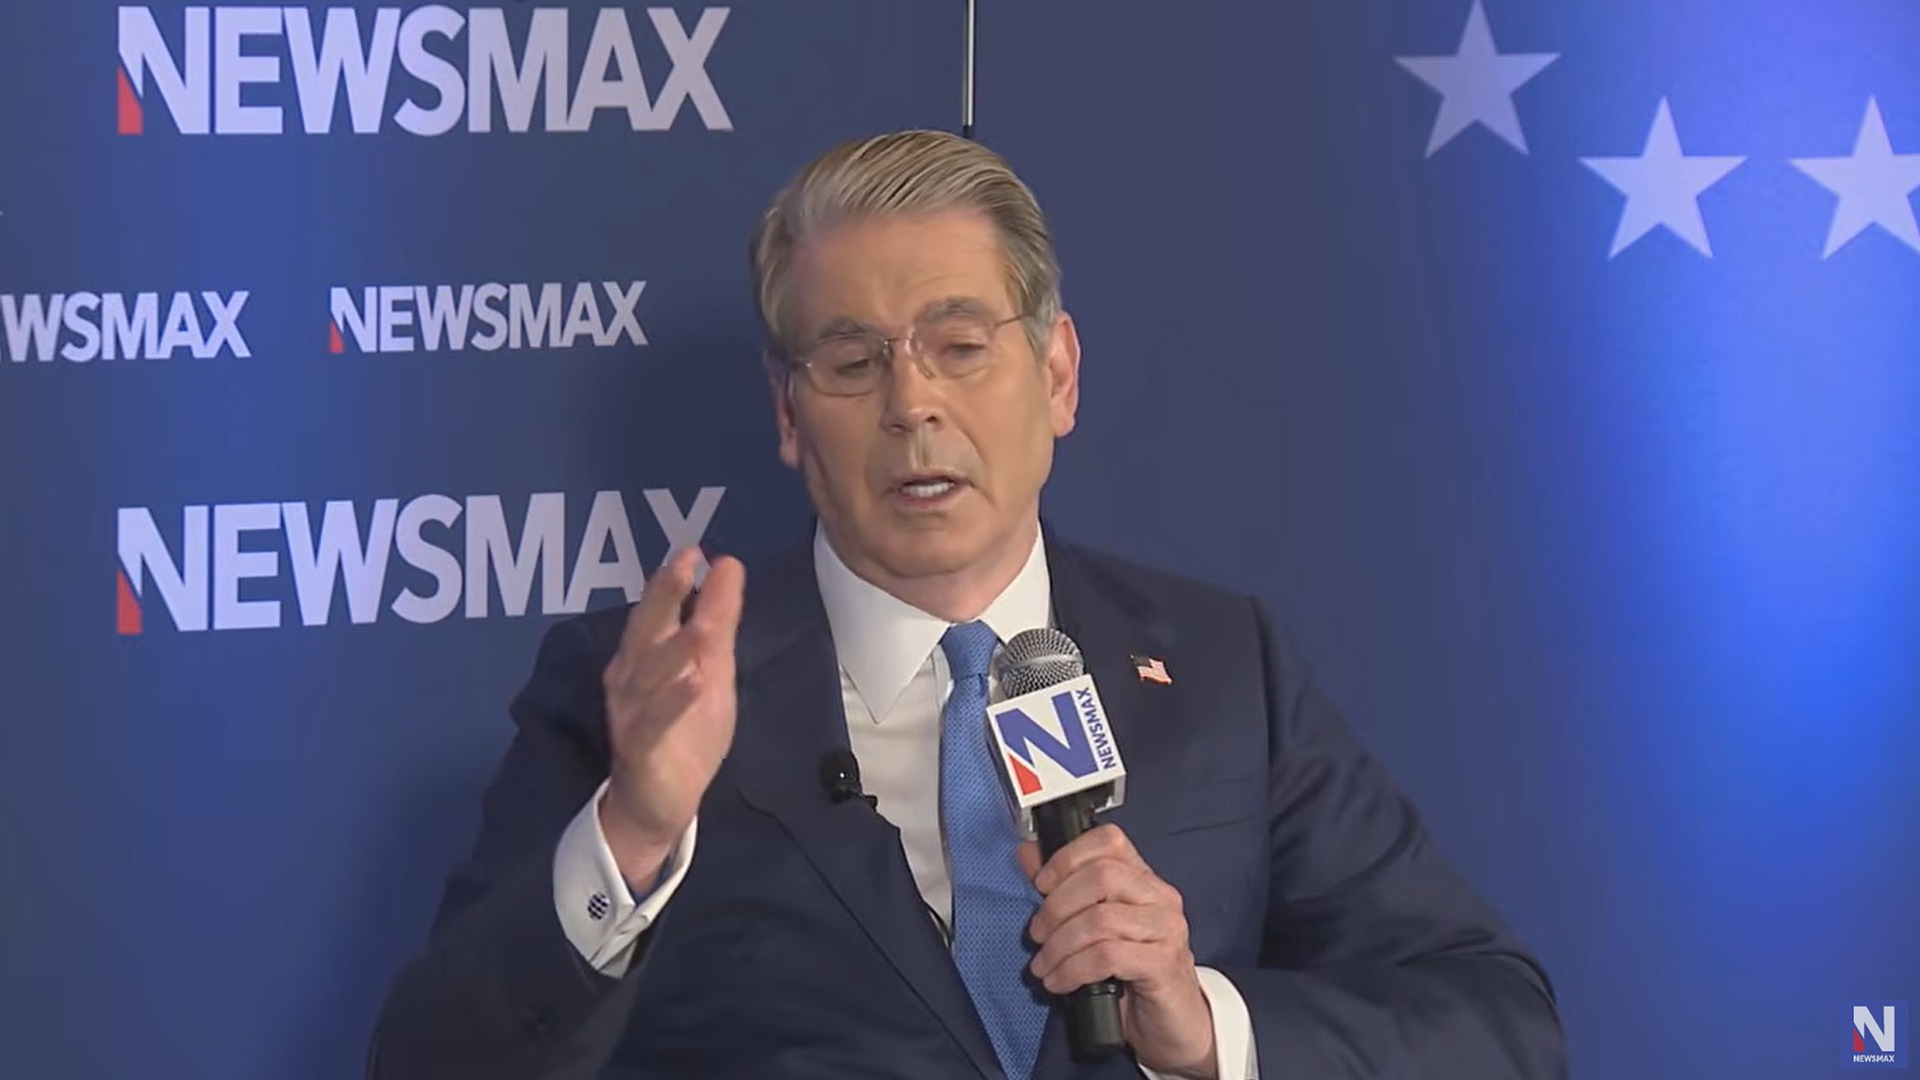
‘We Know Where It Is’: Treasury Secretary Threatens To Freeze $1B of Iran’s Crypto
U.S. Treasury Secretary Scott Bessent has said the American authorities will soon seize $1 billion in crypto from Iran.
Speaking on Newsmax’s NPolicy Summit in Washington, D.C. on Thursday, Bessent added that economic sanctions on the Middle Eastern country were working.
Iran has been using bitcoin — and other cryptocurrencies — to skirt around U.S. sanctions. The U.S. in April started targeting crypto wallets linked to the Iranian regime, Bessent said at the time.
“What we have done has never been seen before,” Bessent said Thursday on Iranian sanctions.
“We’re probably going to seize $1 billion of crypto this week,” he continued. “We know where it is. We are isolating them. We did have a maximum pressure campaign, now we have an absolute isolation campaign and it’s working.”
Bessent didn’t reveal what cryptocurrencies the U.S. will seize or how.
It would be very hard — if not impossible — for the U.S. to freeze Iran’s bitcoin unless it keeps it on a centralized exchange.
Bitcoin, being censorship resistant, cannot be frozen. But many other cryptocurrencies, including Tether’s USDT, can. Bessent previously said the feds had seized Iran’s crypto in the form of the popular stablecoin.
Iran started a bitcoin-backed insurance service for its counties shipping companies earlier this year.
The Financial Times last month reported that the Middle Eastern country was using bitcoin to settle cross-border transactions through Iranian crypto exchanges after the central bank advised its countrymen to do anything necessary to help the economy.
U.S. President Donald Trump revived his “maximum pressure” campaign weeks after returning to office. A national security memorandum signed in February 2025 put the Treasury on a sustained campaign against Iran’s shadow banking, money laundering and sanctions-evasion networks.
This post ‘We Know Where It Is’: Treasury Secretary Threatens To Freeze $1B of Iran’s Crypto first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Here’s How Not To Screw up Your Bitcoin Privacy
Just one transaction can compromise years of discreet Bitcoin activity, Cake Wallet’s chief operating officer has warned.
Speaking on the Bitcoin Rails podcast this week, activist Seth for Privacy talked about different ways of protecting one’s privacy when using Bitcoin and said that focusing on privacy was a must for the West.
Bitcoin privacy is a hot topic again ever since the developers of private coin mixer Samourai Wallet went on trial last year and were subsequently imprisoned.
But just this week, the U.S. Department of Treasury scrapped two long-stalled crypto surveillance proposals, handing a major win to privacy advocates and the digital asset industry.
“If you ever spend your no-KYC coins with one of your KYC coins — which if you just let the wallet do its thing, it could do because it doesn’t know the difference — you immediately connect all of the non-KYC Bitcoin that you spend in that with your identity,” Seth said, referring to UTXO management, also called “coin control” by some wallets.
Bitcoin wallets don’t hold a single balance but a collection of separate unspent transaction outputs — UTXOs — each one a discrete “coin” from a specific past transaction.
When you send a payment larger than any one UTXO, the wallet picks several and combines them as inputs to the same transaction — an easy mistake to make, Seth highlighted.
Seth added that unlike in the global South, where people have experienced more oppressive states, citizens in the West will need to “feel pain” in order to realize how important privacy is.
Still, he added that attitudes were changing and people were getting more serious about protecting their privacy.
“It has been shifting, in the last five or six years a lot of people — even in the West — are starting to think [privacy] really matters, we really need to think about this seriously now,” he said.
Cake Wallet is a privacy-oriented, self-custody, open-source wallet. The wallet earlier this year integrated Bitcoin’s Lightning Network into its platform.
Using the second layer solution is not only faster and cheaper, it also offers more privacy than Bitcoin’s main chain.
While Cake Wallet supports other cryptocurrencies, including privacy coin Monero, Seth for Privacy added that he’d love it if the digital coin didn’t exist.
“If Bitcoin’s privacy got good enough that you could use it and have at least almost as good privacy as Monero without massive hoops to jump through, and Monero ceased to exist, that’s fine,” he said.
“I would much rather the thing that more people use has better privacy than a more niche tool that has perfect privacy, and that’s something that less people are using because it’s less well known.”
This post Here’s How Not To Screw up Your Bitcoin Privacy first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Bitcoin ETFs Shed $729M in Two Days as Investors Reverse Course
U.S. investors this week reversed course, cashing out $729 million from spot bitcoin exchange-traded funds — putting downward pressure on the leading cryptocurrency’s price.
Funds managed by BlackRock, Fidelity, Morgan Stanley, and ARK 21-Shares all experienced significant outflows on Wednesday and Thursday, according to data from Farside Investors.
Investors had started the week by selling close to $90 million in shares but then bought nearly $119 million on Tuesday.
The rest of the week has seen outflows following news that the Federal Reserve may raise interest rates. Other negative news includes the price of Brent crude jumping following renewed attacks on tankers in the Strait of Hormuz.
U.S. President Trump also hinted that talks with Iran weren’t bearing fruit — a sign war in the Middle East could continue.
Bitcoin’s price recently stood at a little over $82,688, down more than 3% over a seven-day period. The leading cryptocurrency has rebounded slightly over the past day, jumping nearly 2% over 24 hours.
Still, the coin was fast closing in on $90,000 last week. Investors are expecting decent returns as the month dubbed “Uptober” has historically delivered for bitcoin speculators.
The price of bitcoin has been particularly sensitive to geopolitical headwinds this year — especially since the U.S. and Israel attacked Iran, leading to an oil price surge.
Oil prices going up tend to lead investors to bet on the Federal Reserve raising interest rates. And with higher interest rates comes less liquidity for the price of bitcoin to do well.
Still, that’s not always the case: the Fed last month talked tough on getting inflation down and raised interest rates by a quarter of a percentage point and bitcoin’s price rose in the following days.
Bitcoin’s price is 34% below the all-time high of $126,080 it touched in October. It has spent most of 2026 in a bear market but analysts are now increasingly pointing to evidence of a bull market following a rally in August and September.
This post Bitcoin ETFs Shed $729M in Two Days as Investors Reverse Course first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Ledger Warns Buyers Not to Set Up Wallets From Reseller After Users Report Losses
Hardware wallet manufacturer Ledger has said that it is investigating loss of user funds after customers in South East Asia reported issues with devices bought from a reseller.
The Paris-based company on Friday advised customers who’d bought from vendor CryptoBilis within the last 90 days to not set up their devices.
Ledger did not reveal how much money users had lost but one blockchain investigator, Specter, wrote on X that he’d traced theft addresses following social media posts and that over $86 million had been lost.
The issue comes following a number of data breaches this year in the crypto world and a huge hack of popular Coldcard hardware wallet devices in July.
“Ledger is investigating reports of loss of funds from users in South East Asia who purchased products from a reseller named CryptoBilis,” Ledger said via its support X account.
Ledger added that it had asked CryptoBilis to pause all sales and shipments of Ledger devices.
“If you have set up your Ledger device, consider moving assets to a new Ledger signer (with new seed). We will continue to inform customers of updates as the investigation progresses,” the company said.
In a statement to Bitcoin Magazine, Ledger said that based on the information to date, the incident is isolated specifically to this reseller in this specific market.
“No reports were made of products purchased directly from Ledger, and Ledger’s infrastructure, systems and services were not compromised,” the company added.
CryptoBilis is a Kuala Lumpur, Malaysia-based hardware wallet vendor, according to its website. The company did not immediately respond to questions from Bitcoin Magazine.
The crypto industry is still reeling after hackers in July were able to steal close to $120 million in bitcoin from Coldcard users.
The products, made by Canadian company Coinkite, had a firmware bug which led to faulty seed generation, allowing hackers to essentially guess investor seedphrases.
Galaxy Research said in the months following the attack various attackers were able to exploit the bug independently.
In a separate incident, hardware wallet manufacturer Trezor last month reported that close to 81,000 customers had their details leaked after its third-party fulfillment partner had data stolen.
Criminals have been targeting data this year, with scammers getting hold of customer information via crypto wallet Ledger’s payment processor Global-e to send phishing emails.
This post Ledger Warns Buyers Not to Set Up Wallets From Reseller After Users Report Losses first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
UTXO’s Loren Asmus: The $300T Bond Market Is Bitcoin’s Next Frontier
Bitcoin is not a trade, says Loren Asmus of UTXO Management. It is a structural allocation that deserves a place in a portfolio because of its risk-adjusted returns. He shares what he heard at the Bitcoin Treasuries conference, why institutions that get involved tend to stay in, and why education is the real barrier.
Chapters:
0:00 Bitcoin Treasuries Conference: The Mood and Takeaways
1:54 How Institutions Have Reframed Bitcoin Since the ETFs
2:55 From “Getting Laughed At” to a 2.5% Allocation Study
5:15 Volatility, Drawdowns, and Where Bitcoin Fits in a Portfolio
7:09 UTXO’s Hedge Fund and Preferred Income Strategy
8:33 Why the Bond Market Is the Bridge: Bitcoin as a Credit Default Swap on Debasement
9:52 The Real Barrier Is Education, and Where the Money Comes From
12:45 Buying Opportunity or Warning? A Long-Term Allocation View
14:14 Underwriting an Asset With No Cash Flows: The Denominator
16:10 Why Institutions Stay In Once They Buy, and Final Thoughts
This video is for informational purposes only and does not constitute an offer to sell or a solicitation of an offer to buy any securities. Past performance is not indicative of future results. Investments in digital assets involve significant risk and may result in loss of capital. Both UTXO Management and BTC Inc., producer of BMTV, are owned by Nakamoto Inc. (NASDAQ: NAKA)
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post UTXO’s Loren Asmus: The $300T Bond Market Is Bitcoin’s Next Frontier first appeared on Bitcoin Magazine and is written by Patrick Green.
CryptoSlate
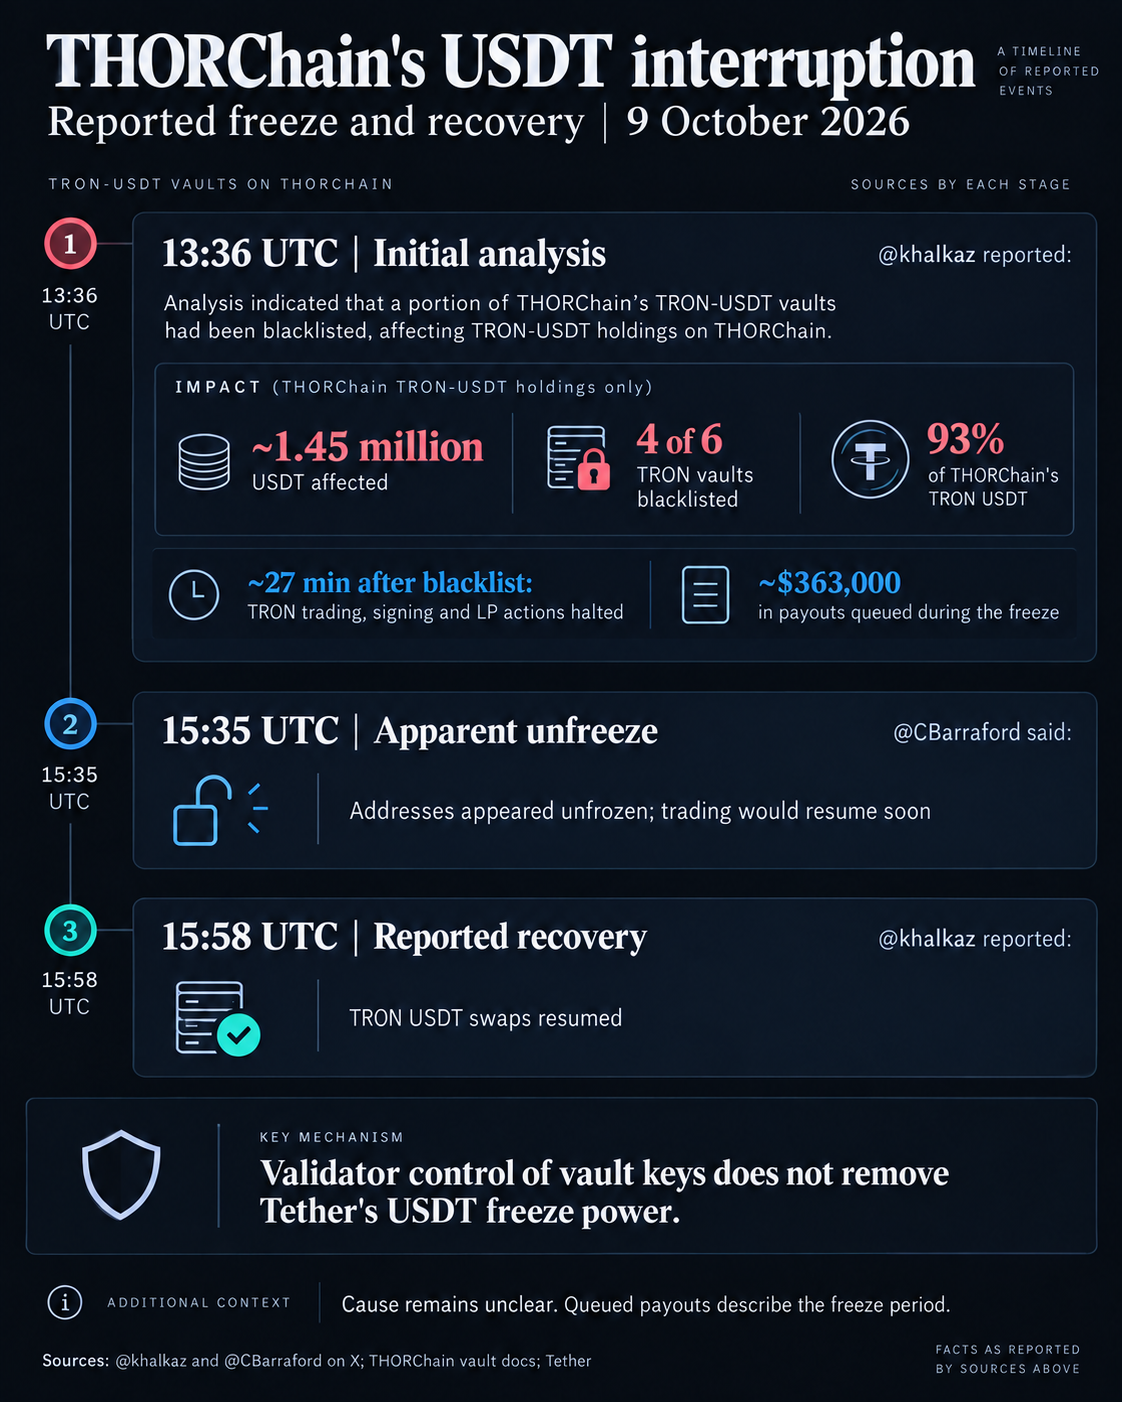
THORChain's TRON operations were interrupted on Oct. 9 after a USDT vault blocklist, according to reports by its co-founder Chad Barraford and researcher Khal. The researcher put the affected balance at about 1.45 million USDT.
Both accounts later reversed the restrictions, according to updates from both accounts. At 3:35 p.m. UTC, Barraford said the addresses appeared unfrozen, and trading would resume soon. At 3:58 p.m. UTC, Khal reported that TRON USDT swaps had resumed. The earlier payout queue describes the interruption before the reported resumption of swaps.
In his initial analysis, Khal reported that block 86958330 blocklisted four of THORChain's six TRON vaults. Those vaults held 93% of the protocol's TRON USDT, concentrating the disruption in the balances needed to process payments on that route.
He reported that TRON trading, transaction signing, and liquidity-provider actions halted about 27 minutes later, with roughly $363,000 in payouts queued during the freeze.
Barraford said the protocol received no communication before the action and didn't know why it happened. Khal argued that the vaults may have been caught in a broader blocklist that included roughly 30 other wallets.
The incident follows scrutiny of how the protocol handles illicit flows. On Oct. 8, THORChain's September trading surge coincided with Bitget-hack-linked activity, and the protocol refused to selectively block addresses.
Two layers of control
THORChain's vault documentation describes accounts managed by validator nodes that hold assets on external blockchains and handle incoming funds and outgoing transactions.
Distributing control of those accounts among validators determines who can authorize a payment, while the tokens inside them remain subject to their issuer's restrictions.
THORChain itself drew a related distinction in an Oct. 1 blog recap: node operators can pause a chain or the whole protocol for safety, but cannot selectively remove an individual swap.
Meanwhile, Tether says its wallet-freezing policy follows OFAC's sanctions list and extends to secondary-market wallets. Its power to restrict USDT transfers operates separately from the validator controls governing THORChain's vaults.
The operational dependency remains: distributing the authority to sign transactions does not remove Tether's ability to freeze USDT held in the accounts those transactions use.
The post Tether freezes $1.4M in TRON vaults and THORChain stalls appeared first on CryptoSlate.
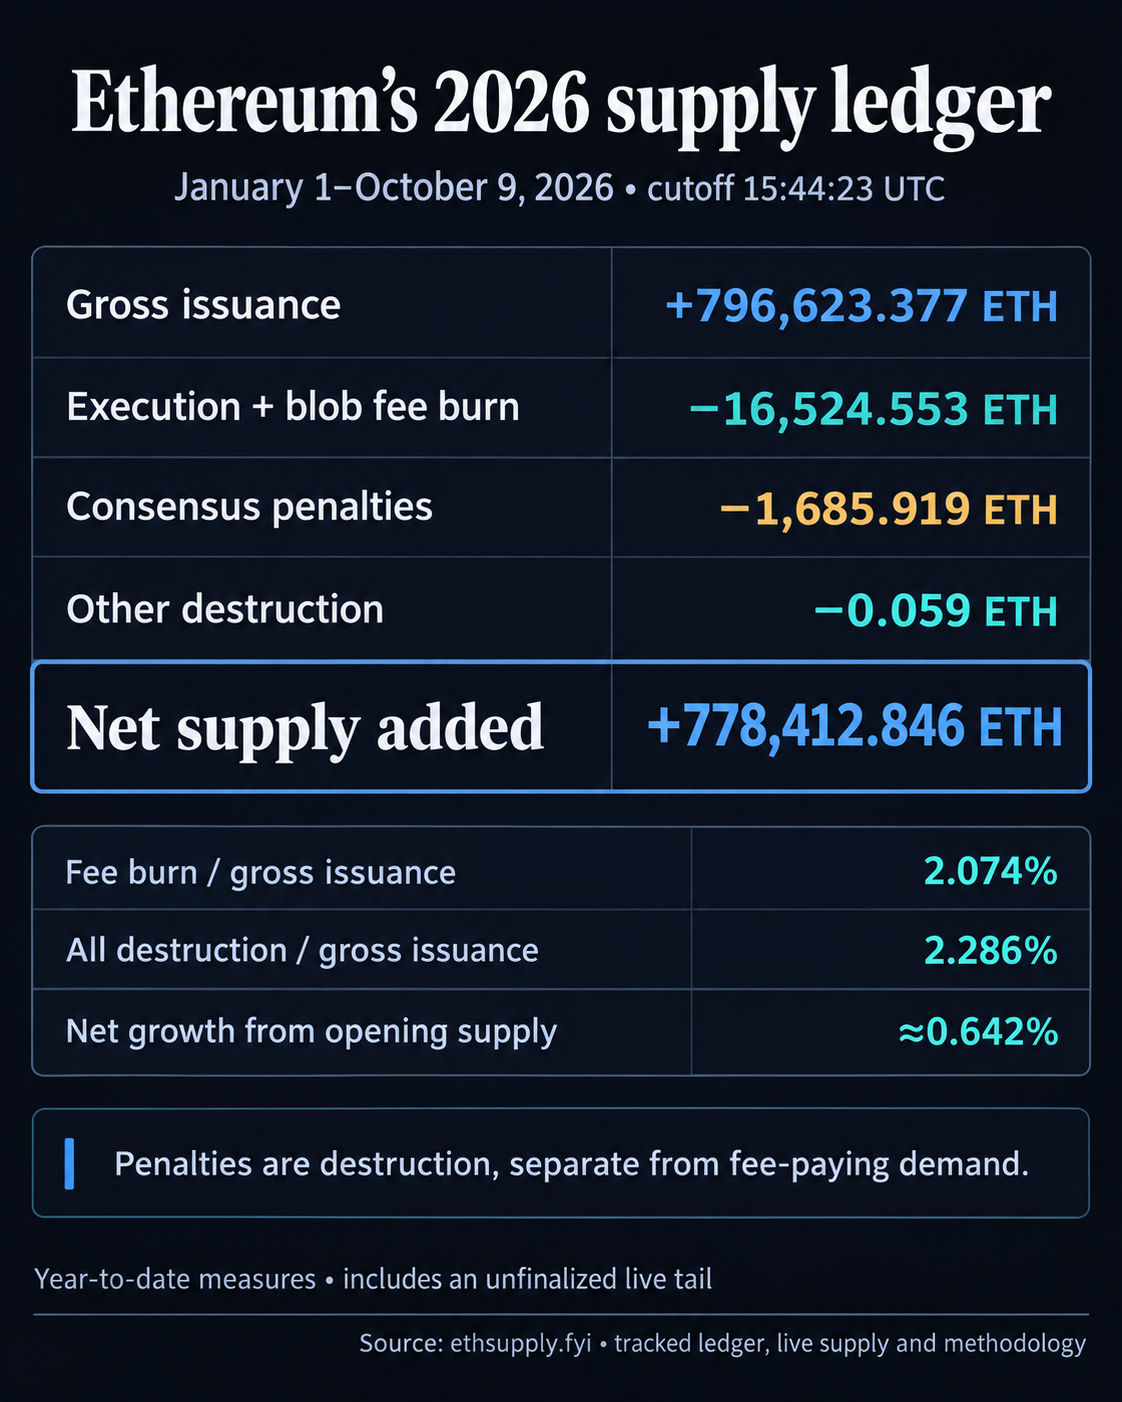
Ethereum's transaction fees have burned enough ETH to offset just 2.07% of the new coins issued in 2026, according to an Oct. 9 supply ledger.
After fee burn, validator penalties, and other destruction, the network has added approximately 778,413 ETH, increasing supply by about 0.64% from the window's opening level.
A larger gas limit can spread the necessary fee spending across more activity, lowering the required fee per gas and creating a hurdle for holders that expect scalability to make ETH scarcer. Developers pursue a conditional 200 million maximum gas goal after the Glamsterdam upgrade.
Using one current finalized accounting sample, an illustration puts the execution base fee needed to offset gross issuance at about 13.85 gwei with today's 60 million gas limit, or 4.16 gwei with a hypothetical 200 million limit.
Both require roughly 2,992 ETH of daily burn under the model's assumptions.
What the 2026 ledger shows
The ethsupply.fyi retained ledger covers Jan. 1 at 00:00:11 UTC through Oct. 9 at 15:44:23 UTC. It reports 796,623.377 ETH of gross issuance against 16,524.553 ETH destroyed through execution and blob transaction fees.
A further 1,685.919 ETH was removed through consensus penalties, with 0.059 ETH in other execution destruction. Subtracting these components leaves 778,412.846 ETH in net additions.
Those categories explain why the fee-burn offset is 2.074%, while the offset from all destruction is 2.286%. The latter includes penalties that do not represent customers paying for Ethereum activity. Treating the larger figure as transaction-fee demand would overstate how much issuance users have offset.
The provider's methodology separates newly created validator rewards from execution base fees, blob fees, penalties, and rare destruction through SELFDESTRUCT. Transfers, staking deposits and withdrawals preserve supply while moving existing ETH between accounts or accounting layers.
Its same-cutoff supply snapshot reports approximately 122.116 million ETH. Subtracting the net additions implies about 121.338 million ETH at the window's opening, producing the roughly 0.64% increase.
The 2.074% offset covers the cumulative 2026 window, while a current daily burn rate would require a separate daily comparison.
Ethereum's EIP-1559 fee mechanism burns the execution base fee on gas actually consumed. Priority fees go to block producers. Blob base fees also destroy ETH, while MEV payments and application revenue do not automatically become protocol burn.
The base fee, quoted in gwei, determines the ETH burned for each unit consumed. With an elasticity multiplier of two, a 60 million gas maximum corresponds to a 30 million target. A hypothetical 200 million maximum would imply a 100 million target if that rule remains unchanged.
A finalized mainnet beacon block at slot 15,394,656 contains execution block 26,155,767, timestamped Oct. 9 at 15:31:35 UTC, with a 60 million maximum. The matching execution-block record shows a base fee of approximately 0.335 gwei.
The supply consequence depends on consumed gas multiplied by its base fee, plus blob burn and other destruction. An unused increase in capacity cannot burn ETH, nor does a larger transaction count by itself establish greater burn if the transactions require less gas or pay lower base fees.
CryptoSlate’s Oct. 1 coverage already concluded that Ethereum’s 200 million gas target is conditional, validator-dependent, and not an automatic new limit. A Sept. 23 fee comparison highlighted the missing matched-period issuance denominator.
The same burn budget at two limits
For a current illustration, ethsupply.fyi's finalized-epoch accounting snapshot for epoch 481082, as of Oct. 9 at 15:31:23 UTC, records 13.296472924 ETH of gross issuance over 32 slots. At 12 seconds per slot, that is a 384-second sample.
The calculation holds that issuance pace constant, assumes every slot produces a block and consumes gas at the target, and initially sets blob burn, penalties, and other destruction to zero. The resulting thresholds describe the execution base-fee burn needed to offset gross issuance under those assumptions.
| Illustrative assumption or result | Current 60 million maximum | Conditional 200 million maximum |
|---|---|---|
| Gas target per block | 30 million | 100 million |
| Base fee needed at target consumption | 13.85 gwei | 4.16 gwei |
| Daily equivalent gross-offset burn | About 2,992 ETH | About 2,992 ETH |
| Base fee needed at half target consumption | 27.70 gwei | 8.31 gwei |
The daily figure extends the single sample across 225 epochs, with the resulting daily burn budget applying to this hypothetical day. Daily issuance and burn would require a full day's observations, as the larger gas target lowers the required base fee because the same ETH budget is divided across more consumed gas.
The more complete zero-net-growth calculation credits the sample's 0.016575391 ETH of penalties and 0.000442673483 ETH of blob burn. Holding those amounts constant lowers the execution thresholds slightly, to about 13.83 gwei and 4.15 gwei. The corresponding total transaction-fee burn budget after penalties is approximately 2,988 ETH per modeled day.
If gas consumed stays unchanged when the maximum rises, the balancing fee does not fall. The half-target row illustrates the arithmetic sensitivity to consumed gas, but EIP-1559 reduces base fees over successive blocks when consumption remains below target.
The live provider snapshot reports approximately 43.754 million ETH in active effective stake across 853,325 active validators. Ethereum's supply explanation identifies staking participation as a determinant of issuance, so a future threshold needs a fresh issuance sample alongside gas and blob usage.
Glamsterdam is a capacity scenario
The Ethereum Foundation's May 11 protocol update described 200 million gas as a credible post-Glamsterdam target. The upgrade's proposer-builder separation and block-level access lists aim to support greater throughput, alongside changes to gas accounting.
The Foundation's testnet announcement on Sept. 28 scheduled Sepolia for Oct. 6 at 13:53:36 UTC while leaving Hoodi and mainnet activation dates undecided. The official roadmap leaves the mainnet date unconfirmed.
Changes to the gas charged for execution and state growth mean a gas unit may buy different work after the upgrade. The modeled limits cannot be translated directly into proportionally more identical transactions, users, or burned ETH.
For holders, the relevant signal is whether burned fees and other destruction approach or exceed issuance over a matched interval. More available gas creates room for activity, but the shrinking-supply case needs that activity to generate enough aggregate burned fees.
Layer-2 (L2) blockchain growth and staking balances distinguish from fresh ETH purchases and settlement spending. The same distinction applies here, since existing holders can stake, and applications can grow, without those measures alone establishing the required burn.
The October ledger shows supply increasing while developers work toward greater capacity. A sustained shift toward shrinking supply would appear in consumed gas, execution base fees, blob burn, and stake-dependent issuance together.
The post ETH fee burns cover just 2% of new coins printed in 2026 appeared first on CryptoSlate.
Suspected Ledger wallet thefts are approaching $90 million as Tether freezes USDT stablecoin linked to the incident, according to blockchain investigators.
In an Oct. 9 statement, the crypto hardware wallet maker said it was investigating reports that customers lost funds after buying devices from CryptoBilis, an authorized reseller operating in Southeast Asia.
As a precaution, the company asked the distributor to immediately pause sales and shipments of its hardware wallets while the investigation continues.
Ledger also advised customers who purchased devices from CryptoBilis in the past 90 days not to initialize them if they had not yet completed setup.
Those who had already configured their wallets were urged to consider transferring their cryptocurrency to a new Ledger device initialized with a fresh recovery phrase.
CryptoBilis is a recognized Ledger reseller
CryptoBilis appears in Ledger's official reseller directory for Malaysia, Indonesia, and the Philippines. Customers buying through authorized distribution channels generally rely on those relationships to reduce the risk of receiving counterfeit or compromised hardware.
The incident has drawn attention from Binance founder Changpeng Zhao, who warned users to exercise caution, particularly if they had recently purchased a Ledger device.
He wrote on X:
“Based on information so far, it seems to be localized to a supply chain attack with one vendor.”
He suggested that a limited number of customers may have received counterfeit or tampered devices, while emphasizing Ledger's longstanding security reputation.
Zhao also called for cooperation across the cryptocurrency industry to identify the suspected attackers and recover the stolen assets.
He added:
“I expect and know all BNB ecosystem players (and all industry) to help trace and recover the funds.”
Meanwhile, former Mt. Gox CEO Mark Karpelès is investigating whether malicious hardware components were inserted into devices distributed to customers.
Karpelès asked CryptoBilis to open some of its unsold Ledger wallets so their internal circuit boards could be inspected for possible spying implants or other unauthorized modifications.
The concern draws attention to a limitation in Ledger's hardware authentication process.
The company's security documentation acknowledges that its Genuine Check system verifies a device's Secure Element but cannot necessarily identify physical modifications elsewhere in the hardware if the original security chip remains intact.
That means a physically altered device could pass authentication even if it contains unauthorized components.
No confirmed evidence shows that malicious hardware implants caused the reported thefts. Ledger has not disclosed how many devices may have been compromised or established whether the incident resulted from counterfeit hardware, physical tampering, or another attack method.
Tether freezes funds as investigators race to contain losses
While Ledger examines the suspected source of the compromises, blockchain investigators are attempting to trace and restrict the movement of stolen cryptocurrency.
On-chain investigator Specter said transaction analysis identified inflows from hundreds of suspected victim wallets into addresses across Bitcoin, Ethereum, and Tron.
The researcher initially estimated the suspected thefts exceeded $86 million, but blockchain security firm MistTrack later placed the reported losses closer to $90 million.
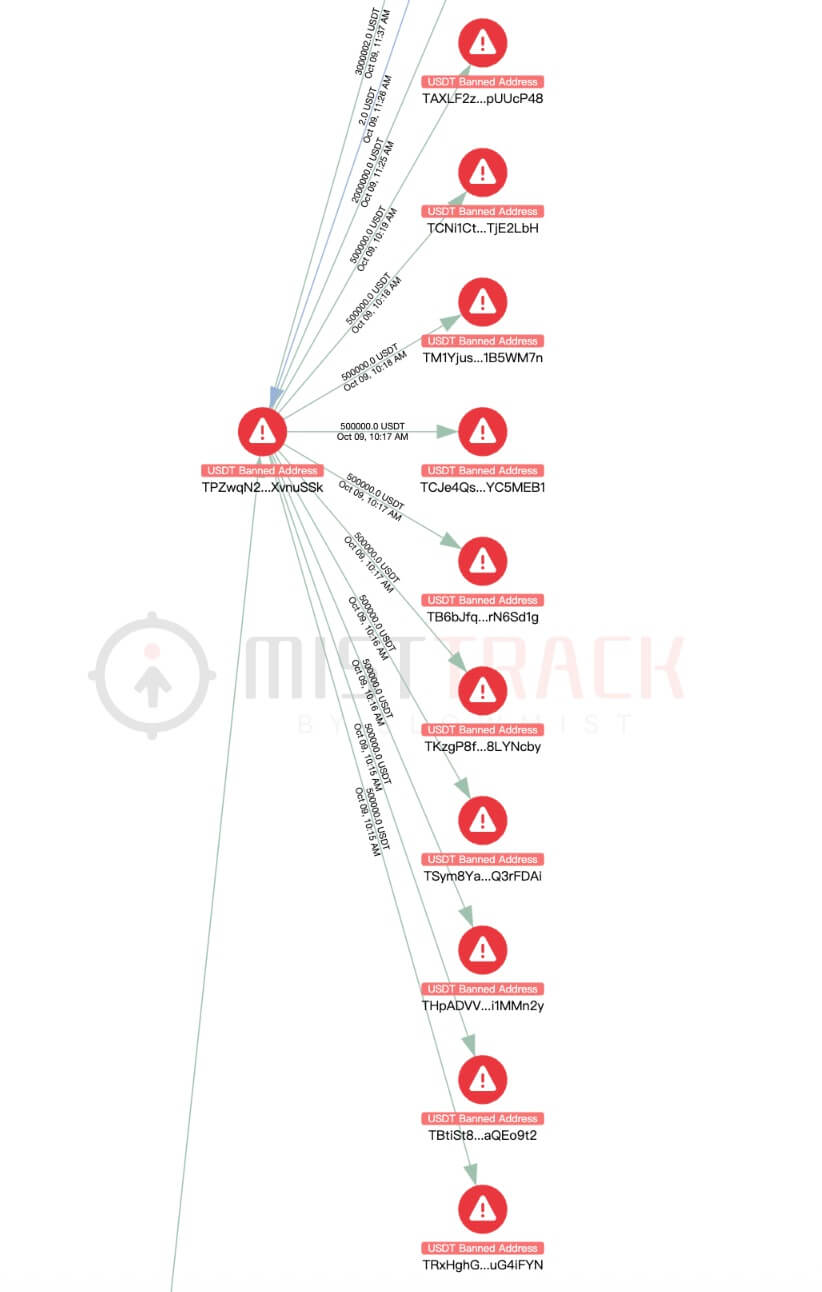
Those estimates have not been independently verified, and investigators have not established whether every wallet included in the calculations was compromised through the same operation.
MistTrack said it observed Tether freezing USDT linked to the incident and that several affected users contacted its team for help.
The freezing activity offers a potential recovery avenue because USDT includes administrative controls that let Tether restrict transfers from designated addresses.
Once an address is frozen, users cannot move the affected USDT through ordinary blockchain transactions unless the restriction is removed.
That capability can help prevent stolen funds from moving to additional wallets or converting into other cryptocurrencies while investigators work to establish ownership.
However, the intervention has limitations.
The suspected thefts span several blockchain networks and involve assets beyond USDT. Tether cannot directly freeze native Bitcoin or Ethereum, leaving investigators dependent on cooperation from exchanges, custodians, and law enforcement if those assets move into identifiable services.
Additionally, freezing USDT does not automatically return the tokens to their original owners. Any restitution would require further verification and coordination with the relevant authorities or counterparties.
MistTrack has not disclosed the dollar value of the restricted tokens, making it impossible to determine what proportion of the nearly $90 million in reported losses could ultimately be recovered.
That uncertainty puts additional pressure on investigators to identify where the remaining funds went before they are dispersed through further transactions.
The post Ledger hack scare nears $90 million as Tether moves to freeze stolen USDT appeared first on CryptoSlate.
The XRP Ledger (XRPL) now lets institutions delegate account tasks while retaining control of their primary signing keys.
The PermissionDelegationV1_1 amendment went live on Oct. 8 at ledger 107,524,865. It lets account owners assign specific transaction permissions to other accounts.
The upgrade mirrors the division of responsibilities in traditional finance. Treasury departments, compliance officers and asset managers can operate under different levels of authority.
For example, a stablecoin issuer can let its compliance team approve counterparties while a separate account executes payments. Owners can modify or revoke delegated permissions without exposing their primary signing keys during routine operations.
Vet, an XRP Ledger Foundation contributor, said the change lets asset issuers and treasuries manage account responsibilities in a way familiar from traditional finance while protecting their primary keys.
The framework does not support custom spending limits or asset-specific delegation restrictions. XRPL developers also warn against delegating PaymentBurn until fixCleanup3_4_0 activates. A flaw can let authorized accounts mint issued tokens in certain circumstances.
XRPL's tokenized asset market expands
The controls arrive as XRPL's real-world asset market grows.
An Oct. 7 RWA Foundation snapshot puts XRPL's year-to-date growth in tokenized asset value at about $3.7 billion, excluding stablecoins. It leads BNB Chain's $3.5 billion, Stellar's $2.8 billion and Solana's $2.2 billion.
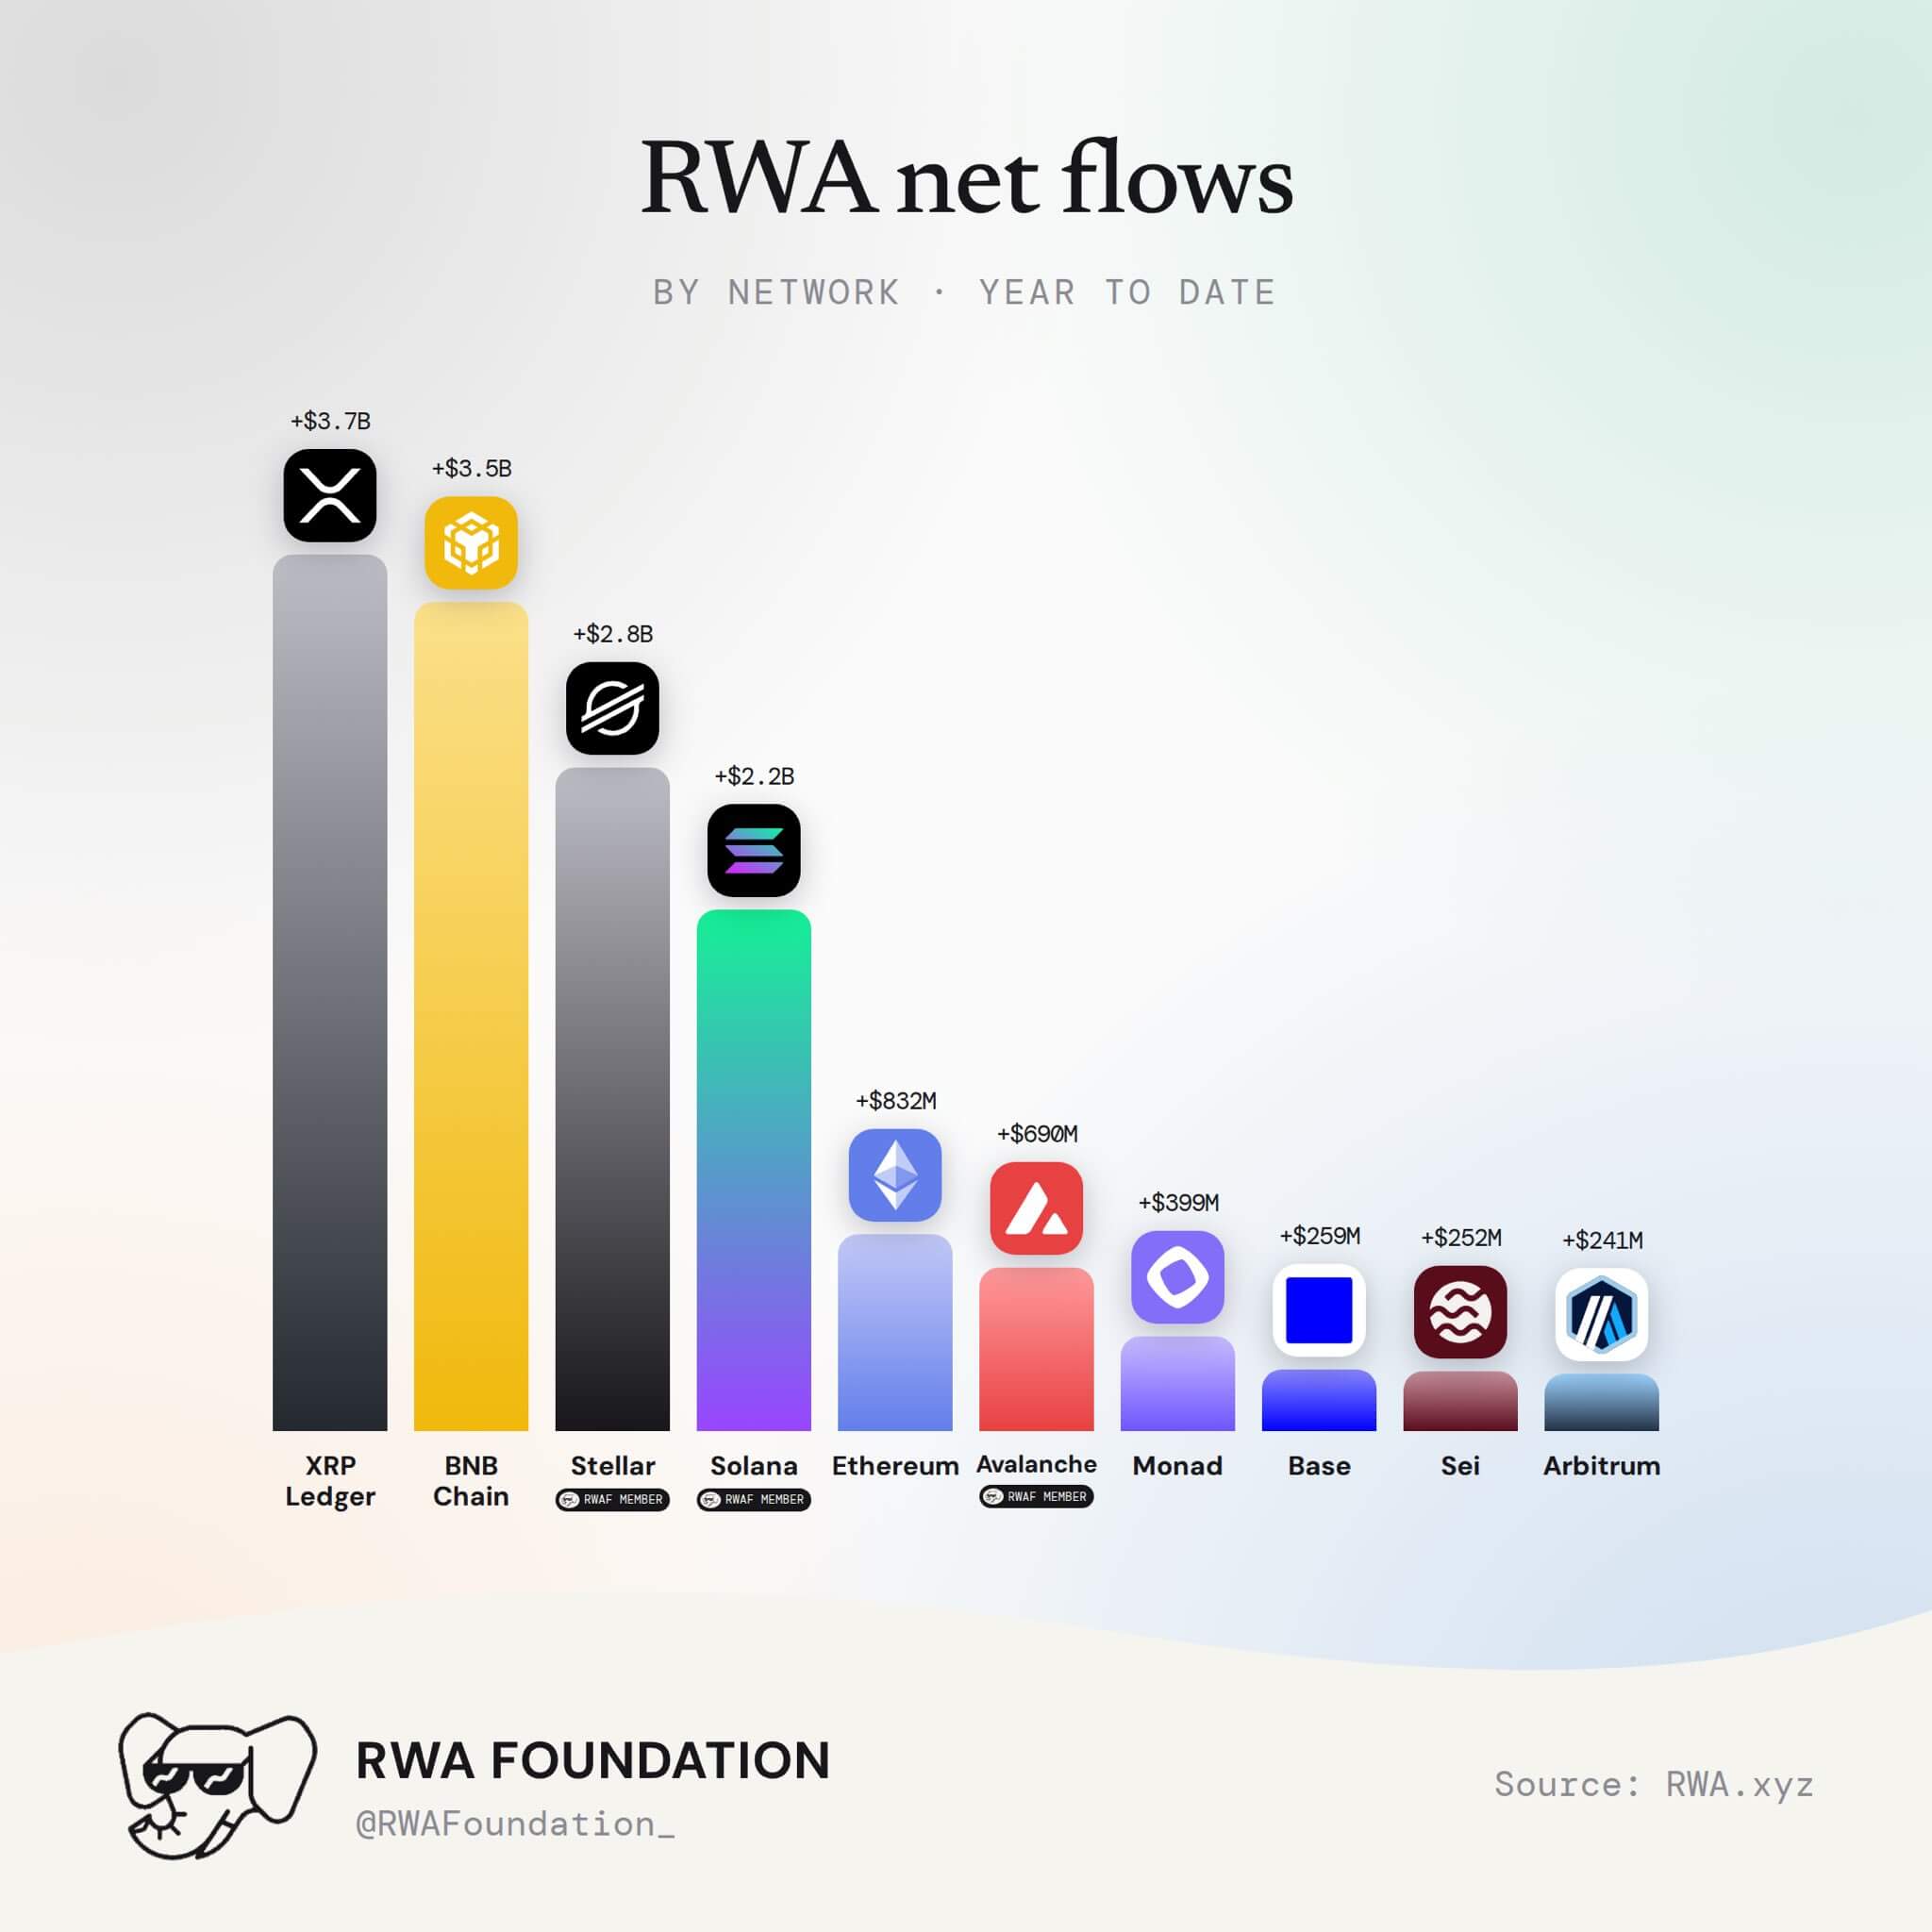
The four networks account for roughly $12.2 billion of the $14.9 billion recorded across the chart's 10 blockchains, highlighting competition for tokenization activity.
The figures track changes in tokenized asset value, including issuance, redemptions and valuations.
Meanwhile, RWA.xyz's Oct. 9 network table lists about $4.54 billion of represented real-world assets on XRPL and $499 million of distributed assets, excluding stablecoins. XRPL ranks 10th by distributed asset value.
Under RWA.xyz's definitions, represented assets use blockchain records but remain on the issuer's platform. Distributed assets can move between holders outside that platform, including through permissioned transfers.
In July, Aviva Investors launched a tokenized share class of its US Dollar Liquidity Fund on XRPL, following approval from the Central Bank of Ireland.
Eligible investors can access the fund through tokenized holdings. The share class retains the conventional fund's investment objective, liquidity characteristics and regulatory protections.
The launch involved institutional custodian Komainu and tokenization infrastructure provider Licuido, with the fund's underlying assets held by BNY Mellon.
Ripple subsequently announced investments in Licuido and transfer-agency technology provider ZILO. The investments expand its capabilities in digital asset issuance, fund administration and collateral management.
RippleX lays groundwork for round-the-clock collateral transfers
The next stage of XRPL's institutional infrastructure development focuses on using tokenized assets as collateral outside conventional banking hours.
In an Oct. 8 technical article, RippleX outlined five capabilities: Permission Delegation, Atomic Batch, Confidential Transfers, Dynamic Multi-Purpose Tokens and Sponsored Fees.
RippleX illustrated the idea with a hypothetical bank borrowing stablecoins against $50 million in tokenized money market funds on a Sunday evening.
The bank could pledge fund shares for stablecoins, with the collateral and payment settling together. Ripple has also positioned its RLUSD stablecoin as a cash leg for delivery-versus-payment settlement.
Atomic Batch is now live: BatchV1_1 activated on Oct. 9 at ledger 107,540,993. Its all-or-nothing mode lets linked transfers succeed together or revert together.
Confidential Transfers would hide Multi-Purpose Token transfer amounts while giving selected parties, including auditors and regulators, access to the information.
Dynamic Multi-Purpose Tokens would let issuers update designated token properties as financial instruments change. Sponsored Fees would let third parties cover charges and reserves for institutions unable to hold XRP directly.
RippleX says the combination could move tokenized assets into secured financing and liquidity management.
Permission Delegation and Atomic Batch are live, while ConfidentialTransfer, DynamicMPT and Sponsor still await validator approval. Those remaining upgrades would supply the privacy, token-update and fee-sponsorship components of RippleX's plan.
The post XRP Ledger lets institutions share account duties without sharing their keys appeared first on CryptoSlate.
Cardano founder Charles Hoskinson accused Vitalik Buterin of undermining quantum-resistant cryptography with speculative warnings about AI-driven mathematical breakthroughs.
In an Oct. 9 post, Hoskinson challenged the Ethereum co-founder's skepticism toward lattice-based cryptography, arguing that decades of security research had already accounted for the technology's known weaknesses.
He warned that encouraging developers to abandon established approaches could slow the adoption of protections already being deployed across internet infrastructure, leaving systems exposed to future quantum attacks.
The criticism follows Buterin's warning that AI-assisted mathematical discoveries could weaken cryptography designed to resist quantum computers.
Buterin said Ethereum's long-term “lean” roadmap has moved toward hash-based signatures and proofs, avoiding lattice-based designs.
Hoskinson rejected that reasoning, accusing Buterin of being too invested in Ethereum's existing research direction to reconsider its approach.
“The case against lattices is the GNFS story, a.k.a. a hunch about ‘structure,' and a multiplier pulled out of thin air,” Hoskinson wrote.
The dispute concerns post-quantum alternatives to the elliptic-curve signatures used by Bitcoin and Ethereum.
Hoskinson challenges the mathematical case against lattices
Buterin's concern draws partly on the history of integer factorization, where mathematical advances such as the general number field sieve dramatically improved techniques for attacking RSA encryption.
He suggested that AI could deliver decades of comparable mathematical progress in a much shorter period, potentially revealing unexpected shortcuts against lattice-based systems.
Hoskinson said the number field sieve emerged from techniques involving arithmetic relationships and smooth numbers, while no comparable mechanism has been demonstrated against the lattice problems underpinning modern post-quantum standards.
The Cardano founder pointed to more than four decades of research, including advances in lattice reduction and sieving algorithms, that have progressively improved attacks without producing a general breakthrough capable of defeating properly configured systems.
The US National Institute of Standards and Technology standardized ML-KEM for key encapsulation and ML-DSA for digital signatures in 2024. Hoskinson said their security parameters account for those known attacks.
Hoskinson also rejected Buterin's illustrative suggestion that multiplying key sizes by ten might protect public-key encryption against AI-driven mathematical advances.
“Multiply key sizes by ten” is “numerology,” Hoskinson wrote, arguing that security parameters must be adjusted according to measurable improvements in attack algorithms.
A change in attack efficiency might justify moderately larger parameters, while a fundamental mathematical breakthrough could require replacing an algorithm altogether.
Ethereum's hash-based strategy faces its own questions
Hoskinson also challenged the assumption that hash-based cryptography offers greater protection against unforeseen mathematical discoveries.
He cited historical weaknesses in MD5 and SHA-1 as evidence that hash functions can contain exploitable structures, although those failures do not establish vulnerabilities in modern constructions such as SHA-256.
His criticism extended to Poseidon and Poseidon2, hash functions designed for efficient use in zero-knowledge proofs and relevant to Ethereum's longer-term cryptographic research.
The Ethereum Foundation has funded research into Poseidon's resistance to algebraic attacks, including investigations using Gröbner bases and other cryptanalytic methods.
Hoskinson argued that these designs also present potential targets for AI-assisted mathematical discoveries, questioning why lattice-based systems should face greater skepticism.
Hash-based signatures can provide quantum-resistant transaction authorization. Lattice techniques also support key encapsulation for encryption and other advanced cryptographic constructions.
Abandoning lattice research could therefore limit options available to developers building privacy systems, secure communications, and other applications requiring those capabilities.
The post Hoskinson says Vitalik’s AI warning could delay the internet’s quantum defenses appeared first on CryptoSlate.
CryptoTicker.io
The XRP price stands at $1.39 on Friday evening, around 1.9 percent higher than 24 hours earlier. The day's news, though, is not in the chart. Ripple has recently begun earning fees for funding leveraged funds on Wall Street, in a business that belonged to the banks for decades. If you hold XRP, there is one figure to know first: none of those fees reach the token itself.
Ripple Prime Funds Leveraged Funds Through Total Return Swaps
Ripple Prime is the company's investment banking arm, and it provides funding to several issuers of leveraged ETFs through what are known as total return swaps. The service is set to be extended to hedge funds and other asset managers. The Wall Street Journal reported it first on October 7, and CoinDesk picked it up on October 8.
A total return swap is an exchange between two parties. One side promises the other the entire performance of an underlying asset, meaning price gains plus distributions, and receives a running payment in return. A fund that wants to track twice the daily move of a stock therefore does not have to buy the stock itself at twice the size. It buys the performance and pays a financing fee for it. The counterparty usually hedges its own risk through share purchases or other trades and keeps the fee.
Ripple Prime is now exactly that counterparty. The business has nothing to do with payments, with stablecoins or with the XRP Ledger. It is classic prime brokerage for American equity funds.
The Tradr 2X Long SNDK Pays Four Percentage Points Above the Overnight Rate
One specific set of terms appears in the report. The Tradr 2X Long SNDK Daily ETF, designed to track twice the daily move of the memory chip maker Sandisk, pays Ripple the Overnight Bank Funding Rate plus four percentage points. At today's level of interest rates, that works out at roughly eight percent a year.
That figure applies to a single fund and is not a company average. The terms nevertheless show how comfortable the margin is in this niche business. For comparison: a German saver on an overnight deposit currently receives a fraction of it, and the fund is not paying that rate out of distress, but because its own product construction does not work without outside funding.
593 Leveraged ETFs and $256 Billion, the Market Behind the Business
According to Morningstar data cited in the coverage, there are 593 leveraged ETFs in the United States with more than $256 billion in assets under management between them. All of these products need funding on a rolling basis, and all of them pay for it.
For a long time the large banks handled that. Tighter capital and risk requirements made the business more expensive for them, and non-banks such as Jane Street, Clear Street and now Ripple Prime are moving into the gap. Ripple laid the groundwork a year earlier: the acquisition of the prime broker Hidden Road for $1.25 billion was announced in April 2025 and completed in October 2025. Hidden Road has traded as Ripple Prime since then, covering foreign exchange, derivatives, bonds, equities and digital assets. Since May the unit has raised up to $475 million through credit lines and corporate bonds, according to reports, with the bonds carrying a BBB rating. The hedge fund Brevan Howard was among the clients named.
The Swaps Run in Dollars, Not Over the XRP Ledger
This is where the company story and the token story part ways. A total return swap on an American stock is priced in dollars, collateralised in dollars and settled in dollars. No step in that chain requires XRP, and none of it creates demand for the token. Ripple the company earns. The token is left out.
That can be put in rough numbers. Apply the eight percent documented for the one fund to the up to $475 million in funding that Ripple Prime has raised since May, and you arrive at a rough ceiling of about $38 million in gross annual revenue. This is a back-of-the-envelope calculation with the method disclosed, not a company figure: there is no evidence that all of the funds are lent out at that rate, and refinancing costs are not deducted. Measured against XRP's market capitalisation of around $87 billion, even that upper figure would amount to roughly 0.04 percent. The leveraged ETF market, with its $256 billion, is on its own almost three times the size of the entire XRP supply as valued on the market, and it still does not move the token price.
One confusion is worth avoiding at this point: the American spot ETFs on XRP are an entirely different matter. There, a fund actually buys XRP and holds it in custody. Ripple Prime funds equity funds. Both stories carry the word ETF, and only one of them touches demand for the token.
XRP Price at $1.39, With $1.36 and $1.41 Framing the Day
On Friday evening XRP is quoted at $1.39. The daily low was $1.36 and the daily high $1.41, so the day's range covers less than four percent. Trading volume over the past 24 hours comes to around $1.88 billion, and market capitalisation stands at about $87.4 billion. That leaves the price some 62 percent below the all-time high of $3.65. The figures come from CoinGecko, as of the evening of October 9.
Those two levels are not analyst targets but the actual turning points of the current day. As long as $1.36 holds, the recovery after this week's slump stays intact. If the price drops below it, the next evidenced reference is the overnight low from Thursday into Friday, which sat between $1.32 and $1.33 depending on the data source.
Since Yesterday's Delegation Report, $1.34 Has Held
On Thursday this column looked at permission delegation on the XRP Ledger and at the question of whether the $1.34 level would hold. It held. When that piece was published the price was in the same range as today, and it did not fall through $1.34 on any sustained basis during the day, not even during the overnight weakness.
Two things have changed since. Delegation has been live since October 8, so the feature update is done and no longer works as a price driver. And the funding story now puts a narrative on the table that lifts Ripple as a company without touching the token. If you took away from Thursday's piece the expectation that protocol progress carries the price, today delivers the counterpart to it.
One date remains in the calendar. Evernorth, the vehicle holding around 473 million XRP, is due to list on the Nasdaq under the ticker XRPN on October 12. cryptoticker reported that on October 2. That date affects the token directly; the swap funding does not.
Our Assessment of Revenue and Token Price
In the view of this newsroom, the funding story is strong for Ripple as a company and all but meaningless for XRP as an investment. The evidence is set out above: the swaps are settled in dollars, the documented revenue sits in the tens of millions and therefore at about 0.04 percent of the token's valuation, and no stage of the transaction chain calls for XRP.
There is one counterargument that deserves to be taken seriously. Ripple itself holds a substantial amount of XRP in escrow and has historically financed itself partly by selling it. A company with running fee income from a banking business is under less pressure to release tokens. That affects supply and thereby, indirectly, the price, only weakly and with a delay, and it can only be evidenced in future escrow reports. Trading the news as a direct price driver means trading against your own arithmetic.
US Spot ETFs Lack the Key Information Document for German Retail Investors
Whenever American crypto ETFs are in the news, readers in Germany face the same practical question, and the answer is a sober one. The PRIIPs Regulation, Regulation (EU) No 1286/2014, requires a standardised key information document for distribution to retail investors in the European Economic Area. American fund companies generally do not produce that document for their domestic products, because European retail distribution plays no part for them. Without it, a broker supervised in the EU may not sell the security to a retail client.
In practice that means the American spot ETFs on XRP are not available to German retail investors through ordinary brokers. Individual houses open them up to professional clients; for everyone else two routes remain, direct purchase on an exchange and the European ETP. Which products are actually tradable in Germany is set out at length in our overview of crypto ETFs in Germany.
Exchange-listed XRP products from Europe are called ETPs, ETNs or ETCs and are legally, in most cases, collateralised debt securities rather than funds. The 21Shares XRP ETP with the ISIN CH0454664043, for example, is fully physically backed with XRP according to the issuer and is held in cold storage at an institutional custodian. Its total annual cost ratio is 2.50 percent. Market overviews list further issuers as tradable via Xetra and SIX.
The Delivery Claim Separates Section 23 From Section 20
For tax purposes, direct purchase and an ETP are two different worlds in Germany, and the difference costs or saves a great deal of money depending on how long you hold. A direct purchase falls under Section 23 of the Income Tax Act. Hold XRP for more than a year and the gain is sold tax-free. Under a year, your personal tax rate applies, along with an exemption threshold of 1,000 euros a year. Lawmakers recently confirmed this twelve-month rule after an attempt to abolish it was rejected.
With an ETP, the classification hangs on a single contractual question, namely the delivery claim. If the product grants the right to have the underlying coins delivered, there is a strong case for treating it like direct ownership, that is, under Section 23 with the twelve-month period. Without that claim, it looks more like another form of capital claim, and then Section 20 applies, with 25 percent withholding tax plus the solidarity surcharge, with no holding period at all, but with the saver's allowance and with loss offsetting against other investment income.
This classification is a tax assessment, not settled case law. Whether a particular XRP product grants a delivery claim is stated in the prospectus and in the key information document and nowhere else. For meaningful sums, the question belongs with a tax adviser, not in a forum.
For a decision, that translates into something concrete: if you are planning on a horizon of more than a year, direct purchase with your own custody is usually the better route for tax. If you think in shorter terms, or value the withholding tax as a cap, the ETP can be the quieter solution despite its running fee. The 2.50 percent a year is no minor item: over a holding period of three years it already amounts to around seven percent of the capital deployed.
Ripple Prime: Fees Flow to the Company, Not to the Token
The day's news is a company story. The price at $1.39 still depends on supply of and demand for the token, not on the margins of a prime brokerage unit. Three steps follow from that for the days ahead.
- Settle your access route before the next impulse arrives. American spot ETFs are not open to you as a retail investor. Check instead which broker prices the European ETP and which prices direct purchase more cheaply; the terms and spreads are in our broker comparison.
- Read up on the delivery claim and weigh your holding period against it. Get the product's key information document and look for the passage on the right of delivery. Which software documents the deadlines and acquisition dates cleanly is shown in our overview of tax tools and portfolio trackers.
- With a direct purchase, settle the custody question. The twelve-month period is of little use if the coins sit on an exchange and an incident intervenes there. Which devices are suited to the job is set out in the hardware wallet comparison.
October 12, with Evernorth's Nasdaq listing, is the next date that affects the token directly. Until then, $1.36 and $1.41 remain the levels against which the day is measured.
(As of October 9, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Wallets attributed to the US government moved 17,733 Bitcoin worth roughly $1.48 billion into accounts at Coinbase Prime over three days. Not one of those coins has been sold, as far as the public record goes. The gap between those two sentences is what the market tripped over on Thursday and Friday: Bitcoin fell to its October low and recovered again, and in between, leveraged positions worth more than a billion dollars were wiped out.
Here is the sequence, with the figures that are documented and the points where the counts contradict each other.
17,733 Bitcoin at Coinbase Prime: What the On-Chain Data Shows
According to an analysis by TokenPost, 17,733 BTC worth about $1.48 billion reached Coinbase Prime by October 9, spread over three days. A further 750 WBTC worth around $62 million went the same way. Caution is warranted already at this point: the WBTC figure ranges between 50 and 750 coins depending on the analysis, and anyone who attributes wallets differently arrives at different totals. A second count, based on addresses ascribed to the Bitfinex seizure complex, puts the figure at 12,267 BTC, or roughly $1.01 billion.
The range from 12,267 to 17,733 BTC is not sloppiness. It follows from an attribution that always remains an interpretation. Analytics firms label addresses using patterns, court records and earlier movements. A tag such as "US government" on an address is a reasoned assumption with a good hit rate, not an entry in an official register. Pass on either number as the single truth and you leave out the part that is disputed.
Where These Holdings Come From
The holdings ascribed to such wallets trace back to seizures, among them the one connected to the Bitfinex hack. They are disposed of through the regular channel, the US Marshals Service, the enforcement arm of the Justice Department. Coinbase Prime has been its custody and trading provider for years. That is what makes the movement both worth explaining and unspectacular: an owner who already custodies there will move coins there for reasons that have nothing to do with a sale.
Coinbase Prime Is a Custodian, Not a Sales Desk
A transfer to a custody address looks exactly like the first step of a sale in on-chain data. It is not one. Coinbase Prime bundles custody, settlement and trading for institutional clients. A deposit there can be a reshuffle between an owner's own accounts, preparation for an auction, a change in the technical form of custody, or indeed the opening move of a sale. Which of those applies only becomes visible once coins move into trading books or an agency says so.
TokenPost states this explicitly in its own report: the movements do not prove that the government sold Bitcoin or caused the price decline. That caution has often been lost in the coverage of recent days. What remained was a narrative in which a state pushes the market down, and a narrative moves prices faster than a fact does.
$1.09 Billion in Liquidations Within 24 Hours
What moved the price is better documented than the reason assigned to it. According to CoinGlass data reported by The Cryptonomist, positions worth $1.09 billion were force-closed in the 24 hours to Friday morning. Long positions accounted for $1.05 billion of that, a little over 96 percent. Other counts covering overlapping windows give $1.06 billion to $1.14 billion; the direction is the same in every set, while the size depends on the window and on which exchanges are captured.
A 96 percent share on the long side does not describe an attack from outside. It describes positioning that was too one-sided. When almost everyone is betting on rising prices, and almost all of them with borrowed money, a moderate pullback is enough to set off a chain.
How a Liquidation Chain Builds: Margin, Funding Rate and Forced Selling
A leveraged position is a loan against collateral. You post an initial margin and trade a multiple of it. If the price falls, the collateral shrinks; once it drops below a threshold, the exchange closes the position automatically and sells the collateral into the market. That forced sale pushes the price down a little further, which brings the next position to its own threshold. This is how the cascades form in which hundreds of millions of dollars disappear within minutes.
The funding rate is the price one side pays the other for holding a perpetual futures position. When it stays clearly positive over a longer stretch, buyers are the ones paying, and that reveals an overweight on the long side. The liquidation price is the level at which your collateral no longer suffices. Both are fixed before you enter and can be calculated, and both are more often estimated than recalculated in day-to-day trading.
In practice, that means traders in perpetual futures carry a risk that does not depend on the price alone, but on how everyone else is positioned. Our comparison of perp DEX platforms shows how fees, leverage tiers and liquidation rules differ between venues. The gaps are wider than the advertised leverage suggests.
The October Low Sits Between $80,350 and $80,475
This week's low is quoted differently depending on the venue, and that spread is part of the picture. The Cryptonomist cites $80,350 on Bitstamp, the weakest level since September 18. TokenPost gives $80,420 as the October low. Our own analysis of the daily range on the Kraken exchange puts the BTC/USD pair at a daily low of $80,474.70 and a daily high of $83,462.90. cryptoticker.io collected that data itself on October 9, 2026; the basis is one verified trading pair at one venue.
The spread of roughly $125 between the figures is irrelevant for a decision and important for understanding it: there is no single Bitcoin price, only as many as there are venues. If a stop level sits exactly on a reported low, it may have been triggered on your exchange and not on another.
By Friday afternoon Bitcoin traded at around $82,650, about 1.2 percent above its level 24 hours earlier (as of October 9, 2026, Kraken). That leaves a good $2,100 above the low and some $800 below the daily high.
How to Check the Movements of Government Wallets Yourself
You do not have to rely on anyone else's reading. The addresses in question are public, and their movements are in the blockchain. A block explorer or one of the labelling services shows inflows and outflows for an address with a timestamp and an amount. Four things are worth a look before you follow a headline:
- Direction and destination. Does the balance go to an exchange's custody address or to a trading address? The two look similar and mean different things.
- The label and its age. Since when has the address carried the attribution, and which source does the service cite? A label without a reason is an assertion.
- The offsetting entry. Does the amount show up in the exchange's reserves, or does it spread across new addresses? The latter argues against a sale.
- The comparison with trading volume. A billion dollars sounds enormous and is a small share of daily Bitcoin volume. Without that yardstick, every large number looks like an event.
This second route through the on-chain data is why the story of a state selling off its holdings is so hard to sustain. The price recovered on Friday while the holdings sat at Coinbase Prime. A seller pushing 17,733 Bitcoin into the market leaves a different picture behind.
ETF Outflows of $244.13 Million on a Second Straight Day
The week's pressure had a second, more sober source. The US spot Bitcoin ETFs recorded net outflows of $244.13 million on October 8, according to SoSoValue; Farside Investors arrives at $244.1 million. It was the second day of outflows in a row. For October 7, Farside gives $484.9 million and SoSoValue $487.07 million, putting the two days together at roughly $729 million.
Most of it came from a single fund: Fidelity's FBTC lost $197.1 million on October 8. BlackRock's IBIT gave up $5.5 million after $207.7 million had left in the session before. Franklin's EZBC was the only fund with a gain, taking in $4.71 million. Total assets across the product group stand at $104.91 billion.
ETF outflows work differently from futures liquidations. They run more slowly, they involve real holdings rather than borrowed positions, and they last longer, because allocation decisions sit behind them rather than margin thresholds. Investors in Germany who want to hold such products will find the routes and their limits in our overview of crypto ETFs for German investors.
Holding Period, Leverage and Custody: What Concerns Investors in Germany
For tax purposes, this week's drop is above all a question of the calendar. In Germany, gains from selling crypto assets are tax-free after a holding period of one year; within that year they are taxable as a private disposal. The logic cuts both ways: a loss you realise inside the one-year window can be offset against gains from other private disposals. Once the deadline has passed, the gain is tax-free and the loss is worthless for tax purposes. If you are weighing a sale in a slump, the purchase date is therefore the first thing to look at.
With Leverage, the Supervisory Framework Decides
With leverage, the difference between the trading routes is bigger than the difference between the providers. CFD brokers under German supervision have been subject to a hard cap on crypto leverage for retail clients since BaFin's general administrative act of July 23, 2019, together with a ban on additional margin calls: you cannot lose more than your deposit there. The specific tier is set out in your broker's contract terms, and it sits well below what unsupervised platforms offer.
On perp DEX platforms without European authorisation, those protections do not apply. Double-digit leverage is common there, supervisory law imposes no loss limit, and in a dispute there is no route to a German regulator. A large share of the $1.05 billion in closed long positions originated on such venues.
Custody: The Difference Between Possession and Claim
The episode at Coinbase Prime leads to a question that outlasts the day. Coins in an account at a custodian are not ownership of keys but a claim against a company. For large institutions that is a deliberate choice, because audit duties and insurance depend on it. The same choice has different consequences for a private holder: if your holdings sit at an exchange, you carry its default risk. If they sit on your own hardware wallet, you carry the risk of a lost key. There is no third option, and anyone presenting it otherwise is selling something.
Our Assessment: The Price Reacted to Leverage, Not to the State
In the view of this newsroom, the narrative of state selling pressure does not bear the weight placed on it this week. Three documented points argue against it. First, no sale is on the record; the source reporting the transfer says so explicitly. Second, long positions accounted for $1.05 billion of the $1.09 billion in liquidations, which points to one-sided positioning rather than to supply from outside. Third, the price recovered on Friday to around $82,650 even though the holdings sit unchanged with the custodian.
What argues the other way is what we do not know. Nobody outside the responsible agencies knows the purpose of these transfers, and a disposal in the coming weeks remains possible. A sale that is not documented is not a sale that is ruled out. Deriving a price forecast from this replaces one unproven narrative with a second. The only robust observation is that the market suffered this week from its own leverage structure.
What Has Changed Since the October 8 Slump
The link to the previous day matters, because the situation has shifted. On October 8 we described the drop below $81,000 and its causes (Crypto crash: why Bitcoin fell below $81,000). Three things have changed since then. The price has won back the $81,000 mark and trades above it again at around $82,650. Liquidations crossed the billion-dollar line at $1.09 billion in 24 hours, exceeding the previous day's magnitude. And the explanation has switched: macro pressure became, overnight, the state as seller, without any evidence being supplied for it.
Two dates are concrete for the days ahead. The US consumer price index on October 14 will move rate expectations and with them risk appetite across the whole market. And the daily ETF figures will show whether the outflows break off after two days or continue; a third day in the series would be the more telling signal than any wallet movement.
Government Bitcoin at Coinbase Prime: 17,733 BTC, No Documented Sale
What remains of this week can be worked through in three steps:
- Separate the transfer from the interpretation. 17,733 Bitcoin sit with a custodian, and nothing has been sold. If you are reviewing your buying route anyway, compare fees, custody models and supervision across venues in our overview of the best crypto exchanges rather than reacting to a headline.
- Recalculate your liquidation price before the next pullback comes. With a 96 percent long share in the forced closures, the initial margin decides the outcome. If you trade with leverage, the hardware wallet comparison will not give you the platform terms, but it will answer the question of where the rest of your holdings sits more safely than in a margin position.
- Sort out your purchase date, not your mood. Whether a sale in this slump makes sense for tax purposes hangs on the one-year deadline. The tools in our comparison of crypto tax tools give you a clean overview of your acquisition dates.
(As of October 9, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Winklevoss Asset Services filed an S-1 with the US Securities and Exchange Commission on October 6, 2026 for a spot ETF on Zcash. The fund is to run on the Nasdaq under the ticker WINK and cost 0.25 percent a year. That is one tenth of what the only US Zcash ETF so far charges. For a portfolio in Germany the fund stays closed all the same, and the date that really lies ahead for ZEC holders here is not in this filing but in European anti money laundering law.
An S-1 is the registration form with which an issuer in the United States submits new securities for approval. It is an application, not a permission: the prospectus states explicitly that the information may change and that no shares may be sold while the registration is not yet effective.
An S-1 at the SEC: Winklevoss Asset Services applies for a spot ETF on Zcash
The applicant is Winklevoss Asset Services, LLC as sponsor. The issuer itself is a Delaware statutory trust, appearing in the prospectus as the Winklevoss Zcash ETF. The filing carries the SEC accession number 0001104659-26-113940 and is held in the register under identifier 0002158471, with a business address in Wilmington, Delaware.
Spot means the fund holds the cryptocurrency itself instead of tracking its price through futures contracts. The prospectus describes exactly that: the trust holds ZEC directly and works with neither leverage nor derivatives. The distinction matters for the price, because a spot fund has to take real coins off the market on an inflow, while a futures fund merely swaps contracts.
The exchange is named in the filing as the Nasdaq Stock Market, LLC, subject to notice of issuance. That too is a statement of intent and not an approval. The prospectus at the SEC is open to inspection.
0.25 against 2.5 percent: the fee gap to the Grayscale Zcash ETF
So far there is exactly one spot ETF on Zcash in the United States. Grayscale listed it on August 25, 2026 under the ticker ZCSH on NYSE Arca, converted from an existing trust that began as a private placement in 2017. It charges 2.5 percent a year. Grayscale has announced that it will channel the revenue from that fee back into the Zcash ecosystem in the first year, for instance into marketing and education.
The Winklevoss fund as filed sets 0.25 percent. The prospectus states that the trust pays the sponsor "an annual unified fee of 0.25% of the Trust's ZEC Holdings". Unified fee means that this single charge covers the running costs instead of billing custody, administration and auditing separately.
Convert the gap into a sum and it becomes tangible. On $10,000 invested, ZCSH costs $250 a year and the fund as filed $25. Over five years and with no change in price that is $1,250 against $125. On a product that does nothing beyond holding a cryptocurrency, the fee is the only item an investor knows for certain.
Unified fee: what a sponsor charge takes out of fund assets
The sponsor fee is not debited separately. It is taken out of the fund's assets, usually by the fund selling a small share of its coins on a running basis. An ETF with a 2.5 percent fee therefore holds around 2.5 percent fewer coins per share after a year than at the start, even if the price were unchanged. The share price follows the market, while the backing per share falls.
That is where the real leverage of this filing sits: a competitor ten times cheaper works on existing holdings and not only on new investors. A holder of ZCSH who sees WINK approved has a calculable reason to switch, and a switch between two spot funds runs through redemption at one and subscription at the other. That is precisely what produces outflow figures which look like selling pressure without a single coin leaving the market on balance.
Gemini Trust Company as custodian: a custodian from the same house
The custodian is to be Gemini Trust Company, LLC. The prospectus describes it as an affiliate of the sponsor. The ZEC are to sit in segregated cold storage, meaning custody with no connection to the internet.
That proximity is not an accusation, and it stands openly in the filing. It is, however, a point the regulator examines regularly in ETF applications, because sponsor and custodian then belong to the same circle of owners. What matters most here is the direction of travel: a house that runs both the exchange and the custody can offer a fund more cheaply than a sponsor who has to buy both in. The 0.25 percent are therefore a fighting price and a consequence of the firm's own structure at once.
A $100 million indication of interest: what a non binding undertaking is worth
The prospectus states that the Winklevoss Capital Fund, LLC has, through one or more affiliates, indicated an interest in purchasing shares worth up to $100 million. An indication of interest of this kind is expressly not binding. The prospectus itself says the buyers may acquire more shares, fewer, or none at all.
Undertakings like this appear in prospectuses because a fund with no starting volume is barely tradable on an exchange. As evidence of future demand the figure is of no use. It says the sponsor is willing to place its own money alongside the product, and it names an order of magnitude. It carries nothing beyond that.
ZEC at $1,219: the October 6 filing has not carried the price
Zcash trades at $1,218.82 on the OKX spot market and at $1,216.60 on Coinbase Exchange on October 9, 2026. Against the rolling 24 hour window that is a gain of 8.5 percent (OKX) to 9.1 percent (Coinbase). The day's range runs from $1,112 to $1,247, and market value stands at around $19.9 billion, putting it tenth.
That gain is no reaction to the filing, however, and reading it that way draws the wrong conclusion. On October 6, the day of submission, ZEC closed at $1,367.26. The price has lost 10.8 percent since. The daily gain is a recovery from the slide of October 8, when the price fell from $1,327.62 to $1,186.61 and touched $1,112.27 along the way.
Over seven days Zcash is therefore down while the broad market recovers on this day: Bitcoin adds 2.2 percent, Ether 2.1 percent. An application for a cheaper investment product is evidently no driver of the price while the approval remains open.
Since our report of October 5: 8.8 percent lower, a daily low of $1,112
On October 5 we reported on the first weekly outflow from the Grayscale Zcash ETF, $93.56 million in one week at the time. Against that day's close of $1,337.45, ZEC sits 8.8 percent lower today. The fourteen day high of $1,697.45 from September 26 now stands 28 percent above the current price.
The order of events produces a picture that neither report yields on its own. First money left the expensive fund, then the price fell to a multi week low, and only after that did a competitor file a product at a tenth of the fee. An issuer filing into a weak phase is aiming at tomorrow's fee market, hardly at today's price.
WINK on the Nasdaq: for a German portfolio the fund stays out of reach
A US spot ETF on crypto assets is practically unbuyable for retail investors in Germany. The reason sits in the European distribution rule: a fund may only be distributed to retail clients in the EU if a key information document under the PRIIPs Regulation exists in the relevant national language. US issuers do not produce that document, because they do not serve the EU retail market. Brokers in Germany therefore block such securities from trading.
The same applies to ZCSH, and a second, cheaper US fund will change nothing about it. The fee question currently being settled in the United States touches a German portfolio only if you are considering a route around that block. That is not advisable, because it removes the investor protection on which the block is founded.
The route via ETPs and crypto exchanges: holding period, custody and market access
Two other routes are open in Germany. The first runs through an exchange traded crypto security, usually called an ETP or ETN. This is a debt instrument that tracks the price of a cryptocurrency and is tradable on a European exchange, but legally it is not a fund. Whether you can buy one depends on which trading venues your broker offers. How the product categories differ is set out in our overview of crypto ETFs for investors in Germany.
The second route is buying the coin itself through a crypto exchange with MiCA authorisation. MiCA is the EU regulation on markets in crypto assets; since it took effect, providers need a permission from a European supervisor to offer services in the EU. Which houses can show that permission is set out in our overview of regulated crypto exchanges.
Tax treats the two routes very differently. With a directly held coin the speculation period under Section 23 of the German Income Tax Act applies: after a holding period of one year a gain on sale is free of tax, while within the year it counts as a private disposal. With a security the flat rate withholding tax on investment income applies, regardless of the holding period. Holding the coin yourself means keeping it either at the exchange or in your own hands; the device types for self custody differ considerably in handling and in how they are secured.
Article 79 of the EU anti money laundering regulation: regulated trading ends on July 10, 2027
Here lies the date that carries more weight for ZEC holders in Germany than any US approval. Regulation (EU) 2024/1624, the European anti money laundering regulation, prohibits credit institutions, financial institutions and crypto asset service providers in Article 79(1) from keeping anonymous accounts. The wording expressly covers accounts allowing the concealment of transactions, "including through anonymity enhancing coins".
Under Article 90 the regulation applies from July 10, 2027, with an exception for certain obliged entities for which July 10, 2029 is the relevant date. The text of the regulation in the Official Journal is freely available. Our report of October 5, 2026 gave July 1, 2027 at this point; the date in Article 90 is the one that governs.
The regulation addresses providers, not you. Private ownership of Zcash is untouched by it. What falls away is orderly market access: an exchange authorised in the EU will not be able to carry ZEC in trading or in custody after that date. The point at which selling or moving is still practically easy therefore lies before that date, not after it.
What the filing does not say: timetable, approval and the risk of a withdrawal
Three pieces of information are missing from the prospectus, and with a first filing that is normal. There is no date for approval, no launch date and no commitment from the Nasdaq on the listing. An S-1 can be amended, withdrawn, or commented on by the regulator over months before it becomes effective. The Grayscale fund needed the route through an existing trust and a conversion rather than a fresh registration.
It is also open whether the SEC will assess a second spot fund on a cryptocurrency with a shielding function differently from the first. The filing says nothing on that question, and an assessment at this point would be a guess without foundation.
Our assessment: a fee fight without approval stays a paper application
In this newsroom's view, this filing is significant for the American fund market and for the moment a footnote for German investors. Three pieces of evidence from this text support that: the fee difference from 2.5 to 0.25 percent is calculable and reaches existing holdings; the price reaction is absent, since ZEC sits 10.8 percent lower than on the day of filing; and the PRIIPs block keeps US funds out of German portfolios regardless of their fee.
One argument stands against it that we do not wish to play down: if fee competition in the United States draws capital into Zcash products, that works through the spot market onto the price paid in Europe as well. Only that route is indirect and tied to the approval, which is still outstanding. We derive no recommendation to buy or sell from it; crypto assets can lose their value entirely.
Zcash ETF: without approval, July 10, 2027 remains the harder date
Three steps follow from the situation:
- Settle the product category before you place an order. ZCSH and the filed WINK are US funds and blocked for you; what is tradable are European securities and the coin itself. The differences are in our overview of crypto ETFs for investors in Germany.
- Settle the venue's authorisation. If you buy or hold ZEC directly, take a provider with a European permission; the state of play is in our overview of regulated crypto exchanges.
- Take July 10, 2027 into your planning. From that date, authorised EU providers may no longer trade or hold Zcash. Anyone moving the coins into self custody before then will find the device types in our overview of hardware wallets.
(As of October 9, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Bitcoin Cash costs $273.80 this Thursday, 7.3 percent below its level 24 hours earlier. Bitcoin trades 0.6 percent higher over the same window. Both prices broke down on the evening of October 8, yet only one of them has come back: Bitcoin has recovered 88 percent of the decline, Bitcoin Cash 16 percent. Anyone holding BCH therefore faces a different question from the broad market, and the answer depends less on the price than on whether this weakness has a cause that outlasts a single trading day.
cryptoticker.io compiled this analysis itself on October 9, 2026, based on the daily prices of Bitcoin Cash and Bitcoin at three trading venues. The two price pairs were examined over ten trading days.
Bitcoin Cash at $273.80: 16 percent of the slide recovered, Bitcoin 88 percent
The comparison starts on October 8. Bitcoin Cash stood at $300.20 before the slide, fell to $268.80 and now sits at $273.80. Bitcoin stood at $83,323, fell to $80,400 and now sits at $82,960.
Counting the distance between starting point and low as the full decline, Bitcoin has won back 88 percent of it and is only 0.4 percent away from where it began. Bitcoin Cash has won back 16 percent and is still 8.8 percent short. Measured from the low, that is 3.2 percent higher for Bitcoin and 1.9 percent for Bitcoin Cash.
That figure is the real finding of the day. A slide the whole market joins is no news for a single coin. A recovery the whole market joins and one coin does not is news.
The spread between venues puts Bitcoin Cash's daily loss between 7.3 and 7.7 percent, depending on which venue supplies the reference price from 24 hours earlier. The day's high was $295.50, the low $268.80.
303 Bitcoin Cash for one Bitcoin: the exchange ratio since October 8
Bitcoin Cash emerged from Bitcoin in 2017 and has moved in step with the larger chain for years, usually with wider swings in both directions. How far the two diverge is shown better by the exchange ratio than by any dollar price.
One Bitcoin buys 303 Bitcoin Cash today. Twenty four hours ago it bought 279. The BCH to BTC ratio has therefore lost 7.9 percent, on a day when Bitcoin itself gained. A holder who counts the stack in Bitcoin has given up almost eight percent on this day without anything changing at Bitcoin Cash.
The ratio is also the yardstick for the coming days. If Bitcoin Cash rises more strongly than Bitcoin again, the weakness was a trading day. If the ratio stays below its October 8 level, the market has repriced Bitcoin Cash.
The zone below $293 has gone, the daily low sits at $268.80
Our October 8 coverage of the CME launch of Bitcoin Cash futures named two levels: $319.62 on the upside and the zone below $293 on the downside. The price stood at $294.93 at the time, just above the lower level.
That zone went on the evening of the same day, and it did not go narrowly. The price ran through to $268.80 and has not worked its way back above $283 since. Against the level from our article of a good day ago, 7.2 percent is missing.
The road upwards has lengthened accordingly. The monthly high of October 5 was $321.90, a distance of 14.9 percent. The old lower level at $293 has turned from support into resistance: as long as the price stays below it, every upward move is a recovery inside a decline and not a reversal.
The $268.80 of October 8 is therefore the level that counts. If it holds on a second test, the market has found a floor. If it goes, there is no level at all from the past four weeks until the area around $250.
No trigger of its own at Bitcoin Cash: hack, delisting and protocol change all absent
For a daily loss of seven percent, the first thing to look for is the news that explains it. At Bitcoin Cash on this October 9 there is none. No report of an attack on the network has appeared, no announcement by a large trading platform that it will stop trading BCH, and no protocol change that would force holders to act.
That is an observation and not an explanation. Without a documented trigger of its own, two readings remain, and both are plausible on this day. Either holders are selling the coin because it carried large gains after the jump of September 22 and a falling market is an occasion to take them. Or the market is pricing out its expectations for October 19 again, having priced them in during September.
Which of the two applies cannot be settled from price data alone. All that is observable is that the recovery is absent while the rest of the market is having one.
A funding rate of 0.009 percent: the state of the perpetual market
The funding rate is the balancing payment that flows between buyers and sellers of a perpetual futures contract every eight hours. When it is positive, those betting on a rising price pay the other side. It therefore shows which side is making itself more expensive.
At Bitcoin Cash it stands at 0.009 percent per eight hour period this Thursday. That is just above zero and close to the value that settles in under balanced positioning. The contract's premium over the spot price is nil.
That yields an uncomfortable reading for holders hoping for a quick counter move: the futures market shows no discernible overshoot to the downside that would have to unwind. After a slide carried by over leveraged selling, the funding rate sits clearly negative because too many are betting on further losses. That pressure is missing here. The price has fallen without either side overextending, so a rebound out of technical necessity is not built in.
Ten days before the CME launch on October 19, the approval is still outstanding
The CME Group announced on September 22 that it would list futures contracts on Bitcoin Cash from October 19, a standard contract covering 250 BCH and a smaller one covering 25 BCH, traded through its own Globex platform. The announcement was subject to regulatory review from the outset, and as of the reporting on October 8 that condition had not yet been cleared (CME Group statement, Cryptobriefing).
For a holder in Germany the date changes nothing directly. These contracts are aimed at institutional market participants; through a German broker they are not accessible to retail investors. The date acts on the price, not on your portfolio.
And that effect is more limited than September's price move suggested. The contracts are cash settled rather than delivered in coins. Buying such a contract is not buying Bitcoin Cash: at the end of the term the difference to a reference price is settled in dollars. A futures market therefore generates no spot demand of its own that would support the price. What it generates is the ability to bet on falling prices without owning the coin, and for a group of market participants that previously could not do so through regulated channels.
Spread and liquidity: what a thin market costs when you sell
By market value Bitcoin Cash is one of the twenty five largest crypto assets, but it sits in the lower part of that group. The difference from Bitcoin or Ether shows up when selling, and it shows up in two places.
The first is the spread, the gap between the price at which you can sell and the one at which you could buy. With smaller crypto assets that gap is wider, and it widens further when the price falls. The second is order book depth: how much you can sell before your own sale pushes the price down.
Both are why a comparison of trading venues is worth more for a coin like Bitcoin Cash than for Bitcoin. With Bitcoin the spread is narrow almost everywhere. With BCH the venues differ markedly, and in a selling into a falling market that difference decides a noticeable share of the proceeds. Before selling, check whether your venue even runs an order book for BCH against euros or only offers the detour through a dollar stablecoin, because that detour costs the spread twice.
Selling at a loss: what happens to the loss pool with crypto assets
Anyone selling now sells at a loss at many entry prices. For tax purposes that is not a pure disadvantage, and the rules differ from those for shares.
Crypto assets count as other economic assets in Germany. A sale within one year of purchase is taxable, a sale after more than a year remains free of tax. That one year holding period works in both directions: a gain after a year goes untaxed, but a loss after a year can no longer be used for tax either.
Within the year the picture differs. A realised loss from a sale can be offset against gains from other sales of the same kind in the same year, and an excess can be carried into other years. So anyone who realised gains from short term sales in 2026 can set a loss on Bitcoin Cash against them. Which acquisition counts as sold depends on the order you document for your wallet, and it is exactly this documentation that most cases fall down on. A tax tool with portfolio tracking carries that order along, and without a clean allocation of acquisition dates the loss pool cannot be evidenced to the tax office.
This account is no substitute for tax advice, and with larger amounts the trip to someone who knows your case is worth it.
Stop loss, limit and slippage: how a sell order is filled in a falling market
Between the decision to sell and the money in the account lies the execution, and in a market like that of October 8 this is no formality.
A stop loss order is no guarantee of a price. It is an instruction that becomes a market order once a level is reached, and a market order takes the price the order book offers at that moment. If the price falls quickly, the price achieved sits below the level set. That deviation is called slippage, and it was considerable among smaller crypto assets in the night to October 9, because the price ran from $300 to $269 within hours.
A limit order inverts the relationship: it names the price and leaves the execution open. You get no less than the limit, but you may get no fill at all. In a falling market a sell order with a limit above the market price simply sits there while the price keeps falling.
Leveraged products work differently again. There the point is not the price achieved but the liquidation: once the collateral no longer suffices, the provider closes the position and the loss is final. A decline of 7.3 percent in the underlying already wipes out three quarters of the stake at tenfold leverage. Anyone who wants to engage with that mechanism and its costs will find it broken down at the perp DEX platforms; for a holder simply weighing a sale, that is the wrong route.
Our assessment: what the numbers give and what stays open
In this newsroom's view, the absent recovery is the signal, not the daily loss. Two documented points support that: Bitcoin has recovered 88 percent of its decline and Bitcoin Cash 16 percent, and the exchange ratio lost 7.9 percent on a day when Bitcoin rose. A coin that fails to join a recovery day in the market is being priced differently by that market at this moment than it was a week earlier.
Against it stands the brevity of the period. Twenty four hours are no trend, and with a coin that rose 29 percent within a single day in September, swings in both directions are the rule. Against it stands the funding rate near zero as well: it shows no built up pressure that would force a further move down.
We therefore regard the situation as open and the BCH to BTC ratio as the metric on which it will be decided. That is no recommendation to buy or sell, and with crypto assets a total loss is possible.
Bitcoin Cash: below $268.80, October 19 becomes a footnote
The CME date is the reason Bitcoin Cash rose in September. If the price fails to hold the October 8 low, the market has cleared that expectation away entirely and the date remains a diary entry with no effect on the price. Three steps you can line up against it:
- Settle custody if you are holding. Anyone intending to hold through a weak phase does not need the stack on a trading account. Custody of your own takes the provider's risk out of the calculation; the hardware wallet comparison names the devices that support BCH.
- Document losses if you are selling. Record the acquisition date, the quantity and the price, otherwise the offset cannot be evidenced to the tax office later. A tax tool with portfolio tracking carries those details along for every purchase.
- Keep leverage out of the calculation. A decline of 7.3 percent wipes out three quarters of the stake at tenfold leverage, and the liquidation arrives before any recovery. What the futures venues charge in funding and fees is set out in the comparison of perp DEX platforms.
The next test of this assessment lies with the low of $268.80 and with the exchange ratio of 303 BCH to one Bitcoin.
(As of October 9, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Positions worth $7.82 million were force closed on the futures market for Dogecoin within 24 hours. Of that, $7.32 million hit long positions, meaning bets on rising prices, and $503,630 hit short positions. Just under 94 percent of the losses therefore sat on one side. The data service CoinGlass puts the imbalance between the two sides at 1,453 percent, U.Today reports.
The interesting part is less the sum than the question behind it: how much leverage sits in Dogecoin at all, and how much of it may a retail investor in Europe use? On Friday afternoon we counted every open perpetual futures contract on DOGE and set the result next to Bitcoin, Ethereum, Solana and XRP. The answer differs from what the meme coin's reputation suggests.
$7.32 million: what was force closed on the futures market
A liquidation is not a decision to sell. It is triggered as soon as the capital posted against a leveraged position no longer covers the paper loss. The exchange then closes the position itself, at whatever price is available. The investor is not consulted.
That almost everything sat on the long side says something about positioning ahead of the sell off: most leveraged traders were on the side of rising prices when the market gave way. In the short term that acts as an amplifier. Every forced closure of a long position is itself a sale, which pushes the price down further and can trigger the next position. That cascade explains why price moves in leveraged markets arrive in bursts instead of evenly.
There is also the spot market. In the four days to October 8, about $55 million flowed out of Dogecoin spot positions, according to CoinGlass figures. On October 8 the transaction tracker Whale Alert also reported a transfer of 304,709,765 DOGE, worth a good $27 million, to the exchange Binance. That equals just under 0.2 percent of the circulating supply of around 156.25 billion DOGE. A transfer to an exchange is not yet a sale; it merely makes one possible.
Where Dogecoin stands today, and what has changed since yesterday
On Friday afternoon DOGE trades at $0.084663, around 1.9 percent firmer than 24 hours earlier. The day's range ran from $0.081186 to $0.08548. The wave of liquidations is therefore already behind the market, and the price has recovered slightly since.
Yesterday in this slot we described the issuance without a cap, at $0.087 at the time and with 13.55 million new DOGE a day. Since then the price has given up around 2.7 percent while defending the $0.0832 we had marked as the lower edge on October 5. The daily low of $0.081186 sat below it; the closing area did not. What has been added since is the imbalance on the futures market, the subject here.
$1.9 billion in open positions: our count across 106 contracts
For this article we pulled the derivatives data from CoinGecko and counted every perpetual futures contract on Dogecoin listed there as active. The result: 106 contracts across various venues holding $1,899,522,358 in open positions between them. Open positions, known in the trade as open interest, describe the notional value of all contracts currently running and not yet closed.
The largest blocks are spread more widely than many assume. Binance leads with $219.7 million, followed by Gate with $206.9 million, Bybit with $120.1 million, MEXC with $118.8 million and Bitget with $115.8 million. No single venue holds more than 12 percent of the total. Trading on a decentralised perp exchange means moving within the same overall mass, only with a different counterparty.
A leverage ratio of 14.4 percent: Dogecoin is level with Ethereum and far above Bitcoin
The absolute sum says little until it is set in proportion. We therefore divided open futures positions by the market capitalisation of each coin. That ratio shows how much leveraged speculation sits on a market, measured against its size.
| Coin | Open futures positions | Market capitalisation | Leverage ratio |
|---|---|---|---|
| Solana | $9.74bn | $64.48bn | 15.10 percent |
| Ethereum | $43.70bn | $303.74bn | 14.39 percent |
| Dogecoin | $1.90bn | $13.23bn | 14.36 percent |
| XRP | $4.34bn | $87.16bn | 4.98 percent |
| Bitcoin | $63.41bn | $1,661.44bn | 3.82 percent |
Own count of all perpetual futures contracts, data source CoinGecko, as of October 9. Market capitalisation from the same survey.
Dogecoin therefore carries a leverage ratio of 14.36 percent, putting it practically level with Ethereum, slightly below Solana and almost four times as high as Bitcoin at 3.82 percent. The finding cuts against the familiar story in two directions. On the futures market Dogecoin is no outlier at the top but mid table among the large altcoins. Strikingly low instead are Bitcoin and XRP, where a far greater share of market value rests on unleveraged holdings.
For a holder that yields a sober reading. If 14 percent of market value sits in leveraged positions, comparatively small price moves are enough to trigger forced closures. Bitcoin needs considerably more. That explains the larger daily swing in Dogecoin better than any description of sentiment.
Split funding rates: the venues where long positions are paying right now
Perpetual futures contracts have no expiry date. To keep their price pinned to the spot rate anyway, the long and short sides pay each other a fee at fixed intervals, the funding rate. When it is positive, long positions pay the short positions; when it is negative, the flow reverses. The rate therefore works as a sentiment gauge and a running cost at the same time.
In our survey that rate runs in both directions. On Binance and MEXC it stood at 0.0034 percent, on Bitget at 0.0097 percent, and on OrangeX, Phemex and WhiteBIT at 0.01 percent. There, the long positions are paying. On Bybit it stood at minus 0.0034 percent, on OKX at minus 0.0017 percent and on Gate at minus 0.0014 percent. There, the short positions are paying.
A uniform picture looks different. After a wave of liquidations that hit longs 94 percent of the time, a consistently negative rate would have been the expectation. The side switching from venue to venue points to mixed positioning rather than a clear direction.
Scale these numbers up to a year before dismissing them as small. A funding rate of 0.01 percent typically falls due every eight hours, so three times a day. That makes 0.03 percent daily and around 11 percent a year in running fees alone, on top of the spread and the trading fee. A position held for months has to earn those costs back first.
Two to one instead of fifty to one: the BaFin leverage cap for retail clients
The leverage used on global futures exchanges is not available to retail clients in Germany. With a general administrative act of July 23, 2019, BaFin transposed the product intervention measure of the European supervisor ESMA into German law. The act has applied since August 1, 2019 with no end date.
For contracts for difference on cryptocurrencies it requires initial margin of 50 percent of the notional value. That corresponds to maximum leverage of 2:1. For comparison, the other tiers of the same act: 30:1 for major currency pairs, 20:1 for gold and the main indices, 10:1 for other commodities, 5:1 for single shares. Crypto sits at the bottom end, justified by its wider swings.
Three further safeguards apply alongside, and in practice they change more than the leverage figure itself. The position has to be closed as soon as account equity together with unrealised gains falls below half of the total initial margin. Negative balance protection stops the account from going below zero, and retail clients carry no obligation to top up. Providers also have to display standardised risk warnings. Trading with a crypto broker supervised in Germany brings those limits automatically.
Perpetual futures before the supervisor: the ESMA statement of February 2026
This is exactly where the legal position for products such as the Dogecoin contracts counted above becomes interesting. In February 2026 ESMA published a public statement reminding firms to check whether derivatives marketed as perpetual futures or perpetual contracts fall under the national product intervention measures for contracts for difference. The trading name is irrelevant to the classification under MiFID II, the authority said. What counts is whether a derivative conveys leveraged exposure to an underlying and is not settled exclusively by physical delivery. Features such as trading on a venue, a funding rate or voluntary negative balance protection change nothing about that. PwC Legal's reading of the statement summarises the consequences for providers.
ESMA has issued no new rules with this. The authority has said that the existing ones apply. Where a perpetual futures contract on DOGE is distributed to retail clients in the EU and is to be classified as a contract for difference, the BaFin act applies with its 2:1 and its margin close out. Higher leverage is then found only with providers outside that framework, and therefore outside the negative balance protection you can otherwise rely on.
Liquidation price, funding cost and supervisor: the three figures before the next position
Three figures determine whether a leveraged position survives a market move, and none of them is the entry price.
The liquidation price is the first. It appears in the order window before the position is opened and states the price at which the exchange will force the close. Hold it against the daily lows of recent weeks: for Dogecoin this week's low was $0.081186, starting from $0.097 on October 4. A liquidation price that sits inside such a range will be reached at the next opportunity.
Funding costs are the second. Multiply the current rate by three payments a day and by your intended holding period. At 0.01 percent and three months that is around 2.7 percent of the notional value, which your position has to earn first.
The third is your provider's regulatory framework. Check whether it is supervised in Germany or the EU, whether negative balance protection applies and whether the margin close out takes effect at 50 percent. Without those three commitments you are carrying a different risk from the one you priced in.
The reverse test holds just as well. A holding in your own hardware wallet knows neither a liquidation price nor funding. In exchange it costs the full stake and requires you to secure the recovery words yourself. Which of the two forms suits you depends on whether you can sit out a price move or would rather an exchange took the decision for you.
DogeOS and the soft fork: the second strand beside the futures market
While the futures market explains the daily move, a development with a longer horizon is running on the chain itself. At the end of September DogeOS, a project from the team behind the MyDoge wallet, opened a public testnet. It is compatible with the Ethereum Virtual Machine, so developers can carry over existing tools and program code. Technically it is a zero knowledge rollup, an independent layer that writes its state to the Dogecoin blockchain at regular intervals. DOGE serves as the fee currency within it, and no separate network token was issued. According to the project, $6.9 million in funding comes from Polychain Capital.
One limitation belongs with this, and it is rarely mentioned. Dogecoin does not currently verify the zero knowledge proofs of that layer itself. Security rests instead on validators, a protected execution environment and a permissioned sequencer. For the main chain to verify the proofs directly, a protocol change would be needed that so far exists only as a draft. No date has been set for the mainnet launch.
Our assessment of the state of the Dogecoin futures market
In this newsroom's view, this week's wave of liquidations is not a Dogecoin special case but the predictable consequence of a leverage ratio of 14.36 percent. Three pieces of evidence from this article support that: the ratio itself, which practically matches Ethereum's 14.39 percent; the broad spread of open positions across 106 contracts with no dominant venue; and the split funding rates, which no longer show one sided positioning. Against it stands the fact that our snapshot captures a single day; whether the ratio sits that high structurally can only be said over several weeks. What the numbers do not yield is any statement about price direction. The ratio describes the violence of moves, not their sign.
Dogecoin leverage: in Germany the cap is 2:1, not 50:1
What you can take from this day's figures comes down to three steps:
- Check what leverage your provider works with and whether it is subject to the BaFin act. An overview of supervised providers is in the crypto broker comparison.
- Before any leveraged position, calculate the liquidation price against the weekly low and the funding costs against your holding period. Which venues offer which terms is shown by the perp exchange comparison.
- Decide deliberately between a leveraged position and a holding. A holding needs custody you control yourself, for instance from the hardware wallet comparison.
(As of October 9, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy. Trading leveraged products can lead to the total loss of the capital employed.)
Decrypt
Executives are war-gaming the political fallout of a major AI-driven cyberattack and preparing to brief Congress fast if and when necessary.
Sen. Richard Blumenthal wants Cantor Fitzgerald to open its records on Tether and on how much Commerce Secretary Howard Lutnick's family has earned from its business deal.
The crypto platform filed for designated contract market and futures commission merchant licenses, which would let it run its own regulated event-contract venue instead of relying on overseas partners.
Bitcoin bounced after dipping to around $80,000. Traders are placing increasingly high odds BTC slips further before October is over.
Starknet is "actively considering" becoming its own blockchain, a move it says would make it the first fully quantum-resistant network by 2027.
U.Today - IT, AI and Fintech Daily News for You Today
Crypto majors and large-cap altcoins are consolidating after sharp pullbacks, with traders watching key moving averages for the next directional move.
A dangerous iPhone exploit continues to threaten crypto holders, with hackers targeting popular wallets such as Coinbase, MetaMask and Trust Wallet to steal sensitive data and recovery phrases.
Avalanche founder Emin Gün Sirer has warned that AI could uncover critical vulnerabilities in the XRP Ledger.
Binance founder Changpeng Zhao advises a two-week freeze on new devices after an $86 million exploit hits Ledger.
Ethereum reserve on Binance drops to its six-month low with over 10 million ETH withdrawn from the exchange in just three days.
Blockonomi
TLDR
- Eli Lilly stock gains 0.62% as new Phase 3b findings highlight treatment gains.
- Combined therapy changes 482 proteins versus 140 with Taltz alone by Week 36.
- Gene activity shifts span 467 genes with both drugs, versus 16 on Taltz alone.
- Taltz and Zepbound deliver improved skin clearance and weight loss at Week 36.
- Researchers report consistent safety findings, but no new approved indication.
Eli Lilly and Company stock rose 0.62% to $1,176.80 on Friday, gaining $7.20 during the trading session. The company announced new Phase 3b findings showing broader biological responses from combined Taltz and Zepbound treatment. The results expand earlier evidence of improved psoriasis symptoms and weight reduction among adults living with psoriasis and obesity.
Eli Lilly and Company, LLY
Eli Lilly Reports Stronger Phase 3b Results for Taltz and Zepbound
Eli Lilly released new exploratory findings from its TOGETHER-PsO Phase 3b clinical trial examining two existing prescription medicines. Researchers compared the combined use of Taltz and Zepbound against Taltz alone in adults with moderate-to-severe plaque psoriasis. The study also included participants with obesity or overweight alongside at least one additional weight-related medical condition.
The latest analysis identified broader changes in proteins and genes among participants receiving both medicines compared with Taltz alone. By Week 36, researchers identified changes involving 482 proteins in the combination group, compared with 140 in the other group. Similarly, gene expression changes affected 467 genes with combined treatment, against only 16 genes with Taltz alone.
These biological differences appeared as early as Week 12, according to the pharmaceutical company’s newly released findings. Researchers also identified stronger reductions in inflammatory immune activity among participants receiving both treatments over the study period. Eli Lilly presented the findings at the 2026 Fall Clinical Dermatology Conference in Las Vegas.
Combined Treatment Improves Skin Clearance and Weight Reduction
The latest findings build on earlier clinical results showing better treatment outcomes among participants receiving Taltz alongside Zepbound. At Week 36, the combination delivered superior skin clearance and meaningful weight reduction compared with Taltz alone. Furthermore, participants maintained or improved these clinical benefits through Week 52, according to Eli Lilly’s previously reported findings.
The analysis also examined neutrophils, which play an important role in the body’s inflammatory immune response. Researchers found that combined treatment produced greater changes in inflammatory pathways associated with these immune cells. Changes in certain neutrophil-related markers partly explained the additional improvement in psoriasis severity scores among combination-treatment participants.
The TOGETHER-PsO trial included 274 adults across multiple clinical research centers, with participants divided equally between two treatment groups. One group received Taltz alone, while the other received Taltz and Zepbound through injections under the skin. Both groups also received guidance on reducing calorie intake and increasing physical activity throughout the clinical study.
Eli Lilly Expands Research Into Psoriasis and Obesity
Eli Lilly designed the study to examine the relationship between metabolic health and inflammatory skin conditions. Approximately 61% of Americans with psoriasis also experience obesity or overweight alongside another weight-related medical condition, according to Lilly. The findings provide additional research into how treatments targeting different biological processes may influence both conditions.
Taltz works by blocking interleukin-17A, an immune signaling protein involved in inflammation and several related inflammatory conditions. Zepbound targets GIP and GLP-1 receptors, helping regulate appetite and support weight management in eligible adults. The two medicines therefore act through different biological pathways, providing the basis for investigating their combined clinical effects.
Eli Lilly reported that the combination’s safety findings matched the established safety profiles of the individual medicines. The exploratory results do not establish a new approved indication for using the medicines together. The company continues examining the relationship between immune and metabolic processes as researchers assess broader approaches to psoriasis management.
The post Eli Lilly and Company (LLY) Stock: Rises as Taltz and Zepbound Show Promising Results appeared first on Blockonomi.
TLDR
- ASTS stock plunges 12.01% as BlueBird satellite deployment remains a key focus.
- AST SpaceMobile targets 45 satellites by early 2027 to expand mobile coverage.
- The company needs 45 to 60 satellites for continuous service in key markets.
- AST SpaceMobile reports $3.7 billion in funding to support satellite expansion.
- Commercial satellite service could generate nearly $1 billion in annual revenue.
AST SpaceMobile, Inc. stock dropped 12.01% to $50.10 on Friday, losing $6.83 during the trading session. The decline comes as the company works to expand its BlueBird satellite network and prepare commercial broadband services. Its satellite deployment targets remain central to future revenue growth and the company’s long-term business plans.
AST SpaceMobile, Inc., ASTS
AST SpaceMobile currently operates 13 spacecraft in orbit, according to its second-quarter 2026 update. The company needs a substantially larger constellation to provide continuous mobile coverage across its target markets. Management expects to reach approximately 45 satellites by early 2027, supporting its planned commercial network expansion.
AST SpaceMobile Targets 45 BlueBird Satellites by Early 2027
AST SpaceMobile reported 13 spacecraft in orbit during its August 10, 2026, earnings call. The company estimates that continuous broadband coverage requires between 45 and 60 satellites across major international markets. These markets include the United States, Europe, and Japan, where the company plans to introduce satellite-based mobile connectivity.
The BlueBird network aims to provide broadband services directly to standard smartphones without requiring special equipment. AST SpaceMobile plans to extend mobile coverage into areas where traditional cellular infrastructure remains limited. Its technology could support telecommunications providers seeking broader network coverage without building additional ground infrastructure across remote regions.
The company has established partnerships with more than 60 mobile network operators across different international markets. These telecommunications partners serve more than 3 billion subscribers, creating a substantial potential customer base. Commercial availability depends on satellite deployment, network integration, regulatory approvals, and agreements with participating mobile operators.
AST SpaceMobile Revenue Targets Depend on Network Expansion
AST SpaceMobile generated $31.5 million in revenue during the second quarter of 2026, according to its financial results. Government contracts and infrastructure projects for commercial partners provided revenue during the reporting period. The company continues developing its satellite network before launching commercial mobile broadband services at a larger scale.
Over the previous twelve months, AST SpaceMobile recorded approximately $100 million in revenue from its existing operations. Management has outlined an ambitious target of nearly $1 billion during its first year of commercial service. Achieving that target requires substantial network capacity and successful service agreements with telecommunications companies across multiple geographic regions.
The company’s valuation also reflects expectations surrounding its future commercial operations and satellite deployment progress. AST SpaceMobile trades at approximately 147.7 times sales, compared with around 3.0 times sales for the S&P 500. Is approximately $600 million annual net loss highlights the financial demands of developing a global satellite communications network.
AST SpaceMobile Funding Supports BlueBird Satellite Deployment
AST SpaceMobile estimates that each satellite will cost approximately $21 million to $23 million, including launch expenses. The company intends to develop a constellation exceeding 90 satellites, extending beyond its initial continuous coverage requirements. Based on those estimates, 90 satellites would require approximately $1.89 billion to $2.07 billion in combined satellite and launch costs.
The company reported more than $3.7 billion in pro forma cash, cash equivalents, and restricted cash following recent financing. This figure incorporates $1.15 billion in gross proceeds from convertible senior notes issued during July 2026. Management expects those financial resources to support additional satellite launches, manufacturing expansion, and the broader network development program.
AST SpaceMobile continues to face financial and operational challenges as it expands its satellite infrastructure. A shareholder class action alleges that the company misrepresented aspects of its capital resources and liquidity position. Satellite manufacturing schedules, launch execution, and commercial network activation remain important factors influencing its future financial performance.
The post AST SpaceMobile, Inc. (ASTS) Stock: BlueBird Launches Hold the Key to Future Gains appeared first on Blockonomi.
TLDR
- Amazon (AMZN) stock surges 2.70% to $260.92 despite another round of job cuts
- Amazon reportedly cuts fewer than 1,000 jobs across the US, UK, and India
- Fresh layoffs affect customer service, marketplace support, and engineering teams
- Amazon’s earlier restructuring plans covered approximately 30,000 job cuts
- Amazon targets former employees for AI and cloud roles despite fresh layoffs
Amazon (AMZN) stock surged 2.70% to $260.92 during Friday’s intraday trading, gaining $6.86 despite reports of fresh workforce reductions. The company reportedly eliminated fewer than 1,000 positions across several business units in three countries. The latest layoffs extend Amazon’s restructuring efforts following approximately 30,000 previously announced job cuts.
Amazon.com, Inc., AMZN
Amazon Announces Fresh Layoffs Across Retail Operations
Amazon employees in the United States, India, and the United Kingdom reported receiving job termination notices this week. According to Business Insider, workers received emails Tuesday confirming the elimination of their positions. The reductions affected several departments, including customer service, marketplace support, and engineering teams within retail operations.
Employees shared information about the layoffs through an internal Slack channel containing nearly 37,000 members. Their messages identified affected departments and raised questions about the company’s ongoing restructuring process. Workers also sought clarification about severance packages, internal job opportunities, and the possibility of further reductions.
Amazon confirmed to Business Insider that it eliminated a limited number of positions, primarily within its Stores division. The company linked the changes to organizational restructuring and efforts to improve operational efficiency. Amazon also said it would provide support to affected employees during their employment transitions.
Amazon’s Previous Job Cuts Total Approximately 30,000
The latest reductions follow Amazon’s January announcement of approximately 16,000 job cuts across its global operations. Company leadership outlined plans to simplify management structures and reduce unnecessary administrative processes. The restructuring also aimed to increase employee ownership and improve decision-making across business divisions.
Amazon previously announced another 14,000 corporate job reductions in October 2025, expanding its workforce restructuring program. Together, those two announcements covered approximately 30,000 positions, representing nearly 1% of its reported 1.56 million employees. The reductions reached Amazon Web Services, retail operations, Prime Video, and corporate human resources functions.
The company also targeted its People Experience and Technology division during the broader workforce adjustments. These changes affected several major operations rather than concentrating reductions within one business segment. Amazon continued reorganizing departments while maintaining investments in technology and other priority business areas.
Amazon Expands AI Hiring Despite Workforce Reductions
Amazon has also pursued recruitment initiatives targeting specialists in artificial intelligence and cloud computing. Last month, reports indicated that the company sought former employees, including workers affected by earlier layoffs. The recruitment effort focused on professionals with experience in artificial intelligence, machine learning, and related technologies.
AWS Vice President Swami Sivasubramanian leads the company’s artificial intelligence agent organization and its recruitment initiative. The program, called Swami’s Boomerang Reengagement Initiative, aims to reconnect Amazon with former technical employees. Its recruitment efforts operate alongside the company’s broader restructuring and workforce reduction measures.
Amazon’s latest layoffs and specialized recruitment efforts reflect separate changes across its business operations. The company continues adjusting staffing within retail while pursuing technical expertise for artificial intelligence development. Meanwhile, its recent workforce changes span multiple countries and several divisions across its global operations.
The post Amazon (AMZN) Stock: Surges as Company Announces Fresh Layoffs appeared first on Blockonomi.
TLDR
- IonQ shares fall 0.33% to $39.32 despite a major quantum networking breakthrough.
- Researchers achieve over 1,000 entanglement events per second using light links.
- The new quantum interconnect surpasses the earlier trapped-ion record fourfold.
- IonQ’s breakthrough supports DARPA research into faster quantum hardware links.
- New system sales in Maryland and South Korea highlight early commercial demand.
IonQ (IONQ) stock slipped 0.33% to $39.32 during Friday’s intraday session, losing $0.13 despite a new quantum computing breakthrough. The company achieved more than 1,000 entanglement events per second between two different quantum systems. The development advances IonQ’s efforts to connect quantum processors and build larger computing networks.
IonQ, Inc., IONQ
IonQ Achieves Major Quantum Interconnect Milestone
IonQ announced that its researchers achieved entanglement rates exceeding 1 kilohertz through a photonic connection. The experiment linked a trapped ion qubit with solid-state quantum memory using light to transfer quantum information. This connection allows separate quantum components to share information and operate within a larger computing system.
The company reported that its demonstration exceeded the previous trapped-ion interconnect record by more than four times. IonQ researchers worked with collaborators from Duke University, including research associated with company co-founder Chris Monroe. The results establish a new performance benchmark for connecting trapped ion systems with other quantum hardware.
IonQ Chairman and CEO Niccolo de Masi identified quantum interconnects as essential infrastructure for larger computing networks. He compared future quantum systems with traditional data centers that connect processors, memory, and networking equipment. The company aims to use similar architecture to expand quantum computing capacity beyond individual processors.
IonQ Advances Quantum Memory and Networking Technology
IonQ conducted the experiment using an end-to-end connection between a trapped ion system and a silicon vacancy qubit. The setup incorporated its existing quantum memory technology and transmitted quantum information through a photonic interconnect. This approach combines the coherence advantages of trapped ions with efficient light connections from solid-state memory.
The achievement also supports IonQ’s participation in the Defense Advanced Research Projects Agency’s HARQ program. DARPA seeks to develop high-speed quantum connections that support different types of quantum computing hardware. IonQ expects its technology to support trapped ions, neutral atoms, and superconducting systems using suitable conversion devices.
Meanwhile, IonQ continues to expand commercial applications for its quantum memory and interconnect platform. The company announced its first commercial system sale to the University of Maryland in April. It followed that agreement with a second system sale to South Korean technology company SDT in September.
IonQ Stock Performance Meets Expanding Commercial Operations
The latest announcement adds to IonQ’s research activities as the company develops quantum networking products. Its technology targets connections between separate quantum devices rather than relying entirely on individual processors. Such connections form part of the infrastructure needed to distribute computing tasks across multiple quantum systems.
IonQ also develops hardware that supports different approaches to quantum computing through its interconnect architecture. The company expects this flexibility to create applications in modular computing and networked quantum sensing. However, commercial deployment depends on further engineering, system integration, and performance testing across supported hardware platforms.
The latest technical results strengthen IonQ’s quantum networking roadmap and add evidence from operational hardware testing. Its commercial agreements also demonstrate early demand for the company’s memory and interconnect systems. Friday’s stock decline occurred despite these developments, reflecting a weaker intraday performance following the announcement.
The post IonQ (IONQ) Stock: Quantum Breakthrough Hits 1,000 Entanglements Per Second appeared first on Blockonomi.
TLDR:
- Hinkal joins Mastercard’s Crypto Partner Program to advance privacy-focused digital asset payment applications.
- Zero-knowledge proofs help verify transfers without publicly exposing transaction amounts, senders or recipients.
- Existing integrations include Polygon Wallet, Tether’s Wallet Development Kit, Turnkey and Avvio.
- Screening and viewing keys aim to balance transaction confidentiality with regulatory and audit requirements.
Hinkal has joined Mastercard’s Crypto Partner Program, bringing blockchain privacy infrastructure into a global payments initiative focused on digital assets. The partnership connects Hinkal with Mastercard’s ecosystem as stablecoins expand into payments, settlements, and commercial transactions.
Hinkal provides infrastructure that allows platforms to process private stablecoin transfers without exposing transaction amounts or counterparty relationships publicly. Its technology uses zero-knowledge proofs to verify transfers while keeping sensitive transaction details confidential.
The integration could help businesses explore onchain payments without making their financial activity visible to everyone on public blockchains.
Hinkal Brings Privacy to Mastercard’s Crypto Partner Program
Mastercard’s Crypto Partner Program connects blockchain companies with its payments teams and a broader network of industry participants. Members include stablecoin issuers, blockchain infrastructure providers, crypto card enablers and companies supporting digital asset transactions.
According to an announcement, the initiative supports practical digital asset applications through partner collaboration, industry connections and go-to-market opportunities. Selected members can also access financial institutions across Mastercard’s issuing and acquiring network, alongside regulatory and compliance support.
For Hinkal, joining the program creates an opportunity to bring confidential transaction infrastructure into payment products. Rather than requiring companies to build privacy systems independently, Hinkal allows wallets and platforms to integrate its technology through software development kits (SDKs) and APIs.
The infrastructure supports private settlements and payouts across fintech platforms, payment providers and wallets. Hinkal operates across Ethereum, Polygon, Solana, TRON and other major EVM-compatible networks.
Existing integrations demonstrate how the technology can fit into products already serving users.
Polygon Wallet offers Private Send powered by Hinkal, while Tether’s Wallet Development Kit includes its private-send functionality. Turnkey wallets can also integrate privacy through Hinkal’s SDK, and Avvio operates private payments through its interface.
These integrations allow partner platforms to maintain their products while adding transaction confidentiality as a feature.
Why Does Stablecoin Payment Privacy Matter?
Stablecoins can transfer value around the clock, but public blockchain transactions can expose financial relationships and payment amounts. That transparency may create challenges for businesses handling payroll, supplier payments, treasury movements and other commercially sensitive transactions.
Hinkal addresses this issue through zero-knowledge proofs, which allow a network to verify transfers without publicly revealing their underlying details. Its system keeps transaction amounts, senders and recipients confidential from public observers.
However, privacy does not mean eliminating compliance oversight. Hinkal says funds undergo screening before entering its system, while viewing keys allow users and businesses to share transaction histories with authorized auditors or regulators.
This approach aims to balance confidentiality with the oversight required for regulated financial activity. It could prove useful as payment providers explore stablecoins for cross-border transfers, business transactions and settlement flows.
Mastercard’s program provides a framework for connecting these technical capabilities with established payment infrastructure. However, Hinkal’s membership does not itself confirm a direct Mastercard product integration or a commercial launch.
The post Mastercard Adds Hinkal as Stablecoin Privacy Takes Center Stage appeared first on Blockonomi.
CryptoPotato
The UK sanctioned crypto payment processors Cryptomus and Heleket and Kyrgyzstani exchange TokenSpot on October 8, after blockchain analytics firm Chainalysis linked the services to illicit financial flows and networks associated with Russia’s sanctions evasion.
The designations target parts of the infrastructure used to move money through crypto, including payment services that received funds from thousands of illicit counterparties and exchanges connected to a ruble-backed token network.
Chainalysis Traces Illicit Funds Through Three Crypto Services
In an analysis published alongside the announcement, Chainalysis reported that Cryptomus and Heleket, both operated by Xeltox Enterprises Ltd., had received funds from more than 15,000 distinct illicit counterparties across every criminal category tracked by the firm.
In several categories, including scams, sanctioned jurisdictions and terrorist financing, their illicit inflows exceeded those received by all mixing services in its dataset combined.
Illicit counterparties linked to the two processors increased to more than 900 in a single month in late 2025. Chainalysis suggested the closure of Russian exchange Garantex may have contributed, as some users already held accounts with Cryptomus or Heleket. The firm cautioned that new sanctions designations can also cause historical transactions to be reclassified as illicit exposure.
Cryptomus had also advertised crypto payments and conversions without know-your-customer (KYC) or know-your-business (KYB) checks on Russian-language cybercrime forum BHF and the Nulled forum, Chainalysis reported. In October 2025, Canada’s financial intelligence unit imposed a CAD 177 million penalty on Cryptomus for anti-money laundering and counter-terrorist financing violations.
TokenSpot’s connections followed a different route. Chainalysis traced funds from the Kyrgyzstani exchange, alongside those from previously sanctioned exchanges Grinex and Meer, to a shared HTX deposit address that received more than $308 million.
The firm identified links to addresses associated with Moldovan businessman Ilan Shor and the A7A5 instant swapper, which exchanges ruble-backed tokens for dollar-backed stablecoins.
Earlier Cases and the Wider Package
As CryptoPotato reported earlier, Grinex was set up in Kyrgyzstan in December 2024 and presented as a replacement for Garantex, which processed over $100 billion in transactions while sanctioned.
In April, Grinex suspended operations after a hack that took more than 1 billion rubles, about 13.74 USDT, and TokenSpot reportedly went offline around the same time. HTX, formerly Huobi, was sanctioned by the UK in May for channeling more than $1.5 billion to Russia.
The UK also sanctioned oil companies Zarubezhneft and INK Capital, bringing its coverage to more than 90% of Russia’s oil production capacity, along with the bank Stolichny Kredit and twelve shadow fleet tankers.
Seventeen individuals and entities importing machine tools, electronics and materials allegedly used in ballistic missiles and drones were named too.
The post UK Sanctions 3 Crypto Firms Over Russia Ties appeared first on CryptoPotato.
Binance will restrict eight products and services and delist 22 tokens for users in Brazil from October 27 as it restructures its local operations to comply with Central Bank regulations.
The changes also move customers’ Brazilian-real operations to a locally authorized payment account, while new reporting requirements for international crypto transfers take effect on November 1.
Binance Sets October 27 Deadline for Product Restrictions
In an announcement published on October 8, Binance Brasil explained that customers in Brazil will have individual payment accounts with Binance Brasil Corretora de Câmbio e Valores Mobiliários SA by October 29.
Virtual asset services will be provided by BBrasil Sociedade Prestadora de Serviços de Ativos Virtuais Ltda., another company in the Binance Group. The exchange listed eight services that will be restricted from October 27: Loans, Binance Pool. Cloud Mining, Margin, Launchpool, Megadrop, HODLer Airdrops and Alpha 2.0.
Users with existing positions in affected products will generally be able to close or reduce them and transfer remaining balances to their Spot accounts, but they will not be able to open new positions. Binance also listed 22 tokens for delisting in Brazil: XVG, USDE, USTC, DCR, DUSK, PIVX, BB, MANTRA, ONE, GMT, TFUEL, ZIL, ONT, RVN, ACX, HIT, PYR, VANRY, VIC, ICX, SCRT and STORJ.
Trading will remain available until October 27. After that, holders can withdraw or reinvest their remaining balances. The exchange added that bStocks will remain restricted.
The changes do not require customers to repeat identity verification, although users with outdated registration details may be asked to update them. Furthermore, deposit addresses for crypto assets will remain unchanged, and Binance says transaction histories from before and after migration will still be available.
Futures users face a separate decision, with customers who already have an international account with Binance’s Abu Dhabi entity being able to choose to move existing futures positions there. Otherwise, those positions will switch to reduce-only mode in the Brazilian account.
Binance also cautioned that crypto derivatives traded through the overseas entity are not regulated by Brazil’s Central Bank or securities regulator, the CVM.
International Transfers Face New Reporting Rules
A separate change begins November 1, with Binance explaining in an October 2 FAQ that users sending crypto abroad or receiving it from overseas must provide the transfer’s purpose and confirm details about the other party.
Binance will report the information to Brazil’s Central Bank monthly, and withdrawals cannot proceed until the required details are submitted, while incoming transfers may remain pending.
The October 8 announcement also confirms that Brazilian residents must migrate to the local service if they want to keep using Binance. Customers who do not want to migrate can withdraw their assets and end their relationship with the exchange before October 27, while users based outside the country with valid proof of residence will stay on the global platform.
The post Binance to Restrict 8 Services and Delist 22 Tokens in Brazil appeared first on CryptoPotato.
Bitcoin’s on-chain regime model from BIT has returned to a 67% net-long position for a second consecutive month, with five indicators now in territory historically associated with bull markets.
The reading suggests a potential recovery in Bitcoin’s cycle, although a recent $7,000 price decline and two important on-chain price levels leave room for further weakness.
Five Bitcoin Indicators Turn Bullish as Model Raises Exposure
In an October 9 post, BIT explained that its rules-based model moved from 100% net long on October 1, 2025, to 33% on November 1, before dropping to zero on December 1. It remained there through most of the subsequent drawdown before returning to 67% on September 1, 2026.
The model has now maintained that allocation for two consecutive months, with BIT noting that five indicators have simultaneously entered historically bullish territory, a combination last seen in October 2025.
First is Bitcoin’s short-term realized price, which provides an estimate of the average cost incurred in buying units recently. BTC dipped below this level to $112,300 in October 2025 but jumped above it to $68,800 in August 2026, and this measure is now at $74,319, taking Bitcoin above its cost basis.
The second measure, the True Market Mean, tracks the cost basis of active capital. It stands at $77,460, compared with BTC’s price of approximately $82,000 in the latest CoinGecko data. BIT argues that sustained trading above this threshold would strengthen the bullish interpretation.
The other three are Market Value to Realized Value (MVRV), which compares market value with realized value, and stands at 0.20; the Net Unrealized Profit/Loss (NUPL), which measures investors’ paper gains and losses, and has turned positive for the first time since October 2025; and the Value Days Destroyed (VDD), which tracks the movement of coins based on their age and value, which has also turned bullish.
However, BIT cautioned that the model is not fully invested because some indicators have yet to turn bullish and others have only recently crossed their thresholds. Furthermore, the firm pointed out that a sustained break below both the short-term realized price and True Market Mean would be an early warning that recovery is losing track.
Bitcoin Retreat Tests the Bullish On-Chain Reading
The model’s improving signals contrast with Bitcoin’s recent price action. As mentioned earlier, CoinGecko data put the OG cryptocurrency at around $82,000 at the time of writing, down 4.5% over seven days and more than 32% in the past year.
Bitcoin fell nearly $7,000 after failing to break above $87,000, with the decline coinciding with substantial US government BTC transfers to Coinbase Prime, spot ETF outflows totaling $731 million on October 7 and 8, and profit-taking exceeding $1 billion in realized gains.
The post These 5 Bitcoin Indicators Have Turned Bullish for the First Time Since 2025: Report appeared first on CryptoPotato.
Ledger CTO Charles Guillemet has rebuffed fears that AI could break Bitcoin’s cryptography in the coming months.
He said there is no sign of an imminent breakthrough that could break the Elliptic Curve Digital Signature Algorithm (ECDSA), the cryptographic system used to secure Bitcoin transactions.
Is Fear Overblown?
Guillemet went on to explain that if asymmetric cryptography were broken, “Bitcoin will be the least of our problems.” Internet security, banking systems, secure communications, and critical infrastructure could all face serious problems. While he admitted that recent mathematical advances are impressive, the exec said they do not represent a practical breakthrough against ECDSA.
“And if your logic is that nothing can be trusted until it’s proven unbreakable, congratulations. By that standard, nothing is safe, including hashes.”
Guillemet urged people to follow cryptography research and take potential risks seriously. But he warned against treating theoretical progress as a sign that a cryptographic crisis is just months away.
The comments come after Ethereum Foundation researcher Justin Drake made a startling warning about the potential risks AI poses to cryptography. Drake urged the industry to calmly prepare for “bunker mode” and said crypto holders should consider moving funds to fresh addresses whose public keys have never been exposed. He believes ECDSA could potentially be broken within months rather than years.
Drake cited recent mathematical breakthroughs and OpenAI’s latest release as reasons to take the risk seriously. However, he added that holders should not rush into moving their assets, while warning that a hurried migration could do more harm than good. The researcher called on major crypto platforms to strengthen their cold storage security and urged the industry to accelerate its shift towards hash-based cryptography. He said the industry should prepare without panicking.
Theoretical Threats Can Wait
While Vitalik Buterin also believes that the rapid progress in AI-assisted mathematics could pose new risks to existing cryptographic systems, he warned against rushing into wallet migrations. The Ethereum co-founder asserted that moving funds without proper planning could create fresh risks for users.
Meanwhile, prominent Bitcoin developer and Casa co-founder Jameson Lopp said that worrying about cryptographic breaks is getting ahead of ourselves. He added that the industry has “much more pressing actual issues to deal with.”
“Theoretical future problems can wait.”
The post AI, ECDSA, and Bitcoin’s Endgame? Ledger CTO Pushes Back Against Cryptographic Apocalypse Predictions appeared first on CryptoPotato.
What goes up must come down, right? Bitcoin and the crypto market certainly proved that thesis right in the past week after gaining serious traction in late August and September.
Our Market Update from last Friday showed a 2% increase in the largest cryptocurrency, which traded near $86,000 at the time. The first signs of weakness occurred later that night when the asset tumbled below $84,000. Nevertheless, it recovered to over $84,000 on Saturday and climbed to $85,000 on Sunday. It even tried to take down the familiar yet stubborn resistance level at $87,000 on Monday morning, but to no avail.
That’s where the actual troubles began. In the following hours, bitcoin dipped to $85,000 but quickly rebounded to $86,600. However, that was another fake-out, and the cryptocurrency slumped again: this time, to under $84,000. After another unsuccessful bounce-off, BTC experienced its most severe crash since the mid-August breakout.
In the span of just a day or so, it crumbled to under $80,400, reaching its lowest price tag since September 21. We dived into what could have brought this decline and found at least six reasons, which you can read in this article. Some of them include substantial profit-taking, ETF outflows, macro developments, and the FUD started by major transfers from wallets linked to the US government.
After losing nearly $7,000 in days, BTC was due for a more profound rebound, which took place today, with the asset climbing to over $83,000 as of press time. However, it remains to be seen whether this is another dead-cat bounce or an actual recovery.
The weekly scale is still in the red, though, with BTC dropping by over 3%. ETH has slumped by more than 8%, XRP is down by 8.6%, while ZEC, DOGE, LINK, RAIN, XLM, and BCH have marked double-digit declines. Naturally, the total crypto market cap has plummeted by over $150 billion since last Friday.
Next week is expected to be even more volatile as the CPI numbers for September will be announced on Wednesday.
Market Data

Market Cap: $3.050T | 24H Vol: $113B | BTC Dominance: 56.6%
BTC: $85,670 (+1.9%) | ETH: $2,710 (+0.4%) | XRP: $1.51 (-4.8%)
This Week’s Crypto Headlines You Can’t Miss
These 3 Factors Could Shape Bitcoin’s Post-Midterm Performance. The US midterm elections are right around the corner, and history shows BTC has overperformed in the first 12 months after they conclude. However, XWIN Japan warned that past gains do not necessarily translate into a repeat.
Charles Hoskinson Disputes Vitalik Buterin’s Warning Against Lattice Cryptography. In a verbal debate on X, Cardano founder Charles Hoskinson disputed Vitalik Buterin’s concerns over lattice-based cryptography, suggesting that there’s no credible attack that has been identified against it. Hoskinson argued that hash-based cryptography is not inherently safer.
While America’s CLARITY Stalls, Russia’s Crypto Market Gets Official Operators. Although the US failed to move forward with the CLARITY Act, Russia has registered its first digital asset operators, marking a significant move toward a more regulated crypto market overseen by the local central bank.
Arthur Hayes: AI Is Overbuilt, and Bitcoin Could Benefit From It. The former CEO of BitMEX doubled down on his belief that the AI industry is overcrowded and predicted a crash in data centers that can ultimately benefit BTC.
Metaplanet Sold 10,000 BTC – Then Bought Back Even More: Here’s Why. In its Q3 filing, the largest Asian corporate holder of BTC said it had sold 10,000 units during that period. However, it bought back 11,000 (at slightly higher prices) and said the idea was to prove that its treasury can be easily converted to cash if necessary.
3 in a Row: Strategy Ramps Up Bitcoin Purchases as Holdings Hit 848,000 BTC. The overall largest corporate holder of the cryptocurrency announced its third purchase in a row and, perhaps more importantly, its bitcoin stash reached a new all-time high of 848,000 units.
Charts
This week, we have a chart analysis of Ethereum, Ripple, Cardano, Binance Coin, and Hyperliquid – click here for the complete price analysis.
The post Bitcoin Crashes, Strategy’s BTC Stash Hits Record High, CPI Looms: Weekly Crypto Recap appeared first on CryptoPotato.