Cryptocurrency Posts
Crypto Briefing
Nvidia's soaring revenue per employee underscores the transformative impact of AI advancements, highlighting potential margin pressures ahead.
The post Nvidia now makes about $7 million in revenue per employee appeared first on Crypto Briefing.
Nvidia's stability amid AI credit concerns highlights the market's preference for firms with stronger balance sheets, impacting investment strategies.
The post Nvidia shrugs off the AI credit jitters hitting Broadcom and Oracle appeared first on Crypto Briefing.
Tron's readiness for post-quantum cryptography could set a precedent for blockchain security, but adoption and governance hurdles remain.
The post Justin Sun says TRON can go quantum-resistant at any time appeared first on Crypto Briefing.
Tokenized commodities' shift to yield-bearing assets could democratize access to institutional-grade returns, reshaping investment landscapes.
The post Paxos Labs and Theo bet tokenized commodities can do more than sit there appeared first on Crypto Briefing.
The crypto market's bifurcation highlights Bitcoin and Ether's institutional appeal, while altcoins face volatility and limited growth potential.
The post One year after 10/10, Bitcoin and Ether liquidity is back while altcoins lag appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Bitcoin Life Insurer Meanwhile Raises $37.5M as Wealthy Families Look to Pass On Their BTC
Meanwhile, the first life insurer licensed to operate entirely in Bitcoin, has raised $37.5 million in new funding from its existing investors, the company announced.
Bain Capital Crypto led the round, with participation from Haun Ventures, Framework Ventures, Pantera Capital, Apollo, Northwestern Mutual Future Ventures and Morgan Creek Digital. The raise brings Meanwhile’s total funding to more than $180 million. Sam Altman is also among its backers.
The company said the round follows a surge in demand for its Bitcoin life insurance policies outside the US, particularly in Asia, Europe and the Middle East, amid broader macroeconomic instability.
“Wealthy families around the world already hold Bitcoin. What they haven’t had is a regulated way to pass it on,” Zac Townsend, Meanwhile’s co-founder and CEO, said in a statement.
“Brokers came to us because their clients kept asking. This round lets us keep up with them.”
In early 2026, Meanwhile launched BTC Life 1-Pay, a single-premium whole life policy aimed at high-net-worth clients outside the US. It is the company’s second product line, after BTC 10-Pay, which is designed for US taxpayers.
Under BTC Life 1-Pay, a client pays one premium in Bitcoin and receives a guaranteed death benefit in Bitcoin for life. The policy’s value grows in Bitcoin, and after the first year the owner can borrow up to 90% of it, with no repayment schedule and no margin calls.
Policies can be owned by individuals, trusts or companies, which the company says makes them suited to succession and estate planning.
Since launch, Meanwhile has signed 15 brokers serving wealthy families, including in Singapore, Hong Kong, the UAE and Switzerland. Partners include Lioner, an insurance, trust and family office group with offices in Hong Kong, Singapore and Zurich, and Apeiron Group, a marketplace for high-net-worth life insurance.
“We’re reaching a turning point where more high-net-worth clients are asking not just how to hold Bitcoin and digital assets, but how to plan around them and ultimately transfer that wealth to the next generation,” said Justin Man, CEO of Apeiron Group. Digital assets.
Meanwhile said its net long-term underwriting income has already passed last year’s total and is on track to more than double in 2026. The company did not disclose specific figures.
“Meanwhile owns every layer of a regulated life insurer and builds it like an AI-enabled startup,” said Stefan Cohen, partner at Bain Capital Crypto. “The growth this year proves the model, and we’re glad to back them again.”
The company’s operating entity, Meanwhile Insurance Bitcoin (Bermuda) Limited, holds the first Class IILT license granted by the Bermuda Monetary Authority. It received the license in July 2024 after two years in the regulator’s sandbox.
The insurer’s balance sheet, reserves and audited financial statements are all denominated in Bitcoin. Policyholder Bitcoin is held with regulated institutional custodians.
This post Bitcoin Life Insurer Meanwhile Raises $37.5M as Wealthy Families Look to Pass On Their BTC first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
‘We Know Where It Is’: Treasury Secretary Threatens To Freeze $1B of Iran’s Crypto
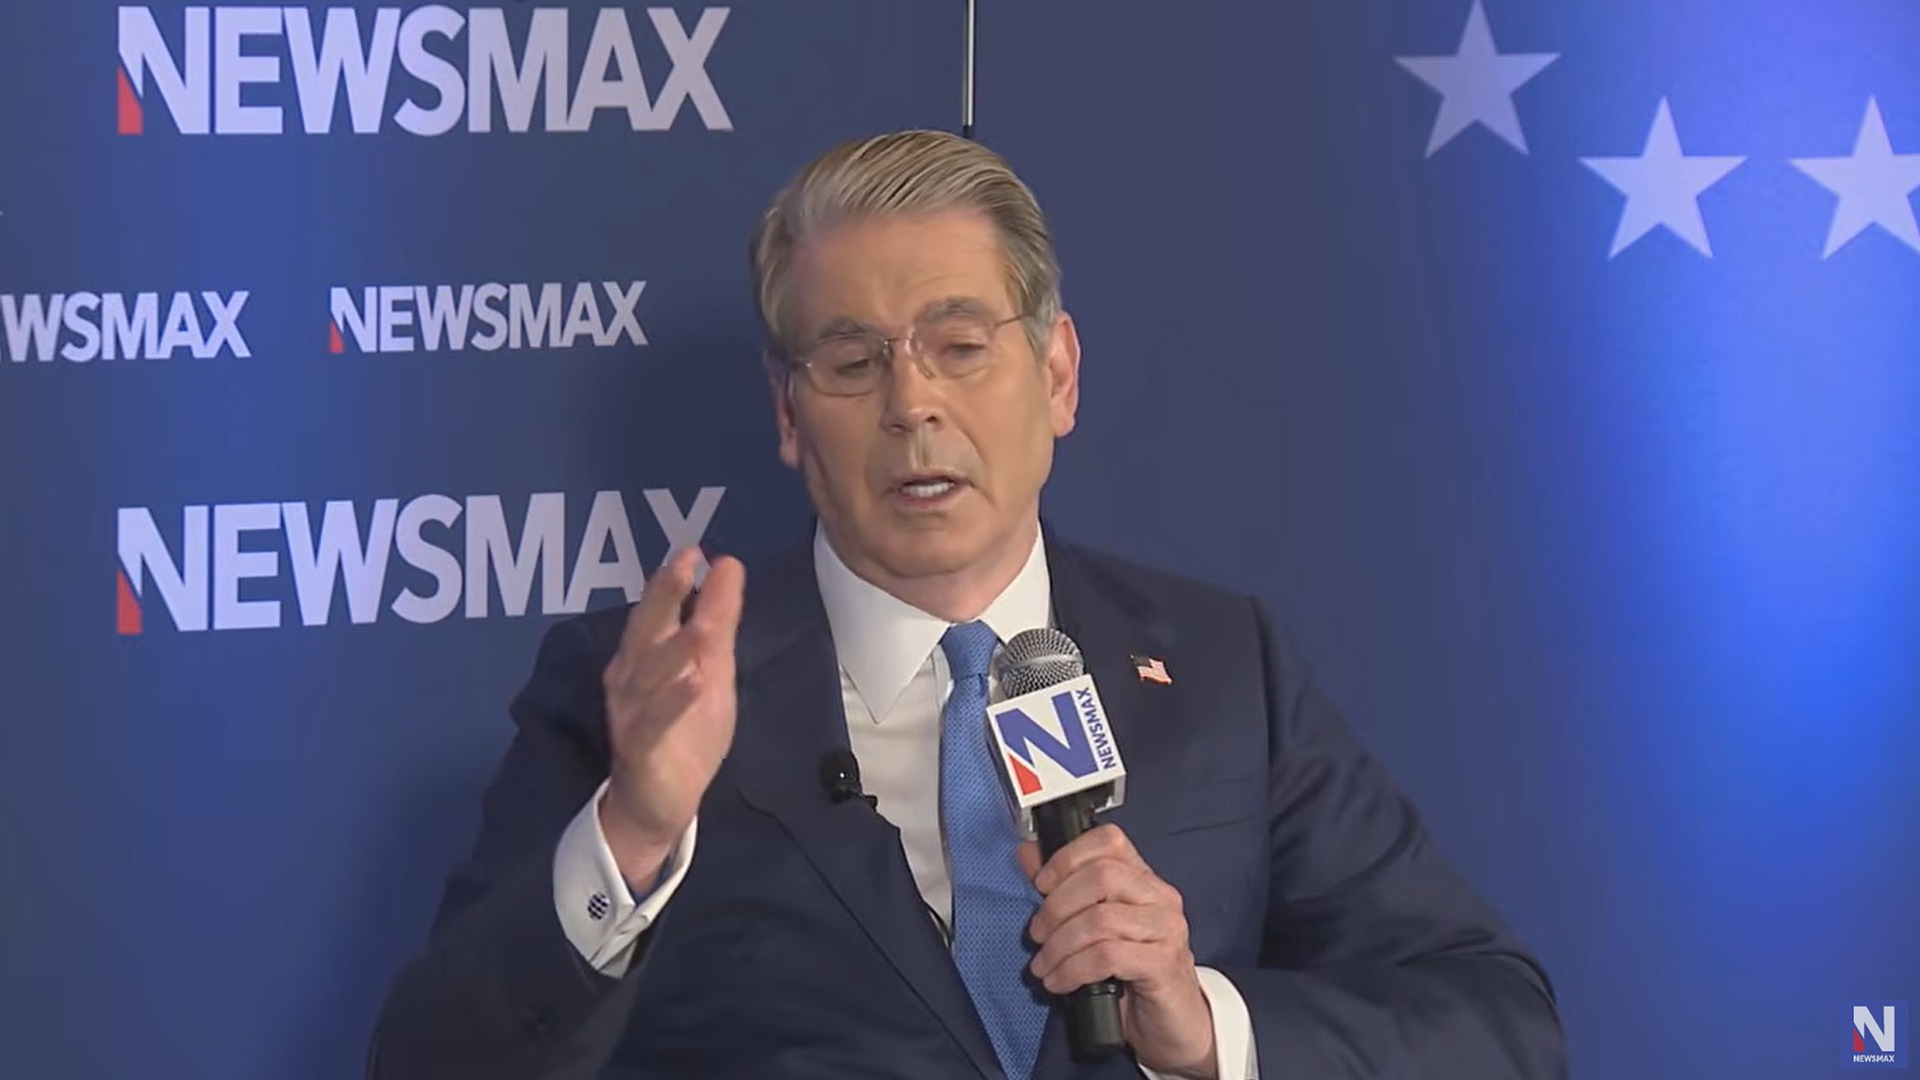
U.S. Treasury Secretary Scott Bessent has said the American authorities will soon seize $1 billion in crypto from Iran.
Speaking on Newsmax’s NPolicy Summit in Washington, D.C. on Thursday, Bessent added that economic sanctions on the Middle Eastern country were working.
Iran has been using bitcoin — and other cryptocurrencies — to skirt around U.S. sanctions. The U.S. in April started targeting crypto wallets linked to the Iranian regime, Bessent said at the time.
“What we have done has never been seen before,” Bessent said Thursday on Iranian sanctions.
“We’re probably going to seize $1 billion of crypto this week,” he continued. “We know where it is. We are isolating them. We did have a maximum pressure campaign, now we have an absolute isolation campaign and it’s working.”
Bessent didn’t reveal what cryptocurrencies the U.S. will seize or how.
It would be very hard — if not impossible — for the U.S. to freeze Iran’s bitcoin unless it keeps it on a centralized exchange.
Bitcoin, being censorship resistant, cannot be frozen. But many other cryptocurrencies, including Tether’s USDT, can. Bessent previously said the feds had seized Iran’s crypto in the form of the popular stablecoin.
Iran started a bitcoin-backed insurance service for its counties shipping companies earlier this year.
The Financial Times last month reported that the Middle Eastern country was using bitcoin to settle cross-border transactions through Iranian crypto exchanges after the central bank advised its countrymen to do anything necessary to help the economy.
U.S. President Donald Trump revived his “maximum pressure” campaign weeks after returning to office. A national security memorandum signed in February 2025 put the Treasury on a sustained campaign against Iran’s shadow banking, money laundering and sanctions-evasion networks.
This post ‘We Know Where It Is’: Treasury Secretary Threatens To Freeze $1B of Iran’s Crypto first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Here’s How Not To Screw up Your Bitcoin Privacy
Just one transaction can compromise years of discreet Bitcoin activity, Cake Wallet’s chief operating officer has warned.
Speaking on the Bitcoin Rails podcast this week, activist Seth for Privacy talked about different ways of protecting one’s privacy when using Bitcoin and said that focusing on privacy was a must for the West.
Bitcoin privacy is a hot topic again ever since the developers of private coin mixer Samourai Wallet went on trial last year and were subsequently imprisoned.
But just this week, the U.S. Department of Treasury scrapped two long-stalled crypto surveillance proposals, handing a major win to privacy advocates and the digital asset industry.
“If you ever spend your no-KYC coins with one of your KYC coins — which if you just let the wallet do its thing, it could do because it doesn’t know the difference — you immediately connect all of the non-KYC Bitcoin that you spend in that with your identity,” Seth said, referring to UTXO management, also called “coin control” by some wallets.
Bitcoin wallets don’t hold a single balance but a collection of separate unspent transaction outputs — UTXOs — each one a discrete “coin” from a specific past transaction.
When you send a payment larger than any one UTXO, the wallet picks several and combines them as inputs to the same transaction — an easy mistake to make, Seth highlighted.
Seth added that unlike in the global South, where people have experienced more oppressive states, citizens in the West will need to “feel pain” in order to realize how important privacy is.
Still, he added that attitudes were changing and people were getting more serious about protecting their privacy.
“It has been shifting, in the last five or six years a lot of people — even in the West — are starting to think [privacy] really matters, we really need to think about this seriously now,” he said.
Cake Wallet is a privacy-oriented, self-custody, open-source wallet. The wallet earlier this year integrated Bitcoin’s Lightning Network into its platform.
Using the second layer solution is not only faster and cheaper, it also offers more privacy than Bitcoin’s main chain.
While Cake Wallet supports other cryptocurrencies, including privacy coin Monero, Seth for Privacy added that he’d love it if the digital coin didn’t exist.
“If Bitcoin’s privacy got good enough that you could use it and have at least almost as good privacy as Monero without massive hoops to jump through, and Monero ceased to exist, that’s fine,” he said.
“I would much rather the thing that more people use has better privacy than a more niche tool that has perfect privacy, and that’s something that less people are using because it’s less well known.”
This post Here’s How Not To Screw up Your Bitcoin Privacy first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Bitcoin ETFs Shed $729M in Two Days as Investors Reverse Course
U.S. investors this week reversed course, cashing out $729 million from spot bitcoin exchange-traded funds — putting downward pressure on the leading cryptocurrency’s price.
Funds managed by BlackRock, Fidelity, Morgan Stanley, and ARK 21-Shares all experienced significant outflows on Wednesday and Thursday, according to data from Farside Investors.
Investors had started the week by selling close to $90 million in shares but then bought nearly $119 million on Tuesday.
The rest of the week has seen outflows following news that the Federal Reserve may raise interest rates. Other negative news includes the price of Brent crude jumping following renewed attacks on tankers in the Strait of Hormuz.
U.S. President Trump also hinted that talks with Iran weren’t bearing fruit — a sign war in the Middle East could continue.
Bitcoin’s price recently stood at a little over $82,688, down more than 3% over a seven-day period. The leading cryptocurrency has rebounded slightly over the past day, jumping nearly 2% over 24 hours.
Still, the coin was fast closing in on $90,000 last week. Investors are expecting decent returns as the month dubbed “Uptober” has historically delivered for bitcoin speculators.
The price of bitcoin has been particularly sensitive to geopolitical headwinds this year — especially since the U.S. and Israel attacked Iran, leading to an oil price surge.
Oil prices going up tend to lead investors to bet on the Federal Reserve raising interest rates. And with higher interest rates comes less liquidity for the price of bitcoin to do well.
Still, that’s not always the case: the Fed last month talked tough on getting inflation down and raised interest rates by a quarter of a percentage point and bitcoin’s price rose in the following days.
Bitcoin’s price is 34% below the all-time high of $126,080 it touched in October. It has spent most of 2026 in a bear market but analysts are now increasingly pointing to evidence of a bull market following a rally in August and September.
This post Bitcoin ETFs Shed $729M in Two Days as Investors Reverse Course first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Ledger Warns Buyers Not to Set Up Wallets From Reseller After Users Report Losses
Hardware wallet manufacturer Ledger has said that it is investigating loss of user funds after customers in South East Asia reported issues with devices bought from a reseller.
The Paris-based company on Friday advised customers who’d bought from vendor CryptoBilis within the last 90 days to not set up their devices.
Ledger did not reveal how much money users had lost but one blockchain investigator, Specter, wrote on X that he’d traced theft addresses following social media posts and that over $86 million had been lost.
The issue comes following a number of data breaches this year in the crypto world and a huge hack of popular Coldcard hardware wallet devices in July.
“Ledger is investigating reports of loss of funds from users in South East Asia who purchased products from a reseller named CryptoBilis,” Ledger said via its support X account.
Ledger added that it had asked CryptoBilis to pause all sales and shipments of Ledger devices.
“If you have set up your Ledger device, consider moving assets to a new Ledger signer (with new seed). We will continue to inform customers of updates as the investigation progresses,” the company said.
In a statement to Bitcoin Magazine, Ledger said that based on the information to date, the incident is isolated specifically to this reseller in this specific market.
“No reports were made of products purchased directly from Ledger, and Ledger’s infrastructure, systems and services were not compromised,” the company added.
CryptoBilis is a Kuala Lumpur, Malaysia-based hardware wallet vendor, according to its website. The company did not immediately respond to questions from Bitcoin Magazine.
The crypto industry is still reeling after hackers in July were able to steal close to $120 million in bitcoin from Coldcard users.
The products, made by Canadian company Coinkite, had a firmware bug which led to faulty seed generation, allowing hackers to essentially guess investor seedphrases.
Galaxy Research said in the months following the attack various attackers were able to exploit the bug independently.
In a separate incident, hardware wallet manufacturer Trezor last month reported that close to 81,000 customers had their details leaked after its third-party fulfillment partner had data stolen.
Criminals have been targeting data this year, with scammers getting hold of customer information via crypto wallet Ledger’s payment processor Global-e to send phishing emails.
This post Ledger Warns Buyers Not to Set Up Wallets From Reseller After Users Report Losses first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
CryptoSlate
North Korean hackers stole around $1.5 billion from Bybit in February 2025. While the hack itself has been widely covered and analyzed, few have focused on what happened afterward and what became of the stolen funds.
To move all that money, hackers needed to rely on an entire network of people willing to handle stolen assets, creating a chain of relationships that someone prepared to spend enough money could infiltrate.
That's what ZachXBT, a pseudonymous blockchain investigator, did. He committed 349,700 USDC and accepted a 5% loss on each completed order while posing as a client of a Chinese laundering network.
He eventually obtained information that helped him trace more than $12 million in Bybit-linked funds and, according to his account, contributed to Tether freezing 442,000 USDT.
His investigation led him to a network he believes laundered more than $1 billion from crypto thefts linked to the North Korean Lazarus Group, including proceeds from the Bybit attack.
The implications of his investigations extend to a much larger market for criminal financial services that American authorities have spent the past two years trying to disrupt.
In September, the US Treasury sanctioned Xinbi Guarantee, a marketplace it said has processed more than $24 billion in digital assets and fiat currency through its platforms since 2022, and explicitly identified North Korean hackers among the illicit actors reported to have used its services.
Treasury also acknowledged that criminals tried to preserve their operations by moving from Huione to Xinbi after it was sanctioned, showing how removing one marketplace doesn't eliminate the relationships and demand that supported it in the first place.
Believe it or not, hacking an exchange and stealing funds is actually the easiest part of this crime. Converting stolen crypto into fiat or another form of real purchasing power is where it gets difficult.
To do that, hackers rely on payment services and other shady relationships that let investigators and regulators intervene.
The $349,700 customer
The FBI attributed the Bybit theft to North Korean hackers on Feb. 26, 2025, identifying the activity as TraderTraitor and warning that stolen assets were being converted into Bitcoin and other cryptocurrencies before being distributed across thousands of blockchain addresses.
While it took no time to identify the hackers, identifying the intermediaries handling the stolen money required much more investigative work.
According to ZachXBT, he began that work when he saw more than 15 accounts in public Telegram and Discord groups seeking help with transactions tied to the stolen Bybit funds, suggesting that at least part of the subsequent laundering process involved intermediaries openly soliciting or arranging services.
He contacted several of those accounts and eventually developed a relationship with someone using the Telegram alias Jimmy Green, who presented himself as someone who needed help moving cryptocurrency between networks.
On March 6, 2025, ZachXBT says he funded a new Ethereum address with 349,700 USDC and began exchanging the dollar-linked token for USDT on Tron through the contact, accepting unfavorable exchange terms while trying to establish himself as a credible customer.
The 349,700 USDC represented capital committed to the transactions rather than a disclosed net investigative loss, while the 5% he says he lost on each order is the cost he was prepared to accept for access to information that ordinary blockchain analysis could not provide.
The arrangement also carried the risk that the intermediary could just disappear with the funds.
Hackers depend on intermediaries who might steal from them in turn, and without enforceable commercial protections, reputation and personal familiarity become especially important to keeping those relationships working.
That gave ZachXBT a way into the operation, since a customer willing to conduct repeated transactions became more valuable to the person providing the service.
The relationship eventually produced information beyond wallet addresses, including discussions of planned fund movements before the transactions occurred, allowing ZachXBT to compare statements made privately with activity subsequently recorded on public blockchains.
In one instance, the intermediary discussed moving funds to Solana before the corresponding movement took place, while other exchanges and wallet connections allegedly helped identify a larger cluster of assets linked to the Bybit theft.
This was a major turning point in his investigation, because on-chain data can't identify the person behind the transaction or its intent. Private conversations about a transaction provided the key evidence about who controlled it and what they used it for.
Even though ZachXBT's investigation still doesn't completely match the FBI's official record, it's still one of the most significant investigative efforts we've seen in a while. It showed that personal and commercial relationships can provide evidence blockchain alone can't, and that similar tactics could help investigate and eventually resolve other thefts.
Tracing $12 million differs from recovering it
ZachXBT said information from his relationship with Jimmy Green helped identify a cluster with more than $12 million in Bybit-linked funds, including transactions across several networks.
He also reported that Tether later froze 442,000 USDT linked to the North Korean hack. This showed that quickly identifying stolen assets, while they remain accessible through issuer-controlled tokens like USDT or USDC, can be crucial to recovering the funds.
The two amounts should not be confused: tracing more than $12 million does not mean the entire amount was frozen, and freezing 442,000 USDT does not mean the tokens were seized or returned to Bybit.
The specific 442,000 USDT figure and its connection to ZachXBT's investigation come from his account, although Tether has separately disclosed larger freezes tied to the Bybit theft.
There's a considerable distance between observing stolen cryptocurrency, identifying the people handling it, and obtaining legal or technical control over the proceeds.
Public blockchains don't prevent the assets from moving again, especially when they pass through services that refuse to cooperate with investigators or operate beyond the reach of relevant authorities.
Centrally issued stablecoins create a potential intervention point because their issuers can retain the administrative ability to restrict transfers from designated addresses.
Native Bitcoin has no equivalent issuer-controlled restriction, although authorities can still restrain assets held by custodians or seize the keys controlling them when they obtain the necessary access and legal authority.
That leaves investigators dependent on more than tracing accuracy, since an identified balance must also remain within reach of someone who has the technical ability and authority to act.
During Bybit's recovery effort, court orders and cooperation from financial intermediaries could restrict assets long after the initial theft, without guaranteeing full recovery.
The problem is that stolen cryptocurrency can become increasingly fragmented as it moves between wallets, chains, custodians, and trading counterparties, with each additional service potentially requiring another source of evidence or another legal process before the pursuit can continue.
That's why investigators can see where the funds traveled but have no way to stop the next transaction or recover the funds.
$4 billion in crypto laundering
The use of outside intermediaries isn't limited to the Bybit theft, and American enforcement records show a longer history of attempts to identify businesses that convert stolen crypto into assets criminals can use.
In March 2020, the Justice Department charged two Chinese nationals, Tian Yinyin and Li Jiadong, with laundering more than $100 million worth of crypto, primarily through activity connected to exchange hacks.
These charges show how individuals who don't carry out the hack can still play an essential role in the crime.
The Treasury's sanctions announcement also revealed that Tian converted nearly $1.4 million in Bitcoin into prepaid Apple iTunes gift cards, showing how laundering can eventually involve ordinary retail instruments rather than the more elaborate financial services usually associated with international cybercrime.
The same economic requirement operates on a much larger scale through marketplaces that connect criminals with merchants offering settlement, exchange, payment and other services.
In May 2025, the Treasury's Financial Crimes Enforcement Network identified Cambodia-based Huione Group as a financial institution of primary money laundering concern, finding that its operations had laundered at least $4 billion in illicit proceeds between August 2021 and January 2025.
Of that amount, FinCEN identified at least $37 million in crypto stemming from North Korean cyber thefts, along with other proceeds from investment fraud and cyber scams.
The $4 billion figure reflects illicit activity across several crime categories, and the $37 million represents the minimum North Korean-linked component identified in the agency's findings.
FinCEN's assessment also identified serious deficiencies in anti-money-laundering and customer-verification controls across the group, including an acknowledgment that inadequate checks had allowed one component to indirectly receive funds connected to a North Korean heist.
The significance of those findings extends beyond any individual transaction because an intermediary that offers repeated access to payment services can become infrastructure for multiple criminal customers, reducing the need for each organization to build its own arrangements for converting stolen assets.
That concentrates activity around businesses that can become targets for sanctions, seizures, restrictions on banking relationships and other enforcement measures.
Huione's marketplace handled a substantial volume of transactions and illicit services, and operators tried to keep operating after Telegram disrupted access to parts of the network.
Those marketplace transaction figures and FinCEN's narrower estimates of identified illicit proceeds measure different categories of activity, making it key not to treat all funds moving through a platform as proven criminal proceeds.
The customers moved
The difficulty is that a criminal marketplace can lose infrastructure without losing the demand that made its services profitable, particularly when users can still contact alternative providers.
In June 2026, the Justice Department announced the seizure of a cloud computing account that hosted backend infrastructure used by Huione Group subsidiaries allegedly involved in moving proceeds from fraud, cyber scams and other criminal activity.
The action followed earlier US restrictions on the group and targeted technology that supports the transfer and concealment of illicit funds.
Removing that infrastructure doesn't automatically eliminate relationships between customers and the intermediaries willing to serve them.
The Treasury made that limitation particularly explicit on Sept. 9, when it sanctioned Xinbi Guarantee, describing an illicit marketplace that connected criminal organizations with merchants providing financial services, technology, and other resources needed to support their operations.
According to Treasury, Xinbi had processed the equivalent of more than $24 billion in digital assets and fiat currency since approximately 2022, with its services primarily supporting transactions involving Southeast Asian markets.
The scale makes the platform relevant to enforcement efforts against the broader financial infrastructure that serves criminal organizations.
Treasury also said cybercriminals had attempted to preserve their operations by migrating activities from Huione-related services to Xinbi following FinCEN's earlier action, with the new marketplace offering substantially similar services to an overlapping group of customers.
The agencies described a commercial market where participants could seek another provider when enforcement made their previous arrangements less reliable.
During the Huione crackdown, Telegram removed thousands of channels associated with Huione Guarantee as merchants moved to alternative marketplaces.
This is why a crackdown's success cannot be measured solely by the number of websites, accounts, or servers taken offline, since customers who still need an illicit financial service can try to rebuild access through providers that remain operational.
The disruption still imposes costs, particularly when balances are frozen, settlements fail, or established counterparties become unavailable, but the economic incentive to move stolen funds continues as long as the underlying crime remains profitable.
The problem for enforcement agencies is making those services increasingly expensive and unreliable across the network of potential replacements.
Tether's freezes push crypto laundering networks toward other payment options
The enforcement action against Xinbi shows how financial restrictions can disrupt criminal operations while prompting the businesses involved to change their payment arrangements.
A series of Tether freezes restricted over $45 million in USDT across at least 22 wallets associated with Xinbi's operations.
The marketplace responded by telling users it would move toward USDD, a stablecoin structure that doesn't offer the same issuer-controlled address-freezing mechanism as USDT.
That was an important shift because the ability to freeze a token can be valuable to investigators when suspected proceeds remain within the issuer's administrative reach, while customers attempting to avoid those restrictions have an incentive to move toward instruments with different controls.
The move shows how restrictions on one part of the payment system can redirect transactions toward another, requiring investigators to follow both the assets and the businesses that provide access to them.
During the September crackdown, authorities also targeted Xinbi-linked infrastructure and restrained over $52 million in cryptocurrency, while withdrawals accelerated and competing marketplaces reportedly began restricting laundering-related merchants.
Those developments differ from the 442,000 USDT freeze ZachXBT attributes to North Korean hackers, since public reporting does not establish that the same addresses, participants, or funds were involved.
Both cases show that criminal operations depend on financial intermediaries whose services can create opportunities for intervention even after the original theft is complete.
Where a token issuer can freeze assets, the relevant exposure may be the balance held in an identifiable address. Where a marketplace serves multiple criminal groups, its vulnerability may extend to the infrastructure, merchant relationships, and settlement arrangements supporting those customers.
Both routes can reduce the ability to move and use stolen money without additional cost or risk.
People behind the transfers are harder to replace
ZachXBT's investigation made an impact because he described how a paid relationship produced information about the people arranging the transactions.
Criminal intermediaries who repeatedly handle stolen cryptocurrency develop a commercial reputation, establish preferred counterparties, and learn which services can complete transactions without interfering with the proceeds.
Those relationships can make an operation more effective over time, especially when customers need to move large amounts of money without revealing their identities or risking that a counterparty will keep the assets.
However, they also create dependencies that are hard to replicate quickly when an established provider disappears, especially if alternatives charge higher fees, reject suspicious funds, or prove less reliable.
Those dependencies also provide investigators with another source of evidence because a service provider can reveal what it knows about future transactions, other participants, and the payment infrastructure required to complete an order.
Investigators still need to test the information against observable activity and other records, and the fact that an address receives funds connected to a theft does not establish the recipient's intent or knowledge.
But comparing private communications with subsequent blockchain movements can narrow that uncertainty in ways tracing transactions alone cannot.
The broader enforcement record points out that making criminal financial services less attractive requires more than periodically taking down their websites, because the customers and commercial incentives supporting those services can outlast the equipment used to deliver them.
Seizing assets, restricting financial access, prosecuting service providers, and identifying the people who control settlement arrangements can change that calculation, though the point at which those costs outweigh revenue from serving illicit customers will differ across businesses.
This is also why the dollar value of a cryptocurrency theft cannot automatically be treated as money successfully converted into spendable revenue for the responsible government, much less as a verified amount used for any particular military or state expenditure.
The original theft, the amount moved through intermediary addresses, the value successfully converted into other forms of purchasing power, and the amount ultimately recovered by authorities are separate measures that require separate evidence.
For North Korean hackers, relying on laundering services adds risk after the initial intrusion succeeds, since gaining control of stolen assets doesn't eliminate the need for others to accept, exchange, and ultimately spend them.
ZachXBT's reported infiltration shows how that requirement can turn a customer relationship into an investigative opening, while the US actions against Huione and Xinbi demonstrate how the surrounding businesses can become enforcement targets even when criminal customers attempt to migrate elsewhere.
The essential weakness is that stealing cryptocurrency and using it in practice are different, and the second still depends on commercial arrangements whose participants have assets, reputations, and financial interests to protect.
North Korean hackers' efforts to make that money spendable can still pull them back into relationships that require trust, and the people providing it have something to lose.
The post Stealing $1.5B in crypto is easy, cashing out is the trap appeared first on CryptoSlate.
The Fed can stop raising rates before inflation reaches 2% if officials believe the economy's already heading there without another increase.
September's meeting left most unconvinced, with strong spending and persistent price increases outweighing the strain expensive borrowing was putting on parts of the economy.
The minutes released Oct. 7 explain the thinking behind that month's unanimous decision to raise its main interest rate to 3.75%-4%.
Most participants expected another hike by year-end, but their reasons differed: many saw higher rates as insurance against inflation sticking around, while others thought the economy would need higher rates anyway.
Those views can overlap, but they leave different amounts of room for persuasion. Evidence that temporary price increases are fading could reassure someone seeking insurance, while an official who thinks spending is too strong would also want to see people and businesses spending less freely.
That discussion helps explain what could stop another hike, although officials didn't agree on a set of conditions that would rule it out.
Cheaper gasoline won't do all the work
Higher rates make borrowing more expensive and saving more attractive, discouraging some spending and making it harder for businesses to charge more. The effects take time, and they don't reach everyone equally: homebuyers may pull back while companies with plenty of cash keep investing.
The Fed can't produce oil or remove an import tax, so raising borrowing costs won't fix the shortages behind some price increases. It can reduce spending enough to make those increases harder to pass along, lowering the risk that an initial jump in costs turns into persistent inflation across the economy.
In September, officials described higher energy costs alongside heavy spending on the equipment and data centers needed for artificial intelligence.
Some businesses appeared better able to pass their costs to customers, and several participants pointed to continued price increases in services other than housing. Cheaper fuel would help those businesses, but customers willing to keep spending could still let them raise other prices.
Repeated reports showing slower price increases across different purchases would give the Fed more reason to wait. Inflation falling just means prices are rising more slowly, so groceries can still feel expensive while the data improves. Officials would look for evidence that businesses are losing the ability or need to keep charging more.
They'd also need to separate economic improvement from revisions to how it's measured. The minutes noted that a planned revision to the inflation calculation would reduce how much software prices and investment-management fees added to the reported rate.
Better measurement can improve policy decisions, but a lower reading from a revised calculation doesn't mean businesses have simply reduced their price increases.
Officials thought people still expected inflation to settle around the 2% goal over time, although they worried that more years above target could lead workers to seek larger pay increases and businesses to plan bigger price increases.
Slower price increases across more of the economy, with people still expecting inflation to come down, would give officials less reason to raise rates as a precaution before the target is reached.
The jobs market doesn't have to collapse to count
The Fed's responsibility to support employment limits how far it should go in making borrowing more expensive.
In September, participants generally saw steady employment with relatively few people out of work, and most thought it had strengthened somewhat, giving the Fed room to act against inflation.
Some said pay was rising fast enough for inflation to return to 2%, or that the jobs market wasn't currently driving inflation. Several noted that hiring and layoffs were both unusually low, while people out of work had difficulty finding another job.
Low layoffs can make employment look healthy to someone who already has a job, while weak hiring makes it miserable for someone seeking one. If employers start cutting staff before hiring improves, people who lose their jobs have fewer places to go, potentially turning a stable unemployment rate into a much less reassuring picture.
Repeated unemployment increases alongside broader layoffs would make another hike harder to justify, even if inflation hadn't improved as much as officials wanted. One disappointing jobs report could reflect temporary conditions or be revised, so evidence across several reports would carry more weight than a single number.
Slower inflation with stable employment would give the Fed a better reason to stop. In September, officials generally saw roughly equal chances of employment doing better or worse than expected, while inflation seemed more at risk of being too high.
Continued weak hiring or more job losses would give them reason to reconsider without waiting for a recession.
Your mortgage rate can feel expensive while money still flows
Several officials thought interest rates were doing little to slow the economy, despite expensive mortgages and strain on lower-income households.
Many businesses could still borrow money, investment in AI was strong, and stock-market gains were supporting spending among wealthier households.
People struggling to buy a home and the companies financing new projects experienced the same economy very differently. The Fed has to judge whether their combined spending is slowing enough to bring inflation down, which is why painful housing borrowing costs don't automatically settle the decision.
Economists describe an interest rate that neither speeds up nor slows down the economy as neutral, but they have to estimate where it is. Two officials had raised their estimates of that rate, meaning they thought a higher interest rate was needed to slow the economy by the same amount.
Lenders becoming more cautious and spending slowing down would provide evidence that existing borrowing costs were doing more of the work.
Market rates can also rise without another Fed hike, although longer-term loan rates don't automatically move in step with the short-term rate the Fed controls. Officials would need to see those costs actually slowing borrowing and spending.
Lower inflation with employment holding up could give investors reason to expect cheaper borrowing while keeping them willing to own Bitcoin and other assets with large price swings. If job losses and difficulty getting loans instead persuaded the Fed to pause, investors could be selling those assets to keep more money in cash at the same time.
Holding rates steady wouldn't promise cuts or make financing cheap again. Officials meet next on Oct. 27–28, and these minutes just describe their September judgment.
Evidence that price increases are slowing without another rate hike would give them a reason to wait, while evidence that more people are losing jobs would make another increase harder to defend, with much less for Bitcoin investors to celebrate.
The post Inflation target of 2% may not stop the next Fed rate freeze appeared first on CryptoSlate.
Bankrupt crypto lender Celsius founder Alex Mashinsky has agreed to a permanent ban from the securities, commodities, and crypto business under a New York settlement announced on Oct. 9.
The agreement also sets conditional state payment obligations of up to $35 million, without creating a new payout to Celsius creditors.
The deal resolves New York’s civil suit, filed in January 2023, and adds state obligations to a separate federal criminal case. Mashinsky is serving a 12-year prison sentence.
What the $35 million figure means
The first obligation is $25 million in damages to New York. Under paragraph 2 of the annexed consent order, that obligation is deemed satisfied by a qualifying $10 million payment to the US Department of Justice under paragraph 11 of his federal forfeiture order.
DOJ payments made after May 20, 2025, may count dollar for dollar toward that $10 million. If the specified payment is not made, New York's Attorney General is due the entire $ 25 million.
The second obligation is a separate $10 million monetary judgment payable to New York. Paragraph 3 says it is deemed satisfied by completion of Mashinsky’s imprisonment under the federal judgment entered May 12, 2025, subject to express exceptions.
Those exceptions cover a sentence overturned or reduced by a court, including through a Section 2255 challenge. The clause also lists compassionate release, good-time credits, earned-time credits, First Step Act early release, and home confinement through a Bureau of Prisons program.
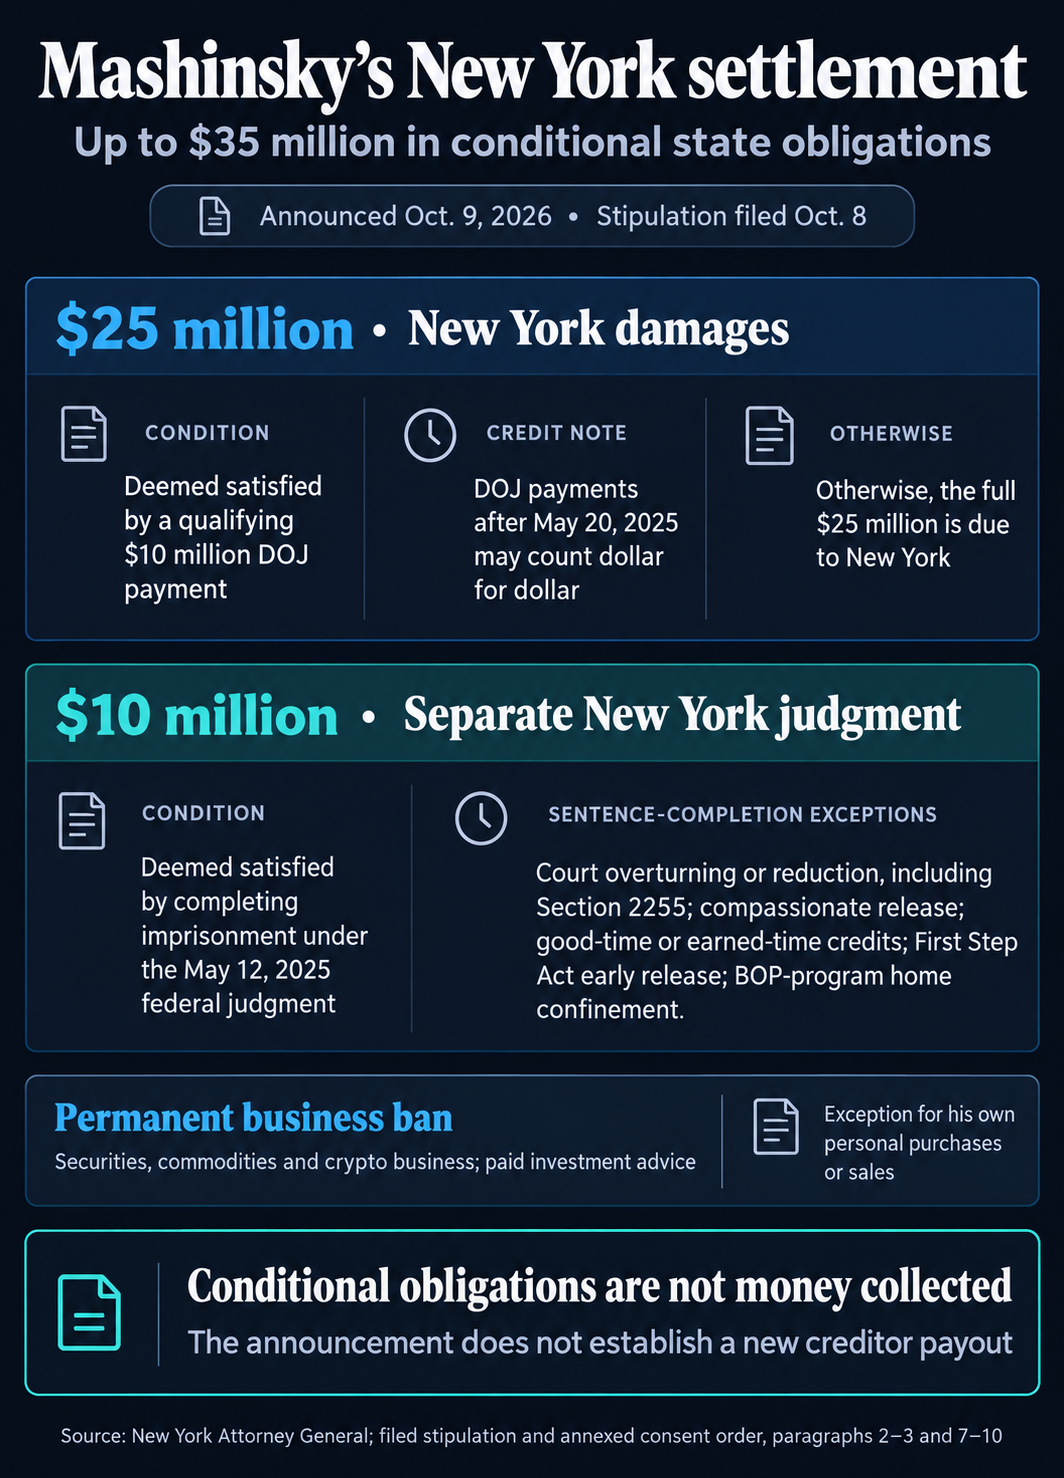
Beyond the payment conditions, New York describes the industry ban as permanent. The agreed restrictions cover securities and commodities businesses, including crypto, and roles such as broker, investment adviser, manager, officer and consultant. They also prohibit investment advice distributed for compensation or economic benefit.
The terms retain an exception for Mashinsky’s own personal purchases or sales. The stipulation also records his admission that he misled investors about Celsius’s regulatory approval and his own sales of Celsius’s CEL token.
The court sentenced Mashinsky on May 8, 2025, and the stipulation records federal forfeiture ordered at $48.4 million.
The New York Attorney General says Celsius distributed more than $3.4 billion to creditors as of August 2026. Qualifying DOJ payments would establish compliance with one settlement condition, but wouldn't establish another creditor distribution.
The post Celsius founder faces lifetime ban, but can trade his own crypto appeared first on CryptoSlate.
Solana has doubled its targeted block-production frequency after activating 200-millisecond slots on mainnet, completing a months-long effort to accelerate the blockchain.
The Oct. 9 upgrade reduces Solana's original 400-millisecond slot target by half, allowing the network to create five block-production opportunities per second instead of 2.5. It also shortens the time required to complete a network epoch to approximately 24 hours from 48 hours.
Anza, the developer behind Solana's Agave validator client, confirmed the activation, declaring that the SIMD-0525 upgrade had been completed.
“Blocks land twice as often as they did at genesis. An epoch now takes about a day instead of two,” Anza stated.
Jacob Creech, the Solana Foundation's vice president of technology, also celebrated the milestone, saying the network continues to improve with successive software releases.
“Solana continues to improve release after release, proving to be the best place to build,” Creech said, before identifying Alpenglow as the network's next major upgrade.
Early performance data indicated that the change was already producing faster slots, although the network had yet to consistently reach its new target.
CryptoSlate's sampling of Solana's public mainnet RPC showed an average of approximately 222 milliseconds across 1,413 slots following activation, compared with roughly 268 milliseconds under the previous 250ms target.
The latest change completes a four-stage rollout that began in August, when Solana first reduced its slot target to 350 milliseconds. Subsequent reductions to 300ms and 250ms prepared validators for Friday's final adjustment.
Faster slots put Solana's next upgrade in focus
The shorter intervals could improve transaction responsiveness for applications operating on Solana, particularly decentralized trading platforms and market makers that depend on rapid updates to prices and orders.
Under the SIMD-0525 proposal, each validator's nominal four-slot block-production window has fallen to 800 milliseconds from the original 1.6 seconds, reducing how long individual validators can control transaction inclusion.
However, the upgrade does not automatically double Solana's transaction-processing capacity. Developers proportionally reduced the computational budget available within each slot, keeping the network's approximate execution capacity per second unchanged.
The faster cadence also introduces operational adjustments.
According to the Solana Foundation, transaction blockhashes now have an expiration window of approximately 30 seconds, compared with 60 seconds under the original configuration. That gives applications using offline signing or delayed transaction submission less time before transactions require refreshing.
Infrastructure providers must also accommodate more frequent blocks, while validators face tighter deadlines for producing and propagating them.
Those demands make sustained performance and skipped-slot rates important measures of the upgrade's success.
Meanwhile, community attention now shifts to Alpenglow, Solana's planned consensus overhaul targeting transaction finality of approximately 150 milliseconds, compared with roughly 12.8 seconds under the existing TowerBFT system.
Alpenglow has undergone deployment on Solana's testnet and devnet, but a mainnet activation date has not been announced.
The post Solana doubles block production speed to 200ms as network prepares for Alpenglow upgrade appeared first on CryptoSlate.
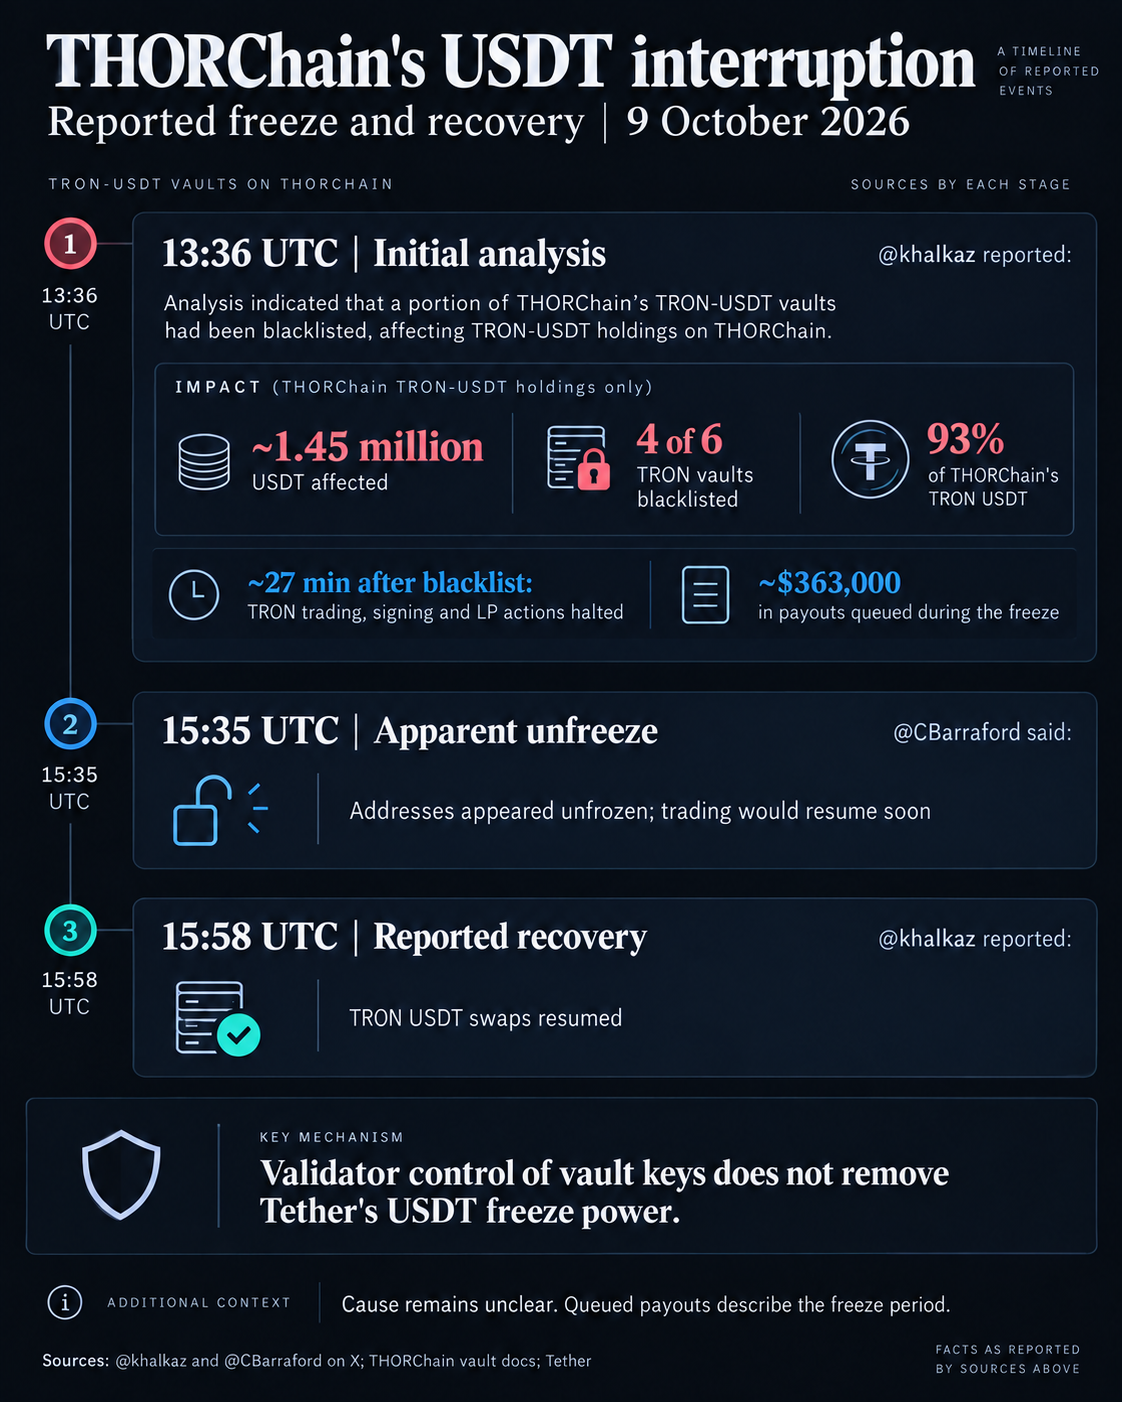
THORChain's TRON operations were interrupted on Oct. 9 after a USDT vault blocklist, according to reports by its co-founder Chad Barraford and researcher Khal. The researcher put the affected balance at about 1.45 million USDT.
Both accounts later reversed the restrictions, according to updates from both accounts. At 3:35 p.m. UTC, Barraford said the addresses appeared unfrozen, and trading would resume soon. At 3:58 p.m. UTC, Khal reported that TRON USDT swaps had resumed. The earlier payout queue describes the interruption before the reported resumption of swaps.
In his initial analysis, Khal reported that block 86958330 blocklisted four of THORChain's six TRON vaults. Those vaults held 93% of the protocol's TRON USDT, concentrating the disruption in the balances needed to process payments on that route.
He reported that TRON trading, transaction signing, and liquidity-provider actions halted about 27 minutes later, with roughly $363,000 in payouts queued during the freeze.
Barraford said the protocol received no communication before the action and didn't know why it happened. Khal argued that the vaults may have been caught in a broader blocklist that included roughly 30 other wallets.
The incident follows scrutiny of how the protocol handles illicit flows. On Oct. 8, THORChain's September trading surge coincided with Bitget-hack-linked activity, and the protocol refused to selectively block addresses.
Two layers of control
THORChain's vault documentation describes accounts managed by validator nodes that hold assets on external blockchains and handle incoming funds and outgoing transactions.
Distributing control of those accounts among validators determines who can authorize a payment, while the tokens inside them remain subject to their issuer's restrictions.
THORChain itself drew a related distinction in an Oct. 1 blog recap: node operators can pause a chain or the whole protocol for safety, but cannot selectively remove an individual swap.
Meanwhile, Tether says its wallet-freezing policy follows OFAC's sanctions list and extends to secondary-market wallets. Its power to restrict USDT transfers operates separately from the validator controls governing THORChain's vaults.
The operational dependency remains: distributing the authority to sign transactions does not remove Tether's ability to freeze USDT held in the accounts those transactions use.
The post Tether freezes $1.4M in TRON vaults and THORChain stalls appeared first on CryptoSlate.
CryptoTicker.io
Polygon has opened its payment stack to TRON. Since the announcement of October 8, 2026, companies can settle a complete stablecoin payment through the Open Money Stack on the TRON chain: take in money in local currency, convert it into USDT, hold it on TRON, forward it to other chains when needed and finally pay it out again to a bank account, a card or a cash pickup point. For holders of TRON (TRX) this is not a price story but news about the chain's role in payments. Whether it turns into demand for the token hangs on a single quantity, and that one appears further down.
The price itself has barely moved. TRX trades at $0.3306, 0.4 percent below the previous day and 1.1 percent below the level of a week ago, according to CoinGecko as of Saturday morning. Market capitalisation stands at $31.4 billion, which puts it eighth.
What Polygon's Open Money Stack now settles on TRON
The Open Money Stack, or OMS, is Polygon's toolkit for firms that want to settle payments in stablecoins without building the technology themselves. Open Money Stack in one sentence: a set of ready-made building blocks for taking in, holding, forwarding and paying out stablecoins, which a company plugs into its own product via interfaces.
According to Polygon's announcement, the TRON integration covers five steps. A customer pays in by bank transfer, card, cash or crypto. The money arrives as USDT in the TRC-20 standard on TRON. There it sits in a custodial or an embedded wallet. From there the company can set when and where it flows on. At the end it goes to a bank account, a card, a cash pickup point or another wallet.
The fixed deposit address
One practical point sits in the detail: every customer receives a permanent TRON deposit address that can be reused for every further deposit. Incoming USDT is automatically matched to the right customer. A company therefore needs no new address per transaction and no reconciliation process of its own to assign incoming payments to accounts. Anyone who has tried to attribute hundreds of deposits without a payment reference to the right users will see why this point sits so near the top of the announcement.
Polygon names the Philippines, Mexico, Argentina and Nigeria as target markets, and remittance services, gig-work platforms, trading venues and fintech start-ups as target customers. Germany is explicitly absent from that list, and there is a reason for it, which appears in the MiCA section below.
USDT on TRON: $93.44 billion in circulation, 50.7 percent of all Tether dollars
Polygon justifies the move with the size of the chain, citing more than $94 billion in USDT on TRON, over half of the entire stock across all chains. We checked that figure, and it holds, but only under one of two possible readings.
According to Tether's own transparency page, 94.25 billion USDT are authorised on TRON. Of those, 0.81 billion sit in Tether's own treasury and are therefore issued but not in the market. In circulation, then, are $93.44 billion. Across all 19 chains Tether reports, circulation adds up to $184.25 billion. TRON's share therefore comes to 50.71 percent.
Ethereum, the second large rail, carries $86.05 billion in circulation and thus 46.70 percent. The gap between the two chains amounts to roughly $7.4 billion. All of the remaining 17 chains together come to less than three percent; Solana follows in third place with $2.94 billion.
This analysis was compiled by cryptoticker.io itself on October 10, 2026, on the basis of the 19 chains Tether reports on its transparency page.
Authorised, treasury, circulating: three numbers for the same stablecoin
Here lies the point at which most reports turn imprecise. For the same stablecoin on the same chain there are three different numbers, and they differ by billions.
The authorised supply is what Tether has issued on a chain. It appears as total supply in the contract on the chain and comes to 94.25 billion on TRON. The treasury holding is the part of that which sits in Tether's own wallets and has not yet been released into the market, 0.81 billion on TRON. The circulating supply is the difference, so 93.44 billion.
Calculate TRON's share against the authorised supply of all chains and you arrive at 48.68 percent, below half. Calculate it against circulating supply and it is 50.71 percent, above. Polygon's wording is accurate, but accurate only for the second calculation, and the lead over Ethereum is narrower than a statement about half makes it sound. Anyone wanting to check a figure like this has to know which of the three quantities is meant.
Two further numbers belong to the scale of the contract on TRON, and they show the breadth of use: 77.2 million addresses hold USDT on the chain, and the contract has recorded around 3.72 billion transfers so far.
Energy and bandwidth: how a TRC-20 transfer consumes TRX
Now to the quantity on which the price question hangs. A payment in USDT on TRON is not free of charge, even if it often feels that way to the user. Every transfer of a TRC-20 token consumes computing resources from the network, and those are measured in two units.
Bandwidth covers the raw data volume of a transfer. Energy covers the execution of contract code, and a USDT transfer needs precisely that, because USDT on TRON is a contract and not a native coin.
For both there are two routes. Either a user freezes TRX and is allotted bandwidth and energy on an ongoing basis, or he pays directly, in which case TRX is burned. The price for it is fixed as a network parameter: one unit of energy costs 100 SUN, that is 0.0001 TRX. The more USDT payments run over the chain, the more energy is consumed, and the more TRX is either frozen or destroyed. Therein lies the link between payment volume and token, and it is the only robust transmission channel from the one quantity to the other.
Polygon Trails: USDT from TRON to Polygon without a bridge
The second technical building block of the announcement is called Polygon Trails and forwards USDT and other supported assets between TRON and the chains of the Ethereum family in a single operation. Polygon names Polygon itself, Base, Arbitrum, Avalanche and Optimism among the destinations.
The difference from the previous route is that the user does not operate a bridge. A bridge is a contract that locks assets on one chain and issues an equivalent on another; bridges were for years among the largest single items in the sector's loss statistics. With Trails the service handles the forwarding in the background.
Polygon cites as an example an operation in which 100 USDT from TRON arrive as 99.98 USDC on Polygon. The difference of two cents is the price for forwarding and conversion in that example. That is a figure from the provider and not a value we measured; what a real operation costs depends on size, destination chain and load.
MiCA and USDT: stablecoin trading in Germany after July 1, 2026
Now the part that counts if you hold the token in Germany. As large as USDT is on TRON worldwide, the framework here is that narrow. Tether has not applied for authorisation of USDT as an e-money token under the European MiCA regulation. With the final expiry of the transition period on July 1, 2026, USDT has therefore all but disappeared from MiCA-regulated trading venues in the EU; the large houses had already halted trading for EU customers in the months before.
What this means in practice can be put in three points, and none of them is a ban on you personally:
- On a platform regulated in Germany you will as a rule no longer be able to buy or sell USDT. Which providers still carry which stablecoins is worth a look in the crypto exchange overview, because the pairs differ from house to house.
- Holding USDT in your own wallet and transferring it between your own addresses remains permitted. The restriction is addressed to regulated platforms, not to private ownership.
- As a substitute on regulated platforms, USDC and EURC have established themselves, their issuers holding European authorisation.
For the Polygon announcement this means: the target markets Polygon names lie outside the EU, and that is no coincidence. A German merchant who wants to accept payments in stablecoins ends up, as things stand, with an authorised euro or dollar token, not with USDT. If you want to spend crypto in everyday life, the route here runs more readily via a crypto credit card that settles in euros in the background.
TRX price at $0.3306: 23 percent below the 2024 all-time high
The token itself has not reacted to the news so far. TRX stands at $0.3306 and thus 0.4 percent below the previous day. Over seven days that works out to a loss of 1.1 percent. Circulating supply stands at 94.99 billion TRX, and the distance to the all-time high of $0.4313 of December 3, 2024 comes to 23.3 percent.
What is remarkable is less the direction than the narrowness. The daily values of the past week ranged between $0.3306 and $0.3361. That is 1.7 percent between the highest and the lowest value, in a week in which the broader market swung considerably more and ether gave up around seven percent over seven days.
What has changed since the DeFi Summer start on October 4
On October 3 we reported here on the start of the third round of DeFi Summer on TRON: 60 days of running time, $2 million in rewards for TRX, USDD, JST and SUN, and a price that had at the time been moving within a six percent range for a month.
A week later it can be said what the campaign has done to the price, and the answer is: nothing measurable. Since October 4 the daily value has fallen from $0.3354 to $0.3306, a loss of 1.4 percent. The range has not widened but narrowed, from six percent over the month to 1.7 percent in this week. A rewards programme worth $2 million has therefore not lifted the token out of its track, and that is the sober yardstick against which the payments news now has to measure up as well.
What is new is that TRON now carries two stories at once: a time-limited incentive programme on one side, a permanent integration into an outside payment stack on the other. The second works more slowly, but it does not expire after 60 days.
Levels above and below: $0.3361 as the week's highest value
The levels follow from the week itself and from round numbers, not from a price target. Above, the highest daily value of the week sits at $0.3361, a good 1.7 percent above the current level. Beyond that, $0.35 begins the next round level, which repeatedly formed the ceiling in September.
Below, the current level sits at the lower edge of the week itself. The next round level beneath it is $0.32, around 3.2 percent away. Both are observation points for the question of whether the narrow range holds, and not an expectation that they will be reached.
Custody, leverage and holding period: what to check as a German holder
Four points that apply irrespective of the price and that you can look up yourself.
Route to purchase and authorisation
TRX itself is unaffected by the MiCA question surrounding USDT and is tradable on regulated platforms in Germany. With the provider, what counts is whether it holds authorisation under MiCA and how it handles deposits and withdrawals in euros. Fee models differ considerably between a flat charge per order and a percentage mark-up; with small amounts that decides the outcome more than the price on the day of purchase.
Custody
Anyone holding TRX or USDT for the long term should know the difference between custody at the provider and a wallet of their own. With self-custody, responsibility for the recovery phrase lies entirely with you, and a lost phrase cannot be replaced. Which devices are suitable differs above all in the way the recovery phrase is secured. For TRON there is also this: you need energy for your own transfers. A wallet without any TRX cannot pay for a USDT transfer, even with USDT sitting in it.
Leverage and liquidation
TRX is also traded as a futures contract with leverage. With a token that moves 1.7 percent in a week, only high leverage produces meaningful amounts, and that same leverage means a small countermove closes the position. Work with twenty-fold leverage and a five percent countermove leaves you, arithmetically, at zero, before funding costs.
Holding period and tax
In Germany the one-year holding period under Section 23 of the Income Tax Act continues to apply to crypto assets held privately: after one year a disposal gain is tax-free, before that it counts as a private disposal. Since January 2026 providers have been reporting data to the Federal Central Tax Office; the first submission for the 2026 reporting year is due in 2027. This reporting duty changes nothing about the tax rules themselves, it only changes what the tax authorities know anyway. This is not tax advice; in case of doubt a tax adviser settles it.
Our assessment: payment volume is not yet TRX demand
In the newsroom's view, the announcement matters more for TRON as a network than for TRX as a token, at least for now. Three verifiable points speak for it, and one against.
In favour: with $93.44 billion in circulation TRON is the largest USDT rail, and the integration into an outside payment stack tends to cement that position rather than erode it. In favour too: the integration is not time-limited, unlike the rewards programme of October 4. And in favour: with energy there exists a genuine transmission channel from payment volume to token demand, not merely a narrative pattern.
Against it speaks the order of magnitude. Polygon's OMS targets remittance services and fintech start-ups in the Philippines, Mexico, Argentina and Nigeria. How many of them adopt the toolkit is open, and Polygon gives neither a number nor a timetable for it. As long as the number of transactions over the chain does not visibly rise, energy consumption does not rise either, and without that the news remains a report about the chain's role and not one about the price. The week since the DeFi Summer start shows how little an incentive alone moves the price.
What can be checked is consumption itself: if transfers of the USDT contract on TRON climb clearly beyond the 3.72 billion recorded so far in the coming weeks, the thesis can be substantiated. If they stay flat, it is refuted. This is an assessment of the situation and not a recommendation to buy or sell; with crypto assets a total loss is possible.
TRON as a payment rail: no TRX boost without more energy consumption
Three steps that follow from this week:
- Establish which stablecoin you can trade at all. USDT has been all but unbuyable on regulated platforms in Germany since July 1, 2026; USDC and EURC are not. Which pairs your provider carries and what they cost is shown in the crypto exchange overview.
- Look at your TRON wallet for energy. If USDT sits there but no TRX, you cannot move anything. Anyone holding larger amounts in self-custody should also look at the hardware for it; the hardware wallet comparison offers a starting point.
- Watch consumption, not the headline. Whether the Polygon integration turns into demand for TRX shows up in the number of transfers on the chain, not in the announcement. If you want to use crypto in everyday life, the crypto credit card remains the more workable route in Germany for the time being.
(As of October 10, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
The money that pushed Bitcoin to its all-time high is now heading for the exits. US spot Bitcoin and Ethereum ETFs recorded $986.3 million in combined net outflows through Thursday, according to Farside Investors, and Friday's numbers pushed the October total over the $1 billion mark. Zoom out to every crypto ETF on the board and the picture gets uglier: $1.29 billion left $Bitcoin, $Ethereum, $Solana, $Zcash and $Hyperliquid funds in a single week.
That is the largest wave of selling since June. So what is going on, and should you care?
Why Are Bitcoin ETFs Seeing Outflows Right Now?
Bitcoin ETFs lost $678.9 million between Monday and Friday, a sharp reversal from the $241.1 million they attracted the week before. Wednesday alone saw $484.9 million walk out the door, the biggest single-day outflow since June 25, followed by another $244.1 million on Thursday.
The selling was not evenly spread. Fidelity's FBTC shed $380.3 million and ARK 21Shares' ARKB lost $207.2 million, together accounting for the lion's share of the damage. BlackRock's IBIT, the world's largest Bitcoin fund, finished the week almost flat at a $1.1 million inflow, after a $207.7 million Wednesday withdrawal wiped out two strong days of buying.
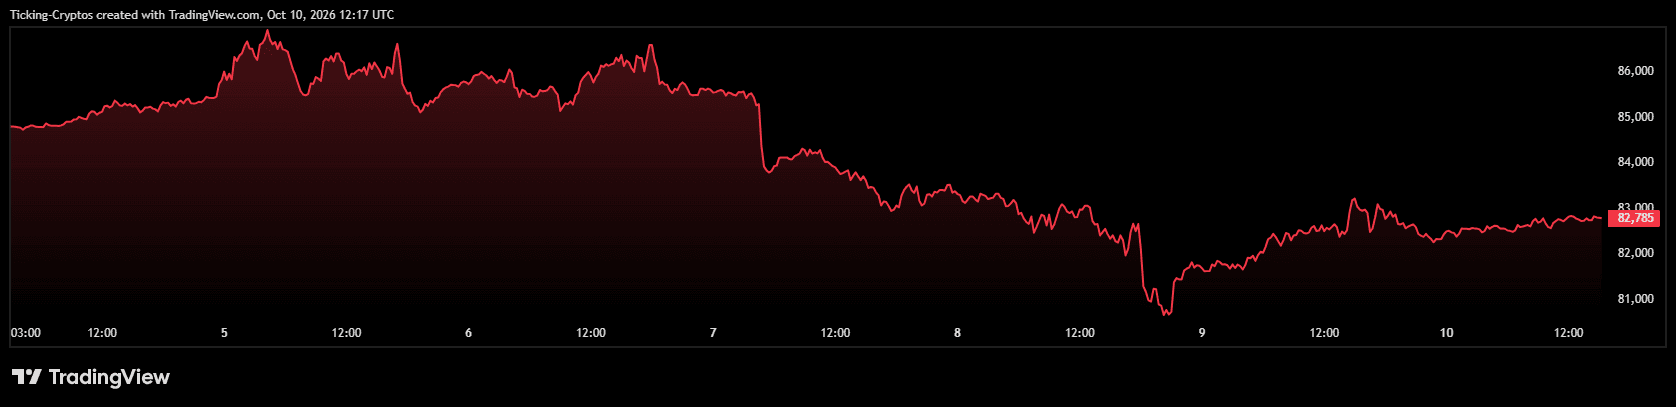
The timing matters. The Bitcoin price slid to a Thursday low of $80,427 before bouncing back above $82,000, and the ETF selling coincided with that drop rather than causing a rally. When institutions sell into weakness, it usually means they are reducing risk, not rotating into something else.
Which Ethereum ETF Is Behind the Outflows?
If Bitcoin ETFs had a bad week, Ethereum ETFs are having a bad month. Ether funds have now posted net outflows for nine consecutive trading sessions, a streak that began on September 29 and has drained roughly $700 million from the products. October alone accounts for well over half a billion dollars of that.
One fund dominates the story: BlackRock's ETHA. It was responsible for $477.1 million of the week's $542.2 million in Ethereum ETF outflows, roughly 88 percent. On Tuesday, ETHA's $201.9 million withdrawal was the entire category's loss for the day. Morgan Stanley's new MSSE fund was the only Ether ETF to finish the week in positive territory, with a modest $1.3 million inflow.
For context, Ethereum ETFs now hold around $15.6 billion in net assets, compared with roughly $105 billion across Bitcoin funds. A $542 million weekly outflow is a far bigger dent in ETH than the same number would be in BTC.
Are Solana, Zcash and Hyperliquid ETFs Bleeding Too?
Yes, and that is what makes this week different. Solana ETFs lost $25 million across five straight negative sessions, most of it from Bitwise's BSOL. The Zcash fund ZCSH gave back $30.8 million, on top of $77.6 million the week before, for a two-week bill of $108.4 million. Hyperliquid products shed $9.4 million.
None of these numbers is huge in isolation. Together they tell you that every crypto ETF category was in the red at the same time, something that has not happened since the summer.
What Do the Crypto ETF Outflows Mean for the Bitcoin Price?
ETF flows are not the only driver of price, but they are the most visible one. On-chain analytics firm Glassnode noted this week that Bitcoin's recent breakout needs stronger spot volume and renewed ETF buying to prove it had real support. Right now it is getting neither.
The silver lining is Friday. Bitcoin ETFs returned to a small net inflow of $21.1 million, led by IBIT. One green day does not end a trend, but it does suggest the panic selling may have exhausted itself for now. You can track the broader market mood, including liquidations and the Fear and Greed index, on the CryptoTicker charts page.
Is This a Buying Opportunity or a Warning Sign?
It depends on your timeframe. Short term, a nine-day Ethereum outflow streak and the biggest Bitcoin ETF redemption since June are hard to spin as bullish. Medium term, ETF outflows have historically clustered around local lows, and the funds still hold well over $120 billion in combined crypto assets. Wall Street has not left the building, it has stepped out for air.
The number to watch next week is simple: does ETHA stop bleeding? Until BlackRock's Ethereum investors stop hitting sell, the broader market will struggle to find a floor.
LayerZero's next lock-up expires on October 20, and it is larger than the unlock calendars suggest: around 23.63 million ZRO become tradable, equal to 5.92 percent of the circulating supply. Both allocations go to insiders, none to users. Measured against daily trading volume, however, the tranche amounts to only about half a trading day, and the decision facing you as a holder sits between those two numbers.
This article works the date out for you: how big the tranche really is relative to the market, who receives the tokens, what the LayerZero Foundation's buybacks put up against it, and which German tax deadline also weighs on the decision if you want to sell before the date.
What leaves the LayerZero lock-up on October 20
LayerZero is a protocol for transmitting messages and value between different blockchains; ZRO is its token. Total supply is capped at one billion ZRO, and a large share of that sits in allocations that become tradable only step by step.
Lock-up (vesting): An allocation that belongs to its recipient but is contractually not yet transferable. At LayerZero this runs in monthly instalments, and each instalment makes a further block of tokens tradable.
For October 20 the unlock calendars list around 23.63 million ZRO; a scheduling report dated October 6 gives the same amount and the same split. Provider figures diverge slightly: depending on the data basis they range between 23.08 million and 23.63 million ZRO, and none of these providers is the official source. What holds up is the date and the mechanics of the release, not the third digit of the amount. The calculations in this article therefore take the upper figure, because it does not make the selling pressure look smaller than it is.
5.92 percent of the circulating supply: why unlock calendars often show too low a figure
Most unlock calendars show a percentage next to each tranche. That percentage is only as good as the number it is divided by, and the errors start exactly there. If a calendar divides the tranche by the total amount already unlocked, or by an outdated figure, the result is a markedly smaller percentage.
As of October 10 the circulating supply stands at 399.2 million ZRO out of one billion in total. For a tranche of 23.63 million ZRO that works out to a share of 5.92 percent. Divide instead by 654 million, a number that appears in scheduling overviews of this event but is not the circulating supply, and you land at 3.61 percent, understating the figure by almost two thirds.
Three supply concepts are regularly confused here, and they deliver three different results: the circulating supply (tradable, and therefore the correct denominator), the unlocked supply (no longer locked, but in part not yet on the market) and the total supply (one billion here, the denominator for fully diluted valuation). How to set this calculation up yourself for any token is covered at length in our guide to ZRO's monthly dilution from August 2026, which also explains the difference between cliff and linear vesting.
Core contributors and strategic partners: who receives the 23.63 million ZRO
According to the unlock overviews, the October tranche splits into two items: around 10.63 million ZRO to core contributors, meaning the core team and the protocol's contributors, and 13 million ZRO to strategic partners, meaning backers and partners from the early funding rounds. No share for users, from an airdrop or distribution programme, is listed for this date.
That split is the real difference from unlocks where a large part goes to many small recipients. Backers and teams hold large single positions, have an entry price far below today's level and answer to deadlines of their own towards their investors. Whether they sell cannot be read off the date, but the option of selling in a single block is greater with two recipient groups than with ten thousand wallets.
The price adds context. At $2.02, ZRO trades around 73 percent below its all-time high of $7.47, yet it has gained roughly 92 percent over thirty days and about 15 percent over seven. The recipients of this tranche are therefore looking at a vigorous recovery rather than a trough, the sort of setting in which profit-taking becomes more rather than less likely.
Measured against daily trading volume, the tranche equals half a trading day
A percentage of the circulating supply tells you how much new supply can appear. It does not tell you whether the market absorbs that supply. For that you need a second yardstick, and it is trading volume.
At $2.02, the tranche is worth roughly $47.7 million, or about €42.5 million. ZRO's daily trading volume runs between $89 million and $103 million depending on the data source. The tranche therefore equals 0.46 to 0.53 daily volumes, or about half a trading day. Even if every recipient sold everything immediately, the amount would be a volume the market turns over in half a day anyway.
This yardstick separates harmless dates from heavy ones better than any percentage. An unlock worth two percent of the circulating supply can weigh ten daily volumes on a thinly traded token and depress the price for weeks. An unlock worth six percent on a liquid token is worked through in two sessions. ZRO belongs in the second category: large percentage, small weight on the market. If you want to assess such dates regularly, it helps to look at the volume profile of the venues where the token is liquid at all. Our crypto exchange comparison shows which venues offer depth for tokens like this and which merely quote a price.
The LayerZero Foundation's buybacks cover one tenth of a single monthly tranche
A buyback programme runs against the unlocks. The LayerZero Foundation buys ZRO back on the market and funds this out of ecosystem revenue; its own overview lists the purchases month by month. These figures are the cleanest counterweight to the unlock calendar, because they come from the entity doing the buying.
The position after thirteen reported months, from September 2025 to September 2026: 2,537,790 ZRO bought back, for $3,680,825. That comes to 0.25 percent of total supply. The figures are published openly in the LayerZero Foundation's buyback overview.
Now the comparison that appears in no unlock calendar: all buybacks from thirteen months together equal barely eleven percent of a single monthly tranche. The strongest buyback month on record, November 2025 with 346,020 ZRO for $514,058, covers 1.5 percent of the October unlock. The most recent reported month, September 2026 with 162,433 ZRO for $351,543, covers 0.7 percent.
The buyback programme is therefore not a counterweight to the unlock but a signal: it shows that revenue accrues in the ecosystem and flows back into the token. As a buffer against 23.63 million newly tradable tokens, at this order of magnitude it does not serve. Anyone arguing from the buyback has to state that ratio alongside it.
One qualification belongs with this. The overview reports months up to September 2026. No line exists for October yet, and how much is bought in the current month depends on the month's revenue. The foundation lists Stargate as its only active revenue source, the bridge whose overhaul we described in August when LayerZero shut down fifteen chains.
The fee switch has been voted down four times, and that keeps the buyback small
One lever could enlarge the buybacks considerably, and it has never been pulled. The fee switch is a vote on whether the protocol charges a fee for every message it transmits. Were that fee to accrue, it would, by the foundation's own description, be swapped into ZRO and burned, permanently shrinking the supply.
The LayerZero Foundation's governance page lists four completed votes on this, each in December and June: December 2024, June 2025, December 2025 and most recently June 2026. All four ended with the same result, namely no fee. The protocol lever therefore remains off, and the buybacks stay tied to the revenue of individual applications.
For holders this means a structural counter-effect to the monthly unlocks exists on paper but has failed to win a majority four times over. Betting on that effect means betting on a vote whose outcome has repeated itself four times. No announcement of a next round appears on the page.
An unlock is not yet a sell order
The most common fallacy around unlock dates is to infer selling pressure directly from the unlocked amount. Unlocked means transferable. It does not mean that the recipient sells, nor that he sells immediately, and least of all that he sells at the price on the day.
In practice large recipients spread sales over weeks, sell over the counter to individual buyers, or hedge via futures long before the tokens become tradable. That second option explains why price pressure around large tranches often appears before the date rather than on it: anyone who wants to hedge does so while the price still holds. Watch the days ahead of October 20 as well, and, if you follow the derivatives market, the funding rates of perpetual contracts, which you can read off the venues in our perp DEX comparison.
Which ZRO tranches still follow after October 20
October 20 is not a one-off event but one instalment in a series. The allocations to the core team and to backers continue in monthly instalments after an initial lock, and the unlock calendars list further tranches running into 2027. The order of magnitude per month stays similar, because the instalments come out of the same allocation.
That leads to a sober expectation: every month adds a block of supply the size of half a trading day, for as long as the series runs. No catastrophe and no reason to panic, but a permanent headwind that any price expectation has to price in. Conversely the headwind shrinks as volume grows: double the daily volume and the same tranche weighs half as much.
Selling before the date: the one-year holding period under German tax law
For investors in Germany, a decision before the unlock date has a second side that has nothing to do with the price. Gains from selling crypto assets are private disposals under Section 23 of the German Income Tax Act (EStG). Sell within one year of buying and the gain is taxable at your personal income tax rate. If the purchase is more than a year old, the gain remains tax-free.
This period runs per acquisition, not per token, and it is set by your purchase date, not by LayerZero's unlock date. In concrete terms: anyone who bought ZRO only during the recovery of recent weeks is in taxable territory when selling before October 20, and with a price gain of around 92 percent over thirty days the tax can exceed the difference between two selling dates. A tax-free allowance applies to small gains; once it is exceeded, the entire gain is taxable. Which amounts and deadlines apply in your case depends on your tax return, and for documenting purchase data a tool from our crypto tax software comparison is worth having.
Anyone who swapped STG for ZRO holds precisely this token
One group of readers is directly affected by this date without ever having bought ZRO: everyone who swapped their STG for ZRO in the course of the Stargate and LayerZero merger. Whoever did so holds, today, the token whose insider tranche unlocks on October 20. The deadlines, the fixed exchange rate and the terms of that swap are set out in swapping STG for ZRO.
For this group the tax position deserves particular scrutiny, because the swap itself can count as a disposal and thus start a new period. The purchase date that counts for Section 23 may then not be the original STG purchase but the moment of the swap.
Our assessment: the percentage frightens more than the market does
In the newsroom's view, the October tranche is the case where a large headline number conceals a small market effect. The evidence sits above: 5.92 percent of the circulating supply sounds heavy, yet it equals 0.46 to 0.53 daily volumes, and even a complete sell-off would be executed within half a trading day. We name what argues against it just as plainly. The tranche goes exclusively to two insider groups holding large single positions, the price stands, after roughly 92 percent in thirty days, in a zone where profit-taking suggests itself, and the buyback programme, at barely eleven percent of one monthly tranche out of thirteen months, puts up no counterweight. The structural lever that could change this has been voted down four times.
Our conclusion is therefore not a statement about the price but about method: sorting unlock dates by percentage of circulating supply sorts them wrongly. The yardstick is the ratio to daily trading volume. By that yardstick, October 20 at ZRO is a mid-sized date in a long series. Total loss is possible with any crypto asset, and an unlock can amplify a downward move in a weak market that began for other reasons.
ZRO unlock: 23.6 million tokens against 2.5 million in buybacks
The numbers for the date are in, and on both sides they point the same way: plenty of new supply, little counterweight, but a market that turns the volume over in half a day. Three steps that turn this into a decision of your own:
- Work out your own yardstick. Divide the tranche in dollars by daily trading volume, not by the circulating supply. Below one daily volume a date is manageable; above five it becomes a problem. Tools for volume and schedule overviews are listed in our comparison of crypto analytics platforms.
- Check your purchase date before you check the price. If your acquisition is less than a year old, selling costs tax on the gain. Keep purchase dates and amounts documented without gaps, most easily with one of the crypto tax tools.
- Decide on custody, not only on selling. If you intend to hold through the unlock series, there is no need to leave the tokens sitting on an exchange. Which devices are suitable is shown in our hardware wallet comparison.
(As of October 10, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
The crypto market is finishing a rough week. Bitcoin sits at $82,768 after a 2.2% weekly dip, Ethereum is down 7.1% to $2,493, and Solana, XRP and BNB are all nursing losses between 2% and 8%. Twelve of the top 17 coins by market cap closed the week in the red.
That makes the exceptions stand out. NEAR Protocol and Cardano were the only two large caps to post a weekly gain, and Zcash is still the second-best performer of 2026 in the top 20, despite a pullback. When the whole market sells off and a handful of coins refuse to follow, that relative strength is often where the next leg up starts.
Here are the three coins to watch next week, with their current stats and the catalysts that could send them higher. Live prices for every coin in this article are on the CryptoTicker crypto prices page.
| Coin | Price | 24h | 7d | YTD | Market cap | 24h volume |
|---|---|---|---|---|---|---|
| NEAR Protocol ($NEAR) | $5.22 | +7.98% | +11.63% | +245.34% | $6.83B | $945.85M |
| Cardano ($ADA) | $0.2560 | +6.73% | +5.21% | -23.06% | $9.42B | $582.34M |
| Zcash ($ZEC) | $1,225.39 | +0.20% | -6.86% | +133.43% | $20.72B | $810.37M |
Stats as of Saturday, 10 October 2026.
Why Is NEAR Protocol the Top Coin to Watch Next Week?
$NEAR is the strongest coin in the top 20 right now, full stop. It gained 7.98% in the last 24 hours and 11.63% over the week while almost everything else bled, and it is up 245% year to date. At $5.22 it has climbed from under $2 in early September, one of the most explosive monthly moves in its history.
The difference between NEAR and most momentum plays is that this rally has a real spot buyer behind it. Bitwise launched the first spot NEAR ETF in the US (ticker NRR) at the start of October, and the fund pulled in roughly $58 million in its first week. ETF creations require actual NEAR purchases, so every inflow day tightens the float. Add the growth of NEAR Intents, the chain abstraction layer that routes cross-chain swaps, and the AI narrative that keeps dragging capital toward NEAR, and you have a story that institutions can actually buy.
The risk is obvious: NEAR Intents suffered a $3.8 million exploit on 8 October. The team pledged full reimbursement and the price shrugged it off within a day, which is itself a bullish tell. But a rally this fast is full of short-term holders sitting on triple-digit gains, and the 2022 bagholders between $6 and $10 will be looking for exits.
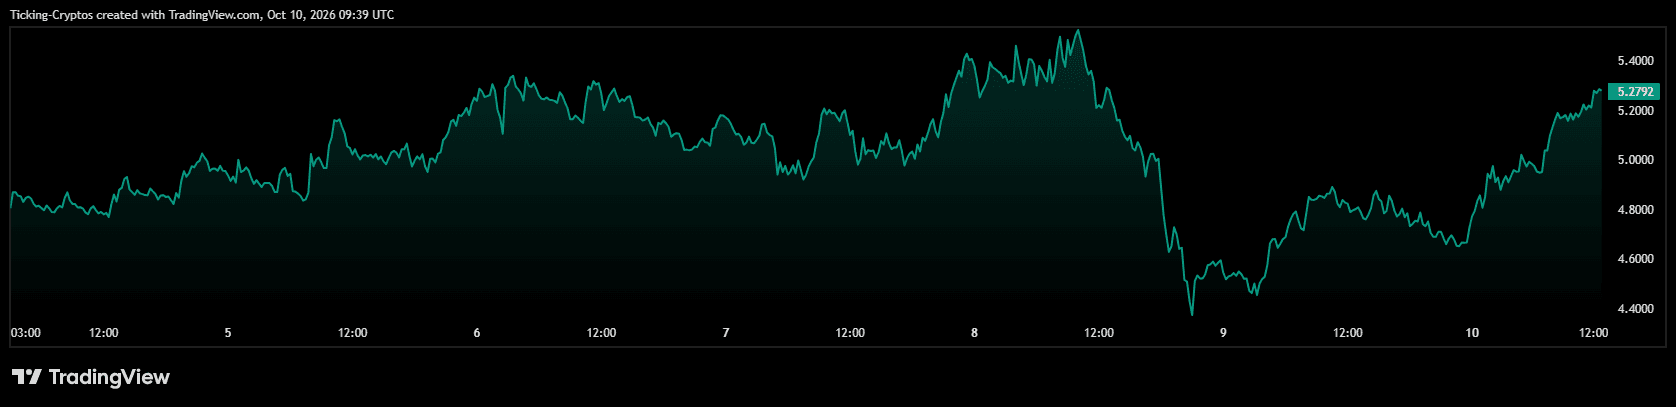
- Levels to watch: $5.60 to $6.20 is the resistance band that capped every bounce since 2022. A clean weekly close above $6.20 opens the door to $7.30 and $8.30 on the Fibonacci extensions. Support sits at $4.50; lose that and the move is probably over for now.
- Why it could explode: continued NRR inflows, a second ETF filing from another issuer, or a market-wide bounce would all land on a coin that is already outperforming in a down tape.
Can Cardano Finally Break Out Above $0.26?
$Cardano is the comeback story of the week. ADA broke out to a multi-month high near $0.28 on Monday, got slammed back to $0.23 by Thursday as Bitcoin slid and Treasury yields rose, and then roared back 6.73% in the last 24 hours to $0.2560. It is one of only two large caps in the green over seven days, up 5.21%, while remaining 23% down for the year. That combination of a deep YTD discount and fresh weekly strength is exactly what a bottoming chart looks like.
What makes this dip different from the summer lows is that the network is getting busier while the price was falling. Santiment data showed Cardano daily active addresses climbing to around 27,500 on 7 October even as ADA dropped 13%, a divergence that usually resolves upward. Whale wallets have been accumulating, the RealFi push launched on 1 October, the Mastercard tie-up is live, and a fee-cut proposal that would make the chain cheaper to use has moved to a vote.
The chart is also in better shape than the headlines suggest. ADA is trading above its 50-day, 100-day and 200-day exponential moving averages, and the 20-day average sits below the price, so the short-term trend still points up. Thursday's flush cleared out leveraged longs and reset funding, which is often the fuel for the next leg.
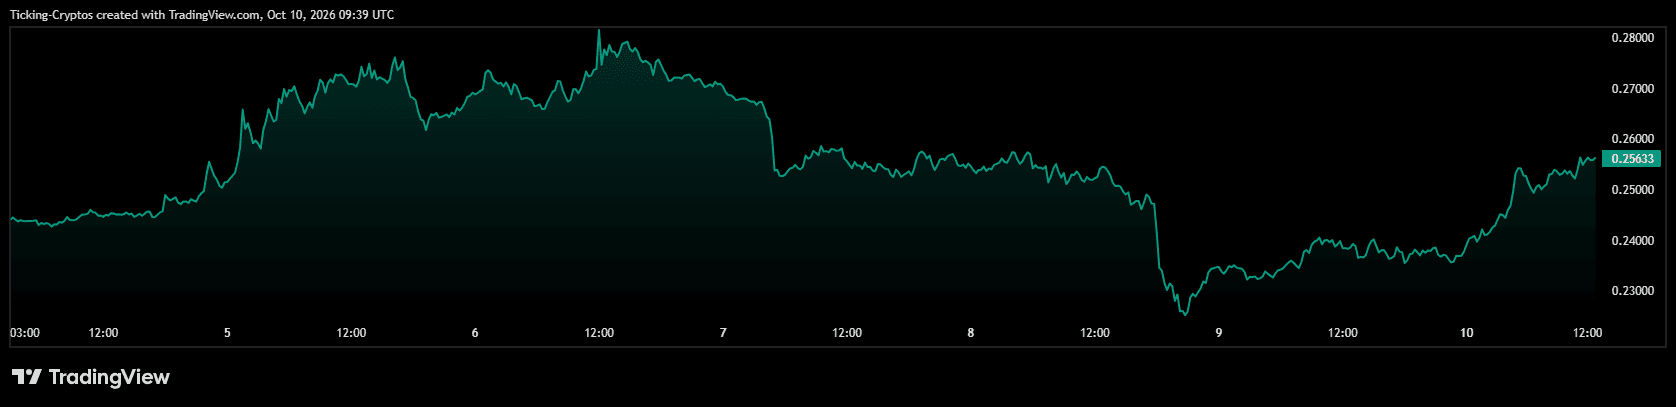
- Levels to watch: $0.258 to $0.263 is the resistance zone that has rejected ADA repeatedly. A daily close above $0.263 targets $0.27 first and the Monday high near $0.28 next. On the downside, $0.24 is the line that has to hold, with $0.23 as the last defence.
- Why it could explode: ADA is the most oversold of the three on a yearly basis, with the biggest short base to squeeze. A green week for Bitcoin would likely send ADA to the top of the leaderboard, as Friday's 6.7% bounce already showed.
Is the Zcash Dip a Buying Opportunity Before the NU7 Upgrade?
$Zcash is the contrarian pick. ZEC is down 6.86% on the week and dropped more than 10% on Friday alone, yet it is still up 133% year to date and sits at $1,225 with a $20.7 billion market cap, bigger than Dogecoin. The privacy-coin trade that defined 2026 has cooled, but the pipeline of catalysts for the coming weeks is the fullest of any coin on this list.
Start with the calendar. The NU7 network upgrade passed its testnet activation on 6 October and the mainnet activation height is confirmed for 20 October. NU7 brings a 300% speed boost to shielded transactions, lays the groundwork for Zcash Shielded Assets and introduces a sustainability mechanism that redirects 60% of fees into a long-term miner reserve. Traders tend to front-run upgrades of this size, and next week is the last full week before it goes live.
Then there is the institutional angle. Gemini's Winklevoss twins filed with the SEC on 6 October for a spot Zcash ETF that would trade on Nasdaq under the ticker WINK. THORChain switched on native ZEC swaps on 8 October, giving the coin direct cross-chain liquidity without a wrapped token. And the Zcash developers just set a January target for quantum-resistant payments, a narrative that is only getting louder.
The risk is that privacy coins remain a regulatory lightning rod, and the existing ZEC fund has posted a run of October outflows. A sharp rally like this one also leaves a lot of air below: ZEC was trading under $100 as recently as a year ago.
- Levels to watch: $1,180 to $1,200, Friday's low, is the support that has to hold. A reclaim of $1,350 puts the recent range high at $1,420 back in play, and above that the September highs around $1,560 open up. The 50-day EMA near $1,095 is the deeper support if the market keeps sliding.
- Why it could explode: an oversold bounce into a confirmed hard fork date, a live ETF filing and fresh DEX liquidity is a strong setup. If Bitcoin stabilises, ZEC has historically been one of the fastest coins to recover its losses.
What Should Traders Watch Next Week?
All three setups depend on the same thing: Bitcoin holding $80,000. BTC is at $82,768 and sitting just above that round number after a week of ETF outflows and rising Treasury yields. If it holds, the relative strength in NEAR and ADA and the oversold bounce in ZEC have room to run. If it breaks, even the strongest altcoins will get dragged lower before they can rally. Market-wide data such as total market cap, Bitcoin dominance and the Fear and Greed index is on the CryptoTicker charts page.
The quick checklist for the week ahead:
- NEAR: daily NRR ETF flow numbers and a weekly close above $6.20
- Cardano: a daily close above $0.263, the fee-cut vote result and the Santiment active-address trend
- Zcash: holding $1,180, positioning ahead of the 20 October NU7 activation and any SEC movement on the WINK ETF filing
Of the three, NEAR has the clearest momentum, Cardano has the most room to squeeze and Zcash has the biggest catalyst on the calendar.
On Saturday 17 October 2026 the Bored Ape Yacht Club celebrates its ApeFest, this time at the Beeple Studios in Charleston, South Carolina. The official site apefest.com gives the evening as 7pm to midnight local time, which is 1am to 6am on Sunday in Germany. Around the evening there are community side events from Thursday to Sunday, from ice skating to a poker tournament.
We are part of the Ape community ourselves. And we will say it openly: in our circle in Germany we know almost nobody making the trip to Charleston this year. That is not a verdict on a city or on the people who are flying over. It is feedback from the German community to Yuga Labs, the company behind the Bored Ape Yacht Club, and it runs: right now there are more disappointed holders than excited ones.
ApeFest 2026 in Charleston: date, venue and tickets
ApeFest 2026 takes place on 17 October at the Beeple Studios, the studio and event grounds of the digital artist Beeple in Charleston. Admission goes to holders of Bored Apes and Mutant Apes, with one ticket per NFT. According to reports by the community paper Bored Ape Gazette and by EGamers, holders put down a deposit of $99 for this, refunded once the ticket is scanned on site, while guests pay a fixed price. Last year in Las Vegas the deposit was still $169. The check on whether somebody really owns an Ape NFT has been handled this year by the service Glyph.
The programme includes a short question-and-answer session with James Hall, who runs the Otherside metaverse project at Yuga. Yuga has not signalled any major announcements in advance.
From spectacle to small stage: what became of ApeFest
ApeFest was once the big event of the NFT world. In 2022 in New York, Snoop Dogg and Eminem were on stage. In 2023 the festival moved to Hong Kong, with around 2,000 guests from 60 countries, and made headlines because visitors complained of eye pain after the evening. Yuga Labs later attributed that, according to Fortune and other media, to UV light in part of the hall. In 2024 ApeFest saw the launch of Yuga's own blockchain ApeChain; in 2025 it was held in Las Vegas. In 2026 it is one evening in an artist's studio.
Smaller does not have to mean worse. A party in an artist's studio actually suits the collection's origins better than an arena. But the shrinking mirrors what has happened across the ecosystem, and that is the part the German community is talking about.
Yuga Labs in 2026: a company being rebuilt, an ecosystem on a low flame
Yuga Labs has rebuilt a great deal over the past eighteen months. The ApeCoin DAO, through which APE holders used to vote on grants, was dissolved in 2025 and replaced by the company ApeCo, which Yuga controls. Yuga gave up the trademark rights to CryptoPunks and Moonbirds in 2025 in order to concentrate on the Apes and Otherside. Since 24 April 2026 Michael Figge has led the company, with co-founder Greg Solano becoming chairman.
Otherside, Yuga's metaverse, has been open to everyone since 12 November 2025, in the browser, with an email address or a wallet. On 9 September 2026 Yuga announced a resource economy with 74 raw materials on the blockchain; there is no date for it. Player numbers have not been published by Yuga as far as we know. On ApeChain, capital locked stood at around $3.1 million on 26 September according to DefiLlama, more than 80 percent below the high of late 2024. ApeCoin was recently trading around 99 percent below its all-time high. We put the figures together in detail three weeks ago in our piece on ApeCoin and ApeChain before ApeFest.
On top of this came a scare for many holders in September: attackers exploited old marketplace approvals connected with Limit Break's payment processor to drain NFTs and WETH, on ApeChain too. Yuga helped bring more than 23,000 NFTs to safety. Anyone who has not yet cleaned up their approvals should do so before trading again. Valuable NFTs sit most safely on your own hardware wallet, and our hardware wallet comparison gives an overview of the models.
Why the German Ape community is staying home
What we hear in our circle can be summed up in three sentences.
What is missing is the new. For months little has come from Yuga that surprises or excites. Announcements such as the resource economy in Otherside remain without a date. At a time when small teams build with AI in weeks what used to take years, that pace looks out of step with the age.
What is missing is what binds the community. A say over ApeCoin disappeared with the DAO. Joint projects that holders can contribute to have become rare. We no longer know anybody in Germany who plays Otherside regularly.
The journey is long and the value unclear. A flight to Charleston, a hotel and several days of time for one evening that nobody knows will amount to more than a party: for most holders in Europe that does not add up. There has never been an ApeFest in Europe.
What Yuga Labs could make of ApeFest
Disappointment is feedback, not a farewell. The Ape community is still one of the strongest communities in the crypto market, and many holders would join in again immediately if there were a reason. What would help, as we see it:
- A clear roadmap for Otherside with dates and published player numbers, so that holders can see whether the project is growing.
- A new form of participation after the end of the DAO, so that APE holders have a say again instead of only watching.
- A gathering in Europe or official regional meetups, instead of staking everything on one evening in the United States.
- Applications on ApeChain that people actually use, instead of new collectibles.
Whether Yuga delivers any of that on 17 October, we will see on Sunday morning. Anyone who does not want to sleep through the announcements will find them on the Bored Ape Yacht Club's X channel. If you want to buy or sell NFTs from the Ape world now, the marketplaces and their fees are in our NFT marketplace comparison. ApeCoin itself is best traded in Germany through a provider from our comparison of regulated crypto exchanges.
ApeFest 2026: our verdict from the German community
ApeFest 2026 is smaller, quieter and further from Europe than ever before. We wish everyone flying to Charleston a great evening. But Yuga Labs should read the empty seats from Germany for what they are: a request to build something again that brings the community together. The festival on 17 October is the chance to make a start.
Disclosure: Dennis Weidner, founder of Cryptoticker, is part of the Ape community and owns the ApeCar. This piece is a comment. (As of October 9, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
Executives are war-gaming the political fallout of a major AI-driven cyberattack and preparing to brief Congress fast if and when necessary.
Sen. Richard Blumenthal wants Cantor Fitzgerald to open its records on Tether and on how much Commerce Secretary Howard Lutnick's family has earned from its business deal.
The crypto platform filed for designated contract market and futures commission merchant licenses, which would let it run its own regulated event-contract venue instead of relying on overseas partners.
Bitcoin bounced after dipping to around $80,000. Traders are placing increasingly high odds BTC slips further before October is over.
Starknet is "actively considering" becoming its own blockchain, a move it says would make it the first fully quantum-resistant network by 2027.
U.Today - IT, AI and Fintech Daily News for You Today
The listing marks key step in Midnight’s expansion into the Japanese market.
Bitcoin has closed the last ETF weekly trading session on a weak note as netflow provides a negative balance amid rising sell activity.
XRPL developers remediate critical flaw that could have let attackers create XRP.
Here's everything you need to know about the Ledger-related $92.9 million wallet drain across Bitcoin, Ethereum, TRON, BNB Chain and Polygon.
Ripple Prime gains top honor as it becomes an award-winning brokerage firm for institutional market services.
Blockonomi
TLDR:
- The Bitcoin price fell 3.6% for the week after touching $80,400, then recovered above $83,000 following Thursday’s sharp decline.
- NEAR lost just 0.3% in the weekly comparison after a 91.7% monthly advance, then jumped more than 10% to about $5.25 on October 10.
- Monero’s 1.3% weekly decline beat Bitcoin’s loss, though price performance alone cannot show whether trading activity or buying demand drove the difference.
- Bitcoin ETF outflows reached $244 million in one day, while XRP funds saw $8.2 million in inflows even as XRP fell 9% for the week.
The Bitcoin price fell to a weekly low near $80,400 on October 8 as a crypto market selloff accelerated. By October 9, BTC had recovered to $83,247, leaving it 3.6% lower for the week. Most large tokens lost more over that same seven-day period.
NEAR Protocol and Monero were exceptions, down 0.3% and 1.3%, respectively, in the weekly comparison. Yet those figures capture only one point in a volatile stretch. NEAR had climbed 91.7% over the prior month, then rose more than 10% on October 10. The Bitcoin price and altcoin moves show resilience in the data, but not its cause.
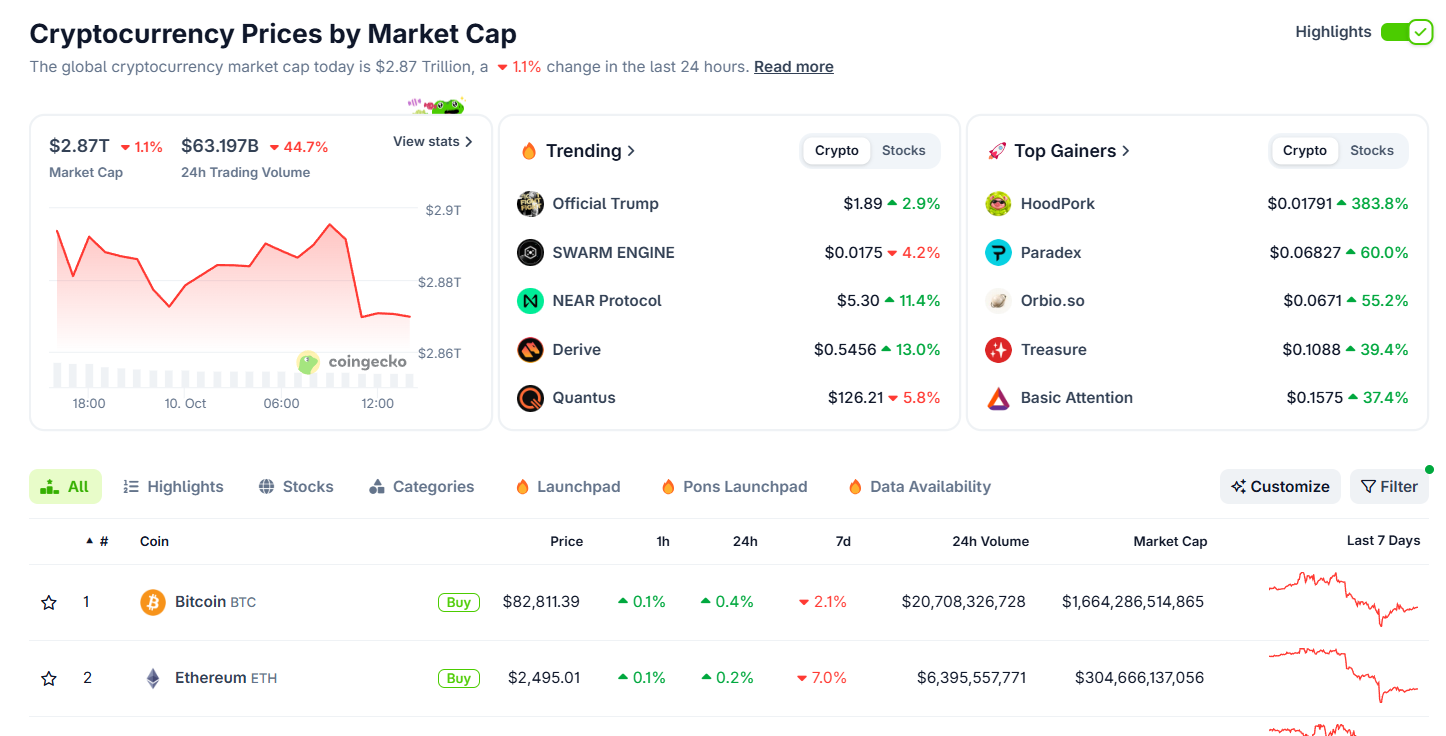
Bitcoin Price Slide Put NEAR and Monero Under Scrutiny
The selloff followed several failed attempts by BTC to reclaim $87,000. After slipping below $84,000 earlier in the week, Bitcoin fell to $80,400 on Thursday. The decline erased nearly $7,000 in a few days before buyers lifted BTC above $83,000. Bitcoin price weakness contrasted with the narrower weekly losses in NEAR and Monero.
NEAR’s small weekly drop deserves context. Its token price had climbed 91.7% in the previous month. That run can change how a weekly selloff appears. Even an intraday pullback may leave a token close to its starting price for the week. NEAR then gained more than 10%, reaching roughly $5.25 on October 10.
BTC price rebound shows how quickly the comparison shifted as prices recovered. Monero’s 1.3% loss also compared favorably with BTC. But a small decline alone cannot show whether buyers were accumulating, holders were inactive, or trading was thin.
ETF Flows and Weekend Recovery Point to Uneven Demand
Gains were not broad among large-cap coins. Thirteen of 16 tracked major tokens fell more than BTC during the measured week. Stellar posted the steepest decline at 13.5%. XRP lost 9%, despite XRP funds recording $8.2 million in inflows. Bitcoin ETFs, meanwhile, had $244 million in daily net outflows. Those flows complicate a simple demand narrative. Positive fund subscriptions did not protect XRP from falling. BTC declined despite its ETFs recording daily net outflows.
Bitcoin’s dominance increased to 59.5% as its market capitalization stood around $1.66 trillion. The total crypto market value rebounded to about $2.8 trillion after losing roughly $200 billion from its high to low. ETH recovered toward $2,500 after falling to $2,400, while XRP moved from $1.34 to around $1.41. The bounce restored some lost value but left several large tokens below recent levels.
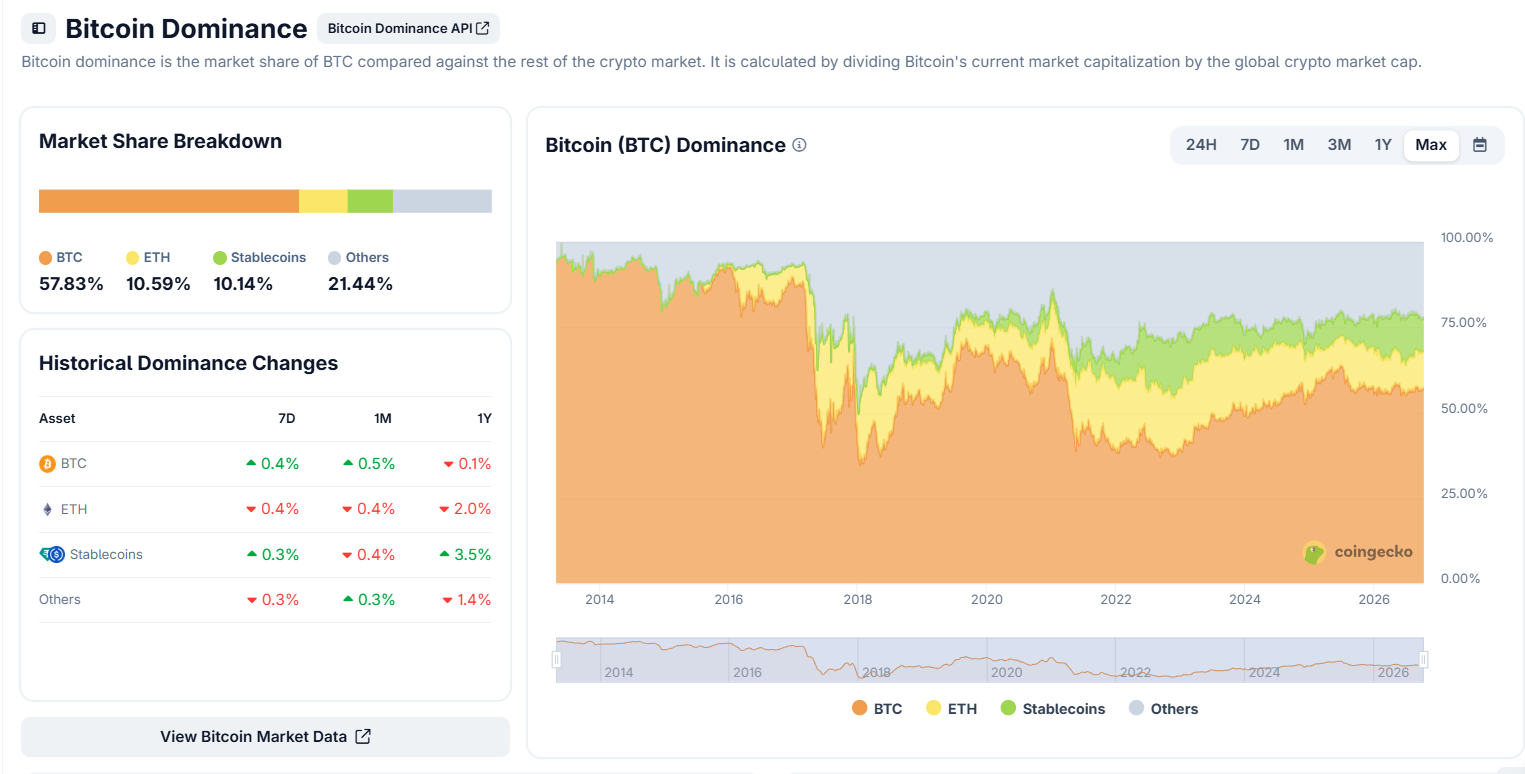
NEAR and ADA led the daily rebound among larger altcoins. Cardano rose about 7%, reclaiming $0.255, while NEAR’s advance outpaced peers. The Bitcoin price remained near $83,000 on October 10, below Monday’s $87,000 test and above Thursday’s low. This places the weekly outperformance beside a quick bounce, without confirming a lasting change in market leadership.
That matters for the Bitcoin price beside smaller tokens. Daily changes can look calm if trading is light, but weekly returns alone do not reveal activity. The same result can emerge from steady demand, limited selling, or a sharp drop followed by a rebound.
The post Bitcoin Price Holds Near $83K as NEAR and Monero Defy Selloff appeared first on Blockonomi.
TLDR:
- Strive Bitcoin funding through SATA generated an estimated $55 million during the week of Oct. 5, enough to purchase roughly 638 BTC at recent prices.
- SATA traded above its $100 par value on Oct. 5 and for much of Oct. 6, then stayed below par through Oct. 9, slowing estimated issuance.
- Strive held 29,462 BTC on Oct. 2 after buying 2,000 BTC at an average price near $84,422 between Sept. 28 and Oct. 2, while quarter-to-date BTC Yield reached 18.5%.
- Strategy sold zero STRC shares from Sept. 28 to Oct. 4, yet bought 334 BTC using MSTR common stock, lifting its holdings to 848,000 BTC.
Strive Bitcoin funding is accelerating through its SATA preferred stock program. The company generated an estimated $55 million during the week beginning October 5. That amount could purchase about 638 BTC at current prices. SATA traded $317 million in total volume during the period. However, issuance depends on shares trading at or above the $100 par value.
The preferred stock spent three sessions below that level. Most estimated proceeds came during Monday and Tuesday. Bitcoin traded near $82,800 on Friday, valuing 638 BTC at roughly $53 million. The result closely links Strive’s Bitcoin treasury strategy to Strategy’s capital markets playbook.
Strive Bitcoin Funding Depends on SATA Trading Above Par
That distinction matters because volume is not the same as corporate funding. Traders can exchange SATA below par without creating new proceeds. Strive therefore needs active demand and a supportive price. The next filing will actually determine how much cash reached its Bitcoin treasury.
Market trackers estimate that Strive sold about $55 million through its at-the-market program. The estimate uses eligible SATA volume and a capture ratio. That ratio reflects how much trading typically converts into newly issued shares. Past Securities and Exchange Commission filings help calibrate the calculation.
An ATM program lets a company issue shares gradually into public trading. It avoids the timing pressure of a large financing. Yet SATA cannot issue efficiently when its market price falls below par. Selling beneath $100 would weaken the program’s economics and dilute its yield proposition.
SATA traded above $100 on October 5 and for much of October 6. It then remained below par through October 9. Daily volume still reached some of its highest levels. The gap shows that trading activity alone does not guarantee Bitcoin purchases.
For Strive Bitcoin buyers, the distinction between volume and issuance is material. A busy tape can suggest strong demand, yet the company may receive little cash. Only eligible trading produces room for new shares. The estimate therefore remains provisional until the company files its next report.
The mechanism creates a brake. Investors must support SATA at par or higher before Strive can expand supply. When that support disappears, issuance pauses. Bitcoin buying then relies on cash already available or another financing route.
Strive Bitcoin Holdings Grow While Strategy Uses Common Stock
Strive reported 29,462 BTC on October 2. The balance followed a purchase of 2,000 BTC between September 28 and October 2. The average purchase price was about $84,422 per coin.
The company also reported adding 8,137 BTC during the third quarter. Those purchases carried an average cost of $78,885. Strive’s BTC Yield reached 18.5% quarter-to-date and 63.2% year-to-date on September 30. The metric measures Bitcoin growth per share.
The balance sheet has no debt principal. However, SATA carries about $168 million in annualized dividend obligations. Each new preferred share adds to that future payment burden. The model depends on continued investor demand for the income-oriented security.
Strategy provides the larger comparison. Its October 5 filing showed no STRC shares sold between September 28 and October 4. Strategy still bought 334 BTC from October 1 through October 4. It funded that purchase with MSTR common stock, taking its holdings to 848,000 BTC.
Both companies illustrate the same Bitcoin treasury model. Preferred or common equity raises capital for Bitcoin accumulation. The financing channel changes when market prices move. Strive’s SATA program currently shows that constraint more sharply because issuance stops below par.
The next weekly 8-K filings should provide the exact number of Bitcoin bought with SATA proceeds. They will also show whether Strive resumed issuance after the preferred stock recovered above $100.
The post Strive Bitcoin Has Enough for 638 BTC Through SATA Stock Sales appeared first on Blockonomi.
TLDR:
- Ethereum price prediction is bearish below the 50-day SMA, with $2,370 support and the 100-day average near $2,200 shaping the next levels to watch.
- U.S. spot Ethereum ETFs shed about $542 million in the week ended October 9, their largest weekly outflow since late January.
- BlackRock’s ETHA accounted for roughly $477 million in weekly withdrawals, while total U.S. Bitcoin ETF outflows reached $681 million.
- Whales reportedly added more than 166,000 ETH in 72 hours even as exchange balances rose 90,000 ETH and futures open interest declined.
Ethereum price prediction has weakened recently. Ether fell below its 50-day simple moving average. U.S. spot Ethereum ETFs logged their largest weekly outflow since January. ETH traded near $2,491 on October 10. It was down more than 7% in seven days, while trading volume fell 61% to $7.2 billion.
Yet whale data offered a counterpoint: holders added about 166,000 ETH over 72 hours, alongside Bitcoin and XRP purchases. The conflicting signals leave traders watching $2,370 support for now. A break could expose the $2,200 area, while a defense may steady the market. ETF redemptions and rising exchange balances remain risks.
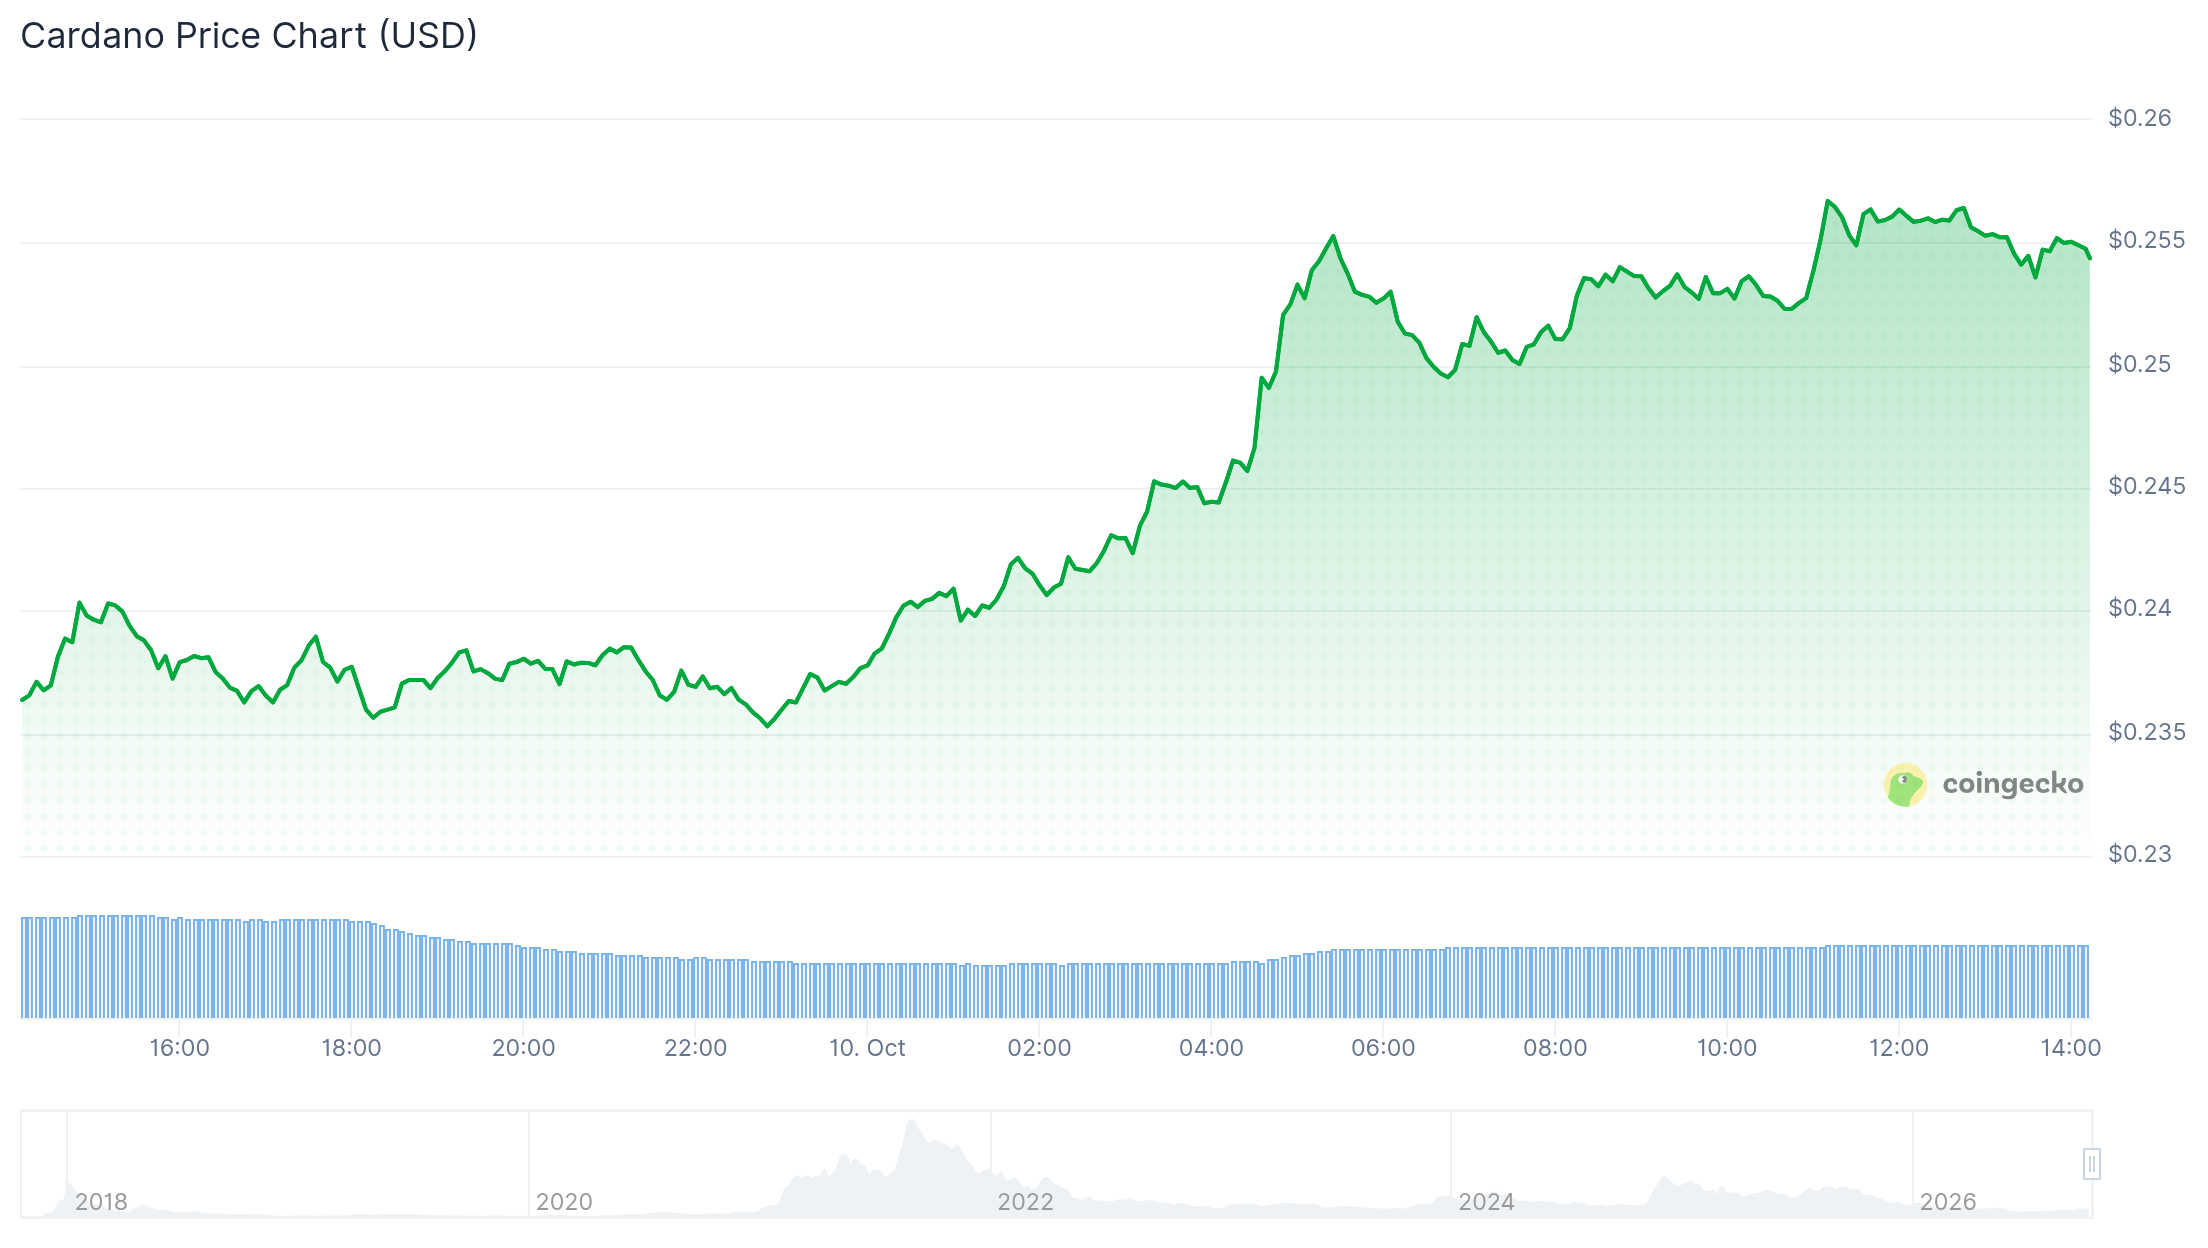
Ethereum Price Prediction Weighs ETF Outflows Against Whale Buying
U.S. spot Ethereum ETFs saw approximately $542 million in net withdrawals for the week ended October 9, SoSoValue data showed. It was their largest outflow since late January. BlackRock’s iShares Ethereum Trust, known as ETHA, accounted for about $477 million. It was the fund’s largest weekly withdrawal since December 2025. Bitcoin ETFs saw pressure, with $681 million leaving during the period.
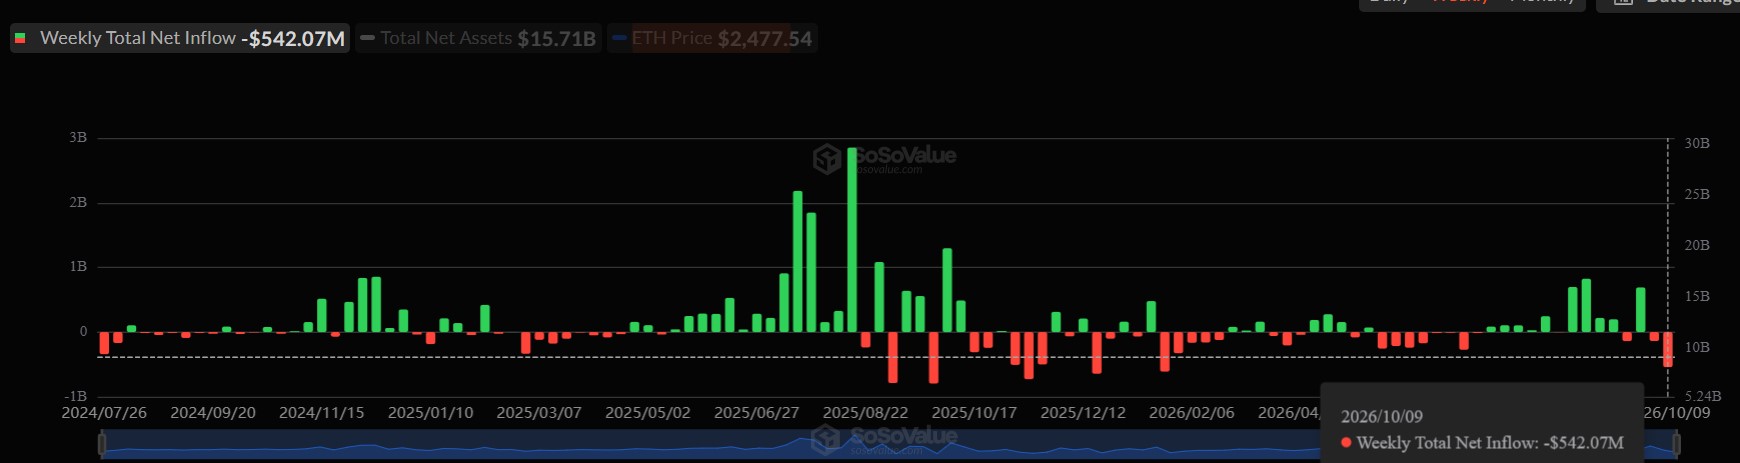
These Ethereum ETF outflows point to reduced exposure. They do not show every investor is selling ETH. However, they weaken a key source of demand during a price decline. An outflow streak could cap attempts to recover above resistance. Whale accumulation complicates that bearish picture. Analyst Ali Martinez says large wallets added roughly 15,000 BTC and more than 166,000 ETH. They also added about 45 million XRP in 72 hours.
Whale balances can rise while smaller holders or funds distribute coins. For the Ethereum price prediction, this divergence matters. Wallet demand may absorb some supply without quickly reversing ETF outflows or retail selling. Traders need follow-through in spot buying to treat the signal as durable.
ETF flows and wallet data track different activity. ETF figures capture listed-product flows; whale estimates track large on-chain balances. Those signals can diverge if ETF investors withdraw while other holders accumulate.
The Ethereum price prediction depends on whether whale buying continues beyond the 72-hour window. Continued purchases could absorb some supply, but a pause would leave ETF redemptions as the clearer demand signal.
Exchange Inflows and Futures Deleveraging Add Pressure on ETH
Exchange data adds caution. CoinGlass figures show Ethereum balances on trading platforms rising from 11.71 million ETH on October 8. They reached 11.8 million the next day. That 90,000-ETH increase marked the highest balance since September 23. Coins transferred to exchanges may be prepared for sale, but transfers alone do not prove liquidation. At the same time, open interest fell from 13.29 million to 12.77 million ETH.
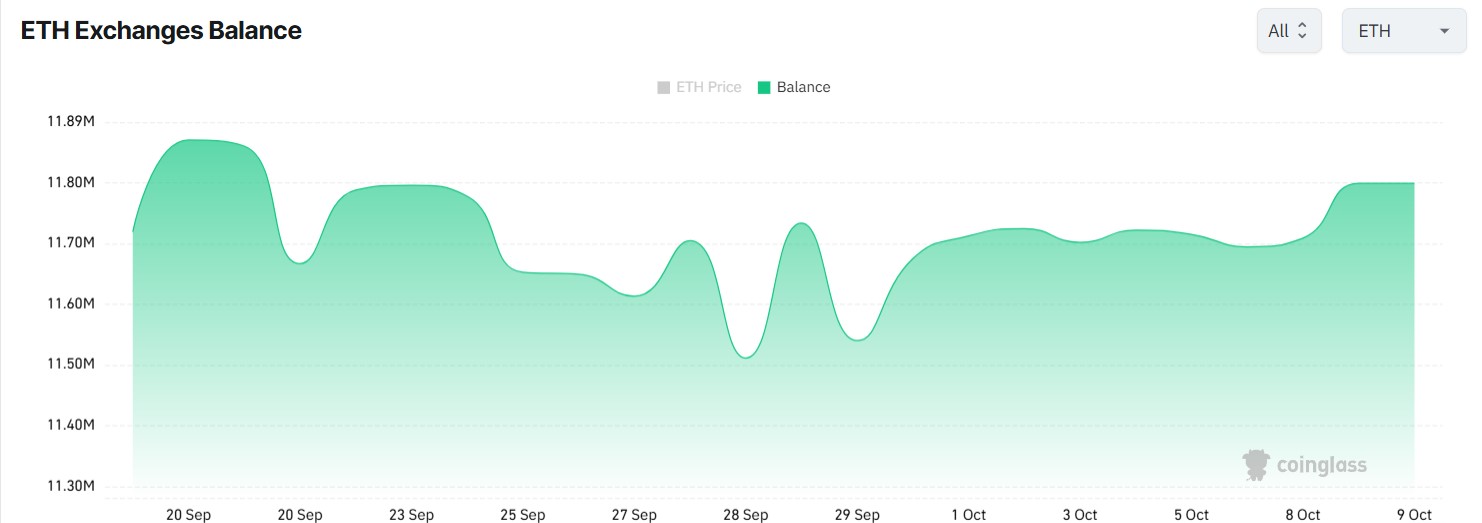
Lower futures open interest points to reduced outstanding positions and possible deleveraging. It can ease liquidation risk, but it also signals weaker appetite for leveraged longs. Combined, rising exchange balances and lower OI suggest traders are reducing exposure as spot supply increases. For the Ethereum price prediction, exchange balances now add another warning.
On the daily chart, ETH’s relative strength index slipped to 39, its lowest reading since June. Price also moved below the 50-day SMA. The $2,500 level has also turned into overhead resistance after ETH fell beneath it. The ETH price forecast hinges first on $2,370. A daily close below that support would strengthen the bearish case.
It would put the 100-day SMA near $2,200 in view. This Ethereum price prediction would need confirmation from continued selling or weak demand. If buyers defend $2,370, ETH could consolidate instead. A recovery above the 50-day average would give bulls a stronger signal. ETH had not reclaimed it by publication.
The post Ethereum ETFs Post Biggest Weekly Outflows Since January as Price Breaks Below $2,500 appeared first on Blockonomi.
TLDR:
- Cardano price rose nearly 7% on Oct. 10 and reached about $0.256 after a short-window rebound.
- ADA reclaimed the $0.2353 moving average and $0.2359 Fibonacci level, while reported volume fell 34.86%, leaving the breakout short of strong confirmation.
- Daily active addresses reached 27,500 and 27,200 on Oct. 7–8 after CIP-0113 launched, but ADA fell roughly 13% over that same period.
- Analyst Andreou’s $0.90 scenario remains conditional: ADA must hold the 0.22–0.25 base, reclaim 0.30–0.35, then clear higher resistance zones.
Cardano’s ADA token climbed 7% on Oct. 10, trading near $0.256 as buyers returned to the market. The Cardano price gain outpaced major cryptocurrencies during the session. The rebound followed an October decline, making this a recovery attempt rather than a confirmed trend reversal.
Cardano price analysis reveal ADA reclaimed its 30-day average near $0.2353 and the 50% Fibonacci level around $0.2359. But reported trading volume fell 34.86%, leaving buyers to prove they can defend the breakout. Network activity had increased earlier in the week.
Cardano Price Rebound Tests Support as Volume Remains Thin
The reclaimed average and retracement level now form a short-term checkpoint. A drop below them would weaken the breakout case. The support band extends from $0.2359 to $0.2276.
Holding that area could leave room for a test of weekly Supertrend resistance near $0.2762. The Cardano price would need a daily close above $0.256 to show that buyers can sustain the bounce. A rejection at that level would raise the risk of a false breakout.
Volume remains a key concern. The 34.86% decline suggests the rally drew less participation than its price move implied. The figure varies by exchange and measurement window, but the direction argues for caution. The Altcoin Season Index rose 5.17% to 61, pointing to stronger relative demand for alternative tokens. That measure describes rotation; it does not prove capital will stay in ADA.
Bitcoin traded near $82,800, a level that matters for altcoins. Spot Bitcoin ETFs shed $729 million over two days, adding pressure to risk assets. Renewed selling could again put ADA support levels under strain.
The immediate test is twofold: defend reclaimed levels and attract stronger spot volume. Until both happen, the Cardano price recovery remains technically constructive but unconfirmed.
ADA Active Addresses Rose After CIP-0113, Then Price Fell
Santiment reported about 27,500 daily active Cardano addresses on Oct. 7 and 27,200 on Oct. 8, around 1.7 times September’s weekday average. The increase coincided with CIP-0113 going live on mainnet on Oct. 7. The standard enables programmable tokens with issuer-defined rules. The Cardano Foundation says issuers can add KYC checks, sanctions screening, and transfer restrictions to native tokens. Wallets and explorers can handle these assets like other Cardano tokens. The standard required no protocol hard fork.
Coincidence does not establish that the upgrade caused the address spike. Santiment’s figures also showed Bitcoin and Ethereum addresses at or below September averages. Active addresses measure participation, not intent.
They cannot show whether users bought ADA, moved tokens, staked, or used applications. The Cardano price fell about 13% from the Oct. 6 close through Oct. 8, despite the increase. That divergence shows network use did not translate into immediate buying pressure.
The Cardano price bounce came on October 10, after both the activity increase and the selloff. It should not be attributed to CIP-0113 without evidence linking buyers to the upgrade. A lasting signal would require elevated addresses to persist beyond launch.

Analyst Giannis Andreou says initial support is present at 0.22–0.25 and first resistance at 0.30–0.35. A weekly reclaim and successful retest would strengthen that recovery case. Higher zones sit at 0.40–0.45 and 0.55–0.65. The $0.90 scenario depends on clearing each barrier, so it remains conditional. A sustained break below $0.22 would weaken the setup.
The post Cardano Price Rises 7% as ADA Tests Key Resistance Near $0.28 appeared first on Blockonomi.
TLDR
- Eli Lilly stock gains 0.62% as new Phase 3b findings highlight treatment gains.
- Combined therapy changes 482 proteins versus 140 with Taltz alone by Week 36.
- Gene activity shifts span 467 genes with both drugs, versus 16 on Taltz alone.
- Taltz and Zepbound deliver improved skin clearance and weight loss at Week 36.
- Researchers report consistent safety findings, but no new approved indication.
Eli Lilly and Company stock rose 0.62% to $1,176.80 on Friday, gaining $7.20 during the trading session. The company announced new Phase 3b findings showing broader biological responses from combined Taltz and Zepbound treatment. The results expand earlier evidence of improved psoriasis symptoms and weight reduction among adults living with psoriasis and obesity.
Eli Lilly and Company, LLY
Eli Lilly Reports Stronger Phase 3b Results for Taltz and Zepbound
Eli Lilly released new exploratory findings from its TOGETHER-PsO Phase 3b clinical trial examining two existing prescription medicines. Researchers compared the combined use of Taltz and Zepbound against Taltz alone in adults with moderate-to-severe plaque psoriasis. The study also included participants with obesity or overweight alongside at least one additional weight-related medical condition.
The latest analysis identified broader changes in proteins and genes among participants receiving both medicines compared with Taltz alone. By Week 36, researchers identified changes involving 482 proteins in the combination group, compared with 140 in the other group. Similarly, gene expression changes affected 467 genes with combined treatment, against only 16 genes with Taltz alone.
These biological differences appeared as early as Week 12, according to the pharmaceutical company’s newly released findings. Researchers also identified stronger reductions in inflammatory immune activity among participants receiving both treatments over the study period. Eli Lilly presented the findings at the 2026 Fall Clinical Dermatology Conference in Las Vegas.
Combined Treatment Improves Skin Clearance and Weight Reduction
The latest findings build on earlier clinical results showing better treatment outcomes among participants receiving Taltz alongside Zepbound. At Week 36, the combination delivered superior skin clearance and meaningful weight reduction compared with Taltz alone. Furthermore, participants maintained or improved these clinical benefits through Week 52, according to Eli Lilly’s previously reported findings.
The analysis also examined neutrophils, which play an important role in the body’s inflammatory immune response. Researchers found that combined treatment produced greater changes in inflammatory pathways associated with these immune cells. Changes in certain neutrophil-related markers partly explained the additional improvement in psoriasis severity scores among combination-treatment participants.
The TOGETHER-PsO trial included 274 adults across multiple clinical research centers, with participants divided equally between two treatment groups. One group received Taltz alone, while the other received Taltz and Zepbound through injections under the skin. Both groups also received guidance on reducing calorie intake and increasing physical activity throughout the clinical study.
Eli Lilly Expands Research Into Psoriasis and Obesity
Eli Lilly designed the study to examine the relationship between metabolic health and inflammatory skin conditions. Approximately 61% of Americans with psoriasis also experience obesity or overweight alongside another weight-related medical condition, according to Lilly. The findings provide additional research into how treatments targeting different biological processes may influence both conditions.
Taltz works by blocking interleukin-17A, an immune signaling protein involved in inflammation and several related inflammatory conditions. Zepbound targets GIP and GLP-1 receptors, helping regulate appetite and support weight management in eligible adults. The two medicines therefore act through different biological pathways, providing the basis for investigating their combined clinical effects.
Eli Lilly reported that the combination’s safety findings matched the established safety profiles of the individual medicines. The exploratory results do not establish a new approved indication for using the medicines together. The company continues examining the relationship between immune and metabolic processes as researchers assess broader approaches to psoriasis management.
The post Eli Lilly and Company (LLY) Stock: Rises as Taltz and Zepbound Show Promising Results appeared first on Blockonomi.
CryptoPotato
Despite the major leg down at the end of the business week, on-chain data showed that the daily active addresses on the Cardano network surged to roughly 1.7 times September’s weekday average following the launch of a new token standard.
At the same time, Cardano reached a substantial milestone in its bid for a .ada internet domain.
On-Chain Activity Pumps
Data from Santiment Intelligence shows that Cardano recorded approximately 27,500 daily active addresses on October 7 and almost as many a day later, which is significantly higher than the average weekday level seen in September. The analysts tested whether the broader market decline could explain the increase but found that active addresses on Bitcoin and Ethereum remained at or below their respective September norms during the same period.
The timing coincided with the October 7 launch of CIP-0113, Cardano’s new programmable token standard. The Cardano Foundation explained that the standard lets issuers of regulated assets such as stablecoins and tokenized funds build requirements, including KYC, sanctions checks, and transfer restrictions, directly into native Cardano tokens.
It went live following multiple independent security audits and has been recognized by the Capital Markets and Technology Association (CMTA), CF said.
Despite this uptick in activity, Santiment warned that it remains below Cardano’s late-August local high. It remains to be seen now whether this increase survives beyond the initial launch period, especially as ADA’s price rally has cooled. The asset recently soared to a multi-month peak of $0.28, where it was rejected, and the subsequent leg down drove it below $0.24 on Friday. However, it’s up by over 7% in the past 24 hours again.
New Cardano Milestone
The activity spike coincided with another potentially important development for the broader Cardano ecosystem. CF revealed at TOKEN2049 earlier this week that its application for the .ada generic top-level domain has advanced to the next phase of ICANN’s New gTLD Program. The proposal previously received approximately 75% support from the Cardano community through an on-chain Governance Action.
If approved, .ada would operate as a genuine internet top-level domain, similar to extensions such as .com or .org. CF believes it could eventually support simplified wallet addresses, decentralized identity integrations, and domain tokenization. However, ICANN still needs to assess the application’s technical, financial, and operational readiness, with successful domains from the current round expected to be delegated between 2028 and 2030.
The post Cardano Just Delivered Two Bullish Signals at TOKEN2049 as ADA Rebounds appeared first on CryptoPotato.
Bitcoin’s price recovery from the Thursday collapse continues as the asset currently sits close to $83,000 after marking a multi-week low at under $80,500.
Most larger-cap alts have remained sluggish on a daily basis, with ETH struggling below $2,500 and XRP barely defending the $1.40 support. ADA and NEAR, though, have posted notable gains.
BTC Eyes $83K
The business week began on the right foot for the primary cryptocurrency, which surged by a few grand on Monday morning to touch $87,000 for the first time since the previous Friday. However, just as it happened at the end of the previous week, BTC was stopped and quickly dipped to $85,000.
The bulls initiated another leg up that resulted in challenging the same resistance, but the bears intervened even faster this time and brought a whole army. Instead of another bounce, bitcoin slumped hard to under $84,000 on Tuesday. It couldn’t really recover on Wednesday, and the bulls lost complete control of the market on Thursday.
At the time, BTC crashed by several grand and dipped to a multi-week low of $80,400. It finally rebounded after this near-$7,000 decline in just days and jumped to $83,400 yesterday. However, it was stopped there and now trades inches below $83,000.
Its market capitalization has pulled back to $1.660 trillion on CMC, but its dominance over the alts has skyrocketed to 59.5%.

ADA, NEAR Pump
Ethereum slipped to $2,400 during the market-wide crash and has recovered slightly to almost $2,500 as of now, but it’s still far away from its local top at $2,800. XRP dipped to $1.34 before it rebounded to $1.41 as of now. BNB is back at $750 after a slight daily increase, similar to DOGE and LINK.
In contrast, SOL, TRX, and HYPE are slightly in the red. Cardano’s ADA has rebounded by 7% and has reclaimed the $0.255 level. NEAR Protocol’s native token has risen the most among the larger-cap alts, rocketing by over 10% to $5.25. DOT, WLD, BTW, and WLF have also charted notable gains.
The total crypto market cap shed $200 billion from top to bottom but has rebounded slightly to $2.8 trillion on CMC now.

The post NEAR Rockets by 10% Daily, BTC Price Eyes $83K: Weekend Watch appeared first on CryptoPotato.
Toobit is an award-winning international cryptocurrency exchange that recently announced that it has been named the Best Exchange for Trading Tokenized Equities at the CoinGape Global Onchain Awards 2026.
Toobit, among other nominees, was evaluated on tokenized equity listings, trading volume, and institutional trading capabilities. Winners were determined through quantitative research, expert jury review, and community participation. The Global Onchan Awards is intended to recognize institutions and innovators that advance the convergence of traditional and onchain finance across tokenization, digital assets, infrastructure, and compliance.

A Foray Into Traditional Finance
Recall that the exchange introduced Stock Futures in February 2026 with 10 major US equities, including Apple (APPL), Tesla (TSLA), and Nvidia (NVDA), available as USDT-settled perpetual contracts.
This move has since been expanded as part of the exchange’s overall TradFi lineup. It now covers over 240 pairs across equities, forex, precious metals, and indices.
Traders are able to access these markets using their existing Toobit account and USDT balance, which makes it very convenient, especially for those who also want to open long and short positions, participate in round-the-clock trading, and rely on up to 500x leverage on selected pairs.
Not the First Award for Toobit
Now, it’s important to note that this is far from being the first award that the exchange has received. In fact, it marks the fifth one in 2026.
Earlier this year, Toobit was named Best New Exchange at the Crypto Awards 2025, Digital Asset Derivatives Platform of the Year at the Hedgeweek Global Digital Assets Awards 2026, Best Crypto Exchange for Day Trading at the CoinGape Web3 Innovation Awards 2026, and Global Exchange of the Year at the FinanceFeeds Awards 2026.
The award also comes as tokenized equities continue to gain traction through the year. The onchain market cap of tokenized equities soared to almost $5 billion in early September, while the active market capitalization is up more than 300% since the start of the year.
Monthly trading volume is soaring, reaching almost $8 billion as opposed to just $240 million in January.
The post Toobit Wins Best Exchange for Trading Tokenized Equities Award appeared first on CryptoPotato.
The XRP-focused treasury company has officially completed its business combination with Armada Acquisition Corp. II, clearing the final major hurdle before its Nasdaq debut.
Evernorth will enter the public markets holding approximately 473 million Ripple tokens and around $300 million in gross cash proceeds.
473M XRP Heads to Nasdaq
The development will allow public-market investors to gain access to one of the largest corporate XRP treasury firms, which intends to do considerably more than passively hold the asset. The closing announced on Friday evening follows the shareholder vote previously reported by us, when roughly 20.5 million Armada shares voted in favor of the merger, compared with just 1.4 million against.
At the time, Evernorth disclosed more than $1 billion raised through the transaction and associated private placements. Previous investors in the company came from prominent names in the crypto and traditional finance space, including Ripple itself, SBI Group, Panter Capital, GSR, and Arrington Capital.
“Our conviction in XRP has always been rooted in the belief that the ecosystem would continue to mature, attracting serious builders and capital. Our support for Evernorth is a natural extension of that thesis. It brings scaled capital, active participation, and the standards of a public company, playing a critical role in the institutional development of this infrastructure,” said Michael Arrington, founder of Arrington Capital.
The final timeline has shifted slightly from earlier expectations, as Evernorth previously anticipated closing the deal on October 7 and beginning trading the following day. The completed transaction now, though, puts the official Nasdaq debut on Monday, October 12, while management expects to ring the closing bell on October 14, reads the announcement.
Not Just XRP Holding
Evernorth described itself as an actively managed XRP treasury. CEO Asheesh Birla said the company intends to deploy capital throughout the XRP economy while pursuing strategies designed to increase XRP per share over time.
The idea is to participate in institutional and DeFi yield strategies, ecosystem infrastructure, on-chain credit markets, and other capital-markets activities. Evernorth’s post noted that this approach distinguishes XRPN from a passive vehicle that simply tracks the price of the cross-border token.
The post XRP’s Nasdaq Moment Is Here: Evernorth Completes Merger appeared first on CryptoPotato.
On-chain researchers estimate that somewhere between $72 million and $86 million may have been stolen, as Ledger begins investigating reports of these major crypto losses from users who bought hardware wallets from an authorized Southeast Asian reseller.
The hardware wallet manufacturer said there is no indication that its own infrastructure, systems, or services were compromised. However, users are piling on X to complain about substantial losses.
How Much Was Stolen?
The official support channel of Ledger on X confirmed yesterday evening that it was investigating user reports from customers of CryptoBilis, which is listed as an authorized reseller in Indonesia, Malaysia, and the Philippines. Ledger asked CryptoBilis to pause all sales and shipments for the time being.
More importantly, the post urged anyone who purchased a device from the reseller in the past 90 days and has not completed installation not to begin setup now. Customers already using such devices were advised to consider transferring their assets to a new Ledger signer using a newly generated seed phrase.
On-chain sleuth tanuki42 traced more than $72 million to suspected theft addresses, while fellow investigator Specter estimated losses exceed $86 million, across BTC, ETH, and TRX. Ledger’s official account didn’t confirm either figure, and it remains unclear whether the two estimates include overlapping transactions.
MistTrack noted that the losses could be closer to $90 million, while Tether reportedly froze USDT held in addresses connected with the incident.
What Happened?
The details on what exactly transpired are still scarce, but Binance co-founder Changpeng Zhao said the currently available information suggests a localized supply-chain attack involving one vendor, with a small number of customers potentially receiving counterfeit or physically tampered Ledger devices.
Former Mt. Gox CEO Mark Karpeles added that he had already been examining modified Ledger devices containing a hidden hardware implant and asked CryptoBilis to open units from its inventory to see whether similar components were present.
He said an implant he examined could monitor internal communications used to display recovery words, potentially allowing an attacker to capture a seed phrase even though the genuine Ledger Secure Element itself remained intact.
Ledger claimed that the reports appear limited to products sold through CryptoBilis and that it has “no indication that Ledger’s security infrastructure, systems, or services have been compromised.”
Meanwhile, users such as Edward Winz have publicly admitted to being victims of the incident, with $1 million reportedly stolen.
The Ledger incident comes just a month after its biggest competitor, Trezor, experienced one of its own, with the personal information of over 80,000 US users compromised.
The post Ledger Investigates $86M Crypto Drain as Reseller Supply-Chain Fears Grow appeared first on CryptoPotato.