Cryptocurrency Posts
Crypto Briefing
The investigation underscores the risks of influencer-driven crypto markets, highlighting the need for transparency and caution among retail traders.
The post Bubblemaps estimates Ethan made $125K from 49 token callouts appeared first on Crypto Briefing.
Increased USDC supply on Solana may enhance network activity and adoption, but market caution persists regarding significant price gains.
The post Circle mints 250M USDC on Solana, boosting liquidity and network potential appeared first on Crypto Briefing.
The drone attack highlights the vulnerability of digital infrastructure to physical threats, potentially impacting investor confidence and tech operations.
The post Drone attack disrupts data centre in eastern Moscow, Russia says appeared first on Crypto Briefing.
Musk's chipmaking ambitions could disrupt the semiconductor industry, potentially reducing reliance on major foundries and lowering costs.
The post Elon Musk claims his companies can make chips better than anyone appeared first on Crypto Briefing.
The reduction in FIL issuance could lead to increased scarcity, potentially boosting token value and influencing similar crypto projects' strategies.
The post Filecoin nears the end of its six-year vesting schedule, cutting FIL issuance by about 75% appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Bitcoin Life Insurer Meanwhile Raises $37.5M as Wealthy Families Look to Pass On Their BTC
Meanwhile, the first life insurer licensed to operate entirely in Bitcoin, has raised $37.5 million in new funding from its existing investors, the company announced.
Bain Capital Crypto led the round, with participation from Haun Ventures, Framework Ventures, Pantera Capital, Apollo, Northwestern Mutual Future Ventures and Morgan Creek Digital. The raise brings Meanwhile’s total funding to more than $180 million. Sam Altman is also among its backers.
The company said the round follows a surge in demand for its Bitcoin life insurance policies outside the US, particularly in Asia, Europe and the Middle East, amid broader macroeconomic instability.
“Wealthy families around the world already hold Bitcoin. What they haven’t had is a regulated way to pass it on,” Zac Townsend, Meanwhile’s co-founder and CEO, said in a statement.
“Brokers came to us because their clients kept asking. This round lets us keep up with them.”
In early 2026, Meanwhile launched BTC Life 1-Pay, a single-premium whole life policy aimed at high-net-worth clients outside the US. It is the company’s second product line, after BTC 10-Pay, which is designed for US taxpayers.
Under BTC Life 1-Pay, a client pays one premium in Bitcoin and receives a guaranteed death benefit in Bitcoin for life. The policy’s value grows in Bitcoin, and after the first year the owner can borrow up to 90% of it, with no repayment schedule and no margin calls.
Policies can be owned by individuals, trusts or companies, which the company says makes them suited to succession and estate planning.
Since launch, Meanwhile has signed 15 brokers serving wealthy families, including in Singapore, Hong Kong, the UAE and Switzerland. Partners include Lioner, an insurance, trust and family office group with offices in Hong Kong, Singapore and Zurich, and Apeiron Group, a marketplace for high-net-worth life insurance.
“We’re reaching a turning point where more high-net-worth clients are asking not just how to hold Bitcoin and digital assets, but how to plan around them and ultimately transfer that wealth to the next generation,” said Justin Man, CEO of Apeiron Group. Digital assets.
Meanwhile said its net long-term underwriting income has already passed last year’s total and is on track to more than double in 2026. The company did not disclose specific figures.
“Meanwhile owns every layer of a regulated life insurer and builds it like an AI-enabled startup,” said Stefan Cohen, partner at Bain Capital Crypto. “The growth this year proves the model, and we’re glad to back them again.”
The company’s operating entity, Meanwhile Insurance Bitcoin (Bermuda) Limited, holds the first Class IILT license granted by the Bermuda Monetary Authority. It received the license in July 2024 after two years in the regulator’s sandbox.
The insurer’s balance sheet, reserves and audited financial statements are all denominated in Bitcoin. Policyholder Bitcoin is held with regulated institutional custodians.
This post Bitcoin Life Insurer Meanwhile Raises $37.5M as Wealthy Families Look to Pass On Their BTC first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
‘We Know Where It Is’: Treasury Secretary Threatens To Freeze $1B of Iran’s Crypto
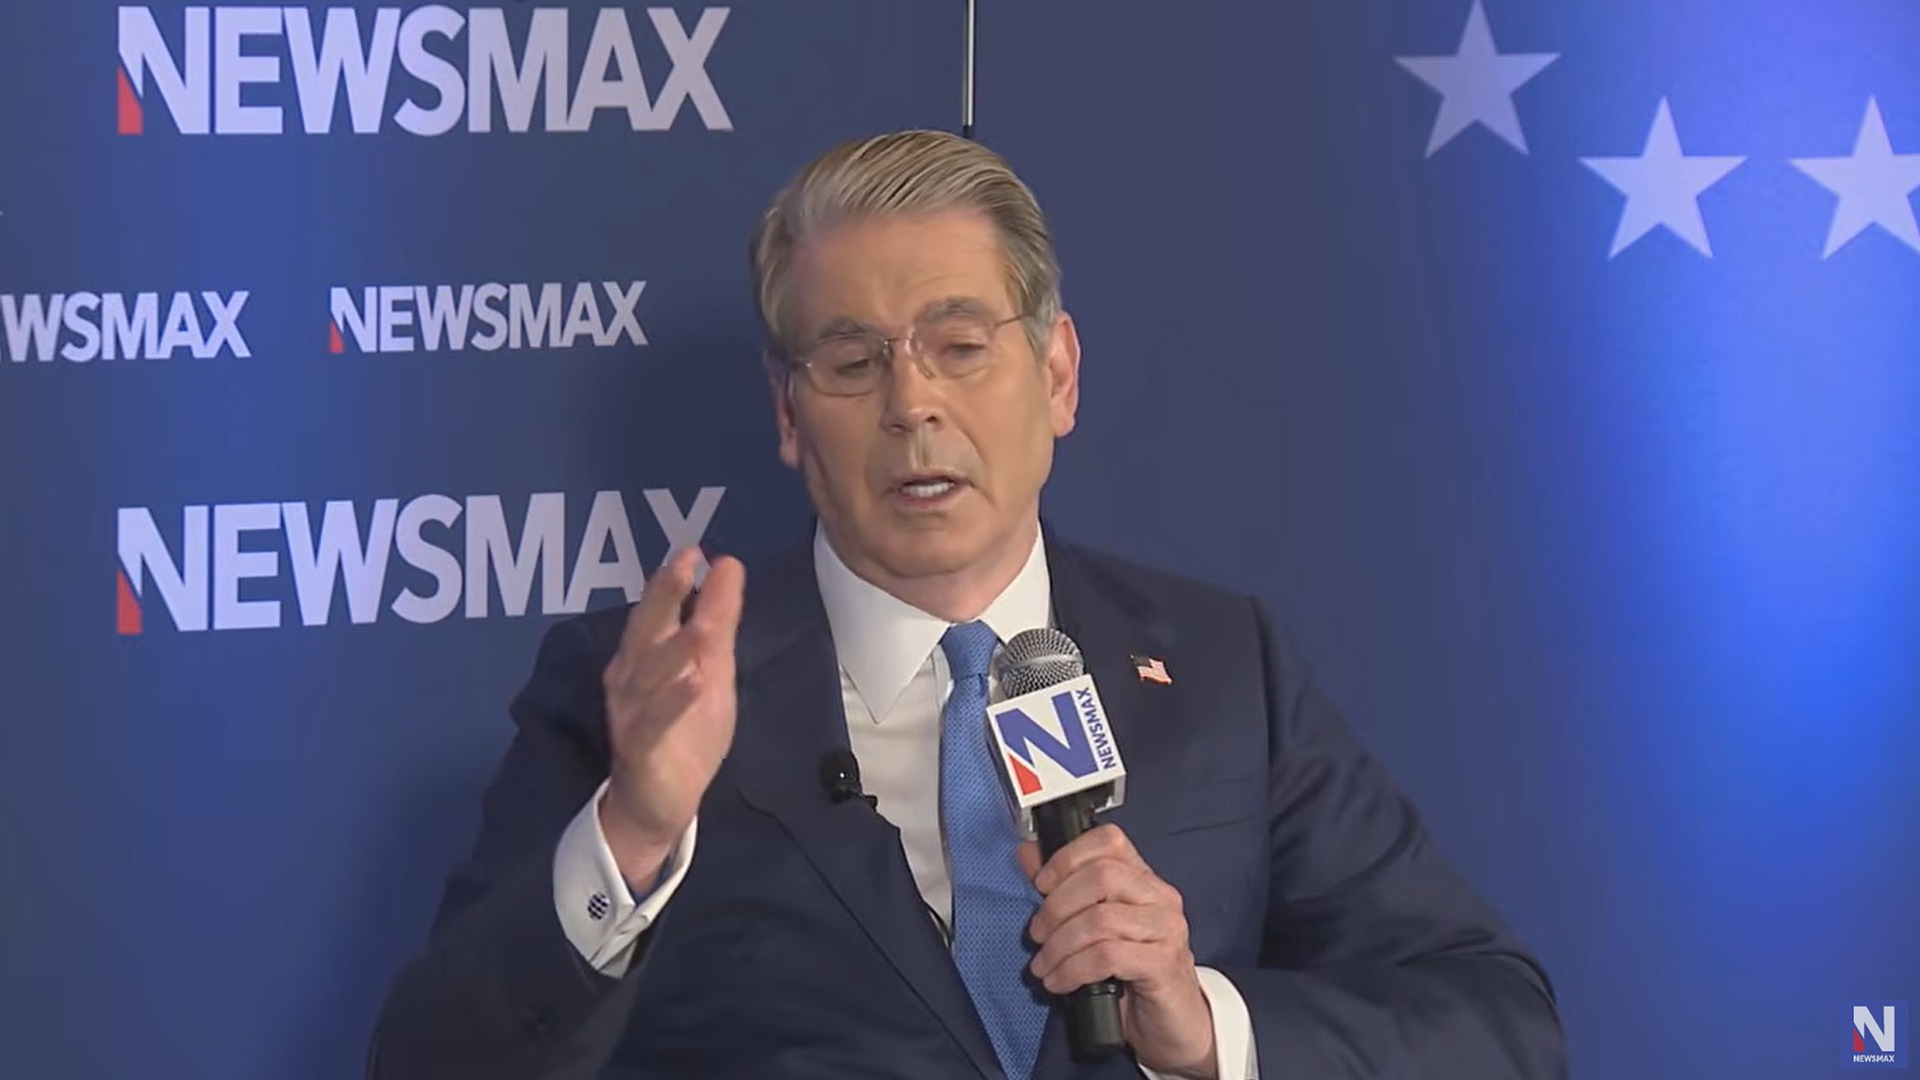
U.S. Treasury Secretary Scott Bessent has said the American authorities will soon seize $1 billion in crypto from Iran.
Speaking on Newsmax’s NPolicy Summit in Washington, D.C. on Thursday, Bessent added that economic sanctions on the Middle Eastern country were working.
Iran has been using bitcoin — and other cryptocurrencies — to skirt around U.S. sanctions. The U.S. in April started targeting crypto wallets linked to the Iranian regime, Bessent said at the time.
“What we have done has never been seen before,” Bessent said Thursday on Iranian sanctions.
“We’re probably going to seize $1 billion of crypto this week,” he continued. “We know where it is. We are isolating them. We did have a maximum pressure campaign, now we have an absolute isolation campaign and it’s working.”
Bessent didn’t reveal what cryptocurrencies the U.S. will seize or how.
It would be very hard — if not impossible — for the U.S. to freeze Iran’s bitcoin unless it keeps it on a centralized exchange.
Bitcoin, being censorship resistant, cannot be frozen. But many other cryptocurrencies, including Tether’s USDT, can. Bessent previously said the feds had seized Iran’s crypto in the form of the popular stablecoin.
Iran started a bitcoin-backed insurance service for its counties shipping companies earlier this year.
The Financial Times last month reported that the Middle Eastern country was using bitcoin to settle cross-border transactions through Iranian crypto exchanges after the central bank advised its countrymen to do anything necessary to help the economy.
U.S. President Donald Trump revived his “maximum pressure” campaign weeks after returning to office. A national security memorandum signed in February 2025 put the Treasury on a sustained campaign against Iran’s shadow banking, money laundering and sanctions-evasion networks.
This post ‘We Know Where It Is’: Treasury Secretary Threatens To Freeze $1B of Iran’s Crypto first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Here’s How Not To Screw up Your Bitcoin Privacy
Just one transaction can compromise years of discreet Bitcoin activity, Cake Wallet’s chief operating officer has warned.
Speaking on the Bitcoin Rails podcast this week, activist Seth for Privacy talked about different ways of protecting one’s privacy when using Bitcoin and said that focusing on privacy was a must for the West.
Bitcoin privacy is a hot topic again ever since the developers of private coin mixer Samourai Wallet went on trial last year and were subsequently imprisoned.
But just this week, the U.S. Department of Treasury scrapped two long-stalled crypto surveillance proposals, handing a major win to privacy advocates and the digital asset industry.
“If you ever spend your no-KYC coins with one of your KYC coins — which if you just let the wallet do its thing, it could do because it doesn’t know the difference — you immediately connect all of the non-KYC Bitcoin that you spend in that with your identity,” Seth said, referring to UTXO management, also called “coin control” by some wallets.
Bitcoin wallets don’t hold a single balance but a collection of separate unspent transaction outputs — UTXOs — each one a discrete “coin” from a specific past transaction.
When you send a payment larger than any one UTXO, the wallet picks several and combines them as inputs to the same transaction — an easy mistake to make, Seth highlighted.
Seth added that unlike in the global South, where people have experienced more oppressive states, citizens in the West will need to “feel pain” in order to realize how important privacy is.
Still, he added that attitudes were changing and people were getting more serious about protecting their privacy.
“It has been shifting, in the last five or six years a lot of people — even in the West — are starting to think [privacy] really matters, we really need to think about this seriously now,” he said.
Cake Wallet is a privacy-oriented, self-custody, open-source wallet. The wallet earlier this year integrated Bitcoin’s Lightning Network into its platform.
Using the second layer solution is not only faster and cheaper, it also offers more privacy than Bitcoin’s main chain.
While Cake Wallet supports other cryptocurrencies, including privacy coin Monero, Seth for Privacy added that he’d love it if the digital coin didn’t exist.
“If Bitcoin’s privacy got good enough that you could use it and have at least almost as good privacy as Monero without massive hoops to jump through, and Monero ceased to exist, that’s fine,” he said.
“I would much rather the thing that more people use has better privacy than a more niche tool that has perfect privacy, and that’s something that less people are using because it’s less well known.”
This post Here’s How Not To Screw up Your Bitcoin Privacy first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Bitcoin ETFs Shed $729M in Two Days as Investors Reverse Course
U.S. investors this week reversed course, cashing out $729 million from spot bitcoin exchange-traded funds — putting downward pressure on the leading cryptocurrency’s price.
Funds managed by BlackRock, Fidelity, Morgan Stanley, and ARK 21-Shares all experienced significant outflows on Wednesday and Thursday, according to data from Farside Investors.
Investors had started the week by selling close to $90 million in shares but then bought nearly $119 million on Tuesday.
The rest of the week has seen outflows following news that the Federal Reserve may raise interest rates. Other negative news includes the price of Brent crude jumping following renewed attacks on tankers in the Strait of Hormuz.
U.S. President Trump also hinted that talks with Iran weren’t bearing fruit — a sign war in the Middle East could continue.
Bitcoin’s price recently stood at a little over $82,688, down more than 3% over a seven-day period. The leading cryptocurrency has rebounded slightly over the past day, jumping nearly 2% over 24 hours.
Still, the coin was fast closing in on $90,000 last week. Investors are expecting decent returns as the month dubbed “Uptober” has historically delivered for bitcoin speculators.
The price of bitcoin has been particularly sensitive to geopolitical headwinds this year — especially since the U.S. and Israel attacked Iran, leading to an oil price surge.
Oil prices going up tend to lead investors to bet on the Federal Reserve raising interest rates. And with higher interest rates comes less liquidity for the price of bitcoin to do well.
Still, that’s not always the case: the Fed last month talked tough on getting inflation down and raised interest rates by a quarter of a percentage point and bitcoin’s price rose in the following days.
Bitcoin’s price is 34% below the all-time high of $126,080 it touched in October. It has spent most of 2026 in a bear market but analysts are now increasingly pointing to evidence of a bull market following a rally in August and September.
This post Bitcoin ETFs Shed $729M in Two Days as Investors Reverse Course first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Ledger Warns Buyers Not to Set Up Wallets From Reseller After Users Report Losses
Hardware wallet manufacturer Ledger has said that it is investigating loss of user funds after customers in South East Asia reported issues with devices bought from a reseller.
The Paris-based company on Friday advised customers who’d bought from vendor CryptoBilis within the last 90 days to not set up their devices.
Ledger did not reveal how much money users had lost but one blockchain investigator, Specter, wrote on X that he’d traced theft addresses following social media posts and that over $86 million had been lost.
The issue comes following a number of data breaches this year in the crypto world and a huge hack of popular Coldcard hardware wallet devices in July.
“Ledger is investigating reports of loss of funds from users in South East Asia who purchased products from a reseller named CryptoBilis,” Ledger said via its support X account.
Ledger added that it had asked CryptoBilis to pause all sales and shipments of Ledger devices.
“If you have set up your Ledger device, consider moving assets to a new Ledger signer (with new seed). We will continue to inform customers of updates as the investigation progresses,” the company said.
In a statement to Bitcoin Magazine, Ledger said that based on the information to date, the incident is isolated specifically to this reseller in this specific market.
“No reports were made of products purchased directly from Ledger, and Ledger’s infrastructure, systems and services were not compromised,” the company added.
CryptoBilis is a Kuala Lumpur, Malaysia-based hardware wallet vendor, according to its website. The company did not immediately respond to questions from Bitcoin Magazine.
The crypto industry is still reeling after hackers in July were able to steal close to $120 million in bitcoin from Coldcard users.
The products, made by Canadian company Coinkite, had a firmware bug which led to faulty seed generation, allowing hackers to essentially guess investor seedphrases.
Galaxy Research said in the months following the attack various attackers were able to exploit the bug independently.
In a separate incident, hardware wallet manufacturer Trezor last month reported that close to 81,000 customers had their details leaked after its third-party fulfillment partner had data stolen.
Criminals have been targeting data this year, with scammers getting hold of customer information via crypto wallet Ledger’s payment processor Global-e to send phishing emails.
This post Ledger Warns Buyers Not to Set Up Wallets From Reseller After Users Report Losses first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
CryptoSlate
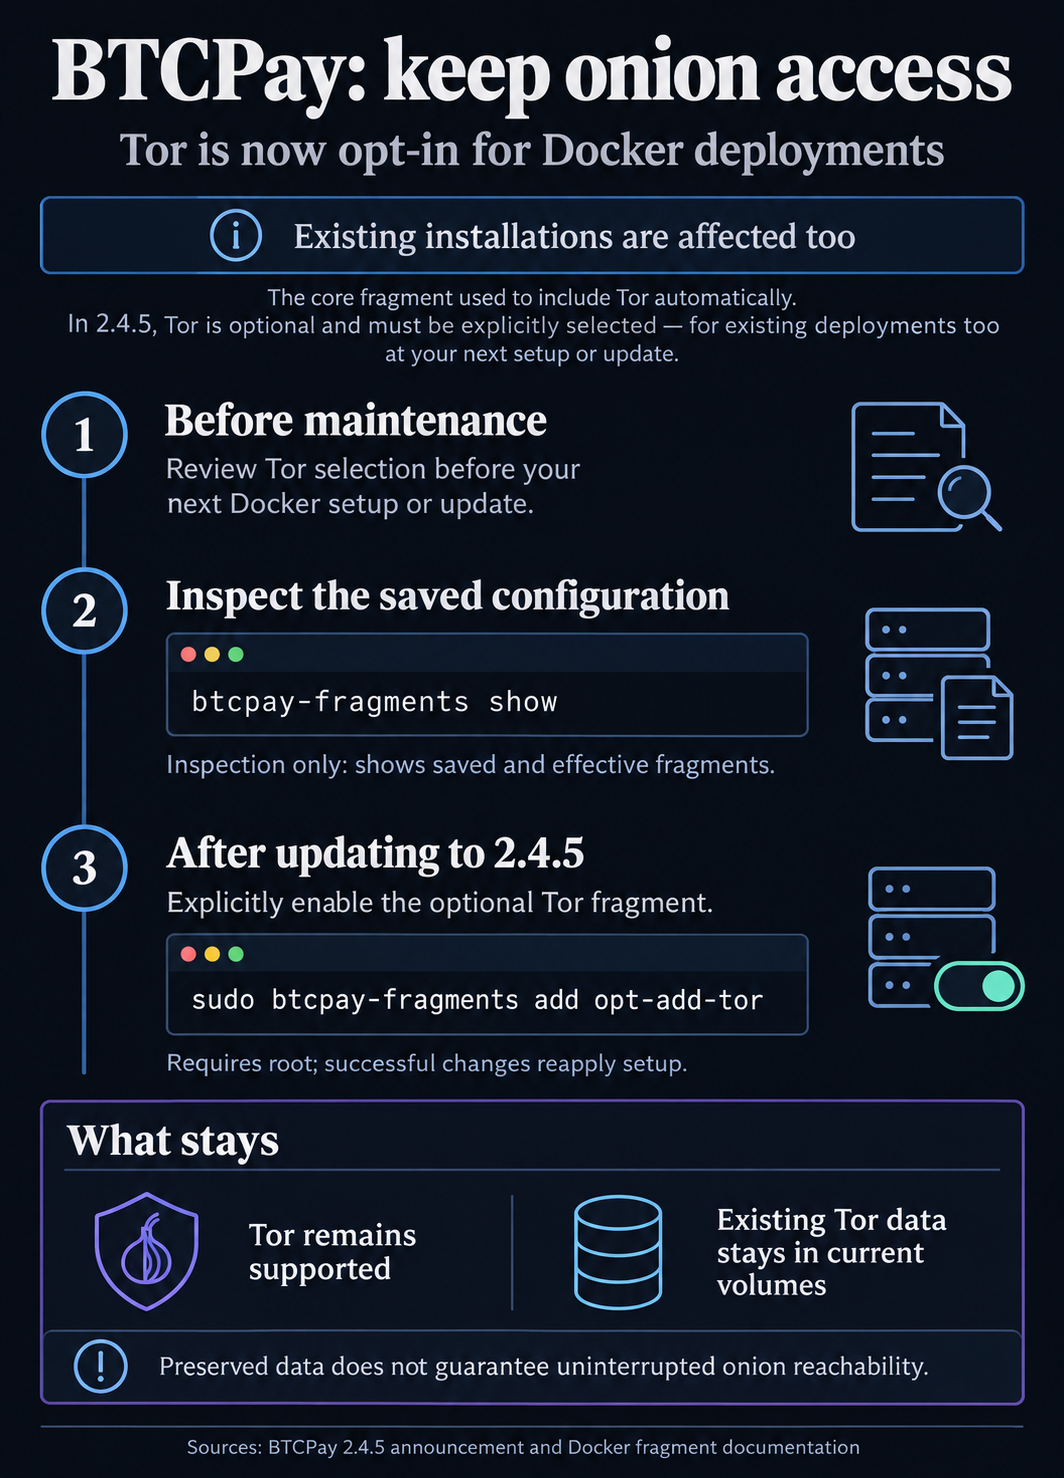
Operators running the Bitcoin payment software BTCPay Server through its standard Docker deployment must explicitly select Tor at their next setup or update if they want to retain onion access. The change removes Tor from the automatically included components, making a previously bundled service an administrator’s configuration choice.
BTCPay detailed the deployment change in its Oct. 5 announcement accompanying version 2.4.5. The official GitHub release page records the software release on Oct. 6. For existing installations, the relevant trigger is their next Docker setup or update.
The change matters to Docker operators who rely on Tor, including access through their server’s onion address, but previously received it through the core BTCPay Server fragment. Fragments are the configuration components used to assemble the Docker stack.
BTCPay advises administrators to review the deployment changes before updating. After updating to 2.4.5, its instruction for enabling Tor is:
sudo btcpay-fragments add opt-add-tor
Tor remains supported, and BTCPay says existing data stays in the current Tor volumes. That preserves stored data; continued onion access still depends on including and running Tor in the deployment.
BTCPay Server documentation describes the optional Tor fragment opt-add-tor as adding hidden services and selected onion connectivity. Operators can inspect configuration using btcpay-fragments show, which does not change configuration and reports saved additional and excluded fragments alongside the effective fragments from the last generated manifest.
Fragment-changing commands require root and reapply setup immediately.
Private services need separate exceptions
The 2.4.5 release notes also identify a breaking change for outbound HTTP requests: private-network destinations are blocked by default for Lightning connections, LNURL requests, invoice notification URLs and webhooks. The restriction is intended to prevent server-side request forgery, or SSRF.
With that protection enabled, operators intentionally using private services must allow the needed destinations through ssrfexceptions.
BTCPay’s operator guide says to restart the application and exercise the affected integration after changing the setting.
The post BTCPay Docker users must opt into Tor at their next update to keep onion access appeared first on CryptoSlate.
Coinbase reported Oct. 7 that newer versions of three major AI model families caught fewer fraudulent payments and a smaller share of fraud value in a historical test of payment screening for its Onramp service, despite an unchanged decision policy. The findings challenge the assumption that upgrading a model improves an existing payment screener.
The company’s evaluation replayed 16,140 transactions across 7,293 users, including 813 confirmed fraudulent transactions. The cohort covered nine weeks before its risk agent rolled out, retaining all matured fraud cases while sampling legitimate traffic.
Each candidate reviewed recent transaction behavior under fixed guidance and the same policy for turning risk classifications into decisions. This isolated the decision model’s behavior within that setup, rather than comparing redesigned screening systems.
Results from a fixed historical replay
Coinbase compared Opus 4.5 with Opus 5, Sonnet 4.6 with Sonnet 5, and GPT-5.4 with GPT-5.6 (sol). Every newer version had lower recall, a lower combined precision-and-recall score called F1, and lower dollar-weighted recall. Recall measures the share of fraud cases a model catches; dollar-weighted recall measures how much of the total fraud value it catches.
Sonnet’s recall fell 22.2 percentage points and its dollar-weighted recall dropped 22.9 points. Opus’s recall declined 0.8 points. Both newer models also had lower precision, meaning a smaller share of transactions they classified as fraud were actually fraudulent.
GPT showed why one improving score can be misleading. Its precision rose 11.5 percentage points, but recall fell 20.7 points and dollar-weighted recall fell 21.8 points. Its fraud flags were more accurate, while more fraud cases and value escaped detection in the replay.
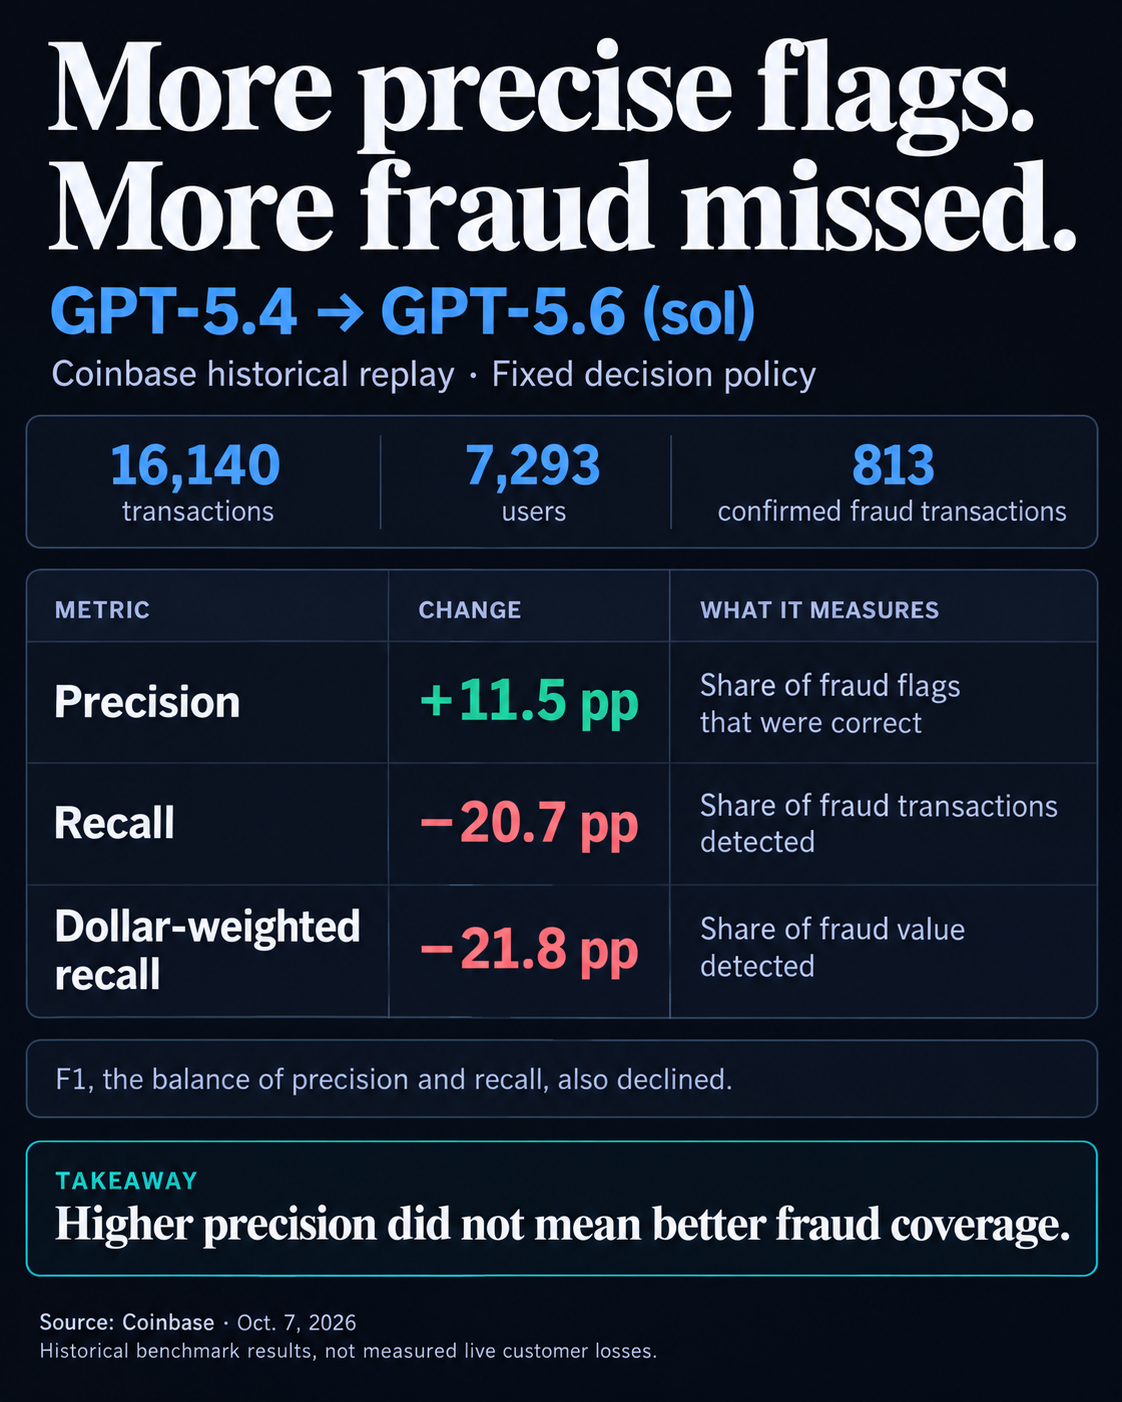
The replay does not establish customer losses from deploying those versions. Coinbase also said it could identify the regressions without establishing their cause.
Coinbase’s earlier online experiment compared adding selective LLM review with the existing models and rules alone. That agent-enabled flow recorded 30% fewer fraudulent transactions and 22% less fraud value; it did not compare newer model versions.
In their limitations, the SR-Fraud researchers say the proprietary dataset cannot be released, restricting independent replication and generalization. Their related payment-fraud study first appeared Sept. 23 and was revised Sept. 30, before the October blogs.
A separate case for a custom model
In its Oct. 8 disclosure, Coinbase reported that a post-trained Qwen3.5-9B model exceeded Opus 4.5 across four fraud-detection metrics. F1 improved 9.6 percentage points and dollar-weighted recall rose 35.4 points. The company specialized it using historical fraud outcomes and deterministic rewards balancing fraudulent and legitimate examples.
Separately, production measurements put median end-to-end LLM-request latency at 0.683 seconds versus 1.515 seconds for Opus 4.5, a 55% relative reduction. Faster inference and stronger benchmark detection came from different evaluations.
For payment providers, the upgrade question is whether a candidate improves fraud coverage under their actual decision setup. Coinbase recommends testing that configuration first, then evaluating changed prompts or thresholds separately, with latency, reliability and cost alongside detection quality.
The post Newer AI models missed more payment fraud in Coinbase’s benchmark appeared first on CryptoSlate.
Bitcoin's next recovery could vindicate your investment thesis but leave your leveraged fund deep in the red, because the fund's daily reset can make waiting a pretty expensive habit.
Getting Bitcoin right and actually making money on Bitcoin are becoming two different skills, especially now that Wall Street is preparing products for people who don't find the ordinary version exciting enough.
On Oct. 2, the SEC approved exchange-listing rules for proposed 3x Bitcoin and Ethereum funds from VS Trust. The approval brings them closer to trading, with the appeal captured neatly in the multiplier: more exposure to a market you already believe will go up.
But what happens between buying the fund and being proved right? Bitcoin can fall, recover, and return to your entry price while a leveraged fund still nurses losses, even when it's doing exactly what the product promised.
That promise covers just one day, a much shorter relationship than many investors intend with their money.
Your Bitcoin conviction doesn't reset
The proposed funds seek three times their benchmark's daily return, before fees and expenses. Holding them for a month doesn't extend that promise to three times the month's return, because each day's gain or loss becomes the starting balance for the next.
The Bitcoin investor thinks about where the market will be in six months, while the fund continually resizes its exposure around how much money it has today.
When the market falls, leverage eats through the fund's capital faster than it reduces the size of its market position. To restore the intended multiple, the fund cuts exposure, leaving it with a smaller position when the rebound begins.
Gains then apply to that reduced balance, so getting the underlying market back to its old level doesn't necessarily get the shareholder there too.
During a rally, profits give the fund more capital, allowing it to take on more exposure for the next session. You can leave your shares untouched while the investment inside them grows and shrinks every day, indifferent to your long-term Bitcoin outlook.
The SEC describes in its investor bulletin on leveraged funds a real four-month period when an unnamed index gained about 8%, while a fund seeking three times its daily return lost 53%. That wasn't a Bitcoin fund or a forecast for these proposed products, but it puts a financial result behind an easily dismissed prospectus warning.
Daily compounding can also work beautifully during a sustained advance, allowing a leveraged fund to earn more than three times the benchmark's cumulative gain. The mechanism rewards some price paths and punishes others, which means a buyer needs to be right about more than the eventual destination.
Bitcoin's reputation for rewarding patience affects this, and not in a good way, since a daily-reset fund continually recalculates how much exposure your remaining money can support.
The ETF wrapper comes with extra paperwork
The listing approval showed that these funds use futures, adding another layer between the Bitcoin price people follow and the return they receive.
Futures are contracts with expiration dates, so maintaining exposure requires replacing contracts as they approach expiry. The prices of those replacements can make the strategy more expensive or work in its favor, depending on the relationship between nearer and later contracts.
Either way, multiplying Bitcoin's spot-price return by three won't reproduce the fund's results.
VS Trust's Oct. 7 amended filing lists a 1.85% annual management fee for both proposed products. Its estimated trading return needed to cover costs is 1.98% for the Bitcoin fund and 2.78% for the Ethereum fund, incorporating other expenses and assumed interest earned on collateral.
Those breakeven estimates describe the return needed to cover the estimated operating bill under the filing's assumptions, before the investor earns anything from taking the risk.
But the familiar ETF comes with less familiar paperwork. These are commodity-pool products outside the Investment Company Act of 1940 framework that governs conventional investment-company ETFs, and the filing anticipates partnership tax reporting through Schedule K-1.
Shareholders may have taxable allocations without receiving cash distributions, adding another complication to a trade likely bought for price appreciation.
The Oct. 7 filing says the funds haven't begun trading, so none of this amounts to a record of returns from BITH or ETHK. The listing decision permits a route to market, while the disclosures explain what buyers would actually own.
When a bad trade becomes a long-term investment
Traders who want amplified exposure over a short period, and understand what they're buying, find a legitimate attraction here. Buying shares with cash can save them the work of managing their own futures margin account, though the leverage remains.
The trouble begins when a short-term position loses money, and its owner promotes it to a long-term investment. Waiting for Bitcoin to recover is more comfortable than accepting a loss.
But the fund keeps rebuilding its position around the capital left inside it, regardless of whether shareholders choose to be patient. Even the prospect of waiting assumes enough capital will remain to participate in a rebound: the issuer warns that the entire investment could be lost in a day or overnight.
Buying a 3x fund means accepting daily exposure adjustments and the possibility that a volatile recovery will leave you far behind the asset you correctly believed in.
Even if Bitcoin recovers, a daily-reset fund has no obligation to restore the money lost along the way. Conviction can't persuade a fund to calculate tomorrow's return on money that disappeared yesterday.
The post Being right about Bitcoin won’t save your 3x leveraged ETF position appeared first on CryptoSlate.
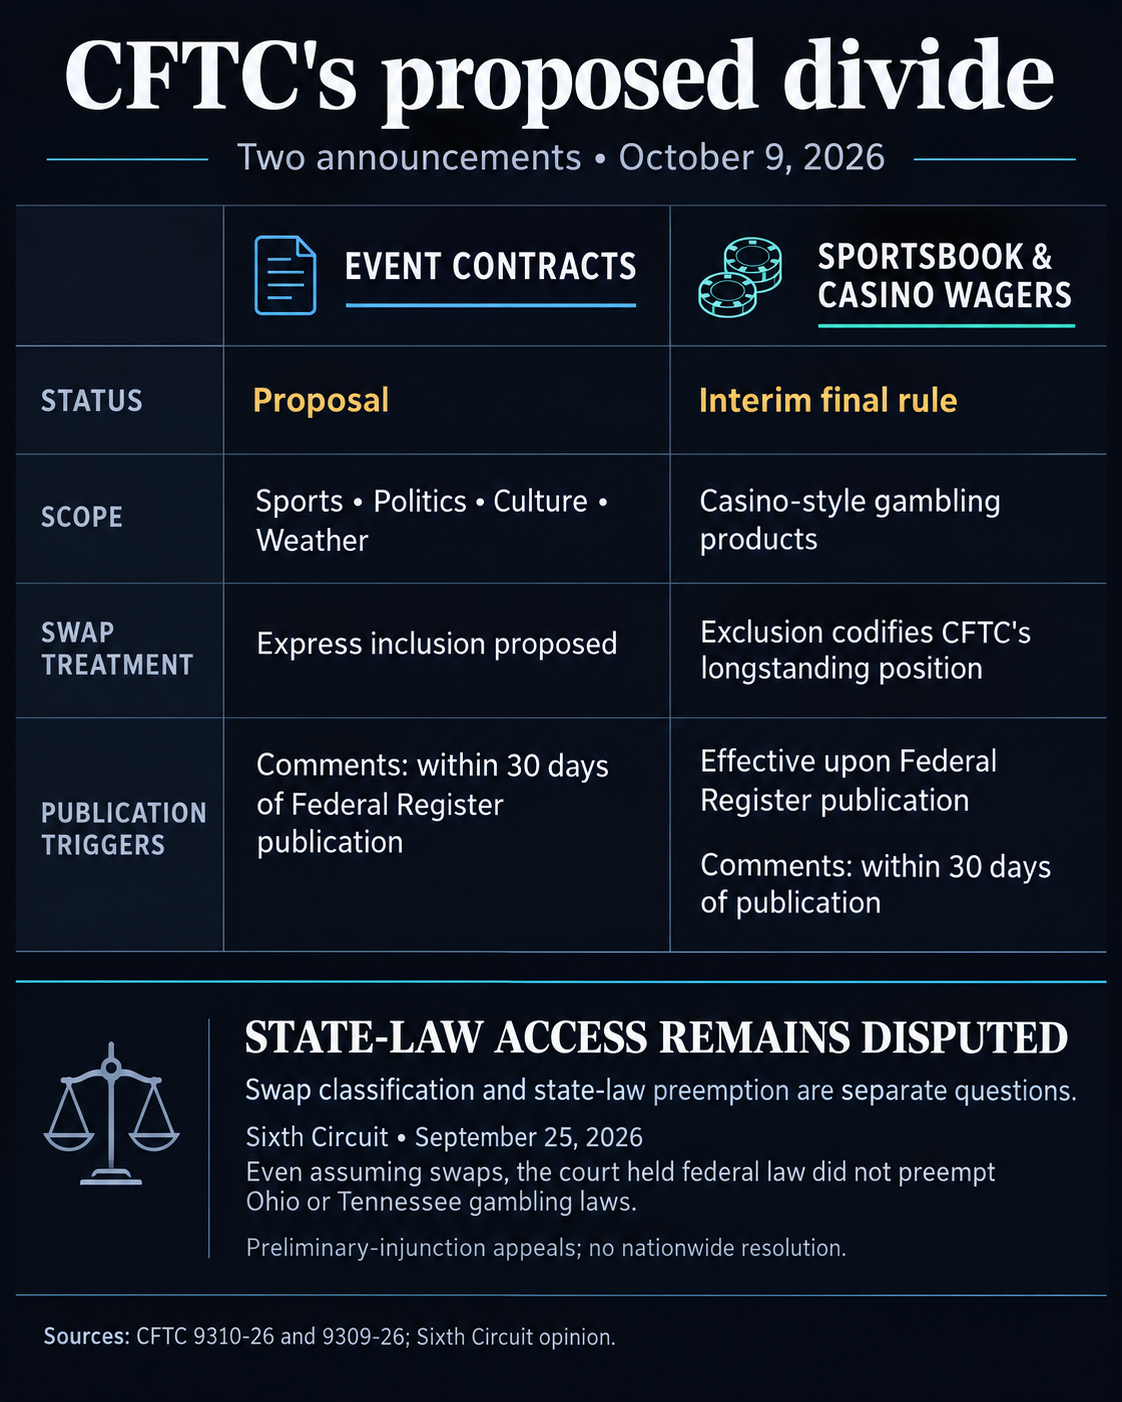
The Commodity Futures Trading Commission announced two actions on Oct. 9 seeking to clarify the federal regulatory boundary between prediction-market contracts and traditional gambling. It proposed expressly including sports and other event contracts in the definition of a swap, a category of financial derivative, while announcing a separate interim final rule to codify the exclusion of sportsbook and casino wagers.
The event-contract proposal covers sports, politics, cultural events and weather-related outcomes. CFTC Chairman Michael S. Selig said these products fall within the agency’s exclusive jurisdiction under the Commodity Exchange Act.
That classification matters because the products can look familiar to bettors. The CFTC explains that event contracts often let traders buy yes-or-no positions on a future outcome, with a fixed payout, usually $1. Their value depends on that outcome, and they can be used to hedge risk or speculate.
The distinction is visible in how platforms present their products: CryptoSlate’s Cloudbet sportsbook review examines odds-based wagers, while its Polymarket review examines tradeable outcome contracts.
The proposed inclusion is not final. The CFTC is seeking written comments through Regulations.gov within 30 days of the proposal’s publication in the Federal Register.
The casino-wager action is an interim final rule. The agency describes it as codifying its longstanding position that casino-style gambling products, including wagers placed on sportsbooks and casino games, fall outside the swap definition.
According to the CFTC, the exclusion takes effect immediately upon publication in the Federal Register. It also carries a 30-day comment window tied to that publication. Neither announcement specifies the Federal Register publication date, so the Oct. 9 date does not establish an effective date or comment deadline.
State-law disputes remain consequential
The agency’s classification position faces a separate legal question: whether federal regulation displaces state gambling laws.
In a Sept. 25 ruling on preliminary-injunction appeals involving prediction-market operator Kalshi, the Sixth Circuit held that the company had not shown its sports-event contracts met the statutory swap definition. It also held, alternatively, that even assuming the contracts were swaps, the Commodity Exchange Act did not expressly or impliedly preempt Ohio’s or Tennessee’s gambling laws.
That alternative holding illustrates the obstacle for operators seeking nationwide access: winning an argument about product classification does not necessarily win the argument over state authority.
The distinction also drew criticism from advocacy group Better Markets. In an Oct. 9 statement, securities-policy director Benjamin Schiffrin argued that sports event contracts enable sports betting and should remain subject to state gambling laws.
The post CFTC proposes a divide between prediction contracts and sportsbook wagers appeared first on CryptoSlate.
Luxor, a Bitcoin mining derivatives provider, reported a 6–13% annualized Bitcoin financing spread in its September lookback, published Oct. 9. It says lenders and Bitcoin treasury companies bought prepaid mining power and paired it with a price hedge, while miners used the reverse trade to obtain financing.
The return comes from the discount a miner accepts for receiving money upfront. The hedge can fix gross BTC receipts if mining delivery and settlement perform, while the investor’s capital remains exposed to failure in that repayment chain. Luxor’s reported September range does not establish an executed return after costs or a quote available today.
Where the Bitcoin return comes from
Mining power, or hashrate, produces revenue at a rate known as hashprice. Luxor’s contracts express that rate in Bitcoin or dollars per unit of computing power per day. Buying future mining power gives the purchaser exposure to the income that power generates over the contract period.
In a deliverable forward, the buyer pays the full purchase price upfront. The seller must deliver hashrate to Luxor’s Bitcoin Mining Pool, with the buyer’s daily BTC settlement tied to the hashprice index and contracted amount of mining power.
That prepayment supplies financing to the miner. Luxor says deliverable forwards typically trade below comparable non-deliverable forwards to compensate the buyer for credit risk and the cost of committing capital. The lower prepaid purchase price is the source of the lender’s potential profit.
Without a hedge, the buyer’s receipts would vary with the mining-revenue rate. The paired trade adds a sale of a non-deliverable forward, or NDF, which settles in cash rather than requiring physical mining-power delivery.
For the NDF seller, daily settlement is the agreed hashprice minus that day’s index rate, multiplied by the contracted hashrate. When the index is below the agreed price, the seller receives the difference. When it is above, the seller owes the difference.
If the two legs use the same BTC denomination, hashrate quantity, settlement dates and index methodology, their price exposures cancel. Fully delivered mining receipts at the daily index rate, plus the NDF settlement, equal receipts at the fixed NDF rate. The profit depends on how much those receipts exceed the prepaid purchase cost and other costs.
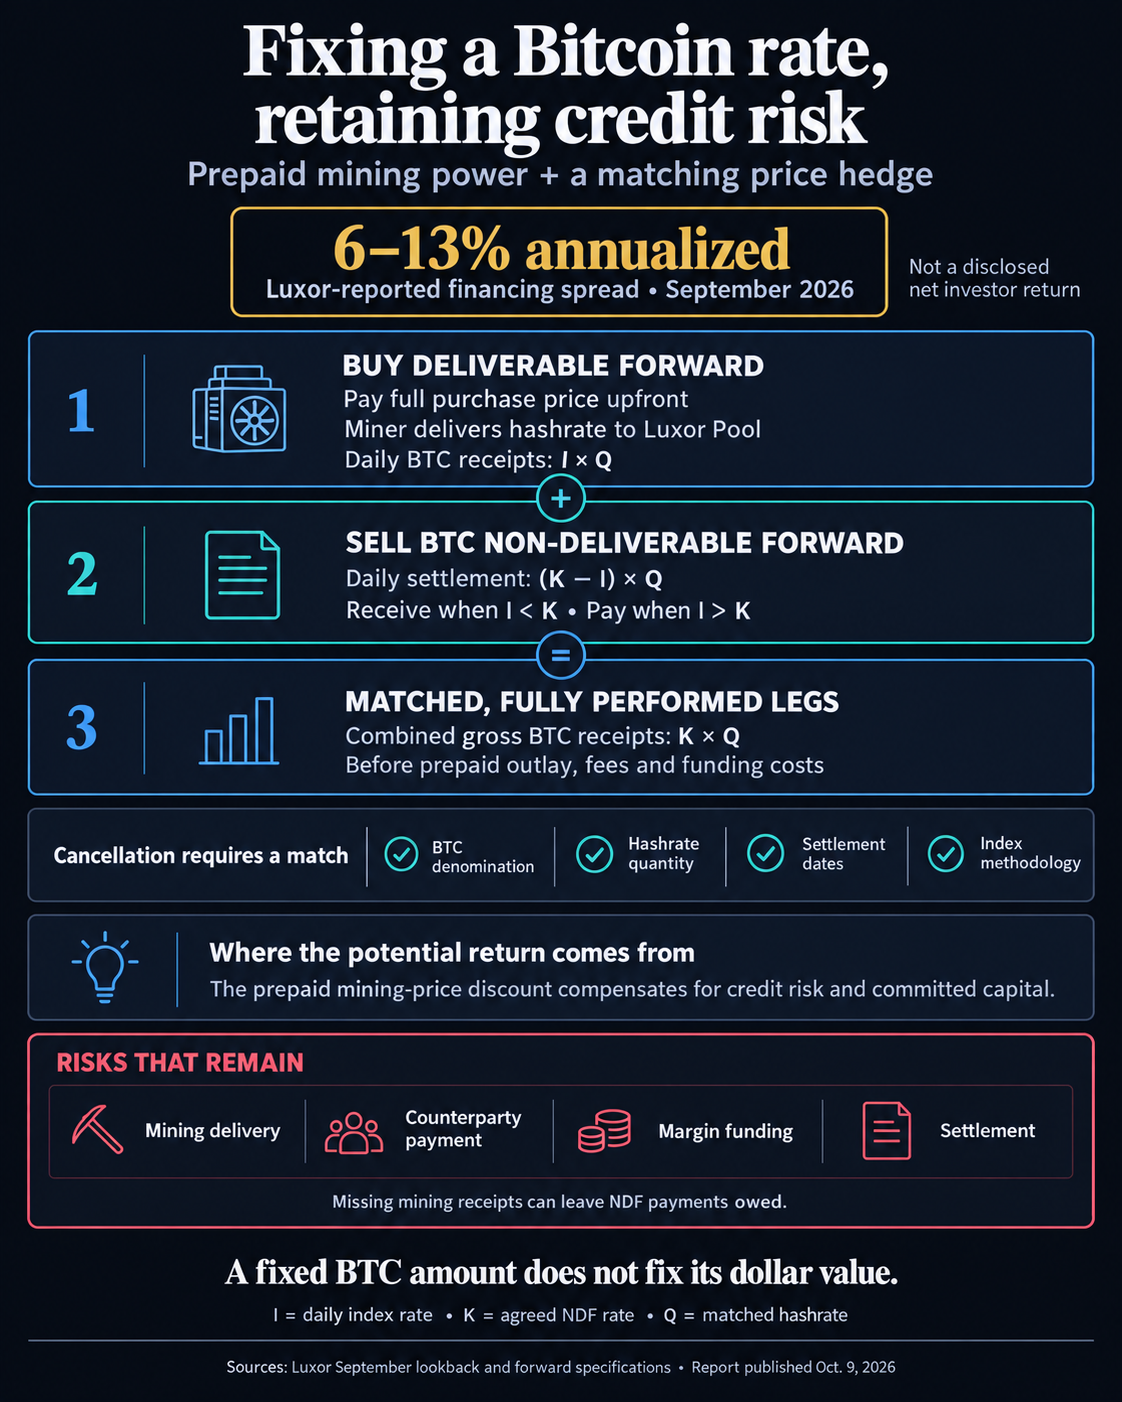
The matching conditions matter. A hedge covering different quantities or dates leaves part of the mining revenue exposed. A dollar-denominated contract also cannot simply be substituted for a BTC-denominated one while preserving the same Bitcoin payoff.
A BTC-denominated hedge also leaves the dollar value of Bitcoin receipts exposed to BTC/USD changes.
Luxor’s product pages describe monthly contracts up to 18 months out and custom durations. That is the general product range; the September financing discussion does not identify which tenors produced the reported 6–13%, or give its annualization formula.
Annualized pricing also does not mean an investor earns the quoted percentage over any shorter contract. The actual contract period, repayment timing, costs and capital committed across both legs determine the return on the investor’s funds.
Delivery failure can leave the hedge running
The cancellation works because the buyer receives the mining revenue against which the NDF settles. If promised mining power is not delivered and the shortfall is not cured, that revenue leg can be smaller than expected while the hedge still has settlement obligations.
When settlement hashprice exceeds the NDF’s fixed rate, the seller owes the difference, expecting higher mining receipts to offset it. If those receipts fail to arrive, the price hedge can require payment without the corresponding income.
There is also a distinction between the miner supplying the output and the investor’s contractual counterparty. Luxor’s order-book documentation says Luxor is counterparty to both the buyer and seller. The platform displays buy and sell orders, and its derivatives team contacts the parties to confirm trades; the book itself is not an execution system.
For an investor, that makes Luxor’s own performance part of the repayment chain alongside the mining operation.
Luxor’s upfront-payment procedures require seller credit profiling before money is advanced. The requirements cover mining-site and power documents, insurance, pool performance, financial statements and future obligations. Its margin policy also lists documentation for a performance bond or guarantor among its supplemental checks.
Credit checks reduce uncertainty about a seller’s ability to perform, while recovery after failure depends on enforceable claims. The public requirements do not specify a complete repayment priority or identify which assets an investor could enforce against after default.
For eligible investors, collateral custody and the ability to exit remain part of the credit exposure. The order book allows open orders to be canceled; that does not establish an exit from a confirmed forward.
Margin changes the capital calculation
Collateral determines how much additional capital may be needed to maintain the hedge. Luxor’s margin policy requires BTC collateral for BTC contracts and collects variation margin when the lower of realized and unrealized margin balances falls below maintenance requirements. Credit-qualified deliverable sellers can have custom procedures based on realized balances.
The policy describes initial margin as protection against potential exposure during the time needed to close out and replace a defaulted position.
The public schedules are not consistent: the NDF page quotes 18% BTC initial margin and the DF page quotes 18% seller hashprice margin plus possible delivery margin, while the general policy lists 17.5% BTC initial and 14% maintenance on non-offset future daily notional. The pages do not explain the difference.
The policy identifies Nov. 14, 2025, as its last initial-margin evaluation. Qualified BTC deliverable sellers can receive discretionary initial terms after supplemental credit profiling, so neither product-page rate establishes a universal requirement for the paired trade.
Prepaid DF buyers are exempt from that leg’s initial-margin schedule because they already pay in full. That exemption does not establish that their NDF leg is collateral-free.
That capital matters when comparing the reported spread with an investor’s net return. Fees, execution prices and any additional funds committed to support the hedge can affect the amount earned relative to the money put at risk.
Luxor’s Steelhead Capital Management case study describes the pairing in practice: Steelhead bought physical hashrate upfront, added an NDF to fix hashprice, and used Luxor Pool for delivery, reward distribution and settlement.
Luxor says daily repayment reduces exposure over the contract’s life. That supports the mechanism of returning funds progressively, while the remaining unpaid amount still depends on performance.
Access is also restricted. Luxor’s resources page says participants must qualify as Eligible Contract Participants. Its examples include entities with more than $10 million in assets and entities with at least $1 million in net worth hedging commercial risk. The structure is not universally available to retail Bitcoin holders.
The post Luxor’s reported 6–13% annualized Bitcoin yield depends on mining delivery appeared first on CryptoSlate.
CryptoTicker.io
Four companies sit behind almost everything still being built in Web3 gaming in 2026: Igloo Inc. with the Pudgy Penguins, Animoca Brands out of Hong Kong, Yuga Labs with the Bored Ape Yacht Club and Sky Mavis with Axie Infinity. Three of them have switched something off or handed something over this year, and one has set a date that concerns you if you hold a balance on the Abstract chain: it ends there on December 15, 2026.
This article works through the four companies one by one. What is still running, what has been discontinued, which token hangs on what, and how much of it a holder in Europe can actually get at. To see what became of the games themselves, the review of Illuvium, Axie and Sandbox is in our Web3 Gaming in 2026 piece. This one is about the companies behind them.
Web3 Gaming in 2026: These Four Companies Still Decide What Gets Built
Web3 gaming describes games whose items, currencies or plots of land sit on a blockchain as tokens, so that players can trade them outside the game. The sector has narrowed sharply since the boom of 2021. What is left is a handful of houses that run a brand, their own blockchain and a token all at once.
That triple role is expensive. A brand needs marketing, a blockchain needs operations and developers, a token needs liquidity. All four companies pulled back on at least one of the three in 2026. At Igloo it is the blockchain, at Yuga Labs the brands, at Animoca the route to the stock market, at Sky Mavis the rewards model.
Igloo Shuts Down the Abstract Layer 2 on December 15, 2026
Igloo Inc., the company behind the Pudgy Penguins, is closing its own blockchain. Abstract will be switched off on December 15, 2026. Chief executive Luca Netz announced the step on October 6, 2026, and the company confirmed it the following day. Once the network is off, balances still sitting on it will no longer be reachable, according to the team.
Abstract carries the only firm deadline in this entire text, and it is a hard one. If you hold tokens, NFTs or stablecoins on Abstract, you have a good two months to bridge them to Ethereum or another chain. Which wallet is up to that, and how custody types differ, is set out in our software wallet comparison.
What a Layer 2 Is, and Why Abstract Had One of Its Own
A layer 2 is a network that bundles transactions away from the main chain and settles them on Ethereum in batches, so that fees and waiting times fall. Abstract was such a layer 2, built for consumer applications rather than financial ones: sign-up without a classic wallet, small amounts, games and collectibles.
Reported reach differs between trade outlets. The figures cited are roughly 400,000 users and somewhere between a good 300 and 325 million transactions over the chain's lifetime. Both numbers come from the coverage of the shutdown rather than from audited accounts, which is why we give them as a range.
No Token, No ICO: Igloo Paid for Abstract Out of Its Own Cash
The notable part of the announcement is what did not happen. Igloo never issued a token for Abstract and never ran a coin offering to raise fresh money. On Netz's account, which several trade outlets report consistently, the company funded the chain quietly for 18 months out of its own pocket and lost a double-digit million sum in the process.
The reasons given for the ending are high running costs, thin liquidity, a weak supply of financial applications and little appetite among institutional investors. For holders, the conclusion is the part that counts: a chain of your own is not a mark of quality but a cost base that somebody has to carry indefinitely.
Pudgy Penguins After the End of Pudgy Party: The Browser Game Pudgy World Is What Remains
Abstract is not the first thing Igloo has discontinued this year. On June 12, 2026, the company announced it would stop developing the mobile game Pudgy Party. Built together with Mythical Games, it came out in August 2025 and was downloaded more than a million times, according to the coverage.
The reaction was blunt. Several trade outlets reported that the announcement named neither a refund nor a way to carry purchased items over into the remaining game. What is documented is the criticism, not a breach of law: whether buyers have a claim, and which, depends on the individual case and on the contract law of the country concerned.
What is left is Pudgy World, a free browser game Igloo has run since the spring of 2026 and on which the firm is now concentrating its resources. Add to that the part of the business that has little to do with blockchain: plush figures and collectibles, sold in US Walmart stores since a partnership struck in September 2023.
The token of the ecosystem is called PENGU, and it fell by around 7 percent after the Abstract announcement; sources date the drop to October 7 or 8, 2026. The point for holders: PENGU runs mainly on Solana and additionally on Ethereum and the BNB Chain, not on Abstract. The shutdown changes nothing there. How the price has moved since is in our PENGU price prediction.
Animoca Brands: The Currenc Group Merger Has Been on Ice Since September 22
Among the four, Animoca Brands is the odd one out: not a games company in the narrow sense but an investment house that has backed a very large number of projects in the sector while running products of its own, The Sandbox among them. The stock market listing was meant to be the big story of 2026. It became one, just not as planned.
On September 22, 2026, Animoca and the Nasdaq-listed Currenc Group said they were suspending their merger discussions. The statement says both sides concluded, after reviewing the expected closing timelines and the changed market environment, that the estimated interim period before completion did not fit their short- and medium-term strategic goals.
Animoca is sticking to the aim. In the same statement it says it remains fully committed to a listing on a major public exchange, and it points to its own timetable on the accounts: the audited annual report for 2023 was published on July 17, 2026, and the one for 2024 is in preparation. Co-founder and executive chairman Yat Siu is quoted saying the company's agility has to take priority and that it will keep pursuing the best routes to a listing.
What a Reverse Merger Is
In a reverse merger, a company that is not listed merges with an already listed shell and reaches a quotation without a conventional stock market flotation. The plan announced in November 2025 provided for Animoca's shareholders to hold roughly 95 percent of the combined company. In a mandatory filing, Currenc recorded that the previously extended exclusivity period had expired without a definitive agreement.
For investors in Europe, this is above all a way of placing the business model: a firm that stands behind many projects as an investor cannot be mapped onto any single token. Buying into Animoca would have required the share, and the share is precisely what remains unavailable on a major exchange for now.
Moca Chain: Animoca's New Layer 1 Aims at Digital Identity, Not at Games
A week after the merger fell away, something else at Animoca got going. On September 29, 2026, the Moca Foundation and Moca Network announced that the Moca Chain mainnet is live. Mainnet means the network is running in real operation with real value, no longer as a test environment.
Moca Chain is a layer 1, an independent blockchain with security of its own, and it is compatible with Ethereum's developer tooling. Its purpose is digital identity: companies can issue, verify, update and withdraw credentials, while the user decides which part of them to disclose. The MOCA token pays the network fees and serves staking as well as the verification processes.
What is striking is what is missing: the game. Animoca is shifting the focus away from playing and towards identity, credentials and applications for AI agents. Coverage of the launch names partners such as SK Planet, Lamborghini, OneFootball and Nansen; one trade service notes, however, that the statement does not distinguish which of these connections are already in production and which are pilots or plans. With ecosystem lists, that distinction is the single most important question.
Yuga Labs: New Chief Executive, Brands Handed Over, Everything on Otherside and ApeChain
Yuga Labs has the best-known brand in the sector and, at the same time, the clearest retrenchment behind it. In April 2026, long-serving product chief Michael Figge took over the leadership; co-founder Greg Solano, chief executive since February 2024, moved to the top of the board and said he would return to creative work.
Before that, the company had let go of two of its best-known acquisitions. The rights to CryptoPunks went to the non-profit Infinite Node Foundation, which is dedicated to preserving digital art, and the trademark rights to Moonbirds were also handed over. Yuga has concentrated on the Apes and on Otherside ever since.
Otherside is the metaverse part, open in the browser since November 12, 2025 and reachable with an email address or a wallet. A resource economy with 74 materials has been announced; no date is fixed for it. Yuga does not publish player numbers either, which makes the progress hard to place. Technically the whole thing runs on ApeChain, and the associated currency is ApeCoin, whose development is covered in our APE price prediction.
Governance has shifted along the way: the ApeCoin DAO, the voting community of token holders, was dissolved in 2025 and replaced by a company that Yuga controls. Anyone who understood APE as a say in decisions has been holding something else since then.
ApeFest 2026 on October 17: One Evening in a Studio in Charleston
How far the sector has shrunk shows in its annual gathering. ApeFest 2026 takes place on October 17 at the Beeple Studios in Charleston, South Carolina, as a single evening. Why barely any of the German Ape community is making the trip, we wrote up in our piece on ApeFest 2026.
Sky Mavis: bAXS Replaces AXS as the Reward, Atia's Legacy Is Stuck in Its Third Playtest
Sky Mavis, the studio behind Axie Infinity and the Ronin blockchain, rebuilt its rewards model in 2026. Since January 2026, a new so-called AppToken named bAXS has replaced the previous payouts in AXS; February brought an airdrop worth around $135,000 to bAXS holders. An airdrop is a free allocation of tokens to a defined group.
June 2026 saw the launch of Terrariums V1, an earnings system for owners of the Axie land plots. In July, Sky Mavis opened the third playtest for Atia's Legacy, the announced role-playing game in the Axie universe, this time with the emphasis on real-time combat. A release date is still not named, even though the game was held out for 2026 when it was announced in March 2025.
In parallel, the studio is handing responsibility over: further development of the original game Axie Classic passed to the player community in August 2026. On the blockchain side, Ronin distributes four- and five-figure dollar sums to developer studios at regular intervals through a programme called Proof of Distribution. How the main token is faring is in our AXS price prediction.
Active Wallets Are Not Players: What the DAUW Figure Really Measures
The metric DAUW, daily active unique wallets, turns up constantly in the sector's press releases. It counts how many addresses triggered at least one transaction with an application on a given day. What it does not count is people.
One person can run ten wallets, and many games reward exactly that. The other way round, a player who spends an hour in a game may trigger only a single transaction, while a script generates hundreds. A high wallet count therefore proves activity on the chain, but neither an audience nor revenue.
Abstract is the cleanest example of this from the past year. The chain reported hundreds of millions of transactions and six-figure user numbers and was discontinued all the same, because liquidity and earnings were missing. When a project shows you wallet numbers in future, the more useful question is: how much revenue stands behind them, and who pays for the operation?
Three Ecosystem Tokens Side by Side: 99 Percent Below Their All-Time Highs, and Still Up
We have laid the three tradable tokens of these four houses next to one another: PENGU for Pudgy Penguins, APE for Yuga Labs and AXS for Sky Mavis. Animoca has no main token of this kind, which is why there are three. The basis is the public price data of the market data service CoinGecko in euros, as of October 11, 2026, three verified values. This analysis was compiled by cryptoticker.io itself on October 11, 2026.
- PENGU: around 0.0072 euros, market value about 455 million euros. Up 9.9 percent over 30 days, down 66.9 percent over a year, and 88.9 percent below its peak of December 17, 2024.
- AXS: around 1.09 euros, market value about 190 million euros. Up 35.3 percent over 30 days, down 24.9 percent over a year, and 99.2 percent below its peak of November 6, 2021.
- APE: around 0.135 euros, market value about 135 million euros. Up 15.3 percent over 30 days, down 59.5 percent over a year, and 99.5 percent below its peak of April 28, 2022.
Two things stand out. First, all three sit far below their peaks, two of them so far that practically nothing of the valuations of the time is left. Second, all three are nonetheless up over 30 days, AXS markedly so. The two fit together once the tokens are read as what they currently are: small, mobile markets whose direction on the day has more to do with the general state of the market than with the progress of the company in question.
The market value also tells you something about the risk. All three sit in the hundreds of millions. At that size, comparatively small buy or sell orders already move the price noticeably, and the gap between bid and ask is wider than it is for the large caps.
MiCA and Custody: Where These Tokens Can Be Traded in Europe
Since the EU's MiCA regulation took effect, crypto services in Germany may only be provided by licensed firms. In practical terms: whether you can buy PENGU, APE or AXS depends not on the project but on whether your trading venue lists the pair and is licensed here. Smaller ecosystem tokens appear less often in the range of regulated providers than at the large international exchanges. Which venues are licensed in Germany and which tokens they carry is in our crypto exchange comparison.
On custody, the Abstract deadline comes on top. If you hold NFTs or tokens on a chain that is being switched off, the best wallet in the world is no help while the value stays there. Check in your wallet which network a holding actually sits on. The display in the app usually names the network right next to the balance.
Tax treatment holds nothing special for these tokens: in Germany, gains from a sale within one year fall under private disposal transactions, and after a holding period of one year the holding rule applies. Moving from one chain to another over a bridge can count as a swap, depending on how it is structured. If you are moving larger holdings, record the transactions with date and value and take tax advice if in doubt.
Web3 Gaming: December 15 Is the Only Hard Deadline
Of all four cases, only one carries a date that asks something of you. Everything else is context.
- Move Abstract holdings out before December 15, 2026. Open your wallet, check the network for every position, and bridge everything that sits on Abstract to Ethereum or another chain. Which wallet shows that cleanly is in the software wallet comparison.
- Check the trading venue before you buy. Small ecosystem tokens are not listed everywhere, and in thin markets the gap between bid and ask eats into part of the stake. The exchange comparison shows who is licensed in Germany.
- With NFTs, think about the marketplace too. A collectible is only as tradable as the marketplace it sits on, and marketplaces get shut down as well. Which ones are still open in 2026 is in the marketplace comparison.
(As of October 11, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
The cryptography protecting your $Bitcoin is nearly unbreakable. The front door of your house is not. France has just put a number on that uncomfortable truth: 90 cases of crypto-related kidnapping, abduction, extortion, threats and violent theft between January 1 and mid-August 2026, according to figures the French Interior Ministry provided to Cointelegraph. That is a new case roughly every two and a half days.
Police made 223 arrests and jailed 126 people over the period. And yet the attacks keep spreading, from Paris to Marseille, Strasbourg, Toulouse, Grenoble and Nantes.
Why Is France the World Capital of Crypto Wrench Attacks?
A "wrench attack" is crypto slang for the oldest hack in the book: skip the encryption and threaten the person holding the keys. France has topped the global leaderboard for years. Jameson Lopp's long-running directory of physical Bitcoin attacks counts 365 cases across 60 countries since 2014, with France in first place. Security firm Gart.io has tracked 73 French attacks so far in 2026, ahead of the United States at 66 and the United Kingdom at 27. Chainalysis counted 30 publicly known violent incidents in France through mid-year and conceded the real figure was almost certainly higher.
The Interior Ministry's 90 blows every one of those tallies out of the water. The ministry only began recording this category of crime on January 1, 2026, so there is no official year-on-year comparison. But Chainalysis data shows French attacks running well above their historical baseline since late 2024, and 2026 is on course to roughly quadruple the 19 known incidents of 2025.
How Did Leaked Tax Data Turn French Crypto Holders Into Targets?
Here is the part that should worry every crypto holder in Europe. Chainalysis head researcher Eric Jardine believes the surge is very likely linked to a significant data breach. In 2024, a tax official in the Paris region leaked personal, financial and crypto-holding information on French taxpayers. Attacks spiked from late November that year. In January 2026, French crypto tax platform Waltio disclosed a breach affecting around 50,000 users, handing criminals a second target list.
Such breaches reveal who owns crypto, how much, where they live and how to reach them. The attacker's hardest job, finding a victim worth the risk, is done before anyone picks up a wrench. Of the French victims with known residency, 93 percent were French nationals, not crypto-rich tourists. Critics such as Bull Bitcoin founder Francis Pouliot have gone further, arguing that the EU's DAC8 crypto reporting regime, which expands mandatory data collection on crypto users, has turned Know Your Customer into a kidnapping manual.
Why Are Criminals Kidnapping the Families of Crypto Investors?
The most chilling trend is who gets grabbed. Globally, relatives and acquaintances made up 25 to 30 percent of violent crypto incidents by early 2026. In France, that figure is over 40 percent.
In May, six men allegedly tried to abduct the wife of The Sandbox co-founder Sébastien Borget from the couple's home near Paris, with one attacker posing as a delivery driver to get the gate opened. In August, a couple in rural France endured three separate break-in attempts after buying a house previously owned by crypto millionaires whose leaked tax records still listed the address. In 2025, the father of a crypto entrepreneur was held for two days in Paris while kidnappers severed part of his finger and demanded $5.6 million. In Finistère this April, five members of one family were held at their home.
Jardine says the pattern shows criminals doing reconnaissance first: social media, blockchain analysis, leaked data, insider tips. French authorities now treat the cases as organized crime and route them through JUNALCO, the national organized-crime jurisdiction.
How Do You Protect Your Crypto From a Wrench Attack?
The standard playbook still matters. A hardware wallet, a metal seed backup stored away from home and a healthy suspicion of phishing links remain the baseline, and the CryptoTicker shop stocks vetted hardware wallets if yours is overdue an upgrade. But none of that stops someone who already knows your address.
The new rules are about information, not keys. Never discuss holdings publicly or on social media. Keep your name off exchange leaderboards and conference badges. Consider a multisig setup where no single person, including you, can move funds alone, and a time-locked "duress" wallet that can be handed over under threat. Check whether your tax software or exchange has had a breach, and if so, assume your address is already in criminal hands. As Cointelegraph put it, cryptography can protect a wallet, but it cannot stop a $5 wrench.
The Coinbase Card charges nothing for the payment itself at the till. Coinbase says as much for the EU version of the card: spending local currency, USD Coin or a supported cryptocurrency carries no transaction fee. The price of the card sits one level down, in the conversion and in the tax.
Neither item appears on any receipt, and both differ according to which balance you assign to the card. Paying with a stablecoin works out differently from selling bitcoin out of a holding. The difference is larger than any annual fee a conventional credit card charges.
Coinbase Card in Germany: A Visa Debit Card That Lives Only in the App
The Coinbase Card is a debit card on Visa rails. The balance does not come from a current account but draws on the balance in your Coinbase account. Before each payment you set in the app which asset feeds the card: euro balance, USD Coin or one of the supported cryptocurrencies.
Coinbase keeps a country list in its EU help pages on which Germany appears, alongside most EU states as well as Norway, Iceland, Liechtenstein and the United Kingdom. The card can be managed only in the mobile app; there is no way to apply through a browser. Sit at a desktop looking for the function and you are looking in the wrong place.
One feature sets the card apart from the US version: the American card is issued by a US bank and advertises a rewards programme. Many English-language reviews describe precisely that variant. Their figures on rewards, card price and ATM fees do not carry over to the European card, and this is where most of the errors in German comparison pieces begin.
No Transaction Fee: What Coinbase Charges for the Payment Itself
On card payments themselves, Coinbase is unambiguous. Its help page on the Coinbase Card for the EU states that no transaction fee applies to spending local currency, USD Coin or supported cryptocurrencies. Coinbase likewise levies no fee of its own on cash withdrawals, but notes that the operator of the machine may charge one.
That page blocks automated retrieval; in a reader's browser it opens normally. Two things are worth taking from it. First, a fee of zero on the payment is a real statement, not a marketing promise. Second, the commitment says nothing about the rate at which your balance is converted into euros, and the lever sits there.
The Conversion Is the Card's Real Price
A card payment out of a crypto balance is two transactions in one. The merchant receives euros, your holding gives up crypto assets. In between sits a sale that Coinbase executes at the moment of payment. The rate of that sale decides how much of your balance reaches the merchant.
Every trading venue earns at this point through the gap between the bid and the ask, the spread. With card business there is also the fact that the conversion does not happen on the professional order book but at the provider's retail price. How far apart the two lie can be measured, and the result is starker than most expect. A broader survey of the providers in this market we give elsewhere.
Our Own Measurement: On the Order Book the Conversion Costs 0.01 Percent
To pin down the order of magnitude, the newsroom analysed Coinbase's public order book for six euro pairs, as of Sunday night shortly after 1am. What was measured is the gap between the best bid and the best ask, precisely the distance a sale has to cross. Cryptoticker.io collected this data itself on October 11, 2026.
For bitcoin against the euro the gap stood at 0.0088 percent, for ether at 0.0116 percent, for USD Coin at 0.0112 percent. Solana came in at 0.0204 percent, XRP at 0.0080 percent, and Cardano, the widest, at 0.0498 percent. The median across the six pairs is 0.0116 percent. Bitcoin was quoted at around 74,020 euros at the time; how the price has moved lately is covered in our bitcoin price prediction.
The finding is awkward for any account that explains high card costs by a thin market. The market itself is practically free at this point. A hundred euros of turnover costs a little over a cent on the order book. Everything you pay above that is the provider's margin on the retail price, not an imperfection in the market.
One caveat belongs with it: what was measured is the professional order book, not the rate the card draws at the moment of payment. The measurement therefore does not prove how expensive your particular payment was. The figure marks where the floor lies, and it makes any claim of two, three or four percent readable as what it is: a mark-up that is set, not one that arises.
USD Coin or Bitcoin: The Balance You Choose Decides the Cost
From this mechanism follows the card's most important setting. Pay out of a euro balance and no conversion happens at all. Pay out of a dollar stablecoin such as USD Coin and only the currency changes, while the value of the balance barely moves. Pay out of bitcoin or ether, by contrast, and every coffee sells off part of your holding at that day's rate.
The independent reviews describe this point identically throughout, even where their figures contradict one another: spending a stablecoin or fiat largely avoids the conversion mark-up, while spending a volatile cryptocurrency pays it on every single payment. The choice of balance in the app is therefore the one setting that governs the card's running costs.
ATMs and Foreign Currency: Where Additional Costs Can Arise
Two items sit outside the zero fee. At the ATM, Coinbase charges nothing by its own account, but the machine's operator is free to bill. Abroad, or on a payment in a foreign currency, Visa's conversion and a possible mark-up from the card programme are added.
This is exactly where the figures in public circulation diverge widely, which is why the next section lays them out rather than adopting one of them. Anyone planning to use the card on holiday should read the foreign-currency rule in the app before departure, not in a review.
Holding Period and Section 23 of the Income Tax Act: Every Card Payment Is a Sale
The second block of costs is fiscal. Crypto assets held privately count as other assets. Handing them over amounts to a disposal within the meaning of section 23(1) sentence 1 no. 2 of the German Income Tax Act, and a card payment is such a handover. Every purchase made with a bitcoin balance is therefore a private disposal.
What matters is how long the coins spent had been in the holding beforehand. Where more than a year lies between acquisition and payment, the gain stays tax-free regardless of size. Within a year, the gain counts towards the year's private disposals. A threshold of 1,000 euros applies there, raised from 600 euros previously, and it is a threshold rather than an allowance: one euro above it makes the entire gain taxable.
The practical consequence is that a card debiting small amounts daily from a young holding generates a long list of tax-relevant events. Each one needs an acquisition date, acquisition cost and disposal proceeds. How to keep that cleanly is set out at length in our piece on the fact that every payment with a crypto credit card is a sale; the tools for it are in our comparison of tax software and portfolio trackers.
MiCA Supervision: Which Entity Coinbase Serves Its EU Customers Through
Since the European crypto regulation MiCA took full effect, every provider supplying crypto services in the EU needs authorisation as a crypto-asset service provider. Coinbase serves the European market through the Luxembourg entity Coinbase Luxembourg S.A., which appears in the public supervisory registers as an authorised provider, among them the white list of the French regulator AMF.
For a cardholder this is no sideshow. The authorisation determines which supervisor is competent, which disclosure duties apply and whom to turn to with a complaint. The same move pays off with every card provider: look for the name of the contracting entity in the small print and check it against the public registers. If nothing is there, that is the answer.
The Figures From Comparison Sites Diverge Widely
Anyone looking for concrete euro amounts for the European card finds contradictory information. One portal cites an issuance fee of 4.95 euros, no monthly fee and a mark-up of 2.69 percent on the payment, plus free withdrawals up to a small amount and one percent thereafter. Another lists a foreign-currency fee of 2.49 percent, a daily limit of 2,500 euros for payments and 1,000 euros at the ATM, and total conversion costs of around four percent. A third, visibly several years old, cites different limits again.
None of these numbers could be confirmed against a primary source, and they contradict one another. They stand here as a range rather than a fact: issuance of the card is given as just under five euros, the foreign-currency mark-up as 2.49 to 2.69 percent, the total cost of a conversion as up to roughly four percent. The only binding figures are those the app shows you before you order and before your first payment.
The gap between a good four percent in a review and 0.0088 percent on the order book is the heart of the matter. The distance shows how much room lies between market price and retail price, and it explains why two users of the same card can have entirely different experiences, depending on what they pay with.
Our Assessment: Without a Stablecoin Balance the Card Rarely Adds Up
In the newsroom's view the Coinbase Card is usable as a means of payment and unsuitable as an investment instrument. Three documented points support it: Coinbase levies no fee on the payment by its own account, the market environment is practically frictionless with a median order-book spread of 0.0116 percent, and the tax consequence can largely be steered through the choice of balance.
Against it, equally documented, stands the fact that the actual retail costs are not cleanly documented in public and that the figures in circulation diverge from the market spread by a factor of a hundred. Paying regularly out of a bitcoin holding younger than a year combines an opaque mark-up with a tax liability on every single purchase. None of this is a recommendation for or against the card; it is the condition under which the card makes sense: as a spending route for euros or stablecoins, not as a sales channel for a long-term holding. Crypto assets can swing sharply, up to total loss.
Coinbase Card: Zero Fee, but Every Payment Is a Sale
- Open the card overview in the app and check which balance feeds the card. If a volatile cryptocurrency is set there, switch to euros or a stablecoin before you next pay. Which cards also allow that switch is shown in our comparison of crypto credit cards.
- Read the fee and limit page in the app before you first use the card abroad. Foreign currency and the ATM are the two items outside the zero fee, and only the app shows the values that apply to your account. For getting started by other routes, our piece on buying bitcoin by credit card helps.
- Set up your records before the first payment runs, not in May of the following year. Every card payment out of a crypto balance needs an acquisition date, acquisition cost and proceeds. The tools for it are in our comparison of tax software and portfolio trackers.
(As of October 11, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Polkadot staking currently pays 2.77 percent a year, and the exit takes 28 days. Those two numbers decide whether nominating is worth it for you. On 1,000 DOT that comes to about 27.7 DOT a year, or roughly 31 euros on a stake of 1,120 euros at a price of 1.12 euros. Over the same period the price can move more in a single day than staking earns in eight months.
This article weighs the two against each other: what the network pays, what is left of it after the validator's commission, how much you need at a minimum, and what the four-week lock-up really costs. All figures are from October 11, 2026.
Polkadot Pays 2.77 Percent a Year: How the Staking Yield Is Built
Staking rewards do not come from a provider but from the protocol itself. Polkadot issues new DOT continuously and hands them to the validators that build blocks and to the nominators that put their stake behind those validators. The data service Staking Rewards puts Polkadot's reward rate at 2.77 percent a year on October 11, with 913.06 million DOT staked and a staking ratio of 53.5 percent.
That ratio is the lever behind the yield. New issuance is spread across every staked DOT. If the ratio rises, more units share the same pot and the rate per unit falls. If the ratio drops, the rate climbs. Just over half of Polkadot's circulating supply sits in staking, and that holds the rate at today's level.
The reward rate describes how much your holding grows in DOT terms over a year, before commissions are deducted. It says nothing about the price. Nominate 1,000 DOT and you hold roughly 1,027 DOT a year later; what those are worth is a separate question.
Nominated Proof of Stake: Your DOT Sit Behind a Validator
Polkadot secures its chain through nominated proof of stake, or NPoS. Validators run the nodes and produce the blocks. Nominators own DOT and name up to sixteen validators to lend their stake to. The election runs afresh every epoch, and the procedure spreads the stake so that as many validators as possible are backed by similar amounts.
Your DOT never leave your control. The units are bonded, not transferred. The validator can neither spend them nor withdraw them. What it can do is make mistakes, and you are liable alongside it. More on that below, under slashing.
The protocol caps how many nominators are considered in any one epoch. The Polkadot wiki puts the number at around 22,500 slots, because the validator election has to finish within the computing time of a single block. Miss the cut and you earn nothing in that epoch.
Unbonding: The 28-Day Lock-Up Ties Up Your DOT for Four Weeks
To take your stake back you start the unbonding process. Twenty-eight epochs then pass, which on Polkadot means 28 days, before the DOT are freely available again. The wiki gives the same period for direct nomination and for nomination pools. For four weeks you can neither sell the units nor send them to another address.
The reason lies in the security of the chain. An attacker who misbehaves should not be able to move capital to safety within seconds. The waiting period is the collateral. How other networks handle this, and where the periods diverge, is set out in our comparison of the staking lock-up across five networks.
While the clock runs you carry the price risk with no way to act. This is where a small yield turns into a serious trade-off.
One 1.98 Percent Day Outweighs Eight Months of Staking Rewards
Break the annual yield down to a single day: 2.77 percent divided by 365 comes to roughly 0.0076 percent a day. DOT moved 1.98 percent in the 24 hours to October 11, according to CoinGecko, to $1.26, or 1.12 euros. That one day's move is worth about 261 days of staking rewards, a little over eight months.
For an investor who intends to hold DOT for years anyway, little changes. They take the 2.77 percent as a bonus and sit out the swings. Anyone who wants to be able to sell within the next few weeks pays for the same bonus with four weeks of immobility. At a price that travels two percent on a quiet day, the lock-up is the more expensive side of the deal.
Nomination Pool From 1 DOT: Entry Without the Direct Nomination Minimum
There are two routes into staking, and their entry barriers differ sharply. With direct nomination you name validators yourself and need a stake above the so-called minimum active bond. With a nomination pool you combine your DOT with those of others; the pool appears to the protocol as a single nominator.
The Polkadot wiki puts the entry threshold for pools at one DOT. At today's price that is 1.12 euros. For small holdings the pool is effectively the only way to take part in staking natively without putting an exchange in between. The pools are non-custodial: the DOT stay under your control, and a pool operator merely makes sure the bundled stake sits behind active validators.
Bundling has one catch. If the entire pool falls below the minimum stake it counts as inactive and earns nothing, for every member at once. And switching pools means unbonding in full first, with the same 28 days of waiting.
Minimum Active Bond: Why the Nominator Minimum Keeps Moving
The minimum active bond is the amount you have to put up under direct nomination to earn rewards in an epoch. No fixed figure for it appears anywhere in the protocol, and the reason is understandable: because only around 22,500 nominators fit into any one epoch's election, the threshold emerges from competition. If many apply with large amounts, it rises; if capital leaves, it falls.
Two things follow for investors. First, a stake that is enough today can be too small a few epochs later without anything having been done wrong. Second, check the current value in the official staking dashboard before you bond a larger amount. Pools do not have this problem at member level, because there the pool as a whole has to clear or miss the threshold.
Validator Commission: What Reaches You Out of the 2.77 Percent
Rewards flow to the validator first. It deducts its commission, and only the remainder is distributed pro rata among everyone standing behind it. The Polkadot wiki describes it that way, and that is precisely why the published network yield is a ceiling rather than a payout.
Commissions vary widely in practice. A validator with a low commission leaves you almost the full rate; one with a high commission can keep back a noticeable share. Because you name up to sixteen validators, your result is a blend of their rates. The same gap between network yield and payout exists on other networks; with Ethereum staking it was recently measurable across 14 providers.
Before nominating, then, it pays to look at each candidate's commission, its uptime and how much stake already sits behind it. If you would rather not make that selection yourself, the alternatives are in our comparison of regulated crypto exchanges.
Slashing: When Your Stake Is Liable for the Validator's Mistake
Slashing is the forfeiture of part of the staked capital when a validator misbehaves. Two cases are typical: the node is unreachable for an extended period, or it signs two conflicting blocks. The stake behind it is hit as well, pro rata.
That is the price of your capital securing the chain. Hand the selection decision to a pool and you carry the risk together with every other member. The wiki describes a deferred procedure for pools, under which the forfeiture is apportioned among the members.
Inflation of 1.48 Percent and a Cap at 2.1 Billion DOT
Where the rewards come from has changed fundamentally. Polkadot used to issue a fixed 120 million new DOT every year. Referendum 1710, implemented in January 2026, set a ceiling of 2.1 billion DOT and a stepped schedule: every two years, 13.14 percent of the remaining distance to that ceiling is paid out, beginning on March 14, 2026. The closer the circulating supply moves to the cap, the less is added.
The arithmetic can be followed through. CoinGecko puts the circulating supply at 1.707 billion DOT, leaving roughly 393 million to the cap. 13.14 percent of that is just under 51.7 million DOT over two years, or about 25.8 million a year. Measured against the circulating supply, the figure is 1.51 percent. Staking Rewards measures inflation of 1.48 percent on the same day, so the formula from the vote and the measured value line up.
Of those roughly 25.8 million new DOT, about 25.3 million go to stakers on the arithmetic, since 2.77 percent of 913.06 million staked DOT comes to exactly that amount. The treasury is left with only a small remainder today, far less than the 15 percent of the old model.
Our assessment: the real value of staking at Polkadot currently lies less in the 2.77 percent than in the ratio to dilution. Holders who do not stake lose roughly 1.51 percent of their share of the total supply each year. Those who do stake receive 2.77 percent, which puts them at about 1.2 percent real growth. The advantage is genuine but small, and it justifies the lock-up only for holdings meant to sit still anyway. Against it stands the volatility of the price: 1.98 percent in a day wipes out that annual edge within hours. None of this is a recommendation to buy, and a total loss remains possible with any crypto asset.
Staking Through an Exchange: The Waiting Period Sits in the Terms
Many investors stake through an exchange that offers the process as a service instead of nominating themselves. That changes the legal setup behind the yield. The wiki draws an explicit line between nomination pools and custodial solutions: in a pool the keys stay with you, at an exchange the DOT sit at the exchange's own address.
The protocol then no longer sets the terms. Payout rhythm, the share withheld and above all the time to release are written into the provider's terms and conditions. Some exchanges settle the exit faster than 28 days because they reshuffle internally; others take longer. Which providers in Germany need a licence for such services at all is set out in our overview of staking under MiCA.
Tax on Staking Income: Receipt, the 256-Euro Threshold and the Holding Period
Staking rewards in Germany are ordinarily other income under section 22 no. 3 of the Income Tax Act. Tax attaches on receipt, meaning the value of the DOT at the moment they are credited to you. The statute sets a threshold for it: such income is not subject to income tax if it came to less than 256 euros in the calendar year.
A threshold is not an allowance. At 255 euros in rewards you pay nothing; at 256 euros the full amount becomes taxable. At today's rate of 2.77 percent and a price of 1.12 euros, you reach that threshold at around 8,250 staked DOT, a stake of just over 9,200 euros. Below that the income is tax-free in itself, provided you have no other income of this kind in the same year.
A separate question is when the DOT themselves can be sold tax-free. Section 23 of the Income Tax Act applies there, with the one-year period for private disposals and a threshold of its own of 1,000 euros per calendar year. The pitfalls between receipt and sale are covered in our overview of staking and taxes in Germany; for the sale of the units received we have written up the two most common tax cases separately.
Setting Up Polkadot Staking: How to Proceed From Purchase to Nomination
Staking natively requires the DOT on an address of your own, not in an exchange account. The route runs through a wallet that supports Polkadot, a transfer of the purchased units to it, and then the choice between a pool and direct nomination. The official staking dashboard makes both routes possible without programming knowledge.
Before bonding, note down three values: the current minimum active bond, the commission of the validators you intend to name, and the date on which you bonded. The last point sounds trivial but decides your tax return, and it decides the point from which the 28 days run should you want to exit.
And keep part of your holding free. Bond everything and you have four weeks with no way to react if something changes in the market or in your own circumstances.
Polkadot Staking: 28 Days Locked Against 2.77 Percent a Year
The numbers are on the table: 2.77 percent in rewards, 1.51 percent in dilution, around 1.2 percent in real growth, against 28 days without access at a price that travels two percent on an ordinary day. Three steps lead from here to a decision:
- Settle the purchase route and custody. Native nomination requires an address of your own. Where to get DOT in Germany, on what terms, and which venues are regulated is shown in our comparison of the best crypto exchanges.
- Decide between a pool and direct nomination. Below the minimum active bond the nomination pool starts at one DOT. Above it the commissions are worth a look, and for custodial offerings our overview of staking platforms helps compare terms.
- Record receipts from the start. Every credit needs a date and a price, or the 256-euro threshold later becomes an estimate. Tools for that are in our comparison of tax software and portfolio trackers.
(As of October 11, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Setting up a Trust Wallet takes less than five minutes. What matters is what happens to twelve words during those minutes: on first launch the app generates a secret phrase, and those twelve words are afterwards the only way into everything the wallet holds. There is no "forgot password" function, and no custodian to help out in case of doubt.
Three mistakes cost beginners money most often, and all three happen during setup: saving the twelve words as a photo or a note on the same phone, putting the backup off until later, and sending the first transfer over the wrong network. This guide walks the path from download to first deposit, then answers the questions that come up in daily use: what a swap in the app really costs, why the network list has been shorter since September 2026, how the German tax office treats self-custodied coins, and why no supervisory authority is responsible for your wallet.
Trust Wallet at a glance: a wallet with no account and no custodian
Trust Wallet is a non-custodial wallet. The term simply means this: the private keys to your coins sit on your device alone, the provider does not know them and can therefore neither dispose of your balance nor freeze it. That sets the app apart from an exchange account, where the coins are held in the exchange's name and you only hold a claim to them.
The wallet was built in 2017 by Viktor Radchenko. Binance acquired it in 2018; it later became an independent company owned by Binance founder Changpeng Zhao. It exists as an app for iOS and Android and as an extension for Chrome, Brave and Edge. According to company figures, more than 220 million people use it in 2026, and it covers over 100 blockchain networks, among them the two largest around Bitcoin and Ethereum.
You do not open an account in the usual sense. There is no email sign-up, no identity check and nothing that could be reset. How the app performs in daily use is covered in our review of Trust Wallet; this article is about setup and about what applies to you legally and fiscally afterwards.
Trust Wallet setup: the guide in six steps
Download the app only from the official App Store, the Play Store or your browser's own store. Fake wallet apps are the single most common trap, and they look deceptively like the original.
The first steps in the app
After launch you choose "Create new wallet". The app first sets up a device lock, meaning a passcode or Face ID. That lock only protects access on the device itself and does not replace backing up the twelve words.
Next you go to settings via the gear icon, select your wallet and start the manual backup. The app asks for confirmation by code or Face ID and makes you tick several boxes confirming that you understand what the secret phrase means.
Backing up the twelve words
Now the app shows the twelve words. Copy them out by hand, in exactly that order. Screenshots and screen recordings are deliberately blocked at this point, and that is not a feature designed to annoy: a photo in your gallery ends up in the phone's cloud backup and therefore on a server you do not control.
In the final step you type the words back in the right order as a check. Only then is the wallet set up, and only then should you send the first amount to it. Reverse that order and deposit first, and a device failure leaves you with nothing.
MiCA and self-custody: no authority is responsible for your own wallet
Under the European crypto regulation MiCA, exchanges and custodians need a licence and fall under supervision, in Germany under BaFin. None of that applies to Trust Wallet, and the reason sits in the regulation itself. Regulation (EU) 2023/1114 defines custody in Article 3(1)(17) as "the safekeeping or controlling, on behalf of clients, of crypto-assets or of the means of access to such crypto-assets, where applicable in the form of private cryptographic keys". A provider that never holds the keys is not supplying that service.
That cuts two ways for you. Nobody can block your balance, and nobody demands an identity check. At the same time none of the protective rules MiCA imposes on licensed providers apply: no duty to segregate client funds, no complaints body, no liability in case of loss. Combining both means buying at a supervised trading venue and then holding the coins yourself; our comparison of regulated crypto exchanges gives an overview.
Receiving addresses in Trust Wallet: one address per network
A receiving address is the string someone sends coins to. You find it in the app by selecting a coin and tapping "Receive". The app then shows the address and a QR code.
The most expensive misunderstanding sits right here: every blockchain has its own addresses, and the same string can look valid on several networks. Send a token over a network on which this wallet does not hold the destination address, and it lands on a key the app never shows you. Technically the coins are not gone; practically you cannot reach them again without a detour via the private key, and on some chains not at all.
Only one route is reliable: select the coin in the wallet, copy the address there, and set the sender to the same network the wallet names. For a first transfer to a new address, a small test amount is worth it before the full sum goes out.
Networks and gas fees: 25 chains fewer since September 2026
The number of supported networks is not a fixed quantity. As we reported on 31 August 2026, Trust Wallet removed built-in support for 25 blockchain networks from the app as of 15 September 2026, among them MultiversX, Polygon zkEVM and Moonbeam. The coins stay on the blockchain and remain yours; what disappeared is convenient access. For most of these chains the network can be added back by hand, for nine of them that route is closed, as our analysis of the 25 networks being dropped sets out case by case.
Before the first deposit, therefore: check whether the chain your token sits on is carried in this wallet at all. For niche chains, a wallet from the project itself is often the more durable choice.
Separately, every transfer costs a network fee, known as gas. That fee goes to the blockchain and not to the wallet provider, and it falls due in the currency of the chain concerned. The practical consequence: without a small remainder of the network currency you cannot move a token, even when it is visible in the app. Sending a token to a fresh chain works best with a little network currency sent after it.
What a swap in Trust Wallet costs
The app can exchange tokens directly, with no detour via an exchange. On its own swap page, Trust Wallet states that it charges no additional service fee for swaps; any costs incurred are network fees and fees of the connected third-party providers, which are independent of the wallet provider. The page names ThorChain, 1inch, Mimic and Axelar among those providers.
A swap is therefore not free. The price sits in the fee of the trading venue the app routes the swap through, and in the price gap between buying and selling. Both become visible in the preview before confirmation, which states the amount that will actually arrive. That preview is the only reliable cost figure, because it hangs on the liquidity of the moment rather than on a fixed percentage.
A note on a feature that has been prominent in the app since 2026: the wallet also offers futures contracts with leverage of up to one hundred times. Leverage like that wipes out the entire amount staked on a price move of just one percent against the position. This product has nothing to do with setting up a wallet for custody.
Through the built-in Web3 browser the app also connects to decentralised applications. Each of those connections asks for an approval that lets a contract move tokens out of your wallet. Such approvals stay in force indefinitely, even long after you have closed the site, and they are one of the most common routes by which balances drain out of a self-custodied wallet. Review the approvals you have granted at regular intervals and revoke whatever you no longer need.
Tax and the tax office: the one-year holding period applies in your own wallet too
For private individuals in Germany, crypto-assets count as other assets within the meaning of the Income Tax Act. Under section 23(1) sentence 1 no. 2 EStG, a sale is taxable if no more than one year lies between acquisition and disposal. After one year the gain is tax-free, whatever its size.
Below that period an exemption threshold applies: under section 23(3) sentence 5 EStG, gains stay tax-free if the total gain from all private disposals in the calendar year comes to less than 1,000 euros. The word threshold is to be taken literally. At a gain of 999 euros you pay nothing; at 1,000 euros the full amount becomes taxable, not merely the part above it.
What moving into your own wallet triggers
Transferring coins from an exchange into your own Trust Wallet is not a sale and therefore triggers no tax. The one-year clock keeps running unchanged from the original purchase. The catch lies in the evidence: the exchange knows when you bought, the wallet does not. Without a record of your own, the very date you need to establish the tax exemption is missing later.
Germany's Federal Ministry of Finance restated the requirements for this in its letter of 6 March 2025 on the income tax treatment of crypto-assets; the cooperation and record-keeping duties appear there from margin number 87. The tax office gains no access to your wallet through that, because there is no interface and no custodian it could ask. The burden sits with you: anyone unable to evidence the acquisition date loses the argument for the tax exemption in case of doubt. So when you move coins, save the exchange statement and note the receiving address along with the date.
Moving to a new phone: the import via the secret phrase
The wallet does not travel with the device, it travels with the twelve words. On the new device you install the app from the official store, choose "I already have a wallet" at launch instead of creating one, opt for the import via the secret phrase and enter the words in the order you backed up. The holdings then reappear; individual tokens occasionally have to be made visible by hand through the search.
One point to understand: your coins never sit in the app, they sit on the blockchain. The twelve words are only the key to them, and they work in other compatible wallet apps as well. That is the real advantage of an open standard, because you are not tied to this one provider.
And that is exactly where the risk sits too. Whoever knows the twelve words needs neither your phone nor your password. Hence the ground rule that outweighs all others: the recovery phrase belongs on paper or metal, never in a photo, a notes app, a cloud password manager or an email to yourself. Which storage forms prove themselves in practice, and where an additional passphrase makes sense, is covered at length in our piece on storing a seed phrase safely.
Software wallet versus hardware wallet: where the line runs for larger amounts
Trust Wallet is a hot wallet. The keys sit on a device connected to the internet, one that also runs a browser, messengers and any number of other apps. The device lock protects against theft of the phone; against malware on that same device it offers only limited protection.
A hardware wallet instead keeps the key on a device that never goes online and requires every transfer to be confirmed by pressing a button. The difference only becomes relevant at amounts whose loss would hurt. A rule of thumb has proved itself: what you move in a month may sit in the software wallet; what you intend to hold for years belongs on a separate device.
That split costs nothing beyond the price of the device, and it can be done at any time later, because the coins sit on the blockchain and only the key moves.
Our view: what Trust Wallet is good for and what it is not
In the newsroom's view, Trust Wallet is a good first wallet and a poor only wallet. Its breadth argues for it as an entry point: over 100 networks in one app, a swap without the provider's own service fee, and an open standard that does not bind you. Against it stand three points that can be evidenced. First, the removal of 25 networks as of 15 September 2026, which shows that the supported scope is a business decision and not a commitment. Second, the absence of any supervision, which follows directly from Article 3 of the MiCA regulation and rules out any complaints body in case of loss. Third, the leveraged products of up to one hundred times, which sit one tap away from custody in the same app and carry an entirely different risk.
That leads us to limit its use rather than pass judgement on the app: yes as an everyday wallet for manageable amounts, no as a vault for the bulk of your assets. Total loss is possible with any form of self-custody, and it hits the person who loses the twelve words just as hard as the one they are stolen from.
Trust Wallet: without a backup of the twelve words the balance is gone
Three steps that keep the setup sound over time:
- Back up first, deposit second. Write the twelve words out by hand, keep them outside your home or in a safe, and test the backup with a small trial amount that you restore on a second device. Which app suits that best is shown in our comparison of software wallets.
- Document from day one. Record the date, amount and origin of every incoming transfer, because the one-year period under section 23 EStG is yours to evidence. Tools that log this automatically are in our overview of crypto tax software and portfolio trackers.
- Draw the upper limit. Decide what amount may sit in the app at most and move everything above it to a separate device. The selection for that is in our hardware wallet comparison.
(As of October 10, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
A proposed rule would expressly fold event contracts tied to sports, politics, culture and weather into the “swap” definition, while an interim rule excludes casino-style gambling—sharpening the agency’s claim to exclusive jurisdiction.
The Bermuda-based insurer, which runs entirely on Bitcoin, drew the funding from existing backers led by Bain Capital Crypto after a record year driven by demand from wealthy families in Asia, Europe and the Middle East.
Physicists at George Washington University say a formula can estimate when an AI chatbot will flip from good answers to bad ones, and early tests on small models back it up.
A National Assembly committee adopted amendments taxing stablecoin swaps and crypto exits by wealthy holders, then rejected the 2027 budget's revenue section.
Executives are war-gaming the political fallout of a major AI-driven cyberattack and preparing to brief Congress fast if and when necessary.
U.Today - IT, AI and Fintech Daily News for You Today
This week’s top stories: October 4–10.
The surge puts Shiba Inu layer 2 Shibarium’s transaction activity back in focus.
BTC Pioneer Adam Back Takes Aim at Ethereum in favor of Bitcoin’s UTXO Model.
Ex-Ripple Exec highlights XRP Ledger’s next growth chapter amid AI payments surge.
A large amount of Solana tokens exit major cryptocurrency exchanges as sellers appear to be dominating the market following its price downturn.
Blockonomi
TLDR:
- The Bitcoin price fell 3.6% for the week after touching $80,400, then recovered above $83,000 following Thursday’s sharp decline.
- NEAR lost just 0.3% in the weekly comparison after a 91.7% monthly advance, then jumped more than 10% to about $5.25 on October 10.
- Monero’s 1.3% weekly decline beat Bitcoin’s loss, though price performance alone cannot show whether trading activity or buying demand drove the difference.
- Bitcoin ETF outflows reached $244 million in one day, while XRP funds saw $8.2 million in inflows even as XRP fell 9% for the week.
The Bitcoin price fell to a weekly low near $80,400 on October 8 as a crypto market selloff accelerated. By October 9, BTC had recovered to $83,247, leaving it 3.6% lower for the week. Most large tokens lost more over that same seven-day period.
NEAR Protocol and Monero were exceptions, down 0.3% and 1.3%, respectively, in the weekly comparison. Yet those figures capture only one point in a volatile stretch. NEAR had climbed 91.7% over the prior month, then rose more than 10% on October 10. The Bitcoin price and altcoin moves show resilience in the data, but not its cause.
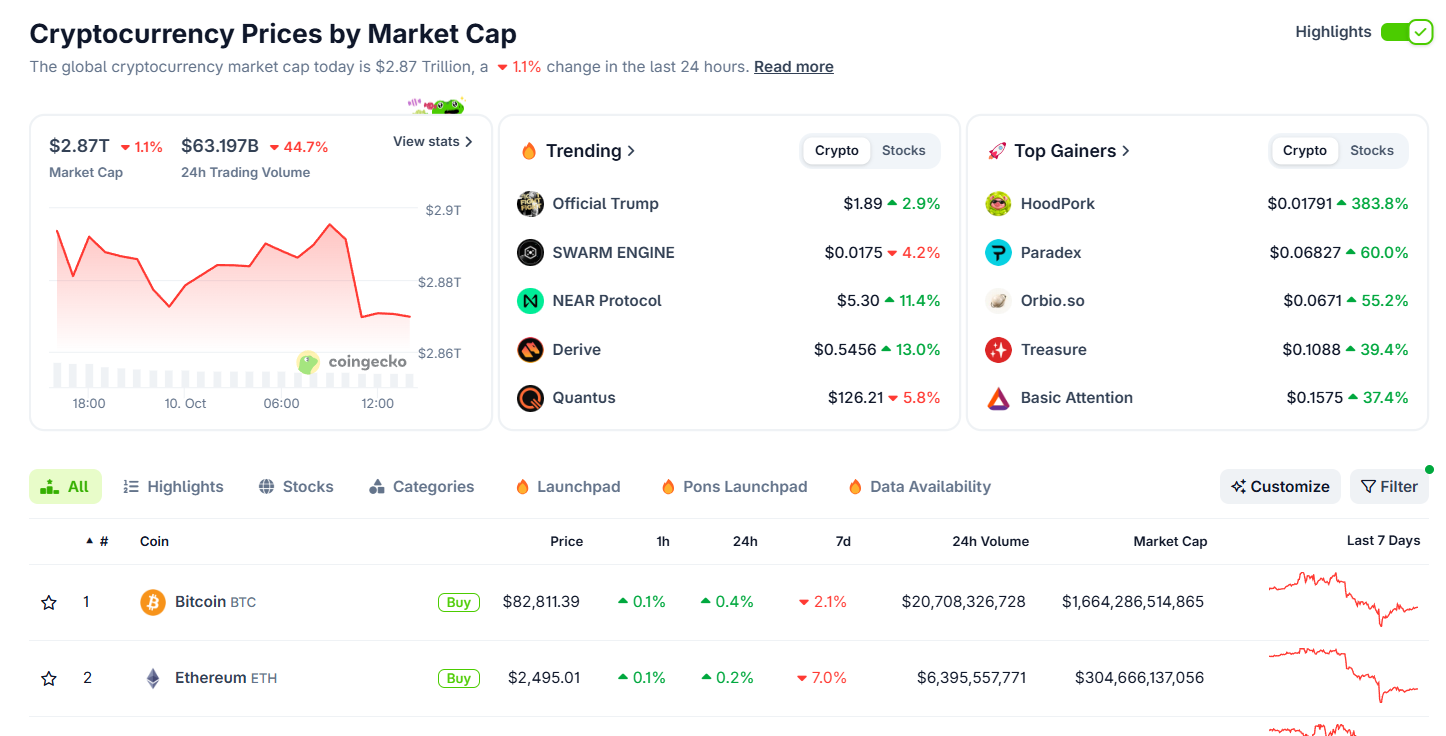
Bitcoin Price Slide Put NEAR and Monero Under Scrutiny
The selloff followed several failed attempts by BTC to reclaim $87,000. After slipping below $84,000 earlier in the week, Bitcoin fell to $80,400 on Thursday. The decline erased nearly $7,000 in a few days before buyers lifted BTC above $83,000. Bitcoin price weakness contrasted with the narrower weekly losses in NEAR and Monero.
NEAR’s small weekly drop deserves context. Its token price had climbed 91.7% in the previous month. That run can change how a weekly selloff appears. Even an intraday pullback may leave a token close to its starting price for the week. NEAR then gained more than 10%, reaching roughly $5.25 on October 10.
BTC price rebound shows how quickly the comparison shifted as prices recovered. Monero’s 1.3% loss also compared favorably with BTC. But a small decline alone cannot show whether buyers were accumulating, holders were inactive, or trading was thin.
ETF Flows and Weekend Recovery Point to Uneven Demand
Gains were not broad among large-cap coins. Thirteen of 16 tracked major tokens fell more than BTC during the measured week. Stellar posted the steepest decline at 13.5%. XRP lost 9%, despite XRP funds recording $8.2 million in inflows. Bitcoin ETFs, meanwhile, had $244 million in daily net outflows. Those flows complicate a simple demand narrative. Positive fund subscriptions did not protect XRP from falling. BTC declined despite its ETFs recording daily net outflows.
Bitcoin’s dominance increased to 59.5% as its market capitalization stood around $1.66 trillion. The total crypto market value rebounded to about $2.8 trillion after losing roughly $200 billion from its high to low. ETH recovered toward $2,500 after falling to $2,400, while XRP moved from $1.34 to around $1.41. The bounce restored some lost value but left several large tokens below recent levels.
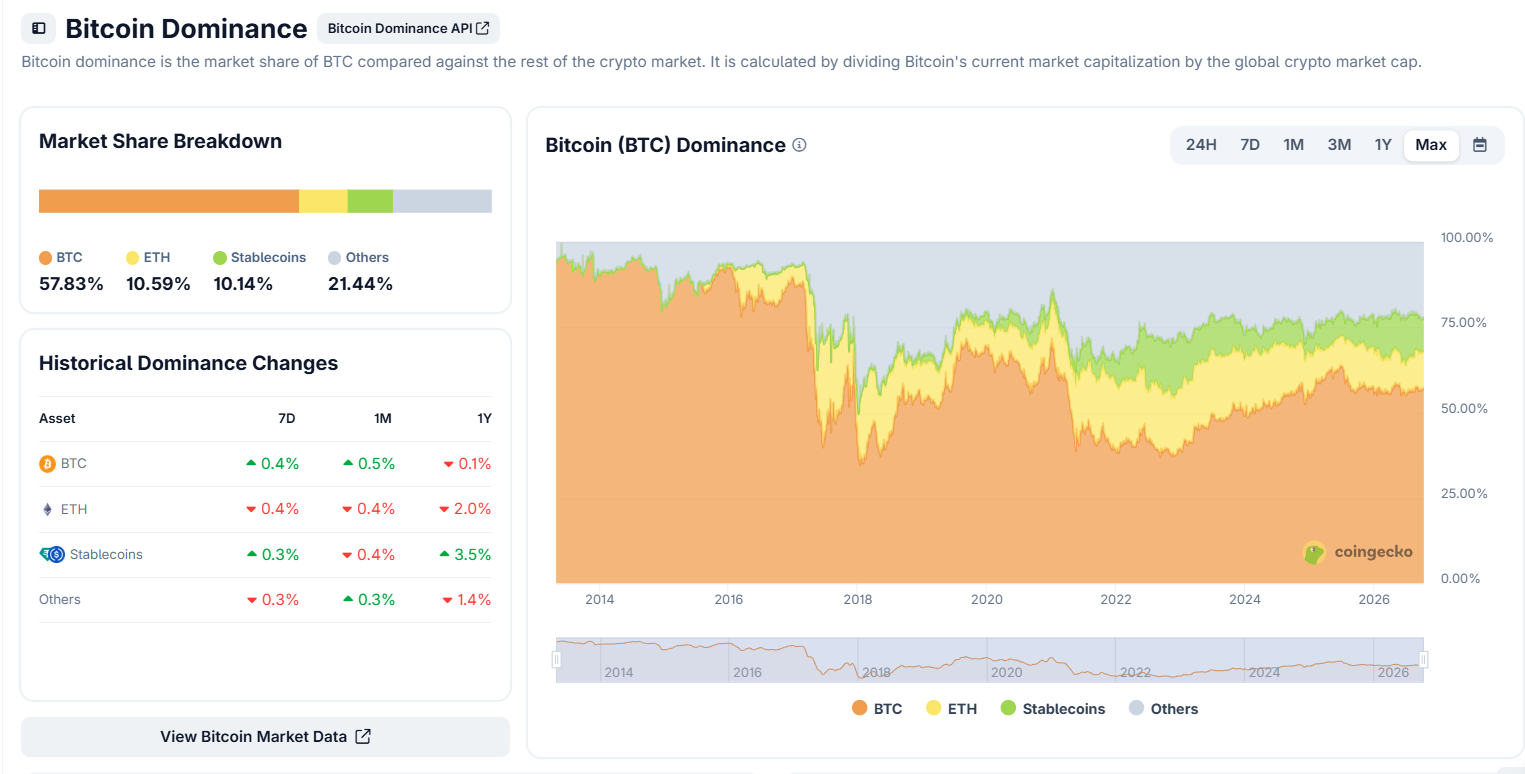
NEAR and ADA led the daily rebound among larger altcoins. Cardano rose about 7%, reclaiming $0.255, while NEAR’s advance outpaced peers. The Bitcoin price remained near $83,000 on October 10, below Monday’s $87,000 test and above Thursday’s low. This places the weekly outperformance beside a quick bounce, without confirming a lasting change in market leadership.
That matters for the Bitcoin price beside smaller tokens. Daily changes can look calm if trading is light, but weekly returns alone do not reveal activity. The same result can emerge from steady demand, limited selling, or a sharp drop followed by a rebound.
The post Bitcoin Price Holds Near $83K as NEAR and Monero Defy Selloff appeared first on Blockonomi.
TLDR:
- Strive Bitcoin funding through SATA generated an estimated $55 million during the week of Oct. 5, enough to purchase roughly 638 BTC at recent prices.
- SATA traded above its $100 par value on Oct. 5 and for much of Oct. 6, then stayed below par through Oct. 9, slowing estimated issuance.
- Strive held 29,462 BTC on Oct. 2 after buying 2,000 BTC at an average price near $84,422 between Sept. 28 and Oct. 2, while quarter-to-date BTC Yield reached 18.5%.
- Strategy sold zero STRC shares from Sept. 28 to Oct. 4, yet bought 334 BTC using MSTR common stock, lifting its holdings to 848,000 BTC.
Strive Bitcoin funding is accelerating through its SATA preferred stock program. The company generated an estimated $55 million during the week beginning October 5. That amount could purchase about 638 BTC at current prices. SATA traded $317 million in total volume during the period. However, issuance depends on shares trading at or above the $100 par value.
The preferred stock spent three sessions below that level. Most estimated proceeds came during Monday and Tuesday. Bitcoin traded near $82,800 on Friday, valuing 638 BTC at roughly $53 million. The result closely links Strive’s Bitcoin treasury strategy to Strategy’s capital markets playbook.
Strive Bitcoin Funding Depends on SATA Trading Above Par
That distinction matters because volume is not the same as corporate funding. Traders can exchange SATA below par without creating new proceeds. Strive therefore needs active demand and a supportive price. The next filing will actually determine how much cash reached its Bitcoin treasury.
Market trackers estimate that Strive sold about $55 million through its at-the-market program. The estimate uses eligible SATA volume and a capture ratio. That ratio reflects how much trading typically converts into newly issued shares. Past Securities and Exchange Commission filings help calibrate the calculation.
An ATM program lets a company issue shares gradually into public trading. It avoids the timing pressure of a large financing. Yet SATA cannot issue efficiently when its market price falls below par. Selling beneath $100 would weaken the program’s economics and dilute its yield proposition.
SATA traded above $100 on October 5 and for much of October 6. It then remained below par through October 9. Daily volume still reached some of its highest levels. The gap shows that trading activity alone does not guarantee Bitcoin purchases.
For Strive Bitcoin buyers, the distinction between volume and issuance is material. A busy tape can suggest strong demand, yet the company may receive little cash. Only eligible trading produces room for new shares. The estimate therefore remains provisional until the company files its next report.
The mechanism creates a brake. Investors must support SATA at par or higher before Strive can expand supply. When that support disappears, issuance pauses. Bitcoin buying then relies on cash already available or another financing route.
Strive Bitcoin Holdings Grow While Strategy Uses Common Stock
Strive reported 29,462 BTC on October 2. The balance followed a purchase of 2,000 BTC between September 28 and October 2. The average purchase price was about $84,422 per coin.
The company also reported adding 8,137 BTC during the third quarter. Those purchases carried an average cost of $78,885. Strive’s BTC Yield reached 18.5% quarter-to-date and 63.2% year-to-date on September 30. The metric measures Bitcoin growth per share.
The balance sheet has no debt principal. However, SATA carries about $168 million in annualized dividend obligations. Each new preferred share adds to that future payment burden. The model depends on continued investor demand for the income-oriented security.
Strategy provides the larger comparison. Its October 5 filing showed no STRC shares sold between September 28 and October 4. Strategy still bought 334 BTC from October 1 through October 4. It funded that purchase with MSTR common stock, taking its holdings to 848,000 BTC.
Both companies illustrate the same Bitcoin treasury model. Preferred or common equity raises capital for Bitcoin accumulation. The financing channel changes when market prices move. Strive’s SATA program currently shows that constraint more sharply because issuance stops below par.
The next weekly 8-K filings should provide the exact number of Bitcoin bought with SATA proceeds. They will also show whether Strive resumed issuance after the preferred stock recovered above $100.
The post Strive Bitcoin Has Enough for 638 BTC Through SATA Stock Sales appeared first on Blockonomi.
TLDR:
- Ethereum price prediction is bearish below the 50-day SMA, with $2,370 support and the 100-day average near $2,200 shaping the next levels to watch.
- U.S. spot Ethereum ETFs shed about $542 million in the week ended October 9, their largest weekly outflow since late January.
- BlackRock’s ETHA accounted for roughly $477 million in weekly withdrawals, while total U.S. Bitcoin ETF outflows reached $681 million.
- Whales reportedly added more than 166,000 ETH in 72 hours even as exchange balances rose 90,000 ETH and futures open interest declined.
Ethereum price prediction has weakened recently. Ether fell below its 50-day simple moving average. U.S. spot Ethereum ETFs logged their largest weekly outflow since January. ETH traded near $2,491 on October 10. It was down more than 7% in seven days, while trading volume fell 61% to $7.2 billion.
Yet whale data offered a counterpoint: holders added about 166,000 ETH over 72 hours, alongside Bitcoin and XRP purchases. The conflicting signals leave traders watching $2,370 support for now. A break could expose the $2,200 area, while a defense may steady the market. ETF redemptions and rising exchange balances remain risks.
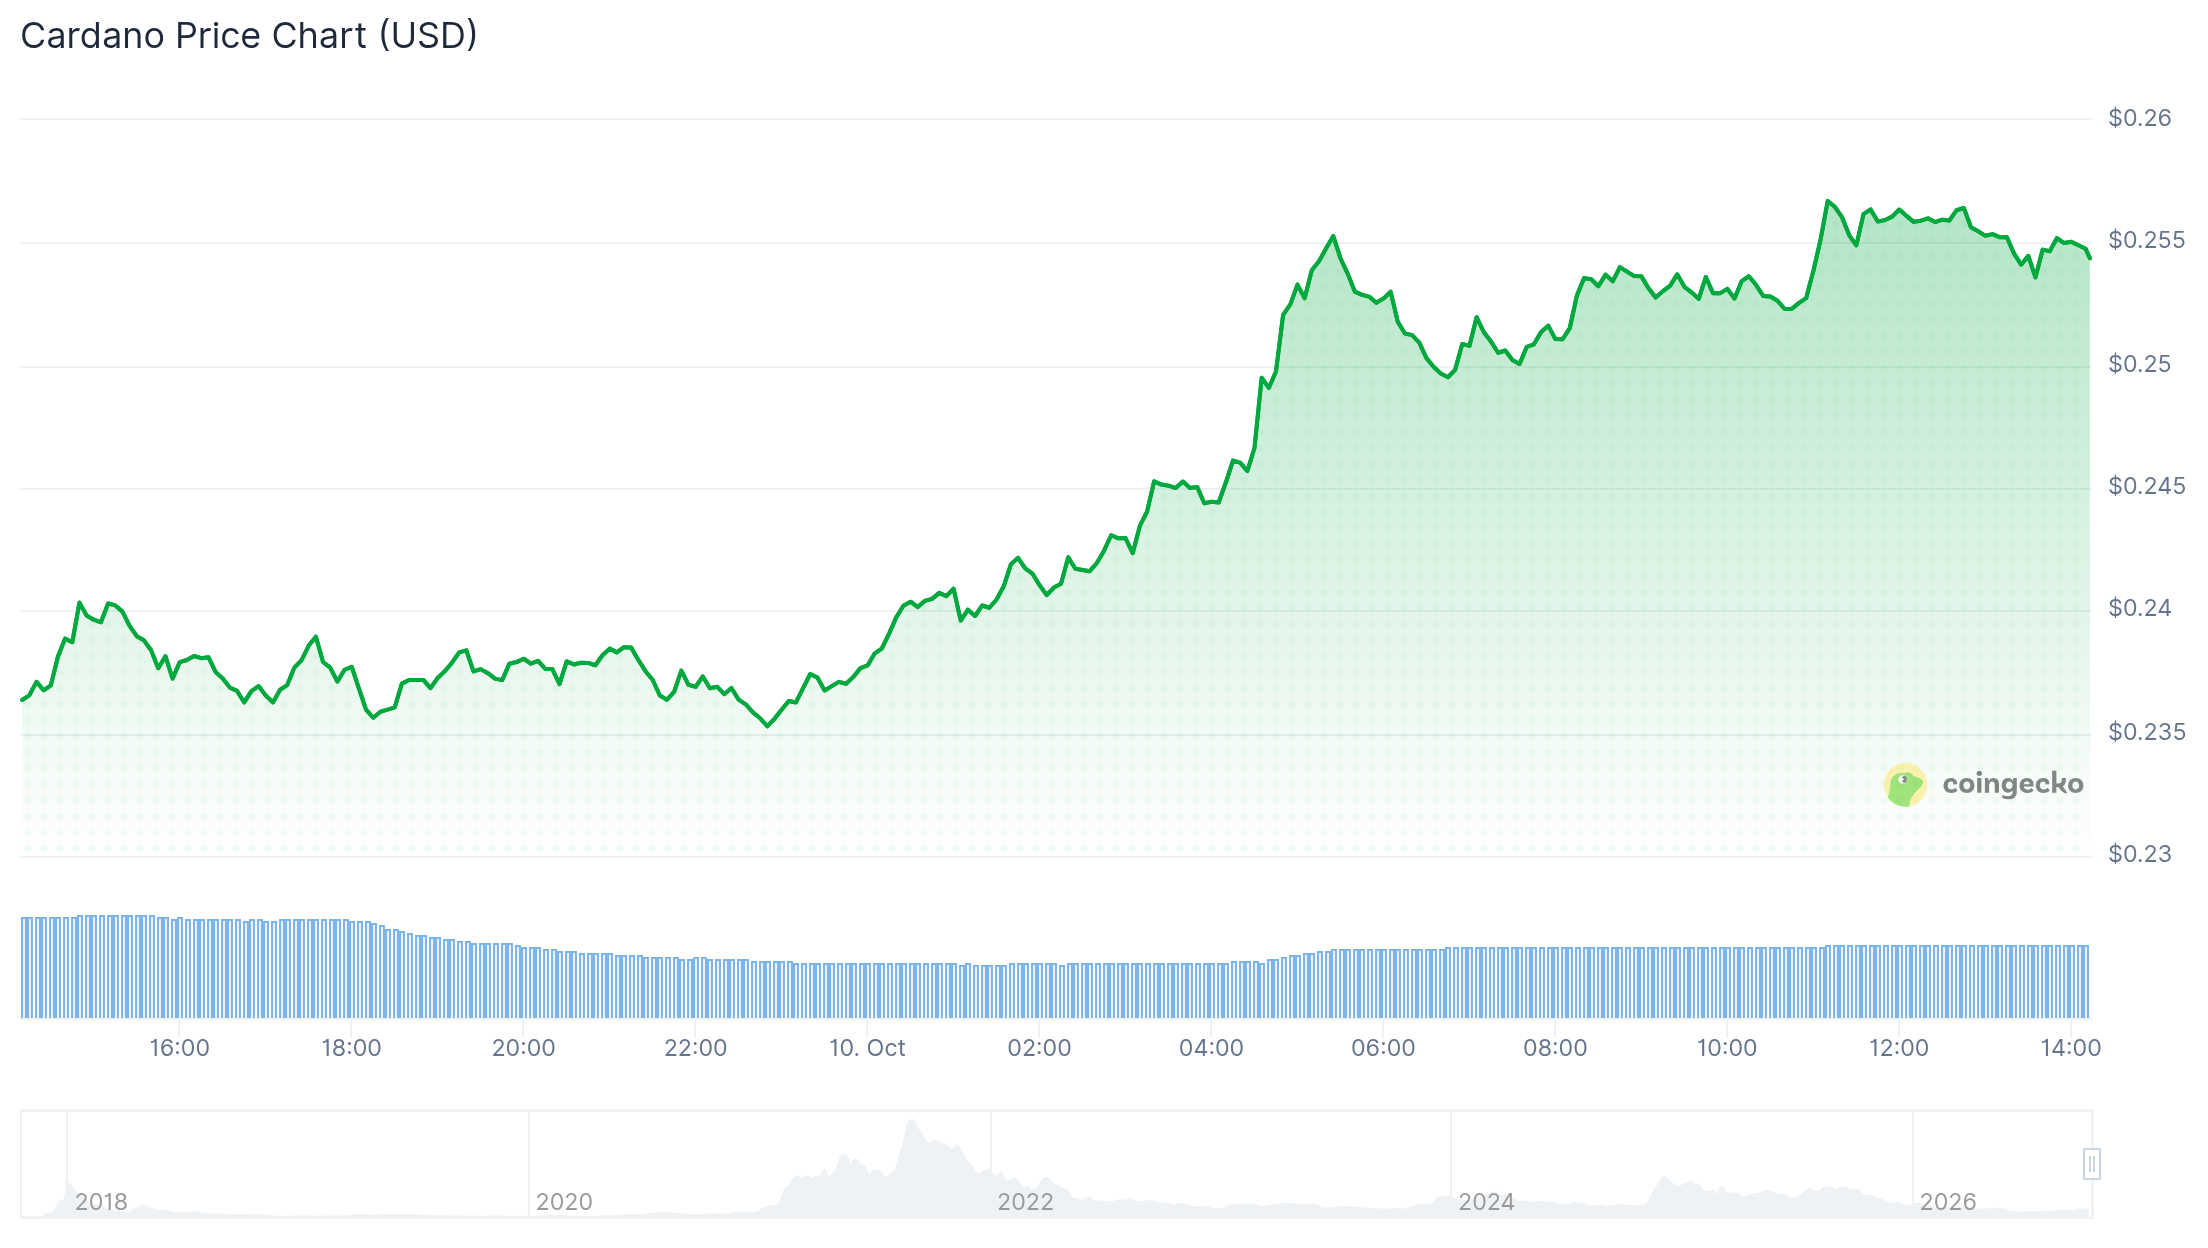
Ethereum Price Prediction Weighs ETF Outflows Against Whale Buying
U.S. spot Ethereum ETFs saw approximately $542 million in net withdrawals for the week ended October 9, SoSoValue data showed. It was their largest outflow since late January. BlackRock’s iShares Ethereum Trust, known as ETHA, accounted for about $477 million. It was the fund’s largest weekly withdrawal since December 2025. Bitcoin ETFs saw pressure, with $681 million leaving during the period.
These Ethereum ETF outflows point to reduced exposure. They do not show every investor is selling ETH. However, they weaken a key source of demand during a price decline. An outflow streak could cap attempts to recover above resistance. Whale accumulation complicates that bearish picture. Analyst Ali Martinez says large wallets added roughly 15,000 BTC and more than 166,000 ETH. They also added about 45 million XRP in 72 hours.
Whale balances can rise while smaller holders or funds distribute coins. For the Ethereum price prediction, this divergence matters. Wallet demand may absorb some supply without quickly reversing ETF outflows or retail selling. Traders need follow-through in spot buying to treat the signal as durable.
ETF flows and wallet data track different activity. ETF figures capture listed-product flows; whale estimates track large on-chain balances. Those signals can diverge if ETF investors withdraw while other holders accumulate.
The Ethereum price prediction depends on whether whale buying continues beyond the 72-hour window. Continued purchases could absorb some supply, but a pause would leave ETF redemptions as the clearer demand signal.
Exchange Inflows and Futures Deleveraging Add Pressure on ETH
Exchange data adds caution. CoinGlass figures show Ethereum balances on trading platforms rising from 11.71 million ETH on October 8. They reached 11.8 million the next day. That 90,000-ETH increase marked the highest balance since September 23. Coins transferred to exchanges may be prepared for sale, but transfers alone do not prove liquidation. At the same time, open interest fell from 13.29 million to 12.77 million ETH.
Lower futures open interest points to reduced outstanding positions and possible deleveraging. It can ease liquidation risk, but it also signals weaker appetite for leveraged longs. Combined, rising exchange balances and lower OI suggest traders are reducing exposure as spot supply increases. For the Ethereum price prediction, exchange balances now add another warning.
On the daily chart, ETH’s relative strength index slipped to 39, its lowest reading since June. Price also moved below the 50-day SMA. The $2,500 level has also turned into overhead resistance after ETH fell beneath it. The ETH price forecast hinges first on $2,370. A daily close below that support would strengthen the bearish case.
It would put the 100-day SMA near $2,200 in view. This Ethereum price prediction would need confirmation from continued selling or weak demand. If buyers defend $2,370, ETH could consolidate instead. A recovery above the 50-day average would give bulls a stronger signal. ETH had not reclaimed it by publication.
The post Ethereum ETFs Post Biggest Weekly Outflows Since January as Price Breaks Below $2,500 appeared first on Blockonomi.
TLDR:
- Cardano price rose nearly 7% on Oct. 10 and reached about $0.256 after a short-window rebound.
- ADA reclaimed the $0.2353 moving average and $0.2359 Fibonacci level, while reported volume fell 34.86%, leaving the breakout short of strong confirmation.
- Daily active addresses reached 27,500 and 27,200 on Oct. 7–8 after CIP-0113 launched, but ADA fell roughly 13% over that same period.
- Analyst Andreou’s $0.90 scenario remains conditional: ADA must hold the 0.22–0.25 base, reclaim 0.30–0.35, then clear higher resistance zones.
Cardano’s ADA token climbed 7% on Oct. 10, trading near $0.256 as buyers returned to the market. The Cardano price gain outpaced major cryptocurrencies during the session. The rebound followed an October decline, making this a recovery attempt rather than a confirmed trend reversal.
Cardano price analysis reveal ADA reclaimed its 30-day average near $0.2353 and the 50% Fibonacci level around $0.2359. But reported trading volume fell 34.86%, leaving buyers to prove they can defend the breakout. Network activity had increased earlier in the week.
Cardano Price Rebound Tests Support as Volume Remains Thin
The reclaimed average and retracement level now form a short-term checkpoint. A drop below them would weaken the breakout case. The support band extends from $0.2359 to $0.2276.
Holding that area could leave room for a test of weekly Supertrend resistance near $0.2762. The Cardano price would need a daily close above $0.256 to show that buyers can sustain the bounce. A rejection at that level would raise the risk of a false breakout.
Volume remains a key concern. The 34.86% decline suggests the rally drew less participation than its price move implied. The figure varies by exchange and measurement window, but the direction argues for caution. The Altcoin Season Index rose 5.17% to 61, pointing to stronger relative demand for alternative tokens. That measure describes rotation; it does not prove capital will stay in ADA.
Bitcoin traded near $82,800, a level that matters for altcoins. Spot Bitcoin ETFs shed $729 million over two days, adding pressure to risk assets. Renewed selling could again put ADA support levels under strain.
The immediate test is twofold: defend reclaimed levels and attract stronger spot volume. Until both happen, the Cardano price recovery remains technically constructive but unconfirmed.
ADA Active Addresses Rose After CIP-0113, Then Price Fell
Santiment reported about 27,500 daily active Cardano addresses on Oct. 7 and 27,200 on Oct. 8, around 1.7 times September’s weekday average. The increase coincided with CIP-0113 going live on mainnet on Oct. 7. The standard enables programmable tokens with issuer-defined rules. The Cardano Foundation says issuers can add KYC checks, sanctions screening, and transfer restrictions to native tokens. Wallets and explorers can handle these assets like other Cardano tokens. The standard required no protocol hard fork.
Coincidence does not establish that the upgrade caused the address spike. Santiment’s figures also showed Bitcoin and Ethereum addresses at or below September averages. Active addresses measure participation, not intent.
They cannot show whether users bought ADA, moved tokens, staked, or used applications. The Cardano price fell about 13% from the Oct. 6 close through Oct. 8, despite the increase. That divergence shows network use did not translate into immediate buying pressure.
The Cardano price bounce came on October 10, after both the activity increase and the selloff. It should not be attributed to CIP-0113 without evidence linking buyers to the upgrade. A lasting signal would require elevated addresses to persist beyond launch.

Analyst Giannis Andreou says initial support is present at 0.22–0.25 and first resistance at 0.30–0.35. A weekly reclaim and successful retest would strengthen that recovery case. Higher zones sit at 0.40–0.45 and 0.55–0.65. The $0.90 scenario depends on clearing each barrier, so it remains conditional. A sustained break below $0.22 would weaken the setup.
The post Cardano Price Rises 7% as ADA Tests Key Resistance Near $0.28 appeared first on Blockonomi.
TLDR
- Eli Lilly stock gains 0.62% as new Phase 3b findings highlight treatment gains.
- Combined therapy changes 482 proteins versus 140 with Taltz alone by Week 36.
- Gene activity shifts span 467 genes with both drugs, versus 16 on Taltz alone.
- Taltz and Zepbound deliver improved skin clearance and weight loss at Week 36.
- Researchers report consistent safety findings, but no new approved indication.
Eli Lilly and Company stock rose 0.62% to $1,176.80 on Friday, gaining $7.20 during the trading session. The company announced new Phase 3b findings showing broader biological responses from combined Taltz and Zepbound treatment. The results expand earlier evidence of improved psoriasis symptoms and weight reduction among adults living with psoriasis and obesity.
Eli Lilly and Company, LLY
Eli Lilly Reports Stronger Phase 3b Results for Taltz and Zepbound
Eli Lilly released new exploratory findings from its TOGETHER-PsO Phase 3b clinical trial examining two existing prescription medicines. Researchers compared the combined use of Taltz and Zepbound against Taltz alone in adults with moderate-to-severe plaque psoriasis. The study also included participants with obesity or overweight alongside at least one additional weight-related medical condition.
The latest analysis identified broader changes in proteins and genes among participants receiving both medicines compared with Taltz alone. By Week 36, researchers identified changes involving 482 proteins in the combination group, compared with 140 in the other group. Similarly, gene expression changes affected 467 genes with combined treatment, against only 16 genes with Taltz alone.
These biological differences appeared as early as Week 12, according to the pharmaceutical company’s newly released findings. Researchers also identified stronger reductions in inflammatory immune activity among participants receiving both treatments over the study period. Eli Lilly presented the findings at the 2026 Fall Clinical Dermatology Conference in Las Vegas.
Combined Treatment Improves Skin Clearance and Weight Reduction
The latest findings build on earlier clinical results showing better treatment outcomes among participants receiving Taltz alongside Zepbound. At Week 36, the combination delivered superior skin clearance and meaningful weight reduction compared with Taltz alone. Furthermore, participants maintained or improved these clinical benefits through Week 52, according to Eli Lilly’s previously reported findings.
The analysis also examined neutrophils, which play an important role in the body’s inflammatory immune response. Researchers found that combined treatment produced greater changes in inflammatory pathways associated with these immune cells. Changes in certain neutrophil-related markers partly explained the additional improvement in psoriasis severity scores among combination-treatment participants.
The TOGETHER-PsO trial included 274 adults across multiple clinical research centers, with participants divided equally between two treatment groups. One group received Taltz alone, while the other received Taltz and Zepbound through injections under the skin. Both groups also received guidance on reducing calorie intake and increasing physical activity throughout the clinical study.
Eli Lilly Expands Research Into Psoriasis and Obesity
Eli Lilly designed the study to examine the relationship between metabolic health and inflammatory skin conditions. Approximately 61% of Americans with psoriasis also experience obesity or overweight alongside another weight-related medical condition, according to Lilly. The findings provide additional research into how treatments targeting different biological processes may influence both conditions.
Taltz works by blocking interleukin-17A, an immune signaling protein involved in inflammation and several related inflammatory conditions. Zepbound targets GIP and GLP-1 receptors, helping regulate appetite and support weight management in eligible adults. The two medicines therefore act through different biological pathways, providing the basis for investigating their combined clinical effects.
Eli Lilly reported that the combination’s safety findings matched the established safety profiles of the individual medicines. The exploratory results do not establish a new approved indication for using the medicines together. The company continues examining the relationship between immune and metabolic processes as researchers assess broader approaches to psoriasis management.
The post Eli Lilly and Company (LLY) Stock: Rises as Taltz and Zepbound Show Promising Results appeared first on Blockonomi.
CryptoPotato
The weekend is going relatively calmly for bitcoin and most of the crypto market, as is typical, but another macro event in the past several hours threatened to disrupt that.
Yemen’s Houthis reportedly attacked the King Khalid International Airport in Riyadh, Saudi Arabia, with at least 12 people killed and over 300 injured. Saudi Arabia’s authorities have vowed to respond to the attack, while the Houthis are yet to comment on it.
Fighting in the region has escalated in the past week or so, as another three people were killed in separate Houthi strikes on two different Saudi airports on October 6 and 7.
International authorities, as well as US Secretary of State Marco Rubio, strongly condemned the recent attacks. Rubio even confirmed an American citizen was killed. Meanwhile, US President Donald Trump suggested that his country is likely to join the strikes against the Houthis:
“We may. We’re going to look at it. We just found out about the recent attack, so we’ll make a decision. We move very quickly.”
The consequences for bitcoin and the altcoins are not evident yet. BTC has remained close to $83,000, while most alts have remained sideways over the past 24 hours. However, history has taught us that the real volatility arrives on Monday morning when most financial markets start to open.
Recall the events from last week. The tension in the Middle East skyrocketed over the weekend again, with Iran saying it has prepared for a fresh US bombing campaign after Trump’s top security officials met at Camp David on Friday in a meeting focused on that war.
BTC stood in a well-defined range over the weekend, before the fluctuations began on Monday morning with an unsuccessful breakout attempt and a violent rejection.
The post Bitcoin Price Under Pressure as Houthis Attack Saudi Arabia and Trump Signals US Involvement appeared first on CryptoPotato.
Most major cryptocurrencies tanked over the past several days, led by bitcoin’s nosedive from $87,000 to under $81,000, which became its lowest price tag in well over two weeks.
Large altcoins such as XRP and ETH were not spared, with the former posting a double-digit decline over the past seven-day period. The question now is what whales were doing during this time, and what’s next for the underlying assets.
The BTC Case
Some of the most probable reasons behind BTC’s crash include substantial ETF outflows, FUD initiated by big transfers from the US government, macro news, and profit-taking. It’s worth exploring what whales did during this time of distress, and Ali Martinez pointed to a growing accumulation spree.
In a recent video on X, the popular analyst said these large market participants pressed the buy button hard on bitcoin, adding over $1.2 billion worth of the asset to their holdings in 72 hours.
In another bullish post, he explained that the TD Sequential has finally flashed a buy signal for the cryptocurrency on the four-hour chart. This came after the asset crumbled by 7% in a few days and hints at a potential rebound.
2/5 The TD Sequential is flashing a buy signal on Bitcoin’s four-hour chart.
It comes after $BTC fell 5.55%, from $86,976 on October 5 to $82,150 today.
The signal suggests this pullback may be nearing an end, with a rebound now worth watching. https://t.co/o9ZS4Q1anl
— Ali Charts (@alicharts) October 8, 2026
Here’s ETH’s Situation
The leading altcoin crashed hard as well, tumbling from over $2,700 to $2,400 before it found some support. Although it rebounded to $2,500 on Friday, where it was stopped, it still remains well in the red on a weekly scale.
According to Martinez, Ethereum whales didn’t just stand on the sidelines. They increased their holdings by 0.64%: in other words, they purchased around 166,000 tokens as the asset’s price corrected.
ETH’s 8% decline also led to a change in the TD Sequential indicator. Similar to BTC, the four-hour chart flashed a buy signal once the asset slipped below $2,550, where it currently sits. Martinez noted that the recovery can take ETH to somewhere between $2,620 and $2,650.
What About XRP?
Ripple’s native token remains down by double digits on a weekly scale, even though it rebounded from the local low at $1.34. On the plus side, the rejection at $1.51 and the subsequent retracement allowed whales to resume their accumulation spree.
Martinez said these big market players bought over 45 million tokens, worth around $63 million, during the nosedive. And, not to be outdone by BTC and ETH, XRP’s four-hour chart also saw a new buy signal, according to the TD Sequential.
“An earlier sell signal aligned closely with XRP’s local high. Now, the question is whether this buy signal marks a local low,” added Martinez.
The post BTC, ETH, XRP Crash Sparks Whale Accumulation as Buy Signals Appear appeared first on CryptoPotato.
Bitcoin is trading around $83K after the rejection from the $86K to $90K resistance zone weakened short-term structure, while the Coinbase Premium Index has turned sharply negative, suggesting US-based buying demand may be fading. BTC is attempting to stabilize, but buyers need to reclaim nearby resistance to improve the outlook.
Bitcoin Price Analysis: The Daily Chart
Bitcoin’s daily chart shows a substantial recovery from the June lows near $58K to the recent highs around $86K. However, the rally has encountered strong resistance, and the latest price action suggests that sellers are regaining control in the short term.
BTC has been rejected at the $86K to $90K resistance zone, with the lower end of that zone, around $86K, acting as the immediate barrier to a renewed advance. A broader resistance area appears around $95K, which would matter if Bitcoin reclaims the nearer supply zone and resumes its recovery.
Still, the price is above the 100-day and 200-day moving averages, both currently near $72K, after a bullish crossover. Although BTC remains comfortably above these averages, their recent crossover and upturn reflect improved medium-term structure following the summer recovery. The moving averages could become important dynamic support if the correction deepens, but they are not immediate downside targets while the market remains above the nearer support zones.
The first key downside area to watch is the $77K demand zone created by the bullish order block that initiated the final leg of the recent rally. If this area is lost and the price closes below $75K, it would weaken the recovery structure and expose the mentioned moving averages around $72K.
Yet, for now, the daily structure remains in a recovery phase, but the rejection from resistance and a potential loss of short-term support could suggest that Bitcoin may need to undergo a deeper correction before attempting another advance.
BTC/USDT 4-Hour Chart
On the 4-hour chart, the asset has broken below a rising wedge after getting rejected from the $86K region. The breakdown below the pattern’s lower trendline indicates the pattern has resolved bearishly, at least in the short term.
Following the breakdown, BTC declined toward the $80K area before staging a modest rebound toward $83K. This recovery suggests that buyers are attempting to stabilize the price, but the bounce remains limited as a bearish order block has formed near $85K that could push the asset lower once more.
On the downside, the $80K low represents the nearest area where buyers have recently attempted to step in. If BTC loses this zone, the next major support is the same $75K to $78K demand area visible on the daily chart.
The 4-hour RSI has also recovered from the oversold territory and is now in the mid-40s, suggesting that selling momentum has eased somewhat. However, it remains below the neutral 50 level, meaning the rebound has not yet established convincing bullish momentum.
The short-term outlook therefore remains cautious. Bitcoin could continue consolidating around $82K to $84K if buyers manage to defend the recent lows. However, another rejection below $86K followed by a break under $80K would increase the likelihood of a deeper move toward the $75K to $78K demand zone.

Sentiment Analysis
The Coinbase Premium Index chart shows that the metric has turned sharply negative in the latest reading, falling to approximately -0.1 while Bitcoin trades near $82.7K. The index measures the price difference between Bitcoin on Coinbase and a comparable market price, with a negative reading generally indicating that BTC is trading at a discount on Coinbase relative to the reference market.
A persistently positive premium can indicate stronger buying pressure on Coinbase, often associated with US-based spot demand. Conversely, a negative premium suggests weaker relative demand or stronger selling pressure on the platform. However, the metric is not a direct measure of total US investor flows, and it can also be affected by differences in liquidity and market conditions across exchanges.
The latest deterioration is notable because it coincides with Bitcoin’s rejection from the $86K resistance region and its subsequent breakdown from the four-hour rising wedge. The alignment between weakening price structure and a negative Coinbase Premium suggests that spot demand may not currently be strong enough to support an immediate continuation of the rally.
The index has displayed repeated swings between positive and negative territory throughout the chart, so the latest decline should not be interpreted as definitive evidence of sustained distribution. Still, a continued negative premium alongside further price weakness would reinforce the bearish case, particularly if BTC loses the $80K support area.

The post Bitcoin Price Analysis: Is BTC’s Recovery Over as US Demand Turns Negative? appeared first on CryptoPotato.
XRP is attempting to stabilize after a sharp correction from its September highs, with the price currently trading around $1.40. While buyers have managed to trigger a rebound from the $1.30 support area, the broader technical picture remains mixed. XRP needs to claim nearby resistance to continue the recovery, while another rejection could expose lower support levels.
Ripple Price Analysis: The USDT Pair
XRP’s daily chart shows a significant recovery from the August lows below $1, followed by a sharp rally that carried the asset toward the $1.60 region. However, the market has rejected this level twice, suggesting bullish momentum has weakened considerably.
The price is currently hovering around $1.40, with the $1.30 zone serving as the key nearby support area. This region has already attracted buying interest, as demonstrated by the recent rebound. Holding this zone could allow the asset to consolidate and attempt another move higher. A decisive breakdown, however, would weaken the recovery structure and bring the $1 support zone back into focus.
The 100-day and 200-day moving averages are also converging for a potential bullish crossover near the $1.30 zone, adding to this level’s importance for XRP’s short- to mid-term trend. Yet, with the RSI dropping below the neutral 50 level, bullish momentum is clearly weak, putting the market at significant risk of losing the key support zone.
The 4-Hour Chart
The 4-hour chart highlights the recent correction more clearly. XRP has been trading beneath a descending resistance trendline drawn from the September highs, with successive lower highs reflecting persistent selling pressure. The latest decline pushed the price toward the $1.30 support zone before buyers stepped in and initiated a modest rebound toward $1.40.
Despite this recovery, XRP remains below the $1.45 resistance area. This zone is particularly important because it aligns with the descending trendline, making it a key level for determining whether the latest rebound can develop into a broader recovery. A convincing breakout above $1.45 could invalidate the immediate bearish structure and allow the price to target the $1.60 region once more.
Conversely, a rejection near $1.45 could send XRP back toward the $1.15 imbalance which was formed during the almost vertical rally mid-August. With the 4-hour RSI climbing back above the oversold region to approximately 40, selling pressure has moderated, although the indicator remains below 50 and does not yet confirm a bullish momentum shift.
Overall, XRP is at a pivotal point. The defense of $1.30 offers the bulls an opportunity to extend the rebound, but the descending 4-hour trendline and resistance near $1.45 remain significant obstacles. A breakout above this barrier would strengthen the recovery case, while a renewed loss of $1.30 would increase the risk of a deeper correction.
The post Ripple Price Analysis: XRP Tests Critical Trendline Following Recent Correction appeared first on CryptoPotato.
Ethereum is trading near $2.5K after a sharp correction from the $2.7K resistance area, with the latest price action putting a key support zone under pressure. While ETH remains above its daily 100-day and 200-day moving averages, weakening momentum and a recent rebound in the exchange supply ratio suggest that traders should watch for further volatility before assuming the broader recovery will resume.
Ethereum Price Analysis: The Daily Chart
Ethereum’s daily chart shows a strong recovery from the June lows near $1.5K, followed by a sharp rally that carried the asset through the $2K region and into the $2.4K area. ETH subsequently climbed toward the $2.7K resistance zone, where it consolidated for the last few weeks before sellers regained control in early October.
The latest rejection from the $2.7K supply zone has pushed ETH back toward $2.4K, the immediate support area. Buyers have started to respond after the latest sell-off, as yesterday’s candle wicked through the support and bounced, but the rebound remains modest and has yet to establish a convincing bullish reversal.
If this support holds, ETH could attempt to recover toward the major resistance around $2.7K. A sustained breakout above the level would improve the near-term structure and potentially reopen the path toward $3K.
However, a decisive daily close below the $2.4K support zone would weaken the recovery structure, as the ascending channel that has carried the price higher from June lows would also get broken to the downside. In that scenario, the next notable support area lies around $2K-$2.2K where the 100-day and 200-day moving averages have recently printed a bullish crossover.
The Relative Strength Index (RSI) has also dropped to approximately 40, indicating weakening momentum and a shift toward bearish territory. Although the indicator is approaching oversold levels, it has not yet reached the conventional threshold below 30. A recovery above 50 would provide a stronger indication that buyers are regaining control, while continued weakness below 40 would leave ETH vulnerable to another test of support.
ETH/USDT 4-Hour Chart
The 4-hour chart provides a clearer picture of the recent selling pressure. Ethereum spent much of late September consolidating between approximately $2.6K and $2.8K before breaking lower aggressively earlier this week. The move accelerated as ETH lost the $2.6K lows, eventually driving the price toward the $2.4K region.
The latest candles show a modest recovery toward $2.5K following the sharp downside moves. This suggests that buyers have stepped in around support, but the rebound is still too limited to confirm that the correction has ended.
The immediate resistance area is around $2.6K to $2.7K, where ETH must climb through the bearish imbalance formed during the drop. On the downside, the $2.4K support zone is the first level to monitor. ETH has reacted positively from this area, but a renewed breakdown could push the price below this region, and the market would potentially test the broader $2.2K support zone if this scenario materializes.
Meanwhile, the 4-hour RSI has recovered from a deeply oversold reading to approximately 40. This rebound indicates that selling pressure may be easing, but momentum remains relatively weak and below the neutral 50 level. The indicator would need to strengthen alongside price to support a more convincing recovery.

On-Chain Analysis
The exchange supply ratio measures the proportion of Ethereum’s circulating supply held on centralized exchanges relative to the broader supply tracked by the metric. It can help illustrate changes in the amount of ETH available on exchanges, although it does not independently establish whether holders intend to sell.
The chart shows a prolonged decline in the exchange supply ratio throughout much of 2026. The indicator fell from approximately 0.142 at the beginning of the year toward 0.124 in September. Over the same period, ETH’s price recovered from its summer lows and climbed toward $2.7K.
This behavior is notable. The declining ratio suggests that exchange-held supply has generally become smaller relative to the total supply represented by the metric. Reduced exchange availability can be consistent with accumulation or withdrawals into self-custody, potentially lowering the amount of ETH immediately available for spot selling. However, the chart alone cannot establish the reasons behind these movements.
More recently, however, the exchange supply ratio has rebounded from its lows. The increase is relatively modest compared with the decline seen earlier in the year, but it warrants monitoring alongside ETH’s latest price correction.
If the ratio continues to rise while ETH struggles below $2.7K, it could suggest that a larger proportion of supply is returning to exchanges, potentially increasing available selling liquidity. That interpretation would be more concerning if accompanied by continued price weakness and stronger exchange inflows, and could overwhelm demand and push the price even lower in the coming weeks.

The post Ethereum Price Prediction: Rebound Ahead or Will ETH Breakdown Toward $2K? appeared first on CryptoPotato.