Cryptocurrency Posts
Crypto Briefing
The temporary stability in corporate credit markets may lead to increased volatility and risk for investors once issuance resumes and spreads widen.
The post Goldman Sachs sees calm in corporate credit, but expects it to fade soon appeared first on Crypto Briefing.
Bipartisan push for AI cybersecurity standards signals a shift towards unified national security measures, impacting compliance and innovation.
The post Senators Cantwell and Rounds press Trump administration for coordinated AI cybersecurity response appeared first on Crypto Briefing.
OP's rise highlights growing interest in layer-2 solutions, but future token unlocks and competition may impact sustained momentum.
The post Optimism’s OP jumps 18%, extending four-week gain to 66% appeared first on Crypto Briefing.
Wang's leadership at Meta Superintelligence Labs highlights the strategic importance of talent density and innovation in AI market success.
The post Alexandr Wang’s run at Meta Superintelligence Labs draws a fresh endorsement appeared first on Crypto Briefing.
The incident underscores the critical need for robust security measures in tech firms to protect sensitive information and maintain trust.
The post FBI arrests OpenAI engineer after hidden recorder found in executive conference room appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
The Amount of Bitcoin on Exchanges Is Shrinking. Is a Rally Imminent?
Bitcoin’s price could be due a move upwards as the supply of the leading cryptocurrency on exchanges shrinks.
That’s according to a researcher at data firm CryptoQuant, who wrote in a Monday report that bitcoin on exchanges has dropped to 2.67 million from 2.8 million since February.
The price of bitcoin was recently $83,485, unmoved over a 24-hour period but up 8% over the past 30 days after having its best quarter in years. Its surge in August and September has led a number of analysts to declare the bear market is over.
“If buying demand continues to improve while exchange supply remains low, BTC could benefit from a supply-demand imbalance, creating favorable conditions for a longer-term upward trend,” the report by on-chain researcher Rei Researcher read.
It added: “More importantly, in recent weeks, bitcoin has recovered from its lows while exchange reserves have continued to decline. This is a notable development, suggesting that the supply readily available for trading is decreasing even as the market recovers.”
The report further noted that it was possible investors were taking bitcoin off exchanges to put in cold storage solutions.
Bitcoin’s price was mostly trading under $65,000 for the first half of 2026. The coin spent most of this year in a bear market following the all-time high of $126,080 it hit in October 2025.
But that all changed in August. News that the U.S. Treasury would double the size of its liquidity-support buyback operations, weakening the dollar but strengthening bitcoin and other non-yield bearing assets.
Now, the so-called debasement trade — where investors throw money at an asset to hedge against a currency losing its value — is hot again. Bitcoin is benefiting from the trade, analysts say, as it did in 2024 and 2025.
Bitcoin’s price is still more than 30% below its record.
This post The Amount of Bitcoin on Exchanges Is Shrinking. Is a Rally Imminent? first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Trezor Reduces Number of Resellers Following Ledger Drainage Incident
Hardware manufacturer Trezor has said it has reduced the number of resellers it works with following supply-chain incidents related to its competitor Ledger.
The Prague, Czech Republic-based company added in a Tuesday post on X that it was in the process of checking which vendors it works with.
It added that there were no reports of any issues with Trezor devices. “Let us be very clear: there is not a single piece of evidence that Trezor devices have been compromised,” the company wrote.
“This is a preventive step, taken out of an abundance of caution.”
Signing device manufacturer Ledger last week said it had started an investigation after customers in South East Asia reported they’d lost funds after buying from Malaysia-based reseller, CryptoBilis.
Ledger then said that one of the impacted users’ devices contained an unauthorized hardware implant.
More reports of what appear to be tampered devices have since surfaced on social media but Ledger said Tuesday that only devices sold through CryptoBilis have been linked to lost funds.
It added that it had only confirmed an unauthorized hardware implant in one affected user’s device. The implant, according to Ledger, was able to read a seedphrase when it appeared on the device.
Ledger did not reveal how much money had been lost but blockchain investigator Specter said $86 million had been drained from devices.
“We have not confirmed the total number of affected users or the total value lost,” Ledger added on X. “Figures circulating online come from third parties and Ledger has not fully verified them.”
Ledger did not respond to Bitcoin Magazine’s questions.
CryptoBilis has also stopped selling devices, Ledger added, and advised customers who bought from CryptoBilis to not set up their devices and contact the Ledger support team.
Criminals have been targeting hardware wallets this year. Hackers in July were able to steal close to $120 million in bitcoin from Coldcard users due to a firmware bug in the devices.
Canadian company Coinkite, which makes the popular products, said that the bug led to faulty seed generation, allowing hackers to guess investor seedphrases.
In a separate incident, hardware wallet manufacturer Trezor last month reported that close to 81,000 customers had their details leaked after its third-party fulfillment partner had data stolen.
Scammers earlier this year were able to get hold of customer information via crypto wallet Ledger’s payment processor Global-e to send phishing emails.
This post Trezor Reduces Number of Resellers Following Ledger Drainage Incident first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Strive Buys More Bitcoin, Crosses 30,000 BTC Mark
Nasdaq-listed Strive isn’t slowing down with its bitcoin buys.
The company now has more than 30,000 BTC after buying 3,311 coins last week, according to a Tuesday filing.
Strive now holds 32,773 coins worth $2.7 billion at today’s prices, keeping its position as the fifth biggest publicly traded bitcoin company, according to Bitcoin Treasuries.
Strategy, Twenty One, Metaplanet, and MARA all hold more bitcoin than Strive.
BREAKING:
— Bitcoin Magazine (@BitcoinMagazine) October 13, 2026Public company Strive purchases 3,311 Bitcoin worth $275 million!
This brings their total to 32,773 BTCpic.twitter.com/oNguyCU24N

Strive’s stock (ASST) was trading slightly lower on Tuesday. Unlike other treasuries, though, Strive shares are up significantly this year: year-to-date, ASST has risen by close to 60%.
A number of top bitcoin treasuries have seen their stock plummet this year since the price of bitcoin took a hit. Some top treasuries have had to sell bitcoin or rethink their model altogether.
Dallas, Texas-based Strive debuted as an official bitcoin treasury last year, following in the footsteps of software company Strategy, the biggest corporate holder of bitcoin.
Unlike Strategy, though, Strive hasn’t used debt to buy the cryptocurrency. CEO Matt Cole has described the company as debt-free with zero margin requirements and zero encumbered bitcoin.
Like with other digital asset treasuries, the idea is that investors can get amplified returns from Strive’s stock.
In January 2026, it completed the acquisition of Semler Scientific in an all-stock deal — the first instance of a publicly traded Bitcoin treasury company acquiring another such company.
The company was founded by former Ohio gubernatorial candidate and tech entrepreneur Vivek Ramaswamy.
This post Strive Buys More Bitcoin, Crosses 30,000 BTC Mark first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Alex Gladstein: How The Bitcoin-AI Convergence Impacts the Fight for Freedom
Is the biggest AI risk really the end of humanity? Alex Gladstein says no: the real danger is AI centralized in the hands of dictators, governments, and a few large corporations. In this interview, the HRF Chief Strategy Officer explains why “AI will kill us all” claims are largely propaganda, and why local AI on your own laptop and phone could be a huge win for human rights. Tune in to hear his vision for AI that’s in our control.
Chapters:
0:00 – Alex Gladstein on Freedom AI vs. Corporate AI
1:26 – How HRF Trains Human Rights Activists to Use AI
2:57 – The Freedom Stack: Encrypted Inference, Open Weights and Local AI
5:45 – The Real AI Risk: Centralization in the Hands of Dictators
8:20 – HRF and Bitcoin Park Hackathons for Activists
9:57 – Why CBDCs Are a Tool of Repression
12:35 – Living on Bitcoin in Kenya With Tando and M-Pesa
15:25 – Building Your Own Freedom Tech With AI Agents
17:39 – Venezuela After Maduro and Bitcoin as a Lifeline
20:25 – What “Freedom Money” Really Means
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Alex Gladstein: How The Bitcoin-AI Convergence Impacts the Fight for Freedom first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Matt Dines: Why a Rising Dollar is Bullish for Bitcoin
The dollar is rising, and so is Bitcoin. Matt Dines says that’s a bullish signal. The Build Asset Management CIO explains how capital is leaving the old post-World War II offshore dollar system for a new U.S.-led Western Hemisphere financial system. He makes the case that Bitcoin is part of that system’s future, and covers what the DXY is really telling investors right now.
Chapters:
0:00 – Matt Dines on France’s Bond Crisis and the ECB’s Pontes CBDC Bridge
2:11 – How the Strait of Hormuz Disruption Rewired Global Trade
3:22 – French-German Spreads and European Contagion Risk
4:23 – Bank of England’s Digital Gilt and Tokenized Sovereign Debt
5:54 – Why Dollar Up, Bitcoin Up Is a Bullish Signal
7:47 – Signals to Watch Before Pressure Hits Bitcoin
10:25 – Treasury Buybacks and the Coming Bond Market Repricing
12:50 – Why Treasury Is Buying Back Old, Illiquid Bonds
14:28 – How Buybacks Pull Capital Into the Dollar and Bitcoin
15:40 – Why the Buybacks Aren’t QE and What It Means for Bitcoin
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Matt Dines: Why a Rising Dollar is Bullish for Bitcoin first appeared on Bitcoin Magazine and is written by Patrick Green.
HTTP error 429 on https://cryptoslate.com/feed/
Failed to fetch feed: https://cryptoslate.com/feed/
Failed to fetch feed.
CryptoTicker.io
Since the afternoon of October 13, a proposal has been up for a vote on Polkadot's governance platform that would set a new course for the network's most important body. Referendum 1954 is titled "[Wish For Change] DOT DAO Strategy Mandate", and after a good three hours 26.8 percent of weighted votes were in favour and 73.2 percent against. In absolute terms that is 19,370 weighted DOT against 53,030. The approval rate is the clearest rejection any strategy proposal has drawn in its opening hours this year.
The proposal comes from PCF, the Polkadot Community Foundation, and it is expressly not a technical specification. "It constitutes a strategic mandate, not a technical specification", the text states. What it demands is a ranking: user acquisition ahead of every other metric. In its own words, the DOT DAO should "for the present time, prioritise user-acquisition over other KPIs".
What Referendum 1954 asks of the DOT DAO
The proposal names four areas. First, user acquisition is to rank ahead of ecosystem size and ahead of capital locked in contracts; the competitive frame thereby shifts from other smart contract platforms to Web2 and mobile applications. The proposal puts that as a target state: "fewer products/integrations with more users is a more desirable position for Polkadot to be in".
Second, the network is to gain permissionless, DOT-backed assets with a fixed exchange rate, which the proposal calls dotStables. As a model it cites Liquity, a design in which users lock up collateral and mint a dollar-pegged asset against it. One such implementation is to receive support and a grant from the DAO.
Third, the proposal sets out a product platform on which users and applications meet directly and on which incentives are paid per person rather than per account, with a cap per human being. Fourth, Polkadot is to feel like a Web2 application, with free entry tiers, readable names and access from a phone, without giving up self-determination, privacy and access without sign-up. The proposal itself describes this fourth point as a target state rather than a commitment.
Wish For Change: the track that pays out no treasury money
The proposal runs on the "Wish For Change" track, number two at Polkadot. That track is a governance peculiarity and the reason the numbers above are easier to read than they look: a referendum passed on this track pays out no money and changes no code. It merely records that token holders wish for a change. Implementation stays with the funded entities, with the technical fellowship and with the teams that then have to file proposals of their own.
For holders of DOT, that means for now: no till is being opened here. The decision period runs 28 days, to November 10, with a confirmation period of one day after that. So far there has been no attempt to move the referendum into confirmation; the counter for that stands at zero.
73 percent against at 0.00 percent support: what the numbers say
The second figure is the more important one, and most reports leave it out. Alongside the approval rate, Polkadot runs a second value called support. It measures how much of total supply voted at all, unweighted. That value stands at 0.00 percent, 5,458 DOT in absolute terms. Against it stands total issuance of roughly 1.68 billion DOT.
Worked out, that is 0.00032 percent of supply. Put differently: of every 10,000 DOT in circulation, not even one has voted. A vote with that turnout says next to nothing about the stance of Polkadot holders, and that applies to the no as much as to the yes.
Conviction voting: why 53,030 votes can come from 8,838 DOT
Anyone wanting the percentages in their proper place has to know a component of Polkadot governance that many exchange users have never seen. Conviction voting means a vote weighs more heavily the longer the voter is barred from moving the tokens afterwards. The multiplier ranges from 0.1 to 6.
That changes the arithmetic fundamentally. In the extreme case, the 53,030 weighted no votes could come from 8,838 actual DOT, namely if every no voter picked the highest tier. At the price of $1.17 on Tuesday evening, that is worth roughly $10,300. On the same assumption, the yes side would amount to 3,228 DOT, about $3,780. A single holder with a five-figure dollar amount and patience can therefore tip a strategy vote in this network within its opening hours.
That is not a flaw in the system but its intent: whoever commits for years is meant to carry more weight than someone looking to sell again the same evening. The lesson for reading governance news still holds: a percentage without the number of tokens involved and without the conviction tiers is a headline, not information.
The lock-up periods from 7 to 224 days in detail
The tiers are set out in the Polkadot wiki and are fixed. Every doubling of the lock periods raises the multiplier by one:
- 0.1x: no lock, 0 days
- 1x: 1 period, 7 days
- 2x: 2 periods, 14 days
- 3x: 4 periods, 28 days
- 4x: 8 periods, 56 days
- 5x: 16 periods, 112 days
- 6x: 32 periods, 224 days
The period starts only once the referendum has ended, not when you vote. Vote today at the highest tier and the referendum ends on schedule on November 10, and you will not be able to transfer your DOT until around the end of June 2027. Count the period from the day you voted and you will be a good four weeks out.
The distinction between a lock and a freeze matters. During a governance lock you can still use the tokens to vote and still use them for staking; what is barred is only the transfer to another account. Staking yield therefore keeps running, and the terms on which providers pass it on are in the staking platform comparison. The 28-day unbonding period in Polkadot staking itself and the current yield of 2.77 percent we broke down on October 11 in a separate article; it runs independently of the governance lock and can overlap with it.
Voting works only from your own wallet, not from an exchange
This is the point at which the vote ends in practice for most German investors. In Polkadot's governance, only whoever holds the private keys to an account has a vote. If your DOT sit in an exchange account, the account belongs to the exchange, and so does the vote. None of the large providers passes it through to customers.
Voting therefore requires a wallet of your own and a transfer of the DOT to it. That costs network fees and brings responsibility for the key with it; which devices are suitable is in the hardware wallet comparison. If you do not want to take that route, you can delegate your vote to another account, though that too only from a wallet of your own. From an exchange account there is no path into the vote, and to see first what the transfer costs at your provider, the fee models are in the exchange comparison.
Holding period and staking during the lock
For tax purposes, the governance lock is not a separate event in Germany. Under Section 23 of the Income Tax Act, the one-year holding period applies to crypto assets, and it only runs out on a disposal. A lock under which the tokens stay in your own account and nobody else can access them is not a disposal. The holding period therefore keeps running, and a sale after the lock expires is tax-free if the year is complete by then.
Staking, which is allowed to continue during the lock, is a different matter. Rewards received are taxable in the year they arrive, at the price at the moment of receipt. Voting and staking at the same time therefore puts two separate matters in one position: an untouched holding period on the stock and continuously taxable inflows alongside it. Only a tax adviser can settle that bindingly, and the tax authorities have so far issued no statement of their own on individual governance locks.
dotUSD is already live: what the mandate would change about it
The proposal's second point is not new; it is already reality. Referendum 1944 approved the launch of dotUSD with 98.4 percent in favour, and the asset has been running since the start of October. It is backed by USDT for now, with the switch to DOT as collateral set down in the documents for later. After several revisions, the launch pool stood at roughly three million dollars, half USDT for issuance and half DOT for the trading pool. What dotUSD means for German investors, and why MiCA authorisation is the decisive open question there, we set out in detail on October 9.
Referendum 1954 would turn that into a principle: not one stablecoin but a class of permissionless, DOT-backed assets, one implementation of which the DAO would support with money. That is precisely where part of the opposition comes in. With an implementation already running, a mandate of this kind ties the network to one design before the first version has been through its stress test.
The ETP route: $12.37 million without a vote
A second way into DOT runs through exchange-traded products, and it shows how small interest in this asset currently is. The 21Shares Polkadot Staking ETF on Nasdaq, ticker TDOT, had net assets of $12.37 million on October 12 against cumulative net inflows of $3.33 million. That day's trading volume was $324,223. For comparison: total DOT trading across all venues came to roughly $236 million on Tuesday.
For the vote, the same applies on this route as on an exchange, only one step more strictly: a share in a fund or certificate is not an account on the blockchain. No voting rights arise from it, not even when the product stakes the underlying DOT. Shaping governance means taking custody yourself.
The price is not reacting to the mandate so far
DOT traded at $1.17 on Tuesday evening, 3.87 percent below where it stood 24 hours earlier. The daily high was $1.22, the daily low $1.12. The decline roughly matches what the broad altcoin market gave up that day, and it set in before the referendum was filed. No price reaction to the proposal is visible in the data.
Market capitalisation stands at around $1.99 billion, which corresponds to rank 50. DOT is 97.9 percent away from its all-time high of $54.98. Two levels are justifiable for the coming days: the daily low at $1.12 on the downside, because buyers stepped in there on Tuesday, and the daily high at $1.22 on the upside. Both come from today's trading and not from a model.
Our assessment: a declaration of intent, not a price signal
From the editorial team's point of view, the headlines on this referendum considerably overstate its reach, and the evidence sits in the figures on the voting page itself. The track pays out no money. Support stands at 0.00 percent, 5,458 of roughly 1.68 billion DOT. The weighted no votes could arithmetically come from tokens worth about as much as a mid-range car. A mandate that obliges nobody to anything, and in which not even a ten-thousandth of supply takes part, is weak as news about Polkadot's direction.
One point runs the other way, and it is not a small one: the substantive question the proposal raises is a fair one. Polkadot has delivered technically in recent years with JAM, with Agile Coretime and with dotUSD, and still stands 97.9 percent below its high. Whether a formal resolution changes that is doubtful. That the question about users is being asked is not. Holders of DOT should therefore watch the 28 days to November 10 less for the outcome than for whether turnout rises. A vote still showing 0.00 percent support in November says more about the state of governance than any result.
DOT DAO mandate: turnout is what decides by November 10
Three steps make sense over the coming weeks if you hold DOT:
- Settle the custody question. Check whether your DOT sit in an account of your own or in a provider's custody. Only in the first case do you have a vote at all. Which devices are suitable and what they cost is in the hardware wallet comparison.
- Work out the conviction tier before you vote. Take the tier whose lock you can see through to the end, and count it from the end of the referendum on November 10, not from the day of your vote. The 6x tier ties you until around the end of June 2027. If you still want to reshuffle beforehand, check your provider's transfer fees in the exchange comparison.
- Keep staking and the lock apart. The governance lock bars only the transfer; staking keeps running. Which providers offer which yield and which notice periods is shown by the staking platform comparison.
(As of October 13, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Anyone in Germany buying crypto assets through an exchange with an EU licence remains in BaFin's hands in Bonn and Frankfurt, even after the agreement of October 9, 2026. EU finance ministers have agreed to place only the largest crypto service providers under the direct supervision of the European Securities and Markets Authority, ESMA. On estimates from the Council, that covers 10 to 15 of roughly 360 authorised firms. All the others keep the supervisor that granted their licence.
The agreement is a negotiating position, not law in force. For the exchange you trade on today, nothing changes for now. The position becomes interesting where it reveals something about the next two years: who will handle complaints, who will examine custody and own funds, and which authority an enquiry actually gets results from.
What the EU Council decided on October 9
The EU Council has settled the core elements of its negotiating position on the Market Integration and Supervision Package, or MISP. The MISP is a legislative package through which the EU wants to concentrate supervision of financial markets more firmly at European level; it is the centrepiece of the savings and investments union. The crypto part is just one chapter among several.
The European Commission's proposal from December 2025 went considerably further. It would have moved supervision of all crypto-asset service providers from national authorities to ESMA. Little of that survives in the Council text. According to the Council's statement, only the most significant providers are to fall under European supervision, and the group is to be delimited by thresholds.
The same package moves supervision of significant central counterparties and central securities depositories to EU level, as well as of the most significant cross-border trading venues. Germany secured an exemption for parts of Deutsche Börse in the process, as the trade publication Ledger Insights reports. ESMA itself gains a full-time executive board with a chair and five independent members.
15 million users or several significance criteria: the thresholds for direct supervision
So far, the EU's Markets in Crypto-Assets Regulation, MiCA, knows only one hard line: a provider counts as significant from 15 million active users in the EU. At most a handful of platforms reach that number. The Council has therefore added alternative criteria that bite further down.
Accounts of the detail differ, and that has to be said. CryptoSlate describes the mechanics as ESMA supervising providers directly from 15 million active EU users, or those meeting three of five significance criteria; the ones named are more than one million active users, over one billion euros of crypto assets in custody and more than four billion euros of customer transactions a year. Ledger Insights sets out the same construction, noting that a provider with a good one million users could be caught if at least two further tests are added. The Council text itself has not yet been published in final form, so the exact thresholds are not yet settled.
What the thresholds mean in practice
Assets in custody and annual volume hit large trading venues, but hardly a custodian with German clients or a broker that carries crypto assets only as a sideline. That was precisely the point of contention: the Commission wanted supervision for everyone, while the Council draws a line behind which national competence remains. An existing MiCA licence stays valid, incidentally, even if a provider moves into direct supervision. Nobody faces a second authorisation procedure.
10 to 15 of roughly 360 providers: whom ESMA will supervise itself
The order of magnitude comes from the Council and was reported by Reuters: 10 to 15 providers out of around 360. That is a good three to four percent. Public analyses of the ESMA register arrive at somewhat lower totals; the site casptracker.eu counted more than 330 authorised providers across Europe as of September 7, 2026, and put Germany at the top with 81 authorisations, ahead of France with 35 and the Netherlands with 29. Another overview cites around 100 German providers as of the register on October 6, 2026, and describes itself as a lower bound. What is solid here is the ranking, not the second digit: Germany is the largest authorisation location under MiCA.
That produces a quirk often lost in the debate. The more licences an authority grants, the more work stays with it when direct supervision skims off only the top. BaFin therefore remains Europe's most important crypto supervisor, measured by the number of firms it oversees. How laborious such a procedure is shows in the German legal framework: the Crypto Markets Supervision Act implements MiCA nationally and sets out what BaFin bases its licences and warnings on.
For most crypto providers in Germany, BaFin stays in charge
For customers, competence is no formality. It determines where a complaint goes, which language the procedure runs in and which authority steps in when withdrawals stall. With a provider holding a German licence, that is BaFin. With a provider licensed in Malta, Ireland or Lithuania it is the authority there, even if the company has almost only German customers.
What supervision delivers and what it does not
A MiCA licence is a permission to operate under supervisory conditions. What gets examined is organisation, own funds, custody and complaints handling. Deposit insurance is not part of it, and the licence does not help against price losses either: with crypto assets there is nothing equivalent to the statutory deposit guarantee of €100,000 per customer and bank. If you do not want to carry counterparty risk, you take custody yourself. Which devices are suitable and where their limits lie is in our hardware wallet comparison.
The reverse also holds: without an EU licence, a provider may not actively approach German customers at all. How supervisors handle platforms that invoke the customer's own initiative shows in the debate around so-called reverse solicitation, the claim that the customer sought out the provider unprompted.
Passporting and the peer review of Maltese supervision
Behind the whole debate sits a design feature of MiCA called passporting: a firm authorised in one member state may offer services in all 27 and remains largely supervised by its home state's authority. That saves procedures and creates a gradient. Responsibility for a provider winning millions of customers across Europe stays with the authority that issued its licence once.
How robust that is was doubted early on. CryptoSlate points to an ESMA peer review from July 2025 on an authorisation by the Maltese financial supervisor MFSA. The finding there: no sufficient evidence was found that the authorisation review had adequately addressed questions of corporate governance, conflicts of interest, technology, custody and parts of money laundering risk. The MFSA countered in September 2025 that MiCA was too new to justify an additional layer of regulation.
The Council text does not resolve that gradient; it softens it. For providers below the thresholds, ESMA is to work with guidelines, peer reviews, coordinated investigations and certain powers of intervention in order to even out unequal enforcement. That is less than supervision of its own and more than today's state of affairs.
Two years of transition: how competence is meant to change hands
The Council provides for a transition period of two years. During that time, teams led by ESMA and staffed with European and national experts are to transfer information, procedures and expertise. No cut-off date from which ESMA actually supervises appears in the text; that depends on the outcome of the negotiations.
For investors, that means the practical effect arrives at the end of this decade at the earliest. Anyone waiting for stricter European supervision as an argument for a platform will be waiting a long time. The authorisation itself, by contrast, applies today. That is a feature you can look up straight away, and it stands in the register, not in the advertising. What a MiCA licence demands of a provider is something we have set out in our overview of MiCA obligations.
The Commission regrets the compromise
The responsible commissioner's reaction was unusually blunt. Maria Luís Albuquerque told ministers, according to Ledger Insights, that under the compromise "only some providers would be supervised by ESMA", and that the Commission "deeply regrets the proposed compromise". The commissioner's criticism referred to several parts of the package, of which crypto was one.
A commissioner publicly criticising a Council agreement says something about what comes next. The Commission will try in the trilogue to win back parts of its proposal, and on questions of European competence it often has the Parliament as an ally.
Checking the ESMA register: where your exchange's supervisor is listed
A provider's supervisory authority is a matter of public record, regardless of what its website says. Three places carry the information: ESMA's MiCAR register with the providers authorised under Article 63, BaFin's company database for German licences, and the Bundesanzeiger. The registers are updated at intervals, so a fresh authorisation appears with a few days' delay.
The difference between two statements matters. "Licensed in the EU" names the country that granted the licence and whose authority is competent. "Available in Germany" says only that the platform can be used here. As things stand, the first statement remains the decisive one for the large majority of providers even after the MISP.
It is worth a look in particular at providers that received their licence during 2026. The MiCAR transition period in Germany ended on July 1, 2026, and grandfathering does not constitute an authorisation. That BaFin also rejects applications it showed in October 2026, when it refused the operator of bitcoin.de a MiCAR licence.
What MiCA 2, the EU summit and Parliament can still shift
Three procedures are running at the same time, and they are readily confused. The MISP governs who supervises. The review of MiCA itself, informally called MiCA 2, governs what applies; its consultation closed in August 2026. And the agreement of October 9 is only the Council's position, which still has to be formally adopted.
Negotiations begin only once the European Parliament has adopted a position of its own. Until then, a great deal can still change in the shape of the package, in the thresholds as much as in the question of which trading venues are covered. According to reports, heads of state and government could take up the compromise again at their meeting on October 15 and 16, 2026.
For context, that means the direction is set, the numbers are not. Anyone concluding from the news that their exchange will now be supervised at European level is jumping ahead. The opposite is more likely, namely that national supervision stays in place permanently for the large majority of providers.
ESMA supervision: first Parliament, then two years of transition
- Establish your exchange's licensing country. Look up in ESMA's MiCAR register or BaFin's company database which authority granted the licence. Which firms can demonstrate an EU authorisation is shown in the overview of regulated crypto exchanges.
- Cap counterparty risk. A licence is no substitute for deposit insurance. Decide which share of your holdings has to sit on the trading platform and which belongs in your own custody; the devices for that are in the hardware wallet comparison.
- Weigh costs against authorisation. An EU licence costs the provider money, and that shows up in the fees. Compare trading and withdrawal costs before moving over supervision, for instance in the exchange comparison.
The Council's negotiating position is set out in its statement of October 9, 2026 (Council of the EU).
(As of October 13, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
On Friday, October 16, the Bitcoin network will make itself more expensive. At around 14:00 UTC the blockchain reaches height 971,712, and the next mining difficulty adjustment takes effect. On Tuesday afternoon's reading, it comes out at 5.49 percent to the upside. That is the third-largest increase of this year, and it hits an industry whose product trades 33.8 percent below its record of $126,080.
This is not a technical footnote for investors. Difficulty determines how much computation a new Bitcoin costs, and with it the floor below which a miner would rather sell its coins than hold them. This article works through how much more expensive production becomes on Friday, which levels the price has behind it, and what you can check before the date.
132.72 trillion: what mining difficulty is showing right now
Mining difficulty is a number the Bitcoin network resets every 2,016 blocks. It governs how hard it is to find a valid block, and so keeps the average block time at ten minutes. When computing power on the network rises, difficulty follows it up. When computing power falls, difficulty falls.
It currently stands at 132.72 trillion. The last adjustment on October 3 was effectively a non-event at minus 0.03 percent. Since then, miners have brought too much power to the network: blocks are arriving every 9.49 minutes on average instead of every ten, roughly half a minute too fast. That half minute is exactly what the protocol takes back on Friday.
On Tuesday afternoon, 438 of the current period's 2,016 blocks were still outstanding, with 78.3 percent of the window elapsed. The further a period has run, the more stable the estimate becomes. At 78 percent, experience suggests the expected figure moves only by a few tenths of a percentage point, as long as no large mining fleet is switched off.
Friday at around 14:00 UTC: how the 5.5 percent figure comes about
On reaching the target height, the protocol compares how long the past 2,016 blocks actually took with the 20,160 minutes they should have taken. The ratio between the two gives the new difficulty. If blocks ran 5.2 percent fast, difficulty rises by roughly 5.5 percent.
The date itself does not depend on the clock but on the block counter. The estimated time of 13:59 UTC is a projection from the current block speed. If the remaining blocks arrive faster, the date moves half an hour forward; if they arrive more slowly, it slips back. That is not a timetable, but it is a reliable order of magnitude.
$82,500 did not hold: where things stand since Monday
Our Bitcoin forecast from Monday centred on the $82,500 level, together with the inflation print on October 14 and the rate decision on October 28. That level did not hold at the low. Over the past 24 hours the price fell as far as $81,018, almost $1,500 below it, and then came back.
On Tuesday afternoon, Bitcoin trades at $83,412. Against Monday's close of $81,795 that is 2.0 percent higher. Over one week the price is still down 2.7 percent, over 30 days up 8.2 percent. The move back below $82,500 was therefore not a break in the uptrend, but it shows that this line is softer than it looked on Monday.
What has been added since is Friday's date. On Monday it was not yet firmly in view, because the current period was only half elapsed and the estimate was swinging accordingly.
1.00 zettahash per second: the computing power behind the adjustment
Behind the increase sits a figure the network reached only recently: computing power stands at 1.00 zettahash per second. One zettahash is 1,000 exahash, a one followed by 21 zeros in computing operations every second. Averaged over the past three days, the figure ranged between 0.999 and 1.029 zettahash.
That power is the actual reason for the adjustment. Miners have switched on machines over the past two weeks even though the price has given ground since the start of October. This is the classic pattern after a hardware delivery: new machines go online because they were ordered and paid for, not because the price argues for it right now.
Why revenue per terahash falls by 5.2 percent
Here is the mechanism that links the technology to your portfolio. The network pays out a fixed amount per block, currently 3.125 Bitcoin plus fees. The difficulty adjustment does not change that amount. What changes is the number of competitors for the same pot.
If difficulty rises by 5.49 percent, a miner with unchanged hardware receives only the reciprocal of that, 94.80 percent of its previous share. Its revenue per terahash of computing power falls by 5.20 percent. Its electricity bill stays the same. A miner sitting just above its costs before Friday sits below them afterwards.
That is where the selling pressure discussed around such dates comes from. A miner that can no longer cover its bill out of current revenue has to sell coins from its holdings or switch off machines. If it switches off, computing power falls, and the adjustment after next comes out to the downside again. This feedback loop has run since 2009, and it is the reason the network keeps going even after heavy price losses.
450 Bitcoin a day against $32 billion of turnover
The scale belongs in the picture, however, or real cost pressure turns into an overblown price story. The network produces roughly 450 Bitcoin a day from the block subsidy, about $37.5 million at $83,412. Trading turnover in Bitcoin over the same 24 hours came to $32.4 billion.
Even if miners sold their entire daily output immediately, that would be around 0.12 percent of daily turnover. The cost pressure from the adjustment is existential for the companies affected; for a single day's price it is a small quantity. Fund flows weigh far more heavily at the moment: according to Farside Investors data cited by CoinDesk, Bitcoin funds saw net outflows of $65.4 million on October 12, and roughly $681 million in the week to October 9.
Reading the adjustment as the sole explanation for the price therefore overstates it. Ignoring it means missing a cost threshold that shows up in the quarterly numbers of the listed miners.
The third-largest increase of the year: every 2026 adjustment compared
Whether 5.5 percent is a lot only becomes clear in hindsight. We read out every adjustment of this year from the block data at mempool.space and set them against each other.
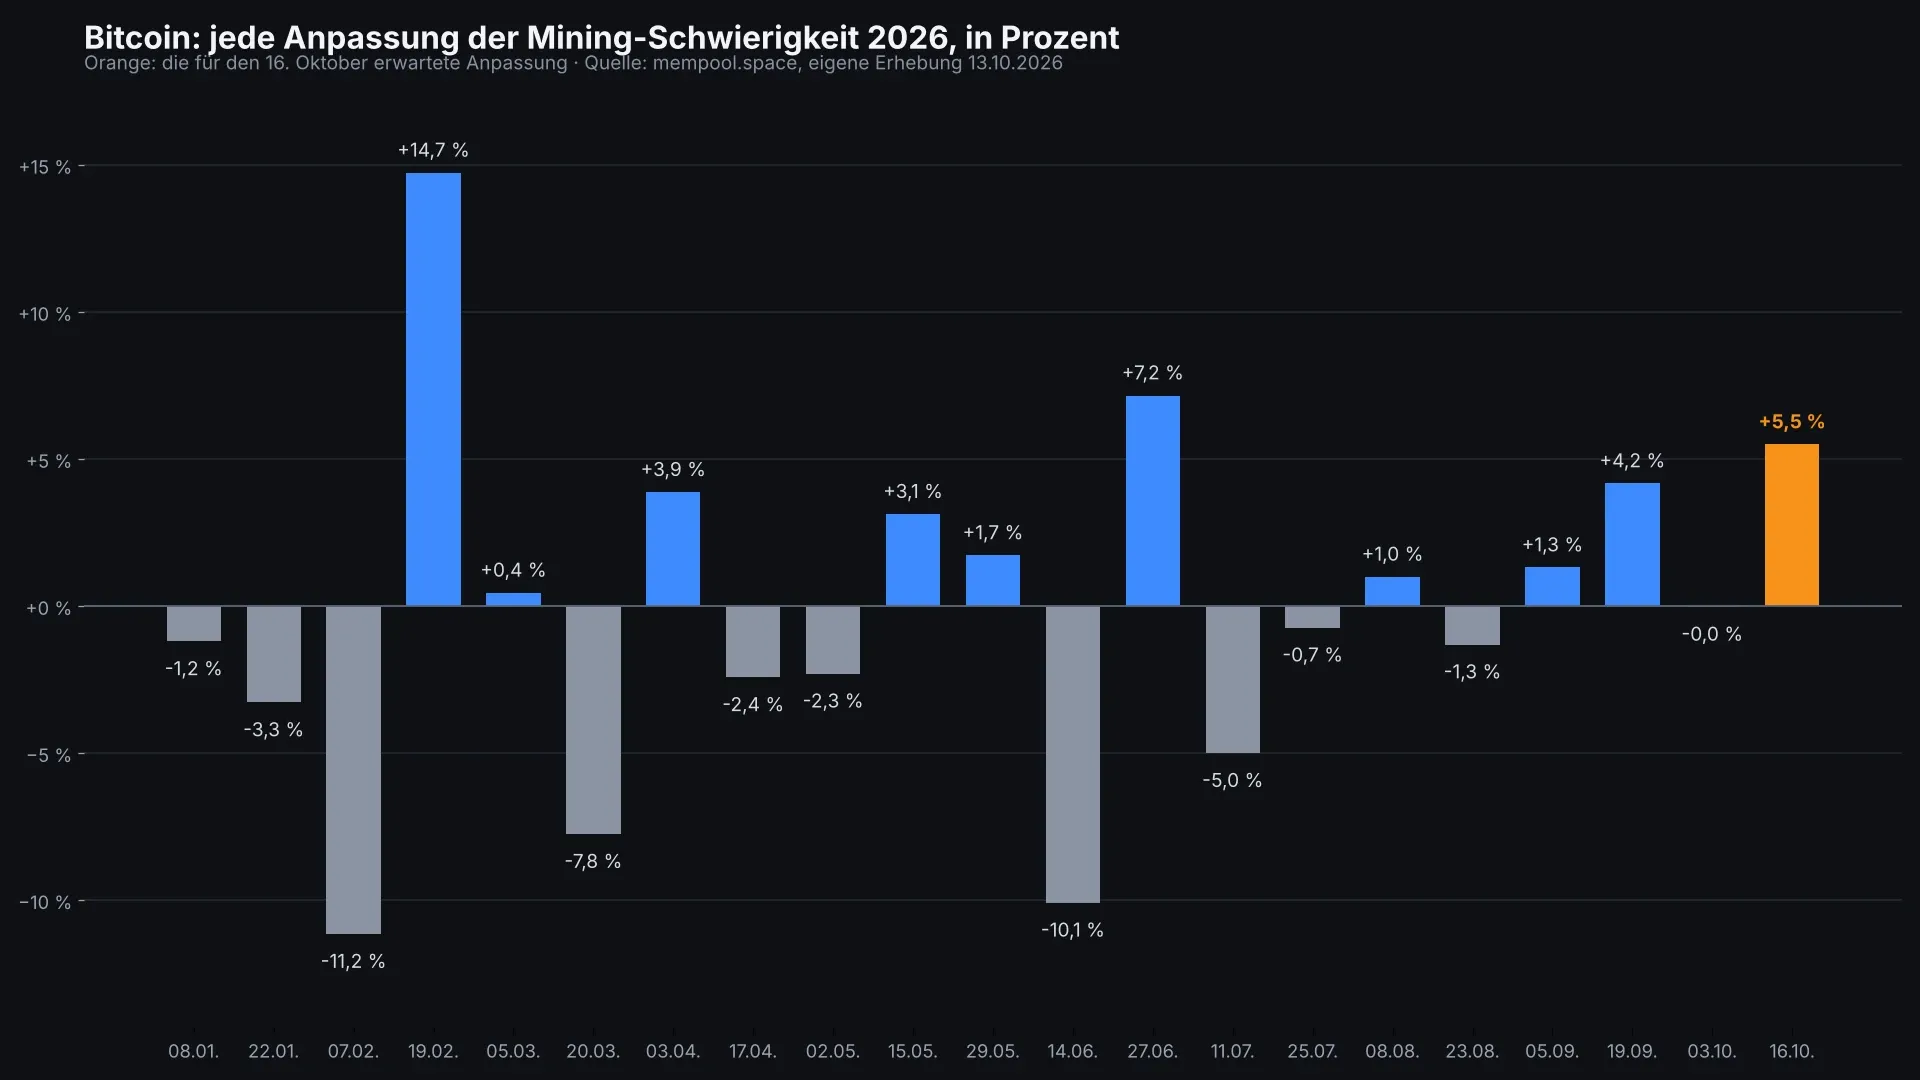
Only two increases were larger in 2026: 14.7 percent on February 19 and 7.2 percent on June 27. Friday follows with 5.5 percent, ahead of the 4.2 percent on September 19. The downside swings were sharper: minus 11.2 percent on February 7 and minus 10.1 percent on June 14.
Across the past 26 adjustments, a good year, difficulty rose 11 times and fell 15 times. On balance, the network lost power rather than gained it in 2026. Friday runs against that trend, and that is what makes it notable: computing power is growing into a weak price.
$81,018 and $84,074: the levels for the coming days
For the price, that yields clear checkpoints. On the downside sits the daily low of $81,018. Below it comes the 50-day line at $81,110, which the price currently sits 2.8 percent above. The two levels are so close together that they form a zone rather than two separate lines. If the price breaks through there, the next demonstrable stop is the monthly low of $75,590.
On the upside stands the daily high of $84,074, and above it the monthly high of $86,597. The 200-day line sits far below at $72,123: the price has 15.7 percent of headroom above it. As long as that gap holds, the long-term uptrend is intact, even with the short-term lines under pressure.
Friday's adjustment does not create any of these levels. The date concerns costs, not the price. Deriving levels from it means measuring the wrong thing.
Savings plans and fees: what a €100 instalment really costs
For investors in Germany, the practical question on a date like this is rarely whether to buy, but at what cost. There is a lever here that you control, unlike the price itself.
An example: on a monthly instalment of €100, an instant purchase through an exchange's trading window costs between 0.99 and 1.49 percent depending on the provider, so 99 cents to €1.49. The same instalment placed in the order book of the same exchange often costs 0.1 to 0.4 percent, so 10 to 40 cents. Over twelve months that is a difference of around €13 on €1,200 committed. That is more than most price moves of a single week come to on that amount.
You can check this in three places: your provider's fee schedule, the statement from your last savings-plan execution, and the spread, the gap between the buy and sell price at the moment of execution. Which providers run which models is in our comparison of Bitcoin savings plans; if you place the instalment in the order book yourself instead, the fee tiers are in our overview of crypto exchanges.
A second point concerns the execution day. Many providers let you choose it freely. A fixed day is preferable to trying to dodge dates such as Friday: the cost advantage of a well-chosen day cannot be demonstrated, whereas the disadvantage of a skipped instalment can.
How to check the next adjustment yourself
You do not need a paid data source for this. The block data is public, and the route takes less than a minute.
Open the mining overview at mempool.space. Four figures there add up to the picture: current difficulty, the expected change in percent, the number of remaining blocks and the estimated time to the date. If remaining blocks are below 500, the estimate is reliable. If they are above 1,500, the period is still near its start, and the percentage can halve or double.
The fifth figure you work out yourself: divide 1 by the factor of the change. At plus 5.49 percent, 1 divided by 1.0549 gives 0.948. Revenue per unit of computing power falls by those 5.2 percent. The same calculation works for a decrease and then gives a plus.
From the editorial team's view: the adjustment raises production costs, it does not turn the price
Our read on Friday is sober. Three pieces of evidence support it: daily production of 450 Bitcoin equals 0.12 percent of the $32.4 billion in daily turnover; the previous week's fund outflows, at $681 million, were many times larger; and across the past 26 adjustments the price has shown no discernible regularity around these dates.
One argument runs the other way, and we will not play it down: if the increase meets a stretch of persistently weak prices, the miners with the highest electricity costs come under pressure, and their sales land in an already thin market. That effect is real, but it shows up over weeks in the holdings of mining companies, not on a Friday afternoon in the candle chart.
In short: October 16 is a cost date for an industry, not a turning point for the price. Positioning a portfolio around it confuses the production side with the demand side. If you want to know how solid the network is, rising computing power is a strong argument in its favour.
Mining difficulty: October 16 makes every new Bitcoin more expensive
Friday's adjustment lifts production costs by a good five percent while the price sits a third below its record. Three steps follow from that:
- Keep an eye on the zone between $81,018 and $81,110. The daily low and the 50-day line sit almost on top of each other there. If that zone holds, Monday's picture stands. If you want to place a buy order there, the fee models are in our comparison of crypto exchanges.
- Recalculate your own purchase costs. Instant purchase and order book are around one euro apart on a €100 instalment, roughly €13 over a year. The models are in our overview of Bitcoin savings plans.
- Review leveraged positions before October 28. Two weeks with several scheduled events lie between Friday's adjustment and the rate decision. If you work with leverage, the terms are in our comparison of crypto brokers.
(As of October 13, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
A new trading venue lost roughly $1.28 million from its own liquidity pool within eight hours on October 10, 2026, and nobody had to find a security hole in its code to do it. Moving the price the platform used to settle its trades was enough. The Papertrade case shows how sensitive leverage of 1,000 becomes once the reference price comes from outside and the capital behind it is thin.
Papertrade launched with 1,000x leverage, and the counterparty was a protocol-owned liquidity pool
Papertrade is an exchange for perpetual futures, known as perpetuals, and runs on HyperEVM, the Ethereum-compatible execution layer of the Hyperliquid blockchain. Trading opened on October 10, 2026 at 10 a.m. Eastern time. The venue advertised leverage of up to 1,000, meaning a position a thousand times the size of the capital committed.
Before the launch, DefiLlama figures put deposits in the protocol at roughly $85.3 million. Accounts of the later figure diverge: one analysis cites $118 million, another $138 million from 11,465 addresses. We report the range as the sources give it rather than declaring one of those numbers a fact.
The decisive piece of the design is not the size of the leverage but the question of who stands on the other side of a trade. On a conventional futures exchange, every buyer finds a seller. At Papertrade, every position runs against a pool the protocol holds itself. Winners are paid out of that pool, and losers pay into it. According to the provider's documentation, this removes the funding payments normally exchanged between the long and short sides, and no matching futures contract trades on Hyperliquid itself. The trades are synthetic.
The execution price came from the midpoint of the Hyperliquid spot order book
Settling a synthetic trade requires a price. Papertrade took the midpoint between the best bid and the best offer in Hyperliquid's spot order book, the mid of the BBO, or best bid and offer. That single sentence is the heart of the whole episode: whoever shifts the quotes on the Hyperliquid spot market shifts, directly, the price at which Papertrade values and closes positions.
A midpoint price is a clean choice in itself, because it splits the spread between buy and sell side neutrally. It does assume, however, that the market it comes from is deep enough not to be moved by a single order. On launch day, someone tested that assumption.
6,060 Ether on the spot market and a three-dollar price move
The sequence, described independently by several trade publications, followed a simple pattern. First, one address opened a large position on Papertrade. The same address then bought and sold Ether repeatedly on the Hyperliquid spot market. A purchase of roughly 6,060 Ether lifted the price there by about three dollars, according to the available figures.
Three dollars sounds like nothing against an Ether price in the region of $2,500. It is around 0.12 percent. At leverage of 1,000, however, a 0.12 percent price move turns into a change in committed capital many times over. Leverage is not a side issue here; it is the amplifier that translates an economically trivial move into a seven-figure sum. If you trade Ether, our Ethereum price prediction tracks the current picture and the levels that matter.
$52,000 in fees, $1.28 million out of the liquidity pool
The back and forth on the spot market was not free. According to the available reports, the address paid roughly $52,000 in trading fees and moved Ether worth about $231 million that day. Against that stood a withdrawal from Papertrade's liquidity pool that most sources put at $1.28 million; one analysis cites $1.54 million. Sources also disagree on whether that figure is the gross withdrawal or the net profit.
The address is no casual participant. Available data show it trading on Hyperliquid since February 2025, starting with roughly $2 million, reaching total volume of $14.2 billion and a net profit of $13.1 million. One report also cites a later loss of around $450,000 after a short position on Ether opened with 660x leverage was liquidated. Leverage cuts both ways, including for the side that believes it has mastered it.
Ten billion dollars of open interest against $54 million of cover
The second number that explains this case is open interest, the sum of all open positions. Analyses of blockchain data cite a peak of $10.1 billion for October 10; another source puts it at roughly $11 billion, against only $54 million of cover. Even at the low end of that range, open positions and posted capital stand in a ratio of about 185 to 1.
A pool carrying that much position volume has to absorb every move in the reference price. That is why a three-dollar shift was enough to displace a seven-figure sum. After the incident, open interest fell by 88 percent, according to the reports.
Papertrade's statement: loose exposure limits, not an overlooked bug
Papertrade has addressed the episode publicly. The provider confirmed attempts to move the reference prices for Bitcoin and Ethereum and said it had already tightened position limits. It rejected the charge of an overlooked bug: the initial caps on risk exposure, it said, had been set deliberately wide to give the launch room. The provider also said the trader had returned most of the profit to the liquidity pool. According to the outlets reporting it, that claim could not be verified independently, and we therefore carry it as the provider's statement rather than an established fact.
One further point from the same documentation is worth knowing: protocol governance can halt new positions, freeze markets and change fee parameters. For a venue acting as the counterparty to its own pool that is understandable, and it also limits what you can rely on if things go wrong.
Spot price manipulation: 32 cases and $68.65 million this year
Papertrade is not an isolated case but the latest entry in a group that has grown steadily through 2026. The basis is DefiLlama's public incident list with 1,301 entries, from which we counted all 294 incidents dated in 2026. cryptoticker.io compiled this analysis itself on October 13, 2026.
This year's 294 incidents add up to $2,245 million. Forty-two of them are classified as oracle manipulation, together $74.65 million. After access control with 53 cases and accounting errors involving shares and tokens with 50 cases, that is the year's third most frequent category. Within that group, the technique also described at Papertrade carries the label spot price manipulation: 32 cases, together $68.65 million.
Two figures put the scale in context. The median case in this group stands at $0.40 million, the largest at $18.40 million, recorded on April 16, 2026 for Rhea Lend. At $1.28 million, Papertrade sits a good three times above the typical case and far below the record. The pattern has become routine this year; the amounts have not.
What stands out is the shift in the attack surface. The spring cases mostly hit lending protocols, where a shifted price made a position appear wrongly overcollateralised. Papertrade, by contrast, was hit at settlement, not at collateralisation. Both times the cause was the same: a price from outside whose market was shallower than the leverage behind it.
A pool as counterparty bears the risk differently from an order book
The design is worth a look, because it decides who ends up paying. On a perp DEX with an order book, other traders provide the other side. One loses, another wins, and the protocol mediates. When a price breaks down there, insurance funds and automatic deleveraging step in, as we set out for several providers in our comparison of the best perp DEXs.
What a protocol-owned pool changes for you
With a pool on the other side, all traders together are positioned against that pool, and its depth is the hard ceiling on any payout. Two things follow. First, risk is decided by the ratio between open positions and posted capital, not by the level of leverage on offer. Second, a successful attack on the reference price hits the pot every other trader draws profits from, rather than a single opponent. Traders in profit at Papertrade on October 10 were hanging on the same pool the $1.28 million flowed out of.
That gives you a yardstick for a venue before you deposit capital: where does the price come from, how deep is the market behind it, and how far may open interest rise relative to cover? Papertrade answered the third question only after the incident.
A 2:1 leverage cap and 25 percent tax: the framework for investors in Germany
Leverage of 1,000 is out of reach for retail investors in Germany through regulated channels, and that is no accident. The European Securities and Markets Authority, ESMA, capped leverage on contracts for difference by underlying in its 2018 product intervention measures and applied the strictest tier to cryptocurrencies. The cap covers retail clients; professional clients fall outside it. In Germany, BaFin has carried those requirements over into permanent national measures. Our assessment of leverage caps on perpetuals from October 3, 2026 describes how this breaks down across the individual product types: perpetuals and the MiFID leverage cap.
A venue such as Papertrade sits outside that framework because it does not operate as an authorised investment firm in the EU. For Hyperliquid itself, we noted on September 15, 2026 that no MiCA authorisation is in place. In practice, that means neither a deposit guarantee nor a German complaints body applies when a pool runs dry. If you are looking for leveraged products inside the regulated framework, the route runs through authorised providers; which houses set which leverage and costs is in our overview of the best crypto brokers.
On tax, the difference from buying coins is substantial. Under our breakdown of October 12, 2026, the tax office treats profits from perpetuals and futures as investment income at 25 percent plus the solidarity surcharge, and does so from the first trade onwards. The one-year holding period for cryptocurrencies does not apply here. The details, including loss offsetting, are in our piece on tax on crypto futures and perps.
Our assessment of Papertrade's launch day
From the editorial team's point of view, the episode is less an attack than a pricing question asked too late. Three pieces of evidence support that: the reference price came, per the documentation, from the midpoint of a spot order book; open interest reached $10.1 billion against $54 million of cover, according to blockchain data; and the provider itself describes its initial risk limits as widely set. Tie leverage of 1,000 to a market that 6,060 Ether move by 0.12 percent, and the real ceiling sits in the order book, not in the leverage figure.
Against that, the mechanism worked as intended: the pool paid, the limits were tightened, open interest fell by 88 percent. No balance was lost to a software bug. Whether the profit was in fact returned remains open as long as only the provider confirms it. None of this is an assessment of the platform as an investment, still less a recommendation to buy or sell.
Papertrade's limits: 185 to 1 was the real problem
Three steps put the situation in order for you:
- Read the price source and the market depth together. With any leveraged venue, ask which order book the settlement price comes from and what volume it takes to move it by a tenth of a percent. Which providers average their prices across several sources and which hang on a single one is in our comparison of the best perp DEXs.
- Set open interest against cover. A ratio such as 185 to 1 is a warning sign regardless of the advertised leverage. Inside the regulated framework, leverage for retail clients on cryptocurrencies stays on ESMA's strictest tier; which houses charge what is shown in our overview of the best crypto brokers.
- Settle the tax position before the first trade. In Germany, perpetuals count as investment income at 25 percent plus the solidarity surcharge, with no holding period and with their own rules on loss offsetting. Anyone settling a lot of trades needs clean records; you will find tools for that under crypto tax software and portfolio trackers.
(As of October 13, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
NEAR costs around $5.09 at midday on October 13, putting it 11.7 percent lower than 24 hours earlier. Bitcoin shed 0.3 percent over the same period and Ether 2.3 percent. At its intraday low NEAR stood at $4.90, below the round five-dollar mark; the jump a report from New York set off on Sunday has been given back in full. Nasdaq-listed SVRN, Inc. has bought FastNEAR, the operator of the servers through which practically every NEAR wallet and every NEAR app talks to the blockchain.
The details of the acquisition are in the Form 6-K that SVRN filed with the US Securities and Exchange Commission on October 9. What it says is more concrete for holders than any price figure, because it concerns the route by which your balance appears on the display at all.
What SVRN bought with FastNEAR: RPC servers, archive nodes and the NEARDATA service
RPC stands for remote procedure call and denotes the interface through which a wallet or an app asks something of a blockchain node or hands it a transaction. An RPC provider therefore runs the servers that hold a current copy of the blockchain and answer on behalf of users.
According to the press release in the SEC filing, FastNEAR operates three things: a fleet of such RPC servers, an archive infrastructure holding NEAR's complete transaction history, and NEARDATA, a data service developers use. SVRN cites more than 3.5 billion requests a month and more than 100 terabytes of data. FastNEAR has been a wholly owned subsidiary since October 8; co-founders Evgeny Kuzyakov and Mike Purvis have moved to SVRN. The company does not name the purchase price.
SVRN chief Sal Ternullo justifies the purchase in the release by saying that everything built on NEAR depends on infrastructure most people never see. When a wallet shows a balance or an application submits a transaction, something has to answer, fast and correctly, every time. The company announces that it will invest in reliability and capacity; for existing customers the services are meant to continue without interruption.
Why buying an RPC operator moves the NEAR price
The mechanism behind it is simpler than the technology sounds. SVRN holds NEAR on its own balance sheet and thereby gives its shareholders exposure to the token. Until now it was a pure holding company with staking. FastNEAR adds an operating business that has revenue of its own from paying customers and whose value does not depend on the NEAR price. For the market that means a listed buyer is binding itself more deeply to a network it can no longer exit cheaply without damaging its own business.
That fits what SVRN writes in the same release about its other role. The company stakes its holdings with validators that secure the network and takes part in governance; it co-authored the programme that has paid operators of MPC nodes according to performance since February 2026. A buyer that bundles technology, voting rights and balance sheet in the same network is a different signal for investors than a fund that merely collects tokens.
NEAR, Bitcoin and Ether over 24 hours: minus 11.7 against minus 0.3 against minus 2.3 percent
Over one day the gap is clear. NEAR lost 11.6 to 11.7 percent depending on the data provider, Bitcoin 0.3 percent, Ether 2.3 percent. Over a week the picture reverses: NEAR is down around 3.2 to 4.2 percent, just behind Bitcoin, which shed around 2.9 percent, but ahead of Ether at around 7.5 percent. The daily loss hits NEAR considerably harder than the broad market; measured over seven days Ether is the weakest of the three. NEAR's trading volume over those 24 hours came to around $1.28 billion.
Market capitalisation stands at around $6.65 billion, trading volume over the past 24 hours at $1.04 to $1.14 billion. On the ranking the providers diverge: CoinGecko lists NEAR in 21st place, Coinpaprika in 24th. Anyone reading a figure such as "top 20" should therefore know that it depends on the chosen provider and not on any official list.
NEAR Intents: $33.57 billion in total volume and $122.8 million in a day
The second reason that comes up in reporting on the NEAR rally is NEAR Intents. It is a swap system in which users declare a desired swap and competing service providers execute it, instead of tokens being locked across a bridge and minted anew. According to DefiLlama data the system has turned over $33.57 billion in total.
That sum is a cumulative figure since launch and says nothing about what is happening there today. The current values are smaller: $122.8 million over 24 hours, $1.15 billion over seven days, $4.74 billion over 30 days. The daily figure is therefore around 20 percent below the previous day's, even though the price rose. Read the 33 billion as current volume and you overestimate demand by more than twentyfold. In the autumn part of the volume came from Zcash swaps, that is, from a single fashion that can ebb away again.
What changes for NEAR holders: wallet, RPC endpoint and custody
The sale of FastNEAR changes nothing about your coins. Your keys remain your keys, and the balances still sit on the blockchain. What changes is the ownership of one of the routes by which you reach the blockchain. In practice that means three things.
First: in many wallets you can see and change the RPC endpoint in the settings. Take a look there at which provider is entered. An endpoint is interchangeable, and knowing several providers is the simplest safeguard against the failure of a single one.
Second: an RPC server sees which address asks what and when. A wallet that sends all requests through one provider leaves a movement profile there. That is not a theft risk, but it is a data protection point that takes on a different quality with a listed owner than with a small team.
Third: anyone holding larger balances separates custody from access. The keys sit on a hardware wallet, and which server queries the blockchain is then purely a question of convenience with no access to the assets. That separation is the real protection, not the choice of provider.
Staking and validators: 412 nodes secure NEAR, and FastNEAR is not among them
This gets confused often, so here is the clear distinction: validators produce blocks and secure consensus, RPC servers answer requests. Those are two separate layers. NEARBlocks currently counts 412 nodes online, block time is 0.6 seconds, and more than 5.46 billion transactions have been processed in total. The acquisition has changed nothing at that layer.
That is the most important framing of the day: whoever buys FastNEAR buys access, not control over the network. A buyer could raise prices, discontinue services or log requests. It could not forge a transaction, roll back a block or take anyone's coins away. Anyone who sees SVRN staking and infers influence over consensus from it is confusing the balance sheet with the technology; the staking confers voting weight in the network, the RPC purchase does not.
MyNearWallet closes on October 31: the key migration is still running
Independently of the acquisition, a deadline is running in the NEAR orbit that is more concrete than any price level. MyNearWallet is ceasing operation as of October 31. If you hold your NEAR there, you have to move the keys into another wallet beforehand, otherwise the familiar access is gone after the cut-off date. Cryptoticker covered the shutdown in detail on October 8.
Both processes have the same core, even though they have nothing to do with each other: access to a blockchain runs through services that can change owner or close. The blockchain itself remains, the access does not. That is exactly why a look into the wallet settings pays off now and not on October 30.
Buying NEAR in Germany: which route is open under MiCA
NEAR is available in Germany through regulated trading venues. Since the EU's MiCA regulation took effect, providers addressing retail customers in the EU need authorisation as a crypto asset service provider; a BaFin licence, or one from another member state used in Germany, is the minimum to look for in a buying route. Which venues carry NEAR and what fees they charge is shown in our crypto exchange comparison.
In the purchase itself, after a day with almost 12 percent of movement, the order type makes the difference. A market order in a thin order book buys at the next available price and can be filled well above the price you last saw. A limit order names your maximum price and may not be filled at all. With a daily range of $4.90 to $5.76, those are not rounding errors.
If you want not just to hold NEAR but to earn on it, you end up at staking. The proceeds are income and depend on the validator you delegate to; the lock-up period when you withdraw belongs in the calculation. Which platforms quote which terms is set out in our overview of staking platforms.
Tax on NEAR gains: holding period, exemption limit and the exchanges' reporting duty
In Germany, gains from the sale of crypto assets count as private disposals. After a holding period of one year the gain is tax-free; before that it counts towards your other income. The exemption limit for such gains is 1,000 euros in the calendar year and falls away entirely as soon as it is exceeded. Staking proceeds are valued at the time of receipt and have to be considered separately.
Documentation is what matters. Anyone rearranging a portfolio after a jump like the one from Friday to Sunday creates transactions whose acquisition data has to remain traceable next year. A tax tool or portfolio tracker takes over the logging; the duty to file correctly stays with you. The fact that trading venues pass data on to the tax authorities does not make clean records of your own unnecessary, it makes them more important.
The levels after the break below five: $4.90 below, $5.76 above
Three values are well founded for the coming days. Below sits the intraday low at $4.90: that is where the price slipped under the round five-dollar mark during October 13 before pulling back to around $5.09. The mark has therefore failed once and now sits just below the current price. Above sits the intraday high at $5.76, around 18 percent above the low. Whether the return above five dollars holds will show in whether the price leaves Tuesday's low untouched.
For context on the upside: the all-time high of $20.44 dates from January 2022. From today's price that is more than 70 percent away. The last time Cryptoticker wrote about NEAR, on October 10, the price stood at $4.93. The intraday low of October 13 at $4.90 was even below that, so the level around 5 dollars discussed then has been worked through. You will find the state of play at the time in the article on the volatility range of October 10.
Our assessment: a Nasdaq company at the access point, not at the blockchain
In the editorial team's view the acquisition is positive for NEAR over the medium term and overdrawn in the short term. Positive, because a listed owner brings money and accountability into an infrastructure that a small team ran at low prices until now; SVRN expressly announces investment in reliability and capacity. Overdrawn, because the network's daily figures were already not keeping pace on October 12: $122.8 million of daily volume at NEAR Intents stood against a cumulative total of $33.57 billion, and the token's trading volume of around $1.04 to $1.14 billion did not support a ten percent jump in a quiet overall market. The price path of October 12 has confirmed that reading.
Something else argues against it: the purchase price was not disclosed. Without it there is no judging whether SVRN bought cheaply or whether its own share price carried the cost. Assessing the acquisition as a piece of business is not possible with the figures published; assessing its direction is. Crypto assets can fall to a total loss; this assessment is not a recommendation to buy or sell.
NEAR's RPC plumbing: a Nasdaq company serves 3.5 billion requests
- Open the wallet settings and note the RPC endpoint. If larger balances sit with a single provider, separate custody from access and put the keys on a device from the hardware wallet comparison.
- Check the venue and the order type before buying. Authorisation under MiCA, NEAR on offer, a limit order rather than a market order after a day with almost 12 percent of movement: the terms are in the exchange comparison.
- Weigh the lock-up period against the yield when staking. The proceeds are taxable on receipt, and withdrawing takes time; you will find the terms at the staking platforms.
The primary source on the acquisition is the SEC Form 6-K from SVRN, Inc. of October 9, 2026. The volume figures for NEAR Intents are at DefiLlama.
(As of October 13, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
A Saudi national working at OpenAI allegedly hid an encrypted audio recorder behind a TV in an executive meeting room. OpenAI says its own models helped trace it back to him.
The chatbot app once valued at $1 billion is up for sale in a Delaware court, two weeks after launching new models. If nobody buys it, it shuts down.
Binance will discontinue Binance Pool, Pool Savings, Cloud Mining, and other related services in a retreat from mining infrastructure.
A wallet that received 4,581 BTC in March 2020, worth about $40 million then, moved its stash today when it was worth about $377 million.
The Nasdaq-listed asset manager bought the Bitcoin at an average of about $84,500 during a rough week for the market, lifting its total stash to 32,773 BTC.
U.Today - IT, AI and Fintech Daily News for You Today
Ripple has partnered with Stripe-owned Privy to bring AI-powered payments to the XRP Ledger, expanding its push into agentic commerce.
Hardware wallet giant Trezor is severing ties with a significant portion of its authorized resellers following the massive Ledger supply-chain security scare, introducing stricter controls to protect customers from potential attacks.
SEC report exposes who really owns Nasdaq's new XRP stock, revealing massive stakes held by Chris Larsen, Ripple, and SBI Holdings.
Tesla still boasts nearly a billion dollars worth of Bitcoin years after Elon Musk directed the electric vehicle maker to invest $1.5 billion in the leading crypto asset.
Ripple has minted another 19.6 million RLUSD on Ethereum amid heightened treasury activity, with the latest transactions coinciding with a major institutional custody breakthrough.
Blockonomi
TLDR
- Walmart stock gains 0.25% as AI chatbot recommendations boost retail visibility.
- UBS research shows Walmart leads AI shopping suggestions for everyday products.
- Gartner finds 34% of US consumers willing to use AI for holiday gift shopping.
- Walmart’s strong retail presence supports its position in AI shopping results.
- High stock valuation remains a challenge despite new AI-driven growth prospects.
Walmart Inc. rose 0.25% to $113.36 during Tuesday’s intraday trading, gaining $0.28 as shares advanced modestly. The increase came as UBS research highlighted Walmart’s strong position in artificial intelligence-powered shopping recommendations. Analysts identified the retailer as a frequent recommendation across AI chatbots, creating another potential channel for attracting customers.
Walmart Inc., WMT
UBS Research Highlights Walmart’s Strength in AI Shopping
UBS analysts examined how leading AI chatbots recommend retailers when consumers search for everyday products and shopping advice. The research covered several shopping categories, including groceries, household supplies, and other essential consumer goods. Results showed Walmart frequently appeared among the leading recommendations, reflecting its established retail presence and competitive pricing.
The analysts tested 12 shopping questions across New Jersey, New York, and Minnesota to evaluate different recommendation patterns. They examined responses from ChatGPT, Claude, Gemini, and Muse to identify which retailers appeared most frequently. Walmart performed strongly across multiple categories, while Costco and Aldi also gained recognition for their respective retail strengths.
The findings highlight how artificial intelligence could influence where consumers begin their shopping journeys. Chatbots help users compare products, identify retailers, and narrow purchasing decisions without reviewing multiple websites. Walmart could attract additional customer interest as more households incorporate these tools into everyday shopping activities.
Gartner Survey Shows Growing Demand for AI Shopping Tools
A Gartner survey found that 34% of American consumers expressed strong willingness to use AI for holiday gift recommendations. Researchers surveyed 1,004 consumers in August 2026 to examine changing shopping habits ahead of the holiday season. The findings indicate growing acceptance of automated product suggestions, particularly among consumers seeking faster purchasing decisions.
Traditional shopping channels continue playing a central role despite increasing interest in artificial intelligence. Gartner found that 77% of respondents planned to shop in physical stores during the holiday period. Additionally, 75% expected to purchase products through Amazon, highlighting continued demand for established retail platforms.
Walmart’s extensive store network gives the company an established position across both physical and online retail markets. Its product selection covers groceries, electronics, clothing, household goods, and other frequently purchased consumer products. Customers can combine online searches with store visits, pickup services, and home delivery options.
Walmart Stock Valuation Remains a Key Growth Challenge
Despite the potential benefits of AI recommendations, Walmart shares have delivered relatively modest gains during 2026. The stock has advanced approximately 2% this year, trailing the broader market despite the company’s established retail operations. Its valuation exceeds 40 times trailing earnings, placing greater emphasis on future revenue and profit growth.
Walmart generated more than $730 billion in revenue over the preceding 12 months, reflecting its substantial operating scale. However, that size also means incremental sales from AI referrals may produce limited changes in overall growth. The company would need significant additional spending from customers to produce a meaningful improvement in its revenue trajectory.
Walmart continues developing its digital operations while maintaining its position in the competitive US retail market. Its broad product selection and established reputation for affordable goods support its visibility across emerging shopping platforms. The UBS findings identify another potential source of customer traffic, although they do not establish additional sales or earnings.
The post Walmart Inc. (WMT) Stock: AI Chatbot Recommendations Fuel Growth Potential appeared first on Blockonomi.
TLDR
- UnitedHealth stock rises 0.25% as management outlines stronger growth for 2027.
- UnitedHealth raises its 2026 earnings forecast following stronger Q3 results.
- Management targets 13% to 16% long-term earnings growth as operations improve.
- AI tools reduce clinical review times by 33% as UnitedHealth cuts paperwork.
- Optum expands pharmacy services while Medicare and Medicaid reforms advance.
UnitedHealth Group Incorporated (UNH) rose 0.25% to $379.47 on Tuesday following its third-quarter 2026 earnings announcement. The healthcare company raised its annual earnings outlook and outlined plans for stronger financial performance in 2027. Management emphasized operational improvements, artificial intelligence adoption, and medical cost controls as major drivers of future growth.
UnitedHealth Group Incorporated, UNH
UnitedHealth Group Raises Earnings Outlook After Strong Q3 Performance
UnitedHealth Group reported third-quarter revenue of $112.7 billion, while operating earnings reached $6.6 billion during the reporting period. Adjusted earnings reached $4.69 per share, exceeding Wall Street expectations as the company improved its cost management. Management raised its full-year 2026 adjusted earnings guidance to at least $20.50 per share.
The company also reduced its medical care ratio to 88.4%, compared with 89.9% a year earlier. Management attributed the improvement to pricing discipline, benefit adjustments, and stronger coordination across its healthcare operations. Specialty pharmacy expenses and higher treatment intensity continued to pressure medical spending across several business segments.
UnitedHealth expanded its operational modernization efforts across UnitedHealthcare and Optum to improve service delivery and efficiency. Approximately 40% of employed clinicians now use AI-powered documentation tools, reducing medical record review times by 33%. The company plans to eliminate 30% of prior authorization requirements by year-end to simplify patient access.
Management Targets Stronger Earnings Growth in 2027
UnitedHealth management expressed confidence in reaching the lower end of its long-term adjusted earnings growth target for 2027. The company maintains a growth framework of 13% to 16%, supported by stronger execution and operational improvements. Chief Financial Officer Wayne DeVeydt also indicated that current analyst earnings estimates may underestimate the company’s recovery potential.
The company’s Medicare Advantage strategy prioritizes health maintenance organizations and specialized plans serving patients with complex medical needs. These offerings include Chronic Special Needs Plans and Dual Special Needs Plans, which support targeted healthcare management. UnitedHealth expects its quality improvement programs to strengthen its competitive position across government-sponsored insurance markets.
Management also expects Optum Insight to advance its technology offerings through new AI-focused products during 2027. The company anticipates further expansion in 2028 as these services gain commercial traction across healthcare organizations. Optum Rx continues developing transparent pharmacy services, with external customers accounting for more than half its membership.
Medical Costs and Regulatory Reforms Shape Recovery
Despite improving operating performance, UnitedHealth continues managing medical expenses and regulatory requirements across its insurance businesses. Medicaid margins remain under pressure, although management expects them to reach their lowest point during 2026. The company targets stronger profitability by 2028 through reimbursement negotiations and improved care for patients with complex needs.
Management identified the No Surprises Act arbitration process as another source of elevated healthcare costs. The company reported that related disputes account for up to 6% of medical spending in certain regions. Consequently, UnitedHealth continues advocating regulatory changes while improving its internal claims management and payment processes.
UnitedHealth also expects 75% of its Medicare Advantage membership to enter plans with ratings of four stars or higher. The target applies to 2028 ratings and reflects continued spending on service quality and patient outcomes. Separately, the United Health Foundation committed $1 billion toward rural healthcare, workforce education, and broader community health programs.
Management expects fourth-quarter performance to reflect seasonal medical spending alongside additional investments in technology and clinical operations. The company will continue expanding administrative automation while strengthening its healthcare delivery network and insurance offerings. These initiatives form part of UnitedHealth’s broader plan to improve operating margins and support earnings growth beyond 2026.
The post UnitedHealth Group Incorporated (UNH) Stock: Climbs as Management Targets Strong 2027 Growth appeared first on Blockonomi.
TLDR
-
Applied Materials (AMAT) stock plunges 8.19% despite strong demand for AI chips.
-
Applied Materials targets over two percentage points of market share gains by 2030.
-
Applied Materials expects its eBeam equipment revenue to reach $2 billion in 2026.
-
Applied Materials projects semiconductor service revenue above $12 billion by 2030.
-
Applied Materials plans to more than double its research and production capacity by 2030.
Applied Materials (AMAT) stock plunged 8.19% to $456.77 during Tuesday’s intraday trading, losing $40.76 despite strong demand for AI chips. The decline followed the company’s presentation of ambitious semiconductor equipment growth targets through 2030. Meanwhile, Applied Materials outlined expansion plans across advanced manufacturing, research facilities, and semiconductor services.
Applied Materials, Inc., AMAT
Applied Materials Targets Stronger Growth in AI Chip Equipment
Applied Materials presented its long-term growth strategy during the 2026 SEMICON West Investor Breakfast on Tuesday. The company expects expanding AI infrastructure to support sustained demand for wafer fabrication equipment. Its strategy focuses on advanced chip production, memory technology, and semiconductor packaging.
CEO Gary Dickerson identified AI infrastructure development as a major driver of future semiconductor equipment spending. He emphasized the company’s leadership in technologies that improve computing performance, energy efficiency, and production costs. Applied Materials expects broader AI adoption to increase demand for advanced silicon manufacturing.
The company projects three semiconductor segments will generate approximately 75% of wafer fabrication equipment growth between 2025 and 2030. These segments include leading-edge foundry logic, DRAM memory, and advanced packaging technologies. Applied Materials aims to increase its equipment market share by more than two percentage points during this period.
Applied Materials Expands Semiconductor Services and eBeam Technology
Applied Materials expects its electron-beam inspection equipment business to generate $2 billion in revenue during calendar 2026. The technology helps semiconductor manufacturers identify production defects and improve yields during advanced chip manufacturing. Additionally, its imaging systems support faster production processes and more efficient factory operations.
The company also expects its semiconductor services revenue to increase more than 20% during 2026. Management projects annual services revenue will exceed $12 billion by 2030, supported by a mid-teens compound growth rate. These services help semiconductor manufacturers improve equipment performance, factory productivity, and manufacturing efficiency.
Chief Financial Officer Brice Hill outlined plans to strengthen profitability while expanding research and development spending. According to Hill, previous technology investments have established the company’s position across important semiconductor manufacturing processes. The company now plans to increase operating leverage as semiconductor equipment demand expands.
Applied Materials Plans Major Manufacturing Expansion Through 2030
Applied Materials plans to more than double its research laboratory and manufacturing capacity by 2030. The expansion supports expected growth in semiconductor production and demand for advanced manufacturing equipment. The company continues investing in facilities that support collaboration with semiconductor manufacturers.
On Monday, Applied Materials unveiled its Equipment and Process Innovation and Commercialization Center in Silicon Valley. The new facility supports joint research into semiconductor process technology and equipment development. The company has already announced 15 partnerships involving chipmakers, technology companies, equipment manufacturers, and universities.
Applied Materials has also expanded its manufacturing infrastructure across several international locations. These facilities include operations in Austin, Texas, Singapore, and Treviso, Italy. The investments support the company’s long-term production strategy as semiconductor manufacturers expand capacity for increasingly complex computing applications.
The post Applied Materials (AMAT) Stock: Sinks 8% Despite Strong AI Chip Demand appeared first on Blockonomi.
TLDR
- BigBear.ai (BBAI) stock climbs 3.83% as new government awards surpass $225M.
- BigBear.ai secures over 25 generative AI awards across major U.S. agencies.
- FBI, NASA, and the Coast Guard join BigBear.ai’s growing government client base.
- BigBear.ai expands defense operations with new military and intelligence awards.
- BigBear.ai reports a $270M backlog, with only 29% funded as of June 30, 2026.
BigBear.ai Holdings (BBAI) stock rose 3.83% to $2.3877 during Tuesday’s intraday trading, gaining $0.0877. Shares stabilized after an early surge above $2.50, following developments in the company’s government business. BigBear.ai announced more than $225 million in awards across several U.S. agencies since July.
BigBear.ai Holdings, Inc., BBAI
BigBear.ai Secures $225 Million in New Awards
BigBear.ai reported new business and renewals across homeland security, defense, intelligence, and civilian agencies. The agreements support its expansion in national security, trade, and travel technology markets. The latest wins also strengthen its relationships with existing customers while expanding its government presence.
According to the announcement, BigBear.ai secured more than 25 new generative AI awards. Customers include the FBI, NASA, U.S. Coast Guard, Department of Energy, and Department of Veterans Affairs. These projects cover specialized technology services for law enforcement, security operations, and civilian applications.
CEO Kevin McAleenan identified customer retention and new agency relationships as major drivers of the company’s recent activity. He highlighted continued work with Customs and Border Protection alongside new partnerships with security organizations. The developments reflect broader adoption of advanced technology across government operations.
BigBear.ai Expands Defense and Intelligence Operations
BigBear.ai also secured agreements supporting U.S. Central Command, U.S. Southern Command, and classified intelligence operations. These projects extend its services into additional military and intelligence environments. Meanwhile, demand for secure AI platforms continues to shape the company’s product offerings.
Its generative AI products provide access to models and automated tools from leading technology providers. Government teams can select available systems according to their operational requirements and security standards. The platforms also support disconnected networks and restricted environments that require tighter data controls.
BigBear.ai retained important work with U.S. Customs and Border Protection through two competitive renewals. The company supports border operations involving traveler screening, cargo movement, and customs security. Its technology helps personnel assess shipments, process information, and make operational decisions.
BigBear.ai Reports $270 Million Backlog
BigBear.ai reported approximately $270 million in total backlog as of June 30, 2026. The company identified only 29% of that amount as funded at the reporting date. This distinction separates secured financial commitments from the broader value of outstanding business.
The announced $225 million includes potential award values, unexercised options, and maximum contract limits. Consequently, actual revenue will depend on government funding decisions, project execution, and exercised options. Agencies also retain the authority to modify agreements, reduce spending, or terminate work.
The post BigBear.ai Holdings (BBAI) Stock: Gains on $225M Federal AI Contract Wins appeared first on Blockonomi.
TLDR
- Goldman Sachs (GS) stock rises 0.27% as Q3 revenue jumps 23% to $18.68 billion.
- Goldman Sachs reports $5.29 billion in Q3 profit as earnings reach $17.01 per share.
- Equities revenue surges 72% as stronger financing and derivatives lift results.
- Investment banking fees climb 21% as mergers and underwriting activity rebound.
- Goldman Sachs returns $4.49 billion to shareholders and declares a $5 dividend.
Goldman Sachs Group (GS) stock rose 0.27% to $896.36 during Tuesday’s intraday trading, gaining $2.41 after retreating from earlier highs. The bank reported third-quarter revenue growth of 23% to $18.68 billion, driven by stronger trading and investment banking activity. Meanwhile, net earnings reached $5.29 billion as its major business divisions delivered improved annual results.
The Goldman Sachs Group, Inc., GS
Goldman Sachs Reports Strong Q3 Earnings Growth
Goldman Sachs reported diluted earnings per share of $17.01, up from $12.25 during the same quarter last year. However, earnings declined sequentially from $20.98 per share in the second quarter. The bank recorded an annualized return on average common shareholders’ equity of 18.7%.
For the first nine months of 2026, the company generated $56.24 billion in revenue and $17.55 billion in earnings. Its book value per common share also increased 4.2% during the period to $372.64. These results reflected stronger banking operations and improved profitability compared with 2025.
Operating expenses increased 20% annually to $11.31 billion, primarily due to higher transaction costs and employee compensation. Meanwhile, provisions for credit losses reached $368 million, reflecting impairments related to wholesale loans. Despite these costs, the bank improved its nine-month efficiency ratio to 59.4% from 62.1%.
Investment Banking and Equities Support Revenue Growth
Global Banking & Markets generated $13.46 billion in quarterly revenue, representing a 32% increase from the previous year. Investment banking fees climbed 21%, supported by higher completed merger transactions and increased underwriting activity. Stronger initial public offerings and secondary share sales also contributed to the division’s performance.
Equities revenue surged 72% annually, supported by stronger financing operations and derivatives trading. Meanwhile, fixed income, currency, and commodities revenue remained largely unchanged despite mixed performance across trading products. Higher currencies and commodities revenue helped offset weaker mortgage, credit, and interest rate activity.
Asset & Wealth Management revenue increased 14% from the previous year, supported by higher management and incentive fees. Increased average assets under supervision contributed to stronger recurring fee income during the quarter. However, weaker investment returns and private banking revenue partly offset the division’s growth.
Goldman Sachs Announces Dividend and Capital Returns
Goldman Sachs declared a quarterly dividend of $5.00 per common share on October 12, 2026. The company scheduled payment for December 30 to shareholders of record on December 2. The announcement followed continued capital distributions through dividends and share repurchases.
During the third quarter, the bank returned $4.49 billion to common shareholders through its capital return program. Share repurchases accounted for $3 billion, while common stock dividends represented the remaining $1.49 billion. The company also maintained its shareholder payout strategy alongside increased investment banking activity.
Meanwhile, average global core liquid assets increased to $574 billion from $555 billion in the previous quarter. Headcount also rose 3% sequentially, reflecting the timing of new graduate recruitment. However, the investment banking backlog declined from the second quarter despite stronger completed transactions.
The post Goldman Sachs Group (GS) Stock: Gains as Q3 Revenue Jumps 23% and Profit Hits $5.29B appeared first on Blockonomi.
HTTP error 429 on https://cryptopotato.com/feed/
Failed to fetch feed: https://cryptopotato.com/feed/
Failed to fetch feed.