Cryptocurrency Posts
Crypto Briefing
Bitwise head of research Ryan Rasmussen says investors underestimate institutional adoption of NEAR and HYPE as ETFs, token buybacks and network activity grow.
The post Bitwise head of research says investors underestimate institutional adoption of NEAR and HYPE appeared first on Crypto Briefing.
Rising US interest rates could strain AI firms' growth, impacting their financial stability and investor confidence in long-term returns.
The post Oracle shares drop 7% as US rate hike bets rise, impacting AI firms appeared first on Crypto Briefing.
OpenAI's leadership change amid massive compute spending highlights potential challenges in maintaining strategic continuity and innovation.
The post OpenAI’s head of computing capacity to depart next month appeared first on Crypto Briefing.
High development activity in crypto projects may signal future growth potential, guiding investors and builders in strategic decision-making.
The post Santiment ranks top crypto projects by 30-day development activity appeared first on Crypto Briefing.
Broadcom's financing strategy could reshape AI infrastructure funding, influencing market dynamics and raising potential conflict concerns.
The post Broadcom lines up more than $50 billion in debt to bankroll AI infrastructure appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Kraken Parent Company Payward to Buy Saldo Bank in European Banking Push
Payward, the parent company of crypto exchange Kraken, has signed a definitive agreement to acquire Saldo Bank, gaining an EU banking license and a footprint across five European markets.
Payward is buying Saldo Finance Oy, a Finnish holding company whose subsidiary, Saldo Bank UAB, is a digital-first specialized bank licensed in Lithuania. The bank operates in Lithuania, Finland, Sweden and Germany, with a passport into the Netherlands.
Payward did not reveal the financial terms of the deal, which is expected to close in 2027, subject to regulatory approvals.
It comes as Kraken, like other crypto exchanges, pushes further into the traditional finance world, allowing users to trade stocks, bonds and other assets. The company has sold its app as a “primary account for everything.”
“A regulated EU bank is the piece that lets us serve European clients the way a primary financial institution should: one place to hold assets, move them freely, and put them to work,” said Arjun Sethi, Payward’s co-CEO. “We are starting in the EU, and the ambition is global.”
Payward said that once completed, the acquisition is expected to let Payward Banking offer interest on deposits, SME and consumer loans, credit cards, and banking-as-a-service tools such as card issuance, SEPA payments access and embedded lending for partners.
Saldo already offers retail term deposits in all four of its operating markets, consumer lending in Lithuania, Finland and Sweden, and a credit card in Finland.
Payward says it already holds a Federal Reserve limited-purpose master account in the U.S. and an e-money license from the Central Bank of Ireland, and has originated more than $2 billion in loans.
The deal comes shortly after Payward this week announced plans to launch in the UAE following full approval from Dubai’s Virtual Asset Regulatory Authority.
In September, Bloomberg reported that Nasdaq Inc. was investing $100 million in Payward at a $21 billion valuation, citing people familiar with the matter. Payward and SoFi Technologies also recently agreed to route SoFi customers’ crypto orders through Kraken Prime, Kraken’s prime brokerage arm.
This post Kraken Parent Company Payward to Buy Saldo Bank in European Banking Push first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Standard Chartered Debuts Bitcoin Trading For Wealthy UAE Clients
British multinational Standard Chartered on Wednesday announced a bitcoin trading service for affluent clients in the United Arab Emirates.
The service is the first such service offered by an international bank in the UAE, Standard Chartered said.
It comes after the bank last month debuted bitcoin trading for institutional clients in the Arab nation. Standard Chartered became one of the first global banks to enter the spot crypto trading space when in 2025 it set up a trading desk for bitcoin and other cryptocurrencies in London.
JUST IN: Standard Chartered becomes the first international bank in the UAE to offer Bitcoin trading directly through eligible clients' bank accounts
— Bitcoin Magazine (@BitcoinMagazine) October 14, 2026pic.twitter.com/uPVQV9D8SJ
“As client interest in digital assets continues to grow, this launch represents a significant milestone for Standard Chartered as we bring digital assets into our core wealth offering,” said Samir Subberwal, Standard Chartered’s global head of wealth solutions, retail products, data and analytics.
“With digital assets moving into mainstream wealth conversations, clients are increasingly looking not only for access, but also for the security, trust and confidence that comes from investing through a regulated and trusted institution.”
Rola Abu Manneh, Standard Chartered’s chief executive officer UAE, Middle East and Pakistan, added: “We are proud to be the first international bank in the UAE to launch a cryptocurrency trading offering.”
The service will allow clients to buy bitcoin via their bank accounts. No third-party apps or wallets will be needed, the bank said.
Standard Chartered said it will manage end-to-end custody and settlement through a closed-loop model, reducing exposure to third-party wallet risks.
The British bank is expanding its crypto-related offerings worldwide. Earlier this month, it said it had plans to offer crypto custody services for institutional clients in Singapore.
Standard Chartered already offers the service in the UAE, Luxembourg, and Hong Kong.
Banks worldwide are integrating or offering bitcoin-related products and services.
A number of U.S. and European banks have started offering crypto-related services by custodying assets for institutions. Others are offering trading via their flagship apps.
This post Standard Chartered Debuts Bitcoin Trading For Wealthy UAE Clients first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
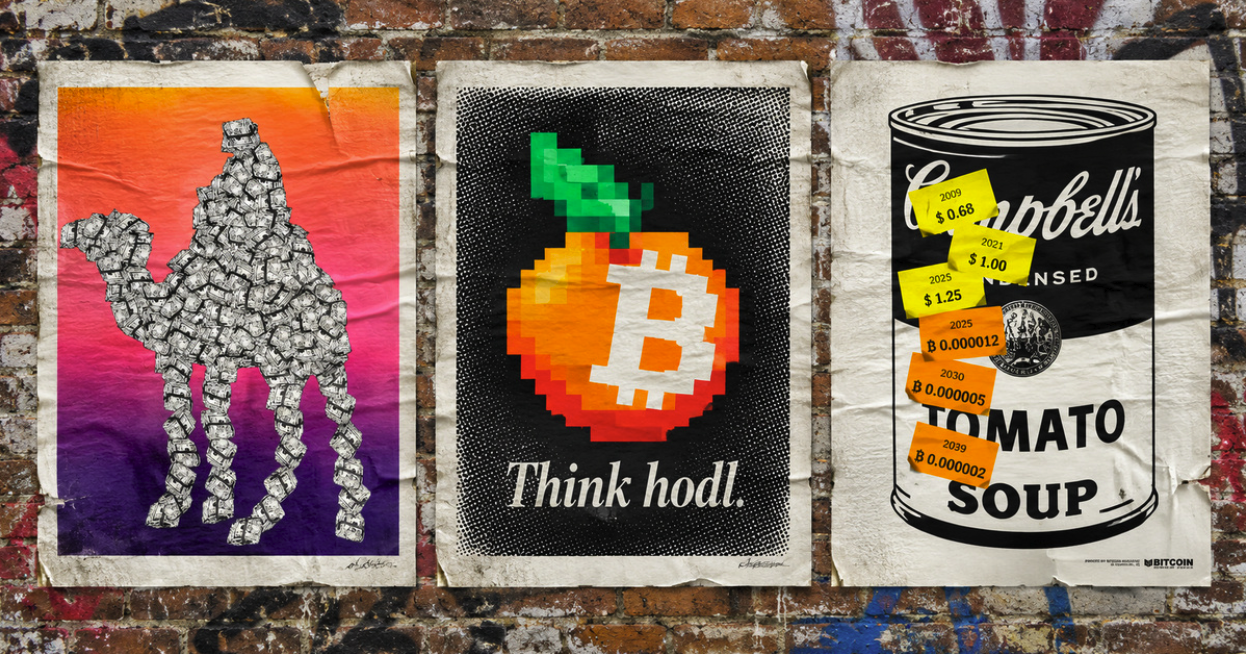
The Undercurrent: Three European Artists on Making Money Visible
Amsterdam helped lay the foundations of modern finance, but its artists were among its earliest critics. When speculative bubbles burst across Europe in 1720, Amsterdam printers and satirists responded with The Great Mirror of Folly, a collection of engravings and plays exposing the excesses of financial speculation.
Nearly three centuries later, the city hosted another monetary experiment. David Chaum, the cryptographer whose work on anonymous communication helped lay the groundwork for the cypherpunk movement, came to Amsterdam in the 1980s to work at CWI, the Dutch national research institute for mathematics and computer science. Around 1990, he founded DigiCash to develop private electronic cash. The company went bankrupt in 1998, a decade before bitcoin, but the dream of digital money was already taking shape.
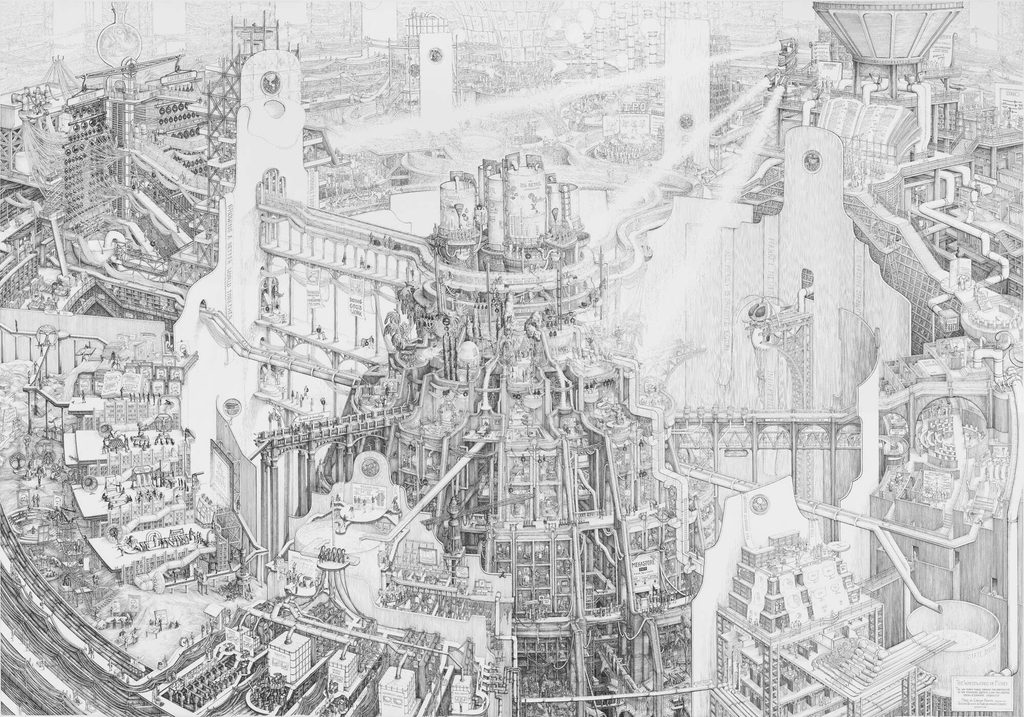
Last year at Bitcoin Amsterdam, BMAG exhibited The Waterworks of Money, in which Dutch artist Carlijn Kingma, working with financial journalist Thomas Bollen and researcher Martijn Jeroen van der Linden, depicted the monetary system as a vast irrigation network, with some areas flooded by liquidity while others remain dry. The drawing makes a complex financial system legible, exposing the mechanisms through which money is created, distributed, and concentrated.
This tradition of questioning money and making its hidden dimensions visible continues in the work of three European artists exhibiting at Bitcoin Amsterdam this November. ZETRA, RYR, and Cypherpunk Now draw from graffiti, political printmaking, hacker culture, and early bitcoin communities to explore the changing meaning of money.
Martin Fischer joined the Prague art collective Ztohoven in 2003, a group known for inserting a fictional nuclear explosion into a live Czech Television broadcast. In 2014, the collective opened Paralelní Polis, a hackerspace whose café accepted only bitcoin, and Fischer designed its logo. As he told Bitcoin Magazine’s Aaron van Wirdum in 2020, the arrival of a screen-printing press the following year prompted him to produce his first prints. Since 2020, he has worked under the name Cypherpunk Now, developing a visual record of bitcoin’s evolving culture.
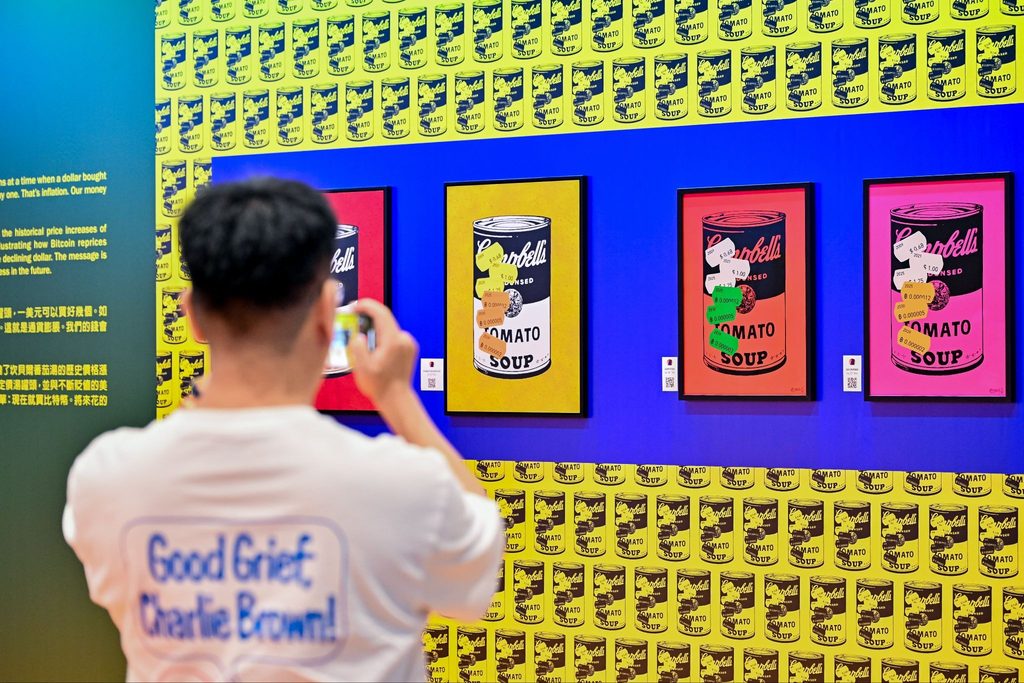
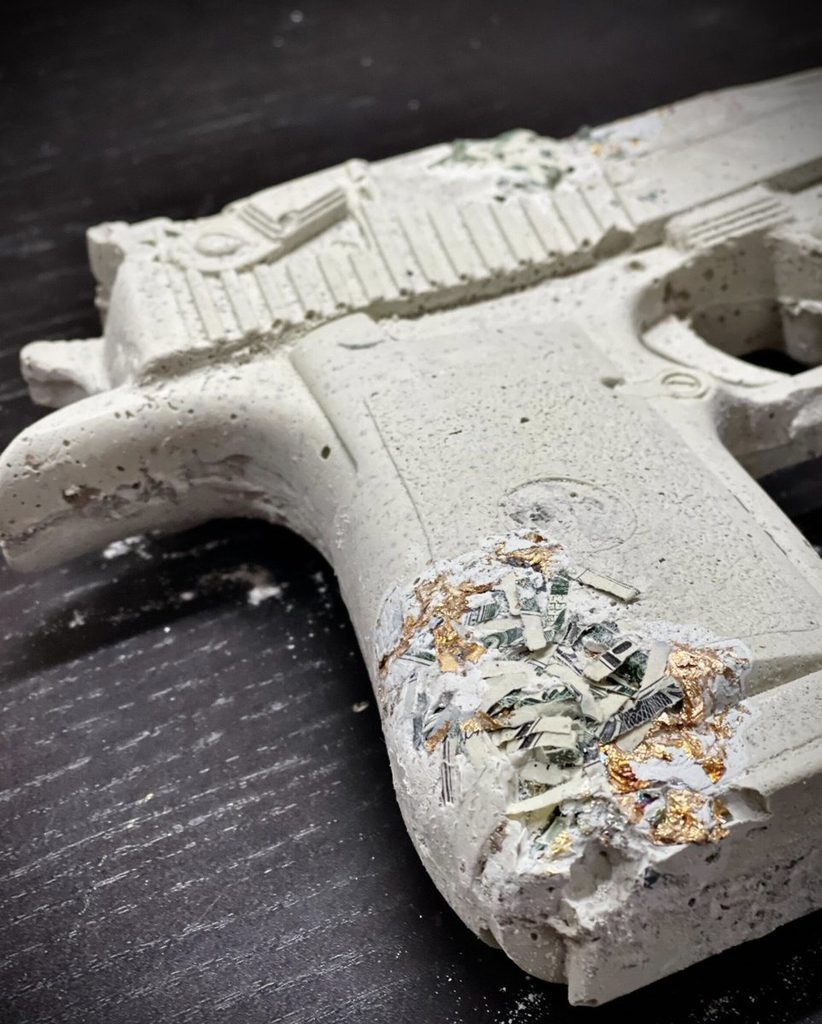
RYR and ZETRA both emerged from Germany’s graffiti scene but approach money from different directions. RYR uses currency itself as material, making paper from shredded banknotes, pigment from their ashes, and concrete grenades filled with shredded cash that he calls “artifacts from the future.” ZETRA, who began painting in the early 1990s and discovered bitcoin in 2017, examines what money can buy. His TOMATOSOUP paintings revisit Andy Warhol’s iconic Campbell’s Soup Cans to chart changing prices in dollars and bitcoin, while THE BIP39 SERIES explores the 2,048 words used in bitcoin wallet recovery phrases, including 1206/NOTE, a collaboration with Polymerbit.
Bitcoin has shaped these artists’ practices, their livelihoods, and the communities around them. Its growing acceptance by banks, investment funds, and corporations has also prompted some difficult questions about the movement’s original ideals and where its culture is heading.
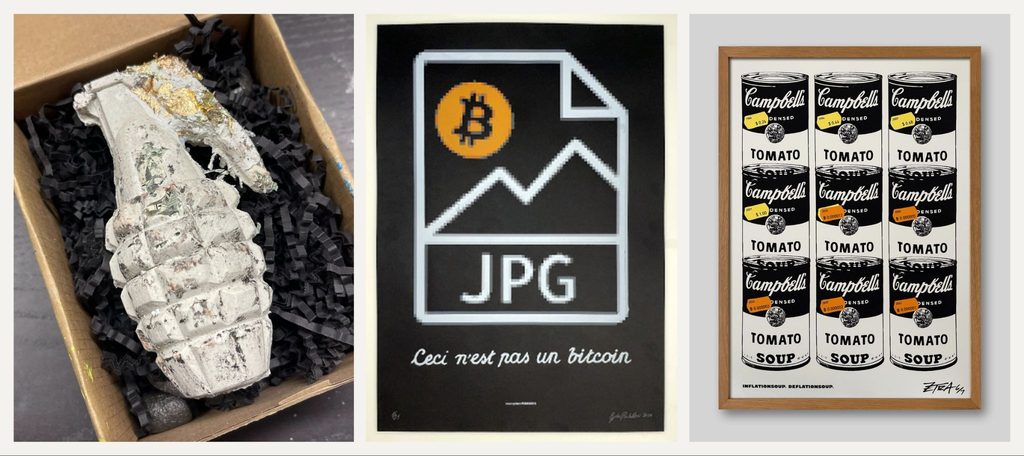
BMAG: Andy Warhol turned Campbell’s soup into an icon of consumer culture, taking an ordinary commodity and elevating it into fine art. Your TOMATOSOUP series returns to that image but introduces something Warhol largely left outside the frame: the changing value of money itself. How did the idea of reworking Warhol’s Campbell’s Soup Cans first come about, and do viewers immediately recognize the commentary on inflation?
ZETRA: We frequently see iPhones and houses in our bitcoin Twitter timelines, showing how they become cheaper in BTC terms. I thought it would be fun to take something from art history instead, something more visually appealing, like Warhol’s iconic Campbell’s Soup Can.
For my TOMATOSOUP painting, I used real stickers placed on the can to show how the price of soup has increased in USD over the past decades, compared with the lower prices we might expect in BTC terms in the decades to come.
Bitcoiners looking at TOMATOSOUP generally understand it immediately. They know they’re in a better position as the purchasing power of fiat money continues to decline through inflation. Other viewers usually need a bit of explanation, and I’m always happy to help them understand.
BMAG: In THE BIP39 SERIES, you draw from the 2,048 words used to generate bitcoin wallet recovery phrases, turning ordinary words into artworks with a deeper significance for bitcoin holders. Can you unpack the different layers of inspiration behind the series and what they reveal about bitcoin, language, and the ownership of money for someone unfamiliar with these concepts?
ZETRA: Everyone who moves their precious sats into cold storage encounters 12 or 24 of these significant words, often early in their journey as a bitcoin newcomer. As mentioned, there are 2,048 words in a carefully curated list representing the power of self-custody.
I started going through the words one by one, imagining how each could be visualized in a physical form: the key visual for the word, its corresponding number, the style, and the medium I would choose. There are millions of possibilities for bringing these words to life through bitcoin art.
1044/LIST was the obvious choice to kick off THE BIP39 SERIES. Naturally, it features all 2,048 words presented as a list. As an ’80s kid, I had to choose 1638/SMILE as the second piece: a proper yellow smiley face, with the number 1638 in place of the eyes. It’s a fine art print on Alu-Dibond beneath a 6 mm acrylic glass cover. So clean.
Another work in the series is 0388/CORN, an obvious homage to Warhol once again. THE BIP39 SERIES will be an ongoing project for many years to come.
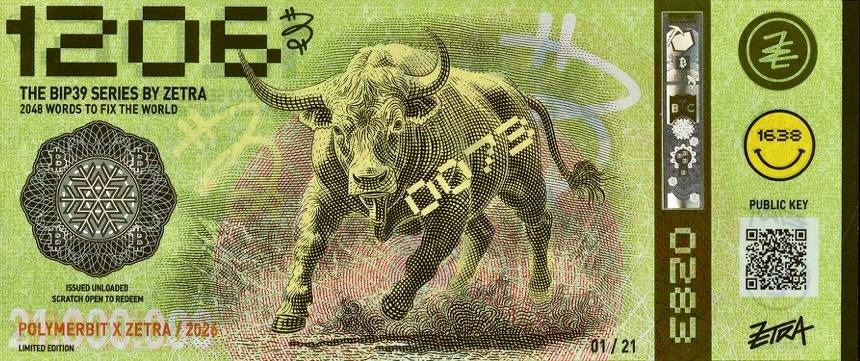
BMAG: You shred banknotes into paper and burn them to produce pigment. Artists have long manipulated currency to question where its value resides, but your work goes a step further by making destruction part of the creative process. Is there a contradiction in destroying money to create an artwork that may ultimately be worth much more?
RYR: Money is essentially a narrative system built on collective belief and obedience. It has worked for hundreds of years because we collectively agree on the story it tells and the value it represents. I’ve always been fascinated by that idea, particularly how something as ordinary as a banknote can carry so much meaning, authority, and perceived value.
I was looking for a different way to tell that story, both conceptually and physically. Back in 2017, I had an exhibition title in mind: To Cut a Long Story Short. I liked the cheekiness of it, especially in relation to money and the stories we attach to it. Shredding banknotes became a very literal interpretation of that title, but it also opened up an entirely new artistic medium for me.
Ultimately, I’m not simply destroying money. I’m taking an existing story, cutting it into pieces, and using those pieces to tell a new one.
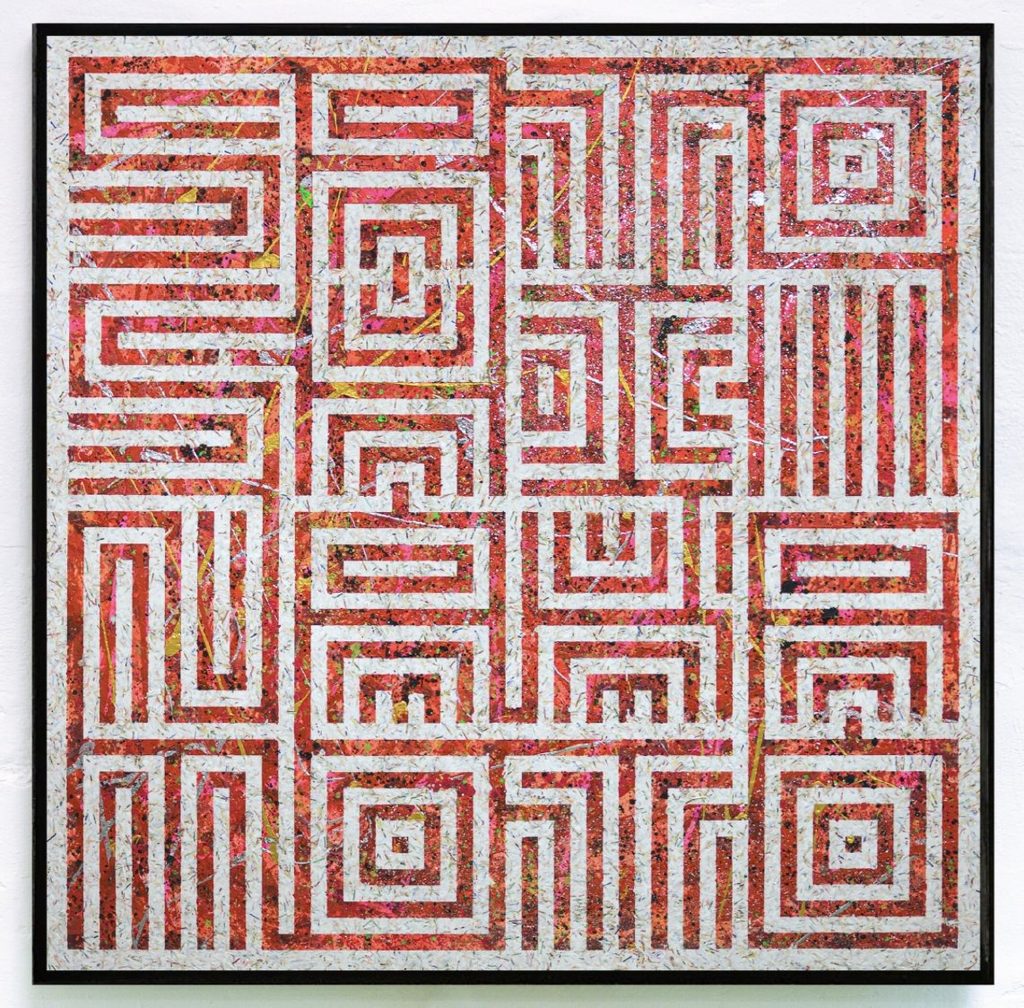
BMAG: Your concrete weapons are presented as relics from a future in which the fiat wars have already ended. Yet bitcoin is increasingly held through the very financial institutions it was designed to circumvent. Is that a victory for the movement, or have the institutions simply absorbed the alternative?
RYR: I think that’s precisely what makes the story so interesting. When I created the concrete weapons, I imagined a future in which the traditional financial system had already fought its battle for survival. The weapons had become fossils, archaeological artifacts from a monetary conflict that future generations might struggle to understand.
My concrete weapons represent a future in which that battle is already history. Whether bitcoin ultimately wins or becomes part of the very system it challenged remains to be seen.
BMAG: Much of your work is made from the physical remains of money, at a time when currency is becoming increasingly digital and invisible. Do you think people are losing something in their understanding of money as it disappears from everyday physical experience?
RYR: I think we’re losing a physical connection to money, but not necessarily our understanding of it. Money has always been a narrative built on collective trust, whether printed on paper or represented by numbers on a screen. What fascinates me is how something as abstract as value can be represented by a physical object.
I don’t necessarily believe that art has to be authentic or entirely original. Almost everything has been done before. To me, art is a wonderfully human, almost plebeian way of expressing an opinion and giving ideas a physical voice.
Bitcoin will likely evolve into a much broader and increasingly regulated financial asset, but I hope its grassroots culture and artistic identity remain visible. That’s something my fellow artists and I will continue to contribute to, preserving the spirit of a movement that was cultural long before it became institutional.
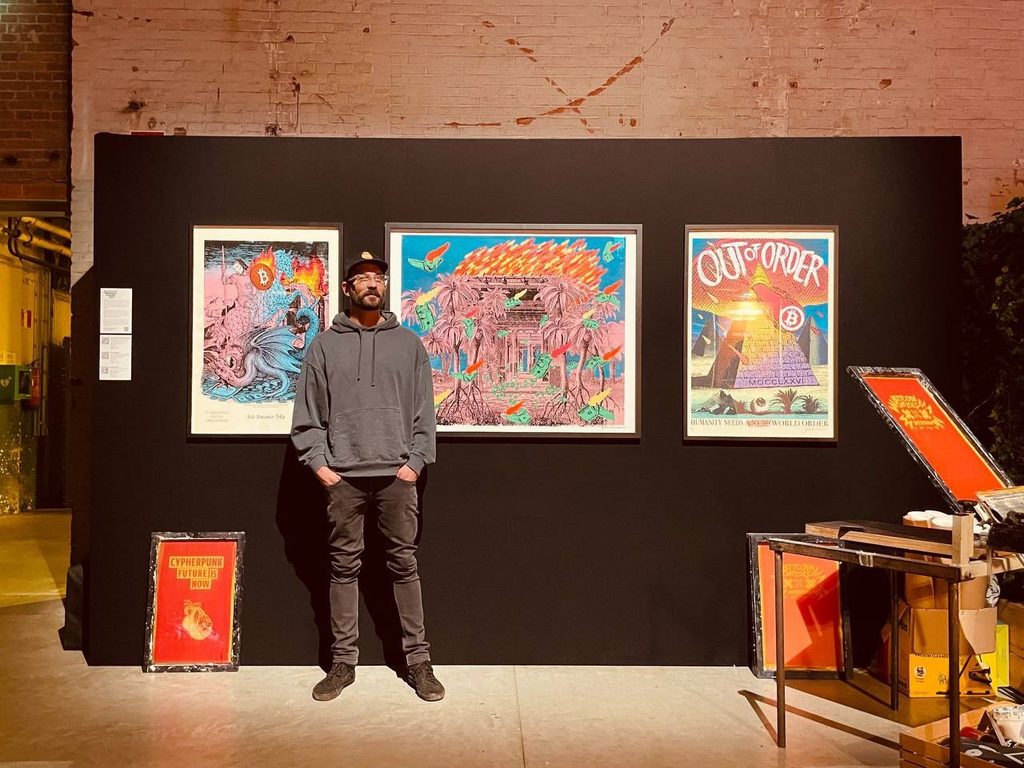
BMAG: Paralelní Polis wasn’t just a place to discuss alternative monetary systems or a hacker meetup; its café was one of the first to adopt bitcoin as money. What were the early years of Paralelní Polis like, and what has your own experience been selling artwork for bitcoin?
Martin Fischer: Paralelní Polis was founded in 2014, during a bear market. The funny thing is, none of us who founded it even knew what a bear market was. We didn’t think of bitcoin as something that could make us rich. We saw it as uncensorable money and understood the changes it could bring to society. There was no speculation involved, and that’s what made those early days so great.
I sold my first screenprint for bitcoin in 2017, almost ten years ago, and many more since then. But practically every sale was a matter of survival. I spent most of the bitcoin I earned financing my next projects and continuing to make art.
I never managed to accumulate much bitcoin, but looking back, it gave me something far more valuable than investment returns: the freedom to remain an independent artist.
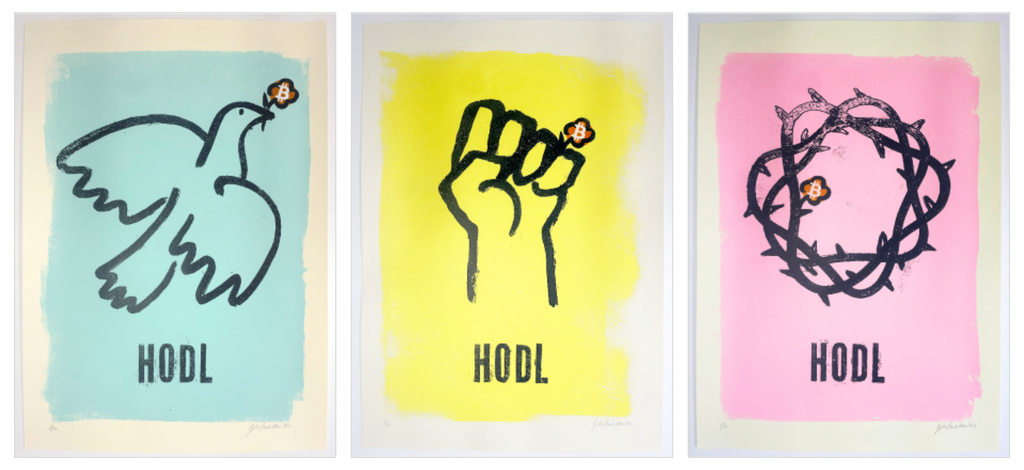
BMAG: Political printmaking has a long history in Europe, from Amsterdam’s financial satires of 1720 to twentieth-century protest posters. Your work emerged from Ztohoven, a collective that famously hacked a live television broadcast to show a fictional nuclear explosion—an audacious intervention, even by today’s standards. Ztohoven challenged institutions through disruption, while bitcoin uses game theory and economic incentives to create an alternative. Do you see bitcoin as a continuation of that same spirit of intervention, and your prints as an extension of it?
Martin Fischer: I think there’s a connection, but I wouldn’t say it’s exactly the same thing. With Ztohoven, we used art to question authority, challenge institutions, and expose how easily reality can be manipulated. Bitcoin doesn’t need to make a statement or provoke anyone. It simply offers an alternative that works without asking anyone for permission. That’s a much more interesting form of disruption to me.
But today, bitcoin has become so corporate and so intertwined with traditional banking that it’s hard to still see it as an anti-establishment movement. I don’t see this as a betrayal of its original ideals, but rather as a natural consequence of its success. That doesn’t mean I like where things are going.
What’s strange is that bitcoin’s fundamental principles haven’t really changed, but the way people perceive and use it certainly has.
And my screenprints? I still work with the original idea of separating money from the state while exploring the myths, memes, and legends of the bitcoin age. That’s what I enjoy most.
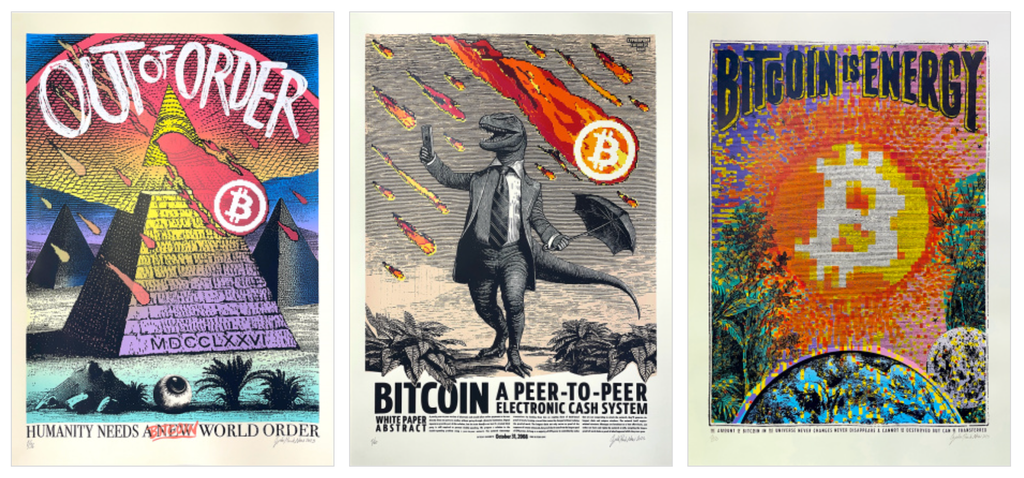
BMAG: Your Amsterdam presentation brings together more than a decade of work documenting bitcoin’s evolution from an underground movement to an increasingly institutionalized financial system. Looking across those prints today, has the movement changed more than you expected, or has your own perspective changed? Which of your prints are your favorites?
Martin Fischer: I like remembering the old days, when we were all part of the same tribe and our main enemy was Faketoshi.
Today? We have culture wars over JPEGs, Ordinals, BIPs, OP_RETURN, over what’s spam and what should or shouldn’t belong on bitcoin. What makes me saddest is that people who once fought together against censorship and for freedom now spend enormous amounts of energy fighting each other over what others should or shouldn’t be allowed to do with bitcoin.
Maybe it’s a natural consequence of bitcoin’s success. The bitcoin community has changed enormously, and so has my perspective on it. I’m definitely much more skeptical today of the idea that technology alone can automatically change society for the better.
As for my favorite works, Bitcoin Meteorite is definitely one of them. In this piece, I reworked the meme of banking dinosaurs watching their own extinction, incorporating the abstract from the Bitcoin white paper. It gave me my fifteen minutes of fame when Max Keiser and Stacy Herbert brought it into the spotlight.
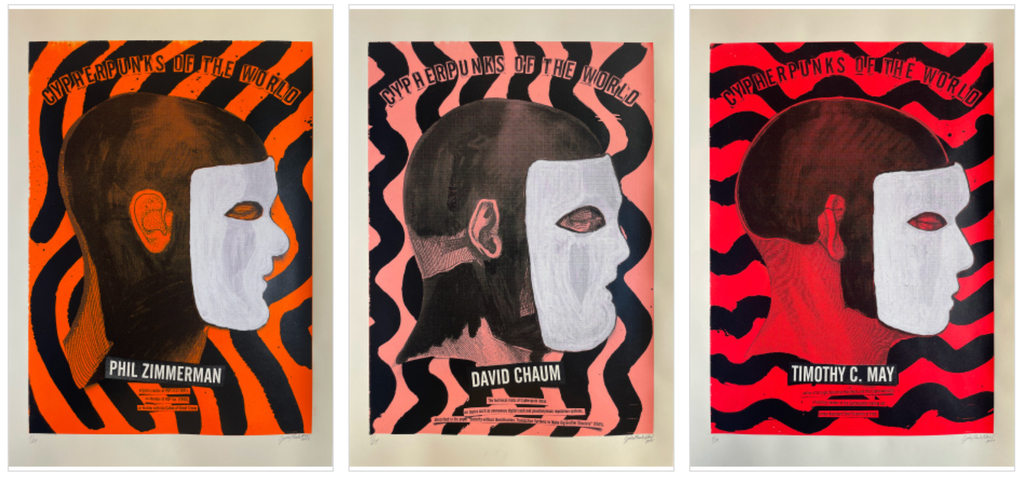
Then there’s Cypherpunks of the World. This project is important to me not only as a celebration of the cypherpunks and their legacy, but also because of its complexity. It started as a series of original collages, continued through handmade screenprints, and eventually evolved into animated NFTs and a virtual gallery. It’s one of my most elaborate projects, connecting different techniques and media while staying true to the original idea.
Among my more recent works, I really like Out of Order from 2023. It’s an incredibly detailed screenprint, and the first one where I finally managed to make absolutely no printing mistakes. That alone makes it special to me.
I also love St. Satosius Contra Draconem (2025), which is inspired by the classic depiction of Saint George fighting the dragon, reimagined through bitcoin mythology.
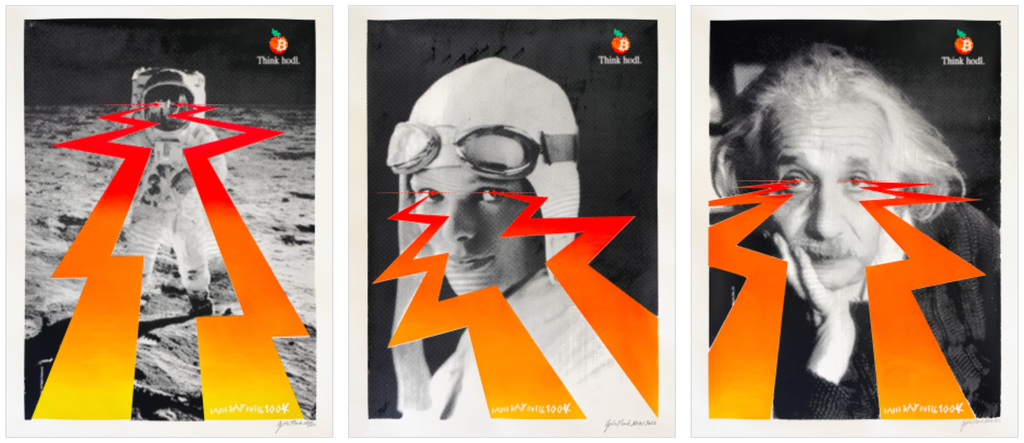
Works by ZETRA, RYR, and Cypherpunk Now, alongside other European artists, will be presented at Bitcoin Amsterdam, November 4–6, 2026, as part of the Bitcoin Museum & Art Gallery (BMAG) programming. Additional artworks and editions will be available through https://shop.museum.b.tc.
Explore more work by the featured artists at ZETRA, RYR, Cypherpunk Now, and www.martin-fischer.cz.
The Bitcoin Museum & Art Gallery (BMAG) organizes international exhibitions, auctions, and artist collaborations exploring bitcoin and its cultural implications. Learn more at museum.b.tc.
Join us at Bitcoin Amsterdam, Get your tickets here and use code BA26-BMAG20 for discounted admission.
This post The Undercurrent: Three European Artists on Making Money Visible first appeared on Bitcoin Magazine and is written by Dennis Koch.
Bitcoin Magazine
Bitcoin Slips Below $83,000 After Hotter-Than-Expected US Inflation Data
The price of bitcoin slid Wednesday after data dropped showing that U.S. consumer prices shot up more than expected in September due to rising gasoline prices.
The biggest cryptocurrency by market cap was recently trading for close to $82,827 after dropping nearly 1% over a 24-hour period. At one point on Wednesday morning in New York, bitcoin fell as low as nearly $82,331.
Over the past seven days, the coin has dropped by more than 1%. Bitcoin’s price had its best quarter in years after rallying in August and September and leading many analysts to declare it to have exited a bear market.
But sticky inflation is still weighing — in the short-term — on the cryptocurrency.
Data Wednesday showed that the Consumer Price Index rose 0.6% in September after climbing 0.4% in August.
In the 12 months through September, the CPI advanced 3.7% after rising 3.4% in August, the Labor Department’s Bureau of Labor Statistics said.
High prices in the U.S., in part spurred by the Trump Administration’s decision to attack Iran with Israel this year, have led the Federal Reserve to hint it may keep interest rates higher for longer.
The central bank in September said getting inflation down was its number one priority and hiked rates.
Bitcoin’s price has been sensitive to interest rate hikes in the past because higher borrowing costs restrict the liquidity the digital coin needs to run — along with other “risk-on” assets like stocks.
Still, the price of bitcoin rose in September despite the Federal Reserve talking tough on inflation.
The central bank will reveal what it plans to do with interest rates on October 28. As of Wednesday, fed funds futures were pricing a 47% chance of a rate hike at the Fed’s October meeting, according to CME Group’s FedWatch tool.
This post Bitcoin Slips Below $83,000 After Hotter-Than-Expected US Inflation Data first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Capitalism is Broken and Bitcoin is the Great Equalizer | Natalie Brunell
Young people are angry at capitalism, billionaires, and even their parents, but Natalie Brunell says they’re blaming the wrong thing. The Bitcoin Is for Everyone author explains how our financial system has become “socialism for the banks,” with privatized gains and socialized losses. She shares why Bitcoin could be the greatest equalizer for a generation that’s lost hope of owning a home or starting a family.
Chapters:
0:00 – Natalie Brunell on Leaving Legacy News for Bitcoin
1:09 – Fleeing Communism in Poland and Chasing the American Dream
2:17 – Losing Everything in the Great Financial Crisis
3:37 – Why People Still Don’t Understand Bitcoin
7:01 – Bitcoin as a Savings Technology: Start Small, Stack Sats
9:40 – What “Broken Money” and the Cantillon Effect Really Mean
12:33 – Why Young People Are Losing Hope in Capitalism
14:40 – Socialism for the Banks: Privatized Gains, Socialized Losses
17:56 – Is Bitcoin Being Painted as Partisan?
20:46 – Decentralized Media and the Collapse of Trust in Legacy News
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Capitalism is Broken and Bitcoin is the Great Equalizer | Natalie Brunell first appeared on Bitcoin Magazine and is written by Mark Mason.
CryptoSlate
ZkSync announced Airbender Prime, a prover that Matter Labs says handled 99% of 7,200 consecutive Ethereum mainnet blocks in under 10 seconds each on a single NVIDIA RTX PRO 6000 Blackwell GPU. The announcement came five days after Starknet said it is actively considering becoming an independent layer-1 (L1) blockchain, targeting full quantum resistance in…
Read the full story on CryptoSlate
Understand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
A hypothetical $500 million SATS financing assigns $387.5 million to Bitcoin, while actual pricing and capital deployment remain open.
Read the full story on CryptoSlate
Understand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
İhlas News Agency says the HEX and PulseChain founder was detained in a Beşiktaş police operation linked to an Interpol Red Notice requested by Finland.
Read the full story on CryptoSlate
Understand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
The September 25 ruling relied on corroborated Reactor testimony and a case-specific failure to justify source-code access.
Read the full story on CryptoSlate
Understand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
Bitcoin fell below $83,000 on Wednesday as hotter-than-expected US core inflation data revived expectations of further Federal Reserve interest rate hikes, triggering a fresh wave of liquidations across the cryptocurrency market. CoinGlass data showed that over $100 million in leveraged positions were liquidated in the hour after the inflation report was released. This also pushed…
Read the full story on CryptoSlate
Understand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
CryptoTicker.io
The Ethereum price stands at around $2,417 on Wednesday afternoon, roughly 2,179 euros. That is a good four percent less than 24 hours earlier, and the slide carries a timestamp: at 12:30 p.m. Central European time the US Labor Department published consumer prices for September. The headline rate rose to 3.7 percent year on year, where 3.6 percent had been expected. The core rate excluding energy and food came in at 2.6 percent.
With that, the level that had held twice this week has gone. On Monday the price turned higher at $2,495.93; yesterday it was still at $2,534. Today it sits below, and the daily high of $2,524.82 dates from the hours before the figure.
The inflation figure in detail: a 3.7 percent headline rate, a 2.6 percent core rate
Consumer prices are the single most important date for rate expectations in the markets. The September reading of 3.7 percent sits a tenth of a point above what economists had expected on average, and it sits clearly above the US Federal Reserve's two percent target. The core rate of 2.6 percent is the figure the central bank watches more closely, because energy and food prices swing sharply and are barely steerable by monetary policy. The numbers are in the press release of the Bureau of Labor Statistics.
A tenth of a point sounds like little. For the futures market it is not, because what trades there is not the figure itself but its deviation from expectations. That deviation fell today against every asset that lives on cheap money.
How an inflation figure feeds through to the Ethereum price
The route from an American price statistic to a price in euros runs through three stations, and it takes minutes, not days.
First, rate expectations. If inflation falls faster than thought, the market counts on earlier rate cuts. If it rises more than thought, as today, the market pushes that expectation back. Second, the discount rate. A higher expected rate makes safe assets more attractive and at the same time makes every position running on credit more expensive. Third, leverage. Positions in the futures market carry margin; if the price falls below a certain threshold, they are closed automatically, which triggers further sell orders.
That third station explains why price moves after data releases often turn out steeper than the news itself warrants. It is not only people with a view on inflation who sell. Systems that have no view at all also close positions.
Twelve months of Ethereum: 41 percent below the level of a year ago
Today is one frame. To place it, we pulled the daily readings of the past twelve months from CoinGecko and charted them ourselves. A year ago Ethereum stood at $4,126, the one-year high at $4,159, the one-year low at $1,566. From the level of twelve months ago, today's price is around 41 percent away.
The chart also shows that the recovery since the one-year low was no straight line. Between $1,566 and today's level lies a rise of a good 54 percent, interrupted by several pullbacks.
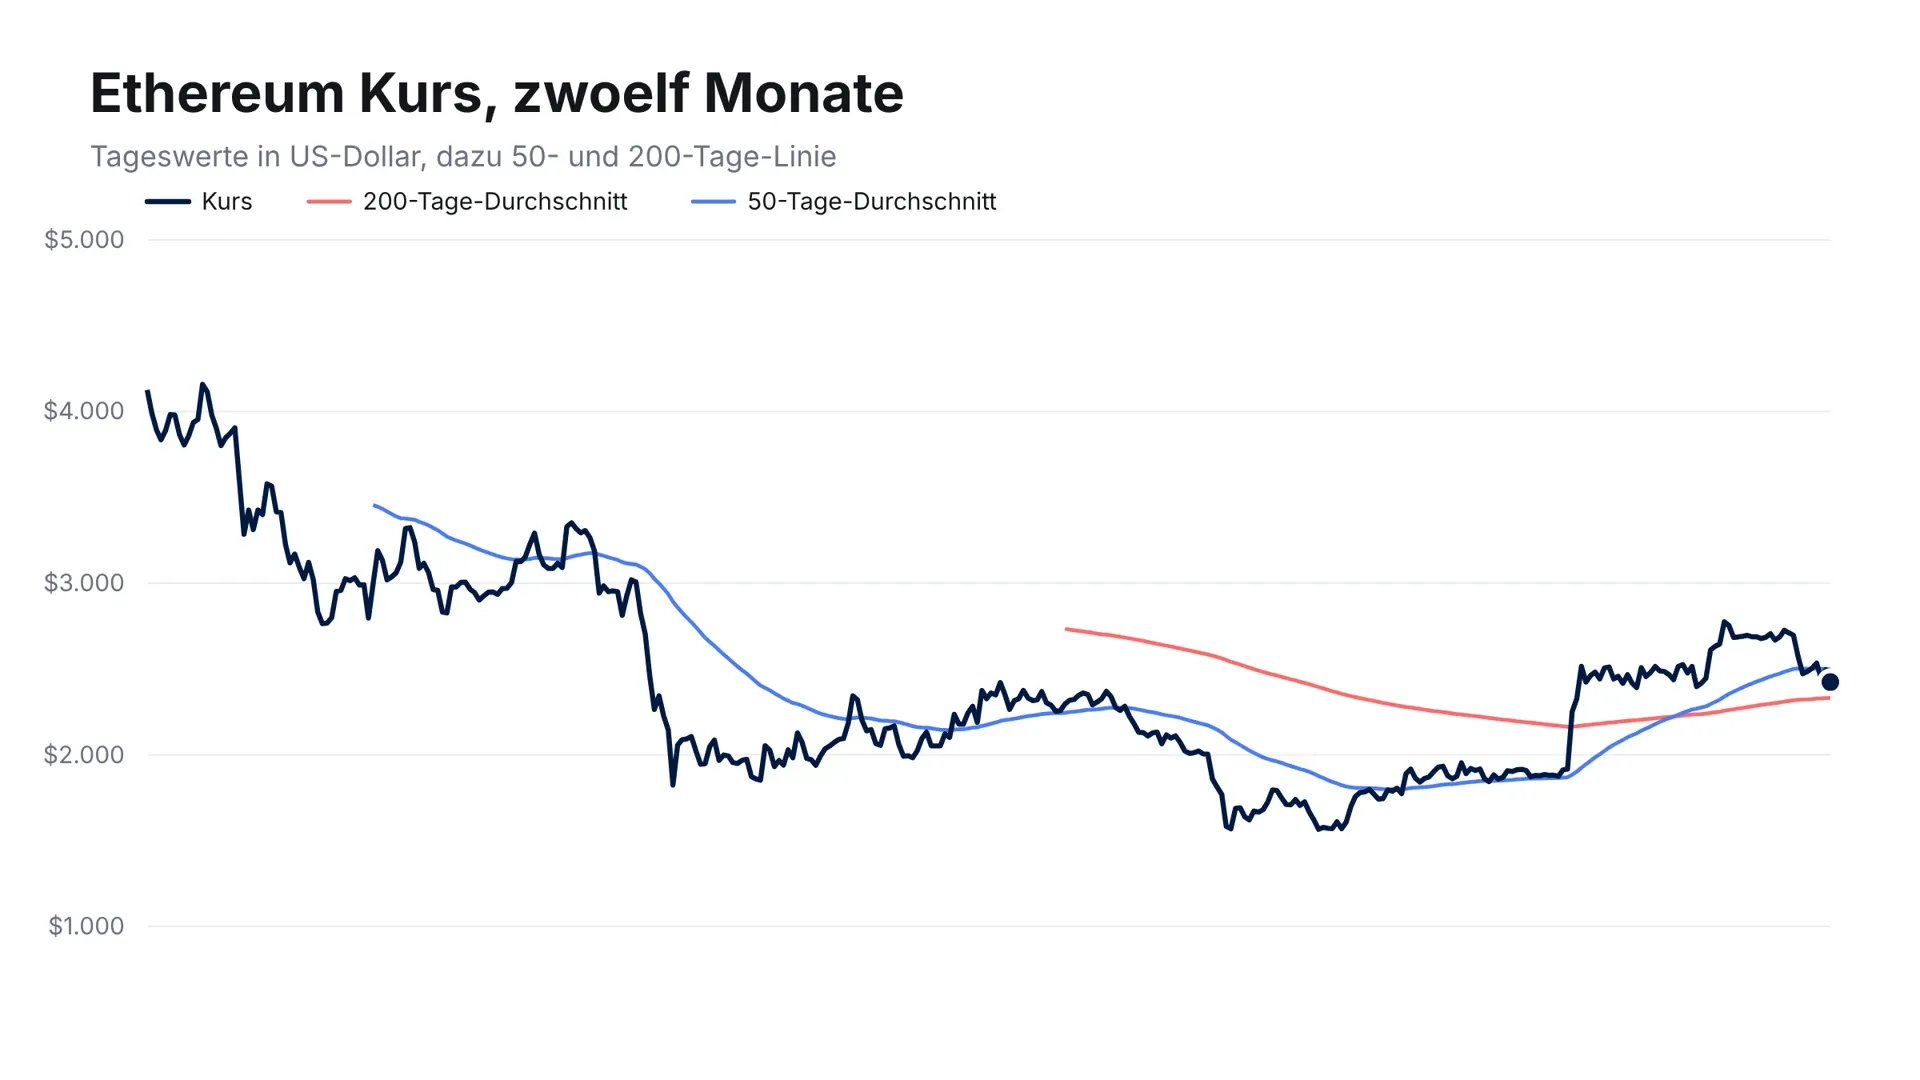
The 50-day line and the 200-day line: the Ethereum price sits in between
Two moving averages place the price. By our calculation the 50-day average sits at $2,497, the 200-day average at $2,331. A moving average is the mean of the past 50 or 200 daily closing prices; it smooths the daily swings and shows the direction of the longer move.
Today's price of $2,417 therefore sits below the short line and above the long one. For the coming days those are the two numbers from which it can be read whether today's slide stays a one-day move or becomes more. Should the price fall below $2,331, that would be the first close beneath the 200-day line in weeks. Should it climb back above $2,497, today will be smudged out of the chart.
Tuesday's deleveraging and what has happened to the Ethereum price since
On Tuesday we described in this space that open positions in the futures market had fallen by 16 percent within five days; the price stood at $2,534 at the time. That is set out in our analysis of the deleveraging of 13 October.
Two things have changed since. The price sits around $117 lower, and the $2,495 level, which on Monday still served as a turning point, has been breached. The deleveraging itself works in the other direction: fewer open positions mean fewer forced closures when things go down. Today's slide of a good four percent is therefore remarkably shallow for a data release of this size.
ETF inflows: $24.8 million on Tuesday
Beside the chart, the fund flows are worth a look, and right now they tell a different story from the price. Around $24.8 million net flowed into the American spot ETFs on Ether on Tuesday, according to market data. That is a small sum measured against the outflows of previous weeks, but it is a change of sign: in early October a single week showed $542 million of outflows on the books.
For investors in Germany these products are not directly accessible; comparable investments run here as ETNs or ETPs via the exchange. What works in Europe and what does not is covered in our overview of crypto ETFs and their European equivalents. The reason the American numbers count anyway: this data is the only daily published indicator of whether big money is flowing in or out.
28 October as the next date in the calendar for the Ethereum price
The Federal Reserve's next monetary policy meeting falls on 27 and 28 October 2026, with the decision published on the second day. The dates are in the official meeting calendar of the Federal Reserve. Until then, today's inflation figure is the most recent hard data point on which expectations rest.
In practice that means the market works with this one figure for two weeks. Anyone trading larger amounts in that time does better to reckon that 28 October will be a day of elevated swings, as this afternoon was.
Buying under MiCA: which exchanges are authorised in Germany
Since the European crypto regulation MiCA came into force, every provider addressing retail clients in Germany needs authorisation as a crypto asset service provider. Authorisation is the first check before any purchase: if the provider is in the register of BaFin or another European supervisor, the European rules on custody and client funds apply. If it is not there, they do not. Which houses hold the authorisation and what they charge for an Ethereum purchase is shown by our comparison of crypto exchanges for European investors.
The second point is custody. Ether sitting on an exchange belongs to you economically, but technically the exchange manages the keys. Anyone holding larger amounts and not trading them usually withdraws them to a wallet of their own.
Holding period and tax: what 31 December means for German investors
A price slide in Germany is also a tax question, and in both directions. Gains from selling Ether are tax-free under section 23 of the Income Tax Act if more than one year lies between purchase and sale. Within that year they are taxable as a private disposal transaction, with an exemption threshold of 1,000 euros per calendar year. Threshold means: if it is exceeded, the entire gain is taxable, not only the part above it.
That gives a concrete cut-off date. Losses from private disposal transactions can only be offset against gains of the same kind, and the calendar year ends on 31 December. Anyone who has realised gains within the one-year period this year and is currently sitting on loss positions has until then to bring both together in the same year. Anyone close to the end of the one-year period, by contrast, gives away the tax exemption with a sale now.
Which acquisition happened when can only be answered, with several purchases, from a clean record. The common tools for that are in our comparison of crypto tax software and portfolio trackers. These details place the legal position and replace no tax advice.
Staking: a 2.66 percent network yield and the question of the holding period
Stake your Ether, meaning put it to work securing the blockchain, and you receive a payment for it. The network most recently paid around 2.66 percent a year; at the providers, a good 2.2 percent arrives after fees. How the providers differ is broken down in our comparison of staking providers.
For tax purposes staking is to be viewed on its own: the running income is taxable as other income as soon as it is received. The one-year holding period for the staked Ether itself is untouched by that under the current view of the tax authorities.
Our assessment: the market is pushing back the rate turn, not the Ethereum story
In the editorial team's view today's move was a reaction to a tenth of a point, not to Ethereum itself. Three observations support that. First, the whole market fell with it: Bitcoin gave up around two percent the same afternoon, Solana a good four. Second, ETF flows have been slightly positive again since Tuesday, which argues against a flight out of Ether. Third, the level of leverage after last week's unwinding is lower than in the summer, and the daily loss still stayed in single digits.
Against it stands the fact that the $2,495 level has now been tested twice and breached on the third attempt. A level loses force the more often it is approached. As long as the market reckons with later rate cuts, the price lacks the fuel for the way back above the 50-day line at $2,497. This is an assessment of the situation and not a recommendation to buy or sell; crypto investments can lead to a total loss.
Ethereum at $2,417: without a rate turn the push above $2,500 is missing
Three things decide the price over the coming two weeks, and all three can be read off a single number.
- The $2,331 line. A daily close below it would be the first time in weeks that the price loses the long average line. If you want to buy, the authorised venues are among the authorised exchanges named above.
- 28 October. The Federal Reserve's rate decision is the next date that either confirms today's figure or devalues it.
- 31 December. The tax year ends, and with it the chance to offset gains and losses of the same year. The tools for that are in the tax software comparison.
(As of October 14, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
The Mantle network manages a treasure of $2.25 billion, and around $99 million of it sits on its own blockchain. That ratio of roughly 23 to 1 explains more about Mantle than any price level: the organisation behind it is rich, the network beneath it is small. Anyone holding MNT or thinking about it should know both figures, because the token hangs on the first and the utility on the second.
This article works through the network in order: technology, treasury, token, applications, access, trading venues for European investors and risks. cryptoticker.io compiled the figures for capital on the blockchain itself on 13 October 2026 from the public data of DefiLlama; the treasury values come from the project's overview page. How the price has moved since is covered in our Mantle price prediction.
What the Mantle network is and who stands behind it
Mantle is a layer-2 blockchain on Ethereum. A layer 2 settles transactions in a network of its own and passes the bundled result on to Ethereum, so that they become cheaper and faster than they would be directly on Ethereum mainnet. Mantle carries chain ID 5000 and works with Ethereum's developer tooling, so contracts can be ported across with little effort.
The network is carried by an organisation with its own coffers, grown out of the former BitDAO. Those coffers are called the Mantle Treasury and are the real difference from most other layer 2s. Other networks raise capital from investors; Mantle brings an existing stock with it. What happens to it is decided by token holder votes, with governance running through public proposals.
The products under the roof are called Mantle Network for the blockchain itself, mETH Protocol for staking Ether, Function for a Bitcoin connection, Mantle Index Four for a fund product and UR for an app that lets balances be spent and converted back into euros or dollars. The blockchain is therefore one part of the house, not the whole house. That layout later explains why the figures on the blockchain and the figures of the organisation sit so far apart.
From optimistic rollup to ZK validity rollup: what Mantle v2 changed in the technology
A rollup is a blockchain that executes its transactions itself and only presents the result to Ethereum. What matters is how Ethereum learns that this result is correct. An optimistic rollup initially assumes it is, and leaves a window open in which someone can prove the opposite. A validity rollup instead supplies a mathematical proof, a so-called ZK proof, which Ethereum verifies.
Mantle has made that switch. The network's technical documentation describes today's architecture as a ZK validity rollup, introduced with version Mantle v2 under the name Skadi. A service called Mantle-Succinct-Proposer passes the proofs on to a contract on Ethereum at regular intervals. The documentation no longer names a challenge period, because a verified proof does not need one.
For holders that has one practical consequence: on the way back to Ethereum the long waiting time familiar from optimistic rollups falls away. For security it means the validity of blocks hangs on the correctness of the proof programs and the contracts. Anyone wanting to read up on the architecture in detail finds the building blocks described in the same documentation.
Ethereum blobs instead of a data layer of its own: where the transaction data sits today
Every rollup has to store the data of its transactions somewhere, so that the state of the network can be reconstructed even without its operators. That property is called data availability, and it decides whether a network lives on without outside help if the worst happens.
Mantle solved this point through a layer of its own for a long time, Mantle DA, which built on EigenDA's technology. Today's documentation describes a different route: a service called op-batcher writes the rollup data into blob-carrying transactions under the Ethereum standard EIP-4844, directly onto Ethereum. The data therefore sits where the proofs are verified as well.
Mantle is built modularly: execution, data availability and settlement on Ethereum are separate modules that can be swapped out individually. The change of data layer, which left the rest of the infrastructure untouched, shows exactly that. The architecture builds on the OP Stack, an open construction kit for rollups that other layer 2s develop on too. For developers that means short routes: work on Ethereum and you bring your contracts and tools with you, while execution outside mainnet takes care of scalability.
What the documentation leaves open is who operates the sequencer, the service that sets the order of transactions. It describes node operators passing transactions on to it, and that the transaction pool is deliberately not publicly viewable. A statement on whether this service is spread across several independent operators is not there. Young layer 2s usually sit in that position, and it is at the same time the point at which real decentralisation can be measured later.
The treasury holds $2.25 billion, 71.78 percent of it in MNT
The project's treasury page reports a total value of $2,252,971,490 for 13 October 2026. The split: $1,617,206,536 in MNT, which is 71.78 percent, plus $283,593,226 in ETH at 12.58 percent, $237,810,643 in BTC at 10.55 percent, $111,168,807 in stablecoins at 4.93 percent and a small remainder in COOK.
This split carries a risk of its own. Almost three quarters of the treasure consists of the very token whose value the treasury is meant to support. If MNT falls, the coffers shrink in step, and the frequently quoted billion-dollar figure shrinks with them. Truly independent of its own price are only the stablecoins and the Ether and Bitcoin holdings, together around $632 million.
The money is used among other things for distributions to MNT holders via a rewards page of its own. The treasury page lists past distributions for this, including 4,000,000 ENA from a collaboration with Ethena, 570,000 EIGEN from the connection to EigenLayer and 200,000,000 COOK. Alongside that stands an EcoFund, which the project describes as a capital pot of $200 million for applications and technology partners in its own ecosystem.
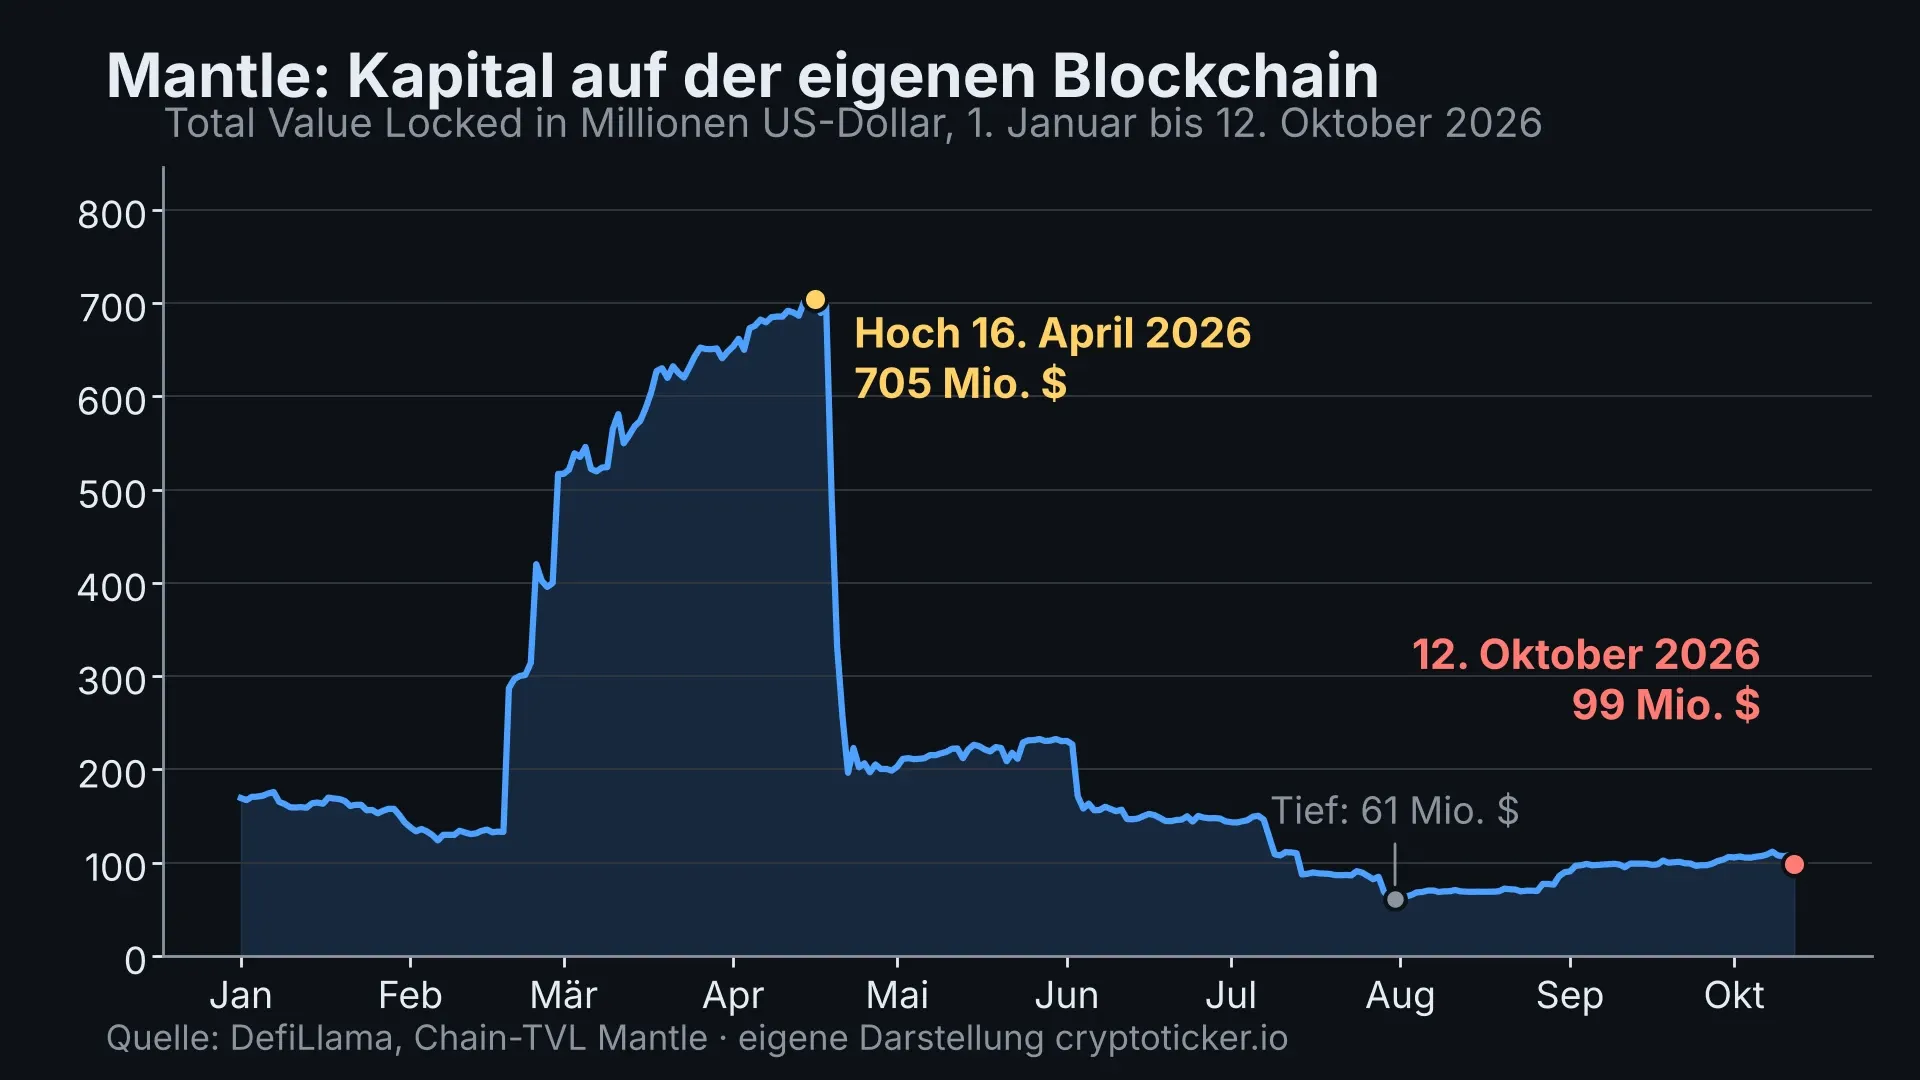
99 million dollars on its own blockchain: the gap to the treasure
Total value locked, TVL for short, measures how much capital is deposited in the applications of a blockchain. The figure says nothing about profits and little about user numbers, but it does show how much trust capital places in a network. For Mantle, cryptoticker.io analysed the course of 2026 from the public data of DefiLlama, with three verified readings.
At the start of the year $169 million sat on the blockchain. By 16 April the value had risen to $705 million, the highest level of the year. After that it collapsed: on 1 June it was $230 million, on 1 July $143 million, and on 31 July the series marked its lowest point at $61 million. Since then it has been slowly climbing again; on 11 October $108 million was on the books, on 12 October $99 million.
From the April peak to today that is around 86 percent less, while measured from the trough at the end of July it is a good 60 percent more. In the ranking of blockchains by deposited capital, Mantle therefore sits in 28th place. For scale: Ethereum carries around $51 billion, Base a good $6 billion, Arbitrum $1.4 billion and Polygon $675 million.
The treasury is untouched by this. The holdings sit predominantly in MNT, ETH and BTC on Ethereum, so outside the network's own blockchain. That is precisely where the gap between around $2.25 billion and $99 million comes from. Our ecosystem series has described a similar pattern at another network before, when we worked through Ronin after the Karst upgrade.
MNT pays the network fees, 3.3 of 6.2 billion tokens are in circulation
MNT performs two jobs in the network: the token pays the gas fees, meaning the network fees for every transaction, and it counts in votes on the treasury. No claim on profits or earnings of the project comes with it, which holds for most network tokens and matters when weighing the price.
The supply picture, taken from CoinGecko on 13 October 2026: 3,302,003,383 MNT are in circulation, the maximum supply stands at 6,219,316,795 tokens. A good half is therefore in circulation, 53.1 percent. The price stands at 0.47 euros, market capitalisation at around 1.57 billion euros, which means 59th place among all cryptocurrencies. Taking the whole supply at today's price gives a fully diluted valuation of around 2.95 billion euros.
The price record is clearly negative. Over seven days it is down 17.7 percent, over thirty days 5.4 percent, over a year 75.7 percent. From the all-time high of 2.45 euros on 8 October 2025 the price is 80.6 percent away. In trading, around 25 million euros most recently changed hands within a day.
The difference between circulating and maximum supply is the point holders should keep in view: around 2.9 billion MNT are not yet in the market. A large part of that sits in the treasury, and therefore in the hands of the organisation itself.
Aave V3, CIAN and Agni Finance: where the capital on Mantle sits
Behind the $99 million stand concrete applications. The largest positions according to the DefiLlama data of 13 October 2026: the yield manager CIAN Yield Layer holds $107 million, the lending market Aave V3 around $52 million, the exchange Agni Finance $16 million and Merchant Moe $12 million. Behind them follow Fluxion Network with $7 million, the derivatives venue IntentX with $2.3 million and the lending markets INIT Capital and Compound V3 with around $1.7 to $1.9 million each.
That the individual positions add up to more than the value of the blockchain has a technical reason: a yield manager deposits capital in other protocols, and in the TVL of a blockchain such capital is only counted once. The ranking is untouched by that.
As DEXs, meaning decentralised exchanges, Mantle mainly offers Agni Finance, Merchant Moe and Fluxion Network. A launchpad of its own for new tokens, or a notable NFT marketplace with measurable capital, does not appear in the data. Anyone looking for NFTs or fresh tokens currently finds little on Mantle; the weight lies clearly with lending, yields and tokenised assets.
The project sets its priorities there too. Its own page reports for 2026, among other things, the launch of OpenStock with pre-IPO stakes in July, the addition of tokenised equities, the move of its in-house bridge Super Portal from LayerZero to Chainlink CCIP, and since 3 September the stablecoin USDG from issuer Paxos. At its third anniversary in July the project named $116.4 million in tokenised active strategies.
Alongside its own products the house invests in those of others. The EcoFund of $200 million is the tool for that: it finances applications and technology partners building on Mantle, and such investments are the usual route for a young network to keep developers. It becomes visible in the partnerships of recent months, from stablecoin issuer Paxos through tokenisation provider Securitize to Chainlink's bridge technology. Which of these is a pilot and which runs in production is something such lists rarely distinguish; the question is worth asking at every ecosystem.
mETH, Function and Mantle Index Four: the products beside the blockchain
The largest single product of the house does not sit on Mantle but on Ethereum. The mETH Protocol takes in Ether, stakes it and issues the token mETH in return, which remains tradeable. Around $583 million is deposited there according to the DefiLlama data. A variant for restaking, cmETH, and a restaking arm with a further $41 million belong to it. If this form of yield interests you in principle, the providers are in our comparison of staking platforms.
Function is described by the project as a decentralised Bitcoin solution that makes BTC usable for applications on blockchains. Mantle Index Four, MI4 for short, is a fund product launched together with tokenisation provider Securitize in April 2025. The treasury committed up to $400 million as an anchor investment, agreed through a vote. The basket covers Bitcoin, Ether, Solana and dollar stablecoins, is reweighted quarterly and folds in staking yields via mETH, bbSOL and sUSDe. The project does not name a current fund size; the $400 million is a commitment, not a documented holding.
UR, finally, is an app for payments and for converting back into local currency. Taken together the result is a house whose revenue sources stand broader than its own blockchain. For MNT holders that is opportunity and catch at once: the products strengthen the organisation, but the token grants no direct claim on their earnings.
Super Portal, explorer and network fees: how you get onto the Mantle blockchain
The route onto Mantle runs across a bridge. The project operates the Super Portal for this, which takes in balances from Ethereum and further networks and has worked through Chainlink CCIP technology since July 2026. In your wallet you enter the network with chain ID 5000, after which it appears like any other. Which wallet is suitable for it is shown in our comparison of software wallets.
The network fees are paid in MNT. A small holding of it therefore belongs in every wallet that is to do anything on Mantle, otherwise even bridging back stalls. Serving as block explorer, meaning the public register of all transactions and contracts, is mantlescan.xyz; the former link explorer.mantle.xyz redirects there. Every transfer can be traced there and every contract address checked before you grant it anything.
One note on the order: bridge first, application second. Send a balance straight from an exchange to an address on the wrong network and you lose time at best and the amount at worst. The check costs a minute and happens in the explorer.
MNT in euros: Kraken lists the pair, Coinbase and Bitvavo do not
For investors in Europe what counts in the end is where MNT can be bought at all, ideally against euros and at a provider with European authorisation. cryptoticker.io checked that question itself on 13 October 2026 by querying the public trading registers of several exchanges.
The result: Kraken lists MNT against both euros and US dollars. At Coinbase, MNT does not appear in the register of tradeable pairs, nor does it at Bitvavo, and at Bitpanda no price page for the token exists. Of the large venues authorised in Europe, that leaves above all Kraken for a direct euro purchase.
This situation is typical for MNT and not meant reassuringly: a token tradeable against euros at only a few authorised venues is harder to sell again in case of doubt than a standard asset. If you nonetheless want to buy, compare the fees and the authorisation of providers beforehand in our exchange comparison. A purely price-based view of MNT is also available in our assessment of whether Mantle is a good buy at current prices.
Holding period, staking and total loss: the risks for German investors
For tax purposes German law treats MNT like other crypto assets, as another type of economic asset. Gains from a sale within one year of purchase fall under the private disposal transactions of the Income Tax Act and are taxable above the exemption threshold; once a year has elapsed the gain remains tax-free. Earnings from staking count separately and are recorded in the year they are received. Which program records the transactions cleanly is covered in our comparison of tax tools. An individual case is settled by a tax adviser, not by an article.
The remaining risks lie in the open. First, the concentration risk of the treasury: 71.78 percent in a single token means that treasure and price run in the same direction. Second, the technology: a validity rollup hangs on the correctness of its proof programs and its contracts on Ethereum, and on the distribution of the sequencer the documentation makes no statement. Third, the supply: around 2.9 billion MNT are not yet in circulation. Fourth, tradeability, described above.
There is also the fundamental point that applies to every network token: a total loss is possible. Prices 80 percent below the all-time high count in this market as the normal case for tokens whose usage lags behind expectations.
From the editorial team's view: the treasure does not prove the usage
Mantle is frequently described through the size of its coffers, and the figure is right: $2.25 billion is a lot of money. It is just that those coffers face a network with $99 million on its own blockchain, one that sits in 28th place in the ranking of blockchains and has lost around 86 percent of its deposited capital since April. That the money sits predominantly in MNT, ETH and BTC outside its own blockchain is no reproach, it only shifts the yardstick: Mantle today is more a holding house with an attached blockchain than a layer 2 with full coffers.
In favour of that reading is the fact that the strongest products of the house, mETH with $583 million and the fund product MI4, do not run on Mantle at all. Against it is the fact that the blockchain has gained a good 60 percent again since the trough at the end of July and carries building blocks that attract serious applications, with Aave V3, CIAN and the Paxos stablecoin USDG. Neither case is settled. The direction can be checked against a single figure: if deposited capital moves back towards the $230 million of June in the coming months, the network is growing. If it stays at around $100 million, it is mainly the coffers that carry it. This is expressly not a recommendation to buy or sell.
Mantle: 99 million in usage against a 2.25 billion treasure
Three steps if you want to look into MNT more closely:
- Clarify the venue and its authorisation. Check whether your provider lists MNT against euros at all and what authorisation it holds in Europe. The fees and the authorisation status of the large houses are in the exchange comparison.
- Settle custody before you bridge. A balance on the blockchain needs a wallet that knows the network with chain ID 5000, and a small MNT holding for the network fees. Which wallet fits is shown by the software wallet comparison.
- Record transactions from the start. Purchases, bridge transactions and staking income belong in the documentation without gaps, otherwise the one-year period turns into an arithmetic exercise later. Suitable programs are in the comparison of tax tools.
(As of October 13, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Anyone who bought Bitcoin on 14 October 2025 is looking at a price today that sits roughly a quarter below their own entry. A year ago one Bitcoin cost $115,226 or 99,310 euros; by Wednesday midday it is $82,709 and 74,239 euros. That is 28.2 percent less in dollars and 25.2 percent less in euros. For exactly this vintage the one-year speculative period under German tax law expires today, and what changes with it is not the price but the calculation behind it.
The figures come from CoinGecko's price series for each calendar day. Deribit's futures index stood at $82,844 at the same time, $135 above the spot value. That spread of 0.16 percent is normal and shows how closely the cash market and the futures market sit together on this quiet day.
The year-on-year comparison: 99,310 euros then, 74,239 euros today
A year-on-year comparison looks at first like an accounting exercise. In Germany, though, it decides which tax rules can still be applied to a sale at all, and it frames the situation better than any single day's change. On Wednesday the price moved 0.67 percent lower; over seven days it is down 0.4 percent, while over 30 days it is up 7.08 percent.
These three figures do not contradict each other, they simply measure different windows. The monthly number carries the late-summer recovery, the annual number carries the slump from winter and spring. Look only at the day and the market seems motionless. Look only at the year and it seems to have failed. Both readings miss the situation.
| Reference date | Price in dollars | Price in euros |
|---|---|---|
| 6 October 2025, all-time high | 126,080 | no daily series |
| 14 October 2025, one year ago | 115,227 | 99,310 |
| 27 October 2025, one-year high | 114,419 | 98,195 |
| 1 July 2026, one-year low | 58,566 | 51,474 |
| 14 October 2026, today | 82,709 | 74,239 |
From the one-year low on Wednesday 1 July, the price has recovered by 41.4 percent. From the all-time high on Monday 6 October 2025, it is still 34.4 percent short. Both stretches belong to the same twelve-month span.
Why the loss in euros is smaller than in dollars
Three percentage points separate the two loss figures, and they have nothing to do with Bitcoin. The difference comes from the exchange rate. In October 2025 a euro bought around 1.16 dollars; currently it buys around 1.114. The dollar has therefore gained against the euro, and an asset quoted in dollars loses less when seen from Germany.
This distinction is not a technicality. The tax office calculates in euros. A German investor who works out a gain or loss in dollars, because that is how the trading interface displays it, arrives at a different result from the tax return. What counts is the euro value at the time of acquisition and at the time of disposal.
A worked example makes the difference tangible. Anyone who put in 10,000 euros a year ago holds a value of around 7,475 euros today. Calculated in dollars, $11,600 would have become around $8,330. The dollar calculation shows a loss a good 300 euros larger than the one that actually appears in the tax return.
The all-time high of 6 October 2025 is now more than a year old
The highest price ever paid is $126,080, set on 6 October 2025. Since last Tuesday that record has been more than twelve months old. The highest level of the past 365 days was $114,419 on 27 October 2025, already below the record.
For context that means the market has not seen a new peak in a full year. Phases like this have occurred several times in Bitcoin's history, and they have lasted for varying lengths of time. No statement about the direction of the coming months follows from that, but one about expectations does: anyone who has been betting on a quick new record since autumn 2025 has now waited longer than most timetables allowed for.
236 of 366 days closed below today's price
This is where the year-on-year comparison gets interesting. Counting through the daily closing prices of the past 366 days, 236 of them were below today's level. That is 64.5 percent. The current price is therefore not a weak reading within the year, but one that only a good third of all days exceeded.
That finding only appears to contradict the 25 percent loss. Both statements are correct because they answer different questions. The year-on-year comparison measures two points; the day count measures the whole distance in between. Anyone who bought a year ago caught one of the most expensive entries of the entire period.
The 200-day line at $72,204 and what has changed since 11 October
The 200-day line is the average of the closing prices of the past 200 trading days. It smooths out outliers and serves many market participants as a rough dividing line between a rising and a falling market. It currently sits at $72,204, putting the price 14.7 percent above it.
In our analysis of 11 October that gap was still 15.4 percent. The buffer has shrunk by 0.7 percentage points since then, and not because the price fell sharply but because the average line keeps rising. The line is gradually pulling the low prices of early summer out of its window. That shortens the gap even in a sideways market.
Tuesday's market report had seen Bitcoin at $83,200, with clear relative strength against Solana. That strength persists, the gap has only narrowed slightly: over seven days Bitcoin is down 0.4 percent, Solana 8.97 percent.
The 50-day line at $81,190 as the next level below
Much closer sits the 50-day line at $81,190. The price stands just 2.0 percent above it. That makes it the first level against which a pullback can be measured, and it has been tested several times in recent weeks.
If you work with leverage, know this number before opening a position. At five times leverage a 20 percent decline is enough for liquidation; at ten times leverage 10 percent suffices. From the current level to the 200-day line is 12.8 percent down. A ten-times leveraged position does not survive a move that far, arithmetically speaking. Look up your liquidation price in the table and you find the one number that counts if the worst happens.
What the volatility expectation in the futures market shows
The volatility index of the options exchange Deribit, DVOL for short, measures the range of movement the futures market is pricing in for the coming 30 days. It stands at 38.44 points. On 3 October it was at 35.36; over the past 90 days it moved between 33.59 and 43.41. Expectations have therefore been rising for eleven days, but remain in the middle of their range. The live readings are on Deribit's metrics page.
A rising DVOL with a barely moving price means that hedging becomes more expensive before anything moves. The nearest reason is the calendar: US consumer prices are due on Wednesday, and on Wednesday 28 October the US Federal Reserve decides on its key interest rate. Both dates fall inside the window the index covers.
The one-year period under section 23 of the German Income Tax Act and the 1,000-euro threshold
Bitcoin held as private assets falls in Germany under private disposal transactions pursuant to section 23 of the Income Tax Act. A gain is taxable if no more than one year lies between acquisition and sale. Once that year has passed, the sale is no longer a private disposal transaction and the gain remains tax-free.
The governing letter from the Federal Ministry of Finance dated 6 March 2025 replaced the version of 10 May 2022 and confirmed this line. It also makes clear that the extension of the period to ten years does not apply to payment tokens such as Bitcoin, not even when the holdings generate income through lending or staking.
Within the year an exemption threshold of 1,000 euros per calendar year applies. Threshold means: if it is reached or exceeded, the entire gain is taxable, not only the part above it. The threshold also applies to all private disposal transactions of a year taken together, so to gold or other tokens as well.
The uncomfortable side of this system concerns losses. A loss from a private disposal transaction can only be offset against gains from private disposal transactions, in the same year, through a carry-back to the previous year, or through an unlimited carry-forward. Sell at a loss after the year has elapsed, however, and you sell outside section 23. There is then no taxable gain, and consequently no loss that could be offset either. For the October 2025 vintage that is precisely the case as of today. Suitable tools for this calculation are in our comparison of crypto tax software.
How the tax office determines the order of purchases
Very few investors bought on a single day. For them the order decides which units count as sold. Where an individual unit cannot be clearly allocated, the Federal Ministry of Finance letter treats the Bitcoin acquired first as disposed of for the purposes of the holding period. This method is known as first in, first out, or FIFO.
In practice that means: buy in October 2025 and in July 2026, sell part of it today, and you give up the old pieces first. Those have been held for more than a year, so they are tax-free and at the same time carry no offsettable loss. The cheap pieces from July 2026 stay in the holding and only become tax-free in July 2027. Without knowing this order, you plan around your own tax burden.
Clean documentation is the precondition. For each purchase you need the date, the quantity and the euro equivalent at the time of acquisition, plus the same details for every sale. If your holdings are spread across several exchanges and wallets, pull this history together before you trade, not in the spring while filling in the Anlage SO form.
Our assessment ahead of the Fed meeting on 28 October
In the editorial team's view the current situation is less weak than the year-on-year comparison suggests, and less stable than the monthly gain of 7.08 percent promises. Three documented points support that. First, the price is above 64.5 percent of all daily closing prices of the past year. Second, the 14.7 percent gap to the 200-day line maintains a noticeable buffer. Third, the priced-in range of movement is tightening from 35.36 to 38.44 points, and doing so ahead of two dates whose outcome is open.
Against it stands the proximity to the 50-day line at $81,190, just 2.0 percent below the current price. Should the price fall below it, the next well-founded support is only 12.8 percent lower. This assessment evaluates the situation; it is not a recommendation to buy or sell. With crypto assets a total loss is possible.
What a sale costs in fees
Anyone who does want to give up holdings after this calculation meets a second cost item that has nothing to do with the price. Between trading venues the differences for Bitcoin are substantial depending on the model, and on a four-figure amount the fee saving quickly exceeds what an hour of price movement amounts to. Providers' terms are in our comparison of ways to sell Bitcoin.
Part of that comparison is the question of whether the balance needs to be sold at all. Moving it into self-custody triggers no tax, because no disposal takes place. It changes nothing about the running holding period, though, since that attaches to the acquisition, not to the place of storage.
Bitcoin after one year: below $72,200 the picture turns
The year since 14 October 2025 has shown two things. The entry at 99,310 euros was one of the most expensive of the period, and today's level is nonetheless above two thirds of all days of that year. What matters for the coming weeks is whether the 200-day line at $72,204 holds. Three steps put your own position in order:
- Collect purchase dates and euro equivalents for each position and check which parts have passed the one-year period. Tools for that are in our comparison of crypto tax software.
- Before a sale, set the fees of the venues in question side by side, as listed in our comparison of selling routes.
- If you want to keep building and soften the entry timing, spread the purchase over instalments instead of a single amount. The providers for that are in our savings plan comparison.
This text does not replace tax advice. A tax adviser is responsible for assessing an individual case.
(As of October 14, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
The WhiteBIT Coin price is at $78.68 and has risen 7.59 percent over the past 24 hours. If you are wondering how the WBT price stands today against the broader market: Bitcoin is down 0.86 percent over the same period, while WBT (WhiteBIT Coin) gains clearly. That divergence stands out, but on the available sources it cannot currently be tied to any single, reliably reported catalyst such as a listing, a macro event or a specific company announcement.
The data behind the striking move in the WBT price
The key figures at a glance:
- Current price: $78.68
- 24-hour change: +7.59 percent
- 24-hour high: $78.83
- 24-hour low: $72.57
- 24-hour volume: $96,426,985
- Market capitalisation: around $9.28 billion
- Market rank: 16th
The WhiteBIT token is tied to the WhiteBIT and Whitechain ecosystem, so it does not track the crypto market as a whole but demand inside one specific platform environment. Trading volume describes no more than the value of the WBT traded within 24 hours. High volume shows elevated trading activity, yet it says nothing about who the buyers are or what prompted them.
The WBT price rise lands in an already positive month
The daily gain does not stand on its own. Over seven days WBT added 9.70 percent, over 30 days 40.50 percent. A trend in this sense describes a price direction that stays visible across several time frames, yet it is no guarantee of future performance. Sharp gains can also bring sharper short-term swings, without any particular next price target following from them.
WBT performance over three time frames
24 hours · +7.59 percent
7 days · +9.70 percent
30 days · +40.50 percent
Bar length relative to the largest value (30 days, +40.50 percent). Source: the price data cited in this article, as of 14 October 2026.
What can responsibly be said about the background to the WBT move
On the current state of knowledge there is no clearly reported single trigger for the WBT rise. A rising price and elevated trading volume do broadly fit momentum-driven spot demand, a situation in which an ongoing price move draws additional attention and trading interest. Spot trading here means buying and selling the token directly, as opposed to derivatives such as futures. With an ecosystem token like WBT, platform-specific factors such as usage, fee benefits, liquidity and general market sentiment can all play a part, as the official WhiteBIT explanation of WBT also describes. That is not evidence, however, that these factors actually caused the current move.
Which levels in the WBT price are being watched now
Market watchers are currently looking at the most recent trading range, meaning the area between the daily high and the daily low. The high sits at $78.83, the low at $72.57, the current reference price at $78.68. These levels are not signals, targets or trading recommendations. The Bitcoin comparison at -0.86 percent over 24 hours only underlines that WBT is standing apart from the broader market on this day, without any lasting relative strength or any cause following from it.
What a crypto price alert actually tells you about WBT
A crypto price alert reports a price move and nothing else, not an assessment. It makes sense to cross-check price, volume and timestamp against reliable data sources, to check official project and exchange statements for matching information, and not to confuse a 24-hour move with a confirmed long-term trend. As the German consumer advice centre explains for crypto assets, such assets can swing sharply and cause substantial losses.
The WhiteBIT Coin price stands at $78.68, with WBT up 7.59 percent on a 24-hour view. The daily high, the elevated trading activity and the positive seven-day and 30-day record make the move stand out. On the available sources a specific trigger remains open, which is why price data, market comparison and possible explanations should be kept clearly apart.
(As of October 14, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
A hardware wallet is a small device that generates the private key to your cryptocurrencies, stores it and never releases it. It looks like a USB stick or a chip card, usually carries a small display, and is connected to a computer or a phone only when you want to sign something. Everything that follows explains why this particular design makes the difference.
The question has a practical side right now. Reports of tampered devices, fake manufacturer websites and drained wallets have piled up through October 2026. To work out which of those attacks a device can actually fend off, you need to know what happens inside it.
A hardware wallet holds keys, not coins
The first and most important point contradicts the name. There is no money inside a wallet. Bitcoin and every other cryptocurrency exist purely as entries in a blockchain, a ledger kept on thousands of machines at once. Those entries cannot be moved and cannot be slotted into a device.
What a wallet holds is the private key: a very large number that proves you are entitled to dispose of a particular entry. Whoever holds that key can spend the associated coins. Whoever loses it can no longer reach them, and nobody can reset it. There is no bank here to issue a new password for a forgotten one.
That sets the entire engineering task for such a device: the key has to be usable without ever becoming visible.
The private key never leaves the device
Hardware wallets solve this by generating the key inside the device and keeping it there. Manufacturer Trezor describes the procedure in its own documentation: the private key never leaves the hardware wallet and at no point comes into direct contact with the internet-connected device.
A computer the wallet is plugged into therefore never sees the key, even with malware running on it. It receives only the result: a finished signature. Historically this answers a concrete problem. In the early years, private keys sat in encrypted files on ordinary computers, and malware emptying an entire wallet was nothing unusual. The first hardware wallet, the Trezor Model One, was built in 2014 at SatoshiLabs in Prague as a counter-design.
What really happens when a transaction is signed
The sequence has four steps, and it explains why an infected computer is less dangerous than it sounds.
First you assemble the transfer in an application on the computer or phone: recipient address, amount, fee. Those details go to the hardware wallet. Its display shows them there, independently of the computer. You confirm with a button on the device. Only then does the chip compute the signature and hand it back, at which point the application broadcasts the signed transfer to the network.
The third step is the decisive one. Because the display belongs to the device and not to the computer, malware can propose a false recipient address, but it cannot stop the real address from appearing on that small screen. Read it there and compare, and the swap shows up. Press the button blind, and it does not. The device moves security to a place the attacker cannot reach, and asks for a glance at the display in return.
Secure element and PIN: the two locks inside the device
Two layers of protection work against direct access to the device, and they work differently.
The first is the PIN. Without it the device cannot be operated, and after a manufacturer-dependent number of failed attempts it wipes its memory. A stolen device is therefore worthless to the thief at first.
The second is the secure element, a dedicated chip of the kind also found in bank cards and passports. It is designed to withhold secrets even when somebody grinds it open, measures its power draw or knocks it off its clock with targeted voltage spikes. Not every device on the market carries one; some manufacturers rely on open-source components instead and argue for verifiability over tamper resistance. Which route is better has been disputed in the industry for years, and the answer depends on the attack you want protection from.
Both locks share one limit: they protect the device, and the recovery phrase sits outside their reach.
The recovery phrase: 12 or 24 words under BIP-39
During initial setup the device shows a sequence of words, usually twelve or twenty-four. This recovery phrase, often called a seed phrase, is the key in human-readable form. From it the entire set of keys can be rebuilt at any time, on any device, including one from a different manufacturer.
Behind the procedure stands an open standard called BIP-39, published in 2013 and in use ever since. It defines how a random number becomes a sequence of words and how the words become a key again. That is exactly why no manufacturer can lock you in: if a device breaks, you restore your holdings onto a new one with the same phrase.
The standard is also clear about what it is not meant for. It exists to make randomness generated by the device readable, and expressly not to turn a self-invented sentence into a key. Inventing a phrase instead of having one generated defeats the whole protection.
2048 words, 11 bits per word: where the phrase gets its strength
A short calculation pays off here, because it makes clear why guessing is out of the question.
The standard's word list contains exactly 2,048 entries. 2,048 is the eleventh power of two, so each word carries precisely 11 bits of information. Twelve words give 132 bits, of which 128 are the actual random number and four form a checksum; twenty-four words give 264 bits, 256 of them random and eight a checksum. That checksum is why a device usually spots a mistyped phrase immediately.
128 bits of randomness mean around 340 sextillion possible phrases, a number with 39 digits. At 256 bits it has 78 digits. For comparison, the visible universe holds somewhere around 10 to the power of 80 atoms on common estimates. Working through a 24-word phrase exceeds any conceivable computing power; the limit here is set by physics.
The practical consequence is an uncomfortable one. Since nobody will guess the phrase, every successful attack runs through the human being: a photographed phrase, a fake website, a tampered device. That is exactly where the losses happen.
Hot wallet, software wallet, hardware wallet: where the difference lies
Three terms get mixed up regularly, and the difference always comes down to one question: where does the private key sit?
With an exchange wallet it sits with the provider. You have an account and a password, but no key. If the exchange fails or is attacked, you are a creditor. In exchange you can buy and sell there, and a forgotten password can be reset. Provider terms are set out in our comparison of crypto exchanges.
With a software wallet, or hot wallet, the key sits on your computer or phone, encrypted, but on a device with an internet connection. You control it yourself, while sharing the device with everything else running on it.
With a hardware wallet the key sits on a device that does nothing else and stays disconnected most of the time. The technical terms for this are cold storage, for custody without a network connection, and air gap, for the space in between.
In practice this does not make one of them right and the others wrong. A split is common: the amount being traded stays at the exchange or in the software wallet, and the holding meant to sit still goes into the device. Everyone decides for themselves at what sum the effort pays off; the devices cost between roughly 50 and 200 euros depending on the model.
Blind signing: the gap the device does not close
One weakness concerns the very step that is supposed to carry the security. For simple transfers the display shows the address and amount in plain text. For more complicated operations, such as approving a program on Ethereum, the device runs out of space or of the ability to translate, and shows nothing but an unreadable block of data. Confirm then, and you sign something you have not read. This is called blind signing.
Several manufacturers have improved on it in recent months and can now display considerably more operations in plain text. What can be changed in your own device settings we set out in detail in September.
Supply chain and fake sites: the real attack routes of 2026
This year's attacks target the device's route to the buyer and the person in front of it, leaving the mathematics untouched.
In October 2026 Ledger confirmed that an additional component had been found inside devices where it does not belong; reports of it reached Europe too. We gathered the case and the checks to run on the device. Shortly before that, according to those affected, 86 million dollars disappeared from wallets, and that case too ran through tampered devices rather than broken encryption. In parallel a fake manufacturer site topped the Google results and asked visitors there for recovery phrases.
An earlier case pointed to the same lesson, one in which a faulty random number generator made keys computable and cost 130 million dollars: a device is only as good as its provenance. Buy from the manufacturer or a named reseller, never second hand, and set it up yourself. A device that arrives with a recovery phrase already printed on it is always an attempted fraud; no manufacturer mails out phrases.
What a hardware wallet does not do
Four things are beyond even the best device, and they belong in an honest answer to the question in the title.
It offers no protection against price falls, because it stores value without judging it. It offers none against a transfer to the wrong address, because a confirmed transaction cannot be recalled. It offers none against a phrase somebody else has seen, whether in cloud storage, in a photo or on a note in a drawer. And it offers none against your own forgetting: without the phrase and without the PIN, the holding is gone once the device fails. What to do in that case, and how the tax office treats such a loss, we wrote up separately.
Tax and the holding period: what the move to your own device triggers
For investors in Germany, moving from an exchange to a device of your own is uncritical for tax purposes. A transfer between your own wallets is not a sale and triggers no taxable event; the one-year holding period under Section 23 of the German Income Tax Act keeps running and does not restart.
Two things still need attention. The acquisition date has to remain provable, because gains are tax-free after a year has passed, and the proof is yours to supply. Keep the exchange statements that show date and quantity. Second, allocating holdings remains your job once they sit spread across several wallets.
Our assessment: the device is the smaller half of security
From the newsroom's perspective, a hardware wallet makes sense for anyone holding a position for the longer term and not moving it constantly. The reason differs from the one in the advertising.
This year's evidence supports it. None of the large losses traced back to broken encryption. The causes were tampered devices, a fake site in search results and a faulty random number generator. The protection the device provides mathematically failed in none of those cases.
Nothing argues against the device itself, but plenty against the expectations placed on it. Buy a hardware wallet and then photograph the phrase, and you have spent money for nothing. Security emerges only from the combination: a device from a known source, set up by you, a phrase kept only on paper or metal, and the display read at every confirmation. Drop one of those four and the rest will not carry.
No recommendation for a particular model follows from this, and a total loss remains possible with any cryptocurrency, however well it is stored.
Hardware wallet: the phrase decides, not the device
If you want to take the step, three steps in this order are enough:
- Choose a device and buy it directly. From the manufacturer or a reseller it names, never second hand and never from a marketplace third party. Which models offer which protection is set out in our comparison of hardware wallets.
- Set it up yourself and write the phrase down by hand. Paper or a metal plate, two locations, no photo, no cloud storage and no typing it into a computer. For smaller amounts that stay in motion, a software wallet still does the job alongside.
- Transfer a small amount first. Send it back once before the rest follows, and keep the purchase statements for the holding period. The matching tax tools take the allocation off your hands later.
How randomness becomes a sequence of words and then a key again is set out verbatim in the BIP-39 specification; the description of the signing process comes from Trezor's documentation.
(As of October 14, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
The British bank won Dubai regulatory approval to let affluent clients buy BTC and ETH straight from their bank accounts, with custody and settlement kept in-house.
In a detailed technical post, the exchange argued Bitcoin’s multi-year migration to quantum-resistant cryptography must begin before any “Q-Day,” laying out requirements spanning block space, custody and dormant coins.
September CPI hit 3.7%, above forecasts, sending Treasury yields higher and dragging crypto down with stocks.
Turkish police and intelligence officers reportedly seized cash, phones, jewelry and firearms at the crypto founder's address in Beşiktaş.
European electronics chain MediaMarkt Saturn has also halted Ledger sales after a customer in Germany reported finding an implant.
U.Today - IT, AI and Fintech Daily News for You Today
Ripple is making a major push into traditional finance through a new partnership with global brokerage infrastructure provider DriveWealth.
Phong Le, Strategy CEO, forecasts a historic surge in Bitcoin banking as AI agents and inflation push Wall Street integration to 34%.
Ancient Ethereum whale takes profits after selling nine-year-old Ether stash for $15.95 million, securing substantial gains.
Stellar taps Chainlink infrastructure to activate billions in dormant RWA reserves and challenge Ethereum in structural DeFi.
The latest setup comes amid a challenging stretch for SHIB, with its price dropping to trade below $0.000005.
Blockonomi
TLDR:
- Polymarket’s October rate hike odds rose about 25 percentage points to 43%, while unchanged rates held 57%.
- U.S. CPI inflation climbed to 3.7% in September, exceeding the 3.6% forecast and August’s 3.4% reading.
- Core CPI gained 0.3% monthly and 2.6% annually, both exceeding forecasts of 0.2% and 2.5%, respectively.
- September PPI arrives October 15; the October 27–28 Fed decision comes before September PCE on October 29.
An inflation miss of just 0.1 percentage point triggered a much larger market repricing on October 14, lifting October rate-hike odds to 43%. September’s consumer price report delivered the catalyst, with annual U.S. CPI inflation reaching 3.7% against a 3.6% forecast. That comparison became a focal point for markets assessing whether inflation progress had stalled before the interest rate decision.
On Polymarket, the probability of a 25-basis-point increase climbed approximately 25 percentage points during Wednesday’s trading. However, unchanged rates retained a 57% probability ahead of the October 27–28 policy meeting. The figures captured a rapid shift in expectations without making another increase the favored outcome.
The report also showed core inflation running above forecasts, placing attention on price pressures beyond gasoline. The difference matters as energy-driven increases and broader inflation carry distinct implications for the central bank’s 2% inflation objective.
September CPI Hits 3.7% as Core Inflation Exceeds Forecasts
Headline prices increased 0.6% in September, accelerating from August’s 0.4% monthly gain. Similarly, gasoline costs jumped 9.1% and accounted for more than half the increase. Meanwhile, the broader energy index climbed 5.2%, explaining much of the immediate pressure on household budgets. That left other categories contributing to a report dominated, but not defined, by energy.
Yet the increase extended into other spending categories. Shelter prices rose 0.4%, alongside higher prices for used vehicles, airline fares, medical care, and apparel. Those movements showed that inflation was not confined to fuel. These increases showed price pressure outside energy, an important distinction when interpreting the core inflation figures.
Core consumer prices, excluding food and energy, advanced 0.3% monthly, above the expected 0.2%. Annual core inflation reached 2.6%, compared with forecasts of 2.5% and August’s 2.4%. Both annual inflation readings remained above the central bank’s target.
CME Hike Odds Reach 43.7% Ahead of PPI and October Meeting
The Fed had already increased its benchmark rate by 25 basis points to 3.75%–4.00% on September 16. Meeting minutes showed most policymakers considered another increase appropriate before year-end, while keeping decisions dependent on incoming economic data.
The shift was visible beyond Polymarket. CME FedWatch put the likelihood of an October increase at 43.7%, up from 22.1% before the inflation release. That represented a 21.6-percentage-point increase in expectations. Two-year Treasury yields climbed, the dollar strengthened, and U.S. equities declined as financial markets reacted.
Higher borrowing costs also affect liquidity conditions surrounding Bitcoin and Ethereum, although the inflation report provided no cryptocurrency price figures. Attention now turns to September’s Producer Price Index on October 15. September Personal Consumption Expenditures data are also scheduled for October 29, one day after the policy meeting concludes. For now, unchanged rates remain the leading October outcome.
The post October Fed Rate Hike Odds Surge to 43% as U.S. CPI Inflation Hits 3.7% appeared first on Blockonomi.
TLDR:
- Polygon completed its Coinme acquisition on October 14, extending its payments reach across 48 U.S. states.
- The acquired business operates with 37 state money transmitter licenses and 11 applicable exemptions.
- Coinme brings more than 1 million app users and access to roughly 50,000 U.S. retail locations to Polygon.
- Tazapay, Mesh, Toku and Kira are integrating services, but associated payment volumes remain undisclosed.
Polygon Labs completed its acquisition of Coinme on October 14, giving its U.S. payments operation regulated money-transfer infrastructure across 48 states. The deal extends its role beyond blockchain transactions into services connecting bank accounts, cash channels and stablecoins.
That footprint includes 37 state money transmitter licenses and 11 applicable exemptions. The acquired business is also registered with FinCEN as a money services business. However, federal registration is not an operating license, and specific payment services remain subject to state requirements.
The expansion addresses a practical gap in digital-dollar payments. Blockchain transfers alone do not handle every stage of customer funding or bank withdrawals. The transaction now places fiat access alongside wallets and settlement within a single payments framework. That distinction matters for companies sending funds across national borders, where recipients often require access to familiar, established local payment networks.
Polygon Adds Licensed Payment Infrastructure Through Coinme
Polygon first disclosed agreements to acquire Coinme and wallet provider Sequence in January. Together, the transactions were valued above $250 million, although no standalone price was disclosed for the payments acquisition.
Founded in 2014, Coinme developed digital-asset buying and selling channels through retail cash outlets, debit cards and banking connections. Before the deal, it had more than one million app users and access to roughly 50,000 U.S. retail locations.
These services fit into Open Money Stack, which combines customer deposits, stablecoin conversions, digital wallets, transaction routing and blockchain settlement. Businesses can receive funds, convert them into digital dollars and arrange local-currency payouts through one integration.
The arrangement connects regulated entry and exit points with token transfers, resolving a practical limitation of blockchain-only payment systems. That reach matters most when the payer and recipient rely on different payment methods or banking systems.
Four Payment Firms Join Polygon’s Stablecoin Payment Stack
Four initial customers cover cross-border payments, funding, payroll and banking. Tazapay serves over 1,000 clients across 30-plus countries. Its stablecoin services operate through a registered Canadian entity.
It is using wallet and conversion infrastructure to connect stablecoins with local payment networks. Meanwhile, Mesh is integrating fiat funding into its network of more than 300 wallets, exchanges and financial companies. The service adds a funding route.
Among the first customers adopting Polygon Open Money Stack:
Tazapay: cross-border business payments
See the full announcement: https://t.co/MXEsssJDt9
— Polygon (@0xPolygon) October 14, 2026
Toku is incorporating wallet and payout functions into payroll operations across more than 100 countries, allowing stablecoin earnings to be converted into local currency. Kira is expanding stablecoin options alongside U.S. bank accounts, ACH, Fedwire, FedNow and international transfers.
Although Open Money Stack is operating, its unified integration remains in technical preview for selected customers, according to independent reporting. Related transaction volumes, revenues and processing fees for the four integrations have not been publicly disclosed.
The post Polygon Completes Coinme Acquisition, Gains Payments Reach Across 48 U.S. States appeared first on Blockonomi.
TLDR
- State Street (STT) stock plunges 7.97% to $160.23 despite a 33% earnings jump.
- State Street Q3 revenue slips 1.1% quarterly to $4 billion despite annual growth.
- State Street reports a 33% annual EPS increase to $3.69 as net income rises 27%.
- State Street assets under management reach a record $6.3 trillion, rising 16%.
- State Street returns $651 million to shareholders despite rising operating costs.
State Street Corporation (STT) stock plunged 7.97% to $160.23 during Wednesday’s morning trading, losing $13.87 following its third-quarter earnings release. The decline followed a 1.1% quarterly revenue decrease, despite stronger annual earnings and record assets under management. The company reported 33% annual growth in diluted earnings per share, although revenue missed market expectations.
State Street Corporation, STT
State Street Revenue Slips 1% Despite Strong Annual Growth
State Street reported third-quarter revenue of $4.004 billion, down from $4.048 billion in the previous quarter. However, revenue increased 13% from $3.545 billion during the corresponding period last year. Total fee revenue declined 1.5% quarterly to $3.14 billion, although it increased 11% annually.
Net interest income reached $864 million, representing a 21% increase from the previous year. Servicing fees increased 10% annually to $1.492 billion, supported by organic growth and higher market levels. Management fees also climbed 20% to $797 million, reflecting stronger asset valuations and long-term inflows.
However, foreign exchange trading revenue declined 14% quarterly to $427 million despite increasing 17% annually. Other fee revenue dropped 29% to $98 million, largely reflecting market-related adjustments. These declines contributed to weaker quarterly revenue, while stronger servicing and management fees provided partial support.
State Street Q3 Earnings Jump 33% as Expenses Increase
State Street reported diluted earnings of $3.69 per share, representing a 33% increase from $2.78 last year. Net income climbed 27% annually to $1.09 billion, compared with $861 million during the previous year. However, total operating expenses increased 8% annually to $2.62 billion, reflecting higher compensation and technology investments.
The company recorded a pretax margin of 34.6%, compared with 31.1% during the previous year. Return on average common equity increased to 16.4%, while tangible common equity returns reached 25.1%. Meanwhile, compensation expenses increased 8%, and information systems costs rose 15% following continued infrastructure investments.
Despite higher expenses, State Street returned $651 million to common shareholders during the third quarter. The total included $400 million in share repurchases and $251 million in declared dividends. Its standardized common equity tier 1 capital ratio reached 11%, compared with 11.3% a year earlier.
State Street Assets Reach Record Levels Despite Cash Outflows
State Street reported record custody and administration assets of $59.2 trillion, representing 15% annual growth. Assets under management also increased 16% annually to $6.3 trillion, supported by higher market valuations. However, quarterly net asset inflows reached only $7 billion after substantial withdrawals from cash products.
Exchange-traded funds attracted $69 billion in net inflows, while cash portfolios recorded $62 billion in withdrawals. Consequently, overall net flows declined from $114 billion during the second quarter. The company also secured $429 billion in new servicing mandates during the latest quarter.
State Street expanded its investment management business through 38 new products and solutions during the reporting period. The company also announced plans to acquire Santander CACEIS Latam Securities Services, subject to regulatory approvals. Meanwhile, its liquidity coverage ratio stood at 106%, unchanged from the corresponding quarter last year.
The post State Street (STT) Stock: Sinks 7% as Q3 Revenue Falls 1% Despite 33% Earnings Jump appeared first on Blockonomi.
TLDR
- Faraday Future (FFAI) stock jumps 5.42% following a $200 million robotics deal.
- Faraday Future signs a deal to transfer its robotics business to Nasdaq-listed FFR.
- FFAI will retain a 65.7% stake in FFR following the proposed robotics transaction.
- FFR secures up to $10 million in financing to support robotics development plans.
- Faraday Future targets Robotaxi expansion as its robotics deal nears completion.
Faraday Future Intelligent Electric (FFAI) stock climbed 5.42% to $1.1699 during Wednesday’s morning trading, gaining $0.0599. The increase followed the company’s announcement of a $200 million robotics business sale agreement. However, shares retreated from an earlier session peak near $1.50.
Faraday Future Intelligent Electric Inc., FFAI
Faraday Future Signs $200 Million Robotics Agreement
Faraday Future signed definitive agreements with FF EAI Robotics Ecosystem (FFR) to transfer its entire robotics business. The transaction values the robotics operations at approximately $200 million and FFR at $60 million. The agreement advances a previously announced proposal into a formal transaction framework.
Under the agreement, FFAI will receive newly issued FFR shares at an agreed value of $2.246 each. This valuation represents approximately a 50% premium to FFR’s referenced market price. The companies also removed the previously proposed special stock dividend to simplify the transaction.
Following completion, FFAI expects to control approximately 65.7% of FFR on a fully diluted basis. Management and employees will hold approximately 18.2%, while PIPE participants will own another 5.5%. Meanwhile, existing FFR shareholders will retain approximately 10.7% under the proposed ownership structure.
FFR Secures $10 Million Financing for Robotics Expansion
FFR has secured up to $10 million through private investment in public equity financing. The company structured the financing without discounted shares or warrants to limit dilution. Additionally, the proceeds will support robotics development, commercial operations and expansion.
The combined business plans to develop humanoid and bionic robotics through its integrated artificial intelligence ecosystem. Its operations will cover manufacturing, research, deployment, supply chains and related services. FFR intends to pursue a leading industry position within five years.
FFAI management projects robotics revenue of approximately $7 million in 2026 and $45 million in 2027. Its preliminary forecasts also indicate cumulative revenue approaching $1.98 billion through 2030. FFR has not adopted these estimates as official company guidance.
Faraday Future Plans Robotaxi and Shared Mobility Expansion
Faraday Future plans to shift its remaining operations toward shared mobility and intelligent vehicle services. The company intends to collaborate with RoboShare on Robotaxi networks and connected vehicle technology. This approach would reduce its reliance on traditional vehicle manufacturing operations.
The proposed strategy also includes integrating intelligent cabin technology into shared vehicles. Through RoboShare, FFAI plans to expand vehicle deployment, operational services, and customer access. These initiatives would connect its existing electric vehicle technology with emerging mobility services.
The companies expect to complete the robotics transaction by the end of October 2026. FFAI will retain majority ownership, while FFR will operate through a separate Nasdaq-listed corporate structure. Following closing, Faraday Future plans to announce its next business strategy and operational priorities.
The post Faraday Future (FFAI) Stock: Climbs on $200M Robotics Business Sale appeared first on Blockonomi.
TLDR
- HONA stock slipped 0.82% to $156.88 during Wednesday’s early trading session.
- Honeywell Technologies unveiled Forge Cognition with NVIDIA and Dell support.
- Forge Cognition uses AI agents to improve building maintenance and energy use.
- NVIDIA’s Voyager pilot reduced unnecessary facility alerts by up to 90% on average.
- HONA operates separately from Honeywell Technologies after its June spin-off.
Honeywell Aerospace (HONA) stock fell 0.82% to $156.88 during Wednesday’s early trading, losing $1.29 after retreating from above $159. Meanwhile, Honeywell Technologies introduced Forge Cognition, an AI platform developed using NVIDIA and Dell Technologies infrastructure. The announcement expands Honeywell Technologies’ automation business, although Honeywell Aerospace now operates as a separate publicly traded company.
Honeywell Aerospace Inc, HONA
Honeywell Technologies Launches AI Platform With NVIDIA and Dell
Honeywell Technologies introduced Forge Cognition to improve building management, industrial operations, and equipment maintenance through automated systems. The platform combines digital simulations with AI agents to analyze facility conditions and coordinate operational responses. Furthermore, it connects with existing infrastructure to support equipment reliability, energy management, and maintenance planning.
The system helps facility operators identify equipment problems, assess operational conditions, and respond to building management alerts. Its predictive maintenance features analyze HVAC equipment data to detect potential failures before major disruptions occur. Meanwhile, energy management tools simulate operational adjustments to identify opportunities for lower consumption without compromising comfort.
Honeywell Technologies developed the platform using NVIDIA’s computing technology and Dell’s enterprise infrastructure. NVIDIA Nemotron models support automated analysis, while Omniverse tools provide simulations of physical environments. Dell contributes PowerEdge servers, data storage systems, and supporting services through its Dell AI Factory.
Honeywell Reports Early Results From Forge Cognition Deployments
Honeywell Technologies has started testing Forge Cognition across several commercial, educational, and industrial facilities. These locations include NVIDIA’s Voyager campus, Dubai’s Fairmont Hotel, Singapore’s NEX Mall, and Vanderbilt University. The company also operates pilot programs at its facilities in Bangalore and Richardson, Texas.
At NVIDIA’s Voyager campus, the platform reduced unnecessary operational alerts by up to 90% on average. The pilot also identified opportunities to reduce energy and utility consumption by up to 10%. Furthermore, facility operators maintained comfort scores above 95% across monitored building zones.
The platform offers manual, semi-autonomous, and autonomous operating modes, allowing facility teams to determine appropriate oversight levels. Operators can also override automated decisions when operational conditions require direct intervention. Honeywell Technologies plans to expand deployment capabilities across its existing customer network of more than 300,000 sites.
Honeywell Aerospace Operates Independently Following June Spin-Off
Honeywell Aerospace became an independent public company on June 29, 2026, following its separation from Honeywell Technologies. The aerospace business began trading under HONA, while Honeywell Technologies retained the HON ticker. The Forge Cognition announcement concerns Honeywell Technologies rather than Honeywell Aerospace’s direct product portfolio.
Honeywell Aerospace focuses on aviation and defense technologies, including systems supporting commercial aircraft and military operations. Its separation established a dedicated aerospace company with independent management and business priorities. Meanwhile, Honeywell Technologies continues developing automation solutions for buildings, industrial facilities, and connected infrastructure.
The latest stock decline follows Honeywell Aerospace’s transition into an independent aerospace and defense supplier. However, the Forge Cognition announcement does not establish a direct connection between the platform and HONA’s financial performance. Honeywell Technologies continues pursuing industrial automation opportunities through its collaboration with NVIDIA and Dell Technologies.
The post Honeywell Aerospace (HONA) Stock: Falls Despite Major AI Launch With NVIDIA and Dell appeared first on Blockonomi.
CryptoPotato
Coinbase, the custodian holding about 5% of all BTC, published a technical blog on October 13 outlining what it wants from Bitcoin’s move to quantum-resistant security.
Its central point is that choosing a new digital signature scheme is only one piece of the job, since any plan also has to fit Bitcoin’s scarce block space and work for custodians and everyday wallets.
Work to Begin Before Quantum Threat Is Certain
In the blog post, the exchange said it is already preparing its own systems, convening talks with Bitcoin developers and backing open-source work through the Bitcoin Security Consortium.
The company pointed to P2MR, proposed in BIP-360, and P2TRv2 as possible output designs that could accommodate future post-quantum signature systems without requiring a complete redesign each time the cryptography changes.
It also proposed evaluating hybrid arrangements in which a wallet could spend funds through either a conventional ECDSA/Schnorr signature or a post-quantum key during the transition.
Coinbase raised particular concerns about stateful post-quantum signatures. Although these schemes can be smaller and faster than stateless alternatives, reusing signing state can make forgery possible. The company warned that recovering from failed updates or lost state could be difficult for exchanges running multiple signing servers, as well as individuals managing their own wallets.
Its suggested evaluation criteria include signature size, verification speed, transaction fees, full-node workload, hardware wallet compatibility, and multi-party computation, or MPC, which allows parties to produce signatures without relying on one complete private key held in a single place. Coinbase also named ML-DSA, the prospective FN-DSA standard, and SHRINCS as candidates for assessment.
Freeze Proposals and Exposure Estimates Frame the Debate
Wallets that migrate late are the last open item. If Bitcoin eventually limits or ends ECDSA and Schnorr spending, Coinbase wondered whether and how those users could move funds afterward.
The issue is already being considered, with BIP-361, fronted by Jameson Lopp and five other developers, proposing to first restrict sending to quantum-vulnerable addresses and later stop old-style signatures from spending, with an unconfirmed third phase that might let people recover funds after a missed deadline.
The plan has drawn objections that protocol-level freezes cut against censorship resistance and self-responsibility for funds. But in April, BitMEX Research floated a “canary” alternative, where a freeze would trigger only if funds leave a special address whose private key nobody knows, since such a spend would prove a quantum computer exists.
The post Coinbase Lays Out Post-Quantum Needs for Bitcoin Custody appeared first on CryptoPotato.
Amid weakening demand for Bitcoin and Ethereum exchange-traded funds, US-listed SUI ETFs are moving in the opposite direction.
The funds have recorded five consecutive weeks of inflows.
Fresh Catalysts
The funds have accumulated around 14 million SUI during that period. Several developments are adding to the momentum, according to the latest findings by Ali Martinez. These include AI agent payments, mobile USDC, Bitcoin finance, and cross-chain transfers, which are strengthening the network’s outlook.
With these catalysts gaining attention, the analyst said that “SUI appears to be preparing for its next leg higher.” This week, the SuperTrend indicator also flashed a buy signal on its 4-hour chart. The last time a similar signal appeared, SUI rallied over 77%.
Last week had a lot going on for Sui. One of the biggest highlights came at Basecamp, where the network reportedly handled over 40 million transactions per second during a live stress test, which is more than six times its previous record. The test simulated AI-agent activity using over 10,000 programmable tunnels, with transactions settled on Sui.
Sui also announced a collaboration with Alibaba Cloud to bring cloud and AI inference services into its Agent Payments system. This could allow AI agents to pay for services using stablecoins within set spending limits. Another development involves Samsung Wallet. Sui is being integrated into its USDC offering, which targets 82 million eligible Galaxy devices in the United States. The integration will support stablecoin transfers without gas fees.
Meanwhile, Sui’s Bitcoin finance project, Hashi, is preparing for a phased mainnet rollout this month. It has secured over $500 million in capital commitments, attracted more than 20 participating institutions, and named Anchorage Digital as a launch partner. Circle’s Cross-Chain Transfer Protocol V2 has also launched on Sui. This allows native USDC to move between Sui and 29 other supported blockchains, opening more options for payments and DeFi.
In yet another milestone, the network surpassed 5 billion total transactions. According to BSCN, the figure now stands at around 5.02 billion, putting it ahead of many major Layer 1 networks.
Outages
While the network has reported 100% uptime over the past 30 days, it did face a few major setbacks earlier this year. In May, for instance, Sui suffered three major outages within 48 hours, resulting in more than 15 hours of downtime.
Prior to that, a consensus bug halted block production and transaction processing for around five hours and 52 minutes in January. Validators eventually restored normal operations.
The post SUI Demand Explodes as US ETFs Rack Up Five Straight Weeks of Inflows appeared first on CryptoPotato.
Artificial Intelligence (AI) has emerged as one of the most popular and widely adopted technologies in recent years, and cryptocurrencies in that niche now have a combined market capitalization of nearly $25 billion.
Well-known altcoins in that sector include Bittensor (TAO), Internet Computer (ICP), and NEAR Protocol (NEAR). See which of these could post the most substantial price gains in the final quarter of 2026 (according to three AI-powered chatbots).
Those in Favor of NEAR
ChatGPT picked NEAR because it has several potential Q4 catalysts aligning together. First, the platform highlighted growing token usage and rising trading volume. Then, it moved to the new collaborations of the project, noting the integration of Robinhood Chain into near.com and its NEAR Intents cross-chain trading layer.
The chatbot also outlined that the cryptocurrency combines confidential AI, privacy, and cross-chain finance, positioning it for a strong rally in an eventual bull run and giving it an edge over competitors. Last but not least, it mentioned the launch of the first US spot NEAR ETF. The product saw the light of day toward the end of September and was introduced by Bitwise. The investment vehicle has generated a cumulative net inflow of almost $80 million so far, after a solid debut day and less impressive performance in the following weeks.

Perplexity shared ChatGPT’s thesis. It said NEAR has the strongest combination of an AI-agent narrative, concrete Q4 roadmap milestones, greater liquidity, and a less crowded valuation than TAO.
“TAO could outperform if its demand-based emission reforms and subnet activity accelerate sharply. ICP looks like the laggard of the three unless its inflation-reduction and enterprise/AI adoption story becomes more tangible,” it added.
At the same time, Perplexity reminded that NEAR has posted a 110% monthly price increase, raising the risk of a sharp correction. As of this writing, the asset trades around $4.95 (per CoinGecko), and the chatbot sees $6 as a major psychological and technical barrier.
“NEAR got rejected there, and analysts identify a weekly close above roughly $6 as the confirmation needed for a broader continuation; until that happens, the market is in a conservative or consolidation phase rather than a confirmed breakout,” it concluded.
Gemini Doesn’t Agree
Google’s chatbot didn’t align with the predictions above and picked Bittensor (TAO). It argued that it functions as a high-beta asset, which tends to deliver sharper percentage gains during bull markets.
According to Gemini, TAO holds a “distinct advantage” in institutional access, with Grayscale’s Bittensor Trust and certain European ETPs giving traditional capital a direct route into the asset’s ecosystem.
As of this writing, the token is worth just over $270, up 16% in the last month. Gemini said the most realistic bullish target for TAO in Q4 is a retest of the $350-$450 range, warning that such a rise would depend heavily on Bitcoin’s performance.
The post TAO vs. ICP vs. NEAR: Which AI-Related Altcoin Will Perform the Best in Q4? (3 AIs Speculate) appeared first on CryptoPotato.
XRP whale activity on Binance is picking up pace, at least compared with the rest of the exchange market.
CryptoQuant’s latest data revealed a sharp jump in the gap between whale and retail outflows over the past six days.
Whale Activity
From October 7 to 13, Binance’s seven-day average Whale vs Retail Spread rose from 53% to 63.5%. This is a 10.5-point jump. Across all centralized exchanges, the same reading increased from 46% to 47.7%, a much smaller 1.7-point rise. Binance’s increase was roughly 6.2 times larger. The spread tracks the relative difference between large and small XRP exchange outflows. A higher reading indicates that larger transfers are playing a bigger role.
However, it does not confirm that whales are accumulating XRP or withdrawing more coins in absolute terms.
The gap between Binance and the broader market now stands at 15.8 points. That puts it close to the 18-point difference seen on August 3. Back then, the crypto asset traded near $1.07 before climbing about 46% to $1.56. XRP is currently hovering around $1.38.
CryptoPotato had previously reported that spot volume across centralized exchanges fell by $1.943 billion between August 26 and October 11. On Binance, the spot-to-futures ratio slid from 31% to 12.7%, meaning futures activity now dwarfs spot trading. CryptoQuant explained that some traders could be waiting for a cheaper entry.
XRP sentiment, meanwhile, has slipped into negative territory as bullish comments trailed bearish ones at a ratio of 0.92 across social platforms. This growing pessimism could leave room for a rebound if market conditions improve and buying interest returns.
Despite the short-term struggle, a German analyst believes XRP could still hit a new all-time high before the year ends. He flagged that the crypto asset has tested a key resistance zone seven times but failed to break above it convincingly. That rejection sent XRP briefly back toward $1.29. The next major hurdle now stands at the $2.15-$2.20 range.
Institutional Demand Paused?
The institutional side of things looks less encouraging. Data compiled by SoSoValue revealed that US-listed spot XRP ETFs have recorded zero net flows for three consecutive days. October has seen just three days of inflows and one day of outflows so far, with total inflows sitting a little above $12 million.
While the monthly figure remains positive, the recent lack of fresh money shows that institutional interest has been fairly muted.
The post XRP Whales Are Making a Bigger Mark on Binance as Outflow Gap Nears August Levels appeared first on CryptoPotato.
Ethereum is stabilizing around $2.5K after another sharp test of demand near $2.4K. Buyers have defended the recent lows, but the recovery remains below key resistance, leaving the market caught between a potential base and another leg lower.
Ethereum Price Analysis: The Daily Chart
On the daily timeframe, Ethereum remains within its broader ascending channel despite the recent correction. The decline from approximately $2.8K pushed the price below the channel’s midpoint and into the highlighted $2.36K–$2.46K demand zone. Two pronounced lower wicks into this region suggest buyers are responding to selling pressure, though subsequent rebounds have remained relatively modest.
The latest recovery toward $2.52K keeps ETH above demand, but a move through the recent rebound highs around $2.56K–$2.58K is needed to demonstrate improving momentum. Beyond that, the former consolidation around $2.67K–$2.75K represents an important resistance area. Reclaiming it could support another challenge of the broader $2.79K–$3.05K supply zone.
Conversely, renewed weakness would bring the $2.36K–$2.46K demand zone back into focus. This area overlaps with the channel’s rising lower boundary, making it a significant support confluence. A sustained breakdown beneath both would weaken the broader recovery structure and increase the risk of a deeper correction toward $2.3K and $2.2K.
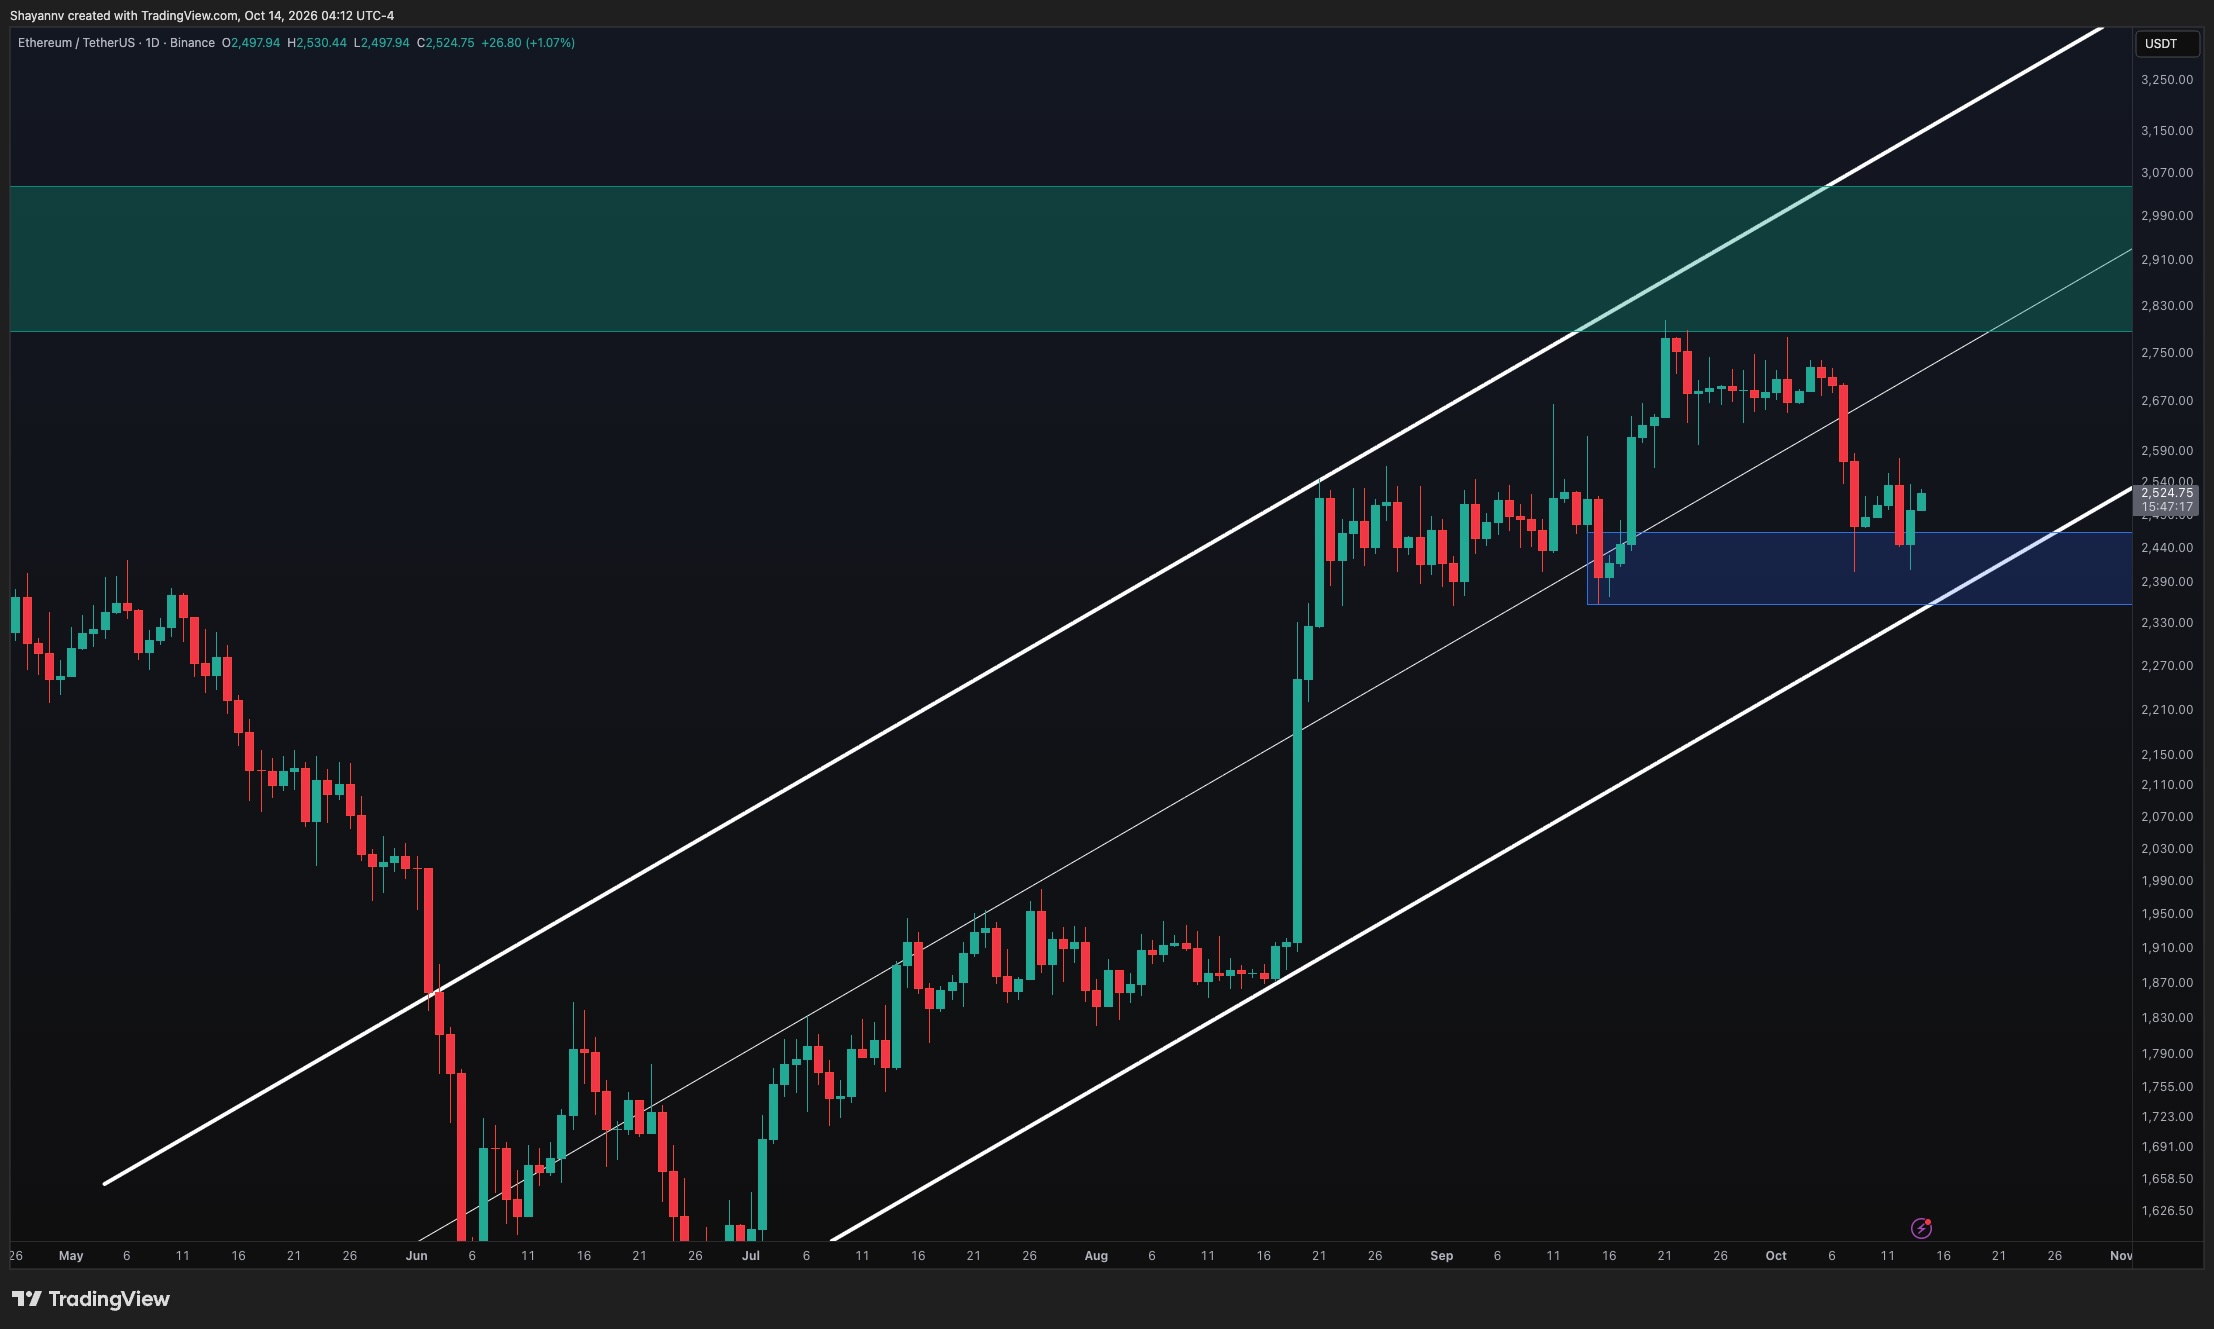
ETH/USDT 4-Hour Chart
The 4-hour chart highlights two sharp declines toward the rising lower trendline around $2.4K–$2.42K, each followed by a rebound. These reactions suggest that buyers are defending the lower portion of the structure, but the latest recovery has yet to clear the previous rebound high near $2.58K.
In the immediate term, ETH is consolidating around $2.5K–$2.53K. A sustained break above this narrow range could bring the $2.56K–$2.58K resistance area into play. Clearing that barrier would strengthen the base-building scenario and open the way toward the marked $2.68K–$2.74K supply zone, where the earlier consolidation broke down.
On the downside, losing $2.48K would expose the upper boundary of demand near $2.46K and potentially trigger another test of the rising trendline around $2.41K. Repeated tests make the response at this support increasingly important. A decisive loss of the trendline and the $2.36K demand boundary would undermine the current stabilization attempt.

Sentiment Analysis
The two-week Binance ETH/USDT liquidation heatmap shows substantial estimated liquidation concentrations above the current price. The nearest prominent overhead band sits around $2.58K–$2.6K, followed by another strong cluster near $2.63K–$2.65K. Additional concentrations remain higher around $2.74K–$2.8K.
The nearby $2.58K–$2.6K cluster aligns with the recent rebound high, making this region relevant to both price structure and leveraged positioning. A sustained advance through it could trigger short liquidations and accelerate the recovery toward the next overhead pool. However, reaching these levels would not itself confirm a lasting bullish reversal.
Below price, estimated liquidation bands remain around $2.47K–$2.49K and the broader $2.37K–$2.4K region. Another loss of nearby support could expose these concentrations and amplify selling through long liquidations. The heatmap therefore highlights potential volatility on both sides, with a break above $2.58K or renewed weakness beneath $2.48K likely to clarify the immediate direction.

The post Ethereum Price Analysis: What’s the Worst-Case Scenario if ETH Loses $2.5K Support? appeared first on CryptoPotato.