Cryptocurrency Posts
Crypto Briefing
Strive's increased Bitcoin holdings highlight growing corporate interest in cryptocurrency as a strategic asset, influencing market dynamics.
The post Strive lifts Bitcoin holdings to 43,000 BTC after largest-ever purchase appeared first on Crypto Briefing.
Hyperbolic's GPU marketplace could reshape AI investment strategies by offering a hedge against fluctuating demand and compute costs.
The post Ex-Citadel quant’s Hyperbolic builds a GPU marketplace to hedge AI demand risk appeared first on Crypto Briefing.
Collector Crypt's revenue surge highlights the potential of strategic partnerships but underscores challenges in sustaining profitability and user diversity.
The post Collector Crypt’s weekly revenue reaches all-time high of $5.31 million appeared first on Crypto Briefing.
BNB Standard's Nasdaq debut highlights its strategic pivot, emphasizing transparency and crypto exposure, potentially attracting institutional investors.
The post BNB Standard rings the Nasdaq Opening Bell to mark its new chapter appeared first on Crypto Briefing.
Strive's aggressive Bitcoin acquisition strategy could heighten financial risk, impacting shareholder value if BTC prices fall below cost basis.
The post Strive buys 6,182 more Bitcoin, lifting its treasury to 43,000 BTC appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Strive (ASST) Buys 6,182 Bitcoin For $511 Million, Lifts Treasury To 43,000 BTC
Strive, Inc. (ASST) acquired 6,182 bitcoin for $511.4 million between October 17 and October 23, according to an SEC filing published on Monday. The company paid an average price of $82,732 per bitcoin.
The purchase lifts Strive’s holdings to 43,000 BTC. Cash and marketable securities rose by $187.7 million to $554.6 million over the same period.
The buy comes one week after Strive closed its upsized initial public offering of SATS, its 15% Perpetual Series A Preferred Stock. The company sold 7 million shares at $90 each for $630 million in gross proceeds. Dividends accrue at 15% on a $100 stated amount, which works out to a 16.67% yield at the issue price. Payments, if declared by the board, start November 9 and land on each business day.
Strive opened the SATS offering with a $500 million target and raised the size by 2 million shares on demand. The stock trades on the Nasdaq. The company has set aside a $157.5 million dividend reserve, which covers 18 months of payments on the new shares.
JUST IN:
— Bitcoin Magazine (@BitcoinMagazine) October 26, 2026Public company Strive purchases 6,182 Bitcoin for $511.4 million!
pic.twitter.com/5KImRceLzA
A $1 billion ATM for SATS
The filing disclosed a new at-the-market program under which the company can sell up to $1 billion of SATS over time. Cantor Fitzgerald, Barclays, Clear Street, StoneX, B. Riley Securities, Maxim Group and H.C. Wainwright serve as sales agents.
The structure mirrors the one Strive built for SATA, its first preferred stock, which carries a variable dividend and pays cash each business day. Strive set up a $500 million ATM for SATA in December 2025. That vehicle absorbed more than the entire daily bitcoin mining supply on a single day in May.
Under the SATS program, Strive can issue preferred shares when demand supports the price and route the proceeds into bitcoin. The company has said proceeds may fund bitcoin purchases, income-generating assets, working capital, buybacks or acquisitions.
Strive’s climb up the treasury rankings
Strive went public as a bitcoin treasury company in 2025 through a reverse merger and completed its all-stock acquisition of Semler Scientific in January, the first case of one public bitcoin treasury buying another. Holdings stood near 7,525 BTC in December 2025. The figure has since grown to more than five times that amount.
The company reported 36,818 BTC on October 20 after a purchase of 4,045 BTC between October 12 and 16. Monday’s filing adds 6,182 BTC to that total.
Strive funds its purchases through common and preferred equity and carries no debt: no bonds, no credit lines and no leveraged positions.
Chairman and CEO Matt Cole called the SATS IPO “a critical milestone in our strategy to maximize long-term total returns for our common equity investors.”
Strategy, the largest corporate holder with 848,517 BTC, proposed daily dividends across its five preferred stocks in September.
This post Strive (ASST) Buys 6,182 Bitcoin For $511 Million, Lifts Treasury To 43,000 BTC first appeared on Bitcoin Magazine and is written by Micah Zimmerman.
Bitcoin Magazine
NY Seeks $1.37 Billion Judgment Against Operators of NovaTech Crypto Ponzi Scheme
New York Attorney General Letitia James is trying to secure a $1.37 billion judgment against the operators of NovaTech and its predecessor AWS Mining, two successive cryptocurrency investment schemes that allegedly defrauded hundreds of thousands of investors worldwide out of more than $1 billion.
Alleged founders Cynthia and Eddy Petion never appeared in court and, according to the AG’s office, fled the country.
“NovaTech and AWS Mining scammed thousands of vulnerable New Yorkers by telling them they were making a safe investment when in reality, they were victims of a pyramid scheme,” James said in a statement. “These scammers targeted immigrant and religious communities with the promise of a better life but instead robbed them of their life savings.”
The schemes, AWS Mining and later NovaTech, relied on promoters who recruited heavily in Haitian and other immigrant communities — through prayer groups, WhatsApp chats, and ads in Haitian Creole.
AWS Mining sold crypto mining contracts promising 15 to 20 percent monthly returns and 200 percent within 15 months. It collapsed in 2019. The Petions then launched NovaTech, marketed as a registered hedge fund broker, promising weekly trading returns of two to four percent — more than 140 percent a year.
Those returns were fabricated, according to prosecutors. Records from B2Broker, which supplied NovaTech’s white-label trading platform, show that of the more than $1 billion investors deposited between 2019 and 2023, only about $26 million was ever actually traded — and NovaTech’s traders lost $18.2 million of that. Returns to earlier investors came from newer deposits, not trading. When NovaTech collapsed in mid-2023, tens of thousands of investors could not withdraw their funds.
The AG is also seeking $134.5 million the Petions allegedly withdrew to their own wallets from the investor account Cynthia Petion solely controlled, plus $4.7 million tied to the earlier AWS Mining scheme. A default judgment entered in August 2025 already bars the couple and their companies from the securities, commodities, and cryptocurrency industries.
Separately, four of the scheme’s top promoters have agreed to pay nearly $6 million in disgorgement to victims and accepted the same industry bans.
This post NY Seeks $1.37 Billion Judgment Against Operators of NovaTech Crypto Ponzi Scheme first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Blockstream Launches Institutional Consulting Services, Opens Lugano Office
Blockstream has launched a consulting business for financial institutions and opened an office in Lugano, Switzerland, the company shared today. The expansion gives banks, asset managers and other institutions direct access to the firm’s engineering teams and Bitcoin infrastructure, Blockstream said.
Blockstream Consulting Services will support institutions through the evaluation, design and implementation of Bitcoin-based financial infrastructure. The company said the business will develop solutions for tokenized asset issuance, confidential settlement and related infrastructure, with services spanning technical strategy, system architecture, integration and implementation.
From Lugano, Blockstream plans to serve clients across Switzerland, including Zurich, Geneva and Zug. The company said the office will serve as a hub for its European operations, supporting client relationships, strategic partnerships and collaboration with the region’s financial and technology communities.
“Switzerland is an important market for Blockstream given its longstanding banking tradition and supportive regulatory framework for digital assets,” said Peter Bain, chief marketing officer of the company. “We look to provide regional expertise in markets where we see demand for Bitcoin infrastructure. Our consulting business, combined with our new office in Lugano, will bring tailored Bitcoin solutions to financial institutions across Europe.”
Founded in 2014, Blockstream develops technology and services across Bitcoin custody, settlement, payments, asset issuance and self-custody. Its products include the Liquid Network sidechain, Elements, Simplicity, Core Lightning, the Jade hardware wallet and the Blockstream App. This year, the company launched Simplicity smart contracts on Liquid and added Lightning support to Jade.
Bitcoin adoption by financial institutions
The company said the consulting business draws on that experience, with capabilities in cryptography, protocol engineering, security and financial technology. Multidisciplinary teams will give institutions access to the firm’s technical staff from initial evaluation through deployment.
“The next phase of Bitcoin adoption is its integration into existing financial systems,” said Adam Back, Blockstream’s co-founder and CEO. “Our extensive experience in Bitcoin cryptography, protocol development and engineering gives Blockstream the technical expertise to address the complexities of integrating Bitcoin into traditional financial infrastructure.”
The company framed the move as part of a long-term commitment to Switzerland and a broader strategy of building a presence in key markets to support institutional Bitcoin adoption.
The country has become a center for digital asset firms, with Zug’s “Crypto Valley” and a regulatory framework that permits banks to hold and trade bitcoin on behalf of clients.
There was no pricing disclosed, headcount for the Lugano office or named clients for the consulting business. The company said the Lugano office is open and that consulting engagements are available to institutions across Europe.
This post Blockstream Launches Institutional Consulting Services, Opens Lugano Office first appeared on Bitcoin Magazine and is written by Micah Zimmerman.
Bitcoin Magazine
Bitcoin Core Ends Long Embargoes for Bugs AI Can Rediscover
Bitcoin Core has changed its security disclosure policy to speed up fixes for vulnerabilities that large language models can find with little effort, ending the months-long embargoes those bugs once received.
Maintainers merged the change to the project’s security policy on Thursday. Chaincode Labs developer Antoine Poinsot, who wrote the proposal, announced it in a message to the Bitcoin Development Mailing List the same day.
“We recently experienced an increase in the number of reports for security vulnerabilities that can be easily (re-)discovered,” Poinsot wrote. “This is largely due to LLMs drastically reducing the bar to find certain classes of issues or identify covert fixes.”
How the policy worked before
Bitcoin Core, the software that runs on most nodes in the Bitcoin network, has graded each reported vulnerability by severity and timed its disclosure to match. Low-severity flaws were made public two weeks after the next major version shipped.
Medium- and high-severity issues stayed under embargo until two weeks after the last affected release reached end of life, a span that could stretch to a year.
The extended timelines gave node operators, many of whom upgrade at a slow pace, time to move to patched software before details became public. In practice, the approach meant fixes went unreleased for older maintained versions and arrived with the next major release.
Poinsot argued that this tradeoff fails for bugs that are easy to rediscover. “The embargo period achieves little but it delays the availability of a fixed release,” the policy reads.
What changes
During triage, Bitcoin Core can flag a vulnerability as “easily discoverable,” a category the policy defines as issues that can be found “with minimal effort, such as through a simple LLM prompt.” The label is open to flaws found by other means as well.
For those issues, the project will backport a fix to every maintained major version, cut point releases as soon as possible and publish a security advisory with some details at the same time as the fixed software.
Poinsot acknowledged that such fixes will have less testing time before they reach users.
Vulnerabilities outside that category keep the existing severity-based schedule. Critical bugs, those that could enable coin theft at the protocol level, inflate the supply or cause a permanent chain split, remain outside the standard policy and will be handled case by case.
Developer Antoine Riard pushed for an option to ship a fix without an advisory and withhold details on a case-by-case basis. Poinsot declined, writing that alerting users without details “could create more risk unnecessarily” by prompting a rushed migration among users who would otherwise be unaffected.
A summer of AI-driven reports
The change follows months of heightened pressure on Bitcoin’s open-source projects. In late July, a volunteer group of 16 developers known as the Bitcoin Red Team ran AI models across 390 bitcoin repositories in about a day and logged 4,962 findings, including 85 rated critical.
Within days, a BTCPay Server flaw the group had reported in private was exploited on live merchant servers, draining Lightning nodes.
In August, Core Lightning developers told operators to upgrade or disconnect after AI-generated reports to the project proved accurate.
The Red Team effort followed a Coldcard hardware wallet exploit in which attackers drained 594 BTC in 25 minutes on July 30. Losses across four sweeps approached $114 million.
This post Bitcoin Core Ends Long Embargoes for Bugs AI Can Rediscover first appeared on Bitcoin Magazine and is written by Micah Zimmerman.
Bitcoin Magazine
Bitcoin ETFs Lose Over $635M In One Day Following Oil Price Spike
U.S. investors quickly reversed course on Thursday, cashing out over half a billion dollars from spot bitcoin exchange-traded funds as risk-off sentiment surfaced again.
A total of $635.6 million left the funds on Thursday, data from Farside Investors shows. The redemptions put downward pressure on the price of bitcoin, which dropped under $81,000 at one point.
The coin has since rebounded and was recently trading for nearly $81,669, down just 1% over a 24-hour period.
BlackRock’s iShares Bitcoin Trust saw the biggest outflows, with investors cashing out over $254 million. Fidelity’s Wise Origin Bitcoin Fund followed, losing close to $218 million.
Over $109 million left the ARK 21Shares Bitcoin ETF; Morgan Stanley’s fund and Bitwise’s ETF lost nearly $30 million and over $27 million, respectively.
But the investment vehicles this week have this week received net positive investment of over $439 million.
Investors went into “risk-off” mode after flare ups in the Middle East sent the price of oil higher. Brent crude hit its highest price in five months after Yemeni rebel group the Houthis on Thursday attacked Saudi Arabia, sparking concerns over more disruption to energy supplies.
Bitcoin’s price has been rattled this year since the U.S. and Israel attacked Iran, halting oil supplies as ships have struggled to pass through the strategic Strait of Hormuz, where a fifth of the world’s oil passes through.
A higher oil price can hurt the price of bitcoin and other “risk-on” assets because it increases the chances of the U.S. central bank raising interest rates.
Bitcoin has typically done well in a low interest rate environment because it means the asset has more liquidity to rally.
Investors on Thursday also sold off tech stocks, which had rallied earlier in the week off the back of SpaceX’s impressive earnings.
Analysts are saying bitcoin is entering a bull market again. Data last month showed that the leading cryptocurrency crossed above its 365-day moving average — a typical sign it is out of a bear market — following a strong run in August.
Bitcoin notched a record of $126,080 in October 2025 but then began to sink later that month after the biggest liquidation event in crypto history saw over $19 billion in bets closed.
The coin spent the first half of 2026 trading well below that level but picked up again in August and September, having its best quarter in years.
This post Bitcoin ETFs Lose Over $635M In One Day Following Oil Price Spike first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
CryptoSlate
The operator accepted the PHP challenge solve despite a wallet mistake, while the harder question remains who turns discoveries into deployed fixes.
Read the full story on CryptoSlate
Understand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
September’s 66.3% commodities-and-services quote collection rate shows survey coverage while leaving the direction of any inflation bias unresolved.
Read the full story on CryptoSlate
Understand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
IOG’s Leios roadmap targets initial gains of three to five times today’s capacity, with later increases subject to new votes and mainnet evidence.
Read the full story on CryptoSlate
Understand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
Version 4.8.3 fixes a malicious-server attack that can turn a manual fee increase into approval of an attacker-directed payment.
Read the full story on CryptoSlate
Understand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
The nonbinding consultation lists unhosted-wallet due diligence as good practice and criticizes unexplained third-party scores and rigid tracing rules.
Read the full story on CryptoSlate
Understand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
CryptoTicker.io
WhiteBIT took more of its own tokens off the market and destroyed them on October 25, 2026: 31,847 WBT worth 2,499,639 USDT, according to the exchange's buyback overview. It was the fourth buyback of the month and the smallest of all four, by number of tokens as well as by value.
If you hold WBT, this is the single most important metric for the token, because WBT has no protocol earning fees and no staking yield from a network. Its value rests on a promise by the exchange: a share of its revenue flows into the buyback and permanently reduces supply. If that flow shrinks, so does the argument.
The buyback of October 25: 31,847 WBT for 2,499,639 USDT
The exchange lists its buybacks in a public overview. The entry for October 25 names 31,847 WBT and 2,499,639 USDT, recorded at 10:25. The tokens go to an address from which they cannot be withdrawn again. With that they have disappeared from supply, unlike a share buyback, where a company's own shares stay on the balance sheet and can be sold again later.
Token burn means destroying tokens for good: they are sent to an address with no private key and are beyond anyone's reach from then on. The maximum supply stays the same, the amount actually available falls.
Four buybacks in October: 131,188 WBT taken out of supply
Add up the four October entries and you get 131,188 WBT. The series by date:
- October 1: 32,426 WBT for 2,716,488 USDT
- October 5: 33,105 WBT
- October 15: 33,810 WBT
- October 25: 31,847 WBT for 2,499,639 USDT
The token counts move in a narrow band between 31,847 and 33,810. There is no collapse here, and reading a downward trend into four entries would be overinterpretation: the figure for October 15 was higher than the one for October 1. All that holds up is that the latest buyback was the smallest of the four.
cryptoticker.io reported on the October 1 entry on October 3, with 32,426 tokens as the figure for that day; that number appears in our piece on the weekly buyback.
Where the money comes from: 33 percent of trading fees
The exchange describes the mechanism itself: each week it buys back a quantity of coins equal to the sum of 33 percent of trading fees and 5 percent of its other revenue. The buyback is therefore not a voluntary gesture but a formula with two inputs.
That has a consequence worth knowing when you judge the figures. The amount deployed measures the exchange's business, not the mood of its management. If trading volume falls, the buyback automatically falls with it. The number of burned tokens is closer to a one-line business report than to a supply policy.
What the amount deployed reveals about the price
From the token count and the value you can derive the average price the exchange paid per token. On October 1 it was 83.77 USDT, on October 25 it was 78.49 USDT. The value therefore fell by roughly 8 percent, the token count by only 1.8 percent.
The larger part of the decline thus comes from the lower price, not from collapsing trading. cryptoticker.io produced this calculation itself on October 26, 2026, on the basis of the four October entries in the buyback overview.
The buyback price fell from $83.77 to $78.49 per token
The formula works in both directions. A falling price means the same amount of fee revenue buys more tokens, which supports the count. A rising price buys fewer. Look at the token counts alone and draw conclusions about the exchange's business, and you will be wrong on a regular basis; the amount deployed in USDT says more.
WBT at $76.99: 12.4 percent below its all-time high
WBT trades at $76.99 or 68.63 euros according to CoinGecko, as of Monday morning. Over seven days it is down 4.7 percent, over 30 days down 8.1 percent. The token reached its all-time high of $87.91 on September 21; the gap to that level is 12.4 percent. Market capitalisation stands at $9.14 billion, which puts it at rank 15.
On the exchange itself, WBT last traded at 77.24 USDT, on daily turnover of around 30.5 million USDT in the pair against the dollar stablecoin. Total daily turnover across all venues came to $106.8 million according to CoinGecko. For a token at rank 15 that is a thin market, and it is the reason individual larger sales move more here than they do with Bitcoin or Ether.
Circulating supply: the figures diverge between 118 and 293 million WBT
With this token, look closely at which supply your provider uses, because the figures differ considerably. Maximum supply is 400 million WBT. CoinGecko reports 118,720,983 WBT as circulating and 293,290,482 as total supply.
On Ethereum, 165,290,481 WBT have been issued according to the state of the token's own contract. cryptoticker.io obtained that figure itself on October 26, 2026, directly from the token contract on Ethereum. It sits between the two CoinGecko values, which is explained by the token existing on several networks and part of the issued supply not counting as circulating.
This is no quibble. A market capitalisation based on 118.7 million tokens produces a different value than one based on 293.3 million. Compare two providers using different supply figures, and you are comparing two different metrics. When in doubt, check which supply sits behind the valuation you are shown.
What the buyback actually changes about supply
131,188 tokens a month sounds like a lot. Measured against the circulating supply reported by CoinGecko it is roughly 0.11 percent. Extrapolated over a year the order of magnitude would be a good one percent, provided fees and price stay at today's level. The buyback therefore works slowly and steadily, not as a price driver over a week.
MiCA and the way in: an EU licence with passporting across the EEA
To buy WBT in Germany, the route runs in practice through the exchange that issues the token, because that is where the deepest market sits. For the legal framework, MiCA has been the reference since this year: the transition period for providers in the EU ended on July 1, 2026, and since then every provider needs authorisation. The exchange's European arm, WB-Shield Innovations GmbH, based in Vienna, received its MiCA authorisation on June 19, 2026 from the financial market authority there; through passporting, such an authorisation applies across the entire European Economic Area and therefore in Germany as well.
What an authorisation does and does not do can be put briefly: it governs how a provider has to operate, how it segregates client funds and what it has to disclose. It says nothing about how a token's price will develop. We have set out the duties behind it in our overview of the MiCA obligations for crypto companies. If you want to compare which platforms operate with authorisation in Germany, you will find that in our overview of regulated crypto exchanges.
Holding period and custody: one year of holding and the question of the key
For tax, WBT in Germany is treated like any other crypto asset held privately. Sell at a profit within a year of buying, and that profit is taxable as a private disposal; after a holding period of one year it is tax free. The period runs separately for every purchase, which is why allocating acquisition dates becomes the real work when there are many small buys. With many small purchases it therefore pays to record the date and amount of each one from the start.
Custody adds a particularity that is often overlooked with exchange tokens. The benefits such tokens are designed for, fee discounts or taking part in promotions, usually depend on the token sitting in the account at the exchange. Self-custody protects you if the platform fails, but costs exactly those benefits. That trade-off is yours to make, and it comes out differently depending on whether you hold the token for the discounts or as an investment.
Leverage and liquidation
At daily turnover of around $107 million, the market is comparatively thin. Anyone using leverage should know that the distance to liquidation melts away faster in markets like this than with large coins, because individual sales hit the price harder. Work out the price at which your position gets closed before you open it, not afterwards.
Levels up and down: $81.60 as the weekly high, $76.37 as the daily low
On the upside, the first level to watch is the weekly high of $81.60, reached on October 22. Above that comes $83.77, the average price the exchange paid in its buyback on October 1, and only then the all-time high at $87.91.
On the downside, the daily low of $76.37 marks the next level to watch, and below it the round number at $75. These are observation points, not price targets: none of these levels says anything about where the price is heading, they only say where trading actually took place in recent days. If you set alerts, verifiable levels like these are a more useful basis than a forecast.
WBT buyback: without more fees the burn keeps shrinking
The buyback is this token's load-bearing argument, and it hangs on a formula you can recalculate. Three things follow from it concretely, without you needing a view on the price:
- Track the amount deployed, not the token count. The USDT amount per buyback shows how the exchange's business is going; the token count also rises when nothing but the price falls. Which venues operate with authorisation in Germany and what they cost is set out in our overview of the best crypto exchanges.
- Check the supply behind the figure. Between 118.7 and 293.3 million tokens sits a factor of 2.5. Look up which supply underlies the valuation you are shown before you compare it with other tokens. Tools for that are in our overview of the best analytics platforms.
- Record the acquisition date. The one-year period decides whether your profit is taxable, and it runs separately for each purchase. The tools in our overview of tax software and portfolio trackers take the matching off your hands.
The exchange's buyback overview is public and is added to after every operation: history of WBT buybacks. The entries with value and timestamp can also be found on the exchange's token page.
(As of October 26, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
An attacker took over the governance of the Ethereum project X100 Global on Saturday, October 24, 2026, and emptied its treasury. No stolen key and no bug in the program code were needed: the attacker borrowed money for the length of a single transaction, bought voting weight with it and took two of the three seats on what the protocol calls its senate. According to Bitcoin.com News, the security firm Blockaid tracked roughly $4.85 million in USDT and about 550,000 X tokens leaving the protocol across three transactions. The X token lost more than 96 percent of its value.
If you lock tokens in a protocol, to vote or to earn a yield, this case is less a story about a small project than a list of things to check. Every one of those protocols carries the same component: a vote that decides about money. Whether that vote lets time pass before it takes effect is a setting you can look up before you deposit.
What happened at X100 Global on October 24
X100 Global runs on Ethereum. Its treasury is called the Freezer, and a three-member body the project calls the senate decided over it. Those seats were not filled by an election but by the amount of X tokens locked in the Freezer: the three largest depositors held them.
According to the account of the security firm BlockSec, relayed by the news service MarsBit and published by KuCoin in its news section, the attack ran as follows. The perpetrator took out a flashloan, bought X tokens with it and spread them across two contracts he had set up himself beforehand. Both contracts locked their tokens in the Freezer. That pushed out two of the sitting senators and handed him the majority on the body, all inside the same transaction.
A flashloan is a loan that needs no collateral, because it is taken out and repaid inside a single blockchain transaction. If repayment fails, the whole transaction is discarded and the lender loses nothing. For the attacker that meant buying voting weight with someone else's capital without ever owning it. Bitcoin.com News puts the loan at roughly 1.94 million USDT and names the lending protocol Aave as its source.
Flashloan, Freezer and senate: the attack in four steps
The sequence is short enough to read in full, and that is exactly what makes it so uncomfortable. All of it happened without a waiting period in which anyone could have stepped in.
- Take out the loan. The attacker borrowed roughly 1.94 million USDT and bought X tokens on the market with it.
- Build up voting weight. The purchased tokens went to two self-deployed contracts, each of which locked a little more than 19,000 X in the Freezer. That moved both of them into the senate.
- File a proposal and execute it at once. With two of three votes, the attacker resolved to sell 400,000 X out of the treasury into a liquidity pool he had created himself shortly before. He set the minimum output to zero.
- Clear the treasury and repay the loan. The pool held almost no USDT. For the 400,000 X, only about 35.68 USDT flowed back into the Freezer, according to BlockSec. The attacker then withdrew his liquidity, sold part of the tokens in another pool and repaid the flashloan.
The third step is the actual theft. The treasury did not lose its tokens, it formally sold them, at a price the buyer had set himself. Technically, every single action was permitted.
400,000 X for 35.68 USDT: how the treasury proposal got through
The minimum output is the safeguard that stops anyone in any normal swap from selling at an absurd rate. Swap 400,000 tokens with zero as the floor, and you declare every possible consideration acceptable, $35.68 included. Nobody would do that with an ordinary exchange order. In a governance proposal voted through by a bought majority, it is precisely the point where the money leaves the protocol.
On the pool, the accounts differ. BlockSec places the pool that was set up on PancakeSwap V3, while Bitcoin.com News names Uniswap V3 for the sale that followed and for further access to liquidity positions. Both can be correct, because setting up and selling off are separate steps.
Why $4.75 million and $4.85 million can both be right
Two figures are circulating for the size of the loss. BlockSec arrives at about $4.75 million, Blockaid at roughly $4.85 million in USDT plus about 550,000 X tokens. The range of $4.75 million to $4.85 million is not a contradiction but a question of where the line is drawn: the higher figure counts follow-up transactions that ran only after the first report. At the time of its statement, Blockaid described an operation that was still under way and said about 12.2 million X were still sitting in the Freezer.
Read figures like these and watch the word behind them. USDT that has left is a fixed amount. Project tokens that have left are not, because their price collapses at the very moment they are sold. In an attack on a small token, a loss figure in dollars is always a snapshot.
No code bug: the three missing safeguards
Both reports reach the same conclusion about the cause, and it is not a programming error. Bitcoin.com News describes the failure as a design flaw in the governance, BlockSec speaks of a weakness in the design of the voting mechanism. Three components were missing.
Voting snapshot: voting weight as of a record date
The snapshot freezes voting weight at a point in time before the proposal. With it, the tokens the attacker acquired only after the proposal had been filed would not have counted. According to Bitcoin.com News, X100 used none.
Minimum holding period: borrowed tokens do not vote
The minimum holding period requires tokens to sit locked for a set time before they confer voting rights. It makes the flashloan useless as a tool, because it provides capital only for fractions of a second. That was missing too.
Execution delay: the deadline that makes an attack visible
The execution delay, or timelock, is the most important of the three. It puts a fixed period, usually 24 or 48 hours, between a resolution and its effect. In that window third parties read the proposal in plain language and can raise the alarm, and in many protocols an emergency body can stop it. Without it, no checkpoint is left between proposal and outflow.
None of these three mechanisms is exotic. Large DeFi protocols have run them for years, and they are set out in the documentation, not in the program code. You can look them up without understanding a line of Solidity. Lock capital in a protocol to earn a yield, and you will find the terms in the provider's governance rules; which platforms disclose their lock-up periods and voting rights at all is shown in our comparison of staking platforms.
The X token after the attack: a 96 percent price loss and empty liquidity pools
The price reacted at once. Bitcoin.com News reports a drop from $50 to $60 before the attack to around $1.75, which is more than 96 percent. Individual readings of liquidity on decentralised exchanges fell to a few dollars. No official statement from the project was available at the time of reporting; X100 Global had not confirmed the incident through its own channels.
That is the part that is repaired least often. A protocol can in principle replace stolen USDT if it holds reserves. A treasury that has handed over its own tokens at a price of zero, and a market in which those tokens are now being sold, cannot be turned back. Holders of X tokens do not have a price problem but a backing problem: the counter-value that gave the token a floor is sitting with the attacker.
For a sense of scale: Ether trades at around $2,329 on October 26, 2026 and has given up about 4.6 percent over seven days, with Bitcoin at around $80,227. The broader market did not react to the incident. That is typical for attacks of this size and at the same time the reason they are easily overlooked: four to five million dollars do not move the Ether price, but they hit every holder of the affected token in full.
Governance attacks are no isolated case: Bonk DAO and Term Finance
X100 is the third case of its kind we have reported on this year, and the pattern repeats itself. In July 2026, Bonk DAO lost around $20 million from its treasury, again without a hack in the narrow sense, but through the vote itself. In August it was Term Finance and a governance exploit, in which audited program code did not protect deposits, because the weakness sat in the rulebook above the code.
That leads to an uncomfortable conclusion for anyone valuing DeFi projects: an audit checks whether the program code does what the specification says. It does not check whether the specification makes sense. A protocol can be fully audited and still allow a majority bought in seconds to empty the treasury. The audit badge on a project page says nothing about that risk.
Put plainly: the question about the audit is the second question. The first is who can resolve a payout from the treasury, and how much time passes between the resolution and the payout.
What MiCA does not regulate about DeFi governance
Under the European crypto regulation MiCA, providers that hold, exchange or broker crypto assets in the EU need authorisation and come under supervision. For a customer of an authorised exchange, that means segregated client funds and reporting duties, among other things. We have set out those duties in detail in our overview of the MiCA obligations for crypto companies.
A protocol such as X100 does not fall under it. MiCA covers service providers, that is companies with customers. A governance in which anonymous contracts vote on a treasury has neither a provider in the sense of the regulation nor a body that could apply for authorisation. That is not a gap someone forgot, but a consequence of the design: where no service provider stands, no service-provider law applies.
Two sober consequences follow for holders. First, a loss in a DeFi protocol leaves no supervisory complaint and no deposit protection; legal action runs against unknown operators and is closed off in practice. Second, responsibility for checking shifts entirely to you. Buying through a regulated exchange in Germany and holding the tokens in self-custody carries a different risk profile than locking tokens in a protocol. How to hold your own keys and which devices manage it is shown in our hardware wallet comparison.
One note on tax, because the question comes up regularly after losses: in Germany, private disposals of crypto assets are subject to a one-year holding period, and a loss realised inside that period can in principle be offset against gains from the same kind of transaction. Whether a total loss through a protocol attack counts as a disposal for tax purposes is a question for your tax adviser in the individual case, not one an article can answer.
Timelock, quorum, snapshot: the terms that decide your risk
Four terms are enough to assess the governance of a protocol. They appear in any decent documentation, and if they do not appear there, that is the answer.
Timelock
The period between an accepted resolution and its execution. Common values run from 24 to 72 hours; zero hours is the warning sign from this case.
Snapshot
The point in time at which voting weight is fixed. If it lies before the proposal is filed, tokens bought afterwards are worthless for the vote.
Quorum
The share of all votes that must at least take part for a resolution to be valid. A three-seat body filled by deposit size effectively has no quorum in the sense of participation.
Emergency stop
A named body that can halt a resolution in progress. It is a concession to reality and a risk in itself, because it concentrates power. Its complete absence alongside a missing timelock is the combination that led to the total loss of the treasury at X100.
All of this can be checked in a few minutes. The governance documentation of a protocol names these values, and the voting portal shows for every proposal when it was filed and when it can be executed. If no interval appears there, that is not sloppy documentation but the setting itself.
Governance risk: without a timelock, one transaction decides
The attack on X100 has shown that the most expensive weakness in a protocol need not sit in the program code, but in a setting anyone can look up. Three steps turn that insight into action.
- Look up the governance deadlines of your protocols. For every protocol in which you have locked tokens, open the governance documentation and search for the timelock. If you find no deadline and no documentation, treat the capital there as tied up at short notice. Which providers disclose their lock-up periods and voting rules is set out in the comparison of staking platforms.
- Split your holdings. Tokens you want to hold for the long term do not belong in a governance contract but in your own custody. Which devices cover that and what they cost is shown in the hardware wallet comparison.
- Watch for authorisation on the way in. For buying and selling in Germany, an exchange authorised under MiCA remains the route with supervision and segregated client funds; the duties that apply there are set out in our overview of the MiCA obligations.
A final point for context: governance attacks hit almost exclusively small protocols with few voters, because a majority is cheap to buy there. The risk falls as a project's market capitalisation rises, and it falls much further with the quality of its deadlines. Neither costs you anything but the time you spend looking it up.
(As of October 26, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Most $Bitcoin thefts need your seed phrase. This one did not. A flaw in Electrum, one of the oldest Bitcoin wallets, let a malicious server replace a pending payment with a fake one and then wait for you to do something completely routine: speed it up. The moment you approved the higher fee, you signed the attacker’s transaction instead of your own. At least one user lost funds before the fix landed on October 24. Here is what happened and why it matters even if you have never used Electrum.
How does the Bitcoin fee bump trap work?
Light wallets like Electrum do not download the whole blockchain. They ask external servers for your transaction history and for broadcasting payments. Confirmed transactions are checked against the chain, but pending ones were simply taken on trust from the main server the wallet happened to be connected to.
That gap was the opening. An attacker running one of those servers could intercept an outgoing payment before it reached the network, then feed the wallet a counterfeit version. The counterfeit spent your coins to an address the attacker controlled, in at least one case with the same last four characters as the real recipient, and it carried a fee so low that it would never confirm. The wallet displayed it as a legitimate pending payment.
Then came the bait. A stuck transaction naturally pushes users toward Replace-by-Fee, the standard Bitcoin feature for bumping a slow payment. In Electrum, bumping the fee meant re-signing the transaction shown in the history. Since that transaction was the attacker’s, the signature was valid, the coins moved, and the theft looked like a normal fee increase.
Who was affected by the Electrum vulnerability?
Electrum disclosed the issue on October 24 and confirmed that some servers were actively exploiting it. The first report came on October 11 from a user running a two-of-three multisig setup with two hardware wallets, who spotted a foreign outgoing transaction in the history but did not lose funds. A second user was not so lucky. The developers have not disclosed the amount stolen or named the servers involved.
Users who connect only to their own server or to a server they trust were never exposed. Everyone else running a version below 4.8.3 remains vulnerable as long as the wallet can land on a rogue server.
What does the fix in Electrum 4.8.3 change?
Version 4.8.3 adds signature checks for unconfirmed transactions that spend coins from your own wallet. A server can no longer slip an invalid transaction into your history and have the wallet present it as real. Download the update only from electrum.org, never from an in-wallet pop-up or a link in a message. Electrum users were hit by exactly that kind of fake update prompt in 2019, when rogue servers drained more than $4.6 million.
How to protect your Bitcoin wallet from this kind of attack
The lesson goes beyond one wallet. Any software that trusts a third party for unconfirmed data has the same weak spot, so a few habits are worth keeping:
- Treat every fee bump as a new transaction. Check the full receiving address and the amount on the signing screen, not just the last few characters.
- Confirm on the device. If you use a hardware wallet, verify the destination on its display. The multisig user caught this attack precisely because the hardware showed something different.
- Prefer your own node or a server you control. The attack only works when a stranger feeds your wallet its history.
- Keep wallet software current and verify downloads with the developer’s signature when you can.
Self-custody puts you in charge of security, and that includes the boring steps. A thirty-second address check is still the cheapest insurance in crypto. You can track the current Bitcoin price and the wider market on our prices page.
A coin has a blockchain of its own, a token sits on somebody else's blockchain. That is the whole difference between coin and token, and it decides which fee you pay when you send, who is allowed to change the rules, and what happens when you pick the wrong network on a withdrawal.
How large that difference is in practice shows in the ranking. Among the 20 largest crypto assets by market capitalisation, October 26, 2026 counts thirteen coins and seven tokens (our own analysis of market data from CoinGecko). The seven tokens together weigh in at around $317 billion, the thirteen coins at a good $2,230 billion. The majority of the big names therefore run a blockchain of their own, while the majority of all listed crypto assets do not. Of the 22,501 entries CoinGecko lists on the same day, 6,070 carry a contract on Ethereum.
This article sorts out both terms, shows the common types of token, explains the fee rule that catches many newcomers the first time, and sets out what supervisors and the tax office in Germany make of the distinction. If your first question is what a cryptocurrency actually is, read our primer on that.
Coin or token: the difference sits in having a blockchain of its own
A coin is the native means of payment of its own blockchain. It comes into being through the rules of that network itself, it is created by its nodes, and with it you pay for transactions in precisely that network. A token, by contrast, is an entry in a smart contract that runs on an existing blockchain. It has no infrastructure of its own, no nodes of its own and no cryptography of its own. It borrows all of that.
The comparison with a currency and a voucher carries a long way, as long as nobody overstretches it. Bitcoin is the coin of the Bitcoin blockchain: without it there would be no network, and without the network there would be no bitcoin. A token such as Chainlink's LINK token is a program that somebody published on Ethereum. Were Ethereum to fail, LINK in its present form could no longer be transferred. Were Chainlink to fail, Ethereum would carry on unmoved.
That direction of dependency is the heart of the matter. The blockchain carries the token, and the token never carries the blockchain, which is where everything else in this article follows from.
What is a coin? The native means of payment of a layer-1 blockchain
Layer 1 denotes the base layer of a blockchain, meaning the network that produces blocks itself and confirms its transactions itself. Every layer-1 blockchain has exactly one coin, and that coin performs three jobs there at once.
First, it pays the fee. Send a transfer on Bitcoin and you pay in bitcoin; do something on Ethereum and you pay in ether. Second, in many networks it secures the protocol: under proof of stake, validators deposit units of the coin as a pledge and lose it if they cheat. Third, it is the reward with which the network pays its own operators.
That is why a coin cannot be produced in an afternoon. Behind it stand a protocol, consensus rules and a network of machines that somebody has to run. Bitcoin, Litecoin, Monero, XRP, Solana, Cardano and Tron are coins in this sense. Many of them fall under the collective term altcoins, which simply means everything except bitcoin and says nothing about the technical form.
Token: an entry in the smart contract of somebody else's blockchain
A smart contract is a program that sits on a blockchain and runs to fixed rules every time it is called. A token is nothing other than a table inside such a program: a list of addresses and the amount belonging to each address. Send a token and the contract deducts the amount from you and credits it to the recipient. The coin that changes hands in the process does not exist; there is only an altered entry.
That explains why tokens are so numerous. Issuing a token requires no network, no validators and no mining hardware, only a few dozen lines of code and the fee for publishing them. The count reflects that: the 6,070 entries with an Ethereum contract in the CoinGecko list are merely the ones that made it into a directory at all.
The same ease is the flip side. Behind a coin there is always a running network; behind a token there is sometimes no more than a contract somebody wrote in an hour. The technical form therefore says nothing about the quality of a project, though it does say something about the effort behind it.
The 20 largest crypto assets: 13 coins and 7 tokens
The theory becomes tangible once the ranking is counted through. On October 26, 2026 the twenty largest crypto assets by market capitalisation look like this (market data from CoinGecko, as of Monday morning):
Coins with a blockchain of their own (13): Bitcoin, Ether, BNB, XRP, Solana, Tron, Zcash, Hyperliquid, Dogecoin, Monero, Cardano, Stellar and NEAR.
Tokens on somebody else's blockchain (7): Tether (USDT), USD Coin (USDC), Figure Heloc, USDS, WhiteBIT Token, Chainlink (LINK) and LEO.
Two things stand out. First, the coins sit at the front: the thirteen carry around $2,230 billion of the $2,709 billion this list weighs in total. Second, four of the seven tokens are stablecoins. The largest token by a wide margin is Tether at around $182 billion, which puts it ahead of every coin except bitcoin and ether.
Look deeper into the list and the pattern holds: among the 100 largest crypto assets, 39 of the tokens run on Ethereum, eight on the BNB Chain, five on Solana and three each on Arbitrum and Tron. Ethereum is therefore the home blockchain of most large tokens, and has been for years.
ERC-20, BEP-20 and TRC-20: what the token standards stand for
A token standard is a list of functions every contract has to offer so that wallets and exchanges understand it. On Ethereum that standard is called ERC-20, set down in EIP-20. It states that a contract must be able to name its total supply, report the balance of an address and execute a transfer: six functions and two events, no more.
That frugality is the reason for its success. A wallet that handles ERC-20 can display any ERC-20 token, including one created only yesterday. Other blockchains have copied the standard: on the BNB Chain it is called BEP-20, on Tron TRC-20, and the functions are largely the same.
What matters in practice is the consequence: the same token can exist on several blockchains, and those versions are separate contracts. Tether exists as an ERC-20 on Ethereum and as a TRC-20 on Tron. Both are called USDT and both are worth one dollar, yet they are not the same piece of software, and they do not sit on the same blockchain.
Types of token: utility tokens, governance tokens and security tokens
The technical form says where a token runs. Which types of token exist depends instead on what it is for. Three categories come up most often in practice.
Utility tokens provide access to a service. The EU regulation MiCA defines them in Article 3(1)(9) as a crypto asset intended solely to provide access to a good or a service supplied by its own issuer. An example from our own coverage is Quant's QNT token, with which licence fees are settled.
Governance tokens grant voting rights in a protocol. Holders may vote on proposals, on fee levels or on the distribution of a treasury, for instance. UNI from Uniswap and AAVE are well-known representatives. The voting right applies within the protocol, not within a company: a governance token is not a share in a firm.
Security tokens, by contrast, represent exactly that: a claim that otherwise sits in a security, such as a bond or a share of profits. In Germany the Act on Electronic Securities governs this form, and securities law applies to it rather than crypto law. Anyone wanting to offer such instruments needs the corresponding permission from BaFin.
Alongside those there are variants that fit none of the three boxes: LP tokens, which document the share in a liquidity pool in the DeFi sphere, or tokens that represent a deposit in staking. Technically they too are nothing other than entries in a contract.
Non-fungible tokens: when every unit is unique
All the tokens named so far are fungible tokens: every unit equals every other, just as one ten-euro note equals any other ten-euro note. A non-fungible token, NFT for short, reverses that. Every unit carries a number of its own, and the contract keeps individual pieces with their owners rather than mere amounts.
Technically an NFT is therefore the same thing as an ERC-20 token, only with different bookkeeping: instead of “address A holds 500 units” it reads “address A holds piece number 4711”. The standard for it on Ethereum is called ERC-721. What that piece means, whether a picture, an admission ticket or a land-register entry, is set by the contract and not by the blockchain.
The tokenisation of real assets works by the same procedure: a property, a fund unit or an ounce of gold is given a digital counterpart on a blockchain. Whether that turns into robust ownership is decided by the contract behind it and by the law of the country in question, not by the technology.
Stablecoins carry coin in the name and are tokens all the same
The name misleads, and it does so reliably. A stablecoin is as a rule a token, even with the word coin inside it. USDT, USDC, DAI and PYUSD run as contracts on Ethereum, Tron, Solana and further blockchains; not one of them has a blockchain of its own.
That is more than a question of terminology. Holding USDT makes you dependent on two things: on the issuer that manages the backing, and on the blockchain its contract sits on. With a coin the first dependency falls away, and in exchange there is nobody standing behind the value.
The same risk of confusion runs in the other direction. In everyday use every project is called a “coin” sooner or later, even when it is a token. For your purchase decision that makes no difference; for the question of which network you choose on a withdrawal it very much does. At large crypto exchanges the withdrawal form therefore asks for the network the token sits on alongside the name.
Fees: every token transfer costs the coin of its blockchain
This is where the difference gets expensive for the first time. You always pay for a transaction in the coin that the blockchain belongs to, never in the token you are moving. Send LINK from one wallet to another and you pay the fee in ether. Transfer USDT on Tron and you pay in TRX. Send a BEP-20 token and you need BNB.
Many newcomers meet the consequence the first time round: the wallet shows a token balance in the four-figure range, the transfer fails all the same, because not a single unit of the network coin sits in it. The balance is not lost, it is merely immovable until some ether, TRX or BNB arrives.
That gives a rule of thumb for every wallet of your own: put a small reserve of the matching coin next to every token. Which blockchain that is stands in every wallet next to the token itself. The same applies to a hardware wallet, because it too only signs what the blockchain then calculates.
MiCA sorts by function rather than by technical form
For the European supervisor the question of whether something is a coin or a token is secondary. The Regulation on Markets in Crypto-Assets, MiCA for short (Regulation (EU) 2023/1114), knows three categories, and none of them is called coin.
E-money tokens keep their value stable against a single official currency, the euro or the dollar for example. Only credit institutions or electronic money institutions may offer such tokens in the EU. Asset-referenced tokens lean on something else: a basket of currencies, a commodity such as gold, or several crypto assets at once; their issuers need prior authorisation. Everything else falls into the residual category of other crypto assets, and that is where utility tokens land along with bitcoin and ether.
The rules for those two stablecoin categories have applied since June 30, 2024, and the licensing requirement for crypto-asset service providers since December 30, 2024. In Germany BaFin runs the supervision; the Crypto Markets Supervision Act regulates competence, procedure and fines alongside it. What that means for providers in Germany is set out at length in our overview of the MiCA obligations.
For investors, that mainly means this: whether a crypto asset may be traded in the EU, and under which conditions, hangs on its function and not on whether it brings a blockchain of its own.
Tax in Germany: one year of holding period for coin and token
The tax office does not draw the distinction either. Coins and tokens count as other assets, and for their sale out of private holdings section 23 of the Income Tax Act applies: a gain is taxable only if no more than a year lies between acquisition and sale. Once that year has run, the gain stays free of tax, whether you sell bitcoin or an ERC-20 token.
An exemption threshold comes on top: gains from private disposal transactions stay free of tax if the total gain in the calendar year sits below 1,000 euros. Once that limit is exceeded, the entire gain is taxable, not merely the part above it. The Federal Ministry of Finance last summarised the details in its circular of March 6, 2025, and tightened the record-keeping obligations in it as well.
One particularity concerns both technical forms equally: every swap counts as a sale. Swap token for token, on a decentralised exchange for instance, and you trigger a disposal transaction, even without a single euro moving. Anyone swapping a great deal cannot manage without clean records; tax software and portfolio trackers take over that bookkeeping.
Wrong blockchain, money gone: the most expensive mistake when sending
Because the same token exists on several blockchains, the withdrawal form of every exchange has two fields: the address and the network. Choose the wrong network and the transfer goes to an address that belongs to nobody there you can reach.
That is particularly treacherous with Ethereum and the BNB Chain, because addresses look identical on both. A withdrawal of USDT over the BNB Chain to an Ethereum address will be executed, and the coins then sit on the BNB Chain at an address whose key you do hold, but whose access your wallet displays only if it knows that network. In the best case the balance is reachable with some effort, in the worst it is permanently lost.
What matters before any withdrawal is first that the network at the exchange matches the one your wallet expects and in which it actually displays the token. A small test amount up front costs one fee and may save the entire balance. The same principle applies to project migrations, for example when a token moves to a blockchain of its own, a process in which the old version of the token is often withdrawn from circulation.
Coin or token: without the coin of the blockchain, the token stays put
The difference between coin and token is technically small and practically large. Technically it turns on whether something has a blockchain of its own. In practice precisely that decides the fee you pay, the network you choose when sending, and how many parties your balance depends on. For supervisors and the tax office, function counts rather than technical form.
- Settle the technical form before you buy. Does the asset stand on a blockchain of its own or on somebody else's? With a token, the blockchain comes in as a second risk. Trading venues that state both cleanly are in the comparison of regulated crypto exchanges.
- Keep a fee reserve next to every token. A small amount of the network coin belongs in every wallet that holds tokens, otherwise the balance stays immovable. Which wallet suits that is shown by the hardware wallet comparison.
- Document every swap. The one-year deadline under section 23 of the Income Tax Act runs separately for each purchase, and every swap starts a new one. Record it as you go and you spare yourself the reconstruction in spring; the tools for it are in the overview of crypto tax software.
(As of October 26, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
What is documented: Ripple holds its in-house Swell conference in New York from October 27 to 29, 2026, by its own announcement with more than 80 sessions, over 100 speakers and more than 1,500 attendees. On Wednesday, October 28, the US Federal Reserve publishes its rate decision at 7 p.m. German time. XRP trades at $1.29 on Monday morning, around 1.15 euros. Our assessment of that follows further below: the conference delivers headlines, the rate decision moves the entire market on the same day, and at the last Swell in November 2025 XRP lost 12.6 percent within two days.
If you hold XRP, you have two dates in the calendar this week, and both fall on the same Wednesday. Where the price can point over a horizon of months is set out in our XRP price prediction. This piece stays with the next three days and with the figures that can be measured today.
Swell 2026 in New York: 80 sessions from October 27 to 29
Swell is Ripple's own industry conference, where the company has brought together banks, payment providers and supervisors since 2018. This year's venue is The Shed in Hudson Yards in Manhattan. On the official event page Ripple names three stages, more than 80 sessions and over 100 speakers, among them Brad Garlinghouse as well as representatives of BNY, Robinhood and ICE.
The agenda lists capital markets and settlement, stablecoins, tokenisation, payments, regulation, privacy and the utility of XRP. For October 28 a conversation is announced between David Schwartz, CTO Emeritus at Ripple, and Ayo Akinyele of RippleX, which is to turn on privacy, artificial intelligence and institutional DeFi.
Important for the context: Ripple has so far confirmed no product announcement for the three days. Historically, new services have been presented at Swell on several occasions, but there is no guarantee of that this year. Price in an announcement and you are trading on an expectation, not on a fact.
XRP at $1.29: the day's low sits at $1.27
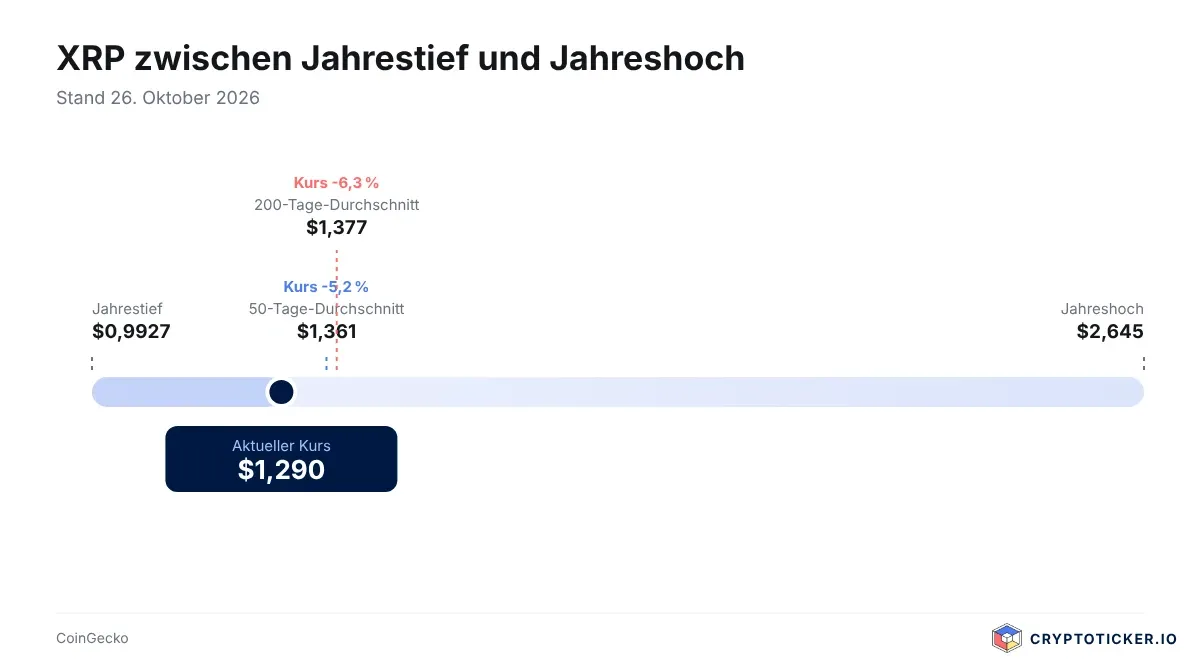
On Monday morning, October 26, XRP stands at $1.29. Over the past 24 hours the price moved between $1.27 and $1.31, leaving it down 0.6 percent. On a weekly view 1.8 percent is missing, over 30 days it is 16.9 percent. The high of the past 30 days came on September 26 at $1.57, and today's level is at the same time the 30-day low. Market capitalisation stands at $81.7 billion, daily turnover at $1.09 billion, and XRP ranks fifth by market value. In circulation are 63.35 billion of the 99.99 billion XRP created in total. All figures come from CoinGecko.
Two levels matter more for the coming days than today's price. On the downside the day's low sits at $1.27, a good 1.5 percent below the current price. Should that zone withstand the rate decision, the tight range of the past week stays intact. On the upside the 200-day average runs at $1.38 and the 50-day average at $1.36. Both lie above the price, which is therefore 6.3 and 5.2 percent below them. As long as XRP stays under those two lines, every recovery is technically a counter-move in a falling market.
A look at the full year puts that in order: the low for the year is $0.99, the high for the year $2.65. From the record of $3.65, reached on July 17, 2025, XRP is 64.6 percent away. The chart below shows where the current price sits between those two ends.
What has changed since Sunday
On Sunday, our XRP analysis of October 25 centred on the shrunken daily range: 1.54 percent between high and low, a figure that speaks for calm ahead of a date. That calm is over. Between $1.27 and $1.31 lie around 3.1 percent today, so the range has doubled within a day.
The environment has shifted as well. Bitcoin trades at $80,271 on Monday morning, 0.2 percent lower than the previous day, Ethereum at $2,329. The broad market therefore enters the week weak, and XRP is holding marginally better than the two larger assets. The price itself, at $1.289, is only 0.7 percent below Sunday's level.
Fed decision on Wednesday at 7 p.m.: two dates on one day
The Federal Open Market Committee meets on October 27 and 28 according to the official meeting calendar. The decision is published on the second day at 2 p.m. New York time, which is 7 p.m. in Germany. The statement therefore lands in the middle of the second conference day of Swell.
The link to XRP runs through interest rates and not through the blockchain. If the policy rate falls, fixed-income investments become less attractive and capital tends to move into assets without a running yield. If the rate stays high or the central bank signals a pause, the calculation reverses. Crypto does not react to the resolution alone, but to the deviation from what was expected. That deviation cannot be measured beforehand.
In practice, that means two streams of news meet on Wednesday evening, one monetary and one corporate. For the price it is an hour with thinner order books and larger jumps, and that holds even when both pieces of news turn out friendly taken on their own.
Swell 2025: XRP lost 12.6 percent in two days
A look back helps with the context, even though a single case makes no rule. Swell 2025 took place on November 4 and 5, 2025 at Convene Hudson Yards in New York. By our analysis of CoinGecko daily data, XRP cost $2.53 on November 3, 2025, the day before the conference. On November 5, the second conference day, it was $2.21. That is a loss of 12.6 percent in two days.
A week later, on November 12, 2025, XRP traded at $2.39 and thus 5.4 percent below the level of the day before the conference. The price made up part of the decline without reaching its starting level. The market was weak overall at the time, and the fall cannot be attributed to the conference alone. As a guide to expectations it still serves: an in-house conference did not carry the price last year.
Sell the news: how a conference works on the price
Sell the news describes the case in which an expected event is priced in before it happens and the price falls afterwards, even though the news itself turns out positive. The mechanism is simple: whoever speculates on an announcement buys in advance. Once it arrives, the buyers who would carry the next step are missing, and the first profit-taking meets a thin order book.
With a conference a further feature comes in. The announcements almost always concern the commercial side of Ripple, meaning payment settlement, custody or the RLUSD stablecoin. Whether such business generates demand for the XRP token depends on whether XRP is genuinely needed as a bridge currency in settlement. A partnership that builds on RLUSD uses the blockchain but touches the token itself only indirectly. That distinction is worth reading for on Wednesday.
RLUSD and MiCA: the stablecoin is missing from the ESMA register
RLUSD is the stablecoin issued by Ripple, pegged one to one to the US dollar and running both on the XRP Ledger and on Ethereum. Ripple puts the market capitalisation at more than $2.5 billion, of which over $1 billion sits on the XRP Ledger. That is a company figure and not an independently audited one.
According to statements by Ripple and Cross River Bank on October 15, the US bank is embedding RLUSD into its own core banking system so that payment providers can switch between dollars and RLUSD without operating a blockchain connection themselves. The service is available at first in a portion of the US states. In October, Standard Chartered additionally started institutional custody of RLUSD on the XRP Ledger, supervised by the financial regulator in Dubai.
For investors in Germany the decisive point is a different one. In our stablecoin overview, with the register as at September 30, 2026, RLUSD is absent from the register of the European securities regulator ESMA, as are USDT and PYUSD. Under MiCA an e-money token may be offered in the EU only if an authorised issuer stands behind it and a whitepaper has been notified. Concretely: on an exchange with a MiCA licence you will not currently find RLUSD on offer, and a piece of news from New York does not change that in the short term.
How to check your XRP position before Wednesday
Ahead of a date with a known time, three things can be looked up concretely without you having to predict a direction.
First, the order type. A market order in the minute after 7 p.m. is executed at the price then standing in the book, and with thin books that sits noticeably away from the one last seen. A limit order names the price at which you are willing to buy at most or to sell at least. Second, leverage. If you hold XRP on leverage, you should know the liquidation price of your position and hold it against the day's low of $1.27. Leverage of five liquidates arithmetically on a decline of 20 percent, and earlier still once a safety buffer and fees are deducted. Third, the trading platform itself. A provider with a licence under MiCA is subject to obligations on custody and on complaint handling that a provider without EU authorisation does not carry. Where German investors trade and at what cost is shown by our comparison of crypto exchanges.
A fourth point concerns custody. Holders who want to keep XRP for longer do not need to leave the balance sitting on the exchange. A wallet of your own costs fees on withdrawal, but in exchange it takes the provider's risk out of the calculation. The XRP Ledger requires a minimum reserve per account, which you should plan for before the transfer.
Holding period and tax: what applies in Germany after one year
Gains from the sale of XRP count in Germany among private disposal transactions under section 23 of the Income Tax Act. If more than a year lies between purchase and sale, the gain stays free of tax. Within the year an exemption threshold of 1,000 euros applies to all private disposal transactions together. Once it is exceeded, the entire gain becomes taxable and not only the part above it. For allocating acquisition costs the first in, first out method applies, so the holding bought first counts as the one sold first.
If you are weighing a sale before Wednesday, the purchase date is therefore the first thing to look up. A sale a few days before the one-year deadline runs out can prove more expensive than the price move that triggers it. Whether the holding period survives in this form is politically contested; we track the current state of proceedings in our overview of the reform of the crypto holding period.
Our assessment of Swell week
From the point of view of the editorial team, the calendar risk outweighs the news value of the conference this week. Three pieces of evidence speak for that: at the last Swell on November 4 and 5, 2025, XRP fell by 12.6 percent; the price today, at $1.29, sits below both moving averages at $1.36 and $1.38; and the rate decision on Wednesday at 7 p.m. hits the whole market harder than any single partnership. Against it speaks the fact that Ripple has two integrations to show this year, with Cross River and Standard Chartered, which go beyond a letter of intent, and that a product announcement on stage can turn sentiment in the short term.
What follows from that is no directional bet, but a question of scheduling. If you intend to buy or sell in any case, you can avoid Wednesday evening and trade on Thursday with more information. A total loss is possible with crypto assets at any time.
Swell and the Fed: without inflows, $1.38 stays the ceiling
- Check today which platform your XRP sits on and whether it holds a licence under MiCA. The costs and licences of the large providers are set out in the comparison of crypto exchanges.
- Ahead of a possible sale, look up the purchase date and the one-year deadline. Which programs calculate holding period and exemption threshold automatically is shown by the comparison of crypto tax tools.
- If RLUSD is familiar to you from the reports: check which stablecoins are authorised in the EU at all before you use one of them as a parking spot. We track the register status in our stablecoin overview.
(As of October 26, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
Some relief is appearing this morning as oil and rates fall, with a big macro week ahead featuring major earnings, FOMC and key data drops.
Over 100 economists, including former governor Jacob Frenkel, warned of deeper isolation ahead of Israel's October 27 national election.
Twenty-two companies have now objected to having their shares traded on the planned OKX-ICE tokenized stock venue, after Wells Fargo, Cisco, Marvell, Arm, Moderna. and Intuit joined the list.
Spot Bitcoin ETFs finished the week with about $301 million in net inflows, ending a two-week losing streak, even as two straight days of outflows kept October in the red.
A policy change effective Oct. 16 carves out an exception to Google’s long-standing pledge—letting connected Gmail, Drive, and Photos data personalize ads through its Personal Intelligence AI features.
U.Today - IT, AI and Fintech Daily News for You Today
Ethereum's market performance stays suppressed and the 30-day ETF performance perfectly reflects the sentiment we've been witnessing among institutional and retail investors.
XRP Ledger sees a sharp surge in network activity as payment volume spikes in four figures, providing a bullish signal for XRP.
Aviva Investors taps Ripple and XRPL to tokenize its £22 billion liquidity fund, but only 0.4% of it has moved on-chain so far.
Ledger finally secures a substantial increase in the value and payments volume.
Zcash upgrade countdown begins with 25 seconds blocks ahead.
Blockonomi
Crypto staking lets investors earn new tokens by helping to secure a blockchain. Many people ask whether those rewards could replace a salary. The numbers show it is possible, but it takes a large amount of capital or a willingness to accept more risk.
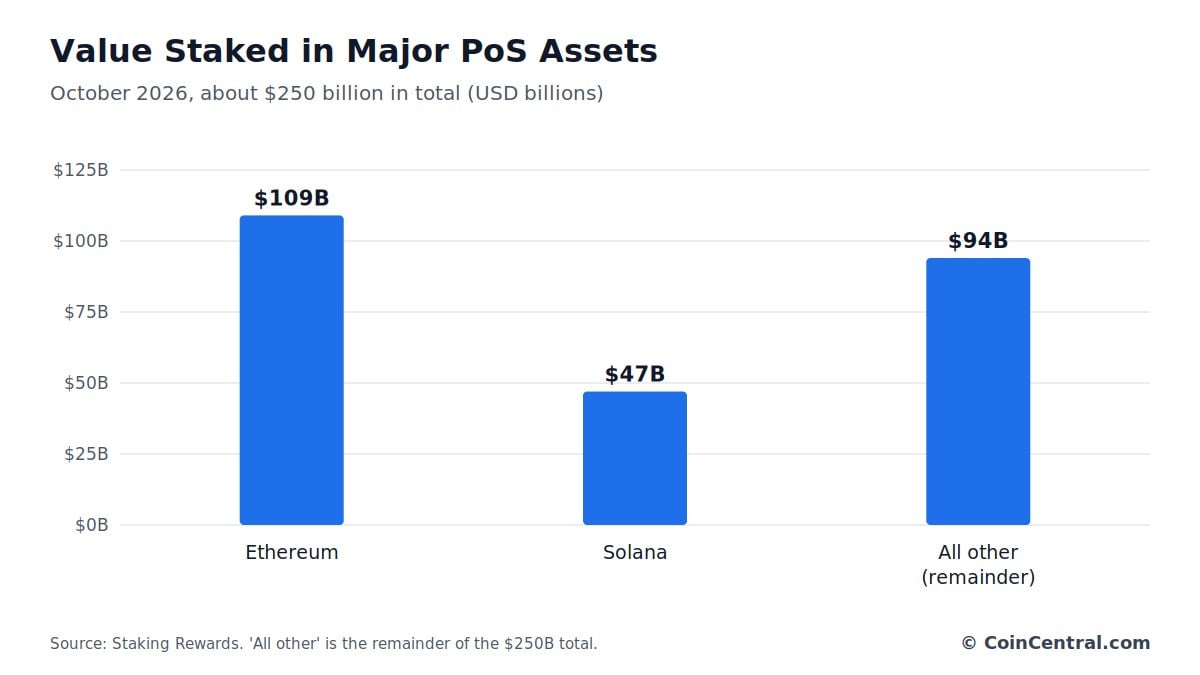
As of October 2026, about $250 billion is staked across the largest proof-of-stake cryptocurrencies, according to Staking Rewards. Advertised yearly rewards range from about 2% for Cardano to close to 20% for Cosmos.
There is a catch. Staking rewards are paid in cryptocurrency, not in dollars, euros or pounds. If the token falls 30%, a 7% staking yield will not stop the investor from losing money.
This article looks at the latest staking statistics from Staking Rewards, Ethereum, Solana, Coinbase, Kraken and Bitwise. It covers yields, the capital needed for a set income, and the risks that can shrink that income.
How Big Is the Staking Market in 2026?
Staking Rewards tracks about $250 billion staked across its leading proof-of-stake assets. Ethereum accounts for more than $100 billion of that total, while Solana holds roughly another $47 billion.
When liquid staking, restaking and other stakeable assets are included, the broader tracked staking universe passes $300 billion. Ethereum and Solana together account for more than $150 billion of staked value.
| Asset | Value staked | Share of $250B total |
|---|---|---|
| Ethereum | $109 billion | About 44% |
| Solana | $47 billion | About 19% |
| All other assets | $94 billion | About 38% |
Depending on the dataset and the date, Ethereum represents around 40% or more of major proof-of-stake staking value. The shares in the table are a simple calculation from the figures above.
These numbers show that staking is no longer a niche activity. Earning staking rewards has become a regular part of crypto portfolio management.
Size alone does not say how much any one investor can earn. It does show that many people and institutions now treat staking as a standard feature of proof-of-stake networks.
How Does Crypto Staking Generate Income?
Proof-of-stake blockchains use validators, not Bitcoin-style miners, to help verify transactions and secure the network. Token holders can take part in several ways:
- Running a validator
- Delegating tokens to a validator
- Joining a staking pool
- Using an exchange staking service
- Using a liquid staking protocol
In return, participants receive more of the network’s token. Ethereum has more than 40 million ETH staked across roughly 900,000 validators. The official Ethereum staking dashboard recently showed an annual percentage rate of about 2.6%.
Bitwise reported that Ethereum staking reached a record 43.8 million ETH at the end of the third quarter of 2026. Staking Rewards puts the share of ETH supply that is staked at about 36%.
Solana uses a delegated proof-of-stake model. SOL holders delegate tokens to validators, and rewards depend partly on network inflation, validator performance and commission. About 69% of eligible SOL supply is staked, according to Staking Rewards.
Staking looks like earning interest, because an investor gets a yearly return on assets they already own. It is different from a bank deposit, though. The principal can rise or fall sharply in value.
The method matters because it changes who keeps the reward. A solo validator keeps more of it but carries the technical work, while a pool or exchange takes a share in return for convenience.
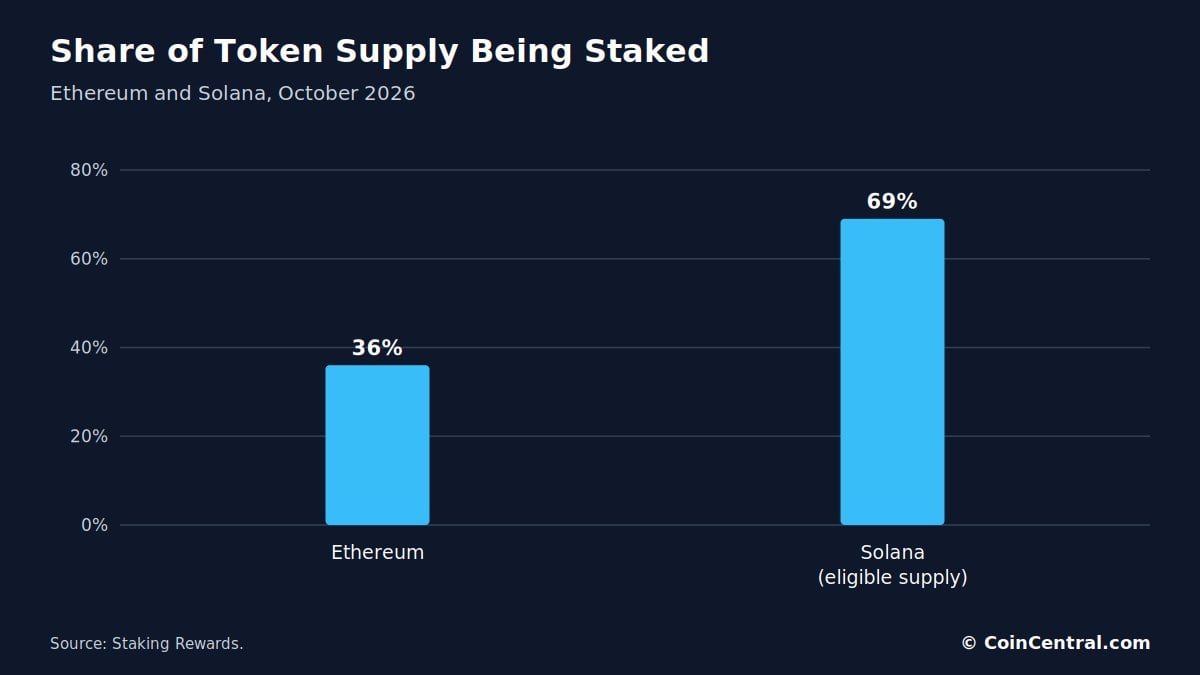
Crypto Staking Rates by Network in 2026
Rates vary widely between networks. Staking Rewards shows the following approximate native staking rewards.
| Cryptocurrency | Approx. native staking reward |
|---|---|
| Ethereum | 2.5% to 2.7% |
| Solana | 4.9% |
| Avalanche | 5.4% |
| Polkadot | 2.8% |
| Cosmos | About 19.8% |
| Cardano | About 2% |
Cosmos pays the most of the six networks, at about 19.8%. That is more than seven times the Ethereum rate. Cardano pays the least, at about 2%.
These rates change all the time. They depend on validator fees, network participation and the staking method used. Some smaller cryptocurrencies advertise even higher rates.
A high rate does not always mean a better deal. Later sections show how token inflation and price changes can cancel much of a high headline yield.
The spread between the lowest and highest rates is wide. Ethereum, Polkadot and Cardano sit near 2% to 3%, while Cosmos sits close to 20%. Solana and Avalanche fall in the middle, near 5%.
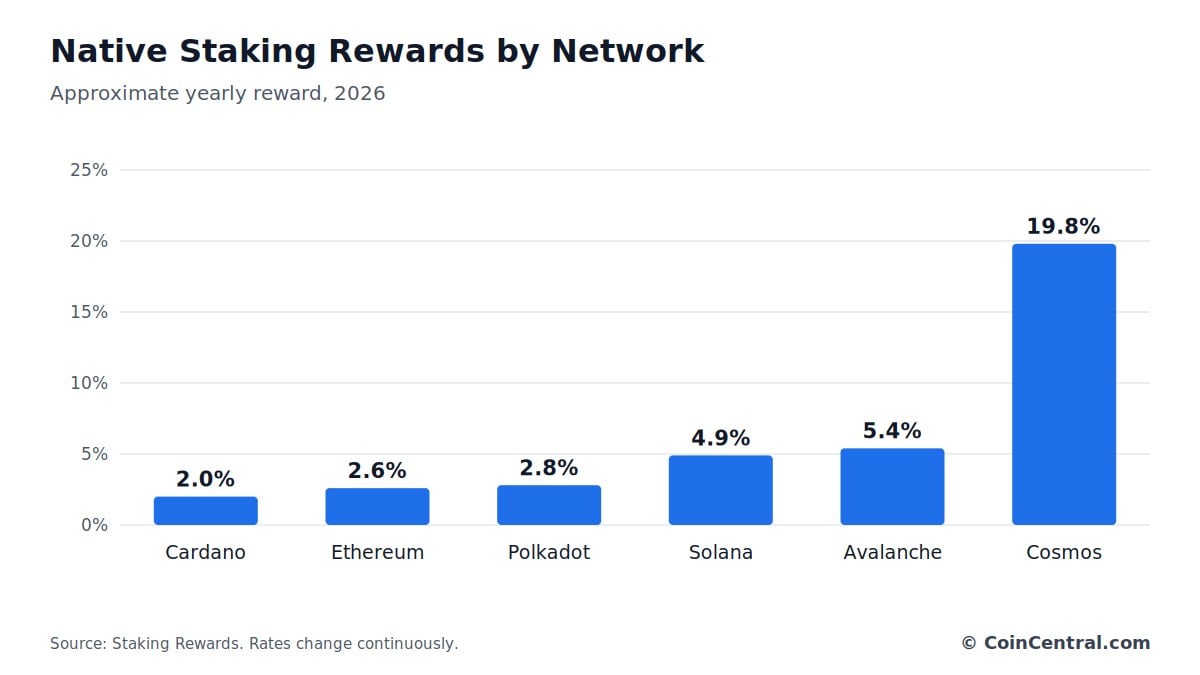
Exchange Staking Rates vs Network Rates
Exchanges often advertise lower rates than the network itself. Coinbase lists about 1.64% for Ethereum, compared with about 2.6% from the network. Kraken’s bonded rate for Ethereum is 2.68%.
| Cryptocurrency | Staking Rewards | Coinbase | Kraken (bonded) |
|---|---|---|---|
| Ethereum | 2.56% | 1.64% | 2.68% |
| Solana | 4.89% | 3.23% | 4.77% |
| Avalanche | 5.43% | 3.38% | 3.57% |
| Polkadot | 2.8% | 2.01% | 3.03% |
| Cosmos | 19.8% | 12.91% | 18.75% |
Coinbase also lists about 1.35% for Cardano. Kraken’s figures are for bonded staking, which can come with withdrawal limits.
The gaps largely reflect fees, staking structures and whether users accept bonding or withdrawal restrictions. Most retail investors use exchanges, pools or liquid staking providers, and these services may keep part of the rewards.
Running an Ethereum validator directly gives closer access to protocol rewards. It also takes technical knowledge and, traditionally, at least 32 ETH to activate a validator. Ethereum now supports validators with higher effective balances as well.
Investors should separate the protocol yield from the yield they actually receive. Convenience has a cost.
Kraken’s bonded rate is higher than the Staking Rewards figure for Ethereum and Polkadot. The Coinbase rate is lower on every network in the table. Readers should compare the terms, not only the percentage.
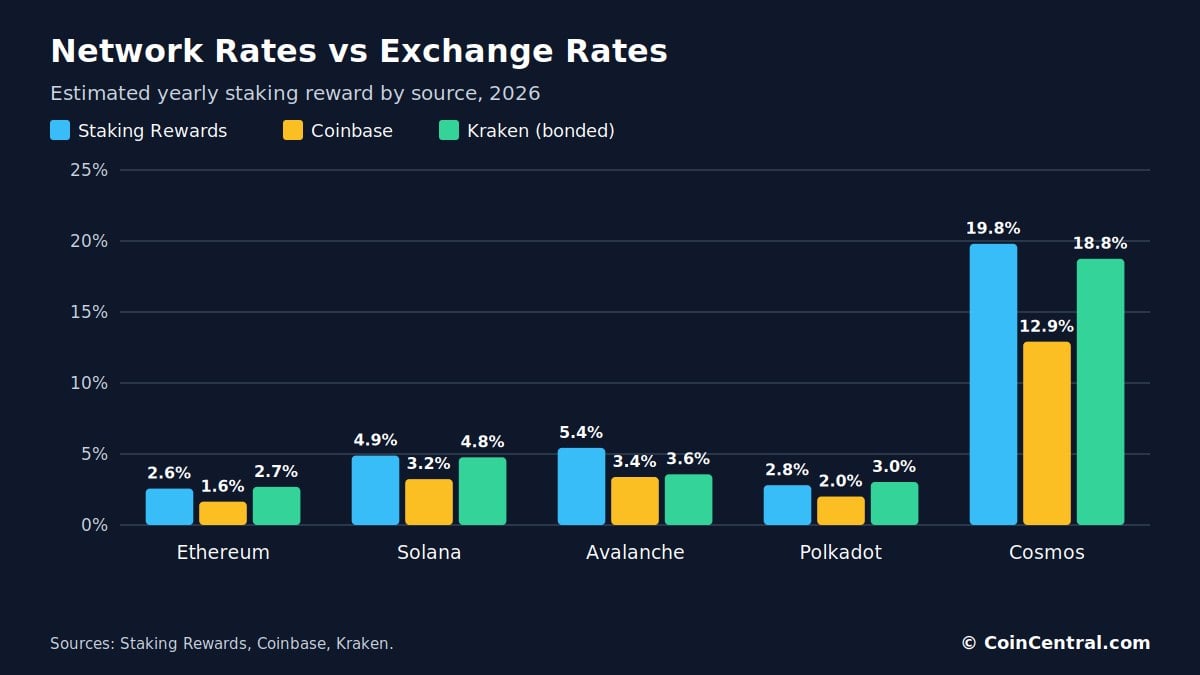
How Much Money Do You Need to Live Off Staking?
Suppose someone wants staking to pay $50,000 a year before tax. The table shows the capital needed at different yields. It ignores compounding, fees and changes in token prices.
| Staking yield | Capital required for $50,000 a year |
|---|---|
| 3% | $1.67 million |
| 5% | $1.00 million |
| 7% | $714,000 |
| 10% | $500,000 |
| 15% | $333,000 |
| 20% | $250,000 |
At first glance, high-yield tokens look far more attractive. Why hold $1.67 million earning 3% when $250,000 earning 20% pays the same amount?
The two choices carry very different risks. A token paying 20% can easily fall more than 20% in price. It may also be issuing large numbers of new tokens to fund those rewards.
The headline yield cannot be judged on its own. The lower capital need comes from taking on more risk, not from a free gain.
A second point is time. Capital figures in the table describe a single year at a fixed rate. Real portfolios face changing rates and prices every year, so the number is a starting point and not a plan.
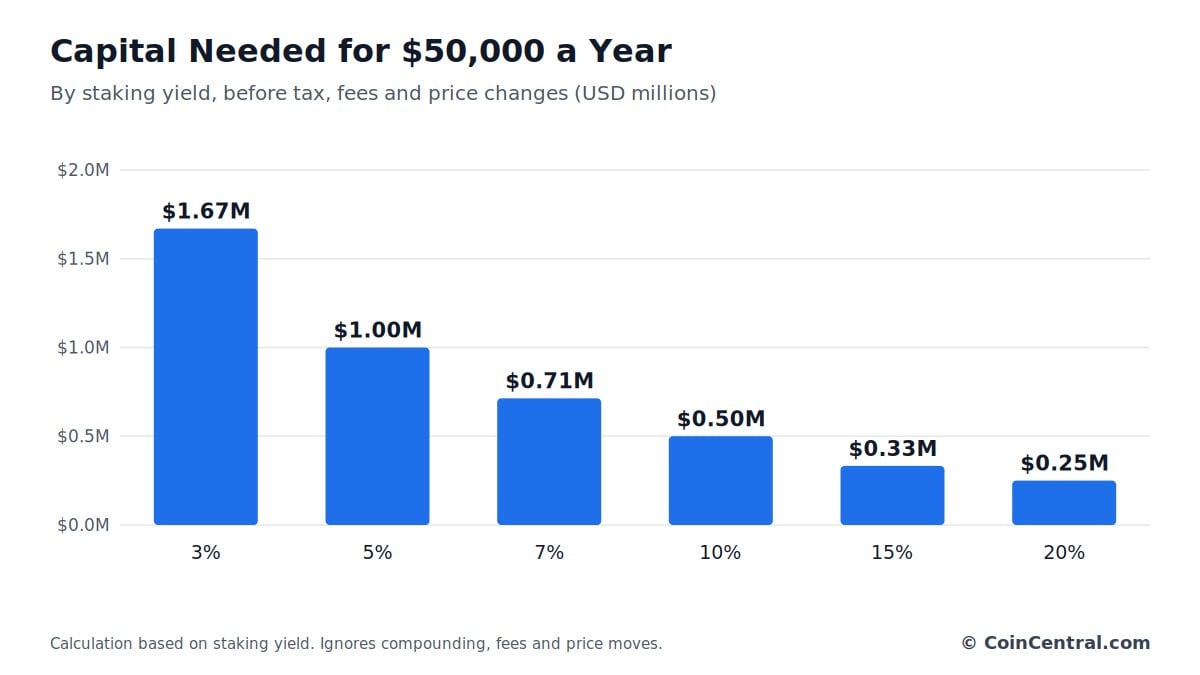
Living Off Ethereum Staking
Ethereum is the clearest example because it is the largest proof-of-stake network by staked value. Staking Rewards estimates about $109 billion of ETH is staked, with a nominal reward of about 2.5% to 2.6%.
Bitwise said the average Ethereum staking yield fell to about 2.63% in the third quarter of 2026, from 2.81% in the previous quarter. As more ETH enters staking, rewards are spread across a larger base.
At a 2.6% return, the capital needed for three income levels is shown below.
| Yearly income | ETH value needed |
|---|---|
| $30,000 | About $1.15 million |
| $50,000 | About $1.92 million |
| $80,000 | About $3.08 million |
These figures assume the value of ETH stays the same. That is a large assumption, and the next section explains why.
The rate is also not fixed, so the capital needed can change from one year to the next.
Ethereum is also the network with the lowest rates among the large ones. That is the trade for its size, which may appeal to investors who want a more established asset.
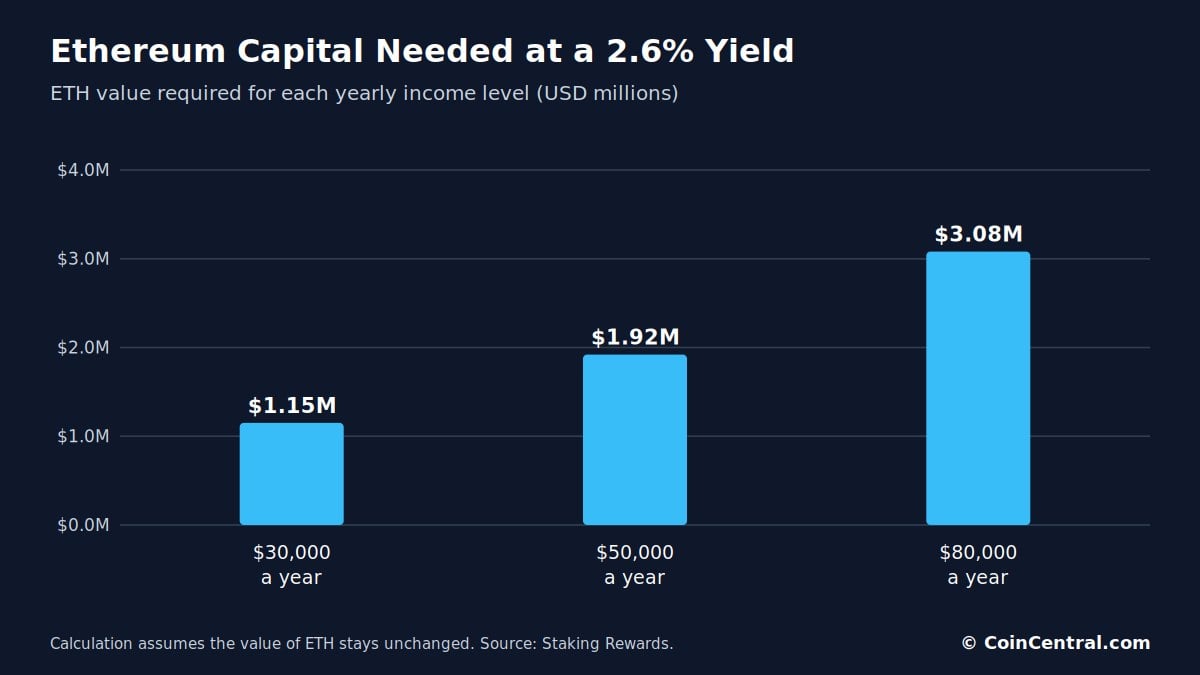
Price Risk Can Overwhelm the Yield
Imagine someone owns $1 million of ETH. At a 2.6% staking yield, the portfolio produces about $26,000 worth of ETH a year.
Now suppose ETH falls 30% during the year. The original $1 million would drop to about $700,000, before counting the extra ETH earned. The $26,000 reward does little to offset a $300,000 change in market value.
The reverse is also true. If ETH rises, both the principal and the dollar value of future rewards go up. Staking income is not like a fixed pension or a bond coupon, because it moves with crypto prices.
Higher-yield tokens show the same problem. Cosmos pays about 19.8%, so $250,000 could earn about $50,000 worth of tokens at today’s price.
But a token can pay 20% more tokens and still fall 50% in dollar terms. In that case the portfolio could be worth far less than the original $250,000. A high APY does not guarantee a high investment return.
The two examples differ in size but not in lesson. Whether the yield is 2.6% or 19.8%, a large price move can outweigh a full year of rewards.
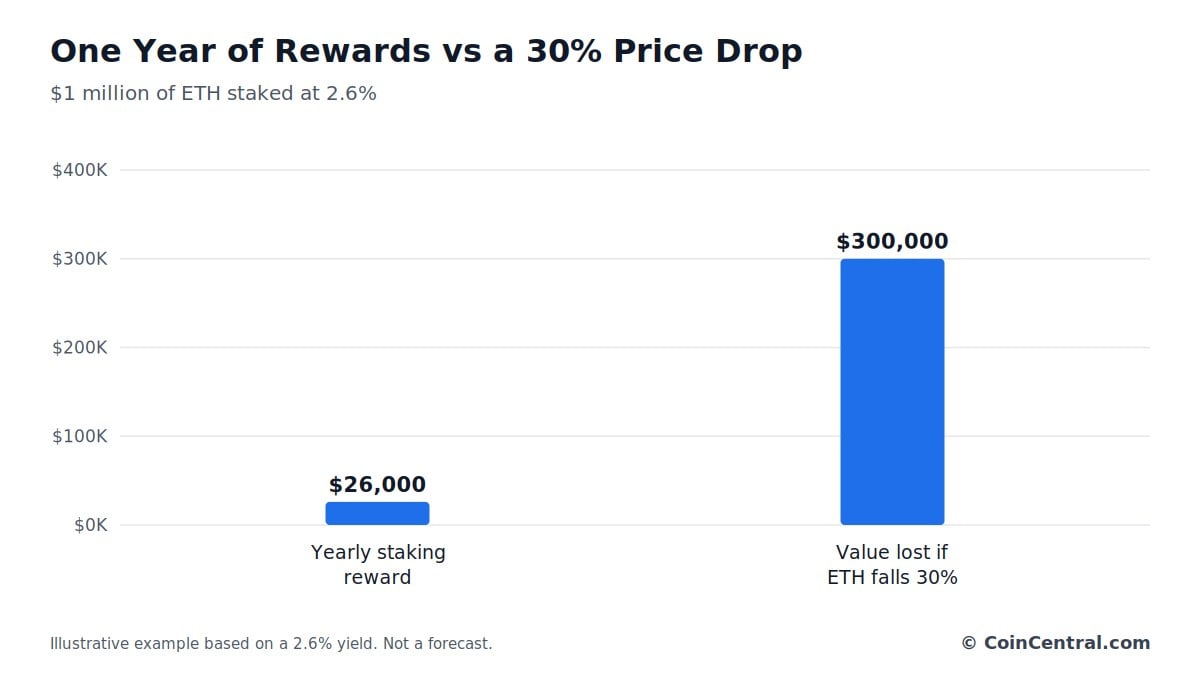
Nominal Yield vs Real Yield After Inflation
A 7% staking APY does not always mean a 7% real return. Many networks pay rewards by issuing new tokens, which grows the total supply.
Consider a token that pays 10% in rewards while its supply grows 8% a year. An investor who does not stake is diluted. The staker is mostly receiving new tokens to offset that dilution.
Staking Rewards shows this gap for several networks.
| Network | Nominal reward | Inflation | Reward after dilution |
|---|---|---|---|
| Ethereum | 2.56% | 0.86% | 1.69% |
| Solana | 4.89% | 3.56% | 1.28% |
| Avalanche | 5.43% | 2.66% | 2.70% |
| Cosmos | 19.8% | 12.7% | About 7.1% (simple subtraction) |
Solana’s documentation says rewards are funded largely by token issuance. Its inflation schedule began at 8% and declines each year toward a long-term rate of 1.5%.
For Cosmos, Staking Rewards puts inflation at about 12.7%. Subtracting that from the 19.8% reward leaves about 7.1%, a simple calculation that is well below the headline rate.
Inflation does not automatically push a token’s price down by the same rate. Demand can offset new supply. Still, it shows why the nominal APY is a weak measure of profit.
Investors can check these numbers before they stake. Staking Rewards lists both the nominal reward and the inflation rate for each asset, which makes the real reward easy to estimate.
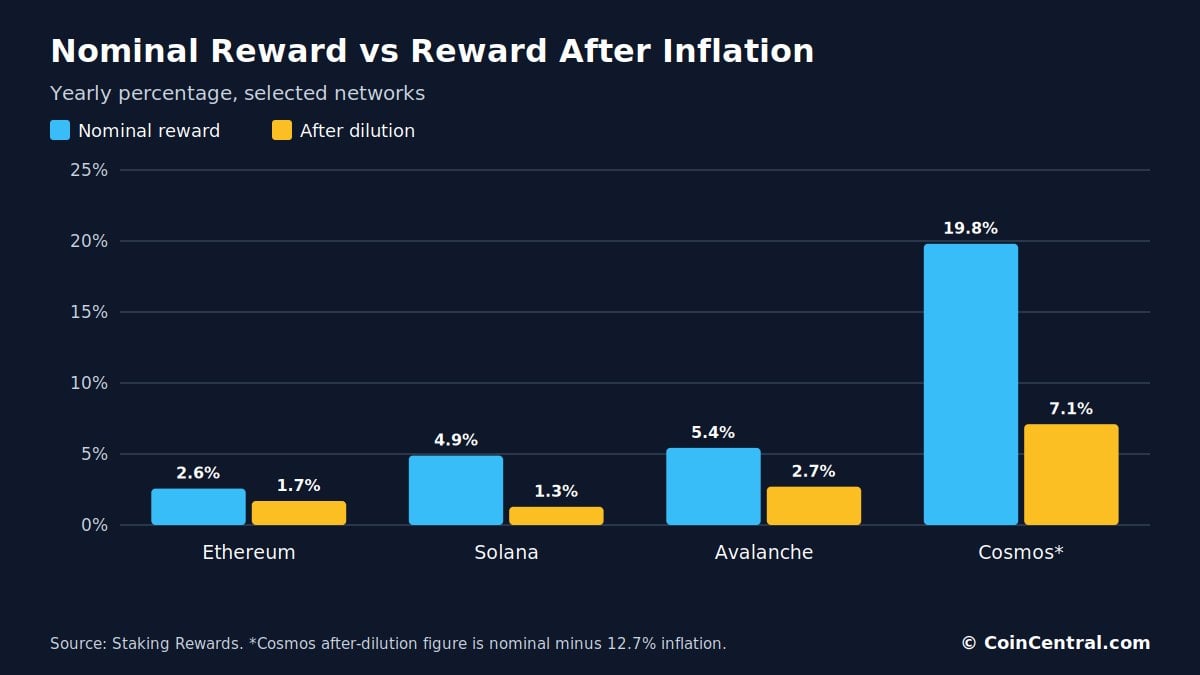
Other Risks: Changing Rates, Fees, Slashing and Lock-Ups
Staking rates are not guaranteed. Ethereum’s falling yield is one example. Rates can change for many reasons:
- More tokens being staked
- Protocol upgrades
- Changes in token issuance
- Network fees and MEV income
- Validator performance and commission
- Governance decisions
- Market conditions
An investor cannot assume that a 6% APY today will still be 6% in five years. A plan that relies on a fixed crypto yield is risky.
| Risk | What it means |
|---|---|
| Slashing | Validators can lose some staked crypto for serious rule breaks |
| Lock-up periods | Some tokens have an unbonding period when assets cannot be sold |
| Liquid staking | Adds smart-contract, price gap, governance and liquidity risk |
| Taxes | Rewards may be taxed when received and again when sold |
Slashing is used on some networks to punish validators. Ethereum notes that validators face penalties for dishonest behavior, and missed duties can also reduce rewards. Delegators may be exposed too, depending on the blockchain. Using established validators and spreading stake across several operators can reduce some risks, but not all of them.
Lock-ups matter in a crash. A token can fall 20% to 40% within days. If unstaking takes weeks, the holder may not be able to sell during the drop.
Liquid staking tokens such as stETH, rETH, JitoSOL and mSOL let investors keep a tradable position. Using them in lending or liquidity pools can add yield, but it also adds ways to lose money.
Taxes also cut spendable income. In many places staking rewards are taxable when received, and selling later can be a second taxable event. Rules differ by country, so large portfolios may need professional advice.
Each of these risks is separate from price risk. A person can face a slashing penalty or a lock-up delay even in a rising market, which is why they need their own planning.
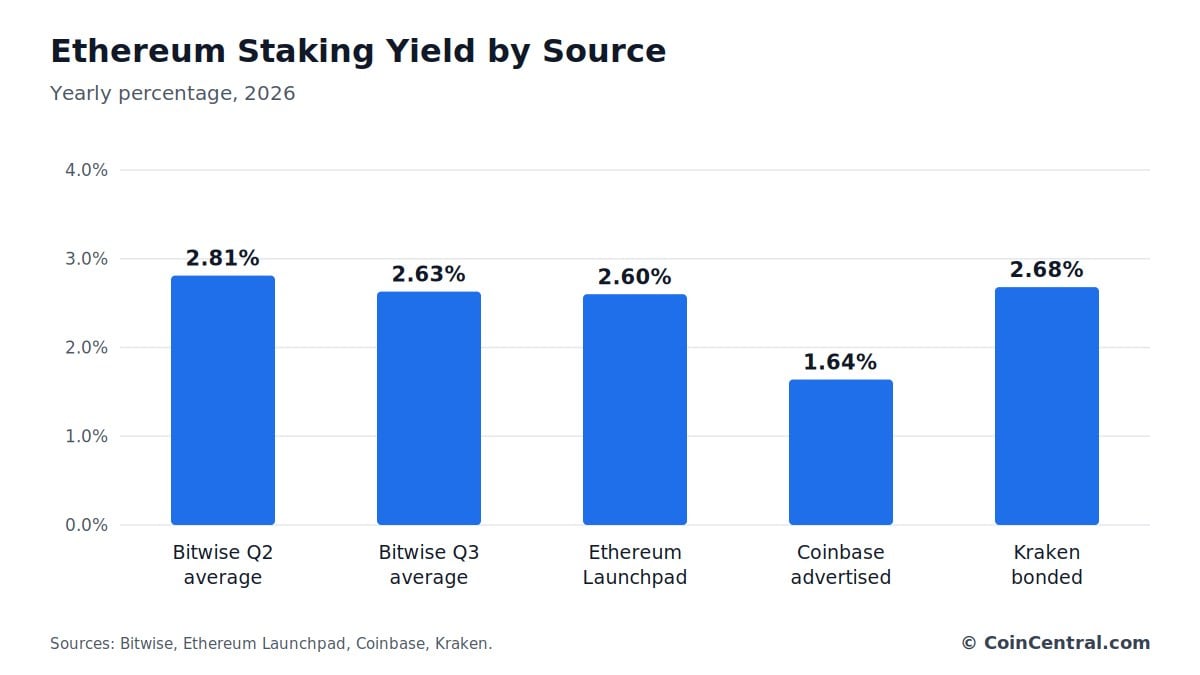
What Can $1 Million in Staking Produce?
A $1 million portfolio shows how much the yield matters. The table lists yearly income at five yields, before any costs.
| Staking yield | Yearly income on $1 million |
|---|---|
| 2.5% | $25,000 |
| 5% | $50,000 |
| 7% | $70,000 |
| 10% | $100,000 |
| 15% | $150,000 |
These figures come before fees, tax, token inflation, price moves, slashing, downtime and currency conversion costs. A headline of $100,000 in passive income may show only half the picture. If the token falls from $1 million to $600,000 in the same year, that reward does not make the investment profitable.
Living from staking means spending the rewards instead of compounding them. If a token’s supply is growing, spending every reward can lower the investor’s share of the network over time. A sustainable plan may reinvest part of the reward and spend only the rest.
Someone who needs $4,000 a month, or $48,000 a year, would need a yield near 4.8% on $1 million just to cover costs before tax. At 2.5%, the same portfolio falls well short.
Spreading stake across several networks lowers the risk that one blockchain fails or one rate is cut. It does not remove crypto market risk. Ethereum, Solana and Avalanche can all fall together in a bear market.
A cash reserve helps with a different risk, which is being forced to sell crypto near a low. Holding a year or more of expenses in cash lets staking be one part of an income plan instead of the only part.
Taken together, the numbers show why income needs differ by person. A retiree with low costs and a large portfolio faces a very different picture from someone with a small portfolio and high spending.
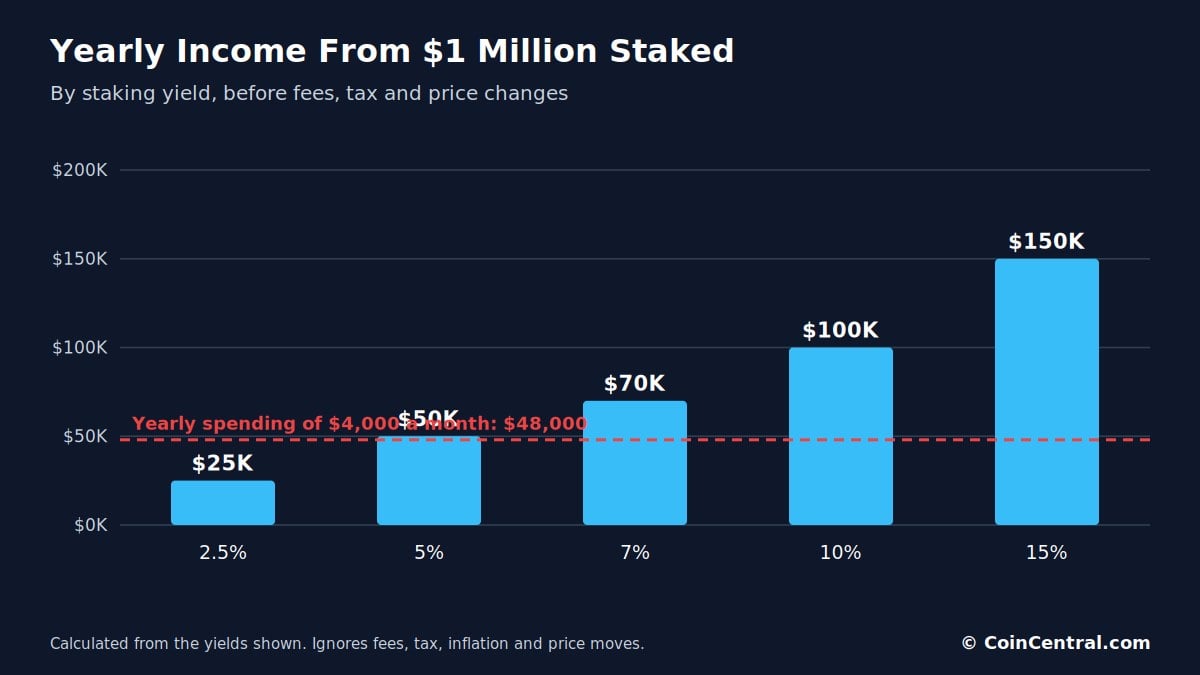
Could You Retire on Staking Rewards? The Bottom Line
Technically, yes. A person with several million dollars in established proof-of-stake coins could earn large yearly rewards. A $2 million portfolio paying 3% yields $60,000 a year, and one paying 5% yields $100,000.
Calling that a normal retirement income would be misleading, though. In a severe crypto bear market, the $2 million could fall to $1 million or less. Crypto has historically seen much larger drawdowns than diversified stock and bond portfolios.
Someone who relies on that capital for decades faces high sequence-of-returns risk. A bad market early in retirement can do lasting damage.
For $50,000 a year, a simple calculation at 3% to 5% needs $1 million to $1.67 million. Taxes, falling rates, fees, inflation, reinvestment, bear markets and cash reserves could push the prudent figure higher.
Choosing tokens that pay 15% to 20% lowers the capital needed on paper but raises asset and inflation risk. If one blockchain pays 2.5% and another pays 20%, investors should ask why the gap exists.
Staking Rewards estimates that Ethereum’s 2.6% nominal yield is about 1.7% after dilution, and that Solana’s 4.9% falls to about 1.3%. None of these figures account for price swings. A 5% yield cannot protect against a 40% fall in the token.
Staking is best seen as a way to put crypto an investor already wants to own to work, not as a replacement for a salary or pension. Someone with a large, diversified portfolio, low expenses and cash reserves could use staking as a useful income source.
The key question is not how high the APY is. It is how much of that yield is sustainable after inflation, fees, taxes and price risk, and whether the investor can still pay bills if the token falls 50%.
No single figure settles the question. The answer depends on the size of the portfolio, the tokens chosen, the tax rules and how much loss the investor can accept.
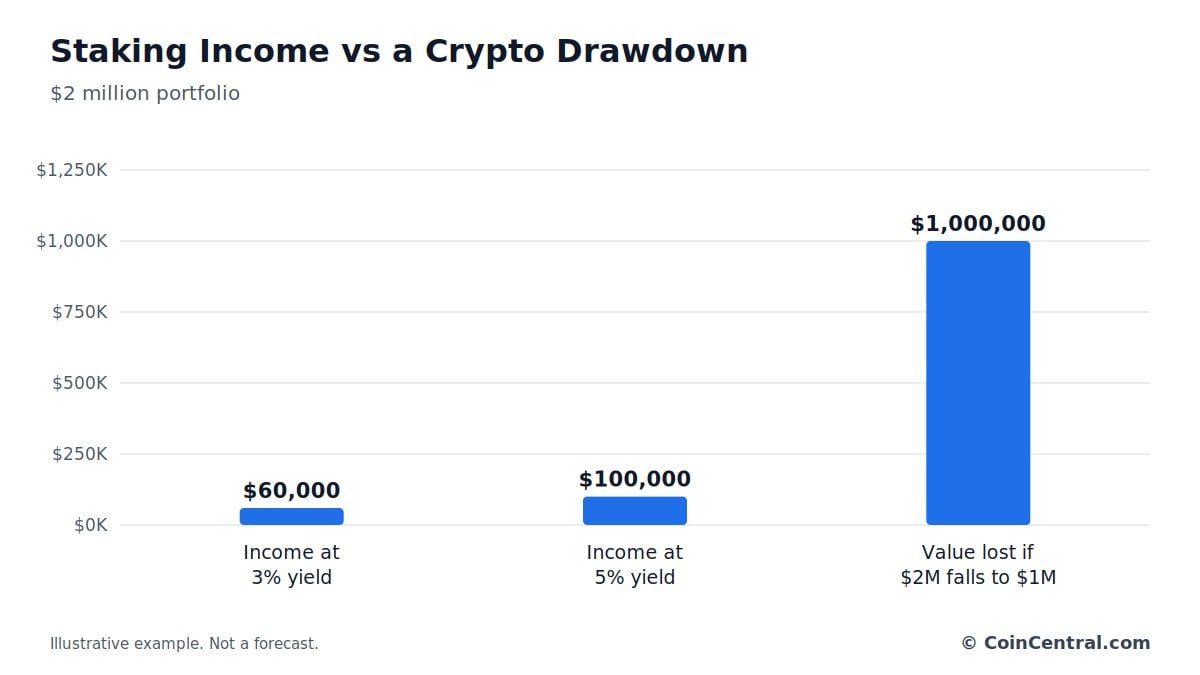
Sources
- Staking Rewards: Proof-of-Stake Assets
- Staking Rewards: All Staking Assets
- Staking Rewards: Cosmos
- Ethereum.org: Ethereum Staking
- Ethereum Launchpad: Staking Statistics
- Solana: Staking and Inflation FAQ
- Coinbase: Staking Rewards
- Kraken: Staking
- Bitwise / The Block: Q3 2026 Staking Report
The post Crypto Staking Statistics 2026: Can You Live Off Staking Rewards? appeared first on Blockonomi.
Crypto has produced large gains for some investors. It has also produced large losses for many others.
Price swings are only part of the story. Research points to timing, risk size, borrowing, scams and weak exit plans as the main causes of losses.
This article looks at seven common mistakes and the statistics behind each one. It draws on research from the Bank for International Settlements (BIS), CoinGecko, Chainalysis, the UK Financial Conduct Authority (FCA) and the OECD.
None of this means everyone loses money in crypto. Results depend on when people buy, what they buy, how much risk they take and how they react when prices fall.
Crypto Loss Statistics at a Glance
Several studies give a picture of how often things go wrong. The BIS estimated that 73% to 81% of retail crypto investors lost money on their first Bitcoin investment during the period it studied.
CoinGecko found that 53.2% of tokens tracked on GeckoTerminal between 2021 and 2025 stopped trading. Chainalysis estimated that scams and fraud took in at least $14 billion in 2025.
| Statistic | Figure | Source |
|---|---|---|
| Retail users who lost money on first Bitcoin investment | 73% to 81% | BIS |
| Tokens that stopped trading, 2021 to 2025 | 53.2% | CoinGecko |
| Token failures in 2025 | 11.56 million | CoinGecko |
| Scam and fraud inflows in 2025 | At least $14 billion, possibly above $17 billion | Chainalysis |
| Leveraged positions liquidated on October 10, 2025 | About $19 billion in 24 hours | CoinGecko |
| UK crypto users paying with a credit card or overdraft, 2024 | 14% | FCA |
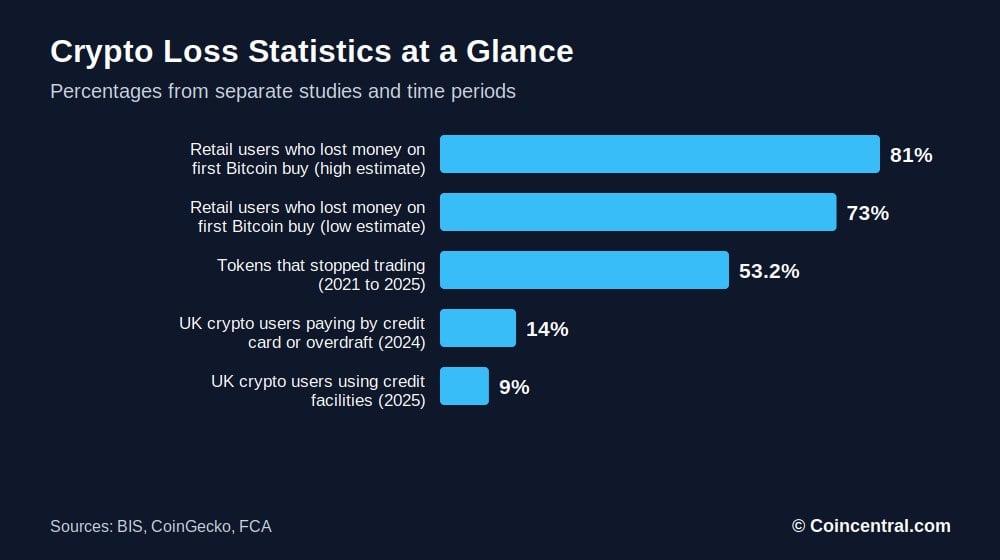
The figures come from different studies, countries and time periods. They are best read as separate warning signs, not as one combined total.
1. Buying After Prices Have Already Surged
One of the most common mistakes is buying because prices are rising fast. This is often called fear of missing out, or FOMO.
An investor sees Bitcoin rise 50%, or a memecoin climb 500%, and decides to buy before it goes higher. By then, much of the gain may already be gone.
What the BIS found
The BIS studied crypto exchange app usage across 95 countries. It found that rising Bitcoin prices were followed by more new users entering the market.
About 40% of these new users were men under 35, a group the researchers described as relatively risk-seeking. The BIS estimated that 73% to 81% of retail investors probably lost money on their first Bitcoin investment.
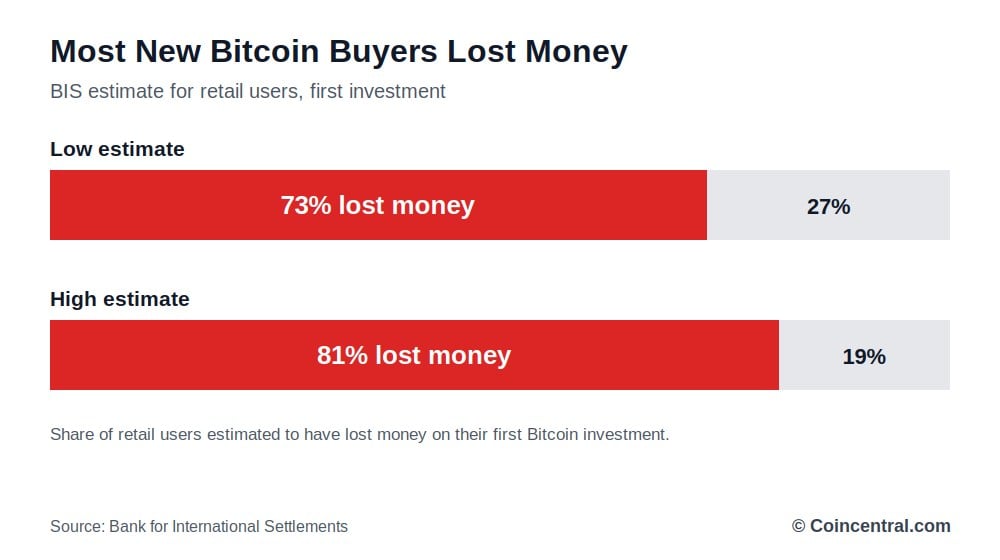
The study also looked at major shocks, including the Terra/Luna collapse and the FTX failure. Larger and more experienced investors tended to sell, while smaller retail investors kept buying.
A common pattern
- Prices rise.
- Media coverage grows.
- New investors enter.
- Early holders take profits.
- Momentum reverses.
- Late buyers take the largest losses.
Buying something only because it went up is not an investment plan. It is momentum chasing.
How to avoid it
Decide what you think an asset is worth, why you want it and how much you will invest before a rally starts. Dollar-cost averaging, which means buying in smaller amounts over time, can reduce the risk of putting everything in at a peak.
Missing a rally is not the same as losing money. Another chance will come.
2. Taking Too Much Risk in Small Altcoins and Memecoins
Bitcoin and a newly launched memecoin are both cryptocurrencies, but their risks are very different. Bitcoin has traded since 2009, has deep global liquidity and a market value in the trillions of dollars.
A small token created last week may have no product, anonymous developers, almost no liquidity and no users. Even so, some investors put more money into these assets because the possible gains look larger.
How many tokens fail
CoinGecko studied tokens that traded on GeckoTerminal from July 2021 to the end of 2025. It found that 53.2% had stopped trading, which means more than 13.4 million tokens failed.
The numbers jumped in 2025, when about 11.56 million tokens failed. CoinGecko linked much of the rise to how easy it has become to launch tokens and memecoins.
| Measure | Figure |
|---|---|
| Tokens tracked in 2021 | About 428,000 |
| Tokens tracked by 2025 | Nearly 20.2 million |
| Tokens that stopped trading, 2021 to 2025 | More than 13.4 million (53.2%) |
| Token failures in 2025 alone | About 11.56 million |
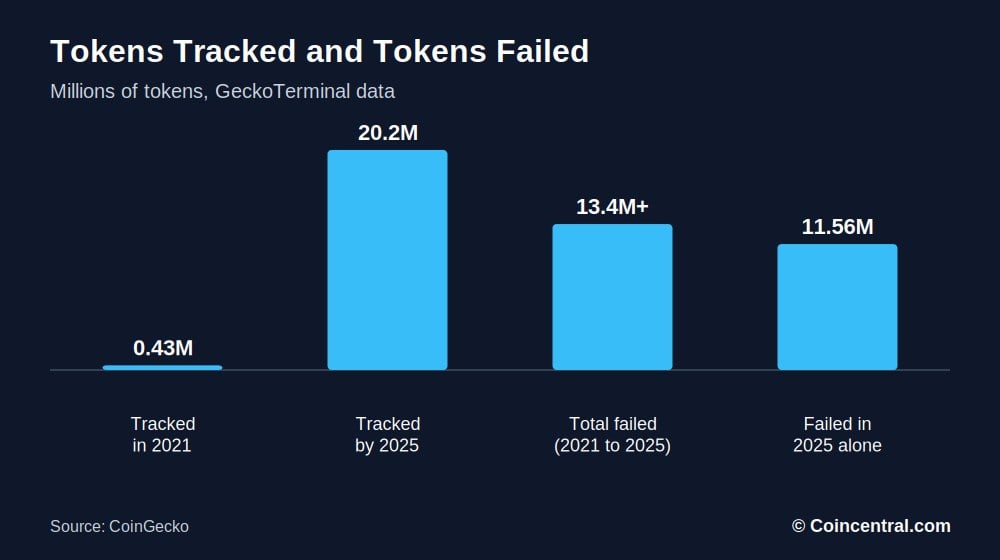
When millions of tokens exist, only a tiny share can build lasting liquidity, users and developers. People see the few big winners but rarely the many that disappear. This is called survivorship bias.
Market cap can mislead
Say a token has 100 million coins and the last trade was at $1. Its market capitalization looks like $100 million.
That does not mean holders could sell $100 million worth at $1. Real liquidity may be a few hundred thousand dollars, and a few large sellers can crash the price.
How to avoid it
Treat small altcoins as a separate risk category. Before buying, check these items:
- Token supply and unlock schedules
- Holder concentration
- Trading liquidity
- Developer activity
- Revenue or real usage
- Market cap and fully diluted valuation
If losing 100% of the money would hurt your finances, the position is probably too large.
3. Using Leverage
Leverage magnifies gains, and it magnifies losses by the same amount. An investor with $10,000 who opens a 10x Bitcoin position controls about $100,000 worth of BTC.
If Bitcoin rises 5%, the gain is about $5,000 before fees, a 50% return on the original money. If Bitcoin falls 10%, the entire $10,000 can be lost.
| Bitcoin price move | Result on $10,000 at 10x | Return on your money |
|---|---|---|
| -10% | -$10,000 | -100% |
| -5% | -$5,000 | -50% |
| -2% | -$2,000 | -20% |
| +2% | +$2,000 | +20% |
| +5% | +$5,000 | +50% |
| +10% | +$10,000 | +100% |
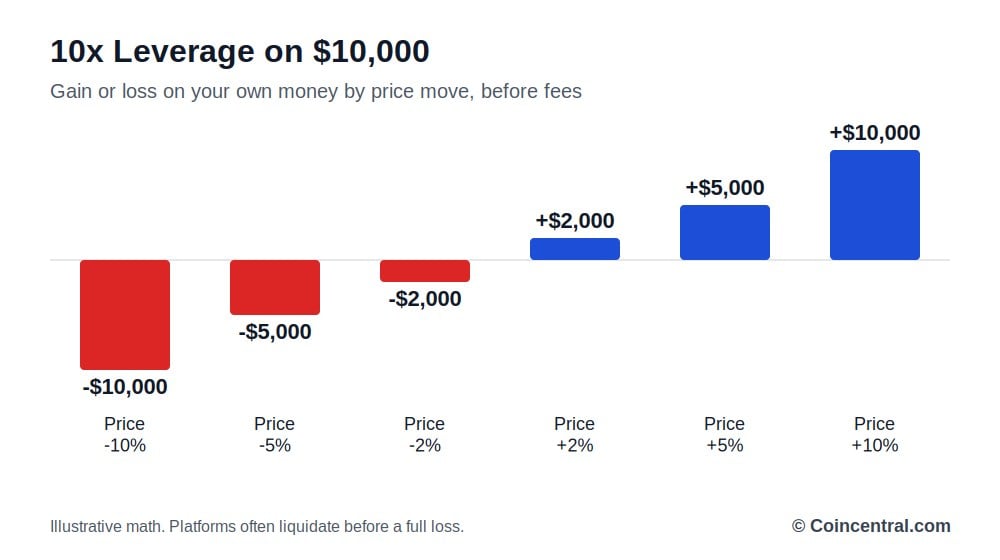
The October 2025 liquidations
CoinGecko’s 2026 analysis pointed to October 10, 2025. About $19 billion of leveraged crypto positions were liquidated in 24 hours, described as the largest single-day deleveraging event in crypto history.
This is why an investor can be right about the long-term direction and still lose everything. Imagine someone opens a heavily leveraged long position at $80,000, expecting $120,000.
Bitcoin drops to $70,000 and later reaches $120,000. An investor without leverage waits it out. The leveraged investor may be liquidated near $74,000 and miss the recovery.
Other costs of leverage
- Funding rates
- Borrowing costs
- Trading fees
- Liquidation penalties
The longer a leveraged trade stays open, the more these costs add up.
How to avoid it
For most long-term retail investors, skipping leverage removes the chance of forced liquidation. Owning an asset without borrowed money means a temporary drop cannot close the position.
4. Investing Money You Cannot Afford to Lose
Crypto losses hurt more when the money was needed for something else. Examples include emergency savings, rent, mortgage payments, credit cards, personal loans and tuition savings.
The FCA warns that cryptoassets are highly speculative and that people should be ready to lose all of their money. Even so, some investors borrow to take part.
UK borrowing data
FCA research found that the share of UK crypto users paying with a credit card or overdraft rose from 6% in 2022 to 14% in 2024. FCA research in 2025 found almost 9% of crypto users were using credit cards or existing credit to buy cryptoassets.
| Year | UK crypto users using credit card or overdraft | Note |
|---|---|---|
| 2022 | 6% | FCA consumer research |
| 2024 | 14% | FCA consumer research |
| 2025 | Almost 9% | Separate FCA research |
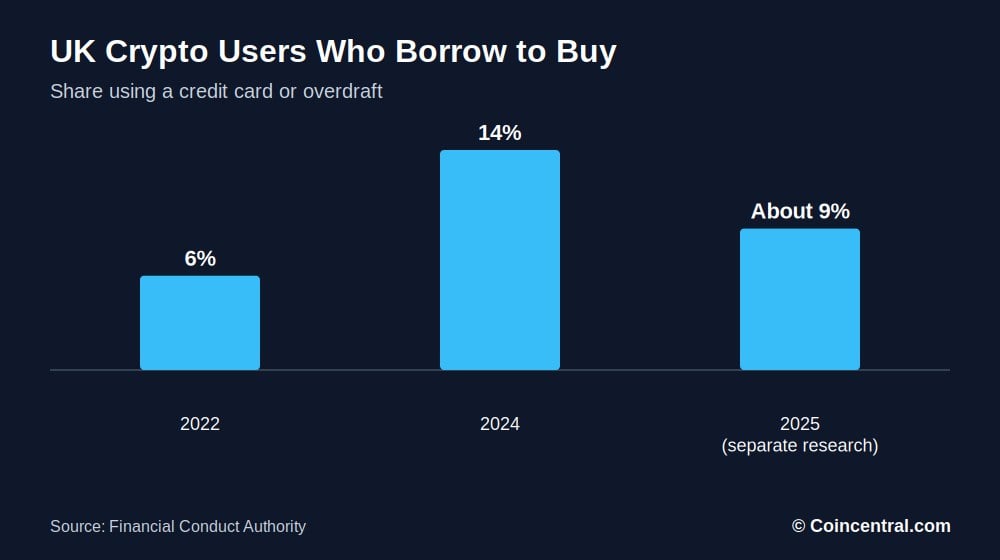
Borrowing creates two risks. The investment can fall, and the debt stays. If someone borrows $10,000 and the crypto drops 70%, they hold $3,000 of crypto and still owe $10,000 plus interest.
Position size changes behavior
A person with 5% of their portfolio in crypto may handle a 30% drop calmly. Someone with all of their savings invested is more likely to panic.
- Panic selling
- Constant trading
- Trying to win back losses
- Poor sleep
- Dropping a long-term plan
How to avoid it
Size crypto so that even a severe drop does not threaten essential goals. The right amount differs for each person, but one rule holds: do not invest money whose loss would force you to change your life.
5. Trading Too Much and Trying to Time Every Move
Crypto markets run 24 hours a day, seven days a week. There is always something moving, which makes overtrading tempting.
An investor may start with a sensible long-term position and slowly turn into a swing trader. They chase breakouts, rotate between altcoins and sell on rumors.
Each trade adds fees, bid-ask spreads, slippage and possible taxes. It also adds another chance to be wrong.
Behavioral biases
The OECD names FOMO, herding, anchoring and overconfidence as biases that raise risks for crypto investors. Overconfidence can be costly after a few winning trades.
In a bull market, almost everything rises. A trader who buys five altcoins and sees all five gain 50% may believe it was skill, when the whole market simply went up.
Timing means being right twice
Selling well means knowing when to get out. It also means knowing when to get back in.
Suppose an investor sells Bitcoin before a 15% drop, then waits too long to return while Bitcoin rallies 40%. In the example below, holding would have ended with more money.
| Approach | Start | After 15% drop | After 40% rally | End value |
|---|---|---|---|---|
| Hold through both moves | $10,000 | $8,500 | $11,900 | $11,900 |
| Sell first, buy back after the rally | $10,000 in cash | $10,000 in cash | $10,000 buys in at the higher price | $10,000 |
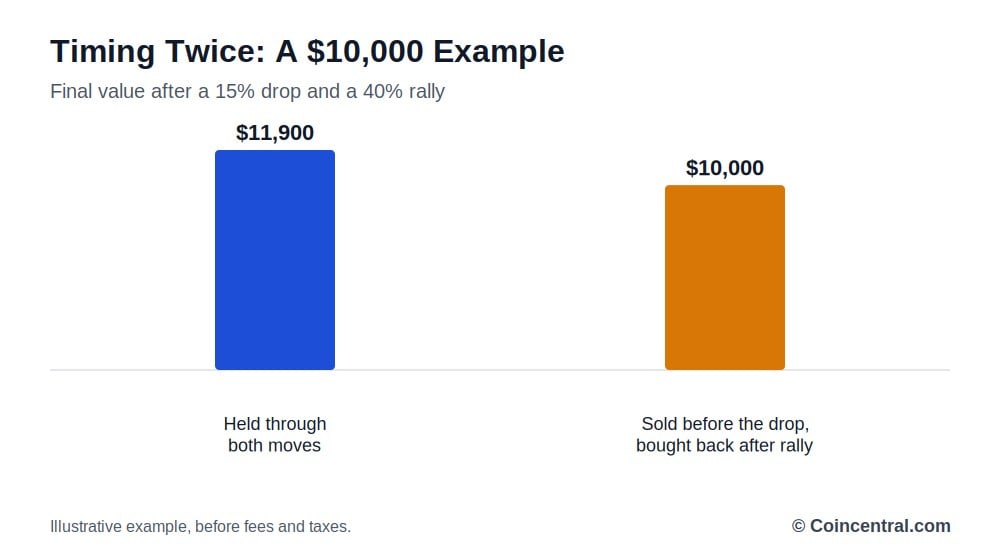
How to avoid it
Separate investing from trading. Keep a long-term core holding, and use only a small, separate amount for speculative trades.
- Set a maximum position size
- Set a maximum share of the portfolio
- Avoid leverage
- Rebalance on a schedule
- Do not buy only because the price is rising
Fewer decisions can lead to better results.
6. Ignoring Scams, Security and Counterparty Risk
A crypto investment can perform well and the investor can still lose everything. Wallet access can be lost, an exchange can fail, a transaction can be malicious or money can be sent to a scammer.
Scam statistics
Chainalysis estimates that crypto scams and fraud received at least $14 billion in 2025. It projects the final total could pass $17 billion as more illicit addresses are identified.
The average scam payment rose from about $782 in 2024 to $2,764 in 2025, an increase of 253%. Impersonation scams rose about 1,400% year over year.
| Chainalysis measure | Figure |
|---|---|
| Scam and fraud inflows in 2025 | At least $14 billion |
| Projected 2025 total | Above $17 billion |
| Average scam payment, 2024 | $782 |
| Average scam payment, 2025 | $2,764 (up 253%) |
| Impersonation scam growth | About 1,400% year over year |
| AI-enabled scam profit vs. traditional scams | About 4.5 times higher |
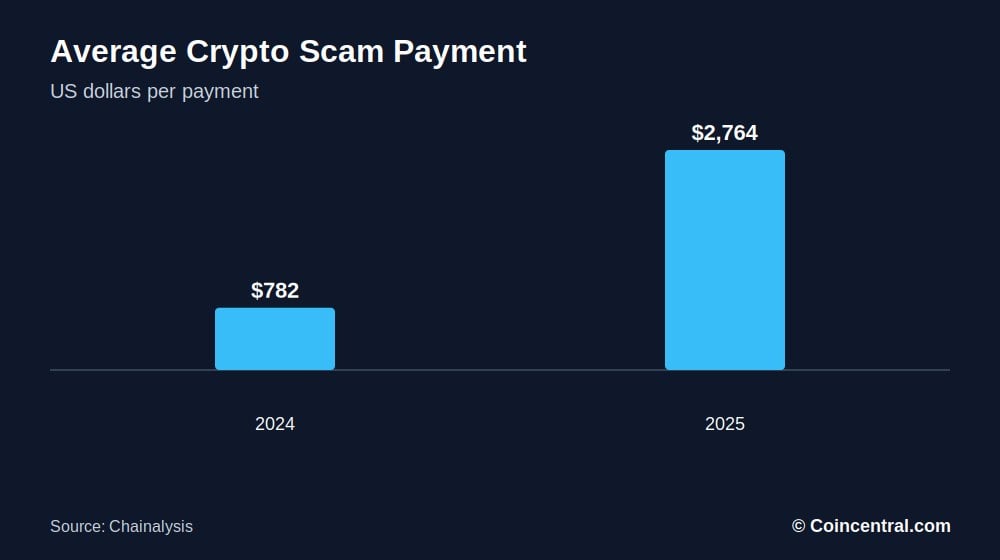
AI is making the problem worse. Chainalysis found AI-enabled scams were about 4.5 times more profitable than traditional scams in its 2025 data.
Common tactics include these:
- Deepfake videos
- Fake celebrity endorsements
- Fake customer-support agents
- Phishing websites
- Investment groups and romance scams
- Fake trading platforms
- Malicious wallet approvals
Security losses go beyond scams
OECD analysis of crypto cybersecurity incidents from 2016 through 2026 found that compromised private keys and wallet phishing caused more than $9 billion in losses.
Exchange risk
Investors learned about platform risk when FTX, Celsius, BlockFi, Voyager and Genesis failed. The FCA notes that Celsius owed users around $4.7 billion when it entered bankruptcy.
A person can pick the right coin and still lose access to it because the company holding it collapses.
How to avoid it
- Use strong, unique passwords
- Turn on two-factor authentication
- Never share a seed phrase
- Check website addresses carefully
- Be wary of unsolicited messages
- Avoid unknown wallet connections
- Consider self-custody for long-term holdings when it suits you
No real support agent needs your recovery phrase.
7. Having No Exit Strategy
Many investors know why they are buying. Fewer know when they will sell.
Imagine a token bought at $1 that rises to $3. The investor waits for $5, then $10, then reads predictions of $20.
The market turns and the token falls to $6, then $3, then $1. A large profit disappears because there was never a plan to collect it.
Bull markets also change expectations. A 100% gain can feel disappointing after seeing other tokens rise 500%.
Unrealized gains are not permanent
Until an asset is sold, its value can change. Bitcoin has had several declines of more than 70%, and smaller coins have often fallen 90% to 99%.
The math works against investors after deep losses. A 90% drop needs a 900% gain just to break even.
| Loss from peak | Gain needed to recover |
|---|---|
| 25% | 33% |
| 50% | 100% |
| 70% | 233% |
| 80% | 400% |
| 90% | 900% |
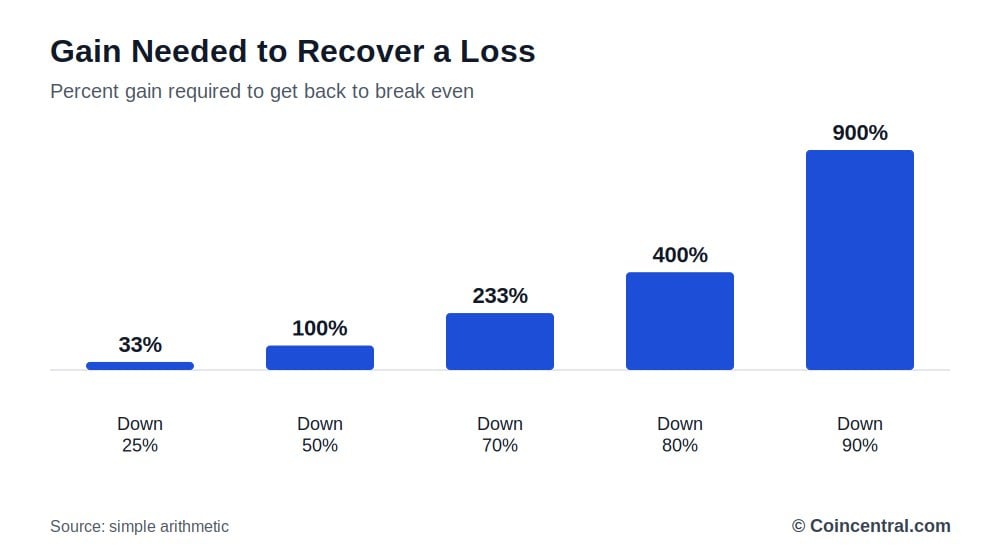
If a token falls from $100 to $10 and then doubles to $20, the investor is still down 80%.
Taking profit does not mean selling everything
An exit plan does not have to be all or nothing. The goal is not to call the exact top, which almost nobody does well over time.
- Recover the original investment after a large gain
- Sell portions at set targets
- Rebalance when crypto grows too large in the portfolio
- Hold a long-term core while taking profits on speculative assets
The aim is to stop a winning trade from becoming a loss because expectations kept rising.
Why Investors Lose Even When Long-Term Prices Rise
A key finding from the BIS is that retail investors can lose money even when an asset does very well over time. Bitcoin’s long-term record is strong, yet the BIS estimated that roughly three-quarters of retail users in its sample lost money.
The reason is that investor returns and asset returns are not the same. Bitcoin might rise 1,000% over several years, but a person who buys after a 700% rally and sells in the next crash can still lose heavily.
Behavior shapes realized returns. What you buy matters, but so do when you buy, how much you buy, whether you use leverage and when you sell.
The dollar amounts involved
| Event or measure | Amount | Source |
|---|---|---|
| Leveraged positions liquidated, October 10, 2025 | About $19 billion in 24 hours | CoinGecko |
| Projected scam and fraud total, 2025 | Above $17 billion | Chainalysis |
| Scam and fraud inflows identified, 2025 | At least $14 billion | Chainalysis |
| Private key and wallet phishing losses, 2016 to 2026 | More than $9 billion | OECD |
| Owed to users when Celsius filed for bankruptcy | About $4.7 billion | FCA |
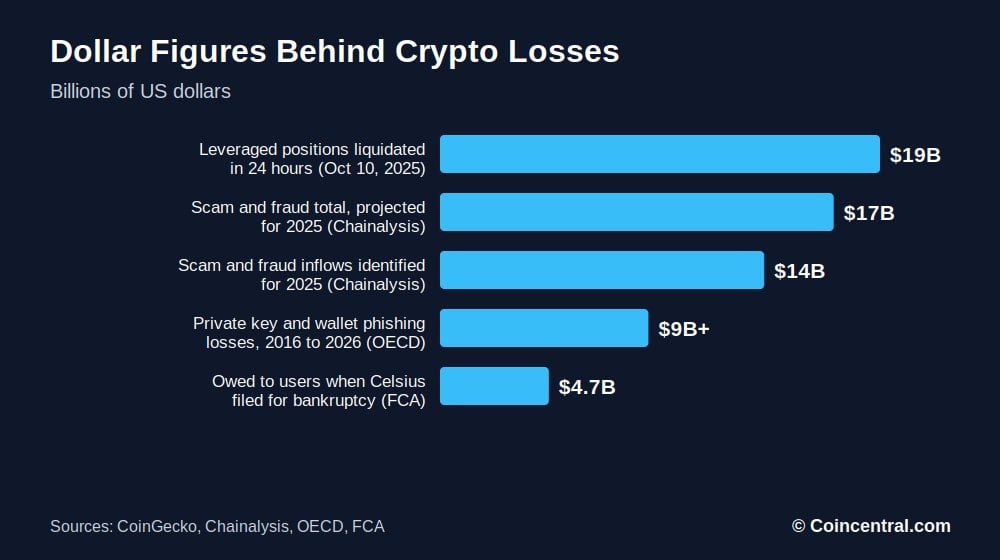
A Simple Framework for Crypto Investing
Avoiding these seven mistakes does not guarantee profits, and crypto remains risky. A set of rules can still cut avoidable losses.
- Understand the asset before investing.
- Keep position sizes manageable.
- Avoid borrowing and excessive leverage.
- Spread money across assets instead of betting on one token.
- Use reputable platforms and strong security.
- Set rules for buying and selling.
- Assume any speculative token could become worthless.
The FCA says crypto investors should be able to lose their entire investment. That does not mean every coin will go to zero, but a portfolio should allow for the possibility.
The Bottom Line
People rarely lose money in crypto because of one factor. The same mistakes appear again and again: buying after surges, taking too much risk in speculative tokens, using leverage, investing money they need, trading too often, underestimating scams and having no exit plan.
The BIS estimated that 73% to 81% of retail users lost money on their first Bitcoin investment. CoinGecko found that 53.2% of tracked tokens stopped trading, and Chainalysis estimated scams could reach about $17 billion in 2025.
These numbers do not mean crypto cannot be profitable. They show that avoiding large losses matters, because an investor who survives a downturn stays invested for the next upswing.
Sources
- Bank for International Settlements: Crypto Trading and Bitcoin Prices: Evidence From a New Database of Retail Adoption. Research estimating that roughly 73% to 81% of retail users lost money on their first Bitcoin investment.
- Bank for International Settlements: Crypto Shocks and Retail Losses. Analysis of investor behavior around the Terra/Luna and FTX collapses.
- CoinGecko: Dead Coins: How Many Cryptocurrencies Have Failed?. 2026 study of token failures in GeckoTerminal data.
- Chainalysis: 2026 Crypto Crime Report: Scams. Estimates of 2025 scam and fraud inflows.
- Financial Conduct Authority: Investing in Crypto. Risk guidance for retail crypto investors.
- FCA: Cryptoassets Consumer Research 2024. Research on crypto ownership and funding methods.
- FCA: Cryptoassets Consumer Research 2025. Updated data on UK crypto investors.
- OECD: Improving the Digital Financial Literacy of Crypto-Asset Users. Research on FOMO, herding and overconfidence.
- OECD: Asia Capital Markets Report 2026: Developments in Crypto-Asset Markets. Analysis of crypto cybersecurity losses.
The post Why Do People Lose Money in Crypto? 7 Common Mistakes appeared first on Blockonomi.
Crypto has created a large group of people with seven-figure wealth. The Henley & Partners Crypto Wealth Report 2026 counts 135,694 crypto millionaires worldwide, each holding USD 1 million or more in digital assets.
Of those, 92,272 are bitcoin millionaires. The report uses market prices from 31 August 2026.
This article reviews the latest crypto millionaire statistics. It covers wealth tiers, market size, bitcoin’s price fall, ownership, spending habits and the countries that attract crypto investors. The figures come from Henley & Partners, New World Wealth and the news outlets that covered their reports.
One point matters before the numbers. The 2026 report uses a new method, so its wealth figures cannot be compared with the 2025 report. The 2025 figures appear in their own section, and no year-on-year change is given for 2026.
How Many Crypto Millionaires Are There in 2026?
Henley & Partners released the Crypto Wealth Report 2026 on 8 September 2026. It says there are 135,694 crypto millionaires in the world. Each one holds at least USD 1 million in digital assets.
Bitcoin accounts for most of this group. The report counts 92,272 bitcoin millionaires, which is about 68% of all crypto millionaires. That percentage is calculated from the two totals in the report.
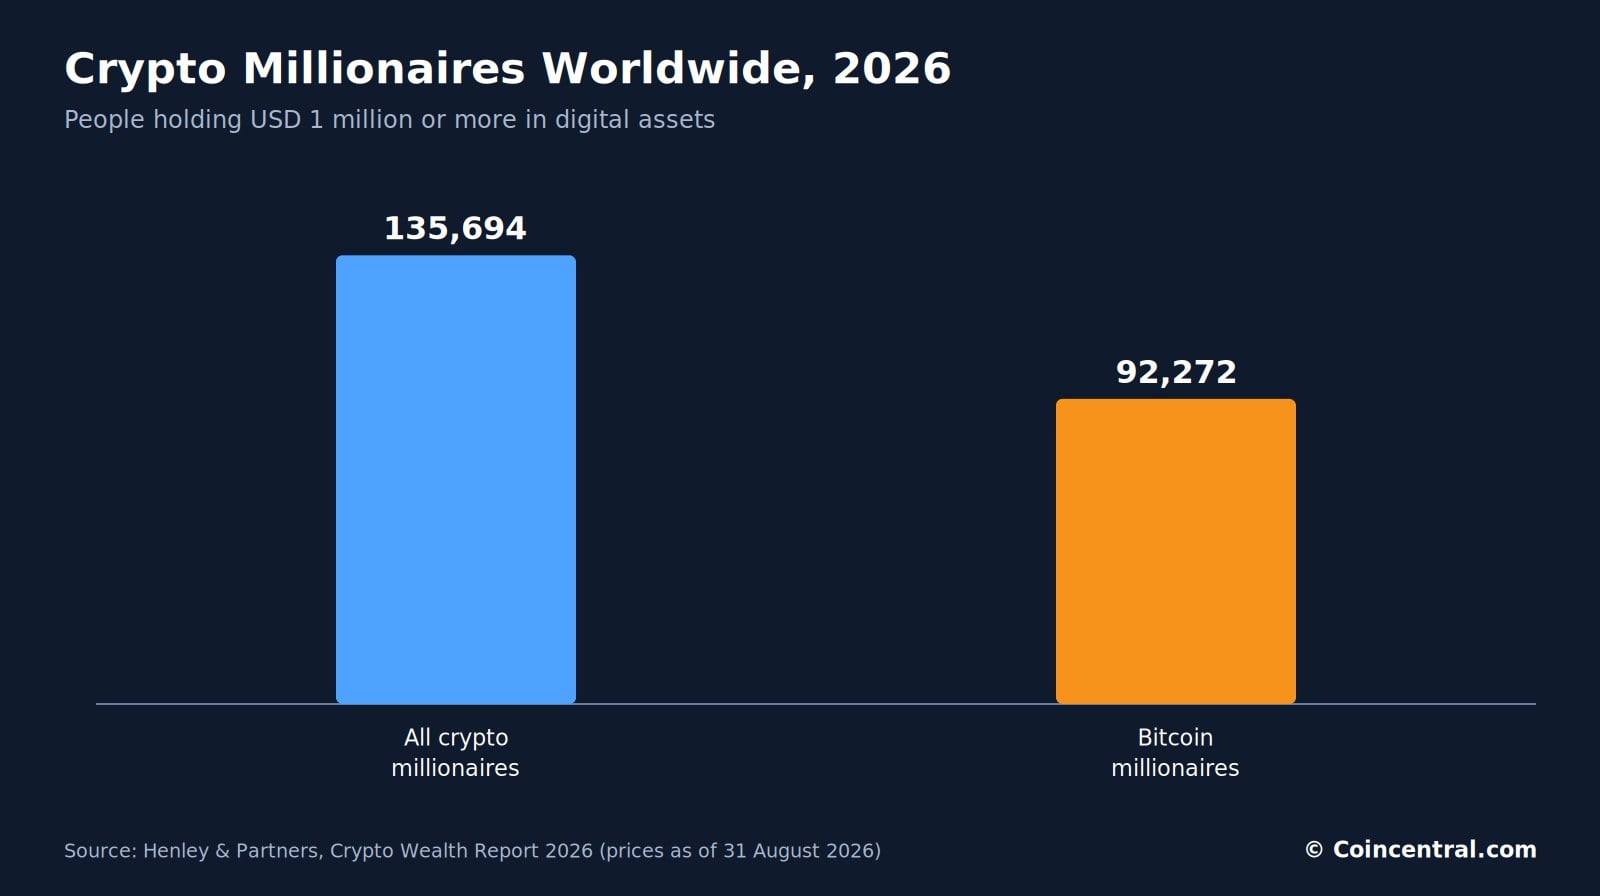
The report features data from New World Wealth, a wealth intelligence firm. Henley & Partners says the figures are calculated on a new method. For that reason, the report publishes no year-on-year change for any wealth figure.
Readers should treat the 2026 numbers as a fresh starting point. Placing them next to the 2025 totals would give a misleading picture of growth or decline.
| Measure (2026 report) | Total | Held in bitcoin |
|---|---|---|
| Crypto millionaires (USD 1 million or more) | 135,694 | 92,272 |
| Centi-millionaires (USD 100 million or more) | 290 | 151 |
| Crypto billionaires | 23 | 9 |
| Individuals holding digital assets | 742 million | 371 million |
Dominic Volek, Group Head of Private Clients at Henley & Partners, said the owners of crypto still live in a specific place. “Crypto may be borderless, but the families who own it are not,” he said. “They still live, pay tax, educate their children, and operate within national legal and regulatory systems.”
Henley & Partners says it has seen growing interest from crypto-wealth holders asking about residence and citizenship options. They are weighing where to base themselves, their families and their wider financial affairs. The firm advises private clients on how investment migration, mobility and long-term wealth planning fit together.
Guenther Dobrauz-Saldapenna, Managing Partner at Henley & Partners Switzerland, said digital assets have changed the link between wealth and geography. “A self-custodied digital asset can move with its owner almost instantly,” he said. That makes a person’s choice of residence and legal setting far more important.
Crypto Centi-Millionaires and Billionaires
Wealth thins out quickly at the top. The report counts 290 centi-millionaires, who hold USD 100 million or more in crypto. Of these, 151 hold that wealth in bitcoin alone.
At the very top are 23 crypto billionaires. Nine of them hold their wealth in bitcoin, which is about 39% of the group.
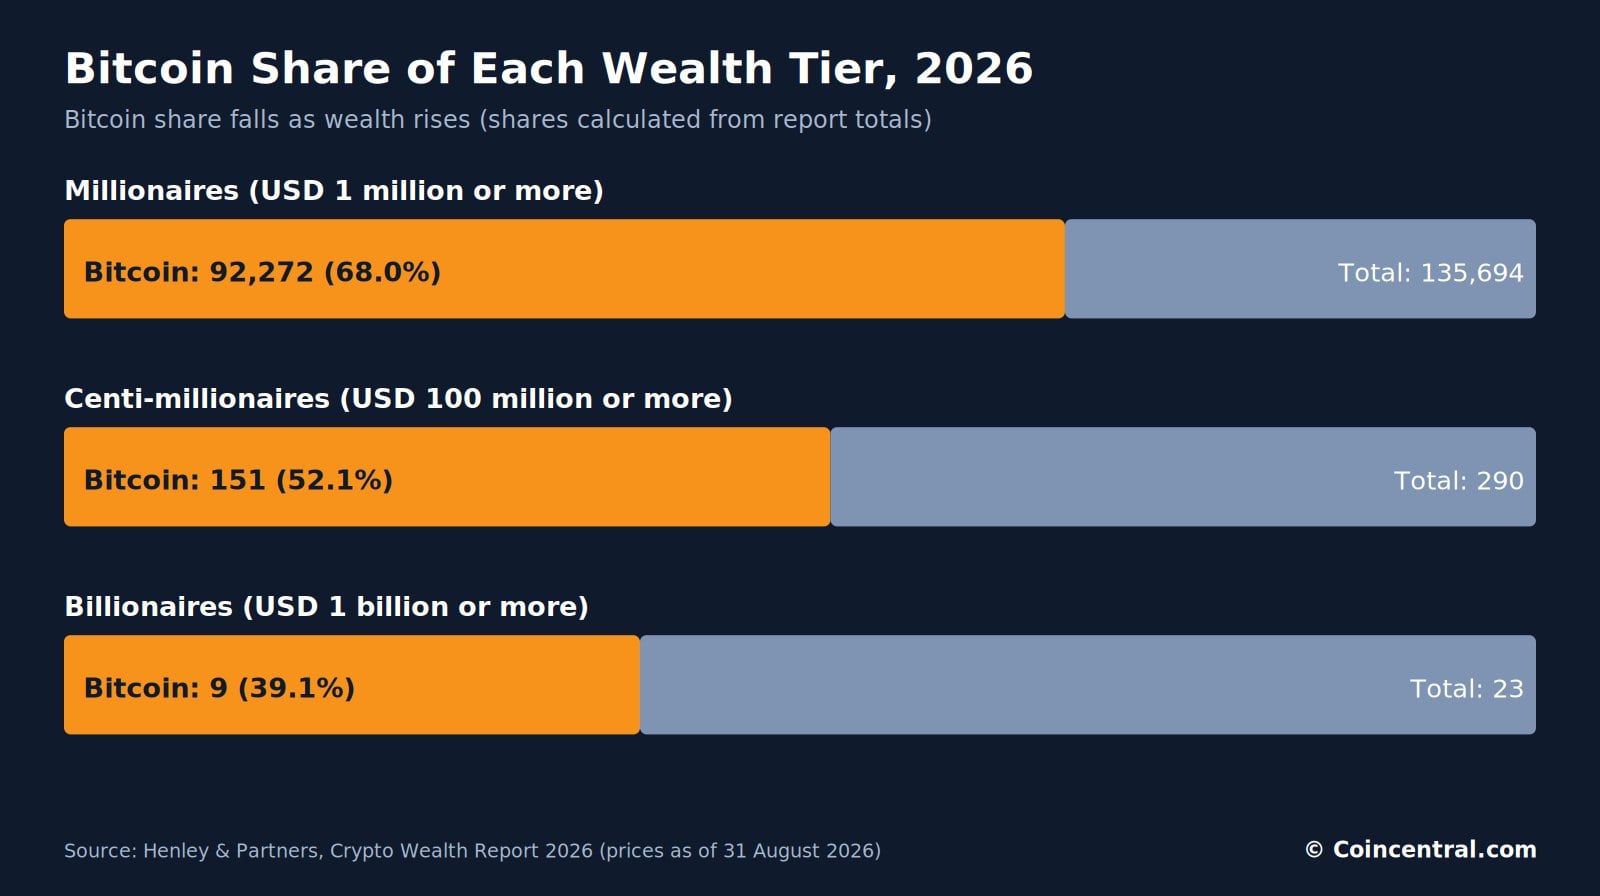
Bitcoin’s share falls as wealth rises. About 68% of crypto millionaires are bitcoin millionaires. The share is about 52% for centi-millionaires and about 39% for billionaires.
The report does not explain this pattern in the material reviewed. It does show that the biggest fortunes are less tied to bitcoin alone than smaller ones. All three shares are calculated from the report’s totals.
| Wealth tier | Total | In bitcoin | Bitcoin share |
|---|---|---|---|
| Millionaires | 135,694 | 92,272 | About 68% |
| Centi-millionaires | 290 | 151 | About 52% |
| Billionaires | 23 | 9 | About 39% |
Crypto also plays a different role from other assets for wealthy people. Andrew Amoils, Head of Research at New World Wealth, said in the 2025 report that crypto and gold have become preferred alternative assets for the wealthy. He compared them to diamonds, which were once used to move money across borders because they are easy to carry.
Global Crypto Market Size in 2026
The global crypto market is worth USD 2.6 trillion, according to the 2026 report. Bitcoin makes up USD 1.6 trillion of that total, or about 62%.
The remaining USD 1.0 trillion is spread across all other digital assets. That figure is calculated by subtracting bitcoin from the total.
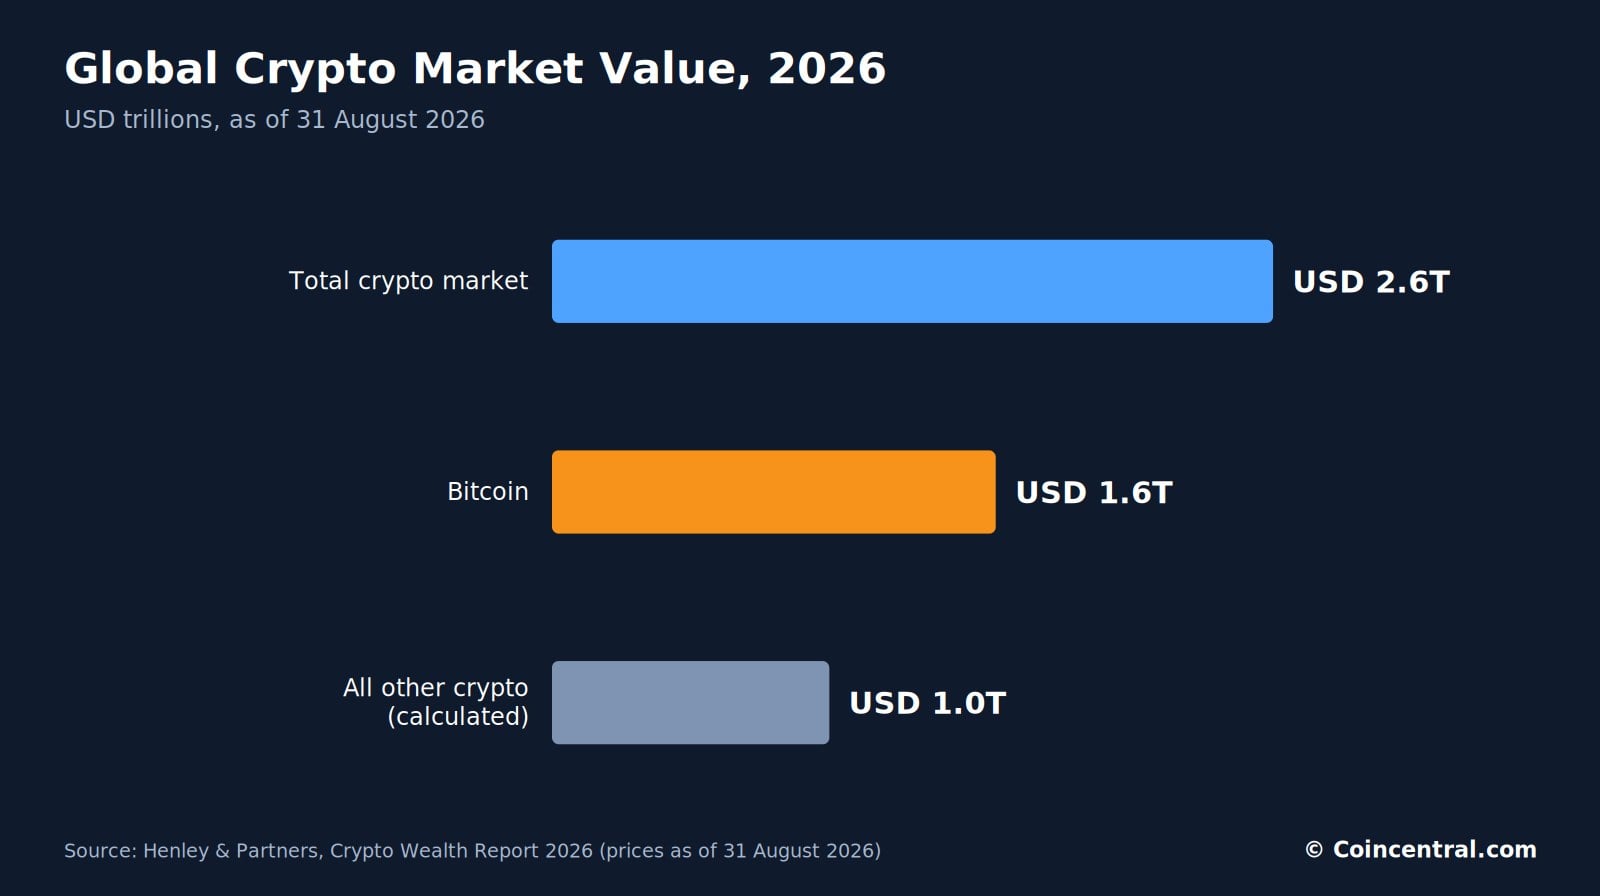
The market was valued higher in 2025. The 2025 Henley report put total market value at USD 3.3 trillion as of June 2025. CNBC reported a total market value above USD 4.3 trillion in October 2025.
These figures come from different sources, methods and dates. They should not be read as a like-for-like comparison with the 2026 total.
Bitcoin’s price peaked in October 2025. CNBC reported that bitcoin topped USD 125,000 for the first time on a Monday in early October of that year. It then settled back to around USD 122,000.
| Measure | Value | As of |
|---|---|---|
| Global crypto market (2026 report) | USD 2.6 trillion | 31 August 2026 |
| Bitcoin market value (2026 report) | USD 1.6 trillion | 31 August 2026 |
| All other crypto (calculated) | USD 1.0 trillion | 31 August 2026 |
| Crypto market value (2025 report) | USD 3.3 trillion | June 2025 |
| Crypto market value (CNBC) | More than USD 4.3 trillion | October 2025 |
Bitcoin’s Price Fall From Its Peak
Bitcoin trades about 38% below its October 2025 peak, according to Henley & Partners. It has recovered from a mid-year slump. The report calls this the mildest of bitcoin’s major winters.
Earlier winters were deeper. The declines after the 2011, 2013, 2017 and 2021 peaks each cut the price by more than 75%. The current fall is well short of those drops.
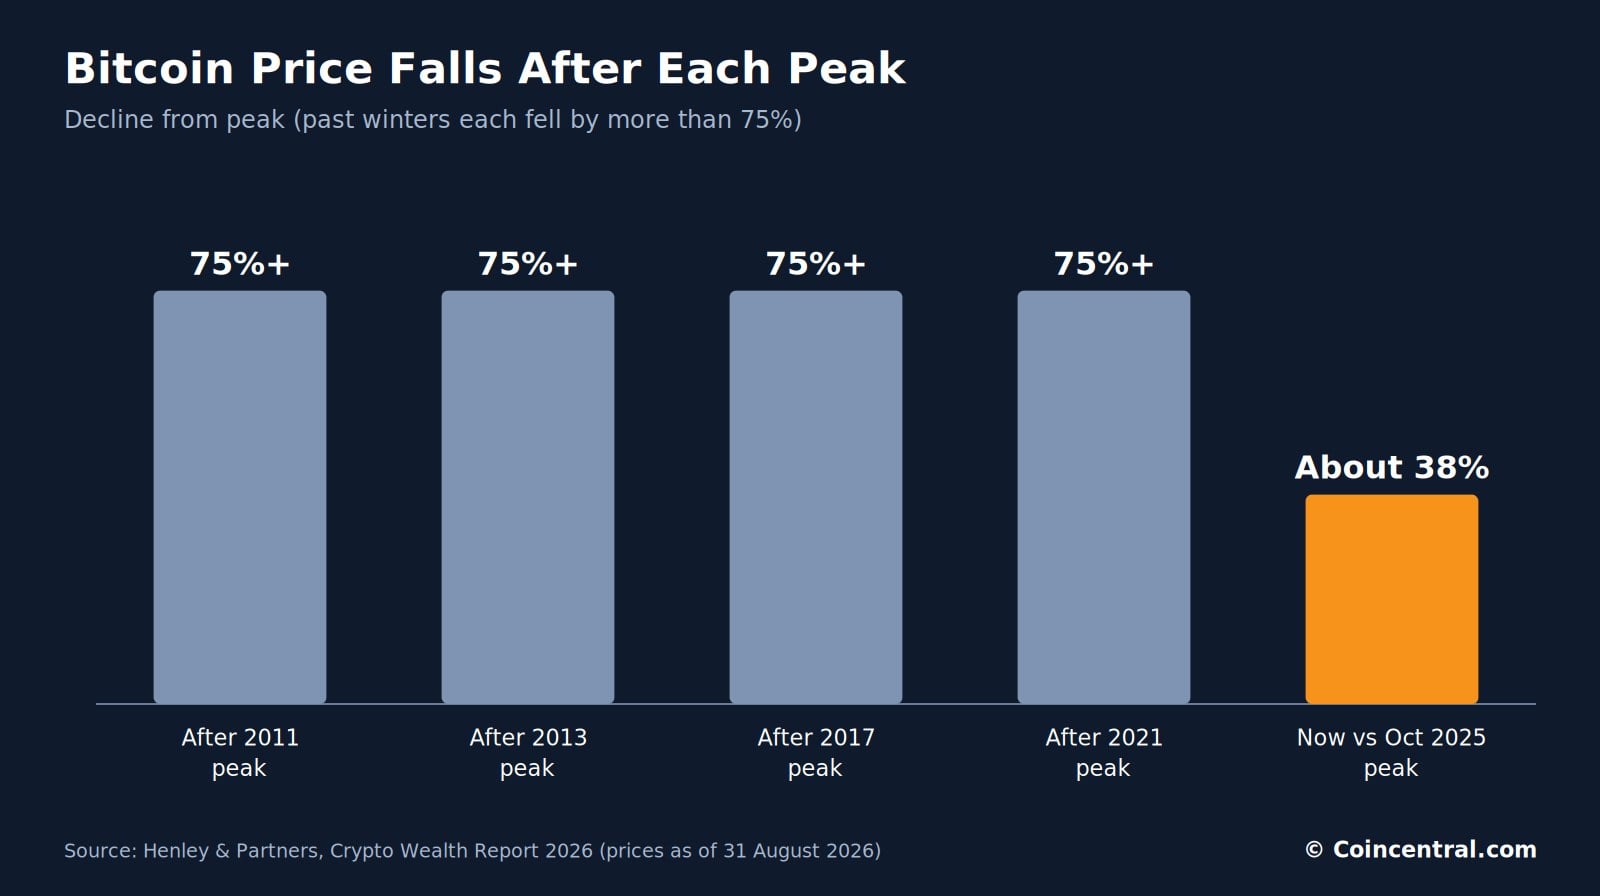
A 38% fall still matters to holders. A person who held exactly USD 1 million in bitcoin at the peak would now hold about USD 620,000. This is a simple illustration based on the 38% figure.
The 2026 millionaire counts reflect prices after this fall. Henley & Partners says the counts use a new method, so the fall cannot be matched to a change in the number of millionaires.
| Period | Price decline from peak |
|---|---|
| After the 2011 peak | More than 75% |
| After the 2013 peak | More than 75% |
| After the 2017 peak | More than 75% |
| After the 2021 peak | More than 75% |
| Current, versus October 2025 peak | About 38% |
Crypto Ownership Around the World
Some 742 million individuals now hold digital assets in some amount. Of those, 371 million hold bitcoin, which is exactly half. The report says ownership kept broadening even as the market shrank.
Millionaires are a very small part of this base. The 135,694 crypto millionaires equal less than 0.02% of all holders. This share is calculated from the report’s totals.
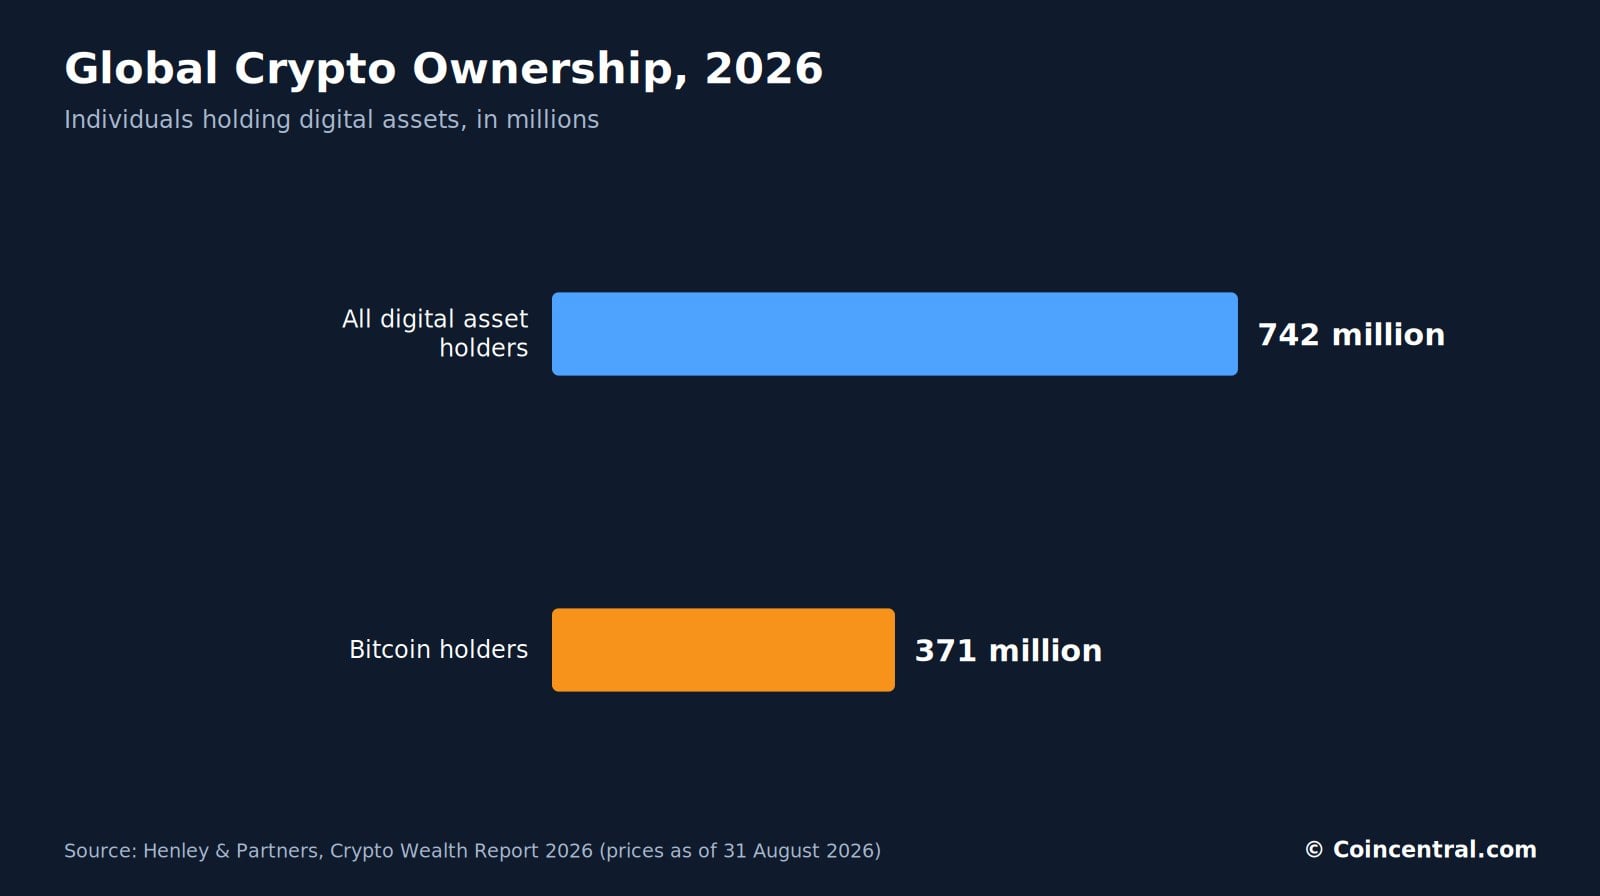
The report says digital asset ownership skews sharply by age. Henley & Partners says its crypto-wealthy clients are younger and more mobile than the private clients it advised a decade ago. The press material did not publish the age split.
Jack Bernstein, Head of the International Tax Group at Aird & Berlis, said priorities are shifting. “For many young entrepreneurs, the focus has shifted from building wealth to preserving it,” he said.
Management styles are changing too. Valeriano Lisanti of Sestertivm said that “active management in crypto markets is no longer a niche pursuit.” Jean-Marie Mognetti, CEO of CoinShares, said advisors now ask how many different ways an allocation can earn a return.
Tomas Mico, Group Data Protection Officer at Henley & Partners, said the practical freedom depends on how coins are held. “Bitcoins held directly move with their owner and follow the owner’s tax residence,” he said.
Banks still face hurdles with this group. Wealth Briefing reports that crypto millionaires meet know-your-client checks, which banks use to confirm source of wealth. Rules differ by country, and the US has taken a more liberal approach under the Trump administration.
| Group | Number |
|---|---|
| Individuals holding any digital assets | 742 million |
| Individuals holding bitcoin | 371 million |
| Crypto millionaires | 135,694 |
| Bitcoin millionaires | 92,272 |
What the 2025 Report Showed
Henley & Partners released its Crypto Wealth Report 2025 on 23 September 2025. It counted 241,700 crypto millionaires, up 40% in 12 months. Bitcoin millionaires rose 70% to 145,100.
The report also counted 450 centi-millionaires, up 38%, and 36 crypto billionaires, up 29%. Total crypto market value was USD 3.3 trillion as of June 2025, a 45% rise on a year earlier.
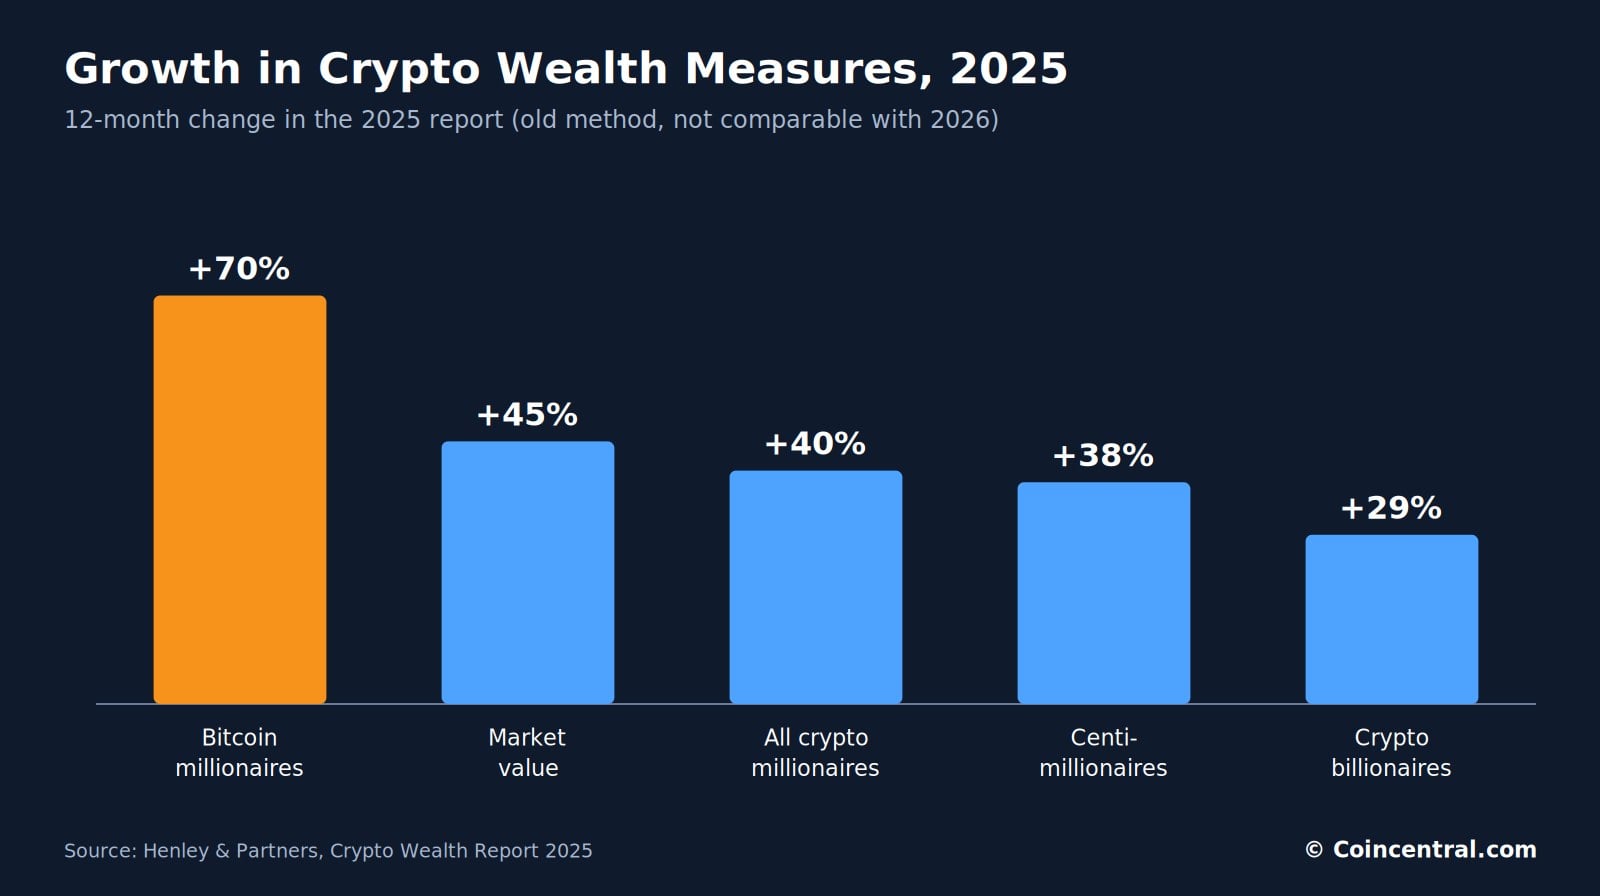
These figures use the older method. The 2026 report says its numbers are not comparable with earlier editions. For that reason, the 2025 and 2026 totals should not be read as a trend.
Market conditions in 2025 were strong. The Evening Standard reported bitcoin trading at just over USD 113,000 on the report’s release date, up 21% for the year. Henley called 2025 a watershed year for institutional adoption, pointing to the first cryptocurrencies launched by a sitting US President and First Lady.
Volek also noted that roughly USD 14.4 trillion of wealth crossed national borders in 2024. He argued that crypto makes geography optional for storing wealth.
The 2025 report also described changes in how investors manage crypto. Machine learning systems were handling a growing share of institutional portfolios, and Switzerland had become a main hub for custody services.
Catherine Chen, Head of VIP and Institutional at Binance, said in that report that “this new, mobility-driven class of investors is increasingly turning to citizenship by investment programs as a strategic route to geographic and financial flexibility.”
| Measure (2025 report) | 2025 figure | Change in that report |
|---|---|---|
| Crypto millionaires | 241,700 | +40% |
| Bitcoin millionaires | 145,100 | +70% |
| Centi-millionaires | 450 | +38% |
| Crypto billionaires | 36 | +29% |
| Total market value (June 2025) | USD 3.3 trillion | +45% |
How Crypto Millionaires Spend Their Money
A study covered by CNBC in October 2025 looked at how crypto gains turn into spending. The authors are professors Darren Aiello, Mark Johnson and Jason Kotter of Brigham Young University, with Scott Baker, Tetyana Balyuk and Marco Di Maggio. They tracked investors using transfers to and from crypto exchanges.
They found that investors spent about 9.7 cents for every dollar of added crypto wealth. This ratio is called the marginal propensity to spend. It was more than two times the level typically found for gains in stocks or home values.
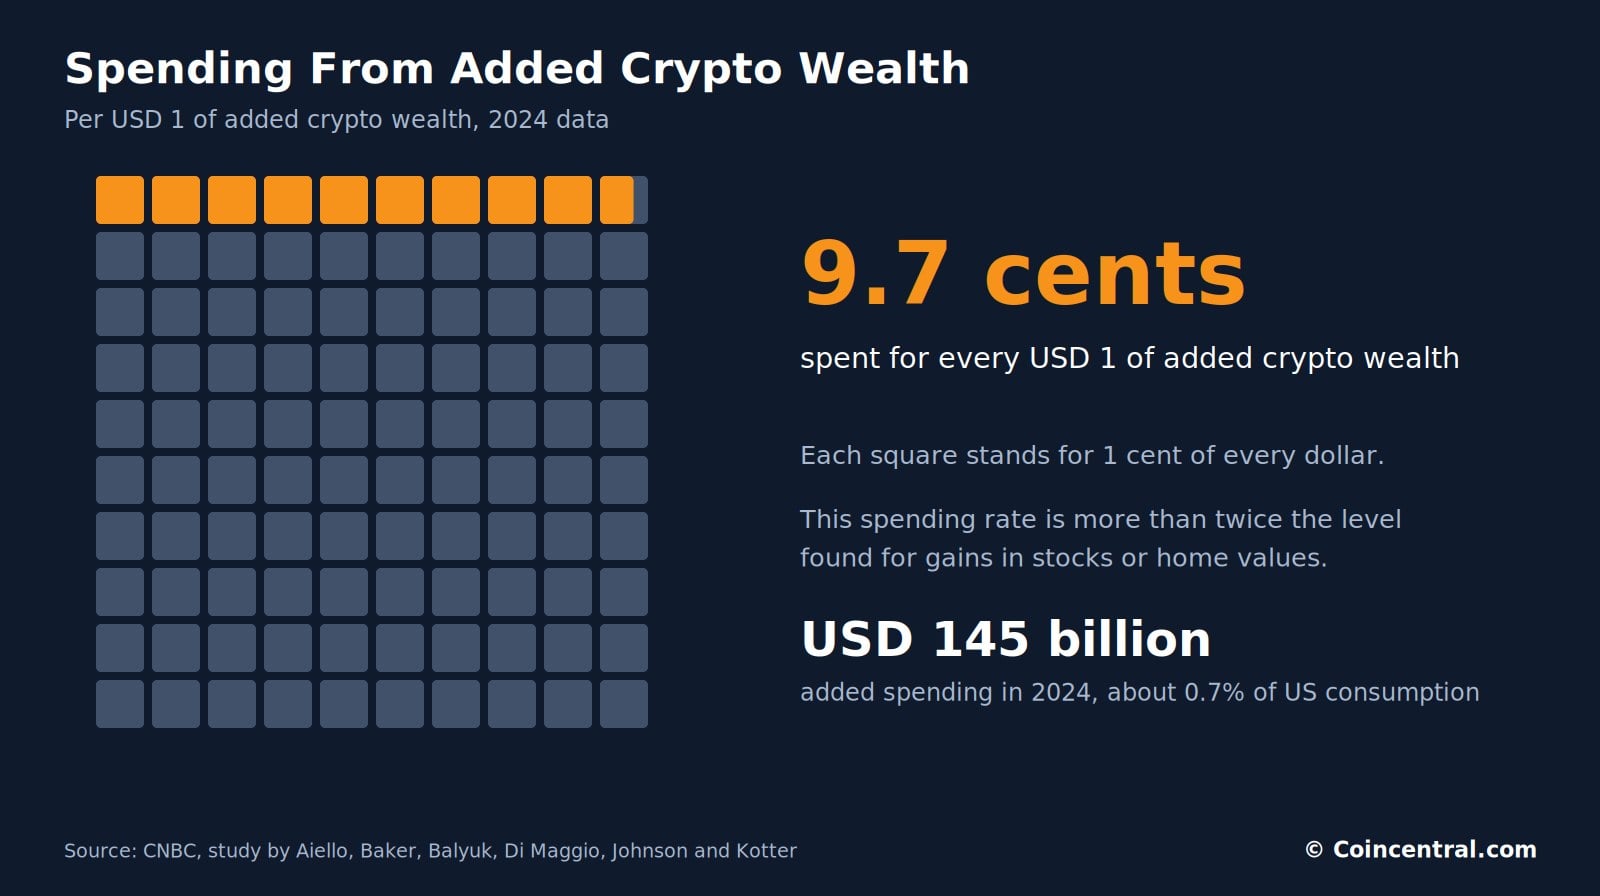
The authors estimate that crypto gains added USD 145 billion in spending in 2024. That is about 0.7% of total US consumption. The effect also works in reverse, and the authors warn that major crashes could pull spending down.
Investors fall into two broad groups. Casual investors hold a small share of their money in crypto, while “all-in” investors hold 100% in crypto. The casual group spends more of its gains, and the all-in group rarely changes its spending.
Most spending goes to restaurants, entertainment and general merchandise. Buyers of Lamborghinis and Rolexes appear to be the exception. An earlier study by the group found that home prices rose 0.46% faster in counties with many crypto holders when bitcoin spiked.
Many wealthy holders are not selling. Tad Smith, a partner at 50T Funds and former CEO of Sotheby’s, said, “They want to be fully invested because this is the moment they’ve been waiting for.” He expects spending to shift toward real estate as holders age and start families.
Borrowing could change spending too. Zac Prince of GalaxyOne said many crypto-rich buyers cannot get approved for mortgages. CNBC reported that Bill Pulte of the Federal Housing Finance Agency directed Fannie Mae and Freddie Mac to consider crypto assets in mortgage underwriting.
| Finding | Figure |
|---|---|
| Spending per USD 1 of added crypto wealth | 9.7 cents |
| Added US spending in 2024 | USD 145 billion |
| Share of total US consumption | About 0.7% |
| Faster home price growth in crypto-heavy counties | 0.46% |
The Henley Crypto Adoption Index 2026
The Henley Crypto Adoption Index ranks countries with residence or citizenship pathways on how they embrace and regulate crypto. The 2026 edition covers 36 countries and more than 900 data points. The 2025 edition covered 29 programs and more than 750 data points.
Countries are scored on six parameters. They are Public Adoption, Infrastructure Adoption, Innovation and Technology, Regulatory Environment, Economic Factors and Tax-Friendliness. In the 2025 edition, the top five were Singapore, Hong Kong, the USA, Switzerland and the UAE.
Singapore leads for the fourth year in a row and holds the highest Innovation and Technology score. The UAE is second, up from fifth. It scores 10 out of 10 for Tax-Friendliness, with no tax on crypto trading, staking or mining.
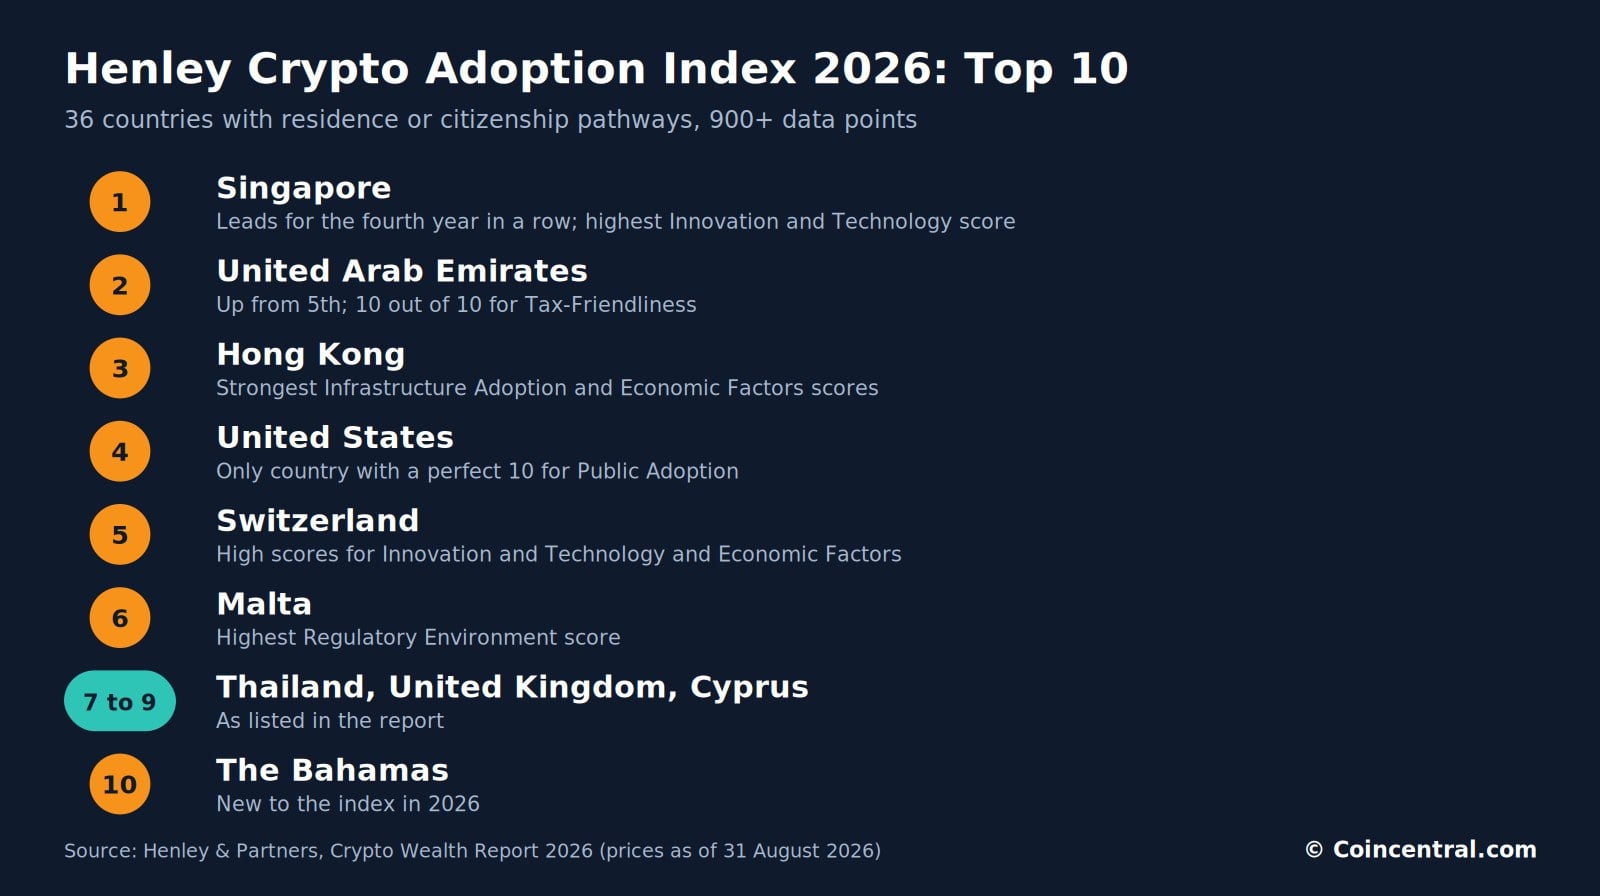
Hong Kong is third, with the strongest Infrastructure Adoption and Economic Factors scores. The United States is fourth and is the only country with a perfect 10 for Public Adoption. Switzerland is fifth.
Malta ranks sixth and has the highest Regulatory Environment score. Thailand, the UK, Cyprus and The Bahamas take the other top 10 places. The Bahamas is tenth.
New entries to the 2026 index include The Bahamas (10th), Cayman Islands (12th), Bahrain (13th), Argentina (26th), Maldives (31st) and Paraguay (35th). The report also names Naoero, which ranks 32nd, as a new entrant.
| Rank | Country | Standout result |
|---|---|---|
| 1 | Singapore | Highest Innovation and Technology score |
| 2 | United Arab Emirates | 10 out of 10 for Tax-Friendliness |
| 3 | Hong Kong | Strongest Infrastructure Adoption and Economic Factors |
| 4 | United States | Perfect 10 for Public Adoption |
| 5 | Switzerland | High Innovation and Technology and Economic Factors |
| 6 | Malta | Highest Regulatory Environment score |
| 19 | Italy | Flat-tax regime for qualifying new residents |
| 23 | Portugal | Exempts gains on assets held over one year |
Stablecoins, CBDCs and New Reporting Rules
Rules for crypto are spreading fast. Seventy-six jurisdictions have signed up to the OECD’s reporting framework for crypto assets. The first exchanges of information between 46 of them are due in September 2027.
In Europe, the Markets in Crypto-Assets Regulation took full effect in December 2024. Niklas Schmidt of Wolf Theiss notes that Europe now has a unified crypto rulebook spanning 30 countries. He asks whether that certainty will attract crypto capital or hold back innovation.
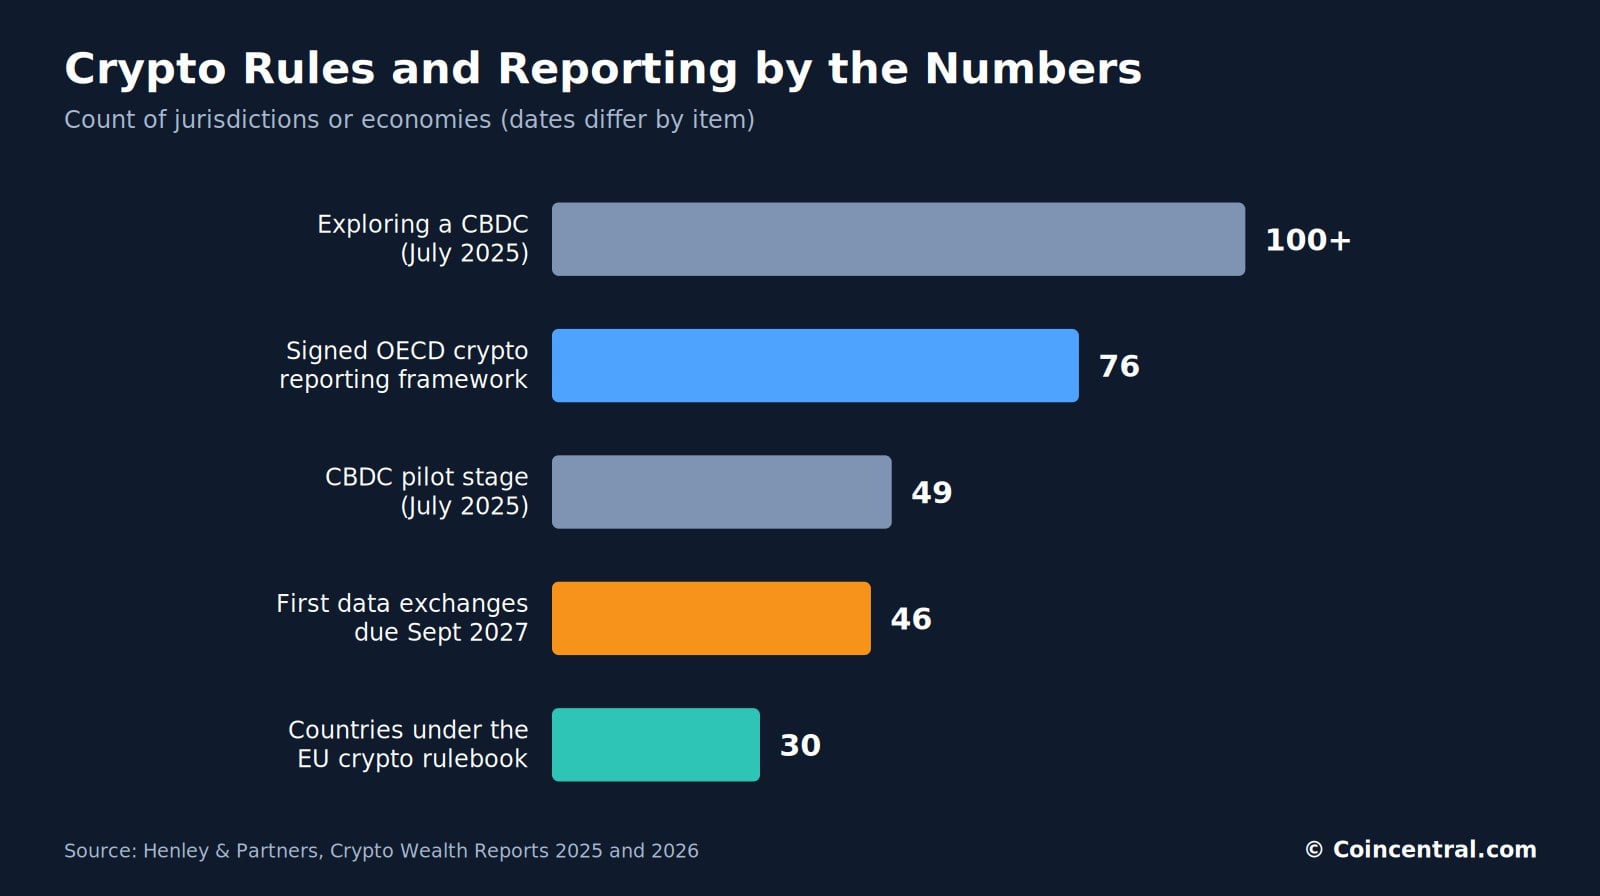
Central bank digital currencies are also under study. In the 2025 report, Dr. Guneet Kaur said more than 100 economies were exploring them, with 49 in the pilot stage as of July 2025.
Stablecoins are drawing rules as well. Bahrain became the first Gulf state to set a dedicated stablecoin framework in 2025, and Hong Kong has adopted stablecoin rules. In April 2025, the US Securities and Exchange Commission said some stablecoins would not fall under federal securities rules.
The US CLARITY Act is still moving through Congress, according to Wealth Briefing. It would give the Commodity Futures Trading Commission authority over spot markets for digital commodities. It would also ban the Federal Reserve from issuing a central bank digital currency.
Kaur said stablecoin rails let dollars move between financial centers “inside minutes rather than days.”
Even so, due diligence remains hard. Daniel Hartnett of LSEG Risk Intelligence said, “A wallet can show that value exists. It cannot tell the whole story of the person behind it.”
| Item | Number | Date or note |
|---|---|---|
| Jurisdictions in OECD crypto reporting framework | 76 | 2026 report |
| Jurisdictions due to exchange data first | 46 | September 2027 |
| Countries under the EU crypto rulebook | 30 | MiCAR in force since December 2024 |
| Economies exploring a CBDC | More than 100 | July 2025 |
| Economies at CBDC pilot stage | 49 | July 2025 |
Where Crypto Wealth Is Moving
Henley & Partners also publishes a Global Wealth Mobility Framework. It measures investor access, quality of life, rule of law and tax competitiveness. The UAE scored 85.3 out of 100, followed by Singapore at 79.5, New Zealand at 75.8, the Cayman Islands at 74.3 and Cyprus at 73.5.
Countries compete on rules and tax. Dubai set up the world’s first standalone regulator for virtual assets in 2022. Singapore licenses digital asset services through its Monetary Authority and charges no capital gains tax on individual investors.
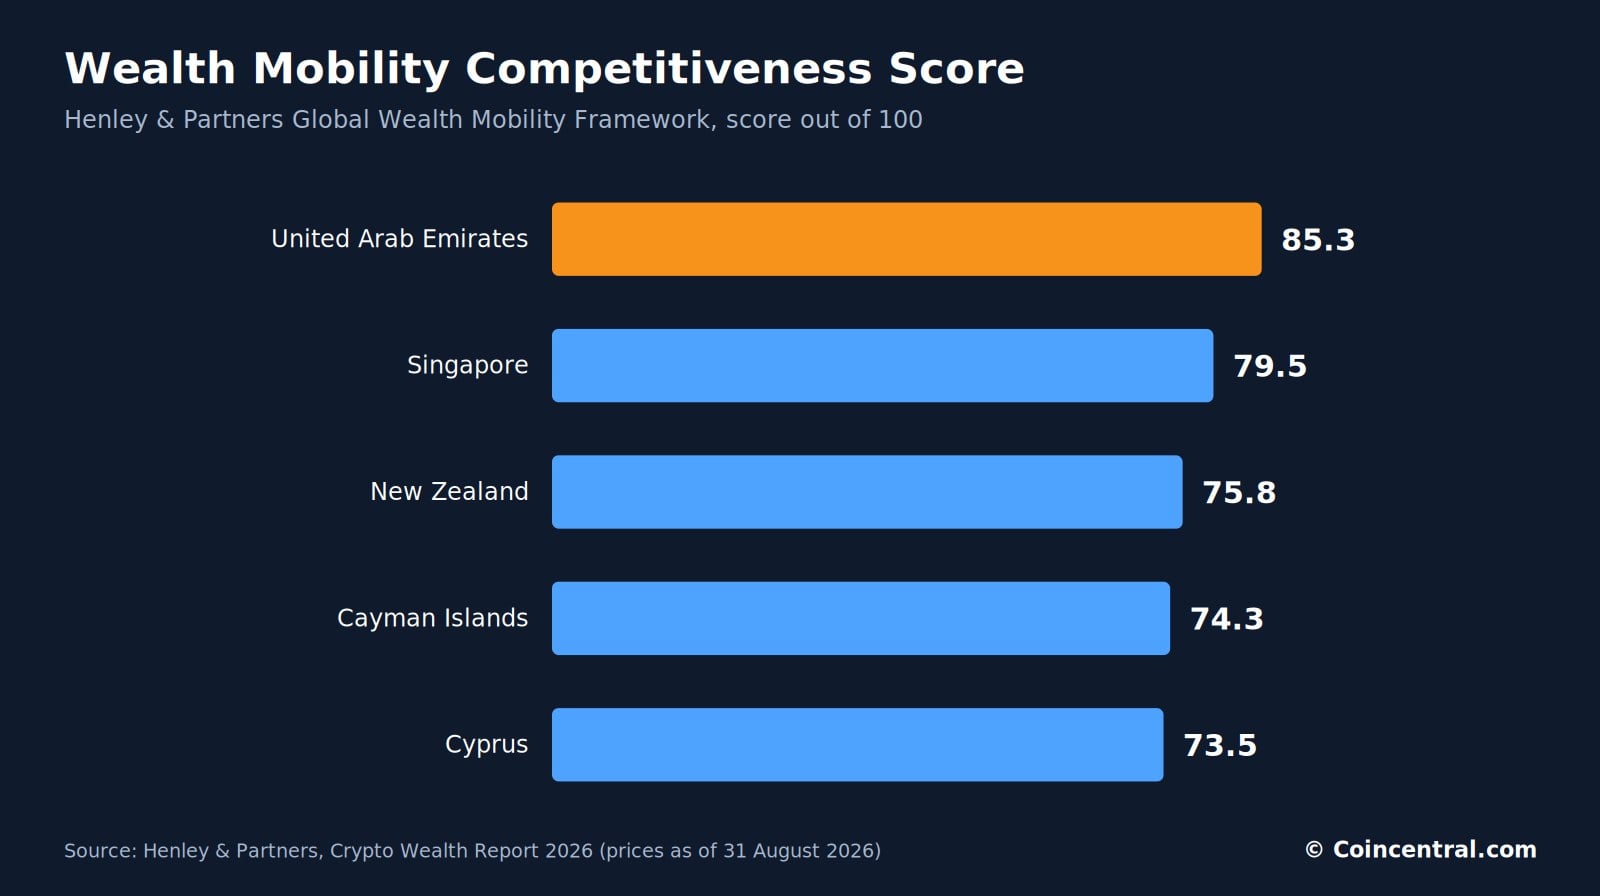
Switzerland hosts the blockchain cluster in Zug and exempts private capital gains. Portugal exempts gains on digital assets held more than a year. Italy offers a flat tax for qualifying new residents, and the annual charge on foreign income has risen twice in two years, to EUR 300,000.
In the Caribbean, Antigua and Barbuda recognizes documented digital assets when applicants show their source of funds. St. Kitts and Nevis accepts digital assets as a partial source of wealth for applicants.
Investors are treating location as part of their plans. António Henriques of Bison Bank said jurisdictions are becoming part of asset allocation. Guenther Dobrauz-Saldapenna of Henley & Partners Switzerland said that when wealth is highly mobile, planning around the person who owns it becomes critical.
The 2026 statistics show a market that shrank in value while ownership grew. They count 135,694 crypto millionaires, 290 centi-millionaires and 23 billionaires on a new method. Reporting rules, price swings and national tax policy will shape how those numbers change next.
| Country | Wealth Mobility Competitiveness Score |
|---|---|
| United Arab Emirates | 85.3 |
| Singapore | 79.5 |
| New Zealand | 75.8 |
| Cayman Islands | 74.3 |
| Cyprus | 73.5 |
Sources
- Henley & Partners: Crypto Wealth Holds Up in 2026 as Bitcoin Retreats from Record Highs
- Henley & Partners: World Nears Quarter Million Crypto Millionaires in Historic Wealth Boom
- CNBC: How the world’s 240,000 crypto millionaires are spending their fortunes
- Evening Standard: Ranks of crypto millionaires boom 40% in a year as Bitcoin races to all time highs
- Wealth Briefing: Report Shows There Are 92,272 Bitcoin Millionaires
The post Crypto Millionaire Statistics 2026: How Many People Hold $1 Million or More appeared first on Blockonomi.
TLDR:
- Aviva Investors launched a tokenized share class of its £22 billion Sterling Liquidity Fund on XRPL.
- It is the firm’s second tokenized fund, after the USD Liquidity Fund launched in July 2026.
- Both tokenized share classes hold over £86 million, including Aviva’s £50 million Sterling investment.
- The digital twin model keeps the off-chain fund intact while holdings are represented on-chain.
Aviva Investors has launched a tokenized share class of its Sterling (GBP) Liquidity Fund on the XRP Ledger. The fund is the firm’s largest, with about £22 billion in assets under management, according to the announcement.
The move follows the July launch of a tokenized USD Liquidity Fund. Aviva Investors and Ripple announced the development on October 26, 2026. The firm is now one of the largest providers of tokenized money market funds in Europe.
Aviva Investors Adds Sterling Fund to Tokenized Lineup
Ripple shared the news on X. The post described the launch as an expansion of the firm’s tokenized fund offering.
The share class is the second tokenized offering from the firm. It follows the tokenized USD Liquidity Fund, which launched in July 2026.
Meanwhile, the fund is an Ireland-domiciled UCITS money market fund launched in 2002. It targets low-risk returns and daily liquidity through high-grade, short-term UK Sterling debt instruments.
Together, the two tokenized share classes hold more than £86 million (116million) in investments.Aviva invested £50million (66 million) in the new Sterling share class.
Mark Versey, CEO of Aviva Investors, commented on the expansion. He said, “We believe tokenised funds can increase efficiency and ultimately lead to improved client outcomes.”
Versey also said the expansion “shows our clear intent to be a leader in this area.” He called the partnership with Ripple vital to these efforts.
Digital Twin Model and XRP Ledger Infrastructure
The fund uses a digital twin model. This approach adds a digital access layer where holdings can be represented on-chain. The existing off-chain fund structure remains intact.
Investors receive the same investment objective, risk profile, liquidity characteristics, and regulatory protections as the conventional fund. Eligible investors with digital wallets can access the new share class.
The Bank of New York Mellon holds all assets as the fund’s custodian. In addition, the structure is designed to operate within existing regulatory frameworks.
Komainu, a regulated institutional digital asset custodian, again supported the launch. Licuido, a digital infrastructure platform that enables asset managers to tokenize and trade real world assets, also provided support. The firms also backed the earlier launch of the USD share class.
The XRP Ledger lets Aviva Investors issue and manage the share class through fast, secure, low-cost transactions. Since 2012, the network has processed more than 4 billion transactions.
It supports nearly 8 million active wallets and 130+ independent validators. Nigel Khakoo, Senior Vice President of Trading and Markets at Ripple, also commented. He said, “Markets are moving to 24/7 access and settlement is moving to real-time, always-on rails.”
Khakoo described Ripple as the bridge between traditional and digital finance. He added that the XRP Ledger is “bringing the compliance, privacy and security features needed by institutions.”
The post Aviva Investors Launches Tokenized Sterling Liquidity Fund on XRP Ledger appeared first on Blockonomi.
TLDR
- ECB board member Piero Cipollone says the digital euro would reduce Europe’s reliance on non-European payment companies.
- A pilot using real transactions by ECB and national central bank staff will start in 2027.
- The digital euro could launch as early as 2029 if EU lawmakers approve the regulation this year.
- There will be limits on how much people can hold, but no limits on payments. Offline payments will also be possible.
- Banks will distribute the digital euro, and the ECB will not open accounts for individuals.
European Central Bank Executive Board member Piero Cipollone says the digital euro could give Europe more control over how its people pay. He made the comments in an interview with Italy’s Milano Finanza, which the ECB published on October 24.
Cipollone said payments are a key part of Europe’s economy. “If the payment system stops working, the economy stops working,” he said.
Why the ECB Wants a Digital Euro
Today, the public can only use central bank money in the form of cash. Cipollone said the digital euro would fill that gap online, where banknotes cannot be used.
He pointed to Italy as an example. Online payments there grew from 6% of all payments in 2019 to 24% in 2024.
Most of those online payments are made by card. Cipollone said two thirds of these card payments run through non-European card schemes.
“In recent years Europe has learned that, for some essential services, we cannot rely only on third parties,” he said. He compared payments to energy and defense but did not name specific companies.
He added that sovereignty does not mean shutting others out. “It means having the power to choose,” he said.
Cipollone also said small shops can pay fees up to four times higher than large businesses. He said legal caps on costs under the digital euro should help lower those fees.
How the Digital Euro Would Work and When It Could Launch
There will be a limit on how much digital euro a person can hold in a wallet. There will be no limit on spending, since larger payments can pull the rest from a linked bank account.
The digital euro will also work offline. Two devices can be tapped together to pay during a power cut or in areas with weak internet.
Cipollone said offline payment details would stay between the buyer and the seller, much like cash. People will be able to use the digital euro through their bank’s app or a standard Eurosystem app.
The ECB will not open accounts for individuals. Banks and other approved firms will distribute the digital euro and manage customer relationships.
The system will run on infrastructure built only by European providers. Cipollone said cash will continue to exist alongside the digital euro.
A pilot using real transactions by ECB and national central bank staff will begin in 2027. So far, 36 market operators, including seven from Italy, are helping with preparations, and the ECB is inviting e-commerce and mobile commerce firms to join.
The ECB Governing Council can only make a final decision after lawmakers in Brussels finish talks on the regulation. If the regulation is approved this year, the digital euro could launch as early as 2029.
“We hope that the regulation will be adopted by the end of the year, enabling the ECB’s Governing Council to issue a formal decision on issuance,” Cipollone said.
The post ECB’s Cipollone Says Digital Euro Pilot Will Start in 2027 appeared first on Blockonomi.
CryptoPotato
CEO Matt Cole announced on X that the company he runs has purchased 6,182 BTC for over $511 million over the past week at an average price of $82,732 per unit.
This was the company’s single biggest bitcoin buy, which exceeds some of the previous major ones from a few weeks ago of 3,311 BTC and the roughly 2,500 BTC haul from May-June.
Strive acquired 6,182 $BTC for $511.4M at an average cost of $82,732 per bitcoin, bringing total holdings to ₿43,000.
– Cash and marketable securities increased by $187.7M to $554.6M.
– Established a $1B $SATS ATM program.$ASST $SATA $SATS https://t.co/pKtqVmFobL
— Matt Cole (@ColeMacro) October 26, 2026
After last week’s more modest acquisition of 1,223 BTC, the company’s total stash was valued at over $3 billion. However, the asset’s price stood slightly higher at the time, while the current battle for $80,000 means that the firm’s USD equivalent has declined.
Although it has spent more than $511 million for its latest purchase, the USD value of its bitcoin fortune is worth just under $3.5 billion. However, the company’s stash in terms of BTC has reached a new all-time high of 43,000 units.
The company also reported that its cash and marketable securities increased by almost $188 million to $554.6 million. This shows effective capital deployment from recent preferred stock raises while maintaining liquidity for dividends and operations.
Strive also initiated a $1 billion ATM program for SATS preferred stock, extending its debt-free model of issuing dividend-bearing securities like SATA and SATS to fund further bitcoin purchases.
The post Strive Makes Largest-Ever Bitcoin Purchase With 6,182 BTC Buy appeared first on CryptoPotato.
Bitcoin’s price struggles around the key $80,000 area continue, as the asset dipped below that line on a couple of occasions during the weekend and barely stands above it now.
Most larger-cap alts are atypically sluggish for a Monday morning, with ETH and XRP posting minor losses, while ZEC and HYPE are up by 1%-3%. QNT, though, has skyrocketed by double digits, followed by ENA.
BTC Struggles at $80K
Things can easily change in the crypto market sometimes in the matter of just days. Recall that the largest digital asset began to climb last Tuesday and peaked on Wednesday at almost $85,000, which became its highest price tag in two weeks. The sentiment was quickly turning, and there were even calls for $90,000.
Instead, reality brought the bulls to their knees. BTC was instantly rejected at the $85,000 resistance and tanked to $83,000 within hours and to under $81,000 a day later. It found some support and remained there until Friday before the bears took it a step further on Saturday.
Although most weekends are typically quite sluggish, this one wasn’t. BTC tanked below $80,000 on Saturday and dipped to a 5-week low of $79,100. It rebounded immediately above $80,000, but slipped below that level a few more times on Sunday.
As of press time, it remains inches above $80,000, but more volatility and uncertainty are expected later this week due to several critical events. Its market cap is down to $1.610 trillion on CMC, while its dominance over the alts stands at 60%.

QNT Pumps Again
Ethereum, Binance Coin, and Ripple’s XRP are slightly in the red once again, posting losses of less than 1%. In contrast, SOL, TRX, DOGE, and LINK are up by similarly insignificant percentages. ZEC has gained 2%, while its privacy coin rival XMR is down by 2.5%. HYPE, NEAR, BCH, and UNI have posted slightly more impressive gains.
QNT has rocketed the most from this cohort of assets, jumping by nearly 18% to $221. ENA follows suit with a 6.6% surge to over $0.20.
The total crypto market cap has remained at essentially the same level as yesterday on CMC at $2.680 trillion.

The post QNT Resumes Recent Bull Rally With 16% Surge, BTC Fights for $80K: Market Watch appeared first on CryptoPotato.
The primary cryptocurrency flexed its muscles last week and seemed poised to reclaim $85,000. However, the bears stepped in again, and the price eventually fell below $80,000.
Popular analyst Ali Martinez suggested the pullback could intensify in the short term, but that could actually work in investors’ favor. Here’s why.
The Next Buying Opportunity?
According to Martinez, Bitcoin appears to have broken below a rising parallel channel on the 4-hour chart. He believes that as long as $82,000 holds as a resistance, the correction could deepen toward a two-month low of $72,500. Nonetheless, the analyst doesn’t seem concerned about the potential decline and views it as a buying opportunity.
Another factor that may point to further downside is the US midterm elections scheduled for November 3. Martinez recently noted that following the 2010, 2014, 2018, and 2022 votes, BTC fell by 72%, 65%, 52%, and 27%, respectively.
His post raised concerns among several X users, who wondered whether they should sell their positions. The analyst advised them to take some profits in late October and potentially jump back in at $73,000 after the midterm elections.
Crypto with Harris ₿ also expects an additional decline. He spotted the break below the psychological $80K zone, saying the chart has shown “clear weakness” since the $85K rejection.
The analyst then identified $79,200 as “the immediate support,” suggesting that losing it could result in a drop to the $75,000-$72,000 range and then possibly to a collapse to $62,000. After that bottom, though, he thinks the bulls would return and push the price above $90,000.
Starting Point for a Rally?
X user Sweep also weighed in, noting that the asset’s daily Relative Strength Index (RSI) has reached the same level it was at when the pump began in August.
“This is what happens during a bull run, and those waiting for $65K will never get an entry,” he added.
The recent whale activity supports the positive scenario. As CryptoPotato recently reported, 40 newly created wallets have withdrawn over $770 million worth of the asset between October 1 and October 23.
Prior to that, large investors holding between 10 and 10,000 BTC scooped up nearly 90,000 coins in just one month. This aggressive accumulation leaves fewer coins available on the open market and could positively impact the price if demand holds. It could also boost confidence among smaller players and encourage them to bring fresh capital into the ecosystem.
The post Bitcoin (BTC) Risks Dropping to $72,500, But That Could Be a Blessing in Disguise: Analyst appeared first on CryptoPotato.
Franklin Templeton has registered two proposed exchange-traded funds with Nasdaq that would invest in US equities and direct dividend income into Bitcoin.
The strategy could give traditional stock investors a way to build Bitcoin exposure through dividends rather than having to sell shares or make separate cryptocurrency purchases.
Franklin Templeton’s Proposed ETFs Target 5% Bitcoin Allocation
Nate Geraci, president of NovaDius Wealth Management, drew attention to the filings in an X post on October 26, describing the products as ETFs that hold US stock and reinvest dividends into Bitcoin.
“Basically like investing in S&P 500 & Nasdaq 100 w/ dividends going to BTC,” Geraci wrote, adding that the funds were “targeting 5% BTC allocation.” He called the structure smart product design and suggested it could give everyday investors an easier route to Bitcoin exposure.
The filing names the products the Franklin US Equity Bitcoin DRIP Index ETF and the Franklin US Innovation Bitcoin DRIP Index ETF. Both are listed for registration on Nasdaq under Franklin Templeton ETF Trust.
The registration document incorporates a description of the funds’ shares from a post-effective amendment filed with the Securities and Exchange Commission (SEC) on October 22, but the Form 8-A itself does not establish that trading has begun or provide a launch date.
The proposed structure links conventional equity investing with Bitcoin accumulation. Rather than relying on investors to allocate part of their paychecks or portfolio balances to crypto, the strategy would channel dividends from the stock holdings into the digital asset. The targeted allocation cited by Geraci gives investors an indication of the intended exposure, although the post does not explain how that target would be maintained or how the funds would handle changing Bitcoin prices.
Bitcoin’s Price Weakness Adds Another Consideration
CoinGecko data at the time of writing put the OG crypto at just under $80,000, down by slightly more than 1% in the last 24 hours and nearly 4% in seven days. Its 30-day decline stands at over 5%, while the asset is still about 29% lower than a year ago and 37% below its all-time high above $126,000.
Liquidation figures from Coinglass point to pressure on leveraged traders, with roughly $33 million in Bitcoin positions liquidated during the previous 24 hours. Long positions accounted for about $27 million of that total, meaning traders betting on higher prices took most of the losses.
Meanwhile, existing spot BTC ETFs took a hit last Friday, bleeding more than $635 million to cut down weekly total inflows to about $442 million, the first green week since the start of October. That amount was buoyed by two days, Monday and Wednesday, that drew more than half a billion each.
The post Franklin Templeton Files for ETFs That Reinvest Stock Dividends in Bitcoin appeared first on CryptoPotato.
Bitcoin, crypto, and the overall financial system enter one of the busiest macro weeks of the year with the Federal Reserve, fresh inflation and GDP data, and a wave of Big Tech earnings all arriving within days.
With BTC already struggling to maintain above the key $80,000 support, the upcoming releases could determine whether the latest correction deepens or buyers finally regain control.
Fed, Inflation, and GDP
The analysts at the Kobeissi Letter noted that the major week begins with the September New Home Sales on Tuesday, before attention shifts firmly to Wednesday’s Federal Reserve meeting. The central bank will announce its rate decision on October 28, followed by the usual press conference.
Nearly all economists surveyed by Reuters expected no changes, with the Fed leaving the federal funds target at 3.75%-4.00%. However, expectations for another hike in December have increased noticeably over the past few weeks, especially after the release of the CPI and PPI readings for September.
Unless there’s a major surprise and a fresh hike on Wednesday, the decision itself may matter less for crypto than the Fed’s guidance. A more dovish tone regarding future tightening could pressure Treasury yields and the dollar while improving appetite for risk assets such as BTC. Conversely, renewed warnings about persistent inflation or further rate hikes could add more pressure.
Thursday could be an even bigger day as the Bureau of Economic Analysis will publish the advance estimate of Q3 US GDP alongside September Personal Income and Outlays, which contains the Fed’s preferred PCE inflation gauge.
Markets currently expect economic growth to remain strong while inflation stays elevated. That combination would reinforce the argument that the Fed has room to maintain restrictive policy, potentially creating another headwind for BTC and crypto.
Big Tech Earnings
The Kobeissi Letter explained that roughly 20% of S&P 500 companies are scheduled to report earnings this week, with Microsoft and Alphabet taking center stage on Wednesday, followed by Amazon and Intel on Thursday. This matters for the crypto market because BTC has increasingly traded alongside broader risk sentiment, particularly during sharp moves in tech stocks.
Investors will be watching whether massive AI spending is translating into sufficient growth at Microsoft, Alphabet, and Amazon after recent concerns surrounding technology valuations weighed heavily on equities.
Bitcoin has suffered in the past week, especially since the rejection at $85,000 last Wednesday. The asset plummeted to a five-week low on Saturday at $79,100 and now fights to stay above $80,000. The spot BTC ETFs were in the green last week, but that couldn’t really help the underlying asset’s price recover.
The post A Perfect Storm for Bitcoin? Fed, PCE, GDP and Big Tech Earnings Ahead appeared first on CryptoPotato.


