Cryptocurrency Posts
Crypto Briefing
The attacks expose Saudi Arabia's defense vulnerabilities, potentially prompting MBS to strengthen alliances or face leadership scrutiny.
The post Houthi strikes hit Saudi Arabia, pressure mounts on MBS to bolster defenses appeared first on Crypto Briefing.
Kansas' emerging role as a battleground could reshape Senate control dynamics, challenging traditional party strongholds and influencing national strategies.
The post Kansas emerges as key battleground in 2026 Senate race appeared first on Crypto Briefing.
Saudi Arabia's event disruptions highlight increased security risks and potential economic impacts, with airspace closure risks being monitored.
The post Growing list of major events Saudi Arabia forced to cancel, postpone appeared first on Crypto Briefing.
The escalation may shift market perceptions, increasing the likelihood of Houthi territorial gains and impacting regional stability and security.
The post Houthi attack on Yemeni military camp kills 18, escalating conflict appeared first on Crypto Briefing.
The experiment could redefine AI development strategies, influencing market dynamics and competitive positioning among leading AI companies.
The post MIT’s Claude Opus 4.7 experiment highlights AI self-directed learning potential appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Poetic Justice: Scammer Lost $5M in Bitcoin After Being Targeted by Ledger Thieves
Call it poetic justice: one of the biggest victims of last week’s Ledger theft happened to be a scammer themself, according to blockchain analysts, and lost nearly $5 million in bitcoin.
In a post Thursday, Chainalysis wrote that a crook lost 60 bitcoins worth about $4.8 million they’d stolen via a so-called task scam.
According to Chainalysis, the address was linked with a con where people were paid to fake sales and reviews of real items. They were told to add their own money in order to get paid — and then stolen from.
But the mastermind behind the task scam moved the stolen money to Ledger addresses which were then targeted by different scammers last week.
“On Sep 22, the person behind the scam moved the proceeds into three separate Ledger addresses,” Chainalysis said. “On Oct 9, thieves emptied all three. One transfer each, into the same wallet. The wallet is reported as stolen funds.”
Paris-based Ledger last week said it had started an investigation after customers in South East Asia reported they’d lost funds after buying from Malaysia-based reseller, CryptoBilis.
Ledger has since said that the scam was a massive organized crime operation where a group installed implants into devices and put them back on the market. The implants could read users’ seed phrases so criminals could then drain wallets.
Calling it one the most “sophisticated attacks” the digital asset industry has experienced, Ledger is yet to reveal how much money has been lost — but blockchain investigator Specter said $86 million had been drained.
And the task scam conman, according to Chainalysis, was one of the victims.
Ledger has said that it is working with law enforcement to “follow the funds and dismantle the attackers’ infrastructure” and has made sure no other vendors have been targeted by scammers.
CryptoBilis has stopped selling Ledger products, the company said.
Criminals have targeted bitcoin hardware sellers this year, with a huge attack taking place in July on the popular Coldcard products.
Crooks were able to steal close to $120 million in bitcoin from Coldcard users because the devices had a firmware bug which led to faulty seed generation, allowing hackers to guess investor seedphrases.
This post Poetic Justice: Scammer Lost $5M in Bitcoin After Being Targeted by Ledger Thieves first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
BFFS26 Denver: Joseph Kelly on Bitcoin Custody and Credit; Alan Lane on Banking Lessons
The Bitcoin for Financial Services Summit (BFFS26) returns to Denver October 20–22, 2026, bringing together CPAs, wealth advisors, attorneys, lenders, and finance leaders who are building Bitcoin into their practices. Now in its second year, the summit has grown to more than 30 sessions across two full program days, with a speaker lineup drawn from the firms defining Bitcoin custody, credit, and advisory.
Headlining the program are Joseph Kelly, CEO and co-founder of Unchained, who opens the summit with a keynote on custody, credit, and trust at scale; Alan Lane, former CEO of Silvergate Bank, on lessons for Bitcoin and banking; Patrick Lowry, CEO of Samara Asset Group, on holding Bitcoin as a public-company treasury reserve; and Colin Crossman, Wyoming’s Deputy Secretary of State, on the regulatory outlook for banks, exchanges, and advisors. Additional speakers include Kate Goldman of Anchorage Digital, Sam Baker of River, Eric Yakes of Epoch Ventures, Daniel Hillery of UTXO Management, Moish Peltz of Falcon Rappaport & Berkman, and CJ Konstantinos of Peoples Reserve.
Sessions focus on practical application: bringing Bitcoin into wealth planning and family offices, Bitcoin-backed lending and mortgages, treasury accounting and valuation, retirement and income planning, charitable giving strategies, mining as an asset class, and fiduciary duty when clients hold Bitcoin. Dedicated workshops will offer continuing education credit for financial advisors and CPAs.
“Last year proved that financial professionals want more than a Bitcoin primer. They want to know how to serve clients who already own it,” said Jordan Guess, CPA, co-host of the summit in a press release shared with Bitcoin Magazine. “This year’s program is built around the questions advisors and accountants are actually getting from clients, answered by the people building the infrastructure.”
The summit opens Tuesday, October 20, with the Better Money Invitational golf tournament at City Park Golf Course, hosted with Bitcoin Sports Network, followed by a welcome party at The Space sponsored by Falcon Rappaport & Berkman. Evening programming includes wine and whiskey tastings, and Thursday begins with an optional sunrise hike in the Rocky Mountains.
BFFS26 is co-hosted by Jordan Guess and Wyatt O’Rourke of BFFS Media, producers of the Bitcoin for Financial Services podcast. Sponsors include Unchained, Anchorage Digital, UTXO Management, River, SOUND HSA, SustainHash, and Stormrake.
Registration is open now at https://www.bffs.media/summit.
Media contact: Wyatt O’Rourke, wyatt@bffs.media
This post BFFS26 Denver: Joseph Kelly on Bitcoin Custody and Credit; Alan Lane on Banking Lessons first appeared on Bitcoin Magazine and is written by Juan Galt.
Bitcoin Magazine
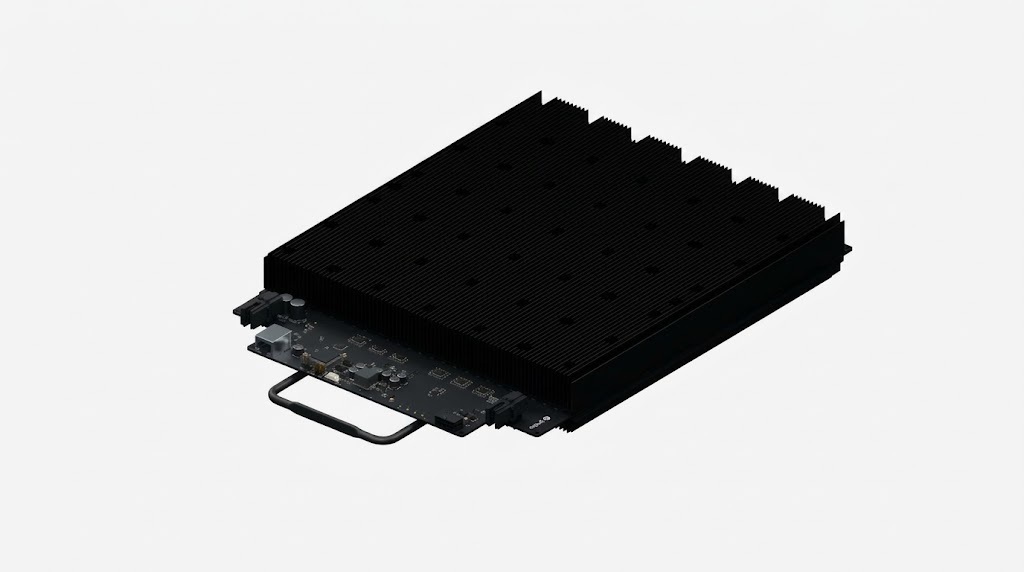
Sazmining Now Sells Jack Dorsey’s Proto Immersion Hashboards
Bitcoin mining just got a lower barrier to entry.
Sazmining announced Thursday that it is now selling Proto’s immersion hashboards directly to individual and institutional buyers through its mining-as-a-service platform. Previously, the hardware was mostly in the hands of large-scale operators.
Each hashboard delivers roughly 200 TH at around 15 J/TH, and buyers own them outright while Sazmining handles deployment, monitoring and maintenance at a US facility. Mining rewards go straight to the owner’s wallet.
The move follows a multi-megawatt supply deal between Sazmining and Proto — the bitcoin mining arm of Jack Dorsey’s Block (NYSE: XYZ) — which both companies expect to expand as demand grows.
“Because of our aligned-incentive model, Sazmining only earns when we produce bitcoin for our clients,” said Kent Halliburton, CEO and co-founder of Sazmining.
He also pitched mining as a form of bitcoin acquisition diversification: rather than paying the market price on the day of purchase, a miner’s costs are spread across the machine’s working life.
Wyoming-based Sazmining, founded in 2018, operates renewable-powered facilities across the US, Paraguay, and Norway. It says its fleet runs more than 20 percentage points ahead of the Bitcoin network’s carbon-free share.
Proto is Jack Dorsey’s Block’s bitcoin mining play. The Twitter founder has spent years arguing bitcoin is the foundation of “a more open financial system,” funding everything from Cash App’s buy-and-send rails to the Bitkey self-custody wallet, and he framed mining as the obvious missing piece back in 2021: “Bitcoin mining should be as easy as plugging a rig into a power source.”
Block formally announced it was building an open bitcoin mining system in January 2022, with the stated aim of making mining “more distributed and efficient.”
This post Sazmining Now Sells Jack Dorsey’s Proto Immersion Hashboards first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Hot Inflation Data Puts Bitcoin Under Pressure, but ‘Difficult’ Isn’t ‘Bearish’: CoinShares
Bitcoin’s price has dropped this week as new inflation data has come in hot.
But while the largest cryptocurrency’s near-term setup is difficult, it’s not “fundamentally bearish,” according to European asset manager CoinShares’ Head of Research, James Butterfill.
In a report Friday, the analyst said that bitcoin’s near-term challenge stems from a macro environment that’s caught in an awkward middle ground: inflation is too elevated for the Fed to ease up, while the economy is too resilient to force a policy pivot.
“Bitcoin and the broader digital asset market have moved lower on the resulting hawkish repricing, a reminder of how sensitive Bitcoin remains to monetary policy over short horizons,” he wrote.
Bitcoin’s price recently stood at $81,473, down 2% over a seven-day period.
The price of the leading cryptocurrency dropped Wednesday after data showed that U.S. consumer prices shot up more than expected in September.
Then, on Thursday, the Labor Department’s Bureau of Labor Statistics said that U.S. producer prices rose in September at the fastest pace in more than four years.
This has weighed on bitcoin’s price because higher inflation means the Federal Reserve may hike interest rates. Higher borrowing costs can restrict the liquidity the digital coin needs to rally.
The Federal Reserve hiked rates in September and will meet at the end of this month.
But Butterfill added that investors should be patient and advised investors to instead think in the long-term and not react to any single weekly data point.
“For investors, that argues for reading the coming weeks as a data-driven range rather than a trend, and for sizing digital asset exposure against a strategic allocation rather than against this week’s print,” he wrote.
Bitcoin spent the first half of 2026 in a bear market but had its best quarter in years after surging in August and September. Analysts have now said the leading cryptocurrency is now back in a bull market after trading above its 365-day moving average.
This post Hot Inflation Data Puts Bitcoin Under Pressure, but ‘Difficult’ Isn’t ‘Bearish’: CoinShares first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Deutsche Bank To Debut Bitcoin Custody Within Weeks: Report
German multinational Deutsche Bank is just weeks away from its crypto custody service, according to reports.
The lender — which is Germany’s biggest — also plans to expand the custody platform into Asia next year, according to a Friday Reuters report, which quoted its corporate banking chief.
Top banks worldwide are debuting or planning to debut crypto custody services, with BNY Mellon, State Street, Standard Chartered, U.S. Bank, and Citigroup all committing to direct crypto custody over the past 18 months.
JUST IN:
— Bitcoin Magazine (@BitcoinMagazine) October 16, 2026€732 billion Deutsche Bank to launch Bitcoin custody to its 28 million clients
pic.twitter.com/TAh9EwLkIX
Deutsche Bank first officially announced plans to debut a bitcoin custody service for European corporate and institutional clients in September, with the German multinational at the time saying service was subject to the completion of the applicable regulatory timeline.
Friday’s report added that the service will support custody of major cryptocurrencies such as bitcoin before moving to services that help clients move money into and out of stablecoins.
Gerald Podobnik, co-head of the corporate bank, was quoted by Reuters saying that the financial system will need to “offer tokenized or blockchain solutions.”
A number of top banks have started using the technology that powers bitcoin, the blockchain, for their own products in recent years.
Stablecoins and tokenization in particular have become a hot topic as traditional financial firms aim to accelerate certain services.
Crypto custody is often a starting point for banks moving into the digital asset space. BNY Mellon in 2022 became the first major U.S. bank to offer digital asset custody services.
Banks like Citi and Standard Chartered have this year debuted or announced plans for bitcoin custody around the world.
This post Deutsche Bank To Debut Bitcoin Custody Within Weeks: Report first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
CryptoSlate
Sentora’s Firelight coverage pays premiums from vault yield, while FXRP providers’ shared backing can absorb validated losses after a stablecoin buffer.
Read the full story on CryptoSlate
Understand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
US-listed XRP exchange-traded funds ended a 13-week inflow streak as investors withdrew nearly $576 million from four major cryptocurrency ETF categories. Data from SoSoValue showed that XRP funds recorded $1.84 million in net outflows during the week ended Oct. 16, reversing the $11.31 million inflows registered a week earlier. The withdrawal ended the longest active…
Read the full story on CryptoSlate
Understand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
The completed exchange expands Cipher's share base as it adds $850 million in zero-coupon debt to support data-center development.
Read the full story on CryptoSlate
Understand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
The Oct. 16 notice cites unfinished creditor procedures and payment-processing issues, without assigning individual distribution dates.
Read the full story on CryptoSlate
Understand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
NU7 would leave legacy funds issued but unspendable, even with intact keys, while the mainnet activation decision remains pending.
Read the full story on CryptoSlate
Understand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
CryptoTicker.io
On Thursday, October 29, 2026, the Governing Council of the European Central Bank decides on euro area interest rates. The decision falls on the second day of the meeting, after which ECB President Christine Lagarde steps in front of the press. For your crypto portfolio this ECB rate decision matters for a reason that has little to do with the price on the day: the risk-free rate in euros now sits above the yield Ethereum staking delivers. Hold crypto and from this autumn you are no longer comparing against zero but against 2.5 percent.
This piece sets the date in context: where the rates stand today, why the central bank raised them at all, what a further step would mean for the price, for staking yields and for leveraged positions, and which points can be settled calmly in the ten days before the meeting. You will not find price forecasts for October 29 here. Anyone telling you how Bitcoin reacts to a decision nobody yet knows is guessing.
The Governing Council of the European Central Bank meets on October 28 and 29
The meeting calendar of the European Central Bank lists October 28 as day one of the monetary policy meeting in Frankfurt and October 29 as day two, followed by the press conference. That is the usual sequence: deliberation starts on Wednesday, the decisions and their reasoning come on Thursday. The decision is published in the early afternoon Central European Time, with the press conference following a good half hour later.
What matters for planning is the date after it. The next monetary policy meeting of the Governing Council is not in the calendar until December 16 and 17, 2026. Whatever is decided on October 29 therefore holds for around seven weeks. There is normally no interim decision; the central bank departs from that only in severe market disruption.
Deposit rate 2.5 percent: where the policy rates have stood since September 16
The ECB steers the money market through three rates. The most important is the deposit facility rate, the rate banks receive for overnight deposits with the Eurosystem. Since the decision of September 10, 2026, effective from September 16, the central bank's official rate table carries these values:
- Deposit facility: 2.50 percent. The rate that overnight money and short-term euro deposits take their bearings from.
- Main refinancing operations: 2.65 percent. The rate at which banks borrow weekly against collateral.
- Marginal lending facility: 2.90 percent. The overnight credit rate, the ceiling of the corridor.
The path to those levels explains why the subject counts right now. In June 2025 the deposit rate stood at 2.00 percent, the trough of the easing cycle. On June 17, 2026 the ECB lifted it to 2.25 percent, and on September 16 to 2.50 percent. Two increases in one year, after years of falling rates: since the summer of 2026 the euro area has been in a tightening cycle again, not in a phase of cuts.
Inflation at 3.8 percent: the reason for September's rate step
Price developments supply the reasoning. On October 16 Eurostat confirmed the annual euro area inflation rate for September 2026 at 3.8 percent, after 3.2 percent in August. That is the highest reading since September 2023 and sits well above the two percent target the central bank has set itself.
The rise comes almost entirely from one direction. Energy grew 18.9 percent more expensive within a year and so accounted for the bulk of the jump; without that rise in energy prices the rate would sit close to target. Core inflation excluding energy, food, alcohol and tobacco, by contrast, edged up only slightly to 2.5 percent. For Germany, Eurostat reports 3.3 percent.
That breakdown is decisive for assessing the date. A central bank can treat inflation driven mostly by energy prices differently from inflation that has settled into wages and services. Energy prices act with a lag and can fall back just as quickly. Whether the Governing Council adds another step on October 29 or waits hangs on precisely that question.
Fed on the 28th, ECB on October 29: two rate decisions in 24 hours
The week carries a peculiarity that often gets lost in European calendars. The US Federal Reserve meets on October 27 and 28 according to its own meeting calendar, the ECB on October 28 and 29. About a day lies between the two decisions.
For the crypto market the order carries weight. The Fed decides first, and the crypto market trades in US dollars: Bitcoin dominance stood at 60.2 percent on October 19, with total market capitalisation at around $2.77 trillion. If a marked move runs through the market on the evening of October 28, it very probably originates in Washington rather than Frankfurt. The ECB decision lands the following day on a market that has already priced the Fed in.
In practice that means anyone planning an order or a savings plan execution around those days should reckon with two jolts rather than one. And anyone seeing a large move on Thursday should check first whether it has anything to do with the ECB at all.
ECB rate decision and crypto: the three channels the policy rate works through
The link between monetary policy and cryptocurrencies runs through three channels, and none of them is magic.
The price of money
A higher policy rate makes credit more expensive. Companies and households have less free money, and some of it would otherwise have flowed into risky assets. Crypto sits well down that order of preference, behind equities and bonds. It shows up in inflows from companies and funds, not in a single day's price.
The alternative without price risk
As long as overnight money paid nothing, holding Bitcoin cost no forgone interest. At a deposit rate of 2.50 percent that changes. Any asset delivering no running income now competes with a rate you receive without price risk. The same applies to Bitcoin and to gold. Specialists call it opportunity cost.
The euro-dollar exchange rate
If euro area rates rise faster than US rates, the euro tends to firm against the dollar. Bitcoin is quoted in US dollars. A firmer euro lowers the euro price of a coin even when the dollar quote does not move. On October 19 Bitcoin stood at around $82,700 and around €73,700; Ethereum at about $2,428 and €2,164. Count in euros, then, and you never see exactly the same move as an observer watching the dollar quote.
Staking yield against the risk-free rate: 2.20 against 2.50 percent
This is where the rate decision gets concrete for crypto investors. The yield from Ethereum staking currently sits below the ECB deposit rate. DefiLlama data show an annual yield of around 2.20 percent for Lido, the largest liquid staking provider, on roughly $23.4 billion of deposited capital, and around 1.98 percent for Rocket Pool. Our own measurement of October 18 came to 2.21 percent and set it against the ECB rate of 2.50 percent; the assessment is in our analysis of the staking yield below the ECB rate.
The comparison limps in one place by design, and that belongs in the picture. A staking yield accrues in ether and carries the cryptocurrency's full price risk, plus smart contract risk and, at some providers, a withdrawal period. The central bank's deposit rate, by contrast, is interest on euro balances. Two yields in two different currencies with two different risks cannot be set cleanly against each other.
Something shifts nonetheless. Hold ether solely for the staking yield and above a certain rate level the argument weakens. If the ECB raises again on October 29, that gap widens. Which platform pays out how much and which lock-up periods apply is shown in our comparison of staking platforms; a look at the actual net yield after fees pays off before any renewal.
Bitcoin on rate days: leverage and liquidation in a thin order book
Dates with a fixed time create a pattern of their own. Ahead of publication many traders pull their orders out of the book, because nobody wants to stand on the wrong side of a surprise. The order book thins out, and in a thin book the same order size moves the price further than usual.
For leveraged positions that is the dangerous part. A liquidation is the forced closing of a position when the margin no longer suffices. It is triggered by the brief spike in between, not by the closing price. Trade with leverage and you check the distance between the current price and your own liquidation price before days like these, then decide deliberately whether that buffer is enough for a rate decision.
Without leverage the subject is calmer. A spot holding survives a swing of a few percent without consequence, as long as you do not have to sell.
Euro balances, stablecoins and overnight deposits between the dates
A rising deposit rate also affects the money sitting on an exchange between two purchases. Three routes are open, and they differ in one point that is easily overlooked.
A euro balance in a German overnight deposit account earns interest, and the level follows the central bank's deposit rate at some remove. A euro balance on a crypto exchange as a rule earns nothing; it sits there ready as a means of payment. Euro stablecoins, in turn, are tokenised euro claims; the interest income from the backing reserves accrues to the issuer, not to the holder.
At a deposit rate near zero that difference was immaterial. At 2.50 percent, a larger balance sitting unremunerated on a trading platform for months costs noticeable money. Leave longer gaps between purchases and you move the part you do not need back to the bank account. Which venues offer a euro deposit without the detour through a stablecoin is set out in our crypto exchange comparison.
Analysts' expectations point to December, not to October
A rate decision cannot be predicted, but it is possible to show what professional observers reckon with. In its Kapitalmärkte Weekly of October 2, 2026, LBBW writes that it expects two further increases of 25 basis points each in the euro area by the end of the first quarter of 2027; the bank sees the peak at a deposit rate of 3.00 percent. It names the Governing Council's December meeting as the most likely date for the next step.
Against an increase as early as October 29 stands the composition of the inflation: the jump to 3.8 percent came from energy prices, while the core rate stayed comparatively calm at 2.5 percent. For it stands the fact that the headline rate sits as far above target as it last did in 2023, and that the central bank has already acted twice this year. Both readings are defensible, and the Council takes the decision with data that will be fresher on October 29 than it is today.
For your own planning, then, a different question is more useful than the one about the outcome: what changes in the portfolio if the deposit rate stays at 2.50 percent, and what if it rises to 2.75 percent? Think both cases through once beforehand and there is nothing to decide on the day.
Rate rise or rate cut: why both directions count for assets without interest
The effect of monetary policy on crypto fits into one sentence: rising rates raise the price of parking money in an asset with no running income, falling rates lower it. The crypto market shares that role with gold, which also pays no interest and whose course is routinely watched on rate days.
So for assets without interest a cut usually works in the opposite direction from a rise, and through the same mechanism. Financial markets trade the deviation from expectations, not the decision itself: a rate that comes in exactly as priced moves little. What counts is the tone of the reasoning, that is, whether the central bank signals further measures or hints at the end of the cycle.
For investors in Europe a second factor comes on top that does not apply in the United States. The rate decisions of the ECB and the Fed have not moved in step since 2026, and the gap between the two rate levels helps set the euro-dollar rate. Live in the EU and pay in euros, and you carry that exchange rate influence with every purchase, regardless of how the dollar quotes of the cryptocurrencies develop.
The position in the autumn of 2026 is therefore unusual: two large central banks are tightening at the same time, and the ECB deposit rate sits above the yield of the largest staking market for the first time in years. What effect that has on inflows into crypto products can only be measured credibly over several quarters, not on a decision day.
The US Federal Reserve moves the crypto market more than the ECB
A look at coverage over past years shows a stable pattern: European crypto media mostly pick up ECB rate decisions the day after, and the market reactions come out weaker than after Fed dates. There are two sober reasons for that.
First, the crypto market trades predominantly in US dollars and is moved by US capital. Second, the greater part of institutional demand flows through US products such as the spot ETFs. Fed monetary policy therefore acts more directly on liquidity and risk appetite in the crypto market than the ECB's does.
It does not follow that the ECB rate decision is irrelevant to you. It acts less through the daily price and more through your own arithmetic: through the interest on your euro account, through the yield your crypto holding has to deliver against it, and through the cost of a loan if you have one running. That effect is slower and more durable than any price swing on a Thursday afternoon.
The tax view before year-end belongs in the same planning
Two months lie between October 29 and the end of the year, and in exactly that window more is decided for German investors than on the rate date itself. Under current German tax law, gains from selling cryptocurrencies are tax-free as a private disposal after a holding period of one year; within the period the personal income tax rate applies, provided the exemption threshold is exceeded. What governs in each case is the acquisition date of the individual position.
Anyone wanting to shift part of a holding into euros because rates have risen therefore looks at the purchase date first, not at the price. A sale eleven months after the purchase can cost more than the same sale four weeks later, and no rate decision makes up for that. The evidence sits in the transaction data of your trading venues; tools that bring that data together we have set side by side in our comparison of tax tools. These lines do not replace tax advice.
ECB rate decision: ten days of lead time remain until October 29
The date is fixed, the decision is not. Three steps can be dealt with calmly in the days beforehand, and none of them calls for an opinion on how the meeting turns out.
- Set your holding's yield against the euro rate. Note what your staking or lending positions actually deliver after fees, and put the deposit rate of 2.50 percent beside it. What the platforms currently pay out and which lock-up periods apply is shown by the comparison of staking platforms.
- Go through the euro balance on the trading platform. Amounts you will not need over the coming weeks sit better in an interest-bearing account than unremunerated on the exchange. Which venues allow direct euro deposits and withdrawals is in the exchange comparison.
- Sort purchase dates and holding periods before you sell anything. For every position its own acquisition date counts. A portfolio tracker gives you that overview; the selection is in the comparison of tax tools and trackers.
On October 29 itself little then remains to be done: read the decision, add the reasoning from the press conference, and run your own arithmetic through once with the new rate. The next date is not until December 17.
(As of October 19, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
In the 24 hours to Monday morning, tokens worth $1.57 billion changed hands on Solana's decentralised exchanges. On Ethereum the same period brought $706 million. Solana therefore turns over more than twice as much, even though its applications hold only an eighth of the capital. That divergence is the real finding of the week's opening, and it says more about the state of play than the price itself: SOL stood at $105.80 on Monday morning, 2.7 percent above the previous day but still 6.0 percent below its level a week ago (CoinGecko, as of October 19, 8:45 UTC).
Over a monthly view the question is not how much gets traded but whose money is being moved. Where the price can point over a span of months is set out in our Solana price prediction. This article works out the metric that connects the two, and shows what it means for your tax position and your buying route in Germany.
Solana turns over $1.57 billion in a single day
The figures come from the data at DefiLlama, queried on Monday morning. Across all decentralised exchanges on Solana combined, volume over the preceding 24 hours came to $1.566 billion. That is 25.0 percent more than the day before. Over seven days trading adds up to $14.03 billion, a rise of 22.6 percent on the previous week.
A Sunday is not a strong trading day. That turnover picked up anyway, while the price slipped on a weekly view, is the first sign that positions were being rotated rather than added. Solana's market capitalisation stood at $62.4 billion on Monday morning, with 589.4 million SOL in circulation out of a total of 636.0 million.
Ethereum reaches $706 million on eight times the capital
The same query for Ethereum returns $705.9 million over 24 hours, up 20.5 percent, and $8.07 billion over seven days, here only 1.2 percent more than the week before. Solana traded 2.22 times Ethereum's volume on Sunday, and on a weekly comparison the gap is widening.
It is the second figure that makes the comparison meaningful. In total value locked, the capital committed to a blockchain's applications, Ethereum stands at $49.86 billion and Solana at $5.89 billion. That is a ratio of 8.5 to 1 in Ethereum's favour. Two networks whose committed capital differs by a factor of eight come out in reverse order on trading volume.
The turnover: 26.6 against 1.4 percent of committed capital
Those two figures yield a metric that the usual dashboards do not carry: daily turnover. It sets a day's trading volume against committed capital and answers the question of how often the same dollar is moved in a day.
For Solana the sum is $1.566 billion divided by $5.89 billion, so 26.6 percent. Every day a good quarter of all committed capital is pushed through trading once. For Ethereum the same sum reads $706 million divided by $49.86 billion, so 1.4 percent. Turnover on Solana is therefore around 19 times as high. Both values are our own calculations from the DefiLlama figures cited above for October 19; the platform itself does not publish this ratio.
As a metric, turnover is neither good nor bad; it describes the design. High turnover means a network serves a lot of trading on little capital. Low turnover means capital sits and works there rather than being moved.
Why bots move the same capital several times a day
The explanation lies in the costs. A transaction on Solana costs fractions of a cent, and a block closes in under a second. Under those conditions a trade pays off at tiny price differences. Trading bots and aggregators buy the same token several times a day on one exchange and sell it on the next, each time for a spread of a few tenths of a percent. Every one of those passes shows up in the statistics as volume, even though no new money has entered the network.
A second data point supports that reading. The stablecoin base on Solana, the money standing ready in dollar-pegged tokens such as USDC, came to $15.49 billion on Monday (DefiLlama, October 19). That base is therefore around two and a half times the size of the committed capital of $5.89 billion. On Ethereum, $144.04 billion sits in stablecoins against $49.86 billion of committed capital, a ratio of just under 3 to 1. On Solana, then, an above-average share of money is parked in trading liquidity and a below-average share is tied up in lending and yield applications.
Total value locked describes the sum of all deposits held in a blockchain's financial applications, for instance in lending markets, liquidity pools and staking derivatives. When that figure rises, investors have brought capital into the network and committed it there. When it falls, they have withdrawn it, or the price of the deposited tokens has dropped.
Counted in SOL, the network holds less capital than in June
A TVL measured in dollars mixes two things: how many tokens are deposited and what those tokens cost. If the price falls, the dollar figure drops even when nobody has withdrawn anything. So the counter-calculation in SOL is worth doing. For that, DefiLlama's daily TVL was divided by CoinGecko's respective daily closing price, over the past 120 days.
The result: on October 19 the committed capital corresponded to 55.68 million SOL. On October 18 it was still 57.04 million, on October 10 it was 56.47 million. Ninety days ago, on July 21, 63.75 million SOL sat in the network, and the window's high dates from June 25 at 69.08 million. From that high, 19.4 percent of the deposited tokens have gone in not quite four months, and that is independent of the price. On only 20 of 120 days was the figure lower than today; the window's low falls on September 29 at 54.09 million SOL.
This calculation is not someone else's analysis but our own work from two freely available series. The counter-calculation separates the price problem from the quantity problem and shows that the decline in committed capital does not hang on the fallen price alone.
What has changed since Sunday's emission article
On Sunday evening we worked through Solana's emission here: 22.88 million new SOL a year and $1.56 billion sitting in the funds, as set out in our piece on the emission of 22.9 million SOL a year. Three things have shifted since.
First the price: on Sunday SOL averaged $103.36 over the day, on Monday morning $105.80, a rise of 2.4 percent. Second the committed capital: it fell from $5.896 billion to $5.890 billion, and counted in SOL from 57.04 million to 55.68 million. The decline in the token quantity is therefore much larger than the one in the dollar sum, because the higher price masks the difference. Third the trading: daily volume picked up by a quarter.
Taken together that means the price rise from Sunday to Monday came with more trading but less deposited capital. Sunday's emission question remains open, because no vote has been held on proposal SIMD-0550 since.
The levels: $100.48 below, $106.05 above
On October 14 we named the $100 level here as a test. The level has held since, but without much room. In the 24 hours to Monday morning the low was $100.48 and the high $106.05 (CoinGecko). The current price therefore sits 5.3 percent above the daily low and 0.2 percent below the daily high.
What justifies those two values is that they were actually traded this weekend, not a chart pattern. To the upside the next marker is the level of October 12, when SOL averaged $111.25 over the day; the figure $109.07 dates from October 10. To the downside the round $100 stands, and its defence has now been running for five days. SOL is 63.9 percent away from its all-time high of $293.31 on January 19, 2025.
$9.71 million in fees in one day, and who gets them
High turnover is not without consequence; it generates income. Fees accruing on the Solana blockchain added up to $9.71 million in the 24 hours to Monday morning and to $79.76 million over seven days (DefiLlama, October 19). Measured against committed capital of $5.89 billion, the daily figure amounts to a rate of 0.16 percent, which annualised puts it in the order of 60 percent of the capital committed today.
That extrapolation is an arithmetic check, not a forecast, because fees swing with trading. The check does show what the turnover ratio means in economic terms: a network with little committed capital and a lot of trading earns from movement, not from sitting still. Part of that income flows through the block reward to the validators and hence to the stakers, the rest to the applications the trading went through.
How to work out the turnover yourself
The metric needs no paid data source. Two values are enough, and both are freely available online.
- Open the blockchain's page at DefiLlama, for instance the overview page for Solana. It carries the current TVL and the 24-hour trading volume of the decentralised exchanges.
- Divide the volume by the TVL and convert the result into percent. For Solana on October 19: 1.566 divided by 5.89 gives 0.266, so 26.6 percent.
- Repeat that for a second blockchain and compare. The important thing is to read both values on the same day and at the same time, because the 24-hour volume shifts continuously.
Anyone recording the series over several weeks will see whether a network is drawing in capital or only trading. If volume rises while TVL falls, turnover grows and the network lives more off short-term trading. If both rise, new money is arriving. For judging a coin that is the more honest series than the volume figure alone, which projects like to advertise with.
Every swap starts the one-year period again
High turnover in the network has a tax counterpart in the portfolio, and in Germany that hits everyone who swaps actively. Gains from selling cryptocurrencies are a private disposal under section 23 of the Income Tax Act. If more than twelve months lie between purchase and sale, the gain stays tax-free. Below that it is taxed at your personal income tax rate as soon as the sum of all private disposal gains for a year reaches the exemption threshold of €1,000.
What counts as a disposal is decisive here. Swapping SOL into a stablecoin or into another token is also a disposal, and for the newly acquired holding the one-year period starts from scratch. Take part in the turnover and swap back and forth several times within a few weeks, and at the end of the year you hold not one position with one holding period but many, each with a fresh one. We track the current state of the political debate about that period on our page on the crypto holding period.
In practice that means you need a record of every swap with the date, the amount and the euro value, because the tax office assesses the holding period per acquisition. Which programs build that allocation out of exchange data is shown in our comparison of crypto tax software and portfolio trackers. A separate rule applies to staking income: staking rewards count on receipt as other income under section 22 number 3 of the Income Tax Act, with its own exemption threshold of €256 a year.
Buying route and custody: where the paths differ
Since the EU regulation MiCA came into full effect, anyone wanting to buy SOL in Germany has essentially two routes. The first runs through an authorised service provider that holds the tokens for you. There the key sits with the provider, access is simple, and losing your login details can usually be remedied. Which providers charge what and which authorisation they hold is set out in our overview of the best crypto exchanges.
The second route is self-custody on a hardware wallet. You then hold the private key yourself, nobody can freeze your holding, and you carry the risk of losing the key alone. For staking SOL the difference is concrete: with self-custody you delegate to a validator yourself and pick its commission, whereas with a custodian the custodian decides on the offer and keeps part of the income. The range of terms is shown in the comparison of staking providers.
To put the yield in context: the reward for staking SOL comes out of the emission of new tokens and out of part of the network fees. Since emission keeps falling under the schedule described on Sunday, the future yield hangs more heavily on the fees, and therefore on precisely the turnover this article is about.
Our assessment: trading without new money
From the newsroom's point of view the turnover carries the story of Solana as the fastest trading venue, but it does not carry the story of capital inflows. The evidence sits above: volume rose 22.6 percent over seven days, while committed capital counted in SOL fell from 56.47 to 55.68 million and the price lost 6.0 percent. More trading on fewer deposited tokens with a falling price is the pattern of rotation within the network.
Against that stands the fee side. $79.76 million over seven days is real income, not a bookkeeping entry, and part of it flows to the stakers. A network that earns from movement does not strictly need growing committed capital to work economically. Anyone holding SOL should therefore follow both series and not the volume figure alone, because on its own it does not answer the question of new money. This is explicitly not a recommendation to buy or sell.
Solana at $105.80: the turnover carries, the inflow is missing
Monday morning's position can be worked through in three steps.
- Work out the turnover ratio for Solana and a comparison blockchain yourself once and note it with the date, so that in two weeks you have a series of your own. The instructions are above.
- Check the purchase date for every SOL holding in your portfolio, and with it when the one-year period expires. Which programs build that out of exchange data is shown by the comparison of crypto tax software.
- Decide deliberately between custody at a provider and your own wallet, because the staking terms hang on it. Provider terms are in the overview of staking platforms.
(As of October 19, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
A token unlock is the date on which a project's locked tokens become tradable. Nothing is created in the process: the supply has existed all along, it was simply held in a contract that would not release it before a given date. What matters, then, is how that figure compares with circulating supply and the schedule under which it comes free, not the headline with the big number. Two patterns shape that schedule: the cliff, a single large release after a lock-up, and linear vesting, where the same supply trickles out in instalments over months.
The difference is not a technicality. With a cliff, the entire supply hits the order book on one day. With linear vesting, the same supply spreads across twelve or twenty-four dates, none of which stands out on its own. Tell the two patterns apart and a vesting schedule shows you when selling pressure builds and when it has already been priced in.
What a token unlock is, and why nothing new is created
When a token is issued, a project sets out how total supply is divided: to the team, to early investors, to a foundation, to reward programmes, to the open market. Only part of that is tradable on day one. The rest sits in a vesting contract, program code on the blockchain that will not hand the tokens over before a set point in time. An unlock is the moment that contract releases part of the supply.
That is why the phrase "new tokens are coming to market" misleads. Total supply does not change, only the tradable share does. Two terms keep the distinction clear. Circulating supply is the number of freely tradable tokens. Total supply covers every token in existence, locked ones included. Total supply times the price gives the fully diluted valuation, or FDV. When FDV sits far above market capitalisation, a lot of supply is still inside the contract. Why freshly listed tokens with that gap often collapse is worked through with examples in our analysis of FDV and circulating supply.
Cliff: a lock-up, then a single large release
A cliff is a lock-up at the end of which a large amount comes free in one step. Six or twelve months after trading starts is typical. The original purpose is a sound one: team and early investors should not be able to sell on day one. The price for that is a fixed date on which supply jumps.
How big that jump can get shows up in individual cases in our own coverage. At Kite a one-year lock ends in early November, and on our count of October 17, 2026 that frees 1.11 billion tokens, equal to 43 to 46 percent of circulating supply there — set out in our assessment of the Kite unlock in early November. A cliff on that scale is a different animal from a monthly tranche of two percent.
What counts is not the absolute figure but the share of circulating supply. A billion tokens sounds large, yet against a circulating supply of a hundred billion it is one percent. That same billion against a circulating supply of two billion is half. The number alone says nothing; the ratio says everything.
Linear vesting: the same supply, spread across many dates
Under linear vesting the contract releases equal portions at equal intervals, usually monthly, sometimes weekly or block by block. The total at the end is the same as under a cliff, but the effect on the price differs sharply: recurring small releases work like a steady stream of supply the market can adjust to, not like a single blow.
Many projects combine the two: a cliff first, then linear tranches. At Plasma, as we reported on October 15, 2026, a cliff became a schedule of 24 monthly tranches in which the first tranche amounts to around five percent of circulating supply — the details are in our piece on the XPL unlock on October 25. At Arbitrum, on our count of September 30, 2026, 92.6 million ARB leave the lock every month, a pattern we broke down under Arbitrum and the end of the lock-up.
For assessment purposes that means a single date in a linear schedule is rarely an event. The schedule as a whole is one, because it tells you how much supply is still to come over the next twelve months.
Who receives the tokens, and why that decides the effect
The same supply acts entirely differently depending on whose hands it lands in. Four recipient groups are typical, and each behaves in its own way.
Early investors and venture capital
These backers bought in an early round at a fraction of today's price. Even a sale well below the current level remains a profit for them, and many funds owe their own investors a duty to realise gains. This group generates the hardest selling pressure.
Team and founders
For team and founders the tokens are compensation. A partial sale is routine and no warning sign in itself. It becomes notable when the entire allocation starts moving shortly after the cliff, because that can be traced on the blockchain.
Foundation and project treasury
These tokens go into grants, partnerships and developer programmes, and reach the market with a delay, by many small routes. Effect on the price: real, but dispersed.
Rewards for users, staking and liquidity
Here tokens flow to many recipients in small amounts. Some are sold at once, some are left alone. Whether the supply can be sold at once at all hangs on a second lock that is often overlooked: the waiting period for unstaking. How long that runs at the large networks is set out in our piece on the staking lock-up period and the duration of unstaking.
Locked, incidentally, does not always mean nobody can sell. Anyone expecting locked tokens can hedge them in advance through futures or hand them on at a discount in the over-the-counter market. The selling pressure then builds before the date rather than on it. That a large locked amount shifts expectations on its own we described using the case of 700 million HYPE outside circulation.
Four numbers that make a vesting schedule readable
A vesting schedule consists of a handful of figures, and four of them are enough for an assessment.
First, the share of circulating supply. Divide the amount coming free by current circulating supply. Below two percent is a routine date, above ten percent an event, above thirty percent a doubling of supply within reach.
Second, the ratio to daily turnover. Set the cash value of the amount coming free against average daily trading turnover. If the release equals twenty times daily turnover, the market cannot absorb it in a day even if everyone wanted to sell. If it equals a fraction of it, the figure is a headline without consequences.
Third, the recipient group. Does the schedule say what share goes to early investors, to the team, to the foundation and to rewards? Without that breakdown, half the information is missing.
Fourth, what remains in the contract. How much is still locked after this date, and until when? A project with 90 percent of total supply still inside the contract has an unlock ahead of it every month.
These four numbers sit in a project's tokenomics documentation and in the unlock calendars of the analytics providers. Which tools show such calendars, circulating supply and on-chain movements together is covered in our comparison of analytics platforms.
Why the price often falls before the date rather than on it
An unlock date is public, often years in advance. So it behaves differently from a piece of news: the market can price it in. In practice a decline often shows up in the days or weeks before the date, as traders cut positions or bet against it through futures, followed by calm afterwards when the expected wave of selling fails to arrive.
No trading recipe follows from that, only a reading aid: a decline before a large unlock is no proof of a problem at the project, and a quiet unlock day is no proof that nobody sold — the sales may have happened earlier. The assessment only becomes solid once you track the movement of the released addresses on the blockchain, and at most projects that can be done a few days after the date.
Tax in Germany: when a released token starts a holding period
This is where a market topic becomes a topic for your tax return, in two distinct cases.
If you already hold a token and are merely watching a project's unlock, nothing changes for you in tax terms. What governs is section 23 of the Income Tax Act: gains from private disposals stay tax-free when more than a year lies between purchase and sale. Within that period they are taxed at your personal rate as soon as total gains for the year exceed the exemption threshold. Sell out of worry about an unlock shortly before your year is up, then, and the tax can cost more than the price decline you are trying to avoid.
If you receive released tokens yourself — from a reward programme, from staking, from an airdrop or as compensation — the case is different. What then counts is the value at which the tokens arrive and when the holding period begins. That classification depends on the type of inflow and is a matter for tax advice in the individual case; the only certainty is that you have to document the time of the inflow and the price at that moment, because you cannot reconstruct them later. A tool from our comparison of crypto tax software records that data automatically.
Tradability in Germany: an unlock is no help without a venue
A practical point that unlock reports regularly leave out: a supply being technically released does not mean you can buy or sell it from Germany. Many of the projects with large vesting schedules are young tokens listed at only a few venues, and under Regulation (EU) 2023/1114 providers may only supply crypto services in the EU with authorisation. In practice that means checking first whether the token is tradable at an authorised provider, and only then what an unlock date means for it. An overview of venues and their costs is in our exchange comparison; anyone trading mainly in large names such as Bitcoin will rarely meet the unlock question anyway, because no vesting contracts are still running out there.
The second practical point is market depth. A token traded for a few million dollars a day cannot take a release in the tens of millions without individual sales moving the price. Sell into a market like that with a large market order and you pay the discount yourself.
Our assessment of how to handle unlock dates
From the newsroom's point of view, large unlock figures are regularly overvalued in coverage and the schedules behind them undervalued. The evidence comes from the cases in our own coverage: a cliff covering 43 to 46 percent of circulating supply, as at Kite on our count of October 17, 2026, is categorically different from the first of 24 monthly tranches at Plasma at around five percent on our report of October 15, 2026 — yet both appear in reports as an "unlock" with a big number in the title. What follows is this: the two figures that carry an assessment are the share of circulating supply and the ratio to daily turnover, and neither appears in the headline. Against that stands the fact that even a perfectly read schedule says nothing about recipients' intentions; whether a fund sells only shows on the blockchain after the date. No recommendation to buy or sell follows from any of it, and with young tokens carrying large locked amounts a total loss is possible.
Token unlock: the date sits in the vesting schedule, not in the chart
An unlock creates no new money and no new tokens; it only shifts the boundary between locked and tradable. Whether that step means selling pressure comes down to three figures you can gather in a few minutes:
- Calculate the share and daily turnover. Divide the amount coming free by circulating supply and set its cash value against daily turnover. Both values come from the tools in our comparison of analytics platforms.
- Look up the remainder in the contract. Check in the tokenomics documentation how much stays locked after this date and until when. A project with a schedule running for years has a date ahead of it every month; which exchanges list the token at all is shown by the exchange comparison.
- Document your own inflows. If you receive released tokens yourself, record the date and price of the inflow, because valuation and holding period hang on them. A tool from the tax software comparison takes over the bookkeeping.
(As of October 18, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
The NEAR mainnet still mints up to 2.5 percent new tokens a year. The proposal to cut that ceiling to 1.6 percent was not part of the protocol on October 18, 2026. It still carries draft status, and by its own wording it cannot take effect through a vote alone. Anyone staking NEAR should therefore keep calculating with the old rate until a protocol upgrade lands.
The price is moving the other way. NEAR trades at $4.69, down 6.2 percent over 24 hours and 17.56 percent over the past week. That makes NEAR the weakest of the 25 largest cryptocurrencies on a weekly view, ahead of Zcash at minus 16.52 percent and Cardano at minus 15.88 percent. Bitcoin lost 3.23 percent over the same stretch, Ether 7.33 percent. Every price in this article comes from CoinGecko market data as of October 18, 2026.
The emission figure in the NEAR protocol still reads 2.5 percent
The annual ceiling for new NEAR is a protocol parameter, not a foundation pledge. The protocol holds it as a fraction: one fortieth, or 2.5 percent of total supply. The project's developer documentation describes the same value as a target and states that the target is calculated to amount to 2.5 percent of total supply per year (NEAR documentation).
That value sits unchanged in the live mainnet on October 18, 2026, in protocol version 86. In units, it works out like this: at a total supply of 1,309.3 million NEAR, up to 32.7 million new tokens may be created in a year. At a 1.6 percent ceiling it would be 20.9 million.
Why the emission rate is the more important number for stakers
NEAR staking rewards do not come out of transaction fees. Fees are burned after the contract rebate, and rewards come out of emission. If the emission rate falls, so does the pool every staker is paid from. If the amount of bonded tokens rises at the same time, that same pool is split across more stake. Together, those two figures produce the yield that actually arrives.
What the draft cut to 1.6 percent sets out
The proposal has sat in NEAR's governance forum since October 7, 2026. It was filed by Sal Ternullo for SVRN, which the document identifies as OceanPal Inc., listed on NASDAQ under the ticker SVRN. It envisages a linear glide in maximum annual emission from 2.5 to 1.6 percent over 24 months, roughly 3.75 basis points a month. Ahead of that sits a grace period the document puts at 90 days in one place and at a full quarter in another.
The reward split stays at 90 percent for staking participants and 10 percent for the project treasury under the draft; measured, the document cites 10.13 percent, correcting the often quoted 96-to-4 split. Over the 24 months of the glide path, the draft's own arithmetic has 11.8 million NEAR never created, equal to 0.86 percent of supply. Over six years the document names 66.1 million NEAR, or 4.36 percent, valued at around $284 million at a price of $4.30.
On yield, the draft's table cites 5.268 percent gross today and 3.372 percent at the 1.6 percent target, both assuming a staking ratio of 42.71 percent. A different section of the same document carries 4.80, 3.93 and 3.07 percent for the first two years. That spread stands as the document leaves it: planning with one of those numbers means planning with a figure from a draft that does its own maths two different ways.
A vote on its own does not change the emission rate
The decisive sentence sits in the draft itself: the proposal cannot take effect through a House of Stake vote alone. The ceiling is a protocol parameter, and changing it requires validators to adopt it through the usual upgrade process. The document lists two stages for that, ratification in governance and then adoption in the protocol. Formally the proposal is filed as a decision requiring a supermajority, and it still reads as a draft.
Our October 3 report described the proposal ahead of the vote. Two weeks on, the finding reads differently: the hurdle is not the vote but the upgrade behind it. Until validators run the new value, 2.5 percent stands, whatever a governance round decided.
The staking yield hangs on two figures, not one
The formula behind the draft's numbers is plain: take the emission rate, subtract the treasury share, divide the result by the staking ratio. With the document's assumptions that gives 2.5 percent times 0.9, divided by 42.71 percent, hence the 5.268 percent cited. The same formula with 1.6 percent gives 3.372 percent. The calculation holds up, but it rests entirely on the staking ratio inside it.
That ratio is no constant. It shifts with every staker who bonds or withdraws tokens, and it moves faster than a protocol parameter. So it is worth looking at where it actually stands today. If you are planning around a yield, current provider terms are in our staking platform comparison; the figures calculated here are protocol gross values, before any validator or exchange fee.
Our own survey: 601.0 million NEAR sit with 403 validators
On October 18, 2026, 601.0 million NEAR are bonded to active validators on the NEAR mainnet, spread across 403 addresses. Against total supply of 1,309.3 million NEAR that works out to a staking ratio of 45.90 percent. Because circulating supply at NEAR is effectively identical to total supply, the choice of denominator changes nothing here. From the previous epoch, a further 13 validators dropped out of the active set.
The basis is the NEAR mainnet's protocol values and the stakes of all 403 active validators, plus total supply from the latest block. That covers 403 validator stakes and four protocol values. cryptoticker.io collected this data itself on October 18, 2026.
An epoch runs twelve hours
The length of an epoch follows from the same protocol values: 43,200 blocks at one block a second, so twelve hours. The figure matters in practice, because rewards and changes in the validator set follow epochs rather than calendar days. Unstake your NEAR and you do not get them straight back; release takes several epochs. Exactly how many depends on the validator or the provider and is set out in their terms.
At today's ratio the yield comes out below the draft's figure
Feed the ratio we measured, 45.90 percent, into the draft's formula and both ends shift down. Today the calculation gives 4.90 percent gross rather than the 5.268 percent cited. At the 1.6 percent target it gives 3.14 percent rather than 3.372 percent. The reason is not a new decision but arithmetic: the same emission spreads across more bonded tokens.
The draft names no denominator for its 42.71 percent, so the two ratios are not necessarily measured on the same definition, and part of the 3.19 percentage point gap may come from that. The direction holds regardless. The more NEAR sits in staking, the less is left for each individual stake, and the yield a draft from October 7 works with is not the yield a staker sees on October 18.
Minus 17.56 percent over seven days, plus 27.91 percent over thirty
The price picture depends on the window, and both windows belong in the same view. On a weekly view NEAR is down 17.56 percent, putting it last in the top 25. Over 30 days it is up 27.91 percent. The weekly high was $5.89 on October 12, the daily high $5.05, the daily low $4.63. At a market value of $6.15 billion and daily turnover of $620.6 million, NEAR ranks 20th.
In our view the emission dispute does not account for the weekly loss on its own. Against that reading stands the breadth of the move: Zcash, Cardano and Stellar lost 16.52, 15.88 and 15.05 percent over the same period with no emission proposal of their own. For it stands the ranking: NEAR fell harder than those three, and for a token whose yield hangs on an open parameter, an unresolved position is a discount. Either way this is a correlation, not a cause, and no price target follows from it.
What has changed since our NEAR article of October 16
NEAR stood at $5.26 on October 16, when we reported on the confidential deposit route for SOL on NEAR. By October 18 that had become $4.69, down 10.8 percent in two days. The $5 level, which held at the time, broke in that window and has not been reclaimed since; the daily high of $5.05 sat just above it, the daily low of $4.63 well below.
Nothing has been added to the protocol since, and that is precisely the finding. Between October 16 and October 18 the emission rate did not move, the staking ratio stands at 45.90 percent, and the ceiling reads 2.5 percent. The only thing that changed is the price at which that yield is bought.
Buying in Germany: MiCA authorisation of the exchange, and custody after that
Since the European crypto regulation MiCA, anyone buying NEAR in Germany buys from a provider that has to be authorised for it. MiCA is the EU regulation on markets in crypto-assets; it sets out which providers may offer and hold crypto-assets in the EU. In practice, when getting in: check which authorisation your trading venue works under, and whether it will keep supporting NEAR after a protocol change. Costs differ sharply between venues, and the comparison at the end of this article puts them side by side.
Staking adds the custody question. Hand NEAR to a validator or an exchange and control over it is no longer yours for the duration of the bond. At a calculated 4.90 percent gross that is a different trade-off than at ten percent, and a different one again if the yield is meant to glide towards three percent over 24 months.
Leverage and liquidation: what a 17.56 percent weekly loss triggers
A leveraged NEAR position survives a week like this one only with room to spare above the liquidation threshold. At ten times leverage a move of roughly ten percent against you wipes out the stake; NEAR lost 10.8 percent between October 16 and October 18 alone. Daily high to daily low spanned 8.3 percent. If you trade with leverage, measure that range against your buffer, not against the closing price.
Holding period and tax: staking income runs differently from sale proceeds
For German investors, income tax law separates two events that coincide in staking. Selling NEAR falls under private disposals in section 23 of the Income Tax Act, with the one-year period set out there. Ongoing staking rewards are assessed separately and regularly land under other income in section 22.
In practice each individual reward counts in staking, with its timestamp and its value. At a calculated 4.90 percent gross and a payout per epoch, so twice a day, a few hundred individual events add up over a year. Keeping that by hand costs time; the usual tools take the counting off your hands. Your own case remains a matter for a tax adviser, and this text does not replace one.
NEAR staking: 2.5 percent emission stands until the protocol changes
- Recalculate your own yield. The protocol gross figure on October 18, 2026 works out at 4.90 percent; what reaches you sits below that after validator or exchange fees. Provider terms are in the staking platform comparison.
- Collect the records for the tax year. Every reward counts with its timestamp and value, and at two payouts a day that adds up. A tool from the tax software comparison takes the counting off your hands.
- Check the venue before you buy more. Authorisation, costs and NEAR availability differ sharply; the exchange comparison puts them side by side. You can follow the draft itself in NEAR's governance forum.
(As of October 18, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy. Crypto-assets are highly volatile and a total loss is possible.)
When you transfer euros to a crypto exchange and leave them there until you buy, that money sits somewhere. Not with you, not in your wallet, but in an account somebody else runs. Which account that may be, and in whose name it has to be held, is what the European Securities and Markets Authority, ESMA, spelled out in a new answer on October 16, 2026. The short version: a payment service provider without a banking licence is a staging post for no more than one business day, and the account at the bank has to be in the exchange's name, not in the name of the provider in between.
What ESMA answered on MiCA article 70 on October 16
ESMA published five new questions and answers that day. Four concern crowdfunding platforms and the calculation of the active account under the EMIR 3 reform, and are of no relevance to retail investors. The fifth, Q&A 2949, is addressed to crypto asset service providers, and therefore to every exchange where you hold a euro balance.
A market participant had asked two things. First: may an authorised crypto asset service provider park client funds temporarily in an account at a payment service provider without a banking licence, such as an e-money institution or a payment institution? Second: may the funds stay there longer if the account does sit at a genuine bank but is held in the name of that payment service provider and kept technically separate from its other accounts?
ESMA answers the first question with a qualified yes and the second with a plain no. The answer is dated October 6, 2026 and was published ten days later.
MiCA article 70: the duty that holding client funds triggers
A crypto asset service provider, CASP in the rulebook, is any firm that commercially trades, exchanges, holds or arranges crypto assets in the EU and needs a MiCA authorisation for it. Every exchange you can legally buy through in Germany falls under it.
Article 70 of the MiCA regulation governs what such a firm has to do with its clients' money. Paragraph 2 requires arrangements that safeguard clients' ownership rights in their funds and prevent those funds being used for the firm's own account. Paragraph 3 then sets the actual duty: the money belongs in an account at a credit institution or a central bank.
The contrast with the crypto side matters. Different paragraphs of the same rulebook apply to your coins. Article 70 covers only the euros you have deposited and not yet invested, and the euros sitting in your exchange account after a sale. That money is precisely what raises the hardest questions if an exchange becomes insolvent. How supervision of these firms will be organised from 2027 is set out in our overview of ESMA's direct supervision of crypto providers.
The one-day limit: when the money has to sit at a credit institution
The first part of ESMA's answer is a permission on a short leash. When a crypto asset service provider receives client money, whether directly from the client or from a third party on the client's behalf, it may hold that money temporarily in a payment account at a non-bank payment service provider. Throughout that time it must continue to meet the safeguarding requirements of article 70 paragraph 2.
Then comes the deadline. By the end of the business day following receipt of the money at the latest, the provider has to place it in an account at a credit institution or a central bank. That is not a new rule, it is what article 70 paragraph 3 says. What is new is the clarification that a stop at an e-money institution neither extends nor replaces that deadline.
In practice that means: transfer on a Monday and your money should be in a bank account by the close of Tuesday at the latest. What happens at weekends and on public holidays depends on what counts as a business day in the country concerned. On this reading, a transfer on a Friday evening can be in transit until Monday evening without any rule being broken.
Why an account in the payment provider's name is not enough
The second part of the answer is the tougher one. ESMA writes that the account at the bank or central bank must be opened and maintained directly in the name of the crypto asset service provider, or in line with whichever legal regime on asset segregation applies.
An account held in the name of a non-bank payment service provider does not satisfy article 70 paragraph 3 on this reading. The authority's reasoning is a legal one, but it has tangible consequences: in that construction the crypto asset service provider would merely hold a claim against the payment service provider, instead of being the account holder vis-a-vis the credit institution itself. And according to ESMA that applies expressly even where the account was set up for that single crypto asset service provider and kept technically separate from every other account.
A claim is an entitlement against a firm. An account balance is an entitlement against the bank that holds the account. If another firm sits between you and the bank and fails, you have to join the queue in its insolvency proceedings. Keeping that chain of staging posts short is exactly what the rule is for.
How quickly that turns practical was shown by the case of the broker Trive, which we reported on in September: Trive froze client funds, and holders of crypto CFDs could not reach their money. The more staging posts lie between your money and a bank account, the longer it takes to establish who owns what.
E-money institution, payment institution, credit institution: the three terms apart
ESMA's answer hangs on a distinction almost nobody draws in everyday life. It is worth a look.
- A credit institution is what people colloquially call a bank. It holds a banking licence, may take deposits from the public and grant loans, and it belongs to a statutory deposit guarantee scheme.
- An e-money institution issues electronic money and runs payment accounts. It may not take deposits and does not lend out client money. Instead it safeguards client funds through trust accounts or insurance.
- A payment institution processes payments without issuing e-money itself. Here too there is no banking licence and no classic deposit guarantee.
All three are supervised, and all three are legitimate business models. But only the first is a permissible permanent home for your euro balance at a crypto exchange under article 70 paragraph 3. Under the new answer, the other two may only be the staging post of at most one business day.
Deposit guarantee: your euro balance on the exchange is not a bank balance
Here is the point where many investors assume something the rule does not give them. The fact that your money ends up in an account at a bank does not make you a client of that bank. Your counterparty remains the exchange.
The statutory deposit guarantee in the EU covers deposits up to 100,000 euros per client and institution. Whether and how it applies where an account is held in a provider's name and pools many clients' funds depends on the specific legal structure of that account and on national law. ESMA does not address this in Q&A 2949 and answers a narrower question: who has to be the account holder.
That is precisely why the answer matters to you. The more directly the path runs between your money and a credit institution, the fewer parties can fail in between. If you would rather not leave a euro balance sitting on a trading platform permanently, withdraw it after buying or selling, and hold the coins yourself. Which devices are suitable for that we have gathered in our hardware wallet comparison.
Interest on client funds: what Q&A 2486 awards the client
The new answer does not stand alone. It builds on an older one that shows how tightly the supervisor reads article 70 as a whole. Q&A 2486, last updated on February 18, 2026 and answered by the European Commission, dealt with interest.
The question was whether a crypto asset service provider may earn interest on client funds it places in a savings account at a credit institution. The answer is no. On that reading, CASPs are obliged to place client funds in risk-free savings accounts and may not earn interest from them for themselves. The duty serves the protection of clients alone. Any interest arising from compliance with article 70 paragraph 3 has to be passed on to the client, because the income comes from the client's money.
That differs from what some platforms do in other jurisdictions, where interest income on client deposits is a revenue line of its own. In the EU, on the Commission's reading, that income belongs to the client. Whether and how exchanges implement it is in their price and service lists, and it is a question worth asking.
What a Q&A does legally and what it does not change
Some perspective belongs here so the reach of these answers is not overstated. ESMA puts a note in front of its own Q&As: these answers explain provisions that already stand in applicable law. They do not extend rights and obligations, they introduce no additional requirements, and they are meant only to help authorities and firms with application. Only the Court of Justice of the European Union can interpret Union law bindingly.
In practice it carries weight all the same. National supervisors such as Germany's BaFin take their bearings from these answers when they examine business models. A crypto asset service provider that permanently routes client funds through an account in a payment provider's name has to expect questions after this answer.
ESMA has also declared digital finance and innovation a supervisory priority for 2027, so clarifications of this kind are unlikely to be the last. Another, considerably harder deadline is already running: for stablecoins without MiCA authorisation the authority has given platforms until January 8, 2027, which we set out in our piece on ESMA's stablecoin deadline.
Your exchange's documents: where the custodian for euros is named
You cannot look up where your money sits tonight. But you can read what your exchange commits to. Three places are worth it.
The terms and conditions almost always have a section on client funds or the holding of monies. That is where it says whether the funds sit in trust or pooled accounts and who the account holder is. The risk disclosures say whether the provider claims a deposit guarantee for euro balances, and if it makes no such claim, that is the answer. The price and service list tells you whether interest on balances is credited.
If one of those statements is missing or stays unclear, that is not an accusation but a reason to ask the provider. A list of the platforms that can show a MiCA authorisation in the EU is in our overview of regulated crypto exchanges. Anyone comparing anyway should look at that section of the documents as closely as at the trading fee.
Euro balances: after one business day the bank has to hold them
ESMA's answer changes nothing about your balance today. What it does sharpen is the question you can put to your exchange, and it hands you three steps.
- Read up on who the account holder is. Find the section on client funds in your platform's terms and check whether a credit institution is named there and in whose name the account runs. Whether your platform holds an EU authorisation at all is shown in our overview of regulated crypto exchanges.
- Keep the euro balance small. What you do not intend to invest does not have to sit on the trading platform. A current account at a bank is covered by the deposit guarantee; an exchange balance is legally something else.
- Separate trading from storage. Coins you intend to hold for longer do not belong on an exchange permanently. Which hardware is up to the job and what it costs is in the hardware wallet comparison.
(As of October 19, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
The victim was hit over the head before his teenage sister alerted police, who arrested all three men at the scene in May.
Zakura says a single published Zcash address could let a future quantum attacker link every payment a wallet has ever received.
MapQuest’s app now offers an optional map layer that plots known license plate readers from Flock Safety and other vendors, as backlash against the cameras grows.
Bitcoin ETFs lost a net $228.6 million this week, following a $681.1 million drain the week before and pushing October deep into the red.
A Bank for International Settlements working paper found that stablecoin growth slows when U.S. banks raise deposit rates, with Circle’s USDC most sensitive.
U.Today - IT, AI and Fintech Daily News for You Today
Unless exchange withdrawals increase and buying momentum strengthens, SHIB could face another decline toward $0.00000460.
NEAR's chain-abstraction protocol just absorbed $130 million in daily swaps as token testing key $5 resistance.
XRP might finally recovery for the first time since September plunge.
Binance founder Changpeng Zhao (CZ) has mocked longtime Bitcoin critic Peter Schiff over his history of bearish BTC predictions, joking that the gold advocate will eventually be right only after changing his mind.
Ripple's David Schwartz has hinted at a major breakthrough in XRP Ledger-based decentralized finance.
Blockonomi
TLDR
- Cross River Bank announced on October 15 that it is adding Ripple’s RLUSD stablecoin to its Core Operating System.
- The integration includes support for the XRP Ledger, where transactions are designed to settle in about three to five seconds.
- Fintech customers could use stablecoin rails alongside ACH, wire transfers and other bank payment services.
- Compliance checks, currency conversion and off-ramps can still add time before money reaches the final recipient.
- Neither company called the deal a replacement for existing payment networks.
Cross River Bank is adding Ripple’s stablecoin to the system it uses to move money for fintech customers. The bank announced the move on October 15.
The stablecoin is called Ripple USD, or RLUSD. Cross River said it is integrating RLUSD into its own Core Operating System, with support for the XRP Ledger.
A stablecoin is a digital token built to hold a steady value. RLUSD is designed to track the US dollar.
How the RLUSD Integration Works
Cross River is a US bank that provides financial infrastructure to other businesses. Many of its customers are fintech companies that rely on the bank to handle payments.
The bank said the goal is to give fintech customers access to blockchain settlement alongside conventional payment rails. It is not meant to be a separate payment product.
Businesses that connect through Cross River could use stablecoin rails next to the systems they already know. These include ACH transfers, wire transfers and other bank payment services.
For Cross River, adding stablecoin support is part of a wider effort. The bank wants to give customers access to different payment methods through a single integration.
For Ripple, the deal gives RLUSD another way into regulated banking. It places the stablecoin inside the daily workflows of a US bank.
Speed and Cost on the XRP Ledger
The XRP Ledger is a public blockchain network. Transactions on it are designed to settle in about three to five seconds, and each one can cost a fraction of a cent.
These features are part of why Ripple is pitching RLUSD for certain uses. They include cross-border payments, merchant settlement and treasury transfers.
Many of these payments do not fit well into normal banking hours. A blockchain network can process transactions at any time of day.
However, blockchain speed is not the same as the total time it takes to deliver money. Several steps can add time before funds reach the person or business receiving them.
Compliance reviews are one of those steps. Currency conversion and moving funds back into a bank account, known as the off-ramp, can also slow things down.
Neither Cross River nor Ripple described the deal as a replacement for current payment networks. Neither company said existing systems would be phased out.
For now, the integration means a bank is adding another settlement tool for its customers. Fintech companies will decide for themselves whether to use it.
Actual use of RLUSD on the platform will depend on which fintechs find it useful enough to build into their operations. The bank announced the integration on October 15.
The post Cross River Bank Integrates Ripple’s RLUSD Stablecoin Into Payment System appeared first on Blockonomi.
TLDR
- Fidelity Digital Assets agreed to pay California $500,000 to settle claims over past crypto withdrawal limits.
- Fidelity must give written notice if it stops letting retail customers transfer crypto to outside wallets.
- Crypto IRAs are excluded from the transfer terms and are still not offered in California or Oregon.
- Fidelity denies wrongdoing, and the deal does not create a customer compensation fund.
- California customers have been able to move crypto off the platform since June 2025.
Fidelity Digital Assets has agreed to pay $500,000 to settle a California investigation into past limits on crypto withdrawals. The deal also adds a promise to warn customers before ending crypto transfers.
California Attorney General Rob Bonta announced the settlement on Oct. 16. It centers on claims about withdrawal restrictions at Fidelity Digital Asset Services.
The settling company, Fidelity Digital Assets, National Association, is the successor to that entity. Fidelity denies any wrongdoing and did not admit to breaking any law.
What the Settlement Requires
The $500,000 payment goes to the attorney general’s office. It covers fees and costs tied to the investigation and settles the potential claims released in the deal.
The agreement does not set up a fund to pay back customers.
The settlement describes a period from November 2022 through April 2025. During that time, California retail customers could buy and sell crypto on Fidelity but could not send it directly off the platform.
Fidelity received regulatory permission in April 2025. The transfer feature then reached all California customers by June 2025.
The agreement recognizes that customers can now move crypto to outside wallets, subject to applicable law. If Fidelity decides to stop offering this feature to retail customers, it must give California customers reasonable written notice.
Fidelity still keeps the right to restrict or block transfers. It can do this to protect its platform or individual account holders.
Crypto IRAs Follow Separate Rules
Tax-advantaged accounts are not covered by the transfer terms. This includes individual retirement accounts, also known as IRAs.
The deal also excludes accounts subject to federal rules on tax-free transfers between retirement accounts.
The agreement says Fidelity plans to launch Fidelity Crypto IRA accounts in California. It does not give a launch date.
Fidelity’s current IRA help page says the product is still not available in California or Oregon.
In states where the Crypto IRA is offered, customers cannot transfer crypto. They also cannot withdraw money or crypto directly from the account.
Instead, they can move money from the account’s U.S. dollar position to a linked Fidelity brokerage IRA. From there, they can use that account’s withdrawal options.
Fidelity’s state availability page, checked on Oct. 18, still lists crypto deposits and withdrawals for regular Fidelity Crypto accounts in California.
The post Fidelity Pays $500,000 to Settle California Crypto Withdrawal Probe appeared first on Blockonomi.
TLDR
- On-chain investigator Specter issued a warning on October 17 about stolen crypto flowing into Zcash.
- The warning covered funds tied to the Bitget breach and other reported security incidents.
- A September 30 trace found about 2,746 ZEC, worth roughly $3.9 million, moved into Zcash’s Ironwood shielded pool.
- Shielded transactions hide sender, recipient and amount details, making funds harder to trace.
- The activity does not show that Zcash’s cryptography has been broken.
Investigators are raising new concerns about stolen cryptocurrency moving into Zcash. The privacy-focused network has become a hard place for analysts to follow funds taken in hacks.
On October 17, on-chain investigator Specter issued a warning about reported flows tied to several crypto security incidents. These included the Bitget breach and other reported thefts.
The warning builds on earlier tracing work. On September 30, analysts tracked roughly 2,746 ZEC entering Zcash’s Ironwood shielded pool.
At the time, those coins were valued at about $3.9 million. Investigators linked the wallets that sent the funds to the Bitget attacker.
How Shielded Pools Affect Tracing
Before funds reach a shielded pool, analysts can often see a lot. They can sometimes identify funding wallets, transfers and swapping patterns on public blockchains.
Once the assets enter the pool, that trail becomes harder to follow. Shielded transfers do not publicly show the same details about the sender, the recipient or the amount.
This means investigators may gather clues up to the point of entry. After that, tracking where the money goes next becomes much more difficult.
Specter and other analysts describe this as a recurring tactic. Thieves may leave a visible path on public chains before moving funds into a privacy system.
What the Flows Do and Do Not Show
The movement of stolen funds into Zcash does not mean the network’s cryptography is broken. The system is working as designed by hiding transaction details.
The presence of suspect funds also does not prove wrongdoing by everyone who uses private transactions. Privacy is a legitimate feature of many cryptocurrencies.
The situation shows a long-running tension in crypto. Users value financial privacy, while investigators need visibility to follow stolen money.
Some figures remain uncertain. The combined total of flows from the newer incidents is less firmly established than the earlier Bitget transactions.
Analysts say estimates from different incidents should not be added together without checking each transaction. The same funds may pass through several intermediaries, which can lead to double counting.
For exchanges and forensic teams, timing matters. The most useful point to step in may be before stolen assets leave public view.
Once funds are inside a shielded pool, options for tracking them shrink. That puts more weight on spotting suspicious activity on public chains first.
Specter’s October 17 warning has put renewed attention on these transfers. Investigators continue to monitor reported flows linked to Bitget and other recent thefts.
The post Zcash Shielded Pools Face Scrutiny Over Stolen Crypto Transfers appeared first on Blockonomi.
TLDR
- Former Mt. Gox CEO Mark Karpelès says Ledger received reports of spy hardware implants as early as December 2025.
- He claims better communication could have prevented more than $90 million in losses tied to reseller CryptoBillis.
- Ledger’s Gauthier dismissed the criticism as virtue signalling and pointed to Karpelès’ past at Mt. Gox.
- Ledger says the attack is limited to Southeast Asia, but Karpelès claims it reached other regions.
- Trezor and OneKey have removed third-party resellers and tightened distribution checks.
Mark Karpelès, the former CEO of the Mt. Gox exchange, has publicly criticized hardware wallet maker Ledger. He says the company did not respond well to early warnings about spy hardware hidden inside its devices.
The criticism centers on a supply chain attack linked to CryptoBillis, a Ledger reseller. Users who bought devices from the reseller lost more than $90 million.
Early Warnings Raised in December 2025
Karpelès said Ledger received reports of hardware implants as early as December 2025. He said the company’s only public response was a blog post about a compromise in March 2026.
He believes clearer communication could have prevented the losses. “I do know a better communication on this at the time could have saved 90+ million USD in losses,” Karpelès wrote on X.
He added that he could not understand how the company failed to be alarmed by “mass-produced advanced implants.”
Karpelès also admitted his own failures at Mt. Gox. He said he held Ledger to a higher standard because he “trusted you to do better by learning of my failure.”
Ledger Pushes Back on the Claims
Ledger’s Gauthier rejected the criticism. He described Karpelès’ comments as virtue signalling and pointed to his past at Mt. Gox.
The exchange between the two became personal. It moved away from the main question of whether the attack and the stolen funds could have been avoided.
Karpelès also accused Ledger of downplaying the incident. He said the company treated it as limited to CryptoBillis, even though similar implants were reported in other regions.
Ledger has disputed reports that devices in Europe were affected. The company reached that view after analyzing a reported case in Germany.
Karpelès disagreed and said the attack reached further. He said he had helped several users check their devices for signs of tampering.
He asked Ledger to share clearer information. “An end user doesn’t know that, and shouldn’t have to worry if their device is altered or not,” he wrote.
Many members of the crypto community sided with Karpelès. They pressed Ledger to be more open about the attack.
In early October, Ledger confirmed that devices sold by CryptoBillis contained unauthorized implants. The implants scanned users’ seed phrases and sent them to a private server.
Ledger paused sales from CryptoBillis and the wider Southeast Asian region. Losses from the attack later passed $100 million.
Other wallet makers, including Trezor and OneKey, removed third-party resellers. They also tightened checks on how their devices are distributed.
As of October 18, Ledger maintains that the compromise is limited to Southeast Asia. Karpelès and others continue to claim the attack has spread to other regions.
The post Former Mt. Gox CEO Criticizes Ledger Over Response to $90M Supply Chain Attack appeared first on Blockonomi.
TLDR
- Thai Immigration Police arrested Chinese national Wu Chaoshuai, accused of leading a crypto laundering ring that moved over $74 million.
- Wu allegedly managed 133 bank and cryptocurrency exchange accounts opened by people he hired.
- He entered Thailand on a tourist visa in December 2019 and stayed for over three years after it expired.
- Wu used fake license plates, forged documents, a repainted car and frequent moves to avoid police.
- He will be charged with overstaying his visa, and Thai police will coordinate his extradition to China.
Thai Immigration Police have arrested a Chinese national accused of running a cryptocurrency money laundering network. Officials say the group moved more than $74 million for a transnational criminal organization.
The suspect, Wu Chaoshuai, was found hiding in a luxury house in Bangkok. He had stayed in Thailand for years after his tourist visa expired.
Thai authorities said the arrest followed an investigation that involved several immigration police officials. Officials described Wu as a money laundering kingpin who fled China to avoid arrest.
How the Alleged Laundering Network Worked
Chinese authorities allege that Wu worked as an account mule for the organization. An account mule is a person who uses bank or exchange accounts to move money for others.
According to the allegations, Wu hired other people to open bank accounts and cryptocurrency exchange accounts. These accounts were then used to move illegal funds.
Wu is accused of managing 133 accounts in total. Through these accounts, he reportedly processed more than $74 million in transactions.
Authorities say the accounts were used to hide the source of illicit money. They also made it easier to move the funds between people and platforms.
Years on the Run in Thailand
The third division of the Thai Immigration Police said Wu entered Thailand on a tourist visa in December 2019. He stayed in the country after that visa expired.
Police believe he remained to avoid contact with immigration officials. Leaving the country or being detected could have led to his extradition to China.
To avoid being tracked, Wu moved around Thailand often. Thai media reported that he rented houses and luxury condos in different communities and did not stay in one place for long.
He also took other steps to stay hidden. Reports say he changed the color of his car, used fake license plates and carried forged documents.
Despite these efforts, police located Wu in a luxury house in the Ramkhamhaeng area of Bangkok. By the time of his arrest, his visa had been expired for more than three years.
The arrest comes as Thai authorities increase their oversight of cryptocurrency activity and related crimes. The country has also introduced stricter checks on high-volume stablecoin trades.
In June, Thailand’s Department of Special Investigation broke up a separate crypto mining money laundering group. That organization was accused of laundering more than $300 million a year from online scams and gambling platforms.
Wu now faces a charge in Thailand for staying in the country after his visa expired. Thai police said they will work with Chinese authorities to arrange his extradition to China.
The post Thai Police Arrest Chinese National Accused of $74 Million Crypto Money Laundering appeared first on Blockonomi.
HTTP error 429 on https://cryptopotato.com/feed/
Failed to fetch feed: https://cryptopotato.com/feed/
Failed to fetch feed.