Cryptocurrency Posts
Crypto Briefing
AI credit stress highlights potential systemic risks, prompting a shift towards safe-haven assets and impacting future bond market dynamics.
The post Deutsche Bank maps US bonds, flags stress in AI credit appeared first on Crypto Briefing.
GRAFT's deletable adapter could revolutionize AI training by reducing reward hacking, potentially leading to more reliable AI systems.
The post GRAFT method uses a deletable adapter to curb reward hacking in AI models appeared first on Crypto Briefing.
The US Treasury's actions could destabilize oil markets and increase scrutiny on global financial and crypto sectors, impacting regional economies.
The post US Treasury disrupts Iran’s financial networks under Operation Economic Outcast appeared first on Crypto Briefing.
Overbuilding data centers amid idle GPUs may strain AI industry finances, prompting a shift towards optimizing existing infrastructure use.
The post AI industry may be building too many data centers while existing GPUs sit idle, strategist warns appeared first on Crypto Briefing.
The significant financial opposition to California's wealth tax highlights the broader tension between wealth redistribution efforts and economic influence.
The post Billionaires invest $300M to oppose California wealth tax in 2026 election appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
US Hoovers up Bitcoin While the World Runs on Its Digital Dollars: Report
America is accumulating bitcoin while exporting dollar-pegged stablecoins to everyone else, according to a new Chainalysis report.
The blockchain data said in its Wednesday report, “North America: Inside the Growth of Agentic Commerce,” that the U.S. became a net importer of Bitcoin in 2026 — for the first time since 2022.
According to the data, institutions this year have been buying bitcoin while retail largely sells.
“A dollar stablecoin is a way to hold dollars without an American bank account, and Americans already have one,” the report read.
“The rest of the world is pivoting to a digital dollar because it meets a need that American users don’t share. Meanwhile, Americans are leaning harder on bitcoin as an infinitely scarce store of value.”
It added that U.S. dominance keeps climbing: Since the 2024 launch of spot bitcoin exchange-traded funds, America’s share of global Bitcoin activity has risen every single reporting period — even as the overall U.S. crypto economy ($2.78 trillion) contracted 2.2% in a brutal bear market, retaining most of 2025’s near-doubling.
The U.S. Securities and Exchange Commission approved bitcoin ETFs in January 2024 after a decade of denying the products.
Managed by Wall Street titans like BlackRock, Fidelity, and most recently, Morgan Stanley, the funds had the most successful debut in the history of ETFs.
Institutions and Wall Street can now buy shares of the funds which track the price of bitcoin and take care of buying and selling the digital coin.
The approval of the ETFs has helped the industry mature, the report noted, and helped the U.S. become an overall bigger bitcoin investor.
Stablecoins, meanwhile, have turned U.S. debt into a “currency-of-choice for peer-to-peer economies as well as businesses working across borders,” the report continued.
“In the 2026 period we continued to see stablecoins enter new use cases most especially abroad, benefitting the U.S. companies, and the U.S. government, with billions of dollars in economic activity,” it added.
Since Donald Trump became president, he has signed a number of pro-crypto laws and executive orders. The GENIUS Act, signed in 2025, allows banks and other entities to issue stablecoins if they back the tokens with assets like U.S. Treasuries and provide monthly disclosures of their reserves.
This post US Hoovers up Bitcoin While the World Runs on Its Digital Dollars: Report first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Ledger Says Organized Crime Group Spent Millions Targeting Hardware Wallet Users
Ledger has issued a statement following reports from customers of loss of funds and tampered devices, calling it one the most “sophisticated attacks” the digital asset industry has experienced.
The hardware manufacturer said Thursday that a “highly organized criminal group” bought Ledger devices and installed implants that could read users’ seedphrases before then putting them back into the supply chain via resellers.
Paris-based Ledger last week said it had started an investigation after customers in South East Asia reported they’d lost funds after buying from Malaysia-based reseller, CryptoBilis.
The company then said it confirmed that one of the impacted users’ devices contained an unauthorized hardware implant.
It isn’t clear how much money has been lost from the tampered devices but blockchain investigator Specter said $86 million had been drained. Ledger did not respond to Bitcoin Magazine’s written questions.
“[The criminal group] built their own logistics and technology infrastructure with seeds collector servers, draining and laundering infrastructures. They were patient, they spent millions, and they struck in one coordinated operation, draining wallets,” Ledger said in a Thursday statement.
“There was no flaw in Ledger’s chip, operating system or servers. Ledger’s systems were not compromised. This was an attack on the distribution channel after the devices left our control.”
The company said that in its “largest investigation to date” it sent employees to other markets — including Europe — to make sure other supply chains hadn’t been targeted.
It said that screened devices were clean and authorized resellers and distributors in Southeast Asia and Hong Kong have suspended their sales.
Ledger added that it was working with law enforcement to “follow the funds and dismantle the attackers’ infrastructure.”
It isn’t clear how many customers had been targeted from Ledger’s statement.
The crypto industry is still reeling after hackers in July were able to steal close to $120 million in bitcoin from Coldcard users.
There have also been a number of data breaches this year, with scammers targeting Ledger to get customer information via the company’s payment processor Global-e.
This post Ledger Says Organized Crime Group Spent Millions Targeting Hardware Wallet Users first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Bitcoin Briefly Slides Below $80,000 On More Hot Inflation Data
Bitcoin’s price momentarily dipped below $80,000 on Thursday following more hotter-than-expected U.S. inflation data.
The price of the biggest cryptocurrency recently stood at $81,028 after dropping as low as $79,805 on Thursday morning in New York.
Over a 24-hour period, it’s only down over 1% after making a recovery. But over the past week, it’s shed nearly 3% of its value.
Data Thursday from the Labor Department’s Bureau of Labor Statistics showed U.S. producer prices rose in September at the fastest pace in more than four years.
The numbers came one day after September’s Consumer Price Index came out higher than expected.
Bitcoin has news that high prices won’t go away in the world’s largest economy — leading traders to bet that the Federal Reserve may keep interest rates higher for longer.
The Federal Reserve will make a decision on what to do with interest rates at the end of this month.
Bitcoin’s price has previously done well in a low interest rate environment as when borrowing costs are cut, more liquidity can be used to buy the cryptocurrency.
But the Fed this year has raised interest rates, with the head of the central bank claiming that getting inflation down in the U.S. is its number one priority.
The biggest cryptocurrency is currently nearly 36% below the record of $126,080 it touched last October.
Despite the dip this week, analysts have declared the asset to be out of the bear market it spent most of 2026 following a rally in August and September.
This post Bitcoin Briefly Slides Below $80,000 On More Hot Inflation Data first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Latin America’s MSTR: How OranjeBTC is Running the Saylor Playbook in Brazil | Gui Gomes
Bitcoin is “likely the best collateral one could ask for,” says OranjeBTC CEO Gui Gomes. He explains how digital credit, Bitcoin-backed loans, and new financial products are pushing Bitcoin deeper into global financial markets, including a first-of-its-kind Bitcoin-backed loan in Brazil. He also shares why every step brings Bitcoin closer to becoming the world’s reserve currency.
Chapters:
0:00 – OranjeBTC CEO Gui Gomes on Running the Strategy Playbook in Latin America
0:32 – Why Brazil Ranks No. 1 in Grassroots Bitcoin Adoption
1:57 – Brazil’s Advantages for Building a Bitcoin Treasury Company
3:38 – Brazil’s New Bitcoin Regulations and VASP Licensing
5:23 – Brazil’s Elections and the Shift Toward a Pro-Market Economy
7:22 – Lower Rates, the Real and Brazil’s Next Growth Phase
8:27 – How Global Investors Can Buy OranjeBTC Shares
9:21 – DIGI11: Bringing STRC and SATA to Brazilian Investors
11:21 – How DIGI11 Delivered Its First Dividend
14:08 – Bitcoin as Collateral and the Future of Digital Credit
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Latin America’s MSTR: How OranjeBTC is Running the Saylor Playbook in Brazil | Gui Gomes first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Charles Edwards: Why Quantum Risk Could Be MASSIVE BTC Upside Catalyst
What will it take for Bitcoin to break to new all-time highs? Charles Edwards says something substantial has to happen, whether it’s real progress on quantum, a shift in Fed policy, the U.S. government buying Bitcoin, or a stimulus event. He also discusses how institutional buying through ETFs is keeping the backdrop strong.
Chapters:
0:00 – Charles Edwards on Rates, Liquidity and Bitcoin’s Market Outlook
1:36 – ETFs vs. Treasury Companies: Who’s Driving Bitcoin Buying?
2:54 – How AI-Driven Unemployment Could Change the Fed and Bitcoin
4:01 – Hash Ribbons: Why Rising Hash Rate Is a Bullish Signal
6:13 – Is This Hash Rate Cycle Different With AI?
8:14 – Is Bitcoin Still Undervalued? Production Cost, Energy Value and MVRV
10:37 – Global Liquidity, 5% Rates and Bitcoin’s Uncharted Territory
14:50 – Quantum Computing: Why a Roadmap Could Be an Upside Catalyst
17:21 – Can AI Break Bitcoin? Superintelligence and Encryption Risk
19:15 – What Could Trigger Bitcoin’s Next All-Time High
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Charles Edwards: Why Quantum Risk Could Be MASSIVE BTC Upside Catalyst first appeared on Bitcoin Magazine and is written by Patrick Green.
CryptoSlate
Streami and Pravang are among 16 affected financial companies as the FSC outlines plans for a wider security overhaul.
Read the full story on CryptoSlate
Understand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
Hyperliquid force-liquidated 1,650 ETH early on Oct. 15, and the tracked wallet held a new 2,500 ETH long by 13:16 BST.
Read the full story on CryptoSlate
Understand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
Bitcoin registered an intraday low of $79,730 before recovering to around $82,000 as surging US wholesale inflation intensified a cryptocurrency selloff that triggered nearly $940 million in liquidations. This price action extended losses as stronger-than-expected inflation data raised concerns about another interest rate hike by the Federal Reserve. According to CoinGlass, 176,506 traders were liquidated…
Read the full story on CryptoSlate
Understand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
President Donald Trump's crypto agenda has lost a White House negotiator as Patrick Witt confirms his departure and the administration's flagship digital-asset legislation remains stalled in Congress. On Oct. 15, Patrick Witt, executive director of the White House Crypto Council, confirmed his departure after nearly two years in the administration, leaving the government for an…
Read the full story on CryptoSlate
Understand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
The proposed A$200,000 custody floor comes with asset and revenue tests and requirements for the outside custodian.
Read the full story on CryptoSlate
Understand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
CryptoTicker.io
Babylon Labs wants Aave V4 to accept real Bitcoin as collateral without that Bitcoin ever leaving the Bitcoin blockchain. The proposal has been in Aave's governance forum since Wednesday, October 14, 2026. Nothing has been decided: this is an ARFC, the stage before the vote. Holders of Aave therefore get a concrete template for the first time showing how much the protocol would earn from Bitcoin collateral.
What Babylon has proposed for Aave V4
The proposal is titled “Onboard Native BTC as Collateral to Aave V4 via Babylon Trustless Bitcoin Vaults” and was filed by Babylon Labs. It was preceded by a temperature check, which the proposal passed. The first use case is named clearly: borrowing stablecoins against native Bitcoin.
At Aave an ARFC is not a decision but a proposal with a rationale and a blueprint. It gathers feedback from the community and the assessment of the risk service providers before any vote takes place. The sequence is set at Aave, and it appears in this proposal too: first feedback and risk analysis, then a Snapshot vote, then an AIP with the full risk parameters for the on-chain vote.
ARFC stands for Aave Request for Final Comments. It is the stage at which a proposal is technically described in full but has not yet received a single vote.
Aave price $148.30, 13 percent below last week's level
Aave costs $148.30, or €132.39, according to CoinGecko as of Thursday midday. Over seven days that is 13.16 percent less, over 24 hours 6.56 percent. The weekly high stood at $171.52 on Monday, the weekly low is $148.19 and therefore practically at the current price. The day's range ran from $147.94 to $158.98.
The 30-day view turns the picture around: there it shows a gain of 16.59 percent. The week was weak, then, the month was not. With a market capitalisation of $2.29 billion Aave sits at rank 46, on daily turnover of $269.4 million. From its high of $661.69 in May 2021 it is 77.59 percent short. In circulation are 15.44 million AAVE of the 16 million maximum that will ever exist.
Almost the entire crypto market fell this week, and Bitcoin gave up considerably less than Aave in the process. Babylon's proposal is therefore not a price driver that could be seen in the weekly numbers. It is news about the protocol's revenue, and that works through quarters, if at all.
Trustless Bitcoin Vaults: the Bitcoin stays where it is
The heart of the proposal is the custody question. The Bitcoin stays in a Taproot UTXO on the Bitcoin blockchain. It is not wrapped, not sent across a bridge and not held by a custodian. That is the difference from everything running as Bitcoin collateral in DeFi so far.
A Taproot UTXO is an unspent output of a Bitcoin transaction whose spending conditions are set through the Taproot format. Put simply: an amount of Bitcoin with a condition attached as to who may move it and under what circumstances.
On Ethereum a representation token is created for it under the ERC-20 standard with eight decimal places. It is minted when a vault is activated and burned when the position ends. It can only be transferred between the contracts of the integration itself, and the total amount always corresponds exactly to the Bitcoin tied up in active positions. The representation is therefore not a freely tradable token but an accounting entry.
Two new spokes in the hub-and-spoke architecture
Aave V4 is built on a hub-and-spoke pattern: a hub holds the liquidity, the spokes are the markets drawing on it. The proposal wants to set up two new spokes. The Babylon Spoke lists native Bitcoin as its only collateral. The BTC Vault Swap Spoke handles settlement after a liquidation. Both draw their liquidity from an Aave V4 hub; which hub instance that is, the proposal does not specify.
Four settings are already fixed and are not meant as adjustable levers. Native Bitcoin is collateral only and cannot be borrowed. The liquidation fee is set to zero. The option for liquidators to receive shares instead of collateral is switched off. And the target health factor, which otherwise determines how far a position is wound back in a liquidation, has been removed.
What happens to the Bitcoin in a liquidation
The most interesting part of the proposal is not in the figures but in how a liquidation runs, and it explains why the liquidation fee can be zero. Until now a liquidator at Aave takes part of the collateral and sells it on the market. Bitcoin on the Bitcoin blockchain cannot be realised that way, because the liquidator works on Ethereum.
The proposal solves this in three steps. First, a liquidation always seizes exactly one BTCVault, not a percentage of a position. Second, any liquidator may sell the seized vault to the BTC Vault Swap Spoke without permission and receives WBTC at the oracle price, less a discount. WBTC is the wrapped Bitcoin token the integration starts with. Third, arbitrageurs step in, repay the WBTC debt and redeem the real Bitcoin on the Bitcoin blockchain in return.
The discount on the sale is thus the liquidator's actual compensation, and it replaces the liquidation fee. Three values at the swap spoke are adjustable: this sale discount, a minimum reserve for the arbitrageurs' profit and the recipient of the fees. The proposal gives figures for none of these three.
To see how collateralised loans differ across platforms, the terms sit side by side in our crypto lending comparison. The mechanics of liquidation are the point where providers differ most.
The revenue split: the first $500,000 goes entirely to the Aave DAO
Here the proposal becomes unusually precise, and here lies the actual substance for AAVE holders. Two income streams count as qualifying revenue: the hub liquidity fee on the interest that borrowers pay in the Babylon Spoke, and the liquidation fees arising through the adapter and the BTC Vault Swap Spoke.
The first $500,000 of that income per year goes entirely to the Aave DAO. Above that a tiered split applies, divided in each case between the DAO, Babylon and token buybacks:
- $500,000 to $2 million: 78 percent DAO, 18 percent Babylon, 4 percent token buyback
- $2 million to $4 million: 72.5 percent DAO, 22.5 percent Babylon, 5 percent buyback
- $4 million to $6 million: 67 percent DAO, 27 percent Babylon, 6 percent buyback
- above $6 million: 61.5 percent DAO, 31.5 percent Babylon, 7 percent buyback
The buyback splits 85 percent into AAVE and 15 percent into BABY, Babylon's token. The repurchased tokens go in equal parts to the Aave DAO and the Babylon Foundation. Distribution is monthly. In addition, the adapter may charge a Babylon interest fee, a share of the base interest the borrower pays at Aave. How large that share is does not appear in the proposal.
The share flowing directly into AAVE buybacks is in single digits at every tier: 4 to 7 percent of qualifying revenue. Even at $6 million of annual income that would be around $420,000 for buybacks, 85 percent of it in AAVE. Against a market capitalisation of $2.29 billion that is a small number, and nobody should read it as a price driver.
Which risk parameters are still missing
The figures on which everything hangs for borrowers do not appear in the proposal. There is no loan-to-value ratio, no liquidation threshold and no supply cap. On this the proposal says in as many words that the risk parameters for both spokes would be supplied by Aave's risk service providers. That is the usual procedure at Aave, but it also means there is no basis today for estimating how much stablecoin a single Bitcoin would support.
Without a liquidation threshold, the risk of a margin call cannot be quantified either. For judging the proposal that is no shortcoming; for an investment decision it is.
The proposal does not stand alone in the forum
Aave's governance forum holds further proposals in the same week. On October 15 an ARFC arrived on onboarding USAT, the US dollar token from Tether America, into the V3 Core instance and the V4 Core hub on Ethereum. On October 14 a risk framework for tokenised equities on Aave V3 X Layer was put up for discussion, and on October 13 a CAPO SnapshotRatio adjustment via Aave V3.
The pattern is the same in every case: Aave is taking on collateral that has not sat in DeFi lending markets before. Native Bitcoin is the largest piece of that, because it concerns the largest amount of capital that has so far simply been sitting there.
Our assessment of the Babylon proposal
From this newsroom's point of view, the solid part of this proposal is the custody construction and the secondary part is the revenue split. The design speaks for it: the Bitcoin stays in the Taproot UTXO, the representation on Ethereum is non-transferable and equal in amount to the Bitcoin tied up, and a liquidation seizes a whole vault rather than a share. These three points are set out in the proposal and are not statements of intent.
Against it speaks the stage of the process. The loan-to-value ratio, liquidation threshold and supply cap are missing, as are the values for the sale discount and the Babylon interest fee. Until the Snapshot vote and the AIP that follows it, whether and with what limits this starts remains open. The income from the tiers weighs too little against $2.29 billion of market capitalisation to move a price. Buying AAVE for the buybacks means counting on single-digit percentage shares of revenue that does not yet exist. A total loss remains possible in any crypto investment.
The proposal is public and readable without an account
The proposal is public and readable without an account. It sits in Aave's governance forum, and Babylon describes its Trustless Bitcoin Vaults on its own site. For context, three points are worth a look: the list of fixed settings, the tiers of the revenue split and the section on next steps.
In practical terms the route is not yet usable for investors in Germany. As long as no AIP has passed, there is no market in which Bitcoin could be put up as collateral. Anyone holding Bitcoin and thinking about loans against it is dealing with the existing providers until then, and there the MiCA rules apply, including the authorisation requirement for the service provider.
One point often lost in loans against crypto: coins put up as collateral and then lost in a liquidation count as a sale for tax purposes. The one-year holding period for private disposals then decides whether the transaction stays tax-free. That applies today and regardless of how the proposal at Aave turns out.
Aave V4 and Bitcoin: without a Snapshot vote it stays a proposal
Three steps make sense now:
- Read the proposal in the original, not the summary. The fixed settings and the revenue tiers are there in full; the risk parameters are absent there just as fully. How other platforms set their yields and terms is shown in the comparison of staking and yield platforms.
- Keep your own custody separate from the lending idea. Bitcoin serving as collateral is tied up, even when it does not leave the blockchain. For holdings meant to sit still, self-custody remains the simpler route; the devices for it are in our hardware wallet comparison.
- Track the holding period for every piece of collateral. A liquidation is a sale, and without an acquisition date the one-year period cannot be evidenced later. The tools for that are under crypto tax tools and portfolio trackers.
(As of October 15, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Trading in Shiba Inu is currently taking place for the larger part not on the spot market but on the futures market. In the 24 hours to Thursday evening, around $257.4 million changed hands in SHIB futures contracts, against $77.5 million on the spot market. That puts the factor at 3.3. Anyone trying to understand how the SHIB price moves is looking in the wrong place by watching only purchases and sales of the tokens themselves.
These figures are our own counts from CoinGecko market data, taken on Thursday evening. SHIB cost $0.00000510 at that point, or €0.00000455. Over 24 hours the price moved by 0.05 percent, so it stood practically still. Within the day, however, the high and the low were 4.89 percent apart: $0.00000511 at the top, $0.00000486 at the bottom. That range is the most important number in this article, and further down it becomes clear why.
$257 million in futures trading, $78 million on the spot market
The market data covered 61 live SHIB futures contracts across 28 trading venues. Combined turnover in those contracts of $257.4 million over 24 hours stands against spot turnover of $77.5 million. Both figures measure the same thing, turnover in one day, and are therefore directly comparable.
Dogecoin, the other large meme token, helps place that. There, the same evening saw $4.50 billion in futures turnover against $1.55 billion on the spot market, a factor of 2.9. Both tokens hang on the futures market, SHIB somewhat more so than DOGE. The difference stands out but marks no break: the meme sector as a whole is currently traded through contracts rather than through tokens.
Open interest: the metric and its $169 million
Open interest is the sum of all futures positions still open at the end of a day, measured in dollar equivalent. Unlike turnover it counts no movement but a stock: it says how much money is currently tied up in bets on the price.
For SHIB that stock stood at $169.0 million on Thursday evening. Spot turnover for a whole day came to $77.5 million. More than twice what the spot market turns over in a day is therefore tied up in open contracts. At Dogecoin that ratio is 1.4, at SHIB 2.2.
Comparing stock with turnover mixes two quantities, and that should be said openly: a stock is not a daily figure. It is informative all the same, because it shows how thick the leverage layer lies over a comparatively thin spot market. If that layer is unwound by force, the counter-move has to run through exactly this thin spot market.
Which venues carry the open interest
Open interest is spread widely, with one clear peak. The count below names the ten largest positions on Thursday evening, in millions of dollars:
| Trading venue | Open interest | Share |
|---|---|---|
| OrangeX | 25.7 | 15.2 percent |
| Binance | 22.4 | 13.3 percent |
| KCEX | 14.8 | 8.7 percent |
| LBank | 12.5 | 7.4 percent |
| CoinW | 10.9 | 6.4 percent |
| Bitget | 10.0 | 5.9 percent |
| MEXC | 8.2 | 4.8 percent |
| Bybit | 7.5 | 4.4 percent |
| Deepcoin | 7.3 | 4.3 percent |
| BVOX | 7.2 | 4.3 percent |
No single venue holds more than a sixth. The ten largest together carry around 74 percent. That spread across many jurisdictions is the reason why, for investors in Germany, the question of permitted leverage depends on the individual provider.
The spot market runs almost entirely through USDT
On the spot market the distribution looks different. Of SHIB spot turnover, 76.9 percent ran through pairs against the dollar stablecoin USDT, 9.3 percent against the Korean won, 5.4 percent against the Turkish lira and 3.0 percent against the US dollar. Euro pairs accounted for 2.1 percent, or $1.62 million in equivalent terms.
Euro liquidity comes for the larger part from houses with EU authorisation: Bitvavo supplied $0.74 million, Kraken $0.29 million, Bit2Me $0.28 million, with smaller amounts at WhiteBIT, Coinbase and Bitstamp. Buying SHIB in euros is therefore possible, but it means reckoning with a small sub-market.
Negative funding on 20 of 61 perpetuals
Most of these contracts are perpetuals, that is, futures contracts without an expiry date. To keep their price from drifting away from the spot price, the two sides pay each other a balancing fee at short intervals, the funding rate. When it is positive, buyers pay sellers; when it is negative, the reverse applies.
On Thursday evening the funding rate was negative on 20 of the 61 contracts, with the mean across all contracts at 0.002 percent per settlement. The picture is therefore close to balanced, with a slight overhang on the seller side. No directional statement about the price follows from that. What does follow is the cost side: a position left open for longer pays or receives this fee day after day, and with a token at this price level such incidental costs weigh heavily in proportion.
The ESMA statement of February 24, 2026
Perpetuals were long treated as something European supervisory rules did not cover. That has changed. On February 24, 2026 the European securities regulator ESMA published a statement under reference ESMA35-243228190-8024, titled Statement on identifying derivatives within the scope of the national product intervention measures on CFDs.
The core in one sentence: in ESMA's view, perpetual futures are likely to fall under the existing national product intervention measures on contracts for difference, provided they meet the definition of a CFD. What governs is the design of the product, not the name a provider gives it. ESMA expressly also names products that give leveraged exposure to crypto assets.
Where that classification applies, five things hold for retail clients: a leverage cap, a mandatory risk warning, forced closure when a margin threshold is breached, protection against a negative account balance, and a ban on bonuses and other incentives to trade. ESMA does not itself set the level of the leverage cap. That sits in the national measures, which for Germany means BaFin.
50 percent initial margin in BaFin's general administrative act
The relevant rule is BaFin's general administrative act on contracts for difference of July 23, 2019, in force since August 1, 2019. That act tiers the required initial margin by underlying. In the wording of the act, crypto carries 50 percent of the notional value of the CFD where the underlying is a cryptocurrency.
A 50 percent initial margin means leverage of at most 2:1. For comparison, the other tiers of the same act: 3.33 percent for pairs of two major currencies, 5 percent for large equity indices and for gold, 10 percent for other commodities, 20 percent for shares. Crypto therefore carries by far the strictest tier, and by a factor of 15 stricter than a currency pair.
In practice that means a provider authorised in Germany may grant a retail client at most 2:1 leverage on a crypto contract for difference. For regulated venues, there is an overview in our comparison of regulated crypto exchanges. Providers without EU authorisation are not subject to this act, and the leverage offered in the market varies accordingly.
A worked example of liquidation at 2:1 and at 50:1
Now back to that daily range of 4.89 percent. Take a position with a notional value of €1,000.
At 2:1 you post €500. BaFin's act requires forced closure when your balance falls below half the required initial margin, here below €250. That would take a loss of €250, which is 25 percent of the notional value. The price would have to move a quarter against you.
At 50:1 you post €20. A loss of around €20, roughly 2 percent of the notional value, already eats up that margin. The range between the day's high and low on Thursday was 4.89 percent, and that on a day when the price moved 0.05 percent over 24 hours, so it barely budged.
A position at 50:1 would have been stopped out on this quiet day in the ordinary back and forth; a position at 2:1 would not have come close. That is the whole difference, and it is not a theoretical one: the range comes from the price data of this single day.
Margin close-out and negative balance protection
Alongside the leverage cap, the ESMA statement names two further protections that are more concrete than the percentage. The first is the margin close-out: the provider has to close the position before the balance is used up entirely. The second is protection against a negative account balance. It limits your loss to the money you hold in the trading account, which rules out any demand for more than that balance.
Added to that is the ban on bonuses and other incentives. An authorised provider may not promise you a bonus or a benefit in kind for opening such a position. Three points therefore count when looking at an offer: the level of leverage available, the commitment to negative balance protection, and the question of which supervisor the provider answers to.
Spot purchase and perpetual on holding period and custody
The difference between the two routes does not end at leverage. It carries on into tax and custody, and there the paths part clearly.
Buy SHIB on the spot market and you hold the token. It sits in an account at the exchange or in your own wallet, and you can withdraw it. For tax, the sale is a private disposal under section 23 of the German Income Tax Act, to which the one-year period applies.
A perpetual, by contrast, is a forward transaction. You hold no token but a claim against the provider, you can withdraw nothing, and the one-year period does not apply here: income from forward transactions counts as investment income. Mixing the two therefore brings two different tax treatments into one portfolio. Which records you need for that depends on the provider; the documentation for a forward transaction looks different from that for a spot purchase.
Where SHIB stands after a year
The longer series belong to the overall picture. Over 14 days SHIB gave up 11.21 percent, but over 30 days only 0.36 percent: the decline of the last two weeks has therefore worked off a gain from the first half of October. Over a year it shows a loss of 51.04 percent, so the token has roughly halved in twelve months. From its high of $0.00008616 on October 27, 2021 it is 94.09 percent away. Market value on Thursday evening was $3.00 billion, rank 37 in the overall market, with 589.24 trillion tokens in circulation.
The most recent look at the same token dates from Wednesday: at that point SHIB daily turnover was 76 percent below the year-earlier figure, with the price at around $0.00000504. The price has gained a good half a percentage point since then, and the thin spot side of that day is exactly the side set against triple the futures turnover in this article. Wednesday's finding and today's are two sides of the same thing.
Our assessment of the pace in the SHIB market
From this newsroom's point of view, the futures market currently sets the pace in SHIB, not the spot market. The evidence stands above: $257.4 million of futures turnover against $77.5 million on the spot market, $169.0 million tied up in open contracts, and a daily range of 4.89 percent on a day with no net movement. Against that: Dogecoin shows a similar picture with a factor of 2.9, so SHIB is no special case here but a somewhat more pronounced version of the meme sector's norm. And the ratio of open interest to spot turnover compares a stock with a day's turnover, so it serves for orientation, not as a precise measure. No statement about the direction of the price follows from any of these figures, and the funding rates do not yield one either.
SHIB futures: $169 million open, 2:1 is the EU limit
Three steps follow from this:
- With a leverage offer on SHIB, check first what leverage is available there and which supervisor the provider answers to. A provider authorised in Germany stops at 2:1. An overview of venues for perpetual contracts is in our perp DEX comparison.
- Work out before the order what price move would eat up your margin, and hold it against the token's daily range. For SHIB on Thursday that was 4.89 percent. If you would rather hold the token itself, the venues are in our crypto exchange comparison.
- Keep the records for spot purchases and forward transactions apart from the start, because the two are treated differently for tax. Tools for that are in our comparison of crypto tax tools.
All price and market figures in this article are our own counts of CoinGecko market data from Thursday evening. The legal references stand in the two ESMA and BaFin documents linked above.
(As of October 15, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Animoca Brands is not going public for now. The Hong Kong investment house behind the game The Sandbox, the MOCA token and more than 620 minority stakes suspended talks on its planned Nasdaq listing on September 22, 2026. The company has not named a date for a fresh attempt.
That removes the part of the story which had drawn most of the attention since November 2025. What remains is what stands in the company's own interim update of September 8: a portfolio book with a fair value of $411 million, a radically shrunken games business and a new blockchain for digital identity that has been running since September 29. These three parts decide what the Animoca name is worth today, and they tell a soberer story than any listing announcement.
What Animoca Brands is: an investment house with over 620 minority stakes
Animoca Brands started out in 2014 as a games developer and is today primarily a holding company. A holding company is a business whose activity consists mainly of holding and realising stakes in other firms rather than selling products itself. In its own interim update the company describes its position as minority stakes in over 620 portfolio companies across more than 20 sectors.
That figure is the core of the business model and at the same time its biggest valuation problem. Holding 620 small stakes, most of which have no market price, means working with estimates rather than quoted values. Animoca puts the fair value of those holdings at $411 million as at December 31, 2025. Alongside that the company reports $68 million in cash and stablecoins, digital assets of $177 million and off-balance-sheet token reserves of $306 million.
The best-known names in that book are The Sandbox, Open Campus, Anichess, GAMEE and TinyTap. How widely the house spreads beyond them shows in its own 2026 newsflow: a collaboration with Franklin Templeton on tokenised assets, a masternode validator on the XDC network, a majority takeover of GAMEE by Alpha Compute and a programme of up to $10 million for developers on the AI agent platform Minds. To place the breadth of this field, the four large Web3 gaming houses and their shutdowns are set out in our overview of Yuga, Animoca, Pudgy and Sky Mavis.
The reverse merger with Currenc Group: what the deal provided for
On November 3, 2025 Animoca announced its route to the Nasdaq through a reverse merger. In a reverse merger an already listed company buys an unlisted one, whose owners then hold the majority of the combined house. The listing is thus taken over rather than applied for afresh, and that is exactly what makes the route faster and cheaper than a conventional initial public offering.
The buyer on paper was Nasdaq-listed Currenc Group. On the figures given at the time, Animoca's shareholders would have held around 95 percent of the combined company. The third quarter of 2026 was the target date for completion. In May 2026 both sides extended the exclusivity period, that is, the window in which no negotiations with third parties are permitted. Valuations for the plan cited in press coverage ranged from around $1 billion up to $2.4 billion, and neither side ever confirmed any of them.
The merger has been on ice since September 22
In its announcement of September 22, 2026 Animoca speaks of a mutual suspension of the talks. Both sides give as the reason that the estimated time to completion does not fit their respective short- and medium-term strategic objectives. Co-founder and executive chairman Yat Siu is quoted as saying: “While we hold our proposed merger with Currenc Group in high regard, our corporate agility must take precedence.”
Two formulations from the same announcement matter more for context than the cancellation itself. The talks could be resumed if and when circumstances permit, a back door without a deadline. And Animoca says it remains fully committed to the goal of being listed again on a major public exchange. The word “again” is no accident, and there is more on that below.
Why the audited accounts are the real bottleneck
The same announcement contains the sentence that describes the position best: Animoca filed its audited annual accounts for 2023 only on July 17, 2026 and is working on those for 2024. A company still finishing its 2024 accounts in October 2026 simply cannot list on a major exchange, no matter how attractive its portfolio book looks.
The mechanism behind that is straightforward and applies at every regulated venue. An admission to listing requires audited figures from an issuer for several past financial years, prepared to a recognised standard and confirmed by an auditor. For a house with 620 holdings that is particularly laborious: every stake needs a traceable valuation, every token reserve an allocation, and for many of these items there is no liquid market from which a price could simply be read off. Animoca itself expressly marks the figures in its interim update as unaudited and not prepared under IFRS.
One plain consequence follows from that sequence for anyone speculating on a listing: as long as the 2024 accounts are outstanding, any date for a listing is a statement of intent, not an appointment. A merger partner can be found in weeks; a multi-year audit opinion cannot.
The return to a major exchange is a relisting
Animoca has been listed before. On March 9, 2020 the Australian exchange ASX removed the company from its official list under Listing Rule 17.12. In its letter of December 18, 2019 the exchange had raised several points of corporate governance, along with the involvement in cryptocurrency activities and the extensive use of SAFEs, that is, convertible funding agreements issued by subsidiaries. Animoca replied on February 28, 2020 with a 39-page submission and was removed all the same.
That history explains today's choice of words. Speaking of a relisting means having behind you an exchange that once did not want you, and having to deliver more than a good story at the next attempt. The 2020 removal also explains why the company sought the route through an existing listing rather than through a regular admission procedure.
Bookings of $173 million: the 2025 financial year figures
The interim update for the 2025 financial year reports bookings of $173 million for the twelve months to December 31, 2025. Bookings is not an accounting revenue measure but a self-defined metric for the group's total sales and earnings activity. Operating costs stood at $175 million, $65 million below the previous year, with non-cash items such as share-based compensation stripped out.
The comparison over time is the most interesting part of these figures, and it appears in no press release. For 2023 the company reported bookings of $280 million, for 2024 the figure was $314 million. From 2024 to 2025 bookings therefore fell by around 45 percent. Costs came down by $65 million over the same period, and for 2026 management says it will continue and accelerate that course. These are the accounts of a house that is shrinking and cutting faster than it loses business, not those of a growing technology group. That costs and bookings were practically level in 2025 also shows how narrow the margin has become.
The Sandbox after the restructuring: from 240 to 92 roles
Nowhere is that restructuring clearer than at the best-known product. The Sandbox, the virtual world with the SAND token, had 240 roles according to the interim update and now stands at 92. Operating costs in the division fell by more than 75 percent against the previous year. The company describes the seventh Alpha Season as the last operational outing on the existing architecture before a rebuild with AI integration follows.
For holders of the token that cuts both ways. A product going from 240 to 92 roles delivers less content, and the existing technical base is being retired before its successor is in place. If you hold SAND, the price history and the figures behind it are in our SAND price prediction. That the wider field is faring no better shows in the marketplace count: several of the large NFT trading venues have closed within a year, as set out in our review of the NFT marketplaces in 2026, and with the shutdown of Blur on November 12 the next one goes.
Moca Chain since September 29: a layer-1 blockchain for digital identity
On September 29, 2026 the Moca Foundation and Moca Network launched the Moca Chain mainnet, which had been announced back in June 2025 with a target in the fourth quarter of 2025. Moca Chain is a standalone layer-1 blockchain with the EVM identifier 2288 and can be operated with the usual Ethereum tooling. Its purpose is digital identity: institutions issue credentials, such as a completed identity check or a membership, and users carry those credentials into other applications.
What is a verifiable credential?
A verifiable credential is a digitally signed attestation about an attribute of a person whose authenticity any third party can recompute without asking the issuer. Moca Chain combines that with zero-knowledge proofs. A zero-knowledge proof establishes that a statement is true without disclosing the data it rests on: you can prove that you are of age without showing your date of birth.
In this design the MOCA token is intended for staking and for fees that arise when credentials are issued, stored and verified, and in identity oracles. For the AIR product layer, which ties together identity, payment and loyalty programmes, the project names partners including SK Planet, Open Campus, OneFootball, Automobili Lamborghini and Nansen. On uptake there are two figures from two points in time: in its interim update Animoca reported more than 2.6 million MocaID users as at December 31, 2025, while at the mainnet launch the talk was of more than 3.3 million accounts connected through AIR. The 700 million reachable users also cited, by contrast, are an estimate across the entire portfolio, not a count of accounts on this blockchain.
What remains open is the question that decides the economic value: whether regulated companies may rely on a credential issued by another company in order to meet their own customer due diligence duties. The launch announcement does not answer that, and without such recognition the benefit stays confined to voluntary applications.
MOCA in the portfolio: 98 percent below the December 2024 record
MOCA is trading in mid-October 2026 at about $0.0085, or roughly €0.0076. Market capitalisation is around $36 million; data services quoted values between $32 million and $37 million for July and September, so the token has been moving in that order of magnitude for months. Circulating supply is around 4.23 billion tokens according to CoinGecko against a maximum supply of 8.89 billion, while other services put circulation at 3.6 billion to 4.0 billion. From the record price of $0.4774, set on December 25, 2024, it is around 98 percent short.
These figures matter more for context than they first sound. Animoca valued its own MOCA reserve at $131 million as at December 31, 2025. The token's entire market capitalisation today is a fraction of that. A reserve amounting to a multiple of the whole market value cannot be sold at that price, and that holds for any token holding that is large relative to its market. Buying MOCA therefore means buying a very small instrument with a large reserve in the background, and at this size a total loss is possible.
The name clash matters too: a token called Museum of Crypto Art also runs under the MOCA ticker, on Polygon, with a market capitalisation in the six figures. What counts when buying is the contract address, not the ticker.
MiCA and the ESMA register: how to check your exchange's licence yourself
For investors in Germany the trading question is the one that matters most in practice. CoinGecko lists around 33 trading pairs for MOCA. The largest of them sit at exchanges outside the European Union, among them Bybit, KuCoin, Bitget and Gate, alongside decentralised venues such as Uniswap on Ethereum and Aerodrome on Base. MOCA is not available at a German bank or a German broker.
A hard legal framework has applied since the start of the year. Under section 50 of the German Crypto Markets Supervision Act, the German transition period for crypto service providers ended with the close of December 31, 2025; across the EU the transition ran out on July 1, 2026 at the latest. Anyone offering crypto asset services to customers in Germany has since needed authorisation as a crypto asset service provider under MiCA, a CASP. Which providers hold that authorisation is recorded in the register of the European securities regulator ESMA, with German institutions additionally in BaFin's company database. Both registers are public, and a look inside takes two minutes. A selection of houses with EU authorisation is in our comparison of regulated crypto exchanges.
Going through a decentralised venue removes the provider question but puts custody on you: lose access to your wallet and you lose the tokens, and there is no body that retrieves them. For tax, the one-year holding period under section 23 of the German Income Tax Act continues to apply to private sales. The cabinet date for the announced abolition passed in mid-October without a decision, so the December 31 cut-off stays as it is for now; the state of play is in our report on the cabinet date that passed.
Our assessment: the portfolio book holds, the listing story wobbles
From this newsroom's point of view the cancelled merger is the smaller story. The portfolio book stands at $411 million of fair value, $68 million in cash and stablecoins and $177 million in digital assets; Animoca can work off that substance for a long time, and costs cut by $65 million extend that room. Against it stand three documented points: bookings down from $314 million to $173 million in a year, a flagship product down from 240 to 92 roles, and 2024 accounts that are still unaudited in October 2026. As long as those are missing, a listing is an intention, not an appointment.
The most solid part of the story is therefore not the exchange but Moca Chain: a product that has been running since September 29, with named partners and a clear task. What will decide it is whether regulated companies recognise the credentials issued there. This assessment judges the situation and is not a recommendation to buy or sell; with a token at $36 million of market value, a total loss is possible.
Animoca Brands: without audited accounts the listing stays open
- Separate the company from the token. As a retail investor you cannot currently take a stake in Animoca Brands, and the MOCA token is something other than a share in the holding company. If you want to buy it, find a venue with EU authorisation and compare the costs beforehand in our exchange comparison.
- Look at the surroundings, not just the name. The Sandbox is rebuilding, and the NFT market is losing venues. Which marketplaces are still open and what they cost is in our marketplace comparison.
- Document every purchase from the start. For the one-year holding period you need the purchase date, quantity and price for each acquisition. Tools that record this automatically are in our comparison of tax tools.
(As of October 15, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Memeland is the crypto project behind the joke platform 9GAG, and MEME is its token. Three years after the launch, two figures capture where it stands: MEME trades around 99 percent below its record of March 2024, and the floor price of the project's best-known NFT collection has fallen from 9.73 Ether to 0.02 Ether. We measured both ourselves at midday on Wednesday.
This is not a report on a single day but a stocktake. Anyone coming across Memeland today finds a well-known brand, two fully minted NFT collections, a token with 64.8 billion units in circulation and no published development plan. This article sets out what of that is documented, how pricing works in collections of this kind, and what a loss on a sale means for tax in Germany. If you are looking for a venue to trade meme tokens, our overview of crypto exchanges licensed in Germany helps place the providers.
Memeland, 9GAG and the idea behind the meme ecosystem
9GAG is one of the older platforms for internet humour, founded in Hong Kong in 2008. Memeland is the Web3 arm of that house and describes itself on its own site as a Web3 venture studio and ecosystem. The thinking behind it was common at the time: a brand with wide reach issues NFT collections, the buyers of those collections form a community, and later that community receives a token.
An NFT is an entry on a blockchain tied to a single item, which is why it cannot be swapped for an equivalent piece the way one unit of Bitcoin can be swapped for another. What rights an NFT actually transfers is set by the issuer's licence alone, not by the blockchain. On that basis Memeland issued two collections: The Potatoz and The Captainz, each with 9,999 pieces.
How the token came about
MEME launched in November 2023 and reached further trading venues in January 2024. According to CoinGecko's classification, the token belongs to the Binance Launchpool and to the portfolio of YZi Labs, formerly Binance Labs. It runs on Ethereum rather than on a blockchain of its own, and the house has not disclosed an investment figure in the reports available.
The MEME token: 69 billion units and a price of $0.0005
At midday on Wednesday MEME stood at $0.000515, or €0.00046. Market capitalisation was around $33.4 million and trading volume over the preceding 24 hours around $4.9 million. CoinGecko ranks the token 617th by market capitalisation.
The supply side matters more than the price. Maximum supply is 69 billion MEME, of which 64.77 billion are in circulation, just under 94 percent. According to the token page on the Ethereum explorer, around 738,000 addresses hold it. A unit count that high against a small market capitalisation has an arithmetic consequence: every cent of price movement would be a multiple of today's level, which is exactly why price targets that the supply side rules out circulate around tokens like this. At 69 billion units, a price of one cent would imply a valuation of $690 million.
99 percent below the record: what the MEME price figures say
MEME reached its high on March 4, 2024, at $0.056324. From today's price that is a gap of 99.1 percent. Over twelve months the token is down 69.3 percent, but over the last thirty days only 2.3 percent: the large move lies further back than those thirty days.
A low from August of this year sits at $0.0004437 according to CoinMarketCap, just under today's price. The token has therefore been moving in a narrow band close to its low for months. For context, that means neither a slump nor a recovery defines the picture, but a long sideways stretch at a low level.
The Captainz: from a 9.73 Ether floor price to 0.02
The trend reads more clearly in the NFT collections than in the token. For The Captainz, the better known of the two, the highest floor price ever reached was 9.73 Ether, around $21,226 at the time. At midday on Wednesday the price tag read 0.01999 Ether, or $49.65. That is 99.8 percent less.
The collection comprises 9,999 pieces spread across 2,969 addresses. That works out at a total valuation of around $496,000 for the whole collection. Trading volume over the last 24 hours came to 0.10 Ether, roughly $250 for the entire day.
The Potatoz: same unit count, a different path
The Potatoz came before the Captainz and also comprises 9,999 pieces, spread across 2,329 addresses. At midday on Wednesday the floor price was 0.025 Ether, or $62.87, and therefore above that of the Captainz. The highest floor price ever reached was 6.78 Ether, around $16,143, leaving a gap of 99.6 percent.
The relationship between the two collections is worth noting. The Captainz counted as the higher-grade collection and held the higher record, yet today they sit below the Potatoz. Trading volume tells a similar story: 0.68 Ether for the Potatoz against 0.10 for the Captainz over 24 hours. Buying or selling today means meeting a market in which, on some days, only a handful of pieces change hands in either collection. For an overview of the venues that trade collections like these, see our comparison of NFT marketplaces.
Why a floor price is not a market price
The floor price is the cheapest active sell offer in a collection. It says at what price someone would be willing to sell, not that anyone is buying at that price. In a collection of 9,999 pieces with a daily turnover of a few units, that distinction carries real weight: the floor price can stand for weeks without a single sale going through.
A caution follows for any valuation. The calculation of unit count times floor price, which we made above as well, produces a theoretical number. If all 9,999 Captainz were offered at once, the achievable price would be lower than today's floor. The figure works for comparison over time, not as a statement of wealth.
What Ether as the unit of account changes
Floor prices for NFT collections on Ethereum are quoted in Ether, not in euros. If the Ether price falls, the euro value of a collection falls too, even when its floor price in Ether stays the same. In the Captainz both directions coincide: the floor price in Ether is down 99.8 percent, and in dollar terms the figure comes out at almost the same 99.8 percent, because the Ether price today sits at a similar level to the time of the record.
No official roadmap: what the valuation rests on instead
According to CoinMarketCap's classification there is no published development roadmap for MEME, and the valuation therefore rests on the brand and on community interest. The same service lists recent activity around MemeDay events, the Meme69 Awards and brand collaborations.
That assessment comes from a data service, not from the project itself, and should be read as such. The counter-check is documented: on the official project pages of Memeland and of the token, no development plan with dates was findable on Wednesday. What is missing is not an accusation but a finding about the information available. It matters for valuing a token all the same: without an announced function or use of revenue, there is no measure against which a price could be tested.
The technical question behind it
Utility in crypto usage means the function a token performs within a system: paying fees, voting on changes, securing computing power. A token without such a function is not therefore worthless, but its price forms purely out of supply, demand and attention. More on that distinction and on what sets the segment apart is in our overview of meme tokens.
Binance Launchpool and YZi Labs: how MEME reached the exchanges
MEME entered circulation through the Binance Launchpool, a scheme in which users lock existing balances for a limited period and receive units of a new token in return. For a young project that route brings reach and a widely distributed initial supply; for the participants it brings units at no purchase price. Both shape trading in the first months, because part of those holdings is sold early.
Added to that is the classification as a YZi Labs holding, formerly Binance Labs. A stake points to a funding round, but it is not a mark of quality and not a commitment for the future. The size of the investment has not been published in the reports available, so no valuation can be derived from it either.
What separates a meme token from a network token
A network token such as Ether belongs to a blockchain and is needed there to pay transaction fees. A meme token, by contrast, is usually a contract on someone else's blockchain; in MEME's case a standard contract on Ethereum. The technical bar is low, so what distinguishes two meme tokens is not the technology but the reach behind them.
On reach Memeland had a genuine head start, namely an existing platform with a large audience. Today's figures show that the advantage did not carry the price over three years. That is the sober lesson from this case, and it holds beyond Memeland: reach generates attention at launch, but it does not replace continuing demand. How other houses of the same years have fared, we counted up in our review of the state of the Web3 gaming companies and in our review of Illuvium, Axie and Sandbox.
Tax in Germany: how to treat losses on crypto sales
Selling tokens or NFTs at a loss can be used for tax purposes in Germany, but only within narrow limits. Crypto assets count as other economic goods under section 23 of the Income Tax Act. A loss on their sale therefore reduces only gains from private disposals in the same year, not gains from shares or interest. Any remainder can be carried back to the previous year or forward into coming years.
Two points are easy to miss here. First, a sale has to actually take place: a price decline on its own creates no usable tax loss while the position is held. Second, the same one-year period applies as it does to gains. If the purchase lies more than a year back, a gain is tax-free, and consequently a loss is then irrelevant for tax too. How a complete write-off differs from that, we set out in the case of a total loss.
What belongs in the records
For every position you need the purchase date, purchase price, sale date and sale price, and for NFTs the contract address and the item number as well. For a collection traded across several marketplaces, that statement rarely sits in one place. Only the tax office or a tax adviser can give binding answers on an individual case.
Where MEME can be traded in Germany and what MiCA has to do with it
Since the European regulation on markets in crypto assets, MiCA for short, providers addressing customers in the European Union need authorisation from a national supervisor. In Germany, BaFin grants it and supervises them. The licence says nothing about the quality of an individual token: what is examined is the provider, its custody, its capital adequacy and its duties towards customers.
In practice, for a token well outside the large caps that means this: it appears in the range of licensed providers less often than on unlicensed platforms. Before buying, it is worth checking whether the chosen venue holds a European licence and how it keeps the tokens in custody, because that determines what can be recovered if something goes wrong.
MEME token: without a roadmap, attention alone decides
Memeland remains a well-known brand with two fully minted collections and a widely held token. What the figures lack is demand reaching beyond the launch phase. Three steps help in judging a case like this soberly:
- Look at the supply side before the price. Multiply maximum supply by your target price and see what valuation comes out. At 69 billion units, one cent already means $690 million. Where a token can be traded at what cost, and which providers hold European authorisation, is shown in our exchange comparison.
- Read trading volume alongside the floor price. A floor price without turnover is an offer, not a price. Check the number of sales over recent days and the number of holding addresses next to the floor price. Which venues generate any turnover at all for a collection is in our comparison of NFT marketplaces.
- Document losses before you sell. Purchase and sale data for each position determine whether a loss is usable and against which gains. For pulling records together across several marketplaces, portfolio trackers with tax reporting help.
(As of October 14, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
The first American spot fund on Polkadot manages $11,567,725.24, according to its provider. That is the reading from October 14, 2026, a good seven months after it launched on March 6. By way of comparison: the DOT spot market turned over $160.9 million in the past 24 hours. The fund meant to bring institutional money into Polkadot is therefore smaller than a fifteenth of a single trading day.
This article answers three questions. What exactly sits inside the fund, and what that says about demand for DOT. Why a vehicle of this size neither carries the price nor weighs on it. And what investors in Germany gain from it when they cannot buy the product in the first place. The shortest answer to the third question up front: the American fund costs 0.30 percent a year, while the route open to you in Germany costs 2.50 percent. More hangs on that gap than on any price level this week.
What the 21Shares Polkadot ETF has gathered since March 6
The product is called the 21shares Polkadot Staking ETF and trades under the ticker TDOT on the Nasdaq. On the issuer's product page, 21Shares gives March 6, 2026 as the launch date, 0.30 percent as the management fee and the $11,567,725.24 above as assets under management, as of October 14. The page lists BitGo Bank & Trust, Coinbase Custody and Anchorage Digital Bank as custodians. The word staking in the name means the fund does not merely hold the DOT in custody but stakes them in the network and collects the rewards.
A spot ETF is an exchange-traded fund that holds the asset itself, here real DOT with a custodian, rather than futures contracts on it. The share price therefore follows the coin price directly, less the fee.
At the data service SoSoValue, whose daily figures the industry outlet TokenPost reported on October 14, TDOT shows cumulative net inflows of $3.33 million. The fund was unchanged that day and the day before, so no money flowed in or out. The same table gives trading turnover of $111,586 and a ratio of 0.62 percent. It names no reference figure for that percentage. Checked against the market capitalisation of DOT, which stood at $1.847 billion on Thursday, $11.57 million comes to exactly 0.626 percent. The figure therefore refers to the share of the entire Polkadot market.
Measured in DOT, at a price of $1.082 that is around 10.7 million units. Circulating supply is 1.707 billion DOT. The largest American fund on Polkadot thus holds fewer than one in every hundred coins.
$111,586 in a trading day: the size against the DOT spot market
The more telling figure is not the assets but the turnover. Trading volume of $111,586 in a day sounds like little, and in relative terms it is less still: the DOT spot market turned over $160,945,583 in the same period. By our calculation, ETF trading accounts for 0.069 percent of that, barely seven hundredths of a percent.
That ratio is why the fund figures are practically meaningless for the price. A spot ETF acts on the price by buying coins in the market on inflows and selling them on outflows. No inflows, no buying power. At the Bitcoin ETF launch in January 2024 precisely the reverse happened: billions flowed in over the first weeks, and the funds had to buy in the spot market every day. At TDOT, seven months have produced $3.33 million of net inflows.
The Dogecoin case: the size at which an altcoin fund gets closed
How small an altcoin fund can get before its provider gives up has just been shown elsewhere. On October 10 we wrote about the wind-down of the Bitwise Dogecoin ETF. That vehicle, ticker BWOW, held around 8.2 million DOGE according to the holdings on its fund page, roughly $707,000 at the price of the time. It traded for the last time on October 14, just under eleven months after launch.
At $11.57 million, TDOT is therefore about sixteen times the size of the Dogecoin fund on its final trading day. The product is a long way from closure, and nobody should read an imminent wind-down out of the weak inflows. What the comparison shows is something else: the American fund industry launched a run of altcoin products in 2026, and demand is spread very unevenly. Bitcoin and Ethereum draw the money, while the remaining funds collect sums that have no measurable effect on the price of their coin.
Polkadot price at $1.08: 14 percent below the September 28 high
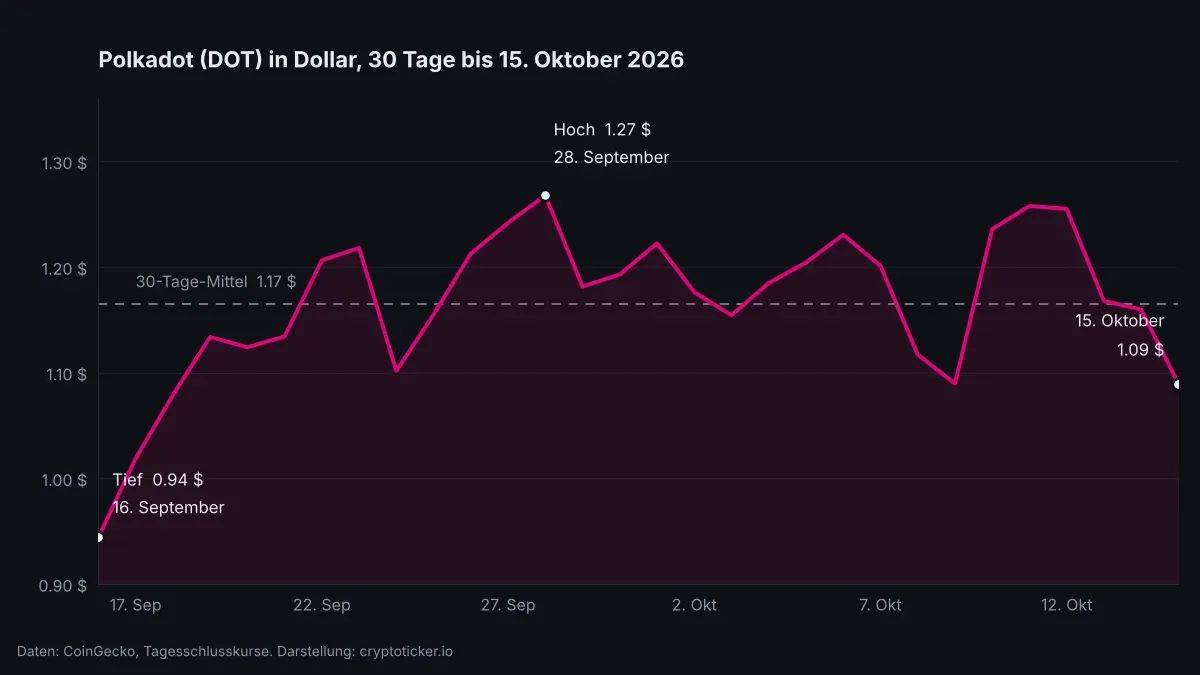
DOT trades at $1.082 on Thursday afternoon, 3.4 percent below the previous day. The high of the day was $1.16, the low $1.05. The wider market gave up considerably less that day: Bitcoin lost 0.5 percent, Ethereum 1.6 percent. Polkadot is therefore falling about six times as hard as Bitcoin.
Over 30 days the picture is the one in the chart above. CoinGecko daily closes give a low of $0.9441 on September 16 and a high of $1.2677 on September 28. DOT has recovered 15.4 percent from the low and is 14.1 percent short of the high. The average of those 30 days is $1.1652, putting today's price 6.5 percent below it.
From the all-time high of $54.98, reached on November 4, 2021, the price is around 98 percent away. That number belongs in any honest assessment of DOT, even if it says little about today's question.
Authorized participants: when a spot ETF has to buy DOT at all
The mechanism takes three sentences. A spot ETF creates and destroys shares through so-called authorized participants, large traders who deliver or take in coins in exchange for shares. When demand for shares appears, those traders have to source DOT in the market, and that purchase hits the order book. When demand stays away, nothing happens at this point.
What counts is the ratio between the volume to be moved and daily turnover. At a 0.069 percent share of trading volume, any move by the fund disappears into the noise of an ordinary morning. Even if TDOT had to sell its entire assets on a single day, that would be 7.2 percent of one day's turnover, spread across several venues. The daily range between $1.05 and $1.16 is 10.5 percent today. The fund's move would therefore stay inside what the market produces on a normal day anyway.
For the price question that means anyone betting on ETF inflows as a driver for DOT is waiting for leverage that does not work at this order of magnitude. This week's price move comes from the wider market and the futures market, not from Nasdaq share certificates.
Since October 13: what has changed since referendum 1954
We last wrote about Polkadot on October 13, then on the vote 1954 and the mandate of the DOT DAO, which stood at 73 percent against. The price that day was $1.1679. DOT has lost 6.7 percent since. The $1.10 level, which held twice over the past fortnight, was breached intraday today for the first time since October 9.
The governance question of then and the fund question of today are connected more loosely than they appear. Both are attempts to pull money and attention towards Polkadot, once through the treasury, once through the American capital market. The fund figures deliver a sober verdict on the second: the Wall Street route has produced $3.33 million in seven months.
0.30 against 2.50 percent: European investors pay eight times the rate
Here is the part that counts in practice. The American fund cannot be bought in Germany. US ETFs may not be offered to retail investors in the EU because they lack the key information document in German required under the PRIIPs regulation. Your broker will not put TDOT in your portfolio, however cheap the product is.
The route open to you runs through an exchange-traded product of European construction. 21Shares offers the 21Shares Polkadot ETP for that purpose, listed on the SIX Swiss Exchange in dollars and on Börse Stuttgart in euros, with the ISIN CH0593331561. The ongoing charges of that product are 2.50 percent a year. The same fund house charges 0.30 percent in America and more than eight times the rate in Europe.
What that difference adds up to over time is quickly worked out. Invest 5,000 euros and you pay 125 euros in the first year with the European product, against 15 euros with the American one. Over five years and at an unchanged price it is around 595 euros against 75 euros. That fee keeps running whether the price rises, falls or stands still. For a wider view of the products tradable in Germany, see our overview on buying crypto ETFs and ETPs in Germany.
The alternative is a direct purchase on an authorised exchange. There you pay a trading fee and a spread on the way in and on the way out, and no ongoing product fee after that, but you carry responsibility for custody yourself. Which providers are authorised in Germany and what their trading costs is set out in the comparison of regulated crypto exchanges.
How to check the delivery claim on your certificate
The second difference between the portfolio route and a direct purchase is a tax one, and over a longer holding period it weighs more than the fee. On a direct purchase the holding period under Section 23 of the German Income Tax Act applies: hold a crypto asset for more than a year and the gain is untaxed. That rule continues unchanged. The federal cabinet did not pass the decision on abolishing the holding period expected for October 14, the draft is stuck in departmental consultation, and the December 31, 2026 cut-off date named in it would separate old holdings from new ones.
With an exchange-traded product the position cannot be answered across the board. We set that out in detail on October 10 on the crypto offering at ING: whether the one-year period applies to your certificate depends on whether it grants you a delivery claim on the real coin. Certificates without that claim are treated as a capital claim, and there the flat-rate withholding tax applies with no one-year period. Certificates with a delivery claim are classed by parts of the advisory profession like a direct investment. There is no supreme court ruling covering every product design, and no issuer decides this for your tax office.
Three steps lead to a sound answer. First, take the ISIN of your certificate and read in the key information document which product type is stated there. Second, request the final terms from the issuer and look in them for a provision on physical delivery. Third, have the result confirmed for your case by a tax adviser before you rely on the one-year period. Document the acquisition dates with a tool from our comparison of crypto tax software, because with a savings plan the period runs separately for every instalment.
Our assessment: the fee is certain, the tax effect is not
In the view of the editorial team, the product question at Polkadot currently matters more than the price question, and the answer is an uncomfortable one. What is evidenced: the European product costs 2.50 percent a year, the American one 0.30 percent, and both come from the same provider. Evidenced too: the one-year holding period applies on a direct purchase, while on a certificate it depends on a delivery claim that few investors have checked. Our conclusion: hold DOT for longer than two years and you pay a certain fee in a securities account for an uncertain tax effect. There is a serious argument against, and we do not play it down: lose your private key and you lose everything, and not everyone wants to carry that responsibility. For investors who prefer the securities account for exactly that reason, the surcharge is the price of custody they need not attend to. This assessment weighs up the situation and is not a recommendation to buy or sell.
Polkadot in a securities account: 2.50 percent a year against an open tax question
The first American spot fund on DOT manages $11.57 million after seven months and trades $111,586 in a day, which is 0.069 percent of the spot market. For the price that carries no weight. What counts for you is the layer beneath: which product you buy, and what it costs over the years.
- Project the product fee onto your intended holding period. At 2.50 percent a year that is around 595 euros on 5,000 euros over five years. Set that against the one-off trading fee of a direct purchase, which you can look up in the comparison of regulated crypto exchanges.
- Settle the delivery claim before you rely on the one-year period. The ISIN, the key information document and the final terms supply the answer, and a tax adviser confirms it. Which products are tradable in Germany at all is set out in the overview of crypto ETFs and ETPs.
- Document every acquisition date from today. Should the draft with its December 31, 2026 cut-off arrive, that date decides between old and new holdings. A tool from the comparison of crypto tax software keeps track of the periods for you.
(As of October 15, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
Speaking after BlackRock’s Q3 earnings, Fink said AI infrastructure spending has become so central to growth that a construction halt would be dangerous—calling the backlash “misinformation” as data centers become a midterm flashpoint.
Google DeepMind's first internal audit of AI-driven research finds no measurable speedup in AI progress.
The first major integration since Mastercard’s $1.8 billion BVNK acquisition lets banks, fintechs and enterprises hold, convert, and spend fiat and stablecoins through a single API, with agentic commerce support planned.
Hot inflation data revived Fed rate-hike bets, and leveraged bulls paid the bill as nearly $1 billion in crypto positions were liquidated.
Market analysts say that macro factors are pushing altcoin prices down, after ETH, XRP, and SOL all dropped on the day.
U.Today - IT, AI and Fintech Daily News for You Today
Three members of the Canadian Armed Forces are among seven suspects charged in connection with a shocking cryptocurrency-related kidnapping in Toronto.
Overnight liquidations hit $932 million as XRP, DOGE, and NEAR face deep corrections before a sudden market reversal.
Dogecoin whale activity may be rising as the ongoing market volatility pushes traders to dump their crypto holdings to hedge against further losses.
Bitcoin is missing from Google trends as global search interest collapses to multi-year lows.
Cardano’s 5,747% liquidation Imbalance raises fresh questions for ADA bulls.
Blockonomi
TLDR
- CleanSpark’s September Bitcoin production fell nearly 11% to 529 BTC from 593 BTC in August.
- CleanSpark sold 702 BTC and closed September with Bitcoin holdings of 13,530 BTC.
- CleanSpark discontinued monthly mining reports while advancing its $2.276 billion data center financing.
- BitFuFu’s cloud mining output fell to 69 BTC as an electricity dispute threatened its Ethiopia acquisition.
- Canaan mined 44 BTC, while its Nordic heating project supplied recovered heat to approximately 2,800 homes.
CleanSpark mined 529 Bitcoin in September, down from 593 in August, while rival BitFuFu also recorded lower production. Canaan held steady at 44 BTC. The three publicly traded miners reported different changes to their operations.
CleanSpark reduces production and ends monthly updates
CleanSpark finished September with 13,530 BTC, compared with 13,703 at August’s end. It sold two BTC on spot markets and another 700 through exercised call options. The company reported an average sale price of $72,928, including option premiums.
Its average daily production reached 17.64 BTC. CleanSpark reported 50 exahashes per second in operational computing power and nearly 200,000 deployed mining machines. The company will now report quarterly rather than release monthly mining updates.
Data center investment remains a priority
CleanSpark closed a $2.276 billion secured bond offering to fund construction at Sandersville, Georgia. It expects a data center lease there to generate approximately $6.6 billion during its initial term. A separate report on AI chip supplies examined potential problems for miners.
On October 13, Bitcoin Magazine shared an X discussion about Bitcoin mining and artificial intelligence computing. CleanSpark said the bond financing covers Sandersville through completion, while its mining business continues operating.
BitFuFu faces an Ethiopian power dispute
BitFuFu produced 167 BTC in September, versus 174 in August. Its own mining increased from 88 to 98 BTC, but customer cloud mining fell from 86 to 69 BTC. Total managed computing power dropped to 19.4 exahashes per second.
Its proposed Ethiopian mining acquisition remains unfinished because of a dispute involving the site’s electricity supplier. BitFuFu paid $4.1 million and deployed around 13,700 machines there. Separately, Binance announced plans to close its cloud mining service in November.
Canaan maintains output and expands heat recovery
Canaan ended September holding 1,875 BTC, up from 1,868 at August’s close. Its non-joint-venture computing capacity remained at 10 exahashes per second, while joint ventures operated at 4.18. September mining production matched the previous month.
Thursday’s trading also followed a wider fall in Bitcoin mining shares. CleanSpark traded at $8.76, BitFuFu at $1.27 and Canaan at $0.25. Several rival miners had fallen more than 12% during Wednesday’s stock market selloff.
Canaan said its eight-megawatt Nordic heating facility now supplies recovered mining heat to about 2,800 homes. The company is also preparing a similar heat-recovery project for Canadian greenhouses, pending final site inspections.
The post CleanSpark Mines 529 BTC, but Reporting Takes a Turn appeared first on Blockonomi.
TLDR
- Ledger introduces tighter sales controls following the discovery of modified hardware wallets sold through resellers.
- Criminals installed hidden components that captured customers’ 24-word recovery phrases and transmitted them through mobile networks.
- Bitquery estimates $102 million was stolen from 324 wallets, exceeding Specter’s earlier $86 million estimate.
- Ledger says inspections found no tampering in the retail and warehouse samples its teams examined.
- Authorized dealers must keep devices off display shelves, while returned wallets remain barred from resale.
Ledger has introduced tougher rules for hardware wallet sellers after criminals altered genuine devices and stole cryptocurrency. In its October 15 statement, the company reaffirmed its ban on reselling returned wallets and ordered retailers to keep new devices away from display shelves.
Criminals altered devices before resale
Ledger said attackers purchased legitimate wallets, fitted hidden components, and returned them to reseller channels in Southeast Asia. The company said the group spent months preparing the operation and built systems to collect recovery phrases and move stolen funds.
The investigation began on October 9 after customers reported missing assets from devices sold by Malaysia-based CryptoBilis. An earlier Ledger wallet theft investigation connected the complaints to the reseller, which subsequently halted sales.
How the hidden implants worked
Ledger’s security team found an implant that copied the 24-word recovery phrase displayed during wallet setup. The component then sent those words through a mobile data connection using a built-in electronic SIM card.
The company said the device’s security chip and operating system remained intact. Binance founder Changpeng Zhao warned on X on October 9 that the evidence pointed to an attack through one seller, rather than a problem across all Ledger wallets.
Loss estimates rise as investigators trace funds
Blockchain researcher Specter initially estimated losses above $86 million. However, Bitquery’s October 15 update traced $102 million from 324 wallets across six networks. Earlier confirmation of device tampering established that investigators found an unauthorized component. Ledger has not confirmed total losses or the number of affected customers.
Bitquery said Tether froze $10 million in USDT linked to the theft. Its investigation also tracked stolen funds through swaps and privacy services. The researchers counted wallets, not individual customers, and noted that one owner could control several affected addresses.
Ledger changes distribution and customer guidance
Ledger said its teams examined devices from stores in Germany and stock held in warehouses. Those samples showed no tampering. In an October 14 X update, the company called for a pause in sales across seven markets, including Hong Kong. Resellers in Asia suspended wallet sales as the investigation continued.
Authorized dealers must now store wallets away from public shelves and hand them to buyers at purchase. Ledger advises CryptoBilis customers against setting up unused devices. Those who already used one should move assets to a new wallet with a fresh recovery phrase.
The post Ledger Reveals How Hidden Chips Exposed Crypto Wallets appeared first on Blockonomi.
TLDR
- Trump Media stock recovered intraday Thursday after six consecutive losing sessions.
- Similarweb estimated Truth Social’s September audience at 260,000 daily users, below its June 2025 peak of 420,000.
- Trump Media reported an 89% quarterly revenue increase despite weaker Truth Social advertising sales.
- DJTB tokenized shares fell approximately 8% over 24 hours in the cited Thursday morning quote.
- Binance’s DJTB token offers economic exposure to Trump Media without direct share ownership or voting rights.
Trump Media stock recovered from an early Thursday decline while new estimates showed shrinking traffic on Truth Social. Shares traded at $7.34 around 12:40 p.m. Eastern, after an earlier quote near $7.10.
The rebound followed six consecutive losing sessions for Trump Media & Technology Group (NASDAQ: DJT). The Washington Post published the audience findings after Wednesday’s market close. Thursday’s session had not ended.
Trump Media & Technology Group Corp., DJT
Trump Media Stock Rebounds After Six Losses
Trump Media stock closed Wednesday at $7.22, down 6.84% for the session. The stock had fallen from $8.65 on October 6, a drop of 16.5% across six sessions.
Wednesday’s losses came during a broader selloff after annual U.S. inflation reached 3.7% in September. The Nasdaq fell 1.88%, amid declines across several technology and financial stocks.
Truth Social Audience Estimates Fall
Similarweb estimated roughly 260,000 daily Truth Social users in September 2026, compared with about 420,000 at its June 2025 peak. That peak comparison spans approximately fifteen months.
The research firm also estimated a traffic decline exceeding 30% over the latest year. These are third-party estimates rather than daily user totals released by Trump Media. The figures measure users, not advertising sales or subscription income. The company has not yet reported its September advertising results.
Trump Media operates Truth Social, its Truth+ streaming platform, and financial products under Truth.Fi. Separately, Binance’s expansion into U.S. shares includes blockchain-based stock products linked to public companies.
Advertising Revenue and Tokenized Shares
Trump Media’s June-quarter filing recorded lower Truth Social advertising revenue from a year earlier. Total quarterly revenue nevertheless rose 89% to $1.67 million, helped by barter advertising, streaming subscriptions and fund management fees. Its second-quarter net loss reached $238.1 million, company filings show.
A Thursday morning quote placed DJTB, the token linked to DJT, near $7.17, down about 8% over 24 hours. Separately, Kraken recently detailed plans to offer tokenized shares in the UAE.
Binance listed DJTB on August 26. Its issuer, BTech Holdings Limited, holds underlying securities, but token buyers do not directly own DJT shares or gain voting rights. DJTB’s round-the-clock trading means its daily price change cannot be directly compared with Nasdaq’s regular session.
The post Trump Media Stock Rebounds, but Truth Social Faces a Test appeared first on Blockonomi.
TLDR
- Binance bStocks surpassed $1 billion in managed assets four months after launching in June 2026.
- The tokenized stock platform recorded over $40 billion in trading volume and nearly 100 listed securities.
- Binance users converted $6 billion between tokenized shares and direct stock positions at 1:1 parity.
- Around 62% of bStocks trading in July occurred outside regular U.S. market hours.
- Borrowing against deposited bStocks collateral reached 46.2%, while decentralized finance deployment rose to 11.2%.
Binance tokenized stocks surpassed $1 billion in assets under management four months after launch. Binance announced the October 15 milestone, citing Dune data and claiming the fastest rise to that level.
Binance tokenized stocks expand beyond launch
Binance launched bStocks on June 11 with five tokenized U.S. stocks and exchange-traded funds. Its list now covers nearly 100 securities. The exchange reported over $40 billion in trading, averaging more than $300 million daily.
Users converted $6 billion between bStocks and direct stock holdings, according to Binance. Each token has one-to-one backing through securities held in custody. The conversion figure measures cumulative activity, not assets held today.
In an October 5 X post, Binance told eligible users they could switch between stocks and tokens. Separately, the exchange plans to close its mining pool in November as it expands access to American securities overseas.
Most trading happens outside Wall Street hours
In July, only 38% of bStocks trades occurred during regular U.S. market hours. Binance compared that with 89.2% for conventional equities. Eligible customers can trade tokens on weekends and transfer them into compatible personal wallets.
Shunyet Jan, Binance’s head of exchange and trading, said continued market activity matters beyond launch. He said customers trade bStocks, pledge them as collateral, and convert them into direct stock positions.
Other companies are also developing tools for tokenized securities. Chainlink recently expanded tools that connect financial networks. Binance reported that 11.2% of bStocks value was deployed in decentralized finance by early October 2026, exceeding comparable products by 3.8 percentage points.
Collateral borrowing rises with tokenization
Borrowing against Binance tokenized stocks reached 46.2% of deposited collateral by September 10, up from 5.5% at June’s end. The exchange extended collateral access to eligible retail customers in September, with account checks and risk controls.
Traders can pledge supported bStocks for margin and futures positions, with borrowing up to five times their collateral. Binance said 58.5% of early users also traded perpetual futures or direct shares by late July.
The trend comes as banks expand tokenized deposits, including Wells Fargo. Binance also estimated tokenized stock transfers exceeded $100 billion during the third quarter, compared with $6 billion during the first. Binance says bStocks are backed by underlying securities, but holders do not receive direct shareholder rights.
The post Binance Tokenized Stocks Hit $1B. What Fueled Growth? appeared first on Blockonomi.
TLDR
- Amazon (AMZN) shares slip 0.27% to $253.40 following new Bee device launch
- Bee Frontier costs $74.99, while the Eclipse phone accessory sells for $99.99
- Amazon introduces Bee Pro at $11.99 monthly with extended AI service features
- Bee devices turn daily conversations into reminders, summaries, and task lists
- Amazon links Bee with Alexa+ and says raw audio is deleted after processing
Amazon expanded its personal technology lineup on Thursday as its shares declined during the session. Amazon (AMZN) stock fell 0.27% to $253.40, a decline of $0.68. The company introduced two Bee devices and a monthly service for organizing information from everyday conversations.
Amazon.com, Inc., AMZN
Amazon Introduces Two Bee AI Devices
Amazon unveiled Bee Frontier, a wearable device priced at $74.99, for its hardware lineup. The company also introduced Bee Eclipse, a magnetic phone attachment with a listed price of $99.99. Amazon plans to release both products in the coming weeks through its newly expanded Bee product lineup.
The devices capture spoken conversations and convert the information into reminders, summaries, and organized tasks. Users can review the resulting information through dedicated mobile and desktop applications after the devices process conversations. The products target routine activities, including appointments, discussions, and personal task management during ordinary daily work and activities.
The launch extends Amazon’s work on voice-based digital services beyond Echo. The company also connects voice features with portable devices. Bee adds a wearable format and a phone accessory to Amazon’s range of tools.
Amazon Bee Pro Adds Monthly Subscription Features
Amazon introduced Bee Pro alongside the hardware, at $11.99 monthly. The paid tier provides advanced integrations, third-party application connections, and unlimited processing of past conversations. The service combines hardware purchases with software functions.
The company also linked its Bee ecosystem with Alexa+ and its online retail platform. Through that connection, subscribers can request conversation summaries using compatible Echo devices. They can also receive product recommendations based on information captured during earlier interactions.
Amazon already operates consumer services spanning shopping, voice assistance, and connected devices. The Bee integration brings those services together around information collected through daily conversations. However, the new offering creates another paid service within Amazon’s consumer business.
Amazon Details Audio Handling and Market Context
Amazon said its Bee devices delete raw audio immediately after processing spoken input. It called this a zero-storage system. Consequently, the devices retain processed information rather than the raw audio used to create it.
The announcement enters a consumer technology market where major companies continue developing voice-enabled personal features. Apple and Meta have also introduced products and services that support hands-free digital interactions. Both companies support personal assistance through devices and applications.
Amazon’s announcement covered the two devices, the Bee Pro subscription, and connections with existing services. The company outlined pricing and planned availability, but did not disclose initial subscription figures. Thursday’s share movement accompanied the product news, as Amazon expanded its devices.
The post Amazon (AMZN) Stock: Falls as Company Launches New Bee AI Wearables appeared first on Blockonomi.
CryptoPotato
The primary cryptocurrency posted substantial gains in September, fueling expectations that the uptrend would continue this month. In fact, BTC started October on the right foot and briefly surged to nearly $87,000 at one point.
However, the bulls couldn’t maintain momentum, and the asset headed south. The past 24 hours brought more pain for investors as Bitcoin dipped below $80,000 after US inflation came in hotter than expected, while South Korea’s KOSPI index crashed over 7% on the day. The latest red wave, though, might be just a temporary correction before a renewed rally, and here’s why.
The Bullish Signals
Let’s start with the fact that October has historically been one of the best months for BTC, earning it the nickname “Uptober.” The asset has finished the period in the red on only 3 of 13 occasions. We still have more than two weeks left to see whether bulls can regain control and secure another successful “Uptober.”
Next is whale activity. Not long ago, Ali Martinez revealed that large investors used the slump from $87K to $80K to stack an additional 16,010 coins (worth nearly $1.3 billion).
An analysis published by CryptoQuant also shows that whales have launched a buying spree. The team revealed that big wallets (excluding exchanges and mining pools) have increased their total holdings to 3.03 BTC, the highest combined balance since November last year.
This accumulation is generally seen as a bullish signal, as large investors are often considered smart money with a longer-term investment horizon. Their buying leaves fewer coins available on the open market, which, combined with steady demand, could trigger a price uptick. In addition, these efforts can encourage smaller players to join the ecosystem, bringing in fresh capital.
Last but not least, we will observe BTC’s price movement after the previous US CPI data. The asset saw major initial volatility after the last four announcements (similar to what we witnessed over the past 24 hours), but X user Crypto Rover noted that the bulls eventually gained control each time, and Bitcoin rallied hard. It remains to be seen whether this time will be the same.
The Latest Predictions
According to the X account Wealthmanager, BTC has “major bid zones” stacked between $75,000 and $80,000. That said, the price could sweep lower toward that range before resuming its next big move.
X user Aman claimed that Bitcoin might be developing a “head-and-shoulders” pattern. The analyst suggested that if this plays out, $76,000-$77,000 could become “the next area to watch.”
“Not saying it will happen for sure, but the setup is there. Better to prepare for the possibility now than panic if BTC actually breaks down,” they added.
Martinez also recently chipped in. He identified $84,000 as a key level marking the 50 SMA and potentially unlocking the next rally.
The post 3 Reasons Why Bitcoin (BTC) Could Bounce Back Quickly After the Latest Pullback appeared first on CryptoPotato.
XRP is approaching a key technical inflection point after weeks of declining price action erased much of its August recovery. Trading around $1.30, the asset is testing an important support zone on both the daily and 4-hour charts. The next move around this area could determine whether buyers manage another rebound or sellers push XRP toward lower support levels.
Ripple Price Analysis: The USDT Pair
The daily chart shows XRP maintaining a broader bearish structure after falling from its early-2026 highs above $2.30. The asset has formed a series of lower highs, while the descending orange trendline continues to reflect the prevailing downward pressure, as the price has once again dropped below it and failed to continue higher. Although XRP staged a sharp recovery from the $1.00 region in August, the subsequent rally toward $1.70 failed to establish a sustained bullish reversal.
The latest decline has brought the token back to the $1.30 support zone. This area is key because it previously consolidated before the June sell-off. Holding above it could help XRP stabilize and attempt another recovery, while a decisive daily close below it would raise the risk of a deeper correction.
If support breaks, the $1.15 zone represents the next major downside area visible on the chart. Below that, the $1.00 region remains an important floor, having preceded the sharp August rally.
On the upside, XRP would first need to reclaim the $1.50 region created by recent highs to show signs of improving short-term structure. Beyond that, the $1.70 resistance zone stands out as the major obstacle, and the main level buyers must break through to start a new long-term rally.
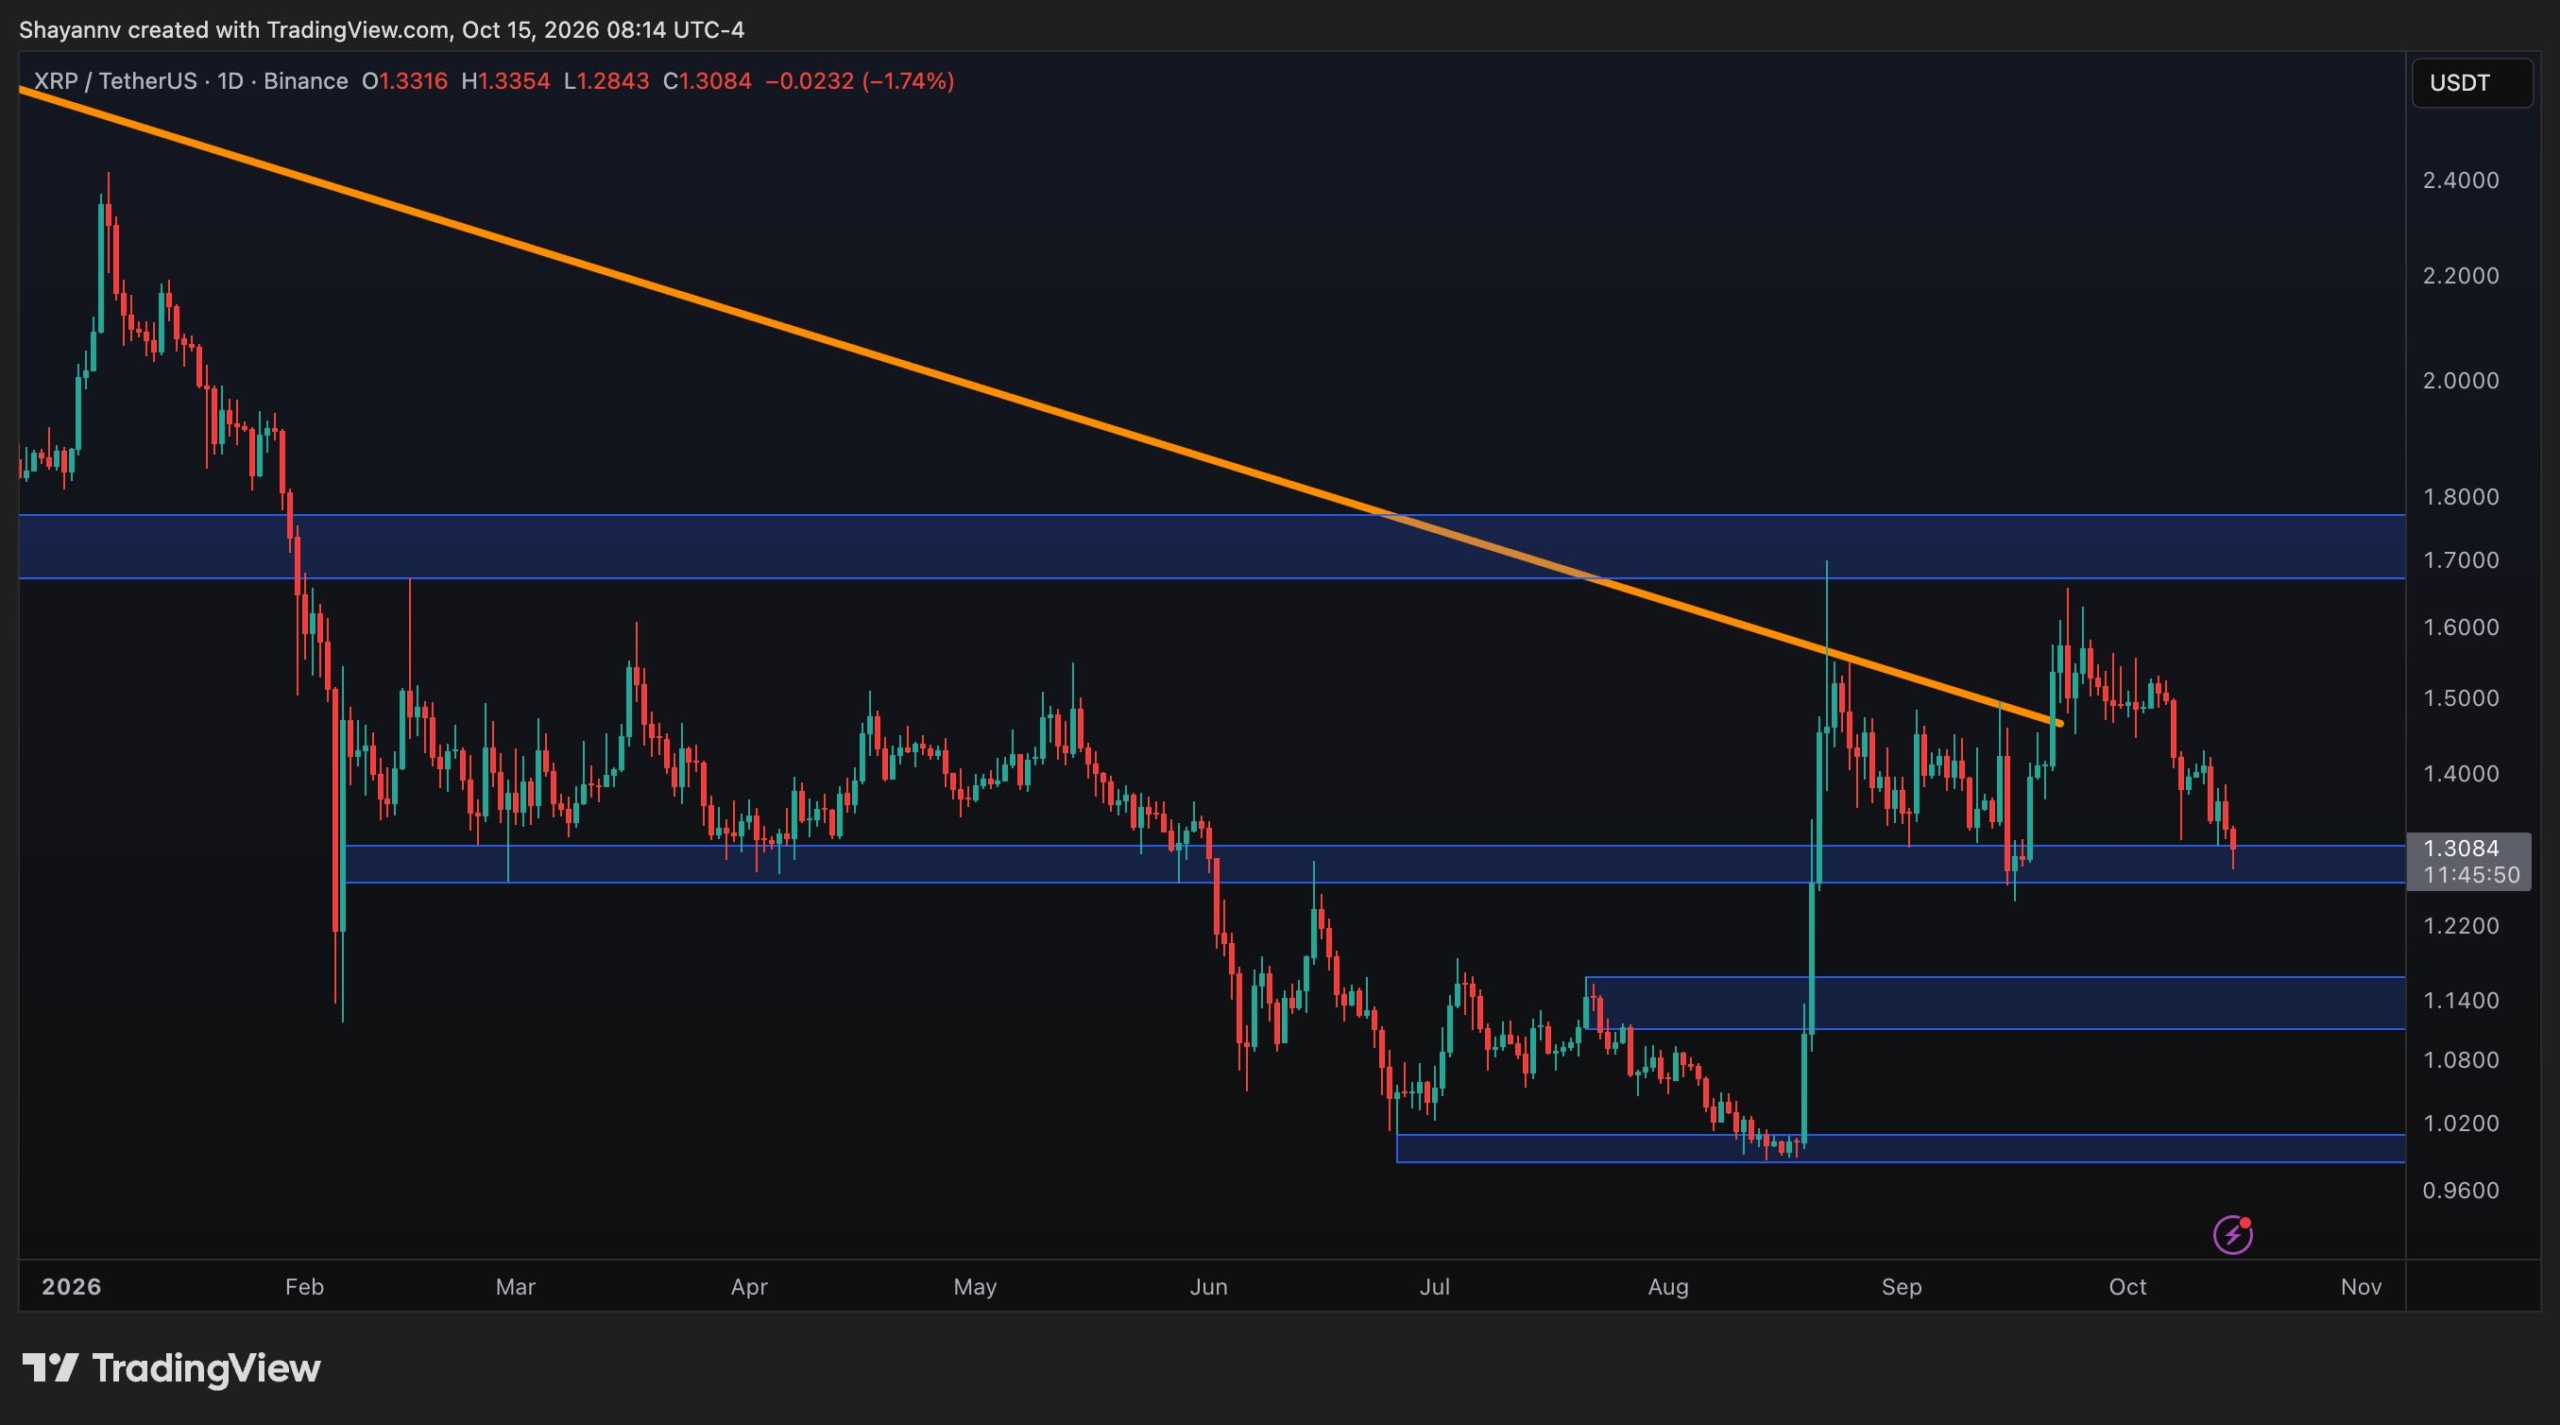
The 4-Hour Chart
The 4-hour chart offers a clearer view of immediate selling pressure. Since reaching approximately $1.65 in late September, XRP has been trading within a descending channel, characterized by lower highs and lower lows. Both channel trendlines remain relevant, with the upper boundary acting as dynamic resistance and the lower boundary marking the area where buyers could attempt to defend the price.
XRP is now testing the $1.30 support zone, which overlaps with the lower boundary of the descending channel. This confluence makes the current area particularly important for the short-term outlook. The latest candles show the price pressing against this support, but the chart does not yet confirm a decisive breakdown or a valid bullish reversal.
If buyers defend the zone, the asset could attempt a relief rally toward the $1.40 region, where the upper channel boundary is located. A breakout above this resistance would weaken the immediate bearish structure and potentially bring the $1.60-$1.70 area back into focus.
However, a confirmed move below $1.30 would suggest that buyers are losing control of the current support area. In that scenario, XRP could face further downside pressure, with the daily $1.15 zone emerging as the next major support region.
The descending channel therefore remains the dominant short-term pattern. While its lower boundary could provide a foundation for a rebound, a bullish shift would require XRP to reclaim nearby resistance and eventually break above the channel’s upper trendline.

The post Ripple Price Analysis: Is the Worst Over for XRP After Holding $1.30? appeared first on CryptoPotato.
Bitcoin is facing renewed selling pressure after failing to continue its recent advance through the $88K resistance area. With BTC now trading around $82K, the market is approaching a key support zone that could determine whether the latest pullback remains a correction within the broader recovery or develops into a deeper bearish move.
Meanwhile, the Bull-Bear Market Cycle Indicator points to a more complicated market backdrop, suggesting that the price rebound has not yet fully resolved the broader cycle uncertainty.
Bitcoin Price Analysis: The Daily Chart
Bitcoin continues to trade within a broad ascending channel, with the lower and upper boundaries defining the broader recovery structure. However, the latest rejection from the $88K region has weakened the short-term outlook, pushing BTC back toward a critical support area.
The immediate focus is on the $80K-$81K zone, which represents the recent bullish order block before the final rally toward resistance. Bitcoin is currently trading around $82K after dipping below $80K briefly earlier today, as bears are trying to push the price below the mentioned demand zone. Yet, if buyers manage to hold, the market would likely stabilize and attempt another move toward the $88K area.
Below the $80K support level, the more significant demand zone is located around $75K-$77K. If the $80K area fails to hold on a daily closing basis, this lower region could become the next downside target.
For now, the ascending channel remains intact, but the rejection from its upper region and the subsequent loss of short-term momentum suggest that buyers need to defend support quickly. A breakdown through the lower channel boundary would weaken the bullish case and increase the risk of a full bearish reversal in the upcoming months.
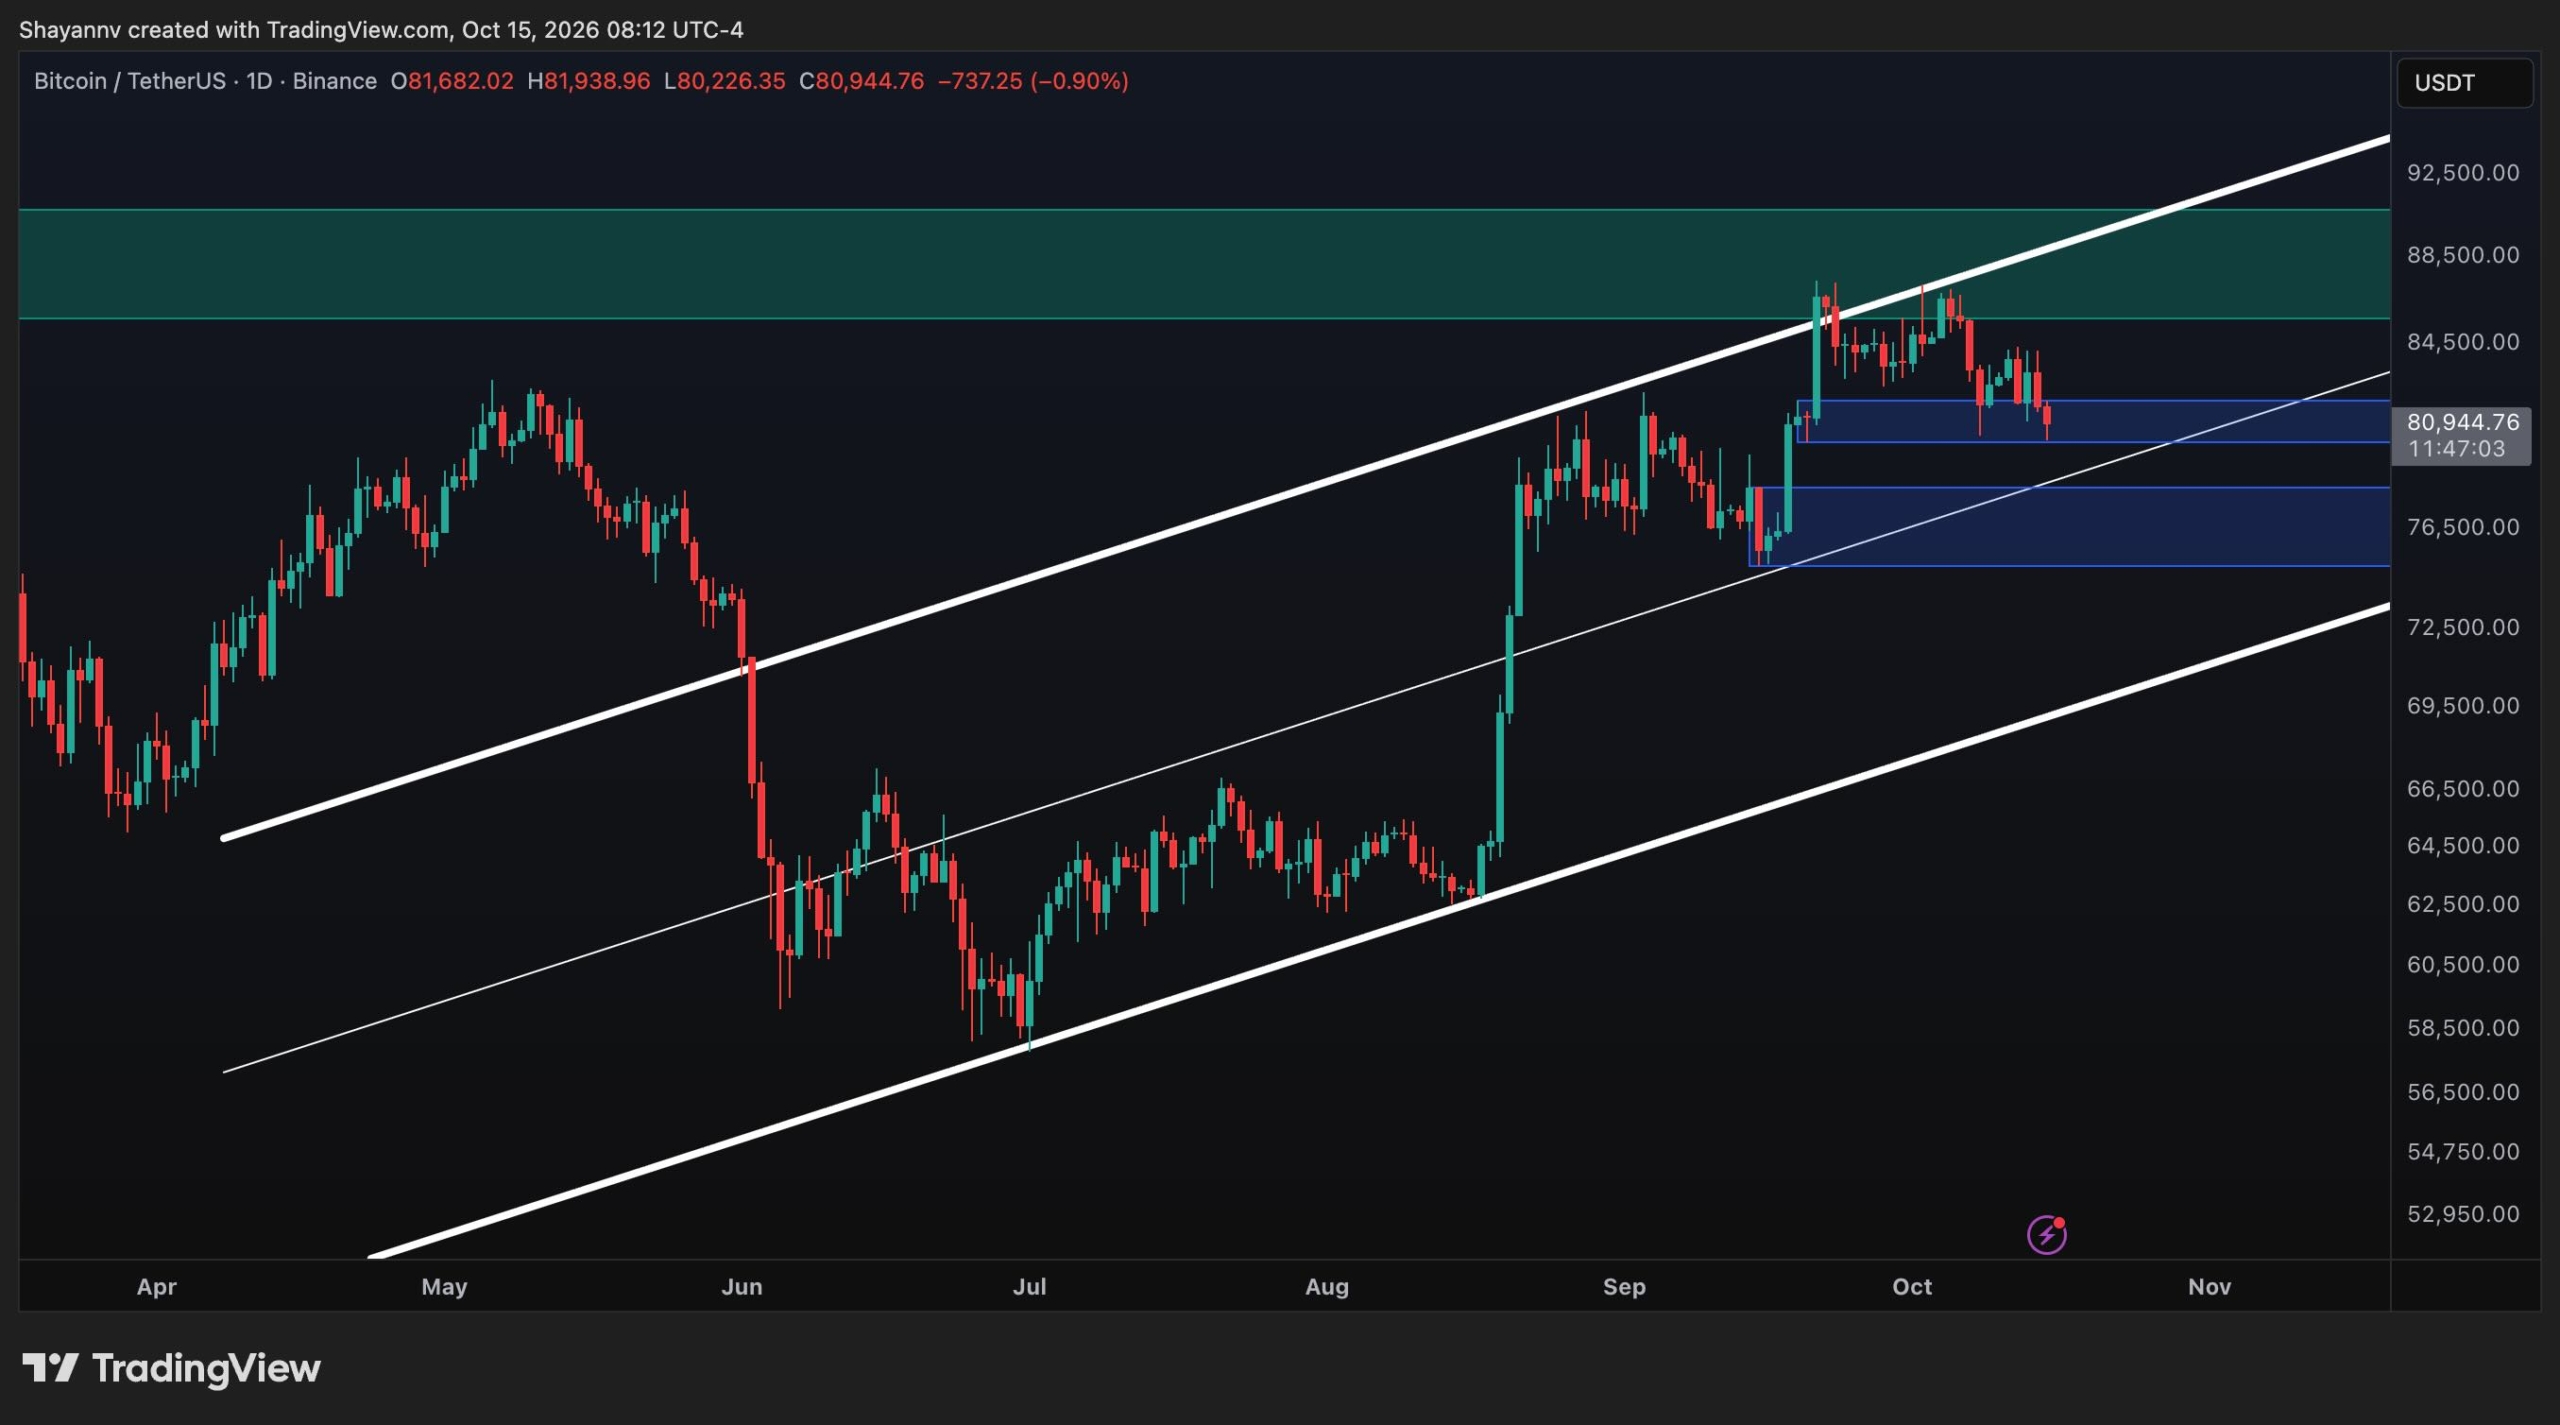
BTC/USDT 4-Hour Chart
The 4-hour chart shows a clear deterioration in market structure. After repeatedly failing to establish a sustained breakout above $87K, Bitcoin began forming lower highs before experiencing another sharp sell-off. The latest decline has brought BTC into the marked buyers’ decision zone between approximately $80K and $81K.
The immediate concern is that price has slipped below the short-term rising trendline, which had been supporting the recovery from the September lows. This breakdown suggests that the trendline is no longer providing reliable near-term support. Bitcoin is now testing whether horizontal demand around $80K can absorb the selling pressure.
A successful defense of the $80K region could produce a relief bounce toward $84K short-term highs. However, buyers would need to reclaim this area rapidly to improve the short-term outlook. Until that happens, rebounds could encounter selling pressure before reaching the more significant resistance zone.
On the contrary, if the $80K demand zone fails, the next downside level would likely be the $75K order block, which is the base of the significant rally initiated in September. In any case, the short-term structure favors caution. Bitcoin is testing support after losing its rising trendline, and the next move will likely depend on whether buyers can defend the $80K area or sellers can turn it into resistance.

On-Chain Analysis
The Bull-Bear Market Cycle Indicator on CryptoQuant provides a more nuanced view of Bitcoin’s position than price action alone. The indicator measures the distance between the P&L Index and its 365-day moving average, with positive readings associated with bull-cycle conditions and negative readings associated with bear-cycle conditions.
The chart shows that the indicator spent a prolonged period in bearish territory from late 2025 through much of 2026, including an extended and deep negative phase during the first half of 2026. This coincided with Bitcoin’s decline toward the $60K region before the subsequent recovery.
More recently, the indicator has moved back into positive territory, with the latest readings appearing in the orange bull zone. The 30-day moving average has also turned sharply higher, while the 365-day average has flattened after its extended decline. These developments suggest that the market’s underlying cycle momentum has improved considerably from its earlier bearish phase.
However, the recovery in the indicator should not automatically be interpreted as confirmation that a sustained bull market is underway. The 365-day moving average remains an important longer-term reference, and the indicator’s recent transition into positive territory still needs to be assessed alongside price behavior. The latest pullback toward $80K adds further uncertainty to that assessment.
Overall, the cycle indicator suggests that Bitcoin’s underlying momentum has recovered from the earlier bearish phase, but the price chart shows that sellers remain active near resistance. The divergence between improving cycle momentum and weakening short-term price action makes the $80K support zone especially important.

The post Bitcoin Price Analysis: Has the $80K Drop Killed BTC’s Bullish Setup? appeared first on CryptoPotato.
The company behind XRP and RLUSD has expanded its institutional trading business again, launching support for real-world asset perpetual swaps through its prime brokerage, Ripple Prime.
The offering allows clients exposure to more than 100 reference markets 24/7, spanning stocks, ETFs, metals, energy, currencies, and other traditional assets.
Ripple Prime Goes Further
The official announcement published by Ripple earlier today states that its prime brokerage will offer the swaps as principal and reference perpetual futures listed by trade.xyz on Hyperliquid. Unlike traditional stock and commodity markets, which operate during fixed hours, Ripple’s alternatives can trade continuously, including weekends.
The company argued that this gives institutions far greater flexibility to react to market developments and manage risk outside normal exchange sessions.
“Institutions want exposure to equities, commodities, and currencies with the round-the-clock access and efficiencies of digital infrastructure. Ripple Prime was built to operate in both worlds, with deep experience clearing trades and managing digital collateral and risk across venues, 24/7.
With RWA swaps, we are enabling clients to execute increasingly sophisticated trading strategies and actively manage their portfolios in response to today’s dynamic global markets,” said Michael Higgins, International CEO, Ripple Prime.
Clients can also cross-margin their RWA swap positions against other asset classes supported by Ripple Prime, while RLUSD can be used as collateral for trades. This allows institutions to manage multiple exposures through one counterparty and consolidate margin and risk management across their portfolios.
Ripple’s Wall Street Expansion Grows
Earlier this month, CryptoPotato reported that Ripple Prime expanded its relationship with Brevan Howard, providing the investment giant with multi-asset prime brokerage, clearing, and financial services. Ripple has also moved into leveraged ETF swap financing, a market historically dominated by large banks.
This expansion builds on the company’s major acquisition of Hidden Road last year for $1.25 billion, which it later rebranded as Ripple Prime.
The post Ripple (XRP) Deepens Wall Street Push With 24/7 RWA Swaps for Institutions appeared first on CryptoPotato.
GMGN is a cryptocurrency trading platform with a twist. It’s designed to help users discover, analyze, and trade meme coins.
It provides real-time token data, smart money tracking, wallet analytics, automated trading tools, and more in a single interface, along with a range of other features that I will be exploring in this review.
Overall, the goal is to make it easier to spot emerging opportunities in the fast-moving trenches market.
Unlike traditional cryptocurrency exchanges, GMGN is focused entirely on on-chain trading activity. Users are able to monitor profitable wallets, track newly launched tokens and analyze different patterns. They can also execute trades without having to switch between multiple platforms.
In the following review, I will take a look at some of its key features, supported networks, trading fees, security, and overall usability. The goal is to help you decide whether it’s the right platform for your specific trading needs and requirements.
Before we continue!
GMGN is hosting a major global trading championship that starts on October 16th. It will feature 10 days of relentless live, on-chain trading, with the top six users heading to a Grand Final in London during the flagship conference Solana Breakpoint. Entry is completely free and the champion will win a custom Aston Martin Vantage. Check out the GMGN Global Championship and sign up here.

What is GMGN?
As mentioned above, GMGN is a multi-chain cryptocurrency trading platform. It’s designed to help you discover, analyze, and ultimately trade meme coins. The protocol combines real-time market data with wallet tracking, token security checks, and automated trading tools. You can access this through a single interface, which is convenient.
How does GMGN work?
GMGN aggregates on-chain information to help you identify trading opportunities and analyze the activity of a certain token. You can explore trending tokens, search using contract addresses, examine price charts, as well as monitor transactions from other wallets.
The platform also supports automated trading through limit orders, take-profit, and stop-loss settings. It also features copy trading. You can configure various execution parameters, including slippage tolerance and priority fees. This can help you manage the way your transactions are prioritized and processed.
Supported Blockchains and Trading Markets
GMGN supports multiple networks. These include:
- Solana, which is the core primary network for high-speed meme coin trading
- BNB Smart Chain (BSC)
- Base
- Ethereum
- MegaETH
- Robinhood Chain
- Monad
- TRON
However, the protocol also supports cross-chain integration support for networks such as Solana, BSC, Rohinhood, Base, ETH, Arbitrum, Stable, Arc, Xlayer, HyperEVM, MegaETH, Monad, and Tron.
Who Should Use GMGN?
Now, GMGN is primarily suited to active meme coin traders who look for real-time market insights and advanced trading capabilities. Its wallet tracking and copy trading tools, however, may also appeal to users who want to monitor experienced traders. That said, if you have no previous experience in dabbling in the world of on-chain meme coin trading, there might be a learning curve to go through.
That said, beginners can use GMGN to explore tokens and analyze market activity. Of course, most of its advanced capabilities make understanding of on-chain transactions and adjacent trading risks very important.
Key Features of GMGN
GMGN provides a range of different tools that can help you discover new meme coins, analyze on-chain activity, and execute trades. Let’s have a look at some of the most important ones.
Meme coin discovery and token tracking
The platform’s core functionality allows you to discover newly launched and trending tokens through dedicated market lists. You can filter tokens using various criteria, including but not limited to market capitalization, transaction activity, price movements, and trading volume.
Every single token has a dedicated page that displays price charts, transaction histories, holder information, and trading activity. GMGN is also designed to support cross-chain multicharts, allowing users to monitor multiple charts at the same time.

These features can help you identify emerging tokens and compare market activity. You won’t have to switch between multiple analytics platforms, which is a considerable benefit.
Smart money and wallet tracking
The platform’s smart money tracking feature is designed to allow you to monitor wallet addresses that are associated with profitable traders, whales, and other market participants that you may find interesting.
You can follow individual wallets and receive notifications when those addresses execute transactions. Trading activity can also be categorized by the type of wallet, including KOLs, smart money, developers, and snipers.
Another notable feature is Wallet Radar, which helps users identify profitable wallets by analyzing trading activity across the selected tokens. Some of the factors used to categorize addresses include:
- Highest profit
- Earliest bought
- Most bought
- Shared holdings
You can analyze multiple tokens at the same time and add discovered addresses to your list for copy trading. Naturally, this brings me to the next feature.
GMGN copy trading
Now, copy trading has become particularly popular in the crypto space, and GMGN supports automated copy trading, which allows you to replicate buying and selling made by selected wallet addresses.
You can configure fixed purchase amounts or set maximum follow-buy limits. Selling options also include automatically copying a wallet’s sales or using separate take-profit and stop-loss conditions.

The platform also offers a Lightning Mode. This is designed to accelerate trade execution while copy trading. However, it’s worth noting that this introduces additional risks because it uses unconfirmed blockchain transaction data.
All in all, copy trading can definitely save time, but users should also account for slippage, transaction costs, as well as the differences between the original trade and its execution.
Token security analysis
This is another very important feature for on-chain traders because a lot of the upcoming and trending meme coins have not been verified by anyone. That’s why GMGN includes token security checks that can help you identify potentially suspicious assets.
Depending on the network, the platform can display indicators such as:
- Honeypot detection: Identifies tokens that may restrict selling.
- Liquidity status: Shows whether liquidity pool tokens have been locked or burned.
- Mint authority: Indicates whether additional tokens can be created.
- Holder concentration: Highlights potential risks associated with concentrated token ownership.
- Contract permissions: Shows whether certain administrative privileges have been relinquished.
- Rug pull indicators: Provides information about potential rug pull risks and previous token creator activity.
These checks can help you assess common warning signs before committing to a trade. Of course, these can never guarantee complete accuracy and even GMGN recommends consulting multiple security tools before coming to a conclusion.
Trading tools and automated orders
GMGN offers several features that are designed to automate trade execution and manage your positions.
Traders are able to place instant buy and sell orders, configure limit orders, and establish automatic take-profit or stop-loss strategies.
Specialized automated trading strategies such as Dev Sell are also included. This allows you to trigger a sale when a token creator sells a specified portion of their holdings. There are also Migrated Sells, which allow the user to automate selling when eligible Solana tokens migrate to a decentralized exchange liquidity pool. This is important for those traders who participate in launchpads such as Pump.fun, for instance.
On top of that, users are able to adjust execution settings such as slippage tolerance, priority fees, and Anti-MEV protection. The latter is designed to reduce exposure to sandwich attacks. However, stronger transaction protection could also involve additional fees or slower execution, so it’s a trade-off that you would have to consider.
It’s also important to understand that while all of these features reduce the need for constant market monitoring, automated transactions remain subject to other factors such as liquidity conditions, execution failures, network congestion, and more – all of which bring challenges that you need to take into account.
Wallet analytics and profit tracking
Another interesting feature is the ability to analyze a lot of compiled data. GMGN provides wallet-level analytics. These allow you to examine transaction histories and evaluate trading performance. You can then use the conclusions to determine whether a certain trader is worth following.
You can review metrics such as realized and unrealized profit, total buying and selling activity, average purchase prices, and current holdings.
The platform also displays historical trading activity, making it possible to investigate how individual wallets have interacted with particular tokens.
These analytics complement GMGN’s tracking and copy trading features by helping users assess wallet activity before deciding whether to follow another trader.
However, wallet performance data should be considered alongside transaction costs and market conditions, as historical profitability does not guarantee future returns.
How to Use GMGN
Getting started with the platform is going to feel incredibly familiar to anyone who has previously done any sort of on-chain trading and a bit intimidating for those who are new to it. That said, the learning curve is not that steep once you get the hang of it.
GMGN does a fairly good job of dividing the interface in clear sections, which become easy to follow once you connect your wallet.
Getting started
Once you have landed on the homepage, you can select your preferred blockchain network and start exploring trending meme coins, newly launched tokens, and market activity. If you don’t want to trade, that’s fine, you’re not required to. GMGN also allows you to search for specific tokens using their contract addresses.
When you’re ready to trade, you can connect a compatible wallet or log in through Telegram, which can expand the available automated trading features.
Setting up and funding a wallet
GMGN supports different types of wallet connection methods including Telegram-based wallets and compatible Web3 wallets such as Phantom and MetaMask, for example.
Once you have done that, you can select the deposit option, which is found in your account tab in the top-right section of the main navigation menu.
Finding and Trading Tokens
Once the wallet is funded, you can browse GMGN’s token discovery lists or search for a token using its contract address.
Before trading, you can review price charts, liquidity, transaction activity, holder distribution, and available security indicators.
To execute a trade, users select the desired token, enter the purchase amount, and configure transaction settings such as slippage tolerance and priority fees. They can then submit the transaction through the trading interface.
GMGN also allows you to configure automated orders and exit strategies, including take-profit and stop-loss conditions.
Before confirming a transaction, you should review the expected execution costs. GMGN charges a 1% trading fee, while blockchain gas fees, priority fees, tips, and any applicable token launchpad fees may increase the total cost.
Is GMGN Safe and Legit?
GMGN is a well-known and established name in the world of on-chain crypto trading. It provides several safety features, but it’s important to know that these do not eliminate the possibility of losses or malicious activity pertaining to events that are not directly associated with the platform itself. That said, let’s have a look.
Wallet Security and Asset Custody
GMGN supports external Web3 wallets alongside Telegram-based wallets for automated trading.
Now, when you connect an external wallet, you retain full responsibility for protecting your private keys and recovery phrases.
In essence, if you connect your wallet, you retain full custody of your funds. However, if you decide to use the Telegram bot, then you also need to export the private key of the newly created wallet. That said, there are caveats, so I highly recommend that you check here.
Potential Risks and Limitations
Despite the non-custodial model, there are several risks that you need to account for, all of which are not really manageable by the platform but stem from the nature of trading meme coins and newly launched cryptocurrencies.
- Severe volatility: newly launched tokens and meme coins can experience sudden price crashes and liquidity shortages.
- Copy trading risks: you can get different results based on execution delays and slippage.
- Transaction risk: blockchain congestion, network failures, and incorrect execution settings can cause unfavorable trades or failed transactions
- Phishing threats: fake websites and Telegram bots may attempt to compromise your wallet
GMGN also discussed these at length in their documentation. Overall, though, the platform provides a useful set of security and risk-analysis tools but as with all on-chain platforms, it shouldn’t be considered risk-free.
GMGN Pros and Cons
Pros
- Advanced token discovery
- Smart money tracking
- Automated trading
- Built-in security indicators
- Multiple trading products
Cons
- Trading fees
- Steep learning curve for beginners
Final Verdict: Is GMGN Worth Using?
If you are an on-chain trader, GMGN is absolutely worth using. It offers valuable tools for discovering up-and-coming tokens, meme coins, analyzing on-chain activity, and automating trading strategies. Its combination of wallet analytics, copy trading, token security indicators, and wallet tracking makes it a very appealing choice for active crypto traders.
However, it’s also worth noting that a 1% trading fee on top of common execution costs can add up, especially if you are a frequent trader.
That said, GMGN is worth considering, especially if you are an experienced meme coin and on-chain trader. If you are a beginner, you should approach the platform with caution and familiarize yourself with all the features and potential risks before committing funds.
The post GMGN Review 2026: Features, Fees, Trading Tools, and Safety appeared first on CryptoPotato.