Cryptocurrency Posts
Crypto Briefing
The potential need for cryptographic upgrades highlights the ongoing challenge of securing digital communications against evolving AI threats.
The post Vitalik Buterin says public-key cryptography may need one or two more upgrades appeared first on Crypto Briefing.
The incident highlights the growing risks of crypto ownership, emphasizing the need for enhanced security measures and regulatory oversight.
The post UK crypto trader robbed of about $800,000 in violent home invasion appeared first on Crypto Briefing.
An AI market correction could significantly impact global economic stability, affecting investment confidence and economic output projections.
The post IMF’s Vamvakidis warns an AI market correction could spill over into the real economy, depending on its severity appeared first on Crypto Briefing.
AI risks could destabilize global finance, necessitating enhanced cross-border cooperation and robust contingency planning to mitigate systemic threats.
The post IMF warns AI risks could push more global banks to fail appeared first on Crypto Briefing.
Valente's optimism suggests Bitcoin's resilience, highlighting the crypto community's proactive stance on evolving security challenges.
The post ARK Invest’s Lorenzo Valente is more optimistic Bitcoin will beat Q Day appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine

Moscow Exchange to Launch Bitcoin Trading, Testing Underway
The Moscow Exchange plans to let clients trade cryptocurrencies starting in December and has begun testing operations with professional market participants, a senior executive said last week.
“We are actively testing. We started a week ago,” Boris Blokhin, the exchange’s senior managing director for sales and business development, told journalists on the sidelines of the Sber Investments forum, according to a Thursday Interfax report.
The exchange — the biggest in Russia — will work with a partner settlement digital depository, where market participants will open accounts. It won’t need any additional permits or licenses to launch trading, Blokhin added.
JUST IN:
— Bitcoin Magazine (@BitcoinMagazine) October 12, 2026Russia's Moscow Stock Exchange will allow its 40.1 million clients to invest in Bitcoin and crypto assets
pic.twitter.com/ZJOxEPWNNv
The plan follows Russia’s law on digital currencies and digital rights, which took effect in September and sets comprehensive rules for crypto in the country.
Trades can run through existing infrastructure such as exchanges, brokers and trust managers. New players will also join, including crypto exchangers, where assets are bought and sold, and digital depositories, which record ownership.
Russia’s largest bank, Sberbank, announced last month it was the first in the country to have been approved to custody bitcoin. The Bank of Russia gave it the green light for “digital currency record-keeping” and to facilitate the transfer of such assets, covering bitcoin and other, smaller cryptocurrencies.
Russia’s relationship with Bitcoin is complicated. President Vladimir Putin in 2024 seemed to praise the original cryptocurrency back in 2024. “For example, Bitcoin, who can ban it? Nobody,” he said at a forum at the time.
But the Kremlin keeps a tight grip on what citizens can do with it. Using crypto as a form of payment has been illegal in Russia since 2022; unqualified investors can buy bitcoin and stablecoins capped at 300,000 rubles ($3,556) a year through a single intermediary.
Qualified investors can buy any cryptocurrency traded on exchange and over-the-counter markets, with no limit.
President Putin in October signed a law to set in stone the regulation of digital currencies and digital rights in the country.
This post Moscow Exchange to Launch Bitcoin Trading, Testing Underway first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine

South Korean Lender Jeonbuk Bank to Offer Bitcoin-Backed Loans
Jeonbuk Bank has become the first bank in South Korea to offer won-denominated loans backed by bitcoin, according to reports.
The subsidiary of JB Financial Group has started offering the loans, according to exclusive Monday reporting by the country’s Edaily paper.
For now, the product is limited to corporate customers raising working capital, and bitcoin is the only eligible collateral. The bank said it may expand the service depending on regulatory changes and market demand, the report added.
JUST IN:
— Bitcoin Magazine (@BitcoinMagazine) October 12, 2026South Korea's Jeonbuk Bank will offer the first ever bitcoin-backed won loans for clients
Jeonbuk Bank won’t own or control the bitcoin itself. The collateral is held by a specialized custodian, limited to virtual asset service providers registered under Korea’s Act on the Reporting of Specific Financial Information, it further noted.
If a borrower defaults, the bank won’t take the coins but will rather liquidate them through enforcement procedures such as a court-ordered sale and recover the loan from the proceeds.
The bank said it chose bitcoin for its market capitalization and trading volume, the largest of any digital asset, and that its own stress tests showed bitcoin held up as collateral even during sharp price declines. To value the collateral, it uses an index based on a weighted average of prices across multiple global exchanges.
Similar products already exist abroad. JPMorgan Chase debuted bitcoin-backed loans for institutional clients in March, and Switzerland’s Sygnum Bank offers comparable credit.
The loan is the first concrete result of the “Crypto Bank” vision put forward by Jeonbuk Bank President Park Chun-won. The lender is the only regional bank to provide real-name verified accounts to crypto exchanges, and it is preparing an “all-in-one wallet” that combines fiat accounts and digital asset wallets.
“This loan is an example of designing a risk management and recovery structure that allows us to utilize existing bank lending and collateral management systems without directly holding virtual assets,” said Jeong Sang-hoon, executive vice president of the bank’s digital division.
This post South Korean Lender Jeonbuk Bank to Offer Bitcoin-Backed Loans first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Bitcoin Extends Slide — Can ‘Uptober’ 2026 Beat Last Year’s?
Bitcoin’s price dipped further on Monday, sliding 2% over a 24-hour period to trade at a little over $82,423.
The coin over the past week has dropped by 3%, and so far this month, it’s trading down.
October is usually a strong month for the OG cryptocurrency. Data from Coinglass shows that it has finished eight of the last 10 Octobers in the green.
Last year was one of the exceptions: while bitcoin’s price notched an all-time high of $126,080, it then started to enter a bear market after October 10 — when the biggest crypto liquidation event in history battered the asset’s price.
Markets across the board got hit hard following tariff threats from U.S. President Donald Trump. Crypto long positions got wiped out and over $19 billion in digital asset bets were liquidated.
Bitcoin then spent most of 2026 in a bear market.
The good news? That the coin just had its best quarter in years and a good September — historically a rough month for the cryptocurrency. Analysts now are saying that while it’s got off to a bad start so far in “Uptober”, signs of a bottom this month may already be in.
Writing for data firm CryptoQuant, Japanese asset management platform XWIN said it could be up from here.
“Now, signs of a potential bottom are emerging,” XWIN said in a note. “On October 12, markets priced roughly an 18% chance of an October Fed hike, while Brent crude had eased from nearly $110 to around $103.”
It added: “‘Uptober’ need not mean uninterrupted gains: a correction can build the foundation for the next advance.”
High oil prices have — at least in the short-term — hurt bitcoin’s price as investors then expect the Federal Reserve to hike interest rates in order to control inflation.
But while the U.S. central bank last month raised interest rates, bitcoin’s price was unfazed and rose following the news.
Other analysts have now said the biggest cryptocurrency is out of a bear market due to it crossing its 365-day moving average — a signal that has marked the start of its bull markets in past cycles.
This post Bitcoin Extends Slide — Can ‘Uptober’ 2026 Beat Last Year’s? first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
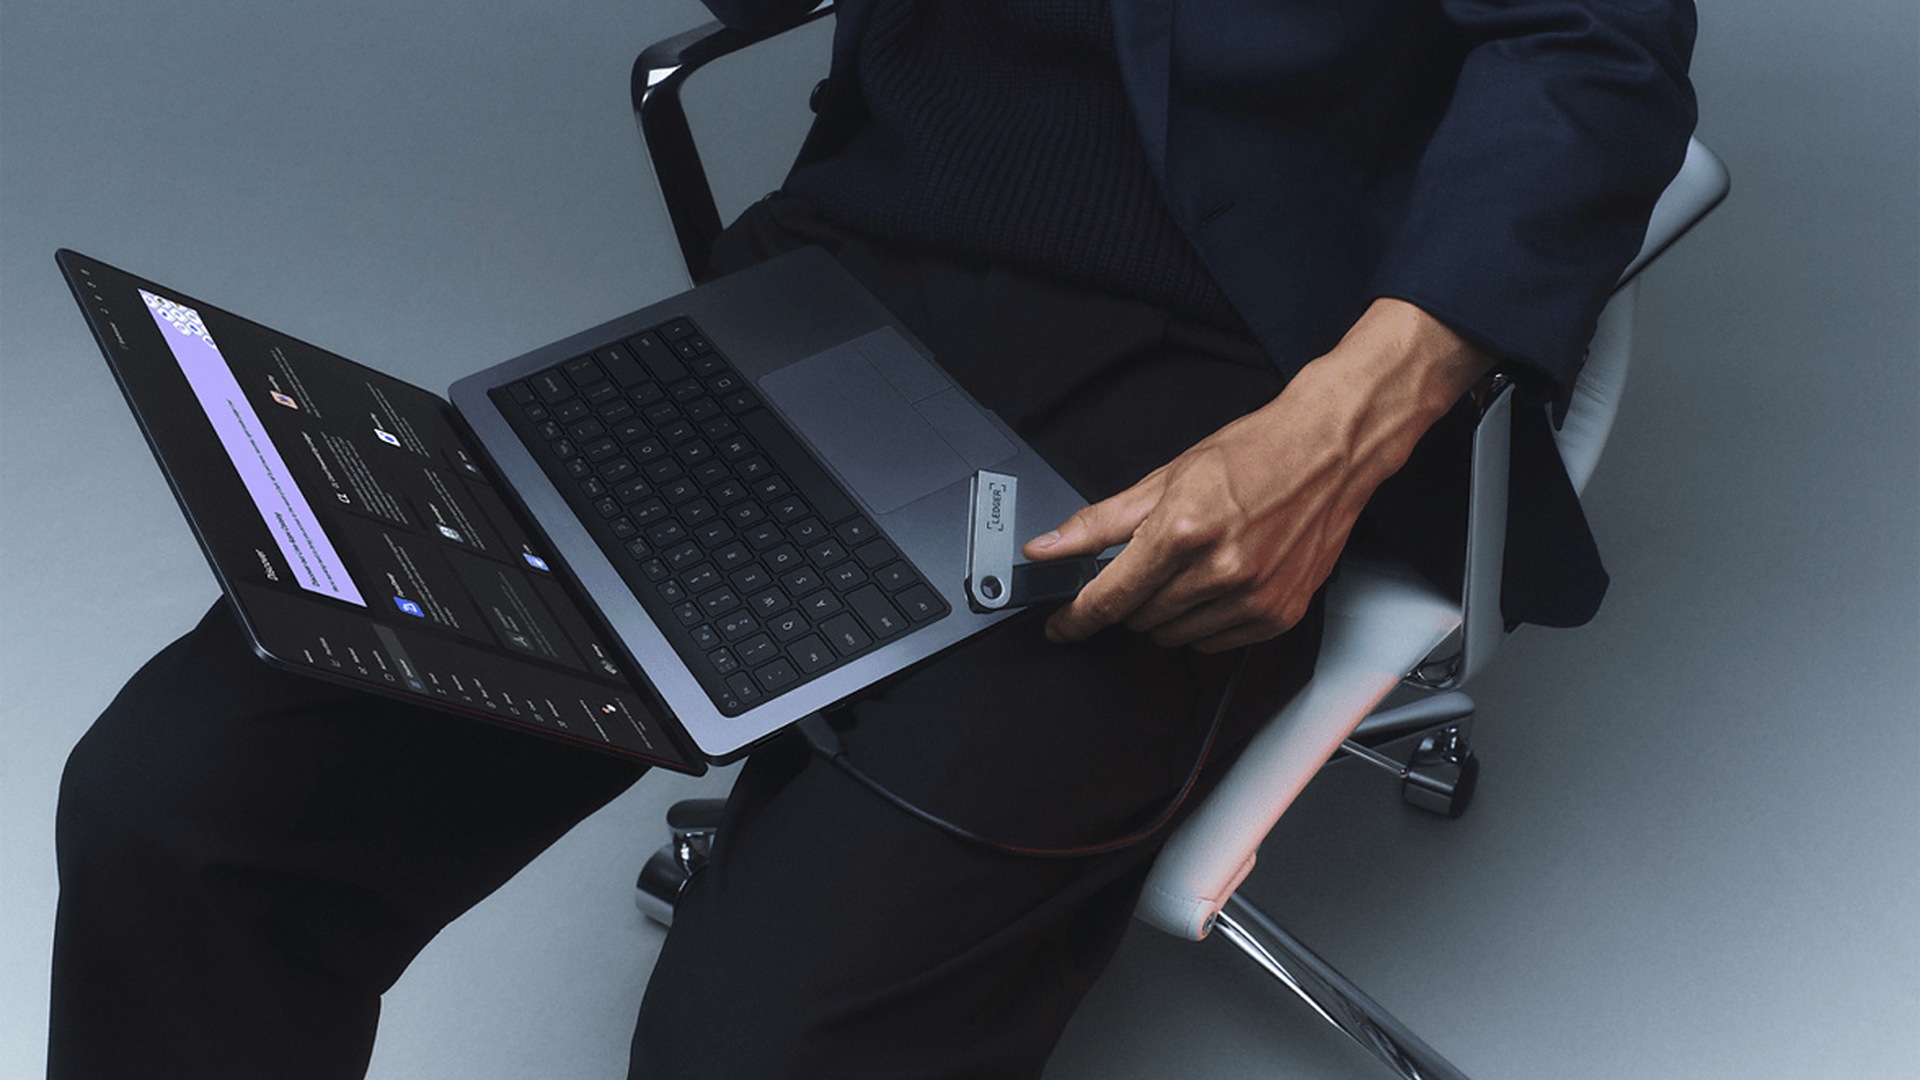
Ledger Investigates Fund Losses Tied to Southeast Asian Reseller After Implant Found in Device
Ledger has said it is working with authorities after users last week reported losing funds and one received a tampered device. But the company reassured customers that the number of impacted products was “limited.”
The hardware wallet manufacturer added in an announcement on Sunday that it had reached out to affected customers.
Paris-based Ledger on Friday said it had started an investigation after customers in South East Asia reported they’d lost funds after buying from a reseller.
Then, on Saturday, Ledger said it confirmed that one of the impacted users’ devices contained an unauthorized hardware implant.
Ledger would not confirm the amount of money lost but blockchain investigator Specter said $86 million had been drained from devices.
“As the investigation continues, we are working with relevant authorities,” Ledger wrote on Sunday.
It added: “Also, we strongly advise users not to purchase from unauthorized resellers, where the risk of buying suspicious, counterfeit or modified devices is important as nothing operates under ledger security guidelines.
“Security isn’t static and this incident underscores why we continuously review and strengthen our distribution and anti-tamper processes.”
Customers in South East Asia last week reported losing funds after buying from Kuala Lumpur, Malaysia-based vendor CryptoBilis.
Ledger then advised customers who’d bought from CryptoBilis to not set up their devices.
CryptoBilis has since stopped selling its hardware wallets, Ledger said on Sunday.
People on social media posted picture evidence of devices implanted into Ledger products, claiming it could get users’ private keys. It isn’t clear how many of Ledger’s signing devices contained the implant.
Neither Ledger nor CryptoBilis immediately responded to questions from Bitcoin Magazine.
Hardware wallet security has been a hot topic ever since hackers in July were able to steal close to $120 million in bitcoin from Coldcard users.
The products, made by Canadian company Coinkite, contained a firmware bug which led to faulty seed generation, allowing hackers to essentially guess investor seedphrases.
In a separate incident, hardware wallet manufacturer Trezor last month reported that close to 81,000 customers had their details leaked after its third-party fulfillment partner had data stolen.
Criminals have been targeting data this year, with scammers getting hold of customer information via crypto wallet Ledger’s payment processor Global-e to send phishing emails.
This post Ledger Investigates Fund Losses Tied to Southeast Asian Reseller After Implant Found in Device first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Strategy Smash Buys $21.5M in BTC as It Continues Bitcoin Accumulation
Bitcoin juggernaut Strategy has bought more BTC as it pivots back to accumulating on a weekly basis.
The Nasdaq-listed bitcoin treasury spent $21.5 million on 250 bitcoins from October 5 and October 11, according to a Monday filing.
It added that it also spent $192.4 million repurchasing its STRC preferred stock.
Strategy now holds 848,250 bitcoins worth $70.2 billion at today’s prices. Its stock (MSTR) on Monday was trading nearly 2% higher.
The company — formerly MicroStrategy — has spent the past four weeks buying bitcoins after months of more sporadic buys or sometimes halting purchases for months altogether in order to build a bigger cash buffer.
Monday’s filing also shows that the company bought last week’s bitcoin using net proceeds from MSTR Stock sales with its USD Cash buffer. Strategy has two cash reserves: “USD Reserve”, used to support the payment of dividends on the company’s preferred stock offerings and interest on its outstanding indebtedness, and “USD Cash”, which it uses to buy bitcoin.
It first bought the cryptocurrency in 2020 to protect its shareholders from inflation. Since then, it has aggressively bought the asset and pivoted to being a bitcoin treasury.
Investors can now buy its shares to get heightened exposure to the cryptocurrency, or get paid a yield via its digital credit products.
The company is now focusing on products that pay investors yield via its STRF, STRC, STRK, and STRD preferred shares.
Its Nasdaq-listed stock is down over 50% over the past year after the price of bitcoin took a hit.
But since the company started buying bitcoin in August 2020, MSTR has appreciated by nearly 1,000%.
This post Strategy Smash Buys $21.5M in BTC as It Continues Bitcoin Accumulation first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
CryptoSlate
The Financial Stability Board (FSB) warned that stablecoins could face redemption crises if, during market stress, reserves become inaccessible across borders.
In an Oct. 12 report, the global financial watchdog said stablecoin issuers operating through affiliated entities in different countries could struggle to meet concentrated withdrawal demands when their reserve assets are held elsewhere.
The warning comes ahead of an Oct. 15 meeting of G20 finance ministers and central bank governors, as regulators confront growing risks from a stablecoin market valued at approximately $300 billion in mid-2026, with 99% of its value pegged to the US dollar.
FSB Chair Andrew Bailey said international regulatory coordination remains underdeveloped, leaving authorities without mature arrangements for managing cross-border stablecoin failures.
Stablecoin reserves face cross-border stress test
The FSB identified particular vulnerabilities in stablecoins issued by multiple affiliated companies that share liability for the same token while maintaining separate reserves.
Under such arrangements, holders may be able to redeem their tokens through any participating issuer, regardless of where the stablecoins were originally issued.
That flexibility can create liquidity mismatches when redemption demand concentrates in one jurisdiction while much of the collateral backing the tokens remains in another.
Moving reserves between entities could resolve the imbalance under normal conditions. However, banking restrictions, settlement delays and differences in national regulations could complicate those transfers during a market panic.
The speed at which stablecoins circulate amplifies the risks.
Digital tokens can move across borders and trade around the clock, while the Treasury securities, bank deposits and other traditional assets backing them remain subject to local financial-market operating hours and settlement arrangements.
The FSB warned that delays in meeting redemptions could push holders to sell stablecoins at discounts on secondary markets, potentially destabilizing their dollar pegs.
A sufficiently large run could also spill into traditional finance if issuers liquidate reserve assets rapidly or withdraw substantial deposits from banks to meet redemption requests.
For context, Circle's European stablecoin arrangements illustrate how cross-border reserve management can affect redemption procedures.
Under its redemption policy, updated in September, Circle co-issues USDC through its French entity for the European Economic Area and its US entity for markets outside the region.
The policy allows Circle France to adjust or defer certain redemption requests during a defined stress event when the two entities cannot complete reserve rebalancing.
Those measures could include temporary redemption limits for European crypto-asset service providers, while preserving holders' rights to redemption at par.
The provisions describe contingency arrangements rather than an existing liquidity failure. They also operate under Circle's specific jurisdictional redemption rules, which differ from the FSB's unrestricted cross-issuer redemption model.
Nevertheless, the regulator's concerns extend to affiliated issuers' legal responsibilities when a stablecoin faces distress.
The FSB noted that issuers may struggle to identify where their tokens are held because blockchain transactions can be pseudonymous, complicating efforts to determine which entities are responsible for particular redemption obligations.
Differences in national insolvency laws could create additional uncertainty over which regulator has authority to intervene and how remaining reserves should be distributed.
Those challenges are compounded by uneven regulatory development.
The FSB's 2025 assessment found substantial gaps in countries' implementation of its global stablecoin recommendations, increasing opportunities for issuers to structure operations across jurisdictions with different supervisory requirements.
FSB seeks stronger regulatory regime
In response, the watchdog is seeking stronger international information-sharing arrangements and closer monitoring of where stablecoins circulate, where redemptions occur and where reserve assets are held.
It also wants regulators to assess the depth of secondary-market liquidity and develop more coordinated approaches to handling stablecoin distress or insolvency.
However, regulators face significant information gaps. The FSB said blockchain analytics providers often use different methods to estimate stablecoin activity, and reliably establishing holders' geographic locations and cross-border transactions can be hard.
The proposed measures build on the FSB's 2023 recommendations and are non-binding, leaving national authorities responsible for implementing any changes.
At this week's G20 meeting, officials will receive the FSB's findings as part of discussions on financial stability.
The watchdog has identified further work on cross-border monitoring, information sharing and crisis planning, but has not established a timetable for common procedures governing a stablecoin issuer's failure across multiple jurisdictions.
The post Global watchdog warns the $300 billion stablecoin market could face bank runs even with full reserves appeared first on CryptoSlate.
SWI Group has raised €800 million to expand AI infrastructure, advancing its plan to repurpose FTX-backed Bitcoin miner Genesis Digital Assets.
On Oct. 12, the Amsterdam-listed company announced a capital increase backed by institutional investors, valuing the group at €6.1 billion and bringing total equity raised since March above €1 billion.
The financing will support data-center development, power infrastructure and computing deployments across Europe and the United States, where SWI is converting its digital infrastructure portfolio toward artificial intelligence and high-performance computing.
The expansion includes Genesis Digital Assets (GDA), a former major investment of bankrupt crypto exchange FTX's trading affiliate, Alameda Research, which SWI acquired control of earlier this year.
The fundraising comes as Bitcoin miners increasingly redirect capital toward AI infrastructure, attracted by stronger projected profitability and rising valuations for companies with access to electricity and data-center capacity.
Former FTX investment becomes foundation for AI expansion
Genesis was among Alameda Research's largest venture investments before FTX collapsed in November 2022.
The trading firm invested approximately $1.15 billion in Genesis between 2021 and 2022, when the miner was valued at about $5.5 billion.
The investment later became the subject of bankruptcy litigation, with FTX's recovery trust seeking to reclaim funds it alleged Alameda improperly transferred. The trust dismissed the lawsuit in June 2026.
SWI has since consolidated control of Genesis, completing the acquisition of a stake exceeding 70% in August through share purchases and restructuring.
The company plans to rename the miner SWI Digital and use its US mining infrastructure as a foundation for high-performance computing and AI services.
Genesis's existing power-connected sites are central to that strategy, giving SWI access to infrastructure it can redevelop for more demanding computing workloads.
SWI previously disclosed that its combined European and American digital infrastructure portfolio exceeded 4 gigawatts of power capacity, with more than 80% of its capital allocated to the sector.
The group also plans to develop its own AI cloud platform, extending its business beyond data-center ownership into computing services for enterprises and developers.
SWI Chief Executive Max-Hervé George said the latest fundraising would help the company expand alongside growing demand for computing capacity.
The new shares will be issued in several series, although SWI did not identify the participating investors or disclose how much of the proceeds would be allocated specifically to Genesis.
Bitcoin miners' AI pivot delivers stronger returns
SWI's expansion follows a sharp divergence in the financial outlook for Bitcoin mining and AI infrastructure.
According to CoinShares' second-quarter mining report, AI computing infrastructure could generate approximately $1.5 million in annualized profit per megawatt, compared with an estimated $500,000 from Bitcoin mining.
That threefold difference has helped drive a substantial revaluation of former mining companies pursuing AI opportunities.
CoinShares found that 10 of the 12 publicly traded mining companies it tracked gained between 70% and 195% during the second quarter.
Companies focused on AI infrastructure, including Hut 8, Cipher Mining, TeraWulf and Core Scientific, traded at an average of 19.4 times forward sales, compared with 6.6 times for a group of more mining-focused competitors.
The shift reflects growing investor demand for companies with existing electricity connections and infrastructure capable of supporting AI workloads.
However, converting those assets remains capital-intensive.
CoinShares estimates that developing AI-grade facilities from mining infrastructure can cost $8 million to $15 million per megawatt, compared with approximately $700,000 to $1 million for mining infrastructure.
The report also found that more than $100 billion in disclosed AI computing contracts across the covered companies supported only about $1.1 billion in annualized revenue, with roughly 550 megawatts generating billings against more than 4 gigawatts of contracted capacity.
That gap has made project execution increasingly important as investors assign higher valuations to companies transitioning away from Bitcoin mining.
SWI's €800 million capital increase provides additional financing for its expansion, but the company has not disclosed which Genesis facilities will be converted first, their development costs or when they will begin generating AI computing revenue.
The post FTX’s former Bitcoin mining bet gets new life as parent raises €800 million for AI appeared first on CryptoSlate.
Standard Chartered has launched custody for Ripple's RLUSD stablecoin as it prepares to expand its use as collateral for institutional trading.
On Oct. 12, the bank announced that eligible institutional clients can now hold RLUSD issued on the XRP Ledger (XRPL) through its Dubai International Financial Center branch, regulated by the Dubai Financial Services Authority.
The launch forms part of a broader arrangement with Ripple and trading group LMAX that would allow institutions to use RLUSD as collateral while keeping their stablecoin holdings with Standard Chartered.
Under the proposed model, the bank would mirror the value of eligible RLUSD holdings to LMAX, enabling clients to support trading positions without transferring the underlying tokens directly to the venue.
The arrangement could reduce counterparty exposure and operational risks associated with moving assets between custodians and exchanges, while allowing institutions to deploy capital across trading activities.
Ripple expands RLUSD's institutional reach after rapid supply growth
The development comes as RLUSD emerges as one of the fastest-growing stablecoins by absolute market value added, reflecting Ripple's efforts to expand its use across financial markets.
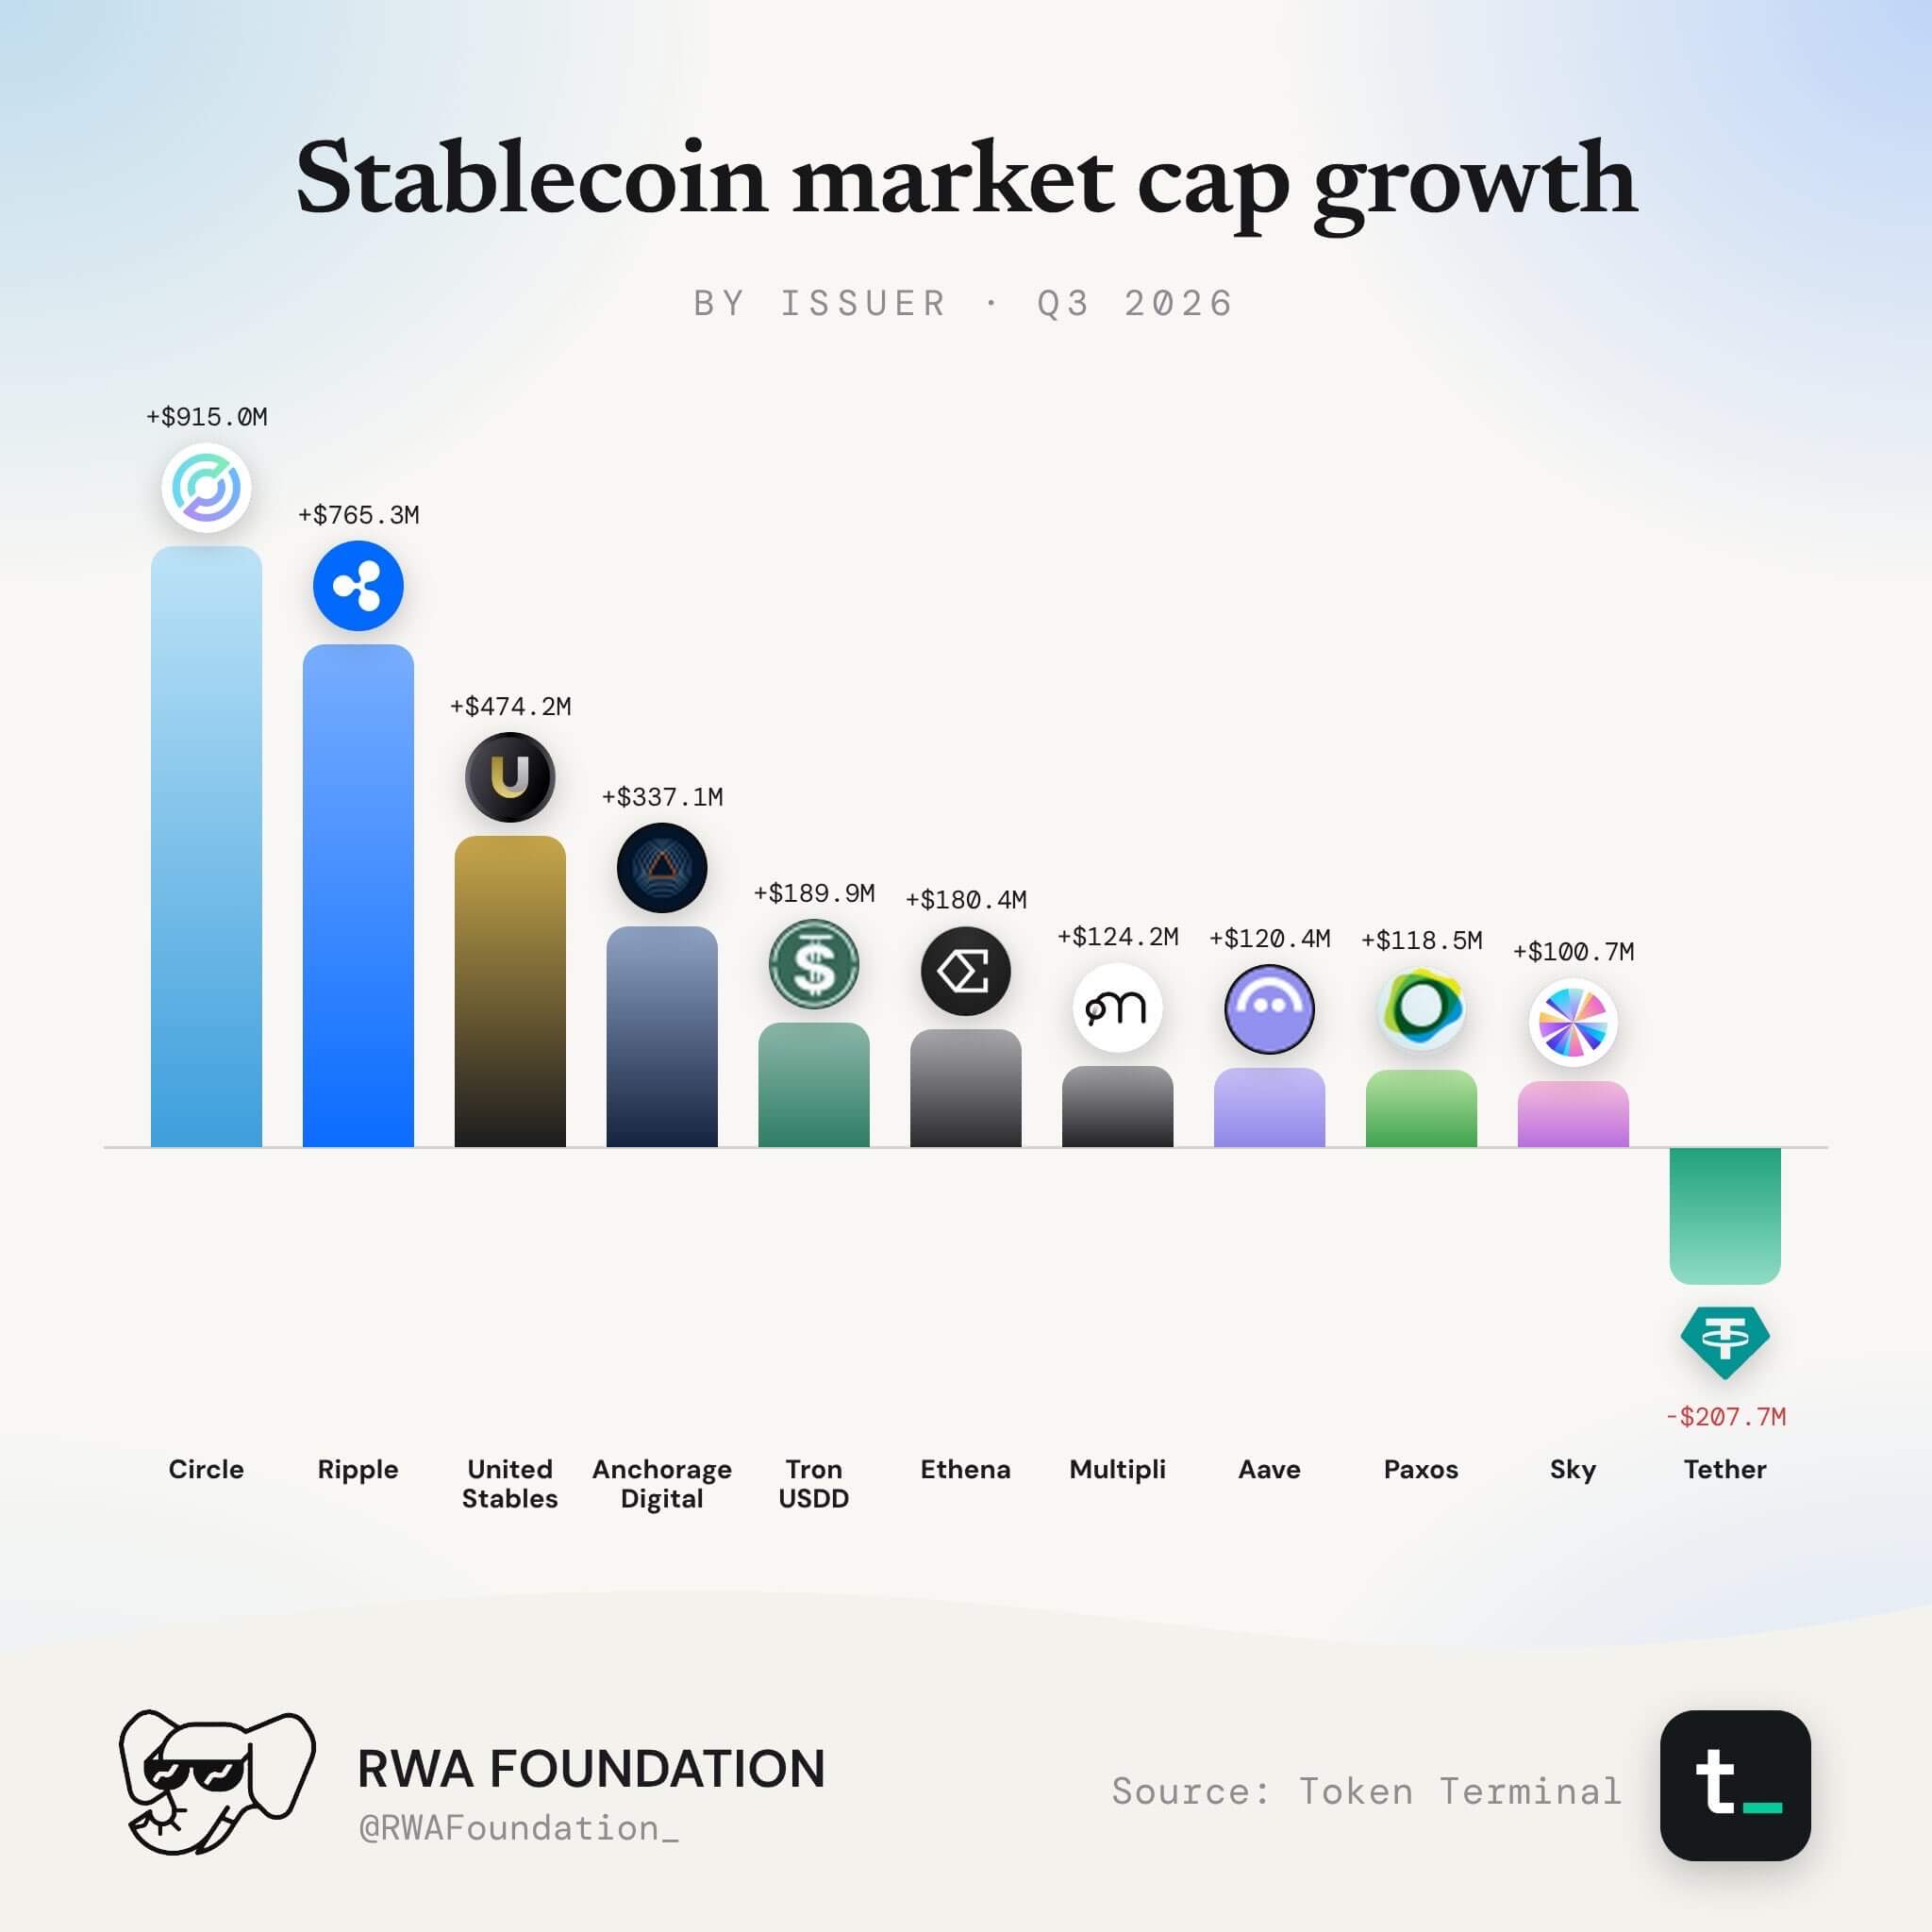
According to RWA Foundation, Ripple recorded the second-largest increase in stablecoin market capitalization during the third quarter, adding $765.3 million over 90 days.
Only Circle's USDC posted a larger increase, $915 million, while United Stables ranked third at $474.2 million.
Data from DeFiLlama shows RLUSD's total circulating supply has since climbed to about $2.4 billion, with about $1.14 billion issued on XRPL and another $1.3 billion on Ethereum.
The expansion gives Ripple a larger pool of dollar-denominated tokens as it seeks to establish RLUSD beyond payments and transfers, including as collateral for institutional trading.
That effort gained momentum in January when Ripple and LMAX announced a multiyear partnership to integrate RLUSD across the trading group's infrastructure.
Ripple committed $150 million in financing to support LMAX's expansion, with the agreement targeting RLUSD adoption across spot cryptocurrency trading, perpetual futures, contracts for difference, and other institutional products.
Standard Chartered's involvement adds a traditional banking custody channel to the arrangement, allowing participating institutions to maintain custody arrangements with the bank while accessing LMAX's trading infrastructure.
Waqar Chaudry, Standard Chartered's global head of digital assets in Securities Services, said institutional investors increasingly want to participate in digital asset markets without compromising asset safeguarding and risk management.
For Ripple, accepting RLUSD as trading collateral could drive additional demand from banks, brokers, and investment firms that need dollar-denominated assets to support their positions.
However, the commercial impact will depend on how widely institutions adopt the arrangement and which LMAX products ultimately accept the stablecoin.
Standard Chartered has not disclosed the amount of RLUSD held in custody or identified participating institutional clients.
The companies have also not announced when the collateral integration will become operational. Implementation remains subject to final documentation, technical testing, regulatory requirements and internal approvals across relevant jurisdictions.
Those remaining steps will determine when institutions can begin using RLUSD held at Standard Chartered to support trading positions on LMAX.
The post Standard Chartered brings Ripple’s RLUSD into banking custody after $765 million quarterly surge appeared first on CryptoSlate.
Bitcoin options expiring Friday carry substantial put exposure below the market price, while short-term volatility pricing has fallen ahead of Wednesday's US inflation report.
Data from Coinbase-owned Deribit, a crypto options exchange, showed that in an Oct. 12 snapshot the Oct. 16 settlement carried approximately 15,502 BTC in outstanding options, comprising 9,128 BTC in puts and 6,373 BTC in calls. The put-to-call ratio stands at 1.43, with about $451 million in underlying notional exposure concentrated in puts at $76,000, $78,000 and $80,000.
The snapshot put Bitcoin near $83,450 after last week's selloff, while derivatives platform Laevitas reports declining short-term volatility expectations ahead of the Consumer Price Index (CPI) release.
Bitcoin puts cluster between $76,000 and $80,000
Deribit's options data shows the largest concentration of puts at the $80,000 strike, with outstanding contracts carrying about $188 million in underlying notional exposure.
Another $162 million is concentrated at $78,000, while the $76,000 strike accounts for approximately $101 million.
Combined, the three levels represent nearly 35% of the $1.29 billion options expiry, highlighting the scale of downside positioning after Bitcoin briefly fell toward $80,000 during last week's market downturn.
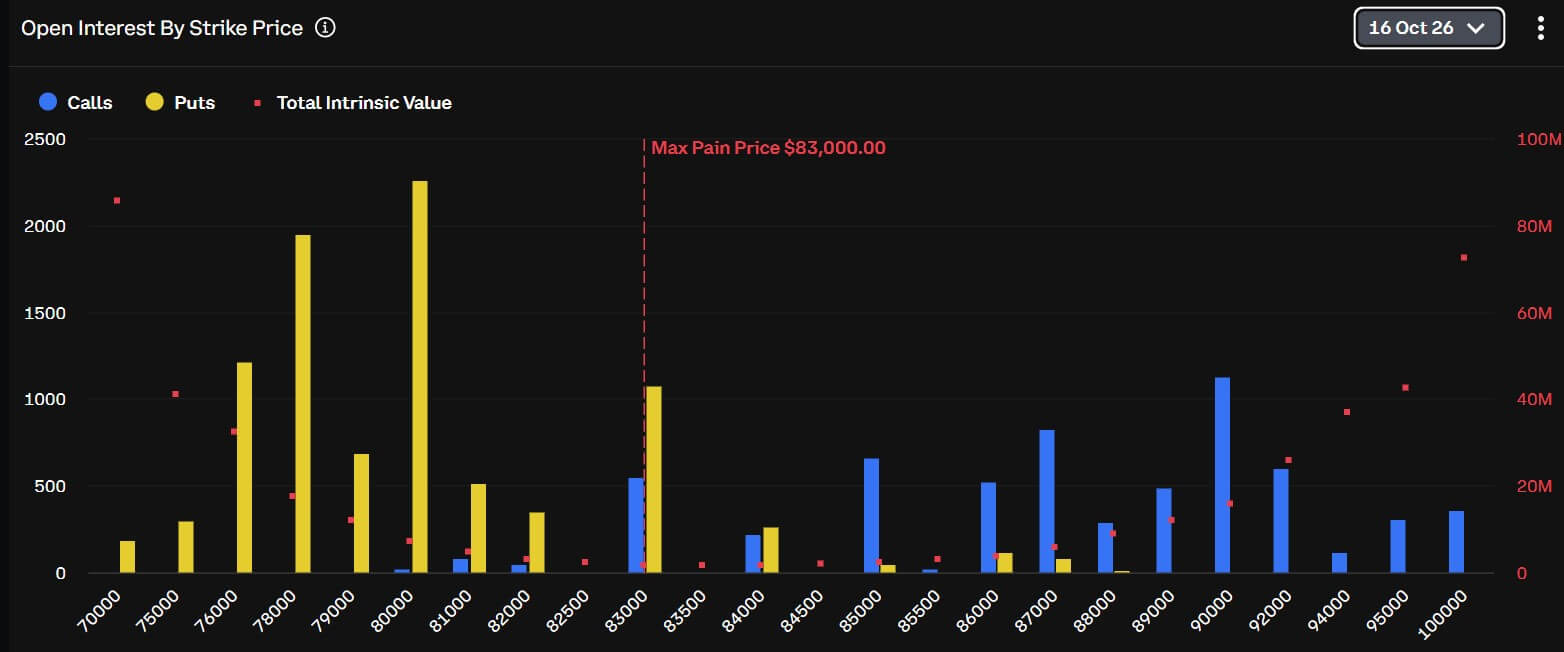
Additional put exposure worth about $89 million is concentrated at $83,000, near Bitcoin's current trading price.
The concentration suggests traders remain concerned about renewed selling pressure, although put open interest also includes contracts sold by investors seeking to collect premiums rather than exclusively buyers seeking protection.
Deribit data shows approximately $94 million in call exposure at $90,000, followed by $70 million at $87,000 and $55 million at $85,000.
Together, the three levels account for $219 million in outstanding notional exposure, less than half the amount concentrated at the three major downside put strikes.
The distribution leaves Bitcoin's largest downside positions relatively close to prices tested during the recent decline, while the $90,000 call strike requires an advance of nearly 8% from current levels.
Meanwhile, Deribit's maximum pain calculation stands at $83,000, indicating the settlement level that would minimize the aggregate intrinsic value of outstanding options based on current positioning.
Later-dated Bitcoin options also carry substantial upside exposure: Deribit’s Oct. 30 expiry has approximately $4.54 billion in call notional across the $90,000, $95,000 and $100,000 strikes.
Bitcoin volatility expectations retreat before Wednesday's CPI
Laevitas’s Oct. 12 brief described a volatility curve that prices Wednesday’s CPI as a non-event.
Bitcoin's seven-day at-the-money implied volatility declined to 32.01% from approximately 34.5% a week earlier.
That compares with 34.66% for 30-day contracts, 37.29% for 90-day options and 38.24% for 180-day maturities.
For illustration, converting the annualized seven-day implied volatility to a weekly move at the $83,450 snapshot price gives a one-standard-deviation move of roughly 4.4%, or $3,700, under conventional volatility assumptions.
That would place the modeled weekly range between approximately $79,750 and $87,150, encompassing the $80,000 put strike but falling short of the substantial call concentration at $90,000.
Meanwhile, Laevitas reported that Bitcoin's seven-day 25-delta options skew shifted from +1.98 to -2.40 over the past week, a 4.38-point reversal.
Laevitas characterized the move as an unwind from a call-bid extreme toward nominally put-bid pricing, with puts still cheaper relative to calls than their 52-week median.
Bitcoin perpetual-futures open interest fell 1.9% over the past week to approximately $29.33 billion, while annualized funding rates stood at 5.6%, according to Laevitas.
The positioning comes as investors assess whether US inflation could prompt the Federal Reserve to raise interest rates again at its Oct. 27-28 policy meeting.
MarketWatch’s Oct. 12 preview cited expectations for September headline inflation to accelerate to approximately 3.7% annually from 3.4% in August, partly reflecting higher energy costs. Monthly core inflation, which excludes food and energy, is forecast to rise 0.2%.
Laevitas described an October increase as close to priced out, with December pricing around an 85% probability of a hike.
However, elevated oil prices and Treasury yields continue to complicate the outlook for risk assets, with stronger-than-expected inflation potentially reviving expectations of another rate increase.
In illustrative price scenarios, hotter inflation could pressure Bitcoin toward the heavily populated $78,000–$80,000 put strikes, while softer inflation could encourage a recovery toward the higher call concentrations.
The CPI report arrives Wednesday, Oct. 14, at 8:30 a.m. Eastern Time, followed by producer-price inflation and retail-sales data Thursday, Oct. 15, giving traders two days of economic releases to absorb before Friday's $1.29 billion options expiry.
The post Bitcoin options price a quiet CPI week while shorts cluster at $76,000–$80,000 appeared first on CryptoSlate.
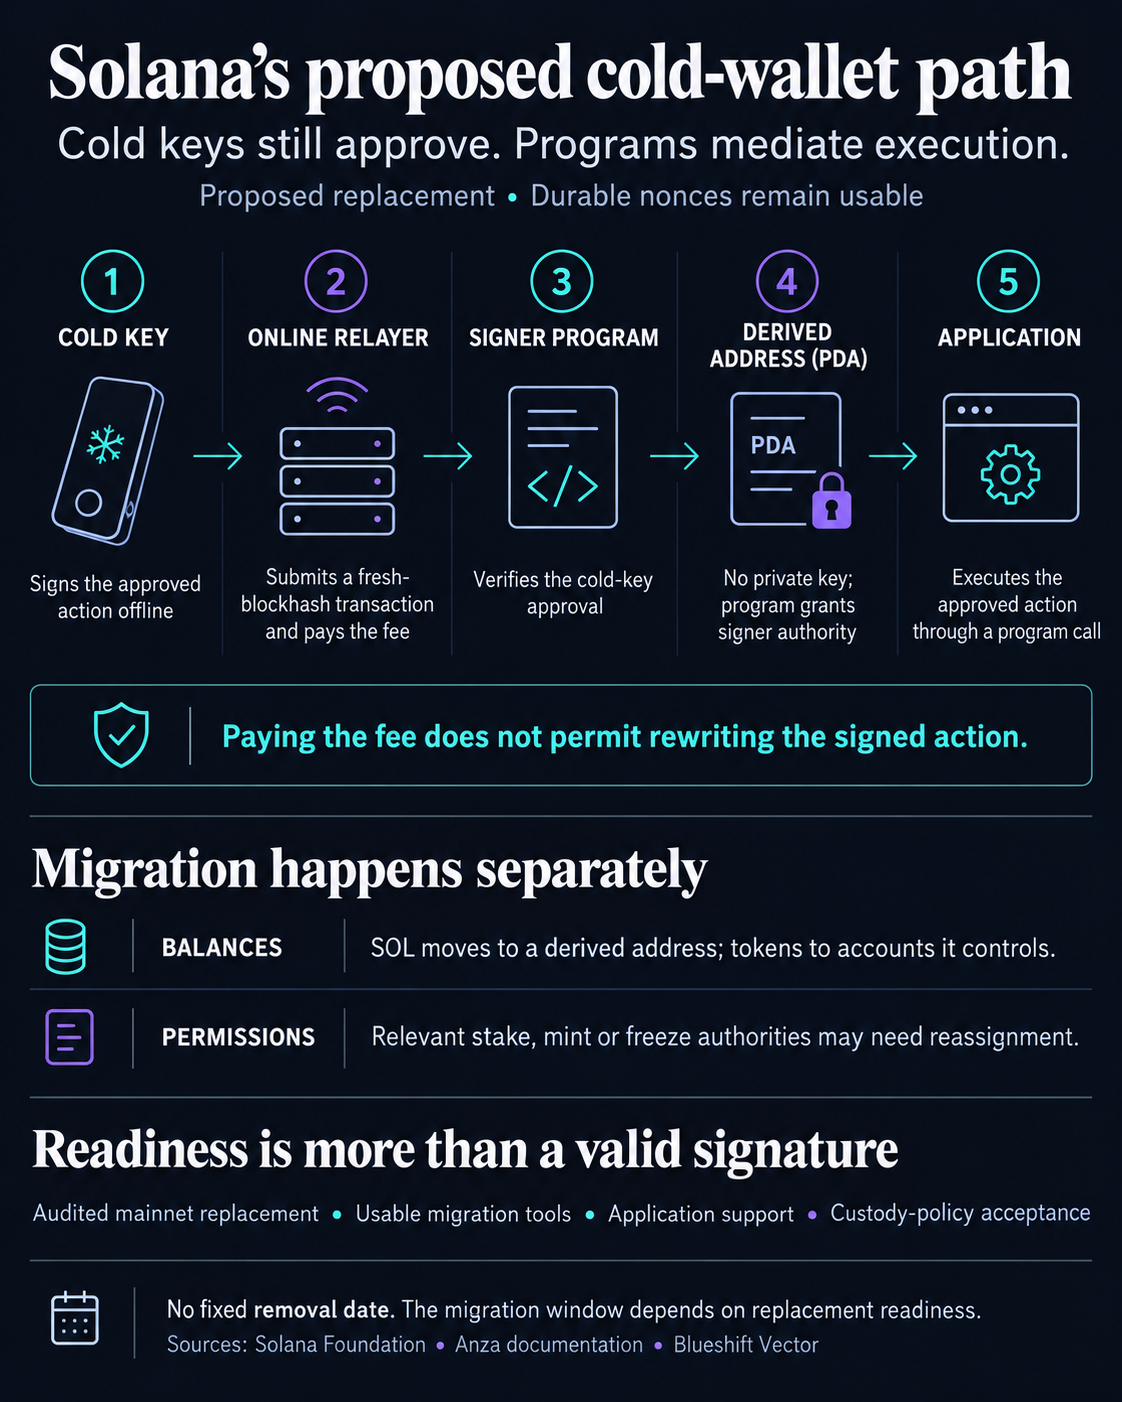
Solana’s plan to retire durable nonces, which let transactions be signed offline and broadcast later, would preserve cold-key approval while changing which addresses control the affected assets. For exchanges, custodians and treasury operators using that signing method, the proposed replacement adds a program between the cold key’s approval and execution.
The Solana Foundation’s October deprecation plan points to onchain signer programs that verify an offline signature and execute its approved instructions. A program-derived address, or PDA, would control the affected accounts. The original key would still authorize actions, while a separate online operator submits them and pays the network fee.
The replacement creates a different custody architecture: operators must migrate the relevant assets or permissions, applications must accept actions arriving through another program, and risk teams must approve the new signing path.
Durable nonces remain usable. The Foundation has not set a removal date or made a final choice between Anza’s Programmatic Signer and Blueshift’s Vector. Its roughly six-month migration window is conditional on a suitable replacement being ready, audited and live on mainnet.
The key keeps approving, but the account changes
Durable nonces solve a timing problem. Instead of signing a transaction tied to a recent blockhash that soon expires, an offline signer can approve one using a stored nonce. That allows approval and broadcast to happen at different times.
Solana’s separate 200ms slot upgrade reached its final mainnet stage on Oct. 9. Faster block production leaves less wall-clock time for ordinary blockhash-based approvals, although expiry depends on block production rather than a guaranteed timer. CryptoSlate’s earlier coverage examined that timing change; the nonce proposal concerns the architecture used to avoid the short approval window.
Under Programmatic Signer, the cold key signs an authorization message rather than the transaction sent to the network. A relayer places that approval in a fresh-blockhash transaction. The signer program verifies the authorization and executes the approved instructions with the key’s derived address as signer.
The PDA has no private key of its own. Its ability to act comes from the signer program verifying the original key’s approval. Deriving the address does not move any assets or permissions: those must be transferred separately.
The migration guide describes moving native SOL into the derived address, transferring token balances into accounts controlled by it, and moving mint or freeze permissions to it. Stake accounts can move the staker authority, withdraw authority or both, depending on the permission being migrated. These are separate controls, rather than one universal wallet switch.
The Foundation proposes completing those handoffs while legacy durable nonces still work. For an affected treasury, approving the new signing software is therefore only part of the job. Its account inventory and the permissions each key currently holds determine what must change.
The two candidate designs also handle native SOL differently. Programmatic Signer’s derived SOL account is System-owned and can send SOL through an approved ordinary transfer. Vector initializes a program-owned account and releases SOL through its own authorized withdrawal or closing operation.
What the cold signature lets a relayer do
The implementation choice affects how tightly an approval constrains the transaction around it.
Programmatic Signer’s message documentation says the cold signatures bind the executor, nonce account and embedded execution message. A relayer cannot alter those authorized bytes while retaining valid signatures. It can, however, choose the outer fee payer and blockhash and add instructions before or after the submission.
Vector commits to the top-level instruction buffer, including the data and accounts used to pass approved actions into other programs. Instructions surrounding those actions must already be included when the cold key signs. A relayer cannot insert, remove or reorder them afterward without invalidating the approval.
Programmatic Signer allows an execution context to be assembled around an approved action; Vector requires the surrounding instruction sequence to be approved in advance. In both cases, paying for broadcast does not grant permission to rewrite the signed action.
| Control | Programmatic Signer | Vector |
|---|---|---|
| Cold approval covers | The authorization and embedded execution message | The committed top-level instruction buffer |
| Extra surrounding instructions | Relayer may add them outside the authorization | Must be included before signing |
| Replay state | A separate program nonce account | Nonce stored in the Vector account |
| Derived-address setup | No signer-address registration | Account initialized under the Vector program |
A failed execution attempt can leave a cold approval executable later. A current durable-nonce transaction that passes validation but fails during execution still consumes its nonce. Programmatic Signer’s architecture commits the nonce advance and application changes together, or rolls them back together. Vector documents the same ability to retry a failed action.
For operators, retryability means a failed submission has not necessarily invalidated the approval. Without an enforced deadline, it can remain available for later execution while its nonce is unchanged.
Vector explicitly warns that a relayer could withhold a transaction until conditions change, or that a signature exposed by a failed attempt could execute later. A timeout included in the signed instructions can reject execution after a deadline. Revocation requires a separately authorized nonce advance to land. A deadline rejection itself does not consume a nonce whose changes roll back with the failed transaction.
Application access is a separate custody test
The Foundation’s rationale is to simplify validator handling. Durable nonces require special replay-prevention rules, complicate asynchronous execution and make invalid transactions harder to filter. Moving approval and replay state into ordinary programs leaves validators processing normal blockhash transactions.
Applications then receive approved actions through cross-program invocation, or CPI: one program calls another. That can conflict with an application’s rule that an action must arrive directly as a top-level instruction. Checks that inspect only top-level repayment or signature-verification instructions can also miss an action nested inside the signer program.
More available call depth does not resolve a rule that rejects the call’s position or cannot inspect the nested instructions. The Foundation suggests supporting known signer programs or offering another execution path. Whether an application accepts a PDA’s signature is consequently a different question from whether the offline approval is cryptographically valid.
Token-2022’s CPI Guard shows why compatibility needs a precise account-level assessment. With the guard enabled, CPI transfers and burns require delegate authority; approvals through CPI are prohibited, and changing the owner is prohibited even outside CPI. Permanent delegates have transfer and burn exceptions.
Those rules are more specific than a blanket ban on every PDA action. A delegate-based transfer route may exist, but establishing or using that authority introduces its own permission and custody-policy decision.
Institutional concerns raised in March centered on application access and the controls under which funds may move. In the March 4 discussion, a participant identifying himself as Michael from Fireblocks supported nonce deprecation while objecting to CPI Passthrough’s migration, contract dependence and DeFi compatibility burdens. He favored transaction envelopes, with Sudo as an alternative, rather than the proposed CPI-based signing path.
Grant, who identified himself as being at Unit 410, said the same day that a small, auditable signer program might make authority migration acceptable. He rejected a workaround that temporarily moves assets to a hot signer, even for an atomic operation, because funds must remain associated with cold storage in its noncustodial model.
A testable design still needs a production migration path
Programmatic Signer’s current documentation reports devnet deployment and audits in progress, with remediation required before its v1 release and any mainnet deployment. Its interfaces may change. The usage documentation still marks simulation and relay submission as coming soon, while several migration operations are similarly unfinished in the guide.
Vector publishes implementation code and program IDs; its README does not state an audit or mainnet deployment status.
Meanwhile, Fireblocks’ current protocol onboarding kit still describes automatic durable-nonce injection for selected WalletConnect integrations, including Jupiter and Kamino, with a default provider-managed 15-minute validity window. That describes an existing approval workflow which a replacement must accommodate.
An operational migration needs an audited mainnet replacement, usable tools and application paths that retain each operator’s approval controls.
The post Solana’s offline-signing proposal would keep approvals valid after failed transactions appeared first on CryptoSlate.
CryptoTicker.io
Chainlink has issued invitations to New York for 29 October. The event is called Link:NYC, it runs for one day, and the organiser describes it on its own page as a meeting point for executives rebuilding the global financial markets. If you hold Chainlink, you will see an entry in the calendar first of all. What makes it interesting is a number that has nothing to do with the price: 28.
That is how many days it takes for staked LINK to become freely available again. Start the exit today and you reach your coins on 9 November, eleven days after the event. Anyone who wants to react on 29 October with LINK sitting in staking has therefore already made that decision today, without noticing.
Link:NYC on 29 October: what Chainlink has announced for the date
Chainlink's event page names five topic blocks: institutional real-world assets, agentic financial applications, interoperability, market infrastructure, and stablecoins and payments. A venue is not given there, nor is an attendance figure. Speaker names sit in a tab of their own that reveals nothing publicly so far. Officially settled, then, are the date, the city and the list of topics.
That is less than the figures circulating in recent days. Several crypto outlets wrote of more than 35 executives expected and listed institutions said to be attending. Chainlink itself confirms none of those details, and the organisers have pointed out explicitly that the presence of individual houses is not an announcement of new partnerships. Anyone treating the 35 as a settled figure is working with a number nobody has evidenced so far. The official description is on Chainlink's event page.
Who is in the room: banks, market infrastructure and institutional allocators
The target audience, by contrast, Chainlink names clearly. Banks, operators of market infrastructure, asset managers and institutional allocators are invited. This group does not decide on code but on budgets, and on the question of which infrastructure a house will settle on two years from now. Link:NYC is explicitly not a developer conference.
That is why dates like this move LINK at all. Chainlink does not sell an application to retail customers. The project supplies data connections and transfer routes between chains, and between chains and the old financial world. Every contract with a large house is therefore news about future revenue, not present revenue. With LINK the market regularly trades the expectation rather than the revenue.
LINK at $13.07: where the price stands 17 days before the event
On Monday evening LINK trades at $13.07, or EUR 11.72. That is 1.7 percent less than 24 hours earlier and 6.7 percent less than a week ago. Over 30 days, a gain of 12.6 percent still stands. Market capitalisation is $10.0 billion, 766.8 million LINK are in circulation, and coins worth $295.3 million changed hands in 24 hours. The figures come from CoinGecko, as of Monday 12 October.
The daily range ran from $12.85 to $13.49. That leaves the price some three quarters below the all-time high of $52.70. Between today and 29 October lie 17 days in which none of these figures stands still.
Swift and Infosys in September: how LINK reacted to the last institutional news
A date on its own says little. More useful is a look at what happened at Chainlink after comparable announcements, and there were two in September.
On 29 September we reported on 11,500 institutions being connected to the Swift ledger, with a quote from Chainlink co-founder Sergey Nazarov. The price jumped above $15 at the time. A day later the counter-move was already in our own pages: LINK slid from $15.44 to $14.14, a drop of 8.4 percent, without anything about the Swift news having changed. Measured against that high, the price today sits 15.4 percent lower.
The pattern is nothing new for LINK. An institutional story carries the price for hours, rarely for weeks, because it confirms an expectation already in the price. For 29 October that means the move, judging by recent weeks' own experience, tends to come before the date rather than after it. That is not proven; it is an observation from two cases.
65.6 percent in large addresses: the second look alongside the chart
Alongside the price, a movement is running in the wallets that a chart does not show. Addresses holding between one million and 100 million LINK held 65.6 percent of the circulating supply on 12 October. On 1 October it was 65.38 percent. The change is small but the direction is unambiguous: while the price gave way over that period, coins moved into larger addresses. The survey comes from TokenPost and names no data provider, which is why it serves as an indication and not as proof.
Two points matter about it. High concentration means comparatively few addresses can move the market. And part of those holdings sits in staking, so it cannot be sold immediately, which cushions downward moves and delays upward ones.
Two dates in two days: the Fed decides on 28 October, Chainlink hosts on the 29th
One point has been going missing in the coverage of Link:NYC so far. The Federal Reserve's meeting calendar lists a session of the open market committee for 27 and 28 October, with the decision falling on 28 October. Link:NYC lies exactly one day after it.
For the market that means two things. On Wednesday evening Central European time, a rate decision moves the entire crypto market, Chainlink included, regardless of what Chainlink itself does. On Thursday, news out of New York meets a market still digesting the rate move. Anyone attributing the price reaction on 29 October to the event may be confusing two causes. Know that sequence before you read a move on the evening of the 29th.
The calendar beats the news: working backwards to be able to act on the date
This is where the date turns into an action. Chainlink staking has run since version 0.2 with a cooldown of 28 days followed by a withdrawal window of seven days. Both are set out in the official overview of Chainlink Staking v0.2.
Work it through on your own calendar. Start the exit today, 12 October, and the cooldown ends on 9 November. From then until 16 November there is time to withdraw the LINK. Miss that window and the coins move automatically back into staking, with the 28 days starting over. On 29 October, the day of the event, you are in the middle of the period in every one of those cases.
A plain consequence follows. On 29 October, staked LINK is not a holding you can dispose of but one you watch. Anyone who wants it otherwise acts today and forgoes the staking income of the next four weeks. Which providers set which periods and rates is in the comparison of staking providers; the periods differ considerably between staking in the protocol and staking through an exchange.
A second deadline runs independently of that. Buy LINK today and hold the coins as private assets, and the one-year speculation period under Section 23 of the Income Tax Act ends on 12 October 2027. From 13 October 2027, a gain on sale stays tax free. That applies to real coins, not to a certificate on LINK; we worked that distinction through on 10 October using the LINK funds as an example.
Custody before the date: access, firmware and records
On days with heavy trading volume, the result depends less on the choice of exchange than on whether you have access at the right moment. Three points can be checked beforehand, without haste.
Access and withdrawal routes
If your LINK sits on an exchange, check whether the withdrawal function is enabled and whether a change to two-factor authentication is still pending. Many houses lock a newly stored withdrawal address for 24 to 72 hours. Anyone seeing that lock for the first time on 29 October has seen it too late. Which providers in Germany are licensed under the European crypto regulation MiCA, and what their fees look like, is in the exchange comparison.
Self-custody
If the holding sits on a hardware wallet, check the firmware before the date and whether the recovery words are where you can reach them if it matters. A device that demands an update first costs half an hour at the decisive moment. Check too whether your device supports the token at all before you send coins to it.
Records
Note the purchase date, amount and price as soon as you trade. For the one-year period the day counts, not the month, and the tax office accepts no estimate. An export from the exchange on the day of purchase saves a reconstruction the following year.
Levels above and below: $13.49 at the daily high, $12.09 as the weekly low
Two values from current trading can be checked and serve as orientation. Above sits the daily high at $13.49. It lies around 3.2 percent above the current price and marks the point at which the market last sold today. Below, the daily low sits at $12.85, a good 1.7 percent under the price.
Further down waits the weekly low of 8 October at $12.09, which TokenPost reports for last Thursday. Between that low and today's price lie 8.1 percent. As long as the price stays above it, the move since Thursday is intact; fall below and the recovery of the past four days has been worked off. Both levels come from trading and not from a model, and neither is a forecast.
Our assessment: a calendar entry is not yet a price driver
From this newsroom's point of view, Link:NYC is for the next two and a half weeks above all a date that expectations can attach to, and not yet an event with documented content. Three observations argue for that. Chainlink has announced neither speakers nor outcomes. The attendance figures in circulation are second-hand. And the two institutional stories in September, Swift on the 29th and the Infosys connection the week before, each carried the price for hours and then gave way; LINK today sits 15.4 percent off the high of 30 September.
Against that stands the timing. A meeting with banks and market infrastructure one day after a rate decision can amplify a move that is running anyway, and the shift into larger addresses shows that somebody is accumulating at today's prices. Anyone drawing a purchase decision from that is betting on an expectation and not on a number. A total loss is possible at any time with crypto assets.
Link:NYC: 17 days remain until 29 October
Three steps can be worked through before the date, and all three cost nothing.
- Clarify your staking status. Look up whether and where your LINK is locked and when the period runs. Anyone who wants to be able to dispose of it on 29 October starts the exit today. Providers' terms are in the staking comparison.
- Check your access. Go through the withdrawal address, two-factor authentication and firmware once while there is no deadline pressure. The provider situation in Germany is in the exchange comparison.
- Note the deadlines. Record the purchase date and amount, plus 28 October for the rate decision and 29 October for Link:NYC. Keeping both dates separately in the calendar makes the price move afterwards easier to read. A tax tool helps with the records.
(As of October 12, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Cardano processed exactly 1,780,896 transactions in the five days between 6 and 11 October 2026. The chain has never moved more in its history; the previous high, from November 2021, sits 13.7 percent below it. The Cardano price has not responded: ADA stands at around $0.2384, about 5.3 percent below where it was 24 hours earlier.
Most reports name the Cardano governance votes as the cause, above all the proposal for a minimum fee of 75 ADA for stake pools. That explanation does not add up arithmetically. We counted the votes on that proposal one by one: there were 148. This article sets out what the chain data supports about the record, why the proposal has since lapsed, and what follows from it if you hold ADA in Germany.
The figures in this article rest on the public block data of the Cardano chain itself, analysed across all 662 epochs since the chain launched, and on the full list of votes on the proposal in question. cryptoticker.io compiled this analysis itself on 12 October 2026.
Epoch 660: 1,780,896 transactions between 6 and 11 October
Cardano counts in epochs rather than days. An epoch is a fixed stretch of five days in which the chain produces blocks, settles rewards and fixes voting rights. Epoch 660 began on 6 October 2026 at 9:44 p.m. and ended on 11 October at the same time.
Within that window, 1,780,896 transactions were written into 21,243 blocks. For comparison: epoch 659, the five days before, carried 158,011 transactions. The jump is 11.3-fold. Epochs 653 to 657 all sat between 89,353 and 130,442 transactions, in other words within the usual band. Epoch 660 is not a trend but a single, extremely sharp spike.
The previous high dates from epoch 304 in November 2021
The old record stood at 1,566,974 transactions and was set in epoch 304, which ran from 21 to 26 November 2021. ADA was then just past its all-time high, the market was in the closing phase of the last big cycle, and the chain had only recently gained smart contracts.
That comparison is the genuinely interesting part, and most coverage leaves it out: in 2021 the load came out of a hot market with prices to match. In 2026 it comes at a price 92.3 percent below the all-time high of $3.09. The same throughput, an entirely different price base. Anyone reading network activity as a price driver gets a counter-example here straight from the chain data.
83.8 transactions per block: the block count stayed the same, the load did not
The decisive observation lies in the ratio, not in the total. Cardano produces a quantity of blocks per epoch set by the chain, and that quantity has not changed: 21,243 blocks in epoch 660 against 21,207 in epoch 659. A difference of 36 blocks, which is to say nothing.
Per block that works out at 83.8 transactions against 7.45 the week before. The blocks were roughly eleven times fuller, not more frequent. The look back is interesting too: in the 2021 record epoch 304, a block held 74.3 transactions at an almost identical block count. The chain packed more into the same frame in 2026 than in 2021, even though block size has not multiplied in that time.
For the technology that means the load was not spread across a larger infrastructure, it was pressed into the existing one. The chain carried that without an outage, and that is the solid finding of the week. It has nothing to do with a capacity upgrade or a protocol change.
337,720 ADA in fees over five days, 0.19 ADA per transaction
The fees draw the same picture from a second angle. Epoch 660 generated 337,720 ADA in transaction fees, where epoch 659 produced 49,495 ADA. The factor is 6.8.
Notably, fees rose less steeply than the transaction count, 6.8-fold against 11.3-fold. In arithmetic terms that means an average fee of 0.19 ADA per transaction in epoch 660, against 0.31 ADA in epoch 659. The transactions were more simply built than usual, then: few inputs and outputs, no demanding smart-contract calls. On Cardano the fee follows the size and complexity of a transaction, not an auction procedure as on Ethereum. A mass event made up of many small, uniform transfers therefore produces exactly this pattern.
At 337,720 ADA and a price around $0.2384, we are talking about roughly $80,500 in fees over five days. For the stake pool operators, whose remuneration was at issue over the same period, that is not a sum that turns a situation around. Precisely that is why the fee question became political on Cardano at all.
The minPoolCost vote on 75 ADA lapsed in epoch 661
minPoolCost is the fixed amount a stake pool retains from rewards each epoch before anything at all is distributed to delegators. That amount stands at 170 ADA today. The proposal voted on since epoch 654 wanted to cut it to 75 ADA. Small pools would have become more competitive, and delegator returns would have shifted slightly.
When we reported on this vote on the minimum fee on 10 October, it stood at 34 percent in favour with the deadline approaching on 11 October. The result is now in, and it moved, but not enough: the delegated representatives' yes votes ended at 44.18 percent of the active voting power, the no votes at 55.82 percent. The majority was therefore missed. The proposal lapsed when its deadline passed in epoch 661, meaning it was neither adopted nor enacted. The 100,000 ADA deposit goes back to the submitters, and the minimum fee stays at 170 ADA.
For delegators that means, concretely: nothing changes in how your staking rewards are distributed. How hard that fixed amount actually presses on returns depends on the size of your pool; across the pools we recalculated at the start of October, returns ran between 2.1 and 2.7 percent a year.
148 votes cast: why the governance explanation does not add up
Now to the question of cause. Several trade outlets trace the transaction record to a rush on the governance votes: users are said to have moved their wallets in order to vote on network parameters, with the deadline coinciding with the end of the epoch. That sounds plausible, because the timings line up.
It can be counted, though, and we counted it. The full list of votes on the minPoolCost proposal contains 148 entries: 87 yes votes and 37 no votes from delegated representatives, plus 19 abstentions and 5 yes votes from the constitutional committee. Each of those votes is one transaction on the chain.
148 transactions against 1,780,896. That is 0.008 percent of the record. Even counting every other open proposal in the epoch and assuming similar participation for each, you do not get beyond a few hundred votes. The governance explanation does not carry the record even as an order of magnitude.
The reason lies in how the system is built: on Cardano it is not individual holders who vote but DReps, delegated representatives who exercise the bundled voting weight of many wallets. A holder who has delegated their voting power to a DRep once need not send a single transaction for any further vote. The whole purpose of the design lies in that bundling. A voting deadline on Cardano therefore produces almost no chain load, structurally.
629 stake pools vote permanently to abstain, 17 to “no confidence”
The vote list shows something else that matters more for placing the vote itself than for the record: not one stake pool voted actively on this proposal. 629 pools sit on the permanent default of "always abstain", bringing a voting weight of some 12.22 billion ADA with them, and 17 more on "no confidence". Among the delegated representatives, a further 10.5 billion ADA or so sits on permanent abstention.
Measured against the active stake of roughly 21.27 billion ADA in this epoch, Cardano parameters are therefore decided by a fairly small, alert share of participants, while the large remainder parks on a default setting. That distribution is what the chain data says and is no judgement on those involved. Anyone who does not want to leave their voting weight unused has to delegate it actively to a representative; with a hardware wallet in self-custody that works directly from the wallet, while with ADA on an exchange it generally does not work at all.
A stake pool report names a HOSKY campaign as the driver of the first three days
If it was not the vote, then what? The only concrete attribution so far comes from the epoch report of a stake pool operator, quoted by the outlet TechBullion. On that account, some 1.08 million transactions fell in the first three days of epoch 660 alone, and most of them traced back to a campaign around the Cardano token HOSKY, in which participants were to send ADA to an address and receive tokens back. A post on the exchange platform KuCoin credits the same campaign with a peak of 440 transactions per second in a single block.
We cannot confirm that attribution. Both accounts rest on the same source, and we have not recalculated a single campaign's share of 1.78 million transactions from the chain data. What we can say is that the pattern fits. An event in which many people send small amounts back and forth produces exactly what the data shows, namely very many very simple transactions at a below-average fee each. The vote does not produce that pattern.
Our assessment: the record is real and the chain carried it without disruption, but it is not a demand signal for ADA. Three pieces of evidence point that way. First, 148 votes do not explain 1.78 million transactions. Second, the fee per transaction, at 0.19 ADA, came in below the previous week's, which argues for mass simple transactions and against economically heavy use. Third, the current epoch 661 is already well lower again. Against that it could be objected that even an artificially generated load test proves resilience, and that is true. Only nobody pays a higher ADA price for resilience.
$66.5 million in Cardano DeFi: the record does not come out of capital
A second angle, alongside price and transaction count, is the capital actually at work on the chain. Around $66.5 million is currently deposited in Cardano applications. That means the sum working in trading venues, lending protocols and similar applications on the chain.
That figure puts the record in proportion. Cardano carries a market capitalisation of roughly $8.95 billion, which places it 17th among the largest cryptocurrencies; 37.55 of a maximum 45 billion ADA are in circulation. Against that stand $66.5 million of active capital in the applications. For comparison: on Solana that value is around $6.1 billion, on NEAR around $262 million. A record number of transactions coming off such a narrow base of capital points to many small movements rather than to new money.
ADA at $0.2384, 92.3 percent below the 2021 all-time high
The price itself gives the record week no confirmation. ADA trades at around $0.2384, after a daily high of $0.2556. Over 24 hours that is about 5.3 percent lost, over seven days around 11.4 percent. Only over 30 days does a gain of about 14.8 percent stand. The all-time high of $3.09 from September 2021 sits 92.3 percent above today's level. Trading volume over the past 24 hours comes to roughly $376 million.
The pattern is striking: the most transaction-heavy week in the chain's history coincides with a week in which ADA loses a good tenth of its value. Anyone reading the record as a reason to buy should read that sentence twice. Network activity and price ran in opposite directions on Cardano this week, and the chain data supplies an explanation for it in the fee per transaction.
Delegation, holding period and purchase route: four points for ADA holders in Germany
A failed vote and a throughput record yield four concrete points for you.
The minimum fee stays at 170 ADA. Do not calculate your staking income with 75 ADA. The fixed amount is retained per epoch and per pool before anything is distributed. With a small pool it eats a markedly larger share of your reward than with a large one. Anyone who meant to move their delegation depending on the outcome of the vote now has no occasion to.
Your voting weight does not lapse, it rests. As long as you have not delegated your voting power to a representative, it counts as an abstention in every vote. That is the default setting where, according to the chain data, the largest share of the stake sits. Delegating and staking are two separate acts: you can have your ADA in a pool and your voting weight nowhere at all.
Staking income is taxable in Germany. Rewards from staking count as other income and are taxed in the year they are received. For the ADA itself, the one-year holding period for private assets applies: sell at a gain within a year and that gain is taxable, after that it is not. Whether and how staking affects that period depends on the arrangement; anyone delegating regularly should document the inflows as they come rather than reconstruct them in March of the following year.
The purchase route decides your access to governance. If your ADA sits on an exchange, the exchange holds the keys. You generally cannot vote then, and delegating to a representative drops away too. Anyone who wants that needs the coins in their own wallet. Anyone who does not need it gets along more easily with an exchange licensed in the EU.
Cardano record: epoch 661 is running at 28 transactions per block
As of this analysis, the current epoch 661 has processed 118,374 transactions in 4,269 blocks. That is 27.7 transactions per block: clearly above the normal band of around 7 in the preceding weeks, but far below the 83.8 of the record epoch. The spike is not holding, in other words. Three steps follow from that:
- Check where your ADA sits and whether the trading venue is licensed in the EU. Since MiCA, providers targeting customers in Germany have to show an authorisation. Which exchanges hold one and what they charge in fees is set out in the overview of MiCA-regulated crypto exchanges.
- Document your staking inflows now, not at tax return time. Every reward has its own date of receipt and its own price. Gathering that after the fact costs time and records. We compare the tools for it under crypto tax software and portfolio trackers.
- Decide whether fees or a say weigh more heavily when you buy. The cheap route over an exchange and the route with your own keys are not mutually exclusive, but both cost something. The terms offered by trading venues are in our comparison of the best crypto exchanges.
Both can be checked without a detour: the figures for epoch 660 are on Cexplorer's epoch page, and the outcomes of the votes are in Cardano's official governance portal.
(As of October 12, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
If you hold G tokens, USDC, USDT, WETH, DAI or WBTC on Gravity Alpha Mainnet, you have until 1 November 2026 to get them off the blockchain. Galxe is shutting down its first own network that day. Anything still sitting on it after that can no longer be transferred, the provider says: not a temporary halt, but the end of mobility. Galxe's own guide therefore explicitly advises bridging balances out before the date.
Two things make that deadline harder than it looks on paper. First, different tokens use different exits, and they are not interchangeable: anyone trying to send USDC over the familiar bridge will not find the balance there at all. Second, the classic route carries a waiting period of roughly seven days. Together that means the real edge in the calendar is not 1 November but a week earlier.
What happens to Gravity Alpha Mainnet on 1 November 2026
Gravity Alpha Mainnet is the older version of the Gravity network and ran as a layer 2, a side chain that draws its security from Ethereum. Galxe launched it in 2024 on the Arbitrum Nitro stack, with chain ID 1625. With Gravity L1, a standalone layer 1 with ID 127001, now in full operation, the Alpha chain has lost its purpose.
The developer documentation now lists the old chain openly as "legacy" and puts a warning in front of it: all balances should be moved back to Ethereum before 1 November. The help pages for end users put the same sentence more plainly. Gravity Alpha Mainnet will remain available until 1 November 2026, it says, after which it will be decommissioned, and whatever is still on it will no longer be transferable.
For holders this is not a price question. G traded at around $0.0041 on Monday evening, its market capitalisation stood at just under $30 million, which places it 524th among crypto assets. The price sits about 82 percent below its February 2025 peak of roughly $0.023. The sums are small for most holders, in other words. The difference between a small amount and a lost amount is the same all the same, and that is the point here.
Why Galxe is switching off its own layer 2
Galxe announced the step back in July. The reasoning: Gravity Alpha was the first stage of its own blockchain plans, carried real traffic and exposed the bottlenecks that mattered when building the new chain. Out of that experience, by the company's account, came parallel execution of smart contracts, confirmation times below one second and a price oracle that sits directly in the protocol. An oracle is the feed through which a blockchain learns data from outside, such as prices.
Put differently, the Alpha chain was a test rig that has served its purpose. That fits a development we have described several times this year. Blast is being discontinued, Abstract Chain faced the same question in October, Mintchain also set a deadline, and at NEAR it was MyNearWallet that went rather than the chain. The reason is the same in each case: too many side chains compete for too little usage, and whoever runs one pays for every block.
Different tokens, different exits
This is where most of the mistakes happen. Two different kinds of token sit on Gravity Alpha, and they leave the chain by separate routes. What decides is how a token got there in the first place.
Only three assets come out through the official Gravity bridge: the network's own G, plus DAI and WBTC that were deposited through the standard Arbitrum gateway. For those three the canonical bridge, the exit built into the rollup, is the one that applies.
USDC, USDT and ETH or WETH do not come out there. Those three were issued on Gravity Alpha by Stargate, a service that works with liquidity pools, and not by the standard gateway. The canonical bridge does not know them and cannot process them. The Gravity documentation flags this as a hazard warning and adds a sentence worth taking seriously: no further route will be added. For these three tokens, Stargate is the only exit.
One detail that will otherwise send you down the wrong path: on Stargate, USDC is not called USDC but USDC.e. Search for "USDC" and you may not find your balance and take it for gone. The three assets appear there as USDC.e, USDT and WETH with Gravity as the source network.
The seven days of the canonical bridge
Gravity Alpha was an optimistic rollup. The name describes the procedure: the chain first assumes its settlements are correct, then leaves others a window to object. That window is called the challenge period and runs for roughly seven days on Gravity Alpha. Only after it can you collect a withdrawal on Ethereum.
The documentation therefore says to start well before 1 November so the withdrawal can complete. Do the arithmetic: start on 25 October and the standard route, with its seven-day wait, just fits inside the window. Start on 29 October and that route no longer gets you out.
One more point the help pages set out separately: withdrawals you have already submitted through the canonical bridge continue under the old procedure and cannot be sped up after the fact. A transfer already running on a seven-day clock stays on seven days, even if you hear about the faster route afterwards.
Fast Withdraw: ten minutes instead of seven days
For G there is now a second exit, and Galxe itself calls it the recommended choice. Fast Withdraw sits on the official Gravity bridge and sends G to Ethereum without the seven-day wait. The guide gives about ten minutes as the typical duration.
The process has four stations: open the bridge, connect the wallet, select Fast Withdraw, enter the amount and confirm the withdrawal in the wallet. Once the G tokens have arrived on Ethereum, set the destination to Mainnet and bridge on from Ethereum to Gravity L1. For that second step you need some ETH in the wallet, because the network fee on Ethereum is paid in ETH. That is the item holders of small G balances should price in beforehand: the fee depends on how busy Ethereum is, not on the size of your balance.
Anyone who needs G on Ethereum faster and would rather not take the official route will find a pointer in the documentation to Symbiosis, a liquidity-pool route that works in minutes. The same caution applies as with any pool service: you trade waiting time for trust in one more provider, and you usually pay a discount for it.
Staked G has to come out of staking first
This part is easy to miss and costs the most if you do. The G staking page at Galxe goes with the chain. Staked G cannot be withdrawn afterwards, because the interface for it no longer exists. Anyone with G in staking therefore needs two steps in this order: unstake first, then bridge.
Allow extra time for it. Many staking contracts have a cooldown phase in which a withdrawal is announced but not yet paid out. Check in the interface which period your stake carries before you count on the bridging time. Whether a platform states its withdrawal periods clearly is one of the points our staking comparison looks at, and this case shows why that is no side issue.
The detour via a centralised exchange
If neither the bridge nor the pool route appeals, Galxe's guide names a third way: an exchange that accepts G deposits directly from Gravity Alpha. OKX and Bitget are named there. The process consists of three stations. You send G from Gravity Alpha to your exchange account, withdraw from the exchange over the Ethereum network to your own wallet, and bridge from there to Gravity L1. Here too you need ETH for the fee on the last step.
The route has one solid advantage: you avoid the waiting period. It also has two drawbacks worth knowing in advance. The deposit address has to support the Alpha chain, and it has to still support it when you send. Exchanges often close deposits for a chain before it is switched off. So check the network selection in the deposit dialogue immediately before sending, not against a guide from the week before last. And as long as the tokens sit in the exchange account, the exchange holds the keys, not you: leave them there only as long as the move takes.
Your Galxe claim fails while G sits on the old chain
The deadline is not the only reason to act now. The contracts for Galxe Quests, meaning Loyalty Points and Token Rewards, have already moved from Gravity Alpha to Gravity L1. Anyone collecting points or rewards with a direct web3 wallet needs G on Gravity L1. The system looks there and nowhere else.
If your G is still on the Alpha chain, the claim fails. The help pages give the exact error message users then see: too few G tokens, even though the balance is visibly there. The fix is the same as above. Check in the wallet which chain your G tokens are actually on, bridge them to Gravity L1, switch the network in the wallet and try the claim again.
Galxe also names a more convenient variant called Smart Balance, which lets network fees across several networks be paid out of one balance. For the plain task of rescuing holdings before 1 November you do not need it; for regular participation in quests it takes work off your hands. If you pick up tokens through tasks like these, our airdrop overview lists the current opportunities.
December 2026 and the contradiction in the sources
For context, one point that stands out in the research and that you could stumble over if you read up yourself. The announcement and the exchange notices give 1 November 2026 as the day network operation ends. Gravity's developer documentation gives the same withdrawal date but writes alongside it that the network will be "unsettled" in December 2026, meaning no longer settled.
Do not read that as an extension. Both sources require withdrawal by 1 November, and the December reference concerns the technical wind-down of the chain, not your window. Anyone relying on December is relying on a reading that neither source offers. What binds you is 1 November, and on the standard route 25 October.
Developers and operators on chain ID 1625
For developers more than a balance hangs on the date. Galxe requires that dApps, bots and scripts running on Gravity Alpha be redeployed to Gravity L1. That includes things that run invisibly day to day: a trading bot with a hard-coded chain ID, a monitoring script, a data collector that queries the old endpoint.
Two notes from the documentation help with the move. The chain ID changes from 1625 to 127001, and the contract addresses for G and the other tokens differ between the two networks. Anyone with addresses fixed in code has to swap them, not merely redirect the endpoint. The reference pages for the old chain will remain as an archive, according to Gravity, but the endpoints themselves will not.
Staying clean on tax: what counts in Germany
A chain switch is no trivial event for tax, and the position here is less clear-cut than it should be. Private disposals of crypto assets in Germany fall under Section 23 of the Income Tax Act: after a holding period of more than a year a gain is tax free, while within the year an exemption threshold of EUR 1,000 applies to all private disposals in a year taken together. Exceed that threshold and the entire gain is taxable, not only the part above it.
What is open is how the individual routes should be classified. When the canonical bridge moves the same token across chains, there is economically no exchange but a transfer. A route over liquidity pools, by contrast, gives you units out of a pool at the destination and can thereby take on the character of a swap, and a swap is a disposal under Section 23. The tax authorities have not commented explicitly on bridging, and a binding classification is not something this text can give you.
What you can do yourself is useful regardless: record the time, the amount and the addresses involved for every step while the old chain still answers queries. After the shutdown you will reconstruct that evidence less easily, because the public endpoints disappear. For larger amounts, or for a pool route, asking a tax adviser is worth the money.
Gravity Alpha: after 1 November your balance stays where it is
The situation is manageable as long as you deal with it now. Three steps, in this order:
- Review your holdings, today. Connect your wallet to Gravity Alpha and look at what is there and in what form. G, DAI and WBTC go over the official Gravity bridge; USDC, USDT and WETH only over Stargate. If G is in staking, unstake it first. Which form of custody is the right one afterwards is shown by the comparison of hardware wallets, where the keys stay with you.
- Pick a route and start by 25 October. Fast Withdraw for G takes about ten minutes, the canonical bridge roughly seven days, Stargate works in minutes. Anyone taking the standard route starts by 25 October. If it is to run through an exchange account instead, check beforehand whether deposits from Gravity Alpha are still open there; our exchange comparison shows which houses operate under European supervision.
- Collect the records before the chain closes. Note the date, amount and addresses of every transfer and file the confirmations. After 1 November that trail is hard to reconstruct. The tools for it are in our overview of tax software and portfolio trackers.
The sources for this article are Galxe's bridging guide and the withdrawal page of the Gravity documentation, which sets out the routes per token and the waiting period in detail.
(As of October 12, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Ledger has confirmed that at least one device belonging to an affected user contained an unauthorised hardware implant. According to the manufacturer, every confirmed case traces back to a single reseller in South-East Asia. Since 11 October, users have also been reporting devices bought from European retail, and that is where the case starts to matter for you: if the sales channel is the point of attack, the brand on the box counts for less than the question of whose hands your device passed through.
What Ledger confirmed on 11 October, and what it explicitly did not
In a status report 72 hours after the incident, Ledger wrote on X that all confirmed cases of the theft disclosed on 9 October involved devices sold through the South-East Asian reseller CryptoBilis. The security publication Help Net Security documents that wording. The manufacturer also confirmed that one affected device contained an unauthorised additional circuit board.
Two things Ledger did not do. It did not explain how the implant works technically. And it did not give the number of affected devices. The company does state that its own systems and its direct sales channel were not compromised. Ledger says it is working with the relevant authorities and is contacting affected users.
That distinction is no side note. An attack on manufacturing would affect every device in a production run. An attack on one station in the distribution chain affects the devices that passed through that station. The difference decides how many people have to act, and so far the evidence points to the second case. How the incident began, we set out on 10 October in our review of the CryptoBilis case.
CryptoBilis in Indonesia, Malaysia and the Philippines: the confirmed route into the device
CryptoBilis is an authorised reseller and serves customers in Indonesia, Malaysia and the Philippines. The company had changed owner shortly before. Ledger told the retailer to stop sales and shipping; on the manufacturer's account, CryptoBilis has ceased selling hardware wallets.
The instruction Ledger then issued to all authorised retailers is the notable part: source goods only through authorised channels, and never return a returned product to the shelf. The second half describes the likely lever. A returned device, opened and resealed, looks like new stock in a shop.
A supply-chain attack does not hit the product at the manufacturer. It hits a station on the way to the buyer: warehouse, transport, returns processing, shop shelf. For buyers, that means the security of a hardware wallet does not begin when the device is first switched on.
Hardware implant under the display: microcontroller, LTE chip and e-SIM
The most detailed technical description so far comes not from the manufacturer but from Mark Karpelès, the former head of the Mt. Gox exchange. He says he bought a tampered device himself in Malaysia and has published photographs and video. They show a small circuit board under the screen, in the place that otherwise holds only a piece of padding.
On his account, that board carries a microcontroller, an antenna, an LTE module and an e-SIM. An e-SIM is a permanently fitted, digitally writable SIM card; it needs no card slot and is invisible from the outside. Karpelès describes the component reading along with whatever the screen displays, capturing the recovery phrase in the process and sending it to the attacker over the mobile network.
The recovery phrase, also known as the seed phrase, is the sequence of 24 words from which every private key in your wallet can be recomputed. Anyone who knows it no longer needs your device. That makes setup, the moment when those words appear on the display once, the most valuable moment for an attacker. Ledger has not confirmed this account of how the implant works, and it rests so far on a single investigation, if a technically documented one.
Karpelès also reports a second suspect device, obtained through a listing on Amazon Japan with stock that came from Malaysia. That too points to the trade route rather than to manufacturing.
Genuine Check passed: the real secure chip stays real, the extra board stays invisible
The most uncomfortable finding of the case concerns the very check buyers have relied on until now. The Genuine Check is the authenticity test in which Ledger's software runs a cryptographic key exchange with the secure chip inside the device and then confirms that the unit is genuine.
Karpelès says his tampered device arrived in intact shrink wrap and passed that test. The reason is obvious once you have heard it: the secure chip was real. The implant sits next to it and the check does not cover it. On his assessment, opening the device is the only reliable way to find the additional board.
There is an awkward consequence for everyday practice. A passed authenticity check is still a good sign, but it is not proof that nothing foreign sits inside the case. Anyone holding a second-hand device, or one from a channel with an unclear chain of custody, cannot rest on that signal alone. Which devices are built in what way, and where the differences lie, our hardware wallet comparison sets out.
$72 million to more than $93 million: why the damage estimates differ
There is no official damage figure. The on-chain analysts at Bitquery arrive at a suspected total of more than $93 million. Other independent assessments come out lower; the range of published estimates runs from around $72 million to more than $93 million, spread across hundreds of wallets. One analysis names $93.4 million across more than 300 addresses.
Balances on several blockchains are affected, with Bitcoin, Ethereum and Tron named. The figures diverge because of method: anyone attributing addresses to an incident has to decide which movements still belong to it. We therefore give the range and do not smooth the values into a single number.
Bitquery analysis: eight in ten drained wallets first received funds in June or later
The single finding that matters most to you is not the damage total. It sits in a time window. Bitquery traced the drained wallets back and finds that more than eight in ten first received a balance in June or later. That suggests devices bought at CryptoBilis as early as June can be affected too.
That reaches beyond Ledger's own advice. The manufacturer had told buyers from the past 90 days to move their holdings to a new device. Counting back from the incident on 9 October, that window ends in early July. The on-chain trail begins a month earlier. Anyone who bought a device through this retailer in June falls outside the manufacturer's recommendation, but not outside the data.
European retail: what the reports establish and what they do not
On 11 October a report from Europe became public. A user writing on X as @0xJohannes_ says he bought his device in a branch of an official European reseller; the channel Crypto Banter carried the case further the same day. On his description, the device held additional cables that do not appear in genuine units, and the build resembled an older variant of the implant even though the purchase was only weeks old. Karpelès, who posts on X as @MagicalTux, pointed to an antenna whose marking suggested a "Eurasian" version.
Care matters more than speed here. No balance was taken from this device. Which retail chain is meant does not emerge from the report itself. It is named only in adjacent coverage; the trade publication Crowdfund Insider writes exactly that and refrains from confirming the case itself. Ledger has not commented in detail on the European report and continues to attribute the confirmed cases to the South-East Asian retailer. Several observers regard the published images as insufficient evidence and warn against inferring broad contamination of European retail from individual cases.
Something is left for your decision all the same. There is one confirmed implant case, a documented route through the intermediate trade, and a manufacturer's instruction not to restock returns. That is enough to retrace your own purchase route once, and not enough to panic.
Bought in a shop or direct from the maker: the purchase route is the criterion for buyers in Germany
Ledger's recommendations for affected customers are clearly worded. Anyone who bought at CryptoBilis and has not yet set the device up should not initialise it. Anyone who has already set it up should move their holdings to a new device with a newly generated recovery phrase, ideally one bought directly from the manufacturer. Contact should run through the official channels, and the company explicitly recommends filing a report with the local police.
For the German market there is no confirmed case. The reports from European retail do give reason, though, to make the purchase route the criterion. Buying a device directly from the manufacturer, or from a retailer with a traceable supply chain, costs nothing but a little patience. A device from a marketplace, from a classified ad or as a return from unclear hands carries a risk that cannot be checked from the outside.
What you should not do matters as well: opening your own device to look for a board destroys the warranty and, without reference images and measuring equipment, gives you no reliable answer. The route via a new recovery phrase on a cleanly sourced device is cheaper and safer than any tinkering with the case.
MiCA custody and self-custody: who is liable when something goes wrong
This incident touches a decision many investors take once and then never revisit: self-custody or custody by a service provider. Self-custody means that you hold the private key yourself and nobody else can dispose of your assets.
The price is that there is no counterparty when something goes wrong. Anyone who loses a seed through a tampered device has no claim against a custodian. What remains is a damages claim against whoever tampered with the device, and that person is usually unknown. With a custodian authorised under the EU's MiCA regulation, the customer by contrast holds a claim against a supervised company, with duties to segregate client holdings. In exchange, that customer gives up the key. Which providers hold an EU licence, our overview of regulated crypto exchanges shows.
Both are defensible, and most investors fare better with a split than with a pure solution. What counts is knowing which part of your assets you answer for yourself if the worst happens.
Phishing after the incident: Ledger does not call and never asks for the 24 words
Every major security incident is followed by a second wave, and it reaches more people than the incident itself. Ledger explicitly warns that fraudsters are exploiting the situation and makes one point clear: the company does not call, does not send direct messages and never asks for the 24-word phrase. Any message that does precisely that is an attack, however genuine the sender and the design may look.
The same incident has already pushed fake Ledger pages into search results. How to spot them, we set out in our analysis of the fake Ledger websites. The rule behind it is short: the phrase never leaves the device, on no channel, for no support agent.
In the market the news has moved little so far. Bitcoin trades at around $82,400 on CoinGecko data, a good one percent below the previous day, and the market as a whole lost about 3.7 percent in 24 hours. The incident is grave for those affected and, for the price, a side issue so far.
Ledger implant: a new seed is the only reliable answer
If a doubt about the purchase route remains, no test on the case will settle it. Only a fresh key on a device whose origin you know. These three steps get you there:
- Establish the purchase route. Check the invoice and the retailer of your device. If it came from the manufacturer or from a retailer with a clear supply chain, nothing needs doing as things stand. If you bought second-hand or from an unclear source, assume risk. Which devices are candidates is set out in the software wallet comparison for the interim and among the hardware models.
- Generate a new recovery phrase. Set up a cleanly sourced device from scratch, write the new words down offline and move your holdings across in full. The old phrase counts as burned from that moment, even if nothing has happened. For the interim, part of it can be parked with a regulated custodian holding an EU licence.
- Follow up on your accounts. Change the credentials everywhere the old device was connected, and set up two-factor protection again. Where you hold which accounts and at what fees, the exchange comparison puts in order.
(As of October 12, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
An account on X claimed on Monday that the SHIB airdrop was back, and circulated a link for checking your own wallet. Mazrael, a long-standing member of the Shiba Inu community and an adviser to the game Shiba Eternity, called the post a scam the same day: “care. no such airdrop. this is a drainer.” Anyone holding Shiba Inu loses nothing from a click alone. The holding goes only with a signature, and that is exactly what such pages present as a harmless check.
The case: what ran across the timelines on October 12
The fake account posed as an official source and spoke of a new round of free tokens. Anyone following the shortened link landed on a page that at first asked only for the wallet to be connected. A window then opened that looked like an ordinary transaction. Mazrael wrote that such posts were flooding the timelines right now, and advised against clicking and in favour of reporting the accounts. The industry outlet U.Today picked up the episode at 11:25 UTC on October 12.
Two things are missing from the report, and both matter for the assessment. Neither the domain of the scam page nor a loss figure is named. There is therefore no documented number for victims or tokens drained, and anyone reading such a number should ask for its source. What is documented is the episode itself and the warning from someone close to the project.
The project's official point of contact is shib.io. Anything that would be a genuine project airdrop would appear there and in the channels linked from it. An offer that surfaces only on X and presses for haste is therefore suspect before any technical check.
Wallet drainers: how an approval turns into an outflow
A wallet drainer is not a virus that sneaks onto your computer. It is a contract on the blockchain that the victim itself gives permission to move its tokens. In the language of the Ethereum standards, that permission is called an approval or allowance. It is granted with the approve call, and three details are fixed in the process: which token, which recipient and which amount.
The catch lies in the amount. Many interfaces enter the highest possible value there by default, so the user does not have to sign again on every trade. An unlimited approval of that kind stays in place until someone revokes it. It covers not only today's holding but every SHIB that later arrives at the same address. The attacker does not even have to be in a hurry after that. They can wait weeks and pull the holding out once it has grown large enough.
Signature or transaction: the difference the window does not show
There are two routes to signing, and the wallet displays them with differing clarity. A transaction costs a fee and appears later in the block explorer. A pure signature under the EIP-2612 standard, known in practice as permit, costs nothing and never shows up in your own history at all. The attacker submits it and pays the fee. Anyone looking only at the transaction list therefore sees nothing unusual, even though the permission was granted long ago.
Here is how to recognise the situation: when a page promises free tokens but demands a signature granting the other side access to your holding, the direction is wrong. A genuine airdrop sends tokens to your address. It needs no permission from you, because nobody requires authorisation to send you something.
Why Shiba Inu in particular works as bait
Memecoins suit this trick especially well for two reasons. The first is the unit count. In circulation, according to CoinGecko data, are around 589.24 trillion SHIB, with total supply at 589.50 trillion. Of the original quadrillion, 41.05 percent is therefore gone, burned or permanently locked. Anyone seeing quantities like that in their portfolio easily loses the feel for the value behind them. Ten million SHIB sounds like a lot and is worth around 47.80 euros on Monday evening.
The second reason is expectation. Shiba Inu grew out of an airdrop and out of distribution campaigns, and that is precisely the story the fraudsters retell. Add to that the state of the price: after a year down 49.9 percent, the hope of free tokens is an effective lever. The longer a holding sits at a loss, the more readily its owner reaches for an offer that evens out the sum.
Shiba Inu price on October 12: $0.00000533 and $63 million in turnover
On Monday evening SHIB trades at $0.00000533, or 0.00000478 euros, according to CoinGecko. The daily range runs from $0.00000530 to $0.00000555, and the 24-hour loss comes to 2.6 percent. Over the week there is a 9.3 percent loss, over 30 days a gain of 0.6 percent, and over one year a loss of 49.9 percent. Market capitalisation stands at $3.14 billion, or 2.81 billion euros, ranking 37th. In trading, $63.1 million changed hands within a day.
SHIB is 93.8 percent short of its all-time high of $0.00008616 from October 27, 2021. For the scam, that figure is no footnote: bridging exactly that gap is what an offer of free tokens promises.
Yesterday, in this spot, we worked through Shibarium's network utilisation after the 151 percent jump. The price has moved a further 2.6 percent down since then, and the daily low of $0.00000530 sits close to the current level. The mark that still left room below it yesterday has become the day's line. Nothing has changed on the chain itself in these 24 hours that would explain the price. The pressure comes from the broad market, in which Bitcoin and Ethereum are also down over the week.
Hardware wallet or exchange: what custody changes for your SHIB
The trick works only where you sign yourself. If your SHIB sits with an exchange, no page on the internet can get you to grant an approval, because you do not hold the keys at all. In exchange you carry the custodian's risk. Since December 30, 2024, providers in the EU need authorisation under the MiCA regulation for this business, and a scam page never holds that authorisation. Deposit protection of the kind that applies to a bank account does not exist for crypto, not even with a licensed provider.
If you hold your own keys, the relationship reverses. Nobody can freeze your holding, but every signature is yours. A hardware wallet shifts that line once more: the key never leaves the device, and the operation has to be confirmed on the device. Against an approval you confirm on the device yourself, however, that does not help. It protects against theft of the key, not against your own consent. If you want to compare the devices and their differences, you will find them in our hardware wallet comparison.
A middle route that stands up well to this trick is separation by purpose. One address for day-to-day use with small amounts, a second address without any approval at all for the holding that is meant to sit still. Connect only the first to outside pages and the damage stays capped, in the worst case, at the small amount.
Revoking approvals: how to check your SHIB permissions
Revocation is the only operation that undoes an approval once granted. Technically it sets the permitted amount to zero. It costs a network fee, because it is itself a transaction, and it takes effect as soon as it is confirmed in a block.
Here is how to go about it. Open an approval checker such as revoke.cash or the corresponding page of a block explorer and enter your address. The list shows, for each token, which contract may move how much. Pay particular attention to entries with unlimited amounts and to contracts whose names you cannot place. Set each of these approvals to zero, starting with the largest position.
Two points are often overlooked. First, the list always covers one chain only. SHIB runs on Ethereum, on Shibarium and, since the start of October, in bridged form on Solana as well, and each chain keeps its own approvals. Second, a signature granted under EIP-2612 does not disappear from the list if it has not yet been submitted. If you suspect such a signature was handed out, the only remedy left is moving to a fresh address with a new key.
If you want to bring your holdings together in one place anyway, check the terms of the licensed venues first: which provider lists SHIB at all, and what a transfer there costs, decides whether the move is worth it for a holding worth tens of euros.
Stolen SHIB and the tax office: holding period, exemption limit and the loss
For investors in Germany, theft has an uncomfortable tax side. Gains from selling crypto assets fall under private disposals as set out in section 23 of the German Income Tax Act. After a holding period of one year the gain stays tax-free; below that it counts towards the rest of your income, and since 2024 the exemption limit has stood at 1,000 euros per calendar year. If that limit is exceeded, the entire gain becomes taxable, not just the part above it.
Theft, however, is not a sale. The disposal is missing, and on the line taken in the German finance ministry's guidance on crypto assets no loss arises that could be offset against gains from other private disposals. The holding is gone and the tax burden on earlier gains remains. That is why the half hour spent revoking old approvals pays off more reliably than any attempt at rescue afterwards.
The duty to keep records applies regardless. Anyone holding SHIB across several addresses and chains should keep acquisition dates cleanly, otherwise the one-year period cannot be proven in case of doubt. Tools that handle this automatically read the purchases straight from the addresses. Classifying an individual case remains a matter for your tax adviser, and this text does not replace one.
Our assessment: the bait grows as the price shrinks
From this newsroom's point of view, the timing of this trick in this particular week is no coincidence. The evidence is in plain sight: SHIB stands 93.8 percent below its 2021 high, down 49.9 percent over the year, and daily turnover of $63.1 million is thin for an asset with a $3.14 billion market capitalisation. In such an environment, a promise of free tokens meets holders who have been waiting months for a countermove. Mazrael made the same observation in his post when he spoke of a flood of such accounts.
Against that, the trick has not changed technically. Approvals as a route of attack have existed for years, and every wallet now displays warnings. Anyone going through the approval list for their addresses once a quarter removes the basis for this attack, no matter how convincing the next page looks. No statement about the further course of the price follows from this, and this section is not a recommendation to buy or sell.
SHIB security: three steps before the next approval
- Check and revoke approvals. Go through the list for every address and every chain on which you hold SHIB, and set unlimited amounts to zero. If your holding sits with a custodian anyway, check its licensing in the overview of crypto exchanges.
- Separate your holdings. Set up one address for day-to-day use and a second that is never connected to an outside page. For the second, a device that confirms the signature separately from the browser makes sense; you will find these in the hardware wallet comparison.
- Record acquisition data. Note the date, quantity and price for every purchase, so that the one-year period under section 23 of the German Income Tax Act stays provable. The suitable tools are in the comparison of crypto tax software.
(As of October 12, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
IMF chief Kristalina Georgieva says AI investment is holding global growth near 3%, with Asian chipmakers winning big, while warning of a 'slow-moving tsunami' for young workers.
The bank's Dubai branch now offers custody for Ripple's RLUSD stablecoin and plans a link with LMAX that lets institutions post it as trading collateral while the coins stay put.
Meta's new flagship beats GPT-6 Astra and Claude on memory, legal and marathon coding tests, but independent rankings still put Anthropic's Opus 5.5 on top.
REA, a free toolkit that hands AI agents the keys to reverse engineering, crossed 100,000 GitHub stars in a week as AI-decompiled game mods, console ports, and Adobe clones flood the internet.
The Nasdaq-listed company now holds about 2.59 million SOL, but its weekly purchases keep shrinking.
U.Today - IT, AI and Fintech Daily News for You Today
Multiple assets are above their long-term moving averages, which might not save the market's outlook for the future.
The U.K. High Court has delivered a pivotal ruling in the battle over 61,000 seized Bitcoin, potentially denying thousands of Chinese fraud victims access to the cryptocurrency's massive price gains.
Bitcoin is facing mounting selling pressure as the U.S. Dollar Index (DXY) surges to an 18-month high, with bearish derivatives activity and a wave of long liquidations adding to concerns about the cryptocurrency's near-term outlook.
Peter Schiff has declared Michael Saylor’s Bitcoin strategy a failure in 2026.
Cardano logs a historic 1,780,896 transactions in Epoch 660, marking its highest network usage since late 2021.
Blockonomi
TLDR
- CME Group shares slide 1.18% despite faster Globex cloud performance test results.
- Google Cloud testing delivers faster trading response times for CME Globex systems.
- Aurora Cloud Region construction advances ahead of schedule for 2027 testing.
- CME Group targets late 2027 for its livestock market migration to Aurora cloud.
- Dallas disaster recovery testing continues as CME drops interim relocation plans.
CME Group (CME) stock fell 1.18% to $277.24 on Monday, October 12, losing $3.32 despite progress on its cloud migration. The company completed initial performance testing for CME Globex on Google Cloud, achieving faster trading response times. Meanwhile, CME Group confirmed an accelerated construction schedule for its Aurora Cloud Region, supporting its planned market migration.
CME Group Inc., CME
CME Group Stock Declines Despite Cloud Trading Milestones
CME Group shares reversed earlier gains during Monday’s session as selling pressure increased throughout trading. The decline came as the company announced progress toward modernizing its global derivatives trading infrastructure. However, the announcement did not prevent the stock from ending the session lower.
CME Group completed initial performance tests for CME Globex, its electronic trading platform, using Google Cloud infrastructure. The tests achieved faster round-trip times, which measure how quickly trading systems process and return messages. Consequently, the results marked progress toward delivering ultra-low-latency trading through cloud technology.
The company also reported faster construction progress at its Aurora Cloud Region and co-location facility. Google Cloud will provide specialized infrastructure designed to support the trading requirements of CME Group’s markets. CME Group expects the Aurora facility to become available for client testing by mid-2027.
Google Cloud Migration Advances Toward 2027 Launch
CME Group Chairman and CEO Terry Duffy said the migration program continues to advance faster than initially expected. He attributed the accelerated schedule to construction progress and strong results from initial performance testing. Furthermore, the company expects its cloud infrastructure to support ultra-low-latency trading services ahead of its original schedule.
CME Group plans to move its livestock markets to the Aurora Cloud Region during late 2027. Previously, the company considered an interim relocation to Dallas before completing the transition to Aurora. However, faster construction progress eliminated that requirement and allowed CME Group to simplify its migration plans.
CME Group’s Dallas disaster recovery facility has supported client testing since June 2026. The facility remains part of the company’s broader infrastructure modernization program. Additionally, CME Group expects clients to access Google Cloud-managed services and co-location capabilities in Aurora during late 2027.
CME Group Expands Cloud Infrastructure for Global Markets
CME Group operates one of the world’s largest derivatives marketplaces, serving participants across several major asset classes. Its exchanges provide futures and options tied to interest rates, equities, currencies, cryptocurrencies, energy, agricultural commodities, and metals. The company also operates BrokerTec, EBS, and CME Clearing across its trading and clearing businesses.
CME Globex supports electronic futures and options trading, making reliable infrastructure essential to CME Group’s daily operations. The Google Cloud migration aims to combine specialized computing systems with the speed requirements of electronic markets. The transition will provide clients with managed cloud services and physical co-location options.
The latest milestones strengthen CME Group’s planned transition while establishing clearer testing and deployment targets for 2027. However, Monday’s stock decline contrasted with the operational progress outlined in the company’s announcement. CME Group will continue preparing its Aurora infrastructure as it advances the next stages of cloud migration.
The post CME Group (CME) Stock Falls as Google Cloud Migration Accelerates appeared first on Blockonomi.
TLDR
- HIMS stock drops 0.91% to $30.64 despite Hers launching across Australia nationwide.
- Hers expands into Australia with new treatments for weight loss and women’s health.
- Hims & Hers completes its Australian expansion following the Eucalyptus acquisition.
- Hers introduces round-the-clock care and personalized treatments for women nationwide.
- Australia’s growing telehealth market offers Hims & Hers new expansion opportunities.
Hims & Hers Health (HIMS) stock declined 0.91% to $30.64 on Monday, despite the company’s expansion into Australia’s women’s healthcare market. Shares lost $0.28 during regular trading before slipping another 0.13% to $30.60 in after-hours trading. Meanwhile, the company launched its Hers platform nationwide, expanding access to personalized healthcare services for Australian women.
Hims & Hers Health, Inc., HIMS
Hims & Hers Health Expands Women’s Healthcare Services Across Australia
Hims & Hers announced the official launch of Hers in Australia on October 12, expanding its international healthcare operations. The platform offers treatments covering weight management, hair regrowth, menopause, and perimenopause through digital consultations. Women can access healthcare professionals, medication support, and a dedicated care team available around the clock.
The expansion follows the company’s acquisition of Eucalyptus earlier this year, strengthening its position in Australia’s digital healthcare sector. Under the transition, Eucalyptus’ existing women’s healthcare platform, Juniper, will operate under the Hers brand. Meanwhile, the earlier rebranding of Pilot to Hims in August completed the company’s broader Australian platform rollout.
The company introduced specialized weight management programs that combine medical treatment with nutritional guidance and fitness support. Furthermore, Hers provides hair regrowth treatments and services addressing hormonal health concerns throughout different life stages. The platform also allows patients to request female practitioners and access a community exceeding 27,000 women.
Hers Targets Healthcare Access Gaps With Digital Treatment Programs
Hers plans to address healthcare access challenges affecting women across Australia’s metropolitan and regional communities. According to company research, 52% of surveyed Australian women reported experiencing weight-related judgment from healthcare professionals. Among those respondents, 72% subsequently avoided seeking clinical assistance, highlighting barriers to routine treatment.
The company also identified healthcare costs and geographic limitations as obstacles to accessing specialized medical services. Nearly 30% of Australians live in regional and rural communities, where specialist appointments can require extended waiting periods. Hers aims to connect patients with medical professionals through remote consultations and continuous digital support.
Rebecca Holdt, the company’s international product vice president, emphasized digital healthcare’s role in improving nationwide access to treatment. Meanwhile, Australian Chief Medical Officer Matt Vickers highlighted the need for evidence-based services addressing women’s broader healthcare requirements. Existing Juniper patients will retain their Australian practitioners while gaining access to additional treatment options.
Australia Expansion Strengthens Hims & Hers International Operations
The Australian launch extends Hims & Hers’ existing international presence across North America and Europe. Furthermore, the company enters a growing telehealth market with increasing demand for accessible digital healthcare services. Industry projections cited by the company estimate Australia’s telehealth market could reach $2.56 billion by 2034.
Gus Wood will oversee Australian operations as general manager, supported by Chief Medical Officer Matt Vickers. Hers Chief Medical Officer Jessica Shepherd will provide clinical oversight to maintain the company’s international healthcare standards. The leadership structure combines local medical expertise with the company’s wider technology and treatment infrastructure.
Despite the expansion, Hims & Hers Health stock ended Monday’s session lower, extending its losses into after-hours trading. The company’s latest rollout broadens its healthcare offerings beyond existing services and establishes a unified brand across Australia. However, Monday’s stock decline contrasted with the company’s continued expansion into international digital healthcare markets.
The post Hims & Hers Health (HIMS) Stock: Slides Despite Major Australia Expansion appeared first on Blockonomi.
TLDR
- IREN stock closes at $34.80 as Anthropic partnership reports drive market interest.
- Anthropic reportedly signed a multiyear cloud agreement with IREN Limited.
- IREN’s undisclosed AI customer could be Anthropic, according to new reports.
- IREN shares gain 0.86% after hours despite Monday’s 1.11% closing decline.
- Legacy data center concerns challenge IREN’s expanding AI cloud ambitions.
IREN Limited stock closed Monday at $34.80, down 1.11%, before recovering 0.86% to $35.10 in after-hours trading. The movement followed reports linking the company to an undisclosed multiyear cloud agreement with Anthropic. The development renewed market interest in IREN’s expanding artificial intelligence infrastructure business.
IREN Limited, IREN
The stock had gained approximately 8% in overnight trading on Sunday following speculation about the partnership. Monday’s regular session erased those early gains as shares finished below the previous closing level. The reported agreement could strengthen IREN’s position in the growing market for high-performance computing infrastructure.
IREN Limited Stock Gains Attention Over Anthropic Cloud Agreement
The Information reported that Anthropic maintains an unannounced multiyear cloud agreement with IREN, citing people familiar with the arrangement. The report examined Anthropic’s efforts to expand data center capacity and meet growing computing requirements. Neither company has publicly confirmed the partnership or disclosed its financial terms.
The report also connected Anthropic’s infrastructure expansion to several companies with backgrounds in Bitcoin mining. These included Hut 8, TeraWulf, IREN, and Nscale, which provide computing infrastructure and access to large power resources. Such providers can help technology companies expand capacity without developing every facility independently.
Anthropic’s reported relationship with IREN would support the company’s transition from cryptocurrency mining toward artificial intelligence cloud services. Growing demand for advanced computing infrastructure continues to create opportunities for specialized data center operators. A confirmed agreement would add another prominent customer to IREN’s expanding business network.
IREN’s Earlier Customer Disclosure Strengthens Anthropic Speculation
In August, IREN disclosed several multiyear cloud agreements during its fiscal fourth-quarter earnings call. CEO Daniel Roberts identified customers including Cohere, Prometheus, Perplexity, Figure AI, Fal AI, and Higgsfield AI. He also mentioned a separate agreement with a leading frontier artificial intelligence laboratory without naming the organization.
The earlier disclosure created a connection between IREN’s existing contracts and the latest Anthropic report. IREN has not established whether Anthropic represents that previously unnamed customer or a separate agreement. The reported partnership therefore remains an unconfirmed development rather than a newly announced company contract.
IREN has expanded its infrastructure business through agreements with technology companies seeking additional computing capacity. Its broader customer network and existing facilities support its move into specialized cloud services. The company also faces competition from CoreWeave, Nebius, and other operators expanding their artificial intelligence infrastructure businesses.
IREN Stock Faces Data Center Concerns Despite Bullish Sentiment
IREN has faced criticism concerning the operational quality of its older data centers in British Columbia. Research firm SemiAnalysis recently highlighted reported customer complaints involving facilities in Prince George and Mackenzie. These concerns introduced additional scrutiny of IREN’s infrastructure as the company expands its artificial intelligence operations.
Despite those concerns, retail sentiment strengthened following reports connecting IREN with Anthropic. The stock reached the top of Stocktwits’ trending list as traders discussed the possible partnership. Some market participants anticipated further gains, while others questioned the lack of official confirmation.
IREN shares have also struggled against several competing cloud infrastructure stocks during 2026. The company entered Monday’s session with a year-to-date decline of approximately 7%, according to the earlier market report. The Anthropic speculation lifted trading interest, Monday’s lower close showed that the initial rally had faded.
The post IREN Limited (IREN) Stock: Eyes Big Gains on Anthropic Deal Buzz appeared first on Blockonomi.
TLDR
- Navitas (NVTS) stock rebounds 6.21% after hours following a 7.33% daily decline.
- Navitas and NVIDIA introduce a 24 kW power board for next-generation AI data centers.
- The new power delivery board targets 97% efficiency to reduce AI energy losses.
- Navitas’ 800 V-to-12 V technology simplifies power conversion for advanced GPUs.
- Navitas plans to showcase its latest NVIDIA-linked power technology at OCP Summit.
Navitas Semiconductor Corporation (NVTS) stock fell 7.33% to $9.99 at Monday’s close before rebounding 6.21% to $10.61 after hours. The recovery followed developments surrounding its latest AI data center power technology, developed alongside NVIDIA. The company introduced a 24 kW power delivery board designed to improve efficiency across next-generation computing infrastructure.
Navitas Semiconductor Corp, NVTS
Navitas Expands NVIDIA Collaboration With New Power Technology
Navitas Semiconductor announced its latest 800 V-to-12 V power delivery board for NVIDIA’s MGX ecosystem. The technology uses GaNFast components to support advanced power systems across high-performance AI data centers. Furthermore, the development expands Navitas’ existing portfolio of power solutions for demanding computing applications.
The new board delivers 24 kW while targeting 97% efficiency under full operating loads. It also achieves power density exceeding 2,000 watts per cubic inch, supporting increasingly demanding AI hardware. Consequently, the system delivers substantial power within a compact design suited for modern computing infrastructure.
Navitas developed the board using NVIDIA’s latest 400 mm by 60 mm form factor. This configuration allows manufacturers to position power components closer to processors and reduce transmission losses. Additionally, the design supports higher computing demands without requiring larger power delivery systems.
New Architecture Targets AI Data Center Efficiency
The technology converts 800 VDC directly into 12 VDC through a single-stage power architecture. This approach removes an intermediate conversion stage commonly found in existing power delivery systems. As a result, operators can reduce energy losses, hardware requirements, and overall system complexity.
The board incorporates 16 NV6034 GaNFast transistors within its primary power conversion architecture. These components use a stacked half-bridge configuration and Navitas’ latest dual-cooled semiconductor packaging. Together, these features support efficient power delivery and improve thermal management during demanding computing operations.
Navitas previously introduced a 20 kW power board that converts 800 VDC into 6 VDC. The latest development extends that earlier collaboration with NVIDIA and introduces another option for system designers. Meanwhile, both solutions support the industry’s transition toward higher-voltage power infrastructure for AI computing.
Navitas Semiconductor Advances Its AI Infrastructure Strategy
The latest announcement supports Navitas’ broader transformation strategy, which focuses on advanced power semiconductor technologies. Through this initiative, the company aims to replace traditional silicon components with gallium nitride and silicon carbide alternatives. These materials support higher efficiency and greater power density across demanding electrical applications.
Navitas President and CEO Chris Allexandre identified efficient power delivery as an important requirement for expanding AI infrastructure. He also emphasized the company’s work with NVIDIA to simplify power conversion between electrical systems and GPUs. The new technology addresses growing energy requirements across increasingly powerful computing platforms.
Navitas plans to display the new board at the NVIDIA AI Factory MGX Wall during OCP Global Summit 2026. The presentation will highlight its latest power delivery capabilities within NVIDIA’s expanding computing ecosystem. Meanwhile, the stock’s after-hours rebound followed a difficult regular session as the company advanced its AI infrastructure strategy.
The post Navitas Semiconductor Corporation (NVTS) Stock: Rebounds as NVIDIA Unveils New AI Power Tech appeared first on Blockonomi.
TLDR
- Intel Corporation (INTC) stock drops 3.20% to $101.35 despite new AI GPU plans.
- Intel unveils GPU D-series with up to 480GB memory for large AI inference tasks.
- New Xeon 6+ rack designs support over 46,000 cores for enterprise AI workloads.
- Intel’s GPU D-series delivers 1.3 petaflops of compute within a 350-watt limit.
- Intel expands open AI infrastructure with new GPU designs and software upgrades.
Intel Corporation (INTC) stock fell 3.20% to $101.35 at Monday’s close before recovering 0.22% to $101.57 in after-hours trading. The decline came as Intel revealed new GPU specifications and Xeon server designs at the Open Compute Project Global Summit. The announcements highlighted Intel’s efforts to expand its data center business through efficient artificial intelligence infrastructure.
Intel Corp., INTC
Intel Unveils GPU D-Series for Large AI Workloads
Intel introduced further technical details for its GPU D-series, previously known as Crescent Island, during the OCP Global Summit. The new processor uses Intel’s Xe3P architecture and targets memory-intensive AI inference across enterprise data centers. Meanwhile, the company aims to improve processing efficiency while reducing infrastructure costs and power consumption.
The GPU architecture supports up to 480GB of LPDDR5X memory and delivers 1.5TB/s of memory bandwidth. Additionally, the design provides 1.3 petaflops of FP8 computing performance within a 350-watt power limit. These specifications support large language models, long-context processing, and multiple inference workloads running simultaneously.
Intel said a single GPU can support models containing up to 300 billion parameters. Furthermore, an eight-GPU configuration can handle models exceeding one trillion parameters. Customer sampling has started, while Intel continues collaborating with hardware manufacturers and software providers on deployment solutions.
Intel Expands Xeon Server Capacity for Agentic AI
Intel also presented new Xeon-based rack designs that support growing computing requirements across enterprise AI systems. The designs use open infrastructure standards, including Open Rack v3, to simplify integration into existing data centers. Consequently, organizations can expand processing capacity without completely replacing their current infrastructure.
Select Xeon 6+ configurations deliver more than 46,000 processor cores per rack. These systems operate at 133.45 kilowatts of total rack power while supporting high-density computing operations. Intel designed the configurations to handle data processing, workload coordination, and communication between specialized accelerators.
Agentic AI systems require processors to manage several connected tasks rather than complete isolated requests. Therefore, Intel positions Xeon processors alongside GPUs to handle workflow management and data movement. This approach supports concurrent AI applications while improving resource allocation across enterprise computing environments.
Intel Strengthens Open Software and Infrastructure Development
Intel outlined additional software improvements that support applications across its CPU and GPU product lines. The company continues integrating established AI frameworks, inference tools, and open development environments into its platforms. These efforts aim to simplify application deployment and reduce software compatibility barriers.
Intel also highlighted its contributions to the Open Compute Project, including standardized accelerator card designs. Since 2011, the company has submitted 116 contributions supporting open data center infrastructure. Its latest work focuses on improving hardware compatibility and giving system manufacturers greater design flexibility.
The announcements extend Intel’s strategy of combining general-purpose processors, specialized accelerators, and interoperable software. Meanwhile, the company plans further technical presentations during the OCP Summit on October 13. Its expanding hardware portfolio targets enterprise demand for scalable AI processing and more efficient data center operations.
The post Intel Corporation (INTC) Stock: Slides as New AI GPU Details Emerge appeared first on Blockonomi.
CryptoPotato
XRP spot trading activity has plunged sharply in recent weeks, even as futures trading takes on a larger role. Data compiled by CryptoQuant shows that combined spot volume across centralized exchanges fell by $1.943 billion between August 26 and October 11.
Binance accounted for $429 million of that decline, after its seven-day average spot volume dropped from $597 million to $168 million.
Spot Trading Takes a Hit
Other centralized exchanges saw a much larger fall. Their combined volume fell from $2 billion to $485.8 million, a reduction of $1.514 billion. This decline was 3.53 times greater than the drop recorded on Binance. The weakness is also visible in Binance’s spot-to-futures volume ratio. The metric compares spot trading volume with futures activity. It fell from 31% on September 26 to just 12.7% on October 11.
At current levels, futures volume is roughly 7.9 times spot volume. Fifteen days earlier, it was about 3.2 times higher. The ratio is currently approaching its August 16 low of 11%. At that time, XRP was trading below $0.99. The token now trades around $1.40, but the recovery hasn’t brought a similar increase in spot trading activity.
CryptoQuant explained that traders may be staying on the sidelines while waiting for lower entry prices. Interestingly, a similar pattern appeared in mid-August, when spot participation weakened relative to futures trading. XRP later staged a sharp price rebound that month.
A possible turning point for the crypto asset could come from Evernorth, which is set to begin trading on Nasdaq under the ticker XRPN on October 12th. The company completed its business combination with Armada Acquisition Corp. II last week, following a fundraising round that brought in more than $1 billion through the deal and related private placements. It also has around $300 million in gross cash proceeds.
Evernorth said that it plans to do more than simply hold XRP. It is gearing up to invest in institutional yield strategies, on-chain credit, infrastructure, as well as other projects across the XRP ecosystem.
ETFs Keep the Green Streak Alive
US-listed spot XRP ETFs continued to attract money last week and stood out while much of the crypto market struggled. The funds recorded $11.31 million in net inflows, even as three of the five trading days showed no reportable activity. Inflows came on October 6, when the ETFs brought in $3.14 million. On October 8, another $8.17 million came in. The figures pushed cumulative net inflows to a fresh record of $1.8 billion.
Additionally, XRP ETFs have now posted positive weekly flows for 13 consecutive weeks. The streak began in mid-July, with inflows exceeding $300 million since then.
The post XRP’s Rally Faces a Reality Check as Spot Trading Activity Dries Up appeared first on CryptoPotato.
BitMine said on Monday it bought 12,532 Ethereum in the week to October 11, its third small weekly purchase in a row, taking the treasury to 6,028,946 ETH, or 4.9% of the 122.1 million ETH in supply.
The purchase followed the 15,112 ETH BitMine added in the week to October 4, and the company bought 17,362 ETH the week before that.
BitMine Is Done Stacking
The company marked its ETH at $2,544 per token, using Coinbase prices. At those levels, its crypto, cash, and equity stakes total $16.2 billion. Cash and marketable securities came to $612 million, down from $643 million a week earlier. BitMine’s release gives no reason for the cash decline.
BitMine reported 5,067,309 ETH staked, or 84% of its ether. Chairman Tom Lee projected $336 million a year in revenue from that staked ether, based on a 2.61% seven-day yield. He said that would rise to $400 million once all of the company’s ether is staked.
Lee said in May that BitMine had slowed its ETH accumulation to reach the 5% target in late 2026 instead of mid-July. He returned to that target in a video message whose transcript BitMine filed with the SEC on October 7. In that message, Lee said BitMine built its position in 15 months, during a bear market.
“So we need to get about 100,000 more ETH, and that’s about it,” Lee said. He then said BitMine is done stacking while a bull market starts.
Monday’s release still says BitMine has bought ETH every week since its treasury strategy began on June 30, 2025. The same release, in its note on forward-looking statements, cites a management statement that the company is largely finished buying ETH.
Buyback Ended on August 17
In that same message, Lee said that BitMine started buying back its own shares on July 14, when the company repurchased 21 million shares for $350 million and completed the program on August 17. None of the weekly updates BitMine has filed since then report a repurchase.
BitMine also raised money this year through its 9.5% perpetual preferred stock, which trades as BMNP. BitMine had planned the preferred stock offering to fund more Ethereum buying, among other uses. It sold 3.5 million shares at $80 each on June 10. Those preferred shares last closed at $99.53, and Lee put their current yield at 9.56%.
The post BitMine’s Weekly ETH Buys Shrink to 12,532 as Tom Lee Says Stacking Is Done appeared first on CryptoPotato.
The Smarter Web Company has raised £10 million ($13.2 million) in the initial public offering (IPO) of its new preferred shares, which start trading on the London Stock Exchange’s Main Market under the ticker MORE at 8:00 a.m. on Wednesday, October 14.
That is £5 million ($6.6 million) below the bottom range in the company’s prospectus, a shortfall the CEO has acknowledged.
Retail Investors Supplied Most of the Money
According to Monday’s announcement, the institutional offer brought in £2.4 million, or just over $3.1 million, and the retail offer £7.6 million ($10 million), roughly 75% of the total as noted by CEO Andrew Webley. Net proceeds after expenses come to about £8.3 million, which is nearly $11 million at current rates.
“I know £10 million is at a lower range of what we were targeting, and I won’t pretend otherwise,” Webley wrote on X.
As the executive described it, institutional demand was “disappointing” because several investors the company expected to take part decided against it, though many want to see how the shares trade and could join as the issue grows.
UK financial promotion rules limited what the company could communicate during the offer, the CEO added, and traditional media coverage was thin. Even so, the raise cleared the £10 million minimum set for the IPO to go ahead.
In the announcement, he called the listing “a proud moment for Smarter Web” and said the company believes MORE will pay the first weekly dividend by a London-listed commercial firm. On X, he described MORE as the first preferred share from a Bitcoin treasury company on a main market outside the US.
The company will issue 111,112 preferred shares at £90 each ($119), with another 100,000 going into an at-the-market facility that sells new shares gradually, held by or on behalf of Tennyson Capital.
Preferred holders have no vote at shareholder meetings but receive a cumulative, variable weekly dividend starting at 12% a year on £100 ($132), meaning missed payments carry forward and the board can adjust the rate within limits set in the prospectus. The first payment is £0.2301 per share, translating to $0.30, payable by November 9 at the latest to holders on the October 23 record date.
Because the total landed below £15 million, the company intends to apply net proceeds in the priority order set out in the prospectus. About £3.85 million (just over $5 million) covers working capital and general costs, including cash reserves for dividends, while £4 million goes toward more Bitcoin and £500,000, or $661,000, to the operating business.
What the CEO Said Treasury Companies Risk
As CryptoPotato reported earlier this month, the Smarter Web CEO told Bitcoin advocate Stephen Livera that treasury companies amplify BTC’s price swings, which investors welcome on the way up and dislike on the way down.
Management is the other risk, because capital structure choices that let a firm grow faster could come at shareholders’ expense, while the cryptocurrency itself “has no management.”
Smarter Web began as a public company in April 2025 with a £2.1 million fundraise, and Webley says it has since become the UK’s largest public Bitcoin treasury company, holding a 2,747 BTC stash worth around $229 million, and ranks 29th in the global top 30.
The post UK Bitcoin Treasury Firm Smarter Web Closes £10M Share Offering appeared first on CryptoPotato.
Crypto analyst Doctor Profit expects the world’s largest crypto asset to resume its upward move soon, even though BTC failed to overcome $84,000 on Monday morning.
He has a new price target of $94,000.
New Bullish Forecast
In the latest Sunday report, the analyst said the recent market correction could set the stage for the next leg of the bull market. Doctor Profit believes Bitcoin has moved past the correction phase and is now preparing for another rally. He previously expected the asset to reach $88,000 after breaking above $82,500. BTC later reached that target before pulling back to around $80,300.
The analyst now expects it to regain momentum and climb toward $94,000. However, he said the price must first recover the $86,000 to $89,000 region. This area will be important in determining whether the market can support another move higher. Buying demand is also expected to strengthen around $86,000. He believes this zone could turn into support instead of facing the selling pressure seen during the previous rally.
A similar bullish outlook came from crypto analyst Crypto Patel, who projected a potential path toward $100,000. He said Bitcoin had broken above the $67,000 resistance level and could retest it before moving higher. If buyers defend this zone, BTC could form a higher low and gain momentum for another rally.
Meanwhile, $82,800 was flagged as immediate structural support, while $59,809 remains a major downside level.
New analysis by xWIN, meanwhile, revealed that Bitcoin may be showing signs of a potential bottom in October. Several factors have weighed on prices, such as high US bond yields, rising oil costs, and profit-taking. However, conditions now appear to be improving.
Weak Institutional Demand
ETF outflows remain a risk to the recovery outlook. US-based spot Bitcoin ETFs had their worst week of outflows since late June. The investment vehicles saw nearly $90 million leave on Monday, followed by a brief recovery on Tuesday with $118.86 million in inflows. Selling picked up again on Wednesday and Thursday, when investors withdrew a total of over $731 million. Friday brought a small return of $21.13 million, but it did little to offset the earlier losses.
Overall, weekly outflows reached $681.1 million, amid weaker investor demand.
The post Bitcoin Could Rally to $94K, but First It Must Break Through This Key Price Zone appeared first on CryptoPotato.
Transaction fees averaged just 0.64% of Bitcoin miner revenue in the last 30 days, according to analyst Axel Adler Jr.
And with BTC oscillating between $83,000 and $84,000, miners’ finances depend mostly on the asset’s price and the electricity their machines burn, since fees add almost nothing.
Almost All Miner Revenue Still Comes From Newly Issued Coins
In dollar terms, fees brought in an average of 64 cents out of every $100 of daily miner revenue, and newly issued BTC supplied the rest. A week earlier, the 30-day average was 0.65, a change Adler described as small, though the indicator has stayed below 1% since mid-August 2025.
Bitcoin has climbed from $59,000 to $84,000, and the analyst credits that rise for most of the improvement in miners’ conditions. The fee share is the figure to watch: a sustained return above 1% would show fees contributing more to revenue and point to greater network activity.
At an electricity price of $0.05 per kilowatt-hour, the report compared two Bitmain machines. Mining one BTC with an Antminer S19 costs $86,700 in electricity alone, more than the asset is worth even after the price recovery. An S21 needs about $44,300 of power per BTC, leaving more room for equipment, maintenance and other expenses.
Fees at this level do not confirm that miners are shutting down machines or selling reserves, Adler added, since each operator’s position depends on its hardware, power rate and other expenses. The electricity figure also omits equipment purchases and cooling costs, so the full cost of mining a coin is higher.
Bitcoin’s Price Decides How Much Cushion Miners Have
Further price gains would narrow the S19 shortfall and widen the S21 cushion, according to the report, while a decline would cut revenue for both models. CoinGecko data put BTC near $83,000 at the time of writing, up 8% across the last 30 days. However, the seven-day change is more than a 3% decline, and the price is sitting 25% lower than a year ago and nearly 34% below its all-time high of over $126,000.
As CryptoPotato reported earlier today, the September Consumer Price Index report, a gauge of inflation, is due Wednesday, October 14, with producer prices and retail sales following on Thursday. A hotter-than-expected reading could add pressure on BTC, which has not regained most of the losses from last Thursday’s crash.
Miners have also been looking beyond Bitcoin for income. MARA posted a $611.3 million net loss for the second quarter in August, and several public miners sold more than 32,000 BTC in the first quarter of 2026 and put the proceeds into AI contracts worth an estimated $70 billion industry-wide.
The post Bitcoin Miner Fees Fall to Just 0.64% of Revenue, Analyst Says appeared first on CryptoPotato.