Cryptocurrency Posts
Crypto Briefing
India's data center market is set for exponential growth, driven by AI adoption, with major players like Adani and Reliance leading expansion.
The post CoreWeave enters India with first data centers through Adani Group partnership appeared first on Crypto Briefing.
Tokenized trading on bStocks enhances market accessibility but raises concerns about price alignment and interconnected financial risks.
The post StablecoinX shares go tokenized on Binance’s bStocks platform appeared first on Crypto Briefing.
The Surface Laptop Ultra's local AI processing could redefine data privacy and cost efficiency, influencing future laptop designs and market dynamics.
The post Microsoft and Nvidia unveil Surface Laptop Ultra with Grace Blackwell chip at San Francisco event appeared first on Crypto Briefing.
Meta's Muse app's rapid rise highlights the challenge of sustaining user engagement, crucial for leveraging AI investments and monetization strategies.
The post Meta’s Muse hits No. 1 on the App Store, but daily habits are harder to win appeared first on Crypto Briefing.
The incident underscores the persistent security vulnerabilities in crypto trading, highlighting the need for enhanced protective measures and vigilance.
The post Crypto trader Frogman hacked for over $4 million during TOKEN2049 appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Crypto Card Payments Hit Record $12.5 Billion as Stablecoin Adoption Surges
Payment volume processed on crypto cards has climbed to a record $12.5 billion, up 140% year-to-date, according to data from paymentscan.xyz, first shared by The Kobeissi Letter.
The figure is also 247% higher than levels recorded in October 2025.
The surge is being driven by growing use of stablecoins as a payment rail and a broader push for cheaper, faster cross-border transactions, The Kobeissi Letter said.
QR-code payments are another bright spot: demand for QR-based spending helped push activated cards on Jupiter Spend, one of the largest on-chain card providers, up 55% quarter-over-quarter.
“Crypto cards are the next phase of crypto adoption,” The Kobeissi Letter said.
The figures come as major players move into the space of crypto cards. Fold Holdings (NASDAQ: FLD) announced earlier this year that it had started issuing its Fold Bitcoin Credit Card to select waitlist members, with wider access rolling out in batches over the coming weeks and months.
The card runs on the Visa network, is powered by Stripe Issuing and is accepted at 175 million merchants. It offers a base rate of 1.5% back in bitcoin, rising to as much as 4% through behavior-based boosts and partner offers. Cardholders who pay their bill in bitcoin earn an extra 0.5% back.
Aven has taken a different approach. Its Aven Bitcoin Visa Card, unveiled at the Bitcoin Conference 2026 in Las Vegas, lets holders borrow up to $1 million against their bitcoin without selling it, with rates starting at 7.99% APR and repayment terms of up to 10 years.
Collateral is held by BitGo, while Coastal Community Bank issues the card.
This post Crypto Card Payments Hit Record $12.5 Billion as Stablecoin Adoption Surges first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
$350M St Cloud CEO: The First Credit Union to Put Bitcoin on Core Ledger | Jed Meyer
A credit union founded by postal workers in 1930 is now custodying real Bitcoin for its members. St. Cloud Financial Credit Union CEO Jed Meyer explains how its patent-pending hybrid custody model gives each member individual Bitcoin ownership in a multisig vault. He also covers how the credit union has grown to more than 20 BTC under custody without even trying.
Chapters:
00:00 St. Cloud Financial Credit Union’s Path to Bitcoin
01:08 Stablecoins, Dollars, and Bitcoin as New Money Networks
02:26 Bitcoin ETF vs. Credit Union Custody: The Hybrid Custody Model
03:18 Bringing Main Street Into Bitcoin With Direct Buy and Sell
04:45 Minnesota Custody Law, NCUA Exams, and the CLARITY Act
07:32 20+ Bitcoin in Member Vaults and Lightning Plans
09:38 What It Takes for a Credit Union to Own Bitcoin
10:57 The Cloud Dollar Stablecoin and the Cooperative Ownership Model
12:59 How Credit Unions Decide Which Digital Assets to Offer
14:10 Educating Skeptics and Why Credit Unions Must Own Their Rails
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post $350M St Cloud CEO: The First Credit Union to Put Bitcoin on Core Ledger | Jed Meyer first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Housingwire’s Logan Mohtashami: Real Estate vs Bitcoin & Bond Market Outlook
Mortgage rates just hit their highest level in nearly three years, and homebuyers are already pulling back. HousingWire Lead Analyst Logan Mohtashami explains why the 10-year Treasury yield keeps climbing since talks with Iran broke down, and why the Federal Reserve has turned hawkish. He also explains how mortgage spreads are keeping 30-year rates from climbing above 8%.
Chapters:
00:00 30-Year Mortgage Rates Hit 7.28%, Highest in Nearly Three Years
00:52 Iran Talks, the Fed, and Why the 10-Year Yield Keeps Rising
01:58 Mortgage Spreads Explained: Why Rates Aren’t Above 8.6%
03:28 What It Would Take to Get Meaningful Home Price Cuts
04:43 Homebuilders, Profit Margins, and Mortgage Rate Buydowns
06:17 Why Today’s Housing Market Isn’t 2008
08:13 Bitcoin vs. Real Estate: Competing for Monetary Premium?
09:52 Borrowing Against Bitcoin for a Home Down Payment
10:52 Grant Cardone’s Bitcoin and Real Estate Model
13:15 2027 Outlook for Mortgage Rates, Home Prices, and Affordability
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Housingwire’s Logan Mohtashami: Real Estate vs Bitcoin & Bond Market Outlook first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Leon Wankum: BTC Taking on Real Estate’s $300T Monetary Premium
For generations, property has been the default place to store wealth, but Leon Wankum says that run is over. The author of Digital Real Estate, published by Bitcoin Magazine Books, explains how fiat debasement since 1971 inflated a monetary premium in real estate. He argues Bitcoin, as absolutely scarce money, is now pulling that premium away. He also explains why both residential and commercial real estate will feel the shift.
“Digital Real Estate is required reading for anyone who owns property and hasn’t yet considered how Bitcoin is set to disrupt the real estate market.” 
Buy Leon Wankum’s ‘Digital Real Estate’ now in the Bitcoin Magazine bookstore 

https://store.bitcoinmagazine.com/collections/books/products/digital-real-estate
Chapters:
00:00 Leon Wankum’s “Digital Real Estate” Thesis
00:35 Why Real Estate’s Run Since 1971 Is Over
01:39 The Monetary Premium in Residential and Commercial Real Estate
03:58 Saving in Bitcoin vs. Spending It on a Home
05:57 Bitcoin as Collateral: Borrowing vs. Renting and Stacking
08:19 Why the Housing Crisis Is a Crisis of Ownership
09:56 Pricing Real Estate in Bitcoin
10:57 Homeowners, Banks, and Bitcoin-Backed Mortgages
14:14 Bitcoin Mining and Treasury Strategies for Real Estate Developers
16:04 Why Grant Cardone’s Bitcoin Real Estate Funds Could Lead
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Leon Wankum: BTC Taking on Real Estate’s $300T Monetary Premium first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
StoneX’s Mark Palmer: $435 MSTR Price Target Explained – DAT Consolidation Outlook
Strategy just spent six times more buying back Stretch than buying Bitcoin. Is that the right move for MSTR shareholders? StoneX Senior Equity Research Analyst Mark Palmer explains why STRC is foundational to Strategy’s fundraising, and how the $4.9B USD Reserve is pushing the preferred stock back toward par. He also explains why Strategy won’t simply raise the dividend rate.
Chapters:
00:00 StoneX Analyst Mark Palmer on Strategy (MSTR)
00:12 Stretch Buybacks vs. Buying Bitcoin: $176M vs. $29M
01:00 The $4.9B USD Reserve and Stretch’s Path Back to Par
01:56 Why Strategy Won’t Raise the Stretch Dividend Rate
04:17 Daily Dividends and Ex-Dividend Date Volatility
06:53 June’s Stretch Sell-Off and Institutional Investors
07:21 Where Bitcoin Treasury Balance Sheet Stress Shows Up First
09:21 Perpetual Preferreds vs. Convertible Notes: Strive’s Approach
11:54 USD Cash, Convert Paydowns, and Metaplanet’s U.S. Push
13:09 Why StoneX Cut Its MSTR Price Target to $435
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post StoneX’s Mark Palmer: $435 MSTR Price Target Explained – DAT Consolidation Outlook first appeared on Bitcoin Magazine and is written by Patrick Green.
CryptoSlate
S&P Global is bringing ratings-style risk assessments to crypto lending vaults as the fast-growing market confronts fresh security failures.
The ratings firm launched its Vault Risk Assessment framework on Oct. 4, creating a standardized approach for comparing the likelihood that investors suffer impairment in lending vaults. Deposits in the products reached about $10 billion in September, up from $1.5 billion two years earlier, according to S&P.
The launch came the same day blockchain security firm CertiK flagged suspicious movements involving an unnamed vault on Coinbase-backed Base network.
According to the blockchain security firm, the newly deployed proxy borrowed about 1,783 aBaswstETH, worth roughly $6 million, from the vault before redeeming the tokens through Aave for around 1,783 wstETH.
The incident did not exploit Aave itself. Instead, it highlighted a problem that grows more relevant as vaults become more popular: investors can be exposed to risks introduced by the contracts, permissions, and managers between their deposits and the underlying lending protocols.
That distinction sits at the heart of S&P's new framework. Vaults pool investor assets and allocate them according to predefined strategies, with those decisions either automated through smart contracts or overseen by human managers known as curators. Investors receive tokens representing claims on the pooled assets and returns.
Vault growth brings new layers of risk
S&P's framework evaluates six areas: portfolio credit quality, liquidity mismatch, curator risk, blockchain risk, protocol risk, and vault security and governance.
The assessment is designed to move beyond the point-in-time transparency provided by blockchain transactions and examine how a vault could behave as conditions change.
That becomes more important as vaults increasingly resemble onchain versions of managed investment products. S&P said the structures can replicate functions associated with money-market, private-credit, private-equity and hedge funds, while allowing pooled capital to operate directly on blockchains.
The added flexibility also introduces additional failure points. A depositor may ultimately have exposure to a large lending protocol, but losses can still emerge from a curator's allocation decisions, weak withdrawal liquidity, changes to smart-contract permissions or vulnerabilities in the vault itself.
S&P's grades use a “(v)” suffix, with AAA(v) representing the lowest relative risk category. They are not credit ratings, do not assess expected yields and do not guarantee that investors will recover their capital. The agency describes them instead as forward-looking opinions about the relative risk of impairment.
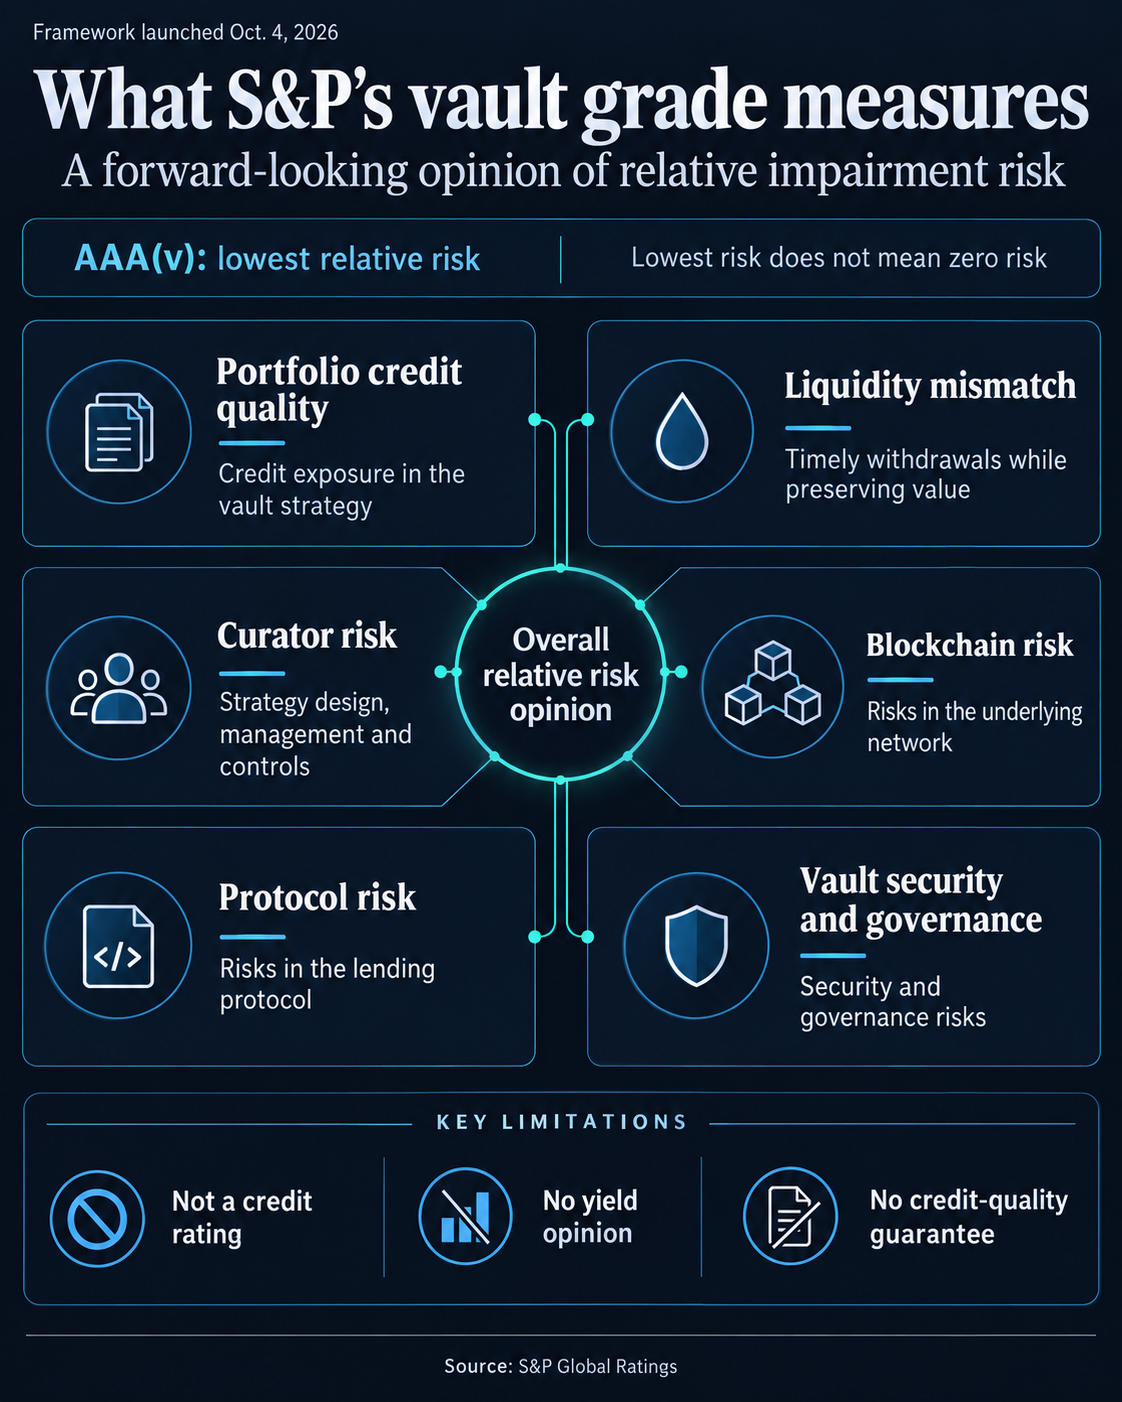
Assessments can also change as eligible assets, their risk profiles, smart-contract features or liquidity conditions evolve. That gives S&P scope to reassess vaults whose structures become riskier even when their historical on-chain record remains clean.
The next test will come when S&P begins publishing assessments for individual vaults, which it said will follow in future announcements.
Those grades could give institutional allocators a common benchmark for comparing strategies in a market that has expanded almost sevenfold in two years.
They could also raise the stakes for vault managers if investors demand higher returns from weaker-rated products or direct deposits toward structures with stronger assessments.
The post S&P brings ratings-style scrutiny to $10 billion crypto vault market as $6 million Base incident exposes risks appeared first on CryptoSlate.
Abstract will shut down on Dec. 15 despite onboarding more than 400,000 users, hosting 144 apps, and landing brands including Disney and Red Bull Racing.
The consumer-focused Ethereum layer-2 (L2) cited stagnant growth, thin liquidity, restricted DeFi activity, and limited institutional crossover.
Igloo CEO Luca Netz said the company had lost “tens of millions of dollars” supporting the network and chose to forgo a token launch as a lifeline. Abstract says funds left on the chain at the deadline will become inaccessible.
Users arrived, and liquidity stayed home
DefiLlama's snapshot shows that Abstract’s 41,078 daily active addresses produced $9.7 million in DeFi total value locked (TVL), $6.4 million in stablecoins, $398,134 in daily DEX volume and $2,876 in daily chain revenue, roughly $1 million annualized.
In comparison, Coinbase-backed Base logged 325,671 daily active addresses, $6.4 billion in DeFi TVL, $5.2 billion in stablecoins and over $1 billion in daily DEX volume.
This means that Base's active-address count runs about 7.9 times Abstract's, while its DeFi TVL runs about 662 times higher and its DEX volume about 2,722 times higher. Each daily active address on Base carries roughly $19,756 of DeFi TVL against about $237 on Abstract.
| Metric | Abstract | Base | Base / Abstract |
|---|---|---|---|
| Daily active addresses | 41,078 | 325,671 | 7.9x |
| DeFi TVL | $9.7M | $6.4B | 662x |
| Stablecoins | $6.4M | $5.2B | 800x+ |
| Daily DEX volume | $398,134 | $1B+ | 2,700x+ |
| Daily chain revenue | $2,876 | — | — |
| DeFi TVL per active address | ~$237 | ~$19,756 | 83x |
Abstract's list of what it lacked reads like the same table in words: liquidity, DeFi depth, institutional crossover, and scale.
Ethereum Layer 2 shutdowns became budget decisions
Blast announced its shutdown days earlier, saying maintenance costs exceeded revenue and that economic sustainability looked out of reach.
Users have until Oct. 26 to move assets back to Ethereum mainnet. Silicon stopped accepting new bridge deposits on Sept. 3 and gave users until Dec. 31 to withdraw. Blast and Abstract both cite economics.
Sophon reached the same arithmetic in June and chose migration. It sunset its L2, moved its consumer apps to Base, and cut annual burn by about $3 million, from roughly $3.4 million a year spent on chain infrastructure, rollup services, data, and tooling.
| Network | Outcome | Trigger / rationale | User deadline or impact | Strategic takeaway |
|---|---|---|---|---|
| Abstract | Shutdown | Stagnant growth, thin liquidity, restricted DeFi, limited institutional crossover | Dec. 15 deadline; funds left become inaccessible | Users alone did not sustain the chain |
| Blast | Shutdown | Maintenance costs exceeded revenue | Oct. 26 deadline to move assets back to Ethereum | Revenue failed to justify operations |
| Silicon | Shutdown process | Network wind-down after bridge deposits stopped | Dec. 31 withdrawal deadline | Wind-downs create stranded-asset risk |
| Sophon | Migration to Base | Chain costs too high; annual burn cut by ~$3M | Apps moved rather than chain kept alive | Migration can replace shutdown |
At Abstract's current revenue run rate, a chain carrying Sophon's cost stack would need about 3.2 times the revenue to break even, before counting team, incentive, and business-building costs.
L2Beat tracks $34.3 billion of value secured across rollups, and Base's $16.3 billion plus Arbitrum One's $11.4 billion add up to about 80.6% of it.
DefiLlama's figures for other chains show a long tail operating far below those leaders. Scroll has about $8.7 million in DeFi TVL and $57 in daily chain revenue. Metis has $2.6 million in TVL and $59,318 in daily DEX volume, and Mode has nearly $2 million in TVL and $1,741 in DEX volume.
Taiko has $243,822 in TVL and about $205 in DEX volume, and Zora has $47,528 in TVL and $1.86 in DEX volume. These readings show how many networks carry the fixed cost of independent infrastructure on a fraction of the liquidity and fee base available on the leaders.
What the closures mean for crypto
Ethereum's scaling roadmap has delivered, with a recent academic paper finding that upgrades through March 2026 doubled throughput on mainnet and L2s.
Mainnet median fees fell from above $2 to below $0.02, and L2 median fees dropped more than 95%, from $0.05 to $0.0015. Cheap execution is becoming abundant, so the defensible layer sits in liquidity, distribution, compliance, app revenue, and institutional access.
Abstract shows that a chain can onboard hundreds of thousands of wallets while building shallow markets.
If standalone chains find reasons to exist beyond generic cheap EVM execution, such as gaming rails, brand distribution layers, identity networks, or compliance-focused venues, the long tail narrows to chains that earn their keep.
Their teams would measure success by fee revenue and enterprise value, and the Abstract and Blast closures become evidence for which designs deserve to continue.
If more teams run the same burn-versus-revenue comparison and land where Blast, Abstract and Sophon did, chains with thin liquidity and sub-$10 million DeFi footprints face a choice.
| Path | What it means | Best fit | Risk |
|---|---|---|---|
| Keep subsidizing | Team continues funding the chain despite weak revenue | Strategically important ecosystems with long-term backing | Burn continues without clear payback |
| Migrate | Apps move to Base, Arbitrum, or another larger venue | Consumer apps that need liquidity and distribution more than sovereignty | Loss of chain identity |
| Specialize | Chain narrows around gaming, identity, brands, compliance, or app-specific use | Networks with a clear non-generic reason to exist | Niche may still be too small |
| Shut down | Users are told to bridge out before a deadline | Chains with low revenue, thin liquidity, and no credible path to scale | Stranded assets, phishing, reputational damage |
They can subsidize the chain, migrate to Base or Arbitrum, or shut down. Each wind-down sets a deadline for users to bridge out, which turns a corporate economics decision into a user-protection problem around stranded assets and phishing.
Ethereum needs rollups, and Abstract's 400,000 users failed to sustain the idea that every crypto product benefits from owning one.
The post Why Abstract is killing its Ethereum L2 instead of launching a token to save it appeared first on CryptoSlate.
Cardano's value has climbed about 42% since Sept. 16, taking ADA from roughly $0.19 to $0.27, and the positioning behind the move has expanded faster than the dollar liquidity beneath it.
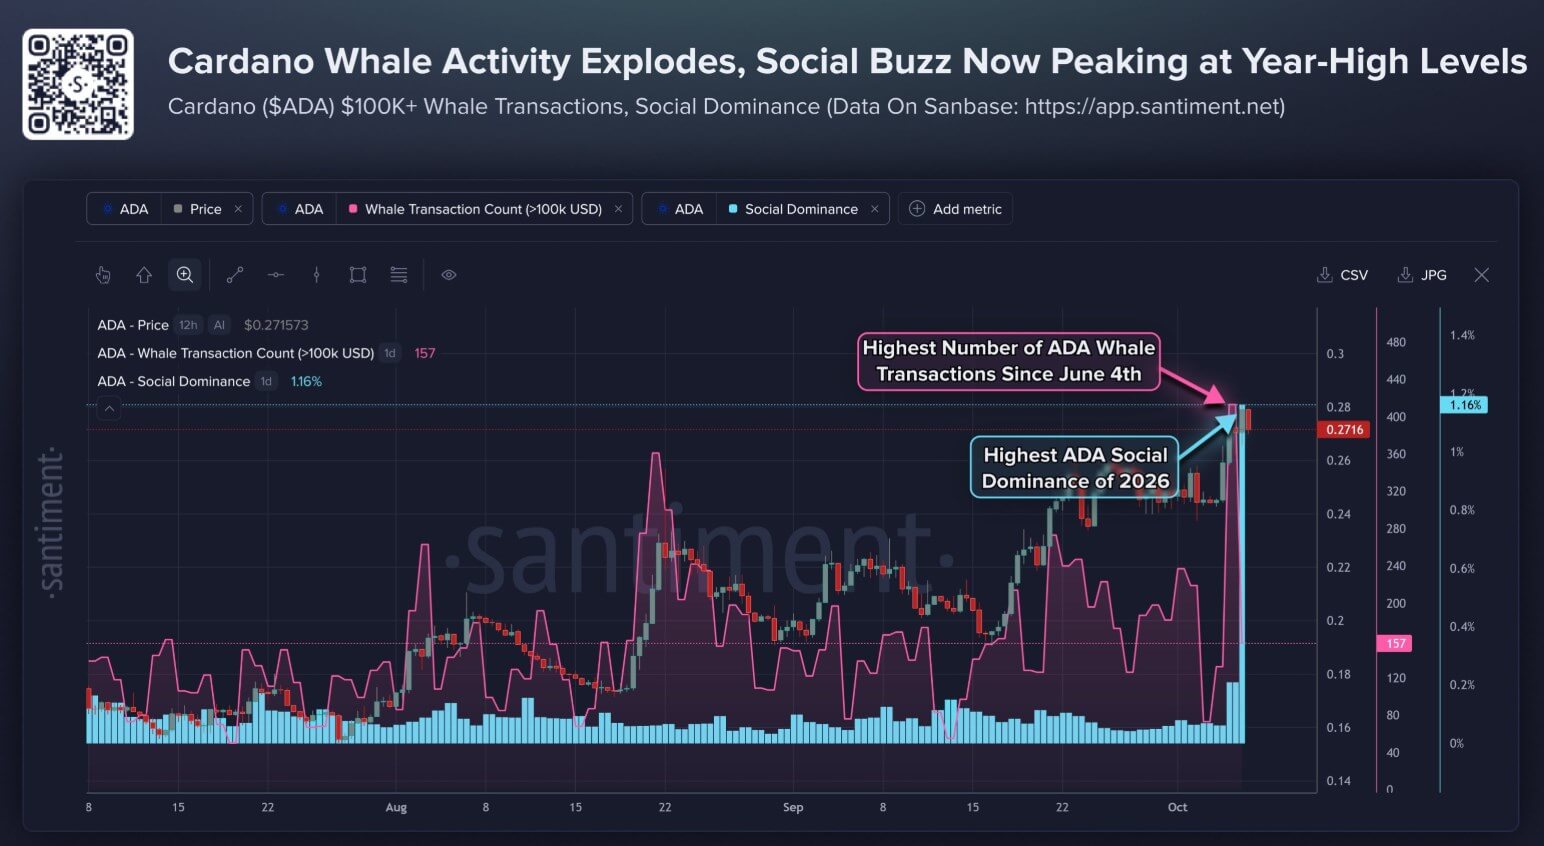
Santiment counted 413 transactions of $100,000 or more on Oct. 5, the highest since June 4 and about 2.2 times the recent weekday baseline, while social volume ran near 1.1 times its baseline.
ADA registered an intraday high above $0.28 on Oct. 6, but the zone that serves as the near-term breakout test quickly rejected it.
Traders added new bets
Santiment's data shows ADA gaining about 10% from Oct. 3 to Oct. 5 while open interest jumped about 25% to $304 million.
Measured in ADA, open interest also rose 13%, removing the effect of the higher price. Closing shorts reduces open interest, so an increase of that size points to new positions. Funding also moved from its most negative reading in a month to positive territory as ADA climbed.
DefiLlama shows Cardano's seven-day DEX volume at $42.6 million, up 147%, with DeFi TVL at $71 million. The turnover extends beyond centralized-exchange price action and confirms the move on-chain.
Cardano holds $66.8 million in stablecoins, down 0.74% over seven days, so the pool of on-chain dollars shrank through a week of surging turnover. Seven-day DEX volume equals about 64% of that stablecoin base, which fits existing liquidity turning over faster as the volume rose.
Santiment's $304 million in open interest is about 4.6 times Cardano's stablecoin supply, and comparing derivatives exposure with on-chain dollars across venues offers risk context.
What $0.28 decides
RealFi went live on Oct. 1 with USDrf and sUSDrf, credit-backed dollar-token products, and Cardano's own channels list Leios prototype work and Fireblocks support for Cardano native tokens expected by March 2027.
ADA's social dominance reached 1.16%, its highest level of 2026. These developments explain why traders returned, and the on-chain data shows what they did once they arrived: more leverage and faster turnover on a stablecoin base that slipped.
Price and open interest climbing together can confirm conviction, and the open question is whether liquidity broadens enough to carry the added exposure. If ADA clears and holds $0.277 to $0.28 while open interest stays elevated, remaining shorts get forced out and the new longs are validated.
Confirmation would come from stablecoin supply turning higher, DEX volume staying elevated beyond the initial price spike, and funding staying moderate.
If ADA stalls or reverses near that zone while funding stays positive and open interest stays high, a larger pool of leveraged longs sits exposed to liquidation.
Long liquidations could accelerate the move lower as DEX volume fades and whale transactions thin out. Stablecoin inflows would absorb some of that selling if they arrive.
Whether ADA holds $0.28, how long open interest stays elevated, and whether stablecoin supply starts climbing will show if Cardano's rally broadens into new liquidity or exposes leverage that outran it.
The post Cardano’s price breakout could trigger the next ADA squeeze or trap leveraged bulls appeared first on CryptoSlate.
The published design of Solana’s new institutional settlement program requires the full cash and asset legs of a trade to be available before it can execute the trade.
Its atomic transaction can prevent a buyer from paying without receiving the asset, but the program supplies neither the cash nor the financing needed to reach that point.
The Solana Foundation announced Solana DvP on Oct. 6 as an open-source standard for delivery-versus-payment settlement. The published design puts each side’s tokens into a separate escrow, then moves both agreed amounts together. It also explicitly excludes netting, the process of offsetting obligations before paying the remaining balance.
Institutions may benefit from a shorter wait for proceeds, while still needing to source the full amount for every trade they submit.
The announcement provides no measured capital-saving result or total-cost comparison.
Full funding and faster reuse
Under the published program limits, one trade record covers one exchange between two parties. Both legs must be token accounts on Solana, and partial fills are not allowed. A bank-account payment made on another rail falls outside this atomic exchange.
The settlement code at the documented source commit checks that each escrow balance is at least the amount agreed for that leg before transferring either agreed amount.
An underfunded side causes settlement to fail, and excess tokens are returned to the named party rather than increasing what the counterparty receives.
The economic responsibility remains with the participants and whoever finances them. A buyer must arrange the cash token, a seller must arrange the asset token, and a lender could finance either position through a separate arrangement, but that would leave the financing relationship outside the DvP program.
Funding itself uses an ordinary checked token transfer, according to the funding instructions. A custody or treasury system can supply the tokens without a special funding call.
Both balances must meet the agreed amounts at settlement, and the settlement authority must sign to exchange them.
That authority, a third address named in the trade, must sign the settlement instruction. The destinations are fixed when the record is created.
If a required transfer cannot complete, the settlement transaction reverses, and the earlier funding transfers are separate transactions.
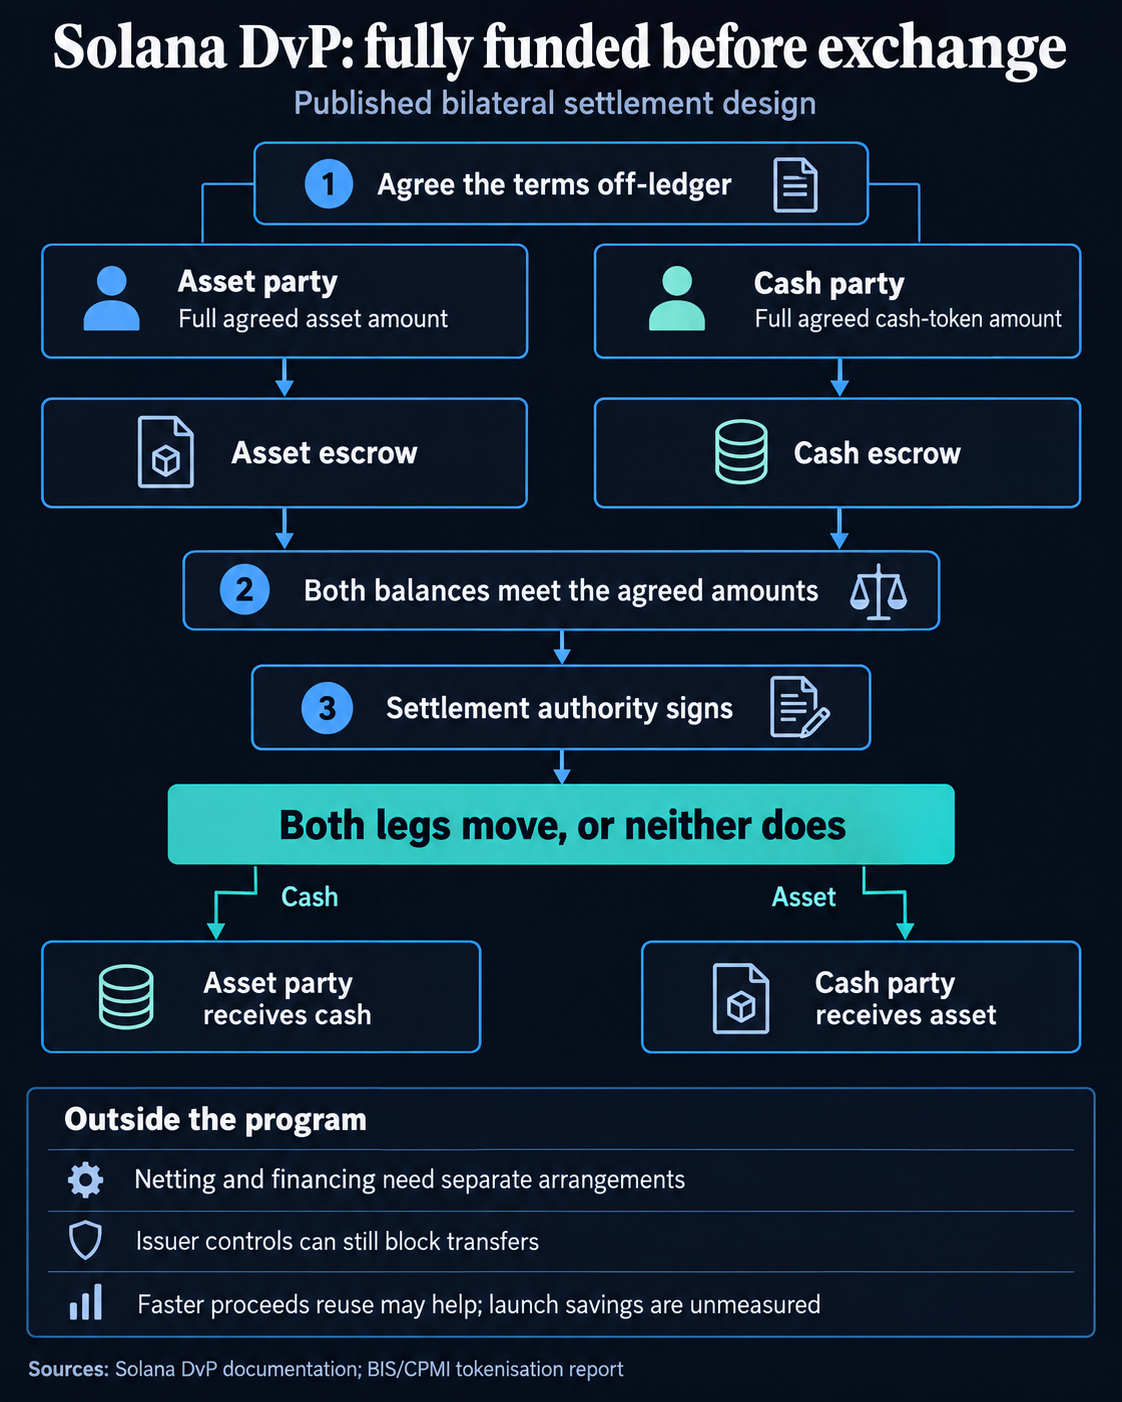
Gross funding asks how much must be available for a trade, while funding duration asks how long it remains unavailable for other uses. Solana DvP’s bilateral design requires the full amounts at settlement but does not require institutions to keep those balances idle permanently.
A participant that receives usable cash or assets sooner may be able to put them into a subsequent trade sooner. That could reduce how long it needs external financing or how much liquidity it holds against a sequence of obligations.
The benefit depends on when funding is required and when the proceeds can actually be used.
Offsetting obligations can reduce the amount that needs to move in the first place. Solana DvP does not perform that calculation across trades. Institutions that need netting or credit must arrange those functions elsewhere before deciding how much to send to their escrows.
The Bank for International Settlements and the Committee on Payments and Market Infrastructures describe this tradeoff in their October 2024 tokenization report, on pages 12 and 13. Immediate gross settlement can require more liquidity than netting arrangements.
The report also identifies the countervailing benefit: quicker access to money and assets can reduce the opportunity cost of liquidity tied up during settlement.
For Solana DvP, the resulting total cost depends on the funding arrangement and the timing of usable proceeds.
A CryptoSlate analysis of tokenized deposits examined the same distinction between moving cash faster and reducing the amount needed. Its Oct. 2 Roughrider coverage described a bank-payment arrangement on Solana in which token transfers and burning sit alongside daily netting of bank-account movements.
That service combines token movement with a separate process for offsetting obligations.
What the atomic exchange protects
The protection is principal delivery risk within the token exchange: neither side hands over its agreed leg without the other leg also moving. The source repository describes that exchange, but the broader financial relationship still depends on the instruments being exchanged.
A cash token carries its issuer’s credit and redemption risks, and a regulated asset token can also retain controls that affect transfers. Freeze, pause, and permanent-delegate powers remain relevant while tokens sit in escrow.
The unwind instructions let either party reclaim its own leg while leaving the trade open, or reject the trade and refund both legs. The settlement authority can cancel it, and a separate recovery instruction handles deposits arriving after closure, subject to the token’s transfer rules.
These powers do not override an issuer that freezes an escrow or blocks transfers. A fully funded trade can still fail to complete, and refunds can depend on issuer cooperation. The authorized settlement signer must also be available.
Under the trade-creation terms, refunds and reclaims return to the named party’s token account even when a custodian supplied the deposit. Agreed settlement destinations can receive proceeds, but the refund route may differ from the funding route.
| Function | Program behavior | Remaining dependency |
|---|---|---|
| Exchange | Both agreed token legs move atomically | Full balances and a valid authority-signed settlement |
| Funding | Separate escrows hold the agreed amounts | Participants arrange tokens, financing and any netting |
| Recovery | Parties can reclaim or reject; authority can cancel | Issuer and token transfer controls still apply |
The documentation tells operators to recognize settlement when the transaction reaches Solana’s finalized commitment. Whether that also constitutes legally final settlement depends on the parties’ agreements and applicable regimes.
Deployment, audits and institutional use
The Foundation’s documentation lists an upgradeable program on mainnet-beta and devnet using observations dated Oct. 2. The mainnet table identifies an upgrade authority, an address with the power to change the deployed program. Institutions depend on its governance and settlement rules.
The client documentation points to a specific public source revision, with the latest revision dated Sept. 30 in the public version history.
Security reviewer Cantina’s May 21-28 audit covers an earlier repository and specific fixes. Its four medium findings are marked fixed, while three low-risk and six informational findings are acknowledged.
The Foundation says the program is ready for real funds, while inviting design partners and early participants ahead of production release.
JPMorgan’s role is limited too. The bank supplied securities-settlement-practice input, and the announcement expressly disclaims any role in the program's design, development, operation, approval, endorsement, or guarantee.
For institutions, the useful next evidence would connect actual settlement use with the amount and duration of funding, the financing cost, and whether proceeds become spendable sooner.
Solana DvP offers a defined atomic exchange, and turning that exchange into a capital-saving service still depends on the cash, assets, and financing surrounding it.
The post Solana DvP settlement requires 100% upfront cash for every trade appeared first on CryptoSlate.
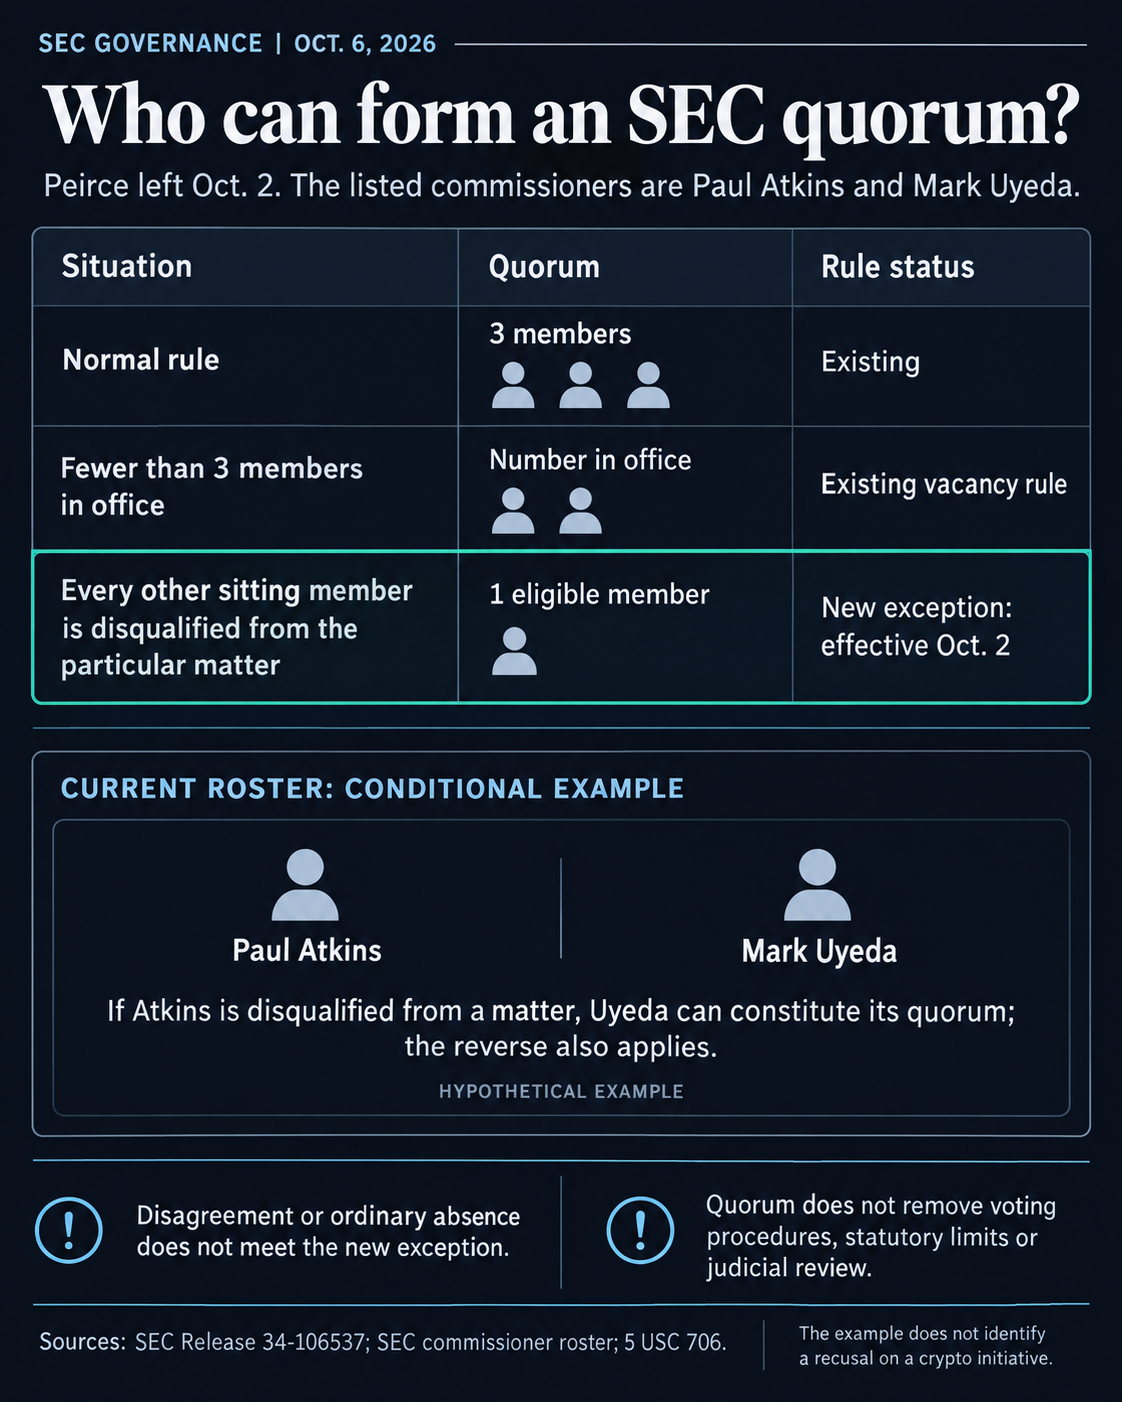
Hester Peirce’s Oct. 2 resignation has left Paul Atkins and Mark Uyeda as the SEC’s two listed commissioners. A new rule permits one eligible member to constitute a quorum when every other sitting member is disqualified from a particular matter.
Under the current roster, that combination puts future Commission decisions on crypto policy in fewer hands.
The one-member exception says it depends on disqualification from the specific matter, and it can allow either remaining commissioner to act as the Commission’s quorum in that situation.
Peirce’s resignation letter, dated Sept. 21, made her departure effective Oct. 2. The current commissioner roster, updated Oct. 3, lists Chairman Atkins and Commissioner Uyeda. The SEC’s historical service table also records Peirce’s tenure ending Oct. 2.
Custody reform and a new offering regime remain proposals, while tokenized-stock trading relief is already an issued conditional order. With the roster reduced to two members, further Commission-level decisions rest with a smaller body, subject to the rules and legal limits governing each action.
The quorum amendment, dated Sept. 30 and effective Oct. 2, changes 17 CFR 200.41, the rule defining how many commissioners must be eligible to conduct Commission business.
The existing vacancy exception already allowed the number of commissioners in office to constitute a quorum when fewer than three were serving. Two filled seats did not prevent the SEC from operating, and that exception already covered even a Commission with only one sitting member.
Previously, the separate provision for disqualifications accommodated two eligible commissioners after others were disqualified. The amendment extends that provision to one eligible commissioner, for the matter concerned, when every other member in office is disqualified.
Under the current roster, if Atkins were disqualified from a particular matter, Uyeda could constitute its quorum, and the same would apply in reverse.
The distinction keeps vacancies, nonattendance and recusal from becoming interchangeable. An eligible commissioner’s disagreement with a proposal does not meet the new provision’s disqualification condition.
In the published rule, the SEC explains that disqualifications arise and that the agency needs to continue conducting business. It describes the amendment as promoting flexibility and finality, and finds that it concerns internal management and organization rather than substantive regulation.
That administrative rationale accompanies a change with practical consequences for who can make Commission decisions. Meanwhile, Peirce’s letter expressed confidence that Atkins, Uyeda and SEC staff will continue to balance individual choice with sensible regulatory protections.
Crypto measures still require different kinds of action
One pending rulemaking is the Oct. 1 custody proposal. It addresses how regulated investment companies may custody crypto securities and similar investments, how registered advisers may custody client crypto funds and securities, and related modernization and reporting requirements.
In his October statement, Atkins placed custody reform alongside the offering proposal, Commission interpretations, and staff tokenization work. That inventory spans several kinds of regulatory action, with different roles for commissioners and staff.
The SEC’s page still classifies the release as proposed and now lists Dec. 7 for public comments. The existence of a smaller Commission, or a new quorum exception, does not turn a proposed custody framework into operative permission.
The action also supplies a concrete example of how the agenda moved before Peirce left. The October voting record shows Atkins, Peirce, and Uyeda all approving release IA-7023 on Oct. 1.
Those were approvals to propose the custody rules, before her resignation and the quorum amendment took effect.
A second pending measure is Regulation Crypto Assets, issued Aug. 18 and published Aug. 21. It would create offering exemptions for certain investment contracts involving crypto assets, alongside disclosure requirements and continuing antifraud and antimanipulation obligations. It also proposes a conditional safe harbor concerning investment-contract status.
Tokenized-stock access is at a different stage. The Sept. 17 Innovation Exemption is a temporary conditional exemptive order that covers specified tokenized National Market System (NMS) stock trading venues and certain liquidity providers.
The order’s fact sheet describes five-year conditional relief, with limits on stock symbols and volume, equivalent shareholder rights, public auditable smart contracts, and operating disclosures. For stock tokenized by an unaffiliated third party, it also requires issuer notice and an opportunity to object.
Those conditions remain part of the pathway available to qualifying participants. A future Commission decision on that relief would occur under the applicable quorum arrangements, but the new quorum rule itself neither broadens the exemption nor removes its safeguards.
A quorum does not replace voting or legal authority
For decisions circulated among commissioners, the SEC’s seriatim rule says a matter is not final until each member reports a vote or intended nonparticipation to the secretary.
Any commissioner can request that a circulated matter be withdrawn and scheduled for joint deliberation.
Under 17 CFR 200.60, commissioners should carefully weigh qualification in matters involving interests and relationships, and an individual member’s qualification rests with that member. The amended quorum clause also covers members otherwise disqualified.
Staff no-action and tokenized-securities statements are a separate part of the policy inventory described by Atkins.
The statutory delegation provision allows delegation through published orders or rules, while excluding general rulemaking from that authorization. It preserves Commission review and permits one member to bring a delegated action before the Commission for review.
The smaller body also remains constrained by applicable law. The Administrative Procedure Act provides notice-and-comment requirements for covered rulemaking, with specified exceptions. The SEC’s finding that its organizational quorum amendment did not require notice and comment is not a general exemption for future crypto rules.
Under judicial-review law, reviewing courts can set aside agency action found unlawful, beyond statutory authority or taken without required procedure. Reducing the number of eligible commissioners does not supply additional substantive authority or insulate a decision from review.
The SEC’s currently posted October tally contains the three-member custody vote, with no later one-member crypto decision listed. The agency says it generally posts votes only when the matter is final, so that tally supports a limited observation rather than an exhaustive claim about every action.
For crypto businesses, the next concrete milestones are the Oct. 20 offering-rule comment deadline, the Dec. 7 custody deadline, and any subsequent Commission decisions on those proposals or conditional trading relief.
Their legal status, recorded approvals, and participating members will show how the reduced Commission operates.
The new exception preserves an ability to act through disqualifications. Its effect on crypto policy will depend on which specific matters arise, who remains eligible to consider them, and the decisions they make.
The post SEC drops to 2 members, and 1 hidden rule shifts crypto power appeared first on CryptoSlate.
CryptoTicker.io
If you hold crypto assets at bitcoin.de, the short answer is this: on the operator's own account your balance is still there, but you cannot trade with it for the time being. The German Federal Financial Supervisory Authority (BaFin) has refused futurum bank AG, the operator of bitcoin.de, authorisation as a provider of crypto-asset services. The parent company Bitcoin Group SE announced this on Tuesday, October 6, in a mandatory disclosure, stating at the same time that customers' assets would continue to be held securely until their transfer to an alternative regulated custodian and that all customer claims would remain unaffected.
An ongoing procedure has thereby turned into a decision. At the end of September the position was still that the application sat with the supervisor and the platform was waiting for the permission; we wrote about that on September 29. This piece sets out what the refusal triggers in practice: what happens to your balance, which routes Bitcoin Group SE itself names, what a change of custodian means for your holding period, and how you can tell at another exchange whether it holds the permission that has just been refused here.
The BaFin refuses the MiCAR authorisation, and the forbearance ends with it
MiCAR is the European regulation on markets in crypto-assets, Regulation (EU) 2023/1114; it sets out who may offer crypto-asset services commercially in the European Union and which duties come with that. A crypto-asset service is any commercial activity involving other people's crypto assets, from exchange through trading venue to custody. Whoever offers one needs authorisation from the competent supervisor; in Germany that is the BaFin.
It is precisely that authorisation the authority has refused futurum bank AG. The Bitcoin Group SE disclosure contains the sentence that changes the situation: with it, the previous forbearance of the provision of crypto-asset services by futurum bank AG no longer exists either. Forbearance is the supervisor's tacit acceptance of an activity while a procedure is running. It is not a permission, and the forbearance ends as soon as the procedure is decided.
The company itself relays the reasoning. In the BaFin's view, according to the disclosure, the current degree of progress on implementation and operationalisation, and the further progress achievable in the short term, were insufficient, making a refusal of authorisation unavoidable at this point. Moritz Eckert, chief executive of Bitcoin Group SE, calls the decision a setback in the same disclosure, considers it wrong on the substance and points out that the implementation of the required points had already been advanced. That account comes from the company affected; no public reasoning of its own from the supervisor on the matter is available.
Important for placing this: a refused authorisation is an administrative decision about requirements on organisation, processes and documentation. It says nothing about a company's solvency and nothing about the existence of customer claims.
The wording on custody: customer assets secured, claims unaffected
For you as a customer, everything hangs on two sentences of the mandatory disclosure. The first: futurum bank AG continues to hold customers' assets securely until their transfer to the alternative regulated custodian. The second: all customer claims remain unaffected. Both sentences appear in a publication by a listed company, which stands behind their content.
Custody here means that a service provider holds the keys to your crypto assets and manages them for you, while the assets are economically yours. It is precisely that separation between holding and being entitled which explains why the disclosure makes two separate commitments: one on custody and one on claims.
What the disclosure does not say is at least as important. A date for the transfer to the alternative custodian is not stated there, the future custodian is not named, and on the question of whether and from when withdrawals are possible there is not a sentence. All that is announced is that futurum bank AG will inform customers on its own website in the near future about the specific arrangements, the steps required of customers and the timetable. Anyone planning a withdrawal today therefore has an assurance about existence, but no date.
From marketplace to broker: the chronology since June 12
The refusal hits a platform that has not been running normally for months. According to the trade publication Cointelegraph, trading at bitcoin.de has been largely suspended since June 12. Behind it is a rebuild: the original marketplace, on which buyers and sellers were brought together directly, was to become a broker model, with more than a hundred crypto assets, with swap functions and with staking. The launch was scheduled for the end of June and was postponed because the authorisation was missing.
In a statement in August, according to the same report, the customers' holdings had already been moved to a new custody infrastructure and the old trading system had been switched off. That explains why holdings and trading are two different things here: the assets sit in a new environment, only the marketplace on top of it is missing. How the standstill began, we set out in August, and what the shareholder meeting at the end of August produced on it is covered in a separate piece.
The order of magnitude makes the situation relevant: Bitcoin Group SE states more than 1,100,000 registered users for bitcoin.de and an operating history of over ten years. By its own account, the holding owns 100 percent of futurum bank AG and 50 percent of Sineus Financial Services GmbH, an investment firm supervised by the BaFin. Anyone affected here is therefore not part of a niche but of one of the best-known addresses in the German crypto market.
Crypto assets are not deposits: deposit insurance does not apply here
One expectation dissolves at this point. The statutory deposit guarantee protects money in an account up to 100,000 euros per customer and institution. Crypto assets, however, are not deposits but assets held in custody, and there is no deposit guarantee for crypto balances in Germany; we described that on October 4 in our overview of the Crypto Markets Supervision Act.
A different principle takes the place of deposit insurance: the segregation of holdings. Crypto assets held in custody are to be kept separate from the service provider's own assets, and the Crypto Markets Supervision Act regulates in Section 45 how crypto assets held in custody are allocated in an insolvency. That is a general rule for every custodian in Germany. It is expressly not a statement about futurum bank AG; on its own situation, Bitcoin Group SE states that all customer claims remain unaffected.
In practice that means the protection of your balance here does not hang on a guarantee fund, but on the holdings being kept cleanly segregated and transferred correctly. That is why the announced move to a regulated custodian is the decisive event of the coming weeks, and why it is worth reading the official announcements on it.
Objection, new application, cooperation: the three routes of Bitcoin Group SE
The disclosure names three routes, and none of them carries a date. The first is the objection, the formal appeal against an administrative act lodged with the authority that issued it. The company writes that it is reviewing the decision and has the opportunity to object. A deadline for that is not stated in the disclosure; anyone naming a concrete deadline is not reading it from this source.
The second route is a renewed application for MiCAR authorisation at a later point. The third is the one the company says it is currently pursuing: a cooperation agreement with regulated German companies, one for trading and one for custody, so that trading becomes possible again through the technically renewed bitcoin.de app. The time horizon the disclosure gives for that reads: within the next few weeks.
For you, the combination of three routes and zero dates means above all one thing: there is no predictability at present. Anyone who depends on being able to trade at a particular moment should not tie that part of their holdings to an assurance without a date. Anyone who can leave things sitting has, going by the wording of the disclosure, no cause for hasty decisions.
What a change of custodian triggers for the holding period and documentation
For crypto assets held privately, a one-year holding period applies in Germany under Section 23 of the Income Tax Act: if more than twelve months lie between acquisition and disposal, a gain from the private disposal stays tax-free. Within the year the tax liability applies, and the proof of the acquisition date and acquisition cost lies with you, not with the platform.
What a transfer to another custodian triggers in tax terms depends on the specific arrangements, which futurum bank AG has not yet published. As long as those conditions are open, any blanket statement on it is unserious. What holds up is the preparation: pull a complete export of your transactions now, while access to the account exists, secure the account statements and trading records, and note the holding per crypto asset with a date. If the custodian changes later, you will have the earlier position in black and white.
The second part of the preparation concerns custody itself. A hardware wallet is a device that keeps your private keys offline, so that no service provider stands between you and your crypto assets. Anyone holding part of their stock for the long term can remove exactly that part from dependence on authorisation procedures; a market comparison is in our overview of hardware wallets. The price for it is personal responsibility: whoever loses the key loses the coins, and nobody can retrieve them.
Transitional permission, the KMAG and the company database: the frame around the decision
MiCAR applies directly throughout the European Union, but it contains no German procedural rules. That gap is closed by the Crypto Markets Supervision Act, KMAG for short: it is the German implementation of the MiCA regulation, entered into force as Article 1 of the Financial Market Digitalisation Act and replaced the crypto rules in the Banking Act, where they had until then been treated as crypto custody business.
Decisive for understanding the present case is the transitional permission: under Section 50 of the KMAG, providers already in the market were allowed to keep working at first while they applied for the new authorisation. That transitional permission expired on December 31, 2025. Since then there has been no grey area left for crypto providers in Germany, and that is exactly why the forbearance mentioned in the disclosure was the last thing the operation could rest on. The duties an authorisation brings with it in detail we have set out separately in our overview of the MiCA obligations.
Anyone wanting to complain about the relationship between customer and provider will also find the route in the regulation: which deadlines apply to a complaints procedure and when the supervisor is brought in, we explained in August.
How a MiCAR authorisation becomes visible at another exchange
The case supplies a test question that reaches beyond bitcoin.de: does the provider holding your money and your coins actually have the permission, or is it merely applying for one? Two registers answer that. The BaFin's company database is the official register of authorisations granted in Germany; the public register of the European securities supervisor ESMA lists the authorised providers of crypto-asset services across the whole union. If a provider is not in there, that is not a detail but the answer.
Two qualifications belong with it. First, an entry says nothing about price losses: an authorisation covers supervision, capital and organisational requirements, it is no guarantee for your money and no promise of rising prices. Second, websites keep turning up that advertise with genuine register numbers belonging to other companies; a cross-check is therefore only worth anything via the name, the address and the domain together. Which venues in Germany can show a permission and how they differ on fees and selection is shown by our comparison of regulated crypto exchanges.
A note of our own on the market environment: Bitcoin and the large altcoins carry on moving independently of this procedure. The refusal concerns access through one particular provider, not the crypto assets themselves.
bitcoin.de: Your next three steps
- Secure the holding and the history while access stands. Export transactions, acquisition data and the account statement and file them separately from the platform. Tools that log exactly that permanently are in our comparison of tax and portfolio tools.
- Wait for official announcements and ignore third parties. Bitcoin Group SE has announced that it will publish the timetable and the required steps on its own website. In situations like this, supposed helpers typically get in touch by email, telephone or messenger; nobody reputable asks for your seed or requests an advance payment to recover funds. If you need an alternative venue, pick it from the comparison of regulated crypto exchanges and look up the register entry yourself.
- Take the long-term part out of third-party custody. What you intend to hold for years anyway does not belong on a trading venue. Which devices are candidates for that and how they differ is set out in the hardware wallet comparison.
(As of October 7, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
The burn is running and the price is falling all the same. Over the past 24 hours, 38,000 UNI have landed at Uniswap's burn address and are therefore permanently out of circulation. Over the same period the price has lost 8.4 percent. Anyone who reads scarcity as a price driver gets the opposite delivered on this day.
In the end it is a question of scale. cryptoticker.io compiled this analysis itself on October 7, 2026. It rests on the transfers to the burn address of the UNI contract on Ethereum; the 16 transfers of the past 24 hours were examined, along with the total holding at that address. What comes out of it reframes the story of the deflationary token.
Uniswap price on October 7: $8.11 and the biggest move in the top 25
UNI trades at $8.11, or €7.22. The loss of 8.4 percent in dollars and 8.6 percent in euros is the sharpest swing among the 25 largest crypto assets on this day. For comparison: Bitcoin gives up around 1.7 percent, Ethereum 3.4 percent, Cardano 5.5 percent. Over seven days UNI stands at minus 7.5 percent.
Market capitalisation is $5.07 billion, which corresponds to rank 24. Trading volume over the past 24 hours comes to $690 million. There are 625.1 million UNI in circulation.
There is no trigger on this day that concerns Uniswap alone. No hack, no delisting, no lawsuit, no protocol failure. The price is moving with a weak overall market and with the positioning of leveraged traders. That is a more honest account than any explanation supplied after the fact.
38,000 UNI in 24 hours: the measurement at the burn address
At Uniswap, burned tokens remain part of the total supply in accounting terms and move to an address to which nobody holds the key. Everything that arrives there is lost in practice. Those inflows are precisely what can be counted.
Over the past 24 hours there were 16 transfers totalling 38,000 UNI. At the day's price that equals roughly $308,000 or 274,000 euros.
The uniformity stands out. Thirteen of the 16 transfers were for exactly 2,000 UNI, the remaining three for exactly 4,000 UNI. Odd amounts did not occur. That is no coincidence, nor is it the behaviour of retail investors destroying their tokens out of conviction. It is the signature of a standardised process that always uses the same denominations.
TokenJar and Firepit: fees only come out against burned UNI
Behind the even amounts sits a construction that Uniswap describes in its proposal on the so-called UNIfication. Two contracts interlock.
TokenJar is an immutable contract on the blockchain in which the protocol fees accumulate. Every fee the protocol takes in collects there until somebody claims it.
Firepit is the contract that ties the claiming to a condition. Fees can only be taken out of the TokenJar if UNI is burned in the Firepit. Anyone who wants the accumulated fees must therefore destroy their own tokens first.
What arises from that is a trade, not a sacrifice. Whoever claims gives up UNI and receives in return the value sitting in the TokenJar. It pays off precisely when the claimed fees are worth more than the burned tokens. That the amounts arrive in fixed steps of 2,000 and 4,000 UNI fits a process settled automatically as soon as the sum works out.
112.6 million UNI at the burn address: 11.26 percent of total supply
The total supply of UNI is one billion tokens. Of those, 112,641,581 sit at the burn address, measured on October 7, 2026. That is 11.26 percent of the total supply and, measured against the actual circulation of 625.1 million UNI, around 18 percent. At the day's price the holding equals about $0.91 billion.
That number sounds enormous, and it misleads if you read it without its origin.
The retroactive burn: 100 million UNI from the treasury
By far the largest part of the holding comes from a single event. In its proposal, Uniswap describes a retroactive burn of 100 million UNI from its own treasury, intended as compensation for fees that would hypothetically have accrued since the token launched. That was a one-off entry, not an ongoing reduction in supply.
Strip out those 100 million and around 12.64 million UNI are left that have accumulated at the address. That is the amount the running mechanism has gathered. Measured against circulation, it is about two percent.
The difference is decisive for any valuation. A one-off write-down from the project's own coffers changes the circulating supply exactly once. A running burn changes it a little every day. Anyone throwing both into one figure confuses an entry about the past with an expectation about the future.
Burn rate against circulating supply: 0.0061 percent in a day
The 38,000 UNI of the measured day equal 0.0061 percent of the circulating supply. Extrapolated over a full year and at an unchanged pace, that would be roughly 13.9 million UNI, or 2.2 percent of circulation. This extrapolation is the projection of a single day and not a forecast; the actual pace depends on how much the protocol takes in fees, and that fluctuates with trading volume.
Even so, the figure gives a reliable order of magnitude. A reduction of a good two percent a year is nothing trivial for a token. Only on this day it stands against a price move of 8.4 percent that took place within 24 hours. The ratio is about one to four hundred when you set the daily burn against the daily move.
Protocol fees on v2 and v3: where the revenue comes from
The fees are not drawn from the whole Uniswap universe. By the protocol's own description, the first stage covers the v2 pools plus a selection of v3 pools which together account for 80 to 95 percent of liquidity fees on the Ethereum mainnet. Further sources on other networks and in newer protocol versions are planned, but are not the same thing as revenue already flowing.
For you as a holder that means the burn rate is tied to trading activity on a defined part of the protocol. If trading volume falls, the burn falls. A mechanism that hangs on fees amplifies the market situation rather than working against it.
The burn as a price driver: 2.2 percent a year against 8.4 percent in a day
That answers the opening question. A reduction rate of a good two percent a year cannot absorb a daily move of 8.4 percent. It works over months and years, not over hours.
That does not devalue the mechanism. It places it. Anyone holding UNI because of the burn holds a token with a slowly shrinking circulating supply and with every price risk of an altcoin at rank 24. Both apply at once. The reduction in supply is an argument for the long run, and it is no shield against a weak market.
How quickly the story tips in either direction is clear from a look back: when the fee switch took effect in September, UNI jumped above nine dollars. The same mechanism, the same mechanics, a different market environment.
Holding period and Section 23 of the Income Tax Act: a burn is a disposal
For investors in Germany the process itself is worth a close look. Anyone claiming fees through the Firepit gives up UNI and receives other crypto assets in return. In tax terms that is an event in which one asset is given up and another obtained.
German tax law has so far treated gains from the sale or exchange of crypto assets held privately as a private disposal under Section 23 of the Income Tax Act. What counts there is the one-year period between acquisition and disposal, along with the threshold for the sum of a year's gains. Whether the tax authorities classify a burn through the Firepit the same way as an ordinary exchange on an exchange is not expressly settled. There is no binding ruling on it. That gap is resolved in the end by a tax adviser, not by an article.
In practice it affects very few people directly. The even denominations on the measured day suggest that claiming runs mostly automatically and is not triggered by individuals through an interface. For you as an ordinary holder, the plainer question therefore counts: when did you acquire your UNI, and how long have they been sitting there? A tax tool with a portfolio tracker answers that more reliably than memory, because it records the acquisition dates for each tranche.
On top of that, the legal position is currently moving. The German finance ministry has put forward a draft that reworks the taxation of certain privately held crypto assets; we have written up the state of play before the cabinet stage separately. Anyone whose acquisition data is clean now will not have to reconstruct it later.
Leverage and liquidation: $690 million in volume against a $5.07 billion market value
The daily volume of $690 million equals roughly 13.6 percent of market capitalisation. For an altcoin of this size that is brisk trading, and it explains why moves of eight percent within a day are possible without any news behind them.
For leveraged positions that is the real danger. A move of this size clears out positions working with fivefold leverage or more before any fundamental consideration takes hold. Anyone running leverage in UNI should know the distance between entry and liquidation threshold, as a number and not as a feeling. Where leveraged products are offered under German supervision and what they cost is set out in the broker comparison.
Buying UNI in Germany: authorisation, spread and custody
On the buying route the same points apply as with any altcoin, and they are readily overlooked as long as attention hangs on the price.
Pay attention to whether the provider is authorised under the European crypto regulation and whether that also covers its German business. Do not compare the advertised order fee alone, but the spread between the buying and selling price, because with altcoins the larger share of the cost regularly sits there. Settle before buying whether you want to hold the tokens yourself or leave them with the provider, and how a withdrawal to your own wallet works. An overview of the venues available in Germany is given by the comparison of crypto exchanges.
What the burn does not change for custody
A common misunderstanding on the side: the burn happens in the protocol and not in your wallet. Nobody takes tokens from you because a mechanism destroys tokens. The only people affected are those who enter the Firepit themselves. Your holdings stay untouched; their share of the total supply even rises minimally when others burn.
The Uniswap burn: the key points for your decision
The mechanism works, it can be verified, and it is smaller than its reputation. Three points stay with you:
- Order of magnitude instead of narrative. Set the burn rate against the circulating supply before you take it as a price argument. A good two percent a year works over years and not over days. Where you can trade UNI and on what terms is set out in the comparison of crypto exchanges.
- Record the acquisition dates. In Germany the one-year period decides the tax burden, and the draft bill in progress makes clean records more important rather than less. A tax tool with a portfolio tracker keeps the dates for each tranche.
- Know your leverage or leave it alone. Eight percent in a day without any news is normal for UNI. Anyone running leverage needs the liquidation threshold as a number; the terms for that are shown in the broker comparison.
Uniswap has described the details of the mechanism itself in its UNIfication proposal.
(As of October 7, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Shiba Inu stands at $0.00000557 on Wednesday morning, down 4.79 percent in 24 hours. That is the heaviest one-day loss among the six largest coins we track. Over the same period Bitcoin gives up 1.15 percent, Dogecoin 3.66 percent, Ethereum 2.75 percent, XRP 1.29 percent and Solana 0.64 percent. Anyone holding Shiba Inu is not watching a slump of its own making, then, but four times the swing of a market that has barely moved lower.
The figure that matters more in practice sits in the order book. Shiba Inu turns over $83.11 million in trading volume on the day against a market capitalisation of $3.28 billion. That is a turnover ratio of 2.53 percent. Dogecoin records $1.087 billion in volume against $14.21 billion in market capitalisation, or 7.65 percent. The bigger memecoin trades three times as intensively relative to its size. That ratio decides what an exit costs you at the moment you need one.
Shiba Inu price at $0.00000557: 4.79 percent down in 24 hours
Converted at the European Central Bank euro reference rate of October 6, which stood at $1.1269 per euro, the current level equals €0.00000494. Last night the same conversion still gave €0.00000514. The euro value has therefore fallen by roughly four percent within a day, even though the euro firmed slightly against the dollar over the same stretch.
Over seven days Shiba Inu is 3.49 percent lower. Over 30 days it still shows a gain of 1.63 percent. These three signs belong together, and they are the reason a single daily loss says little about this coin on its own: the month is still positive, the week is negative, the day is clearly negative. What has sharpened is the pace.
Shiba Inu is 93.54 percent below its all-time high of $0.00008616. Dogecoin sits 87.57 percent under its record, Bitcoin 33.11 percent. Those gaps are not a forecast but the starting point of any price-target calculation you draw up. A coin trading 93.54 percent below its high needs to multiply fifteenfold to get back there.
Dogecoin down 3.66 percent, Shiba Inu 4.79 percent: 13 times more volume at DOGE
The two large memecoins move in the same direction on the day, but with different force. Dogecoin trades at $0.09096, or €0.08072, and loses 3.66 percent. Shiba Inu loses 4.79 percent. The gap of 1.13 percentage points sounds small. On a position of 2,000 euros it comes to 22.60 euros in a single day, on a day when the broader market barely gave ground.
The real difference lies in trading volume. Dogecoin turns over $1.087 billion on the day, Shiba Inu $83.11 million. The ratio is 13 to 1, against a market capitalisation only 4.3 times as large. In practice that means the same sell order moves the Shiba Inu price considerably more than the Dogecoin price.
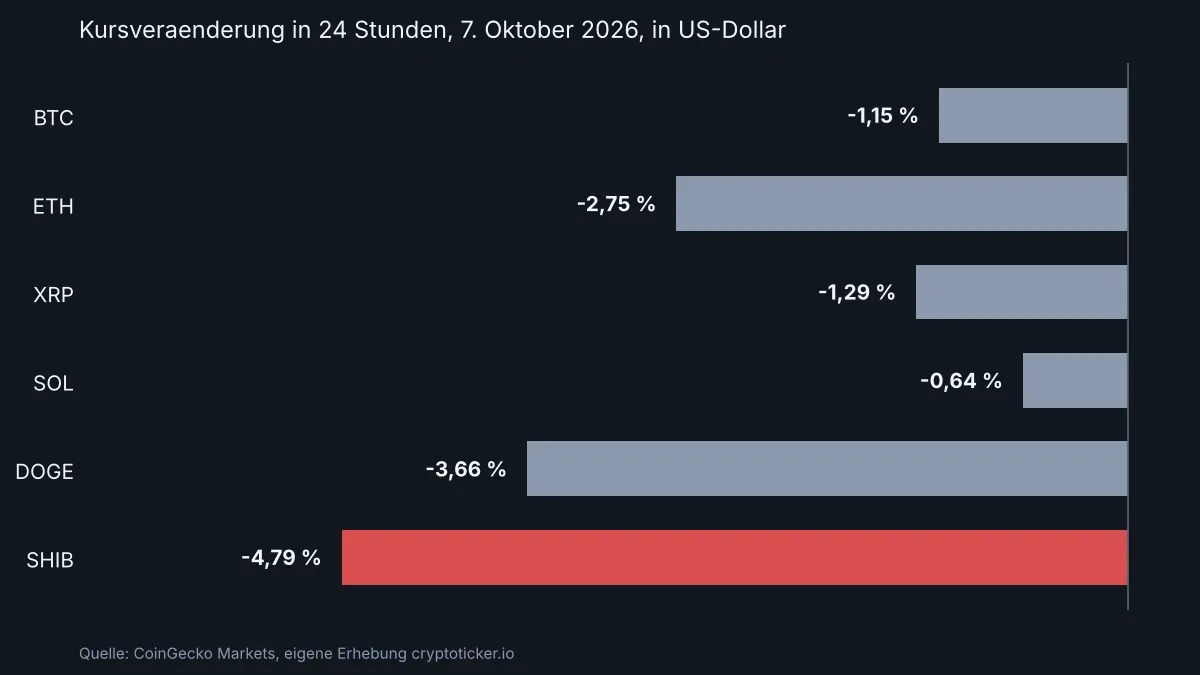
Turnover ratio as a gauge of thin markets: 2.53 percent at SHIB, 7.65 percent at Dogecoin
The turnover ratio is daily volume divided by market capitalisation. It describes what share of the entire supply actually changes hands in a day. A high ratio means plenty of counterparties in the order book, a low one means thin books. For Shiba Inu it stands at 2.53 percent this Wednesday, for Dogecoin at 7.65 percent, for Bitcoin at 1.90 percent.
That Bitcoin has the lowest ratio is no contradiction. Behind every percentage point at Bitcoin sits an absolute depth of $32.27 billion in daily turnover. Behind 2.53 percent at Shiba Inu sit only $83.11 million. The ratio is therefore useful for comparing coins of similar size, not across every size class. Between the two memecoins the comparison holds, and it comes out plainly.
cryptoticker.io compiled this analysis itself on October 7, 2026. It rests on market data for the six coins Bitcoin, Ethereum, XRP, Solana, Dogecoin and Shiba Inu, together with the euro reference rate of the European Central Bank. Six coins and one exchange rate were examined.
What a thin market costs in everyday trading
A thin market shows up in the gap between bid and offer and in the depth behind it, not in the price you see on an exchange home page. With Shiba Inu there is an added quirk that German investors rarely note: the price sits in the eighth decimal place. The smallest tradable tick at many exchanges is $0.00000001, and at a price of $0.00000557 that already amounts to 0.18 percent. A market order that runs through two ticks therefore costs you a third of a percent before any fee applies.
The $0.0000055 level: how much of the October 5 floor still holds
On October 5, in its own burn review of the Solana route, cryptoticker.io named the $0.0000055 mark as the lower floor. That is exactly where the price stands this Wednesday morning. The daily value on October 6 was $0.00000589, the current one is $0.00000557. The level is being tested, then, not broken.
What follows from that hangs on a single observation: if the price holds above $0.0000055 on a daily basis, the range of the past 30 days stays intact. If it drops below, the next documented catchment zone is the 30-day low. Both can be examined without having to believe any forecast.
Shiba Inu levels on the upside: $0.0000059 from October 5, then $0.0000061
The weekly high is $0.00000592 and dates from October 5. That is the first level on the upside, and it is only 6.3 percent away. Above it comes the 30-day high of $0.00000610, which is 9.5 percent above the current level. Only once both marks are cleared on a daily basis can one speak of a trend reversal, and even then only for the monthly window.
The second level is the more important one because it has held for a month. A high that has not been exceeded in 30 days acts as a supply zone on the next attempt: that is where the sell orders of those who bought too dearly last time are waiting.
Shiba Inu levels on the downside: $0.0000049 as the 30-day low
The low of the past 30 days is $0.00000494. From the current level that is 11.3 percent down. This number is the most honest figure in this article, because it maps out a range in which the price has actually moved for a month: from $0.00000494 to $0.00000610, a span of 23.5 percent between floor and ceiling.
Anyone planning a position works with that width rather than with a price target. A coin that has run through a 23.5 percent range in 30 days and loses 4.79 percent in a single day can sit at the lower edge of that range within five days without anything out of the ordinary having happened.
Shiba Inu beta against Bitcoin: a factor of 4.17 in a single day
Divide Shiba Inu's daily loss by Bitcoin's and this Wednesday gives a factor of 4.17. At Dogecoin the same factor is 3.18, at Ethereum 2.39, at XRP 1.12, at Solana 0.55. The calculation is a snapshot of one day and not a statistical beta over a longer period. As a snapshot it still says something usable.
The order matches market capitalisation in reverse: the smaller the coin, the larger the swing from the same market move. Shiba Inu ranks 37th by size, Dogecoin 12th, Bitcoin 1st. Anyone holding a Shiba Inu position is, arithmetically, holding a leveraged position on the general direction of the market without having bought any leverage.
That is the point at which position size matters more than the price target. A position that arithmetically loses 42 percent when Bitcoin falls ten percent has to be sized from the outset so that this loss is bearable. Anyone working with leveraged products on top multiplies that factor once more, and the liquidation threshold then moves closer than the price levels from the two sections above.
Shibarium at $170,913 in locked capital: the network is not carrying the Shiba Inu price
Shibarium is the Shiba Inu project's own layer-2 network. Layer 2 means a second tier that bundles transactions and settles them more cheaply, while security rests with the chain underneath. The capital locked in Shibarium applications comes to $170,913 on October 7.
That figure stands in a ratio of 1 to 19,200 against the market capitalisation of $3.28 billion. Put differently: for every dollar working in the network there are $19,200 of market expectation. That is not a charge against the project but a frame for your forecast. Anyone explaining the price through usage of the network needs numbers for that case which are not currently available.
The same applies in the other direction: a weak network does not explain the daily loss of 4.79 percent, because it was just as weak yesterday. What explains the day is the direction of the market, multiplied by the factor from the section above.
Position size and limit orders: getting around thin Shiba Inu order books
A concrete action follows from the 2.53 percent turnover ratio. With thin books a market order costs more than the quoted price, because it eats through several ticks. A limit order fixes the price you pay at most or receive at least. In exchange it is not guaranteed to fill. With a coin trading 13 times less than Dogecoin, that trade-off is usually the better one.
Two numbers help in setting the limit: the smallest tick is 0.18 percent of the current price, and last week's range ran between $0.00000556 and $0.00000592. A limit more than one weekly range away from the current price will not fill on a quiet day. A limit within two or three ticks usually will. Which German venues even quote a euro pair for Shiba Inu, and which order types they offer, differs considerably; the section below names the two examinations for that.
A euro pair or the detour through the dollar
If an exchange quotes no euro pair for Shiba Inu, your purchase runs via a stablecoin or via the dollar. You then pay a spread twice, once on the swap into the stablecoin and once on the purchase of the coin. At a turnover ratio of 2.53 percent, the second spread is the dearer one. Before buying, look at whether the pair is quoted directly in euros, and compare the price effectively paid with the quoted market price.
Buying Shiba Inu under MiCA and two contract addresses since October 4
Since October 4 Shiba Inu has existed not only on Ethereum but also on Solana, delivered over the Sunrise infrastructure. For you that means there are two different contract addresses for the same token. If you withdraw SHIB from an exchange to your own wallet, the network has to match on both sides. A withdrawal on the Solana network to an Ethereum address is as a rule lost.
Under the EU's MiCA regulation, only authorised providers may hold and trade crypto assets for retail clients in Germany. In practice that means two examinations before buying: whether the provider appears in the register of authorised service providers, and which network it picks for a withdrawal. The same network problem applies to self-custody afterwards, which is why with a hardware wallet you make sure it supports both chains; our hardware wallet comparison sets out an overview.
Shiba Inu holding period under Section 23 of the Income Tax Act: one year and a 1,000 euro threshold
Gains from the sale of crypto assets count in Germany as a private disposal under Section 23 of the Income Tax Act. If more than twelve months lie between purchase and sale, the gain is tax-free. Within the twelve months a threshold of 1,000 euros a year applies to the sum of all private disposals. Threshold means: once it is exceeded, the entire amount is taxable and not merely the part above it.
With a coin that moves 4.79 percent in a single day, the holding period is the decisive calculation. A sale eleven months after the purchase costs you your personal tax rate on the whole gain, a sale thirteen months after it nothing. Anyone no longer sure of their purchase dates obtains them as a transaction list from the exchange before selling. Tools that turn such lists into a tax calculation read the list in as a file and match every sale to the corresponding purchase.
Offsetting losses at 93.54 percent below the record
Anyone who bought Shiba Inu near its all-time high is sitting on a paper loss. Losses from private disposals can only be set against gains from the same category of income, that is against other crypto or precious-metal gains within the one-year window, not against equity gains and not against salary. An unused loss is carried forward and remains available in future years.
Such a loss is only realised through a sale within the twelve months. Once the holding period has elapsed, a loss is worthless for tax purposes, just as the gain would be tax-free. This is one of the few places where the calendar matters more than the price; towards the end of the year it is therefore worth a look at your own transaction list. On handling older SHIB holdings and the holding period, cryptoticker.io published a separate calculation on October 3.
Shiba Inu price prediction: Your next three steps
- Follow the $0.0000055 level on a daily basis. If the daily value holds above it, the 30-day range from $0.00000494 to $0.00000610 remains the frame. If it falls below, the 30-day low is the next documented zone. Where you buy in euros and which order types your venue offers, you compare in the exchange comparison.
- Size the position by the factor of 4.17, not by the price target. Work through what a ten percent fall in Bitcoin means for your Shiba Inu position. If you are also working with leverage, examine the liquidation threshold beforehand at the perp DEX providers.
- Find the purchase date of every tranche. Within the twelve months the 1,000 euro threshold applies; after that the gain is tax-free and a loss worthless. You obtain the transaction list from the exchange; the evaluation is handled by the tools in the tax tool comparison.
(As of October 7, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Anyone who wants Bitcoin in a securities account has three routes available in Germany: the coin itself through a crypto exchange, an exchange-traded security tracking Bitcoin, that is an ETN, and a certificate issued by a bank. All three move with the same price. What separates them is the question of who owns the Bitcoin, who owes you the money if things go wrong, and which section of the tax code the tax office applies to your gain.
The price is the smallest difference. Bitcoin traded at $85,543 and €76,040 on Wednesday morning, down 0.43 percent on the previous day, according to CoinGecko as of 03:00 on Wednesday. That figure sits inside all three products. The gap opens up afterwards: in the tax treatment, in the costs, and in the question of what happens if the provider becomes insolvent.
What separates a Bitcoin certificate from a Bitcoin ETN
Both are debt securities, both trade on an exchange, and both sit in an ordinary securities account. They are still two different things.
An ETN (exchange traded note) is an exchange-traded debt security that tracks exactly one underlying, here the Bitcoin price, and that is backed by real Bitcoin at the common European providers. The term is usually open-ended, there is no leverage, and the ratio to the underlying stays the same over the years, less the ongoing fee.
A certificate is the umbrella term for structured securities issued by a bank that promise a payout according to a formula fixed in advance. That formula can be simple, but it can also contain leverage, a knock-out barrier or a fixed maturity. Backing with real Bitcoin is not part of it.
In practice this means an ETN is built for holding over the long run, a leveraged certificate for short phases. Lump the two together as a “Bitcoin product” and it is easy to buy the wrong one.
ETN, ETP, ETC: three words for the same product family
All three abbreviations turn up on the providers' product pages. ETP (exchange traded product) is the collective term for every exchange-traded product of this kind. ETN is the sub-form structured as a debt security, ETC (exchange traded commodity) the label that originally emerged for commodities such as gold and that some issuers also use for crypto assets. In legal terms, European crypto ETPs are almost always bearer debt securities, whichever of the three letter codes appears in the product name.
Bitcoin ETN: a bearer debt security with a redemption right
A bearer debt security is a security under which the issuer owes the holder a payment or a delivery. That is the decisive sentence about every Bitcoin ETN: you do not own Bitcoin, you own a claim against the issuer.
The large European providers soften that by backing the notes they issue with real Bitcoin and storing those coins with a separate custodian. Many products also grant the investor a redemption right, meaning the right to demand the deposited coins instead of cash. Both are set out in the key information document and in the terms of issue, and both differ from product to product.
What does not arise here is segregated fund assets. A fund holds investors' money legally separate from the fund company's own assets, and that is precisely the protection a debt security does not provide. In its place comes the collateral, which is promised by contract and not guaranteed by law.
No Bitcoin spot ETF in the EU: the UCITS limit of 20 percent
The United States has Bitcoin spot ETFs, the European Union does not, and the reason is a sober one rooted in fund law. An ETF for retail investors falls under the UCITS rules in the EU, and those rules require diversification: no single component may account for more than 20 percent of net asset value. A fund holding nothing but Bitcoin reaches 100 percent and therefore cannot be authorised.
That is why every European Bitcoin product you can hold with a German broker is not a fund but a debt security. Search engines may suggest a Bitcoin ETF, but in Germany the search inevitably ends at ETNs and ETPs. Which of these products trade on German exchanges and what matters in picking one is covered in the overview of crypto ETFs in Germany.
There is a side effect for savings plans and retirement provision: because it is not a fund, some custodian banks treat crypto ETPs differently from ETFs, for instance in savings plans, in lending against securities or inside managed portfolios. That is not a question of the price but of your provider's house rules.
Bitcoin certificate: knock-out, factor and the risk of total loss
Two designs are particularly common among certificates on Bitcoin, and both behave markedly differently from an ETN.
A knock-out certificate works with a fixed barrier. If the price touches that barrier, the note expires and the amount invested is gone, even if the price climbs again an hour later. The leverage follows from the distance between price and barrier, so it is not constant.
A factor certificate, by contrast, keeps leverage constant by resetting daily against the closing price. In choppy sideways phases that produces a loss in value even if the Bitcoin price is back at its starting point by the end of the week. The effect is called path dependency, and it is regularly underestimated.
For both designs the same holds: the certificate is likewise a debt security of the issuing bank, only without coins deposited behind it. Issuer risk is therefore added to market risk, and with leveraged products comes the possibility that the stake is wiped out entirely while the underlying still exists. Anyone looking to trade leveraged products on crypto assets will find the providers' terms in the crypto broker comparison.
The coin itself: self-custody, seed phrase and wallet risk
The third route runs through a crypto exchange and ideally ends in a wallet of your own. Self-custody means you keep the private key to your coins yourself and no company stands between you and the balance. The seed phrase is the sequence of words from which that key can be restored.
Issuer risk disappears entirely at that point. There is nobody who could become insolvent, because nobody owes you anything. Other risks take its place, and they are not smaller: a lost device with no backup, a seed phrase somebody else finds, a contract approved by mistake in a wallet app. None of these risks can be passed on to a third party.
In between sits the case most newcomers actually choose: the coins stay on the exchange. You then do own real Bitcoin, but not the keys, and you depend on a company again, this time on one that needs authorisation as a crypto-asset service provider under the European MiCA regulation. Whether a trading venue holds that authorisation can be looked up in the supervisor's public register, and that is exactly what belongs before the first deposit.
Issuer risk and physical backing: the distance to segregated fund assets
Issuer risk is the danger that the issuer of a security cannot meet its obligation. With a crypto ETN it is the central factor, because in legal terms the note is nothing other than that obligation.
Physical backing is meant to limit the damage. The issuer buys real Bitcoin for every note issued, has it stored with an independent custodian and pledges it in favour of the investors. In an insolvency that holding is meant to go to the noteholders first rather than to the other creditors. In practice the effect hinges on three points you can look up in the key information document: whether the backing is complete, who the custodian is, and whether a trust structure has been inserted in between.
None of the three routes comes with deposit insurance. The statutory protection of €100,000 per customer and bank applies to balances in accounts, not to securities and not to crypto assets. Confuse the two and you will think a note is safer than it is.
Tax on a Bitcoin ETN: 26.375 percent capital gains tax from the first euro
This is where the difference that adds up to the largest amount over the years sits. ETNs and certificates are securities, and their gains count as investment income under Section 20 of the German Income Tax Act (EStG). A separate tax rate applies to that income: under Section 32d (1) sentence 1 EStG, income tax on it is 25 percent. On top comes the solidarity surcharge, which under Section 4 of the Solidarity Surcharge Act amounts to 5.5 percent of the tax. Together that makes 26.375 percent, slightly more for those liable to church tax.
This system knows no holding period. Whether you hold the ETN for three weeks or eleven years makes no difference to the rate. The tax is usually withheld directly by the institution holding the account, and you will find it in the settlement statement.
Relief comes only from the saver's allowance. Under Section 20 (9) EStG, €1,000 a year is deductible, and €2,000 jointly for married couples filing together. That amount covers all investment income together, interest and dividends included, and it is used up quickly.
One advantage of the securities form remains: losses on ETNs can be offset against other investment income, and the bank runs the loss-offset pot automatically. With directly held coins you have to track that yourself in your tax return.
Holding period under Section 23 EStG: one year and the €1,000 threshold
Directly held Bitcoin runs under a different section. Such coins count as other assets within the meaning of a private disposal transaction, and Section 23 (1) sentence 1 no. 2 EStG only captures transactions “in which the period between acquisition and disposal does not exceed one year”. Hold for more than a year and then sell, and no income tax is due on the gain.
Within that year the personal tax rate applies, running from zero to 45 percent depending on income, rather than the flat 26.375 percent. On a high income, selling coins short term is therefore more expensive than the same gain inside an ETN; on a low income it is cheaper.
There is also a threshold that is frequently misquoted. Section 23 (3) sentence 5 EStG states: “Gains remain tax-free if the total gain realised from private disposal transactions in the calendar year was less than 1,000 euros.” That is an exemption threshold, not an allowance. If the total gain is exactly €1,000, the full amount is taxable, not just the euro above the line.
For the order in which coins are deemed sold, the allocation is decisive, in practice usually on the principle that the holdings bought first count as sold first. Anyone who has bought in tranches over several years needs a clean record of every single purchase for that.
The December 31, 2026 cut-off in the finance ministry's draft
This coexistence of two tax systems is not meant to last. On September 30, 2026, the Federal Ministry of Finance published its draft bill on reforming the taxation of certain privately held crypto assets. According to the ministry's explanatory memorandum, the current classification under other income no longer does justice to crypto markets that have grown since; the draft is in interdepartmental consultation, and consideration by the cabinet is planned.
In substance, gains on crypto assets are to count as investment income in future. The one-year holding period would fall away, and the same rate that already applies to ETNs would take effect. Several tax firms read a grandfathering provision out of the draft in the same way: the new rules are to cover only crypto assets acquired after December 31, 2026, while the current holding period continues to apply to holdings bought earlier.
Two caveats belong with that. A ministerial draft is not a law, and deadlines and details can still change during the legislative process. And even if it arrives as drafted, it bears on today's purchase decision: purchases made by the end of the year would fall into the protected existing holdings, purchases after that would not.
What that means for the comparison of the three routes
As long as the holding period stands, the directly held coin has the clear tax advantage for long-term holding. If it falls away for new acquisitions, that lead shrinks to the differences in costs, custody and loss offsetting. Anyone making a decision today for the years ahead should run the numbers on both situations, not only on today's.
How to check who stands behind your Bitcoin ETN
The details sit in two documents every issuer has to publish: the key information document and the terms of issue. Both are reachable through the product page and through the exchange page for the security.
- Issuer and domicile: who issues the note, in which country is the company based, and which insolvency law therefore applies if things go wrong?
- Degree of backing: is every note fully backed with Bitcoin, and does that appear as a commitment in the terms or only as an intention in the marketing?
- Custodian: which company holds the coins, is it independent of the issuer, and how is the holding evidenced?
- Redemption right: may you demand delivery of real coins, from what quantity upwards, and at what cost?
- Term and early redemption: is the note open-ended, and under what conditions can the issuer call it early?
With a certificate the formula components come on top: knock-out barrier, leverage, subscription ratio and maturity date. A note whose payout formula you cannot explain in a single sentence does not belong in a portfolio.
Costs per year: management fee, spread and custody charge
The costs of the three routes arise in different places, and that makes the comparison hard at first glance.
With an ETN there is an ongoing management fee that the issuer takes pro rata out of the deposited holding. You will see no statement for it; the effect sits inside the price of the note. On top come your broker's order fee, the spread between bid and ask on the exchange and, depending on the provider, a custody charge.
Buying directly, you pay the exchange's trading fee, a spread again, and a network fee when withdrawing to a wallet of your own. There is no ongoing annual fee; anyone choosing self-custody has the cost of buying a hardware wallet instead.
With a certificate, the order fee and the spread are often joined by a financing component that accrues daily on leveraged products and weighs heavily over longer holding periods. The actual rates change and differ widely; they sit in the key information document for the particular note and are to be looked up there before buying.
As a rule of thumb over long periods: ongoing fees act like a headwind that blows equally hard every year, while one-off costs lose weight the longer you hold.
Bitcoin in your portfolio: the key points for your decision
The three routes lead to the same price and to very different obligations. This order helps with the decision.
- Settle the holding period first, and with it the tax question. Anyone planning in years weighs today's holding period against the planned capital gains tax; anyone trading short term can cut the comparison down to costs and tradability. Which trading venues are authorised for direct purchases under MiCA is covered in the crypto exchange comparison.
- Set up the record before you buy. Purchase date, quantity, price and fees per tranche decide your tax return later, and with directly held coins nobody keeps that record for you. You will find tools for it among the crypto tax software and portfolio trackers.
- Decide custody separately from the purchase decision. With an ETN the issuer's custodian takes on that job; with the coin you choose between an exchange and a device of your own. The differences between the devices are set out in the hardware wallet comparison.
The sentence that holds it all together: with an ETN and a certificate you carry the risk of a company and get convenient settlement in your securities account; with the coin you carry responsibility for the key and keep the holding period for now. Which of these two burdens sits more easily with you is the real question.
(As of October 7, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
A finfluencer is someone who talks about investing on social media and recommends individual products while doing so. Whether a crypto tip of that kind has been paid for shows up in three places: in the disclosure as advertising or a paid promotion, in affiliate links and discount codes that lead to one particular exchange, and in the pattern of the pitch, which works on urgency and peer pressure. How often that lands in Germany is something the financial regulator BaFin has had in hard numbers since October 1.
Of the 1,000 crypto investors assessed, roughly half pay attention to recommendations from finfluencers. Thirty percent have acted on them when investing. And around 40 percent were not aware that finfluencers are often paid for their recommendations. That is the core of the finding: the recommendation itself is not the problem, the invisible consideration behind it is.
The BaFin survey in numbers: 4,340 respondents, 1,000 crypto investors assessed
A market research institute surveyed 4,340 people aged 18 to 59 on behalf of BaFin. The fieldwork ran online in late March and early April 2026. The answers assessed were those of the 1,000 respondents who held crypto-assets at the time or had held them in the years before. The results appear in the regulator's specialist article, “Soziale Medien treiben Kryptoinvestments”.
What gets held is mostly the obvious. Seventy-nine percent of this group had bought Bitcoin at some point, 39 percent Ether. The assets were used predominantly as an investment. On motives, 39 percent said they had wanted to “try something new”, while 30 percent each cited the prospect of high returns and the wish for a small allocation in their portfolio.
That mix matters for understanding the rest. Someone who gets in out of curiosity, with no firm expectation of the product, tends to choose on the basis of whatever crosses their path. That is exactly where recommendations do their work.
How to spot a paid crypto tip: disclosure, affiliate link, discount code
A paid recommendation online usually takes one of two forms. Either the sender receives a fixed fee for a post, in which case that post has to be labelled as advertising or a paid promotion under German media law. Or they receive a share of the revenue when you open an account through their link and trade. This second form is called an affiliate or partner link: a link with an identifier attached, by which the exchange recognises who sent you.
Four features can be checked without any prior knowledge. First, a note such as “advertising”, “ad” or “paid partnership”, often small at the start or right at the end of a post. Second, a link with an identifier after the question mark, frequently carrying abbreviations such as “ref” or “partner”. Third, a discount or voucher code that runs under the sender's name. Fourth, a bonus promise tied to a minimum deposit.
None of these features makes a recommendation wrong by itself. Advertising is allowed to advertise, but it does tell you that the sender has a commercial interest of their own in your decision, and that belongs in your assessment. If you are looking for a trading venue anyway, the comparison of regulated crypto exchanges is the more sober route there than a code from a video.
35 percent bought because the finfluencer called the right moment
BaFin also asked what made the recommendation convincing. Among those who acted on a finfluencer recommendation, 35 percent invested because the claim was that now was the right moment. That is the most frequent reason in the entire survey.
The sentence “now is the right moment” has a property that makes it so usable for advertising: it cannot be verified at the moment it is made. Whether an entry point was good only becomes visible later, and whoever calls it carries no risk if they are wrong. A verifiable statement would look different and would name a quantity you can recalculate, such as a trading volume, a flow of funds or a date in the protocol.
From that follows a simple counter-move: take the claim and find the number for it yourself. Trading volume, inflows and outflows at exchanges or the distribution of holdings are available in freely accessible data tools; which of them does what is set out in the comparison of analytics platforms. If you find no number for the claim, you already have your answer.
FOMO as a sales argument: 29 percent followed the reference to the majority
The second most frequent reason was the reference to everyone else. Twenty-nine percent of this group bought because, according to the finfluencer, many others were doing so at the time. BaFin uses the English term for this in its assessment: fear of missing out, or FOMO for short.
FOMO says nothing about the crypto-asset itself. The claim describes the behaviour of other people; it can be accurate and still leave open whether the price is worth the risk. On top of that, the claim that a lot of people are buying right now is hard to verify for small tokens, because a few large addresses can generate a trading volume that looks like broad demand.
Both findings together describe the same mechanism from two directions: urgency and crowd. Anyone who hears either one in a recommendation has a reason to let a day pass before acting.
Memecoins and gambling: what BaFin's consumer protection staff say word for word
Nineteen percent of the crypto investors surveyed have bought memecoins at some point. Among the motives they named were “fun” and “having a punt”. A memecoin is a token with no use of its own and no promise of yield, whose price results purely from demand.
The regulator's assessment is blunt. “Investing in memecoins is in fact comparable to placing a bet in a game of chance,” says BaFin consumer protection expert Dr Markus Nielsen; memecoins are therefore particularly risky. Consumer protection officer Christian Bock places the whole market in context: “Consumer interest in crypto-assets is rising,” he says, “yet most of these assets are highly speculative.” Price movements, he adds, are tied neither to a particular currency nor to a tangible asset, and with memecoins there is also no cap on supply.
For a German supervisory authority to compare an asset class with gambling is notable, and it links the finding explicitly to the subject of this article: with memecoins in particular, the danger is especially great that finfluencers move the price by talking an asset up excessively or talking it down. The leverage here is greater than with large assets, because little capital is enough to shift the price.
Concentration risk in the portfolio: 27 percent hold more than a fifth of their wealth in crypto-assets
One figure from the survey can be applied directly to your own portfolio. Twenty-seven percent of respondents said they had invested more than 20 percent of their wealth in digital assets. For 5 percent it was more than half.
The technical term for this is concentration risk: a single building block in a portfolio is so large that its performance determines the overall result. In an asset class that swings by double digits within a few days, that share decides whether a setback is merely annoying or existential. The regulator names no upper limit for it, and there is no official one either. The figure still works as a yardstick: if your own share sits well above what you could stomach losing, that is a finding in its own right, independent of any recommendation.
The connection to the rest of the survey is plain. Anyone who settles their position size in the moment of enthusiasm settles it according to that enthusiasm. Anyone who settles it beforehand already has an answer ready for the next tip.
Five features to check before acting on any crypto tip from social media
The findings of the survey boil down to a short routine that runs before a purchase and takes a few minutes.
- Look for the disclosure. Does it say “advertising”, “ad” or “paid partnership” anywhere? Look in the description under the video and in the first comment as well, because that is where it tends to be parked.
- Take the link apart. Does the recommendation run through an identifier or a code? Then money flows to the sender when you open your account.
- Look into the provider. Does the platform named hold a licence for this business in Germany? BaFin maintains a public company database for exactly this, and it publishes warnings about unauthorised providers on an ongoing basis.
- Find a second source. Does the central claim also appear somewhere that gains nothing from your buying? If nothing turns up, it remains a single opinion.
- Set the position size beforehand. Decide the amount before you finish listening to the recommendation, and stick to it. This is the only point on the list that nobody but you can influence.
This routine is no substitute for your own view of a crypto-asset; it only separates the question of whether something is a good investment from the question of who earns money when you buy it, and the second question was not on the radar at all for 40 percent of respondents.
Holding period and tax: what an impulse purchase after a finfluencer tip triggers with the tax office
One point does not come up in the survey and yet belongs to every spontaneous purchase. In Germany, transactions in crypto-assets held as private assets count as private disposal transactions under Section 23(1) sentence 1 number 2 of the Income Tax Act (Einkommensteuergesetz). If you sell at a profit within one year of buying, that profit is taxable; after a holding period of one year it is not. A threshold of 1,000 euros applies to the total of all private disposal transactions in a year. Threshold means that once it is exceeded, the entire gain is taxable, and not only the part above it.
Two things follow from this for a purchase made after a tip. First, the one-year period for this specific position begins on this specific day, regardless of how long you have already held the same cryptocurrency. Second, a quick resale, which the same dynamic of urgency and peer pressure frequently leads to, is the least favourable case for tax purposes. Someone who buys and sells three weeks later in disappointment has a taxable event if there is a gain and documentation work if there is a loss.
In practice that means recording the purchase date, quantity and price, and doing so on the day of the purchase. It costs a minute and saves back-calculating across several exchanges if there is ever any doubt. Individual tax questions belong in the hands of a tax adviser; this section is no substitute for advice.
MiCA, BaFin and advertising: which rules apply to finfluencers today and which ones ESMA wants
Since the European crypto regulation MiCA came into force, providers of crypto services in the EU need a licence, and their marketing communications have to be identifiable as such, fair and not misleading. These duties are addressed to the providers. An independent sender on social media who is not a service provider does not automatically fall under them, and that is exactly where the gap sits that the BaFin figures describe. Which obligations the regulation sets out in detail is covered in our overview of the MiCA licensing requirements for crypto companies.
The European securities regulator ESMA wants to change that. In its opinion on the review of MiCA, which reached the EU Commission at the end of September, it explicitly calls for “stricter rules for the marketing of crypto-assets, particularly when they are promoted by influencers and third parties”. Which six changes the authority proposes in total we have broken down in our article on the ESMA opinion on MiCA.
Between a demand and applicable law lies a legislative procedure that runs for months. Until then the labelling requirement from media law remains the most important lever, and its enforcement depends on someone noticing the missing disclosure. That is what makes the survey finding so uncomfortable: a protection that rests on recognition by the audience comes to nothing for 40 percent of that audience.
Two authorities have thus marked the same spot within two days, one with a demand from Paris, the other with figures from Germany.
Finfluencer tips: the key points for your decision
The survey describes the normal case: around half of the crypto investors surveyed pay attention to recommendations from social media, and two in five do not know the business model behind them. Three steps turn that into something manageable.
- Separate the recommendation from the trading venue. Decide first whether a crypto-asset convinces you, and choose the platform separately afterwards. A look at the comparison of regulated crypto exchanges shows which providers hold a licence in the EU.
- Get the number behind the claim. Every statement about timing or demand can be cross-checked. Which analytics platforms disclose volume, inflows and the distribution of holdings is set out in the comparison.
- Document on the day of purchase. Record the date, quantity and price so the holding period can be proven later. Tools for this are in the comparison of crypto tax software and portfolio trackers.
(As of October 7, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
The EU police agency expects blockchains to adapt to the threat, while a second report weighs the risk of data stolen now and cracked later.
The Tornado Cash founder hit back in a tweet, noting FinCEN withdrew a proposed mixer rule over concerns it could chill legitimate activity.
Unveiled at TOKEN2049 Singapore, the Morpho-powered Crypto Loan feature lets users borrow stablecoins against wrapped Bitcoin while keeping private keys and final approval on their hardware device.
Google's new image model, Nano Banana 2.1, is live. It costs about half as much as its predecessor, but the performance claims come from Google's own tests.
Nothing in Circle's posts announces a sponsorship, but replies dug up Khaled's 2018 SEC settlement over a crypto fraud he promoted. The internet never forgets.
U.Today - IT, AI and Fintech Daily News for You Today
XRP futures market now resetting after the sharp imbalance with what comes next now being watched.
Shiba Inu's overall improvement on the spot market is followed by a substantial decrease in short-term support.
Nasdaq trading for the 473 million XRP 'pure play' treasury firm is officially on hold until Monday, October 12.
The cryptocurrency ETF market is largely dominated by a single asset and it's not that good.
Ripple has minted another 30 million RLUSD in a single transaction.
Blockonomi
The power of combining interactive community engagement with a utility-driven rewards layer has been unleashed during the initial stage of a partnership between Predictfully, a free-to-play sports fan engagement platform built on the Avalanche blockchain, and the nGRND Gold Protocol, an ecosystem designed to bridge the legacy gold industry with the emerging digital economy.
Launched on September 17, 2026, the joint Participation Stream Partnership integrated Predictfully’s white-label capable fan engagement platform with the nGRND Gold Protocol Staking & Rewards Ecosystem using a custom Predictfully Dynamic Soulbound Token (DSBT). By October 6, 2026, just nine days into the rollout, the initiative sparked explosive growth across all primary user metrics. New account growth skyrocketed by 472%, active players increased by 465%, and market predictions grew by 299%, driving a 56% increase in total accounts overall.
The integration proved highly effective at converting passive sports fans into verified web3 participants without the friction of stakes, odds, or a traditional house. The custom Predictfully nGRND DSBT program rapidly scaled to 35,589 total users, maintaining exceptionally high data and identity verification standards across the board. Digital wallet verification reached a flawless 100%, while email and Telegram verification levels hit 92% and 95% respectively.
Rather than creating “empty” accounts, the campaign prioritized deep, protocol-level engagement, encouraging fans to climb the leaderboards to win rewards funded by clubs and sponsors, ranging from merchandise to matchday experiences. Within the first twenty days, 32,834 users successfully completed the Predictfully DSBT process to activate their profiles, earn their first virtual NGRND, and enter the broader staking ecosystem.
Acting as a digital passport, the DSBT provides exclusive access to participation streams and dynamically tracks on-chain activity and credentials. To date, these activated participants have completed 294,502 micro-tasks to earn Reward Points, validating the partnership’s focus on sticky, repeatable user behavior over short-term speculation.
The early performance of this joint case study underscores a larger shift in decentralized growth strategies, blending sports engagement with participation-driven opportunities backed by Preserved Gold and network engagement.
By offering a plug-and-play rewards infrastructure, the nGRND Gold Protocol allows ecosystem partners to boost user acquisition and retention without exhausting internal development resources. For Predictfully, which licenses its platform to professional clubs and rights holders, the collaboration provides a continuous loop of player activation, while the nGRND Gold Protocol successfully expands its footprint of verified, high-intent network participants. Users can find out more or get started by visiting predictfully.app and nGRND.io.
The post Predictfully and nGRND Gold Protocol Secure Massive Engagement Surge in 20-Day Campaign appeared first on Blockonomi.
TLDR
- BTCC launched a refreshed Trust Center on October 7, 2026, as it marks 15 years in operation.
- The exchange says monthly Proof of Reserves reports show a 100% reserve ratio at all times.
- BTCC holds a $25.5 million Risk Reserve Fund and says it has had $0 in hacker theft since 2011.
- CertiK runs independent security audits, with support from Chainalysis, Forter, and SEON.
- BTCC now offers US stocks, gold, forex, and commodities alongside crypto.
BTCC, a cryptocurrency exchange founded in 2011, has launched a refreshed Trust Center. The company announced the update on October 7, 2026, from George Town in the Cayman Islands.
The launch comes as BTCC marks its 15th year in operation. The exchange calls itself the world’s longest-serving cryptocurrency exchange.
BTCC is also a Platinum Sponsor of TOKEN2049 Singapore this year. The company says it serves over 12 million users in more than 100 countries.
What the Trust Center Includes
The Trust Center brings together BTCC’s security tools, financial protections, and transparency commitments in one place. It is meant to show users how their funds are kept safe.
Security features include multi-signature cold storage, 1:1 asset storage, and multi-layer risk monitoring. The exchange also runs anti-money laundering (AML) controls 24 hours a day.
CertiK carries out independent security audits for the exchange. BTCC also works with Chainalysis, Forter, and SEON.
The exchange publishes monthly Proof of Reserves reports. BTCC says these show a total reserve ratio of 100% at all times.
BTCC also holds a $25.5 million Risk Reserve Fund. The company says this fund acts as an extra buffer against market disruptions.
According to the exchange, it has recorded $0 in losses to hackers since it was founded in 2011.
The 0-Barrier Trading Theme
These security measures make up what BTCC calls its “0 Panic” commitment. It is part of a wider “0-Barrier Trading” theme the exchange introduced for its 15th year.
The theme has four parts. Besides 0 Panic, there is 0 Fees, which offers zero trading fees across more than 380 pairs every week.
0 Distance refers to 24/7 support in traders’ native languages. 0 Friction covers copy trading and TradingView integration.
Alex Hung, BTCC’s Head of Operations, said the exchange has faced bull markets, bear markets, high volatility, and changing regulations. “Any exchange can be built to grow,” Hung said. “The harder thing to build is the resilience to last.”
He said security comes before everything else. “Users do not hand us an account. They hand us their assets and trust,” Hung said.
BTCC now offers US stocks, gold, forex, and commodities alongside its crypto products. “Traders no longer think in asset classes,” Hung said. “They want to move between crypto, stocks, and forex without switching platforms.”
When asked if BTCC wants to be the world’s largest exchange, Hung said no. “We don’t aim to become the biggest. We aim to be the ones that raise the standard.”
The refreshed Trust Center is available now. Visitors at TOKEN2049 Singapore can find the BTCC booth at 1F (PB1-7), where the team is hosting games and handing out swag bags.
The post BTCC Crypto Exchange Launches Refreshed Trust Center for 15th Anniversary appeared first on Blockonomi.
TLDR
- Winklevoss Asset Services has filed with the SEC for a spot Zcash ETF that would trade on Nasdaq under the ticker WINK.
- Gemini Trust Company would hold the ZEC, and authorized participants would use only cash to create and redeem shares.
- Cypherpunk Technologies is named in the filing and bought a $33.33 million Zcash mining fleet in August.
- ZEC rose more than 5% in 24 hours and traded above $1,375 after the filing.
- The Zcash team will decide on the NU7 upgrade activation height on October 20, with a launch planned for November 5.
Winklevoss Asset Services has filed for a spot Zcash ETF with the US Securities and Exchange Commission. The fund would hold ZEC directly and seek a Nasdaq listing under the ticker WINK.
The filing was made through an S-1 registration statement. The fund would not use futures or other derivatives to track the price of ZEC.
Gemini Trust Company would act as custodian for the fund. Authorized participants would use cash, not ZEC, to create and redeem shares.
How the Spot Zcash ETF Would Work
Under the proposed structure, Gemini would hold the ZEC that backs the ETF shares. Authorized participants would buy and sell shares using cash only.
Winklevoss Asset Services would then use that cash to trade ZEC as the fund requires. This setup gives the fund direct exposure to the token.
The filing also names Cypherpunk Technologies as a provider of services tied to the Zcash network. Its role is separate from Gemini’s custody duties.
The registration does not mean the fund can begin trading. The product still needs SEC approval before it can list.
Cypherpunk Technologies already had ties to Zcash before the filing. In August, the Nasdaq-listed company said it bought a Zcash mining fleet and hosting deals.
The deal was worth $33.33 million and was made with companies linked to Winklevoss Capital. The fleet of Bitmain Z15 Pro machines runs in US facilities.
Cypherpunk estimated the equipment made up about 18% of computing power on the Zcash network. It expected monthly output of around 7,800 ZEC, depending on mining difficulty and competition.
Payment was made through a pre-funded warrant on 43,290,042 common shares. The shares were valued at $0.77 each, with an exercise price of $0.001.
ZEC Price and the NU7 Upgrade
ZEC rose more than 5% over 24 hours after the filing and traded above $1,375, according to CoinMarketCap. The wider crypto market gained nearly 1% over the same period.
The token climbed from around $1,290 to $1,350, then pulled back to about $1,320. It later rose again toward $1,380.
Market data showed resistance at $1,375 to $1,380. Support sat near $1,355 to $1,360, with a lower level at $1,340 to $1,345.
The proposed NU7 upgrade would cut the target block time from 75 seconds to 25 seconds. Daily ZEC issuance would stay the same because the block reward would also be reduced.
The upgrade would also disable version 4 transactions at activation. This would block further spending from the older Sprout pool, since version 5 transactions cannot do that.
The Zcash team is set to decide on the NU7 mainnet activation height on October 20. A launch planned for November 5 depends on the results of the testnet review.
The post Winklevoss Files for Spot Zcash ETF on Nasdaq Under Ticker WINK appeared first on Blockonomi.
TLDR
- Coinbase plans to relaunch Coinbase Pro by the end of 2026 for spot, futures, perpetuals, options and equities trading.
- Coinbase completed its Deribit integration, creating Coinbase Global Exchange.
- Coinbase Financial Markets will connect eligible U.S. clients to global crypto derivatives liquidity.
- Spot margin trading is coming, with leverage of up to 10 times on selected major assets.
- U.S. retail traders are expected to get access to Deribit options later this year.
Coinbase plans to bring back its Coinbase Pro trading platform by the end of this year. The crypto exchange operator also said it has finished integrating Deribit, the options exchange it bought last year.
The integration has created a new entity called Coinbase Global Exchange. Coinbase shared the news at the Token2049 Singapore event.
“For the first time in market history, we are connecting U.S. and international derivatives markets into a single liquidity pool,” Coinbase said.
Deribit Integration Links U.S. and Global Markets
Coinbase Financial Markets, the company’s U.S.-regulated futures commission merchant, will soon connect eligible U.S. clients to global crypto derivatives liquidity. Coinbase said guidance issued by the Commodity Futures Trading Commission in May allows this.
According to the company, U.S. institutional clients will now have a regulated way to access options and perpetual futures. Before, these products required offshore entities, multiple counterparties and separate trading venues.
Coinbase said it will roll out Deribit-powered options, spot margin and unified portfolios in the coming weeks. Eligible traders outside the U.S. will get access to options in that time frame.
U.S. institutional clients will be able to trade Deribit options and perpetual futures through Coinbase Prime. Onboarding is already open, and options trading is expected to begin in the coming weeks.
Coinbase said institutional clients will be able to trade spot, futures, perpetuals and options on one platform. They will also be able to use custody, financing and staking services in the same place.
Coinbase bought Deribit, one of the world’s largest crypto options exchanges, for about $2.9 billion in August 2025. Deribit had more than $30 billion in bitcoin options open interest as of Sept. 30, according to Coinbase.
The exchange also processed over $1 trillion in trading volume last year, the company said.
Coinbase Pro Returns With Spot Margin
The new Coinbase Pro will support trading in spot, futures, perpetuals, options and equities. Coinbase said the platform has been “rebuilt from the ground up.”
The company said it will offer faster order routing, improved execution flows and advanced tools. These are designed for high-volume active traders using complex strategies.
Coinbase shut down the original Coinbase Pro in 2022 after moving advanced trading into its main app. The move to Coinbase Advanced was completed in November 2023.
Coinbase also plans to add spot margin trading. This will let eligible traders borrow against their collateral to make larger spot trades.
Leverage will go up to 10 times on selected major assets. Other supported assets will have leverage of up to five times.
Coinbase has also added a new matching engine and shortened its onboarding process. The company changed fee tiers for Coinbase Advanced as well.
The new fee tiers start at $10,000 in qualifying volume. Both spot and derivatives trading count toward that total.
U.S. retail traders are expected to get access to Deribit options later this year, around the same time Coinbase Pro is set to return.
The post Coinbase to Relaunch Coinbase Pro by Year-End After Deribit Integration appeared first on Blockonomi.
TLDR
- Conduit Technology sued Tether in New York federal court over $2.76 million in frozen USDT.
- Tether blacklisted Conduit’s treasury wallet on Sept. 24, 2025.
- Conduit says Brazilian police never asked Tether to freeze its wallet.
- The company wants access restored, at least $2.76 million in damages, punitive damages and reserve income.
- Tether had not publicly responded to the allegations as of Oct. 7.
Cross-border payments company Conduit Technology has sued Tether over $2.76 million in USDT. The funds have been frozen since September 2025.
The complaint was filed on Oct. 5 in the U.S. District Court for the Southern District of New York. It names Tether Holdings, Tether International, Tether Operations and Tether Investments as defendants.
Conduit says the frozen USDT was part of its own working capital, not customer money. The company claims Tether restricted the funds without any legal claim against it.
Conduit Says Brazil Never Targeted Its Wallet
The dispute is linked to a Brazilian Federal Police investigation opened in 2024. The probe involves financial intermediary Bull Intermediação de Negócios and a related company, Onix Intermediações.
Conduit once provided payment services to Onix. It says that relationship ended on April 22, 2025, almost a month before it created the treasury wallet on May 20.
The company says neither Onix nor Bull owned the wallet, sent money to it or used it for transactions.
According to the complaint, Brazilian police shared a list of suspected crypto addresses with Tether’s T3 Financial Crime Unit. Conduit says its address was not on that list.
Conduit points to a July 2026 filing from Brazilian authorities. It says this showed T3 found other addresses through its own analysis, which is how Conduit’s wallet was flagged.
Conduit’s lawyers say Brazilian investigators told them they had not picked the address for blocking. The Brazilian filing was not made public with the U.S. complaint.
Tether’s Terms and Conduit’s Claims
Unlike Bitcoin, USDT can be frozen by its issuer. Tether’s terms allow freezes when required by law, when an address is tied to an investigation, or when the company considers it prudent.
Conduit does not dispute that Tether can technically freeze tokens. It argues Tether had no legal grounds and no enforceable contract allowing it to freeze these funds.
The company says the wallet handled 4,427 transactions with 78 counterparties, worth over $1.1 billion, between May and September 2025. It links the freeze to lower payment capacity, layoffs and office closures. The court has not tested those claims.
Conduit says its lawyers contacted Tether in June 2026 and sent a formal demand on Aug. 19. Tether had earlier pointed Conduit to Brazilian authorities but did not release the funds.
The lawsuit includes claims of conversion, unjust enrichment, breach of fiduciary duty and federal computer-fraud violations. Conduit has asked for a jury trial.
It seeks restored access, at least $2.76 million in damages and punitive damages. It also wants any income Tether earned on reserves backing the frozen tokens.
The case follows a separate August lawsuit from two Thai businessmen. They are challenging Tether’s freeze of about $42.4 million in USDT across 10 Ethereum addresses in October 2025.
Tether often works with law enforcement. In April, it said it supported freezing more than $344 million in USDT tied to two TRON addresses targeted by U.S. authorities.
As of Oct. 7, Tether had not publicly responded to Conduit’s allegations. The next steps include serving the lawsuit and a response from Tether.
The post Tether Sued in New York Over $2.76M in USDT Blacklisted Since 2025 appeared first on Blockonomi.
CryptoPotato
Meritz Securities is stepping further into digital assets through a new partnership with Ripple. The South Korean securities firm said on October 7 that it signed a strategic agreement with the blockchain company to explore digital asset infrastructure for the domestic market.
The deal will focus on custody and tokenization as digital assets move closer to formal recognition within South Korea’s financial system.
Ripple’s Korean Expansion
The partnership was signed on October 1 at Meritz Securities’ headquarters in Seoul’s Yeouido district. Its chief executive, Jang Won-jae, and Ripple President Monica Long attended the ceremony, along with other officials.
As part of the agreement, the companies will look at how Ripple’s tokenization infrastructure and Ripple Custody can be used in South Korea’s capital markets. Both solutions are already available to financial institutions globally. Their initial cooperation will stay within current securities business rules and other existing regulations, with plans to expand the partnership gradually as the country’s digital asset rules develop.
Meritz Securities has already been reviewing several digital asset businesses, such as spot ETFs, fractional investment products, security token offerings, trading platforms, as well as won-based stablecoins.
Ripple has been expanding its footprint in South Korea’s digital asset market this year. In April, internet-only lender K Bank moved beyond initial blockchain remittance trials through a new partnership with the company. The bank is testing whether Ripple’s network can make cross-border transfers faster, cheaper, and more transparent.
Its second proof-of-concept phase includes account integration and on-chain transfer tests with partners in the UAE and Thailand. KBank also plans to replace its in-house wallet with Ripple’s SaaS-based Palisade wallet during the next phase.
Ripple has also worked with Kyobo Life Insurance on institutional digital asset infrastructure. The focus is on tokenized government bond transactions.
Meanwhile, XRP has been particularly popular among Korean investors in their twenties. It accounted for 20.7% of their portfolios, compared with a combined 17.5% for Bitcoin and Ethereum, which put XRP 3.2 percentage points ahead.
A Bigger Institutional Push
The company is also expanding its institutional business elsewhere. For instance, Ripple partnered with Brazil’s CSD BR to use the XRP Ledger for recording and auditing tokenized financial assets. The first phase will focus on investment fund shares from BTG Pactual.
The system will run alongside CSD BR’s existing infrastructure and give eligible participants near-real-time access to blockchain records. Access will be limited to approved corporate and banking clients.
Ripple has also deepened its relationship with Brevan Howard. The investment manager will use Ripple Prime for multi-asset prime brokerage, clearing, and financing.
The post Ripple (XRP) Lands New South Korea Deal as Meritz Securities Explores Digital Asset Custody appeared first on CryptoPotato.
It was just yesterday that we wrote about ADA breaking out, as the asset had climbed to a multi-month peak of over $0.27 and analysts had just turned highly bullish, with massive price predictions flying left and right.
However, the asset was rejected badly. In fact, ADA is down by over 8% in the past 24 hours and now sits below $0.255. This is rather surprising given the latest developments on the whale front.
Whales Waking Up
Data provided by Santiment Intelligence indicates that there’s a significant increase in activity among the largest market participants in the broader Cardano ecosystem. Transactions worth at least $100,000 jumped to 314 on October 5, the highest level of such activity in over four months.
It’s worth noting that higher whale transaction counts show that large holders are becoming more active again, but do not reveal whether they are buying or selling. Cardano crowd interest is on the rise again as ADA’s social dominance reached 1.16%. This became its highest reading for the year after the token rallied from under $0.19 to over $0.27 within a few weeks.
Santiment explained that fresh developments, including the October 1 RealFi mainnet launch, anticipation surrounding Leios, Fireblocks support, and additional institutional integrations, have helped put Cardano back on the social media map. After all, the asset’s market cap gained over 42% since September 16 before today’s pullback drove it south.
Cardano Whales Wake Up, ADA Marketcap Now Up 42% Since September 16th!
Cardano’s +42% run since September 16th has whales moving again. ADA transactions worth at least $100K surged to 413 in one day, marking the highest whale activity since June 4th.
The crowd has suddenly arrived to the party as well. ADA’s social dominance hit 1.16%, its highest level of 2026. The altcoin’s move from ~$0.19 to ~$0.27 has clearly pulled Cardano back into the crowd’s spotlight.
What’s causing all this? Fresh project developments are adding fuel. RealFi launched on Cardano mainnet October 1st, while anticipation around Leios, Fireblocks support, and new institutional integrations is helping drive Cardano’s biggest discussion spike of the year.
Our Live Cardano Chart: https://t.co/txYFvaHIzO
— Santiment Intelligence (@SantimentData) October 6, 2026
Was Leverage to Blame?
As mentioned above, ADA has slumped over 8% in the past day, making it the worst-performing altcoin among the 30 largest digital assets. Some of the blame could be on leveraged positions. As reported yesterday, ADA open interest increased by 25% in just days to over $300 million.
That made the rally more than a simple short squeeze, but it also meant more leverage exposure was sitting in the market when price direction flipped. ADA was up by almost 11% to over $0.27 on October 5, but the subsequent market-wide liquidation flush has now erased a major portion of those gains.
The post Why Is ADA’s Price Down 8% Today Even as Cardano Whales Wake Up? appeared first on CryptoPotato.
Bitcoin was rejected again at $87,000 on Monday, and the bears took it a step further earlier this morning, pushing it south hard to under $84,000.
BTC’s decline dragged most of the altcoins with it. Ethereum slipped below $2,600, XRP dumped further away from the $1.50 support, and HYPE is close to breaking below $90.
BTC Below $84K
After the positive PCE data last Wednesday, which sent BTC up and down within minutes, the asset went on the offensive on Friday. It had climbed above $86,000 even before the US jobs report went live, which was weaker-than-expected. The bulls initiated another leg up, driving the cryptocurrency to over $87,000.
However, the bears stepped up at this point. Bitcoin slumped in the following hours and ultimately crashed below $84,000. It rebounded to just over that level on Saturday and climbed to $85,000 on Sunday. It tried to take down the crucial $87,000 support on Monday, but it was quickly stopped and dipped to $85,000.
Another breakout attempt followed on Tuesday, but BTC couldn’t go past $86,600 this time. It pulled back by a grand and stood there for a few hours before it suddenly slumped by over $2,000 on Monday morning in minutes to $83,600. Its rebound stalled at $84,400, and the asset is now struggling at $84,000.
Its market capitalization is down to $1.680 trillion, while its dominance over the alts has remained at the same level as yesterday at 59% on CMC.
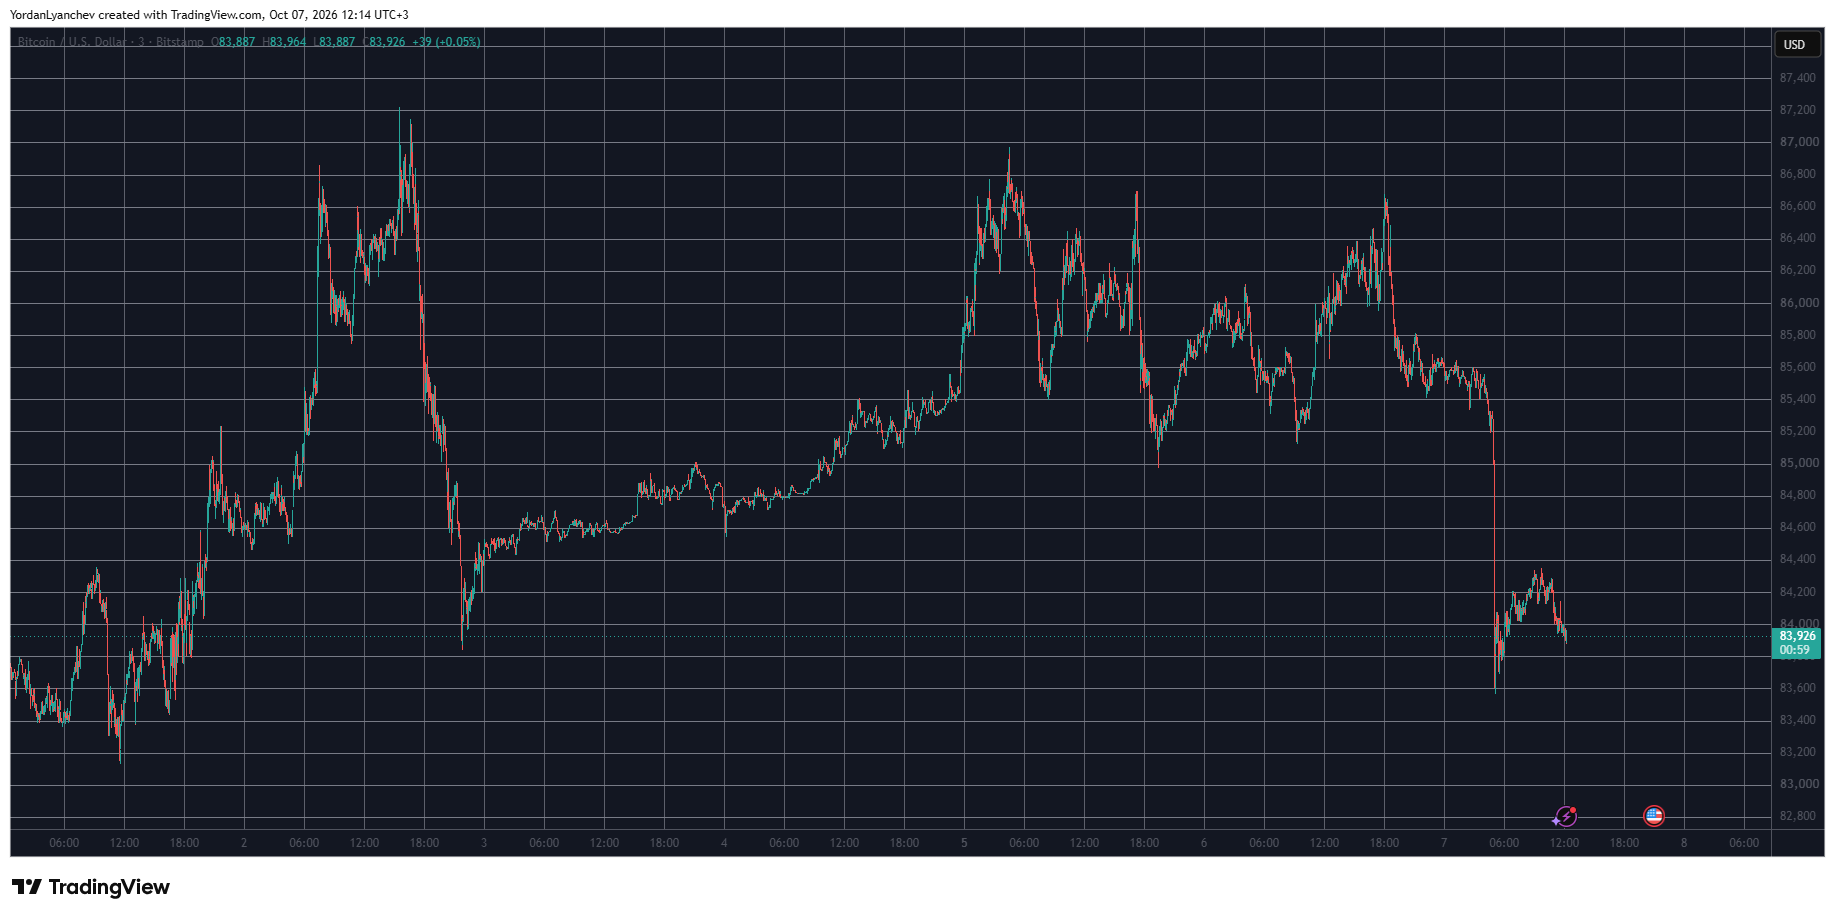
Alts Bleed Out
ETH was among the hardest-hit larger-cap alts today, dropping by over 4% at one point to under $2,600. XRP has seemingly lost the $1.50 support after a 3% decline pushed it to $1.46. BNB, SOL, TRX, and ZEC are also slightly in the red.
More painful declines come from the likes of ADA (-6.5%), UNI (-8.5%), CRO (-5.5%), SHIB (-6%), as well as WLD, CC, SUI, CRO, and HBAR. DOT has plummeted by 9%, while MNT has decreased by 10%. BTW is among the few exceptions among the larger-cap alts.
The total crypto market cap has shed over $60 billion in a day and is down to $2.850 trillion on CMC.
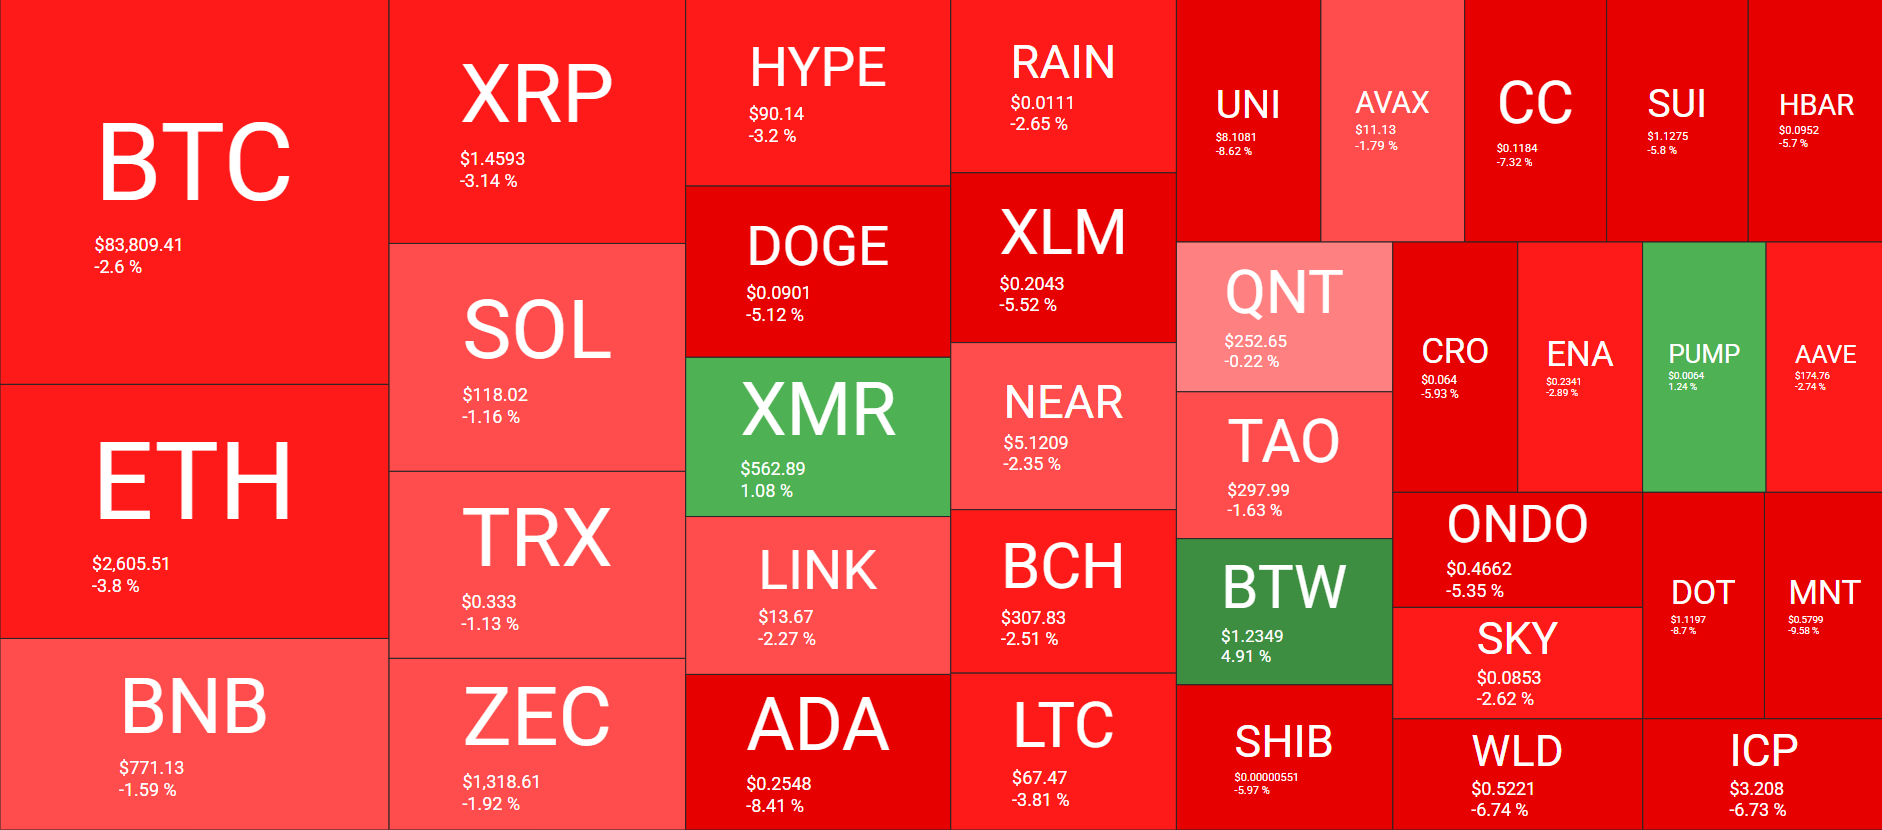
The post These Altcoins Bleed the Most After Bitcoin’s Sudden Drop Below $84K: Market Watch appeared first on CryptoPotato.
BTC held on exchanges has dropped notably, according to Santiment. On Monday, about 24,073 units left exchanges on a net basis.
This is the largest daily outflow in seven months.
Fresh Bullish Hopes
The last similar move came on March 1. Data compiled by Santiment showed that exchange-held Bitcoin has now fallen to around 6.50% of the total supply. Large outflows are often seen as a positive sign because fewer coins remain readily available for selling. If demand stays steady, tighter supply could support higher prices. The analytics platform added,
“Persistent withdrawals can signal investors shifting BTC toward longer-term custody rather than preparing to sell. Outflows alone guarantee nothing, but falling exchange supply strengthens the bullish setup.”
The latest data from CryptoQuant adds to the bullish picture. Its analysis revealed that mid-size Bitcoin inflows have fallen on some major exchanges even as the crypto asset has climbed more than 33% since mid-August. On Binance, the 7-day average of mid-size inflows fell from 4,155 BTC on August 16 to 2,648 units on October 7, a decline of over 36%. Bitcoin was trading near $63,000 in mid-August and is now above $84,000.
This means the drop has come even as the price has been trading on the higher side. Coinbase Prime also saw a similar decline, with mid-size inflows falling from 1,620 to 1,370 BTC, down around 15%.
Coinbase Advanced, on the other hand, moved in the opposite direction. Mid-size inflows there increased to 4,760 from 2,520 BTC in August. But the latest reading remains below the 5,000 BTC level. Current mid-size inflows on Binance and Coinbase Prime are well below some of the bigger spikes recorded earlier this year, including those seen in February, June, and late August.
The trend is important because lower exchange inflows can point to less selling activity. Mid-size investors do not appear to be rushing to send coins to exchanges.
ETF Inflows Turn Positive
On the institutional side of things, US spot Bitcoin ETFs saw a quick change in investor mood this week. After starting Monday with almost $90 million in net outflows, the funds bounced back on Tuesday with combined inflows of $119 million.
BlackRock’s IBIT led the recovery after pulling in $122 million in fresh money and recording the biggest inflow among the ETFs. Morgan Stanley’s MSBT also attracted $7.84 million in capital. Meanwhile, the Grayscale Bitcoin Mini Trust saw the biggest outflow, losing around $11 million.
The post 24,000 BTC Just Left Exchanges: Is Bitcoin’s (BTC) Supply Crunch Heating Up? appeared first on CryptoPotato.
[PRESS RELEASE – GEORGE TOWN, Cayman Islands, October 7th, 2026]
BTCC, the world’s longest-serving cryptocurrency exchange and Platinum Sponsor of TOKEN2049 Singapore, today announced the launch of its refreshed Trust Center. The relaunch reflects a view that Alex Hung, Head of Operations, has held since BTCC’s earliest days: that security has to be built, tested, and proven over time.
15 Years of Building Trust
As BTCC marks its 15th anniversary and joins TOKEN2049 Singapore as a Platinum Sponsor this year, Hung reflects on what the exchange’s track record actually represents.
While other exchanges compete on fees and product listings, BTCC has been navigating what he calls a continuous pressure test: bull markets, bear markets, extreme volatility, and a constantly changing regulatory landscape. “Any exchange can be built to grow,” Hung said. “The harder thing to build is the resilience to last.“
Security, in his view, is the foundation of the exchange’s growth. “Users do not hand us an account. They hand us their assets and trust. That is a different kind of responsibility. And it means security has to come first, not as a selling point, but as the ground everything else is built on.”
The Refreshed Trust Center
The enhanced Trust Center brings together BTCC’s security measures, financial protections by leading partners in the industry, and transparency commitments:
- Multi-signature cold storage, 1:1 asset storage, multi-layer risk monitoring, and 24/7 AML controls
- Independent security audits by CertiK, supported by Chainalysis, Forter, and SEON
- Monthly Proof of Reserves reporting a total reserve ratio of 100% at all times
- $25.5M Risk Reserve Fund as an additional buffer against market disruptions
- $0 in hacker theft recorded since founding in 2011
Together, these form the exchange’s 0 Panic commitment, which is part of the 0-Barrier Trading theme introduced earlier as the exchange enters its 15th year in operation:
- 0 Panic: Trading with a battle-tested exchange that has never suffered losses to hacks
- 0 Fees: Zero trading fees across 380+ pairs every week
- 0 Distance: 24/7 localized support in traders’ native languages
- 0 Friction: Seamless copy trading and TradingView integration
The security foundation also supports BTCC’s expansion beyond crypto. “Traders no longer think in asset classes. They want to move between crypto, stocks, and forex without switching platforms,” Hung said. “The industry is responding, and so are we.” BTCC today offers US Stocks, Gold, Forex, Commodities, and more alongside its core crypto products. “We started in crypto, and we won’t stop there.”
Building for the Long Term
When asked whether BTCC’s goal is to become the world’s largest exchange, Hung is direct. “We don’t aim to become the biggest. We aim to be the ones that raise the standard.” For him, that means security built from the inside out and a future where the boundaries between crypto and traditional financial instruments no longer have to be as rigid as they are today.
“We want to build a platform that is more secure, more compliant, and genuinely connected to global markets,” Hung added.
BTCC’s refreshed Trust Center is now available here. Traders attending TOKEN2049 Singapore are also welcome to drop by the BTCC booth at 1F (PB1-7) to meet the team, join interactive games, and collect exclusive swag bags.
#BTCCTOKEN2049 | #BTCC15 | #BTCC0Fees
About BTCC
Founded in 2011, BTCC is a leading global cryptocurrency exchange serving over 12 million users across 100+ countries. As the official regional sponsor of the Argentine Football Association (AFA), BTCC offers secure and accessible cryptocurrency trading services, focused on delivering a user-friendly experience while adhering to applicable regulatory standards.
Official website: https://www.btcc.com/en-US
X: https://x.com/BTCCexchange
The post BTCC Exchange Launches Refreshed Trust Center: Alex Hung on 15 Years of Earning Traders’ Trust appeared first on CryptoPotato.