Cryptocurrency Posts
Crypto Briefing
The lack of insurance for catastrophic AI risks could lead to significant financial exposure for AI firms and influence regulatory actions.
The post OpenAI, Google, Meta, Anthropic lack insurance against catastrophic AI risk appeared first on Crypto Briefing.
Kling AI's IPO could redefine market valuations for AI video tech, influencing strategic dynamics among major tech investors and competitors.
The post Kuaishou’s Kling AI lines up CICC, Goldman Sachs and UBS for a $1 billion Hong Kong IPO appeared first on Crypto Briefing.
Artizen's operational pause raises concerns about the future of community-funded projects and the stability of ART token investments.
The post Artizen pauses operations, tells users to claim payouts or withdraw funds appeared first on Crypto Briefing.
Moonshot AI's rapid valuation growth and IPO plans highlight the increasing global influence and competitive dynamics of Chinese AI firms.
The post Moonshot AI hits $50 billion valuation, eyes Hong Kong IPO in early 2027 appeared first on Crypto Briefing.
Grayscale's move to diversify custodianship could enhance security and operational efficiency, impacting investor confidence and market dynamics.
The post Grayscale adds BitGo as custodian for its Hyperliquid staking ETF in new 8-K filing appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Coinbase’s Ryan VanGrack: CFTC Approval “Opens Many Doors” for Bitcoin
The SEC’s proposed custody rules could make it easier for investment advisors to help clients own Bitcoin directly. Coinbase’s Ryan VanGrack explains why institutional capital tends to flow where there are clearer rules, and why he sees direct ownership and ETFs as “both and, not either or.” He also shares why traditional finance is accelerating its push into Bitcoin and digital assets.
Chapters:
00:00 Coinbase Wins CFTC Approval for Its Own Clearinghouse
01:29 Can SEC Guidance Last Without the Clarity Act?
02:40 SEC Custody Proposal: Helping Advisors Hold Bitcoin Directly
04:14 Tokenization: The Biggest Upgrade Since Electronic Trading
05:41 How Tokenization Cuts Out Wall Street’s Middlemen
07:34 What Washington Still Needs to Fix for Bitcoin Holders
08:56 Institutional Adoption Accelerates After the Clarity Act Vote
11:07 How Coinbase Is Bringing Digital Asset Infrastructure to Community Banks
12:01 Sponsor: Square
12:34 Is Crypto Really a Tool for Illicit Finance?
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Coinbase’s Ryan VanGrack: CFTC Approval “Opens Many Doors” for Bitcoin first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Coinbase Business Chief: Big Banks Increasing BTC Exposure | Shan Aggarwal
New SEC rules could open the door for financial advisors to hold Bitcoin for their clients, and Coinbase is already at the center of that custody story. Shan Aggarwal, Coinbase’s first-ever Chief Business Officer, explains how Coinbase custodies most of the Bitcoin ETFs and supports the advisor community. He sees the advisor rule as expanding the pie for Bitcoin access, with Coinbase providing the infrastructure behind it.
Chapters:
00:00 How the SEC’s New Advisor Rules Could Bring Bitcoin to Wealth Managers
01:13 What BlackRock and JPMorgan Want From Bitcoin Infrastructure
02:16 What Will Drive the Next Wave of Bitcoin Adoption
03:28 Can the Coinbase One Card Turn Spenders Into Bitcoin Owners?
04:22 Coinbase’s Trillion-Dollar Stablecoin Opportunity
05:14 Coinbase and Citi Bring Stablecoin Payments to Merchants
05:56 Sponsor: SALT Lending
06:26 How Coinbase Customers Are Using Bitcoin Lightning
07:37 Will AI Agents Pay in Bitcoin or Stablecoins?
08:30 Coinbase Expands Into Collectibles and Everyday Bitcoin Rewards
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Coinbase Business Chief: Big Banks Increasing BTC Exposure | Shan Aggarwal first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
TD Cowen’s Lance Vitanza: BTC to $132k in 2027 & MSTR Price Outlook
Institutions are no longer debating whether to own Bitcoin. Now the question is how. TD Cowen Managing Director Lance Vitanza explains why Bitcoin is evolving from a standalone asset into a capital markets ecosystem of common stock, preferreds, bonds and income products. He shares what he heard at the Bitcoin Treasuries conference in New York and why institutional investors increasingly evaluate Bitcoin within a portfolio.
Chapters:
00:00 Bitcoin Is Evolving From an Asset Into a Capital Markets Ecosystem
01:36 Bitcoin Preferreds, Bonds and Dividend-Paying Instruments
03:25 How Analysts Are Evaluating Digital Credit
05:23 Which Bitcoin Treasury Companies Survive a Downturn
07:28 Strive, Metaplanet and Nakamoto: Why Operating Businesses Matter
10:24 Could MSCI Index Removal Hurt Bitcoin Treasury Companies?
12:27 Blockchain Surveillance, Front-Running and Trust in Bitcoin Prices
14:20 Sponsor: Cash App
15:01 TD Cowen’s Bitcoin Price Target for 2027
16:38 Why Well-Run Bitcoin Treasury Companies Could Outperform Bitcoin
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post TD Cowen’s Lance Vitanza: BTC to $132k in 2027 & MSTR Price Outlook first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Lyn Alden: Nothing Stops This Train – BTC, AI Equities, Bond Market Analysis
Silicon Valley promises an AI-driven age of abundance, but does that mean an end to inflation? Lyn Alden separates AI price deflation from monetary inflation. AI can make white-collar services radically cheaper without slowing money printing or lowering the price of truly scarce assets like Bitcoin. She also explains how a peak in AI stocks could rotate capital back into Bitcoin.
Chapters:
00:00 Nothing Stops This Train: Why US Fiscal Deficits Can’t Be Stopped
01:30 Fiscal Dominance and Why the Fed Can’t Control Inflation
03:18 AI Age of Abundance vs. Monetary Inflation
07:00 What Would Force the Fed to Support the Treasury Market
09:10 Lyn Alden’s Gold Outlook After the Pullback From Record Highs
10:38 Why Bitcoin and Gold Trade Differently
13:17 Could a Peak in AI Stocks Rotate Money Into Bitcoin?
14:40 Lessons From Egypt’s 15% Inflation and Broken Money
16:03 Do Stablecoins Actually Strengthen the US Dollar?
17:49 Japanese Yen Intervention and Scott Bessent’s Edge
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Lyn Alden: Nothing Stops This Train – BTC, AI Equities, Bond Market Analysis first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Caitlin Long: Fiscal Dominance, Stablecoins & the Macro Case for Bitcoin
Will tokenized bank deposits crowd out stablecoins? Caitlin Long, founder and CEO of Custodia Bank, says stablecoins are about $300 billion against roughly $5.7 trillion in traditional demand deposits, and that bringing tokenization into the banking system could be the bigger story. She also explains why the Treasury wants tokenized dollars and what the Fed is doing about it.
Chapters:
0:00 Fiscal Dominance and “Nothing Stops This Train”: Intro to Caitlin Long
1:53 Why Washington Is Pushing Tokenized Dollars and Where the Fed Stands
3:28 Tether, New Treasury Demand, and the GENIUS Act Rules
7:14 Community Banks vs. Megabanks: The Deposit Flight Debate
13:03 SVB, AI Agents, and a Banking Model Under Pressure
16:26 The Eurodollar Parallel and the Fed’s Reluctance
19:29 Tokenized Deposits vs. Stablecoins, and Tokenized Equities
26:50 Treasury Market Stress, Fed Hikes, and the AI Debt Question
30:24 Bitcoin as Digital Gold: Retail Ownership and Holding Long Term
35:25 Treasury Buybacks, Lessons From Volcker, and Life After the Clarity Act
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Caitlin Long: Fiscal Dominance, Stablecoins & the Macro Case for Bitcoin first appeared on Bitcoin Magazine and is written by Patrick Green.
CryptoSlate
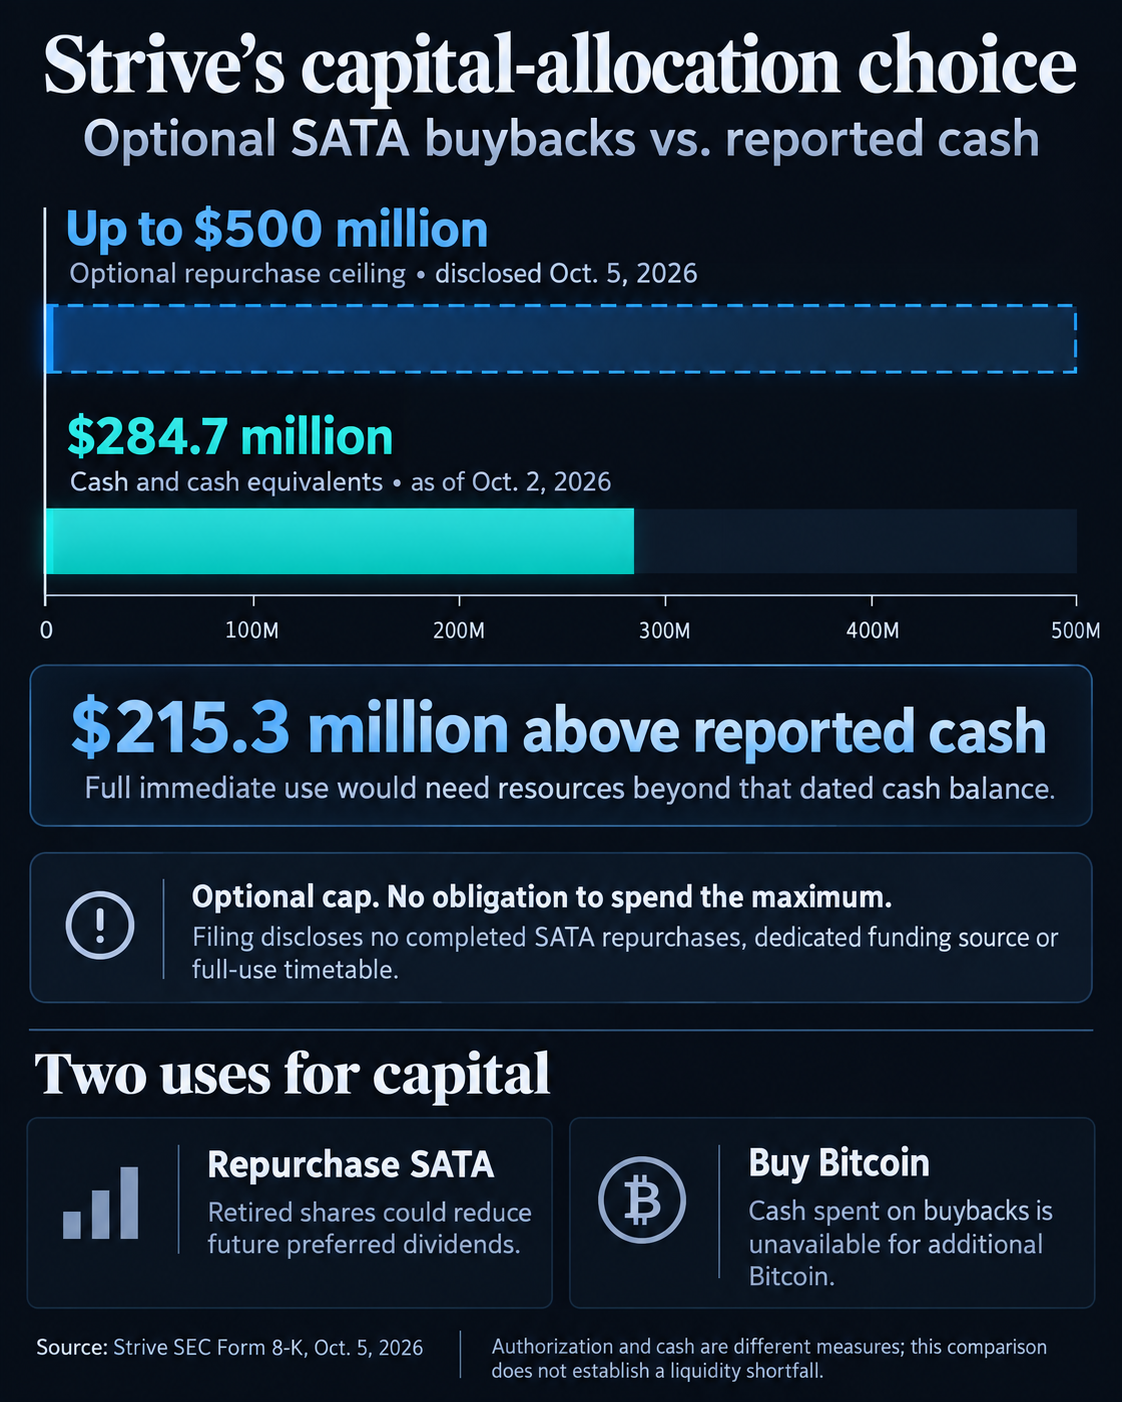
Bitcoin treasury company Strive disclosed an optional program to repurchase up to $500 million of its variable-rate perpetual preferred stock, traded as SATA, on Oct. 5.
The program exceeds its reported $284.7 million cash balance and lets management weigh further Bitcoin purchases against retiring dividend-paying preferred shares.
The SEC filing gives management discretion to repurchase shares from time to time. The ceiling is $215.3 million above reported Oct. 2 cash, so immediate full use would require resources beyond that dated balance.
The optional cap creates no obligation to spend the maximum and does not establish a liquidity shortfall. The filing discloses no completed SATA repurchases, dedicated funding source, or timetable for using the full capacity.
Strive reported 29,462 BTC as of Oct. 2 after buying 2,000 Bitcoin between Sept. 28 and Oct. 2 at an average price of approximately $84,422, including fees and expenses. Those holdings are separate from its preliminary, unaudited Sept. 30 figures, which showed 28,000 BTC and remained subject to change.
Buying Bitcoin or reducing dividends
Strive's preferred-funded Bitcoin strategy carries recurring cash costs. Its website presents SATA dividends at $13 per share annualized, equivalent to 13% of the $100 stated amount.
The rate can change, and cash payments require board declaration. Under SATA's terms, dividends accumulate even when they are not declared, while declared cash payments are divided across business days.
Strive reported 13,498,082 SATA shares as of Oct. 2, up from 12,193,180 on Sept. 25, including shares sold through the filing's 4 p.m. cutoff for issuance on the following business day.
Retiring shares could reduce future dividend commitments and the preferred claims that rank ahead of common shareholders.
The savings would depend on how many shares were retired and the applicable dividend rate, while the purchase price would determine the cash cost. Money spent buying back SATA would also be unavailable for additional Bitcoin purchases.
SATA's amended terms permit market repurchases separately from contractual optional redemption, which has a base price of $110 per share plus applicable unpaid dividends. The new facility does not set a $110 price for every buyback.
Strive says it intends to remain debt-free and may consider capital-allocation and financing alternatives.
Preferred equity still carries dividend commitments, and the company cautions that its Bitcoin-per-share metrics do not capture the additional senior claims created when preferred issuance funds Bitcoin purchases.
For common shareholders, the next useful disclosure is actual repurchase spending and shares retired, alongside updated cash and Bitcoin balances. Those figures will show whether the facility reduces the preferred dividend burden and how much capital remains for Bitcoin accumulation.
The post Bitcoin treasury Strive risks cash reserve to fund $500M buyback and trim dividends appeared first on CryptoSlate.
Kraken's parent company, Payward, has connected to Singapore Gulf Bank's SGB Net clearing network, opening round-the-clock US-dollar funding for selected institutional clients in Asia and the Gulf.
The companies say participating clients in eligible jurisdictions can deposit cash with Payward and use it immediately.
In their release dated Oct. 5, the companies describe an initial dollar settlement offering. SGB also plans to use Payward markets to price digital asset trades for its own customers over the coming months, giving the partnership a live funding service and a separate planned trading component.
Through SGB Net, participating SGB clients can fund Payward accounts at any hour, the companies say. The dollar connection is available 24 hours a day, seven days a week. Its immediate practical benefit is greater flexibility over when those institutions move cash for digital-asset activity.
The releases do not name participating clients or list eligible countries, so they do not provide an institution outside that group with a country-by-country guide to availability. The reference to Asia and the Gulf describes the regional focus, while the jurisdiction restrictions limit where the service can be used.
The companies intend to add more clients and currencies over time, but give no exact expansion date.
Although the connection is operating for some institutions, the rollout announced so far is confined to the initial clients and dollars. The expansion plans concern both who can use the connection and which money it can move.
Adding clients would extend participation, while adding currencies would expand the service beyond its initial US-dollar scope.
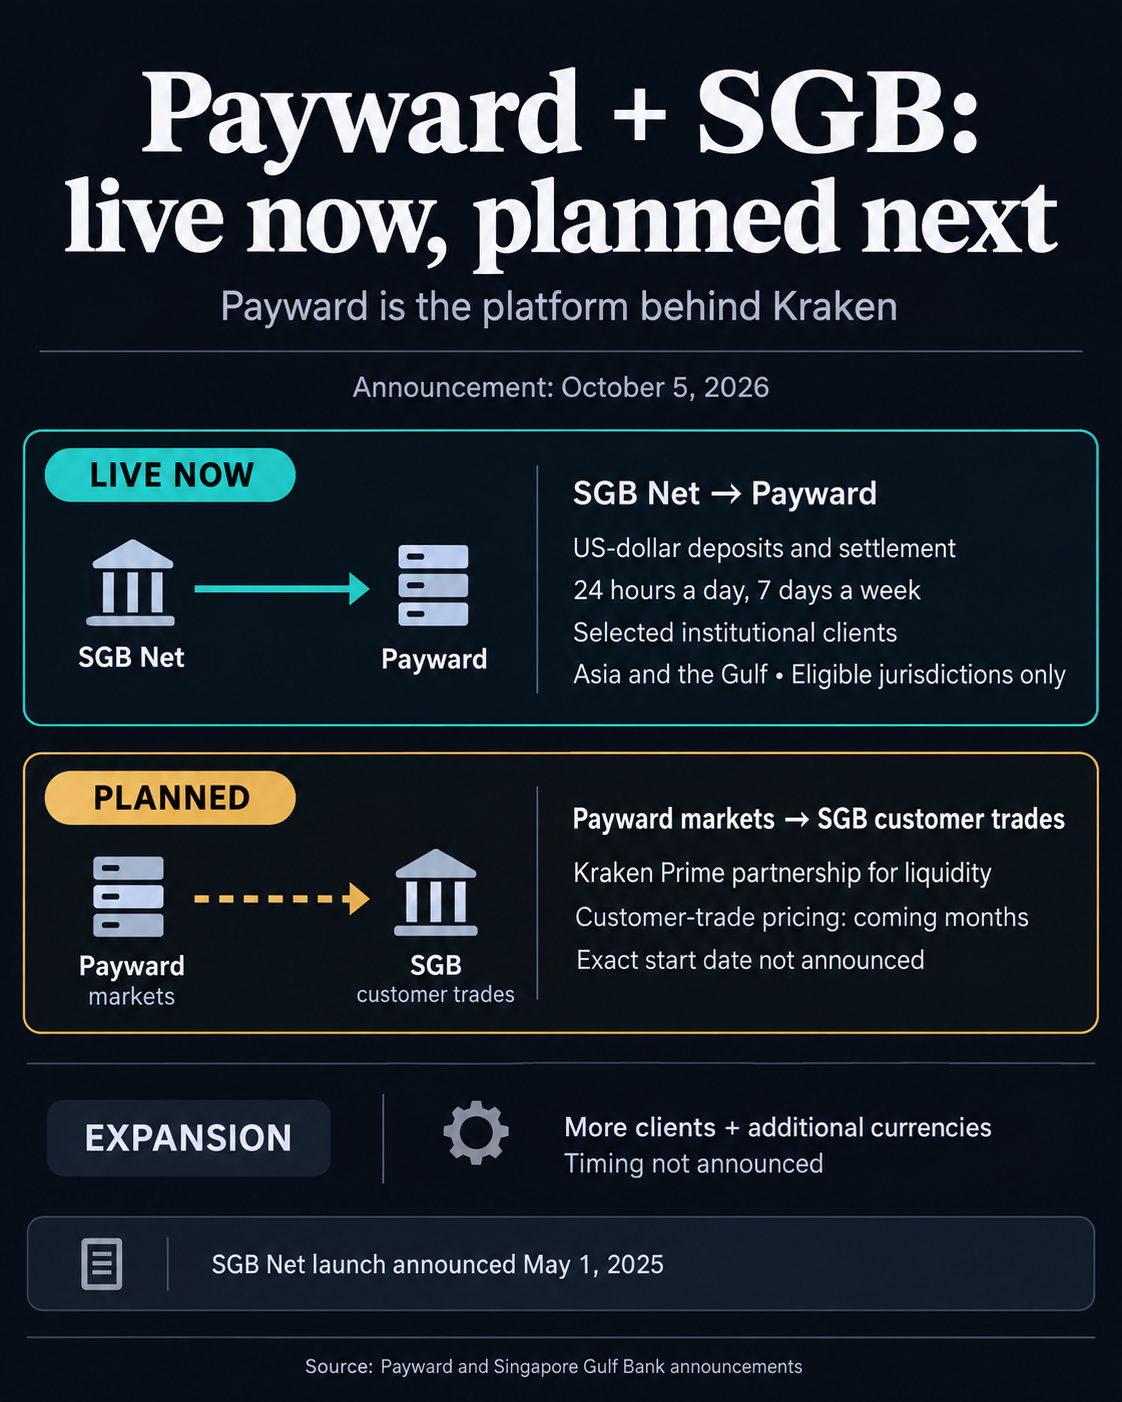
Singapore Gulf Bank announced the network's launch on May 1, 2025, and Payward is now connecting to that existing system, adding a funding route for the institutions included in the initial offering.
SGB expands partnership with Kraken
SGB is also partnering with Payward's Kraken Prime for digital asset liquidity. The bank plans to draw on Payward markets to price its customers' trades over the coming months. The announcement supplies that broad horizon but no specific date for starting the customer-pricing service.
The live connection lets participating institutions move their dollars into Payward and deploy them immediately. The planned pricing use concerns SGB sourcing liquidity for digital asset trades offered to its own customers.
The next developments to watch are the start of SGB's customer-pricing use and the addition of settlement clients and currencies. Pricing has a stated horizon of the coming months, while the wider funding rollout remains undated.
The post Kraken parent joins Singapore Gulf Bank, opening 24/7 institutional dollar rails appeared first on CryptoSlate.
The Commodity Futures Trading Commission (CFTC) is offering US crypto exchanges a federal route to retail leverage as Congress remains stalled on market-structure legislation.
On Oct. 5, the financial regulatory agency opened rulemaking for Regulation Crypto Asset Transactions (CTX) and Regulation Crypto Asset Markets (CAM), which would create a national framework for platforms offering retail customers margined, leveraged, or financed crypto trading.
Participation would remain optional for ordinary spot exchanges because the agency acknowledges it cannot compel the broader crypto market onto CFTC-regulated venues without congressional action. The incentive is access to leveraged products that state money-transmitter licensing alone does not provide.
The initiative gives the CFTC a way to use authority it says already exists under the Commodity Exchange Act while Congress has yet to enact comprehensive legislation governing crypto spot markets.
CFTC turns leverage into its regulatory carrot
The framework would effectively create three regulatory paths depending on what an exchange wants to offer US customers.
Ordinary spot exchanges could remain primarily under state licensing regimes, supplemented by the CFTC’s existing anti-fraud and anti-manipulation authority.
Platforms offering leveraged or financed retail crypto transactions could seek federal registration under the new framework, while venues offering futures, perpetuals and other derivatives would remain under the agency’s existing designated contract market regime.
CAM would sit in that middle category.
The structure would allow existing designated contract markets to offer CTXs under tailored rules while giving crypto platforms another route into federal supervision without requiring them to operate as conventional derivatives exchanges.
The CFTC is relying on Section 2(c)(2)(D) of the Commodity Exchange Act, which covers certain leveraged retail commodity transactions.
Hyperliquid Policy Center said the resulting structure could give market participants a clearer regulatory ladder, with state licensing covering ordinary spot activity, federal CFTC oversight applying where leverage is introduced, and the existing derivatives framework covering futures and perpetual contracts.
The proposal could also narrow one of the biggest product gaps between US exchanges and offshore rivals.
Leveraged trading and perpetual contracts have helped offshore venues attract active traders and generate substantial volumes. US platforms have generally operated with a narrower product menu because of regulatory constraints.
That creates the central commercial bargain.
Federal registration could give exchanges access to products that have historically strengthened the economics of offshore competitors, but accepting CFTC oversight could also force changes to the vertically integrated model through which many crypto venues combine exchange, brokerage and custody functions.
Larry Florio, deputy general counsel at synthetic-dollar developer Ethena Labs, described retail leverage as the proposal’s central attraction, arguing that it could be enough to draw exchanges voluntarily into a single federal framework.
Whether leverage generates enough additional volume and revenue to justify those constraints may determine how many major platforms enter the regime.
FTX shapes the cost of opting in
The regulatory bargain would extend well beyond permission to offer leverage.
CFTC Chairman Michael Selig framed the initiative around lessons from FTX's bankruptcy, arguing that regulators should establish preventive safeguards rather than rely primarily on enforcement after customers have suffered losses.
Selig said on Oct. 5 that “the lesson from FTX’s failure should have been obvious,” arguing that protecting customers from fraud should coexist with responsible crypto innovation.
CAM operators would face core requirements already associated with designated contract markets, including rules governing financial integrity, surveillance, conflicts of interest and operational safeguards.
The agency is also considering crypto-specific requirements.
Exchanges could have to assess token concentration, distribution methods, vesting schedules, lockups, programmatic issuance and buybacks when determining whether an asset can be traded without being readily susceptible to manipulation.
Platforms holding customer property in omnibus accounts could also face proof-of-reserves requirements, a safeguard Selig directly linked to risks exposed by FTX.
Customer CTX trades would meanwhile be intermediated through registered futures commission merchants, bringing customer accounts and property under requirements covering capital, disclosures and segregation.
FCM involvement would also bring customer-facing activity within applicable Bank Secrecy Act obligations, including anti-money laundering controls, customer identification and suspicious-activity reporting.
Those provisions raise the cost of opting into the federal framework beyond registration fees or compliance staffing. Exchanges could gain access to leverage while surrendering some of the structural flexibility that has allowed crypto platforms to keep trading, brokerage and custody under one roof.
That trade-off will be central to whether the framework attracts the large US exchanges whose participation would give it meaningful scale.
CFTC draws a boundary around onchain markets
The commission is also beginning to define where decentralized markets and software developers fit within federal commodities law, although that effort sits partly outside the CTX and CAM initiative.
The CTX proposal would clarify the Commodity Exchange Act’s “actual delivery” exception by treating transfers to a customer’s external non-custodial wallet within 28 days as generally satisfying the exemption from exchange-trading requirements for certain leveraged retail commodity transactions.
Separately, Selig said the agency is considering how to treat developers who publish software without taking customer orders, controlling execution or holding customer assets.
He said:
“A person should not have to register as an introducing broker simply because that person shipped code.”
The CFTC is consulting developers about where control resides in onchain venues and when software activity begins to resemble regulated financial intermediation.
However, the more immediate question is economic for centralized exchanges.
The Oct. 5 action is an advance notice of proposed rulemaking, and the agency is seeking public input before drafting detailed rules covering leverage, asset eligibility, custody, reserves and intermediary requirements.
That leaves major elements of the framework unresolved, including leverage limits, capital standards and the extent to which FCM intermediation could reshape existing exchange business models.
Agency rules also remain less durable than legislation, and a future commission could revise them.
The CFTC is testing a relatively simple proposition: whether access to federally regulated retail leverage is valuable enough to persuade crypto exchanges to accept substantially deeper oversight.
If major platforms decide that it is, the agency could begin pulling trading activity now concentrated on offshore venues into regulated US markets without waiting for Congress to settle the broader fight over crypto spot-market jurisdiction.
The post CFTC makes its biggest move yet to bring offshore crypto trading back to the US appeared first on CryptoSlate.
Blockchain investigator ZachXBT said he infiltrated a Chinese laundering syndicate by posing as a cryptocurrency client and funding repeated stablecoin trades.
In an Oct. 5 disclosure, he alleges the network laundered more than $1 billion across exploits for Lazarus Group.
He said he fronted 349,700 USDC to build a relationship with a contact using the alias Jimmy Green. According to his account, the repeated exchanges led to private conversations about moving funds stolen from Bybit in 2025.
He reported tracing a cluster involving more than $12 million in Bybit funds and a later 442,000 USDT freeze by Tether.
Becoming a client
ZachXBT said the investigation began after the February 2025 Bybit exploit, when he noticed at least 15 accounts asking for help with orders he linked to stolen funds in public Telegram and Discord groups.
He contacted several of those accounts. One was Jimmy Green, the Telegram alias of the person with whom he subsequently exchanged funds.
On March 6, 2025, ZachXBT said he funded a new Ethereum address with 349,700 USDC in preparation for transactions with the contact. The arrangement involved sending his USDC on Ethereum in exchange for the contact's USDT on Tron. He then completed additional transactions to build trust.
As he built trust through repeat exchanges, ZachXBT said the contact began discussing movements of Bybit funds for North Korea before they occurred. The conversations also included details about operations in Hong Kong and mainland China.
In one example, he said the contact told him funds would move to Solana, and the movement happened the following day.
On March 12, 2025, ZachXBT said the contact sent a screenshot of a cross-blockchain transfer. He matched its amounts and timing to an order on the THORChain transaction explorer created within minutes of the message.
According to ZachXBT, the contact also supplied three Solana addresses. He said these exposed a cluster involving more than $12 million in Bybit exploit funds moving through Bitcoin, Ethereum, Solana and Tron.
He separately reported that Tether later froze 442,000 USDT linked to the cluster. That is the specific freeze amount described in this part of his investigation; the larger cluster figure represents funds he said he traced.
The account also reaches beyond Bybit. ZachXBT said the contact mentioned a team whose funds had been frozen in 2024. He said that matched an on-chain freeze of 332,000 USDC tied to the Poloniex exploit.
The Bybit backdrop and the cost of access
In a Feb. 26, 2025 alert, the FBI said North Korea stole approximately $1.5 billion in virtual assets from Bybit on or about Feb. 21. It called the specific malicious activity TraderTraitor.
At the time, the FBI said some stolen assets had been converted into Bitcoin and other virtual assets dispersed across thousands of addresses on multiple blockchains. It urged private-sector services to block transactions connected to the laundering addresses.
The syndicate's total and the links to Jimmy Green remain ZachXBT's findings, separate from the FBI's attribution of the theft.
Allegations involving a Chinese over-the-counter trader surfaced in October 2024. The latest account describes how ZachXBT obtained information by becoming a trading counterparty himself.
ZachXBT said he fronted 349,700 USDC for the case and lost 5% on each order. The amount advanced is distinct from his net loss, which he did not quantify in the disclosed figures.
He appealed for continued foundation grants and individual donations to support higher-risk investigations. He said intelligence from these trades helped freeze funds tied to the Bybit exploit.
The post ZachXBT infiltrates $1B crypto syndicate to expose Lazarus Group appeared first on CryptoSlate.
US corporate credit spreads widened beyond the weakest borrowers from September 25 to October 1, creating a broader test of whether tighter financing and reduced institutional risk-taking could pressure Bitcoin. The largest increase remained concentrated in CCC-and-lower debt, while investment-grade bonds showed a much smaller rise.
These option-adjusted spreads measure the premium over a Treasury curve. Their widening shows investors demanding more compensation to hold corporate debt. A borrower's total interest cost also depends on the Treasury component.
The ICE BofA CCC credit spread climbed from 11.28% to 12.15%, an increase of 87 basis points. Over the same dates, the broad high-yield spread rose from 2.93% to 3.24%, or 31 basis points. The investment-grade corporate spread increased from 0.81% to 0.86%, or 5 basis points.
All three comparisons use daily closing observations for September 25 and October 1, 2026. FRED's October 5 updates added October 2 readings of 12.02% for CCC-and-lower debt, 3.10% for broad high yield and 0.85% for investment-grade debt. All three eased from October 1 while remaining above their September 25 levels.
The investment-grade move is the clearest evidence that repricing extended beyond the lowest-rated debt. CCC-and-lower bonds are already included in the broader high-yield index, so those two increases are overlapping evidence. The picture is broader but unequal pressure.
How credit spreads could reach Bitcoin
For Bitcoin, transmission would depend on how credit repricing changes capital costs and risk-taking. If financing becomes more expensive, leveraged investors may need to shrink positions. Institutions could reduce crypto exposure as they reassess how much risk they are willing to carry across their portfolios.
The authors of the 2023 IMF working paper The Crypto Cycle and US Monetary Policy describe a related mechanism. Their historical analysis finds that monetary tightening can raise capital costs, encourage crypto investors to reduce leverage and lower aggregate crypto prices, with institutional participation reinforcing transmission.
The paper examines historical monetary-policy shocks; the current figures measure corporate credit premiums. Applying its mechanism to this episode remains conditional. The spread observations establish credit repricing, while current Bitcoin selling and its cause remain unestablished.
The Chicago Fed National Financial Conditions Index provides a broader check. Its latest reading was -0.548 for the week ending September 25, released September 30. That negative value indicates looser-than-average financial conditions. The observation predates the newest spread readings.
The next test is whether widening persists beyond the weakest borrowers and coincides with worsening broad financial conditions and weaker Bitcoin demand. That combination would strengthen the case for wider pressure on institutional risk-taking. Narrowing spreads and resilient Bitcoin demand would weaken it.
The post US credit spreads eased on October 2 after widening beyond the weakest borrowers appeared first on CryptoSlate.
CryptoTicker.io
Swapping Bitcoin for a gift card is not a purchase for tax purposes, it is a sale. The moment you pay for a gift card, a good or a service with crypto assets, you hand over the coins and receive something else in return. The tax office treats that transaction exactly like a sale on an exchange: as a private disposal under section 23 of the German Income Tax Act, the EStG.
Whether tax actually falls due hangs on two numbers. If more than twelve months lie between the purchase and the gift card payment, the gain stays tax free. Below that it counts, and it counts together with every other private disposal of the year against the threshold of 1,000 euros. So if you buy Bitcoin in January and pay for a gift card with it in March, you have a tax relevant transaction on the books, even though not a single euro has landed in your account.
The gift card purchase is a disposal, not an exchange
A disposal within the meaning of section 23 EStG is any transfer of an asset for consideration. The fact that what you receive in return is a gift card rather than euros changes nothing: for consideration simply means that something flows the other way. On February 14, 2023, the Federal Fiscal Court confirmed that crypto assets are other assets in this sense and fall under the provision.
That is what sets the gift card purchase apart from a gratuitous transfer. Anyone who gives coins away or hands them to a charitable organisation is not disposing of them, because nothing flows the other way; different rules apply there, which we have written up under claiming Bitcoin donations against tax. A gift card is consideration with a quantifiable value, and the whole calculation hangs on that.
In practice that means there is no free pass for spending coins by way of a gift card in order to sidestep the tax. The opposite is true, because unlike with a sale on an exchange you are afterwards left without the exchange statement as evidence.
What counts as the disposal proceeds: the market value of the gift card
The disposal proceeds are the value of what you received for the coins. With a gift card that is its face value in euros, meaning the sum printed on the card that you can redeem with it. From that you deduct the acquisition cost, meaning the euro amount the coins you handed over cost you when you bought them, plus the incidental purchase costs at the time.
An example with round figures: you bought coins for 400 euros and eight months later pay for a gift card worth 700 euros with them. The taxable gain is 300 euros. Had you instead sold the same coins on an exchange for 700 euros, the result would be identical. The gift card merely stands in for the euro as consideration.
You need to pay attention when the provider takes a premium and you hand over coins with a market value of 730 euros for a gift card worth 700 euros. What then governs is what you actually received. The premium reduces your result, and you should be able to document it, because otherwise the higher market value of the coins can be used as the basis.
The one-year holding period decides the tax
The holding period begins on the day after the purchase and ends after twelve months. Redeem the gift card after that and the gain stays tax free, however large it is. Within the period it is taxable at your personal income tax rate.
What is decisive is the date of the payment, not the date on which you later use the gift card in a shop. The swap of coins for a gift card is the moment that counts for tax. Anyone who wants to see the mechanics of the period in context will find them in our comparison of the loss sale and buyback within the holding period.
The 1,000 euro threshold: why a gain of 1,001 euros is taxable in full
Private disposals are subject to a threshold of 1,000 euros per calendar year. A threshold is not an allowance: once it is reached or exceeded, the entire gain becomes taxable, not just the part above it. On a gain of 999 euros you pay nothing; on 1,001 euros you are taxed on 1,001 euros.
The limit applies to all private disposals of a year taken together, not per transaction and not per coin. Two gift card purchases with a gain of 600 euros each breach the limit jointly. Gains from other private disposals in the same year count towards it as well. Losses from such transactions reduce the total and therefore need documenting just as carefully as gains.
FIFO or specific identification: which coins the gift card purchase uses up
Anyone who has been adding over months holds coins with different acquisition dates. On the question of which of them the gift card purchase uses up, there are two routes. Under specific identification you demonstrate which particular coins were handed over, for instance because they sat in a wallet of their own. Where that cannot be allocated, the FIFO method comes into play: first in, first out, with the oldest holdings treated as handed over first.
FIFO often works against you when prices are rising, because the oldest holdings carry the lowest acquisition cost and therefore show the highest gain. In exchange, those holdings are also the most likely to be older than a year and therefore tax free. Which variant comes out cheaper depends on the individual case and belongs with a tax adviser, not in a rule of thumb.
Wallet separation matters here: anyone who keeps coins for everyday spending in a wallet of their own and the long term holdings separately from it can substantiate the allocation in the first place. That separation costs nothing and cannot be created after the fact.
The BMF circular of 6 March 2025 replaces the 2022 version
The tax authorities' position on the taxation of crypto assets is set out in a circular from the Federal Ministry of Finance dated March 6, 2025. It replaces the earlier circular of May 10, 2022, and classifies, among other things, airdrops, forks, transactions on decentralised platforms and the boundary between private asset management and commercial activity.
Two things about it matter for the gift card purchase. First, the classification of the payment as a disposal remains in place. Second, the circular expressly stressed the requirements for records and cooperation, and that bites precisely on transactions for which no exchange issues a statement. An administrative circular binds the tax offices, incidentally, not the courts.
Part of the legal position is also what does not currently apply: a bill to abolish the one-year tax exemption was rejected in the Bundestag. The discussion continues, but nothing has been decided. Until then the twelve-month period stands.
VAT stays out of it: the swap counts as a payment
Alongside income tax, the question of VAT comes up regularly. For private holders the answer is short: anyone using coins as a private individual to pay with is not supplying anything subject to VAT. The tax authorities treat crypto assets as equivalent to conventional means of payment for VAT purposes, in so far as they are purely means of payment.
The VAT on the good or service is still owed by the merchant, and it is already baked into the gift card value. You pay it along with everything else, just as with any other method of payment. The position is different for businesses holding crypto assets as operating assets; separate rules apply there, and this page deals with the private case.
Evidence for the tax office: price, date and gift card value
With a sale on an exchange the platform supplies a statement. With a gift card purchase nobody supplies one, and the burden of proof sits with you. So secure four details for every transaction: the date of the payment, the face value of the gift card in euros, the quantity of coins handed over, and the acquisition date together with the purchase price of those coins.
Add to that the records you do receive: the provider's confirmation, the transaction in your wallet or in the block explorer and, where there is one, the invoice for the premium. Evidence of the price on the day of the transaction belongs there too, because the market value of the coins handed over is the cross-check against the gift card value. Programs that keep track of these transactions and produce a report for the tax return are listed in our comparison of crypto tax software and portfolio trackers.
You should keep these records for as long as the tax office can examine the transaction. For private individuals that means, in practice, until the tax assessment for the year in question is final, and longer if in doubt.
Where you can pay for gift cards with Bitcoin, and what the premium costs
Gift cards against crypto assets are brokered by specialised providers, and in some cases by individual merchants directly. The process is similar everywhere: you choose the gift card, the provider quotes an amount in coins, you transfer, and the code arrives by email or in your customer account. Three items determine the price.
First, the premium on the face value, with which the provider covers its price risk and its margin. Second, the network fee for the transfer, which weighs heavily on small amounts. Third, the price the provider calculates with, and the window for which it guarantees that price. So always work the gift card out as a total price in euros and compare it with the route through a sale on an exchange and an ordinary card payment. What that detour costs on an exchange is set out in our comparison of the best crypto exchanges.
Check as well whether the provider offers returns or refunds at all. A redeemed gift card code is as a rule not revocable, and in a dispute you have no payment service provider chargeback available of the kind you know from a credit card.
The gift card itself triggers no further crypto tax later
After the swap you no longer hold a crypto asset, you hold a claim denominated in euros. When you redeem the gift card in a shop weeks later, that is not a private disposal, because no asset within the meaning of the provision is being disposed of any more. The transaction that mattered for tax was complete when the coins changed hands.
That has a practical consequence: if the price keeps rising after the gift card purchase, you have no share in it any more, and a later slide in the price does not shrink the tax that has already arisen. The gain is fixed as at the moment of the swap. Anyone planning the transaction shortly before the turn of the year should keep that in view, because the gain falls into the year of the payment.
If a gift card expires unused, the transaction still stands for tax purposes. The loss of the gift card value is a private financial loss and not a reduction of the disposal gain that arose back then.
Bitcoin for a gift card: How to proceed now
- Check the holding period before you pay. Look up when the coins you intend to hand over were bought. If the purchase is more than twelve months ago, the gain is tax free; below that you count it against the threshold of 1,000 euros. A tool from our comparison of crypto tax software carries those periods parcel by parcel.
- Work the total price out against the exchange route. Add up the premium, the network fee and the price gap and compare the sum with the route through a sale and an ordinary payment. What a sale on an exchange costs is shown by our comparison of the best crypto exchanges.
- Secure the records the same day. The date, the gift card value, the quantity of coins handed over, the price and the provider's confirmation belong together in one folder before the email sinks in your inbox. Anyone paying with crypto assets regularly will find solutions that document the transaction together with a statement in our comparison of crypto credit cards.
The legal position in this article rests on the circular of the Federal Ministry of Finance dated March 6, 2025, file reference IV C 1 - S 2256/00042/064/043, whose changes against the 2022 version are set out in detail by PwC, and on section 23 of the Income Tax Act. This article is no substitute for tax advice.
(As of October 6, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Selling MemeCore currently only works by a detour: none of the 14 markets that CoinGecko lists for the token M trades against the euro. Every single pair runs through the stablecoin Tether or through USDC, with two pairs available only on decentralised exchanges on the BNB Smart Chain. Anyone who wants to unwind an M position therefore sells first into a dollar stablecoin and swaps that into euros afterwards. It is workable, but it costs an extra step, an extra fee and a second event that counts for tax.
The other half of the answer lies in the size of the market. According to CoinGecko data, M carried a market capitalisation of $2.32 billion on October 6, on daily volume of $2.39 million. That puts the ratio at roughly 971 to 1. On the thinnest days of the past two months it sat at about 3,500 to 1. For a small position that is of no consequence. For a large one it is the real question of this article.
Selling MemeCore today means Tether, not euros
A trading pair is the combination of the token you give up and the value you get for it. With M those pairs are, without exception, M/USDT, M/USDC or, on the two decentralised exchanges, M against a dollar stablecoin on the BNB Smart Chain. CoinGecko's ticker list carries no M/EUR pair, and no M/USD either.
In practice that means a two-stage exit. In the first step you sell M against USDT or USDC. In the second you move the stablecoin to a platform that pays out euros and sell it there. Which providers do that reliably in Germany, and what they charge for it, is set out in our comparison of the best crypto exchanges. Why the Tether detour is so widespread and where it costs money, we have written up at greater length using the case of the missing euro trading pairs.
An important point for tax: swapping M into USDT already counts as a disposal, and so does the later swap from USDT into euros. Both events count on their own, and both need documentation. More on that below.
What MemeCore is: a layer-1 chain with Proof of Meme as its consensus
MemeCore is not a conventional meme coin sitting on somebody else's chain. It is its own layer-1 blockchain, meaning a network with its own consensus mechanism and its own fees. The project says the mainnet has been running since February 12, 2025. The token M pays the transaction fees on the network and is staked by validators and delegators.
The project calls its consensus mechanism Proof of Meme: whoever secures the network should be rewarded not only for computing power or capital at stake, but also for measurable cultural contributions. Whether that promise holds is an open question, and for exiting a position it is of secondary importance. What counts for classification is this: M is a network token with meme positioning, and it sits in the risk class we report on continuously in our meme token section.
The all-time high came on July 2, 2026, at $5.64. At $1.02 today, M stands roughly 82 percent below that. Over seven days the price is down 11.4 percent, over 30 days 10.1 percent. From the interim high of $1.51 on September 20 it is 32.6 percent lower.
13 trading venues, one order book: HTX carries 75 percent of ticker volume
CoinGecko lists 14 markets for M across 13 trading venues. The distribution is the opposite of broad. HTX accounts for $1.80 million of the reported daily turnover, or 75.1 percent of the entire ticker volume. The three largest venues together carry 87.0 percent. The remaining ten share what is left, and the smallest reports less than $5,000 a day.
Those venues include Biconomy, BTCC, MEXC, Hotcoin, Bitget, Gate, Ourbit, Hibt, BitKan and WEEX, plus two decentralised markets on the BNB Smart Chain. The platforms through which German investors usually buy with euros are absent from that list: according to CoinGecko's ticker list, Bitpanda, Coinbase, Kraken and Bison do not carry M.
This concentration has two consequences. First, the tradable price hangs essentially on a single order book. If that venue goes down, stalls or suspends withdrawals, the bulk of the liquidity goes with it. Second, you cannot simply fetch a better price from a competitor, because the competition has barely any volume. Anyone moving from one venue to another should also know that a pure transfer between your own accounts is not a sale, but the acquisition data has to travel with it.
Market cap $2.32 billion against $2.39 million daily volume: a ratio of 971
Market capitalisation is the circulating supply multiplied by the current price, and it says what a position is worth on paper. Daily volume says how much of that actually changes hands in a day. With M, $2.32 billion of paper value stands against $2.39 million of turnover.
The volume series of the past 60 days swings widely: the weakest day came in at $0.66 million, the strongest at $7.08 million, the mean at $2.71 million and the median of the past 30 days at $1.35 million. Depending on which of those figures you apply, the market capitalisation equals between 971 and 3,493 times a single day's turnover. That spread is not imprecision, it is the risk itself: how quickly you get out of a position depends on which day you hit.
For comparison: with a heavyweight such as Bitcoin that ratio usually sits in the double or triple digits. The higher the number, the longer the market would need, on paper, to turn over the entire circulating supply once.
Slippage: why a large order in a thin book sets its own price
Slippage is the difference between the price you see when you send an order and the price at which it is actually filled. It arises when your order is bigger than what sits on the other side of the order book at the next best price. The order then works its way through ever worse price levels.
In a market that turns over less than a million dollars on a quiet day, a position in the mid five figures is enough to trigger that. A market order of $50,000 is no fringe event there, it is a noticeable share of the day's business. That is precisely why a limit order, where you set a minimum price, is the more important tool in thin markets: such an order fills more slowly or not at all, but it protects you from pushing your own price down. How to read the depth of an order book yourself before you hit send is described in our guide to checking slippage.
Eleven monthly tranches of 56.1 million M have landed without a price slump
An unlock or a tranche is the moment when locked tokens become freely available to the team, the foundation, investors or the community. The expectation behind it usually runs like this: more freely available tokens mean selling pressure and therefore a falling price. With M it is possible to test whether that has happened, because the series is long.
According to the vesting schedule at DefiLlama, eleven equally sized tranches of 56,111,111 M each have landed since December 2, 2025, month after month. Before those came two smaller events of 35,972,222 M each in October and November 2025, plus a one-off starting block of 1.4 billion M in July 2025. The cadence is impossible to miss.
The price reaction was muted all the same. Ahead of the tranche on September 2, M stood at $1.0950, on the day itself at $1.0623 and two days later at $1.0402, a combined 5.0 percent lower. Around the tranche on October 2 it went from $1.0403 to $1.0506 and then to $1.0328, so 0.7 percent lower. Between the two tranche days lies a monthly gap of 1.09 percent to the downside. A slump on the date is not to be found in these numbers.
One explanation for that lies in the order book itself. A tranche of 56.1 million M equals 2.46 percent of the circulating supply and, calculated at today's price, roughly $57.0 million. That is about 24 complete daily turnovers at today's volume and about 86 at the weakest day of the series. A quantity that a market of this size cannot absorb in a day does not get sold in a day either. The pressure works its way out over weeks, and that is exactly what makes it invisible on a daily chart.
The next tranche falls on 1 November per the vesting schedule, and only one source dates it
The vesting schedule at DefiLlama lists the next tranche for November 1, 2026, shortly before midnight UTC, which in Germany means the first hour of November 2. The quantity matches its eleven predecessors: 56,111,111 M, split across four pots with 24,305,556 M for the community, 12,500,000 M for investors, 11,666,667 M for the foundation and 7,638,889 M for the team.
Caution is warranted here, and explicitly so: that exact date rests on a single source. Other vesting registers list no releases for M or are not publicly viewable, and the project documentation itself contains no tokenomics table with dates. What is backed by two sources is the monthly cadence: eleven equally sized tranches in a row, dated in the vesting schedule and traceable in the volume series as spikes on the tranche days. Rely on the regularity, then, rather than on the calendar day as hard fact. We have written up the release calendar and the mechanics behind it in our article on the MemeCore unlock, and the distribution of supply among insiders in our onchain analysis of the insider share.
22.8 percent in circulation: 7.7 billion M are still to come
The circulating supply is the quantity of tokens that is freely tradable. With M that comes to 2,283,037,154 units. The maximum supply, the ceiling that is ever meant to exist, stands at 10 billion. That puts 22.8 percent in circulation. CoinGecko reports a total supply of 5.42 billion M, so considerably more than is circulating and considerably less than the maximum.
For a position that means the larger part of future supply has yet to reach the market. Every monthly tranche grows the circulating supply by a good two and a half percent, and it does so against an order book that is not growing with it. This calculation is the reason why the question of sellability matters more with M than the question of the next price target. This article deliberately names no price target.
The opposite direction matters too: a total loss is possible with a token of this size and market structure. Anyone holding a position should hold it in a size whose complete failure would not put their own portfolio into difficulty.
Holding period and the 1,000 euro threshold: what section 23 EStG means for your M position
Gains from the sale of crypto assets count in Germany as a private disposal under section 23 of the Income Tax Act, the EStG. The holding period is one year: if more than a year lies between acquisition and sale, the gain stays tax free. Sell within the year and the gain is taxable at your personal income tax rate.
On top of that comes a threshold of 1,000 euros per calendar year for all private disposals taken together. That limit is not an allowance: once it is reached or exceeded, the entire gain becomes taxable, not merely the portion above it. A sale with a gain of 1,050 euros is therefore taxable in full, one of 950 euros is not.
With M, two particulars come into play. First, swapping M into USDT already counts as a disposal, and the subsequent swap from USDT into euros as a second one. Second, each individually purchased parcel has its own holding period; anyone who has been adding over months has several periods running in parallel. Buying in over months therefore calls for a breakdown by parcel, not just a portfolio value.
A reform is under discussion: a bill to abolish the one-year tax exemption was rejected in the Bundestag, but the subject remains on the agenda. Until something is decided, the legal position above applies. Individual tax questions are for a tax adviser, not for an article.
From USDT proceeds to euros: the route through a regulated exchange
Once the proceeds sit in USDT or USDC, you need a way back into euros. Three steps are customary. First, transfer the stablecoin from the venue where you sold M to a platform that pays euros out to a bank account. Second, sell the stablecoin against euros there. Third, trigger the payout to your own account.
Before the first step, check three things at the receiving provider: whether it accepts the stablecoin in the form you hold it, meaning on the right network; what fee the deposit and the withdrawal cost; and whether it is authorised to trade crypto assets in the EU. Since the European regulation on markets in crypto assets, MiCA for short, took effect, providers need a licence for that. Whether a provider holds one is stated in its legal notice and in the register of the competent supervisor.
Mind the minimum amounts for withdrawals while you are at it. With small positions, the sum of the fees for transfer, swap and payout can eat a substantial share of the proceeds. Work that out beforehand, ideally with the provider's actual figures.
Total loss is possible: what a delisting does to a position
A delisting is a trading venue's decision to stop trading a pair. The platform usually announces a close of trading and a later deadline for withdrawing the tokens. After the close of trading you can no longer sell on that venue, and after the withdrawal deadline you can no longer move the tokens there; some platforms then liquidate remaining balances compulsorily.
With M this question is especially serious because of the concentration. If the largest venue drops the pair, three quarters of the reported turnover falls away at a stroke, and what remains are markets with daily volumes that in some cases run below $20,000. A sale at the displayed price is then no longer a given.
Three things help in concrete terms. First, subscribe to your own venue's announcement page, because delistings are published there first. Second, know which address and which network you would withdraw M to before you need it in a hurry. Third, size the position so that a total loss remains bearable. This article is explicitly not a recommendation to buy, hold or sell M.
Selling MemeCore: How to proceed now
- Fix the trading route and check the depth. Look up which venue your M position sits on and how much turns over there in a day. If your position exceeds one percent of daily volume, work with limit orders in partial steps rather than a market order. Which platform pays out euros and what it charges for that you will find in our comparison of the best crypto exchanges.
- Compile the holding periods parcel by parcel. Write down the date and the acquisition price for every parcel you bought before you sell. That shows which part is tax free after a year and which part eats into the 1,000 euro threshold. A tool from our overview of crypto tax software takes over that bookkeeping.
- Prepare the route back into euros. Decide which authorised provider is to take the USDT proceeds into euros and on to your bank account, and check the network, the fees and the minimum withdrawal in advance. The houses licensed for the EU market are listed in our overview of regulated crypto exchanges.
The data in this article comes from the vesting schedule at DefiLlama and the market data at CoinGecko.
(As of October 6, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Virtune completed the monthly rebalancing of the Virtune Crypto Altcoin Index ETP on October 5, 2026. One line in it matters most for you: Gram (GRAM) has left the index and Litecoin (LTC) is newly in. All ten positions then stand at exactly 10.00 percent again.
This is not a product that concerns Scandinavian accounts alone. It trades on Deutsche Börse Xetra under ISIN SE0023260716 and German securities number A4AKW6, ticker VRTA, in euros. Anyone holding it has had a different mix in their account since the reporting date than in September. The reasons for that lie not in a market view but in the rules of the index itself.
What Virtune changed in the altcoin index on October 5, 2026
Virtune is a Swedish issuer of crypto ETPs based in Stockholm. The company publishes the composition of its altcoin index monthly, each time after the reporting date. This time two snapshots are available: the weighting as at September 29, 2026, before the rebalancing, and the one as at September 30, after it.
Before the rebalancing the basket looked like this: Bitcoin Cash 11.11 percent, Chainlink 11.08 percent, Solana 10.86 percent, Cardano 10.07 percent, Stellar 9.91 percent, XRP 9.79 percent, Canton 9.78 percent, Hyperliquid 9.47 percent, BNB 9.26 percent and Gram 8.68 percent.
After the rebalancing there are ten names with an identical share: Canton, Cardano, Bitcoin Cash, BNB, Solana, Stellar, XRP, Hyperliquid, Chainlink and Litecoin, each at 10.00 percent. Nine of the ten names were already there before. Exactly one position was swapped.
Important for placing the timing: the announcement is dated October 5, while the composition itself applies as at September 30. Several days therefore lie between the change taking effect in the index and its publication. Anyone reconciling the monthly figures of their account against the index should use the reporting date, not the date of the announcement.
Gram out, Litecoin in: the only change of position in the index
Before the rebalancing Gram sat in last place in the basket with 8.68 percent. That is no accident but a consequence of equal weighting: start the previous month at 10.00 percent, then run weaker than the other nine, and you slide down by the next reporting date. Gram, incidentally, is the name of the token that ran as Toncoin until it was renamed; cryptoticker.io described the change at the end of September 2026.
Litecoin takes that place. The coin belongs to the oldest networks in the market and stood at around $70 on October 5, 2026, down 0.9 percent within a day and up 0.8 percent over the week. That is a quiet picture, and it shows something important: inclusion in the index does not coincide with a jump in the price.
Why an index inclusion is not a recommendation
An index provider makes no investment decision in the individual case. It applies a rule. According to the issuer, the Virtune Crypto Altcoin Index takes in up to ten leading alternative crypto assets, expressly without Bitcoin and without Ethereum, and weights each of them equally. Whoever belongs to the leading ten by the index's measure in a given month is in; whoever drops out is out. No statement about the further course of the price lies in that.
Equal weighting at 10.00 percent: how the Virtune Crypto Altcoin Index calculates
Equal weighting means every position in the basket gets the same share, regardless of the size of the coin. A network with a market value of several hundred billion dollars therefore carries just as much weight as one worth a few billion. In Virtune's index, with ten positions, that is 10.00 percent each.
That equality does not hold by itself. As soon as trading resumes, the ten prices pull apart and the shares shift. This is why there is a monthly reset. The mechanism has a consequence many buyers underestimate: on the reset, the month's winners are systematically trimmed and the losers built up. In September that visibly affected Bitcoin Cash and Chainlink, which stood on top at over 11 percent and were brought back to 10.00 percent.
This is neither good nor bad, but it is a deliberate decision by the index provider. Anyone who believes an altcoin basket automatically bets on the strongest trends has it wrong: equal weighting works in the opposite direction to momentum.
ETN rather than fund: what sits in your account when you buy the Virtune ETP
A closer look pays off here, because the terms get muddled in everyday use. The trading venue data of Börse Frankfurt list the security as type: ETN. An ETN, an exchange traded note, is in law a debt security of the issuer and not a fund. No segregated fund assets arise, of the kind you know from a UCITS fund.
In practice that means for you: alongside the price risk of the ten altcoins you also carry a risk attached to the issuer. How that is secured in the individual case is not stated in a press release but in the base prospectus and the provider's product documents. Reading those documents before money moves is no formality with a debt instrument.
How exchange-traded crypto securities are classified in Germany in general, which structures exist and how they differ, we have put together in our overview of crypto ETFs and ETPs for investors in Germany. It also sets out why the term "crypto ETF" in German usage mostly means something other than a genuine fund.
Trading hours of 9:00 to 17:30: the weekend hole between Xetra and the crypto market
One point that rarely appears in product descriptions and gets expensive when it matters: the trading hours do not match. Regular Xetra trading runs from 9:00 to 17:30 according to Börse Frankfurt, with early and late trading from 8:00 to 22:00. The crypto market itself knows no break.
So if a piece of news moves one of the ten coins by 15 percent on a Saturday afternoon, you cannot sell the ETP. You see the move, but you cannot reach it. Only on Monday morning does the first price reflect the interval, and it does so all at once. Anyone sitting on a direct purchase through an exchange could have traded on the Saturday.
That gap is the strongest argument for getting clear about your route of access before buying. Which broker offers which trading hours, spreads and order fees for exchange-traded crypto securities differs considerably; our comparison of crypto brokers gives an overview.
What the spread has to do with trading hours
The thinner the trading in a security, the wider the bid and ask prices sit apart. In early and late trading the volume is as a rule lower than in the core session. Anyone placing a larger order in those fringe hours pays that difference. A limit instead of a market order is not a nicety for the advanced here but the obvious protection.
Litecoin in the index: the new entry is not a price signal
After every index inclusion, readings appear that put more into it than is there. Litecoin is by market value one of the smaller networks in the leading ranks and quoted at about $70 on October 5, 2026. The inclusion says the coin met the index criteria on the reporting date. It says nothing about October.
The same holds in reverse for Gram. Leaving the index is no verdict on the project but the result of a ranking on a given date. A token can drop out one month and slip back in the next without anything having changed in the network.
Tax and holding period: a security in your account or a coin in your own wallet
This difference is probably the most consequential for investors in Germany, and it is readily overlooked at the point of purchase. On the private sale of cryptocurrencies you hold yourself, the system of private disposals under section 23 of the German Income Tax Act applies, with its familiar one-year period. For a securitised instrument in a securities account, taxation follows a different logic.
How an individual crypto ETN is treated in concrete terms depends on its legal structure and cannot be answered across the board for every security. That is precisely why the question belongs before the purchase and not in the following year's tax return. Settle it with your tax adviser, and have the issuer's documents to hand for it.
What you can do in any case: document cleanly. Purchase date, quantity, price, trading venue and fees belong on the record, and with coins the wallet addresses as well. Tools that take this on spare you the reconstruction at the end of the year.
Canton, Hyperliquid, Gram: what ten equally weighted altcoins say about spread
The index deliberately leaves out Bitcoin and Ethereum. That is the core of the product, and it changes its risk profile markedly. The two largest networks carry the bulk of the market value and a large part of the liquidity. A basket without them is not a picture of the crypto market but a targeted bet on everything except the two heavyweights.
On top of that, the ten names are built very differently. Among them stand established payment networks such as Bitcoin Cash and Litecoin, large platform chains such as Solana and Cardano, the exchange token BNB, the oracle network Chainlink, and younger names such as Hyperliquid and Canton. Ten identical percentages conceal that the projects earn from quite different things and are tradable to quite different depths.
For spread that means: ten positions are more than one, but equal weighting alone creates no diversification across different kinds of risk. If the altcoins fall together in a weak market, an equal distribution helps little.
Plus 15.39 percent in September: what the monthly figure says and what it does not
Virtune reports a result for the ETP of 15.39 percent for September. That is a monthly figure for a single calendar month, and it describes a phase in which altcoins did well overall. Deriving an expectation for October from it would be exactly the error that monthly returns provoke so reliably.
The figure is useful all the same, as a gauge of the swing. A basket that can add a good 15 percent in one month can lose correspondingly in another. Anyone who cannot bear that range in their account solves the problem not through the choice of product but through the size of the position.
How to spot the next rebalancing
The rebalancing is monthly. You do not have to wait for it, but you should know that the composition of your security changes as a matter of course without your doing anything. If you want to know the basket you are holding right now, the issuer's current announcement is the only reliable source. A composition from the previous month is simply out of date.
Virtune altcoin ETP: your next three steps
- Reconcile your account and your watchlist. Check whether you hold the security under ISIN SE0023260716 or German securities number A4AKW6. If so, it now contains Litecoin instead of Gram. If you would rather hold the coins directly, the route runs through a regulated trading platform; the differences in fees and custody are in our comparison of crypto exchanges.
- Read the issuer's papers before you buy. Because this is an ETN, the legal structure counts. Take the base prospectus and the product documents in hand, and settle the tax treatment for your case. For documenting your purchases, a portfolio tracker with a tax function helps.
- Match your route of access to the trading hours. If you want to be able to react at the weekend, a security with Xetra trading hours is the wrong tool for it. Then the coins belong in your own custody, and the question of keys arises at once; which devices come into consideration is shown by our hardware wallet comparison.
You will find the announcement on the rebalancing at Virtune in the original, and the trading venue data including ISIN, German securities number, instrument type and trading hours at Börse Frankfurt.
(As of October 5, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
The US spot ETF on Zcash has lost money for the first time. In the week to October 5, 2026 investors pulled a net $94 million or so out of the Zcash products; at the level of the fund itself the figure is $93.56 million. It is the first weekly outflow since trading began on August 25, 2026. Nothing changes legally for you as a holder, but the demand side looks different from how it looked in September.
Zcash trades at $1,340.09 or €1,194.29 (October 6, 2026, CoinGecko). In dollar terms that is 0.98 percent below the previous day and 7.36 percent below a week ago. Over a month there is still a gain of 33.89 percent. The two figures belong together, and anyone who reads only one of them comes away with the wrong picture.
The first weekly outflow since the Zcash ETF launched on August 25, 2026
The fund is called the Grayscale Zcash ETF and trades under the ticker ZCSH on NYSE Arca. It is a spot product, so it holds real ZEC and does not track the price through futures contracts. Since the launch on August 25, 2026 the direction was unambiguous: money flowed in, week after week. That run has now broken.
A weekly outflow at a spot fund means more shares were redeemed than newly issued. To meet that, the issuer releases ZEC from the fund's assets and passes the proceeds on to the redeeming holders. This is part of the normal mechanism of an exchange-traded fund and is not a fault. It is simply working in the opposite direction from the six weeks before.
The figure sits in the context of a week in which the large crypto funds pulled apart. On the flow data of the provider SoSoValue, the Bitcoin products took in $241.1 million, their third consecutive week of inflows. The Ethereum funds gave up $138 million. Solana saw $2.4 million of inflows and XRP $4.7 million. That made Zcash the second largest outflow of the week after Ethereum, even though its fund is the youngest of the group.
$93.56 million in a week: how the individual trading days ran
The outflow did not arrive on one day and not as a single large sale. On the fund data, redemptions at the end of September and the start of October ran between $26 million and $30 million on several trading days. A pattern like that argues against the story of a single large investor heading for the exit and in favour of a broader reallocation over several days.
September 30 as the heaviest single day
The heaviest single day was September 30, 2026, with $30.25 million of outflows. The date is no accident: it is the last trading day of the quarter. Fund managers and asset managers square their books on that reporting date, and positions that have run hard during the quarter are frequently trimmed in the process. With a gain of more than 30 percent over the month, Zcash was exactly such a position.
$751 million in fund assets against $212.56 million of net inflows
Here lies the most interesting figure in the whole episode. Fund assets stand at around $751 million at the start of October. But the sum of all net inflows since launch comes to only $212.56 million. The difference of a good $538 million is not fresh money; it is the price gain on the ZEC already held.
Put another way: less than a third of the fund's assets is paid-in capital. The rest is valuation. A fund with this structure reacts sensitively to falling prices, because the assets shrink twice over when the price gives way and shares are redeemed at the same time.
Set the outflow against the inflows: before the outflow week, around $306 million net stood on the books. The $93.56 million amount to a good 30 percent of that. In a single week, then, close to a third of all the net capital ever gathered has gone back out. The peak in fund assets came in September, between $915 million and $979 million depending on the reporting date and the price level.
Zcash loses 7.4 percent in seven days while Bitcoin gains 2.9 percent
This weakness is not the weakness of the wider market. Bitcoin stands at $85,912 or €76,565 and has gained 2.92 percent in seven days. Ethereum is at $2,715.22 or €2,419.81, up 1.34 percent over the same week. Zcash lost 7.36 percent in that period. The gap to the market is therefore around ten percentage points.
Within the last 24 hours ZEC moved between $1,281.40 and $1,361.16. Trading turnover came to $820.67 million. That keeps Zcash in tenth place by market capitalisation. The price is 58.02 percent below the all-time high of $3,191.93 set in October 2016.
The monthly balance of 33.9 percent remains despite the weak week
Anyone who has only been watching for a week sees a falling price and a fund losing money. Anyone looking back a month sees a gain of 33.89 percent. Bitcoin managed 7.79 percent in the same month, Ethereum 9.71 percent. Over thirty days Zcash was therefore markedly stronger than the two large names and only fell back in the final week.
That spread is the honest description of the position. A rally that lifts an asset by a third in four weeks creates gains that get realised at some point. That this happens at quarter end is unsurprising. What the figures do not say is whether the outflows continue. Flow data describe the past; they say nothing about the week ahead.
One point often lost in the coverage: an outflow from a fund is not a sale on the crypto market in the usual sense. The issuer gives up ZEC, but the shareholder who redeems can just as easily put the money into another crypto product. Flow data show reallocation and demand, not automatically flight from the asset class.
ZCSH, ZCASH and ZEC: three names for three different things
The similarity of the names causes expensive mix-ups, so here is the difference in brief. ZEC is the coin itself, which you buy on a crypto exchange and transfer into your own wallet. ZCSH is Grayscale's US spot ETF, whose outflow this article is about. ZCASH is the ticker of a European security that tracks the same price.
ZCSH stays closed to German retail investors
The fund that saw the outflow is not available to you as a retail investor in Germany. US funds of this kind have no key information document under the European PRIIP regulation, and without that document a broker may not offer the security to retail clients in the EU. cryptoticker.io described this route to purchase in detail on August 29, 2026. In practice that means the outflow figure is information about demand for you, not a call to act on your own account.
The reverse conclusion holds too. That US investors are redeeming shares says nothing about how European investors are behaving. The European products are younger, smaller and listed on different exchanges.
21Shares and Valour: the European securities on Zcash
Since September 22, 2026 there has been an exchange-traded security on Zcash in Europe. The Swiss issuer 21Shares runs the 21Shares Zcash ETP under the ticker ZCASH, ISIN CH1608218801, German securities identification number A4AXHY. The annual fee is 2.50 percent. The paper is listed on Euronext Amsterdam and Euronext Paris, and at launch not on a German exchange.
Alongside it, Valour, a subsidiary of DeFi Technologies, launched a Zcash ETP at the end of September on Sweden's Spotlight Stock Market, settled in Swedish kronor, with an annual fee of 1.9 percent.
Two issuers, two fee models
The difference of 0.6 percentage points in the annual fee sounds small, and over a short holding period it is. Over five years, on an investment of €10,000, it comes to around €300 before any price gain has arisen at all. Whether your broker connects to the Euronext venues or to Spotlight decides which of the two papers is reachable for you. A query to the broker settles that before you place an order. Which routes exist for exchange-traded crypto products in Germany is set out in our overview of crypto ETFs and ETPs for German investors. cryptoticker.io examined broker access, fees and the holding period for the Zcash ETP in detail on September 22, 2026.
Holding period and capital gains tax: the consequences for your tax return
This is the point at which coin and security part company most clearly, and the decision falls before the purchase, not after it.
If you hold ZEC directly in your own wallet, section 23 of the German Income Tax Act applies. Sell within a year of buying and the gain is taxable as a private disposal, at your personal rate. Once a year has passed the gain is tax free. That holding period is the reason many investors in Germany prefer the coin to the security.
What runs differently with a security than with the coin
An ETP in a securities account is treated for tax purposes like a security. Gains are subject to the flat-rate withholding tax of 25 percent plus the solidarity surcharge and, where applicable, church tax, regardless of how long you have held. Your bank normally remits the tax directly. For physically backed crypto-asset ETPs with a delivery claim, the classification is contested in tax practice; do not rely on a blanket statement here and have the individual case examined. A tax tool or portfolio tracker documents purchase dates and holding periods in a way that lets you prove them if it comes to that.
July 1, 2027 and the EU ban on anonymity-enhancing crypto assets
There is one date that weighs more heavily for Zcash in Europe than any weekly flow figure. Regulation (EU) 2024/1624 on the prevention of money laundering prohibits credit and financial institutions as well as crypto service providers, in article 79, from maintaining accounts holding anonymity-enhancing crypto assets. The provision applies from July 1, 2027.
Zcash falls under that definition because the network permits shielded transactions. For licensed providers in the EU this means no listing, no custody, no brokerage for such assets. Monero, Dash and comparable projects are affected in exactly the same way.
Two things the regulation expressly does not prohibit. You may continue to hold ZEC in your own wallet, and transfers between self-custodied wallets are out of scope. The ban is addressed to supervised businesses, not to private individuals. In practice it still means that the convenient route through a regulated exchange in the EU falls away by mid-2027. Anyone intending to hold ZEC for the long run is therefore better off settling custody sooner rather than later.
How this deadline affects buying, selling and custody was written up by cryptoticker.io in detail on August 23, 2026.
NU7 on November 5: what to watch on old ZEC balances
The next network date comes before the regulatory one. On cryptoticker.io's reporting of September 18, 2026, the Zcash upgrade NU7 is scheduled for November 5, 2026; the consequences for old balances in the Sprout pool were described on September 23, 2026.
This is relevant for you if you have held ZEC for a very long time and never moved it. Balances in older shielded pools may under some circumstances have to be transferred into a current pool before the upgrade. Anyone holding their coins on an exchange or in an ETP is unaffected, because there the provider takes care of the technical side. Anyone self-custodying should check the pool type of their address in good time, not on the eve of the date.
Zcash ETF outflow: the key points for your decision
The record outflow is a demand figure, not a verdict on the network. It shows that US investors took profits after a strong September, and it coincides with the quarterly reporting date. Three steps that make sense independently of it:
- Settle your route of access before you trade. ZCSH is not available to you, the European ETPs depend on your broker's exchange connections, and the coin itself runs through a crypto exchange. Which regulated crypto exchanges are authorised in Germany under MiCA decides where you can get ZEC at all.
- Decide coin or security on the tax, not on the headline. One year's holding period on the directly held coin against flat-rate withholding tax on the ETP: that is a bigger lever on your return than 0.6 percentage points of fee difference. A tax tool records the deadlines in provable form.
- Set your custody up for July 2027. If licensed EU providers may no longer hold Zcash in custody from July 1, 2027, you will need your own arrangement for long-held ZEC. A hardware wallet is the route this deadline does not touch.
(As of October 6, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Fifty euros a month is the figure most people start with when they first consider a Bitcoin savings plan. The short answer to whether it pays off: anyone who began in January 2017 and has bought 50 euros every month since has paid in €5,900 and holds 0.7137 Bitcoin for it. At the price on October 5, 2026 that is around €54,500, a good nine times the money paid in. Anyone who only started in January 2024 is up just 14.5 percent on the same instalments.
Both figures come out of the same calculation, and that is precisely the point: what a savings plan ends up delivering is decided above all by the entry date and the time in the market. This article works through five periods, sets each instalment plan against a lump sum of the same amount, and shows where fees and German tax law cut in. Bitcoin traded between €76,300 and €76,400 on Monday; every closing value below is calculated at that level.
What 118 instalments of 50 euros in Bitcoin since January 2017 produced
A savings plan buys a fixed amount on fixed dates, whatever the price. When Bitcoin is high, your 50 euros buy little; when it is low, they buy a lot. Across 118 monthly instalments since January 1, 2017 that works out at an average entry price of €8,267 per Bitcoin. Today a Bitcoin costs around €76,400, so 50 euros still buy 0.000655 BTC.
The table shows five entry dates. Each line assumes an instalment of 50 euros on the first of the month, and the value refers to October 5, 2026.
| Start | Instalments | Paid in | Bitcoin | Value today | Return | Average price |
|---|---|---|---|---|---|---|
| January 2017 | 118 | €5,900 | 0.71370 BTC | €54,514 | +824.0 percent | €8,267 |
| January 2021 | 70 | €3,500 | 0.08975 BTC | €6,855 | +95.9 percent | €38,998 |
| January 2022 | 58 | €2,900 | 0.07336 BTC | €5,603 | +93.2 percent | €39,531 |
| January 2024 | 34 | €1,700 | 0.02549 BTC | €1,947 | +14.5 percent | €66,689 |
| October 2025 | 13 | €650 | 0.00971 BTC | €742 | +14.2 percent | €66,909 |
The middle row stands out. Anyone who started in January 2022, shortly after the high of the time had broken, is almost exactly as well off today as someone who got in a year earlier. The reason is the average price: both sit at around €39,000, because the instalments paid during 2022 were executed at very low prices and dragged the average down.
Cost averaging: why the Bitcoin savings plan lands at an average price of €8,267
Cost averaging describes a plain mechanism: because the amount is fixed and the price moves, you automatically buy more units when prices are low than when they are high. Your average price therefore always sits below the arithmetic mean of every price in the period.
Across the 118 instalments since 2017 that difference is enormous. The average price of €8,267 did not exist on any single day. It comes about because the instalments paid between 2017 and 2019 bought at a few hundred to a few thousand euros per Bitcoin and still account for the bulk of the units held. The instalments from 2024 on cost ten times as much per unit and contribute correspondingly little to the quantity. We worked this effect through in detail on September 19, 2026, using an example with a 100 euro monthly instalment over twelve payments.
The effect has a flip side that rarely appears in marketing copy: it only lowers your entry price if the market actually falls along the way. In a market that rises from start to finish, the savings plan is the more expensive route, because every later instalment costs more than the first.
Bitcoin savings plan vs lump sum: when the monthly instalment is the worse route
The honest counter-test is the lump sum, where the same total is invested on the first day of the period instead of spread across months.
| Start | Same total | Savings plan today | Lump sum today | Ahead |
|---|---|---|---|---|
| January 2017 | €5,900 | €54,514 (+824.0 percent) | €475,019 (+7,951.2 percent) | Lump sum |
| January 2021 | €3,500 | €6,855 (+95.9 percent) | €11,063 (+216.1 percent) | Lump sum |
| January 2022 | €2,900 | €5,603 (+93.2 percent) | €5,283 (+82.2 percent) | Savings plan |
| January 2024 | €1,700 | €1,947 (+14.5 percent) | €3,245 (+90.9 percent) | Lump sum |
| October 2025 | €650 | €742 (+14.2 percent) | €491 (−24.5 percent) | Savings plan |
In three of the five periods the lump sum would have done better, in the longest one by a wide multiple. That is neither an accident nor an argument against savings plans. It follows from the fact that Bitcoin has risen steeply over ten years: invest everything early and you are invested for longer.
The catch in this comparison is that nobody in January 2017 knew it would turn out that way, and that hardly anyone puts €5,900 at once into an asset that had fallen by more than 80 percent twice in the years before. A savings plan does not buy you a higher return. It buys you the chance to start at all. We looked at the two routes side by side against the current market on October 3, 2026.
Since October 2025 the picture flips: plus 14.2 percent against minus 24.5 percent
The bottom row of the table is the most interesting case. On October 1, 2025 a Bitcoin cost around €101,100; today it is around €76,400. Anyone who had invested €650 in one go back then would be sitting on €491, a loss of 24.5 percent. Anyone who instead transferred 50 euros thirteen times holds €742 today and is up 14.2 percent.
The gap of almost 39 percentage points arises purely because the later instalments were executed at markedly lower prices. This is exactly the situation a savings plan is built for: a falling or sideways market. The reverse also holds. The lead melts away as soon as the price climbs back above the entry point.
What a 1.5 percent spread costs a savings plan over 118 instalments
Crypto savings plans often advertise free execution. You still pay, only through the spread. The spread is the difference between the price at which a provider buys and the price at which it sells; it sits inside the quote and never appears as a separate line on a statement. We pulled together the terms nine providers disclose on this from their own fee pages on August 14, 2026.
How hard that bites can be shown on the 118 instalments above. The higher the mark-up per execution, the less Bitcoin lands in the account, and that shortfall in quantity grows along with the price.
| Mark-up per instalment | Total fees | Value today | Difference against zero |
|---|---|---|---|
| 0.0 percent | €0 | €54,514 | – |
| 1.0 percent | €59 | €53,969 | −€545 |
| 1.5 percent | €88 | €53,696 | −€818 |
| 2.0 percent | €118 | €53,423 | −€1,090 |
€88 in fees turns into €818 less in final value over nine years. The reason is that every fraction of a Bitcoin not bought takes no part in the whole subsequent rise. On an instalment of 50 euros this is the single most important cost lever, more important than account charges or withdrawal fees.
The claim that execution is free, and what it leaves out
"Free execution" only means that no order fee is charged. What matters is whether the provider names a reference price its own quote can be measured against. Without that figure you cannot establish the actual mark-up. A high-street bank or a broker may also offer a certificate or a debt security instead of coins, which is a different thing in law. Comdirect, for instance, lists 29 certificates with no order charge in its savings plan but not a single genuine coin, as we read out of its price list on October 4, 2026.
Minimum instalment, interval and execution day: the levers on a crypto savings plan
Three settings determine how a savings plan runs, and all three have a measurable effect.
The minimum instalment sits between one and 25 euros at most providers. At 50 euros a month you clear that bar everywhere. The more relevant question is whether the provider trades fractions: without fractions, a 50 euro instalment simply could not be executed at a price of €76,400.
The interval can be weekly, fortnightly or monthly. More frequent instalments smooth the entry price somewhat more, but they raise the number of executions and with it the sum of the spreads. For a fixed annual amount the difference in return over long periods is small; the fee side argues for less often, the smoothing for more often.
The execution day is often overstated. The calculations above use the first of the month. There is no systematically better day for Bitcoin, because the market runs seven days a week and has no settlement dates around which patterns could form.
Which providers in Germany run a genuine coin savings plan, and what the terms are, is in our comparison of Bitcoin savings plans. Check as well whether the provider holds a MiCA authorisation in the EU, because since 2025 crypto service providers may only operate here with that permission.
Holding period under section 23 EStG: every instalment has its own purchase date
Here lies the difference between a savings plan and a lump sum that shows up in no return table. Under current law Bitcoin counts as one of the other assets, and for those section 23 paragraph 1 number 2 of the German Income Tax Act sets a period of one year: disposals are only taxable if no more than one year lies between acquisition and sale. Once that year has passed the gain is tax free, however large it is.
A savings plan creates a separate acquisition with its own date for every instalment. Of the 118 instalments since 2017, 106 are now more than a year old. Those instalments account for 0.70448 Bitcoin and therefore for around €53,800 of the total value. The twelve younger instalments are worth about €704 between them and would fall into the tax net on a sale today.
The €1,000 threshold and the order of sale
A threshold applies to taxable gains: under section 23 paragraph 3 sentence 5 EStG gains stay tax free if the total gain from private disposals in the calendar year comes to less than €1,000. That is a threshold, not an allowance. Reach €1,000 or more and the entire gain is taxable, not merely the excess.
Which instalments count as sold in a partial disposal is determined in practice by the order of acquisition: the units bought first count as sold first. For a savings plan running over years that means the oldest and therefore tax-free instalments go first. Documenting that allocation cleanly is barely possible by hand across 118 separate purchases; that is what tax tools and portfolio trackers are for, reading the purchase dates straight out of the exchanges. We set out in more detail on August 11, 2026 how the holding period and a savings plan interact.
The December 31, 2026 cut-off splits your Bitcoin savings plan in two
On September 30, 2026 the German Federal Ministry of Finance sent its draft bill on reforming the taxation of certain crypto assets held privately into interdepartmental consultation. The draft reassigns income from crypto assets to investment income, on which a tax deduction of 25 percent of the investment income is levied. Under article 2 of the draft the law is to take effect on January 1, 2027.
For a savings plan already running, the application provision is the decisive part. The explanatory note on item 7 reads: "The substantive changes in law are to be applied from January 1, 2027 and cover exchange crypto assets acquired or received after December 31, 2026." And further: "For legacy holdings, sections 22 and 23 EStG otherwise continue to apply unchanged."
Applied to an instalment of 50 euros on the first of the month, that means the instalments of October 1, November 1 and December 1, 2026 would be legacy holdings under the draft and would keep the one-year holding period. Every instalment from January 2027 would fall under the new rule. A savings plan that runs past the turn of the year would therefore consist of two tax-wise different parts inside the same holding, and that split would remain permanently.
The qualification matters: a departmental draft is not yet a law. The text passes through cabinet, Bundestag and Bundesrat and may change in its deadlines, cut-off dates and rates along the way. Basing a purchase decision on this cut-off alone would be a bet on a process whose outcome is open. We assessed on October 3, 2026 what the draft means for the choice between instalment, lump sum and certificate.
Custody: when 50 euros a month justify a move to your own wallet
A savings plan sits with the provider to begin with. As long as only a few hundred euros are held there, a withdrawal to your own wallet is often uneconomic, because the network fee for a Bitcoin transaction is charged regardless of the amount and weighs heavily in percentage terms on small sums.
A workable rule is not to withdraw every instalment separately but to bundle them at intervals. At 50 euros a month, transferring once a year moves €600 in one transaction instead of twelve. The holding at which a dedicated device pays for itself depends on what you are willing to spend on security; that class of device starts in the low double digits. Only one thing matters here: a transfer to your own address is not a sale and triggers no tax, as long as you remain the owner. The holding period of each individual instalment keeps running.
What argues against a 50 euro savings plan
Three objections deserve to be taken seriously. First, a standing order ties up money that is better kept as an emergency fund; anyone forced to sell in a bad market phase loses precisely the advantage the long run is meant to deliver. Second, the automation invites you never to review the position, even though providers, fees and the legal position all change. Third, Bitcoin remains an asset that has lost more than 70 percent several times in the past. The 14.5 percent gain on the 2024 instalments in the table above is a thin result after not quite three years, and it could just as easily have been a loss.
Bitcoin savings plan: the key points for your decision
Whether 50 euros a month pay off hangs on the time in the market, on the fees and on your own staying power. These three steps will take you further:
- Work out the mark-up before you set up the standing order. Compare a provider's execution price with a reference price and check whether it holds a MiCA authorisation. Our exchange comparison gives an overview of the authorised venues.
- Document every instalment with its date and price from the start. Across 118 separate purchases that is barely possible to reconstruct after the fact, and without those records the holding period cannot be proven. There are tax tools and portfolio trackers for it.
- Decide at what holding you will transfer out. Bundle the withdrawals instead of moving each instalment on its own, and settle beforehand where they go. The classes of device and how they differ are in our hardware wallet comparison.
(As of October 5, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
Built with input from J.P. Morgan, the open-source "DvP" program lets institutions settle trades atomically on Solana with finality in seconds instead of days.
The Nasdaq-listed bitcoin treasury company, co-founded by Vivek Ramaswamy, paid roughly $169 million for 2,000 coins last week and now holds 29,462 BTC.
Nasdaq-listed DeFi Development Corp's latest SEC filing shows its Solana stash grew 1%, to about 2.56 million SOL and SOL equivalents—roughly half the prior week's gain and well below mid-September's pace.
Investigators say a Bonita Springs woman's Claude "diary" tripped Anthropic's safety filters. A human review team sent it to police, and Anthropic's own terms allow exactly that.
An anonymous 4chan user called Bitcoin's October 2025 peak to the day way back in 2023. Could they be right again?
U.Today - IT, AI and Fintech Daily News for You Today
Ripple effect from growth on larger cryptocurrencies have reached smaller networks.
The XRP Ledger has moved a step closer to launching Smart Escrow after developers rolled out the ninth Devnet release.
The CFTC is moving to build a new federal rulebook for crypto markets, proposing purpose-built regulations that could bring leveraged retail crypto trading.
ADA outpaces the market in its deepest rally since May while Cardano founder Charles Hoskinson teases a major scalability upgrade.
Barry Silbert flags his 2011 market prophecy as RWA tokenization and 24/7 trading transforming Wall Street.
Blockonomi
TLDR:
- Zeta Global signed an agreement to acquire Y Combinator-backed AI engineering firm Senso on Oct. 5.
- Senso’s technology already powers Zeta’s Generative Engine Optimization offering for AI answers.
- Zeta aims to improve brand visibility across ChatGPT, Gemini, Claude, and Google AI Overviews.
- Senso co-founder and CEO Saroop Bharwani and the Senso team will join Zeta after the acquisition closes.
Zeta Global acquires Senso to boost AI marketing tools, according to an announcement made on Oct. 5, 2026. The New York-based company, listed as NYSE: ZETA, signed an agreement to buy the Y Combinator-backed AI engineering firm.
Senso’s technology already powers Zeta’s Generative Engine Optimization (GEO) offering. The deal brings that technology in-house.
It also adds engineering talent and stronger links to frontier models. Senso’s team will join Zeta once the acquisition closes.
GEO Offering Gains Frontier Model Connections
Zeta shared the news on an official announcement. The post stated that Senso will strengthen Zeta’s connections to leading frontier models.
It added that Senso’s technology already helps power the GEO offering. Zeta described the deal as an addition of technology, talent, and model connectivity.
GEO helps brands understand how they appear in AI-generated answers. In addition, it shows who those answers reach. Zeta said Senso will help improve how brands appear across leading AI platforms.
The release names ChatGPT, Gemini, Claude, and Google AI Overviews among those platforms. Combined with the Zeta Data Cloud, Senso will speed up tools that help enterprises optimize and remediate brand reach.
CEO Outlines the Infrastructure Strategy
Under the agreement, Zeta plans to connect AI insights to customer intelligence and marketing activation. The stated aim is measurable business outcomes.
Zeta defines intelligent AI infrastructure as a layer that connects what an enterprise knows to AI. Senso will extend that connection to AI platforms where customers discover brands.
David A. Steinberg, Zeta’s co-founder, chairman, and CEO, commented on the deal. “Models are increasingly ubiquitous,” he said. He added that infrastructure creates the advantage by connecting “an enterprise’s data and context to those models.”
Steinberg also described what Senso brings. “Senso will bring AI engineering talent and deeper connectivity to the frontier models and personal agents,” he said. Furthermore, he noted the deal stands apart from announcements planned for Zeta Live 2026.
Senso Leadership Explains Its Approach
Saroop Bharwani, Senso’s co-founder and CEO, will join Zeta with the rest of the team. He has more than 20 years of experience working with regulated enterprises. Bharwani founded Senso as an AI research lab during the early wave of enterprise deep learning.
Bharwani described the company’s founding principle. “Senso was founded on the simple principle of making AI more useful in the real world, not more conversational,” he said.
Senso combines applied research and engineering to help businesses turn trusted information into better AI interactions.
He also addressed AI discovery. “AI discovery is becoming an increasingly important part of the customer journey, but visibility alone is not enough,” he said.
Zeta will work closely with the Senso team to provide continuity for customers. LUMA Partners advised Senso on the transaction. However, the release does not state a closing date or a purchase price.
The post Zeta Global Signs Deal for Senso to Strengthen AI Discovery Offerings appeared first on Blockonomi.
TLDR
- AbbVie Phase 3 lymphoma trial cuts progression or death risk by 51% in DLBCL
- Epcoritamab plus R-CHOP delivers a major Phase 3 win in frontline lymphoma care
- AbbVie gains fresh lymphoma data as EPCORE DLBCL-2 meets its primary endpoint
- Phase 3 results strengthen AbbVie’s bispecific strategy in frontline DLBCL care
- AbbVie and Genmab plan regulatory talks after positive lymphoma trial results
AbbVie reported positive Phase 3 lymphoma trial results after its shares closed 1.12% higher at $265.76. The EPCORE DLBCL-2 study showed a 51% reduction in disease progression or death risk. The findings could strengthen AbbVie’s position in frontline treatment for diffuse large B-cell lymphoma.
AbbVie Inc., ABBV
AbbVie Phase 3 Trial Meets Key Lymphoma Goal
AbbVie and Genmab tested epcoritamab with standard R-CHOP therapy in newly diagnosed DLBCL patients. The trial enrolled patients with International Prognostic Index scores ranging from two to five. Researchers compared the combination directly with R-CHOP treatment alone.
The study met its progression-free survival goal with statistically significant and clinically meaningful results. Epcoritamab plus R-CHOP reduced progression or death risk by 51% compared with standard therapy. The trial reported a hazard ratio of 0.49 and a p-value below 0.0001.
The companies also reported a generally manageable safety profile for the combination treatment. Researchers found the safety findings consistent with earlier results from epcoritamab and R-CHOP separately. AbbVie therefore gained stronger Phase 3 evidence supporting epcoritamab in earlier lymphoma treatment.
Epcoritamab Could Expand AbbVie’s Frontline Lymphoma Strategy
DLBCL represents an aggressive form of non-Hodgkin lymphoma and often requires immediate treatment. R-CHOP has remained a core frontline therapy for many patients for more than two decades. However, some patients still experience disease progression or relapse after initial treatment.
Epcoritamab uses a bispecific antibody approach that engages T cells against cancer cells. AbbVie and Genmab designed the treatment to target CD3 on T cells and CD20 on B cells. The approach aims to increase immune activity against malignant B cells.
The latest results could expand epcoritamab beyond later treatment settings if regulators approve the combination. AbbVie already sees bispecific antibodies as an important part of its hematology development strategy. The Phase 3 outcome gives the company additional clinical data supporting that strategy.
AbbVie and Genmab Prepare Regulatory Discussions
AbbVie and Genmab plan to present detailed EPCORE DLBCL-2 results at a future medical meeting. The companies will also discuss the findings with regulatory authorities across major global markets. Those talks will help determine the next development and filing steps.
The combination remains investigational and currently lacks regulatory approval for newly diagnosed DLBCL patients. Regulators will assess the complete efficacy and safety data before making any authorization decision. AbbVie must therefore complete further regulatory work before commercial use in this setting.
Epcoritamab forms part of a broader AbbVie and Genmab collaboration in blood cancer treatment. Both companies have continued studying the medicine across several lymphoma settings and treatment stages. The latest Phase 3 result adds frontline DLBCL to that growing clinical development program.
The post AbbVie Inc. (ABBV) Stock: Phase 3 Lymphoma Trial Cuts Progression Risk 51% appeared first on Blockonomi.
TLDR
- AST SpaceMobile and TELUS complete their first satellite network integration test.
- TELUS plans direct-to-smartphone satellite services for customers within a year.
- Satellite coverage will target remote areas beyond traditional Canadian cell towers.
- AST SpaceMobile technology supports calls, texts and broadband on standard phones.
- TELUS satellite integration could improve emergency access and network resilience.
AST SpaceMobile stock closed at $58.44, down 0.02%, before rising 0.27% to $58.60 after hours. The move followed a successful network integration test with Canadian telecom operator TELUS. The test advanced plans to extend direct satellite connectivity across areas beyond traditional cellular coverage.
AST SpaceMobile, Inc., ASTS
AST SpaceMobile Stock Gains Support From TELUS Test
TELUS and AST SpaceMobile completed their first integration test between terrestrial wireless and space-based cellular networks. The companies tested technology designed to connect standard smartphones directly with satellites. Therefore, the milestone moves their Canadian satellite broadband partnership closer to commercial deployment.
The system supports broadband data, voice calls, and text messaging without requiring specialized satellite phones. AST SpaceMobile operates low Earth orbit satellites equipped with large communication arrays. Meanwhile, TELUS provides the terrestrial network infrastructure required to connect satellite services with existing cellular systems.
The integration creates another coverage layer for locations where conventional towers cannot provide reliable service. This approach could extend connectivity across highways, wilderness areas, parks, and remote communities. It could also strengthen network resilience when terrestrial infrastructure faces coverage limitations or service disruptions.
TELUS Plans Satellite Smartphone Service Within Next Year
TELUS expects to introduce the satellite service to eligible customers within the next year. Customers will use compatible smartphones already designed for conventional cellular connections. Consequently, users will not need separate satellite equipment when accessing supported space-based services.
The planned service aims to improve connectivity for travelers and people living outside major urban areas. It will also support workers across energy, forestry, construction, and natural resources operations. These sectors often operate across remote locations where traditional mobile infrastructure remains limited.
Emergency communications represent another major use case for the partnership. TELUS plans to use satellite connectivity to extend access to emergency services across uncovered locations. As a result, users could gain another communication option when conventional cellular coverage becomes unavailable.
AST SpaceMobile Expands Direct-to-Device Network Strategy
AST SpaceMobile develops a satellite network designed to connect directly with ordinary mobile phones. Its business model works with established wireless carriers instead of requiring customers to adopt separate devices. The TELUS integration therefore supports its broader strategy of extending existing mobile networks through space.
The Canadian partnership also adds to TELUS’ continuing investment in nationwide wireless infrastructure. TELUS has expanded 5G+, LTE coverage, network speeds, and signal availability across several Canadian communities. Satellite coverage will complement those terrestrial investments rather than replace existing cellular infrastructure.
Canada presents a significant use case because large areas remain difficult to cover with traditional cell towers. Satellite-to-smartphone technology could reduce those gaps while using infrastructure already operated by wireless carriers. Therefore, the successful integration gives AST SpaceMobile another commercial milestone as it expands its direct-to-device network.
The post AST SpaceMobile (ASTS) Stock: Rebounds as TELUS Satellite Test Expands Canada Coverage appeared first on Blockonomi.
TLDR:
- Binance AI is free for all users and adapts its “For You” tab to each user’s knowledge level.
- Binance AI Pro turns plain-language ideas into strategies, with a Premium plan at 19.99 USDC monthly.
- Each live strategy runs in a dedicated sub-account that users fund manually, so agents cannot move funds.
- Binance Agent OS launched in August 2026 and has now passed 280,000 daily calls from developers.
Binance Intelligence is a new AI product stack unveiled by the exchange on October 5, 2026. Co-CEO Richard Teng and VP of Product Jeff Li presented it during a livestreamed event in Abu Dhabi.
The suite includes Binance AI, Binance AI Pro, and Binance Agent OS. Binance says the stack aims to narrow the knowledge gap between everyday users and market professionals. Each product serves a different audience, from beginners to developers.
Binance AI Adapts Market Information to Each User
Within Binance Intelligence, Binance AI is a free feature set that personalizes market information. It uses generative UI to adjust layouts to a user’s knowledge level, interests, and products. These views appear in a new “For You” tab.
Teng described the broader goal during the event. “Blockchain is giving everyone access to markets; AI gives everyone the knowledge to navigate them,” he said. The tab also offers a Market Brief covering crypto, stocks, and macro topics.
The brief refreshes every four hours and reflects the user’s holdings. Users can read it as text or listen to it as audio.
Other tools include Smart Tool Tips, tailored widgets, and Master Trade profiles. Binance AI rolls out progressively to all users from October 5.
Binance AI Pro Converts Ideas Into Strategies
Binance AI Pro is a finance-focused agent that turns plain-language ideas into executable strategies. Users describe a goal, such as monitoring a portfolio. The agent then produces an initial strategy with a visual flowchart. Live strategies run 24/7 within Binance.
On desktop, the screen splits between the conversation and the workflow. Users can click modules to adjust, add, or remove components.
Li said the product is built around user input. “Users bring their ideas in plain language; everything a strategy needs is already built in,” he said.
Each live strategy runs in a dedicated sub-account that the user funds manually. The agent cannot move funds on its own, and users approve any workflow before execution.
Rollout begins in the second half of October on a freemium model. The Premium plan costs 19.99 USDC per month and adds live deployment and paper trading.
Binance Agent OS Targets Developers
Binance Agent OS connects AI applications to Binance trading, market data, wallet, payment, and on-chain capabilities.
The platform launched in August 2026 and has passed 280,000 daily calls. Developers and quantitative trading teams are building AI-driven strategies on it.
It combines Binance APIs, BinanceWallet Agentic Hub, Binance x402, and Binance Skill Hub. In addition, it supports the Model Context Protocol.
Users can authorize agents through ChatGPT, Claude Code, Codex, and Cursor. Agents can access market data, view account information, and place supported trades.
Each agent can use a dedicated subaccount, and access can be revoked at any time. Teng said Binance Intelligence places an intelligent partner inside the app users already use.
The post Binance Intelligence Launches AI Suite for Users, Traders, and Developers appeared first on Blockonomi.
TLDR
- Rezolve AI stock rallies after Mastercard signs a worldwide reseller agreement.
- Mastercard can now market and sell Rezolve AI software across global markets.
- The deal expands Rezolve AI’s reach to merchants, banks, and enterprise clients.
- Rezolve AI will support joint sales, demonstrations, and customer evaluations.
- The agreement strengthens Rezolve AI’s push into agent-driven global commerce.
Rezolve AI stock jumped after the company secured a worldwide reseller agreement with Mastercard. RZLV gained 8.25% to $2.23 at Monday’s close. The stock then added 0.45% to $2.24 during after-hours trading.
Rezolve AI PLC, RZLV
Mastercard Deal Expands Rezolve AI’s Global Sales Reach
The agreement allows Mastercard to market and sell subscriptions to Rezolve AI software worldwide. Mastercard will lead customer coordination and contract directly with resale customers. The arrangement operates on a non-exclusive basis across international markets.
Rezolve AI will provide its commerce technology through this new distribution channel. Its services cover conversational commerce, product discovery, intelligent search, and catalogue enrichment. The platform also supports personalization, recommendations, and checkout orchestration.
Mastercard can introduce these services through its existing customer relationships. Rezolve AI will provide technical support during presentations and product evaluations. Both companies can also coordinate proposals and demonstrations for prospective customers.
RZLV Stock Gains on Expanded Commercial Opportunity
The agreement strengthens Rezolve AI’s ability to reach businesses across international markets. Mastercard already maintains broad relationships with merchants, banks, and other commercial customers. Therefore, the arrangement gives Rezolve AI another route for securing enterprise subscriptions.
Mastercard will manage key parts of the sales process under the agreement. Rezolve AI will support customer evaluations with technical expertise and product demonstrations. This structure could help move prospective customers from initial discussions toward commercial deployments.
However, individual deployments will require separate statements of work between the relevant parties. Those agreements will determine geography, selected products, and specific commercial conditions. Rezolve AI will generate revenue as successful customer engagements develop into subscription contracts.
Rezolve AI Targets Growing Agentic Commerce Market
Rezolve AI develops technology designed for digital shopping and automated commerce interactions. Its platform connects customer requests with product information and personalized recommendations. The technology also supports shopping journeys from product discovery through checkout.
Businesses increasingly use automated systems to improve product search and customer engagement. Rezolve AI provides tools that organize product data and improve recommendation accuracy. Its platform also includes governance, policy controls, and analytics for business deployments.
The company serves retailers, brands, financial institutions, and commerce platforms through its technology. Rezolve AI also operates Reward, its financial engagement platform. Together, these operations support its broader push into personalized and agent-driven commerce.
The Mastercard agreement adds a major distribution route without restricting Rezolve AI to one reseller. It also provides a formal framework for Mastercard to sell Rezolve AI subscriptions internationally. That structure supports Rezolve AI’s strategy of expanding its commercial footprint through large global partners.
Rezolve AI now has another pathway to reach enterprise customers through Mastercard-led sales activity. Mastercard brings established commercial relationships, while Rezolve AI supplies the underlying commerce technology. The partnership strengthens the company’s position as businesses adopt more automated shopping tools.
The post Rezolve AI (RZLV) Stock: Surge as Mastercard Deal Opens Worldwide Sales Channel appeared first on Blockonomi.
CryptoPotato
US President Donald Trump doubled down on his promise to distribute a $5,000 “dividend” to every adult US citizen if Republicans retain control of Congress in November.
Popular analyst Crypto Rover outlined his take on the matter and why he believes the enormous liquidity injection, which is far from being certain at this point, could send tens of billions of dollars into BTC and other digital assets.
Billions Into BTC?
Before we dive into Crypto Rover’s statement, we need to start with a disclaimer. Trump’s promise continues to face significant political and economic hurdles, as even some Republicans have spoken out against it. However, he has proven to make unpopular decisions in the past, so we can’t really dismiss this one.
So, Crypto Rover noted that the potential impact on digital assets is being underestimated, even though many other analysts speculated recently that it could lead to major rallies, especially for alts. His thesis is pretty straightforward: households would undoubtedly use much of the money for bills, consumption, and debt, but even a relatively small portion finding its way into investments could represent substantial new demand for crypto.
He estimated that 5%-10% of a $1.7 trillion liquidity injection would amount to somewhere between $85 billion and $170 billion potentially entering the market. However, here’s the catch.
Trump promised the payment to adult US citizens, not every American. New estimates from major news organizations put the program’s likely cost at around $1.2-$1.3 trillion, rather than the initially considered $1.7 trillion.
But even with this lower figure, a hypothetical 5%-10% allocation would represent $60 billion-$130 billion. Rover argued that today’s market is considered better positioned to absorb retail capital than during previous stimulus cycles, pointing to spot ETFs, broader institutional infrastructure, improved access, and a much more developed regulatory framework.
Far From Guaranteed
This part is far too important to explain with just a few sentences in the first paragraph, as there are substantial obstacles before any such liquidity boosts can materialize. As noted above, several Republicans have expressed skepticism about Trump’s proposal, concerned that payments exceeding $1 trillion could worsen the federal deficit and further reignite inflation. According to Reuters, some GOP lawmakers instead want additional government revenue directed toward reducing debt.
Separately, Congress would have to authorize the spending if Republicans win in November. Consequently, Rover’s scenario involved several major assumptions: a GOP victory, congressional approval, actual distribution of the checks, and recipients subsequently allocating even a small portion of that amount to crypto.
The post Trump’s $5,000 Checks Could Send Billions Into Bitcoin and Crypto: But There’s a Catch appeared first on CryptoPotato.
Strive CEO Matt Cole is pitching his company as the likeliest “fastest horse” among Bitcoin treasury firms in the next bull market, and he backed it with seven principles on competition posted on X.
His broader argument, however, is that Strive and Strategy need each other to expand the market for Bitcoin-backed digital credit rather than simply fight for the same investors.
Strive Claims Twice Strategy’s Amplification
“I think Strive has emerged as the leading contender to be the fastest horse in the next bull market,” Cole told Podcaster Robin Seyr. “What will drive the highest total returns will be one, having a high amplification ratio; two, being able to maintain a high amplification ratio; and three, not giving up Bitcoin upside for that amplification ratio.”
Amplification compares a company’s preferred stock and debt with the value of its Bitcoin. Strive’s own tracker puts its ratio at 51.4%, all of it from SATA preferred shares, with no debt, while Strategy’s is roughly 25%, putting Cole’s firm at about twice the amplification of Michael Saylor’s.
According to him, the next bull run could see Bitcoin go anywhere from $400,000 to $500,000 by late 2029, tied to a US debt crisis that pushes long-term yields down and weakens the dollar, and he described that as conservative.
The Strive chief was equally keen to play down any feud with Saylor’s company, pointing to a long article in which Strategy’s co-founder pictured the two firms working together.
SATA trades at between 25% and 50% of STRC’s daily volume, he noted, which some Strategy investors read as lost market share, but he called that “a really bad argument,” considering that had Strategy captured all of SATA’s roughly $1 billion, STRC would be only about 10% bigger. According to Cole, what matters more is whether the pool of digital credit can grow exponentially over the next three and a half years.
Institutions face issuer limits, he added, so large buyers need several issuers. He also claimed each firm has copied the other, citing Strategy’s move to daily dividends and its cash reserve.
“I’m glad that they innovate based on what we do and we innovate based on what they do,” he told Seyr.
On X, Cole wrote that every management team owes its first duty to its own shareholders and that “competing and collaborating are not mutually exclusive.”
Strive Holds 29,462 BTC to Strategy’s 848,000
As CryptoPotato reported earlier, Strive bought 2,000 BTC for $169 million on October 5, the same day Strategy announced 334 BTC for $28.7 million. That leaves Strive with 29,462 BTC and Strategy with 848,000.
ASST was trading near $30 at the time of writing, up about 137% in three months and down about 42% over a year. Meanwhile, SATA is paying a 13% dividend daily, against 12% on Strategy’s STRC.
The post Strive CEO Says ASST Can Outrun Strategy in the Next Bitcoin Bull Market appeared first on CryptoPotato.
OKXICE LLC, a venture formed by cryptocurrency exchange OKX and NYSE parent company ICE, made a filing on October 4 with the US Securities and Exchange Commission (SEC) to launch a tokenized stock trading exchange.
The filing makes OKX one of the first crypto exchanges attempting to offer tokenized US stocks through a regulated exchange under the temporary SEC regulations.
OKXICE Seeks Approval for 63 NYSE Stocks
According to a report by Bloomberg, OKX plans to seek approval to offer tokenized shares of an initial 63 NYSE-listed companies. Under the SEC framework, those companies have 30 days to opt out before trading can begin, meaning the launch still depends on that notice period and other requirements.
OKX’s blockchain infrastructure would be paired with ICE’s market technology. ICE acquired a stake in OKX in March at a $25 billion valuation, and the companies have agreed to work together on US-regulated crypto futures.
The SEC introduced its temporary Innovation Exemption in September, allowing certain tokenized securities venues to facilitate secondary trading of tokenized US stocks through permissioned automated makers and liquidity pools.
Tokenized shares must carry the same shareholder rights as the underlying securities, including dividends and voting rights. Smart contracts must also be auditable and run on public, permissionless blockchains, while trading must stop if the underlying stock is suspended on its primary exchange.
OKX Joins a Growing Tokenized-Stock Race
As CryptoPotato reported, Coinbase announced in June that it planned to offer tokenized stocks to customers outside the US, with shares backed 1:1 by the underlying assets and carrying shareholder rights.
That move came before the SEC’s September exemption and showed how crypto exchanges were already pursuing ways to connect stock trading with blockchain infrastructure.
The SEC’s exemption followed stalled legislative progress around the CLARITY Act. The regulator had reportedly been working on the exemption for more than a year and had planned to release it in May before delaying it during negotiations over the bill.
For OKX, the filing gives a use to the relationship with ICE beyond its March investment. The two companies are now seeking to combine exchange infrastructure and blockchain-based trading under a framework that could let US-listed stocks trade around the clock, subject to the SEC’s conditions.
The post OKX and ICE File to Trade 63 Tokenized NYSE Stocks appeared first on CryptoPotato.
Binance has told users in Brazil that from November 1, they must state the purpose of every crypto transfer to or from outside the country and identify who is on the other end. The exchange will report these operations to Brazil’s Central Bank every month.
The change brings international crypto transfers into Brazil’s foreign exchange rules, and nothing goes through without the answers.
Binance Sets New Requirements for International Transfers
Binance outlined the changes in an FAQ, explaining that users sending crypto abroad or receiving it from overseas will need to state the purpose of the transfer and identify the counterparty. Corporate accounts will also have to disclose whether the counterparty belongs to the same economic group.
The exchange stressed that this is not the Travel Rule. That requirement will apply separately to domestic and international transactions in 2027 and 2028, respectively.
For the new Brazilian foreign-exchange process, a transfer is considered international when the other party is outside Brazil or when users move their own assets between Brazil and an overseas account. Transfers between Brazilian residents, including transfers to a Brazilian exchange, are not affected.
Users will choose a purpose from a Central Bank classification system. Transfers of up to $50,000 have a simplified list of 10 purposes, while transactions above that amount require a complete list containing 96 options. Binance says there is no generic “others” option for transfers above $50,000.
A separate limit also applies. International transfers involving counterparties that are not institutions authorized to operate in Brazil’s foreign-exchange market are capped at $100,000 per transaction under the current rules, although Binance says that limit may later become $500,000.
What Users Need to Know Before November
The practical effect will be most noticeable when users move assets between Binance and foreign accounts. Withdrawals cannot be submitted until the questionnaire is completed, while deposits from abroad can remain pending and may sometimes be returned to the sender if the required information is not provided.
Self-hosted wallets are treated differently. Users do not have to provide a transfer purpose when sending crypto to or receiving it from their own wallet, but they must confirm ownership. Those transactions will still be reported to the Central Bank in a separate category.
Binance also says the information must reflect the actual reason for each transfer. Users can contact customer support if they make a mistake, while only foreign exchanges assessed under the Central Bank requirements will appear in the available exchange list.
The changes come as the exchange faces regulatory adjustments in some markets, including dealing with questions from European regulators over its continued operations after failing to secure a MiCA license. In September, the exchange separately announced the closure of UAH deposits and withdrawals and the removal of the USDT/UAH trading pair for Ukrainian users.
For Brazilian customers, however, the immediate issue is narrower: every international deposit and withdrawal will require the new information once the rules take effect.
The post Important Binance Announcement Concerning Brazilian Users appeared first on CryptoPotato.
Peter Schiff has warned that Bitcoin’s recent resilience could make a later reversal more painful for Strategy, arguing that the company has lost the ability to use STRC to raise fresh money for Bitcoin purchases.
His broader view is that markets have absorbed worsening economic signals without fully pricing the risks he sees.
Schiff Sees Strategy’s Financing Problem
In the latest Peter Schiff Show, the economist noted that Bitcoin had gained almost 1% on the week and was trading around $84,500 at the time of recording. He also pointed to Strategy’s STRC price, which had recovered to about $99.40 after falling to $75 during the summer.
He attributed that recovery to Strategy repurchasing STRC and Bitcoin’s move back above $80,000, which may have improved confidence and prompted short covering. But he argued that the rebound does not solve the financing problem.
“There’s no way that he’s going to be able to start selling more STRC. And that means he’s not going to be able to raise money to really start buying more Bitcoin,” Schiff stated, referring to Strategy’s Michael Saylor.
Strategy’s latest figures show 848,000 BTC, equal to just over 4% of total supply, alongside $4.8 billion in USD reserves and $833 million in cash. Its STRC position has an $8.93 billion notional value, with a 12% variable dividend and 12.07% effective yield.
Bitcoin has since moved higher, with CoinGecko data at the time of writing putting it around $86,000, up more than 4% in seven days and over 8% across 30 days, while remaining down 30% from where it was one year ago.
But despite what Schiff says, Strategy has continued buying the asset. As CryptoPotato reported earlier today, the company acquired 334 BTC for about $28.7 million. It also repurchased another $176 million of STRC. This latest buy is quite smaller than the 1,665 units bought for about $142.8 million in late September, which came together with $152 million of STRC.
Schiff Links Bitcoin Risk to a Wider Market Break
Schiff’s argument extends beyond Strategy’s capital structure. He believes Bitcoin is benefiting from a stock market that has so far absorbed weak economic and bond-market signals without a larger correction.
He referred to softer PCE inflation numbers, poorer-than-expected employment figures, and lower expectations of an interest rate hike in October, but maintained that bond prices were falling. The oil price stood at about $91 a barrel following a promise by the G7 to release 100 million barrels from their strategic reserves.
Schiff’s worry is that the markets are taking resiliency as an indicator that the bad news no longer matters, but he thinks things are only going to keep getting worse.
“At some point, Bitcoin is going to roll over, especially if we get a pullback in the tech market, which we haven’t had yet,” he warned.
The post Peter Schiff Predicts Bitcoin Will Drop If Tech Stocks Pull Back appeared first on CryptoPotato.