Cryptocurrency Posts
Crypto Briefing
Anthropic's massive AI compute investment could reshape industry dynamics, potentially elevating its market position and valuation significantly.
The post Anthropic plans to spend ~$518 billion on AI compute over the next decade appeared first on Crypto Briefing.
Solana's hackathon highlights growing interest in 24/7 tokenized stock trading, potentially reshaping access to pre-IPO and private equities.
The post Solana’s Stocklana hackathon draws 604 submissions chasing $126K in prizes appeared first on Crypto Briefing.
Aave's rate hike could stabilize GHO's value but may deter borrowing, impacting liquidity and user strategies in the DeFi ecosystem.
The post Aave raises core GHO borrow rate as redemption reserves run thin appeared first on Crypto Briefing.
Google's Superprojects could revolutionize productivity by seamlessly integrating diverse digital tools, enhancing collaborative efficiency.
The post Google is building Superprojects to unify Gemini workspaces appeared first on Crypto Briefing.
ZachXBT's risky personal investment highlights the potential for independent actors to disrupt illicit networks, impacting global cybercrime dynamics.
The post ZachXBT fronted $349,700 to get inside an alleged Lazarus laundering ring appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
$1.3B iTrust Capital CEO: 50% of Clients are Buying Bitcoin | Kevin Maloney
Are investors putting cash back to work in Bitcoin? Kevin Maloney, CEO of iTrustCapital, says about $1 billion went to work on his platform last quarter, including a couple hundred million dollars from clients’ cash positions. He explains what he’s seeing from what he says are more than 100,000 clients, why he says investors aren’t “chasing candles,” and what the shift tells him about the cycle.
Chapters:
0:00 Meet iTrustCapital’s Kevin Maloney: $1 Billion Went to Work Last Quarter
2:01 Is October the Low? What Client Behavior Shows
2:43 Investor Fatigue and the Clarity Act’s Failed Vote
4:09 How Retirement Investors Allocate: 5 to 15% and “Stickier Capital”
5:13 Custody, Vendors, and Where Bridging Bitcoin and Traditional Finance Can Break
6:24 Stocks, ETFs, and Chasing Yield: Why iTrustCapital Expanded
8:33 Q: The Quantitative Trading Tool and Who Uses It
11:18 What Regulation Is Still Needed After the Clarity Act?
12:32 Macro Outlook, ETF Flows, and Maloney’s 18-Month View
15:13 Gold vs. Bitcoin, Q Pricing, and Final Thoughts
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post $1.3B iTrust Capital CEO: 50% of Clients are Buying Bitcoin | Kevin Maloney first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
VanEck’s Matthew Sigel: Path to $500k BTC Runs Through Gold
Bitcoin miners with power contracts may own one of the scarcest assets in the AI economy. Matthew Sigel, head of digital assets research at VanEck, explains why AI changed the value of mining energy contracts, how 10 to 20 year leases with investment-grade counterparties changed miners’ correlation with Bitcoin, and why he sees an “underappreciated optionality.”
Chapters:
0:00 Macro Backdrop and VanEck’s Ten-Year View on Bitcoin
1:22 Seller Exhaustion, Buying Dips, and the Macro Bear Cases
3:12 Why Bitcoin Miners Own a Scarce AI Asset: Power
5:01 Gold vs. Bitcoin: Sizing and Portfolio Roles
6:46 Bitcoin, the Dollar, and the Bitcoin-to-Gold Ratio
8:26 Quantum Computing: A Real Risk, Not a Reason to Sell
10:11 Why Bitcoin Doesn’t Need More Regulation
12:56 Inflation, Fiscal Dominance, and Bitcoin as a Hedge
14:35 Is the Bottom In? Price Targets and Bitcoin Adoption
15:16 Half of Gold’s Market Cap as Bitcoin’s North Star
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post VanEck’s Matthew Sigel: Path to $500k BTC Runs Through Gold first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
CryptoQuant: BTC “Bull Run Has Started” – 3x to 5x Cycle Outlook | Ki Young Ju
Is the next Bitcoin move a 10x or a 3 to 5x? CryptoQuant founder Ki Young Ju says he expects about 3 to 5x from the lows, not another 10x, because institutional ETF and custody flows dampen volatility. He explains why he thinks the bear market ended this summer and what on-chain data is showing right now.
Chapters:
0:00 What On-Chain Data Shows: Fresh Capital and No More Whale Selling
1:44 The Bear Market Is Over: 3 to 5x, Not Another 10x
3:19 The PNL Index and ETFs as the Cycle’s Liquidity Channel
5:39 ETF Cost Basis in the Low-to-Mid $80Ks: The Institutional Bull-Bear Line
6:18 How Institutions Changed On-Chain Analysis: Custodial and Accumulation Wallets
9:18 Nearly $700 Billion in Realized Cap and Trillions Next Cycle
10:36 Who Is Buying? Reading Coinbase’s Wallet Flows
13:35 Top Signals: Behavioral, Not Price Levels
15:22 Is the Four-Year Cycle Invalidated?
16:31 Miner Costs and What They Imply for Price
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post CryptoQuant: BTC “Bull Run Has Started” – 3x to 5x Cycle Outlook | Ki Young Ju first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Jim Rickards: Stabelcoins “Dangerous” for Bond Market – $10,000 Gold Outlook
Why could gold hit $10,000 sooner than most analysts expect? Jim Rickards says it is “fifth grade math”: going from $9,000 to $10,000 is only an 11% move, much smaller than the jump from $3,000 to $4,000. He also explains why central bank buying puts a floor under gold, and why a strong dollar and a falling gold price do not mean what the debasement crowd thinks.
Chapters:
0:00 Jim Rickards and the 1998 LTCM Rescue
0:31 What Breaks First: Why Crises Start a Year Before They Hit
3:10 Where’s the Leverage? The Yen Carry Trade vs. Private Credit
5:13 Gold as a Dollar Signal: Why “King Dollar” Contradicts the Debasement Trade
7:33 The Case for $10,000 Gold by Mid-2027
10:24 Bitcoin vs. Gold: Rickards’ Skeptical View
13:07 Will Bitcoin Be a Safe Haven or a Risk Asset in the Next Crisis?
14:45 MoneyGPT: AI Risk and the Fallacy of Composition
17:49 Why Rickards Calls Stablecoins the Most Dangerous Thing in the World
22:58 The Fed’s September Rate Hike and What Comes Next
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Jim Rickards: Stabelcoins “Dangerous” for Bond Market – $10,000 Gold Outlook first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Coinbase Asset Management President: Bitcoin to $300k by 2030 | Anthony Bassili
What’s Coinbase’s asset manager’s Bitcoin price target? Anthony Bassili, president of Coinbase Asset Management, says his team’s target is north of $300,000 by 2030. He also explains why he expects Bitcoin’s cycle returns to shrink from a larger base, and why gold parity is a longer-term trend.
Chapters:
0:00 What Does Coinbase Asset Management Do?
1:01 How Pensions, Endowments, and Sovereigns Approach Bitcoin
3:29 Wealth Advisors and the 1–5% Bitcoin Allocation
4:04 The Coinbase Bitcoin Yield Fund: Who Uses It and Why
7:34 Bitcoin Price Target and Why Cycle Returns Keep Shrinking
10:08 Tokenization: Tokenized Funds and the iCapital Feeder
12:10 Why Tokenization Will Take Time to Reach Advisors
15:54 Will Sovereign and Pension Allocations Keep Rising?
18:14 Bitcoin and Gold: Correlations in the Fiscal Dominance Era
19:23 The Store of Value Index: Bitcoin and Gold in One Wrapper
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Coinbase Asset Management President: Bitcoin to $300k by 2030 | Anthony Bassili first appeared on Bitcoin Magazine and is written by Patrick Green.
CryptoSlate
Blockchain investigator ZachXBT said he infiltrated a Chinese laundering syndicate by posing as a cryptocurrency client and funding repeated stablecoin trades.
In an Oct. 5 disclosure, he alleges the network laundered more than $1 billion across exploits for Lazarus Group.
He said he fronted 349,700 USDC to build a relationship with a contact using the alias Jimmy Green. According to his account, the repeated exchanges led to private conversations about moving funds stolen from Bybit in 2025.
He reported tracing a cluster involving more than $12 million in Bybit funds and a later 442,000 USDT freeze by Tether.
Becoming a client
ZachXBT said the investigation began after the February 2025 Bybit exploit, when he noticed at least 15 accounts asking for help with orders he linked to stolen funds in public Telegram and Discord groups.
He contacted several of those accounts. One was Jimmy Green, the Telegram alias of the person with whom he subsequently exchanged funds.
On March 6, 2025, ZachXBT said he funded a new Ethereum address with 349,700 USDC in preparation for transactions with the contact. The arrangement involved sending his USDC on Ethereum in exchange for the contact's USDT on Tron. He then completed additional transactions to build trust.
As he built trust through repeat exchanges, ZachXBT said the contact began discussing movements of Bybit funds for North Korea before they occurred. The conversations also included details about operations in Hong Kong and mainland China.
In one example, he said the contact told him funds would move to Solana, and the movement happened the following day.
On March 12, 2025, ZachXBT said the contact sent a screenshot of a cross-blockchain transfer. He matched its amounts and timing to an order on the THORChain transaction explorer created within minutes of the message.
According to ZachXBT, the contact also supplied three Solana addresses. He said these exposed a cluster involving more than $12 million in Bybit exploit funds moving through Bitcoin, Ethereum, Solana and Tron.
He separately reported that Tether later froze 442,000 USDT linked to the cluster. That is the specific freeze amount described in this part of his investigation; the larger cluster figure represents funds he said he traced.
The account also reaches beyond Bybit. ZachXBT said the contact mentioned a team whose funds had been frozen in 2024. He said that matched an on-chain freeze of 332,000 USDC tied to the Poloniex exploit.
The Bybit backdrop and the cost of access
In a Feb. 26, 2025 alert, the FBI said North Korea stole approximately $1.5 billion in virtual assets from Bybit on or about Feb. 21. It called the specific malicious activity TraderTraitor.
At the time, the FBI said some stolen assets had been converted into Bitcoin and other virtual assets dispersed across thousands of addresses on multiple blockchains. It urged private-sector services to block transactions connected to the laundering addresses.
The syndicate's total and the links to Jimmy Green remain ZachXBT's findings, separate from the FBI's attribution of the theft.
Allegations involving a Chinese over-the-counter trader surfaced in October 2024. The latest account describes how ZachXBT obtained information by becoming a trading counterparty himself.
ZachXBT said he fronted 349,700 USDC for the case and lost 5% on each order. The amount advanced is distinct from his net loss, which he did not quantify in the disclosed figures.
He appealed for continued foundation grants and individual donations to support higher-risk investigations. He said intelligence from these trades helped freeze funds tied to the Bybit exploit.
The post ZachXBT infiltrates $1B crypto syndicate to expose Lazarus Group appeared first on CryptoSlate.
US corporate credit spreads widened beyond the weakest borrowers from September 25 to October 1, creating a broader test of whether tighter financing and reduced institutional risk-taking could pressure Bitcoin. The largest increase remained concentrated in CCC-and-lower debt, while investment-grade bonds showed a much smaller rise.
These option-adjusted spreads measure the premium over a Treasury curve. Their widening shows investors demanding more compensation to hold corporate debt. A borrower's total interest cost also depends on the Treasury component.
The ICE BofA CCC credit spread climbed from 11.28% to 12.15%, an increase of 87 basis points. Over the same dates, the broad high-yield spread rose from 2.93% to 3.24%, or 31 basis points. The investment-grade corporate spread increased from 0.81% to 0.86%, or 5 basis points.
All three comparisons use daily closing observations for September 25 and October 1, 2026. FRED's October 5 updates added October 2 readings of 12.02% for CCC-and-lower debt, 3.10% for broad high yield and 0.85% for investment-grade debt. All three eased from October 1 while remaining above their September 25 levels.
The investment-grade move is the clearest evidence that repricing extended beyond the lowest-rated debt. CCC-and-lower bonds are already included in the broader high-yield index, so those two increases are overlapping evidence. The picture is broader but unequal pressure.
How credit spreads could reach Bitcoin
For Bitcoin, transmission would depend on how credit repricing changes capital costs and risk-taking. If financing becomes more expensive, leveraged investors may need to shrink positions. Institutions could reduce crypto exposure as they reassess how much risk they are willing to carry across their portfolios.
The authors of the 2023 IMF working paper The Crypto Cycle and US Monetary Policy describe a related mechanism. Their historical analysis finds that monetary tightening can raise capital costs, encourage crypto investors to reduce leverage and lower aggregate crypto prices, with institutional participation reinforcing transmission.
The paper examines historical monetary-policy shocks; the current figures measure corporate credit premiums. Applying its mechanism to this episode remains conditional. The spread observations establish credit repricing, while current Bitcoin selling and its cause remain unestablished.
The Chicago Fed National Financial Conditions Index provides a broader check. Its latest reading was -0.548 for the week ending September 25, released September 30. That negative value indicates looser-than-average financial conditions. The observation predates the newest spread readings.
The next test is whether widening persists beyond the weakest borrowers and coincides with worsening broad financial conditions and weaker Bitcoin demand. That combination would strengthen the case for wider pressure on institutional risk-taking. Narrowing spreads and resilient Bitcoin demand would weaken it.
The post US credit spreads eased on October 2 after widening beyond the weakest borrowers appeared first on CryptoSlate.
Aave’s Ethereum Core market lists a 4.5% borrowing rate for GHO, aligning the stablecoin’s borrowing cost with the savings rate TokenLogic reported on Oct. 2.
The next test is whether the change brings USDC or USDT into the reserves available to savers who choose to convert withdrawn GHO into USDC or USDT.
Aave describes its savings token (sGHO) as redeemable instantly into GHO, so a holder who wants USDC needs a separate conversion. A higher borrowing rate can change the incentive to repay, but the route used to acquire that repayment GHO determines whether stablecoins enter the reserves.
The DAO service provider reported a depleted USDC GHO Stability Module (GSM) on Oct. 2, and said the rate increase should help replenish reserves if borrowers obtain repayment GHO through the modules.
The effect on reserves depends on borrowers bringing stablecoins into those modules, and the new rate alone does not demonstrate improved USDC conversion liquidity.
Aavescan’s Core GHO data dated Oct. 5 displays a 4.5% borrow APR. Its daily snapshots show 4.25% at midnight UTC on Oct. 3 and 4.5% at midnight on Oct. 4 and Oct. 5, locating the change between daily readings.
TokenLogic’s Oct. 2 notice proposed moving Core from 4.25% to 4.5%. It said borrowers could previously pay 4.25% to acquire GHO on Core and earn 4.5% in sGHO, leaving the DAO to fund the 25-basis-point difference. At an unchanged savings rate, the new Core rate eliminates that stated gap.
That alignment is specific to Core and the 4.5% savings rate reported on Oct. 2.
TokenLogic proposed a 3% base rate, up from 2.75%, and a 4.25% APR at optimal utilization, up from 4%. Aavescan’s Prime page displayed 4.17% on Oct. 5 at 86.35% utilization, versus 4.22% in its midnight snapshot.
Repayment replenishes reserves only through the right route
TokenLogic describes two ways a borrower needing GHO can acquire it: buy on the secondary market, or exchange USDC or USDT through a GSM.
Buying GHO can support its market price, while bringing stablecoins into a GSM adds the inventory that another GHO holder can later redeem against.
That makes a fall in outstanding debt an incomplete measure of conversion liquidity, since repayment can occur without USDC reaching a module. Improved conversion liquidity requires stablecoins entering the reserve, beyond any change in GHO debt.
Core’s midnight snapshots recorded 116 million GHO borrowed on Oct. 2 and 115.8 million on Oct. 5.
Aave’s native sGHO documentation says users deposit GHO, receive vault shares, and redeem those shares for GHO without a cooldown. It also says deposited funds are not rehypothecated.
Aave also documents a pause state and user-specific withdrawal limits. Those conditions affect live vault availability, separately from the inventory and liquidity needed to exchange the resulting GHO.
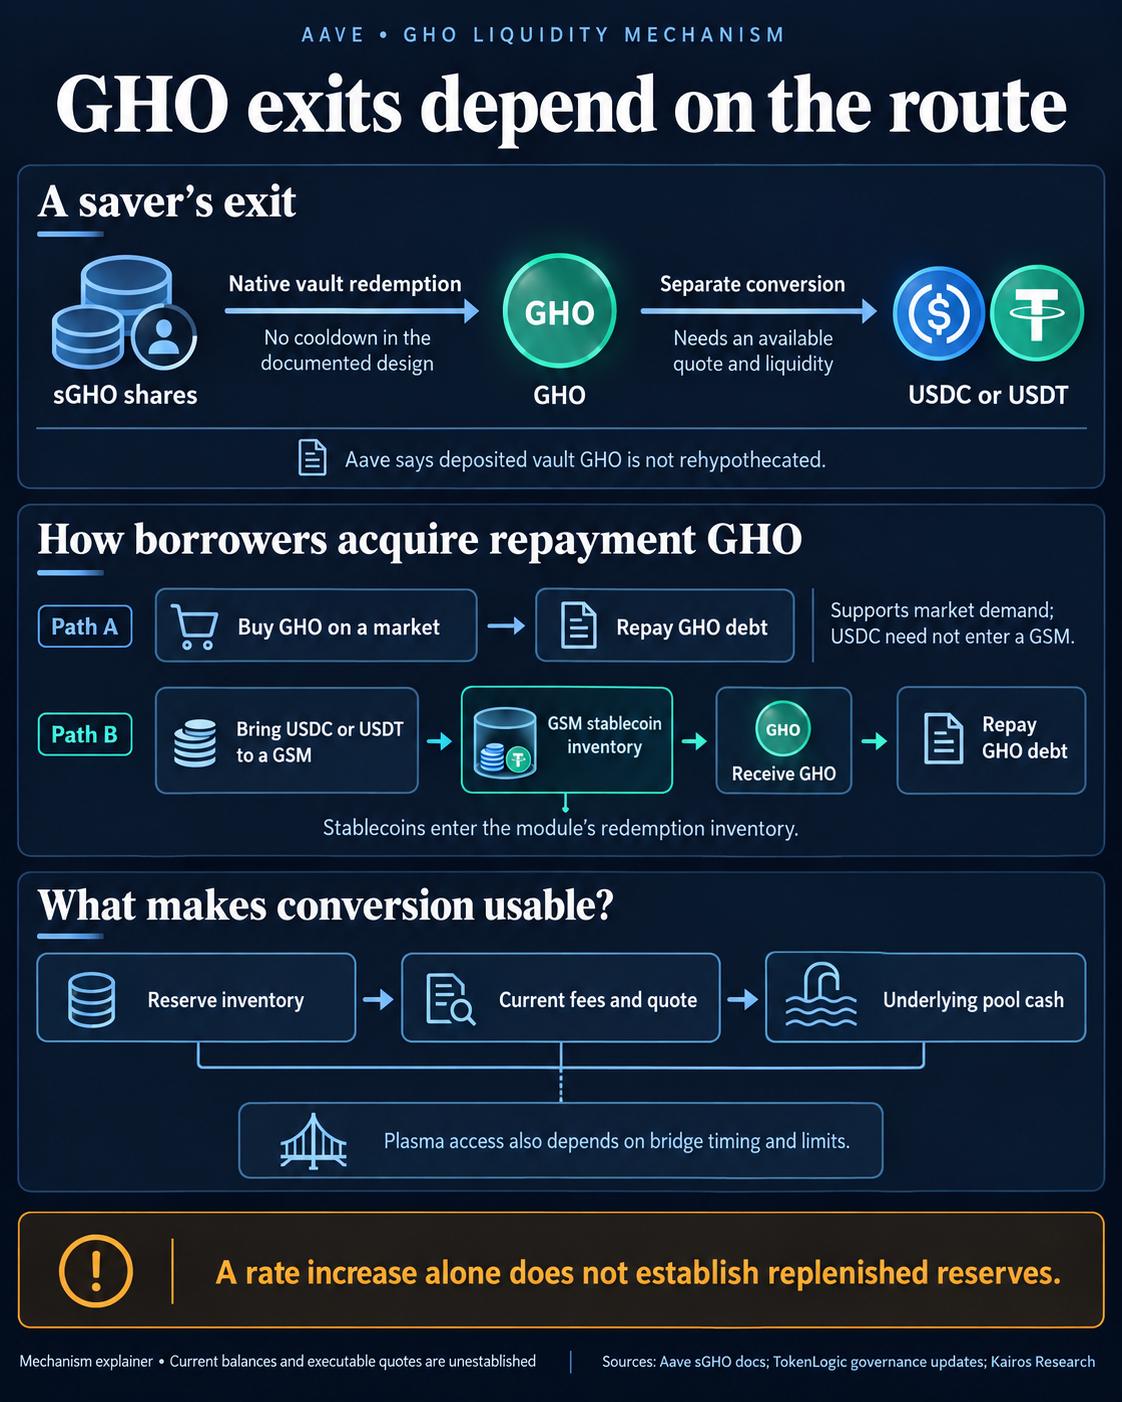
The RemoteGSM architecture, described by TokenLogic in March, makes the inventory distinction explicit. Governance-approved facilitators supply preminted GHO to a GhoReserve, and GSMs draw and restore it under assigned limits.
Room to distribute GHO is separate from the stablecoin inventory available for redemption. A higher limit can permit incoming swaps, but users still have to deliver the USDC or USDT.
Aave Labs’ institutional proposal reported 19.2 million USDT on Ethereum and 40.7 million on Plasma as of Sept. 24, totaling 59.9 million USDT. It excluded USDC instances because their redeemable balances were negligible.
TokenLogic’s Oct. 2 update reported approximately 22.5 million USDT in a USDT GSM without labeling the network scope. Comparing that figure with the earlier Ethereum-plus-Plasma total would not establish an aggregate decline. Neither statement supplies matched Oct. 5 balances.
Plasma provides a potential route to USDT inventory beyond Ethereum through Chainlink CCIP. Its usefulness depends on the time needed to bridge GHO and turn the module’s assets into usable stablecoins.
Kairos Research’s September analysis, using Sept. 8 readings, reported 40.6 million in nominal Plasma GSM redemption inventory against 38.6 million in underlying lending-pool cash.
Kairos also estimated at least 9.7 hours of rate-limit time to move 40 million GHO to Plasma under the bridge settings it measured. That assumed a full initial bucket and no competing traffic, and excluded message delivery and subsequent conversion steps.
Fees require the same care. TokenLogic’s September parameter notice proposed 15-basis-point USDC redemption fees on Ethereum, Monad and Arbitrum, a 10-basis-point Ethereum USDT fee and zero mint fees.
Its implementation language does not establish current executed fees. A usable exit depends on the current quote, inventory, and underlying liquidity together.
Institutional funding adds a duration test
Aave Labs seeks a 25-million-GHO facilitator and a separate route borrowing up to $25 million of USDC or USDT against DAO balance sheet assets. The planned initial balance-sheet route would use no GSM conversion inventory, and Aave Labs said on Oct. 1 that the proposal had advanced to Snapshot.
For the GHO route, the proposal prioritizes matched sGHO inflows, then secondary-market liquidity, then GSM reserves. TokenLogic’s Sept. 30 response adds a condition: matched inflows must last at least as long as the borrower’s draw.
That condition connects the rate story to the exit story. A matched inflow can provide lending currency while preserving GSM inventory at conversion, but TokenLogic argues that the funding must persist for the loan’s duration to resolve the liquidity pressure.
The duration condition applies to the proposed funding arrangement, while Aave describes deposited GHO in the native savings vault as held without rehypothecation.
Evidence of success would be stablecoin inventory arriving and remaining available for conversion, with executable routes that account for fees, pool cash, and cross-chain access.
Larger reserves or durable matched inflows could make exits easier. The higher Core APR establishes a change in borrowing cost, while its liquidity benefit depends on where the repayments and new deposits send the money.
The post Aave hikes GHO borrow rates to rescue depleted stablecoin pools appeared first on CryptoSlate.
Strategy (formerly MicroStrategy) made its smallest positive Bitcoin purchase of 2026 even as a 43% quarterly rally in the cryptocurrency helped generate a $20.9 billion gain on its digital-asset holdings.
In an Oct. 5 filing with the US Securities and Exchange Commission (SEC), the Michael Saylor-founded company said it bought 334 Bitcoin for $28.7 million between Oct. 1 and Oct. 4 at an average price of $85,838.80, taking its holdings to 848,000 BTC. The acquisition fell below the previous yearly low of 520 BTC bought in June.
The slowdown contrasts with the performance of Strategy’s existing Bitcoin position. Bitcoin gained about 43% during the third quarter, lifting the carrying value of the company’s holdings to $70.82 billion as of Sept. 30.
Strategy estimated a $20.91 billion digital-asset gain for the quarter under fair-value accounting. The gain does not represent realized trading profit, but the rally pushed its Bitcoin value above its roughly $63.97 billion aggregate acquisition cost.
Chaitanya Jain, Strategy’s head of investor relations, said:
“Every $1,000 increase in BTC price [during the third quarter represented] a $848 million fair market value gain to Strategy.”
Yet comparatively little new capital went toward adding to that position during the past week.
Strategy sold 92,894 MSTR shares for $15.7 million to help finance the latest purchase and supplied another $13 million from cash. It acquired 848,000 BTC at an average cost of $75,440.70 each.
At the same time, the company continues to commit considerably more capital to STRC, its variable-rate perpetual preferred stock.
STRC support enters another phase
Strategy spent $176.3 million repurchasing about 1.77 million STRC shares between Sept. 28 and Oct. 4, more than six times what it spent buying Bitcoin during the latest reporting period.
The purchases pushed total spending under its preferred-stock repurchase authorization to roughly $1.45 billion, leaving $547.2 million available under a program that Strategy doubled to $2 billion in September.
Despite that intervention, STRC has yet to return sustainably to its $100 stated amount.
Strategy's own investor materials say its objective is for STRC to trade over time between $99 and $100. The preferred security last closed at $100 in mid-May and has remained below that level for nearly 100 consecutive trading sessions, even after recovering sharply from its summer lows.
The company has already taken several steps to close that gap.
It raised STRC's annual dividend rate to 12%, began systematic repurchases and shifted dividend payments from monthly to semi-monthly earlier this year. Strategy said that June change was intended to improve the product's trading characteristics.
It is now proposing another redesign.
In a definitive proxy filed Monday, Strategy asked MSTR shareholders to approve daily dividends across its four US-listed preferred securities. STRC dividends would accrue on every calendar day, including weekends and holidays, and be payable on the next business day.
The annual dividend rate would not increase solely because of the amendment. Instead, Strategy argues that shortening the gap between earning and receiving dividends could reduce price fluctuations, improve liquidity, and attract additional demand.
For STRC specifically, the company says the proposal is intended to support trading at or near its $100 stated amount. Its September investor presentation reiterated that the company's objective remains for STRC to trade between $99 and $100 over time.
That makes the proposal the latest step in an increasingly expensive effort to establish STRC as a stable funding instrument for Strategy's broader Bitcoin strategy.
Oct. 28 vote tests Strategy’s preferred-stock funding model
The stakes extend beyond whether STRC can close the remaining gap to $100.
Strategy has increasingly relied on preferred securities as another route to raise capital without issuing only common stock or debt.
The company told shareholders that improving liquidity and demand across those securities could make future preferred-equity issuance more efficient, potentially expanding the pool of capital available for Bitcoin purchases.
That puts the Oct. 28 vote directly into Strategy’s Bitcoin-financing strategy.
MSTR shareholders of record as of Sept. 25 will decide whether STRC and Strategy’s three other US-listed preferred securities can move to daily dividend accruals. STRC holders themselves will not vote on the amendment.
If approved, STRC would begin accruing dividends daily on Nov. 1, with the first payment under the revised schedule due Nov. 2.
The proposal arrives after an earlier recovery benchmark passed without STRC returning to par. Strategy had highlighted the roughly 70 trading days the security needed to reach $100 after its original launch, a comparison that pointed to early September during the latest rebound.
STRC has since moved much closer to that level but remained below $100 after nearly 100 consecutive trading sessions.
The vote therefore gives Strategy a near-term test of whether changes to STRC’s market structure can reduce the amount of company capital required to support the security.
Failure to establish STRC sustainably around $100 would leave Strategy with a harder choice: continue using cash for repurchases, tolerate a persistent discount that could make future preferred issuance less attractive, or adjust the product's economics again.
Any of those outcomes would affect how efficiently Strategy can finance the next phase of its Bitcoin accumulation.
The post Strategy buys just 334 Bitcoin as preferred-share buybacks reach $1.45 billion appeared first on CryptoSlate.
Metaplanet sold 10,000 Bitcoin and later bought back 11,000 BTC to strengthen its credit profile and expand beyond accumulation during the third quarter.
The Tokyo-listed company said it converted enough Bitcoin into cash during the third quarter to exceed the outstanding principal of its bonds, borrowings, and other interest-bearing debt. It subsequently rebuilt the position at a higher Bitcoin price, ending Sept. 30 with 44,000 BTC, up a net 1,000 for the quarter.
The transaction forms part of a broader attempt to convince rating agencies and fixed-income investors that Metaplanet's Bitcoin reserves can be monetized when obligations come due.
The company plans to seek a credit rating and use a stronger financing profile to support a new business that borrows through bonds, preferred stock and Bitcoin-backed facilities before investing in higher-yielding assets.
The liquidity demonstration came at a price
Bitcoin rose between Metaplanet's sale and repurchase, leaving the company paying substantially more to rebuild the position it had sold.
According to the preliminary, unaudited figures in its statement, Metaplanet disposed of 10,000 BTC at an average price of ¥12.47 million per coin, generating ¥124.7 billion in proceeds. It later purchased 11,000 BTC at an average price of ¥13.63 million per coin, spending ¥149.9 billion.
The roughly ¥1.16 million difference between the sale and repurchase prices implies an adverse price differential of about ¥11.57 billion on the 10,000 BTC needed to replace the original position. Metaplanet said the higher reacquisition price reflected Bitcoin's rise between the two transactions.
The company said it conducted the transactions separately rather than as a simultaneous exchange. It first sold the Bitcoin, held the proceeds in cash, and only later repurchased the asset, a sequence intended to demonstrate that its reserves could actually be converted into cash rather than merely pointing to Bitcoin's market liquidity.
That distinction is central to Metaplanet's push into credit markets. The company said rating agencies and fixed-income investors can discount Bitcoin's liquidity value if an issuer is unwilling to sell it when required. Metaplanet wants the Q3 transaction to show creditors that its long-term accumulation strategy does not prevent management from monetizing Bitcoin to meet financial obligations.
The sale also produced a US capital-loss carryforward. Metaplanet estimates subsidiaries of its US holding company could recognize a deferred tax asset of about $97 million, potentially available to offset future capital gains. The estimate remains subject to closing procedures and auditor review, and the company said the asset may ultimately be smaller or not recognized at all.
Metaplanet said the tax treatment could offset some or all of the effect of the gap between its sale and repurchase prices and transaction costs if it recognizes the deferred tax asset.
Metaplanet wants to turn cheaper funding into recurring income
The company plans to use any improvement in credit access for more than financing additional Bitcoin purchases.
Its newly announced Net Interest Income Strategy plans to raise capital through instruments including perpetual preferred stock, corporate bonds known as BitBonds and Bitcoin-collateralized credit facilities. Metaplanet would deploy that money into assets carrying yields above its all-in financing costs, retaining the difference as net interest income.
The company expects preferred securities issued by Bitcoin treasury companies and similar issuers to be among its principal investment targets. Those investments will sit inside a strategic allocation that Metaplanet expects to represent about 10% to 15% of total assets, with Bitcoin remaining about 85% to 90%.
That would move Metaplanet closer to a financial intermediary inside the growing Bitcoin treasury market. Rather than relying predominantly on rising Bitcoin holdings and equity issuance, the company wants to raise money at one cost, invest it at a higher yield, and recycle the resulting cash flow into debt service, preferred dividends, and further Bitcoin purchases.
Metaplanet sees Japan as one potential source of that funding advantage. It said yen-denominated financing generally carries lower interest rates than dollar funding, while Metaplanet Securities gives it direct distribution to Japanese investors seeking Bitcoin-linked yield products.
The company also expects its pending investment in Super League Enterprise to expand its access to US capital markets, potentially allowing it to choose between jurisdictions, maturities and financing structures depending on market conditions. The transaction has not yet closed and remains subject to conditions including regulatory procedures and shareholder approval.
Metaplanet's new income strategy keeps Bitcoin risk close
Metaplanet's attempt to diversify its earnings base could still leave much of the balance sheet exposed to the same underlying asset.
The company acknowledges that securities issued by Bitcoin treasury companies may move with Bitcoin, creating correlation between its core reserves and some investments intended to provide recurring income. Metaplanet said credit, issuer concentration, currency and leverage risks will be managed within limits approved by its board.
Its revised capital policy also distinguishes between borrowing used to acquire Bitcoin and leverage used for strategic investments. Bitcoin-related borrowings are generally targeted below about 10% of BTC net asset value, while financing attached to the strategic investment portfolio will be managed separately under an asset-liability framework.
Metaplanet expects the new net interest income strategy to have an immaterial effect on its 2026 consolidated results, leaving the credit-rating effort and future financing terms as the more immediate tests. The company has cautioned that it has no assurance it will receive a rating, what level it would receive, or whether it can issue future bonds and preferred shares on the terms it wants.
The next phase will therefore depend on whether creditors reward Metaplanet for proving it is willing to sell Bitcoin when necessary. A lower cost of capital would give the company room to scale its spread strategy; without it, the economics of borrowing to buy yield-bearing Bitcoin-linked securities become considerably tighter.
The post Metaplanet sold 10,000 Bitcoin in a credit-rating bid, only to buy back 11,000 BTC at a higher price per coin appeared first on CryptoSlate.
CryptoTicker.io
Quant is a British technology company that connects banks and public authorities to blockchains without obliging them to commit to a single chain. The product behind it is called Overledger, supplemented since June 2026 by the Fusion Rollup, which according to the company brings 74 networks together in a shared execution environment. The associated token carries the ticker QNT.
The name became widely known most recently through a mandate from a US clearing house. This article takes a step back and explains what the technology actually delivers, where its limits lie and what role the token plays in it. For the current price there is a separate Quant price prediction; here the subject is the substance behind it.
What Quant is and what banks use the network for
Quant does not build a blockchain of its own. That is the most important sentence about this project, and it is often skimmed over. The company sells an intermediate layer that connects existing networks to one another.
The need for it arises from a practical problem. A bank working with digital assets today deals with several networks at once: public ones such as Ethereum or Bitcoin, permissioned ones such as Hyperledger Fabric or R3 Corda, plus internal systems. Each of these networks speaks a protocol of its own. Building an application for every single one and maintaining it permanently is expensive and ties up staff.
This is exactly where Quant comes in. The bank's application now talks to one interface only, and that interface translates into the respective networks. Technically, such a thing is called an abstraction layer: an intermediate level that conceals differences and presents a uniform picture to the outside.
Overledger: the layer applications dock onto only once
Overledger is the product with which this translation happens. An application connects once, reaches several ledgers through it and does not have to know the quirks of the individual chains. A ledger here is nothing other than a distributed bookkeeping system, that is the database behind a blockchain.
From the perspective of an IT department, the appeal of this design is easy to name. If a new network joins, ideally nothing changes for your own application, because the connection happens one level down. If a network falls away, the same applies. The dependency does shift, though: away from many individual chains and towards the provider of the intermediate layer.
That shift is no footnote but the central objection to the model. Anyone using Overledger trades technical diversity for dependence on a single company. For a bank that is a classic trade-off between effort and supplier lock-in, and it does not fall automatically in favour of the intermediate layer.
Why banks do not simply take a bridge
For moving between blockchains, bridges have existed for years. Such constructions lock a value on one chain and issue an image of it on the other. In private use that works; in banking it runs into three limits.
The first is security. Bridges have for years been among the most frequently attacked components in the industry, because they concentrate large holdings in a single place. The second is legal in nature: an image of a value is not necessarily the same value in law, and for the deposits of a regulated institution that is a problem. The third is settlement. A bank needs certainty that delivery and payment either succeed together or fail together; specialists call this delivery versus payment.
Quant promises to solve these points differently, namely through a shared execution level instead of pairwise bridges. Whether that holds up in practice can only be judged credibly once real payment volumes run across it. So far they do not.
The Fusion Rollup since June 2, 2026: 74 networks in one environment
On June 2, 2026, Quant switched the Fusion Rollup live on the main network. A rollup is a level above a blockchain that bundles many operations and writes only the result back to the main chain. That lowers costs and raises throughput.
According to the company, Fusion is connected to 74 networks at launch. On the public side these include Ethereum, Bitcoin, Solana, Polygon, Avalanche, Arbitrum, Base, BNB Chain, the XRP Ledger, Stellar and XDC. On the permissioned side stand enterprise chains such as Hyperledger Fabric and R3 Corda. Further networks are to be added on request.
Layer 2.5 and the classic rollup: what sets them apart
An ordinary rollup hangs off exactly one parent chain and writes its results back there. According to the company, Fusion is anchored simultaneously to several connected networks and writes its state roots to several destinations. Quant therefore describes the design as Layer 2.5 rather than Layer 2.
The practical difference shows up in an outage. A classic rollup stands still when its parent chain stands still. A level that hangs off several chains is meant to survive that. The price for it is complexity: several anchorings mean more parts that have to work at the same time, and more assumptions about which state applies in a dispute.
Technically, Fusion is EVM-compatible. EVM stands for the Ethereum Virtual Machine, Ethereum's execution environment; compatibility means that existing contracts and tools largely run without rebuilding. For developers that lowers the barrier to entry considerably.
A further promise concerns assets that today lie scattered across the chains in dozens of variants. Fusion is meant to merge them into one uniform form each. Whether that merging holds up everywhere in legal and accounting terms is an open question and not a technical one.
The US clearing house mandate and the timetable to 2027
On September 24, 2026, The Clearing House, the settlement body of the large US banks, selected Quant as technology partner for a network for tokenised deposits. According to those involved, the initiative is backed by 25 large US institutions. For participating houses the network is due to open in the first half of 2027.
Tokenised deposits are not a stablecoin. They are a bank's book money represented on a blockchain; the claim continues to run against the institution and remains subject to its supervision. That is the reason banks prefer this route to the detour via private payment tokens. What exactly was commissioned and what is still open we set out in the report on the clearing house mandate.
Quant takes a second route into the banks via software. Since March 2026 the company has been working with the provider Murex, whose MX.3 platform runs in trading, risk management and post-trade at many institutions. At the industry gathering Sibos, held from September 28 to October 1, 2026 in Miami, both houses jointly demonstrated the settlement of tokenised assets. The thinking behind it is obvious: whoever lands in systems that are running anyway does not have to talk any bank into changing systems.
What role the QNT token really plays in this
Here the technology parts company with the investment, and at this point precision pays. Using Overledger incurs an annual licence fee that is settled in QNT. The tokens used for it are locked for the term of the licence and are not available on the market during that time. When this model was introduced in December 2021, the company named an amount of 100 pounds a year per licence.
According to reports, a customer can also pay in another currency; Quant then locks a corresponding quantity of its own tokens. For demand for QNT on the open market that makes a considerable difference, and it is exactly at this point that the chain of evidence ends.
What remains open is the question that matters most to investors: whether and to what extent the future revenue of the US clearing house runs through the token is not publicly documented. Neither the timetable nor the statements of those involved give figures on it. Anyone claiming that every settled deposit generates demand for QNT goes beyond what is documented.
Does the banks' revenue really flow through QNT?
Two readings stand opposed on this question, and both deserve a fair presentation.
The one: the licence model couples usage to token demand. The more institutions deploy Overledger, the more QNT sit locked, and the smaller the freely tradable quantity. With a maximum supply of fewer than 15 million tokens, every permanently locked quantity carries weight.
The other: a licence fee is a fixed annual sum and does not grow with the volume settled. Ten banks moving billions pay no more under this model than ten banks moving little. The connection between the success of the technology and demand for the token is therefore weaker than it looks at first glance.
Documented is the model itself and nothing more. Everything beyond that hangs on contracts that are not public. Anyone investing in QNT is therefore investing not only in a technology but also in an assumption about how it is billed.
QNT for investors in Germany: venues, licensing and the holding period
QNT is one of the larger crypto-assets and ranks between 33rd and 42nd by market capitalisation, depending on the data service. On October 5, 2026 the price stood at around $263 or about 235 euros, with market capitalisation between $3.2 billion and $3.8 billion. The range arises because the services assume different circulating supplies.
The same applies to supply. As a maximum quantity, figures between 14.61 and 14.88 million QNT can be found, and as a circulating quantity statements between a good 12 and 14.5 million. Anyone calculating with such numbers should write the source alongside, otherwise the result cannot be retraced later.
One point of context, because it shapes every discussion these days: QNT has risen very sharply within a month, in the order of around 300 percent, and is thereby approaching its peak of $427 from September 2021 again. A move like that raises the risk of a setback, but on its own it proves nothing whatsoever about the technology. An assessment of the valuation can be found in our analysis of the current price.
Where QNT can be traded
QNT is listed on numerous venues, including some with a direct euro pair. For investors in Germany what counts above all is whether the provider is authorised as a crypto-asset service provider under the European MiCA regulation. That can be looked up in the public register of the European securities regulator ESMA; decisive is the company with which you conclude the contract. We keep an overview in the comparison of regulated crypto exchanges.
What the tax office sees
Gains from the sale of QNT held as private assets count as private disposal transactions pursuant to Section 23 of the German Income Tax Act. After a holding period of more than twelve months the gain remains tax-free; before that it is charged at the personal income tax rate. Below 1,000 euros of total gain in the calendar year an exemption threshold applies; if it is exceeded, the full amount is taxable. Exchanging QNT for another cryptocurrency also counts as a disposal.
How progress can be read over the coming months
For a project whose promise reaches far into the future, verifiable intermediate steps are needed. Three of them are scheduled or at least observable.
The first is the launch of the deposit network in the first half of 2027. By then it will become apparent whether the selection of a technology partner turns into live operation or into a postponed date. The second is the number of networks connected to Fusion: if it stays at 74, the launch was a one-off event; if it grows, the model is taking hold. The third is the licences themselves. Every new Overledger licence locks tokens, and that lock is in principle traceable on the chain.
What is not a signal of progress, by contrast: an announcement without a contract, an appearance at an industry trade fair or a price move. The gap between a declaration of intent and a productive system is often a span of years with infrastructure projects.
Quant and Overledger: how to proceed now
- Separate the technology from the token question. Overledger and Fusion solve a real problem for banks; whether the success of that technology arrives at the token depends on the licence model and is not publicly quantified. Anyone deriving an investment decision from it should know which of the two questions they are answering. Where QNT can be traded at all and what the purchase costs is shown by the comparison of crypto exchanges.
- Settle custody before the amount grows. QNT is a token on Ethereum and can accordingly be held in any wallet that supports the standard. With larger holdings the key belongs out of the exchange; the devices for that are listed in the hardware wallet comparison.
- Document the purchase date and purchase price from the outset. The one-year period governs the tax exemption, and later it can only be demonstrated with records. Anyone buying across several accounts keeps the record best with a tax tool.
(As of October 5, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Dogecoin costs $0.0942 on Monday afternoon, the equivalent of 0.0842 euros. The number on its own explains nothing. What is interesting is what two moving averages are doing right now: the 50-day line stands at $0.0875, the 200-day line at $0.0878. There is 0.37 percent between them. In mid-September it was a good eleven percent. If Dogecoin closes at or above $0.0832 on Tuesday, the shorter line crosses the longer one, and from Friday that cross can no longer be prevented arithmetically at all. What this means for a portfolio in Germany hangs on three things: on the levels of $0.1004 and $0.0801, on a deadline that expires on October 14, and on your own holding period.
Dogecoin price at $0.0942: 0.37 percent separates the two moving averages
A moving average is the mean of the closing prices of the past 50 or 200 days, recalculated daily. It smooths out individual swings and shows where the bulk of the prices of recent weeks or months sat. Dogecoin currently trades 7.3 percent above its 200-day line and 2.2 percent above the 20-day line. The price itself is therefore long since through on the upside. The 50-day line lags behind because it is still dragging the weak August days along with it.
cryptoticker.io compiled this analysis itself on October 5, 2026, on the basis of 365 daily closing prices. The result is unambiguous in one respect: across those twelve months the 50-day line was not above the 200-day line on a single day. The cross now being discussed has no precedent anywhere in the observation period.
How fast the gap was closed
On September 14 the 50-day line was still 11.03 percent below the 200-day line. On September 21 it was 8.49 percent, on September 28 4.33 percent, on October 3 1.51 percent, and on Sunday 0.94 percent. The gap has been shrinking for three weeks by roughly half a percentage point a day, and remarkably evenly at that. This is not coincidence but arithmetic, and it can be quantified precisely for the days ahead.
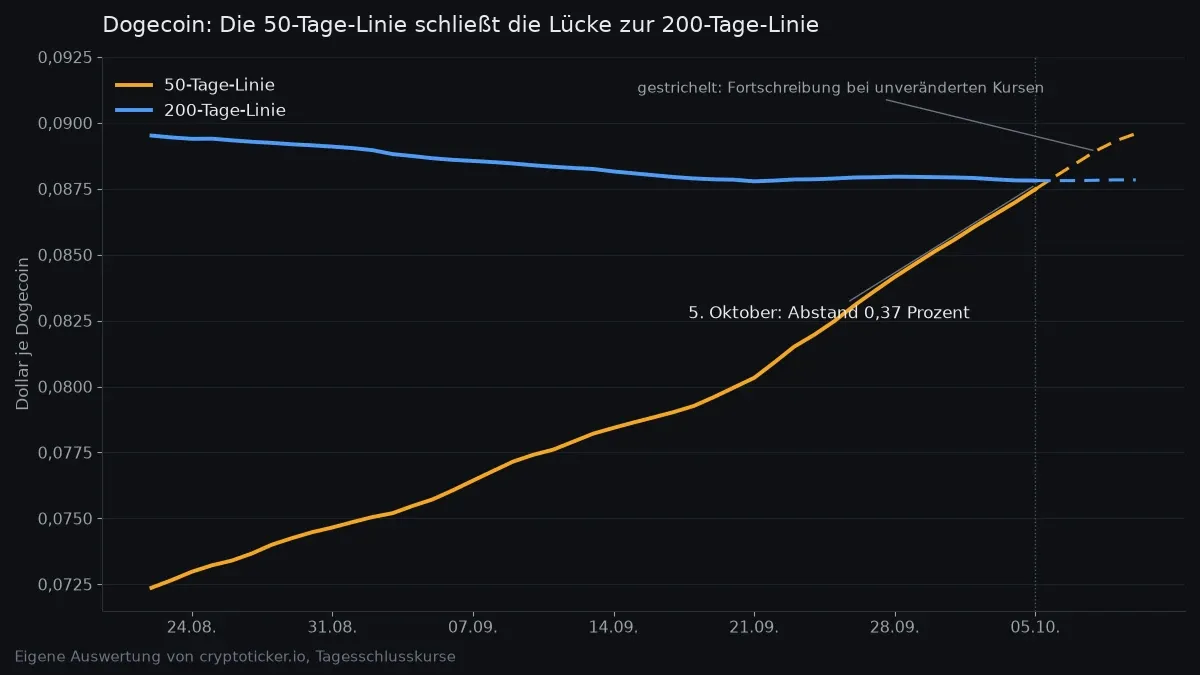
Why the Dogecoin cross is arithmetically settled by Friday at the latest
A moving average changes every day for two reasons: a new closing price joins at the front, and the oldest one drops out of the window at the back. In the case of the 50-day average, the days dropping out this week are precisely those on which Dogecoin was cheapest. That lifts the mean even if the price stands still.
Simply carrying today's price forward produces the following picture: on Tuesday the 50-day line sits at $0.0880 and therefore 0.19 percent above the 200-day line. On Thursday the lead comes to 1.26 percent, and on Sunday 2.00 percent. What counts, though, is the other calculation, the one for the price that would just about still prevent the cross.
The threshold for Tuesday sits at $0.0832
For the 50-day line to stay below the 200-day line on Tuesday, Dogecoin would have to close below $0.0832. That is 11.7 percent under the current price, in a single day. For Wednesday that threshold falls to $0.0514, which would be a 45 percent collapse. For Thursday it sits at $0.0202, so 79 percent lower. From Friday even a price of zero would no longer be enough, because the departing August days carry the mean upwards on their own. In practice, then, the cross is decided on Tuesday and arithmetically certain by Friday.
Four August days dropping out of the 50-day Dogecoin window
The cause sits in the late-summer data. Dropping out of the 50-day window this week are August 17 at $0.0695, August 18 at $0.0704, August 19 at $0.0702 and August 20 at $0.0750. Each of those days sat around 25 percent below today's price. As soon as they disappear from the calculation, the mean jumps upwards.
The one-year low fell in the same phase: on August 7 Dogecoin closed at $0.0690. Anyone who bought then is up 36.5 percent today, without anything fundamental having changed about Dogecoin itself. That is exactly why a moving-average cross is no argument in its own right. It describes the past, not the future.
$0.1004 above and $0.0801 below: the Dogecoin levels for October
For the coming weeks, two values from our own analysis carry more weight than any target from an analyst note. On the upside, the high of the past 30 days sits at $0.1004. That is where Dogecoin last failed, and that is where the sell orders of those who bought at higher prices are waiting. The distance to it is 6.6 percent.
On the downside the 30-day low sits at $0.0801, a good 15 percent below the current price. Beneath that follows the low of August 7 at $0.0690. In between lies the 200-day line at $0.0878, which after a cross from above becomes a catching line. Anyone looking for levels for a stop or a staggered purchase therefore has three traceable values instead of one round number.
What trading volume adds to the picture
Averaged over the past 30 days, around $978 million of Dogecoin changed hands daily. On October 3 it was $1.13 billion, on Sunday $392 million. Market value stands at $14.7 billion, the equivalent of 13.1 billion euros. A breakout above $0.1004 that happens without rising volume is historically the less reliable one. That is a rule of thumb from trading and no law of nature, but it costs nothing to keep an eye on.
Dogecoin versus Bitcoin and Ethereum: the distance to each one-year high
On October 7, 2025, exactly one year ago the day after tomorrow, all three assets marked their twelve-month high on the same day. Dogecoin stood at $0.2668, Bitcoin at $124,740 and Ethereum at $4,691. Today Dogecoin is 64.7 percent short of that level, Ethereum 42.6 percent and Bitcoin 31.6 percent.
That ranking matters more for placing the moving-average cross in context than the cross itself. Dogecoin has lost considerably more over the past year than the two large assets, and since the start of the year it is down 19.8 percent. The 50-day line is therefore rising not because Dogecoin is strong but because the August benchmark was particularly weak. Anyone selecting an exchange for the purchase should know that difference before building a position.
What the Dogecoin moving averages do not say
A cross of the 50-day line above the 200-day line is referred to in trading as a golden cross. That is a descriptive term for exactly this constellation, not a signal with a documented hit rate. Both lines consist solely of past prices; they contain no information about inflows, network usage or regulation.
On top of that comes a tangible objection: because the cross falls as early as Tuesday on any halfway normal price path and is arithmetically settled by Friday at the latest, it is no longer a surprise to the market. Anyone who recalculates the data knows it today. An event whose occurrence is certain is rarely priced in only on the day it happens. As a forecasting instrument the cross is therefore of little use, while as a description of the situation it serves well.
Bitwise is closing its Dogecoin ETF: October 14 is the last trading day
Alongside the price situation, a deadline with a fixed date is running. On September 10 the asset manager Bitwise resolved to wind up its Dogecoin ETF, ticker BWOW. The filing with the US Securities and Exchange Commission names three dates: the last trading day on NYSE Arca is Wednesday, October 14, 2026. Decisive for the settlement is the net asset value of October 21. On Thursday, October 22, remaining shareholders receive that value in cash.
A net asset value is the value of the fund's assets per share, so here the proportionate Dogecoin holding less costs. For holders, the wind-up means this: after October 14 the share can no longer be sold on the exchange, and repayment happens compulsorily at a cut-off price that nobody can steer.
For German portfolios the ETP route counts, not the US fund
A piece of context is needed here that many reports leave out: BWOW is a US product on a US exchange. A retail investor in Germany could as a rule not buy this fund through an ordinary broker in any case, because US funds lack the documents required under the EU regulation on key information documents. The closure therefore mostly does not affect German portfolios directly.
It is relevant all the same, as an indication of the rules of the game for this product type. Anyone wanting exposure to Dogecoin on an exchange rather than through a crypto platform uses an ETP in Germany, that is an exchange-traded debt security on the price, tradable for instance via Xetra. An ETP, too, can be terminated by the issuer, usually with a notice period stated in the prospectus. Before buying it is therefore worth a look at exactly that section of the key information document, specifically at the notice period and at whether the issuer deposits the coins.
Buying route via an exchange with a MiCA licence
The second route is the direct purchase. Since the EU regulation on markets in crypto-assets, MiCA for short, has applied in full in Germany, providers require a licence and are supervised by BaFin. In practice that means: before a first purchase you establish whether the provider operates under that licence, what fee is buried in the price as a spread, and whether payout in euros runs without extra cost. A cheap trading price is of little help if one percent is lost on withdrawal.
Holding period and the 1,000-euro exemption threshold when selling Dogecoin
For most German investors this is the point with the greatest leverage, and it depends not on the price but on the purchase date. The sale of crypto-assets falls under private disposal transactions pursuant to Section 23 of the German Income Tax Act. Subsection 1 no. 2 there covers disposals of assets where the period between acquisition and disposal is no more than one year.
Anyone who has held Dogecoin for longer than a year therefore sells the gain tax-free. Anyone selling earlier pays tax on it at their personal income tax rate. On top of that comes an exemption threshold: under subsection 3 sentence 5, gains remain tax-free if the total gain from private disposal transactions achieved in the calendar year came to less than 1,000 euros. Exemption threshold means literally what it says: at 1,000 euros of gain the entire amount is taxable, not just the euro above it.
The concrete calculation for the August low
An example with our own figures. Anyone who bought at $0.0690 on August 7 is up 36.5 percent today. On a stake of 2,000 euros that would be around 730 euros of gain, so below the exemption threshold, as long as no further private disposal transactions arise in the same year. On a 3,000-euro stake the gain comes to around 1,095 euros, and with that the entire amount is taxable. The difference between the two cases turns on a few hundred euros, and it can be worked out before the sale. A tax tool with a clean acquisition history takes the allocation of individual purchases off your hands, which quickly becomes confusing with several partial purchases.
Leverage and liquidation: $0.0754 on a fivefold Dogecoin position
Anyone trading Dogecoin with leverage should hold the levels from the fourth section against their own liquidation threshold. A rough calculation without fees and without margin calls: at fivefold leverage a long position becomes arithmetically worthless if the price falls by a fifth, so at about $0.0754. At threefold leverage that threshold sits at around $0.0628, and at tenfold leverage already at $0.0848.
The $0.0848 is the critical value, because it lies only 3.4 percent below the current price and therefore within the normal swing of a few days. Over the past 30 days Dogecoin moved between $0.0801 and $0.1004, a range of 25 percent. A tenfold leveraged position would not have survived that range. Anyone using leveraged products will find the differences in financing costs and margin obligations in the broker comparison.
Custody: Dogecoin calls for a wallet decision of its own
Dogecoin runs on a blockchain of its own and not as a token on Ethereum. A wallet that manages ether and ERC-20 tokens therefore cannot automatically take Dogecoin. Before a withdrawal from the exchange, it belongs to the routine to establish whether your own hardware wallet supports the Dogecoin chain at all and whether the receiving address starts with the correct prefix. A transfer to an address on the wrong chain is as a rule not recoverable.
There is no staking with Dogecoin. The network runs on proof of work and is mined jointly with Litecoin, so returns arise only from mining, not from holding. Anyone offered a yield on their holding is dealing with a lending platform, and therefore with a counterparty risk that has nothing to do with the network.
Dogecoin forecast: your next three steps
The moving-average cross falls on Tuesday on any normal path and is settled by Friday at the latest, the ETF deadline expires on October 14, and the holding period depends solely on your own purchase date. From that follow three steps that can be dealt with this evening.
- Gather your purchase dates. List all partial Dogecoin purchases with date and amount and work out which of them already satisfy the one-year period under Section 23. Anyone with several partial purchases transfers that into a portfolio and tax tool rather than reconstructing it afresh every year.
- Write down levels instead of gut feel. $0.1004 as the next target on the upside, $0.0878 as the catching line and $0.0801 as the lower edge of the past 30 days. Anyone trading with leverage enters their liquidation threshold alongside and looks in the broker comparison at what financing costs accrue daily in the process.
- Settle custody before it gets urgent. Establish whether your own wallet carries the Dogecoin chain, and send a small test transfer ahead before the whole holding is moved. Which devices support which chains is set out in the hardware wallet comparison.
(As of October 5, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
The price of Bitcoin stood at $85,662 on Sunday afternoon, equivalent to 76,487 euros, according to data from price provider CoinGecko. It is exactly one year since the cryptocurrency reached its all-time high: on the morning of October 6, 2025, a single Bitcoin cost $126,080. The gap between that record and today's level comes to $40,418, or 32.1 percent. In euros the gap is smaller, and it is precisely that difference which determines what the Bitcoin price means for investors in Germany, both for tax purposes and in practice.
Bitcoin price on October 5, 2026: $85,662 and 76,487 euros
Over the past 24 hours Bitcoin has gained 0.63 percent in dollar terms. Measured in euros the gain is 1.19 percent, almost twice as much. The daily range ran from $85,172 to $86,949, putting $1,777 or a good 2 percent between the session low and the session high. Over one week the Bitcoin price shows a gain of 3.4 percent, and over one month a gain of 8.4 percent.
Market capitalisation stands at $1.72 trillion and trading turnover over the past 24 hours at $30.3 billion. There are 20,093,759 Bitcoin in circulation. A turnover-to-market-value ratio of roughly 1.8 percent describes a quiet trading day, not a panic in either direction.
The key figures at a glance
| Figure | In dollars | In euros |
|---|---|---|
| Price on October 5, 2026 | 85,662 | 76,487 |
| All-time high of October 6, 2025 | 126,080 | 107,662 |
| Gap to the all-time high | 40,418 (32.1 percent) | 31,175 (29.0 percent) |
| Rise required to reach the record | 47.2 percent | 40.8 percent |
| Change over 24 hours | plus 0.63 percent | plus 1.19 percent |
One year after the all-time high: Bitcoin is $40,418 short of its record
An anniversary is not a price story, but it is an honest yardstick. Anyone who bought at the peak on October 6, 2025 is sitting on a paper loss of 32.1 percent in dollar terms. A gain of 32.1 percent is not enough to get back to that entry price. It takes 47.2 percent, because a loss always has to be made up from a smaller base. That asymmetry is why the moment of entry weighs so heavily with a volatile asset.
At the same time, the past year shows that the market has not collapsed but moved sideways. Over 30 days the Bitcoin price is up 8.4 percent, over seven days 3.4 percent. The price is working its way up from below towards the range it occupied over the summer. For an investor that means the question is less whether the market is broken than whether their own position still fits the plan they set out with when they bought.
Paper loss is a term that is often misread. It describes the difference between purchase price and current price for as long as nothing has been sold. For tax purposes it does not exist. Only a sale turns a paper loss into a realised loss, and only then does the question arise whether the tax office recognises it.
Why the euro gap to the Bitcoin all-time high is smaller than the dollar gap
In euro terms Bitcoin was quoted at 107,662 euros on October 6, 2025. Today it is 76,487 euros. That is a gap of 31,175 euros or 29.0 percent, a good three percentage points less than in dollars. The reason lies not with Bitcoin but with the exchange rate. At the all-time high the price ratio corresponded to a euro-dollar rate of around 1.17. Today the implied rate is about 1.12. The euro has therefore lost value against the dollar, and that cushions the balance sheet of an investor who counts in euros.
The same mechanism explains the daily picture. Bitcoin rising 1.19 percent in euros but only 0.63 percent in dollars is down to the euro giving ground on the same day. How wide that wedge can grow was on display on October 3, when the price lost 4.4 percent in dollars and only 0.5 percent in euros. We worked that case through at the time in a separate article on the difference between the dollar and euro quotation.
In practice this means two things. Anyone tracking their holdings in an app that defaults to dollars is looking at a number that is not theirs. And anyone declaring gains or losses to the tax office has to count in euros in any case. The dollar display is market information; the euro amount is the figure that counts for tax.
The one-year holding period under Section 23 EStG: October 6, 2026 is the cut-off for last year's buyers
In Germany Bitcoin falls under private disposal transactions pursuant to Section 23 (1) sentence 1 no. 2 of the German Income Tax Act. A sale is taxable only if less than one year lies between acquisition and disposal. Once that one-year period has run, the transaction is no longer taxable.
This rule has two sides, and the second one is easily missed. A gain after more than a year stays tax-free, which is the familiar side. But a loss after more than a year is equally outside the tax net and therefore worthless for tax purposes. There is nothing left to offset it against.
For anyone who bought around October 6, 2025, that becomes concrete in these very days. The one-year period is calculated under Section 108 of the German Fiscal Code in conjunction with the time-limit provisions of the Civil Code. For a purchase on October 6, 2025 it ends at the close of October 6, 2026; from October 7 the transaction sits outside the period. Which day applies in an individual case depends on the exact moment of acquisition and belongs in the hands of a tax adviser before any decision.
Offsetting crypto losses: what stops working once the one-year period expires
Under Section 23 (3) of the German Income Tax Act, losses from private disposal transactions may be offset only against gains from the same category of income. Such losses therefore do not reduce employment income, nor investment income from shares or interest. Within that limit they can be carried back one year and carried forward without a time limit, so they can neutralise gains from future private disposal transactions.
For anyone who has already realised gains from short-term crypto sales this year, the question is no formality. A loss realised inside the one-year period can reduce those gains. The same loss realised a day later cannot. That is no reason to pin an investment decision to a date, but it is a reason to know the date.
A third point comes on top, the exemption threshold. Since the 2024 assessment period, gains from private disposal transactions remain tax-free up to 1,000 euros a year. An exemption threshold is not an allowance. Once it is exceeded, the entire gain is taxable, not just the part above the line.
Which order applies after multiple purchases
Anyone who has bought more over a period of months does not own one Bitcoin holding but many tranches with acquisition dates of their own. For allocating them, the Federal Ministry of Finance set out the first-in-first-out method in its ruling on virtual currencies of May 10, 2022, applied per wallet or exchange account. First in, first out means that the units acquired first count as the ones sold first. Without clean records of the individual purchases this cannot be demonstrated, and that is exactly where many crypto tax returns come apart. A crypto tax tool or portfolio tracker handles that allocation automatically and supplies the supporting documents with it.
Reference rate and conversion: the German tax office counts the euro amount
Gains and losses are determined in euros, even where the trade was settled in dollars or in a stablecoin. The conversion requires a traceable rate at the time of acquisition and of disposal. The euro reference rates of the European Central Bank are set on every bank business day and are a common source, as is the rate of the trading platform on which the transaction took place. What matters is that you stick with one method and can document it.
At weekends there is no new reference rate. Anyone selling on a Sunday like today uses the rate of the last bank business day or the rate of the exchange. Both are defensible; switching between the two depending on the result is not.
Levels above and below: $86,949 from the daily range and $90,000 as the round hurdle
Levels are not a prophecy but places where a lot of trading happened in the past. On the upside the session high of $86,949 is the first marker, followed by the round level of $90,000, where sell orders tend to gather. On the downside the session low of $85,172 marks the edge of today's trading, and below that $80,000 is the next round number.
Translated into euros, that lands at around 77,600 euros for the session high and about 76,000 euros for the session low. Because the exchange rate moves along with it, these euro levels shift even when the dollar price does not budge at all. Anyone placing buy or sell orders in euros should factor that in.
Buying Bitcoin under MiCA: the licence a provider in Germany needs
The European regulation on markets in crypto-assets, MiCA for short, has applied in full since December 30, 2024. It requires every provider that holds, exchanges or brokers crypto-assets in the EU to be authorised as a crypto-asset service provider. In Germany it is accompanied by the Crypto Markets Supervision Act, with BaFin as the supervisor. How large a role that act now plays in practice shows in the fact that it underpins the majority of the recent BaFin warnings about unauthorised providers.
For you as a buyer this has boiled down to a single question that takes a few minutes to settle: is the provider listed with an authorisation in the register of BaFin or of another European supervisory authority? A provider without that licence is not allowed to approach you in Germany, and in a dispute no supervisor stands at your side. Our comparison of the best crypto exchanges gives an overview of authorised venues and their terms.
Fees when buying Bitcoin: spread, order fee and the card payment surcharge
At a price of $85,662, one percentage point of fees weighs more heavily than most daily moves. Three items determine the real price. The order fee is the stated charge per purchase. The spread is the difference between the bid and ask price; it appears in no fee schedule yet costs real money. On top of that come surcharges for particular payment methods.
How large that third item can become is something we worked through on October 4: with a Bitcoin purchase by credit card the surcharge ran up to 9.94 euros per 100 euros of purchase value, depending on the provider. Via a SEPA transfer it usually falls away entirely. Anyone using a savings plan should also establish whether they are acquiring real coins or merely a certificate, because that governs whether the one-year period under Section 23 applies at all.
Custody after a year of sideways Bitcoin trading: exchange, hardware wallet and counterparty risk
A year below the all-time high means that for many investors their holdings have sat on an exchange longer than originally planned. With that, a risk grows that has nothing to do with the price. At an exchange you hold a claim against the company, not the coins themselves. MiCA does require client and proprietary holdings to be kept separate, but a provider failure remains a scenario that only self-custody protects against.
A hardware wallet takes that counterparty risk off your hands and gives you a different one in return, namely responsibility for the recovery words. Lose them and the holding is gone for good. For amounts beyond play money, self-custody is nevertheless the normal case, and the one-year period keeps running throughout: a transfer between your own wallets is not a disposal and does not reset the clock.
Bitcoin after the all-time high: the key points for your decision
- Dig out your acquisition dates. Look through your transaction history to see which tranches date from October 2025 and when their one-year period ends. A crypto tax tool or portfolio tracker reads the data out of exchange and wallet and allocates it by the first-in-first-out method.
- Price in the cost of the buying route. Compare your provider's order fee, spread and payment method before you buy more. The crypto exchange comparison sets the terms of authorised venues side by side.
- Match custody to your holding period. If your holding sits longer than planned, it does not belong on an exchange account permanently. Which devices suit which amounts is covered in the hardware wallet comparison.
(As of October 5, 2026. This article is not investment advice and not tax advice. Prices and fee structures change; check the terms with the provider before you buy, and tax questions with a tax adviser.)
At 11:37:12 UTC on October 17, 2026, the lock-up on 618,333,333 DBR ends at deBridge. That is roughly 10.4 percent of the amount in circulation today and, at the price on October 5, a value of about $11.9 million. The figure a holder can really read the size from, though, is a different one: the tranche equals around ten and a half days of total worldwide DBR trading turnover.
This piece works through the date, shows the six pots the tranche comes from, and explains why different data services quote very different percentages for exactly the same event. On top of that comes what matters in practice for investors in Germany: where DBR can be traded in euros and how the tax office treats a sale. Nobody here claims a price direction.
What exactly happens at deBridge on October 17, 2026
A token unlock is the end of a contractually fixed lock-up period. Tokens that have existed since the project launched but could not be transferred until now become movable at a fixed point in time. No new tokens are created, and nobody has to sell them. Only one thing changes: from that moment they can be moved.
At deBridge that point falls on a Saturday, October 17, 2026, with the minute stamp 11:37:12 UTC. The odd time is neither a coincidence nor a typo, because the minute stamp derives from the moment of the original token launch on October 17, 2024, and every quarterly tranche has shifted by a few hours since.
This tranche is the eighth in a series. The mechanism behind it is set out in deBridge's project documentation and summed up there in one sentence: the remainder of an allocation is subject to a "3 year quarterly vesting, starting 6 months after TGE". TGE stands for Token Generation Event, the day a token first exists and becomes tradable.
The project document names the mechanism and the amounts, but no date for the individual tranche. The day and the time come from the public release schedule attached to the contract. The two can be checked against each other, and that is exactly why this date can count as established: the amounts of the first two releases match the percentages from the project documentation precisely.
What deBridge does and what role the DBR token plays in it
deBridge is a protocol for transfers between different blockchains. Anyone wanting to move value from one chain to another needs a bridge, because blockchains do not talk to each other on their own. deBridge runs a network for that, taking orders on one chain and executing them on the other.
The DBR token itself lives as what is called an SPL token on Solana. SPL is that chain's token standard, comparable to ERC-20 on Ethereum. Anyone holding DBR therefore needs a wallet that can hold Solana tokens.
What function the token has is described in the project documentation above all through the governance of the protocol: it is about "handing power over to the community through a thriving governance system". DBR is therefore first and foremost a governance token, that is, a voting right. One of the six allocations, the validators' one, also comes with a condition attached: the tokens are released quarterly as long as the operators continue to show reliable performance. Whether that condition was checked for an individual tranche is not apparent from the release schedule.
Six pots, one tranche: where the 618 million DBR come from
The 618,333,333 DBR are not a single position but the sum of six separate allocations that fall due at the same moment. This is how the tranche breaks down:
- Ecosystem: 191,666,667 DBR
- Core Contributors: 133,333,333 DBR
- Strategic Partners: 113,333,333 DBR
- Community & Launch: 83,333,333 DBR
- deBridge Foundation: 83,333,333 DBR
- Validators: 13,333,333 DBR
These six pots correspond to the split of the total supply of ten billion DBR as the project documents it: Ecosystem 26 percent, Community & Launch 20 percent, Core Contributors 20 percent, Strategic Partners 17 percent, deBridge Foundation 15 percent and Validators 2 percent.
For placing the event, a summary is more useful than the individual lines. Three of the pots belong to the project and its orbit: Ecosystem, Community & Launch and the foundation. Together those come to 358,333,333 DBR, or 58 percent of the tranche. The remaining 259,999,999 DBR, or 42 percent, go to Core Contributors, Strategic Partners and Validators, that is, to the team, to early backers and to the operators of the infrastructure.
The difference is not a detail. Tokens in a foundation or ecosystem treasury are typically spent over months on incentive programmes, liquidity or partnerships. Tokens in the hands of team members and early backers, by contrast, can land on an exchange at any time and in one piece. Anyone assessing the tranche should look at the two halves separately.
Why the same date carries three percentages at three data services
Anyone looking up October 17 finds figures that lie far apart depending on the source: a good ten percent of the circulating supply in one place, around seventeen percent elsewhere, and the dollar value swings by several million too. All of these figures can be arithmetically correct. The reason lies in two quantities that no two data services set the same way.
First: which circulating supply sits in the denominator
The percentage of a tranche is nothing more than the tranche divided by the circulating supply. Only the circulating supply is not an objective number. Some services count every unlocked token, others deduct holdings that demonstrably sit in project and foundation addresses and do not move. For DBR the reported circulating supply on October 5 is around 5.93 billion tokens out of ten billion in total. With that denominator, 618 million is exactly 10.43 percent. If a service instead uses 3.6 billion because it strips out project holdings, the identical tranche suddenly reads around 17 percent.
Second: at which price the calculation is made
The dollar value of a tranche is a snapshot. DBR traded at about $0.0193 on the morning of October 5 and about $0.0192 at midday. That movement alone shifts the value of the tranche by roughly $100,000. A figure such as "$11.9 million" is therefore not a property of the unlock but a property of the moment someone looked.
In practice that means a percentage without a stated denominator is worthless, and so is a dollar value without a price level. How to recalculate both yourself in a few minutes is set out step by step in our method article token unlock math.
The metric for holders: tranche against daily turnover
Percent of the circulating supply sounds precise and still says little about whether a market can absorb an amount. There is a more robust measure for that, and it needs only two numbers: the value of the tranche and the daily trading turnover.
For DBR the calculation on October 5 looks like this. Worldwide turnover across all trading venues came to about $1.13 million in twenty-four hours. The tranche was worth around $11.9 million at the same moment. Divided, that gives roughly ten and a half trading days: that is how long all worldwide DBR trading would have to run to move a volume the size of the tranche.
This metric swings with turnover, and markedly so. Early on the morning of the same day, daily turnover still stood at around $1.01 million; the same tranche then came to just under twelve trading days. Realistically the value therefore moves in a range of about ten to twelve trading days. Anyone recalculating on the day before the date gets a different number again, and that is not a flaw in the method but its point.
For comparison: with large tokens and high turnover, a quarterly tranche often equals only a fraction of a single trading day. A value in the double-digit day range means that even a small part of the released amount would be visible on the market. We last ran the same calculation for the releases at CARV and RAIN, both in October.
Unlocked does not mean in circulation: where the tokens go after the cut-off
A common misunderstanding is that unlocked tokens automatically reach the market. In fact they first move only into the control of those they are allocated to. What happens after that is for each recipient to decide.
With DBR that can be read off the overall arithmetic. Adding up all releases since October 2024 produces considerably more tokens than are reported as the circulating supply. The difference sits in addresses assigned to the project and the foundation, from which nothing has flowed to trading venues so far. In pure arithmetic the reported circulating supply rises after October 17 to about 6.55 billion DBR, so to around 65 percent of the total supply, assuming the data services book the full tranche immediately.
For your own assessment that means: after the date, watch the movements rather than the calendar. Public blockchain data shows whether tokens move from vesting addresses to exchange addresses. Only that step is the signal that counts. A blockchain explorer or an analytics tool that watches vesting addresses is enough for it.
October 17 is not a one-off date, the series runs to January 2028
Anyone treating the date as a one-off event measures too short. Under the quarterly schedule, four further tranches of identical size follow, 618,333,333 DBR each:
- January 16, 2027
- April 18, 2027
- July 18, 2027
- October 17, 2027
The series closes on January 17, 2028 with a smaller remaining tranche of 260,000,000 DBR. That remaining tranche comes out smaller because the three pots assigned to the project will have run out entirely by then; only Core Contributors, Strategic Partners and Validators are left.
From that follows a sober perspective. Over the coming fifteen months, around 2.7 billion DBR come out of lock-up in arithmetic terms, on top of the October tranche. Anyone planning an entry or an exit is planning against a known calendar and not against a surprise. That is precisely what separates a vesting schedule from a news event.
Where DBR can be traded in euros and what a MiCA authorisation means for that
DBR is listed on around two dozen trading venues. The large majority of them quote exclusively against the dollar stablecoin USDT. A direct euro pair is distinctly rarer and found only at individual providers; alongside those there are dollar pairs and, on Solana itself, decentralised trading venues.
For investors in Germany that has two practical consequences. First, without a euro pair every purchase and every sale brings an additional exchange step that costs fees and spread. Second, swapping one cryptocurrency for another is a separate transaction for tax purposes and not merely a technical way station.
Since the European MiCA regulation, providers that actively address customers in the EU need authorisation as a crypto-asset service provider from a member state. Whether a particular trading venue holds that authorisation can be looked up in the public register of the European securities regulator ESMA; what counts there is the company you actually enter the contract with, and that is named in the terms of use. Which providers carry a European authorisation, what trading costs there and which deposit routes are open is in the comparison of crypto exchanges.
One point that becomes concrete on October 17: the date falls on a Saturday. Crypto trading runs around the clock, but many providers' customer service does not. Anyone wanting to trade that weekend should have sorted out verification, two-factor protection and withdrawal limits beforehand, not during the event.
Tax on DBR gains: the holding period under Section 23 of the Income Tax Act and the €1,000 exemption limit
First the reassurance: a token unlock in itself triggers no tax for a private holder who does nothing. What becomes relevant for tax is a disposal, that is, a sale for euros or a swap into another cryptocurrency.
The framework for that is in Section 23 of the Income Tax Act, under private disposals. Three points decide the outcome.
The one-year period
If more than twelve months lie between acquisition and sale, the gain stays tax-free in private assets. Within the period it is charged at the personal income tax rate, not at the flat withholding rate. For calculating the period, the day the particular tokens were acquired counts, not the day of an unlock.
The exemption limit
If the total gain from all private disposals in a calendar year stays below €1,000, no tax arises. That is an exemption limit and not a tax-free allowance: if it is exceeded by even one euro, the entire gain becomes taxable.
The order of sales
Anyone who bought DBR at different times needs a traceable allocation of which tokens were sold. The usual method, and one the tax administration accepts, is "first in, first out": the tokens bought first count as the ones sold first, and that applies per wallet. Anyone using several wallets and exchange accounts needs clean records across all of them.
This account is no substitute for tax advice. With larger sums, with staking income or with tokens from an airdrop, a trip to a professional is worth it.
Is the date already in the price?
There is no provable answer to that question, but there are two comprehensible readings, and both deserve their place.
The first reading: the calendar has been public for two years, the quarterly rhythm is known, and professional market participants know it. What everyone knows tends to be worked into prices already. Seven tranches of the same size have already fallen without a recurring pattern becoming readable in the price.
The second reading: the market's capacity to absorb is limited. With daily turnover around a million dollars, even a small sold share of the tranche is enough to become visible. And the 42 percent that go to the team, partners and validators are subject to no spending mandate.
None of that is established, and anyone naming you a price target for October 17 has invented it. What can be established is the amount, the time, the split and the ratio to turnover. A decision of your own needs no more than that, and less is not enough.
deBridge release: your next three steps
- Recalculate the tranche on the day before the date. Divide the value of the 618,333,333 DBR by the daily turnover at that point. If the result is well below ten trading days, the market has gained depth; if it is above, the opposite has happened. You can read the daily turnover at any trading venue or in a tool from the comparison of analytics platforms.
- Sort out before the weekend where you could trade at all. Account status, two-factor protection and a possible euro pair belong sorted beforehand, not on Saturday morning. Which trading venues carry a European authorisation and what they cost is in the comparison of regulated crypto exchanges.
- Know your own holding period before a sale is even up for discussion. A sale within twelve months of the purchase is taxable, beyond that it is not. Anyone unsure of the purchase date will find it in the trading venue's transaction overview or can have it read out by a tax tool.
(As of October 5, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Cardano rose 10.61 percent on October 5, 2026 and trades at $0.27121. That is the highest level in three months and the only daily gain above five percent among the 25 largest cryptocurrencies. Bitcoin managed 0.83 percent on the same day, ether 0.43 percent.
The trade press names a golden cross as the reason: the 50-day line is said to have crossed the 200-day line for the first time in 14 months. We recalculated it, and two points stand out that the reports leave out. First, the crossing did not happen today but on October 1. Second, Cardano last produced this signal on August 13, 2025, and anyone who bought in afterwards was 42.4 percent down 83 days later.
This article places both in context: what the price actually did today, what a golden cross says and what it does not, and which level decides whether the signal holds. On top of that comes what an investor in Germany can check on the buying route, the holding period and leverage.
The basis for our own figures is 721 daily candles for the ADA against US dollar pair on the Kraken trading platform, from October 15, 2024 to October 5, 2026, together with market data from CoinGecko on the 25 largest cryptocurrencies. cryptoticker.io compiled this analysis itself on October 5, 2026.
Three-month high at $0.2749: what ADA did on October 5
The daily range ran from $0.244191 to $0.274928. The high comes out marginally differently depending on the venue; on the Kraken platform the daily candle stood at $0.275337. In both cases it is the highest point ADA has reached in the past 90 days, which establishes the three-month high. It is not a six-month high: on May 10, 2026, Cardano stood at $0.2885, roughly five percent above today's daily high.
Turnover carries the jump. Within 24 hours, ADA worth $1.12 billion changed hands. Against a market value of $10.19 billion and 37.54 billion units in circulation, that equals a turnover of eleven percent of market capitalisation in a single day. Cardano therefore sits at rank 15 among the largest cryptocurrencies.
Measured over the year, the picture nevertheless stays unfriendly. On January 1, 2026, ADA cost $0.3560. Today that has become $0.2715, a loss of 23.7 percent. The high for the year is $0.4215 from January 13, the low for the year $0.1435 from June 25. From the low the price has almost doubled; from the high it is 35.6 percent away.
Anyone wanting to place the move needs both figures. A three-month high sounds like a breakout, a yearly loss of 23.7 percent like a recovery inside a downtrend. Both are true at once.
Golden cross on ADA: the 50-day line crossed the 200-day line on October 1
By our calculation, the 50-day line stood at $0.2150 on October 1, 2026 and the 200-day line at $0.2136. On that day the shorter line cut through the longer one from below. The closing price at the time was $0.2462.
Since then the gap has widened. On October 5 the 50-day line stands at $0.2211 and the 200-day line at $0.2131. The shorter one is therefore 3.75 percent above the longer one. Between the crossing day and today ADA has added 10.3 percent, spread over four trading days, of which today carries the largest share.
This is the point where the account in the reports and the finding part company. Anyone reading on October 5 that the golden cross triggered the rally is told a sequence the data does not support. The signal was already in place when the price still stood at $0.2462. What happened today is a ten percent daily jump on a four-day-old signal.
The gap to the previous golden cross is 414 days, or 13.6 months. The figure of 14 months in the coverage is therefore within range; the crossing day itself was August 13, 2025.
The last golden cross, on August 13, 2025, ended 42.4 percent lower
On August 13, 2025, ADA closed at $0.9041, the 50-day line stood at $0.7216 and the 200-day line at $0.7203. Four days later, on August 17, the price ran up to $0.9614. That was the high of that episode.
After that the move turned over. Measured from the crossing day, ADA traded 2.6 percent lower after a week, 6.0 percent lower after two weeks, 1.5 percent higher after a month and 22.4 percent lower after two months. On November 4, 2025, the 50-day line cut back below the 200-day line, the so-called death cross. The price stood at $0.5207 that day, 42.4 percent below the level at the golden cross.
Eighty-three days lay between the two crossings. Within that window ADA moved between $0.9614 and $0.5207. Anyone who took the signal as an entry marker had four good days and then nearly three months of losses.
What a single precedent tells you
One case is not a statistic. Our data series reaches back two years and therefore contains exactly two golden crosses. No hit rate can be derived from that, and anyone claiming the signal never works on Cardano goes beyond the data. All that is established is this: the last time this signal appeared on ADA, it did not hold. That precedent is absent from today's reports, even though it concerns the same data series.
What a golden cross is and why it lags the price
A golden cross is the moment when the average of the last 50 closing prices rises above the average of the last 200 closing prices. There is nothing more behind it. It is an arithmetic operation on past prices, not information about supply, demand or project progress.
From that follows the most important property: the signal lags the price. By the time the 50-day average reacts, the price must long since have made the move. On ADA the price had already recovered 71.6 percent between the yearly low of June 25 and the crossing day of October 1. The cross confirmed that recovery; it did not announce it.
The counterpart, the death cross, works the same way and with the same delay. Neither line says anything about whether a move continues; they only condense what has been.
For placing the signal, that means a golden cross is a descriptive tool. It marks that the medium-term average has pushed above the long-term one. Whether that becomes a trend is decided by buyers and sellers in the weeks that follow, not by the lines.
$0.2131: the 200-day line as the boundary for the signal
Anyone wanting to watch the golden cross needs no forecast, just two figures from their own calculation. The 200-day line sits at $0.2131, the 50-day line at $0.2211. As long as the shorter one stays above the longer one, the signal stands. If it falls below, the signal is done.
The buffer between the two lines is 3.75 percent today. Because averages are slow-moving, that does not take a one-day slump but a run of weak closing prices. In the 2025 case, exactly that took 83 days.
On the upside the trade press names $0.28 and $0.30 as the next hurdles. The Crypto Times cited those two levels on October 5, 2026, along with the account that the golden cross is driving the rally. They are assessments by market observers, not measured quantities. Our own series produces a third, harder number: $0.2885 from May 10, 2026. Only above that would it be more than a three-month high.
On the downside, today's daily low of $0.244191 marks the range the move came out of. Below it, the next established level is the closing price from the crossing day, $0.2462, and only then the area around the two average lines.
ADA in euros at 0.2424: the euro figure sits below the dollar figure
Anyone buying in Germany pays in euros and settles the gain in euros. Today ADA costs €0.242448, after a daily range of €0.216985 to €0.245999. Euro trading turned over 26.75 million ADA.
The difference is not a rounding error. A dollar price of 0.27121 and a euro price of 0.242448 produce a ratio of roughly $1.12 per euro. If the exchange rate moves, your result shifts without ADA having risen or fallen by a cent. On a ten percent move in a day that barely registers; over a holding year it can amount to several percentage points.
For the tax office only the euro figure counts anyway. Anyone noting purchases in dollars has to convert them for the tax return at the rate on the purchase day and the sale day. Anyone buying directly in euros is spared that step.
Buying through a MiCA-authorised exchange: spread, order fee and custody
Since January 1, 2026, only providers authorised under the EU regulation MiCA may supply crypto-asset services in Germany, and BaFin supervises them. The first check before a purchase is therefore always the same: does the provider hold that permission. A look at the comparison of crypto exchanges shows which platforms carry it and what they cost.
On price, two items matter that often get confused. The order fee is in the fee schedule and easy to find. The spread, the gap between the buy and sell price, usually is not, and on smaller assets like ADA it is regularly the larger item. A spread is the distance between the price at which you can buy immediately and the price at which you could sell at the same moment.
At a price of $0.27, spreads quickly reach a range that eats up several days of price movement. That is checkable before buying: put the buy and sell price side by side and divide the difference by the buy price. The result is the spread in percent.
On custody there are two routes. If the ADA stays on the exchange, you carry that provider's risk. If they go into your own wallet, you carry the risk of your own key custody. ADA can still be delegated in either case; staking does not depend on the coins sitting on an exchange.
Twelve-month holding period: buying in today sets the tax clock to October 5, 2027
In Germany, gains from selling crypto assets are free of income tax after a holding period of more than twelve months. If you sell sooner, the gain counts as a private disposal under Section 23 of the Income Tax Act and is charged at your personal tax rate, to the extent that all such gains in the year together exceed the exemption limit of €1,000.
For an entry that reacts to a price signal, that is the most awkward figure in the whole article. A golden cross is a medium-term signal; the window the trade press talks about is weeks. The holding period spans twelve months. Anyone buying today and selling when $0.30 is reached pays tax on the gain, because October 5, 2027 has not yet arrived.
Anyone already holding ADA has the reverse question: from when is which part of the position free. That hangs on the individual purchase dates and not on the average price the exchange app displays. Anyone who has bought in over months therefore keeps a separate date for each tranche.
Since January 1, 2026, the reporting obligation under DAC8 also applies. Providers report their clients' transactions to the tax administration; the first report, for the year 2026, is due by July 31, 2027. That changes nothing about the tax rules themselves, but a great deal about visibility.
Leverage on ADA: liquidation price, funding rate and the missing holding period
A daily jump of 10.61 percent attracts leveraged positions. Three figures decide the outcome there, and none of them is the price.
The liquidation price is the price at which the exchange force-closes your position because the collateral is used up. At five times leverage it sits roughly 20 percent below the entry, at ten times roughly ten percent. ADA ran through a daily range of $0.244191 to $0.274928 today, so 12.6 percent between low and high. A ten-times leveraged position would not necessarily have survived that day, depending on when it was opened.
The funding rate is the running payment between buyers and sellers of a perpetual futures contract. If a price rises quickly, it becomes expensive for the buy side, because more money pushes onto the rising side. Over several days that costs return, even when the direction is right. Which platforms carry which rates is in the comparison of perp DEXes.
The third point is a tax one. A gain from a leveraged product is not a private disposal subject to a twelve-month holding period; it is recorded differently. The tax exemption after a year that applies to held ADA does not bite there. Anyone mixing the two needs two sets of calculations.
Bitcoin carried twelve of these signals since 2014: what our measurement found there
Cardano supplies two data points; Bitcoin supplies more. Two weeks ago we ran the same calculation across the entire Bitcoin history and found twelve golden crosses since 2014. The analysis is in the article on the Bitcoin golden cross.
The comparison has a limit that has to be stated. Bitcoin is more liquid, older and held by different groups of buyers. A hit rate from there cannot be transferred to ADA. What can be transferred is the method: note the crossing day, record the price on that day, and only look weeks later at what came of it.
That is exactly what is not yet possible with Cardano today. The cross is four days old. Any statement about its outcome would be guesswork, and guesses about quantities do not belong in an article built on figures.
Golden cross on Cardano: your next three steps
- Check the permission before you trade. Buy ADA through a platform with MiCA authorisation and put the spread and the order fee side by side beforehand. Which providers carry the permission is shown in the overview of regulated crypto exchanges.
- Note the two lines, not the headline. $0.2211 for the 50-day line, $0.2131 for the 200-day line. If the shorter one falls below the longer one, the signal is done, regardless of what is written about price targets.
- Record the purchase date. Every additional purchase starts its own twelve-month period. Anyone not writing that down miscalculates later; a tool from the comparison of tax and portfolio tools takes it over.
(As of October 5, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
An anonymous 4chan user called Bitcoin's October 2025 peak to the day way back in 2023. Could they be right again?
FinCEN withdrew a 2020 proposal to track transactions with self-custodial crypto wallets and a 2023 plan to designate crypto mixing as a primary money laundering concern.
The on-chain sleuth says he posed as a customer of a Chinese crime syndicate, fronting $349,700 and eating 5% on every order, to track Lazarus Group's Bybit loot in real time.
The agency approved a Cboe rule letting six Volatility Shares funds that triple the daily moves of Bitcoin, Ethereum, gold, silver, oil, and natural gas list on a U.S. exchange.
The CFTC is seeking public comment on a framework that would create a new federal license for crypto exchanges, with leverage offers as the trigger for oversight.
U.Today - IT, AI and Fintech Daily News for You Today
The XRP Ledger has moved a step closer to launching Smart Escrow after developers rolled out the ninth Devnet release.
The CFTC is moving to build a new federal rulebook for crypto markets, proposing purpose-built regulations that could bring leveraged retail crypto trading.
ADA outpaces the market in its deepest rally since May while Cardano founder Charles Hoskinson teases a major scalability upgrade.
Barry Silbert flags his 2011 market prophecy as RWA tokenization and 24/7 trading transforming Wall Street.
Strategy’s STRC preferred stock is closing in on the critical $100 level.
Blockonomi
TLDR:
- CFTC crypto regulations would address retail crypto transactions involving leverage, margin, or financing, rather than ordinary direct cash purchases.
- The agency is considering a crypto asset market registration category designed for venues that list qualifying retail commodity transactions.
- Public comments will help shape potential rules under the Commodity Exchange Act, as Congress has not completed a wider market-structure law.
- The initiative could establish clearer compliance expectations, but it cannot settle authority over every spot crypto transaction or exchange activity.
The Commodity Futures Trading Commission has begun a new rulemaking process for crypto transactions using leverage, margin, or financing. CFTC crypto regulations would address qualifying retail commodity transactions involving crypto assets. Ordinary cash purchases would remain outside this narrow proposal.
The agency issued an Advanced Notice of Proposed Rulemaking on October 5. The CFTC announcement requests public input before any final rules are written. It relies on existing authority under Section 2(c)(2)(D) of the Commodity Exchange Act.
The notice explores a dedicated crypto asset market registration category. That category could offer a clearer path for platforms handling leveraged crypto trading. It would not create blanket federal oversight for every token trade.
CFTC Crypto Regulations Set Framework for Retail Trades
The proposal centers on retail commodity transactions that use borrowing, margin, or leverage. Those transactions can expose users to rapid losses and counterparty risks. The CFTC wants comments on rules that could address those exposures before misconduct occurs.
BREAKING:
CFTC proposes its first-ever rules to regulate the U.S. crypto market.
The rules would focus on:
1. Stopping abusive practices across crypto markets.
2. Setting clear standards for common crypto industry practices.
3. Creating a crypto-specific market…
— Ash Crypto (@AshCrypto) October 5, 2026
Chairman Michael S. Selig said the process aims to deliver clarity and consumer protections. He also framed the work as part of a broader federal market-structure agenda. The commission emphasized that its approach rests on authority Congress already granted.
The CFTC crypto regulations would seek a uniform national regime for qualifying transactions. The agency asked how it could prevent abusive practices across these markets. It also wants views on disclosures and compliance practices tailored to crypto assets.
That focus matters because crypto platforms often combine trading, custody, and financing services. A leveraged transaction can create different risks than a direct asset purchase. Rules would need to distinguish those products without treating every crypto activity identically.
The notice also asks about industry practices that can inform compliance expectations. Some safeguards may already be common among established market operators. The commission wants to identify which practices deserve clearer regulatory treatment.
CFTC Crypto Regulations Leave Direct Spot Trades Open
The agency is considering a subcategory of designated contract market registration called a crypto asset market. That status would be purpose-built for qualifying retail commodity transactions. It could give eligible venues a defined supervisory framework.
For crypto exchanges, CFTC crypto regulations may clarify registration expectations for margin products. They may also raise operational costs for platforms serving U.S. customers. The details will depend on the final definitions and scope of any later rulemaking.
The proposal does not settle the wider spot-market question. Simple, fully paid crypto purchases do not automatically fall within the retail commodity transaction provision. This leaves a significant policy gap for lawmakers and other federal regulators.
The Securities and Exchange Commission retains separate responsibilities where crypto assets meet securities-law tests. The CFTC process therefore adds an important piece, rather than a single rulebook. Venue operators may still face overlapping obligations based on each product.
The CFTC crypto regulations also remain at an early consultation stage. Public comments will shape whether the commission proposes detailed requirements later. Comments must arrive within 60 days after publication in the Federal Register.
Any eventual framework would begin with notice-and-comment procedures. It would not take effect merely because the agency requested views. Market operators would have another opportunity to examine formal rule text and implementation dates.
CFTC crypto regulations do not resolve Congress’s broader market-structure debate. They instead test how far the agency can act under present law. The next phase will depend on the feedback received from exchanges, investors, and consumer advocates.
Market participants will likely focus on definitions, registration thresholds, and customer protections. They may also assess how a crypto asset market category would interact with existing exchange models. The agency has invited written submissions through Regulations.gov.
The post CFTC Joins SEC in Crypto Rule Push, but Spot Trading Is Excluded appeared first on Blockonomi.
TLDR:
- South Korea led East Asia with a $449.1B crypto economy and strong AI-token trading.
- Hong Kong’s institutional platforms captured 16% of service inflows during 2026.
- Japan’s DEX market share reached 34.5%, led by growing retail participation.
- China’s unique stablecoin P2P wallets grew 43x between Q1 2024 and Q2 2026.
East Asia’s crypto economy exceeded $1.2 trillion, with South Korea leading at $449.1 billion during 2026. Chainalysis found sharply different market structures across South Korea, Japan, Hong Kong, China, and Taiwan.
The region contracted modestly overall during the period, aligning with the global bear market. Yet individual markets moved in different directions, shaped by regulation, taxation, institutional access, and local trading preferences.
South Korea Leads East Asia’s Crypto Economy
South Korea recorded a $449.1 billion crypto economy, growing 12.3% period over period. Exchange-related flows also increased by $51.1 billion, reflecting the strength of its retail-driven market.
The Chainalysis blog report found that South Korean traders showed an unusually strong preference for AI-related cryptocurrencies. By June 2026, AI cryptocurrencies represented the largest defined thematic category by won-denominated trading volume.
Worldcoin (WLD) led the category with $7.41 billion in volume. SAHARA recorded $3.2 billion, followed by VIRTUAL at $2.7 billion, BIO at $2 billion, and NEAR at $1.7 billion.
AI-crypto activity was far stronger in South Korea than comparable markets. AI assets accounted for a 19.5-times larger share of won trading than yen trading.
Japan’s $228.3 billion crypto economy showed a different pattern. DEX activity reached 34.5% of its services market, while DEX engagement rose more than 200% since 2022.
Chainalysis also found that roughly one in four Japanese exchange users later deposited funds into DeFi protocols. Smart contract tokens increased their share of yen trading volume from 10% to 15.4%.
Tax treatment remains a major factor for both markets. Japan’s maximum marginal crypto tax rate reached 55% during the study period, while South Korea had no crypto profits tax.
South Korea has a 22% crypto profits tax scheduled for 2027. Japan also advanced tax reforms in July 2026 that could shift eligible crypto gains toward roughly 20% separate taxation.
Hong Kong and China Show Opposite Crypto Trends
Hong Kong’s $192.2 billion crypto economy stood out for its institutional activity. Institutional platforms captured 16% of service inflows, nearly three times higher than any regional neighbor.
That share rose from around 9% two years earlier. Custody providers, prime brokers, and market-making desks represented 85% of the institutional category.
Hong Kong also received nearly $24 billion in inbound service-to-service transfers. Cumulative net business-to-business inflows reached $17.4 billion by mid-2026.
China presented the opposite model. Despite its longstanding ban on crypto services, Chainalysis estimated its crypto economy at least $176.3 billion.
Domestic peer-to-peer activity represented 59.1% of China’s crypto economy. Unique wallets sending stablecoin P2P transactions grew 43 times between Q1 2024 and Q2 2026.
Stablecoin activity accelerated from March 2025, with monthly additions rising from roughly $240 million to nearly $5 billion a year later. However, Chainalysis described the potential connection with China’s expanded social credit system as a working hypothesis.
China’s self-custodied stablecoins also showed unusually high turnover. Holdings circulated at 33.2 times annually, compared with a global average of 9.3 times.
East Asia has no single crypto-market model. South Korea remains retail-led, Japan combines retail and institutional activity, Hong Kong concentrates regulated institutional flows, while China relies heavily on P2P stablecoin transactions.
The post East Asia’s $1.2T Crypto Economy Splits Between Retail and Institutions: Chainalysis appeared first on Blockonomi.
TLDR:
- Plume launched nBND, a tokenized vault primarily backed by Fidelity’s FBND bond ETF.
- FBND provides exposure to investment-grade, high-yield, and emerging markets debt.
- The launch expands tokenized fixed income beyond short-duration Treasury products.
- Plume says institutional allocators increasingly want duration and active bond management.
Plume has launched nBND, a tokenized vault primarily backed by Fidelity Total Bond ETF (FBND), expanding onchain fixed-income access.
FBND is an actively managed ETF focused on investment-grade, high-yield, and emerging markets debt. The launch moves tokenized fixed income beyond short-duration Treasuries and money market equivalents.
The product targets capital allocators seeking longer duration and actively managed strategies onchain. It also brings traditional fixed-income exposure into Plume’s infrastructure for institutional assets.
Why is Plume Expanding Tokenized Fixed Income With nBND?
Plume said nBND responds to demand from capital allocators seeking longer duration and actively managed products. The vault gives allocators onchain exposure to a bond strategy managed by a major financial institution.
Chris Yin, Plume’s CEO and co-founder, said short-duration Treasuries were an initial step for onchain fixed income. He added that institutional allocators now want duration and active management.
The distinction matters because bond portfolios can carry different maturity profiles and credit exposures. Short-duration products generally focus on assets with limited interest-rate sensitivity.
nBND instead uses FBND as its primary reserve asset, bringing broader fixed-income exposure into Plume’s onchain environment. The structure connects traditional portfolio management with blockchain-based infrastructure.
Plume describes itself as an Open Finance platform for institutional assets. Its EVM-compatible chain provides infrastructure for tokenized financial products and related applications.
The launch also reflects a broader shift in how real-world assets can be represented onchain. Instead of focusing only on Treasury products, issuers are adding diversified financial assets.
That expansion gives the tokenized fixed-income market a wider range of potential portfolio building blocks. It also creates a bridge between established asset managers and crypto-native infrastructure.
nBND Adds Institutional Bond Exposure to Plume’s Tokenized Fixed-Income Market
The launch comes as tokenized U.S. Treasuries continue to expand. According to Plume’s press release, the market grew from $12 billion in April 2026 to $15 billion in June.
That $3 billion increase occurred over two months, while the global fixed-income market exceeds $100 trillion in assets. Plume said this highlights the potential scope for broader fixed-income tokenization.
The company is positioning nBND as part of a wider fixed-income market rather than another isolated yield product. That distinction centers on access to established financial assets through programmable blockchain infrastructure.
Fidelity’s Cynthia Lo Bessette said tokenized assets and onchain applications are becoming more integrated with mainstream market infrastructure. She said collaboration can expand investment access and enable greater portfolio programmability.
She also pointed to potential collateral utility and access to capital. Those functions could make tokenized assets useful beyond simply holding an investment product.
For traders and investors, the key development is the expansion of tokenized fixed income into actively managed bond exposure. nBND links an established ETF structure with an onchain vault.
The post Plume Brings Fidelity’s Bond ETF Onchain With New nBND Vault appeared first on Blockonomi.
TLDR:
- Bitmine holds 6,016,414 ETH, about 4.9% of total supply, and now sits 99% of the way to its 5% ETH goal.
- Strategy bought 334 BTC at an average of $85,839 from October 1-4, lifting total holdings to 848,000 BTC.
- Bitmine has staked 5,067,309 ETH worth $13.8 billion and projects $363 million in yearly staking revenue.
- Strategy repurchased $176.3 million of STRC shares and estimates a $20.91 billion Q3 digital asset gain.
Bitmine is now 99% of the way to owning 5% of all ETH. The firm added 15,112 ETH last week. Its total stands at 6,016,414 ETH, or about 4.9% of the 122.1 million supply.
Strategy, the world’s largest crypto treasury, kept stacking BTC at the same time. It bought 334 BTC for $28.7 million between October 1 and 4, bringing its total to 848,000 BTC. It also repurchased about $176.3 million of STRC shares between September 28 and October 4.
Crypto Treasury Leaders Bitmine and Strategy Add to Their Stack
Bitmine’s holdings now equal about 4.9% of Ethereum’s 122.1 million supply. The firm says it is 99% of the way toward owning 5% of all ETH.
Bitmine has bought ETH every week since launching its ETH treasury strategy on June 30, 2025. Chairman Tom Lee called that record unmatched among public companies.
According to the company’s release, 5,067,309 ETH is staked. That stake is worth $13.8 billion at $2,726 per ETH. Staking means locking ETH to help secure the network in return for rewards.
Lee said annualized staking revenue is now projected at $363 million. Bitmine’s total crypto, cash, marketable securities and other investments stand at $17.4 billion.
Its portfolio also includes 214 BTC, a $180 million stake in Beast Industries and a $117 million stake in Eightco Holdings. Cash and marketable securities total $643 million.
Strategy took a different route. As reported by WuBlockchain, it bought 334 BTC between October 1 and 4 at an average price of $85,839. Total holdings now cost about $63.97 billion.
The purchase was funded with $15.7 million from MSTR share sales and $13 million in cash. Strategy also repurchased about $176.3 million of STRC preferred shares between September 28 and October 4.
Why the Crypto Treasury Model Matters for Markets
Strategy’s 8-K filing estimates a $20.91 billion gain on digital assets for Q3. Its bitcoin was valued at $70.82 billion as of September 30.
Bitmine’s release ranks Strategy as the top global treasury and itself as number two. It cites Strategy’s holdings at 847,666 BTC, worth roughly $78 billion.
Lee argues that crypto is entering a bull market. He said ETH fell 10% in the first nine months of 2026, while BMNR fell 3%. He also said ETH beat the S&P 500 by 6,832 basis points in the third quarter. These are the company’s claims, not independent findings.
The two strategies differ in one key way. Bitmine stakes its ETH to earn yield. Strategy holds bitcoin, which does not generate staking rewards, and leans on equity sales and buybacks.
Liquidity is another signal. Fundstrat data shows BMNR averaged $827 million in daily dollar volume over five days to October 2. That ranks it 125th among 5,704 US-listed stocks.
Lee will give a keynote at Token2049 on October 7 at 10 a.m. in Singapore. Traders will watch for any update on the 5% goal.
Bitmine is nearly at its 5% ETH target, and Strategy keeps stacking BTC while buying back preferred stock. The crypto treasury race is still running at scale.
The post Crypto Treasury Giants Keep Buying: Bitmine Nears 5% of All ETH as Strategy Hits 848,000 BTC appeared first on Blockonomi.
TLDR:
- Payward will offer 24/7 instant settlement through SGB Net to selected institutional clients.
- The service initially supports U.S. dollar transactions across selected Asian and Gulf markets.
- SGB Net now processes more than $20 billion in fiat transactions each month.
- SGB will use Kraken Prime for digital-asset liquidity and pricing for its customers.
Payward, the parent company of Kraken, has partnered with Singapore Gulf Bank (SGB) to provide 24/7 instant settlement for institutional digital asset clients in selected Asian and Gulf markets.
The partnership connects Payward to SGB Net, SGB’s real-time, multi-currency clearing network. The service will initially support U.S. dollar transactions for a select group of clients, with more clients and currencies planned.
How Payward’s 24/7 Settlement Network Works
SGB Net allows institutional clients to move funds between banking and digital asset infrastructure without waiting for traditional banking cut-off times.
Historically, bank settlement has followed business hours and fixed processing windows. Digital asset markets, however, operate continuously throughout the week.
Under the new arrangement, an SGB client can deposit funds with Payward and deploy them instantly. This could reduce delays between funding an account and accessing digital asset markets.
The initial rollout covers U.S. dollar transactions for selected clients in specific jurisdictions across Asia and the Gulf region. Payward and SGB plan to expand the service over time.
SGB Net launched in 2025 for digital asset businesses with increasing operational requirements. According to the companies, the network now processes more than $20 billion in fiat transactions each month.
The partnership also links SGB with Kraken Prime, Payward’s full-service prime brokerage platform. SGB will use Kraken Prime as an additional source of digital asset liquidity and pricing for its customers.
Payward Banking Expansion Connects Settlement and Liquidity
The partnership extends Payward’s broader effort to strengthen its banking infrastructure for institutional clients.
Payward Banking serves as the money layer supporting deposits, payments, cards, custody, and lending across the platform. Adding regulated banking partners can help connect traditional financial services with continuously operating digital asset markets.
For institutional traders, the key change is the timing of capital movement. Faster settlement can allow eligible clients to fund digital asset activity without waiting for the next banking window.
SGB is regulated by the Central Bank of Bahrain and is backed by Bahrain’s sovereign wealth fund Mumtalakat and Singapore’s Whampoa Group.
SGB Chief Executive Officer Shawn Chan said liquidity becomes more useful when clients can move funds when needed. The partnership therefore combines two important parts of institutional crypto infrastructure: access to liquidity and access to settlement.
For traders and institutions, the immediate offering remains limited to selected clients and U.S. dollar transactions. Its broader significance depends on whether Payward expands access across additional jurisdictions and currencies.
The SGB Net handles real-time fiat clearing while Kraken Prime provides digital asset market access. Together, the infrastructure will bring banking settlement closer to the continuous operating model of crypto markets.
The post Kraken’s Parent Payward Taps SGB for Instant Crypto Settlement appeared first on Blockonomi.
CryptoPotato
OKXICE LLC, a venture formed by cryptocurrency exchange OKX and NYSE parent company ICE, made a filing on October 4 with the US Securities and Exchange Commission (SEC) to launch a tokenized stock trading exchange.
The filing makes OKX one of the first crypto exchanges attempting to offer tokenized US stocks through a regulated exchange under the temporary SEC regulations.
OKXICE Seeks Approval for 63 NYSE Stocks
According to a report by Bloomberg, OKX plans to seek approval to offer tokenized shares of an initial 63 NYSE-listed companies. Under the SEC framework, those companies have 30 days to opt out before trading can begin, meaning the launch still depends on that notice period and other requirements.
OKX’s blockchain infrastructure would be paired with ICE’s market technology. ICE acquired a stake in OKX in March at a $25 billion valuation, and the companies have agreed to work together on US-regulated crypto futures.
The SEC introduced its temporary Innovation Exemption in September, allowing certain tokenized securities venues to facilitate secondary trading of tokenized US stocks through permissioned automated makers and liquidity pools.
Tokenized shares must carry the same shareholder rights as the underlying securities, including dividends and voting rights. Smart contracts must also be auditable and run on public, permissionless blockchains, while trading must stop if the underlying stock is suspended on its primary exchange.
OKX Joins a Growing Tokenized-Stock Race
As CryptoPotato reported, Coinbase announced in June that it planned to offer tokenized stocks to customers outside the US, with shares backed 1:1 by the underlying assets and carrying shareholder rights.
That move came before the SEC’s September exemption and showed how crypto exchanges were already pursuing ways to connect stock trading with blockchain infrastructure.
The SEC’s exemption followed stalled legislative progress around the CLARITY Act. The regulator had reportedly been working on the exemption for more than a year and had planned to release it in May before delaying it during negotiations over the bill.
For OKX, the filing gives a use to the relationship with ICE beyond its March investment. The two companies are now seeking to combine exchange infrastructure and blockchain-based trading under a framework that could let US-listed stocks trade around the clock, subject to the SEC’s conditions.
The post OKX and ICE File to Trade 63 Tokenized NYSE Stocks appeared first on CryptoPotato.
Binance has told users in Brazil that from November 1, they must state the purpose of every crypto transfer to or from outside the country and identify who is on the other end. The exchange will report these operations to Brazil’s Central Bank every month.
The change brings international crypto transfers into Brazil’s foreign exchange rules, and nothing goes through without the answers.
Binance Sets New Requirements for International Transfers
Binance outlined the changes in an FAQ, explaining that users sending crypto abroad or receiving it from overseas will need to state the purpose of the transfer and identify the counterparty. Corporate accounts will also have to disclose whether the counterparty belongs to the same economic group.
The exchange stressed that this is not the Travel Rule. That requirement will apply separately to domestic and international transactions in 2027 and 2028, respectively.
For the new Brazilian foreign-exchange process, a transfer is considered international when the other party is outside Brazil or when users move their own assets between Brazil and an overseas account. Transfers between Brazilian residents, including transfers to a Brazilian exchange, are not affected.
Users will choose a purpose from a Central Bank classification system. Transfers of up to $50,000 have a simplified list of 10 purposes, while transactions above that amount require a complete list containing 96 options. Binance says there is no generic “others” option for transfers above $50,000.
A separate limit also applies. International transfers involving counterparties that are not institutions authorized to operate in Brazil’s foreign-exchange market are capped at $100,000 per transaction under the current rules, although Binance says that limit may later become $500,000.
What Users Need to Know Before November
The practical effect will be most noticeable when users move assets between Binance and foreign accounts. Withdrawals cannot be submitted until the questionnaire is completed, while deposits from abroad can remain pending and may sometimes be returned to the sender if the required information is not provided.
Self-hosted wallets are treated differently. Users do not have to provide a transfer purpose when sending crypto to or receiving it from their own wallet, but they must confirm ownership. Those transactions will still be reported to the Central Bank in a separate category.
Binance also says the information must reflect the actual reason for each transfer. Users can contact customer support if they make a mistake, while only foreign exchanges assessed under the Central Bank requirements will appear in the available exchange list.
The changes come as the exchange faces regulatory adjustments in some markets, including dealing with questions from European regulators over its continued operations after failing to secure a MiCA license. In September, the exchange separately announced the closure of UAH deposits and withdrawals and the removal of the USDT/UAH trading pair for Ukrainian users.
For Brazilian customers, however, the immediate issue is narrower: every international deposit and withdrawal will require the new information once the rules take effect.
The post Important Binance Announcement Concerning Brazilian Users appeared first on CryptoPotato.
Peter Schiff has warned that Bitcoin’s recent resilience could make a later reversal more painful for Strategy, arguing that the company has lost the ability to use STRC to raise fresh money for Bitcoin purchases.
His broader view is that markets have absorbed worsening economic signals without fully pricing the risks he sees.
Schiff Sees Strategy’s Financing Problem
In the latest Peter Schiff Show, the economist noted that Bitcoin had gained almost 1% on the week and was trading around $84,500 at the time of recording. He also pointed to Strategy’s STRC price, which had recovered to about $99.40 after falling to $75 during the summer.
He attributed that recovery to Strategy repurchasing STRC and Bitcoin’s move back above $80,000, which may have improved confidence and prompted short covering. But he argued that the rebound does not solve the financing problem.
“There’s no way that he’s going to be able to start selling more STRC. And that means he’s not going to be able to raise money to really start buying more Bitcoin,” Schiff stated, referring to Strategy’s Michael Saylor.
Strategy’s latest figures show 848,000 BTC, equal to just over 4% of total supply, alongside $4.8 billion in USD reserves and $833 million in cash. Its STRC position has an $8.93 billion notional value, with a 12% variable dividend and 12.07% effective yield.
Bitcoin has since moved higher, with CoinGecko data at the time of writing putting it around $86,000, up more than 4% in seven days and over 8% across 30 days, while remaining down 30% from where it was one year ago.
But despite what Schiff says, Strategy has continued buying the asset. As CryptoPotato reported earlier today, the company acquired 334 BTC for about $28.7 million. It also repurchased another $176 million of STRC. This latest buy is quite smaller than the 1,665 units bought for about $142.8 million in late September, which came together with $152 million of STRC.
Schiff Links Bitcoin Risk to a Wider Market Break
Schiff’s argument extends beyond Strategy’s capital structure. He believes Bitcoin is benefiting from a stock market that has so far absorbed weak economic and bond-market signals without a larger correction.
He referred to softer PCE inflation numbers, poorer-than-expected employment figures, and lower expectations of an interest rate hike in October, but maintained that bond prices were falling. The oil price stood at about $91 a barrel following a promise by the G7 to release 100 million barrels from their strategic reserves.
Schiff’s worry is that the markets are taking resiliency as an indicator that the bad news no longer matters, but he thinks things are only going to keep getting worse.
“At some point, Bitcoin is going to roll over, especially if we get a pullback in the tech market, which we haven’t had yet,” he warned.
The post Peter Schiff Predicts Bitcoin Will Drop If Tech Stocks Pull Back appeared first on CryptoPotato.
Bitcoin is approaching a key resistance area again after recovering from its late-September pullback. The price structure remains constructive, but nearby technical resistance and holder cost bases suggest that buyers still face a meaningful barrier to further gains.
Bitcoin Price Analysis: The Daily Chart
On the daily timeframe, BTC is trading around $85.2K, near the lower boundary of the $86K–$90K resistance zone. Following the initial rejection around $87K, buyers defended the $83K–$84K area and pushed the price back toward the recent highs. This relatively shallow correction suggests that demand remains resilient, although a sustained breakout has yet to materialize.
Meanwhile, the two displayed moving averages are converging around $71.5K, with the rising yellow average approaching the orange average from below. The highlighted potential bullish crossover would reinforce the broader recovery backdrop, but confirmation is still needed, and the asset remains well above both averages.
A sustained move above the recent $87K–$87.5K highs could allow Bitcoin to advance further into the $88K–$90K resistance area. Clearing that broader zone would open the way toward the next major supply region at $94K–$98K. Conversely, another rejection followed by a loss of the $83K support area would increase the risk of a deeper correction, with the $75K–$78K demand zone serving as the main highlighted support below.
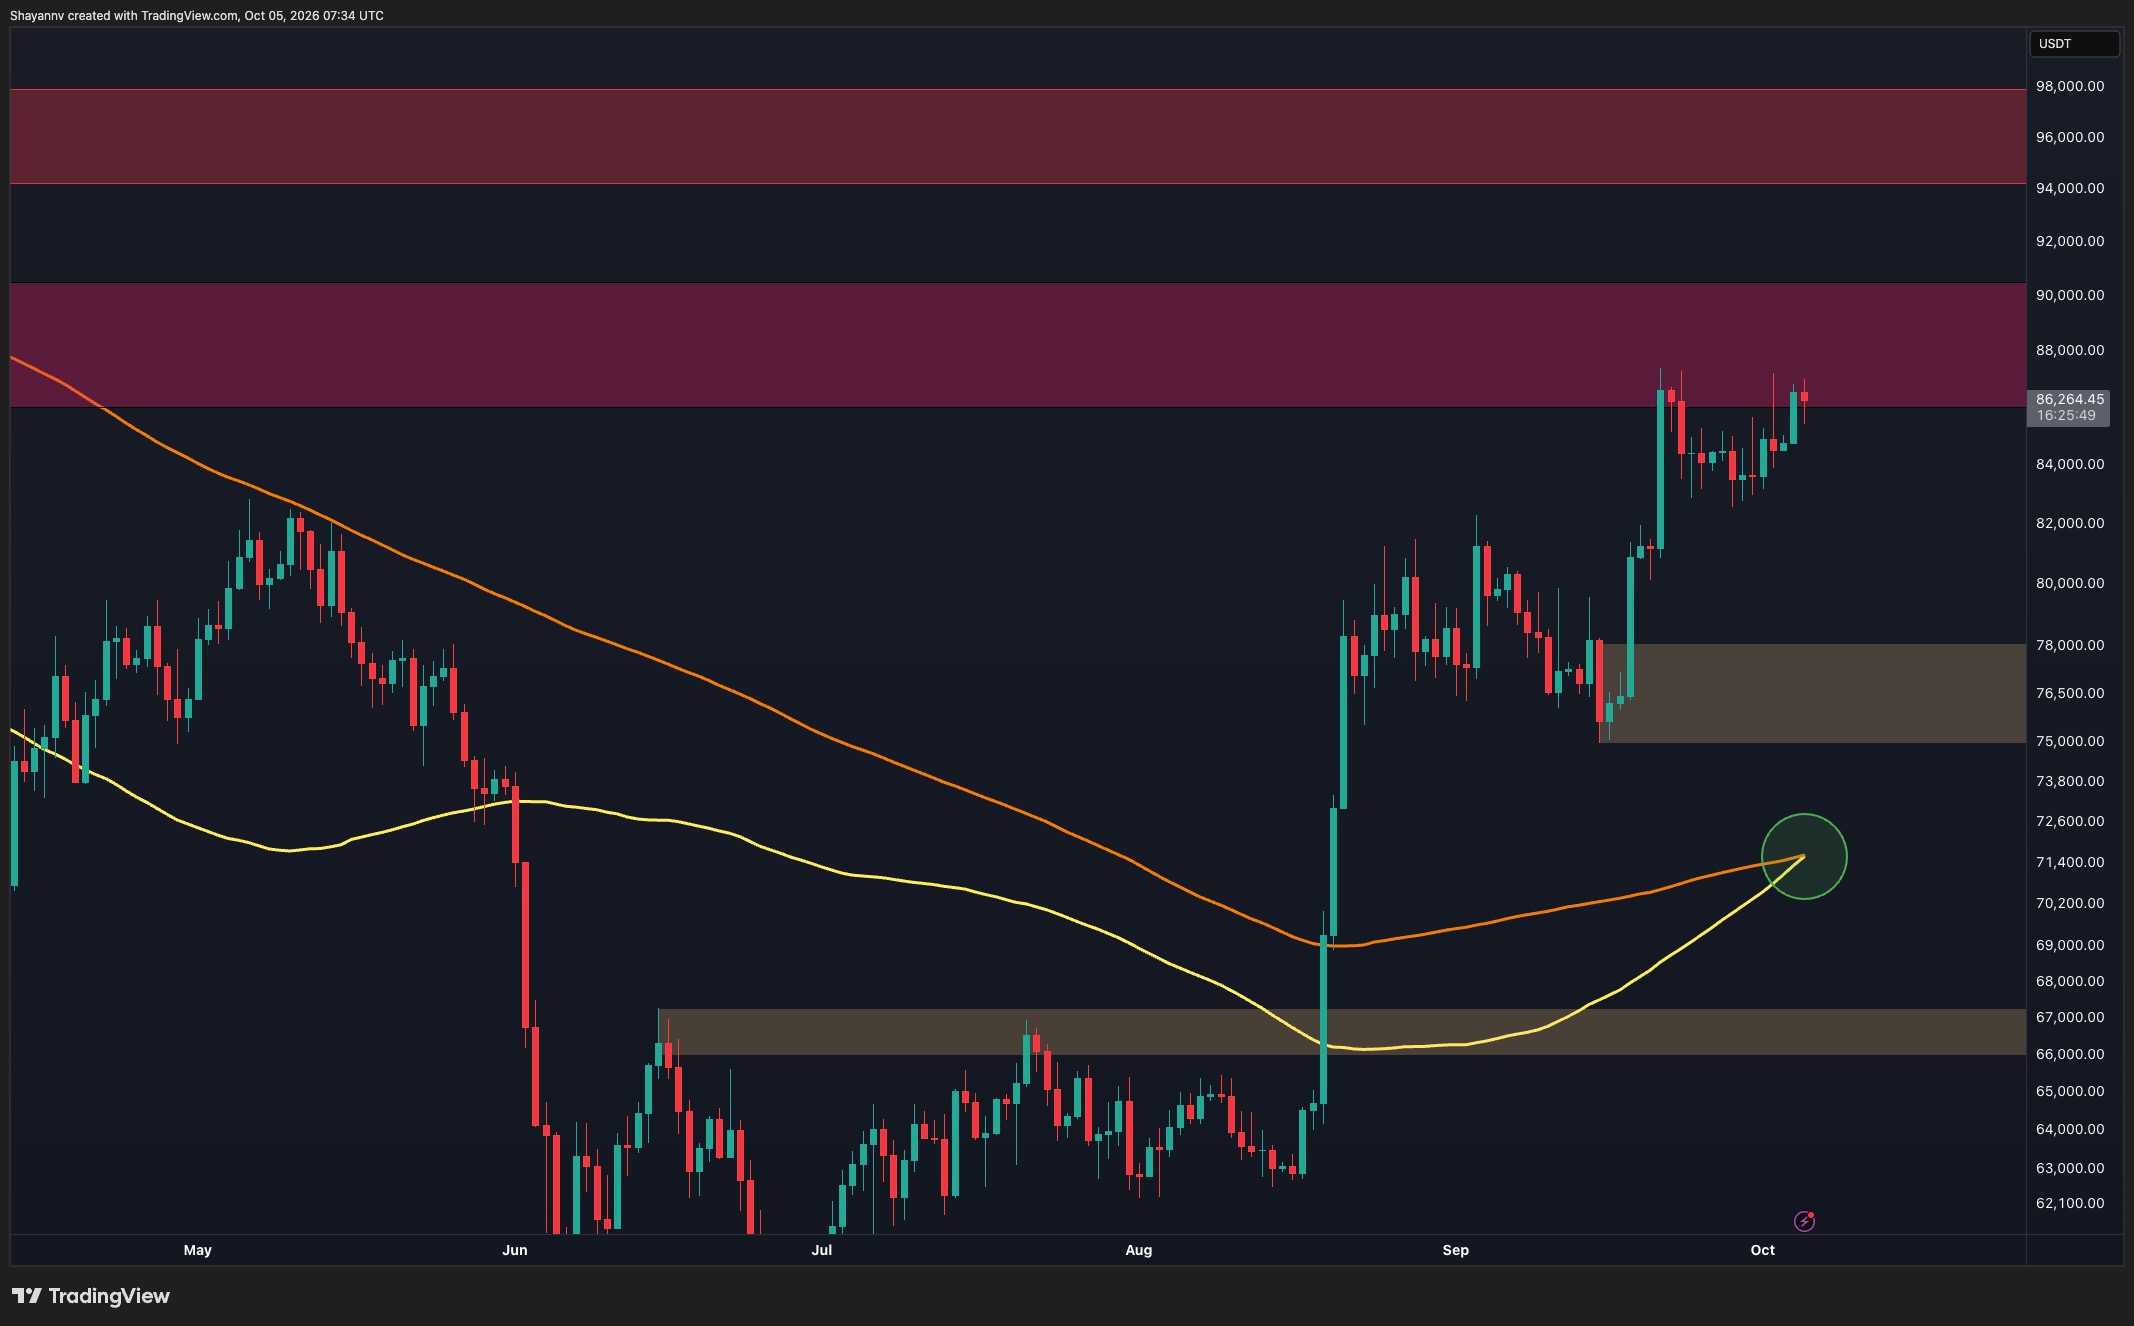
BTC/USDT 4-Hour Chart
The 4-hour chart shows an ascending triangle developing within the broader rising channel. Repeated highs around $87K–$87.3K form a relatively flat resistance boundary, while the ascending white trendline supports progressively higher lows. Bitcoin is currently trading near the upper portion of this formation after another test of overhead resistance.
This compression suggests that buyers continue to challenge supply, but the pattern requires a confirmed breakout. A decisive 4-hour close above $87.3K, followed by sustained acceptance above that level, could support a move toward $89K–$90K, where the broader supply zone and upper channel boundary would become relevant.
On the downside, the ascending triangle support currently sits around $84.5K–$85K. Losing this trendline would weaken the continuation setup and expose the recent lows around $82.5K–$83K. Further selling could then bring the broader channel midpoint near $81K into focus, followed by the $75K–$78K demand zone.

Sentiment Analysis
The Realized Price UTXO Age Bands chart tracks the average on-chain cost basis of coins grouped by age, providing context for the profitability of different holder cohorts.
With Bitcoin around $85K, the price remains above the realized prices of the 1-to-3-month and 3-to-6-month cohorts, positioned near $69K and $71K, respectively. These cohorts are therefore in aggregate unrealized profit. However, Bitcoin is still below the closely aligned realized prices of the 18-month-to-2-year and 6-to-12-month cohorts, both near $88K–$89K.
This cost-basis cluster overlaps with the daily resistance zone, adding significance to the $88K–$90K area. As price approaches these levels, some holders may use a return toward breakeven to reduce exposure, potentially increasing selling pressure. The metric alone does not confirm that such selling will occur, but it identifies a region where supply could emerge.
A sustained move above $89K–$90K would place Bitcoin above both cohort cost bases and strengthen the bullish continuation scenario. Until then, the convergence of technical resistance and realized prices remains an important hurdle for the recovery.

The post Bitcoin Price Analysis: Is BTC Running Out of Steam After Another Rejection at $87K? appeared first on CryptoPotato.
BitMine has acquired 15,112 ETH in the week to October 4, taking its treasury to 6,016,414 tokens, though that purchase was smaller than the 17,362 ETH BitMine bought a week earlier.
It was also the company’s smallest weekly buy since the week to August 16, when it added 9,926 ETH, according to its SEC filings. The treasury now equals 4.9% of the 122.1 million ETH in supply, short of BitMine’s 5% target.
Buyback Total Matches August Figure
BitMine valued its ETH at $2,726 per token, using Coinbase prices. At that price, its ETH, other crypto, cash and equity stakes total $17.4 billion. The total also covers 214 Bitcoin (BTC), a $180 million stake in Beast Industries and $117 million of Eightco Holdings (ORBS).
Cash and marketable securities account for $643 million of that total. That figure fell from $672 million a week earlier and from $714 million on September 20.
“We believe that as crypto enters a cycle we view as a bull market, what is notable is Bitmine’s share price outperformance of ETH during the bear market of 2025-2026,” said BitMine Chairman Tom Lee.
Lee said the company’s shares fell 3% in the first nine months of this year, while ETH fell 10%, and he tied that gap partly to BitMine’s share buyback. He said the company has acquired 21 million of its own shares this year, and called it the largest equity buyback by any crypto treasury.
Moreover, BitMine’s August 17 update put repurchases since July 1 at 20.8 million shares, which they ran under a $4 billion authorization. None of the six weekly updates filed from August 24 to September 28 reported a repurchase.
New Staking Deal Sets 1.5% Fee
Ethereum Towers had managed BitMine’s staking operations since March, in return for a share of net staking revenue. The two companies ended that agreement on September 3, as BitMine disclosed in a September 8 filing, with the company stating it incurred no material early termination penalty.
Likewise, since September 4, Ethereum Towers affiliate American Validator has advised MAVAN, the staking platform BitMine launched in March. The affiliate earns 1.5% of the rewards on ETH that BitMine stakes.
BitMine reported 5,067,309 ETH staked, or 84% of its Ether. That staked count has not moved in nine weekly updates, starting August 9.
The post BitMine Lifts ETH Treasury to 6.02 Million With Smallest Buy Since Mid-August appeared first on CryptoPotato.