Cryptocurrency Posts
Crypto Briefing
Bitmine's aggressive ETH acquisition strategy could amplify Ethereum's market influence and attract increased institutional investment.
The post Bitmine acquires 15,112 Ethereum, raising total to 6.02M ETH appeared first on Crypto Briefing.
The decline in meme coins' market share highlights shifting investor preferences and could signal potential volatility or a future rebound.
The post Meme coins hit record low share of altcoin market, CryptoQuant analyst says appeared first on Crypto Briefing.
BofA's revised target for Coinbase highlights the growing importance of stablecoin revenue and the impact of monetary policy on future earnings.
The post Bank of America raises Coinbase price target to $203, keeps Buy rating appeared first on Crypto Briefing.
The surge in onchain options trading highlights growing market interest and competition, potentially reshaping the DeFi landscape.
The post Derive leads onchain options market as volume doubles to $5B appeared first on Crypto Briefing.
TeraWulf's power expansion at Muskie enhances its competitive edge in AI/HPC, but future revenue hinges on phased capacity realization.
The post TeraWulf doubles contracted power at Muskie AI/HPC campus to 1 GW appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
IMF Praises El Salvador — But Still Tries To Scale Back Its Bitcoin Project
The International Monetary Fund has praised El Salvador for improving its economy — but scolded it at the same time for its ongoing Bitcoin experiment.
In a statement Friday, the IMF said that it had approved a $139 million disbursement to the Central American nation while also trying to “reduce the state’s involvement in Bitcoin-related activities.”
El Salvador in 2021 made Bitcoin legal tender, much to the ire of the IMF and other major institutions. The Latin American country was at the time negotiating a development loan with the agency.
“El Salvador’s economy continues to perform strongly”
— Nayib Bukele (@nayibbukele) October 1, 2026https://t.co/Rvaerha9QA
The IMF in September said that El Salvador wasn’t buying bitcoin; the country’s Bitcoin Office has repeatedly said that it does buy the cryptocurrency.
“Economic activity has exceeded expectations, supported by sustained improvements in security and investor confidence, as macroeconomic imbalances continue to be addressed,” the IMF said.
It continued: “However, certain performance criteria were not met, including on the Bitcoin accumulation front, for which waivers were granted based on strong corrective measures and renewed commitments.”
The IMF further said that the Salvadoran state’s involvement in Bitcoin-related activities is being unwound and that “no further bitcoin accumulation is envisaged beyond the documented donations.”
Salvadoran president Nayib Bukele in 2022 said the country would buy one bitcoin per day but it was never clear where the money was coming from — or if he was actually buying at all.
The IMF said in September that El Salvador was — at least for some time —not using public funds to accumulate bitcoin but rather had received bitcoin from private donations.
El Salvador and the IMF entered a $1.4 billion loan agreement at the end of December but the fund asked for the country to scale back certain aspects of its Bitcoin strategy.
The Salvadoran state gifted its citizens bitcoin in 2021 and debuted a wallet with the hope of getting more citizens using the cryptocurrency in the dollarized country.
President Bukele in 2024 admitted that Salvadorans weren’t using the cryptocurrency to buy things as expected, but always boasted that the government was still stacking sats.
This post IMF Praises El Salvador — But Still Tries To Scale Back Its Bitcoin Project first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
South Africa’s Absa Becomes First Bank on the Continent to Custody Bitcoin: Report
South African bank Absa has become the first African lender to custody bitcoin, according to reports.
As reported first by Bloomberg on Friday, the Johannesburg-based lender will serve institutional clients, mostly by custodying bitcoin — but other digital assets will also be a part of the service.
Banks worldwide are integrating or offering bitcoin-related products and services. A number of U.S. and European banks have started offering crypto-related services by custodying assets for institutions.
JUST IN:
— Bitcoin Magazine (@BitcoinMagazine) October 2, 2026Absa has become the first African bank to offer Bitcoin custody
pic.twitter.com/JaDza3S7Ez
Rob Downes, head of digital assets at Absa’s corporate and investment banking unit, was quoted saying that while bitcoin was the biggest asset the bank would custody, others would follow.
Absa did not immediately respond to questions from Bitcoin Magazine.
The African continent has a large crypto-native base, with data firms frequently highlighting the high adoption — particularly in countries where currencies have been significantly debased.
In Chainalysis’s 2025 report, South Africa’s $36.0 billion in on-chain value made it second in Sub-Saharan Africa. Nigeria alone received $92.1 billion, nearly three times the total of second-place South Africa.
On the global index, South Africa ranked 30th for crypto adoption.
The character of its market is different from Nigeria‘s: it’s more institutional, with regulatory clarity resulting in hundreds of licenses being issued to VASPs and attracting professional investors and traditional finance.
BNY Mellon in 2022 became the first major U.S. bank to offer digital asset custody services. And this month, German multinational Deutsche Bank said it would debut a bitcoin custody service for European corporate and institutional clients later in 2026.
This post South Africa’s Absa Becomes First Bank on the Continent to Custody Bitcoin: Report first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Bitcoin Price Surges Above $87,000 on Softer-Than-Expected Jobs Data
The price of bitcoin surged above $87,000 on Friday morning in New York, buoyed by constant exchange-traded fund flows and a jobs report showing that unemployment in the U.S. had ticked up.
Bitcoin’s price recently stood at $85,990 after a 2% jump over a 24-hour period. Over the past week, it has also risen by more than 2%.
Nonfarm payrolls increased 29,000 last month after a downward revision to the prior two months, Bureau of Labor Statistics data showed Friday.
JUST IN: Bitcoin jumps to $87,000 as U.S. Unemployment Rate comes in at 4.2%, higher than expectations
— Bitcoin Magazine (@BitcoinMagazine) October 2, 2026pic.twitter.com/jqtU8Q9zsd
Weaker-than-expected jobs data can give a lift to riskier assets like bitcoin and stocks, whose prices tend to swing more sharply.
A softer labor market typically means less consumer spending, which eases pressure on prices. That could make the Federal Reserve less inclined to keep raising interest rates to fight inflation.
Many economists and politicians have said the U.S. is in the midst of an affordability crisis, and the topic is a hot one ahead of the November midterm elections.
The Federal Reserve’s new chair, Kevin Warsh, has said that prices in the world’s biggest economy are too high and that the central bank is fully focused on making life more affordable again.
Bitcoin investors shrugged off the central bank’s interest rate hike in September, climbing on the news.
The largest cryptocurrency started rallying in August on news that the U.S. Treasury Department said it would more than double the size of its government debt repurchases. The coin had its best run in three years and third best August ever.
The coin’s price has benefited from the so-called debasement trade: when investors buy certain assets to hedge against currency being devalued. The dollar slid in value in August.
It continued to have a good September, rising nearly 6% over a 30-day period.
October has historically delivered good returns for bitcoin investors, with traders dubbing the phenomenon “Uptober.”
This post Bitcoin Price Surges Above $87,000 on Softer-Than-Expected Jobs Data first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Impacts of Daily Dividends on Digital Credit
In May 2026, Strive rebranded itself as “The Daily Dividend Company,” then moved SATA to daily cash dividends beginning June 16. Strategy has now pushed the same idea into its own digital credit engine. On September 24, its board proposed moving STRC, STRF, STRK and STRD to daily dividends, subject to shareholder approval at an October 28 special meeting. The proposal keeps the annual dividend economics unchanged and changes the cadence of cash payments.
STRC spent much of the summer below its $100 stated amount even as Strategy raised its dividend rate to 12% and deployed more than $1 billion buying back STRC. The move to daily dividends by Strategy could be seen as the latest attempt to make the security more attractive and help it trade near par.
Now that the overton window has fully shifted in favor of digital credit paying daily dividends, we should take a look at the actual impacts of daily dividends.
Daily Dividends Fit Onchain Finance
Digital credit is increasingly becoming an input for other financial products—so called “digital money” or “digital yield” products. Strategy estimated in mid-May that more than $440 million of STRC exposure had moved into DeFi through stablecoins, tokenized securities, yield products and other structures.
However, there is a cash flow mismatch. Crypto products commonly accrue and distribute yield at high frequency. A security that pays monthly or twice monthly forces the product sitting on top of it to bridge the period between economic accrual and actual cash receipt.
Daily dividends compress that gap to one day. The protocol, fund or issuer receives cash from the underlying asset at almost the same cadence that users expect to receive yield. That simplifies liquidity management and reduces the cash needed between dividend dates. This is much more impactful to a financial product funding daily distributions or redemptions than to a long term investor focused on total return. The crypto-heavy setting of the “Layer 3” products on top of digital credit raises the attractiveness of daily dividends.
Daily Dividends Are Primarily a Retail Feature
For investors focused strictly on total return, dividend payment frequency makes little difference in underlying economic value. The asset’s price accrues between distribution dates and adjusts post-payment, meaning annual, quarterly, monthly, and daily payouts produce comparable long-term results.
The true advantage of daily dividends lies in product psychology and user experience. Cash arriving every day provides immediate visibility and an engaging feedback loop. Investors can spend, withdraw, or automatically reinvest the payout while leaving their principal position intact, turning an abstract yield metric into tangible recurring cash flow.
This dynamic mirrors the strategy of Realty Income, which built a massive retail follower base by branding itself as “The Monthly Dividend Company.” As a member of the S&P 500 Dividend Aristocrats Index, Realty Income has paid and raised dividends for 31 consecutive years.
Daily dividends on digital credit extends this product concept even further: SATA pairs frequent daily payouts with a target price near $100 and a double-digit yield.
While institutional investors prioritize yield spreads, liquidity, tax structure, and balance sheet coverage, daily payments offer their strongest appeal to retail buyers. If the overarching objective is to raise capital to purchase Bitcoin, optimizing security design for retail investor preferences is the most effective approach.
Options Get Cleaner Too
Daily dividends also change options mechanics. STRC currently pays $0.50 twice monthly. SATA pays roughly five cents each business day. Larger dividend events create larger discrete adjustments in the underlying price, which affects option pricing and early exercise decisions. Daily payments spread the same annual cash flow across much smaller adjustments.
The total value of dividends over an option’s life is a key economic input. The more interesting effect comes from the price stability created by daily dividends. If daily dividends, variable rates and active par management keep SATA and STRC trading in narrower ranges, realized volatility should fall. Implied volatility can follow as the market gains confidence in that behavior.
The Biggest Test
The real test is whether daily dividends increase demand enough to eventually lower the required yield.
If investors consistently support SATA near the top of its target range, Strive can theoretically reduce the dividend rate while attempting to keep SATA near par. Success would show that a Bitcoin company can issue permanent preferred capital, manage it around a stable price, and adjust its yield with market demand. The benefit of the variable rate preferreds was, from inception, the eventual opportunity to lower the rate and reduce the cost of capital without upsetting price stability. In comparison, fixed rate credit locks in fixed rate forever.
Conclusion
Strategy adopting daily dividends would move the feature from a SATA differentiator toward a digital credit category standard. The annual economics barely change but the retail appeal and crypto composability become meaningful improvements.
This post Impacts of Daily Dividends on Digital Credit first appeared on Bitcoin Magazine and is written by Allard Peng.
Bitcoin Magazine
Frank Holmes: They Will Print $100 Trillion – Why to Buy Bitcoin & Gold
Bitcoin miners already have the power, the land, and the substations that AI needs. Frank Holmes, executive chairman of HIVE Digital Technologies, explains why he calls Bitcoin mining a “tier one” data center, how GPUs that once mined Ethereum led HIVE into AI, and why he thinks the next wave of AI factories will be built on mining infrastructure from Paraguay to Canada.
Chapters:
0:00 Frank Holmes on HIVE: From Gold Investor to Bitcoin Miner to AI Compute
2:12 How ETFs Changed Bitcoin: From the Fear Trade to the Love Trade
4:20 The Binance $19 Billion Liquidation and the $350 Trillion Money Supply
5:45 Gamers, Younger Quants, and Why Bitcoin Will Keep Gaining Adoption
7:29 Covid’s $40 Trillion of Money Printing and the Global MMT Risk
9:24 China, Russia, and Why Bitcoin Is a Tier One Data Center
11:33 China’s Bitcoin Mining, $1.4 Trillion of Lending, and Central Banks Buying Gold
13:44 Paraguay’s Central Bank and Bitcoin Mining as an Export
14:57 Compute as a Commodity: Canada’s AI Push and Bitcoin Miners’ Power Advantage
20:34 Where to Find Frank Holmes’s Weekly Investor Alert Newsletter
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Frank Holmes: They Will Print $100 Trillion – Why to Buy Bitcoin & Gold first appeared on Bitcoin Magazine and is written by Patrick Green.
CryptoSlate
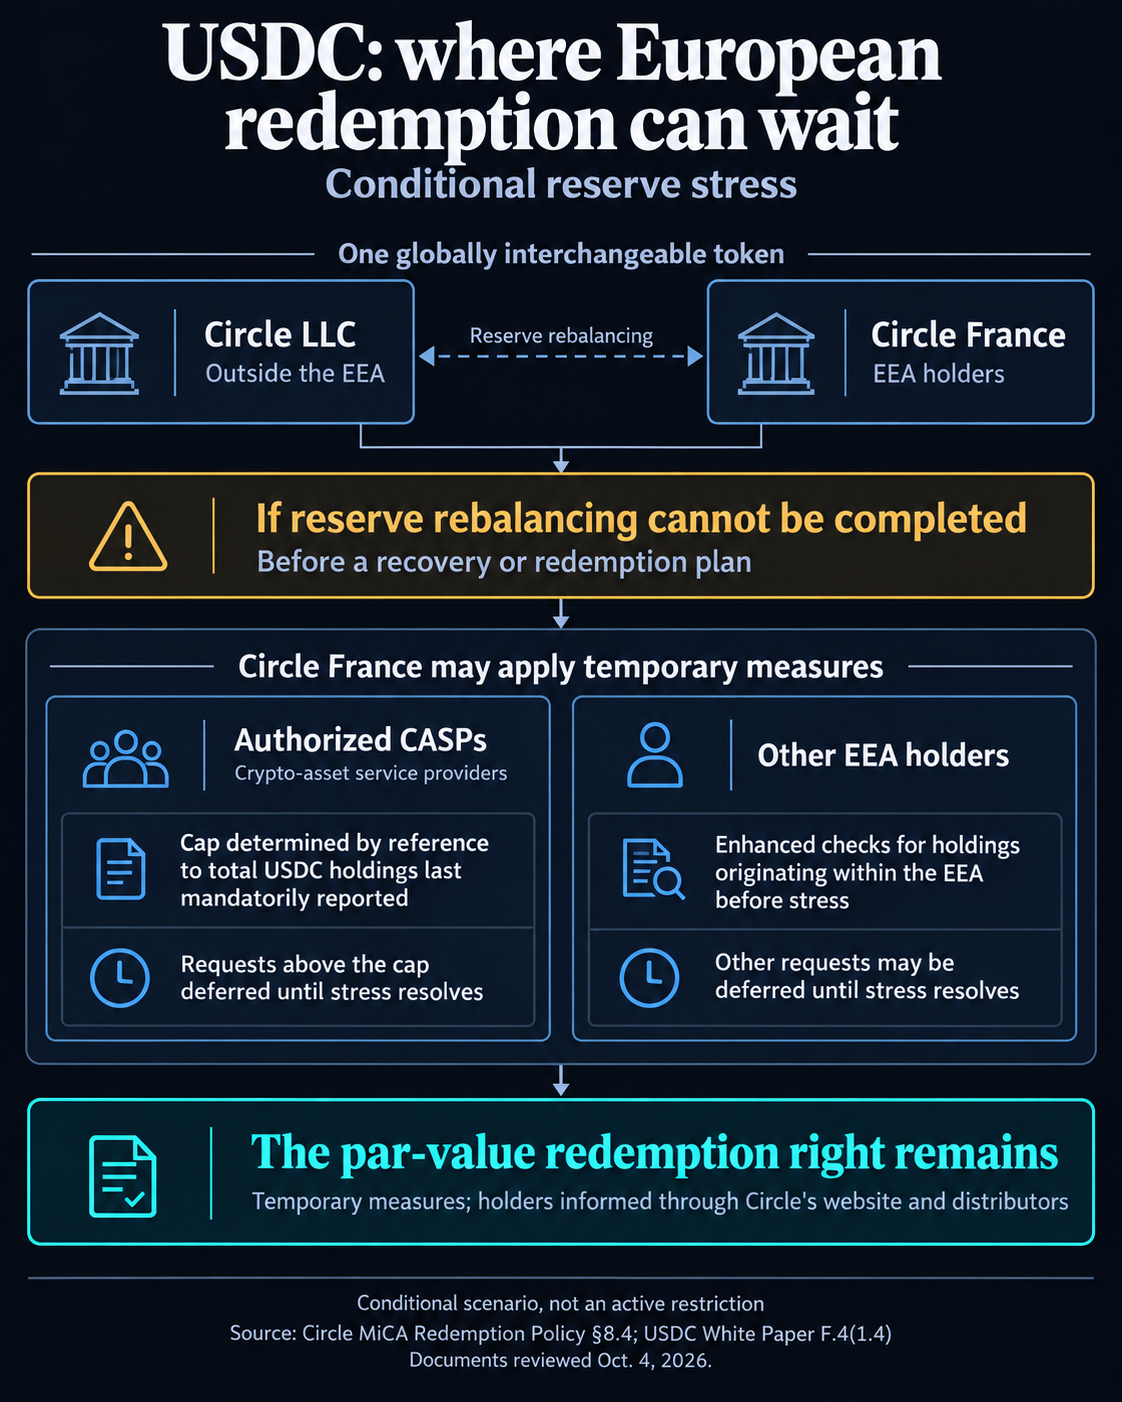
European USDC holders seeking dollars from Circle could have to wait if reserves cannot move between its French and U.S. issuers, even while retaining their claim to a dollar. Circle’s current European redemption policy allows temporary delays during failed reserve rebalancing, exposing a cash-access boundary inside a token that is interchangeable worldwide.
That boundary matters as Circle presses Europe to preserve cross-border co-issuance. Its Oct. 1 response to the European Commission’s MiCA review argues that the structure keeps global stablecoin liquidity within Europe’s regulatory perimeter. The existing terms show what can happen when the reserve transfers supporting that structure cannot be completed.
The controls distinguish authorized crypto service providers from other European Economic Area holders. Providers may face a redemption cap based on previously reported holdings; other holders may face checks establishing that their holdings originated within the EEA before the stress began.
These are contingency provisions. The public documents reviewed do not establish an active reserve-transfer failure or an imposed reserve-stress redemption restriction as of Oct. 4. They nevertheless qualify what European users can assume about access to issuer cash during stress.
Under Circle’s MiCA redemption policy, Circle France, formally Circle Internet Financial Europe SAS, handles redemption for USDC holders established in the EEA. Holders established outside the EEA exercise their redemption rights with Circle Internet Financial, LLC under its own agreement.
The policy says that allocation preserves the right to redemption at par under Article 49 of MiCA. For a holder, however, the amount of the claim and the timing of the payment are separate questions.
Circle’s current EEA Mint terms make the timing distinction explicit. A customer may submit a redemption request at any time, but execution remains subject to legal, regulatory, compliance, prudential, liquidity and operational conditions.
The redemption policy is marked Sept. 15, 2026, and the USDC white paper lists an amendment on that date.
Two ways redemption can be deferred
Section 8.4 of the redemption policy defines a Stress Event as a period when USDC reserves cannot be rebalanced between Circle France and Circle LLC, before a Recovery Plan or Redemption Plan is activated. During that period, Circle can adjust the processing and order of redemption requests, including deferring execution beyond ordinary policy timing.
The USDC white paper, in Section F.4(1.4), sets out the holder-specific measures:
- Authorized crypto-asset service providers: Circle France may impose a temporary maximum redemption limit referenced to the provider’s total USDC holdings as last reported under its mandatory reporting obligation. Requests above it would be deferred until the stress is resolved.
- Other EEA holders: Circle France may temporarily restrict redemption to holdings that enhanced checks clearly identify as originating from USDC holdings within the EEA before stress. Other requests could be deferred until resolution.
Circle describes the adjustments as temporary and non-discriminatory, preserving redemption at par. Its policy provides for informing holders through its website and distributing providers. If rebalancing is not restored, redemption is managed under the recovery or redemption arrangements.
The controls can therefore affect both an intermediary seeking issuer cash and an EEA holder seeking to redeem directly. Being able to receive USDC during stress would not, by itself, establish that a non-provider’s new holdings satisfy the pre-stress EEA condition.
A secondary-market sale could still provide an immediate exit while issuer redemption waits, if a buyer or intermediary is willing to pay. The conditional cash-flow implication is that another party must supply the cash before Circle settles. A buyer could purchase the tokens outright using its own liquidity; no loan would necessarily be involved.
An exchange promising to pay before Circle would depend on its own cash arrangements and available liquidity. The token’s continuing par-value claim does not automatically fund that payment. An intermediary choosing to advance cash would take on the timing gap until it could redeem or otherwise dispose of the tokens.
The reviewed documents identify no named intermediary commitment to provide unrestricted immediate cash-outs under this reserve-stress scenario, nor an available stress-market bid or financing cost. A sale would depend on a willing buyer and the terms offered.
Global backing disclosures answer a different question. Circle’s transparency page describes reserve disclosures and monthly third-party assurance of backing.
The white paper describes a French minimum reserve requirement equal to EEA USDC holdings and an inter-issuer rebalancing procedure. That requirement has to accommodate changes in where tokens are held. The paper expressly identifies the risk that Circle LLC cannot rebalance reserves when holdings and redemption requests shift toward the EEA.
The reserve-transfer test behind Circle’s policy case
Circle’s Oct. 1 response recommends preserving multi-issuance and formalizing safeguards, including dynamic rebalancing between global and EU-specific reserves. It argues that restricting the structure would push stablecoin use toward offshore providers and outside MiCA’s protections.
Europe’s systemic-risk watchdog has advanced a different position. In its 2025 recommendation on third-country multi-issuer stablecoins, the European Systemic Risk Board asked the Commission to interpret the existing MiCA framework as not permitting such schemes. If the Commission considered otherwise, it recommended a dedicated framework with safeguards.
Adopted Sept. 25, 2025, the recommendation also called for assessing barriers to reserve mobility and obtaining evidence that supporting institutions can promptly sell assets, transfer funds across borders and retain access to payment systems.
Circle’s terms show why those operational questions matter to holders. Rebalancing is a safeguard when cash can move to the issuer facing redemption requests. When it cannot, temporary restrictions can shift the wait onto service providers and other EEA holders, even while the par-value right continues.
The practical tests are therefore reserve-transfer readiness, the treatment of holders’ requests and any intermediary’s actual cash-out undertaking. Circle’s policy case depends on keeping global liquidity accessible in Europe; its current redemption terms acknowledge the conditions under which European access to that liquidity could slow.
The post Circle can delay European USDC redemptions if reserves cannot cross borders appeared first on CryptoSlate.
The US Bureau of Labor Statistics (BLS) revised July and August payroll gains down by 60,000 on Oct. 2, weakening the labor-based case for another Federal Reserve hike and potentially easing one policy pressure on Bitcoin.
The September employment report put payroll growth at 29,000. July’s estimate flipped from 21,000 jobs added to 10,000 lost; August’s fell from 162,000 to 133,000. The 60,000 adjustment revises earlier estimates, rather than identifying new September job losses.
Average hourly earnings for all employees on private nonfarm payrolls rose 0.1% monthly and 3.0% annually, below the 0.3% and 3.1% originally reported for August.
The numbers arrive after the Fed’s Sept. 16 quarter-point hike to a 3.75%–4% target range. Its statement said job gains had kept pace with the workforce and inflation remained elevated. Friday’s release gives policymakers a softer payroll picture than the earlier estimates suggested.
Weak hiring and slower reported wage growth provide less support for tightening policy to restrain labor demand.
Inflation still gives the Fed a reason to consider further tightening. August personal consumption expenditures (PCE) inflation, released Sept. 30, ran at 3.4% annually, or 3.0% excluding food and energy. Both exceeded the Fed’s 2% goal.
For Bitcoin, a softer labor case could reduce the threat of higher discount rates, a potential pressure on speculative assets. A February 2023 New York Fed staff study found Bitcoin largely unresponsive to monetary and macroeconomic surprises in an intraday event study.
The separate household survey offered a different picture. Employment rose an estimated 406,000, participation moved from 61.6% to 61.8%, and unemployment edged from 4.1% to 4.2%. The labor force grew by 485,000, allowing employment and unemployment to rise together.
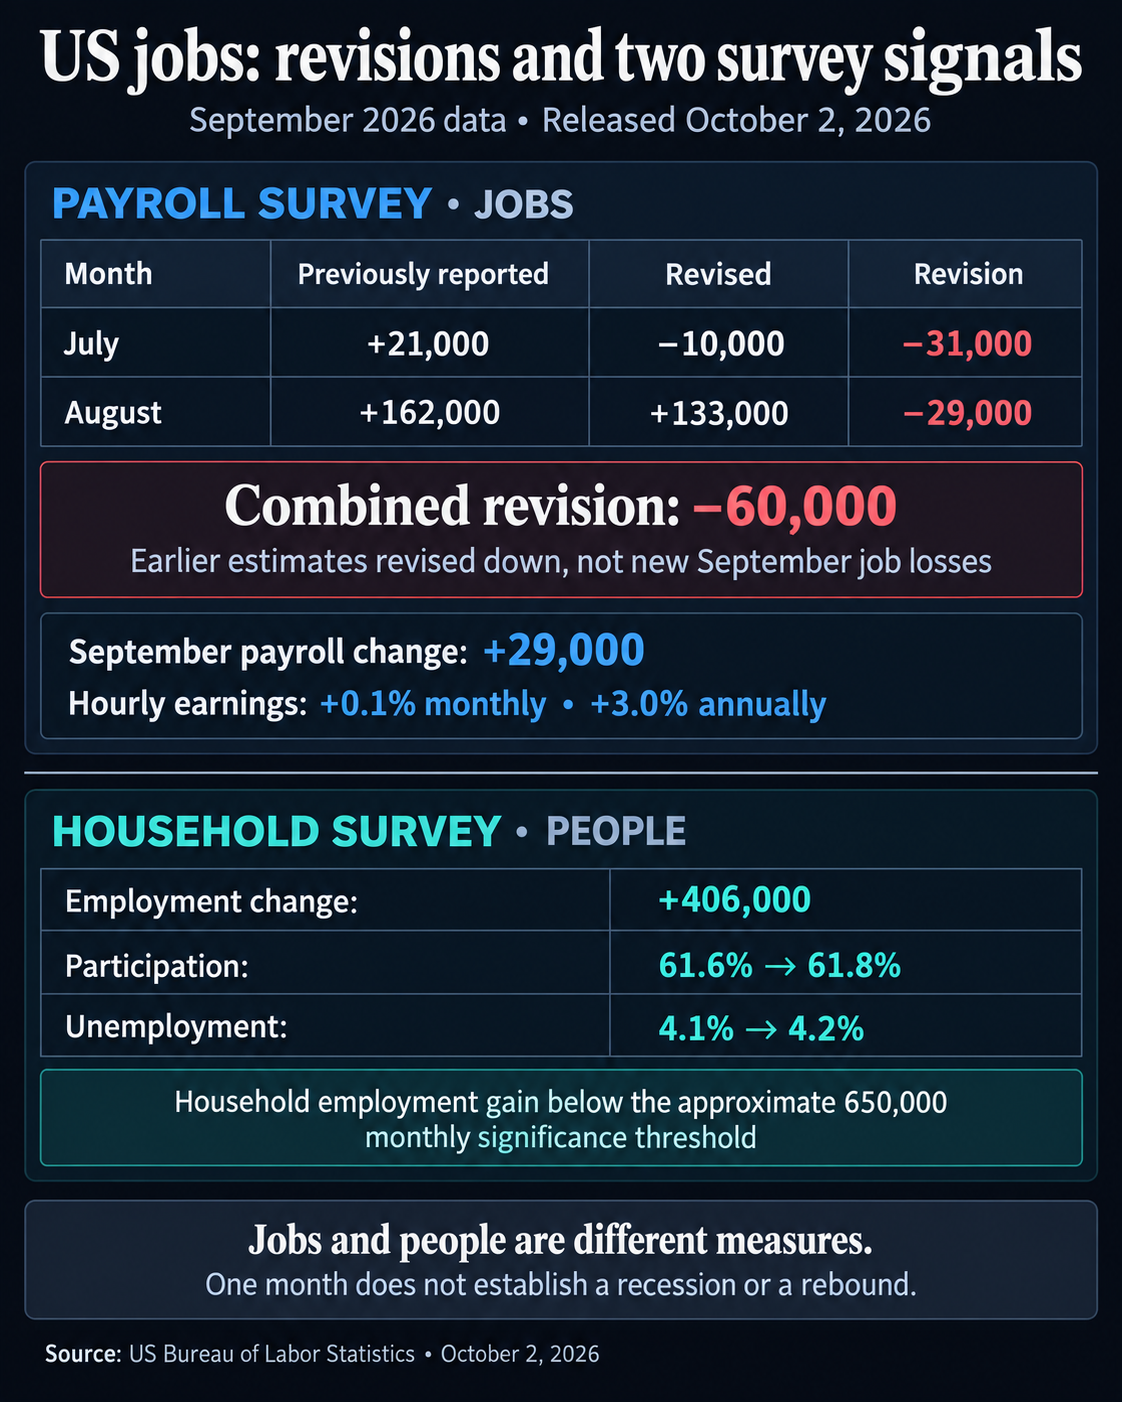
These figures count people, while payrolls count jobs. The household survey also covers workers excluded from payroll data. September’s monthly employment changes were below BLS’s approximate significance thresholds of 650,000 for households and 122,000 for payrolls.
The mixed picture limits both a recession declaration and a claim of a decisive employment rebound. Weaker payrolls offer a reason to question further tightening, while the household figures complicate treating the report as evidence of an employment slump.
Stronger subsequent inflation or hiring would weaken that interpretation. The next jobs release is scheduled for Nov. 6.
The post US jobs revision turns July’s 21,000 gain into a 10,000 loss appeared first on CryptoSlate.
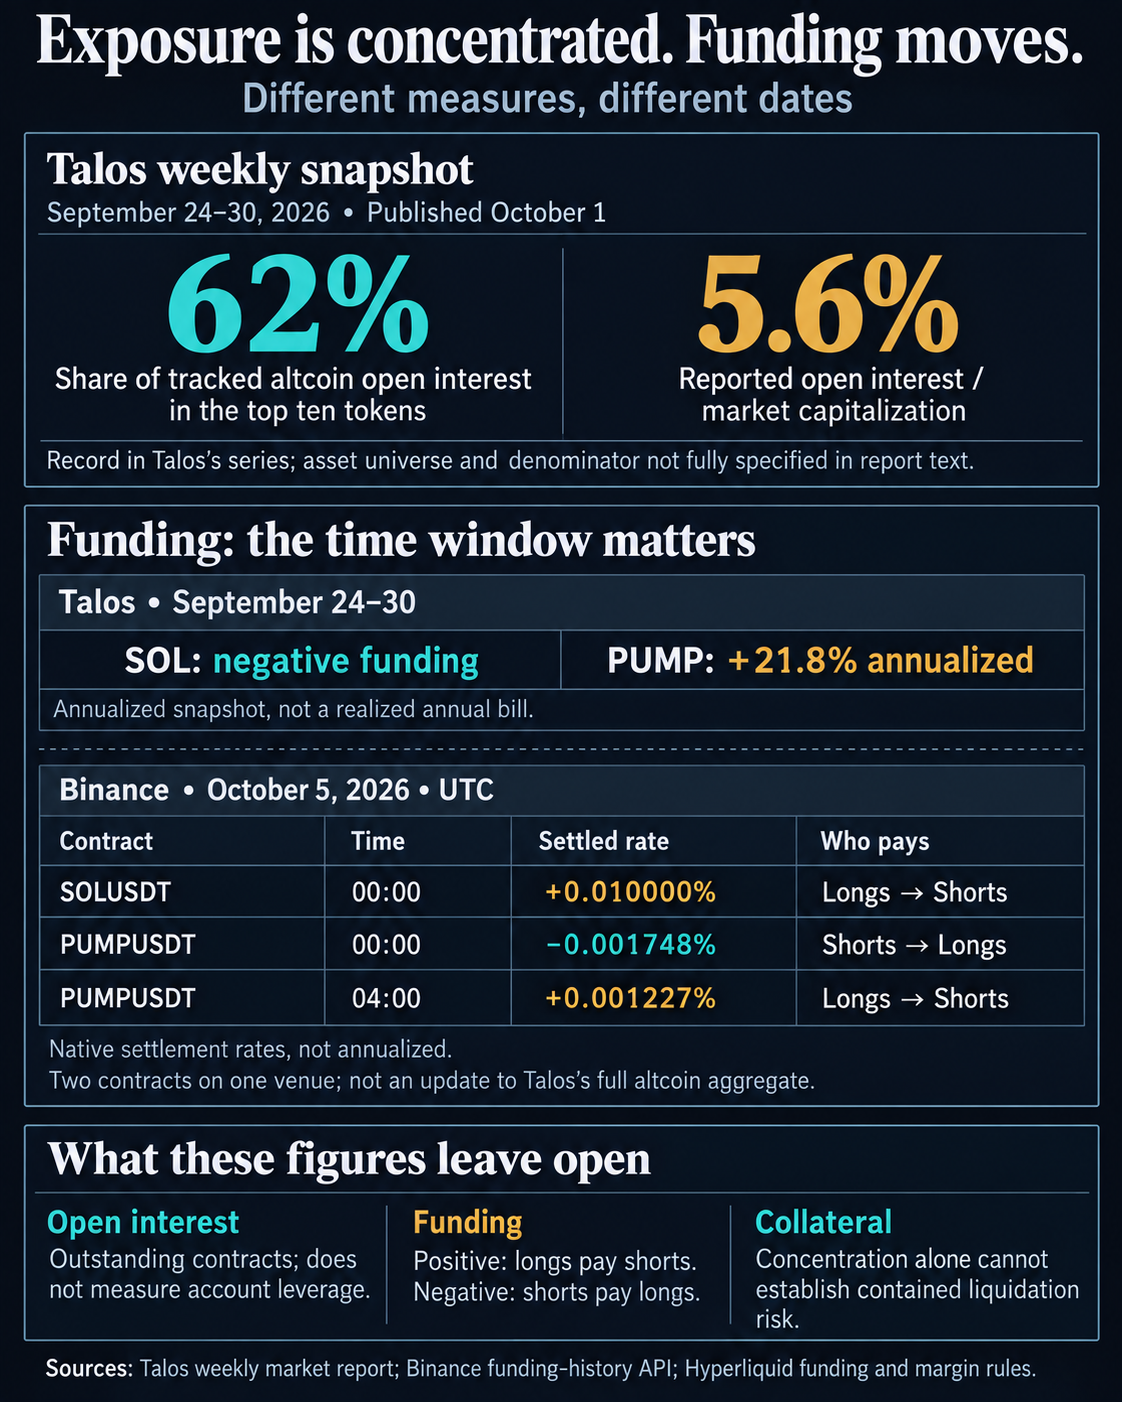
Ten tokens accounted for 62% of outstanding altcoin futures exposure, known as open interest, in Talos’s weekly market report covering September 24–30, 2026. That concentrated exposure came with different financing burdens: the report put SOL funding below zero while PUMP funding reached +21.8% annualized.
Published October 1, the market report also put altcoin open interest relative to market capitalization at 5.6%, a record in Talos’s series. For investors entering the October trading week, those numbers identify a concentrated derivatives footprint, while later Binance settlements show how quickly the cost of holding a particular contract can change.
Funding pressure can change within hours
Perpetual futures use funding payments to help keep the contract price aligned with the underlying market. As Hyperliquid’s funding mechanics explain, positive rates transfer money from long holders to short holders. Negative rates reverse that direction. A trader’s financing burden therefore depends on the contract, side and funding interval, even when two tokens both have substantial open interest.
The October 5 refresh covers two Binance contracts, rather than a matching update to Talos’s altcoin aggregate. Their settled payment records, retrieved shortly after 04:20 UTC, show positive SOL funding and a PUMP rate that changed sign within four hours.
| Binance contract | Settlement, Oct. 5, 2026 (UTC) | Native settled funding rate | Paying side |
|---|---|---|---|
| SOLUSDT | 00:00 | +0.010000% | Longs pay shorts |
| PUMPUSDT | 00:00 | -0.001748% | Shorts pay longs |
| PUMPUSDT | 04:00 | +0.001227% | Longs pay shorts |
Sources: Binance’s SOL settlements and PUMP settlements. Rates are native settlement percentages, not annualized rates.
SOL’s preceding observed payment, at 16:00 UTC on October 4, was also +0.010000%, eight hours before the midnight payment. PUMP’s two observed payments were four hours apart.
PUMP’s midnight payment charged shorts; its 04:00 payment charged longs. The change illustrates a financing burden that can reverse while the underlying contract remains the same. SOL’s positive midnight payment also differs from the negative funding described in the earlier Talos snapshot.
Annualization puts periodic rates on a common comparison basis, rather than locking in a year’s costs. Coin Metrics’ per-market documentation distinguishes the period a rate applies to from the input window used to calculate it. Hyperliquid settles hourly while dividing an eight-hour formula into hourly payments.
Coin Metrics’ aggregate methodology weights normalized market rates by dollar open interest and scales longer aggregate periods linearly. Its daily series is a boundary sample rather than a daily average. Those definitions describe available metrics; they do not identify the precise series or averaging window behind Talos’s +21.8% PUMP figure.
What the concentration figures measure
Talos named SOL, XRP, HYPE and ZEC among the largest markets in its top-ten group. The 62% share identifies where exposure sat within its tracked altcoin bucket. Establishing whether those tokens carried unusually large derivatives positions for their size would require comparing their exposure share with their share of market value, using the same assets and timestamp.
The report’s text leaves the historical starting date and precise ETH treatment unspecified. These limits keep the record tied to Talos’s series and prevent extending the 62% share into a claim of disproportionate crowding.
The 5.6% ratio answers a separate question: how large outstanding exposure was relative to the value of the covered tokens. Coin Metrics’ capitalization definitions distinguish the value of current issued supply, estimated circulating supply and free-float supply. Those measures can assign different values to the same token, especially when supply sits in escrow or with strategic holders. The report’s text does not identify which convention supplies its denominator, so the 5.6% should remain a Talos-reported ratio rather than a universal measure of altcoin leverage.
Under the standard open-interest definition, every outstanding contract has a buyer and a seller, with one side counted. Open interest therefore describes unresolved contractual exposure.
Dollar values add another distinction. Binance’s market-data fields separate outstanding quantities from their value. A higher dollar figure can reflect changes in prices, quantities or both. For a single linear contract with a matched price basis and unchanged quantity and supply definition, a price move can cancel out in the ratio. Across a basket, relative prices and constituents still matter.
The refreshed exposure observations are similarly specific. Binance reported approximately $1.045 billion of SOLUSDT open-interest value at 04:20 UTC on October 5. Its PUMPUSDT observation was approximately $142.876 million at 04:15 UTC.
Concentrated positions can share collateral
Talos interpreted its exposure concentration as limiting risk to relatively few tokens. Its September 29 sector analysis also characterized the rally as higher quality.
Hyperliquid’s margin rules illustrate why the distinction matters. Cross margin shares collateral across eligible positions; isolated margin confines collateral to a position. With shared collateral, losses in one holding can affect the resources supporting another. The scope of that sharing depends on the account mode and markets involved.
Its liquidation rules trigger action when account equity falls below maintenance requirements. The venue initially attempts to close positions through the order book, with a backstop available under specified conditions. Funding payments and losses on other cross-margin positions can affect an account’s actual liquidation conditions.
An exposure share cannot reveal those account balances, liquidation distances or available book depth. It consequently cannot establish either that a cascade is inevitable or that risk remains contained within the tokens with the largest open interest.
CryptoSlate’s earlier coverage of ETF concentration and altcoin spot turnover examined other dimensions of the rotation. Fund flows describe allocations, turnover describes trading activity, open interest describes outstanding contracts, and funding describes periodic financing conditions.
For investors assessing this market, the next useful evidence is a matched comparison of exposure and token value, a sequence of settled funding payments, and the collateral and liquidity conditions behind the positions. The reported 62% concentration identifies a starting point for that assessment. The October 5 settlements show how quickly the financing burden at that starting point can move.
The post Ten tokens held 62% of altcoin futures exposure, but shared collateral can put other positions at risk appeared first on CryptoSlate.
Circle is urging the European Union to open its Markets in Crypto-Assets Regulation (MiCA) to foreign-regulated stablecoins and loosen reserve rules that constrain global issuers.
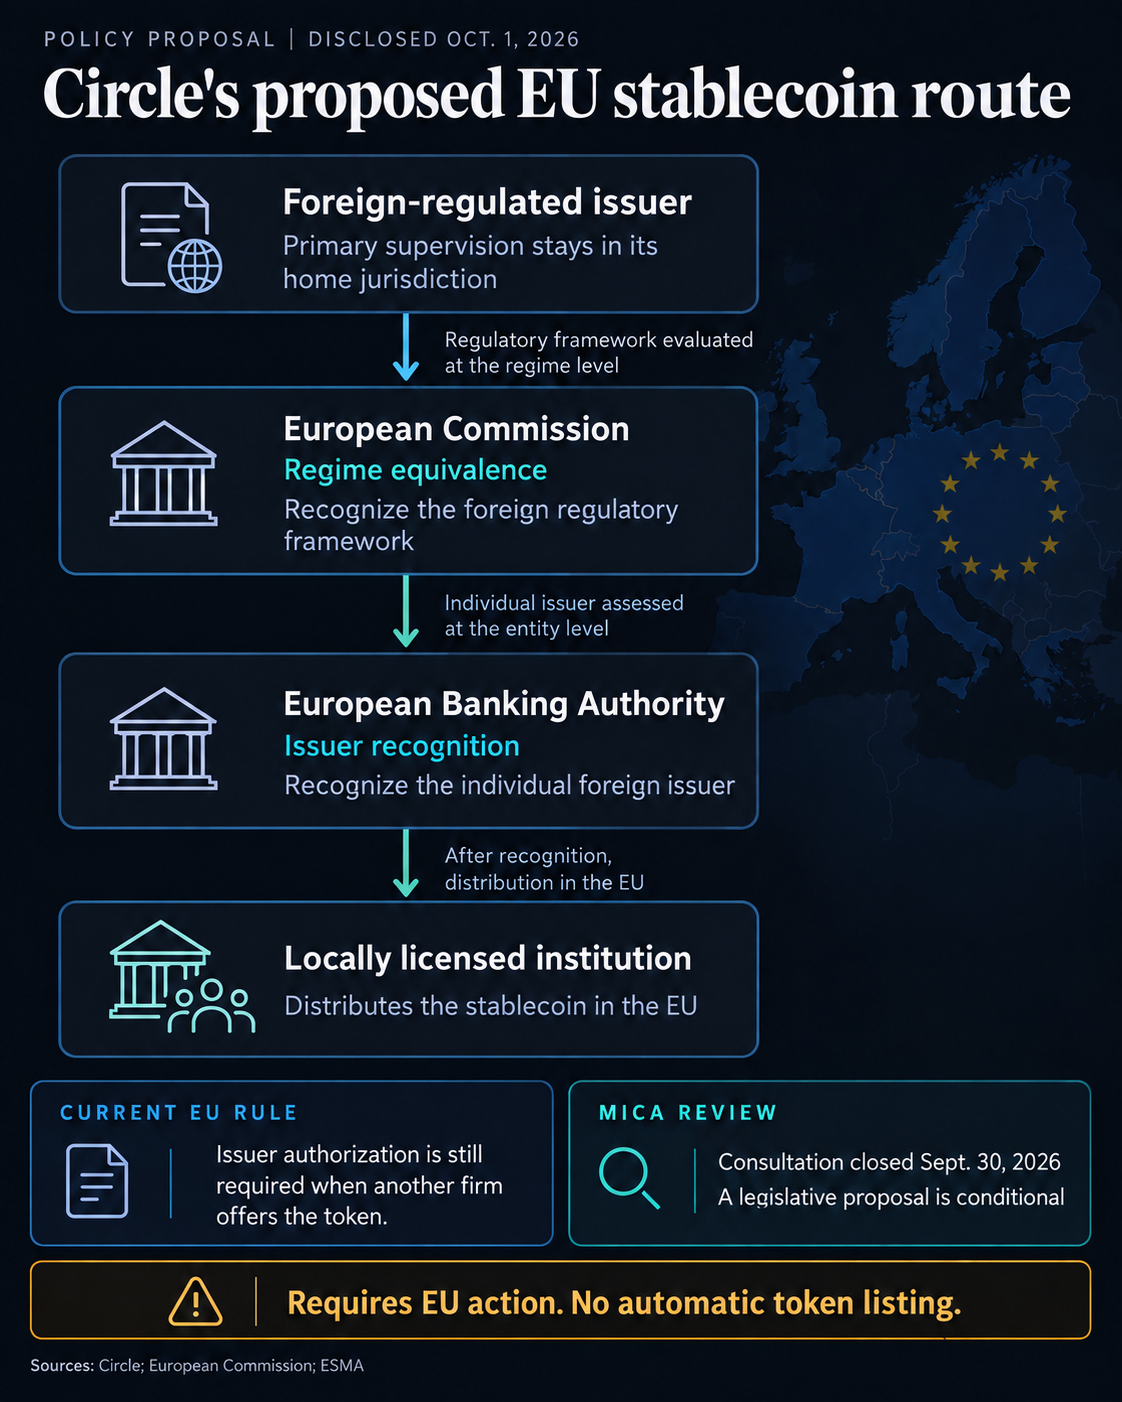
The USDC issuer proposed a recognition regime that could let qualifying overseas stablecoin companies distribute tokens in Europe without becoming fully authorized EU issuers, as part of a broader push to bring more of the global market inside the bloc’s regulatory perimeter.
Circle said only three of the world’s 25 largest stablecoins by market value, USDC, USDG and EURC, are currently regulated under MiCA, despite roughly 30 e-money tokens securing authorization since the framework took effect.
Under its proposal, the European Commission would first determine whether a foreign jurisdiction’s regulatory regime is equivalent to EU standards. The European Banking Authority (EBA) would then recognize individual issuers, which would remain primarily supervised in their home countries while distributing tokens through locally licensed institutions.
That would create an alternative to current MiCA rules, which generally require e-money token issuers seeking public distribution or trading in the bloc to obtain EU authorization.
Circle also wants regulators to preserve multi-issuance, where a MiCA-authorized European entity co-issues a globally circulating stablecoin with a foreign-regulated counterpart. The company said restricting that structure risks pushing European users toward offshore platforms and tokens outside MiCA’s protections.
MiCA stablecoin bank reserve rule draws wider opposition
Circle is also challenging a requirement that e-money token issuers keep at least 30% of reserves in commercial-bank deposits, rising to 60% for tokens classified as significant. It wants the requirement replaced with a broader liquidity standard, arguing mandatory deposits increase issuers’ exposure to bank credit and counterparty risk.
That argument echoes criticism previously made by Tether Chief Executive Officer Paolo Ardoino, who warned that forcing large stablecoin issuers to place substantial reserves in banks could create systemic vulnerabilities if those institutions failed or could not meet large withdrawals. Ardoino said last month that Tether declined to seek an EU license because of the same requirement.
The overlap is notable because Circle chose to comply with MiCA while Tether kept USDT outside the framework. Both now argue that requiring stablecoin issuers to concentrate liquidity in commercial banks can introduce risks regulators are seeking to contain.
Circle also wants the EU to remove a 35% cap on exposure to a single sovereign and a rule limiting deposits with an individual bank to 1.5% of that lender’s total assets. It said the restrictions can prevent dollar stablecoins from relying heavily on high-quality sovereign securities and force large issuers to spread reserves across dozens of banks.
Yet regulators are considering tighter controls elsewhere. The EBA last month urged the Commission to strengthen MiCA against risks arising from third-country multi-issuer stablecoin structures, warning that reserves, redemptions and other critical functions can sit beyond effective EU supervision.
The Commission’s MiCA review consultation closed Sept. 30, and its findings could lead to legislative amendments. Circle’s recognition proposal therefore offers no immediate route into Europe: foreign issuers remain subject to the existing framework while Brussels decides whether opening MiCA to more global liquidity is worth loosening some of the barriers that kept it out.
The post Circle and Tether find common ground against MiCA’s bank reserve rules appeared first on CryptoSlate.
The US sanctioned two French charities and three individuals after alleging they helped channel cryptocurrency and other funds to Hamas.
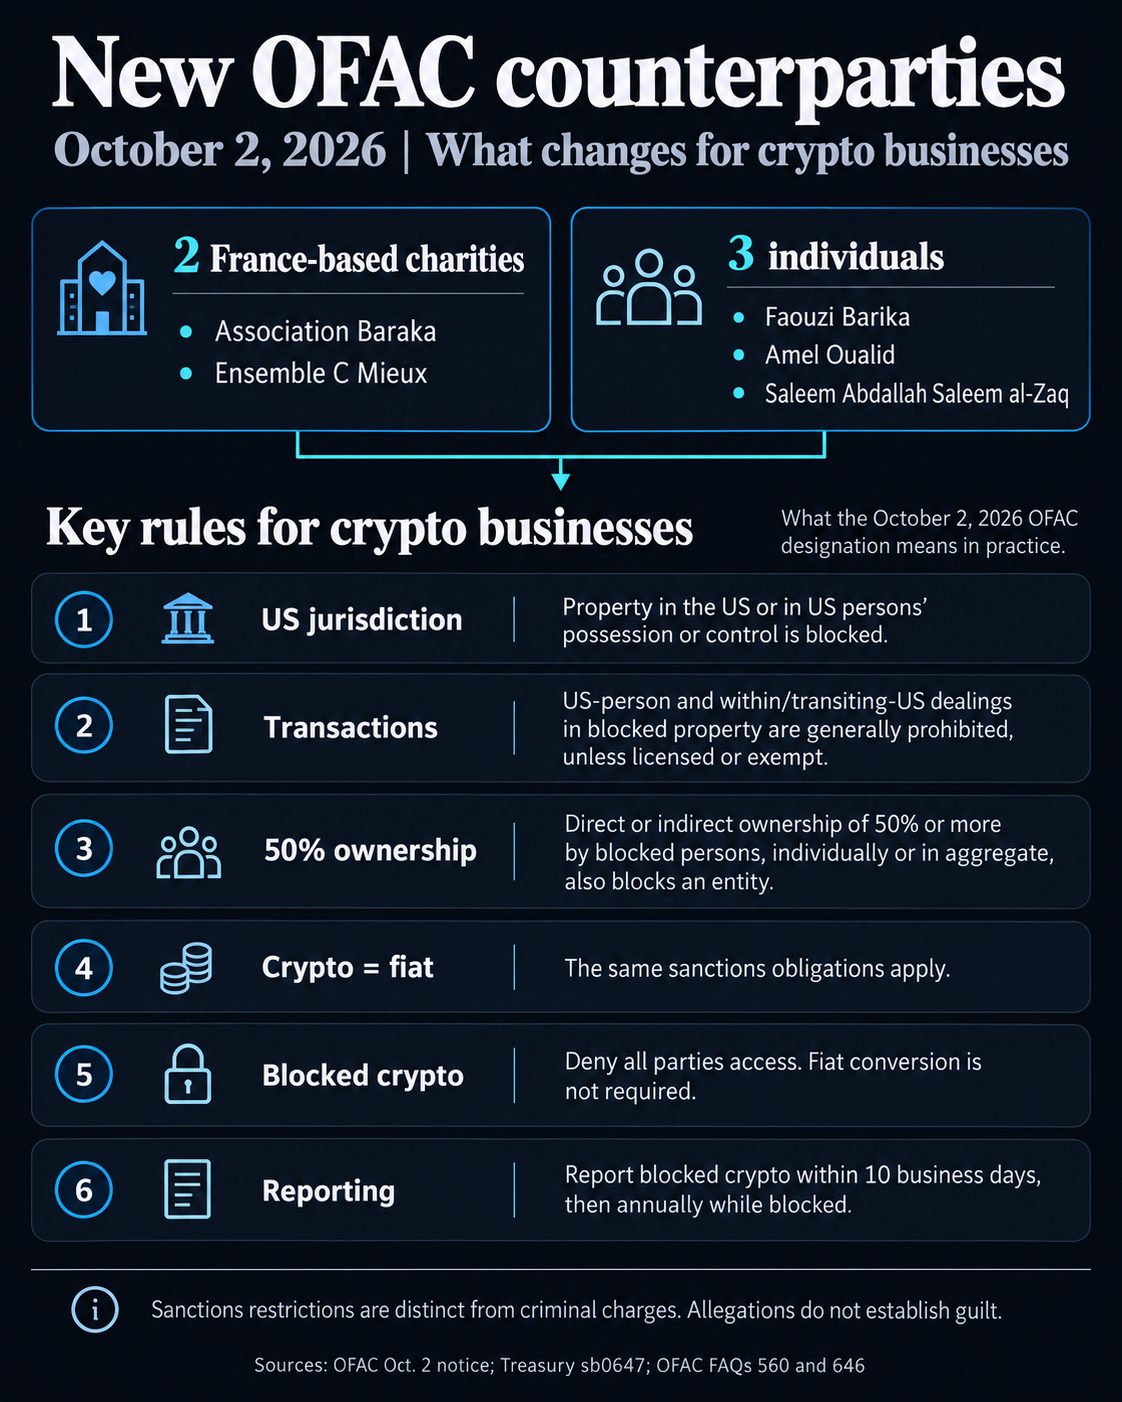
The Treasury Department’s Office of Foreign Assets Control (OFAC) added Association Baraka, Ensemble C Mieux, Faouzi Barika, Amel Oualid and Saleem Abdallah Saleem al-Zaq to its sanctions list on Oct. 2, expanding the roster of counterparties that crypto exchanges and payment firms subject to US rules must screen.
Treasury alleges Barika and Oualid, both based in France, sent hundreds of thousands of dollars in cryptocurrency to al-Zaq, whom the agency described as a Gaza-based deputy battalion commander in Hamas’ military wing. The two fundraisers and associated organizations collected more than $2 million for Hamas between 2020 and 2026, according to Treasury.
The agency did not say that the entire $2 million was transferred using digital assets, distinguishing that broader fundraising figure from the cryptocurrency transactions it specifically attributed to Barika and Oualid.
The designations extend US efforts to disrupt Hamas financing networks at a time when authorities are increasingly tracing digital-asset transfers alongside traditional banking and cash-based channels. They also immediately bring the sanctioned parties within OFAC’s existing restrictions governing property held by US persons or moving through US jurisdiction.
Crypto firms face new screening obligations
US exchanges, custodians and payment processors must block property in which the designated parties have an interest when that property comes within their possession or control, unless an OFAC license or exemption applies.
That requirement also reaches companies owned 50% or more, directly or indirectly, by one or more blocked persons, meaning compliance teams may need to identify entities beyond the five names published by Treasury.
OFAC treats digital assets under the same sanctions framework as fiat currency and other property. A US-regulated crypto company that identifies assets belonging to a blocked person must deny access to them and report the property to the agency within 10 business days. Blocked assets are also subject to annual reporting requirements.
The agency does not require firms to convert frozen cryptocurrency into dollars, allowing custodians to keep the assets in their existing form while preventing sanctioned parties from accessing or transferring them.
The sanctions may also have consequences outside the US. Treasury warned that foreign financial institutions could face secondary sanctions for knowingly facilitating significant transactions for parties designated under the relevant authority, raising the potential compliance exposure for offshore exchanges and other intermediaries servicing the network.
That provision does not amount to a worldwide freeze on every blockchain transaction connected to the sanctioned parties. Enforcement depends on jurisdiction, ownership, the involvement of blocked property and, in some cases, the significance and knowledge surrounding a transaction.
The next test for crypto firms will be whether US authorities publish or identify additional wallet addresses, intermediaries or entities tied to the sanctioned network. Any such disclosures could broaden the screening burden beyond the names added this week and force exchanges to reassess historical exposure to the alleged fundraising operation.
The post US expands Hamas sanctions after tracing crypto transfers from France appeared first on CryptoSlate.
CryptoTicker.io
A paper wallet is a sheet of paper with a single private key and the matching bitcoin address printed on it. For a few years that counted as the safest way to store coins, because the key touched no device and no network. Today developers and wallet makers advise against this form of storage, and not because of the idea behind it but because of the many points at which it goes wrong in practice. The Bitcoin Wiki lists it as an obsolete and insecure method that was widespread between 2011 and 2016.
This article explains what is actually written on such a sheet, which six weak points the storage method has, and how to wind up an existing paper wallet today without losing coins along the way. Where your key is best kept, if not on paper, is covered in the second half.
What a paper wallet is: a printed key pair with no wallet functions
The name is misleading. A wallet in the usual sense is a program that manages keys, knows the balance and builds transfers. A paper wallet can do none of that. It carries two strings of characters: the address someone can send bitcoin to, and the private key with which those coins can be spent again. Usually both also appear on the sheet as a QR code, so that they do not have to be typed out.
A private key is simply a very large random number. Anyone who knows it can dispose of the coins at the matching address, with no password, no account and no further question asked. That is precisely why everything about this form of storage comes down to how the key came into being and who set eyes on it along the way.
The difference from a seed phrase
A seed phrase is a sequence of twelve or twenty-four words from which a wallet derives as many keys as it needs, rather than just a single one. The standard behind it is called BIP-39, the derivation itself BIP-32. You copy the words down by hand, no printer is involved, and the wallet generates a fresh address for every incoming payment. That difference sounds technical, but it explains almost all the problems below.
Why paper wallets were popular between 2011 and 2016
In those years there were no widely available hardware devices and no established word list. Anyone wanting to put coins away for the long term had the choice between a program file on a computer that was attached to the network and a printout that went into the safe. The printout looked like the lesser evil, and websites that generated such key pairs in the browser made it convenient.
On top of that came the physical variant: metal coins with a private key stuck under a hologram. It was for exactly this purpose that BIP-38 was created in 2012, a standard that encrypts a private key with a passphrase so that a printed sheet is not immediately loot if somebody finds it. That the same standard today carries, in its official comment line, the note that implementing it is unanimously discouraged says a great deal about the road the industry has travelled since.
The printer as a weak point: spooled jobs, the network and shared devices
To get a key pair onto paper, it has to go through a printer. Many office machines have a built-in hard drive and file every print job there. Anyone who later reads out that device finds the key in plain text. Machines in offices, schools or copy shops log jobs centrally as well, and with a wireless connection the job travels unencrypted through the air if the network is poorly secured.
This gap cannot be configured away, it belongs to the method. A seed phrase avoids it entirely, because the words appear on the device that generated them and travel from there onto paper or metal by hand. What such a record should look like is set out in our guide to storing a seed phrase safely.
One key, one address: address reuse and the trail in the blockchain
A paper wallet has exactly one address. Anyone using it more than once collects every payment in one place, and because every transfer stands publicly in the blockchain, any observer can read off the entire holding and the whole payment history at that address. With a modern wallet every incoming payment gets a new address, and the connection between the payments is considerably harder for outsiders to establish.
There is also a practical point that is often overlooked: the sheet itself does not know whether any money has arrived at all. To see the balance you have to look the address up with a blockchain explorer, that is, with an outside service that can remember who took an interest in which address.
The change problem: after a partial payment the remainder sits on a change address
This is where owners most often lose money. A bitcoin transfer always spends the entire amount sitting at an address and sends the part that is not needed back to a new address as change. This change address belongs to the software that built the transfer, not to the paper.
So anyone who imports the key into a wallet, sends a partial amount and then believes the remainder is still sitting on the sheet is mistaken. The remainder sits in the software. If that software is lost and the paper was kept as a supposed backup, the change is no longer reachable.
Importing and sweeping are two different things
When importing, a wallet takes on the foreign key and manages it alongside its own. The key remains a one-off, though, and is not covered by that wallet's seed phrase. Anyone who destroys the paper afterwards and later restores the wallet from its words no longer has the imported key. When sweeping, by contrast, the wallet transfers the entire amount from the old key to an address of its own that belongs to the seed phrase. After that the paper is worthless, and that is precisely the aim.
Misread characters, water damage and QR codes: weak error correction on paper
A private key is usually printed in small type. A capital B and an eight, a one and a lower-case L look almost the same in many typefaces, and a single character read wrongly makes the key useless. The format does contain a checksum that reports the error, but no tool for lay users that corrects it.
QR codes are not built for that either. The patterns tolerate a little dirt, but water, heavy creasing and folding make them unreadable. A word list is far more forgiving at this point: words remain legible even in poor handwriting, and the list is chosen so that the first four letters identify a word unambiguously.
A third point concerns the formats themselves. Whether a wallet understands an old key depends on the notation it was printed in. There have been cases in which coins were initially stuck after a format change. How differently manufacturers handle standards is shown in our article on restoring a seed phrase with a different manufacturer.
BIP-38 and passphrase encryption: a standard its own developers advise against
BIP-38 was the attempt to fix the paper's biggest weakness. The private key is encrypted with a passphrase and printed as a string of 58 characters, protected by a procedure that makes brute-force attacks expensive. Anyone finding the sheet can do nothing with it without the passphrase.
The price for that is a second secret that can be lost just as easily as the first, and a dependency on software that still handles the format. The BIP-38 specification states in the header of its comments that implementing it is unanimously discouraged. A technical community can hardly bury a procedure of its own making more clearly than that.
Sweep instead of import: winding up an existing paper wallet safely
If there is still a printed sheet in your drawer, the cleanest route is to move the entire amount into a modern wallet and to treat the paper afterwards as done with. For that you need a wallet that can sweep, and a little calm.
- Set the destination wallet up completely and back up its seed phrase before you even pick up the old key. Which programs are candidates for that is set out in our comparison of software wallets.
- Look at the holding of the old address in a blockchain explorer, so that you know which amount has to arrive.
- In the new wallet, expressly choose the function for sweeping, not the one for importing, and enter the private key from the sheet.
- Wait for the transfer to be confirmed and make sure the old address is empty afterwards and the amount, less the network fee, is in the new wallet.
- Destroy the sheet only once that reconciliation adds up. As long as something is still sitting at the old address, the paper is the only way in.
What matters is the place where you enter the key. Never type it on someone else's computer, and never on a website that offers to build the transfer for you. From the moment of entry the key is known on that device, which is why the address counts as permanently burned afterwards.
Seed phrase and hardware wallet: today's alternatives to paper storage
The job the paper was meant to do is handled today by two building blocks. A hardware device generates and keeps the keys without ever releasing them, and signs transfers on the device itself. The seed phrase serves as the backup should the device break, be lost or be replaced. The two together keep the key away from every printer and every browser.
The difference between a permanently connected wallet on a phone and separated storage remains in place, and for the choice it matters more than the brand of the device. How the two forms differ is something we took apart in our article on hot wallets and cold wallets. Which devices are available in Europe and what they cost is shown by our hardware wallet comparison.
Tax and proof in Germany: what applies when winding up an old paper wallet
A sweep is not a sale. You are transferring coins between two addresses that both belong to you, and no change of ownership takes place. For the holding period under section 23 of the Income Tax Act, what therefore still counts is the day on which you originally acquired the coins, not the day of the transfer. Tax only arises on a sale within a year of acquisition, and gains remain tax-free if the total gain from all private disposal transactions in a calendar year stays below 1,000 euros.
Harder than the legal position, with old holdings, is the proof. Anyone who printed a sheet in 2014 rarely still has the purchase receipts. So collect everything that supports the acquisition date: the time of the first payment to the address from the explorer, old bank statements, confirmation emails from the exchange of the day. Tools that document such holdings on a lasting basis are set out in our comparison of crypto tax tools and portfolio trackers. This section is no substitute for tax advice, and with old holdings carrying large gains a trip to a specialist is worth the money.
When a printed sheet still turns up anyway
The form has not vanished entirely. Some cryptocurrency cash machines print customers without a wallet of their own a receipt carrying a key, and at trade fairs or as gifts, metal coins with a key under the hologram are still going round. For these cases the same rule applies as above: the receipt is a means of transport, not a store. Anyone who receives one moves the amount promptly into a wallet of their own.
A second case is inheritances and house clearances. If such a sheet turns up, a look in the explorer is worth it before it ends up in the waste paper. The reverse also holds: a sheet whose address is empty has no value, even if it once did.
Paper wallet: How to proceed now
- Look at the holding and prepare the destination. See in an explorer whether anything is still sitting at the address, and set the new wallet up beforehand. The candidates are in our comparison of software wallets.
- Wind it up with a sweep. Move the entire amount to an address of your new wallet and destroy the paper only after the reconciliation. For larger amounts the key belongs on a separate device, as the hardware wallet comparison shows.
- Document the acquisition. Record the date, the number of coins and where they came from, while you can still gather the receipts. The tools for that are in the comparison of crypto tax tools.
(As of October 4, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
XRP is trading at $1.51 or €1.35 on Monday morning, 0.7 percent above the previous day. This week's pacemaker, though, is not in the chart but in the protocol: three voting deadlines are running out on the XRP Ledger, and they go live one after another on Thursday evening and Friday afternoon. We did not take the deadlines from a press release but read them directly from the chain's ledger. Between the first and the last activation lie 17 hours and 21 minutes.
What that means for you depends on where your coins are kept. Anyone holding XRP on a trading platform may run into brief maintenance stops in these two windows. Anyone holding their own coins needs wallet software that knows the new rules. And anyone planning to sell should know beforehand how the German holding period counts to the day.
XRP price at $1.51: the ledger is counting down three deadlines
The price stands at $1.51 on Monday morning, €1.35 in euros. Over 24 hours that is a gain of 0.74 percent in dollars and 1.22 percent in euros, over a week 2.95 percent and over 30 days 7.84 percent. Market capitalisation comes to around $95.4 billion, and $1.65 billion changed hands in trading over the most recent day. All figures in this paragraph are based on market data from CoinGecko.
Among the six large names that puts XRP in the middle of the field. Bitcoin managed 3.94 percent over the week, Dogecoin 4.58 percent, Ethereum 2.86 percent and Solana 2.52 percent. XRP remains just under 59 percent away from its record of $3.65 set on July 17, 2025. So there is no exceptional move this week that would justify any haste, just a calendar of dates.
Three amendments in 17 hours: the deadlines sit in the mainnet, not in a press release
An amendment is a protocol change to the XRP Ledger that the chain's validators vote on and that only takes effect after an uninterrupted majority of 14 days. The validated ledger carries its own entry for this, and that entry can be queried from any public node.
That is exactly what we did on Monday morning. In the ledger with sequence number 107,446,929, 94 amendments were active, and three more were sitting in the waiting window with a majority:
- PermissionDelegationV1_1, majority since September 24, activation on Thursday, October 8, 11:25 p.m. German time (9:25 p.m. UTC).
- A second entry with the identifier 14A2B45E, majority since September 25, activation on Friday, October 9, 4:12 p.m. Consistent trade reports list it as a security fix, fixBatchV1_2; at the time of our query it was not yet listed in the developers' public amendment list.
- BatchV1_1, majority since September 25, activation on Friday, October 9, 4:46 p.m.
We matched the first and the third identifier against the public amendment list of the XRP Ledger developers, where the same checksums appear. That Permission Delegation is not due on October 5, as initially reported, but only on October 8, is something we had already recorded in our report on the activation in the XRP Ledger; Monday's measurement confirms it to the minute.
Permission Delegation explained: one account hands individual rights to another
Permission Delegation means that an account on the XRP Ledger can assign individual powers to another account without handing over the private key. Until now the chain mainly knew the coarse grid of full access or no access at all.
For private investors that changes little at first. It becomes interesting for custodians, payment service providers and companies that run accounts under dual control: an accounting department can then initiate payments without at the same time being able to change trust lines or re-key the account. That separation is exactly what auditors demand of regulated institutions, and it is why the function counts in the industry as a building block for institutional use.
The back story belongs with the assessment. An initial version of the function was already contained in an earlier release of the node software and was switched off again after a reported bug: one account could charge transaction fees to any other account and drain it that way. The developers documented the finding in a separate disclosure report; the version now coming up therefore carries the suffix V1_1.
Batch and the correction: both functions had been switched off once before
Batch groups several transactions together so that they apply together or fail together. For trading applications that is the difference between a clean swap and a half-executed operation that has to be cleaned up. This amendment too ran once already and was deactivated again after a bug, before it came back as BatchV1_1.
Two of this week's three changes are therefore repairs of the project's own mistakes, and the third is explicitly a security fix to the batch procedure. That is no cause for concern, because public bug handling is the desired behaviour in protocols. It is, however, a good reason to look at the week soberly: technology is being brought up to date here, no product is being launched.
The XRP Ledger's two-week rule: a supermajority, 14 days in a row
An amendment needs the approval of at least 80 percent of the trusted validators, and for two weeks without interruption. If approval drops below the threshold in between, the count starts again from the beginning. That is why the three dates above are not a guarantee but a projection from the current state of the ledger.
How real that caveat is BatchV1_1 shows itself. Activation had, according to industry reports, already been expected for September, then support slipped below the necessary threshold, and the counter jumped to October 9. So anyone tying a selling decision to an exact date is building on a value that can still shift until Thursday.
Amendment and the XRP price: the billion from escrow moved almost nothing on October 1
The obvious question is whether such dates feed through to the price at all. For XRP there is a fresh test case, and it is only four days old: on October 1 one billion XRP was released from the monthly escrow plan, which we covered in our analysis of the escrow release.
We recalculated the daily closing prices around that event: $1.4901 on September 30, $1.4896 on October 1, $1.4941 on October 2. The release day therefore cost 0.03 percent, and that is less than the usual swing of a quiet trading hour. An announced event with a known date is in the price before it happens.
For the protocol change the same logic applies with one limitation: announced technology rarely moves the price, a botched changeover does. So the sensible way to handle these two days is not a bet on a direction but the question of whether your access to the market works during these hours. If you are planning to switch trading venue anyway, it is worth looking at fees and deposit routes first in the crypto exchange comparison.
Software version before October 9: node release, maintenance windows and the amendment blocked state
A node that does not know an activated protocol change stops following the network. In the jargon this state is called amendment blocked: the software keeps running but no longer delivers reliable data and no longer accepts transactions. That is precisely why trading venues and wallet providers announce maintenance windows ahead of such dates.
Our query on Monday morning went to a public node of the XRPL cluster. It reported software version 3.4.1, 200 connected peers and no blocked state. The infrastructure is therefore prepared; the open question is whether every individual provider has followed suit.
In practice that means for you: do not schedule XRP deposits and withdrawals for Thursday evening after 11:25 p.m. or Friday afternoon between 4 p.m. and 5 p.m. of all times. Your provider's status page will tell you whether a maintenance window has been set. And if you are considering moving to a provider under German supervision: since the end of the national transition period every service provider in the EU needs an authorisation as a crypto-asset service provider under the MiCA regulation. Whether your provider holds one is listed in BaFin's company database.
Self-custody for XRP: account reserve 1 XRP, object reserve 0.2 XRP, network fee 0.00001 XRP
Anyone moving their coins off the exchange this week meets a peculiarity on the XRP Ledger that does not exist in this form at Bitcoin or Ethereum: every address has to hold a minimum amount permanently. We queried these values too directly at the node on Monday.
- Account reserve: 1 XRP. This amount stays locked as long as the address exists and corresponds, at the current price, to around $1.51 or €1.35.
- Object reserve: 0.2 XRP. Every additional trust line, every order in the decentralised order book and every further object locks this amount on top.
- Network fee: 0.00001 XRP per transaction, that is, ten drops. It rises at load peaks; the base value was at the bottom end on Monday.
From that follows a rule that first transfers regularly fall foul of: a new XRP address that has never been used cannot receive an amount that is below the account reserve. The first transfer to a fresh address therefore has to be larger than 1 XRP, otherwise the network rejects it. Which device is suitable for that and what it costs is set out in the hardware wallet comparison.
Holding period and the exemption limit: what a sale around October 9 triggers for tax
In Germany, section 23 of the Income Tax Act applies to crypto assets held privately. If you sell XRP within a year of buying, the gain is a private disposal transaction and is taxable at your personal rate. After a year has passed the gain is tax-free, regardless of its size.
Two points are often confused here. First, the exemption limit of 1,000 euros per calendar year: this limit applies to the total of all private disposal transactions, and it is not an allowance. If you are at 1,001 euros of gain, the entire amount is taxable and not just the one euro above it. Second, the ordering: for matching purchases to sales, the first in, first out method generally applies per wallet or account, so the coin bought first counts as the one sold first.
A transfer from the exchange to your own address is not a sale and triggers no tax. Nor does it interrupt the holding period. Even so, you should record the date, the amount and the price of the transfer, because the burden of proving the acquisition rests with you. Anyone with many movements gets through considerably faster with one of the tools from our overview of crypto tax tools than with a spreadsheet of their own.
The range of the past ten days: $1.4846 at the bottom, $1.5681 at the top
For levels without reading the tea leaves, a look at our own daily closing prices of the past ten days is enough. The high is $1.5681 from September 26, the low $1.4846 from October 3. Between them lie 5.6 percent, and the current price of $1.51 sits in the upper third of that range.
On the downside, the October low of $1.4846 is therefore the first line at which it will show whether the recovery of the past two days holds. On the upside, the September high at $1.5681 stands in the way first, and it has capped the market for nine trading days. Both values are observed prices and not a forecast; they say where trading last took place, not where it will take place next.
Anyone looking for an outside assessment will find it at the moment mainly on the supply side: the monthly escrow releases increase the theoretically available stock, while this week's activations change nothing about the circulating amount. A protocol change creates no new coins and burns none. Anyone expecting a price reaction expects it from changed usage, and that shows up at the earliest in the weeks afterwards.
XRP price prediction: How to proceed now
- Test your access before the windows open. Look at your trading venue's status page by Thursday evening and move planned XRP deposits or withdrawals out of the two time windows. If your provider does not inform you, that is an argument for moving to an exchange with clean status communication.
- Sort out custody and the reserve. If you move coins to an address of your own, allow for the account reserve of 1 XRP and send more than that amount to a fresh address. The devices and their costs are in the hardware wallet comparison.
- Look up the holding period before you sell. Use your purchase records to work out which partial holdings have been sitting for more than a year; only there is the gain tax-free. A tool from the tax tool overview pulls the deadlines for you automatically.
(As of October 5, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Anyone still holding unclaimed S tokens from the first two airdrop rounds of Sonic has until October 15, 2026 to act. After that date the amounts that have not been claimed are removed from the contract and are gone for good. The Sonic airdrop therefore has a hard ending, and it is not a deadline anyone can extend: the project has ruled out minting new tokens for these allocations.
The good news for everyone who still has something sitting there: claiming has not cost a penalty since the spring. Holders who claimed in the first few months had to hand back part of their allocation. That window is over, and until the cut-off date the full allocation is available.
32.69 million S sit unclaimed in the airdrop contract
Sonic Labs put the figure out itself: around 32,690,000 S from the Season 1 and Season 2 allocations are still sitting unclaimed in the contract and will be burned on October 15, 2026 if they have not been collected by then. That is what the project's announcement says, and it has been up since the beginning of April. The end point has been fixed for half a year, and hardly any German-language outlet has picked it up so far.
For a sense of scale: at a price of around four cents, 32.69 million S come to roughly 1.19 million euros. Spread across everyone who is eligible, that is often a three-figure sum for the individual holder, sometimes more. So it is worth a quick look, even if the position had long been forgotten.
Until now the matter has shown up here only as a line in the weekly round-up, most recently in the most profitable crypto airdrops of the week. Other distributions that are still running, and their deadlines, are collected in the airdrop overview.
fNFT: the locked position the S tokens are released from
An fNFT is a non-divisible token that represents a locked balance and can only be converted into the actual coin once a lock-up period has expired. That is exactly the form the Sonic airdrop takes: eligible users did not receive the S tokens themselves, but a position they have to unlock.
This is the most common reason why people assume they received nothing. Instead of an S balance, the wallet shows only an inconspicuous entry that looks like nothing without the claim portal. Anyone who took part in Season 1 or Season 2 back then should therefore query their address directly in the project's portal. The token balance in the wallet says nothing about it.
How to tell whether this concerns you
Eligible addresses are the ones that collected points in the two seasons at the time. There is no qualifying after the fact, and no way to buy an entitlement either. Anyone who used several addresses goes through each one separately: the allocation is attached to the address, not to a person or an account.
Season 1 claimable without a penalty since April 18, Season 2 since May 24
The schedule ran in two stages, and both seasons went through it independently. In the first stage a claim was possible, but it cost a penalty on the portion that was still locked. In the second stage the lock-up has run out completely, and the remaining allocation can be claimed without any deduction.
- Season 1: until April 18, 2026 a claim came with a penalty, since April 18, 2026 in full and without a penalty.
- Season 2: until May 24, 2026 a claim came with a penalty, since May 24, 2026 in full and without a penalty.
As things stand today, that means anyone claiming now hands back nothing. The penalty that put so many people off has not been an issue for months. Anyone who deliberately waited back then waited correctly, but now has to see the decision through.
October 15, 2026 closes both claim windows at the same time
Although the two seasons were unlocked at different points in time, they end on the same day. The project names October 15, 2026 as the date without specifying a time of day. Betting on the last day therefore carries an avoidable risk: an hour of uncertainty is enough to lose a position that would have taken a few minutes to claim.
In practice that argues for a buffer of a few days. Network trouble, a forgotten recovery phrase or a hardware wallet that is not to hand right now quickly cost more time than expected.
After the cut-off date any address can trigger the burn in the contract
A burn is the permanent removal of tokens from circulation, usually by a transfer to an address nobody can access. At Sonic this step is built into the contract, and the project describes it explicitly as open: once the date is reached, the burn of the remaining locked amount can be triggered by anyone.
This design is the reason there will be no leniency. There is nobody who could grant an exception, because the process hangs on a condition in the code and not on a decision. A request to support will not change anything after the cut-off date either.
Claiming through the portal and the gas fee on Sonic
The claim runs through the project's airdrop portal at my.soniclabs.com/airdrop. The wallet is connected, the position you are entitled to appears, and the claim is confirmed as an ordinary transaction on the Sonic network. A gas fee is the charge a network levies for executing a transaction; it is payable in the network's own currency and is low on Sonic, but not zero.
From that follows a small detail that is regularly overlooked: a wallet that holds nothing except the locked position cannot pay for the transaction. A small balance of the network currency is needed on the same address before the claim can even start.
The usual stumbling blocks
- The address used to take part back then is a different one from the address in use today.
- The balance for the gas fee is missing on precisely that address.
- The recovery phrase of an old wallet can no longer be found. In that case the position is lost regardless of the deadline.
- Fake claim pages are going round for every well-known deadline. The portal address belongs typed in by hand, never taken from a direct message or a search advert.
- A page that asks for the recovery phrase is a fraud attempt in every case. A genuine claim asks only for a signature in the wallet.
Anyone who wants to hold the claimed tokens for longer is better off not keeping them in the hot wallet the portal was connected to. Which devices are suitable for that and how they differ is set out in the hardware wallet comparison.
Selling instead of claiming: the fNFT order book on PaintSwap
There is a second route, and the project names it itself: the locked positions are tradable. An order book on PaintSwap at airdrop.paintswap.io lets fNFT positions be sold to other participants instead of being claimed.
For the vast majority of holders this is now the worse route. As long as a penalty was looming, selling below value had a logic to it. Since both seasons are fully unlocked, a direct claim delivers the whole amount, while selling the position requires a buyer, a price and a spread. The route remains interesting mainly for holders who, for tax or practical reasons, do not want to come into contact with the tokens at all.
Anyone who wants to sell the claimed S afterwards needs a trading venue that lists the token. Whether a provider is authorised in the EU can be looked up in the company database of BaFin, the German financial supervisor; which venues are an option for European investors in the first place is set out in our crypto exchange comparison.
Tax in Germany: the finance ministry letter separates allocation and consideration
The letter of March 6, 2025 from the German Federal Ministry of Finance deals with airdrops explicitly and distinguishes two cases. If someone is allocated crypto assets without doing anything for them, then on this reading of the administration there is no taxable income at the moment of allocation. If, on the other hand, the recipient has to provide something, such as supplying data or carrying out an action on social networks, other income under section 22 number 3 of the German Income Tax Act comes into consideration.
The letter also records that an element of chance can override the link between the service and the consideration, and that crypto assets are to be recognised at the market price at the time of acquisition. If no market price can be established at that moment, a valuation of zero euros is also possible.
For the Sonic airdrop that means the classification depends on what exactly was required in the two seasons, and that is a question of the individual case. Anyone claiming a larger position settles it with the tax office or a tax adviser rather than relying on a blanket answer. Tools that document inflows and disposals automatically are set side by side in our comparison of crypto tax tools.
Holding period, the exemption limit and the open point on the acquisition date
The holding period under section 23 of the German Income Tax Act is one year for crypto assets held privately; once it has run out a disposal gain remains tax-free, before that it counts as a private disposal transaction, for which an exemption limit of 1,000 euros per calendar year has applied since 2024. If that limit is exceeded, the whole gain is taxable and not just the part above it.
The delicate point in this case is when the period starts. Whether it runs from the original allocation of the locked position or only from the claim of the S tokens cannot be answered across the board and depends on how the individual case is set up. So anyone planning to sell soon after claiming should put exactly that question first, because it decides whether the gain is taxable. What belongs in the records in any case is the date of the claim, the amount claimed and the price on that day.
1.19 million euros against a 158 million market capitalisation: no supply pressure
For context, because the matter is easily mistaken for a price story: the 32.69 million S amount to just under 0.9 percent of the circulating supply and to about four percent of what is traded on a single day. Measured against a market capitalisation of around 158 million US dollars, that is a small figure.
On top of that comes the direction: a burn reduces supply, it does not increase it. Reading looming selling pressure into the date gets the matter the wrong way round. Nor does it work as a price driver, for which the amount is too small. The value of this date lies solely with the people affected, and there it is concrete.
For the price itself, the same applies as to every smaller token: a total loss is possible, and the swings are considerably larger than with the big names. Claiming an allocation is no reason to keep it, and just as little a reason to sell it immediately.
After the claim: self-custody and the trading venue
With the claim, a locked position turns into ordinary tokens on your own address. That shifts the task from the deadline to custody. Anyone holding larger amounts is well advised to separate the wallet used to connect to portals from the wallet the holdings sit in.
MiCA is the EU regulation on markets in crypto assets, which has applied in stages since 2024 and requires providers to hold an authorisation and to meet uniform obligations. For a sale that means, in practical terms: before tokens move to a trading venue, it is worth looking at whether the provider is authorised in the EU and how it holds customer balances.
Sonic airdrop: The key points for your decision
The date is irreversible, the effort is small, and the penalty that used to argue against claiming no longer exists. Anyone with an entitlement from Season 1 or Season 2 should settle the matter in the next few days rather than in the final week.
- Go through the addresses and claim. Query each address separately in the portal, keep a small balance ready for the gas fee and complete the claim before October 15. For custody afterwards, the hardware wallet comparison helps.
- Document the transaction. Record the date, the amount and the price on the day of the claim, and settle the open question on when the holding period begins before you sell. Tools for that are in the comparison of tax tools.
- Only then decide about selling. The trading venue should list the token and be authorised in the EU; an overview is offered by the exchange comparison.
(As of October 5, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Bitpanda has reported a loss of around 14 million euros for the 2025 financial year. A year earlier the same line showed a profit of 61.7 million euros. Revenue actually grew: adjusted revenues climbed from 321 to 371 million euros, an increase of 16 percent. The deficit arises somewhere else in the accounts, and that place is exactly what decides whether the figure concerns you as a customer.
For you as an investor in Germany two things count: which company in the group carries this loss, and whether your balance appears in the same accounts at all. Both can be checked without having to rely on anybody's assessment.
What the 2025 annual accounts say
The accounts belong to Bitpanda GmbH, registered in Vienna, the group's operating trading company. They were published in the official gazette and were picked up independently by several business desks. Der Standard gives the 14 million euro loss after tax and the prior-year profit of 61.7 million euros, while BTC-Echo adds the intermediate lines of the profit and loss account.
The key figures at a glance, 2025 against 2024 in each case:
- Adjusted revenue: 371 million euros against 321 million euros
- Adjusted EBITDA: 13 million euros against 52 million euros
- Operating result: plus 4.1 million euros
- Financial result: minus 18.3 million euros
- Result for the year after tax: around minus 14 million euros against plus 61.7 million euros
- Marketing spend: just under 107 million euros, 56 percent more than the year before
- Employees: 555 against 486
One number stands out: 7.72 billion euros of sales revenue appears in the accounts. That is not the company's earnings but the trading volume passing through it. Anyone buying crypto assets at a broker generates revenue of that size and at the same time a cost of almost the same size. What stays with the house is one line lower as gross profit, and that has fallen from 320.7 to 261.5 million euros.
Adjusted revenue, EBITDA and gross profit are moving apart
Three measures point in different directions in these accounts, and that is the real finding. Adjusted revenue rises, gross profit falls, adjusted EBITDA almost quarters. Adjusted revenue means revenues after deducting directly attributable trading costs; EBITDA is the result before interest, tax, depreciation and amortisation, an intermediate measure meant to show how much the running business throws off.
If adjusted revenue rises by 16 percent and adjusted EBITDA falls from 52 to 13 million euros, then more money came in and considerably more went back out. The company itself explains this as a decision. It told the industry outlet "brutkasten": "We deliberately invested in our expansion and in building out the Bitpanda brand." That reading is consistent with the numbers, because the largest single increase is in marketing.
Why the operating result is positive and the accounts are still in the red
This is the point at which many short reports lose precision. Operationally the company made money in 2025, namely 4.1 million euros. What turned the account negative was the financial result at minus 18.3 million euros. Behind that sit write-downs on holdings and higher interest expenses, items that do not come from the trading business with customers.
For the assessment that means a house whose running business carries itself and whose financial items weigh on the result stands differently from a house whose revenues are collapsing. The numbers describe an expensive year of growth, not a slump in demand. The headcount supports that: 555 people instead of 486, a build-up of a good 14 percent.
There is a discrepancy in the figures you should know about. Individual analyses put the 2024 result at 81 million euros, others at 61.7 million euros. The range is explained by one figure being measured before tax and the other after. We quote it as a range rather than netting it into a single number.
Marketing spend of just under 107 million euros
Marketing spend rose by 56 percent to just under 107 million euros, from around 69 million euros the year before. Measured against adjusted revenue of 371 million euros, almost 29 percent of revenues therefore go into advertising and brand building. For comparison: staff costs sit below that at about 75 million euros.
That is a setting of priorities a customer can see, once they know where to look. It also explains how a house with rising revenue can report a negative result for the year without anything having gone wrong in the trading business. Whether the spending paid off cannot be said from a single set of accounts; that would need the development of customer numbers over several years, and those are not in the reports available.
Which company holds your crypto assets and who supervises it
This is the most important distinction in the whole subject, and short reports routinely pass over it. The loss of 14 million euros appears in the accounts of Bitpanda GmbH in Vienna. That company is supervised by the Austrian financial market authority FMA and received authorisation from it in April 2025 under the EU regulation on markets in crypto assets.
There are further authorised entities within the group. Bitpanda Asset Management GmbH is based in Germany and is supervised by BaFin. Which of these companies is your contractual partner depends on which product you use. You will find that detail in your terms of use and in the legal notice of your account. That is exactly where your check begins, and it takes two minutes.
An authorisation says nothing about balance sheet figures; it binds the house to ongoing duties. That a licence can also bring sanctions with it is shown by a case from the same house: on August 18, 2026, we covered the FMA's first published MiCA penalty against Bitpanda, which concerned a faulty MiCAR white paper.
Segregation of assets: why a loss-making year does not touch your balance
Segregation of assets means a service provider has to hold its customers' crypto assets and money separately from its own assets. The EU regulation on markets in crypto assets requires this of every authorised custodian. The purpose is precisely the case we are discussing here: if the company runs into trouble, the separately held customer holdings do not fall into its estate.
In practice that means a result for the year of minus 14 million euros at an authorised provider makes no direct statement about the safety of your coins. The balance sheet figure and your holding sit in separate books. What you can check is whether the segregation is documented at your provider: authorised houses describe in their materials how they hold assets and which parts of the holdings sit offline.
There remains a difference from a bank account that you need to know. For crypto assets there is no statutory deposit guarantee, in no EU country and at no provider. The protection of up to 100,000 euros per customer applies to bank deposits at an authorised credit institution, not to bitcoin or ether in custody. If you hold a euro balance at your provider, it depends on whether that money is held as a deposit at a bank or as a means of payment at the service provider itself. Which case applies is in the terms, and that is the second place you should read up on.
Anyone wanting to take custody out of the equation altogether holds their assets themselves. What that requires technically and which devices come into question is set out in our hardware wallet comparison. It dissolves the counterparty risk and creates a new one, namely responsibility for your own key.
What a loss-making year can mean for fees and the offering
Here we leave the documented figures and come to what you can watch. A house that spends almost 29 percent of its adjusted revenues on marketing while reporting a negative result for the year has two levers: cut costs or raise earnings per customer. Both would show up for you in the same place, namely in the terms.
What matters there is less the stated order fee than the spread, the gap between the buying and the selling price. It is the part of the cost that does not show up as a fee and that you only see when comparing two prices at the same moment. We broke this provider's cost structure down in detail on October 1, 2026, including the range of 0.99 to 2.49 percent. If anything changes there, that is where a cost-cutting drive arrives first.
If you want to set terms against one another, it helps to look at houses with comparable authorisation. Our overview of regulated crypto exchanges lists the providers with EU authorisation along with their fee models, and for leveraged trading or securities alongside it you will find the terms in the crypto broker comparison. A switch then becomes a calculation you ought to be doing once a year anyway, and stays a response to terms rather than to a balance sheet figure.
Holding period and tax when you change provider
If you are thinking about a switch, a tax point belongs with it, and it matters particularly this autumn. If you transfer crypto assets from one custody arrangement to another without selling them, that is not a disposal. The acquisition data, and with it the one-year holding period under Section 23 of the Income Tax Act, keep running. If instead you sell into euros and buy back at the new provider, you have realised a sale, with all the consequences for the deadline and for the tax.
That difference costs money right now, because the framework is changing. The German finance ministry has put a draft bill on the taxation of crypto assets out for consultation; the cabinet is due to decide on it on October 14, 2026. What it contains and why December 31, 2026, becomes the decisive date is set out in our report on the draft bill before the cabinet. Anyone re-acquiring holdings through a sale shortly before that cut-off may be moving them into a different regime.
On the transfer itself, documentation is what counts. Record the time, the amount and the address, so that the acquisition data stay traceable later. If that history is lost, you may have to reconstruct it for the tax office, and that is more work than a screenshot at the right moment.
What the numbers do not say
Honesty requires naming the limits of these accounts. They are the separate accounts of one company in the group and not consolidated accounts, so they do not cover the whole business. They refer to 2025 and therefore to a period that ended nine months ago. On customer numbers, on the size of the holdings in custody and on the equity position, the reports available contain no reliable figures, which is why you will not find them here either.
In particular, no statement about a company's solvency follows from a loss-making year. Operationally positive, turned negative by financial items, with revenue grown and headcount built up: that is the picture the numbers show, and it does not reach further than that.
Bitpanda's accounts: how to proceed now
Three steps that turn the report into something you can verify:
- Establish your contractual partner. Open the terms of use and the legal notice in your account and read which company is your contractual partner and which authority supervises it. In the same step, check where any euro balance is held.
- Recalculate the terms. For the amount you actually move, compare your provider's fee and spread with two houses from the overview of regulated crypto exchanges. Anyone trading leveraged products or securities alongside should also take the crypto broker comparison.
- Decide on custody. Set out which share of your holdings should sit with a service provider and which in your own custody. For the second part, the hardware wallet comparison lists the devices and their differences. If you transfer holdings in the process, document the time and the amount for the holding period.
(As of October 5, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Transferring bitcoin to a joint marital wallet: who the coins are attributed to for tax
A married couple manage their bitcoin together on a hardware wallet. Both know the seed, both can initiate transactions. Does that automatically mean each spouse owns 50 percent of the bitcoin?
For tax purposes the answer is: not necessarily.
In Austria, attributing an asset turns in principle on beneficial ownership and on the overall picture of the actual circumstances.
Technical access alone does not decide the question
The fact that both spouses know the seed or private key does not in itself prove ownership is split in half for tax purposes.
What can matter includes:
- who bought the bitcoin,
- whose assets financed the purchase,
- who is allowed to decide on sales,
- who benefits economically from gains and losses,
- what arrangements exist between the spouses.
The Austrian Administrative Court ties beneficial ownership in particular to the actual ability to dispose of an asset and to exclude others from interfering with it on a lasting basis.
Moving your own bitcoin to a joint wallet
Suppose spouse A has owned 1 BTC for years and moves it to a new hardware wallet whose seed spouse B will also know in future. The technical transfer to a new wallet on its own need not amount to a gift.
If A remains the sole beneficial owner and B merely gains technical access for administration or backup, the attribution for tax can continue to rest with A.
Different when half is genuinely transferred
If, by contrast, B is actually to receive half of the bitcoin and to dispose of that share freely in future, a transfer of assets may exist in economic terms. It then has to be examined whether a gift of 0.5 BTC has taken place.
With gifts between spouses the Austrian duty to report gifts can in turn become relevant once the statutory value thresholds are exceeded.
Keeping the tax history cleanly separated
A joint wallet can become particularly awkward where both spouses already hold their own bitcoin with different acquisition costs.
An example:
- A contributes 0.5 BTC with acquisition costs of 5,000 euros.
- B contributes 0.5 BTC with acquisition costs of 20,000 euros.
Merging them technically on one wallet should not lead to the different tax histories becoming impossible to follow.
On later sales the acquisition date and the cost basis can become decisive.
Which is why your own records matter
It makes sense to keep:
- the original wallet addresses in each case,
- the owner of each holding,
- purchase dates,
- acquisition costs,
- the date of the merger,
- an internal ownership agreement,
- later sales and withdrawals.
A joint hardware wallet should not be confused with a joint bank account.
Conclusion
Bitcoin on a joint marital wallet does not automatically belong to both spouses in equal shares for tax purposes. What counts is beneficial ownership: who can actually dispose of the bitcoin, and to whom are the opportunities and risks of the holding economically attributable? If the transfer is deliberately intended to pass ownership to the other spouse, a gift may additionally be involved.
(As of October 1, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
The firm's Bitcoin holdings hit a record 848,000 BTC, while the quarterly gain is a fair-value mark carrying $1.88 billion in deferred tax.
Rating agencies ask if a Bitcoin company will actually sell when obligations fall due. "We answered by doing it," said CEO Simon Gerovich.
Crypto majors and alts are rallying to start October. What’s driving the early action and will it continue?
An association for AI enthusiasts was allegedly the recruiting vehicle, and two anonymous tips to a government portal started the case.
Filed under the SEC's new Innovation Exemption, the notice lists more than 60 stocks, including Nvidia and SpaceX, paired with stablecoins.
U.Today - IT, AI and Fintech Daily News for You Today
Shiba Inu just launched on Solana via Sunrise bridge, sparking an immediate 4% price surge for the coin.
Shiba Inu might avoid a substantial surge in selling pressure after overall exchange netflows are decreasing.
Samson Mow challenges Zcash’s 1,000% rally, predicting a crash just as the NU7 hard fork goes live.
Shiba Inu's trading volume skyrocketed to over $95 million in just a few hours after it launched on the Solana blockchain, sparking fresh interest from investors.
Dogecoin marks first 2026 golden cross on the daily timeframe, with what comes next now being watched.
Blockonomi
TLDR:
- Payward will offer 24/7 instant settlement through SGB Net to selected institutional clients.
- The service initially supports U.S. dollar transactions across selected Asian and Gulf markets.
- SGB Net now processes more than $20 billion in fiat transactions each month.
- SGB will use Kraken Prime for digital-asset liquidity and pricing for its customers.
Payward, the parent company of Kraken, has partnered with Singapore Gulf Bank (SGB) to provide 24/7 instant settlement for institutional digital asset clients in selected Asian and Gulf markets.
The partnership connects Payward to SGB Net, SGB’s real-time, multi-currency clearing network. The service will initially support U.S. dollar transactions for a select group of clients, with more clients and currencies planned.
How Payward’s 24/7 Settlement Network Works
SGB Net allows institutional clients to move funds between banking and digital asset infrastructure without waiting for traditional banking cut-off times.
Historically, bank settlement has followed business hours and fixed processing windows. Digital asset markets, however, operate continuously throughout the week.
Under the new arrangement, an SGB client can deposit funds with Payward and deploy them instantly. This could reduce delays between funding an account and accessing digital asset markets.
The initial rollout covers U.S. dollar transactions for selected clients in specific jurisdictions across Asia and the Gulf region. Payward and SGB plan to expand the service over time.
SGB Net launched in 2025 for digital asset businesses with increasing operational requirements. According to the companies, the network now processes more than $20 billion in fiat transactions each month.
The partnership also links SGB with Kraken Prime, Payward’s full-service prime brokerage platform. SGB will use Kraken Prime as an additional source of digital asset liquidity and pricing for its customers.
Payward Banking Expansion Connects Settlement and Liquidity
The partnership extends Payward’s broader effort to strengthen its banking infrastructure for institutional clients.
Payward Banking serves as the money layer supporting deposits, payments, cards, custody, and lending across the platform. Adding regulated banking partners can help connect traditional financial services with continuously operating digital asset markets.
For institutional traders, the key change is the timing of capital movement. Faster settlement can allow eligible clients to fund digital asset activity without waiting for the next banking window.
SGB is regulated by the Central Bank of Bahrain and is backed by Bahrain’s sovereign wealth fund Mumtalakat and Singapore’s Whampoa Group.
SGB Chief Executive Officer Shawn Chan said liquidity becomes more useful when clients can move funds when needed. The partnership therefore combines two important parts of institutional crypto infrastructure: access to liquidity and access to settlement.
For traders and institutions, the immediate offering remains limited to selected clients and U.S. dollar transactions. Its broader significance depends on whether Payward expands access across additional jurisdictions and currencies.
The SGB Net handles real-time fiat clearing while Kraken Prime provides digital asset market access. Together, the infrastructure will bring banking settlement closer to the continuous operating model of crypto markets.
The post Kraken’s Parent Payward Taps SGB for Instant Crypto Settlement appeared first on Blockonomi.
TLDR
- S&P Global launches a new risk tool for the $10 billion crypto vault market.
- The framework assesses six major risks across digital asset lending vaults.
- Crypto vault deposits surged from $1.5 billion in 2024 to $10 billion in 2026.
- SPGI stock closed 0.49% lower before edging 0.07% higher in pre-market trade.
- The launch extends S&P Global’s broader push into blockchain finance and data.
S&P Global has launched a new risk assessment framework for digital asset lending vaults, targeting a rapidly expanding $10 billion market. The move strengthens the company’s growing role in blockchain-based finance and expands its analytical services beyond traditional credit markets. SPGI stock closed at $386.27, down 0.49%, before rising 0.07% to $386.54 in pre-market trading.
S&P Global Inc., SPGI
S&P Global Launches Vault Risk Assessment
S&P Global Ratings introduced the Vault Risk Assessment to evaluate impairment risks linked to digital asset lending vaults. The framework provides forward-looking analysis designed to improve transparency across blockchain-based pooled investment structures. It also addresses limited strategy and risk disclosures across many existing vault products.
The assessment covers six major areas that influence the overall risk profile of a digital asset vault. These include portfolio credit quality, liquidity mismatches, curator exposure, blockchain risks, protocol weaknesses, and governance security. S&P Global designed the approach to offer a standardized view across different vault structures.
However, the company does not classify the assessment as a traditional credit rating. The framework also avoids evaluating potential yields offered through specific vault strategies. Instead, it measures relative impairment risks affecting deposited capital and positions within individual vaults.
Digital Asset Vault Market Reaches $10 Billion
Digital asset lending vaults have expanded rapidly as blockchain finance attracts more institutional activity. Total deposits reached about $10 billion by September 2026, according to S&P Global. That figure stood near $1.5 billion during September 2024.
Vaults pool digital asset deposits and deploy those funds under defined lending or investment strategies. Smart contracts can manage these strategies automatically, while human managers can also control allocations. Depositors generally receive blockchain tokens representing their proportional ownership of underlying vault assets.
These structures increasingly mirror products found across traditional financial markets. Their functions can resemble money market funds, private credit vehicles, private equity structures, or hedge funds. However, blockchain technology allows these pooled strategies to operate directly through onchain infrastructure.
S&P Global Expands Digital Asset Strategy
The new product extends S&P Global’s broader expansion into digital asset risk, data, and blockchain infrastructure. The company previously introduced stablecoin assessments and issued a credit rating covering decentralized finance protocol Sky. It also rated a Bitcoin-backed structured finance transaction linked to digital asset lender Ledn.
S&P Dow Jones Indices has also worked with Kaiko to tokenize the iBoxx U.S. Treasuries Index. Meanwhile, S&P Global led a strategic investment in Kaiko during September 2026. That transaction deepened the company’s exposure to digital asset data, indices, and market infrastructure.
S&P Global also announced an agreement to acquire blockchain security company OpenZeppelin during September. The planned acquisition adds security expertise to its expanding portfolio of digital asset services. S&P Global Ratings plans to publish its first Vault Risk Assessments through future announcements.
The post S&P Global (SPGI) Stock: New Vault Risk Tool Targets $10B Crypto Market appeared first on Blockonomi.
TLDR
- Metaplanet stock gains 2.06% as Bitcoin stays central to its treasury strategy.
- Metaplanet plans to keep 85% to 90% of its total assets allocated to Bitcoin.
- Bitcoin-related credit facility borrowings will stay below about 10% of BTC NAV.
- Strategic investments will account for about 10% to 15% of total company assets.
- Project Nova targets recurring cash flow to support further Bitcoin purchases.
Metaplanet Inc. (3350.T) stock closed at ¥297.00, gaining 2.06% after recovering from early session weakness. The gain followed a revised capital allocation policy that keeps Bitcoin at the center of the company’s balance sheet. Metaplanet plans to hold roughly 85% to 90% of total assets in Bitcoin under the updated framework.
Metaplanet Inc., 3350.T
Metaplanet Stock Gains as Bitcoin Remains Core Asset
Metaplanet revised its capital allocation policy as its Bitcoin treasury strategy expands into a broader financial platform. The company originally established the policy in October 2025 and revised several provisions in March 2026. The latest changes now cover both capital raising and asset allocation across the group.
Bitcoin will remain Metaplanet’s primary treasury reserve asset under the updated structure. The company plans to allocate approximately 85% to 90% of total assets to Bitcoin. It will also continue using BTC Yield to measure growth in Bitcoin holdings per share.
Metaplanet held 44,000 BTC as of September 30, up from 30,823 BTC in October 2025. The increase reflects continued Bitcoin purchases funded through equity, bonds, and credit facilities. Management now plans to support further accumulation through permanent capital and recurring cash flows.
Capital Policy Limits Dilution and Bitcoin Leverage
Metaplanet plans to rely mainly on perpetual preferred stock and selected common stock issuance for Bitcoin purchases. The company generally will avoid issuing common shares when its mNAV falls below 1.0 times. However, it may use rights offerings when large Bitcoin purchases support longer-term shareholder interests.
The company also set a guideline limiting Bitcoin-related credit facility borrowings to about 10% of BTC net asset value. Metaplanet views its Bitcoin-backed credit facility as temporary financing rather than a permanent funding source. Therefore, it plans to shift longer-term financing toward preferred stock and other permanent equity capital.
Metaplanet may also conduct share buybacks when mNAV drops below 1.0 times. Management can authorize buybacks above that level when it considers the shares materially undervalued. Funding could come from cash, preferred stock proceeds, credit facilities, or Bitcoin income activities.
Project Nova Expands Cash Flow Strategy
Metaplanet will allocate roughly 10% to 15% of total assets toward strategic investments. These assets may include acquisitions, income-producing securities, and capital for its planned asset management business. The company expects these investments to support recurring cash flow and strengthen future financing capacity.
Project Nova already includes Metaplanet Securities and a planned investment in Nasdaq-listed Super League Enterprise. Metaplanet plans to contribute 2,100 BTC and $2.5 million for securities issued by SLE. The transaction could give Metaplanet control of SLE after regulatory and shareholder approvals.
Metaplanet will also introduce a Net Interest Income Strategy to generate recurring returns from income-producing assets. The strategy will target yields above the company’s financing costs while matching liabilities with related asset cash flows. Management plans to use resulting income to support obligations, financing capacity, and additional Bitcoin purchases.
The post Metaplanet Inc. (3350.T) Stock: Climbs on 85% Bitcoin Allocation Plan appeared first on Blockonomi.
TLDR
- CSHR stock gains 0.41% as CoinShares publishes a major affluent crypto survey.
- Crypto ownership reaches 70% in the US, UK, and Germany, with Sweden at 54%.
- Current holders in the US, UK, and Germany show 91% intent to raise exposure.
- Bitcoin remains dominant, while 89% of Bitcoin holders also own other crypto.
- About 69% would consider wealth managers with specialist digital asset expertise.
CoinShares PLC stock ended Monday at $4.95, gaining 0.41% as the company released a major digital asset survey. The research covered 2,230 affluent participants across seven major markets in Europe and the United States. Results showed widespread crypto ownership, rising allocation plans, and strong demand for professional digital asset services.
CoinShares PLC Ordinary Shares, CSHR
CoinShares PLC Stock Gains Following Crypto Survey
CoinShares PLC shares added $0.02 during the session, placing CSHR stock at $4.95 by the close. The move followed the release of the CoinShares Affluent Investor Crypto Report. CoinShares conducted the research with strategic consultancy Vardaxoglou Advisory.
The study surveyed respondents across the US, UK, France, Germany, Italy, Sweden, and Switzerland. Digital asset ownership reached about 70% in the US, UK, Germany, and Switzerland. Sweden recorded the lowest ownership rate, although 54% of respondents still held digital assets.
The results also showed resilient demand following the sharp February 2026 market downturn. Germany recorded the strongest response, with 54% becoming more likely to allocate funds afterward. Only 23% of German respondents reported lower investment interest following the market decline.
Crypto Demand Remains Strong Across Major Markets
Current crypto holders showed strong plans to increase their digital asset exposure during 2026. The US, UK, and Germany each recorded a 91% rate among current holders. France followed at 87%, while Italy recorded an 85% rate.
Portfolio allocations also reflected a longer-term approach rather than short-term trading activity. Average digital asset exposure clustered around 10% of portfolios across the surveyed markets. Only 6% of respondents identified short-term trading as their main approach.
Bitcoin remained the dominant digital asset, with 80% of crypto holders owning the asset on average. However, 89% of Bitcoin holders also owned other digital assets, showing broader portfolio diversification. Bitcoin-only portfolios represented just 5% of US crypto holders and 15% in France.
Regulation and Wealth Services Support Market Growth
Government policy also influenced digital asset demand across the seven surveyed markets. About 79% supported stronger regulation, while US policy developments produced the strongest positive response. The US Administration’s crypto agenda increased investment intent among 68% to 79% of respondents.
Demand for wealth management services also emerged as a major theme in the CoinShares report. About 69% would consider working with wealth managers offering specialist digital asset knowledge. Meanwhile, 88% acknowledged they lacked enough knowledge to allocate funds with full confidence.
Younger respondents also reported higher portfolio allocations than older groups across every surveyed market. Those aged 18 to 44 allocated roughly twice as much in four markets. Their stronger participation could become significant as trillions of dollars move toward younger generations.
CoinShares has conducted digital asset research since 2013 across wealth management, mining, protocols, and hybrid finance. The latest study expands that research toward affluent market participants and their portfolio decisions. For CSHR stock, the report highlights demand trends linked directly to CoinShares’ core digital asset business.
The post CoinShares PLC (CSHR) Stock: Gains as Crypto Survey Signals Strong Demand appeared first on Blockonomi.
TLDR
- Cardano (ADA) rose 11% in 24 hours, trading between $0.24 and $0.27.
- The token now faces immediate resistance at $0.28 and strong resistance at $0.29.
- Open interest fell 11.68% during the rally, which points to a short squeeze.
- Stochastics at 93.46 and RSI at 69.66 show overbought conditions.
- Top traders remain 71.9% net long, with $0.25 serving as immediate support.
Cardano (ADA) rose 11% over the past 24 hours, trading between $0.24 and $0.27. The token now sits near $0.27, just below resistance at $0.28.
The move came with real trading activity. Spot volume on Binance reached $84.8 million over the same period.
In recent weeks, Layer-1 tokens like ADA and SOL have moved more sharply than Bitcoin in both directions. That pattern showed up again in this session as market sentiment turned positive.
According to Blockchain.news analysis, the rally pushed out short sellers positioned below $0.26. Price then ran into the upper Bollinger Band at $0.28.
Technical Indicators Show Mixed Signals
ADA is trading above all of its major moving averages. The 7-day simple moving average (SMA) sits at $0.25, the 20-day at $0.24, the 50-day at $0.22, and the 200-day at $0.21.
Momentum readings are less clear. The MACD histogram has flattened at zero, which suggests the buying push behind the rally has slowed.
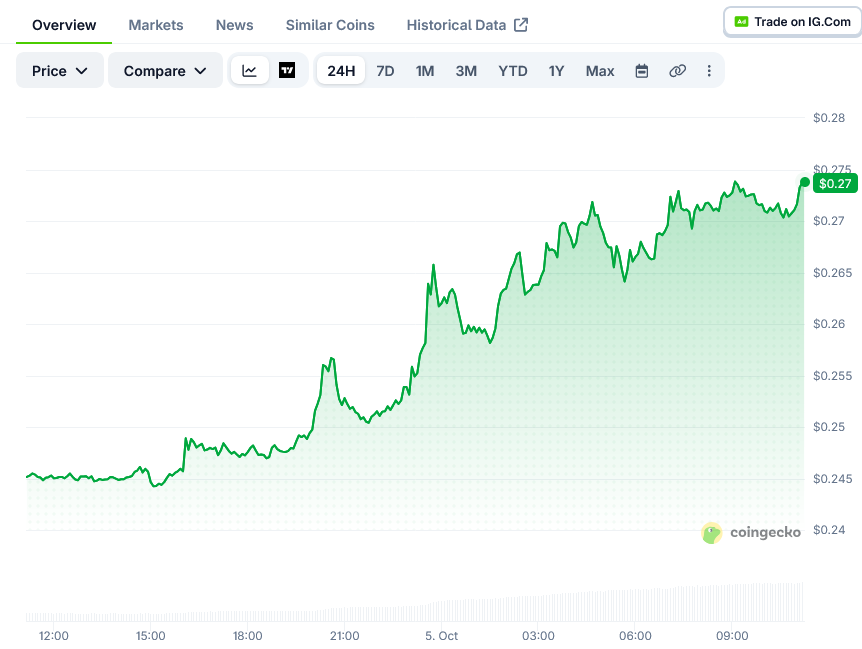
The Relative Strength Index (RSI) stands at 69.66, just under the overbought level of 70. The stochastic oscillator reads 93.46, which is deep in overbought territory.
ADA’s Bollinger %B is 0.91, meaning price is close to the upper band. The band’s midline is at $0.24, and the pivot point is at $0.26.
The average true range (ATR) is $0.02. That gives ADA room to move about $0.02 in either direction in a single session.
Derivatives Data and Key Levels
Open interest fell 11.68% over 24 hours while price climbed 11%. This means traders were closing positions rather than opening new ones.
The analysis links this to a short squeeze, where short sellers were forced to cover and pushed price higher. Fresh long positions did not chase the move in large numbers.
Positioning still leans bullish. Top traders are 71.9% net long, with a long/short ratio of 2.55, while retail traders are 68.5% long.
The taker buy/sell ratio is 1.135, showing more aggressive buying than selling. Funding rates are neutral at 0.01%.
The analysis gives a 55% chance to a bullish path. In that case, ADA would hold between $0.25 and $0.27 for three to seven days before closing above $0.28, with $0.29 and then $0.32 to $0.34 as targets.
The bearish path carries a 45% chance. Under that view, sellers defend $0.28 and ADA falls back to $0.25 support, with $0.23 as the next support level.
A daily close below $0.25 would cancel the bullish outlook. A close below $0.23 would end the short-term recovery setup.
At the time of writing, ADA traded at $0.27, up 0.18% on the latest one-minute data. The $0.28 level remains the main resistance traders are watching.
The post Cardano (ADA) Price: Token Climbs 11% to Test $0.28 Resistance appeared first on Blockonomi.
CryptoPotato
Strive CEO Matt Cole just announced that the company spent $169 million to acquire 2,000 BTC last week at an average price of $84,422.
This brings its total holdings to 29,462 units, accumulated at an average price of somewhere between $90,400 and $90,700.
Strive acquired 2,000 $BTC for $169M at an average cost of $84,422 per bitcoin, bringing total holdings to ₿29,462.
61.5% of capital raised came from SATA, with warrants generating $56.7M.
Today’s 8-K also highlights key metrics and KPIs through 3Q26.
$ASST $SATA https://t.co/HS4ADPQ8mJ
— Matt Cole (@ColeMacro) October 5, 2026
This rather impressive weekly purchase, significantly larger than the one from the previous week, is actually the third-largest in the company’s history according to on-chain data.
The single biggest was actually not a direct buy, but came from the merger with Semler Scientific, in which 5,816-5,817 BTC (worth $675 million) were involved. Then came the 2026 record of 2,500 BTC, accumulated for $185.2 million in late May and early June.
Thus, the company has ramped up its accumulation spree at times when the largest corporate holder of bitcoin has slowed down. Although Strategy has extended its consecutive weekly purchase streak to three now, its actual buy was a lot lower than Strive’s at just 334 BTC.
The post Strive Completes Its Third-Largest Bitcoin Purchase, Adding 2,000 BTC appeared first on CryptoPotato.
Macro uncertainty and political turmoil have failed to deter Strategy from continuing its recent bitcoin accumulation spree, with the company adding another 334 units for $28.7 million.
Although this particular purchase was a relatively modest one compared with some of the firm’s massive acquisitions completed until several months ago, its impact was still significant and two-fold. First, Strategy extended its weekly accumulation spree to three in a row. Second, and perhaps more importantly, its total holdings reached a new all-time high of 848,000 BTC.
Strategy has solidified its spot as the world’s largest corporate holder of the leading cryptocurrency. Its purchases began over six years ago, and the firm has spent almost $64 billion (average price of $75,441 per unit) to build its fortune.
Given today’s prices of around $86,000, Strategy sits at an unrealized gain of almost $9 billion. Interestingly, Saylor’s post reads that the company has reported a $21 billion gain on digital assets in Q3 2026.
Strategy reports a $21 billion gain on digital assets in Q3 2026. Last week, we acquired 334 $BTC and repurchased $176M of $STRC. As of 10/4/26, we hold 848,000 BTC and $5.7B of USD Assets. $MSTR https://t.co/jvwiJahdMm
— Michael Saylor (@saylor) October 5, 2026
The company has also repurchased $176 million worth of STRC as its recovery continues. The stock’s price slumped far below its par level of $100 to $75 during the summer, but it has rebounded to nearly $99.5 as of Friday’s close.
The post 3 in a Row: Strategy Ramps Up Bitcoin Purchases as Holdings Hit 848,000 BTC appeared first on CryptoPotato.
The cross-border token is approaching the apex of a narrowing technical structure as accumulation continues on certain scales, and several analysts expect the volatility to resume and possibly expand soon.
While the direction is not guaranteed, the majority believe the upside potential is higher. This is somewhat in contrast to the recent growing FUD around the popular altcoin.
$1.53 Can Unlock the Next Leg Up
Ali Martinez highlighted a triangle formation that has continued to tighten as XRP moves closer to its apex. Interestingly, this comes despite the lack of major moves from whales in the past week or so. Recall that these large market participants went on a wild accumulation spree on several occasions in the past few months, but Martinez said they have remained on the sidelines lately, with no significant changes in their holdings.
This leaves the technical structure as the immediate factor to watch rather than fresh capital coming from whales. The analyst added that a close above $1.53 on the 4-hour chart could confirm a bullish breakout and open the door toward the next major target at $1.62.
Celal Kucuker shared a similar opinion, indicating that XRP has approached the tip of its triangle. However, his momentum indicators are mixed: MACD is recovering, but RSI is still below 50, meaning the asset has not yet entered what he calls a strong bullish zone. Nevertheless, Kucuker puts the probability of an upside breakout at around 65%-70%, compared with 30%-35% for a move south.
Bird also believes XRP has reached a “major decision point” and outlined a chart showing that the asset is currently testing the same resistance at around $1.51-$1.53.
We’re back at the major decision point for $XRP guys
https://t.co/cNIk9AqwxH
— Bird (@Bird_XRPL) October 5, 2026
Certain Accumulation Continues
Although whales might not have been as active as they used to be during the August and September breakouts, CryptoQuant’s CW added an on-chain angle to the setup, showing that smaller investors have been accumulating heavily for seven consecutive days.
CW added that this phase has not yet finished, and the next meaningful price move could begin once it concludes. They also pointed to the strengthening MACD and EMA trends in recent tweets as evidence that bullish momentum is developing.
Separately, Dark Defender, a well-known XRP bull, highlighted a significantly more aggressive long-term scenario, which sees the token skyrocketing to $4.10 first, followed by $7.07, and then all the way up to $36.76. The analyst based his theory on the Elliott Wave pattern, suggesting that XRP has completed Wave 1 and is currently progressing through Wave 2.
Obviously, even the first, most modest target sounds a bit far-fetched right now, since XRP can’t really break out of the $1.51-$1.53 range. Nevertheless, the token has staged mind-blowing price rallies in the past, which leaves many fans hopeful for another similar run.
The post XRP Is Coiling for a Big Move: Analysts Point to Breakout Levels and Rising Bullish Momentum appeared first on CryptoPotato.
Somewhat surprisingly, following the weekend developments on the Middle East front, BTC’s price soared to $87,000 once again but met the same rejection fate.
Most altcoins, though, including ADA, NEAR, DOGE, and HYPE, have posted notable gains over the past 24 hours. Some of the few exceptions are RAIN and QNT.
BTC Stopped at $87K Again
The primary cryptocurrency has been highly sensitive to macro news lately, including last week’s PCE data, which came out on Wednesday. As the reading showed slowing inflation, BTC skyrocketed from $83,000 to $85,600 within minutes before it was rejected and returned to its starting point.
After a quiet Thursday, bitcoin went on the offensive once again on Friday. The weak US jobs report helped the cryptocurrency gain additional traction and pushed it to over $87,000 for the first time in ten days. However, the bears were quick to reemerge. Within the next few hours, BTC crashed below $84,000, leaving nearly $600 million in liquidations.
It found some support over the weekend and climbed past $84,000. It continued its gradual ascent on Sunday to $85,000 before surging to $87,000 on Monday morning, despite warnings of escalating tensions in the Middle East.
The rejection scenario repeated, and BTC dumped to under $85,500 before it bounced off slightly and now sits close to $86,000. Its market cap is up to $1.720 trillion on CMC, while its dominance over the alts stands still at 59%.
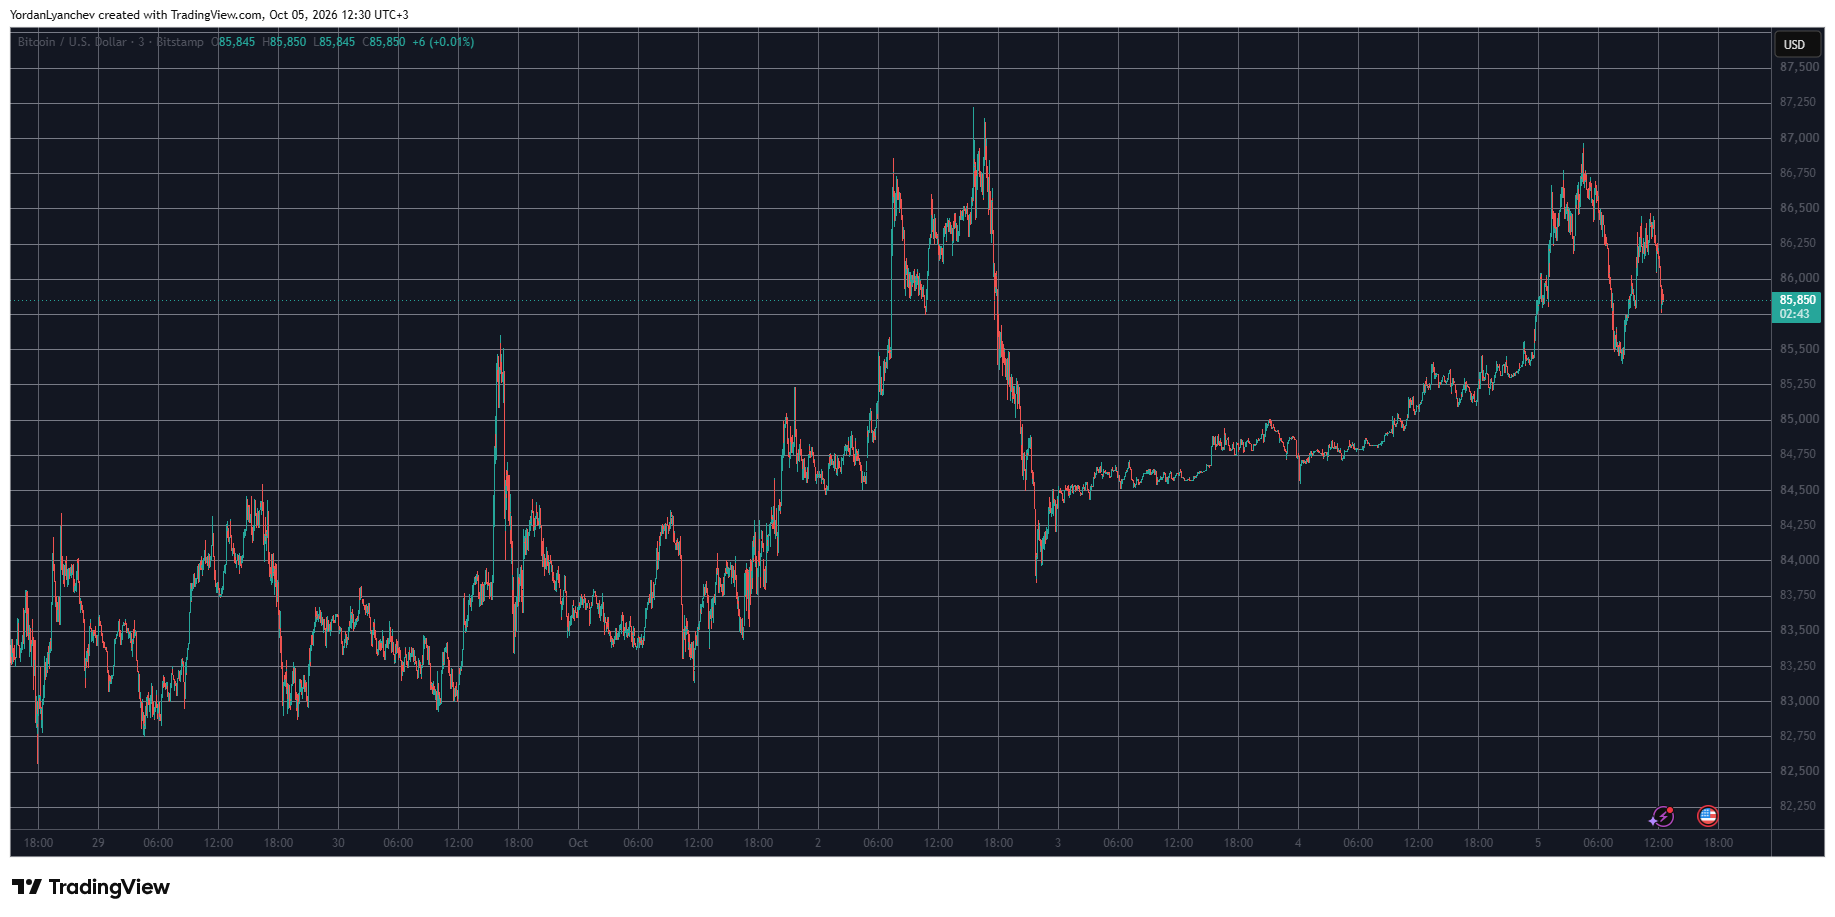
ADA Flies
Ethereum has jumped to just over the key $2,700 resistance after a minor increase. XRP is above $1.50 as well, following a 1.2% daily rise. More impressive gains are evident from the likes of HYPE (3.5%) and DOGE (3.75%). NEAR has reclaimed the $5 level after a 5% daily increase. Cardano’s ADA has soared the most from this cohort of alts, jumping by almost 11% to $0.27.
Other notable gainers include SUI, CC, SHIB, ONDO, and especially ENA, which is up by 7.5%. Meanwhile, FET has rocketed by over 15%, while VIRTUAL is up by 12%.
The cumulative market capitalization of all crypto assets has gained 1% and is up to $2.930 trillion on CMC.
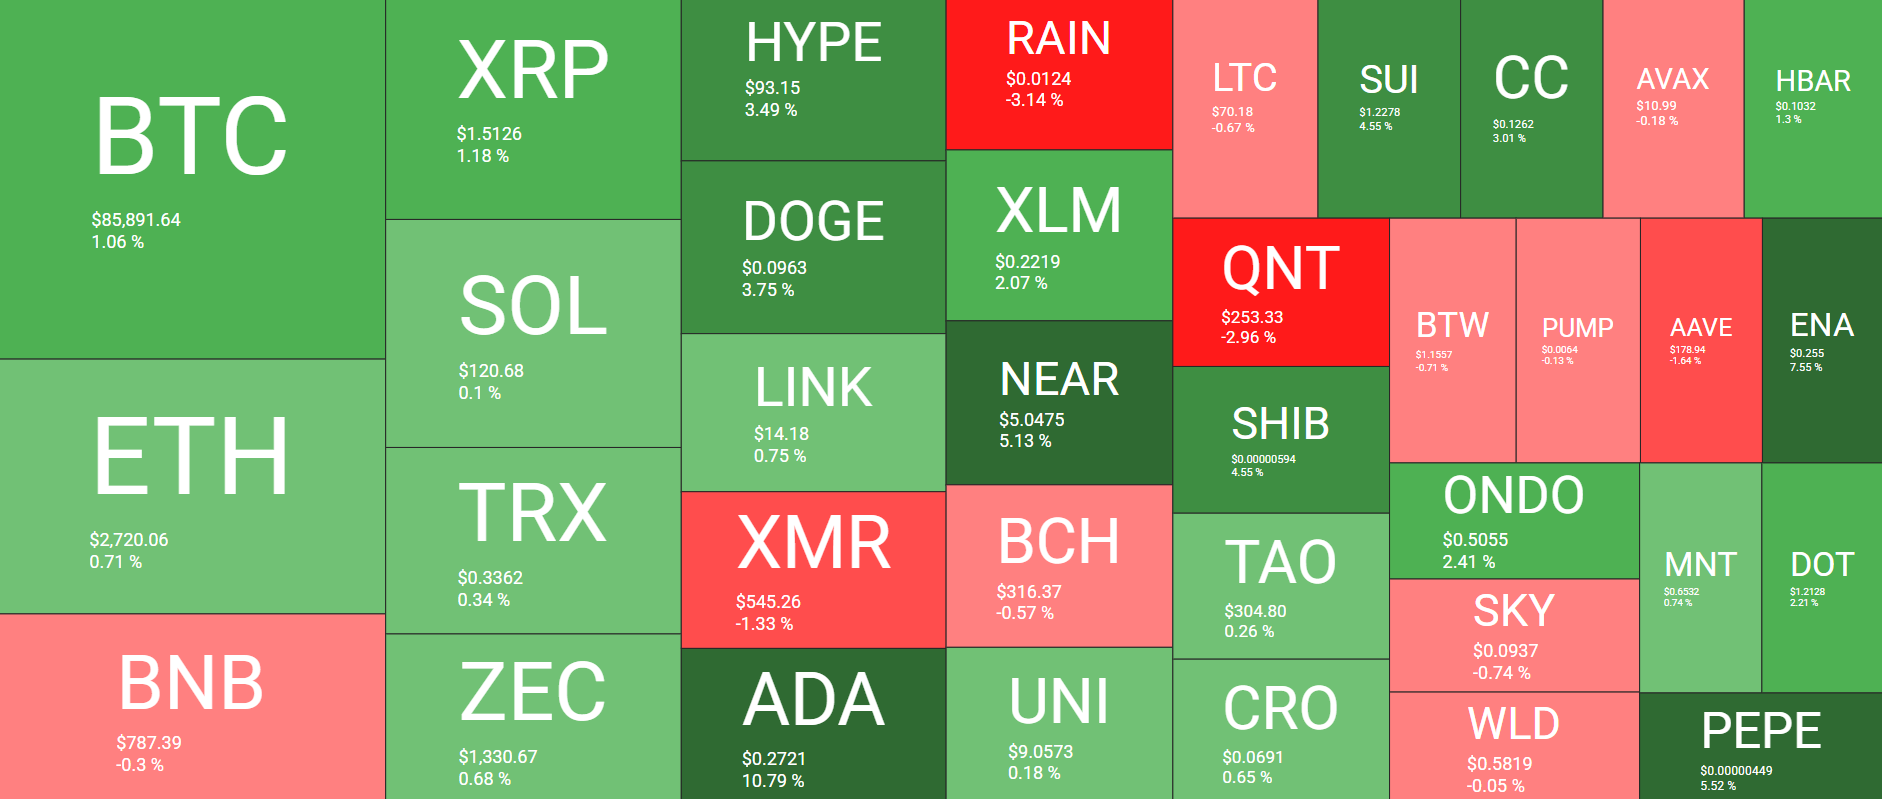
The post Bitcoin (BTC) Rejected at $87K Again, Cardano (ADA) Soars 11%: Market Watch appeared first on CryptoPotato.
Bitcoin’s Sunday rally has brought a familiar pattern back in focus, with analyst Ali Martinez warning on October 4 that BTC could be in for a Monday pullback.
Multiple Sunday to Monday reversals and new TD Sequential sell signals on Bitcoin, Ethereum and Solana are signs of caution, according to him.
Five Sundays, Five Reversals
Martinez wrote that Bitcoin’s Sunday moves have often reversed on Monday over the past month. Sunday rallies were followed by pullbacks, while Sunday declines were followed by rebounds. With BTC up more than 1% on October 4, the analyst argued that the pattern had returned to focus.
The market watcher shared a table covering five Sunday-Monday pairs between August 29 and September 28, and every pair flipped direction. For example, Sunday gains of 0.50% on August 29 and 0.66% on September 6 were followed by Monday losses of 0.68% and 1.54%. Sunday dips of 0.57% on September 13 and 0.10% on September 20 were followed by Monday gains of 1.75% and 6.71%. On September 27, BTC finished up 0.01% and slid 1.12% on Monday.
One thing though, five weeks may feel like a thin sample, and that last Sunday gain was close to flat.
A second warning comes from the TD Sequential indicator, a technical tool that attempts to identify points where an existing price move may be losing strength. Martinez noted that Bitcoin’s four-hour chart had flashed a sell signal, with each of the previous four comparable signals followed by a correction. Earlier examples he shared showed declines of 1.74%, 4.37%, 3.11% and 1.96%.
Ethereum and Solana have also produced similar signals. The last two comparable Ethereum readings preceded declines of 5.40% and 3.31%, while Solana’s previous three were followed by corrections of 2.44%, 5.76% and 5.30%.
Bitcoin Sits Higher Across Most Recent Timeframes
The price of BTC moved above $87,000 after an unexpectedly weak US jobs report on Friday before falling below $84,000, with Lacie Zhang of Bitget Wallet research saying that $87,500 is the critical resistance level, while the support level is in the range of $82,000 to $85,000.
At the time of writing, CoinGecko data put the OG cryptocurrency a couple of hundred bucks above $86,000, up about 1.5% in 24 hours and nearly 4% in the last seven days. The two-week and 30-day gains were almost 6% and over 8%, although the price was still down roughly 31% on the year and about the same distance below its all-time high of over $126,000.
The post Analyst Warns of Bitcoin Monday Dump After Sunday Gain appeared first on CryptoPotato.