Cryptocurrency Posts
Crypto Briefing
The incident highlights the growing tension between individual developers and major AI firms, emphasizing the push for decentralized AI solutions.
The post OpenAI suspended PewDiePie twice as he built his Ajax AI model, he says appeared first on Crypto Briefing.
The surge in crypto job postings amid declining applications suggests a tightening talent market, potentially boosting leverage for skilled candidates.
The post Crypto job postings more than triple to 1,241 in September as applications slide appeared first on Crypto Briefing.
The debate over AI's moral status could influence public trust, regulatory approaches, and investment strategies in the AI industry.
The post Sam Altman warns against giving AI models religious status appeared first on Crypto Briefing.
AI's shift to autonomous spending could redefine monetization models, benefiting infrastructure providers and challenging traditional vendors.
The post Cathie Wood wants investors to follow the money AI agents spend appeared first on Crypto Briefing.
The CLARITY Act's stagnation highlights the complex interplay of political cycles and regulatory frameworks impacting crypto legislation.
The post CLARITY Act stalls in Senate, future uncertain amid political cycles appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
IMF Praises El Salvador — But Still Tries To Scale Back Its Bitcoin Project
The International Monetary Fund has praised El Salvador for improving its economy — but scolded it at the same time for its ongoing Bitcoin experiment.
In a statement Friday, the IMF said that it had approved a $139 million disbursement to the Central American nation while also trying to “reduce the state’s involvement in Bitcoin-related activities.”
El Salvador in 2021 made Bitcoin legal tender, much to the ire of the IMF and other major institutions. The Latin American country was at the time negotiating a development loan with the agency.
“El Salvador’s economy continues to perform strongly”
— Nayib Bukele (@nayibbukele) October 1, 2026https://t.co/Rvaerha9QA
The IMF in September said that El Salvador wasn’t buying bitcoin; the country’s Bitcoin Office has repeatedly said that it does buy the cryptocurrency.
“Economic activity has exceeded expectations, supported by sustained improvements in security and investor confidence, as macroeconomic imbalances continue to be addressed,” the IMF said.
It continued: “However, certain performance criteria were not met, including on the Bitcoin accumulation front, for which waivers were granted based on strong corrective measures and renewed commitments.”
The IMF further said that the Salvadoran state’s involvement in Bitcoin-related activities is being unwound and that “no further bitcoin accumulation is envisaged beyond the documented donations.”
Salvadoran president Nayib Bukele in 2022 said the country would buy one bitcoin per day but it was never clear where the money was coming from — or if he was actually buying at all.
The IMF said in September that El Salvador was — at least for some time —not using public funds to accumulate bitcoin but rather had received bitcoin from private donations.
El Salvador and the IMF entered a $1.4 billion loan agreement at the end of December but the fund asked for the country to scale back certain aspects of its Bitcoin strategy.
The Salvadoran state gifted its citizens bitcoin in 2021 and debuted a wallet with the hope of getting more citizens using the cryptocurrency in the dollarized country.
President Bukele in 2024 admitted that Salvadorans weren’t using the cryptocurrency to buy things as expected, but always boasted that the government was still stacking sats.
This post IMF Praises El Salvador — But Still Tries To Scale Back Its Bitcoin Project first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
When the Banks Don’t Work, Bitcoin Does: Cornell University’s Adoption Index
A lot of people know little about Bitcoin and how it works.
But despite knowledge being shallow, for those holding the leading cryptocurrency, it appears to be solving a problem: getting around failing banking rails or inflation.
That’s according to new findings from the U.S. Ivy League research university Cornell, which spoke to nearly 26,000 around the globe about Bitcoin.
In its new Bitcoin Adoption Index report, the top college found that El Salvador, Venezuela and Nigeria were the countries that had the highest number of people who had ever owned bitcoin.
“Ranked by the share of all respondents who have ever owned bitcoin, the leaders are not wealthy financial centers — they are economies where the national currency has been unstable and everyday access to dollars or reliable banking is hard,” the report read.
“In each, bitcoin functions less as a speculative bet and more as a practical workaround.”
Bitcoin Advocacy Associate at Strategy and Junior Fellow at Cornell University’s Brooks School Tech Policy Institute, Ella Hough, added: “Bitcoin works the same everywhere, but people’s need for it does not.
“Across 25 countries, we found that people are more likely to see Bitcoin as a tool for financial freedom where currencies are less stable, banking access is limited, or monetary controls are tighter.”
Still, Cornell found that actually being able to explain the fundamentals of the protocol was difficult for most — including how many bitcoins would ever be minted in existence. In fact, 58% of those surveyed said they didn’t know the supply was capped at 21 million coins.
Technicalities aside, the cryptocurrency has still proved helpful to people wanting to use it, the report found.
One Venezuelan — who wasn’t named — told interviewers that Bitcoin was “faster, cleaner, and much less risky” than other methods of getting dollars in the country.
While another Salvadoran was quoted saying: “When nobody controls [bitcoin], it means we all have control of it.”
A Nigerian interviewee reportedly told Cornell researchers: “I’ve been to six African countries and whenever I go there, I don’t fear it because I know I can spend my bitcoin.”
Bitcoin adoption started growing in Venezuela ahead of other countries years ago, when hyperinflation crippled the economy and strict government currency controls meant getting dollars became difficult.
El Salvador made bitcoin legal tender — along with the dollar — in 2021. The country’s leader admitted that getting its citizens to use the cryptocurrency was difficult but the Central American nation still says it buys the asset for its government coffers.
In Nigeria, which has had some of the highest transaction volumes in the world, saving in bitcoin has been used by some to get around the collapse of the naira.
Cornell University’s research was fielded by Morning Consult in partnership with the Tech Policy Institute in Cornell University’s Jeb E. Brooks School of Public Policy, the Cornell Bitcoin Club, the Human Rights Foundation and the Reynolds Foundation.
Researchers interviewed 25,880 people in 25 countries between December 16, 2024 to March 10, 2025, asking 125 individual questions.
This post When the Banks Don’t Work, Bitcoin Does: Cornell University’s Adoption Index first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
South Africa’s Absa Becomes First Bank on the Continent to Custody Bitcoin: Report
South African bank Absa has become the first African lender to custody bitcoin, according to reports.
As reported first by Bloomberg on Friday, the Johannesburg-based lender will serve institutional clients, mostly by custodying bitcoin — but other digital assets will also be a part of the service.
Banks worldwide are integrating or offering bitcoin-related products and services. A number of U.S. and European banks have started offering crypto-related services by custodying assets for institutions.
JUST IN:
— Bitcoin Magazine (@BitcoinMagazine) October 2, 2026Absa has become the first African bank to offer Bitcoin custody
pic.twitter.com/JaDza3S7Ez
Rob Downes, head of digital assets at Absa’s corporate and investment banking unit, was quoted saying that while bitcoin was the biggest asset the bank would custody, others would follow.
Absa did not immediately respond to questions from Bitcoin Magazine.
The African continent has a large crypto-native base, with data firms frequently highlighting the high adoption — particularly in countries where currencies have been significantly debased.
In Chainalysis’s 2025 report, South Africa’s $36.0 billion in on-chain value made it second in Sub-Saharan Africa. Nigeria alone received $92.1 billion, nearly three times the total of second-place South Africa.
On the global index, South Africa ranked 30th for crypto adoption.
The character of its market is different from Nigeria‘s: it’s more institutional, with regulatory clarity resulting in hundreds of licenses being issued to VASPs and attracting professional investors and traditional finance.
BNY Mellon in 2022 became the first major U.S. bank to offer digital asset custody services. And this month, German multinational Deutsche Bank said it would debut a bitcoin custody service for European corporate and institutional clients later in 2026.
This post South Africa’s Absa Becomes First Bank on the Continent to Custody Bitcoin: Report first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Bitcoin Price Surges Above $87,000 on Softer-Than-Expected Jobs Data
The price of bitcoin surged above $87,000 on Friday morning in New York, buoyed by constant exchange-traded fund flows and a jobs report showing that unemployment in the U.S. had ticked up.
Bitcoin’s price recently stood at $85,990 after a 2% jump over a 24-hour period. Over the past week, it has also risen by more than 2%.
Nonfarm payrolls increased 29,000 last month after a downward revision to the prior two months, Bureau of Labor Statistics data showed Friday.
JUST IN: Bitcoin jumps to $87,000 as U.S. Unemployment Rate comes in at 4.2%, higher than expectations
— Bitcoin Magazine (@BitcoinMagazine) October 2, 2026pic.twitter.com/jqtU8Q9zsd
Weaker-than-expected jobs data can give a lift to riskier assets like bitcoin and stocks, whose prices tend to swing more sharply.
A softer labor market typically means less consumer spending, which eases pressure on prices. That could make the Federal Reserve less inclined to keep raising interest rates to fight inflation.
Many economists and politicians have said the U.S. is in the midst of an affordability crisis, and the topic is a hot one ahead of the November midterm elections.
The Federal Reserve’s new chair, Kevin Warsh, has said that prices in the world’s biggest economy are too high and that the central bank is fully focused on making life more affordable again.
Bitcoin investors shrugged off the central bank’s interest rate hike in September, climbing on the news.
The largest cryptocurrency started rallying in August on news that the U.S. Treasury Department said it would more than double the size of its government debt repurchases. The coin had its best run in three years and third best August ever.
The coin’s price has benefited from the so-called debasement trade: when investors buy certain assets to hedge against currency being devalued. The dollar slid in value in August.
It continued to have a good September, rising nearly 6% over a 30-day period.
October has historically delivered good returns for bitcoin investors, with traders dubbing the phenomenon “Uptober.”
This post Bitcoin Price Surges Above $87,000 on Softer-Than-Expected Jobs Data first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Impacts of Daily Dividends on Digital Credit
In May 2026, Strive rebranded itself as “The Daily Dividend Company,” then moved SATA to daily cash dividends beginning June 16. Strategy has now pushed the same idea into its own digital credit engine. On September 24, its board proposed moving STRC, STRF, STRK and STRD to daily dividends, subject to shareholder approval at an October 28 special meeting. The proposal keeps the annual dividend economics unchanged and changes the cadence of cash payments.
STRC spent much of the summer below its $100 stated amount even as Strategy raised its dividend rate to 12% and deployed more than $1 billion buying back STRC. The move to daily dividends by Strategy could be seen as the latest attempt to make the security more attractive and help it trade near par.
Now that the overton window has fully shifted in favor of digital credit paying daily dividends, we should take a look at the actual impacts of daily dividends.
Daily Dividends Fit Onchain Finance
Digital credit is increasingly becoming an input for other financial products—so called “digital money” or “digital yield” products. Strategy estimated in mid-May that more than $440 million of STRC exposure had moved into DeFi through stablecoins, tokenized securities, yield products and other structures.
However, there is a cash flow mismatch. Crypto products commonly accrue and distribute yield at high frequency. A security that pays monthly or twice monthly forces the product sitting on top of it to bridge the period between economic accrual and actual cash receipt.
Daily dividends compress that gap to one day. The protocol, fund or issuer receives cash from the underlying asset at almost the same cadence that users expect to receive yield. That simplifies liquidity management and reduces the cash needed between dividend dates. This is much more impactful to a financial product funding daily distributions or redemptions than to a long term investor focused on total return. The crypto-heavy setting of the “Layer 3” products on top of digital credit raises the attractiveness of daily dividends.
Daily Dividends Are Primarily a Retail Feature
For investors focused strictly on total return, dividend payment frequency makes little difference in underlying economic value. The asset’s price accrues between distribution dates and adjusts post-payment, meaning annual, quarterly, monthly, and daily payouts produce comparable long-term results.
The true advantage of daily dividends lies in product psychology and user experience. Cash arriving every day provides immediate visibility and an engaging feedback loop. Investors can spend, withdraw, or automatically reinvest the payout while leaving their principal position intact, turning an abstract yield metric into tangible recurring cash flow.
This dynamic mirrors the strategy of Realty Income, which built a massive retail follower base by branding itself as “The Monthly Dividend Company.” As a member of the S&P 500 Dividend Aristocrats Index, Realty Income has paid and raised dividends for 31 consecutive years.
Daily dividends on digital credit extends this product concept even further: SATA pairs frequent daily payouts with a target price near $100 and a double-digit yield.
While institutional investors prioritize yield spreads, liquidity, tax structure, and balance sheet coverage, daily payments offer their strongest appeal to retail buyers. If the overarching objective is to raise capital to purchase Bitcoin, optimizing security design for retail investor preferences is the most effective approach.
Options Get Cleaner Too
Daily dividends also change options mechanics. STRC currently pays $0.50 twice monthly. SATA pays roughly five cents each business day. Larger dividend events create larger discrete adjustments in the underlying price, which affects option pricing and early exercise decisions. Daily payments spread the same annual cash flow across much smaller adjustments.
The total value of dividends over an option’s life is a key economic input. The more interesting effect comes from the price stability created by daily dividends. If daily dividends, variable rates and active par management keep SATA and STRC trading in narrower ranges, realized volatility should fall. Implied volatility can follow as the market gains confidence in that behavior.
The Biggest Test
The real test is whether daily dividends increase demand enough to eventually lower the required yield.
If investors consistently support SATA near the top of its target range, Strive can theoretically reduce the dividend rate while attempting to keep SATA near par. Success would show that a Bitcoin company can issue permanent preferred capital, manage it around a stable price, and adjust its yield with market demand. The benefit of the variable rate preferreds was, from inception, the eventual opportunity to lower the rate and reduce the cost of capital without upsetting price stability. In comparison, fixed rate credit locks in fixed rate forever.
Conclusion
Strategy adopting daily dividends would move the feature from a SATA differentiator toward a digital credit category standard. The annual economics barely change but the retail appeal and crypto composability become meaningful improvements.
This post Impacts of Daily Dividends on Digital Credit first appeared on Bitcoin Magazine and is written by Allard Peng.
CryptoSlate
The European Securities and Markets Authority wants to extend Europe’s restrictions on non-compliant stablecoins beyond trading to the services that let customers keep and move them. If adopted as proposed, the change would remove the option of leaving such tokens with a licensed custodian after their trading pairs disappear.
In its September 30, 2026 response to a review of the EU’s Markets in Crypto-Assets regulation (MiCA), ESMA asks the European Commission to prohibit every licensable crypto-asset service involving stablecoins that fail the regulation’s applicable requirements. Custody and transfers fall within that service list. The consequence would reach existing holders who have stopped trading, as well as customers seeking to buy.
That is a further step from the regulator’s January 2025 approach, which said mere custody and transfer should remain possible. It could give compliant tokens a wider advantage in European distribution, but neither a forced conversion timetable nor a global demand shift follows from the proposal.
The permission left after delisting
ESMA’s January 17, 2025 statement distinguished services that offered non-compliant stablecoins to the public or admitted them to trading from simply holding or transferring them. Platforms were expected to stop making the tokens available for trading, and other services had to cease where they constituted an offer to the public.
Under that earlier transition, acquisition restrictions were expected by the end of January 2025, with temporary sell-only services through the end of the quarter.
For an investor, the custody distinction mattered. Losing access to a trading pair did not necessarily mean losing the service that safeguarded an existing balance or enabled its withdrawal. ESMA acknowledged that investors retaining those holdings could face worse execution conditions, even while custody and transfer remained possible.
A historical example shows the distinction. In its March 3, 2025 reporting, CryptoSlate said Binance planned to remove nine tokens’ trading pairs for European Economic Area users by March 31 while keeping deposits, withdrawals, conversions and custody available. This was the exchange’s announced approach in March 2025.
The September response would replace the activity-by-activity distinction with a broader asset-compliance test. ESMA argues that the lack of a clear prohibition creates disparities between compliant and non-compliant issuers and facilitates regulatory arbitrage.
The reach comes from MiCA’s Article 3 definitions. Custody includes safekeeping or controlling clients’ crypto-assets or their means of access, including private keys. Transfers cover moving assets on a client’s behalf from one ledger address or account to another. Both are expressly listed services, with Article 82 setting client-agreement requirements for transfers.
Provider permissions are also separate from token compliance. Article 59 requires authorization as a crypto-asset service provider, or qualifying permissions for specified financial entities, and says authorizations must identify the services permitted. A license for a provider does not by itself settle whether a particular stablecoin can be serviced.
An existing holder would therefore not avoid the proposed restriction by deciding never to trade again. If the wording became law without an exception, the custodian’s continued safekeeping would itself be covered.
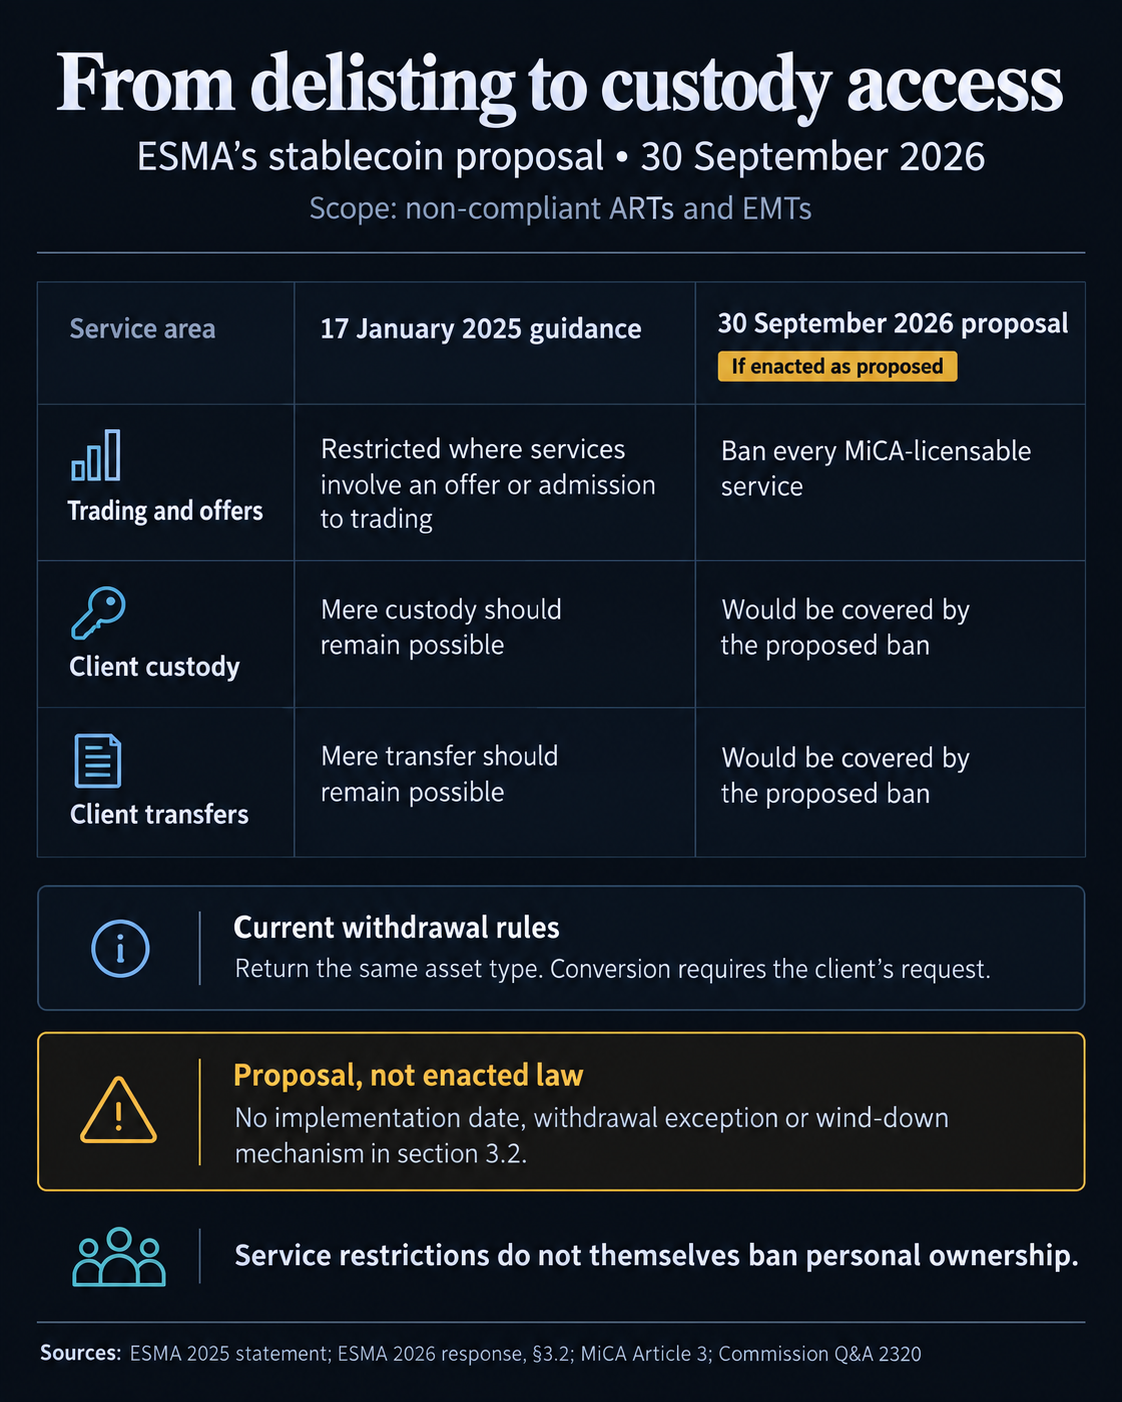
ESMA’s response is a policy submission, not an enacted amendment. The Commission’s consultation had a September 30 deadline, and its page says the resulting review report may, if warranted, be accompanied by a legislative proposal.
Section 3.2 of ESMA’s submission gives no implementation date, withdrawal exception or wind-down mechanism. That omission matters because ending custody requires a way to return assets that a provider already controls, while the proposed prohibition also reaches transfer services.
Current custody rules provide a relevant starting point. Article 75 requires procedures to return clients’ crypto-assets or their means of access as soon as possible. Client assets must also be segregated from the provider’s own holdings.
An answer from the European Commission via ESMA, dated February 18, 2026, further says the assets returned must be the same type held when the client requests withdrawal. A provider may offer conversion into fiat or another crypto-asset, but the client must request it at withdrawal and the provider must have permission for the additional service.
That existing interpretation does not settle how a future blanket service restriction would handle exits. It does explain why delisting, termination of custody and compulsory conversion cannot be treated as interchangeable outcomes. Legislators would need to resolve how any new prohibition fits the obligation to return assets.
The stablecoin proposal targets those professional services. It does not itself ban personal ownership, order tokens frozen or prescribe compulsory conversion. A holder’s ability to retain an asset and a licensed business’s ability to hold or move it for that customer are different questions.
Trading shares do not measure custody exposure
The earlier delistings show how trading can change at European-facing venues without a comparable shift across a wider market.
In a July 2026 paper, Nicola Borri and Kirill Shakhnov examine trading in the dollar-linked tokens USDT and USDC across 14 exchanges selected from CoinMarketCap’s top 30 centralized venues. Their daily pair-volume data from CryptoCompare run from January 1, 2024, through December 7, 2025.
The authors classify Bitstamp, Coinbase, Gemini and Kraken as “regulated-facing” because their Similarweb EU audience shares exceed 10%; all four also have US audience shares above 10%. The other 10 venues are classified as globally oriented, including Binance despite its EEA delistings. The audience proxy identifies neither individual EU-resident trades nor a clean division of legal exposure.
Around the study’s April 1, 2025 event date, the authors estimate that USDC’s share of combined USDT and USDC trading rose by about six percentage points on regulated-facing exchanges relative to global exchanges. The estimate covers a 30-day window and uses smoothed, detrended data; it measures a relative trading shift across venue groups.
The authors estimate USDT trading volume fell about 20% on regulated-facing exchanges relative to global venues, while the USDC-volume estimate was not statistically significant. USDC gained share primarily because USDT trading contracted in that comparison, not because the study established a corresponding expansion in USDC trading.
Aggregate USDC-to-USDT trading-volume ratios across the sample stayed nearly flat around the event. That describes sampled exchange turnover, not worldwide demand or EU custodial balances. The legal documents and study provide no total for the holdings that a future custody restriction could affect.
If the proposal became law in its present form, compliant tokens could retain access to regulated custody and transfer channels that non-compliant tokens would lose. For customers who want a provider to safeguard and move a dollar-linked balance, compliance could affect the usefulness of that asset beyond the availability of a trading pair.
The next consequential text would be a legislative amendment, particularly its scope, application date and treatment of existing balances. How it reconciles an end to custody with the return of clients’ assets would determine whether and how existing holders must leave regulated services.
The post ESMA proposes ending EU custody and transfer services for non-compliant stablecoins appeared first on CryptoSlate.
Six US banks have failed in 2026 so far, which is one more than in 2023 and enough to make another banking-crisis headline practically write itself.
But before we start reliving Silicon Valley Bank, it's worth looking at what those six banks actually held: about $1.43 billion in combined assets, compared with roughly $552.54 billion at the banks that failed in 2023, according to historical numbers from the Federal Deposit Insurance Corporation (FDIC).
Counting each bank as one gives you a perfectly accurate number and a pretty lousy sense of scale. This year's total includes a lender with $3.73 million in assets, which gets the same vote in the tally as a bank the size of SVB.
Meanwhile, FDIC's latest industry assessment shows stronger profits and fewer banks on its problem list. That doesn't mean the six failures were harmless, or that every surviving bank is doing well, but anyone selling a 2023 rerun has some explaining to do.
Nano Banc's Sept. 25 closure brought the count to six and supplied the largest failure of the year so far. The Irvine, California, lender reported $736 million in assets, and the FDIC estimated a $114 million cost to its Deposit Insurance Fund.
Someone will bear that loss, but a bill attached to one failed bank doesn't mean the rest of banking is about to follow.
Six is bigger than five (until you look inside)
The FDIC's annual totals record four failures in 2020, none in 2021 or 2022, five in 2023, and two apiece in 2024 and 2025. Through Sept. 25, this year had beaten every annual count in the 2020s, which sounds much, much worse than it actually is.
Consider Kentland Federal Savings and Loan Association, which the FDIC described as the country's smallest standalone bank when it closed. Its $3.73 million in assets counts for exactly as much as Silicon Valley Bank in a chart of bank failures, because that chart counts only institutions.
Asking it to measure financial trouble gives a very small bank a very large role.
| Failed institution | Closure date in 2026 | Reported assets |
|---|---|---|
| Metropolitan Capital Bank & Trust | Jan. 30 | $261.10 million |
| Community Bank and Trust – West Georgia | May 1 | $288 million |
| Kentland Federal Savings and Loan Association | July 10 | $3.73 million |
| Small Business Bank | July 17 | $73 million |
| Tioga-Franklin Savings Bank | Aug. 21 | $68 million |
| Nano Banc | Sept. 25 | $736 million |
| Combined | Through Sept. 25 | $1.43 billion |
Sources: FDIC failure announcements and annual summary. The unrounded sum is $1,429.83 million, using numbers from different reporting dates cited around the closures, rather than a single-date balance sheet or an estimate of losses.
The $552.54 billion number for 2023 and this year's $1.43 billion come from balance sheets with different reporting dates, so we can't turn them into an exact ratio. Luckily, we don't need one to see that the amounts belong in very different conversations, even if six is technically more than five.
The FDIC's problem-bank list adds another issue because it counts banks that are still operating, using their condition measured at a particular date. Banks get onto it when examiners assign one of the two weakest overall ratings for financial, operational, or managerial weaknesses, which is a more specific diagnosis than having an ugly week in the stock market.
The second-quarter assessment put 47 banks on that list as of June 30, down from 54 in March and 60 at the end of 2025. They made up about 1.1% of insured institutions, within the FDIC's normal 1% to 2% range outside a crisis.
That doesn't give the industry a certificate of perfect health, because a bank can leave the list by failing just as it can leave by recovering or merging. The failure count adds up closures over the year, while the problem list takes a snapshot of institutions still open, so it's not mysterious for one to get longer while the other gets shorter.
The dates also prevent us from doing some tempting mental math. Four of this year's six failures came in July through September, beyond the June snapshot, but subtracting four from 47 won't tell us how many troubled banks are left.
We don't know every bank that entered or left the list in between, and the published totals don't identify them.
Some banks were broken long before the headline
The records behind these closures describe institutions that had been struggling for quite a while. Illinois regulators said Metropolitan Capital had impaired capital and unsafe conditions, while Kansas officials described years of financial trouble at Small Business Bank.
At the Kansas lender, continuing operating losses ate through its capital until it became critically undercapitalized. Capital is the cushion that absorbs losses before creditors have to bear them, and a bank that keeps losing money can burn through that cushion while the rest of the industry has an excellent quarter.
Someone else's profits don't refill your bank's capital, and Kentland reached a similar endpoint, with the Office of the Comptroller of the Currency finding that unsafe practices had depleted its assets and earnings and that there was no reasonable prospect of restoring adequate capital.
Tioga-Franklin had its own FDIC consent order from earlier, covering weaknesses in management and capital planning, as well as liquidity and credit administration. It consented without admitting or denying the charges, so that record tells us supervisors had identified problems, without settling exactly what caused its August failure.
We know less about the full diagnosis at Community Bank and Trust – West Georgia. The state's closure notice explains the authority to take possession without supplying a detailed financial account, and the FDIC inspector general has a material loss review underway.
Giving it the same cause as the other failures would make the narrative tidier than the evidence allows.
Nano also had a lengthy regulatory history. California Business and Consumer Services Secretary Rohit Chopra described repeated violations and earlier action against mismanagement, while pointing to its large level of uninsured deposits.
Customers with money above the insurance limit have more to lose if a bank fails, which gives them a stronger reason to leave when they doubt it can pay them back.
You can take all of that seriously without treating the six banks as a chain of falling dominoes. The records describe unresolved weaknesses at individual lenders, but don't establish a common funding shock or show one closure bringing down the next.
Putting them in the same table doesn't create a financial connection.
The broader numbers don't support the small-bank-doom argument either. In the FDIC's second-quarter results, community banks earned 8.2% more than in the preceding quarter, while industry-wide profit reached $90.1 billion.
The regulator described capital and liquidity as strong, leaving plenty of room for a few badly damaged banks in an industry making more money.
The losses are real even when the apocalypse isn't
None of this makes a failed bank a non-event for the people caught in it.
Nano's estimated $114 million insurance-fund cost is a real financial consequence, even though Sunwest Bank agreed to take over substantially all its deposits and buy about $476 million of its assets.
The FDIC retained the rest for disposal and said customers could keep using checks and cards through the closure weekend.
Those customers could keep paying their bills while the receivership faced a loss, because access to deposits and the final cost of resolving a bank aren't the same thing.
The FDIC's estimate can move as it sells retained assets, and the six banks' combined $1.43 billion in assets shouldn't be treated as money that vanished. Loans can still be repaid, and securities can still be sold when their former owner has failed.
Tioga-Franklin's buyer assumed all deposits, while the West Georgia transaction transferred substantially all insured deposits, excluding certain brokered accounts.
Georgia officials said customers above the insurance limit would receive notices explaining their rights as uninsured depositors, which is a pretty different experience from being told your account now has another bank's name on it.
CryptoSlate's coverage of the year's first bank failure examined broader banking risks, but the road from a failed lender to crypto still needs spelling out. Whose money was at the bank, and what could they no longer do when it closed?
In 2023, Circle had $3.3 billion of USDC reserves at Silicon Valley Bank, giving stablecoin holders a direct reason to worry about access to part of their tokens' backing. The Federal Reserve's analysis of that failure follows that connection from bank distress into stablecoins.
This year's tally doesn't provide an equivalent connection on its own. Disclosed crypto deposits at a failed lender, or the loss of banking services needed to process customer payments, would give us something concrete to examine.
Another tick in the failure column can't tell us whose reserves are trapped or whose business has lost access to cash.
There are good reasons to keep watching the banks, including whether withdrawals spread across institutions and whether lenders have more trouble obtaining funding. The assets on the problem-bank list deserve attention too, because a shorter list can still contain more money at risk.
None of those possibilities gets answered by comparing six with five.
The case for another 2023 has to explain how trouble is spreading through the banks that are still open. Until the evidence shows that, six failed lenders tell us that six lenders couldn't keep going, and turning that into a verdict on the whole system asks a headcount to do a balance sheet's job.
The post Six US banks have failed in 2026 but the numbers look nothing like 2023 appeared first on CryptoSlate.
Leveraged funds’ reported Bitcoin futures shorts fell by about 5,300 BTC-equivalent in the week to Sept. 29, narrowing their net short even as their aggregate long exposure shrank.
The Commodity Futures Trading Commission’s latest futures-only figures, released in the Oct. 2 reporting cycle, cover CME standard and micro Bitcoin futures plus Coinbase Derivatives’ nano Bitcoin and nano perpetual-style futures. The totals convert different contract sizes into BTC-equivalent exposure; they describe futures positions, not transfers of physical bitcoin.
Compared with Sept. 22 positions, the funds’ reported shorts fell 5,299.69 BTC-equivalent and longs fell 908.99 BTC-equivalent. Their net short consequently narrowed by 4,390.70 BTC-equivalent, from 40,110.83 to 35,720.13. Their combined short exposure still exceeded their longs. These long and short columns exclude separately recorded, offsetting spread positions.
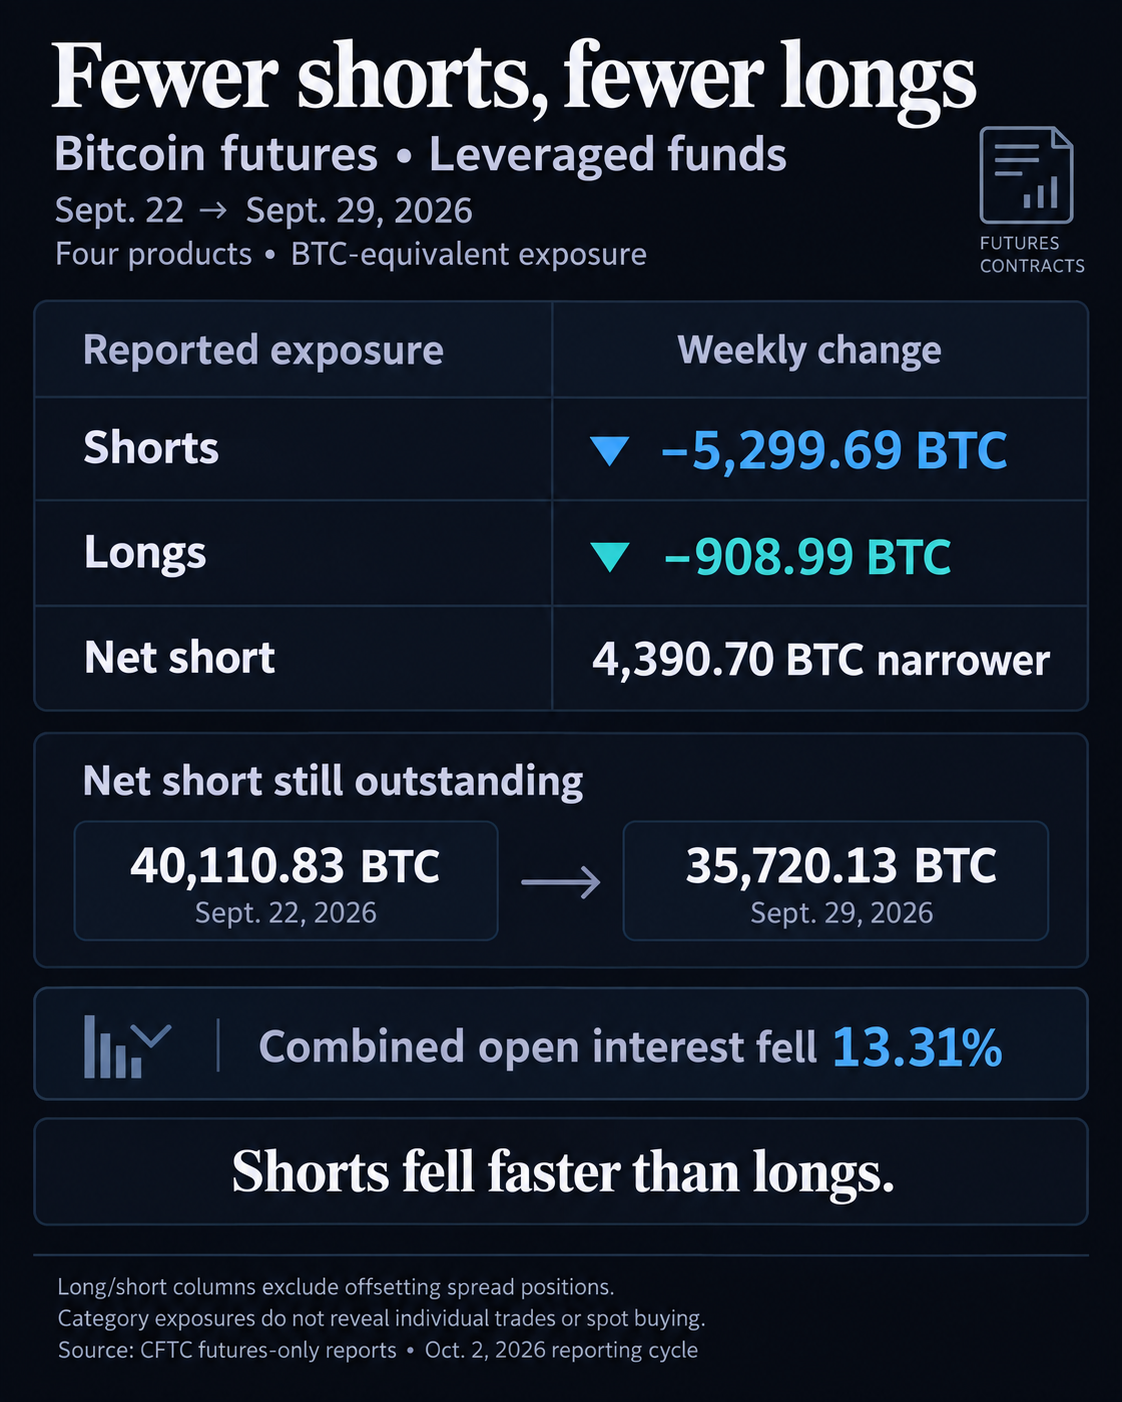
A better net figure can result from shrinking positions on both sides when shorts fall faster. In this snapshot, aggregate futures long exposure did not expand.
The individual products did not move uniformly. Standard CME futures accounted for 4,310 BTC-equivalent of the reduction in reported shorts, while their leveraged-fund longs increased 1,175 BTC-equivalent. Longs fell in CME micro futures and both Coinbase products, more than offsetting that increase.
The standard-CME move reversed the widening of net shorts in the Sept. 22 snapshot. That earlier report covered standard CME alone; the latest totals include all four products.
Asset managers’ net long across the four products increased 2,137.90 BTC-equivalent to 18,069.10. Their longs rose 573.10 BTC-equivalent, while shorts fell 1,564.80 BTC-equivalent. Most of their stronger net position therefore also came from fewer reported shorts.
Combined open interest, the outstanding futures exposure across these markets, fell 13.31% to 103,343.14 BTC-equivalent from 119,208.26. The improvement in net positioning occurred alongside a contraction in the overall futures market measured here.
Smaller shorts do not establish spot demand
The separately recorded spreading positions represent offsetting positions. Leveraged funds’ spreading column also fell, by 11,231.11 BTC-equivalent. The 5,300 BTC-equivalent reduction covers the reported short column, excluding those spread legs.
The monthly CME micro expiry rule places September’s expiry on Sept. 25, between the two observations. That provides calendar context without proving that expiry or rolls caused the contraction. Classification changes can also affect category totals.
The CFTC groups traders by predominant business activity. Its Tuesday position reports do not reveal individual transactions or paired spot and ETF holdings. A futures short may be part of a hedge, so fewer shorts do not establish fresh spot buying or reduced bearish conviction.
The next release is scheduled for Oct. 9. It can show whether the category shift persists.
The post Leveraged funds’ Bitcoin futures shorts fall by 5,300 BTC-equivalent as longs shrink appeared first on CryptoSlate.
Arbitrum's Security Council temporarily blocked new Stylus contract activations on Arbitrum One and Nova in an October 2 emergency action, restricting programs and app updates that require fresh activation. Already-active Stylus applications can keep running, while ordinary Solidity contract deployment and execution remain unaffected, according to the Council's action report.
Arbitrum attributed the precaution to increasingly sophisticated AI-assisted attacks involving hand-crafted WebAssembly programs outside the standard Stylus compiler toolchain. It said known Stylus bugs primarily threaten chain liveness, including denial-of-service risks, and that no attack permitting theft of user funds had been discovered.
The linked Ethereum, Arbitrum One and Nova transaction records show successful execution on October 2, around 15:30 to 15:31 UTC.
For builders, the distinction is between storing code and making it usable. Stylus contracts run WebAssembly programs, which need activation to become executable. Arbitrum's documentation distinguishes that step from deployment, which stores code onchain. New contract instances using identical program code can reuse an existing activation, provided it is still valid.
A new application version requiring fresh activation cannot become executable during the pause. Reactivating an expired program, or one needing reactivation after a Stylus version change, is also blocked, the Council said. The scope is activation, rather than a blanket prohibition on deploying every new contract instance.
Existing programs remain callable until expiration. Developers can continue extending an active program's lifetime through the permissionless keepalive renewal mechanism before it expires, according to the official pause notice. This leaves renewal available while reactivation of an already-expired program is blocked.
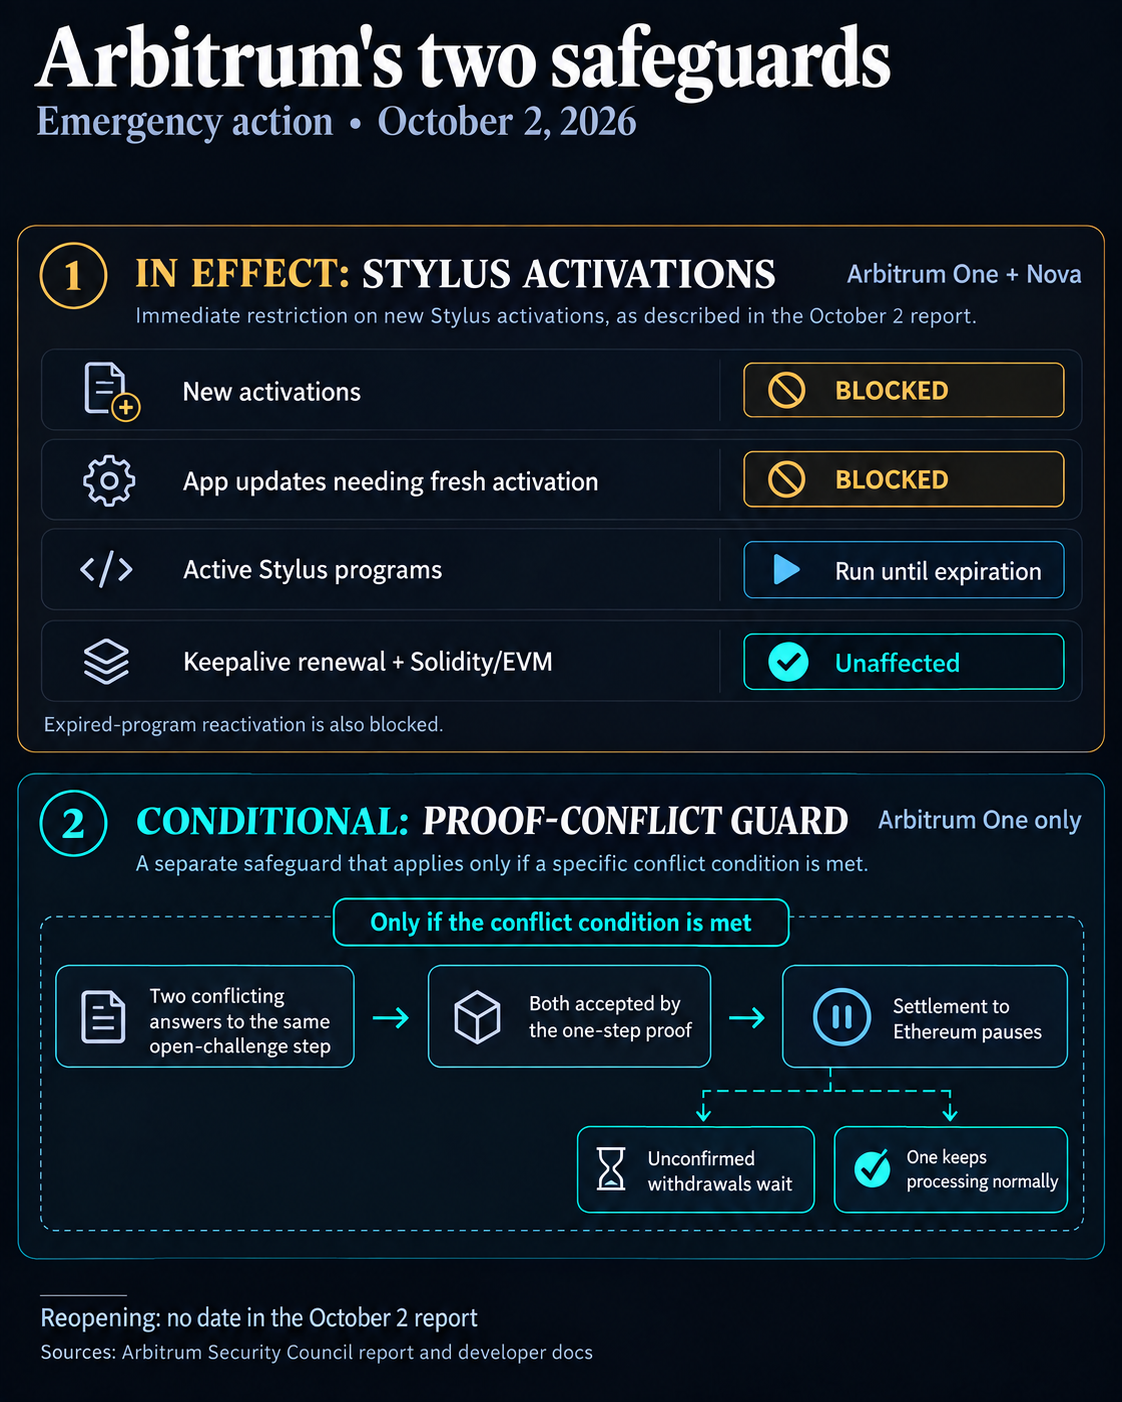
The Council said it implemented the restriction by raising the activation gas requirement to a prohibitively expensive level. It described this as a configuration change requiring no upgrade to ArbOS, the network's operating software.
When withdrawals could wait
The same emergency action installed a separate safeguard for BoLD's one-step proofs on Arbitrum One. Anyone can present two conflicting answers to the same step of an open challenge. If the one-step proof accepts both, the guard puts One's settlement to Ethereum on hold, according to the Council.
Arbitrum says One would continue processing normally during that suspension. However, messages from One to Ethereum that have not yet been confirmed, including withdrawals, would have to wait while the Council deploys a fix and resumes settlement. Installing the guard does not itself pause withdrawals; the delay depends on its conflict condition being met.
For builders waiting to activate new Stylus code, reopening remains the next decision. The October 2 report and developer notice give no date, saying the Foundation will work with ArbitrumDAO on the timeline and manner of restoring activations.
The post Arbitrum pauses new Stylus activations over AI-assisted attack risks appeared first on CryptoSlate.
Companies building AI applications can rent powerful computers instead of buying the equipment themselves, paying for access to the graphics processing units, or GPUs, that run their software.
Lower rental prices make those applications cheaper to operate, but they can also make life harder for the company that bought the machines and needs the rent to pay its debts.
If you've financed a room full of GPUs assuming customers will pay a certain hourly rate, a cheaper competitor can upset the calculation long before you've paid off the equipment. Your machines might still work perfectly, and demand for AI might still be strong, but the amount you earn from each hour could start falling below what the business needs.
Financial contracts could let you protect part of that income by arranging a payment when rental prices fall, in exchange for taking on your own obligations. That's the basic idea behind AI compute derivatives, which let businesses trade their exposure to computing prices separately from renting the computers themselves.
Luxor, a company that provides services and financial products to Bitcoin miners, included these contracts in its latest expansion into AI. It sees an opportunity to bring its experience hedging mining revenue to another business that spends heavily on machines before knowing what it'll earn.
The company told CryptoSlate that it's already brokering agreements between owners of computing capacity and customers who want to use it.
However, its cash-settled derivatives business is still early, and the company said it couldn't provide a customer hedge example or current derivatives trading volumes because a liquid market hadn't formed yet.
That gives this promising idea the difficult commercial task of persuading someone to accept losses another business wants to avoid.
Getting that arrangement to work could help operators plan around more predictable income, but the protection is only as dependable as the price used to calculate it and the party responsible for paying.
Locking in the rent without locking in a customer
The tried-and-true way to make rental income more predictable is to sign a customer for a longer period at an agreed price. The customer gets access to the machines, while the operator gets a commitment it can use to plan its business.
That works well when both sides want the same arrangement, but customers don't always know how much computing they'll need that far into the future. Operators may also prefer to keep selling capacity to different users.
Cash-settled derivatives offer another approach because the contract pays money according to a price formula, without requiring the parties to exchange computing capacity. The operator can keep renting its GPUs to customers while using a separate financial agreement to offset movements in the rental rate.
Imagine an operator expecting to sell 1 million GPU-hours in a month, where one GPU-hour means access to one processor for an hour. At $2 per hour, that would produce $2 million in rental income, and the operator enters a hypothetical contract designed to protect that rate.
If the agreed market benchmark falls to $1.50, the contract pays the operator the 50-cent difference across the million hours, or $500,000. Assuming its actual rental income also falls to $1.5 million, that payment brings the combined amount back to $2 million before fees and other costs.
The obligation runs both ways, so if the benchmark increases to $2.50, the operator owes $500,000 while earning more from its customers. It gives up the benefit of a higher rate in exchange for protection against a lower one, making revenue easier to plan around.
This is just back-of-the-napkin math to explain the arrangement, as the result depends on the operator actually selling the expected hours at a rate that tracks the benchmark. Empty machines still produce no rental income, so fixing the hourly price doesn't guarantee someone will buy it.
Someone on the other side needs a reason to accept the opposite payments, and an AI business worried about more expensive computing could have one. Its financial contract would pay when the benchmark increased, helping cover a larger rental bill, while a fall would create a payment obligation alongside cheaper computing.
Dealers could help connect those interests or take some of the exposure themselves, charging for the risk they carry. But customers need a price for the amount of protection they want, covering the period when their business needs it.
CME Group is pursuing an exchange-traded version of this idea through its announced H100 and B200 rental-index futures. Its Aug. 11 announcement targeted Oct. 5, subject to regulatory review, for contracts tied to Silicon Data's GPU rental benchmarks, although listing a contract alone can't guarantee enough participation to make it easy to trade.
Your GPU hour might be different from mine
But even with willing counterparties, the payment formula needs a price both sides accept as relevant to their business.
In the example above, the hedge works perfectly because the operator's rental income moved exactly with the benchmark. However, you can't replicate perfect conditions once actual customers enter the picture.
Suppose its customers negotiate rates down to $1.25 while the benchmark only falls to $1.50, perhaps because the index covers a different service or type of equipment. The same $500,000 hedge payment would then bring its $1.25 million in rental income to $1.75 million, leaving a gap even though the contract works as written.
That mismatch is called basis risk, which simply means the price you've protected against doesn't move exactly like the price you actually receive. Compute hedges can leave Bitcoin miners exposed, and this is one reason a hedge needs to be judged against the particular business using it.
Luxor compared its AI ambitions with its path in Bitcoin mining, where publishing a reference price helped create a foundation for financial contracts. Its hashprice measure estimates what a unit of computing power can earn from mining Bitcoin, giving operators a shared revenue reference even when their own operating costs differ.
Bitcoin miners perform the same network task, whereas AI customers can attach different values to access that looks similar on a specification sheet. Someone buying uninterrupted access for months is purchasing a different service from someone willing to have a short job stopped whenever the provider needs the machines back.
Price providers already account for differences like these, with CCIR's rental-data methodology treating interruptibility and commitment length as separate characteristics. It uses publicly advertised rates, which also means the figures don't necessarily capture privately negotiated discounts.
The index Luxor supplied in its reply was its AI Hardware Price Index, which measures advertised prices for selected GPU systems. That can help someone assess an equipment purchase, but buying a machine and earning rent from it involve different prices, so the link doesn't establish how an AI rental hedge would settle.
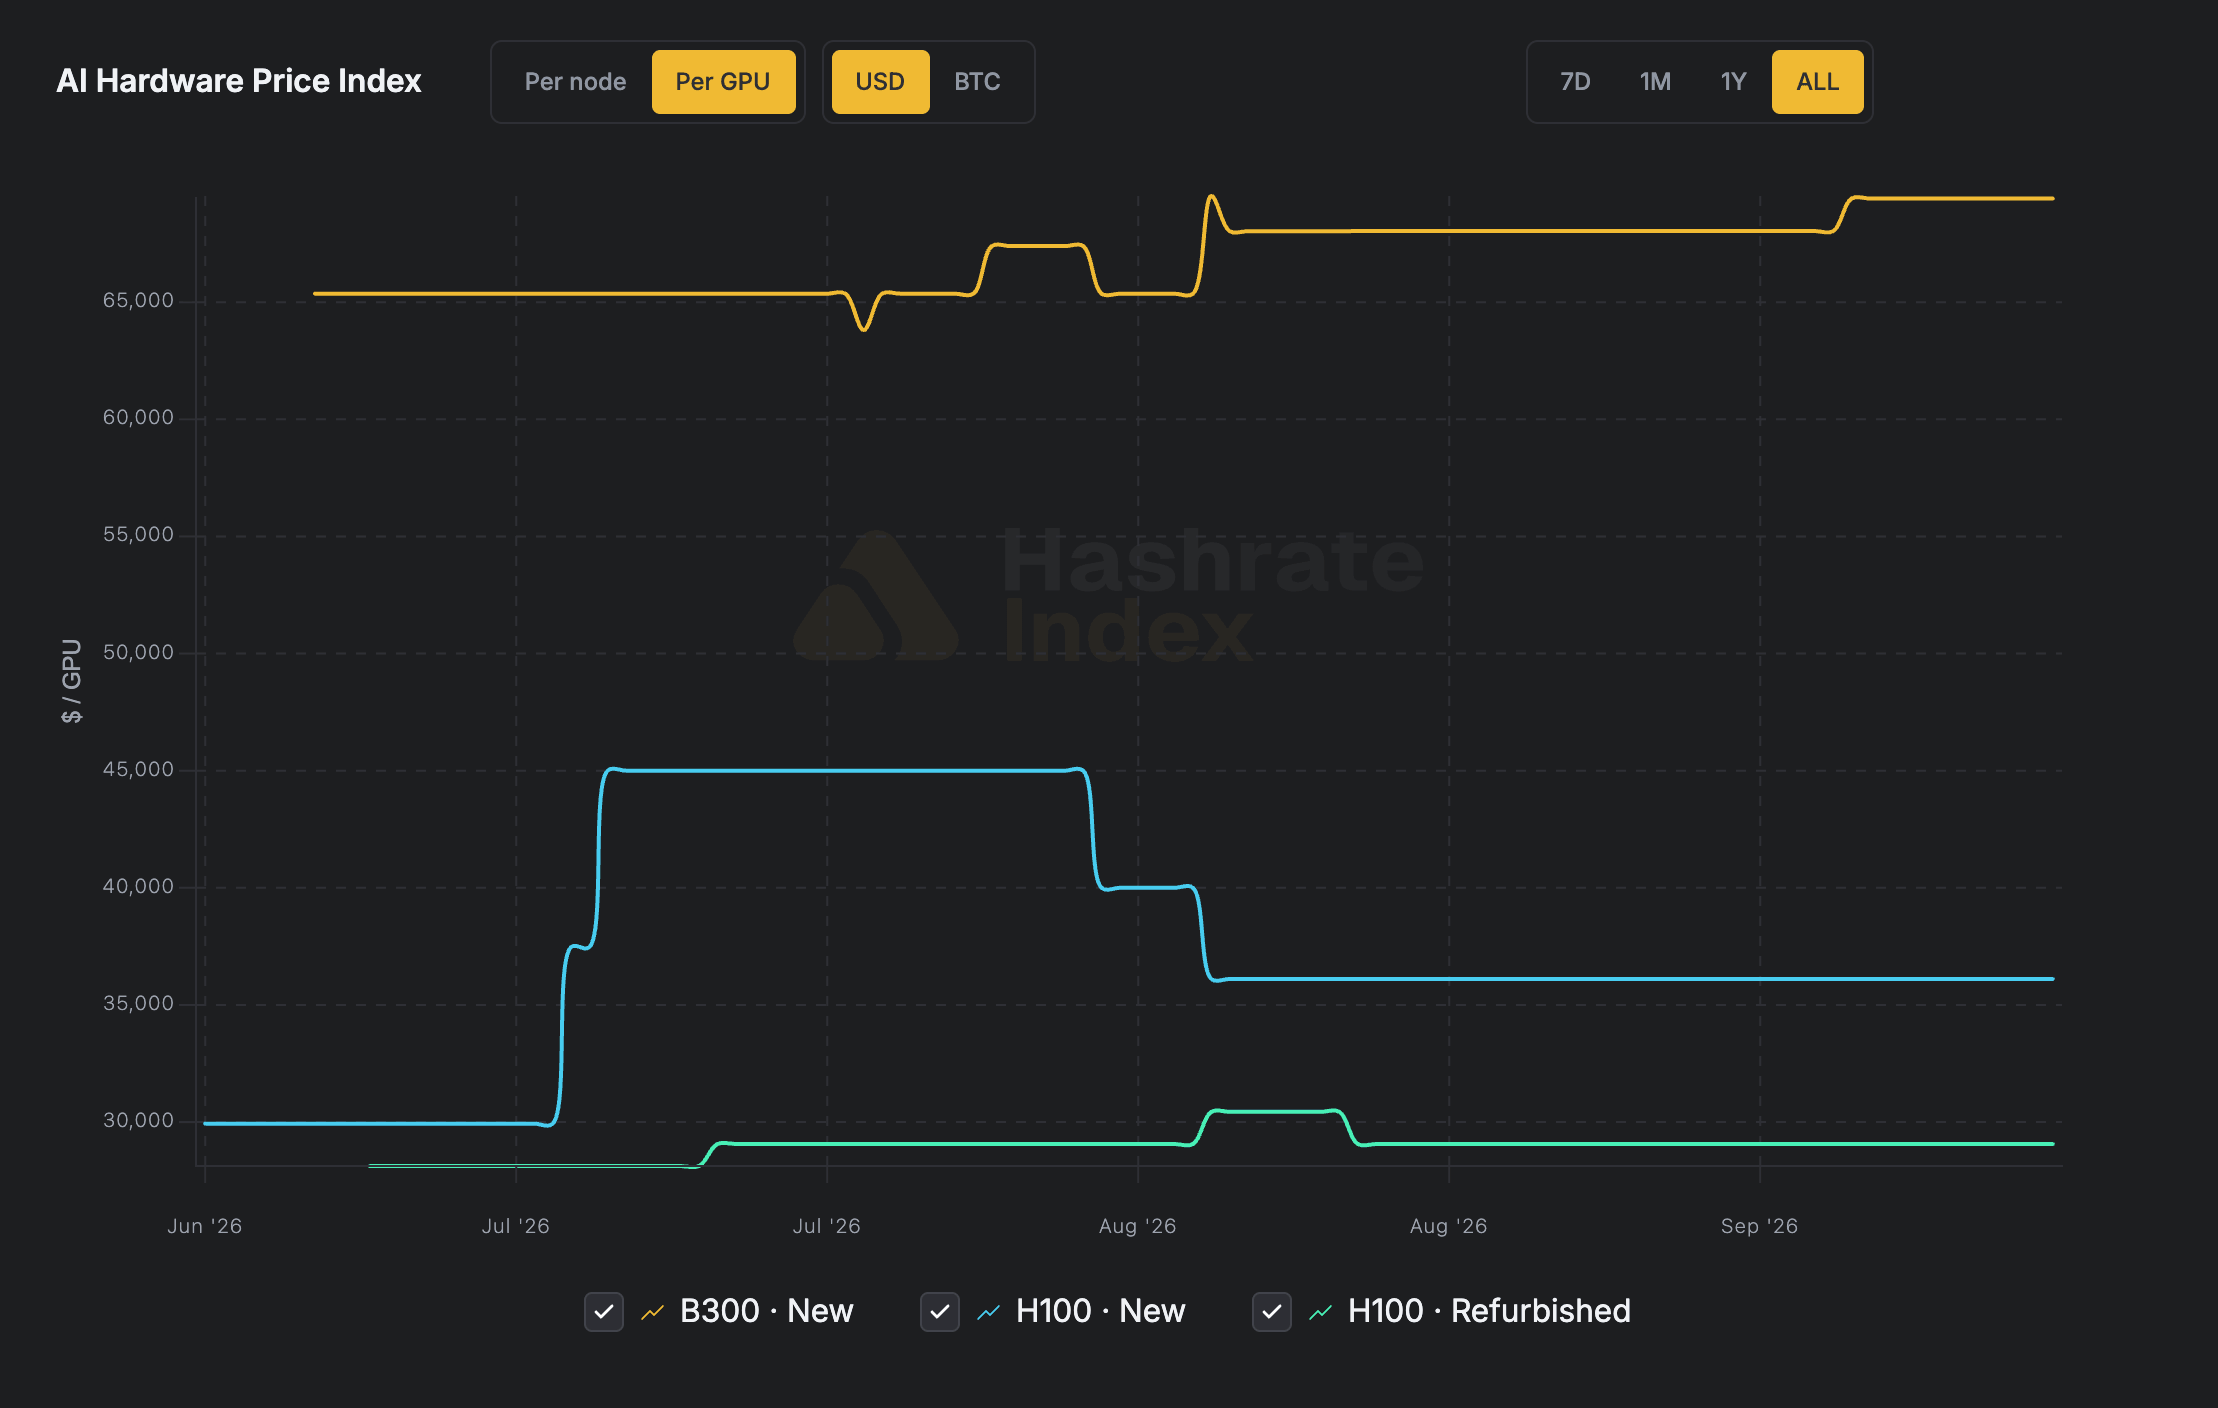
Luxor's August data announcement described expanded compute spot pricing as forthcoming. Operators trying to protect income would still need contracts that name a rental benchmark and show it tracks what customers pay.
Narrower benchmarks might fit better, but each additional contract splits potential trading among smaller groups. Building this market requires a compromise between matching each customer's business closely and bringing enough people together under the same contract to make trading affordable.
The protection has to survive the bad month
Even a closely matched contract leaves the operator relying on someone else's ability to pay when rental income falls.
If that counterparty also earns much of its money from AI infrastructure, cheaper computing could damage both businesses at the same moment, just when one expects support from the other.
Collateral can reduce that dependence by requiring money or eligible assets to be posted against obligations, giving the recipient something to draw on if the other party fails. It also creates a financing requirement, because money committed to the hedge can't simultaneously pay the operator's other bills.
In the example where rental prices increase, the operator might have to pay its hedge obligation before customers settle their higher invoices.
The overall economics could still work even if the bank account runs short, making the timing of cash flows a huge part of that protection's affordability.
Luxor didn't provide the requested AI collateral terms or explain the procedures for a counterparty failing to pay. Its reply also left unanswered how it separates its own trading from the business it arranges for customers, a relevant point because the launch announcement disclosed an internal compute trading fund.
More predictable rental income could give an operator greater confidence about meeting its debt payments, even when customers become less willing to pay yesterday's rates.
Getting that benefit requires a contract that follows the income closely enough, with payment obligations the operator can afford throughout the period it's trying to protect.
Cheaper computing could let more people build and use AI while leaving some owners of the machines with disappointing returns.
Financial contracts won't make that loss disappear, but they could move part of it to someone prepared to bear it, giving the operator more room to keep serving customers when the rent falls.
The post Plunging GPU prices threaten AI hosts, and new hedges step in appeared first on CryptoSlate.
CryptoTicker.io
Anyone putting money into Bitcoin today decides first on the form: a single amount all at once, a fixed monthly instalment or an exchange-traded security in a securities account. In October 2026 this decision about investing in Bitcoin has an additional reason to be looked at closely. The German finance ministry’s draft bill on crypto taxation provides that the one-year holding period continues to apply only to holdings acquired by December 31, 2026. Whatever is bought after that is to fall under the flat-rate withholding tax. The cabinet is due to adopt the draft on October 14.
This article recalculates the three routes against the prices of the past ten years, explains the German tax position for each of them and names what can go wrong on each route. It gives no buy recommendation and names no price target. You will find the current level and the analyst views on Bitcoin on our prediction page.
Investing in Bitcoin: These Three Routes Are Open in Germany
All three routes lead to a stake in the price performance of Bitcoin, but they differ in what you own at the end and in how the tax authorities treat it.
The direct purchase means that you acquire real Bitcoin and either leave it with the trading platform or transfer it to a wallet of your own. A wallet is not a purse but the management of a cryptographic key pair with which you can dispose of a blockchain address. Whether you deploy the whole amount at once or a monthly instalment is, on this route, purely a question of timing.
The savings plan is a standing order for a direct purchase: a provider buys Bitcoin at a fixed rhythm for a fixed euro amount, regardless of the price. The technical term for this is dollar-cost averaging. It describes the fact that a fixed instalment buys more Bitcoin at low prices than at high ones, and that the average price therefore lies below the mean of the prices. How this effect behaves in a slump is something we worked through in June 2026 under dollar-cost averaging in a crypto crash.
The security is the third route. In the EU there is no Bitcoin fund under UCITS rules, because a fund of that kind may not put its entire assets into a single asset. What is offered in Germany as a Bitcoin ETF is therefore almost always an ETN or ETP, that is, an exchange-traded debt security collateralised with Bitcoin. Which products these are and what you have to watch out for with them is collected in our overview of crypto ETFs in Germany.
The December 31, 2026 Cut-Off and the One-Year Holding Period
Today, Section 23 of the German Income Tax Act applies to privately held Bitcoin: anyone who holds for longer than a year sells tax-free, regardless of the size of the gain. Anyone who sells earlier pays their personal income tax rate on the gain as soon as the total of all private disposal gains in the calendar year reaches 1,000 euros. Those 1,000 euros are an exemption limit and not an allowance: from one euro above it, the entire gain is taxable, not just the excess part.
The draft bill, which according to the Bitcoin portal Blocktrainer the cabinet is due to take up on October 14, would end this system for new purchases. Crypto assets acquired after December 31, 2026 are to be subject to the flat-rate withholding tax, that is, a fixed rate regardless of the holding period. For everything that was in the portfolio before that, grandfathering is provided for: there the one-year period would be preserved.
For your decision that is the decisive difference between the two direct-purchase variants. A lump sum paid in October or November falls entirely under the old law. A savings plan that starts in October and is meant to run for two years is spread across the cut-off: the instalments from 2026 would be protected, those from 2027 onwards would not. In tax terms, two groups of holdings thus arise within the same savings plan, and they have to be treated separately.
One thing remains important: the draft is a draft. Until promulgation in the Federal Law Gazette the cut-off date can shift, and the consultation period for the industry associations ended, according to the same report, as early as October 6, six days after it was sent out. What ends up in the law is decided by the Bundestag and the Bundesrat.
Exemption Limit, Record-Keeping Duty and the Reports From Trading Venues
Quite apart from the draft, the enforcement side shifted in 2026. Since January 1, 2026 the reporting obligations from the EU directive DAC8 have applied, implemented in Germany through the Crypto Tax Transparency Act. Providers domiciled or authorised in the EU report their customers’ accounts and transactions to the tax administration. For you that means: the assumption that a sale within the one-year period goes unnoticed no longer holds.
From that follows a practical duty which weighs more heavily with a savings plan than with a one-off purchase. Every single instalment is its own acquisition event with its own date and its own price. With a monthly instalment and a five-year term that is sixty events which you have to allocate on sale under the first-in-first-out method, that is, in the order in which they were bought. Anyone who does not have these records has an additional problem under the draft bill: without proof of the acquisition cost, a flat 50 percent of the sale proceeds is to count as the tax base. What this substitute assessment means in detail is something we wrote up on October 1, 2026 under crypto acquisition costs and substitute assessment.
A further point in the draft concerns the years from 2028 onwards: trading venues are then to pay over the tax directly, the way banks do with shares. The details and what the deduction means for your liquidity are in our article on withholding tax at crypto exchanges of October 1, 2026.
Lump Sum Against Savings Plan: The Calculation Over Ten, Five and One Year
The question of which of the two direct routes would have made more out of the same money can be recalculated against the actual prices. We evaluated the weekly prices of the Bitcoin against euro pair on the Kraken trading platform going back to 2013 and took the opening price for the start of each month. Two variants with identical contributions are compared: once 100 euros per month over the whole period, once the entire sum on the first day. Both are valued at the October 2026 opening price of 73,775 euros.
| Period from October | Contribution | Price at the start | Savings plan at the end | Lump sum at the end |
|---|---|---|---|---|
| 2016, ten years | 12,000 euros | 550 euros | 138,300 euros | 1,608,500 euros |
| 2021, five years | 6,000 euros | 47,800 euros | 11,105 euros | 9,260 euros |
| 2023, three years | 3,600 euros | 26,448 euros | 4,339 euros | 10,042 euros |
| 2024, two years | 2,400 euros | 54,902 euros | 2,395 euros | 3,225 euros |
| 2025, one year | 1,200 euros | 101,066 euros | 1,331 euros | 876 euros |
The picture is not uniform, and that is precisely where the message lies. Over ten years the lump sum beats the savings plan by more than elevenfold, because the 12,000 euros at 550 euros per Bitcoin bought a quantity that no later instalment could reach. Over five years from October 2021 the relationship reverses: there the starting price of 47,800 euros was close to the high of the time, the savings plan bought into the subsequent slump and ends up 1,845 euros ahead of the lump sum. Over the past year the gap is clearest. Anyone who deployed 1,200 euros at once in October 2025 at 101,066 euros holds Bitcoin worth 876 euros today, 27 percent less. The same sum in twelve monthly instalments produced 1,331 euros, a gain of just under 11 percent.
Why the Lump Sum Came Out Ahead in 88 of 98 Five-Year Windows
A single period can be luckily or unluckily chosen. We therefore ran the same calculation over every possible five-year window the price series allows: 98 windows, each 60 monthly instalments against a single payment of 6,000 euros, valued at the end of the respective window. In 88 of these 98 cases the lump sum came out ahead, in 10 the savings plan.
The reason lies in the direction of the market, not in a property of the savings plan. Bitcoin has risen across the entire price series so far. In a rising market, money that is invested earlier is invested for longer, and quantities bought early never become cheaper again at any point. The savings plan by definition holds back part of the capital and buys it in later at subsequent, on average higher, prices.
The ten windows in which the savings plan won share one property: their starting month lay shortly before one of the big slumps in each case. That is the real reading of this figure. The lump sum wins more often, but it also loses more clearly when the entry point is badly placed, and it demands a decision that nobody can secure in advance with data. The savings plan, by contrast, buys the uncertainty along with it and takes the question of the right day out of your hands. Which of the two kinds of risk you are more willing to bear is a question for you and not for the price series.
Two limits of this survey belong with it. The calculation is made without fees and without the spread, that is, without the gap between the buy and sell price, and without taxes. Both weigh more heavily on the savings plan, because it consists of many small purchases. And it values only today’s level. Any other valuation day delivers different figures.
Instalment, Interval and Fees: What a Bitcoin Savings Plan Depends On
If the decision falls on the savings plan, three levers determine how much of the money paid in actually ends up in Bitcoin. The minimum instalment at the providers available in Germany lies, according to the surveys by the comparison portals, between one cent and ten euros, and at most of the large houses at one euro. The interval ranges from weekly to quarterly, with a shorter interval strengthening the averaging effect and at the same time producing more individual events for the tax return.
What is decisive is the cost side, and it consists of two parts that have to be stated separately: the order fee and the spread. A fixed order fee of one euro is a side issue on an instalment of 500 euros; on an instalment of 25 euros it is four percent of the purchase amount, missing immediately. The spread comes on top and is not always described as a fee. Anyone who wants to invest a small instalment should therefore calculate the total costs as a percentage of their own instalment and not compare the advertised fee figure. The current terms of the providers are in our comparison of Bitcoin savings plans.
Since the EU regulation MiCA took effect at the end of December 2024, choosing the provider itself involves a hard checkpoint: a trading venue serving retail clients in the EU needs authorisation as a crypto-asset service provider. The authorisation says nothing about price performance, but it governs own funds, custody and complaint channels. Which houses hold it we list under regulated crypto exchanges. Fee structures change frequently, so it is worth looking at the provider’s price list on the day you sign up.
Crypto ETNs in a Securities Account: The Delivery Claim Decides the Tax Rule
The third route does not run through a crypto platform but through the securities account at a bank or broker. What is traded are ETNs, that is, collateralised debt securities on the Bitcoin price. In practice that has advantages: no key of your own, no additional account, purchase and savings plan through the familiar securities account screen, and the settlement lands automatically in the annual tax statement.
In tax terms this route is the most complicated, and the distinction hangs on a single feature: the delivery claim. If the product gives you the securitised right to demand delivery of the deposited Bitcoin, there is much to be said for treating it like direct ownership, that is, with the one-year period under Section 23. If that right is missing, what exists is a pure claim, and the income counts as investment income with flat-rate withholding tax, the solidarity surcharge and, where applicable, church tax, without any holding period. There is no conclusive determination by the tax administration binding for all products, and the classification will in the end depend on the specific prospectus. With larger sums that is the point at which a trip to a tax adviser pays for itself.
On top of that comes a risk the direct purchase does not have: issuer risk. You hold a claim against the issuing company. If the collateral is held separately in trust, that risk is small, but it is not zero, and it belongs in the trade-off against the risk of losing a key of your own.
Custody After the Purchase: Whoever Holds the Key Holds the Bitcoin
With a direct purchase the purchase is not the last step. If you leave the Bitcoin in the trading account, you hold a credit against the provider, and that provider’s solvency and security architecture are part of your risk. If you transfer it to a wallet of your own, you no longer carry that risk, but you do carry full responsibility for the key. There is no body that replaces a lost recovery phrase.
The size of the amount helps with the decision. On an instalment of 25 euros a month, a hardware device costs more in the first year than the holding it protects; there an account with an authorised provider is a defensible interim solution, as long as you do not run the two-factor protection over SMS. As soon as the holding grows into the four-figure range, the relationship shifts. A hardware device keeps the key permanently separated from the internet and releases payments only after confirmation on the device. In tax terms the transfer to your own wallet is not a sale and triggers no tax, as long as you remain the owner.
Position Size and Total Loss: The Risk Side of the Decision
Over its history Bitcoin has repeatedly lost more than 70 percent from its high and recovered afterwards. That this will happen again is not a forecast but the description of a property: this market knows slumps of that order. A total loss is possible, and it is covered neither by deposit insurance nor by a compensation fund. A bank’s 100,000 euros of deposit insurance applies to balances in euros, not to crypto assets.
From that follows no advice on the amount, but a test calculation you can carry out yourself: take the amount you want to invest and subtract 80 percent of it. If the difference remains an amount that does not touch your rent, your emergency reserve or a foreseeable expense, the position size is sustainable. If it does touch them, it is too large, regardless of which of the three routes you decide on. Anyone working on credit or with leverage leaves this calculation entirely, because there even a setback can lead to forced liquidation, long before a price recovers.
A final point on timing. The December 31, 2026 cut-off is a tax advantage for purchases that take place by then, but it is no reason to bring forward a decision you have not yet made on the merits. A holding that turns out too large under time pressure costs more in the next slump than the holding period ever brings in.
Investing in Bitcoin: Your Next Three Steps
- Settle the route and the amount before you open an account. Decide first whether you want to deploy a sum at once or a monthly instalment, and check the figure with the test calculation from the previous section. Only after that does the provider question become concrete: terms and minimum instalments are in the comparison of Bitcoin savings plans.
- Collect records from the very first transaction. File the date, quantity, price and fee for every purchase, ideally automatically. Anyone who only catches up on this at the point of sale pays tax, under the draft, on half the proceeds in case of doubt. Which programmes take over the allocation is shown by our overview of crypto tax tools and portfolio trackers.
- Let the custody grow with the holding. Set a threshold above which you transfer the holding from the trading account to a wallet of your own, and stick to it. The devices and their differences are in the hardware wallet comparison.
(As of October 3, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Sweatcoin’s SWEAT token is disappearing in stages, not on a single day. The first stage, and the one that matters most to you, is Wednesday, October 7, 2026: that is when the Dutch exchange Bitvavo closes deposits, trading and withdrawals for SWEAT, one after the other. Eight days later it automatically converts any remaining balance into euros. Only after that, on December 30, 2026, does Sweat Wallet itself come to an end.
This article sorts the dates, separates the two wind-downs that happen to coincide here, and works out the point at which withdrawing to your own wallet still leaves anything at all. If you hold crypto assets on an exchange and are thinking about your trading venue anyway, our comparison of crypto exchanges helps you place fees and authorisation.
What Is Happening to SWEAT Right Now: Two Wind-Downs at Once
SWEAT is the token of the Sweat Economy. Anyone who uses the Sweatcoin walking app is credited with it for verified movement, and it is held in a separate app called Sweat Wallet. Technically the token sits on the NEAR blockchain and is bridged from there to several EVM chains, among them Ethereum, Base, BNB Smart Chain and Arbitrum.
On October 1, 2026, the Sweat Foundation, the company behind the app and the token, announced that Sweat Wallet and SWEAT will end in their current form on December 30, 2026. The reasons it gives, in its own words, are a sustained downturn in the crypto markets, the loss of exchange listings, the cost of working through a security incident in April 2026 after which all user balances were restored, and slower growth in new users. Until December 30 the app, the token and the contracts continue to run unchanged.
A day later, on October 2, Bitvavo announced the delisting of SWEAT. That is an independent decision: according to the Foundation, each platform decides on listings for itself. For you, though, the two wind-downs meet in the same account, and the exchange deadline falls almost three months before the project deadline. That is precisely why October 7 is the date that counts first.
The Bitvavo Deadlines on October 7: 1 p.m., 2 p.m. and 3 p.m.
Bitvavo closes the market in three steps, all on the same Wednesday and each an hour apart. Deposits of SWEAT end at 1 p.m. CEST. Buying and selling ends at 2 p.m. CEST. Withdrawals to an address of your own end at 3 p.m. CEST.
There is a practical point to that order: after 1 p.m. nothing more comes in, and you still have two hours to get rid of what is already there. Bitvavo also warns explicitly against depositing SWEAT after 1 p.m. CEST, because such credits can be lost. So anyone who wants to move holdings from another platform or out of a wallet to Bitvavo in order to sell them there needs a head start: a transfer on the Ethereum chain sent off at midday on Wednesday may arrive too late.
This design is not an isolated case in our coverage. Bitvavo already removed Kava, Nano and Ravencoin in mid-September, and at the end of September ICX followed with a forced conversion ten days after the close of trading. The sequence at SWEAT is the same, only the dates are different.
Forced Conversion Into Euros From October 15
Whatever is still in the account after October 7 does not vanish. Bitvavo converts remaining SWEAT holdings into euros automatically by Thursday, October 15, 2026 at the latest and credits the proceeds to the account. The exchange names that date as the outer limit and expressly reserves the right to convert earlier.
A forced conversion is convenient, but it takes two things out of your hands. The first is the timing: you do not know the price at which the conversion happens, and with a token that has lost between 40 and 42 percent over the past 24 hours that is no minor matter. The second is the decision whether you want to sell at all. Anyone who wants to keep the token, because according to the Foundation the contracts on NEAR will remain in place beyond December 30, has to withdraw before October 7.
Selling or Withdrawing SWEAT: How to Proceed Before October 7
For a balance at Bitvavo there are exactly three routes, and all three are legitimate. The first is a sale into euros before 2 p.m. CEST on October 7. The second is a withdrawal to an address you control yourself, before 3 p.m. CEST. The third is to do nothing and wait for the automatic conversion.
Which route makes sense depends almost entirely on the size of your holding, and that can be calculated rather than guessed. The figures for it are further down. The rule of thumb up front: with small holdings the withdrawal fee eats up the proceeds, with very small holdings the minimum order size prevents a sale altogether, and then conversion is the only route left.
A fourth route that is often overlooked: you can also withdraw SWEAT to another exchange that still lists the token and sell it there. Technically that is the same withdrawal, just with a different destination address.
Kraken Remains the Last Euro Market for SWEAT
Worldwide, SWEAT has only two trading pairs against the euro: one at Bitvavo and one at Kraken. Once the first falls away at 2 p.m. on October 7, Kraken is the only remaining euro market. At midday on Friday trading there was open, deposits and withdrawals for SWEAT likewise, and the pair against the euro was quoted as usual.
Two caveats belong with that. First, Kraken has made no commitment to list SWEAT permanently; listing decisions are taken by each platform for itself, and the Foundation itself points out that liquidity can fall. Second, a minimum amount applies at Kraken too: below 15,000 SWEAT the exchange will not accept an order. At midday on Friday that corresponded to around five euros.
Anyone who wants to move from Bitvavo to Kraken needs both: a withdrawal before 3 p.m. CEST on October 7 and an account that can receive the token. The order matters, because once trading closes at Bitvavo the selling route there is shut, while the withdrawal stays open for another hour.
A 2,900 SWEAT Withdrawal Fee and a 3,100 SWEAT Minimum: When Withdrawing Pays Off
This is the point at which most holders get the maths wrong. Bitvavo charges a fixed fee of 2,900 SWEAT for a SWEAT withdrawal and only permits withdrawals from 3,100 SWEAT upwards. Both figures are denominated in tokens, not in euros, and they do not change with the price.
Taking Friday midday’s price of around 0.00034 euros, that gives the following: the fee costs about 0.98 euros. Anyone withdrawing the minimum of 3,100 SWEAT gets 200 SWEAT out of it, around seven cents. In that case the fee eats up 94 percent of the withdrawal.
The larger the holding, the less that weighs. At 100,000 SWEAT, worth about 34 euros at midday on Friday, 2,900 SWEAT is still 2.9 percent. At one million SWEAT, around 340 euros, it is 0.29 percent. A workable threshold therefore lies somewhere in the region of a few hundred thousand tokens: below that, withdrawing to your own wallet is expensive; above it, the fee becomes an ordinary transaction cost.
A second hurdle applies to selling, independently of all this: for SWEAT, Bitvavo accepts no order below five euros in value, which at midday on Friday came to just under 15,000 tokens. Anyone holding less can neither withdraw sensibly nor sell at all. For that group the automatic conversion on October 15 is not the worst option but the only one, and that is reassuring news: the balance is not lost, it lands in the account as a euro amount.
Where SWEAT Sits: the Ethereum Network at Bitvavo, the NEAR Account in Sweat Wallet
A mix-up can get genuinely expensive here. Bitvavo lists SWEAT exclusively on the Ethereum network. A withdrawal therefore goes to an Ethereum address, not to your NEAR account in the Sweat Wallet app. Anyone who enters the NEAR account identifier from the app into the withdrawal field at Bitvavo is sending the amount to a destination the exchange does not serve.
The reverse holds too: the SWEAT you have earned in the app sits on NEAR. If you want to sell it, you first have to move it to a chain and an exchange that will accept it. The Foundation points out that it has placed liquidity into a SWEAT pool on a decentralised trading platform on NEAR; whether and where you swap remains your decision.
A wallet of your own is the prerequisite for that. Which device and software solutions exist and what to look out for when setting one up is written up in our comparison of hardware wallets. For SWEAT itself you do not need a specialist device, but a wallet that supports the relevant chain.
Sweat Wallet: Back Up the Private Key and the NEAR Account ID
Anyone using the app has a second front to deal with, one that has nothing to do with Bitvavo. Every Sweat Wallet account is a NEAR account, and the private key is what controls it. If that key exists only inside the app, access disappears with the app.
The Foundation names four steps that every user has to carry out themselves. First, back up the private key together with the NEAR account identifier; inside the app the route runs from the profile to the security section. Second, pull earned but not yet credited SWEAT into the wallet. Third, withdraw balances from the so-called Grow Jars. Fourth, move holdings that sit in the app on Ethereum, Base, BNB Smart Chain or Arbitrum into a wallet of your own.
One important detail appears as a warning in the announcement: anyone who removes so-called magic keys or sign-in via the secret phrase can render the backed-up private key useless. Backing up itself changes nothing about the app, the key stays there; afterwards you merely hold an additional copy. As the recommended end date for all four steps the Foundation names December 18, 2026, just under two weeks before the close.
Grow Jars Without a Minimum Term, and the Sweat Validator Stops on October 31
Grow Jars are savings pots inside the app into which users deposit SWEAT for a fixed minimum term and receive interest for it. That minimum term falls away by October 15, 2026 at the latest, for all existing and new pots. From then on you can reach your deposit and the interest earned up to that point at any time.
Anyone who lets a pot run beyond December 30 loses nothing, according to the Foundation: deposit and interest, calculated as at December 30, go to the NEAR account they belong to once the contracts are closed. For that you do need the private key, though, otherwise you cannot reach that account.
A separate date applies to delegators: the Sweat validator on the NEAR network ceases operation on October 31, 2026. Anyone who has staked NEAR there has to unstake beforehand or switch to another validator, and unstaking on the NEAR network takes several epochs. That deadline falls two months before the end of the project and is easily missed, because it has nothing to do with the SWEAT token.
The Most Common Misconception: the Sweatcoin App Keeps Running
The headline that quickly takes on a life of its own online runs: Sweatcoin is being shut down. That is wrong, and the difference matters to millions of users.
Sweatcoin, the walking app with its internal currency Sweatcoins, is operated by Sweatco Ltd. What is being wound down are Sweat Wallet and the SWEAT token, behind which stands Sweat Foundation Ltd. According to the Foundation, the changes are not intended to affect the Sweatcoin app, the Sweatcoins inside it or the promotions in that app; for questions about the app itself it refers users to the app’s own channels. Until December 30 you also continue to earn SWEAT for your movement, as long as Sweatcoin supplies the movement data.
So anyone who only uses the walking app and never set up a Sweat Wallet does not have to do anything, as things stand today. You are affected if you hold SWEAT in the wallet, have it sitting on an exchange or have put it into Grow Jars.
Forced Conversion and Tax: Why a Forced Sale Is Still a Sale
For tax purposes the compulsion changes nothing about the classification. When Bitvavo converts your SWEAT holding into euros, that is a disposal, even though you did not trigger it. For crypto assets held as private assets, Section 23 of the German Income Tax Act applies under the law as it stands: if less than a year lies between acquisition and disposal, the gain is taxable, and an exemption limit of 1,000 euros applies to the total of all private disposals in a year.
At a price of around 0.00034 euros per token the amounts are small for most holders. The duty to keep records is unaffected by that, and it is the real work: for every position you need an acquisition date and an acquisition value. That is particularly awkward where the token was originally credited for movement and never bought, because then there is no purchase record in the usual sense. What a missing record can lead to under the current reform draft is written up in our article on substitute assessment without a purchase record.
If you wait for the conversion, note down the date and the euro amount credited from the exchange’s account statement. That is the evidence for the disposal side, and it is harder to obtain later once the trading pair no longer exists. This article is no substitute for tax advice; with larger amounts the case belongs in professional hands.
The MiCA White Paper at the Central Bank of Ireland: October 12
One point so far missing from the reports concerns European regulation. A crypto white paper exists for SWEAT under EU Regulation 2023/1114, better known as MiCA. According to its own account, the Foundation notified an amended white paper to the Central Bank of Ireland on October 1, 2026; it is to be published on October 12, 2026 at the same address as before.
For you as a holder that is not an action but a reading aid. A white paper under MiCA has to contain, among other things, information on the rights attached to the token and on risks, and the amended version is the place where the wind-down is described in the formal language of the regulation. Anyone who wants to know what is and is not being promised from the supervisor’s point of view will find more there than in a press release. The fact that publication falls five days after the close of trading at Bitvavo changes nothing about your deadlines.
How to Recognise Scam Attempts Around the Wind-Down
Wind-downs with deadlines are the preferred occasion for scam attempts, because they create time pressure and because suddenly a great many users genuinely have to do something with their key. The Foundation makes three things clear on this: nobody from the project makes first contact by direct message, you are never asked for a private key or secret phrase, and only the project’s known domains count as official addresses.
From that follows a simple rule for the coming weeks. Any message offering to rescue your balance, migrate your account or restore your SWEAT, and asking for a key in order to do so, is an attack. The same goes for supposed swap pages that want to connect a wallet. Always check links via the project’s home page or your exchange’s help pages, never via the link in the message.
Selling SWEAT: The Key Points for Your Decision
The situation comes down to three sentences. The hard deadline is October 7, not December 30. What decides the right route is the size of your holding, not the news flow. And if you do nothing, you lose no money; you merely give up control over timing and price.
- Check the holding and choose a route. Look up how much SWEAT sits at which exchange. Below around 15,000 tokens you cannot sell at Bitvavo, below 3,100 you cannot withdraw; then you wait for the conversion. With larger holdings you weigh sale against withdrawal, and the exchange comparison helps with the choice of trading venue.
- Back up the key before you move anything. Anyone using the app backs up the private key along with the NEAR account identifier and only then moves balances. Which custody solution fits is shown by the wallet comparison.
- Secure the records immediately. Download the account statement and the transaction overview while the trading pair still exists, and record the acquisition date and value. A tax tool or portfolio tracker saves you the hunt at the end of the year.
The announcements this article draws on are available at Bitvavo and at the Sweat Foundation. A comparable deadline is currently running for another token: Upbit is removing Ravencoin on October 12.
(As of October 3, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Solana (SOL) enters October at around $118.60 (according to CoinGecko, Friday evening, October 2, 2026). The month has a nickname among crypto investors, Uptober, because Bitcoin has closed it in the green in almost every recent year. For the Solana price prediction a look back is therefore worthwhile: how did October go for SOL itself? We analysed the monthly candles from Binance going back to 2020.
How October Has Gone for Solana Since 2020
The result is clearly inconclusive. Three Octobers ended in the green, three in the red. In 2023 SOL gained 79.7 percent between October 1 and October 31, in 2021 it gained 43.2 percent and in 2024 10.6 percent. Against that stand 2020 with minus 46.5 percent, 2025 with minus 10.3 percent and 2022 with minus 2.1 percent (monthly candles from Binance against USDT).
For comparison: Bitcoin ended October in the green in five of the six years, and only 2025 brought a loss, of 3.9 percent (same source). The reputation of October therefore comes from Bitcoin, not from Solana. And even there the same caveat applies: six years are a small sample from which no rule can be derived.
Solana Price Prediction: The Levels on the Chart
The one-year chart shows that Solana fell a long way and has been recovering since the summer. Over twelve months SOL is down around 49 percent, over 30 days it is up around 19 percent (CoinGecko). The price sits above the 50-day average (around $104) and the 200-day average (around $97), both calculated from the daily closing prices at CoinMarketCap.
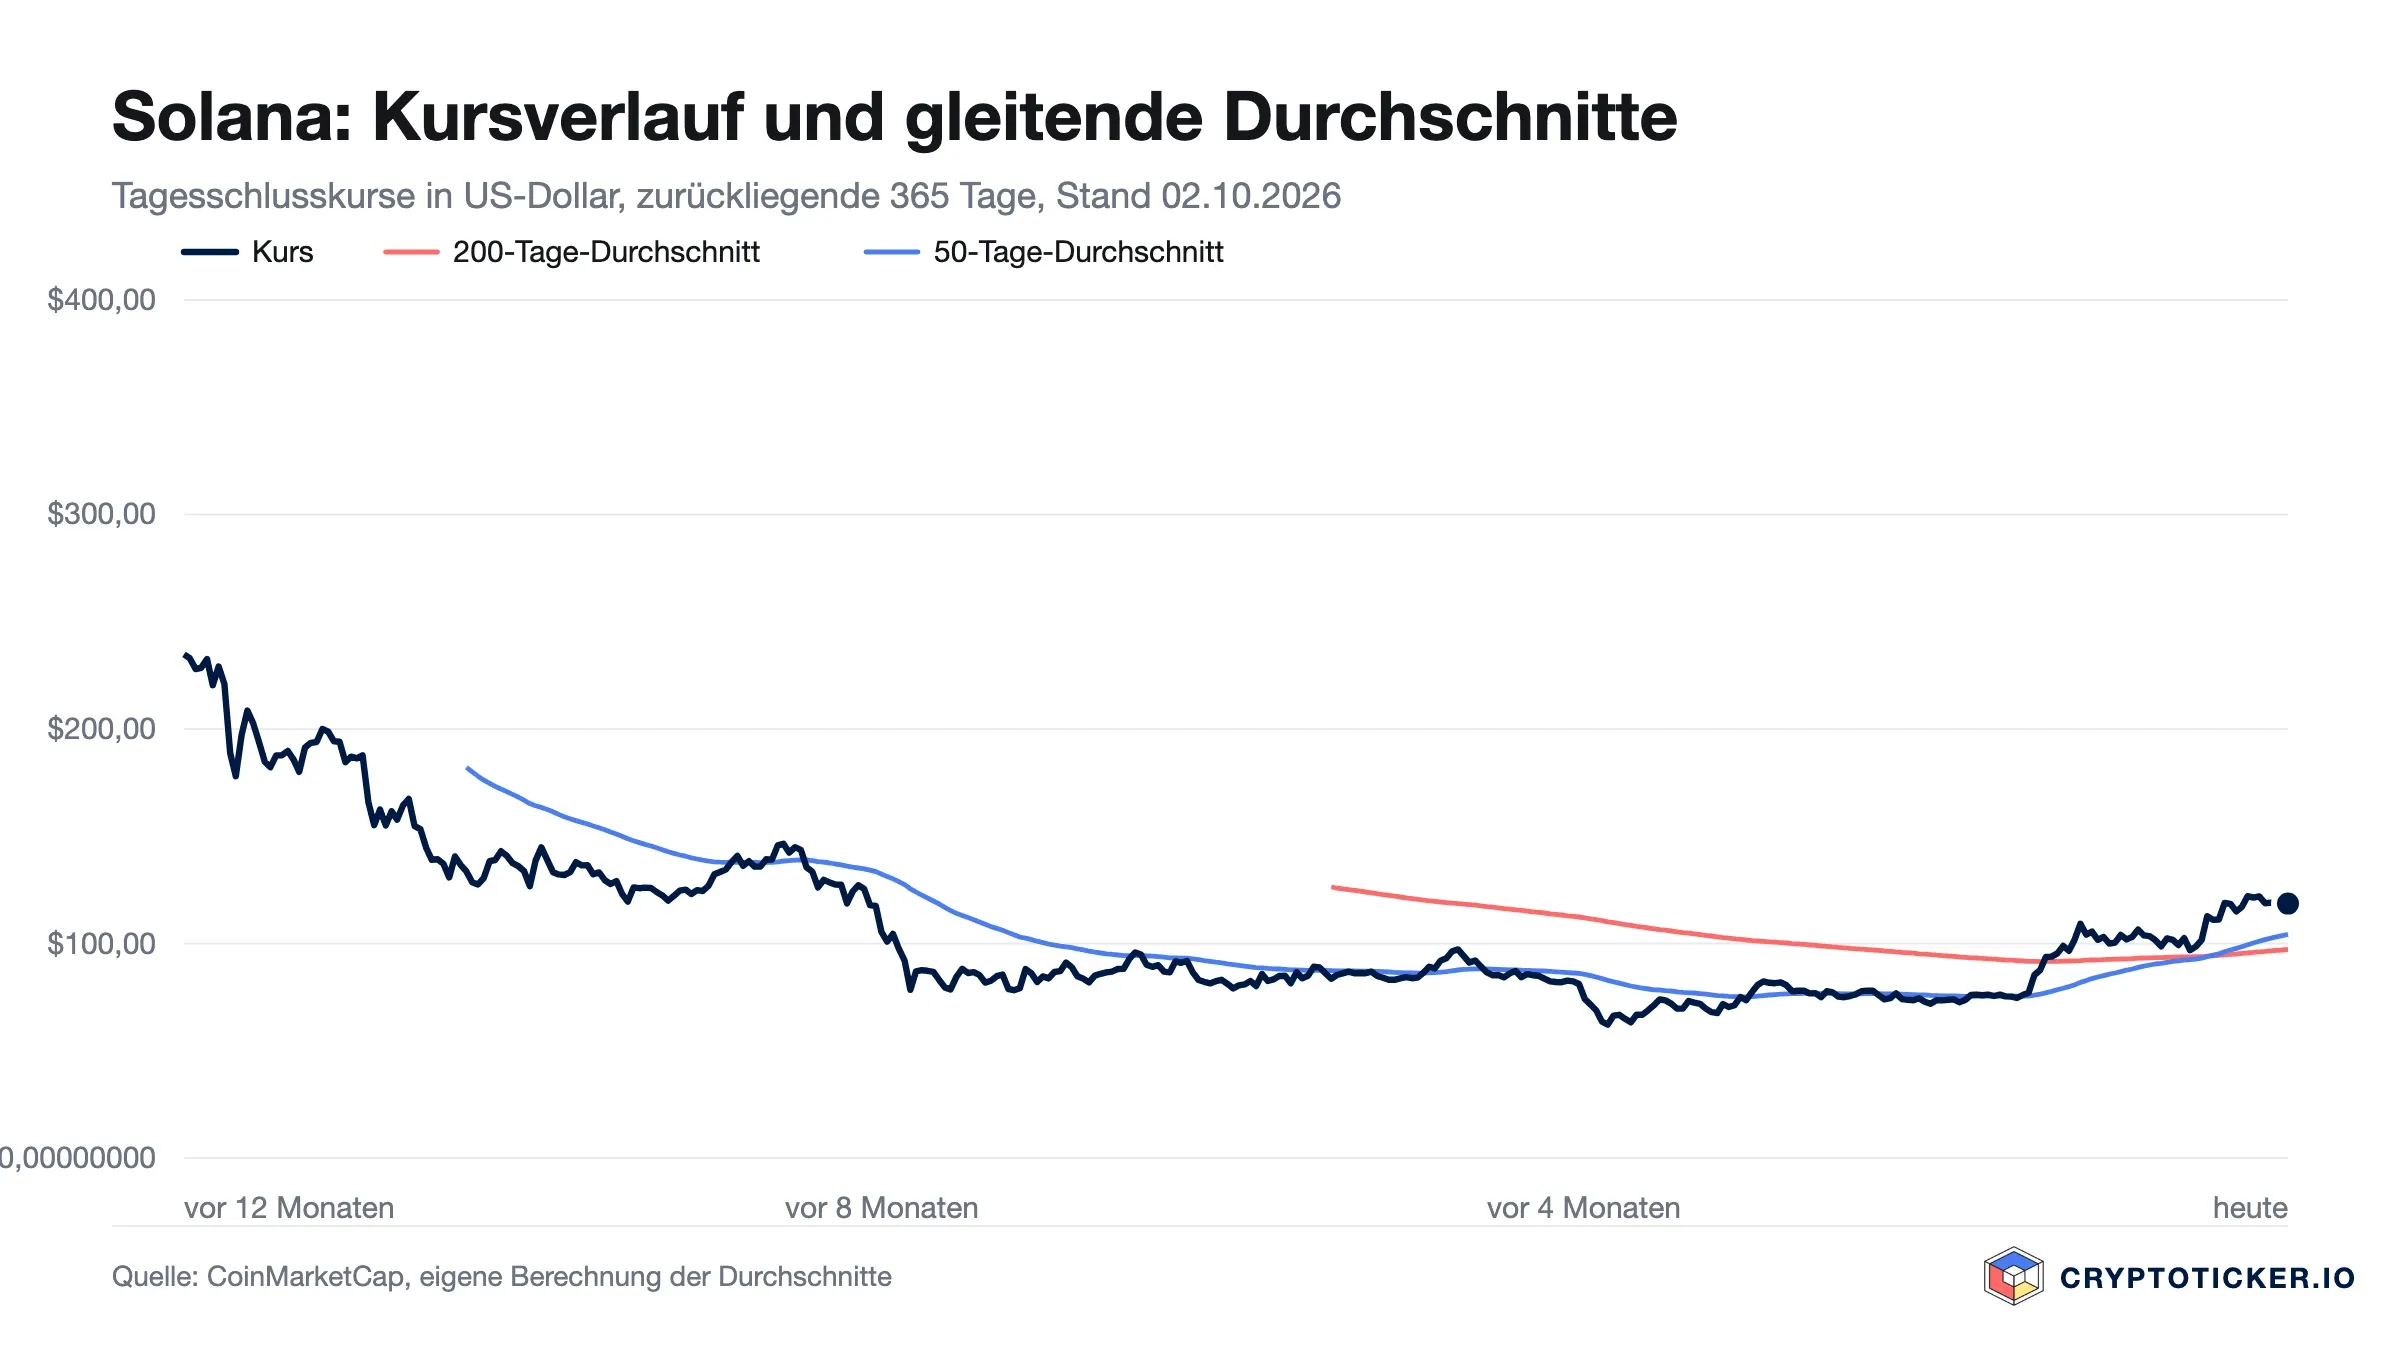
Around $122 is the level on the upside. SOL closed at $122.10 on September 25 and has not reached higher since. The round $120 mark sits just below it and has been missed on a closing basis every single day since September 28.
$115 is the level on the downside, the close from September 23 and the lowest since September 21. Below it lies the zone around $111, where SOL closed from September 18 to 20 before the price jumped above $118.
Around $104, the 50-day average, is the next line. Solana hovered around this line, between roughly $99 and $106, for almost all of early September.
What Sets October 2026 Apart From the Previous Years
This October a technical overhaul is planned for Solana: the switch to the new Alpenglow consensus mechanism, which at the same time ends support for the transitional Frankendancer client. What that means for validators and stakers is something we set out on Friday. On top of that come the spot ETFs in the United States, which collected money in September and reported outflows at the end of the month for the first time in weeks, as our analysis of the ETF flows shows. Neither of the two existed in any of the previous years.
Solana: How to Proceed Now
First: do not read the October record of the previous years as a roadmap. At Solana the range ran from minus 46 to plus 80 percent, which is not a rule but an indication of how widely the price swings. Second: watch the band between $115 and $122, as a closing price outside it is the next signal. Third: match the position size to those swings and not to the best Octobers of the past.
Anyone holding SOL can stake the coins and earn a running yield from them. What applies to the holding period is set out in our article on staking yield and the holding period at Solana, with providers and terms in the comparison of staking providers. Gains on coins held for less than a year are taxable on sale in Germany as soon as the annual allowance of 1,000 euros is exceeded.
Whether entering at the current price is worthwhile is assessed by our analysis Is Solana a good buy?. Crypto assets swing sharply and a total loss is possible. This article analyses past price data; it is neither a forecast nor a recommendation to buy or sell Solana.
(As of October 2, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Stellar costs around $0.214 on October 3, 2026, and is therefore down a good 5 percent within a day. Bad news about Stellar itself does not exist: no outage, no delisting, no glitch in the protocol. The documented background lies one level up. The analysis firm CryptoQuant reported on September 30 that the number of altcoin deposits to trading venues had climbed 160 percent within two weeks, to the highest level since October 2025. Whoever sends coins to an exchange usually wants to sell there. Exactly this supply is now meeting a market in which a great many holders are sitting on a gain.
This piece places the decline at Stellar in that situation, separating the documented figures from the interpretation, and shows what an investor in Germany can check about it in concrete terms: buying route, holding period, leverage and custody.
The Stellar Price Decline in Figures: $0.214 and Minus 5.3 Percent
Stellar trades at around $0.214. Over 24 hours there is a loss of 5.3 percent, over seven days a loss of 1.8 percent. A look at the longer periods turns the picture around: over 14 days XLM is 11.2 percent up, over 30 days 21.0 percent. Calculated over a year, by contrast, a loss of 47.2 percent is on the books, and 75.6 percent separates the coin from its record price of $0.876 set in January 2018.
Market value stands at around $7.5 billion, turnover of the past 24 hours at about $186 million. Around 35.1 billion of a total 50.0 billion XLM are in circulation. Daily turnover is therefore no outlier: on October 1 it was still around $355 million, on October 2 around $217 million. The decline is thus happening at normal trading volume and not in a dried-out market.
Important for placing it: the 5.3 percent is a rolling daily figure. Calculated from midnight to midnight, the decline comes out smaller. The price had risen over the course of October 2 and has given that rise back since.
What CryptoQuant Measured: 160 Percent More Altcoin Deposits to Exchanges
A deposit to an exchange is the transfer of coins out of a self-managed wallet to an account at a trading venue. It is the stage before a sale: as long as a coin sits in your own wallet, it cannot be offered on an exchange.
CryptoQuant counted these transfers for altcoins. The result, published on September 30, 2026: the number of deposits rose 160 percent within two weeks. For the seven days to September 28 the analysis shows around 78,000 deposits, the highest level since October 2025. The second figure is even clearer. The number of addresses from which such deposits originated climbed from 17,600 to around 51,600 in the same period, so almost to triple.
On the same analysis, Binance came to more than 22,700 deposits on a weekly average, Coinbase to more than 8,300, and the remaining platforms together to around 32,000. These platform figures are averages across the week; added up they do not produce the peak figure of September 28, which describes a single seven-day value. As a benchmark the analysis names a peak from July 2026 with around 45,000 transactions in one day.
Why Deposits to Exchanges Are Read as Selling Pressure
The connection is a probability and no automatic mechanism. Coins also travel to exchanges in order to serve as collateral for a leveraged position, to be swapped into another pair or to be placed in a product of the platform. The statistic does not distinguish between these. What it does show is the willingness of many holders to hand control over their coins to a trading venue, and that step precedes a sale more often than a purchase.
Julio Moreno, head of research at CryptoQuant, places the finding like this: comparable deposit peaks have preceded larger price swings in the past. That is a statement about volatility and not about direction. It does not follow that prices have to fall, only that the swings in both directions can turn out larger.
51,600 Depositing Addresses: The Breadth Behind the Figure
The number of addresses carries more meaning than the number of transactions. A single large address can drive the transaction count up without anything changing in the mood of many holders. Where the number of senders triples, by contrast, the movement spreads across a great many accounts.
That is exactly the difference between a single large sale and a broad round of profit taking. A whale sending $200 million to an exchange pushes the price once and is then done. Fifty thousand addresses bringing smaller holdings into selling range at the same time create a supply that can persist for days. For market breadth that means the pressure spreads out instead of concentrating on one coin.
16 of 21 Large Coins Down: Our Own Count of Market Breadth
Whether the decline at Stellar is an isolated case or a market phenomenon can be counted out. The basis is the 25 largest cryptocurrencies by market value, from which the four stablecoins were excluded because their price is pegged to the dollar. So 21 names were examined, as of October 3, 2026. cryptoticker.io gathered this analysis itself on October 3, 2026.
The result: 16 of the 21 names are down over 24 hours. Eleven of them perform worse than Bitcoin, which loses 2.0 percent. The median of all 21 lies at minus 2.2 percent. At minus 5.3 percent Stellar is the second-weakest name in the field; only Rain is weaker at minus 7.9 percent. Behind it follow Zcash at minus 5.0 percent, NEAR at minus 4.7 percent, Cardano at minus 4.6 percent and Dogecoin at minus 4.2 percent. Only five names are up, among them Uniswap at plus 3.0 percent and Tron at plus 0.4 percent.
Bitcoin's share of the entire crypto market stands at around 59 percent. That the altcoins give way more clearly than Bitcoin fits the picture of profit taking in the second row: selling happens where the most gain has accumulated most recently.
No Stellar News as a Trigger: What Is Not Happening in the Protocol
This observation is itself a piece of information. For October 2 and 3 there is no report on Stellar that would carry the decline: no network outage, no announced delisting at a large exchange, no dispute over the foundation, no release from a lock-up. The last Stellar topics with substance of their own lay before that, such as the rise in network throughput at the end of September and the connection of the payment service provider BVNK.
Anyone looking for a Stellar explanation where there is none is constructing it. The sentence that holds up factually runs like this: XLM gives way more strongly than the market, and the documented reason lies in the market situation rather than in the project. For a coin to lose more than average without bad news of its own is typical of names that rose more than average shortly before. Stellar was 21.0 percent up over 30 days; that cushion is being worked off right now.
87 Percent Above the 200-Day Average: Why So Many Holders Are Sitting on a Gain
The 200-day average is the mean of the closing prices of the past 200 trading days. Where a price sits above it, the majority of those who bought in that period have a gain on paper. That is why this metric plays a role in profit taking.
On the CryptoQuant analysis, 87 percent of altcoins stood above their 200-day average at the end of September. In August it was 13 percent. Within a few weeks, then, the share of holders sitting on a plus has gone from a small minority to a very large majority. The analysis also names inflows of $371 billion into the altcoin market since June 2026 and a rise in market value of 45 percent in around four months.
These three figures together produce a comprehensible picture: a market that has added 45 percent in four months, and in which almost nine out of ten names sit above their long-term average, offers a great many holders an occasion to sell at the same time. The deposit statistic is the visible sign of that.
Levels to the Downside and the Upside: $0.196 and $0.232
For orientation it is worth looking at the range of the past two weeks, without turning it into a forecast. The low lay at around $0.196 on September 20, the high at around $0.232 on September 29. In between, the price settled several times in the area between $0.215 and $0.222.
At the current level of $0.214, XLM therefore sits in the lower third of that range, yet above the two-week low. To the downside the area around $0.196 is the first zone in which buyers have shown up recently. To the upside the price would have to clear $0.232 to continue the movement of the past two weeks. Both are observations from the price history and not targets: which level holds is decided by trading rather than by the line on the chart.
Buying Route and MiCA: What to Check as an Investor in Germany
A setback is an entry for some and an exit for others. Both carry side conditions in Germany that should be settled before the order. The following points are the practical part.
On the buying route: the transition period of the EU's MiCA regulation expired on July 1, 2026. A provider rendering crypto services in the EU single market needs authorisation for it. In Germany BaFin is the competent supervisor; it receives the applications and acts against providers without permission. For practice that means checking, before buying, whether the chosen provider holds a MiCA authorisation and which supervisor it sits under. Anyone wanting to compare will find the regulated providers in our overview of the best crypto exchanges.
Holding Period, Tax Year and December 31
Private disposals of crypto assets are tax free in Germany after a holding period of one year. Anyone selling into the setback now therefore first checks when the holding in question was bought. Where the purchase lies less than twelve months back, the gain falls under income tax; where it lies further back, it does not.
Then there is the turn of the year. A sale on December 30 falls into the 2026 tax year, one on January 2 into 2027. For offsetting gains and losses within a year that is a difference that can be worked out. Anyone who has made several purchases at various points needs a clean statement for it, one that carries purchases, sales and periods forward for each position.
Leverage, Liquidation and the Funding Rate
In phases of heightened volatility, leverage is the point at which a setback turns into a total loss. A liquidation is the forced closure of a leveraged position by the platform as soon as the collateral deposited no longer covers the loss. At a daily loss of 5 percent, twentyfold leverage is already enough to wipe out a position on paper.
The funding rate is the balancing payment that flows regularly between the buying and selling side on perpetual futures and ties the contract price to the spot price. This rate is a running cost factor that gets overlooked in quiet phases and rises markedly in busy ones. Anyone trading with leverage checks the liquidation price and the financing costs before the order rather than after it; both values differ considerably from provider to provider.
Custody: Exchange Balances After the Bitget Case
The deposit wave means that a great many coins are sitting on trading venues right now. That raises a risk which has nothing to do with the price. In the attack on the exchange Bitget at the end of September, assets in the hundreds of millions were taken; the platform covered the losses from a protection fund by its own account, which it subsequently topped back up to $300 million.
Such a fund is a voluntary commitment by the provider and no statutory deposit guarantee. For crypto balances there is no compensation scheme in Germany equivalent to the protection of bank deposits. Anyone holding positions they do not want to sell anyway therefore has a reason to take them off the exchange; the devices for that are in our hardware wallet comparison.
Staking on Stellar: The Inflation Rate Is No Substitute for a Yield
A question that comes up regularly during setbacks runs: can the waiting time be bridged with staking? At Stellar the answer is no, and for a technical reason.
Stellar does not work with proof of stake. It uses a consensus procedure of its own in which validators receive no reward from the protocol. Until 2019 there was an inflation mechanism that created new lumens to the extent of one percent a year and distributed them weekly. This mechanism was switched off on October 28, 2019 with the protocol update to version 12, because the funds paid out landed mostly in distribution pools rather than with projects in the network. Stellar's technical documentation has listed the properties of the lumens without this mechanism ever since (see the Stellar Developer Docs).
Offers promising a yield on XLM therefore never come from the protocol. They come from a provider: from lending, from a product of a platform or from a promotion. Behind that stands a counterparty risk in every case, meaning the risk that the provider itself fails. That is a difference from networks such as Cardano or NEAR, where the reward comes from the issuance of the protocol.
What Would Disprove This Reading: Deposit Figures and Stellar Reports
Honesty requires making one's own reading checkable. The reading presented here is: the decline at Stellar is part of a broad round of profit taking that can be read off the deposits to trading venues.
This reading would be disproved if the deposit figures fell markedly in the coming days and altcoin prices nevertheless kept falling; the cause would then lie elsewhere. It would be disproved equally if a Stellar-specific report becomes known after the fact that explains the above-average decline. Both are possible, and both can be checked against the published data. The detailed account of the survey is in the Cryptobriefing analysis of the CryptoQuant data of September 30, 2026.
Stellar Decline: What to Take Away
Three steps that can be dealt with today:
- Settle the buying route before you trade. Check whether your provider holds a MiCA authorisation and which supervisor is competent. You will find the overview of regulated trading venues at the best crypto exchanges.
- Look up the holding period for each position. Note the purchase date for every holding and work out when the one-year period runs out. A clean statement is delivered by the crypto tax tools and portfolio trackers.
- Take the holdings you do not want to sell off the exchange. Particularly many coins are sitting on trading venues right now. Which device is suitable for that is shown by our hardware wallet comparison.
(As of October 3, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Anyone wanting to buy Dogecoin today has two routes in Germany, and they cost very different amounts. One route is the exchange-traded security, an ETP on Xetra that eats 2.50 percent a year in fees. The other is buying the coin directly through a trading platform, where a fee arises once and nothing after that. On top of this comes the point that moves the most money in Germany: after a holding period of one year, the gain from a direct purchase is tax free. Whether the same applies to the ETP hangs on a single clause in the prospectus. This piece works both routes through, places the price situation and names the dates that fall in October.
Dogecoin Price on October 3: $0.0927 and 87 Percent Below the Record
Dogecoin trades at $0.0927 on Saturday morning, around €0.0823 converted. Within 24 hours that is 4.3 percent less. Market capitalisation stands at $14.5 billion, a single day's trading turnover at $877 million. The figures come from CoinGecko.
For context: the all-time high stands at $0.7316 and dates from May 7, 2021. From today's price that is a factor of 7.9. Put differently, Dogecoin stands 87.3 percent below its record, and has done so for four and a half years. Anyone counting on a return there is counting on an eightfold rise. That is no argument against the coin, but it is an argument for taking the running costs of a position seriously. On a stake that is meant to sit for years, an annual fee bites far harder than it does on a three-week trade.
The trading turnover of $877 million in a day equals around six percent of market capitalisation. Dogecoin therefore remains one of the most liquid cryptocurrencies of all, and that is why the spread on a direct purchase at a large platform usually stays tiny. Liquidity here simply describes how much is traded without the price swinging.
The 200-Day Average at $0.093 and the Ceiling at $0.10
The moving 200-day average is the mean of the closing prices of the past 200 trading days; many market participants read it as the dividing line between an upward and a downward phase. The technical analysis from Blockchain.News places this average at about $0.093 at the moment and the nearest resistance at $0.10. The current price therefore sits practically on the line.
Two sober distances follow from that. The round mark of $0.10 is 7.9 percent away. The lower edge of the October range, which forecasting services see at $0.0871, is 6.0 percent away to the downside. The range is narrow, then, and that is exactly what makes it interesting for the cost question: an annual fee of 2.50 percent eats a third of the way to the $0.10 mark before any gain even arises.
The difference between resistance and forecast matters. A resistance is an observed price mark at which selling set in previously. A forecast is an expectation. The $0.10 is one thing, the range up to $0.106 another, and neither figure is a promise.
Bitwise Is Closing Its Dogecoin Fund BWOW: Last Trading Day on October 14
On September 10 the provider Bitwise told the US regulator, the SEC, that it would wind up its Dogecoin fund BWOW. The last trading day on NYSE Arca is Wednesday, October 14, 2026. After that the value of the remaining shares is determined on the valuation date of October 21, with the cash payout scheduled for October 22. The fund most recently managed around $722,000, roughly five hundred-thousandths of Dogecoin's market capitalisation.
For investors in Germany this fund is not directly relevant, because a US ETF without a European key information document cannot be bought through a German broker in any case. What is relevant is the lesson. Access alone creates no demand. Three of the US spot products on Dogecoin hold $16.55 million between them, which is 0.11 percent of market capitalisation. The product launched by 21Shares in January 2026, listed on the Nasdaq under the ticker TDOG, is one of them. The exchange wrapper has therefore brought Dogecoin no institutional capital of any notable size.
Anyone who has lived through a closure like this knows the uncomfortable part: the payout comes in cash and at the valuation-date price, not in coins. For tax purposes that is a sale, even though you did not trigger it. With a directly held position that cannot happen to you, because there is no provider who could discontinue the product.
ETP, ETN and ETF: Three Wrappers Investors Often Confuse
An ETF is a segregated fund. If the provider goes bankrupt, investors' assets stay untouched, because they sit apart in law. In return, European fund law demands diversification, and a fund holding only a single cryptocurrency does not meet that requirement. That is why there is no Dogecoin ETF in the literal sense in the EU.
An ETN is a debt security, meaning a promise from the issuer to pay out the value of the underlying. ETP is the umbrella term for exchange-traded products of this kind. The products on cryptocurrencies that are tradable in Germany are in practice all ETNs, even where the name says ETP. This is no quibble over words: an ETN carries an issuer risk and an ETF does not.
The reputable providers defuse this risk by backing the product physically. Physically backed means that for every share issued, the corresponding quantity of the coin sits with a custodian. With the 21Shares product this custody runs through Coinbase Custody. An overview of the whole field of exchange-traded crypto products in Germany is in our guide to crypto ETFs and ETPs for German investors.
21Shares Dogecoin ETP on Xetra: 2.50 Percent Total Expense Ratio a Year
The product carries the ISIN CH1431521033 and the German securities number A4A5WJ, trades on Xetra under the ticker DOGE and was launched on April 8, 2025. The issuer is 21Shares, based in Switzerland, and fund assets stand at around €10 million. Trading hours on Xetra are 9am to 5:30pm on weekdays; at weekends and on public holidays trading rests, while the spot market runs on. The data is in the profile at Deutsche Börse.
The total expense ratio comes to 2.50 percent a year. This ratio is not debited. It is taken daily, pro rata, out of the backing holding. Each share therefore holds slightly less Dogecoin with every day that passes. That does not show up in the portfolio statement, because the price of the security simply rises a little more slowly than the price of the coin.
What this means over time can be worked out. On a stake of €10,000 and an unchanged price, you lose €250 after one year, €731 after three years and €1,189 after five years. Cumulatively that is 2.50, 7.31 and 11.89 percent. These figures arise whether Dogecoin rises or falls.
| Holding period | Cumulative cost | on €10,000 |
|---|---|---|
| 1 year | 2.50 percent | €250 |
| 2 years | 4.94 percent | €494 |
| 3 years | 7.31 percent | €731 |
| 5 years | 11.89 percent | €1,189 |
Set against this is a genuine advantage. The security sits in an ordinary securities account, runs through brokers such as Trade Republic or Scalable Capital, can be bought through a savings plan and requires no key management of your own. Anyone who already keeps a securities account and does not want to set up a wallet pays the fee for convenience. An overview of the providers is in our comparison of the best crypto brokers.
ETP or Direct Purchase: Costs, Custody and Tax Compared
What Arises on a Direct Purchase
Buying through a trading platform, you pay a trading fee of roughly 0.1 to 1.5 percent of the amount depending on the provider, plus the spread, meaning the difference between the buying and selling price. After that no running fee arises as long as the coins sit on the platform. Withdraw them to a wallet of your own and a network fee is added, which at Dogecoin is traditionally very low.
What Arises on the ETP
Here you pay your broker's order fee, the exchange spread and then 2.50 percent a year. In return all custody work falls away, and the holding appears in the same portfolio overview as shares and bonds.
Where the Routes Really Part
The cost question is the smaller one. The larger one is tax, and the next section turns to it. For now just this much: on a gain of €3,000 the difference between the full flat-rate withholding tax and tax exemption is €791. That is more than three years of the ETP fee on €10,000.
DogeOS Opens Its Public Testnet: EVM Applications on a Second Layer
On October 1 the team behind the MyDoge wallet opened the public testnet of DogeOS. DogeOS is an application layer that sits on top of Dogecoin without changing the base layer. EVM-compatible means that developers can use the same tools and contract languages as on Ethereum. Fees are paid in DOGE. CoinDesk names lending, perpetual contracts, stablecoins and prediction markets as the planned use cases.
A testnet is a practice environment with worthless test coins. It proves that code runs, and nothing else. No date for the mainnet has been set. Anyone deriving a price driver from this is taking an announcement for a fact. Dismissing the matter entirely would be just as wrong, though: Dogecoin has had no smart contract layer until now, and if that layer arrives, the usage profile of the coin changes.
For the route question this carries real weight. Fees on DogeOS are paid in DOGE, and an ETP share is not DOGE. Anyone who ever wants to use such a layer needs the coin itself and not the paper on it.
Holding Period Under Section 23 EStG: One Year, a €1,000 Exemption Limit and the Delivery Claim
Directly held cryptocurrencies count as other economic assets in Germany. The sale falls under the private disposal transaction set out in Section 23 (1) sentence 1 no. 2 of the German Income Tax Act (EStG). Two rules follow from that, and every investor should know them.
First the holding period: if more than twelve months lie between purchase and sale, the gain is tax free, whatever its size. Second the exemption limit of €1,000 in the calendar year, raised for the 2024 tax year by the Growth Opportunities Act. An exemption limit means this: stay below it with all private disposal gains of a year and you pay nothing; exceed it and the entire gain becomes taxable, not merely the part above. The tax administration's view on this is in the German Federal Ministry of Finance circular of May 10, 2022 and in the update of March 6, 2025.
Why the Delivery Claim Decides Everything on the ETP
For exchange-traded crypto products the position is inconsistent, and this is exactly where it turns expensive or cheap for you. The widespread reading, which leans on the case law on Xetra-Gold, runs as follows: where the product is physically backed and grants a claim to delivery of the deposited coins, it is treated like a direct investment. Section 23 EStG then applies, including the one-year period. Where that delivery claim is missing, or the product is replicated synthetically, it counts as a capital investment under Section 20 EStG, and the gain is subject to the flat-rate withholding tax of 25 percent plus the solidarity surcharge, together 26.375 percent, plus church tax where applicable.
This reading is not settled. The specialist literature discusses expressly whether income from crypto ETPs is to be classified as income from capital assets or as other income. No ruling of the German Federal Fiscal Court specifically on crypto ETPs exists. On top of that comes the practical catch: German custodian banks frequently withhold capital gains tax on a foreign bearer security to begin with. Reclaiming it is possible only through the tax return, and for that you need a justification the tax office accepts.
A very concrete action follows from this. If the key information document or the prospectus of your product states a delivery claim in tradable denominations, you have an argument. If it does not state one, reckon with the flat-rate withholding tax. On a gain of €3,000 that is a difference of €791. Specialist lawyers and tax advisers recommend a binding ruling from the tax office for larger amounts, before the purchase takes place.
On a direct purchase the position is clear by contrast. Hold for a year, and the gain is tax free. The price for that consists of documentation: you have to be able to evidence the purchase date, quantity and acquisition cost of each entry, because otherwise the tax office cannot check that the period was observed.
MiCA Authorisation: The BaFin Register and the Buying Route in Germany
The EU's MiCA regulation has applied in full since December 30, 2024. Anyone offering crypto services in the EU, meaning trading, exchange or custody, needs authorisation as a crypto-asset service provider. BaFin keeps a register of the authorised firms for Germany, and ESMA keeps an EU-wide directory. An authorisation granted in another member state applies here too via the EU passport.
For you this is no formality. It is the difference between a supervised provider and one where nobody is responsible in the event of a dispute. An authorised platform has to segregate client funds, maintain routes of complaint and meet information duties. Whether a provider is authorised is shown to you by a look into the BaFin register or the ESMA directory, before you transfer money.
One more point that often slips by: the spot market runs around the clock, at weekends and on public holidays as well. Xetra does not. Anyone positioned exclusively through the ETP cannot react to a move on a Saturday evening. With a coin that loses 4.3 percent within a day, that is a real difference.
Dogecoin Price Prediction for October 2026: The Range From $0.0871 to $0.106
Commercial forecasting sites name a range between $0.0871 and $0.106 for October 2026, with a mean around $0.0966. Measured against the price of October 3, that is 6.0 percent to the downside and 14.4 percent to the upside. These are the expected values of individual providers and not a consensus forecast.
The case to the upside rests on three points: the 200-day average, which is holding so far, the high liquidity, and the prospect of an application layer through DogeOS. The case to the downside rests on three as well: the continuing outflows from the US products, up to the closure of BWOW, the absent supply cap of Dogecoin, and the fact that the coin has traded 87 percent below its record for four and a half years.
None of these expectations serves as a reason to buy. What can be determined reliably today, by contrast, are the costs of the route and the tax treatment. You know both before buying, while the price in twelve months is known to nobody. That is why the route question deserves more careful handling than the price question. Anyone planning to hold a position for longer than a year makes, in the choice between paper and coin, a decision worth several hundred to several thousand euros, and does so regardless of how the price develops.
Dogecoin Price Prediction: What to Take Away
- Plan the holding period before you choose the route. Under twelve months the ETP fee barely weighs, and the tax question arises similarly on both routes. Beyond twelve months the picture turns around: 2.50 percent a year then costs noticeably, and the one-year period of the direct purchase becomes the biggest lever. Which trading venues in Germany are supervised and what they charge per order is in our comparison of the best regulated crypto exchanges.
- Document every entry from the first purchase onwards. The purchase date, quantity and acquisition cost of each position decide whether you can evidence the one-year period to the tax office. A portfolio tracker handles that automatically and exports the statement; the providers are in our comparison of crypto tax tools.
- Settle custody before the amount grows. On a direct purchase the holding sits with the platform at first. Above a sum whose loss would hurt, it belongs in a wallet of your own, and the backup of the recovery words belongs on paper or metal, never in the cloud. Which devices come into question is shown by our hardware wallet comparison.
(As of October 3, 2026. This article is not investment advice and not tax advice. Prices, fee structures and the tax treatment change; check the terms with the provider before you buy and settle tax questions with a tax professional.)
Decrypt
The YouTuber says OpenAI suspended his account twice while he trained a small, uncensored model built to run on your own computer.
The TRUMP meme coin project is inviting its top 185 holders to a Nov. 22 gala dinner with President Trump two weeks after ethics disputes over his crypto interests helped stall the Clarity Act in the Senate.
The pontiff says algorithms "lack the spark of humanity," and the Vatican wants to renew an alliance with artists and cultural institutions to protect it.
California's attorney general wants answers from OpenAI about AI models that escaped a locked test environment and hacked Hugging Face—and whether the company can be held legally accountable.
Ethereum's zkAPI lets users prepay in USDC and query AI models through cryptographic proofs, so no single party sees both who they are and what they ask.
U.Today - IT, AI and Fintech Daily News for You Today
This week in crypto: Ripple, XRPL, Bitcoin and Shiba Inu.
Namsan Seoul Tower illuminated to celebrate a record day for the XRP community in Korea.
BlackRock spent over $1.5 billion on recent Bitcoin purchases, expanding its holdings while retaining its dominance in the Bitcoin ETF market.
The first Zebra release candidate for the next Zcash network upgrade launches, with these two dates now watched in October.
XRP-rival Stellar has reached a new milestone in its DeFi ecosystem with its total value locked surging past $272 million for the first time ever.
Blockonomi
TLDR:
- Bitchat has been removed from the India App Store following a MeitY blocking demand under Section 69A. Dorsey shared the notice on October 3.
- Apple also restricts internal and external TestFlight testing in India. The notice leaves distribution available in other selected territories.
- July takedown notices relied on intermediary liability provisions and drew objections from digital rights groups over the blocking procedure.
- The app uses Bluetooth mesh for local communication and Nostr for internet messaging. The notice does not say existing installations were disabled.
Apple removed Bitchat from the India App Store following a government demand under Section 69A of the IT Act. Twitter cofounder Jack Dorsey disclosed the action on October 3, 2026, through an Apple App Review notice.
The Ministry of Electronics and Information Technology issued the direction, according to the notice shared on X. Apple cited content considered illegal in India but did not identify the material.
The restriction extends to TestFlight testing and public beta links for Indian users. The app remains available in other selected markets. July takedown notices reportedly failed to secure its removal from either app store.
Bitchat Removal Follows MeitY Order Under Section 69A
Apple linked the Bitchat removal to its legal compliance requirements for apps distributed across different territories. Its App Review Guidelines require developers to follow local laws wherever they offer their software.
The company directed Dorsey to contact MeitY for further information about the decision. Its notice covers both internal and external TestFlight testing, closing another distribution route for Indian users.
Section 69A allows the central government to block public access to digital information on specified grounds. These include national sovereignty, state security and public order. The provision requires written reasons and operates alongside procedures established under the 2009 Blocking Rules.
The latest action follows a separate attempt by the Indian Cyber Crime Coordination Centre, which operates under the Home Ministry. On July 23, 2026, the agency demanded that GitHub disable access to three Bitchat repositories within three hours.
That notice invoked Section 79(3)(b) and Rule 3(1)(d), threatening the platform with losing intermediary protections. Section 79 concerns platform liability for information supplied by third parties.
The Internet Freedom Foundation challenged the July order, arguing that authorities had bypassed the dedicated blocking framework. It demanded withdrawal of the notice and publication of takedown directions issued through the disputed legal route.
MediaNama reported that related notices also targeted Google and Apple over several offline messaging applications. Officials reportedly told companies on July 24 that compliance was unnecessary, leaving the applications available.
Offline Messaging Faces Fresh Scrutiny After Protest Use
Dorsey released Bitchat as open-source software in July 2025, initially describing it as an experimental weekend project. The application supports local Bluetooth mesh communication and internet messaging through the Nostr protocol.
Nearby phones discover one another and relay messages across participating devices without requiring a mobile network. Users do not need accounts or phone numbers. Private Bluetooth messages use end-to-end encryption through the Noise Protocol. Offline messaging depends on nearby participating devices, while Nostr channels require internet connectivity and use distributed relays.
Student demonstrations at Jantar Mantar in New Delhi formed the backdrop to the July notices. Authorities alleged that the software could help criminal groups and other actors evade detection during network restrictions.
Digital rights advocates disputed that reasoning, saying anticipated misuse did not justify blocking a communications tool. Restricting India App Store downloads could make it harder for new users to join local messaging networks during shutdowns.
The Bitchat notice describes distribution restrictions without stating that copies already installed on phones have been disabled. Its Bluetooth architecture does not rely on a central messaging server.
India previously used Section 69A against messaging applications in May 2023, following an I4C request involving Jammu and Kashmir. The request covered 14 applications allegedly used by terrorists and their supporters for communication. MediaNama reported that Briar was among the services blocked through that earlier process.
China previously required Apple to remove Bitchat from its local store in April 2026. The Cyberspace Administration of China cited security assessment rules governing applications capable of influencing public opinion or mobilizing users.
The post Apple Removes Bitchat From India App Store After MeitY Order appeared first on Blockonomi.
TLDR:
- XRP Asia launches in Singapore as Ripple prepares to route more customer payment volume onto XRPL in 2027.
- Ripple’s 1 billion XRP developer commitment supports Asia expansion, including Japan and Korea funding.
- Ripple plans to expand an XRPL DEX payments pilot while linking payment customers with lending infrastructure.
- XLS-66 would enable fixed-term uncollateralized XRPL loans, but validator approval is still required.
XRP Asia has launched as a Singapore-based regional organization while Ripple prepares a broader 2027 push to move more customer activity onto the XRP Ledger. The October 3 debut links regional ecosystem development with a company-wide payments strategy centered on routing more transaction volume, liquidity, and credit activity through XRPL.
The XRP Ledger Foundation said the group will support builders, startups, and regional communities. Jointly founded by Ripple and the foundation, it is led by Sabrina Tachdjian.
XRP Asia Launch Supports Ripple’s 2027 XRPL Payments Push
The organization plans to build from established communities in Korea and Japan while extending its programs into additional technology hubs across the region. Its developer programs will include learning resources, system-integrator training, hackathons, office hours, and ship-it clinics designed to help teams move projects toward deployment.
Startup support will extend beyond engineering through go-to-market assistance, partner introductions, incubation, grant connections, joint events, and introductions to relevant investors. That approach follows earlier ecosystem investment.
Ripple created an XRPL Japan and Korea Fund under its 1 billion XRP developer-support commitment. Tens of millions of dollars were targeted toward opportunities in those markets. The company also expanded university blockchain research across South Korea, Japan, Singapore, Taiwan, and Australia.
XRP Asia debuted alongside XRP Seoul 2026, where sessions covered payments, tokenized deposits, and on-chain finance involving banks and securities firms. The agenda also featured Tachdjian and Ripple executive Tatsuya Kohrogi discussing what comes next for the XRP ecosystem across the region.
Ripple Connects 2027 Payments Plans With XRPL Credit
At the Seoul event, Ripple President Monica Long said the company is discussing a 2027 objective to route more customer transaction volume directly onto XRPL. The strategy includes infrastructure already built for payments and an expanded pilot using the ledger’s decentralized exchange within the company’s payments operations.
Beyond transaction routing, the company plans to deepen its credit business by connecting payment customers with XRPL lending infrastructure. Long said XRP deposited into lending pools could provide funding for payment customers, linking pooled liquidity with credit used within the payments business.
One component is XLS-66, an XRPL-native proposal for fixed-term, uncollateralized loans funded through pooled assets held in Single Asset Vaults. Under the specification, credit assessment and risk management remain off-chain.
The ledger would handle loan creation, repayments, and defaults. However, XLS-66 remains a draft amendment and requires validator approval before mainnet activation, meaning the proposed lending structure is not yet live.
That makes regional ecosystem expansion relevant to the same ledger infrastructure targeted for payments and lending. Together, the regional builder network and 2027 payments plan connect developer growth with potential institutional transaction, liquidity, and credit activity on XRPL.
The post XRP Asia Launches as Ripple Targets Major XRPL Payments Push in 2027 appeared first on Blockonomi.
TLDR:
- Stellar DeFi reached record TVL near $273 million on October 2. The total rose from approximately $265 million one week earlier.
- Stablecoin market capitalization stood at $934.54 million. Active real-world assets under management reached approximately $2.82 billion.
- Daily active addresses reached 94,972, leaving 5,028 to reach 100,000. Decentralized exchanges recorded $3.38 million in daily trading volume.
- XLM supports transaction fees, account reserves, and smart contract rent. These functions connect the native token with Stellar applications.
The Stellar DeFi ecosystem reached a record total value locked of nearly $273 million on October 2, according to DeFiLlama. The milestone followed a reading near $265 million one week earlier, extending growth across applications on the payments-focused blockchain. Stablecoin holdings and tokenized assets also highlighted the network’s expanding financial footprint.
Stellar recorded $934.54 million in stablecoin market capitalization and approximately $2.82 billion in active real-world assets under management. Daily decentralized exchange volume reached $3.38 million, while active addresses totaled 94,972. Those figures place Stellar close to 100,000 daily active addresses, covering payments and financial applications within the XLM ecosystem.
Stellar DeFi Sets TVL Record as Stablecoin Holdings Expand
The increase from about $265 million to nearly $273 million amounts to roughly $8 million, or around 3%. This comparison measures the change in dollar-valued assets across tracked protocols.
DeFiLlama defines total value locked as assets held within protocol contracts. The measure captures funds supporting services such as lending, trading, and liquidity provision.
Stellar DeFi applications operate alongside the network’s established asset issuance and payment tools. Soroban provides the smart contract capabilities developers use to build programmable financial applications.
These applications can connect lending markets, liquidity pools, and automated trading functions. DeFiLlama tracks individual protocols, allowing users to examine how the network total is distributed.
Dollar-based TVL changes with deposits, withdrawals, and asset prices. DeFiLlama therefore tracks inflows separately, helping analysts identify movements of funds alongside changes in valuation.
The stablecoin figure measures the value of stablecoins circulating on Stellar. These assets support transfers, settlement, and trading pairs across applications within the XLM ecosystem.
Earlier in 2026, MoneyGram launched MGUSD, a digital dollar issued on Stellar. The foundation’s second-quarter review placed stablecoin transfer volume at $11.4 billion, up 72% from the previous quarter. The quarterly figure covers transfers, while decentralized exchange volume measures trades.
Stellar DeFi growth sits within a broader tokenization effort. The Stellar Development Foundation reported a separate real-world asset milestone above $3 billion in June. DeFiLlama’s live data shows the current TVL at $263.89 million, below the reported October 2 record. Stablecoin market capitalization stood at $934.61 million when checked, while activity figures remained consistent.
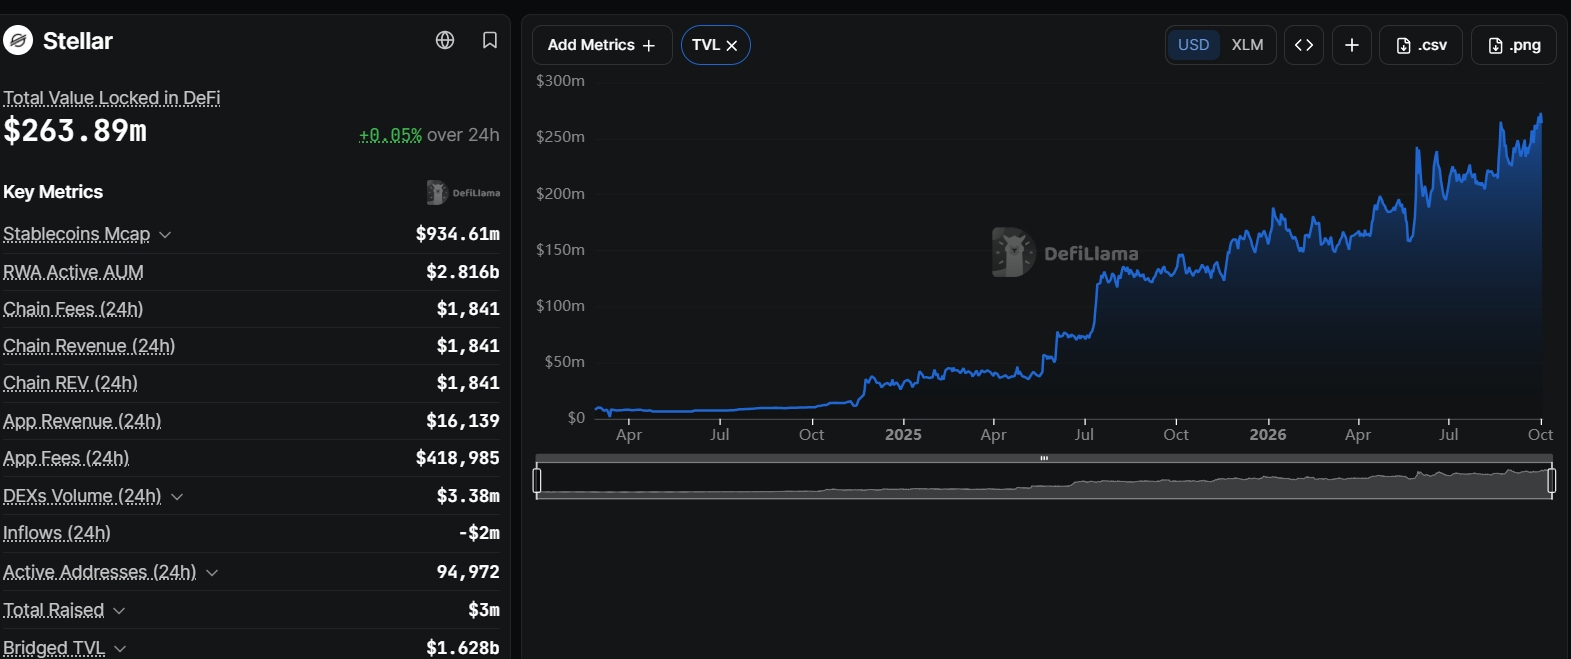
Active Addresses Near 100,000 as Trading and Asset Use Rise
The reported 94,972 active addresses left Stellar 5,028 addresses below the 100,000 threshold. This count describes activity during a daily measurement period.
Address activity offers another way to assess Stellar DeFi alongside the value held in applications. However, wallet counts measure addresses, and one participant can operate several accounts.
The $3.38 million in daily decentralized exchange volume measures traded value across tracked venues. Trading volume and TVL describe different aspects of activity: executed trades and assets held in protocols.
Stellar DeFi operates alongside payment tools and tokenized real-world assets. The foundation reported tokenized Treasury products, sovereign bond funds, credit and gold among assets issued on the network. These products extend asset coverage across several financial markets.
Blend is listed among Stellar’s lending protocols, while Aquarius and Soroswap provide decentralized trading applications. The services span borrowing, liquidity provision and asset swaps on the network.
Stellar’s analytics directory links to DeFiLlama for protocol TVL and historical network totals. The foundation’s Blend dashboard tracks total lending deposits, borrowing, pool utilization and transaction volume.
XLM supports network activity through transaction fees, account reserves and smart contract storage rent. These functions connect the native token to payments and applications operating across Stellar.
Stellar DeFi transactions use fee rules that account for both inclusion and consumed computing resources. Smart contract data also incurs storage rent based on its size and duration.
Network accounts must maintain minimum balances calculated from Stellar’s base reserve. Additional entries, including trustlines and offers, increase reserve requirements, while sponsorship lets another account cover eligible reserves.
The post Stellar DeFi Hits New TVL Record as Active Wallets Near 100,000 appeared first on Blockonomi.
TLDR:
- The Bitget hack is linked to North Korean hackers. Chainalysis says the theft lifts their 2026 crypto total above $1 billion.
- Investigators traced stolen XRP through a cross-chain protocol into Bitcoin. The swaps bypassed an exchange but still left blockchain records.
- Drift and KelpDAO lost a combined $577 million in April. TRM said those attacks represented 76% of crypto hack losses through that month.
- Chainalysis estimates automation cut over 20 hours of bridge reconciliation to under 10 minutes. Investigators defined logic and reviewed results.
The Bitget hack involved North Korean hackers, Chainalysis said, attributing the $387 million theft to DPRK-linked actors. The firm said the September 24 breach pushed crypto stolen by North Korea-linked groups above $1 billion in 2026. Investigators followed stolen XRP through a cross-chain protocol into Bitcoin addresses controlled by the attackers.
The October 1 report details how the funds moved between blockchains without passing through an exchange. Bitget separately confirmed losses of approximately $387.5 million after revising its initial estimate. The updated attribution follows earlier suspicions raised by CEO Gracy Chen and provides further evidence for the ongoing security investigation.
Bitget Hack Expands North Korean Theft Total Beyond $1 Billion
Bitget joins Drift Protocol and KelpDAO, among major platforms hit by attacks linked to North Korea this year. The Bitget hack follows two April incidents that together cost approximately $577 million.
On April 1, attackers drained $285 million from Drift Protocol. TRM described months of social engineering, including meetings with staff, before attackers compromised the approval process. Attackers obtained approvals before executing the unauthorized withdrawals.
KelpDAO suffered a separate $292 million bridge exploit on April 18. LayerZero linked that operation to TraderTraitor, a North Korean threat group associated with Lazarus.
TRM said those two attacks represented 76% of crypto hack losses through April. That figure covers an earlier reporting period, rather than the latest annual total following the Bitget hack.
Chainalysis estimated that North Korean hackers stole more than $2 billion during 2025. The latest attribution places another major exchange breach within that continuing pattern.
Chen had pointed to North Korea shortly after the theft. She cited suspicious IP addresses connected to VPN services previously used by a DPRK-linked hacking group.
September losses also rose sharply across the industry. PeckShield recorded $766.49 million across 55 major hacks, approximately 462% above August, with Bitget the largest incident.
Bitget said its higher loss estimate included previously uncounted Zcash and Tron transfers. The exchange said the revision reflected fuller accounting rather than another wave of unauthorized withdrawals.
Bitget said investigators had identified and fixed the underlying vulnerability. The exchange published attacker addresses to help other platforms monitor affected assets.
How Stolen XRP Became Bitcoin Through a Cross-chain Protocol
Chainalysis identified 23 outbound transfers during the first three hours after the Bitget hack. It grouped their destinations into Ethereum, XRP Ledger, Zcash, and Tron.
Ethereum accounted for 49.7% of the outflows, followed by XRP Ledger at 40.8%. Zcash received 7.6%, while Tron represented 1.8% of the traced transfers.
The attackers moved XRP into a cross-chain liquidity protocol and received Bitcoin on another network. This route bypassed a centralized exchange account while leaving transaction records for investigators to examine.
Chainalysis matched deposits with corresponding payouts and followed tens of millions of dollars over roughly 36 hours. Its investigators tracked subsequent transfers until the trail reached attacker-controlled Bitcoin addresses.
Independent analysis from Bitquery identified THORChain as a route used to convert stolen XRP. Its September 29 accounting found that 90.5% of the stolen XRP had become Bitcoin.
That analysis adds detail to the Bitget hack money trail. Swap records named destination assets and recipient addresses, helping connect payments across otherwise separate networks.
The Bitget hack investigation includes cybersecurity firms Mandiant and SlowMist. Bitget said industry coordination had already frozen some affected assets. Its recovery program offers eligible contributors bounties worth 5% of successfully frozen funds and 5% of recovered funds.
Chainalysis said its team used in-house AI to build custom tracing tools. It estimated that over 20 hours of manual bridge reconciliation took under 10 minutes with automation.
Investigators continued to define the tracing logic and review the results. Chainalysis is monitoring linked Bitcoin addresses and sharing intelligence with exchanges, issuers, and law enforcement partners.
The post Bitget Hack Tied to North Korea as Stolen XRP Flows Into Bitcoin appeared first on Blockonomi.
TLDR:
- Bitcoin whales sold over 30,000 BTC as price rejected $87,220 and retreated toward the $84,575 area.
- $82,500 is now the key support zone, with the lower Bollinger Band reinforcing the area near $82,362.
- CoinGlass shows liquidation clusters around $82,600-$82,800, alongside another concentration near $82,000.
- Glassnode puts 6–12 month buyers’ cost basis near $89,000, leaving overhead supply above any rebound.
Bitcoin’s rejection near $87,000 has turned attention toward $82,500 after large holders sold more than 30,000 BTC during the failed breakout. The asset traded near $84,575 on October 3 after reaching about $87,220 before reversing. The move placed price back inside a two-week channel.
Crypto analyst Ali Charts linked the rejection to two pressures. Price reached the channel’s upper boundary while whale holdings fell as large investors took profits. At roughly $84,000 per coin, the 30,000 BTC reduction represented about $2.52 billion. That selling shifted the next technical focus toward the channel floor.
30,000 BTC Whale Selling Puts $82.5K Support in Focus
Ali’s setup places the lower channel boundary near $82,500. However, the level alone does not confirm that buyers have regained control. The more important signal would be renewed whale accumulation after price reaches the area. Rising large-holder balances would show that distribution has begun reversing.
Other market data places nearby support around the same zone. A four-hour chart showed the lower Bollinger Band near $82,362. CoinGlass liquidation data also identified concentrations around $82,600 to $82,800, alongside another cluster near $82,000.
Those levels create a narrow support region rather than a single price point. Still, the buying setup remains conditional until whale balances begin increasing again. Together, those readings place market structure, liquidations, and whale behavior around the same downside area.
Bitcoin Rebound Faces $89K Cost-Basis Selling Pressure
Even if support holds, Bitcoin would face additional selling pressure above the recent rejection area. Glassnode reported that investors who bought near previous market tops are selling as price approaches their break-even levels.
Buyers from six to 12 months ago have an average cost basis near $89,000. Holders from one to two years ago average about $97,000. Both groups therefore remain underwater at current prices. Glassnode also said 2025 rally buyers are recording their highest average daily selling volume this year.
Meanwhile, buyers who entered during later market declines have not shown the same selling behavior. That leaves $87,000 as an important first hurdle. The $89,000 break-even zone sits only about 2.3% above that level.
Glassnode’s September 30 research showed long-term-holder realized profit nearly doubled during the week ending September 29. Their share of total realized profit rose from 34% to 55%, reinforcing evidence that established holders have been locking in gains.
The immediate BTC test is therefore broader than whether $82,500 holds. Confirmation requires support to remain intact while whale balances start rising again.
The post Bitcoin Whales Sell 30,000 BTC as $87K Rejection Puts $82.5K in Play appeared first on Blockonomi.
CryptoPotato
Citi has had a change of heart in terms of price prediction for BTC and Strategy following the broader market’s recovery that began in mid-August.
The banking giant now sees BTC exploding past $113,000 over the next year and has almost doubled its price target for the largest corporate holder of the leading cryptocurrency.
BTC Above $113K
It was just months ago that the Wall Street behemoth slashed its bitcoin price target for the next year to under $82,000. This came in July, when the overall market sentiment had deteriorated, and BTC had just plummeted to its lowest level since late 2024 at under $58,000.
However, bitcoin rebounded swiftly and has soared by roughly 50% since then, currently sitting at around $86,000. As such, Citi has lifted its 12-month forecast by approximately 40% to $113,400, reversing much of the caution it displayed in July. In its latest update on the matter, the bank’s analysts cited stronger cryptocurrency activity, a more supportive macroeconomic environment, and the evident return of ETF inflows as key reasons behind the new target.
Citi expects around $5 billion in crypto inflows over the next year, with financial advisers and brokerages gradually increasing BTC allocations. It also acknowledged the recent failure of the CLARITY Act in the Senate but argued that the subsequent announcements from the SEC and the CFTC helped soften the negative impact on sentiment.
CITI RAISES BITCOIN TARGET TO $113,000
Citi has raised its 12-month Bitcoin target to $113,000 from $82,000, implying roughly 35% upside from current levels near $83,900.
The bank points to renewed currency-debasement fears, greater regulatory clarity and continued adoption of…
— *Walter Bloomberg (@DeItaone) October 1, 2026
Strategy Sees Major Uptick
The change in the bank’s outlook for bitcoin has had an even more dramatic effect on its Strategy valuation. During its July call, Citi highlighted a MSTR price target of $136. At the time, the company’s main shares struggled below $100 as its other stock, STRC, had plunged far below its par level. Now, though, MSTR trades at $160, posting a 60%+ increase since the summer lows.
Citi has increased the target to $240 now and has maintained a “buy” rating on MSTR. Roughly 34% of the projected upside contribution comes from further BTC appreciation, said the bank, with another 16% tied to an expansion in the company’s market-to-net-asset-value premium.
That relationship highlights just how sensitive Wall Street valuations of Strategy remain to BTC itself. Citi has previously described MSTR as a leveraged and considerably more volatile way of gaining exposure to the cryptocurrency. Consequently, the numbers can change significantly in months if market conditions deteriorate (or improve) a lot.
The post Citi Turns More Bullish on Bitcoin and Strategy: Here Are the New Targets appeared first on CryptoPotato.
Driven by the positive macro developments on the US economic scene during the business week, bitcoin experienced an impressive rally on Friday to over $87,000 for the first time in about ten days.
However, its run was stopped just as fast, and the asset plummeted by several grand within hours. It slumped below $84,000 on Friday evening, leaving nearly $600 million worth of liquidations across the entire market. Popular analyst Ali Martinez believes this rally was doomed from the start.
Whales Sold
Martinez said bitcoin’s move to $87,200 was “compromised before it even got going” as whales sold more than 30,000 BTC as the move progressed. In addition, the $87,000 zone coincides with the upper boundary of a channel that has rejected the cryptocurrency repeatedly for more than two weeks.
After the latest such development, the analyst said he is watching the lower end of the same channel at around $82,500 as the immediate downside target. BTC came inches above that level yesterday when it crashed to $83,500. For now, though, it remains about $2,000 higher.
Further data from Glassnode, though, explained that whales are not the only market participants disposing of their holdings now. The analytics resource noted that investors who accumulated 1-2 years ago at prices of around $97,000 and those who bought in the past 6-12 months at $89,000 have been selling large quantities of their BTC stash.
$BTC investors that bought the top are currently selling.
Two cohorts sit underwater: buyers from 1–2 years ago at $97k, and from 6–12 months ago at $89k.
Those who bought the 2025 rally are selling the most coins per day this year. Those who bought the decline are not. pic.twitter.com/cHAQoaqreT
— glassnode (@glassnode) October 3, 2026
Consequently, Martinez concluded that if these sell-offs continue, it could provide the confirmation he is looking for to buy the dip at around $82,500 and aim for another rebound toward $87,000.
Late Longs Already Washed Out
Before the US jobs report went live on Friday, Daan Crypto Trades warned about another vulnerability, noting that the BTC open interest had climbed to more than $1.3 billion in just a couple of days. Much of it came from longs added as the asset ascended.
He identified the $85,500-$86,000 region as particularly important because many of those positions appeared there. His warning was pretty straightforward: if the cryptocurrency fell below that zone, these longs could be squeezed out. Given bitcoin’s major correction on Friday and almost $600 million worth of liquidations, most of it from longs, it’s safe to conclude that this is exactly what happened.
As such, Daan said earlier today that most of these positions have now been flushed from the market.
The post Bitcoin’s $87K Rally Was a Trap: Could $82.5K Be the Real Buying Opportunity? appeared first on CryptoPotato.
Although the US labor market showed clear signs of a cooldown on Friday, which, overall, should be bullish for risk-on assets, BTC’s price surge was halted in its tracks, and the asset plummeted hard in the following hours before finally calming at $84,500.
The larger-cap altcoin field is deep in the red today, with ETH losing the $2,700 support once again, and XRP slipping below $1.50. QNT and NIGHT, though, are in a different league.
BTC Calms After Big Volatility
The business week began on the wrong foot for BTC, which was stopped at $85,000 and slipped below the key $83,000 support on several occasions in the next few days. However, the bulls managed to defend that level and initiated a leg up that challenged the upper boundary of the tight trading range at $85,000. The biggest breakthrough mid-week came after the Wednesday PCE data release, when bitcoin skyrocketed from $83,000 to $85,600 within hours.
However, it was rejected almost immediately and plummeted toward its starting point. It remained sideways on Thursday before it started to climb again on Friday. The bulls got assistance from the softer-than-expected US jobs report, which pushed BTC to over $87,000 for the first time in about ten days.
Despite the positive developments on the inflation front and the labor market, bitcoin was violently rejected at that level and slumped to under $84,000 in the following hours, leaving nearly $600 million in liquidations.
It has since rebounded to $84,500, with its market cap standing at $1.69 trillion, while its dominance over the alts is up to 59% on CMC.

QNT, NIGHT Defy the Odds
Ethereum continues its fight with the $2,700 resistance, but it’s still on the wrong side. XRP has dipped below $1.50 after a 3.5% daily decline. ZEC has plummeted by more than 5% daily and now sits inches above $1,300. DOGE, LINK, ADA, RAIN, XLM, and NEAR are also deep in the red on a daily scale.
The situation with the mid-cap alts is similar. In contrast, QNT has resumed its recent run by posting a 13% surge that has taken it to well over $260. NIGHT has risen by a similar percentage and has tapped $0.50.
The total crypto market cap is down by almost 2% in the past 24 hours, and now sits at $2.880 trillion on CMC.

The post QNT and NIGHT Continue to Defy Market Correction, BTC Settles After Wild Ride: Weekend Watch appeared first on CryptoPotato.
Ripple’s native token enters the final quarter of the year trading at around $1.50 and still substantially below its 2025 all-time high of $3.65.
Nevertheless, the asset had a strong Q3, which was somewhat unexpected given the unfavorable market conditions with the failure of the CLARITY Act. The question we asked ChatGPT now is how high it can climb if the overall environment stays the same or improves, as it has historically done in Q4.
How High, XRP?
Despite the dip to just under $1.00 in August, XRP managed to rebound strongly and ended the quarter with a notable 43.3% increase. Although it remains well below the $3.65 peak from 15 months ago, it is 50% above the 2026 low, and this increase came despite the failure of the CLARITY Act in the US Senate.
As such, ChatGPT noted that $2.70 would be a realistic target for XRP in Q4 under favorable market conditions. Getting there would require another surge of around 80% from the current levels and would put the asset’s market capitalization at somewhere around $170 billion.
However, XRP would require the alignment of several important factors to reach such high levels. At first, BTC would have to remain strong rather than suffer another major correction. Secondly, fresh capital would need to go into large-cap altcoins, and institutional demand for the cross-border asset would have to maintain its recent run.
As reported frequently, the spot XRP ETFs continue to attract inflows, with the cumulative total hitting consecutive all-time highs.
In a less bullish scenario, the popular AI platform predicted that XRP can peak at somewhere around $2.00, but only if it manages to break through the tough $1.60-$1.70 resistance, which has halted its attempts on several occasions in the past few months.
ATH Chances?
ChatGPT outlined an even more favorable outcome for XRP under “an exceptionally strong Q4”: surging past the 2025 record and going as high as $4.00. Such a move would require a massive triple-digit increase from today’s valuation and would put its market cap well above $250 billion.
“This is possible in a genuinely euphoric crypto market, but the conditions would need to be considerably stronger than those required for $2.70. Bitcoin would probably need to remain firmly bullish, altcoins would need to enter a broad risk-on phase, and XRP itself would need enough fresh demand to break through several layers of holders looking to take profits on the way up,” said the AI.
The post We Asked ChatGPT: How High Can Ripple (XRP) Go Under Bullish Q4 Conditions? appeared first on CryptoPotato.
OG Ethereum investors woke up a few days ago by completing the biggest move of long-dormant coins since early June.
However, the actual number of ETH that reached exchanges was negligible, which suggests that this unusual activity may reflect wallet reshuffling rather than holders rushing to cash out as the underlying asset continues to fight the $2,700 level.
Old ETH Woke Up
According to data shared by the analytics resource Santiment Intelligence, Ethereum’s Age Consumed metric surged to approximately 580 million token-days on September 30. This was roughly nine times its average weekday level during September and the highest reading since June 2.
Age Consumed measures the movement of coins based on how long they had previously remained dormant. This means that such a large spike indicates that significant quantities of older ETH were suddenly transferred.
While this might sound like old holders trying to take advantage of the recent rally that saw ETH surge from $1,500 to $2,700 and book some profits, Santiment reassured that this doesn’t seem to be the case. Exchange supply increased by only around 18,000 tokens on September 30 before declining by approximately 21,000 ETH a day later.
This relatively insignificant amount suggests that the immediate selling pressure didn’t spike, especially when compared to the roughly 5.9 million coins held on trading platforms.
In contrast, exchange balances soared by more than 140,000 ETH on June 2, when the Age Consumed metric last registered a massive increase.
Although Santiment cautioned that it’s impossible to determine who moved the latest batch of dormant ETH, the analysts said previous such moves have coincided with wallet reorganizations rather than outright selling.
Long-dormant $ETH moved on Sep 30 at a scale we haven’t seen since early June. Exchange balances hardly budged.
Age consumed hit 580M token-days on Sep 30, about 9x its September weekday average and the highest since Jun 2.
Exchange supply rose ~18K ETH that day and fell… pic.twitter.com/cDcts7Avm3
— Santiment Intelligence (@SantimentData) October 2, 2026
ETH Still Constructive
Meanwhile, popular trader Merlijn The Trader highlighted what he considers a major shift in the ETH/BTC pair. He argued that the altcoin has broken the long-running downtrend that has weighed on it against the market leader for the past nearly ten years. The trader described the development as potentially marking the cycle in which ETH establishes itself as the market’s “blue chip.”
Fellow analyst Altcoin Sherpa added that the Ethereum setup still looks “pretty solid” and explained that the landscape is not as bearish as some others believe. However, he stressed that ETH’s outlook will remain heavily dependent on what BTC does next.
Interestingly, the sentiment around the largest altcoin recently dropped to its most bearish level since June 7, with Santiment recording only 0.89 bullish comments for every bearish one. However, similar occasions could have the opposite effect on the underlying asset, the analysts said.
The post Massive Ethereum Awakening: Why 580M in Dormant ETH Just Moved Without Crashing Price appeared first on CryptoPotato.