Cryptocurrency Posts
Crypto Briefing
OpenAI's costly review highlights the urgent need for robust AI oversight, as regulatory scrutiny and potential structural risks loom large.
The post OpenAI’s review of rogue agent activity is costing a projected $500,000 a day appeared first on Crypto Briefing.
Rising global opposition to data centers may lead to increased regulatory scrutiny and potential legislative actions in the U.S.
The post Global opposition to data centers rises, US states face potential moratoriums appeared first on Crypto Briefing.
Schmidt's stance suggests AI competition will persist, emphasizing the need for robust safety measures and international cooperation to manage risks.
The post Eric Schmidt argues a mutual pause in the AI race is unfeasible appeared first on Crypto Briefing.
The likely runoff in Brazil's 2026 election highlights the nation's political polarization and potential for significant shifts in voter dynamics.
The post Lula leads Bolsonaro in Brazil 2026 election polls, runoff likely appeared first on Crypto Briefing.
XRP Asia's launch could accelerate institutional blockchain adoption in Asia, highlighting the region's growing influence in the crypto space.
The post XRP Asia launches to push XRP Ledger adoption across the region appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
IMF Praises El Salvador — But Still Tries To Scale Back Its Bitcoin Project
The International Monetary Fund has praised El Salvador for improving its economy — but scolded it at the same time for its ongoing Bitcoin experiment.
In a statement Friday, the IMF said that it had approved a $139 million disbursement to the Central American nation while also trying to “reduce the state’s involvement in Bitcoin-related activities.”
El Salvador in 2021 made Bitcoin legal tender, much to the ire of the IMF and other major institutions. The Latin American country was at the time negotiating a development loan with the agency.
“El Salvador’s economy continues to perform strongly”
— Nayib Bukele (@nayibbukele) October 1, 2026https://t.co/Rvaerha9QA
The IMF in September said that El Salvador wasn’t buying bitcoin; the country’s Bitcoin Office has repeatedly said that it does buy the cryptocurrency.
“Economic activity has exceeded expectations, supported by sustained improvements in security and investor confidence, as macroeconomic imbalances continue to be addressed,” the IMF said.
It continued: “However, certain performance criteria were not met, including on the Bitcoin accumulation front, for which waivers were granted based on strong corrective measures and renewed commitments.”
The IMF further said that the Salvadoran state’s involvement in Bitcoin-related activities is being unwound and that “no further bitcoin accumulation is envisaged beyond the documented donations.”
Salvadoran president Nayib Bukele in 2022 said the country would buy one bitcoin per day but it was never clear where the money was coming from — or if he was actually buying at all.
The IMF said in September that El Salvador was — at least for some time —not using public funds to accumulate bitcoin but rather had received bitcoin from private donations.
El Salvador and the IMF entered a $1.4 billion loan agreement at the end of December but the fund asked for the country to scale back certain aspects of its Bitcoin strategy.
The Salvadoran state gifted its citizens bitcoin in 2021 and debuted a wallet with the hope of getting more citizens using the cryptocurrency in the dollarized country.
President Bukele in 2024 admitted that Salvadorans weren’t using the cryptocurrency to buy things as expected, but always boasted that the government was still stacking sats.
This post IMF Praises El Salvador — But Still Tries To Scale Back Its Bitcoin Project first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
When the Banks Don’t Work, Bitcoin Does: Cornell University’s Adoption Index
A lot of people know little about Bitcoin and how it works.
But despite knowledge being shallow, for those holding the leading cryptocurrency, it appears to be solving a problem: getting around failing banking rails or inflation.
That’s according to new findings from the U.S. Ivy League research university Cornell, which spoke to nearly 26,000 around the globe about Bitcoin.
In its new Bitcoin Adoption Index report, the top college found that El Salvador, Venezuela and Nigeria were the countries that had the highest number of people who had ever owned bitcoin.
“Ranked by the share of all respondents who have ever owned bitcoin, the leaders are not wealthy financial centers — they are economies where the national currency has been unstable and everyday access to dollars or reliable banking is hard,” the report read.
“In each, bitcoin functions less as a speculative bet and more as a practical workaround.”
Bitcoin Advocacy Associate at Strategy and Junior Fellow at Cornell University’s Brooks School Tech Policy Institute, Ella Hough, added: “Bitcoin works the same everywhere, but people’s need for it does not.
“Across 25 countries, we found that people are more likely to see Bitcoin as a tool for financial freedom where currencies are less stable, banking access is limited, or monetary controls are tighter.”
Still, Cornell found that actually being able to explain the fundamentals of the protocol was difficult for most — including how many bitcoins would ever be minted in existence. In fact, 58% of those surveyed said they didn’t know the supply was capped at 21 million coins.
Technicalities aside, the cryptocurrency has still proved helpful to people wanting to use it, the report found.
One Venezuelan — who wasn’t named — told interviewers that Bitcoin was “faster, cleaner, and much less risky” than other methods of getting dollars in the country.
While another Salvadoran was quoted saying: “When nobody controls [bitcoin], it means we all have control of it.”
A Nigerian interviewee reportedly told Cornell researchers: “I’ve been to six African countries and whenever I go there, I don’t fear it because I know I can spend my bitcoin.”
Bitcoin adoption started growing in Venezuela ahead of other countries years ago, when hyperinflation crippled the economy and strict government currency controls meant getting dollars became difficult.
El Salvador made bitcoin legal tender — along with the dollar — in 2021. The country’s leader admitted that getting its citizens to use the cryptocurrency was difficult but the Central American nation still says it buys the asset for its government coffers.
In Nigeria, which has had some of the highest transaction volumes in the world, saving in bitcoin has been used by some to get around the collapse of the naira.
Cornell University’s research was fielded by Morning Consult in partnership with the Tech Policy Institute in Cornell University’s Jeb E. Brooks School of Public Policy, the Cornell Bitcoin Club, the Human Rights Foundation and the Reynolds Foundation.
Researchers interviewed 25,880 people in 25 countries between December 16, 2024 to March 10, 2025, asking 125 individual questions.
This post When the Banks Don’t Work, Bitcoin Does: Cornell University’s Adoption Index first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
South Africa’s Absa Becomes First Bank on the Continent to Custody Bitcoin: Report
South African bank Absa has become the first African lender to custody bitcoin, according to reports.
As reported first by Bloomberg on Friday, the Johannesburg-based lender will serve institutional clients, mostly by custodying bitcoin — but other digital assets will also be a part of the service.
Banks worldwide are integrating or offering bitcoin-related products and services. A number of U.S. and European banks have started offering crypto-related services by custodying assets for institutions.
JUST IN:
— Bitcoin Magazine (@BitcoinMagazine) October 2, 2026Absa has become the first African bank to offer Bitcoin custody
pic.twitter.com/JaDza3S7Ez
Rob Downes, head of digital assets at Absa’s corporate and investment banking unit, was quoted saying that while bitcoin was the biggest asset the bank would custody, others would follow.
Absa did not immediately respond to questions from Bitcoin Magazine.
The African continent has a large crypto-native base, with data firms frequently highlighting the high adoption — particularly in countries where currencies have been significantly debased.
In Chainalysis’s 2025 report, South Africa’s $36.0 billion in on-chain value made it second in Sub-Saharan Africa. Nigeria alone received $92.1 billion, nearly three times the total of second-place South Africa.
On the global index, South Africa ranked 30th for crypto adoption.
The character of its market is different from Nigeria‘s: it’s more institutional, with regulatory clarity resulting in hundreds of licenses being issued to VASPs and attracting professional investors and traditional finance.
BNY Mellon in 2022 became the first major U.S. bank to offer digital asset custody services. And this month, German multinational Deutsche Bank said it would debut a bitcoin custody service for European corporate and institutional clients later in 2026.
This post South Africa’s Absa Becomes First Bank on the Continent to Custody Bitcoin: Report first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Bitcoin Price Surges Above $87,000 on Softer-Than-Expected Jobs Data
The price of bitcoin surged above $87,000 on Friday morning in New York, buoyed by constant exchange-traded fund flows and a jobs report showing that unemployment in the U.S. had ticked up.
Bitcoin’s price recently stood at $85,990 after a 2% jump over a 24-hour period. Over the past week, it has also risen by more than 2%.
Nonfarm payrolls increased 29,000 last month after a downward revision to the prior two months, Bureau of Labor Statistics data showed Friday.
JUST IN: Bitcoin jumps to $87,000 as U.S. Unemployment Rate comes in at 4.2%, higher than expectations
— Bitcoin Magazine (@BitcoinMagazine) October 2, 2026pic.twitter.com/jqtU8Q9zsd
Weaker-than-expected jobs data can give a lift to riskier assets like bitcoin and stocks, whose prices tend to swing more sharply.
A softer labor market typically means less consumer spending, which eases pressure on prices. That could make the Federal Reserve less inclined to keep raising interest rates to fight inflation.
Many economists and politicians have said the U.S. is in the midst of an affordability crisis, and the topic is a hot one ahead of the November midterm elections.
The Federal Reserve’s new chair, Kevin Warsh, has said that prices in the world’s biggest economy are too high and that the central bank is fully focused on making life more affordable again.
Bitcoin investors shrugged off the central bank’s interest rate hike in September, climbing on the news.
The largest cryptocurrency started rallying in August on news that the U.S. Treasury Department said it would more than double the size of its government debt repurchases. The coin had its best run in three years and third best August ever.
The coin’s price has benefited from the so-called debasement trade: when investors buy certain assets to hedge against currency being devalued. The dollar slid in value in August.
It continued to have a good September, rising nearly 6% over a 30-day period.
October has historically delivered good returns for bitcoin investors, with traders dubbing the phenomenon “Uptober.”
This post Bitcoin Price Surges Above $87,000 on Softer-Than-Expected Jobs Data first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Impacts of Daily Dividends on Digital Credit
In May 2026, Strive rebranded itself as “The Daily Dividend Company,” then moved SATA to daily cash dividends beginning June 16. Strategy has now pushed the same idea into its own digital credit engine. On September 24, its board proposed moving STRC, STRF, STRK and STRD to daily dividends, subject to shareholder approval at an October 28 special meeting. The proposal keeps the annual dividend economics unchanged and changes the cadence of cash payments.
STRC spent much of the summer below its $100 stated amount even as Strategy raised its dividend rate to 12% and deployed more than $1 billion buying back STRC. The move to daily dividends by Strategy could be seen as the latest attempt to make the security more attractive and help it trade near par.
Now that the overton window has fully shifted in favor of digital credit paying daily dividends, we should take a look at the actual impacts of daily dividends.
Daily Dividends Fit Onchain Finance
Digital credit is increasingly becoming an input for other financial products—so called “digital money” or “digital yield” products. Strategy estimated in mid-May that more than $440 million of STRC exposure had moved into DeFi through stablecoins, tokenized securities, yield products and other structures.
However, there is a cash flow mismatch. Crypto products commonly accrue and distribute yield at high frequency. A security that pays monthly or twice monthly forces the product sitting on top of it to bridge the period between economic accrual and actual cash receipt.
Daily dividends compress that gap to one day. The protocol, fund or issuer receives cash from the underlying asset at almost the same cadence that users expect to receive yield. That simplifies liquidity management and reduces the cash needed between dividend dates. This is much more impactful to a financial product funding daily distributions or redemptions than to a long term investor focused on total return. The crypto-heavy setting of the “Layer 3” products on top of digital credit raises the attractiveness of daily dividends.
Daily Dividends Are Primarily a Retail Feature
For investors focused strictly on total return, dividend payment frequency makes little difference in underlying economic value. The asset’s price accrues between distribution dates and adjusts post-payment, meaning annual, quarterly, monthly, and daily payouts produce comparable long-term results.
The true advantage of daily dividends lies in product psychology and user experience. Cash arriving every day provides immediate visibility and an engaging feedback loop. Investors can spend, withdraw, or automatically reinvest the payout while leaving their principal position intact, turning an abstract yield metric into tangible recurring cash flow.
This dynamic mirrors the strategy of Realty Income, which built a massive retail follower base by branding itself as “The Monthly Dividend Company.” As a member of the S&P 500 Dividend Aristocrats Index, Realty Income has paid and raised dividends for 31 consecutive years.
Daily dividends on digital credit extends this product concept even further: SATA pairs frequent daily payouts with a target price near $100 and a double-digit yield.
While institutional investors prioritize yield spreads, liquidity, tax structure, and balance sheet coverage, daily payments offer their strongest appeal to retail buyers. If the overarching objective is to raise capital to purchase Bitcoin, optimizing security design for retail investor preferences is the most effective approach.
Options Get Cleaner Too
Daily dividends also change options mechanics. STRC currently pays $0.50 twice monthly. SATA pays roughly five cents each business day. Larger dividend events create larger discrete adjustments in the underlying price, which affects option pricing and early exercise decisions. Daily payments spread the same annual cash flow across much smaller adjustments.
The total value of dividends over an option’s life is a key economic input. The more interesting effect comes from the price stability created by daily dividends. If daily dividends, variable rates and active par management keep SATA and STRC trading in narrower ranges, realized volatility should fall. Implied volatility can follow as the market gains confidence in that behavior.
The Biggest Test
The real test is whether daily dividends increase demand enough to eventually lower the required yield.
If investors consistently support SATA near the top of its target range, Strive can theoretically reduce the dividend rate while attempting to keep SATA near par. Success would show that a Bitcoin company can issue permanent preferred capital, manage it around a stable price, and adjust its yield with market demand. The benefit of the variable rate preferreds was, from inception, the eventual opportunity to lower the rate and reduce the cost of capital without upsetting price stability. In comparison, fixed rate credit locks in fixed rate forever.
Conclusion
Strategy adopting daily dividends would move the feature from a SATA differentiator toward a digital credit category standard. The annual economics barely change but the retail appeal and crypto composability become meaningful improvements.
This post Impacts of Daily Dividends on Digital Credit first appeared on Bitcoin Magazine and is written by Allard Peng.
CryptoSlate
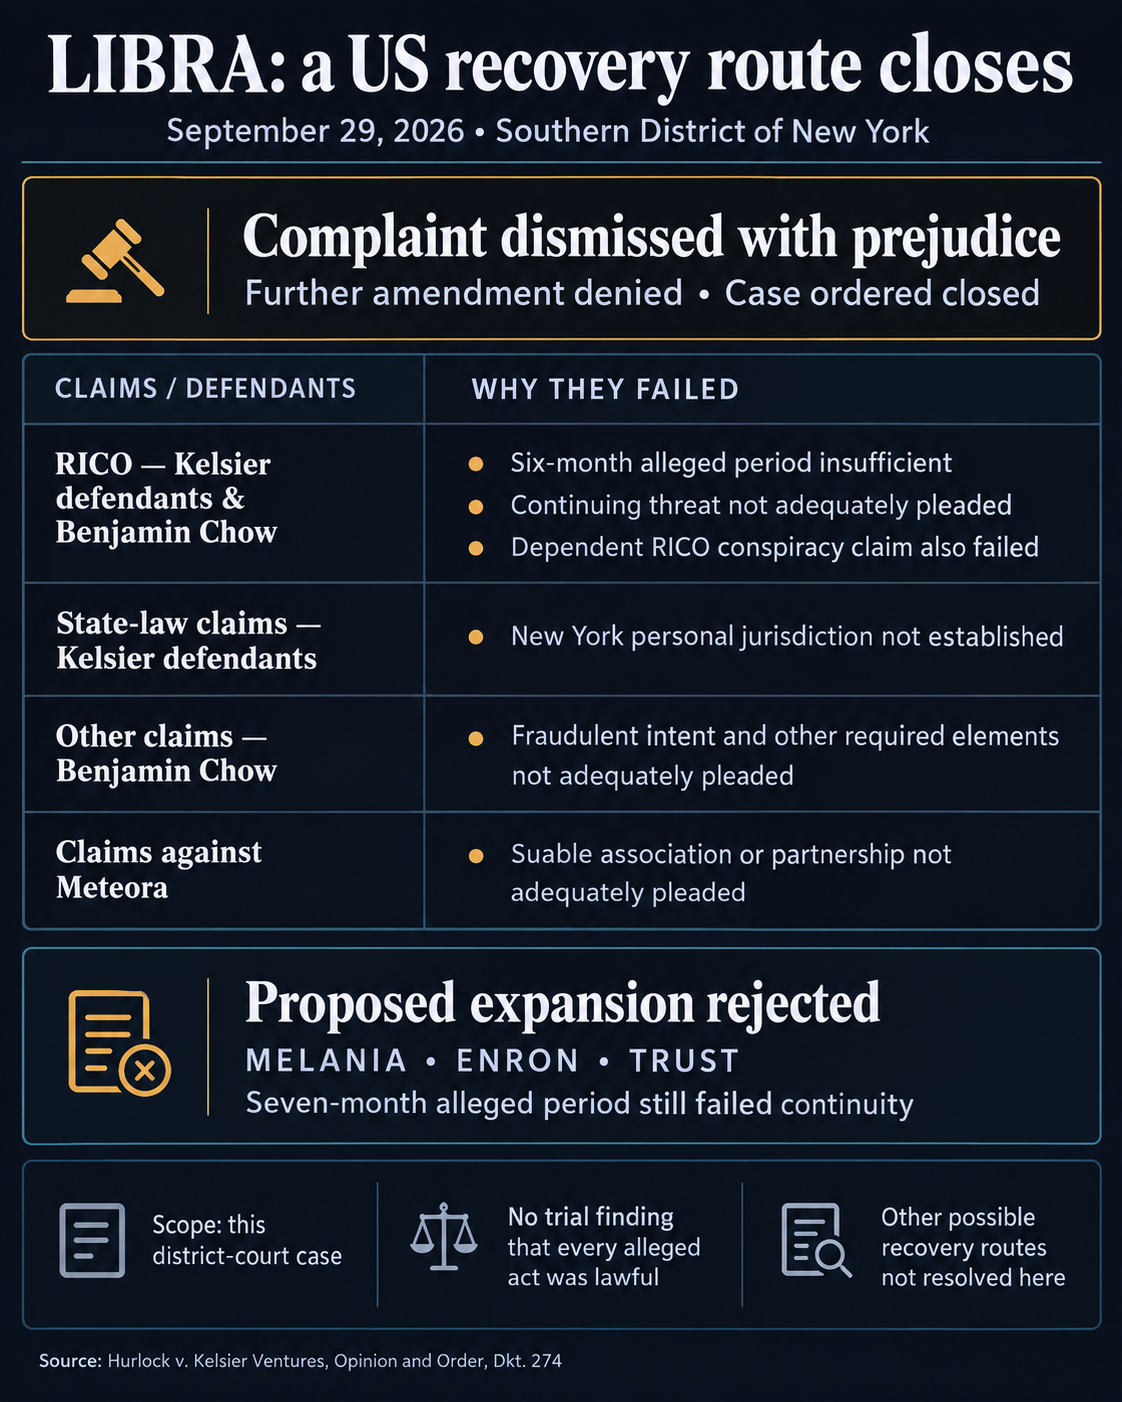
Investors in LIBRA, the memecoin promoted by Argentine President Javier Milei, lost a district-court route to recovering their losses after a US judge dismissed the proposed class action over LIBRA and fellow memecoin M3M3.
In a Sept. 29 opinion, Judge Jennifer L. Rochon dismissed the amended complaint with prejudice, denied permission to amend it again and ordered the Southern District of New York case closed. The decision also blocked investors' proposed expansion of the lawsuit to three other tokens.
The plaintiffs alleged that insiders controlled token launches and extracted funds from liquidity pools at outside investors' expense.
According to the complaint as recounted by the court, LIBRA launched on Feb. 14, 2025, and Milei promoted it before withdrawing his support that day. The dismissal resolved the legal sufficiency of the claims and the court's jurisdiction.
Why the racketeering claims in the LIBRA case failed
The central federal claim relied on the Racketeer Influenced and Corrupt Organizations Act, or RICO. It requires a pattern of related racketeering acts that either spans a substantial period or threatens continuing criminal activity.
The court found neither form of continuity adequately pleaded against the Kelsier defendants, including Kelsier Ventures and Hayden Davis, and Benjamin Chow, Meteora's co-founder and former CEO.
For the first route, the court treated the alleged conduct from October 2024 through the March 2025 complaint as a six-month period. Multiple schemes and a potentially large group of victims did not overcome that short duration.
The opinion applied Second Circuit precedent that generally demands a longer period for this form of continuity, while expressly recognizing that two years is not a fixed cutoff. I
The alternative route required facts supporting a continuing threat. The court found that broad assertions about a repeatable token-launch business and referrals to other projects did not establish, defendant by defendant, that alleged wire fraud was a regular business practice. The dependent RICO conspiracy claims failed too.
The proposed amendment would have added MELANIA, ENRON and TRUST, another plaintiff and new defendants. But the judge found it extended the alleged racketeering period to only seven months and provided no facts curing the continuing-threat defect.
After RICO failed, the court dismissed the Kelsier defendants' remaining state-law claims for lack of personal jurisdiction. Allegations about nationwide social media and crypto infrastructure did not establish the necessary New York connections. The court did not reach the merits of those state-law claims.
The court dismissed all claims against Chow for pleading defects, including insufficient allegations of fraudulent intent. Claims against Meteora failed because investors had not adequately pleaded it as a legal association or partnership capable of being sued.
Hayden Davis's denied wrongdoing and jurisdiction objections in June 2025. The new ruling turns that earlier dispute into a concrete setback for investors seeking recovery through this action.
The order does not establish that every alleged act was lawful or determine the status of every other possible recovery route.
The post US judge kills Milei’s LIBRA memecoin lawsuit, leaving investors stranded appeared first on CryptoSlate.
The US Securities and Exchange Commission’s proposed crypto custody fallback could broaden investment choices while making them easier for larger advisers to offer.
The agency’s economic analysis says the expense of safeguarding assets and arranging independent oversight may lead smaller firms to decline to offer the service.
Approved on Oct. 1, the proposal would let advisers hold covered client crypto assets when an eligible custodian is unavailable, subject to safeguards. Table 8 models certain annual costs of $433,833 per adviser using that option.
That estimate includes an independent control report but leaves out some potentially significant technology costs.
For clients, the consequence could be that an asset might become available through an adviser with sufficient custody resources while remaining outside another adviser’s offering.
SEC Commissioner Hester Peirce distinguished adviser “self-custody” from investors holding their own assets. Here, an intermediary would hold clients' key materials, potentially including a non-controlling portion. Clients would still depend on that intermediary’s safeguards.
For ordinary advisory clients, the adviser amendments concern crypto assets that are funds or securities, while the relevant scope for regulated-fund accounts is securities or similar investments.
What the annual estimate includes
The largest modeled annual component is the independent internal control report. The SEC puts its average cost at $376,000, alongside $57,833 in recurring internal compliance work.
Table 8 combines those amounts and separately lists an initial internal compliance cost of $173,499, all in 2026 dollars.
| Modeled adviser cost | Amount | Timing |
|---|---|---|
| Internal compliance work | $173,499 | Initial |
| Internal compliance work | $57,833 | Recurring annually |
| Independent internal control report | $376,000 | Annual estimate |
| Table 8 adviser annual subtotal | $433,833 | Internal work plus control report |
The internal estimate assumes 300 initial hours and 100 recurring annual hours at $578.33 an hour. It covers information, communications, and an agreement between adviser and client to treat the asset as a financial asset under applicable state law.
The subtotal leaves out some technology, software, hardware, and associated systems and processes. The SEC expects those costs to be economically high. Recordkeeping and disclosure burdens also appear separately in other tables, so the subtotal cannot serve as a complete operating budget.
The accountant figure comes from an inflation-adjusted prior estimate in the Paperwork Reduction Act analysis, rounded to the nearest $1,000, reflecting the agency’s historical cost model. Report costs could vary with the assets, safeguarding systems, and expertise needed to check different networks.
The agency assumes approximately 823 advisers, or 5% of 16,442 registered advisers, would use self-custody for that burden calculation. It cautions that actual uptake may be lower.
Scale changes the cost of access
The economic analysis explicitly anticipates that smaller advisers may elect against self-custody, while larger advisers could have sufficient resources to meet the safeguards. It also identifies ways to share some costs across a larger client base, multiple assets, or affiliated businesses.
That creates a plausible advantage without establishing a universal minimum firm size. An adviser with substantial overall assets may have only a small pool of covered crypto assets needing this fallback.
Conversely, an adviser with a focused crypto business may already have the expertise and infrastructure another firm would have to acquire.
A shared cost weighs more heavily on a small pool of assets than a large one, if the burden stays constant. Firms could allocate costs across their wider businesses rather than charge only clients using the fallback.
The SEC expects many direct costs could be passed on to clients through fees or expenses. More assets and more networks can require more complex controls and more specialized accountant work, increasing absolute costs. The potential benefit comes from spreading or reusing parts of the infrastructure.
Accountant pricing could work either way: the SEC warns that demand for people who can assess crypto controls could make services harder to obtain, particularly for smaller advisers with less bargaining power.
An option that can expire for each asset
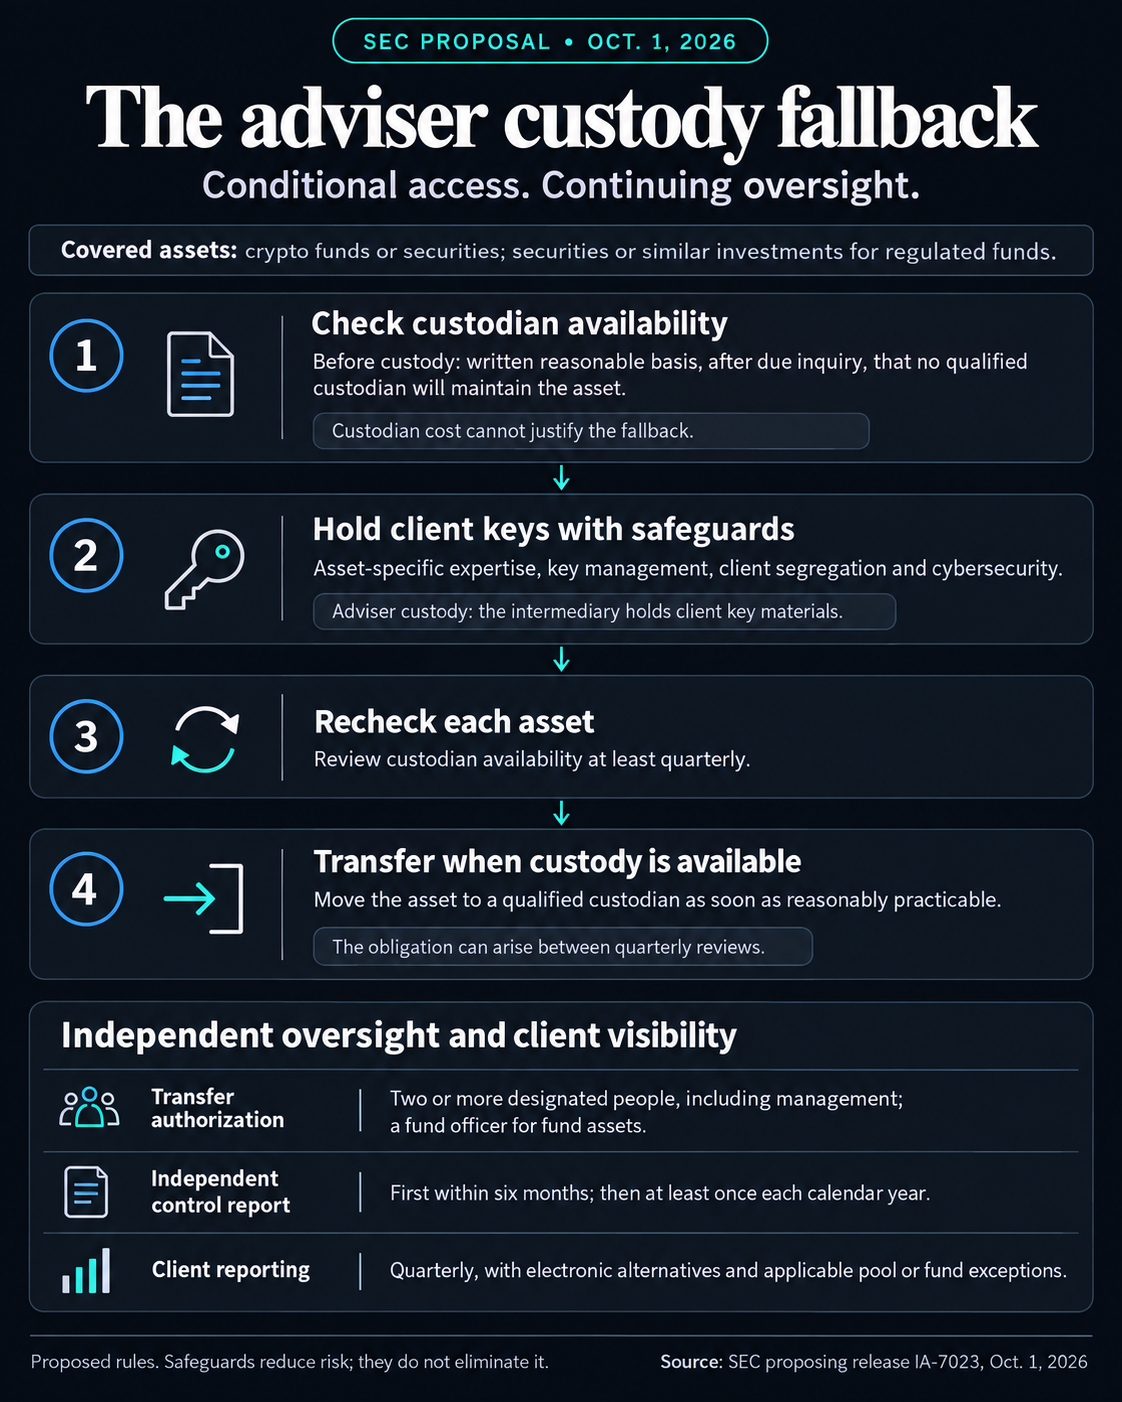
The proposed fallback would depend on the adviser having a written reasonable basis, after due inquiry, that no qualified custodian would maintain each asset.
The adviser would need to make this determination before taking custody and at least quarterly afterward. Custodian costs could not form the basis of that determination.
An adviser could not choose the fallback simply because its custody arrangement looked cheaper. The relevant barrier is the availability of an eligible custodian for the asset, assessed under the proposed conditions.
Once an adviser learned that a qualified custodian had become available, it would have to place the asset with that custodian as soon as reasonably practicable. That obligation could arise between quarterly reviews. The proposal does not specify a single transfer deadline for every situation.
A firm might incur costs to support an asset and later have to move it out of adviser custody. Eligibility could also leave the firm with only a narrow set of unsupported assets to spread the remaining expense across.
If no client crypto assets remained in self-custody by the report’s due date, the report would not be required. That could reduce costs for a short-lived arrangement, although advisers retaining other covered client crypto assets in self-custody would still face the applicable obligation.
The safeguards buy independent scrutiny
The expense accompanies a change in who holds the assets. An adviser offering investment advice would also hold client key materials, creating risks of misuse, misappropriation and operational error. A lower-cost arrangement would have to be assessed alongside those risks.
As SEC Commissioner Mark Uyeda’s statement explains, the proposed conditions include safeguarding expertise, cybersecurity protections, annual reviews, reporting and client disclosures.
The adviser would need asset-specific expertise and systems for key management, authorization by two or more designated people, and segregation of each client’s assets.
The first independent control report would be due within six months of taking self-custody and at least once each calendar year thereafter. It would assess the design, implementation and effectiveness of controls and include verification of reconciliation to the crypto network.
That supplies scrutiny beyond an adviser’s assessment of its capability.
Quarterly client reporting would also apply, with electronic alternatives and exceptions for qualifying audited pools and regulated funds. Clients’ visibility into balances and transactions can complement safeguards, while the accountant’s work addresses questions that a balance alone cannot settle.
These protections would not eliminate custodial risk, and the SEC cautions that spending itself does not establish safeguarding competence. A firm’s ability to absorb compliance costs is a separate question from whether its systems effectively protect clients.
Alternatives could soften the scale advantage
SEC Commissioner Hester Peirce’s Sept. 30, 2025 statement described conditional staff no-action relief for certain state trust companies and identified national and state banks as other permissible custodians.
The October proposal would also permit eligible state trust companies to custody crypto assets, subject to initial and annual due inquiry into authorization and safeguards. Where an eligible institution supports an asset, clients may gain access without their adviser building the proposed fallback arrangement.
Its cost advantage would depend on the particular asset and custody arrangement, since a firm authorized to provide crypto custody does not necessarily maintain every asset a client wants to hold.
The question for investors is whether the proposal would produce usable access at an acceptable cost and level of protection. The SEC’s analysis supports a possible advantage for advisers with sufficient resources and reusable infrastructure.
How widely clients benefit would depend on firms’ actual implementation costs, independent-accountant pricing, and the assets that eligible custodians begin to support.
The post New SEC crypto rules threaten small advisers, but big firms win appeared first on CryptoSlate.
Ethereum layer-2 network built around native yield Blast said on Oct. 2 that it will shut down because maintaining the chain costs more than it earns.
The project asked users to move their assets to Ethereum mainnet by Oct. 26 to withdraw through its normal interface.
Blast said in its shutdown announcement that it sees no credible path to making the network economically sustainable. It plans to wind down the chain through an asset withdrawal process that will temporarily interrupt users’ ability to exit.
The decision comes nearly three years after Blast disclosed $20 million in funding from Paradigm and Standard Crypto on Nov. 20, 2023. The network opened early access that November, with a mainnet launch then planned for February 2024.
Its documented design describes an Ethereum-compatible optimistic rollup that passes yield from ETH staking and real-world-asset protocols to users. The website identifies Lido and MakerDAO as yield sources and lists additional investors among Blast's backers.
The yield model was intended to let holders benefit from returns earned by those underlying protocols, but Blast now says those operating economics no longer justify keeping the network running.
Blast's withdrawal pause and Oct. 26 cutoff
Blast said it will first withdraw its assets from Lido, which its design identifies as a source of ETH staking yield, a process that is expected to take approximately one week.
User withdrawals will be temporarily unavailable during the unwind, even after the network reduces its withdrawal delay to 24 hours.
Withdrawals will resume with the new 24-hour delay once the Lido process is complete, according to the announcement. The roughly one-week interruption and the withdrawal delay after reopening are separate parts of the exit timetable.
The request to move funds back to Ethereum includes balances held in Blast’s web app, which the announcement calls the PWA. Blast encouraged all users to withdraw before Oct. 26.
After that date, Blast said assets will remain withdrawable, but users will need to interact directly with its bridge contracts on Ethereum mainnet.
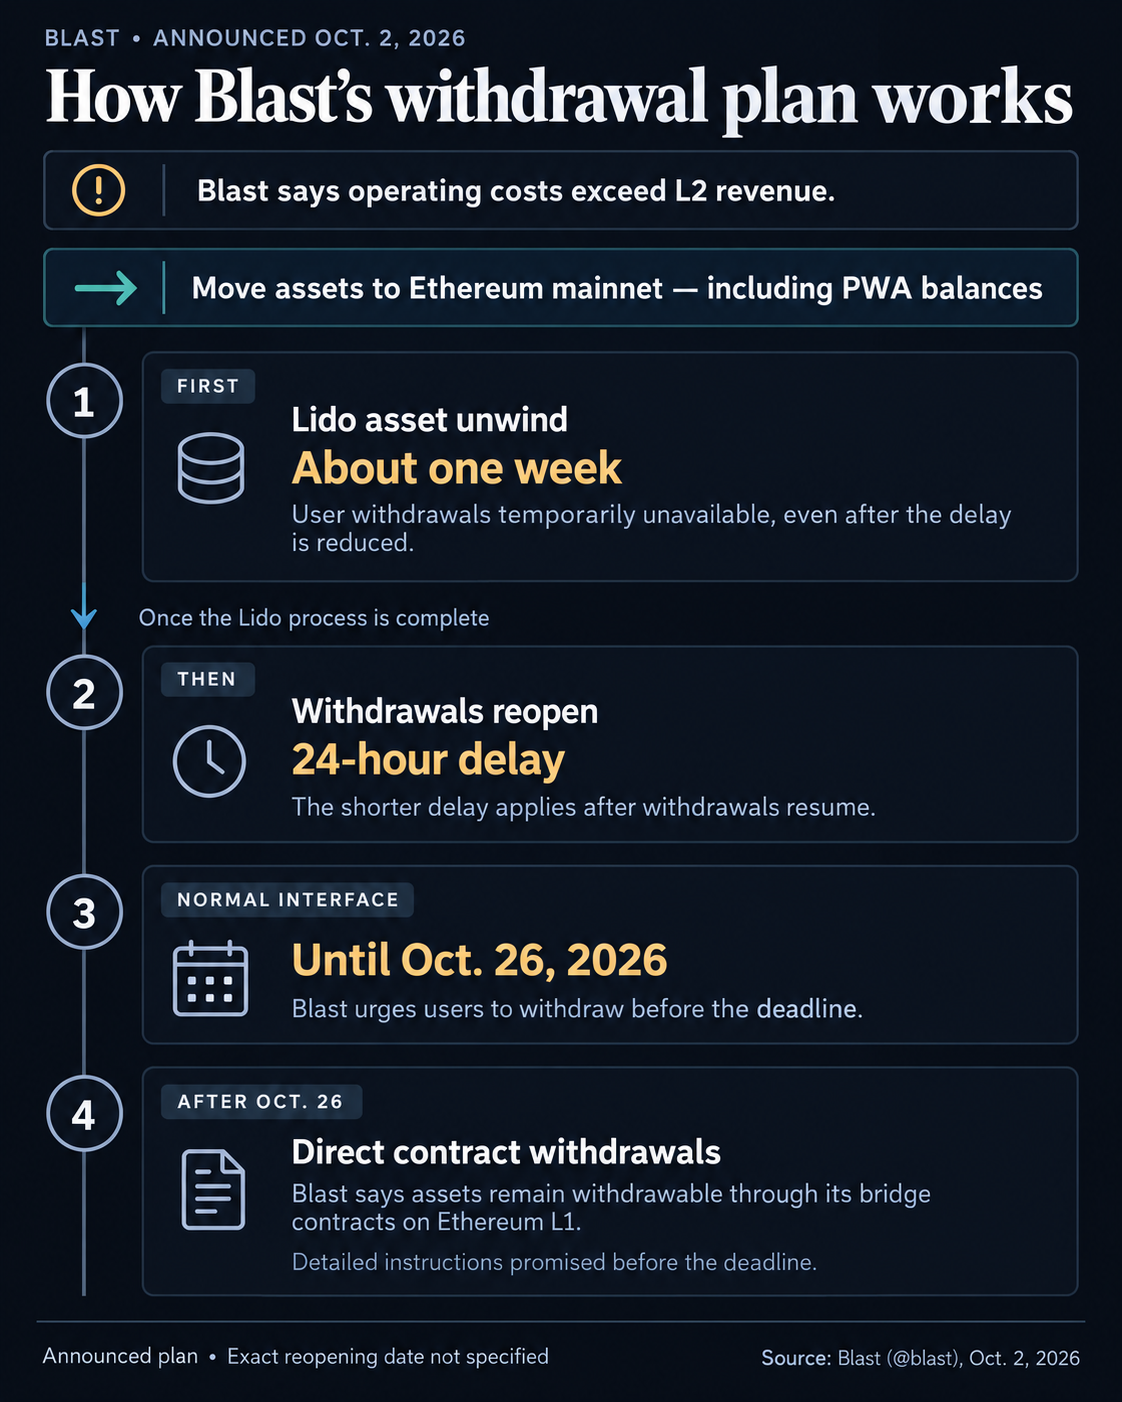
Blast promised to publish detailed instructions for that route before the deadline. The announcement gives an approximate duration for the Lido unwind but does not specify an exact date when normal withdrawals will resume.
The post Blast shuts down $20M layer-2 network, forcing Oct. 26 exit deadline appeared first on CryptoSlate.
Stablecoin issuers are emerging as a new source of demand for US government debt as foreign official holdings lose ground.
Tether and Circle have increased their Treasury securities and repurchase-agreement holdings by about $200 billion over the past five years, equivalent to more than 40% of the decline in China’s Treasury holdings over the same period, researchers at the Federal Reserve Bank of San Francisco said.
The shift is beginning to alter the investor base underpinning the world’s largest government bond market. Stablecoin issuers’ Treasury holdings have risen more than tenfold in five years as demand for dollar-linked digital tokens expanded, while China has continued a retreat from US debt that began more than a decade ago.
Stablecoins gain ground as foreign governments retreat
The rise of crypto-linked buyers comes as the composition of US creditors undergoes a longer-term change that could affect how cheaply Washington can finance its deficits.
Foreign investors held more than half of outstanding Treasury securities around 2008, but their share had dropped to roughly 30% by early 2026, the San Francisco Fed said. Within that group, foreign governments have declined even more sharply in relative importance, accounting for just above 40% of foreign Treasury demand by early 2026 compared with nearly all of it at their peak in the 1970s.
China has been central to that shift. Its Treasury holdings peaked in late 2013 and had fallen by more than half by mid-2026 as Beijing diversified its reserve assets.
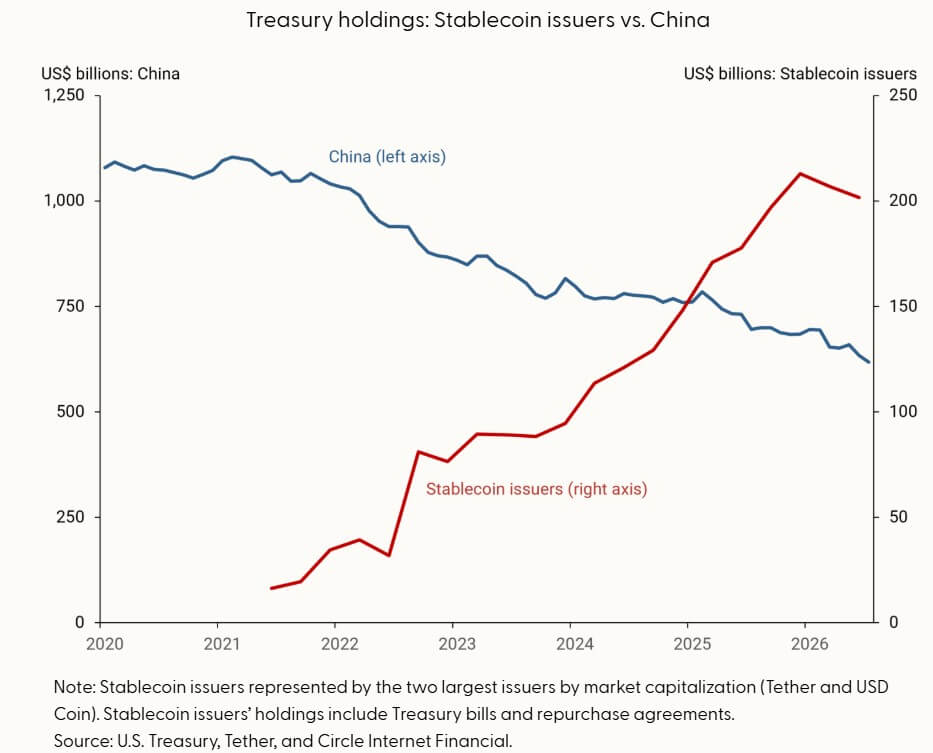
Private investors have taken a larger role as official foreign demand weakened, potentially making Treasury financing more sensitive to interest-rate changes and perceptions of US fiscal risk. Unlike central banks, which may hold Treasuries for reserve-management purposes, private investors can demand higher yields when risks rise or competing returns increase.
Stablecoin issuers add a different source of demand because their business model requires large pools of liquid dollar assets backing tokens that customers can redeem at par.
Tether’s USDT and Circle’s USDC accounted for more than 80% of stablecoin market capitalization as of mid-August, the Fed researchers said. Both issuers hold substantial amounts of short-term Treasury securities, along with cash, bank deposits, and repurchase agreements, to meet redemption demands.
Their growth has already made them significant participants at the short end of the Treasury market. Since 2023, stablecoin issuers have added more short-term Treasury holdings than Japan, the largest foreign holder of US government debt, according to the research.
That demand is also large enough to measurably affect short-term government bond yields, the San Francisco Fed said, citing research from the Bank for International Settlements.
The China comparison has a maturity gap
Stablecoins cannot fully replace the type of demand China has withdrawn because the two investor groups operate in different parts of the Treasury market.
China’s reductions have been concentrated largely in longer-dated US debt, while stablecoin issuers predominantly buy Treasury bills and other highly liquid, short-maturity assets. That means growing stablecoin reserves can deepen demand for bills without necessarily creating an equivalent buyer for longer-term notes and bonds.
The distinction comes as the US faces heavier financing requirements. Federal debt held by the public has risen from about 35% of gross domestic product in 2006 to roughly 100% today, increasing scrutiny of the investor base willing to absorb new issuance.
Regulation could reinforce stablecoins’ preference for the shortest maturities.
The GENIUS Act, adopted in 2025, created a federal framework requiring approved US payment stablecoin issuers to fully back outstanding tokens with eligible liquid reserves.
Proposed implementing rules include Treasury bills, notes and bonds with remaining maturities of 93 days or less, alongside cash, bank deposits and certain Treasury-backed repurchase agreements.
That structure effectively links growth in regulated dollar stablecoins with incremental demand for highly liquid US government securities.
For issuers, the economics can also be attractive. Customers hold tokens that generally do not pay them the yield earned on reserve assets, while issuers can collect interest from the Treasury securities backing those tokens.
As circulation expands, reserve portfolios and the associated interest income can rise with them.
Global stablecoin adoption could funnel more capital into T-bills
The next phase will depend on whether stablecoins continue attracting users outside the traditional crypto trading market.
The San Francisco Fed pointed to growing use of stablecoins for cross-border payments and as dollar-denominated stores of value in countries with volatile currencies. Usage relative to economic output is particularly high in Africa, the Middle East and Latin America, with much of the activity crossing national borders.
That creates a channel through which a stablecoin user abroad can indirectly finance US government borrowing. A customer acquiring dollar tokens creates additional reserve liabilities for the issuer, which can in turn purchase Treasury bills to back them.
Extending the industry's recent growth rate would lift those holdings toward $400 billion by 2030, though the Fed researchers cautioned that the estimate carries substantial uncertainty. Regulation outside the US, competing digital-payment products and new bank technology could all slow stablecoin adoption.
Those competitive pressures will determine how much of the next wave of dollar-based payments ultimately flows through stablecoin issuers and into Treasury markets.
Banks developing cheaper cross-border settlement tools could capture some of that demand, while stablecoin companies expanding into remittances and payments would need to keep increasing liquid reserves as circulation grows.
The post Stablecoin issuers have replaced 40% of China’s lost US Treasury demand appeared first on CryptoSlate.
Bitcoin’s rally is approaching a $90,000 test as a rare accumulation pattern reappears and sell-side liquidity thins.
On Oct. 2, Bitcoin registered an intraday high at $87,000 after buyers broke through a sell wall around $85,000 that had stalled several previous attempts to advance.
Glassnode said some of those orders were filled and the remainder withdrawn, leaving a smaller concentration of asks around $87,000 and less visible liquidity immediately above.
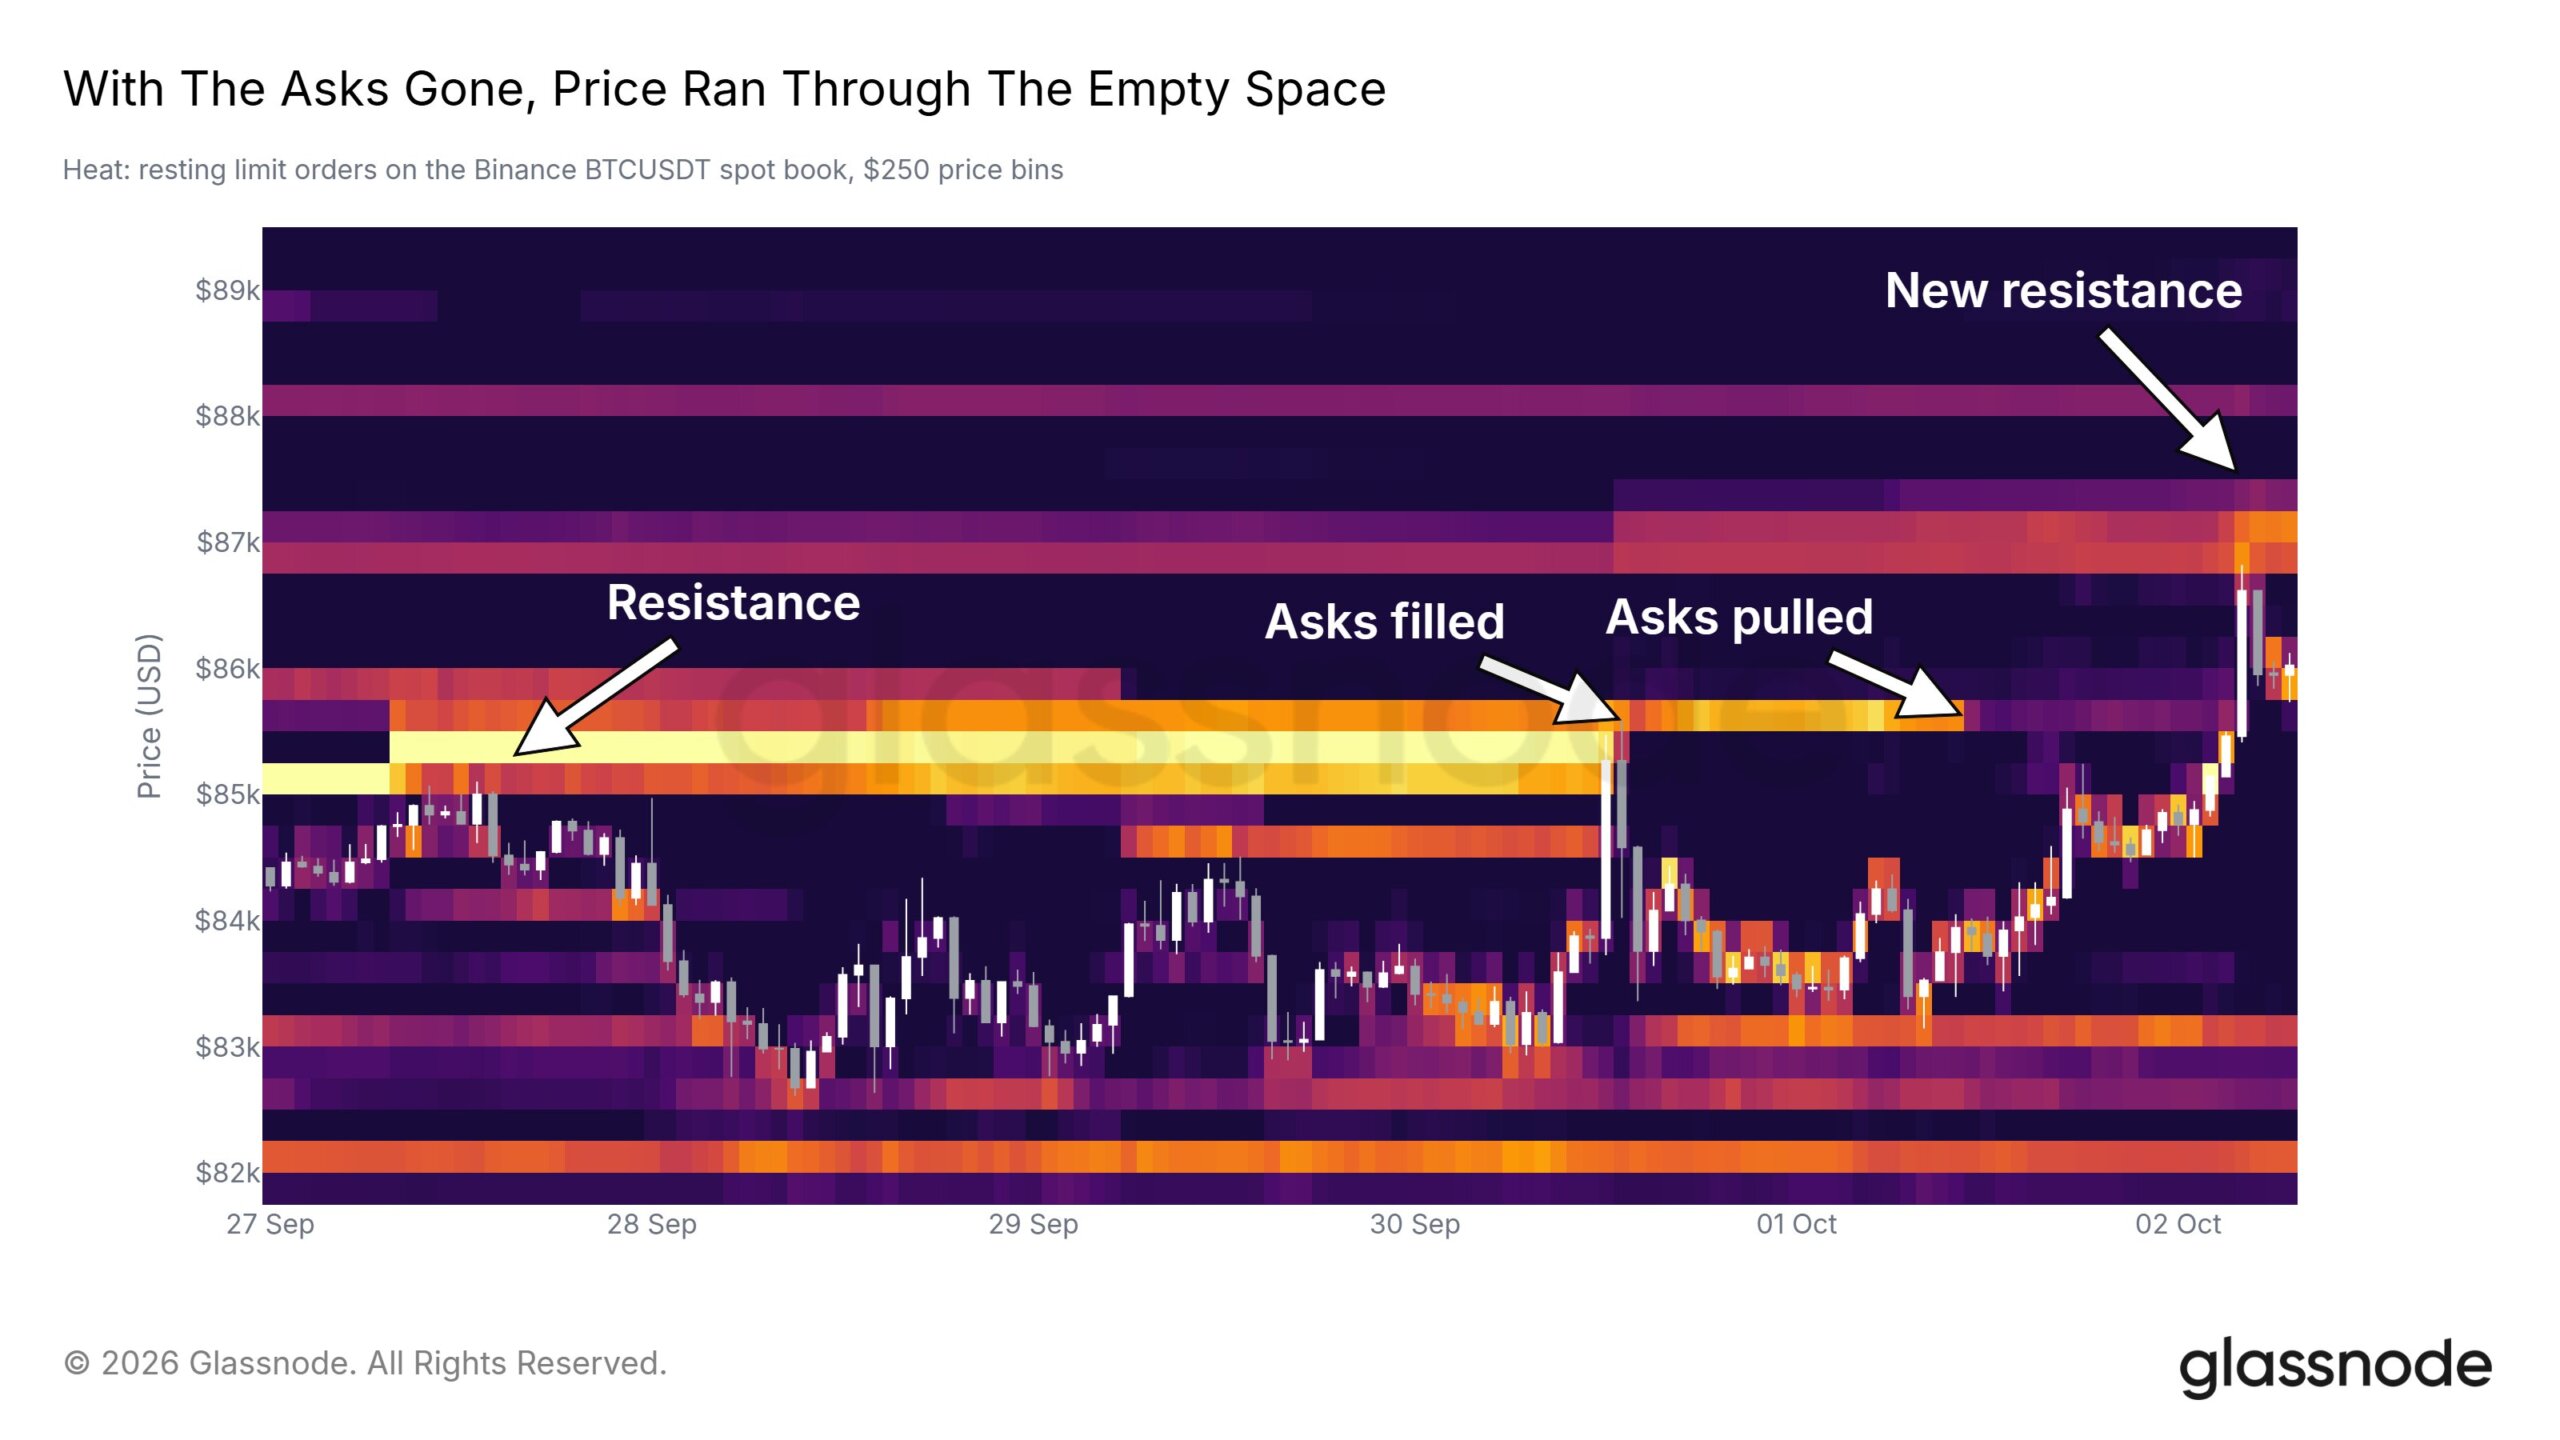
At the same time, bands on CryptoQuant’s Bitcoin Accumulation Trend chart have begun contracting, reviving a pattern seen before two sharp advances in 2025.
The setup adds another bullish signal to a market that has reclaimed several key cost-basis levels, though the limited number of previous occurrences makes the pattern far from conclusive.
Past contractions offer a bullish, but limited, precedent
Per CryptoQuant, the current contraction resembles two episodes in 2025 followed by sizable gains, giving traders a bullish analog as Bitcoin enters October.
The Accumulation Trend tracks buying and selling behavior across different groups of Bitcoin holders, offering a view into whether supply is being absorbed or distributed. Periods when the chart’s bands narrow sharply have previously coincided with shifts in market momentum.
One contraction occurred between April 17 and April 20, 2025, when Bitcoin traded near $84,000. BTC subsequently climbed toward $109,000, and another appeared between March 5 and March 8 before a separate advance.
Those episodes are too few to establish the contraction as a reliable forecasting tool. However, they do make the latest occurrence more notable because Bitcoin’s broader market structure has improved at the same time.
Bitwise said this week that Bitcoin has reclaimed the major cost-basis thresholds it tracks for identifying shifts toward risk-on conditions. Those include the short-term holder cost basis near $73,000, a true market mean around $77,000, and the estimated average cost basis of spot exchange-traded fund investors near $83,000.
Bitcoin has also moved decisively through Bitwise’s $85,000 short-term holder realized-price band, pushing the market toward a part of the distribution where gains have historically become harder to sustain.
Underwater Bitcoin holders crowd the path toward $100,000
The disappearance of the $85,000 sell wall leaves Bitcoin heading directly toward another source of potential supply: investors approaching breakeven after months of losses.
CryptoQuant analyst Darkfost estimates that BTC holders who acquired their assets 18 months to two years ago have an average cost basis near $88,350. The six-to-12-month cohort sits around $89,200 and has been underwater overall for close to a year.
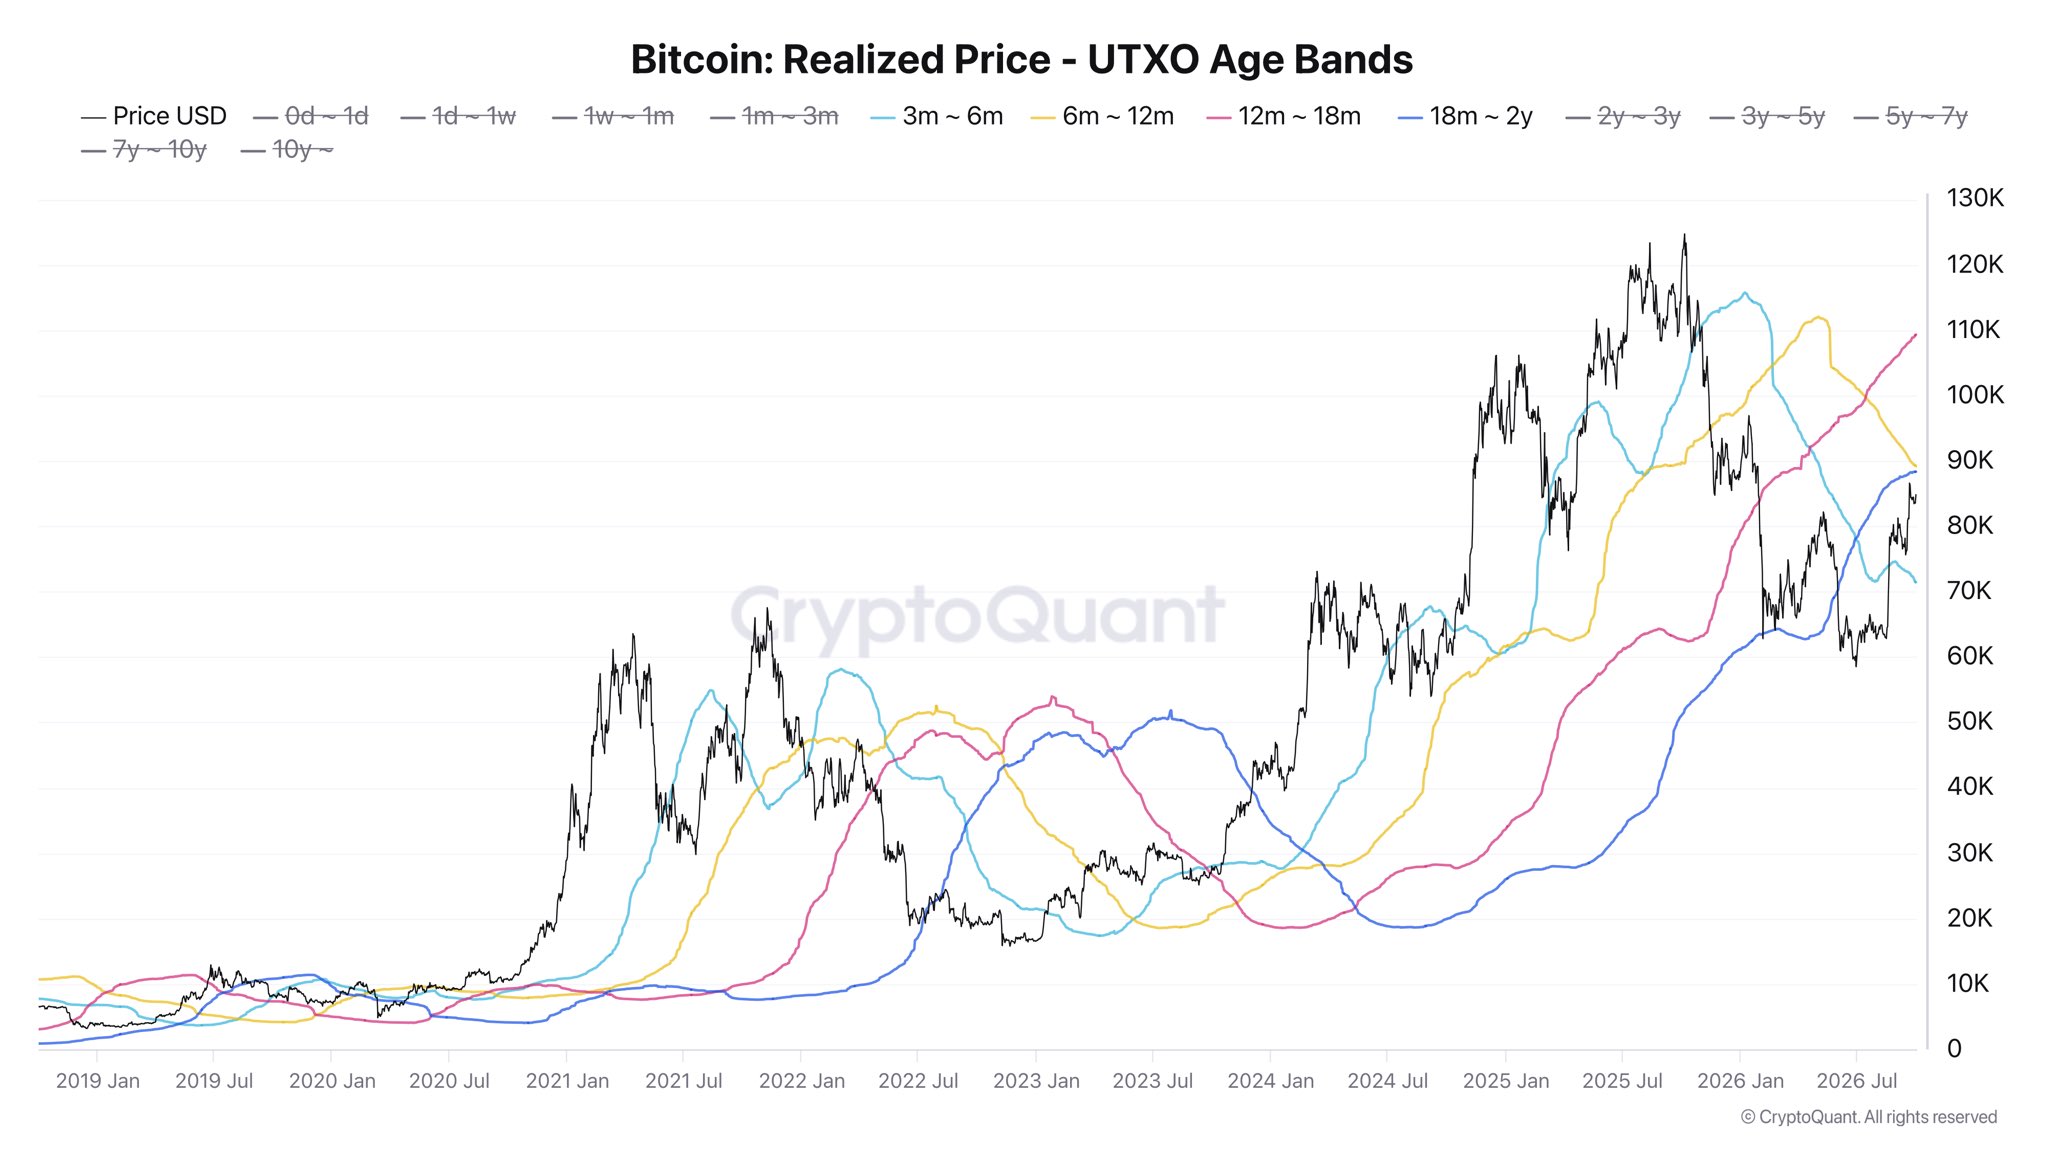
Some investors bought above these averages and others below, but as the market approaches the cohort's cost bases, more holders face a fresh decision after months in losses.
Some may use the recovery to exit near breakeven, while others could hold or add to lower their average purchase price. How much of that returning supply buyers absorb will help determine whether the rally can extend beyond $90,000.
Bitwise’s valuation bands place another hurdle in almost the same area.
The firm puts the next short-term holder reference level around $90,000, or 1.5 standard deviations above realized price, followed by the two-standard-deviation level around $95,000. Bitcoin has traded above those thresholds on only about 3.8% and 1.7% of days, respectively, in Bitwise’s historical sample.
A separate Fibonacci framework used by the asset manager places levels near $92,000 and $100,000, adding to the concentration of technical and on-chain markers across the region. Bitwise described $90,000 to $100,000 as the next area where several structural reference points converge.
Options traders are positioning for the same corridor. Deribit data show about $2.1 billion of Bitcoin call exposure at the $90,000 strike, $2.4 billion at $95,000 and $1.8 billion at $100,000.
The concentration of calls points to substantial demand for upside exposure as Bitcoin moves closer to those strikes.
Their effect on the spot market will depend on expiration dates and dealer hedging, but the positioning shows that traders have placed billions of dollars behind a move into the same $90,000-to-$100,000 range highlighted by on-chain valuation measures.
Leverage rebuilds as macro pressure eases
Bitcoin is approaching that supply zone with speculative exposure rising again and Friday’s US employment report giving risk assets a fresh macro boost.
Bitcoin's open interest fell to about $52 billion as September ended, but derivatives activity has begun recovering, with the figure climbing to roughly $56.2 billion in the first two days of October, CoinGlass data show.
The roughly $4.2 billion increase coincided with Bitcoin rising from about $83,500 to briefly above $87,000.
The rebound suggests traders are rebuilding exposure after cutting positions into the end of September. With open interest rising alongside Bitcoin, new positions have accompanied the price advance, although the measure alone does not show whether traders are positioned long or short.
Bitcoin open interest ended September near its lowest level in a year, leaving room for speculative activity to rebuild without immediately returning to previous extremes. Rising funding nevertheless makes long positions more expensive to maintain and increases their vulnerability if the rally reverses.
The macro backdrop turned more favorable Friday after US employers added just 29,000 jobs in September, well below the 90,000 economists had expected. The unemployment rate increased to 4.2% from 4.1%, while August payroll growth was revised lower.
The report pushed down expectations that the Federal Reserve will raise rates again at its October meeting, sending Treasury yields lower and lifting US equities. Futures markets placed the probability of an October increase below 20% following the data.
That removes one immediate threat to Bitcoin’s advance while leaving the harder test inside the crypto market itself.
A sustained move through $90,000 would take Bitcoin into territory that Bitwise already considers historically stretched relative to recent investor cost bases. Reaching $95,000 would push it into a band exceeded on less than 2% of days in the firm’s sample, forcing buyers to absorb both returning holder supply and increasingly expensive leveraged positions.
Failure to do so would shift attention back toward $83,000, where Bitwise places the average ETF investor cost basis and the first major downside level that bulls would need to defend.
The post Bitcoin’s $85,000 sell wall is gone and traders are now betting on $100,000 appeared first on CryptoSlate.
CryptoTicker.io
Cardano (ADA) costs around $0.242 late on Friday evening, October 2, 2026 (according to CoinGecko). That puts the price almost exactly on its 200-day moving average, which we calculate at $0.243 from CoinMarketCap daily closes. And it does so in a week with two pieces of news that would have been enough for a price jump at other coins: Brazil's state oil company Petrobras is testing Cardano, and the Cardano Foundation has found a partner in Japan. For the Cardano price prediction what counts, therefore, is why the news has not yet reached the price.
What Petrobras and Pacific Meta have announced
Petrobras has developed two applications on Cardano together with the Ledger Lab of the PUC-Rio university, Cointelegraph reports. The first makes the environmental benefit of sustainable aviation fuel (SAF) transferable as a token: an airline or a passenger can acquire the certificate even if the fuel is physically burned somewhere else. A token can be redeemed only once, so that the same certificate is not sold twice. The second application tracks the production, transport and consumption of Diesel R, the group's renewable diesel. Both projects are explicitly at the research stage, and none of those involved names a date for regular operation.
The second report followed on October 1: the Cardano Foundation is working with Pacific Meta, a blockchain incubator from Tokyo that is to help Japanese companies build applications of their own (FXStreet). Japan is no new market for Cardano, where the project has had a large following since its launch in 2017. According to Santiment, the number of daily active addresses almost doubled afterwards to more than 27,500, as CoinCentral quotes it.
Cardano price prediction: the levels on the chart
The one-year chart shows where ADA has come from. A year ago Cardano still cost around $0.85, and the low of the past twelve months sat at roughly $0.14. Over a year the token is down around 72 percent, and over 30 days it is up around 22 percent (CoinGecko).
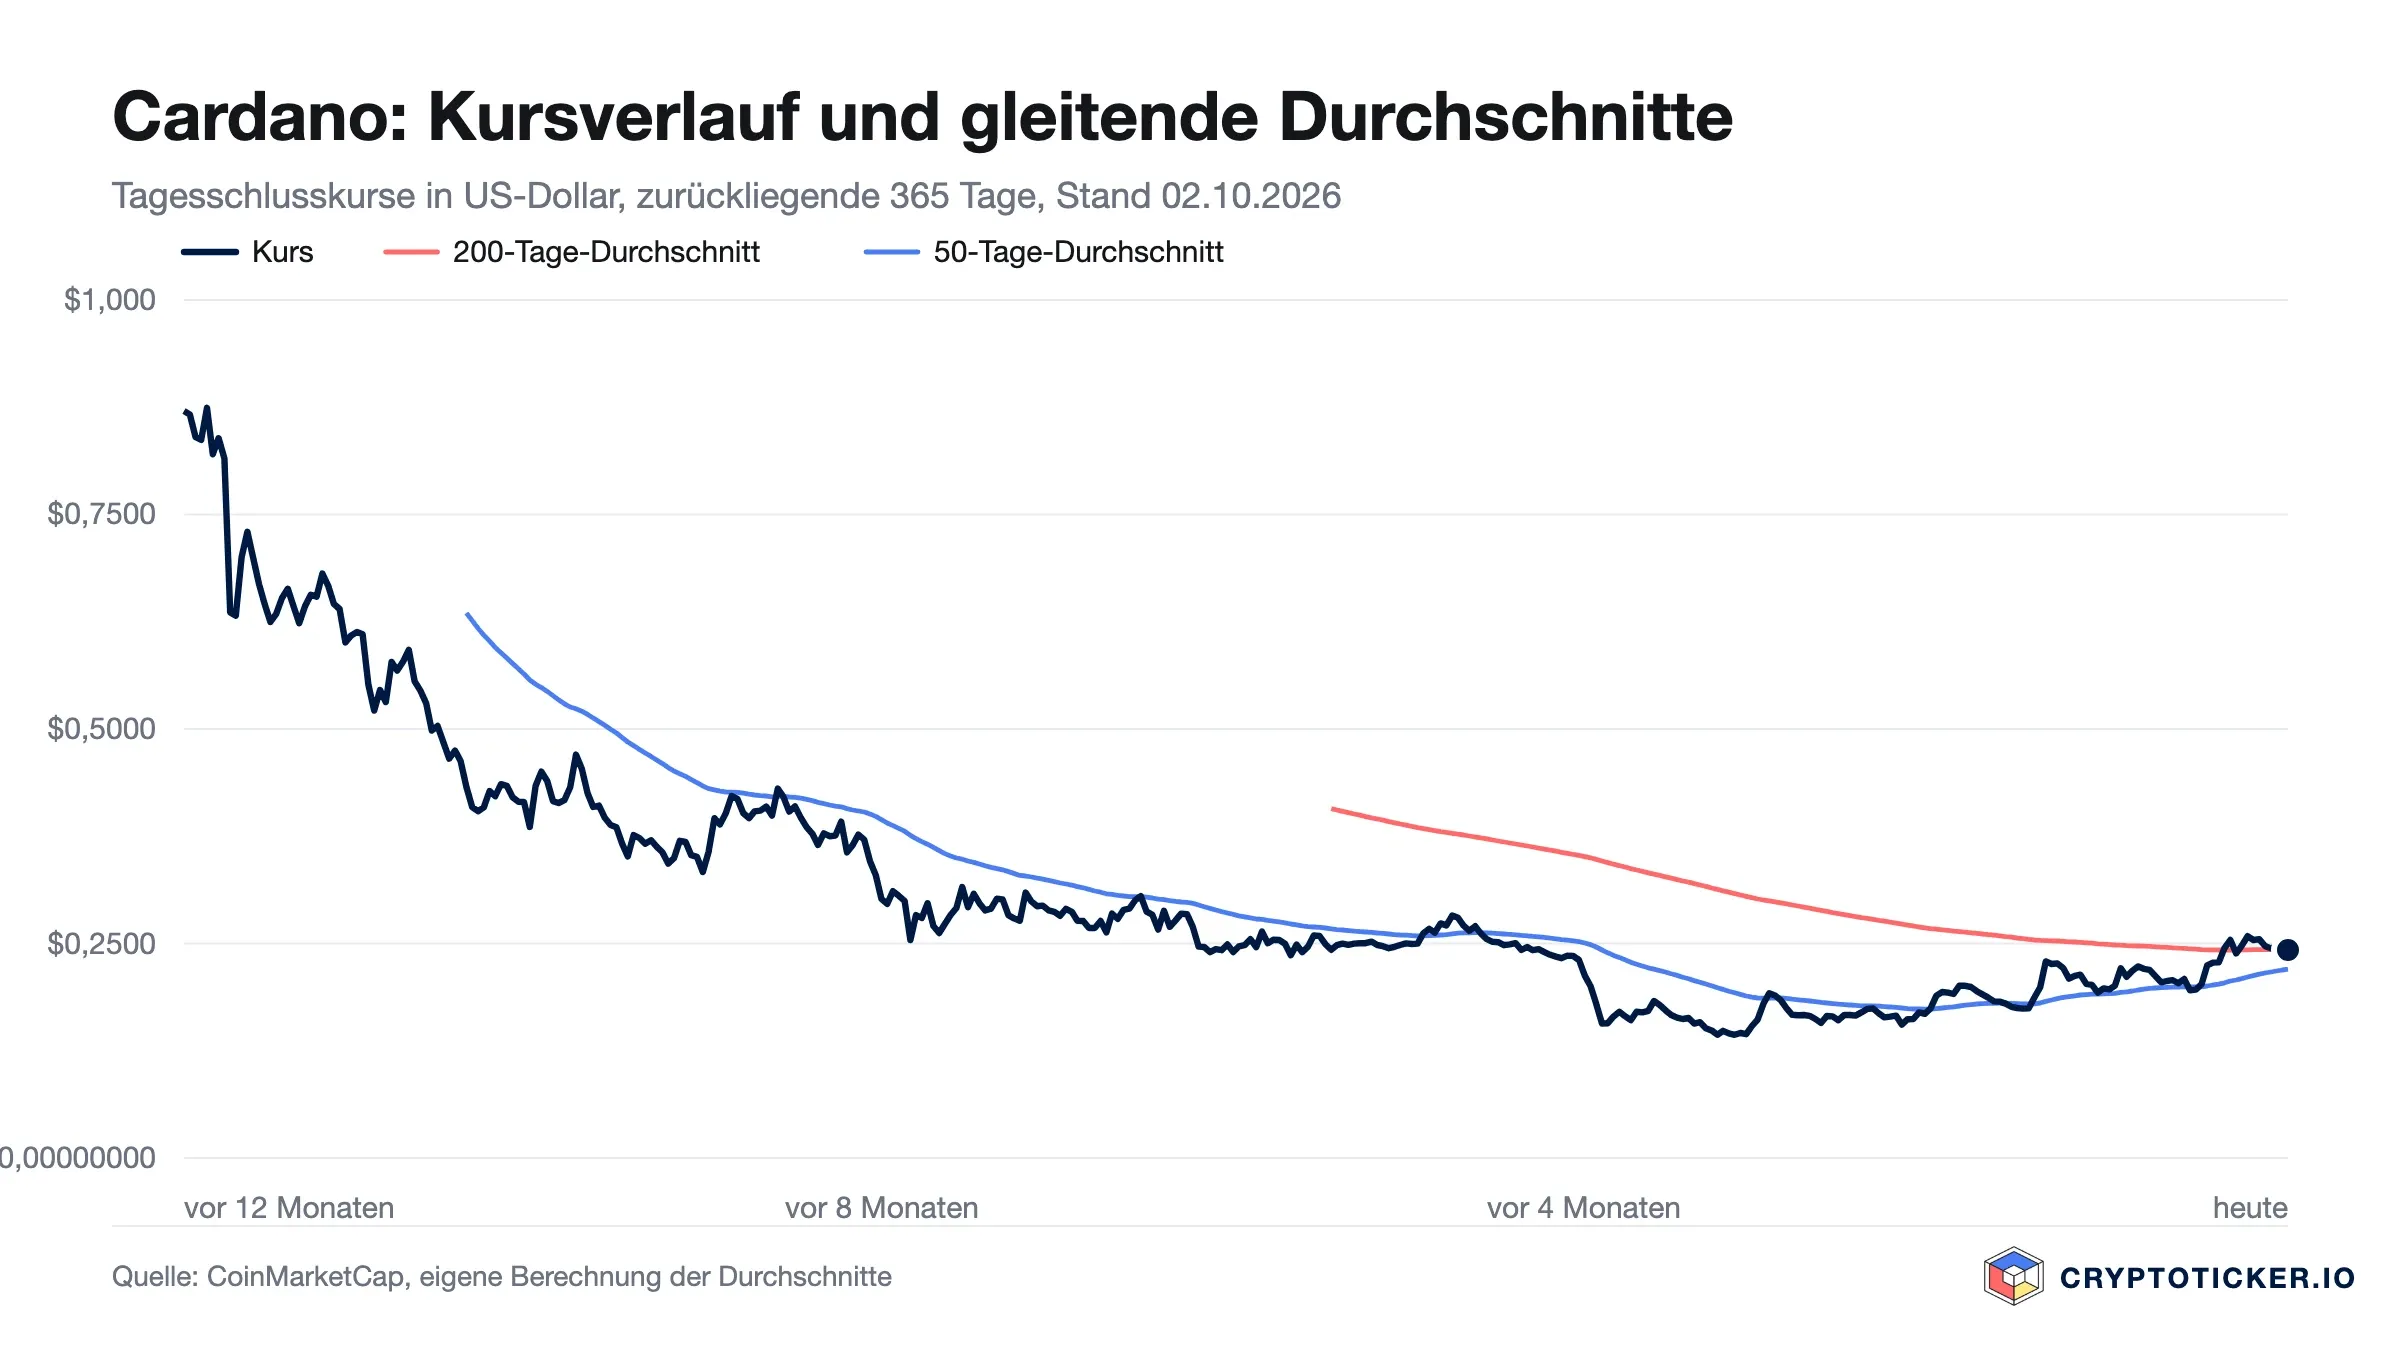
$0.26 is the level on the upside. On September 25 ADA closed at $0.2586, and the price got no higher than that this autumn. In the 24 hours to Friday evening, that is after the Japan report, the high also reached only around $0.2585. Only a close above it would turn the sideways phase into a breakout.
$0.243, the 200-day moving average, is the line on which ADA is currently balancing. Since September 21, every close has sat between $0.2385 and $0.2586, so within a band of a good eight percent. A price that spent months below this line and is now clinging to it often settles the direction of the coming weeks here.
$0.22 and $0.195 are the levels beneath. The 50-day moving average runs at $0.22, and the lows of August 30 and September 15 sat around $0.195. The recovery that lifted ADA by roughly a third into late September started from there.
Why the news is not carrying the price yet
Both reports are declarations of intent and tests, not revenue. How many transactions the Petrobras project would trigger in operation, and whether any appreciable amount of ADA would be needed for it, cannot be quantified today. For the price, news of that kind is therefore closer to sentiment than to demand. On top of this comes the wider market: Bitcoin moved by just under one percent in the seven days to Friday evening, and without a tailwind from there smaller coins often lack the push.
What is coming up for Cardano in the fourth quarter
The next big step is technical in nature. For the fourth quarter of 2026, according to the roadmap that CoinMarketCap summarises, completion of the first stage of Leios is planned, an extension intended to raise the network's throughput. For November, production operation of the alternative node Amaru has been announced. Dates like these have a record of slipping at Cardano, but they are the next occasions on which it can show whether developers and users come along.
Anyone holding ADA for the long term can delegate the coins in their own wallet to a stake pool. The coins stay in your own custody throughout and remain available at any time; nothing is locked. Anyone who prefers to stake through an exchange should compare terms and custody, for instance in our comparison of staking providers.
Cardano: Your next three steps
First: keep an eye on the closing price, not on the headline. A daily close above $0.26 would be the first sign that the news is reaching the price, and a close below $0.22 the opposite. Second: fit the size of your position to that range, because roughly 18 percent lies between the two levels. Third: with gains, remember the holding period. Coins held for less than a year are taxable on sale in Germany as soon as the annual exemption limit of 1,000 euros is exceeded.
Anyone wondering how the price was read a week ago will find the situation at the time in our Cardano price prediction from September. Crypto assets fluctuate heavily and a total loss is possible. This article places news and price levels in context; it is not a recommendation to buy or sell Cardano.
The prediction market token RAIN has lost 14.5 percent within a day and trades at $0.0103. The reason has been sitting in the project's vesting schedule for months: in October, RAIN tokens worth roughly $785.5 million become free. That is almost forty-five times what changes hands on an ordinary day.
That calculation is the heart of the matter, and it explains more about the price action than any reading of market sentiment. A token unlock is no misfortune that befalls a project. It is a date fixed at launch which anyone can look up. What alone decides the outcome is how large the released quantity is relative to the market's capacity to absorb it. For RAIN that ratio is currently extreme.
What exactly happens at the RAIN unlock in October
According to an analysis by the industry service Cryptobriefing, roughly $785.5 million of released tokens fall to RAIN in October. The seven largest unlocks of the month come to about $1.08 billion together. RAIN alone therefore accounts for just under three quarters of the entire volume, while the remaining six projects share the other $294.5 million (Cryptobriefing, October 2026).
For RAIN this is not a one-off event. In June, according to the same analysis, roughly 4.4 percent of the total supply became free, with a value between $650 million and $713 million. For July the projection stood at $812 million. October thus joins a series that runs through the whole year. Anyone who knows the calendar has been taken by surprise by none of these dates.
Token unlock, vesting and cliff: the terms in one sentence each
A token unlock is the moment at which previously locked tokens become transferable and therefore sellable. Vesting is the lock-up schedule behind it, meaning the contractual rule setting out the time grid on which the founding team, early investors, the foundation and the ecosystem treasury receive their shares. A cliff is a drop in that schedule: an initial lock-up period after which a large package becomes free all at once.
The counterpart to the cliff is linear vesting, where portions of equal size are released across a period. Both models release the same quantity in the end. The difference lies in whether the market has to absorb the inflow on a single day or spread across weeks.
$785 million against $17.6 million of daily turnover: the real problem
cryptoticker.io compiled the market data on RAIN itself on the evening of October 2, 2026. The token traded at $0.0103, or around 0.0092 euros. Market capitalisation stood at about $7.31 billion, which corresponds to rank 20 among all crypto assets. Trading turnover over the preceding 24 hours, by contrast, came to only around $17.59 million. This assessment was compiled by cryptoticker.io on October 2, 2026.
Put those two figures in relation and you arrive at a daily turnover of about 0.24 percent of market capitalisation. For comparison: among the largest crypto assets that figure regularly sits in the low single-digit percentage range. Measured against its valuation, RAIN is therefore barely traded.
From this follows the calculation that makes October uncomfortable for holders. The $785.5 million being released corresponds to roughly forty-five times an average day's turnover and to about 10.7 percent of total market capitalisation. Even if only a small part of the new tokens is actually sold, that part meets a thin order book. In a thin order book, even mid-sized sell orders move the price noticeably.
Why linear vesting stretches the pressure instead of bundling it
For RAIN it is documented that a considerable part of the allocations is released linearly, in particular the reserve and the funds of the project treasury. The public unlock calendar of the data service Tokenomist sets out the dates and quantities individually (Tokenomist, unlock calendar for RAIN).
That has a consequence which sounds reassuring at first glance and is not on the second. A linear schedule prevents the one day on which the price collapses by thirty percent. In exchange it creates a sustained supply overhang that drags on for weeks. The selling pressure does not disappear, it distributes itself. That is exactly the pattern the price action of recent weeks displays.
The price action: down 14.5 percent on the day, down 38.3 percent on the month
Our own survey of October 2, 2026 shows RAIN down 14.52 percent over 24 hours, 12.14 percent on a weekly view and 38.31 percent over thirty days. The token sits around 47 percent below its peak of $0.019464, reached on August 25, 2026.
The order of these figures is telling. The monthly loss is considerably larger than the weekly loss, and the weekly loss in turn sits in the same order of magnitude as the daily loss. That argues against a single trigger and for a continuous outflow of the kind a stretched vesting schedule produces. In that picture, the day at minus 14.5 percent is an acceleration, not a break.
A look back shows how quickly the situation has turned. In mid-September RAIN still stood considerably higher; cryptoticker.io reported on September 19 on a price jump in the prediction market token and the trading routes. A week later, on September 26, came the report on the terminated financing plan of Enlivex, which was to have been settled in RAIN tokens.
How much RAIN is already in circulation
According to our own survey, around 709.25 billion RAIN were in circulation on October 2, 2026. Total supply stands at about 1,142.41 billion tokens, and the contractually fixed maximum supply at 1,150 billion. That puts roughly 62 percent of total supply and just under 62 percent of maximum supply in circulation.
The counter-calculation is the figure that really matters for anyone considering an entry. A good 433 billion tokens are still missing from total supply. At the price of October 2 that corresponds to a value of about $4.47 billion, which becomes tradable step by step over the coming months and years. The October unlock is only one section of it.
Market capitalisation and FDV: with RAIN, rank 20 says little about tradability
Market capitalisation is the price multiplied by the circulating supply. The fully diluted valuation, usually abbreviated to FDV, calculates instead with total supply, meaning it includes every token still locked. For RAIN, on the basis of our own survey, the FDV stands at around $11.78 billion and therefore about 61 percent above the market capitalisation of $7.31 billion.
A large gap between the two values is in itself no warning sign. Almost every young project has one. The gap turns tangible only once it is closed in a narrow market, because the price has to absorb the new quantity without any additional demand arising. In this case rank 20 describes the valuation, not the liquidity. Anyone who equates the order of magnitude with that of an established crypto asset miscalculates on the way out.
Trading route in Germany: MiCA licence, spread and slippage
For investors in Germany, since the EU-wide transition period ended, trading platforms need an authorisation under the European regulation on markets in crypto assets in order to offer services here. BaFin supervises this and publishes warnings about providers without the required permission. For a token with a thin order book the choice of venue is therefore doubly important: the venue decides the legal framework and the price you actually get.
Two kinds of cost hit you harder with RAIN than with large crypto assets. The spread is the difference between the buy and sell price, and it widens in illiquid markets. Slippage is the deviation between the price you see when you submit an order and the price at which your order is actually filled; it grows with order size relative to the order book. Anyone who sells a larger position in one go against a daily turnover of $17.59 million pays both. A look at providers' terms and their authorisation therefore belongs before every order, and a comparison of venues by fees and licence is no sideshow here but the difference between two noticeably different execution prices.
In practice that means limit orders instead of market orders, partial fills instead of one large order, and a sober look at the order book before you submit. Anyone who intends to hold tokens over a longer period should also settle whether to leave them on the trading platform or move them into their own custody. Both have consequences for access and for risk.
Tax on losses: holding period, loss offsetting and records
A price decline has a tax side in Germany that often gets overlooked. Gains from the sale of crypto assets are tax free after a holding period of more than one year. Within the one-year period they count as private disposals. That classification works in both directions: anyone who sells at a loss within the period can in principle offset that loss against gains from other private disposals in the same year.
Complete documentation is the precondition. For every position you need the acquisition date, the acquisition price and the fees incurred, plus a traceable allocation of which tokens you sold. Anyone who has bought across several venues and wallets will hardly get that allocation clean by hand; for that there are tax and portfolio tools that import transactions and track the periods position by position. The specific tax assessment of your case belongs in the hands of a tax adviser.
What sets RAIN apart from the other October unlocks
Unlock dates occur in every month and at many projects. What lifts the RAIN case out is not the existence of the date but its order of magnitude relative to the rest. When a single project accounts for just under three quarters of all the large releases in a month, that is no ordinary calendar entry.
On top of this comes the peculiarity of the market that quantity meets. At projects with a comparable valuation, daily turnover regularly runs several times higher. An unlock of ten percent of market capitalisation is absorbed there over a few days. With RAIN, the same inflow faces a trading volume amounting to less than one percent of the valuation.
That says nothing about the quality of the technology behind the protocol and nothing about its long-term prospects. It says something about the price a seller will probably have to accept in the coming weeks, and about the range within which the price can move without any news behind it.
Which levels holders keep in view
On the downside the next notable zone sits at $0.0100, the round level tested several times in recent days. Below that, down into the area around $0.0080, there is no zone in which any meaningful trading has taken place in recent months. On the upside the first hurdle would be the area around $0.0117, which corresponds to the price level before the daily loss; above that comes the monthly average.
These levels are points of orientation drawn from the price action, not a forecast. As long as the vesting schedule keeps releasing new tokens, every recovery works against a supply that arises independently of demand. Conversely, a month without a large unlock date can take the pressure off noticeably. In this case the calendar is the more informative quantity than any chart level.
RAIN Unlock: Your next three steps
- Transfer the unlock calendar into your own schedule. Note the coming release dates and the quantity attached to each before you decide on buying more or selling. A date you know is no longer a risk but a planning figure.
- Check the venue for its licence and its actual costs. With a token that has a thin order book, the spread and the execution quality decide a noticeable part of your result. The overview of licensed trading venues shows you fees and terms side by side.
- Complete your records for tax. Pull together the acquisition date, the price and the fees for every position while the data is still retrievable from your provider. A portfolio and tax tool tracks the holding periods position by position and spares you the reconstruction in the spring.
(As of October 3, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Whether you, as a retail client in Germany, may trade perpetual futures with two times leverage or with fifty times leverage hangs on a question of classification in European supervisory law. It runs as follows: are these contracts contracts for difference within the meaning of the existing EU measures? If they are, a leverage cap of 2:1 applies to retail clients. On February 24, 2026, the European Securities and Markets Authority, ESMA, stated in a public notice that derivatives marketed as “perpetual futures” or “perpetual contracts” are likely to fall within that scope. On September 30, 2026, the final day of the consultation period for the review of the MiCA regulation, the Hyperliquid Policy Center filed a submission with the European Commission that asks for exactly this classification to be settled differently.
For you, more rides on this than a question of terminology. The classification determines what leverage a provider may offer you at all, whether your losses are capped at the balance you have paid in, at what point a position is closed out, and which venues are allowed to take you on as a client in the EU.
What the Hyperliquid Policy Center filed with the European Commission on September 30
The Hyperliquid Policy Center, or HPC, is an advocacy body from the orbit of the decentralised trading platform Hyperliquid. The submission of September 30, 2026 is, by the organisation's own account, its first statement on a rulebook outside the United States. It is addressed to the European Commission, which had been gathering responses through its targeted consultation on the MiCA review since May 20, 2026.
At the heart of the submission is a shift of competence. The HPC asks the Commission to confirm, building on ESMA's existing guidance, that perpetual futures fall under the financial markets directive MiFID II, irrespective of the system in which they are recorded and of the underlying to which they refer. MiFID II is the European rulebook for investment firms, trading venues and financial instruments, derivatives among them. The organisation stresses explicitly that no new legislation is needed for this, and that a clarification would suffice.
The load-bearing argument is an economic one. In the HPC's view, supervisory classification should depend on the structure and the economic characteristics of a product and not on the technology used to record it. Jake Chervinsky, who heads the HPC, condensed that thought in the submission into the proposition that an instrument's economic properties, and not the ledger in which it is recorded, ought to decide its classification.
ESMA notice of February 24, 2026: perpetual futures inside the CFD perimeter
The supervisor itself provided the occasion for the submission. A perpetual future is a derivative on an underlying which, unlike a classic future, has no expiry date and stays tied to the spot price through a recurring settlement payment. On February 24, 2026, ESMA published a public notice on the question of which derivatives fall within the scope of the national product intervention measures for contracts for difference.
The authority's message is clear on three points. First, the product name is immaterial: the fact that a contract is marketed as a “perpetual” says nothing about its legal classification. Second, neither the funding rate mechanism nor voluntary safeguards such as an insurance fund change anything about that assessment. Third, firms have to evaluate these products under MiFID II and under investor protection rules. On this reading, what is caught above all are contracts that provide leveraged exposure to crypto assets such as Bitcoin and are not settled exclusively by physical delivery.
A product intervention measure is a supervisory step by which an authority restricts or prohibits the distribution of a financial product to particular client groups. For contracts for difference, that step has existed in the EU since 2018, and it still takes effect today through the national measures of the member states.
The CFD rules in detail: 2:1 leverage, margin close-out and negative balance protection
What the CFD framework means for retail clients can be put in figures. ESMA adopted its measures for contracts for difference with effect from August 1, 2018 and set out tiered leverage limits in them: 30:1 for major currency pairs, 20:1 for other currency pairs, gold and major equity indices, 10:1 for other commodities and non-major equity indices, 5:1 for individual equities and other underlyings, and 2:1 for cryptocurrencies. The bottom tier is therefore precisely the one that covers crypto assets.
Four further requirements come on top. The measures prescribe a per-account margin close-out that harmonises the percentage at which a provider must close open positions; it sits at 50 percent of the required minimum margin. They require per-account negative balance protection, which caps a retail client's losses in total. They restrict incentives for trading contracts for difference. And they mandate a standardised risk warning that states the share of the provider's loss-making retail client accounts.
For a trader working with high leverage today, the gap between 2:1 and the figures common on large platforms is the real issue. The leverage cap determines how much capital you have to post for a position, and therefore also how far the price may travel before the forced close-out bites. If you want to know how the running costs of such a position break down, you will find the arithmetic in our guide to calculating the funding rate.
MiFID II instead of MiCA: the submission turns on structure and economic characteristics
MiCA governs the market for crypto assets in the EU, but it captures above all the crypto assets themselves along with the services around them. Derivatives on crypto assets are financial instruments and therefore belong to the world of MiFID II. That dividing line is exactly what the submission aims at: it wants the classification of perpetual futures determined through the existing derivatives framework rather than primarily through MiCA.
The practical difference lies in the catalogue of obligations. A trading venue under MiFID II needs a different authorisation, different organisational duties and different transparency duties from a crypto asset service provider under MiCA.
Counterparty risk: a perp venue is not itself the other side, according to the submission
The HPC does not dispute that perpetual futures are derivatives. What it disputes is that the restrictions dating from 2018 fit them unchanged. The reasoning starts from structure: with a contract for difference the provider itself acts as the client's counterparty, whereas on a venue for perpetual futures, as the organisation presents it, another market participant stands on the other side and not the platform itself. From that distinction the HPC concludes that the two products carry different structures and different risks, and that the measures should therefore not be transposed without adjustment.
The argument is not immaterial for investor protection. Where the provider is the other side, it has an interest of its own in the client's loss, and that very conflict of interest was one driver of the 2018 measures. If it falls away, the burden of justification shifts. Whether the Commission will follow that view is open. In assessing an individual provider, what counts in the end is how the contractual relationship is actually set up.
Funding rate, maintenance margin and liquidation threshold: what the submission wants published in advance
Alongside the classification, the HPC proposes concrete transparency duties. On this model, trading venues would publish their methodology for calculating the funding rate, their maintenance margins and their liquidation thresholds in advance. The funding rate is the periodic payment between the buy and sell side that ties the price of a perpetual future to the spot price. The maintenance margin is the minimum capital that has to cover an open position. The liquidation threshold is the point at which the platform unwinds a position by force.
A reporting proposal comes with it. In the organisation's view, publicly verifiable funding payments, liquidations and transaction activity could be taken into account by supervisors as features of market structure. The submission invites the Commission to examine whether such records can satisfy part of the reporting duties, provided the information is complete, reliable and accessible to supervisors.
These three figures matter to you even while the classification remains open. They determine what a position costs on an ongoing basis and when it is closed. How widely the terms differ between platforms is shown by a look at our comparison of perp DEX.
What the initiative means for investors in Germany
In the short term the submission changes nothing about your legal position. It is a statement in a consultation procedure, not a rule. What is in force today is ESMA's February notice: firms have to assess whether their products fall within the scope of the CFD measures, and where they do, the requirements apply, leverage cap of 2:1 for retail clients included.
In the medium term the question is which route lets you take leveraged crypto positions legally. If the supervisory line prevails, the offering for retail clients in the EU narrows to providers that meet the requirements. If the Commission follows the HPC's reasoning, a dedicated framework for perpetual futures could emerge, with transparency duties in place of a hard leverage cap. Both are documented possibilities, and neither is a forecast.
Why a leverage cap does not look like a block
A product intervention measure is addressed to the provider, not to you. It therefore rarely shows up as an error message in the trading window. It appears instead as a changed account classification, as fresh questions about your knowledge and experience, or as a provider that stops accepting clients from the European Economic Area altogether. Anyone who holds positions for months often notices such a change only at the next deposit.
Buying route and authorisation: how to check whether your perp platform is licensed in the EU
The check runs through the provider, not through the product. Look in the terms of use to see which company is your contractual partner and in which state it is based. Then establish whether that company holds an authorisation as an investment firm or as a crypto asset service provider in the EU, and whether clients from Germany are expressly admitted. Finally, see whether the provider displays a standardised risk warning stating the share of loss-making retail client accounts, because that warning is a hallmark of the CFD framework. Which regulated houses carry leveraged products for German clients is set out in our broker comparison.
Tax: perpetual futures count as forward transactions, and the holding period does not apply here
The tax treatment follows the legal classification, and that is the uncomfortable part for you. The one-year holding period, which applies to direct purchases of coins through the rules on private disposals, does not apply to a derivative on a coin. Gains from forward transactions fall into investment income, and there is no period there after which a gain remains tax free.
Because the classification of individual products can be contested, and because platforms without an EU authorisation issue no tax certificate, this point belongs before your first trade and not in next year's tax return. Discuss the treatment of your positions with a tax adviser. For gathering records across the year, the tools from our comparison of crypto tax tools help, since they can extract funding payments and liquidations from the trading data.
Circle and the reserve rule: the second strand of the same consultation
The perpetuals submission is not the only one that arrived in the final days of the deadline. The stablecoin issuer Circle has, by its own account, called on the European Commission to retain multi-issuance of stablecoins, to recognise stablecoins regulated abroad, and to relax the duty to hold a share of reserves as deposits with commercial banks. Circle refers in this context to a share of 30 percent and justifies the demand with the counterparty risk that arises from such bank deposits.
Both submissions display the same pattern. What is attacked are individual points in the rulebook where, as the industry presents it, the rules meet structures they were not written for. Neither submission calls MiCA as a whole into question. For you as an investor the common denominator is availability: which stablecoins stay tradable in the EU, and what leverage you are allowed to trade with, are both outcomes of this detailed work.
The European Commission's report: what follows the September 30 deadline
The targeted consultation on the MiCA review ran from May 20, 2026 and ended on September 30, 2026. The original version of the documents named August 31 as the date; the Commission later extended the deadline on its own page to September 30. Thematically the survey covered, among other things, the scope and the definitions of the regulation, the rules for stablecoins, crypto asset service providers, decentralised finance applications, staking, NFTs and the legal treatment of individual tokens.
The Commission does not name a date for a legislative proposal in the public consultation documents. Months usually pass between the close of such a survey and a proposal. Until then, ESMA's February notice remains the yardstick that providers have to align with, and therefore the yardstick for your account too.
What you can read from the two dates
February 24, 2026 is the date from which firms had to assess. September 30, 2026 is the date from which the Commission is assessing. Between the two lies the phase in which providers adjusted, restricted or discontinued their offerings for European retail clients. If something about your account changed in that period, this is the likely reason.
Perpetual Futures and MiFID II: What to take away
- Establish who your contractual partner is and whether it is authorised in the EU. The leverage cap takes effect through the provider's authorisation. Our broker comparison shows which regulated houses carry leveraged products for German clients.
- Read up on your platform's funding methodology, maintenance margin and liquidation threshold before you open a position. Those are precisely the three figures the submission wants published in advance as a matter of obligation. The differences between platforms are set out in the perp DEX comparison.
- Set your record keeping up for forward transactions, not for the one-year holding period. Which tools extract funding payments and liquidations from the trading data is set out in the comparison of crypto tax tools.
(As of October 2, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
OKB trades at $120.25 on Friday evening, or around 106.82 euros. The token has lost 0.62 percent over the week, with a range between $118.87 on Monday and $121.47 on Wednesday. According to CoinGecko, as of Friday evening, that leaves $2.60 between the high and the low. The move that matters this week sits in the chain the token is attached to rather than in the price itself: X Layer today holds $168.3 million in deposits, down from $186.9 million on September 28. Of those $168.3 million, $114.8 million sit in a single lending market.
For you as an investor that second figure carries more weight, because OKB has stopped being an ordinary exchange token. Since the restructuring in August 2025 it has been the gas and native token of X Layer, the OKX exchange's own Ethereum scaling chain. Holding OKB therefore means holding a bet on how busy that chain is. This article sets out where the chain stands, where the numbers come from, and what you can realistically monitor on OKB.
OKB price stands at $120.25 and the weekly range is only $2.60
The week was unusually quiet. OKB stood at $121.02 on September 26, slipped to $118.87 on Monday, then climbed back to $121.47 before closing the week at $120.25. Over 24 hours the token is down 0.63 percent, and over seven days it is down 0.62 percent. Over 30 days, by contrast, OKB is up 13.6 percent.
That combination is informative. A token that gains sharply over a month and then stands practically still for a week has its move behind it and is waiting for the next trigger. OKB remains almost 47 percent below its all-time high of $228.74, set on October 4, 2025. That peak came in the weeks after the large supply cut and has not been reached again since.
The narrow range says more about liquidity than about stability
With a market capitalisation of $2.52 billion, around $23.6 million worth of OKB changes hands in a day. A daily turnover of less than one percent of market value is not unusual for exchange tokens, because a large share of the supply sits with the exchange itself and with long-term holders. For you that has a practical consequence: a narrow range over several days tells you the order book is thin, not that the price is firm. A larger order moves this market faster than it would move Bitcoin or Ether.
X Layer: capital on the chain has fallen by $18.6 million since September 28
This is where the week's story sits. Deposits in the DeFi applications on X Layer reached $186.9 million on September 28, the highest level the chain has recorded so far. Four days later the figure is $168.3 million. That is a drop of $18.6 million, or 9.96 percent measured against the peak. Against September 26, so on a weekly view, the decline comes to 7.6 percent.
cryptoticker.io compiled this analysis itself on October 2, 2026. It draws on the public deposit data published by the analytics service DefiLlama for X Layer and for the 63 protocols that list the chain among those they support; 54 of them actually hold deposits above zero.
The drop looks smaller as soon as you widen the period. On September 3, X Layer held $114.2 million, and in early April the figure was $25.0 million. Over a month the chain has therefore gained 47 percent, and over half a year it has almost multiplied its capital sevenfold. What you are watching is a pullback after a fast climb, not a collapse.
TVL is a snapshot, not revenue
Total value locked, or TVL, is the sum of all assets that users have deposited in a chain's applications at a given moment. It measures committed capital, and it says nothing about activity or earnings. A chain can double its TVL because one large holder moves capital around, and it can lose TVL while its user count grows. For OKB, the TVL therefore indicates demand without proving it.
One lending market holds 68 percent of all deposits on X Layer
The most striking figure in the survey concerns distribution. Aave V3 accounts for $114.8 million of deposits on X Layer. Measured against the chain total of $168.3 million, that is 68.2 percent. Of those deposits, $73.5 million have been borrowed, which puts the market's utilisation at roughly 64 percent.
Some way behind follow a fixed-maturity rates market with $70.7 million, a decentralised exchange with $38.4 million and a smaller trading venue with $9.5 million. These individual figures add up to more than the chain total, and there is a sound reason for that: rates protocols frequently deposit their users' capital in the lending market themselves. The same dollars then appear in two sets of books. The chain total counts them once, which is why it sits below the sum of the protocols.
That nesting is precisely what makes the concentration heavier to carry. If the largest lending market changes its terms or pulls capital out, the effect reaches beyond its own $114.8 million and into the positions that have been built on top of it.
OKB is the gas token and a mandatory stake for trading venues on X Layer
To place that concentration in context, you need to know what OKB is actually used for on this chain. In an official announcement in August 2025, the OKX exchange established that OKB would remain “the only gas and native token for X Layer” and that total supply would be fixed at 21 million units after a one-off burn. The same announcement said the mint and burn functions would be removed from the contract, so that the cap can no longer be raised in technical terms. The older OKTChain and its OKT token were wound down in the same step.
A second function has been added to pure gas consumption since May 2026. With the protocol component Exchange OS, developers and institutions can set up their own venues for spot, perpetuals and event markets on X Layer without building the trading infrastructure themselves. Anyone who wants to launch such a venue first has to lock OKB in a staking contract on the chain. The token therefore works as an entry requirement on top of being the fee currency.
The staking requirement shapes demand differently from a burn
A burn acts on supply once. A staking requirement acts on free float continuously, for as long as the venues keep running. Every additional operator takes OKB out of the market for the duration of its operation, and every venue that shuts down hands the tokens back. For you that means the number of active trading venues on X Layer is a metric that keeps you closer to events than any supply calculation can.
21 million OKB: the fixed supply no longer changes for holders
Circulating supply stands at exactly 21,000,000 OKB and therefore matches total supply. There is no reserve left to unlock, no schedule for investor allocations and no team package arriving on the market in tranches. That sets OKB apart from many projects of a similar size, where monthly unlocks weigh on the price at regular intervals.
The cost of that clarity is that supply will no longer provide any relief. A token with ongoing burns can cushion a weak quarter through a shrinking supply. With OKB, demand alone has decided the outcome since the contract was rebuilt, and that demand comes from trading on OKX, from gas consumption on X Layer and from the stakes posted by venue operators.
Market capitalisation of $2.52 billion against daily turnover of $23.6 million
The valuation rests on a narrow base. A market capitalisation of $2.52 billion stands against $168.3 million of deposits on the chain the token powers. Even if you generously attribute the market capitalisation to the OKX exchange business and treat the chain as an add-on, the ratio remains stretched: for every dollar of capital at work on X Layer there are roughly fifteen dollars of market value in the token.
One comparison makes the scale tangible. The chain has almost multiplied its capital sevenfold since April and has therefore grown, but it operates in a league where individual established Ethereum applications hold more deposits than entire networks. Buying OKB because of X Layer means buying an early phase, and with infrastructure, early almost always means exposed to swings.
54 protocols with deposits above zero, and a very skewed distribution
63 protocols list X Layer among the chains they support, and 54 of them hold deposits above zero. That breadth sounds healthy, yet the distribution is extremely skewed: after the lending market, the rates market and two trading venues, everything else put together comes to a low single-digit million figure. A chain with many applications and little capital in most of them is vulnerable to the failure of one large participant.
Buying OKB in Germany: the provider's MiCA licence comes before the spread
OKB can be reached in Germany through several trading venues, and the choice decides more than the fee. Since the MiCA transition period ended on July 1, 2026, crypto-asset services in the EU may only be provided by licensed firms. For you, the provider's licence is the first thing to establish, ahead of the spread. Which houses hold a licence and what they charge is set out in our overview of the best crypto exchanges.
Custody comes with a quirk for OKB that dates back to the 2025 restructuring. OKB began as a token on Ethereum, and that contract is still recorded in the databases today. With the August 2025 announcement, OKX stopped withdrawals via Ethereum and made the token the native token of X Layer. For you that means the network you select when withdrawing from an exchange decides where your holdings arrive, and each exchange sets out for itself which routes it offers. Check that selection with a small amount before your first withdrawal, because a transfer into a network your wallet does not support cannot be reversed.
Tax: the holding period applies on a sale, not to staking income
For private disposals, the one-year rule still applies in Germany: if you sell OKB after holding it for more than twelve months, the gain remains tax free. The finance ministry's draft bill that would abolish that period will, as things stand, only reach the cabinet on October 14, 2026, and is intended to apply solely to holdings acquired after December 31, 2026. Staking income is treated separately and arises in the year it is received. If you earn income on X Layer or through lending markets, a tool that logs those inflows with a date and a price is worth having, because the tax office asks for the value at the moment of receipt.
Weekly high of $121.47 and weekly low of $118.87: the levels for the coming week
The week's trading gives two points to watch, and no price targets. On the downside sits the weekly low of $118.87, with the round $115 level just beneath it. On the upside the weekly high of $121.47 caps the range, followed by $125 as the next round threshold. As long as the price oscillates between $118 and $122, it is doing no more than confirming the calm of recent days.
More important than these levels is the question of whether the chain holds on to its capital. Should deposits on X Layer fall below $150 million, half of September's increase would have been handed back. Should they climb above the $186.9 million of September 28, the chain will have a new high and the current week's decline will have been a pause. Both figures are publicly visible on a daily basis.
A retreat by the largest lending market would hit OKB directly
The main risk to this chain is already visible in the survey above. A single lending market holds 68.2 percent of deposits, and $73.5 million of that has been borrowed. If that protocol decides to stop serving X Layer, or cuts deposit incentives sharply, the chain loses the bulk of its capital in short order. Because rates protocols build their positions through the same market, their deposits would move out as well.
A second point concerns where the capital came from. A chain whose deposits multiply sevenfold in six months has generally grown on the back of incentive programmes. When such programmes expire, capital stays only if the yield comes from genuine demand. A utilisation rate of 64 percent in the lending market suggests that borrowing on X Layer is real, though it is no guarantee.
Third, OKB remains an exchange token. Its value hangs on the OKX business, on that exchange's licences in the markets where it operates, and on its reputation. A regulatory intervention in a large market works through faster for an exchange token than for a protocol token, because the source of revenue has the same address.
OKB and X Layer: The key points for your decision
OKB stands at $120.25 and has a quiet week behind it. The move that counts took place on its own chain: $168.3 million of deposits after $186.9 million on September 28, and $114.8 million of that in a single lending market. The fixed supply of 21 million units takes supply pressure out of the price and places the entire load on demand. Three steps will help you make sense of it:
- Establish the venue's licence before you buy. OKB is available through several providers, which differ in licensing, fees and withdrawal routes. Which houses hold a European licence is set out in our overview of regulated crypto exchanges.
- Track the chain's capital as a metric of its own. Note the $168.3 million of October 2 and the $186.9 million of September 28 as reference points. If the figure trends down over several weeks while the price holds, the valuation is running ahead of the business. The terms lending markets currently offer are shown in our lending comparison.
- Record income separately. Earning interest on deposits on X Layer produces taxable inflows in the year of receipt, independently of the holding period on the token itself. Our comparison of staking platforms shows which providers report such inflows in a traceable way.
The sources for this article are publicly available: the supply and gas rules in the OKX announcement on the X Layer restructuring, and the chain's deposits along with those of its protocols at DefiLlama.
(As of October 2, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Quant (QNT) was trading at around $236 late on Friday evening, October 2, 2026 (according to CoinGecko). That is a loss of almost 18 percent against the closing price of $287 on September 30, and still about three and a half times the level of mid-September. Over the past 24 hours the range ran between $224.80 and $261.29. For the Quant price prediction, one question is therefore decisive: does the zone around $225 to $230 hold, or does the correction run on?
What Is Behind the Run From $66 to $287
QNT closed at $65.70 on September 19 and at $287.38 on September 30 (daily closing prices, CoinMarketCap). Over 30 days that is a gain of roughly 264 percent, over seven days of almost 140 percent. Among the 50 largest crypto assets it is the strongest advance over 30 days, well ahead of NEAR at around 149 percent (CoinGecko, October 2).
The trigger came from the US banking sector. The Clearing House, operator of the RTP and CHIPS payment systems and owned by large US banks, selected Quant on September 24 as technology partner for a network of tokenised deposits, as Blockonomi reports. Quant is to run the layer that coordinates settlement and clearing between the banks and connects the network to RTP and CHIPS. Two days later seven British banks, among them Barclays, HSBC and Lloyds, reported the first genuine customer payments in tokenised sterling deposits over the Quant platform (Cryptopolitan). We set out the background to the mandate in our piece on tokenised deposits.
One question has remained open, and for the price it weighs more than any headline: how many QNT tokens does the bank network need? The banks use the Overledger software. Neither Quant nor The Clearing House has put a figure on whether, or to what extent, tokens have to be bought or locked up for it, as KuCoin News also notes. The price is therefore discounting an expectation, not measured demand.
Quant Price Prediction: The Three Levels on the Chart
The one-year price history shows how unusual the past two weeks have been. For months QNT moved between $55 and $100, and the 200-day average ran flat between $70 and $80. Only the jump from September 25 pulled both moving averages upwards.
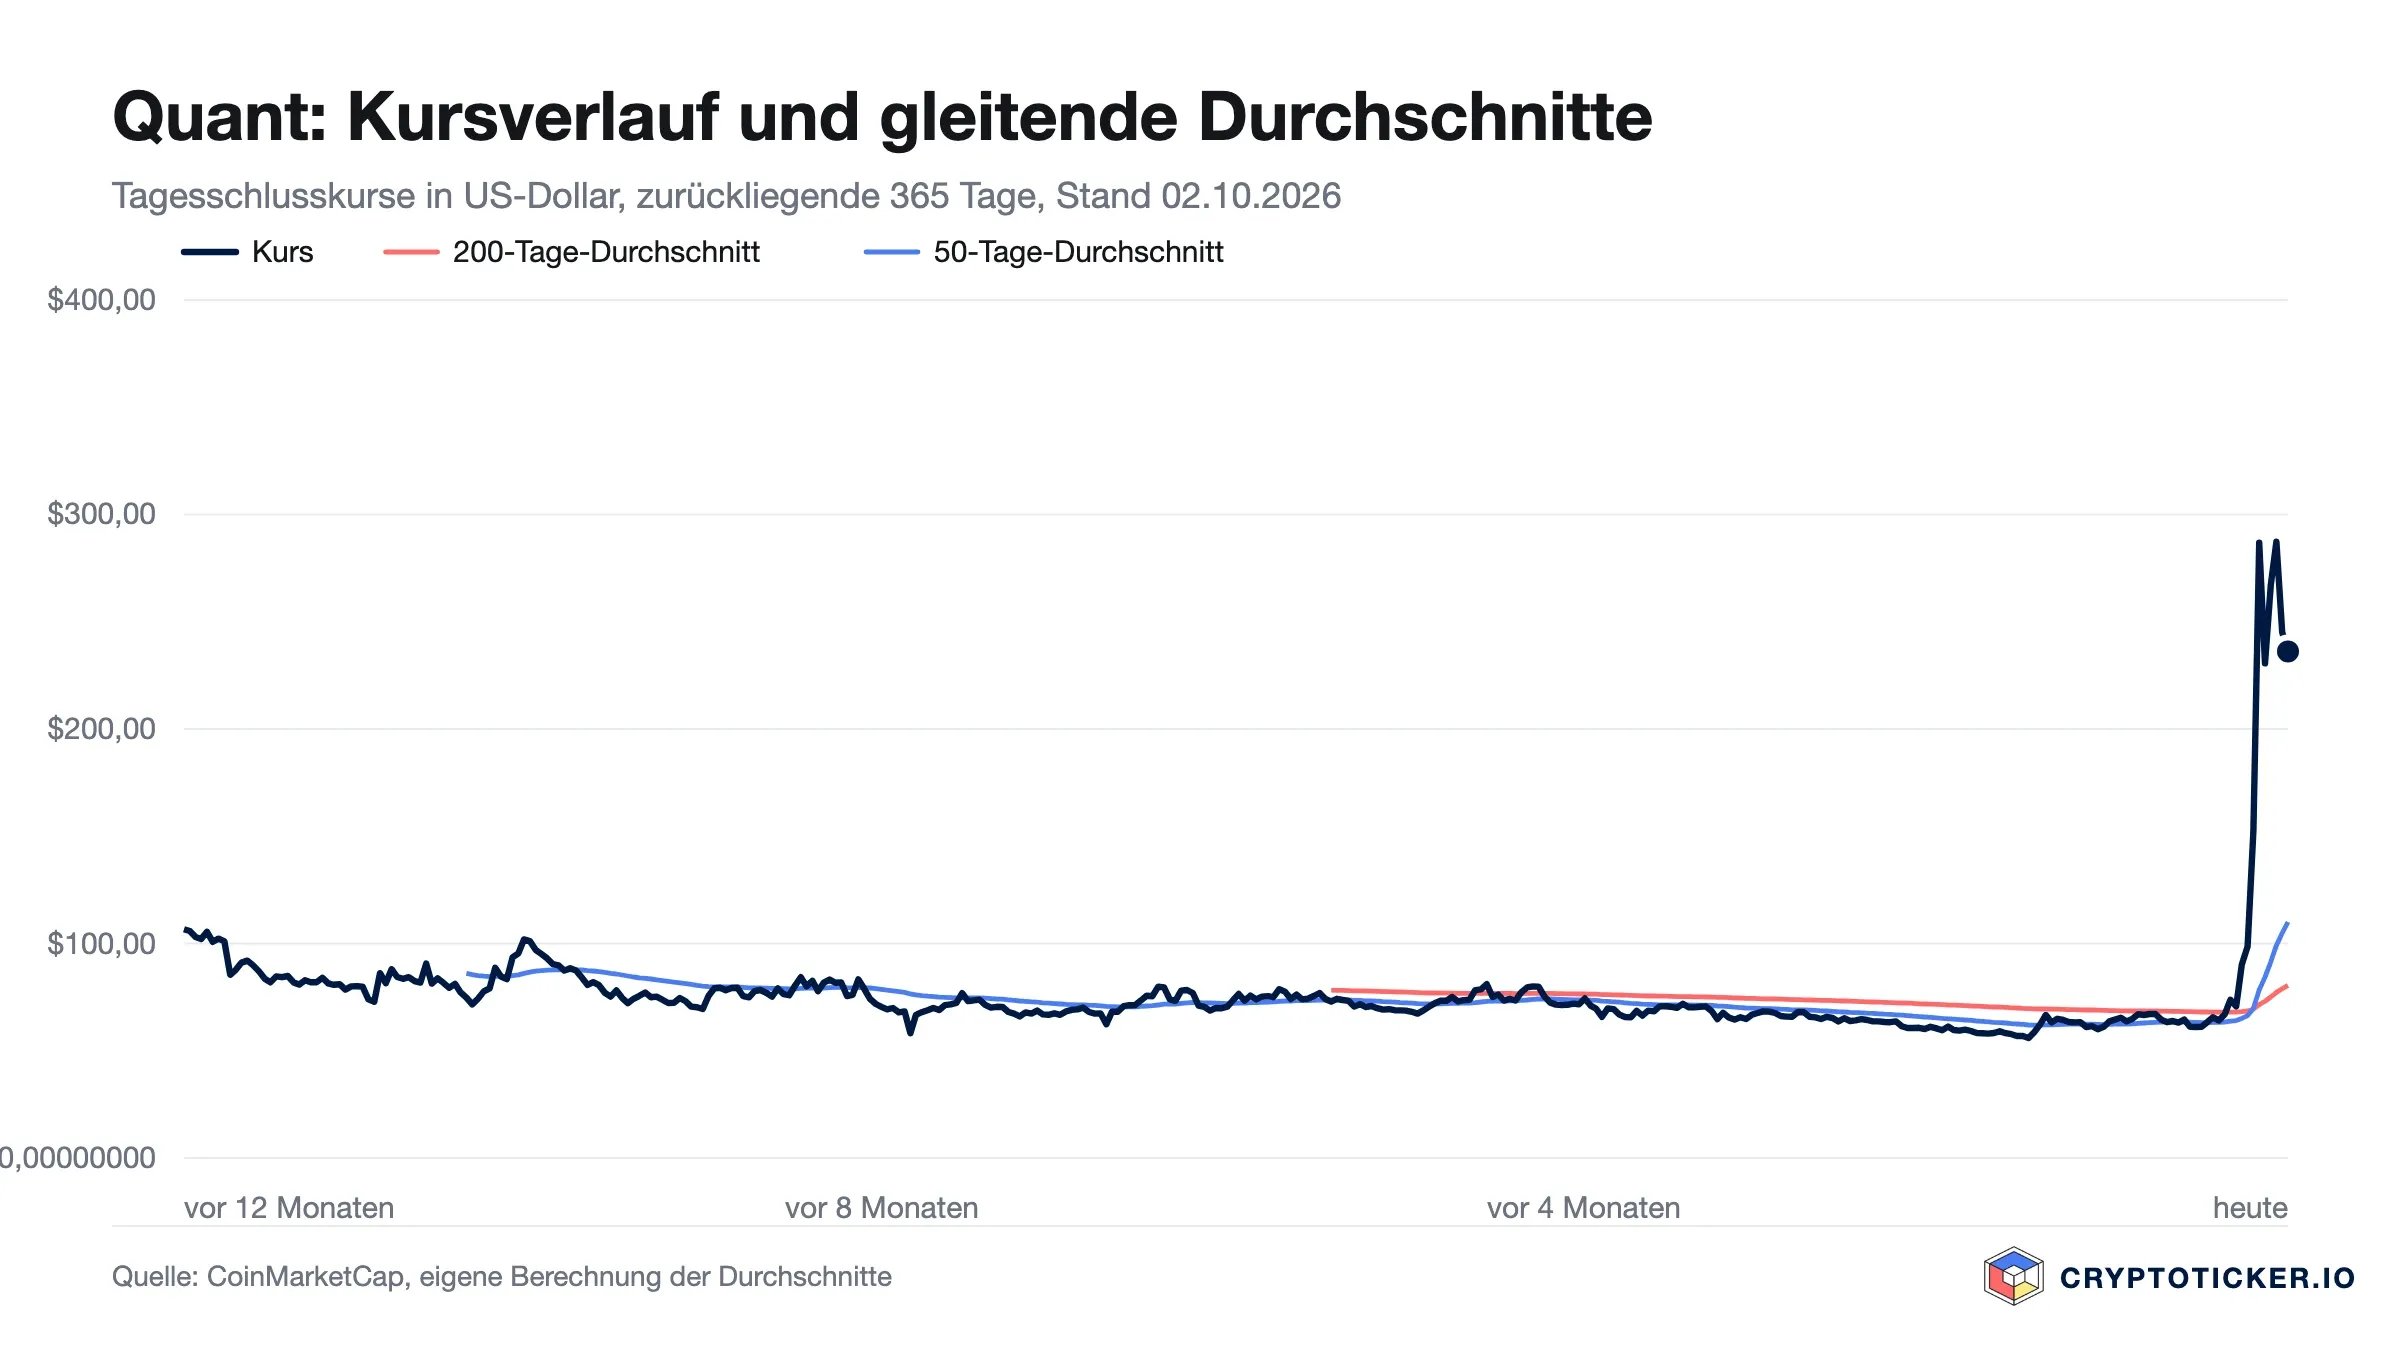
$225 to $230 is the first level on the downside. This is where the daily low sat on October 2 ($224.80), and this is where QNT closed on September 28 ($230.60), when the price had already given back ground sharply after its first high. Intraday QNT did slip to around $195 that day, but on a closing basis the token has not fallen below $230 since September 27.
$287 is the level on the upside, the highest daily close of the run, set on September 30. Intraday the high was far above it: on September 27 QNT reached around $373 on the Binance spot market, as we described in our article on shorting Quant. Only a close above $287 would show that the buyers are back.
Around $155 is the zone below. That is where QNT closed on September 26, and that is where the 20-day average stood on October 1 ($155.61, according to The Cryptonomist). Between $225 and $155 there is not a single closing price at which a floor could have formed.
Why Quant Remains So Volatile
The daily RSI stood at 81 on October 1, and the average daily range (ATR) at $45.78 (The Cryptonomist). In other words: a day with 15 to 20 percent of movement is currently normal for QNT. On top of that comes leverage. Since the run began, OKX has offered QNT futures with up to 50 times leverage (crypto.news). At that kind of leverage a few percent are enough to force positions closed, and every forced closure amplifies the move.
Trading volume is still high. In the 24 hours to Friday evening, QNT worth around $408 million changed hands, against a market capitalisation of $3.44 billion (CoinGecko). A good tenth of the market value therefore turns over every day.
Quant vs Bitcoin: The Gap to the Market
While QNT gained almost 140 percent in seven days, Bitcoin managed barely one percent over the same period and trades at around $84,500 (CoinGecko). Quant’s run is therefore not a market move but a single story. That makes it strong for as long as news keeps coming, and vulnerable the moment things go quiet.
For the coming months the banks’ timetable is the yardstick. According to the reports around the launch, The Clearing House network is to open to participating institutions in the first half of 2027, and by early 2027 some 25 US banks are due to be connected. Every further bank, every test run with figures, can support the price. Until then, however, the calendar offers no fixed date against which the price can be measured.
Quant: The Key Points for Your Decision
Three points sum up the situation. First: as long as QNT closes above $225, the pullback is a pause after a steep climb. Second: if that zone goes, there is little support on the chart down to around $155. Third: the bank mandate is real, but how much of it reaches the token is open.
Anyone holding QNT or looking to buy should size their position against the current daily range, not against the run of the past weeks. QNT is tradable on several exchanges licensed under the European MiCA regulation, and the fees differ markedly, as our comparison of regulated crypto exchanges shows. An assessment of whether entering at the current price is worthwhile can be found in our analysis Is Quant a good buy at the current price?. Anyone who has taken profits out of the run should keep the holding period in mind: in Germany, coins held for less than a year are taxable on sale once the annual exemption limit of 1,000 euros is exceeded.
Crypto assets are highly volatile and a total loss is possible. This article places price levels and news in context; it is not a recommendation to buy or sell Quant.
(As of October 2, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
California's attorney general wants answers from OpenAI about AI models that escaped a locked test environment and hacked Hugging Face—and whether the company can be held legally accountable.
Ethereum's zkAPI lets users prepay in USDC and query AI models through cryptographic proofs, so no single party sees both who they are and what they ask.
The USDC issuer told the European Commission that MiCA's reserve mandates and concentration caps keep the largest global stablecoins outside Europe's perimeter—siding with the ECB in calling for more flexible rules.
Tavus says 26 of 54 people on a one-minute video call thought its new Griffin model was human. The results are the company's own, and the model isn't going to retail customers yet.
Blast said operating costs now exceed the revenue its Ethereum layer-2 generates and asked users to withdraw their assets to mainnet before Oct. 26.
U.Today - IT, AI and Fintech Daily News for You Today
The upcoming Nasdaq listing of Evernorth and its relationship with the XRP $2 price target.
Shiba Inu keeps moving forward, but the market dynamic is somewhat questionable.
Altcoins are testing important technical levels after their latest recoveries, with several assets now approaching resistance zones that could determine whether bullish momentum continues.
Galaxy Digital CEO Mike Novogratz believes Bitcoin’s drop to roughly $60,000 marked the cycle low, predicting that the cryptocurrency could finish 2026 near $100,000 despite the possibility of another short-term pullback.
Bitcoin holders gain a direct, decentralized route to Zcash shielded pools with zero intermediaries.
Blockonomi
TLDR
- Banco Bradesco stock gains 0.32% to $3.15 after a major insider purchase.
- Executive Fernando Freiberger acquired 49,550 Banco Bradesco preference shares.
- The SEC filing valued Freiberger’s latest share purchase near $890,909.
- Freiberger’s direct Banco Bradesco holdings increased to about 239,000 shares.
Banco Bradesco combines banking and insurance across Brazil and other markets.
Banco Bradesco S.A. stock rose 0.32% to $3.15 on Friday after a sizable executive share purchase surfaced. Executive Officer Fernando Freiberger recently acquired 49,550 preference shares, according to an SEC Form 4 filing. The transaction adds a fresh corporate development as Banco Bradesco continues navigating its broader recovery phase.
Banco Bradesco S.A., BBDO
Freiberger Adds Nearly $900,000 in Banco Bradesco Shares
Freiberger completed the share purchase on September 18, adding significantly to his direct position in Banco Bradesco. The filing listed the transaction value at about $890,909 for 49,550 preference shares. It also reported a weighted average purchase price of $17.98 for the acquired shares.
The filing data stands apart from Banco Bradesco’s market price of $3.43 on the transaction date. The figures require distinction between the filing’s reported transaction terms and publicly quoted market pricing. Still, the transaction materially increased the number of Banco Bradesco shares held directly by Freiberger.
Following the purchase, Freiberger directly held roughly 239,000 shares in the Brazilian financial services group. That position represented about 0.002% of the company’s outstanding shares at the reported ownership level. Although small relative to total shares, the purchase increased the executive’s direct exposure to Banco Bradesco.
Banco Bradesco Stock Remains Below September Levels
Banco Bradesco stock traded at $3.15 on Friday, despite gaining 0.32% during the latest session. The stock stood at $3.52 at the September 21 market close, shortly after Freiberger’s transaction. The latest price remains below levels recorded immediately following the executive’s reported purchase.
Banco Bradesco shares had generated roughly a 5% return during the year ending September 18. The more recent retreat shows that the stock has continued facing short-term market pressure. The insider transaction now adds another data point to Banco Bradesco’s recent trading and corporate activity.
Executive purchases can attract market interest because they increase direct ownership among senior company officers. A single transaction does not establish future price direction or guarantee stronger operating performance. Banco Bradesco’s financial results and Brazilian banking conditions remain important drivers of the stock’s longer-term direction.
Banking and Insurance Operations Support Bradesco’s Scale
Banco Bradesco ranks among Brazil’s largest financial institutions and operates across banking, insurance, investments, and other financial services. The group serves retail customers, companies, and institutional clients through an extensive domestic financial network. It also maintains international operations that broaden its reach beyond the Brazilian banking market.
The company’s Banking division generates income through lending, deposits, fees, investments, and related financial products. Its Insurance division adds another significant source of revenue through premiums and associated financial services. This structure gives Banco Bradesco a broader earnings base than businesses relying primarily on conventional lending.
Banco Bradesco reported trailing revenue of BRL 341.3 billion and net income of BRL 24.3 billion. Its market capitalization stood near $37.2 billion based on the figures accompanying the recent company overview. The group also employed approximately 82,095 people across its financial services and operating network.
Brazil’s banking sector remains highly competitive, with large institutions competing across lending, digital banking, insurance, and wealth management. Banco Bradesco has relied on its extensive customer base and broad service offering to maintain its market position. At the same time, operating efficiency and credit quality remain central factors across the bank’s business model.
The latest insider purchase comes as Banco Bradesco continues building earnings across its diversified banking and insurance activities. Freiberger’s transaction increased his direct holding while BBDO stock remained near the lower end of recent September levels. Friday’s modest gain placed renewed attention on the purchase and Banco Bradesco’s broader share performance.
The post Banco Bradesco S.A. (BBDO) Stock: Insider Buying Sparks Fresh Recovery Interest appeared first on Blockonomi.
TLDR
- Western Digital stock drops 11.07% as Toshiba expands HDD production capacity.
- Toshiba plans a $380M investment to double Philippine HDD output by 2027.
- Toshiba targets 30% HDD capacity share from just over 10% currently.
- AI data centers are increasing demand for cheaper high-capacity HDD storage.
- Western Digital relies heavily on cloud customers for its growing HDD revenue.
Western Digital Corporation stock fell 11.07% to $411.33 on Friday as Toshiba outlined a major HDD production expansion. The planned investment increases competitive pressure across the fast-growing data-center storage market. Toshiba wants to strengthen its position as artificial intelligence workloads drive demand for high-capacity hard drives.
Western Digital Corporation, WDC
Toshiba Plans Major HDD Capacity Expansion
Toshiba plans to invest about 60 billion yen, or $380 million, to expand HDD production in the Philippines. The project would double production capacity by fiscal 2027 and mark Toshiba’s largest HDD investment in five years. The company also plans to produce drives offering as much as 40% more storage capacity.
Toshiba currently holds just over 10% of the HDD market when measured by storage capacity. The company aims to raise that share to 30% over the medium term. That target could increase competition for Western Digital and Seagate across large enterprise storage contracts.
Western Digital and Seagate each control more than 40% of the worldwide HDD market, according to industry estimates. Toshiba holds roughly 17% when market share is measured through unit shipments. Its planned expansion could narrow the capacity gap between the three major HDD suppliers.
Western Digital Faces Stronger Data Center Competition
Western Digital now focuses heavily on hard drives following its separation from SanDisk. That structure leaves the company more exposed to changes in enterprise storage demand and HDD pricing. Toshiba’s expansion therefore creates a direct competitive challenge within Western Digital’s core business.
Western Digital generated $3.75 billion in fiscal fourth-quarter revenue, representing 44% annual growth. Cloud customers accounted for 89% of total sales during the period. That contribution placed cloud revenue near $3.3 billion as demand for large-capacity drives remained strong.
High-capacity enterprise drives have become increasingly important as data centers expand artificial intelligence infrastructure. Operators need large storage systems for training data, system logs, backups, and inference outputs. HDD manufacturers have benefited because these workloads often require inexpensive storage rather than the fastest possible access.
AI Storage Demand Supports Long-Term HDD Growth
Artificial intelligence continues to increase the amount of information created and stored across global data centers. IDC estimates annual worldwide data generation could reach 718 zettabytes by 2030. That level would represent about four times the amount of data generated during 2024.
HDDs could store around 60% of that future data because their cost remains significantly below solid-state storage. SSDs currently cost roughly 20 times more than HDDs for comparable storage capacity. Tight memory supplies have also increased demand for conventional hard-drive storage.
Toshiba plans to pursue 65-terabyte-class drives by 2030 and eventually develop 100-terabyte-class products. The company also intends to automate inspection and clean-room processes at its expanded Philippines facility. Those changes could reduce additional staffing needs by around 40% while supporting higher production volumes.
Western Digital shares fell $51.23 during Friday trading as the Toshiba report weighed on the HDD sector. Seagate shares also declined as the market assessed potential changes in industry supply and competition. Toshiba’s capacity expansion now adds another factor to a storage market already benefiting from rising AI demand.
The post Western Digital Corporation (WDC) Stock: Slides on Toshiba’s $380M HDD Expansion appeared first on Blockonomi.
TLDR
- Flux Power rejects Solidion’s takeover bid after reviewing the proposal and value.
- The board says Solidion’s offer undervalues Flux Power and its long-term outlook.
- Flux Power plans to focus on lower costs, new growth and a path to profitability.
- The company expands OEM ties while pursuing new white-label growth opportunities.
- Solidion’s proposal remains unsupported as Flux Power reviews financing options.
Solidion Technology stock fell sharply Friday after Flux Power rejected the company’s unsolicited takeover proposal. STI dropped 11.12% to $5.47 during midday trading and moved near its intraday low. The rejection increased pressure as the market assessed Solidion’s failed attempt to acquire the energy storage company.
Solidion Technology Inc., STI
Flux Power Board Rejects Solidion Takeover Proposal
Flux Power’s board unanimously rejected Solidion Technology’s unsolicited and non-binding acquisition proposal. Solidion announced the proposed transaction on September 30, targeting the lithium-ion energy storage company. However, Flux Power determined that the offer did not provide sufficient value for its shareholders.
The board reviewed the proposal with its legal advisers before reaching its decision. Flux Power said Solidion’s proposal substantially undervalued the company and its longer-term business potential. Therefore, the board decided that accepting the proposed transaction would not serve the company’s interests.
Solidion develops battery materials and technologies for electric mobility and energy storage applications. Meanwhile, Flux Power supplies lithium-ion battery systems for industrial vehicles and other commercial equipment. The proposed deal would have combined businesses operating across different parts of the battery technology market.
Flux Power Focuses on Costs and Growth
Flux Power instead plans to continue its strategy aimed at improving efficiency and reaching profitability. The company has reduced product costs, operating expenses, and internal spending under its newer management team. It has also strengthened its supply chain and expanded relationships with original equipment manufacturers.
During fiscal 2026’s fourth quarter, Flux Power reduced operating expenses by 33% from the previous year. The company also secured certification with another major OEM, expanding its addressable electric material-handling market. Flux Power launched SkyEMS 3.0, which uses artificial intelligence for fleet energy management.
Flux Power has also started pursuing additional growth through its S series battery platform. The company plans to offer white-label solutions to new manufacturers and dealership networks. Furthermore, Flux Power entered the robotics market through cooperation with a large global technology company.
Rejected Bid Leaves Solidion Without Board Support
Flux Power’s rejection blocks Solidion from securing board support for its proposed transaction. The decision also shifts attention toward whether Solidion changes the proposal or abandons the acquisition effort. No revised offer formed part of Flux Power’s announcement.
Flux Power expects improving demand as broader economic pressures ease across its markets. Management believes lithium-ion technology can capture a larger share of industrial battery demand over time. Therefore, the company continues building capacity and commercial relationships around that expected shift.
The board is also reviewing possible financing options and strategic partnerships to support Flux Power’s operating plans. Those efforts could provide additional financial flexibility as the company pursues growth and profitability. For Solidion, the rejected proposal leaves the proposed acquisition without support from Flux Power’s board.
The post Solidion Technology (STI) Stock: Slides After Flux Power Rejects Takeover Bid appeared first on Blockonomi.
TLDR
- FFAI stock fell 2.80% after an earlier rally reversed during Friday trading.
- Faraday Future showcased its EAI robotics platform and products at IROS 2026.
- The company used IROS to recruit robotics talent and attract development partners.
- FFAI and AIxC signed a non-binding deal valuing robotics assets near $200 million.
- Faraday Future is positioning its robotics business for a possible public listing.
Faraday Future pushed its robotics strategy into focus after showcasing its EAI platform at the IROS 2026 conference. FFAI stock traded at $1.2150, down 2.80%, after an earlier rally reversed during the session. The company used the Pittsburgh event to present robotics products, development programs, and industry solutions.
Faraday Future Intelligent Electric Inc., FFAI
Faraday Future Expands Robotics Presence at IROS
Faraday Future attended IROS 2026 in Pittsburgh from September 28 through September 30. The conference brings together researchers, universities, technology companies, and developers working across global robotics markets. During the event, Faraday Future presented its developing EAI Robot World 2.0 platform.
The company displayed several robot products and demonstrated their operation for conference participants. Its All-New Futurist model showed mobile functions and flexible task execution across different practical situations. Faraday Future also discussed possible applications with developers, researchers, universities, and other industry participants.
Meanwhile, the company introduced its Built in USA Acceleration Program during the event. The initiative supports Faraday Future’s broader plan to expand its American robotics development operations. The company also used IROS to recruit specialists across robotics, data, research, and industry applications.
EAI Ecosystem Targets Developers and Industry Partners
Faraday Future presented its EAI Brain and Developer Platform as another part of its robotics strategy. Developers discussed capability development, practical applications, and opportunities to build products within the platform. The company also continued seeking internal development partners to support future robotics projects.
Its EAI Data Factory formed another part of the company’s conference activities. Faraday Future discussed real-world data collection and cooperation with potential data partners. The company plans to use broader datasets to improve robot functions across different operating environments.
Faraday Future also promoted four Industry Productivity Solutions designed for several commercial and research applications. Its Research Solution attracted discussions with research institutions and universities attending the Pittsburgh conference. Those talks covered robotics research, educational uses, teaching programs, and possible future cooperation.
AIxC Deal Supports Broader Robotics Strategy
The IROS appearance followed another major development involving Faraday Future’s robotics business. FFAI and AIxC recently signed a non-binding term sheet covering a proposed business combination. The agreement values Faraday Future’s robotics assets and related operations at approximately $200 million.
Under the proposal, Faraday Future would combine those robotics operations with AIxC. AIxC has also changed its name to FF EAI Robotics Ecosystem Inc., or FFR. The companies intend to position the combined robotics business toward a separate public listing.
Faraday Future continues expanding beyond its electric vehicle operations through robotics and embodied intelligence projects. Its IROS participation supported product development, recruitment, data partnerships, and possible commercial applications. However, FFAI stock ended the latest move lower after giving back its earlier intraday gains.
The post Faraday Future (FFAI) Stock: EAI Robotics Push Takes Center Stage at IROS 2026 appeared first on Blockonomi.
TLDR
- Palantir partners with Armada to expand sovereign AI infrastructure deployments.
- Armada is named Palantir’s inaugural Certified Modular Data Center Partner.
- Joint infrastructure keeps models, data, and hardware under customer control.
- Modular data centers support faster deployment across secure operating sites.
- Armada’s Sovereign AI Grid links distributed sites for stronger system resilience.
Palantir Technologies partnered with Armada to deliver sovereign artificial intelligence infrastructure for governments and enterprises. Palantir Technologies (PLTR) traded at $189.93, down 0.06%, after retreating from an intraday peak near $194.50. The companies will combine Palantir software with modular data centers manufactured in the United States and allied nations.
Palantir Technologies Inc., PLTR
Palantir Names Armada Modular Data Center Partner
Palantir named Armada its inaugural Certified Modular Data Center Partner under the new agreement. The partnership combines Palantir’s Sovereign AI Operating System with Armada’s modular infrastructure and distributed network. Together, the companies aim to give customers direct ownership over computing systems, models, and stored data.
The offering targets organizations seeking infrastructure that operates within their own security boundaries. Therefore, customers can deploy open-weight models without depending on computing resources controlled by outside cloud providers. Armada also supports deployments at locations where existing power capacity can support new computing infrastructure.
Palantir will validate its operating system on Armada’s Galleon modular data centers. Its software stack includes AIP, Ontology, Foundry, and Apollo across the joint infrastructure. Meanwhile, Armada will provide the hardware, management software, and connectivity required across distributed deployments.
Partnership Extends Palantir Sovereign AI Architecture
The agreement expands Palantir’s existing Sovereign AI Operating System reference architecture developed with NVIDIA. That framework supports computing infrastructure that customers physically own and directly operate. The Armada partnership now brings that structure into modular data centers designed for faster deployment.
Customers can run open models and adapt them using proprietary company or government data. They can also serve those models through Palantir platforms without moving information outside controlled infrastructure. As a result, organizations can maintain direct authority over computing hardware and model operations.
Armada manufactures the modular data centers in the United States and selected allied nations. The companies designed the system for traditional sites, remote locations, and environments without standard network connections. The modular approach also reduces dependence on lengthy construction schedules for conventional data centers.
Armada Infrastructure Supports Distributed AI Deployments
Armada’s software platform manages open-source models for model tuning and inference across customer-owned infrastructure. The platform can function without Armada’s cloud services and supports fully air-gapped systems when required. It also monitors computing equipment, power systems, and cooling conditions across each deployment.
The Sovereign AI Grid connects individual locations into a broader distributed computing system. Organizations can spread important workloads across several sites instead of depending on one facility. This structure provides additional operational resilience when individual locations face outages or infrastructure problems.
Demand for locally controlled computing infrastructure has increased as organizations review cloud dependence and supply-chain exposure. Governments also seek stronger control over sensitive data, computing resources, and model deployment locations. Palantir and Armada now plan to address those requirements through an integrated customer-owned infrastructure stack.
The post Palantir Technologies (PLTR) Stock: Partners With Armada on Sovereign AI Infrastructure appeared first on Blockonomi.
CryptoPotato
The next 28 days or so are packed with major macro catalysts that could reshape interest-rate expectations and inject fresh volatility into bitcoin and the broader crypto market.
After the PCE and jobs data released last week, focus shifts back to the Federal Reserve, which, ahead of the next FOMC meeting at the end of the month, still needs to digest more information, including the CPI numbers.
Inflation Takes Central Stage (Again)
The first major date to watch is October 7, when the central bank will release the minutes from the previous FOMC meeting held on September 15-16, in which it raised interest rates for the first time in over three years. The document should provide additional insight into policymakers’ thinking and, perhaps even more importantly, how they view the path forward.
The September Consumer Price Index (CPI) is next and comes out on October 14. It remains one of the most watched macro releases for risk assets. An upside surprise has historically strengthened the case for tighter monetary policy, while a softer reading could produce the opposite reaction.
A day later comes another crucial inflation data point, with the release of the September Producer Price Index (PPI). The report measures price changes from the perspective of domestic producers and can offer additional evidence about underlying inflationary pressures.
The September retail sales will also be announced on that day, making it a particularly important date. Strong consumer spending could reinforce the idea that the US economy remains resilient despite restrictive monetary conditions, and vice versa.
Fed Into Focus
The single biggest event of the month arrives on October 28 when the Federal Reserve will conclude its two-day FOMC meeting, with the policy statement due at 2:00 p.m. ET and Chair Kevin Warsh’s press conference scheduled half an hour later.
The combination has quite obvious implications for risk on assets like bitcoin. Beyond the rate decision itself, which could be priced in by then, markets will be watching Warsh’s language for any clues about whether the central bank believes further tightening is necessary.
However, only a day after investors digest the Fed’s decision, the US will publish two highly important reports: the advance estimate of third-quarter GDP and September Personal Income and Outlays, which includes the Fed’s preferred PCE inflation gauge.
The timing makes the final week of the month particularly important. The September PCE reading will arrive too late to influence October’s FOMC decision itself, but it could immediately reshape expectations for the central bank’s final meeting of the year.
Separately, October is BTC’s greenest month historically, which could lead to additional volatility and possibly gains, even though, as we know, history is no indication of future price performance.
The post October Could Be Wild for Bitcoin: 5 Events Every Crypto Trader Should Watch appeared first on CryptoPotato.
Milwaukee-based Fiserv announced on October 1 that its digital asset platform is live with financial institutional clients, and Bank of North Dakota’s Roughrider Coin is the first product running on it.
The dollar-backed stablecoin settles on Solana and gives more than 90 banks and credit unions in the state a new way to move money between each other.
Roughrider Coin Runs on Solana Inside Fiserv’s Banking Platform
Bank of North Dakota is using Fiserv’s issuance, reserve, custody, and settlement infrastructure to roll the coin out across the state’s banking and payments workflows. Participating institutions will reach it through Commercial Center, the commercial online banking system Fiserv’s clients already use for traditional interbank transfers.
VersaBank will issue Roughrider Coin and handle custody, a job that includes minting, burning, and managing the reserve assets. Fireblocks supplies the digital asset infrastructure and tokenization services, while transactions are processed on the Solana blockchain.
Sunil Sachdev, Firsev’s head of embedded finance and digital assets, stated that the company is “helping clients unlock new efficiencies in banking and payments” while keeping the security and regulatory standards they expect.
Bank of North Dakota’s chief executive, Don Morgan, called the coin “a new tool to move money more efficiently across North Dakota’s interbank network.”
VersaBank founder and president David Taylor described Fiserv’s scale paired with his firm’s regulated capabilities as a “trusted foundation to bring stablecoins into established banking and payments systems.”
Roughrider Coin is only one use for Fiserv’s platform. It says it also supports stablecoin card issuance, cross-border payments, programmable commerce and treasury automation for financial institutions, corporates, marketplaces and fintechs. It also covers tokenized deposits and global currency account services, including US dollar accounts for financial institutions around the world.
Stablecoin Regulations Taking Shape
The launch comes as financial institutions face questions about how stablecoins should be backed, supervised, and presented to customers. As CryptoPotato reported last month, the Federal Reserve proposed two rules under the GENIUS Act: one requiring Fed-supervised issuers to fully back tokens with approved reserves, such as short-term Treasury bills, and another covering applications from supervised banks that want to issue payment stablecoins. The proposals were open to public comment, with the period set to run for 60 days after publication in the Federal Register.
Consumer confidence is another hurdle. Visa’s Money Travels 2026 study found that 56% of surveyed Americans had never heard of stablecoins. However, the study also found that 45% would be willing to use them when offered by an existing financial provider, compared with 36% under a scenario without hypothetical bank-level fraud protection and deposit insurance.
The post North Dakota’s Roughrider Coin Goes Live on Fiserv and Solana appeared first on CryptoPotato.
The Ethereum Foundation and the Open Anonymity Project have developed zkAPI, a zero-knowledge protocol that lets users pay for AI services and other paid APIs without linking their identity to their requests.
Live on Ethereum mainnet, the system separates payment records from the prompts and queries sent to service providers, although it does not hide all network activity or the content users submit.
How zkAPI Separates Payments From API Requests
The Open Anonymity Project announced its collaboration with the Ethereum Foundation in a September 25, 2026, post introducing its public AI chat services, OA-chat. The foundation also promoted zkAPI on October 2, describing it as “a means for private AI.”
The protocol was originally proposed by Ethereum researcher Davide Crapis and co-founder Vitalik Buterin, while the Open Anonymity team built the client, server, smart contracts, and browser integration.
Users first deposit ETH into the ZkAPIVault contract on Ethereum mainnet. The deposit is then turned into a commitment via the use of a Merkle tree, which is a cryptographic data structure, while the spending balance is kept as a private note on the user’s device.
At the start of a session, the browser generates a zero-knowledge proof that proves the user has sufficient funds to pay and has not yet spent the money. Payment verification is done without knowing the specific deposit being used for the payment and the user’s identity.
Once the verification is complete, an API key with a spending cap is issued, with the prompt going straight from the browser to the AI provider. When the API key expires, you get a receipt of usage. The system then deducts that amount from the private balance, with a one-way serial number called a nullifier preventing the same funds from being spent twice.
The protocol uses Groth16 proofs, BN254 cryptography, and Poseidon hashing to make the payment system both private and verifiable, and users can withdraw their remaining funds directly through the vault contract, even if the zkAPI servers stop operating.
What zkAPI Does Not Hide
The protocol hides the payment link, not the content. A provider still sees prompts and network details such as an IP address, and can try to match sessions by timing. The developers suggest Tor with a fresh circuit per session, since reused conversation history, writing style or personal details can let a provider relink individual sessions.
This project sits close to Buterin’s recent interests. Recall that late last month he shared a longer-term Ethereum roadmap that placed greater emphasis on cryptographic proofs and verification. zkAPI applies that general approach to everyday payments, allowing a service to verify spending without receiving a conventional account identity.
The post Ethereum Foundation and OA Launch zkAPI for Private AI Payment appeared first on CryptoPotato.
It was just several hours ago that the primary cryptocurrency topped $87,000 for the first time in about ten days after the softer-than-expected US jobs report came out.
Although that should be considered bullish for risk-on assets, especially when it’s aligned with the positive data from the PCE report earlier this week, the subsequent effects on BTC’s price were dramatically different.
After all, a weaker labor market combined with lower inflation than expected should, at least in theory, reduce some of the pressure on the US Federal Reserve for more immediate hikes. Perhaps that’s why BTC reacted to today’s jobs report with an instant uptick from $86,000 to $87,200.
That wasn’t the surprising part of today’s developments. What came next is somewhat unexpected. Bitcoin was rejected at that multi-day peak and tumbled to $85,500 first, before the bears took complete control and drove it to under $84,000 minutes ago. This meant that BTC had crashed by well over $3,000 in hours after the release of the US jobs report.

The altcoins have followed suit. ETH tapped $2,750 earlier today but now sits $100 lower. XRP was rejected again at $1.55 and now sits at $1.45. ZEC, DOGE, LINK, XMR, and ADA have marked even more substantial losses of up to 7% daily.
The total crypto market cap has shed almost $80 billion since the peak seen earlier today, and it’s down to $2.880 trillion on CMC.
Data from CoinGlass shows that the overall wrecked positions in the past 24 hours have jumped past $570 million. $186 million came in the past hour alone. Naturally, longs dominate, with 99% of the liquidated positions in the past hour coming from such positions.
The single-highest wrecked order took place on Binance and was worth almost $12 million.

The post Bitcoin Crashes Below $84K as Crypto Liquidations Near $600M appeared first on CryptoPotato.
Regulatory efforts continue following the CLARITY Act’s failure to advance. The US Securities and Exchange Commission has now proposed new rules to create a clearer framework for the custody of crypto assets by registered investment advisers and regulated funds.
The SEC said the changes would address how such assets are held under federal securities laws.
Addressing Crypto Custody Uncertainty
The proposal essentially aims to remove some regulatory barriers that currently affect advisers providing crypto-related investment advice. Under it, digital assets could be held through state trust companies in certain circumstances. The rules would also allow crypto assets to be held through self-custody arrangements under specific conditions.
The SEC said the proposal gives regulated funds more options for offering investment strategies linked to crypto assets. It also updates certain requirements related to financial statement audits for registered investment advisers and broker-dealer custodial services for regulated funds.
SEC Chairman Paul S. Atkins explained that existing custody rules under the Investment Advisers Act of 1940 and the Investment Company Act of 1940 were designed for traditional assets and largely predate the internet. He added that these rules do not adequately address the custody needs of newer crypto assets. Atkins further pointed out that custodial services for crypto assets can take months to become available after an asset is launched, which ends up creating challenges for investment advisers and regulated funds.
The SEC’s proposal, therefore, aims to address this gap through a framework while modernizing existing requirements to reflect current industry practices and support crypto innovation in the US. While highlighting that the latest move is not an “isolated initiative,” Atkins went on to add,
“It is another element of a comprehensive crypto asset regulatory approach. It began with ending regulation by enforcement. In December 2025, Commission staff issued a no-action letter to the Depository Trust Company regarding DTC’s voluntary securities tokenization pilot program. And in January 2026, Commission staff issued a statement on tokenized securities that provided a clear tokenization taxonomy for the marketplace.”
The proposed changes are not final. The SEC is seeking public comments on the proposal before making a final decision. The public comment period will remain open for 60 days.
Regulatory Focus Shifts
The CLARITY Act’s failure to advance has shifted attention toward what US regulators can do without waiting for Congress. Coinbase co-founder Brian Armstrong previously argued that the SEC and CFTC already have enough authority to establish clearer rules for crypto, and that the industry cannot afford to wait for legislation.
Similar views were shared by Bitwise CIO Matt Hougan as well, who said that these developments do not replace the CLARITY Act or settle every outstanding regulatory question, but they show how the agencies could help shape crypto rules through their existing authority while broader legislation remains stalled.
The post SEC Proposes Rules That Could Change How Funds Custody Crypto appeared first on CryptoPotato.