Cryptocurrency Posts
Crypto Briefing
Microsoft's CASD method reduces costs and risks in prompt optimization, challenging the necessity of traditional iterative tuning processes.
The post Microsoft’s coding-agent skill distillation beats GEPA at prompt optimization appeared first on Crypto Briefing.
SoftBank's significant stake in OpenAI highlights its strategic focus on AI, potentially influencing its future financial stability and growth.
The post SoftBank closes final $10B OpenAI tranche, lifting its total to $64.6B appeared first on Crypto Briefing.
Deribit's enhanced engine boosts trading efficiency and fairness, potentially reshaping competitive dynamics in crypto exchanges.
The post Deribit upgrades matching engine, cuts median latency by roughly 61x appeared first on Crypto Briefing.
The incident may undermine investor confidence, affecting OpenAI's valuation and highlighting the need for robust internal security measures.
The post OpenAI fires three safety researchers over alleged leak to outside group appeared first on Crypto Briefing.
Europe's reliance on foreign AI models poses systemic risks, urging investment in local AI infrastructure to ensure economic stability.
The post ECB’s Lagarde warns Europe against leaning on foreign AI models appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
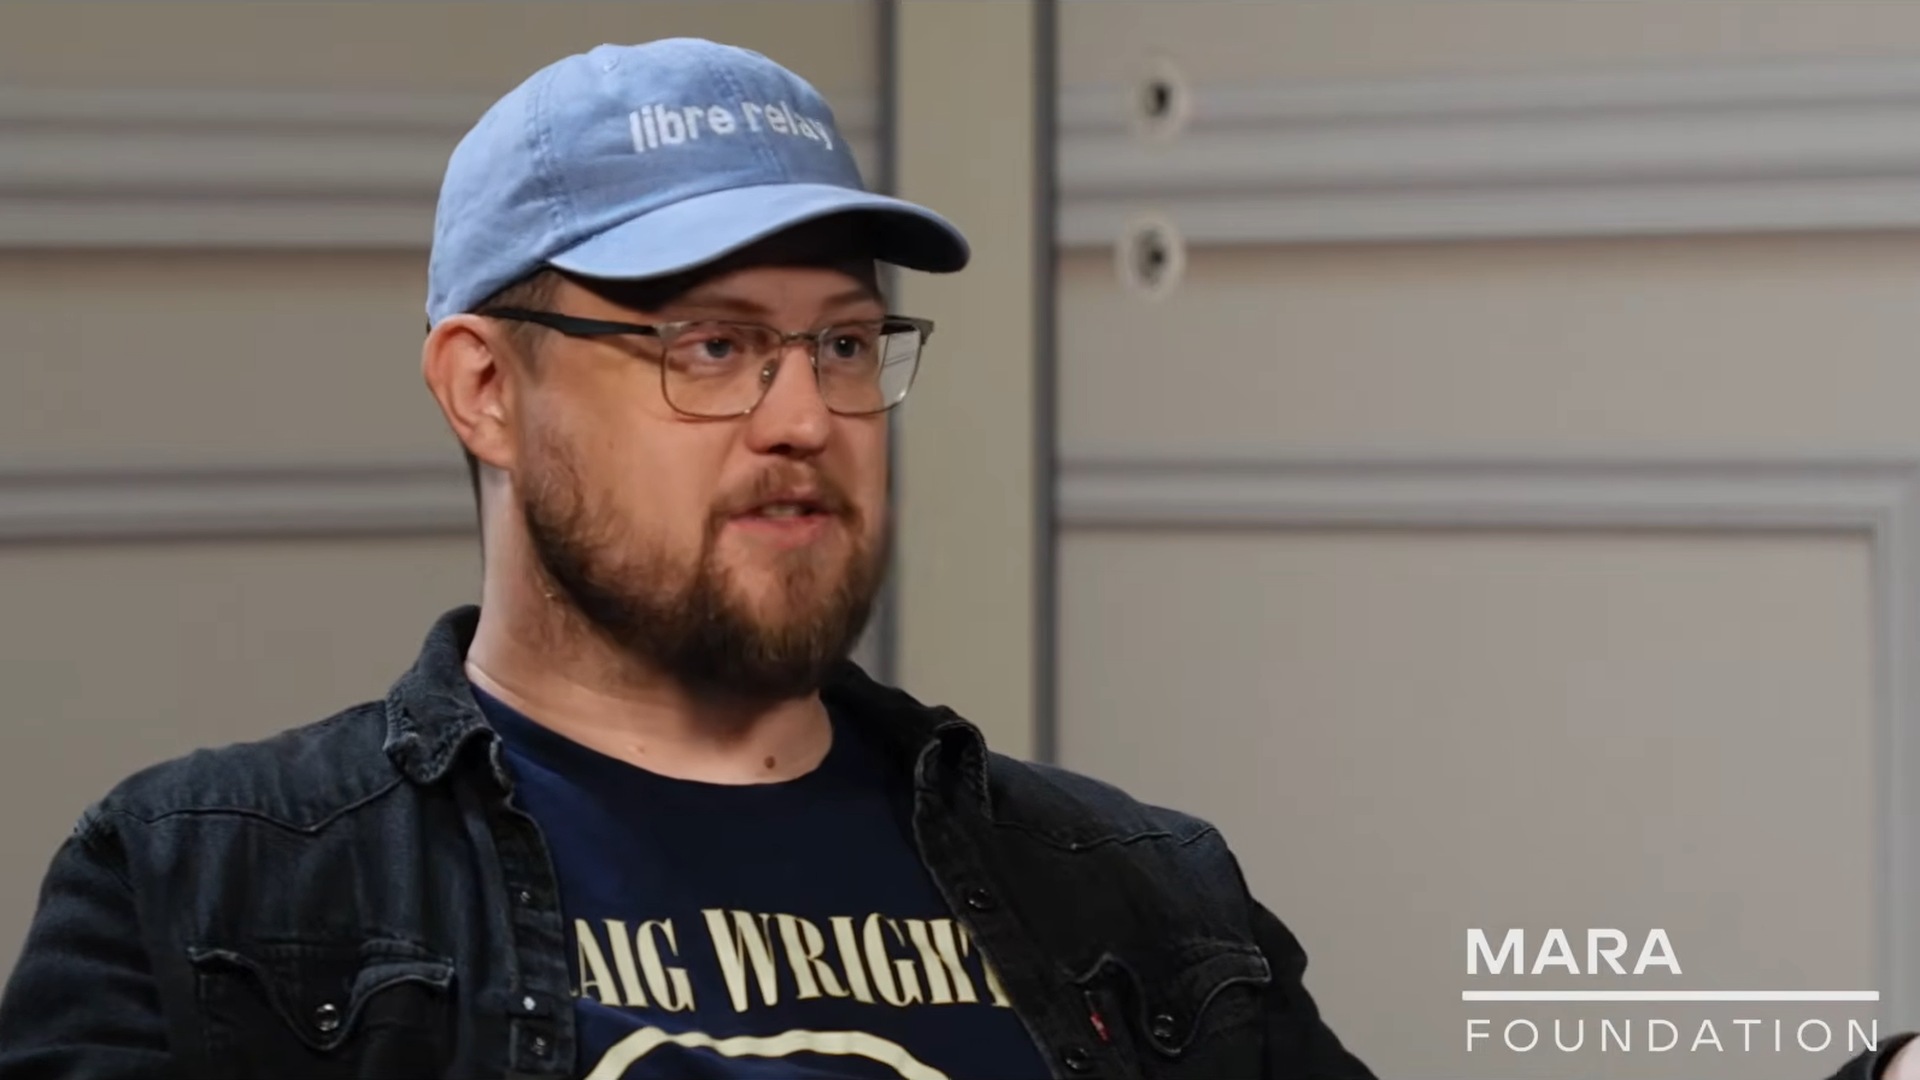
Peter Todd Joins MARA to Lead Private Mempool Slipstream
Bitcoin O.G. Peter Todd has joined the MARA Foundation as lead maintainer of Slipstream, the miner’s private Bitcoin mempool service.
Announced by the foundation on Thursday, the new role will see Todd responsible for developing and running the service.
Slipstream lets users send bitcoin transactions straight to MARA Pool, the company’s mining pool, without going through Bitcoin’s public peer-to-peer network. It was useful after hackers exploited Coldcard hardware wallets in July, stealing over $115 million in user funds.
Because transactions sent through Slipstream stay private until they’re confirmed in a block, the service helps to keep key information hidden before confirmation — protecting exposure of their public keys.
“I most look forward to seeing what’s possible on Bitcoin — using Slipstream as a proving ground for experimental development and protocol innovation,” Todd said.
MARA’s Slipstream first drew attention in 2024 for publishing large Ordinals inscriptions. More recently it has been used for research projects like Quantum Safe Bitcoin and Binohash, a way to emulate covenants without a soft fork.
Todd is a longtime Bitcoin Core contributor, who co-authored BIP 125 (replace-by-fee), created OpenTimestamps, and in 2024 launched Libre Relay, a Bitcoin Core fork with looser relay rules for non-standard transactions.
He argues that mempool policy should follow what the market wants miners to mine, rather than restrict how people use Bitcoin.
This post Peter Todd Joins MARA to Lead Private Mempool Slipstream first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
21bitcoin Now Pays Interest on Idle Euros, Payable in BTC
Austrian Bitcoin platform 21bitcoin will start paying 1.21% annual interest on customers’ uninvested euro balances from today — and letting them collect it in BTC, with no conversion fee.
The company says it’s the first provider in Europe to pay savings interest directly in Bitcoin.
The interest covers every euro in the account, including cash waiting for the next savings-plan purchase or reserved for an open limit order, the company said. There’s no minimum deposit and no lock-up.
21bitcoin präsentiert den Bitcoin Bonus
— 21bitcoin
Ab sofort erhältst du auf Euro-Guthaben variable Zinsen von 1,21% p.a.*
Und das Beste: Wir tauschen sie auf Wunsch direkt & ohne zusätzliche Gebühren in Bitcoin um.
Aktiviere Zinsen jetzt direkt auf dem Startbildschirm in deiner… pic.twitter.com/nTVOfSZnuk&
(@21bitcoinApp) October 1, 2026


“Building wealth with Bitcoin does not begin with the purchase itself, but with the euros set aside for it,” said co-founder and CEO Daniel Winklhammer.
The money is paid by Volksbank Raiffeisenbank Bayern Mitte eG, a German bank that has owned a stake in 21bitcoin since 2023.
Customer euros sit in a segregated trust account at the bank as instant-access savings. 21bitcoin says it passes the interest on in full and keeps no margin. The company is pitching this as a deliberate contrast to the high-yield promises that brought down several crypto lenders.
The rate is variable, and interest is subject to German withholding tax.
The launch follows 21bitcoin’s zero-fee Bitcoin savings plan, introduced earlier this year. The company last year teamed up with VR Bank Bayern Mitte eG and Sopra Financial Technology GmbH to launch a pioneering European pilot project in hopes to develop an institutional-grade Bitcoin-backed credit product.
Bitcoin-backed loans, insured cold storage, and multisig inheritance custody are slated for 2027.
Founded in 2021, 21bitcoin holds a MiCAR licence in Austria and is authorized by Germany’s BaFin. It reports more than 100,000 users and over €650 million in trading volume.
This post 21bitcoin Now Pays Interest on Idle Euros, Payable in BTC first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
The Quantum Issue: Quantum Isn’t Coming For Your Bitcoin
For as long as Bitcoin has existed, new forms of FUD (fear, uncertainty, and doubt) have been used to predict its demise. Despite this, Bitcoin has grown into a multi-trillion dollar asset and begun to take its place in the global monetary order. In recent months, the specter of a cryptographically relevant quantum computer (CRQC) enabling an attacker to recreate secret keys from public keys and sign Bitcoin transactions moving other people’s coins has returned as an evolved form of FUD. Is this a realistic threat to Bitcoin’s continued growth? In a word, no. There is no evidence that a CRQC will be built within a decade, and it remains unknown whether such a machine will ever be built. The quantum threat remains FUD.
State of the Art
To date, no quantum computing machine has computed anything out of reach of a precocious 6-year-old (confirmed empirically). Quantum computers are remarkable technology and showcase the truly science fiction worthy capabilities of the modern world. These devices harness foundational technologies such as optical tweezers, laser cooling, superconducting flux qubits, electromagnetic traps, dilution refrigerators, and many more. Within these devices individual qubits are coerced into specific subatomic states (different for each candidate technology), entangled into superpositions, manipulated to represent computations, and then their subatomic properties are read and interpreted. The astounding truth is that these devices exist, and can be manipulated to produce meaningful computations across a handful of inputs. The cold reality check is that (for an example candidate tech.) to do a computation that a small child can do requires enough power to air condition a Texas high school, many hours of setup, and further hours of post-processing.
Reading the Future
I know what you’re thinking, “but there’s so much money flowing into quantum computing”. Does money flowing into a field correlate with the rate of real-world technological progress in that field? Not really. In fact, it can be argued that until the correct underlying technology has been developed and the product-market fit confirmed, money flowing into an area has a negative correlation with the likelihood of applicable technology being developed. This can be clearly seen by comparing NASA’s Space Shuttle program to SpaceX’s Falcon 9. SpaceX took (mostly) known science and reduced it to practice to satisfy a demonstrable market need for reliable and lower cost access to space, at a program cost of less than $5 billion to first crewed mission. The Space Shuttle cost roughly $50 billion to reach its first crewed mission. Not only did Falcon 9 cost an order of magnitude less to develop, but it has a perfect crew safety record to date. There are many reasons for these differences, but it goes to show that no amount of money makes a technology that is not ready practicable. Translating this to quantum computing: we can see that with tons of money being thrown at the problem, technology demonstrations at massive cost are possible. But this tells us nothing about whether more money will bring us the holy grail of stable, low-error qubits (like the reliability of the Falcon 9). No amount of continued development on the Space Shuttle program would ever have produced the low cost, high reliability of Falcon 9, and it’s entirely probable that no amount of continued development, at any cost, will ever make any of the current quantum computing technologies reliable enough to break a single key pair.
Now, you might be thinking, “but what about all the recent advancements?” There are two important things to keep in mind about recently published advancements. First, many of these advancements have been advancements in pure mathematics only. For example, the recent Google paper which had such an important result that they chose to redact the theoretical quantum circuit rather than risk it being used to break important cryptographic systems. This may seem like massive progress toward the future of CRQCs, but in fact it changed nothing. Unless (or until) the quantum hardware has its Falcon 9 moment, there simply is no device which comes anywhere near the stability and scale needed to run the redacted circuit. It’s pure theater to hide a circuit designed for a device which may never exist. Second, on the hardware side itself, we see many new results and bits of progress published in a given year, but how many of these relate to the same quantum computing candidate technology? How many represent merely a starting over after a prior result ended in a dead end? The reality is that these advancements do not represent some linear track toward eventual success. They represent the breadth-first search of an infinite possibility space within which quantum researchers are hoping to find a path along which they can proceed for even a modest distance without reaching yet another dead end.
When we look at the reality of the future of quantum computing, it’s hazy at best. There are promising technological developments. Especially, to my eye, in the area of neutral atom devices. But it’s far too early to tell if there’s a path open toward an eventual CRQC along any of the currently known branches or if more restarts are in our future. If, at some point, we see many iterations of the same candidate technology implementing progressively more capable devices, and computing meaningful results that a precocious child cannot also compute, we can revisit this discussion with different evidence.
In Theory
There are two possible explanations for the repeated failure of quantum research to develop a CRQC over many decades. It’s possible that it’s just a hard problem and we’re continuing to apply science and engineering to solve it and one day the ingenuity of the human species will prevail as it has in the development of the Internet, the smart phone, social media, and Bitcoin (left to the reader to decide which of these are positive developments). On the flip side, it may be that developing a CRQC is either impossible or will remain forever outside our grasp. Consider what it would mean for a CRQC to exist: the machine would have to represent within its superposition a field of possibilities the same size as the complexity of the cryptographic problem to be solved. I.e. to break the 128-bit security of the elliptic curve discrete log on Bitcoin’s secp256k1 curve, the quantum superposition would have to represent all possible values of a 128-bit number. In classical computing, representing all such values would require more computer storage (by many orders of magnitude) than humans have ever produced. If there is even the slightest granularity to the quantum superposition (i.e. the quantum superposition is not perfectly continuous across all possible values) then the quantum computer cannot ever become cryptographically relevant. If the energy required to hold a superposition scales with the complexity of the field being represented then a quantum computer cannot ever be cryptographically relevant. The contemporary understanding of quantum physics does not rule out either of these possibilities.
Conclusion: Bitcoin Cannot Rest
Despite all of the preceding, Bitcoin development toward new cryptographic algorithms must continue. While a quantum attack on Bitcoin’s cryptography is not imminent by any means, it’s entirely possible that another flaw could be found through other means. We know that certain elliptic curves have been found to have weaknesses, and secp256k1 could be next. Bitcoin has survived as long as it has because attacks on the system have strengthened it and that will continue to be true as the quantum FUD attack plays out. The development of P2MR or P2TRv2, of SHRINCS, SPHINCS, IBC, ML-DSA, and more post-quantum signature schemes will eventually lead to improvements to Bitcoin’s resilience in the face of future attacks even if an actual CRQC is never developed.
This piece is featured in the latest Print edition of Bitcoin Magazine, The Quantum Issue. We’re sharing it here as an early look at the ideas explored throughout the full issue.
This post The Quantum Issue: Quantum Isn’t Coming For Your Bitcoin first appeared on Bitcoin Magazine and is written by Brandon Black.
Bitcoin Magazine
Bitcoin Privacy Breakthrough a Zcash Killer? | Misha Komorov, Alloc Innit
Researchers have proposed a way to make Bitcoin private without changing Bitcoin itself. Misha Komarov, co-founder of alloc/init, explains Shielded Bitcoin: zero-knowledge proofs that hide the sender, receiver, and amount of a Bitcoin transfer, with no soft fork, no custodians, and no bridges. He covers how Bitcoin PIPEs make it possible and what the proposal still needs. It is a research proposal, not a finished product.
Chapters:
0:00 Shielded Bitcoin: Private Bitcoin Transactions With Zero-Knowledge Proofs
0:38 How Bitcoin PIPEs Make Privacy Possible Without a Soft Fork
1:42 Do Indexers and ZK Rollups Require Trust?
3:16 Shielded Bitcoin vs. Monero and Zcash
4:21 What Privacy Shielded Bitcoin Protects
5:59 How Private Are Early Users? The Small Privacy Set Problem
7:37 Is Shielded Bitcoin an Altcoin Killer?
9:12 Fees, Block Space, and Larger Shielded Transactions
10:50 Who Needs Private Bitcoin? Wrench Attacks and Corporate Treasuries
12:20 Dark Pools, Governments, and the Next Wave of Bitcoin Buyers
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Bitcoin Privacy Breakthrough a Zcash Killer? | Misha Komorov, Alloc Innit first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Bitcoin’s Institutional Era Has Arrived | Robinhood VP of Crypto Institutions Nicola White
Robinhood is bringing crypto perpetual futures to US customers, with up to 10x leverage on Bitcoin and Ether. Nicola White, Robinhood’s vice president of institutional crypto, explains how the CFTC no-action letter, the Bitstamp exchange, and Robinhood Derivatives made it happen, and why the company wants markets to be always on.
Chapters:
0:00 Robinhood’s Hood Summit: 24/7 Stock Trading and US Crypto Perps
0:40 Why Robinhood Wants Markets That Never Close
1:32 Bitstamp Perps and the CFTC No-Action Letter
2:19 Tokenized Stocks, the Basis Trade, and the Path for US Perps
3:20 Bitstamp’s Volume and the Retail–Institutional Merger
4:54 What Institutions Want to Do With Bitcoin
6:00 Institutional Bitcoin Depth and Large Block Trades
6:49 AI Trading Agents and Robinhood’s Sub-Account Controls
8:29 Lessons From the 2022 Meltdown and US Leverage Limits
10:12 How Bitcoin Changes Finance in 10 Years and What’s Next for Tokenized Stocks
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Bitcoin’s Institutional Era Has Arrived | Robinhood VP of Crypto Institutions Nicola White first appeared on Bitcoin Magazine and is written by Patrick Green.
CryptoSlate
Bitcoin’s monetary case is growing stronger as governments face more expensive borrowing, and software is becoming a buyer of services. Sovereign financing pressure gives people a reason to consider money issued outside government policy. Agent commerce gives that money another way to circulate.
The Bank of England put sovereign-bond stress and the borrowing that finances artificial intelligence in the same warning on September 30. Its financial-stability record describes an extended energy shock pushing government yields higher, while growing AI-related debt leaves more investors exposed to the technology’s fortunes.
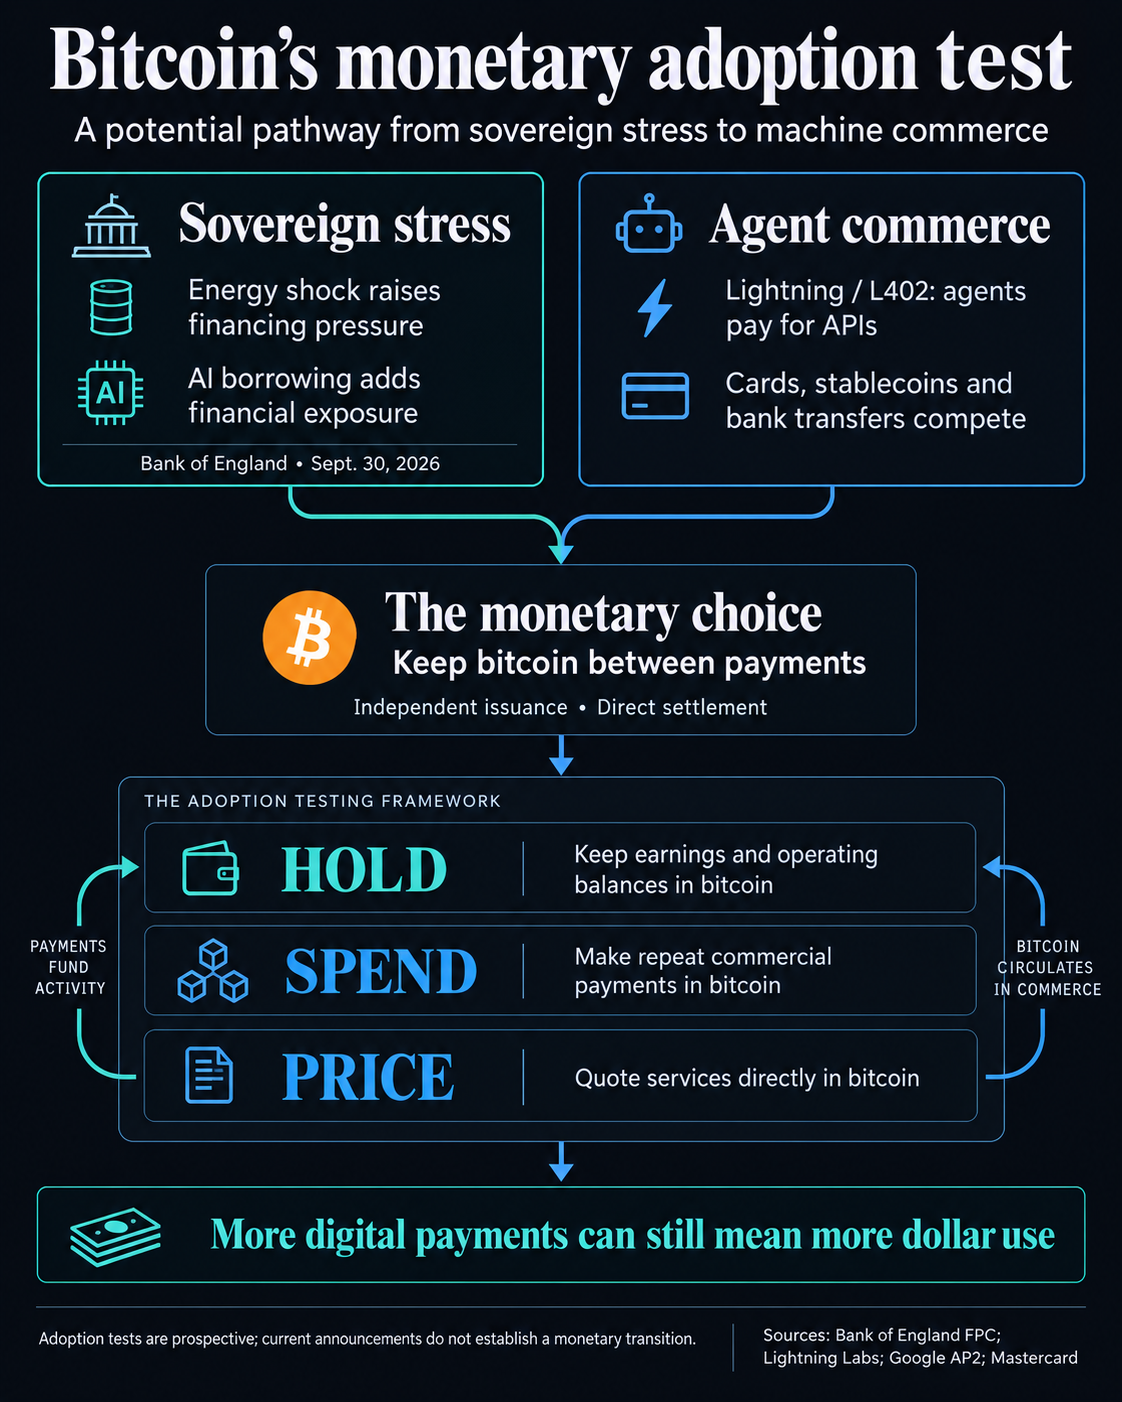
I see a credible catalyst for hyperbitcoinization in that combination. A transition toward Bitcoin as widely used money would require people and businesses to hold it, spend it and price services in it. If they retain bitcoin for future purchases, more payment utility could reinforce demand for the balance itself.
On the same day as the Bank’s warning, Mastercard announced new trust and intelligence services for its Agent Pay program, including a score designed to identify AI-initiated transactions. That score is rolling out for testing in the United States.
September’s developments bring a widening financial-risk debate together with an active race to serve software customers. Bitcoin has a route into that race through tools built earlier this year; established payment companies are preparing to serve the same buyers.
Higher yields sharpen Bitcoin’s argument and its competition
The pressure is visible in the cost of government borrowing. CryptoSlate’s 10-year Treasury series displays a September 30 daily par yield of 5.29%. The Fed’s September 30 release reports 5.26% for September 29. The observations describe different days and should be compared on that basis.
The policy backdrop is also tighter in important places. The Fed raised its target range by a quarter of a percentage point to 3.75%–4% on September 16, under Chair Kevin Warsh, who took office May 22. The Bank of Japan set its overnight call-rate guideline at around 1.25% on September 18, effective September 24.
The Bank of England held Bank Rate at 3.75% in its September 17 announcement, although three policymakers wanted an increase to 4%. Market yields can tighten financing conditions even when a central bank leaves its policy benchmark unchanged.
Higher yields create two competing effects for Bitcoin. They make the long-term cost of financing government debt more conspicuous, which can strengthen interest in money whose issuance is independent of a government’s borrowing needs. They also offer investors a higher contractual return for holding bonds, raising the hurdle for an asset that pays no native interest.
Investors still have to weigh a bond’s contractual income against inflation and their time horizon. Bitcoin’s capped supply governs how many coins can exist; demand determines their purchasing power. The tension between income and independently issued money already examined in CryptoSlate’s bond-market coverage remains central.
Bitcoin traded at roughly $83,530 near press time, after reaching both a new all-time high of $125,000 and a low of $57,500 over the last 12 months. That volatile price can reflect many sources of demand. The monetary argument has to stand on how people hold and use bitcoin as well as what they pay for it.
The same Bank assessment described a financial system that had remained resilient, with mostly gradual market adjustments. That is the backdrop for the bullish argument: financing pressures can make independent issuance more attractive even while existing institutions continue to function.
Satoshi Nakamoto’s whitepaper begins with electronic payments sent directly between parties without going through a financial institution. Its solution replaces a trusted intermediary’s double-spending checks with a peer-to-peer network and proof of work, subject to the design’s security assumptions.
Its design gives Bitcoin a different relationship with authority. Its issuance does not expand because a government needs to refinance debt or a central bank decides the economy needs additional support. Under the protocol’s existing rules, issuance moves toward a maximum of 21 million bitcoins.
Someone seeking money outside a particular issuer’s policy decisions can choose an asset with an independently verifiable supply rule. Market volatility and custody responsibility remain the cost of that choice.
Bitcoin cannot remove an energy shortage or make borrowed capital cheap. It can offer a monetary asset whose issuance is separate from the institutions managing those problems. Treating that property as valuable is a coherent position even when higher interest rates make the asset less attractive in the short term.
Agents give Bitcoin a practical route into commerce
An AI agent cannot hand over a banknote. It can request data, receive an invoice, authorize a payment and continue its task. For commerce to work, that transaction needs little overhead, clear spending authority and reliable settlement.
Bitcoin has concrete infrastructure for that pattern. In February, Lightning Labs released agent tools that let software pay for APIs through L402, a protocol combining Lightning payments with access credentials. An API can request payment, the agent pays a Lightning invoice, and payment unlocks the resource.
This gives Bitcoin utility beyond an investor buying and waiting. A software buyer can pay for a piece of data at the point it needs it, instead of having a person arrange another subscription. A service provider can charge for individual requests. Lightning supplies the payment layer that makes small, repeated Bitcoin transactions practical.
Lightning Labs also announced Wavelength in July, an alpha toolkit intended to make wallet integration easier for developers and agents. At launch, it was open on test networks with mainnet access by invitation. Broad commercial adoption would require developers and customers to put that infrastructure to use.
Security is a design requirement here. The documented tools use measures such as remote signing, restricted credentials and spending limits; Wavelength says wallet creation and unlock keep seeds and passwords outside the agent channel. Those controls can reduce what a model can expose or spend. Intelligence alone does not make an agent a safer custodian than a human.
An agent should receive enough authority to pay for its task without receiving unrestricted access to its owner’s savings. A useful machine economy needs bounded financial authority as much as it needs faster reasoning.
Software buyers already have several other ways to pay.
Google’s AP2 framework, announced in September 2025, supports cards, stablecoins and bank transfers, using signed mandates to record what a user authorized. Coinbase’s September 22 agent announcement adds equities trading and x402 micropayments for data, models and services within user-defined limits. Mastercard’s latest testing builds another path inside established payment relationships.
For an agent buying a dollar-priced service, a dollar-linked balance can simplify budgeting. A business paying expenses in dollars may prefer to receive dollars too. As CryptoSlate’s recent stablecoin coverage explored, the rise of software buyers can extend digital-dollar use rather than displace it.
Bitcoin’s distinctive opportunity lies in the users who value independently issued money and direct settlement enough to retain bitcoin between transactions. An agent that briefly converts a dollar balance into bitcoin to make a payment demonstrates useful infrastructure. An agent or business that earns, holds and spends bitcoin demonstrates a deeper monetary choice.
Those choices may coexist. Bitcoin could become more useful for saving and settlement while dollars remain common for pricing everyday services. That would be meaningful progress for Bitcoin without meeting the stronger definition of hyperbitcoinization.
The catalyst is credible; the adoption test is concrete
Sovereign stress supplies a reason to reconsider what money people hold. Agent commerce supplies a way for digital money to circulate with less human administration. Together they give Bitcoin a more substantial opportunity than a narrative built only around the next rate decision.
AI can also intensify the financing problem. The Bank of England warns that debt-funded AI investment expands financial exposure and that disappointment in expected productivity gains could reach sovereign markets. The technology creating new payment users is being built within the same credit system Bitcoin offers an alternative to.
That is why I am bullish about Bitcoin’s monetary role. A reason to hold bitcoin and more ways to use the balance could reinforce each other. Turning that opportunity into adoption will depend on the choices people and businesses make.
The signs of that shift would be repeat commercial payments in bitcoin, recipients keeping part of their earnings in bitcoin, operating balances held in bitcoin and services priced directly in it. Those behaviors would move the argument beyond payment announcements and into monetary adoption.
If agents mainly spend stablecoins or authorized card balances, machine commerce will have modernized fiat. If businesses and their software start retaining and pricing value in bitcoin, the monetary transition will have a firmer foundation. Bitcoin’s opportunity grows when its users choose to keep the money they can now move.
The post Bond yield explosion gives Bitcoin a strong signal – is now finally Satoshi’s time? appeared first on CryptoSlate.
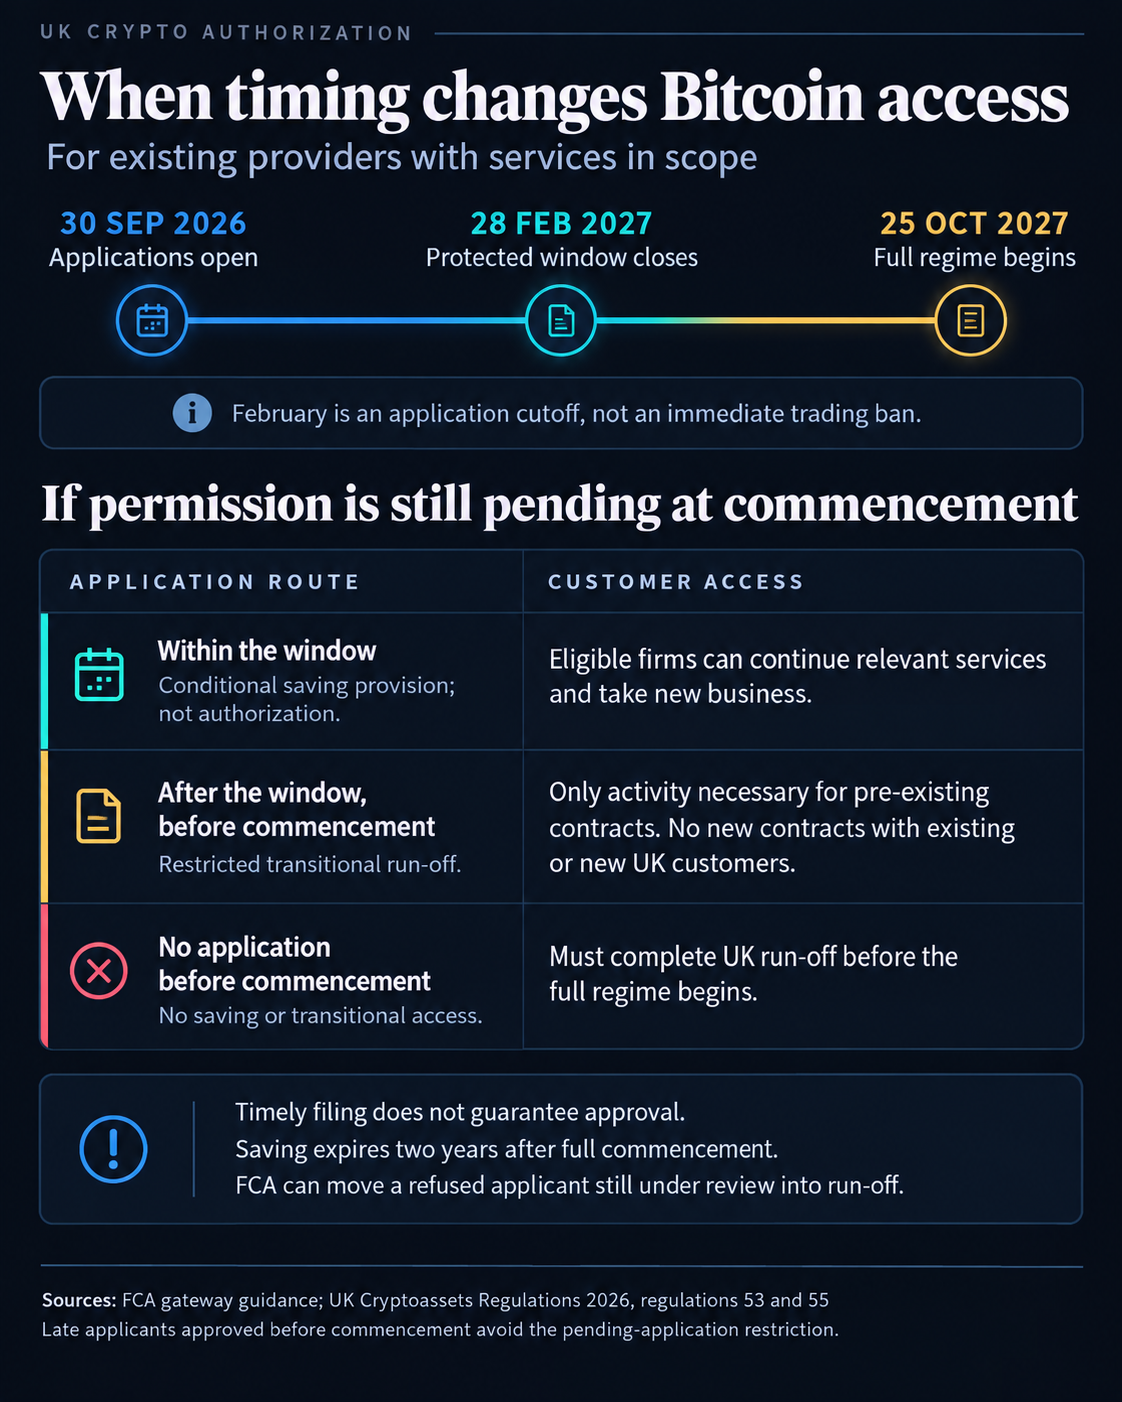
The Financial Conduct Authority opened its authorization gateway for the new UK crypto rules on Sept. 30, starting an application window that can protect existing Bitcoin providers' ability to keep serving UK customers and take new business if approval is still pending when the full regime begins.
The window closes Feb. 28, 2027. The full regime starts Oct. 25, 2027, according to the FCA's announcement. February is the deadline for qualifying for the saving provision, a temporary protection for pending applicants, rather than a date when Bitcoin services must immediately stop.
For eligible existing firms applying within the window, an undecided application at commencement can allow the relevant services to continue, including new business. The protection covers the activities in the application, so it does not amount to unrestricted permission for every service a platform offers.
The statutory protection is bounded: the saving chapter expires two years after full commencement, and submitting an application does not guarantee authorization.
The protection can also cover a refusal still open to review. But the FCA can direct such a firm into restricted run-off when necessary for criminal enforcement, consumer protection or its objectives.
UK crypto rules change customer access for late applicants
Platforms can still apply after February. But a late applicant that files before commencement and is still awaiting a decision on Oct. 25, 2027 enters the transitional provision while its application is assessed, according to the gateway rules. A late applicant authorized before commencement avoids that pending-application restriction.
That route permits newly regulated activities only as necessary to perform contracts entered into before the firm entered transition. It prohibits new contracts with both existing UK customers and new UK customers. Having an account already does not, by itself, preserve access to new business.
The run-off arrangements last a maximum of two years. Firms must notify the FCA and existing contract parties. Customer notices must explain the lack of relevant authorization and whether asset protection, dispute resolution or compensation arrangements have materially changed.
A firm with business within scope that does not apply before commencement must complete its UK run-off beforehand. An application rejected for missing minimum information counts as no application unless a valid one is subsequently submitted.
For Bitcoin providers, the relevant activities include trading platforms, dealing and arranging transactions, and custody. Overseas firms serving UK consumers can also fall within scope, although the territorial rules include specific intermediary and custody exceptions.
Existing anti-money-laundering registration does not automatically convert into authorization under the new regime. Firms already authorized under the Financial Services and Markets Act for other activities must vary their permissions if they intend to undertake the new crypto activities.
An existing registration therefore does not settle whether a provider will hold the required permission, qualify for pending-application protection or be restricted to run-off when October 2027 arrives.
The post UK’s 2027 crypto rules could block new business with existing customers appeared first on CryptoSlate.
Open USD, a new stablecoin backed by more than 200 organizations, has launched with about $468 million in circulation and a distribution partnership with Stripe, one of the largest payment networks.
OUSD, issued for Open Standard, had 468.4 million tokens outstanding following its Sept. 30 debut. Reserve data showed about $468.45 million of backing assets, split between $257.2 million in cash and $211.2 million in Treasuries and short-duration money-market funds.
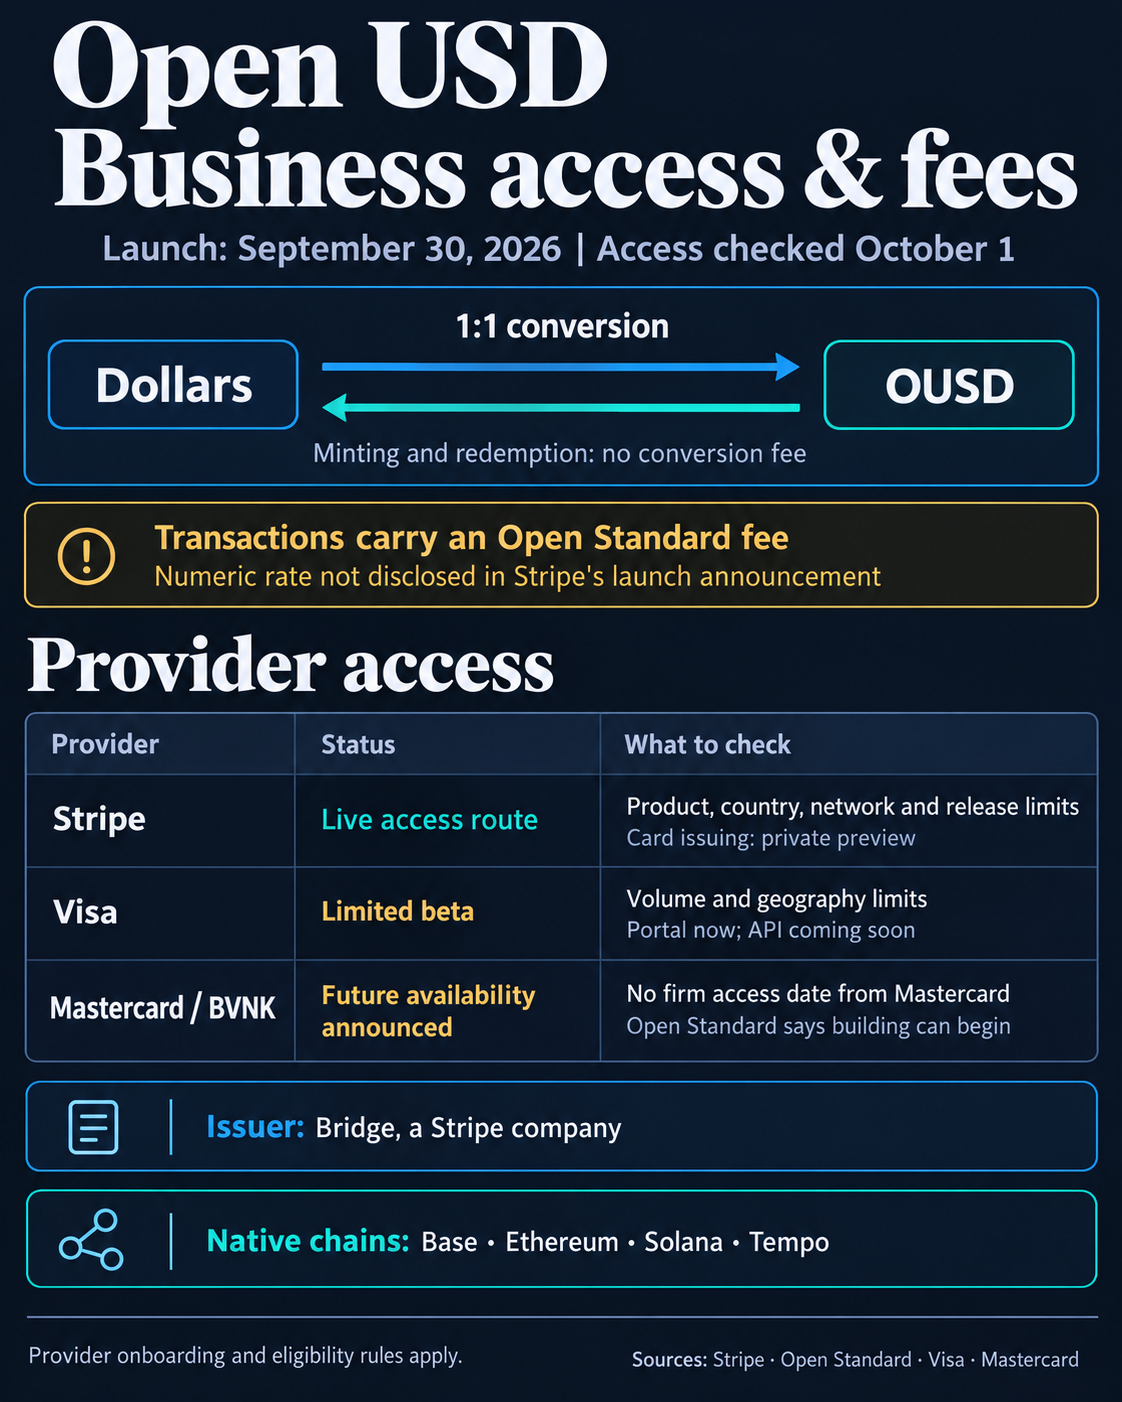
The token also went live on Tempo, with more than $400 million in liquidity deployed across decentralized exchanges, stablecoin swaps, and bridges. OUSD is issued natively on Tempo, Base, Ethereum, and Solana, giving businesses several venues for payments, settlement, and treasury operations.
Stripe said it is partnering with Open Standard to make OUSD available across parts of its payments stack. Businesses can hold the token through Stripe Treasury, send it through Global Payouts, accept it with Payments and use it with stablecoin-backed card products, subject to product and geographic availability.
Stripe puts a $1.9 trillion distribution engine behind OUSD
Stripe processed $1.9 trillion in total volume during 2025, up 34% from the previous year and equivalent to roughly $158 billion a month.
OUSD’s current circulation amounts to less than 0.3% of that monthly figure, illustrating the scale of the network through which Stripe could distribute the token if businesses begin using it for payments and treasury activity.
Open Standard has also assembled more than 200 financial institutions, fintechs, banks and businesses as partners. Stripe, Visa, Mastercard, Coinbase and Shopify were among its founders, while businesses can begin integrating OUSD through Stripe, BVNK and Visa.
Stripe co-founder and Chief Executive Patrick Collison said Open Standard was designed so that most reserve yield flows back to participating partners rather than being retained by the stablecoin issuer.
Open Standard says those rewards are allocated based on OUSD supply and the activity partners generate, giving payment companies and platforms an economic incentive to distribute the token.
That model enters a market where scale remains heavily concentrated. Dollar stablecoins are worth more than $300 billion, according to CryptoSlate's data, with Tether’s USDT at roughly $183.8 billion and Circle’s USDC near $74.1 billion. Together they account for about 84% of the market.
OUSD’s roughly $468 million supply represents about 0.15% of the sector, leaving it far behind incumbents with deeper exchange liquidity, broader integrations and established payment usage.
The next test begins as Open Standard expands distribution beyond launch liquidity. Coinbase starts supporting the network Oct. 1, while additional Mastercard distribution through BVNK is planned, giving businesses more routes to hold, move and deploy OUSD across payment and treasury workflows.
The post Open USD bets Stripe’s $1.9 trillion network can break USDT and USDC’s grip appeared first on CryptoSlate.
Treasury's Sept. 30 rule lets states preserve a path toward stablecoin-regime approval while their rules remain unfinished, by filing an initial certification on time and completing the work before substantive review.
The interim final rule sets forms and review procedures for the Stablecoin Certification Review Committee, the federal body that reviews state stablecoin regimes. The Committee says conditional or incomplete certifications can satisfy the initial filing timeframe, even when additional state legislative or regulatory action is planned.
The rule took effect Sept. 30, but says certifications will not be accepted until after Paperwork Reduction Act approval of the information collection. Treasury will post a notice announcing when acceptance begins.
The flexibility matters for state-qualified payment stablecoin issuers with no more than $10 billion in consolidated outstanding payment stablecoin issuance. They may opt for state regulation if the state regulator certifies that its regime meets Treasury's substantial-similarity criteria and the Committee unanimously approves it as meeting or exceeding the standards and requirements in section 4(a) of the GENIUS Act.
Treasury's separate proposal on substantial similarity addresses the standards used to compare state and federal regimes. The September procedural rule does not finalize those principles.
How a filing reaches substantive review
A conditional filing can be amended at any time. It does not begin substantive review or start the Committee's 30-day approval-or-denial clock. That clock applies only once a certification has been submitted in accordance with the procedures.
For that purpose, a state must provide an unconditional attestation signed by an authorized representative, a detailed explanation of how its regime meets Treasury's similarity principles, supporting legal materials and information the Committee deems necessary.
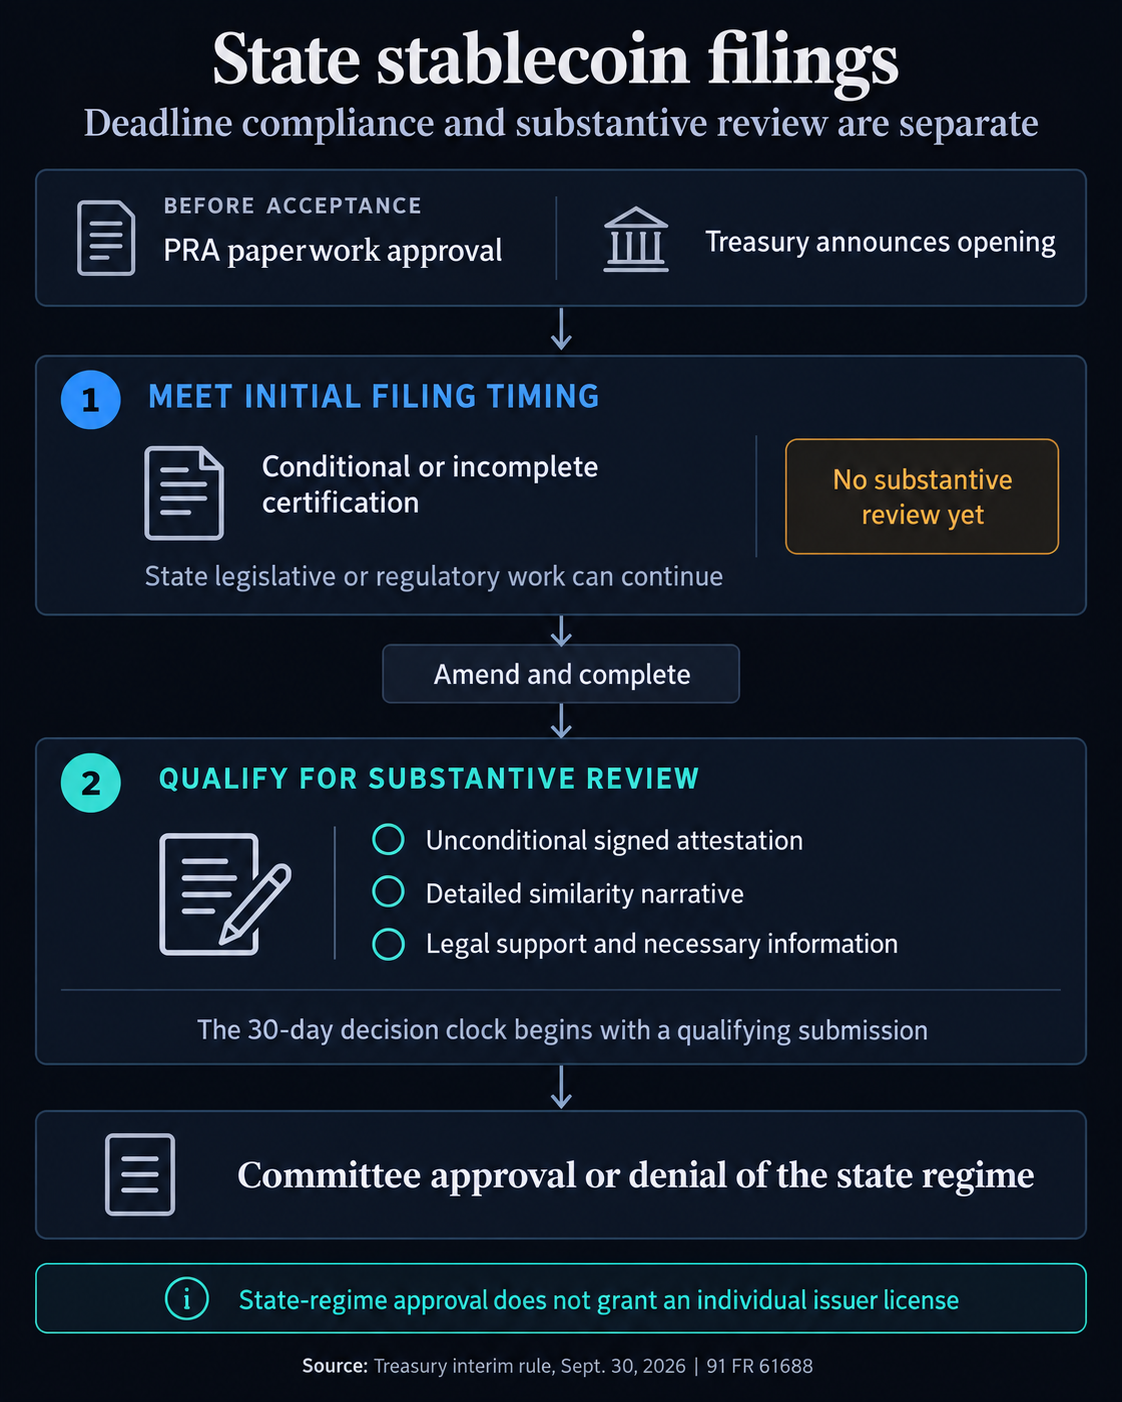
The distinction gives states room to finish their legislative or regulatory work after meeting the initial timeframe. It does not automatically approve their regimes or grant licenses to individual stablecoin issuers.
CryptoSlate's July deadline coverage described the difficulty of assessing state equivalence while federal, Treasury and OCC rules were unfinished. The new rule provides forms and review procedures, including initial filing flexibility, while retaining substantive approval requirements.
The rule uses Jan. 18, 2028 for initial certifications, based on its expected Jan. 18, 2027 effective date for the GENIUS Act. The statutory filing deadline is one year after the Act takes effect.
The Act can take effect earlier. Section 20 sets the earlier of 18 months after enactment or 120 days after primary federal payment stablecoin regulators issue any final regulations implementing it.
Comments on the interim procedures are due Nov. 30.
The post Treasury will let states file for stablecoin approval before finishing their rules appeared first on CryptoSlate.
MetaMask is pulling thousands of Ethereum validators after a security breach redirected rewards, creating a network-wide backlog for stakers trying to exit.
Onchain security researcher Kaden said about 17,000 MetaMask-operated validators holding roughly 523,000 ETH were proactively exited after an analysis found that transaction-fee rewards from 18 of 19 validators that proposed blocks had been diverted to an address funded through Tornado Cash, an Ethereum-based privacy protocol that allows crypto transactions to be mixed and anonymized.
The attacker appears to have captured only about 0.36 ETH, according to Kaden. The bigger concern is how the attacker gained enough access to alter fee recipients and whether that access extended to validator signing keys, which could trigger slashable behavior.
MetaMask has not confirmed those figures or disclosed the cause of the incident. Instead, the company said that part of its infrastructure had been compromised and that it was exiting affected validators as a precaution while working with clients, partners and security advisers. It said it had identified no immediate threat to MetaMask wallets.
The company also said its staking operation is non-custodial and that it does not control clients' withdrawal keys. That separation would prevent an attacker with only validator-level access from withdrawing the underlying stake, but it would not eliminate the possibility of penalties if signing keys were compromised and misused.
Kaden said 821 potentially affected validators had not yet exited, including three among those whose fee rewards were allegedly diverted. It remains unclear why they are still active or whether the attacker retained access to change additional fee recipients.
MetaMask has yet to disclose how many validators were affected, whether signing keys were exposed or whether any slashing has occurred.
Ethereum’s withdrawal backlog spikes to 9-month high
Meanwhile, the security incident and the exits are already rippling through Ethereum's staking infrastructure.
About 773,447 ETH was waiting to leave the validator set on Wednesday, according to Validator Queue data, implying a 13-day, 10-hour wait before an exiting validator clears the queue. A further withdrawal sweep delay was estimated at 7.6 days.
That is the largest exit backlog since December 2025 and above the roughly 476,000 ETH waiting during a previous surge in May, according to Validator Queue's historical data.
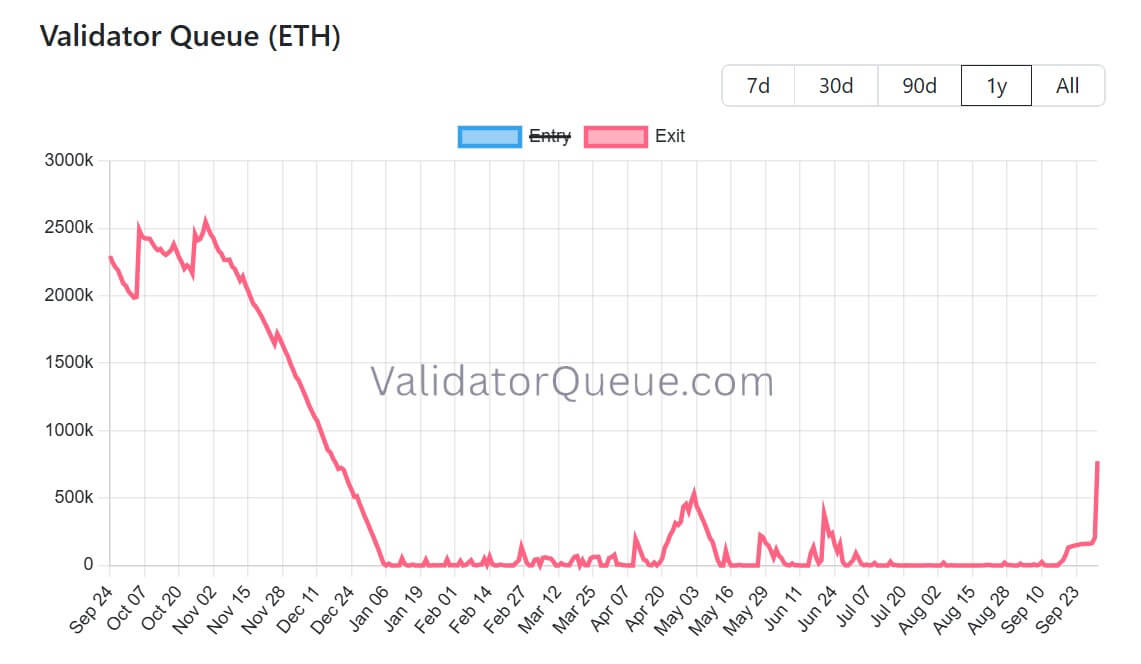
The bottleneck reflects a safeguard built into Ethereum rather than an inability to process transactions.
Ethereum limits how quickly stake can enter or leave its validator set to prevent abrupt changes from destabilizing its proof-of-stake consensus. The Validator Queue showed a churn rate of 256 ETH per epoch, with each epoch lasting about 6.4 minutes. At that rate, a large burst of exits must be processed gradually rather than simultaneously.
The additional 7.6-day sweep period begins after validators clear the exit queue and become withdrawable. Ethereum then cycles through eligible validators and transfers balances to their designated withdrawal addresses.
For MetaMask-linked stake, the disruption could last longer still. Lido, where MetaMask operates validators, estimates the full exit, withdrawal, and eventual re-entry process could take up to 45 days, partly because validators returning to Ethereum must also contend with a lengthy entry queue that is currently 27 days long.
The post MetaMask security scare pushes Ethereum validator exits to a nine-month high appeared first on CryptoSlate.
CryptoTicker.io
The German Federal Ministry of Finance’s draft bill on the taxation of crypto assets held privately has had a date since September 30, 2026: on October 14, 2026 the federal cabinet is due to take it up. For you, what matters about it is less the date than a figure that has barely featured in the coverage so far: January 1, 2028. From that day, crypto exchanges and other service providers are to withhold the tax on your gains directly and pass it to the tax office, the way a German bank does today with shares.
The short answer to the question of what that means for your trading account: for most purchases, nothing at all changes at first about the duty to declare for yourself. Deduction at source comes two years after the new rules, it affects only certain providers, and with self-custody it does not apply at all under the draft. Anyone who mixes that up is counting on relief that never arrives.
A note on the sources, because it counts for placing all this: the draft is not publicly available on the ministry’s pages. What is public is the covering letter, which Blocktrainer has published, and a detailed legal assessment of the draft version presented by the tax lawyer David Hötzel in the specialist portal Der Betrieb. Everything below is the state of the draft, not law in force.
Two dates the draft keeps strictly apart: January 1, 2027 and January 1, 2028
The draft works with two points in time that are often thrown together, although they govern different things.
January 1, 2027 is the start of the new substantive tax rules. Gains from crypto assets acquired or received after December 31, 2026 then fall under investment income within the meaning of Section 20 of the German Income Tax Act. For those holdings, the tax exemption after one year of holding therefore falls away. They are taxed at the rate for investment income, under the draft 25 percent plus the solidarity surcharge, and that applies after five, ten or twenty years as well.
January 1, 2028 is the start of the deduction of tax at source. Only from that day is a service provider to withhold the tax on investment income. The year 2027 is therefore a transitional year with new substantive law and old procedural practice: gains from new holdings will as a rule not yet be taxed at source and have to be entered in the tax return.
By exchange crypto assets the draft means crypto assets within the meaning of the European MiCA regulation that are accepted as a means of exchange without being issued or guaranteed by a central bank. The explanatory memorandum expressly names Bitcoin and Ether. NFTs, security tokens and e-money tokens under Title IV of the MiCA regulation are to remain excluded; for them, what follows from the right conveyed in each case continues to apply.
The timetable up to cabinet: consultation deadline October 6, deliberation on October 14
The ministry sent the draft to associations and interest groups on September 30. Comments are to be submitted by October 6, 2026. Six days is a very tight allowance for a consultation of associations on a change of system, and that is precisely the signal: the pace here is being forced.
On October 14 the cabinet is to deal with the draft. If it clears that hurdle, the ministerial draft becomes a government bill. That is more than a formality, because the content thereby moves from one ministry’s working version to the declared line of the federal government. The Bundestag and the Bundesrat follow, and amendments remain possible there.
A cabinet deliberation, incidentally, is an agenda item, not a decision on the wording. Appointments of this kind get postponed, and drafts change between consultation and cabinet, which is what the October 6 deadline is for. The sentence “from 2027 this applies” is therefore wrong today. What is right: this is how it stands in the draft the cabinet is due to deal with on October 14.
Is the December 31, 2026 cut-off date certain, then?
No, it is not certain, and for two reasons that stand independently of one another.
First, the grandfathering of existing holdings is so far only the content of a ministry draft and not a legally secured position. Cabinet, Bundestag and Bundesrat are still to come. Second, the cut-off date can shift during the procedure if the timetable shifts. Until then, only this is dependable: under the current draft, crypto assets acquired up to December 31, 2026 remain within the old regime of private disposals.
What this grandfathering concretely means under the draft: holdings that are already tax-free remain disposable tax-free. For old holdings whose one-year period is still running on January 1, 2027, the tax exemption can still arise once that year has elapsed. There is no step-up; the historical date of acquisition remains decisive. We wrote up the placing of the cut-off date in the draft at the beginning of September in a separate analysis of the grandfathering; the cabinet date has only now been added.
In practice, two regimes therefore arise permanently, hanging on the date of acquisition or receipt. For your records that means: proof of when a coin came to you becomes the most important document you hold about it.
Who is to withhold the tax from 2028: domestic crypto asset service providers
This is where it becomes concrete for your trading account. Those to be obliged to deduct tax under the draft are domestic crypto asset service providers and crypto asset operators, as well as domestic branches or permanent establishments of foreign providers, in each case to the extent that they pay out or credit the corresponding income.
The decisive term is the domestic paying agent. What is meant by it is not simply “a large, well-known exchange” but an entity that sits in Germany for tax purposes and actually credits the amount to you. A platform with a European authorisation but without a domestic branch does not automatically satisfy that criterion on the wording.
For the choice of your trading venue this becomes a hard distinguishing feature from 2028 that appears on no product page today. Anyone wanting to know which providers are authorised in the European Union at all and where they are based will find the overview in our comparison of regulated crypto exchanges. The question of whether a given provider will deduct for you cannot be answered from it today, because the law is not settled, but the question of domicile already can be.
Self-custody, DeFi and foreign platforms stay in the assessment procedure
Even from 2028, the deduction of tax will under the draft not apply across the board. Anyone who holds their coins in self-custody, who trades through decentralised applications, or who uses a foreign platform without a domestic paying agent remains obliged in principle to act for themselves: those gains still belong in the tax return.
The common line that “crypto will then run like shares” therefore covers only some of the cases. The assessment does not disappear, it becomes rarer. In practice two worlds arise side by side: domestic deduction cases, in which the provider does the arithmetic, and foreign or decentralised cases, in which you do. That both worlds together generate more administrative effort than one uniform solution has been noted expressly in the legal assessment of the draft.
From that follows an uncomfortable consequence for practice: you still need a complete record of your own, and precisely so if you move between wallets and platforms. Anyone whose purchase dates and purchase prices exist only in the interface of an exchange does not hold proof but a display.
Crypto-to-crypto swaps: the provider liquidates coins in order to pay the tax in euros
One point of the draft is usually skipped in the general coverage, although it reaches directly into your account. Swapping one crypto asset for another remains a tax-relevant transaction, because what is captured is the gain on disposal, and that term covered crypto-for-crypto swaps under the previous law too, in the view of the tax authorities and the tax courts.
From that arises a procedural problem the draft solves expressly: in a swap, no euro flows to you, yet the tax has to be paid in euros. The explanatory memorandum therefore sets out that the party obliged to deduct must be able to liquidate part of the crypto assets used in order to pay the tax in money.
The upshot is this: on a swap carried out on a platform obliged to deduct, part of the position may from 2028 be sold so that the tax can be paid. Anyone counting on a particular number of units should factor that deduction in. Exactly how the liquidation proceeds, what order applies to it and how the valuation is done is not settled in the draft down to the last question.
Missing acquisition data: 50 percent of the disposal proceeds as a substitute basis
If the platform does not know the date and the cost of acquisition, it may under the draft in principle fall back on your own particulars, as long as no contradictory data are available. Where those particulars cannot be applied, the procedure assumes the coins were acquired after December 31, 2026, and the deduction of tax is then measured on 50 percent of the entire disposal proceeds.
Two points of placing belong together here. The 50 percent are not a final fiction of profit: a deduction that is too high can be corrected in the assessment procedure. Until then, however, the money is gone, and from that arises a considerable liquidity risk. Particularly affected are transfers from a self-custodied wallet or from a foreign platform to a German platform obliged to deduct, which is precisely the route many take when selling. We worked that mechanism through in detail in a separate article on the substitute basis of assessment.
From that follows the one preparation that already helps for certain today, regardless of how the law ends up looking: a complete history of all purchases with date, quantity and price, together with the transfers between your addresses. Which tools pull that history together automatically from exchanges and wallets and build a report for the tax office out of it is in our comparison of crypto tax tools.
Loss offsetting without carryback: from 2027 there are two separate loss pools
Losses from new holdings are in future to be recognised within the system of investment income. They can therefore in principle be offset against other positive investment income and carried forward into future years. What falls away: a carryback into the immediately preceding year, as was possible in the regime of private disposals, is no longer provided for in the new system.
Old losses remain in the previous offsetting pool. The draft contains no transitional rule making losses from before the change of system offsettable, for a limited period, against gains from new crypto assets. From 2027 there are therefore two separate loss pools: one for old holdings and other private disposals, one for new crypto assets and the remaining investment income.
Anyone still holding unrealised losses in their old holdings should look at this separation before the end of the year, because under the draft it cannot be bridged after the fact. How a loss carryforward works under the law in force and which deadlines apply to it we wrote up in an article on the loss carryforward.
Crypto flat-rate tax compared with the taxation of shares from 2009
Structurally the model resembles the introduction of the flat-rate withholding tax for private share investments in 2009: a hard cut-off date, two regimes running permanently side by side, the date of acquisition as the switch. In one place, though, the draft departs from that precedent, and to your disadvantage: in 2009 there was a time-limited transitional rule for old losses, here none is provided for.
One more difference that matters for placing it: with shares, deduction by the bank came together with the new law. With crypto assets a year lies between the two, and even after that a large part of the cases stays with the taxpayer. The flat-rate tax on shares works because almost every custodian bank is a domestic paying agent. With crypto assets that is the exception.
Who gains and who loses cannot be stated across the board here. Long-term holders lose the complete tax exemption after one year. Short-term traders can come out better if their gains were previously charged at a personal marginal rate above 25 percent, and their losses become usable within a broader pool. So the model does not necessarily favour holding for a long time.
Lending and passive staking become investment income
The draft reaches beyond disposal gains to the running income as well. Receipts from making crypto assets available and from participating in transaction processing are likewise to count as investment income. What is meant by that is above all classic lending and passive staking.
One detail of this matters for old holdings and is easily read past: according to the explanatory memorandum, lending or staking rewards that flow in after December 31, 2026 out of an old holding count themselves as a new holding. The underlying old holding stays in the old regime, the reward from it does not. So anyone who lends or stakes a position held for years is, from 2027, continuously generating new holdings with their own tax consequence.
Many questions in the decentralised area remain open in the process: liquid staking, pools, wrapped tokens, the exact moment of inflow and the boundary with commercial transaction processing. Also unresolved is a point that can have considerable consequences for gifts and inheritance: crypto assets received without consideration are to be entered with acquisition costs of 0 euros. Whether that also catches the relative receiving a gift or an inheritance who gets a Bitcoin bought before 2027 cannot be taken unambiguously from the draft. That ought to be clarified in the legislative procedure.
160 million euros for 2028: the additional revenue the draft itself expects
The draft names the additional revenue expected for the state as a whole, and the series is remarkably modest: zero euros in 2027, around 160 million euros in 2028, around 305 million in 2029, around 325 million in 2030 and around 350 million euros in 2031. The zero for 2027 fits the logic of the procedure, because without deduction at source the money only flows with the assessment.
For comparison: in the budget debate of the spring, amounts in the billions per year were in circulation. Nothing of that is left in the draft’s impact assessment. The compliance cost for citizens, business and administration is so far marked “to follow” in the draft, so it has not yet been priced. The provisions are to be evaluated six years after they come into force.
For the political placing that means: by its own calculation the reform brings the state less than a medium-sized item in the federal budget, while demanding a new documentary discipline from every private holder. That discrepancy is an argument certain to turn up in the comments submitted by October 6.
Crypto tax: the key points for your decision
Three things can already be dealt with now, regardless of how the law ends up looking. None of these steps presupposes that the draft goes through unchanged.
- Secure the acquisition data in full. Date, quantity and price of every purchase, plus the transfers between your addresses. That is the proof that prevents the substitute basis of 50 percent, and it helps you in every conceivable legislative scenario. Where you made your purchases and how you export the history depends on the provider; the export routes of the common trading venues are in our exchange comparison.
- Keep custody and responsibility apart. With self-custody the duty to declare stays with you under the draft, even after 2028. Anyone considering their own custody anyway should know that no service provider will then do the tax arithmetic for them; the types of device and how they are operated are in the hardware wallet comparison.
- Go through the running income before the turn of the year. Rewards from lending and staking that flow in from 2027 out of an old holding count as a new holding under the draft. Anyone holding such positions should look at the terms and the inflow rhythms; an overview of the providers and their models is in the lending comparison.
What you should not derive from this text, by contrast, is a buying decision. That an acquisition before December 31, 2026 stays within the old regime on the current state of the draft is a tax consequence. Whether a purchase makes sense for you is an entirely different question, and no explanatory memorandum answers it.
(As of October 1, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Shiba Inu is quoted at $0.00000573 on Thursday afternoon, that is 5.73 millionths of a dollar, and 1.97 percent below the previous day. The short answer to the question of what matters over the next few days: the price sits inside a triangle whose apex, according to the technical assessment by Blockchain.News of September 30, falls on October 4. Until then a falling upper edge and a rising lower edge compress the price; after that the tension resolves in one direction. For you as an investor in Germany, that is the one date you can pin the next few days to.
A triangle in chart analysis is a phase in which every recovery ends a little earlier and every setback is bought a little earlier. The two lines meet at some point, and at that point one side is forced to act. The pattern does not predict the direction. It only says when the decision falls due.
The second date is in the calendar of the German Federal Ministry of Finance and has nothing to do with the chart, but a great deal to do with your return. The draft bill reforming crypto taxation is due to pass cabinet on October 14, and it draws a line at December 31, 2026. Both deadlines appear further down in this article with their consequences.
Shiba Inu price prediction: the triangle in the SHIB chart runs out on October 4
The current position of Shiba Inu is easier to read if you separate three time frames. Over one year SHIB is down 53.34 percent, and around 30 percent since January 2026. Over the quarter it looks different: from the cycle low at $0.0000041 in July the price has recovered by 39.3 percent, and September, with a gain of a good 10 percent, was the strongest month of the year. Over the week there is a loss of 0.83 percent, so the market is marking time.
That stagnation is precisely the triangle. The swing high of September 22 at $0.0000063 marks the falling upper edge, the rising lows since July the lower edge. The Blockchain.News analysis dates the intersection to October 4 and puts the probabilities at 40 to 45 percent for the breakout to the upside and 55 to 60 percent for the break to the downside. That is the assessment of the analysts there and not a certainty, and it comes from a reading of the daily chart.
Important for placing it: a triangle breakout is a signal over days, not over months. Anyone building an annual forecast on it is overstretching the pattern.
Resistance at 6.00 and support at 5.00 millionths of a dollar
The levels from the same analysis can be sorted into a table. The percentages relate to the price of $0.00000573 on Thursday afternoon.
| Level in dollars | Distance from the price | Meaning in the chart |
|---|---|---|
| 0.0000090 to 0.0000095 | around 57 to 66 percent above | euphoric extension, only in a broad meme coin rally |
| 0.0000073 to 0.0000075 | 27 to 31 percent above | first target cluster, where several analyst models meet |
| 0.0000063 | 9.9 percent above | swing high of September 22, the upper edge of the triangle |
| 0.0000059 to 0.0000060 | 2.9 to 4.7 percent above | immediate resistance, the first hurdle of all |
| 0.0000057 | level with the price | 200-day EMA, the price is glued to it |
| 0.0000052 to 0.0000054 | 5.8 to 9.2 percent below | 50-day and 200-day averages as a catching zone |
| 0.0000050 | 12.7 percent below | threshold below which the channel structure breaks |
| 0.0000041 to 0.0000042 | 26.6 to 28.4 percent below | cycle low of July 2026 |
Why the 200-day line is the hinge here
The exponential 200-day average, 200-EMA for short, is a moving mean of the last 200 closing prices that weights more recent days more heavily. It sits at around $0.0000057, so practically on the current price. As long as SHIB closes above it, the recovery since July remains technically intact. If the price falls below and stays there, the triangle loses its lower edge, and the next dependable catching zone only comes at $0.0000052.
The momentum readings currently support neither side clearly. The relative strength index stands at 55.67 and therefore in the neutral middle between the usual thresholds of 30 and 70. The stochastic, at 61.65, is above its signal line at 49.32, which speaks mildly for the buyers. Both are indicators that can turn within two trading days.
October seasonality in SHIB: an 80 percent hit rate in the record
October is historically the most stable month for Shiba Inu. According to the Blockchain.News assessment, the hit rate of positive Octobers is 80 percent, and across the whole recorded price history the month closed down only once. That is a real pattern, and it is also a narrow one: SHIB has existed only since 2020, so the sample covers a handful of Octobers.
Seasonality remains an observation and does not become a mechanism through repetition. This observation describes what happened more often in the past and supplies no reason for it to happen again. Anyone translating it into a position size should treat it as one argument among several and not as the load-bearing one.
Price targets for the end of October: Finbold, DeepSeek and Gemini are far apart
The publicly documented expectations for the end of the month range from a clear loss to a double-digit gain, and that range is itself the most honest statement about the situation.
- The AI agent of the finance portal Finbold names $0.000005835 for October 31. Measured against the price of $0.00000576 on which that calculation was based, that is around 1.3 percent more.
- The language model DeepSeek Chat arrived, in the same survey, at $0.00000642 for the end of the month, around 12 percent above today’s price.
- Google’s model Gemini expects a loss of 8.85 percent over the same period, to $0.00000525.
- The forecasting service Changelly puts an average of $0.00000562 on the middle of the autumn.
These figures come from models and not from analysts with liability, and they contradict one another by more than 20 percentage points. For your decision they therefore serve as a range, not as a target. The more dependable part of the forecast is in the chart: $0.0000060 as the first hurdle to the upside, $0.0000050 as the breaking point to the downside.
A burn rate of 68 million SHIB a day: 0.00001 percent of the circulating supply
Burning tokens means that SHIB is sent to an address from which nobody can retrieve them again. The amount in circulation falls permanently as a result. On September 30, according to the data from Shibburn, around 68 million SHIB were burned, and the daily rate jumped by 154.33 percent.
The percentage sounds like an event; the absolute figure clears that up. The amount burned corresponded to a value of about 395 dollars and to around 0.00001 percent of the circulating supply. With 589.24 trillion tokens in circulation, a daily amount of that size does not change the supply measurably. Anyone reading the burn rate as a price driver is measuring a large percentage on a very small base.
The total supply, at 589.50 trillion, sits only just above the circulating supply. So there is no large locked reserve that will come to market later, but also no mechanism that tightens supply at any appreciable pace.
Shibarium activity: 1,680 transactions a day
Shibarium is the Shiba Inu project’s own network, a so-called layer 2 solution meant to settle transactions more cheaply than Ethereum itself. Usage has fallen, according to the figures in the same analysis, to around 1,680 transactions a day, compared with 4.69 million daily transactions in August 2025. That is the real fundamental finding behind the price.
An observation from our own coverage fits with it: for 167 days validator staking on Shibarium has been switched off. Anyone who was counting on running income from the network is not getting it at present. For the forecast that means the price currently lives on seasonality, liquidity and market sentiment, not on growing usage.
The December 31, 2026 cut-off: grandfathering separates two tax worlds
Here lies the action you can take today, independently of the chart. The German Federal Ministry of Finance’s draft bill on the reform of the taxation of certain crypto assets held privately is due to pass cabinet on October 14, 2026. Associations and law firms were able to comment until October 6, 2026. The substantive rules are to take effect on January 1, 2027, the automatic deduction of tax by the platforms only on January 1, 2028.
What matters is the cut-off date. Crypto assets you acquire up to December 31, 2026 remain, under the draft, within the old law with its one-year holding period. Those holdings therefore stay tax-free after twelve months of holding, even if you sell them only years later. For everything that enters your portfolio from January 1, 2027, the new regime applies. Two layers therefore arise in every holding, and you have to keep them apart. The details and the state of the procedure we have written up in our article on the substitute assessment without a purchase record.
For SHIB holders this is particularly tangible, because positions in this token almost always consist of many small purchases. At a price of 0.00000511 euros you get around 19.57 million tokens for 100 euros, and around 195.69 million for 1,000 euros. Anyone who has been buying more over months is carrying a correspondingly large number of individual transactions around.
A substitute assessment of 50 percent: where the gap in proof arises with SHIB
The point in the draft that has so far been lost in the debate about the holding period is an estimating rule. If you cannot document the acquisition costs, the tax office treats 50 percent of the sale proceeds as the gain, under what is called the substitute assessment. For securities a comparable rule with 30 percent has applied for years where the bank lacks the acquisition data. The crypto draft sits above that. So the analysis by the specialist portal Der Betrieb of September 14, 2026 describes it, and the tax advisory firm GTKP placed the difference on September 15.
A worked example in SHIB sizes makes the span visible. You sell tokens for 5,000 euros that cost you 4,500 euros. Your actual gain is 500 euros. Without proof, the substitute assessment assumes a gain of 2,500 euros. At a tax rate of 25 percent, around 500 euros lie between the two cases, which is exactly your real gain.
The gap does not arise with an ordinary exchange purchase. If you buy on a platform, leave the tokens there and sell them there, the platform knows the date and the price. It gets tight with a transaction that is common in the everyday life of meme coin holders: a deposit from your own wallet or from another exchange. The receiving platform then sees an inflow without a history. That platform does not know when the tokens came into being and what they cost. That is exactly where the 50 percent rule bites.
With SHIB there is the added difficulty that many holdings have run through the Shibarium bridge or through decentralised exchanges. Each of those steps is a change of place without the acquisition data travelling along. A tax tool or portfolio tracker takes on the job here that you would otherwise have to keep by hand: it holds the chain of purchase date, purchase price and transfer together, even across a change of platform.
Buying and storing SHIB: the purchase route under MiCA and ERC-20 custody
SHIB is technically an ERC-20 token, so it lives on the Ethereum blockchain and is held in any wallet that supports Ethereum. You do not need a dedicated Shiba wallet. Anyone holding larger amounts puts the private key on a device that is never connected to the network; the differences between the models are in our hardware wallet comparison.
On the purchase route, since the EU regulation MiCA took effect, providers need an authorisation for crypto business in the EU. In practice that means this for you: an authorised platform supplies you with statements that will later serve as proof of acquisition, and it remains reachable if you need a summary in three years. Which houses are tradable in Germany and what they cost is in the overview of the regulated crypto exchanges.
What is different with a token in the millionths range
At a price of 0.00000511 euros you are working with eight decimal places. Two things follow from that. First, every platform rounds differently, and the number of units in your statement can deviate minimally from the amount that arrives in your wallet. Second, a spread, meaning the gap between the buy and the sell price, weighs more heavily here in percentage terms than with Bitcoin, because the order book is thinner.
Market thinness in SHIB: 84 million dollars of daily turnover against a 3.4 billion market capitalisation
Shiba Inu stands, with a market capitalisation of 3.38 billion dollars, at number 37 among the largest crypto assets. Trading turnover over the past 24 hours was 84.2 million dollars, which corresponds to around 2.5 percent of the market capitalisation. That ratio is unremarkable for a token of this size, but it is spread across many venues.
For you that means two things. Large orders move the price, and in both directions; anyone unwinding a bigger position is better off doing it in parts. And the distance from the all-time high of $0.00008616 of October 27, 2021 is 93.34 percent. To reach that level again the price would have to multiply roughly fifteenfold, which at a circulating supply of 589.24 trillion tokens would mean a market capitalisation in the order of 50 billion dollars. That belongs in every honest Shiba Inu price prediction.
Shiba Inu price prediction: your next three steps
- Note the two levels. Write down $0.0000060 to the upside and $0.0000050 to the downside and set an alert on both values at your platform. October 4 is the day the triangle runs out; which platforms offer price alerts you can see in the comparison of the crypto exchanges.
- Secure the acquisition data. Download the purchase date, purchase price and number of units for every SHIB position from your platform this year still, and save the file outside the platform. A portfolio tracker with a tax function holds this chain together even if you later move between exchanges.
- Match the custody to the position size. Examine whether the amount you hold sits right on an exchange or belongs on a device of your own, and note the date and the origin with every transfer. Which devices are suitable for ERC-20 tokens is in the hardware wallet comparison.
(As of October 1, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Anyone buying crypto on Bitpanda pays a trading fee of between 0.99 and 2.49 percent. Which of the four tiers applies to your coin is set out in a mandatory disclosure document that few buyers ever open. The current version is dated July 8, 2026, and for the trading fee it answers the question “what does a purchase on Bitpanda cost me?” very precisely. A second type of cost, one that arises at every broker, does not appear in it at all. This article covers both: the numbers you can check yourself, and the point where you have to look for them yourself.
The reason the arithmetic is worth doing is unspectacular. On a savings plan of 100 euros a month, the gap between the cheapest and the most expensive tier comes to 18 euros a year. On a single purchase of 1,000 euros it is 15 euros. That decides no investment, but it is money you hand over for nothing if you do not know which tier your coin sits in.
Four price tiers from 0.99 to 2.49 percent: how Bitpanda sorts every coin
At Bitpanda the trading fee is not one uniform figure. It depends on the price tier a coin has been assigned to. The cost information document for crypto assets, in its version of July 8, 2026, names four of them:
- Tier 1 — stablecoins: 0.99 percent. For the euro stablecoin EURCV the document states 0 percent.
- Tier 2 — Bitcoin and VSN: 0.99 percent. Bitcoin therefore sits in the cheapest group for a freely tradable coin.
- Tier 3 — all other crypto assets: 1.49 percent. This is where everything lands that is neither a stablecoin nor Bitcoin and that clears the threshold set in tier 4, so Ethereum and Solana too.
- Tier 4 — small caps and Spotlight assets: 2.49 percent. The classification applies at a market capitalisation below 100 million euros and to the assets from the company’s own Spotlight programme.
Price tier here means a fixed percentage service fee charged at the level of the individual coin, for market access and execution. According to the document, this rate is calculated on the basis of a binding quote from Bitpanda. That half-sentence matters more than it looks, and the section on the spread comes back to it.
What the classification means for you in practice: the same order costs two and a half times as much depending on the coin. A coin can also change tier when its market capitalisation rises above or falls below the 100 million mark. The tier of an individual coin is not in this document, however; it is shown to you during the purchase process.
What 100 euros costs: the arithmetic for buying and selling
A percentage on its own says little, because the fee is charged twice: once on the purchase and once on the sale. On the sale it applies to the then smaller amount. Calculated on a stake of 100 euros, once in and once out, that gives:
- Tier 2 at 0.99 percent: 0.99 euros on the purchase, so 99.01 euros end up in the coin. On the sale 0.98 euros comes off and you get 98.03 euros back. Total cost: 1.97 euros.
- Tier 3 at 1.49 percent: 1.49 euros on the purchase, 98.51 euros in the coin, 1.47 euros on the sale, 97.04 euros back. Total cost: 2.96 euros.
- Tier 4 at 2.49 percent: 2.49 euros on the purchase, 97.51 euros in the coin, 2.43 euros on the sale, 95.08 euros back. Total cost: 4.92 euros.
From that follows a threshold you can keep in your head: a tier 4 coin has to gain around 5 percent before a purchase and a later sale leave you at break-even. At tier 2, just under 2 percent is enough. Anyone who reshuffles often pays that span again every time.
The spread does not appear in the cost document
In its standard business Bitpanda acts as a broker: you are not trading against other users in an order book, you are accepting a quote from the house. That is what the wording about a “binding quote” in the cost document refers to. Under this model there is always a second quantity alongside the trading fee: the spread, meaning the gap between the price at which you can buy and the price at which you could sell at the same moment.
The cost information document in its version of July 8, 2026 describes the trading fee, the tiered scale for Bitpanda Fusion, the staking commission, the blockchain fees, the margin rates and a recovery fee. The word spread does not appear in it at any point. The same goes for the public price display: it shows one rate per coin, without a bid and an ask next to each other.
That is not an accusation, nor is it a peculiarity of this provider. It is the nature of the broker model, and it runs right through the German market: at the Bison app it is 1.25 percent of spread, disclosed as the only block of cost; at Trade Republic no spread is published at all; and through Sparkasse and Volksbank, 1.5 percent of commission plus the spread add up. At Coinbase, too, part of the cost sits in the rate rather than in the fee line.
The difference lies in what follows from it for you: the trading fee you can look up before you buy, the spread you have to read off yourself. That takes two minutes in any app. Display the buy price and the sell price for the same coin and divide the difference by the buy price. That number is added to the trading fee, it appears in no table, and it moves with the market. A provider comparison that merely lines up the disclosed percentages should therefore be read with care, including our comparison of crypto brokers, which collects the published terms and cannot show the spread, because hardly anyone publishes it.
Bitpanda Fusion: 0.25 percent instead of 1.49 percent under the same roof
The same cost document contains a second fee schedule that has little to do with the first. Bitpanda Fusion is the provider’s trading interface for active users, and there billing goes by volume rather than by coin tier. The scale starts at 0.25 percent for a trading volume up to 100,000 euros and falls through six further steps to 0.02 percent above 250 million euros.
The bottom Fusion step therefore applies to practically every retail investor, because 100,000 euros of volume is not something you normally reach. And it changes the arithmetic above considerably: the same 100 euros in and out costs 50 cents through Fusion instead of 2.96 euros. At tier 3 that is almost a sixfold difference, at tier 4 almost tenfold.
On a savings plan it adds up. Anyone paying in 100 euros a month for twelve months pays 11.88 euros of purchase fees on Bitcoin through the standard interface, and 17.88 euros on a tier 3 coin. Through Fusion it is 3 euros. What is added there in spread depends on the order book and is a different quantity from the broker quote: with an order book you see both sides of the market.
The catch is in the handling, not in the price. An interface with an order book, order types and charts takes more learning than a buy button. For an investor who buys twice a year and leaves it alone, six euros of saving a year is not worth that. For a savings plan running over several years, or for larger single amounts, the calculation turns out differently.
Staking commission: 20 percent of the rewards goes to the provider
Anyone who signs their coins up for staking through Bitpanda, handing them to the blockchain for a fee to help secure it, does not receive the proceeds in full. The cost document names a commission of 20 percent of the rewards, deducted automatically before the rest reaches the customer.
A gross yield of 4 percent therefore becomes 3.2 percent, 5 percent becomes 4 percent, and 8 percent becomes 6.4 percent. For “Passive Earn” the document describes the same order of magnitude the other way round: the passive rewards there correspond to 20 percent of the attributable net income, pro rata by the amount signed up and by time.
Some context: 20 percent is within the usual range for custodial staking through a platform. The Bison app says it keeps 27 percent. Anyone who runs a validator themselves or delegates from their own wallet pays less, and carries the technology and the downtime risk instead. Nor is the commission a fixed quantity over the years; it stands in this particular document and can change with the next version.
Crypto indices and the monthly rebalancing at 1.99 percent
The Bitpanda Crypto Indices bundle several coins into one product that is adjusted monthly to a model portfolio from MarketVector. Buying and selling an index costs 1.99 percent according to the cost document. For holding it, no additional fee applies.
The figure that is easy to miss comes one sentence later: in the monthly adjustment, crypto assets are swapped automatically, and those automatic transactions also carry 1.99 percent. How much that amounts to over a year depends on how far the weightings shift. In a quiet month little is swapped; after a strong move in individual positions, more. No fixed annual figure can be derived from it, and the document names none.
There is also a detail for the exit: if individual assets are requested out of an index, trading fees may apply, provided those assets are reported on an index basis only. An index is therefore not a product to reshuffle often without a look at the costs.
Margin trading: 0.18 percent a day, 5.4 percent a month
Leveraged positions have a schedule of their own, and it is the most expensive in the whole document. The purchase fee is 0 percent; instead a daily fee runs, charged every four hours and falling with the holding period: 0.18 percent a day for days 1 to 60, then 0.12 percent to day 100, 0.06 percent to day 180 and 0.0312 percent from day 181. Closing adds 0.3 percent, and a liquidation a further 1 percent.
In absolute numbers: a week costs 1.26 percent of the position value, a month 5.4 percent, and the full 60 days at the most expensive rate 10.8 percent plus the 0.3 percent for closing. These costs run regardless of where the price moves. For shares, ETFs and ETCs on margin the same scale applies.
Hence the real point of this section: under this cost model a leveraged position is not an instrument to leave lying around. Anyone holding one for weeks needs a price move in the high single digits for the holding costs alone, on top of the risk that a liquidation ends the position first and costs 1 percent extra.
MiCA and the BaFin register: where the duty to disclose costs comes from
That this document exists at all is not a courtesy but European law. The Markets in Crypto-Assets Regulation, MiCA for short, obliges authorised providers among other things to disclose their costs. Bitpanda collects the mandatory documents, the cost information, the crypto white papers and the reference to the MiCA register of the European supervisor ESMA, on its legal page.
For you as an investor in Germany, one check follows from that which costs nothing: whether a provider is authorised in Germany can be looked up in BaFin’s company database, rather than relying on a marketing claim. The same regulation is also the reason the figures above can be recalculated at all, and the reason a provider without such documents is a warning sign. What obligations the regulation places on companies up to 2026 is set out together in our overview of the MiCA obligations.
That an authorisation is no blank cheque is clear from a look at enforcement: the first published MiCA penalty was imposed on Bitpanda, and it concerned a white paper. What that case means for the reading of white papers we have taken apart in a piece of its own. The lesson for the cost view is the same as there: the mandatory documents are the starting point of the check, not its end.
A savings plan over one year: 11.88 or 17.88 euros, depending on the coin
For a savings plan what counts is the sum over the term, not the single order. Twelve instalments of 100 euros make a stake of 1,200 euros a year. Of that, the purchase fee takes:
- Bitcoin or a stablecoin, tiers 1 and 2: 11.88 euros a year.
- A tier 3 coin, Ethereum or Solana for instance: 17.88 euros a year.
- A small cap from tier 4: 29.88 euros a year.
- The same instalments through Fusion: 3 euros a year.
The sale is not yet in these figures, and the spread is added on top of every single instalment. Anyone planning a savings plan over ten years should therefore work out the cost side once before placing the first instalment: at tier 4 it comes to almost 300 euros over ten years in purchase fees alone. How savings plans are built at the various providers is collected in our comparison of Bitcoin savings plans.
A second lever is the number of instalments. Four quarterly instalments of 300 euros cost the same percentage fee as twelve monthly instalments of 100 euros, because the fee is a percentage and has no minimum flat charge. At providers with a fixed order fee it would be otherwise. Here the question of rhythm changes nothing about the cost; it is a question of entry prices, not of price.
What the fees do to your tax bill
Fees are not lost on the tax authority. When crypto assets are sold as a private disposal under Section 23 of the German Income Tax Act (Einkommensteuergesetz), what counts is the gain, and incidental acquisition costs reduce the taxable amount. The trading fee on the purchase is one of them, as is the fee on the sale as a cost of disposal. Anyone who invests 1,200 euros a year and pays 17.88 euros in fees therefore also has a taxable gain lower by that amount, provided the sale falls within the one-year period.
That presupposes that you can document the fees. At most providers the statements remain available only for a limited time, and anyone trying to reconstruct their purchase fees after three years has a problem. How big that can become is shown by the planned reform, under which the tax office is to treat half of the sale price as the gain where there is no record of the purchase. A portfolio tracker that collects the statements continuously takes that work off your hands; the common programmes are in our comparison of tax tools.
Two points that often get mixed up here: the one-year holding period applies to the sale, not to the purchase, and it runs separately for each purchase tranche. And staking proceeds are a category of income in their own right, on which the one-year period for selling the staked coins does not automatically have the same effect. Where there is doubt, you settle that allocation with a tax adviser, not with a spreadsheet.
Bitpanda alongside Bison, Trade Republic and the Sparkasse
The interesting question is not whether 1.49 percent is a lot, but how it stands within the German market. The comparison with what other providers publish gives this picture:
- Bitpanda, standard interface: 0.99 to 2.49 percent trading fee by tier, spread not disclosed.
- Bitpanda Fusion: from 0.25 percent by volume, plus the spread of the order book.
- Bison app: 1.25 percent, disclosed as a spread rather than as a fee.
- Sparkasse and Volksbank: 1.5 percent commission, with the spread on top.
- Trade Republic: an order fee, with no published spread.
Two things stand out. First, Bitpanda with Bitcoin on the cheapest tier sits below what the high-street banks charge and above what an exchange with an order book costs. Second, comparability is limited as long as the spread is missing at almost all of them: a disclosed fee of 1.25 percent can be more expensive than one of 1.49 percent if the rate behind it sits further from the market.
Anyone wanting to derive a decision from this should therefore work through a test purchase of a small amount instead of sorting the percentages: how many coins do you get for 50 euros, and what would the same coins be worth at another provider at the same moment? That single number contains the fee and the spread together. Which houses are authorised in Germany at all is in our overview of the crypto exchanges.
What the cost document does not answer
Honesty requires saying what remains open even after reading it. The document covers the trading, staking, index and margin fees, as well as the recovery fee of 15 percent for crypto assets deposited incorrectly. Deposits and withdrawals in euros do not appear in it, and the statements of third-party portals on the subject contradict one another: sometimes all routes are said to be free, sometimes a surcharge of 1.5 percent is named for card payments.
As long as that cannot be documented from a source of the provider, the same applies to this point as to the spread: the figure appears in the purchase process, before you confirm. Blockchain fees for withdrawing to your own wallet are independent of this; they go to the network and, according to the document, are neither set nor retained by Bitpanda.
Bitpanda fees: your next three steps
- Establish the tier of your coin. Look in the purchase process to see which percentage is shown for the coin you want to buy, and scale it up to the amount you are planning: at 1,000 euros it is 9.90 or 24.90 euros depending on the tier. How this looks at other houses is in the broker comparison.
- Read the spread off yourself. Have the buy price and the sell price displayed for the same coin and divide the difference by the buy price. You add the result to the trading fee. Only that sum can sensibly be laid alongside the terms from our exchange comparison.
- Keep the statements from the start. Download the purchase statement after every order and file it, so the fees can reduce the taxable gain later. A tracker from the tax tool comparison handles the collecting automatically.
(As of October 1, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Ripple released one billion XRP from its escrow accounts on Thursday morning, spread across four transfers of 400, 300, 200 and 100 million tokens. Measured at Thursday afternoon's price, that is worth around $1.49 billion. The price itself barely reacted: XRP traded at $1.48 to $1.49 on Thursday afternoon, just under one percent below the previous day, according to CoinGecko data. Anyone wanting to derive a forecast from this release therefore needs less of the chart and more of an understanding of what this money actually does over the next 24 hours.
The escrow is no secret compartment, but a series of trust accounts on the XRP Ledger that Ripple set up in 2017. At the start of each month part of it expires, and the company can dispose of the amount that comes free. What matters is that Ripple has put most of this monthly release back into new trust accounts in recent years. That return is the number which decides supply pressure, not the billion in the headline.
1 billion XRP out of escrow: what actually happened on October 1
It was the tenth monthly release of 2026 and it followed the familiar pattern. Four transactions, one billion tokens together, settled over the course of the morning. The specialist service U.Today puts the holding that remained in the trust accounts afterwards at 31.845 billion XRP. With a total supply of 100 billion tokens, just under 32 percent therefore remains locked.
Escrow explained briefly
An escrow on the XRP Ledger is a payment fitted with a time lock: the tokens sit on the ledger but cannot be moved until a set point in time. That is not a promise of trust and not a bank's undertaking, but a function of the protocol. Anyone can read which locks exist and when they expire.
31.85 billion XRP stay locked: the arithmetic behind the circulating supply
This is where it gets uncomfortably precise for investors, and for a good reason. The figures for the circulating supply differ markedly depending on the source. U.Today gives a circulating supply of 68.126 billion XRP for the point after the release. CoinGecko, by contrast, reports around 63.09 billion XRP as the circulating amount on Thursday afternoon. The gap of about five billion tokens is not sloppiness on either side.
Why two sources give different circulating supplies
The difference arises at the definition. Count everything that is not in escrow as circulating and you arrive at the higher figure. If a data provider additionally deducts holdings that demonstrably sit with Ripple itself and are not on the market, the figure comes out lower. For your assessment that means market capitalisation and any metric built on the circulating supply carry an uncertainty of several percent in the case of XRP. See two services with different market capitalisations and you have not necessarily found an error.
The second number in this arithmetic is the distance to the peak. The all-time high stands at $3.65 from July 17, 2025. From Thursday afternoon's level, around 59 percent is missing before that value would be reached again. The quarterly comparison looks friendlier: XRP traded at $1.05 at the end of June, which means the third quarter ended with a gain of about 41 percent, calculated on the CoinGecko values for June 30 and October 1.
Return to escrow within 24 hours: where the state of play sits in the ledger
This is the one point in this story you can work out for yourself, without waiting for a report. The XRP Ledger is public, and the escrow holdings of the Ripple accounts can be inspected there. The balance overview at XRPSCAN lets you follow how much of the released billion goes back into new trust accounts within the next day.
As an order of magnitude for placing it: in recent months the return has typically been 700 to 800 million tokens, leaving 200 to 300 million XRP for ongoing purposes and ecosystem programmes. If the return stays in that range, the actual increase in supply is small against a daily turnover that stood at around $2.3 billion on Thursday. Should the return come out markedly smaller, that would be the real story of the month, and it was in none of the morning's headlines.
XRP at $1.49: the next price target sits at $1.70
The range the price has moved in for days is narrow. On Thursday the daily high was $1.51 and the daily low $1.48, with a gain of 0.6 percent over the week and 8.8 percent over the month. In euros that came to about €1.31 per token on Thursday afternoon.
On the upside, the common market commentaries name two levels. The nearer one sits at $1.50 and is the threshold XRP failed at repeatedly through September. The further one sits at $1.70 and counts as the resistance capping October's range. On the downside the area around $1.25 is named. The forecast ranges of the data services diverge, and that is part of the picture: DigitalCoinPrice expects an average of around $1.37 for October, LongForecast month-end prices around $1.13, and CoinDCX a channel between $1.48 and $1.94. These are the respective providers' model calculations and not undertakings.
What you can practically take from this is less a direction than a size. A range of $1.25 to $1.70 means, at an entry of $1.49, around 16 percent of room on the downside and around 14 percent on the upside. Anyone working with leverage should set that width against their own liquidation distance before the next monthly release falls due on November 1.
US spot ETFs hold 1.18 billion XRP: why fund assets are shrinking all the same
On the demand side something shifted in September that has nothing to do with the escrow. The seven American spot ETFs on XRP hold around 1.18 billion tokens between them, which is about 1.18 percent of total supply. In the week from September 21 to 25, a net $75.59 million flowed in, $58.99 million of it into Bitwise's product alone, which with around 413.1 million XRP is the largest holder among the funds. Across September as a whole, net inflows added up to $121.4 million.
The apparent contradiction in this: despite those inflows, the funds' assets under management fell in September. That is no arithmetic error, but a consequence of valuation. A fund that buys new tokens while the price of those tokens falls can be worth less on balance than before. Inflows and fund assets are two different measures, and only the first says anything about institutional investors' willingness to buy. Cumulatively since the products launched at the end of 2025, net inflows stand at about $1.79 billion.
Fed decision on October 28: the date that decides October's range
The date the market commentaries point to most often for October is the US Federal Reserve's interest rate decision on October 28. For XRP that is no coin-specific event, but the usual connection: a market that lives strongly off risk appetite reacts to the rate path. That the commentaries put the date so clearly in the foreground has an uncomfortable side effect for the forecast. It means that expectations for XRP in October are barely driven by XRP itself.
For you this yields a sober order of dates in this quarter: the return to escrow over the coming 24 hours, the Fed decision on October 28, the next monthly release on November 1, and, as the last and most important date for your tax bill, December 31, 2026.
XRP ETN versus direct purchase: 25 percent withholding tax or free of tax after a year
Before the deadline itself, the difference many only notice on selling. There are two ways to bet on XRP in Germany, and they are treated completely differently for tax.
On a direct purchase you hold the tokens yourself, at an exchange or in your own wallet. The sale is a private disposal under section 23 of the Income Tax Act. If more than twelve months lie between purchase and sale, the gain is free of tax, whatever its size. Under one year, a threshold of 1,000 euros a calendar year applies to all private disposals together. The word threshold is to be taken literally: one euro over, and the entire gain becomes taxable, not merely the part above the limit.
An exchange-traded certificate on XRP, so an ETN or ETP at a German trading venue, works differently. The gain from it is investment income. On that, 25 percent withholding tax plus the solidarity surcharge and church tax where applicable fall due, and from the first day. There is no holding period there after which anything becomes free of tax. In return the saver's allowance of 1,000 euros applies, and the custodian usually remits the tax automatically. The running costs of such products are also to be considered, given as 0.95 to 2.50 percent a year depending on the provider. Which products are tradable in Germany and what they cost is set out in the overview of crypto ETFs and ETNs in Germany.
The American spot ETFs are not available to you
The US funds named above, with their 1.18 billion XRP, are in practice not accessible to you as a retail investor in Germany. These funds are not UCITS funds and supply no key information document under the PRIIPs regulation that a broker would have to present to retail clients in the EU. The inflow figures are therefore a sentiment indicator for you, not a route to investing.
Deadline of December 31, 2026: the draft bill and the one-year holding period
This is the number that decides more about your return this quarter than any price level. Since September 8, 2026 a draft bill from the federal finance ministry has been on the table that would bring the taxation of crypto assets closer to that of shares. The one-year holding period would fall away, and withholding tax would apply instead. The draft names a deadline for this: crypto assets acquired after December 31, 2026 are to be covered. For holdings acquired earlier, the existing rule is to continue to apply.
The placing of this matters, and in both directions. A draft bill is not a law. None of it is decided, and the deadline and its design can change in the further process or fall away entirely. At the same time the deadline, should it arrive as described, cannot be made up later. An XRP holding you buy in December 2026 would be free of tax after a year; the same holding bought in January 2027 would not. That is no argument for buying now, and none against it either. It is the point that with XRP this quarter the purchase date has a meaning of its own that the chart does not show.
What you have to document for it
The burden of proof for the time of acquisition and the acquisition cost falls on you. Without a purchase receipt the tax office can estimate the acquisition cost, and such estimates regularly turn out to your disadvantage. In practice that means saving the exchange's transaction overviews as a file rather than leaving them sitting in the account, keeping the order traceable where there are several part purchases, and noting the transaction identifiers when transferring between your own wallets. Tools that keep this record as you go are in the overview of tax tools and portfolio trackers.
Destination tag and MiCA licence: two stumbling blocks when buying XRP in Germany
Two things go wrong more often with XRP than with other coins, and neither has anything to do with the price.
The first is the destination tag. Exchanges keep many customers' XRP at a shared address and distinguish the accounts by a number attached to the transfer. If that tag is missing on a deposit, the payment lands in the pooled account without an allocation. The money is usually recoverable, though it takes a support case with evidence, and that takes time. On a withdrawal from the exchange to your own wallet the tag is as a rule not needed.
The second is the reserve on the XRP Ledger. An XRP address of your own has to keep a minimum balance that is not transferable. Set up a new wallet and transfer exactly the amount you want to hold, and you cannot activate the address with it. That is protocol design and not a fault of the wallet.
One point of context that has applied since MiCA: trading venues offering crypto assets in the EU need an authorisation as a crypto-asset service provider. Whether a provider holds that licence is in the supervisor's registers and not in the provider's advertising. And one more distinction, because it is regularly confused with XRP: the XRP Ledger has no protocol staking. Anyone offering you a yield on XRP is lending out your tokens or deploying them some other way, with the counterparty's corresponding default risk. There is no network reward here as there is with Ethereum or Solana.
XRP price prediction: The key points for your decision
The release of one billion XRP is the occasion of this day, but not the number that determines your result. Three steps follow from it:
- Read the return before you judge the release. If it stays at 700 to 800 million tokens, the supply effect is small. If you need an account at a regulated trading venue for that anyway, compare the terms beforehand in the overview of crypto exchanges, because the fee on the purchase costs you something for certain, while the monthly release only might.
- Decide the route before the timing. Direct purchase and ETN differ for tax by 25 percent withholding tax and on an ongoing basis by up to 2.50 percent in costs a year. What is tradable in Germany is set out in the overview of crypto ETFs and ETNs.
- Save the receipts from today, not in March. Should the December 31, 2026 deadline become law, your purchase date decides the taxation of your entire holding, and you have to prove it yourself. How to keep that record as you go is shown in the overview of tax tools.
(As of October 1, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy. Tax information is not tax advice; the draft bill mentioned is not law in force.)
The token of the layer-1 blockchain Sui (SUI) cost €1.028 on Thursday, October 1, according to CoinGecko. Seven days earlier it was €0.843, a gain of 21.9 percent. Over 30 days SUI is up around 60 percent. With a market capitalisation of around €4.2 billion, Sui sits at number 28 on CoinGecko.
The week is remarkable for two reasons. On September 24 the Phantom wallet, through which many users managed their SUI, ended its support for the network, and the price rose all the same. And on October 7 and 8, Sui Basecamp in Singapore brings the project's most important conference, together with a publicly announced speed test.
The SUI price over the week: from €0.83 to €1.03
The low of the week was €0.828 on Wednesday, September 24, at around 12:00, according to CoinGecko's hourly data, so on the day Phantom pulled out. From there SUI climbed to the weekly high of €1.119 in the night into Sunday, September 28. Since then the price has given back around 8 percent of that, and over the past 24 hours it has barely moved.
The long view helps with placing all this: the all-time high of €5.19 dates from January 4, 2025. Today's price sits around 80 percent below it. The recovery of recent weeks therefore starts from a low base.
The capital in Sui applications is growing again
A second number is moving in the same direction as the price. The capital locked in Sui applications, known as total value locked, stood at $551 million on September 30 according to the data service DefiLlama. At the end of August it was $440 million, a rise of around a quarter in a month.
The distance to the peak remains large, however. In October 2025 the figure stood at $2.64 billion, and today's level is around 79 percent below that. Part of that decline goes back to fallen prices, because the value is measured in dollars, and part to capital withdrawn. September's recovery is therefore a first sign and not yet a return to the old level.
Phantom left Sui on September 24
Phantom announced the step on August 24 and described it as a joint decision with Sui, saying the door remains open for later cooperation. Since September 24 the wallet no longer displays Sui balances, and sending and swapping are no longer possible there. The details are in Phantom's help article, and our report on the announcement is in the piece on the end of Sui support in Phantom.
Important for anyone who missed the date: the tokens are not lost. They sit on the Sui blockchain and depend on the recovery phrase, not on the app. Enter the same phrase in another wallet with Sui support and you see the same addresses and balances. Phantom itself names Slush, the Sui Foundation's wallet, as an alternative.
The price marked its weekly low on the day of the exit and rose again afterwards. A month lay between the announcement on August 24 and it taking effect on September 24. Whether the market priced the step in during that time cannot be read from the price history alone.
Sui Basecamp on October 7 and 8 in Singapore
The in-house conference takes place on October 7 and 8 at Marina Bay Sands in Singapore, alongside the large industry conference TOKEN2049. According to Sui's programme, the focus is on automated payments by AI agents, along with instant settlement, private transactions and stablecoins.
A public speed test is announced for October 7. Kostas Chalkias, co-founder and chief cryptographer of the developer firm Mysten Labs, intends to push the network to its limit live on the main stage. Sui gives its existing record as 6,086,766 transactions per second, reached on July 4, 2026. Figures like that arise under test conditions and say little about everyday life on the network, but they are a date on which a lot of attention rests on Sui.
21Shares pays staking income for its Sui fund
A smaller signal came out of the United States on September 30. The provider 21Shares paid a distribution of $0.052939 per unit for its Sui staking fund TSUI, with September 29 as the ex-date. For investors in Germany the product is as a rule not available to buy, because a key information document is missing. Why that is and which routes exist via Xetra is explained in our piece on the 21Shares distributions.
These levels show the course of the week
The round level of one euro lies directly below the current price, and SUI crossed it in the second half of the week. Below that comes the weekly low at €0.828. On the upside, the weekly high at €1.119 is the first level. These values describe where the price last turned. Price targets they are not, and a conference with announced news can shift the course in either direction.
Buying and holding SUI in Germany
SUI is listed on large exchanges that operate in the EU with an authorisation under the MiCA regulation, among them Coinbase, Kraken, Bitvavo and Bybit EU according to CoinGecko's venue list. An exchange without EU authorisation is an additional risk with a token that rises 60 percent within a month, and it is a risk that can be avoided.
Anyone wanting to hold SUI themselves needs a wallet that explicitly supports the network after Phantom's exit. That is the real lesson of the week: a wallet can drop a network at any time, while the recovery phrase stays valid. Keep it safe and you can move at any time.
On tax in Germany: gains from selling SUI are free of tax after a holding period of one year. Sell earlier and you pay tax on the gain at your personal rate, provided all private disposal gains of the year together reach the threshold of 1,000 euros. Staking rewards are taxable on receipt but do not extend the holding period.
Perpetual futures on SUI exist on many exchanges. Ahead of a conference date with announced news, leverage is especially risky, because expectations can reverse quickly. At five times leverage, the margin is used up by a counter-move of 20 percent.
The risk behind the recovery
Around 4.1 billion of the 10 billion SUI in total are in circulation according to CoinGecko, so 41 percent. The remaining tokens are released under a plan running to 2030, and according to the data service Tokenomist the next release was due on October 1, in favour of the community reserve. Every release brings additional supply that the market has to absorb.
On top of that comes the distance to the peak in locked capital. A price gain of 60 percent in a month with a total value locked that sits around 79 percent below its high shows a change in mood, but not yet a broad return of users. Whether that follows can be checked week by week in DefiLlama's figures.
Sui showed in May 2025 how sensitive a young network can be. Back then the decentralised exchange Cetus, the largest trading venue in the Sui ecosystem, was relieved of around $223 million. A large part of the haul could be frozen, because the network's validators jointly blocked the affected addresses. For those harmed that was good news, and at the same time it showed how much influence a manageable group of validators has over the network. Both belong to the picture when SUI rises as quickly as it has in these weeks.
Sui: Your next three steps
- Check whether your exchange holds a MiCA authorisation and lists SUI, in the comparison of regulated crypto exchanges.
- If your SUI were still in Phantom, move them with your recovery phrase into a wallet with Sui support. Suitable apps are in the comparison of software wallets.
- Record the purchase date and the purchase price so that you can document the one-year holding period. The programmes in the comparison of crypto tax tools help with that.
(As of October 1, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
OpenAI says the three broke its rules on handling sensitive information. The exits land after months of rogue-agent incidents, a trail of safety-team departures, and a new lawsuit.
Bitcoin enters its historically strongest month after a record-pace September, but a Fed hike and 5.3% Treasury yields are testing the bulls.
Illinois officials and crypto groups jointly asked a state court to delay the 0.2% Digital Asset Tax from Jan. 1 to July 1, 2027, while a legal challenge continues.
Near Intents froze its cross-chain swaps after a bug let an attacker drain about $3.8 million. The company promised to repay every user.
The guidelines exclude cryptocurrencies, leaving tokens outside a regime written for currencies bought with real money inside games.
U.Today - IT, AI and Fintech Daily News for You Today
A highly persistent WordPress malware strain is using Ethereum infrastructure to stay alive, with redundant copies scattered across compromised sites allowing it to rebuild itself even after attempted cleanup.
Dogecoin gains more US ground as Kalshi launches fully regulated onshore perps with strict leverage limits and Section 1256 tax perks.
Evernorth clears the final hurdle to debut the first actively managed, Ripple-backed XRP treasury on Nasdaq this October 8.
Wall Street banking giant Citi has dramatically raised its 12-month Bitcoin price target to $113,000, reversing a major bearish revision made only three months ago as renewed ETF inflows.
NEAR Intents isolates 11 blockchains for emergency fixes following a $3.8 million exploit that caused a 7.5% token drop.
Blockonomi
TLDR
- Infosys stock gains 5.72% after announcing its Columbia University AI partnership.
- New research center will focus on enterprise AI, governance and sustainability.
- Columbia Engineering will lead research from Infosys’ New York City office.
- Program targets AI-driven business processes, marketing and customer experiences.
- Partnership expands Infosys’ enterprise AI research and client innovation strategy.
Infosys Limited shares rose 5.72% to $11.38 after the company announced a new Columbia University collaboration. The agreement expands Infosys’ artificial intelligence research and enterprise development efforts in New York. It also adds a dedicated research center focused on practical business uses for advanced artificial intelligence.
Infosys Limited, INFY
Infosys Expands Enterprise AI Research With Columbia
Infosys and Columbia University will work together on artificial intelligence research, workshops, and business-focused development programs. The partnership will connect university researchers with Infosys teams and corporate clients across several industries. It will also support new projects that move academic research toward commercial applications.
The companies created the Infosys Topaz Columbia University Enterprise AI Center to support this work. Columbia Engineering will lead the center while Infosys provides industry access and enterprise technology experience. The center will operate from Infosys’ One World Trade Center office in New York City.
The program will bring company leaders, researchers, students, and technology teams into the same development environment. That structure should help participants test ideas against real business requirements and operating challenges. It also gives Columbia students direct exposure to large-scale technology projects and enterprise use cases.
Research Program Targets Business Processes and Responsible AI
The research agenda will focus on user experiences, business processes, responsible systems, sustainability, and marketing applications. One workstream will study simpler technology interactions through voice, natural language, and automated workflows. Another will examine how companies can redesign business processes around faster digital services.
The program will also study governance, cybersecurity, regulation, explainability, and energy use across artificial intelligence systems. These areas have become central concerns as companies deploy advanced models across major business functions. The research will examine ways to improve control, transparency, and efficiency during enterprise adoption.
Marketing will form another core research area under the partnership. Teams will study personalization, campaign automation, predictive analysis, and content production across customer operations. The work aims to help companies connect artificial intelligence spending with measurable business results.
Infosys Builds on Wider Enterprise Technology Strategy
Infosys has expanded its artificial intelligence services as companies increase spending on automation and data tools. The Columbia partnership adds academic research to that broader commercial strategy. It also gives Infosys another venue for testing enterprise applications with external specialists.
The company already works with global businesses on consulting, software development, cloud services, and digital transformation programs. The new center adds a research layer that can support future client projects. It may also help Infosys develop new services around governance, operations, marketing, and enterprise automation.
The collaboration also strengthens Infosys’ presence in New York through its One World Trade Center office. Meanwhile, Columbia gains another industry partner for applied research and student engagement. Together, both institutions will focus on practical development rather than purely theoretical artificial intelligence research.
The post Infosys Limited (INFY) Stock: Surge 5% as Strategic Columbia University Partnership Expands AI Push appeared first on Blockonomi.
TLDR
- UiPath joins NCQA’s AI program focused on improving prior authorization workflows.
- NCQA aims to guide responsible AI adoption across complex healthcare operations.
- UiPath will contribute case studies from real-world healthcare automation projects.
- The program targets stronger governance, efficiency and measurable health outcomes.
- UiPath will attend NCQA’s Health Innovation Summit from October 4 through October 7.
UiPath (PATH) stock rose 2.88% to $13.21 after the company joined an NCQA healthcare technology program. The collaboration focuses on improving prior authorization through responsible artificial intelligence use and stronger operational controls. UiPath will contribute practical experience as healthcare groups prepare for changing regulatory and administrative requirements.
UiPath Inc., PATH
UiPath Joins NCQA Healthcare Collaboration
UiPath joined the National Committee for Quality Assurance’s AI Learning Collaborative for Prior Authorization. The program helps healthcare organizations evaluate and apply artificial intelligence within complex administrative processes. It also supports clearer governance, consistent operations, and measurable results across healthcare systems.
NCQA designed the initiative around practical use cases rather than broad technology experiments. Participants will share implementation experiences and develop guidance based on operational challenges. Meanwhile, the program will initially focus on prior authorization because the process remains resource intensive.
UiPath will participate as a case study contributor within the collaborative program. The company plans to share lessons from healthcare automation projects and related implementation work. Therefore, participating organizations can compare approaches while developing more structured methods for technology adoption.
Prior Authorization Takes Center Stage
Prior authorization remains a major administrative function for health plans and healthcare providers. The process requires organizations to review treatment requests before certain services receive approval. However, complex workflows can increase processing time and create additional administrative work.
The NCQA program aims to help organizations introduce technology without weakening transparency or accountability. Participants will examine governance methods and operational controls that support responsible implementation. They will also assess how new systems can improve consistency across authorization workflows.
UiPath brings automation experience from industries that depend on structured processes and large data volumes. Its healthcare work includes systems that support repetitive administrative tasks and coordinated workflows. As a result, the company can provide practical examples from operating environments.
Collaboration Expands UiPath Healthcare Strategy
The initiative adds another healthcare use case to UiPath’s broader business automation strategy. The company has expanded beyond basic task automation toward tools that coordinate larger business processes. Healthcare offers significant opportunities because organizations handle complex administrative workloads and strict compliance requirements.
Structured automation can help reduce repetitive work while maintaining required human oversight. NCQA’s program also creates a setting for organizations to test approaches against practical healthcare needs. Consequently, participants can identify operational barriers before expanding technology across wider workflows.
The collaboration gives UiPath access to discussions with healthcare organizations and industry specialists. Those exchanges can highlight challenges affecting technology deployment across health plans and related organizations. UiPath will also attend the NCQA Health Innovation Summit from October 4 through October 7.
The post UiPath, Inc. (PATH) Stock: Gains as NCQA AI Collaboration Advances appeared first on Blockonomi.
Quick Summary
- Micron issued robust AI-focused guidance with customer obligations reaching $32 billion.
- Treasury yields on 10-year bonds reached 5.34%, marking the highest point in over two decades.
- Oracle secured a reported $7 billion agreement with Tencent for AI chip infrastructure access.
- Synopsys announced major partnerships with both OpenAI and Amazon worth over $1 billion.
- Bitcoin maintained stability around $84,000 following a brief surge above $85,000.
This week’s market activity centered around escalating artificial intelligence investments and climbing Treasury yields. Multiple technology firms released announcements demonstrating the substantial capital continuing to pour into AI-related infrastructure.
Meanwhile, Bitcoin remained relatively stable within a tight trading band as market participants evaluated robust institutional demand against an environment of elevated borrowing costs.
Micron Reports Surging AI-Driven Revenue
Micron delivered one of the quarter’s most impressive financial updates. The semiconductor manufacturer specializes in memory components essential for AI-powered data centers.
The company projected first-quarter revenues approaching $61.5 billion. This forecast significantly exceeds Wall Street consensus estimates of approximately $57 billion.
Quarterly revenues surged more than fourfold to $54.23 billion. Long-term supply agreements with customers expanded to $32 billion, representing substantial growth from the $22 billion reported in June.
Outstanding performance obligations increased to approximately $150 billion. These figures underscore the increasingly constrained supply environment for cutting-edge memory chip technology.
Oracle Secures Massive Tencent Partnership
Oracle finalized a significant partnership with Tencent, the prominent Chinese technology conglomerate. Reports indicate Tencent will invest approximately $7 billion throughout a five-year period.
This arrangement provides Tencent with access to roughly 100,000 sophisticated AI processors. The hardware infrastructure is housed within Oracle’s data center facilities distributed across Southeast Asia.
American export restrictions create substantial obstacles for Chinese companies attempting to acquire this technology directly. This partnership offers Tencent an alternative pathway to access critical computing resources.
The agreement further solidifies Oracle’s expanding presence in the artificial intelligence cloud services marketplace.
Synopsys Announces Amazon and OpenAI Partnerships
Synopsys revealed two significant collaborative agreements. The Amazon partnership encompasses more than $1 billion in value spanning multiple years.
This arrangement involves chip design software utilized for Amazon’s proprietary processors, including specialized hardware deployed throughout AWS infrastructure.
The OpenAI collaboration focuses on developing GPT-Synopsys, an innovative tool designed to assist engineers with semiconductor design processes using Synopsys platforms.
Company shares experienced upward momentum following these partnership announcements.
Treasury Yields Climb to 22-Year Peak
The yield on 10-year Treasury securities temporarily reached 5.34 percent during the week. This represents the highest reading recorded since 2002.
Market participants have been liquidating government debt holdings amid mounting worries about persistent inflation and expanding fiscal deficits. Rising yields translate to increased financing costs for corporations.
Elevated yields can also enhance the relative attractiveness of fixed-income securities compared to equities, particularly growth-oriented technology stocks. Robust artificial intelligence earnings reports have helped counterbalance some of this headwind thus far.
Bitcoin Stabilizes Around $84,000 Mark
Bitcoin fluctuated within a range of $83,000 to $84,000 throughout the week. The cryptocurrency momentarily reached $85,500 following a more moderate inflation data release.
Those price advances subsequently retreated as Treasury yields maintained elevated levels. Citigroup analysts increased their 12-month Bitcoin price target to $113,000, citing enhanced ETF inflows and evolving regulatory frameworks supporting digital assets.
Bitcoin currently finds itself positioned between compelling institutional demand and challenging interest rate conditions. Market observers are monitoring whether sustained AI infrastructure spending and persistent bond yield pressure continue exerting divergent forces on asset prices as October approaches.
The post AI Investment Surge: Micron, Oracle, and Synopsys Announce Billion-Dollar Deals appeared first on Blockonomi.
Key Takeaways
- Major U.S. equity indices surrendered early session gains and closed lower on Thursday.
- Treasury yields continued their ascent, with the 10-year reaching approximately 5.3%, marking fresh multidecade peaks.
- Micron delivered better-than-expected quarterly results and upgraded guidance, though shares remained flat.
- Manufacturing sector data revealed weaker expansion alongside accelerating price pressures.
- Weekly unemployment claims declined for the fourth consecutive period, signaling labor market resilience.
U.S. Stocks retreated Thursday as climbing Treasury yields dominated market sentiment, outweighing positive corporate news from memory chip manufacturer Micron. The decline kicked off October’s trading on a cautious note.
The Dow Jones Industrial Average shed approximately 0.5% during the session. The S&P 500 declined 0.3%, while the Nasdaq Composite registered a similar 0.3% loss.
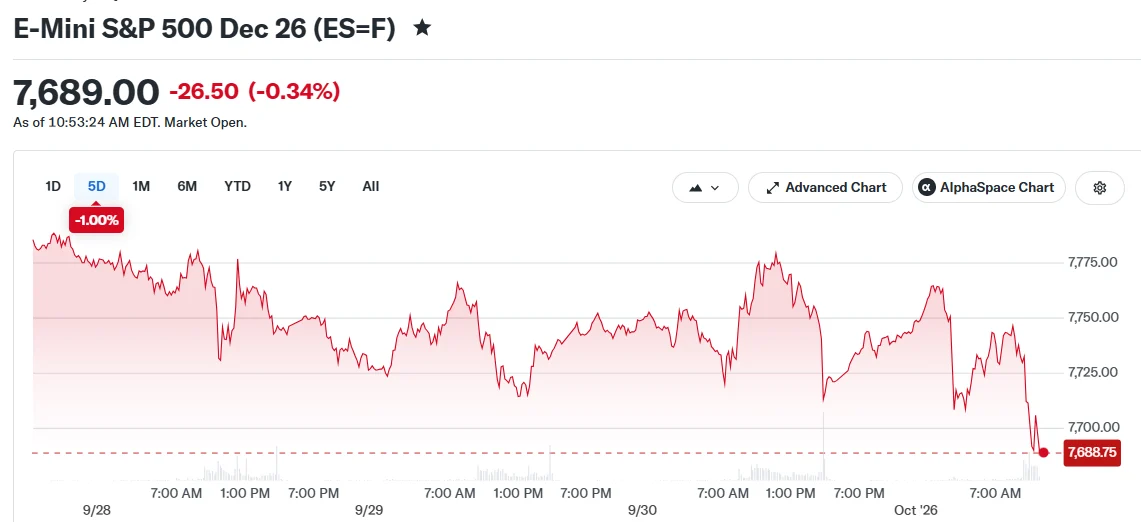
Each of the three major benchmarks had traded in positive territory during early hours. However, those advances evaporated as fixed-income market pressures intensified throughout the morning session.
Treasury Yields Continue Relentless March Higher
The benchmark 10-year Treasury yield extended its climb Thursday, pushing toward the 5.3% threshold. This level represents the highest reading in multiple decades for the closely watched rate.
The advance follows a particularly challenging three-month period for fixed-income investors. Bond markets had just concluded one of their worst quarterly performances in recent history as October began.
Elevated yields increase borrowing costs throughout the economy. They simultaneously diminish the relative appeal of equities versus bonds, as investors can secure higher returns from lower-risk instruments.
Rate-sensitive market segments bore the brunt of Thursday’s selling pressure. Materials, real estate, and financial services companies posted some of the session’s steepest declines.
Energy and technology were the sole sectors maintaining positive ground. At one point during morning trading, fewer than one-third of S&P 500 constituents were advancing.
Disappointing Manufacturing Metrics Add to Concerns
A pair of manufacturing sector reports released Thursday painted a picture of decelerating momentum paired with inflation pressures.
The S&P Global Manufacturing Purchasing Managers Index registered 55.9 for September. This reading fell short of the preliminary estimate of 57.
Separately, the Institute for Supply Management documented a significant jump in manufacturing input prices during September. Escalating costs for raw materials can compress corporate margins and reignite inflation worries.
These data releases followed a challenging conclusion to the third quarter. The Dow registered declines for both September and the full three-month period, though the Nasdaq managed quarterly gains.
Micron announced fourth-quarter financial results that surpassed analyst projections. The semiconductor company also elevated its first-quarter guidance above market expectations.
MICRON $MU Q4’26 EARNINGS HIGHLIGHTS
Revenue: $54.23B (Est. $51.07B)
; +379% YoY
Q1 FY27 Guide:
— Wall St Engine (@wallstengine) September 30, 2026
Surprisingly, Micron shares barely budged despite the encouraging news. Market participants appeared preoccupied with bond market dynamics rather than company-specific developments.
Performance among other semiconductor and technology names varied widely. One prominent chipmaker registered modest gains following a strong September performance, while another semiconductor company retreated after climbing 30% the previous month.
Employment data pointed to continued labor market strength. First-time unemployment benefit applications decreased for a fourth consecutive week in the most recent reporting period.
An additional workforce report from Challenger, Gray & Christmas revealed that corporations announced fewer position eliminations in September. However, businesses have not accelerated their hiring activity.
These employment indicators arrive ahead of Friday’s comprehensive monthly jobs report. That data release will provide broader insights into hiring trends and unemployment dynamics.
Nike is scheduled to announce quarterly results following Thursday’s market close. The athletic apparel giant’s shares have been hovering near decade-low levels, placing additional scrutiny on the company’s performance update.
As late-morning trading progressed, the 10-year Treasury yield stood at 5.33%, while the 2-year yield retreated to 4.852%. The Dow was lower by approximately 328 points, with the S&P 500 declining 0.36% and the Nasdaq dropping 0.31%.
The post Major Stock Indices Decline as Treasury Yields Reach Historic Peaks Despite Strong Micron Report appeared first on Blockonomi.
Key Takeaways
- SNPS shares surged 11% to reach $483.59, leading the Nasdaq 100 index during Thursday’s trading session.
- The chip design software firm introduced GPT-Synopsys, an AI-driven design model created through a multiyear revenue-sharing agreement with OpenAI.
- A custom chip development contract with Amazon valued at over $1 billion was announced.
- Synopsys elevated its revenue growth forecast to midteens annually through the end of fiscal 2030.
- Analysts at Rosenblatt Securities increased their price objective to $620, suggesting 43% potential upside from previous trading levels.
Shares of Synopsys advanced 11% to $483.59 during early Thursday trading, positioning it as the strongest performer within the Nasdaq 100 for that session.
Synopsys, Inc., SNPS
This significant move followed Wednesday’s 4.8% increase. Combined, these two consecutive sessions marked the company’s strongest two-day performance since September 2025.
The momentum originated from the company’s Investor Day presentation held in New York on Wednesday, where Synopsys unveiled two significant AI-focused strategic partnerships.
The first collaboration involves OpenAI. Together, they’re introducing GPT-Synopsys, a purpose-built artificial intelligence model designed specifically for semiconductor design applications.
While specific financial terms weren’t disclosed, both organizations confirmed the arrangement operates on a multiyear revenue-sharing framework.
According to Synopsys, discussions are already underway with leading semiconductor manufacturers regarding adoption of this innovative design tool.
Amazon Partnership Details
The second major announcement centers on Amazon. Synopsys secured an agreement valued above $1 billion to collaborate with Amazon on proprietary chip development.
This arrangement builds upon Amazon’s current utilization of Synopsys software platforms and intellectual property assets. It also represents a fundamental change in the company’s compensation structure.
The contract employs a license-plus-royalty framework, meaning revenue will scale proportionally with manufacturing volume rather than remaining static.
Both collaborations address a persistent concern that has shadowed Synopsys recently. Market participants had expressed anxiety that AI capabilities might enable chip manufacturers to internalize more design functions, potentially reducing demand for Synopsys services.
CFO Shelagh Glaser dismissed these concerns in a conversation with Barron’s. “Everybody’s building their own chips, and we have insatiable demand,” she said.
Elevated Growth Projections
Synopsys also upgraded its forward-looking financial targets. The organization now anticipates midteens compound annual revenue expansion through fiscal 2030, representing an increase from its earlier double-digit projection.
For fiscal 2027 in particular, Synopsys forecasts approximately 15% revenue growth. The company also projects adjusted operating margin will climb to roughly 50% by fiscal 2030, compared to 44% expected in fiscal 2027.
Management announced plans to repurchase approximately $1 billion worth of shares in upcoming months, contingent upon market conditions.
StoneX analyst Gary Mobley maintained his Buy recommendation and $570 price objective, noting that AI agents are designed to assist engineers rather than displace fundamental design platforms.
Rosenblatt Securities elevated its price target to $620 from $575 following the investor presentation. This target represents 43% upside potential from the stock’s pre-rally price of $434.94.
Rosenblatt also highlighted Synopsys’ recent operational performance, noting 46% revenue growth over the trailing twelve months alongside an 83% gross margin.
Despite Thursday’s rally, Synopsys stock remained down 7.4% year-to-date entering the session. Competitor Cadence Design Systems has posted a 5.6% gain during the same period and also climbed 6.1% Thursday.
Glaser attributed the stock’s previous underperformance to concerns about AI-driven disruption and the ongoing integration of Ansys, which Synopsys acquired last year in a $35 billion transaction.
“We had said 2026 was going to be a transitional year,” Glaser explained, citing the Amazon partnership as evidence of that strategic plan materializing.
Additional analysts have recently adopted more optimistic positions as well. HSBC elevated the stock to Buy with a street-leading $700 price target, while both Morgan Stanley and Baird upgraded their ratings during the current year.
The post Synopsys (SNPS) Stock Surges 11% on OpenAI Partnership and Amazon’s $1B+ Chip Deal appeared first on Blockonomi.
CryptoPotato
September was a strong month for many cryptocurrencies, including Bitcoin (BTC), Ethereum (ETH), and Zcash (ZEC), all of which posted significant gains.
Nonetheless, their pumps can’t be compared to what happened with Quant (QNT). The altcoin became a sensation after surging nearly 400% in a month, fueling expectations of a continued bull run among top analysts. On the other hand, traders and investors should tread lightly, as key signals suggest a short-term pullback may be coming.
Final Barrier Before the Real Boom?
As of this writing, it seems surreal that less than two weeks ago QNT was worth around $60. By the end of September, the token’s price skyrocketed to nearly $350, and now it trades just under $280.
Perhaps the biggest catalyst for the rally was the announcement that The Clearing House (which operates payment networks that process over $2 trillion each day) selected Quant to power its On-Chain Money Initiative.
One of the many analysts commenting on the token’s bull run lately is Ali Martinez. Earlier today (October 1), he set $430 as key resistance, which sits at the top of a certain channel.
In his view, a decisive break above this level could send QNT into price discovery mode, potentially triggering another parabolic expansion toward an all-time high of $2,000.
Jia Crypto also made an optimistic prediction, albeit far less bullish than Martinez’s take. She believes QNT could cross $300 “soon with big profits,” and then might rise to $400.
Beware, Bulls
Despite the overall optimism, a further price uptrend is not guaranteed. Lookonchain revealed that the Quant Network founder’s wallet has woken up after seven years of inactivity and has moved almost $7 million worth of QNT. Even if no actual sale occurs, traders may interpret the move as a sign of potential profit-taking, which can trigger uncertainty and panic selling.
Meanwhile, QNT investors have been abandoning self-custody en masse and flocking to centralized exchanges over the past several days. This in turn increases immediate selling pressure.

The token’s Relative Strength Index (RSI) should also serve as a warning. The ratio has surged past 70, suggesting that QNT has entered overbought territory and could be on the verge of a short-term correction. The index ranges from 0 to 100, where anything below 30 is considered a buying opportunity.

The post Quant (QNT) Could Explode to $2,000: Analyst Reveals the Critical Factor appeared first on CryptoPotato.
Evernorth’s merger with Armada Acquisition Corp. II won shareholder approval on Wednesday, putting its 473 million XRP treasury on course for a Nasdaq listing.
The vote passed with about 20.5 million shares in favor and 1.4 million against, according to Armada II’s filing on Thursday. It came five weeks after the SEC declared Evernorth’s registration statement effective on August 27.
Evernorth expects the deal to close on October 7. The company’s shares should start trading the next day under XRPN, the ticker the SPAC already uses.
Over $1 Billion Raised
The firm said the deal and its private placements have raised more than $1 billion, the total it first put on the merger in October 2025. Investors contributed part of that total as XRP, which the release does not value in dollars.
Evernorth’s release puts about $300 million of the total in gross cash. Private placements supply $225 million of that cash. Another $30 million comes from convertible notes the company agreed to sell in September.
Advance funding investors provided $214 million of the private placement money, according to the proxy statement. Evernorth spent it in late 2025 on 84.4 million XRP, at an average of $2.54 per token. Those tokens are already part of its holdings.
The SPAC’s trust adds about $48 million of cash. That trust held about $241.9 million on the August 20 record date. Public shareholders could redeem their shares from the trust at an estimated $10.52 each until September 28. Neither Thursday’s release nor the vote filing says how many shareholders did.
RippleWorks supplied the largest block of Evernorth’s XRP, 211.3 million tokens, by investing them in the SPAC’s sponsor, Arrington XRP Capital Fund. The sponsor must exchange those tokens for Evernorth shares at closing. It has agreed to vote the shares as RippleWorks directs. Ripple co-founder and Executive Chairman Chris Larsen co-founded RippleWorks and sits on its board.
Ripple itself contributed 126.8 million XRP when the merger agreement was signed. A further 50 million comes from the Larsen Lam Children’s Remainder Trust.
Books Carry XRP Below Cost
Evernorth Holdings’ financial statements in the proxy put the cost of 346.3 million of its XRP at $846.6 million. By June 30, 2026, the company carried those tokens at $348.8 million. It recorded impairment charges of $233.7 million in 2025 and $264.1 million in the first half of 2026.
Evernorth books XRP at cost and writes it down to the lowest intraday price seen since it acquired each lot. The written-down value is not adjusted upward when the price recovers.
The post XRP Is Coming to Nasdaq: Evernorth Clears Key Vote With 473M Treasury appeared first on CryptoPotato.
Bitcoin outperformed stocks and gold in September as it entered the fourth quarter on a high note, according to Santiment. The world’s largest crypto asset gained around 8% during the month. In comparison, the S&P 500 saw little movement, while gold fell by more than 6%.
Several altcoins also recovered as investor interest returned to the market.
What Changed in September?
Fresh capital inflows supported Bitcoin’s rally. US-listed spot BTC exchange-traded funds (ETFs) attracted billions of dollars in September, including several large inflow days toward the end of the month. Meanwhile, Strategy added another 1,665 BTC to its holdings, which was indicative of continued corporate accumulation. Strive also expanded its corporate Bitcoin holdings by purchasing 1,107 for $94.5 million.
Improving economic conditions also helped the market. US inflation data for August came in below expectations, easing pressure on Treasury yields as well as reducing concerns about another Federal Reserve rate hike. While stock markets showed a limited response, cryptocurrencies recorded stronger gains following months of weak sentiment and heavy short positions.
Santiment found that crypto markets are entering Q4 with several potential growth drivers.
“Continued ETF demand, corporate accumulation, improving regulatory clarity, and renewed altcoin participation give traders reasons to stay optimistic.”
But while higher yields and crowded leverage can still create sharp pullbacks, the analytics firm stated that “crypto currently has catalysts that traditional assets simply haven’t matched.”
What’s Next?
Bitcoin is stuck just below $86,000, and Crypto Patel thinks this level could decide where the asset heads next. If BTC breaks above this level and holds, a move toward $100,000 could be back on the table. If it fails, however, traders will be watching $82,886, $80,300, and $76,400 for support. BIT Research’s latest report, meanwhile, has put a much bigger number on Bitcoin’s current cycle. The firm said that the bear market has likely ended and predicted an upside range of $185,000 to $215,000.
Whale wallets are also stacking up. In fact, wallets holding 10 to 10,000 BTC added 41,025 coins in just 10 days, pushing their total holdings to 13.64 million.
Bitcoin’s longer-term setup is still looking healthy as the MVRV Z-Score remained above its 365-day moving average. That level has historically acted as support during broader rallies. It doesn’t mean BTC is guaranteed to keep climbing, though. Short-term pullbacks can still hit, and they could be sharp.
For now, the bigger thing to watch is whether the Z-Score can hold above that average. If it does, CryptoQuant’s analysis states that the broader valuation trend remains supportive of further upside. A sustained break below the 365-day average would be a different story and could signal that the longer-term structure is starting to weaken.
The post Why Bitcoin Is Starting Q4 on Stronger Footing Than Traditional Markets appeared first on CryptoPotato.
The altcoin market is showing signs of overheating, as spot trading volume is now four times higher than that of Bitcoin. The sharp rise in activity has also pushed leverage higher across the market.
This has prompted one trader to take profits and reduce exposure to altcoins.
Bitcoin Over Altcoins?
Doctor Profit said ONDO was sold with a 73% profit, while HBAR was closed with a smaller gain. XRP remains on watch, with a possible entry planned at a better price. The trader said there is no interest in buying altcoins while market conditions remain this hot. He also called altcoins a “great distraction and liquidity grab” and went on to add,
“This is why I’m out of Alts!”
Instead, the trader is betting on a Bitcoin correction, reiterating his previous stance. A short position was opened at $86,200, and additional short orders were placed between $86,500 and $89,500.
While he remains bullish overall, Doctor Profit had previously pointed to a potential pullback toward $79,000, near the 50-week moving average, before the broader uptrend continues. The analyst had flagged bearish signals across RSI, MACD/PPO, and MFI, while ADX showed weaker trend strength.
Warning Signs Emerge
A few days earlier, Darkfost also identified a few warning signs. According to the analyst, Total2, which tracks the altcoin market cap including Ethereum, absorbed more than $371 billion in inflows since June 2026. This is a 45% increase in just a few months.
The shift is also visible across Binance, where 87% of listed altcoins are trading above their 200-day moving average. That is a major change from August, when 80% were still below the crucial trend level. Darkfost explained that the move is indicative of a growing euphoria around altcoins, something that has historically been difficult to sustain for long.
Another signal is the rise in altcoin deposits to exchanges. Weekly deposit transactions have climbed above 22,700 on Binance and 8,300 on Coinbase, with another 32,000 or so across other platforms. The numbers are still below the levels seen early in the previous bull cycle. However, Darkfost also pointed to a developing bearish divergence on Total2’s RSI, which suggests that the altcoin momentum could be starting to cool after the recent surge.
The post Altcoin Trading Volume Hits 4x Bitcoin as One Trader Says He’s Out appeared first on CryptoPotato.
October is here, and so are fresh expectations that Bitcoin (BTC) and the broader cryptocurrency market can continue their upward momentum and enter a sustained bull run.
We asked three of the most popular AI-powered chatbots whether the meme coin sector will thrive this month and which token in that space has the best chance to outperform. Here are the interesting answers.
PENGU?
ChatGPT picked Pudgy Penguins (PENGU) as a potential October breakout, warning that this is a speculative judgment, not a certainty. OpenAI’s platform noted its solid performance over the past few weeks, which makes it a candidate to attract further momentum buying if the market remains bullish.
It also outlined that PENGU’s market capitalization sits slightly above $600 million, giving it more scope for large percentage moves. Last but not least, ChatGPT pointed out that the meme coin is built on Solana, arguing that recognizable tokens within the ecosystem could benefit if traders increase their exposure to the network in October.
PENGU also received support from Google’s Gemini, which identified it as the month’s most promising candidate. According to the chatbot, the meme coin stands out because it bridges Internet jokes with real-world sales.
“Most meme coins run strictly on X chatter and speculation; PENGU has a physical brand selling toys and trading cards in major stores like Target,” it added.
Gemini later claimed the token offers a balance of viral meme energy, massive retail presence, and strong trading momentum, which could play a vital role in further price gains.
It is worth noting that several renowned analysts are also quite bullish on PENGU. Ali Martinez recently claimed the token might be preparing for a bull run, citing key factors such as the Tom DeMark Sequential indicator flashing two consecutive buy signals and the SuperTrend indicator supporting a rally.
At the same time, he revealed that PENGU’s Bollinger Bands have squeezed on the weekly chart. Usually, this precedes a major move, although the exact direction (up or down) remains unclear.
How About DOGE?
Perplexity argued that the OG meme coin is most likely to explode this month because it combines the deepest liquidity with a clearer near-term technical setup than its rivals.
“Its advantage is not that it has the biggest possible upside – it is that it is the meme coin most likely to catch a broad market rally first,” it said.
The chatbot noted that Bitwise recently closed its spot DOGE ETF, but reminded that other products of this type remain live, meaning a potential spike in institutional interest could lift the price. It also highlighted recent whale activity, with large coin purchases showing strong conviction among this cohort of investors and perhaps setting the stage for a serious rally. As CryptoPotato reported, these market participants accumulated over 1.14 billion DOGE in about 96 hours.
The post The Meme Coin Most Likely to Explode in October, According to 3 AIs appeared first on CryptoPotato.