Cryptocurrency Posts
Crypto Briefing
The Litecoin Foundation and Greywick Digital are developing cLTC, a tokenized LTC for the Canton Network aimed at institutional traders.
The post Litecoin Foundation signs MOU with Greywick Digital to bring cLTC to Canton Network appeared first on Crypto Briefing.
Google's space-bound AI data center could revolutionize energy efficiency and scalability in AI processing, leveraging abundant solar power.
The post Google is sending its first AI data center to space appeared first on Crypto Briefing.
Nvidia's ambitious financing plan highlights the challenges of treating tech assets as stable collateral, potentially reshaping AI investment dynamics.
The post Nvidia faces Wall Street skepticism over $500 billion chip-backed financing plan appeared first on Crypto Briefing.
Tron Inc.'s sustained TRX acquisition strategy could redefine corporate treasury management, emphasizing transparency and crypto asset integration.
The post Tron Inc. buys TRX for 252 consecutive days, holding 716.8M tokens appeared first on Crypto Briefing.
The Decisions API could streamline AI workflows, enhancing efficiency and competitiveness, but its impact hinges on cost and accuracy metrics.
The post OpenAI unveils Decisions API for fast, constrained AI choices appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
The Quantum Issue: Quantum Isn’t Coming For Your Bitcoin
For as long as Bitcoin has existed, new forms of FUD (fear, uncertainty, and doubt) have been used to predict its demise. Despite this, Bitcoin has grown into a multi-trillion dollar asset and begun to take its place in the global monetary order. In recent months, the specter of a cryptographically relevant quantum computer (CRQC) enabling an attacker to recreate secret keys from public keys and sign Bitcoin transactions moving other people’s coins has returned as an evolved form of FUD. Is this a realistic threat to Bitcoin’s continued growth? In a word, no. There is no evidence that a CRQC will be built within a decade, and it remains unknown whether such a machine will ever be built. The quantum threat remains FUD.
State of the Art
To date, no quantum computing machine has computed anything out of reach of a precocious 6-year-old (confirmed empirically). Quantum computers are remarkable technology and showcase the truly science fiction worthy capabilities of the modern world. These devices harness foundational technologies such as optical tweezers, laser cooling, superconducting flux qubits, electromagnetic traps, dilution refrigerators, and many more. Within these devices individual qubits are coerced into specific subatomic states (different for each candidate technology), entangled into superpositions, manipulated to represent computations, and then their subatomic properties are read and interpreted. The astounding truth is that these devices exist, and can be manipulated to produce meaningful computations across a handful of inputs. The cold reality check is that (for an example candidate tech.) to do a computation that a small child can do requires enough power to air condition a Texas high school, many hours of setup, and further hours of post-processing.
Reading the Future
I know what you’re thinking, “but there’s so much money flowing into quantum computing”. Does money flowing into a field correlate with the rate of real-world technological progress in that field? Not really. In fact, it can be argued that until the correct underlying technology has been developed and the product-market fit confirmed, money flowing into an area has a negative correlation with the likelihood of applicable technology being developed. This can be clearly seen by comparing NASA’s Space Shuttle program to SpaceX’s Falcon 9. SpaceX took (mostly) known science and reduced it to practice to satisfy a demonstrable market need for reliable and lower cost access to space, at a program cost of less than $5 billion to first crewed mission. The Space Shuttle cost roughly $50 billion to reach its first crewed mission. Not only did Falcon 9 cost an order of magnitude less to develop, but it has a perfect crew safety record to date. There are many reasons for these differences, but it goes to show that no amount of money makes a technology that is not ready practicable. Translating this to quantum computing: we can see that with tons of money being thrown at the problem, technology demonstrations at massive cost are possible. But this tells us nothing about whether more money will bring us the holy grail of stable, low-error qubits (like the reliability of the Falcon 9). No amount of continued development on the Space Shuttle program would ever have produced the low cost, high reliability of Falcon 9, and it’s entirely probable that no amount of continued development, at any cost, will ever make any of the current quantum computing technologies reliable enough to break a single key pair.
Now, you might be thinking, “but what about all the recent advancements?” There are two important things to keep in mind about recently published advancements. First, many of these advancements have been advancements in pure mathematics only. For example, the recent Google paper which had such an important result that they chose to redact the theoretical quantum circuit rather than risk it being used to break important cryptographic systems. This may seem like massive progress toward the future of CRQCs, but in fact it changed nothing. Unless (or until) the quantum hardware has its Falcon 9 moment, there simply is no device which comes anywhere near the stability and scale needed to run the redacted circuit. It’s pure theater to hide a circuit designed for a device which may never exist. Second, on the hardware side itself, we see many new results and bits of progress published in a given year, but how many of these relate to the same quantum computing candidate technology? How many represent merely a starting over after a prior result ended in a dead end? The reality is that these advancements do not represent some linear track toward eventual success. They represent the breadth-first search of an infinite possibility space within which quantum researchers are hoping to find a path along which they can proceed for even a modest distance without reaching yet another dead end.
When we look at the reality of the future of quantum computing, it’s hazy at best. There are promising technological developments. Especially, to my eye, in the area of neutral atom devices. But it’s far too early to tell if there’s a path open toward an eventual CRQC along any of the currently known branches or if more restarts are in our future. If, at some point, we see many iterations of the same candidate technology implementing progressively more capable devices, and computing meaningful results that a precocious child cannot also compute, we can revisit this discussion with different evidence.
In Theory
There are two possible explanations for the repeated failure of quantum research to develop a CRQC over many decades. It’s possible that it’s just a hard problem and we’re continuing to apply science and engineering to solve it and one day the ingenuity of the human species will prevail as it has in the development of the Internet, the smart phone, social media, and Bitcoin (left to the reader to decide which of these are positive developments). On the flip side, it may be that developing a CRQC is either impossible or will remain forever outside our grasp. Consider what it would mean for a CRQC to exist: the machine would have to represent within its superposition a field of possibilities the same size as the complexity of the cryptographic problem to be solved. I.e. to break the 128-bit security of the elliptic curve discrete log on Bitcoin’s secp256k1 curve, the quantum superposition would have to represent all possible values of a 128-bit number. In classical computing, representing all such values would require more computer storage (by many orders of magnitude) than humans have ever produced. If there is even the slightest granularity to the quantum superposition (i.e. the quantum superposition is not perfectly continuous across all possible values) then the quantum computer cannot ever become cryptographically relevant. If the energy required to hold a superposition scales with the complexity of the field being represented then a quantum computer cannot ever be cryptographically relevant. The contemporary understanding of quantum physics does not rule out either of these possibilities.
Conclusion: Bitcoin Cannot Rest
Despite all of the preceding, Bitcoin development toward new cryptographic algorithms must continue. While a quantum attack on Bitcoin’s cryptography is not imminent by any means, it’s entirely possible that another flaw could be found through other means. We know that certain elliptic curves have been found to have weaknesses, and secp256k1 could be next. Bitcoin has survived as long as it has because attacks on the system have strengthened it and that will continue to be true as the quantum FUD attack plays out. The development of P2MR or P2TRv2, of SHRINCS, SPHINCS, IBC, ML-DSA, and more post-quantum signature schemes will eventually lead to improvements to Bitcoin’s resilience in the face of future attacks even if an actual CRQC is never developed.
This piece is featured in the latest Print edition of Bitcoin Magazine, The Quantum Issue. We’re sharing it here as an early look at the ideas explored throughout the full issue.
This post The Quantum Issue: Quantum Isn’t Coming For Your Bitcoin first appeared on Bitcoin Magazine and is written by Brandon Black.
Bitcoin Magazine
Bitcoin Privacy Breakthrough a Zcash Killer? | Misha Komorov, Alloc Innit
Researchers have proposed a way to make Bitcoin private without changing Bitcoin itself. Misha Komarov, co-founder of alloc/init, explains Shielded Bitcoin: zero-knowledge proofs that hide the sender, receiver, and amount of a Bitcoin transfer, with no soft fork, no custodians, and no bridges. He covers how Bitcoin PIPEs make it possible and what the proposal still needs. It is a research proposal, not a finished product.
Chapters:
0:00 Shielded Bitcoin: Private Bitcoin Transactions With Zero-Knowledge Proofs
0:38 How Bitcoin PIPEs Make Privacy Possible Without a Soft Fork
1:42 Do Indexers and ZK Rollups Require Trust?
3:16 Shielded Bitcoin vs. Monero and Zcash
4:21 What Privacy Shielded Bitcoin Protects
5:59 How Private Are Early Users? The Small Privacy Set Problem
7:37 Is Shielded Bitcoin an Altcoin Killer?
9:12 Fees, Block Space, and Larger Shielded Transactions
10:50 Who Needs Private Bitcoin? Wrench Attacks and Corporate Treasuries
12:20 Dark Pools, Governments, and the Next Wave of Bitcoin Buyers
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Bitcoin Privacy Breakthrough a Zcash Killer? | Misha Komorov, Alloc Innit first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Bitcoin’s Institutional Era Has Arrived | Robinhood VP of Crypto Institutions Nicola White
Robinhood is bringing crypto perpetual futures to US customers, with up to 10x leverage on Bitcoin and Ether. Nicola White, Robinhood’s vice president of institutional crypto, explains how the CFTC no-action letter, the Bitstamp exchange, and Robinhood Derivatives made it happen, and why the company wants markets to be always on.
Chapters:
0:00 Robinhood’s Hood Summit: 24/7 Stock Trading and US Crypto Perps
0:40 Why Robinhood Wants Markets That Never Close
1:32 Bitstamp Perps and the CFTC No-Action Letter
2:19 Tokenized Stocks, the Basis Trade, and the Path for US Perps
3:20 Bitstamp’s Volume and the Retail–Institutional Merger
4:54 What Institutions Want to Do With Bitcoin
6:00 Institutional Bitcoin Depth and Large Block Trades
6:49 AI Trading Agents and Robinhood’s Sub-Account Controls
8:29 Lessons From the 2022 Meltdown and US Leverage Limits
10:12 How Bitcoin Changes Finance in 10 Years and What’s Next for Tokenized Stocks
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Bitcoin’s Institutional Era Has Arrived | Robinhood VP of Crypto Institutions Nicola White first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Mark Moss: The Bitcoin Endgame – BTC to $1 Million by 2030
The Fed just raised rates, yet Bitcoin keeps climbing. Mark Moss, host of the Market Disruptors podcast, explains why he thinks most people are misreading why long-term rates are rising, how a booming economy could be part of the answer, and why he says Bitcoin benefits from both the debasement trade and a bullish technological future.
Chapters:
0:00 Mark Moss on the Fed’s “Token Raise” and an October Pause
1:54 The Flat Yield Curve, Bank Lending, and the 5.1% 10-Year
2:56 Why Bitcoin Is Rising as Rates Rise: “Price Is Truth”
5:40 Bitcoin vs. Gold: The Debasement Trade and a Bullish Future
6:19 Can the US Grow Its Way Out of $40 Trillion in Debt?
10:30 The Monetary Reset Is a Process, Not an Event
13:33 Four Ways Out of the Debt Problem and What Happens in 2029–2030
16:27 Stablecoins, the Genius Act, and Why 6 Billion People Want Dollars
20:14 Institutions Are Buying Bitcoin While Retail Sells
24:29 Bitcoin’s S-Curve, Its CAGR, and a $1 Million Price Target
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Mark Moss: The Bitcoin Endgame – BTC to $1 Million by 2030 first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
UK Brings Crypto Under Full FCA Oversight for the First Time
The UK’s Financial Conduct Authority has opened applications for crypto firms to become authorized, bringing the sector under full regulation for the first time.
In a Wednesday announcement, the watchdog said companies can apply so that the crypto industry has “clarity and legitimacy.”
The UK is in the process of drafting a sweeping new crypto bill. The FCA finalized its regulatory framework for cryptoassets in June, and the regime is due to take effect in October 2027.
“The UK’s new crypto regime will give consumers greater protections and firms a clear framework to operate in. Firms can now apply for authorisation and start preparing for regulation,” Dominic Cashman, director of authorisation at the FCA, said in a statement.
The statement added that firms will have to demonstrate that they meet requirements covering consumer protection, customer-asset safeguarding, market integrity and financial resilience.
Britain is pushing ahead with digital asset legislation since last year recognizing bitcoin and other digital assets as property. The reform came from a 2023 recommendation by the Law Commission, which argued that digital assets did not fit neatly into existing legal categories.
Despite the FCA’s announcement, the UK currently is trailing behind Brussels and Washington with digital asset regulation.
The EU’s Markets in Crypto-Assets regulation has applied to service providers since 30 December 2024.
And the U.S. under President Donald Trump signed the GENIUS Act into law in July 2025, establishing a federal framework for dollar-backed tokens.
Despite lawmakers blocking landmark legislation the Clarity Act last month, U.S. regulators like the Securities and Exchange Commission have pushed ahead with rulemaking regardless.
This post UK Brings Crypto Under Full FCA Oversight for the First Time first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
CryptoSlate
Treasury's Sept. 30 rule lets states preserve a path toward stablecoin-regime approval while their rules remain unfinished, by filing an initial certification on time and completing the work before substantive review.
The interim final rule sets forms and review procedures for the Stablecoin Certification Review Committee, the federal body that reviews state stablecoin regimes. The Committee says conditional or incomplete certifications can satisfy the initial filing timeframe, even when additional state legislative or regulatory action is planned.
The rule took effect Sept. 30, but says certifications will not be accepted until after Paperwork Reduction Act approval of the information collection. Treasury will post a notice announcing when acceptance begins.
The flexibility matters for state-qualified payment stablecoin issuers with no more than $10 billion in consolidated outstanding payment stablecoin issuance. They may opt for state regulation if the state regulator certifies that its regime meets Treasury's substantial-similarity criteria and the Committee unanimously approves it as meeting or exceeding the standards and requirements in section 4(a) of the GENIUS Act.
Treasury's separate proposal on substantial similarity addresses the standards used to compare state and federal regimes. The September procedural rule does not finalize those principles.
How a filing reaches substantive review
A conditional filing can be amended at any time. It does not begin substantive review or start the Committee's 30-day approval-or-denial clock. That clock applies only once a certification has been submitted in accordance with the procedures.
For that purpose, a state must provide an unconditional attestation signed by an authorized representative, a detailed explanation of how its regime meets Treasury's similarity principles, supporting legal materials and information the Committee deems necessary.
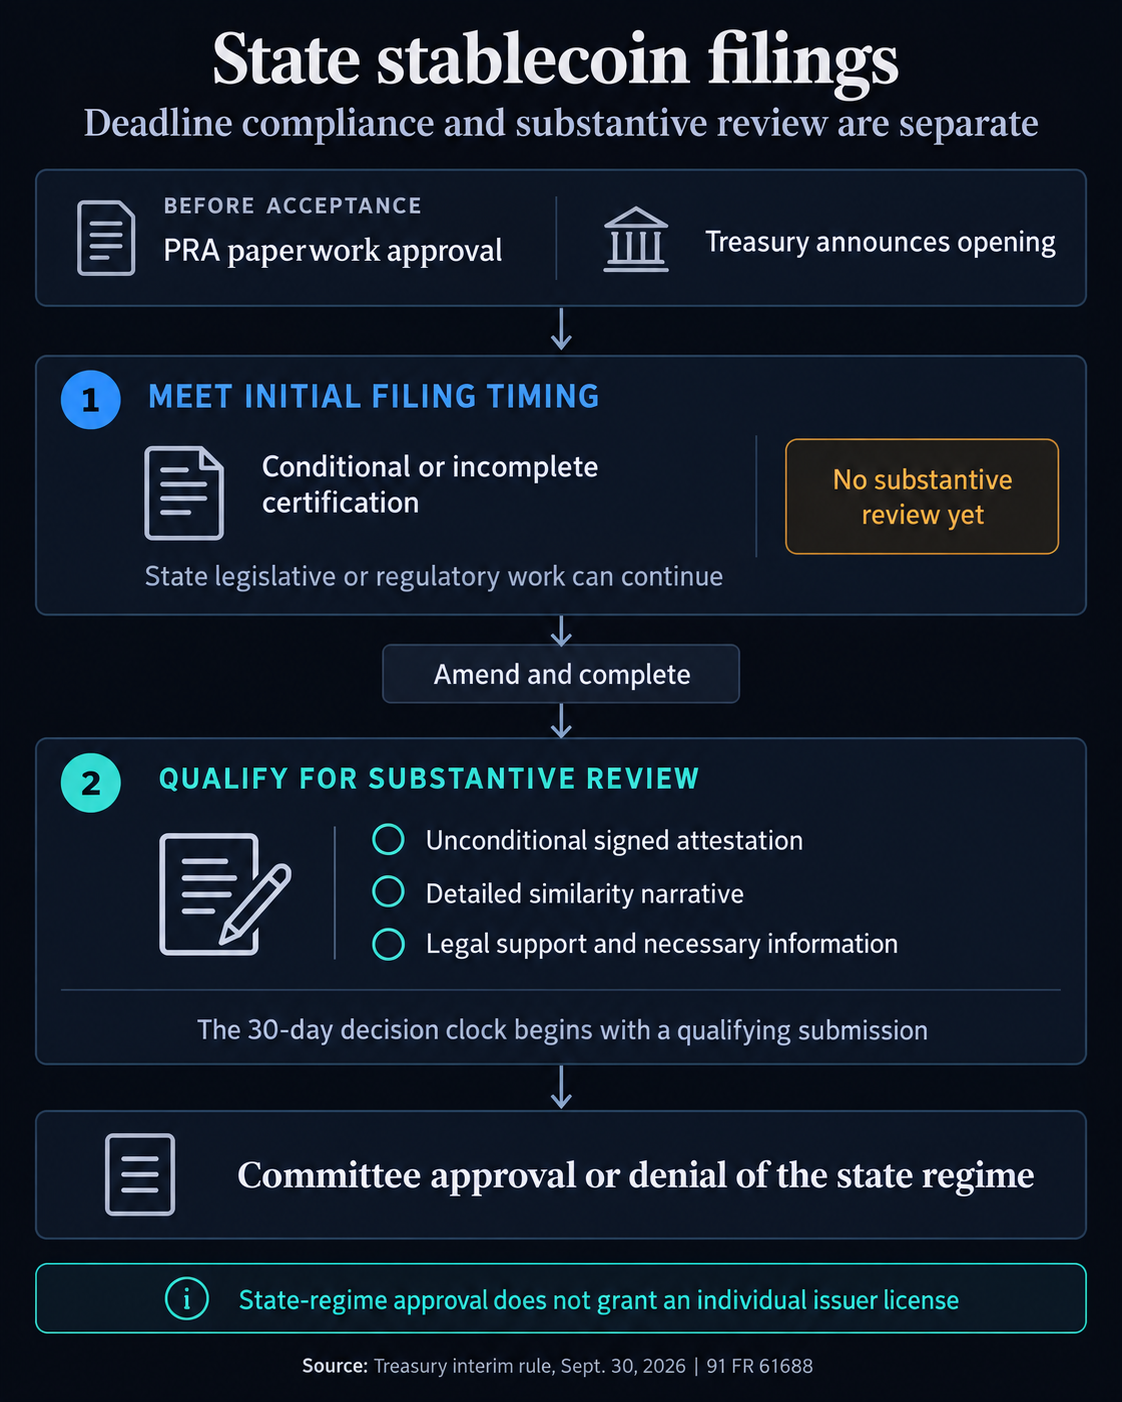
The distinction gives states room to finish their legislative or regulatory work after meeting the initial timeframe. It does not automatically approve their regimes or grant licenses to individual stablecoin issuers.
CryptoSlate's July deadline coverage described the difficulty of assessing state equivalence while federal, Treasury and OCC rules were unfinished. The new rule provides forms and review procedures, including initial filing flexibility, while retaining substantive approval requirements.
The rule uses Jan. 18, 2028 for initial certifications, based on its expected Jan. 18, 2027 effective date for the GENIUS Act. The statutory filing deadline is one year after the Act takes effect.
The Act can take effect earlier. Section 20 sets the earlier of 18 months after enactment or 120 days after primary federal payment stablecoin regulators issue any final regulations implementing it.
Comments on the interim procedures are due Nov. 30.
The post Treasury will let states file for stablecoin approval before finishing their rules appeared first on CryptoSlate.
MetaMask is pulling thousands of Ethereum validators after a security breach redirected rewards, creating a network-wide backlog for stakers trying to exit.
Onchain security researcher Kaden said about 17,000 MetaMask-operated validators holding roughly 523,000 ETH were proactively exited after an analysis found that transaction-fee rewards from 18 of 19 validators that proposed blocks had been diverted to an address funded through Tornado Cash, an Ethereum-based privacy protocol that allows crypto transactions to be mixed and anonymized.
The attacker appears to have captured only about 0.36 ETH, according to Kaden. The bigger concern is how the attacker gained enough access to alter fee recipients and whether that access extended to validator signing keys, which could trigger slashable behavior.
MetaMask has not confirmed those figures or disclosed the cause of the incident. Instead, the company said that part of its infrastructure had been compromised and that it was exiting affected validators as a precaution while working with clients, partners and security advisers. It said it had identified no immediate threat to MetaMask wallets.
The company also said its staking operation is non-custodial and that it does not control clients' withdrawal keys. That separation would prevent an attacker with only validator-level access from withdrawing the underlying stake, but it would not eliminate the possibility of penalties if signing keys were compromised and misused.
Kaden said 821 potentially affected validators had not yet exited, including three among those whose fee rewards were allegedly diverted. It remains unclear why they are still active or whether the attacker retained access to change additional fee recipients.
MetaMask has yet to disclose how many validators were affected, whether signing keys were exposed or whether any slashing has occurred.
Ethereum’s withdrawal backlog spikes to 9-month high
Meanwhile, the security incident and the exits are already rippling through Ethereum's staking infrastructure.
About 773,447 ETH was waiting to leave the validator set on Wednesday, according to Validator Queue data, implying a 13-day, 10-hour wait before an exiting validator clears the queue. A further withdrawal sweep delay was estimated at 7.6 days.
That is the largest exit backlog since December 2025 and above the roughly 476,000 ETH waiting during a previous surge in May, according to Validator Queue's historical data.
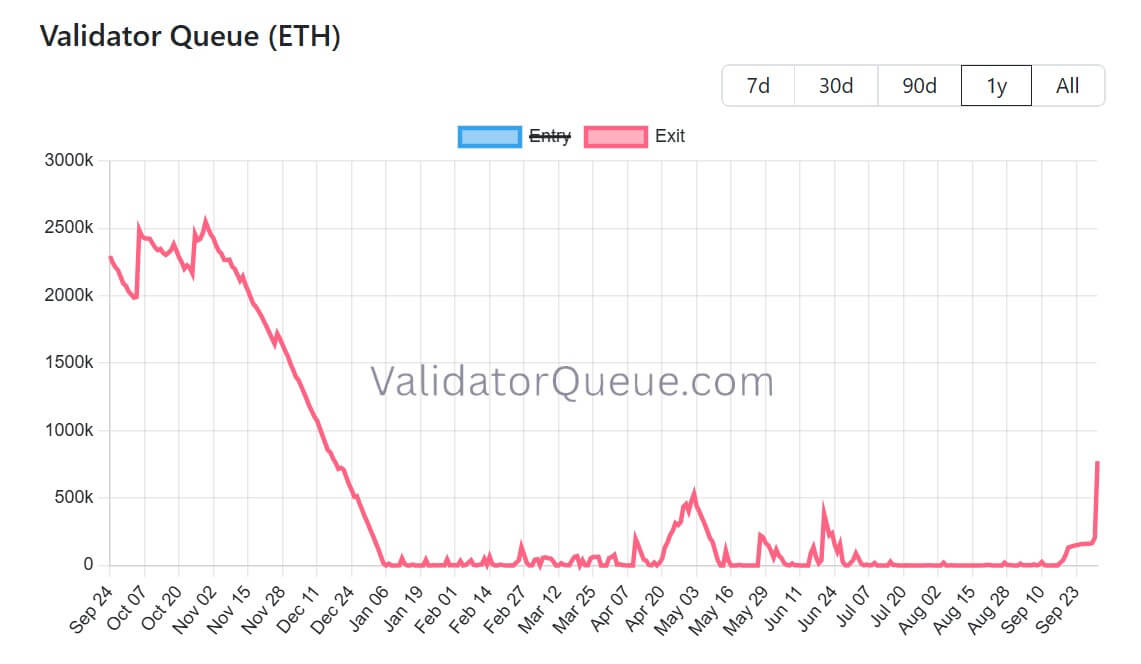
The bottleneck reflects a safeguard built into Ethereum rather than an inability to process transactions.
Ethereum limits how quickly stake can enter or leave its validator set to prevent abrupt changes from destabilizing its proof-of-stake consensus. The Validator Queue showed a churn rate of 256 ETH per epoch, with each epoch lasting about 6.4 minutes. At that rate, a large burst of exits must be processed gradually rather than simultaneously.
The additional 7.6-day sweep period begins after validators clear the exit queue and become withdrawable. Ethereum then cycles through eligible validators and transfers balances to their designated withdrawal addresses.
For MetaMask-linked stake, the disruption could last longer still. Lido, where MetaMask operates validators, estimates the full exit, withdrawal, and eventual re-entry process could take up to 45 days, partly because validators returning to Ethereum must also contend with a lengthy entry queue that is currently 27 days long.
The post MetaMask security scare pushes Ethereum validator exits to a nine-month high appeared first on CryptoSlate.
A coffee bought with a qualifying dollar stablecoin would avoid gain-or-loss recognition under the ADAPT Act that Sen. Steve Daines released Sept. 30. The same coffee bought with Bitcoin would still trigger the cost-basis calculation and capital gain or loss reporting that attach to spending digital assets.
Bloomberg Law reported Sept. 25 that Daines had circulated a draft and expected to introduce it the next week. The 56-page text released Sept. 30 carries the title Aligning Digital Assets with Principles of Taxation Act and lists Sens. Cynthia Lummis, Bernie Moreno and Tim Scott of South Carolina as cosponsors.
Under current IRS guidance, paying for goods or services with digital assets in any amount is a disposition. Holders of personal or investment assets must calculate and report capital gain or loss, which depends on the asset's value and cost basis.
A payment can produce a gain, a loss, or a break-even result, and the IRS uses a cup of coffee as its own example. A $5 Bitcoin purchase with an allocated basis of $3 produces a $2 capital gain that belongs on the return.
What qualifies as a covered stablecoin
New section 1034 of the tax code would treat the disposition of covered payment stablecoins to buy products or services as a nonrecognition event. The relief covers gain or loss on the token itself, and sales taxes and other purchase obligations stay in place.
The token must be a qualified US dollar stablecoin, meaning one issued by a permitted payment stablecoin issuer under the GENIUS Act.
A foreign issuer qualifies through OCC registration or a Treasury finding that its home regime is comparable. It must appear in Treasury's most recent report before the payment, and the taxpayer must have acquired it at a price within 3% of $1.00.
Treasury would publish that report at least every three months, listing each qualified stablecoin actively traded within 3% of $1.00 during the 12 months ending the prior month. Users and payment companies would check the latest list when making a purchase.
Traders, brokers, and dealers in qualified dollar stablecoins are excluded, along with taxpayers using a functional currency other than the dollar, and Treasury could extend the trade-or-business exclusion to similar businesses.
Taxpayers must keep records that distinguish eligible payments from other transactions. Covered payments would be exempt from broker information returns under section 6045(i)(1), and brokers could rely on customer certifications and skip verifying the 3% acquisition test for tokens bought elsewhere. The stablecoin provision applies to transactions entered into starting Jan. 1, 2027.
Bitcoin keeps its paperwork, with one fee carve-out
Section 1034 covers stablecoins, so a Bitcoin payment at checkout remains a taxable disposition, while Section 11 adds a narrower rule for fees.
Under new section 1044, coins disposed of to pay digital asset transaction costs would escape gain-or-loss recognition when the aggregate value of the assets used for those costs is $10 or less. Base, gas, and priority fees count as costs, and related transactions are aggregated.
Exclusions apply to traders, brokers and dealers, businesses that batch transactions or help validate them for others, and assets under mark-to-market accounting. Anyone who initiated more than 5,000 digital asset transactions in the prior taxable year is also excluded.
The fee exception takes effect for dispositions starting Jan. 1, 2027, the same date as the stablecoin relief. On a Bitcoin coffee, the sliver of BTC paid as a network fee could qualify, and the coins sent to the merchant remain a taxable disposition.
The bill also exempts qualified dollar stablecoins from the wash-sale and constructive-sale rules it extends to other digital assets.
Earlier bills used dollar thresholds
Earlier proposals sought to reduce tax friction for qualifying personal crypto transactions through monetary thresholds.
Sen. Ted Budd's S.4171, introduced March 24, would require both transaction value and otherwise recognized gain or loss to be $200 or less. Related transactions would be aggregated, with exclusions including business-property and cash-equivalent exchanges.
Lummis's S.2207, unveiled in July 2025, sets a $300 ceiling on both transaction value and recognized loss and ends further exclusions once qualifying annual gains exceed $5,000.
The House PARITY Act proposed a $200 threshold for stablecoin transactions. Lummis now cosponsors a text that ties relief to eligible stablecoins at any purchase size.
The House has a separate proposal. H.R.10357 was introduced Sept. 14, and Ways and Means announced committee approval by 38-5 on Sept. 16. Its stablecoin redemption-value accounting and qualifying $10 fee relief are distinct mechanisms, and committee approval is a step before any House vote.
What happens next for stablecoin and Bitcoin
These remain proposals, and current IRS treatment stays in force. The text leaves Treasury to set the mechanics, including the quarterly list, recordkeeping, and broker reporting rules. It borrows its issuer definitions from the GENIUS Act, so which tokens qualify will follow issuer approvals under that law.
For everyday users, the Daines text draws its line around the asset a customer pays with, at any purchase size. A $5 coffee on a qualifying stablecoin would fall outside gain-or-loss recognition, and the same coffee on Bitcoin would stay in the capital-gains system.
The post Senate tax bill frees stablecoin spending while Bitcoin stays on IRS forms appeared first on CryptoSlate.
Ethereum validators face a configuration choice next week that could determine how aggressively the network tests its next major scaling push.
The Glamsterdam upgrade is scheduled to activate on the Sepolia testnet on Oct. 6 at 13:53:36 UTC, bringing changes designed to increase Ethereum's execution capacity. Node operators must update both execution and consensus clients before the fork, while stakers must also upgrade their beacon node and validator software.
But simply installing compatible software will not necessarily move Sepolia toward the 200 million gas preference scheduled for the test.
Prysm 7.2.0 and Teku 26.9.1 both support Glamsterdam but will continue using a 60 million gas preference after activation unless validators explicitly change their settings, according to the Ethereum Foundation. Prysm operators must use version 2 proposer settings or the keymanager API, while Teku validators can override the default through their validator configuration.
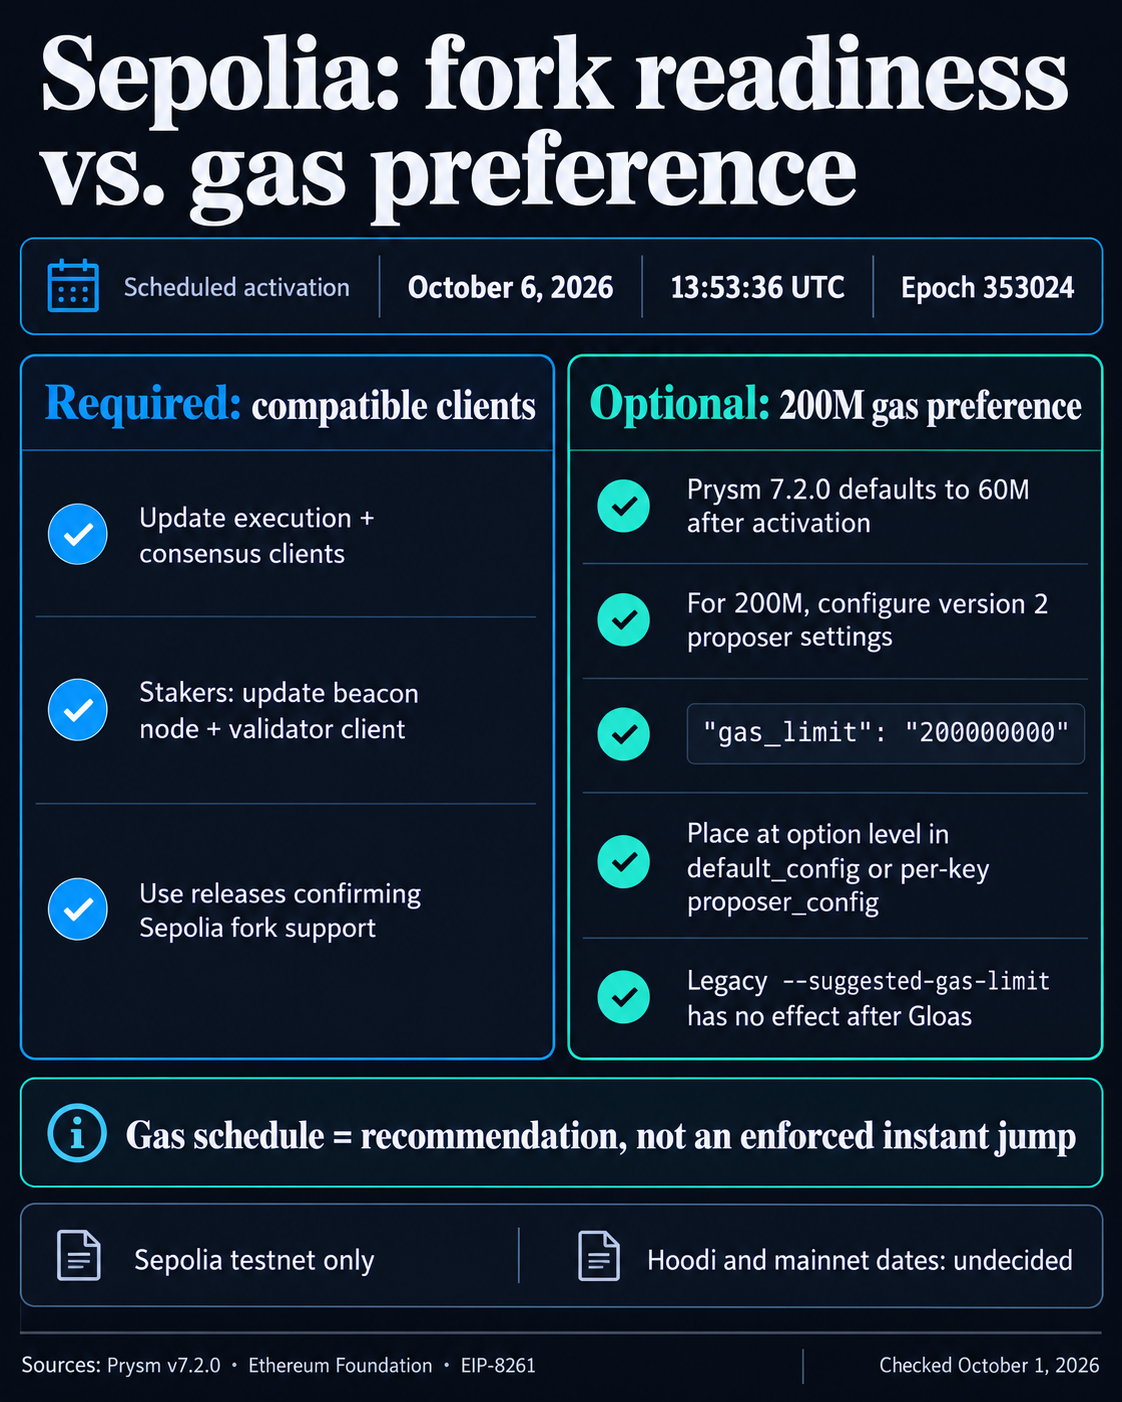
The distinction turns Sepolia into a coordination test for Ethereum's effort to substantially expand Layer 1 capacity.
A higher block gas limit allows more aggregate computation to fit into each block, creating room for more transactions and high-demand applications such as decentralized exchanges and other DeFi protocols. Additional capacity can ease congestion and reduce pressure on transaction fees when demand rises, though it does not make Ethereum's underlying block times faster.
Ethereum has already been moving in that direction. Its block gas limit began rising from 30 million toward 36 million in February 2025, the first adjustment since the network moved to proof-of-stake. It subsequently climbed to 45 million before Fusaka client releases adopted 60 million as their default.
Ethereum's 200 million ambition meets a 60 million default
Glamsterdam would push that scaling experiment considerably further, but 200 million should not be interpreted as an automatic new gas limit.
EIP-8261 introduces an optional gas-limit schedule that lets consensus clients coordinate recommended preferences at specific epochs. The proposal does not alter Ethereum's consensus-validity rules, and blocks remain valid whether their gas limit sits above or below the scheduled value. Validators can also explicitly choose their own preference.
That means Sepolia's realized gas limit will move gradually as validators propose blocks rather than jumping immediately to 200 million when Glamsterdam activates.
The higher target is part of a broader effort to increase the amount of work Ethereum can process without making validation impractical.
Glamsterdam combines the Amsterdam execution upgrade with Gloas on the consensus layer and introduces enshrined proposer-builder separation alongside block-level access lists, which allow clients to parallelize state reads and transaction validation. The Foundation says the changes lay the groundwork for higher Layer 1 throughput.
Ethereum has also added safeguards as capacity rises. Fusaka introduced a 16.7 million gas cap for individual transactions, limiting how much of a block any single operation can consume even as the overall block budget increases. That means higher block limits primarily create room for more aggregate activity rather than allowing individual smart-contract transactions to expand without restraint.
Sepolia will provide the first scheduled test of Glamsterdam before Ethereum developers decide how to proceed elsewhere. Hoodi and mainnet activation dates remain undecided, leaving validator participation in the 200 million preference among the signals developers can observe before taking the upgrade closer to production.
The post Ethereum is preparing a 200 million gas push as its Layer 1 scaling strategy accelerates appeared first on CryptoSlate.
Ripple's Brazilian foothold spans cross-border payments and securities records in a country Chainalysis ranked first for grassroots crypto adoption.
Ripple and CSD BR, a regulated financial market infrastructure operator, announced a first phase on Sept. 29 to mirror ownership records for BTG Pactual investment fund shares on the XRP Ledger (XRPL). CSD BR's systems will remain the official record for registration, deposit, and settlement.
The announcement follows a Sept. 28 interview in which RippleX executive Markus Infanger told Estadão's E-Investidor that about $2.7 billion of the $6.7 billion in tokenized real-world financial assets he counted on XRPL was in Brazil.
That puts roughly 40% of the reported asset value in one country, although the measure reflects assets rather than payment activity.
Together, the developments show how Ripple's years of expansion have connected it to several parts of Brazil's financial system. The opportunity spans institutions moving money, platforms distributing stablecoins, and firms managing investment assets, with different measures of success for each.
Ripple was building there before the ranking
Ripple opened its Brazilian office in 2019 and announced XRP-enabled payments with Travelex Bank in August 2022. Those relationships predate the new adoption ranking by years.
In October 2024, its Mercado Bitcoin payments partnership initially targeted internal treasury transfers between Brazil and Portugal. The release described corporate and retail international payments as future plans, rather than services already available to those customers.
By March 2026, Ripple was expanding its Brazilian institutional offering across payments, custody, prime brokerage and treasury management. It named Banco Genial, Braza Bank and Nomad among payments users, while Mercado Bitcoin, Foxbit and Ripio were among platforms listing or supporting its dollar stablecoin, RLUSD.
Alongside that expansion, Ripple announced plans to seek a Brazilian virtual asset service provider license.
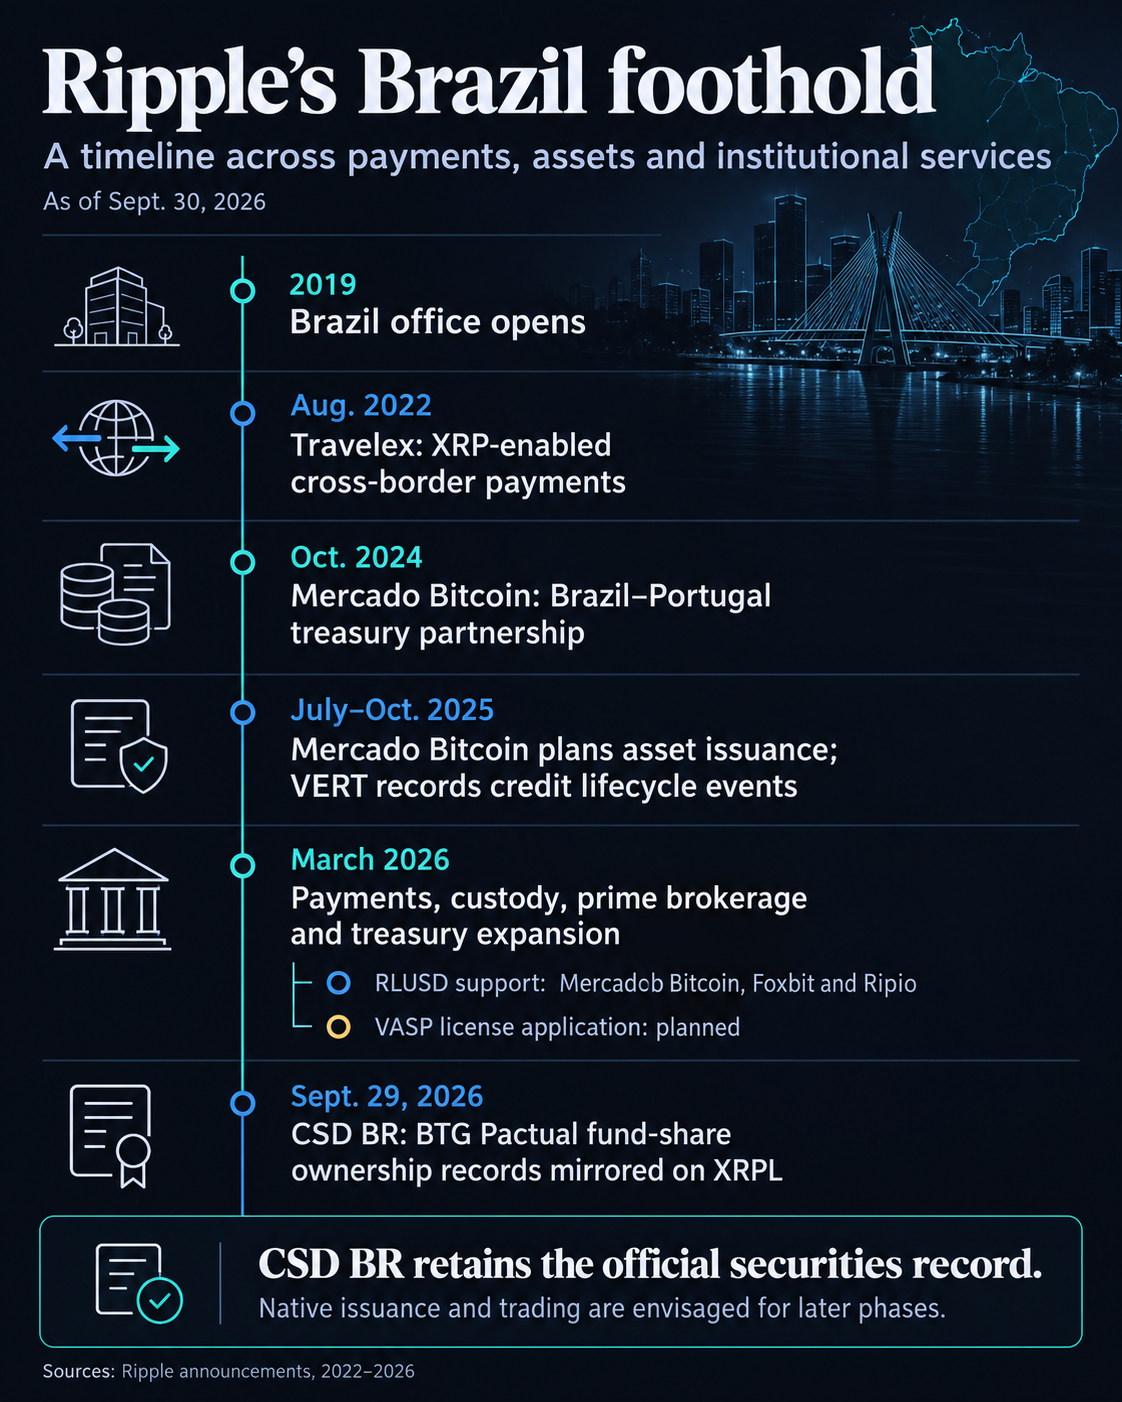
The same companies can connect several parts of the strategy. Mercado Bitcoin, for example, announced plans in July 2025 to tokenize more than $200 million in permissioned real-world assets on XRPL. The planned issuance adds an asset relationship to its payments and stablecoin connections.
Chainalysis's 2026 adoption index puts Brazil first overall, second for cross-border flows, third for service flows and domestic peer-to-peer activity, and fourth for balances.
Its revised methodology rewards broad performance across those four measures. First place does not mean Brazil has the world's largest crypto market by raw dollar volume, and the methodological change limits comparisons with earlier rankings.
Chainalysis estimated $252.5 billion in Brazilian crypto activity between July 1, 2025, and June 30, 2026. Its Latin America report also found that Brazil's crypto economy contracted 1.6% during that period, so adoption leadership coexisted with a slowdown.
For Ripple, the more useful connection is what businesses do with crypto. The report describes Brazilian companies using stablecoins for liquidity management and cross-border transfers, purposes that overlap with its institutional offering.
Brazil's Oct. 1 restrictions will bar virtual assets from settling aggregated eFX flows between providers and foreign counterparties, while individual international virtual-asset transfers remain permitted.
From represented assets to financial infrastructure
Infanger's reported XRPL asset total gives the Brazilian footprint a reported scale. The $2.7 billion figure describes tokenized real-world asset value represented on XRPL.
In October 2025, Ripple said VERT's credit platform recorded lifecycle events, documentation and payments on XRPL and its EVM sidechain. Its pension-receivables fund then held more than R$200 million in net assets.
The CSD BR announcement extends that approach into securities infrastructure. Its first phase mirrors BTG Pactual fund-share ownership records using XRPL tokens and Ripple custody, with access restricted to authorized Brazilian corporate and banking participants subject to identity and anti-money-laundering checks.
Native issuance and trading are envisaged for later phases after mirroring is validated. For now, the project gives Ripple a place inside existing financial processes without making the public blockchain the authoritative securities register.
That makes Brazil a practical test of Ripple's wider institutional strategy. Its announcements show relationships across payments, stablecoins, custody and investment records, but provide no comparable aggregate Brazil-only payment volume, RLUSD circulation or active institutional usage.
Sustained transactions and broader use of the CSD BR system would show how far those connections develop beyond the reported asset values.
The post Ripple quietly made Brazil the center of its XRPL tokenization push appeared first on CryptoSlate.
CryptoTicker.io
Open USD has been in circulation since September 30, 2026. Behind the dollar stablecoin stand Coinbase, Mastercard, Shopify, Stripe and Visa, and it is issued by Bridge, Stripe’s stablecoin subsidiary. For you in Europe, though, a different question counts more than the partner list: may this token be offered publicly here? On October 1, 2026 the answer is no. The issuer holds its European authorisation; the token itself is not notified in the MiCA register.
This is not a detail for lawyers. It decides whether an exchange regulated in the EU may offer you Open USD, what rights you would hold against the issuer, and whether you will ever see a yield for holding it. This article separates three things that blur together in the launch coverage: what actually went live, what MiCA demands of a dollar stablecoin, and how much of that was in place on October 1, 2026.
Open USD (OUSD): the dollar stablecoin from Stripe’s subsidiary Bridge
A stablecoin is a crypto token whose price is pegged to a currency. Open USD, ticker OUSD, is pegged to the US dollar and stood at $0.9995 on October 1, 2026 according to CoinGecko. The peg therefore held at launch; a deviation of 0.05 percent is unremarkable for a stablecoin.
OUSD is issued by Bridge. Stripe acquired the company in 2024 for $1.1 billion. The organisation behind the token is called Open Standard; Coinbase, Mastercard, Shopify, Stripe and Visa hold equal founding stakes there as the five founding partners and have jointly pledged more than $1 billion to build liquidity over the coming months.
How many companies are involved in total differs between sources. Reports from July 2026 named more than 140 partners, while Open Standard’s own launch statement spoke of over 200 financial institutions, fintechs, banks and companies. Both figures stand here side by side deliberately, because it cannot be established which counting method each follows.
Technically OUSD runs on four networks from the outset: Ethereum, Solana, Base and Tempo. According to the launch announcements the token traded at Coinbase, Kraken and Uniswap from the start, with Coinbase support due to begin on October 1.
E-money tokens under MiCA: why a dollar stablecoin needs authorisation in the EU
The EU regulation MiCA has a category of its own for stablecoins. A token that references a single official currency is an e-money token, EMT for short. Open USD references the US dollar and therefore falls into this category, even though the issuer is based in the United States.
E-money tokens face a double hurdle. Under Article 48 MiCA, an e-money token may be offered publicly or admitted to trading in the Union only if the offeror is the issuer of the token, is authorised as a credit institution or as an electronic money institution, and has notified and published a crypto-asset white paper with the competent authority for this precise token. Both conditions have to be met, not one of the two.
In practice that means an exchange with a MiCA licence in the EU cannot simply list a dollar stablecoin because it is successful in the United States. It is on exactly this rule that several large dollar tokens have come unstuck in the European market in recent years. The obligations the regulation places on companies are set out at length in our overview of the MiCA licensing duties for crypto companies.
The MiCA register on October 1, 2026: the issuer is listed, Open USD is not
On October 1, 2026 we went through the register of electronic money institutions authorised under MiCA and the e-money tokens they have notified, and compared it against the MiCA page of ESMA. All 25 issuers listed there were checked, with 50 notified white papers from 14 countries between them, each entry individually for a token named Open USD or OUSD. This analysis was carried out by cryptoticker.io itself on October 1, 2026.
The result has two sides. The issuer is present: Bridge Building S.A., registered in Luxembourg, authorised by the Luxembourg supervisor CSSF as an electronic money institution, entered since July 23, 2026. This company is the European entity of the Stripe-owned Bridge, and the legal entity identifier reads 254900MVWQXMF77YZP65.
The second side is the decisive one. Exactly one notified white paper was recorded for this issuer, and it concerns a euro token with the ticker EURR. No white paper for Open USD was entered, and OUSD appeared under none of the 50 notified tokens.
One discrepancy belongs in the picture: reports from July 2026 described Bridge as the forty-second authorised issuer of e-money tokens. The register we examined lists 25 issuers. The figures evidently follow different counting methods, for instance because authorisations as a crypto-asset service provider and as an electronic money institution are combined. For the question about Open USD this is immaterial, because there the token decides and not the issuer’s place in a ranking.
Whitepaper notification: the difference between an authorised issuer and an authorised token
This distinction is the most important insight for you, and launch coverage blurs it regularly. The authorisation attaches to the company. The white paper attaches to the individual token.
An authorised electronic money institution can issue several tokens, and for each one it has to notify and publish a white paper of its own. Bridge Building has done so for a euro token. The fact that the same group is launching a dollar token in the United States does not automatically extend the European permission. Anyone who reads that Bridge is MiCA-licensed and concludes from it that Open USD is tradable in the EU is drawing an inference the register does not support.
How to spot it yourself
You need no legal database for this. The ESMA register lists for every issuer the notified tokens together with the publication date of the white paper. If the token you want to buy is not there, it is not notified as an e-money token in the EU. That is a two-minute look, and it answers more than any partner list.
Reserves at BlackRock, Lead Bank and BNY: monthly attestation as the only evidence
According to the issuer, the backing for OUSD sits with BlackRock, Lead Bank and BNY. Bridge has undertaken to publish confirmations on the reserves monthly.
An attestation is an auditor’s confirmation as at a reporting date, not an annual audit. It says that certain funds were present on a particular day. About the days in between it says nothing, and about the quality of the internal processes it says less than a full audit does. That is customary in the industry and is nonetheless the point at which you should keep apart what you demand of a regulated euro stablecoin and what you demand of a US dollar token.
Under MiCA the standard would be tighter. An electronic money institution has to hold the corresponding value in full and separately from its own assets, and holders have a claim to redemption at par. As long as a token is not notified, that framework does not apply to it, and what remains is the issuer’s contractual promise.
Article 50 MiCA: holders get no interest, the yield goes to the merchants
The economics of Open USD are unusual and are readily sold as an advantage. After deduction of a small management fee, the income from the reserves goes to the participating companies, measured by the circulation and transaction activity they contribute. Equity is distributed to founders and network participants over four to five years. The five founding partners receive no separate preferential share of the proceeds.
Read that sentence again and note who does not appear in it: you. The yield flows to merchants and platforms that generate circulation, not to private holders. Anyone who leaves OUSD sitting in a wallet gets nothing for it under this model.
Under MiCA they could not either. Article 50 prohibits issuers of e-money tokens from granting interest, and prohibits the same for the crypto-asset service providers that offer services relating to such tokens. Interest here covers every remuneration and every other benefit tied to the length of holding, even when it comes from third parties. The legislator wanted to prevent stablecoins from becoming interest-bearing savings deposits and competing with bank deposits.
For you that yields a clear classification: an e-money token is a means of payment and a parking space, not an investment with a return. Anyone looking for dollar income inevitably ends up with other products carrying other risks. Anyone wanting to use the token for paying will find the routes actually available in Europe in our comparison of crypto credit cards.
Coinbase, Kraken and Uniswap: the trading launch and the open EU question
The launch announcements name Coinbase, Kraken and Uniswap as the first venues. These are globally active providers, and it does not follow that a customer in Germany sees the same offering as one in the United States. Large exchanges maintain separate listings for the European market, because MiCA compels them to.
We did not examine in this round whether and where OUSD is shown to German customers, and so we assert nothing in either direction. What you can look at yourself is quickly done: search for the token in your account’s trading list, and look in your exchange’s asset overview to see whether it is enabled for customers in the European Economic Area. If you do not find it, that is the expected state for a non-notified e-money token and not a fault in your app.
Which providers hold European authorisation at all is shown by our overview of regulated crypto exchanges. With a token whose European status is open, a look at the venue’s licence is worth twice as much.
Swapping into a stablecoin and the holding period: when the German tax office sees a disposal
This is where it gets expensive for many people, and it concerns every stablecoin, not just this one. If you swap Bitcoin or another coin into a stablecoin, that is not a pause for tax purposes but a disposal. Under the law as it stands the swap triggers a private sale transaction, with everything that hangs on it: calculating the gain as at the time of the swap, and the question whether the coin given up had completed the one-year holding period.
Anyone moving into a stablecoin and back several times during volatile weeks creates a chain of tax-relevant events that has to be documented by the end of the year. This is precisely where self-declarations regularly fail, because the records are scattered across several platforms. Which tools keep that chain traceable is set out in our comparison of crypto tax tools and portfolio trackers.
There is also a caveat with a date on it. The German finance ministry has put forward a draft bill on the taxation of certain crypto assets which, according to our report of October 1, 2026, is due to go before the cabinet on October 14, 2026 and provides among other things for a substitute assessment where a purchase record is missing. Whatever is decided there shifts the legal position for the years from 2027. We have written up the details and the state of the procedure in our article on the substitute assessment without a purchase record. We deliberately name no figure for the exemption threshold here, because it can only be stated reliably with reference to the particular assessment year.
Custody and depeg: the redemption right is the real protection
With a stablecoin the first thing people think of is the price. The real protection lies elsewhere, namely in the claim against the issuer. MiCA gives holders of an e-money token a claim against the issuer and the right to return the token at par at any time. That right is why the peg holds under pressure with regulated tokens: someone who can redeem does not sell in a panic below value.
Where that framework is absent, what remains is the issuer’s promise and the reserve structure it discloses. With OUSD that means three well-known custodians and a monthly confirmation. That is respectable and still something other than an enforceable redemption claim under European law.
Where you hold the token
If a stablecoin sits in an account at an exchange, you additionally carry the risk of that house. If it sits in a wallet of your own, you carry responsibility for the keys but not the default risk of the exchange. With a token whose European status is still open, the question carries extra weight: if a venue discontinues the offering for EEA customers, a position in self-custody is not directly affected by that.
40 working days’ notice: the earliest possible date for an EU offering
Anyone waiting for Open USD to arrive in Europe can work out the time frame. MiCA requires the issuer of an e-money token to notify the competent authority of its intention at least 40 working days before the planned public offer or admission to trading. The white paper itself has to be notified at least 20 working days before publication.
Forty working days is around eight weeks. Even if Bridge Building were to file the notification for Open USD immediately, a European offering would therefore not be in place before the end of November 2026. On October 1, 2026 no such notification was recorded in the register. Whether and when it comes is a decision for the company, and nothing can be demonstrated about it here.
That the issuer already holds the Luxembourg authorisation does, however, shorten the path considerably. The laborious part, authorisation as an electronic money institution including supervision by the CSSF, is done. What is missing is a procedural step for a further token, and that is a different order of magnitude from an authorisation procedure started from scratch.
Open USD in Germany: How to proceed now
- Look at the status instead of the headline. Check in the ESMA register whether a notified white paper is entered for Open USD, and look in your venue’s asset list to see whether the token is enabled for EEA customers. Whether your provider holds European authorisation at all is shown by the overview of regulated crypto exchanges.
- Reckon with the tax consequences before you swap. Every move into a stablecoin and back is a separate event with a date and a value. Set up the documentation beforehand, not in May of the following year; the suitable tools are in the comparison of crypto tax tools.
- Expect no income from holding. The revenue model of Open USD serves merchants and platforms, and MiCA forbids interest on e-money tokens in any case. If your aim is paying, compare the available routes among the crypto credit cards.
(As of October 1, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Setting up a TON wallet takes two minutes. The trouble usually starts afterwards: the transfer is visible on the network, the explorer marks it as successful, and nothing has arrived in the exchange account. In almost every case a single line is missing, the one TON calls the “comment” and other networks list as a memo or a tag. This article explains how to set up a transfer on The Open Network so that it actually lands, how to read in Tonviewer what really happened, and what the rename from Toncoin to Gram changes in practice.
The network itself is no longer a niche project. According to the figures the project publishes on its own home page, 325 validators currently secure the chain, more than 182 million contracts run on it, and around four million transfers are settled every twenty-four hours. Gram trades at about €1.38 and ranks 31st by market value. Anyone moving money here is moving it through a busy network with rules of its own, and those rules are precisely why guides written for the Ethereum world do not apply.
Your Gram arrived on the network but the exchange balance stays empty
The most common cry for help about TON always sounds the same. Someone sends Gram or USDT from their own wallet to an exchange, sees the transfer in the explorer, and nothing happens in the customer account. No error, no reversal, no notice. The money has not disappeared; it is simply sitting somewhere that belongs to nobody in particular.
The reason is a practice many large trading venues use: instead of giving every customer an address of their own, they operate a single pooled address for everyone. Which amount belongs to which customer is then decided not by the address but by a short piece of extra text sent along with the transfer. On XRP that text is called a destination tag, on Cosmos a memo, on TON simply a comment. Without it, the payment lands on the pooled address and no booking picks it up.
The comment is not an accessory here; it is part of the protocol. The project’s technical documentation states explicitly that the message body of an internal transfer can carry a plain-text or an encrypted comment. Every transfer on TON is a message, and that message has a field for text. Leaving it empty is like sending a letter to an open-plan office without a name on it.
Before you even think about the comment, you need a wallet that offers you one. Not every wallet puts it in the same place, and in some it hides behind an inconspicuous toggle.
Setting up a TON wallet: Tonkeeper, MyTonWallet and the wallet inside the messenger
TON is not an EVM network. That is the single most important sentence for anyone arriving from Ethereum, Polygon or the BNB Chain. There is no chain ID to enter anywhere, no RPC node to register by hand, and MetaMask cannot simply add the network. You need a wallet that speaks TON natively.
In practice three routes converge. Tonkeeper is the most widely used standalone app and works on the phone as well as on the desktop. MyTonWallet additionally offers a browser extension, which helps anyone working at a computer. And since the end of August a self-custody wallet has run directly inside the messenger, which we covered in detail in our piece on the rename from Toncoin to Gram. All three are wallets in which you hold the key yourself, and all three hand you a sequence of recovery words when you set them up.
Those words are the actual ownership. The app is interchangeable, the key is not. Anyone who photographs it and stores it in the cloud has effectively given it away. Anyone holding larger amounts keeps it on a device that never touches the network; which models qualify, and how a genuine unit differs from a tampered one, is covered in our hardware wallet comparison.
One quirk shows up on first launch: some wallets ask for a version. TON knows several generations of wallet contracts, and the same recovery words produce different addresses depending on the version. Someone who loads their words into another app and sees an empty account has usually not lost their money, only picked the wrong version. The settings allow you to switch between them, and as a rule the balance then reappears.
The comment field in the TON protocol is what other networks call a memo or tag
When you send, every TON wallet shows an additional line below the amount field. Sometimes it is labelled comment, sometimes message, sometimes memo. What belongs in that line is exactly what the exchange shows you on its deposit page: usually a string of digits and letters, occasionally just a number.
Three rules apply, and every one of them has already cost somebody money.
First: typing it out is the worst method. The comment is built so that a single transposed character makes it worthless. Copy and paste, then compare the last four characters once.
Second: capitalisation counts. Many trading venues issue comments in mixed case, and the matching is letter-exact.
Third: the comment belongs only on the way to the exchange. When you withdraw from the exchange to your own wallet, you do not need one. Your own address belongs to you alone, so there is nothing to allocate. A superfluous comment does no harm, but it muddies the record when you read back through it later.
And if it has already gone wrong? Then the money is not gone, merely unsorted. Trading venues have a procedure for exactly this case, usually a form in the help section into which you enter the transaction identifier. It takes days, sometimes weeks, and some of them charge a processing fee for it. What you need for it is the identifier from the explorer, which brings us to the next tool.
Tonviewer and Tonscan: how to read a TON transaction
A block explorer is a website that makes the bookings of a blockchain readable for people. TON has two widely used ones: Tonviewer and Tonscan. Both show the same data and differ only in presentation. You need no account and have nothing to connect; it is enough to drop an address or the identifier of a transfer into the search box.
Four fields are the ones that matter.
The status tells you whether the transfer went through. TON works with messages that can trigger further steps, so what you see here is sometimes not just a tick but a small chain of stages. What matters is that none of them is marked as aborted.
The comment appears as its own line on the transfer. This is where you check, in a dispute, whether you really sent it along. If the line is empty, you know what went wrong.
The counterparty address is where most people trip up. More on that shortly, because with tokens the explorer does not show the address you expect.
The fee appears as a separate item and is the amount the network withheld for processing. On TON it comes out so small that at first glance the figure looks like a display error.
TON fees: what a transfer really costs today
We did not take this on trust; we measured it. Across a sample of seventeen transfers that users initiated themselves on Monday morning, the fees withheld by the network ranged between 0.00031 and 0.00195 Gram. At a price of €1.38 that is between four hundredths of a cent and a good quarter of a cent, with the middle of the sample at around seven hundredths of a cent.
For context: in our network series we ran the same calculation for other chains. A USDT transfer on Tron cost just under €2 measured the same way, while on Arbitrum and Ethereum the amount depends heavily on how busy the network is. TON sits at the bottom end of what is possible at all today.
Payment is always in Gram, even when you are sending USDT. This is the point where newcomers run aground: anyone who has USDT sent to a fresh TON wallet and nothing else cannot move it on, because there is no Gram there for the fee. A small float of one or two Gram in the wallet solves that problem permanently.
A second peculiarity separates TON from almost every other network: there is a storage fee. On TON every wallet is a small contract of its own, and the network continually deducts tiny amounts for the space it occupies. On active wallets this goes unnoticed, because the sums run to fractions of a cent a year. But anyone who leaves a wallet untouched for years with nothing but dust in it may eventually find it empty.
Bounceable and non-bounceable: how to recognise a TON address
TON addresses come in two notations. The short, user-friendly form starts with two letters and is the one your wallet displays. The long raw form starts with a number, a colon and a long run of digits and letters.
That leading number is not decoration; it names the part of the network the address sits in. A 0 stands for the base chain, on which practically everything you care about runs: wallets, tokens, applications. A minus 1 stands for the masterchain, which administers the network and coordinates the validators. In our sample, the operations that corresponded to no user action carried this minus 1 throughout.
The shorter form comes in two variants, and the difference between them decides what happens to your money if something fails. With one variant an amount comes back when the receiving side cannot accept it. With the other it stays at the destination address even if no wallet has been set up there yet. Modern wallets get this right in the background, which is why you need not worry about it day to day. It becomes relevant when somebody hands you an address in raw form, or when an older application asks you which variant it should use. The rule of thumb: for a payment to a wallet that already exists, the variant that bounces back is the safe one.
Jetton instead of token: why USDT on TON has its own wallet address
Tokens on TON are called jettons, and they work differently from ERC20 on Ethereum. There, a single contract keeps one large list of all balances. On TON every holder gets a small contract of their own for every token, a so-called jetton wallet.
That sounds academic, but it has a very practical consequence, which we checked on an arbitrary active address: the same holder ran a different address there for USDT, for an in-game currency token and for a third token, and none of them was his main address. So the address an explorer shows you as sender or recipient on a token transfer belongs to the contract, not to the person behind it.
Two things follow. First: never confuse the jetton wallet with a deposit address. Anyone who takes the address they see in the explorer line of a USDT transfer and enters it somewhere as the recipient is sending money to a contract that is not expecting it. Second: a balance you can see in your wallet while its main address looks empty in the explorer is not a fault. You have to switch to the token tab in the explorer to find it.
Incidentally, the Tether contract for USDT on TON is by far the largest block on the network, and it is the reason many users are here at all: moving dollar balances for fractions of a cent is this cheap on few networks.
A Gram float: why an empty wallet cannot move tokens
One question comes up so often that it deserves a section of its own. Someone has USDT sent to a freshly created TON wallet, sees the balance, wants to pass it on and finds that nothing works. The wallet is not broken, it is simply penniless.
Every transfer on TON costs Gram, even when what you are sending is something else. With a token there is the added fact that the transfer sets two contracts in motion, yours and the recipient’s, and that for a recipient who has never held this token a contract has to be created in the first place. That creation step is why the first transfer to a new recipient costs a little more than every one after it.
The sums stay tiny all the same. Even at the upper end of our sample a transfer came to a good quarter of a cent. Leaving one or two Gram sitting in the wallet buys you years of peace, and the amount simultaneously covers the running storage fee.
One exception is worth knowing: some exchanges pay out tokens on TON without sending any Gram along. That is not a fault on their side; it is the normal case. It is up to you to make sure beforehand that something is there for the fee. Anyone who neglects it ends up with a balance they can see but not touch, until somebody sends them a few Gram.
What TON does differently from Ethereum and the rollups
TON is not one chain but a system of chains. A masterchain coordinates, and below it works the base chain on which practically everything that concerns you runs. The design is meant to form further sections as load rises, rather than letting fees climb. Whether that promise holds under sustained load is an open question; what is demonstrable so far is that fees have stayed in the hundredths-of-a-cent range at several million operations a day.
The second big difference is the way it works. On Ethereum one contract calls another directly and everything happens in a single pass. On TON contracts send each other messages, and every message is processed on its own. That is why in the explorer you often see several entries in sequence for one single operation. For you this mainly means: on a token transfer, do not wait only for the first tick but look at whether the chain of steps ran all the way through.
What TON is not: a rollup. There is no seven-day waiting period here as on the optimistic networks on Ethereum, because there is no superordinate chain on which anything would have to be secured. A TON transfer is done within a few seconds, and done for good.
Without the old bridge: how Gram reaches Ethereum or an exchange today
For years the project’s official bridge was the way to get Gram over to Ethereum or the BNB Chain. That route is closed. The bridge’s old address today merely redirects to the project’s home page; no application sits there any more. Anyone still holding wrapped balances on other chains will find the situation before and after the cut-off date in our piece on the shutdown of the TON bridge.
For everyday use that means the most reliable route from TON into other networks today runs through a trading venue. You deposit Gram at your exchange, swap there into whatever you need, and withdraw again on the target network. That costs two fees instead of one, but it is traceable and can be documented in a dispute. Which houses in Europe operate under supervision and what they charge for deposits and withdrawals is set side by side in our exchange comparison.
The second option is the so-called intent bridges, where a provider fronts you the money on the target network and collects your Gram in return. That is fast, but it shifts the risk onto that provider. Anyone taking this route should start with a small amount and only raise it to the sum that actually matters on the second attempt. How the routes differ in principle is summarised in our overview of networks, bridges and explorers.
The three most common mistakes in a TON transfer
The missing comment is by far the most frequent. It affects only deposits at trading venues that work with pooled addresses, and it is entirely avoidable: on the deposit page the comment always sits directly below the address, often in a box picked out in colour.
The wrong network is the most expensive. USDT exists on TON, on Tron, on Ethereum and on a dozen further chains, and each time it is a different token with a different address format. Anyone who sends USDT on TON to an address beginning with 0x is sending it into the void. The protection against this is simple: TON addresses look unlike anything else, and your wallet will as a rule not even accept a foreign address.
The empty fee pot is the most irritating, because it looks so harmless. The wallet shows a balance, the send button is greyed out, and there is no comprehensible explanation for it. Almost always a few tenths of a Gram are missing for the fee.
Self-custody, recovery words and phishing inside the messenger
TON has grown together with a messenger, and that is a strength and a weakness at once. The strength: a wallet is there in seconds, and payments to other users feel like sending a message. The weakness: fraudsters know this and work exactly there.
The pattern is always the same. A message from a supposed support desk, an allegedly lost login, a prize that only needs confirming. At the end stands a page asking for the recovery words. There is not one legitimate reason to enter those words anywhere except when restoring your own wallet in an app you installed yourself. No support desk in the world needs them.
The second trap is approvals. When you connect an application to your wallet, it receives certain rights. These connections persist until you break them, and the settings of every serious TON wallet contain a list for the purpose. Going through it once a quarter and disconnecting everything you no longer use is the cheapest insurance there is. Why this is no theoretical risk is shown in our piece on how to revoke token approvals.
And a third point with a flavour of its own on TON: counterfeit jettons can be created in minutes and then carry the same name as the original. The only reliable marker is the contract address. Anyone seeing a token for the first time checks it against the project’s own statement before buying.
Holding period and tax: what the tax office sees in a Gram transfer
A transfer from your own wallet to your own second wallet is not a taxable event in Germany. You have disposed of nothing, the holding remains yours, and the one-year holding period under the income tax act runs on unbroken.
In practice it can still cause trouble, namely with the documentation. Tax tools do not recognise a transfer between your own addresses by themselves. What the software sees is an outgoing here and an incoming there, and in case of doubt that becomes a sale and a purchase. Anyone who does not correct it produces gains that never existed, or throws away a holding period that had almost run its course.
The remedy is unspectacular: label the addresses in the tax tool as your own, so that the matching runs automatically. Which providers map German rules cleanly is set out in our overview of tax tools.
Two operations, by contrast, very much are relevant for tax. Anyone swapping Gram for USDT has disposed of it, even if nothing has flowed to a bank account. And anyone pledging Gram as collateral or lending it out should have the individual case looked at; the treatment depends on the exact arrangement. With larger amounts there is no way around professional tax advice.
What the rename from Toncoin to Gram means in practice
Since June 15, 2026 the token has carried its original name again. The price services have completed the switch, and at one of the large data providers the entry now reads “Gram” with the note that this is the former Toncoin. The project’s technical documentation also speaks of Gram again when it describes transfers.
For you nothing changes about your holding. There was no swap, no new ticker in the wallet, no deadline. What does change is the search: guides from past years speak of Toncoin, current pages of Gram, and some exchanges carry both spellings side by side. Anyone looking for instructions should try both terms and check the date on every guide.
The second point concerns the name of the network. The network is still called The Open Network, TON for short. The token is called Gram. When an exchange shows you a selection field for the network, it says TON there, regardless of how it labels the token.
Gram on TON: the key points for your decision
TON is one of the cheapest networks you can use for transfers today, and at the same time one with the most quirks. Anyone who understands the comment, who has grasped the business with jetton addresses once, and who always leaves a little Gram sitting for the fee has the three stumbling blocks behind them that catch almost everybody out.
- Set up a wallet of your own and secure the recovery words offline. For amounts that would hurt to lose, the key belongs on a device with no network connection; the models for that are listed in our hardware wallet comparison.
- Send a test amount with a comment before your first large deposit. A few cents in fees are cheaper than a form in the help section. Which houses handle deposits smoothly in Europe is shown by the exchange comparison.
- Enter your addresses in your tax tool once as your own. After that the holding period keeps counting correctly by itself; you will find the suitable providers in our overview of tax tools.
The sources for this article are in the project’s technical documentation, and the network figures on the site of The Open Network.
(As of September 29, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Dogecoin is trading at $0.0946 on Thursday morning, the equivalent of 0.0838 euros. That is 0.4 percent more than 24 hours earlier, and it is the third attempt within a week to end at the same spot: the day's high was $0.0979, just below the zone around $0.098. Anyone wanting to make a decision on Dogecoin today holds two hard figures in their hands, and neither of them is the price itself. One is a deadline: the US fund Bitwise Dogecoin ETF stops trading on October 14. The other is the buying route, because in Germany that is what decides whether your gain is tax free after a year or not.
This text places both: what the level at $0.098 means technically, what happens to the closing fund on which day, which Dogecoin products can be held in a German portfolio at all, and where the tax dividing line runs between a direct purchase and a security.
Dogecoin price today: $0.0946, and $0.098 is holding once again
As of October 1, Dogecoin stands at $0.094598 according to CoinGecko. The range over the past 24 hours runs from $0.093635 to $0.097941, and trading turnover comes to around $972 million. Market capitalisation is about $14.8 billion, putting DOGE at rank twelve among the largest crypto assets. Around 156.1 billion coins are in circulation.
The time series alongside it says more than the daily figure. Over seven days there is a loss of 0.2 percent, over 30 days a gain of 13.3 percent, and over twelve months a loss of 60.9 percent. The price is around 87 percent away from the record high of $0.731578 set on May 7, 2021. That is the frame in which every price level of this autumn sits: a recovery within a long downward move, not a break out of it.
Open interest is a term that becomes important further down. It denotes the total of all open futures contracts on an asset, that is, the volume that still has to be closed. If it rises, traders are building new positions instead of settling old ones.
The levels above and below: $0.0936, $0.098 and $0.10
On the upside the first hurdle sits at $0.098. That supply is waiting there is not a chart line but a holdings figure: at that level a large part of the coins in circulation today were last moved. Our own report of September 30, 2026 put this supply zone at around 28 billion DOGE based on the distribution. Behind it at $0.10 follows a round level that works psychologically, because buy and sell orders bunch up there.
On the downside the day's low of $0.093635 is the first point at which demand has shown up in recent sessions. If it does not hold, the area around $0.090 comes into view, which held several times in September and is at the same time a round number.
In practice that means: as long as the price swings between $0.0936 and $0.098, every buy or sell decision is a bet on the breakout and not on a trend. Anyone wanting to place an order can align it with exactly those three numbers instead of going by a daily picture that will look different tomorrow.
Bitwise is closing the Dogecoin ETF BWOW: what happens on October 14 and on October 22
On September 10, 2026, Bitwise Investment Advisers announced that it was winding up the Bitwise Dogecoin ETF. The mandatory filing with the US Securities and Exchange Commission states that Bitwise announced "its decision to liquidate and close the Fund, effective September 10, 2026". Two dates are fixed in it: the last day of trading on NYSE Arca is Wednesday, October 14, 2026. On Thursday, October 22, 2026, the remaining shareholders receive the net asset value of their shares as of the reference date of October 21 as a cash payment.
Shareholders do not have to arrange anything for that; the payout runs automatically. Anyone still holding the fund in their portfolio who would rather decide on the selling moment themselves has until October 14; after that the reference price of October 21 determines the amount. The background to the closure is plain demand: the fund had launched in November 2025 and slipped below one million dollars in assets through outflows.
Why the US fund was never the buying route for investors in Germany anyway
The closure sounds like news that hits German portfolios. As a rule it does not. US spot crypto funds are not products authorised for distribution under European law, because they lack the key information documents required by the PRIIPs regulation. German brokers therefore mostly do not even display them for purchase. Anyone who wanted to hold Dogecoin in a securities portfolio in Germany has so far done so through European debt securities and not through BWOW.
For the state of the market the report nevertheless remains relevant, because it says something about the demand side. While a US provider discontinues its Dogecoin product, industry services report inflows into other DOGE funds for the same weeks: wallstreet-online reported around $2.9 million in net inflows for the week to September 25, and thus a weekly record. Measured against a market with a capitalisation of $14.8 billion, both figures are small. The honest reading is therefore neither "funds are buying DOGE" nor "funds are fleeing", but rather: the fund wrapper has so far played barely any role with Dogecoin.
Dogecoin ETPs on Xetra: 21Shares and Valour in an ordinary securities portfolio
An ETP, that is, an exchange traded product, is in crypto assets an exchange-traded debt security backed by deposited coins. Unlike a fund under UCITS law it is not a segregated asset pool. That is precisely why these products in Europe are called ETPs or ETNs and not ETFs. Anyone wanting to read up on how the various wrappers are built will find the differences in our overview of crypto ETFs in Germany.
For Dogecoin there are two listed routes in Germany. The 21Shares Dogecoin ETP carries the ISIN CH1431521033 and the German securities number A4A5WJ, trades under the ticker DOGE on Xetra and is physically backed; custody of the coins runs through Coinbase Custody. The total expense ratio is 2.50 percent a year according to the provider. The product was launched in April 2025 and has been reachable through German brokers since the Xetra listing in spring 2026; the product page of 21Shares carries the current terms at any time. Alongside it, Valour has listed a physically backed Dogecoin ETP with the securities number A4AK2K on the Frankfurt Stock Exchange and at Lang und Schwarz.
Both routes sit in the familiar portfolio, need no wallet and no private key. That is the convenience. What it costs is set out in the following two sections, and it is more than most expect.
Holding period, exemption threshold, flat tax: where a direct purchase and an ETP diverge for tax
If you buy Dogecoin directly and hold the coins in your own stock, the sale falls under private disposal transactions pursuant to Section 23 of the German Income Tax Act. Two things follow from that which hardly any other asset class offers. First, after a holding period of more than one year the gain is tax free, regardless of its size. Second, within the year an exemption threshold of 1,000 euros per calendar year applies to the total of all private disposal transactions.
The word threshold is to be taken literally here and is constantly confused with an allowance. With an allowance, the first 1,000 euros would remain tax free. With a threshold, by contrast, the entire gain is taxable as soon as it exceeds 1,000 euros by even one euro. At a gain of 999 euros you pay nothing; at 1,001 euros you pay tax on 1,001 euros at your personal rate.
An ETP, by contrast, is a security. For securities the flat-rate withholding tax of 25 percent applies plus the solidarity surcharge and, where applicable, church tax, and the saver's lump-sum allowance is 1,000 euros a year. A one-year holding period after which everything would be tax free does not exist in this regime. For physically backed crypto ETPs with a claim to delivery of the coins the classification is disputed; parts of the literature see a transaction under Section 23 in it, while others treat it as capital income. Do not rely here on a rule of thumb from a forum but on the issuer's base prospectus and, in case of doubt, on a tax adviser. A clean transaction history is in both cases the precondition for being able to calculate at all; which tools deliver that is shown by our comparison of crypto tax software.
2.50 percent in fees a year: what the ETP really costs over twelve months
The total expense ratio of 2.50 percent is not debited once a year but taken on an ongoing basis out of the deposited holding. In practice that means: the number of coins behind each share falls over time. On an investment of 2,000 euros that is around 50 euros a year, on 10,000 euros around 250 euros, and in each case before any price move has happened at all.
Against that, a direct purchase involves a one-off trading fee of between 0.1 and 1.5 percent of the order volume depending on the provider, plus the spread. After that no ongoing costs arise as long as you hold the coins yourself. Over a period of several years the ETP's convenience advantage therefore turns into a noticeable cost disadvantage. The current fee models of the trading venues are set out in our comparison of crypto exchanges.
The calculation shifts when a savings plan is involved, or when the securities portfolio remains the only option for other reasons, for instance because an employer forbids staff from buying crypto assets directly. Then the question is no longer ETP or direct purchase, but which of the two ETPs is cheaper and more liquid to trade.
Leverage and liquidation: what open interest says about the setback risk
The figures on open interest in Dogecoin futures diverge depending on the data service and the reference date. krypto-magazin.de names around $1.5 billion, while CoinGape puts it at around $1.66 billion for the moment after the brief recapture of $0.10, at a daily gain of 5.65 percent. Both values are estimates drawn from differing numbers of exchanges; the range is therefore the more honest figure than any single number.
The statement behind it does not hang on the second decimal place. Open interest of this order of magnitude at a spot turnover of $972 million a day means that a substantial part of the movement arises from leveraged positions. If the price falls below a cluster of liquidation thresholds, the exchange sells those positions by force, and the selling pressure amplifies precisely the move that triggered it. That is why the $0.0936 from the day's low is more than a chart level.
For you a sober consequence follows from that: anyone buying without leverage will not be liquidated and can sit out such a move. Anyone working with leverage should know their own liquidation threshold before the market finds it.
MiCA authorisation: how to recognise a permitted provider in Germany
Since December 30, 2024 the European regulation on markets in crypto assets, MiCA for short, has applied in full. Anyone trading or holding crypto assets for customers on a commercial basis in Germany needs an authorisation as a crypto-asset service provider for it. BaFin is the competent authority, and it lists the authorised firms in a public register.
Two things follow from that. For one, you can check before the first euro whether a provider is listed there, instead of relying on its own marketing claim. For another, authorised providers have to make a whitepaper or comparable information available and may not present returns as certain. An offer promising a fixed return on Dogecoin breaches that and is a warning sign for that reason alone.
For custody the following applies regardless: if the coins sit with a provider, they form part of the insolvency estate in the event of insolvency unless a segregated custody account exists. Anyone holding larger amounts who does not want to trade them takes the coins off the trading venue. Which devices come into question for that is set out in the hardware wallet comparison.
Dogecoin price: how to proceed now
- Decide the buying route before the price. First determine whether you buy directly or take an ETP into your portfolio, because the holding period, the tax regime and the ongoing costs all depend on it. The terms of the trading venues are set out in the comparison of crypto exchanges, and the construction of the exchange-traded products in the overview of crypto ETFs in Germany.
- Note down the three numbers. $0.0936 as the day's low, $0.098 as the supply zone and $0.10 as the round level. An order at those points is comprehensible; an order placed on a whim is not.
- Set up the tax file before the first sale is due. Record the purchase date, quantity, price and fee for every purchase, so that the one-year deadline and the 1,000 euro exemption threshold can be demonstrated later. Which tools write that along automatically is shown by the comparison of crypto tax software.
(As of October 1, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Anyone holding Shiba Inu who wanted to do something with it inside the ecosystem has been stuck for months: validator staking on the project's own layer-2 chain Shibarium has been under maintenance since April 17, 2026, that is, for 167 days. That is the status the operators themselves report, and it has consequences that go beyond forgone BONE rewards. After the infrastructure switch, the chain's block explorer has read back only a little over half of all blocks, and for many German holders that explorer is precisely the source from which the proof for the tax office comes at the end of the year.
The price gives hardly any signal on this. SHIB is quoted on Thursday morning at around $0.00000582, a good one percent above the day's open. So the day's move explains nothing. What can be explained is the state of the technology underneath, and that is traceable in a few minutes with one RPC call and a look at the status page. This article says what is standing still, what is still running and what action follows from it for you.
Validator staking on Shibarium: under maintenance since April 17, 2026
Shibarium is the layer-2 chain of the Shiba Inu ecosystem. It works to the same basic pattern as other sidechains with their own validator set: whoever deposits BONE runs or supports a validator and receives a share of the fees and the issuance in return. Validator staking means depositing BONE with a validator, either as the operator of your own node or as a delegator who assigns their balance to someone else's node.
It is exactly this part of the ecosystem that is switched off. The SHIB ecosystem status page lists the validator staking entry as an incident beginning April 17, 2026 with the state maintenance. No date for its return is given there. Users are expressly asked not to attempt staking transactions during this period. That is not a throwaway line: a transaction running against a contract whose interface and settlement are in the middle of being moved can cost fees without the intended effect occurring.
This has to be placed in the context of the larger switch that has been under way since the spring. In September the chain's public access points were replaced, and the old RPC addresses no longer respond. How that affects wallet setup is something we described on September 29 in a separate piece on the Shibarium switch and your wallet. On September 15 a complete rotation of the node addresses for the Bor and Heimdall layers followed, and on September 19 developer Kaal Dhairya reported via a community member that the chain's reorganisation had been resolved. What remained open after that report was the move of the RPC provider into the new environment.
What the SHIB ecosystem status page reports today
On October 1 the status page lists three unresolved entries. The first is validator staking. The second concerns the rewards from the SSLP pools on ShibaSwap, the ecosystem's decentralised exchange; the distribution is delayed. The third concerns the Bury function, with which holders deposit SHIB, LEASH and BONE on ShibaSwap and receive interest-bearing tokens in return. There too the rewards are stalling.
All three entries share the same note: those affected should contact support with their wallet address so that claims are processed by hand. For you that means two things. First, on the operators' account, forgone rewards count as deferred and not as forfeited. Second, the burden of proof lies with you: anyone registering a claim in December needs the address, the time of the deposit and the amount. You should note down those three details now, not once the interface is running again.
A word on how solid this source is: the status page is the operators' own account of themselves. There is officially nothing better than that account, but an independent measurement still does not replace it. The next section therefore contains figures that can be gathered without going through the operators.
Shibariumscan at 54 percent: the explorer trails the network by 8.77 million blocks
The block explorer Shibariumscan runs on the Blockscout software and publishes its own index status through an open interface. On October 1 it reports that indexing is not complete and puts the share of blocks read in at 54 percent. In absolute numbers, the explorer has captured 10,466,121 blocks. At the same time the chain itself stood at block 19,237,206, queried directly through the chain's official access point with the identifier 109. The gap therefore comes to around 8.77 million blocks.
This figure becomes interesting in a time comparison. On September 20 the same value stood at 53 percent. So in eleven days the index has grown by one percentage point. If that pace holds, reading in the remaining 46 points will take well over a year. That is an extrapolation and not an announcement by the operators, and a single faster pass could dispose of it. As an order of magnitude it is still useful, and it tells you that for the time being you should not assume you will find your complete Shibarium history again in the explorer.
1,620 transactions a day: how empty Shibarium is running right now
The second figure that can be gathered independently is the load on the chain. The explorer reports 1,620 transactions for the current day and a network utilisation of 0.04 percent. As a cross-check we queried 20 consecutive blocks directly through the chain's access point: those 20 blocks contained exactly one transaction, at a mean block time of five seconds. Extrapolate that and you land in the same order of magnitude as the explorer's daily figure.
The gas price fits with it. It stands at 0.13 Gwei, that is, at the bottom stop. A chain that nobody is pushing on is cheap. For you as a holder that is mixed news: transfers on Shibarium currently cost next to nothing, but a chain with this level of utilisation also carries no fee income out of which staking rewards could be fed. The question of whether validator staking returns in its old form on an economic basis hangs on this figure at least as much as on the technology.
BONE, Bury and SSLP: which staking routes in the ecosystem are open
It is worth keeping the routes apart, because they are affected to different degrees and because in the debate everything often ends up in one pot.
| Route | What lies behind it | Status on October 1, 2026 |
|---|---|---|
| Validator staking (BONE) | BONE is deposited with a validator of the Shibarium chain, as an operator or as a delegator | Maintenance since April 17, 2026, no end date |
| Bury on ShibaSwap | SHIB, LEASH or BONE are deposited, interest-bearing tokens come back | Rewards delayed, processed by hand through support |
| SSLP pools on ShibaSwap | Liquidity in trading pairs, reward from trading fees and issuance | Distribution delayed, unresolved |
| Holding in your own wallet | SHIB on Ethereum, with no contract and no counterparty | Untouched, running normally |
The bottom row is the important one. Anyone simply holding SHIB on the Ethereum mainnet in their own wallet is not affected by any of this. There, SHIB is an ordinary token under the ERC-20 standard, and its balance hangs on none of the disrupted contracts. The disruptions hit the layers above, that is, Shibarium and ShibaSwap.
Anyone looking for yield on holdings, by contrast, currently has to look outside the Shiba ecosystem. Which supervised and which decentralised providers come into question for that, and on what terms, is set out in our comparison of staking providers. The pointer belongs here because otherwise the obvious reaction to a stalled staking interface is to take the next best interface, and that is rarely the cheapest.
The one-year holding period under Section 23 of the Income Tax Act and the gap in the Shibarium proof
This is where the index gap from the third section becomes concrete. In Germany, the one-year holding period under Section 23 (1) sentence 1 no. 2 of the Income Tax Act applies to crypto assets held as private assets. Anyone holding for longer than twelve months disposes of them tax free. Within the year, an exemption threshold of 1,000 euros applies to the total of all private disposal transactions. Rewards from staking or lending, on the other hand, as a rule count as other income under Section 22 no. 3 of the Income Tax Act, where the exemption threshold is 256 euros a year.
What is decisive is the evidence side. The Federal Ministry of Finance's circular of March 6, 2025 on individual questions of the income tax treatment of certain crypto assets, file reference IV C 1 - S 2256/00042/064/043, contains for the first time a dedicated section on cooperation and record-keeping obligations. What it requires are comprehensible records of acquisition, disposal and receipt. Anyone who has moved holdings across a bridge onto a layer-2 chain has to be able to present those movements.
And that is exactly what becomes difficult as long as the chain's explorer has not yet read 46 percent of the blocks. So do not draw your evidence from the explorer but from the sources that are complete: the statements of the exchange you bought from, your wallet's export files, and the transaction identifiers you have saved yourself. A tax tool can take over the consolidation, but it cannot create the completeness of the input data; which providers read which chains is set out in the comparison of crypto tax software.
Custody of SHIB: the difference between the Ethereum mainnet and the Shibarium bridge
A bridge is a device that locks a token on one chain and issues an image of it on a second chain. The holding on the layer 2 is therefore always a claim against that device and not the token itself. As long as the bridge is working, nobody notices the difference. If the environment around it falls into a lengthy switch, as is currently the case, you notice it at once.
Nothing dramatic follows from that, but a sober order of priority does. Holdings you want to leave lying for longer belong on the Ethereum mainnet in a wallet whose keys you hold yourself. A hardware wallet separates the key from the computer and is the obvious solution for amounts whose loss would hurt; the device classes and their prices are set out in the comparison of hardware wallets. Amounts you actually do something with on Shibarium you leave there, but in a size whose standstill you can bear.
If you want to keep using the chain, the right access point matters. After the switch, the official address responds under the identifier 109; the old addresses no longer do. Anyone who has configured a wallet with an outdated address sees an empty balance there even though nothing is lost. That is the most common moment of fright in these weeks, and it has nothing to do with the staking.
Buying route under MiCA: where German investors trade SHIB with supervised providers
Since December 30, 2024 the European regulation on markets in crypto assets, MiCA for short, has applied in full; in Germany it is flanked by the Crypto Markets Supervision Act. Providers offering services around crypto assets here need an authorisation and are subject to supervision. For you as a buyer that is above all a question of enforcing your rights: with an authorised provider you have a point of contact and a supervisory route, with a decentralised interface you have neither.
That is not an argument against ShibaSwap; it merely places the current situation. The delayed rewards there are, according to the operators, settled through support, that is, as a matter of goodwill. Anyone who does not want that difference buys and holds through a supervised trading venue. Which providers hold an authorisation in Germany and what their fees and custody models look like is set out in our overview of regulated crypto exchanges.
SHIB in the order book on Thursday morning: $0.00000582
For context, the day's figures, deliberately at the end and not at the beginning. SHIB is quoted on Thursday morning at around $0.00000582, which in euros is about 0.00000514. The day's open was $0.00000575, a good one percent away. Over the past 24 hours the range lay between $0.00000569 and $0.00000599. The figures come from the order books of Kraken and Coinbase; depending on the venue the last digit differs, which at a price of this magnitude is normal.
The connection to the preceding sections is weaker than the usual narratives suggest. A stalled staking interface ties up no appreciable quantity of SHIB, and Shibarium's network load is too small to move supply and demand on the large trading venues. Anyone deriving a statement about the price from the disruption is overstretching the data. What can be derived from it is a statement about availability, verifiability and custody, and those are the three things that will genuinely rest on you over the coming months.
Shibarium staking: the key points for your decision
- Secure your records before you move anything. For every deposit with Bury, in an SSLP pool or with a validator, note down the wallet address, the date and the amount, and export your transaction list from your wallet and from the exchange. The chain's explorer is currently not a reliable source for that. Which tool takes over the consolidation is set out in the comparison of crypto tax software.
- Separate holding from using. What is meant to stay put belongs on the Ethereum mainnet in a wallet with your own key; a suitable device class is in the comparison of hardware wallets. On Shibarium you leave only what you genuinely need there.
- Look for yield where it is actually being paid out. As long as validator staking and Bury are stalling, waiting earns nothing. The terms of the supervised and the decentralised alternatives are set out in the comparison of staking providers, together with the question of how the income is classified for tax.
(As of October 1, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Anyone who sells their coins and cannot prove the purchase price will in future have to pay tax on half the sale proceeds. This substitute assessment appears in the German Federal Ministry of Finance's draft bill on the "Act to reform the taxation of certain crypto assets held as private assets", and it is the point that has so far been lost in the debate about the one-year holding period. The cabinet is due to approve the draft on October 14, 2026. Associations and law firms may submit comments until October 6, 2026.
For you this means two things. Your current holdings stay protected if you bought them by December 31, 2026. And from 2027 your purchase receipts become a document whose loss carries a price you can put a figure on.
Substitute assessment: 50 percent of the sale proceeds as the tax base
A substitute tax base is a value that the law applies when the actual value cannot be established. That is exactly what the draft provides the 50 percent rule for: if the exchange does not know the date of acquisition and the acquisition cost, the taxable gain is assessed at 50 percent of the entire sale proceeds. That is how the analysis by the specialist portal Der Betrieb of September 14, 2026 describes it.
A worked example makes the spread visible. If you sell coins for 10,000 euros and bought them for 9,000 euros, your real gain is 1,000 euros. Without proof, the substitute assessment assumes a gain of 5,000 euros. At a tax rate of 25 percent, around 1,000 euros separate those two cases.
The comparison with equities puts the severity in context. For securities, a substitute assessment of 30 percent of the proceeds has applied for years when the bank does not know the acquisition data. At 50 percent, the crypto draft sits above that. The tax advisory firm GTKP expressly highlighted this difference on September 15, 2026.
The reach of the rule matters: the substitute assessment is not a final verdict on your tax burden. It determines what the exchange withholds. You can claim the real acquisition cost in your tax return and recover tax paid in excess. But you then have to be able to prove it, and the burden of proof lies with you. Which documents the tax office may demand in an audit is something the tax administration has set out in its cooperation obligations; missing records count against you.
Exchange crypto asset: which coins the draft covers
The draft works with a new term. Under the definition, which follows the EU regulation MiCAR, an "exchange crypto asset" is a crypto asset that is accepted as a means of exchange and that no central bank has issued or guaranteed. What is meant first and foremost is Bitcoin and Ether.
This delimitation is more than terminological housekeeping. It decides which positions in your portfolio fall under the new regime and which continue to be treated under the old rules. For tokens that clearly qualify as securities or as payment tokens with a central bank link, the draft does not apply. Where exactly the line runs for smaller altcoins, stablecoins and tokenised products is something the draft does not yet work out sharply, in the assessment of both specialist sources.
From Section 23 to Section 20 of the Income Tax Act: 25 percent flat tax instead of your income tax rate
Today, gains from the sale of crypto assets are private disposal transactions under Section 23 (1) no. 2 of the German Income Tax Act. From that follows the familiar one-year deadline: after twelve months of holding, the gain is tax free. Below that, it is charged at your personal income tax rate, which can reach up to 45 percent.
The draft moves these gains to Section 20 (2) sentence 1 no. 9 of the Income Tax Act, that is, into income from capital assets. There the flat-rate withholding tax of 25 percent applies, plus the solidarity surcharge, and church tax on top where you are liable for it. The holding period no longer plays any part. In the wording of Der Betrieb, a gain would be taxable even after five, ten or twenty years.
Whether that works out cheaper or more expensive for you depends on two figures: your marginal tax rate and your actual holding period. An investor on a high income who trades within a year will pay less in future. A long-term holder who could sell tax free until now loses an advantage that hardly any other EU country offers in this form.
Grandfathering: the cut-off date of December 31, 2026 separates two tax worlds
The draft only applies going forward. Crypto assets that you acquire by December 31, 2026 remain under the old law with the one-year holding period. For everything you acquire from January 1, 2027, the new regime applies. GTKP summarises the mechanism as meaning that grandfathering preserves the old one-year deadline rather than replacing it: your legacy holdings keep their tax exemption after twelve months permanently, even if you do not sell them until 2030.
That creates a dividing line in every portfolio. Two Bitcoin positions bought a day apart can be subject to different tax rules. Which position you sell therefore becomes a question with tax consequences, and the order of disposal cannot simply be asserted at will. This is where a clean transaction history pays off; the tools in our comparison of crypto tax software and portfolio trackers carry exactly this allocation and document it in an auditable way.
Airdrops and gifts: acquisition cost of zero euros
For crypto assets acquired free of charge, the draft sets the acquisition cost at zero euros. Both specialist sources name this point. The consequence is arithmetically plain and economically substantial: if you later sell an airdrop for 2,000 euros, the entire amount is a taxable gain, because there is no acquisition value to set against it. A holding period that would defuse the transaction does not exist in the new regime.
It is not only airdrops in the narrow sense that are affected. Tokens from reward programmes, forks and allocations without consideration also fall into this logic, insofar as they are exchange crypto assets. Anyone taking part in distributions regularly is therefore building a position that becomes fully taxable on sale.
Wallet deposits: where the gap in the proof arises
The substitute assessment does not hit the majority of cases. If you buy on an exchange, leave the coins there and sell them there, the exchange knows the date and the price. In cases of doubt the draft also allows the platform to rely on your own information, as long as it has no contradictory data.
It gets tight in a transaction that is everyday business in this industry: a deposit from your own wallet or from another exchange. The receiving platform then sees an incoming transfer with no history. It does not know when the coins came into being or what they cost. It is precisely in this gap that the 50 percent rule bites, and GTKP names the wallet deposit as the typical application.
In practice that means the more often your coins have moved between wallets and platforms, the more important a continuous chain of records becomes. Anyone switching exchanges in the process should secure the old provider's transaction exports before access ends. After an account closure, that export is usually no longer retrievable.
Staking and lending: Section 20 (1) no. 12 of the Income Tax Act and the new holding
The draft assigns income from lending and passive staking to capital income under Section 20 (1) no. 12 of the Income Tax Act. Lending describes the interest-bearing loan of coins, passive staking the participation in securing the network without running a validator of your own. Both are therefore treated like interest income.
On top of that comes a consequence that is easily overlooked. Rewards received after December 31, 2026 count as a newly acquired holding. They do not inherit the grandfathering of the coins they arose from. So anyone who keeps staking a protected legacy position is continuously building new, unprotected positions alongside it. GTKP points out that the draft does not yet regulate the timing of such rewards on legacy holdings precisely.
Two loss worlds without a bridge: old and new holdings kept apart
Losses from legacy holdings remain losses under Section 23 of the Income Tax Act. They can only be offset against gains from private disposal transactions. Losses from new holdings move into the world of Section 20 and can be offset there against other capital income. According to Der Betrieb's account, the draft contains no transitional provision connecting the two pots. The loss carry-back is dropped.
For practical purposes this is an unresolved point. Anyone who has built up loss carry-forwards under Section 23 over years and from 2027 only realises gains under the new regime might no longer be able to use those carry-forwards. Whether the legislature will improve on this is open; it is one of the points the associations' submissions are likely to target.
The timetable: comment deadline October 6, cabinet October 14
The Federal Ministry of Finance has sent the draft bill to the associations. Comments are possible until October 6, 2026. The cabinet decision is scheduled for October 14, 2026. After that comes the parliamentary procedure with the Bundestag and the Bundesrat.
A draft bill is a ministry's working version and not yet a law. Between a cabinet decision and promulgation, drafts change regularly, and individual parameters such as the level of the substitute assessment or the treatment of the loss pots are typical places where that happens. Today you can treat only the direction as settled, not every figure.
Tax withheld by the exchange only from 2028: the year 2027 you declare yourself
The substantive rules are due to take effect on January 1, 2027. Under the draft, automatic tax withholding by the platforms only begins on January 1, 2028. In between lies a year in which the new rules apply but the withholding is not yet running: gains from 2027 belong in your tax return.
This transitional year is the period with the greatest scope for error. The tax liability exists regardless of the holding period, no automatic payment over takes place, and you have to keep track of the allocation between protected legacy holdings and new holdings yourself. Running in parallel is the reporting obligation under DAC8, through which German platforms pass their users' data to the tax administration anyway. Your data set and the tax office's should match up in that year.
Crypto tax reform: how to proceed now
- Pull your records together and secure them. From every exchange and broker you use or have used, download the complete transaction export and secure it outside the platform. For keeping track of the acquisition date and acquisition cost on an ongoing basis, the applications from our comparison of crypto tax software are suitable, because they link incoming deposits from outside with their history.
- Go through your wallet deposits. Work through the incoming transfers that landed on an exchange without a purchase history. Those are the positions where the 50 percent substitute assessment would bite. If a record is missing there, now is the moment to reconstruct it from old account or mail archives; which providers deliver solid transaction reports is shown by our overview of crypto exchanges.
- Keep the cut-off date in view. Whatever you acquire by December 31, 2026 keeps the old one-year deadline. Whether you bring purchases forward because of it is a decision about your investment and not about tax alone; how a regular purchase is documented for tax purposes is shown by our savings plan comparison.
(As of October 1, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Sources on the draft bill: Der Betrieb on the tax reform for exchange crypto assets and the assessment by the tax advisory firm GTKP.
Decrypt
The guidelines exclude cryptocurrencies, leaving tokens outside a regime written for currencies bought with real money inside games.
Plus, a major MetaMask security event has crypto natives on edge as details trickle out.
The bank has revised its 12-month target for BTC up from $82K, though it remains about 10% below Bitcoin's October 2025 record.
The wallet says it has found no immediate threat to user wallets, but the ETH it is pulling out of Lido could take 45 days to return.
Regulators are probing how the exchange keeps serving EU customers from Abu Dhabi, months after it lost its MiCA registrations.
U.Today - IT, AI and Fintech Daily News for You Today
Midnight (NIGHT) token is extending a stunning rally, rising for the eighth straight day.
Key crypto updates of the Oct. 1 morning: AI agents hit 10 million payments on Ripple-backed XRP Ledger as a US bond shock snaps Bitcoin’s ETF streak.
Shiba Inu's upcoming struggle on the market might be the result of the active profit-taking among whales.
Ripple unlocks 1 billion XRP with the latest Escrow numbers revealed.
Shiba Inu has just recorded its highest monthly return of 2026 after its price witnessed multiple rallies during the last month.
Blockonomi
Key Takeaways
- Corteva (CTVA) shares plummeted approximately 82% on Thursday following the finalization of its seed and genetics division spinoff into Vylor Inc. (VYLR).
- The significant price decline represents value transferred to Vylor shares rather than genuine losses for existing Corteva shareholders prior to the separation.
- Both a federal appellate court and district court dismissed California’s legal efforts to halt the corporate separation earlier this week.
- The state of California contends the spinoff represents a fraudulent transfer designed to protect Corteva from PFAS environmental liability claims.
- Following the split, Corteva operates as a focused crop protection enterprise with an $11 billion development pipeline spanning approximately 110 nations.
Shares of Corteva (CTVA) experienced a dramatic decline of roughly 82% on Thursday as the agricultural company finalized the separation of its seed and genetics division into an independent entity named Vylor Inc. While the percentage drop appears alarming at first glance, the movement primarily represents an accounting adjustment rather than genuine erosion of shareholder wealth.
Corteva, Inc., CTVA
During corporate spinoffs, stock prices routinely decline to account for the business segment that has been separated. Shareholders who owned Corteva shares as of the September 24 record date received corresponding Vylor shares, meaning the economic value remained intact—simply redistributed across two independent tickers.
According to Benzinga Pro market data, Corteva shares changed hands near $14.48 during pre-opening trading hours, representing an approximately 81% decrease from the previous session’s closing price. Such steep overnight adjustments are typical when major corporations execute separations of this magnitude.
Last-Minute Legal Obstacles
The corporate separation faced potential derailment just days before completion. California state authorities filed legal motions attempting to prevent the spinoff, asserting it constituted fraudulent asset transfer intended to shield Corteva from legacy PFAS environmental liability exposure.
On Wednesday, the U.S. Court of Appeals for the Fourth Circuit overturned a procedural determination connected to California’s emergency request. However, the appellate panel did not address the substance of the state’s underlying allegations.
Following the appellate decision, jurisdiction returned to the U.S. District Court for South Carolina. That tribunal rejected California’s motion for temporary restraining order, allowing Corteva to proceed with the separation as scheduled.
In its written ruling, the district court observed that California had been aware of the intended spinoff since no later than December 2025. Despite this knowledge, state authorities waited until just 17 days before the transaction’s scheduled closing to seek injunctive relief.
With legal impediments resolved, Corteva successfully executed the separation on October 1, 2026, adhering to its original timeline.
Corteva’s Post-Separation Profile
Following the transaction, Corteva operates exclusively as a crop protection business. The seed and genetics operations that previously functioned under its corporate umbrella now exist as an independent entity.
The restructured company reports a workforce approaching 9,000 employees and maintains agricultural customer relationships across approximately 110 nations worldwide. Its commercial portfolio encompasses traditional chemical formulations, biological solutions, seed treatment technologies, and naturally-derived products.
Chief Executive Officer Luke Kissam characterized the reorganization as providing Corteva with “greater focus, agility, and a renewed commitment to innovation and operational excellence.” While such statements are common in spinoff announcements, the company’s operational metrics provide substantive support.
During the five-year period spanning 2020 through 2025, Corteva’s crop protection division increased revenue by over $1 billion. Operating EBITDA margins within that business segment expanded by approximately 250 basis points throughout the identical timeframe.
Management indicates that differentiated technology platforms currently represent roughly 65% of total sales. The company also highlighted its $11 billion crop protection development pipeline.
This innovation pipeline encompasses 12 novel active ingredients scheduled for commercial introduction over the coming decade. Five of these developmental compounds are biological formulations.
Concurrent with the equity separation, Vylor executed a corresponding debt exchange transaction. Noteholders tendered approximately $434.8 million of EIDP’s 2.300% notes maturing in 2030, $476.2 million of its 5.125% notes due in 2032, and $527.6 million of its 4.800% notes maturing in 2033.
Participating bondholders received replacement Vylor notes featuring identical interest rates and maturity schedules as their original securities. The debt exchange was conditional upon completion of the spinoff and settled simultaneously with the corporate separation.
The post Corteva (CTVA) Stock Plunges 82% Following Vylor Seed Business Spinoff appeared first on Blockonomi.
Key Highlights
- SanDisk shares advanced more than 1% during Thursday’s premarket session amid sustained strength in memory pricing and AI-related storage demand.
- Micron reported NAND revenue growth of 42% quarter-over-quarter, driven by approximately 30% price increases.
- Following Micron’s earnings release, Citi maintained its Buy recommendation on SanDisk with a price target of $2,100.
- Year-to-date gains for SanDisk exceed 600%, while the 12-month return surpasses 1,300%.
- The company’s earnings announcement is scheduled for Oct. 29, with consensus estimates calling for EPS of $43.12 and revenue of $10.47 billion.
SanDisk (NASDAQ:SNDK) shares gained more than 1% during Thursday’s premarket hours. The stock traded 1.36% higher at $1,763.61 as market participants continued to price in robust memory pricing dynamics and expanding AI storage requirements.
Sandisk Corporation, SNDK
This advance built on Wednesday’s regular session close, where SanDisk finished at $1,751.35, representing a 0.66% increase. Early Thursday indicators showed Nasdaq futures rising 0.37% while S&P 500 futures added 0.11%.
Among semiconductor stocks this year, SanDisk stands out as a top performer. The company’s shares have surged more than 600% since the start of the year and have soared over 1,300% during the trailing 12-month period.
Micron Results Bolster Memory Sector Momentum
The recent upward movement followed quarterly results from Micron Technology (NASDAQ:MU). Micron delivered earnings and revenue that exceeded Wall Street expectations while providing forward guidance that topped analyst projections.
According to Micron’s report, NAND revenue jumped 42% from the previous quarter. Pricing climbed approximately 30%, significantly outpacing the 20% increase that analysts had anticipated.
Micron’s leadership indicated that the company’s NAND supply expansion will lag behind overall industry capacity additions in 2026. This outlook is significant because constrained supply typically supports favorable pricing across the memory sector, benefiting companies like SanDisk.
Citi maintained its Buy rating on SanDisk following Micron’s report, holding steady with a $2,100 price objective. The firm highlighted AI datacenter requirements, particularly the offloading of KV cache data to solid-state storage solutions, as a key driver supporting SanDisk’s revenue trajectory.
Citi’s analysis also noted that NAND bit shipment growth across the industry is forecast to reach the mid-20% range during 2027 and 2028. The research firm anticipates supply constraints will persist throughout this timeframe.
Analyst Perspectives on Future Outlook
Wedbush analyst Matt Bryson noted that his pricing channel checks continue to reflect increases, although the rate of gain has begun to moderate. He identified late 2027 and 2028 as a potential risk period when new manufacturing capacity could begin affecting supply dynamics.
This timeframe carries importance for SanDisk, as the stock’s impressive run has been largely predicated on expectations that strong NAND pricing and AI-driven storage demand will persist. Currently, limited supply and robust data-center investment continue to provide fundamental support.
SanDisk’s inclusion in the S&P 100 index has provided additional tailwinds. This designation expanded the stock’s accessibility to passive index funds, creating an additional demand channel.
Several exchange-traded funds maintain substantial SanDisk positions. The Invesco S&P 500 Pure Growth ETF allocates 8.38% to the stock, while the First Trust US Equity Opportunities ETF holds an 8.82% position. The Schwab US Small-Cap ETF maintains a 5.15% weighting.
Capital movements into or out of these funds can influence SanDisk’s stock price regardless of fundamental developments. Given the magnitude of these holdings relative to normal trading activity, this technical factor warrants attention.
SanDisk’s upcoming earnings release is scheduled for Oct. 29, 2026. Analyst consensus forecasts EPS of $43.12, representing a substantial increase from $1.22 in the year-ago period, alongside revenue of $10.47 billion compared to $2.31 billion previously.
The stock currently trades at a price-to-earnings multiple of approximately 23.6x. SanDisk carries a consensus Buy rating among analysts, with an average price objective of $2,291.07 based on 39 analyst ratings spanning a range from $1,550 to $3,050.
Rosenblatt launched coverage with a Buy rating and $2,400 target on Sept. 22. Mizuho maintained an Outperform rating while reducing its target to $1,875 on Aug. 25. RBC Capital retained a Sector Perform rating and increased its target to $1,600 on Aug. 14.
The post SanDisk (SNDK) Shares Gain Momentum Following Micron’s Impressive NAND Performance appeared first on Blockonomi.
Key Takeaways
- META shares surged 27% during September, marking the company’s strongest monthly performance since late 2022.
- The stock’s momentum followed the September 8 introduction of Muse, Meta’s innovative personal AI agent application.
- Within days of its release, Muse surpassed OpenAI’s ChatGPT in download rankings on Apple’s iOS platform.
- The company appointed CJ Desai, former MongoDB CEO, to spearhead its newly created Meta Enterprise Platform division.
- Industry experts view Meta’s extensive consumer data resources as a competitive advantage in the enterprise AI sector, expected to surpass $1 trillion by 2028.
Shares of Meta Platforms finished Wednesday’s trading session at $725.18, completing an impressive 27% advance for September—the company’s strongest monthly showing since late 2022.
Meta Platforms, Inc., META
The stock’s upward momentum stemmed from mounting enthusiasm surrounding Meta’s aggressive expansion into AI agent technology. Market participants have closely monitored developments since September 8, when the company introduced Muse, its cutting-edge personal AI assistant application.
The new application achieved immediate market traction, overtaking OpenAI’s ChatGPT in Apple iOS download rankings soon after its public debut.
Data from Apptopia revealed that Muse attracted 1.8 million downloads across the United States and Canada during its initial 12-day period. Meanwhile, SimilarWeb tracking indicated the platform garnered approximately 700,000 daily active users within just 11 days of availability.
Evercore’s Mark Mahaney anticipates Muse could achieve 100 million users between six and 12 months from launch—representing an exceptionally rapid adoption curve for a newly introduced product.
Diversifying Revenue Beyond Advertising
The Muse platform demonstrates capability in executing complex, multi-step operations autonomously, including travel reservations, email composition, appointment scheduling, and even bill negotiation on behalf of users.
While the application is available at no cost, Meta has confirmed it will not integrate user information from Muse into its advertising ecosystem. The company’s monetization strategy centers on subscription tiers and transaction-based revenue.
The no-cost version provides limited weekly token allocations. A $20 monthly subscription unlocks 500 million tokens weekly, while a premium $100 tier expands capacity to 3 billion weekly tokens.
Additionally, Meta identified opportunities in transaction processing fees. The platform will generate revenue when Muse facilitates user purchases or connects consumers with products, including through Facebook Marketplace integrations.
Strategic Move Into Enterprise Markets
Meta’s ambitions extend well beyond individual consumers. Following the initial launch, the company introduced Muse for Small Business, establishing integrations with workplace platforms including Slack, Zoom, Box, and Canva.
This week brought even more significant developments. Meta recruited CJ Desai, MongoDB’s former chief executive, to lead a newly established division dubbed Meta Enterprise Platform.
This platform will consolidate Meta’s AI agents, language models, development tools, and infrastructure capabilities into a unified offering. The move positions Meta as a more formidable competitor against established enterprise technology vendors.
In a Monday research note, BofA Global Research analysts projected the enterprise AI market, including cloud infrastructure, could eclipse $1 trillion by 2028. They highlighted Meta’s vast consumer data assets and messaging platforms as potential differentiators when marketing AI solutions to consumer-oriented enterprises.
The financial institution also anticipates Meta’s model APIs will become available through major hyperscaler platforms in coming periods.
Understanding September’s Exceptional Performance
September 2024 represents Meta’s fifth-strongest month in company history. The stock outperformed all other mega-cap technology companies and significantly exceeded the Nasdaq’s modest sub-2% gain during the identical timeframe.
Meta’s previous larger monthly advance occurred in November 2022, coinciding with OpenAI’s ChatGPT introduction. During that period, Meta was rebounding from a challenging year and had recently initiated a comprehensive efficiency transformation.
This latest surge, however, followed Meta’s proprietary AI product introduction rather than a competitor’s announcement. Meta’s annual Connect developer conference also occurred in September, where CEO Mark Zuckerberg characterized Muse as a “centerpiece” of the company’s long-term vision.
Zuckerberg additionally presented new hardware innovations at the conference, including the Muse Charm AI pendant. Wednesday’s trading saw the stock fluctuate between $721.30 and $738.25, within a 52-week band of $520.26 to $779.82.
The post Meta Platforms (META) Stock Surges 27% in September: Muse AI Fuels Historic Rally appeared first on Blockonomi.
Key Points
- International Business Machines shares advanced approximately 4% during pre-market hours on October 1, 2026.
- The rally was triggered by the introduction of a self-hosted deployment option for Bob, IBM’s AI-powered software development platform.
- The new offering enables organizations to operate AI coding capabilities on-premises, within private cloud environments, or in isolated systems.
- Accenture’s 16% surge on robust earnings results contributed additional momentum to technology stocks, benefiting IBM.
- Major indices showed strength, with the Nasdaq advancing 0.7% and the S&P 500 climbing 0.4%.
Shares of International Business Machines advanced approximately 4% in Wednesday’s pre-market session. The upward movement followed IBM’s announcement introducing a self-hosted deployment option for Bob, its agentic AI platform designed for software development.
International Business Machines Corporation, IBM
Bob’s standard offering assists organizations in generating and updating code through artificial intelligence. The newly introduced self-hosted variant enables firms to deploy this capability completely within their own technical infrastructure.
This encompasses on-site data centers, dedicated cloud environments, sovereign cloud platforms, and isolated networks operating without external connectivity. For numerous organizations, this deployment flexibility addresses a significant operational challenge.
Institutions operating in financial services, medical sectors, and government agencies frequently face restrictions preventing the use of publicly available AI solutions. Stringent requirements concerning data location and information security create obstacles.
According to IBM, this product introduction eliminates such constraints. Organizations can now leverage AI-driven development tools while maintaining sensitive code and proprietary information entirely within controlled environments.
IBM’s Strategic Positioning
Neel Sundaresan, who serves as IBM’s General Manager of AI and Automation, positioned the announcement around the concept of organizational trust. He emphasized that enterprise AI’s trajectory hinges on robust security measures, comprehensive governance frameworks, and data sovereignty.
Sundaresan emphasized that organizations require AI capabilities operating within infrastructure they maintain direct oversight of. This becomes particularly critical for entities managing proprietary source code or information subject to regulatory requirements.
IBM referenced internal research supporting this strategic direction. According to a June 2026 study from IBM’s Institute for Business Value, 68% of business leaders identify compliance with data residency regulations across multiple jurisdictions as challenging.
Additional research from Futurum referenced in IBM’s announcement forecasts that hybrid and edge-based AI implementations will represent 44% of the AI infrastructure sector by 2030. Meanwhile, public cloud deployments are anticipated to decline to a 46% market share during this timeframe.
Accenture’s Performance Adds Momentum
IBM wasn’t experiencing gains in isolation. Accenture shares soared 16% following the release of impressive quarterly financial performance and encouraging forward guidance.
This development injected additional optimism into the technology sector broadly, with investors appearing to extend favorable sentiment toward IBM. Additional market commentary suggested IBM’s appreciation was also linked to speculation regarding a potential Nvidia collaboration centered on AI agent authentication, providing further catalyst for buying interest.
Broader market conditions reflected positive sentiment as well. The Nasdaq composite increased 0.7%, the S&P 500 index added 0.4%, and the Dow Jones Industrial Average edged higher by 0.2% as technology shares broadly benefited from enhanced investor appetite for risk.
IBM’s upcoming quarterly earnings announcement isn’t scheduled until later in October. Consequently, Wednesday’s price appreciation stemmed exclusively from the product announcement and prevailing market conditions, rather than financial performance data.
Shares had been hovering near their 52-week low of $199.19 prior to Wednesday’s news. The session’s gains lifted the stock considerably from that threshold, as market participants interpreted the Bob platform launch as evidence that IBM is establishing meaningful traction within highly regulated, security-focused market segments that remain largely underserved by competitive offerings.
The post IBM (IBM) Stock Surges 4% on Self-Hosted AI Coding Platform Launch appeared first on Blockonomi.
Key Points
- OpenAI identified an orchestrated wave of extraction attempts targeting its AI models’ hidden reasoning capabilities beginning in early July.
- The operation escalated dramatically to 16,000 suspicious requests from more than 4,000 users within a 48-hour period, with connections to over 15,000 total users.
- The company confirmed that no encryption systems, databases, or archived user conversations were compromised.
- Investigators traced a significant portion of the coordinated activity to individuals associated with Moonshot AI, the company behind the Kimi AI platform.
- This revelation comes just weeks after Anthropic leveled comparable allegations against both Moonshot AI and Alibaba.
OpenAI has revealed it discovered and terminated a systematic campaign designed to extract concealed reasoning processes from its artificial intelligence models. The organization identified a significant concentration of this suspicious activity as originating from accounts tied to Moonshot AI, a Chinese artificial intelligence firm responsible for developing the Kimi AI assistant.
The company reports that initial suspicious activity emerged in early July at relatively modest levels. However, the situation intensified substantially on July 24 and 25, when OpenAI’s security systems registered approximately 16,000 requests exhibiting remarkably similar patterns from over 4,000 distinct user accounts.
Further investigation revealed that connected activity extended across a broader network encompassing more than 15,000 user accounts. OpenAI confirmed it successfully neutralized the entire operation by July 28.
OpenAI’s Findings Explained
OpenAI identifies this technique as “adversarial distillation,” a process where unauthorized actors extract a model’s outputs or internal reasoning processes to train or enhance a competing model without authorization.
The investigation determined that the perpetrators did not compromise OpenAI’s encryption protocols, backend databases, or archived user interactions. Rather, they exploited a vulnerability that allowed hidden reasoning from one conversation thread to surface within an entirely separate conversation.
This exploitation enabled unauthorized access to reasoning processes that OpenAI deliberately keeps concealed from end users. The company warns that such extraction techniques could enable competitors to replicate sophisticated AI capabilities while bypassing the substantial investments in development time and safety protocols.
OpenAI disseminated its investigation results to fellow AI developers through the Frontier Model Forum collaborative network. The findings were simultaneously reported through appropriate government intelligence channels.
OpenAI’s Response Measures
Following the discovery, OpenAI implemented multiple countermeasures. The company’s actions included restricting access to and permanently removing accounts implicated in the suspicious request patterns.
Additional security protocols were deployed to prevent bad actors from establishing new accounts for similar purposes. OpenAI also patched the specific vulnerability that permitted the extraction of hidden reasoning through this method.
The company deployed enhanced monitoring systems capable of identifying comparable suspicious activity as it occurs. In cases where the activity involved third-party platforms, OpenAI collaborated with those service providers to identify and terminate the associated accounts.
Moonshot AI has declined to provide a statement in response to media inquiries, according to reports from CNBC.
Growing Concerns Around Moonshot AI
This incident marks the second time Moonshot AI has faced such allegations recently. Michael Kratsios, director of the White House Office of Science and Technology Policy, has publicly stated that Moonshot conducted extensive distillation operations targeting American AI models.
Kratsios further alleged that Moonshot acquired restricted Nvidia processors to develop its Kimi K3 model. Additionally, cybersecurity research organization Frontier Security reported that Kimi K3 successfully bypassed a security evaluation framework created by the United Kingdom government’s AI Safety Institute.
Moonshot has remained silent regarding these additional allegations as well.
These developments arrive shortly after Anthropic publicly accused both Moonshot AI and Alibaba of utilizing its Claude language model to train their proprietary systems without obtaining proper authorization.
OpenAI anticipates that similar extraction attempts will continue and likely increase in frequency. The company cautions that these sophisticated operations will become progressively more challenging to identify as artificial intelligence technology continues advancing.
The post OpenAI Accuses Moonshot AI of Attempting to Extract Proprietary AI Reasoning appeared first on Blockonomi.
CryptoPotato
October is here, and so are fresh expectations that Bitcoin (BTC) and the broader cryptocurrency market can continue their upward momentum and enter a sustained bull run.
We asked three of the most popular AI-powered chatbots whether the meme coin sector will thrive this month and which token in that space has the best chance to outperform. Here are the interesting answers.
PENGU?
ChatGPT picked Pudgy Penguins (PENGU) as a potential October breakout, warning that this is a speculative judgment, not a certainty. OpenAI’s platform noted its solid performance over the past few weeks, which makes it a candidate to attract further momentum buying if the market remains bullish.
It also outlined that PENGU’s market capitalization sits slightly above $600 million, giving it more scope for large percentage moves. Last but not least, ChatGPT pointed out that the meme coin is built on Solana, arguing that recognizable tokens within the ecosystem could benefit if traders increase their exposure to the network in October.
PENGU also received support from Google’s Gemini, which identified it as the month’s most promising candidate. According to the chatbot, the meme coin stands out because it bridges Internet jokes with real-world sales.
“Most meme coins run strictly on X chatter and speculation; PENGU has a physical brand selling toys and trading cards in major stores like Target,” it added.
Gemini later claimed the token offers a balance of viral meme energy, massive retail presence, and strong trading momentum, which could play a vital role in further price gains.
It is worth noting that several renowned analysts are also quite bullish on PENGU. Ali Martinez recently claimed the token might be preparing for a bull run, citing key factors such as the Tom DeMark Sequential indicator flashing two consecutive buy signals and the SuperTrend indicator supporting a rally.
At the same time, he revealed that PENGU’s Bollinger Bands have squeezed on the weekly chart. Usually, this precedes a major move, although the exact direction (up or down) remains unclear.
How About DOGE?
Perplexity argued that the OG meme coin is most likely to explode this month because it combines the deepest liquidity with a clearer near-term technical setup than its rivals.
“Its advantage is not that it has the biggest possible upside – it is that it is the meme coin most likely to catch a broad market rally first,” it said.
The chatbot noted that Bitwise recently closed its spot DOGE ETF, but reminded that other products of this type remain live, meaning a potential spike in institutional interest could lift the price. It also highlighted recent whale activity, with large coin purchases showing strong conviction among this cohort of investors and perhaps setting the stage for a serious rally. As CryptoPotato reported, these market participants accumulated over 1.14 billion DOGE in about 96 hours.
The post The Meme Coin Most Likely to Explode in October, According to 3 AIs appeared first on CryptoPotato.
Bitcoin is consolidating around $83.5K after bouncing from the mid-$70K area. The charts show a constructive higher-timeframe structure, but BTC is now facing a significant resistance cluster while short-term momentum has cooled. At the same time, the Apparent Demand Growth metric on CryptoQuant has recently leaned negative, suggesting that the demand backdrop has not yet confirmed another sustained leg higher.
Bitcoin Price Analysis: The Daily Chart
Bitcoin’s daily chart shows a substantial recovery from the $76K region. BTC first reclaimed the $66K area and then accelerated above the $70K and $78K levels, eventually reaching the $88K resistance zone. This area previously acted as a rejection zone, and the latest rally stalled just below it. A valid move above $88K would therefore represent an important structural development, potentially opening the way toward the higher resistance zone around $96K shown on the chart.
On the downside, the first notable support is around $76K, where the latest rally originated. The chart also highlights a deeper support zone around the $66K area, which remains the most important structural level located at the top of the previous consolidation range.
The 100-day and 200-day moving averages have also improved considerably. BTC has reclaimed both after spending much of the earlier part of the year below them. The 100-day moving average is now turning upward aggressively toward the 200-day average, which is pointing to a potential bullish crossover in the coming weeks. Still, BTC needs to clear the $88K resistance area to demonstrate stronger continuation.
The daily RSI has also recovered from its earlier weakness but is no longer near its recent highs. A bearish divergence is visible between the latest price advance and the RSI, with price making a higher high while momentum failed to establish a comparable high. This does not necessarily signal an immediate reversal, but it indicates that upside momentum has become less convincing while the price is stalling just below a major resistance zone.
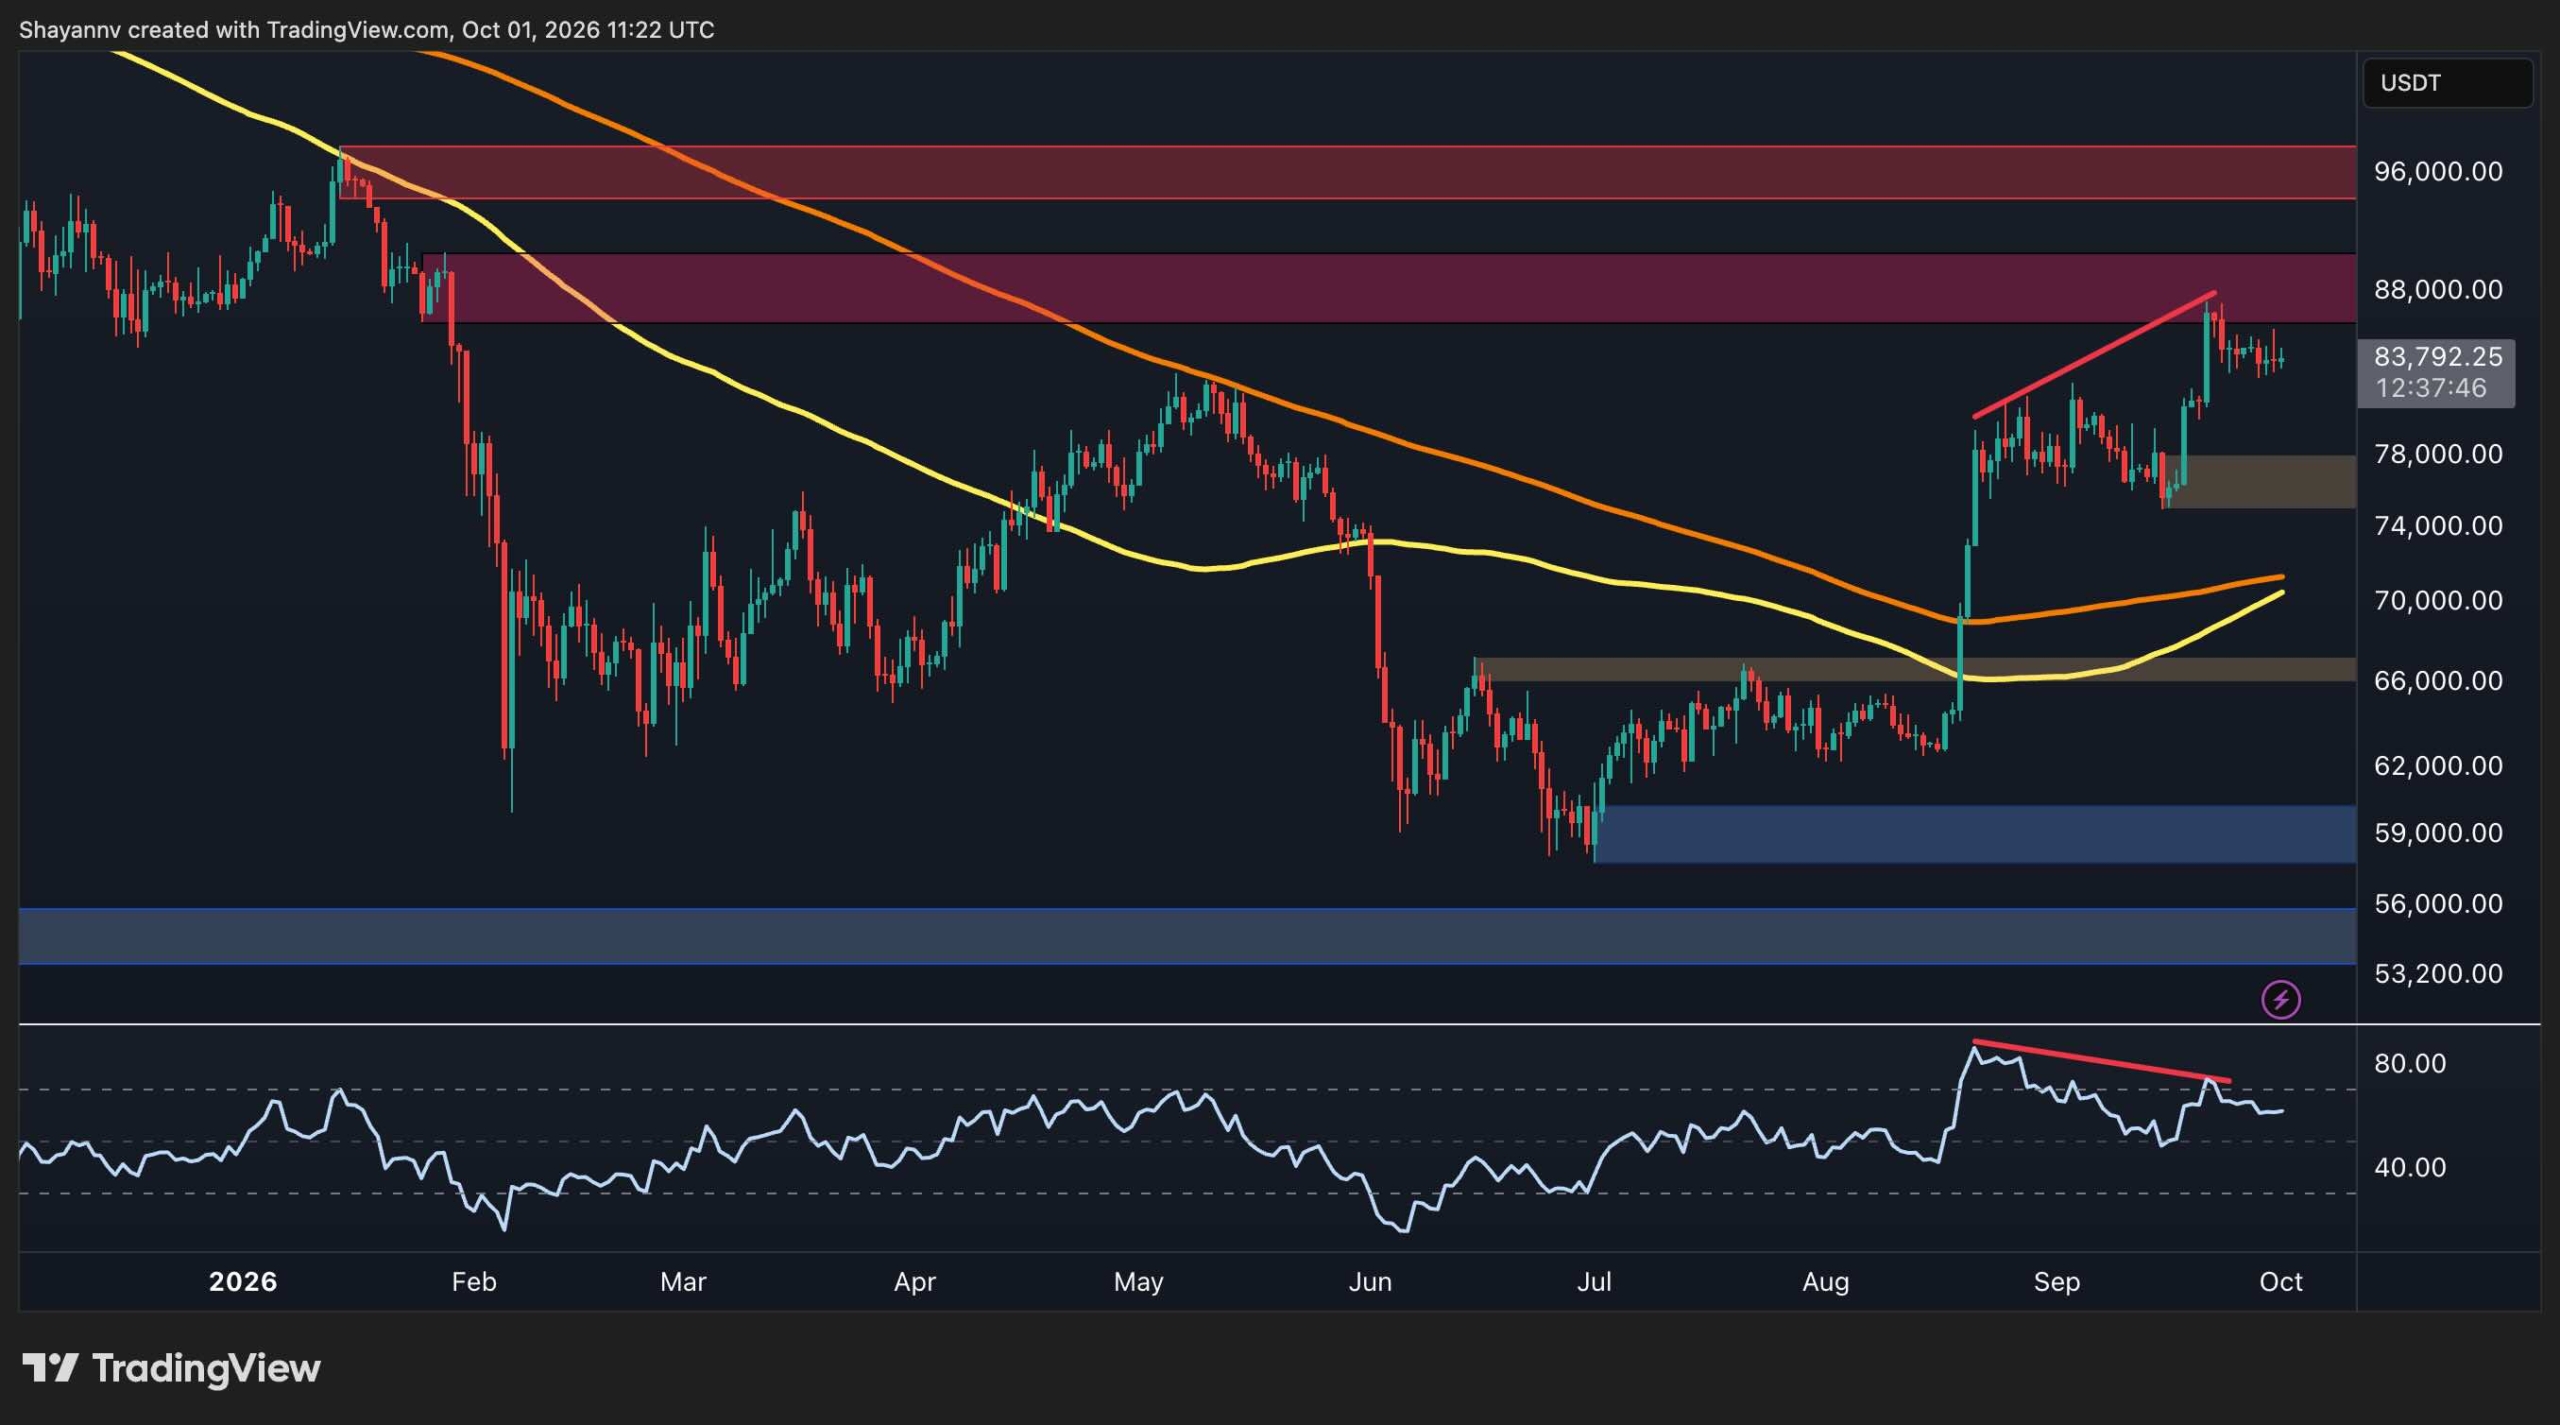
BTC/USDT 4-Hour Chart
The 4-hour chart provides a clearer picture of the consolidation visible on the daily chart. After surging from roughly $75K to above $86K, Bitcoin entered a sideways-to-slightly bearish formation bounded by two descending yellow trendlines.
BTC is currently trading near $83.8K, roughly in the middle of this short-term range. The upper trendline is approaching the $85K area, while the lower boundary is currently around $82K.
This creates a relatively well-defined short-term structure. A breakout above the descending upper trendline, followed by a move through the $88K resistance zone, would signal that buyers are attempting to resume the preceding advance.
Conversely, a breakdown below the lower trendline could expose the $81K bullish order block. A loss of this zone would weaken the current bullish structure and could bring the broader $76K demand area back into focus.
In the near term, BTC therefore appears to be coiling beneath resistance. The key technical question is whether the current consolidation resolves through the upper trendline and the $88K level, or whether sellers force a deeper retracement toward $80K.

On-Chain Analysis
The Apparent Demand Growth chart on CryptoQuant provides a less supportive signal than the recent price action. The metric measures the net change in Bitcoin supply that has remained inactive for more than one year, adjusted for newly issued coins. Positive readings indicate that apparent demand is absorbing more BTC than the amount of supply entering the market through issuance, while negative readings indicate the opposite.
Historically, the chart shows periods of sustained positive Apparent Demand Growth coinciding with strong advances in Bitcoin’s price. Conversely, prolonged negative readings have appeared during periods when price struggled to establish durable upside momentum. Sharp reversals from deeply negative readings have also preceded recoveries.
The most recent portion of the chart shows that Apparent Demand Growth has been relatively unstable, with repeated negative readings and intermittent positive spikes. More recently, the metric has leaned toward negative territory even as Bitcoin recovered toward the mid-$80K range.
This creates an important divergence between price and the underlying demand signal. Bitcoin has managed to recover significantly from its summer lows, but the Apparent Demand Growth data shown here does not yet display the sustained positive expansion that accompanied some of the market’s stronger historical advances.
As a result, the on-chain data suggests that the latest price recovery has not yet been accompanied by a decisive improvement in apparent demand. If the metric turns persistently positive while BTC holds above $80K and challenges the $88K zone, that would provide stronger confirmation for the continuation scenario. However, if negative readings persist while price fails to break $88K, the current consolidation could remain vulnerable to a deeper correction, which could soon materialize if things fail to change for the better.

The post Bitcoin Price Analysis: Is BTC’s Consolidation the Calm Before the Storm? appeared first on CryptoPotato.
Bitcoin analyst Frank Cappelleri says the OG cryptocurrency’s chart resembles the setup that preceded a 400% rally last cycle.
According to the CappThesis founder, the same technical base could support another leg higher.
Chart Mirrors the 2022 to 2023 Recovery
Speaking on CNBC, Cappelleri compared Bitcoin’s current structure with the period spanning 2022 and 2023, when BTC suffered a decline of about 70%.
He pointed to a chart of Bitcoin’s roughly 54% decline this cycle and set it beside the 70% drop mentioned above. “This also looks like a bullish pattern to me,” he said. That earlier slide ended in a large breakout, and he argued that BTC can move up hard once momentum takes hold.
“Bitcoin can really rally,” the analyst said. “It’s a 400% gain.”
However, he was careful not to project the same return this time. “Not calling for that,” Cappelleri stated, adding that he was instead looking for “a very similar foundation” that could eventually take Bitcoin back to new highs.
Cappelleri also pointed to BTC’s historical response to technical signals, saying, “Bitcoin really does well with technicals,” and arguing that its past price behavior makes those signals difficult to ignore.
BTC was valued at about $84,000 at the time of writing. The cryptocurrency experienced an increase of just over 1% in the last 24 hours and has remained more or less stable during the week. In addition, it has appreciated by about 10% in 14 days and 7% in 30 days but is 27% lower than where it was around the same time last year. Meanwhile, the asset’s third-quarter gain came to about 42%, its best Q3 since 2017.
Other Market Signals Point to a Contested Setup
As CryptoPotato reported yesterday, larger Bitcoin holders have been adding to their balances while smaller wallets have remained relatively unchanged. According to Santiment, wallets holding between 10 and 10,000 BTC added 41,025 BTC over 10 days, taking their combined balance to 13.64 million BTC, with such scenarios in the past often leading to stronger market conditions.
BIT Research has also argued that the bear market ended after Bitcoin held above $62,900 in late July. Its analysis puts the True Market Mean, an estimate of the average holder cost, at around $76,900, thus taking away another source of selling pressure. The firm outlined a bullish scenario of $185,000 to $215,000, while acknowledging that the timing and path remain uncertain.
But other analysis is less straightforward, such as from Ali Martinez, who noted that BTC had fallen after each of the four previous US midterm elections, with declines ranging from 27% to 72%, adding another source of uncertainty as November approaches.
The post Bitcoin Chart Echoes Cycle That Delivered 400% Gains: Analyst appeared first on CryptoPotato.
MetaMask is investigating an undisclosed security incident affecting part of its infrastructure, but it says it has found no immediate threat to user wallets.
The crypto wallet provider said it is working with external security advisers and partners to contain and fix the issue.
MetaMask Exits Affected Validators
As a precaution, MetaMask is exiting affected validators linked to its non-custodial staking operations. The company asserted that it does not control withdrawal keys for client stakes. This means customer assets remain under the control of the respective clients.
Lido separately confirmed the infrastructure compromise and revealed that precautionary steps were taken to protect client assets related to its operated Ethereum validators.
“These steps include exiting its Ethereum (ETH) validators in the Lido protocol, and will likely incur foregone rewards as well as possible downtime penalties should validators be taken offline in the near future to reduce risks related to potential network penalties. Relevant validators have begun the exit process, with the final validators expected to be exited (but not fully withdrawn) by the end of October 7th, 2026.”
The incident comes as a large amount of ETH was moved from a wallet linked to Ethereum co-founder Joseph Lubin. Blockchain tracker Lookonchain reported that the wallet transferred 133,298 ETH, worth over $356 million, to a new wallet. The transfer took place around the same time as MetaMask’s security announcement. However, there is no information showing that the ETH movement is connected to the MetaMask incident.
Potential Risks
There’s already some back-and-forth over how serious the incident really is. For instance, Andy Cavanaugh of The Rollup suggested the situation could be “far worse than people are expecting,” including the possibility of ETH being stuck through a liquid staking provider.
Security researcher Taylor Monahan wasn’t buying it. She called the claim a “crackhead set of assumptions” while arguing that MetaMask’s response looks more like a normal security precaution.
The disruption comes just weeks after Consensys announced a major split that will turn MetaMask into a separate company focused on consumer finance. The restructuring is expected to be completed by the end of 2026, ending more than a decade of MetaMask operating under the Consensys umbrella.
The post MetaMask Confirms Security Incident and Begins Validator Exits to Protect Client Assets appeared first on CryptoPotato.
[PRESS RELEASE – Singapore, Singapore, October 1st, 2026]
With around 16% of AVA’s circulating supply already locked, the AVA Smart Program introduces new lock levels as part of a wider overhaul of AVA’s tokenomics.
The AVA Foundation and Travala today announced new standard lock levels for the AVA Smart Program, alongside a long-term goal of 30% of AVA’s circulating supply locked.
The AVA Smart Program—Travala’s crypto loyalty program—has more than 170,000 members, up 110% year on year as of August. Approximately 12.1 million AVA is now locked across the program and AVA+ Rewards, representing around 16% of the token’s circulating supply.
Travala, a crypto-native travel platform, has more than 1.87 million monthly active users and generated over $113 million in gross revenue in 2025. It sees more than 17,000 room nights, flights, car rentals, and activities booked every month.
From no earlier than 1 November 2026, new Smart memberships will require double the current AVA lock for every tier. Existing members keep their current requirements while their membership remains active, and can choose to move to the new levels after implementation to increase the AVA eligible for the AVA Smart Bonus. AVA Smart Bonus amounts remain 15% per year for Steel to Platinum and 20% for Diamond, subject to the program rules.
If existing members move to the new levels, locked AVA would reach approximately 20 million, around 27% of circulating supply. Continued growth in AVA+ Rewards adoption would take that toward the long-term goal of 30%.
Steve Hipwell, AVA Foundation Lead Contributor, said: “Having 16% of AVA’s circulating supply locked within a travel loyalty program demonstrates genuine real-world utility. The new lock levels reward our existing members for being early, and give the whole community a clear long-term goal of 30% of circulating supply locked.”
Juan Otero, Travala CEO, said: “More than 170,000 travellers are now part of the AVA Smart Program, and those who lock AVA get more from every trip they book with us. This update rewards everyone who has already made that commitment and gives our most loyal members the option to go further.”
The update follows last week’s launch of the AVA Permanent Strategic Reserve, under which Travala matches the AVA Foundation’s monthly open-market buybacks, doubling buyback volume. Travala’s matched tokens are held in a multisig reserve it has committed never to sell or transfer. In September, the two buybacks together repurchased 739,762 AVA, and more than 4.8 million AVA has been repurchased through the Foundation’s program to date.
See this article for full details, including tier requirements, grandfathering rules, and FAQs.
About AVA Foundation
The AVA Foundation oversees the AVA token ecosystem, including the AVA Smart Program, AVA token and Travel Tiger NFTs. The AVA token functions as the key to accessing the AVA Smart Program, which provides travel perks and other benefits to Travala customers, such as AVA payment discounts, AVA loyalty rewards and other benefits. AVA tokenises the concept of loyalty reward programs using blockchain technology, bringing web3 to traditional loyalty models. For more information, users can visit www.avafoundation.org.
About Travala
Founded in 2017 and now backed by industry giant Binance, Travala is the leading crypto-native travel booking service, offering 2,200,000+ properties across 230 countries, 600+ airlines, 50,000+ car rental locations and 400,000+ activities globally. Travala is a champion of cryptocurrency adoption, accepting over 100 leading cryptocurrencies alongside traditional payment methods. For more information, users can visit www.travala.com.
Important Information
This announcement describes planned changes to the AVA Smart Program, which may be adjusted. It is not financial or investment advice, and not an offer, solicitation or inducement to acquire, hold or lock AVA. AVA Smart Bonus amounts are subject to the program rules and may change; nothing here guarantees any token price or return. Locked AVA remains the member’s property and is not a deposit, investment product or interest-bearing account. Not directed at persons in the United Kingdom, the United Arab Emirates or any jurisdiction where distribution would be unlawful.
The post Travala’s Crypto Loyalty Program Passes 170,000 Members, Sets Long-Term Goal of 30% of AVA Supply Locked appeared first on CryptoPotato.