Cryptocurrency Posts
Crypto Briefing
Broadcom's financial backing of Anthropic's infrastructure leases highlights the growing interdependence between tech giants and AI development, potentially reshaping industry dynamics and investment strategies.
The post Broadcom to backstop up to $42B for Anthropic infrastructure leases appeared first on Crypto Briefing.
The backlash against O'Leary's project highlights the growing influence of local communities in shaping large-scale development initiatives.
The post Kevin O’Leary faces backlash over Utah’s Wonder Valley data center project appeared first on Crypto Briefing.
The projected growth of tokenized equities could significantly transform financial markets, emphasizing the importance of asset utilization.
The post Binance Research projects tokenized equities could hit $349 billion by 2030 appeared first on Crypto Briefing.
The decline in XRP open interest on Binance suggests a cautious market sentiment, potentially impacting future price stability and trader strategies.
The post XRP open interest on Binance falls 15% from six-month high appeared first on Crypto Briefing.
RRSI's self-improving AI harnesses could significantly enhance AI adaptability and efficiency, impacting various industries and applications.
The post Google’s RRSI framework lets AI agents rebuild their own harnesses appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Bitcoin Privacy Breakthrough a Zcash Killer? | Misha Komorov, Alloc Innit
Researchers have proposed a way to make Bitcoin private without changing Bitcoin itself. Misha Komarov, co-founder of alloc/init, explains Shielded Bitcoin: zero-knowledge proofs that hide the sender, receiver, and amount of a Bitcoin transfer, with no soft fork, no custodians, and no bridges. He covers how Bitcoin PIPEs make it possible and what the proposal still needs. It is a research proposal, not a finished product.
Chapters:
0:00 Shielded Bitcoin: Private Bitcoin Transactions With Zero-Knowledge Proofs
0:38 How Bitcoin PIPEs Make Privacy Possible Without a Soft Fork
1:42 Do Indexers and ZK Rollups Require Trust?
3:16 Shielded Bitcoin vs. Monero and Zcash
4:21 What Privacy Shielded Bitcoin Protects
5:59 How Private Are Early Users? The Small Privacy Set Problem
7:37 Is Shielded Bitcoin an Altcoin Killer?
9:12 Fees, Block Space, and Larger Shielded Transactions
10:50 Who Needs Private Bitcoin? Wrench Attacks and Corporate Treasuries
12:20 Dark Pools, Governments, and the Next Wave of Bitcoin Buyers
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Bitcoin Privacy Breakthrough a Zcash Killer? | Misha Komorov, Alloc Innit first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Bitcoin’s Institutional Era Has Arrived | Robinhood VP of Crypto Institutions Nicola White
Robinhood is bringing crypto perpetual futures to US customers, with up to 10x leverage on Bitcoin and Ether. Nicola White, Robinhood’s vice president of institutional crypto, explains how the CFTC no-action letter, the Bitstamp exchange, and Robinhood Derivatives made it happen, and why the company wants markets to be always on.
Chapters:
0:00 Robinhood’s Hood Summit: 24/7 Stock Trading and US Crypto Perps
0:40 Why Robinhood Wants Markets That Never Close
1:32 Bitstamp Perps and the CFTC No-Action Letter
2:19 Tokenized Stocks, the Basis Trade, and the Path for US Perps
3:20 Bitstamp’s Volume and the Retail–Institutional Merger
4:54 What Institutions Want to Do With Bitcoin
6:00 Institutional Bitcoin Depth and Large Block Trades
6:49 AI Trading Agents and Robinhood’s Sub-Account Controls
8:29 Lessons From the 2022 Meltdown and US Leverage Limits
10:12 How Bitcoin Changes Finance in 10 Years and What’s Next for Tokenized Stocks
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Bitcoin’s Institutional Era Has Arrived | Robinhood VP of Crypto Institutions Nicola White first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Mark Moss: The Bitcoin Endgame – BTC to $1 Million by 2030
The Fed just raised rates, yet Bitcoin keeps climbing. Mark Moss, host of the Market Disruptors podcast, explains why he thinks most people are misreading why long-term rates are rising, how a booming economy could be part of the answer, and why he says Bitcoin benefits from both the debasement trade and a bullish technological future.
Chapters:
0:00 Mark Moss on the Fed’s “Token Raise” and an October Pause
1:54 The Flat Yield Curve, Bank Lending, and the 5.1% 10-Year
2:56 Why Bitcoin Is Rising as Rates Rise: “Price Is Truth”
5:40 Bitcoin vs. Gold: The Debasement Trade and a Bullish Future
6:19 Can the US Grow Its Way Out of $40 Trillion in Debt?
10:30 The Monetary Reset Is a Process, Not an Event
13:33 Four Ways Out of the Debt Problem and What Happens in 2029–2030
16:27 Stablecoins, the Genius Act, and Why 6 Billion People Want Dollars
20:14 Institutions Are Buying Bitcoin While Retail Sells
24:29 Bitcoin’s S-Curve, Its CAGR, and a $1 Million Price Target
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Mark Moss: The Bitcoin Endgame – BTC to $1 Million by 2030 first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
UK Brings Crypto Under Full FCA Oversight for the First Time
The UK’s Financial Conduct Authority has opened applications for crypto firms to become authorized, bringing the sector under full regulation for the first time.
In a Wednesday announcement, the watchdog said companies can apply so that the crypto industry has “clarity and legitimacy.”
The UK is in the process of drafting a sweeping new crypto bill. The FCA finalized its regulatory framework for cryptoassets in June, and the regime is due to take effect in October 2027.
“The UK’s new crypto regime will give consumers greater protections and firms a clear framework to operate in. Firms can now apply for authorisation and start preparing for regulation,” Dominic Cashman, director of authorisation at the FCA, said in a statement.
The statement added that firms will have to demonstrate that they meet requirements covering consumer protection, customer-asset safeguarding, market integrity and financial resilience.
Britain is pushing ahead with digital asset legislation since last year recognizing bitcoin and other digital assets as property. The reform came from a 2023 recommendation by the Law Commission, which argued that digital assets did not fit neatly into existing legal categories.
Despite the FCA’s announcement, the UK currently is trailing behind Brussels and Washington with digital asset regulation.
The EU’s Markets in Crypto-Assets regulation has applied to service providers since 30 December 2024.
And the U.S. under President Donald Trump signed the GENIUS Act into law in July 2025, establishing a federal framework for dollar-backed tokens.
Despite lawmakers blocking landmark legislation the Clarity Act last month, U.S. regulators like the Securities and Exchange Commission have pushed ahead with rulemaking regardless.
This post UK Brings Crypto Under Full FCA Oversight for the First Time first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Bitcoin Surges 40% in Its Best Quarter Since Late 2024
Bitcoin is having one of its best quarters ever — another indication that the biggest cryptocurrency is in a bull market.
As noted by the The Kobeissi Letter this week, the price of bitcoin is now up close to 30% since August 19, when the U.S. Treasury announced it planned to more than double the size of its government debt repurchases.
Over the past quarter, the bitcoin price has surged by 40% — its best quarterly performance since Q4 2024.
Bitcoin’s price recently stood at nearly $83,698, unmoved over a 24-hour period but up 6% over a 30-day period.
The coin has benefited from news that the Treasury would try to lower bond yields — which have soared to highs not seen since the 2000s.
Bitcoin has done well with lower long-term yields because it reduces the opportunity cost of holding non-yielding assets like bitcoin and gold, and generally supports risk-on sentiment.
But despite the Treasury stepping in to try and tame the bond market, yields have continued to stay high.
Bitcoin investors don’t seem that bothered. The asset is still doing well as the dollar continues to slip. The so-called debasement trade — where investors throw money at an asset to hedge against a currency losing its value — is hot again after total U.S. debt topped $40 trillion for the first time in July.
The price of Bitcoin had been battered since notching a new all-time high of $126,080 in October, dropping by over 50%. Still, it has experienced the shallowest bear market — so far — in its history.
CryptoQuant said in a report last week that bitcoin was back in a bull market after crossing above its 365-day moving average — the “definitive technical signal” that has marked the start of Bitcoin’s bull markets in past cycles.
The coin has shrugged off the Federal Reserve raising interest rates and lawmakers blockage of landmark crypto legislation, the Clarity Act.
This post Bitcoin Surges 40% in Its Best Quarter Since Late 2024 first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
CryptoSlate
Ripple's Brazilian foothold spans cross-border payments and securities records in a country Chainalysis ranked first for grassroots crypto adoption.
Ripple and CSD BR, a regulated financial market infrastructure operator, announced a first phase on Sept. 29 to mirror ownership records for BTG Pactual investment fund shares on the XRP Ledger (XRPL). CSD BR's systems will remain the official record for registration, deposit, and settlement.
The announcement follows a Sept. 28 interview in which RippleX executive Markus Infanger told Estadão's E-Investidor that about $2.7 billion of the $6.7 billion in tokenized real-world financial assets he counted on XRPL was in Brazil.
That puts roughly 40% of the reported asset value in one country, although the measure reflects assets rather than payment activity.
Together, the developments show how Ripple's years of expansion have connected it to several parts of Brazil's financial system. The opportunity spans institutions moving money, platforms distributing stablecoins, and firms managing investment assets, with different measures of success for each.
Ripple was building there before the ranking
Ripple opened its Brazilian office in 2019 and announced XRP-enabled payments with Travelex Bank in August 2022. Those relationships predate the new adoption ranking by years.
In October 2024, its Mercado Bitcoin payments partnership initially targeted internal treasury transfers between Brazil and Portugal. The release described corporate and retail international payments as future plans, rather than services already available to those customers.
By March 2026, Ripple was expanding its Brazilian institutional offering across payments, custody, prime brokerage and treasury management. It named Banco Genial, Braza Bank and Nomad among payments users, while Mercado Bitcoin, Foxbit and Ripio were among platforms listing or supporting its dollar stablecoin, RLUSD.
Alongside that expansion, Ripple announced plans to seek a Brazilian virtual asset service provider license.
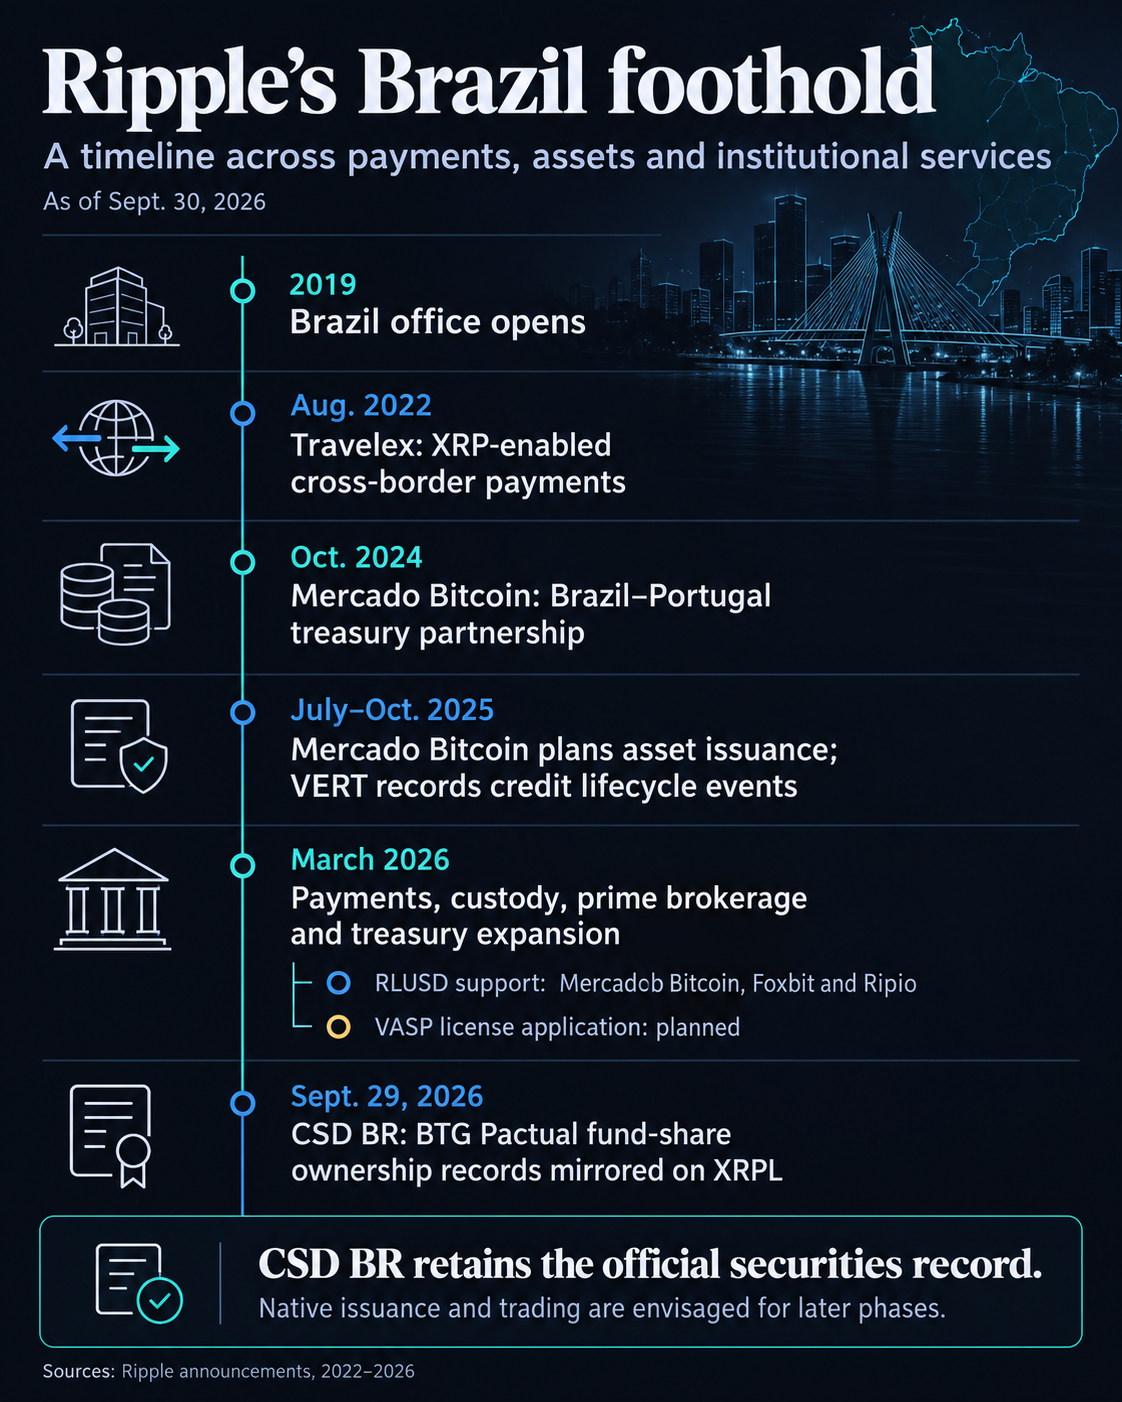
The same companies can connect several parts of the strategy. Mercado Bitcoin, for example, announced plans in July 2025 to tokenize more than $200 million in permissioned real-world assets on XRPL. The planned issuance adds an asset relationship to its payments and stablecoin connections.
Chainalysis's 2026 adoption index puts Brazil first overall, second for cross-border flows, third for service flows and domestic peer-to-peer activity, and fourth for balances.
Its revised methodology rewards broad performance across those four measures. First place does not mean Brazil has the world's largest crypto market by raw dollar volume, and the methodological change limits comparisons with earlier rankings.
Chainalysis estimated $252.5 billion in Brazilian crypto activity between July 1, 2025, and June 30, 2026. Its Latin America report also found that Brazil's crypto economy contracted 1.6% during that period, so adoption leadership coexisted with a slowdown.
For Ripple, the more useful connection is what businesses do with crypto. The report describes Brazilian companies using stablecoins for liquidity management and cross-border transfers, purposes that overlap with its institutional offering.
Brazil's Oct. 1 restrictions will bar virtual assets from settling aggregated eFX flows between providers and foreign counterparties, while individual international virtual-asset transfers remain permitted.
From represented assets to financial infrastructure
Infanger's reported XRPL asset total gives the Brazilian footprint a reported scale. The $2.7 billion figure describes tokenized real-world asset value represented on XRPL.
In October 2025, Ripple said VERT's credit platform recorded lifecycle events, documentation and payments on XRPL and its EVM sidechain. Its pension-receivables fund then held more than R$200 million in net assets.
The CSD BR announcement extends that approach into securities infrastructure. Its first phase mirrors BTG Pactual fund-share ownership records using XRPL tokens and Ripple custody, with access restricted to authorized Brazilian corporate and banking participants subject to identity and anti-money-laundering checks.
Native issuance and trading are envisaged for later phases after mirroring is validated. For now, the project gives Ripple a place inside existing financial processes without making the public blockchain the authoritative securities register.
That makes Brazil a practical test of Ripple's wider institutional strategy. Its announcements show relationships across payments, stablecoins, custody and investment records, but provide no comparable aggregate Brazil-only payment volume, RLUSD circulation or active institutional usage.
Sustained transactions and broader use of the CSD BR system would show how far those connections develop beyond the reported asset values.
The post Ripple quietly made Brazil the center of its XRPL tokenization push appeared first on CryptoSlate.
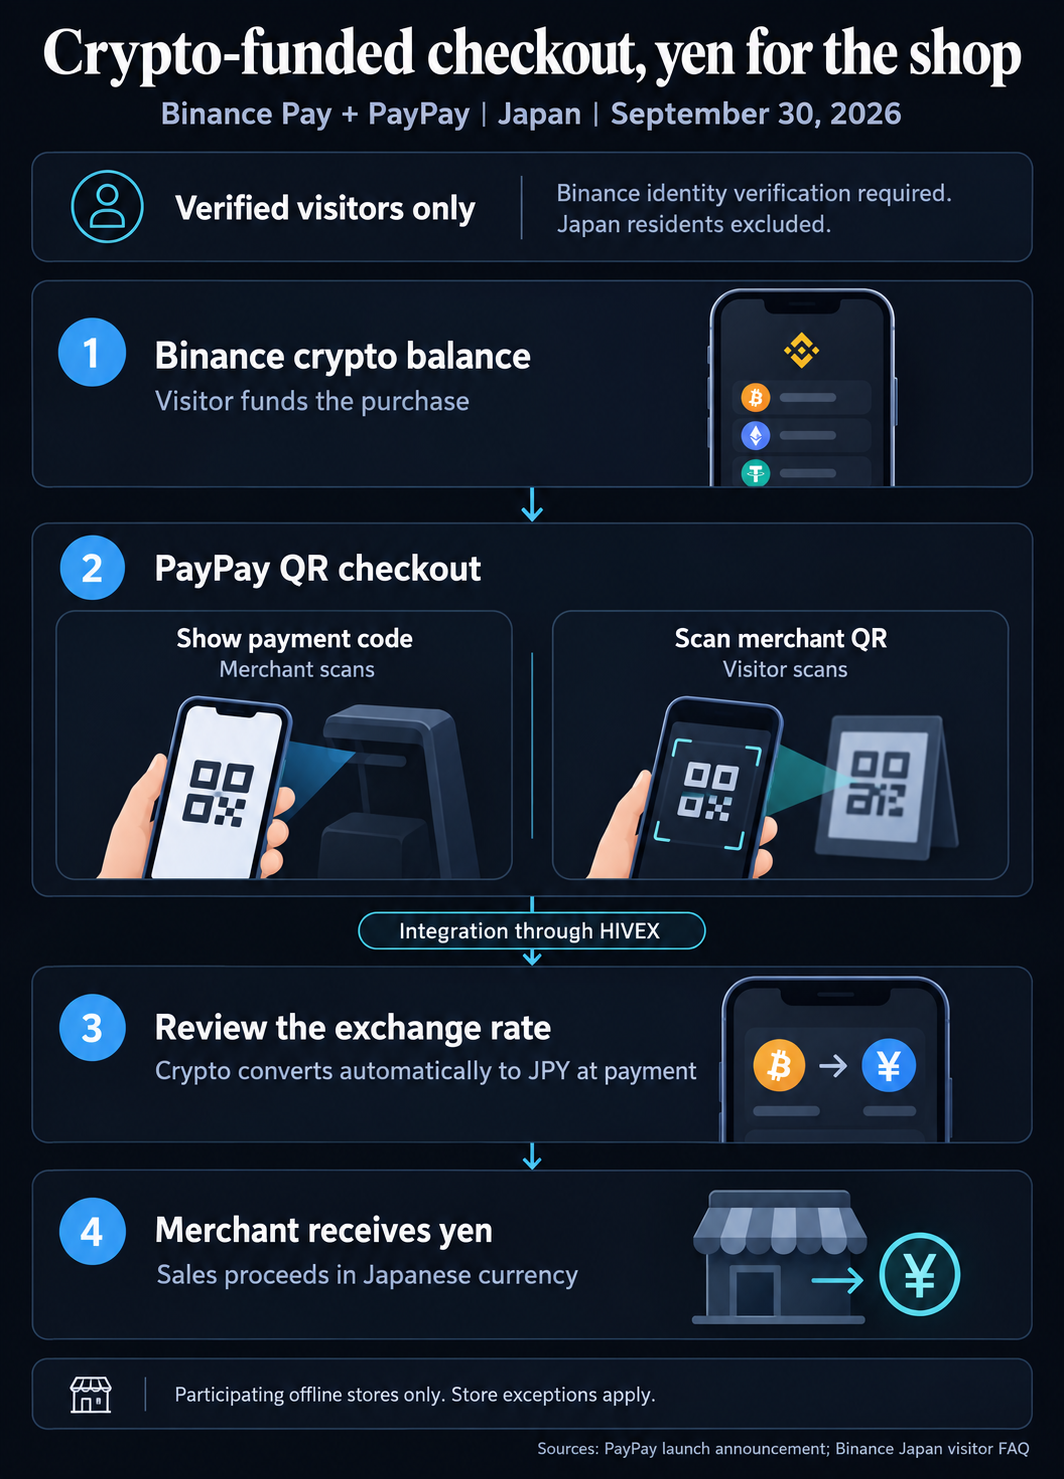
Japanese payment provider PayPay added Binance Pay on Sept. 30, letting eligible overseas visitors pay from their crypto balances at participating offline stores in Japan. Merchants receive the proceeds in Japanese yen.
PayPay's launch announcement says the integration runs through HIVEX, a cross-border payment network. For visiting Binance users, funds held in their crypto accounts can cover a yen-denominated purchase, with conversion handled during payment.
Binance says the feature is exclusively for visitors who have completed its identity verification and is unavailable to Japan residents. Its launch blog sets out that restriction, while PayPay specifically excludes Binance Japan users residing in Japan.
This visitor-payment launch does not extend the checkout feature to the exchange’s domestic customers.
How visitors pay
The payment tools sit inside the Binance app. A visitor can show a PayPay payment code for the merchant to scan, or scan a participating merchant’s PayPay QR code.
Both modes use the customer’s Binance balance, so the new payment option works through QR checkouts rather than requiring the merchant to receive crypto.
Binance’s Japan visitor FAQ says users can review the exchange rate before confirming. It says it supports more than 100 cryptocurrencies, including USDT, USDC, Bitcoin, Ethereum, and BNB.
The customer’s crypto is automatically converted to yen, and the store’s sales proceeds remain in Japanese currency.
Binance's FAQ says payments and refunds are distinct transactions, and the amount returned can differ because of rate fluctuations and applicable foreign-exchange spreads. It does not specify a numerical spread, so the fee statement does not establish a cost-free currency conversion.
Exclusions include online platforms, some taxis and vending machines, PayPay Money-only stores, certain barcode-payment merchants, and some stores that do not support cross-border payments. Binance’s FAQ also excludes merchants that require Japanese identity verification.
A PayPay sign alone does not guarantee that the Binance-funded route will work. Travelers need both an eligible account and a store that accepts the cross-border service, whether they show their own code or scan the merchant’s.
For eligible visitors, the immediate benefit is being able to fund an accepted yen purchase directly from a Binance crypto balance after reviewing the exchange rate.
The post Japan’s biggest payment network opens its doors for crypto via Binance Pay appeared first on CryptoSlate.
Base’s Cobalt upgrade, scheduled for mainnet Sept. 30 at 18:00 UTC, will let issuers of B20 tokens configure balance seizures separately from ordinary transfer restrictions. For a token that enables the feature, a holder could remain free to transfer while still being eligible for administrative reassignment.
B20 is Base’s native ERC-20-compatible token standard, offered in Asset and Stablecoin variants. It already gives administrators control over roles and policies governing balance movements, and now it will also govern the administrative powers over those balances.
Role assignments identify who can exercise a particular power, while policy settings determine which accounts an operation can affect. Changing a token’s rules and executing a balance operation involve distinct permission checks.
Separate seizure permissions
The new administrative operation, called seizeWithMemo, moves a specified amount from a holder to another address. It preserves total supply and skips ordinary transfer policies and holder allowances.
An issuer must configure which accounts lose their exemption before the function can take their tokens. The setting, SEIZE_EXEMPT_POLICY, exempts everyone when left unset. Configuring eligibility alone is insufficient: execution requires SEIZE_ROLE, an unpaused seizure function, a permitted recipient, and sufficient balance.
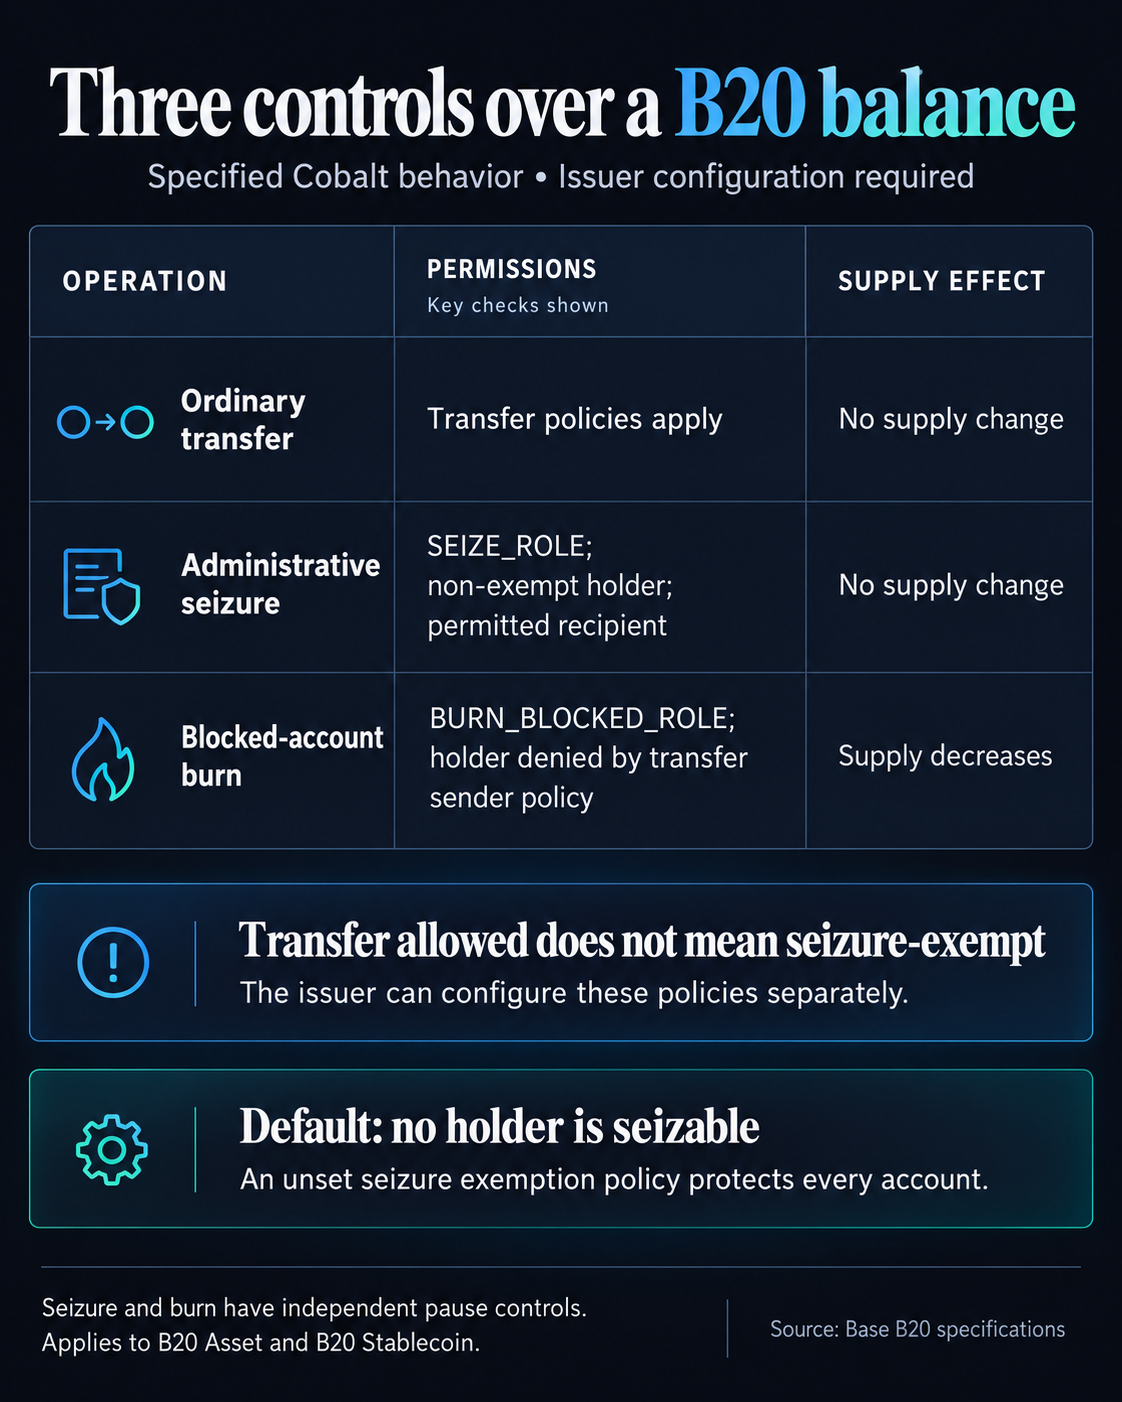
A separate recipient policy determines where the seized tokens can go, and leaving that policy unset allows any otherwise valid destination. The holder’s ability to make an ordinary transfer does not answer either seizure-policy question.
B20’s existing transfer policies check the sender and receiver, plus the executor for certain transfers on another account’s behalf. Administrators can update those policies. Approving a spender does not remove the checks on the eventual transfer, but those ordinary transfer permissions are distinct from Cobalt’s seizure rules.
B20 also already has burnBlocked, which lets an authorized caller destroy tokens held by an account denied by the transfer sender policy. Cobalt marks that function deprecated but keeps it callable with its existing behavior.
That leaves issuers with different ways to remove a holder’s balance. Reassignment keeps the tokens in circulation at another address, while destroying the seized supply requires a subsequent burn. Seizure and burning have separate administrative roles and pause controls.
Base’s status page lists the mainnet upgrade as scheduled, with maintenance from 18:00 to 20:00 UTC. The upgrade overview lists Sepolia as live since Sept. 23 and mainnet as shipping on Sept. 30.
The v1.4.2 release adds Cobalt mainnet support and instructs node operators to upgrade by Sept. 30 at 18:00 UTC.
The post Base’s Cobalt upgrade adds another rule to affect token balances appeared first on CryptoSlate.
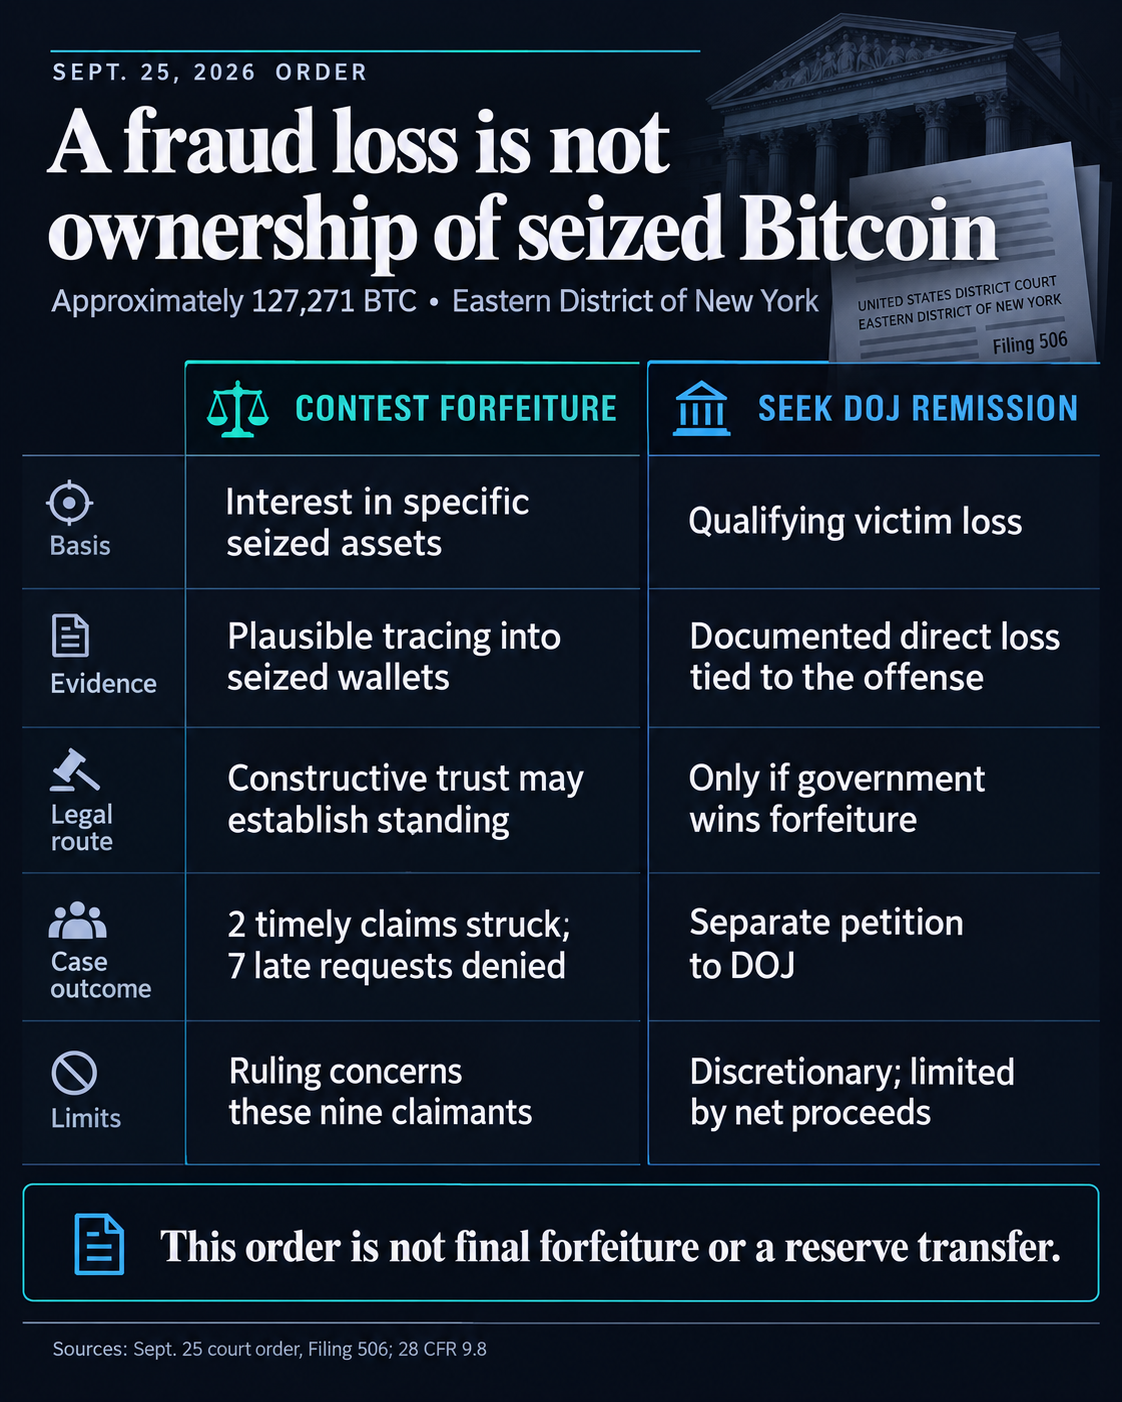
Judge Rachel P. Kovner rejected claims by nine alleged fraud victims seeking to contest forfeiture of approximately 127,271 Bitcoin in a Sept. 25 order.
Their filings did not plausibly connect their lost funds to the specific seized wallets, leaving them with a different potential recovery route if the government wins the forfeiture case.
The Eastern District of New York judge struck the timely claims of Ath Leepinyo and Connie Wilson and denied seven other claimants permission to file late. All nine lacked Article III standing, the legal threshold for contesting the action.
The case began with a civil forfeiture complaint filed on Oct. 14, 2025. DOJ said then that the Bitcoin was in US custody and alleged links to fraud and money laundering involving Prince Holding Group, a Cambodian conglomerate, and its chairman, Chen Zhi.
The court treated these claimants’ plausible allegations as establishing, at most, the position of general unsecured creditors: people seeking compensation without a qualifying interest in the particular assets being forfeited.
A loss tied to an alleged fraud did not establish ownership of coins in these wallets.
The order recognized that a constructive trust could give a claimant an equitable ownership interest and standing. That remedy can recognize an interest in property derived from a person’s assets. However, here none of the claimants plausibly alleged the necessary connection between their funds and the seized Bitcoin.
Lawrence D. Van Dyn Hoven, for example, relied on an investigator’s belief that his stolen cryptocurrency was part of the seizure. Kovner found that his filings offered no supporting facts explaining that belief.
What remission could provide
Kovner pointed to victim remission if the government succeeds in forfeiting the Bitcoin. That process allows eligible victims to petition DOJ for recovery from forfeited property even when they lack a present ownership interest in it.
Under 28 CFR 9.8, petitioners must document a specific financial loss directly caused by the offense underlying forfeiture or a related offense, and satisfy other eligibility conditions. Other conditions include no knowing participation in or benefit from the offense, and no willful blindness.
Petitioners must also show they have not been compensated for the loss and lack reasonably available alternative assets for recovery.
When the forfeited property cannot cover petitions in full, recognized victims may receive proportionate shares. Remission is capped at a victim’s share of the associated net forfeiture proceeds, so the size of the Bitcoin seizure is no promise of full repayment.
The Sept. 25 order resolves these nine claimants’ standing. Their potential recovery depends on government success in the forfeiture action and a separate discretionary decision on a documented-loss petition.
The post US court blocks victims from 127,000 seized Bitcoin, and petition rules are blamed appeared first on CryptoSlate.
Uniswap’s StablePair fee hook is designed to keep more of the value from rebalancing stablecoin pools with liquidity providers.
Yet the rule deciding which trade counts as a correction depends on a configured reference rate.
StablePair is a Uniswap v4 hook, a contract that changes a pool’s behavior. Its fee logic compares a cached pool price with a reference stored in the hook’s configuration. The design prices trades around that benchmark, leaving providers exposed if a token’s economic value moves away.
Uniswap Labs announced the two Ethereum pools, USDC/USDT and USDC/USDG, on Sept. 10. Its Sept. 16 explanation noted that Providers allocating capital now are choosing a fee mechanism alongside the token inventory it requires them to hold.
What the dynamic fee captures
The deployment documentation lists one-for-one reference rates for both pools. The implementation’s fee path uses that stored reference and the pool’s price, without consulting an external market-price feed.
Inside a narrow band around the reference, the fee varies by swap direction to target a consistent bid and ask before price impact. When the pool sits exactly at the reference, both directions pay the configured optimal fee. As it moves toward an edge, the fee in one direction falls while the other rises.
For a simple illustration, assume an optimal fee of one basis point (0.01%). At the reference, a swap with 10,000 input units would pay one input unit in LP fees.
Outside the band, the fee rules split trades by direction. A swap classified as moving farther from the reference pays zero LP fee, while a swap classified as pulling the pool toward it faces a decaying fee.
A trade pushing the pool away can give LPs a favorable price relative to that benchmark. The reverse trade lets an arbitrageur capture the gap by restoring the pool’s price. A single static fee rate charges both directions equally.
StablePair instead offers progressively better terms for the corrective trade as blocks pass.
If a trader accepts the fee, LPs collect it while the trade rebalances the pool. Uniswap Labs says the design captures the “vast majority” of rebalancing profit.
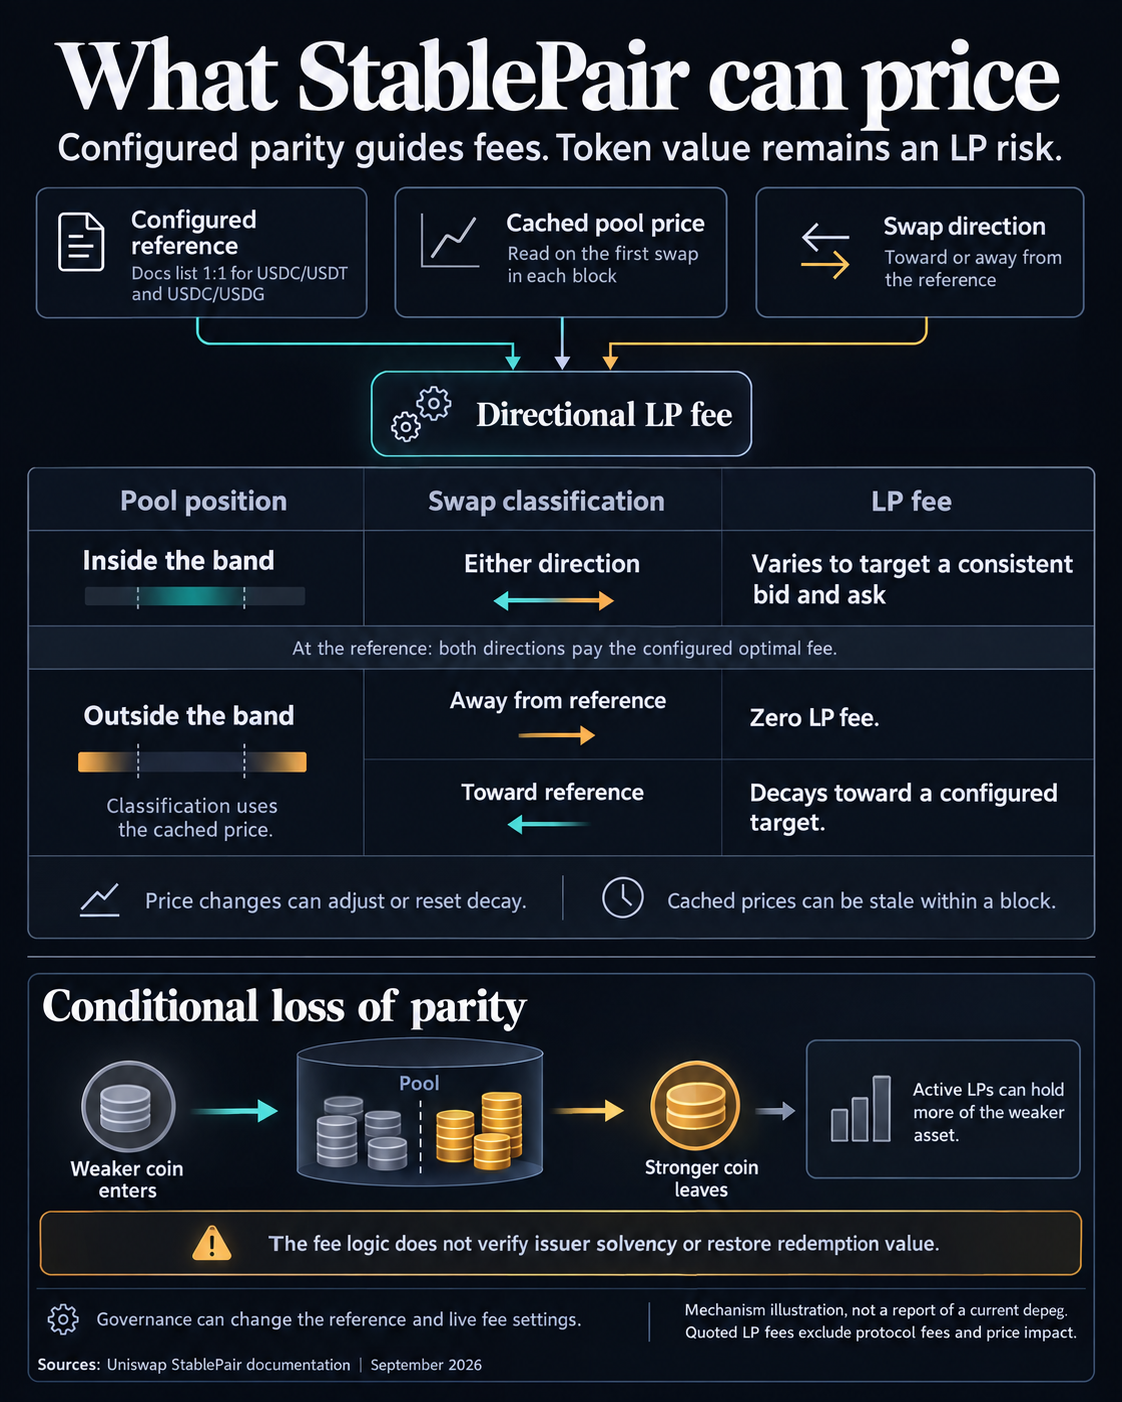
The first swap in each block caches the pool price used for later fee calculations. That removes the same-block fee advantage from splitting corrective swaps, but later trades can face stale inputs. If the live price crosses the reference mid-block, the cached classification can assign fees to the opposite directions until the next block.
Inventory risk and the evidence on returns
The boundary appears when the outside market stops treating the two coins as equal.
Consider a conditional issuer shock that reduces one coin’s external value while the configured reference still assumes one-for-one exchange. Selling that weakening coin for the stronger coin can move the pool farther from the reference while moving its price closer to the outside market.
A trade the fee rule classifies as moving away from the reference may then reflect price discovery, rather than a temporary imbalance.
The fee logic cannot verify issuer solvency or restore redemption value. This scenario is hypothetical and should not be read as a report of a current depeg, exploit, or loss in either StablePair pool.
If an LP holds 10,000 hypothetical coins and their external value falls from $1 to $0.90 each, that inventory is worth $9,000, a $1,000 decline before fees. Capturing income from rebalancing trades does not by itself reimburse that change in token value.
Trades can also change what the provider owns. Selling the weaker coin into available liquidity removes the stronger coin and leaves active LP positions with more of the weaker asset. An away-from-reference trade charged zero LP fee contributes no LP fee to offset that added exposure.
The amount exchanged still depends on available liquidity, the provider’s chosen range, and price impact. StablePair's zero-fee classification also depends on the cached price, so it should not be read as a rule that every sale of a weakening coin is always free.
On Sept. 30, the Uniswap interface’s Stats panels showed the USDC/USDT StablePair pool with about $6.1 million in total value locked and $117.9 million in 24-hour volume around 15:59 UTC. The USDC/USDG pool displayed about $2.6 million and $8.7 million, respectively, around 15:57 UTC.
A same-pair reference was available: the Ethereum USDC/USDT v3 pool charging 0.01% displayed about $34.2 million in TVL, $15 million in 24-hour volume, and $1,100 in 24-hour fees around 16:02 UTC.
The observations were not synchronized, the pools have different fee rules and liquidity conditions, and the StablePair panels supplied no comparable absolute fee total or realized position-level return.
In economic terms, testing that return claim would require comparable periods and active liquidity ranges, fee income, and inventory valuation. Volume alone cannot show how much better an LP did than in another pool or by holding the assets.
Governance controls the benchmark, with limits on the hook
Under Uniswap’s documented role model, governance controls live fee configurations, implementation upgrades, and role administration.
Changing the reference changes the benchmark used to classify and charge swaps. The deployment page directs integrators to read live configuration from the hook because governance can change parameters.
Separate limits apply to what an upgrade can do. The hook’s permanent address permissions exclude remove-liquidity callbacks and custom accounting deltas.
According to Uniswap’s security documentation, upgrades cannot use those capabilities to block LP withdrawals or alter swap amounts to skim additional fees. The ability to withdraw does not guarantee the market value of the tokens received.
Uniswap says OpenZeppelin reviewed a non-upgradeable predecessor’s core fee mechanism from Feb. 9 to 13, 2026, and resolved the splitting issue through block caching. The later upgradeability and role model were outside that review.
For LPs, StablePair changes the price of supplying liquidity for rebalancing. The remaining economic decision is whether the assets still justify the reference around which that liquidity is supplied, and whether earned fees compensate for the inventory ultimately held.
The post Three hidden flaws in Uniswap’s StablePair hook drain LP returns appeared first on CryptoSlate.
CryptoTicker.io
Anyone holding Shiba Inu who wanted to do something with it inside the ecosystem has been stuck for months: validator staking on the project's own layer-2 chain Shibarium has been under maintenance since April 17, 2026, that is, for 167 days. That is the status the operators themselves report, and it has consequences that go beyond forgone BONE rewards. After the infrastructure switch, the chain's block explorer has read back only a little over half of all blocks, and for many German holders that explorer is precisely the source from which the proof for the tax office comes at the end of the year.
The price gives hardly any signal on this. SHIB is quoted on Thursday morning at around $0.00000582, a good one percent above the day's open. So the day's move explains nothing. What can be explained is the state of the technology underneath, and that is traceable in a few minutes with one RPC call and a look at the status page. This article says what is standing still, what is still running and what action follows from it for you.
Validator staking on Shibarium: under maintenance since April 17, 2026
Shibarium is the layer-2 chain of the Shiba Inu ecosystem. It works to the same basic pattern as other sidechains with their own validator set: whoever deposits BONE runs or supports a validator and receives a share of the fees and the issuance in return. Validator staking means depositing BONE with a validator, either as the operator of your own node or as a delegator who assigns their balance to someone else's node.
It is exactly this part of the ecosystem that is switched off. The SHIB ecosystem status page lists the validator staking entry as an incident beginning April 17, 2026 with the state maintenance. No date for its return is given there. Users are expressly asked not to attempt staking transactions during this period. That is not a throwaway line: a transaction running against a contract whose interface and settlement are in the middle of being moved can cost fees without the intended effect occurring.
This has to be placed in the context of the larger switch that has been under way since the spring. In September the chain's public access points were replaced, and the old RPC addresses no longer respond. How that affects wallet setup is something we described on September 29 in a separate piece on the Shibarium switch and your wallet. On September 15 a complete rotation of the node addresses for the Bor and Heimdall layers followed, and on September 19 developer Kaal Dhairya reported via a community member that the chain's reorganisation had been resolved. What remained open after that report was the move of the RPC provider into the new environment.
What the SHIB ecosystem status page reports today
On October 1 the status page lists three unresolved entries. The first is validator staking. The second concerns the rewards from the SSLP pools on ShibaSwap, the ecosystem's decentralised exchange; the distribution is delayed. The third concerns the Bury function, with which holders deposit SHIB, LEASH and BONE on ShibaSwap and receive interest-bearing tokens in return. There too the rewards are stalling.
All three entries share the same note: those affected should contact support with their wallet address so that claims are processed by hand. For you that means two things. First, on the operators' account, forgone rewards count as deferred and not as forfeited. Second, the burden of proof lies with you: anyone registering a claim in December needs the address, the time of the deposit and the amount. You should note down those three details now, not once the interface is running again.
A word on how solid this source is: the status page is the operators' own account of themselves. There is officially nothing better than that account, but an independent measurement still does not replace it. The next section therefore contains figures that can be gathered without going through the operators.
Shibariumscan at 54 percent: the explorer trails the network by 8.77 million blocks
The block explorer Shibariumscan runs on the Blockscout software and publishes its own index status through an open interface. On October 1 it reports that indexing is not complete and puts the share of blocks read in at 54 percent. In absolute numbers, the explorer has captured 10,466,121 blocks. At the same time the chain itself stood at block 19,237,206, queried directly through the chain's official access point with the identifier 109. The gap therefore comes to around 8.77 million blocks.
This figure becomes interesting in a time comparison. On September 20 the same value stood at 53 percent. So in eleven days the index has grown by one percentage point. If that pace holds, reading in the remaining 46 points will take well over a year. That is an extrapolation and not an announcement by the operators, and a single faster pass could dispose of it. As an order of magnitude it is still useful, and it tells you that for the time being you should not assume you will find your complete Shibarium history again in the explorer.
1,620 transactions a day: how empty Shibarium is running right now
The second figure that can be gathered independently is the load on the chain. The explorer reports 1,620 transactions for the current day and a network utilisation of 0.04 percent. As a cross-check we queried 20 consecutive blocks directly through the chain's access point: those 20 blocks contained exactly one transaction, at a mean block time of five seconds. Extrapolate that and you land in the same order of magnitude as the explorer's daily figure.
The gas price fits with it. It stands at 0.13 Gwei, that is, at the bottom stop. A chain that nobody is pushing on is cheap. For you as a holder that is mixed news: transfers on Shibarium currently cost next to nothing, but a chain with this level of utilisation also carries no fee income out of which staking rewards could be fed. The question of whether validator staking returns in its old form on an economic basis hangs on this figure at least as much as on the technology.
BONE, Bury and SSLP: which staking routes in the ecosystem are open
It is worth keeping the routes apart, because they are affected to different degrees and because in the debate everything often ends up in one pot.
| Route | What lies behind it | Status on October 1, 2026 |
|---|---|---|
| Validator staking (BONE) | BONE is deposited with a validator of the Shibarium chain, as an operator or as a delegator | Maintenance since April 17, 2026, no end date |
| Bury on ShibaSwap | SHIB, LEASH or BONE are deposited, interest-bearing tokens come back | Rewards delayed, processed by hand through support |
| SSLP pools on ShibaSwap | Liquidity in trading pairs, reward from trading fees and issuance | Distribution delayed, unresolved |
| Holding in your own wallet | SHIB on Ethereum, with no contract and no counterparty | Untouched, running normally |
The bottom row is the important one. Anyone simply holding SHIB on the Ethereum mainnet in their own wallet is not affected by any of this. There, SHIB is an ordinary token under the ERC-20 standard, and its balance hangs on none of the disrupted contracts. The disruptions hit the layers above, that is, Shibarium and ShibaSwap.
Anyone looking for yield on holdings, by contrast, currently has to look outside the Shiba ecosystem. Which supervised and which decentralised providers come into question for that, and on what terms, is set out in our comparison of staking providers. The pointer belongs here because otherwise the obvious reaction to a stalled staking interface is to take the next best interface, and that is rarely the cheapest.
The one-year holding period under Section 23 of the Income Tax Act and the gap in the Shibarium proof
This is where the index gap from the third section becomes concrete. In Germany, the one-year holding period under Section 23 (1) sentence 1 no. 2 of the Income Tax Act applies to crypto assets held as private assets. Anyone holding for longer than twelve months disposes of them tax free. Within the year, an exemption threshold of 1,000 euros applies to the total of all private disposal transactions. Rewards from staking or lending, on the other hand, as a rule count as other income under Section 22 no. 3 of the Income Tax Act, where the exemption threshold is 256 euros a year.
What is decisive is the evidence side. The Federal Ministry of Finance's circular of March 6, 2025 on individual questions of the income tax treatment of certain crypto assets, file reference IV C 1 - S 2256/00042/064/043, contains for the first time a dedicated section on cooperation and record-keeping obligations. What it requires are comprehensible records of acquisition, disposal and receipt. Anyone who has moved holdings across a bridge onto a layer-2 chain has to be able to present those movements.
And that is exactly what becomes difficult as long as the chain's explorer has not yet read 46 percent of the blocks. So do not draw your evidence from the explorer but from the sources that are complete: the statements of the exchange you bought from, your wallet's export files, and the transaction identifiers you have saved yourself. A tax tool can take over the consolidation, but it cannot create the completeness of the input data; which providers read which chains is set out in the comparison of crypto tax software.
Custody of SHIB: the difference between the Ethereum mainnet and the Shibarium bridge
A bridge is a device that locks a token on one chain and issues an image of it on a second chain. The holding on the layer 2 is therefore always a claim against that device and not the token itself. As long as the bridge is working, nobody notices the difference. If the environment around it falls into a lengthy switch, as is currently the case, you notice it at once.
Nothing dramatic follows from that, but a sober order of priority does. Holdings you want to leave lying for longer belong on the Ethereum mainnet in a wallet whose keys you hold yourself. A hardware wallet separates the key from the computer and is the obvious solution for amounts whose loss would hurt; the device classes and their prices are set out in the comparison of hardware wallets. Amounts you actually do something with on Shibarium you leave there, but in a size whose standstill you can bear.
If you want to keep using the chain, the right access point matters. After the switch, the official address responds under the identifier 109; the old addresses no longer do. Anyone who has configured a wallet with an outdated address sees an empty balance there even though nothing is lost. That is the most common moment of fright in these weeks, and it has nothing to do with the staking.
Buying route under MiCA: where German investors trade SHIB with supervised providers
Since December 30, 2024 the European regulation on markets in crypto assets, MiCA for short, has applied in full; in Germany it is flanked by the Crypto Markets Supervision Act. Providers offering services around crypto assets here need an authorisation and are subject to supervision. For you as a buyer that is above all a question of enforcing your rights: with an authorised provider you have a point of contact and a supervisory route, with a decentralised interface you have neither.
That is not an argument against ShibaSwap; it merely places the current situation. The delayed rewards there are, according to the operators, settled through support, that is, as a matter of goodwill. Anyone who does not want that difference buys and holds through a supervised trading venue. Which providers hold an authorisation in Germany and what their fees and custody models look like is set out in our overview of regulated crypto exchanges.
SHIB in the order book on Thursday morning: $0.00000582
For context, the day's figures, deliberately at the end and not at the beginning. SHIB is quoted on Thursday morning at around $0.00000582, which in euros is about 0.00000514. The day's open was $0.00000575, a good one percent away. Over the past 24 hours the range lay between $0.00000569 and $0.00000599. The figures come from the order books of Kraken and Coinbase; depending on the venue the last digit differs, which at a price of this magnitude is normal.
The connection to the preceding sections is weaker than the usual narratives suggest. A stalled staking interface ties up no appreciable quantity of SHIB, and Shibarium's network load is too small to move supply and demand on the large trading venues. Anyone deriving a statement about the price from the disruption is overstretching the data. What can be derived from it is a statement about availability, verifiability and custody, and those are the three things that will genuinely rest on you over the coming months.
Shibarium staking: the key points for your decision
- Secure your records before you move anything. For every deposit with Bury, in an SSLP pool or with a validator, note down the wallet address, the date and the amount, and export your transaction list from your wallet and from the exchange. The chain's explorer is currently not a reliable source for that. Which tool takes over the consolidation is set out in the comparison of crypto tax software.
- Separate holding from using. What is meant to stay put belongs on the Ethereum mainnet in a wallet with your own key; a suitable device class is in the comparison of hardware wallets. On Shibarium you leave only what you genuinely need there.
- Look for yield where it is actually being paid out. As long as validator staking and Bury are stalling, waiting earns nothing. The terms of the supervised and the decentralised alternatives are set out in the comparison of staking providers, together with the question of how the income is classified for tax.
(As of October 1, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Anyone who sells their coins and cannot prove the purchase price will in future have to pay tax on half the sale proceeds. This substitute assessment appears in the German Federal Ministry of Finance's draft bill on the "Act to reform the taxation of certain crypto assets held as private assets", and it is the point that has so far been lost in the debate about the one-year holding period. The cabinet is due to approve the draft on October 14, 2026. Associations and law firms may submit comments until October 6, 2026.
For you this means two things. Your current holdings stay protected if you bought them by December 31, 2026. And from 2027 your purchase receipts become a document whose loss carries a price you can put a figure on.
Substitute assessment: 50 percent of the sale proceeds as the tax base
A substitute tax base is a value that the law applies when the actual value cannot be established. That is exactly what the draft provides the 50 percent rule for: if the exchange does not know the date of acquisition and the acquisition cost, the taxable gain is assessed at 50 percent of the entire sale proceeds. That is how the analysis by the specialist portal Der Betrieb of September 14, 2026 describes it.
A worked example makes the spread visible. If you sell coins for 10,000 euros and bought them for 9,000 euros, your real gain is 1,000 euros. Without proof, the substitute assessment assumes a gain of 5,000 euros. At a tax rate of 25 percent, around 1,000 euros separate those two cases.
The comparison with equities puts the severity in context. For securities, a substitute assessment of 30 percent of the proceeds has applied for years when the bank does not know the acquisition data. At 50 percent, the crypto draft sits above that. The tax advisory firm GTKP expressly highlighted this difference on September 15, 2026.
The reach of the rule matters: the substitute assessment is not a final verdict on your tax burden. It determines what the exchange withholds. You can claim the real acquisition cost in your tax return and recover tax paid in excess. But you then have to be able to prove it, and the burden of proof lies with you. Which documents the tax office may demand in an audit is something the tax administration has set out in its cooperation obligations; missing records count against you.
Exchange crypto asset: which coins the draft covers
The draft works with a new term. Under the definition, which follows the EU regulation MiCAR, an "exchange crypto asset" is a crypto asset that is accepted as a means of exchange and that no central bank has issued or guaranteed. What is meant first and foremost is Bitcoin and Ether.
This delimitation is more than terminological housekeeping. It decides which positions in your portfolio fall under the new regime and which continue to be treated under the old rules. For tokens that clearly qualify as securities or as payment tokens with a central bank link, the draft does not apply. Where exactly the line runs for smaller altcoins, stablecoins and tokenised products is something the draft does not yet work out sharply, in the assessment of both specialist sources.
From Section 23 to Section 20 of the Income Tax Act: 25 percent flat tax instead of your income tax rate
Today, gains from the sale of crypto assets are private disposal transactions under Section 23 (1) no. 2 of the German Income Tax Act. From that follows the familiar one-year deadline: after twelve months of holding, the gain is tax free. Below that, it is charged at your personal income tax rate, which can reach up to 45 percent.
The draft moves these gains to Section 20 (2) sentence 1 no. 9 of the Income Tax Act, that is, into income from capital assets. There the flat-rate withholding tax of 25 percent applies, plus the solidarity surcharge, and church tax on top where you are liable for it. The holding period no longer plays any part. In the wording of Der Betrieb, a gain would be taxable even after five, ten or twenty years.
Whether that works out cheaper or more expensive for you depends on two figures: your marginal tax rate and your actual holding period. An investor on a high income who trades within a year will pay less in future. A long-term holder who could sell tax free until now loses an advantage that hardly any other EU country offers in this form.
Grandfathering: the cut-off date of December 31, 2026 separates two tax worlds
The draft only applies going forward. Crypto assets that you acquire by December 31, 2026 remain under the old law with the one-year holding period. For everything you acquire from January 1, 2027, the new regime applies. GTKP summarises the mechanism as meaning that grandfathering preserves the old one-year deadline rather than replacing it: your legacy holdings keep their tax exemption after twelve months permanently, even if you do not sell them until 2030.
That creates a dividing line in every portfolio. Two Bitcoin positions bought a day apart can be subject to different tax rules. Which position you sell therefore becomes a question with tax consequences, and the order of disposal cannot simply be asserted at will. This is where a clean transaction history pays off; the tools in our comparison of crypto tax software and portfolio trackers carry exactly this allocation and document it in an auditable way.
Airdrops and gifts: acquisition cost of zero euros
For crypto assets acquired free of charge, the draft sets the acquisition cost at zero euros. Both specialist sources name this point. The consequence is arithmetically plain and economically substantial: if you later sell an airdrop for 2,000 euros, the entire amount is a taxable gain, because there is no acquisition value to set against it. A holding period that would defuse the transaction does not exist in the new regime.
It is not only airdrops in the narrow sense that are affected. Tokens from reward programmes, forks and allocations without consideration also fall into this logic, insofar as they are exchange crypto assets. Anyone taking part in distributions regularly is therefore building a position that becomes fully taxable on sale.
Wallet deposits: where the gap in the proof arises
The substitute assessment does not hit the majority of cases. If you buy on an exchange, leave the coins there and sell them there, the exchange knows the date and the price. In cases of doubt the draft also allows the platform to rely on your own information, as long as it has no contradictory data.
It gets tight in a transaction that is everyday business in this industry: a deposit from your own wallet or from another exchange. The receiving platform then sees an incoming transfer with no history. It does not know when the coins came into being or what they cost. It is precisely in this gap that the 50 percent rule bites, and GTKP names the wallet deposit as the typical application.
In practice that means the more often your coins have moved between wallets and platforms, the more important a continuous chain of records becomes. Anyone switching exchanges in the process should secure the old provider's transaction exports before access ends. After an account closure, that export is usually no longer retrievable.
Staking and lending: Section 20 (1) no. 12 of the Income Tax Act and the new holding
The draft assigns income from lending and passive staking to capital income under Section 20 (1) no. 12 of the Income Tax Act. Lending describes the interest-bearing loan of coins, passive staking the participation in securing the network without running a validator of your own. Both are therefore treated like interest income.
On top of that comes a consequence that is easily overlooked. Rewards received after December 31, 2026 count as a newly acquired holding. They do not inherit the grandfathering of the coins they arose from. So anyone who keeps staking a protected legacy position is continuously building new, unprotected positions alongside it. GTKP points out that the draft does not yet regulate the timing of such rewards on legacy holdings precisely.
Two loss worlds without a bridge: old and new holdings kept apart
Losses from legacy holdings remain losses under Section 23 of the Income Tax Act. They can only be offset against gains from private disposal transactions. Losses from new holdings move into the world of Section 20 and can be offset there against other capital income. According to Der Betrieb's account, the draft contains no transitional provision connecting the two pots. The loss carry-back is dropped.
For practical purposes this is an unresolved point. Anyone who has built up loss carry-forwards under Section 23 over years and from 2027 only realises gains under the new regime might no longer be able to use those carry-forwards. Whether the legislature will improve on this is open; it is one of the points the associations' submissions are likely to target.
The timetable: comment deadline October 6, cabinet October 14
The Federal Ministry of Finance has sent the draft bill to the associations. Comments are possible until October 6, 2026. The cabinet decision is scheduled for October 14, 2026. After that comes the parliamentary procedure with the Bundestag and the Bundesrat.
A draft bill is a ministry's working version and not yet a law. Between a cabinet decision and promulgation, drafts change regularly, and individual parameters such as the level of the substitute assessment or the treatment of the loss pots are typical places where that happens. Today you can treat only the direction as settled, not every figure.
Tax withheld by the exchange only from 2028: the year 2027 you declare yourself
The substantive rules are due to take effect on January 1, 2027. Under the draft, automatic tax withholding by the platforms only begins on January 1, 2028. In between lies a year in which the new rules apply but the withholding is not yet running: gains from 2027 belong in your tax return.
This transitional year is the period with the greatest scope for error. The tax liability exists regardless of the holding period, no automatic payment over takes place, and you have to keep track of the allocation between protected legacy holdings and new holdings yourself. Running in parallel is the reporting obligation under DAC8, through which German platforms pass their users' data to the tax administration anyway. Your data set and the tax office's should match up in that year.
Crypto tax reform: how to proceed now
- Pull your records together and secure them. From every exchange and broker you use or have used, download the complete transaction export and secure it outside the platform. For keeping track of the acquisition date and acquisition cost on an ongoing basis, the applications from our comparison of crypto tax software are suitable, because they link incoming deposits from outside with their history.
- Go through your wallet deposits. Work through the incoming transfers that landed on an exchange without a purchase history. Those are the positions where the 50 percent substitute assessment would bite. If a record is missing there, now is the moment to reconstruct it from old account or mail archives; which providers deliver solid transaction reports is shown by our overview of crypto exchanges.
- Keep the cut-off date in view. Whatever you acquire by December 31, 2026 keeps the old one-year deadline. Whether you bring purchases forward because of it is a decision about your investment and not about tax alone; how a regular purchase is documented for tax purposes is shown by our savings plan comparison.
(As of October 1, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Sources on the draft bill: Der Betrieb on the tax reform for exchange crypto assets and the assessment by the tax advisory firm GTKP.
From the coming network upgrade onwards, NEAR will burn every single gas fee. Until now, 30 percent of the fees that accrue when a smart contract is called flowed back to the owner of that contract; the remaining 70 percent left circulation. With version 2.14 of the network software nearcore, that rebate drops to zero. After that, the full amount is burned. Reports put the date at around October 5, 2026, but that is not a firmly committed deadline.
For you as a holder this means two things: the supply of NEAR will shrink faster whenever a lot is happening on the network, and part of the revenue that applications on NEAR could count on until now falls away. The market priced the decision in long ago, but the technical execution is still ahead.
100 percent instead of 70 percent: what nearcore 2.14 changes in the gas model
Gas on NEAR is the computing fee for every transaction. Whoever calls a smart contract pays for it in NEAR. Until now that amount was split: the protocol burned 70 percent, and 30 percent went as a reward to the account that owns the contract being called. Inside the protocol this share sits in a single parameter named burnt_gas_reward, set at three tenths until now. The upgrade sets it to zero.
Technically this is a small intervention, economically a large one. After the change, a function call pays nothing back to the contract account. Every fee a user settles leaves circulation completely and for good. Burned tokens cannot be restored, and there is no office that could reverse the entry.
Implementation hangs on the rollout of the client software. The release notes for nearcore 2.14 list the change as part of the package. Validators have to install the version, and the new rule only takes hold in live operation once enough of them have switched over. Anyone writing a deadline into the calendar is therefore better off writing a week than a day.
HSP-027: how the decision came about in the House of Stake
The decision is not new, only its execution is. The governance body House of Stake adopted proposal HSP-027 on July 8, 2026. The result was unambiguous: 46 votes, which together carried 4.66 million veNEAR, were in favour, while two votes with 1,819 veNEAR between them were against. veNEAR is the voting weight that arises from locked NEAR; whoever locks for longer weighs more heavily.
The reasoning comes from NEAR co-founder Illia Polosukhin. The rebate was once meant to reward developers for building reusable components. On his account, the mechanism no longer reflects how applications on NEAR earn their money today: projects mostly cover their users' gas costs themselves and bring in revenue through spreads, subscriptions or advertising. Polosukhin called the vote a good test of governance ahead of further proposals, and he said he was pleased to be steering NEAR's economics explicitly through governance from now on. The protocol gains in simplicity, and some contract operators lose a source of income.
That a body votes on a protocol parameter and the result lands in a client version four weeks later is the actual process behind the headline. What matters in it for you is that a vote of locked tokens stands behind the rule, not a company decision. By the same route it can be changed back.
Deflation by usage: the burn hangs on network load
A higher burn share does not lower supply automatically. It lowers it only to the extent that the network is used. What gets burned is what accrues in fees, and fees accrue when transactions run. If activity stays low, the additional effect stays small as well. If it rises, the loss of the rebate works like an amplifier: out of every euro in fees, 100 percent instead of 70 percent will disappear in future.
Around 1.308 billion NEAR are currently in circulation, and there is no fixed upper limit. That is what sets it apart from Bitcoin: with NEAR, scarcity arises from the running ratio between issuance and burning, without a fixed wall in the code. It is exactly this ratio that the upgrade shifts, without touching issuance.
How you can read the effect
The figure that counts is the total of fees per day, not the price. A network with many small transactions burns more than one with a few large ones. At NEAR the main driver is held to be the Intents system for swaps across chains, whose volume has risen from under one billion to more than 32 billion dollars within twelve months according to industry reports. How this area works and where its catches lie is something we took apart in our piece on NEAR Intents.
NEAR price at $5.46: 11 percent in a day, 175 percent in 30 days
On Thursday morning NEAR is trading at $5.46, the equivalent of 4.83 euros. According to CoinGecko data that is 11.3 percent more than 24 hours earlier. On a weekly view the gain sits between 22 and 27 percent depending on the point of measurement, and over 30 days at around 175 percent. Market capitalisation therefore comes to about $7.14 billion, rank 21 among all crypto assets, on trading volume of around $1.59 billion in 24 hours.
This run puts the news in its place. NEAR is still around 73 percent away from its all-time high of $20.44 from January 2022. But a threefold gain within a month also means that a large share of the most recent buyers are sitting on profits and can sell at any moment. Whoever gets in now is not buying into a quiet situation.
Part of the push comes from outside. Since September 29, 2026, a Bitwise spot ETF on NEAR has traded on NYSE Arca under the ticker NRR. Figures for the first trading day diverge: an inflow of $35.5 million and a trading volume of $15.1 million are reported. In both cases it is a double-digit million sum on day one. What this instrument means for a portfolio in Germany, and why you cannot simply buy it here, is set out in our text on the NEAR ETF NRR.
Buying route in Germany: MiCA authorisation before the fee comparison
For access to NEAR itself, a clear order has applied in Germany since the MiCA regulation. What counts first is whether the provider holds an authorisation as a crypto-asset service provider in the EU and is supervised by BaFin or another European authority. Only after that is it worth looking at spreads, order fees and withdrawal costs. A platform without European authorisation can close access for German users tomorrow, and a cheap tariff will not help you then. Which trading venues clear this hurdle is shown by our overview of crypto exchanges compared.
Staking and validators: the loss of the rebate does not hit delegators
This is where the most common mix-up arises, so one step at a time. The rebate of 30 percent went to the owners of smart contracts, that is, to the operators of applications. It did not go to validators, and not to users who delegate their NEAR to a validator. The reward for staking comes out of the protocol's issuance and is a different pot. The upgrade does not touch that pot.
In practice that means your staking income does not fall because of the change. Anyone running an application on NEAR that has covered part of its costs through the gas rebate until now, by contrast, has to recalculate. For holders the second group is only of indirect interest, namely when a heavily used application changes its prices or leaves the network as a result.
Staking through an exchange or directly with a validator
When you stake through a trading platform, the platform keeps the keys and often part of the reward. When you delegate directly to a validator, control stays with you, but you carry the risk of picking a validator with poor availability. In both cases an unbonding period applies, during which the tokens are not available. How the terms look at various providers is something we have set side by side in our overview of staking platforms.
Holding period: one year decides whether your NEAR gains are tax free
In Germany, gains from the sale of crypto assets count as private disposal transactions. If you sell within a year of buying, the gain is taxable at your personal income tax rate; below an exemption threshold of 1,000 euros per year it stays tax free. After a holding period of more than one year the gain is tax free regardless of its size.
With a coin that has almost tripled within 30 days, that is no side issue. A sale in October 2026 falls fully into the tax net if the purchase dates from September 2026. Anyone who wants to use the deadline needs proof of the purchase date and purchase price for every single tranche. Staking rewards follow their own rules here and count as other income in the year they are received.
The gas model upgrade itself does not trigger any taxable event for you. What gets burned is fees inside the protocol, not tokens out of your wallet. So there is no inflow you would have to declare, and no acquisition that starts a new deadline.
Leverage and liquidation: perp positions are especially exposed ahead of the upgrade
After a rise of this magnitude, leveraged positions are the most sensitive spot in the market. A perpetual future on NEAR costs funding on an ongoing basis, and at a leverage of ten a countermove of ten percent is enough to use up the margin. NEAR gained more than 11 percent on Thursday alone; a move of that size in the other direction is just as much within the realm of the possible.
Around an upgrade a second point comes into play. Dates that are imprecisely set produce positions that bet on a date. If the rollout shifts by days, those bets come to nothing, and the unwinding moves the price more than the technical change itself.
Custody: hardware wallet, exchange account and control over the keys
Anyone who wants to hold NEAR for months in order to reach the holding period has a custody problem to solve. On an exchange account the tokens sit within the platform's reach. That is convenient for staking and for quick sales, but it exposes you to the risk that the platform fails or halts withdrawals. On a hardware wallet the keys sit with you, but you have to keep the recovery words safe and separate.
An intermediate solution that has proven itself is splitting things up: the portion you trade or stake with on the platform, the holding earmarked for the deadline in self-custody. What matters is that every movement between the two worlds is documented, because the tax office will want to see the acquisition when you later sell.
What the burn does not deliver
A complete fee burn is not a promise about the price. It shifts one quantity in the supply, and whether that shows up in the price depends on demand and on network load. Projects with deflationary mechanisms have both risen and fallen in the past. Anyone taking the change as an argument to buy should measure it against the total of fees, not against the headline.
Just as little does the decision settle the open question of issuance. As long as new NEAR come into being and no upper limit exists, the net effect remains a calculation with two entries. The upgrade only improves one of them.
NEAR gas fees: the key points for your decision
- Check access before you think about fees. Take a trading venue with European authorisation, so that your access does not hang on a supervisory decision. The candidates are listed in the comparison of crypto exchanges.
- Assess staking separately from the change. Your rewards come out of issuance and remain untouched by the loss of the gas rebate; compare unbonding periods and deductions instead, in the overview of staking platforms.
- Record the purchase date and purchase price for each tranche. Without that proof the one-year deadline cannot be demonstrated later; a tracker handles it on an ongoing basis, see tax tools and portfolio trackers.
The date itself is best treated as a window rather than a cut-off day. The decision is confirmed and the delivery is scheduled; only the rollout among the validators turns both into the new rule. Whoever builds positions beforehand builds them on an expectation, and whoever waits for the change misses no mechanism, at most a move.
How the proposal was argued in detail and how the vote turned out is documented at The Cryptonomist.
(As of October 1, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Anyone searching for “buy Ethereum with PayPal” usually expects a button in the PayPal app. In Germany there is none. PayPal does not trade crypto-assets here, and nothing about that changed at the start of October 2026 either. What does work is a detour: you top up a crypto exchange with euros from your PayPal account and buy Ethereum there. That detour costs you two things an ordinary bank transfer does not: a fee you do not know before you click, and three days during which your ETH may not leave the exchange.
This article works through both. It shows what actually arrives in ether out of 100 euros along the three routes SEPA, debit card and PayPal, why the lock-up period weighs more heavily for Ethereum than the difference in fees, and what can go wrong when you move the coins on to a wallet of your own. We have already answered the same question for Bitcoin: buying Bitcoin with PayPal. With Ethereum two points come on top that do not arise in that form with Bitcoin, namely the choice of network and the question of what staking does to the holding period.
PayPal does not sell crypto-assets in Germany
The distinction matters, because many guides blur it: PayPal as a dealer in crypto-assets and PayPal as a payment route are two different things. The first exists in the United States, the second in Germany.
That can be established from PayPal's own presence. The product page for buying and selling cryptocurrencies exists on PayPal's US site. On the German site the corresponding address leads nowhere. More telling still is a look at the terms of use: in the German version, last updated on September 7, 2026 and a good 150,000 characters long, the word cryptocurrency does not appear at a single point. A service a provider does not mention in its own contractual documents is a service it does not offer.
For you that means: every page promising you can buy ether “directly at PayPal” either describes the US market, or it describes the detour via an exchange and names it imprecisely. There is no third case.
The only route runs through a euro deposit at a crypto exchange
The actual process has four steps, and PayPal is involved in only one of them. You open an account at a crypto exchange and verify your identity. You deposit euros and choose PayPal as the payment route. You buy ether with the euro balance. And if you want to hold the coins yourself, you then transfer them to a wallet of your own.
Crypto exchange here means a trading venue that swaps crypto-assets for euros and holds the balance for you. In this process PayPal is neither dealer nor custodian, only the till at the door. That division of roles explains most of the peculiarities that follow: the exchange determines what the purchase costs and when you may move your coins, not PayPal.
PayPal appears as a deposit route at several providers. The position is only verifiable, though, where the provider publishes its fees and deadlines in full. Kraken does so with a table anyone can inspect and which was last updated on August 17, 2026. That is why this article works with those figures. At other houses, contradictory statements circulate on comparison portals, from “free since July 2025” to “2 percent”; anyone wanting to deposit there should check the terms with the provider before buying. Which trading venues come into question in Germany at all is shown in our comparison of providers with PayPal deposits.
The 72-hour lock is the real price of the PayPal deposit
The point missing from most guides is stated expressly in Kraken's fee table: after a deposit by PayPal, a withdrawal lock of 72 hours sits on the account. The lock applies not only to euros but to all withdrawals, crypto-assets included. For three days your freshly bought ETH therefore stay on the exchange, whether you like it or not.
The reason for that is not harassment but chargeback risk. A PayPal payment can be disputed after the fact. If the coins bought could be withdrawn immediately, the exchange would be left without any counter-value in a dispute. The same logic applies to card payments, but not to the SEPA transfer: there the table shows no lock.
Withdrawal lock does not mean your balance is frozen. You can trade straight away, you simply cannot get out of the building. For an investor who leaves their ETH on the exchange anyway, that has no consequences. For anyone holding by the principle of “not your keys, not your coins”, it is three days of counterparty risk they would not have had with a transfer. The year 2026 has served as a reminder, through several exchange incidents, that those three days are not a theoretical risk.
At Kraken the PayPal fee appears only on the final confirmation page
For every other type of deposit the table names a figure. SEPA from the European Economic Area: free, minimum amount 1 euro, credited within zero to three banking days or instantly. Debit card: minimum amount 10 euros, 0.25 euros plus 3.75 percent, credited almost instantly. A transfer over the international SWIFT network: 3 euros, one to five banking days.
For PayPal, the word “processing fees” stands in place of the figure, together with a footnote: the fees depend on the region and are displayed on the final confirmation page. Minimum amount 1 euro, credited almost instantly, lock 72 hours.
That is the most remarkable finding of this research, and it is no reproach to a single provider but a property of the payment route: of all the deposit types, PayPal is the only one whose price cannot be looked up beforehand. You learn it at the moment when all that is left is to confirm. Anyone wanting to compare has to run the process through to the final page and break off there.
100 euros in ETH via SEPA, debit card and PayPal: the cost calculation
Let us work the purchase through once, with the published figures and an ether price of around 2,367 euros, as it stands on October 1. On top of the deposit fee comes the trading fee in every case: Kraken charges 1 percent on instant purchases and recurring purchases, and 1.5 percent on orders you place yourself.
Via SEPA, a full 100 euros out of 100 euros arrive in the exchange account, because the transfer costs nothing. The purchase takes off 1 percent, so 1.00 euro. What goes into ether is 99.00 euros, around 0.0418 ETH.
Via the debit card, the deposit costs 0.25 euros plus 3.75 percent, 4.00 euros together. That leaves 96.00 euros, from which 1 percent trading fee comes off, so 0.96 euros. What goes into ether is 95.04 euros, or around 0.0402 ETH. Against the transfer, 3.96 euros are missing, which converts to around 0.0017 ETH.
Via PayPal, this line cannot be filled in. The deposit fee is not known beforehand. If it is zero, the result matches the SEPA route; if it is at card level, around four euros are missing. Nothing more can seriously be said, and that is exactly the point: on a purchase of 100 euros it is a single-digit euro amount, on a purchase of 5,000 euros a three-digit sum that you see only on the final page.
The spread sits in the purchase price and appears in no fee line
The calculation above is deliberately incomplete, because it captures only the stated fees. For instant purchases, Kraken expressly points out that a spread is additionally contained in the price displayed.
The spread is the distance between the price at which the exchange buys and the one at which it sells. It never appears on a statement as an item of its own, because it already sits in the price you confirm. To you it works like a fee, but it turns up in no fee overview.
In practice that means two things. First, any comparison that merely sets the stated percentages side by side is calculated too favourably, and that holds for every provider. Second, it pays to look at the difference between the convenient instant purchase and an order you place yourself in the trading area: the trading fee is stated higher there at 1.5 percent, but the spread falls away because you set the price yourself. With larger amounts the relationship therefore often reverses. There is no generally valid threshold, because the spread fluctuates with market conditions.
The network fee for the ETH transfer runs to fractions of a cent
Many newcomers put off the transfer to their own wallet because they fear expensive network fees. That worry comes from the years when a simple Ethereum transfer could cost double-digit euro amounts. Nothing of that is left at present.
At the start of October, the base fee in the Ethereum network sits at about 0.12 gwei. Gwei is the usual unit of account for network fees, a billionth of an ETH. A simple transfer of ether consumes 21,000 gas units. That produces around 0.0000025 ETH, less than a cent at today's price.
The catch: what the exchange charges you for a withdrawal is not that network fee but a rate of its own, which it sets itself and which appears on the confirmation page. It can lie considerably above. The network fee is therefore good as a lower bound, not as an expectation. What remains is the all-clear: the network is no longer the reason to leave coins on the exchange.
ERC-20 or layer 2: the wrong network costs you your ETH
Here lies the difference from Bitcoin, and it is the most expensive mistake in this whole process. On a withdrawal the exchange asks which network it should send over. Alongside the Ethereum mainnet, several layer-2 networks are on offer, that is, side chains which bundle transactions and settle them more cheaply, such as Arbitrum or Base.
The address looks the same in all of these networks. Every one of these addresses begins with 0x and has 42 characters. Precisely there lies the trap: if you choose a different network when sending from the one your wallet expects, the transfer is carried out all the same. The money lands at the same address on another chain. In the favourable case you get it back by setting up that network in your wallet. In the unfavourable case, for instance with an address belonging to an exchange that does not support the chain in question, the amount is lost.
The rule against that is plain: the network chosen when sending has to be the same one set at the top of your wallet. If in doubt, send a small amount first and wait for it to be credited before the rest follows. By the calculation above, the cost of that test lies in the range of fractions of a cent, the benefit in the range of the entire purchase amount. Which devices and programs are suitable for custody is set out in the hardware wallet comparison.
PayPal buyer protection does not cover financial products and investments
A widespread misunderstanding holds that the detour via PayPal brings additional protection with it. The opposite is true. The terms of PayPal buyer protection in the version of April 15, 2025 contain a list of transactions the protection does not cover. Alongside payments for gold and cash equivalents such as gift cards, that list expressly includes financial products and investments.
Buying ether through an exchange falls into that group. If the price falls, if the exchange goes down or if you mistype the address, there is no reimbursement on that basis. Buyer protection is intended for purchases of goods, not for capital investments.
Conversely, the chargeback route very much does apply, and that is exactly why the 72-hour lock exists. Anyone disputing a legitimate deposit in order to end up with both coins and money risks having the exchange account blocked, and civil consequences. The lock is the exchange's answer to that risk, and it hits all customers equally.
Holding period and threshold: what Section 23 EStG prescribes for your ETH
For tax purposes, buying ether counts among private disposals. Section 23 of the Income Tax Act regulates them in subsection 1 number 2: a disposal is taxable in the case of assets where not more than one year lies between acquisition and sale. If you sell your ETH later than one year after buying, the gain is free of income tax, whatever its size.
Within the year a threshold applies. Under subsection 3 sentence 5, gains remain tax-free where the total gain from all private disposals in the calendar year comes to less than 1,000 euros. Threshold here means: if the amount is exceeded, the entire gain is taxable, not only the excess part. At a gain of 999 euros you pay nothing; at 1,001 euros you pay tax on the full 1,001 euros at your personal rate.
For the PayPal question only one detail matters, and it is regularly misunderstood: the one-year period begins with the acquisition, meaning on the day of purchase, not at the end of the 72-hour lock and not on the day of the transfer to your own wallet. The lock shifts the start of the period by not a single day. Anyone buying several times needs the individual date for each part-purchase; tools for that are in the comparison of tax and portfolio programs.
Staking does not extend the holding period to ten years
With Ethereum a question arises that does not come up with Bitcoin: what happens to the holding period if you stake your ETH? The reason for the worry sits in the same section. Under subsection 1 number 2 sentence 4, the period extends to ten years where income is earned in at least one calendar year from the use of an asset as a source of income.
Staking means depositing your ETH in the network to help secure transactions, and receiving ongoing returns for it. That sounds like a source of income. The tax administration does not, however, apply the ten-year period to crypto-assets. The Federal Ministry of Finance confirmed this in its circular of March 6, 2025 on the income tax treatment of certain crypto-assets, file reference IV C 1 – S 2256/00042/064/043. The holding period accordingly stays at one year even after staking or lending.
The treatment of the returns themselves is unaffected by that: ongoing staking rewards are taxable in the year they are received, separately from the later gain on sale. Anyone dealing with such returns for the first time should settle the classification with a tax adviser; this article is no substitute for advice in the individual case.
MiCA authorisation: how to recognise an authorised provider
Since the European crypto regulation MiCA, trading venues need authorisation as crypto-asset service providers in order to serve retail clients in the EU. For you that is not a sticker on the wall but an entry in a register, and it can be looked up in two minutes.
Two directories help further: BaFin's company database for providers with German authorisation, and the register of the European securities supervisor ESMA for authorised service providers from all member states. A route via another EU country is normal in this and no warning sign: an authorisation from Ireland or Malta is valid across Europe.
What matters is matching the exact company name. Exchanges frequently run their European business through a company of their own whose name differs from the brand. If you find the operator in neither of the two registers, do not pay money in there, however convenient the PayPal button looks. Vetted trading venues are in our comparison of crypto exchanges.
Buying Ethereum with PayPal: Your next three steps
- Establish whether you really need the convenience. On the terms examined here, a SEPA transfer is free, has no lock-up period and is in many cases credited instantly as well. PayPal pays off above all where your money is sitting there anyway. An overview of the trading venues is in the exchange comparison.
- Run the deposit process through to the final page before you confirm. That is the only place the PayPal processing fee appears. Add it to the trading fee of 1 percent and compare the result with the 100 euros that arrive in full via a transfer.
- Allow for the 72 hours before you take custody of the ETH yourself. Once the lock has elapsed, transfer a small amount first and make sure the network you choose matches your wallet. Suitable devices are shown by the hardware wallet comparison.
The sources for this article: the fees, minimum amounts and lock-up periods come from Kraken's public overview of deposit options.
(As of October 1, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
In brief: in Germany you will usually set up a crypto company as a GmbH or a UG. What decides the matter, though, is not the legal form but the business model: anyone who holds, exchanges or arranges crypto-assets for others has needed authorisation from BaFin since MiCA, plus minimum capital of 50,000 to 150,000 euros depending on the service. Anyone offering software, analytics or content generally gets by without a licence. This guide sets out the steps in the right order.
Step 1: establish whether your business model requires authorisation
Before you call a notary, one question belongs settled: are you providing crypto-asset services within the meaning of the EU regulation MiCA? Those include, among others, the custody of crypto-assets for clients, operating a trading platform, exchanging against the euro or other crypto-assets, the execution and reception of orders, and advice and portfolio management.
If that is the case, you need authorisation as a crypto-asset service provider, CASP for short. In Germany it is granted by BaFin on the basis of MiCA and the German Crypto Markets Supervision Act. The transition periods for existing providers have now expired in all EU member states. Whoever is authorised appears in ESMA's public register; what that looks like in practice is shown by the list of authorised providers, and even banks such as the Volksbanken are having their crypto custody approved.
No authorisation is generally needed by anyone who merely supplies software, such as a non-custodial wallet, an analytics tool, development services or a crypto news outlet. The line is fine in the individual case. When in doubt, an enquiry to BaFin or to a specialist law firm pays off before the first client money flows.
Step 2: choose the right legal form
For crypto start-ups, two legal forms almost always come into question, because they limit liability to the company's assets:
| GmbH | UG (limited liability) | |
|---|---|---|
| Minimum capital | 25,000 euros, of which at least 12,500 euros paid in at formation | from 1 euro, a quarter of profits must be retained |
| Standing with banks and partners | high | lower, often follow-up questions |
| Suitable for | business models requiring authorisation, investor rounds | software, media, a first test phase |
| Formation | by notarial deed, video conference possible | by notarial deed, video conference possible |
Anyone who needs BaFin authorisation starts in practice with a GmbH, because the minimum capital required by the supervisor lies above that of a UG in any case. How the formation runs step by step, from articles of association to the commercial register, is explained in the Gründerfreunde guide to forming a GmbH. For a smaller start there is also a guide there on how to form a UG. Anyone needing a ready-made company quickly can alternatively buy a shelf company.
Step 3: plan capital and the supervisor's requirements
MiCA tiers the minimum capital by type of service:
- 50,000 euros for services such as the reception and transmission of orders, advice, portfolio management or the placing of crypto-assets,
- 125,000 euros where crypto-assets are additionally held for clients or exchanged against money or other crypto-assets,
- 150,000 euros for operating a trading platform.
On top of that come requirements that often cost more than the capital itself: management that is both reliable and professionally qualified, a seat with genuine management in the EU, anti-money-laundering rules, a complaints procedure, IT security under the EU regulation DORA, and the segregated custody of client funds. Allow several months for the authorisation application.
Step 4: issue a token only with a white paper
Many crypto start-ups want a token of their own sooner or later. MiCA applies to that as well: anyone offering crypto-assets to the public has to draw up a white paper and submit it to the supervisor. If the token is a security, securities law applies instead of MiCA. The difference between an ICO and a security token, and what is permitted today, is explained in our guide What is an ICO? What is a security token?
Step 5: bank account, bookkeeping and taxes
Getting a business account is often harder for crypto firms than the formation itself. Banks examine the origin of funds and the business model closely. A clean business plan helps, as does a concept for anti-money-laundering and, where necessary, evidence of BaFin authorisation or of a pending application.
On tax, the position is this: if a GmbH holds crypto-assets, there is no one-year speculation period as there is for private individuals. Gains on a sale are subject to corporation tax and trade tax, together around 30 percent depending on the municipality. Settle the accounting treatment of crypto-assets early with a tax firm that knows the field.
Step 6: use financing and public support
For the first phase the same routes come into question as for any other start-up: equity, business angels, venture capital and public funding. An overview of the funders and what they look for is given in the Gründerfreunde guide to start-up financing. Anyone founding a business while unemployed can apply for a start-up grant. And anyone wanting to test a new business model under supervision should know the options offered by living labs and regulatory sandboxes.
Checklist: setting up a crypto company in Germany
- Test the business model against the MiCA services; when in doubt, ask BaFin or a specialist lawyer.
- Choose the legal form: a GmbH where authorisation is required, otherwise a GmbH or a UG.
- Budget minimum capital and staff for management, anti-money-laundering and IT security.
- Formation before a notary, entry in the commercial register, business registration.
- File the authorisation application with BaFin before client business starts.
- Find a business account and a tax firm with crypto experience.
- Issue a token only with a MiCA white paper, or as a security with a prospectus.
Frequently asked questions
Do I always need a BaFin licence for a crypto start-up?
No. What requires authorisation are crypto-asset services for clients, such as custody, exchange, a trading platform or the reception of orders. Pure software, analytics tools or media offerings generally need no authorisation.
How much capital do I need for a MiCA licence?
Depending on the service, minimum capital of 50,000, 125,000 or 150,000 euros, plus funds for staff, compliance and IT security.
Is a UG enough for a crypto start-up?
For models outside the authorisation requirement, yes. Anyone who needs BaFin authorisation is better off starting with a GmbH, because the capital required is higher than a UG's in any case.
Note: Gründerfreunde, like cryptoticker, belongs to the group of companies owned by Dennis Weidner. This guide is no substitute for legal or tax advice.
Decrypt
The wallet says it has found no immediate threat to user wallets, but the ETH it is pulling out of Lido could take 45 days to return.
Regulators are probing how the exchange keeps serving EU customers from Abu Dhabi, months after it lost its MiCA registrations.
Gemini 4 Argon tops 12 of 18 benchmarks in Google's own table, writes a million tokens per reply and resists hijacking best. Cyber defenders get it first, with the guardrails off.
The team behind the MyDoge wallet opened a public test of DogeOS, a layer that lets developers build lending platforms and games on top of the meme coin network.
An internal memo warned FBI staff that ShinyHunters, the group claiming it hacked the bureau's jobs site, may hold their private details.
U.Today - IT, AI and Fintech Daily News for You Today
The immediate question is now whether EU regulators will allow the exchange to continue operating with its regulatory exemption.
Bitwise CIO Matt Hougan breaks down the strong launch of the first spot NEAR ETF after crossing a major $52.8 million AUM milestone on Day 2.
The cryptocurrency market, especially altcoins, are taking a hit as investors are taking profits.
Flare co-founder and CEO Hugo Philion has called XRP’s muted reaction to a major XRP Ledger infrastructure breakthrough in Brazil "lunacy."
The crypto market remains broadly bullish, although momentum is becoming increasingly uneven as some assets consolidate or correct after September’s strong gains.
Blockonomi
TLDR
- DogeOS opened the public testnet for its Dogecoin application layer on Sept. 30, 2026.
- The layer is EVM-compatible, so Ethereum tools and smart contracts can work on it.
- Testnet fees are paid in Dogecoin, and a faucet gives out 42.069 test coins per day.
- Teams are building lending, trading, stablecoin, prediction market and gaming apps.
- No mainnet launch date has been set yet.
DogeOS opened the public testnet for its Dogecoin application layer on Sept. 30, 2026. The project shared the news in a press release from Dubai.
A testnet is a trial version of a network. Developers use it to test apps before real money is involved.
The team behind the MyDoge wallet founded DogeOS. The project runs as a separate layer and does not change the Dogecoin coin itself.
How DogeOS Works
Jackson Palmer and Billy Markus created Dogecoin in 2013 as a joke. It works as a peer-to-peer digital currency and has grown into a multi-billion dollar network.
DogeOS aims to add apps, which Ethereum is known for. In simple terms, Dogecoin is the ledger and DogeOS is software built on top of it.
The project’s documentation calls it an “Application Layer rollup network on Dogecoin.” It runs on a zkVM, which creates cryptographic proofs showing that transactions are valid.
It is also EVM-compatible. This means smart contracts, wallets and tools built for Ethereum can work on DogeOS.
Fees on the testnet are paid in Dogecoin. A faucet hands out 42.069 free test coins per day.
Teams Building on the Testnet
Several teams are already building apps. Superposition Finance is a lending protocol, and Derps is a perpetual exchange for trading prices with no expiry date.
Barkswap is building a liquidity engine. Split Markets is working on options that cannot be liquidated.
USDoge is a stablecoin backed by locked collateral. Snag is bringing a prediction market aggregator, where people bet on real-world outcomes.
Anoncoin and Starbase are building launchpads. Doge Escape, PlaysOut and DogeFundMe are developing games and consumer apps, and PlaysOut had planned about 15 Doge-themed games by the end of 2025.
DogeOS founder and CEO Jordan Jefferson said the testnet gives builders a place to turn ideas into working apps. “Today marks the beginning of Dogecoin’s evolution from asset to ecosystem,” he said.
Timothy Stebbing, director of the Dogecoin Foundation, also commented. “L1 ledger purity must stay intact while we introduce utility one layer above, and that is what DogeOS represents to me,” he said.
L1 refers to Dogecoin’s base blockchain. Stebbing said he hopes DogeOS becomes “the gateway for the next 100 startups to build on Dogecoin.”
Changing Dogecoin’s base layer is slow. In July 2025, the DogeOS team submitted a proposal to bring zero-knowledge proofs to it, but Dogecoin has no formal on-chain governance.
A change like that needs contributor review, community discussion, security audits and support from miners.
Dogecoin has fallen about 75% from its all-time high. It remains in a bearish trend, even after several Dogecoin ETFs launched.
DogeOS expects to add more developer tools and integrations as the testnet grows. The release did not set a date for the mainnet launch, the live version that would run with real money.
The post DogeOS Opens Public Testnet to Bring Apps to Dogecoin appeared first on Blockonomi.
Key Highlights
- September 2026 vehicle deliveries totaled 37,408 units, representing a 7.7% year-over-year gain.
- Third quarter 2026 deliveries reached 109,178 vehicles, marking a 25% annual increase.
- Year-to-date deliveries through September climbed to 300,301 units, up 49% compared to 2025.
- Total lifetime deliveries surpassed the 1.29 million vehicle milestone.
- The redesigned ES8 SUV achieved 150,000 deliveries while leading its competitive segment.
NIO (NIO) stock advanced roughly 1% following the release of the Chinese electric vehicle manufacturer’s September delivery data. The automaker reported 37,408 vehicle deliveries for the month, representing a 7.7% increase versus the prior-year period.
NIO Inc., NIO
The monthly figures reflect contributions from the company’s three distinct vehicle brands. NIO’s flagship brand accounted for 21,318 units delivered. The ONVO brand contributed 8,763 vehicles, while FIREFLY added 7,327 to the monthly total.
Looking at quarterly performance, the electric vehicle manufacturer delivered 109,178 units throughout Q3 2026. This represents a substantial 25% increase when compared to the corresponding quarter in 2025.
Through the first three quarters of 2026, the company’s total deliveries hit 300,301 vehicles. This figure represents a significant 49% year-over-year expansion, demonstrating accelerating momentum in sales volume.
The company’s all-time delivery count now stands at 1,297,893 vehicles through September 30, 2026. This cumulative figure reflects consistent progress since NIO first began delivering vehicles to customers.
Flagship SUV Models Reach Key Benchmarks
The redesigned ES8 model surpassed 150,000 total deliveries on September 20, 2026. This milestone arrived precisely twelve months following the vehicle’s market introduction.
NIO reported that the ES8 secured the top position in total sales within the large SUV category. The model also dominated sales for vehicles carrying price tags exceeding RMB400,000 throughout its first year on the market.
The premium ES9 model has also demonstrated strong market traction. This flagship offering reached 30,000 total deliveries since customer shipments commenced on May 28, 2026.
The company indicated that the ES9 captured the number-one position in monthly sales among battery-powered electric vehicles priced above RMB500,000. This leading position has been maintained consistently for three consecutive months.
Multi-Brand Approach Drives Market Coverage
The electric vehicle manufacturer operates three distinct automotive brands within its corporate structure. The core NIO brand focuses on delivering premium intelligent electric vehicles to discerning customers.
The ONVO brand specifically targets family-oriented consumers seeking premium features at a more attainable price point. FIREFLY completes the brand portfolio by offering compact, upscale electric vehicles for urban environments.
All three brands are establishing distinct positions within China’s intensely competitive electric vehicle marketplace. September’s delivery figures demonstrate that each brand is generating meaningful volume contributions to the company’s overall performance.
Shares traded on the Hong Kong exchange (9866) exhibited contrasting movement, declining nearly 2% during the same trading session. The company’s announcement made no reference to the pricing divergence between its dual listings.
The monthly delivery announcement contained no forward-looking guidance for October deliveries or revised annual projections. Investors can anticipate NIO’s next operational update when the company releases October delivery statistics in early November.
The post NIO (NIO) Stock Gains Momentum Following Impressive September Delivery Figures appeared first on Blockonomi.
Key Takeaways
- Filtronic stock surged up to 14% following confirmation of a $68.1 million follow-on contract from SpaceX.
- The contract covers Cerus E-band gallium nitride amplifier units, with most deliveries scheduled for fiscal year 2028.
- This represents Filtronic’s biggest SpaceX contract ever, surpassing a previous $62.5 million order placed in 2025.
- Investment firm Cavendish maintained its “buy” recommendation and 290p target price on the shares.
- According to Cavendish, firm orders now account for over 90% of Filtronic’s anticipated FY2028 revenues.
Shares of Filtronic experienced a significant rally on Thursday, jumping as much as 14% to reach an intraday peak of 270p. The surge followed the company’s announcement of a record-breaking $68.1 million repeat order from SpaceX.
Filtronic plc, FLTCF
The contract centers on Filtronic’s Cerus E-band gallium nitride solid-state power amplifier modules. It represents the single largest order SpaceX has awarded to the British technology firm to date.
This new agreement follows a $62.5 million contract secured in 2025 for identical technology. The two deals collectively demonstrate an expanding commercial partnership between Filtronic and Elon Musk’s aerospace company.
Product deliveries under the fresh contract will primarily occur throughout Filtronic’s fiscal 2028. Management emphasized that the order aligns with, rather than alters, its existing FY2028 financial guidance.
Details of the Contract
The amplifier units leverage Filtronic’s gallium nitride (GaN) semiconductor technology. According to the company, GaN delivers superior power output, enhanced efficiency, and better thermal management versus legacy gallium arsenide alternatives.
These components are deployed in ground infrastructure that facilitates SpaceX’s Starlink broadband network. Starlink operates through an extensive constellation of low Earth orbit satellites providing internet connectivity.
Filtronic specializes in manufacturing high-frequency radio frequency components serving aerospace, defense, and telecommunications infrastructure markets. SpaceX has emerged as a critical customer for the firm in recent years.
Investment bank Cavendish responded to Thursday’s announcement by confirming its “buy” recommendation on Filtronic shares. The firm maintained its 290p price objective without adjustment.
Cavendish highlighted that confirmed orders now represent more than 90% of Filtronic’s expected FY2028 turnover. This represents unusually strong revenue visibility for a company of this scale.
Analyst Projections Remain Unchanged
The investment firm kept its earnings estimates unchanged after reviewing the contract announcement. Cavendish continues projecting £75 million in revenues for fiscal 2028.
Adjusted EBITDA is forecasted at £17 million for the same period. The broker indicated expectations that SpaceX will continue expanding its worldwide ground station infrastructure beyond 2028.
Cavendish also identified additional growth opportunities for Filtronic’s GaN platform. These include serving other satellite communication providers and penetrating defense sector applications.
Filtronic has delivered consecutive years of revenue growth coupled with profitability improvements. Operating cash flow has remained consistent, providing the business with enhanced capacity to finance expansion initiatives.
However, the company faces certain challenges. A recent revenue decline, compressed margins, and inconsistent free cash flow generation highlight some vulnerability to large contract timing fluctuations.
Filtronic’s share price has climbed approximately 35% year-to-date. Daily trading volume averages around 1.4 million shares.
The stock currently registers a “buy” signal based on technical analysis indicators. Filtronic’s market value stands at roughly £519.1 million based on recent pricing.
The $68.1 million contract represents Filtronic’s largest SpaceX agreement on record, disclosed Thursday alongside Cavendish’s reaffirmed 290p price objective.
The post Filtronic (FLTCF) Shares Surge 14% on $68M SpaceX Contract Win appeared first on Blockonomi.
TLDR
- The Clarity Act failed in the U.S. Senate on Sept. 15 with 49 votes in favor and 50 against.
- Bitcoin is up nearly 11% and ether about 12% since the vote, with total crypto market value near $2.95 trillion.
- Bitwise CIO Matt Hougan says stablecoin rewards on platforms like Coinbase can continue under the GENIUS Act.
- The SEC approved a five-year exemption letting tokenized U.S. stocks trade on onchain platforms.
- Hougan warns a future administration could reverse these rules since they are not written into law.
The crypto market has climbed since the Clarity Act failed in the U.S. Senate on Sept. 15. Bitwise Chief Investment Officer Matt Hougan says the industry may be better off without the bill.
In a memo posted Wednesday, Hougan argued that crypto lost the certainty of a federal law. But he said it also avoided compromises that would have limited key parts of the industry.
The Senate vote to advance the bill was 49 in favor and 50 against. The bill needed 60 votes after three years of negotiation.
Many expected prices to fall after the vote. Instead, the opposite happened.
Crypto Prices and Stocks Climb After the Vote
Hougan wrote that Bitcoin rose 8% and Ethereum gained 7% in the two weeks after the vote. Some smaller tokens rose much more, including NEAR at 104%, Uniswap at 49% and Avalanche at 43%. Crypto stocks also performed well.
He said many of the best performers use protocol revenue to buy back their own tokens. These include Hyperliquid, NEAR, Uniswap, Lighter and Pump.
Hougan pointed to stablecoins as one area that gained. The final Clarity text banned platforms from paying stablecoin interest or yield “in any form,” with penalties up to $5 million per violation.
With the bill stalled, the GENIUS Act passed in 2025 remains in effect. It bars stablecoin issuers from paying interest but does not address exchanges. Hougan said this lets platforms like Coinbase keep offering rewards on stablecoin balances.
He also said established exchanges such as Coinbase and Kraken benefit. Clarity would have created a national license for spot crypto exchanges, making it easier for new rivals to enter. It also would have limited firms that act as both exchange and broker.
SEC Steps In on Tokenized Stocks and Buybacks
Clarity would have directed the SEC to study tokenized securities. Hougan said that process could have taken years.
Instead, the SEC issued a five-year “innovation exemption” two days after the vote. It allows tokenized U.S. stocks to trade through permissioned automated market makers and liquidity pools.
The order exempts these venues from registering as exchanges. It covers only listed U.S. stocks and caps the volume each venue can handle. Hougan named Securitize, which tokenizes funds for BlackRock, Apollo and KKR, as a key beneficiary.
Last week, SEC staff released an updated FAQ on token buybacks. It said announcing a buyback for an already functioning network does not by itself make a token sale an investment contract.
Hougan said the main risk is that regulation is not law. A new administration in January 2029 could appoint new leaders at the SEC and CFTC who take a harder line.
He said he is not overly worried, since large financial firms will have been building on blockchains for years by then. “Crypto sacrificed long-term certainty and got better rules, faster,” he wrote.
Since the Sept. 15 vote, Bitcoin is up nearly 11% and ether has added about 12%, according to The Block. Total crypto market value now sits at roughly $2.95 trillion, up from $2.65 trillion on the day of the vote.
The post Bitcoin and Coinbase Gain After Senate Rejects Clarity Act appeared first on Blockonomi.
Key Takeaways
- Micron delivered a historic fourth quarter with adjusted EPS reaching $33.42, a massive jump from $3.03 in the prior year.
- The chip manufacturer generated $54 billion in revenue, representing a 379% year-over-year increase and exceeding analyst projections of $51 billion.
- Despite exceptional results, premarket trading saw shares climb only 0.4%, revealing persistent investor skepticism.
- The company secured 26 long-term supply contracts that will account for approximately one-third of revenue through the end of the decade.
- Wall Street analysts, including Cantor Fitzgerald’s C.J. Muse, argue the stock presents compelling value given its modest forward P/E ratio.
Micron Technology turned in a remarkable performance this Wednesday, unveiling one of the strongest quarters in company history. The semiconductor manufacturer reported adjusted earnings per share of $33.42, representing an enormous leap from the $3.03 recorded in the same period last year.
Micron Technology, Inc., MU
Quarterly revenue reached $54 billion, marking a staggering 379% increase compared to the previous year. The figure easily surpassed Wall Street’s consensus projection of $51 billion.
Yet despite these outstanding results, Micron’s stock response was remarkably subdued. Shares advanced a mere 0.4% during Thursday’s premarket session.
MICRON $MU Q4’26 EARNINGS HIGHLIGHTS
Revenue: $54.23B (Est. $51.07B)
; +379% YoY
Q1 FY27 Guide:
— Wall St Engine (@wallstengine) September 30, 2026
This tepid market reaction underscores the deep-seated skepticism investors harbor regarding the memory chip sector’s cyclical nature. Micron currently trades at a forward price-to-earnings multiple of just 6.6, dramatically lower than the S&P 500’s 18.5 valuation.
During the earnings conference call, CEO Sanjay Mehrotra expressed optimism about the road ahead. He indicated that supply and demand dynamics for memory and storage products are likely to grow tighter throughout fiscal years 2027 and 2028.
Exceptional Performance Meets Historical Skepticism
The quarter saw gross margin reach an unprecedented 87%, setting a new company record. Revenue expansion similarly exceeded all projections.
However, for conservative investors, these figures may signal a cyclical peak. Micron’s own forward guidance suggests modest declines in both revenue growth and gross margin for the upcoming first quarter.
The memory chip industry has historically been characterized by extreme volatility. Pricing and inventory levels experience dramatic fluctuations, and investors have previously suffered losses by entering positions at market peaks.
The current boom is largely fueled by insatiable demand from artificial intelligence data centers. Annual data center expenditures now exceed one trillion dollars, with substantial portions allocated to memory and storage components.
This supply constraint has extended into consumer electronics markets, where price increases became commonplace throughout 2026. Additional manufacturing capacity from Micron and competitors SK Hynix and Samsung won’t come online until the middle of 2027.
Strategic Shift Toward Long-Term Contracts
Micron is actively working to mitigate the traditional volatility inherent in its business model. The company has expanded its portfolio of multi-year supply agreements to 26, up from 16 in the previous quarter.
These contracts will secure roughly one-third of Micron’s total revenue through 2030. Unlike conventional annual agreements, they incorporate minimum price guarantees, maximum price caps, and upfront customer deposits.
Mehrotra emphasized that these arrangements should deliver greater financial predictability in future periods. Portfolio manager Hendi Susanto from Gabelli Funds noted that this cycle appears fundamentally different, as major hyperscale customers are securing supply commitments years in advance.
Nevertheless, Wall Street remains cautious and demands additional evidence before revising its perspective. Following the previous quarterly report, analysts upgraded their forecasts and price targets, triggering a 16% stock rally. Those gains have subsequently evaporated.
Micron’s balance sheet has strengthened considerably. The company generated $59 billion in free cash flow during the fiscal year just concluded.
Management deployed this capital to reduce debt by $10 billion, leaving only $5 billion in outstanding obligations. The company also initiated a share repurchase program.
Wall Street projects free cash flow will surge to $129 billion in the current fiscal year. According to Cantor Fitzgerald’s C.J. Muse, Micron trades at merely 5.6 times his 2027 earnings estimate and 4.5 times his 2028 projection.
Muse characterized the quarterly results as “about as straight down the fairway as one could have hoped.” He anticipates significant share buyback activity commencing in December.
The post Micron (MU) Stock: Should You Buy After Historic Earnings Report? appeared first on Blockonomi.
CryptoPotato
The primary cryptocurrency has been in a clear uptrend since July, rising 42% over the past three months. Many analysts have flipped bullish, believing the bear market is over and projecting a pump toward a new all-time high during the next cycle.
However, the US midterms in November may divert BTC from its potential bullish path and trigger a substantial correction. Here’s why.
BTC Dump?
The 2026 US midterm elections will take place on November 3, halfway through the president’s term, when voters elect all House members and about one-third of the Senate. This matters because they can change which party controls Congress, affecting Donald Trump’s ability to pass laws and shape national policy.
According to popular analyst Ali Martinez, the voting may negatively impact BTC, citing historical data. He noted that after the 2010, 2014, 2018, and 2022 elections, the cryptocurrency’s price fell 72%, 65%, 52%, and 27%, respectively.
“That does not prove elections caused the declines, but the pattern is worth watching ahead of November 3, 2026,” he said.
Martinez said the fourth-quarter data tells a similar story. He reminded that BTC pumped almost 400% in Q4 2010, but posted losses of 16.7% in Q4 2014, 42.16% in Q4 2018, and 14.75% in Q2022.
“As Q4 begins, seasonality suggests investors should be prepared for volatility,” the analyst warned.
Last but not least, Martinez paid special attention to Bitcoin’s short-term holder cost basis near $73,000, which could become the key support zone if the upcoming post-midterm pattern repeats.
Just a Speed Bump on the Road Higher?
Several X users who commented on the post asked Martinez whether this is a bearish signal, asking whether they should sell their positions. The analyst advised them to take some profits in late October, expecting the price to jump to $100K then, and then potentially buy again at $73,000 after the midterm elections.
Martinez is hardly the only one anticipating next month to be green. Historically, October has been among the most positive months for BTC, earning it the nickname “Uptober.” The asset has ended in the green in 10 of the past 13 Octobers, and it remains to be seen whether that trend will continue this year.

The post Historical Trap Ahead? This Early November Event Could Derail Bitcoin’s Rally appeared first on CryptoPotato.
Bitcoin experienced some wild price moves after the release of the US PCE data yesterday, surging to $85,600, where it was rejected and driven south by $2,500.
Meanwhile, BTW continues to produce massive fluctuations, surging by 35% today. NIGHT and STX have seen double-digit increases as well.
BTC Calms After Wild Ride
Bitcoin exploded last Monday to over $87,000, which became its highest price tag since late January. It was stopped there twice in the span of 36 hours, but the second rejection was quite vigorous. BTC dumped to under $83,000 in a day after it topped $87,000 for the last time in September.
The following several days were a lot less eventful. Bitcoin established a well-defined trading range between $83,000 and $85,000, while the lower boundary was tested a few times more than the upper one. BTC even dipped below it on a few occasions, but managed to hold.
A few more fluctuations between the two lines followed before the markets turned their attention to the PCE numbers on September 30. As the final results beat expectations, the cryptocurrency skyrocketed from $83,000 to $85,600 within minutes. However, its subsequent move was just as rapid but in the opposite direction. As such, BTC has returned to $83,600 as of press time after failing to capitalize on the positive PCE news.
It enters its greenest month with a market cap of $1.680 trillion, while its dominance over the alts remains flat at 58.6% on CMC.

NIGHT, BTW, STX on the Rise
Ethereum continues its fight with the $2,700 resistance, but it’s still on the wrong side of it. BNB is above $765, while XRP has dipped slightly below $1.50. SOL, TRX, LINK, RAIN, XLM, and BCH have posted insignificant losses over the past day.
In contrast, HYPE has neared $90 once again after a 3% increase. QNT is above $290 following a similar daily jump. BTW has stolen the show once again, rocketing by 35% to $1.41. NIGHT has surged by 26% and trades well above $0.04, while STX is close to $0.4 after a 22% daily rise.
The total crypto market cap is up by just over 1% since this time yesterday, at $2.890 trillion on CMC.

The post NIGHT Explodes 26% While BTC Cools After Wild PCE Swing: Market Watch appeared first on CryptoPotato.
Although BTC is still in the red on a YTD basis, the past three months showed a significant improvement in its overall state, with September closing well in the green as well.
The focus has now shifted to October, which has been BTC’s greenest month since data has been tracked on CoinGlass. The question is: will history repeat, or will last year’s edition reign again?
3 In a Row
The primary cryptocurrency bottomed on July 1 at under $58,000 and rebounded in the following month to close with a 7.36% increase. Although the first half of August was quite sluggish, the second was spectacular as BTC exploded above $75,000 and ended the month with a 25% surge – the most since October 2023.
It entered September at around $77,000 before it quickly skyrocketed to $82,000. The bears were quick to reemerge at this point and didn’t allow it to continue further. Just the opposite; BTC slipped by several grand and slumped to $75,000 in the middle of the month as the CLARITY Act failed in the US Senate and the Fed hiked interest rates.
To the surprise of many, given the aforementioned negative developments, the cryptocurrency bounced off immediately and reclaimed the $80,000 line by the end of that particular week. It hasn’t traded below that level ever since. Moreover, it flew to $87,000 on September 22 and 23, but it was stopped. Despite losing some ground by the end of September, it still closed with a 6.33% pump, making it the third consecutive green month and fifth for the year.

Uptober or Redtober Next?
Ever since CoinGlass started tracking BTC’s performance in 2013, October has been the asset’s greenest month. 10 out of the past 13 editions have brought gains, and only three were in the red. When we add the three-month streak bitcoin has been on since July, the expectations for the next 30 days have increased considerably.
Moreover, many analysts have determined that BTC has reclaimed key resistance levels, which now means that the bull market is on, even though CryptoQuant warned yesterday that it might have slowed down.
Speaking to CryptoPotato, Lacie Zhang, Research Analyst at Bitget Wallet, said yesterday that “October has a strong historical track record for bitcoin,” but “seasonality alone is not an investment thesis.” After all, recall that BTC reached its latest ATH precisely last October before it crumbled in the notorious massacre that left over $19 billion in liquidations in 24 hours and went on a months-long red streak.
“Bitcoin’s median October return has historically been around 11%–14%. ETF inflows, declining exchange balances and corporate buying support the bullish case, while high interest rates, oil prices and renewed inflation pressure remain the main headwinds,” Zhang added.
The researcher outlined the base-case range for the month of $78,000-$95,000, but noted that if BTC holds the key $82,000 support and flips $87,500 into one, then $95,000 should be the next major target. On the other hand, a decisive break below $80,000 would “invalidate the seasonal bullish setup.”
The post Bitcoin Enters Its Most Bullish Month After Massive Q3: Uptober or Redtober Next? appeared first on CryptoPotato.
The Core Team behind the project announced a partnership on X with Open Standard just as the latter’s Open USD (OUSD) stablecoin went live with heavyweight backing from the likes of Visa, Coinbase, Mastercard, and Stripe.
The most interesting part for Pioneers is that the collaboration could eventually bring OUSD-based rewards and additional utility in the broader Pi ecosystem.
What Is Pi Planning?
The intriguing portions of Pi Network’s announcement begin with the timing, which came hours after OUSD officially went live on September 30. Businesses and developers can now integrate the dollar-pegged asset through infrastructure from Visa, Mastercard, Stripe, and Coinbase, while the stablecoin is natively available on Ethereum, Solana, Base, and Tempo. It has already been launched through exchanges like Coinbase, Kraken, and Uniswap.
Open Standard has grown considerably since CryptoPotato first covered the project in late June, when more than 140 companies had signed up to participate. It now says its network includes over 200 financial institutions, fintechs, banks, and global businesses.
Its founding partners include the four giants mentioned above and Shopify, which have committed more than $1 billion in near-term launch liquidity. OUSD itself is issued by Stripe’s Bridge, with reserves held at BlackRock, Lead Bank, and BNY Mellon. All of this makes Pi’s announcement significantly more impactful to its community and raises some major questions, even though there aren’t too many details yet.
Pi Network is partnering with @openstandard, the company powering Open USD (OUSD), a partner-governed stablecoin designed as open infrastructure!
Open Standard brings together more than 200+ partners across payments, finance, technology, and crypto, including Visa, Google, and… pic.twitter.com/TfwDIgGIfB
— Pi Network (@PiCoreTeam) September 30, 2026
Stablecoin Rewards Coming?
Open Standard uses a different economic model from most major stablecoin players. Participating partners can earn rewards based on the OUSD supply and activity they generate on their platforms, while they can also become eligible to earn equity in Open Standard.
Pi has not yet explained exactly how any Pioneer reward program would work, who would qualify, or when it might launch. Nor has it confirmed that OUSD will become natively supported on its blockchain, so we shouldn’t assume such an integration from the partnership announcement alone.
What has been highlighted is still very narrow but notable: Pi Network and Open Standard are exploring ways to bring OUSD-created rewards and broader utility to Pi’s vast user ecosystem.
For a project that has spent much of the past year and a half trying to expand beyond simply holding and transferring the native token, that could represent a more meaningful step toward increasing real-world activity inside the network. For now, though, the details are scarce but we will make sure to cover them once they are live.
The post Pi Network Makes a Mysterious Stablecoin Move: Could Rewards Be Coming to Pioneers? appeared first on CryptoPotato.
SOL had quite a successful September, posting a price increase of almost 20% and currently trading at $120 (per CoinGecko).
Analysts now eye further gains toward $150 and beyond. However, certain technical indicators suggest that a short-term pullback may also be on the horizon.
What’s Next?
Ali Martinez paid special attention to the strong institutional demand, noting that spot US SOL ETFs continue to absorb Solana. He said these products have accumulated roughly 4.37 million coins (worth around $450 million) since July 13, marking 11 consecutive weeks of net inflows. That said, he assumed that SOL might be headed toward $150.
In fact, last week was the second-best for these exchange-traded funds, which accumulated nearly $190 million. As CryptoPotato reported, the cumulative total inflows into the products skyrocketed to a new all-time high of $1.62 billion.
X users Gordon and Scient also weighed in. The former argued that “dips are for buying,” adding that the perfect trading strategy would be to accumulate SOL at around $100 and sell above $500. Scient expects a sell-off at the start of October and plans to short Solana at approximately $120-$121 and open a long position around $110.
However, the actions of a certain mysterious whale support an entirely bullish scenario. X user Max Crypto revealed that the anonymous market participant opened a $20.2 million long position on SOL. The liquidation price is set at $98 (assuming the whale doesn’t add more collateral to prevent that outcome).
What’s interesting is that the investor has made four trades so far and has a 100% win rate, making $4.7 million in profits. This, of course, has sparked speculation that they might have access to inside information the rest of us don’t.
Monitoring These Indicators
Solana’s exchange netflow backs the predictions of Gordon and Scient that SOL may post a short-term correction. Inflows have far exceeded outflows lately, suggesting investors have shifted from self-custody to centralized platforms, which can increase immediate selling pressure.

For its part, SOL’s Relative Strength Index (RSI) has soared past 70. In simple terms, this means the valuation has pumped too much in a short period and entered overbought territory, which is usually a precursor to a move south. Conversely, anything below 30 is interpreted as a buying opportunity.
The post Solana (SOL) Breakout Incoming: How High Can the Price Go? appeared first on CryptoPotato.