Cryptocurrency Posts
Crypto Briefing
Iran's crypto strategy may alter global oil supply dynamics, affecting market expectations and potentially leading to price fluctuations.
The post Iran to boost crypto use for oil sales amid US sanctions crackdown appeared first on Crypto Briefing.
Taiwan's sea drone expansion could significantly enhance its maritime defense capabilities, potentially altering regional security dynamics.
The post Taiwan plans $930 million sea drone buildout to counter China pressure appeared first on Crypto Briefing.
The GENIUS Act's entrenchment of stablecoin regulations could solidify blockchain finance's permanence, fostering global market stability.
The post A16z Crypto’s Miles Jennings says the Genius Act makes the onchain shift hard to reverse appeared first on Crypto Briefing.
AI-driven market risks could reshape UK financial regulations, influencing monetary policy and investor strategies amid rising volatility.
The post Bank of England’s Bailey warns UK to brace for AI-driven market risks appeared first on Crypto Briefing.
Investor fears about AI's impact on bank stocks may be premature, as trust in banks remains a strong competitive advantage.
The post Wells Fargo’s Mike Mayo says the AI scare trade in bank stocks is overblown appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Bitcoin Privacy Breakthrough a Zcash Killer? | Misha Komorov, Alloc Innit
Researchers have proposed a way to make Bitcoin private without changing Bitcoin itself. Misha Komarov, co-founder of alloc/init, explains Shielded Bitcoin: zero-knowledge proofs that hide the sender, receiver, and amount of a Bitcoin transfer, with no soft fork, no custodians, and no bridges. He covers how Bitcoin PIPEs make it possible and what the proposal still needs. It is a research proposal, not a finished product.
Chapters:
0:00 Shielded Bitcoin: Private Bitcoin Transactions With Zero-Knowledge Proofs
0:38 How Bitcoin PIPEs Make Privacy Possible Without a Soft Fork
1:42 Do Indexers and ZK Rollups Require Trust?
3:16 Shielded Bitcoin vs. Monero and Zcash
4:21 What Privacy Shielded Bitcoin Protects
5:59 How Private Are Early Users? The Small Privacy Set Problem
7:37 Is Shielded Bitcoin an Altcoin Killer?
9:12 Fees, Block Space, and Larger Shielded Transactions
10:50 Who Needs Private Bitcoin? Wrench Attacks and Corporate Treasuries
12:20 Dark Pools, Governments, and the Next Wave of Bitcoin Buyers
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Bitcoin Privacy Breakthrough a Zcash Killer? | Misha Komorov, Alloc Innit first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Bitcoin’s Institutional Era Has Arrived | Robinhood VP of Crypto Institutions Nicola White
Robinhood is bringing crypto perpetual futures to US customers, with up to 10x leverage on Bitcoin and Ether. Nicola White, Robinhood’s vice president of institutional crypto, explains how the CFTC no-action letter, the Bitstamp exchange, and Robinhood Derivatives made it happen, and why the company wants markets to be always on.
Chapters:
0:00 Robinhood’s Hood Summit: 24/7 Stock Trading and US Crypto Perps
0:40 Why Robinhood Wants Markets That Never Close
1:32 Bitstamp Perps and the CFTC No-Action Letter
2:19 Tokenized Stocks, the Basis Trade, and the Path for US Perps
3:20 Bitstamp’s Volume and the Retail–Institutional Merger
4:54 What Institutions Want to Do With Bitcoin
6:00 Institutional Bitcoin Depth and Large Block Trades
6:49 AI Trading Agents and Robinhood’s Sub-Account Controls
8:29 Lessons From the 2022 Meltdown and US Leverage Limits
10:12 How Bitcoin Changes Finance in 10 Years and What’s Next for Tokenized Stocks
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Bitcoin’s Institutional Era Has Arrived | Robinhood VP of Crypto Institutions Nicola White first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Mark Moss: The Bitcoin Endgame – BTC to $1 Million by 2030
The Fed just raised rates, yet Bitcoin keeps climbing. Mark Moss, host of the Market Disruptors podcast, explains why he thinks most people are misreading why long-term rates are rising, how a booming economy could be part of the answer, and why he says Bitcoin benefits from both the debasement trade and a bullish technological future.
Chapters:
0:00 Mark Moss on the Fed’s “Token Raise” and an October Pause
1:54 The Flat Yield Curve, Bank Lending, and the 5.1% 10-Year
2:56 Why Bitcoin Is Rising as Rates Rise: “Price Is Truth”
5:40 Bitcoin vs. Gold: The Debasement Trade and a Bullish Future
6:19 Can the US Grow Its Way Out of $40 Trillion in Debt?
10:30 The Monetary Reset Is a Process, Not an Event
13:33 Four Ways Out of the Debt Problem and What Happens in 2029–2030
16:27 Stablecoins, the Genius Act, and Why 6 Billion People Want Dollars
20:14 Institutions Are Buying Bitcoin While Retail Sells
24:29 Bitcoin’s S-Curve, Its CAGR, and a $1 Million Price Target
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Mark Moss: The Bitcoin Endgame – BTC to $1 Million by 2030 first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
UK Brings Crypto Under Full FCA Oversight for the First Time
The UK’s Financial Conduct Authority has opened applications for crypto firms to become authorized, bringing the sector under full regulation for the first time.
In a Wednesday announcement, the watchdog said companies can apply so that the crypto industry has “clarity and legitimacy.”
The UK is in the process of drafting a sweeping new crypto bill. The FCA finalized its regulatory framework for cryptoassets in June, and the regime is due to take effect in October 2027.
“The UK’s new crypto regime will give consumers greater protections and firms a clear framework to operate in. Firms can now apply for authorisation and start preparing for regulation,” Dominic Cashman, director of authorisation at the FCA, said in a statement.
The statement added that firms will have to demonstrate that they meet requirements covering consumer protection, customer-asset safeguarding, market integrity and financial resilience.
Britain is pushing ahead with digital asset legislation since last year recognizing bitcoin and other digital assets as property. The reform came from a 2023 recommendation by the Law Commission, which argued that digital assets did not fit neatly into existing legal categories.
Despite the FCA’s announcement, the UK currently is trailing behind Brussels and Washington with digital asset regulation.
The EU’s Markets in Crypto-Assets regulation has applied to service providers since 30 December 2024.
And the U.S. under President Donald Trump signed the GENIUS Act into law in July 2025, establishing a federal framework for dollar-backed tokens.
Despite lawmakers blocking landmark legislation the Clarity Act last month, U.S. regulators like the Securities and Exchange Commission have pushed ahead with rulemaking regardless.
This post UK Brings Crypto Under Full FCA Oversight for the First Time first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Bitcoin Surges 40% in Its Best Quarter Since Late 2024
Bitcoin is having one of its best quarters ever — another indication that the biggest cryptocurrency is in a bull market.
As noted by the The Kobeissi Letter this week, the price of bitcoin is now up close to 30% since August 19, when the U.S. Treasury announced it planned to more than double the size of its government debt repurchases.
Over the past quarter, the bitcoin price has surged by 40% — its best quarterly performance since Q4 2024.
Bitcoin’s price recently stood at nearly $83,698, unmoved over a 24-hour period but up 6% over a 30-day period.
The coin has benefited from news that the Treasury would try to lower bond yields — which have soared to highs not seen since the 2000s.
Bitcoin has done well with lower long-term yields because it reduces the opportunity cost of holding non-yielding assets like bitcoin and gold, and generally supports risk-on sentiment.
But despite the Treasury stepping in to try and tame the bond market, yields have continued to stay high.
Bitcoin investors don’t seem that bothered. The asset is still doing well as the dollar continues to slip. The so-called debasement trade — where investors throw money at an asset to hedge against a currency losing its value — is hot again after total U.S. debt topped $40 trillion for the first time in July.
The price of Bitcoin had been battered since notching a new all-time high of $126,080 in October, dropping by over 50%. Still, it has experienced the shallowest bear market — so far — in its history.
CryptoQuant said in a report last week that bitcoin was back in a bull market after crossing above its 365-day moving average — the “definitive technical signal” that has marked the start of Bitcoin’s bull markets in past cycles.
The coin has shrugged off the Federal Reserve raising interest rates and lawmakers blockage of landmark crypto legislation, the Clarity Act.
This post Bitcoin Surges 40% in Its Best Quarter Since Late 2024 first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
CryptoSlate
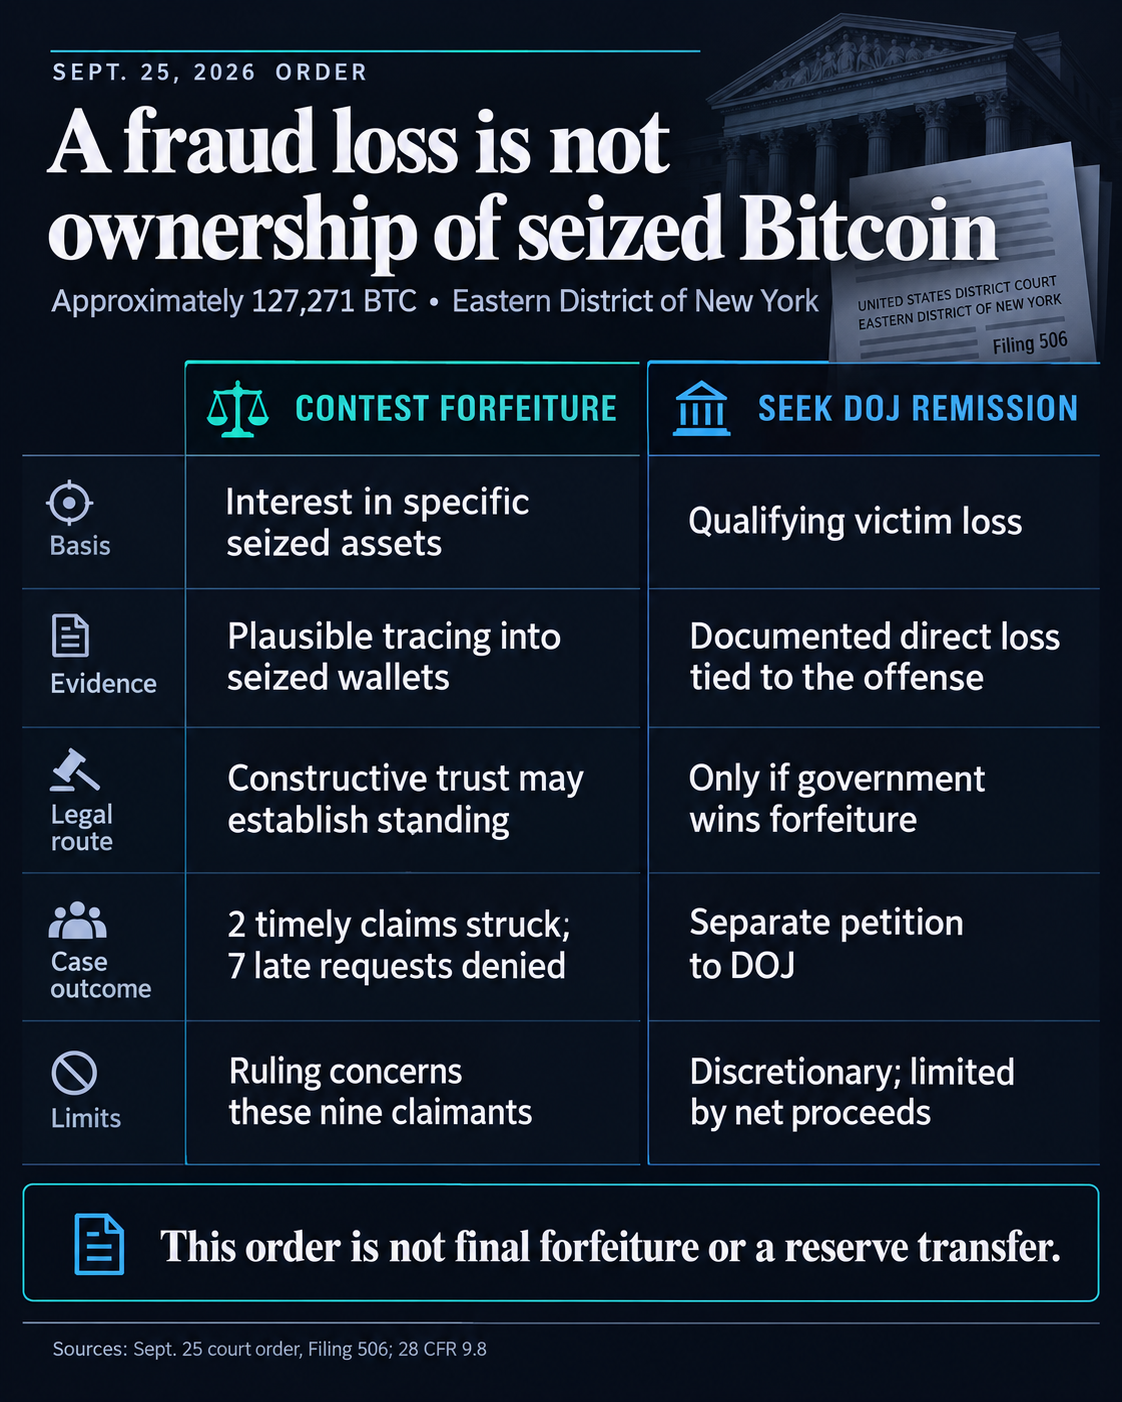
Judge Rachel P. Kovner rejected claims by nine alleged fraud victims seeking to contest forfeiture of approximately 127,271 Bitcoin in a Sept. 25 order.
Their filings did not plausibly connect their lost funds to the specific seized wallets, leaving them with a different potential recovery route if the government wins the forfeiture case.
The Eastern District of New York judge struck the timely claims of Ath Leepinyo and Connie Wilson and denied seven other claimants permission to file late. All nine lacked Article III standing, the legal threshold for contesting the action.
The case began with a civil forfeiture complaint filed on Oct. 14, 2025. DOJ said then that the Bitcoin was in US custody and alleged links to fraud and money laundering involving Prince Holding Group, a Cambodian conglomerate, and its chairman, Chen Zhi.
The court treated these claimants’ plausible allegations as establishing, at most, the position of general unsecured creditors: people seeking compensation without a qualifying interest in the particular assets being forfeited.
A loss tied to an alleged fraud did not establish ownership of coins in these wallets.
The order recognized that a constructive trust could give a claimant an equitable ownership interest and standing. That remedy can recognize an interest in property derived from a person’s assets. However, here none of the claimants plausibly alleged the necessary connection between their funds and the seized Bitcoin.
Lawrence D. Van Dyn Hoven, for example, relied on an investigator’s belief that his stolen cryptocurrency was part of the seizure. Kovner found that his filings offered no supporting facts explaining that belief.
What remission could provide
Kovner pointed to victim remission if the government succeeds in forfeiting the Bitcoin. That process allows eligible victims to petition DOJ for recovery from forfeited property even when they lack a present ownership interest in it.
Under 28 CFR 9.8, petitioners must document a specific financial loss directly caused by the offense underlying forfeiture or a related offense, and satisfy other eligibility conditions. Other conditions include no knowing participation in or benefit from the offense, and no willful blindness.
Petitioners must also show they have not been compensated for the loss and lack reasonably available alternative assets for recovery.
When the forfeited property cannot cover petitions in full, recognized victims may receive proportionate shares. Remission is capped at a victim’s share of the associated net forfeiture proceeds, so the size of the Bitcoin seizure is no promise of full repayment.
The Sept. 25 order resolves these nine claimants’ standing. Their potential recovery depends on government success in the forfeiture action and a separate discretionary decision on a documented-loss petition.
The post US court blocks victims from 127,000 seized Bitcoin, and petition rules are blamed appeared first on CryptoSlate.
Uniswap’s StablePair fee hook is designed to keep more of the value from rebalancing stablecoin pools with liquidity providers.
Yet the rule deciding which trade counts as a correction depends on a configured reference rate.
StablePair is a Uniswap v4 hook, a contract that changes a pool’s behavior. Its fee logic compares a cached pool price with a reference stored in the hook’s configuration. The design prices trades around that benchmark, leaving providers exposed if a token’s economic value moves away.
Uniswap Labs announced the two Ethereum pools, USDC/USDT and USDC/USDG, on Sept. 10. Its Sept. 16 explanation noted that Providers allocating capital now are choosing a fee mechanism alongside the token inventory it requires them to hold.
What the dynamic fee captures
The deployment documentation lists one-for-one reference rates for both pools. The implementation’s fee path uses that stored reference and the pool’s price, without consulting an external market-price feed.
Inside a narrow band around the reference, the fee varies by swap direction to target a consistent bid and ask before price impact. When the pool sits exactly at the reference, both directions pay the configured optimal fee. As it moves toward an edge, the fee in one direction falls while the other rises.
For a simple illustration, assume an optimal fee of one basis point (0.01%). At the reference, a swap with 10,000 input units would pay one input unit in LP fees.
Outside the band, the fee rules split trades by direction. A swap classified as moving farther from the reference pays zero LP fee, while a swap classified as pulling the pool toward it faces a decaying fee.
A trade pushing the pool away can give LPs a favorable price relative to that benchmark. The reverse trade lets an arbitrageur capture the gap by restoring the pool’s price. A single static fee rate charges both directions equally.
StablePair instead offers progressively better terms for the corrective trade as blocks pass.
If a trader accepts the fee, LPs collect it while the trade rebalances the pool. Uniswap Labs says the design captures the “vast majority” of rebalancing profit.
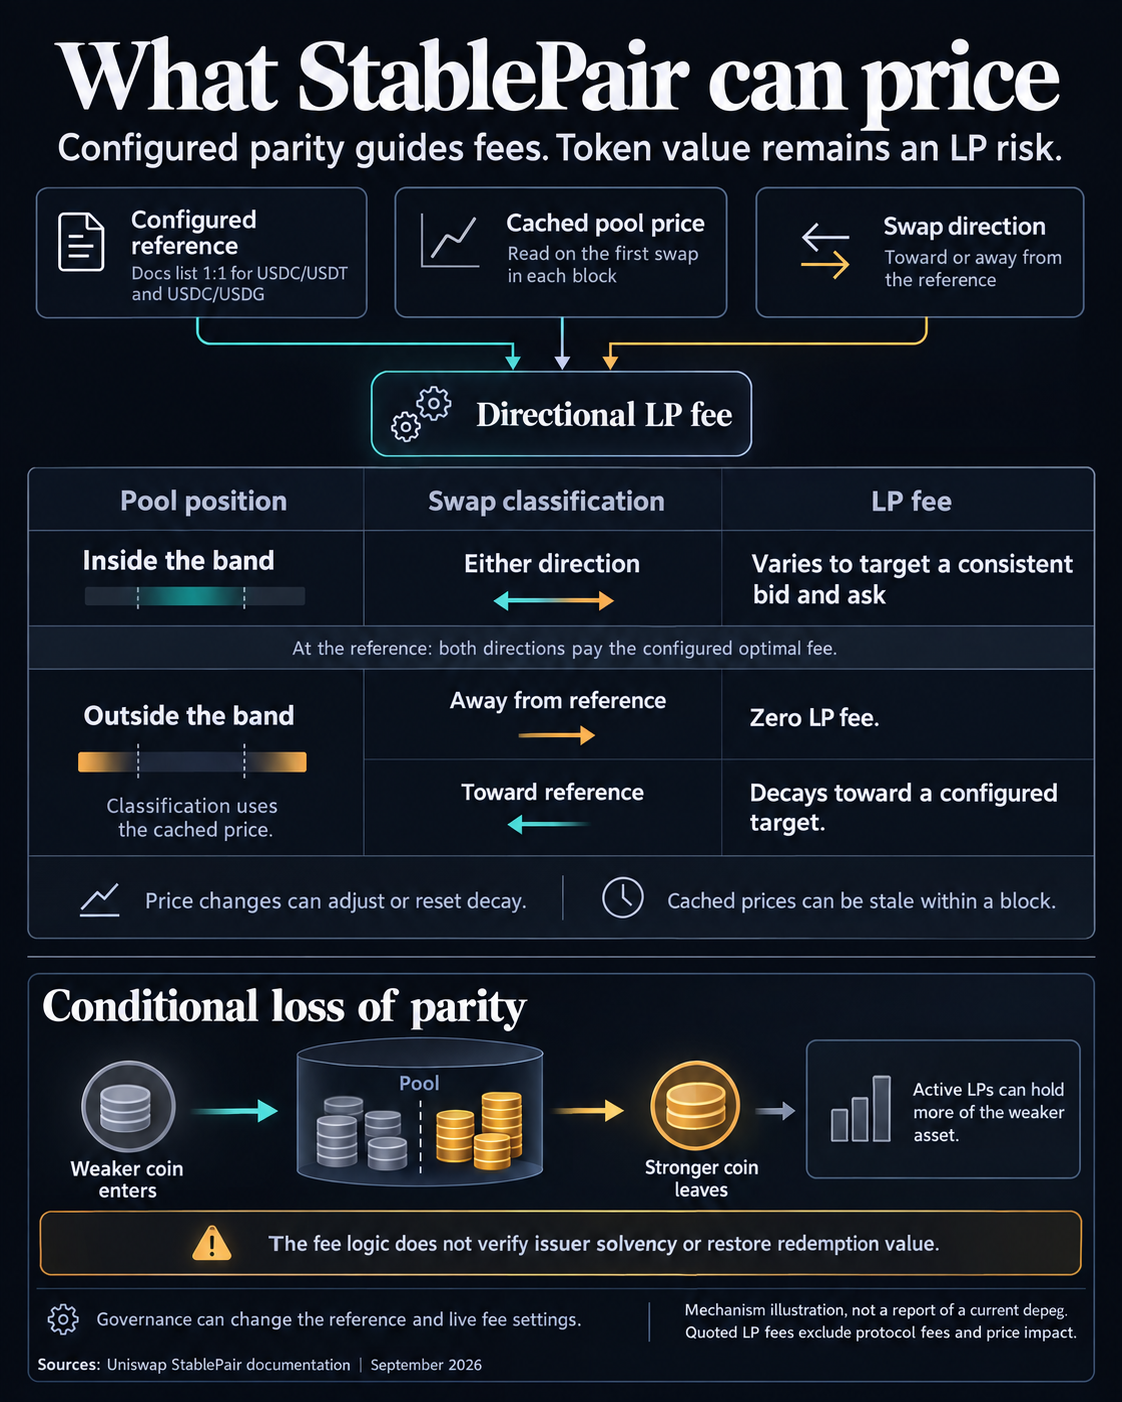
The first swap in each block caches the pool price used for later fee calculations. That removes the same-block fee advantage from splitting corrective swaps, but later trades can face stale inputs. If the live price crosses the reference mid-block, the cached classification can assign fees to the opposite directions until the next block.
Inventory risk and the evidence on returns
The boundary appears when the outside market stops treating the two coins as equal.
Consider a conditional issuer shock that reduces one coin’s external value while the configured reference still assumes one-for-one exchange. Selling that weakening coin for the stronger coin can move the pool farther from the reference while moving its price closer to the outside market.
A trade the fee rule classifies as moving away from the reference may then reflect price discovery, rather than a temporary imbalance.
The fee logic cannot verify issuer solvency or restore redemption value. This scenario is hypothetical and should not be read as a report of a current depeg, exploit, or loss in either StablePair pool.
If an LP holds 10,000 hypothetical coins and their external value falls from $1 to $0.90 each, that inventory is worth $9,000, a $1,000 decline before fees. Capturing income from rebalancing trades does not by itself reimburse that change in token value.
Trades can also change what the provider owns. Selling the weaker coin into available liquidity removes the stronger coin and leaves active LP positions with more of the weaker asset. An away-from-reference trade charged zero LP fee contributes no LP fee to offset that added exposure.
The amount exchanged still depends on available liquidity, the provider’s chosen range, and price impact. StablePair's zero-fee classification also depends on the cached price, so it should not be read as a rule that every sale of a weakening coin is always free.
On Sept. 30, the Uniswap interface’s Stats panels showed the USDC/USDT StablePair pool with about $6.1 million in total value locked and $117.9 million in 24-hour volume around 15:59 UTC. The USDC/USDG pool displayed about $2.6 million and $8.7 million, respectively, around 15:57 UTC.
A same-pair reference was available: the Ethereum USDC/USDT v3 pool charging 0.01% displayed about $34.2 million in TVL, $15 million in 24-hour volume, and $1,100 in 24-hour fees around 16:02 UTC.
The observations were not synchronized, the pools have different fee rules and liquidity conditions, and the StablePair panels supplied no comparable absolute fee total or realized position-level return.
In economic terms, testing that return claim would require comparable periods and active liquidity ranges, fee income, and inventory valuation. Volume alone cannot show how much better an LP did than in another pool or by holding the assets.
Governance controls the benchmark, with limits on the hook
Under Uniswap’s documented role model, governance controls live fee configurations, implementation upgrades, and role administration.
Changing the reference changes the benchmark used to classify and charge swaps. The deployment page directs integrators to read live configuration from the hook because governance can change parameters.
Separate limits apply to what an upgrade can do. The hook’s permanent address permissions exclude remove-liquidity callbacks and custom accounting deltas.
According to Uniswap’s security documentation, upgrades cannot use those capabilities to block LP withdrawals or alter swap amounts to skim additional fees. The ability to withdraw does not guarantee the market value of the tokens received.
Uniswap says OpenZeppelin reviewed a non-upgradeable predecessor’s core fee mechanism from Feb. 9 to 13, 2026, and resolved the splitting issue through block caching. The later upgradeability and role model were outside that review.
For LPs, StablePair changes the price of supplying liquidity for rebalancing. The remaining economic decision is whether the assets still justify the reference around which that liquidity is supplied, and whether earned fees compensate for the inventory ultimately held.
The post Three hidden flaws in Uniswap’s StablePair hook drain LP returns appeared first on CryptoSlate.
Bitcoin is closing its strongest quarter since 2024 after leaving US stocks and gold far behind despite surging bond yields.
The largest digital asset has gained about 43% in the third quarter, putting it on course for its second-best third-quarter since 2013 and its third-strongest quarterly advance since US spot Bitcoin exchange-traded funds began trading in January 2024, according to Bitfinex and CoinGlass.
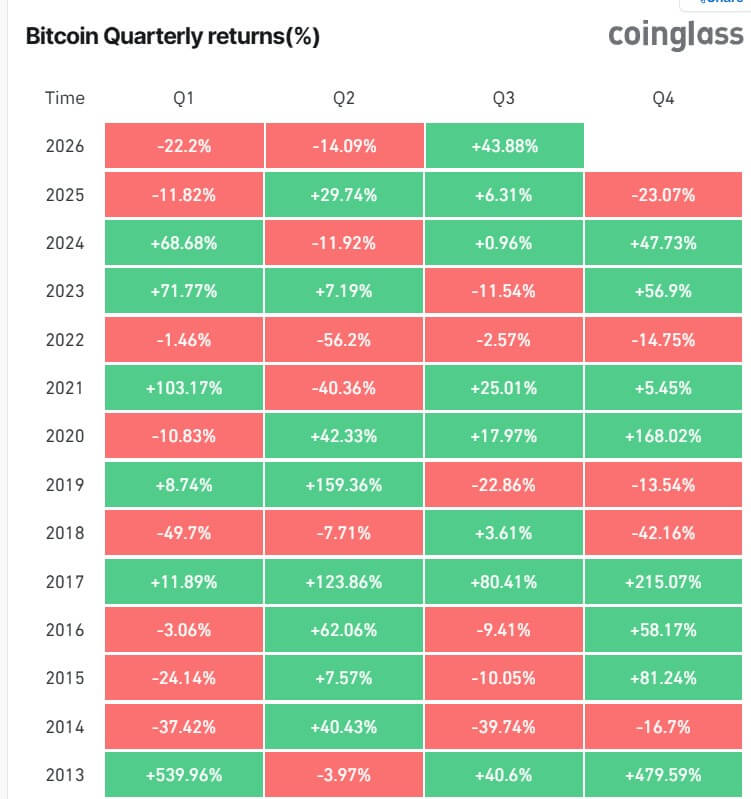
Bitcoin entered July near $58,600 after three consecutive quarterly declines, then accelerated through August and September as institutional demand returned and sellers who had spent much of 2026 underwater were absorbed at progressively higher prices.
Traditional markets barely kept pace. Over roughly the same three-month period through Sept. 29, the Nasdaq Composite gained about 5%, the S&P 500 roughly 4% and gold less than 2%, according to StatMuse data.
Meanwhile, Ethereum was the notable exception, outperforming Bitcoin as the crypto rebound broadened beyond the market leader.
Bitcoin's outperformance accelerated after Aug. 19, even as a Treasury initiative to improve liquidity in longer-dated government debt failed to prevent yields from rising.
The department said it would at least double the maximum size of liquidity-support buybacks for longer maturities to $4 billion per operation, with the increased purchases beginning Sept. 9.
Bitcoin has risen almost 30% since the announcement. However, the 10-year Treasury yield climbed about 81 basis points and long-dated borrowing costs reached multi-decade highs over the quarter, raising the hurdle for assets that produce no yield.
Wall Street money takes over from leverage
US spot Bitcoin ETFs provided a fresh source of capital as financial conditions tightened elsewhere.
The funds moved from roughly $5 billion in year-to-date net outflows at the end of July to about $1 billion in inflows by late September, a swing of about $6 billion in two months.
The reversal culminated last week when the products absorbed $2.39 billion, their largest weekly intake since October 2025. Every session was positive, though daily demand slowed from $999 million on Sept. 21 to about $135 million by Sept. 25.
Analysts at Nexo said Bitcoin enters the fourth quarter with stronger spot demand and an improving market structure, though the outlook still depends on ETF buying persisting, overhead supply being absorbed and inflation remaining contained enough to prevent further Federal Reserve tightening.
At the same time, leveraged traders have been retreating.
Aggregate Bitcoin futures open interest has fallen from more than 700,000 BTC on Sept. 21 to about 644,000, its lowest since early January, according to Bitfinex. The seven-day contraction of roughly 49,000 BTC was the largest since October 2025, while CME open interest dropped 16,075 BTC on Monday alone, its third-biggest daily decline on record.
Futures premiums have also compressed, and implied volatility remains near a one-year low.
The unwind leaves less leverage to accelerate another liquidation-driven selloff, but it also removes speculative buying that can propel sharp advances. That shifts more responsibility onto investors purchasing Bitcoin outright.
Signs of that transition are appearing around current prices. Bitfinex estimates the amount of Bitcoin with a cost basis between $82,500 and $84,000 nearly tripled to 306,000 tokens in three days as buyers absorbed coins sold by both profitable holders below the market and newer investors exiting at losses above it.
A 1.39 million Bitcoin wall waits above $85,000
Bitcoin's improving structure still leaves a substantial concentration of sellers immediately overhead.
Bitfinex estimates investors hold about 1.39 million BTC acquired between $84,000 and $86,500. The group includes long-term holders returning toward breakeven and more recent buyers whose positions slipped underwater after Bitcoin retreated from its Sept. 21 high near $87,400.
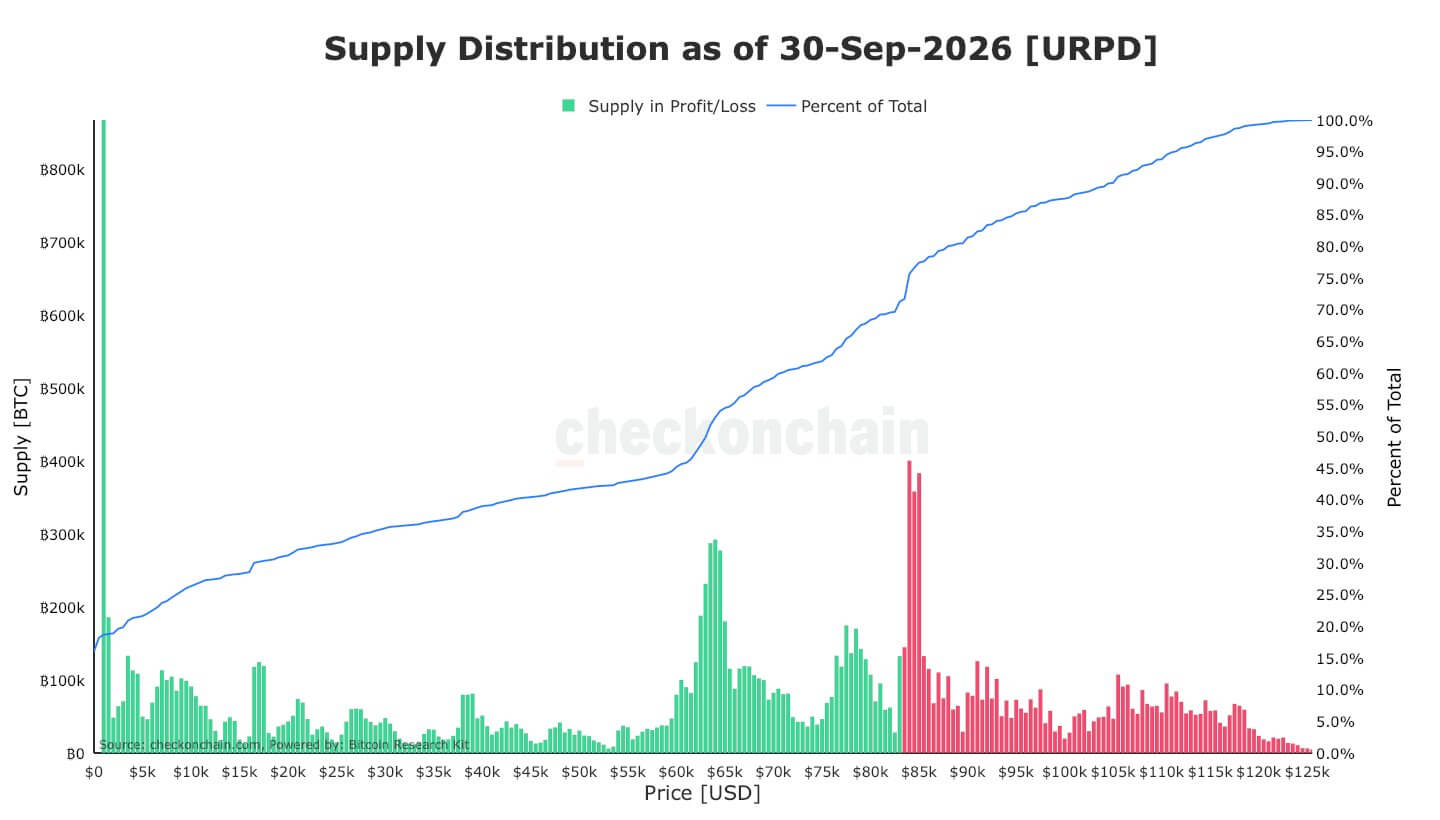
That creates potential selling each time prices push back into the range.
CryptoQuant said Bitcoin reclaimed its 365-day moving average last week for the first time since March 2023. Recoveries above the gauge have accompanied previous transitions into bullish regimes, while sustained moves below it have historically coincided with weaker market phases.
Bitcoin's realized price, which approximates the average cost basis of coins in circulation, has climbed to about $77,000 and held through the latest recovery.
The challenge is whether new demand can clear the supply sitting above spot prices.
Bitfinex's measure of ETF purchases relative to the roughly 450 Bitcoin produced by miners each day fell from 25.6 times issuance during the $999 million inflow session to 1.8 times by Sept. 29. The firm estimates the ratio needs to recover toward five times issuance, equivalent to roughly $190 million of ETF demand a day, to absorb the overhead supply more quickly.
A move above $85,000 would return roughly 760,000 BTC to profit and lift Bitcoin's supply-in-profit measure back toward the 75% threshold Bitfinex associates with stronger bull-market phases. The gauge slipped to 71.3% on Sept. 29 from 78.1% eight days earlier.
Beyond the immediate barrier, Glassnode places another major supply concentration near $88,000 to $90,000, followed by an important level around $96,700.
Options traders are positioned for a break higher nonetheless. Nexo said Bitcoin's put-to-call ratio averaged 0.67 over the past two weeks, while $140,000 calls expiring Dec. 25 represent the largest individual position. Dealer positioning points to the $95,000-to-$97,000 area as another significant test if Bitcoin clears the nearer supply zones.
Bitcoin's best season collides with 5% yields
Seasonality gives bulls another argument heading into October.
The fourth quarter has historically produced Bitcoin's strongest returns, with average gains of roughly 77% to 85% since 2013, depending on the dataset. BloFin Research calculates that matching its 77.07% historical average from current levels would put Bitcoin near $147,000, while its median fourth-quarter return of 47.73% would imply roughly $123,000.
Those are mechanical projections, and successive Bitcoin cycles have delivered progressively smaller advances from their lows.
Monetary policy presents the more immediate constraint.
Markets began this week assigning roughly a 65% probability to another quarter-point Fed increase in October. Softer-than-expected inflation data Wednesday cut those odds to about 38%, showing how rapidly the rate outlook can shift ahead of the central bank's Oct. 27-28 meeting. Another decision follows Dec. 8-9.
Sept. 28 offered an earlier warning about Bitcoin's exposure to broader positioning. The Nasdaq-100, gold and Bitcoin fell together as investors reduced exposure across markets, a pattern Nexo analysts said was more consistent with broad deleveraging than a conventional rotation into safe assets.
For Bitfinex, $81,300 is now an important threshold beneath the recovery. Sustained trading below that level alongside renewed ETF outflows could expose the realized-price region near $77,000.
On the upside, stronger ETF demand and a break through $86,500 would leave Bitcoin approaching its yearly open near $87,700 before the larger supply cluster around $90,000 comes into play.
The Oct. 2 US payrolls report will give traders another read on the economy before the next inflation release and the Fed's October meeting, just as Bitcoin enters its historically strongest quarter with Treasury yields still above 5%.
The post Bitcoin enters its best season after a 43% surge, with $147,000 suddenly on the math appeared first on CryptoSlate.
Bitcoin improvement proposal BIP461 could make a hidden route for leaking wallet secrets easier to detect. The draft defines a common signing procedure for ECDSA, an existing Bitcoin signature scheme.
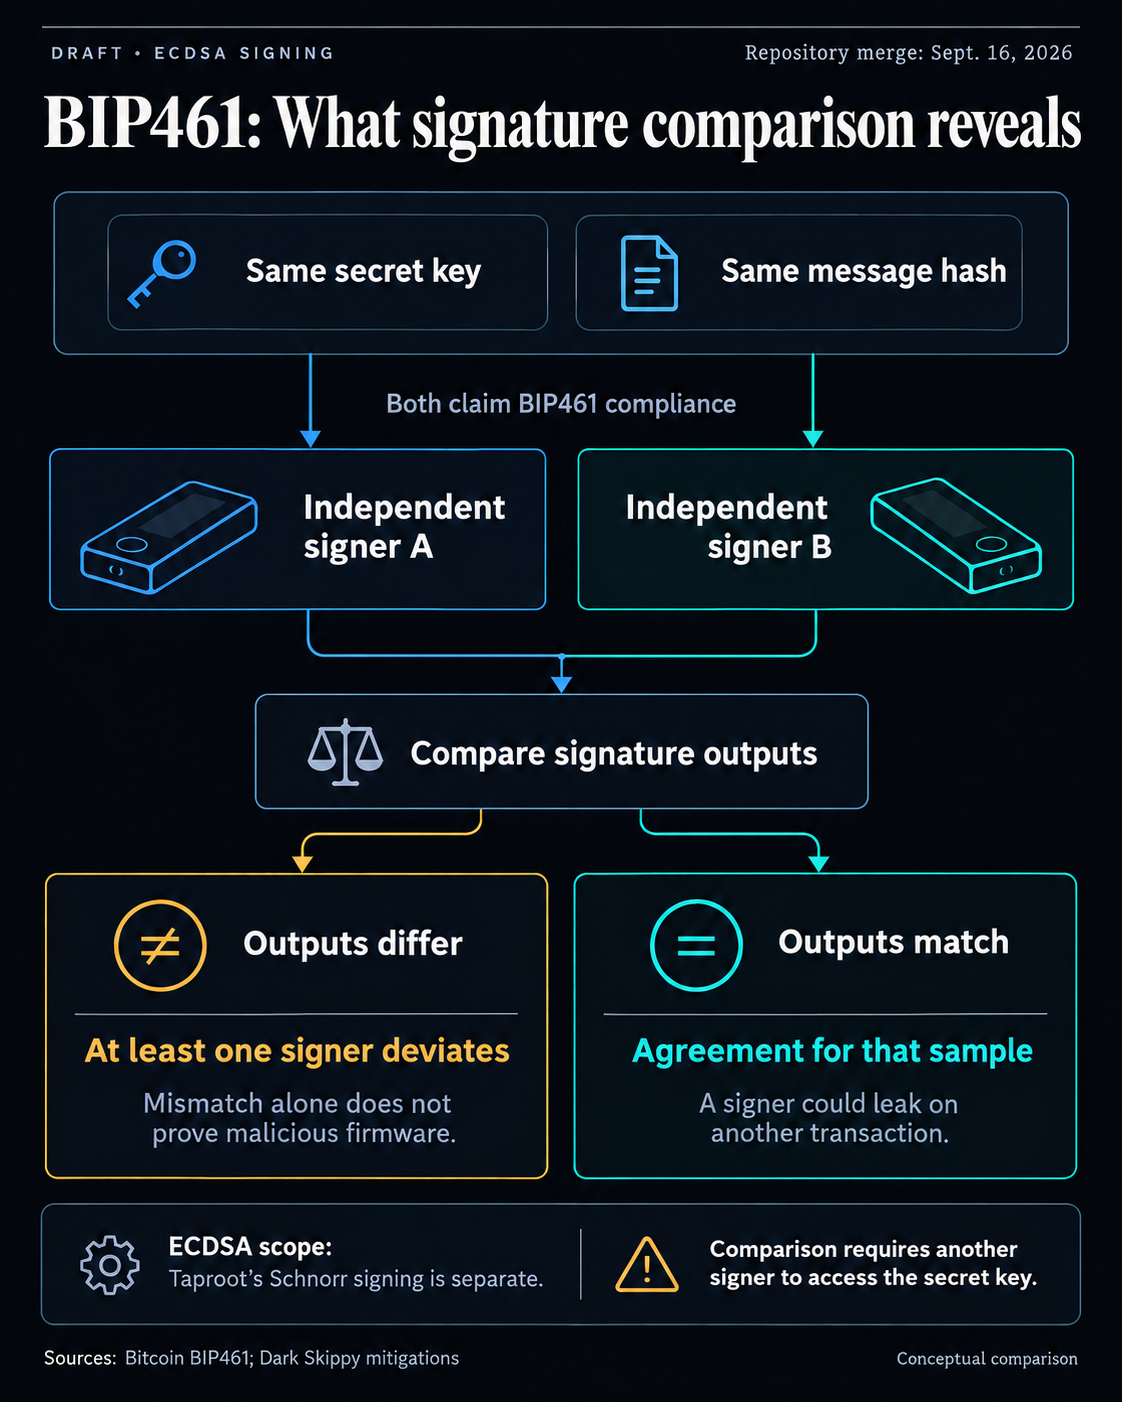
Independent compliant signers should produce identical signatures for the same secret key and message hash, creating a benchmark for detecting departures that could conceal key leakage.
Authored by Liam Gilligan, the proposal was merged into the BIPs repository on Sept. 16 and remains marked Draft. Its signatures work under existing Bitcoin consensus rules, so implementing this signing procedure requires no consensus change.
Comparing signatures for deviations
ECDSA allows a signer choices while creating a valid signature, including the nonce, a temporary value used in signing. Malicious firmware can exploit that freedom to hide key material in signatures that still pass verification, and BIP461 fixes those choices through a specified deterministic procedure.
Bitcoin’s acceptance of a signature cannot establish that its creation kept the key safe. A common specification supplies an expected output against which the signer’s behavior can be checked.
The comparison requires identical inputs and the exact same standard, including access to the secret key on another independent signer. That extra exposure is a practical cost of reproducing the signature. Different results for the same key and message hash show that at least one signer is not following BIP461.
An honest implementation using another valid ECDSA procedure can also disagree. A mismatch warrants investigation into compliance, but its cause remains unresolved. The comparison alone cannot identify a malicious device or demonstrate theft.
The prescribed algorithm also keeps signatures to at most 70 bytes in the standard DER encoding, excluding Bitcoin’s one-byte sighash flag.
The Dark Skippy disclosure pointed out that corrupted firmware can embed seed material in transaction signatures. In their original disclosure, the researchers said they had not seen the technique in the wild.
Dark Skippy’s original demonstration uses Schnorr signing, while BIP461 specifies ECDSA. Taproot uses the separate BIP340 Schnorr scheme, so this draft does not directly standardize a remedy for that demonstration.
The researchers’ mitigation discussion warned that a malicious signer could leak only on a selected transaction, so a device could produce compliant signatures in a test and leak on another transaction.
At the September merge, a reviewer said test vectors and a reference implementation were needed for BIP461 to advance to Complete.
For wallet users, its potential value is a shared benchmark that could make deviations visible. Delivering that value still depends on compliant implementations and comparisons that account for both detection limits and the risks of handling secrets.
The post New Bitcoin upgrade catches hidden key leaks hiding the exact fix appeared first on CryptoSlate.
Petrobras, Brazil's state-controlled energy company, is testing Cardano to track sustainable aviation fuel benefits and prevent double-counting.
The Cardano Foundation said on Sept. 30 that an ongoing research and development collaboration had delivered applications for sustainable aviation fuel (SAF) and Diesel R, Petrobras' renewable fuel brand.
The SAF project addresses a problem that arises when the buyer of a fuel's environmental benefit is different from the buyer or user of the fuel itself. Its Book-and-Claim model lets an airline, company, or passenger receive that benefit even when the SAF is produced or used elsewhere.
Petrobras developed the SAF platform with PUC-Rio University's Ledger Labs and the Cardano Foundation. According to the Foundation's case study, it represents SAF environmental attributes as standardized CS-SAF tokens on Cardano.
Those tokens can be created, transferred, checked, and retired. Retirement prevents the same attribute from being claimed again, while the digital record traces the allocation back to the original fuel certificate.
The crypto analogy is double spending: preventing reuse of a digital asset, applied here to an environmental claim.
Travelers can enter departure and destination airports, calculate a CS-SAF allocation and receive a certificate showing their route, distance and allocation, the Foundation says. That claim remains linked to the original SAF certificate.
The tokens carry metadata aligned with CORSIA, the Carbon Offsetting and Reduction Scheme for International Aviation.
In guidance published June 16, the Roundtable on Sustainable Biomaterials says Book-and-Claim changes neither the physical fuel a buyer uses nor its associated emissions. Airlines should disclose supported reductions separately from operational emissions.
Different value-chain participants can make distinct claims, as long as their disclosures do not misrepresent the overall reduction.
Cardano usage beyond aviation
The Diesel R project, developed with PUC-Rio, proposes checkpoints across production, transportation and use. Its aim is a continuous fuel-lifecycle record that could support Scope 3 reporting, which covers indirect emissions across a company's wider value chain.
That would connect information held by suppliers and logistics providers, giving emissions reporting a more traceable supply-chain history. The Foundation describes this architecture as a proposed model within the R&D work.
The SAF platform illustrates how Cardano can record the allocation and retirement of environmental benefits. Commercial use remains unquantified, as the Foundation's disclosures provide no transaction volumes or revenue figures.
The post Brazil’s largest energy giant tests Cardano to fix carbon double-counting appeared first on CryptoSlate.
CryptoTicker.io
Anyone searching for “buy Ethereum with PayPal” usually expects a button in the PayPal app. In Germany there is none. PayPal does not trade crypto-assets here, and nothing about that changed at the start of October 2026 either. What does work is a detour: you top up a crypto exchange with euros from your PayPal account and buy Ethereum there. That detour costs you two things an ordinary bank transfer does not: a fee you do not know before you click, and three days during which your ETH may not leave the exchange.
This article works through both. It shows what actually arrives in ether out of 100 euros along the three routes SEPA, debit card and PayPal, why the lock-up period weighs more heavily for Ethereum than the difference in fees, and what can go wrong when you move the coins on to a wallet of your own. We have already answered the same question for Bitcoin: buying Bitcoin with PayPal. With Ethereum two points come on top that do not arise in that form with Bitcoin, namely the choice of network and the question of what staking does to the holding period.
PayPal does not sell crypto-assets in Germany
The distinction matters, because many guides blur it: PayPal as a dealer in crypto-assets and PayPal as a payment route are two different things. The first exists in the United States, the second in Germany.
That can be established from PayPal's own presence. The product page for buying and selling cryptocurrencies exists on PayPal's US site. On the German site the corresponding address leads nowhere. More telling still is a look at the terms of use: in the German version, last updated on September 7, 2026 and a good 150,000 characters long, the word cryptocurrency does not appear at a single point. A service a provider does not mention in its own contractual documents is a service it does not offer.
For you that means: every page promising you can buy ether “directly at PayPal” either describes the US market, or it describes the detour via an exchange and names it imprecisely. There is no third case.
The only route runs through a euro deposit at a crypto exchange
The actual process has four steps, and PayPal is involved in only one of them. You open an account at a crypto exchange and verify your identity. You deposit euros and choose PayPal as the payment route. You buy ether with the euro balance. And if you want to hold the coins yourself, you then transfer them to a wallet of your own.
Crypto exchange here means a trading venue that swaps crypto-assets for euros and holds the balance for you. In this process PayPal is neither dealer nor custodian, only the till at the door. That division of roles explains most of the peculiarities that follow: the exchange determines what the purchase costs and when you may move your coins, not PayPal.
PayPal appears as a deposit route at several providers. The position is only verifiable, though, where the provider publishes its fees and deadlines in full. Kraken does so with a table anyone can inspect and which was last updated on August 17, 2026. That is why this article works with those figures. At other houses, contradictory statements circulate on comparison portals, from “free since July 2025” to “2 percent”; anyone wanting to deposit there should check the terms with the provider before buying. Which trading venues come into question in Germany at all is shown in our comparison of providers with PayPal deposits.
The 72-hour lock is the real price of the PayPal deposit
The point missing from most guides is stated expressly in Kraken's fee table: after a deposit by PayPal, a withdrawal lock of 72 hours sits on the account. The lock applies not only to euros but to all withdrawals, crypto-assets included. For three days your freshly bought ETH therefore stay on the exchange, whether you like it or not.
The reason for that is not harassment but chargeback risk. A PayPal payment can be disputed after the fact. If the coins bought could be withdrawn immediately, the exchange would be left without any counter-value in a dispute. The same logic applies to card payments, but not to the SEPA transfer: there the table shows no lock.
Withdrawal lock does not mean your balance is frozen. You can trade straight away, you simply cannot get out of the building. For an investor who leaves their ETH on the exchange anyway, that has no consequences. For anyone holding by the principle of “not your keys, not your coins”, it is three days of counterparty risk they would not have had with a transfer. The year 2026 has served as a reminder, through several exchange incidents, that those three days are not a theoretical risk.
At Kraken the PayPal fee appears only on the final confirmation page
For every other type of deposit the table names a figure. SEPA from the European Economic Area: free, minimum amount 1 euro, credited within zero to three banking days or instantly. Debit card: minimum amount 10 euros, 0.25 euros plus 3.75 percent, credited almost instantly. A transfer over the international SWIFT network: 3 euros, one to five banking days.
For PayPal, the word “processing fees” stands in place of the figure, together with a footnote: the fees depend on the region and are displayed on the final confirmation page. Minimum amount 1 euro, credited almost instantly, lock 72 hours.
That is the most remarkable finding of this research, and it is no reproach to a single provider but a property of the payment route: of all the deposit types, PayPal is the only one whose price cannot be looked up beforehand. You learn it at the moment when all that is left is to confirm. Anyone wanting to compare has to run the process through to the final page and break off there.
100 euros in ETH via SEPA, debit card and PayPal: the cost calculation
Let us work the purchase through once, with the published figures and an ether price of around 2,367 euros, as it stands on October 1. On top of the deposit fee comes the trading fee in every case: Kraken charges 1 percent on instant purchases and recurring purchases, and 1.5 percent on orders you place yourself.
Via SEPA, a full 100 euros out of 100 euros arrive in the exchange account, because the transfer costs nothing. The purchase takes off 1 percent, so 1.00 euro. What goes into ether is 99.00 euros, around 0.0418 ETH.
Via the debit card, the deposit costs 0.25 euros plus 3.75 percent, 4.00 euros together. That leaves 96.00 euros, from which 1 percent trading fee comes off, so 0.96 euros. What goes into ether is 95.04 euros, or around 0.0402 ETH. Against the transfer, 3.96 euros are missing, which converts to around 0.0017 ETH.
Via PayPal, this line cannot be filled in. The deposit fee is not known beforehand. If it is zero, the result matches the SEPA route; if it is at card level, around four euros are missing. Nothing more can seriously be said, and that is exactly the point: on a purchase of 100 euros it is a single-digit euro amount, on a purchase of 5,000 euros a three-digit sum that you see only on the final page.
The spread sits in the purchase price and appears in no fee line
The calculation above is deliberately incomplete, because it captures only the stated fees. For instant purchases, Kraken expressly points out that a spread is additionally contained in the price displayed.
The spread is the distance between the price at which the exchange buys and the one at which it sells. It never appears on a statement as an item of its own, because it already sits in the price you confirm. To you it works like a fee, but it turns up in no fee overview.
In practice that means two things. First, any comparison that merely sets the stated percentages side by side is calculated too favourably, and that holds for every provider. Second, it pays to look at the difference between the convenient instant purchase and an order you place yourself in the trading area: the trading fee is stated higher there at 1.5 percent, but the spread falls away because you set the price yourself. With larger amounts the relationship therefore often reverses. There is no generally valid threshold, because the spread fluctuates with market conditions.
The network fee for the ETH transfer runs to fractions of a cent
Many newcomers put off the transfer to their own wallet because they fear expensive network fees. That worry comes from the years when a simple Ethereum transfer could cost double-digit euro amounts. Nothing of that is left at present.
At the start of October, the base fee in the Ethereum network sits at about 0.12 gwei. Gwei is the usual unit of account for network fees, a billionth of an ETH. A simple transfer of ether consumes 21,000 gas units. That produces around 0.0000025 ETH, less than a cent at today's price.
The catch: what the exchange charges you for a withdrawal is not that network fee but a rate of its own, which it sets itself and which appears on the confirmation page. It can lie considerably above. The network fee is therefore good as a lower bound, not as an expectation. What remains is the all-clear: the network is no longer the reason to leave coins on the exchange.
ERC-20 or layer 2: the wrong network costs you your ETH
Here lies the difference from Bitcoin, and it is the most expensive mistake in this whole process. On a withdrawal the exchange asks which network it should send over. Alongside the Ethereum mainnet, several layer-2 networks are on offer, that is, side chains which bundle transactions and settle them more cheaply, such as Arbitrum or Base.
The address looks the same in all of these networks. Every one of these addresses begins with 0x and has 42 characters. Precisely there lies the trap: if you choose a different network when sending from the one your wallet expects, the transfer is carried out all the same. The money lands at the same address on another chain. In the favourable case you get it back by setting up that network in your wallet. In the unfavourable case, for instance with an address belonging to an exchange that does not support the chain in question, the amount is lost.
The rule against that is plain: the network chosen when sending has to be the same one set at the top of your wallet. If in doubt, send a small amount first and wait for it to be credited before the rest follows. By the calculation above, the cost of that test lies in the range of fractions of a cent, the benefit in the range of the entire purchase amount. Which devices and programs are suitable for custody is set out in the hardware wallet comparison.
PayPal buyer protection does not cover financial products and investments
A widespread misunderstanding holds that the detour via PayPal brings additional protection with it. The opposite is true. The terms of PayPal buyer protection in the version of April 15, 2025 contain a list of transactions the protection does not cover. Alongside payments for gold and cash equivalents such as gift cards, that list expressly includes financial products and investments.
Buying ether through an exchange falls into that group. If the price falls, if the exchange goes down or if you mistype the address, there is no reimbursement on that basis. Buyer protection is intended for purchases of goods, not for capital investments.
Conversely, the chargeback route very much does apply, and that is exactly why the 72-hour lock exists. Anyone disputing a legitimate deposit in order to end up with both coins and money risks having the exchange account blocked, and civil consequences. The lock is the exchange's answer to that risk, and it hits all customers equally.
Holding period and threshold: what Section 23 EStG prescribes for your ETH
For tax purposes, buying ether counts among private disposals. Section 23 of the Income Tax Act regulates them in subsection 1 number 2: a disposal is taxable in the case of assets where not more than one year lies between acquisition and sale. If you sell your ETH later than one year after buying, the gain is free of income tax, whatever its size.
Within the year a threshold applies. Under subsection 3 sentence 5, gains remain tax-free where the total gain from all private disposals in the calendar year comes to less than 1,000 euros. Threshold here means: if the amount is exceeded, the entire gain is taxable, not only the excess part. At a gain of 999 euros you pay nothing; at 1,001 euros you pay tax on the full 1,001 euros at your personal rate.
For the PayPal question only one detail matters, and it is regularly misunderstood: the one-year period begins with the acquisition, meaning on the day of purchase, not at the end of the 72-hour lock and not on the day of the transfer to your own wallet. The lock shifts the start of the period by not a single day. Anyone buying several times needs the individual date for each part-purchase; tools for that are in the comparison of tax and portfolio programs.
Staking does not extend the holding period to ten years
With Ethereum a question arises that does not come up with Bitcoin: what happens to the holding period if you stake your ETH? The reason for the worry sits in the same section. Under subsection 1 number 2 sentence 4, the period extends to ten years where income is earned in at least one calendar year from the use of an asset as a source of income.
Staking means depositing your ETH in the network to help secure transactions, and receiving ongoing returns for it. That sounds like a source of income. The tax administration does not, however, apply the ten-year period to crypto-assets. The Federal Ministry of Finance confirmed this in its circular of March 6, 2025 on the income tax treatment of certain crypto-assets, file reference IV C 1 – S 2256/00042/064/043. The holding period accordingly stays at one year even after staking or lending.
The treatment of the returns themselves is unaffected by that: ongoing staking rewards are taxable in the year they are received, separately from the later gain on sale. Anyone dealing with such returns for the first time should settle the classification with a tax adviser; this article is no substitute for advice in the individual case.
MiCA authorisation: how to recognise an authorised provider
Since the European crypto regulation MiCA, trading venues need authorisation as crypto-asset service providers in order to serve retail clients in the EU. For you that is not a sticker on the wall but an entry in a register, and it can be looked up in two minutes.
Two directories help further: BaFin's company database for providers with German authorisation, and the register of the European securities supervisor ESMA for authorised service providers from all member states. A route via another EU country is normal in this and no warning sign: an authorisation from Ireland or Malta is valid across Europe.
What matters is matching the exact company name. Exchanges frequently run their European business through a company of their own whose name differs from the brand. If you find the operator in neither of the two registers, do not pay money in there, however convenient the PayPal button looks. Vetted trading venues are in our comparison of crypto exchanges.
Buying Ethereum with PayPal: Your next three steps
- Establish whether you really need the convenience. On the terms examined here, a SEPA transfer is free, has no lock-up period and is in many cases credited instantly as well. PayPal pays off above all where your money is sitting there anyway. An overview of the trading venues is in the exchange comparison.
- Run the deposit process through to the final page before you confirm. That is the only place the PayPal processing fee appears. Add it to the trading fee of 1 percent and compare the result with the 100 euros that arrive in full via a transfer.
- Allow for the 72 hours before you take custody of the ETH yourself. Once the lock has elapsed, transfer a small amount first and make sure the network you choose matches your wallet. Suitable devices are shown by the hardware wallet comparison.
The sources for this article: the fees, minimum amounts and lock-up periods come from Kraken's public overview of deposit options.
(As of October 1, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
In brief: in Germany you will usually set up a crypto company as a GmbH or a UG. What decides the matter, though, is not the legal form but the business model: anyone who holds, exchanges or arranges crypto-assets for others has needed authorisation from BaFin since MiCA, plus minimum capital of 50,000 to 150,000 euros depending on the service. Anyone offering software, analytics or content generally gets by without a licence. This guide sets out the steps in the right order.
Step 1: establish whether your business model requires authorisation
Before you call a notary, one question belongs settled: are you providing crypto-asset services within the meaning of the EU regulation MiCA? Those include, among others, the custody of crypto-assets for clients, operating a trading platform, exchanging against the euro or other crypto-assets, the execution and reception of orders, and advice and portfolio management.
If that is the case, you need authorisation as a crypto-asset service provider, CASP for short. In Germany it is granted by BaFin on the basis of MiCA and the German Crypto Markets Supervision Act. The transition periods for existing providers have now expired in all EU member states. Whoever is authorised appears in ESMA's public register; what that looks like in practice is shown by the list of authorised providers, and even banks such as the Volksbanken are having their crypto custody approved.
No authorisation is generally needed by anyone who merely supplies software, such as a non-custodial wallet, an analytics tool, development services or a crypto news outlet. The line is fine in the individual case. When in doubt, an enquiry to BaFin or to a specialist law firm pays off before the first client money flows.
Step 2: choose the right legal form
For crypto start-ups, two legal forms almost always come into question, because they limit liability to the company's assets:
| GmbH | UG (limited liability) | |
|---|---|---|
| Minimum capital | 25,000 euros, of which at least 12,500 euros paid in at formation | from 1 euro, a quarter of profits must be retained |
| Standing with banks and partners | high | lower, often follow-up questions |
| Suitable for | business models requiring authorisation, investor rounds | software, media, a first test phase |
| Formation | by notarial deed, video conference possible | by notarial deed, video conference possible |
Anyone who needs BaFin authorisation starts in practice with a GmbH, because the minimum capital required by the supervisor lies above that of a UG in any case. How the formation runs step by step, from articles of association to the commercial register, is explained in the Gründerfreunde guide to forming a GmbH. For a smaller start there is also a guide there on how to form a UG. Anyone needing a ready-made company quickly can alternatively buy a shelf company.
Step 3: plan capital and the supervisor's requirements
MiCA tiers the minimum capital by type of service:
- 50,000 euros for services such as the reception and transmission of orders, advice, portfolio management or the placing of crypto-assets,
- 125,000 euros where crypto-assets are additionally held for clients or exchanged against money or other crypto-assets,
- 150,000 euros for operating a trading platform.
On top of that come requirements that often cost more than the capital itself: management that is both reliable and professionally qualified, a seat with genuine management in the EU, anti-money-laundering rules, a complaints procedure, IT security under the EU regulation DORA, and the segregated custody of client funds. Allow several months for the authorisation application.
Step 4: issue a token only with a white paper
Many crypto start-ups want a token of their own sooner or later. MiCA applies to that as well: anyone offering crypto-assets to the public has to draw up a white paper and submit it to the supervisor. If the token is a security, securities law applies instead of MiCA. The difference between an ICO and a security token, and what is permitted today, is explained in our guide What is an ICO? What is a security token?
Step 5: bank account, bookkeeping and taxes
Getting a business account is often harder for crypto firms than the formation itself. Banks examine the origin of funds and the business model closely. A clean business plan helps, as does a concept for anti-money-laundering and, where necessary, evidence of BaFin authorisation or of a pending application.
On tax, the position is this: if a GmbH holds crypto-assets, there is no one-year speculation period as there is for private individuals. Gains on a sale are subject to corporation tax and trade tax, together around 30 percent depending on the municipality. Settle the accounting treatment of crypto-assets early with a tax firm that knows the field.
Step 6: use financing and public support
For the first phase the same routes come into question as for any other start-up: equity, business angels, venture capital and public funding. An overview of the funders and what they look for is given in the Gründerfreunde guide to start-up financing. Anyone founding a business while unemployed can apply for a start-up grant. And anyone wanting to test a new business model under supervision should know the options offered by living labs and regulatory sandboxes.
Checklist: setting up a crypto company in Germany
- Test the business model against the MiCA services; when in doubt, ask BaFin or a specialist lawyer.
- Choose the legal form: a GmbH where authorisation is required, otherwise a GmbH or a UG.
- Budget minimum capital and staff for management, anti-money-laundering and IT security.
- Formation before a notary, entry in the commercial register, business registration.
- File the authorisation application with BaFin before client business starts.
- Find a business account and a tax firm with crypto experience.
- Issue a token only with a MiCA white paper, or as a security with a prospectus.
Frequently asked questions
Do I always need a BaFin licence for a crypto start-up?
No. What requires authorisation are crypto-asset services for clients, such as custody, exchange, a trading platform or the reception of orders. Pure software, analytics tools or media offerings generally need no authorisation.
How much capital do I need for a MiCA licence?
Depending on the service, minimum capital of 50,000, 125,000 or 150,000 euros, plus funds for staff, compliance and IT security.
Is a UG enough for a crypto start-up?
For models outside the authorisation requirement, yes. Anyone who needs BaFin authorisation is better off starting with a GmbH, because the capital required is higher than a UG's in any case.
Note: Gründerfreunde, like cryptoticker, belongs to the group of companies owned by Dennis Weidner. This guide is no substitute for legal or tax advice.
The most important inflation figure in the United States came in weaker than expected on September 30. The price index for personal consumption expenditures excluding food and energy, known internationally as core PCE, rose 3.0 percent in August against the same month a year earlier. The market had expected 3.3 percent. For you as an investor in Germany, one thing above all follows from that: the probability that the Federal Reserve turns the interest rate screw once more on October 28 has fallen within a few days from around 70 percent to below half. Higher rates are the counterweight to risk assets, and Bitcoin is one of them.
Core PCE in August: what the BEA release says
The US Commerce Department publishes the figure through the Bureau of Economic Analysis, or BEA. The release carrying the reference BEA 26-43 appeared on Wednesday, September 30, 2026 at 8:30 a.m. local time on the US East Coast, which is 2:30 p.m. German time. It can be read in the BEA's Personal Income and Outlays, August 2026 press release.
The figures in detail, all from that release: the overall PCE price index rose 0.3 percent in August against the previous month and 3.4 percent against the previous year. Excluding food and energy it was 0.2 percent month on month and 3.0 percent year on year. Personal income increased by $66.6 billion, which corresponds to 0.2 percent in the month. Real, meaning inflation-adjusted, consumer spending rose by $92.8 billion, or 0.6 percent.
What core PCE actually measures
Core PCE is the inflation gauge against which the Federal Reserve sets its two percent target. It measures how the prices of the goods and services US households actually buy are changing, and it leaves out food and energy because those prices swing sharply and obscure the underlying trend. That is precisely why rate markets react more strongly to this figure than to the better-known consumer price index.
One detail of this publication matters for context: alongside the August data, the BEA presented the annual revision of the national accounts. Retroactive corrections to earlier months are possible as a result. Anyone comparing time series should therefore take the revised values and not the figures that were in circulation before September 30.
Core and headline rates diverge: why 3.0 against 3.4 percent
At 3.4 percent, the headline rate sits above the core rate of 3.0 percent. That gap of 0.4 percentage points comes from food and energy, which are exactly the two groups stripped out of the core rate. When the headline rate is higher, price pressure comes predominantly from there and less from the breadth of the economy.
For the central bank that is a more comfortable constellation than the reverse case. Energy prices respond to supply, transport routes and political conditions, not to the policy rate. A rate rise barely touches them. Broad services pressure, on the other hand, can be slowed with rates, and that is what the core rate captures. The fact that the core rate eased unexpectedly therefore takes out of the calculation precisely the part of price pressure the Fed would answer with rates.
This is no all-clear. Three percent is still one and a half times the two percent target, and the figure refers to August, not to September. More data is due before the meeting on October 28.
CME FedWatch slips below half: the market reads October 28 differently
How the market assesses the next rate decision can be read off the futures contracts on the US overnight rate. The probability derived from them is usually quoted as CME FedWatch. At the start of the week, the expectation of a further rate rise in October stood at around 70 percent according to reports from several financial media outlets. After a speech by a senior central banker on September 29 and the weaker inflation figure on September 30, it fell below 50 percent.
Exactly how far depends on the source, and the values differ. On September 30, published readings ranged from about 35 to 47 percent for a rise. That range deliberately stands here rather than being reduced to a round number. What counts is the direction: a probable rise has become an open question.
The September 29 speech and the rate curve: what tipped expectations
The trigger came from John Williams, the president of the Federal Reserve Bank of New York. According to reports from financial media, he signalled in a speech on September 29 that he sees no hurry over a further rate step. That is notable because the same central banker had said five days earlier that a further rise by the end of the year could reasonably be expected. Within a week the tone shifted, and the inflation figure the following day supported the softer reading.
Read such statements for what they are: assessments by individual voices on the decision-making body, not decisions. The vote takes place in the Open Market Committee, and its meeting dates are fixed. For the rest of the year there are two, according to the official Federal Reserve meeting calendar: October 27 and 28, and December 8 and 9. The decision comes on the second day in each case.
Bitcoin between $82,951 and $85,518: the range of the past 24 hours
The reaction was visible, but it did not hold. Bitcoin jumped after the release and then gave the jump back. According to CoinGecko market data, the price stood at $83,692 on Thursday morning, 0.52 percent above the level 24 hours earlier. Within those 24 hours the high was $85,518 and the low $82,951. Individual reports put the immediate reaction at just under $85,900, which means the figures for the daily high range from about $85,500 to $85,900 depending on the data source.
Over the week there is a loss of 0.75 percent, and over 30 days a gain of 6.52 percent. That produces a picture a single day cannot explain: the inflation figure has loosened rate pressure, but it has not triggered a breakout. The price continues to move in the range it has been in all week.
Why a brief reaction says nothing about the week
Macro figures work in two stages. First, automated systems react within seconds to the deviation from expectations, and that spike often disappears the same day. Only afterwards does it become clear whether larger addresses actually change their positioning. That can be read off futures market data and the inflows and outflows of exchange-traded products, not off the price in a single hour.
Buying routes in Germany: MiCA exchange, ETN and what the US market does not offer you
Anyone in Germany who wants to position for looser rate policy has two common routes, and both come with rules of their own. The first is the direct purchase through a trading platform authorised in the EU under the regulation on markets in crypto-assets, known as MiCA. The authorisation is publicly verifiable, and it determines what obligations the provider has towards you. Which houses hold it can be looked up in the public register before you open an account.
The second route runs through exchange-traded products. In Germany these are as a rule ETNs or ETPs, which you trade on Xetra through your existing securities account. One distinction matters here that regularly causes misunderstandings: a US spot ETF on a cryptocurrency is normally not tradable for retail investors in Germany, because it is not subject to the European requirements on investor information and fund structure. What launches in New York therefore does not land in your portfolio automatically. What the European route looks like instead is set out in our overview of crypto ETFs and ETNs for investors in Germany.
The two routes also differ in what you own at the end. With a direct purchase you hold the coins, with everything that goes with them, from custody to your own responsibility for the keys. With an ETN you hold a debt security issued by the provider that tracks the price.
The holding period under Section 23 EStG: why the rate path reaches into your tax planning
A particularity applies to the direct purchase in Germany that does not exist in the same form with an ETN. Gains from the sale of cryptocurrencies fall under private disposals under Section 23 of the Income Tax Act. If you sell within a year of buying, the gain is taxable. After a holding period of more than a year, it is not. There is also a threshold for small gains, and you should check its current level with the tax office or in a tax guide before deciding, because the amount has been adjusted in recent years.
The link to the rate path is more immediate than it first sounds. If you hold a position you would actually sell because of the rate outlook, your purchase date determines how expensive that sale becomes. If the purchase was eleven months ago, selling now may cost considerably more than selling in four weeks. That is not a recommendation to hold anything, but a figure that belongs in the decision. Anyone with many purchases spread across different months will hardly keep them apart cleanly without help; tools for that are in our comparison of crypto tax tools and portfolio trackers.
Leverage and liquidation: how thin the buffer at $83,692 really is
On days with macro data in particular, a manageable price swing turns into a total loss once leverage is in play. Work it through with this day's figures. From the level at $83,692 to the 24-hour low at $82,951 is 0.89 percent. At tenfold leverage that move corresponds to a loss of almost 9 percent of your stake, at twentyfold leverage about 18 percent.
Take the whole range of the day, from the high at $85,518 to the low at $82,951, and it is 3.0 percent. Anyone who entered at the high with twentyfold leverage had lost around 60 percent of their margin at the low. These are not exceptional numbers but a quiet trading day with a single macro figure. Ahead of the meeting on October 28, larger swings are more likely than today.
What actually happens in a liquidation
Once the price reaches the liquidation level, the exchange closes the position automatically and the margin is gone. The common offerings do not create an obligation to pay in more, but the loss is not recoverable either if the price turns afterwards. With a direct purchase without leverage this threshold does not exist; there a paper loss stays a paper loss as long as you do not sell.
Levels above and below: $85,518 in the way, $82,951 as the floor
Two orientation points emerge from the daily data that manage without a forecast. Above lies the daily high at $85,518. That is where the price failed after the inflation figure, and as long as it stays below, the impulse from that figure has been absorbed. Below lies the daily low at $82,951. If the price drops under it, the positive reaction to the weaker inflation has been given back in full.
These two values are measurement points from the past 24 hours, not price targets. Anyone working with levels updates them daily, because yesterday's range carries nothing today. For that you need no forecast, only a data source and a fixed rhythm.
October 28 and December 9: the two dates that shape the quarter
Two dates remain for this year, and they are in the Federal Reserve's official calendar. The Open Market Committee meets on October 27 and 28, with the decision on October 28. The last meeting of the year follows on December 8 and 9, with the decision on December 9. The December meeting additionally includes the summary of economic projections, in which members disclose their own rate expectations.
Further data releases fall between today and October 28, among them the next inflation figure. Today's expectation is therefore not the expectation of late October. All that holds today is this: the market no longer treats a rise as the more likely case.
Core inflation and Bitcoin: what to take away
The August figure has loosened rate pressure without removing it. Three things follow from it concretely:
- Settle the buying route before you buy. Decide whether you want to buy directly or go through an exchange-traded product, and for the direct variant establish the provider's MiCA authorisation. The overview is in our comparison of regulated crypto exchanges.
- Settle custody before the sum grows. If you hold coins directly, the decision about the keys belongs with it. Which devices come into question is set out in the hardware wallet comparison.
- Carry the range forward daily. $85,518 above and $82,951 below apply to October 1. Anyone working with levels like these needs a reliable data source; suitable tools are in our overview of analytics platforms.
(As of October 1, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Bitway traded at around $1.32 on Thursday morning, roughly seven and a half percent below the all-time high of $1.43 the token reached on Monday. Over the week, BTW is up between 27 and 28 percent depending on the calculation method, while Bitcoin and Ethereum were practically unchanged over the same period. That is the core of this week: a token ranked 34th moves sharply, and the broad market does not move at all.
For you as an investor in Germany, less hangs on how far the price may still run than on what you are actually dealing with. Three things about Bitway are documented, and they matter more for a decision than any price forecast: only a good quarter of the total supply is in circulation at all, daily turnover is strikingly small against market capitalisation, and none of the exchanges that list BTW holds authorisation under MiCA, the European crypto regulation. This article puts the week in context and goes through the points you can check for yourself.
Bitway (BTW) week in review: price, weekly high and weekly low
According to CoinGecko, BTW stood at $1.32 as of Thursday night, October 1. Market capitalisation is around $3.6 billion, which places Bitway 34th among all cryptocurrencies. The path through the week was unusually wide.
The weekly low was $0.84 on Saturday, September 26. Two days later, on Monday, BTW marked its all-time high at $1.43. For the hourly series of the same week, CoinGecko shows the highest level on Wednesday at $1.41; the two figures come from differently grained series from the same provider, which is why the range stands here rather than a smoothed average. From $0.84 to $1.43 is a good 70 percent in two days, and the pullback to $1.32 has given back about a sixth of that.
Over 30 days, BTW is up around 225 percent. That figure is the real background to the week: the jump to the all-time high came at the end of a move that had already begun in September.
What the week looks like against the broader market
Bitcoin stood at around $83,500 on Thursday morning, down a good one percent over seven days, and Ethereum at about $2,685, also slightly weaker over the week. Anyone holding BTW against that backdrop is dealing with a single move whose cause has to lie in the project itself or in demand for the token. That matters for context, because a move without the market behind it turns faster in both directions.
What is behind the jump from $0.84 to $1.43
Bitway is a project in the field of decentralised finance. CoinGecko lists the token under the tags decentralised finance, yield farming, BNB Chain ecosystem and governance. According to the project's own account on the Bitway project site, BTW is the token that carries network operations, staking and governance votes, and the one tied to the incentives for the provider's yield, payment and financing products.
The immediate driver of the week is documented and carries an expiry date: an incentive campaign has been running through the DeFi section of Binance Wallet since August 19 and closes at the end of this week. Anyone committing capital to the corresponding product takes part in the distribution of rewards in BTW. A campaign that locks up capital and pays out tokens at the same time creates demand for as long as it runs, and that particular window closes on Friday.
A second point belongs to the backstory. According to a review by the data provider Bitquery of 51 larger airdrops on EVM networks this year, three out of four of those tokens later traded below their first-week price. BTW was one of the exceptions in that study and traded clearly above it. That explains part of the attention, but it says nothing about the direction from here: it is a statement about this token's past relative to others, not about its value.
Booster Earn Season 5: the campaign ends on October 2 at 23:59 UTC
The only documented date in the coming days is the end of the current campaign. Under the announcement of August 19, 2026, 00:00 UTC, the programme's fifth round runs until October 2, 2026, 23:59 UTC. For you in Germany that means it closes at 1:59 a.m. on Saturday night. Rewards worth $200,000 in BTW are paid out as a boosted interest rate, and the condition for taking part is a deposit of at least $100 into the corresponding vault product through the DeFi section of Binance Wallet. The campaign dates can be viewed in the events calendar at TradingView.
What counts for the coming week is the expiry, not the participation. An incentive campaign holds capital in place. Once it runs out, the capital that was locked can be withdrawn, and experience suggests part of the rewards in BTW gets sold. Whether and how strongly that feeds through to the price cannot be predicted, and nobody should be quoting you a figure here. The date itself, though, is fixed, and it falls in the same week as the all-time high.
Circulating supply and total supply: 2.71 of 10 billion BTW are free
Here lies the point a price chart does not show. Of the 10 billion BTW set as total and maximum supply, around 2.71 billion are in circulation. That is about 27 percent. The remaining almost three quarters exist, but are not yet on the market.
Circulating supply is the number of tokens that are genuinely free to trade. The market capitalisation of $3.6 billion counts that circulating supply alone. Apply the full supply of 10 billion tokens at the current price instead, and the fully diluted valuation comes to around $13 billion. Both are correct figures for different questions, and with Bitway the gap between them is wide.
In practice that means: every token that enters circulation in future out of reserves, rewards or unlocks meets a market that has to absorb the additional supply. For projects with a circulating share of around 27 percent, the schedule of those unlocks is therefore one of the most important pieces of information there is. Anyone who holds BTW or wants to buy should read that schedule at the provider itself rather than infer it from the price chart.
Why the supply figures differ from one source to the next
Figures for Bitway's circulating supply diverge across data providers, as an analysis by Phemex among others has pointed out. Such divergences arise when providers count locked holdings, reserves or undistributed rewards differently. For you that means: compare the market capitalisation at two providers before you take it as a yardstick. If the circulating supply differs, so does every valuation built on it.
Trading volume and liquidity: $50 million against $3.6 billion in market capitalisation
Turnover in BTW over 24 hours came to around $50 million. Against a market capitalisation of $3.6 billion that is about 1.4 percent. For Bitcoin and Ethereum this ratio is markedly higher on ordinary days.
Liquidity describes how much you can buy or sell without moving the price yourself. A small ratio of turnover to market capitalisation means in practice: larger sell orders meet a thin order book, and the price achieved can sit noticeably below the one you see on the ticker. That also explains the spread of this week. A market that rises 70 percent in two days and then gives part of it back is typically not a deep market.
One consequence for your own planning follows from that, and it has nothing to do with a forecast: anyone who plans a fixed exit price in a thin market should allow for that price being unavailable when it matters.
BTW on exchanges: Bitget, Gate and MEXC, no MiCA licence in the EU
CoinGecko lists 13 trading venues for BTW. On the centralised side these include Bitget, Gate, MEXC, HTX, Poloniex, Toobit, DigiFinex, KCEX, BitKan and Ourbit, each paired against the dollar stablecoin USDT. Added to that are decentralised venues on BNB Chain, among them Uniswap in two versions and PancakeSwap.
None of these venues belongs to the providers authorised as crypto service providers under MiCA and allowed to offer their services in Germany on a regular basis. cryptoticker.io compiled this review itself on October 1, 2026; the basis is the list of 13 trading venues CoinGecko carries for BTW, matched against the providers authorised in Germany. Names such as Bitpanda, Coinbase, Kraken or Bitvavo, which work in Germany with authorisation, do not appear on that list.
That is not a statement about the standing of the exchanges named, but one about your legal framework. Since July 1, 2026 the requirements of the MiCA regulation have applied in full across the EU, and the transition periods have expired. Anyone trading at a provider without EU authorisation does not have the avenues open to them that a supervised provider offers in a dispute, and German deposit protection does not cover crypto assets in any case. Which exchanges hold authorisation is shown in our overview of regulated crypto exchanges.
Leverage and liquidation
Several of the exchanges named offer derivatives on BTW. In a market that rises 70 percent within two days and then shows a range of more than a third in a single day, the arithmetic is simple: tenfold leverage is wiped out in full by a ten percent move the other way. Liquidation is the forced closing of your position as soon as the margin no longer suffices. In a market of this spread that hits leveraged positions regularly.
Custody: two contract addresses on BNB Chain and Ethereum
BTW exists on two networks. On BNB Chain the contract address is 0x444045b0ee1ee319a660a5e3d604ca0ffa35acaa, on Ethereum 0x3a63de3572c69a1307ff08394f3ee7702c16d25d. Anyone moving the token into a wallet of their own has to pick the right network. A transfer to the matching address on the wrong network is as a rule not recoverable.
With tokens on several networks and similarly named imitations, the extra look is worth it: compare the contract address a trading platform or a search result shows you with the address on the project site itself before you buy or transfer. For custody of larger holdings, the same holds as for any token on a smart contract platform, namely that the keys sit better on a device without a network connection than in an exchange account.
Levels above and below: $1.43, $1.04 and the $0.84 area
The levels that follow are observation points from the week's trading, not price targets and not a recommendation. Above stands the all-time high at $1.43, around seven and a half percent over the current price; beneath it lies Wednesday's hourly high at $1.41. On the downside, the price from seven days ago at about $1.04 marks the starting point of the weekly move, and under that sits Saturday's weekly low at $0.84.
The round level at one dollar almost coincides with the start of the week and is therefore the line at which it will show whether the weekly gain holds. Nothing more can be read out of the figures, and anything further would be guesswork about quantities that has no place here.
Tax in Germany: a one-year holding period and the 1,000-euro threshold
The same rules apply to BTW as to other crypto assets held privately. If you sell at a profit within a year of buying, that profit is taxable and charged at your personal income tax rate. After a holding period of more than a year, the gain on the sale stays tax-free. The threshold is 1,000 euros a year, and it is not an allowance: if your gains from private sales exceed that limit, the entire amount is taxable, not just the part above it.
Rewards from an incentive campaign or from staking count separately and are as a rule treated as other income. They are assessed at the time they arrive, at the price prevailing then, with a threshold of their own at 256 euros a year. Anyone taking part in the current campaign should record the price on the day of the credit, because that value later forms the basis for taxation.
Since January 1, 2026 the Crypto Asset Tax Transparency Act, the German implementation of the EU directive DAC8, has applied on top of that. Under it, providers report user and transaction data to the tax authorities; for the current year 2026 those reports have to be filed by July 31, 2027. That applies most clearly to providers based or registered in the EU, and it changes nothing about your own duty to declare gains in your tax return. When trading across several platforms and networks, clean record-keeping from the start helps more than any reconstruction after the fact; an overview of the tools for it is in our comparison of crypto tax tools.
Bitway: Your next three steps
- Settle the access route. Establish whether you can get BTW at a provider with EU authorisation at all, and decide deliberately whether a trading venue without that authorisation is worth the commitment to you. Which exchanges work in Germany on a regular basis is set out in our overview of crypto exchanges.
- Read up on the supply schedule. Look at the project itself for when the remaining almost three quarters of the total supply enter circulation, and only then set a position size. For custody outside an exchange account, the hardware wallet comparison helps.
- Record the date and your tax documents. Note the end of the campaign on Saturday night as well as the purchase date, price and network of every position, so that the holding period and the threshold can be evidenced later. You will find tools for that in the tax tool comparison.
(As of October 1, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
The information provided in this article is for informational purposes only and does not constitute financial advice. Investing in cryptocurrencies carries a high level of risk.
A stock market game is a contest played with virtual money: everyone starts with the same virtual capital, trades at real prices, and in the end whoever sits at the top of the leaderboard wins. The good news first: all six stock market games in this comparison are free. The more important news comes further down: a leaderboard does not necessarily reward good trading, and often rewards the biggest risk instead. Knowing that, you learn more from a stock market game than just how to place an order. Here are the stock market games of 2026 with their period, target group, starting capital and prizes, plus the answer to where crypto is allowed.
Free stock market games: the key points in brief
- All six stock market games in this comparison are free, as of September 28, 2026. Three of them allow cryptocurrencies.
- Planspiel Börse, run by the German savings banks, starts on October 1, 2026 and runs until January 25, 2027, for school and university students.
- Trader 2026 from Société Générale runs from September 7 to October 30, 2026, with two portfolios of €100,000 in virtual money each.
- Trading Masters begins its first playing round on November 9, with €25,000 per portfolio and prizes worth more than €50,000.
- With crypto: Trading Masters and the training portfolio in Planspiel Börse via BSDEX, plus the crypto stock market game from CryptoTicker with 50 coins.
- No stock market game is played with real money. The prizes, by contrast, are real; at Trader 2026 they go up to a car.
The stock market games of 2026 at a glance
| Stock market game | Who it is for | Period | Starting capital | Crypto | Prizes |
|---|---|---|---|---|---|
| Planspiel Börse (savings banks) | School and university students | October 1, 2026 to January 25, 2027 | €50,000 | in the training portfolio | depends on the savings bank |
| Trader 2026 (Société Générale) | Adults aged 18 and over | September 7 to October 30, 2026 | 2 × €100,000 | no | a car as the main prize, weekly prizes |
| Trading Masters (excellents, UBS) | Adults aged 18 and over in Germany and Austria | Rounds from November 9, 2026 and January 11, 2027 | €25,000 per portfolio | yes, via BSDEX | more than €50,000 in total |
| VR-Börsenspiel (cooperative banks) | Schools and apprentices | School game February to May 2026, apprentice game by region until October 23, 2026 | €50,000 (schools) | no | depends on the bank |
| Tradity (WHU) | School students | annual season | 100,000 Tradity coins | no | prize money |
| Crypto stock market game from CryptoTicker | Adults aged 18 and over | Pre-season until the end of 2026, then seasons | €10,000 | yes, 50 coins | planned from January 2027 |
All figures as of September 28, 2026, according to the organizers. Dates and prizes change from round to round.
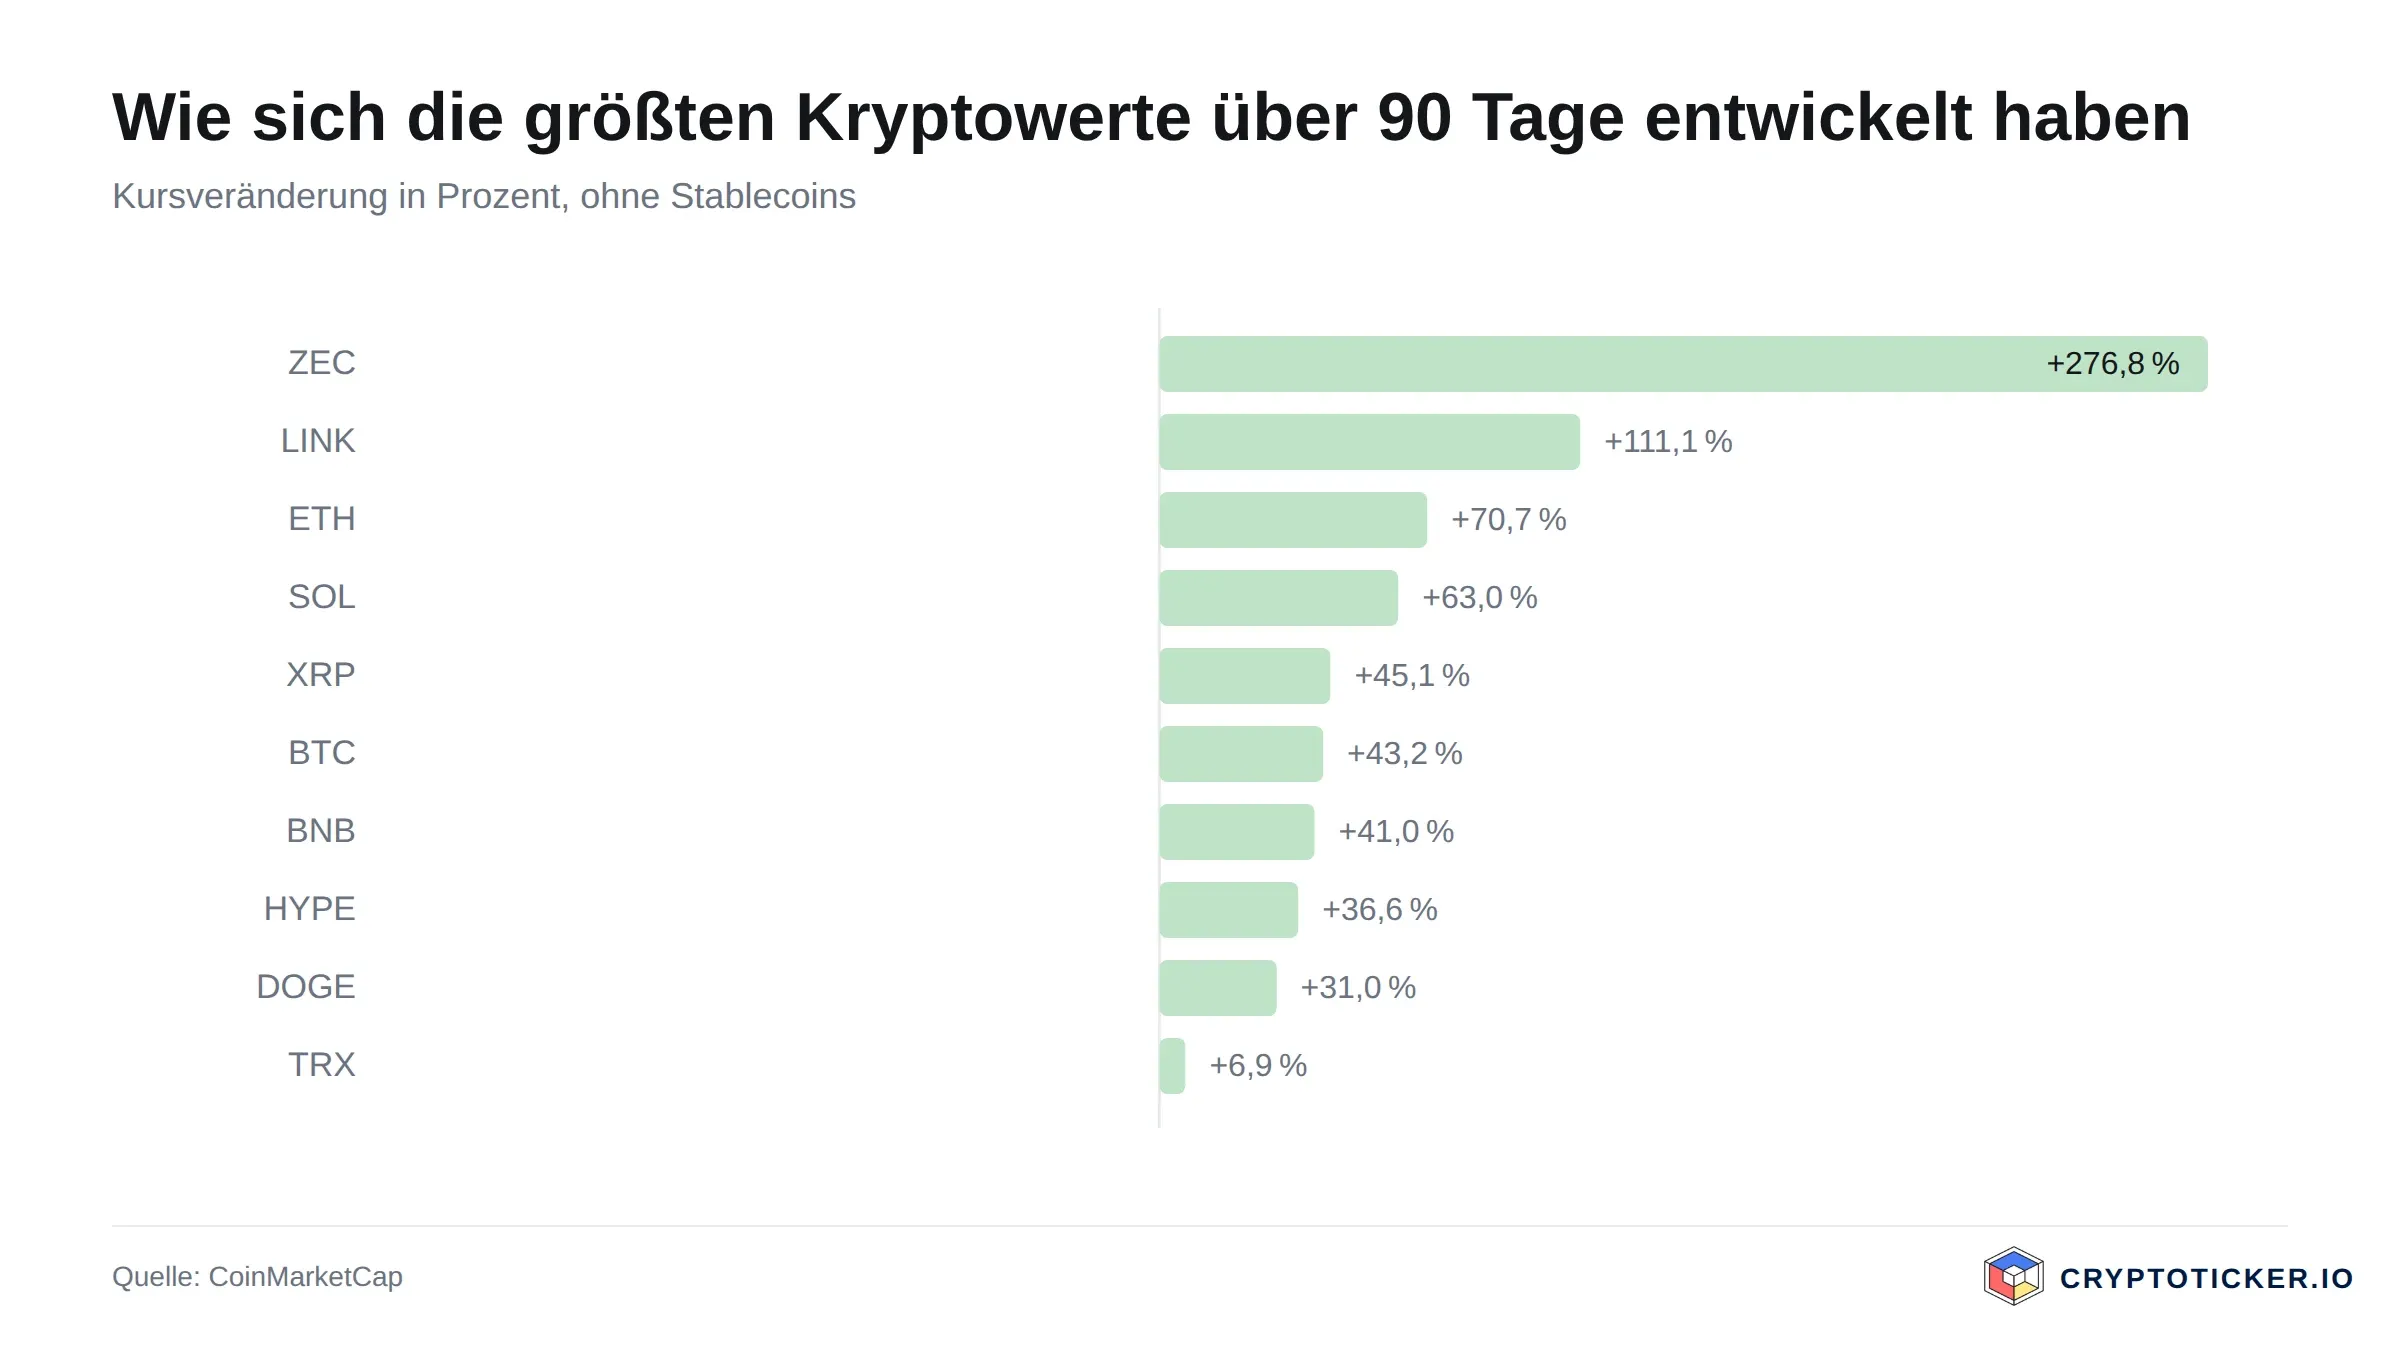
The six stock market games in detail
Planspiel Börse from the German savings banks
The best-known stock market game in Germany is aimed at school and university students. The 2026 round starts on October 1, registration has been open since September 14 and must be completed by November 11; play ends on January 25, 2027. You can take part via the app or in a browser, which requires a registration code from the savings bank or the teacher. The competition portfolio allows trading in shares from well-known indices, funds, ETFs and fixed-income securities. The training portfolio additionally offers cryptocurrencies via the BSDEX exchange, plus certificates. Alongside the portfolio ranking there is a sustainability score.
Trader 2026 from Société Générale
Trader is aimed at adults aged 18 and over and runs for eight weeks in 2026, from September 7 to October 30. Every participant receives two portfolios with €100,000 in virtual money each. Tradable instruments are shares, certificates and warrants listed on the Stuttgart Stock Exchange or issued by Société Générale. The rules put a brake on gambling: a maximum of 20 purchases a day, no single position above 20 percent of the portfolio, leveraged products capped at 20 percent of portfolio value, and a minimum holding time of five minutes. Once a week, a portfolio can be reset. The main prize is a Range Rover Evoque, and there are weekly prizes on top.
Trading Masters
Trading Masters is organized by excellents GmbH, with UBS as the main sponsor. Adults aged 18 and over who are resident in Germany or Austria can take part. Play runs with one equity portfolio and one leverage portfolio of €25,000 each. Tradable instruments are shares via the Stuttgart Stock Exchange, warrants, knock-out products and factor certificates from UBS, as well as cryptocurrencies via BSDEX. The training camp begins on October 26, the first playing round on November 9, 2026, and the second on January 11, 2027. The prizes are worth more than €50,000 in total, and the winner of a round receives €8,000. Taking part is free.
VR-Börsenspiel
The stock market game of the German cooperative banks comes as a school game and as an apprentice game. The 2026 school game ran from February 11 to May 11, with registration opening in November 2025. The apprentice game runs at different times by region: in Weser-Ems and at Genoverband from January 20 to May 20, in Baden-Württemberg and Bavaria from June 23 to October 23, 2026. Schools start with €50,000 in virtual capital; tradable instruments are shares and ETPs, and in the speculative variant leveraged products as well. Cryptocurrencies are not included.
Tradity
Tradity is an educational initiative of WHU, the Otto Beisheim School of Management, and is aimed at school students. The game is free, play starts with 100,000 Tradity coins, and real shares are traded at real-time prices. The season runs once a year; the app announces when the next one begins. There is prize money, and crypto cannot be traded.
The crypto stock market game from CryptoTicker
This one is our own, so here it is in detail and with the caveats: the stock market game in CryptoTicker's Trading Hub is a pure crypto contest. Participation is from age 18. There is €10,000 in virtual money, real prices for 50 coins and two leagues, up to 10x and up to 100x leverage. The first three trades work without an account; after that, one click creates an anonymous account, with no email address and no payment details.
A pre-season runs until the end of 2026: free and without prize money. From January 2027, ranked seasons with a prize pool are planned, and taking part in the ranking is then intended to carry a fee. What is scored is not the highest return but the CT score, the return divided by the largest drawdown. If you only want to practise, you do not need the contest at all: the trading simulator is separate from it, with no sign-up, no credit card and no cap on the number of trades.
Which stock market games are the best?
The best stock market game is the one that fits your situation:
- For school and university students: Planspiel Börse, because it is organized through schools and universities and has a training portfolio that knows crypto. An alternative with real shares and prize money is Tradity.
- For adults who want to win something: Trader 2026 and Trading Masters, both with real prizes and clear trading rules.
- For crypto: Trading Masters or the crypto stock market game from CryptoTicker; anyone under 18 practises crypto in the training portfolio of Planspiel Börse.
- Without a deadline and without a contest: a demo account or a simulator. Which variants exist is set out in our guide to the trading demo account.
Why a leaderboard invites too much risk
A stock market game with a prize for the top places has an uncomfortable property: trade cautiously and you land safely in midfield. Put everything on one card and you usually land far back, but occasionally right at the front. With a thousand participants, what often wins is therefore the biggest lucky hit and not the best strategy. That is a property of the format, and no reproach to the organizers.
Two things work against it. First, rules like those at Trader 2026, which cap single positions and leveraged products at 20 percent of the portfolio. Second, a scoring method that prices in risk, such as the CT score, which divides the return by the largest drawdown. For you as a learner: trade in the stock market game by the rules you intend to keep later with real money, even if that costs you a place in the ranking. One percent of risk per trade means, with €100,000 in virtual money, a loss of at most €1,000 until the stop.
Is the stock market game played with real money?
No. In every stock market game in this comparison you trade with virtual money; no order reaches an exchange, and you cannot lose money of your own. Only the prizes handed out by some organizers are real. If you want to start with real money after the contest, begin small and choose a provider by fees and regulation: for crypto, our exchange comparison helps, and for shares, ETFs and derivatives the comparison of the best crypto brokers.
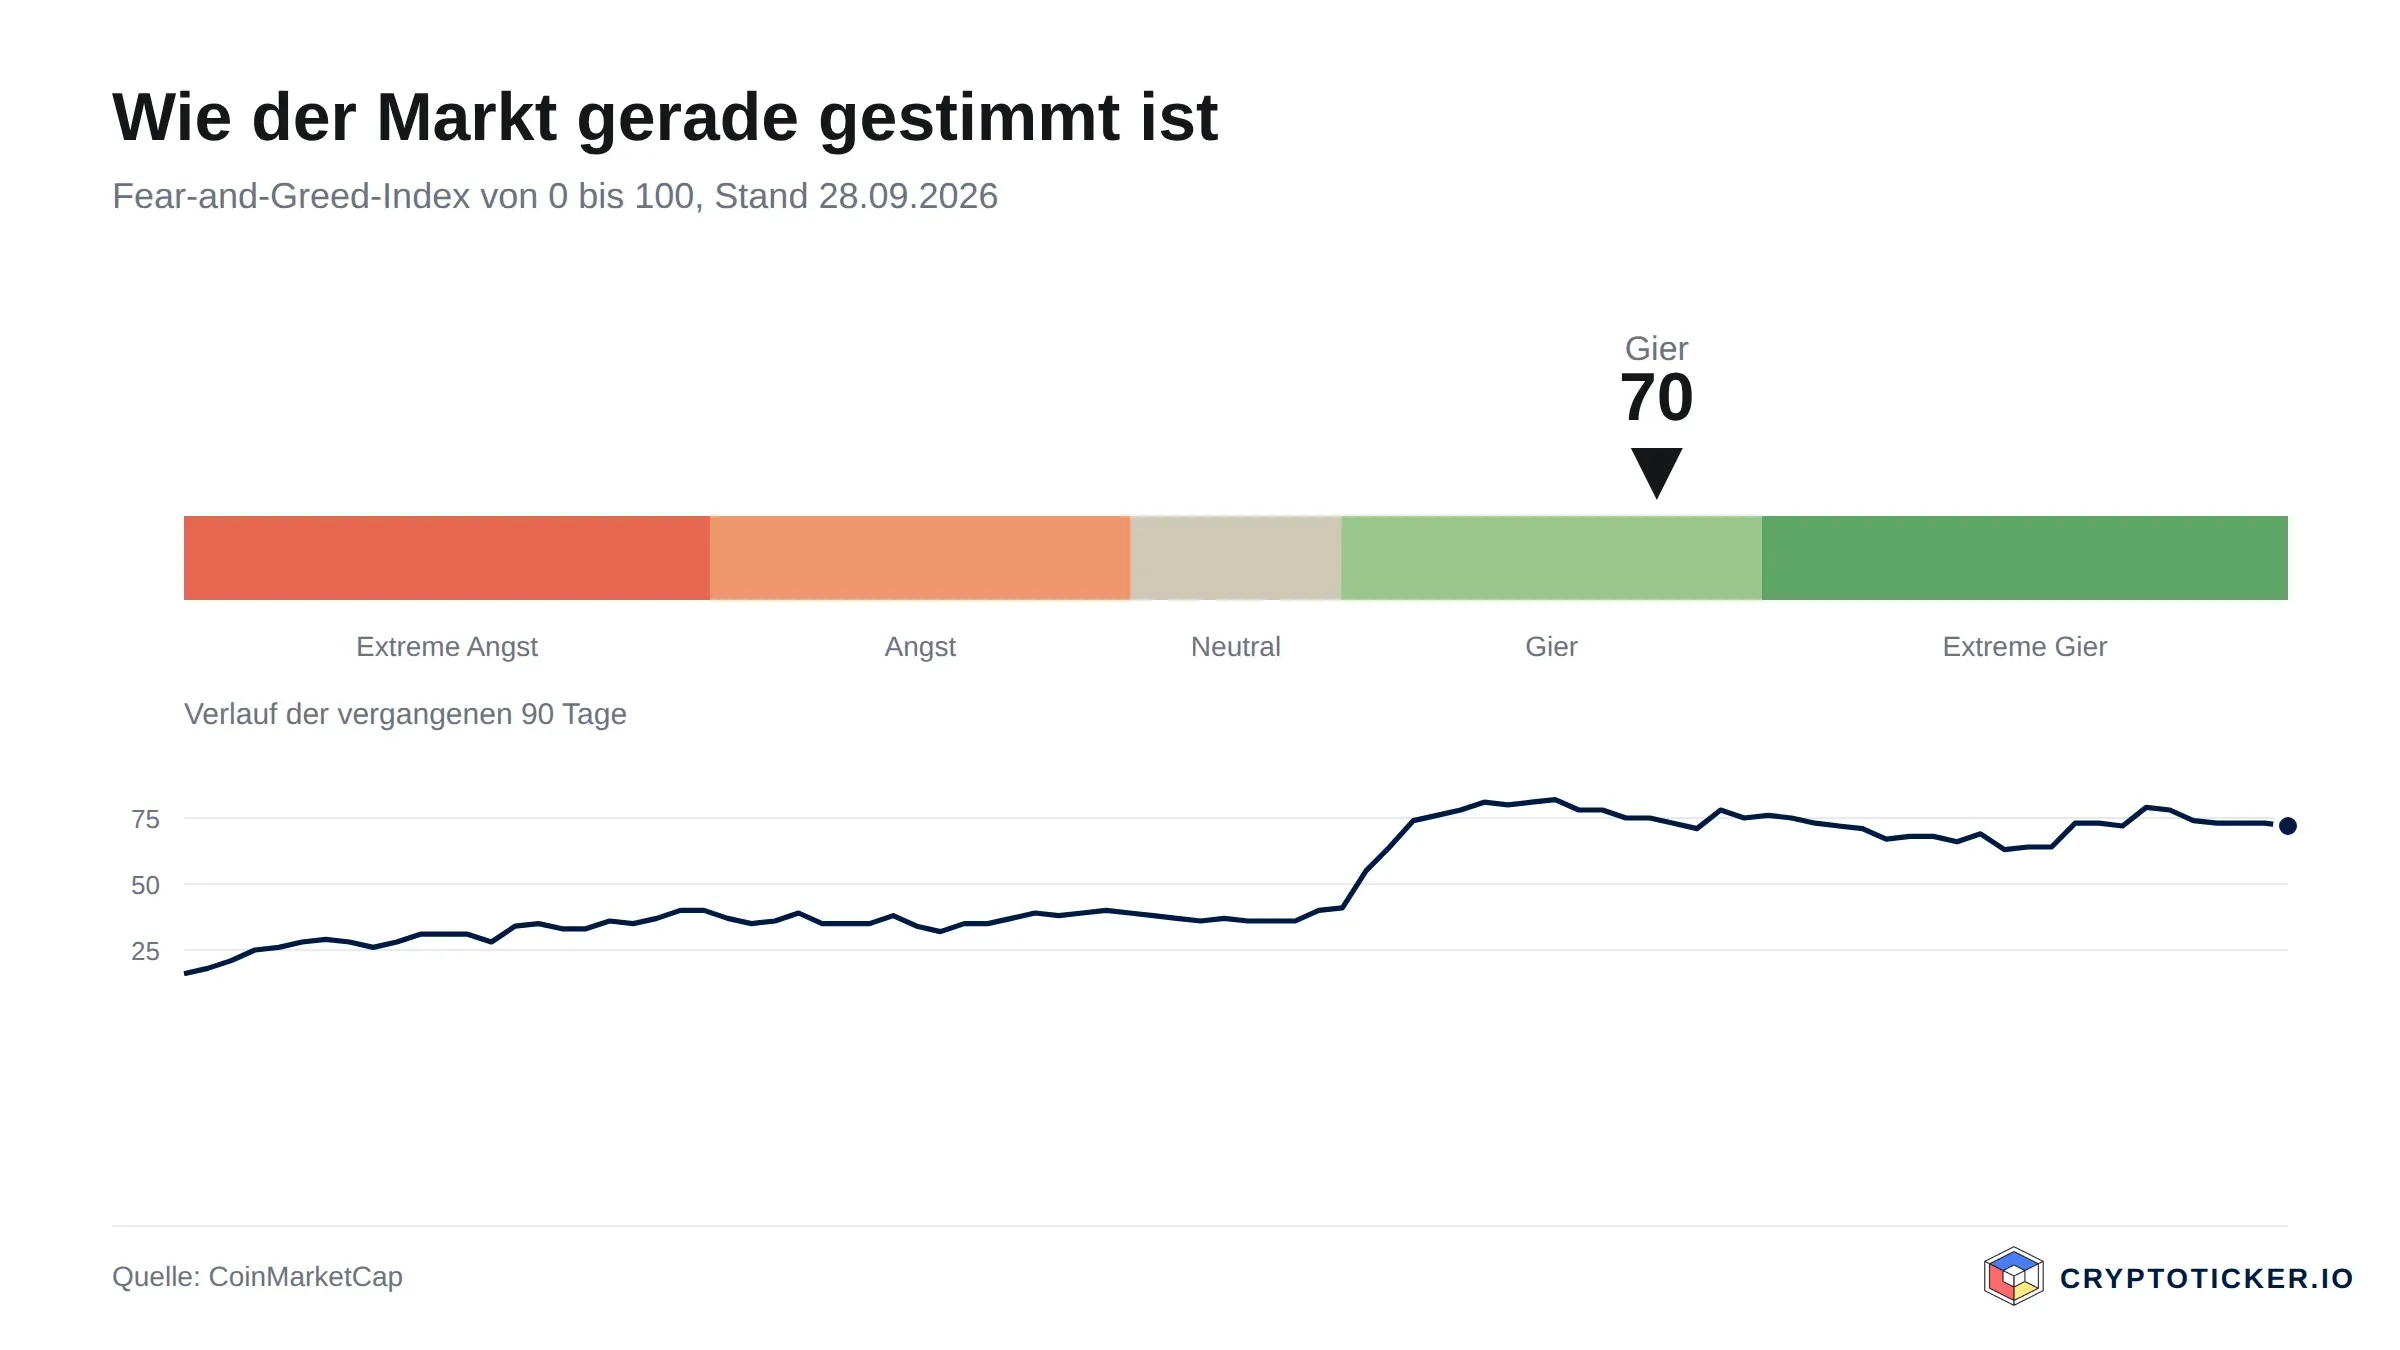
Stock market game, model portfolio, paper trading: the difference
- Stock market game: a contest with a deadline, a leaderboard and often prizes.
- Model portfolio: a virtual portfolio without a contest, mostly for shares and ETFs, to follow a selection over weeks.
- Paper trading and demo account: practice trading at real prices, any time and without a leaderboard, often with stops, shorts and leverage.
If you do not need the contest, you usually learn faster with a demo account, because no leaderboard invites risk. How to start without money and with real prices is set out in our guide Practise trading without money.
How to get from the game to your own rulebook, with order types, position size and a four-week practice plan, is set out in our Learn Trading pillar. If you then want to put real money to work, you will find regulated providers and their fees in the exchange comparison.
Sources
- Planspiel Börse of the German savings banks: dates for the 2026 round and FAQ, as of September 28, 2026.
- Société Générale: terms of participation and prizes for Trader 2026, as of September 28, 2026.
- excellents GmbH: Trading Masters, the stock market game at a glance, as of September 28, 2026.
- DIGITAL PROJECT: VR-Börsenspiel, dates and playing times 2026, as of September 28, 2026.
- WHU Otto Beisheim School of Management: Tradity, as of September 28, 2026.
- CryptoTicker Trading Hub, home page and terms of participation, as of September 28, 2026.
Decrypt
Gemini 4 Argon tops 12 of 18 benchmarks in Google's own table, writes a million tokens per reply and resists hijacking best. Cyber defenders get it first, with the guardrails off.
The team behind the MyDoge wallet opened a public test of DogeOS, a layer that lets developers build lending platforms and games on top of the meme coin network.
An internal memo warned FBI staff that ShinyHunters, the group claiming it hacked the bureau's jobs site, may hold their private details.
The Coinbase-backed group's first Senate endorsements—Republicans Jon Husted and Ashley Hinson and Democrat Chris Pappas—come two weeks after the Clarity Act's collapse, as the industry's fight shifts to the campaign trail.
The attacker behind the $387.5 million Bitget heist has started hiding about $3.8 million in ZEC inside Zcash's Ironwood pool, after Near Intents turned their swaps away.
U.Today - IT, AI and Fintech Daily News for You Today
Flare co-founder and CEO Hugo Philion has called XRP’s muted reaction to a major XRP Ledger infrastructure breakthrough in Brazil "lunacy."
The crypto market remains broadly bullish, although momentum is becoming increasingly uneven as some assets consolidate or correct after September’s strong gains.
The XRP Ledger has moved closer to launching its native lending infrastructure, with the LendingProtocolV1_1 amendment now open for validator voting.
Brazilian oil giant Petrobras is expanding its use of Cardano technology, with two new blockchain applications focused on sustainable aviation fuel and renewable Diesel R.
DogeOS deploys a ZK-Rollup layer on Dogecoin, bringing EVM smart contracts and DeFi apps to native DOGE holders.
Blockonomi
Key Highlights
- Open USD (OUSD) has debuted across Ethereum, Solana, Base, and Tempo networks with commitments exceeding $1 billion in liquidity support.
- Five major corporations—Coinbase, Mastercard, Shopify, Stripe, and Visa—serve as founding partners with equal ownership positions.
- The global stablecoin sector has surpassed $300 billion in total value, dominated by Tether’s USDT and Circle’s USDC.
- Open Standard intends to allocate the majority of company equity to partners proportional to their contribution toward OUSD expansion.
- Financial firm Mizuho reduced Circle’s stock rating in July, highlighting competitive threats from this emerging stablecoin structure.
The digital currency landscape welcomed a fresh entrant this week as Open USD made its official debut. The digital asset launched simultaneously across four blockchain platforms, accompanied by liquidity commitments surpassing the $1 billion threshold.
The initiative originates from Open Standard, a venture backed by several heavyweight industry players including Coinbase, Mastercard, Shopify, Stripe, and Visa.
These five corporations comprise the initial partner group. Every founding member possesses an identical equity portion in Open Standard at launch.
Chief Executive Zach Abrams outlined the vision driving this initiative. According to Abrams, the objective centers on transforming OUSD into practical currency for everyday transactions instead of merely serving as a speculative vehicle.
“We want to be the most useful stablecoin, the same way the U.S. dollar is useful,” Abrams stated. He noted that competing stablecoins function more like investment funds than actual spending money.
Deployment Strategy and Network Expansion
OUSD currently operates on four distinct networks: Ethereum, Solana, Coinbase’s Base platform, and Stripe’s Tempo infrastructure. The founding coalition will contribute support through various mechanisms.
Certain partners might maintain direct OUSD holdings. Additional participants could facilitate market operations or integrate the token within their proprietary ecosystems.
Collectively, these organizations have pledged more than $1 billion dedicated to establishing robust liquidity infrastructure. This commitment ensures adequate OUSD availability for widespread adoption.
Open Standard initially unveiled its stablecoin strategy in June. The announcement mentioned over 140 corporations as prospective collaborators, featuring prominent names like BlackRock, BNY, and Standard Chartered.
Currently, just five organizations have formalized investment agreements. Abrams anticipates the core founding group expanding to approximately 10 to 12 enterprises eventually.
Meanwhile, the broader ecosystem expressing interest in OUSD integration has expanded beyond 200 organizations. Recent participants include Japan’s SBI Holdings, Switzerland’s UBS banking group, and financial technology provider Jeeves.
Challenging Market Leaders Tether and Circle
Today’s stablecoin ecosystem commands a valuation exceeding $300 billion. Tether’s USDT maintains market leadership with approximately $143 billion in active circulation.
Circle’s USDC ranks second with around $74 billion outstanding. Open USD distinguishes itself through an alternative framework for ownership distribution and incentive structures.
Traditional stablecoin providers generate revenue from interest earned on reserve assets. Tether retains the overwhelming majority of these proceeds.
Circle distributes a fraction of USDC-generated income to strategic partners such as Coinbase. Open Standard aims to substantially expand this collaborative revenue model.
Abrams clarified that founding stakeholders will not receive preferential revenue allocations. Compensation will correlate directly with measurable contributions to OUSD supply expansion and transaction volume.
“The overwhelming majority of our cap table is going to be distributed back to founders and non-founders based on how they help grow the network,” Abrams explained.
Open USD eliminates transaction fees for both creation and redemption processes. Dan Romero, Tempo’s chief business officer, suggested this structure could significantly reduce expenses for enterprises conducting substantial financial transfers.
Romero forecasts approximately $1 billion worth of OUSD circulating on Tempo within several months. His projections indicate potential growth exceeding $10 billion by 2027.
Market Impact on Circle’s Valuation
Circle’s market position has experienced headwinds following the Open USD reveal. Mizuho revised its Circle price objective downward from $85 to $50 in July.
The financial institution simultaneously downgraded Circle’s investment rating from Neutral to Underperform. Analysts identified competitive pressure from Open USD as the primary catalyst.
Mizuho increased its projection for Circle’s 2027 distribution and transaction cost ratio from 64% to 73%. Simultaneously, the firm reduced adjusted earnings expectations from $1.09 billion to $699 million.
Notably, Coinbase, Visa, and Mastercard continue maintaining collaborative relationships with Circle’s USDC despite supporting OUSD. Abrams mentioned Open Standard is receiving requests for stablecoins denominated in alternative currencies, particularly from European financial institutions.
The post Payment Giants Visa, Mastercard, and Stripe Back New $1B Open USD Stablecoin appeared first on Blockonomi.
TLDR
- Base deployed Cobalt, its third significant mainnet upgrade, on Wednesday.
- The update introduces Validity Transactions, enabling conditional swap execution based on predefined criteria.
- Enhanced B20 token standard now supports Composite Policies for sophisticated compliance management.
- Token issuers can now pre-schedule balance multiplier adjustments for events like stock splits.
- The seizeWithMemo function enables transparent token seizure from frozen wallets with documented justification.
Base activated its Cobalt upgrade this Wednesday, marking the third substantial enhancement to the Ethereum layer-2 platform. The deployment emphasizes refined transaction management capabilities for traders alongside sophisticated asset administration features for token issuers.
LATEST:
Base launched its third mainnet upgrade, Cobalt, adding Validity Transactions that let users submit time-bound transactions that stay dormant until user-specified conditions are met. pic.twitter.com/wkITdJa8ys
— CoinMarketCap (@CoinMarketCap) October 1, 2026
At the heart of Cobalt sits Validity Transactions, a groundbreaking mechanism allowing users to queue transactions that remain dormant until specific blockchain conditions materialize.
Consider a scenario where a trader sets up a token swap that executes exclusively when an asset reaches a predetermined price point within a specified timeframe. The Base network retains this transaction and evaluates the conditions with each successive block.
Should the target price remain unreached, the transaction simply expires without execution. According to Base, these conditional submissions can maintain privacy until blockchain confirmation occurs.
B20 Token Standard Receives Major Enhancements
The Cobalt deployment significantly expands functionality within the B20 token framework, initially introduced last June. Among the notable additions is Composite Policies.
This capability empowers issuers to merge multiple allowlists and blocklists through Boolean logic operations (OR/AND). For example, an investment vehicle might mandate that purchasers both clear KYC verification and satisfy proprietary accreditation requirements.
Removal from either verification list would automatically block the transfer. Base emphasizes this eliminates redundant list management and manual synchronization across different platforms.
The upgrade also introduces Schedule Multiplier Updates, providing issuers with tools to program display balance modifications, such as those occurring during equity splits.
Wallet-displayed token quantities can adjust without actual minting or burning operations. The core token balance remains constant at the protocol layer.
Enhanced Administration of Restricted Accounts
Cobalt incorporates seizeWithMemo, a functionality granting designated administrators authority to transfer balances from holders when seizure permissions are enabled for specific assets.
Base provided an illustration involving a restricted account where an administrator might relocate shares to a designated recovery address, with the action permanently logged on-chain alongside explanatory documentation.
Base clarified that it lacks independent authority to execute these transfers. Individual issuers retain exclusive control over feature activation and administrator designation.
This upgrade continues Base’s strategic push into tokenized financial infrastructure throughout this year. Last July witnessed the B20 standard launch, specifically designed for stablecoins and real-world asset tokenization.
During that same period, Base founder Jesse Pollak acknowledged the network had overemphasized social applications and messaging platforms initially. He admitted Base had lagged competitors in critical areas including prediction markets and sophisticated trading infrastructure.
Pollak outlined a strategic recalibration prioritizing financial utilities—particularly trading mechanisms and payment systems. His vision positions Base as infrastructure supporting worldwide financial operations.
This strategic pivot yielded tangible results by August when Coinbase introduced tokenized equity products on Base utilizing B20 standards, featuring shares from major corporations including Apple and Nvidia.
Base’s development roadmap extends well beyond Cobalt. The network aims to compress block times from the current two-second interval to just 200 milliseconds within upcoming months.
Additional planned implementations include native smart account integration, gas fee sponsorship mechanisms, and transaction bundling capabilities. Several of these enhancements will incorporate elements from Ethereum’s forthcoming Glamsterdam upgrade.
The post Base Network Activates Cobalt Upgrade, Bringing Conditional Trading Features appeared first on Blockonomi.
Key Takeaways
- DogeOS introduced its public testing network on Wednesday, enabling Ethereum-compatible smart contract functionality for Dogecoin.
- The platform facilitates decentralized finance activities including swaps, borrowing protocols, stablecoins, betting markets, and gaming applications using test tokens.
- Dogecoin currently changes hands around $0.0955, representing a roughly 60% decline year-over-year.
- The OP_CHECKZKP Dogecoin Core enhancement proposal would enable native proof verification by miners, though it remains under development.
- Technical analyst Trader Tardigrade identifies a bullish pennant formation suggesting upside toward $0.124.
Dogecoin maintains its position near $0.0955 while a fresh initiative seeks to expand the cryptocurrency’s functionality beyond simple transactions and speculative trading. DogeOS, a secondary protocol layer constructed atop Dogecoin’s blockchain, activated its public testing environment this Wednesday.
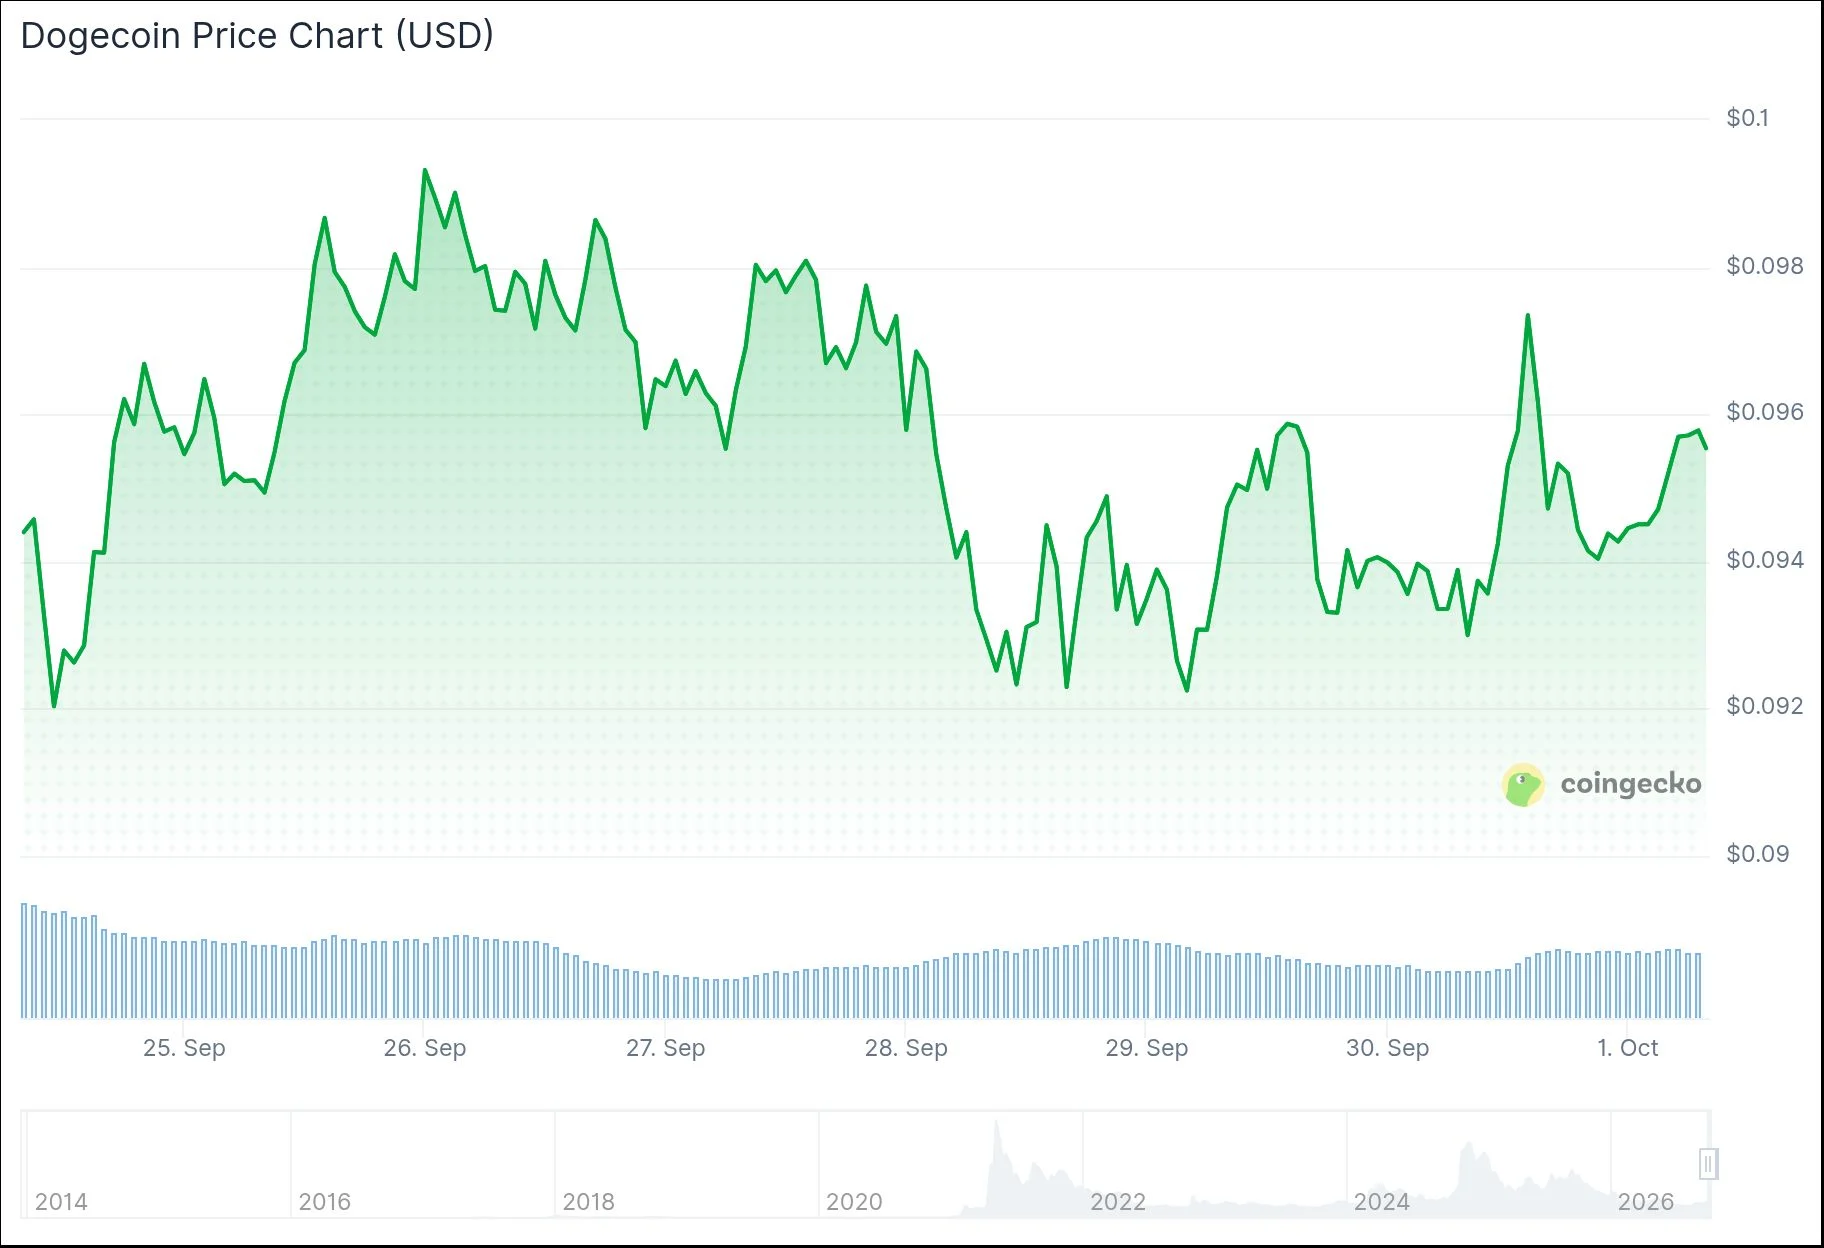
The testing network provides infrastructure for developers to create decentralized applications spanning exchange platforms, credit markets, dollar-pegged tokens, forecasting services, and entertainment products. Transaction costs are paid using testnet DOGE. The architecture maintains compatibility with Ethereum’s development ecosystem, enabling programmers to leverage existing frameworks and toolkits.
With approximately $13 billion in total market capitalization, DOGE’s circulating supply predominantly remains dormant in addresses serving storage or speculative purposes.
DogeOS Technical Architecture
DogeOS functions as an independent chain that periodically commits state changes to Dogecoin’s base layer. The system employs cryptographic proofs to demonstrate computational integrity without requiring full transaction replay.
Currently, the infrastructure operates through authorized participants. A designated sequencer arranges transaction ordering, while validators working alongside secure execution environments verify proof validity. Oversight comes from an appointed Security Council.
Dogecoin miners cannot yet validate these cryptographic proofs natively. DogeOS developers have introduced OP_CHECKZKP, a proposed modification to Dogecoin Core that would grant miners direct proof verification capabilities. Initially published in July 2025 with a preliminary code submission following in December, the enhancement awaits community review and potential activation.
The DogeOS initiative originates from the developers of MyDoge, a Dogecoin wallet application. The organization secured $6.9 million in venture funding during May 2025, with Polychain Capital leading the investment round.
According to CEO Jordan Jefferson, the project addresses Dogecoin’s need for fundamental utility independent of celebrity associations.
“We’re focused on the public testnet, giving developers time to build and test applications while we validate the network,” he stated. The team has not disclosed a timeline for mainnet deployment.
Timothy Stebbing, serving as a director at the Dogecoin Foundation, expressed support for the initiative. “My hopes are that DogeOS becomes the springboard for a wave of new utility engineering, the gateway for the next 100 startups to build on Dogecoin,” he remarked.
Historical Context and Price Movement
Previous initiatives pursued comparable objectives. Dogechain’s 2022 debut attracted $4.6 million in locked value within its initial days, yet current data from DeFiLlama shows protocol holdings under $300. Shibarium, developed by Shiba Inu’s contributors and launched during 2023, has experienced contraction from approximately $6.4 million in peak deposits to roughly $140,000 presently.
DogeOS distinguishes itself through official Dogecoin Foundation recognition, contrasting with Dogechain’s independent status. Additionally, the project pursues integration with Dogecoin’s mining infrastructure through the proposed protocol enhancement.
From a market perspective, analyst Trader Tardigrade published analysis on X indicating Dogecoin is “breaking out of a Bull Pennant” formation visible on the 12-hour timeframe, projecting a price objective of $0.124. This assessment emerged while DOGE fluctuated between $0.094 and $0.0955, reflecting a 60% reduction from year-ago levels.
$Doge/12-hour#Dogecoin is breaking out of a Bull Pennant
Target at $0.124
pic.twitter.com/c1MOwYT71X
— Trader Tardigrade
(@TATrader_Alan) September 30, 2026

Three Dogecoin exchange-traded funds available to U.S. investors have accumulated approximately $12 million in aggregate net capital flows across nearly ten months of operation. Bitwise’s Dogecoin ETF maintained assets below $700,000 prior to the company’s decision to discontinue the product.
The post Dogecoin (DOGE) Eyes $0.124 Target as DogeOS Testnet Launches DeFi Functionality appeared first on Blockonomi.
Key Highlights
- Major banking institution Standard Chartered initiated coverage on Ethena with an ambitious $2 ENA price objective through year-end 2028.
- Analysts anticipate USDe, the protocol’s stablecoin offering, will expand from its current $4.9 billion supply to approximately $40 billion during this timeframe.
- With ENA changing hands near $0.26 on Wednesday, the projection represents roughly 669% potential appreciation.
- The protocol’s fee mechanism allocates 95% of net revenues toward ENA token repurchase programs.
- The token posted gains exceeding 5% after the coverage announcement and has climbed more than 77% during the last 30 days.
In a notable move, Standard Chartered has launched research coverage on Ethena, establishing a $2 valuation target for the ENA token through the conclusion of 2028. The projection from analyst Geoff Kendrick rests on the platform’s expanding influence across stablecoins, tokenization infrastructure, and perpetual derivatives markets.
With ENA positioned at $0.26 during Wednesday’s trading session, the financial institution’s projection represents approximately 669% appreciation from present levels.
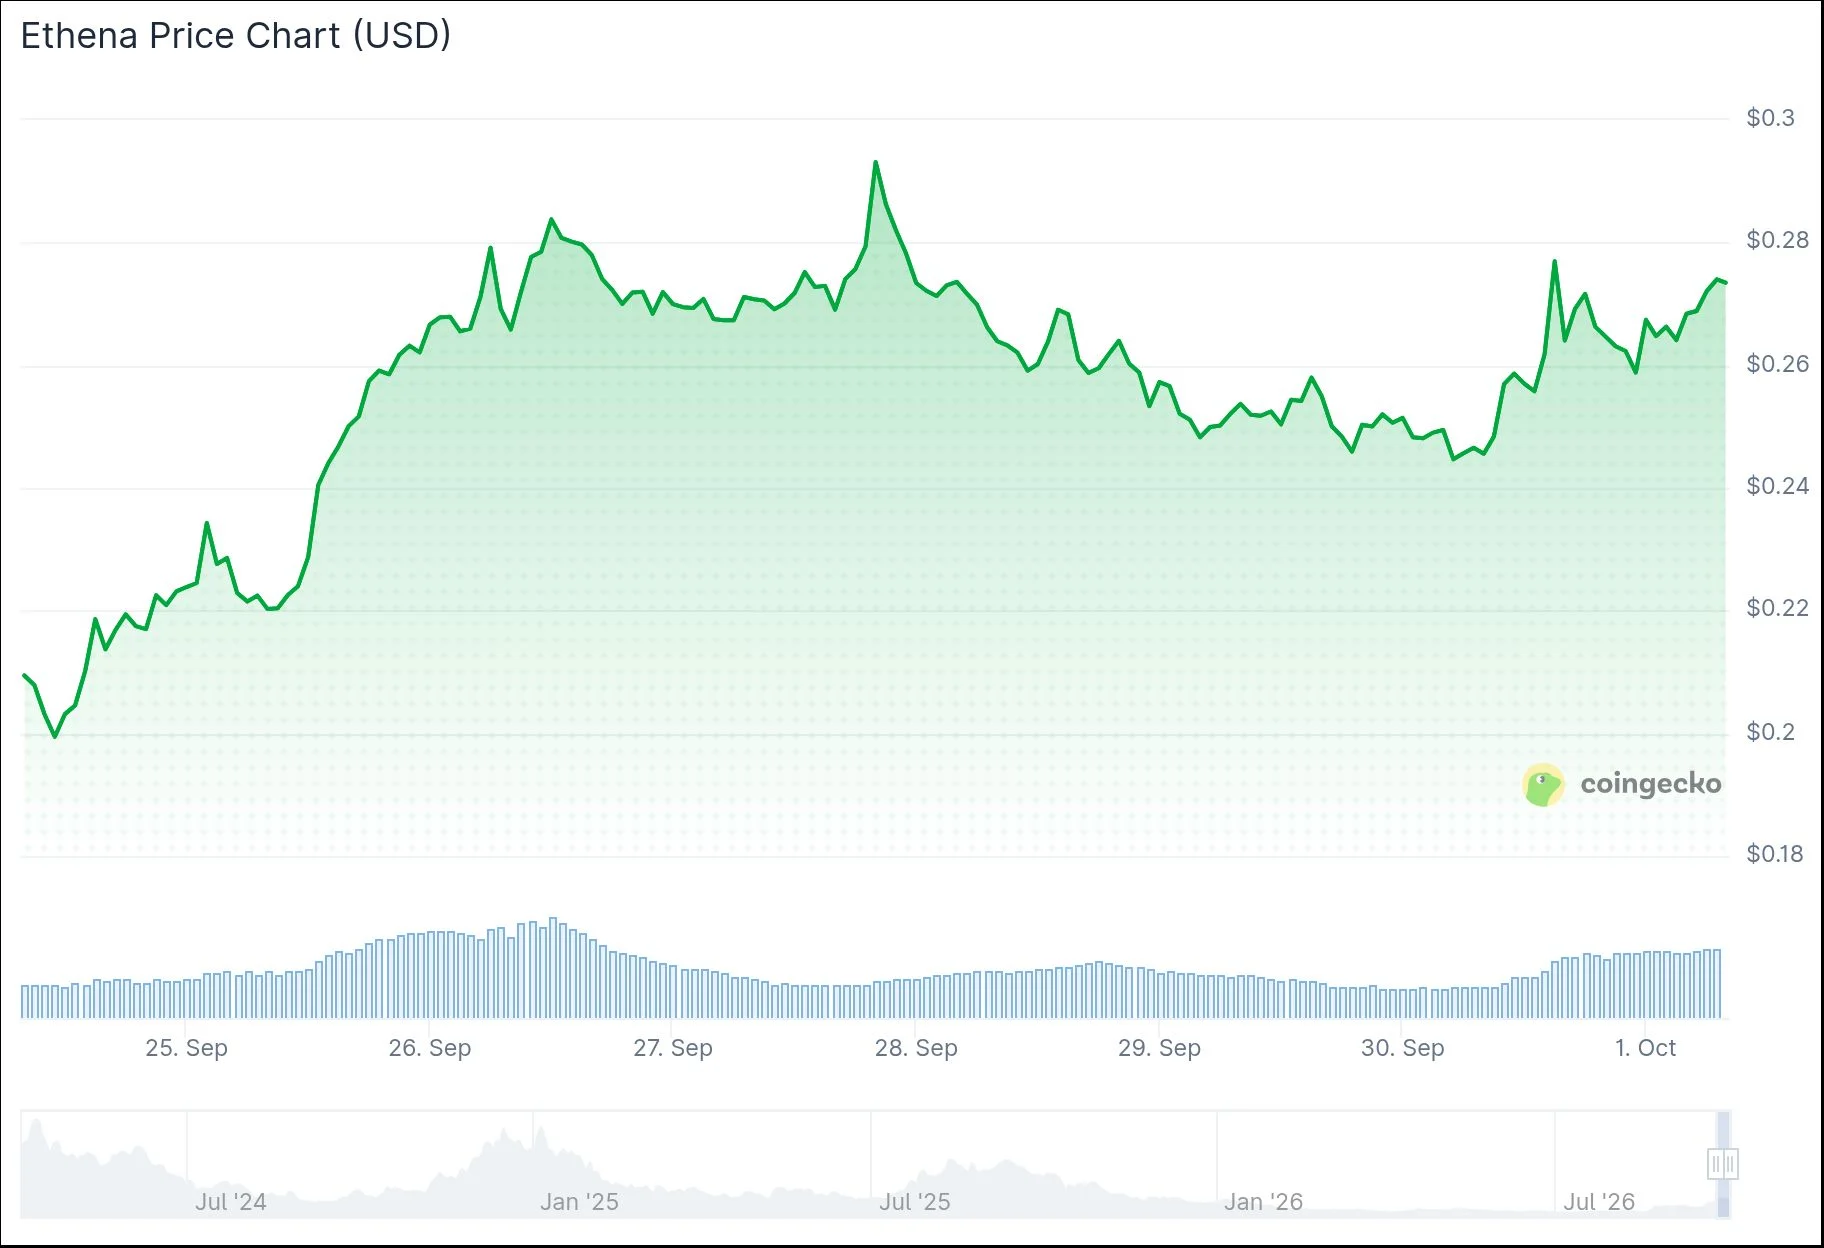
The core of Standard Chartered’s analysis revolves around USDe, the protocol’s stablecoin product. Analysts project USDe circulation will multiply more than eight times, expanding from today’s $4.9 billion to approximately $40 billion within the forecast period.
The platform currently maintains its position as the fourth-largest stablecoin provider globally, positioned behind industry leaders Tether, Circle, and Sky. Among yield-generating stablecoin providers, it holds the number two spot, following Sky.
Diversification of Revenue Streams
According to the banking institution’s analysis, Ethena is actively diversifying USDe’s yield generation mechanisms. Profits derived from cryptocurrency basis trading, the initial strategy supporting USDe returns, have experienced recent declines.
Additional revenue channels now encompass real-world asset integration, decentralized finance lending protocols, institutional credit facilities, and basis trades connected to equities or commodities. The platform has additionally entered tokenized equity markets via Binance’s bStocks offering.
Standard Chartered’s broader market analysis suggests tokenized assets generally, encompassing both stablecoins and additional real-world assets, will achieve $4 trillion in total value by 2028. Current market capitalization stands near $350 billion.
Token Repurchase Strategy
A significant component of the ENA valuation model relies on the protocol’s fee mechanism, which received unanimous approval through governance voting. This framework channels 95% of net revenues generated from Ethena-branded operations toward ENA token repurchase initiatives.
The bank’s calculations indicate that should USDe circulation reach $40 billion while ENA maintains current pricing levels, yearly buybacks would represent approximately 23% of the token’s available supply. Analysts consider this rate unsustainably elevated, suggesting token appreciation would be necessary for the buyback program’s long-term viability.
The analysis draws parallels to Uniswap’s experience. UNI’s annualized repurchase rate stabilized within the 3% to 4% range following its fee mechanism activation in December 2025, with the token appreciating roughly threefold since Standard Chartered initiated coverage last June.
Alternative perspectives exist within the analyst community. Market observer Altcoin Sherpa suggested on X that ENA “probably goes back to $1 in crazy bullish conditions,” representing a more measured outlook compared to the bank’s $2 projection while still indicating substantial appreciation potential from current trading levels.
The banking institution identified slower adoption of yield-bearing stablecoins as the primary risk factor threatening its forecast. Deceleration in real-world asset blockchain migration represents a secondary concern, given the protocol’s growing dependence on these assets for yield generation.
ENA appreciated more than 5% following the research coverage release, trading around $0.26 based on TradingView market data. The asset has advanced over 77% during the preceding month.
This price action coincided with Bitcoin surpassing $85,000, supported by weaker-than-anticipated PCE inflation figures that diminished market expectations for a Federal Reserve rate reduction in October.
The post Standard Chartered Sets Bold $2 Target for Ethena (ENA) — A 669% Surge Ahead? appeared first on Blockonomi.
Key Points
- European authorities are investigating Binance’s reliance on a legal loophole to continue operations.
- The crypto exchange is invoking “reverse solicitation” provisions to serve European Union clients.
- Following the denial of its MiCA license application, Binance faced restrictions on EU market access.
- Multiple regulatory bodies including ESMA, along with French, German, and Greek authorities, are conducting reviews.
- Potential sanctions, including financial penalties, could follow if authorities determine improper use of exemptions.
Regulatory authorities across the European Union have initiated scrutiny of Binance, the globe’s most prominent cryptocurrency trading platform. At issue is whether the exchange is improperly leveraging a regulatory carve-out to maintain customer relationships throughout the bloc.
The Financial Times broke the story on October 1, 2026, with subsequent confirmation of certain details by Reuters and additional media organizations.
Background on Binance’s MiCA Authorization Attempt
The cryptocurrency exchange submitted paperwork seeking authorization under the European Union’s Markets in Crypto-Assets framework, commonly referred to as MiCA. Authorities denied this request during the earlier part of this year.
According to MiCA provisions, digital asset firms required proper authorization before June’s conclusion to maintain operations throughout EU member states. Lacking such credentials, Binance theoretically should have ceased accepting new European clients starting in July.
However, multiple sources indicate Binance has maintained service relationships with certain customers in Europe. The platform has justified this continuation by citing provisions known as “reverse solicitation.”
This regulatory concept permits non-European Union entities to provide services to EU-based customers under narrow circumstances. Specifically, the customer must independently initiate contact with the provider, completely absent any promotional outreach or inducement from the company’s side.
Regulatory Response and Investigation
The European Securities and Markets Authority, commonly abbreviated as ESMA, has become engaged in examining this situation. Authorities at the national level within France, Germany, and Greece have similarly launched inquiries.
According to statements ESMA provided to the Financial Times, reverse solicitation provisions require restrictive interpretation. The authority emphasized these provisions function as limited exceptions rather than alternative pathways to circumvent MiCA compliance obligations.
Several regulatory agencies have already requested documentation from Binance. Should authorities find the company’s explanations insufficient, enforcement measures including monetary penalties remain viable options.
In comments to the Financial Times, Binance representatives stated the organization continues pursuing full MiCA authorization. The company emphasized its commitment to regulatory compliance within all operational jurisdictions.
Reuters noted it was unable to verify all aspects of the Financial Times reporting independently. Neither Binance nor ESMA provided immediate responses to Reuters’ inquiries seeking additional comment.
The implications extend well beyond a single corporate entity. Millions of cryptocurrency traders throughout Europe depend on Binance’s infrastructure for their digital asset transactions.
Market observers monitoring these developments suggest the resolution could establish precedents affecting how competing exchanges approach European Union compliance frameworks. Other centralized trading platforms lacking MiCA credentials may encounter comparable regulatory challenges.
Near-term market projections connected to these reports suggest increased caution among market participants. Certain analysts have noted a strengthening US dollar alongside climbing bond yields as indicators of heightened risk-off sentiment during the current period.
Presently, Binance maintains it is collaborating fully with regulatory expectations. The complete parameters of the European Union’s investigation, along with potential subsequent actions, have not been disclosed publicly.
As of this writing, no monetary penalties or official enforcement proceedings have been formally announced. Binance’s ultimate standing under MiCA regulations remains unresolved pending the conclusion of ongoing reviews.
The post Binance Faces EU Scrutiny Over Legal Exemption Strategy After MiCA Rejection appeared first on Blockonomi.
CryptoPotato
The Core Team behind the project announced a partnership on X with Open Standard just as the latter’s Open USD (OUSD) stablecoin went live with heavyweight backing from the likes of Visa, Coinbase, Mastercard, and Stripe.
The most interesting part for Pioneers is that the collaboration could eventually bring OUSD-based rewards and additional utility in the broader Pi ecosystem.
What Is Pi Planning?
The intriguing portions of Pi Network’s announcement begin with the timing, which came hours after OUSD officially went live on September 30. Businesses and developers can now integrate the dollar-pegged asset through infrastructure from Visa, Mastercard, Stripe, and Coinbase, while the stablecoin is natively available on Ethereum, Solana, Base, and Tempo. It has already been launched through exchanges like Coinbase, Kraken, and Uniswap.
Open Standard has grown considerably since CryptoPotato first covered the project in late June, when more than 140 companies had signed up to participate. It now says its network includes over 200 financial institutions, fintechs, banks, and global businesses.
Its founding partners include the four giants mentioned above and Shopify, which have committed more than $1 billion in near-term launch liquidity. OUSD itself is issued by Stripe’s Bridge, with reserves held at BlackRock, Lead Bank, and BNY Mellon. All of this makes Pi’s announcement significantly more impactful to its community and raises some major questions, even though there aren’t too many details yet.
Pi Network is partnering with @openstandard, the company powering Open USD (OUSD), a partner-governed stablecoin designed as open infrastructure!
Open Standard brings together more than 200+ partners across payments, finance, technology, and crypto, including Visa, Google, and… pic.twitter.com/TfwDIgGIfB
— Pi Network (@PiCoreTeam) September 30, 2026
Stablecoin Rewards Coming?
Open Standard uses a different economic model from most major stablecoin players. Participating partners can earn rewards based on the OUSD supply and activity they generate on their platforms, while they can also become eligible to earn equity in Open Standard.
Pi has not yet explained exactly how any Pioneer reward program would work, who would qualify, or when it might launch. Nor has it confirmed that OUSD will become natively supported on its blockchain, so we shouldn’t assume such an integration from the partnership announcement alone.
What has been highlighted is still very narrow but notable: Pi Network and Open Standard are exploring ways to bring OUSD-created rewards and broader utility to Pi’s vast user ecosystem.
For a project that has spent much of the past year and a half trying to expand beyond simply holding and transferring the native token, that could represent a more meaningful step toward increasing real-world activity inside the network. For now, though, the details are scarce but we will make sure to cover them once they are live.
The post Pi Network Makes a Mysterious Stablecoin Move: Could Rewards Be Coming to Pioneers? appeared first on CryptoPotato.
SOL had quite a successful September, posting a price increase of almost 20% and currently trading at $120 (per CoinGecko).
Analysts now eye further gains toward $150 and beyond. However, certain technical indicators suggest that a short-term pullback may also be on the horizon.
What’s Next?
Ali Martinez paid special attention to the strong institutional demand, noting that spot US SOL ETFs continue to absorb Solana. He said these products have accumulated roughly 4.37 million coins (worth around $450 million) since July 13, marking 11 consecutive weeks of net inflows. That said, he assumed that SOL might be headed toward $150.
In fact, last week was the second-best for these exchange-traded funds, which accumulated nearly $190 million. As CryptoPotato reported, the cumulative total inflows into the products skyrocketed to a new all-time high of $1.62 billion.
X users Gordon and Scient also weighed in. The former argued that “dips are for buying,” adding that the perfect trading strategy would be to accumulate SOL at around $100 and sell above $500. Scient expects a sell-off at the start of October and plans to short Solana at approximately $120-$121 and open a long position around $110.
However, the actions of a certain mysterious whale support an entirely bullish scenario. X user Max Crypto revealed that the anonymous market participant opened a $20.2 million long position on SOL. The liquidation price is set at $98 (assuming the whale doesn’t add more collateral to prevent that outcome).
What’s interesting is that the investor has made four trades so far and has a 100% win rate, making $4.7 million in profits. This, of course, has sparked speculation that they might have access to inside information the rest of us don’t.
Monitoring These Indicators
Solana’s exchange netflow backs the predictions of Gordon and Scient that SOL may post a short-term correction. Inflows have far exceeded outflows lately, suggesting investors have shifted from self-custody to centralized platforms, which can increase immediate selling pressure.

For its part, SOL’s Relative Strength Index (RSI) has soared past 70. In simple terms, this means the valuation has pumped too much in a short period and entered overbought territory, which is usually a precursor to a move south. Conversely, anything below 30 is interpreted as a buying opportunity.
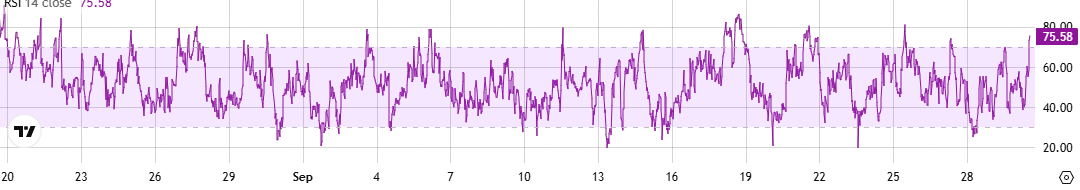
The post Solana (SOL) Breakout Incoming: How High Can the Price Go? appeared first on CryptoPotato.
Ripple’s native token just ended September well in the green, extending its streak that began with a minor increase in July. All eyes are now on October on several fronts. The question is: can XRP continue its run, or will the last two October editions take their toll?
XRP Went Hard in September
Recall that August was the cross-border token’s most successful month in over a year, when it skyrocketed by 30% from start to finish. Moreover, it had dipped to just under $1.00 mid-month, which makes its close even more impressive. XRP entered September on a high note, not only because of the spectacular August but because it had closed all four previous Septembers in the green.
The ninth month of the year was indeed positive on a few fronts. First, the price gained just under 10%, and XRP ended it at over $1.50. It tried to take down the $1.60 resistance on several occasions but to no avail. In addition, the spot ETFs tracking its performance marked some major wins.
Only three days were slightly in the red: September 2, 17, and 18. On a broader scale, though, the funds have not seen a single red week since early July. Data from SoSoValue shows that the ETFs closed September well in the green, adding over $120 million. Moreover, the cumulative net inflows reached a new all-time high of nearly $1.8 billion.
What Does October Hold?
October, as a month, holds particular significance in the hearts of the cryptocurrency community. Major gains over the years earned it a well-deserved nickname, “Uptober.” However, there have been major exceptions over the years at the broader market level, while Ripple’s XRP has not always benefited during the month.
For example, the past two editions delivered double-digit losses for the cross-border altcoin. It plunged by 16.7% in 2024 and experienced a mind-blowing correction, alongside the rest of the market, last year, after the notorious October 10 massacre.
Data from CryptoRank shows that only five out of the last 13 Octobers have been in the green for XRP. The last one was in 2023, when the asset jumped by an impressive 16.5%. As such, XRP enters the new month at a crossroads, given its notable three-month green streak but also its controversial October history.
The post XRP in October: Will Ripple’s Streak Continue After 3 Consecutive Green Months? appeared first on CryptoPotato.
Robinhood plans to launch perpetual futures for eligible US customers in the coming months.
CEO Vlad Tenev said the company is bringing America “its first true perps” in a post on X, adding that profit and loss will settle every 15 minutes.
Eight Crypto Assets, Up to 10x Leverage
The company announced the product on Tuesday at its HOOD Summit in Houston. Customers will be able to go long or short on BTC, ETH, SOL, XRP, DOGE, ADA, LINK, and HYPE.
A perpetual future is a leveraged contract that tracks an asset’s price with no settlement date, so a trader can hold a position as long as they can cover it. Bitcoin and Ethereum contracts allow up to 10x leverage, while the other six are capped at 3x, and Robinhood Derivatives will provide the contracts through Bitstamp.
Trading costs one basis point (0.01%) per trade through the end of the year, which Robinhood describes as some of the lowest fees in the industry. Furthermore, users can set stop-loss and take-profit orders, watch their liquidation price in real time, and get alerts when a position is at risk.
“Ownership doesn’t work without markets, and markets don’t work without traders,” Tenev said. The CEO added that Robinhood wants to be “the best place in the world for active traders” by delivering tools once reserved for hedge funds, big banks and quant firms.
The trading platform also introduced an in-app AI tool called Robinhood Agents that will help customers create strategies, research markets and trade within preset limits, while manual trade approval is turned on by default. According to the firm, more than 15,000 users have opened agentic trading accounts since its May launch, with agents using Robinhood tools almost 30 million times a day.
In addition, the firm is bringing earnings contracts tied to company metrics such as revenue targets and earnings results. Those binary options contracts will be offered through Cboe and require options approval.
Where Robinhood Sits Among Rivals
The broader derivatives push is not limited to Robinhood. As CryptoPotato reported on September 4, Coinbase filed registrations with the SEC to offer single-stock perpetual futures to US investors, although those filings did not guarantee a launch on any set timeline.
Bybit went a different direction on leverage. Its new forex perpetuals, introduced September 8, allow up to 100x and trade around the clock, against Robinhood’s 10x ceiling.
Remember, perpetuals still carry funding costs and liquidation risks, since a position can be closed out when losses grow too large, and Robinhood has also not given an exact launch date beyond “the coming months.”
The post Robinhood to Launch Crypto Perpetual Futures in the US appeared first on CryptoPotato.
Bitcoin (BTC) remains in a bull market after closing above its 365-day moving average last week, but recent on-chain data suggests momentum is slowing. CryptoQuant said in a recent research note that several indicators now point to higher selling pressure and weaker demand.
Despite these concerns, CryptoQuant’s Bitcoin Bull Score Index remains at 90, showing that most tracked indicators still support a bullish structure. BTC recently reached about $87,400, its highest level in eight months, before pulling back toward the low $83,000 range.
Profit-Taking Picks Up
One concern comes from short-term holders, whose unrealized profit margin has risen to 33%. The analytics firm said this is the highest level since December 2024 and that similar levels have preceded profit-taking.
That profit-taking is already showing up in realized gains, with Bitcoin holders cashing out about 25,700 BTC in profit on September 22. It was the largest single-day realized profit figure recorded in 2026, adding to evidence that some holders are selling after the recent price gains.
Selling signals are also appearing beyond Bitcoin, particularly in the altcoin market. Seven-day cumulative altcoin exchange inflows reached 76,000 transactions involving about 51,000 depositors, the highest levels recorded since October 17, 2025.
At the same time, demand is weakening in both the spot and futures markets. Apparent spot demand fell by roughly 170,000 BTC over the past 30 days. Speculative futures demand growth also slowed, dropping from about 164,000 BTC on September 14 to roughly 16,000 BTC more recently.
Key Support Levels Remain
Despite these signals, Bitcoin remains above several important on-chain support levels. CryptoQuant identified the 365-day moving average near $80,000 and the 200-day moving average around $71,000. The firm also identified the trader-realized price near $67,000 as a key level to watch.
According to the analytics firm, a decline toward these levels could signal consolidation. This would not necessarily mean a broader market reversal if support holds. However, continued weakness in demand alongside increased profit-taking could increase the risk of a deeper correction in the near term.
CryptoQuant described the market as still bullish but showing signs of fatigue. The next test will be whether buying demand returns to absorb selling pressure or whether Bitcoin moves closer to those support levels.
The post Bitcoin Bull Market Shows Signs of Cooling: CryptoQuant appeared first on CryptoPotato.