Cryptocurrency Posts
Crypto Briefing
Public demand for AI safety could reshape industry priorities, emphasizing regulation and trust, potentially impacting innovation dynamics.
The post Most Americans back AI safety benchmarks even if progress slows, poll finds appeared first on Crypto Briefing.
Bybit's expanded proof-of-reserves boosts transparency, potentially enhancing trust and stability in the volatile crypto exchange market.
The post Bybit releases 40th proof-of-reserves report as covered assets reach $19.6 billion appeared first on Crypto Briefing.
Anthropic's massive investment signals a strategic push to dominate AI infrastructure, potentially reshaping market dynamics and valuations.
The post Anthropic to invest $518B in cloud, data centers over next decade appeared first on Crypto Briefing.
ESMA's push for stronger enforcement powers could enhance investor protection but may increase compliance costs for crypto firms in the EU.
The post ESMA calls for expanded powers to enforce EU crypto regulations appeared first on Crypto Briefing.
The DOJ probe into Texas Majority PAC could destabilize Democratic strategies, impacting election dynamics and market confidence in Texas.
The post DOJ investigates Texas Majority PAC over alleged vote-buying claims appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Bitcoin Privacy Breakthrough a Zcash Killer? | Misha Komorov, Alloc Innit
Researchers have proposed a way to make Bitcoin private without changing Bitcoin itself. Misha Komarov, co-founder of alloc/init, explains Shielded Bitcoin: zero-knowledge proofs that hide the sender, receiver, and amount of a Bitcoin transfer, with no soft fork, no custodians, and no bridges. He covers how Bitcoin PIPEs make it possible and what the proposal still needs. It is a research proposal, not a finished product.
Chapters:
0:00 Shielded Bitcoin: Private Bitcoin Transactions With Zero-Knowledge Proofs
0:38 How Bitcoin PIPEs Make Privacy Possible Without a Soft Fork
1:42 Do Indexers and ZK Rollups Require Trust?
3:16 Shielded Bitcoin vs. Monero and Zcash
4:21 What Privacy Shielded Bitcoin Protects
5:59 How Private Are Early Users? The Small Privacy Set Problem
7:37 Is Shielded Bitcoin an Altcoin Killer?
9:12 Fees, Block Space, and Larger Shielded Transactions
10:50 Who Needs Private Bitcoin? Wrench Attacks and Corporate Treasuries
12:20 Dark Pools, Governments, and the Next Wave of Bitcoin Buyers
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Bitcoin Privacy Breakthrough a Zcash Killer? | Misha Komorov, Alloc Innit first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Bitcoin’s Institutional Era Has Arrived | Robinhood VP of Crypto Institutions Nicola White
Robinhood is bringing crypto perpetual futures to US customers, with up to 10x leverage on Bitcoin and Ether. Nicola White, Robinhood’s vice president of institutional crypto, explains how the CFTC no-action letter, the Bitstamp exchange, and Robinhood Derivatives made it happen, and why the company wants markets to be always on.
Chapters:
0:00 Robinhood’s Hood Summit: 24/7 Stock Trading and US Crypto Perps
0:40 Why Robinhood Wants Markets That Never Close
1:32 Bitstamp Perps and the CFTC No-Action Letter
2:19 Tokenized Stocks, the Basis Trade, and the Path for US Perps
3:20 Bitstamp’s Volume and the Retail–Institutional Merger
4:54 What Institutions Want to Do With Bitcoin
6:00 Institutional Bitcoin Depth and Large Block Trades
6:49 AI Trading Agents and Robinhood’s Sub-Account Controls
8:29 Lessons From the 2022 Meltdown and US Leverage Limits
10:12 How Bitcoin Changes Finance in 10 Years and What’s Next for Tokenized Stocks
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Bitcoin’s Institutional Era Has Arrived | Robinhood VP of Crypto Institutions Nicola White first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Mark Moss: The Bitcoin Endgame – BTC to $1 Million by 2030
The Fed just raised rates, yet Bitcoin keeps climbing. Mark Moss, host of the Market Disruptors podcast, explains why he thinks most people are misreading why long-term rates are rising, how a booming economy could be part of the answer, and why he says Bitcoin benefits from both the debasement trade and a bullish technological future.
Chapters:
0:00 Mark Moss on the Fed’s “Token Raise” and an October Pause
1:54 The Flat Yield Curve, Bank Lending, and the 5.1% 10-Year
2:56 Why Bitcoin Is Rising as Rates Rise: “Price Is Truth”
5:40 Bitcoin vs. Gold: The Debasement Trade and a Bullish Future
6:19 Can the US Grow Its Way Out of $40 Trillion in Debt?
10:30 The Monetary Reset Is a Process, Not an Event
13:33 Four Ways Out of the Debt Problem and What Happens in 2029–2030
16:27 Stablecoins, the Genius Act, and Why 6 Billion People Want Dollars
20:14 Institutions Are Buying Bitcoin While Retail Sells
24:29 Bitcoin’s S-Curve, Its CAGR, and a $1 Million Price Target
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Mark Moss: The Bitcoin Endgame – BTC to $1 Million by 2030 first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
UK Brings Crypto Under Full FCA Oversight for the First Time
The UK’s Financial Conduct Authority has opened applications for crypto firms to become authorized, bringing the sector under full regulation for the first time.
In a Wednesday announcement, the watchdog said companies can apply so that the crypto industry has “clarity and legitimacy.”
The UK is in the process of drafting a sweeping new crypto bill. The FCA finalized its regulatory framework for cryptoassets in June, and the regime is due to take effect in October 2027.
“The UK’s new crypto regime will give consumers greater protections and firms a clear framework to operate in. Firms can now apply for authorisation and start preparing for regulation,” Dominic Cashman, director of authorisation at the FCA, said in a statement.
The statement added that firms will have to demonstrate that they meet requirements covering consumer protection, customer-asset safeguarding, market integrity and financial resilience.
Britain is pushing ahead with digital asset legislation since last year recognizing bitcoin and other digital assets as property. The reform came from a 2023 recommendation by the Law Commission, which argued that digital assets did not fit neatly into existing legal categories.
Despite the FCA’s announcement, the UK currently is trailing behind Brussels and Washington with digital asset regulation.
The EU’s Markets in Crypto-Assets regulation has applied to service providers since 30 December 2024.
And the U.S. under President Donald Trump signed the GENIUS Act into law in July 2025, establishing a federal framework for dollar-backed tokens.
Despite lawmakers blocking landmark legislation the Clarity Act last month, U.S. regulators like the Securities and Exchange Commission have pushed ahead with rulemaking regardless.
This post UK Brings Crypto Under Full FCA Oversight for the First Time first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Bitcoin Surges 40% in Its Best Quarter Since Late 2024
Bitcoin is having one of its best quarters ever — another indication that the biggest cryptocurrency is in a bull market.
As noted by the The Kobeissi Letter this week, the price of bitcoin is now up close to 30% since August 19, when the U.S. Treasury announced it planned to more than double the size of its government debt repurchases.
Over the past quarter, the bitcoin price has surged by 40% — its best quarterly performance since Q4 2024.
Bitcoin’s price recently stood at nearly $83,698, unmoved over a 24-hour period but up 6% over a 30-day period.
The coin has benefited from news that the Treasury would try to lower bond yields — which have soared to highs not seen since the 2000s.
Bitcoin has done well with lower long-term yields because it reduces the opportunity cost of holding non-yielding assets like bitcoin and gold, and generally supports risk-on sentiment.
But despite the Treasury stepping in to try and tame the bond market, yields have continued to stay high.
Bitcoin investors don’t seem that bothered. The asset is still doing well as the dollar continues to slip. The so-called debasement trade — where investors throw money at an asset to hedge against a currency losing its value — is hot again after total U.S. debt topped $40 trillion for the first time in July.
The price of Bitcoin had been battered since notching a new all-time high of $126,080 in October, dropping by over 50%. Still, it has experienced the shallowest bear market — so far — in its history.
CryptoQuant said in a report last week that bitcoin was back in a bull market after crossing above its 365-day moving average — the “definitive technical signal” that has marked the start of Bitcoin’s bull markets in past cycles.
The coin has shrugged off the Federal Reserve raising interest rates and lawmakers blockage of landmark crypto legislation, the Clarity Act.
This post Bitcoin Surges 40% in Its Best Quarter Since Late 2024 first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
CryptoSlate
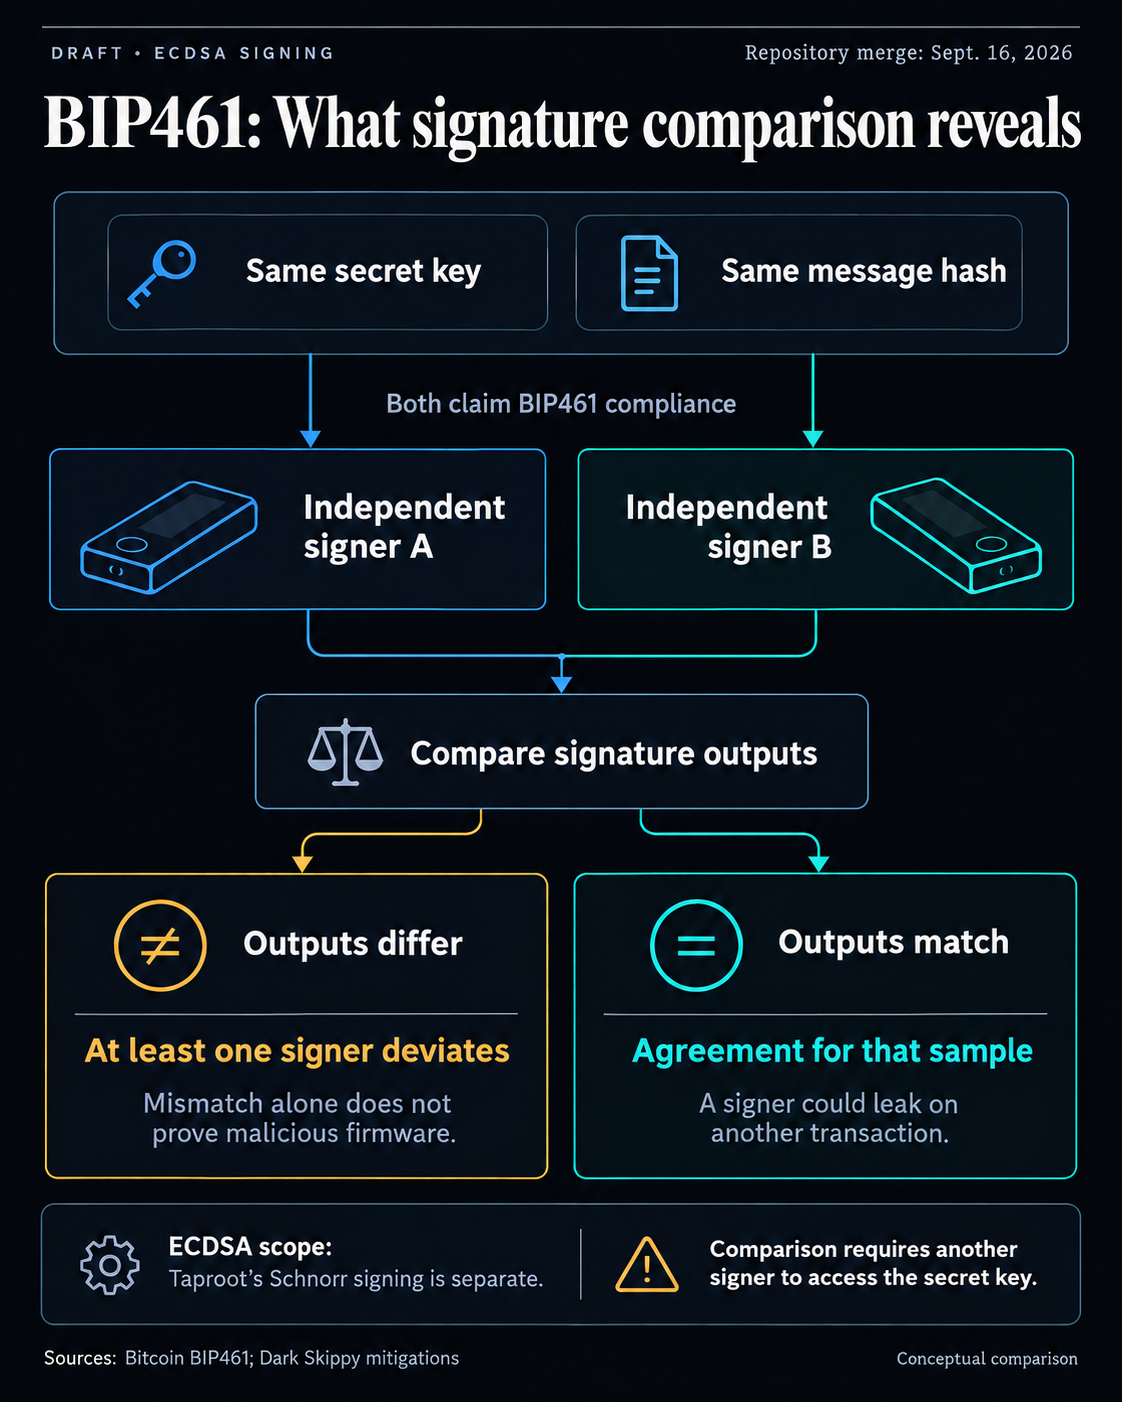
Bitcoin improvement proposal BIP461 could make a hidden route for leaking wallet secrets easier to detect. The draft defines a common signing procedure for ECDSA, an existing Bitcoin signature scheme.
Independent compliant signers should produce identical signatures for the same secret key and message hash, creating a benchmark for detecting departures that could conceal key leakage.
Authored by Liam Gilligan, the proposal was merged into the BIPs repository on Sept. 16 and remains marked Draft. Its signatures work under existing Bitcoin consensus rules, so implementing this signing procedure requires no consensus change.
Comparing signatures for deviations
ECDSA allows a signer choices while creating a valid signature, including the nonce, a temporary value used in signing. Malicious firmware can exploit that freedom to hide key material in signatures that still pass verification, and BIP461 fixes those choices through a specified deterministic procedure.
Bitcoin’s acceptance of a signature cannot establish that its creation kept the key safe. A common specification supplies an expected output against which the signer’s behavior can be checked.
The comparison requires identical inputs and the exact same standard, including access to the secret key on another independent signer. That extra exposure is a practical cost of reproducing the signature. Different results for the same key and message hash show that at least one signer is not following BIP461.
An honest implementation using another valid ECDSA procedure can also disagree. A mismatch warrants investigation into compliance, but its cause remains unresolved. The comparison alone cannot identify a malicious device or demonstrate theft.
The prescribed algorithm also keeps signatures to at most 70 bytes in the standard DER encoding, excluding Bitcoin’s one-byte sighash flag.
The Dark Skippy disclosure pointed out that corrupted firmware can embed seed material in transaction signatures. In their original disclosure, the researchers said they had not seen the technique in the wild.
Dark Skippy’s original demonstration uses Schnorr signing, while BIP461 specifies ECDSA. Taproot uses the separate BIP340 Schnorr scheme, so this draft does not directly standardize a remedy for that demonstration.
The researchers’ mitigation discussion warned that a malicious signer could leak only on a selected transaction, so a device could produce compliant signatures in a test and leak on another transaction.
At the September merge, a reviewer said test vectors and a reference implementation were needed for BIP461 to advance to Complete.
For wallet users, its potential value is a shared benchmark that could make deviations visible. Delivering that value still depends on compliant implementations and comparisons that account for both detection limits and the risks of handling secrets.
The post New Bitcoin upgrade catches hidden key leaks hiding the exact fix appeared first on CryptoSlate.
Petrobras, Brazil's state-controlled energy company, is testing Cardano to track sustainable aviation fuel benefits and prevent double-counting.
The Cardano Foundation said on Sept. 30 that an ongoing research and development collaboration had delivered applications for sustainable aviation fuel (SAF) and Diesel R, Petrobras' renewable fuel brand.
The SAF project addresses a problem that arises when the buyer of a fuel's environmental benefit is different from the buyer or user of the fuel itself. Its Book-and-Claim model lets an airline, company, or passenger receive that benefit even when the SAF is produced or used elsewhere.
Petrobras developed the SAF platform with PUC-Rio University's Ledger Labs and the Cardano Foundation. According to the Foundation's case study, it represents SAF environmental attributes as standardized CS-SAF tokens on Cardano.
Those tokens can be created, transferred, checked, and retired. Retirement prevents the same attribute from being claimed again, while the digital record traces the allocation back to the original fuel certificate.
The crypto analogy is double spending: preventing reuse of a digital asset, applied here to an environmental claim.
Travelers can enter departure and destination airports, calculate a CS-SAF allocation and receive a certificate showing their route, distance and allocation, the Foundation says. That claim remains linked to the original SAF certificate.
The tokens carry metadata aligned with CORSIA, the Carbon Offsetting and Reduction Scheme for International Aviation.
In guidance published June 16, the Roundtable on Sustainable Biomaterials says Book-and-Claim changes neither the physical fuel a buyer uses nor its associated emissions. Airlines should disclose supported reductions separately from operational emissions.
Different value-chain participants can make distinct claims, as long as their disclosures do not misrepresent the overall reduction.
Cardano usage beyond aviation
The Diesel R project, developed with PUC-Rio, proposes checkpoints across production, transportation and use. Its aim is a continuous fuel-lifecycle record that could support Scope 3 reporting, which covers indirect emissions across a company's wider value chain.
That would connect information held by suppliers and logistics providers, giving emissions reporting a more traceable supply-chain history. The Foundation describes this architecture as a proposed model within the R&D work.
The SAF platform illustrates how Cardano can record the allocation and retirement of environmental benefits. Commercial use remains unquantified, as the Foundation's disclosures provide no transaction volumes or revenue figures.
The post Brazil’s largest energy giant tests Cardano to fix carbon double-counting appeared first on CryptoSlate.
Standard Chartered expects Ethena’s ENA token to rise about sevenfold by 2028, provided the protocol can rebuild its shrinking synthetic-dollar business.
The bank initiated coverage of ENA with a $2 year-end 2028 target, up from about $0.28 currently. It forecasts the token reaching $0.42 at the end of 2026 and $1.10 in 2027 before accelerating further the following year.
The projection would leave ENA outperforming Standard Chartered’s expected gains for both Bitcoin and Ethereum over the same period. But reaching it requires Ethena to reverse a contraction that has cut USDe supply by more than half from its peak and expand far beyond the scale it has previously achieved.
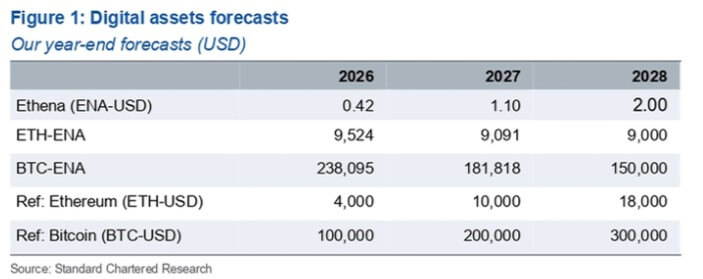
The bank’s thesis rests on Ethena finding new sources of yield as returns from its original crypto trading strategy decline, while generating enough revenue from a much larger USDe base to make ENA increasingly valuable to holders.
Ethena first has to rebuild USDe
USDe became one of crypto’s fastest-growing stablecoins after launching in late 2023, exceeding $10 billion as traders piled into a structure that combined long spot crypto positions with short perpetual futures.
That approach allowed Ethena to capture funding payments while keeping its overall market exposure largely delta-neutral. At times, the strategy generated returns above 20%, helping attract deposits into USDe and its yield-bearing counterpart, sUSDe.
However, those conditions have since weakened amid the ensuing market contraction.
As the trade became more crowded and crypto funding rates compressed, USDe supply fell to about $4.9 billion. Standard Chartered estimates Ethena’s blended yield across its strategies is now about 5.2%.
The bank’s forecast assumes contraction can reverse dramatically. It expects USDe supply to reach $40 billion by 2028, meaning Ethena would first have to regain its previous $10 billion-plus peak and then roughly quadruple again.
Ethena has responded to lower crypto basis returns by broadening where it generates yield. Its strategies now include DeFi lending, institutional lending, liquid stablecoins and real-world assets, alongside newer basis trades tied to equities and commodities.
That diversification is central to Standard Chartered’s growth assumptions.
The bank expects tokenized assets, including stablecoins and other real-world assets, to reach about $4 trillion by the end of 2028 from roughly $350 billion currently. It projects real-world assets deployed on blockchains could rise from about $40 billion to $2 trillion over the same period.
A larger tokenized-asset market would give Ethena more collateral and yield opportunities beyond crypto derivatives, potentially allowing USDe to expand without requiring another period of exceptionally high perpetual-futures funding rates.
Ethena is also building businesses outside the core synthetic dollar, including white-label stablecoins and Ethena Pay. Standard Chartered expects those operations to widen the revenue base as the protocol grows.
However, the first hurdle is much closer than $40 billion.
Ethena’s approved fee-switch framework begins at $7.5 billion of USDe supply, leaving the protocol below the first threshold at which the revenue mechanism underlying Standard Chartered’s valuation begins to take effect.
Why the buyback math leads to $2
Once those thresholds are crossed, the ENA valuation increasingly depends on how much of Ethena’s economics can be directed toward token holders.
The approved framework allocates 95% of qualifying net revenue paid to the Ethena Foundation from covered businesses toward ENA buybacks. Ethena does not retain the full yield generated by the assets supporting USDe, making the distinction between gross and net revenue central to the calculation.
Blockworks Advisory’s analysis modeled the protocol’s share of gross revenue increasing with USDe supply, beginning at about 5% around $7.5 billion and reaching 20% by $20 billion. The model used a 6% protocol yield as an illustrative assumption, not a guaranteed return.
At the much larger scale envisioned by Standard Chartered, those economics become substantial.
The bank estimates that if USDe reaches $40 billion, ENA purchases could amount to roughly 23% of the token’s current market value annually if its price remained unchanged.
Standard Chartered does not expect such a percentage to persist. It argues that investors would capitalize the expected stream of purchases into ENA’s valuation, pushing the token higher and reducing annual buybacks as a percentage of its market capitalization.
The bank points to Uniswap as an analog, saying UNI’s annualized buyback percentage has settled around 3% to 4% as the token appreciated after activating its fee switch. Applying a comparable equilibrium to Ethena underpins Standard Chartered’s $2 target.
But the mechanism introduces its own constraint.
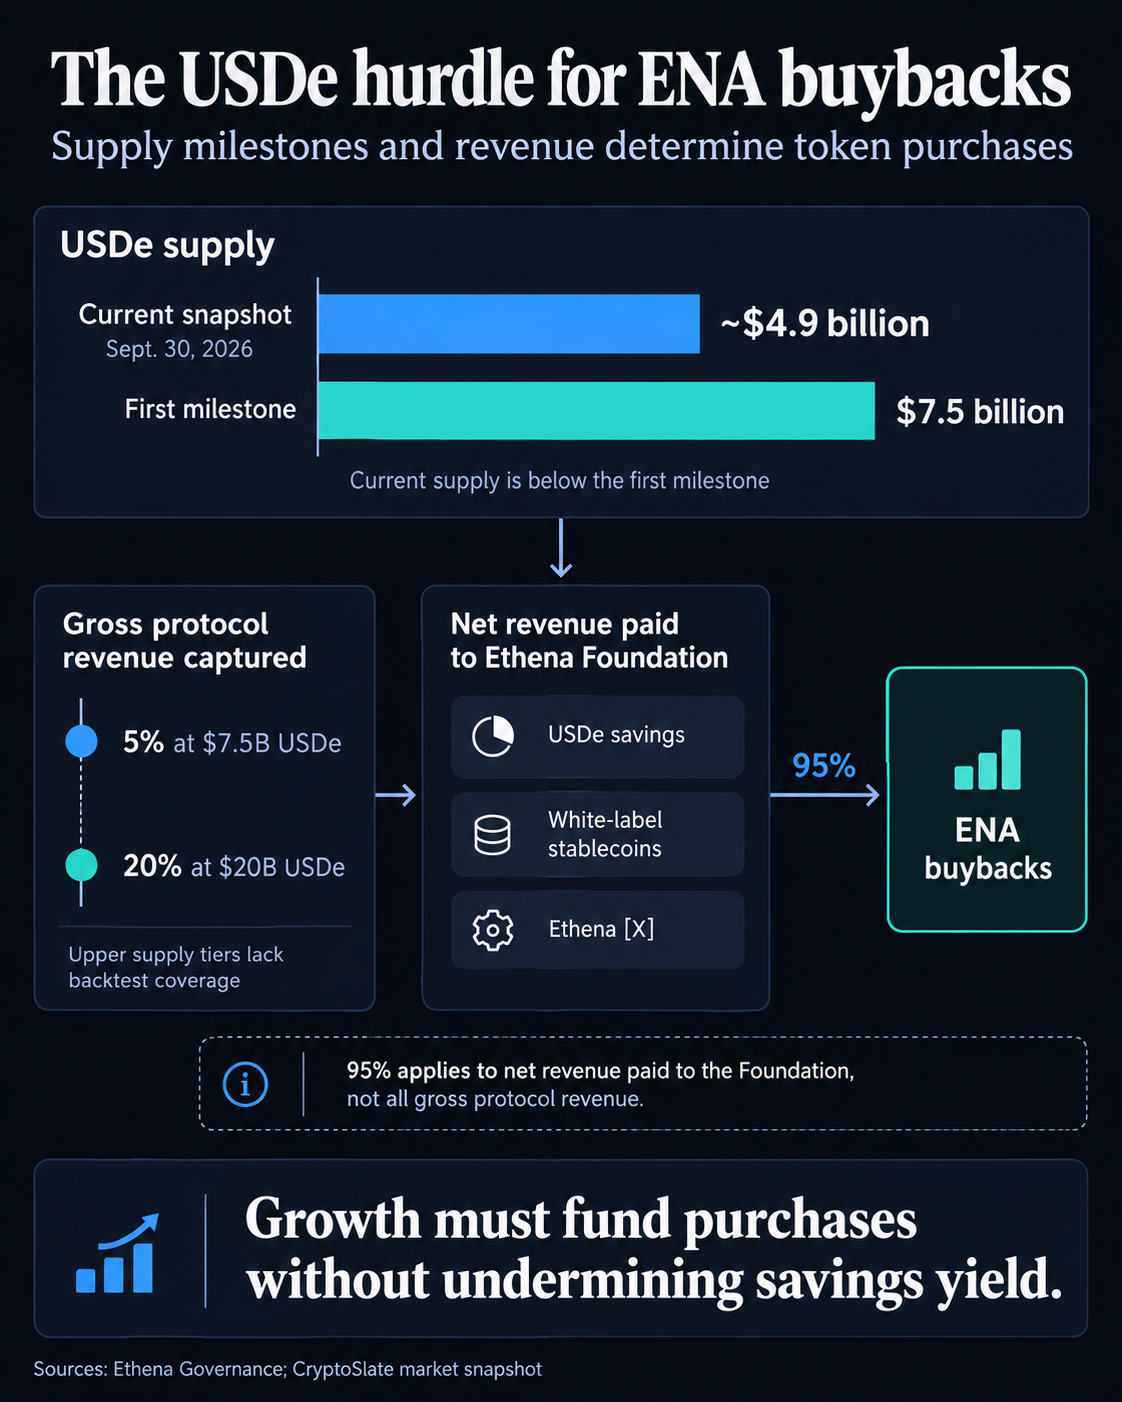
Capturing a larger share of Ethena’s revenue for the protocol can reduce what remains available to sUSDe holders. That creates a balancing act: Ethena needs enough margin to support ENA purchases while maintaining sufficiently competitive yields to keep attracting the deposits required for USDe to grow.
The assumptions become more demanding as supply rises. The 6% return used in the framework has not been guaranteed across market cycles, while the higher revenue-capture tiers have yet to be tested at the scale Standard Chartered expects.
That leaves investors with several nearer-term checkpoints before the $2 target becomes relevant. USDe must first cross the $7.5 billion fee-switch threshold and reclaim its previous peak.
Beyond that, Ethena will have to show that its newer yield strategies can absorb tens of billions of dollars without materially compressing returns. How quickly those thresholds are crossed will determine whether Standard Chartered’s projected buyback engine begins to resemble the one embedded in its valuation model.
The post Standard Chartered says Ethena’s ENA could crush Bitcoin and Ethereum returns by 2028 appeared first on CryptoSlate.
Hackers behind Bitget’s $387.5 million breach are turning to Zcash's privacy features to hide the stolen funds as crypto firms increasingly block other escape routes.
About 2,746 ZEC worth roughly $3.9 million was transferred Wednesday into Zcash’s Ironwood shielded pool through three transactions, according to on-chain activity flagged by blockchain investigator ZachXBT. The amount represents about 15% of the 18,917 ZEC stolen from the exchange.
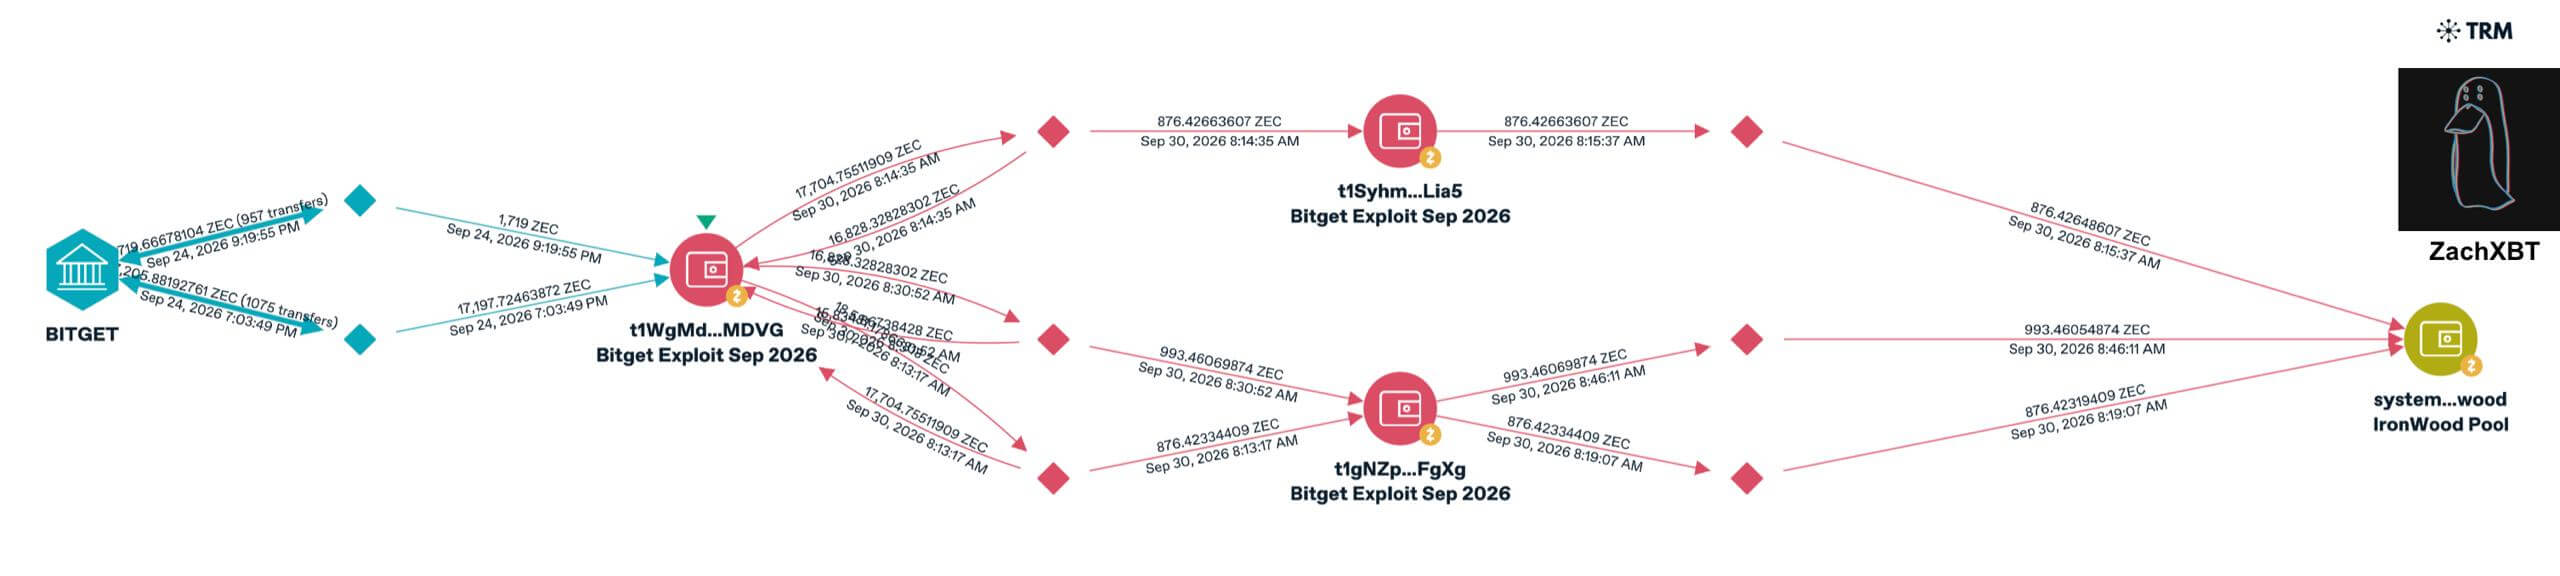
The transfers complicate Bitget’s recovery effort because transactions inside Ironwood can conceal senders, recipients, and amounts, breaking the public transaction trail investigators use to follow stolen assets. Deposits into the pool remain visible, but subsequent movements become considerably harder to link to their origin.
The shift toward Zcash's privacy infrastructure follows attempts by the attackers to move substantially larger sums through cross-chain services, some of which have begun refusing the transactions.
NEAR Intents General Manager Alex Shevchenko said wallets connected to the Bitget theft attempted to process more than $50 million through the protocol. Its SHIELD risk system rejected most of those transactions before execution, while roughly $503,000 was frozen after swaps had begun and about $166,000 successfully passed through.
The rejected assets remained under the attackers’ control, leaving them free to seek alternative routes. The latest Zcash transfers show how that contest is shifting as stolen funds encounter tighter screening across parts of the crypto market.
THORChain volume surges as hackers seek other routes
One alternative has been THORChain, the permissionless cross-chain exchange that has resisted Bitget’s requests to block addresses linked to the theft.
Bitget-linked wallets have repeatedly used the protocol to turn stolen assets into native Bitcoin. Bitquery estimated that about 29,088 ETH, worth roughly $79 million at the time of its analysis, had been sent into THORChain and swapped for Bitcoin through Sept. 29.
As a result, activity on the decentralized exchange has exploded since the breach. THORChain has processed more than $1.5 billion in DEX volume in the days following the incident, compared with roughly $146 million during the week before the attack, according to DeFiLlama data reviewed by CryptoSlate.
The increase has coincided with hacker-linked flows, although total THORChain volume cannot be attributed to the attackers.
THORChain's actions, in contrast to NEAR, highlight a widening divide over how decentralized infrastructure should respond when it identifies stolen assets.
NEAR has argued that permissionless access does not require its liquidity providers to execute known illicit transactions. However, THORChain has maintained that selective censorship would undermine the principles governing its network.
That disagreement has practical consequences for Bitget. Blocking one venue does not freeze assets held in self-custodied wallets. Instead, it forces the attacker to find another source of liquidity, potentially pushing funds toward permissionless exchanges or privacy systems that offer investigators fewer opportunities to intervene.
Bitget absorbs withdrawal rush as operations restart
Meanwhile, Bitget is facing a separate test from its customers as it gradually restores access to funds following the four-day withdrawal freeze.
DeFiLlama data reviewed by CryptoSlate shows more than $700 million has moved out of tracked Bitget wallets since withdrawal channels began reopening, highlighting immediate customer demand to move assets off the exchange. DeFiLlama tracks known exchange wallets, meaning the figure reflects on-chain flows rather than Bitget’s complete internal withdrawal ledger.
Bitcoin accounted for a sizable portion of the initial rush. Bitget said it had processed 9,585 withdrawal requests totaling 4,098 BTC by Sept. 28, hours after reopening Bitcoin withdrawals.
The outflows have continued as the exchange progressively restored other assets. Bitcoin withdrawals reopened Sunday, followed by Ethereum and then USDT across Ethereum, BNB Chain, Solana and Tron. Bitget plans to reopen withdrawals for its remaining cryptocurrencies as well as fiat and peer-to-peer services on Friday.
On Sept. 30, Bitget's Chief Executive Officer Gracy Chen said that the exchange's Protection Fund had also been rebuilt to more than $300 million, restoring a threshold the company had promised to reach after drawing on the fund following the breach.
She said BTC, ETH and USDT withdrawals were already operating and described the business as “gradually back to usual.”
The exchange’s latest proof-of-reserves snapshot provides another measure of its ability to withstand the withdrawals. Bitget reported an overall reserve ratio of 131% across 19 covered assets as of Sept. 29, meaning the assets included in its disclosure exceeded corresponding customer balances by 31%.
Those figures will face a broader stress test when Bitget removes the remaining withdrawal restrictions Friday.
The post Bitget’s hackers turn to Zcash after $50 million laundering route gets blocked appeared first on CryptoSlate.
Kalshi is ending a trader-volume incentive program nearly a year early as scrutiny of activity in its crypto markets intensifies.
The prediction-market operator told the Commodity Futures Trading Commission (CFTC) that its Volume Incentive Program will terminate no earlier than Oct. 13, according to a Sept. 28 filing. The program had previously been scheduled to run until Oct. 1, 2027, making the change a significant acceleration of its planned end date.
The decision comes as Kalshi faces questions over trading patterns in its perpetual futures markets. The CFTC has reportedly examined activity after researchers identified repetitive trades around fixed dollar amounts, including roughly $5,500 in Ethereum perpetuals.
Kalshi has said it is not under investigation and has rejected allegations of wash trading, attributing the repeated transactions to market makers placing fixed-size quotes that other traders repeatedly hit.
The filing does not link the program's termination to those concerns or explain why Kalshi ended it early. Under its terms, the exchange could terminate the program at its discretion.
Launched to increase activity on Kalshi's central limit order book, the program allowed the exchange to designate eligible markets and establish fixed reward pools. Traders received a share based on their proportion of eligible volume, with event-contract rewards capped at half a cent per contract for each participant. Perpetual futures were also eligible and were exempt from the program's normal 3-cent to 97-cent qualifying price range.
That incentive structure is now giving way to a broader framework that gives Kalshi far more flexibility in how it spends money to attract and retain traders.
Kalshi shifts toward targeted trader rewards
Days before filing to terminate the volume program, Kalshi submitted a new Deposit and Trading Reward Incentive Program to the CFTC. The regulator's docket lists a modified version as received Sept. 25, with the filing setting Sept. 28 as the earliest effective date.
The two programs are not formally described as replacements and can overlap before the older program ends. Still, the new framework changes how Kalshi can deploy incentives.
Rather than distributing a fixed pool according to each trader's share of market volume, Kalshi can offer time-limited promotions tied to deposits, trading activity, or both. Promotions can run from three to 90 days and target groups based on criteria including account age, whether an account is funded, previous trading activity, inactivity, geography, and prior participation in particular contract categories.
Individual promotions can pay up to $2,500 per participant, while total rewards are capped at $5,000 per person over the program's planned two-year life. Kalshi can use percentage matches or fixed-value incentives across categories including crypto, sports, economics, financials, politics, weather and entertainment.
The filing also adds more detail on abusive trading. Transactions under inquiry for potential self-matching, wash trading, prearranged trading or other prohibited practices would be excluded from promotional rewards.
Kalshi said its surveillance staff would apply heightened monitoring to participants receiving incentives and could terminate eligibility or pursue disciplinary action.
That gives Kalshi a more targeted customer-acquisition tool at a time when the economics and quality of trading activity on prediction platforms are receiving increased attention.
Record trading supports a $40 billion pitch
The incentive overhaul comes despite little evidence that Kalshi is struggling to generate headline volume.
The exchange has repeatedly broken trading records during September. Data compiled by DeFiRate shows Kalshi handled a record $3.24 billion on Sept. 27, while weekly volume reached $15.66 billion in the seven days through that date. Its share of tracked prediction-market volume stood near 80%, up substantially from levels seen a year earlier.
That growth is increasingly being reflected in what investors are willing to pay for the company.
Kalshi is in advanced discussions to raise about $1 billion at a valuation of roughly $40 billion, Reuters reported, citing people familiar with the talks. Sequoia Capital and Wellington Management are discussing leading the round, with Tiger Global and Dragoneer Investment Group also considering investments.
A deal at that price would almost double the $22 billion valuation Kalshi secured in a $1 billion fundraising round in May. Reuters said the company is also exploring expansion beyond prediction markets into additional asset classes and has held preliminary discussions about a future initial public offering.
That makes the incentive transition consequential beyond the rewards themselves. As Kalshi seeks a valuation closer to established financial-market operators, investors will increasingly have to judge how much of its rapidly rising activity reflects durable customer demand and how much still depends on the economics the exchange creates to stimulate trading.
The post Kalshi’s $40 billion growth story hits tough questions about its trading volume appeared first on CryptoSlate.
CryptoTicker.io
A price target of one cent is not a question of sentiment at Shiba Inu but an arithmetic problem with a very large number in it. With 589.24 trillion units in circulation, one cent per token corresponds to a market capitalisation of around 5.89 trillion dollars. That is roughly three and a half times what Bitcoin was worth in total on Wednesday evening. Anyone who wants to set up a forecast for SHIB seriously therefore calculates in market values and not in price targets.
This article first lays out the figures that every price target has to carry. After that it turns to a decision that faces investors in Germany before the turn of the year. Because while the price question stays open, a deadline that cannot be postponed is running in the background.
Shiba Inu price on September 30, 2026: 5.74 millionths of a dollar and 589.24 trillion tokens in circulation
On Wednesday evening SHIB traded at 5.74 millionths of a dollar, equivalent to 5.06 millionths of a euro. Market capitalisation stood at 3.38 billion dollars, which corresponds to rank 36 in the overall market. Within the preceding 24 hours the price moved between 5.71 and 5.99 millionths of a dollar, so the evening reading was around 4.2 percent below the daily high. The market data come from CoinGecko.
The view across longer windows is mixed. Over seven days there is a gain of 2.5 percent, over 14 days it is 19.1 percent and over 30 days 13.1 percent. Over twelve months, by contrast, there is a loss of 50.9 percent. The upward push of the past two weeks has therefore not made up the yearly loss; it has softened it.
Why the circulating supply is the decisive quantity
Market capitalisation is the product of price and circulating supply. With Bitcoin and its not quite 20 million units, one dollar more or less shifts the market value by around 20 million dollars. With Shiba Inu, every price move is multiplied by 589.24 trillion. That is precisely why price targets that sound unspectacular for other coins look here like a reordering of the entire crypto market.
One cent per SHIB demands a market capitalisation of 5.89 trillion dollars
Let us work through the common price targets once. With 589.24 trillion tokens in circulation, this is the picture:
- 10 millionths of a dollar, a gain of 74 percent: market capitalisation around 5.89 billion dollars.
- All-time high at 86.16 millionths of a dollar, a factor of 15: market capitalisation around 50.8 billion dollars.
- One tenth of a cent, a factor of 174: market capitalisation around 589 billion dollars.
- One cent, a factor of 1,742: market capitalisation around 5.89 trillion dollars.
To place the order of magnitude: on Wednesday evening Bitcoin came to 1.68 trillion dollars and Ethereum to 327 billion dollars. One cent per SHIB would therefore mean that a single memecoin gathers three and a half times the entire Bitcoin capitalisation to itself. The jump to one tenth of a cent, at 589 billion dollars, still lies well above the present market value of Ethereum.
None of this argues against the price being able to rise. It is a yardstick for which targets play in which league. The return to the all-time high of October 2021 demands a market value of 50.8 billion dollars and therefore lies in an order of magnitude that individual coins have already reached in earlier upward phases. One cent demands an order of magnitude that no crypto asset has reached so far.
The road to the 2021 all-time high: a factor of 15 and 50.8 billion dollars in market value
The all-time high dates from October 27, 2021 and stands at 86.16 millionths of a dollar. Counted from that high, 93.3 percent are missing to get there; from today's level it is a factor of 15 upwards. Anyone writing that target into a forecast is at the same time saying that market capitalisation has to grow from 3.38 to 50.8 billion dollars.
A look at trading activity puts into context how much capital is actually being moved at present. Over 24 hours, SHIB worth 93.2 million dollars changed hands, which corresponds to 2.8 percent of market capitalisation. That turnover rate is unremarkable for a memecoin, but it will not carry a move by a factor of 15 within a short time.
Circulating supply and burning: around 41 percent of the original supply has been destroyed
The supply is shrinking, but slowly. Of the originally created stock of one quadrillion tokens, 410.84 trillion have been moved into inaccessible addresses according to the tracker Shibburn, which is 41.08 percent. On that count, 589.16 trillion tokens remain; CoinGecko reports 589.24 trillion as the circulating supply. The gap between the two sources is below one tenth of a percent and changes nothing about the order of magnitude.
Important for placing any forecast: the large burns lie in the project's early days. The ongoing burns move in the range of a few million to a few dozen million tokens a day. With 589 trillion in circulation, a daily burn of 70 million tokens changes the circulating supply by about 0.000012 percent. Anyone citing burning as a driver for a price jump would have to explain how that turns into a noticeable scarcity within any foreseeable time.
Levels up and down: 5.71 millionths as the daily low, 5.99 millionths as the daily high
For the short term, the ranges of recent days are the soberest point of reference. On the downside, the daily low at 5.71 millionths of a dollar marks the nearest zone, a mere 0.5 percent or so below Wednesday evening's level. As solid support this value is therefore of no use; it marks the lower edge of the day's activity.
On the upside the daily high lies at 5.99 millionths of a dollar, around 4.4 percent away. Above that begins the area in which the price traded over the course of the past two weeks, because the 19.1 percent of the 14-day balance largely arose within that window. Anyone setting levels here sensibly works with percentage distances, because absolute figures in the sixth decimal place are hard to read.
Holding period under Section 23 of the Income Tax Act: one year separates taxable from tax free
At this point the price question turns into a decision with a date. In Germany crypto assets count as other assets within the meaning of Section 23 of the Income Tax Act. A private disposal transaction only exists if no more than one year lies between acquisition and sale. The updated circular of the Federal Ministry of Finance of March 6, 2025 (BStBl 2025 I p. 658) sets out the administrative view on this in more detail.
The familiar side of this rule: anyone holding for longer than a year sells the gain tax free, regardless of its size. The less familiar side is currently the more important one for SHIB holders. If a sale falls outside the one-year window, it is no longer relevant for tax. A loss realised after the holding period has expired therefore cannot be offset either.
What that means concretely: anyone who bought SHIB more than twelve months ago and is now down around half of the amount staked is holding a loss that the tax office no longer recognises. Anyone who bought within the past twelve months, by contrast, holds a loss that is usable for tax, but only until their personal one-year deadline expires.
The deadline runs per purchase, not per account
The one-year period begins on the day after acquisition and runs separately for every single acquisition. Anyone who bought in tranches over months has correspondingly many deadlines running alongside each other. For matching purchases and sales, the first-in, first-out method applies in practice, meaning the assumption that the units bought first are sold first. A tax tool or portfolio tracker resolves that matching automatically and is hard to replace where there are many small purchases.
Exemption limit of 1,000 euros: from the first euro above it, the entire gain becomes taxable
If the total gain from all private disposal transactions in a calendar year stays below 1,000 euros, it remains tax free. That amount has applied since 2024 and replaced the earlier 600 euros. The construction of the rule is what matters: the legislator grants an exemption limit here and not an allowance. Anyone reaching 1,000 euros or more in the calendar year pays tax on the full amount and not only on the part above the threshold.
All private disposal transactions of the year flow into that total, so gains from other coins and from sales outside the crypto sphere count too, as far as they fall under Section 23. Anyone down on SHIB but up on another coin sets both off against each other in the same pot.
Offsetting losses on SHIB: losses reduce gains from private disposal transactions alone
The wording of the law is tight at this point. Losses from private disposal transactions may only be offset up to the amount of the gain you have made from private disposal transactions in the same calendar year. A deduction from other income, for instance from wages or from capital income on shares, is excluded.
An excess loss is not lost because of that. In accordance with Section 10d it reduces income from private disposal transactions of the immediately preceding year or of the following years. A one-year carry-back and a carry-forward unlimited in time are therefore possible, but both always within the same category of income.
For a loss to enter the assessment at all, it has to be declared in the tax return, even if there are no gains to set against it in the same year. Anyone who does not declare it has nothing to carry forward later.
Purchase route and custody under MiCA: authorised providers and your own wallet
Since the European regulation on markets in crypto assets became fully applicable, crypto service providers in the EU may only operate with authorisation. For you as an investor in Germany that mainly means you can check when buying whether a provider holds such authorisation and whether it offers trading in SHIB at all. You will find an overview of the trading venues authorised here in the comparison of crypto exchanges.
On custody, the same applies to a memecoin as to larger assets. Anyone wanting to hold a position for longer, for instance to sit out the one-year period, takes the trading platform's default risk out of play by transferring the tokens to their own wallet. One point matters for tax here: a transfer between your own wallets is not a sale and does not interrupt the holding period. What counts is the time of acquisition, and you have to be able to document it.
Records you will need later
For every acquisition you need the date, the quantity and the value in euros, and the same for every sale. At exchanges that stop trading or close a market, the statements are not always retrievable later. An annual export of the transaction history costs a few minutes and is the basis for every later loss assessment.
What makes a forecast for Shiba Inu robust
A solid expectation for SHIB starts at three points, and the price alone is not one of them. First at market capitalisation, because it translates every price target into a comparable quantity: 5.89 billion dollars for 10 millionths, 50.8 billion for the all-time high, 5.89 trillion for one cent. Second at the circulating supply, which moves through the ongoing burns in the order of ten-thousandths of a percent a day and therefore drops out as a price driver in the short term. Third at liquidity, which at 2.8 percent turnover in 24 hours describes how much capital is actually working in the market at present.
The bull case can be formulated cleanly with these figures. Where risk appetite across the market is broad, double-digit percentage moves are the rule for memecoins, and the 19.1 percent of the past 14 days show that the asset is capable of that at any time. The bear case stands alongside it: over twelve months there is a loss of 50.9 percent, and a fall back below the range of recent days would have little in the thin turnover rate to slow it down.
What cannot be formulated seriously, by contrast, is one cent as a target within any manageable period. That figure demands a market value no crypto asset has reached so far, and it demands it on top of everything standing in the market today.
Shiba Inu forecast: your next three steps
- Convert your price target into market capitalisation. Multiply the target price by 589.24 trillion. If the result is a figure above today's Bitcoin capitalisation of 1.68 trillion dollars, the target is no longer a forecast but a bet on a completely different market order.
- Check the acquisition date of every single tranche. If a purchase lies less than twelve months back and is down, the loss is still usable for tax; after that it is not. A tax tool or portfolio tracker matches purchases and sales on a first-in, first-out basis and shows which deadline expires when. The tax assessment of your individual case belongs in the hands of a tax adviser.
- Separate your trading holdings from your long-term holdings. Whatever you want to hold beyond the one-year period belongs in your own custody rather than on the trading venue, and a transfer between your own wallets does not interrupt the holding period. Which devices are suitable for that is shown by the comparison of hardware wallets, and where you trade with authorisation by the comparison of crypto exchanges.
(As of September 30, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Quant (QNT) has one of the steepest moves of the year behind it. On September 21, 2026 the token cost around 64 US dollars; on September 27 it reached an intraday high of 373 US dollars on the Binance spot exchange, almost six times as much in six days. On Wednesday evening, September 30, QNT trades at around 292 US dollars (Binance, 18:20 UTC). Many readers are therefore asking right now how Quant can be shorted, meaning how to bet on a decline. This article sets out the routes, the costs and the risk that is most often underestimated.
We explained the trigger for the run in the background piece on the selection by The Clearing House; the technical picture is in the Quant price prediction and in the analysis Is Quant a good buy at the current price?. This piece is about the other side.
How the run unfolded, and why it tempts people to short
The path up was anything but even. After the high of September 27, QNT fell the following day to 195 US dollars, a drop of almost 48 percent within a day. Since then the price has recovered and reached an intraday high of 329 US dollars on September 30. Between the daily low and the daily high there were around 25 percent on that Wednesday alone.
A price that multiplies within a week looks overstretched, and the idea of betting on a return suggests itself. That is precisely the idea a great many market participants are having at the same time. This is the point at which a short can become expensive, and more on that shortly.
Which exchanges let you short Quant
The usual route is open-ended futures contracts, known as perpetual futures. On September 30 we checked the exchanges' public interfaces for where a QNT contract is listed. The result: Binance (USDT futures), Bybit, OKX, Bitget, Kraken Futures, MEXC and BingX each run a perpetual on Quant. At Binance, positions worth around 53 million US dollars were open in these contracts, at Bybit around 30 million. Bybit permits leverage of up to 75 times.
A second route is the margin short on a spot exchange: you borrow QNT, sell it and buy it back later. Kraken offers this for the QNT/USD pair with two or three times leverage, but not for QNT/EUR. On the Coinbase spot exchange, Quant is listed only for buying and selling; a short is not possible there. On the decentralised derivatives exchange Hyperliquid there is currently no QNT market.
Anyone who already owns QNT and wants to lock in gains often needs no short at all. A partial sale is the simplest and cheapest way to reduce risk. Hedging via a future is more worthwhile for larger holdings that are not to be sold for tax or other reasons.
Important before opening an account: in the EU, crypto derivatives do not fall under the crypto regulation MiCA but under the securities rules of MiFID II. Whether a provider enables futures for customers resident in Germany is its own decision, and one it changes occasionally. That is set out in the terms of use and should be checked before the first deposit. Which providers operate in the EU with a licence is shown by our comparison of regulated crypto exchanges.
What of this applies to investors in Germany
For customers resident in Germany the list becomes considerably shorter. In the EU, OKX offers its own futures regulated under MiFID II, the so-called X-Perps with leverage of up to ten times. Quant is not among them on September 30: QNT is missing from the 242 contracts OKX runs for the European market. The OKX QNT contract mentioned above is aimed at customers outside the EU. Bitpanda offers short positions only in the older CFD product Bitpanda Leverage, according to its help page for Bitcoin, Ethereum and other large coins; we did not find a short on Quant there, and Bitpanda describes its newer margin trading only for long positions. Bitget is currently not accepting new customers in the EU. Anyone wanting to short QNT from Germany therefore ends up above all with the margin short via the QNT/USD pair at Kraken, provided the account is enabled for margin trading.
What a Quant short costs right now
With perpetual futures, buyers and sellers settle up every eight hours via what is called the funding rate. If it is negative, the shorts pay the longs. That is exactly the case with Quant at present: on the evening of September 30, Binance reported minus 0.092 percent per eight hours and Bybit minus 0.056 percent. At Binance that works out at around 0.28 percent over a day. A short position of 1,000 US dollars therefore pays around 2.80 US dollars a day to the other side without the price having moved at all.
The rate changes with every period and can quickly turn out higher or lower. What it does show is how the market is positioned: there is more pressure from the selling side than from the buying side.
The biggest risk: the short squeeze
A negative funding rate with a rising price is a delicate mixture. Many shorts mean many positions that will be closed by force on a further advance. Each of those closures is a purchase and drives the price further, which triggers the next shorts. How such a chain runs was shown most recently by the short squeeze in Ethereum in September.
On leverage, a simple calculation pays off. With five times leverage the collateral posted is used up on a rise of 20 percent, with ten times already at 10 percent, and the exchange usually closes the position somewhat earlier still. With Quant the price swung by around 25 percent between the daily low and the daily high on September 30 alone. Anyone who had gone short at the daily low with five times leverage would have lost the position on the way up, even though the price stood lower again in the evening.
What matters before a short
Behind the advance there is not mere sentiment but a mandate from the US banking sector with a date attached: the network for tokenised deposits is to be available to the participating institutions in the first half of 2027. Anyone betting against Quant is therefore betting against a story that can keep delivering news for months. That does not argue against a setback, but it does argue against the assumption that it has to come immediately.
Three questions help with placing this: how high is the funding rate, and what does it cost to hold the position open for a week? At what price will the position be closed, and does that level lie within the usual daily swing? And how much of your own capital may this one trade cost? How leverage, entry and liquidation feel can be practised beforehand without real money, for instance in a trading demo account.
Leveraged derivatives are risky, and a total loss of the capital deployed is possible. This article describes routes and costs; it is not a recommendation to buy or sell Quant.
Ethereum closed the third quarter of 2026 up around 70.6 percent, its strongest third quarter on record. The price rose from $1,569.83 on July 1 to $2,689.39 on the evening of September 30. Bitcoin managed around 42.8 percent over the same period. For you as a holder, the more important question is therefore no longer how good the quarter was, but what the zone just below the quarterly high means for the weeks ahead, and which key dates now belong in your own calendar.
cryptoticker.io compiled this analysis itself on September 30, 2026. The basis is the public price history from CoinGecko for Ethereum and Bitcoin, evaluated across 92 daily values per coin from the start of the quarter to its close.
Ethereum in the third quarter of 2026: the numbers from $1,569.83 to $2,689.39
The course of the quarter falls into two unequal halves. Until the end of July, Ethereum moved within a narrow band; the actual advance began in August and ran into the second half of September. The quarterly high stands at $2,775.17 and was reached on September 22. From there the price gave up around 3.5 percent by the close of the quarter.
The spread between the quarterly low and the quarterly high comes to a factor of 1.77 for Ethereum. For Bitcoin the same figure is 1.48. That is the sober core of the quarterly result: Ethereum swung considerably wider than Bitcoin this quarter, upwards as well as in the pullbacks in between. Anyone who stepped in during August is sitting on a different outcome today than someone who bought at the start of July.
To put the record report in context: specialist media put Ethereum's quarterly gain at 70.6 to 71.0 percent depending on the cut-off moment, and the previous record for a third quarter at 66.55 percent from 2025. Bitcoin, at 42.8 to 44 percent, is on its second-best third quarter since records began. The divergences are explained by the timing of the measurement within the final trading day, not by different data.
Why Ethereum outperformed Bitcoin in the third quarter
Three developments carry the move, and all three are quantified. Spot ETFs on Ethereum in the United States took in between 10 and just under 14 billion dollars over the quarter depending on the survey, with a concentration in August. Companies putting Ethereum on their own balance sheets bought holdings worth more than 15 billion dollars according to industry figures. And the capital locked in DeFi applications on Ethereum and its layer-2 networks grew to around 88 billion dollars.
Total value locked, or TVL for short, denotes the sum of all funds users have paid into an application's contracts. The metric measures usage, not profit, and it also rises when the deposited coins simply become more expensive.
The difference from Bitcoin lies less in the demand itself than in the starting base. Ethereum began the quarter from a level well below its own record of August 2025, while Bitcoin stood closer to its all-time high. An inflow of the same size moves the smaller market value further in that situation. That is an explanation for the quarter just gone and not a promise for the next one.
Spot ETFs and corporate treasuries: where the inflows came from
At this point the origin of the demand is what matters to you, because it says something about how durable it is. Inflows from exchange-traded products are more sluggish than trading on crypto exchanges. Such funds follow investment decisions with a lead time and withdraw in an orderly fashion when sentiment turns. That is exactly what was visible in several weeks of net outflows in the spring of 2026.
Purchases out of corporate treasuries work in the other direction. In the short term they are rare, because a company does not turn its balance sheet position over week by week. In exchange they concentrate on a few addresses, and a single decision can carry more weight there than a thousand retail purchases. If you use the quarterly result for your own planning, you should look at both sources separately rather than adding them into one figure.
A request for caution on the totals: ETF inflows are delimited differently by different providers, depending on whether exchange transactions and staking income are counted in. That is why a range appears here and not a round number. If you work with such values, pay attention to which delimitation the provider states.
The quarterly high at $2,775.17 and the zone below it
At the end of the quarter Ethereum stands some 85 dollars below its own quarterly high. That proximity is the reason the coming trading days deserve more attention than the turn of the calendar itself. A break above $2,775.17 raises the quarterly high into a starting point for the next price band. If the attempt fails repeatedly, the same figure turns into a lid that sellers orient themselves by.
On the downside the first point of orientation lies in the area around $2,500, which served repeatedly as a springboard in September. Below that begins the stretch in which the August advance first took shape. These figures are reference points from the measured course of the quarter and not a forecast. What they state is where a great deal was traded last quarter, not what happens next.
The distinction between a reference point and a price target matters. A reference point describes an area where the behaviour of buyers and sellers has changed in the past. A price target is an expectation. Analyst estimates for the fourth quarter diverge widely, and none of them is presented here as our own assessment.
Bitcoin ends the quarter up 42.8 percent and 3.4 percent below its quarterly high
Bitcoin came from $58,566.09 on July 1 to $83,640.10 at the close of the quarter, with the quarterly high at $86,596.74 on September 22. Both coins therefore reached their high on the same day and give up an almost equally large share of it by the end of the quarter. That argues for a shared driver at the upper end, not for an Ethereum-specific weakness.
On September 30 a macro impulse was added on top. The US price index for personal consumption expenditures came in for August at 3.0 percent year on year, below the expected 3.3 percent, and Bitcoin reacted over the course of the day with a jump into the area around $84,750. If you are interested in how a date like that affects your open positions, the section on leverage and liquidation further down is the relevant one.
Holding period and tax year: which key dates now count for German holders
The turn of the quarter is meaningless for tax. What counts for you in Germany is the purchase date of every single position and December 31 as the end of the tax year. Under the law as it currently stands, a gain from the sale of crypto assets remains tax free if more than one year lies between purchase and sale. Within the year, taxation as a private disposal transaction at your personal tax rate applies, and an exemption limit of 1,000 euros applies to the sum of all private disposal transactions in a year.
In practice that means coins you bought in July or August 2026 only reach their one-year deadline in the summer of 2027. Selling the quarterly gain now would be fully taxable. At the same time the deadline for offsetting losses within the tax year expires on December 31: losses from private disposal transactions can only be offset against gains of the same kind, and for that both have to be realised in the same year.
Which position carries which purchase date can only be answered with a complete record once there have been several purchases over the year. If you bring your transactions together from several sources, you would normally use a tax tool or a portfolio tracker for that, one that keeps the acquisition dates per inflow. The tax treatment of crypto ETFs and ETPs differs from this; if you invest by that route, you will find the classification in the overview of crypto ETFs in Germany. Only tax advice settles your case in a legally binding way.
Buying Ethereum in Germany: MiCA authorisation, fees and custody
Since the European crypto regulation MiCA, providers addressing retail clients in the EU need authorisation as a crypto-asset service provider. MiCA is the EU regulation on markets in crypto assets; it governs authorisation, information duties and the handling of client assets. For you that is not a seal of quality for price performance but information about who is supervised and where to turn with a complaint.
When comparing costs it pays to look at three items that are rarely stated together: the trading fee in percent, the markup in the price itself and the cost of withdrawing to your own wallet. A provider with a low fee and a wide price markup can be more expensive than one with a stated percentage. Which houses work with German clients and what their terms look like is set out in the overview of crypto exchanges for German investors, linked at the end of this article.
The custody question arises independently of that. If the coins stay with the provider, you carry its default risk with it. If they sit in your own wallet, responsibility for access lies with you, and lost access is final. Both are defensible as long as the decision is taken deliberately and not out of habit.
Staking yield on Ethereum: lock-up periods and the difference from price movement
Ethereum is secured through staking, and anyone making their coins available for it receives an ongoing payment in the region of a few percent a year. Two things about that are frequently confused. First, the staking yield is not interest. Payment comes from newly issued coins and transaction fees, and counted in euros the amount falls when the price falls. Second, staked coins are not immediately available. The exit queue stood at times above one million waiting ETH in September 2026, with waiting times of several weeks.
For tax purposes staking income has to be treated as other income in Germany and therefore differently from the price gain. Anyone running both through the same address needs a separate record. The providers with their respective lock-up periods and payout models are set side by side in the overview of staking platforms that you will find at the end of this article.
Leverage and liquidation: why the days after a quarter end are vulnerable
A price standing 3.5 percent below its quarterly high sits in an area where many leveraged positions are tightly set. In a leveraged trade you post only part of the position value as collateral. If that collateral no longer suffices after a price move, the position is closed by force, and that is called liquidation. Because such closures sell in themselves, they amplify the move that triggered them.
Around quarter boundaries this coincides more often: position adjustments by institutional houses, expiring futures contracts and, in this case, the reaction to the US price data of September 30. If you are trading with leverage, the distance between your entry price and your liquidation price is the figure you have to know, not the quarterly return. Without leverage this section does not concern you.
What the quarterly result does not say about the fourth quarter
A record quarter is a statement about the past. No claim to a continuation follows from it, and the statistics of earlier fourth quarters are deliberately not cited here as an argument: the sample is small, and the conditions differ too much from year to year to derive an expectation from them.
Three things are documented at this point: the extent of the advance, the reference points from the measured course and the order of magnitude of the inflows that carried it. Everything said beyond that about October to December is an expectation. Analyst estimates for price targets currently diverge widely, and their spread is itself the most usable information in them.
Ethereum quarterly result: what to take away
- Draw up purchase dates, not quarterly returns. Write down for every position when you bought it, and mark which ones reach the one-year deadline before December 31 and which do not. The tax tools and portfolio trackers are suited to bringing several sources together.
- Note the two reference points. $2,775.17 as the quarterly high and the area around $2,500 below it. Decide in advance what you will do in each of the two cases, rather than in the moment of the move. If part of your coins is staked, the exit period belongs in the same note; the providers' periods are in the overview of staking platforms.
- Check the costs and custody of your own access. Trading fee, price markup and withdrawal costs are rarely stated together on a price sheet. The overview of crypto exchanges shows which providers are authorised under MiCA and what a transfer to your own wallet costs.
(As of September 30, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Sources for further reading: the quarterly result at finanzen.net and the breakdown of ETF inflows at Crypto Briefing.
21Shares has declared a distribution on five of its US-listed staking funds, payable today, September 30, 2026. The money does not come out of the issuer's own pocket but out of the staking income earned by the coins sitting inside the funds. If you invest from Germany, the side note matters more than the figure: the same house's European staking products, the ones you can actually put into your brokerage account via Xetra, distribute nothing at all. They credit the identical income to the fund's assets instead, so it ends up in the price rather than in your cash account.
That difference sounds like bookkeeping, and it is in fact the point where tax burden, compounding and the workload of your annual tax return begin to diverge. Buy a crypto product because it carries the word staking in its name and, depending on the wrapper, you are buying two very different things.
What 21Shares paid out: $0.031602 per share in the Ethereum staking fund
The issuer declared the September distributions on September 28, 2026. Five funds are affected, and the per-share amounts differ widely, because the underlying networks hand out different levels of reward and the share prices sit far apart:
- Ethereum staking fund (TETH): $0.031602 per share
- Solana staking fund (TSOL): $0.076590 per share
- Hyperliquid staking fund (THYP): $0.191360 per share
- Sui staking fund (TSUI): $0.052939 per share
- Polkadot staking fund (TDOT): $0.045029 per share
These amounts are not a dividend. A dividend is paid by a company out of its profit. Here the fund passes on what the networks credited it for helping to validate: if you stake Ethereum, you post capital to the network as collateral, confirm blocks with it and receive newly issued coins plus a share of the transaction fees in return. The fund does nothing else, only on behalf of all shareholders at once and at a scale individual investors cannot reach.
Staking means: you deposit coins in a network that runs on proof of stake and receive an ongoing reward for securing its operation. Unlike a savings account, that reward is not promised; it moves with the number of stakers and with the load on the blockchain.
Record date, ex-date and pay date: how a staking fund distribution is scheduled
Three dates decide who receives the payment. For this distribution the record date and the ex-date both fell on September 29, 2026, and payment follows on September 30. The record date determines whose holding is counted. The ex-date is the first trading day on which a buyer no longer buys the distribution along with the shares; on that day the price gives up exactly the amount distributed. Step in on the ex-date and you save nothing and miss nothing. You simply get the lower price without the payment.
That is why a distribution does not create income out of thin air. The amount merely moves out of the product and into your account. What it does change is the moment the tax office gets access, and the question of whether you have to reinvest the money yourself.
Staking fund and staking ETP: the difference between distributing and accumulating
A distributing product hands the income out in cash. An accumulating one keeps it and adds it to the net asset value, meaning the value of the fund's assets per share. 21Shares describes its European staking products in precisely those terms: the staking yield accrues to the net asset value daily rather than going to holders as a cash distribution.
Three things follow for you. First, an accumulating product produces no incoming payment that you would have to react to, and no reinvestment fee. Second, compounding works automatically, because the income stays inside the product and keeps working. Third, you will not see the income anywhere as a separate position: it sits in the price, and it only becomes visible when you sell. cryptoticker.io already took the two designs apart on August 14, 2026.
The five products belong to the US range: TETH, TSOL, THYP, TSUI and TDOT
All five funds with a September distribution are approved and traded in the United States. That is not a detail at the margin but the heart of the matter for an investor with a German brokerage account: as a rule you will not be able to buy these shares at a German bank, a German broker or a German trading app, however attractive the distribution may look.
Nor do the per-share amounts say anything about the yield on their own. A fund with a high share price can distribute more cents at a lower percentage yield than a cheap share with a high yield. If you want to compare products, convert the distribution into a percentage of the share price, or use the staking yield figure the issuer publishes itself.
PRIIPs and the key information document: why a US fund is missing from your German account
The reason does not lie with the brokers but in European law. The PRIIPs Regulation obliges anyone offering a packaged investment product to retail investors in the EU to provide a standardised key information document in the local language. US funds do not produce that document, because they do not need it for their home market. Without it an issuer may not actively offer the product to retail clients in Germany, and so the large brokers simply shut it out of trading.
In practice that means a report about a distribution at a US staking fund is news about the state of the market for you, not a buying opportunity. The route for retail investors in Germany runs through exchange-traded products approved in Europe, or through holding the coins directly. Which European crypto exchange-traded products exist and how to tell them apart is set out in the overview of crypto ETFs and ETPs in Germany.
The German route via Xetra: what the European staking ETPs do with the income
21Shares runs a separate European range, and that one is reachable through German trading venues. The house's Ethereum staking ETP carries the ISIN CH0454664027 and is listed on Deutsche Boerse Xetra, on the Stuttgart, Duesseldorf and Vienna exchanges, via Gettex and on the SIX in Zurich, among others. The management fee is 1.49 percent a year according to the issuer. For the Solana staking ETP, 21Shares reports a staking yield of 5.28 percent, derived from the network's reward rate.
In legal terms these products are not funds but exchange-traded debt securities collateralised with the coins, and they make no cash distribution. So if you expect an ongoing payment because the name carries the word staking, you are expecting the wrong thing from the European variant. Anyone who wants an ongoing payout is more likely to end up with a platform that passes staking rewards on directly; which providers do that on what terms is worth a piece of research in its own right.
Tax in Germany: how a crypto ETP is classified
Caution is in order here, and genuinely so. The tax treatment of crypto exchange-traded products in Germany has not been settled uniformly. Because they are bearer debt securities, classification as an investment of capital under Section 20 of the German Income Tax Act suggests itself; the flat-rate withholding tax of 25 percent then applies, plus the solidarity surcharge and church tax where relevant, regardless of how long you have held. For physically collateralised products carrying a right to delivery of the coins, the specialist literature also argues for classification as a private disposal transaction under Section 23 of the German Income Tax Act, which would bring the one-year holding period into play.
Which classification holds for your particular product is not something a news report can tell you. It is in the key information document and the securities prospectus, and it hangs on how the delivery claim is construed. That is a question for a tax adviser, not for a rule of thumb. The only certainty is this: a cash distribution of the kind the US funds are making today would be a clear inflow in the year of payment, whereas an accumulating product generates no cash flow at all until you sell. If you want to keep an overview of your positions and their acquisition dates, you will struggle to do without software; the common tax tools and portfolio trackers sit side by side in our comparison.
Regardless of the product question, the new reporting obligation for crypto service providers has applied since January 1, 2026, implementing the EU's DAC8 directive in Germany through the Crypto Asset Tax Transparency Act. The first reporting period is the 2026 calendar year; the first annual report goes to the Federal Central Tax Office by July 31, 2027. The fact that data will reach the tax office anyway changes nothing about the legal position, but it does change the likelihood that a gap in your own records will be noticed.
Fee against yield: what 1.49 percent a year leaves of the income
A management fee of 1.49 percent a year is no small item when the network's staking yield sits in the mid single digits. At a network reward of a good five percent, as 21Shares reports for the Solana product, roughly a quarter to a third of the gross income goes on administration before tax is even discussed. That is the price of someone else running the validators, holding the keys and ensuring tradability on an exchange.
On top of that comes the spread at the trading venue. Crypto ETPs are thinly traded outside main trading hours, and the gap between bid and ask can then be a multiple of the regular one. Place an order without a limit in the evening or at the weekend and you pay that gap. A limit costs nothing and prevents the worst execution.
The calculation that always pays off
Take the staking yield the issuer quotes for the product, subtract the management fee and set the result next to what a platform credits you for the same coin after its own fees. Only that difference says anything about whether the product wrapper is worth its price. The wrapper buys convenience, eligibility for your brokerage account and the liability of a regulated issuer; in exchange it costs the same percentage every year, including in a year without a price gain.
Staking without a product wrapper: what separates direct holdings from an ETP
If you hold the coins yourself and stake them through an exchange or your own wallet, the picture changes. Directly held crypto assets fall under the one-year holding period of Section 23 of the German Income Tax Act: after more than twelve months the disposal gain is tax free, below that your personal income tax rate applies, and the exemption limit for other private disposal transactions is 1,000 euros a year. Exceed that limit and the entire gain is taxable, not just the part above it.
The staking rewards themselves have to be kept separate and accrue to you at the moment they are credited; for tax purposes they count as other income. A fresh holding period then starts for the subsequent sale of the coins received, counted from the inflow. This is precisely where records come apart in the spring: receive small rewards daily over the course of a year and you end up with hundreds of individual acquisitions, each with its own date and its own price.
That is the real trade-off, and it is not a question of yield alone. The product wrapper costs a fee and may take the holding period away from you, but it spares you key management and the bookkeeping over many individual inflows. Direct holdings keep the chance of tax exemption after a year and demand in return that you document cleanly yourself.
Staking distributions: the key points for your decision
The distribution of September 30, 2026 is not an opportunity for retail investors in Germany but a reason to read your own position correctly. Three steps take you further:
- Check your account to see whether your product distributes or accumulates. The detail is in the key information document and on the issuer's product page. Without that information you can assess neither the income nor the tax effect. Which alternatives offer an ongoing payout is shown by our comparison of staking platforms.
- Put the network yield and the management fee on one line. At a fee of 1.49 percent against a good five percent reward, the difference decides, not the headline. Compare the result with what a crypto exchange leaves you for the same coin after deducting its costs.
- Settle the tax classification before you build a position, not in May afterwards. With an ETP it hangs on how the product is construed and belongs with a tax adviser; with direct holdings you need complete documentation of every inflow. The appropriate tax tools and portfolio trackers take the logging off your hands.
Sources for this article: the issuer's product details on the Ethereum staking ETP with ISIN CH0454664027 and the list of the five September distributions per share.
(As of September 30, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
The European securities watchdog ESMA submitted its response to the review of the crypto regulation MiCA to the EU Commission on September 30, 2026. In it the authority calls for, among other things, stricter advertising rules where crypto assets are promoted by influencers, disclosure duties for staking, lending and borrowing, and the power to shut down fraudulent websites and to freeze crypto assets.
None of it applies today. These are recommendations from an authority to the legislator, submitted on the final day of a consultation. This piece sets out what ESMA specifically demands, which of the points would affect your crypto account in Europe, and how long the road is from this paper to binding law.
The submission of September 30: ESMA answers the EU Commission
The EU Commission opened a targeted consultation on the review of MiCA over the summer, asking where the regulation should be improved. The deadline ran out on September 30, 2026, at 23:59 Central European Summer Time. What the Commission had asked we wrote up in the article on the MiCA review and the proposed changes; the deadline itself was the subject of our piece on the consultation and its submission date.
On the last day ESMA filed its answer, a 16-page document with the reference ESMA75-113276571-1721. The authority summarises its aim itself as follows: simplify the framework, improve investor protection and capture new business models such as decentralised finance applications, staking, lending and borrowing.
MiCA is the EU regulation on markets in crypto assets. Since 2024 the regulation has governed step by step who may trade, hold in custody and issue crypto assets in the EU, and it applies directly in Germany, where BaFin grants the authorisations. What duties follow from it for providers is set out in our overview of the MiCA licence.
Advertising by crypto influencers: stricter rules for third parties
The first block of the response concerns investor protection. ESMA proposes stricter requirements for the marketing of crypto assets, explicitly where these are promoted by influencers and other third parties. Today MiCA bites above all at the authorised providers themselves. Anyone advertising a token as a third party often falls through the net in practice.
Alongside that demand the authority names more transparency on costs. Both aim at the same point: whoever makes a purchase decision should know beforehand what it costs and who was paid for the recommendation.
For a reader this is the part with the most immediate bearing on everyday life. If it came in this form, paid posts about individual tokens would have to be more clearly recognisable as advertising, including where the sender is not an authorised provider but a single person.
Staking, lending and borrowing: disclosure before the investment
The second point concerns services MiCA has so far covered only at the margins. ESMA calls for proportionate requirements for staking, lending and borrowing, explicitly including disclosure duties. Named in that context are costs, risks, returns, collateralisation and possible losses, and all of it before an investment decision is taken.
Staking means depositing tokens for the operation of a blockchain and receiving a reward for it. Lending means lending out crypto assets against interest; borrowing is the other direction, taking them up against collateral. The three services differ considerably in risk but are often offered side by side in the interfaces of trading venues.
How things stand in Germany today, which providers need an authorisation and how returns are treated for tax we set out in the piece on staking under MiCA. The ESMA demand would change nothing about the tax there, but it would change what a provider has to give you in writing in advance.
A new licensed service for access to DeFi protocols
The third block is the furthest reaching. ESMA suggests setting clearer criteria for when an activity actually counts as decentralised. In addition it recommends creating a new licensable crypto service: for firms that give users access to DeFi protocols.
DeFi stands for decentralised finance applications, meaning trading, lending or derivatives through programs on a blockchain instead of through a company. The operator of a web interface to such a program is today hard to get hold of in regulatory terms in the EU. That is exactly the gap the proposal aims at.
How unclear the situation currently is shows in the case of a well-known trading platform for perpetual futures, which we described under use without a MiCA licence from Germany. If the new service type came, the question of authorisation there would be answered unambiguously.
Shutting down fraud sites and freezing crypto assets: new supervisory powers
In the section on supervision ESMA asks for more operational enforcement rights. Specifically the authority names the ability to detect, block and shut down fraudulent websites and to freeze crypto assets where there is a suspicion of market abuse or terrorist financing.
This is the point at which a widespread unease would gain an official basis for the first time. A freeze would be tied to a case of suspicion and would concern not arbitrary balances but assets connected to a specific proceeding. How such a power would be shaped and limited is not in the press release; that would be a matter for the legislative process.
Part of the picture is that the authority justifies the same paragraph with the aim of making supervisory action in the EU faster and more uniform and of reducing the scope for shopping between member states.
Third-country providers without a MiCA licence: a tightening on reverse solicitation
Closely connected to that is the call for strengthened supervisory powers over firms from third countries that approach EU investors without being authorised under MiCA. What is meant is so-called reverse solicitation, the exception under which a provider without an EU authorisation may serve whoever seeks it out of their own accord.
ESMA had already set this topic as a focus of its supervisory programme from 2027. What follows from that for users is in our article on reverse solicitation in the ESMA programme for 2027. The response now goes one step further and asks for the matching legal instruments as well.
In practice that affects everyone holding an account at a trading venue outside the EU. A tightening would not forbid the account, but it would narrow the advertising and outreach channel of such providers into the EU.
Stablecoins without MiCA compliance: a ban planned for regulated providers
The fourth block of demands concerns stablecoins. ESMA proposes explicit rules prohibiting regulated crypto firms from offering services around stablecoins that do not meet the MiCA requirements.
A stablecoin is a token whose value is pegged to a currency and which is meant to be covered by reserves. For stablecoins offered in the EU, MiCA requires an authorisation of the issuer and a filed whitepaper. In practice several large tokens of this kind have already been taken off authorised trading venues in the EU.
An explicit rule would end the question of interpretation that has stood so far. For holders this would be the point with the most concrete risk: anyone holding a non-compliant stablecoin at a provider authorised in the EU would have to reckon with trading or custody there being wound down. Which trading venues carry an EU authorisation as things stand is shown by our overview of regulated crypto exchanges.
Hybrid tokens and binding classifications: ESMA wants rules on categorising
A further proposal concerns the categorising of tokens. ESMA recommends rules for how crypto assets are to be classified, explicitly including new products such as hybrid tokens. On top of that the authority would like to receive the power to issue binding opinions on the classification of individual tokens.
The background is a practical one. Whether a token falls under MiCA or is treated as a financial instrument under securities law is today decided by each national supervisor for itself. The same product can be classified differently in two member states. A binding ESMA opinion would end those divergences.
Hybrid tokens are tokens combining features of several categories, for instance a utility function and at the same time a share in revenue. Such tokens are the most common reason for classification disputes, because they fit cleanly into none of the existing boxes.
Simplification and less red tape: less duplication on whitepapers and licensing
Not all the proposals tighten. A section of its own in the response follows the EU's simplification agenda. ESMA proposes simplifying the notification procedures for crypto whitepapers, reducing duplicate authorisation requirements for firms that are already regulated, and framing the prudential own-funds requirements more uniformly.
A whitepaper in the MiCA sense is not a piece of marketing copy but a mandatory document with prescribed information on issuer, rights, risks and technology, which is notified to the supervisor before a public offering. The notification routes for it are regarded in the industry as laborious.
For investors this block is the least conspicuous, but it explains why the response is not to be read simply as a tightening. The authority bundles relief and new duties into one paper.
What already applies today and what is only a proposal
The most important distinction on this topic is the one between binding law and a recommendation. MiCA applies. The authorisation requirement for trading venues and custodians applies, the whitepaper applies, the rules for stablecoin issuers apply.
The six blocks of demands from this response do not apply. Those blocks are the contribution of a supervisory authority to a consultation in which associations, companies and other authorities have answered too. Not one of these demands obliges anyone to anything today.
Anyone reading a text that turns these points into duties already in force is reading a confusion. That goes in particular for the advertising rules and the freezing of crypto assets, because both are easy to present as already decided.
The timetable: from the consultation to a legislative proposal
The further route is laid down in the EU procedure, but it carries no dates. After the close of the consultation the EU Commission evaluates the answers and decides whether and in what form it puts forward a legislative proposal. It has published no date for that.
If a proposal comes, it goes through the ordinary legislative procedure with the European Parliament and the Council. Only after that follow transition periods, which with MiCA itself ran to several years between adoption and full application. A realistic window for changes therefore lies beyond 2027, without that being provable at present.
ESMA itself looks beyond the MiCA review in its response and points to the need for a framework for tokenised securities and for settlement on the blockchain. That is a legislative topic of its own and not part of this review.
MiCA reform: What to take away
The response is a signpost, not a deadline. The paper shows where the European supervisor wants to push the framework, and in doing so names the areas in which something is most likely to change in the coming years. Three things are worth drawing from it.
- Keep an eye on the authorisation status of your provider. The stablecoin proposal and the tightening on reverse solicitation both aim at the line between authorised and unauthorised providers. Which trading venues carry an EU authorisation is in the overview of regulated crypto exchanges.
- Read the terms of staking offers now as closely as the disclosure duty would demand in future. Costs, collateralisation, lock-up periods and possible losses are not everywhere set out with equal clarity today; the differences are shown by the overview of staking platforms.
- With advertising, separate the source from the claim. Until stricter rules for third parties arrive, the judgement stays with you. Anyone wanting to hold crypto assets independently of a provider will find the devices for it in the hardware wallet comparison.
(As of September 30, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
Gemini 4 Argon tops 12 of 18 benchmarks in Google's own table, writes a million tokens per reply and resists hijacking best. Cyber defenders get it first, with the guardrails off.
The team behind the MyDoge wallet opened a public test of DogeOS, a layer that lets developers build lending platforms and games on top of the meme coin network.
An internal memo warned FBI staff that ShinyHunters, the group claiming it hacked the bureau's jobs site, may hold their private details.
The Coinbase-backed group's first Senate endorsements—Republicans Jon Husted and Ashley Hinson and Democrat Chris Pappas—come two weeks after the Clarity Act's collapse, as the industry's fight shifts to the campaign trail.
The attacker behind the $387.5 million Bitget heist has started hiding about $3.8 million in ZEC inside Zcash's Ironwood pool, after Near Intents turned their swaps away.
U.Today - IT, AI and Fintech Daily News for You Today
The crypto market remains broadly bullish, although momentum is becoming increasingly uneven as some assets consolidate or correct after September’s strong gains.
The XRP Ledger has moved closer to launching its native lending infrastructure, with the LendingProtocolV1_1 amendment now open for validator voting.
Brazilian oil giant Petrobras is expanding its use of Cardano technology, with two new blockchain applications focused on sustainable aviation fuel and renewable Diesel R.
DogeOS deploys a ZK-Rollup layer on Dogecoin, bringing EVM smart contracts and DeFi apps to native DOGE holders.
Hyperliquid is set for a massive token unlock next month, with already about $856 million worth of HYPE in line to be unlocked in six days.
Blockonomi
TLDR
- HPE stock gained 5.14% after announcing Vultr’s $1.2 billion order
- Vultr will deploy AMD Helios AI Rack systems across US data centers
- HPE expands AI infrastructure with AMD computing and networking solutions
- The deal strengthens HPE’s position in large-scale enterprise technology
- AMD Helios supports advanced workloads with high-performance infrastructure designs
Hewlett Packard Enterprise Company (HPE) stock advanced after the company secured a $1.2 billion order from Vultr for AI infrastructure systems. The deal strengthens HPE’s position in large-scale computing solutions for advanced workloads. The company will deploy AMD Helios AI Rack by HPE systems across Vultr’s United States data centers.
The stock climbed to $64.65, gaining 5.14%, after breaking above the $61.49 support zone. However, shares moved toward the $65 resistance level and remained near session highs. The market reaction followed news of expanded demand for HPE’s infrastructure products.
Hewlett Packard Enterprise Company, HPE
The agreement marks HPE’s first order involving the AMD Helios system. It combines HPE networking technology with AMD computing solutions. The deployment will support model training and inference workloads for cloud customers.
HPE Expands AI Infrastructure With Vultr Partnership
HPE will provide AMD Helios AI Rack systems through its AI Data Center Solutions portfolio. The platform integrates computing, networking, software, and cooling technologies. It targets organizations requiring high-performance infrastructure.
The AMD Helios system supports large-scale model development and high-volume computing tasks. Each rack includes AMD Instinct MI455X GPUs and AMD EPYC Venice CPUs. It also features AMD Pensando Vulcano AI NICs and AMD ROCm software.
HPE Networking will provide scale-up Ethernet technology for the systems. The solution uses HPE Juniper Networking QFX5252 switch trays within each rack. This design connects GPUs with high bandwidth and low latency.
The partnership builds on nearly three years of collaboration between Vultr and Juniper Networks. HPE expanded its networking capabilities after acquiring Juniper Networks. As a result, the company continues integrating networking solutions into its infrastructure offerings.
Vultr operates cloud infrastructure services for businesses requiring scalable computing resources. The company has increased its focus on supporting artificial intelligence workloads. The HPE agreement supports its expansion into advanced data center services.
HPE and AMD Target Growing Data Center Demand
The AMD Helios AI Rack by HPE represents a broader push toward open infrastructure solutions. HPE designed the system to support large AI workloads through integrated hardware and software. The platform also focuses on efficiency, deployment speed, and operational management.
HPE will provide deployment support through its global services network. The company offers expertise in infrastructure installation and liquid cooling systems. This approach helps organizations manage complex computing environments.
AMD continues expanding its role in enterprise computing markets. The company provides processors, accelerators, and networking technologies for demanding workloads. HPE’s collaboration with AMD combines these technologies into a complete infrastructure solution.
The Vultr order highlights rising demand for advanced computing capacity. Cloud providers continue expanding infrastructure to support new applications. Therefore, HPE aims to capture additional opportunities through integrated data center systems.
HPE operates across enterprise technology markets, including networking, cloud, and computing solutions. The company helps organizations improve operations and manage growing data requirements. The Vultr agreement adds another major deployment to its infrastructure portfolio.
The post HPE (HPE) Stock: Surges After $1.2 Billion Vultr AI Infrastructure Deal appeared first on Blockonomi.
TLDR
- Synopsys stock rises after OpenAI partnership targets faster chip design workflows.
- OpenAI and Synopsys develop GPT-Synopsys for advanced semiconductor engineering.
- New AI tools aim to improve chip performance, verification, and design efficiency.
- Synopsys integrates AI capabilities into its existing semiconductor design platforms.
- Partnership strengthens Synopsys role in the evolving global chip industry.
Synopsys, Inc. (SNPS) stock traded at $425.06, up 2.40%, after recovering from an intraday low near $410. The shares moved toward the $440 resistance level before settling above the $425 support zone. The move followed news of a strategic partnership with OpenAI to advance semiconductor design workflows.
Synopsys, Inc., SNPS
Synopsys Expands Semiconductor Design Capabilities
Synopsys and OpenAI announced a multi-year partnership focused on improving chip design processes. The collaboration combines advanced artificial intelligence models with Synopsys electronic design automation tools. The companies aim to create faster and more efficient semiconductor development workflows.
The partnership will allow engineers to use automated systems for complex design tasks. These systems can analyze results, adjust designs, and improve performance targets. The process focuses on power efficiency, performance levels, and area optimization.
Synopsys will integrate the new capabilities into its Synopsys.ai platform and Autopilot environment. The company will provide access through enterprise infrastructure with security controls. Customer design information will remain protected through encryption and permission management features.
OpenAI Partnership Targets AI Native Chip Development
The agreement introduces a new approach to semiconductor engineering through automated design assistance. The technology will help engineers explore more design options during development cycles. It will also support verification tasks before chip production begins.
Synopsys stated that the partnership expands access to advanced design tools for semiconductor companies. The collaboration supports growing demand for more powerful chips across technology industries. Semiconductor complexity continues increasing as companies develop advanced computing systems.
The joint service will combine computing resources, specialized models, and Synopsys licenses. The offering will support customer systems while maintaining data protection standards. Early technology programs are already underway with semiconductor companies.
Synopsys Builds Position in Growing Chip Market
Synopsys provides electronic design automation software used across the semiconductor industry. Its tools help companies create, test, and verify chip designs before manufacturing. The company has maintained a major role in supporting global semiconductor development.
The OpenAI partnership strengthens Synopsys’ focus on automated engineering solutions. The agreement connects advanced computing models with established chip design expertise. Therefore, engineers can access additional support during complex development stages.
The collaboration arrives as demand rises for advanced semiconductor technology. Companies require faster design methods to support expanding computing applications. Synopsys continues developing solutions that address changing needs across the chip industry.
The post Synopsys, Inc. (SNPS) Stock: Surge as OpenAI Partnership Sparks AI Chip Design Revolution appeared first on Blockonomi.
TLDR
- Robinhood stock falls as HOOD Summit reveals major platform upgrades
- Company adds AI agents to improve research and trading experiences
- New perpetual contracts expand Robinhood’s market access strategy
- Social investing features aim to improve user engagement levels
- Weekend trading and options updates broaden platform capabilities
Robinhood Markets, Inc. traded at $112.82, down 2.93%, after the company unveiled new platform features at its HOOD Summit. The announcements included automated research tools, expanded trading options, and social investing updates. The company continues to expand beyond its traditional retail trading services.
Robinhood Markets, Inc., HOOD
Robinhood introduced several upgrades designed to cover more parts of the investment process. The platform added features for research, strategy development, and trade execution. The company increased its focus on automation and broader market access.
The HOOD Summit highlighted three major areas, including agents, perpetual contracts, and social trading. These developments show Robinhood’s plan to build a wider financial platform. The company also introduced weekend stock trading and expanded margin capabilities.
Robinhood Expands Trading Platform With Automated Tools
Robinhood has integrated automated agents directly into its application to support users. The tools aim to help customers process market information and research more efficiently. The company is moving toward a more connected trading experience.
Previously, Robinhood focused on allowing external automated tools through its Trading MCP system.The latest update places these capabilities inside the platform. This change gives users direct access to automated assistance during their investment activities.
The company sees automated systems as a way to connect users with financial information. As a result, Robinhood can provide more support throughout the trading process. The development reflects wider changes across financial technology platforms.
Robinhood’s automated features focus on improving how users discover and evaluate market opportunities. The company has not provided detailed financial projections from these updates. The long-term impact will depend on adoption and usage across its customer base.
Robinhood Adds Perpetuals and Broader Market Access
Robinhood also highlighted perpetual contracts as part of its platform expansion. The feature adds another trading product alongside existing stocks, options, and other financial services. The company continues developing tools for active market participants.
The expansion of trading products follows Robinhood’s efforts to increase engagement among users. The company has gradually added advanced features while maintaining its retail-focused approach. These changes aim to create a broader ecosystem within the platform.
Weekend stock trading and longer options hours also formed part of the HOOD Summit announcements. These updates increase the periods when users can access certain market activities. Expanded margin options provide additional flexibility for eligible customers.
Robinhood’s latest additions represent a shift toward a wider investment platform. The company continues adding services that cover different stages of the trading journey. The company’s future growth depends on successful execution of these features.
Robinhood Strengthens Social Investing and Platform Vision
Social investing remained another key focus during the event. Robinhood is developing features that allow users to interact more within the investment environment. The approach combines community elements with financial tools.
The company’s strategy connects research, decision-making, and execution within one platform. Robinhood aims to reduce the separation between information sources and trading actions. This approach could reshape how retail users manage investment activities.
Robinhood Chain and tokenization received less attention during the summit. The company continues exploring digital asset technology as part of its broader strategy. The latest announcements focused more on trading automation and user experience.
The HOOD Summit demonstrated Robinhood’s continued expansion across financial services. The company is building a platform that combines traditional trading with new digital tools. The stock market response reflected short-term pressure after the feature announcements.
The post Robinhood Markets, Inc. (HOOD) Stock: Platform Pushes Into AI Trading and Social Investing appeared first on Blockonomi.
TLDR
- Amazon introduces new shipping tools designed to reduce bulky item delivery costs
- AMZN expands logistics support with new options for heavy product sellers
- Amazon Buy Shipping adds less-than-truckload labels starting in October
- Sellers will access regional pricing and faster delivery options through Amazon
- Amazon strengthens bulky product fulfillment with Seller Flex expansion plans
Amazon.com Inc. (AMZN) stock traded at 251.72, up 2.05%, after the company introduced new shipping tools aimed at reducing costs for sellers handling heavy and bulky products. The stock recovered from the $246.70 support area and moved above the $251 level during the trading session. The company announced the updates during the Amazon Accelerate 2026 conference as it expands logistics support for merchants.
Amazon.com, Inc., AMZN
The new features will allow sellers to access less-than-truckload shipping labels for large shipments through Amazon Buy Shipping. The service will become available in October through Seller Central and supported third-party shipping software. Amazon designed the option to help merchants manage bulky deliveries through its existing shipping network.
The shipping upgrades focus on improving delivery options for large items such as furniture, appliances, and other heavy products. Amazon Supply Chain Services Vice President of Product and Software Development Ripley MacDonald presented the changes during the conference. The company said the tools will provide sellers with more shipping flexibility and additional delivery support.
Amazon Adds Regional Pricing and Local Delivery Support
Amazon plans to introduce regional delivery pricing for heavy and bulky items starting in early 2027. The feature will allow sellers to set different shipping fees based on delivery regions. Therefore, merchants can adjust prices according to their delivery locations and shipping needs.
The company will also connect large product sellers with local carriers that support same-day and next-day delivery within nearby areas. This service will focus on sellers operating warehouses that can support faster regional fulfillment. Amazon said the approach will expand delivery options for bulky product categories.
Additionally, Amazon will include heavy and bulky orders in its invite-only Seller Flex program. The program allows approved sellers to fulfill orders directly from their own warehouses. After sellers prepare orders, Amazon manages pickup, delivery, installation, customer service, and returns.
Amazon Expands Seller Flex for Heavy Product Orders
The Seller Flex expansion will provide sellers with more control over warehouse operations while using Amazon logistics services. The program supports products that require special handling because of their size and weight. Amazon said the service aims to improve delivery accuracy for customers.
Amazon reported that heavy and bulky products represent one of its fastest-growing merchant categories. The company continues to develop logistics solutions as demand increases for large household items. The updates follow broader efforts across the retail sector to improve bulky item delivery networks.
Other retailers have also expanded large-item delivery services as online demand grows. Costco expanded its Costco Logistics service for appliances and furniture deliveries in 2024. Wayfair also developed its CastleGate logistics network in 2025 to support large home goods shipments.
The Home Depot introduced real-time delivery tracking for large products, including lumber and appliances. The retailer uses delivery devices to provide customers with shipment updates. Amazon’s new shipping tools add another layer to the growing competition in large-item logistics.
The company’s latest updates strengthen its marketplace infrastructure for sellers handling complex deliveries. Amazon continues to build logistics services that support merchants across different product categories. The new features will roll out through 2026 and 2027 as part of its seller support expansion.
The post Amazon.com Inc. (AMZN) Stock: Launches New Shipping Tools to Cut Seller Costs appeared first on Blockonomi.
TLDR
- JPMorgan Chase stock trades lower as AI safety project gains attention
- Bank joins Nvidia collaboration focused on controlling AI agent actions
- OpenShell and Sentry tools aim to improve agent security measures
- JPMorgan and Citi explore shared technologies for banking workflows
- Valuation concerns remain as JPM stock trades above GF Value estimate
JPMorgan Chase traded at $332.76, down 0.66%, as the bank joined Nvidia’s open agent-safety collaboration. The move placed JPMorgan among financial firms exploring stronger controls for autonomous systems. Market pressure continued as shares faced valuation concerns after recent movements.
JPMorgan Chase & Co., JPM
The banking giant joined the project alongside other financial institutions to develop safer frameworks for advanced software agents. The collaboration focuses on setting limits around automated actions in sensitive banking operations. The initiative highlights the growing need for security standards in financial technology.
JPMorgan’s participation follows increasing adoption of automated tools across the financial sector. The partnership alone does not confirm immediate financial benefits for the company. The impact will depend on future use cases, cost reductions, and wider operational deployment.
JPMorgan Joins Nvidia Safety Project for Banking Automation
JPMorgan joined Nvidia’s open-source agent-safety project announced on September 28. The initiative focuses on creating systems that control how automated agents operate. The project addresses concerns around granting software access to important financial processes.
The collaboration introduces tools designed to manage agent permissions and restrict unwanted actions. OpenShell establishes boundaries for automated systems before they perform assigned tasks. Sentry can isolate an agent quickly when it moves beyond approved limits.
JPMorgan and Citi are developing shared safety technologies through the collaboration. The companies have not disclosed the project’s full scope or expected production timeline. The development shows how banks are building safeguards before expanding automated financial services.
JPMorgan Stock Faces Valuation Pressure After AI Move
JPMorgan stock remains under attention as the company advances its technology strategy. The bank has invested heavily in digital infrastructure and automation across financial services. Valuation remains a key factor influencing market sentiment around the shares.
The company’s stock trades above the GF Value estimate of $308.63. The valuation measure places JPMorgan shares at a premium compared with that estimate. Future performance may depend on whether new technology investments create measurable returns.
The AI safety collaboration could support JPMorgan’s long-term technology goals. The project must demonstrate practical benefits through improved efficiency or reduced operational risks. Market participants continue to assess whether these developments can translate into stronger business outcomes.
Banking Sector Expands Focus on Safer AI Systems
Financial institutions are increasing efforts to adopt automated solutions while maintaining strict controls. Banks require secure systems because automated tools may handle sensitive customer and financial information. As a result, safety frameworks have become an important part of technology development.
JPMorgan’s latest move reflects the wider banking industry’s approach toward controlled automation. Companies are seeking systems that provide efficiency while limiting operational risks. Technology partnerships are becoming a common method for developing these solutions.
The collaboration with Nvidia adds another step in JPMorgan’s technology expansion. The company will need successful implementation before the initiative affects earnings performance. The stock’s future direction may depend on both financial results and progress in digital transformation.
The post JPMorgan Chase (JPM) Stock: AI Collaboration Gains Attention Amid Market Pressure appeared first on Blockonomi.
CryptoPotato
Robinhood plans to launch perpetual futures for eligible US customers in the coming months.
CEO Vlad Tenev said the company is bringing America “its first true perps” in a post on X, adding that profit and loss will settle every 15 minutes.
Eight Crypto Assets, Up to 10x Leverage
The company announced the product on Tuesday at its HOOD Summit in Houston. Customers will be able to go long or short on BTC, ETH, SOL, XRP, DOGE, ADA, LINK, and HYPE.
A perpetual future is a leveraged contract that tracks an asset’s price with no settlement date, so a trader can hold a position as long as they can cover it. Bitcoin and Ethereum contracts allow up to 10x leverage, while the other six are capped at 3x, and Robinhood Derivatives will provide the contracts through Bitstamp.
Trading costs one basis point (0.01%) per trade through the end of the year, which Robinhood describes as some of the lowest fees in the industry. Furthermore, users can set stop-loss and take-profit orders, watch their liquidation price in real time, and get alerts when a position is at risk.
“Ownership doesn’t work without markets, and markets don’t work without traders,” Tenev said. The CEO added that Robinhood wants to be “the best place in the world for active traders” by delivering tools once reserved for hedge funds, big banks and quant firms.
The trading platform also introduced an in-app AI tool called Robinhood Agents that will help customers create strategies, research markets and trade within preset limits, while manual trade approval is turned on by default. According to the firm, more than 15,000 users have opened agentic trading accounts since its May launch, with agents using Robinhood tools almost 30 million times a day.
In addition, the firm is bringing earnings contracts tied to company metrics such as revenue targets and earnings results. Those binary options contracts will be offered through Cboe and require options approval.
Where Robinhood Sits Among Rivals
The broader derivatives push is not limited to Robinhood. As CryptoPotato reported on September 4, Coinbase filed registrations with the SEC to offer single-stock perpetual futures to US investors, although those filings did not guarantee a launch on any set timeline.
Bybit went a different direction on leverage. Its new forex perpetuals, introduced September 8, allow up to 100x and trade around the clock, against Robinhood’s 10x ceiling.
Remember, perpetuals still carry funding costs and liquidation risks, since a position can be closed out when losses grow too large, and Robinhood has also not given an exact launch date beyond “the coming months.”
The post Robinhood to Launch Crypto Perpetual Futures in the US appeared first on CryptoPotato.
Bitcoin (BTC) remains in a bull market after closing above its 365-day moving average last week, but recent on-chain data suggests momentum is slowing. CryptoQuant said in a recent research note that several indicators now point to higher selling pressure and weaker demand.
Despite these concerns, CryptoQuant’s Bitcoin Bull Score Index remains at 90, showing that most tracked indicators still support a bullish structure. BTC recently reached about $87,400, its highest level in eight months, before pulling back toward the low $83,000 range.
Profit-Taking Picks Up
One concern comes from short-term holders, whose unrealized profit margin has risen to 33%. The analytics firm said this is the highest level since December 2024 and that similar levels have preceded profit-taking.
That profit-taking is already showing up in realized gains, with Bitcoin holders cashing out about 25,700 BTC in profit on September 22. It was the largest single-day realized profit figure recorded in 2026, adding to evidence that some holders are selling after the recent price gains.
Selling signals are also appearing beyond Bitcoin, particularly in the altcoin market. Seven-day cumulative altcoin exchange inflows reached 76,000 transactions involving about 51,000 depositors, the highest levels recorded since October 17, 2025.
At the same time, demand is weakening in both the spot and futures markets. Apparent spot demand fell by roughly 170,000 BTC over the past 30 days. Speculative futures demand growth also slowed, dropping from about 164,000 BTC on September 14 to roughly 16,000 BTC more recently.
Key Support Levels Remain
Despite these signals, Bitcoin remains above several important on-chain support levels. CryptoQuant identified the 365-day moving average near $80,000 and the 200-day moving average around $71,000. The firm also identified the trader-realized price near $67,000 as a key level to watch.
According to the analytics firm, a decline toward these levels could signal consolidation. This would not necessarily mean a broader market reversal if support holds. However, continued weakness in demand alongside increased profit-taking could increase the risk of a deeper correction in the near term.
CryptoQuant described the market as still bullish but showing signs of fatigue. The next test will be whether buying demand returns to absorb selling pressure or whether Bitcoin moves closer to those support levels.
The post Bitcoin Bull Market Shows Signs of Cooling: CryptoQuant appeared first on CryptoPotato.
Bitcoin climbed above $87,400 last week, but the rally has since lost momentum. The world’s largest cryptocurrency then tested the $83,000 range before it surged past the upper boundary of its weekly range at $85,000.
Amidst the stagnation, larger holders are increasing their holdings again.
Whale Accumulation Returns
According to blockchain analytics platform Santiment, wallets holding between 10 and 10,000 BTC added 41,025 units over the past 10 days. Their total balance has now reached 13.64 million BTC, equal to about 67.93% of Bitcoin’s total supply. Santiment explained that these whale and shark wallets are now at their highest holdings since the market rally in mid-August.
There is a clear difference between large and small holders. Wallets holding less than 0.01 BTC have remained mostly unchanged during the same period. Santiment revealed that stronger market conditions have historically appeared when larger holders accumulate while smaller traders sell.
However, the analytics firm said the current pattern is not a guaranteed signal for Bitcoin’s price. Market watchers will likely focus on whether large holders continue adding BTC and whether retail investors begin reducing their positions. The trend could provide another indicator of changing market sentiment in the coming days.
Adding to the bullish picture, BIT Research said Bitcoin’s bear market may have already ended. The firm identified the cycle low in late July after the asset held above $62,900 and showed signs of weakening downside momentum. Since then, BTC has reclaimed key levels, including its 21-week moving average at $69,272, and moved above its March 2024 high of $73,084.
The report also highlighted Bitcoin’s cost basis. The True Market Mean currently stands at $76,897, which essentially means that the typical holder is back in profit. This could reduce selling pressure from investors looking to exit at break-even. The firm expects an upside range of $185,000 to $215,000 in its bullish scenario.
However, crypto analyst Doctor Profit speculated a short-term pullback before BTC’s next move higher. He pointed to bearish signals across several indicators, including RSI, MACD/PPO, and MFI, while also noting weaker trend strength on the ADX indicator.
ETF Inflows and Corporate Buying
Even as the market moves through a quieter stretch, institutional demand is still showing up. US-listed spot Bitcoin ETFs, for instance, attracted a whopping $2.4 billion last week. This week started at a slower pace, but the flow has remained positive. The funds raked in just over $31 million on Monday and another $66 million on Tuesday.
Corporate buyers have also stayed active. Strategy added another 1,665 BTC over the past week. The company paid an average of $85,681 per coin, taking its total holdings to 847,666 units. Strive has added to the buying activity as well. CEO Matt Cole said the company spent $94.5 million on 1,107 BTC at an average price of $85,400. Its total holdings have now reached 27,462.
The post Bitcoin’s Biggest Holders Ramp Up Buying While Retail Traders Remain Flat appeared first on CryptoPotato.
US midterm elections have a history of making investors nervous and markets more volatile. According to Ali Martinez, Bitcoin could face more volatility after this year’s highly anticipated event.
In a recent post, the analyst noted that BTC fell 72% after the 2010 midterms, 65% after 2014, 52% after 2018, and 27% after 2022. While this pattern does not prove the elections caused the declines, the historical moves are worth watching ahead of November 3, 2026.
Four Midterms, Four Drops
Martinez also highlighted Bitcoin’s fourth-quarter performance in previous midterm years. BTC gained 391% in Q4 2010 but fell 16.7% in 2014, 42.16% in 2018, and 14.75% in 2022. This data indicates the possibility of increased volatility as the fourth quarter begins.
$73,000 area was flagged as an important level to watch. According to his analysis, this zone represents Bitcoin’s short-term holder cost basis and could act as support if the market sees a post-election decline.
Prediction markets such as Kalshi and Polymarket show Democrats maintaining an advantage over Republicans. The latter’s loss in the 2026 midterms could create fresh uncertainty for the crypto market. Democrats could gain control of the House, Senate, or both, which would make crypto-friendly regulation harder to advance. The CLARITY Act, which aimed to create clearer and lighter rules for digital assets, already failed to clear the Senate in September.
Reset Soon?
Amid all the midterm uncertainty, a Bitcoin pullback appears to be on the cards. For instance, pseudonymous trader “bee” believes the crypto asset may be setting up for a larger move, but sees a possible pullback before the next major rally.
BTC is currently trading between the 50-week moving average near $77,600 and the 100-week moving average around $89,700. The 200-week moving average sits lower, near $66,000. Bitcoin could first hold its current range and climb toward $90,000. A break above the 100-week moving average may attract more liquidity and push BTC higher. However, the trader expects momentum could weaken around the $90,000-$95,000 area.
From there, BTC risks rotating back toward $75,000-$77,000. “bee” isn’t the only one anticipating a correction. Doctor Profit also expects the asset to retest $79,000 before continuing higher.
The post Bitcoin Fell After Four US Midterms: Could 2026 Break the Pattern? appeared first on CryptoPotato.
ZCash has been on a wild ride in the past year or so. The privacy-centric crypto asset has rallied by more than 1,000% within this timeframe, while most other alts have stalled.
Despite this short-term instability and stall near $1,400, ZEC accumulation continues.
More Room to Capture Market Share
A whale has been accumulating the cryptocurrency across multiple wallets over the past week, according to Onchain Labs. The main wallet received around 41,690 ZEC and moved about 18,730 out, which leaves a net balance of roughly 22,960 tokens, worth $31.7 million. The wallet also received another 4,200 ZEC, which is approximately $5.84 million.
Amidst this accumulation spree, Grayscale Head of Research Zach Pandl said that the token may have more room to grow. ZEC has climbed from around $60 to roughly $1,700 in a year before its most recent pullback. Pandl said the move does not necessarily mean the token has reached a valuation ceiling but reflects its low starting point and its potential market size.
Zcash and Bitcoin are both part of the Currencies Crypto Sector. This group includes blockchain projects focused mainly on digital currency use cases. Bitcoin remains the largest asset in the sector. Zcash, however, has increased its market share significantly over the past year. It was worth less than 0.1% of BTC’s market capitalization a year ago. Today, that figure stands around 1.5%.
According to Pandl, if ZEC continues to provide strong privacy capabilities, it could capture more market share from competing cryptocurrencies.
“We think Zcash can continue to capture market share.”
Pandl had previously said that artificial intelligence could trigger a new wave of concerns around financial privacy, and expects AI to create new privacy risks, especially for transparent public blockchains. Bitcoin transactions, for example, are publicly recorded and can potentially be linked to real-world identities. Pandl believes this could increase demand for privacy-focused blockchain solutions, with Zcash emerging as one potential option.
ETFs Face Fresh Pressure
The picture for US-listed Zcash ETFs has been less encouraging. These investment products recorded zero net flows for three straight days from September 23 to 25. Activity turned negative this week. The funds posted their largest single-day outflow so far on Monday, with around $8.12 million leaving.
Despite the recent outflows, the ETFs still hold about 3.75% of Zcash’s total supply, even though they launched only a month ago.
The post Zcash (ZEC) Gains 1,000% and Still Has Room to Grow, Grayscale Research Says appeared first on CryptoPotato.