Cryptocurrency Posts
Crypto Briefing
Ethereum's faster finality could enhance its competitiveness in high-value transactions and cross-chain bridging, reducing delays and risks.
The post Ethereum moves closer to faster finality with decoupled consensus protocol appeared first on Crypto Briefing.
Meta's AI innovations could redefine personal tech, shifting focus from smartphones to wearables, impacting consumer habits and tech markets.
The post Meta unveils AI glasses, personal agents, and wearable hardware at Connect 2026 appeared first on Crypto Briefing.
The potential rise of altcoins like Hyperliquid and Venice Token could diversify the crypto market, challenging Bitcoin's dominance.
The post Hyperliquid, Venice Token may surpass Bitcoin in market value within 5 years: Motley Fool appeared first on Crypto Briefing.
Riot's debt repayment enhances financial flexibility, enabling strategic Bitcoin management and potential growth in data-center ventures.
The post Riot Platforms repays $200M credit facility, releases 5,821 BTC from collateral appeared first on Crypto Briefing.
The intensified immigration debate in Quebec could reshape electoral outcomes, influencing voter sentiment and altering political dynamics.
The post Quebec immigration debate heats up, impacting election dynamics appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Samourai Letter #7: Notes From The Inside
Dear Reader,
It has been many months since I last wrote you. Part of the reason for that is because I spent most of June and part of July in transit from FPC Morgantown to FCI McKean – a four hour drive away. For most of that time I had no access to pen, paper, stamps, or the rudimentary email system that I use to send these letters out.
The other part of the reason why I haven’t written in so long is that once I did finally arrive I was so shell shocked from the entire ordeal that I needed time to decompress and process that month long trauma that is BOP transit.
Six days after arriving at FCI McKean I finally put pen to paper to document the journey but the result was less of a letter and more of a trauma dump to help me process the absolute worst 30 days of my life. I decided to take a step back and give it some time before I sent out this letter. I have been slowly adapting to life here at McKean, and in good time I will tell you all about this place, but for this letter I want to go back to early June.
I want to tackle the entire transit process and explain how what should have been a quick four hour drive turned into 30 days, two trans-continental flights, three multi-hour bus rides, a cell mate doing time for murder, and a cell mate who couldn’t stop shitting (I preferred the murderer). This letter will likely be published in two parts due to the length. Thank you for your continued reading and support.
“I finally put pen to paper to document […] the absolute worst 30 days of my life.”
On June 5th I was told I would be transferred from FPC Morgantown for a drug and alcohol treatment program. Successfully completing the program (which takes about 9-10 months) rewards you with a year off your sentence, so it is seemingly well worth the hassle of moving to take it.
For security reasons they do not tell you when you will be leaving or where you will be going. While being transferred in BOP custody you almost always are put on an airplane being piloted and operated by the US Marshalls to be taken to BOP transit hub in Oklahoma City. After a few days in Oklahoma you are put back on a plane and taken to your destination. From speaking with others I was told to expect 1-2 weeks of transit.
I also heard that it costs around $10,000 per prisoner to be transited through Oklahoma. I figured that since I am classified as minimum security, spent close to two years on pre-trial release, self surrendered, and had no incident reports since being incarcerated I would be a good candidate for what is called a transfer furlough – where I would be responsible for transporting myself to my new institution at my own expense.
I put in my official request for a transfer furlough on June 5th. On June 8th my request was denied without explanation, I would be going through transit, no way around it.
On June 10th I was called to Receiving and Discharge (R&D) at 6:00 AM. Though I did not know it at the time I was about to embark on a month long fever dream through two different holding facilities, share cells with murderers, be locked down behind iron barred cells for 23 hours a day, and much more.
Leaving through R&D is much the same as when I arrived. I was stripped, searched, issued a pair for ill fitting clothes (khaki elastic band trousers, a brown cotton shirt, threadbare boxers, socks that didn’t match, and a pair of slip on blue canvas shoes).
I was put into a holding cell while the other inmates being transferred went through the same process. There were six of us transiting from Morgantown on that day. We were each lined up and called forward so that the officer could fasten shackles to our ankles and cuffs to our wrists.
Once cuffed and shackled the officer wrapped a chain around our waist and attacked the handcuffs to them. The end result being that you could not lift your arms or hands much higher than your waist, and you could walk only in painful short shuffling steps. We were handed a brown paper bag with ‘breakfast’ in it (bread, peanut butter, bologna) and escorted to the waiting bus.

“We were each lined up and called forward so that the officer could fasten shackles to our ankles and cuffs to our wrists.”
The bus was a cross between yellow school bus and a coach (think Greyhound or National Express) and already filled with inmates from other prisons in the area. There were guys from all security levels on the bus. Some guys serving 20 years coming from the “pen” (The US Penitentiary), some guys like me serving short sentences and going to a camp.
The atmosphere was generally friendly on the bus, most of the USP guys were interested in what the camp was like and how much contraband like vapes and phones cost. At the front of the bus behind a metal grate were the driver and three heavily armed officers. They all wore stab vests and carried handguns and long guns.
As we departed Morgantown I was excited to watch the scenery go by. This was the first taste of the outside world I had in 6 months. I took in all the sights. The trailer park, the run down gas station, the XXX store, it all was captivating. After about an hour of driving the bus suddenly exited the highway and stopped on the side of a small road. After 20 minutes idling I noticed one of the officers walking back to the bus with a bag of biscuits from Tudor’s Biscuit World – a West Virginia institution.
We remained on the side of the road as each officer one by one went and bought breakfast, an endeavor that took over an hour. I decided Breakfast sounded good but my bread fell out of bag onto the floor. Breakfast would have to wait. As quickly as we got back on the road we suddenly pulled off again. This time each officer went one by one into a gas station to buy cigarettes and energy drinks.
The metal of the shackles were starting to dig into my ankles, my wrists were cramping, my eardrums were shot beyond comprehension. Many others have said it before, but the one thing you really remember about the prison bus is how unbelievably loud it is. Every bump in the road is followed by a symphony of crashing metal. Inmates at the front of the bus maintain full conversations at full volume with their friends all the way in the back. The volume is at maximum for the entire journey.
After about 5 hours we arrived at the Greenbriar Valley Regional Airport. There were several other prison busses parked off to the side of the runway. For the next hour or so a parade of officers from other busses would climb up and yell out a series of names. We were playing a grand game of musical chairs and for a brief moment I prayed that I would be called to another bus and spirited off to my camp bypassing the free plane ride to Oklahoma.
Eventually musical chairs was over and we were instructed to get off the bus and directed to line of waiting US Marshalls standing in front of a plain white airplane adorned only with a small American flag on the tail fin.
The Marshall patted me down, checked my mouth and feet and directed me to line up and wait by the front of the plane under the cockpit. They packed us in tight on the runway 10 rows of inmates at least 10 men deep. We watched inmates disembark the plane and enter the busses we just left.
The whole thing must be a logistical nightmare for the folks at BOP and I was surprised how smoothly it all was moving. It was by no means quick, but it could have been far worse. Finally I was ordered to wobble up the stairs to board the plane. I felt like Joe Biden before falling up the stairs.
How embarrassing it would be to eat it in front of all the convicts. I made it up without embarrassing myself. On board Air Operations Marshalls replaced flight attendants, though one really couldn’t tell any difference in demeanor between a Delta air steward herding a bunch of fat slobs in sweat suits and a US Marshall herding a bunch of prisoners. We filled each row from back to front at the direction of the Marshalls.
I was sat in the window seat. The guy next to me sported a nifty full face tattoo and informed me he had been down 15 years and was kicked out of the USP for fighting. I informed him I was on my way to a camp and had been down for 6 months. He had nothing else to say to me after that.

“This was the first taste of the outside world I had in 6 months.“
The plane itself had certainly seen better days, it looked to have been dated from The Cold War. The stickers commonly found plastered across the surfaces of airplanes telling you not to smoke or where to find the life vest in case of emergency – how exactly to apply said life vest while shackled and bound was not explained – were all in German and Russian. Where the hell did they get this thing from.
The plane was filled 2/3 of the way with inmates. The final third at the front of the plane were all US Marshalls, at least 30 of them. With that, the plane took off and we were on our way to Oklahoma City. After about an hour an Air Marshall doing their best surly Delta stewardess impression threw a bag of lunch at us. It was the second – but not last – sack lunch containing 4 slices of bread, a pouch of peanut butter, two slices of turkey, and a small pack of cookies (“Cream 4 Fun” a BOP staple that even in my dire circumstances solicited a juvenile chuckle out of me).
Sick to death at this point of the oily BOP peanut butter I happily pawned it off on the face tattoo next to me. I got started trying to fix myself a turkey sandwich – a task made difficult due to the cuffs and limited mobility. The bread was ice cold and the turkey was frozen solid. After brushing off the top layer of ice from the sliced meat and placing it between the now soggy and still freezing bread I took a bite and decided I wasn’t a great fan of turkey popsicle sandwich. The Cream 4 Fun would have to suffice for lunch.
I was thankful for the small bottle of water that was handed out, but was not thrilled when I spilled most of it down my front contorting myself to try and twist the cap off. Shortly after lunch the Marshall went row by row to ask if we needed to use the toilet. Most people did, so the rest of the flight consisted of much jostling and shuffling to the bathroom and back. I refused, preferring to hold it, but the gentleman across the aisle let the entire plane know that he needed to take a shit, a declaration that caused much consternation and debate.
As we approached Oklahoma City the pilot got on the intercom to let us all know it was a beautiful sunny day in Oklahoma City, a balmy 88 degrees. He failed to mention that none of us would see that sun for our entire stay in FTC Oklahoma City.
We landed at OKC airport, went past the main terminal building towards a squat brown concrete building about 6 stories high. After what felt like an eternity we were disembarked row by row through the jet bridge directly into the airport prison.
We shuffled single file through an assembly line of Marshalls who thankfully removed the cuffs and shackles, searched our mouths and feet again, and directed us into a dark concrete holding cell where we were packed in tight like a tin of sardines. In the corner of the room was a single stainless steel combination toilet, sink, water fountain.
Almost immediately several inmates somehow fashioned a lighter and proceeded to get extremely high on K2 – known also as Deuce. In prisons Deuce is commonly just roach spray or rat poison drenched on a small piece of paper.
When you light the paper and inhale the fumes you often freeze where you are standing lean over and are lost to the world around you for several minutes. I was most curious as to where the hell they were hiding these things to make it past no fewer than 3 probing searches.
All I could think of was getting out of this claustrophobic concrete box into a housing unit with other minimum security “campers”. Everyone had warned me that security classifications would be mixed until you were assigned a housing unit. I just had to tough out the intake process.

“You quietly wonder if Dante got it all wrong and all the circles of hell happen to be within the BOP’s Oklahoma City airport transfer facility.“
For being the official transit hub of the BOP, handling thousands of inmates every week, the staff at FTC Oklahoma City were breathtaking in their incompetence. Every last officer was less than useless, all of them wearing an expression of bewilderment as to how they happened to stumble into this predicament of dealing with a plane load of convicts, as if normally they were payroll accountants or copy clerks.
It was as if it was everyone’s first day on the job. After jam packing us ass to elbow in the small concrete room for 4 hours – presumably they were having some sort of crisis meeting trying to determine what exactly they were supposed to do with us – a morbidly overweight officer whose stab-vest appeared to be groaning in protest at the enormity of the task of protecting such an enormous man unlocked the door and shouted that he needed five of us at a time.
Instantly well over 100 men all desperate to be out of this hellish room push and shove their way towards the door. The only ones in no hurry are the deuce heads who have no idea where they are – and if they are indeed aware their limbs are in no mood to take any direction regarding movement – and myself who has no interest in playing grab ass with murderers and rapists.
I wait patiently towards the back of the room and entertain myself by taking covert glances at the inmates around me to try and guess which ones are the ‘chomos’ (child molesters). You may at this point wish to chide me and extoll the virtues of not judging a book by its cover, but these books had covers that all but said “Hey Look! I’m a chomo!”. They have a look about them.
After 45 minutes of 5 men trickling out at a time the room emptied and the deuce heads stumbled back into reality – what a horrible reality to return to from what must be a thrilling escape – and we shuffle out into the convict assembly line.
We are commanded to undress, lift, squeeze, cough under the careful supervision of an officer no doubt cursing the recruiter at the Buttplug County job fair who never said anything about staring at genitals all day.
Once the second strip search of the day concludes you are thrown a bundle of damp clothing with odd stains on them and hurry you further along the conveyor belt towards a long queue to go through a body scanner machine, the kind of thing you would find at an airport designed to find bombs and weapons.
The officer manning the machine sits behind a lead curtain to shield themselves from radiation that leaks out of this whirring machine. The warning sticker helpfully informs you to keep back behind the blue line for your safety, but it turns out this warning is not for you, you are instructed to jam yourself as close as possible to the machine so they make sure to dose you with the radiation of the 6 guys ahead of you.
Once you have been sufficiently irradiated you get pushed along where the medical officer menacingly asks if you have anything medically wrong with you, almost daring you to say anything but “no”.
There is a whirlwind of papers being stamped, collated, duplicated, and filed and before you know it the assembly line ends. You breath a sigh of relief, surely some friendly officer is going to check your papers and notice you are a minimum security ‘camper’ and whisk you away. Instead yet another morbidly obese officer points at a room and makes some sort of grunting noise. You do not speak primate but gather he wants you to wait in the room.
You quickly realize this room is a carbon copy of the first holding room and you quietly wonder if Dante got it all wrong and all the circles of hell happen to be within the BOP’s Oklahoma City airport transfer facility.

“All I could think of was getting out of this claustrophobic concrete box.”
Another couple of hours pass – or years, who can tell at this point – in the second holding room and the Deuce heads are the only ones having a great time. The Deuce dealers have defeated yet another strip search and now a body scanner. Eventually an officer of indeterminate gender unlocks the door and yells out 5 to 10 names and you are escorted to your “range” (prison speak for the floor you live on).
The officer leads us towards the elevator, 10 of us cram in and I get a good look at the men with me. Seven of them have full face tattoos that extend across their shaved heads. Rams horns, Celtic knots, Thor’s hammer, that sort of thing.
At this point I am fully aware that a “camper” only range is a fantasy. I am going into the general population with murderers, rapists, kidnappers, gang members, and career criminals – many of whom have spent more time behind bars than they have in society. I take a deep breath, this is no time to be anxious or afraid. If the sharks smell fear they will strike.
The guard walks us to the heavy metal door that seperates our range from the hallway. He turns the key but the door won’t open. He tries another key with the same result. One of the face tattoos mocks him “what is it your first day or something?” he heckles. The officer now very aware that this is taking way too long fumbles the keys and drops them on the floor. The scene is objectively funny and now several more of the inmates are heckling the clumsy officer.
Finally the door opens from the inside. The range officer must have taken pity and opened it for him. The guys watching on the security cameras must have been pissing themselves. He will probably never hear the end of it in the breakroom.
I am on Range 4D. The room is vaguely triangular in shape as if the architect started drawing a triangle but gave up halfway through. The room is large and painted in a palette of institutional grey and the same sort of pink they paint high schools.
Cells with big metal doors line three of the walls. Two large staircases flank both sides of the room and take you up to an internal balcony where cells line the walls as well. If I remember correctly there are 30 two-man cells on each floor, so each range holds a total of 120 men. As soon as you cross the threshold between hallway and range you are immediately struck by the sheer number of strung out junkies hunched over seemingly frozen in place.
Before you even have a chance to breathe several face tattoos are in your face asking if you want to buy drugs from them. These enterprising fellows apparently are running a fully stocked pharmacy. They offer me deuce, ice, meth, snizzlefizz, and junglerush.
Okay, I made the last two up, but they offered me stuff I have never heard of before. I decline the offer and they move on quickly to a more lucrative mark. The range officer leaves his office and steps over a frozen drug addict and informs us that he is new here and to just give him a minute to get us situated.
I politely wait while the officer – looking more and more flustered by the minute – assigns the guys ahead of me their cells, hands them a roll of toilet paper, and a thin mattress before sending them on their way into the jungle. When it is my turn the officer lets me know that he has run out of toilet paper and but if I give him a minute he will find me some. He gives me my cell number and scurries away back into his office. I follow him and remind him I need a mattress to which he explains he has run out of those as well, but if I just give him a minute he will try and locate one.
From that point forward he was “Officer Just-A-Minute”. I climb over three junkies strung out on the staircase and make my way to the cell I have been assigned.

“This isn’t fucking Guantanamo!”
The cell is small, only a bunk bed, a toilet, a sink, a desk, and a fluorescent light. Inside is a large American Indian. If you asked someone to draw the most racist caricature of an American Indian he would have drawn this guy.
He looks at me and says in a deep voice with a flat affect “I am Shadow”. The strange face tattoos gave him the air of some sort of tribal witch doctor. I said “You sure are” and quickly introduced myself lest he take offense to my glib remark and place a hex on me.
I liked Shadow immediately. I learned that he was on his way to a USP doing 20 years for murder. Before I had a chance to explain that I was on my way to a camp for the fake crime of not having a license I didn’t even need in the first place Officer Just-A-Minute was in the doorway of the cell holding half of a foam mattress.
Decidedly at the end of my tether I looked to him, to the mattress in his hands, back to him and asked incredulously “what the fuck am I supposed to do with that?”. “It is all we have” he responded slightly annoyed. “It is half gone. How the hell am I supposed to sleep on that? My ass and legs will be on bare metal!” I protested. “Welcome to prison” he responded curtly.
I was seriously fed up at this point, plus I had Shadow the murdering witchdoctor to back me up so I pressed further “I understand this is prison. I am well aware of that fact! You still have an obligation to provide us basic amenities like bedding. This isn’t fucking Guantanamo!”
I pushed. He simply shrugged and dropped the mat onto the floor and walked off. “Fuck that guy” said Shadow. I agreed.
A few minutes later Officer Just-A-Minute walked by and locked the cell door. We were locked in for the night. It would be the first time I had been truly locked in a cell. I was mildly surprised there wasn’t some sort of central locking mechanism. The officer needed to walk by 60 cells and manually lock them all. A while after locking us in another officer showed up to perform the 10:00 PM count.
Count concluded I climbed onto my half mattress and waited for the bright fluorescent light to be turned off. By 11:00 PM I asked Shadow what time they usually turned the lights off. “They don’t” he responded.
I sighed and covered my head with the sheet they gave me – it smelled vaguely like motor oil and sawdust – and silently sobbed. Everyone told me that transit was bad, that Oklahoma was terrible. They were not overstating it.
I laid there, ass on bare metal, harsh light shining through the threadbare sheet and asked myself if all this was worth the year off. I regretted ever leaving Morgantown, and I desperately wanted to call my wife Lauren.
The transit story will continue in Part 2. Thank you for reading.
This is a guest post by Keonne Rodriguez. Opinions expressed are entirely their own and do not necessarily reflect those of BTC Inc or Bitcoin Magazine.
This post Samourai Letter #7: Notes From The Inside first appeared on Bitcoin Magazine and is written by Keonne Rodriguez.
Bitcoin Magazine
An Austrian Economist Explains Why AI Will Make Everyone an Entrepreneur w/ Per Bylund
AI is changing how we work, but can it replace the human entrepreneur? Austrian economist Per Bylund, Senior Fellow at the Mises Institute, joins Spencer Nichols to explain why AI is a statistical engine that improves efficiency but can’t imagine the future. He argues we’re moving from an employment economy to an entrepreneurship economy, and explains what that means for jobs, innovation, and value creation.
Chapters:
00:00 Austrian Economics on AI, Innovation, and Entrepreneurship
02:34 Can AI Replace the Entrepreneur?
05:48 Invention vs Innovation: What Bitcoin Teaches About AI
06:29 From an Employment Economy to an Entrepreneurship Economy
09:52 Can Regulators Keep Up With the Speed of AI?
13:06 Remote Work, Capital Controls, and the Future of Money
18:23 Why Every Voluntary Trade Has Two Winners
26:28 The Individual vs the State in US-China Competition
31:17 Steel Stockpiles, Sugar Subsidies, and the Lobbying Behind Protectionism
33:36 OpenAI, Anthropic, and Regulatory Capture in AI
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post An Austrian Economist Explains Why AI Will Make Everyone an Entrepreneur w/ Per Bylund first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
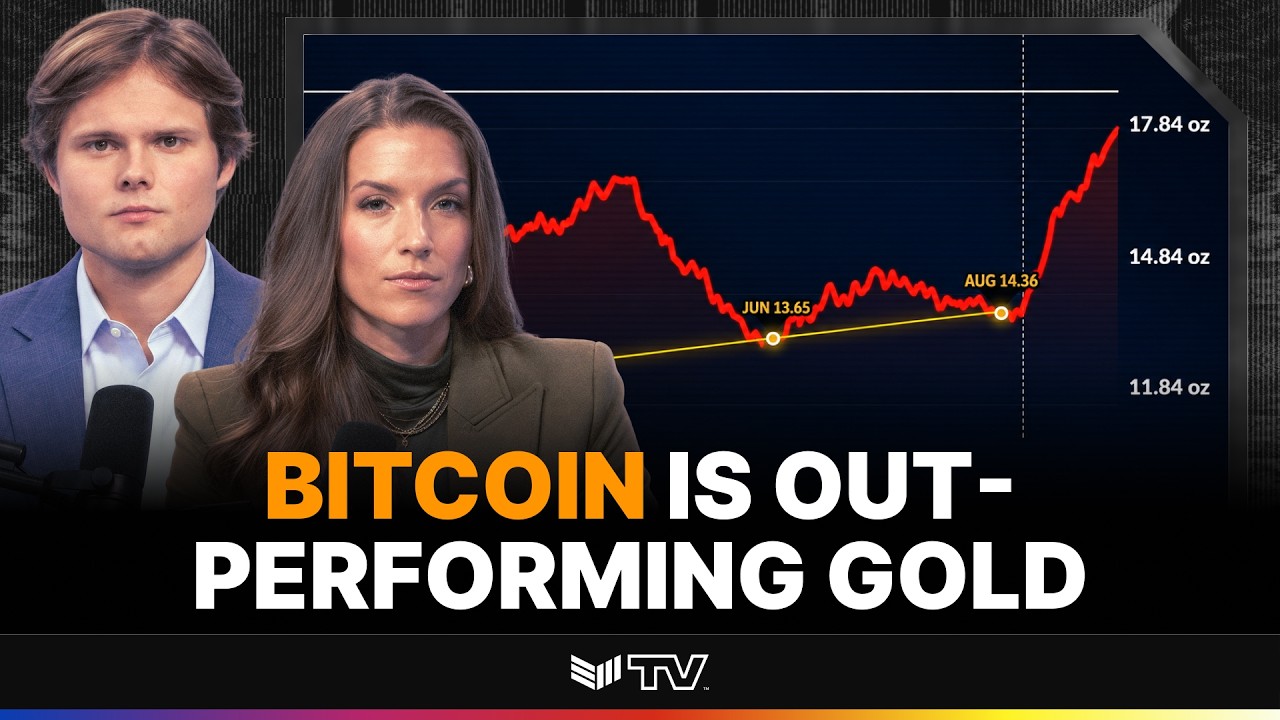
TECHNICAL ANALYSIS: BTC to Cross Key Price Level Against Gold
The 90-day correlation between Bitcoin and gold just hit a six-year high, and Bitcoin is now just 3% away from flipping positive against gold for 2026. In today’s Chart of the Day, Sean breaks down the Bitcoin-to-gold chart, the string of higher lows since February, and the new high above 17.9 ounces.
Chapters:
0:00 Bitcoin-Gold 90-Day Correlation Hits a Six-Year High
0:35 Why Measure Bitcoin in Gold? Stripping Out Dollar Debasement
1:20 Higher Lows and Higher Highs on the BTC/Gold Chart
2:27 From 12.1 oz to 17.9 oz: The Bullish Bitcoin Setup
2:53 The 20.3 oz 2026 Yearly Open and the Levels That Matter
3:21 Next Bitcoin Resistance: 21.5 oz of Gold (~$92K)
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post TECHNICAL ANALYSIS: BTC to Cross Key Price Level Against Gold first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Katie Stockton: $93K BTC is the Key Price Level for the Bull Market
Is the Bitcoin bear market officially over? Katie Stockton, founder of Fairlead Strategies, breaks down the technical signals behind Bitcoin’s rally of more than 50% off its recent lows, including the break above the 200-day moving average and the 83K–84K resistance zone. She explains why the cloud model points to $93,000 as the level where a new Bitcoin bull cycle becomes official. She also covers the flag pattern breakout, the monthly stochastic oscillator, and what could turn her defensive heading into Q4.
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Katie Stockton: $93K BTC is the Key Price Level for the Bull Market first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Grant Cardone: Real Estate “Armageddon” Is Here – Why BITCOIN is the Hedge
Commercial real estate is facing a historic reset, and Grant Cardone is using it to stack Bitcoin. The Cardone Capital founder explains how high interest rates are pushing properties below replacement cost and how he fills that gap with Bitcoin on the balance sheet. He breaks down his goal of 25,000 apartments and 25,000 BTC, and why he calls real estate his “Trojan horse” for Bitcoin.
Chapters:
00:00 Grant Cardone on the Commercial Real Estate Reset and 6.4% Rates
00:51 How Cardone Capital’s Bitcoin Real Estate Deals Work
02:23 Why REITs Can Never Own Bitcoin: Cardone’s Competitive Moat
04:26 From 3,000 to 25,000 BTC: Real Estate as the Trojan Horse
06:50 Michael Saylor’s “P Word” and the $335M Boca Raton Deal
09:01 Will Cardone Capital Go Public?
10:12 Why Commercial Real Estate Faces a Historic Crash
11:02 Why Single-Family Home Prices Won’t Correct
12:31 Why Bitcoin and Real Estate Are the Perfect Hybrid Asset
14:32 Why Other Real Estate Investors Can’t Copy This Strategy
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Grant Cardone: Real Estate “Armageddon” Is Here – Why BITCOIN is the Hedge first appeared on Bitcoin Magazine and is written by Patrick Green.
CryptoSlate
Sydney Sweeney is helping sell sports predictions, which is a pretty good indication that prediction markets have moved beyond the people who enjoy arguing about probability on the internet.
Novig's Sept. 9 campaign announcement introduced the actress as a partner and equity holder in its sports-focused exchange. The campaign, called “Just Sports,” runs across digital, social, video, and outdoor advertising through football season. It's designed to get people to notice an app, recognize the brand, and give it a try, which is exactly what hiring someone as famous and popular as Sweeney is supposed to do.
Without giving in to the controversy that surrounded the campaign, the next most interesting thing is what actually happens when users open the Novig app.
Prediction markets offer a place to turn something you already enjoy, whether that's football, politics, or arguing about who'll win an award, into something you can trade. Your attention becomes a potential edge, and your opinion gets a price.
That's a powerful pitch in a culture where everyone already spends hours keeping up with things. Maybe, just maybe, all that watching, scrolling, and arguing could finally pay?
The industry also sells a much bigger idea: bringing together people willing to risk money can produce better forecasts. That promise and the business of keeping people entertained can coexist, but they reward different behavior. Understanding that difference tells you more about prediction markets than any celebrity ad does.
Finally, a price on your group chat
The basic product is easy to understand. You buy a contract tied to an outcome, and in a standard yes-or-no market the winning contract pays $1. Pay 60 cents and hold it until the result, and you either make 40 cents or lose your 60 cents, before fees. CryptoSlate's guide to prediction markets and sports betting walks through the way they work.
The cultural appeal is just as simple. Most of us already have opinions we'd like some credit for having. We knew that team was overrated, that candidate couldn't win, that film would do well. Prediction markets essentially let you buy a small financial receipt for your judgment before the result is known.
They can also give ordinary leisure a second purpose. Watching a match becomes research, knowing the players becomes expertise, and checking an app becomes keeping up with your positions. That kind of vocabulary is flattering because it recognizes something fans already believe about themselves: they know more than the casual observer.
Sometimes they do. Someone who follows a sport closely can know things a casual viewer has missed. But knowing a lot about the subject and making money at the available price are separate skills.
Imagine buying ten contracts at 90 cents each. Eight win and pay $1 apiece. You've been right eight times out of ten, a result that would make you insufferable in a group chat, and you've still turned $9 into $8 before fees.
That difference is easy to lose when the product is introduced through familiar faces and familiar entertainment. The endorsement can make a platform feel approachable; it can't tell you whether the trade you're considering is worth its price.
The distribution now reaches well beyond individual celebrities. Kalshi's partnership with the NHL includes official data, league branding, and visibility during national broadcasts. Its CNN agreement brings market data into news programming and gives newsroom teams access to political and cultural probabilities.
Taken together, these arrangements place prediction markets on both sides of the viewing experience. They can be something you're invited to participate in during a game and something you're shown as evidence while watching the news.
The crowd has to come from somewhere
There's a serious intellectual case for prediction markets. Economists Justin Wolfers and Eric Zitzewitz have studied how markets combine dispersed information into forecasts. Someone who thinks a contract is mispriced has a reason to put money behind that view, and the resulting trades can make the price much more telling.
But “the crowd” is a convenient phrase for a group of people who found a particular platform, could access it, had money to spare, and chose to trade a particular event. It's worth thinking about how that group gets assembled.
Celebrity marketing recruits people because they recognize or like them, and sports partnerships recruit people where they're already emotionally invested. However, neither is a test of forecasting ability. Those customers can bring knowledge, entertainment spending, or a mixture of both, and the outcome depends on how they trade and who trades against them.
Having more participants can help. Someone with good information needs another person willing to take the other side, and a busier market can make entering or leaving a position easier. Casual money can create opportunities that draw informed traders in.
Still, popularity alone can't establish accuracy. Ten thousand people repeating the same view don't necessarily bring ten thousand independent pieces of information. Nor does attracting money to a championship final automatically tell us more about a less popular economic or political event.
The distinction becomes especially relevant when a price leaves the trading app and appears in a news segment. Viewers see a percentage that looks precise, without necessarily seeing the amount available to trade, the concentration of money behind it, or the contract's exact settlement terms.
There are ways to judge whether those percentages deserve confidence. Over enough comparable events, outcomes priced around 70% should happen roughly seven times in ten if the forecasts are well calibrated. You can also compare them with other forecasts made at the same point. That kind of assessment takes patience and includes the dull misses alongside the spectacular wins.
It measures something different from how many people downloaded an app because they liked the ad.
The prediction market always wants another trade
The business incentives are easier to see in the less glamorous parts of a platform's website. Kalshi's explanation of its fees says it earns money through transaction charges. The exact cost varies by market and order, but the basic commercial relationship is straightforward: trading activity produces revenue.
Novig's optional points program turns participation into a progression system. Executed trades earn points toward monthly tiers, from Starter to Obsidian, with rewards including trading credits and access to a monthly cash pool.
This is familiar consumer-app design. You earn status, move toward a reward, and get another reason to come back. Applied to a trading product, it creates an extra consideration alongside whether an individual position is worth taking: the trade may help you reach a tier.
Someone can enjoy those features and understand exactly what they're doing. Entertainment is a legitimate reason to spend money. The difficult part is keeping track of the full cost when the activity also offers the satisfaction of feeling informed and financially capable.
Here the platform's interests and the customer's can pull apart without anyone breaking a rule. Someone trying to make accurate forecasts might be best served by watching, waiting, or deciding they have no edge. Someone selling transactions benefits when more of those opinions become trades. Sweeney's equity stake is the perfect example of that difference: owning part of the company means participating in the platform's fortunes, a different proposition from buying contracts inside it.
CryptoSlate has already examined the blurred boundary between speculation and gambling. The cultural question goes beyond which label wins. Prediction markets give daily attention a financial outlet, making the things people follow for pleasure feel like opportunities they might be wasting by staying on the sidelines.
That invitation can become exhausting. There'll always be another game, announcement, or award, and being interested in something doesn't create an obligation to put money on it. Nor does reading a market's forecast require becoming its customer.
The most valuable thing prediction markets produce is a probability anyone can look at for free. The most profitable thing for the company is getting that person to place another trade. Keeping those two uses separate leaves more room to enjoy the match.
The post Prediction markets promised better information and hired Hollywood appeared first on CryptoSlate.
Buying a tokenized stock sounds as though it should be simple. You pick a company you know, buy a token representing its shares, and hold it in a digital wallet. The appeal is familiar stock investing with some of the convenience of crypto, potentially including trading beyond the hours of a traditional exchange.
Then you encounter a rule saying trading might have to stop for three months, and the idea of always-available stocks needs a little more explanation.
The pause is part of the SEC's Sept. 17 framework for experimental Tokenized Securities Venues, or TSVs. Repeat breaches of a stock's trading volume limit trigger it. It applies to that stock on the exchange and its affiliates, rather than to every version of that tokenized stock everywhere.
That distinction is a good place to start understanding the whole product. Owning a token, owning the rights attached to a share, and having somewhere to sell it are three related things that an app can make look like one.
Same company, different ways to own it
Stocks are already largely digital. Buying a share through a broker usually gives you an electronic record of ownership through a chain of financial institutions. Tokenization introduces a blockchain into how that ownership (or a claim related to it) is recorded and transferred.
The word “tokenized” describes the format, so you still need to know what the token represents. The SEC's January explanation of tokenized securities separates several models. In one, a company or its agent uses blockchain records as part of its ownership system. In another, a third party holds shares and issues tokens representing an interest in them.
There's also synthetic exposure, where the token gives you a financial return linked to a stock without giving you ownership of that company's shares. Buying something that follows a company's price doesn't automatically give you shareholder rights.
CryptoSlate has covered stock tokens that don't make their buyers shareholders. The lesson there is to look past the familiar ticker and find out who owes you what. If a separate company issues the token, its finances and obligations can become part of your investment risk alongside the business whose name attracted you.
The new SEC experiment takes a more specific approach. As CryptoSlate's account of the framework explains, qualifying tokenized stocks must preserve the economic and governance rights of their traditional equivalents, including dividends and voting, and synthetic exposure just doesn't qualify. Access to the exchange is permissioned, meaning participants or their wallets must meet verification standards.
Within those boundaries, the regulator is allowing a five-year test of trading through automated market makers. That sounds technical, but the basic idea is pretty simple: instead of matching your order with another person's order, software lets you trade against a pool of assets supplied by other participants.
In a simple pool containing stock tokens and a payment asset, buying stock takes tokens out and adds payment assets. The pool's formula adjusts the price as its inventory moves. Uniswap's explanation of liquidity pools describes this general design, although different exchanges can use different formulas and arrangements.
The attraction is a trading system that can operate automatically and connect with other compatible financial software. But software still needs assets available to trade, legal rights behind the tokens, and, most importantly, people willing to supply capital.
How the three-month clock starts
The experiment has limits on both the number of stocks an exchange can offer and how much it can trade in each. The volume allowance is measured against activity in the traditional stock market, using average daily share volume.
The two categories have different limits, summarized in CryptoSlate's coverage of the exemption. Tier 1 includes S&P 500 and Russell 1000 stocks and certain exchange-traded products; Tier 2 covers the other eligible securities.
| Stock category | Maximum symbols across affiliated exchanges | Per-stock volume threshold |
|---|---|---|
| Tier 1 | 75 | 0.25% of the traditional stock's prior-month average daily share volume |
| Tier 2 | 250 | 2.5% of the traditional stock's prior-month average daily share volume |
The SEC order's volume-limit section compares average daily tokenized trading with average daily traditional trading, and combines affiliated exchanges' activity. This is an average-volume test, so a single busy session isn't automatically a breach.
Suppose the traditional stock averaged 10 million shares a day in the previous month. The Tier 1 allowance would correspond to 25,000 shares in average daily tokenized volume. That's the comparison to keep in mind, rather than a fixed dollar amount or a limit on how much one customer can own.
The consequences escalate:
- The first volume breach for a particular stock gets a grace allowance, with the exchange required to ensure future compliance.
- Each later breach in that stock requires an immediate three-month trading pause, including at affiliated TSVs. The clock runs from the breach date. Other stocks can keep trading.
- Exchanges can pause earlier to avoid breaching the threshold. They must notify participants immediately of either kind of volume-related pause and update their public notice within five business days.
The SEC's stated reason for keeping activity small is to limit risks to the wider stock market while it observes the experiment, including the possibility that pool prices diverge from traditional share prices.
You can see how that could happen in a simplified example. Suppose a pool has limited inventory and several customers want to buy at once. Its formula can push the token's price upward even when the wider market's view of the company hasn't moved by the same amount. Traders may be able to profit by bringing the prices back together, but doing so depends on available capital and workable routes between markets.
The regulator is putting a boundary around how large that experiment can become. Crossing it repeatedly carries a substantial operational cost, which gives exchanges a reason to control activity before they reach the limit.
Owning tokenized stocks and selling them are different jobs
The buyer's biggest practical concern is how to get out. Consider someone who buys a tokenized share intending to sell if they need the money for a repair: the trading pause could disrupt that plan even while they continue to own the asset.
Moving a token to another wallet wouldn't, by itself, solve the problem. They'd need an eligible place to trade that exact instrument or a workable redemption process under its terms. Whether either exists depends on the product, the institutions supporting it, and the permissions involved.
The three-month provision shouldn't be seen as a promise that another broker will accept the token, or as a universal prohibition on every possible transfer. Those are separate product-level issues, and buyers need actual answers rather than assumptions based on how easily ordinary tokenized stocks can sometimes move between apps.
This is also why the promise of longer trading hours deserves a second look. Being able to open an app at midnight says nothing about the price at which you can sell a meaningful position. SEC Commissioner Mark Uyeda addressed that trade-off at the agency's 24-hour trading roundtable, noting that additional hours have an almost equal chance of distributing liquidity more evenly and spreading it too thin.
Before buying, the most revealing information would be a worked example from the provider: what happens to this token if this exchange stops trading it? That answer should explain custody, ongoing shareholder rights, permitted transfers, any redemption route, and the costs involved. It should also distinguish what the provider offers now from what it hopes to support later.
There's plenty to like about making shares easier to transfer and connecting ownership records with trading software. Those improvements could remove delays and make financial services more convenient. The SEC's initial five-year opening gives firms room to test that proposition.
The three-month pause brings the buyer back to an ordinary investing consideration: an asset needs a dependable route to sale. Until you understand that route, seeing a stock in your wallet tells you only part of what you need to know.
The post Why your tokenized stock could stop trading for three months appeared first on CryptoSlate.
Crypto projects spent about $638 million with token buybacks through late August 2026, according to Allium Labs data.
That is already a record, up from $545 million over the same stretch of 2025. Hyperliquid accounted for roughly $370 million and Pump.fun for about $200 million, together close to 90% of the total.
On Sept. 25, staff at the Securities and Exchange Commission (SEC) addressed the legal tension that has shadowed those programs since they began. The more openly a project ties its token to business returns, the easier it becomes to argue that holders are investing in a security.
What SEC staff said
The SEC's Division of Corporation Finance addressed buybacks in a new set of crypto FAQs covering networks that are already functional.
Staff said an issuer's buyback announcement for a non-security crypto asset on such a network falls outside the promises of “essential managerial efforts” at the center of the Howey test for investment contracts.
The same answer warns younger projects that on a network yet to reach functionality, pitching a buyback as a source of yield or returns can feed into an investment-contract analysis.
The answer rests on two built-in assumptions, a functional system and a token that already sits outside securities law, and it carries the weight of staff views, which the SEC describes as lacking legal force.
Under the agency's March interpretation, a network counts as functional when its native token can be used according to its programmed utility.
A regulatory life cycle takes shape
The SEC's March interpretation says a token can be sold as part of an investment contract while a team raises money against promises of managerial work. That contract can end once buyers stop expecting profits from those promised efforts.
The pending Regulation Crypto Assets proposal would let projects raise up to $5 million over four years under a startup exemption. A larger fundraising exemption would allow up to $75 million every 12 months, with disclosure requirements attached to both.
Proposed Rule 400 adds a transition filing, the Form TR, in which an issuer certifies on EDGAR that it has completed or permanently ceased its promised managerial efforts and stopped making new ones.
The issuer files it directly, and the agency could later contest whether the conditions were met. In its paperwork estimates, the SEC assumes about 475 issuers a year could rely on that safe harbor, based on 15% of the roughly 3,165 projects launched in 2024. Comments on the proposal close Oct. 20.
Put together, the pieces sketch a path from securities-regulated fundraising to a mature network that can spend real revenue on its own token. The Form TR covers projects that abandoned their roadmaps as well as those that finished them, while the buyback FAQ applies only once a network is functional.
That structure rewards teams that define their build as a finite list of milestones they can eventually complete, and it discourages marketing that frames buybacks as returns before the product works.
| Stage | Regulatory position | What the project can do | Key constraint |
|---|---|---|---|
| Raise | Token sold as part of an investment contract | Raise capital against promised managerial work | Securities-law obligations attach to the fundraising arrangement |
| Build | Promised essential managerial efforts continue | Develop network and deliver disclosed milestones | Marketing returns or buybacks can contribute to Howey analysis |
| Transition | Promised efforts completed or permanently ceased | Proposed Form TR documents the transition | SEC can later challenge whether conditions were actually satisfied |
| Functional network | Token can perform its programmed utility | Operate without the original investment contract necessarily continuing | Token's status still depends on facts and circumstances |
| Mature buybacks | SEC FAQ assumes a functional network and non-security token | Announce revenue-funded token repurchases | Buyback announcement alone is not an essential-managerial-efforts promise |
The money already flowing to token buybacks
Pump.fun says half its revenue goes to buying and permanently burning PUMP. Its dashboard shows roughly $500 million in annualized revenue, about $462.5 million in cumulative purchases, and 167.7 billion tokens destroyed, equal to 16.8% of the original supply.
At the current run rate and allocation, that implies around $250 million in annual purchases,
about 6.4% of Pump.fun's displayed $3.91 billion fully diluted valuation. The figure measures purchasing power against valuation, with the cash going into open-market token purchases.
Hyperliquid has bought and burned roughly $1.3 billion of HYPE since launch, and its documentation says more than $1 billion in annualized fees now flows into programmatic HYPE purchases.
Uniswap switched on protocol fees on Ethereum mainnet in December 2025 and has since extended them to other chains, with outside searchers collecting accumulated fees only by burning UNI in exchange.
Hyperliquid funds staking rewards from a reserve of future emissions even as trading fees burn HYPE. A protocol that burns 5% of supply while issuing 8% through emissions and unlocks ends up diluting holders despite a large headline buyback.
A more useful measure for these tokens is net burns against new issuance before comparing the result to valuation.
Aave's program shows how quickly treasury needs can override a buyback. It acquired more than 205,000 AAVE, about 1.28% of supply, for roughly $42 million in its first ten months.
Governance then debated cutting the annual budget from $50 million to $30 million as revenue softened. The DAO paused purchases on April 19, after the rsETH bridge incident, to preserve balance-sheet flexibility.
Crypto's record remains small next to Wall Street, where S&P 500 companies spent $1.02 trillion on repurchases in the 12 months through September 2025. The growth pace sets crypto apart, rising from about $366,000 in 2024 to $638 million in under eight months of 2026, with mechanisms that automatically convert revenue into market purchases.
| Protocol | Buyback / burn mechanism | Scale cited in article | What can offset or interrupt it |
|---|---|---|---|
| Pump.fun | 50% of revenue allocated to open-market PUMP purchases and permanent burns | ~$500M annualized revenue; ~$462.5M cumulative purchases; 167.7B PUMP destroyed | Revenue declines; future token issuance/unlocks |
| Hyperliquid | Trading fees fund programmatic HYPE purchases and burns | ~$1.3B bought and burned since launch; >$1B annualized fees flowing toward purchases | Staking rewards and future emissions can offset supply reduction |
| Uniswap | Protocol fees accumulate; searchers obtain assets by burning UNI | Fee mechanism active since Dec. 2025 and expanded across chains | Governance controls fee deployment and future mechanism |
| Aave | Treasury-funded open-market AAVE purchases | >205,000 AAVE / ~$42M in first ten months | Treasury needs; program paused after rsETH incident |
What token holders own
The rights attached to these tokens remain thin. Uniswap's documentation says value reaches UNI holders through the burn mechanism and whatever future mechanisms governance approves, with protocol revenue staying under the protocol's control.
The SEC's March interpretation describes digital commodities as assets whose holders lack any inherent right to passive yield, future income, or profits. A buyback can reduce supply and create steady demand, and governance can redirect or pause it at any point.
The same distance from securities law that makes a mature token easier to trade also keeps it apart from the cash flows investors use to value it.
Bitcoin, which the SEC lists as a digital commodity, runs without an issuer or protocol revenue to recycle, so revenue multiples and buyback ratios apply to tokens like HYPE, PUMP and UNI.
Where the token buyback model goes from here
If the SEC finalizes Regulation Crypto Assets close to its current form, teams can raise money under the exemptions, write finite roadmaps, file transition reports, and steer revenue into token purchases once their networks work.
Hyperliquid's fee flows and Pump.fun's allocation alone point to industry buybacks above $1 billion a year at current run rates. Revenue and dilution-adjusted buyback yield would become standard tools for valuing protocol tokens.
| Feature | Public-company shareholder | Mature protocol token holder |
|---|---|---|
| Ownership claim | Equity ownership in corporation | Generally no ownership of protocol/company merely from holding token |
| Right to profits | May receive distributions if declared; residual corporate rights defined by securities/corporate law | No inherent right to future protocol income or profits |
| Buyback effect | Company purchases outstanding shares | Protocol/DAO purchases or burns tokens, potentially reducing supply or adding market demand |
| Guaranteed buybacks? | No | No |
| Who can change the program? | Board/company subject to corporate and securities-law constraints | Governance, protocol rules or other authorized actors depending on design |
| New issuance can offset purchases? | Yes, through new share issuance/compensation | Yes — emissions, incentives and unlocks can overwhelm burns |
| Claim on underlying revenue | Share represents equity rights in the company | Buyback-linked token may have no contractual claim on the revenue funding purchases |
| Useful valuation metric | Earnings, free cash flow, buyback yield, dilution | Protocol revenue, gross buybacks and net issuance/dilution |
If the proposal stalls or emerges in weaker form, the nonbinding staff FAQ becomes the main source of comfort, and projects would keep return language out of their marketing while treating buybacks as discretionary.
Revenue-linked programs shrink mechanically when revenue falls, and a major exploit or bad-debt event could push other treasuries to conserve funds the way Aave did. Holders would then find that a buyback resembles a shareholder return in its market effect while remaining revocable, governance-dependent, and free of any contractual claim.
The SEC is building a route for crypto networks to spend their revenue on their tokens. Holders at the end of that route own an asset tied to a business's success through scarcity and demand, while the business's revenue stays with the protocol.
The post SEC clears regulatory hurdle as crypto token buybacks hit record $638 million appeared first on CryptoSlate.
In 2021, Christie's sold a Beeple NFT for $69.35 million, and Sotheby's took another $24.40 million for 101 Bored Ape Yacht Club NFTs, giving cartoon primates the kind of auction-house treatment usually reserved for Fabergé eggs.
But now, not five years later, one of the marketplaces that helped sell the digital art revolution is explaining how customers could take their belongings with them when it closed.
Nifty Gateway, the NFT marketplace owned by crypto exchange Gemini, announced its closure in January as its parent decided to concentrate on its primary financial app. The exit arrangements included plans for a bulk withdrawal tool and somewhere to host the artwork.
That's a pretty sad and uneventful end for an industry that made ownership sound like a technological breakthrough on the order of discovering fire.
To be fair, there was real art underneath the sales pitch, along with artists who'd found paying audiences and collectors who liked what they bought. But the boom encouraged the assumption that once you'd paid for the token, the business of owning the thing was taken care of, preferably forever.
Marketplace closures have quickly made that assumption incorrect, because the token, the artwork, and the website displaying it can survive for very different lengths of time. As crypto companies close businesses and retire products, somebody has to work out where the files go and who'll keep them available when selling the next collection no longer covers the bills. The person who can answer that has become considerably more relevant to your collection than the person who once assured you that you were early.
Your ape needs a forwarding address
When you buy an NFT, it's easy to think you're putting a picture in your wallet because that's what the app shows you. Underneath that display, though, several separate things are happening, and knowing what lives where explains how you can still own a token while struggling to load the art.
Many Ethereum NFTs use the ERC-721 standard that records who owns each token and allows it to be transferred. The blockchain keeps that ownership record, while the token often points to a separate descriptive file, known as metadata, containing information such as the work's name and a link to its image or video. Your wallet retrieves those files and assembles what you see, so the collection looks like one self-contained possession even when its parts depend on several different services.
Keeping big media files outside the blockchain is a reasonable design choice, but it means those files need their own home. Sending the token to a wallet you control puts you in charge of transferring it; it doesn't automatically download the artwork, take over the server hosting it, or pay the person running that server. If you're picturing your expensive ape safely tucked inside your phone, the app may have given you a rather generous impression of what the transfer accomplished.
Nifty Gateway's closure update addressed this problem, with plans to move descriptive records and media hosting to Arweave, a network designed for long-term storage, but some NFTs created in 2021 or earlier had records permanently linked to its own servers. The company promised to keep hosting that metadata indefinitely and extended its withdrawal window to April 23.
Those promises describe the arrangements the company said it would make, without establishing that every migration succeeded or that any particular artwork was lost. They show us the consequence of making a link permanent: when the address belongs to a company, fixing it in place can preserve your dependence on that company for as long as you want the link to work.
Buyers were supposed to enjoy the freedom of owning something outside a platform's control, and some instead inherited a lasting relationship with its hosting department. The technology can faithfully preserve an ownership record while leaving the owner dependent on a business that has other things it would rather do.
Forever isn't a payment plan
Distributed storage offers a way to reduce that dependence, provided someone actually keeps the files. IPFS, which is used for NFT media, identifies content from the data itself, allowing different computers to provide a verifiable copy without tying its identity to one company's website. That makes it possible for another provider (or the collector) to keep serving the same artwork if the original host stops.
The catch is that joining a network doesn't oblige every computer on it to preserve your collection. The IPFS documentation explains that cached files can be deleted to free space, while a process known as pinning tells a computer to retain specified content. Someone can run that computer themselves or pay a service, but the continuing cost belongs to whoever agrees to keep the copy available.
This also explains why a missing picture doesn't necessarily mean the artwork has vanished. Your browser may retrieve an IPFS file through a gateway, a website that fetches the content for you, and the IPFS guide to NFT storage warns that this route can fail even when the data exists elsewhere. In that case, another gateway can help, but if nobody has retained the data at all, a different web address won't bring it back.
Collectors therefore have to understand whether the problem is reaching their file or finding a surviving copy, which is quite an introduction to network administration for someone who thought they'd just bought a picture. The rare hat on the ape contributes very little to the diagnosis, however much it contributed to the price.
There are ways to reduce these risks, including putting artwork data directly on the blockchain or using storage networks designed to finance retention over many years. Each arrangement has its own dependencies, from the continued operation of the chain to the incentives keeping storage providers involved, so judging a collection means looking at how it's built. The fact that one NFT depends on a company's server tells you very little about another that stores its image data on-chain.
Across those designs, though, the economic problem is the same: selling something brings money in at the moment somebody wants to buy, while caring for it creates work for as long as somebody wants it to survive. Those two periods can be wildly different, especially when the business was built around selling new collections to an excited audience.
Even inexpensive storage needs someone to accept responsibility for it, check that it works, and arrange a successor when the original provider loses interest. Collectors can take on that job, and systems that let them preserve files independently give them real control, but the freedom comes with some administration. Selling people on the future of ownership was always going to be easier than persuading them to become competent custodians of a folder.
The boring people had a point
Museums were thinking about this while the auction records were being set, because caring for art has always involved work that its purchase price doesn't perform. In a December 2021 discussion published by LACMA, digital preservation manager Joey Heinen and computer scientist Elian Carsenat examined the software, storage, and continuing responsibility involved in keeping NFT artworks accessible. While the market was celebrating scarcity, they were considering what would still function in 10 or 30 years.
The profession already had plenty of experience with art that could stop working. In MoMA's 2016 account of restoring Teiji Furuhashi's Lovers, conservator Ben Fino-Radin described a project involving obsolete technology, including MS-DOS and LaserDiscs. Preserving the installation required making its projected images and interactive behavior work again, because keeping old components in storage wouldn't preserve the experience people came to see.
NFT art inherits that responsibility whenever the work depends on software or a live service. Saving a still image is comparatively straightforward, while preserving something interactive can mean documenting how it behaves and maintaining the environment that lets it run. You could retain every original file and still lose the ability to experience the work if nobody knows how its pieces fit together.
That gives the boom's endless arguments about screenshots a pretty funny ending. The token never made the visible image impossible to copy, and preserving faithful copies is precisely what can help the artwork survive. Someone duplicating the media hasn't thereby taken ownership of your token, but by keeping the only surviving copy, they might eventually be doing your collection a favor.
The artists and collectors doing this work deserve better than being treated as props in another joke about expensive JPEGs, even if the market spent several years behaving like a casino with an art department. Some of the work is worth preserving because people care about it, regardless of whether anyone will ever pay its former price again, and digital systems can let those people cooperate without waiting for a marketplace's permission.
That kind of ownership asks more from a collector than clicking buy and watching the valuation. It means knowing where the work lives, keeping what can be copied, and making sure someone else can take over its care when you can't.
If your ape is still visible decades from now, it'll be because people kept doing those jobs long past the point when anyone found them exciting enough to sell.
The post The NFT party is over and everybody now owes storage rent appeared first on CryptoSlate.
The Federal Reserve's proposed rules for the payment stablecoin issuers it supervises include a crisis clock measured in hours. An issuer whose reserves fall below the value of its outstanding tokens would have 24 hours to notify the Fed and submit a plan to restore full backing.
Unless it closes the gap or the Fed directs it to proceed with that plan, the issuer must begin liquidating reserves and redeeming tokens by 5 p.m. on the next business day. The Fed says that window comes to less than 48 hours in many cases.
The 392-page proposal also lets the issuer keep minting new tokens during that rescue window, and the Fed ties that choice to the public nature of blockchains. An abrupt halt in issuance would be visible on-chain and could tip holders off to the problem, speeding up the very run the rules exist to contain.
Comments are open for 60 days once the proposal appears in the Federal Register.
The clock starts at 5 p.m.
The proposal requires reserve assets to equal or exceed outstanding tokens at all times. Issuers must formally record the fair value of those reserves at least once a day at 5 p.m. in the time zone of their supervising Federal Reserve Bank.
The Fed says issuers operating close to the line may need to run that calculation several times a day. The breach clock starts at the beginning of liquidation, and finishing the process can take longer. Once liquidation begins, minting stops and redemption fees are prohibited.
A separate rule for ordinary conditions requires honoring redemption requests within two business days, a timeline that runs independently of the breach clock.
The Fed illustrates the logic with a $100 million stablecoin backed by $95 million in reserves. Split evenly, every holder could recover $0.95 per token. Once $35 million redeems at full par value, $60 million in assets remains against $65 million in tokens, leaving about $0.92 of backing for everyone who holds on.
Extending the same arithmetic, $50 million in par redemptions would leave $0.90 per token, and $80 million would leave $0.75. A fixed reserve hole grows larger per remaining token with every holder who exits at $1, which rewards the fastest redeemers at the expense of everyone behind them.
Forced liquidation is designed to push all holders toward the same pro-rata loss before that happens.
| Par redemptions before liquidation | Reserves remaining | Tokens remaining | Backing per remaining token |
|---|---|---|---|
| $0 | $95M | $100M | $0.95 |
| $10M | $85M | $90M | $0.94 |
| $35M | $60M | $65M | $0.92 |
| $50M | $45M | $50M | $0.90 |
| $80M | $15M | $20M | $0.75 |
Minting stablecoins keeps the rhythm visible, at a cost
Circle's figures show how much routine issuance activity a large stablecoin generates. As of Sept. 21, USDC had $74.6 billion in circulation against $74.8 billion in reserves.
Over the prior 30 days, Circle issued $40.2 billion and redeemed $39 billion, a gross flow of $79.2 billion that exceeds the token's entire supply even though net circulation grew by only $1.2 billion.
For a token with that kind of daily rhythm, a sudden stop in minting would stand out to anyone watching the chain.
Each fully funded new token spreads the existing hole across a larger supply, leaving its dollar size at $5 million. In the Fed's example, $20 million of fresh issuance alongside the $35 million in redemptions would lift coverage to roughly $0.94, with the new buyers absorbing part of a loss that existed before they arrived.
Closing the hole itself requires new capital, recovery of an impaired asset or a rebound in reserve values, and genuine distress can leave few buyers willing to mint.
The proposal asks commenters directly whether issuance should be capped or prohibited the moment the 1:1 threshold is breached.
The OCC chose the opposite trade-off
The Office of the Comptroller of the Currency (OCC) proposed in March that an issuer under its supervision that falls below minimum reserves would have to stop net new issuance immediately, with a narrow exception for moving existing tokens across ledgers.
Mandatory liquidation would kick in only if the shortfall persisted for 15 consecutive business days, a period the OCC could extend. The Fed's rules govern the issuers it supervises, while the OCC and state regulators oversee other issuers under the GENIUS Act, so the two approaches could run side by side.
The Fed's December 2025 research on the March 2023 collapse of Silicon Valley Bank documents how these runs behave. Circle disclosed that $3.3 billion of USDC reserves, about 8% at the time, were trapped at the failed bank.
| After reserves fall below minimum | Federal Reserve proposal | OCC proposal |
|---|---|---|
| New issuance | May continue temporarily | Net new issuance stops immediately |
| Exception | Issuance remains available during remediation window | Tokens may be moved between ledgers if total outstanding issuance does not increase |
| Initial response | Notify Fed and submit remediation plan within 24 hours | Restore reserve compliance; new net issuance remains prohibited meanwhile |
| Liquidation trigger | By 5 p.m. the following business day after the plan deadline unless reserves are restored or Fed directs issuer to proceed with plan | After 15 consecutive business days below minimum reserves |
| Can regulator alter path? | Yes — Fed can direct issuer to proceed with remediation plan | Yes — OCC can extend the 15-business-day period |
| Core trade-off | Avoid making a sudden minting halt an on-chain distress signal | Stop an under-reserved issuer from expanding supply |
Redemptions surged, the primary redemption channel largely shut over the weekend with banking rails offline, and USDC fell as low as $0.86 on secondary markets. Trading volume on those markets hit nearly $2 billion in a single hour on March 11.
The researchers concluded that shutting an issuer's redemption window leaves holders free to keep selling on exchanges, so the run moves venues and keeps going.
In the Fed's view, visible redemptions can prompt more redemptions, while secondary-market trading can absorb selling that would otherwise hit the issuer as par redemptions and forced reserve sales.
Where a stablecoin run would travel next
CoinGecko's survey of the 12 largest centralized exchanges found that 97.7% of stablecoin-denominated trading pairs use USDT or USDC, and most spot volume on those venues trades against stablecoins.
The total stablecoin market stands near $307.3 billion, with USDT at about $183.7 billion and USDC at $76.4 billion as of Sept. 25. Holders fleeing a distressed token could buy Bitcoin, lifting its price quoted in that stablecoin above its dollar price.
They could also exit into fiat or another stablecoin, thinning order books and widening spreads across pairs. Price gaps between Bitcoin's different stablecoin pairs, order book depth, and funding rates would show which path a run was taking.
The GENIUS Act steers reserves toward Treasuries maturing within 93 days and qualifying repo arrangements, and the Fed acknowledges that a large enough Treasury position could be hard to sell in full without moving prices.
An IMF model from January lays out the timing mismatch between stablecoin holders, who can redeem around the clock, and bond and repo markets, which close overnight and on weekends.
A large redemption wave can drain cash buffers and force bond sales as soon as those markets reopen.
| What holders do | First market affected | What to watch | Potential next consequence |
|---|---|---|---|
| Redeem directly for dollars | Issuer reserves | Redemption volume; reserve coverage | Forced Treasury/repo liquidation |
| Sell for another stablecoin | Stablecoin exchanges/DEXs | USDC/USDT or distressed-token spreads | Liquidity concentrates in surviving stablecoins |
| Buy Bitcoin or other crypto | Crypto spot markets | BTC price across different stablecoin pairs | Apparent BTC premium in the weakening stablecoin |
| Sell into fiat | Exchange order books/banking rails | Market depth and bid-ask spreads | Crypto-native dollar liquidity contracts |
| Keep selling while banking rails are closed | Secondary crypto markets | Stablecoin discount; weekend volume | Run continues even when primary redemption slows |
| Issuer sells reserves when markets reopen | Treasuries/repo | Short-term yields, reserve sales | Crypto liquidity shock reaches traditional markets |
If an issuer closes its hole inside the first 24 hours, the episode could pass as a brief dislocation, with minting and redemption resuming their normal rhythm and the Fed's compressed clock working as designed.
A breach that lands late on a Friday, with redemptions and a secondary-market discount feeding each other before the 5 p.m. cutoff, would play out very differently. Each exit at par would thin the backing for the holders who remain, and the scramble would spread into exchange order books.
The issuer's Treasury holdings would wait for Monday's open while its tokens trade all weekend.
The Fed has drafted a run rule for a market where everyone can watch the run in real time. Over the 60-day comment period, regulators will weigh that visibility against the speed they want from a rescue.
The post Fed proposed stablecoin rule could trigger a 48-hour liquidation run appeared first on CryptoSlate.
CryptoTicker.io
Dogecoin trades at $0.0977, or €0.0857, on September 27, 2026 at 11:42 am German time. Almost nothing has moved in the 24 hours before that; the gain comes to 0.64 percent. Days like this one are the most useful days you get, because whatever you work out now about your holding period, your route to buying and your custody, you work out without pressure.
The figures in this article come from CoinGecko's market data interface, retrieved on September 27, 2026 at 09:42 UTC. That is 11:42 am Central European Summer Time. Anyone who works with prices without knowing when they were pulled is working with a number whose age they cannot state.
Dogecoin price on September 27, 2026: the numbers and their source
DOGE is quoted at $0.097699. The range of the past 24 hours ran from $0.095327 to $0.098670, which is roughly 3.5 percent between the low and the high. In euro terms the price stands at €0.085717, with a daily range of €0.083686 to €0.086621.
Market capitalisation comes to $15.24 billion, or €13.38 billion. Circulating supply is 156.09 billion DOGE. Trading volume over the past 24 hours stands at $698.1 million, which is 4.6 percent of market capitalisation. That ratio is the number to watch if you intend to move larger amounts: it tells you how much stock actually changes hands on an average day.
DOGE sits 86.6 percent below its all-time high of $0.731578. That figure is not a price target in either direction. What it gives you is the order of magnitude you need when you value an old position from the peak phase and ask yourself whether a loss from a private disposal is still capable of being offset at all.
Why a quiet Dogecoin price makes the better day for the maths
On days with double-digit swings, investors decide quickly and check little. On a day that moves 0.64 percent, nobody has a decision forced out of their hands. The calendar keeps working regardless, and this autumn it is working on three fronts at once.
First, the 2026 tax year is running towards December 31, and with it the question of which of your Dogecoin holdings satisfy the one-year rule. Second, 2026 is the first year in which crypto service providers have to collect their customers' data for the later report to the Federal Central Tax Office. Third, since January 1, 2026 the transition period for providers without a European authorisation has been over. None of the three has anything to do with the price and everything to do with the date.
Crypto holding period under Section 23 of the German Income Tax Act: counted by the day
For tax purposes, Dogecoin is another asset within the meaning of Section 23(1) sentence 1 no. 2 of the German Income Tax Act. A gain on sale is a private disposal if no more than one year lies between acquisition and disposal. You will find the wording in the full text of Section 23 EStG.
The most common error of reasoning sits in the way the deadline is calculated. The one-year period runs from the day of acquisition, not from the start of the year. If you bought on September 27, 2025, your period ends with the close of September 27, 2026, so a sale from September 28, 2026 onwards no longer falls under Section 23. Buy today and the earliest you leave the period behind is September 28, 2027.
From that follows a very concrete check for this autumn. If you want to unwind a position tax-free while still in 2026, the day of acquisition has to have been December 30, 2025 at the latest. Anything you bought in January 2026 or later is inside the period until New Year's Eve. So look at your purchase records and write the date, the quantity and the acquisition cost of every purchase into a list. Without that list, every further calculation is an estimate.
One point matters for anyone who lends out DOGE or holds it in a product that yields a return: for payment tokens of this kind, the tax authorities do not assume the period is extended to ten years. The Federal Ministry of Finance circular of March 6, 2025, which replaced the version of May 10, 2022, is the governing administrative instruction here. It is also the first to carry its own sections on record-keeping and cooperation duties. We set out the debate over whether the one-year rule survives politically in a separate piece on the holding period on September 25, 2026.
The 1,000 euro exemption limit: one cent decides the whole amount
Section 23(3) EStG leaves gains from private disposals untaxed where the total gain in the calendar year comes to less than 1,000 euros. The word total is meant seriously: all private disposals in the year count together, so the gold you sold and the bitcoin you sold count too, not only your Dogecoin.
What matters is the difference between an exemption limit and an allowance. With an allowance, the base amount would stay untaxed and only the excess would be taxable. With an exemption limit, the entire gain tips into taxability the moment the threshold is reached. Make 999 euros of gains in the calendar year and you pay nothing. Make 1,000 euros and you are taxed on the full 1,000 euros at your personal income tax rate.
A worked example at today's price: 50,000 DOGE at €0.085717 are worth roughly 4,286 euros. Whether that turns into a gain of 300 euros or of 1,400 euros depends solely on your acquisition cost. If you are just over the threshold, the nearest lever is not the price but the split: a partial sale this year, the rest next year. Nothing is lost that way, and in the favourable case it saves the full claim on the whole amount.
FIFO and partial sales: which Dogecoin you sell in December
Anyone who has bought in instalments over several years does not own a single position but a sequence of acquisitions with different dates and prices. On a partial sale the question is which of those tranches counts as sold. In practice the consumption sequence applied is first in, first out: the oldest units count as disposed of first.
In practical terms that means two things. The oldest tranches are usually the ones that have come out of the period, so a partial sale hits the tax-free holding first. At the same time they are often the ones with the lowest acquisition cost, which is where the calculated gain is largest. Together those two points decide whether a December sale is harmless for tax purposes or whether it carries you over the exemption limit.
If your holdings are spread across several providers and several wallets, you need to consolidate them for that. A portfolio tracker that carries acquisition dates along and shows the deadline for each tranche saves you the sheet of paper. Which programs manage that for the German legal framework is set out in our comparison of crypto tax software. Do not rely on any of them blindly: you are the one signing the tax return.
Crypto reporting from 2026: what your provider reports to the BZSt by July 2027
Since January 1, 2026, providers of crypto-asset services with customers in the European Union have been subject to a new collection duty. The basis is Directive (EU) 2023/2226, known in the trade as DAC8, which Germany implements through the Crypto Asset Tax Transparency Act. The first reporting period is the current 2026 calendar year. The first report goes to the Federal Central Tax Office by July 31, 2027.
What gets reported is master data such as name, address, date of birth and tax identification number, along with transaction data: purchases, sales, exchanges, transfers, amounts and timestamps. Exchanges, custodians, wallet providers and transfer services are covered. The private sheet of paper with your recovery words is not.
For you this has a practical consequence that has nothing to do with secrecy and everything to do with reconciliation. What the provider reports is a movement figure and not your taxable gain. Where your tax return diverges from what the tax office already knows from the report, questions follow. We took apart why the reported gross amount and the taxable gain are two different numbers in a piece on the crypto reporting duty.
The task for this autumn is therefore small and concrete. Check that the master data held by your provider is correct, the tax identification number above all. If it is missing or wrongly recorded, the provider will ask in case of doubt and can restrict accounts until the details are complete.
Buying under MiCA: since January 2026 your provider needs an authorisation
The European regulation on markets in crypto-assets has governed the authorisation and supervision of crypto-asset service providers since the end of 2024. The national transitional arrangement has expired: since January 1, 2026 it has been unlawful to provide crypto-asset services in Germany without an authorisation or a valid notification. Supervision is carried out by BaFin, on crypto-asset services.
You can check this yourself, and it takes two minutes. Authorised providers appear in BaFin's company database, and the Europe-wide register is kept by the securities regulator ESMA. A provider that will not name its supervisory authority, or that is absent from the register, is the wrong address for a purchase out of Germany, however attractive the fees look. How the authorised houses differ on fees, deposit routes and withdrawal times is shown in our comparison of crypto exchanges.
Custody: Dogecoin is its own chain, not a token on Ethereum
This point costs money regularly because it sounds so banal. DOGE runs on a blockchain of its own and is not a token under the Ethereum standard. An address intended for ether or for a token on Ethereum will not accept Dogecoin. Send there anyway and the amount is as a rule gone for good, and no provider can reverse it.
Before you withdraw holdings from an exchange, check three things on the device itself. Does your wallet support Dogecoin as its own chain. Does the receiving address begin with the D that is typical for Dogecoin. Does the address your hardware device shows on its own display match the address in the browser window. The third point is the most important one, because it is the only one that malware on the computer cannot forge. Which devices carry Dogecoin and how they differ in daily use is set out in the hardware wallet comparison; on checking against the display we published a separate piece on blind signing after the last device update.
A side effect of self-custody concerns tax. A transfer between your own addresses is not a sale and does not trigger a disposal. It therefore does not interrupt the holding period. Document it with the date and the transaction ID all the same, because your schedule has to explain later why a holding left the exchange without a gain arising.
Issuance and network security: 5.26 billion new DOGE a year
Dogecoin has no cap on its money supply. Each block pays out 10,000 DOGE, and the target block time is one minute. That produces a fixed annual new issuance of around 5.256 billion DOGE.
cryptoticker.io compiled this analysis itself on September 27, 2026: we set the circulating supply of 156.09 billion DOGE from the CoinGecko interface against the fixed block reward. The method in one sentence: 10,000 DOGE per block times 525,600 minutes in the year gives 5.256 billion new DOGE, and divided by the circulating supply that is 3.4 percent of growth in the current year. We verified exactly one quantity, namely the circulating supply at that moment. What we could not verify is how many of those DOGE are permanently lost, because no reliable public figure exists for it.
The share falls year by year, because absolute issuance stays constant while the stock grows. No statement about the price follows from that, but an expectation does: hold DOGE and you hold an asset whose quantity grows by design. A scarcity story of the kind Bitcoin has does not carry here.
The network is secured through proof of work with an additional mechanism that has allowed simultaneous mining alongside Litecoin since 2014. The bulk of the hash rate comes from that merged mining. It makes the network more stable than Dogecoin's size alone would deliver, but it ties the network's security to the economics of mining a second chain.
Leverage and liquidation: why perpetuals do not rescue the period anyway
Dogecoin is traded on many venues as a perpetual futures contract. Trade that way and you own no DOGE. You hold a position on the price, with funding costs that fall due several times a day depending on market conditions.
That has two consequences you should know before you think about leverage. For tax purposes, Section 23 EStG does not apply to a transaction of this kind. It falls into the area of futures transactions, with rules of their own that are in part less favourable. The one-year period you can use when holding directly does not exist there. On the practical side, today's daily range comes to roughly 3.5 percent. At tenfold leverage that is 35 percent of movement on the capital you put up, on a day the market counts as quiet.
If you use futures products, work out the liquidation threshold before you open the position rather than afterwards. And keep it separate from the holding on which you are tracking the one-year period, or you will mix two calculations that have nothing to do with each other in tax terms.
Levels above and below: what the calculation orients itself on
On the downside, the nearest point of orientation is the daily low at $0.095327. Fall below it and the day's range has been left on the downside; that level says no more than that. Above sits the daily high at $0.098670, and beyond it the round ten-cent mark, which in dollar terms is a good two percent away.
Round levels are not a technical statement about a network. Such levels work because many market participants place their orders there, and that is enough to make them noticeable in practice. For the questions in this article they are secondary in any case: your holding period does not turn out differently because DOGE stands short of ten cents or beyond it. The period only helps decide how large the gain is that you weigh against the exemption limit.
The distance to the all-time high of $0.731578 is the third figure that belongs in a sober stocktake. Anyone who bought at the peak in 2021 is sitting on a paper loss that arose well outside the one-year period. A sale there would no longer produce an offsettable loss from a private disposal, because the period applies to losses too.
Dogecoin before the year end: what to take away
- Gather your purchase dates and mark the deadlines. Write down the date, the quantity and the acquisition cost for each purchase and mark which tranches were acquired before December 30, 2025. A tool that carries the deadline for each tranche is in the comparison of crypto tax software.
- Check your provider against the register and complete your master data. Since January 1, 2026 your trading venue needs an authorisation, and from the same date it collects your data for the 2027 report. Check the tax identification number on file and compare fees and withdrawal routes in the comparison of crypto exchanges.
- Match the receiving address on the device before your next withdrawal. Dogecoin needs a wallet that carries its own chain, and the address shown belongs on the device's display, not only in the browser. Which models manage that is set out in the hardware wallet comparison.
(As of September 27, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy. Tax information is no substitute for advice in an individual case.)
$Bitcoin trades at $84,601 on Sunday, September 27, up 5.3 percent on the week after briefly topping $87,000 for the first time since January. The whole top 20 is green on a seven-day view, with NEAR, Chainlink and Cardano leading. Here is where crypto prices stand today and what is behind the move.
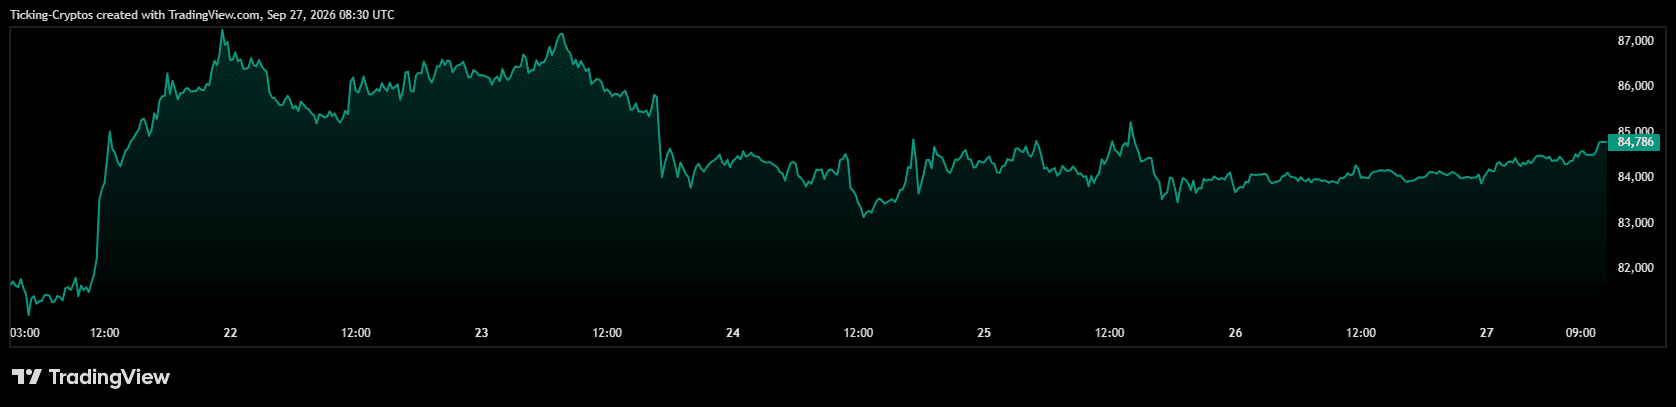
What Are Crypto Prices Today?
The majors, as of Sunday noon UTC:
- $BTC | $84,601 | +0.65% 24h | +5.34% 7d
- $ETH | $2,713 | +0.85% 24h | +5.32% 7d
- $XRP | $1.53 | -1.32% 24h | +11.01% 7d
- $BNB | $777 | +0.48% 24h | +3.80% 7d
- $SOL | $122.18 | +1.31% 24h | +12.54% 7d
- $DOGE | $0.0977 | -0.09% 24h | +14.82% 7d
Bitcoin's market cap sits at $1.69 trillion, Ethereum's at $331 billion. Total 24-hour Bitcoin volume of $15 billion is moderate for a weekend, which fits a market that ran hard mid-week and is now catching its breath. You can compare every major coin live on our crypto prices page.
What Do the Market Metrics Say?
Total crypto market cap stands at $2.9 trillion with Bitcoin dominance at 58.5 percent, almost unchanged over 90 days, and $286 billion parked in stablecoins. The Fear and Greed Index reads 73, firmly in greed but not yet extreme. The Altcoin Season Index sits at 72, just under the 75 threshold, with 36 of the top 50 coins beating Bitcoin over 90 days. Privacy was the strongest sector over 24 hours at +6.8 percent, ahead of AI and Big Data at +4.8 percent. Liquidations were negligible at $266,000, all shorts, a sign the leverage flush from mid-week is done. All of these indicators update daily on our crypto charts.
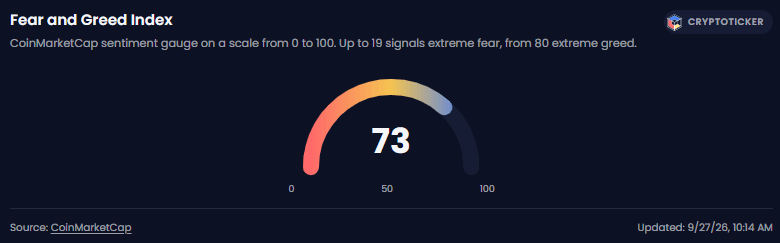
Why Did Bitcoin Rally This Week?
The breakout above $82,000 on Tuesday was a macro trade first and a crypto trade second. Oil and US Treasury yields dipped briefly, shorts got squeezed, and Bitcoin ran to $87,000. Spot Bitcoin ETFs then added roughly $1.7 billion over two sessions, confirming the move rather than starting it. Strategy also resumed buying with 950 BTC after a two-week pause.
The pullback to $84,000 came from the same place. On Wednesday the 10-year Treasury yield jumped past 5.1 percent, its highest since 2007, as markets priced a 64 to 70 percent chance of a second Fed hike in October. Higher yields compete with risk assets for capital, and futures leverage had grown by more than $2 billion during the run. Some of that leverage got flushed, ETF inflows continued, and the net result is a 5 percent week that ended below the high.
Which Altcoins Are Moving?
The weekly leaderboard is unusually broad:
- NEAR Protocol | $5.41 | +56.36% 7d | +258% year to date
- Chainlink | $14.39 | +20.14% 7d
- Cardano | $0.2572 | +17.19% 7d
- Stellar | $0.2186 | +15.09% 7d
- Zcash | $1,662 | +14.79% 7d | +224% year to date
- Monero | $558.56 | +6.59% 7d
NEAR is the standout, up more than 56 percent in seven days and the top performer in the top 20 both on the week and year to date, ahead of Hyperliquid (+266 percent YTD) and Zcash. Privacy coins remain a 2026 theme: Zcash has more than tripled this year and Monero is up 29 percent. XRP's 11 percent weekly gain came despite the Bitget hack, in which roughly 103 million XRP were stolen, and despite a release window of up to 1 billion XRP opening on October 1.
What Could Move Crypto Prices Next?
Three dates matter this week. On Monday, September 28, Bitget begins releasing frozen withdrawals in four stages, starting with BTC at 08:00 UTC, which removes an overhang from XRP and the broader market. On Wednesday, September 30, US core PCE for August lands; July printed 3.3 percent year on year, and a hot number would push October hike odds higher and yields with them. On Friday, October 2, US non-farm payrolls follow, and Hester Peirce leaves the SEC the same day.
The other variable is oil. WTI touched $108 on Thursday and fell back to $94.60 on reports that Iran offered to reopen the Strait of Hormuz. If talks in New York produce a deal, yields fall and Bitcoin likely retests $87,000. If they collapse, $82,000 becomes the level to watch on the downside.
Bitcoin Price Prediction: What Are the Key Levels?
For Bitcoin, $82,000 is the former resistance that now needs to hold as support. Above, $87,000 is the weekly high and the gate to the January range. For Ethereum, $2,700 is holding after a rejection at $2,800, and a clean break of $2,800 opens a run at $3,000. Our Ethereum price prediction and XRP price prediction go deeper on both.
The bigger picture: Bitcoin is up 5 percent on the week but still down 3.3 percent year to date. The rally has not yet erased the first-half drawdown, and it is happening into the most hawkish Fed backdrop since 2023. That is a reason for caution on leverage, not for sitting out.
An asset that hardly any German investor has ever traded sat in tenth place among the largest cryptocurrencies on Sunday morning. FIGR_HELOC, a tokenised home equity loan from the US finance provider Figure, hit an all-time high at 03:58 UTC on September 27, 2026. At the time of our query at 07:48 UTC, CoinGecko listed the token with a market capitalisation of $24.61 billion, placing it directly behind Tron and ahead of Hyperliquid. Tokens worth $1.96 million changed hands in the preceding 24 hours.
That second figure is the real finding. It amounts to 0.008 percent of the token's own valuation. For Bitcoin the same ratio stood at 1.05 percent that morning, around 132 times higher. Anyone reading a league table as a shopping list finds, in tenth place, a holding with exactly one trading venue, and that venue belongs to the issuer itself.
cryptoticker.io compiled this analysis itself on September 27, 2026. The article explains what the token is, why two large data providers value it $9.21 billion apart, and which figure you should read alongside the rank in future before you attach any meaning to a place in a list.
What FIGR_HELOC Is: a Loan Agreement in Token Form
HELOC stands for home equity line of credit. It is a revolving credit facility that a homeowner takes out against the equity in the property they live in and draws on flexibly, much like an overdraft secured by a charge on the property. Figure grants such loans in the United States and, by its own account on its own product page, documents them from origination through to securitisation on the Provenance blockchain.
The FIGR_HELOC token securitises shares in a pool of such loan receivables. Its price of $1.062 is therefore no supply-and-demand price in the sense of a coin; it essentially follows the value of the underlying receivables plus accrued interest. That explains why an all-time high says little about this particular instrument: a paper whose value rises with interest income keeps reaching new peaks without any news behind it.
For your assessment this means an all-time high is no event you can read anything from in this case. The occasion for this piece is the place in the list and the gap between two data providers, not the price level.
Rank 10 at CoinGecko, Rank 4020 at CoinMarketCap
On September 27, 2026 CoinGecko listed the token in tenth place at $24.61 billion. CoinMarketCap reported $15.4 billion for the same token on the same day and placed it at rank 4020. On daily turnover the two providers agree and both state $1.96 million. A third source, DappRadar, came in at $21.14 billion according to search results. The range from $15.4 billion to $24.61 billion is deliberately left standing here, with no average taken.
The cause of the gap can be worked out. CoinMarketCap states a circulating supply of 14.56 billion tokens; multiplied by $1.05 that gives $15.29 billion and matches the figure shown there. From CoinGecko's $24.61 billion and a price of $1.062, by contrast, an implied supply of around 23.17 billion tokens follows. Both therefore calculate in the same way; they simply count different numbers of tokens as circulating.
Which of the two supply figures is the correct one we could not establish. That could only be checked against the pool of tokenised loan agreements itself, and no publicly available schedule exists for that. The difference in rank still carries a clear meaning for you: a place in a list is no property of the asset, but the result of one provider's counting rule.
Method: How We Calculated Valuation Against Turnover
On September 27, 2026 at 07:48 UTC we queried CoinGecko's market data interface for the 25 largest crypto assets, response code HTTP 200, and divided each one's turnover over the last 24 hours by its market capitalisation. We call that figure the turnover ratio. Twenty-five objects were examined, plus, for FIGR_HELOC, the list of recorded trading venues via the same interface and CoinMarketCap's public price page.
What the Turnover Ratio Says, and What It Does Not
The turnover ratio measures what share of the total stock changes hands in a day. A high ratio means a sale disappears into the market. A very low ratio means even a medium-sized order moves the price. The ratio says nothing about the quality of an asset, and just as little about a borrower's creditworthiness. The only question it answers is whether you can actually trade at the price displayed.
What we could not examine is the composition of the loan pool, the default rates of the loans it contains, and whether markets exist beyond the one recorded venue that CoinGecko does not list.
$1.96 Million Daily Turnover Against a $24.6 Billion Valuation
Across the sample of the 25 largest instruments the turnover ratios lay far apart. Bitcoin came to 1.05 percent, Ethereum to 1.97 percent, Zcash to 4.34 percent and NEAR, after its strong week, to 17.39 percent. At the bottom end stood two instruments: FIGR_HELOC at 0.008 percent and the exchange token LEO at 0.006 percent. Only those two out of 25 stayed below 0.05 percent.
A second calculation makes the order of magnitude tangible. At turnover of $1.96 million a day, the market would need around 12,500 days, roughly 34 years, to turn over the stock reported by CoinGecko once in full. For Bitcoin it is 95 days. Both values are arithmetical quantities and no forecast, but they show the proportions involved.
For LEO the low ratio has been known and explicable for years, because a large part of the supply sits with the issuer and in long-term commitments. A related logic applies to FIGR_HELOC: anyone holding a loan receivable holds it for the interest and not in order to trade it daily. The comparison with a coin therefore fails at the root, and the shared league table still places the two side by side.
A Single Trading Venue: Why There Is No Buying Route
At the time of the query, CoinGecko's interface listed exactly one market for FIGR_HELOC: the FIGR_HELOC against US dollar pair on Figure Markets, with a converted volume of $1.96 million. All recorded trading therefore takes place on the marketplace belonging to the token's own issuer.
Figure Markets describes itself as a trading venue on the Provenance blockchain that combines crypto trading with the financing of real-world assets. For credit products the provider names restrictions itself: crypto loans are not available to residents of several US states, and for international clients a list of more than 30 excluded jurisdictions is on file. The provider states that its in-house yield-bearing stablecoin YLDS is registered as a security with the US Securities and Exchange Commission.
For you as an investor in Germany this means the following, and it is deliberately cautious: this token is not listed on the MiCA-authorised trading venues customary in Germany. MiCA is the EU regulation on markets in crypto assets, in full application since December 30, 2024, which requires providers to hold an authorisation and meet disclosure obligations. Whether you would be accepted as a German retail client at a US marketplace at all, which tax and supervisory treatment would then apply and which documents you would receive are questions you have to settle with the provider itself. We have not tested this and make no claims about it.
If you are looking for investments paying ongoing interest, the workable route runs through offerings that are reachable and supervised in Germany. You will find an overview of interest-bearing crypto offerings in our comparison of lending providers, and the route in through regulated trading venues in our overview of crypto exchanges.
Market Capitalisation: What Circulating Supply Times Price Really Says
Market capitalisation is the product of circulating supply and the last price. What does not enter that calculation is how much money was ever invested, how many buyers stand ready, or at what price a larger sale would actually be executed. With an instrument turning over $1.96 million a day, the last price is a snapshot from a very thin order book, and the billions derived from it are a multiplication rather than a measurement of market value.
That is no reproach to Figure. The company does not compile the league table; the data providers do, and they do it for every instrument by the same formula. The error only arises in the reading, when a rank is taken as a measure of significance, tradability or safety.
The lesson reaches beyond this one token. Tokenised loans, bond funds and money market products are growing fast and increasingly appear in the same lists as Bitcoin and Ethereum. How far a tokenised security differs from the token itself is something our editorial team has written up using tokenised equities as the example: anyone holding such a token usually holds a claim against an issuer and not the security itself.
Credit Risk Instead of Price Risk: What Can Go Wrong Here
With a coin the main risk is the price. With a tokenised loan receivable it lies elsewhere, and that changes the examination fundamentally. What matters are the borrowers' ability to pay, the value of the properties pledged, the ranking of claims in the event of defaults and the legal construction between you and the receivable.
A price rising quietly around one dollar can therefore suggest a calm the product does not have. Home equity loans depend on interest rates, the labour market and property prices, and those quantities move slowly, but they move together. A period of stress shows up in such pools only with a delay.
We cannot make reliable statements about the quality of this specific pool, because we found no publicly available schedule of the loans it contains. That is no finding against the provider but the limit of our research. For you it is the decisive point: what you cannot inspect, you cannot assess.
Checking Liquidity: the Figures to Look at Before Any Purchase
The check this case teaches takes two minutes and works for any instrument you find in a league table. It needs four looks.
- Turnover ratio. Divide the 24-hour turnover by the market capitalisation. Below 0.1 percent you should look more closely; below 0.05 percent you have a special case that needs an explanation.
- Number of trading venues. A single market means price and execution depend on one provider. Two or three independent venues with a euro pair are the minimum for a calm entry.
- Quotes in the order book. Look at the gap between the bid and the ask. If it runs to one percent or more, you pay the spread twice, on the way in and on the way out.
- Agreement between the data providers. Where market capitalisation or rank diverge markedly between two providers, they are counting different supplies. The circulating supply is then the question you have to settle.
With FIGR_HELOC all four looks point the same way. That does not make the token bad; it makes it something other than what a tenth place suggests.
Holding Period, Tax and Custody With Tokenised Loan Receivables
With crypto assets you hold for more than a year, a gain on sale is tax-free in Germany under the law as it stands; that is the familiar holding period from the field of private disposal transactions. With an instrument whose return comes from ongoing interest, that classification is precisely not self-evident. Interest-like income is regularly treated differently from price gains, and with tokenised securities the legal structure in the individual case decides.
We deliberately offer no assessment on this, because it depends on documents we do not have. The consequence for you is practical: settle the tax treatment before you buy and not after the first interest payment arrives, and ask for the product documents that state the nature of the return. How widely tokenised paper can differ for tax purposes is shown in our overview of tokenised equities in Germany.
Custody brings a peculiarity you do not meet with a coin. A token held on a special blockchain such as Provenance and tradable on only one marketplace cannot simply be pulled into a wallet of your own and held there. The counterparty risk of the marketplace therefore remains, even though the word token suggests otherwise.
Levels Above and Below: What Is Measurable With This Instrument
This token yields no classic chart picture, and constructing one would be disreputable. The price stood at $1.062 on September 27, 2026, the gain over seven days at 6.00 percent and over 24 hours at 3.68 percent. On the upside the morning's all-time high is the level; on the downside it is the region around one dollar, because that is where the nominal value of the underlying receivables sits.
More telling than any price level here are two other values you can keep an eye on: the number of trading venues and the daily turnover. If turnover rises durably above the range of a few million dollars, or a second, independent trading venue appears, the position changes in substance. A new all-time high on its own does not change it.
Limits of This Analysis
Three things remain open, and they belong in this text. First, we could not establish which circulating supply is correct and why the two providers differ by 8.6 billion tokens; neither set of methodology notes was available in detail at the time of the query. Second, the statement about the single trading venue rests on the markets recorded at CoinGecko, and trading may exist that does not show up there. Third, we did not examine the quality of the loan pool, because no public schedule was available to us.
The figures in this article are snapshots from the morning of September 27, 2026 and age with every trading day. The method does not age: laying valuation and turnover side by side works with every new name that turns up in a league table.
Checking League Tables and Liquidity: What to Take Away
- Calculate the turnover ratio before you believe a rank. The 24-hour turnover divided by the market capitalisation tells you in a second whether an instrument is tradable. Where to find that figure cleanly for the common trading venues and pairs is set out in our overview of crypto exchanges.
- Check the buying route before you take an interest in a product. An asset with no listing on a trading venue authorised in Germany is in practice no investment object for you, whatever its place in a list. Which interest-bearing offerings are reachable here is shown by our comparison of lending providers.
- Separate interest income from price gains. With interest-bearing products the nature of the return decides the taxation and the risk you actually carry. You will find the current yields of the supervised alternatives in our overview of staking and yield platforms.
(As of September 27, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
If your crypto exchange's tax report is wrong, you have to correct it yourself. The German tax office treats that document as an aid and not as proof. You alone are responsible for the figures in your tax return, even when the exchange made the mistake.
That sounds harsh, and it has been clearly settled since the Federal Ministry of Finance's circular of March 6, 2025. Anyone buying or selling through a central trading platform run by a foreign operator has to download and retain the transaction overviews provided there, regularly and in full. Missing records and data losses expressly count against you. This piece shows how to spot a faulty report, how to correct it, and which deadline applies once the return is already with the tax office.
Why an Exchange Tax Report Is Almost Never Complete
A trading platform only knows what happened in its own accounts. The moment you move Bitcoin from an exchange to a wallet of your own, its field of view ends. The platform sees a withdrawal and does not know whether you sold, gave the coins away or merely relocated them. If the same coins arrive on another platform months later, that second platform sees an inflow with no acquisition cost.
This is exactly where the typical wrong amounts come from. One exchange assumes a sale where none took place. Another sets the acquisition cost to zero because it lacks the prior history. Together the two can report a gain that never existed, and in the other direction make a real gain disappear.
On top of that, many reports are built for a different legal system. Providers with an international client base often calculate under rules that do not apply in Germany. Our guide to exporting the tax records from your crypto exchange describes how to get hold of the raw data you need to check any of this.
The Five Most Common Errors in a Crypto Tax Report
In practice the same patterns repeat. Check these five points first.
- Transfers between your own addresses are listed as sales. Moving coins to your own wallet is no disposal and triggers no tax. It still often turns up in the report as an outflow.
- Acquisition costs are missing and set to zero. The full sale proceeds then become the gain. That is the most expensive single error of all.
- The holding period restarts although it was still running. After a transfer some reports set the acquisition date to the day of arrival. Tax-free long-held stock then appears to be a taxable new purchase.
- A swap into a stablecoin is missing as a transaction. Swapping one coin for another is a disposal even when no euro moves. Reports that only count euro movements overlook it.
- Fees and charges are allocated incorrectly. Trading fees belong to acquisition or disposal costs. If they are missing, you pay tax on an inflated gain.
Then come the special cases that defeat almost every piece of automation: income from staking and lending, airdrops, hard forks, payments made in crypto assets and everything that ran through a decentralised protocol. These transactions happen outside the exchange, and that is why they do not appear in its report either.
Who Is Liable When the Report Is Wrong: the Tax Office Comes to You
Under German law the responsibility sits with you, and from two directions. Section 90 of the Fiscal Code obliges you to cooperate, and to a heightened degree where facts lie abroad. The Federal Ministry of Finance circular of March 6, 2025, which replaces the older version of May 10, 2022, turns that into a concrete duty: transaction overviews from the platform are to be downloaded and retained regularly and in full.
The practical core of that sentence is often skipped. An exchange can block your access, cease operations or trim its data holdings after a year-end. Anyone who has saved nothing by then stands without proof, and the loss falls on you rather than on the provider. Anyone using tax software additionally needs process documentation under the principles of proper bookkeeping, meaning a traceable description of which data fed into the result and how.
How to Find the Error: the Reconciliation in Four Steps
The reconciliation is manual work, but it is finite. Four steps are enough for a reliable result.
- Check that the accounts are complete. List every platform, every wallet and every protocol that was active in the tax year. A single forgotten account makes every further calculation worthless.
- Reconcile the balances at the year-end. The prior year's closing balance plus all inflows minus all outflows has to equal the closing balance of the tax year. If the sum does not work out, a movement is missing.
- Pair up every transfer. Every withdrawal from platform A must have a matching inflow on wallet or platform B, with a matching amount and a matching timestamp. Unpaired transfers are the main source of invented gains.
- Recalculate the ten largest transactions individually. The error almost never sits in the mass of small amounts. Check the price, amount, fee and date of the largest items by hand against the raw data.
For the first three steps a tool that merges several accounts and pairs transfers automatically is worth having. Our comparison of crypto tax software and portfolio trackers shows which programs manage this for the German legal framework and where their limits lie. The result still remains your statement and not the program's.
Which Figure Applies in Case of Doubt: Acquisition Cost, Holding Period and Exemption Limit
Before you correct anything you have to know what the right result would have been. For private investors the private disposal transaction under section 23 of the Income Tax Act applies. If you sell within one year of acquisition, the gain is taxable. After a year has passed it stays tax-free. The gain is the disposal proceeds less the acquisition cost and the directly related costs.
Two figures decide almost every correction. First, the exemption limit of 1,000 euros per calendar year for all private disposal transactions combined: if it is exceeded, the entire gain is taxable and not merely the excess. Second, the order in which holdings count as used up. The customary approach is to look at each wallet or account on the principle that the units acquired first are disposed of first. If you switch that method between two years, you create exactly the kind of break that shows up in the report later.
When Data Is Gone for Good: Estimation Under Section 162 of the Fiscal Code
Sometimes data is irretrievably lost, for instance because an exchange was wound up. The tax office may then estimate the tax base under section 162 of the Fiscal Code. An estimate is no blank cheque for the authorities, but it rarely turns out in your favour, and the burden of proving a lower figure then falls on you.
It is therefore better to estimate yourself and to disclose the estimate. Document which data is missing, why it is missing and how you derived the figure you applied, for example from the daily price at a verifiable source for the transaction time evidenced on the blockchain. A reasoned estimate of your own, named in your covering letter, is something entirely different from a figure quietly plugged in.
How Long You Have to Keep the Documents
There is no general retention period for private investors of the kind that applies to businesses. What matters in practice is the assessment period. For income tax it is usually four years, five in cases of reckless tax reduction and ten in cases of tax evasion. As long as it runs, the tax office can take up the case, and for that long you need the records.
Two groups face an explicit duty. Anyone trading or mining commercially falls under the retention duties for accounts and records. And anyone with surplus income of more than 500,000 euros in a calendar year has to keep the underlying records for six years under section 147a of the Fiscal Code. For everybody else the plain rule of thumb applies: download each platform's annual data at the start of the year and file it twice. The effort involved runs to minutes; the effort of reconstructing it three years later runs to days.
Report Corrected, Return Already Filed: Section 153 of the Fiscal Code
If you only notice the error after the tax return has gone out, a separate provision applies. Under section 153 of the Fiscal Code you have to notify and put right without delay once you subsequently realise that a filed return was incorrect or incomplete and that this could lead to an understatement of tax. That applies for as long as the assessment period is still running.
Without delay means without culpable hesitation, so not at the next year-end. In practice you send a short letter to your tax office naming the transaction, stating the corrected figures and enclosing the new documents. Filing the entire return again is not necessary for this. What matters is that the letter makes clear which item changes, how and why.
This correction is the cheap route. Anyone who lets a recognised error lie risks an oversight turning into an accusation after the fact.
The Assessment Has Arrived and It Is Wrong: Appeal Within One Month
Once a tax assessment based on wrong crypto figures exists, the clock counts. Under section 355 of the Fiscal Code the appeal has to be lodged within one month of notification of the assessment. With postal delivery, notification is usually the third day after posting, and not the day you opened the envelope.
An appeal initially needs only form and deadline; you can supply the reasoning later. You should know two points. First, an appeal does not suspend the obligation to pay: anyone who does not want to pay has to apply separately for a stay of enforcement. Second, in appeal proceedings the case is reviewed again in full, including to your detriment. Anyone wanting to correct only a small item should therefore have checked the remaining entries themselves beforehand.
When Income Was Missing Altogether
There is a legal difference between a miscalculated report and an entire category of income left undeclared. Where transactions were not stated at all and that was more than an oversight, the territory of tax evasion comes into play. Section 371 of the Fiscal Code provides for the voluntary disclosure with exemption from penalty, but only with a complete subsequent declaration of all unexpired periods for a type of tax, and only as long as no bar has arisen. An audit that has already been announced is such a bar.
This is the one point in this text where you should not carry on alone. An incomplete voluntary disclosure can fail in its effect and make the position worse. Anyone uncertain here should go to a tax adviser or a lawyer specialising in tax law before writing to the tax office at all.
What the New Reporting Duty Changes From the 2026 Reporting Year
Until recently a faulty report was mainly your own problem. That is changing right now. With the implementation of the European directive DAC8, crypto service providers report their clients' accounts and transactions to the tax authorities, for the first time for the 2026 reporting year. The authorities exchange that data within the EU.
For you this means your figures will in future be held against a second source. If your return diverges from the report, grounds for an audit arise, even where your figure is the correct one. That makes your own documentation all the more important, so you can explain a divergence, for instance a transfer that the reporting platform saw as an outflow and that in truth landed in your own wallet.
A second point concerns the choice of platform. Providers authorised within the European framework generally deliver structured annual data and are set up for the reporting anyway. Anyone trading with a provider outside the European framework has to secure the entire data basis themselves.
Correcting Your Tax Report: What to Take Away
- Treat the report as a draft and not as a result. Run the four-step reconciliation before any figure moves into your return. Which platforms deliver usable annual data can be seen in our crypto exchange comparison.
- Save the raw data yourself every year. A platform failure excuses nothing; under the Federal Ministry of Finance circular the data loss counts against you. A tool from our comparison of tax software and portfolio trackers takes the merging off your hands, but not the retention.
- Act within the deadline. Error spotted before the assessment: correction under section 153 of the Fiscal Code, without delay. Error in the assessment: appeal within one month. And for the 2026 reporting year a platform with European authorisation simplifies the data position, as our comparison of regulated crypto exchanges shows.
(As of September 27, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
This text is no substitute for tax advice in an individual case. Primary sources: the Federal Ministry of Finance circular of March 6, 2025 on crypto assets and section 153 of the Fiscal Code.
Tokenised US equities have sat behind the synthetic dollar USDe since September 25, 2026. Ethena Labs announced that day that it would represent part of the collateral through the equity tokens of the Binance trading platform and hedge the price risk of that position with equity perpetuals. None of this changes the quoted price of USDe. It changes who stands opposite you if things go wrong.
This piece answers four questions. What sits in the reserve now? What return does the construction realistically throw off? What happens to the governance token ENA on October 5? And how much of this is legally accessible to you in Germany at all? You will find no price targets here, because with a stablecoin the question is the backing rather than the price.
What Ethena Announced and What Changes in the USDe Collateral
USDe is a synthetic dollar. That means the token is meant to be worth roughly one US dollar without a real dollar sitting in a bank account behind it. The dollar peg is produced arithmetically instead. Ethena holds crypto collateral and simultaneously opens short positions in derivatives that lose exactly as much value as the collateral gains, and the other way round. This principle is called a delta-neutral strategy, and it has been the core of the protocol since launch.
What is new is the material being worked with. Ethena is taking Binance's equity tokens, known internally as bStocks, into the collateral as the spot leg and selling the matching equity perpetuals of the same trading platform short against them. Allocations began on the day of the announcement, according to the statement. Founder Guy Young calls the step the most significant extension of the USDe funding mechanism since the protocol began, and justifies it with the sheer size of the equity markets.
The scale of the protocol, measured in house: at 06:38 UTC on September 27, 2026, around 4.94 billion USDe were in circulation according to DefiLlama's stablecoin interface. The governance token ENA traded in the same window at $0.2712, or 0.2381 euros, with a market capitalisation of $2.74 billion at rank 40 (CoinGecko, 06:37 UTC). The yield-bearing offshoot sUSDe comes to $1.31 billion across roughly 1.05 billion tokens.
How the Basis Trade With Equity Perpetuals Works
A perpetual future is a futures contract with no expiry date. To stop its price drifting away from the spot price, the two sides pay each other a balancing fee at short intervals, the funding rate. When more traders are leveraged long, those long positions pay the short positions. That payment is precisely the income source of USDe.
The basis trade therefore works like this: Ethena holds the asset in the spot market and sells the same quantity short in the perpetual market. If the price moves, gain and loss largely cancel out. What remains is the difference between the two markets, the basis. Applied to crypto assets, that has been the mechanism behind USDe since 2024. Applied to equities, it is the same procedure with a different underlying.
One practical detail from the statement belongs here, because it counts under stress: Binance grants eligible delta-neutral accounts a lower priority in automatic position reduction. Automatic position reduction, known in the trade as auto-deleveraging, is an exchange's emergency measure when a liquidation tears a hole and profitable counter-positions are closed by force. Whoever sits further back in that queue is pulled out less often. If you are interested in the mechanics of perpetuals in detail, our comparison of perp DEX platforms sets out the differences between the trading venues.
What bStocks Really Are: A Claim Against a Binance Subsidiary
Here lies the point that matters more to the safety of USDe than any yield figure. bStocks are not shares. The issuer is BTech Holdings Limited, a company within the Binance group. Anyone holding a bStock holds a right to securities that this issuer holds in turn. No voting rights from the share come with it. Conversion into the real instrument is envisaged for eligible users, as far as the applicable law permits. Binance launched the first of these tokens in June 2026, among them Nvidia, Tesla, Circle, Micron and Sandisk, and according to Token Terminal data cited by crypto.news the volume had grown to around $610.6 million by August.
The risk analysts who worked the construction through for Ethena's risk committee put the consequence unambiguously. Kairos Research recommended releasing bStocks only once a side letter with the issuer has been signed setting out what the issuer may do with the deposited shares. As long as that letter is missing, the spot leg is unsecured credit risk to a Binance subsidiary and not a claim on the share. That describes what would happen if the issuer became insolvent.
With tokenised equities this distinction is the norm and not the exception. We took it apart at length in a separate analysis of issuer risk in tokenised equities on August 16, 2026. For USDe it means that part of the backing will in future be a claim against a company, and the quality of that claim hangs on a contract that had yet to be signed at the time of the announcement.
Why Ethena Is Looking for Income Outside the Crypto Market
The reason for the rebuild sits in the funding rates. Ethena disclosed its own figures in August: the open-interest-weighted funding rate on Bitcoin averaged 11.0 percent annualised in 2024, 4.9 percent in 2025 and, up to August 11, only 2.2 percent in 2026. The income source from which USDe draws its yield has therefore shrunk to a fifth within two years.
Binance's equity perpetuals came in at an average of 17.5 percent over the comparison period from May 20 to August 11. Open interest in those contracts stands above $2.9 billion and grew by around 105 percent a month on average over 2026. From the protocol's point of view this is a young market paying considerably better than the dried-out crypto perpetual trade.
How High the Equity Basis Really Is: 3.56 Against 7 to 18 Percent
This is where the published figures diverge widely, and anyone reading only one of them ends up with a skewed picture. Kairos Research puts the yield on the admitted Binance instruments at around 18 percent at the end of July and at about 7 percent as of August 26, with two of the instruments even yielding negative at that point. Crypto.news, by contrast, cites an average equity basis of 3.56 percent annualised over the past six months on September 25, likewise drawing on figures from Ethena.
The range therefore runs from 3.56 to 18 percent, depending on the measurement period and the selection of instruments. One thing above all can be relied on in that spread: the yield is falling. The end-of-July figure roughly halved by the end of August. An income source that gives way that sharply within four weeks is no basis for a return expectation you write into your planning for the coming year.
We showed how quickly such a calculation can tip on September 12, 2026 using a concrete case: the popular loop of sUSDe and borrowed stablecoins no longer paid for itself on the arithmetic at that point, because the borrowing rate exceeded the yield. The same logic applies to the new equity source.
What Hurdles an Equity Perpetual Has to Clear
Ethena's risk committee adopted a screening grid in August before the first equity token was allowed into the reserve. A contract only qualifies if it carries at least $25 million of one-sided open interest on a 14-day average, if at least 30 days of funding history exist, and if a matching tokenised spot instrument trades on the same venue. The underlying must be a listed security. Leveraged and inverse products are excluded.
The grid is strict enough to weed out almost everything. When it was applied in August, 17 markets on Binance and three on OKX passed. On Bybit and Kraken not a single one qualified. That is exactly why the extension is starting with one single trading venue, and at the same time why it turns into a concentration risk: the spot leg, the hedging leg and the issuer of the collateral all sit within the same corporate group.
What Else USDe Consists Of: Lending, Stablecoins and Real-World Assets
The equity basis trade is not arriving in a pure crypto reserve, because that ceased to exist long ago. Ethena rebuilt the composition in April 2026 and took in institutional lending and tokenised real-world assets. At the start of July, according to governance data cited by crypto.news, only around $39 million, or one percent, was left in classic crypto basis positions. DeFi lending accounted for about 46 percent, liquid stablecoins around 35 percent, tokenised real-world assets 11.2 percent and institutional lending, at around $310 million, a further 6.9 percent.
Part of that institutional block is a one billion dollar credit line set up with the trading house FalconX in August. Assets from the USDe backing finance over-collateralised loans to institutional borrowers there, settled through a special purpose vehicle, with qualified custodians expected to hold collateral in excess of the outstanding loan amount.
For you as a reader the conclusion is uncomfortable and important in equal measure: what stands behind USDe today has little left in common with the model the protocol set out with. The share of classic crypto basis positions was one percent at the start of July. The rest is a portfolio of loan claims, third-party stablecoins, products close to government bonds and, from now on, equity tokens. Anyone who takes the yield on sUSDe for a kind of interest rate should know that what they are really holding is an actively managed credit portfolio.
October 5: What Unlocks on ENA and Why the Buyback Does Not Cushion It
Alongside the collateral question runs a date that concerns the governance token. On October 5, 2026 the lock-up for the remaining original investor tranches ends. Our own analysis of the vesting plan, dated September 3, 2026, arrived at around 1.41 billion ENA in a single distribution. Measured against today's circulating stock of 10.1 billion tokens, that would be just under 14 percent, or around $382 million at the September 27 price. This figure comes from our calculation and not from Ethena: the protocol does not state the size of the tranche publicly.
The obvious counter-question is whether the agreed buyback mechanism absorbs it. According to our analysis of August 30, 2026, that mechanism only kicks in once USDe in circulation reaches $7.5 billion. Measured against today's 4.94 billion, roughly 2.56 billion are missing, so the protocol would have to grow by a good half. As matters stand today, that buffer is therefore not available for October 5.
To place the price picture, from our own measurement at 06:37 UTC on September 27, 2026: ENA is up 37.0 percent over seven days and 69.1 percent over 30 days, but down 54.0 percent over twelve months. It sits 82.1 percent below the all-time high of $1.52 set on April 11, 2024. We expressly draw no forecast from this. The date and the order of magnitude are what you need to know.
What Applies in Germany: BaFin, MiCAR and the Missing Investor Protection
For German investors the supervisory position is the real sticking point, and it has been unambiguous for a year and a half. On March 21, 2025, in the authorisation procedure of Ethena GmbH, based in Frankfurt am Main, BaFin found serious deficiencies and ordered immediately enforceable measures. Among other things the company was prohibited from continuing to offer the USDe token publicly, the asset reserve had to be frozen by the custodians, and a special representative appointed by the supervisor monitors compliance. BaFin additionally made public its reasoned suspicion that securities had been offered in Germany without the required prospectus.
The substance of the objection connects directly with the subject of this article. Under Article 3 of the European crypto regulation MiCAR, USDe is an asset-referenced token whose stability of value is meant to be maintained by reference to other values. By its own account, Ethena GmbH held only other crypto assets as the asset reserve, and stability was supposed to arise from an algorithm using hedging derivatives. That very construction of the reserve stood at the centre of the procedure. Whatever Ethena has changed in the composition since then makes no difference to the German prohibition. The prohibition attaches to the authorisation procedure as such and therefore to no particular collateral package. We have set out elsewhere which obligations an authorisation under this regulation triggers in the first place.
In practice this means: anyone holding USDe or sUSDe through a trading venue outside the European supervisory framework stands outside the level of protection that MiCAR provides for authorised issuers. There is no redemption claim against a supervised issuer there, no audited reserve under European rules and no deposit guarantee. The whole construction rests on the hedge at a central trading platform working at all times. How we assessed the income source and the consequences of the supervisory wind-down in detail is set out in our analysis of where the USDe yield comes from and the BaFin wind-down.
Tax: What Comes Your Way With USDe and sUSDe
For tax purposes a stablecoin is no euro. In the eyes of the tax office USDe and sUSDe are other economic assets, and swapping euros into USDe, or USDe into another token, is a separate transaction each time. Gains from a sale within one year fall under the private disposal transaction of section 23 of the German Income Tax Act, with an exemption limit of 1,000 euros a year for all private disposal transactions combined. If the limit is breached, the entire gain is taxable and not only the excess.
With sUSDe there is an additional feature that many overlook. No separate income token flows to you; the increase in value sits inside the token itself. A taxable gain therefore usually only arises on sale or exchange. Whether the tax authorities classify the transaction in an individual case as a private disposal transaction or as income from other services depends on the specific arrangement. Settle that with a tax adviser before your return, and keep complete records regardless: since the 2026 reporting year, providers within the EU report to the tax authorities under the DAC8 directive, and discrepancies between your own records and the report stand out.
How to Check the Collateral Yourself in a Few Minutes
You do not have to rely on any announcement. Three checks are enough for a picture of your own and take under ten minutes together.
- Verify the circulating supply. DefiLlama's stablecoin interface shows the outstanding amount of USDe. If it falls over several weeks, capital is leaving, and the protocol has to close positions.
- Read the composition of the reserve. Ethena publishes a transparency page. Compare the share of crypto basis positions there with the share in lending and tokenised assets. As the credit share grows, so does your counterparty risk.
- Watch the funding rates. Every large derivatives exchange displays the current funding rate. If it stays in negative territory for a longer period, the protocol is paying out instead of earning.
A fourth check concerns the new development specifically: watch whether the side letter with the issuer of the equity tokens gets signed. Until then, in the assessment of the protocol's own risk analysts, this part of the backing is a claim against a company and gives no access to a security.
Checking the USDe Collateral: What to Take Away
- Check where you trade before you check what you hold. An offer prohibited in Germany stays prohibited, however good the reserve looks. Our comparison of regulated crypto exchanges shows which trading venues can demonstrate authorisation under European law.
- Do not confuse yield with interest. The income on sUSDe comes from derivatives business and lending, and the equity basis fell from around 18 percent at the end of July to about 7 percent at the end of August. Anyone looking for income should lay the sources side by side: our overview of staking and yield platforms sorts out which risk sits behind which number.
- Document every swap from day one. With a token whose value grows inside the token itself, clean record-keeping decides your later tax bill. You will find tools for that in our comparison of crypto tax software and portfolio trackers.
(As of September 27, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Primary sources: Ethena Labs on extending the basis trade to equities and the BaFin consumer notice on Ethena GmbH.
Decrypt
Bitcoin ETFs have drawn nearly $3 billion over seven straight sessions, erasing post-Clarity Act losses and pushing 2026 flows back into positive territory.
After the Clarity Act failed in the Senate, the SEC, CFTC, and the Fed moved within days to write crypto's rules themselves. Will it be enough?
An open competition run by StarkWare, Yukon Research, and Eigen Labs drove the estimated cost of building a quantum-safe Bitcoin transaction from about $320 to roughly $67, with AI models topping the leaderboards.
Google Vids now lets any Google account holder generate free HD AI video using Gemini Omni 1.1 Flash, with new scene, timing, and watermark controls.
Federal prosecutors are targeting a Montana payments firm and a Caribbean bank accused of moving money without a license.
U.Today - IT, AI and Fintech Daily News for You Today
Bitcoin and USD aren't usually the best friends, which is why a quick.
Bitcoin is on track to post its second-best third quarter on record, with a roughly 43.5% gain that trails only 2017, according to CoinGlass data.
Shytoshi Kusama's prolonged absence has continued to attract attention from SHIB community members.
Traders on Kalshi are betting on XRP's chances of hitting a multi-month high of $1.70 before this month runs out amid the consistent price upswings.
Pump.fun's fee wallets have pushed cumulative SOL sales past $848 million, even as another multi-million-dollar batch moved to Kraken in the last two hours.
Blockonomi
TLDR:
- A prediction-market contract put the CLARITY Act near 14% odds of becoming law in 2026 before the September 15 vote; that was not a 12-month forecast.
- The CFTC’s September 24 FAQ update clarified tokenized forms of already-permitted customer-fund investments and blockchain-based recordkeeping, without widening eligible assets.
- The SEC’s five-year conditional exemption covers certain permissioned venues trading tokenized U.S. stocks, while leaving altcoin products and most crypto platforms outside its scope.
- Agency guidance can move quickly, but it may change or face legal challenges; a statute could set more durable lines for jurisdiction, registration, and customer protections.
The CLARITY Act has stalled, but U.S. crypto regulation continues through agency action. The SEC and CFTC apply authority to tokenization, recordkeeping, and trading. These steps shape compliance as institutions assess digital assets, including altcoins. However, agencies cannot settle questions about jurisdiction, registration, or consumer safeguards that Congress could address.
On September 15, the Senate failed to advance the CLARITY Act in a procedural vote, not a final rejection. Before the vote, a prediction-market contract put the bill’s 2026 passage odds near 14%. That was a calendar-year estimate, not a forecast for the next twelve months. No vote is scheduled.
What the CLARITY Act Could Change for Crypto Markets
The CLARITY Act would set a federal market-structure framework. It would define when tokens qualify as securities or commodities and divide SEC and CFTC oversight. It would also set registration and consumer-protection requirements. Clearer categories could reduce jurisdictional disputes and help firms decide how to operate. The bill would give investors a firmer basis for understanding platform duties.

Those duties matter when an exchange holds customer assets. Users want to know how firms must safeguard funds, keep records, and respond to breaches or losses. Rules under the CLARITY Act could support consistent compliance across platforms. They would not guarantee safety, prevent every hack, or shield investors from losses caused by volatility.
A framework may affect institutional participation. Retirement plans, insurers, and asset managers could assess crypto exposure against clearer responsibilities and safeguards. Registration pathways might attract more buyers and sellers, supporting liquidity and price discovery. Institutions must weigh custody, demand, liquidity, and volatile-asset risk.
SEC and CFTC Rules Move Ahead While Congress Stalls
The CFTC’s September 24 FAQ update offers an example. This matters for compliance across derivatives markets. Staff clarified how registrants may use tokenized forms of investments already permitted for customer funds. They also addressed blockchain systems for keeping and producing required records. The update does not expand the eligible investment list or create a new regime. It applies existing requirements to tokenization and distributed ledgers.
The FAQs build on staff guidance about tokenized collateral. The CFTC says they reflect staff views, create no binding rules, and amend no regulations. The update can guide compliance planning, but is narrower than a statute or agency rule. It concerns registered firms, not a comprehensive definition of digital assets or allocation of SEC and CFTC jurisdiction.
The SEC has acted under existing authority. On September 17, it approved a temporary, conditional exemption for certain venues trading tokenized U.S. stocks in permissioned settings. The five-year measure allows limited on-chain trading while the agency considers broader rules. It does not authorize all crypto platforms or approve altcoins. Its scope covers tokenized national-market-system stocks.
These examples show why the CLARITY Act still matters as regulation advances. Agencies can address narrower questions and test approaches, but their actions depend on current statutes. Guidance may change, exemptions have conditions, and agency measures can face court challenges or leadership shifts. Congress could provide more durable rules for asset classifications, venue responsibilities, registration, and investor protections.
That certainty could help institutions assess crypto, but regulation is not a government endorsement. Bitcoin and other cryptocurrencies remain speculative and volatile. The CLARITY Act would not make those assets safe or eliminate market risk. Stablecoins and distributed-ledger systems may serve payment or settlement uses, especially when tokens represent assets such as U.S. Treasurys. Those uses differ from spending volatile crypto on everyday goods and carry distinct risks.
For now, the CFTC FAQ update clarifies tokenized permitted investments and blockchain recordkeeping within existing rules. The SEC exemption addresses limited trading of tokenized stocks. Unresolved questions include who regulates each market, which firms must register, and what consumer protections users can expect.
The post CLARITY Act Delay Leaves Crypto Rules Moving Through Agencies appeared first on Blockonomi.
TLDR:
- PeerDAS, live since Fusaka in December 2025, lets nodes sample blob data instead of downloading every blob.
- Hegotá, expected in 2027, could be Ethereum’s last broadly familiar fork before deeper cryptographic redesign.
- EIP-7805 adds validator-backed inclusion lists to curb censorship by individual block builders in Hegotá.
- Ethereum targets 2029 for core post-quantum infrastructure, alongside Lean Consensus and recursive STARKs.
Vitalik Buterin has outlined a long-term architecture for Ethereum that could make the network increasingly difficult to describe as a conventional blockchain. The model combines decentralized consensus, zero-knowledge proofs, distributed computation, privacy systems and post-quantum cryptography.
In a September 27 post titled “The cryptographic world computer,” Buterin said the network now blends Bitcoin-era blockchain principles with newer cryptographic research. His framework describes a system where verification relies less on every node repeating every computation and more on proofs, sampling and specialized distributed infrastructure.
That shift is already visible in several parts of the roadmap. Data availability, block construction and consensus are moving toward designs that reduce duplication while preserving verifiability across the network.
Ethereum’s World Computer Shift Rewrites Blockchain Verification
Traditional blockchains require many nodes to download data and independently re-execute transactions. Buterin described an architecture that increasingly replaces that model with data sampling and cryptographic proof verification.
Consensus has also moved from proof-of-work to proof-of-stake, while a more optimized Lean Consensus design remains under development. At the same time, block construction could become more distributed instead of depending heavily on one miner or builder.
PeerDAS provides an early example of that direction. Introduced through the December 2025 Fusaka upgrade, it lets nodes verify blob availability by sampling data rather than downloading every blob.
That reduces bandwidth requirements while supporting higher Layer 2 capacity. As a result, more computation can move outside the base layer without removing Ethereum’s ability to verify results cryptographically.
The next major milestone is Hegotá, currently expected in 2027. Buterin described it as potentially the last upgrade that would remain broadly familiar to developers from earlier network eras.
Hegotá and Lean Ethereum Push Toward Quantum-Safe Design
FOCIL, formally EIP-7805, is scheduled for Hegotá. It introduces validator-backed inclusion lists intended to limit the ability of individual block builders to censor valid transactions.
However, the upgrade’s broader scope remains under development, so additional features and timing could still change. Beyond Hegotá, research increasingly centers on recursive STARKs, formal verification and advanced state management.
EIP-8288 offers one example. The draft proposal would aggregate quantum-resistant signatures and STARK proofs in the mempool before producing one recursive proof for block verification.
Lean Ethereum extends that direction with redesigned consensus, hash-based post-quantum signatures, formal verification and finality targeted in seconds. Separately, the Ethereum Foundation is targeting about 2029 for core post-quantum infrastructure.
Taken together, Buterin’s framework describes a network where decentralized offchain systems handle larger workloads while cryptographic proofs preserve security guarantees. He calls that architecture a “cryptographic world computer.”
The post Vitalik Buterin Maps Ethereum’s Evolution Into a Cryptographic World Computer appeared first on Blockonomi.
Quick Overview
- Wednesday brings the August Personal Consumption Expenditures inflation report, marking the first inflation data release following the Federal Reserve’s September interest rate increase.
- Friday’s September employment report is projected to show 100,000 new positions added, with the jobless rate anticipated to remain steady at 4.2%.
- Micron Technology releases its fiscal fourth-quarter financial results on Wednesday, with Wall Street analysts projecting earnings of $31.52 per share and revenue approaching $51.07 billion.
- Additional earnings releases from CarMax, Carnival, Nike, and Accenture will provide insights into both consumer trends and corporate expenditures.
- Last week saw the 10-year Treasury yield finish at 5.17%, while mortgage borrowing costs reached their peak levels since January 2025.
Wall Street begins this week with attention squarely on inflation metrics, employment figures, and a series of important earnings announcements. The three primary market indexes all posted gains during the previous week. The Nasdaq finished trading near an all-time high, while the Dow ended a three-week decline.
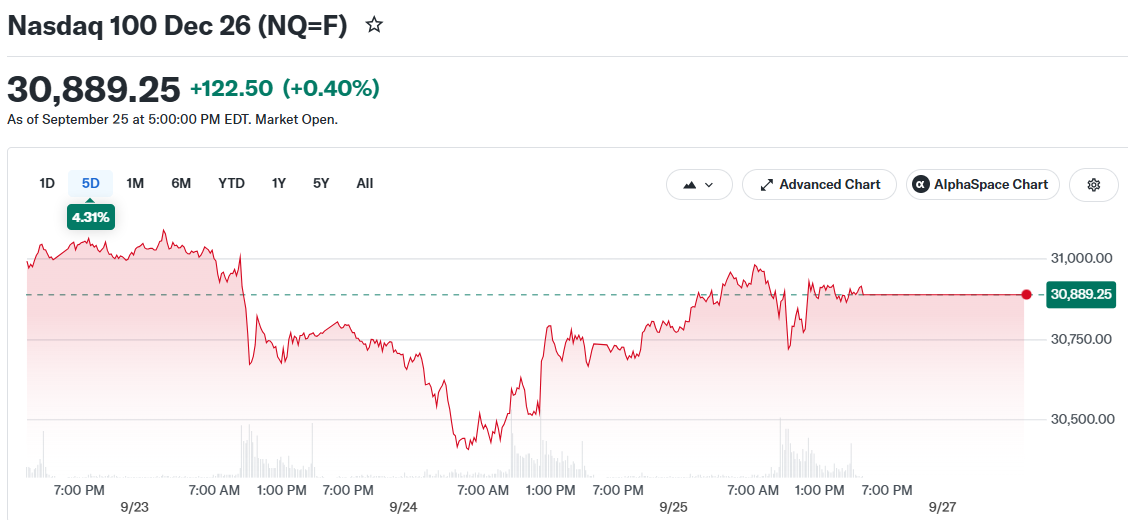
Wednesday will see the Bureau of Economic Analysis publish the August Personal Consumption Expenditures price index. This metric serves as the Federal Reserve’s favored inflation measurement. Additionally, this marks the initial inflation data since the central bank implemented its interest rate increase on September 16.
The previous report showed Core PCE climbing 3.3% on an annual basis. This figure remains considerably above the Fed’s 2% objective. An inflation reading that exceeds expectations could increase the likelihood of an additional rate hike in October.
Employment Numbers and Consumer Sentiment Under Scrutiny
Tuesday brings an update to the Conference Board’s Consumer Confidence Index. The index experienced a decline in August, despite Americans reporting marginally improved perceptions of employment conditions.
Friday’s September employment report is anticipated to show 100,000 new positions created, according to economists polled by Reuters. The jobless rate is projected to hold steady at 4.2%.
While August’s hiring numbers exceeded projections, the gain wasn’t substantial enough to alter the modest hiring and limited layoff trend observed throughout this year. A jobs report that surpasses expectations could strengthen arguments for another Federal Reserve rate increase.
Consumer sentiment faces ongoing challenges. The University of Michigan’s survey revealed sentiment reaching its second-lowest point in the survey’s 74-year existence. Mortgage borrowing costs compound these pressures, with the 30-year fixed rate ascending to 7.45%, marking the highest level since January 2025.
Quarterly Results From Micron, CarMax, and Nike
Micron Technology unveils its fiscal fourth-quarter performance on Wednesday. Wall Street analysts project earnings of $31.52 per share with revenue totaling approximately $51.07 billion. As a memory chip manufacturer, Micron serves as an important indicator of demand connected to AI data center infrastructure.
CarMax announces fiscal second-quarter results on Tuesday. Earlier this year, an activist investor urged the retailer to evaluate price reductions on pre-owned vehicles. The earnings release may indicate whether pricing pressures have diminished.
Carnival Corporation launches the week’s earnings cycle on Monday. Wall Street forecasts $1.35 per share on revenue totaling $8.39 billion. Cruise industry spending remained robust during the summer months despite some consumers reducing expenditures on alternative travel options.
Nike delivers fiscal first-quarter results Wednesday following market close. Analysts anticipate $0.44 per share with revenue of $11.33 billion. The athletic apparel giant’s previous quarterly report revealed a 12% decline in China-based sales.
Accenture releases earnings on Thursday, with analysts projecting $3.18 per share and revenue of $18.03 billion. The consulting giant recently established a five-year AI safety collaboration with Anthropic.
McCormick and Company also announces results Wednesday, with expectations of $0.76 per share on revenue approaching $1.98 billion. The spice manufacturer is planning a merger with Unilever.
Treasury Yields and Overall Market Environment
The 10-year Treasury yield concluded last week’s trading at 5.17%. The 30-year yield hit its highest point in over two decades. Elevated yields diminish the present value of companies’ future earnings streams.
U.S. 30-Year Treasury Yield closes at 5.49%, the highest level in more than 22 years

— Barchart (@Barchart) September 25, 2026
Eight of the eleven sectors within the S&P 500 posted negative returns for September. An equally weighted calculation of the index declined approximately 4% during the month, illustrating how market advances have depended heavily on a limited number of large-cap technology companies.
Gold settled near $4,322.40, crude oil traded around $92.79, and Bitcoin concluded near $83,809. The VIX, which measures anticipated market volatility, dropped to 14.87.
Multiple corporations go ex-dividend during this week, including Cisco Systems, Deere, and Bristol-Myers Squibb. Market participants will evaluate this week’s employment and inflation releases alongside elevated bond yields to determine the market’s trajectory ahead.
The post Key Economic Reports and Earnings to Watch This Week: Jobs, Inflation, and Micron (MU) Results appeared first on Blockonomi.
TLDR
- The fast-food giant introduced its NEXT expansion blueprint at its annual Investor Day, featuring restaurant makeovers and artificial intelligence integration.
- McDonald’s committed approximately $8.5 billion in franchisee assistance extending through 2036, with $5 billion allocated by the end of this decade.
- Shares dropped 5% following the announcement and touched $234.03, marking the lowest level in almost four years.
- Domestic same-store sales dipped into negative territory during July and August, with third-quarter results projected to remain in the red.
- Wall Street firms slashed their price projections across the board, though most maintained bullish outlooks on the long-term potential.
Shares of the Golden Arches have tumbled to levels not seen since early 2021 following a negative market response to the company’s latest expansion roadmap. The stock plummeted nearly 5% last Wednesday and experienced an intraday decline of 6.5% before recovering slightly. Selling pressure continued into Thursday and Friday, bringing year-to-date losses to approximately 23%.
McDonald’s Corporation, MCD
The sharp decline came on the heels of the company’s Investor Day presentation, during which executives unveiled the NEXT initiative. This comprehensive program encompasses restaurant reimagining, menu enhancements, precision marketing campaigns, and artificial intelligence integration for ordering platforms and supply chain management.
The blueprint appears bold and forward-thinking. However, investors are primarily concerned not with the strategic direction, but rather with the financial commitment required and the extended timeframe for returns.
Understanding the Market Reaction
McDonald’s has committed to deploying approximately $8.5 billion in franchisee assistance over the next twelve years. The company will frontload $5 billion of this investment before 2030, including lease subsidies and $1.5 billion to $2 billion in direct capital assistance.
Company leaders project these investments will enhance restaurant-level margins by 2.5 percentage points. This translates to approximately $100,000 in additional annual operating cash per typical U.S. location.
The overarching goal: achieving an adjusted operating margin in the low-to-mid-50% territory by decade’s end. This represents a significant jump from the 47% recorded during the first six months of 2026. Reaching this milestone demands substantial upfront capital deployment, creating anxiety among shareholders focused on immediate financial performance.
Bernstein analyst Danilo Gargiulo identified the investment magnitude as the “biggest surprise” from the presentation. His calculations suggest complete implementation could require roughly $800,000 per average domestic restaurant, layered on top of standard renovation expenses.
Bank of America analysts estimate restaurants would need to generate 7% to 8% sales increases to warrant the investment, based on a 70/30 cost-sharing arrangement between franchisees and corporate. That’s a challenging benchmark considering the current operating environment.
Current Sales Momentum Remains Challenged
Customer traffic patterns are complicating the narrative. The company disclosed that domestic comparable sales posted declines throughout July and August, with third-quarter results expected to finish marginally negative despite sequential improvement during September.
Global comparable sales during the second quarter advanced just 1.3% on a year-over-year basis. This marked a deceleration from 3.8% growth in the opening quarter and 3.1% for the full 2025 calendar year. Domestic customer visits actually declined.
Raymond James analyst Brian Vaccaro noted that NEXT’s effectiveness will be evaluated “in years rather than quarters.” The company hasn’t provided specific deployment schedules for numerous components of the strategy, creating uncertainty around execution timing.
Vaccaro also highlighted a value proposition challenge. Many quick-service meals now command $10 to $13, placing McDonald’s in head-to-head competition with casual dining chains and fast-casual restaurants offering promotional pricing.
Multiple Wall Street firms adjusted their price objectives downward following the presentation. Baird reduced its target to $250 while maintaining a Neutral stance. BTIG lowered its projection to $295 but preserved its Buy recommendation. RBC trimmed to $285 with a Sector Perform designation. JPMorgan decreased to $260 while retaining an Overweight rating.
However, not all analysts adopted a pessimistic view. UBS reaffirmed its Buy recommendation and $320 price objective, emphasizing the NEXT program’s emphasis on same-restaurant sales growth and customer traffic expansion.
J.P. Morgan’s John Ivankoe suggested McDonald’s data capabilities could provide competitive advantages versus independent operators. Deutsche Bank’s Lauren Silberman expressed increasing conviction that AI-driven tools will enhance unit-level economics over the medium term.
BMO’s Andrew Strelzik characterized the margin objectives as realistic and remains positive on the valuation. He anticipates modest near-term price appreciation until the capital investments translate into measurable growth acceleration.
Over half of Wall Street analysts monitored by FactSet continue to assign Buy ratings to the stock. The consensus price target implies approximately 27% upside from current trading levels.
Bernstein maintained its Market Perform rating and $295 valuation, observing that the beverage platform introduction hasn’t generated sufficient sales momentum to counterbalance broader headwinds. The firm also noted that the enhanced chicken offering rollout timeline extends beyond initial expectations.
The post McDonald’s (MCD) Stock Plunges to 4-Year Low: Is This a Buying Opportunity? appeared first on Blockonomi.
Key Highlights
- Berkshire Hathaway expanded its position in Lennar to 11%, representing approximately $2.1 billion in value.
- The conglomerate acquired roughly 1.7 million additional shares over three trading days at approximately $81 per share.
- Shares have declined approximately 20% since the beginning of 2026, ranking among the weakest in the homebuilding sector.
- Third-quarter earnings plummeted nearly 50% to $1.19 per share while sales decreased 9% to $8.05 billion.
- Analyst consensus points to a “Moderate Sell” rating, with a mean price target of $78.93.
Shares of Lennar (LEN) hovered around $82 on Friday, posting modest gains for the session while remaining approximately 20% lower year-to-date. The movement followed Berkshire Hathaway’s disclosure revealing an 11% ownership stake in the homebuilding company, valued at approximately $2.1 billion.
Lennar Corporation, LEN
Between Wednesday and Friday, Berkshire acquired approximately 1.7 million shares at an average cost of $81 per share. This transaction elevated its total position to approximately 26 million shares.
The acquisition pushed Berkshire over a critical regulatory benchmark. Surpassing 10% ownership triggers mandatory reporting requirements for all subsequent trades within two business days rather than quarterly disclosures.
Warren Buffett’s investment vehicle has been accumulating this position steadily over recent months. The stake has nearly doubled since the conclusion of the second quarter.
The accumulation coincides with a challenging period for Lennar. The stock opened 2026 around $102 and has tumbled roughly 39% from its 52-week peak of $133.76.
Mortgage rates lingering near 7% have dampened buyer appetite. Weakened demand, reduced pricing power, and increased buyer incentives have compressed profitability throughout the industry.
Berkshire’s Value Investment Thesis
Lennar currently trades beneath its book value of approximately $90 per share, positioning it as a traditional value investment within a depressed sector. The company’s median home price reached roughly $372,000 during the most recent quarter.
Third-quarter results illustrated the pressure. Net earnings declined to $284 million, equivalent to $1.19 per share, compared to $591 million in the prior year. Home deliveries decreased 3% to 20,840 units while new orders contracted 9%.
Lennar revised its annual delivery guidance downward to 80,000-81,000 homes from a previous estimate of 82,000-83,000. The home-sales gross margin contracted to 15.8% from 17.5%.
Positive developments exist within the challenging data. Construction costs per square foot decreased 6% year-over-year, while construction timelines reached a company record of 116 days.
The company maintains minimal direct land ownership, controlling less than 2.5% of its approximately 488,000 homesites. Its strategic partnership with Millrose Properties facilitates land acquisition financing without requiring substantial internal capital allocation.
Outlook and Analyst Perspectives
Wall Street forecasts Lennar’s fourth-quarter results, scheduled for December 15, will show earnings declining 29% year-over-year to $1.45 per share. Annual EPS is anticipated to fall 40% to $4.85.
Analyst sentiment remains cautious despite Berkshire’s confidence in the investment. Bank of America maintained its “Underperform” designation while reducing its price objective to $70 from $77.
Wells Fargo adjusted its target downward to $80 from $85 while retaining an “Equal-Weight” recommendation. Truist lowered its price target to $80 from $90 with a “Hold” rating.
The consensus rating currently stands at “Moderate Sell.” The mean analyst price target of $78.93 suggests potential downside of approximately 3% from present levels.
Industry observers believe investment manager Ted Weschler likely orchestrated Berkshire’s purchases, as he manages a portion of the firm’s $350 billion equity holdings. Berkshire previously invested in Taylor Morrison and owns Clayton Homes, establishing substantial housing sector exposure.
The Miller family retains control of Lennar through super-voting share structures, creating obstacles for any potential acquisition scenarios.
The post Berkshire Hathaway Expands Lennar (LEN) Holdings to 11% Despite Housing Market Turbulence appeared first on Blockonomi.
CryptoPotato
Bitcoin’s rather calm price behavior continues over the weekend, but the asset is gradually grinding toward the $85,000 mark after defending the $83,000 support on Friday.
Some altcoins have produced impressive gains over the past 24 hours, but Quant’s QNT trades in a league of its own after a recent bullish development.
BTC Eyes $85K
The previous business week began with a bang as the largest cryptocurrency exploded from the $80,000 support and blasted through a few major resistance levels before it topped $87,000 for the first time in eight months. The bears tried to intercept the move and pushed the asset south to $85,000 before another leg up resulted in a surge to $87,300.
The subsequent rejection was more profound. BTC failed at that level and slipped by several grand to $83,000 a few days later. After another rejection at a lower high at around $85,000, bitcoin dipped to $83,000 on Friday once again. However, the bulls stepped up at this point and didn’t allow another leg down.
Instead, BTC rebounded to $84,000 and remained there on Saturday despite Trump’s rejection of Iran’s ceasefire proposal. Moreover, the cryptocurrency has increased slightly and now sits inches below $85,000.
Its market capitalization has jumped to $1.7 trillion on CMC, while its dominance over the alts remains at 58.6%.

QNT Sees Big, Big Gains
QNT is today’s top gainer from the largest 100 alts, posting a 75% surge at one point to over $190 before it was stopped and driven to $160. The most probable reason behind this spectacular increase was announced a few days ago, when The Clearing House selected Quant to power its On-Chain Money Initiative.
Double-digit gains are also evident from the likes of BTW, WLD, GRAM, and GRAY. ZEC has soared by over 8% daily and now sits above $1,650. NEAR has reclaimed the $5 level after a 5.4% daily jump. SOL is close to $125 following a 3% increase. ETH, BNB, LINK, and HYPE are also slightly in the green, while XRP, DOGE, and TRX have posted minor losses.
The total crypto market cap has increased slightly to $2.910 trillion now on CMC.

The post QNT Leads Altcoin Rally, BTC Price Aims at $85K Again: Weekend Watch appeared first on CryptoPotato.
For years and years, the promise of investing in altcoins has been pretty straightforward: accept additional risk in exchange for returns that Bitcoin can no longer deliver as the market leader. That’s the theoretical part, at least. In reality, though, identifying the handful of alts that can actually outperform BTC over a longer timeframe remains remarkably difficult.
Fresh data from Glassnode illustrates the issue: only 9 of the 50 largest alts at the time of BTC’s peak last October have since generated returns better than bitcoin’s.
9 Out of 50
The winner is quite obvious: Zcash (ZEC). The privacy token stands comfortably at the top, delivering almost 14.5 times BTC’s return over the period. HYPE, which is second in line, stands far behind with gains of around 2.9x. XMR and NEAR have produced increases of 2.6x and 2.1x, respectively, compared to BTC. UNI, TRX, LEO, and TAO were also among the outperformers.
That means that 41 of the original top 50 were unable to beat simply holding the largest cryptocurrency. It’s worth noting that even though they underperformed against BTC, it doesn’t mean that they lost money in USD terms. The comparison instead illustrates the opportunity cost of moving capital away from bitcoin in search of larger gains from the more risk-on altcoins.
It also exposes one of the greatest difficulties with the familiar “altseason” narrative. Knowing that some (maybe just a few) alts could outperform is very different from pinpointing which ones beforehand.
Only 9 of the top 50 altcoins have beaten bitcoin:native since its all-time high.
ZEC leads by a wide margin, up 14x against Bitcoin.
HYPE, XMR and NEAR follow at 2–3x. pic.twitter.com/HDAbtE4XRW
— glassnode (@glassnode) September 24, 2026
Is This Starting to Change?
Glassnode’s latest deeper market data suggests that altcoins have recently begun putting up a much stronger fight. Over the past week, more than 72% of those tracked by the monitoring resource outperformed BTC, compared with a peak of just 39 during the breakout rally in August. Glassnode also found little evidence that the latest move was being powered by excessive derivatives leverage, with altcoin perpetual open interest barely increasing over the past month.
This change has even pushed Glassnode’s Altcoin Cycle Signal into altcoin-season territory. However, the broader scale is still different. Glassnode said earlier this month that alts had risen substantially in dollar terms without taking meaningful market share from bitcoin. The 90-day change in altcoin share remained negative at -0.9%, despite their combined market cap jumping 21% over the preceding month.
The post Only 9 of the Top 50 Altcoins Have Beaten Bitcoin Since Its Peak: Picking the Winners Is Brutal appeared first on CryptoPotato.
During a relatively calm weekend trading session in which most larger-cap cryptocurrencies have remained sideways, Quant’s QNT has gone on a tear, skyrocketing by 75% in the past 24 hours alone to over $180.
A major US banking partnership appears to be the most evident catalyst, although on-chain data shows activity began heating up well before the announcement was made public.
Why Is QNT Soaring?
Interestingly, the biggest fundamental development didn’t come in the past 24 hours. It was announced on September 24 when The Clearing House selected Quant to power its On-Chain Money Initiative. The crypto project will provide the interoperability, orchestration, and transaction-management layer for the planned network, allowing financial institutions to clear and settle tokenized deposits while connecting with existing payment infrastructure, including the RTP and CHIPS networks.
Both parties expect to launch the system to participating institutions in the first half of 2027. The scale involved helps explain why this announcement attracted so much attention. The Clearing House says its US payment networks clear and settle more than $2 trillion every day, across wire, ACH, check-image, and real-time payments.
However, the activity around Quant and its native token started to pick up over a week before the partnership made the news. Santiment Intelligence said that active addresses exceeded 870 every day between September 16 and 23, whereas they had not topped 792 during the first half of the month.
New addresses were also running at approximately 1.8 times their earlier September weekday average. After the announcement, though, active addresses exploded to 2,064 on September 24, which marked the highest level in nearly a year. QNT’s price skyrocketed by 27% that day.
$QNT’s on-chain activity stepped up on Sep 16, eight days before its Clearing House headline.
Active addresses topped 870 every day from Sep 16 to 23. From Sep 1 to 15 they never passed 792.
New addresses ran about 1.8x their Sep 1 to 15 weekday average over the same… pic.twitter.com/VIyGPyIhyf
— Santiment Intelligence (@SantimentData) September 25, 2026
How High, QNT?
There’s no way to sugarcoat what happened to QNT’s price in the past day and week. The asset is up by 75% since this time yesterday and by a whopping 185% weekly. It currently trades at $180 after briefly topping $190 earlier today.
Crypto Patel, who outlined the significance of the $115 support recently, noted that QNT has reached a couple of his big targets. However, he warned that investors should not FOMO in and start buying now, trying to catch the next wave up. Instead, he noted that consolidation and retracement become important after such a parabolic move, and predicted that the price could settle somewhere between $50 and $100 before the next big move.
EGRAG CRYPTO shared a similar warning, indicating that investors should buy the retracements on such occasions, as going blindly into a token that has posted such a green candle could prove counterproductive.
The post Quant (QNT) Rockets 75% Today as Major Banking Catalyst Fuels 180% Weekly Rally appeared first on CryptoPotato.
The recent recovery staged by Ripple’s cross-border token has brought several long-term technical setups back into focus, but one of the more unusual comparisons does not involve BTC, another cryptocurrency, or even the greenback.
Instead, EGRAG CRYPTO has focused on XRP’s performance against gold, arguing that the pair could be approaching a stage where the former begins gaining ground relative to the precious metal.
Can XRP Beat Gold?
Notably, the idea is not that XRP is backed by gold or directly linked to it, but that their relative performance may be reaching an important point on the analyst’s long-term chart. The analyst has previously used the XRP/gold comparison to identify periods in which the token dramatically accelerated against the bullion.
His latest chart points again to the possibility that the cryptocurrency could eventually begin appreciating faster than gold if the historical structure repeats. Such a development would represent a substantial shift in relative performance, as gold has enjoyed a strong period with investors seeking protection from fiscal concerns, geopolitical uncertainty, and currency debasement.
XRP, on the other hand, remains far below its 2025 all-time high despite recovering from the sharp declines to $1.00 seen in August.
This narrative is therefore essentially a relative-value argument: XRP does not necessarily need gold to fall, as it could appreciate at a faster rate for the pair to turn decisively higher. However, EGRAG remains a believer that XRP will indeed explode higher while the precious metal will fall.
#XRP/#XAU – SOMETHING HAS TO GIVE US
:
One of them will deliver the move:
GOLD dumps → XRP/XAU explodes higher
But my thesis? BOTH happen.
Gold retraces while #XRP accelerates , a powerful combination for this ratio.
Fib… pic.twitter.com/byiAaVQocc
— EGRAG CRYPTO (@egragcrypto) September 26, 2026
What About USD?
In a separate analysis, EGRAG outlined a much more speculative long-term roadmap for the token, with $1.75 serving as an important threshold in that scenario. Holding above that area could keep open a broader expansion toward major targets of $5-$8 or even $13 in an extreme development.
He also mentioned $365 as a potential target for XRP, but that remains a hypothetical chart projection and, for that matter, in the far-fetched realm as of now.
Meanwhile, fellow analyst ChartNerd identified something similar on XRP’s chart. In another longer-time-framed analysis, he noted that the asset is forming a multi-year cup-and-handle pattern based on Fib targets and outlined some major targets that coincide with those set by EGRAG at $8 and $13.
Something that can support the bullish thesis from above is whales’ behavior. These large market participants have been scooping tokens en masse lately, including a major $720 million accumulation completed over the past several days.
The post Ripple vs. Gold: Is the Tide Finally Turning in XRP’s Favor? appeared first on CryptoPotato.
The major rally that started in August and intensified in September has finally flipped ETH’s higher-timeframe structure bullish, and several analysts agree that only one major resistance remains in the asset’s way.
A decisive break above it could open the door to a much larger move toward $3,000 and beyond.
$2.8K Still in Its Way
The largest altcoin has now reclaimed the 200-day moving average and pushed into the $2,800 region last week, where it was finally stopped. Daan Crypto Traders highlighted the change in its market structure, confirming that a weekly close above the 200 MA and EMA has solidified its bullish reversal.
However, he believes $2,800 is the major obstacle standing in front of ETH, and clearing it would leave relatively little high-timeframe resistance before the $3,000-$4,000 region comes back into play. Aside from last week’s rejection at $2,800, the level has stopped ETH’s progress on several occasions in the past few years.
$ETH The $2.8K level has acted as support & resistance many times over the past 2 years.
Often it caused a big move to follow from that point.
Therefore it is of course the main resistance to watch right now. Especially as price initially rejected it and seems to respect the… pic.twitter.com/SunZLEkSZ5
— Daan Crypto Trades (@DaanCrypto) September 26, 2026
Michaël van de Poppe is also bullish on ETH’s broader structure. In a recent tweet, he claimed that it is “literally a matter of time” before the asset sees another strong breakout to the upside.
Ethereum’s position is relatively straightforward at the moment. The higher-timeframe trend has improved substantially, but the market still needs to prove it can turn one of its most stubborn resistance zones into support.
Flushed Leverage
Fellow analyst CW argued that the size of Ethereum’s high-leverage positions has fallen sharply recently, as longs dropped to roughly $2.1 billion, while shorts stood near $4 billion. This occurred after most of the previously accumulated high-leverage positions were wrecked. The analyst added that the reduced positioning leaves ETH vulnerable to a significant increase in volatility.
This could be particularly important as Ethereum approaches $2,800. Merlijn The Trader, who has been bullish on the altcoin for months, remains constructive on its market structure. Most recently, he called attention to an emptied validator exit queue and argued that much of the forced selling pressure had already been absorbed during the earlier drawdown.
As such, he concluded that “maybe sleeping on Ethereum was the biggest mistake of this cycle,” as the asset sits 80% higher than its July bottom.
The post Ethereum Bulls Are Closing In on a Major Breakout: Is This Resistance the Final Barrier? appeared first on CryptoPotato.