Cryptocurrency Posts
Crypto Briefing
The debate over THORChain's decentralization highlights the tension between protocol control and true permissionless blockchain ideals.
The post GoPlus Security challenges THORChain’s decentralization claims over DPRK-linked funds appeared first on Crypto Briefing.
Saylor's digital rights proposal could democratize capital access, fostering innovation and competition by reducing reliance on traditional IPOs.
The post Strategy’s Michael Saylor proposes bill of digital rights for future economy appeared first on Crypto Briefing.
The imminent launch of Bitwise's NEAR ETF could boost investor interest in staking-focused crypto funds, potentially influencing market dynamics.
The post Bitwise’s NEAR ETF clears NYSE Arca and SEC hurdles, launch imminent appeared first on Crypto Briefing.
Broadcom's AI revenue growth highlights potential market volatility and underscores the importance of meeting forward-looking expectations.
The post Broadcom raises AI sales forecast as stock lingers 29% below its high appeared first on Crypto Briefing.
Anthropic's AI rights exploration could redefine ethical AI development, sparking debates on control, safety, and moral considerations in tech.
The post Anthropic explores potential rights for artificial intelligence systems appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Samourai Letter #7: Notes From The Inside
Dear Reader,
It has been many months since I last wrote you. Part of the reason for that is because I spent most of June and part of July in transit from FPC Morgantown to FCI McKean – a four hour drive away. For most of that time I had no access to pen, paper, stamps, or the rudimentary email system that I use to send these letters out.
The other part of the reason why I haven’t written in so long is that once I did finally arrive I was so shell shocked from the entire ordeal that I needed time to decompress and process that month long trauma that is BOP transit.
Six days after arriving at FCI McKean I finally put pen to paper to document the journey but the result was less of a letter and more of a trauma dump to help me process the absolute worst 30 days of my life. I decided to take a step back and give it some time before I sent out this letter. I have been slowly adapting to life here at McKean, and in good time I will tell you all about this place, but for this letter I want to go back to early June.
I want to tackle the entire transit process and explain how what should have been a quick four hour drive turned into 30 days, two trans-continental flights, three multi-hour bus rides, a cell mate doing time for murder, and a cell mate who couldn’t stop shitting (I preferred the murderer). This letter will likely be published in two parts due to the length. Thank you for your continued reading and support.
“I finally put pen to paper to document […] the absolute worst 30 days of my life.”
On June 5th I was told I would be transferred from FPC Morgantown for a drug and alcohol treatment program. Successfully completing the program (which takes about 9-10 months) rewards you with a year off your sentence, so it is seemingly well worth the hassle of moving to take it.
For security reasons they do not tell you when you will be leaving or where you will be going. While being transferred in BOP custody you almost always are put on an airplane being piloted and operated by the US Marshalls to be taken to BOP transit hub in Oklahoma City. After a few days in Oklahoma you are put back on a plane and taken to your destination. From speaking with others I was told to expect 1-2 weeks of transit.
I also heard that it costs around $10,000 per prisoner to be transited through Oklahoma. I figured that since I am classified as minimum security, spent close to two years on pre-trial release, self surrendered, and had no incident reports since being incarcerated I would be a good candidate for what is called a transfer furlough – where I would be responsible for transporting myself to my new institution at my own expense.
I put in my official request for a transfer furlough on June 5th. On June 8th my request was denied without explanation, I would be going through transit, no way around it.
On June 10th I was called to Receiving and Discharge (R&D) at 6:00 AM. Though I did not know it at the time I was about to embark on a month long fever dream through two different holding facilities, share cells with murderers, be locked down behind iron barred cells for 23 hours a day, and much more.
Leaving through R&D is much the same as when I arrived. I was stripped, searched, issued a pair for ill fitting clothes (khaki elastic band trousers, a brown cotton shirt, threadbare boxers, socks that didn’t match, and a pair of slip on blue canvas shoes).
I was put into a holding cell while the other inmates being transferred went through the same process. There were six of us transiting from Morgantown on that day. We were each lined up and called forward so that the officer could fasten shackles to our ankles and cuffs to our wrists.
Once cuffed and shackled the officer wrapped a chain around our waist and attacked the handcuffs to them. The end result being that you could not lift your arms or hands much higher than your waist, and you could walk only in painful short shuffling steps. We were handed a brown paper bag with ‘breakfast’ in it (bread, peanut butter, bologna) and escorted to the waiting bus.

“We were each lined up and called forward so that the officer could fasten shackles to our ankles and cuffs to our wrists.”
The bus was a cross between yellow school bus and a coach (think Greyhound or National Express) and already filled with inmates from other prisons in the area. There were guys from all security levels on the bus. Some guys serving 20 years coming from the “pen” (The US Penitentiary), some guys like me serving short sentences and going to a camp.
The atmosphere was generally friendly on the bus, most of the USP guys were interested in what the camp was like and how much contraband like vapes and phones cost. At the front of the bus behind a metal grate were the driver and three heavily armed officers. They all wore stab vests and carried handguns and long guns.
As we departed Morgantown I was excited to watch the scenery go by. This was the first taste of the outside world I had in 6 months. I took in all the sights. The trailer park, the run down gas station, the XXX store, it all was captivating. After about an hour of driving the bus suddenly exited the highway and stopped on the side of a small road. After 20 minutes idling I noticed one of the officers walking back to the bus with a bag of biscuits from Tudor’s Biscuit World – a West Virginia institution.
We remained on the side of the road as each officer one by one went and bought breakfast, an endeavor that took over an hour. I decided Breakfast sounded good but my bread fell out of bag onto the floor. Breakfast would have to wait. As quickly as we got back on the road we suddenly pulled off again. This time each officer went one by one into a gas station to buy cigarettes and energy drinks.
The metal of the shackles were starting to dig into my ankles, my wrists were cramping, my eardrums were shot beyond comprehension. Many others have said it before, but the one thing you really remember about the prison bus is how unbelievably loud it is. Every bump in the road is followed by a symphony of crashing metal. Inmates at the front of the bus maintain full conversations at full volume with their friends all the way in the back. The volume is at maximum for the entire journey.
After about 5 hours we arrived at the Greenbriar Valley Regional Airport. There were several other prison busses parked off to the side of the runway. For the next hour or so a parade of officers from other busses would climb up and yell out a series of names. We were playing a grand game of musical chairs and for a brief moment I prayed that I would be called to another bus and spirited off to my camp bypassing the free plane ride to Oklahoma.
Eventually musical chairs was over and we were instructed to get off the bus and directed to line of waiting US Marshalls standing in front of a plain white airplane adorned only with a small American flag on the tail fin.
The Marshall patted me down, checked my mouth and feet and directed me to line up and wait by the front of the plane under the cockpit. They packed us in tight on the runway 10 rows of inmates at least 10 men deep. We watched inmates disembark the plane and enter the busses we just left.
The whole thing must be a logistical nightmare for the folks at BOP and I was surprised how smoothly it all was moving. It was by no means quick, but it could have been far worse. Finally I was ordered to wobble up the stairs to board the plane. I felt like Joe Biden before falling up the stairs.
How embarrassing it would be to eat it in front of all the convicts. I made it up without embarrassing myself. On board Air Operations Marshalls replaced flight attendants, though one really couldn’t tell any difference in demeanor between a Delta air steward herding a bunch of fat slobs in sweat suits and a US Marshall herding a bunch of prisoners. We filled each row from back to front at the direction of the Marshalls.
I was sat in the window seat. The guy next to me sported a nifty full face tattoo and informed me he had been down 15 years and was kicked out of the USP for fighting. I informed him I was on my way to a camp and had been down for 6 months. He had nothing else to say to me after that.

“This was the first taste of the outside world I had in 6 months.“
The plane itself had certainly seen better days, it looked to have been dated from The Cold War. The stickers commonly found plastered across the surfaces of airplanes telling you not to smoke or where to find the life vest in case of emergency – how exactly to apply said life vest while shackled and bound was not explained – were all in German and Russian. Where the hell did they get this thing from.
The plane was filled 2/3 of the way with inmates. The final third at the front of the plane were all US Marshalls, at least 30 of them. With that, the plane took off and we were on our way to Oklahoma City. After about an hour an Air Marshall doing their best surly Delta stewardess impression threw a bag of lunch at us. It was the second – but not last – sack lunch containing 4 slices of bread, a pouch of peanut butter, two slices of turkey, and a small pack of cookies (“Cream 4 Fun” a BOP staple that even in my dire circumstances solicited a juvenile chuckle out of me).
Sick to death at this point of the oily BOP peanut butter I happily pawned it off on the face tattoo next to me. I got started trying to fix myself a turkey sandwich – a task made difficult due to the cuffs and limited mobility. The bread was ice cold and the turkey was frozen solid. After brushing off the top layer of ice from the sliced meat and placing it between the now soggy and still freezing bread I took a bite and decided I wasn’t a great fan of turkey popsicle sandwich. The Cream 4 Fun would have to suffice for lunch.
I was thankful for the small bottle of water that was handed out, but was not thrilled when I spilled most of it down my front contorting myself to try and twist the cap off. Shortly after lunch the Marshall went row by row to ask if we needed to use the toilet. Most people did, so the rest of the flight consisted of much jostling and shuffling to the bathroom and back. I refused, preferring to hold it, but the gentleman across the aisle let the entire plane know that he needed to take a shit, a declaration that caused much consternation and debate.
As we approached Oklahoma City the pilot got on the intercom to let us all know it was a beautiful sunny day in Oklahoma City, a balmy 88 degrees. He failed to mention that none of us would see that sun for our entire stay in FTC Oklahoma City.
We landed at OKC airport, went past the main terminal building towards a squat brown concrete building about 6 stories high. After what felt like an eternity we were disembarked row by row through the jet bridge directly into the airport prison.
We shuffled single file through an assembly line of Marshalls who thankfully removed the cuffs and shackles, searched our mouths and feet again, and directed us into a dark concrete holding cell where we were packed in tight like a tin of sardines. In the corner of the room was a single stainless steel combination toilet, sink, water fountain.
Almost immediately several inmates somehow fashioned a lighter and proceeded to get extremely high on K2 – known also as Deuce. In prisons Deuce is commonly just roach spray or rat poison drenched on a small piece of paper.
When you light the paper and inhale the fumes you often freeze where you are standing lean over and are lost to the world around you for several minutes. I was most curious as to where the hell they were hiding these things to make it past no fewer than 3 probing searches.
All I could think of was getting out of this claustrophobic concrete box into a housing unit with other minimum security “campers”. Everyone had warned me that security classifications would be mixed until you were assigned a housing unit. I just had to tough out the intake process.

“You quietly wonder if Dante got it all wrong and all the circles of hell happen to be within the BOP’s Oklahoma City airport transfer facility.“
For being the official transit hub of the BOP, handling thousands of inmates every week, the staff at FTC Oklahoma City were breathtaking in their incompetence. Every last officer was less than useless, all of them wearing an expression of bewilderment as to how they happened to stumble into this predicament of dealing with a plane load of convicts, as if normally they were payroll accountants or copy clerks.
It was as if it was everyone’s first day on the job. After jam packing us ass to elbow in the small concrete room for 4 hours – presumably they were having some sort of crisis meeting trying to determine what exactly they were supposed to do with us – a morbidly overweight officer whose stab-vest appeared to be groaning in protest at the enormity of the task of protecting such an enormous man unlocked the door and shouted that he needed five of us at a time.
Instantly well over 100 men all desperate to be out of this hellish room push and shove their way towards the door. The only ones in no hurry are the deuce heads who have no idea where they are – and if they are indeed aware their limbs are in no mood to take any direction regarding movement – and myself who has no interest in playing grab ass with murderers and rapists.
I wait patiently towards the back of the room and entertain myself by taking covert glances at the inmates around me to try and guess which ones are the ‘chomos’ (child molesters). You may at this point wish to chide me and extoll the virtues of not judging a book by its cover, but these books had covers that all but said “Hey Look! I’m a chomo!”. They have a look about them.
After 45 minutes of 5 men trickling out at a time the room emptied and the deuce heads stumbled back into reality – what a horrible reality to return to from what must be a thrilling escape – and we shuffle out into the convict assembly line.
We are commanded to undress, lift, squeeze, cough under the careful supervision of an officer no doubt cursing the recruiter at the Buttplug County job fair who never said anything about staring at genitals all day.
Once the second strip search of the day concludes you are thrown a bundle of damp clothing with odd stains on them and hurry you further along the conveyor belt towards a long queue to go through a body scanner machine, the kind of thing you would find at an airport designed to find bombs and weapons.
The officer manning the machine sits behind a lead curtain to shield themselves from radiation that leaks out of this whirring machine. The warning sticker helpfully informs you to keep back behind the blue line for your safety, but it turns out this warning is not for you, you are instructed to jam yourself as close as possible to the machine so they make sure to dose you with the radiation of the 6 guys ahead of you.
Once you have been sufficiently irradiated you get pushed along where the medical officer menacingly asks if you have anything medically wrong with you, almost daring you to say anything but “no”.
There is a whirlwind of papers being stamped, collated, duplicated, and filed and before you know it the assembly line ends. You breath a sigh of relief, surely some friendly officer is going to check your papers and notice you are a minimum security ‘camper’ and whisk you away. Instead yet another morbidly obese officer points at a room and makes some sort of grunting noise. You do not speak primate but gather he wants you to wait in the room.
You quickly realize this room is a carbon copy of the first holding room and you quietly wonder if Dante got it all wrong and all the circles of hell happen to be within the BOP’s Oklahoma City airport transfer facility.

“All I could think of was getting out of this claustrophobic concrete box.”
Another couple of hours pass – or years, who can tell at this point – in the second holding room and the Deuce heads are the only ones having a great time. The Deuce dealers have defeated yet another strip search and now a body scanner. Eventually an officer of indeterminate gender unlocks the door and yells out 5 to 10 names and you are escorted to your “range” (prison speak for the floor you live on).
The officer leads us towards the elevator, 10 of us cram in and I get a good look at the men with me. Seven of them have full face tattoos that extend across their shaved heads. Rams horns, Celtic knots, Thor’s hammer, that sort of thing.
At this point I am fully aware that a “camper” only range is a fantasy. I am going into the general population with murderers, rapists, kidnappers, gang members, and career criminals – many of whom have spent more time behind bars than they have in society. I take a deep breath, this is no time to be anxious or afraid. If the sharks smell fear they will strike.
The guard walks us to the heavy metal door that seperates our range from the hallway. He turns the key but the door won’t open. He tries another key with the same result. One of the face tattoos mocks him “what is it your first day or something?” he heckles. The officer now very aware that this is taking way too long fumbles the keys and drops them on the floor. The scene is objectively funny and now several more of the inmates are heckling the clumsy officer.
Finally the door opens from the inside. The range officer must have taken pity and opened it for him. The guys watching on the security cameras must have been pissing themselves. He will probably never hear the end of it in the breakroom.
I am on Range 4D. The room is vaguely triangular in shape as if the architect started drawing a triangle but gave up halfway through. The room is large and painted in a palette of institutional grey and the same sort of pink they paint high schools.
Cells with big metal doors line three of the walls. Two large staircases flank both sides of the room and take you up to an internal balcony where cells line the walls as well. If I remember correctly there are 30 two-man cells on each floor, so each range holds a total of 120 men. As soon as you cross the threshold between hallway and range you are immediately struck by the sheer number of strung out junkies hunched over seemingly frozen in place.
Before you even have a chance to breathe several face tattoos are in your face asking if you want to buy drugs from them. These enterprising fellows apparently are running a fully stocked pharmacy. They offer me deuce, ice, meth, snizzlefizz, and junglerush.
Okay, I made the last two up, but they offered me stuff I have never heard of before. I decline the offer and they move on quickly to a more lucrative mark. The range officer leaves his office and steps over a frozen drug addict and informs us that he is new here and to just give him a minute to get us situated.
I politely wait while the officer – looking more and more flustered by the minute – assigns the guys ahead of me their cells, hands them a roll of toilet paper, and a thin mattress before sending them on their way into the jungle. When it is my turn the officer lets me know that he has run out of toilet paper and but if I give him a minute he will find me some. He gives me my cell number and scurries away back into his office. I follow him and remind him I need a mattress to which he explains he has run out of those as well, but if I just give him a minute he will try and locate one.
From that point forward he was “Officer Just-A-Minute”. I climb over three junkies strung out on the staircase and make my way to the cell I have been assigned.

“This isn’t fucking Guantanamo!”
The cell is small, only a bunk bed, a toilet, a sink, a desk, and a fluorescent light. Inside is a large American Indian. If you asked someone to draw the most racist caricature of an American Indian he would have drawn this guy.
He looks at me and says in a deep voice with a flat affect “I am Shadow”. The strange face tattoos gave him the air of some sort of tribal witch doctor. I said “You sure are” and quickly introduced myself lest he take offense to my glib remark and place a hex on me.
I liked Shadow immediately. I learned that he was on his way to a USP doing 20 years for murder. Before I had a chance to explain that I was on my way to a camp for the fake crime of not having a license I didn’t even need in the first place Officer Just-A-Minute was in the doorway of the cell holding half of a foam mattress.
Decidedly at the end of my tether I looked to him, to the mattress in his hands, back to him and asked incredulously “what the fuck am I supposed to do with that?”. “It is all we have” he responded slightly annoyed. “It is half gone. How the hell am I supposed to sleep on that? My ass and legs will be on bare metal!” I protested. “Welcome to prison” he responded curtly.
I was seriously fed up at this point, plus I had Shadow the murdering witchdoctor to back me up so I pressed further “I understand this is prison. I am well aware of that fact! You still have an obligation to provide us basic amenities like bedding. This isn’t fucking Guantanamo!”
I pushed. He simply shrugged and dropped the mat onto the floor and walked off. “Fuck that guy” said Shadow. I agreed.
A few minutes later Officer Just-A-Minute walked by and locked the cell door. We were locked in for the night. It would be the first time I had been truly locked in a cell. I was mildly surprised there wasn’t some sort of central locking mechanism. The officer needed to walk by 60 cells and manually lock them all. A while after locking us in another officer showed up to perform the 10:00 PM count.
Count concluded I climbed onto my half mattress and waited for the bright fluorescent light to be turned off. By 11:00 PM I asked Shadow what time they usually turned the lights off. “They don’t” he responded.
I sighed and covered my head with the sheet they gave me – it smelled vaguely like motor oil and sawdust – and silently sobbed. Everyone told me that transit was bad, that Oklahoma was terrible. They were not overstating it.
I laid there, ass on bare metal, harsh light shining through the threadbare sheet and asked myself if all this was worth the year off. I regretted ever leaving Morgantown, and I desperately wanted to call my wife Lauren.
The transit story will continue in Part 2. Thank you for reading.
This is a guest post by Keonne Rodriguez. Opinions expressed are entirely their own and do not necessarily reflect those of BTC Inc or Bitcoin Magazine.
This post Samourai Letter #7: Notes From The Inside first appeared on Bitcoin Magazine and is written by Keonne Rodriguez.
Bitcoin Magazine
An Austrian Economist Explains Why AI Will Make Everyone an Entrepreneur w/ Per Bylund
AI is changing how we work, but can it replace the human entrepreneur? Austrian economist Per Bylund, Senior Fellow at the Mises Institute, joins Spencer Nichols to explain why AI is a statistical engine that improves efficiency but can’t imagine the future. He argues we’re moving from an employment economy to an entrepreneurship economy, and explains what that means for jobs, innovation, and value creation.
Chapters:
00:00 Austrian Economics on AI, Innovation, and Entrepreneurship
02:34 Can AI Replace the Entrepreneur?
05:48 Invention vs Innovation: What Bitcoin Teaches About AI
06:29 From an Employment Economy to an Entrepreneurship Economy
09:52 Can Regulators Keep Up With the Speed of AI?
13:06 Remote Work, Capital Controls, and the Future of Money
18:23 Why Every Voluntary Trade Has Two Winners
26:28 The Individual vs the State in US-China Competition
31:17 Steel Stockpiles, Sugar Subsidies, and the Lobbying Behind Protectionism
33:36 OpenAI, Anthropic, and Regulatory Capture in AI
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post An Austrian Economist Explains Why AI Will Make Everyone an Entrepreneur w/ Per Bylund first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
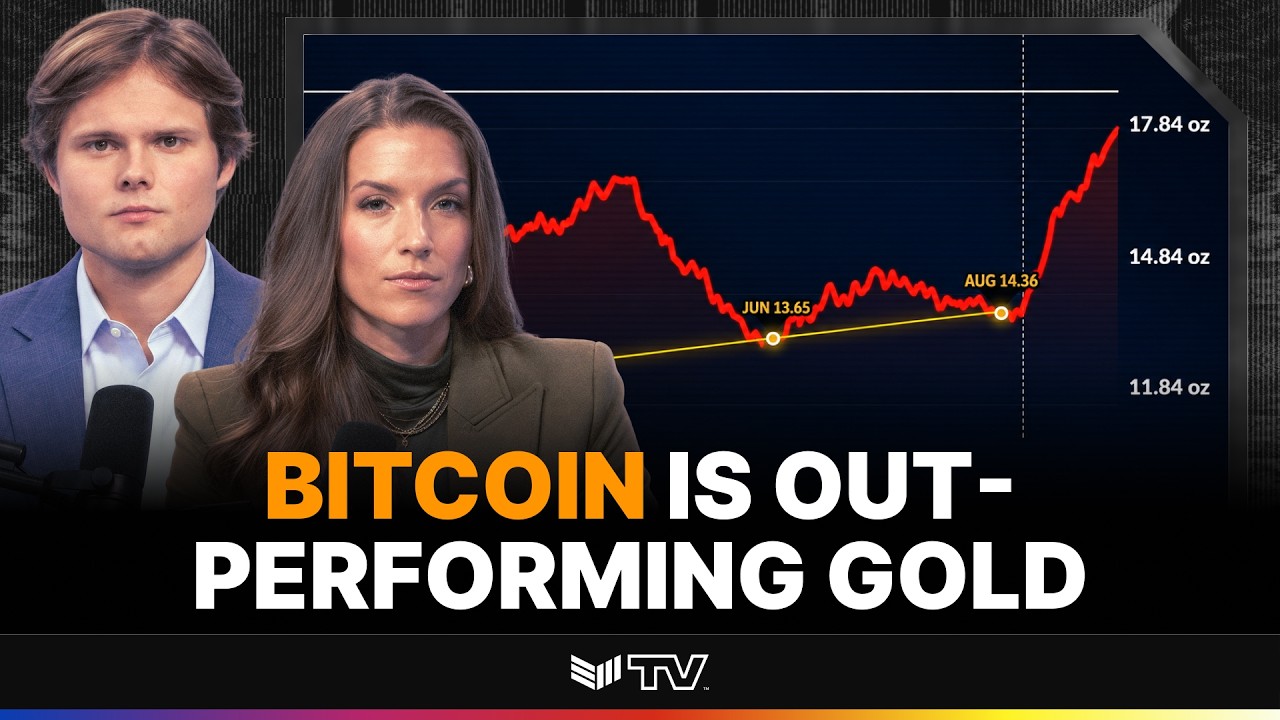
TECHNICAL ANALYSIS: BTC to Cross Key Price Level Against Gold
The 90-day correlation between Bitcoin and gold just hit a six-year high, and Bitcoin is now just 3% away from flipping positive against gold for 2026. In today’s Chart of the Day, Sean breaks down the Bitcoin-to-gold chart, the string of higher lows since February, and the new high above 17.9 ounces.
Chapters:
0:00 Bitcoin-Gold 90-Day Correlation Hits a Six-Year High
0:35 Why Measure Bitcoin in Gold? Stripping Out Dollar Debasement
1:20 Higher Lows and Higher Highs on the BTC/Gold Chart
2:27 From 12.1 oz to 17.9 oz: The Bullish Bitcoin Setup
2:53 The 20.3 oz 2026 Yearly Open and the Levels That Matter
3:21 Next Bitcoin Resistance: 21.5 oz of Gold (~$92K)
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post TECHNICAL ANALYSIS: BTC to Cross Key Price Level Against Gold first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Katie Stockton: $93K BTC is the Key Price Level for the Bull Market
Is the Bitcoin bear market officially over? Katie Stockton, founder of Fairlead Strategies, breaks down the technical signals behind Bitcoin’s rally of more than 50% off its recent lows, including the break above the 200-day moving average and the 83K–84K resistance zone. She explains why the cloud model points to $93,000 as the level where a new Bitcoin bull cycle becomes official. She also covers the flag pattern breakout, the monthly stochastic oscillator, and what could turn her defensive heading into Q4.
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Katie Stockton: $93K BTC is the Key Price Level for the Bull Market first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Grant Cardone: Real Estate “Armageddon” Is Here – Why BITCOIN is the Hedge
Commercial real estate is facing a historic reset, and Grant Cardone is using it to stack Bitcoin. The Cardone Capital founder explains how high interest rates are pushing properties below replacement cost and how he fills that gap with Bitcoin on the balance sheet. He breaks down his goal of 25,000 apartments and 25,000 BTC, and why he calls real estate his “Trojan horse” for Bitcoin.
Chapters:
00:00 Grant Cardone on the Commercial Real Estate Reset and 6.4% Rates
00:51 How Cardone Capital’s Bitcoin Real Estate Deals Work
02:23 Why REITs Can Never Own Bitcoin: Cardone’s Competitive Moat
04:26 From 3,000 to 25,000 BTC: Real Estate as the Trojan Horse
06:50 Michael Saylor’s “P Word” and the $335M Boca Raton Deal
09:01 Will Cardone Capital Go Public?
10:12 Why Commercial Real Estate Faces a Historic Crash
11:02 Why Single-Family Home Prices Won’t Correct
12:31 Why Bitcoin and Real Estate Are the Perfect Hybrid Asset
14:32 Why Other Real Estate Investors Can’t Copy This Strategy
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Grant Cardone: Real Estate “Armageddon” Is Here – Why BITCOIN is the Hedge first appeared on Bitcoin Magazine and is written by Patrick Green.
HTTP error 429 on https://cryptoslate.com/feed/
Failed to fetch feed: https://cryptoslate.com/feed/
Failed to fetch feed.
CryptoTicker.io
Tokenised US equities have sat behind the synthetic dollar USDe since September 25, 2026. Ethena Labs announced that day that it would represent part of the collateral through the equity tokens of the Binance trading platform and hedge the price risk of that position with equity perpetuals. None of this changes the quoted price of USDe. It changes who stands opposite you if things go wrong.
This piece answers four questions. What sits in the reserve now? What return does the construction realistically throw off? What happens to the governance token ENA on October 5? And how much of this is legally accessible to you in Germany at all? You will find no price targets here, because with a stablecoin the question is the backing rather than the price.
What Ethena Announced and What Changes in the USDe Collateral
USDe is a synthetic dollar. That means the token is meant to be worth roughly one US dollar without a real dollar sitting in a bank account behind it. The dollar peg is produced arithmetically instead. Ethena holds crypto collateral and simultaneously opens short positions in derivatives that lose exactly as much value as the collateral gains, and the other way round. This principle is called a delta-neutral strategy, and it has been the core of the protocol since launch.
What is new is the material being worked with. Ethena is taking Binance's equity tokens, known internally as bStocks, into the collateral as the spot leg and selling the matching equity perpetuals of the same trading platform short against them. Allocations began on the day of the announcement, according to the statement. Founder Guy Young calls the step the most significant extension of the USDe funding mechanism since the protocol began, and justifies it with the sheer size of the equity markets.
The scale of the protocol, measured in house: at 06:38 UTC on September 27, 2026, around 4.94 billion USDe were in circulation according to DefiLlama's stablecoin interface. The governance token ENA traded in the same window at $0.2712, or 0.2381 euros, with a market capitalisation of $2.74 billion at rank 40 (CoinGecko, 06:37 UTC). The yield-bearing offshoot sUSDe comes to $1.31 billion across roughly 1.05 billion tokens.
How the Basis Trade With Equity Perpetuals Works
A perpetual future is a futures contract with no expiry date. To stop its price drifting away from the spot price, the two sides pay each other a balancing fee at short intervals, the funding rate. When more traders are leveraged long, those long positions pay the short positions. That payment is precisely the income source of USDe.
The basis trade therefore works like this: Ethena holds the asset in the spot market and sells the same quantity short in the perpetual market. If the price moves, gain and loss largely cancel out. What remains is the difference between the two markets, the basis. Applied to crypto assets, that has been the mechanism behind USDe since 2024. Applied to equities, it is the same procedure with a different underlying.
One practical detail from the statement belongs here, because it counts under stress: Binance grants eligible delta-neutral accounts a lower priority in automatic position reduction. Automatic position reduction, known in the trade as auto-deleveraging, is an exchange's emergency measure when a liquidation tears a hole and profitable counter-positions are closed by force. Whoever sits further back in that queue is pulled out less often. If you are interested in the mechanics of perpetuals in detail, our comparison of perp DEX platforms sets out the differences between the trading venues.
What bStocks Really Are: A Claim Against a Binance Subsidiary
Here lies the point that matters more to the safety of USDe than any yield figure. bStocks are not shares. The issuer is BTech Holdings Limited, a company within the Binance group. Anyone holding a bStock holds a right to securities that this issuer holds in turn. No voting rights from the share come with it. Conversion into the real instrument is envisaged for eligible users, as far as the applicable law permits. Binance launched the first of these tokens in June 2026, among them Nvidia, Tesla, Circle, Micron and Sandisk, and according to Token Terminal data cited by crypto.news the volume had grown to around $610.6 million by August.
The risk analysts who worked the construction through for Ethena's risk committee put the consequence unambiguously. Kairos Research recommended releasing bStocks only once a side letter with the issuer has been signed setting out what the issuer may do with the deposited shares. As long as that letter is missing, the spot leg is unsecured credit risk to a Binance subsidiary and not a claim on the share. That describes what would happen if the issuer became insolvent.
With tokenised equities this distinction is the norm and not the exception. We took it apart at length in a separate analysis of issuer risk in tokenised equities on August 16, 2026. For USDe it means that part of the backing will in future be a claim against a company, and the quality of that claim hangs on a contract that had yet to be signed at the time of the announcement.
Why Ethena Is Looking for Income Outside the Crypto Market
The reason for the rebuild sits in the funding rates. Ethena disclosed its own figures in August: the open-interest-weighted funding rate on Bitcoin averaged 11.0 percent annualised in 2024, 4.9 percent in 2025 and, up to August 11, only 2.2 percent in 2026. The income source from which USDe draws its yield has therefore shrunk to a fifth within two years.
Binance's equity perpetuals came in at an average of 17.5 percent over the comparison period from May 20 to August 11. Open interest in those contracts stands above $2.9 billion and grew by around 105 percent a month on average over 2026. From the protocol's point of view this is a young market paying considerably better than the dried-out crypto perpetual trade.
How High the Equity Basis Really Is: 3.56 Against 7 to 18 Percent
This is where the published figures diverge widely, and anyone reading only one of them ends up with a skewed picture. Kairos Research puts the yield on the admitted Binance instruments at around 18 percent at the end of July and at about 7 percent as of August 26, with two of the instruments even yielding negative at that point. Crypto.news, by contrast, cites an average equity basis of 3.56 percent annualised over the past six months on September 25, likewise drawing on figures from Ethena.
The range therefore runs from 3.56 to 18 percent, depending on the measurement period and the selection of instruments. One thing above all can be relied on in that spread: the yield is falling. The end-of-July figure roughly halved by the end of August. An income source that gives way that sharply within four weeks is no basis for a return expectation you write into your planning for the coming year.
We showed how quickly such a calculation can tip on September 12, 2026 using a concrete case: the popular loop of sUSDe and borrowed stablecoins no longer paid for itself on the arithmetic at that point, because the borrowing rate exceeded the yield. The same logic applies to the new equity source.
What Hurdles an Equity Perpetual Has to Clear
Ethena's risk committee adopted a screening grid in August before the first equity token was allowed into the reserve. A contract only qualifies if it carries at least $25 million of one-sided open interest on a 14-day average, if at least 30 days of funding history exist, and if a matching tokenised spot instrument trades on the same venue. The underlying must be a listed security. Leveraged and inverse products are excluded.
The grid is strict enough to weed out almost everything. When it was applied in August, 17 markets on Binance and three on OKX passed. On Bybit and Kraken not a single one qualified. That is exactly why the extension is starting with one single trading venue, and at the same time why it turns into a concentration risk: the spot leg, the hedging leg and the issuer of the collateral all sit within the same corporate group.
What Else USDe Consists Of: Lending, Stablecoins and Real-World Assets
The equity basis trade is not arriving in a pure crypto reserve, because that ceased to exist long ago. Ethena rebuilt the composition in April 2026 and took in institutional lending and tokenised real-world assets. At the start of July, according to governance data cited by crypto.news, only around $39 million, or one percent, was left in classic crypto basis positions. DeFi lending accounted for about 46 percent, liquid stablecoins around 35 percent, tokenised real-world assets 11.2 percent and institutional lending, at around $310 million, a further 6.9 percent.
Part of that institutional block is a one billion dollar credit line set up with the trading house FalconX in August. Assets from the USDe backing finance over-collateralised loans to institutional borrowers there, settled through a special purpose vehicle, with qualified custodians expected to hold collateral in excess of the outstanding loan amount.
For you as a reader the conclusion is uncomfortable and important in equal measure: what stands behind USDe today has little left in common with the model the protocol set out with. The share of classic crypto basis positions was one percent at the start of July. The rest is a portfolio of loan claims, third-party stablecoins, products close to government bonds and, from now on, equity tokens. Anyone who takes the yield on sUSDe for a kind of interest rate should know that what they are really holding is an actively managed credit portfolio.
October 5: What Unlocks on ENA and Why the Buyback Does Not Cushion It
Alongside the collateral question runs a date that concerns the governance token. On October 5, 2026 the lock-up for the remaining original investor tranches ends. Our own analysis of the vesting plan, dated September 3, 2026, arrived at around 1.41 billion ENA in a single distribution. Measured against today's circulating stock of 10.1 billion tokens, that would be just under 14 percent, or around $382 million at the September 27 price. This figure comes from our calculation and not from Ethena: the protocol does not state the size of the tranche publicly.
The obvious counter-question is whether the agreed buyback mechanism absorbs it. According to our analysis of August 30, 2026, that mechanism only kicks in once USDe in circulation reaches $7.5 billion. Measured against today's 4.94 billion, roughly 2.56 billion are missing, so the protocol would have to grow by a good half. As matters stand today, that buffer is therefore not available for October 5.
To place the price picture, from our own measurement at 06:37 UTC on September 27, 2026: ENA is up 37.0 percent over seven days and 69.1 percent over 30 days, but down 54.0 percent over twelve months. It sits 82.1 percent below the all-time high of $1.52 set on April 11, 2024. We expressly draw no forecast from this. The date and the order of magnitude are what you need to know.
What Applies in Germany: BaFin, MiCAR and the Missing Investor Protection
For German investors the supervisory position is the real sticking point, and it has been unambiguous for a year and a half. On March 21, 2025, in the authorisation procedure of Ethena GmbH, based in Frankfurt am Main, BaFin found serious deficiencies and ordered immediately enforceable measures. Among other things the company was prohibited from continuing to offer the USDe token publicly, the asset reserve had to be frozen by the custodians, and a special representative appointed by the supervisor monitors compliance. BaFin additionally made public its reasoned suspicion that securities had been offered in Germany without the required prospectus.
The substance of the objection connects directly with the subject of this article. Under Article 3 of the European crypto regulation MiCAR, USDe is an asset-referenced token whose stability of value is meant to be maintained by reference to other values. By its own account, Ethena GmbH held only other crypto assets as the asset reserve, and stability was supposed to arise from an algorithm using hedging derivatives. That very construction of the reserve stood at the centre of the procedure. Whatever Ethena has changed in the composition since then makes no difference to the German prohibition. The prohibition attaches to the authorisation procedure as such and therefore to no particular collateral package. We have set out elsewhere which obligations an authorisation under this regulation triggers in the first place.
In practice this means: anyone holding USDe or sUSDe through a trading venue outside the European supervisory framework stands outside the level of protection that MiCAR provides for authorised issuers. There is no redemption claim against a supervised issuer there, no audited reserve under European rules and no deposit guarantee. The whole construction rests on the hedge at a central trading platform working at all times. How we assessed the income source and the consequences of the supervisory wind-down in detail is set out in our analysis of where the USDe yield comes from and the BaFin wind-down.
Tax: What Comes Your Way With USDe and sUSDe
For tax purposes a stablecoin is no euro. In the eyes of the tax office USDe and sUSDe are other economic assets, and swapping euros into USDe, or USDe into another token, is a separate transaction each time. Gains from a sale within one year fall under the private disposal transaction of section 23 of the German Income Tax Act, with an exemption limit of 1,000 euros a year for all private disposal transactions combined. If the limit is breached, the entire gain is taxable and not only the excess.
With sUSDe there is an additional feature that many overlook. No separate income token flows to you; the increase in value sits inside the token itself. A taxable gain therefore usually only arises on sale or exchange. Whether the tax authorities classify the transaction in an individual case as a private disposal transaction or as income from other services depends on the specific arrangement. Settle that with a tax adviser before your return, and keep complete records regardless: since the 2026 reporting year, providers within the EU report to the tax authorities under the DAC8 directive, and discrepancies between your own records and the report stand out.
How to Check the Collateral Yourself in a Few Minutes
You do not have to rely on any announcement. Three checks are enough for a picture of your own and take under ten minutes together.
- Verify the circulating supply. DefiLlama's stablecoin interface shows the outstanding amount of USDe. If it falls over several weeks, capital is leaving, and the protocol has to close positions.
- Read the composition of the reserve. Ethena publishes a transparency page. Compare the share of crypto basis positions there with the share in lending and tokenised assets. As the credit share grows, so does your counterparty risk.
- Watch the funding rates. Every large derivatives exchange displays the current funding rate. If it stays in negative territory for a longer period, the protocol is paying out instead of earning.
A fourth check concerns the new development specifically: watch whether the side letter with the issuer of the equity tokens gets signed. Until then, in the assessment of the protocol's own risk analysts, this part of the backing is a claim against a company and gives no access to a security.
Checking the USDe Collateral: What to Take Away
- Check where you trade before you check what you hold. An offer prohibited in Germany stays prohibited, however good the reserve looks. Our comparison of regulated crypto exchanges shows which trading venues can demonstrate authorisation under European law.
- Do not confuse yield with interest. The income on sUSDe comes from derivatives business and lending, and the equity basis fell from around 18 percent at the end of July to about 7 percent at the end of August. Anyone looking for income should lay the sources side by side: our overview of staking and yield platforms sorts out which risk sits behind which number.
- Document every swap from day one. With a token whose value grows inside the token itself, clean record-keeping decides your later tax bill. You will find tools for that in our comparison of crypto tax software and portfolio trackers.
(As of September 27, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Primary sources: Ethena Labs on extending the basis trade to equities and the BaFin consumer notice on Ethena GmbH.
The most important number in any Shiba Inu price prediction for German investors this autumn sits in the calendar and not in the chart. A draft bill from the Federal Ministry of Finance names December 31, 2026 as the dividing line between the old and the new tax regime for crypto assets. Anyone who buys Shiba Inu after that date could end up permanently under a different regime from someone who buys today. The price itself is giving little cause for excitement.
Shiba Inu Price Prediction: What the SHIB Price Actually Shows on September 27, 2026
SHIB traded at $0.00000592 at 06:40 UTC on September 27, 2026, which works out at roughly 0.0000052 euros. The figure comes from the CoinGecko market snapshot taken at that moment. Over the preceding 24 hours the price moved between $0.00000582 and $0.00000606, a daily gain of 0.16 percent. Market capitalisation stood at $3.486 billion, rank 34 in the overall market, on trading volume of $84.5 million in 24 hours.
The gap between the time frames is more telling than the single day. Over seven days the token is up 9.46 percent, over 30 days 10.71 percent, over 60 days 28.04 percent. Measured over a full year it is down 50.27 percent. SHIB has worked its way up out of a deep hole without recovering even half of what it lost over the year.
The all-time high of $0.00008616 dates from October 27, 2021. The current price sits around 93 percent below it. For SHIB to reach that high again, the price would have to multiply fourteenfold. With the circulating supply unchanged, market capitalisation would then stand at roughly $50.7 billion. Call that a multiplication exercise. It shows the order of magnitude hiding behind a seemingly small number with a lot of zeros.
Circulating supply means the number of tokens actually tradable in the market. For SHIB that is 589.24 trillion units, out of a total supply of 589.50 trillion. This quantity is why every price-target calculation for Shiba Inu looks different from one for Bitcoin or Ether.
Shiba Inu Burn Rate: What 476.96 Million Burned SHIB Change About Supply
On September 26, 2026 the daily burn rate jumped by 585.54 percent, sending roughly 15.16 million SHIB to so-called dead wallets. Industry outlet U.Today reported the jump the same day. A burn is the act of sending tokens to an address with no known key, from which nobody can retrieve them. The tokens are permanently out of circulation.
Percentages like that sound like scarcity. Set them against the supply. An in-house analysis by cryptoticker.io dated September 20, 2026 arrived at 476.96 million SHIB burned over 30 days, which is 0.00008 percent of the circulating supply. At that pace, around 15.9 million tokens a day, the network would need more than 1,000 years to cut the supply by a single percent. We published the full calculation on September 20, 2026.
Set against today's price: 476.96 million SHIB at $0.00000592 come to a value of about $2,823. That is the monthly total of every burn combined, spread across thousands of individual transactions. This order of magnitude belongs in your Shiba Inu price prediction before you read a headline about a four-digit percentage as a buy signal.
Shibarium and Where Real SHIB Demand Is Supposed to Come From
Shibarium is the Shiba Inu project's own layer-2 blockchain, a network that settles transactions more cheaply and reports back to the Ethereum blockchain at regular intervals. Every transaction there generates fees in the BONE token, part of which is swapped into SHIB and burned.
One feature of this mechanism matters most for your assessment. It ties burning to actual network usage. Waves of community sentiment do not move it. Over the medium term, that leaves the Shiba Inu price prediction hanging less on announcements and more on a sober question: how many people use the network for payments, applications and transfers they would have made anyway?
No price chart delivers a solid answer to that. Those answers sit in the chain's usage data, and they change slowly. Buying SHIB today is therefore a bet on network usage; the scarcity argument lies centuries away by arithmetic.
The December 31, 2026 Deadline: Why Your Purchase Date Decides Your Tax
Here is the part you can and should check independently of the price. The Federal Ministry of Finance has circulated a draft bill on the taxation of crypto assets held as private wealth for consultation between departments. According to the account given by the tax firm GTK on September 15, 2026, the draft provides a clear cut-off date for grandfathering.
The key points according to that account: 25 percent flat-rate capital gains tax plus the solidarity surcharge on so-called exchange crypto assets, taking substantive effect from January 1, 2027. Only holdings acquired after December 31, 2026 would be affected. Anyone buying up to and including that day stays in the old regime with the one-year holding period under section 23 of the Income Tax Act. Automatic tax deduction by trading venues is not due to start until January 1, 2028.
Two qualifications come with this, and they matter more than the headline. First, this is a draft bill in inter-departmental consultation, meaning a legal text drawn up inside the ministry. There is no cabinet decision, no Bundestag vote and no Bundesrat vote behind it. The Income Tax Reform Act 2027, which cleared the cabinet on September 2, 2026, did not cover crypto assets at all, as we reported on September 7, 2026. The state of the legislative position on the holding period is changing month by month at present.
Second, the draft defines the term exchange crypto asset narrowly: a crypto asset under the EU's MiCAR regulation that is accepted as a means of exchange and is not issued by a central bank or a public body. Bitcoin and Ether are the main examples named. Whether a memecoin such as SHIB falls under that definition cannot be read unambiguously from the text known so far. This is no quibble. It is precisely the question that decides your tax bill in 2027.
What follows is clear all the same: under the draft as known today, a purchase date before December 31, 2026 can take nothing away from you, and it may well secure grandfathered status. That asymmetry is the one solid argument this quarter for deciding by the calendar rather than by the chart.
Holding Period, Exemption Limit and FIFO: The Three Numbers in Your SHIB Tax Calculation
As long as section 23 of the Income Tax Act stands unchanged, gains from selling or swapping crypto assets are entirely tax-free after exactly one year of holding. Within that year they count as private disposal transactions and are taxed at your personal income tax rate, which can reach up to 45 percent.
The exemption limit has stood at 1,000 euros of annual gains per person from all private disposal transactions since the Growth Opportunities Act. An exemption limit works differently from a tax-free allowance: if your total gain comes to 999 euros, everything stays tax-free. At 1,000 euros the entire amount becomes taxable, not merely the euro above the line. At a SHIB price of 0.0000052 euros, a gain of 1,000 euros corresponds to roughly 192 million tokens, an order of magnitude reached faster with memecoins than many expect.
The order of your sales follows FIFO, first in, first out: the tokens bought first count as the tokens sold first. If you have been buying in over months, you are therefore selling your oldest holdings first for tax purposes, and those are the ones most likely to have cleared the holding period. Since January 1, 2026, trading venues have also reported your transactions automatically to the tax authorities under the DAC8 rules. The days when an incomplete record went unnoticed are over.
In practice this means you need the date, the quantity, the price and the trading venue for every purchase, without gaps. If the December 31, 2026 deadline does become law, that purchase date is the proof of your grandfathered status. Our comparison of crypto tax software and portfolio trackers shows which tools keep this history cleanly and generate a report for your tax return.
Buying Under MiCA: How to Spot a Licensed Provider in Germany
The EU's MiCA regulation has applied in full since December 30, 2024. Anyone trading, custodying or exchanging crypto assets commercially for clients in Germany needs authorisation as a crypto-asset service provider. BaFin is the competent supervisor, and licensed firms can be looked up in the regulator's public registers.
Check three points before a SHIB order. First, whether your provider holds MiCA authorisation in an EU member state and may operate in Germany. Second, whether it lists SHIB for spot trading at all and not only as a contract for difference, because a contract for difference hands you a bet on the price in place of tokens, and it falls under entirely different tax rules. Third, whether you can withdraw the tokens to an address of your own, because without that option your grandfathered status depends on the provider staying in business. Our comparison of the best crypto exchanges sets out which platforms meet these points for German customers.
Storing SHIB: When a Hardware Wallet Is Worth the Effort
SHIB is a token on the Ethereum blockchain and also runs on Shibarium. For custody that means any wallet that handles Ethereum tokens can hold SHIB. A hardware wallet is a device that generates and stores your private key without ever handing it to a computer connected to the internet.
At a price of $0.00000592 the trade-off is the same as for any other token, only the unit counts are larger. What matters is the value in euros, and not the number of tokens. If your holding sits in the low hundreds, the network fee for a withdrawal eats a noticeable share of it. Above a four-figure value that reverses, and the risk of a trading venue failing outweighs the fee. Add the tax point from above: your own key makes you independent of whether your provider still exists in three years and can still hand over your acquisition data. The hardware wallet comparison shows which devices support the common Ethereum tokens properly.
One warning is needed more often with memecoins than elsewhere: your wallet's recovery phrase belongs on paper or metal and never in a cloud, a photo or a chat. Anyone who asks a community for help after a price rise will very probably be messaged by someone whose whole purpose is to extract exactly that phrase.
Spread and Liquidity: What $84.5 Million in Daily Turnover Means for Your Order
SHIB turned over $84.5 million in 24 hours on a market capitalisation of $3.486 billion. That puts the ratio of turnover to market value at around 2.4 percent. For comparison from the same snapshot: Dogecoin came in at $627 million of turnover on $15.1 billion of market value, a good 4.1 percent.
For you as a buyer that is no academic figure. The thinner the market, the further apart the bid and ask prices sit. That distance is called the spread, and it is easy to miss on a token with eight decimal places: between 0.00000592 and 0.00000598 lies one percent, and one percent is more than many trading venues charge in order fees. Always convert the spread into a percentage before you send an order. Our price review of September 26, 2026 sets out which levels are worth watching in day-to-day trading.
A second rule for thin markets: use limit orders in place of market orders. A market order takes whatever price the order book currently offers. On $84.5 million of daily turnover spread across dozens of trading venues, that can work out noticeably more expensive than the quoted price, depending on the time of day.
Levels Above and Below to Measure the Shiba Inu Price Prediction Against
These levels are orientation, and no prediction. They are derived from the measured 24-hour range of September 27, 2026 and the nearest round numbers.
On the downside the daily low at $0.00000582 is the first line. If the price drops below it, the next round level is 0.00000550, a good 7 percent under the current reading. Only below that would the 10.71 percent gain of the past 30 days be fully surrendered.
On the upside the daily high sits at $0.00000606, with the round level of 0.00000600 immediately beneath it. A solid breakout would require a close above 0.00000650, because that is where the level of early September would be regained. The much-quoted level at which a zero disappears sits at 0.0000592, around 900 percent higher. Market capitalisation would then be about $34.9 billion, just under half of what Solana weighed in at on the same day. Anyone who reads that number in a forecast should hold it against this comparison.
What the levels do not deliver: they say nothing about whether Shibarium will be used more in twelve months than it is today. That is exactly what the Shiba Inu price prediction hangs on over a one-year horizon, and so far there is no figure that establishes a direction.
Shiba Inu Price Prediction: What to Take Away
- Check the purchase date before the price. Under the draft bill of September 2026, December 31, 2026 decides whether your holding stays under the one-year holding period or moves into the flat-rate capital gains tax. Nothing has been enacted. A purchase before that date can take nothing away from you under the text as known. If you were going to buy in anyway, check your buying route now in the crypto exchange comparison.
- Secure your acquisition data without gaps. Date, quantity, price and trading venue for every purchase are the only proof of grandfathered status from 2027, and since January 1, 2026 your provider has been reporting to the tax office under DAC8 in any case. A tool from our tax software comparison does this automatically and calculates on a FIFO basis.
- Weigh burn headlines against the supply. 476.96 million SHIB burned in 30 days are 0.00008 percent of the circulating supply and worth around $2,823. Building a price thesis on that means counting in centuries. If your holding is in four figures, custody is the more pressing question, and the hardware wallet comparison answers it.
(As of September 27, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
If a balance is still sitting at CoinEx that is not held in USDT, there are around 46 hours left for it. On September 29, 2026 at 02:00 UTC the exchange ends spot trading, and from that moment holdings that have not been withdrawn in their original currency are liquidated. Coins with liquidity on external markets are sold by the exchange in batches, according to its own statement, with the net proceeds credited as USDT in the spot account. Coins without external liquidity are delisted step by step, and for those the exchange explicitly assumes no further custody and no further redemption once processing has begun.
The difference from the previous understanding of this date is not a detail. Until September 29 you can decide yourself what happens to your holding. After that the exchange decides, in batches, at a price you do not know in advance. Anyone who leaves Bitcoin, Ether or a smaller altcoin at CoinEx and lets the date pass will in the end hold none of those coins but a dollar stablecoin.
Forced conversion at CoinEx: what happens to your coins on September 29 at 02:00 UTC
The rule is set out in the exchange's wind-down notice and can be summed up in one sentence: anyone who wants to keep non-USDT holdings in the original currency has to withdraw them before September 29, 2026, 02:00 UTC. After that, liquidation applies.
For the wind-down the exchange distinguishes two groups. For coins that still have liquidity on external markets, it sells the holding and converts the net proceeds into USDT; the result lands in the user's spot account. For coins without an external market there is no sale, they are delisted, and the associated wallets are, according to the exchange, no longer operated. Processing runs in batches spread across the withdrawal period, and the exchange announces no separate notices for individual batches.
One term, briefly explained: a liquidation is the sale of a holding by a third party without the owner determining the timing or the price. Economically it is a sale like any other, only without your decision on when it takes place.
That fees and deadlines can change on short notice applies with particular force during a wind-down. If you are reordering your holdings anyway, it is worth looking at exchanges with a European licence, because there a market exit does not run without wind-down rules and without supervision.
The wind-down schedule: which stages have already taken effect since September 15
September 29 is the third stage of a schedule that began on September 15. The exchange had announced its closure that day and started the wind-down immediately.
- September 15, 2026: no more new registrations, referral commissions and other forms of remuneration end. Futures move into the mode in which positions can only be reduced. New orders for fiat, margin, loans, savings products, staking and strategic trading are no longer accepted.
- September 22, 2026: all services outside the spot market end. Deposits via the blockchain stop, for the exchange token CET only on September 29. Open futures positions are force-settled at the index price, savings and staking products are repaid uniformly.
- September 29, 2026, 02:00 UTC: spot trading ends, unexecuted orders are cancelled. The in-house blockchain CoinEx Smart Chain and the decentralised exchange OneSwap cease operation. From that moment the liquidation of non-USDT holdings begins.
- December 22, 2026, 02:00 UTC: the withdrawal channel closes, operations end.
Between September 29 and December 22 the platform therefore remains a pure withdrawal counter for just under three months. That sounds like time, but it moves the decisive work forward: what you can still withdraw in that phase is what is left after the liquidation, and for most holdings that is USDT.
On the time of the December date the accounts diverge. Several reports name December 22, 2026 at 02:00 UTC, while another summary of the notice gives the time zone UTC+8 for the same day. The difference of eight hours does not matter as long as you do not wait for the last day, and that is precisely why you should not.
Batch selling without individual notice: why you will not know the execution price
The practical consequence of batch processing is a price risk that cannot be steered. The exchange names no date for the individual coin and no separate notice per batch. You therefore do not know on which day your holding will be sold, and you cannot choose the moment.
How large that risk is depends on the volatility of the coin in question. At the time of our call on September 27, 2026 at 03:48 UTC, Bitcoin stood at around $84,381 according to CoinGecko data and had gained about 4.2 percent in seven days; Ether was at around $2,697, up about 3.0 percent on the week. With smaller altcoins the range is considerably wider: in the field of the 25 largest crypto-assets, weekly changes in the same call ran between minus 2.1 and plus 41.9 percent. A sale whose day you do not know hits one side or the other of that range with such assets.
There is a second point that often gets lost: with a coin that has no external liquidity, no sale takes place at all. There you do not get a bad price, you get no price. The holding is delisted, and the exchange does not continue to operate the associated wallets.
Coins without external liquidity: when delisting puts the holding out of reach
For small and thinly traded positions, delisting is the harder part of the announcement. According to the exchange's statements, once processing has begun it assumes no further custody and no further redemption for these assets. Anyone who wants to keep such a coin has only the window until September 29 to do so, and in the original currency via a blockchain withdrawal.
Whether your coin can be withdrawn at all is not a rhetorical question here. Our own survey at CoinEx on September 15, 2026, published in our article on the closure of the exchange, found 37 currencies whose withdrawal counter was closed that day. That figure is our own measurement on one day and not a permanent state; it does show, however, that the way out is not open for every entry in the account. So check today whether your currency offers a withdrawal, rather than late on Monday evening shortly before the cut-off.
What to check specifically before the window closes
Three questions are enough to begin with. First: is there any network at all to choose from in the withdrawal section for your currency? Second: is your holding above the minimum withdrawal amount for that network? Third: does the destination address you are sending to support exactly that network? The third point is the one where money is lost in practice, because an address can look valid while belonging to a different chain.
Holding period and section 23 of the German Income Tax Act: why a forced sale is still a sale
Here lies the part that the reports on the wind-down do not cover, and which for an investor in Germany can be the most expensive. For tax purposes the liquidation is a sale. That the exchange triggers it rather than you changes nothing about that.
Crypto-assets held privately count as other assets. A sale within one year of purchase is therefore a private disposal under section 23 of the German Income Tax Act, and the gain from it is taxed at your personal rate. After a year has passed, the gain is tax-free. Swapping a coin into a stablecoin is a sale just as swapping into euros is, because you give up one asset and receive another.
If you have held your position for less than a year
Then the liquidation on September 29 creates a taxable event in 2026 that you did not plan. The gain is the proceeds in USDT less your acquisition costs. That stays tax-free only as long as the total gain from all private disposals of the year remains below the exemption threshold of 1,000 euros; once it is reached, the entire gain is taxable, not only the part above it. It is explicitly not an allowance that covers only the excess.
If you have held it for longer than a year
Then the liquidation is unproblematic in tax terms, because after a year the gain lies outside the tax charge. Economically it remains a disadvantage, because you do not determine the moment of sale. Anyone who wants to keep their holding rather than see it shifted into USDT withdraws it, regardless of the tax question.
The records you secure for yourself now
A wind-down has one unpleasant property: the platform that keeps your trading history disappears. So download your transaction and withdrawal statements before operations end, rather than when the tax office asks. Anyone unable to document their acquisition costs will later be negotiating over an estimate, and the burden of proof sits with the taxpayer. A portfolio tracker with tax reporting helps here above all because it makes the data independent of the provider.
A new holding period on the USDT: what the swap means for the twelve-month clock
The second tax effect is easily overlooked. The liquidation does not only end the old holding period, it also starts a new one. The USDT you hold in the account after the sale is a newly acquired crypto-asset with its own acquisition date, and for it the twelve-month period runs again from the day it is credited.
With a stablecoin that sounds harmless, because the price barely moves and a later sale generates hardly any gain. What matters is the holding you have replaced with it: if a coin you have held for eleven months is liquidated on September 29, you lose the month that would have taken you into tax exemption. Anyone close to the one-year mark should therefore look up when they bought before deciding whether to withdraw or to sell.
Withdrawal fee per chain: why the exit costs up to 174,000 times as much
If you withdraw, the chain you choose determines how much arrives at the other end. Our survey on September 15, 2026 read out the withdrawal fees at CoinEx that day and found, for the same USDT, the same amount and the same moment, nine routes with very different prices: from 0.000043 USDT via the Plasma chain to 7.50 USDT via Tron. Between the cheapest and the most expensive exit there was therefore a factor of 174,000, and even between the two most-used routes, BNB Smart Chain and Tron, the factor stood at 949.
The effect hits small residual balances hardest. On a balance of 20 USDT, withdrawing via Tron costs 7.50 USDT according to this measurement, which is 37.5 percent. In 78 of 1,011 combinations of currency and network examined, the fee amounted to at least half of the respective minimum withdrawal amount. Both figures are our own measurement of September 15 and not a statement by the exchange; check the current values yourself before withdrawing, because in a wind-down fee tables change.
For Bitcoin there was exactly one withdrawal route on the measurement day, the Bitcoin network, with a fee of 0.0001 BTC against a minimum amount of 0.001 BTC, that is around a tenth of the smallest possible withdrawal. With Ether the ratio was about 0.2 percent, at a fee of 0.000011 ETH against a minimum of 0.005 ETH. The difference follows the usual costs of the respective chain and is no coincidence.
A 5 percent monthly custody fee: what happens to USDT after December 22
For USDT still sitting in the account on December 22, the exchange has announced an arrangement you should know about. The holding is transferred into separate custody, and for that the company names a monthly custody fee of 5 percent of the original holding, measured on the cut-off date. Claims can, according to statements from the notice, still be registered by email until August 22, 2028.
The basis of assessment makes the difference here. Five percent of the original amount is not a percentage deduction that merely approaches zero, it is a constant deduction. On 500 USDT that would be 25 USDT a month, every month, which would exhaust the holding after 20 months. Anyone who misses the withdrawal date does not lose their balance immediately, then, but foreseeably.
CET buyback at 0.005 USDT: what holders of the exchange token decide by Tuesday
The in-house token CET is being bought back until September 29 at 0.005 USDT per unit, according to the exchange, with no volume cap and no further conditions; CET still sitting in accounts after that is bought back automatically at the same price. The company holds out no prospect of a later redemption. Deposits of CET via the blockchain were the only ones still possible until September 29, while for all other assets they already ended on September 22.
Our measurement of September 15 showed CET in all three calls at 0.005 or 0.005001 USDT, so practically exactly at the announced buyback price. A buyback at a fixed price acts like a floor that the market aligns itself with, and that is precisely how the price behaved that day. For holders that means the difference between selling on the market and waiting for the buyback was, on the measurement day, in the region of the trading fee. We give no recommendation on this, because both routes hang on the same question, namely how reliable you consider the company's commitments to be.
Where to move your holding: your own wallet or an exchange with an EU licence
For the withdrawal you have two sensible destinations, and the choice depends on what you intend to do with the holding. If you want to keep it, your own wallet is the direct route: you receive the coins in the original currency, the holding period continues unchanged because no sale takes place, and you no longer depend on any provider. If you want to keep trading, the route runs via another exchange.
As the reason for the closure the company itself cites a prolonged market downturn, declining trading volume and shrinking liquidity, together with increased regulatory requirements in important jurisdictions, the cost of which in its account had exceeded a reasonable level. For an investor in Germany that is an argument for looking more closely at licensing with the next provider. The duties a provider with a European authorisation has to meet are set out in our overview of the MiCA obligations.
Whatever the destination, the same order applies to the move: first send a small test amount, check that it arrives, then the rest. That minute costs one withdrawal fee and, if something goes wrong, saves the entire holding.
Checking the CoinEx forced conversion: what you take away
- Look today at whether a withdrawal route is open at all. Open the withdrawal section for every currency in your account and check whether a network is offered and whether your holding is above the minimum amount. If there is nothing to be had there, the only option until September 29 is a swap on the spot market into a currency that can be withdrawn. Anyone who wants to keep trading the holding afterwards will find the destination accounts for it at the larger crypto exchanges.
- Check the acquisition date before withdrawing. If the purchase is less than a year ago, a liquidation on September 29 creates a taxable gain in 2026; if it is longer ago, the gain is tax-free, but the moment of sale remains outside your control. Download the trading history while the platform is running, and secure the records in a tax and portfolio tool that works independently of the exchange.
- Pay attention to licensing with your next provider. A market exit without European supervision runs by the provider's rules, not by yours. If you are moving the holdings anyway, this is the cheapest moment to park them at a regulated exchange with an EU authorisation or to take them onto a hardware wallet that you keep yourself.
The exchange's notice itself is in its statement on the orderly cessation of operations. That page loads its text via JavaScript and reads normally in a browser, even though an automated call returns it empty; the dates named here have additionally been cross-checked against two independent trade reports.
(As of September 27, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Toncoin no longer exists, at least not under that name. Since June 15, 2026 at 12:00 UTC, the token of the network The Open Network has been called Gram again, and the symbol reads GRAM instead of TON. For you as a holder, the most important news is reassuring: you do not have to do anything. There is no swap, no bridge, no claim to register and no migration to a new chain. Balances, addresses, contracts, collectibles and running staking positions are unchanged; what changed is the name in the price ticker.
The second piece of news is the more interesting one. Telegram is now building the token directly into the messenger: since late August 2026 the Gram Wallet has been rolling out inside the app, initially for a limited group of users. This wallet is self-custodial, which shifts both the opportunities and the obligations. This article sets out what the rename means in practice, whether the wallet can be reached in Germany yet, how it sits with European supervisory law, and how much is left of the ecosystem that made headlines in 2024 with tap-to-earn games.
What happened to Toncoin: the Gram rename at a glance
The name Gram is not an invention of 2026 but a return. The project's original white paper called the token Gram; only after the legal dispute with the US securities regulator and Telegram's withdrawal from development did a foundation take over the network and carry the token on as Toncoin. The network voted on the return to the old name, and approval came in at 81.22 percent.
A rebranding is something different from a token swap. In a swap, an old contract is retired and you have to exchange your holdings for new units, usually within a deadline and often for a fee. Here only the label changed: the same contract, the same chain, the same keys. If anyone offers you an exchange page for "new GRAM", that is an attempted fraud, and the same applies to any message that pushes you to act because of the name change.
In practice that means the token may currently appear under both names in your wallet and at your exchange. Large market data providers list it as "Gram (prev. Toncoin)" so that the mapping stays unambiguous. The pitfalls sit wherever software has the name hard-coded, for instance in older tax tools or in spreadsheets you built yourself.
Do you have to do anything? What the Gram rename means for your holdings
No, and that is explicitly documented. The network operator has made clear that no action is required. A short review in three places is still worth the time.
First, your trading platform: check whether the trading pair has been renamed and whether deposits and withdrawals are running normally. Exchanges run short maintenance windows during renames, and transfers stand still while they last. Second, your tax records, on which there is more below. Third, your bookmarks and watchlists, because a price ticker under the old symbol can point at nothing.
If you want to place your holding for a possible purchase or sale, our last detailed assessment is in the buying decision on Toncoin from August 15, 2026, which still appeared under the old name. Current price action together with scenarios is covered on the Toncoin price prediction page.
Who runs the network now that Telegram replaced the foundation
The rename is the most visible part of a larger overhaul. On May 4, 2026, Telegram took the place of the Swiss-based TON Foundation as the network's largest validator. A validator is a machine that checks transactions and confirms blocks; whoever holds the largest voting weight largely determines which software changes go through. The step belongs to a multi-stage roadmap that Telegram founder Pavel Durov presented under the name "Make TON Great Again".
Technically the network has improved measurably this year. Transaction fees fell roughly sixfold according to the operator, and an upgrade in April cut the block time from around 2.5 seconds to about 400 milliseconds. The block time is the interval at which new blocks are created, and therefore the lower bound on how quickly a payment can be confirmed.
The price of that acceleration is concentration. A network whose largest validator also operates the app through which almost all users arrive is no longer a distributed system in the original sense. That is not a verdict on the product but a description of a risk you should know: decisions on fees, censorship and software are taken where the voting weight sits.
The Gram Wallet in Telegram: self-custodial, and what that means for you
On August 31, 2026, Durov announced that the Gram Wallet was finished inside Telegram and available to a limited group; the release was to be widened over the following weeks to the entire user base, which the company puts at more than one billion. Other accounts cite around 900 million users, and that range belongs in the picture.
The decisive point is the design: the wallet is self-custodial. That means the private keys sit exclusively on your device, not with Telegram. A private key is the secret number used to move funds; whoever holds it controls the money. The difference from a custodial solution is invisible in everyday use and decisive when things go wrong: at an exchange you can reset a password, under self-custody you cannot. If you lose both the device and the recovery phrase, the holding is gone for good, and no support desk can help.
Two concrete actions follow from that before you deposit amounts that would hurt to lose. Write the recovery phrase down away from the phone and store it separately from the device; a screenshot in your photo gallery is no backup but a target. And treat an app wallet as a current account rather than as a vault. Anyone holding larger amounts keeps custody away from the device in daily use; our hardware wallet comparison shows which devices support the network and what to look for when buying.
Is the Gram Wallet available in Germany yet?
What is documented is a staged rollout, not a release for everyone at once. Whether the wallet appears in your app therefore depends first of all on whether your account sits in the current wave. The company has not published a release list broken down by country, which is why a firm "yes or no for Germany" cannot be given at the moment.
Here is how to check for yourself, without relying on reports: open the settings of the app and look for a wallet entry. If it is missing, searching in third-party channels will not help, and there is no sign-up route that speeds up the queue. Any message promising you earlier access in return for a payment or for a recovery phrase is an attempted fraud. That is the most common damage in staged launches, and it regularly hits people who only wanted to be there sooner.
What MiCA means for a self-custodial wallet inside a messenger
For German users the supervisory classification matters more than any product announcement. The European regulation on markets in crypto-assets, MiCA for short, ties the licensing requirement to the provision of crypto services, which includes custody on behalf of clients. Where users hold the private keys exclusively themselves, the logic of the regulation means there is no custody in the legal sense: pure self-custody therefore falls outside the authorisation requirement for service providers.
What that means for you in practice is uncomfortable. At an authorised platform, duties on organisation, complaint channels and the separation of client funds apply. At a self-custodial wallet none of that applies, because no service provider stands between you and the chain. The protection you have at a regulated exchange is here your own procedure. Where you can trade in Germany under European supervision is set out in our comparison of regulated crypto exchanges.
One note on the situation, without a forecast: supervisory authorities in the EU and in the United States tightened the rules for transfers to self-custodial wallets in 2026. A function preinstalled in an app with one billion users will hardly escape the attention of regulators. How that affects deposit and withdrawal routes is open; anyone using the wallet should keep an eye on changes at their exchange.
How much the network actually carries today
An honest look is worth it here, even if it turns out uncomfortable. The total value locked (TVL) is the sum of the funds deposited in the applications of a chain, and the most common measure of a network's economic use beyond its price. Our own call to the DefiLlama interface on September 27, 2026 at 00:56 UTC returns around $56.6 million for TON.
For comparison, from the same call: Solana comes to about $6.62 billion, Base to around $6.28 billion, Polygon to roughly $794 million. The network with the largest potential audience in the industry thus carries less than 1 percent of the capital working on the leading chains. Reach and usage are plainly two different things, and anyone investing in Gram is so far investing in the expectation that the first will turn into the second.
That this can also move backwards is something the year has shown. The shutdown of a bridge to other chains hit the holdings of users who reacted too late; we broke down the deadline on August 21, 2026 and the remaining balances on September 1, 2026. If you still hold bridged units from that period, that is the more urgent task than any wallet news.
What happened to Notcoin, Hamster Kombat and DOGS
The games that pulled millions of people into the messenger in 2024 are the reason many German investors know about this network at all. The model was called tap-to-earn: users tapped the screen in a mini application and collected points that were later converted into tokens. The record two years on is sober.
At Hamster Kombat the user base has fallen from more than 300 million to about 41 million, according to a market data provider. The DOGS token trades around 96.8 percent below its all-time high, which was reached on August 28, 2024. We have no statement from any of these projects that operations have been discontinued; we therefore explicitly do not write that they have ended. What can be documented is the loss of attention and of market value.
The lesson from that matters more to today's reader than the retrospective. A token whose demand comes out of a campaign loses its basis along with the campaign. Anyone buying such assets should treat a total loss as possible, meaning the loss of the entire amount invested. Background on this class of token is collected on our meme token topic page. How quickly such an ecosystem can come to a standstill was shown by the price slump with network outage of June 6, 2026.
Gram price and all-time high in relation
Our own call to the CoinGecko market data interface on September 27, 2026 at 00:56 UTC returns a price of $1.59 for Gram at rank 30 by market capitalisation. The all-time high stands at $8.25, putting today's price around 80.7 percent below it.
That figure places the rename. A return to the original name and a wallet inside a large app are considerable steps for distribution. They have so far changed nothing about the distance to the peak price, and we name no price target here: how the market values distribution to one billion users is an open question rather than an arithmetic exercise.
Tax in Germany: holding period, the rename and what the tax office sees
For taxation the rename is the friendliest case there is. Because no swap took place, there is no disposal, meaning no event that triggers a taxable gain or loss. Your acquisition dates remain intact, and the holding period therefore runs on unbroken.
That is more important than it sounds. Private disposals of crypto-assets are tax-free under section 23 of the German Income Tax Act after a holding period of one year. Had the rename been a swap, the clock would have started again. In practice you should still do two things: check that your tax tool continues to assign the holding to the same position after the name change instead of carrying it as a new acquisition, and secure the records of the original purchase.
On top of that comes a deadline that concerns every German investor. The German Crypto Asset Tax Transparency Act implements the European reporting obligation DAC8; the 2026 calendar year is the first period for which trading platforms report data to the Federal Central Tax Office, and they have to do so by July 31, 2027. With a self-custodial wallet there is nobody who takes care of that for you: the burden of proof sits entirely with you. Anyone who starts reconstructing a history in the summer of 2027 is looking for data that by then often no longer exists.
The risks you should know before buying Gram
Three points belong together, and none of them is a recommendation for or against the token.
The first is centralisation. When the operator of the app is also the largest validator, network and company hang on each other. News about the company then acts directly on the token, regardless of how the technology performs.
The second is the weak usage, measured by the $56.6 million in TVL. A chain with little deposited capital has thin order books on its decentralised exchanges, which makes larger sales expensive. The third is the plain possibility of a total loss, which applies to every crypto-asset and deserves particular attention with a token whose prospects hang on a single company. Invest only amounts here whose failure would not touch your life plans.
Toncoin and Gram: what you take away
- The rename requires nothing from you. No swap, no deadline, no action. Anyone writing otherwise is after your keys. Just check that your tax tool carries the holding on as the same position.
- Treat the wallet in the app as a current account. Note the recovery phrase away from the phone and keep larger holdings separately. Which devices are suitable is set out in the hardware wallet comparison.
- Trade under supervision if you want to buy. A self-custodial wallet carries no investor protection; the platform you buy through is therefore the more important decision. The comparison of regulated crypto exchanges is the place to start. Reckon with the possibility of a total loss.
Sources to read on: the network's announcements are in the project's official channel, the usage figures of the chain on the TON overview at DefiLlama.
(As of September 27, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
The fourth quarter of 2026 brings the crypto market no single big decision but a chain of around a dozen dates, all of which act on the same three things: on the circulating supply of individual tokens, on rate expectations and on your tax obligations. The key dates before New Year's Eve are October 2 (unlock at DoubleZero), October 5 (final unlock at Ethena), October 9 (activation window of the Batch amendment on the XRP Ledger), October 27 and 28 as well as December 8 and 9 (meetings of the Federal Reserve's open market committee), November 3 (US midterm elections) and December 31 (end of the first reporting year under the German Crypto Asset Tax Transparency Act).
This overview places each date: what happens on the day, how large the effect is in relation to the supply, and how you can tell whether a date will hold at all. Because four of the dates named here are targets from a development roadmap and not deadlines from a statute book. That difference matters more to you than any single figure, and it is exactly where a prominent date collapsed this September.
The Crypto Calendar for the Fourth Quarter of 2026 at a Glance
All times in coordinated universal time (UTC). Germany is two hours ahead until October 25, one hour after that. The "Type" column tells you how solid the date is: a deadline is fixed, a target can move.
| Date | Event | Type |
|---|---|---|
| September 28 | Solana: activation window for Alpenglow opens | Target |
| September 30 | Optimism and Celestia: monthly unlocks | Deadline |
| October 1 | Sui: unlock of roughly $61 million | Deadline |
| October 2 | DoubleZero: 1.655 billion 2Z come free | Deadline |
| October 5 | Ethena: 1.41 billion ENA in a single distribution | Deadline |
| October 6 | Ethereum: Glamsterdam on the Sepolia testnet | Target |
| October 6 | ECB: information event on the digital euro | Deadline |
| October 7 and 8 | TOKEN2049 Singapore | Deadline |
| October 8, 21:25 | XRP Ledger: PermissionDelegation active at the earliest | Target |
| October 9, 14:46 | XRP Ledger: Batch amendment active at the earliest | Target |
| October 16 | Arbitrum: roughly 92.7 million ARB come free | Deadline |
| October 27 and 28 | Federal Reserve rate decision | Deadline |
| November 3 | US midterm elections | Deadline |
| November 3 to 6 | Devcon 8 in Mumbai | Deadline |
| November 15 to 17 | Solana Breakpoint in London | Deadline |
| November 24 | Monad: lock-up on the team tokens ends | Deadline |
| December 8 and 9 | Rate decision with economic projections | Deadline |
| December 31 | End of the first reporting year under the KStTG | Deadline |
What a Token Unlock Is and Why the Date Counts for You
A token unlock is the contractually agreed release of tokens that were allocated to investors, founders or validators at a project's launch but locked for a set period. On the unlock day they move from a locked address into freely available wallets. The supply in the market can rise markedly on a single day without a buyer having appeared.
Two terms are worth distinguishing here. A linear unlock spreads the amount over months, usually in equal tranches; the market has as a rule priced it in. A cliff, by contrast, is a step: on the cut-off date everything locked until then comes free at once. The dates in this quarter are predominantly cliffs, and that is why they belong in a calendar at all.
Important for placing them: an unlock is not a sale. Whether the tokens actually reach the market depends on who holds them and at what cost base. The reliable measure is therefore not estimated selling pressure but the ratio of the released amount to the existing supply. That figure appears below with every date, and it comes from our own query of CoinGecko's public market data interface on September 27, 2026 at 00:43 UTC.
October 2026: Lock-Ups Expire at Sui, DoubleZero, Ethena and Arbitrum
October is the densest month of the quarter. Four unlocks fall in the first sixteen days, and they differ considerably in magnitude.
On October 1 Sui releases a tranche that various analytics services value at roughly $61 million. Sui runs a monthly schedule, so the unlock is announced and recurring.
On October 2 comes the hardest case of the quarter: at DoubleZero, 1.655 billion 2Z come free. Measured against a supply of roughly 3.47 billion tokens, that amounts to an increase of 47.7 percent in a single day, about $116 million at today's price. The recipients are predominantly validators of the network. How that dilution comes about and what remains outstanding in the unlock schedule afterwards, we broke down on September 2, 2026 in our analysis of the 2Z unlock.
On October 5 Ethena distributes the remaining investor tranches in a single unlock: 1.41 billion ENA, roughly 14.0 percent of the supply of 10.1 billion tokens, about $381 million at the current price. After that no investor token remains locked, and the monthly schedule ends around seventeen months earlier than originally planned. Our assessment of the ENA unlock of September 6, 2026 costed the same item at about $213 million at the time; the difference is pure price movement, the token amount is unchanged. That shows you why, with unlocks, the amount is the more reliable measure than the dollar figure.
On October 16 Arbitrum releases roughly 92.7 million ARB, about 1.4 percent of the supply and a good $20 million at today's price. That is the smallest of the four unlocks and sits within this network's usual monthly tranches.
Alongside those, the regular unlocks at Optimism and Celestia run on September 30. Both are monthly and are usually received calmly by the market, because their rhythm is known. If you want to follow such dates systematically you need no subscription for it: the unlock schedules of the large networks are public, and an exchange where you hold the tokens concerned shows the balances anyway. Our comparison of crypto exchanges for investors in Germany sets out which providers sit under European supervision.
October 9 Instead of September 29: Why the XRP Ledger Date Slipped
This case is the best lesson of the quarter. On the XRP Ledger it is not developers who decide on an upgrade but the validators. An amendment is a proposed change to the protocol that only goes live once more than 80 percent of the trusted validators have supported it for two weeks without interruption. Should support dip below that at any point in that time, even briefly, the count starts again at zero.
That is exactly what happened. Until mid-September the counter pointed to September 29 as the earliest activation day for the Batch amendment. Support fell, the counter was reset, and the new majority has been in place since September 25. Our own query of the validated ledger state through the XRPScan interface on September 27, 2026 at 00:38 UTC gives: BatchV1_1 is not activated, supported by 30 validators against a threshold of 28, majority since September 25 at 14:46:02 UTC. Plus fourteen days that yields October 9, 2026, 14:46:02 UTC. For fixBatchV1_2 the same day falls at 14:12:51 UTC, and for PermissionDelegationV1_1 it is October 8 at 21:25:01 UTC.
The words "at the earliest" are to be taken literally: should support fall again, the date moves again. If you run a node of your own, the instructions from our article on the Batch amendment of September 18, 2026 remain correct, only the date in it is out of date: your software has to be on a version that knows the amendment before activation, otherwise the node stops processing. Anyone merely holding XRP at an exchange has nothing to do.
Technical Upgrades: Alpenglow at Solana and Glamsterdam on Sepolia
Two of the largest networks are working on changes to their core protocol in the fourth quarter. Both dates are targets.
At Solana the activation window for Alpenglow opens on September 28. The rebuild replaces the previous consensus procedure, TowerBFT, with a new voting protocol called Votor and removes the voting transactions that today account for a large share of the load on the network. The stated goal is transaction finality in about 150 milliseconds, against roughly 12.8 seconds today. A feature gate is a switch in the software that arms a finished function only at a set point in time; the developers point out expressly that the dates in their plan can change. What validators and delegators should check in concrete terms is set out in our overview of the Alpenglow activation of September 1, 2026.
At Ethereum the developers are aiming for October 6 at 13:53:36 UTC for the activation of Glamsterdam on the Sepolia testnet. The scope includes parallel processing of transactions, slower growth of the network state and the separation of proposer and block builder anchored in the protocol, known as proposer-builder separation. A testnet is a complete copy of the chain with worthless tokens, on which developers try out changes before they reach the main net. For the main net there is no date so far; December counts as the earliest window, and several developers have warned of attack vectors in the new block-building auction. For you as an investor nothing changes on that day: neither your wallet nor your holdings are affected.
October 27 and 28: The Rate Decision as the Most Important Macro Date
The Federal Reserve's monetary policy committee, the Federal Open Market Committee (FOMC), meets twice in the fourth quarter: on October 27 and 28 and on December 8 and 9. The dates are in the Federal Reserve's official meeting calendar, which you can look up for yourself here. The decision is published on the second day at 14:00 Washington local time, followed by the press conference.
Why that counts for cryptocurrencies: the central bank's interest rate determines what risk-free capital yields. When that benchmark rises, the willingness to move into assets without a running return falls; when it drops, the effect reverses. Bitcoin and the broad market therefore react more often to these meetings than to protocol-level news. The December meeting carries additional weight, because that is where the economic projections including each member's rate forecast are published. Those projections give an outlook on 2027 and therefore work for longer than the decision itself.
A note on expectations: what moves the price on these days is rarely the decision but the gap between decision and expectation. Position only on the meeting day and you are trading against a market that priced the likely outcome in long ago.
November 3: The US Midterms and What Becomes of the Clarity Act Afterwards
On November 3 the United States elects a new Congress. For the industry the question hanging on it is whether a law on the market structure for digital assets will still come about in this legislative term. The Clarity Act was meant to redistribute responsibilities between the securities regulator and the commodity futures regulator, and thereby clarify which tokens count as securities. On September 15, 2026 the procedural vote in the Senate on opening the debate failed by 49 to 50, eleven votes short of the required majority of sixty. What follows from that for investors and for supervisory practice we set out on September 18, 2026 in our analysis of the failed Clarity Act.
The remaining window is the session period between the election and the new Congress convening, which runs from November 5 to December 18 and, in the view of several observers, will be taken up by budget matters. For you as an investor in Germany the situation is more relaxed than the headlines suggest anyway: your legal framework is the European regulation on markets in crypto-assets, whose transition period expired on July 1, 2026. A US law does not change that; it mainly influences which products American providers may launch. If you want to invest through a regulated wrapper, our overview of crypto ETFs and ETPs in Germany lists the routes authorised here; spot Bitcoin ETFs of the American kind cannot be acquired by retail investors in Germany.
November and December: The Monad Cliff and the Second Central Bank Meeting
November brings the largest single item of the quarter on November 24. At Monad the one-year lock-up on the team tokens then ends, counted from the launch of the main net. Different figures exist on the magnitude, and that range deserves naming: our own analysis of September 26, 2026 on the end of the Monad lock-up arrives at roughly 10.7 billion MON, corresponding to about 10.7 percent of the initial total supply of 100 billion tokens. A widely used calendar service lists roughly 16.8 billion MON for the same day. Measured against today's supply of 11.8 billion tokens, the lower figure would already amount to about 90 percent and the higher one to over 140 percent. Which counting method holds on the day is open; that it is the weightiest unlock date of the quarter is settled either way.
December is dominated by the second central bank meeting on December 8 and 9. After that the calendar thins out, as it does every year between the holidays. Experience shows trading volumes fall in that phase, which lets individual moves swing wider without more capital being involved.
One date often expected is not in this quarter: the next halving at Bitcoin, the halving of the block reward, is not due until 2028. Anyone arguing with that event in the fourth quarter of 2026 is arguing past the chain.
Which Crypto Conferences and Web3 Events Take Place in the Fourth Quarter
Three major industry dates fall in this quarter, and they are more than networking: at such events technical milestones and products are regularly announced that occupy the market afterwards.
- TOKEN2049 Singapore, October 7 and 8. By its own account the largest conference in the industry, at the Marina Bay Sands, surrounded by an event week from October 5 to 11. Announcements from exchanges and large trading platforms traditionally fall in these days.
- Devcon 8 in Mumbai, November 3 to 6. The Ethereum Foundation's developer conference, in India for the first time, at the JIO World Centre. This is where the state of work on Glamsterdam and on the further roadmap is presented; the programme is on the official Devcon site.
- Solana Breakpoint in London, November 15 to 17. The main conference of the Solana ecosystem, in the United Kingdom for the first time, at Olympia London. For interested parties in Europe it is the most easily reachable of the three dates.
For price developments, conferences are unreliable signals. As a check on the state of an ecosystem they serve well, though: who appears there, which applications are shown, and whether last year's plans were delivered. That says more about a network than any price move in the same week.
What Sets the Framework in Europe in the Fourth Quarter of 2026
The calendar above is American in character, and there is a reason for that: dates that move prices within hours arise predominantly in the United States. The framework for your own actions, by contrast, is set by Europe, and there a development is under way this quarter that is missing from most crypto calendars.
On October 6, 2026 the European Central Bank is holding an information event on the digital euro that is open to consumers as well; in parallel it is looking for merchants for its pilot project. Both dates we broke down on September 17, 2026 in our piece on the ECB pilot project, including the note that they appear only on the English version of the central bank's site. Digital central bank money is not a cryptocurrency in the narrower sense: it is not issued on an open blockchain but by the central bank itself, and it replaces neither Bitcoin nor a stablecoin. For payments in Europe it is nonetheless the bigger building site of this quarter.
Two further European factors have effect without a date of their own. The regulation on markets in crypto-assets has applied since July 1, 2026 with no transition period; authorisation of a trading platform in Europe is therefore no longer a marketing claim but a precondition for operating. And the reporting obligation under the KStTG applies to the whole calendar year, as the next section shows. Anyone holding their investment in DeFi, meaning in applications with no company in between, carries the burden of proof entirely themselves: there is no platform there that will file a report for you in July 2027. November 2026 adds no European cut-off date to this picture, which weights the two Federal Reserve meetings all the more heavily.
December 31, 2026: The First Reporting Year Under the KStTG Ends
This date is the only one in the calendar that affects every investor in Germany directly, and it arrives without an announcement on the screen. The Crypto Asset Tax Transparency Act (KStTG) transposes the European directive on administrative cooperation in its eighth version, DAC8 for short, into German law. It came into force at the end of December 2025, and the reporting obligations apply for the first time to the 2026 reporting year. That means the calendar year ending on December 31, 2026 is the first period on which trading platforms report your data to the tax administration. The providers transmit it by July 31, 2027 to the Federal Central Tax Office, which organises the exchange with the local tax offices and with other EU states. The procedure is described by the Federal Central Tax Office on its DAC8 page.
None of this changes your tax liability. Private disposals of crypto-assets remain tax-free under Section 23 of the Income Tax Act after a holding period of one year, and the exemption limit for gains within that period applies unchanged. What changes is the tax office's knowledge: from the 2026 reporting year it holds data against which your declarations can be checked.
Before New Year's Eve you should therefore settle three things. First, check the completeness of your history, especially at platforms you no longer use, because an account closed in January takes your trading data with it. Second, secure your acquisition dates, because the holding period cannot be proved without a purchase date. Third, label transfers between your own wallets as such, otherwise they look like sales in an analysis. A tool that reads in exchange data and tracks the holding periods per position takes most of this work off you; our comparison of tax tools and portfolio trackers ranks the providers by data import and report format.
How to Turn This Calendar Into a Watchlist of Your Own
A calendar of dates is only useful if it is cut to fit your holdings. The work for that is done in one evening.
Delete everything that does not concern you first. Of eighteen dates, four or five remain for most investors: the unlocks of the tokens you actually hold, the two central bank meetings and December 31. Put those dates in your phone's calendar, with a reminder three days beforehand. Three days is the period in which positioning ahead of an announced event usually builds.
Check the type on every date. With a deadline such as a token unlock you need do nothing on the day but look. With a target such as a protocol activation, a second look shortly beforehand belongs to it, because the date can move. The source for that is always the network itself: a query of the chain state or the developers' notice, not a calendar service and not a post on a social network.
And keep the magnitude in proportion. An unlock of 47.7 percent of the supply in one day is a different event from one of 1.4 percent, even if both sit on the same line of a calendar. The percentage, not the dollar figure, is the meaningful metric here, because the dollar figure fluctuates with the price and thereby tells you the same thing twice.
What Is Deliberately Missing From This Calendar
For three dates that are circulating we found no reliable source, and so they do not appear above: an expected decision by the US securities regulator on options on crypto ETFs around November 11, a date for the collectibles festival ApeFest on October 17, and the release of a game that was announced for October. They may well turn out to be right; none of them could be verified with a source we could link for you here.
Also not included are price targets. This piece names dates and magnitudes, not forecasts. Anyone promising you a price for one of the days named above does not know the market's reaction any better than you do.
Crypto Dates in Q4 2026: What to Take Away
- Check your holdings against the unlock dates. If you hold 2Z, ENA, ARB, SUI or MON, then at least one date in October or November concerns you directly. Where your tokens sit and which supervisor the platform answers to you can see in the crypto exchange comparison.
- Set two reminders for the central bank meetings. October 28 and December 9 are the two days of the quarter on which the whole market reacts at once. If you are invested through a regulated wrapper, the routes authorised in Germany are in the overview of crypto ETFs.
- Get your trading history in order before New Year's Eve. The 2026 reporting year is the first one reported on; after that a missing acquisition record can only be obtained with difficulty. The comparison of tax tools is the place to start.
(As of September 27, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
Bitcoin ETFs have drawn nearly $3 billion over seven straight sessions, erasing post-Clarity Act losses and pushing 2026 flows back into positive territory.
After the Clarity Act failed in the Senate, the SEC, CFTC, and the Fed moved within days to write crypto's rules themselves. Will it be enough?
An open competition run by StarkWare, Yukon Research, and Eigen Labs drove the estimated cost of building a quantum-safe Bitcoin transaction from about $320 to roughly $67, with AI models topping the leaderboards.
Google Vids now lets any Google account holder generate free HD AI video using Gemini Omni 1.1 Flash, with new scene, timing, and watermark controls.
Federal prosecutors are targeting a Montana payments firm and a Caribbean bank accused of moving money without a license.
U.Today - IT, AI and Fintech Daily News for You Today
Prominent tech investor Jason Calacanis has taken aim at meme coins, branding them a “giant scam.”.
Veteran trader Peter Brandt has taken another swipe at XRP’s fiercely loyal community even as his latest chart points to a potentially bullish setup for the Ripple-linked cryptocurrency.
Dogecoin’s ten-cent push returns as Elon Musk steps back into crypto spotlight.
Despite a massive +48.1% surge last quarter, price history shows XRP always hits a painful speed bump in so-called "Uptober".
XRP flashes bullish golden cross on its Bitcoin chart, with bulls now watching for what comes next.
Blockonomi
TLDR:
- Saylor proposes five core rights: create, issue, custody, transfer, and use digital assets freely.
- He sets a goal of financing 10 million new companies through faster digital token issuance.
- Saylor urges banks to custody Bitcoin and extend credit against it under clearer capital rules.
- He criticizes the CLARITY approach and projects a $100 trillion digital asset industry ahead.
Digital asset rights formed the center of Michael Saylor’s policy remarks at the Bitcoin Policy Institute’s Freedom Tech DC summit.
Saylor spoke with Conner Brown about a framework built on five freedoms. These include the right to create, issue, custody, transfer, and use digital assets.
He argued that a more productive economy, driven by artificial intelligence, needs better money and better capital markets. Growth in AI output should be matched by growth in financial access, he said.
Five Freedoms Anchor the Policy Framework
Saylor’s proposal rests on treating digital asset rights as belonging to both individuals and corporations. “Freedom starts with the ability to act,” Saylor said.
Each of the five freedoms serves a distinct purpose, from creating new financial instruments to spending and borrowing against holdings.
The framework also calls for financing structures that support new business formation. Saylor set a goal of enabling 10 million new companies to raise capital through digital tokens.
He described current issuance rules as too costly and complex for entrepreneurs without extensive legal resources. Lowering that cost, he said, would let more founders reach investors directly.
Competition among digital dollar providers formed another part of the discussion. Saylor said banks, fintech companies, and technology platforms should have a clear path to offer dollar-backed digital products.
He also argued that issuers should be permitted to compete on yield. Restrictions that favor institutions paying little interest work against customers, he said.
Bitcoin’s integration into banking and insurance drew separate attention. Saylor called for banks to custody Bitcoin and extend credit against it.
He pointed to the Basel framework’s capital treatment of cryptoasset exposures as an area needing review. Rules should reflect actual risk, he said.
Privacy, Compliance, and Regulatory Priorities
Financial privacy featured prominently in Saylor’s remarks on ordinary transactions. He proposed that lawful transactions below a meaningful threshold should not trigger routine reporting requirements.
Saylor referenced the outdated $10,000 currency-transaction threshold set in 1972 as an example needing inflation adjustment.
Portable compliance credentials also appeared as a policy recommendation. Saylor described repeated identity verification across financial counterparties as costly and inefficient for investors.
He suggested reusable, interoperable credentials could reduce onboarding costs while preserving provider responsibility for monitoring risk. Lower costs, he added, would help new firms compete for customers.
Tax treatment of everyday digital asset spending was another focus area. Saylor argued that a meaningful de minimis exemption would remove the burden of calculating gains on routine purchases. He said thresholds should scale with inflation and eliminate needless transaction-by-transaction recordkeeping.
On regulatory strategy, Saylor pointed to the SEC, CFTC, Treasury, and White House as the near-term path. He criticized the CLARITY approach for emphasizing restrictions over usefulness.
Saylor projected the digital asset industry could reach $100 trillion in value if policy expands rather than limits ownership rights.
The post Michael Saylor Outlines Five Digital Asset Rights to Power AI-Driven Economy appeared first on Blockonomi.
TLDR:
- Ethereum nodes can run on local AI computers, with Buterin’s pruned Geth setup using 461 GiB of storage on one machine.
- Snap sync and EIP-4444 reduce Ethereum’s full-node synchronization time to roughly 12 hours under described conditions.
- Ethereum still recommends a 2 TB NVMe drive, giving node operators additional storage headroom as the blockchain grows.
- Local nodes do not guarantee wallet privacy because applications may still route requests through commercial RPC providers.
Vitalik Buterin says his pruned Geth node occupies 461 GiB, showing how local AI hardware can also support Ethereum nodes. Enthusiasts buying computers for local large language models already receive fast NVMe drives and ample storage.
That overlap eases hardware demands and lets operators check network data directly rather than relying on third-party RPC providers. The 461 GiB figure reflects one setup, while client selection, pruning settings, and Ethereum network growth can alter storage needs.
Ethereum Nodes Fit Within Some Local AI Systems
High-performance desktops built for local AI workloads often include powerful graphics cards and large NVMe drives. Examples include systems using NVIDIA RTX 5090 cards and compact AI workstations such as the DGX Spark.
Those machines need storage for large language model weights and related files. The same capacity can support a pruned database, letting users run AI workloads and an Ethereum node on one computer.local
This overlap lets home computers act as independent verification points rather than terminals that depend on cloud infrastructure. A setup gives operators chain data and a way to check information against the network.
Faster Synchronization Reduces the Setup Burden
Buterin linked the shorter setup time to optimizations in Geth’s snap sync process and work related to EIP-4444. Under the conditions he described, a full node can synchronize in roughly 12 hours.
Snap sync lets Geth obtain a recent network state without replaying every earlier state. Pruning removes older data that a standard full node need not retain, reducing locally stored information.
This combination reduces both the download and processing work required during synchronization. It also means operators can begin using a local Ethereum node sooner under the conditions described by Buterin.
The shorter synchronization period changes the practical experience for new operators. Users can reach a local setup faster, while AI hardware provides the processing and storage for the initial download.
Existing high-end AI workstations can therefore support independent blockchain verification alongside local model workloads.
Ethereum Storage Guidance Still Allows Extra Headroom
The 461 GiB figure describes Buterin’s configuration, not a fixed requirement for every operator. Different clients, settings, and future blockchain growth can change the amount of storage a node requires.
Readers should therefore treat the figure as a current example of a pruned setup. It shows one configuration, but it does not replace Ethereum’s hardware guidance for longer-term installations.
Ethereum’s general guidance still recommends a 2 TB NVMe drive. That capacity gives operators more room than the pruned setup uses and delays immediate hardware changes as the chain grows.
That extra capacity can accommodate future client growth without immediately replacing the drive.
The lower current footprint nevertheless makes home verification more accessible for owners of suitable computers. Instead of only querying remote services, these users can check blockchain data through infrastructure they operate themselves.
That distinction also gives AI hardware a second use between model runs. The computer can support local applications while maintaining the files and processes needed for independent blockchain verification.
Local Nodes Do Not Remove Every Privacy Concern
Running a node locally does not guarantee that wallet activity stays private. A wallet or application can still send requests through a commercial RPC provider, exposing information about addresses and transactions.
Buterin has linked those concerns to work on Kohaku tools and command-line wallets. The wallet software and connection method therefore remain important for users seeking more direct control over their data.
Kohaku focuses on Ethereum wallet tools, while the experimental command-line wallet targets private balances. These efforts address the application layer, while the node supplies local blockchain data.
The planned Glamsterdam upgrade is expected to accelerate synchronization further at Ethereum’s base layer. Its development could reduce setup and maintenance time for individual node operators.
The post Vitalik Buterin Says AI Boom Makes Ethereum Nodes Easier at Home appeared first on Blockonomi.
TLDR:
- UNI price trades near $9.61 after a quarterly breakout, while $12.30 marks the next major hurdle on the daily technical chart.
- Tokenized stocks generated $20.9 billion in DEX volume over 30 days, with Uniswap v4 and v3 processing a combined 60.1% share.
- Uniswap v4 led tokenized-stock DEX trading with a 40.7% share, while Uniswap v3 ranked second at 19.4% during the period.
- Holding $9.33 could support another UNI test of $9.93, while a breakdown would place $8.37 and deeper support back in focus.
The UNI price traded near $9.61 on September 26 after a third-quarter advance reshaped the token’s structure. Market data showed a modest pullback as buyers defended the $9.33 support area. The move followed a rally from $2.35 to $10.85 during the quarter. That advance broke a descending triangle that had contained the token since its 2021 peak.
Meanwhile, Token Terminal reported $20.9 billion in tokenized-stock DEX volume over 30 days. Uniswap v4 led that market with 40.7%, while v3 captured 19.4%. Their combined 60.1% share adds a usage measure to UNI’s price setup.
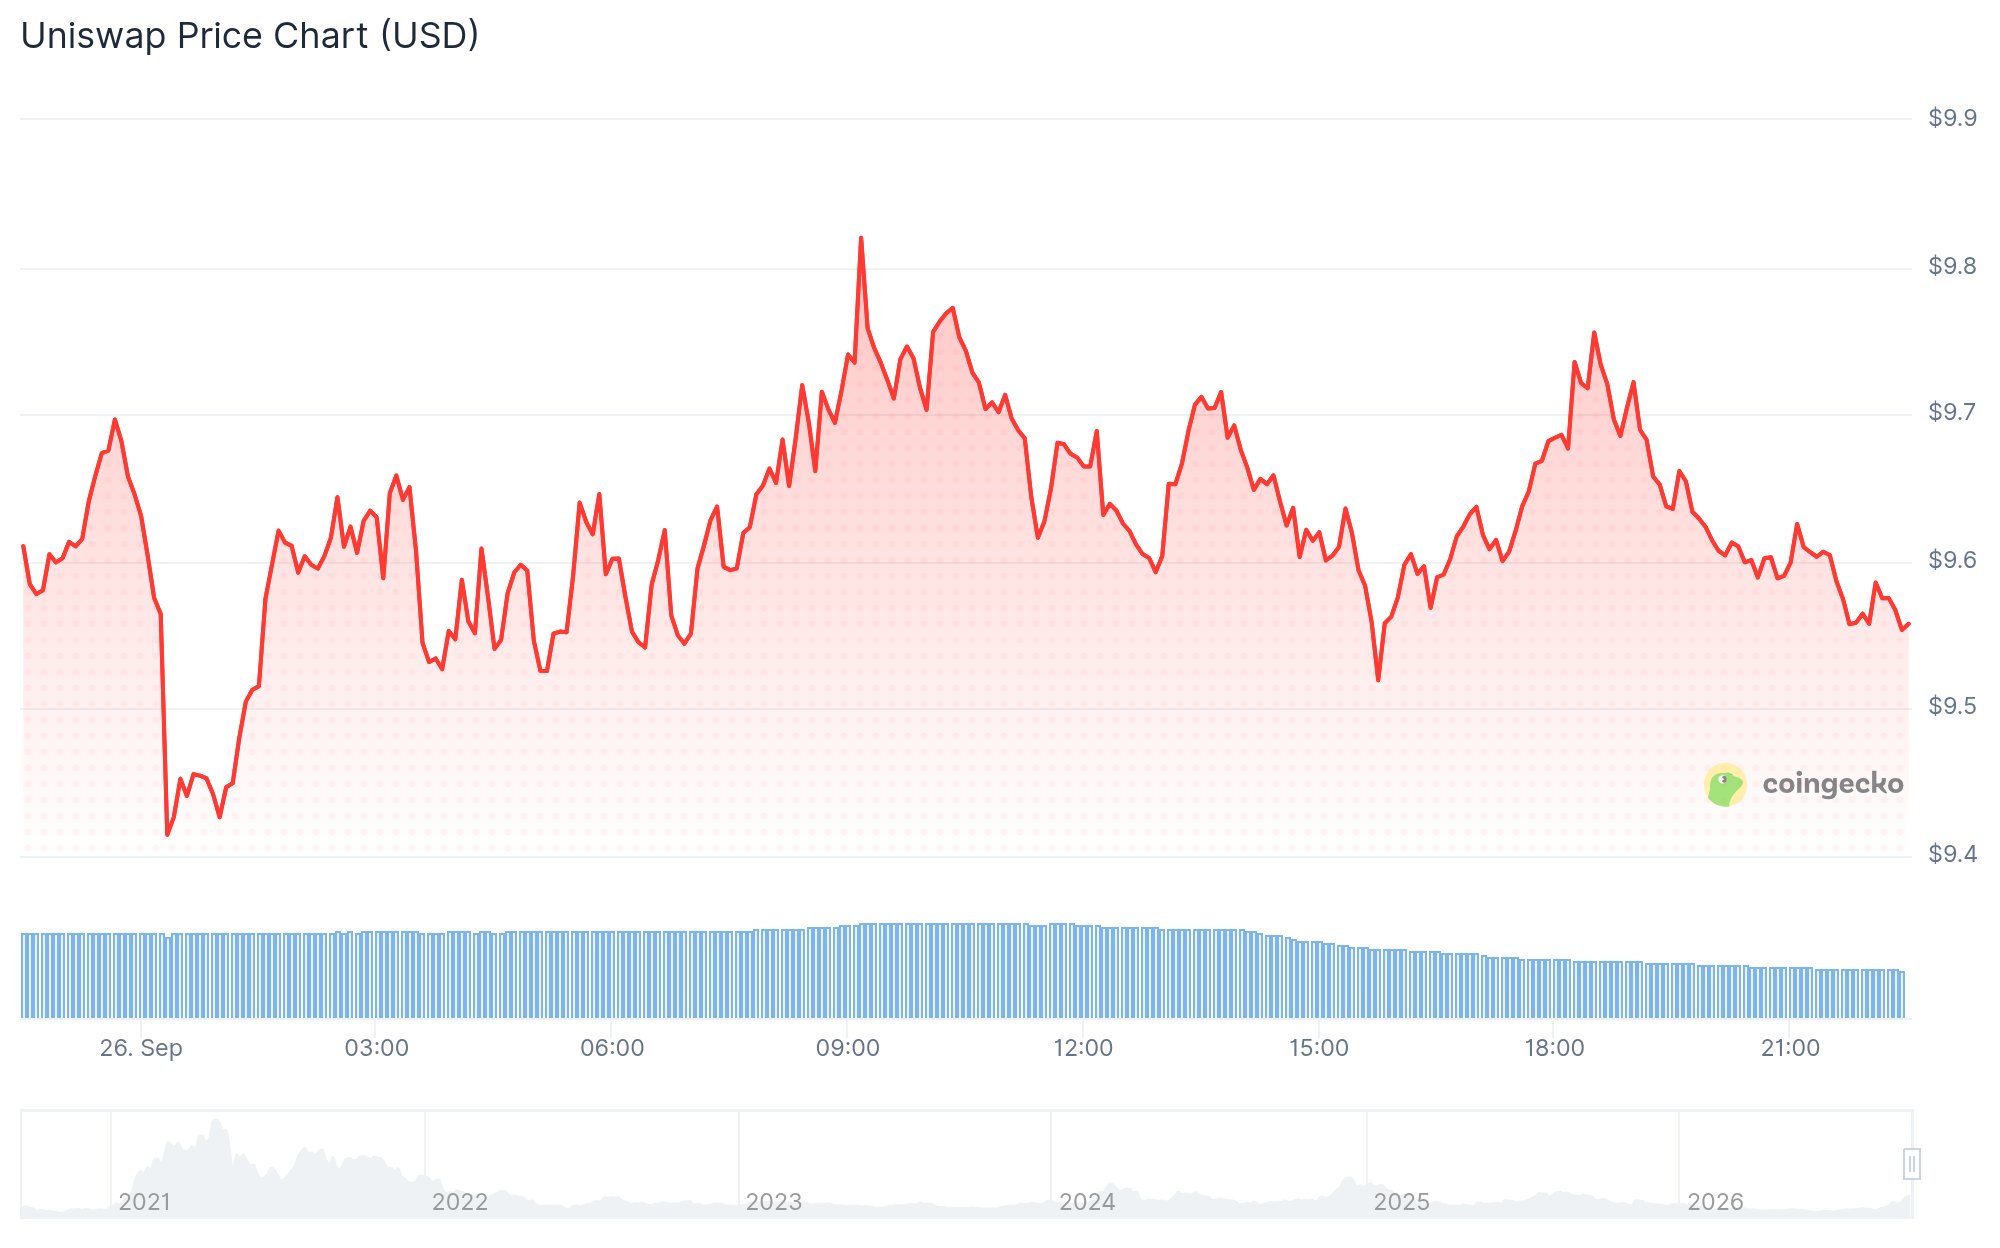
UNI Price Holds Its Breakout Below the $12.30 Hurdle
The Q3 move changed a structure that had restricted UNI. UNI price cleared the triangle and reached $10.85 before sellers slowed the advance. That breakout separates the range from the decline that followed the $45 peak in 2021.
UNI price must first hold the nearer support levels before challenging the larger targets. Market data places immediate support at $9.33 and short-term resistance near $9.93. A move through $9.93 would reopen the path toward the recent swing high. Failure to defend $9.33 could expose $8.37.
The daily chart identifies $12.30 as the next major hurdle above that short-term range. Buyers would need a sustained move above this area to strengthen the breakout structure. The next chart levels stand at $15.10 and $17.50 if $12.30 becomes support.
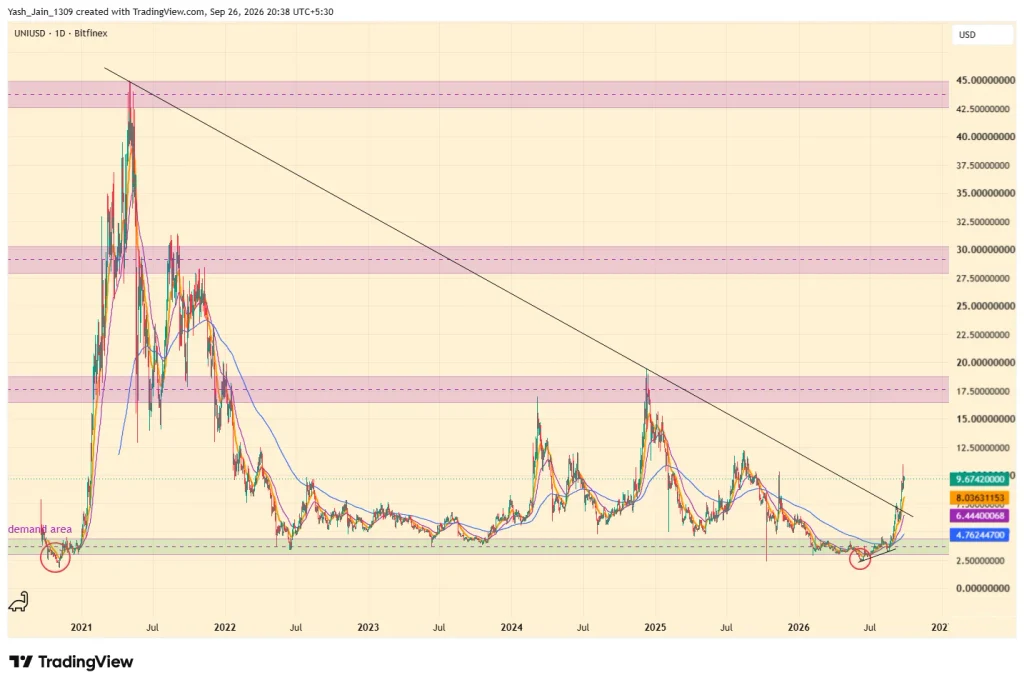
Momentum also cooled after the sharp rise, which reduces the strength of immediate continuation signals. UNI price therefore sits between a confirmed quarterly breakout and unresolved short-term resistance. The next directional move depends on whether buyers protect $9.33 and regain $9.93.
The September 30 PCE inflation report is a scheduled macro event for crypto markets. Changing rate expectations could influence volatility around UNI’s established chart levels.
Tokenized Stock Trading Strengthens Uniswap Activity
Protocol usage provides a separate measure from the token’s technical setup. Token Terminal said tokenized stocks produced $20.9 billion in decentralized exchange volume during the latest 30-day period. Uniswap v4 accounted for 40.7% of that trading, making it the largest venue version in the dataset.

Uniswap v3 contributed another 19.4%. Together, both versions processed 60.1% of tokenized-stock DEX volume. The figures show that activity spans two generations of Uniswap infrastructure rather than one isolated deployment.
A different Ethereum market-share comparison also shows growth for Uniswap v4. Its share reached 50% across Uniswap v2, v3, v4, and Curve, up from 31% in August 2025. V4 held the leading monthly position from March 2026 through the latest reading.
Uniswap v2 moved in the opposite direction. Its share fell from 5% to below 1% over the same period. That shift indicates trading activity migrated toward newer pool architecture as v4 gained adoption.
The two percentages measure different markets. The 40.7% figure covers tokenized-stock DEX volume, while the 50% reading covers the selected Ethereum DEX group. Keeping those datasets separate avoids overstating Uniswap v4’s share across all decentralized trading.
Rising protocol activity does not set a fixed value for UNI. However, it gives traders another operating metric beside chart momentum. The UNI price still needs to clear $9.93 before the market can test the broader $12.30 threshold.
If sellers force a break below $9.33, the short-term setup would weaken despite Uniswap’s volume share. The next support sits at $8.37, followed by the wider breakout zones near $8.25 and $6.35. Defending $9.33 would preserve the immediate range and keep $9.93 as the recovery level.
The post UNI Price Holds Breakout as Stock Token DEX Volume Reaches $20.9B appeared first on Blockonomi.
TLDR:
- Bitcoin ETFs attract $2.4 billion for the strongest week since October 2025, turning 2026 net flows positive at $934.1 million.
- BlackRock’s IBIT leads issuers with $1.2 billion, while Fidelity’s FBTC adds $701.7 million and ARKB receives $294.7 million.
- Ether ETFs reverse a $140 million outflow with $689.9 million in inflows, taking 2026 net additions to about $1.6 billion.
- Solana ETFs register a record $86.7 million inflow as weekly demand reaches $188.2 million and assets rise to $1.5 billion.
U.S. Bitcoin ETFs drew $2.4 billion in net inflows during the week ending Sept. 25. That marks their strongest weekly result since October 2025. The demand pushes their 2026 flow total back above zero. According to SosoValue data, the year-to-date inflows now reach about $934.1 million, reversing a deficit that stood near $5.8 billion two months earlier, in mid-July.
Monday provides the week’s largest daily share with a $999 million inflow. Daily additions then slow through Friday, but the funds extend their streak to seven sessions. Ether ETFs reverse the previous week’s outflow, while Solana ETFs record their largest single-day intake since their October 2025 launch.
Bitcoin ETFs Extend Seven-Day Inflow Streak to $3 Billion
The 12 Bitcoin ETFs collect $714.7 million on Tuesday after Monday’s near-billion-dollar opening. They add $347 million on Wednesday, $190.6 million on Thursday, and $134.5 million on Friday. That sequence takes the seven-session run, which starts September 17, to $3 billion.
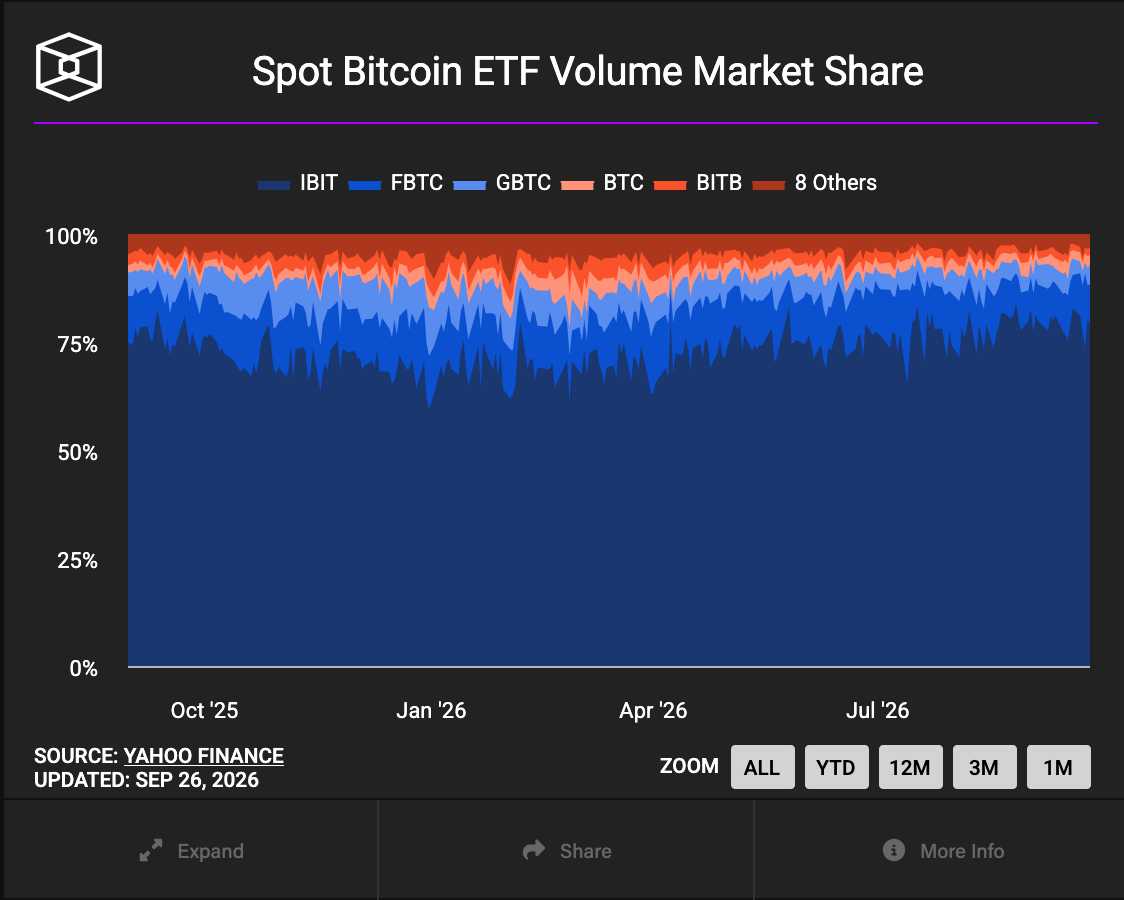
The prior week brings Bitcoin ETFs only $6.2 million, despite a $433 million Friday addition. Monday’s $999 million total ranks as the ninth-largest daily intake since these products launched in January 2024. It also marks their largest daily result since October 6, 2025. Each session records inflows.
BlackRock’s IBIT leads weekly demand with $1.2 billion, its second-largest weekly intake since October 2025. Fidelity’s FBTC follows with $701.7 million, its best result since the week of September 8, 2025. Ark and 21Shares’ ARKB receives $294.7 million, with most arriving during Monday’s session.
Morgan Stanley’s MSBT adds $203.3 million, setting a weekly record since its April debut. Its previous high was $71.1 million in mid-April. These allocations spread demand beyond the two largest funds, although IBIT and FBTC still account for most of the total.
Bitcoin ETFs hold $108.4 billion in net assets by Friday. Bitcoin ETFs’ cumulative inflows reach $57.6 billion since launch. Weekly trading volume falls to $15 billion from $16.2 billion, even as subscriptions rise. The funds therefore attract more new capital during a week with less secondary-market turnover.
The latest run follows the Treasury Department’s plan to increase buybacks of long-dated bonds. Market commentary links $5.3 billion in Bitcoin ETF inflows since the Treasury announcement to the buyback plan. The timing provides liquidity context for the reversal, although fund data do not establish a single cause.
Ether and Solana ETFs Record Strong Weekly Inflows
Ether ETFs collect $689.9 million during the week after losing about $140 million in the prior period. Monday brings $270 million, their strongest daily result since October 7, 2025. Daily additions then range from $66 million to $162.3 million across the next four sessions.

BlackRock’s ETHA leads with $326.2 million, while Fidelity’s FETH attracts $174 million. Grayscale’s Ethereum Mini Trust adds $100.3 million. BlackRock’s ETHB receives $47.5 million, including $31.9 million on Friday.
Ether ETFs now show about $1.6 billion in net inflows for 2026. Net assets reach $17.8 billion, while cumulative inflows since launch stand at $13.9 billion. Weekly trading volume declines to $4.8 billion from $6.9 billion.
Solana ETFs take in a record $86.7 million on Friday, their largest daily inflow since launching in late October 2025. Bitwise’s BSOL supplies $55.7 million, or about 64% of that amount. Weekly inflows reach $188.2 million, trailing only the products’ $199.2 million launch week.
Friday’s record closes a week that finishes $11 million below the launch-period peak. Combined fund assets rise by $300 million, or about 25%, across the same period. That increase takes the group from $1.2 billion to a record $1.5 billion. BSOL holds about 71% of those assets.
Spot XRP ETFs add $75.6 million for the week. Grayscale’s Zcash fund briefly crosses $1 billion in net assets on Thursday, expanding the week’s inflows beyond Bitcoin, Ether, and Solana products.
The post Bitcoin ETFs Turn Positive in 2026 After $2.4B Weekly Inflow appeared first on Blockonomi.
Key Highlights
- The Dow Jones Industrial Average surged 479 points on Friday, marking a 0.9% increase, while both the S&P 500 and Nasdaq advanced 0.5%
- Major equity indexes secured positive weekly performance despite mid-week market turbulence
- The benchmark 10-year Treasury yield climbed to its highest point since 2007, moderating slightly by Friday’s close
- Crude oil markets declined following diplomatic developments regarding the Strait of Hormuz
- Market pricing indicates better than 60% probability of a Federal Reserve rate increase in October
U.S. stocks finished Friday’s session in positive territory, capping off a tumultuous week of trading on Wall Street. The advance occurred despite Treasury yields climbing to heights unseen in nearly two decades.
The Dow Jones Industrial Average advanced 479 points, representing a 0.9% gain, settling at 51,829. Both the S&P 500 and Nasdaq Composite registered approximately 0.5% increases.
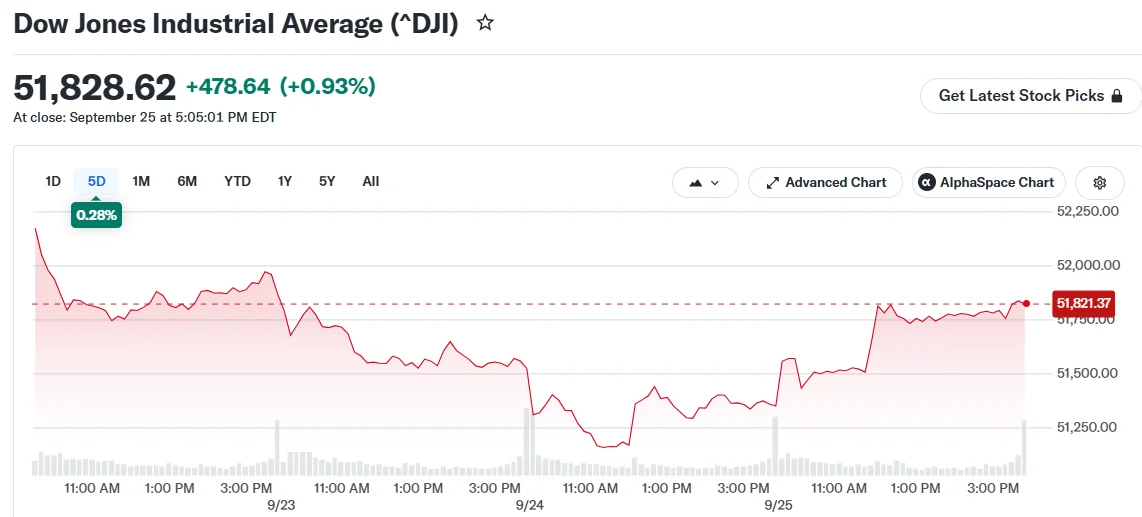
On a weekly basis, the Dow posted a 0.3% advance. The S&P 500 recorded a 1.2% gain, while the Nasdaq climbed 2%, successfully recovering from midweek losses.
Among individual movers, Akamai Technologies stood out with a notable 3% rally following its announcement of an extended partnership agreement with Anthropic.
Meta Platforms delivered impressive weekly performance, surging nearly 13% as investors reacted enthusiastically to the company’s latest artificial intelligence initiative, Muse.
Treasury Market Turbulence Shakes Investor Confidence
Fixed income markets experienced significant fluctuations throughout the week. The benchmark 10-year Treasury yield climbed to its loftiest level since 2007, briefly touching 5.228% before moderating.
By Friday’s close, it stood at 5.18%, marking a new 19-year peak. The 30-year Treasury yield finished at 5.5%, having breached that threshold for the first time in over two decades.
Meanwhile, the two-year yield declined modestly, settling at 4.862%.
Several catalysts have propelled yields higher. Among them are aggressive rhetoric from Federal Reserve policymakers, elevated energy costs stemming from Middle Eastern tensions, and purchasing managers data that exceeded forecasts.
Current Fed funds futures pricing suggests approximately 64% to 66% odds of a rate increase next month. Market participants are anticipating three additional quarter-percentage-point increases through the conclusion of 2027.
Crude Markets Retreat on Diplomatic Progress
Oil prices declined throughout the week following indications that American and Iranian officials were exploring an agreement to resume normal operations through the Strait of Hormuz. Iranian representatives have reportedly requested a return to terms outlined in a June memorandum of understanding.
West Texas Intermediate crude declined 2.33%, finishing at $92.41 per barrel. Brent crude, the global pricing standard, dropped 2.14% to close at $104.32 per barrel.
Market participants also monitored ongoing diplomatic engagement between Washington and Beijing during Chinese President Xi Jinping’s American visit.
Treasury Secretary Scott Bessent indicated that both nations had reached consensus on a two-month extension of their existing trade agreement. Additional specifics regarding the negotiations are anticipated in the near term.
Friday brought fresh consumer sentiment figures from the University of Michigan. The September index weakened from previous levels but exceeded initial projections.
The report revealed elevated inflation expectations among consumers across both near-term and extended timeframes. This development presents another consideration for Federal Reserve officials as they deliberate future monetary policy.
Market observers remain divided on the implications. Some warn that persistently elevated yields could ultimately pressure equity valuations and economic expansion. Others point to the economy’s demonstrated durability thus far.
Looking forward, market participants will remain focused on Treasury yields, energy prices, and trade negotiations for signals on market direction.
The post Stock Market Rallies Despite Treasury Yields Hitting Multi-Decade Highs appeared first on Blockonomi.
HTTP error 429 on https://cryptopotato.com/feed/
Failed to fetch feed: https://cryptopotato.com/feed/
Failed to fetch feed.