Cryptocurrency Posts
Crypto Briefing
The attack highlights the critical need for robust security measures and timely updates to prevent large-scale cryptocurrency thefts.
The post D’CENT app wallet attack drains 12.4M XRP from thousands of users over 10-day spree appeared first on Crypto Briefing.
Tesla's ambitious robot production could redefine its market role, but supply chain challenges may impact timelines and investor confidence.
The post Tesla ramps up Optimus humanoid robot production tenfold, faces ‘extremely challenging’ supply chain hurdles appeared first on Crypto Briefing.
Jev's rise highlights a shift towards specialized, cost-effective AI solutions, emphasizing speed and efficiency over complexity.
The post Jev gains popularity as a faster, cheaper alternative to major AI models appeared first on Crypto Briefing.
The surge in communications equipment orders highlights the critical role of AI infrastructure in reshaping tech investment priorities.
The post Communications equipment new orders rise 40% year over year amid AI infrastructure boom appeared first on Crypto Briefing.
Kuwait's UN accusations against Iran could heighten regional instability, affecting Iran's political climate and market perceptions.
The post Kuwait accuses Iran of illegal aggression at UN amid regional tensions appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Mitchell Askew Explains What 15M Inactive BTC Means for Bitcoin’s Next Move
Bitcoin is rallying despite a Fed rate hike and the failure of the Clarity Act, and the on-chain data suggests sellers may be nearly exhausted. Mitchell Askew, Head of Blockware Intelligence, breaks down long-term holder supply, which hit an all-time high of 15 million BTC this summer. He explains why so many coins sitting still signals more room for price to run. He also shares what Bitcoin ETF flows reveal about institutional buyers returning to the market.
Chapters:
0:00 Mitchell Askew of Blockware Intelligence on Bitcoin’s Rally
0:22 Is Bitcoin Selling Pressure Exhausted? Long-Term Holder Supply
1:36 Bitcoin ETF Flows & Returning Institutional Buyers
2:36 Why the Four-Year Halving Cycle Is Breaking
4:06 AI Data Centers Pulling Compute Away From Bitcoin Mining
5:56 The Hash Rate Bear Market: Should Bitcoiners Worry?
6:58 Stranded Energy, Global Mining & AI Data Center Arbitrage
8:12 Why Gen Z Isn’t Buying Homes
9:58 Will Gen Z Ever Save in Bitcoin?
11:26 Shallower Drawdowns & the Future of Bitcoin Cycles
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Mitchell Askew Explains What 15M Inactive BTC Means for Bitcoin’s Next Move first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Nearly $352M Moved From Crypto Exchange Bitget Wallets in Suspected Hack
An estimated $351.6 million in crypto has been moved from digital asset exchange Bitget’s hot wallets in a suspected hack.
The platform’s CEO said in a Thursday statement that Bitget’s security team activated an emergency response when the movements were detected. Blockchain security firms had flagged the issue earlier in the day.
“At 18:31 UTC on September 24, 2026, Bitget’s security systems detected unauthorized transfers from some of our hot wallets,” Bitget CEO Gracy Chen wrote on X. “Our security team activated emergency response protocols immediately.”
She added: “Bitget has navigated multiple market cycles. We will not run from this. Every dollar and every decision will be accounted for, transparently and in full.”
Victoria, Seychelles-based Bitget is the sixth biggest exchange, processing over $1.1 billion in trading volume per day, according to CoinGecko data.
The incident comes as crypto security is in the limelight after a string of breaches this year have the community reeling. Just in July, hackers targeted a firmware bug in the popular bitcoin hardware wallet, Coldcard, to steal nearly $120 million in user funds.
And this month, purported white-hat hackers withdrew about 4,000 bitcoins — worth about $320 million at the time — from Blockstream’s Liquid sidechain’s federation wallet.
Chen added that the exchange’s cold wallets remained fully secure and that user funds were safe.
She wrote: “Bitget operates a three-tier wallet architecture — the breach contained only a portion of the hot wallet and warm wallet layers.”
According to the statement, deposits and trading remain fully operational but withdrawals are temporarily paused until a security review is complete.
Blockchain data firm Arkham Intelligence created a dashboard soon after the unauthorized transfers showing that a number of different cryptocurrencies — including stablecoins — had been moved from the Bitget hot wallet.
While Bitcoin was not on Arkham’s list, crypto security firm Hacken later said on X that the largest cryptocurrency had been moved.
This post Nearly $352M Moved From Crypto Exchange Bitget Wallets in Suspected Hack first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
New York Sues Polymarket, Calling Prediction Market an Illegal Gambling Operation
New York Attorney General Letitia James and Governor Kathy Hochul on Thursday filed a lawsuit against crypto-based prediction market Polymarket, accusing the platform of running an unlicensed gambling operation in the state.
An investigation by the Attorney General’s office concluded that these markets meet New York’s legal definition of gambling because users stake money on uncertain outcomes they cannot control.
Polymarket never obtained a license from the New York State Gaming Commission, the suit alleges, and so avoided the taxes that licensed casinos and mobile sportsbooks pay. That revenue helps fund public schools, youth sports programs and problem gambling treatment.
The suit comes as regulators like the Securities and Exchange Commission and the Commodity Futures Trading Commission are working to regulate crypto-powered prediction markets.
Polymarket and rival Kalshi argue they aren’t gambling sites at all, but rather federally regulated exchanges offering “event contracts,” a type of derivative, which would put them under the Commodity Futures Trading Commission rather than state gaming laws.
The CFTC agrees, and it has joined the fight on the platforms’ side. In 2026 it sued nine states, arguing that it should have exclusive nationwide authority over the industry.
Thursday’s complaint also says the platform is open to users aged 18 to 20, although New York requires mobile sports bettors to be at least 21.
“By skirting New York’s laws, Polymarket is targeting the most vulnerable,” James said. Hochul added that the company had “knowingly” violated state law and put underage users at risk.
The state is asking a court to bar Polymarket from operating as an unlicensed gambling business in New York. It also wants the company to forfeit its illegal gains, repay harmed users and pay fines equal to three times those gains.
The lawsuit is the latest in a string of New York actions against gambling-adjacent platforms. James and Hochul sued rival prediction market Kalshi in July, and James sued Coinbase and Gemini in April over similar claims. Earlier this month, James secured $8 million from the leading operator of sweepstakes casinos.
Polymarket launched in the United States in December 2025, initially letting users bet on sporting events with plans to expand into markets on a wide range of topics.
This post New York Sues Polymarket, Calling Prediction Market an Illegal Gambling Operation first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
SEC Commissioner Hester ‘Crypto Mom’ Peirce Advocates Privacy-Preserving Tech
Outgoing Securities and Exchange Commission Commissioner Hester Peirce has said that regulators should rethink how they monitor the financial system, and to press for less personal data collection, not more.
In a speech Wednesday focusing on digital identity systems and decentralized networks, Peirce took aim at know-your-customer and anti-money-laundering rules.
U.S. regulators are now racing ahead with crypto rulemaking. Peirce, who earned the nickname “crypto mom” for her friendly approach to watchdogging the space, is set to leave the SEC in November.
“Today society is at a crossroads,” Peirce said at the SIFMA’s Digital Assets Conference in New York.
“Down one path lies the status quo: more data collection, more intermediary surveillance, more ‘know your customer’ requirements that turn our financial rails into a panopticon.”
“Down the other path lies an opportunity to use new technologies to improve our ability to catch criminals while collecting less personal information than ever before, and monitoring more sparingly to protect Americans’ privacy.”
Peirce argued that piling up ever more data on law-abiding customers to help find criminals doesn’t work. In her view, bigger “haystacks” make the needles harder to find, while every stored data point raises the risk of leaks or misuse.
She criticized a regulatory mindset fixated on “data go up,” comparing it to crypto enthusiasts’ obsession with rising prices.
Peirce pointed to cryptographic tools such as zero-knowledge proofs and attribute-based credentials, which can confirm facts like a person’s age, accredited-investor status, or absence from sanctions lists without revealing the underlying personal details.
She also urged the SEC to let firms rely on identity checks already performed by other regulated institutions, rather than making every firm collect and store the same sensitive information.
Under President Joe Biden, the SEC was tough on the crypto space, with its Biden-appointed former Chair Gary Gensler frequently suing major crypto companies for allegedly selling unregistered securities.
Peirce was appointed to lead the Crypto Task Force in 2025. The regulator has taken a far more friendly approach to watchdogging the space since Donald Trump became president again.
Now, regulators are saying they want to create clear rules for the fast-moving industry, despite landmark legislation, the Clarity Act, being blocked last week.
Despite Commissioner Peirce’s alias, she previously said she would not describe herself as an advocate of the industry, but rather a “freedom maximalist.”
This post SEC Commissioner Hester ‘Crypto Mom’ Peirce Advocates Privacy-Preserving Tech first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Jeff Booth: Why $1 Million BTC is Thinking too Small
Is a $1 million Bitcoin price target thinking too small? Jeff Booth thinks so, and he explains why valuing Bitcoin in dollars means pricing it from a game that’s rigged by debasement. He argues that Bitcoin isn’t just a coin or an asset, but the beginning of a decentralized, secure, and private protocol stack that will look a lot like the internet. In his view, Bitcoin is evidence of the first free market that has ever existed.
Chapters:
0:00 Jeff Booth, The Price of Tomorrow & Technological Deflation
0:30 AI Valuations & Why Free Markets Push AI Prices Toward Zero
1:29 AI Deflation vs the Debt-Based Monetary System
2:38 $40 Trillion US Debt, Bond Yields & the $350 Trillion Insolvent System
4:06 AI Singularity Claims, Fear & Monopoly Regulation
6:50 Productivity & Bitcoin’s True Value in a Deflationary Future
8:43 Why a $1 Million Bitcoin Price Target Is Thinking Too Small
10:11 Bitcoin Adoption Timeline & Why Bitcoin Isn’t Just an Asset
12:38 Bitcoin Payments & Circular Economies Scaling Worldwide
13:49 Bitcoin-Backed Private Equity & Owning Businesses Forever
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Jeff Booth: Why $1 Million BTC is Thinking too Small first appeared on Bitcoin Magazine and is written by Patrick Green.
CryptoSlate
US on-highway diesel climbed to $6.529 a gallon on Sept. 21, up 24.4 cents in a week, according to the Energy Information Administration. The rise raises a freight-cost inflation risk for Bitcoin investors watching how long interest rates stay elevated. Because EIA had called the lower Sept. 14 price a record in nominal dollars, the newer, higher reading marks another nominal high. The record describes the dollar price at the pump, without an inflation adjustment.
The fuel buffer also narrowed. EIA data put US distillate stocks at 107.431 million barrels in the week ended Sept. 18, down from 107.859 million barrels a week earlier. The agency published the stock reading on Sept. 23. The inventory decline adds to evidence of constrained supply. EIA also identifies global distillate and crude markets as drivers of the price rise.
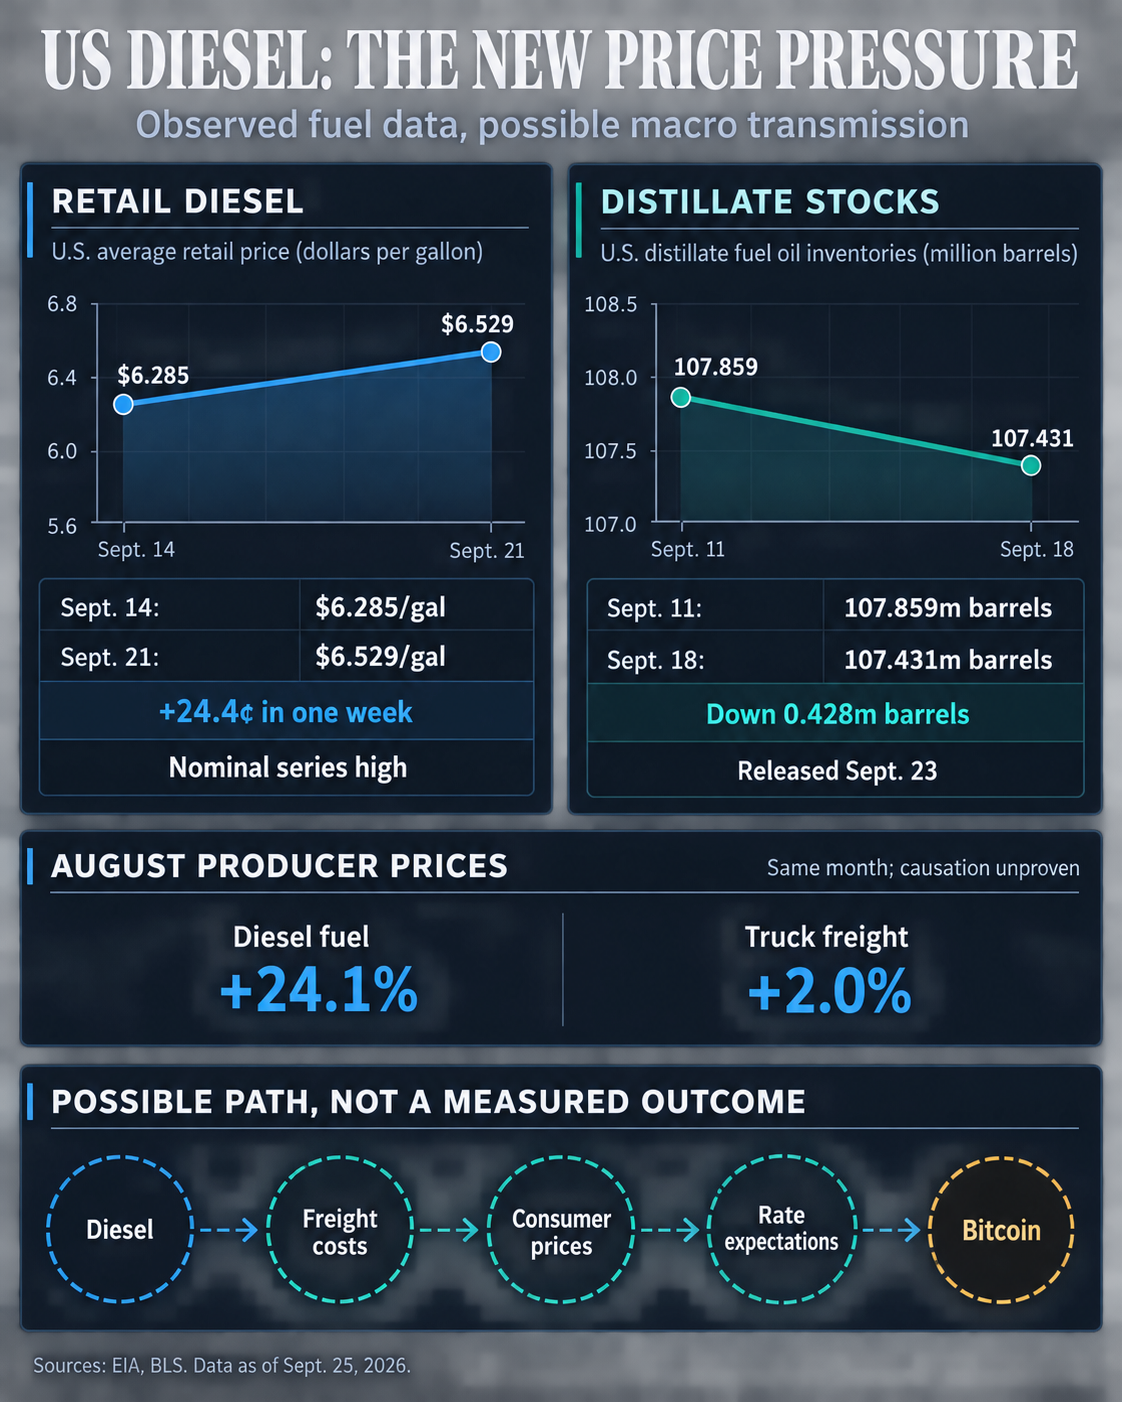
EIA attributes the recent diesel surge to tight global distillate supply and elevated crude prices. Diesel powers freight movement, and the agency says high prices can contribute to higher road and rail shipping costs. Whether companies pass those costs to customers, and how quickly, depends on contracts, competition and the duration of the fuel squeeze. A sustained rise across freight billing cycles would pose a larger inflation risk than one expensive week at the pump.
Earlier producer data show why the channel is worth watching. BLS reported that diesel fuel producer prices jumped 24.1% in August from July, while its truck freight transportation price index rose 2.0%. The two increases occurred before the latest retail diesel record. Together the indexes show upstream price pressure in August. The data leave the cause of the freight increase and any consumer-price effect unsettled.
The possible Bitcoin effect runs through inflation and interest-rate expectations. If sustained fuel and freight costs keep broader inflation firm, investors could expect the Fed to hold rates higher for longer, weighing on assets sensitive to financing conditions. The Fed raised its target range to 3.75%–4% on Sept. 16, citing elevated inflation. The decision preceded the Sept. 21 diesel reading, and the Fed's statement cited elevated inflation broadly. Bitcoin's response to this particular diesel move remains to be seen.
The latest consumer price report covers August, before the new diesel high; the CPI rose 0.4% from July. The next releases will offer a more relevant test. BLS schedules September CPI for Oct. 14 and producer prices for Oct. 15. BEA schedules September Personal Income and Outlays, including PCE price data, for Oct. 29. If diesel eases or freight and consumer prices show little pass-through, the case for a lasting inflation impulse weakens.
The post Bitcoin faces a new inflation test after diesel hits a nominal $6.53 record appeared first on CryptoSlate.
US Securities and Exchange Commission (SEC) Commissioner Hester Peirce wants financial firms to stop stockpiling customer data after breaches exposed the cost of mandatory identity collection.
This week, the SEC Commissioner called for wider use of reusable digital credentials that could establish facts about customers without requiring every financial institution to collect the underlying personal information again.
According to her:
“Today society is at a crossroads. Down one path lies the status quo: more data collection, more intermediary surveillance, more “know your customer' requirements that turn our financial rails into a panopticon. Down the other path lies an opportunity to use new technologies to improve our ability to catch criminals while collecting less personal information than ever before, and monitoring more sparingly to protect Americans’ privacy.”
Her remarks follow recent security incidents at major financial platforms like Revolut that exposed identity documents, addresses, and other information these companies collect to meet customer-verification and anti-money-laundering requirements.
Peirce said regulators should reconsider whether institutions need particular pieces of information or merely need confirmation of the facts those records establish. Attribute-based credentials, she said, could prove whether someone meets an age requirement, holds a particular citizenship or appears on sanctions lists without revealing information such as their name, income or address.
“Does more than one firm need to collect it?” Peirce asked, arguing that technology already exists to reduce the information customers surrender and the number of institutions that receive it. She said the remarks represented her own views rather than those of the SEC.
The question is becoming more consequential as Washington builds a new compliance regime for stablecoins.
The GENIUS Act requires permitted payment stablecoin issuers to maintain customer-identification programs, and regulators are proposing rules that would continue requiring covered issuers to obtain and retain identifying information from customers.
Breaches turn KYC records into targets
Coinbase provided one of the clearest examples of the risk last year.
Attackers bribed contractors or employees working in overseas customer-support roles to obtain information from the exchange's internal systems. Coinbase later disclosed that 69,461 customers were affected.
The compromised information included names, addresses, phone numbers, email addresses, partial Social Security numbers, government-issued identification images, account balances and transaction histories. Passwords and private keys were not stolen, but Coinbase warned that the information could be used in social-engineering attacks against customers.
Chief Executive Officer Brian Armstrong then turned the breach into an argument against how much information financial companies are required to retain.
“We don't want to collect it, and our customers hate it,” Armstrong said while calling for lawmakers to reconsider the Bank Secrecy Act and anti-money-laundering requirements.
He also argued that Congress should review the laws or they should face a constitutional challenge, a position that goes considerably further than Peirce's proposal to change how required information is collected and verified.
The problem resurfaced this month at Revolut through a different route.
The fintech company said an unauthorized party used a legitimate government-agency email domain to send fraudulent information requests.
Revolut disclosed customer information in response, including identity and contact details and copies of passports and driver's licenses. Depending on the customer, the material could also include verification selfies, account statements, and transaction histories. Revolut said its systems and customer funds were unaffected.
The episodes illustrate the vulnerability Peirce is targeting: once institutions accumulate identity records, stealing money does not require breaching private keys or directly compromising financial accounts. Personal information can itself become an asset for extortion, impersonation, and subsequent attacks.
Stablecoin rules preserve the collection model
The policy challenge is that US regulators are simultaneously extending customer-identification requirements to another part of the financial system.
Under the proposed GENIUS Act implementation, a permitted payment stablecoin issuer would generally have to obtain a customer's name, date of birth or formation, address, and identification number before opening a covered account.
The identifying information would then be retained for five years after the account closes, while records describing verification methods and results would generally remain for five years after they are created.
The requirement does not cover every person who receives or holds a stablecoin. It targets customers establishing covered relationships with issuers, including relationships involving direct issuance or redemption.
Regulators say the requirements implement Congress's direction that permitted stablecoin issuers be treated as financial institutions under the Bank Secrecy Act and maintain effective customer-identification programs designed to combat money laundering, terrorist financing and other illicit activity.
The proposal already leaves some room for technology. An issuer may use digital credentials as part of identity verification and, under specified conditions, rely on procedures performed by another regulated financial institution.
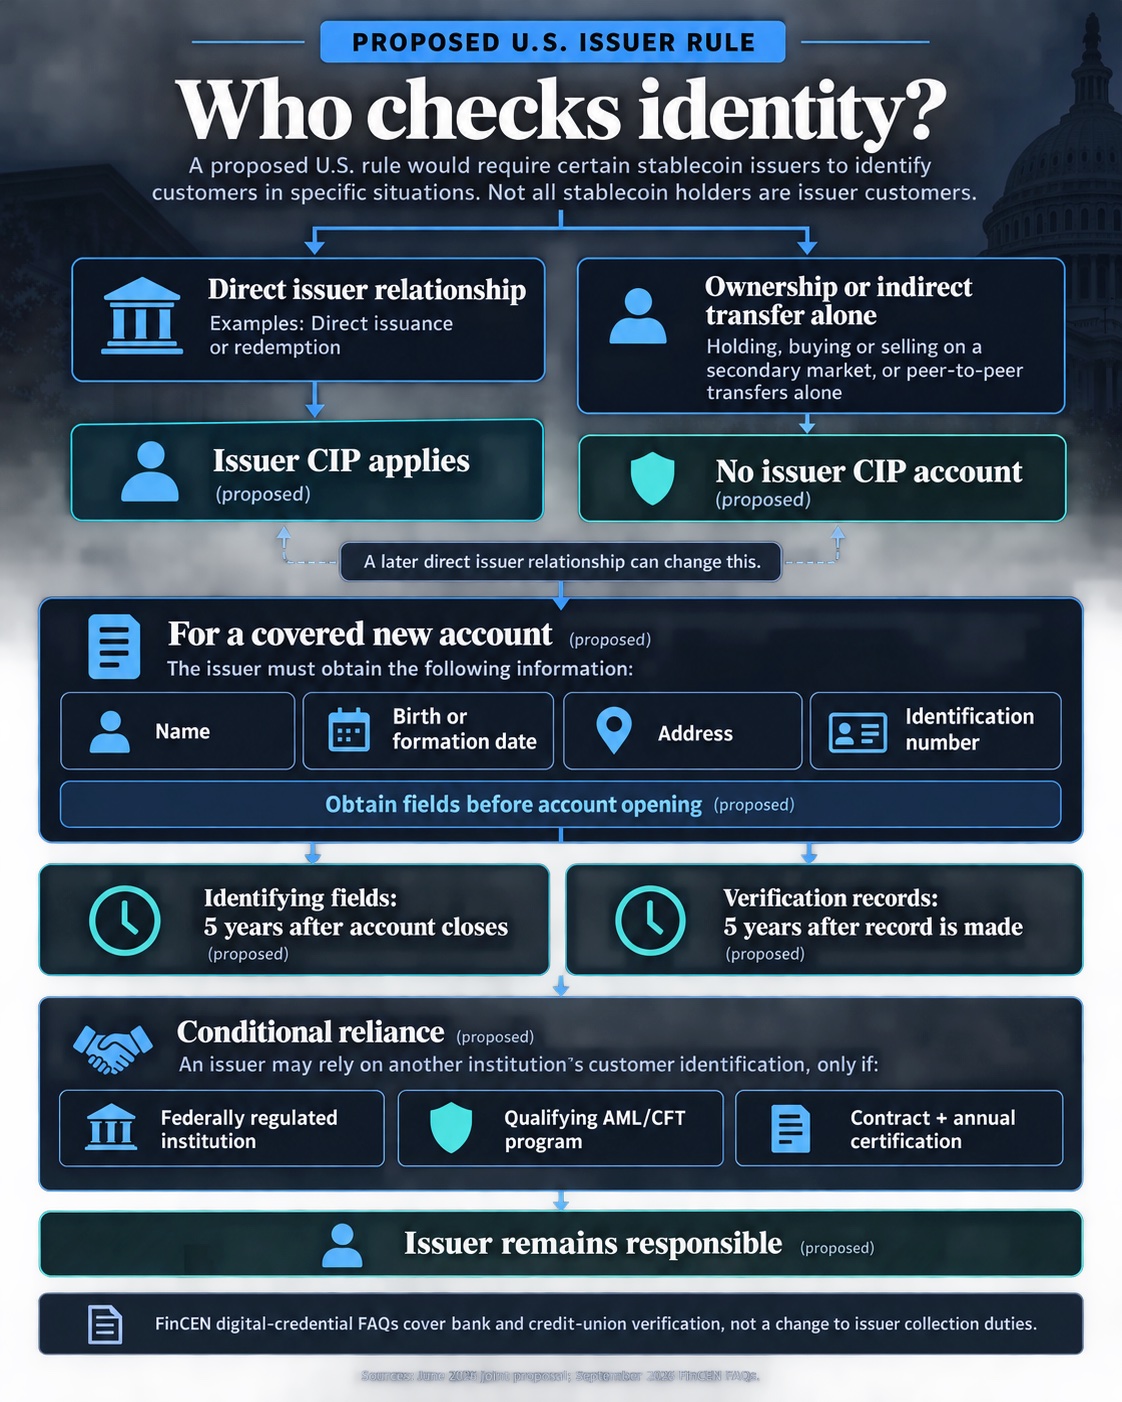
FinCEN also said this month that banks and credit unions may use qualifying government-issued digital credentials, including mobile driver's licenses, within their existing customer-identification programs.
Those mechanisms stop short of the portable model Peirce described. Verification technology can change how an institution confirms an identity without necessarily eliminating its obligation to obtain prescribed customer information or maintain records.
The fight moves to the final rule
Regulators have left that question open.
FinCEN and the banking agencies explicitly asked whether the final stablecoin rule should address digital identity systems or verifiable credentials and what benefits and risks would accompany their use.
They acknowledged that a nongovernmental credential could allow someone to prove who they are without revealing additional information, but declined to include specific verifiable-credential provisions in the proposed regulatory text.
That creates room for the final rules to determine how much duplicate collection survives.
Regulators could broaden the circumstances in which stablecoin issuers rely on identity checks conducted elsewhere, give clearer recognition to cryptographically verifiable credentials, or allow firms to retain evidence that required checks occurred without keeping additional copies of the underlying documents where the law permits.
For stablecoin companies, the outcome will determine whether compliance requires building another generation of databases containing customer identity information or investing in systems designed to verify required attributes while holding less of the raw data themselves.
The GENIUS Act has already settled that regulated issuers must know their customers. The remaining rulemaking will determine how many companies need to keep copies of the information used to prove who those customers are.
The post SEC’s Hester Peirce wants to end crypto’s KYC honeypots before stablecoin rules create more of them appeared first on CryptoSlate.
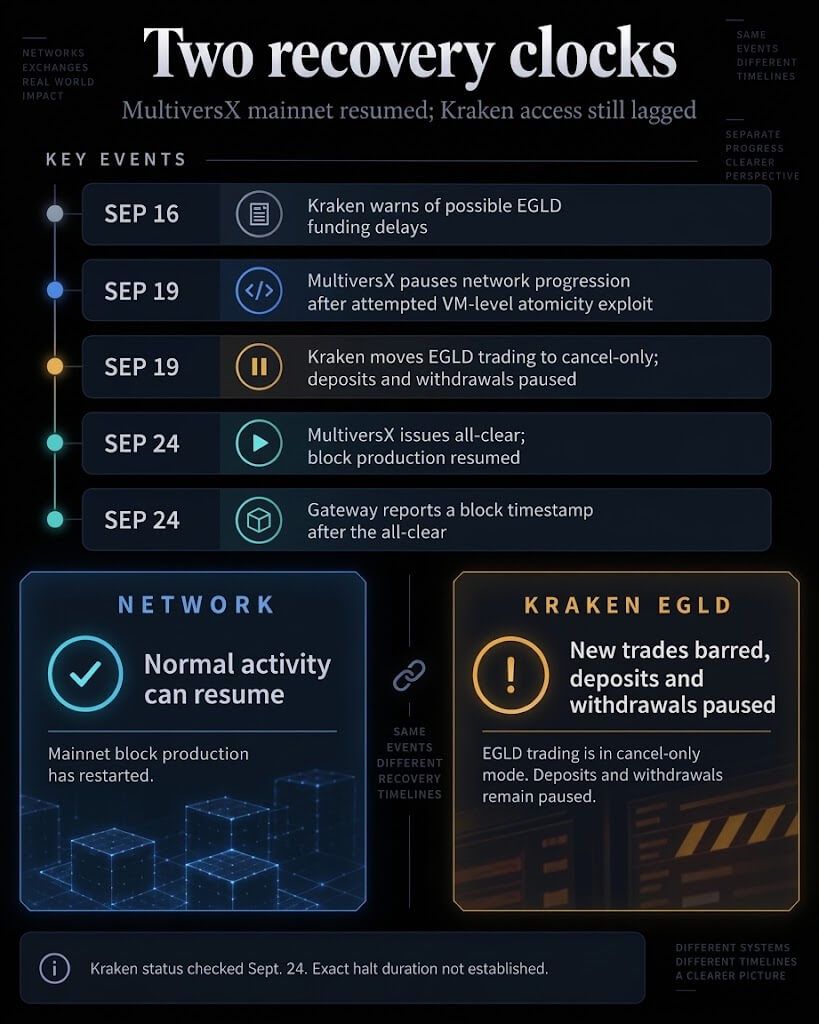
MultiversX, a blockchain network, said its mainnet was back online Thursday, Sept. 24, about five days after an exploit-related halt. Its technical account, @CodeMultiversX, said a recovery upgrade had been deployed, block production had resumed and normal network activity could continue. The official gateway returned a Sept. 24 block timestamp after that all-clear, showing that the network was reporting new blocks.
Kraken's latest posted EGLD notice told a different story for customers of that exchange. Its incident page still showed cancel-only trading and paused deposits and withdrawals when checked Sept. 24, with no resolution notice. Cancel-only lets customers cancel existing orders; it bars new orders and trade execution. The chain's restart therefore did not, by itself, restore the ability to trade EGLD or move it through Kraken.
MultiversX restart in stages
@MultiversX said on Sept. 19 that an attempted exploit of a virtual-machine atomicity issue had caused invalid state changes and prompted a pause in network progression. The Sept. 24 technical update said engineering had completed recovery checks. The two dates put the disruption at about five days, although the statements do not fix the exact stop and restart times.
The MultiversX gateway's post-all-clear timestamp is consistent with the network's report that block production resumed. It cannot show whether a particular customer transaction succeeded or whether a trading venue has reopened its own systems. @CodeMultiversX warned that trading, deposits and withdrawals might remain paused at some exchanges for several more days while those platforms completed their reopening processes. Its all-clear applied to the network, while exchange access required separate confirmation.
That distinction matters for someone deciding which service is available now. The network statement addresses whether on-chain activity can resume; Kraken's notice governs the orders and funding routes handled by Kraken. A new block does not lift an exchange trading restriction or establish that an exchange is accepting deposits. @CodeMultiversX specifically directed users to check their exchange's official updates before using those services. No reopening time appeared on Kraken's incident page at the Sept. 24 check.
Kraken's incident timeline also predates the network halt. The exchange first reported possible EGLD funding-gateway delays on Sept. 16. On Sept. 19 it moved EGLD pairs to cancel-only trading and said deposits and withdrawals remained paused. The initial gateway warning came before MultiversX's exploit announcement, so the dates alone cannot establish a cause for Kraken's original issue or its later escalation.
For EGLD users, the remaining signal is a Kraken update confirming when its trading and funding functions have reopened. Until then, MultiversX's all-clear establishes a path back to on-chain activity, but Kraken's latest posted restrictions still govern what its own customers can do there.
The post MultiversX restarts after exploit halt, but Kraken still bars new EGLD trades appeared first on CryptoSlate.
Bitget said its $351.6 million wallet breach bears the hallmarks of North Korean hackers as investigators race to trace and freeze stolen assets.
The crypto exchange said analysis of IP activity and blockchain transactions showed the Sept. 24 attack closely matched techniques used by known North Korean hacking groups. Bitget has reported the incident to relevant authorities and enlisted blockchain security firms Mandiant and SlowMist to investigate, Chief Executive Officer Gracy Chen said.
Onchain analyst Specter separately linked the XRP taken from Bitget to funds stolen during the $24 million AFX hack in July, which was attributed to the TraderTraitor cluster associated with North Korea’s Lazarus Group. The Bitget attribution remains under investigation and has not yet been independently confirmed by its external security firms.
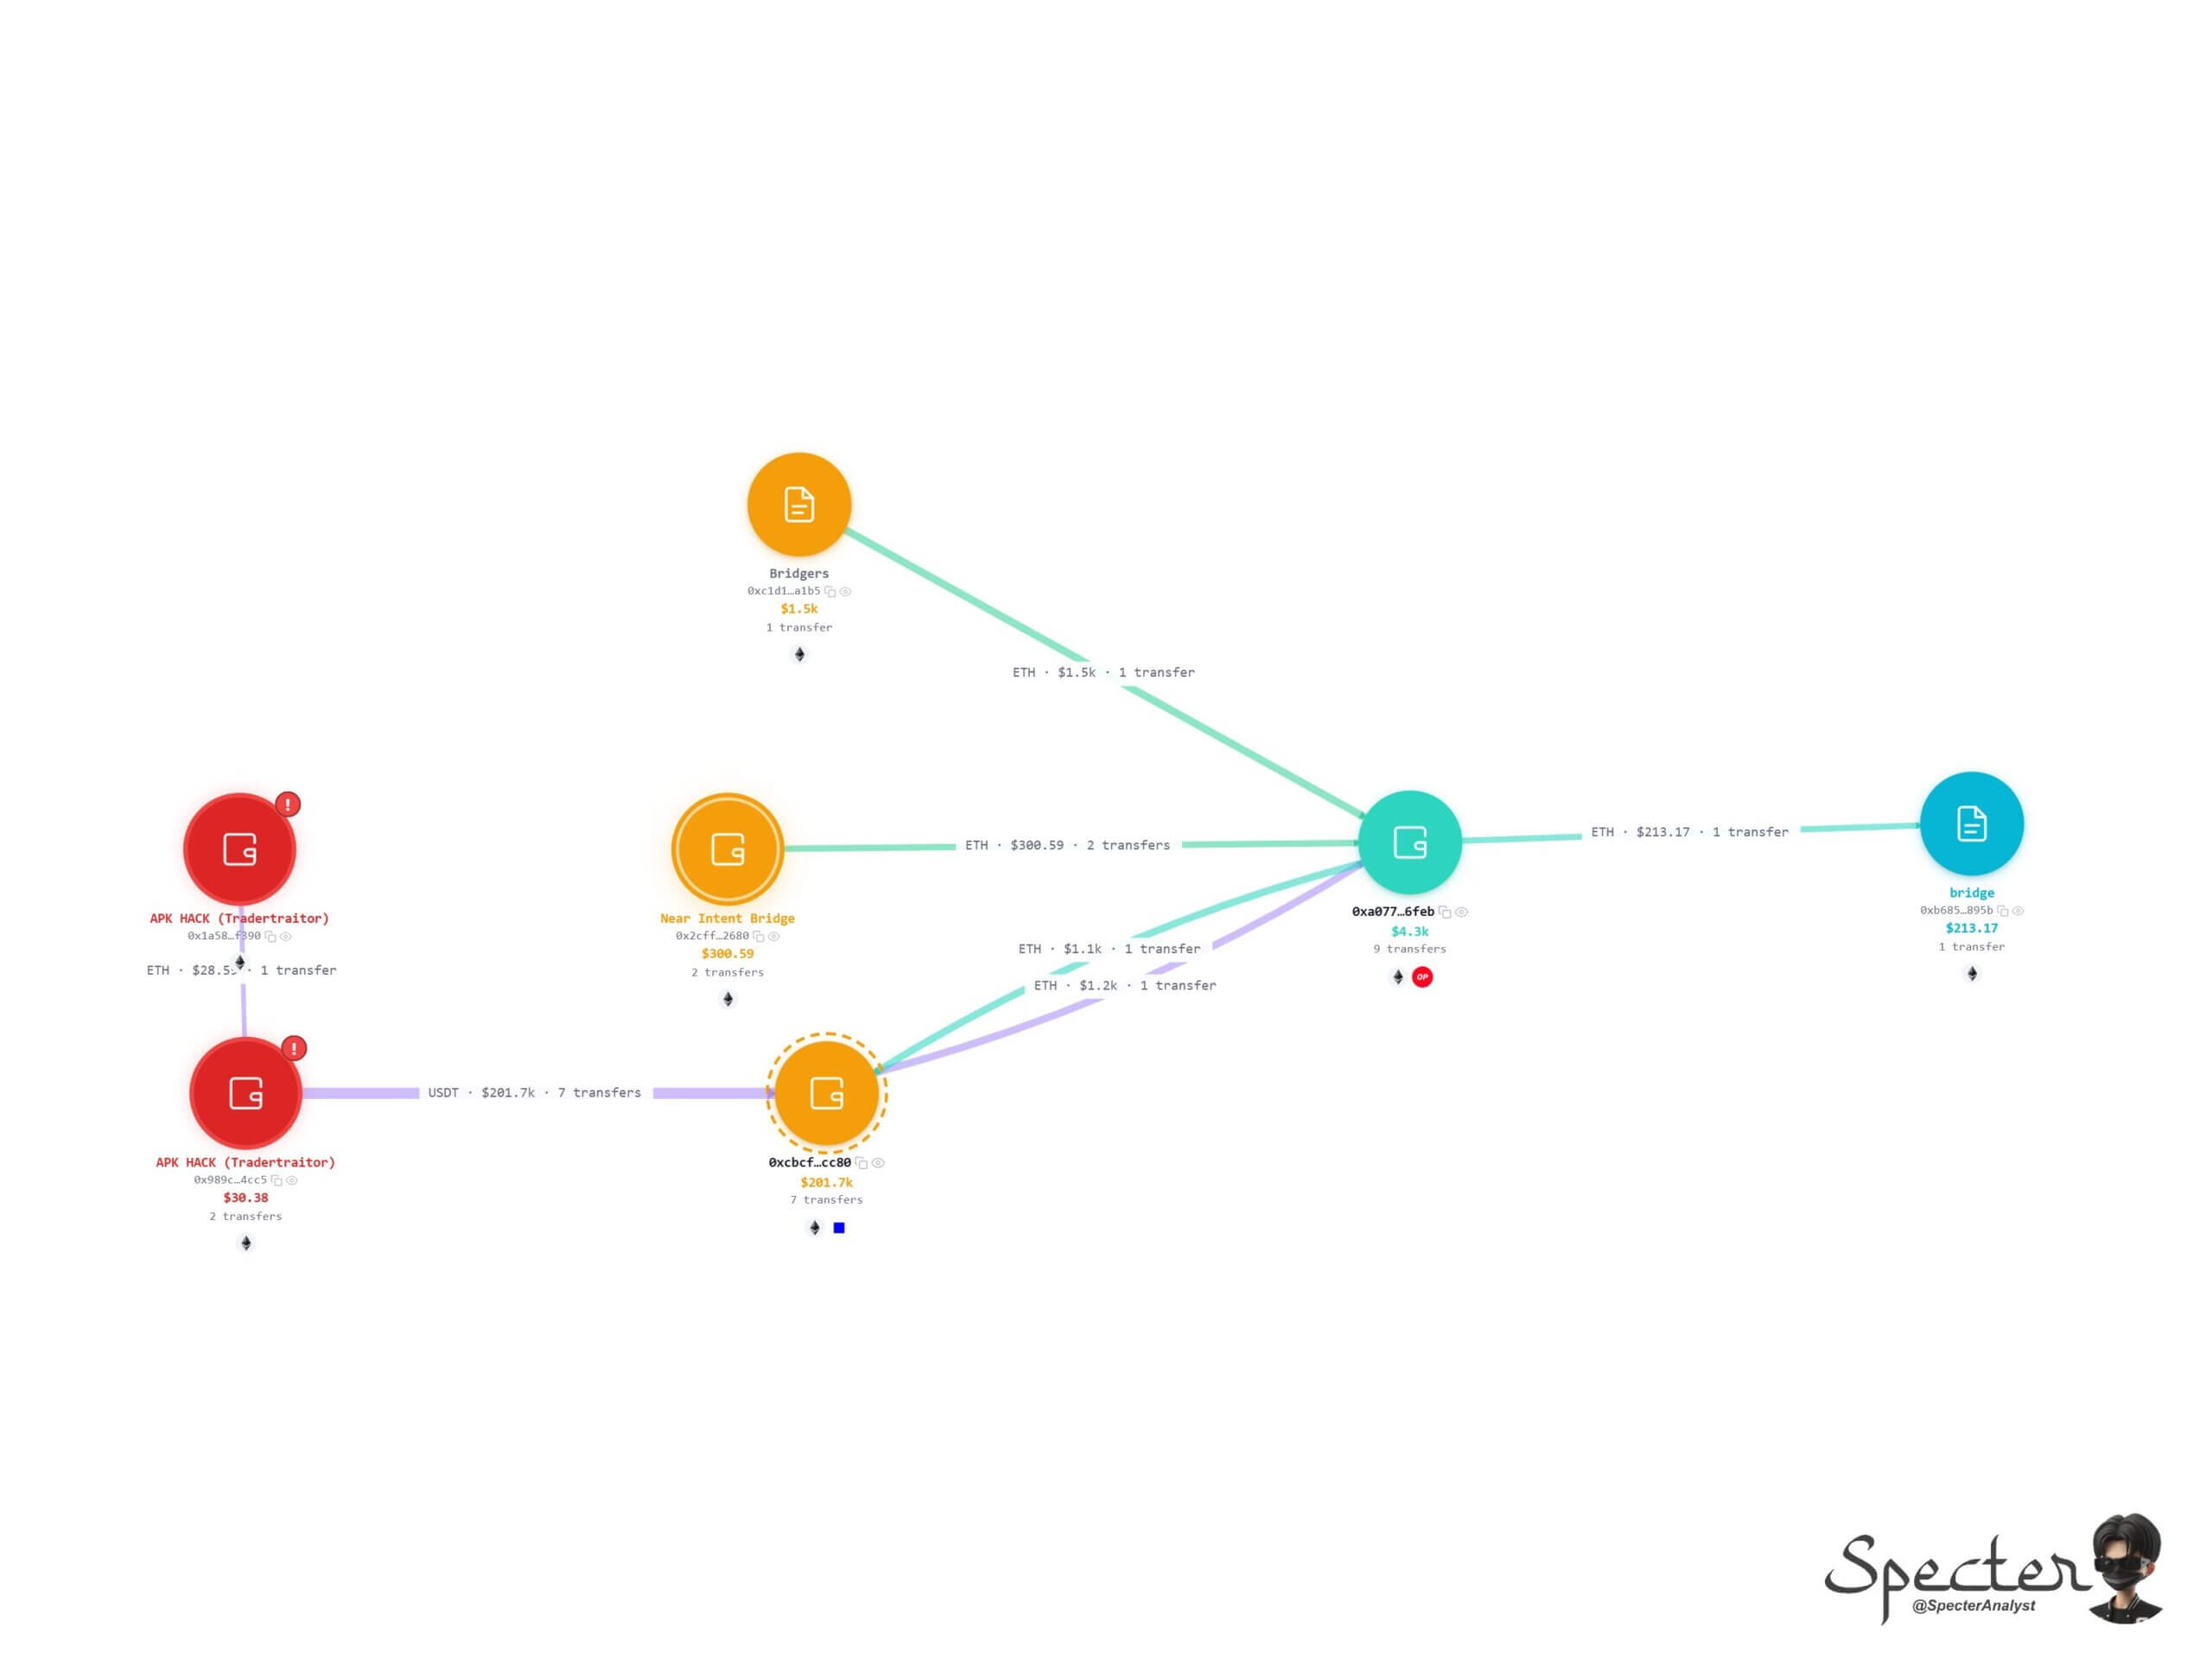
The breach affected ETH, XRP, BNB, AVAX, USDT, USDC and other assets across Ethereum, XRP Ledger, Arbitrum, Avalanche, Optimism, BNB Chain and Base. XRP accounted for the largest loss on a single network, Chen said.
Bitget said some blockchain foundations have already confirmed freezes of addresses associated with the attacker. Any successful recovery could reduce the final loss from the $351.6 million of assets initially identified as affected.
Cold wallets remained secure, according to the exchange, while Bitget Wallet, its separately operated self-custodial product, was unaffected.
Bitget's protection fund faces its largest test
The attack has also put Bitget’s financial backstop under scrutiny as withdrawals remain suspended during a wider security review.
Bitget said losses left after its assessment will be borne by its User Protection Fund, which holds 5,500 Bitcoin valued at more than $464 million. Chen said the company would replenish the fund after covering the incident.
A loss equal to the full $351.6 million estimate would amount to roughly 76% of a fund valued at $464 million. The eventual draw could be smaller if assets are frozen or recovered, while the fund’s dollar value can also change with Bitcoin’s price.
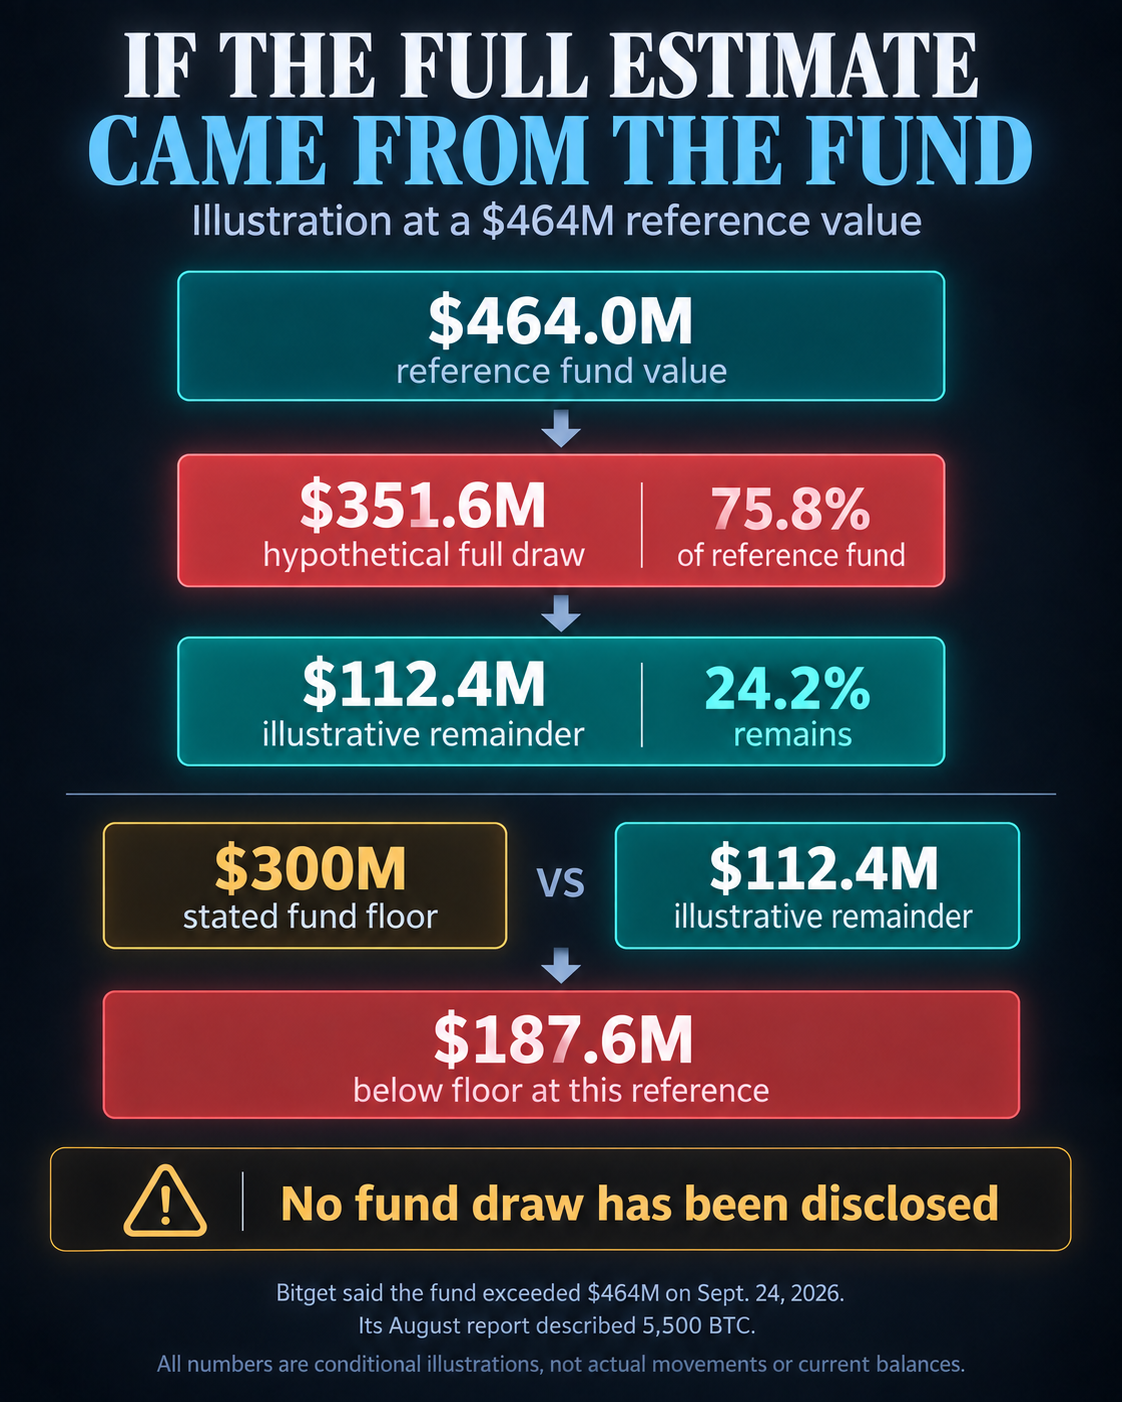
Bitget said it has additional resources beyond the fund. Chen disclosed more than $1 billion in proprietary assets and said customer funds remain backed on a 1:1 basis.
The company has yet to say how much of those resources it will need, how much will come directly from the protection fund, or what the fund will hold after it makes customers whole.
Its latest proof-of-reserves report, published Sept. 17, showed an aggregate reserve ratio of 135% across 19 assets, but the snapshot came before the attack and does not reflect the exchange’s post-breach position.
Withdrawals will remain unavailable until Bitget completes additional security checks. Chen said the company would announce a reopening window once it could do so with confidence rather than commit to a timetable before the review is finished.
That leaves investigators pursuing two outcomes simultaneously: recovering assets before they move beyond reach and determining how much of Bitget’s own balance sheet it will ultimately need before customers regain full access to their funds.
The post Bitget’s North Korea-linked $352 million hack could drain 76% of its protection fund appeared first on CryptoSlate.
Bitquery flagged $117.7 billion in Solana DEX trades in a 30-day sample, where repeated round trips supplied much of the recorded turnover. The blockchain data company's Sept. 24 reconstruction challenges using gross volume as a stand-in for demand from independent traders.
It leaves a question of how much an outside user could actually trade at a useful price in the same pools.
From Aug. 24 through Sept. 22, Bitquery examined $201.4 billion in trades it could value in dollars across Solana pools it indexes. Its rules classified 58.4% of that sample as circular or botlike, and about $111.6 billion of the flagged amount (95%) involved buying and selling the same token through the same pool inside one transaction, according to its Solana analysis.
One Sept. 14 example shows how the number can grow. A wallet bought a token named Claude from a PumpSwap pool, while a second wallet sold nearly as many units back to that pool inside the same transaction.
Bitquery found that both signed it, and the two pool trades recorded about $2,000 of volume. The token name does not indicate a connection to Anthropic.
Bitquery also identified two groups of 20 and 50 wallets with strikingly similar trading records. Together they accounted for $26.3 billion of the flagged amount. The firm grouped wallets by their volumes and token counts, without tracing their funding.
Bitquery counted trades priced in SOL, USDC or USDT in pools covered by its index. Other quote assets and some routed venues fell outside the sample, and the firm says fewer of its checks could run on Solana than on the other chains it studied.
Its figure reflects the activity its rules flagged in one window, not a rate for all Solana DEX trading.
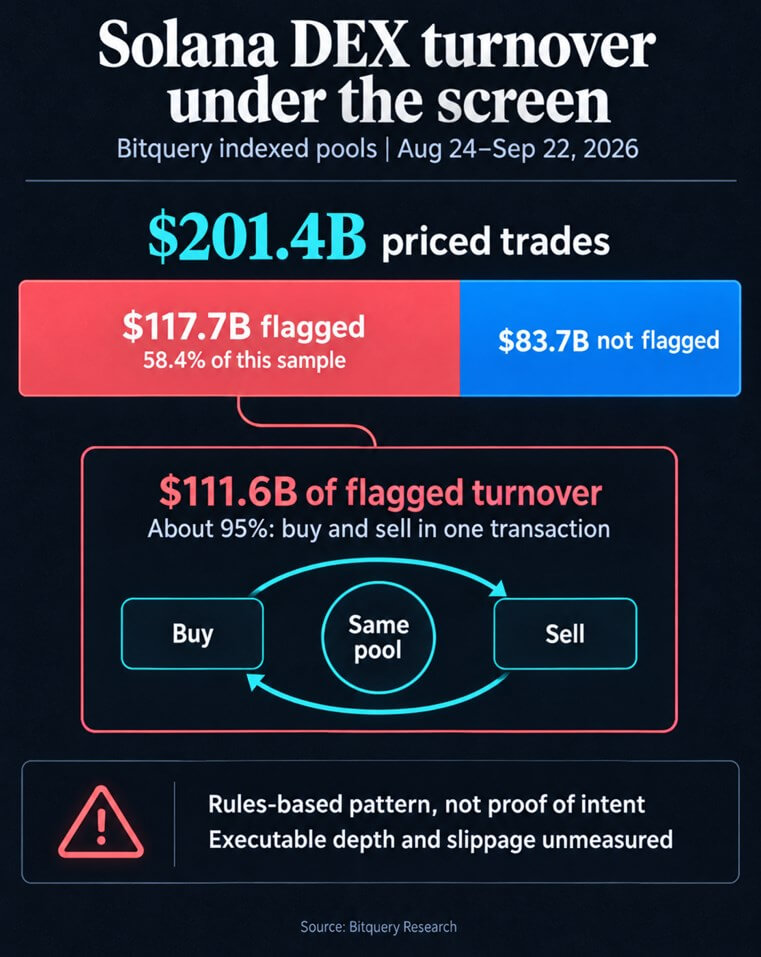
A Sept. 24 snapshot of DefiLlama's Solana DEX dashboard showed $75.9 billion in rolling 30-day volume. Bitquery's window ended two days earlier.
Subtracting Bitquery's flagged dollars from that dashboard total would combine different dates and different pools.
Bitquery also made a same-date comparison, saying $83.7 billion of its indexed Solana trades were outside its flagged category, while DefiLlama counted $78.8 billion across the chain for Aug. 24 through Sept. 22.
Bitquery described the close totals as partly coincidental: DefiLlama includes venues Bitquery misses and excludes pools Bitquery keeps. The $83.7 billion is a remainder under Bitquery's rules, with its independent-user share still unknown.
On PumpSwap, DefiLlama's published method counts pools with specified quote tokens, at least $5,000 in total value locked, and at least 50 unique traders. Its adapter code implements those thresholds.
Bitquery screens transactions and wallet behavior instead. A pool balance and a count of trading addresses alone cannot show whether those addresses represent separate users.
This is why the competitive signal changes after screening. A venue may lead a turnover table while a portion of its recorded activity comes from wallets repeatedly crossing the same pool.
Equally, trades left outside Bitquery's screen remain unclassified by that test. Neither dashboard gives a matched measure of orders an independent trader could execute without substantial price movement.
Solana's pool history is not its depth
The exact Claude/SOL pool in Bitquery's transaction example displayed effectively empty reserves and $0 liquidity in a GeckoTerminal snapshot retrieved Sept. 24.
Its prior trading record could still be large while a new trader faced no meaningful liquidity there at the time of that snapshot.
The relevant execution test needs a token pair, trade size, and timestamp. Jupiter's swap documentation describes a quoted expected output followed by an actual execution result, with prices able to move before a quote is used.
To estimate the liquidity available after repeated round trips are set aside, historical reserves, comparable routes, and realized fills for flagged and unflagged pools are needed. Bitquery's volume total alone supplies none of those measurements.
The token pools in this investigation also sit beside distinct Solana markets. Jump Crypto's April publication examined March fills in SOL/stablecoin markets run through proprietary automated market makers.
Jump participates in that market, and those results cannot describe execution in the PumpSwap token pools Bitquery flagged. One segment's results should not determine the chain's liquidity standing.
Fees offer another incomplete shortcut. DefiLlama's chain-fee table tracks a separate measure from PumpSwap's liquidity-provider, protocol, and creator fees. Neither recorded turnover nor any of those fee totals tells a trader the price impact of a particular order.
Bitquery's new screen shows why Solana's reported DEX activity needs a closer look at who generates it and where.
The $117.7 billion figure applies to indexed pools and rules, while the spendable depth left for independent users remains unmeasured. Solana's competitive position on execution will depend on pair- and size-specific fills across comparable venues.
The post Solana DEX volume spike hides circular trades, and automated bots are blamed appeared first on CryptoSlate.
CryptoTicker.io
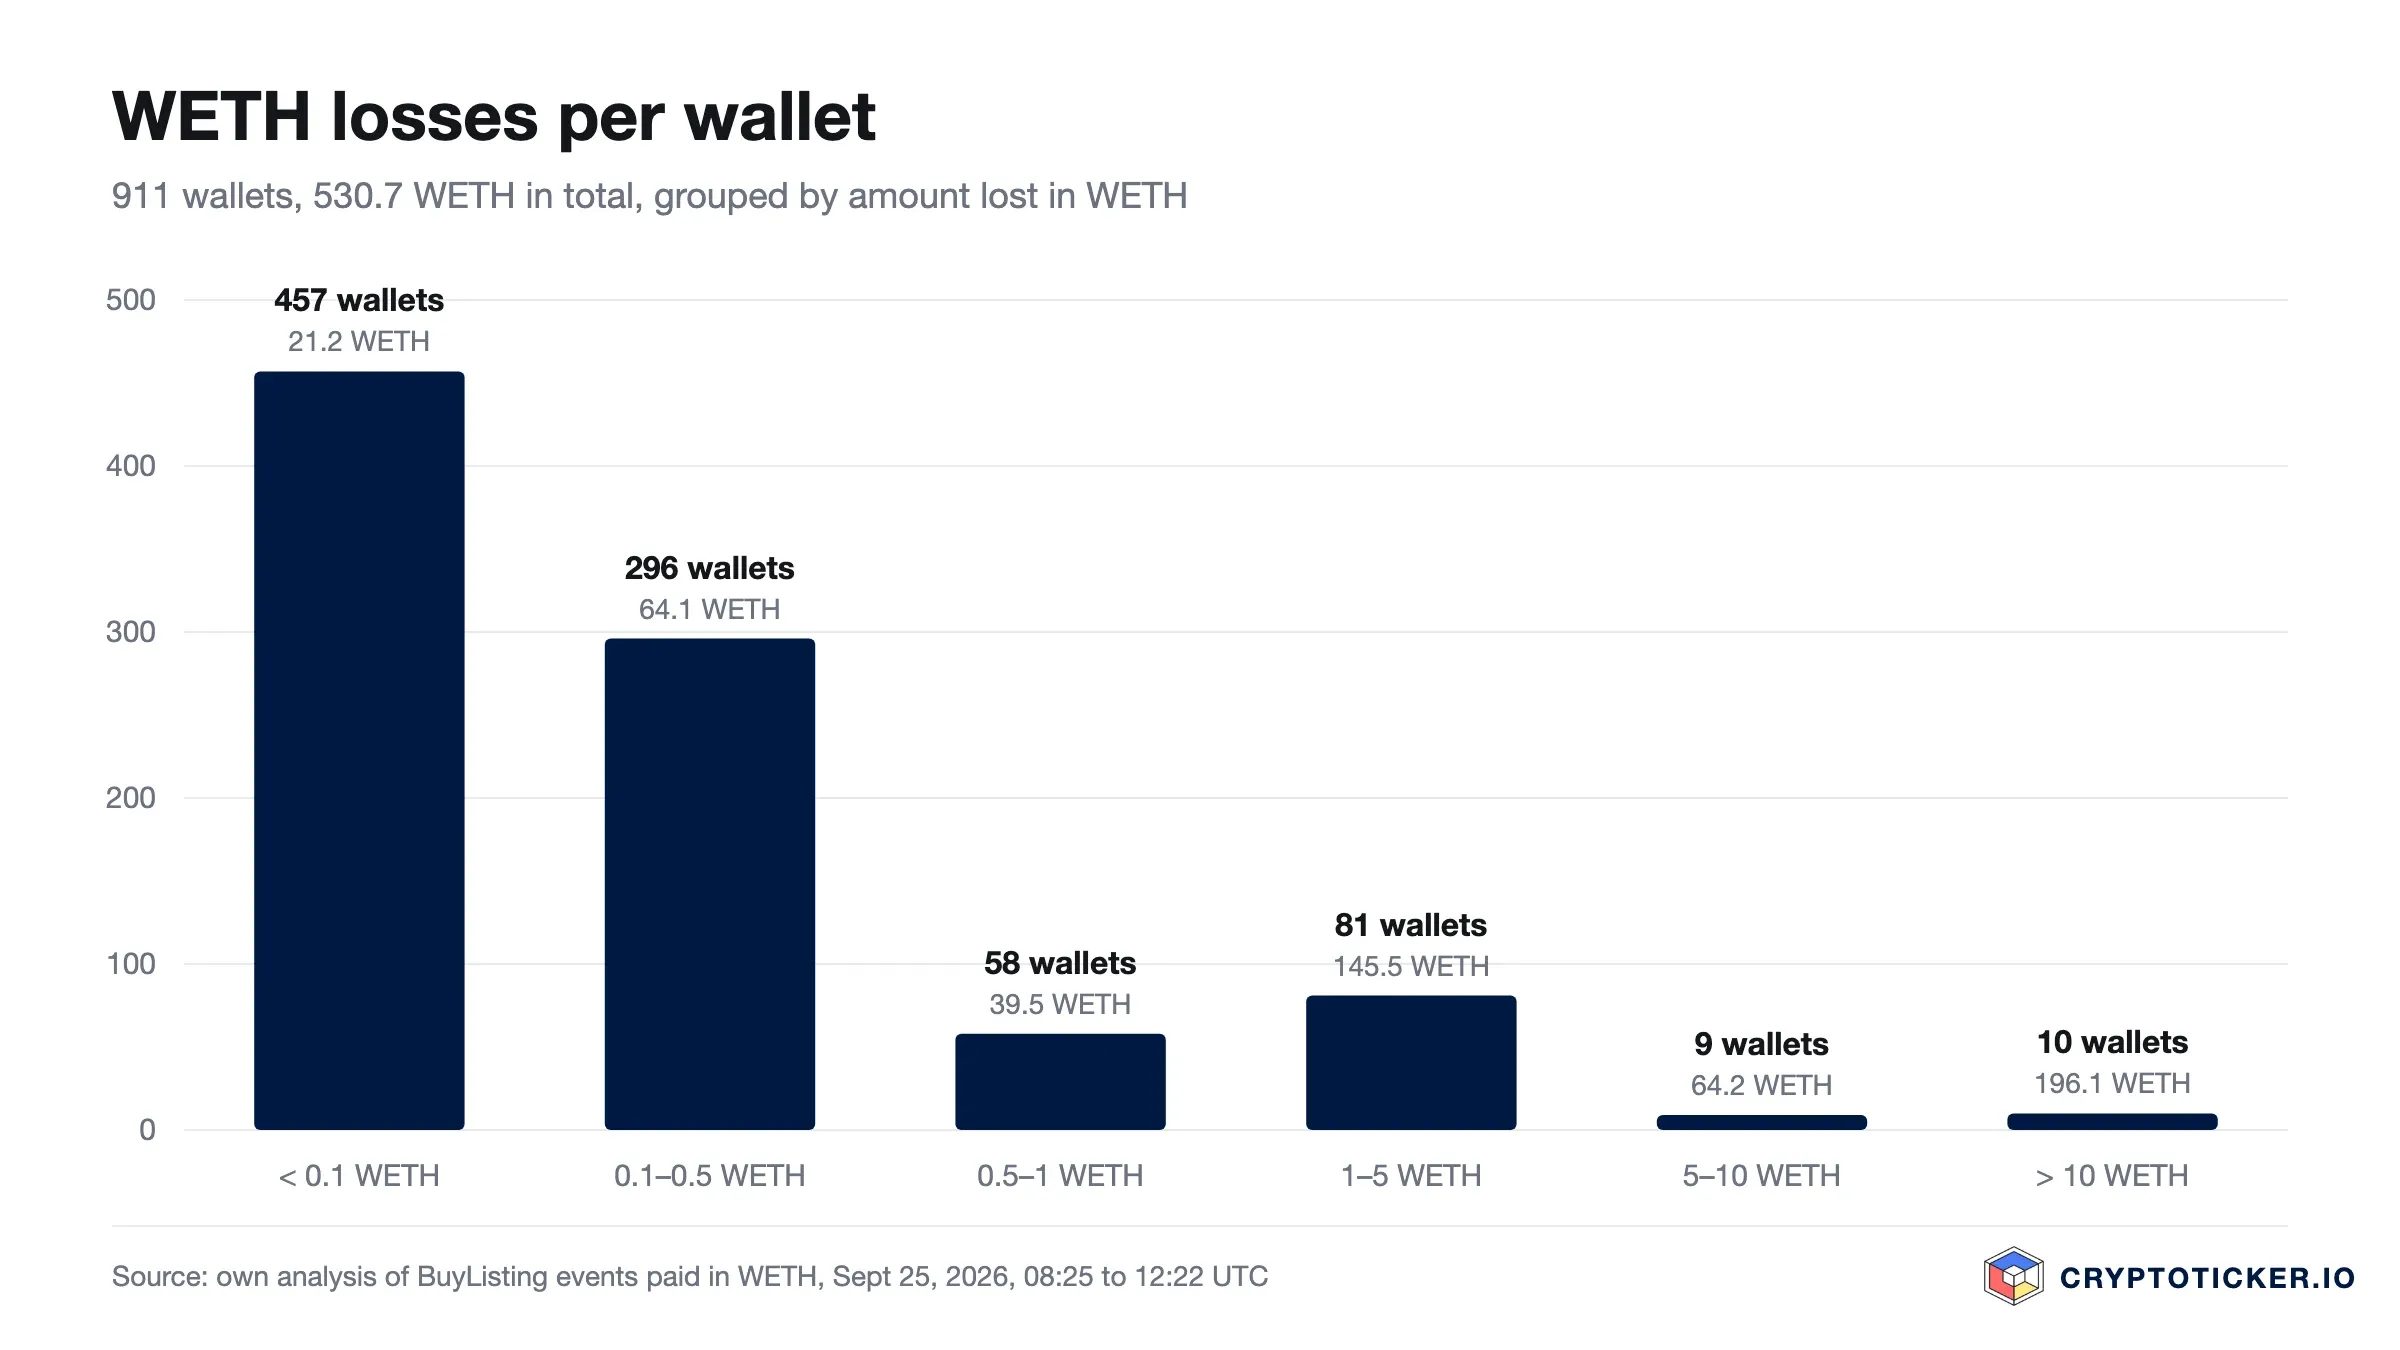
If you listed an NFT, placed an offer or accepted one on Magic Eden's former Ethereum marketplace in 2024, you need to act now. A bug in Limit Break's Payment Processor, the trading protocol behind that marketplace, has been used since Thursday to pull NFTs and Wrapped Ether (WETH) out of other people's wallets. On ApeChain, Wrapped ApeCoin (WAPE) was hit. Our own analysis of the blockchain shows 530.7 WETH gone from 911 wallets, plus thousands of NFTs, and at our last check at 12:40 UTC the drain was still running.
Protecting yourself takes minutes: you revoke the approvals for two contracts. Cancelling a listing is not enough. And a hardware wallet does not protect you here. We explain why in detail below, because it is being misrepresented in many replies on X right now.
Magic Eden and Limit Break: the two approvals you need to revoke now
Two contracts are affected. Quit, VP of Blockchain at Yuga Labs, named them publicly on Friday morning:
- Payment Processor V2 on Ethereum: 0x9A1D00bEd7CD04BCDA516d721A596eb22Aac6834
- Payment Processor V3 on ApeChain: 0x9a1D00000000fC540e2000560054812452eB5366
Magic Eden also names Polygon and Base, because the marketplace used Payment Processor V2 there as well. Check your wallet on all four networks. In your wallet the contract usually shows up as "Limit Break: Payment Processor". That is the name you saw in the signature window back then, when you placed or accepted an offer.
What happened in the Limit Break exploit: the timeline
We built the timeline from three sources: posts by the people involved on X, the incident page on Revoke.cash and our own analysis of the events that the Payment Processor leaves on the blockchain. All times are UTC.
- Thursday, September 24, 13:08: The first attack. A single address pulls 305 NFTs out of a single wallet in three transactions, each as a "sale" at a price of zero. Quit lists 10 Meebits, 50 Otherdeeds, 10 World of Women and 235 Desperate ApeWives, exactly 305. Nobody notices for twelve hours.
- Friday, September 25, around 01:00: Quit comes across the incident and realises that a large number of other wallets can be reached through the same bug. He contacts Limit Break, which pauses Payment Processor V3. V2 on Ethereum cannot be paused.
- 05:46: The rescue begins. Quit and helpers pull at-risk NFTs out through the bug themselves and park them at 0x71cF3f5724bD2B72Ef6464992aCd26216De7fe33.
- 06:31: NFT trader Cirrus raises the alarm because one address is "buying" thousands of NFTs for 0 ETH. At 06:47 Quit confirms that it is his rescue.
- 07:06: The rescue starts on ApeChain as well.
- 08:09: Quit publicly calls on users to revoke their approvals.
- 08:25: The WETH drain begins. The first transaction alone takes 281.66 WETH from 25 wallets. By 09:00, 522.5 WETH are gone.
- 08:51 and 09:10: Other tokens are hit too: 8,380 USDC from 62 wallets and around 549,000 WILD from eleven wallets.
- 09:11: Revoke.cash publishes a dedicated checker page for the incident.
- 09:54: On ApeChain, 7,680 WAPE disappear from 19 wallets in a single transaction.
- 10:11: The last transfer to the rescue address. At 10:19 all activity on the ApeChain contract stops.
- From 09:27 until at least 12:22: Other addresses keep pulling NFTs at zero price, 7,870 transfers from 1,786 wallets in total. The latest WETH drain in our data is at 12:19.
- 12:22 to 12:40: Our follow-up check shows another 2,292 NFT transfers at zero price and another 0.55 WETH from five purchases. The attack is not over.
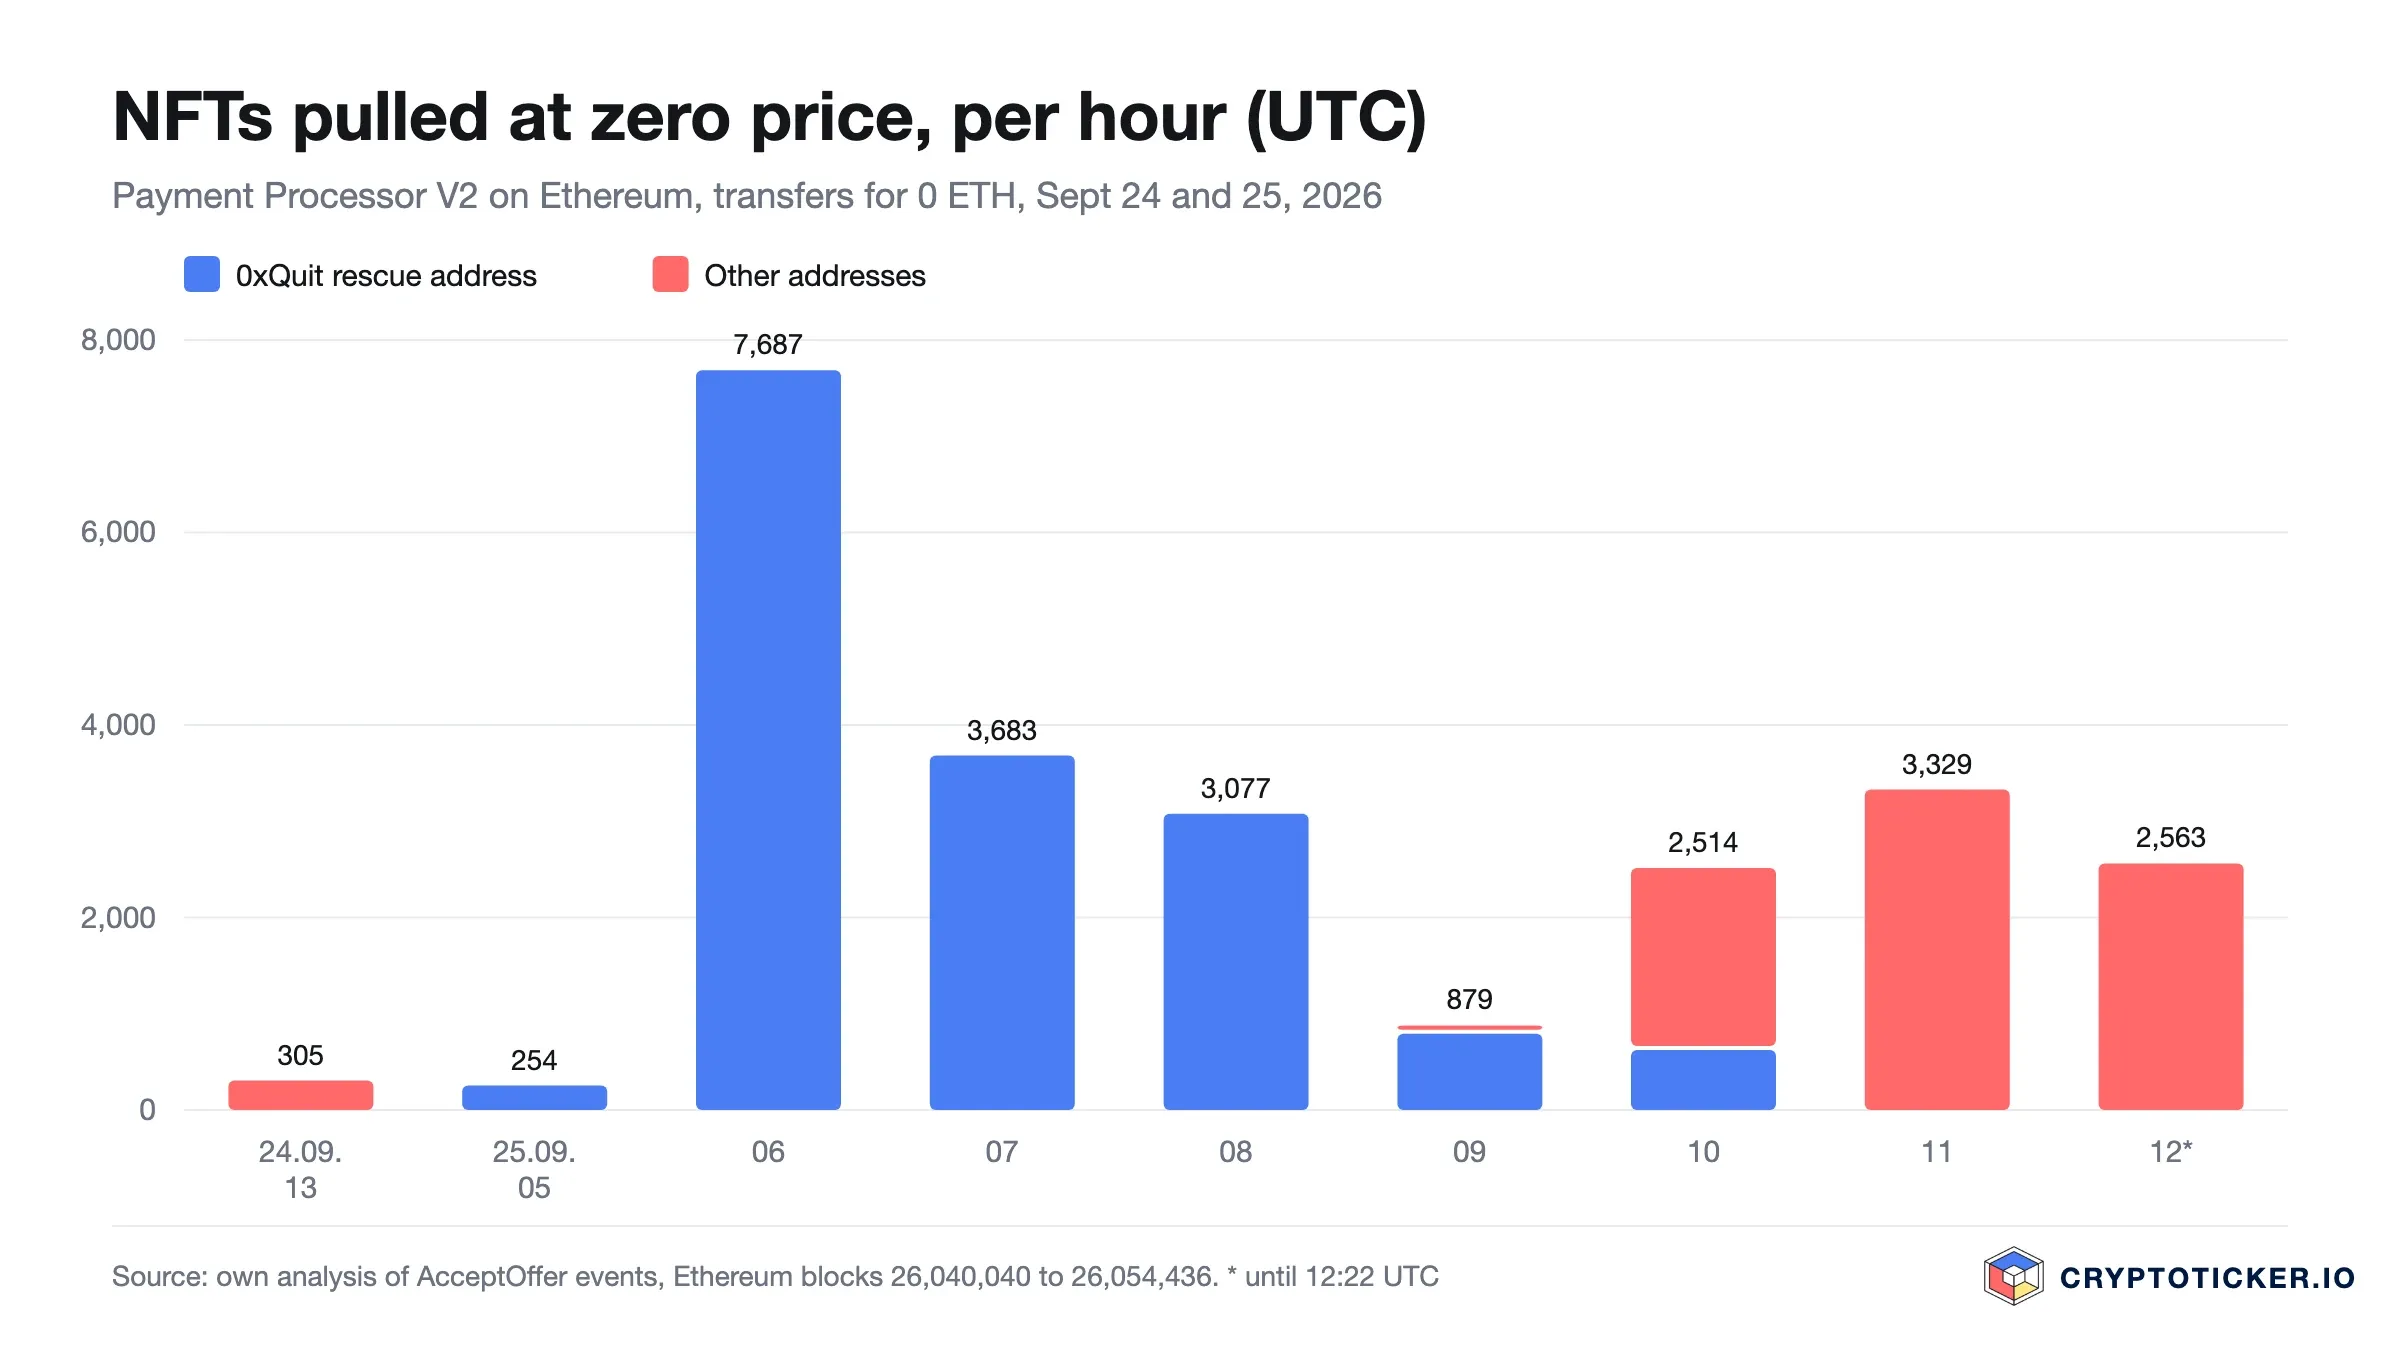
The chart shows the turning point. Until late morning almost every transfer comes from the rescue address. After that, others take over. Who is behind those addresses cannot be read from the blockchain. They could be further helpers or copycats who rebuilt the exploit. For you it makes no difference: as long as the approval stands, anyone can use it.
Quit puts the night's result at 23,155 rescued NFTs worth more than $5.7 million. Our data shows 16,117 transfers to the rescue address on Ethereum and 9,795 on ApeChain. The figures do not match one to one, because one event is not always exactly one NFT; multi-edition tokens can carry several copies. The order of magnitude is right.
Why WETH and WAPE were drained
Many people are asking this, and the answer explains the whole attack. No contract can pull plain Ether out of your wallet. A contract can only move tokens you have given it permission for, an approval in crypto jargon. NFT marketplaces use two kinds.
The NFT approval. Listing an NFT lets the marketplace contract transfer it on sale, usually for the whole collection ("approved for all"). The zero-price NFT transfers went out through this approval.
The token approval. An offer on an NFT is not paid in Ether but in wrapped Ethereum, WETH. It is a token pegged one to one to Ether that can be approved like any other token. So that an offer can be settled automatically later, you allow the Payment Processor to spend your WETH, as a rule in unlimited amounts and with no expiry. On ApeChain it works the same way with WAPE, the wrapped form of ApeCoin.
That is why these two tokens were hit. The USDC, WILD and APE drains in our data show, however, that any token you ever approved for the Payment Processor is exposed.
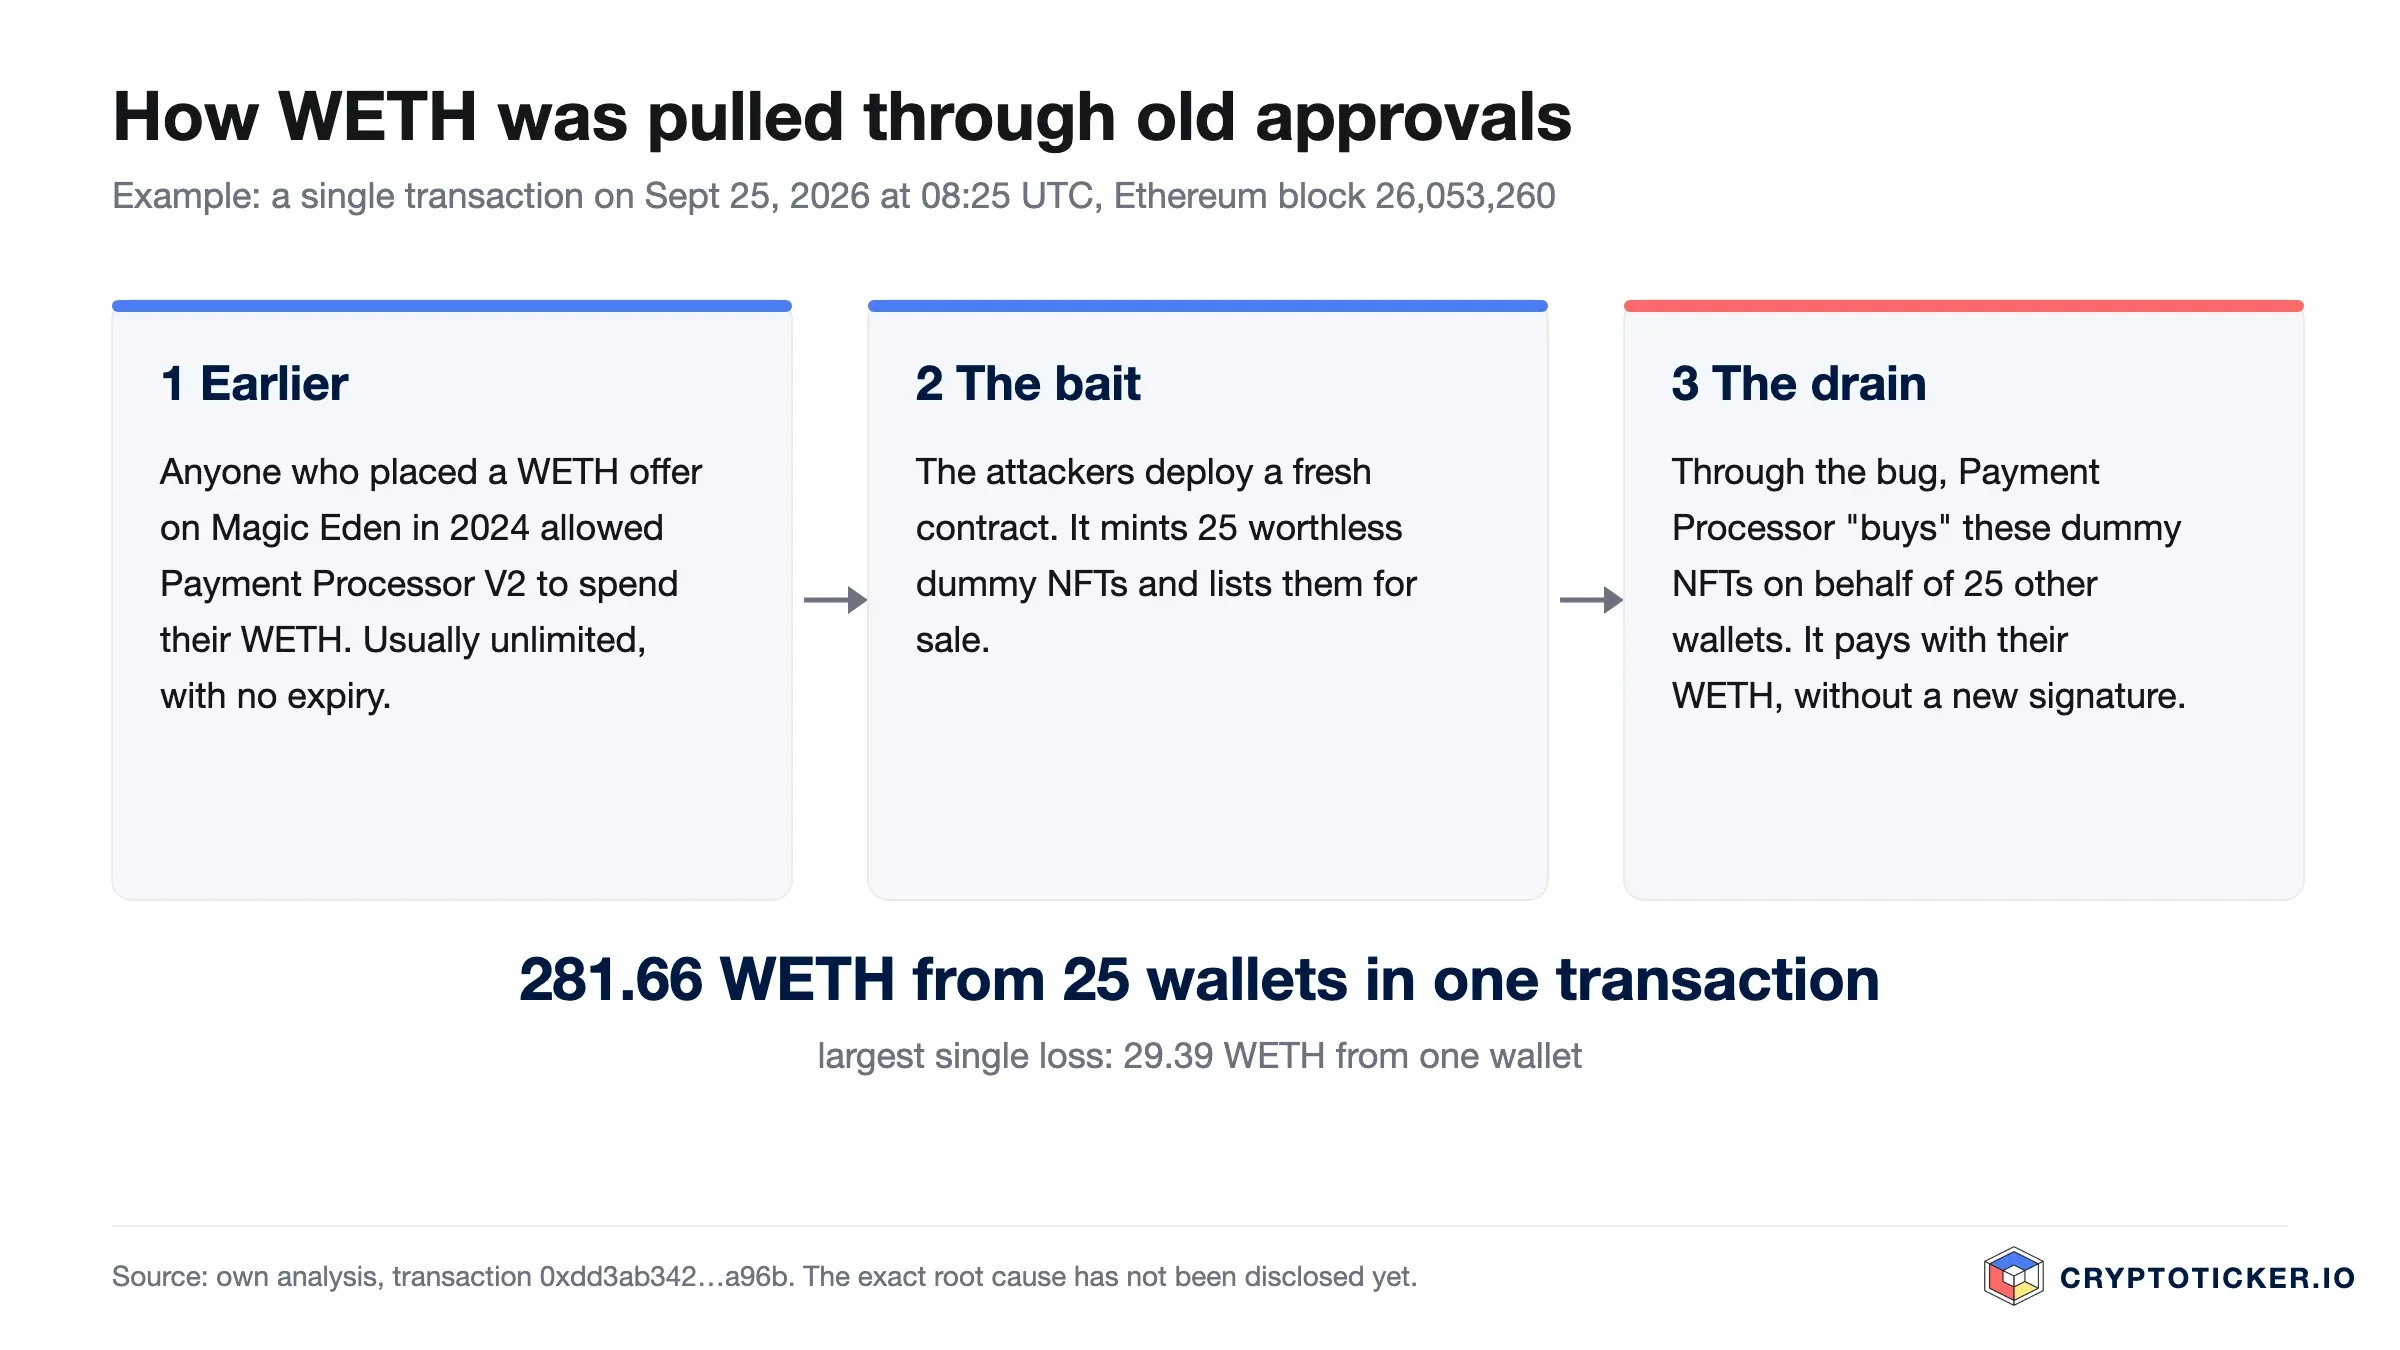
A single transaction shows the trick step by step. The attackers deploy a fresh contract that mints 25 worthless dummy NFTs and lists them for sale. They then have the Payment Processor "buy" these dummy NFTs on behalf of 25 other wallets. Payment comes out of the victims' WETH, via the old approval, without any of them signing anything. The largest single item in this transaction: 29.39 WETH from one wallet. How exactly the contract is made to act on someone else's behalf has not been disclosed by Limit Break or Quit so far.
Important if you still hold or swap WETH: the approval covers every WETH that lands in your wallet, including future balances. If you wrap Ether into WETH or receive WETH in a swap while the approval stands, you put it straight within the attackers' reach. Revoke first, then swap.
"But I had a hardware wallet": why a Ledger does not protect you
Under the warnings on X, some are mocking victims: anyone using a hardware wallet is safe, they say. That is not true here, and many of those affected had one. An acquaintance of our newsroom lost 5.94 WETH despite using a Ledger.
The reason lies in where an approval is stored. A hardware wallet protects your private key. It ensures that nobody can sign in your name without the device. But you already signed the approval, back then, perhaps two years ago, with that very device. Since then it has sat in the token contract on the blockchain: "The Payment Processor may move WETH from this address." When the Payment Processor now pulls WETH, nobody asks your device. The Ledger stays in the drawer, and the money leaves anyway.
A hardware wallet protects against stolen keys, not against rights you granted yourself. Keeping the two apart helps you focus on what actually works in incidents like this. For an overview of devices, see our hardware wallet comparison; you still have to manage your approvals yourself.
How big is the damage from the Magic Eden exploit?
Our count on Ethereum comes to 530.7 WETH from 911 wallets. At an Ether price of $2,702.88 (CoinGecko, September 25, 2026, 12:25 UTC) that is about $1.43 million. Most victims lost small amounts: half the wallets lost less than 0.1 WETH. Ten wallets, by contrast, each lost more than 10 WETH, 196 WETH between them.
Quit speaks of 660 WETH he could no longer rescue, about $1.7 million. The gap to our figure is probably explained by the fact that we only analysed Ethereum; Polygon and Base are missing. On top of that, our data shows 8,380 USDC, about 549,000 WILD (roughly $7,200), 12.9 APE on Ethereum and 7,680 WAPE on ApeChain.
The NFT picture is harder to add up. What sits at the rescue address is due to be returned. What has gone to other addresses since late morning, 7,870 transfers from 1,786 wallets, remains an open question for now.
Quit wrote on Friday morning that he had worked through the night to save around $6 million worth of NFTs, and that all he could think about was the $1.7 million in WETH he was not fast enough for. Since then, victims who lost WETH have been replying under his posts, some of them by their own account having revoked an hour too late.
Who is 0xQuit, the overnight rescuer?
Quit is VP of Blockchain at Yuga Labs, the company behind Bored Ape Yacht Club, CryptoPunks and Otherside. On X he describes himself as a Solidity developer and auditor, and he founded the NFT tool oSnipe. He regularly warns about vulnerabilities on X and, when in doubt, steps in himself before others can exploit them.
It is not his first rescue this year. In June, during a bug in Flooring Protocol, he pulled 68 NFTs worth more than $500,000 out of vulnerable pools, including 29 Bored Apes and two CryptoPunks, and held them for their owners. The approach was the same both times: whoever knows the bug pulls the assets out first, before someone with bad intentions does, and returns them once the danger has passed.
What Magic Eden and Limit Break say
Magic Eden stresses the distinction: the marketplace itself was not attacked. Co-founder and CEO Jack Lu wrote on X that the incident concerns Limit Break's trading protocol and contracts, which Magic Eden stopped using two years ago. According to Magic Eden, it used Payment Processor V2 from February to October 2024 and shut down its EVM marketplace entirely in the first quarter of 2026. Current listings are not affected, and the company says it is talking to Limit Break about further steps.
Limit Break itself had not issued a statement of its own by our deadline. All that is known is what Quit reports: that the team quickly paused V3 on ApeChain. Several NFT projects on ApeChain acted on their own. The team behind Dengs, for example, says it temporarily froze all Deng NFTs, and ApeDroidz reported that some of its collection is among the rescued assets.
If you want to review the marketplaces where NFTs trade today, you will find the comparison below. More on Magic Eden's retreat from the Ethereum business is in our analysis of the Magic Eden shutdown.
Revoke approvals: how to protect your wallet step by step
- Open Revoke.cash and enter your address or connect your wallet. Revoke.cash lists the incident on its own checker page, where you can test your address directly.
- Go through network by network: Ethereum, ApeChain, Polygon and Base.
- Revoke every approval for the Payment Processor, that is 0x9A1D00bEd7CD04BCDA516d721A596eb22Aac6834 on Ethereum, Polygon and Base and 0x9a1D00000000fC540e2000560054812452eB5366 on ApeChain. This covers NFT approvals ("approved for all") as well as token approvals for WETH, WAPE, USDC or APE.
- Each revoke transaction costs a small fee and has to be signed with your wallet, on the device itself if you use a hardware wallet.
- Only then touch WETH again. No swap into WETH and no wrapping of Ether while the approval stands.
What does not help: cancelling listings or bumping the so-called master nonce. Revoke.cash explicitly points out that neither does anything against this bug. And revoking does not bring back what has already gone. It only stops more from leaving.
According to Quit, you will only get rescued NFTs back once your approval has been revoked, otherwise the NFT would be exposed again straight away. There is no official return process yet. Expect scammers to exploit exactly this situation over the coming days: direct messages offering "recovery", fake return pages, requests to sign a message. Do not sign anything someone sends you, and wait for announcements from the known accounts.
What the exploit means for the NFT market
The real lesson of the day is an uncomfortable one: approvals do not expire. Magic Eden stopped using Payment Processor V2 almost two years ago and closed the marketplace this spring. The rights that thousands of users had granted to that contract stayed in place regardless, and the contract itself kept running, with no emergency brake. A platform can close; its contracts on the blockchain do not close with it.
Add to that the industry habit of granting unlimited approvals, so that users do not have to pay for a second transaction with every offer. It saves a few cents and turns every forgotten approval into an open account.
The incident falls in a striking week. On Thursday evening Bitget reported an outflow of about $352 million from hot wallets, the largest hack of the year; what Bitget customers should check now is in our report. The same evening, Quit also counted an attack on Payy worth $1.8 million. The tools are getting better on both sides. Research published this year shows that AI agents can now find and exploit smart contract vulnerabilities at scale, particularly in old contracts that nobody maintains any more. Whether AI played a role in this attack is not known. What is clear: searching for forgotten bugs is getting cheaper, and this night's rescue hinged on one person who happened to be awake.
How we analysed the blockchain data on the Limit Break exploit
We read every trade event that Payment Processor V2 emitted on Ethereum between September 23, 2026, 12:00 UTC and September 25, 2026, 12:22 UTC, blocks 26,040,040 to 26,054,436, queried through public Ethereum nodes. That comes to 25,299 events of the AcceptOffer and BuyListing types. The positive control: for the same block range, three independent nodes returned the same count. On ApeChain we read Payment Processor V3 from September 24 in the same way, 10,041 events.
We count a sale at a price below 0.001 tokens as an NFT drain. A token drain is a purchase in which the victim's wallet pays as the buyer. We checked the mechanism against individual transactions, such as the one with the 281.66 WETH. One cross-check with an outside source: our count for the first attack on September 24 comes to 305 NFTs, the same figure Quit gives.
What the figures cannot do: Polygon and Base are not included. Who is behind the individual addresses, helper or attacker, cannot be read from the data. And one event is not always exactly one NFT. Dollar values are based on prices as of September 25, 2026, 12:25 UTC.
Magic Eden, WETH and old approvals: key takeaways
If you traded on Magic Eden, Otherside or an ApeChain marketplace in 2024, revoke the approvals for the Payment Processor today, on Ethereum, ApeChain, Polygon and Base. Do not wrap Ether into WETH while the approval stands. A hardware wallet protects your key, not rights you have already granted. And beyond today: go through your approvals regularly, say once a quarter, and revoke them immediately when a platform shuts down. Keep valuable assets in a wallet you do not trade from and never approve anything with.
(As of September 25, 2026, 12:45 UTC. This article is not investment advice. The situation is still developing; check official statements from Limit Break and Magic Eden before you act.)
NEAR Protocol stands at $4.99 on September 25, 2026, which puts it almost 39 percent higher on the week. The trigger everyone is talking about, however, sits neither in Tokyo nor in New York but in Frankfurt: the NEAR staking ETP from Bitwise has passed $100 million in assets under management. That figure is currently being read as evidence of institutional demand. We pulled the product's key data ourselves on the same day, and it tells a different story.
The short answer first: assets under management rose because the price rose. Only a very small amount of new money came in. For you as an investor in Germany that is no hair-splitting distinction. It separates a product that capital is flowing into from a product whose headline figures simply breathe with the market. What you can actually check is set out below: the real net yield, the fee structure, the buying route through your brokerage account, and the tax treatment, which differs sharply from directly held coins.
NEAR Price on September 25, 2026: The Numbers and Where They Come From
Our retrieval from CoinPaprika at 11:55 UTC shows a price of $4.9860 for NEAR Protocol. The gain against the previous day ranged between 13.3 and 14.1 percent depending on the moment of retrieval; we give the range because the value moved between two pulls minutes apart. Over seven days the gain stands at 38.93 percent. Market capitalisation comes to roughly $6.52 billion, turnover over the past 24 hours to around $1.52 billion. That places NEAR 25th among the largest crypto assets by market capitalisation.
The move fits into a longer recovery. According to reports from several industry outlets, NEAR climbed from around $2.29 on September 16 to roughly $4.80 at times on September 23. We covered the September 24 setback and the role of the confidential perpetual futures on Hyperliquid on that same day. Today's occasion is a different one, and it has nothing to do with the derivatives market.
Bitwise NEAR Staking ETP: $118.69 Million and 25.98 Million NEAR
The Bitwise NEAR Staking ETP is an exchange-traded security on NEAR that additionally stakes the tokens it holds. It is listed on Deutsche Börse in Frankfurt in the Xetra segment, trades in euros and in US dollars, and carries the ISIN DE000A4A5GV2 and the German securities number A4A5GV. At the listing in July 2025 it was, according to the issuer, the fourth product in its European total-return range. Two dates circulate for the start of trading: the product page names July 1, 2025, while the press release dates the Xetra listing to July 2, 2025.
Our retrieval of the issuer's product page on September 25, 2026 returns the following values, each reported as of the same date: assets under management of $118.69 million, 5,017,271 shares outstanding, a holding of 25,979,238.04 NEAR in cold storage, and a net asset value of $23.66 per share. The total expense ratio is given as 0.85 percent per year and the reported net staking yield as 3.01 percent.
Why the $100 Million Mark Fell Without Meaningful New Money
An ETP grows along two entirely different routes. Either investors buy new shares, in which case the issuer puts fresh capital to work and the number of shares outstanding rises. Or the underlying price rises, in which case the same holding is simply worth more without a single new investor having joined. Both show up in the "assets under management" figure as growth, yet they mean something fundamentally different for you.
The financial outlet DL News, whose analysis Yahoo Finance among others picked up, counted 4,912,271 shares outstanding for Tuesday of this week and derived from that an increase of roughly 30,000 shares, or 0.6 percent, worth about $639,000. Over the same period the price rose by around 135 percent in 30 days on that account. Our own retrieval three days later shows 5,017,271 shares. That is 105,000 shares more than on Tuesday, an increase of 2.14 percent.
Shares, Net Asset Value and Holdings: The Three Numbers to Keep Apart
The order of magnitude can be recalculated from our own values. 5,017,271 shares at a net asset value of $23.66 come to $118.71 million, which tallies almost exactly with the reported assets under management of $118.69 million. Each share accounts for 5.1780 NEAR. Had the share count stayed unchanged over the past week, the price gain of 38.93 percent alone would have lifted assets under management by that same percentage. The jump above $100 million is fully explained by the price move, with no need to assume any inflows at all.
This is no accusation against the issuer, which discloses its figures transparently and states the share count openly. It is a rule for reading them: whoever sees a report about an asset milestone should place the share count beside it. If that count does not rise with it, the headline is measuring the price and not the demand.
Net Asset Value Against Spot Price: Why the Reported Fund Size Lags
A second gap stood out during our retrieval. The holding of 25,979,238 NEAR would be worth around $129.53 million at the spot price of $4.9860. The reported figure is $118.69 million. Divide the reported assets by the holding and you arrive at an implied NEAR price of $4.5686. The distance to the spot price is 9.1 percent. Per share that means a calculated spot value of $25.82 against a reported net asset value of $23.66.
The obvious explanation is the valuation moment: net asset value is struck once a day, and the price has kept running since that point. We cannot document it, because the product page reports no valuation time. The practical consequence for you stays the same either way. The number you see as fund size on a product or comparison page is a reporting-date value and not a live price. Anyone wanting to derive inflows or outflows from it compares two reporting dates of the same metric and never a fund size against a current market price.
Net Staking Yield of 3.01 Percent: What Is Left of the 5.5 Percent at Launch
The real selling point of a staking ETP is the running yield. At the start of trading in July 2025 the issuer advertised a net yield of around 5.5 percent after fees, according to its press release. The product page retrieved today states a reported net staking yield of 3.01 percent. That is a halving in a good fourteen months, and it lies in the nature of the thing: staking rewards depend on the network's distribution parameters and on how many tokens are staked in total. They are not a promise of interest.
The 33 Percent Staking Service Fee and the 0.85 Percent Total Expense Ratio
Two cost blocks stand between the network's gross yield and what reaches you. By its own account the issuer retains 33 percent of the staking rewards earned as a staking service fee, with the remaining 67 percent staying in the product. Alongside that runs the total expense ratio of 0.85 percent per year. Work the reported 3.01 percent net back up to the gross level and you arrive at a gross figure of roughly 4.49 percent. That back-calculation is our own and assumes the reported net figure reflects only the deduction of the revenue share; the issuer publishes no breakdown of that number.
For comparison it is worth looking at what you receive and what you spend when delegating yourself. There you collect the reward without an issuer taking a share of it, but you carry custody and the slashing risk of the validator you pick, and you have to record the income yourself. Which providers offer which terms, and what to watch on lock-up periods, we have compiled in our overview of the best staking platforms.
ETP in Your Brokerage Account or NEAR on a Crypto Exchange: The Buying Route Under MiCA
The practical advantage of the ETP lies in access. You buy it through your ordinary securities account, during Xetra trading hours, settled in euros, under the investor protection rules of securities trading. You need no account at a crypto exchange, no wallet and no seed phrase. That is exactly why many investors reach for such a product instead of getting to grips with custody. Which routes exist for exchange-traded crypto products in Germany and how they differ is set out in our overview of buying crypto ETFs and ETPs in Germany.
The price for that is the running fee and the fact that the tokens are not yours. You hold a debt security against the issuer, collateralised by NEAR. If the issuer fails, everything depends on that collateral and its legal construction. Buy directly on a trading platform authorised under MiCA and you get the tokens themselves, can withdraw them and hold them yourself, but you carry full responsibility for the keys.
Tax in Germany: Holding Period on Coins, Flat Withholding Tax on the Security
Here lies the difference that the reports about the $100 million mark never mention and that can move the most money for you. Directly held crypto assets fall under the private disposal transactions of Section 23 of the Income Tax Act. After a holding period of more than a year the gain is tax-free; within the year an annual exemption limit applies. An exchange-traded security does not follow that logic. The tax authorities regularly treat gains from securities as investment income under Section 20, subject to the flat withholding tax plus the solidarity surcharge and, where applicable, church tax, regardless of how long you held. Keep the account at a German institution and the tax is usually withheld there directly.
How physically collateralised crypto certificates with a delivery claim should be classified is, however, answered inconsistently in the tax literature, and the design of the individual product plays a part. What you can rely on is the statement from your account provider on the specific settlement and the assessment of a tax adviser. On the reform plan to tax crypto gains generally like equity gains in future, the position we keep tracking still holds: it has not been enacted.
In practice, for the choice between the two routes, that means this. If you intend to hold for longer than a year anyway, the tax treatment is an argument for direct ownership. If you want to trade within a year, or you value settlement inside the brokerage account you already know, the picture shifts. Staking income comes on top as a separate question: inside the ETP it stays in the product and raises the value per share, while rewards you collect yourself count as running income at the moment they accrue to you and must be valued on their own.
What Is Carrying the Price Right Now and How Well Documented It Is
Several drivers are named for the move of the past few days, and they are documented to differing degrees. Well documented is the launch of confidential perpetual futures on NEAR through Hyperliquid on September 17, which we covered in detail in our reporting of September 24, 2026. For September 24 several industry outlets additionally report the launch of encrypted AI inference on NEAR by the provider Venice, private limit orders, and a link-up with tokenised equities from Ondo. Those reports come from the trade press rather than from a primary source we retrieved, and we therefore carry them as reports and not as established facts.
On the ETP report itself the position is clearer, because the load-bearing figures sit on the issuer's own page and we read them ourselves. The link between the asset milestone and the price move is arithmetic and not conjecture. Whether institutional interest follows from it is expressly not answered: a share count rising by 2.14 percent documents neither a wave nor its absence.
Levels Up and Down: How to Measure the Move
Instead of drawn chart lines we give you the reference points that arise from the retrieved data itself. On the upside the round $5.00 mark is the next visible marker; it sits a good half a percent above the price at our retrieval and just above the weekly high of roughly $4.80 that several services report for September 23. On the downside the implied price of $4.5686 is the interesting one, since the ETP's current valuation rests on it: should the spot price fall back there, the described gap between net asset value and market price closes by itself.
The starting value of the recovery at around $2.29 on September 16 serves as a further reference point. Between that value and today's price lies the entire advance on which the reports of 135 percent in 30 days rest. Anyone entering now is buying at the upper end of that range. That says nothing about the direction ahead. It states where an entry sits in relation to the most recent move.
Method of Our Survey: Four Sources, One Reporting Date, Three Open Points
cryptoticker.io carried out this analysis itself on September 25, 2026. Method: we retrieved four publicly accessible sources on the same morning and worked their figures against each other, namely the issuer's product page with the product's reporting-date values, the press release on the start of trading with the terms of the launch year, the Deutsche Börse instrument page to check the trading data, and a price source for the spot price. All four answered with HTTP 200.
Three things we could not verify. First, the product page reports no time series of shares outstanding, so we could compare inflows only against the share count reported by DL News for Tuesday and not against a series we collected ourselves. Second, no time is given for the valuation moment of the net asset value, which is why the explanation for the 9.1 percent gap remains a reasoned assumption. Third, at the moment of our retrieval the Deutsche Börse instrument page displayed neither a price nor a fund volume, so we could not cross-read the issuer's figures there.
Checking the NEAR ETP: What to Take Away
- Read the share count before you believe the asset milestone. Assets under management grow even when not a single investor joins. Shares outstanding appear on the same page at any serious issuer. If you want to buy such a product through your brokerage account, check the execution costs and the tradable segments at your provider first; our overview of the best crypto brokers shows who carries which products.
- Work the yield down to your own costs. A reported net yield of 3.01 percent becomes noticeably less after tax, and the total expense ratio of 0.85 percent runs on regardless. Keep the figures from your statements cleanly recorded; a portfolio and tax tool from our comparison of crypto tax tools takes the matching of brokerage statements and crypto holdings off your hands.
- Decide the route before the purchase, not after it. A security in a brokerage account and a token in your own custody differ so markedly on tax, custody and access that switching later costs money. If you want to collect the rewards without an issuer taking a share, the providers' terms are in our overview of staking platforms.
(As of September 25, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy. The terms of the product discussed come from the issuer's announcement on the start of trading and from its product page.)
XRP trades at around $1.56 on Thursday, September 25, 2026. That is 6.85 percent above where it stood 24 hours ago and 16.64 percent above last week (CoinGecko, retrieved 09:47 UTC). The percentage matters less than the question now on the table: buy, hold, or take profits? Because this article is written for investors in Germany, the answer does not rest on the chart alone. It rests on three things that apply here: the buying route permitted since the MiCA deadline, the one-year holding period, and where the coins sit once you own them. Our running read on the price path is in the XRP price prediction.
XRP Price on September 25, 2026: The Numbers at a Glance
The move is no one-day wonder, and it is no straight line up either. The daily close on September 18 was still $1.295. From there the price climbed in steps: $1.396 on September 19, $1.41 on both September 20 and 21, then the jump to $1.535 on September 22 and $1.571 on September 23. September 24 brought a setback to $1.501, and the price has been working its way higher since (all figures: CoinGecko, daily closes).
Over the past 24 hours XRP moved between $1.45 and $1.56. That is a range of roughly 7.6 percent in a single day — a figure that matters again later in this piece, when leveraged products come up. Market capitalisation sits at about $98 billion, turnover over the past 24 hours at some $4.4 billion. That makes XRP the fifth-largest asset in the market.
What Puts the Move in Context
XRP remains around 57 percent below its all-time high of $3.65 from July 2025. Over 30 days the gain stands at 9.06 percent. The weekly gain of a good 16 percent therefore comes almost entirely from the past seven days, while the three weeks before that went sideways on balance. Anyone reading the move as a trend reversal should know that it has exactly one attempt above $1.57 behind it, followed by a setback.
Whale Moves and New Wallets: What the On-Chain Data Says About the XRP Breakout
Coverage points to two observations as the drivers, both drawn from on-chain data compiled by the analytics firm Santiment. First: on September 23, the count stood at 1,917 XRP transfers worth at least $100,000 each — according to the Blockonomi report of September 24, the heaviest large-value activity in roughly 30 days. Second, 3,647 newly created XRP wallets were registered over the same window.
What a large transaction is: a transfer on the blockchain whose value exceeds a set threshold, here $100,000. It tells you that a lot of money moved. It does not tell you in which direction, or who was behind it.
This is precisely where many reports get loose. A transfer of $100,000 can be a purchase, a deposit to an exchange ahead of a sale, an internal rebooking by a custodian, or a shift between two wallets belonging to the same owner. The number of transfers therefore does not support the conclusion that buying took place on the same scale. The count of new wallets is the sturdier signal of fresh interest, though it too fails to distinguish a new investor from an additional address held by an existing one.
Roughly 62.9 billion XRP are currently in circulation against a total supply of just under 100 billion. The gap between those two figures is wider at XRP than at most other large crypto assets, and it belongs on the list of things you should know before you form a valuation.
XRP ETF Inflows in the US: $1.65 Billion in Assets and What Follows From It
The second documented development is the US spot ETFs on XRP. On September 23 they took in net inflows of $18.04 million, according to data from the provider SoSoValue. Of that, $11.54 million went to the Bitwise fund and $6.5 million to the Franklin Templeton fund XRPZ; the Canary fund recorded no inflows that day. Cumulative net inflows across all US XRP ETFs now stand at around $1.75 billion, with net assets under management of some $1.65 billion, equivalent to roughly 1.77 percent of XRP's market capitalisation (source: The Crypto Basic, September 24, 2026, citing SoSoValue).
September so far stands at $79.91 million in inflows, which would make it the third-best month of the year behind August at $159.18 million and May at $131.94 million.
Why This Only Matters Indirectly for You in Germany
These funds are approved in the United States and tradable there. A German retail investor generally cannot buy them through an ordinary brokerage account at a German bank, because they lack the key information documents required under EU law. What is available in Germany are exchange-traded notes on crypto assets, ETPs and ETNs, which are legally a different instrument from a US fund. Our overview of crypto ETFs in Germany sets out the routes available here and how they differ.
The US inflows still matter for the price: they are demand that was not there before, and they are publicly verifiable. As a reason to buy, however, they only carry so far at this scale. Fund assets of $1.65 billion sit against a market capitalisation of roughly $98 billion, and a daily inflow of $18 million amounts to about 0.4 percent of daily turnover.
Buying XRP in Germany: Which Buying Route Is Permitted Since the MiCA Deadline
Here comes the first concrete check. Germany brought forward the transition period of the EU Markets in Crypto-Assets Regulation to December 31, 2025 through its Crypto Markets Supervision Act, a good six months ahead of the EU-wide deadline. Since January 1, 2026, crypto service providers in Germany may only offer their services if they hold a MiCA authorisation as a crypto-asset service provider or are passported in from another EU member state.
What a CASP is: a crypto-asset service provider, meaning a provider authorised under MiCA to offer crypto-asset services, among them custody, the operation of a trading platform, and the exchange of crypto assets for euros.
In practice this means: before you buy XRP, you check whether the provider can show such an authorisation or is permitted to operate in Germany as a passported firm. The disclosure usually appears in the legal notice or in a dedicated regulatory statement. If you cannot find it, you should avoid the provider — the reason is practical rather than a matter of principle, because with an unauthorised service provider you have no route to a German supervisory complaint if a dispute arises. Our comparison of the best crypto exchanges gives a current overview of platforms permitted to trade in Germany.
Three More Points to Check on the Buying Route
- Whether the provider actually delivers XRP as a coin or only offers a contract for difference on it. That changes both the tax treatment and the custody question.
- Whether a withdrawal to your own wallet is possible. Some platforms hold crypto assets internally only.
- Which fee applies when you swap euros for XRP, and whether it is charged as a percentage or built into the spread.
Holding Period and Tax: Why the Purchase Date Decides XRP Tax Exemption
In Germany, crypto assets count as other assets within the meaning of Section 23 of the Income Tax Act. If you sell XRP at a profit within one year of buying it, that profit is taxed at your personal income tax rate as soon as the sum of all private disposal transactions in the year reaches the €1,000 threshold. After a year has passed, the profit is tax-free.
Two details are misread on a regular basis. First, the €1,000 figure is an exemption limit and not an allowance: once it is reached, the entire profit becomes taxable, not merely the portion above the line. Second, the one-year clock runs to the day from the acquisition date and not from the turn of the year. Buy XRP today, on September 25, 2026, and the earliest you can dispose of the position tax-free is September 26, 2027.
The Draft That Could Change the Math
On top of that comes a development that bears on any purchase decision in the autumn of 2026. According to reports, a ministerial draft from the Federal Ministry of Finance has been circulating since September 2026 that would abolish the one-year holding period for new acquisitions and subject crypto gains to the 25 percent flat withholding tax from January 1, 2027. A ministerial draft is an internal working stage of the administration and not law in force; it can be amended in the further process or fail outright. For the 2026 tax year the one-year rule applies unchanged. We covered the possible consequences for long-held positions in more depth on September 24, 2026, in our piece on bitcoin as retirement provision.
Either way, one rule holds: keep a clean record of your purchases from the outset, with date, quantity and acquisition cost. Without that data you can neither document the holding period nor reconstruct the cost-flow method the tax office expects. Tools that automate the work are in our comparison of crypto tax tools.
Leverage and Liquidation: What an XRP Perpetual Costs at Seven Percent Daily Swings
Back to the figure from the opening section: $1.45 to $1.56 in 24 hours, a range of roughly 7.6 percent. That number determines which leverage is viable at all.
What a perpetual is: a futures contract with no expiry date, whose price is tethered to the spot price through a funding rate paid at regular intervals.
The arithmetic is plain. At ten times leverage, an adverse move of around ten percent is enough to wipe out the collateral you put up; forced liquidation usually bites before that, because fees and maintenance margin run alongside. With a daily range of 7.6 percent, the liquidation point of a ten-times leveraged position therefore sits inside the normal swing of a single day. At five times leverage it takes an adverse move of roughly 20 percent, at two times roughly 50 percent.
Then there is the funding rate. It is typically settled every eight hours and flows from long to short positions in a rising market. Hold a leveraged long for weeks and you pay that rate throughout, even on days when the price does not move at all. Three numbers therefore belong on the table before a first leveraged position: the liquidation price, the maintenance margin, and the current funding rate of the contract in question. If you want to trade leveraged products through a regulated provider, the authorised venues are in our broker comparison.
XRP Staking Does Not Exist: What Is Really Behind Yield Promises on XRP
This point returns in every XRP rally, and it is the most common misconception around this crypto asset. The XRP Ledger does not run on a proof-of-stake mechanism. There is no way to lock up XRP in the protocol and earn a protocol reward for doing so. The network's validators receive no payout for their work.
What staking actually is: locking coins in a proof-of-stake network in order to confirm blocks and earn a reward defined in the protocol. At XRP that mechanism does not exist.
If a provider nonetheless offers you a yield on XRP, what you are being sold is something else in substance: a loan of your coins, a structured product, or a payout from a marketing budget. In all three cases you carry counterparty risk, which genuine staking does not involve. The decisive question is therefore never how high the yield is. It is who has what claim on the coins if the provider becomes insolvent. Where the contract terms give no clear answer, the offer is an unsecured loan to the provider dressed up as a yield product.
Storing XRP: Exchange, Software Wallet or Hardware Wallet
A price rise is the moment the custody question raises itself, because the position grows larger measured in euros. Three routes are available, and what separates them is less convenience than the question of who controls the private key.
Leave the coins with the exchange and the provider controls the key. That is convenient and defensible for small amounts, but it ties you to that firm's survival. A software wallet on your own device hands control back to you while shifting the risk onto the security of that device. A hardware wallet keeps the key in a separate device that never discloses it; the individual models are covered in our hardware wallet comparison.
The XRP Quirk You Need to Know
XRP adds a detail that most other crypto assets do not have: an XRP account must hold a minimum reserve for it to exist in the ledger at all. That amount is locked and cannot be transferred for as long as the account exists. Send a very small amount to your own wallet and the transfer can fail simply because it does not cover the minimum reserve. Check the reserve figure currently in force in the wallet of your choice before you trigger a first test transfer.
A second quirk: many exchanges require a destination tag alongside the address when you deposit XRP, an additional string of digits that assigns your deposit to an account inside a pooled address. A transfer sent without a destination tag, or with the wrong one, can often only be recovered through support, and in some cases not at all. This single point costs more lost XRP than any price slump.
Levels Up and Down: Which XRP Price Levels to Anchor Your Decision On
The levels below are not a forecast. They are points taken from the actual price path of the past week that a decision can be anchored on.
On the upside the nearest level is the weekly high so far at around $1.57, the close of September 23. As long as XRP stays below it, last week's breakout remains unconfirmed, a single attempt followed by a setback. Only a daily close above it would document the second attempt.
On the downside the first level is the 24-hour low at around $1.45, the second at $1.41, the level the price sat on for two days on September 20 and 21 before the jump came. Should XRP fall back below it, last week's move has been worked off in arithmetic terms.
What you make of these levels depends on whether you hold an existing position or want to build a new one. For an existing position the question is whether a partial sale at the current level secures the original capital outlay, and what that sale costs in tax if the one-year clock has not yet run out. For a new position the question is whether you are willing to pay for an entry after a weekly gain of 16 percent, or whether you wait for confirmation above $1.57.
Checking the XRP Breakout: What to Take Away
- Check the buying route before the buying decision. Look up whether your provider can show an authorisation as a crypto-asset service provider since the German MiCA deadline on January 1, 2026, and whether it actually pays out XRP. Where to find them is in the comparison of the best crypto exchanges.
- Record the purchase date before you buy. The one-year clock under Section 23 of the Income Tax Act runs to the day, and the €1,000 figure is an exemption limit, not an allowance. Start the record with your first purchase; suitable tools are in the comparison of crypto tax tools.
- Measure leverage against the daily range, not against gut feel. At a 7.6 percent swing in 24 hours, the liquidation point of a ten-times leveraged position sits inside a normal trading day. Anyone who still wants leverage should take it through a regulated provider from the broker comparison and know the liquidation price, the maintenance margin and the funding rate beforehand.
A fourth point needs no link: a yield promise on XRP is not staking. Treat it as what it is, a loan to the provider. The read on this week's on-chain moves is in the report from Blockonomi dated September 24, 2026.
(As of September 25, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
You entered your phone number and your email address into a contact form on a website because an AI-powered crypto trading platform was advertised there. In that case, in the assessment of the German financial supervisor, you very probably never contacted a trading platform at all. You filled in an advertising page whose purpose, according to BaFin's findings, is to collect contact details and pass them on to operators of unauthorized online trading platforms.
BaFin published this assessment on September 23, 2026, together with the names of 39 websites. The most important sentence in it for you is this: the damage does not begin with the first transfer, but at the moment the form is sent. From then on your record exists as tradable goods.
The short version, if you are in exactly that situation right now: pay no money. For the time being, do not take calls from unknown numbers, or end them after the first sentence. Secure the website address, the date and every message you have received. Everything else follows below, ordered by what you have already done.
What BaFin published on September 23, 2026
The Federal Financial Supervisory Authority, BaFin for short, is the German authority supervising banks, insurers and, since European crypto regulation, providers of crypto-asset services as well. The authority is allowed to issue a public warning when it suspects that someone is operating without authorization.
On September 23, 2026 it reported what it calls a platform series. In the language of supervision, a platform series is a group of near-identical websites that differ only in their name and very probably come from the same source. In this case there are 39 addresses, appearing mostly in bundles of three: the same invented name as .com, .net and .org.
The authority describes the mechanism itself as follows: interested parties "are asked to leave their data in a contact form on the websites concerned. According to BaFin's findings, the customer data is then passed on to operators of unauthorized online trading platforms that are not supervised by BaFin." The pages are therefore suspected of "primarily serving to initiate business for crypto-asset services provided without authorization."
Two further findings appear in the same notice. First, according to the supervisor the websites have no legally valid imprint. Second, BaFin points to a possible connection with further series it has already warned about. It names the operators themselves as unknown.
If you want to know what these series looked like in the summer of 2026, the background is in our article on the BaFin warnings about crypto platform series from August. The construction of the pages is known. What is new is their business model.
Why the contact form is more dangerous than the first transfer
The familiar fraud patterns in crypto almost always run through money: you pay in, you see rising gains in a customer area, and when you try to withdraw, demands for payment appear for supposed fees, taxes or releases. That is the scheme consumer advice centers and police have been describing as cybertrading fraud for years.
The series reported now starts one step earlier. On the authority's account the websites take no money at all themselves. What is generated are leads. In sales jargon a lead is a qualified contact record: name, phone number, email, often along with how much someone wants to invest. That record is worth considerably more to the buyer than any random address, because it documents a demonstrated interest in crypto investments.
Three things follow from this that make the difference to the classic scheme.
The contact comes with a delay. Days or weeks can lie between sending the form and the first call, because the record is resold first. Many of those affected therefore no longer connect the call with the page they filled in.
The record stays in circulation. It can be passed on repeatedly. A single completed form can draw calls for months, including from providers that have nothing to do with the original website.
And the page itself disappears without consequence. With no imprint, no named operator and no payment relationship, there is nobody against whom you could assert a claim. That is exactly why securing the evidence stands at the start of this article rather than the question of compensation.
BaFin classifies the approach soberly as business initiation. For you as a crypto investor that means: the valuable part of the business has already taken place before anyone has even spoken to you.
Which 39 websites BaFin names
The authority publishes the addresses with the dot in brackets so that they are not clickable. We reproduce them in the same notation. According to its own account, these are the pages known to BaFin so far:
coravelis(.)com · jorvaki(.)com · jorvaki(.)net · jorvaki(.)org · levorelio(.)com · levorelio(.)net · levorelio(.)org · lexovario(.)com · lexovario(.)net · lexovario(.)org · loravexo(.)com · loravexo(.)net · loravexo(.)org · mavriten(.)com · mavriten(.)net · mavriten(.)org · monvaret(.)com · monvaret(.)net · monvaret(.)org · natrovex(.)com · renvaki(.)com · renvaki(.)net · renvaki(.)org · semtovexo(.)org · solkrane(.)com · solkrane(.)net · solkrane(.)org · tavorello(.)com · tavorello(.)net · tavorello(.)org · varezuno(.)com · varezuno(.)net · varezuno(.)org · vordeli(.)com · vordeli(.)net · vordeli(.)org · zarevuno(.)com · zarevuno(.)net · zarevuno(.)org
Two things can be read from the list that go beyond the individual case. The names are pronounceable invented words without meaning, which mean nothing in any language and can therefore be registered worldwide. And the bundles of three across .com, .net and .org are an indication that the loss of individual domains was planned for from the outset.
Important for your own check: this list is a snapshot. BaFin explicitly writes "known so far" and points to possible connections with further series. If the website you visited is not listed here, that is no clean bill of health. Conversely: if it is listed here, you hold an official assessment that you can present to a bank or the police.
Section 10(7) of the Crypto Markets Supervision Act: the legal basis of the warning
By its own account the notice rests on section 10(7) of the Crypto Markets Supervision Act, abbreviated KMAG in German. The detail looks technical, but it explains why the warning looks the way it does.
The Crypto Markets Supervision Act is the German act accompanying the European regulation on markets in crypto-assets, known as MiCA. It governs who may provide crypto-asset services in Germany and which powers the supervisor has in doing so. Those powers include informing the public about providers suspected of operating without authorization.
The logic of the wording follows from this. The authority writes "according to BaFin's findings" and "are suspected of" because a warning under this provision is not a court ruling and does not require one. What is meant is a supervisory assessment intended to protect consumers before proceedings are concluded. For you that means two things: the warning is solid enough to use towards third parties, and at the same time it is not a criminal finding against named individuals.
The reverse conclusion is what matters in practice. Banking business, financial services and crypto-asset services may only be offered in Germany with an authorization. Anyone offering crypto-asset services without that authorization is acting unlawfully, irrespective of whether anyone was harmed in the end.
How to spot a lead page before you send the form
According to the supervisor's account, the pages warned about share features that can be checked without specialist knowledge. The following points are no substitute for legal advice, but they are worked through in a few minutes.
The imprint. BaFin names the missing legally valid imprint as a shared feature of all 39 pages. A valid imprint contains a name that can be served with legal process, an address, a commercial register number and a contact option that actually works. A bare contact form is not an imprint. Nor is a mailbox address without a register entry.
The authorization status, with one important objection. Check the company name given in BaFin's company database. It shows whether a company is authorized. A hit alone is not enough, however. On its page about fraudulent trading platforms the supervisor explicitly describes how perpetrators pose as staff of reputable companies that are listed in the commercial register or supervised, misusing the names and details of uninvolved firms. From that follows the only check that holds: take the phone number and the address from the database, not the ones from the website, and ask there whether the contact was genuine.
What the page asks for. An authorized trading platform lets you open an account and then identifies you. A page that offers nothing but a contact form and no route to direct registration is collecting contacts, not trading.
The promise. Software that supposedly achieves reliable returns through artificial intelligence does not exist. Where predictable profits are advertised, caution is not an overreaction. How credibly such offers are now presented is described in our article on AI-driven crypto crime.
Where the contact came from. Did the page arrive through an advertisement on a social network, through a message in a messenger app or through a post that looked like a news report? All three routes are common with the series reported. A detailed checklist for providers is in our guide on how to check crypto providers before your first deposit.
What is actually traded on these trading platforms
Anyone who gets drawn into a conversation is rarely offered what the advertising promised. BaFin describes the typical course of these trading platforms in its consumer section, and you should know three points from it before you even think about it.
What is traded is mostly contracts for difference, not coins. A contract for difference, CFD for short, is a bet on the price movement of an underlying without you ever owning that underlying. On the supervisor's account, the supposed advisers push people into such products on commodities, equities, indices, currencies or cryptocurrencies. Anyone who believes they are buying Bitcoin is acquiring no crypto-assets in these cases.
The money runs through a wallet that is not yours. For payment processing, according to BaFin, those affected are told to set up an account at an online trading venue; the money paid in is converted into Bitcoin, and the coins then end up in the criminals' wallet. Sometimes the payment destination given is the account of a private individual who receives the money and forwards it. For that person the process has legal consequences of its own, because anyone making their account available comes under suspicion of money laundering. Never let your account be used for third-party payments, not even for a commission.
Remote access is the point at which it becomes expensive. The offer to support you through the process by remote maintenance software leads, according to the supervisor, all the way to access to your online banking and the opening of accounts and wallets in your name. There is no reason to share your screen with a provider. An authorized exchange never asks for it.
The practical counter-test is simple and works in every one of these cases: demand the wallet address on which your crypto-assets are supposed to sit, and check it in a blockchain explorer. Without verifiable transaction data on a blockchain there are no coins, only a display on a website. The details are with the supervisor itself: a warning about fraudulent trading platforms.
Already entered your data? These five steps count now
If no money has changed hands, your position is considerably better than it feels. The most likely damage is a record in circulation, and something can be done about that.
First: document before anything disappears. Note the full website address, the date and time of your entry and the details you gave. Make a screenshot of the page while it is still reachable. This evidence can neither be obtained nor reconstructed later.
Second: submit nothing further. Send no copy of your ID, no bank details, no wallet addresses and no screen sharing. The request to install remote maintenance software for "verification" is a known pattern and leads to direct access to your devices.
Third: handle calls in a controlled way. You do not have to pick up. If you do pick up, say nothing about your financial circumstances and confirm no data, not even apparently harmless details such as your date of birth. A simple "not interested" and hanging up is entirely sufficient.
Fourth: separate your credentials. If you set a password on the page that you also use elsewhere, change it everywhere immediately. Activate two-factor authentication on your exchange and email accounts, preferably through an app rather than by text message.
Fifth: report the warning. If the website is not on the list, you can report it to BaFin through its contact channels. It costs nothing and is the route by which further series come to light in the first place.
What you do not need in this situation are paid recovery services. As long as no money has changed hands, there is nothing to recover.
The callback: what happens on the phone and what you do not say
The call is the actual sales process, and it follows a recognizable course. Knowing it takes the pressure out of it.
At the start there is almost always a friendly stocktaking: how much experience do you have, what amount could you commit, which cryptocurrencies interest you? These questions feel like advice and are an assessment. The answers decide how intensively the contact is pursued.
Then comes a small entry amount, often in the region of 250 euros, combined with the promise that you can withdraw at any time. The sum is deliberately low, because it lowers the inhibition threshold while establishing a payment relationship.
In the third step a customer area displays gains. That display is a representation on a website and no evidence of actual crypto transactions. Anyone who wants to know whether trading really took place needs verifiable transaction data on a blockchain, that is, wallet addresses that can be checked independently.
Finally comes the point at which the withdrawal fails and demands for payment appear: supposed fees, supposed taxes, supposed release amounts. From here on, police and consumer advice centers describe the process consistently as investment fraud.
Three sentences are enough for the entire conversation. You name no amounts. You confirm no data. You hang up. No reputable provider loses a customer that way, and an unauthorized provider loses access.
A postscript on the second wave: after a loss, supposed recovery services, law firms or consumer advocates often get in touch, offering to retrieve the money. These callers draw their contacts from the same lists. An advance payment for a recovery is as a rule the second loss.
What rights the General Data Protection Regulation gives you against unknown operators
Formally you hold the rights under the General Data Protection Regulation against anyone who processes your personal data. In practice the position with these pages is uncomfortable, and it is fairer to say so openly.
The right of access under Article 15 GDPR obliges a controller to tell you which data it processes about you and to whom it has passed the data on. The right to erasure under Article 17 GDPR obliges it to delete the data when there is no longer a legal basis. Consent once given can be withdrawn at any time.
Both presuppose that a reachable controller exists. With websites that have no legally valid imprint and unknown operators, that is precisely what is missing. A request for access sent to a contact address on these pages leads nowhere at best, and at worst confirms that a reachable person sits behind the address.
Two routes remain worthwhile nonetheless. The first runs through the data protection authority of your federal state, where you can file a complaint. That body has investigative powers you do not have. The second concerns the companies that contact you afterwards: whoever calls you and gives a company name is a tangible controller. Against that caller you can object to the processing, demand information about the origin of your data and require erasure. It is precisely that information which makes the chain of transfers visible.
Record the outcome in writing. A documented refusal can be used by the supervisory authority; a phone call without a note cannot.
Money has changed hands: criminal complaint, bank and complaint to BaFin
If payment has already been made, the order changes. Then speed counts, and the first hours are the most valuable.
Turn first to your bank or payment service provider. With card payments and direct debits there are recovery options tied to short deadlines. With bank transfers the bank can attempt a recall as long as the amount has not yet left the recipient account. Banks look closely at crypto transactions in any case, which works in your favor here.
Then file a criminal complaint with the police, online or at a station. Bring everything you have secured: addresses of the website, names and phone numbers of the callers, payment receipts, screenshots of the customer area and, if available, the wallet addresses to which crypto-assets have gone. Those addresses are often the most solid trail for investigators, because transactions on a blockchain remain permanently traceable.
Report the matter to BaFin as well. The supervisor will not get your money back for you, but tips from the public are the basis for warnings like the one of September 23. The report runs through the authority's contact channels and costs nothing.
To the tax office, because the scheme works with exactly that. One of the most frequent demands before a supposed payout is that a tax must be paid first. That is in no case how it works in Germany. Taxes on investment income or private disposal transactions are settled with the tax office through your tax return, never as an advance payment to a trading platform. No authority and no bank demands money so that a balance is released. Whether and how fictitious gains and actual losses from a fraud case have tax effects is a separate question, which we have covered in our article on phantom gains in crypto investment fraud. Settle it with a tax adviser, not with the caller.
And once more, because it is the most expensive mistake after the first one: pay nothing in order to obtain a payout. No commission, no release fee, no advance tax payment. A demand of this kind is not an obstacle on the way to your money, it is the point of the whole exercise.
Where to buy instead: MiCA authorization and the company database
The practical consequence of a warning like this is not to avoid cryptocurrencies. What makes sense is to check the provider before the first click, and since European regulation there is a solid basis for that.
A company that provides crypto-asset services in the European Union needs an authorization for it. Authorized providers appear in public registers, are subject to requirements on the custody of customer assets and have a complaints office that can be reached. A company listed there may still charge fees you dislike. But there is a company with an address, a register entry and a supervisor.
Three checks are enough in practice. Does the exact company name appear in BaFin's company database or in the register of the competent European supervisor? Does the imprint lead to an address that can be served with legal process, with a commercial register number? And are you identified before you can trade? Anyone answering yes to all three questions has passed the basic check. An orderly comparison is in our overview of regulated crypto exchanges.
The second part concerns custody. If you want to hold Bitcoin for longer, the question of where the keys sit is more important than any fee table. How the price has developed and which assessments are circulating is set out in our Bitcoin price prediction. How to secure holdings independently of an exchange is shown by the hardware wallet comparison. A provider without authorization can offer you neither, because in case of doubt it does not trade at all.
BaFin warning on the AI crypto platform: what to take away
- Check the provider before you enter anything. An imprint with an address that can be served with legal process, the exact company name in the company database, identification before the first trade. If you are looking for regulated points of contact, you will find them in the comparison of regulated crypto exchanges.
- If you have already left data, secure the evidence and submit nothing further. Website address, date, screenshot. After that no copy of your ID, no bank details, no remote access, no payment. Which features unauthorized providers share is set out in the guide to checking crypto providers.
- Separate custody and trading. What you hold long term does not belong permanently in an account whose operator you cannot identify. The options for that are in the hardware wallet comparison.
The full notice with all 39 addresses is with the supervisor itself: BaFin warns about the platform series "AI-powered crypto trading platform".
(As of September 25, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
The crypto market is telling two very different stories today. Bitcoin is nursing an 8% weekly loss and trading just above $84,000, yet scroll one line down the rankings and the screen turns green: XRP, Cardano, Chainlink and Dogecoin are all up double digits on the week, and privacy coins are posting numbers we have not seen since 2016. Money is not leaving crypto, it is rotating. Here is the full breakdown of crypto prices today, why Bitcoin is lagging, and which altcoins are stealing the show.
Why Is the Bitcoin Price Down This Week?
Bitcoin ($BTC) is trading at $84,097, down 0.41% over the past 24 hours and 8.32% over the past seven days. The pullback from September's highs leaves BTC slightly negative for the year at minus 3.90%, with a market cap of $1.68 trillion and around $36.5 billion in daily volume.
The macro backdrop is doing most of the damage. Futures markets are now pricing in as many as four Fed rate hikes by June 2027, and the combination of rising bond yields and a stronger dollar has taken the wind out of both Bitcoin and gold. On top of that, an $80 million wave of long liquidations hit the market as BTC stalled around the $84,000 level, with traders now watching $82,800 as the next line of support.
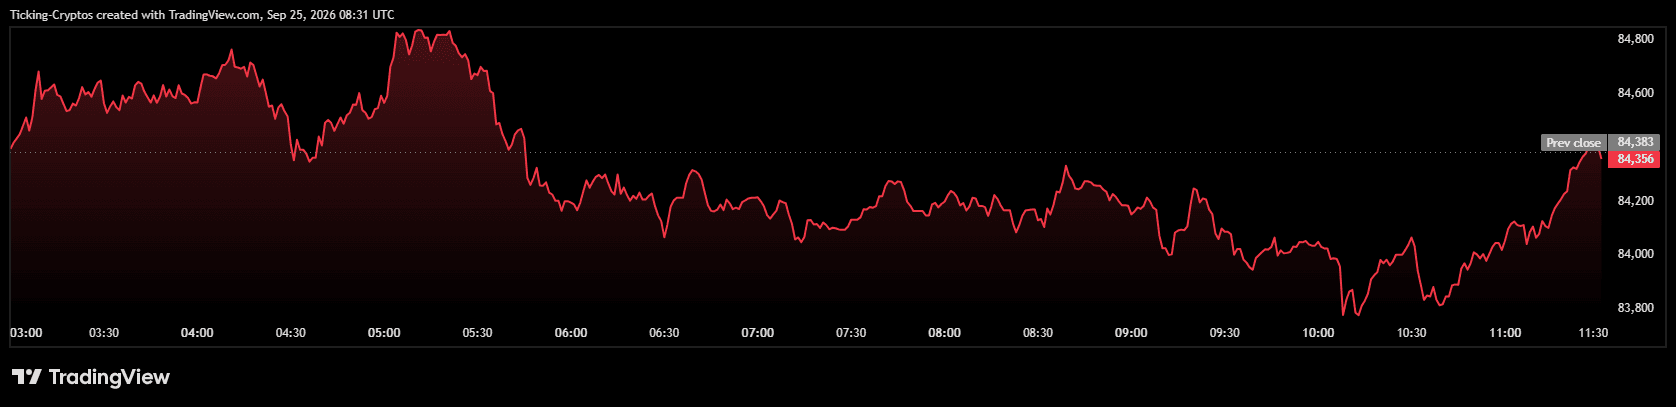
The silver lining: institutions are buying the dip. US spot Bitcoin ETFs have flipped back into accumulation mode, adding around $347 million in a single day with BlackRock and Fidelity leading the buying, part of a roughly $4.6 billion rebound that has erased the year's earlier outflows. Price is falling, but the structural demand story is quietly improving underneath it.
Which Altcoins Are Pumping While Bitcoin Bleeds?
While $Bitcoin gave back 8% this week, the altcoin market barely blinked. Cardano (ADA) leads the large caps with a 16.57% weekly gain to $0.2494, closely followed by XRP, up 15.72% to $1.53, and Chainlink (LINK), up 15.13% to $13.58 and still climbing with an 8.91% move in the last 24 hours alone. Dogecoin (DOGE) added 13.19% on the week, Solana (SOL) gained 10.39% to $116.50, and even Ethereum (ETH) managed a solid 7.74% weekly advance to $2,677 despite the drag from BTC.
This is a classic capital rotation. Derivatives data underlines it: altcoin futures open interest has overtaken Bitcoin's for the first time since 2024, meaning traders are actively positioning in alts rather than simply hiding in BTC. When Bitcoin dominance slips while total market activity stays elevated, altcoin traders usually read it as the early innings of an alt-friendly phase. The caveat: rotations built on leverage can unwind just as fast, as this week's $80 million liquidation flush reminded everyone.
Are Privacy Coins the Biggest Winners of 2026?
The standout story of the year keeps getting bigger. Zcash (ZEC) is trading at $1,574, up another 6.30% this week and an eye-watering 207% year to date, making it comfortably the best performer in the top ten. Zoom out further and the move is historic: Glassnode data puts ZEC's gain at roughly 2,500% over the past year, a run that lifted it from around 82nd place by market cap into the top ten, at levels not seen since 2016.
Several things are feeding the fire. Grayscale converted its Zcash Trust into ZCSH, the first US spot ETF built around a privacy coin, opening the door for institutional money. At the same time, the share of ZEC locked in the fully private shielded pool has grown sharply, which analysts read as holders taking coins off the market rather than preparing to sell. The whole sector has followed: privacy coins now command a combined market cap of over $33 billion and are the only crypto sector trading above their October 2025 levels.
Monero (XMR) tells the same story with less drama, up 1.81% today, 6.01% on the week and 31.62% year to date at $570. One cloud on the horizon: new EU rules set for mid-2027 would bar regulated exchanges from listing privacy coins like Zcash and Monero, so the regulatory endgame for this rally is far from settled.
How Do Crypto Prices Look Today?
Here is the top of the market at a glance:
| # | Coin | Price | 24h | 7d | YTD |
|---|---|---|---|---|---|
| 1 | Bitcoin ($BTC) | $84,097 | -0.41% | -8.32% | -3.90% |
| 2 | Ethereum ($ETH) | $2,677 | -0.42% | +7.74% | -9.76% |
| 3 | BNB ($BNB) | $774.09 | -0.03% | +2.85% | -10.33% |
| 4 | XRP ($XRP) | $1.53 | +1.95% | +15.72% | -16.70% |
| 5 | Solana ($SOL) | $116.50 | +0.96% | +10.39% | -6.41% |
| 6 | TRON ($TRX) | $0.3381 | -1.20% | +0.59% | +18.97% |
| 7 | Zcash ($ZEC) | $1,574 | +3.33% | +6.30% | +207.23% |
| 8 | Hyperliquid ($HYPE) | $92.97 | -0.60% | +5.44% | +265.59% |
| 9 | Dogecoin ($DOGE) | $0.09542 | +1.01% | +13.19% | -18.65% |
| 10 | Monero ($XMR) | $570.22 | +1.81% | +6.01% | +31.62% |
| 11 | Chainlink ($LINK) | $13.58 | +8.91% | +15.13% | +11.42% |
| 12 | Cardano ($ADA) | $0.2494 | +2.97% | +16.57% | -25.06% |
Hyperliquid (HYPE) deserves a special mention: at +265% year to date it is the only asset outperforming Zcash in the top ten, proof that the market keeps paying up for real on-chain revenue. For more crypto insights, check the CryptoTicker charts page.
What Is Next for the Crypto Market?
The short-term script is written by the Fed. As long as markets keep pricing in more rate hikes, Bitcoin will struggle to reclaim its September highs, and the $82,800 level is the support bulls need to defend to keep the structure intact. A decisive break below it would put the psychological $80,000 zone back in play. On the upside, steady ETF inflows from BlackRock and Fidelity suggest that dips are being absorbed by longer-term buyers rather than triggering panic.
For altcoins, the rotation is the trend to watch. If Bitcoin stabilizes, the strength in XRP, ADA, LINK and SOL could accelerate into a broader altcoin run. If macro pressure intensifies, expect leveraged alt positions to unwind first and fastest. And keep an eye on the privacy sector: with an ETF now live and EU delisting rules looming in 2027, Zcash sits at the intersection of the year's most powerful narrative and its biggest regulatory risk.
Decrypt
STRF, STRC, STRK and STRD would accrue dividends on weekends and holidays, in a move Strategy says will dampen volatility.
The bulk of prediction market trades are still sports bets, while valuations are predicated on rising institutional interest.
The biggest financial institutions in the world are bringing more products onchain, and the pace is accelerating.
Two entries in his annual disclosure put the holding somewhere between $16,000 and $65,000, alongside more than $1 million in cash.
Evercrest says LayerZero approved the single-verifier configuration in writing multiple times, then warned a different developer about it.
U.Today - IT, AI and Fintech Daily News for You Today
Cardano setting up for what could become its first major golden cross of 2026.
XRP whales bought 470 million tokens in hope to spark a massive chart reversal, mirroring an August run that could force a fast breakout toward $2.
XRP whale activity is surging alongside the latest price recovery, with major holders reportedly accumulating 1.54 billion XRP in just 96 hours.
XRP is seeing sustained institutional demand as it continues to make big price moves in recent days, with Bitwise consistently buying the asset in large quantities.
Shiba Inu coin enters October with an 80% win rate after an anomalous +39.3% Q3 pump and a technical breakout from a two-year slump.
Blockonomi
Key Takeaways
- CoinMarketCap completed the acquisition of Coinglass, a specialized derivatives analytics platform, with undisclosed deal terms
- Coinglass will maintain its existing brand identity, staff, platform infrastructure, API services and pricing structure
- The platform monitors derivatives metrics including open interest, funding rates, liquidation data and options activity from 28 major exchanges
- With coverage of over 2,500 trading instruments, Coinglass attracts more than 5 million monthly active users
- Binance has owned CoinMarketCap since acquiring the price tracking service in April 2020
CoinMarketCap finalized its purchase of Coinglass, a specialized platform for cryptocurrency derivatives analytics, according to Friday’s announcement. The transaction has been completed, though the purchase price remains undisclosed.
As one of the crypto industry’s most visited price reference sites, CoinMarketCap attracts approximately 115 million monthly visitors who rely on the platform for cryptocurrency valuations and market statistics.
Meanwhile, Coinglass specializes in a more niche segment of digital asset markets. The platform aggregates derivatives metrics including open interest figures, funding rate movements, liquidation events and options market data.
Strategic Value of the Coinglass Platform
Since its 2019 launch, Coinglass has expanded to monitor 28 cryptocurrency exchanges and track more than 2,500 different trading products.
The service attracts over 5 million users monthly. Additionally, more than 10,000 API clients integrate Coinglass data feeds into their proprietary trading systems and analytical frameworks.
Among Coinglass’s popular features are its liquidation heatmap visualizations and comprehensive open interest tracking dashboards. These analytical tools have become widely circulated within online cryptocurrency trading communities.
Derivatives contracts account for the majority of total trading volume across cryptocurrency markets. Consequently, the metrics that Coinglass monitors provide insight into where substantial market activity and leverage exposure exist.
This acquisition enables CoinMarketCap visitors to access derivatives market positioning alongside traditional spot price information. Users will gain visibility into liquidation concentration zones and evolving funding rate dynamics.
Rush, serving as Chief Executive Officer of CoinMarketCap, addressed the transaction. He noted that Coinglass established its market position through concentrated expertise and execution excellence.
He emphasized that CoinMarketCap aims to deliver this specialized data to its broader user base. The company intends to preserve Coinglass’s current operational model without imposing changes.
David Salamon, holding the position of Chief Product Officer at CoinMarketCap, offered additional perspective on the deal. He explained that open interest, funding mechanisms and liquidation patterns reveal where traders are actually deploying capital and accepting risk.
Coinglass Operations to Continue Unchanged
Coinglass has assured users it will preserve its distinct brand identity post-acquisition. The platform’s website, mobile application, complimentary analytics tools, API infrastructure and subscription costs will all remain consistent.
The existing Coinglass team will stay intact after the transaction closes. Management committed to continuing product development that serves their established user community.
This deal represents another chapter in CoinMarketCap’s corporate evolution. Cryptocurrency exchange Binance purchased CoinMarketCap in April 2020.
During that earlier acquisition, Binance pledged that CoinMarketCap would maintain operational independence. The exchange also committed to avoiding any interference with the platform’s cryptocurrency ranking methodologies.
CoinMarketCap has not yet announced plans to embed Coinglass analytics directly within its primary price tracking pages. Currently, both services will function as distinct offerings under common ownership.
The post CoinMarketCap Buys Coinglass in Major Derivatives Data Expansion appeared first on Blockonomi.
Key Takeaways
- AMD achieved a $1 trillion market capitalization on September 21 following a 187% surge in 2026, compared to Nvidia’s $5.45 trillion valuation.
- AMD’s forward price-to-earnings ratio sits at approximately 55.6x, significantly higher than Nvidia’s 18.7x multiple.
- Nvidia generated $96.2 billion in quarterly sales with 106% year-over-year growth, while AMD reported $11.5 billion with 50% growth.
- Nvidia’s Vera Rubin platform has entered production and is projected to contribute 20% of data center sales in the upcoming quarter.
- AMD’s Helios rack system, linked to an Anthropic partnership for up to 2 gigawatts of MI450 infrastructure, has just started its deployment phase.
On September 21, Advanced Micro Devices reached a milestone market capitalization of $1 trillion. The semiconductor company had surged approximately 187% throughout 2026.
Advanced Micro Devices, Inc., AMD
By comparison, Nvidia maintained a substantially larger footprint. As of September 23, the company commanded a market value near $5.45 trillion.
However, the most significant contrast between these two semiconductor giants isn’t their market capitalization—it’s their valuation metrics.
AMD currently commands a forward earnings multiple of roughly 55.6x. Nvidia, meanwhile, trades at just 18.7x forward earnings. This disparity indicates that shareholders are paying considerably more for each dollar of AMD’s anticipated future profits.
Financial Performance Reveals Substantial Divergence
AMD’s second quarter results showed revenue of $11.5 billion, representing 50% year-over-year expansion. The company’s Data Center segment more than doubled, reaching $6.7 billion.
Nvidia’s financial metrics dwarfed those figures. The chip leader posted quarterly revenue of $96.2 billion, marking 106% growth. Its Data Center division climbed 117% to $89.0 billion.
Nvidia maintained a gross margin of 75%. AMD reported 56%.
Looking ahead, AMD projects approximately $13 billion in third quarter revenue, representing 41% growth. Nvidia’s guidance stands at $108 billion.
New Platforms Show Different Deployment Stages
Nvidia’s upcoming chip architecture, Vera Rubin, has already entered mass production. CEO Jensen Huang described it as the company’s most aggressive product launch ever. Analysts expect it to represent approximately 20% of data center sales during the fiscal third quarter.
NVIDIA Corporation, NVDA
Company executives indicated that current supply satisfies roughly 70% of demand for these advanced chips.
AMD’s Helios rack solution has only just begun shipping. CEO Lisa Su informed shareholders that the third quarter represents the initial deployment phase, with meaningful acceleration anticipated in the fourth quarter and another uptick in early 2027.
AMD claims Helios offers up to 30% better token generation efficiency per dollar compared to rival systems.
Nvidia revealed that Vera Rubin produces $40 billion in revenue per gigawatt of installed infrastructure. This compares favorably to $25 billion for the previous Blackwell generation. The company additionally announced a hyperscaler cloud pipeline exceeding $2 trillion.
AMD’s expansion strategy hinges on securing fresh partnerships. Anthropic has committed to installing up to 2 gigawatts of MI450 infrastructure via Helios. This follows previous gigawatt-level commitments from OpenAI and Meta.
Su suggested to Wall Street analysts that the $30 billion revenue target for AMD’s Instinct accelerator portfolio in 2027 might prove conservative.
AMD’s trailing twelve-month price-to-earnings ratio registers at 154. Nvidia’s comparable metric is 29.
According to Insider Monkey’s institutional ownership tracking, 164 hedge funds held AMD positions during the second quarter, climbing from 134 in the previous period. Nvidia’s institutional ownership expanded to 285 funds from 275 during the same timeframe.
As of August 31, AMD’s short interest totaled 41.7 million shares, equivalent to 2.57% of available float.
Nvidia indicated that margin compression should reach its nadir around 71% to 72% in the fourth quarter, driven primarily by escalating memory component costs. The company has simultaneously committed to $279 billion in supply chain obligations.
Wall Street’s consensus estimate for Nvidia’s fiscal 2028 earnings per share currently stands at $15.68, up from $12.88 just thirty days prior.
AMD’s share price has appreciated 185.68% over the trailing six-month period. Upcoming quarterly reports from both manufacturers, especially AMD’s fourth quarter results showcasing Helios deployment metrics, will likely prove decisive in determining investor preference between these two AI semiconductor leaders.
The post Nvidia (NVDA) vs AMD Stock: The Superior AI Chip Investment for 2026 appeared first on Blockonomi.
Key Takeaways
- Shares of Comcast declined more than 2% to $21.64 during Friday’s premarket session, marking the lowest price point since October 2013.
- KeyBanc issued an Underweight rating on Comcast, slashing its price target down to $18 from Sector Weight.
- KeyBanc’s Brandon Nispel forecasts the company will shed 558,000 broadband subscribers in 2026 and an additional 665,000 in 2027.
- Citi reduced its target to $27.50 from $30 while maintaining its Buy recommendation.
- The company halted share repurchases on July 1, 2026, in preparation for the NBCUniversal spinoff.
Comcast shares plunged over 2% to $21.64 during Friday’s premarket hours. The decline positioned the stock for its weakest closing level since October 11, 2013.
Comcast Corporation, CMCSA
The selloff came after KeyBanc’s Brandon Nispel slashed his rating on the cable giant. He downgraded the stock from Sector Weight to Underweight—essentially a Sell recommendation—while establishing an $18 price objective.
Nispel highlighted accelerating broadband subscriber defections as a primary concern. He also raised red flags about weakening theme park performance and uncertainty surrounding the planned NBCUniversal separation.
Mounting Analyst Pessimism
Aggressive pricing from broadband and wireless rivals—with monthly plans dropping as low as $30 to $40—has intensified competitive pressure. Nispel forecasts the telecom company will hemorrhage 558,000 broadband subscribers in 2026, followed by 665,000 more defections in 2027.
He observed that Comcast has characterized competitors’ pricing strategies as unsustainable but has declined to engage in a price war. According to Nispel, this approach creates a no-win scenario where subscriber losses continue regardless.
Citi’s Michael Rollins joined the bearish chorus by reducing his price objective to $27.50 from $30. However, Rollins maintained his optimistic Buy stance on the shares despite the reduction.
Theme park operations have compounded the company’s challenges. Visitor numbers have decelerated dramatically since June, even with the recent launch of Epic Universe in Orlando.
Analysts on Wall Street had anticipated a 9% expansion in theme park revenue for 2027. Nispel now believes growth will remain stagnant instead.
NBCUniversal Separation Concerns
The media conglomerate intends to complete its NBCUniversal separation by mid-2027. Nispel expressed doubt that this corporate restructuring will provide meaningful near-term support for the stock price.
He cautioned that the transaction might eliminate crucial price support, particularly since share buybacks have been suspended since July 1, 2026, during the separation process. Nevertheless, he acknowledged potential for the spinoff to eventually facilitate a merger with Charter Communications.
A hypothetical Comcast-Charter combination would service over 130 million households. Charter shares edged 0.4% higher in premarket activity Friday, diverging from Comcast’s trajectory.
Comcast’s CFO previously cautioned that broadband subscriber losses would show no improvement in the current quarter versus year-ago levels. This guidance has triggered successive waves of selling pressure throughout September.
Broader market conditions did not account for Friday’s weakness. The S&P 500 advanced 0.3%, the Dow Jones climbed 0.2%, and the Nasdaq gained 0.5% during the same timeframe.
This divergence underscored that Comcast’s troubles stem from company-specific issues rather than broader market sentiment. Among 29 analysts monitored by FactSet, the consensus rating on Comcast stands at Hold.
The company is also nearing its third-quarter earnings announcement. Current Wall Street estimates point to year-over-year declines in both earnings per share and total revenue.
The confluence of two reduced price targets, a full downgrade, persistent broadband erosion, and suspended buybacks has intensified downward pressure. Comcast shares now hover near the 52-week low of $21.28.
The post Comcast (CMCSA) Stock Plummets to 13-Year Low Amid Analyst Downgrades appeared first on Blockonomi.
Key Takeaways
- Michael Burry cautions that massive AI infrastructure investments by tech giants may result in significant write-downs in coming years.
- Five major companies—Microsoft, Amazon, Alphabet, Meta, and Oracle—hold approximately $3 trillion in AI-related infrastructure obligations.
- S&P 500 net capital spending reached 2.07% of GDP, marking the highest point in nearly four decades except during the dot-com bubble.
- Burry draws parallels between current AI expansion and the late 1990s telecom boom that ended with massive overcapacity.
- Elon Musk announces xAI’s plan to expand its Nvidia chip deployment significantly by the end of this year.
Michael Burry, the legendary investor known for forecasting the 2008 financial crisis, has issued a stark warning about the surge in artificial intelligence infrastructure spending among major technology corporations. He shared his concerns in a recent Substack publication.
Burry highlighted a critical metric to support his argument. As of June 30, S&P 500 companies’ net capital investment climbed to 2.07% of GDP.
This figure has exceeded current levels only once in the last 38 years—during the immediate aftermath of the Nasdaq’s March 2000 peak.
Burry identifies five major corporations shouldering the bulk of this exposure: Microsoft, Amazon, Alphabet, Meta Platforms, and Oracle.
His analysis suggests these technology behemoths have approximately $3 trillion in AI infrastructure obligations, encompassing leases, construction contracts, and purchase commitments.
Echoes of the Late 1990s Telecom Boom
The investor draws stark parallels between current AI capital expenditures and the telecommunications infrastructure expansion of the late 1990s. That era witnessed companies pouring massive resources into network infrastructure development.
The telecom boom ultimately resulted in significant overcapacity. Firms experienced disappointing returns and were forced to recognize substantial write-downs on depreciated assets.
Burry anticipates a comparable scenario could unfold in the AI sector. He projects potential write-downs may emerge around 2028 or 2029 if AI infrastructure capacity outpaces genuine market demand.
His commentary included particular scrutiny of Oracle, questioning the company’s accounting treatment of customer advance payments and expressing concerns about financing arrangements for its data center developments.
Continued AI Infrastructure Expansion
Elon Musk contributed to AI infrastructure headlines this week, announcing that xAI’s Colossus 2 supercomputing facility plans to more than double its Nvidia processor inventory before year-end.
The current configuration includes 110,000 GB200 chips and 440,000 GB300 chips. The company expects delivery of an additional 220,000 GB300 chips next week, followed by another 220,000 units in November.
In contrast, Goldman Sachs Asset Management has adopted a cautious stance regarding AI infrastructure financing. The investment firm maintains an underweight position on the largest AI-related borrowers.
Lindsay Rosner, the firm’s multi-sector fixed income investing head, attributes this positioning to anticipated increases in hyperscaler debt offerings. Amazon, Meta Platforms, and Alphabet have ranked among this year’s most prolific investment-grade corporate bond issuers.
These technology leaders have leveraged bond markets extensively to finance their AI infrastructure expansion initiatives. Burry’s cautionary message focuses on the potential consequences of this spending trajectory over the coming years.
The ultimate outcome hinges on whether AI adoption and demand can match the unprecedented capacity being constructed. Burry’s analysis introduces a sobering perspective to the enthusiastic narrative surrounding AI investment among the world’s largest technology enterprises.
The post Michael Burry Forecasts Major AI Infrastructure Write-Downs for Tech Giants appeared first on Blockonomi.
Key Highlights
- HSBC elevated Synopsys (SNPS) from Hold to Buy in a Thursday note.
- Price target increased to $700 from $490, representing the highest on Wall Street.
- The new target suggests approximately 65% potential upside from the $424.91 trading level.
- HSBC’s fiscal 2027 earnings projection of $20.01 per share exceeds consensus by 13%.
- The upgrade highlights AI-fueled expansion in EDA and a strategic pivot toward royalty revenue models.
Synopsys (SNPS) shares are currently priced at $424.91 following HSBC’s decision to elevate its stance to Buy from Hold on Thursday. The investment bank simultaneously boosted its price objective to $700 from the previous $490 mark.
Synopsys, Inc., SNPS
HSBC analyst Stephen Bersey arrived at the revised target by applying a price-to-earnings multiple of 35 times the firm’s fiscal 2027 earnings per share projection of $20.01. This forecast stands 13% higher than the Street consensus, positioning it as the most optimistic EPS estimate among Wall Street analysts.
The $700 price objective represents potential appreciation of approximately 65% from present trading levels. As a reference point, Synopsys currently commands a P/E ratio of 75.
HSBC recalibrated its valuation methodology to focus on fiscal 2027 projections, departing from its previous fiscal 2026 framework that employed a 33 times earnings multiple.
Rationale Behind HSBC’s Optimistic Outlook
HSBC analyst Frank Lee outlined a “new business model” with the potential to redefine Synopsys “from a slow-growth software play to a high-growth AI beneficiary.”
Lee highlighted the company’s design IP licensing-plus-royalty framework. He also emphasized the integration of agentic AI capabilities within electronic design automation as a significant catalyst for earnings expansion.
The semiconductor design firm is departing from its traditional “build once, sell many” strategy. Instead, it’s embracing deeper partnerships with semiconductor manufacturers, delivering customized silicon solutions tailored to specific client needs.
“It shifts Synopsys up the value chain by combining licensing revenue with royalties,” Lee noted. He anticipates this will broaden the company’s total addressable market as revenues become directly linked to chip production volumes.
This strategic approach would focus on customers including hyperscalers, ASIC producers, and semiconductor foundries. Lee projects the royalty-based revenue component will deliver substantial margin enhancement.
The Role of Agentic AI
Lee also anticipates agentic AI will fundamentally transform the functionality of EDA platforms. Rather than merely supporting engineers, these advanced tools may soon autonomously handle complete design workflows.
Synopsys is allegedly evaluating a departure from conventional subscription licenses designed for human engineers. The firm is considering subscription-plus-consumption frameworks optimized for AI agents operating independently.
This evolution could enable AI agents to assume greater engineering responsibilities. It may also allow them to coordinate underlying EDA systems at significantly accelerated rates compared to human-driven processes.
InvestingPro data reveals that 16 analysts have recently raised their earnings projections for the upcoming period. The company also boasts gross profit margins reaching 83%, per the same source.
Certain InvestingPro assessments indicate the stock may be trading above its Fair Value calculation, a consideration worth factoring in given the elevated valuation multiple HSBC is utilizing.
HSBC’s call isn’t an isolated bullish perspective on Synopsys lately. Benchmark maintained its Buy recommendation following the company’s second-half fiscal 2026 performance, characterizing it as a beat-and-raise quarter.
Baird similarly raised Synopsys to Outperform from Neutral, referencing an encouraging growth trajectory for fiscal 2027 and establishing a $560 price objective. Morgan Stanley also upgraded the stock to Overweight from Equalweight, highlighting enhanced confidence in the Ansys merger integration and Design IP segment recovery.
These analyst upgrades come on the heels of Synopsys’s fiscal third-quarter 2026 performance, which exceeded Wall Street projections. The company delivered non-GAAP earnings of $3.91 per share alongside revenue of $2.48 billion, surpassing analyst expectations of $3.67 per share and $2.44 billion in sales. Synopsys subsequently elevated its full-year guidance following that quarterly announcement.
The post Synopsys (SNPS) Stock Surges as HSBC Sets Street-High $700 Target on AI Potential appeared first on Blockonomi.
CryptoPotato
Cardano’s native token has been rallying hard lately, posting a 20% weekly increase to surpass $0.25. In fact, it has outperformed many leading cryptocurrencies, including BTC and ETH, over that period.
Several analysts believe the uptrend is just starting, with some envisioning gains of more than 1,000%.
Same as Before?
ADA has been thriving amid the latest market resurgence, but its solid performance shouldn’t be attributed solely to the broader revival. Just a few days ago, the Cardano Foundation joined the x402 payment standard through an official SDK integration, enabling applications and AI agents to pay for API calls and other services using the network’s native token. X user Akshay commented on the move, saying:
“ADA is entering the AI-agent payment race. Cardano has joined Solana and XRP Ledger in exploring infrastructure for AI-agent payments. Imagine software that can autonomously request data, pay for services, and settle transactions. AI needs programmable money.”
Another catalyst for the price could be the recent interaction with the football world. The reigning Spanish champion FC Barcelona launched “Barca Fan Lab” in collaboration with Andamio and using Cardano’s technology.
“The project will allow fans to learn more about the Club’s history and values, participate in community activities and obtain verifiable digital credentials,” the announcement reads.
X user Sssebi described the latest price pump as “textbook of the breakout zone,” predicting that $0.30 is now “in the books.” JAVON MARKS was much more bullish, suggesting that ADA seems to have “based” just like in 2020 before a massive move north.
That said, the analyst anticipates another “monstrous run” and set $2.90 as a target. Such a major increase would represent a giant 1,049% from the current valuation.
Other market observers who have recently weighed in on Cardano’s native cryptocurrency include Jesse Olson and More Crypto Online. The former estimated that the asset has a pending buy signal on the weekly chart, noting that it hasn’t been bullish on the seven-day timeframe in 14 months. The latter maintained that ADA continues to trade within a specific bullish price channel, saying that $0.315 is the next target to watch.
Correction Before the New Big Jump?
Despite the overall bullish sentiment, two key factors suggest ADA may decline in the short term before potentially continuing north. The first one is the Relative Strength Index (RSI), which has increased to 78. This level means the asset has entered overbought territory and could be on the verge of a pullback.

Another bearish element is ADA’s exchange netflow. Over the past few days, inflows have dwarfed outflows, suggesting investors have been moving from self-custody to centralized platforms, increasing immediate selling pressure.

The post History Repeating? Cardano (ADA) Could be Gearing Up for a 1,000% Explosion appeared first on CryptoPotato.
Earlier this week, the second-largest cryptocurrency briefly spiked to nearly $2,800 before slightly retracing to $2,710 (according to CoinGecko).
Some factors suggest it may be gearing up for a new rally, and the actions of one mysterious whale support that view.
Inside Information?
X user Max Crypto recently revealed that one anonymous trader has opened a $99 million long position in ETH with 25x leverage. What’s interesting (and even shocking) is that the market participant has made 3,156 trades so far and has a stunning 100% win rate. Just this week alone, the whale has generated $5.5 million in profits.
The trader opened the massive position when ETH was around $2,660, while the liquidation price is $2,552 (unless the individual adds extra collateral).
Of course, such a flawless track record has sparked huge speculation among X users. Very few commentators described the move as gambling, while most believe the whale has access to inside information that has been key to their successful trades so far.
Meanwhile, the declining amount of ETH stored on exchanges reinforces the bullish bet. Recently, analytics platform Santiment revealed that less than 3.5% of the asset’s supply now sits on tracked platforms, with another 1.16% of the total supply moving off since the beginning of June.
“Fewer coins on exchanges means fewer coins sitting one click away from being sold. It doesn’t guarantee higher prices, but it reduces the pool of ETH readily available to hit the market during the next wave of selling,” the entity explained.
Additional Forecasts
Michal van de Poppe and Gerla have joined the growing chorus of Ethereum bulls. The former said the asset is “looking great,” anticipating a jump toward new highs if the price exceeds $2,708 (as it did) and holds that as support. The latter suggested that ETH is still holding the same bullish structure, describing $2,770 as the key zone.
“If it flips back into support, I’m watching 2,950 first, then 3,080. Same stair-step pattern we’ve seen throughout this move. Higher lows stay intact, trend stays bullish,” he concluded.
For their part, JAVON MARKS argued that ETH appears to be entering another “massive bull run.” The analyst maintained that the price is coming out of a notable accumulation, setting $4,811, $8,500, and even $12,000 as potential targets.
The post This Trader Has Never Been Wrong and Now Bets Big on Ethereum (ETH): Details appeared first on CryptoPotato.
Ondo Finance has rolled out three new on-chain portfolio products based on investment strategies developed by BlackRock as part of its push to bring traditional portfolio management strategies to the blockchain.
The new products are part of Ondo’s Intelligent Portfolios suite.
BlackRock-Based Portfolios
According to the official blog post, each portfolio is packaged into a single on-chain token, which allows investors to gain exposure to a basket of assets without having to buy and manage each position separately. The first three products are Ondo High Income Powered by BlackRock, Ondo Diversified Growth Powered by BlackRock, and Ondo High Growth Powered by BlackRock. The portfolios are built around strategies developed by the asset management giant specifically for Ondo.
The portfolios cover different investment goals. High Income follows a global income strategy, while Diversified Growth uses a diversified allocation. Meanwhile, High Growth is designed around a higher-growth allocation. Ondo revealed that the portfolios will have set asset allocations and target weights when launched and will then be rebalanced on a fixed schedule. The process is handled programmatically.
The underlying positions are built using Ondo Stocks, which is the company’s platform for tokenized equities and exchange-traded funds. These assets are backed by real securities and sourced through traditional market liquidity. The company also revealed that the portfolio allocation, rebalancing, and fee rules are encoded into smart contracts, meaning investors do not need to manually adjust their holdings when the portfolio changes.
The products will be available around the clock, subject to geographic and regulatory restrictions. Their token-based structure also allows them to be transferred and used across supported DeFi applications.
Ondo Founder Dies at 32
Ondo has faced a major leadership change this year after the unexpected death of founder and CEO Nathan Allman at the age of 32. The company did not disclose the cause of death. Allman founded Ondo in 2021 after working on digital asset initiatives at Goldman Sachs.
Under his leadership, Ondo launched products including USDY, OUSG, and tokenized equities. The company credited him with helping build its position in the tokenized real-world asset sector. Following his death, Ondo appointed longtime President Ian De Bode as CEO. De Bode had previously overseen strategy, products, and daily operations for more than two years.
The post Ondo Finance Unveils BlackRock-Backed On-chain Portfolios for Investors appeared first on CryptoPotato.
ZEC has retraced from its 10-year high above $1,650, with one analyst envisioning a potential collapse to $200 under certain conditions. BTC has also slipped over the past few days, but whale activity and other factors suggest the overall bullish trend remains intact.
Solana’s native token has been making headlines, too, as some market observers believe it could be on the verge of exploding to $500.
Brutal Crash for ZEC Comes Next?
Just a few days ago, the popular privacy coin surpassed $1,600 for the first time since 2016, but bulls couldn’t hold the momentum, and it corrected to under $1,500. Over the past 24 hours, ZEC headed north again and is currently worth roughly $1,590 (per CoinGecko).
The asset’s overall uptrend is undeniable, with the valuation skyrocketing by 2,600% on a yearly scale. Still, X user Crypto Patel thinks that after this “extraordinary move,” it might be time for a major pullback.
The analyst argued that a cup-and-handle structure suggests that the $1,600-$2,000 range might have marked the top of the cycle, adding that ZEC has started showing signs of “extreme extension from a psychological perspective.”
That said, they envisioned a potential collapse to $500 if the coin enters a distribution and downtrend phase, and a meltdown to $200 if the long-term structure completely reverses.
Just a Healthy Correction for BTC?
At the start of the business week, the primary cryptocurrency reached $87,000, marking its highest level since January. Its positive performance continued over the next few days before bears finally reclaimed some control. Currently, BTC is worth $84,600, but certain elements suggest this could be a temporary pullback before a new leg up.
The first one is the whale activity. Santiment recently revealed that large investors (those holding between 100 and 1,000 coins) have accumulated almost 114,000 units since July 15. For his part, Ali Martinez said these market participants have purchased over 30,000 BTC (worth more than $2.5 billion) over the past 96 hours.
Other bullish factors include the declining amount of coins stored on crypto exchanges (which reduces immediate selling pressure) and the solid institutional interest. Spot BTC ETFs have registered six green days in a row, attracting nearly $3 billion within that period.

SOL Price Outlook
Solana’s native token has surged by 12% over the last week, currently trading just south of $120. Not long ago, X user Ash Crypto claimed that the asset has one of the most bullish setups among altcoins after reclaiming the weekly MA200, briefly hitting $120 for the first time in eight months, and forming a weekly golden cross.
Veteran trader Peter Brandt and Gerla also chipped in. The former spotted a textbook cup-and-handle pattern on SOL’s price chart, which is typically a precursor to a rally, while the latter envisioned a massive jump to $500.
Meanwhile, September has been a highly positive period for Solana, suggesting that it may indeed finish in the green. CryptoRank data shows the asset has posted gains in five of the past six Septembers.

The post Catastrophic Zcash (ZEC) Prediction, Bullish Bitcoin (BTC) Factors, and More: Bits Recap September 25 appeared first on CryptoPotato.
The popular cross-border token continues with its highly volatile trading sessions, but today it’s in the right direction. After yesterday’s slump to under $1.50, the asset has rebounded swiftly and now sits over 6.5% higher than it was 24 hours ago.
Here are some of the possible reasons why and what’s next.
ETF Inflows Keep Rocking
Although the entire market tanked yesterday, XRP’s nosedive was quite painful on its own, as the asset was violently rejected at $1.65 and slumped to under $1.50 within 24 hours. Today’s situation is rather similar in terms of more profound price moves, but in the opposite direction. BTC is up by 1.6% today, similar to BNB, while ETH has gained under 2.5%. XRP stands out with a daily surge of 6.6% as of press time and now sits at $1.55 after rebounding from the key $1.50 support.
This rather notable volatility has not deterred investors gaining exposure to the asset through the spot Ripple ETFs. Despite the sluggish start with $0.00 in reportable data on Monday, the funds went on a roll in the following three days, attracting $20.02 million on Tuesday, $18.04 million on Wednesday, and another $14.89 million on Thursday, which is our first possible reason behind the impressive rebound.
The cumulative net inflows have skyrocketed to yet another all-time high of over $1.76 billion. Other notable developments in XRP’s recent performance that could have pushed the asset’s price higher include whale activity, as these large market participants acquired over 1.5 billion tokens in 96 hours last week.
Short Squeeze?
Data shared by popular crypto commentator on X, Xaif Crypto, outlined the third possible reason behind today’s remarkable comeback. He noted that the XRP/USD trading pair printed a substantial surge in short liquidations of over 45% on the 4-hour chart. Such developments could lead to a deeper short squeeze as traders have to close their positions and buy tokens to cover their losses. Xaif added that longs followed with a “brutal +16.11% swing right after.”
Meanwhile, fellow XRP Army member Bird speculated that the token has just flashed a “green light” and predicted that the next move higher has begun after a “perfect leveraged long flush and backtest.” His first target sits at $1.80 by the end of the week, which is rather optimistic as of now.
Green light
The next move up for XRP has begun after a perfect leveraged. long flush and backtest.
$1.80 by EOW
pic.twitter.com/lT67PxFVa7
— Bird (@Bird_XRPL) September 24, 2026

The post Why Is Ripple’s (XRP) Price Up Today: September 25 appeared first on CryptoPotato.