Cryptocurrency Posts
Crypto Briefing
US diesel export ban could raise gasoline prices, with crude oil reaching a new all-time high by December 31 at 10.5% YES.
The post US diesel export ban could raise gasoline prices: Morgan Stanley appeared first on Crypto Briefing.
Fortitude's strategic expansion in Zcash mining could influence market dynamics, potentially impacting ZEC's valuation and mining competition.
The post Fortitude raises credit facility to $50M to fuel Zcash mining expansion appeared first on Crypto Briefing.
The rapid growth of AI data centers could strain energy infrastructure, necessitating urgent investment in agile and diversified power solutions.
The post Goldman Sachs warns next-gen AI servers could trigger localized blackouts appeared first on Crypto Briefing.
Rising diesel costs could strain U.S. industries reliant on transportation and agriculture, potentially leading to broader economic challenges.
The post US diesel prices reach record $6.53/gallon amid Iran conflict appeared first on Crypto Briefing.
The VAR token launch could significantly impact the onchain derivatives market by incentivizing early adopters and reducing token supply through burns.
The post Variational plans VAR token launch with 32% airdrop in Q4 2026 appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Bitcoin Price Slips While US Treasury Yields Soar, Oil Prices Climb
Bitcoin’s price slid on Wednesday, just as U.S. Treasuries surged, with the 10-year yield climbing above 5% and reaching — its highest level since 2007.
The price of the leading cryptocurrency was down 2% over a 24-hour period Wednesday afternoon in New York, and was trading hands for $84,357.
Bitcoin’s price had surged earlier in the week as investors piled into exchange-traded funds. At one point, it soared as high as nearly $87,330.
JUST IN:
— Bitcoin Magazine (@BitcoinMagazine) September 23, 2026U.S. Treasury Department to buy back up to $6 billion in longer-term debt tomorrow.
Buy Bitcoinpic.twitter.com/nZm3BNqiVH

But its rally has since cooled. It dropped further on Wednesday afternoon around the time the U.S. Treasury said it will purchase up to $6 billion of longer-dated government debt on Thursday.
Bitcoin previously benefited from the Treasury Department’s announcement of buybacks — having its best run in months — but this time dropped.
The 10-year Treasury yield climbed above 5% on Wednesday for the first time in 19 years, after September’s flash PMI data came in well ahead of forecasts and pushed the composite index to a five-year high.
Inflation details added to the pressure: input costs across manufacturing and services rose to their highest level since October 2022, driven largely by fuel and transportation, while wage pressure also strengthened.
Rising yields are typically a headwind for bitcoin’s price. When safe government bonds pay 5%, holding an asset that generates no income becomes more expensive.
Higher rates also tend to strengthen the dollar and dampen appetite for risk-on assets. Bitcoin has repeatedly retreated this year when yields rose on inflation fears, often with ETF outflows and forced selling by leveraged traders amplifying the move.
This post Bitcoin Price Slips While US Treasury Yields Soar, Oil Prices Climb first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
CFTC Chair Selig Says Regulator Is Preparing for ‘24-7, On-Chain’ Markets
Commodity Futures Trading Commission Chair Mike Selig has said that the regulator was preparing for the transition of markets moving “24-7, on-chain.”
Speaking to CNBC on Wednesday, the regulator said that it was an exciting time to be regulating markets related to crypto and artificial intelligence.
The CFTC is fast pushing ahead with rulemaking for the crypto space, despite lawmakers last week blocking the long-awaited Clarity Act. Following the vote on the landmark crypto legislation, Selig said that the watchdog would still help U.S. President Trump “get the job done” in regulating digital assets.
“Our markets are rapidly evolving,” Selig said. “We really have to reevaluate all of our rules and regulations to make sure that we’re ready and prepared for this transition to 24-7 on-chain and these automated markets that are facilitated through the use of algorithms and agentic finance.”
The Clarity Act wants to formally divide oversight between regulators, distinguishing which digital assets are securities, commodities or stablecoins.
But the bill stalled and stumbled this year as the banking lobby had issues with crypto companies paying customers stablecoin rewards and some lawmakers — mostly Democrats — were concerned about the ethics side of the legislation.
Trump received backing from major industry players while campaigning and since becoming president, his family has made money from digital asset ventures.
Some lawmakers have alleged conflicts of interest; the White House has always denied any wrongdoing.
Despite lawmakers blocking the Clarity Act, the CFTC and Securities and Exchange Commission have charged ahead with rulemaking. The CFTC last week sent a proposal to the White House to regulate crypto transactions and markets.
And the SEC went ahead and approved tokenized stocks trading the same week. In August, it also proposed its own framework for crypto asset offerings, pressing ahead while the landmark legislation stalled.
Formerly chief counsel at the SEC’s Crypto Task Force, Selig was described by White House’s Crypto and AI Tsar, David Sacks, as “instrumental in driving forward the President’s crypto agenda”
President Trump in August urged lawmakers to get the Clarity Act over the line, referring to the legislation as “very, very powerful.”
This post CFTC Chair Selig Says Regulator Is Preparing for ‘24-7, On-Chain’ Markets first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
NYSE and Blockchain.com Working Together To List Tokenized Stocks
The New York Stock Exchange and crypto exchange Blockchain.com have signed a memorandum of understanding to debut tokenized stocks.
According to a Wednesday statement, if approved, Blockchain.com users would be able to trade tokenized U.S.-listed stocks and exchange-traded funds on NYSE’s planned digital alternative trading system.
It comes as Wall Street increasingly eyes up Bitcoin and its related infrastructure. NYSE’s parent company, Intercontinental Exchange, earlier this year announced it had invested in crypto exchange OKX.
“People shouldn’t be limited in owning stocks based on where they happen to live or the brokerage and information they may or may not have access to,” Peter Smith, Blockchain.com’s executive chairman and CEO, said in a statement.
“Connecting to the NYSE digital alternative trading system will enable us to extend the opportunity to invest in these digital assets to tens of millions of Blockchain.com users around the world.”
And NYSE Group President Lynn Martin added: “The future of capital markets belongs to institutions that unite the trust of traditional finance with the innovation and accessibility of digital assets.”
In January, the NYSE said it was building a platform allowing traders to buy and sell tokenized versions of U.S.-listed equities and exchange-traded funds and settle those trades on the blockchain, 24/7.
Wall Street has been eying up crypto companies and their infrastructure particularly because it’s interested in tokenizing assets like stocks. Traditional finance titans like BlackRock and Franklin Templeton for years have used blockchain rails to tokenize money funds.
But things have accelerated since the U.S. elected pro-crypto president Donald Trump and regulators have taken a more friendly stance to watchdogging the space. The U.S. Securities and Exchange Commission last week approved tokenized stocks trading.
In January, the S&P 500 gave crypto platform Trade[XYZ] the green light to debut a new derivative contract on decentralized exchange Hyperliquid, giving traders the ability to trade the stock index 24-7.
And Last month, Payward, the parent company of crypto exchange Kraken, and fintech company SoFi Technologies, announced a deal to route SoFi customers’ crypto orders through Kraken’s institutional trading platform and list SoFi’s stablecoin on the exchange.
This post NYSE and Blockchain.com Working Together To List Tokenized Stocks first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
The Quantum Issue: You Never Really Know The Future
People have been debating whether a quantum computer presents a realistic threat to the Bitcoin network for over a decade. It was a serious topic of conversation over 13 years ago when I first discovered Bitcoin myself.
There has been quite a lot of progress, both in terms of theory and real-world engineering, since long ago when I was just a bumbling idiot trying to figure out what was going on here.
Two major milestones have been reached since then that make a material difference in the likelihood of a viable quantum computer actually being produced sometime in the next decade or so. That doesn’t inherently mean that it will reach a point of ubiquity, or even relative ease of access for those with large amounts of capital.
But it is very possible that a number of viable machines will be produced in the near future.
Error Correction Improvements
The first major improvement has been in error correction. To account for the inherent noise in working with things at this kind of tiny scale, to get a logical qubit that is useful in computation in practice requires the use of multiple redundant physical qubits.
The prior state of the art way of doing this was surface codes, a way of bundling multiple physical qubits together in a grid and using some of them as check qubits that periodically “check on” their neighbors to ensure no internal errors in the superposition have occurred (without collapsing the superposition). Each grid’s empty spaces need to be filled with check qubits.
This check qubit requirement creates an extra overhead that can get close to 1,000 physical qubits per logical qubit in total, and it gets bad at scale because check qubits can only check on the qubits immediately next to them. So every grouping of qubits needs to have checkers in equidistant spacing.
Quantum low-density parity-check (qLDPC) codes remove this bottleneck, allowing check qubits to check other qubits at large distances (either through traces interwoven to communicate across chip sections, or by physically moving atoms like with the neutral atom design) across the device. This has allowed a 10x reduction in the amount of physical qubits necessary to produce a reliable logical qubit.
That is not something to sneeze at. While it might not be a fully functional machine making progress at gaining more efficiency, it is material efficiency gains in the engineering processes that underlie the production of a fully functional quantum computer.
Progress In Proving Fundamentals
The second has to do with a more fundamental question around the assertion that adding more physical qubits leads to a reduction in overall noise in the system rather than an increase. This is really at this point still theory, and you have to keep in mind that to this day there has never been a fully functional quantum computer that has end-to-end performed a computation a classical computer is incapable of.
Google performed an experiment using their Sycamore (and later Willow) chips to experimentally verify the effect of adding more physical qubits. To be very clear, this was not a demonstration of performing computations, but simply a demonstration of storing information in memory without it decaying.
They demonstrated through the use of logical qubits composed of a bundle of 17 physical qubits, a bundle of 49 physical qubits, and a bundle of 101 physical qubits that the logical error rate, the frequency of data corruption, decreased as the physical qubit count went up. This test passed a critical threshold, where the logical qubit being created out of the independent physical qubits maintained coherence longer than any individual physical qubit it was composed of.
Now again, this is not a jump to a fully functional quantum computer performing computations that classical machines are incapable of, but it is material progress proving one of the fundamental assumptions underlying quantum computers.
AI
These aren’t the only things that we are finding better solutions to in this problem space either. Artificial intelligence has become a big component in these systems. It is being used in the actual process of reading and decoding information from a quantum computer, a big bottleneck for actually making use of it at scale.
AI is also being used in the development of new quantum algorithms optimized for these types of machines, and given the recent spate of AI helping to solve (or even disprove existing conjectures) major problems in the field of mathematics, this isn’t really that crazy of a leap to consider the possibility of major breakthroughs brought about by AI.
They are being put to the same use in actually designing the actual physical quantum circuits that are built using different architectures. This is a very complex problem, actually, finding the optimal way to lay out quantum gates in a physical space to minimize noise at the quantum level, without creating so much empty space that you introduce latency, inefficiency, and other problems to solve.
This is a factor that very well could hypercharge progress at solving the necessary fundamental problems.
Outlook Ahead
Ultimately, in my opinion, this comes down to one question: does the assumption that adding more physical qubits reduce noise actually hold when it comes to computation and the active manipulation of quantum information.
If that assumption does hold, and isn’t experimentally disproven sometime in the near future, then I think there is a very realistic case for a viable quantum computer being produced in the next ten years.
There is a massive amount of resources being thrown at this problem, significant (but not overwhelming) progress at solving pieces of the problem, and if there fundamentally is a way to do something, human beings usually figure it out.
I’m not saying that it’s time to panic, but don’t discount the possibility.
This piece is featured in the latest Print edition of Bitcoin Magazine, The Quantum Issue. We’re sharing it here as an early look at the ideas explored throughout the full issue.
This post The Quantum Issue: You Never Really Know The Future first appeared on Bitcoin Magazine and is written by Shinobi.
Bitcoin Magazine
Raiffeisen Bank International to Roll Out Bitcoin Services Across Europe in Expanded Bitpanda Deal
Austrian banking group Raiffeisen is rolling out bitcoin trading for its 18 million customers.
The firm said in a Wednesday statement that it was working with brokerage Bitpanda as part of the initiative.
Raiffeisen’s announcement comes as top banks worldwide launch crypto trading and custody services. BBVA, Santander’s Openbank, Germany’s cooperative and savings banks, SoFi, PNC, Charles Schwab and Morgan Stanley have all either launched or announced retail crypto trading over the past 18 months.
RBI chief executive Michael Höllerer pointed to customer demand as the driving force. “We are seeing growing demand for crypto assets in our markets, which we are addressing with a strong, reputable partner,” he said, adding that the bank is committed to “meeting our customers’ needs in the best possible way.”
The deal builds on an arrangement that began in Austria. In 2024, Raiffeisen Landesbank Niederösterreich-Wien (RLB NÖ-Wien) became the first traditional bank in the European Union to offer crypto trading within its existing banking environment, using Bitpanda’s technology.
The new agreement moves away from striking separate integrations market by market and instead sets up a single approach for the whole group.
Bitpanda Enterprise provides banks, fintechs, brokers, trading firms and family offices with the tools to offer digital asset products to retail and corporate clients. Its services include investment infrastructure, liquidity, custody, payments, stablecoins and tokenisation, with an emphasis on compliance and scalability.
RBI treats Austria and Central and Eastern Europe as its home market, with subsidiary banks in 11 countries in the region. The group has about 42,000 employees serving 18.8 million customers through roughly 1,300 branches, most of them in CEE. Its shares trade on the Vienna Stock Exchange, and the regional Raiffeisen banks own about 61.2 per cent of the company, with the rest in free float.
This post Raiffeisen Bank International to Roll Out Bitcoin Services Across Europe in Expanded Bitpanda Deal first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
CryptoSlate
A new Cardano governance action proposes cutting the minimum from 170 ADA to 75 ADA, this time without the Plutus memory-limit change that brought stake pool operators into the previous ballot.
The proposal drops one voting requirement that stopped the earlier action. Approval is pending, and each pool would still set its own declared fee.
Delegators in a small pool can lose a large share of a thin epoch reward to its fixed charge before their share is calculated. Meanwhile, operators rely on that charge for income, and those with little delegated stake already face uneven block production.
A lower floor would give them more room to compete on price, while leaving each operator to decide whether to use it.
A different ballot leaves the reward question open
The earlier action paired the same pool-cost reduction with higher Plutus memory limits. It expired on Sept. 1 after DRep yes votes reached 68.6%, above the 67% threshold, and five of seven Constitutional Committee members voted yes.
Stake pool operator support reached only 34.5% of counted stake, short of the required 51%. The memory-limit component made an SPO vote necessary for the combined action.
The standalone proposal, submitted Sept. 11, changes only minPoolCost. Cardano's parameter glossary classifies that as an economic parameter that needs DRep and Constitutional Committee approval, but no SPO ballot when changed alone.
That is the governance route for this type of change. DRep and committee votes still determine whether it passes, while operators continue debating its economic effects.
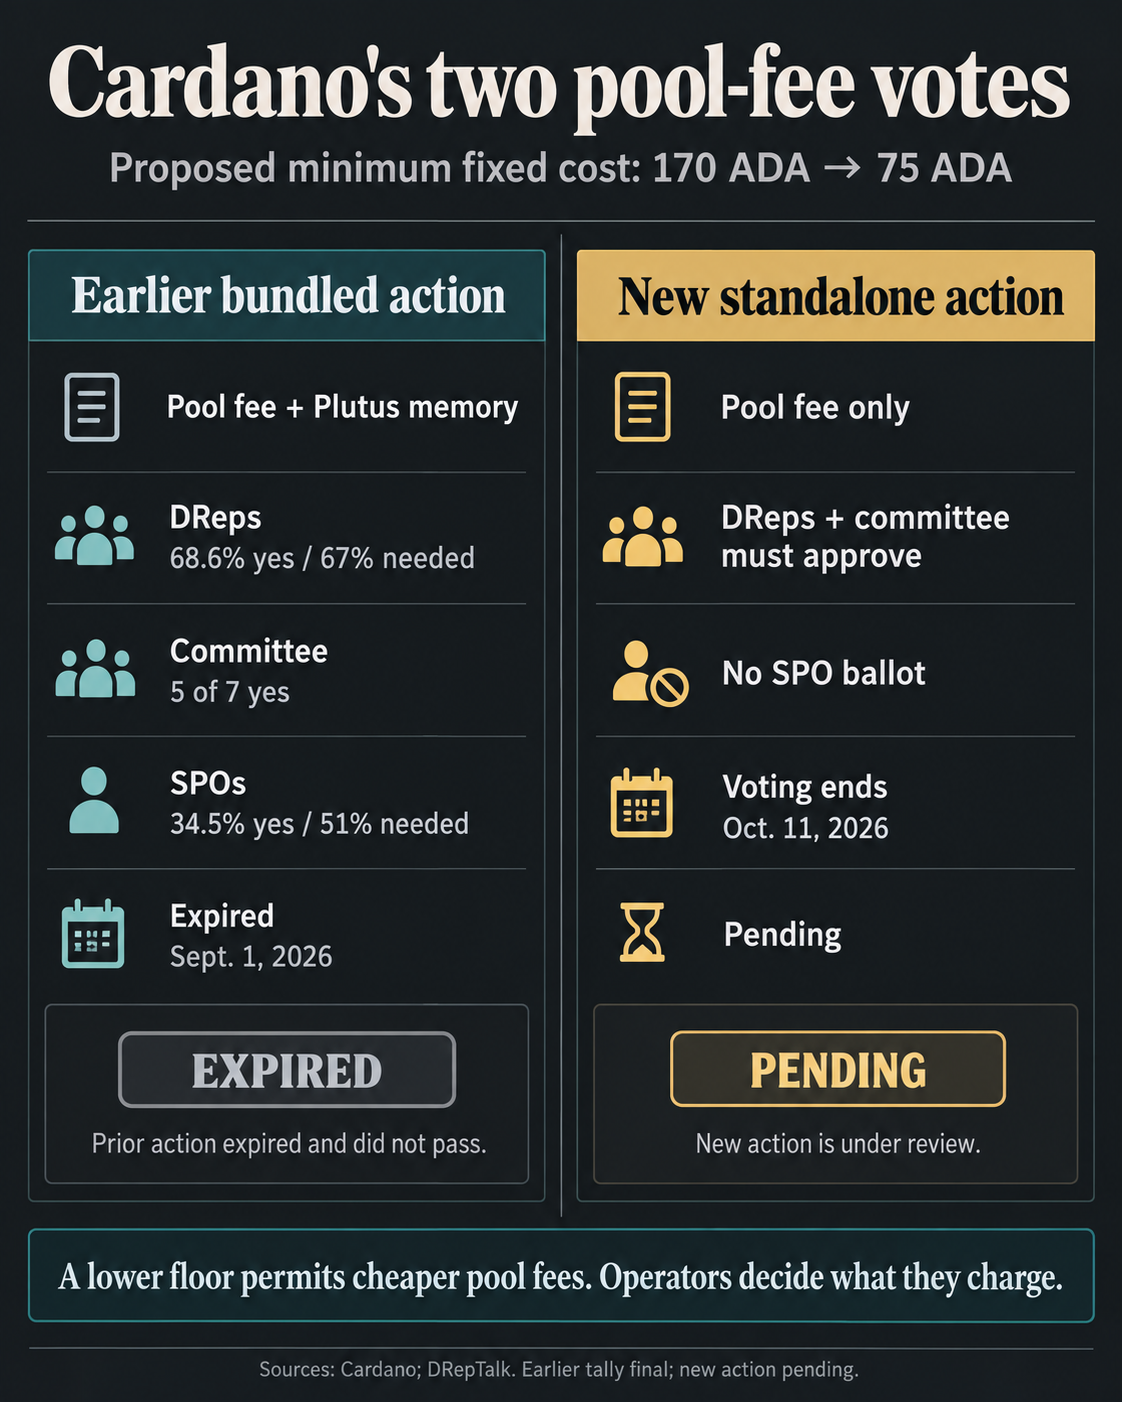
In a cached DRepTalk tally checked Sept. 23, yes votes for the new action represented 11.7% of counted DRep stake, against a 67% threshold. Two of seven committee members had voted yes, or 28.6%, against a 66.7% threshold.
Those figures can change before voting ends in epoch 661 on Oct. 11. A pool's fixed cost is taken from its gross reward each epoch before its margin, and the remainder is distributed across stake. The present mainnet minimum is 170 ADA.
If the proposal passes, an operator could declare 75 ADA, continue charging 170 ADA, or keep a higher fee. Delegators receive a benefit only if a pool with rewards to share actually lowers its charge.
The proposal illustrates the pressure on a small pool with an approximately 300 ADA gross reward from one block. At a 170 ADA fixed cost, about 57% of that reward goes to the fixed charge before margin. At 75 ADA, the share would be 25%.
If an operator charging 170 ADA chose 75 ADA in an epoch with sufficient rewards, 95 ADA more would remain before margin and allocation across stake. Each delegator's gain would depend on stake, margin, and the pool's actual rewards.
The strongest caution comes from how operators reacted to the last floor reduction. An Input Output Research study found that 340 ADA was still the most common declared fixed cost across active pool sizes after Cardano lowered the minimum from 340 to 170 ADA in October 2023.
The 170 ADA fee became a second tier used by smaller challengers. The prior cut expanded pricing options without prompting a network-wide shift to the new minimum. Past fee choices leave the response to a 75 ADA floor uncertain, and the parameter change alone would leave existing declared fees in place.
Small-pool relief has an operator cost
The same study classified pools using a 36-epoch window (epochs 548 through 583) and a viability benchmark tied to 3 million ADA of stake and 5,500 ADA of cumulative rewards. It put 627 active pools in a struggling category below both benchmarks, alongside 246 viable small pools and 741 pools at or above 3 million ADA.
A person or organization can control more than one pool, so pool totals alone cannot show whether ownership is becoming more decentralized.
If a pool lowers its fixed fee, more reward can remain for distribution, but the operator gives up part of a predictable charge. The trade-off is sharpest where block production is irregular and operating income is already thin.
The proposal's author argues that a lower floor could help smaller pools attract stake and describes the change as an interim step toward broader fee reform. Future delegation and operator income will determine whether the lower fee helps those pools become sustainable.
Cardano's wider reward-funding problem also sits outside this vote. Transaction fees covered less than 1% of staking rewards over a 73-epoch period, so changing the floor would alter who may receive a share of rewards in pools that cut their charge.
The immediate test is governance: whether DReps and the committee clear their thresholds by Oct. 11. If they do, the next test is operator behavior.
The measurable benefit for delegators would depend on how many pools actually declare a lower fixed cost, how often those pools earn rewards, and whether the income they retain can support independent operation.
The post Cardano proposal slashes fees by 55%, but it comes with a cost for small pools appeared first on CryptoSlate.
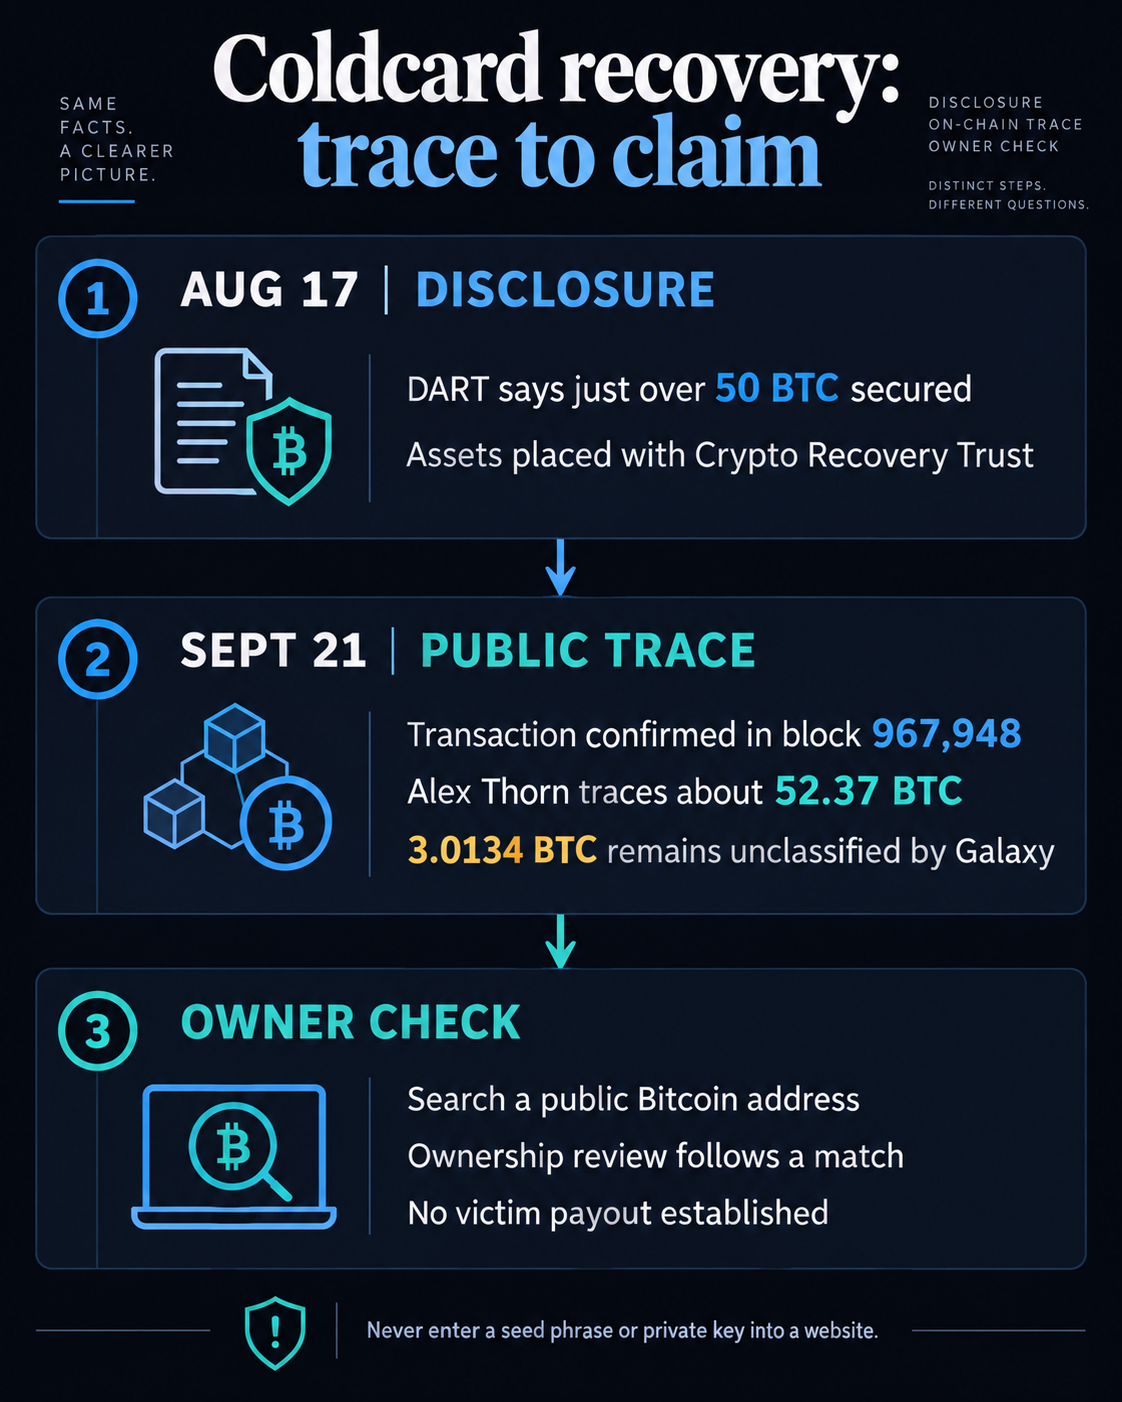
Coldcard owners can publicly check whether white hats recovered coins from their wallets. Galaxy researcher Alex Thorn linked a Sept. 21 Bitcoin transaction carrying a Crypto Recovery Trust claims reference to roughly 52.37 BTC from Coldcard-related clusters.
He directed owners to search their public Bitcoin addresses at the trust's site. A match can begin an ownership claim, with any return subject to verification. The check calls for a public address, never a seed phrase or private key.
Mempool's status record confirmed the transaction in block 967,948. In his Sept. 21 tracing report, Thorn said the amount represented 2.8% of the exploit funds Galaxy tracked.
Thorn also flagged 3.0134 BTC entering the destination from addresses Galaxy had not previously tracked. He considered them possible additional white-hat recoveries, but their Coldcard origin remains uncertain.
In an Aug. 17 report, digital-asset recovery firm DART said it and independent researchers had secured just over 50 BTC, according to its internal ledger, and placed the rescued Bitcoin with Crypto Recovery Trust.
The Sept. 21 transaction gives owners a public trail for a recovery DART had described a month earlier.
What happens after a Bitcoin address match?
DART says its trust process checks recovery records, chain of custody, and proof of ownership, including source-of-funds and exchange records. Sanctions, competing claims, or other restrictions can affect any return.
The Coldcard entropy flaw made some older wallet seeds easier to reconstruct. DART says an existing seed created under affected firmware remains exposed after a firmware update, and owners with exposed funds should follow the manufacturer's migration guidance.
DART also warns against sending seeds, private keys, PINs, or recovery codes through a web form. The initial address check Thorn described needs a public address, while proving ownership is a separate step.
The post White hats recover 52 Bitcoin from Coldcard exploit, and a new public portal lets victims check eligibility appeared first on CryptoSlate.
Bitcoin fell below $85,000 on Sept. 23 after stronger-than-expected US business activity sent Treasury yields higher and flushed leveraged longs.
The reversal broke the momentum behind a rebound that had accelerated as Bitcoin pushed through a large concentration of short positions earlier this week.
Selling intensified after S&P Global released its September flash purchasing managers’ indexes. Within an hour, $135.8 million of crypto positions were liquidated, according to CoinGlass, with longs accounting for $125.9 million. Bitcoin accounted for $47.4 million of the wipeout, and Ether another $23.9 million.
Over the past 24 hours, losses total $510 million across 122,256 traders, with long traders losing $363.83 million.
The reaction reflected how quickly the rate backdrop turned against a market positioned for further upside. The latest economic data showed US growth accelerating as businesses reported renewed cost pressures, strengthening the case for interest rates to remain elevated.
Hot US growth sends Treasury yields above 5%
S&P Global’s composite PMI climbed to 58.4 in September, its highest level in more than five years, while the services index rose to 58.7 and manufacturing reached 57. All three readings came in above expectations.
Chris Williamson, chief business economist at S&P Global Market Intelligence, said historical comparisons suggest the survey is consistent with annualized economic growth of about 5%, with roughly 4% growth signaled for the third quarter overall.
The acceleration came with a less favorable inflation signal. Companies reported the steepest increase in input costs in four years as higher oil prices lifted fuel and transportation expenses, while supply-chain bottlenecks worsened and backlogs increased.
Williamson said the combination of stronger demand and limited capacity was giving companies greater pricing power, raising the risk that cost increases feed into inflation in the coming months.
He added:
“This growth is being accompanied by some of the most severe supply chain bottlenecks seen in the near-two-decade survey history if the pandemic is excluded, with companies also reporting increasing problems finding suitable staff. Backlogs of work are consequently rising sharply. While this accumulation of uncompleted orders bodes well for the further expansion of output and capacity in the coming months, it also indicates that companies are developing more pricing power, and hence is a worry for the inflation outlook”
Bond markets responded immediately. The 10-year Treasury yield moved back above 5% to around levels last seen in 2007, while the two-year yield climbed to its highest level in about 27 months.
The move also revived a broader concern over how much additional yield investors may demand to absorb growing US government borrowing.
James Lavish, the Co-Managing Partner of Bitcoin Opportunity Fund, argued that Treasury supply is increasingly colliding with investor concerns over what he described as structural dollar debasement. In his view, higher yields can become self-reinforcing as rising interest costs increase the government’s financing needs, requiring still more debt issuance.
Lavish added that any eventual monetary intervention to absorb that supply could deepen those currency concerns, creating what he described as a “self-reinforcing loop.”
That structural argument sits on top of the more immediate message from Wednesday’s PMI report. An economy growing faster than expected gives the Federal Reserve greater room to keep policy restrictive, while rising input costs and higher oil prices complicate the inflation outlook.
For Bitcoin, the timing is particularly difficult because much of the bearish positioning that helped propel its latest advance had already been cleared.
The push through $86,000 earlier this week forced shorts to cover and helped accelerate Bitcoin toward $87,000. Wednesday’s move removed that tailwind just as the bond market turned more hostile to risk assets.
That leaves Bitcoin increasingly dependent on fresh spot demand to reclaim $85,000. With Treasury yields above 5% and US growth still surprising to the upside, buyers now have to support the rebound without the same short-covering boost that helped drive the earlier advance.
The post Bitcoin slips below $85,000 as 5% Treasury yield returns to haunt risk assets appeared first on CryptoSlate.
Circle has switched on 24-hour stablecoin foreign-exchange settlement on Arc, targeting a global FX market that moves nearly $10 trillion daily.
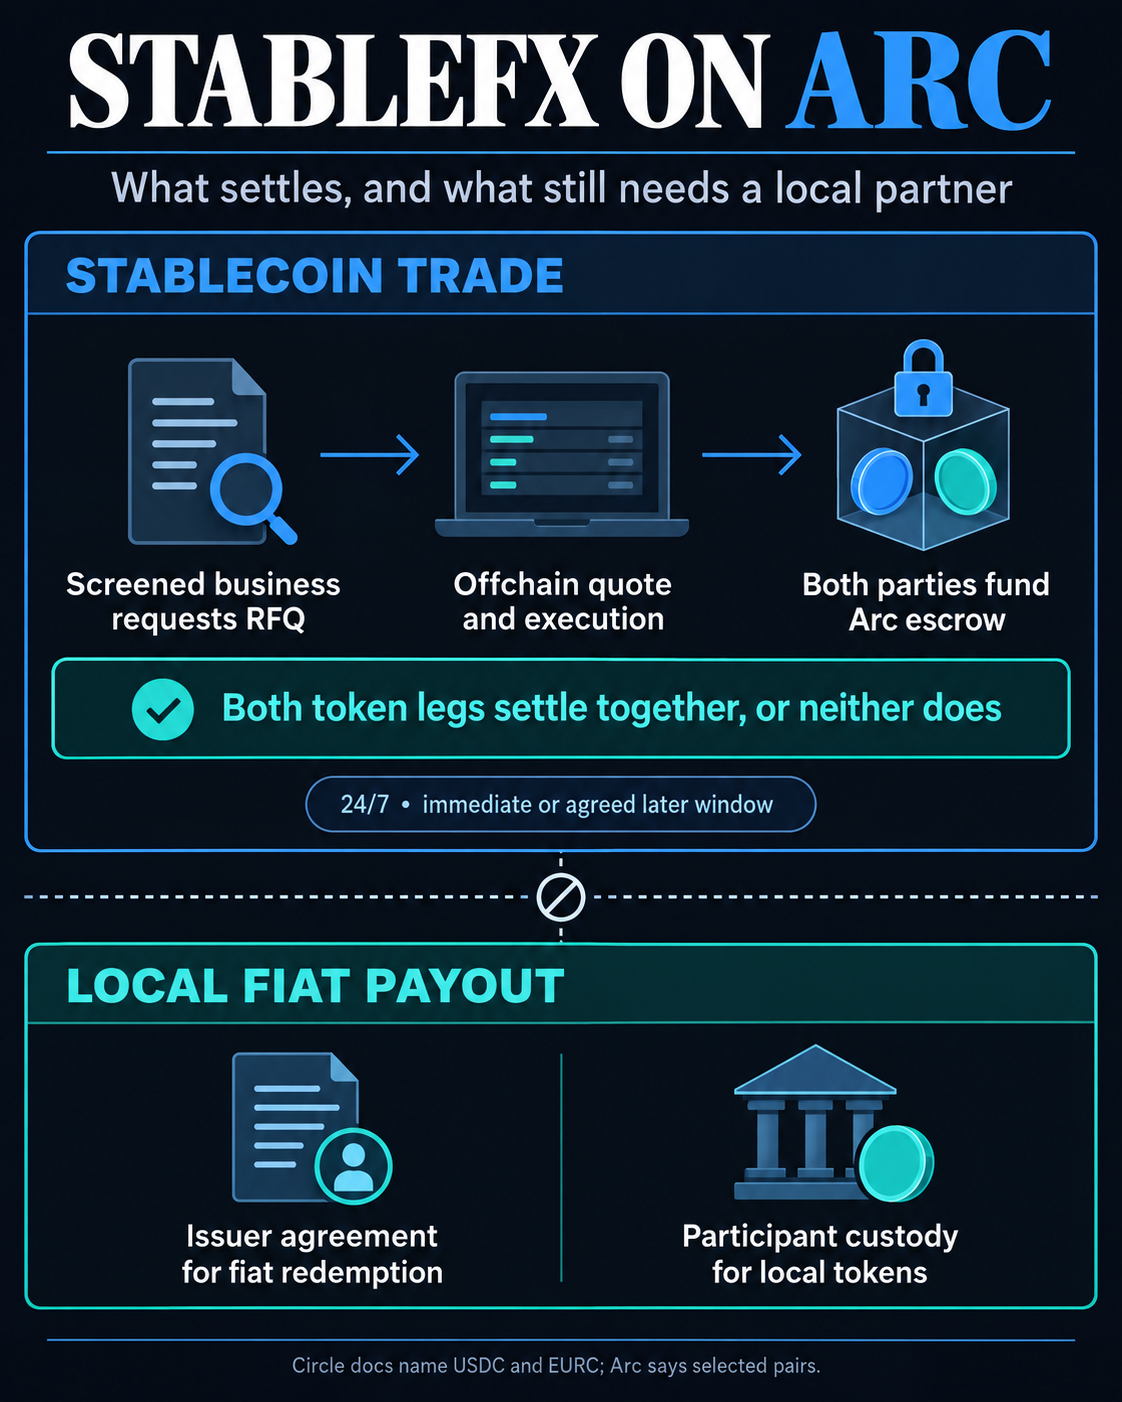
The service, called StableFX, allows screened businesses to request competing quotes from multiple liquidity providers and settle both sides of a stablecoin currency trade simultaneously on Circle’s newly launched blockchain. Users can choose near-instant settlement or defer completion to an agreed window, extending institutional FX activity beyond conventional banking hours.
Circle said much of the global currency market still relies on infrastructure designed around banking schedules even as payments, crypto trading and digital commerce increasingly operate continuously. StableFX is its attempt to move part of that market onto programmable settlement rails.
The system separates trade execution from settlement. Businesses submit a currency pair, amount, and preferred settlement window through a request-for-quote process, allowing approved liquidity providers to compete for the order. Execution happens off-chain before counterparties fund a smart-contract escrow on Arc.
Settlement then occurs on a payment-versus-payment basis: both stablecoin legs transfer together, or neither does. That structure is designed to reduce settlement risk while allowing businesses to contract with Circle once and access multiple vetted counterparties through the same venue.
Circle Chief Executive Jeremy Allaire described StableFX as a “strong emerging primitive” for atomically settled, real-time onchain foreign exchange, pointing to the stablecoin issuers and market participants being assembled around the service.
Arc pushes beyond payments into institutional FX infrastructure
The launch gives Arc an immediate institutional use case less than a week after Circle brought the blockchain to mainnet on Sept. 16.
Circle's developer documentation currently names USDC and euro-denominated EURC, including an example of an exchange between the two tokens. Circle has said it will add additional local stablecoin pairs, though it has not published a complete list of pairs already available for live StableFX trading.
That distinction could determine how quickly the service expands beyond dollar-euro transactions. Circle listed a wider group of stablecoins as active or onboarding to Arc at mainnet launch, but blockchain participation does not automatically make each token available through StableFX.
Access is also restricted. Circle screens counterparties and limits StableFX to eligible incorporated businesses, positioning the service for payment companies, financial institutions and corporate treasury desks rather than retail traders.
For those firms, the attraction is partly operational. A payments company needing to rebalance stablecoin liquidity across currencies could execute the trade overnight or during a weekend rather than wait for traditional banking rails to reopen. Deferred settlement also gives treasury teams flexibility to match execution with their funding schedules.
The harder part begins after settlement.
StableFX exchanges digital currencies but does not automatically turn a local-currency stablecoin into cash in a recipient’s bank account. Firms using partner-issued stablecoins still need arrangements with their issuers for deposits and redemptions, suitable custody, and local payout infrastructure.
Circle Mint can provide USDC and EURC liquidity and fiat conversion in supported markets, but that access does not extend automatically to tokens issued by other companies.
The post Circle launches 24/7 stablecoin FX engine as it chases a slice of the $10 trillion currency market appeared first on CryptoSlate.
BlackRock says AI could create a new class of stablecoin customer: machines that spend continuously without human approval.
The world’s largest asset manager sees increasingly autonomous AI systems purchasing data, accessing software, and acquiring computing resources on their own, potentially adding a new source of transaction demand to digital assets beyond trading and human payments.
That prospect sits at the center of BlackRock’s new report, The Machine-Native Economy, which argues that artificial intelligence could eventually change who initiates economic activity. Instead of people making individual payment decisions, software could execute thousands of small transactions to complete a task.
Stablecoins enter that market with more than $300 billion already in circulation and about $11.2 trillion of adjusted transaction volume in 2025, according to BlackRock. The firm calculated that volume grew at an 80% compound annual rate between 2020 and 2025, compared with roughly 8.5% for the US Automated Clearing House (ACH) network.
ACH still processed about $93 trillion last year, reflecting how far stablecoins remain from the largest traditional payment rails. BlackRock also cautioned against directly comparing stablecoin activity with Visa and Mastercard because the networks measure transactions differently.
The potentially bigger shift, however, is in transaction behavior rather than existing volume.
An AI agent searching for information or computing capacity could pay repeatedly for individual API calls, data feeds, or units of processing power. Those transactions may be worth fractions of a cent and occur around the clock, creating a payment pattern markedly different from card purchases or bank transfers designed primarily around human customers.
That gives stablecoins an opening because software can hold them in programmable wallets and settle transactions without requiring a person to approve each payment.
Stablecoins may win the machine wallet before blockchains win the economics
Payment companies are already competing over how those transactions will move.
Coinbase’s x402 protocol uses the web’s HTTP 402 “Payment Required” status to let a service demand payment before returning data or another resource. An agent can request an API, receive payment instructions, transfer USDC, and get the service without a human completing checkout.
Stripe and Tempo are developing the Machine Payments Protocol, which can settle transactions through stablecoins or traditional payment methods. Stripe and OpenAI’s Agentic Commerce Protocol connect AI agents with existing merchant systems, while Google and Visa are working on separate standards around agent identity and authorization.
The competing approaches complicate any assumption that machine commerce will automatically migrate on-chain.
Traditional payment networks can adapt to autonomous software, particularly where agents transact with established businesses and consumers. Stablecoins appear better positioned where payments become especially small, frequent, or native to software.
That leaves a second contest over where the value from those payments eventually accrues.
If agents generate more stablecoin transactions on Ethereum, greater usage could increase demand for blockspace and validator services. ETH is used in the network’s fee and staking system, providing one route through which higher transaction activity can affect the native asset.
But transaction growth and token demand do not necessarily rise together.
BlackRock said the amount captured by native crypto assets will depend on fee structures, staking economics and gas-sponsorship models. Networks can process large volumes while charging very little, while applications can also shield users and agents from holding the underlying gas token themselves.
Circle’s Arc presents a different model. The payments-focused blockchain uses USDC as its native gas asset, meaning additional activity could strengthen the stablecoin’s role without producing the same transmission mechanism to a separate native token such as ETH.
For investors, that distinction could matter more if machine payments scale. Stablecoin issuers may gain transaction demand while the networks processing those transfers compete separately to turn higher throughput into economic value.
AI compute could make the machine customer considerably larger
BlackRock expects the same payment architecture to eventually reach one of AI’s biggest expenses: computing power.
Cumulative investment in AI infrastructure could exceed $5 trillion between 2025 and 2030, while Bloomberg consensus forecasts cited by BlackRock put combined revenue from Amazon Web Services, Microsoft’s Intelligent Cloud business and Google Cloud at about $1.1 trillion by 2030.
That would create a large resource market for increasingly autonomous agents to navigate.
An agent could compare computing providers by price, hardware, location, latency, or performance; purchase capacity for a specific task; and settle the cost automatically. Payments could occur per job, per use, or potentially per model token.
AI inference would then become a recurring machine-to-machine transaction loop: software finding compute, buying it, consuming it, and paying for the resource without a person intervening at each stage.
BlackRock sees an even larger financial market potentially forming around that activity.
Standardized claims on computing capacity could eventually be traded or pledged as collateral, while futures markets could allow buyers and sellers to hedge changes in compute costs. Such markets would require standards that account for major differences between chips, energy prices, locations, and performance.
That part of the thesis remains largely prospective. Agentic payment activity is still nascent, and traditional financial companies are building their own infrastructure for autonomous commerce alongside crypto firms.
The nearer competition is over the machine’s wallet.
Stablecoin issuers need their tokens to become the default settlement asset for software. Payment protocols need to become the standard agents use to request and pay for resources. Ethereum and rival blockchains face the harder task of ensuring that higher stablecoin throughput translates into demand for their own economic assets.
Traditional payment networks, meanwhile, have an incentive to keep that activity on existing rails.
As AI systems gain more authority to spend, those competing infrastructures will increasingly fight over a customer that never sleeps, can transact thousands of times in the background, and may care more about price, settlement speed, and programmability than which financial network sits underneath the payment.
The post BlackRock sees a new $5 trillion AI trade emerging for stablecoins appeared first on CryptoSlate.
CryptoTicker.io
A trading bot does exactly what you switch it on to do: it trades. Twelve decisions a year quickly become twelve hundred, and in Germany every single one of them is a separate event for tax purposes. That is the point at which many bot users start to think twice, usually in March, when the tax return is due and the trading platform's export button produces a file with a four-digit number of rows.
This guide answers the question behind that: what does a crypto trading bot trigger for tax purposes, and what do you have to set up before it makes its first trade? It is about the holding period, about the FIFO allocation rule, about the tax-free threshold, about the line to commercial trading and about the record-keeping duties that the Federal Ministry of Finance has expressly described since March 2025. At the end there is a setup list you can work through.
Why a bot changes your tax position before it makes any profit
The decisive difference between manual and automated trading lies not in the size of the profit but in the number of transactions. Anyone who buys Bitcoin and leaves it alone for three years has two events for tax purposes: a purchase and a sale. A bot that lays a grid of buy and sell orders across a price range may produce a thousand events in the same period.
Not a single rule changes as a result. What changes is the effort required to comply with them, and the likelihood of making a mistake that gets noticed. Whether running a bot pays off at all we have worked through elsewhere, in our piece on whether crypto trading bots are worth it. This text starts one step later: the bot is already running, and now it is about the tax office.
The principle: every swap is a disposal under section 23 of the Income Tax Act
In Germany crypto assets count as other economic goods within the meaning of the Income Tax Act. Gains from their sale therefore fall under private disposal transactions pursuant to section 23 of the Income Tax Act and not under the withholding tax you know from equities and funds. That has two consequences pulling in opposite directions: there is a holding period after which a gain remains tax-free, but within that period the gain is taxed at your personal income tax rate, which can be higher than the flat 25 percent.
A disposal is to be understood more broadly than the word suggests. It covers every swap, not merely a sale for euros: Bitcoin for Ether, Ether for a stablecoin, a stablecoin back into Bitcoin. That is precisely where bot trading is special. A grid bot that shifts back and forth between two coins without ever triggering a payout in euros still produces a tax-relevant event at every step. That nothing arrives in your bank account is irrelevant to this.
The gain per transaction is calculated as the disposal price less the acquisition cost and the directly attributable costs. In a swap, the disposal price is the market value of what you receive, converted into euros at the time of the transaction. That conversion is the point at which a spreadsheet breaks down at a thousand rows.
The one-year holding period and why a bot practically never reaches it
If more than twelve months lie between acquisition and disposal, the gain remains tax-free under section 23 of the Income Tax Act. That period is the reason many German investors hold crypto assets at all rather than trade them.
A bot works structurally against that period. Its job is to capture price moves within hours or days. Every successful trade resets the holding period of the units concerned to zero. In practice that means you will almost always pay the full tax rate on the holdings the bot moves, and you should factor that into your return expectations before switching it on.
From that follows a design rule that sounds simple and is often ignored in practice: separate the holdings the bot is allowed to touch from the holdings you keep for the long term. That is done most cleanly through separate accounts or separate wallets, because units are allocated on a per-wallet basis. If both run through the same pot, the bot also reaches your older units in the calculation, and then you lose holding periods you had already earned.
FIFO: which unit the bot sells is not up to you
If you have bought Bitcoin at five different points in time and the bot sells part of it, the question arises which of those units it gives up in the calculation. Your instinct may say the most expensive one, so that the gain comes out small. That is not how it works.
FIFO stands for first in, first out and means that the unit acquired first always counts as the one disposed of first. The Federal Ministry of Finance provides for this method of allocation, applied to the respective wallet or account. The consequence is uncomfortable: when the bot sells, it reaches your oldest units in the calculation, that is, the ones with possibly the lowest acquisition cost and the highest gain. What exactly distinguishes FIFO from other methods we have taken apart in our explainer on FIFO and LIFO for crypto assets.
For bot operation the same conclusion follows as in the section before, only from a different direction: separate wallets are not tidiness for its own sake but the only lever with which you steer at all which units the bot reaches.
The 1,000 euro threshold, and why an exemption limit is not an allowance
An annual exemption limit applies to private disposal transactions. Since the 2024 assessment period that limit has been 1,000 euros; before that it was 600 euros.
The difference between an exemption limit and an allowance is regularly confused and, in case of doubt, costs real money. An allowance would always stay tax-free, and only the excess would be taxed. With an exemption limit it is different: if it is exceeded by even one euro, the entire gain is taxable, not merely the excess. On an annual gain of 999 euros you pay nothing; on 1,001 euros you are taxed on 1,001 euros.
For bot users that is more relevant than for buy-and-hold investors, because a bot produces many small gains that add up inconspicuously. Anyone close to the limit towards the end of the year has a solid reason to switch the bot off for the final weeks — or, conversely, with accumulated paper losses, a reason to realise those before the turn of the year. Losses from private disposal transactions can, however, only be offset against gains of the same income type, not against your salary and not against equity gains.
When private trading becomes commercial trading
The question that sooner or later comes up with high trade counts: does the trading become commercial at some point, with trade tax, accounting obligations and the loss of the holding period?
There is no fixed number at which that happens. The much-quoted three-object rule comes from property law and does not apply here. For securities trading, case law has developed a fairly generous standard over decades: even a high trading volume and a high number of transactions regularly remain private asset management, as long as you trade for your own account and do not appear in the market like an investment services firm. Signs pointing the other way are, for instance, trading for the account of others, the systematic use of borrowed capital in the manner of a dealer, or an outwardly visible business operation.
Whether that standard can be transferred one to one to crypto assets has not been conclusively settled by the highest courts, and that is precisely why caution is in order with blanket statements — in both directions. Anyone running a bot for third parties, charging fees for it or co-managing several accounts belonging to other people is visibly moving out of private asset management. We have dealt with the delimitation in more detail in our piece on the difference between private and commercial crypto trading. If your set-up comes anywhere near those features, that is the moment for advice and not for an internet search.
Record-keeping duties: what the finance ministry has expressly required since March 2025
With its circular of March 6, 2025, the Federal Ministry of Finance revised its administrative position on crypto assets and replaced the earlier circular from May 2022. The most important addition for bot users concerns the tax return, cooperation and record-keeping duties, which are now described there separately.
The practical core is this: you must be able to evidence your transactions without gaps. That includes the complete transaction statements of the trading venues used, the allocation of holdings to wallets and accounts, the exchange rates at the relevant time and the origin of the funds deployed. If you cannot do that, the tax authority may estimate the basis of assessment. An estimate is not a formality to be smoothed over later but, as a rule, more expensive than the correct declaration would have been.
The catch with automated trading lies in the transience of the data. Trading venues often keep exports available only for a limited time, bot providers disappear from the market, and API keys expire. What you do not secure today may be impossible to obtain in three years — and three years is a short span in tax matters. That is why the export belongs in the monthly rhythm and not in the week before the return is filed. Which tools take that over automatically and connect directly to the trading venues is shown in our overview of crypto tax tools and portfolio trackers.
What running a bot costs and how those costs are classified
Besides the trades, a bot produces running costs of its own: the trading venue's fee per execution, often a monthly subscription for the software, sometimes the cost of a server on which the strategy runs.
Trading fees directly connected with a single transaction reduce the gain on that transaction — so they belong inside the calculation and not on a separate list. Considerably less clear is the treatment of running costs such as the subscription or the server, because they cannot be allocated to any single transaction. Do not count firmly on being able to deduct them in full here, and have the point clarified rather than deciding it yourself. More important than the tax outcome is the commercial question anyway: a bot whose subscription and fee load eats up the gross return is a loss-making exercise even with perfect tax treatment. Which models bill in which way you can set side by side in our comparison of crypto trading bots.
What to set up before the bot makes its first trade
Five things can be dealt with in advance, and every one of them is laborious to impossible to catch up on later.
- Separate accounts or wallets for the bot holdings and the long-term holdings. This protects earned holding periods from FIFO access and is the single most effective step of all.
- A monthly, automatic export of all transactions. Store it somewhere that exists independently of the trading venue and of the bot provider.
- A tax tool that connects to the trading venues directly. At four-digit trade counts, manual work is no longer a serious option.
- A note on the strategy and on the period in which the bot ran. A year later you will otherwise no longer know why a hundred trades arose on a particular day.
- A tax reserve kept separate from the trading capital. Gains within the holding period are taxed at your personal rate, and that amount is not available to you for further trading, even if it is sitting in the account.
Trading bots and tax: what to take away
- Separate the holdings before you start the bot. Separate wallets for trading and long-term holdings prevent FIFO from using up your old units that are ripe for the deadline. Which provider allows which account and sub-account structure you can see in the trading bot comparison.
- Set up the monthly export, not the annual one. The record-keeping duties fall on you, not on the trading venue, and exports are available only for as long as the provider keeps them. The suitable tools are in our overview of tax tools.
- Check your annual position against the 1,000 euro threshold before the turn of the year. One euro above makes the entire gain taxable. Where the figures end up in the return later is explained in our piece on where to enter crypto in your tax return.
The authoritative texts in the original: the wording of the law on private disposal transactions in section 23 of the German Income Tax Act and the Federal Ministry of Finance circular of March 6, 2025 on individual questions of the income tax treatment of certain crypto assets.
This text is a general classification and does not replace tax advice. How your case is to be treated depends on your set-up, your volume and your other income; settle that with your tax adviser or your tax office.
(As of September 24, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
On September 27, 2026 a deadline expires at the US Securities and Exchange Commission about which nothing has yet been written in German. It does not concern the approval of another crypto fund but the rail beneath it: the question of the conditions under which US exchanges will in future be allowed to list options on crypto ETFs without asking the regulator separately each time. If you hold a crypto ETP on Bitcoin, Solana or XRP in a German portfolio, there is nothing you can do on that day. You will notice the consequence all the same, and in a place few investors watch: in the bid-ask spread of your own security.
This guide explains what the filing numbered SR-ISE-2026-42 contains, why September 27 will in all likelihood not be a decision day at all, and which four things you can check on your own product instead of waiting for a US authority.
What actually happens at the SEC on September 27
The filing comes from the options exchange Nasdaq ISE and was printed on August 13, 2026 in the Federal Register, the official gazette of the US federal agencies. That printing starts a statutory clock.
A 19b-4 filing is the technical term for a rule change that a US exchange submits to the SEC. The regulator then has 45 days to approve the filing, to reject it or to institute formal proceedings. Counted from August 13, that period ends on September 27, 2026.
Three routes are open to the agency on that day. It can approve, it can institute so-called proceedings and thereby take up to 90 days from the date of printing, or it can reject. The second option is the usual course for filings of this magnitude. Running the 90 days through, one arrives at November 11, 2026. Anyone writing September 27 into the calendar as decision day will probably have to strike it out again afterwards.
SR-ISE-2026-42 explained: from case-by-case filing to a rule test
To understand why the filing was made at all, it helps to look at the current state of affairs. Options on spot Bitcoin ETFs have existed on US exchanges since 2024. The road there was laborious: every single listing needed its own filing with the SEC, its own comment period and its own approval. The options on the largest Bitcoin fund were cleared by exactly that route through Nasdaq ISE in the autumn of 2024.
How slow the procedure is can be seen in the counter-example from the same year: the NYSE withdrew its plan to list options on Bitcoin ETFs. We described the episode in our report on the NYSE withdrawal. Taken together, the two events produce the picture of a rail that does exist but has to be laid anew for every additional fund.
That is precisely what SR-ISE-2026-42 seeks to replace. In place of the case-by-case review, a rule test is to apply: a list of measurable criteria a fund has to meet. If they are met, the exchange may list the options without going back to the regulator for that one product. The filing expressly names funds holding Bitcoin, Ethereum, Solana, XRP, Chainlink and Hedera.
The two thresholds in the filing: 85 percent of NAV and $700 million daily market value
At its core the rule test consists of two numbers, and both are set so that only large, liquid products reach them.
The first concerns the composition of the fund. NAV stands for net asset value: the sum of what the fund holds, less its liabilities. Under the filing, at least 85 percent of NAV must be accounted for by assets for which a tradable futures market exists. For the remaining 15 percent there is a buffer in which other digital commodities may also sit. A fund one quarter of which consists of exotic tokens therefore fails the test.
The second number concerns each of those assets individually. Per digital commodity, the filing requires an average worldwide daily market value of $700 million. That is the hurdle that turns a catalogue of criteria into a selection: this threshold separates the two dozen largest assets from the long remainder.
There is a third condition on top, less conspicuous in daily practice but the decisive one in supervisory terms. The derivatives on the fund's holdings must trade on a market monitored by a member of the Intermarket Surveillance Group — an association of exchanges and supervisory bodies that share trading data with one another in order to detect market manipulation. That surveillance, too, must cover at least 85 percent of NAV. Without that evidence, the SEC has in the past hardly ever given its consent.
Why 'digital commodity' instead of 'crypto asset' is more than a change of wording
One change in the filing reads like cosmetics and is not. The term crypto asset is replaced by digital commodity, borrowed from an existing Nasdaq rule for commodity trusts.
Behind it lies a question of jurisdiction that has been unresolved in the United States for years: is a crypto asset a security and therefore a matter for the SEC, or a commodity and therefore a matter for the futures regulator, the CFTC? Classifying a product as a commodity places it in a framework for which tried and tested options and surveillance rules have existed for decades. The filing thus anticipates a classification that the US legislature actually meant to make itself and to this day has not conclusively made. How slow that process is we described in our piece on the new SEC approval rules for crypto funds.
For you as a reader, that is why this inconspicuous filing deserves attention: it moves no prices, but it moves the category in which regulation happens.
Why you as a German investor cannot buy any of these US ETFs
Here the US part of the story ends and the German one begins. The funds whose options are at issue cannot be bought through your broker in Germany, and that is not the broker's doing.
The reason is the European UCITS directive. It requires investment funds sold to retail investors to hold a minimum spread of assets. A fund holding one single asset does not meet that requirement. A pure Bitcoin ETF in the legal sense therefore cannot be set up in the EU.
What trades in Europe instead are ETPs and ETNs. An ETN is in legal terms a debt security: a bond issued by the provider whose redemption is measured against the price of an asset. That is an important difference from a fund, because fund assets are ring-fenced and protected if the management company becomes insolvent. With a debt security they are not. Most European issuers address this issuer risk by actually buying the underlying coins and depositing them with a regulated custodian. Which securities those are in detail, and how to recognise a properly collateralised one, is set out in our guide to what you can actually buy in Germany instead of a crypto ETF.
These securities trade on Xetra, Gettex, Spectrum and the regional exchanges, that is, through the same account that holds your equities. Whether your provider offers all those venues is not a side issue, and the differences are larger than many expect; a look at our comparison of crypto brokers shows which venues are available where.
The transmission path: how options trading works through market makers on your spread
That leaves the question of why a US rulebook for options should reach a German portfolio at all. The route runs through the dealers who quote your prices.
A market maker is a trading firm that undertakes to quote a buying and a selling price continuously. The difference between the two is the spread, and it is the price you pay on entry and exit without seeing it on the statement as a fee. That spread is not arbitrary: it covers the risk the dealer takes on when buying a security from you and holding it on his own book for a while.
That risk is precisely what he hedges, and the cheaper the hedge, the tighter he can quote. A deeper options market on large crypto funds gives him more tools for that: more maturities, more counterparties, lower cost per dollar hedged. That cheapening does not stay confined to the US products, because the same firms often also serve the European ETPs and hedge against the same underlying markets.
A word of caution is in order here: this is a mechanism, not a promise. Spreads also depend on the time of day, on market conditions and on how many dealers serve a particular security at all. Anyone promising you that your bid-ask spread will narrow after an SEC decision is claiming more than can be evidenced. What can be said is that the direction of this relationship is well understood, and it points downwards.
What to check on your crypto ETP: spread, trading venue and collateral
Instead of waiting for September 27, you can measure the four quantities at issue on your own security. None of them requires a paid tool.
First, the bid-ask spread. Open your broker's order screen and look at the bid and ask price of the same security. The difference, divided by the mid-price, gives the spread in percent. Measure it twice: once in the morning and once after the close on the German exchanges. With many crypto ETPs there are worlds between those two readings, and that is information about your security, not about the market.
Second, the trading venue. The same security can cost different amounts on Xetra and at an over-the-counter venue. Compare the two before your next order instead of accepting the default setting's suggestion.
Third, the collateral. The key information document and the prospectus state whether the security is physically backed, who the custodian is and whether you have a claim to delivery of the coins. This point determines your tax position later, see below.
Fourth, the running costs. The total expense ratio is in the key information document. Set it against the spread: with a security you hold for a long time the running costs weigh more heavily; with frequent switching it is the other way round.
Tax: why the claim to delivery decides the holding period on an ETP
In the taxation of crypto ETPs in Germany a great deal hangs on a single feature of the security, namely whether it grants you a claim to delivery of the coins deposited.
The common reading in advisory practice: if the security grants a claim to delivery of the coins and is physically backed, it tends to be treated for tax purposes like the asset itself — that is, as a private disposal transaction under section 23 of the Income Tax Act, with the familiar one-year holding period, after which a gain remains tax-free. If that claim is absent, classification as a capital claim under section 20 of the Income Tax Act is the closer fit, and then withholding tax applies regardless of how long you have held the security.
The words 'tends to' and 'closer fit' are deliberate. This classification is contested in the individual case, it hangs on the specific design of the particular security, and it has shifted several times in recent years. What applies to your product belongs settled before the purchase and not in the year of disposal, when nothing about the design can be changed any more. Evidence for both sides is best collected as you go; which tools take that off your hands is set out in our overview of crypto tax tools. Binding advice on the matter, however, comes neither from a tool nor from this article, but from your tax adviser or your tax office.
A marginal point that is often confused: the European crypto regulation MiCA governs crypto service providers and certain tokens. An ETP is a financial instrument under MiFID II and falls into the securities world. So anyone checking an issuer's MiCA status is not checking the security in their portfolio.
The two caveats you have to read along with this
Two limitations to close with, without which this text would look wrong in four weeks.
The first caveat concerns the date. September 27 is the 45-day mark, not the date of a decision. If the SEC institutes formal proceedings, the matter shifts to the 90-day mark around November 11, 2026, and even that can be stretched further in certain constellations. Extensions are the rule with filings of this kind. So if nothing happens at the end of September, that is not a failure of the filing but the expected course.
The second caveat concerns the subject matter. This is about options on crypto ETFs, not about the funds themselves and certainly not about the approval of new spot products. An SEC approval therefore brings not a single new fund to market and changes nothing about the fact that these funds remain unavailable to you in Germany. The filing makes hedging cheaper for those who trade it anyway. Anyone reading the episode as the starting gun for a new wave of products is reading it wrongly. How an expiry date on the futures market, by contrast, feeds straight through to leveraged positions, we worked through using the example of the Bitcoin options expiry in September.
Options on crypto ETFs: what to take away
- Measure your spread before you think about the SEC. Two readings on a single trading day, morning and evening, tell you more about your actual trading costs than any US headline. If you find conspicuous spreads, compare the security and the trading venue against the alternatives in the crypto broker comparison.
- Check the collateral and the claim to delivery of your ETP in the key information document. Both are set out there in black and white, and both determine issuer risk and tax treatment later on. Which security serves which purpose in Germany is sorted out in our guide to crypto ETFs and their tradable alternatives.
- Put November 11 in your calendar instead of September 27. Until then the matter is open, and until then nothing changes in your portfolio. Anyone thinking about an entry in that period should compare the trading routes beforehand in our overview of crypto exchanges.
The full wording of the filing is in the official notice in the Federal Register of August 13, 2026; the complete submission including the catalogue of criteria is in SEC release 34-106067.
(As of September 24, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Xi Jinping arrives at the White House today, Thursday, September 24, 2026, on an official state visit. For investors that means one thing above all: over several hours, headlines will be produced that the crypto market reacts to immediately, and in both directions. Anyone running leverage should know where their liquidation price sits before that starts. Anyone holding spot has nothing to do today, and no reason to do anything.
The market comes into this appointment with an unusually large profit on the books. Bitcoin traded at $84,339 at around 00:50 UTC on September 24, down 2.47 percent on the day but up 11.59 percent over the week (CoinGecko). Working the weekly figure back, the price stood at roughly $75,600 seven days ago. That calculation is our own derivation from the CoinGecko weekly change and not a figure published there.
The state visit on September 24: what is on the White House schedule
The White House has published the programme itself. President Trump and First Lady Melania Trump receive Xi Jinping and Peng Liyuan for an official state visit; the arrival took place on Wednesday, September 23, at Joint Base Andrews. The State Arrival Ceremony follows on Thursday morning on the South Lawn, on the State Floor and in the Rose Garden, with 479 members of all branches of the armed forces.
A word of context, because it makes the difference: a state visit is the highest form of visit in protocol terms and includes a ceremony, a state banquet and, as a rule, a joint statement. A plain working visit would have neither the programme nor the stage. According to the White House, the last visit of this kind by Xi and Peng lies more than a decade back. What counts for the market is mainly the calendar: there is a fixed window in which statements can be made.
Taiwan, trade and AI: the three flashpoints that can move the price
NBC News names three areas of tension for this summit: Taiwan, trade and artificial intelligence. All three act on crypto only indirectly, through risk appetite in equity markets and through the semiconductor chain. If the tone hardens on Taiwan or on export controls for AI chips, investors first sell whatever trades fastest, and crypto assets are part of that. If the tone softens, the same mechanism runs in reverse.
Exactly that was visible at the two leaders' last meeting in South Korea in October 2025. Announced at the time were the resumption of Chinese rare earth exports under a one-year agreement, purchases of American soybeans and talks on chips; the United States cut tariffs from 57 to 47 percent.
Why the crypto market is sensitive right now
Last week was one of the strongest of the year, and that is the real reason for the nervousness. Among the top 25 by market capitalisation, weekly gains at the time of measurement on September 24 sit far above the normal range: Near Protocol up 68.45 percent, Bitcoin Cash up 54.98 percent, Uniswap up 44.11 percent, Cardano up 23.67 percent, Litecoin up 21.28 percent (all figures CoinGecko, September 24, 00:50 UTC).
On a 24-hour view the picture has already turned. Uniswap is down 9.89 percent, Dogecoin 7.72 percent, Stellar 6.79 percent, Cardano 6.49 percent, Zcash 6.21 percent, Chainlink 5.85 percent and XRP 5.16 percent. The large caps are holding up better: Ethereum trades at $2,684.55, down 2.80 percent, Solana at $115.03, down 3.26 percent.
Large unrealised gains and a dated event are an uncomfortable combination. They generate selling pressure out of pure caution, regardless of what is actually said at the White House. How this altcoin pullback has developed since midweek, we wrote up on September 23 in a separate analysis of the altcoin pullback; this article looks at the scheduled event rather than at the move itself.
What earlier Trump-Xi meetings did to the crypto market
For the meeting of October 30, 2025 there is a usable measurement. FXStreet reported at the time that the market recovered step by step in the early European session after the meeting, with Bitcoin, Ethereum and XRP each adding just under one percent. Substantial liquidations accrued at the same time: the report carries $150 million of long liquidations in its headline, but cites more than $800 million for the market as a whole over the same 24 hours. We give both figures and do not smooth them, because different things can be read from them.
The lesson is uncomfortable for both camps. The price can rise after an event of this kind and leveraged positions can still be closed out by force on a large scale. That happens in the minutes around the first headline, before any direction has formed at all. The only defence against that sequence is a distance between entry price and liquidation price wide enough to absorb such a spike. A view on the negotiating outcome is of no help whatsoever.
We explicitly draw no forecast for today from this. A single meeting in October 2025 is not a sample from which a rule can be built, and the starting position was a different one then.
Liquidation price and funding rate: the arithmetic before the event
How to find your actual liquidation price
The liquidation price is the level at which the collateral behind a leveraged position no longer suffices and the exchange closes it automatically. It hangs on three things: leverage, collateral posted and your provider's maintenance margin. A rough orientation with isolated margin: at ten times leverage it sits around ten percent away from the entry, at twenty times around five percent. The exact figure comes from your provider, and only that one counts. We have set out the arithmetic step by step in our guide to calculating the liquidation price.
Keep an eye on the funding rate alongside it. This is the periodic payment between the long and the short side of perpetual futures, the contracts without an expiry date, which ties the contract price to the spot market. If it is strongly positive, the long positions are paying and the book is one-sided. That one-sidedness is precisely what makes a liquidation cascade more likely when a headline briefly turns the price against the majority. Which platforms disclose their funding history and how the fees differ is shown in our comparison of perp DEX platforms.
A note on the legal position in Germany: perpetuals with high leverage are available to retail investors through EU-licensed providers only to a limited extent, and many of the well-known platforms do not direct their offering at German retail clients. Anyone using them regardless carries the risk of standing without European supervision in a dispute.
Holding period and tax: why selling out of fear can be expensive
Before you sell holdings today, look at the purchase date. In Germany, gains from the sale of crypto assets are tax-free after a holding period of more than one year under section 23 of the Income Tax Act. Within that one-year window they are taxable as a private disposal transaction as soon as total gains in the calendar year reach the allowance of 1,000 euros.
For last week's rally that means something concrete: positions built up in this year's uptrend are, with high probability, not yet a year old. A panic sale on summit day may therefore cost you twice: once in the further course of the price, and on top of that income tax on a gain that would have been tax-free once the period had run. That is not an argument for sitting still at any price, but it belongs in the calculation.
Holding period with several purchases: FIFO in practice
Anyone with several purchases at different prices needs documentation that reflects FIFO, meaning the sale of the oldest holdings first. Which tools output that cleanly for German tax rules is set out in our overview of crypto tax tools and portfolio trackers. Settle that before the sale, not in May of the following year.
Custody and choice of exchange: what MiCA is worth to you on a day like this
Volatile days are the days on which withdrawals slow down and trading interfaces come under load. Where your balance sits is what pays off here. Since July 1, 2026, anyone offering crypto services in the EU needs an authorisation under the MiCA regulation; a provider without that permission may not continue the business. Licensed firms of this kind are called CASPs, crypto-asset service providers.
The most important point for you is the segregation of client holdings: client tokens must be held separately from the firm's own assets and legally ring-fenced, so that they do not fall into the estate in an insolvency. You can check whether your provider is authorised yourself, Europe-wide in the ESMA register and, for German firms, additionally with BaFin. It is a two-minute job and should not wait until the day a problem arises.
For long-term holdings, self-custody remains the answer to provider risk. For amounts you want to trade at short notice, the route runs through a licensed exchange or a regulated broker; which firms operate in Germany with permission and what they cost is set out in our broker comparison.
Levels above and below: how to read the reaction
Two areas give you orientation today, both drawn from verifiable figures and not from chart patterns. On the downside, the calculated start of the week at around $75,600 is the point at which this week's gains would be given back in full. On the upside lies the area around $86,200, where Bitcoin closed on September 22 according to Rio Times Online, before the pullback set in.
The market has been moving between the two for two days. More important than the levels themselves is what you attach to them: a stop sitting just below a round number will be taken out on a news day with high probability, before the direction becomes clear. Anyone setting stops at all today should place them further down than on a quiet day, or reduce the position size and work without a stop entirely.
What probably changes nothing today
For completeness, here is what you can safely ignore. A state banquet and a joint statement as a rule contain no statements on crypto assets, and regulation in Germany and the EU is not up for negotiation today. The MiCA obligations, the holding period and your exchange's reporting duties are untouched by this appointment.
So for anyone holding spot only, with an investment horizon of years and without borrowed leverage, this Thursday is a day like any other. The event is a risk for positions financed with debt and for short-term trades, and there too only for a few hours.
Where you will see the results first
The White House publishes the schedule and the statements on its own briefing pages, and this visit is there with its programme. That is the source with the least delay and without interpretation in between. News agencies and specialist media report interim positions faster, but at the risk of shortening a statement that is clarified shortly afterwards.
In practice that means: do not react to the first line that runs through a feed. On a day with this stage, wordings are corrected within minutes, and each of those corrections produces a price move of its own. Anyone who still has an intact position at the third impulse has fared better than anyone who traded on the first.
Putting summit risk in context: what to take away
- Check your liquidation distance before the ceremony begins. Open every leveraged position and read off the liquidation price your provider shows. If it is less than ten percent away from the current price, cut leverage or size. Which platforms disclose funding and maintenance margin transparently is set out in the perp DEX comparison.
- Check the purchase date before you sell. Holdings under one year of holding period trigger tax on a sale within the one-year window as soon as you are above 1,000 euros of gains in the calendar year. Sort your purchases by FIFO before you take a decision to sell; suitable tools can be found under crypto tax tools.
- Check your provider's authorisation. Look up in the ESMA register and with BaFin whether your trading venue holds a MiCA permission, and move long-term holdings into your own custody. Regulated alternatives for Germany are set out in our broker comparison.
(As of September 24, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Solana's decentralised exchanges booked more individual trades in a single trading week than the New York Stock Exchange. The tracker flipthe.market, which builds on data from Blockworks Research, counts roughly 208 million spot trades on Solana for the week of September 14 to 20, 2026, against 189 million on the NYSE. It is the first documented case of a blockchain overtaking one of the world's largest securities exchanges on trade count alone.
The number is real, and it is still easy to misread. A trade on a Solana DEX and a trade on the NYSE are economically two very different things, and that difference decides whether this record concerns you as an investor at all. This article separates the two questions: first what was measured, then what you should check if you swap on a decentralised marketplace.
Solana DEX versus NYSE: what the count of 208 million trades actually measures
What is measured is the number of trades, meaning how often a buy met a sell at all. What is not measured is how much money moved in the process. Both sides of the survey put the Solana figure at roughly 208 million, but they differ on the comparison value and on the dating: the tracker based on Blockworks data cites 189 million NYSE trades for the week to September 20, while a second analysis built on a Kobeissi Letter chart arrives at around 190 million for the week to September 13. The range is therefore 189 to 190 million, and the sources do not agree on which calendar week saw the first overtake.
A DEX is a decentralised exchange: a program on a blockchain that settles swaps directly between two wallets, without a company holding user funds or matching the orders. That design is precisely why the trade count can run so high, and why the rest of this article is necessary.
Anyone who has ever run a swap on Solana knows the practical difference. The trade settles in under a second, costs a fraction of a cent in network fees and needs no brokerage account. That very many very small trades arise under such conditions is no surprise; it follows from the cost structure.
Memecoin platforms account for roughly 57 percent of trades: why the comparison limps
In the same analysis, about 118 million of the 208 million trades fall to a single memecoin launchpad, roughly 57 percent. These are mostly micro purchases of freshly minted tokens, often worth a few dollars, frequently triggered by automated programs. On the NYSE, a trade as a rule sits behind an equity order of a markedly larger size.
The headline is therefore not wrong, but it describes a different process from the one most readers assume. The blockchain wins the comparison on the number of transactions. On the question of how much capital changes hands, it remains orders of magnitude behind. How wide that gap is can be calculated, and that is what I did.
Own measurement: $3.2 billion in DEX volume in 24 hours across 125 protocols
cryptoticker.io collected this analysis itself on September 23, 2026. Method: a call to DefiLlama's open interface for the trading volumes of every decentralised exchange recorded on Solana, on September 23, 2026 at around 22:10 UTC, HTTP 200, with no post-processing of the raw values. Objects checked: 125 individual DEX protocols on Solana.
The finding: across all 125 protocols together, roughly $3.20 billion was swapped in the preceding 24 hours, roughly $21.22 billion in the preceding seven days and roughly $79.96 billion in the preceding 30 days. Against the previous day, daily volume was 6.8 percent lower. The five largest protocols account for roughly $2.04 billion between them, just under 64 percent of daily volume; the single largest platform came to $634 million.
The distribution is more interesting than the total. The two marketplaces belonging to the memecoin complex stand together for roughly $755 million, around 24 percent of daily volume. On trade count, though, the survey cited at the outset puts them at roughly 57 percent. An average memecoin trade is therefore markedly smaller than a trade on the remaining Solana exchanges. What I could not verify is how many of these trades come from automated trading programs and how many from human beings; the interface does not supply that breakdown.
Roughly $100 per trade on average: what separates trade count from trading volume
Setting the weekly volume against the weekly number of trades produces the figure that puts the record in perspective. On the weekly value of $17.3 billion cited in the survey, the average trade comes to about $83. Using my own seven-day figure of $21.22 billion instead gives roughly $102. The two values refer to slightly shifted time windows, which is why the range appears here and not a smoothed average.
An average trade between $83 and $102 describes a market made up of very many very small transactions. For you as an investor, that is the actual news, because the entire checklist part of this article follows from it. Anyone active on such a marketplace produces, in case of doubt, several hundred transactions a year rather than five. And every single one of them is a separate event for tax purposes.
24 hours against 6.5 trading hours: the structural advantage of the blockchain
The NYSE trades on weekdays from 9:30 to 16:00 New York local time, so 6.5 hours on five days. A blockchain runs continuously, on seven days, holidays included. That alone yields a multiple of the possible settlement time before a single user trades any more than before.
This difference carries half the explanation of the record. Putting the two numbers side by side compares a market with opening hours against one without. That says nothing against the performance of the network; it merely limits what may be inferred from the comparison.
A DEX without CASP authorisation: why MiCA and BaFin do not protect you on a swap
The EU Markets in Crypto-Assets Regulation, MiCA for short, governs providers of crypto-asset services. Such providers need authorisation, in Germany from BaFin, and are bound by duties on custody, complaint handling and disclosure. Recital 22 of Regulation (EU) 2023/1114 states expressly, however, that services provided in a fully decentralised manner without any intermediary should fall outside its scope.
In practice that means the following. If you buy on a regulated exchange, an authorised company stands behind the transaction. If you swap straight out of your own wallet against a smart contract, nobody stands there. No deposit protection, no complaints body, no supervisor that steps in if there is a dispute. Where exactly the line between "still a service provider" and "fully decentralised" runs in an individual case has not been settled to this day; the indicators include administrator keys, custody of user assets and marketing by an identifiable company. We have broken down which duties apply on the regulated side in our overview of MiCA obligations for crypto companies.
For the choice of your entry point, this is the decisive fork. Anyone who prefers the regulated route will find the providers available in Germany in our comparison of crypto exchanges; anyone who deliberately goes to decentralised marketplaces takes on the checks themselves.
Every swap is a disposal: how Section 23 EStG captures DEX trades
Swapping one token for another is not a neutral event for tax purposes but a sale of the one and a purchase of the other. The governing provision is Section 23(1) sentence 1 no. 2 of the German Income Tax Act, the Einkommensteuergesetz. In the wording that applies today, private disposal transactions are disposals "of other assets where the period between acquisition and disposal is not more than one year". Crypto-assets fall under those other assets.
From that follows the one-year holding period many investors know. Hold a token for longer than a year and then sell it, and there is no taxable event any more. Swap within the year, and there is one. In a market averaging around a hundred dollars per trade, that means practically every active user trades inside the period and therefore sits in taxable territory.
The order is not arbitrary either. Anyone who bought the same token several times at different prices has to determine which holding counts as sold first. How swaps, liquidity pools and pool income are to be classified in detail, we have taken apart in our breakdown of DeFi taxes on swaps and liquidity pools.
The 1,000 euro exemption threshold and the one-year period: what is left after hundreds of swaps
Section 23(3) sentence 5 EStG provides: "Gains shall remain tax-free if the total gain realised from private disposal transactions in the calendar year was less than 1,000 euros." Two details of this are regularly overlooked.
First, this is an exemption threshold and not a tax-free allowance. If your total gain comes to 999 euros, it stays tax-free. If it comes to 1,000 euros, the full amount is taxable, and not only the part above the line. Second, the threshold applies to all private disposal transactions of the calendar year taken together, including gains from other transactions that fall under the same section.
Anyone making several hundred small swaps spread across the year accumulates many individual gains and individual losses that net into an overall result. The fact that the individual amounts are small is no help there. What counts is the sum, and the sum cannot be determined at all without clean records.
Loss offsetting under Section 23(3): why DEX losses count only against a narrow pot
Sentence 7 of the same provision limits what happens to losses. They may be offset "only up to the amount of the gain that the taxpayer realised from private disposal transactions in the same calendar year" and may not be deducted under Section 10d. Under sentence 8, however, they do reduce income from private disposal transactions of the immediately preceding or the following assessment periods.
Translated: a loss from a memecoin swap cannot be set against your salary or against interest income. It works only inside the same pot, that is against other private disposal gains, and it can be carried into other years. Anyone running mostly losses in the current year gains nothing from them for tax purposes as long as no gains of the same type stand against them.
No tax certificate from a smart contract: why the record-keeping falls to you
A German custodian bank issues you a tax certificate at the end of the year. A smart contract does not. Every transaction does sit permanently and publicly on the blockchain, but in the form of addresses, token amounts and timestamps, not in euros and not sorted according to German tax law.
The conversion into euros at the relevant moment, the matching of acquisitions to disposals and the determination of the holding period are work you have to do yourself or have done for you. Specialised software exists for exactly that, reading wallet addresses and preparing the events; the providers relevant to the German market are listed in our comparison of crypto tax software and portfolio trackers. What matters most is that you keep the records continuously and do not start in the following year. Anyone who has to reconstruct hundreds of events after the fact is working against themselves.
DAC8 reports service providers, not your wallet: the gap that does not let you off
Under the EU directive DAC8, providers of crypto-asset services report their customers' transaction data automatically to the tax authorities. Data collection has been running since January 1, 2026, and the first transmission is scheduled for 2027. Anyone trading through an authorised exchange must therefore assume that the tax administration sees their activity there in any case.
On a swap out of a self-custodied wallet against a smart contract there is no reporting service provider. Tax exemption does not follow from that. The duty to declare stays entirely with you; what is missing is merely the party that would take it off your hands and confirm your figures. In practice that means a higher burden of proof, not a lower one.
On top of that, the chain as a rule does not run seamlessly outside the reported world. Whoever deposits euros buys from an authorised provider, and that event is recorded. What happens afterwards in your own wallet is something you have to be able to connect to it.
Slippage, priority fee and failed transactions: the costs beside the price
On a decentralised marketplace you rarely pay the price alone. The executed price deviates from the quoted one when other trades pass through between order and execution; that deviation is called slippage and can be capped in the wallet. On Solana there is also a voluntary priority fee, which at times of high network load decides whether your order makes it into the next block at all.
If the transaction fails, the network fee is spent anyway while the swap has not happened. What causes it in an individual case depends on the network load, on the slippage tolerance that was set and on whether the chosen trading route still had enough liquidity at the moment of execution. On an average trade of around a hundred dollars, these side costs can make up a noticeable share of the stake, and they arise on every single attempt.
From euros onto the Solana DEX: which buying route stays regulated in Germany
A decentralised marketplace does not accept euros. The usual route runs through a provider authorised in the EU, where you buy SOL or a stablecoin against euros, from there to a wallet in your own custody and only then onto the DEX. Each of these steps carries its own costs and its own risks.
The move into self-custody is the critical point. From the moment the keys are with you, there is no longer any party that can undo a mistake. A mistyped address, an approval granted carelessly to a contract or a compromised seed phrase lead to a final loss. Anyone moving larger amounts should keep the keys on a device that has never been connected to the internet.
Solana price levels above and below: what the rally is measured against now
SOL was quoted at $114.69 on September 23, 2026 at 22:01 UTC according to CoinGecko. Over 24 hours it shows a decline of 2.97 percent, over seven days a gain of 16.29 percent. The price has therefore ridden the broad weekly upswing and has lately been giving ground again along with the wider market; the all-time high dates from January 19, 2025 and is far away.
To the downside, the mark of $100 is the next psychologically round level; to the upside sits the area around $120, where the price failed most recently. These are reference points and no forecast. You will find the ongoing price development together with analysis on our Solana price prediction. Whether the record number of trades supports the price is open, because a large part of those trades takes place in tokens that share only the infrastructure with SOL itself.
Checking your Solana DEX trading: what you take away from this
The record describes a real shift in market structure, and it describes it in a metric that favours small transactions. What counts for you is less the headline than the question of what you do when you trade on this market. Three steps are worth taking straight away.
- Count your swaps for the current year before the year ends. Every swap inside the one-year holding period is a separate taxable event, and the exemption threshold of 1,000 euros applies to the sum of all private disposal transactions. A tool that reads your wallet addresses and prepares the events in euros is in our comparison of crypto tax software and portfolio trackers.
- Establish which authorised provider your entry runs through. The euro route as a rule goes via a regulated exchange, and its fees and withdrawal options determine the bulk of your costs. The providers available in Germany are in our comparison of crypto exchanges.
- Separate trading funds and long-term holdings physically from each other. What you move on a DEX belongs in a wallet with a limited balance, and the long-term holding belongs on a device with no network connection. Suitable models and their differences are in our hardware wallet comparison.
The figures on the trading week come from the flipthe.market analysis based on Blockworks Research data, the quoted statutory wording from Section 23 EStG at gesetze-im-internet.de. The volume figures in this article rest on the own data call described above.
(As of September 23, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Anyone who holds bitcoin or other crypto assets and gets divorced usually asks the wrong question first, namely this one: do I now have to split my coins? Under German law the answer is, in the overwhelming majority of cases, no, your coins remain your coins. What gets divided is something else, namely the increase in assets accumulated during the marriage, and it is divided as a sum of money. That sounds like a technicality, but it decides whether you have to sell or not, and whether tax falls due when you do.
This piece explains how the equalisation of accrued gains works when part of the assets sits in a wallet: which key dates apply, what you have to disclose, who bears the price risk between the key date and payment, and at which point a family law question turns into a taxable disposal. All the provisions come from the German Civil Code and the Income Tax Act and can be read in the original wording.
One framing note that belongs here: this is a general explanation of the legal position and not legal advice for your case. Family law is decided case by case, and with larger holdings a lawyer’s advice is no luxury.
Community of accrued gains does not mean joint assets
The error is already in the term. Anyone who marries without a prenuptial agreement lives under the statutory matrimonial property regime of the community of accrued gains. Section 1363 paragraph 2 of the Civil Code makes that expressly clear: “The assets of each spouse do not become their joint assets; this also applies to assets acquired by a spouse after the marriage.”
Translated into practice: if you bought bitcoin in 2019 and married in 2021, those bitcoin continue to belong to you alone. The wallet does not become joint property through the marriage, and your spouse acquires no ownership in it. Equalisation happens only at the end, and it happens as a calculation.
The exception is holdings that were genuinely acquired jointly, such as a joint account at an exchange or a wallet to which both hold the keys. There, the additional question arises of who owns which share of the holding, and that is answered not through the equalisation of accrued gains but through ordinary property law.
How the accrued gain is calculated: initial assets, final assets, equalisation claim
The calculation consists of three figures, and each one is defined in the statute.
The initial assets are, under Section 1374 of the Civil Code, the assets belonging to you when the property regime begins, that is on the day of the marriage, after deduction of debts. The final assets are, under Section 1375, the assets at the end of the property regime. The accrued gain is, under Section 1373, simply the amount by which the final assets exceed the initial assets.
From that follows the actual claim. Section 1378 paragraph 1 of the Civil Code: “If the accrued gain of one spouse exceeds that of the other, half of the excess is due to the other spouse as an equalisation claim.” The equalisation claim is a claim for payment in euros and is not directed at handing over particular objects, and therefore not at handing over coins.
A worked example with crypto assets
Suppose you had 10,000 euros in bitcoin at the time of the marriage and nothing else. By the key date at the end of the marriage that has grown to 90,000 euros, and there are no other assets. Your accrued gain therefore comes to 80,000 euros. Your spouse had nothing at the start and savings of 20,000 euros at the end, so their accrued gain is 20,000 euros. The excess is 60,000 euros, and half of that, 30,000 euros, is what you owe by way of equalisation. Whether you sell coins for it, take out a loan or pay from savings is your decision.
One detail often overlooked with crypto assets: under Section 1374 paragraph 2 of the Civil Code, assets acquired by a spouse during the marriage through inheritance or gift are added to the initial assets. Inherited or gifted coins therefore do not increase your equalisable accrued gain by their full amount. Their increase in value during the marriage does, however, feed into the calculation. Anyone who received coins as a gift should be able to evidence the transaction together with its date and the value at the time.
Duty of disclosure under Section 1379: what you must reveal about your wallets
Here lies the point at which crypto assets differ from a savings account. A bank can be questioned by the court, a self-custodied wallet cannot. That is precisely why the duty of disclosure is framed so sharply.
Under Section 1379 paragraph 1 of the Civil Code, each spouse may demand information from the other about their assets, in so far as it is relevant to calculating the initial and final assets, and in addition about their assets at the time of separation. The statutory wording is terse and effective at this point: “On request, supporting documents are to be produced.” It can also be demanded that the schedule be drawn up by a notary or a public authority.
In practice, for crypto assets that means the schedule covers holdings in exchange accounts just as much as self-custodied holdings. Supporting documents may include account statements and transaction overviews from the venues, plus the records of purchases, sales and transfers. Disclosure that names an exchange and stays silent about your own hardware wallet is not complete disclosure.
The fact that the legislator does not use the word wallet changes nothing. The duty attaches to the assets, not to the form of safekeeping.
Three key dates instead of one: marriage, separation, service
One peculiarity of the procedure regularly causes confusion, because three different days play a role and each measures something different.
- Day of the marriage: decisive for the initial assets under Section 1374 of the Civil Code.
- Day of separation: decisive for the additional disclosure under Section 1379 paragraph 1 number 1. This day has a function of its own that is underestimated, and we come to it shortly.
- Day the divorce petition is served: decisive for the final assets. Section 1384 provides that, in a divorce, the end of the property regime is replaced by “the point in time at which the divorce petition becomes pending”.
Pending means the day on which the petition is served on the other spouse. With a volatile asset, that is a date with considerable effect: the value of your holding on precisely that day feeds into the calculation. A price jump a week later no longer counts, and neither does a slump.
Which price applies? Valuing a volatile asset
The statute prescribes no valuation method for crypto assets. What matters is the market value on the key date, that is the price that could be obtained in the market. With an asset quoted differently at dozens of venues, that becomes a question of presentation.
A record stands up when it can be followed: the price on the key date at an established venue, better still the average across several, in each case in euros and stating the time of day. With a holding spread across several wallets and exchanges, complete capture of the quantities comes on top. Anyone reconstructing this only months later has an evidence problem, and it is one that software can solve: portfolio trackers keep holdings and price history together and produce key-date valuations. Our comparison of crypto tax software gives an overview of the usual tools.
It gets harder with holdings that have no functioning market, such as barely traded tokens or locked holdings from staking programmes. There the market value itself is contentious, and there are no blanket answers.
A price slump between the key date and payment: who carries the risk
This is the most uncomfortable feature of the rules, and it hits precisely the person holding crypto assets. Between the key date and the day on which payment actually happens, months frequently pass in practice. The equalisation claim, however, is fixed as a euro amount, calculated on the key date.
If the price halves in that time, your holding shrinks and the debt remains. If it rises, you keep the gain. The price risk over that period therefore sits with whoever holds the coins. Section 1378 paragraph 2 of the Civil Code does cap the claim at the value of the assets present when the property regime ends, but that cap too is measured by the key date and not by the day of payment.
Anyone who can foresee a larger equalisation payment should therefore think early about how to raise it. Shifting part of the holding into a less volatile asset is one option. The tax consequences of that shift are in the next section, and they are the reason this step is not a pure arithmetic exercise.
What happens if a wallet is concealed
The notion that a self-custodied wallet is invisible is persistent. In law it is risky, and that is because of a rule many do not know.
Section 1375 paragraph 2 of the Civil Code adds back to the final assets amounts by which the assets were reduced through gratuitous transfers not made out of a moral duty, through dissipation, or through “acts performed with the intention of disadvantaging the other spouse”. What matters is the sentence that follows: if the final assets fall below the assets stated in the disclosure as at the time of separation, the spouse concerned must set out and prove that the reduction does not rest on such acts.
That reverses the burden of proof, and it is exactly here that disclosure as at the time of separation becomes important. Anyone who states 100,000 euros in coins at separation and only 40,000 euros on the day of service has to be able to explain where the rest went. With a volatile asset that showing is often possible, because a price slump can be evidenced from public data. With a transfer to an unknown address it is not.
On top of that, blockchain analysis has long removed part of the anonymity, and venues in the EU are subject to identification duties. Anyone who has bought at a regulated exchange leaves a trail that can be matched to a name. A deliberately false schedule of assets can moreover carry criminal consequences where it has been affirmed under oath.
Tax: when transferring coins triggers a disposal
Now to the point at which a family law question becomes a tax one. Crypto assets held privately fall, on sale, under private disposal transactions in Section 23 of the Income Tax Act. Within one year of acquisition the gain is taxable, and after that tax-free. An exemption threshold of 1,000 euros per calendar year applies, and once it is exceeded the entire gain counts.
Selling in order to pay the equalisation claim
If you sell coins in order to pay the equalisation in euros, that is an entirely ordinary sale. If the acquisition was less than a year ago, tax falls due. The fact that you are selling because of court proceedings changes nothing. Anyone who has a choice therefore checks which holdings have already completed the one-year period before selling.
Handing over coins instead of money
Some couples agree to satisfy the equalisation claim by transferring coins rather than remitting euros. That is possible under civil law but by no means neutral for tax. On the view prevailing in tax law, performance in lieu is a transaction for consideration, because the coins are given up against the extinction of a claim. A disposal therefore takes place, with the same consequences as a sale. This arrangement accordingly belongs on a tax adviser’s desk before the signature, not after it.
Transfer without consideration: gift tax and the allowance
The position is different where coins are transferred without consideration, that is, not in satisfaction of an equalisation claim. In that case it is a gift. Between spouses, under Section 16 paragraph 1 number 1 of the Inheritance and Gift Tax Act, an allowance of 500,000 euros applies, and it becomes available afresh every ten years.
The allowance applies to spouses for as long as the marriage exists. After the divorce, the parties are unrelated third parties for tax purposes and the allowance falls to 20,000 euros. The timing of a voluntary transfer is therefore anything but arbitrary. How gifts between spouses are treated in detail is something we set out in our piece on gifting bitcoin to your spouse of September 22, 2026.
What a prenuptial agreement can change
Everything described so far applies to the statutory property regime. A prenuptial agreement can change a great deal about it, and for people with highly volatile assets that is a serious thought.
Separation of property excludes the equalisation of accrued gains entirely. More common and milder is the modified community of accrued gains, under which individual assets are taken out of the equalisation or valuation rules are laid down. It is conceivable, for instance, to carve out a particular holding, or to agree for volatile assets an average value over a longer period instead of a key-date price. A prenuptial agreement requires notarial recording.
For proceedings already under way, that comes too late. Anyone who is only now considering it, however, still has the better moment ahead of them.
How to prepare without hiding assets
Between full disclosure and careless unpreparedness lies a lot of room, and that room is lawful. The following points help regardless of which side of the calculation you are on.
Keep a clean schedule of your holdings with acquisition dates and acquisition costs. You need that for your tax return anyway, and if it comes to it, it is the basis of every negotiation. Secure the transaction history of your venues as an export while you still have access. An account at an exchange that leaves the market takes its history with it.
Document the origin of inherited or gifted holdings. Under Section 1374 paragraph 2 of the Civil Code they improve your position, but only if you can evidence them. And record when the separation took place: that day triggers the disclosure under Section 1379 paragraph 1 number 1 and is the reference point for the burden-of-proof rule in Section 1375 paragraph 2.
If holdings have so far sat in exchange accounts, the question of safekeeping is worth a thought in any case. For keeping separated holdings over the long term, your own keys are the cleaner route. What to bear in mind there is shown in our comparison of hardware wallets. Anyone who wants to think through the event of death at the same time will find the parallel questions in our piece on passing on crypto assets.
The most common misconceptions at a glance
Four assumptions crop up particularly often in this context, and none of them withstands scrutiny.
The first misconception holds that the wallet becomes joint property through the marriage. Section 1363 paragraph 2 of the Civil Code says the opposite. The second holds that the equalisation is directed at handing over half of the coins. It is a monetary claim under Section 1378. The third holds that self-custodied holdings are exempt from the duty of disclosure. Section 1379 attaches to the assets, not to the form of custody. The fourth holds that handing over coins instead of money is harmless for tax. On the prevailing view it is a disposal.
Crypto in a divorce: what to take away
- Establish the key date first, then the value. For the final assets, what counts under Section 1384 of the Civil Code is the day the divorce petition is served. Record that day’s price, in euros, with the source and the time of day. Tools that keep holdings and price history together can be found in our comparison of crypto tax software.
- Disclose in full and evidence the origin. The duty of disclosure under Section 1379 of the Civil Code covers exchange accounts and self-custodied holdings alike. Inherited and gifted coins improve your calculation under Section 1374 paragraph 2, but only with evidence.
- Check the holding period before you sell to pay. Holdings held for more than a year are tax-free on sale, more recent ones are not, and handing over coins instead of money counts as a disposal. For keeping holdings separately afterwards, our comparison of hardware wallets will help.
You can read the provisions cited in their original wording, for instance Section 1379 of the Civil Code on the duty of disclosure and Section 23 of the Income Tax Act on private disposal transactions.
(As of September 23, 2026. This article is not investment advice. It is not legal advice either. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
Anthropic says Claude autonomously found a new CRISPR-like enzyme system. Even Dario Amodei admits nobody knows what it actually does.
Anthony Albanese said the agent accessed public and non-public files on a Medicare statistics portal in June, calling OpenAI's three-month delay in disclosing the breach "unacceptable."
OpenAI is giving Ukraine's government access to Daybreak, its AI vulnerability-hunting system, as the country's cyber defenders face a record wave of attacks on hospitals, power grids, and government networks.
China's internet regulator is investigating DeepSeek and Moonshot AI after Anthropic accused both of secretly routing millions of user exchanges through Claude to train their own models.
A tech columnist declined to give Meta's new AI agent access to his messages. It read them anyway, then invented an explanation for how it knew.
U.Today - IT, AI and Fintech Daily News for You Today
Bitcoin Cash explodes toward $350 on CME futures plans, Zcash pushes its massive rally into overbought territory, while Uniswap and Shiba Inu face sharp resistance after their latest breakouts.
Coinbase has disabled trading for IoTeX (IOTX), dealing another blow to the struggling blockchain token after a brutal 85% plunge over the past year.
Coinbase Markets has flagged unusually strong bullish demand in XRP options.
Bitcoin ETFs have staged a stunning comeback.
Zcash cofounder Eli Ben-Sasson names two features that could eventually become baseline requirements across the crypto industry.
Blockonomi
TLDR
- XRP’s one-week 25-delta call-minus-put skew climbed to 9.3 volatility points.
- The reading sits in the 95th percentile, showing unusually strong demand for calls.
- XRP options had mostly negative skew during late 2025 and early 2026.
- The skew briefly moved above 15 volatility points in late August before cooling.
- XRP has gained about 18% over the past seven days, supporting renewed demand for upside exposure.
XRP options traders are paying a higher premium for calls as demand for upside exposure rises. Coinbase Markets said XRP’s one-week 25-delta call-minus-put skew reached 9.3 volatility points, placing the reading in the 95th percentile. The move shows traders are paying more for comparable calls than puts after XRP gained about 18% over seven days.
$XRP options are leaning toward upside convexity.
At the 1w 25Δ point, calls trade 9.3 vol points above comparable puts, a 95th percentile reading.
Sensible positioning, or crowded demand? pic.twitter.com/lLq1cbBfKy
— Coinbase Markets
(@CoinbaseMarkets) September 23, 2026
XRP Options Skew Turns Strongly Positive
Coinbase Markets described the market as leaning toward upside exposure. The +9.3 reading means implied volatility for selected calls stands 9.3 points above comparable puts. It does not mean traders expect XRP’s price to rise by 9.3%, and it does not provide a direct price forecast.
The change follows a period when short-term XRP options favored downside protection. During late 2025 and much of early 2026, the one-week skew stayed negative and sometimes fell below -10 points. More recently, XRP rebounded toward $1.55 after falling near $1.39, while options demand shifted toward calls.
Calls Gain Premium After XRP Rebound
The shift has developed quickly. XRP’s one-week skew briefly moved above 15 volatility points in late August before easing. It has returned toward double-digit territory, showing traders accept higher prices for short-term upside exposure.
A 25-delta risk reversal compares implied volatility of calls and puts with similar sensitivity to price moves. A positive reading means calls carry a higher premium. A negative reading means puts cost more on a comparable basis, reflecting stronger demand for downside protection.
Recent market activity has included changes outside derivatives. XRP Ledger Batch V1.1 moved closer to activation after gaining support from 30 of 35 tracked validators. The update groups linked transactions so several actions can settle together or fail together.
Bullish Positioning Does Not Guarantee Gains
Options skew can show where traders are paying more for protection or exposure, but it cannot confirm what XRP will do next. Strong call demand may reflect bullish positioning, hedging, or traders seeking exposure after a fast price move.
XRP surged above $1.60 during the latest rebound as large-holder activity and new wallet creation increased. That move provides context for renewed call demand, although options premiums can change quickly when volatility, positioning, or spot prices shift.
For now, the 9.3-point skew shows a strong preference for calls relative to puts. Traders will watch whether the skew stays elevated as XRP’s spot market responds to gains and changing demand.
The post XRP Options Turn Bullish After Sharp Price Rebound appeared first on Blockonomi.
TLDR
- Kalshi said the CFTC has not contacted the company and denied knowledge of any formal investigation.
- Reports questioned repeated trade sizes across Kalshi’s Bitcoin and Ether perpetual markets.
- Researcher Beni found $5,500 Ether trades made up a large share of notional volume on several September days.
- Kalshi said its liquidity incentive program can explain repeated trade patterns across its markets.
- The company said it uses surveillance tools and a dedicated team to detect wash trading and self-trading.
Kalshi said the Commodity Futures Trading Commission has not contacted the company and that it does not believe any formal investigation has started. The statement followed reports questioning unusual trading patterns across its Bitcoin and Ether perpetual markets.
Kalshi Pushes Back on CFTC Scrutiny Reports
Spokesperson Elisabeth Diana said Kalshi sends trading data to the CFTC every day. She said routine reviews would not be unusual because the regulator already receives the platform’s market information.
Reports focused on repeated trade sizes across crypto contracts. CoinDesk found many Ether trades near $5,500 and Bitcoin trades near $2,500 or $5,000. Recent wash trading concerns had already drawn attention to the platform’s volume data.
Repeated Trade Sizes Draw Attention
The Wall Street Journal reported that the CFTC was reviewing activity before deciding whether to start an enforcement investigation. It cited nearly one million Ether trades that appeared in similar amounts.
Researcher Beni also questioned the activity after comparing about $539 million in daily Ether perpetual volume with $3.1 million in open interest. His figures came from Kalshi’s public API.
Kalshi Points to Liquidity Incentives
Diana said Kalshi’s liquidity incentive program can produce repeated trade sizes. Such programs reward participants who place orders and help other customers buy or sell contracts more easily. Broader interest in stock perpetual futures has also increased as exchanges seek regulatory approval for new products and compete for new users and trading activity.
Kalshi also said it uses surveillance tools and a dedicated team to detect self-trading and wash trading. Wash trading creates the appearance of activity without changing a trader’s real market exposure. The company said its controls monitor that behavior.
Regulatory Focus Follows Market Growth
Prediction markets have expanded quickly, bringing more attention to reported volume, market surveillance, and trading controls. The CFTC had not responded to the request for comment cited in Tuesday’s report.
Other firms are also seeking approval for new derivatives, including Coinbase’s U.S. perpetual futures filing. That activity shows how regulated crypto-linked products continue to broaden across American trading platforms.
Diana also rejected social media claims about Kalshi and said competitors had fueled some rumors. The company maintains that the trading patterns reflect its incentive structure rather than improper activity, while market participants continue debating the reported data across markets.
The post Is Kalshi Under CFTC Review? Company Responds appeared first on Blockonomi.
TLDR:
- Bitwise found none of 15 institutions cut crypto exposure during the market’s roughly 50% drawdown period.
- Several institutions increased crypto allocations, while most respondents kept exposure between 1% and 2%.
- Bitcoin was held by every surveyed crypto investor and was usually their largest and longest-held asset.
- Farside logged $691.7M of ETF outflows on June 25 and another $444.5M on June 26 during the sell-off.
Institutional crypto investors did not retreat during the market’s roughly 50% drawdown, according to Bitwise’s first Institutional Crypto Adoption Report. The firm interviewed 15 large allocators and found none reduced crypto exposure between October 2025 and April 2026.
Several instead increased allocations. That finding complicates the narrative around heavy Bitcoin ETF outflows. Public fund data showed substantial selling, yet longer-term institutional allocators largely stayed invested.
Bitcoin ETF Allocators Held Firm Through 50% Drawdown
The institutions included endowments, foundations, pension funds, sovereign wealth funds, multi-family offices and public companies. Their portfolios ranged from hundreds of millions to tens of billions.
Crypto allocations ranged from 0.5% to 13% of investable assets, although most respondents held between 1% and 2%. Exposure extended beyond ETF products. Institutions also used directly held crypto, venture investments and hedge funds, giving them several ways to maintain market exposure.
Bitcoin was the common holding across every institution already invested in crypto. It was usually their first, largest and longest-held digital asset. Some allocators paired Bitcoin with gold within broader store-of-value strategies. Ethereum and Solana, however, received less consistent support.
Those assets were generally treated as smaller, shorter-duration technology investments. Continued ownership depended on network adoption translating into token value. Importantly, falling prices alone were not cited as an exit trigger. Respondents instead pointed to thesis failure, regulatory reversals or an industry credibility crisis.
ETF Outflows Masked Longer-Term Institutional Crypto Holding
Market data still showed heavy ETF withdrawals during the downturn. Bitwise described the second quarter as the worst quarter for spot Bitcoin ETF outflows. Farside Investors recorded $691.7 million of withdrawals on June 25 and another $444.5 million on June 26.
Bloomberg ETF analyst James Seyffart said ETF flows and Form 13F filings broadly supported Bitwise’s findings. He said hedge funds and retail investors accounted for much of the selling, while longer-term allocators generally remained invested.
Still, Form 13F data offers only a partial view. Qualifying managers report covered securities quarterly, generally within 45 days. Those filings do not capture every investment vehicle or retail position. Bitwise also found some institutions intentionally used structures that avoided 13F visibility.
The firm therefore argued that reported institutional crypto ownership should be treated as a floor, not a complete measure. The sample was small and anonymized, covering only 15 institutions. Even so, the data draws a clear distinction between ETF outflows and institutional exits.
That distinction matters when interpreting headline fund flows. During the 50% drawdown, surveyed allocators largely held their positions, and some bought more rather than reducing exposure.
The post Bitcoin ETF Allocators Bought the Dip During 50% Drawdown, Bitwise Finds appeared first on Blockonomi.
TLDR
- Intel stock fell nearly 2.5% despite strong gains over the past year.
- IonQ tested a quantum error-correction decoder using a standard CPU.
- The test covered 408 logical qubits and more than 31.5 million operations.
- IonQ said the decoder added only 0.02% to execution time in simulated workloads.
- Intel will cut 52 jobs across four South Bay locations from September 30.
Intel (INTC) stock moved lower Wednesday as investors reviewed quantum research and another round of job cuts. Intel shares fell nearly 2.5% during afternoon trading, despite a 296.73% rise over the past year. The development links Intel’s processor strategy with IonQ’s work on quantum error correction.
Intel Corp., INTC
Intel Stock Faces Quantum Test
Intel CEO Lip-Bu Tan said CPUs, GPUs, and quantum processors could work together in future computing systems. He also identified error correction as one challenge that developers must solve before quantum machines can handle larger tasks reliably.
Recent trading followed Intel’s 12% chip rally earlier this week, when investors responded to stronger interest in server CPUs and other developments. The quantum update adds another area to watch as Intel builds technology across traditional and emerging computing markets.
IonQ Tests Error Correction on CPU
IonQ said it tested a real-time quantum error-correction decoder using one standard CPU. The company used simulated workloads covering 408 logical qubits and more than 31.5 million quantum operations. IonQ reported that the decoder added only 0.02% to execution time under standard noise conditions.
The results came from simulations rather than a live fault-tolerant quantum computer. That distinction matters because simulated performance does not confirm commercial readiness. Intel continues to study quantum processing alongside its established CPU and GPU businesses.
Intel Reduces South Bay Workforce
Intel will cut 52 jobs across four South Bay locations, according to a report. The workforce move follows a Barclays upgrade to Overweight during a busy week for Intel. The company will remove 22 positions from its Mission College Boulevard site and one from its Laurelwood Road office.
The report did not identify the other locations. The cuts will take effect on September 30, and Intel described them as permanent. Intel has completed several workforce reductions as it restructures operations and controls costs.
Quantum Work Joins Wider Intel Strategy
Intel has also attracted attention through SK Hynix partnership talks involving its Ohio manufacturing operations. Reports said the discussions could include leasing space or creating a broader arrangement around the facility as Intel reviews ways to use manufacturing capacity.
For Intel stock, the latest news places quantum research, manufacturing plans, and workforce changes in focus at the same time. IonQ’s CPU decoder test offers a new data point for hybrid computing, while Intel continues adjusting operations across its chip business and future product planning.
The post Intel Stock Falls Despite Fresh Quantum Computing Breakthrough appeared first on Blockonomi.
TLDR
- GOOG stock reversed toward $340 after failing to hold above $360.
- Gemini now serves more than 1 billion monthly active users.
- Google Cloud revenue reached $24.8 billion in Q2 2026.
- Alphabet expects $175 billion to $185 billion in 2026 capital spending.
- The $350 level remains important after the latest share-price reversal.
Alphabet shares reversed from above $360 toward $340 on Tuesday, weakening the recovery. GOOG stock now faces attention as investors balance Gemini expansion with rising infrastructure costs, competition, and regulatory pressure. The move follows a rebound from below $330 that failed to hold near resistance.
Alphabet Inc., GOOG
GOOG Stock Faces Fresh Technical Pressure
Alphabet previously climbed toward $384 after strong earnings and Search and Cloud performance. Shares later fell below $330 before recovering toward $364. The latest rejection above $360 shows buyers have struggled to maintain momentum.
The chart also shows pressure around moving averages. Alphabet slipped below its 50-day and 100-day averages earlier this year before finding support near the 200-day average around $270. Shares later rebounded, but resistance has slowed the recovery.
Gemini Growth Raises Spending Demands
Alphabet continues expanding Gemini across its products, including a desktop version that gives users access without opening a browser. Gemini can answer questions, check information, draft content, and create images or videos. Alphabet says the assistant now serves more than 1 billion monthly users.
A Googlebook launch centered on Gemini AI added a consumer channel for the assistant. Wider adoption supports usage growth, but it also raises demand for chips, networking equipment, and data-center capacity.
Cloud Expansion Keeps Capital Costs Elevated
Google Cloud remains a major growth area after second-quarter revenue reached $24.8 billion, up 82% from a year earlier. Alphabet reported quarterly revenue of $119.8 billion and earnings per share of $9.11.
Infrastructure spending remains central to that strategy. A $22 billion financing deal tied to Google TPUs showed the scale of investment surrounding AI computing. Alphabet expects 2026 capital spending of about $175 billion to $185 billion.
Search and Regulation Remain in Focus
Google Search still generates a share of Alphabet’s advertising revenue. The company must add AI features while protecting its core search business. Growing use of conversational tools adds another competitive factor as users change how they find information.
Regulation remains another issue for GOOG stock. A recent federal court decision required ad-tech reforms but stopped short of ordering a breakup. Alphabet continues facing scrutiny across Search, advertising, and its digital operations.
Traders are watching the $350 area. A sustained move above $360 would strengthen the technical picture, while a break below $350 would leave the rebound more exposed as markets assess spending, competition, regulation, and Gemini’s expanding role.
The post GOOG Stock Recovery Stalls Near Key Resistance appeared first on Blockonomi.
CryptoPotato
The Commodity Futures Trading Commission (CFTC) is reportedly reviewing unusual trading on Kalshi’s Ethereum perpetual futures market. This is according to The Wall Street Journal (WSJ), which found close to one million trades clustered around the same $5,500 order size since August.
The pattern, which the WSJ said accounted for more than $5 billion in volume, has drawn allegations of wash trading that Kalshi flatly denies, arguing the repeated sizes stem from ordinary market-making activity.
What the Trading Data Shows
In a September 22 report, the WSJ said it had found that more than a third of trades in the market over recent weeks clustered around that same $5,500 figure, although Kalshi’s public data does not disclose who is behind individual trades. According to them, the CFTC is reviewing the activity before deciding whether to open a formal enforcement investigation.
Wash trading, which is the practice of making trades with no real economic purpose in order to create a misleading activity, is the specific concern the clustering pattern has raised. However, per the report, Kalshi did respond, saying hundreds of distinct traders took part and that the repeated order sizes reflect market makers keeping fixed resting orders that faster traders keep hitting.
Additionally, the company said self-trading is mechanically blocked and coordinated, while wash trading is barred and monitored. Also, its liquidity programs pay market makers for holding orders at set sizes and spreads rather than for raw volume.
Meanwhile, a separate, temporary program refunds trading fees to qualifying self-clearing members, though never more than what they paid in.
The report identified Jump Trading and Wintermute as among the firms involved in the rapid trades, although Jump said it trades its own profit and uses self-match prevention tools. Furthermore, the firm insisted that it does not coordinate activity with other traders.
A Pattern of Regulatory Friction
The scrutiny has come at a time when Kalshi is pushing further into perpetual futures, a business it opened to crypto in May and is now trying to extend to contracts tied to individual US stocks.
As CryptoPotato has reported numerous times, the company is already fighting legal battles on several fronts. For one, Baltimore sued Kalshi and Polymarket in August over allegedly offering unlicensed sports betting dressed up as event contracts.
New York Attorney General Letitia James also sought to shut down the firm’s operations in the state before the CFTC used emergency powers to keep the platform running there.
Kalshi has also shown it will police its own users when it catches them gaming contracts tied to themselves. It handed former Congressman George Santos a lifetime ban and a $71,356 penalty in late August after finding he traded on whether he would attend the State of the Union, and it separately banned three political candidates for five years each earlier this year after they bet on their own races.
The post Report: CFTC Eyes Unusual $5B Trading Pattern on Kalshi ETH Perpetuals appeared first on CryptoPotato.
Ethereum co-founder Vitalik Buterin has welcomed Trueo’s planned migration from Base to Ethereum mainnet, describing it as a new prediction-market contender focused on decentralization and ethical design.
The move puts Trueo’s dispute-resolution system and plans for wider DeFi integration at the center of its pitch as prediction markets face legal scrutiny and competition.
Trueo Says Ethereum Fits Its Long-Term Plans
In a post on X, Buterin praised the project for being “dedicated to decentralization, and being ethical and not corposlop,” adding that he was glad to see a team trying to do “interesting and meaningful things” with prediction markets.
Trueo announced the move on September 21, explaining that it first launched on Base in March 2025. The team described the Layer 2 network as a useful environment for early experimentation, when the Ethereum mainnet gas costs were higher and parts of the application were still experimental.
But Trueo now wants to build a platform that is “widely adopted, broadly integrated, fully permissionless, mostly immutable, and highly credible.” It believes Ethereum is a better fit for that goal because of its network effects and global integrations, as well as alignment with the project’s philosophy.
The team’s immediate priorities after migration are to attract liquidity in major market categories and release the next generation of its oracle. Trueo argues that prediction markets depend heavily on how outcomes are resolved, and that existing systems lack adequate due process when disputes arise.
Its oracle is designed to process evidence from a broad range of legitimate data sources to reach outcomes. Trueo says user feedback has reinforced its view that this system is one of the application’s main attractions for traders.
The project also sees Ethereum as a route to integrations involving oracle services and yield opportunities for its TYD asset. According to Trueo, the migration will not interrupt trading on Base, and TYD will continue accruing yield.
Existing Base markets that expire after migration will still be accessible through the official app and will use the current resolution system. However, the team advised Base users not to create additional markets expiring after January 31, 2027, and instead to create them on Ethereum once its mainnet instance goes live.
TRUE Skyrockets Following Buterin’s Endorsement
TRUE, which will remain the protocol’s native token, saw its market cap jump from around $1.7 million to more than $12 million in the hours after Buterin’s post.
At the time of writing, CoinGecko data put it around $0.15, up 699% over the past day and nearly 750% across one week, although it is still nearly 50% below the $0.26 all-time high it hit in August 2025.
The announcement has come at a time when rival prediction market operators are facing legal disputes and uneven trading activity, with well-known trader Machi Big Brother declaring “Kalshi dead. Long live $TRUE.”
As CryptoPotato reported in August, Baltimore officials sued Kalshi and Polymarket over alleged unlicensed sports betting. Meanwhile, the former is also facing a separate lawsuit by the New York attorney general, who argued its event contracts violated state gambling laws.
The post Vitalik Buterin Endorses Trueo as Prediction Market Moves to Ethereum appeared first on CryptoPotato.
Cardano’s native token has been thriving amid the latest green environment, with its valuation climbing to a peak not seen since May.
Naturally, the major ascent has drawn multiple bullish predictions from analysts, but certain elements suggest a correction could also be in the cards.
The Next Upward Move?
As of press time, ADA is worth around $0.25, up about 30% in a week. X user CW claimed that the asset is showing an accumulation signal while gradually rising.
“Accumulation is taking place at the current level. It is gathering energy for its next upward move. MACD and EMA trends are forming a bullish momentum,” they added.
For his part, Jesse Olson argued that Cardano’s cryptocurrency has flipped “ultra bullish” on the daily chart, with the price breaking above a vital zone and continuing to make higher highs and higher lows. Shortly after, the analyst estimated that ADA has a pending buy signal on the weekly chart, noting that it hasn’t been bullish on the seven-day timeframe in 14 months.
More Crypto Online also weighed in, saying the token continues to follow a specific bullish price channel and setting $0.315 as the next target to watch.
Somewhat expected, X user Sssebi, who has issued optimistic price predictions even when ADA traded at much lower levels over the past several months, couldn’t stay silent amid the rally. They simply claimed the token could do “something really crazy” without providing a specific target.
Those who want to explore additional forecasts can read our detailed article here.
Short Setup?
X user Mork differentiated themselves from the overall bullish sentiment, describing ADA as one of their favorite short setups right now. The market observer noted the asset’s strong recent performance but said they won’t rush to chase the first move away from resistance.
“I’m waiting for another move into the level. If buyers don’t step in there, I’ll take a closer look at the short,” they said.
Meanwhile, ADA’s Relative Strength Index (RSI) suggests that the asset may indeed experience a short-term correction. The ratio has risen into overbought territory above 70, meaning the price has soared too much in a short period, and it might be time to cool off. Conversely, readings below 30 are usually interpreted as buying opportunities.

The post Top Cardano Price Predictions as ADA Explodes 30% in a Week appeared first on CryptoPotato.
Bitcoin has moved above a key long-term technical level that CryptoQuant says has historically marked major shifts in the cryptocurrency’s market cycle. BTC closed above its 365-day moving average, which stood near $80,500, for the first time since March 2023.
At the time, the asset was trading around $86,000 when it closed above the average. The analytics firm said the move confirms the start of a new bull market. The firm cited similar breaks above the average that preceded major advances in 2019 and 2023.
Bitcoin’s Market Signals Turn Positive
CryptoQuant also pointed to earlier periods when Bitcoin fell below the same average, including the end of the 2021 market peak and the downturn in November 2025. Rather than treating the indicator as a short-term trading tool, analysts described the 365-day average as a marker of broader market cycles.
Bitcoin had remained below the level for an extended period before the latest move, making the reclaim a notable change in its longer-term structure. The move also follows signals from CryptoQuant’s internal market indicators, which had already turned more positive several weeks earlier.
Those indicators, including the firm’s Bull Score Index and Bull-Bear Market Cycle Indicator, both moved toward an early bull-market phase by mid-August. The latest price action has now aligned with those earlier on-chain signals.
BTC Clears Key Supply Zone
Bitcoin has also cleared a major supply barrier between $76,000 and $81,000, held by long-term investors and wallets inactive for over seven years. According to the analytics firm, many of those coins were sold earlier this year, creating significant overhead supply that BTC has now cleared.
The next major supply area sits between $88,000 and $90,000, where another large group of coins is concentrated. That range also lines up with the upper end of traders’ realized price, making it an important level to monitor as BTC moves higher.
Below the current price, support remains around the 200-day moving average near $70,600 and the recently reclaimed 365-day average. CryptoQuant warned that pullbacks can still occur even after a broader market-cycle signal turns positive.
Against this backdrop, the latest move follows months of consolidation after Bitcoin’s decline last year. Market participants will watch whether BTC holds above the 365-day average and approaches the $88,000 to $90,000 supply zone.
The post Bitcoin Just Cleared a Crucial Level – Has the New Bull Market Begun? appeared first on CryptoPotato.
The primary cryptocurrency has climbed roughly 15% over the past week and briefly reached an eight-month high above $87,000. As of this writing, it trades just below $86,000, but overall bullish sentiment remains.
Popular analyst Ali Martinez set $100,000 as the next target, and here’s why it might come sooner than you think.
The Positive Factors
The renowned X user started his bullish observation by noting that BTC has risen more than 50% since bottoming below $58,000 in July. He claimed that even after this evident resurgence, large investors seem reluctant to take profits.
“Yesterday alone, the BTC network recorded more than 2,722 transactions, each worth over $1 million, showing that large entities remain active during the rally,” he said.
Martinez then turned to the ETF front, highlighting that spot Bitcoin exchange-traded funds have accumulated more than $1.6 billion worth of the cryptocurrency over the past 72 hours, adding significant buying pressure.
The analyst claimed that BTC continues trading above strong support at $84,569, where nearly 600,000 coins previously changed hands. The second major demand zone sits near $77,000, he added.
“With strong support below, overhead resistance is thinning out. The next major URPD resistance sits near $104,765, where roughly 283,000 BTC were traded,” Martinez revealed.
Last but not least, he paid attention to the MVRV Pricing Bands, which tell a similar story. Martinez said the mean band near $100,670 is the next key resistance for BTC, while the -0.5 band around $74,361 acts as a major support.
“As long as demand remains strong, $100,000 is in focus,” he concluded.
Don’t FOMO Here?
Bitcoin’s $10,000 price increase in less than a week has undoubtedly sparked huge enthusiasm across the crypto world and has led to the highest FOMO (Fear of Missing Out) since 2024.
This phenomenon happens when traders rush to buy the asset after a strong rally, fearing they will miss the chance to make substantial profits. It is worth noting that such crowded positioning often leaves the market vulnerable, and even a small wave of profit-taking can trigger a pullback, sending prices significantly lower.
X user Gerla recently advised traders and investors not to FOMO at current levels, expecting BTC to potentially correct to roughly $80,000 or higher, which could offer another buying opportunity.
“If we get that chance, I’d rather DCA there than chase $95K-$100K,” he concluded.
The post Bitcoin (BTC) Eyes $100K as Key Bullish Signals Emerge appeared first on CryptoPotato.