Cryptocurrency Posts
Crypto Briefing
Perplexity.AI's improved tool-call efficiency enhances AI reliability, crucial for maintaining competitiveness in the evolving AI search market.
The post Perplexity.AI reduces tool-call failures by 21% with new model training approach appeared first on Crypto Briefing.
Raphinha's contract renewal solidifies Barcelona's long-term strategy, ensuring stability and leadership continuity amid external offers.
The post Raphinha appoints Ali Barat to finalize Barcelona contract renewal until 2030 appeared first on Crypto Briefing.
The proposed exemption could foster innovation in DeFi by reducing regulatory burdens, but may also heighten scrutiny on less decentralized platforms.
The post Andreessen Horowitz, DeFi Education Fund ask SEC to exempt DEXs from registration appeared first on Crypto Briefing.
The rapid growth of Arc and HyperEVM highlights a shifting stablecoin landscape, emphasizing the potential for new platforms to disrupt established players.
The post Arc and HyperEVM lead stablecoin market cap growth by $1.2B in a single week appeared first on Crypto Briefing.
OpenAI's enhanced caching in GPT-6 Sol and Luna significantly lowers operational costs and boosts efficiency, impacting AI deployment strategies.
The post OpenAI improves prompt caching in GPT-6 Sol and Luna for better efficiency appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Bitcoin Investors Buy Nearly $1B in BTC ETFs as Bull Market Returns
The Bitcoin bulls are back — if ETF flows are to be believed.
U.S. bitcoin exchange-traded funds received $999 million in new investment on Monday, according to Farside Investors data.
That’s the most in one day since October 6, when the funds received over $1.2 billion and the price of the leading cryptocurrency hit a new all-time high of $126,080.
Bitcoin’s price recently stood at $86,552 after scraping $87,330 on Monday. Over the past seven days, the coin’s price has surged by nearly 13%.
Bitcoin ETFs in the U.S. — approved by the SEC in 2024 — have helped investors get exposure when they couldn’t before. Now, Wall Street firms can quickly buy shares of funds managed by the likes of BlackRock, Fidelity, Morgan Stanley, and others.
When big investment hits the funds, the price often moves significantly — as what happened on Monday.
Bloomberg ETF analyst James Seyffart on Monday said that the average ETF buyer is now in profit after the estimated ETF cost basis surged above $81,72 for the first time since January.
The ETF to receive the most of Monday’s investment — $381.4 million — was BlackRock’s iShares Bitcoin trust. The ARK 21Shares Bitcoin ETF received $289.1 million; Fidelity’s Wise Origin Bitcoin Fund took in $238.8 million.
Investors have a renewed interest in Bitcoin after the artificial intelligence stock rally cooled and the U.S. Department of the Treasury in August said it would at least double the size of its liquidity-support buyback operations.
Analysts said the move pushed 30-year Treasury yields down, weakened the dollar, and made assets like bitcoin more attractive. Following the announcement, the bitcoin price had its best run in years.
A Tuesday report from crypto market data firm CryptoQuant said that the leading cryptocurrency crossed above its 365-day moving average, a signal that the asset has finished being in a bear market.
This post Bitcoin Investors Buy Nearly $1B in BTC ETFs as Bull Market Returns first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Bitcoin’s Bull Run Is Back — and the Data Agrees
Bitcoin’s run this weekend would have observers believing that the bull market is back. But the data also backs it up.
A new report from data firm CryptoQuant shows that the leading cryptocurrency crossed above its 365-day moving average — a signal that the asset has finished being in a bear market.
Bitcoin’s price surged in August and had its best run in years, spurred by an announcement from the U.S. Treasury saying it would at least double the size of its liquidity-support buyback operations. Its run cooled but then last week shot up again and was recently trading for $86,598 after trading as high as nearly $87,330 on Monday.
JUST IN: $87,000 Bitcoin
— Bitcoin Magazine (@BitcoinMagazine) September 21, 2026pic.twitter.com/Vgl0wCA7uY
“This crossover is the definitive technical signal that has marked the start of Bitcoin’s bull markets in past cycles, and it is the first time price has reclaimed the 365-day moving average since March 2023,” the report read.
It added that the moving average is a “cycle-defining” line and confirmed the start of bull runs in previous years.
“Its track record across cycles is why this reclaim carries real weight rather than being a routine bounce,” the report added.
The report continued that long-term holders appear to have finished selling, making the way for new investors to enter the market.
Bitcoin notched a record of $126,080 in October of last year but then began to sink later that month after the biggest liquidation event in crypto history saw over $19 billion in bets closed.
In the first half of this year it continued its plunge after the Federal Reserve made it clear it was in no hurry to lower interest rates and investors increasingly threw money at artificial intelligence-related stocks to get returns.
But the so-called debasement trade — where investors throw money at an asset to hedge against a currency losing its value — is hot again. Bitcoin and precious metals like gold have done well when the dollar has weakened.
And the Federal Reserve last week raised interest rates to get sky-high inflation in the U.S. under control. Investors shrugged the central bank’s move off and bought up the asset.
Now, people seem more interested in buying an asset that can protect them from government debt and deficit. In August, total U.S. debt topped $40 trillion for the first time.
This post Bitcoin’s Bull Run Is Back — and the Data Agrees first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
White Hats Move Over $4.5 in Bitcoins From Coldcard to Recovery Trust
White hats have moved bitcoin from the hacked Coldcard signing devices to a trust for would-be victims to reclaim, Galaxy Digital’s Alex Thorn has said.
Writing on X on Monday, Thorn said that the funds were taken by white hats to protect potential victims. They are now apparently sitting in an address controlled by Crypto Recovery Trust, a Wyoming Trust created to help white hats return funds to victims.
A total of 52.37 of the bitcoins — worth over $4.5 million at today’s prices — were moved. Thorn added that the funds represented 2.8% of the coldcard exploit.
Criminals started taking bitcoin stored using Coinkite’s popular Coldcard hardware wallet on July 31.
Canadian company Coinkite said that a firmware bug in Coldcard devices caused seed generation to fall back to a weak software Pseudorandom Number Generator instead of the hardware true random number generator, allowing hackers to essentially guess investor seedphrases.
Galaxy Digital tracked the movement of funds and said 1,789.28 bitcoins were lost in the attacks. That’s $154.1 million in bitcoin at today’s prices.
Earlier this month, Nick Bax of universal market protocol Ump Labs said that he was involved in helping recover the funds.
“Finally able to say that at the end of July, I was involved in the rescue of ~50 BTC which were “imminently going to be stolen due to the COLDCARD entropy flaw,” Bax wrote on X.
He added: “The funds are currently held by a Wyoming trust, which will ensure that funds are returned to their rightful owners.”
Since the attack, cautious investors have been moving their coins to other storage solutions — including exchanges.
Coinkite said in a statement that the bug in its software “silently went unnoticed” and “its potential impact grew with every release” of its products.
Days after the first hack, the company urged investors to update their software or move their funds off the popular hardware wallet.
This post White Hats Move Over $4.5 in Bitcoins From Coldcard to Recovery Trust first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Feds Probing Binance Over Iran’s Bitcoin Use: Report
Federal prosecutors — including the U.S. Department of Justice — are investigating whether Binance has allowed Iran to dodge sanctions by using its platform, according to a report from Bloomberg.
The outlet, citing people familiar with the matter, reported Tuesday that feds were investigating whether Binance Holdings Ltd., which operates the world’s biggest crypto exchange, knowingly allowed Iran-linked entities to trade.
It comes after the U.S. Department of Justice last week said it is seizing and seeking to forfeit $61 million in cryptocurrency that it alleges came from black-market sales of sanctioned Iranian oil. The funds, according to the DOJ, were laundered through Binance by Chinese entities.
Iran has been using bitcoin — and other cryptocurrencies — to skirt around U.S. sanctions. The U.S. in April started targeting crypto wallets linked to the Iranian regime, Treasury Secretary Scott Bessent said in a statement.
Bessent went on to say that the Iranian regime’s crypto had been frozen — mostly in the form of Tether’s USDT stablecoin.
And last week, the Treasury designated BitBank, an Iranian crypto exchange, as part of Operation Economic Outcast — the Trump Administration’s whole-of-government economic campaign against the Islamic Republic of Iran and its enablers.
Iran started a bitcoin-backed insurance service for its counties shipping companies earlier this year. Bitcoin cannot be frozen, unlike many other cryptocurrencies.
The Financial Times this month reported that the Middle Eastern country was using bitcoin to settle cross-border transactions through Iranian crypto exchanges after the central bank advised its countrymen to do anything necessary to help the economy.
Binance, which has no headquarters but is incorporated in the Cayman Islands, ran into trouble with U.S. authorities after it allegedly allowed funds linked to virtual theft and terrorism to flow through its exchange undetected.
It exited the U.S. market and agreed to pay $4.3 billion. Its CEO and founder Changpeng Zhao stepped down after pleading guilty to anti-money laundering violations but was later pardoned by President Trump.
This post Feds Probing Binance Over Iran’s Bitcoin Use: Report first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
No Bitcoin Payments in Russia — But the Digital Ruble Is Open for Business
While bitcoin is banned for making payments in Russia, the government is keen on one type of digital money: its own central bank digital currency.
The digital ruble has been available for transactions in the country since September 1, according to a Tuesday report from Tass.
Citing a talk given by Prime Minister Mikhail Mishustin, the news agency said that it was all part of “developing a convenient, fast, and independent payment infrastructure” in Russia.
JUST IN:
— Bitcoin Magazine (@BitcoinMagazine) September 22, 2026Russian Prime Minister Mikhail Mishustin says:
"The circulation of cryptocurrencies has also become legal in the country starting from September 1. The relevant law was signed by the president."

Russia has been fast regulating digital assets this year. President Vladimir Putin in August signed a law regulating the circulation of digital currencies and digital rights in the country.
The law states that only registered entities can operate as exchanges, and puts limits on the amount of crypto retail investors can use.
But what about Bitcoin?
President Putin in 2024 seemed to praise the OG cryptocurrency. “For example, Bitcoin, who can ban it? Nobody,” he said at a forum at the time.
“And who can prohibit the use of other electronic payment instruments? Nobody, because these are new technologies.”
The president has also spoken about how the country has “competitive advantages” when it comes to Bitcoin mining due to the abundance of cheap energy in Russia.
Though the Kremlin still has a tight grip on what its citizens can do with it: Retail investors are limited to trading bitcoin and other liquid cryptocurrencies, capped at 300,000 rubles ($3,556) per year, according to the August law. Qualified investors have no restrictions.
And using crypto as a form of payment has been illegal in Russia since 2022.
Central bank digital currencies — or CBDCs — are a centralized form of digital money, issued by a central bank. Bitcoiners have long criticized the idea of such a product because it can be used by governments to surveil its citizens and ultimately even control their spending.
U.S. President Donald Trump even signed an executive order in 2025 prohibiting federal agencies from establishing, issuing, or promoting a CBDC.
But in Russia, a digital ruble is the best way for keeping citizens in check. The Bank of Russia settled early on an architecture that mixes a centralized ledger it controls with distributed-ledger components. The 2021 concept described the preferred model as hybrid — distributed ledgers combined with centralized components — and the full technical details have never been published.
Bitcoin payments, on the other hand, are being used by companies in international payments to counter Western sanctions, Finance Minister Anton Siluanov admitted in 2024.
This post No Bitcoin Payments in Russia — But the Digital Ruble Is Open for Business first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
CryptoSlate
Even if Bitcoin eventually adopts post-quantum protections for on-chain outputs, five parts of the Lightning Network’s off-chain payment system would still need separate upgrades, according to a Sept. 12 research preprint.
The paper proposes PQLN, a hybrid post-quantum extension implemented as a rust-lightning research prototype. It targets gossip, which distributes node and channel information; encrypted peer connections; signed invoices and reusable payment offers; and onion packets that conceal payment-routing details.
Lightning currently uses secp256k1-based ECDSA, Schnorr signatures or ECDH across those functions. PQLN keeps the classical mechanisms while adding ML-DSA signatures to gossip, invoices and offers. It adds hybrid ML-KEM key exchange to transport, payment onions and BOLT 12 privacy paths.
The authors built a feature-gated rust-lightning fork and a modified ldk-sample node. Their 12-scenario matrix found that post-quantum and vanilla binaries built from the same rust-lightning base could coexist. Depending on the route and settings, mixed setups used classical protection or failed closed.
That compatibility does not establish network-wide readiness. The repositories describe the software as a research artifact, and the study deferred tests against other Lightning implementations.
Communication, rather than raw cryptographic computation, dominated the authors’ results. During static synchronization of a full network graph, the default ML-DSA-44 and ML-KEM-768 design increased gossip downloads 10.2 times and stored graph data 8.8 times compared with vanilla Lightning.
A smaller Falcon-derived FN-DSA configuration reduced the download multiple to 4.2 times, but NIST still lists that scheme as under development rather than a final standard.
Private payment routing carried another bandwidth penalty. A fixed 21.8-kilobyte post-quantum ciphertext list added 19 to 53 milliseconds per hop on an emulated 10 Mbit/s link and 160 to 187 milliseconds per hop at 1 Mbit/s.
By contrast, ML-DSA-44 signing averaged 327 microseconds on the authors’ 16-core AMD Ryzen Threadripper PRO 3955WX workstation with 64 GB of RAM. That author-run, hardware-specific primitive measurement should not be read as end-to-end payment latency.
PQLN also leaves Bitcoin-rooted risks untouched. It does not secure the on-chain keys protecting funding, commitment and HTLC outputs or penalty transactions, so safeguarding channel funds still requires Bitcoin-layer post-quantum changes.
The preprint assumes a future cryptographically relevant quantum adversary; it does not report a present-day quantum compromise of Bitcoin or Lightning. Its prototype suggests Lightning’s off-chain defenses can be tested independently of a Bitcoin upgrade, but not that the network is ready to migrate. In these experiments, the hard operational question was how much extra gossip, storage and payment traffic node operators could absorb.
The post Bitcoin may go quantum-safe while Lightning privacy stays exposed appeared first on CryptoSlate.
Animoca Brands, a digital asset venture, has suspended merger talks with Nasdaq-listed Currenc Group after the companies failed to reach definitive terms on schedule.
On Sept. 22, the companies said they mutually agreed to pause discussions after reviewing projected closing timelines and changing market conditions, concluding that the additional time needed to complete the transaction no longer aligned with their short- and medium-term priorities.
Currenc said in a regulatory filing that its exclusivity period with Animoca had expired without a definitive agreement. Suspending negotiations gives the company greater flexibility to seek financing for growth and operations while preserving the option to restart talks later.
The proposed reverse merger, first outlined in a non-binding term sheet on Nov. 2, 2025, would have provided Animoca with a route back to public markets. Animoca shareholders were expected to own about 95% of the combined company, leaving existing Currenc investors with roughly 5%.
The transaction remained subject to due diligence, definitive documentation and a series of corporate, regulatory and court approvals. The preliminary ownership split could also have changed before closing.
Expired timetable frees Currenc to pursue financing
Animoca co-founder and Executive Chairman Yat Siu said the company was prioritizing flexibility as it works toward a public listing.
“While we hold our proposed merger with Currenc Group in high regard, our corporate agility must take precedence,” Siu said, adding that Animoca was advancing audit work and other compliance requirements needed for a major public exchange.
The companies were still pursuing the transaction in May, when they extended exclusivity through June 30 and maintained a target of closing in the third quarter. The additional time was meant to allow for due diligence and definitive documentation, but the parties never reached a binding merger agreement.
By September, the exclusivity period had expired, and key transaction terms remained unresolved. Animoca cited projected closing timelines and evolving market conditions, while Currenc said suspending discussions would give it greater flexibility to seek financing for growth and operations.
That leaves Currenc free to raise capital without waiting for the merger process to advance, while preserving the option to return to negotiations later.
Animoca is continuing separately with its broader plan to return to public markets. The company said it remains committed to relisting on a major exchange and is preparing its FY2024 audited financial statements as part of a wider compliance push.
The Currenc transaction had offered Animoca a direct route into a Nasdaq-listed company, but no replacement deal, exchange or timetable has been disclosed since talks were suspended.
Both sides have left open the possibility of restarting negotiations if conditions improve. Currenc cautioned, however, that there is no assurance talks will resume or ultimately produce a transaction.
The post Animoca Brands suspends Currenc deal that would have taken it public appeared first on CryptoSlate.
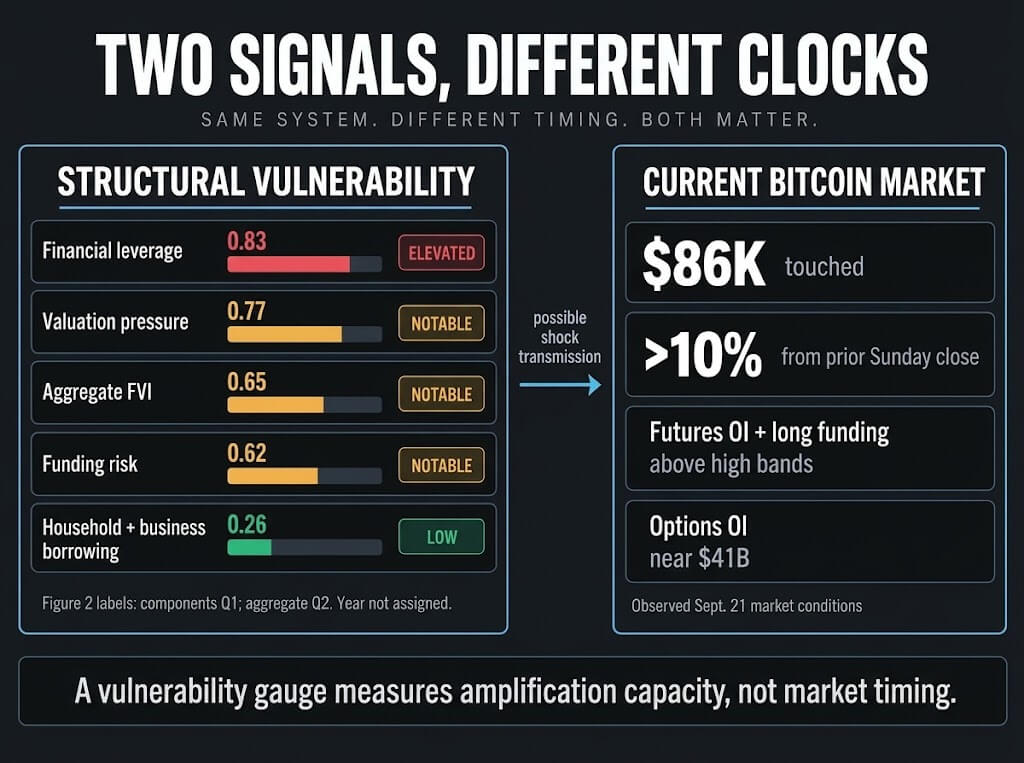
Bitcoin’s rally and the Federal Reserve’s new financial-risk gauge describe two different time horizons. BTC reflects demand and positioning in today’s market. The Fed’s measure tracks structural weaknesses that could magnify the next shock.
The Financial Vulnerability Index is built to capture slow-moving vulnerability rather than coincident market stress. In Figure 2, the final financial-leverage annotation is 0.83, inside the “elevated” band of its historical distribution. The aggregate index is labeled 0.65, valuation pressure 0.77 and funding risk 0.62, all “notable.” Household and business borrowing is lower at 0.26.
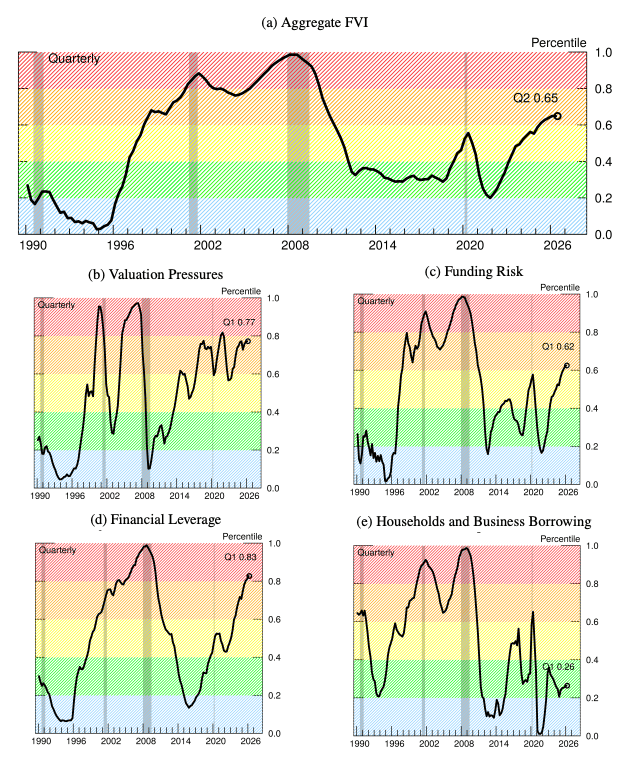
The chart labels the four components Q1 and the aggregate index Q2, with 2026 as the last axis mark. The working paper separately says its dataset and several estimation samples end in 2025:Q4, without explaining whether the endpoints are later-vintage observations, nowcasts or a labeling issue. That limits the safe description to Figure 2’s quarter labels and values, without assigning them a verified 2026 observation date.
The distinction between vulnerability and current conditions explains the apparent split. Conventional financial-conditions indexes rise as credit tightens and visible stress emerges. The FVI can build through calmer periods as leverage and risk-taking accumulate.
Bitcoin’s current move has its own drivers. On Sept. 21 BTC touched $86,000, more than 10% above the prior Sunday close, as spot taker flow turned positive and volume rose. Short liquidations helped Monday’s leg higher. Futures open interest and funding paid by longs were above Glassnode’s high bands, options open interest was near $41 billion, and options were pricing less movement than the market delivered.
How funding stress could reach Bitcoin
A June analysis, “Decomposing Hedge Funds’ U.S. Treasury Exposures,” estimated that large hedge funds had $4 trillion of gross Treasury exposure and $3 trillion of repo borrowing as of September 2025. Its proxy estimates included about $830 billion in cash-futures basis trades and $305 billion in swap-spread trades.
The Fed’s separate review of government bond-backed repo markets found that short-term funding, dealer intermediation, collateral reuse and low haircuts can carry stress across funding, cash and derivatives markets. Higher margin calls or tighter dealer capacity could force liquid-asset sales, weaken crypto spot demand and liquidate leveraged BTC positions. That cross-market sequence remains a scenario; the cited evidence has not observed the full chain.
The working paper’s historical model shows why the vulnerability reading matters. In high-FVI periods, the same modeled business-cycle shock produced deeper declines in consumption and long-term investment than in low-FVI periods. The index is therefore best read as an amplifier gauge: it describes the system’s capacity to turn a shock into wider damage, while Bitcoin’s immediate path remains tied to flows, liquidity and positioning.
The working paper reflects its authors’ analysis and does not indicate concurrence by the Federal Reserve Board.
The post Why Bitcoin’s rally is dangerous according to new Fed data appeared first on CryptoSlate.
Aave governance has advanced a proposal that would give Bitcoin-backed borrowers materially more leverage while leaving less room before liquidation.
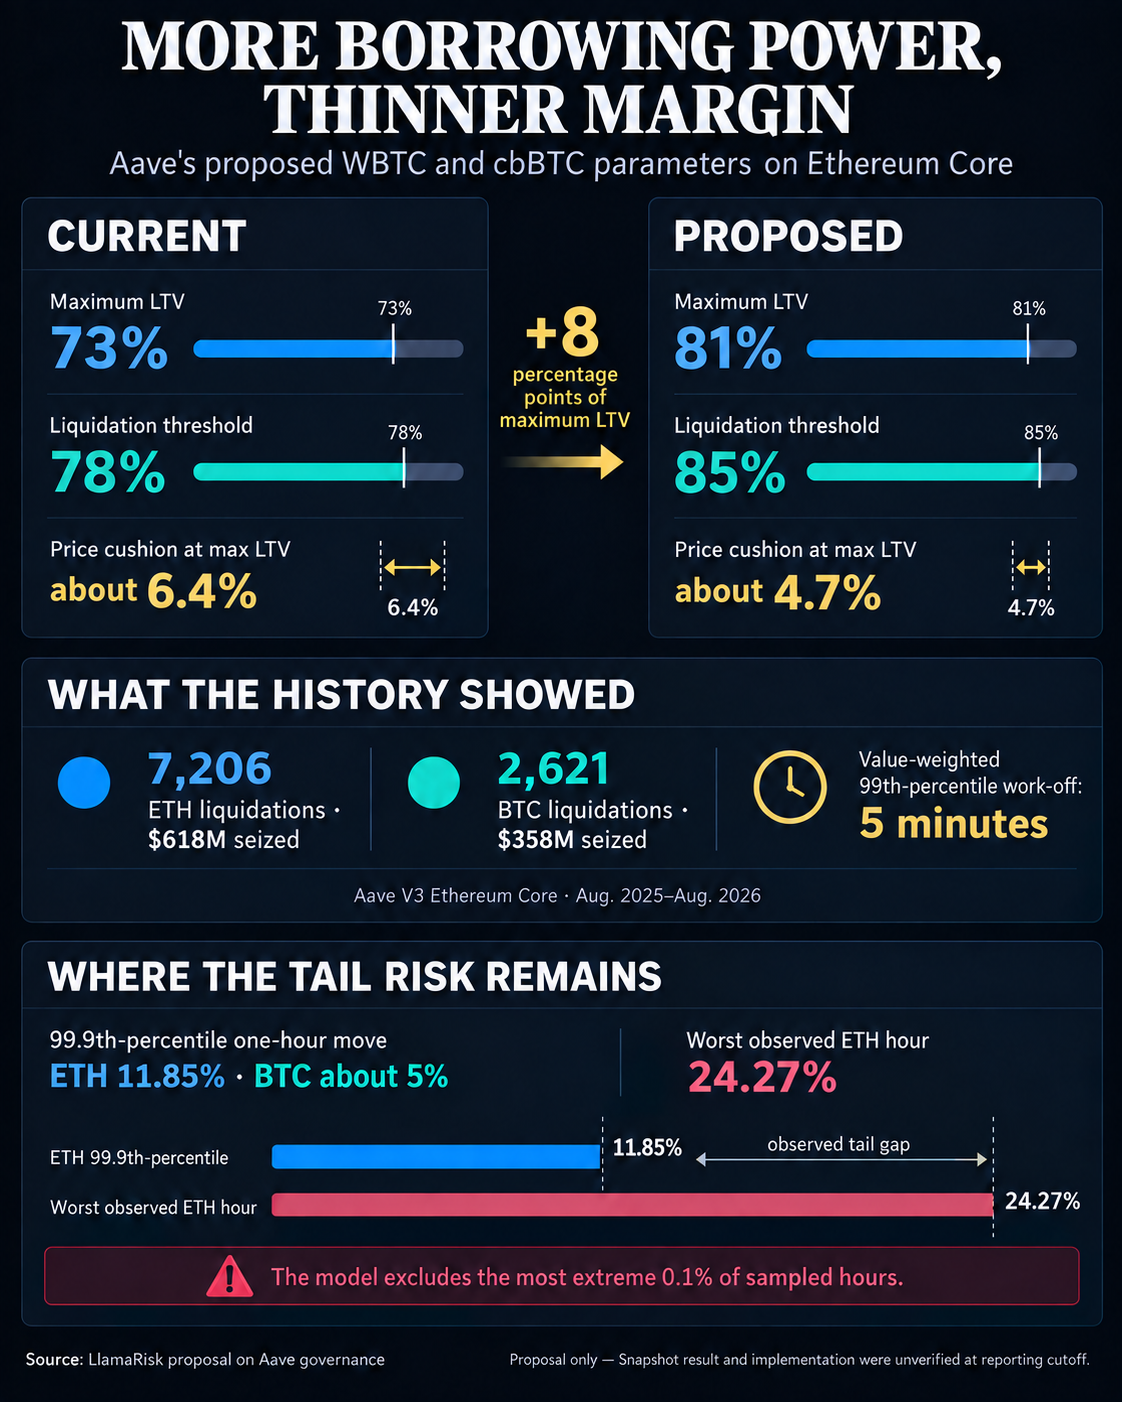
The proposal from risk service provider LlamaRisk would let users on Aave V3 Ethereum Core borrow as much as $0.81 against each $1 of WBTC or cbBTC collateral, up from $0.73. The liquidation threshold would rise from 78% to 85%.
LlamaRisk said on Sept. 21 that the proposal had advanced to Snapshot and voting would begin in less than 24 hours. The vote result and any implementation remained unverified at the reporting cutoff, so the higher limits are proposed parameters rather than live settings.
The case rests on one year of liquidation data showing that economically meaningful positions generally cleared within minutes. That history was recorded under existing parameters. It supports an argument for greater capital efficiency but cannot establish how the proposed settings would perform during the next extreme move.
Eight more cents of Bitcoin borrowing power
Loan-to-value, or LTV, sets the maximum debt that collateral can support. At 73% LTV, $100 of WBTC or cbBTC can support up to $73 of debt before reserve caps, available liquidity, asset eligibility and account-level constraints. At 81%, the same collateral could support up to $81.
The liquidation threshold marks the point where a position becomes eligible for liquidation. On Ethereum Core, the proposal would raise that threshold for WBTC and cbBTC from 78% to 85%.
| Ethereum Core BTC parameter | Current | Proposed |
|---|---|---|
| Maximum LTV | 73% | 81% |
| Liquidation threshold | 78% | 85% |
| Collateral-price decline from maximum LTV to liquidation | About 6.4% | About 4.7% |
The raw distance between LTV and the liquidation threshold would fall from five percentage points to four. The last table row expresses that distance as a collateral-price decline relative to the threshold, assuming debt remains unchanged and Bitcoin is the moving leg. Raising both parameters still narrows the borrower’s price cushion because the borrowing limit moves closer to the new liquidation line.
The changes extend beyond Ethereum Core. The proposal would raise Arbitrum WBTC’s ordinary LTV by five percentage points and Base cbBTC’s by eight points. Ethereum Core WETH, wstETH and weETH would each receive a 0.5-point LTV increase. Selected liquidation thresholds would also rise, while Base cbBTC’s liquidation bonus would fall from 7.5% to 6%. A separate Base cbBTC stablecoin E-Mode would move to 82% LTV and an 85% liquidation threshold.
These figures describe maximum capacity per dollar of eligible collateral. They do not quantify how much debt users would add. The proposal does not disclose a complete current dataset of collateral-enabled balances, debt attributed to each affected asset and account health factors. Total reserve supply would overstate usable collateral because some supplied tokens may be ineligible, disabled as collateral or unconnected to debt. Historical seized volume likewise does not reveal the live distribution of positions.
Minutes of liquidation history meet an hour-long tail model
LlamaRisk studied liquidation behavior from August 2025 through August 2026 across Ethereum Core, Arbitrum and Base.
On Ethereum Core, the analysis counted 7,206 ETH liquidations that seized $618 million and 2,621 BTC liquidations that seized $358 million. For both collateral families, the value-weighted 99th-percentile time a liquidation call spent at or below its execution price was five minutes.
That statistic measures a liquidation work-off window. It is different from saying that 99% of transactions executed within five minutes of an oracle update. Large positions can require several calls because a single liquidation generally repays only part of the debt.
The study separately measured processing after price-feed publications during the February and October 2025 stress windows. Its table reports that 100% of seized volume cleared within five minutes of the feed publication that made liquidation profitable in every listed market during those two events.
February produced no recognized deficit. October produced $0.39 million of event-level bad debt against roughly $128 million, although LlamaRisk said none affected the ETH- or BTC-family collateral analyzed for this proposal. The result suggests that liquidator response was not the binding constraint in those episodes; it does not recreate those events under the proposed higher leverage.
The model then combines a one-hour price excursion with each reserve’s liquidation bonus to derive a ceiling for the liquidation threshold. In the detailed table, the 99.9th-percentile adverse one-hour move was 11.85% for ETH and about 5% for BTC.
That percentile omits the most extreme 0.1% of one-hour observations in the two-year sample. The same record contained much larger moves: a worst one-hour ETH decline of 24.27% and a worst BTC decline of 10.72% in the detailed table. The proposal’s summary gives 11.15% for the BTC worst hour, an internal discrepancy, but either BTC figure is more than twice the roughly 5% percentile input.
The gap defines the residual risk. LlamaRisk’s framework assumes that regular oracle publications and responsive liquidators prevent a maximally leveraged position from sitting untouched for a full hour. A move beyond the percentile can become more damaging if price feeds stall, liquidation activity slows or market depth deteriorates at the same time.
The percentile therefore calibrates a protocol bad-debt buffer rather than a borrower protection level. A maximally borrowing BTC position could reach the proposed liquidation threshold after an approximately 4.7% collateral-price decline under the simplified single-asset calculation, even though the protocol model uses a roughly 5% BTC excursion plus the liquidation bonus to assess post-liquidation coverage.
The proposal leaves BTC thresholds below the model ceiling to account for depth, caps and concentration risks that price history does not capture. ETH receives less room: WETH is set at the model ceiling, while wstETH and weETH sit one point inside their ceilings.
The Bitcoin LTV vote weighs speed against leverage
Aave’s governance choice is whether observed liquidation performance under current parameters justifies allowing future positions to run closer to liquidation.
For Bitcoin collateral on Ethereum Core, the exchange is clear at the borrower level. Maximum LTV would rise eight percentage points, while the simplified collateral-price cushion at maximum leverage would shrink from about 6.4% to 4.7%. Existing borrowers would not automatically add debt, but the new limits would permit new or adjusted positions to carry more.
The protocol-level case is more favorable than the borrower-level cushion alone suggests. In LlamaRisk’s sample, economically meaningful liquidations were processed quickly, and the two studied stress windows left no bad debt on the reviewed ETH- and BTC-family collateral. The model also incorporates the liquidation bonus and keeps recommended BTC thresholds below its calculated ceiling.
Its limits are equally specific. Historical execution does not measure an outage that coincides with an exceptional price move. The worst one-hour declines in the same dataset exceeded the percentile inputs by a wide margin, and the model cannot remove liquidity, concentration or oracle risk.
The aggregate credit effect also remains unknown. Calculating it would require current collateral-enabled balances for every affected asset and market, the debt those positions already carry, their collateral settings and their health-factor distribution. The published proposal supplies the parameter change, not that full position-level dataset.
The forum says an implementation AIP would follow only after a positive Snapshot result. Until a vote and AIP establish the final values, the 81% Bitcoin LTV remains a governance proposal.
LlamaRisk’s study makes a measurable case that fast liquidation work-off can support greater collateral efficiency. The unresolved question is how much confidence Aave should place in that history when the danger lies in the hour that combines an unusually large market move with impaired pricing, liquidation or market depth.
The post Narrowing price cushions leave Bitcoin loans vulnerable to 4.7% price dips as Aave weighs higher leverage appeared first on CryptoSlate.
US spot Bitcoin exchange-traded funds (ETFs) pulled in nearly $1 billion as BTC broke above $86,000, marking their strongest inflow day of 2026.
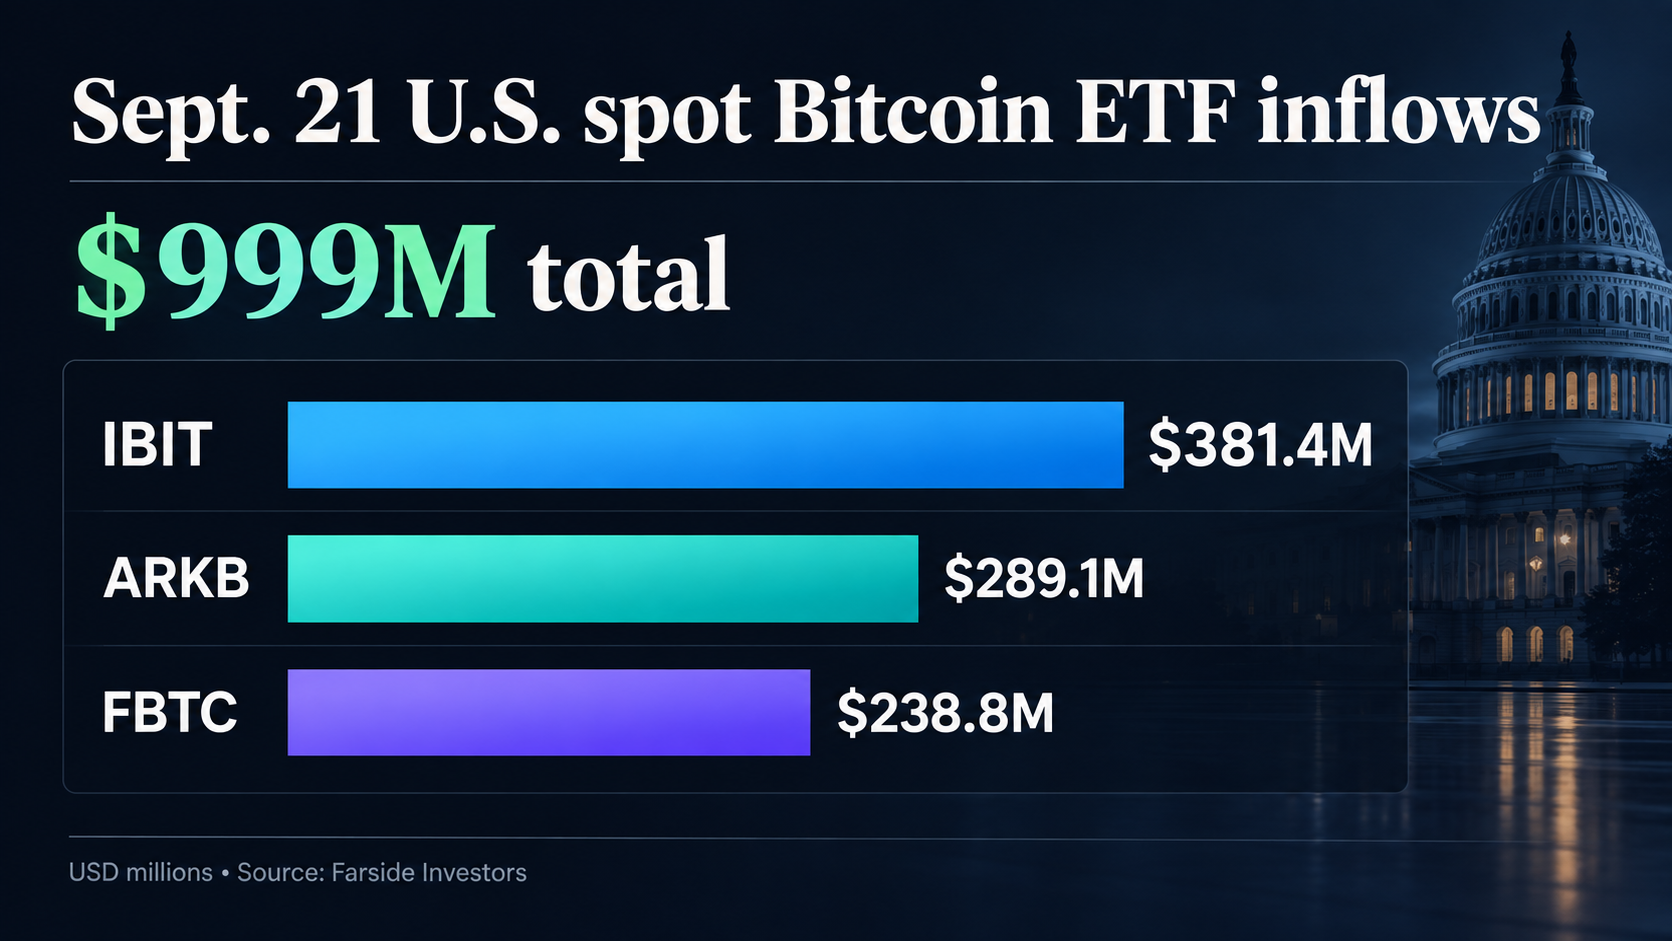
The funds recorded $999 million of net inflows on Sept. 21, the largest daily total since Oct. 6, 2025, when the products attracted about $1.2 billion, according to SoSoValue data.
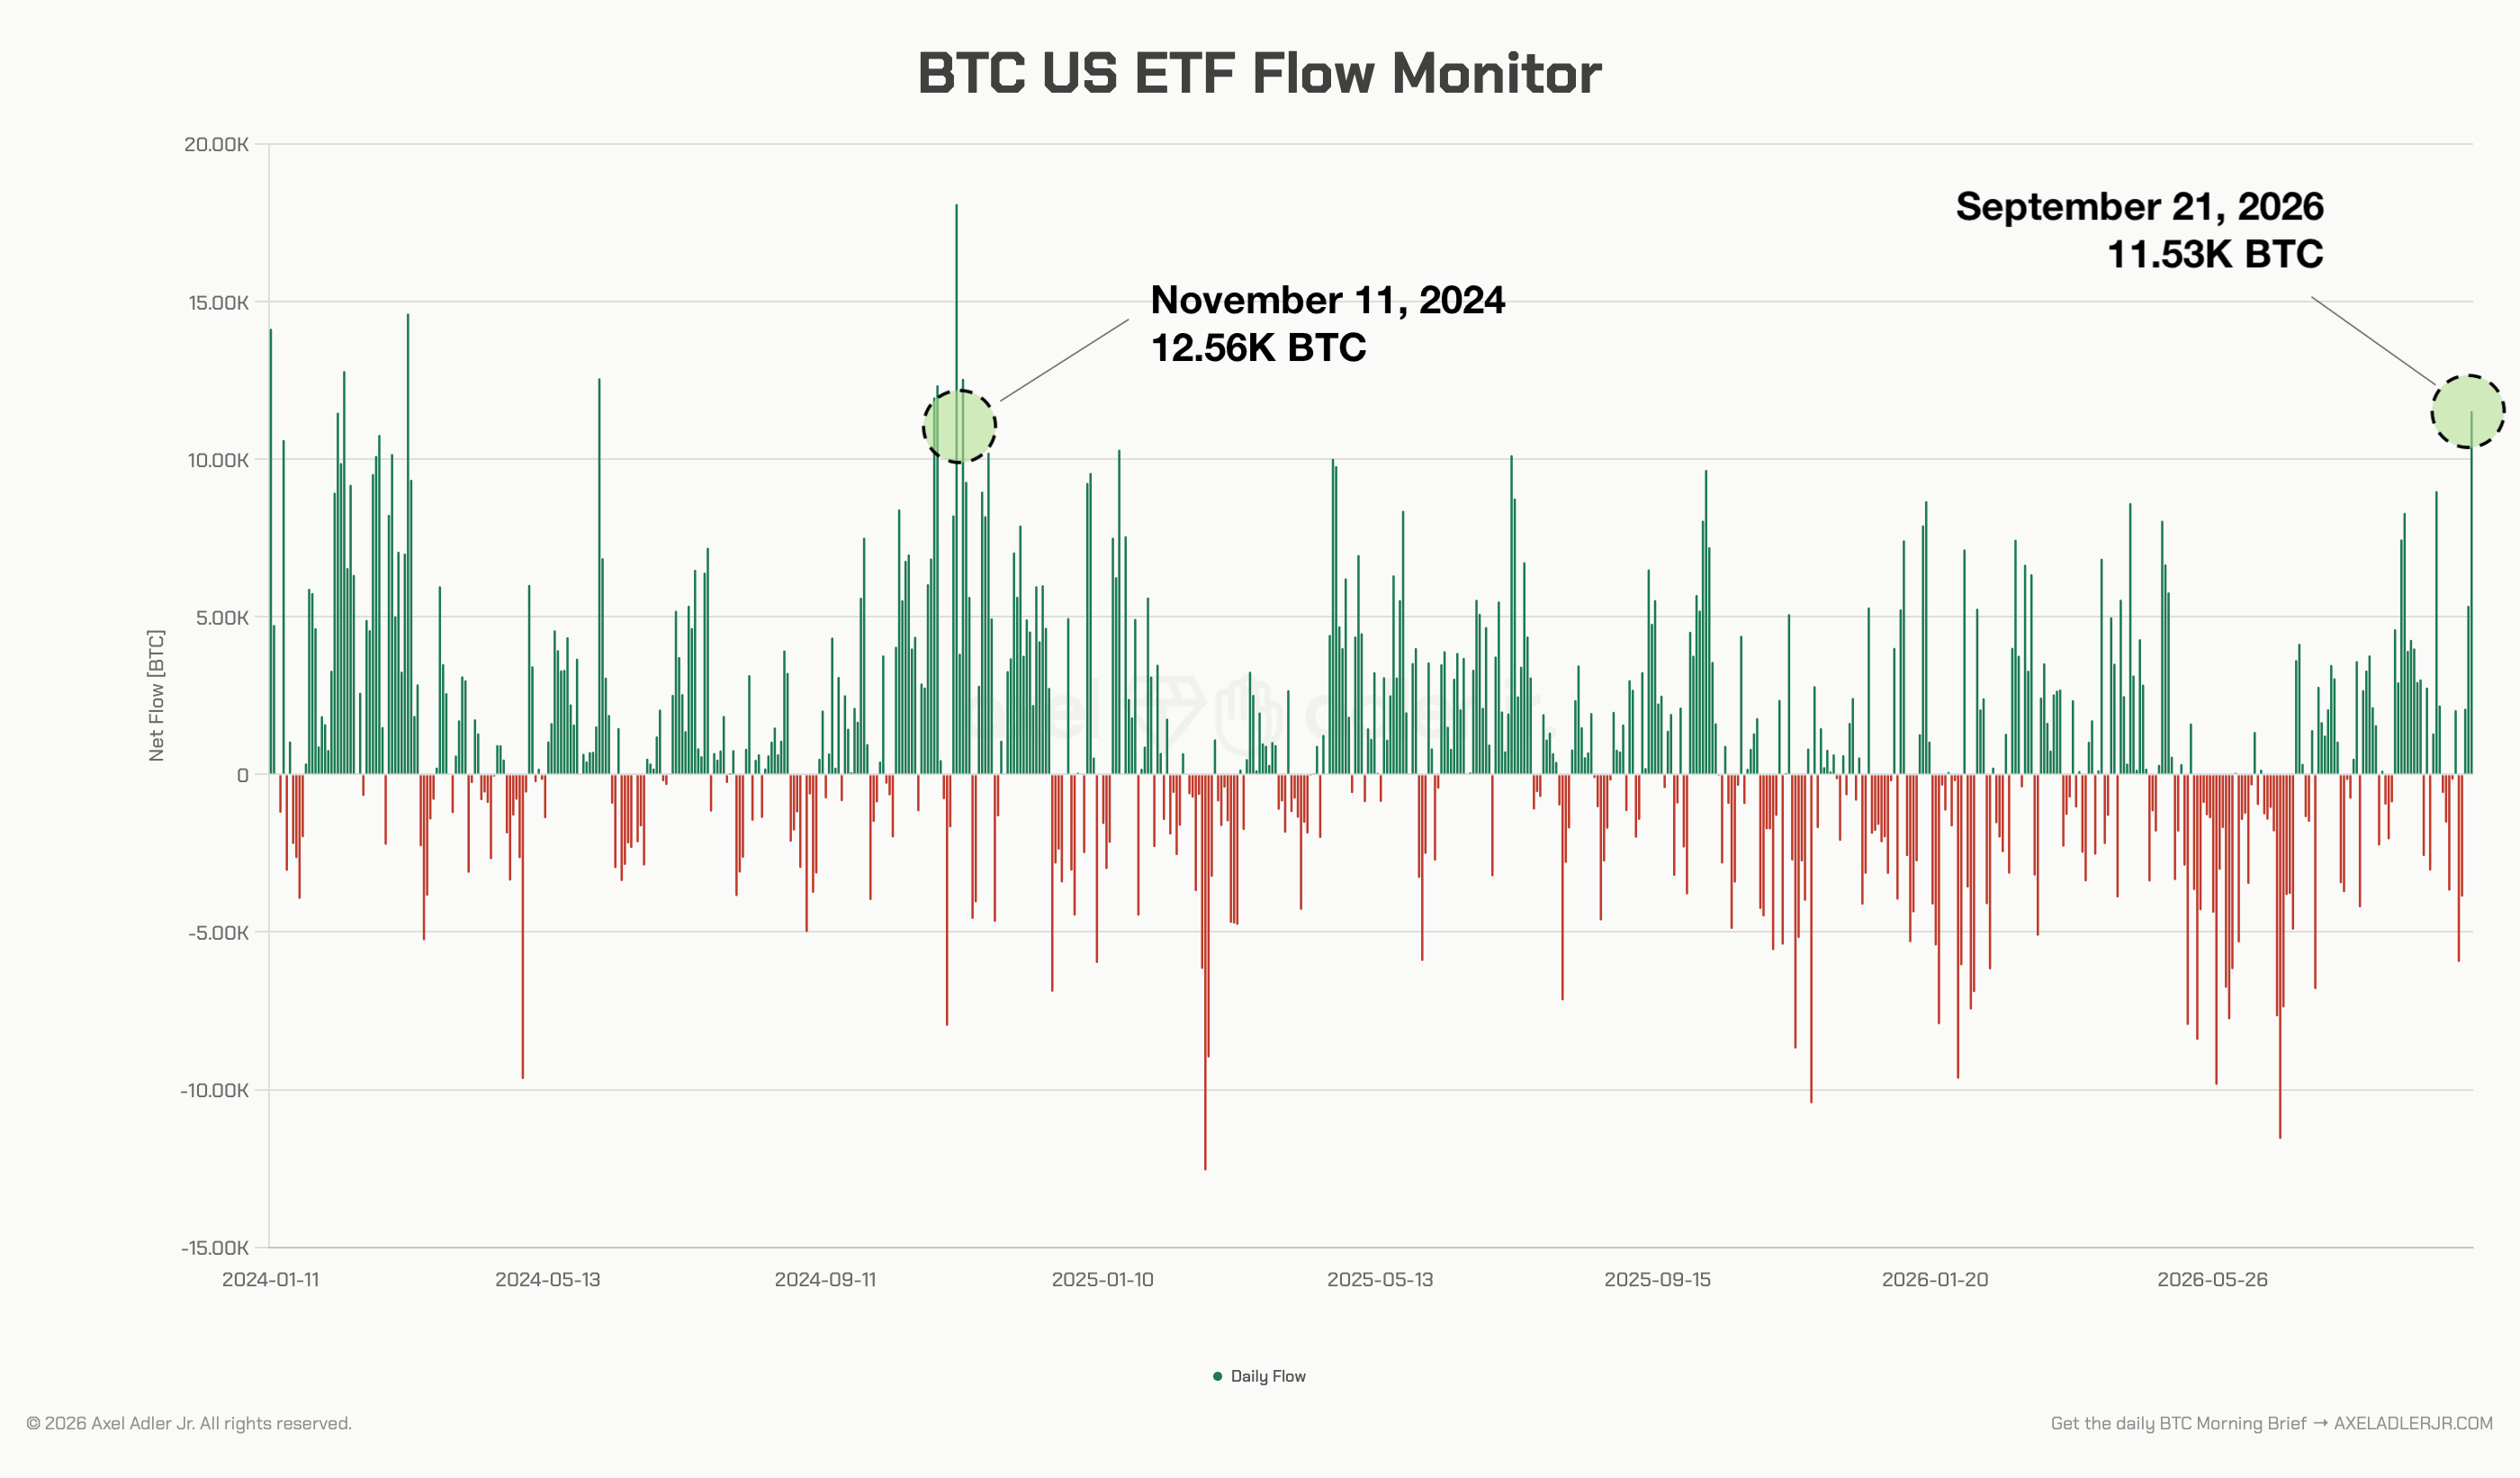
Measured in Bitcoin, the move was even more pronounced. The ETFs absorbed about 11,530 BTC, their largest one-day net intake since Nov. 11, 2024, when they added roughly 12,560 BTC. The latest buying came as Bitcoin surged through $86,000 and briefly traded above $87,000, its highest level since January.
BlackRock’s iShares Bitcoin Trust (IBIT) led with $381.4 million, followed by $289.1 million for the ARK 21Shares Bitcoin ETF (ARKB) and $238.8 million for Fidelity’s Wise Origin Bitcoin Fund (FBTC).
The three accounted for more than $909 million of the total, while each of the six largest products contributed, Bloomberg Intelligence ETF analyst Eric Balchunas said.
For IBIT, the $381 million inflow ranked as its fourth-largest daily intake, Balchunas said. He pointed to the uneven pattern of recent creations as a constructive signal, arguing that irregular inflow days better reflect dispersed investor activity than allocations driven by a single large model or institution.
Record Bitcoin ETF inflows arrive without a trading-volume surge
Meanwhile, the scale of the creations contrasts with secondary-market activity.
Bloomberg Intelligence ETF analyst James Seyffart said US spot Bitcoin ETFs traded about $4.5 billion during the latest session, slightly below the roughly $4.6 billion recorded Friday. The relatively ordinary turnover stood out against Bitcoin’s sharp price move and the size of the reported inflows.
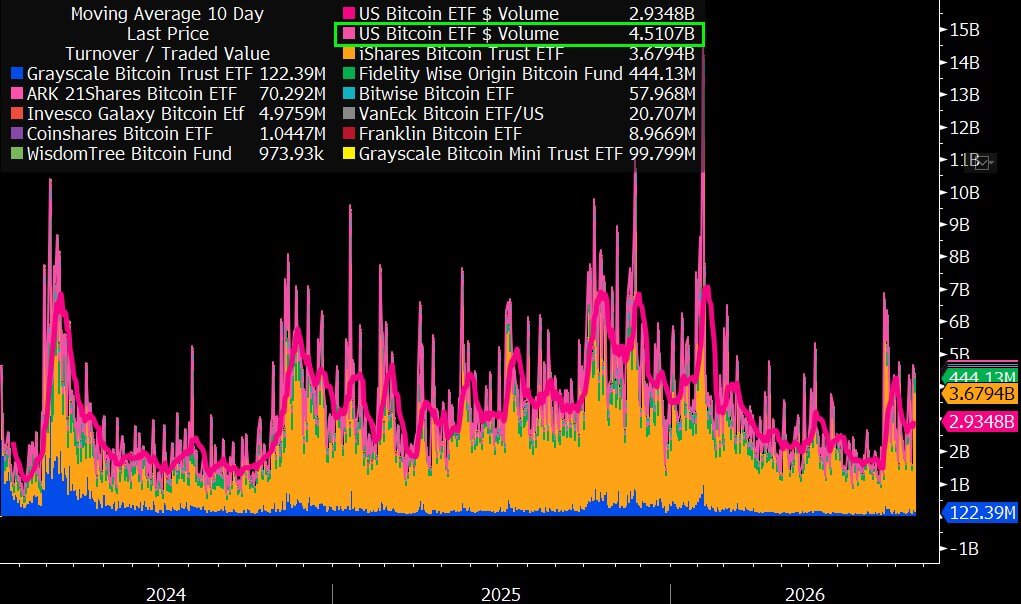
The timing also complicates attempts to connect Monday’s ETF figures directly to Bitcoin’s breakout.
Balchunas said much of the roughly $1 billion inflow probably reflects trading and creation activity from Friday because fund flows are reported with a lag. That means the next batch of disclosures may better show how investors responded once Bitcoin accelerated through $86,000.
“Look for more tonight,” Balchunas said.
That distinction raises the stakes for the next session. If Monday’s rally generated another wave of creations, the ETFs could extend a sharp reversal from the outflows that weighed on the market earlier this year and add a sustained source of spot demand as Bitcoin approaches $90,000.
The post Bitcoin ETFs just absorbed 11,500 BTC in their biggest buying day in nearly two years appeared first on CryptoSlate.
CryptoTicker.io
Ether costs $2,735.96 at 18:41 German time on September 22, 2026. That puts the price around half a percentage point below the $2,750 mark and a good two percent below $2,800, in other words right underneath the zone at which Ethereum has bounced off repeatedly over the past weeks. Anyone looking for a serious ETH price prediction gets no target number here but a to-do list: which purchase date sits in your account, which buying route carries your tax logic, how far your position is from the liquidation price, and what happens to your holding period if you reshuffle now.
The figures in this article come from our own query of CoinGecko market data on September 22, 2026 at 16:41 UTC, which corresponds to 18:41 German time. Prices change by the minute; the calculations underneath them do not.
Where the Ethereum price really stands on September 22, 2026
In the query, Ether is quoted at $2,735.96, down 0.66 percent from its level 24 hours earlier. The daily range runs from $2,716.11 to $2,804.42. That is the single most important finding of the day: the price has already touched the $2,800 mark today and failed to hold it. Market capitalisation sits at roughly $334 billion, trading volume over the past 24 hours at just under $18 billion.
For perspective on the upside: the all-time high of $4,946.05 dates from August 24, 2025. From the current level, that is roughly 81 percent away. Anyone reading a forecast that treats the high as an interim target for the coming weeks should place this figure alongside it.
On September 21, Ether was quoted at $2,703.62 according to market reports, a good five percent above the previous day. The move of the past few days is therefore pointing upwards, but it has not yet cleared the decisive zone.
Why a daily range of 3.2 percent is a metric
Between the daily low and the daily high lie $88.31, or 3.23 percent of the current price. You need that number twice further down: once to judge what a break above $2,800 would actually prove, and once to work out which level of leverage survives a normal day's move.
The zone between $2,750 and $2,800: why analysts are watching exactly there
Resistance is a price area in which, in the past, enough sell orders repeatedly sat to stop an advance. Support is its counterpart on the downside. Neither is a law of nature; they are observations about how market participants behave at familiar prices.
In the coverage by German and international financial portals, among them wallstreet-online and invezz, the zone between $2,750 and $2,800 is consistently named as the next reference point after the price cleared the long-capped $2,600 mark. On the downside, the same assessments name $2,550 and the area around $2,350, along with the moving averages EMA50 and EMA200 at roughly $2,282 and $2,269. A moving average is the mean of the closing prices of the last 50 or 200 periods respectively and serves as a rough trend line.
These levels are quoted analyses, not commitments. They are good for exactly one thing: you decide in advance what you will do if the price reaches one of them, instead of deciding in the moment of the move. From the current level it is 6.8 percent down to $2,550 and 2.3 percent up to $2,800.
ETF inflows from the US: what the contradictory numbers really say
A spot ETF is an exchange-traded fund that holds the coin itself rather than a futures contract. Such products on Ether have been approved in the US since 2024; in the EU they do not exist in that form, more on which below.
The figures of recent days are contradictory, and that is exactly how they belong in a report. According to assessments cited among others by kryptoszene.de, US spot ETFs on Ether lost roughly $140 million on balance in the trading week to September 18, 2026. It was the first negative week since the week to August 14, and it ended a run of four inflow weeks that together had gathered $1.94 billion. Other assessments of the same period cite a single day's inflow of $143.8 million for September 18, of which roughly $114 million went to BlackRock.
Both can be true, because one strong day does not cancel a negative weekly balance. Whoever reads only the daily figure sees demand. Whoever reads only the weekly figure sees selling. For your decision, that means a single ETF day is not a signal; only a run is a direction.
For you in Germany there is the added point that these inflows influence your price but are not your product. US spot ETFs cannot normally be bought by retail investors in Germany, because they lack the European investor information documents.
Holding period under Section 23 of the Income Tax Act: which date in your account counts
The holding period is the span between the acquisition and the disposal of a crypto unit. Under Section 23 of the German Income Tax Act, a gain from a sale is tax-free if more than a year lies between purchase and sale. Below that threshold the gain counts as a private disposal transaction and is charged at your personal income tax rate.
Two details decide matters in practice more often than the tax rate itself. First the exemption limit: if the sum of all private disposal gains in a calendar year stays below 1,000 euros, it remains tax-free. An exemption limit is not an allowance; it falls away entirely once exceeded, and then the whole gain is taxable, not only the part above the limit. Second the allocation: if you sell part of your holdings, the order of acquisition governs which units count as sold, colloquially FIFO, first in, first out. The unit bought first counts as sold first.
The check that takes ten minutes
Export your exchange's purchase history as a CSV file and sort it by date. Mark every tranche whose purchase date lies less than twelve months back. Those tranches are exactly the ones on which a sale at the $2,800 mark would be taxable. If a tranche turns up whose one-year deadline expires in a few weeks, you have a concrete figure for your decision instead of a gut feeling. Tools that keep this allocation automatically can be found in the overview of crypto tax tools and portfolio trackers.
The tax reform planned from 2027: why your purchase date becomes a variable
On April 29, 2026, German finance minister Lars Klingbeil announced that he intends to tax crypto assets differently in future. According to consistent specialist reporting, the model under discussion is a flat withholding tax of 25 percent plus the solidarity surcharge, from the 2027 assessment period at the earliest. A coordinated draft bill had not been tabled as of the reports assessed here.
That is explicitly a plan and not applicable law. For 2026 the one-year deadline under Section 23 of the Income Tax Act continues to apply, and nobody should bring a sale forward on the strength of an announcement alone. What you can do is a piece of date arithmetic: a unit you buy today reaches its one-year deadline on September 22, 2027. Whether a later law will protect existing holdings is open; German constitutional law recognises the protection of legitimate expectations, but its concrete shape is a matter for the legislator.
The practical consequence is unspectacular and useful all the same: document every purchase with date, quantity and euro equivalent, regardless of what the price is doing. If the legal position changes, the quality of your records will decide whether you can demonstrate a favourable transitional rule at all.
Staking on Ethereum: what a 2.6 percent yield leaves after tax
Staking means that you deposit Ether as collateral in the network and receive rewards for it, because your units contribute to securing block production. Current assessments most recently put the yield on Ether at around 2.62 percent a year.
For tax purposes the rewards run into a different line from the price gain. Under the administrative view in the Federal Finance Ministry circular of March 6, 2025, which replaces the version of May 10, 2022, income from passive staking generally counts as other income under Section 22 number 3 of the Income Tax Act. It is taxed at the time it accrues, at the market value on that day, not only on a later sale. This type of income carries an exemption limit of its own, 256 euros per calendar year.
Two points are regularly confused here. First: under the current administrative view, staking does not extend the one-year holding period of the staked units to ten years. That worry stems from an older debate and is off the table for the normal case. Second: the rewards received are themselves newly acquired units, and a one-year deadline of their own begins for them on the day they accrue.
A worked example with round numbers
Anyone staking Ether worth 1,000 euros receives roughly 26 euros a year at 2.6 percent. That sits below the exemption limit of 256 euros, so the amount remains tax-free, but it still has to be recorded. Only from a staked equivalent of about 9,850 euros is the exemption limit breached at this yield, and then the full amount is taxable, not only the part above it. Which providers offer staking at which fees and with what payout logic is shown in the overview of staking platforms.
Coin, ETN or savings plan: what the buying route changes for you under MiCA
MiCA is the EU regulation on markets in crypto-assets, which regulates the operation of trading platforms and custodians uniformly across Europe. Germany brought its national transition period under Section 50 of the Crypto Markets Supervision Act forward to December 31, 2025, six months ahead of the EU-wide cut-off on July 1, 2026. Since January 1, 2026, providers without a licence may no longer render crypto services in Germany. According to a survey published in June 2026, 56 of the licences granted across Europe went to Germany, ahead of the Netherlands with 26 and France with 21.
For you this is a check with one outcome: your provider is in the licence register or it is not. BaFin lists the authorised institutions in its company database. A provider without a licence that continues to serve German clients is not a bargain but a legal risk at the point of withdrawal and proof. An overview of regulated venues and their fee models can be found in the crypto exchange comparison.
The difference that decides your tax
An ETN is an exchange-traded debt security that replicates the price of an underlying. In Europe, crypto products are mostly offered in this form, because under EU fund law a classic fund may not hold only a single asset. For tax purposes one detail in the base prospectus decides the matter: physically backed crypto ETPs with a delivery claim on the coin are treated like a direct investment under the administrative view and therefore fall under Section 23 of the Income Tax Act, one-year deadline included. Products without a delivery claim, by contrast, are classified as a monetary claim, and there the flat withholding tax of 25 percent applies regardless of the holding period.
The check takes a few minutes: search the base prospectus or the key information document of your product for the terms delivery claim and physical backing. Anyone holding the same amount once as a coin and once as an ETN without a delivery claim has two different tax outcomes after a year, with identical price performance.
Leverage and liquidation at the edge of resistance: what to calculate before the order
Liquidation means that the exchange forcibly closes your leveraged position because the collateral posted no longer covers the loss. The distance to that point can be calculated in advance, and it is precisely at a resistance level that the calculation is worth doing, because false breakouts are particularly frequent there.
From the level of $2,735.96, the rough liquidation threshold of a long position at five times leverage sits around 20 percent lower, at about $2,189. At ten times leverage it is around $2,462, at twenty times around $2,599. Fees and financing costs push these values upwards, so the threshold is reached earlier than the pure percentage calculation suggests.
Now set the daily range next to it, 3.23 percent today. A position at twenty times leverage has a buffer of roughly five percent and therefore survives barely one and a half normal daily moves. That is no longer a risk assessment but a coin toss with fees. Anyone trading derivatives should also know the funding rate, the periodic balancing payment between the long and short sides of perpetual futures: when positioning is heavily one-sided, the dominant side pays the other continuously, and those costs run on regardless of the price.
Levels above and below: how to recognise a confirmation
Today's trading session provides an object lesson: the daily high of $2,804.42 was already above the round mark, yet at the time of the query the price stands at $2,735.96. A brief overshoot is therefore not a confirmation.
Three criteria to fix in advance
First, a closing price rather than a wick: what matters is where the price stands at the close, not which peak it brushed along the way. Second, volume: a breakout on markedly elevated turnover carries further than one on thin trading, and the current daily turnover of roughly $18 billion is the benchmark for that. Third, confirmation from outside: if ETF inflows turn positive again in the same week, there is capital behind the move and not merely positioning in the derivatives market.
On the downside the same discipline applies in reverse. If the price falls back below $2,550, the advance of the past few days is arithmetically used up. Anyone who has noted in advance what they will do in that case is spared the decision at the least convenient moment.
Putting an ETH price prediction in context: what to take away
The short-term direction of Ether is open, and every forecast claiming otherwise is selling you a certainty that does not exist. What is not open are the four things you can check today.
- Sort your purchase dates. Export your purchase history and mark every tranche held for less than twelve months. Only then do you know what a sale at the $2,800 mark really costs. The right tools are in the comparison of crypto tax tools and portfolio trackers.
- Check your buying route and its licence. Establish whether your provider has been licensed in Germany since January 1, 2026, and whether your product is a coin or an ETN without a delivery claim. Both change your tax outcome at identical price performance. The overview is provided by the crypto exchange comparison.
- Calculate staking separately. Record every reward with its accrual date and euro value and check the 256-euro exemption limit separately from the 1,000-euro limit for sale gains. Which platform stakes on which terms is shown by the comparison of staking providers.
(As of September 22, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
CME Group announced on September 22, 2026 that it will list futures on Bitcoin Cash and Uniswap from October 19. If you are a retail investor in Germany, the decisive detail is not the start date but a BaFin order from 2022: futures may be sold to retail clients in Germany only under narrow conditions. Anyone who wants to trade the new contracts therefore has to check with their own broker first whether the obligation to post additional margin is contractually excluded, or whether a written hedging declaration is required.
The market priced the news in immediately. In our own query of CoinGecko market data on September 22, 2026 at 15:48 UTC, Bitcoin Cash stood at $327.15, up 23.75 percent on the previous day and the strongest reading among the 25 largest crypto assets. Uniswap traded at $9.29, a gain of 4.51 percent. Over seven days, Bitcoin Cash is up 41.30 percent and Uniswap 38.02 percent.
CME Group lists Bitcoin Cash and Uniswap futures: contract sizes and launch date
A future is an exchange-traded contract in which two parties commit to buying or selling a set quantity of an underlying asset at a fixed price on a fixed date. CME Group runs the world's largest derivatives exchange and has listed crypto futures since December 2017.
According to the company's statement, the expansion covers four contracts. The standard Bitcoin Cash contract represents 250 BCH, the micro contract 25 BCH. For Uniswap the figures are 10,000 UNI in the standard contract and 1,000 UNI in the micro contract. The launch is scheduled for October 19, 2026 and remains subject to regulatory review. Trading takes place on the exchange's round-the-clock platform.
Giovanni Vicioso, Global Head of Cryptocurrency Products at CME Group and responsible for the segment, justifies the move in the statement by pointing to the maturity of the market: participants need a broader set of regulated tools to manage price risk in digital assets. That assessment is a corporate statement, not an independent read on the market.
With the two new assets, the line-up of crypto futures listed at CME grows to eleven underlyings. Contracts on Bitcoin, Ether, XRP, Solana, Cardano, Chainlink, Stellar, Avalanche and Sui are already tradable. In the first half of 2026, an average of 279,800 contracts changed hands daily in the crypto segment according to the exchange, equivalent to a notional value of $8.3 billion; open interest averaged 264,600 contracts, or $15.4 billion notional. The five assets added in 2026 together account for more than $1 billion in notional volume since the start of the year.
Why Bitcoin Cash gains 24 percent and Uniswap only 4.5 percent
The difference in the price reaction comes down to the size of the two markets. Bitcoin Cash ranks 21st by market capitalisation and is the smaller of the two, but it has always reacted sharply to institutional news, because the asset is treated as a highly liquid Bitcoin offshoot by traders who wait for exactly this kind of trigger.
Industry service CoinCodex puts the rise in Bitcoin Cash trading volume around the announcement at 153.8 percent, to roughly $801 million within a day. The peak price it cites, $321.74, sits slightly below our own query value of $327.15; both figures come from different moments of the same trading day and are left side by side here rather than smoothed over.
A second factor is the broader market backdrop. On September 22, Bitcoin opened at $86,597.82 according to Yahoo Finance data, 6.7 percent above the previous day, with Ether at $2,775.96. In that kind of environment, single news items are amplified, because hedges against rising prices have to be closed out. Part of the move in Bitcoin Cash is therefore down to this market mechanism rather than the announcement alone.
For Uniswap, the news lands on a move that has already run. The governance token of the largest decentralised exchange gained 38 percent over the preceding seven days and reclaimed the nine-dollar mark in the process. An additional push of 4.5 percent looks smaller against that backdrop, but it is spread across a considerably larger capitalisation.
Future, perpetual and CFD: how the three leveraged routes are built
It is worth looking at the three product types that allow leveraged bets on crypto prices. They differ less in their economic outcome than in maturity, supervision and settlement.
A classic future has a fixed expiry date and is settled centrally on a supervised derivatives exchange through a clearing house that steps in as counterparty for both sides. A perpetual future, as offered by crypto exchanges and decentralised venues, has no expiry; it is held close to the spot price through a funding rate paid at regular intervals. A contract for difference, or CFD, is by contrast an over-the-counter agreement between you and your broker, with the broker taking the other side itself.
The regulatory treatment follows that split. All three forms count as derivatives under German securities trading law, but they are subject to different BaFin product interventions. Anyone who understands the difference also understands why a CME contract is harder for a German retail investor to access than a perpetual on a crypto exchange. Which platforms come into question for perpetuals at all, and how to assess their fee models, is set out in our overview of perp DEX platforms.
BaFin general order on futures: why you cannot simply buy the CME contract
On September 30, 2022, BaFin issued a general order on product intervention for futures, based on Article 42 of EU Regulation 600/2014 (MiFIR). It took effect on January 1, 2023 and remains in force unchanged. The core of it: investment firms are in principle prohibited from marketing, distributing and selling futures to retail clients.
The supervisor justified this with the obligation to post additional margin. If a position moves against the investor far enough for the posted margin to be used up, a future can create a claim that goes beyond the capital committed. BaFin saw significant investor protection concerns in that, particularly in periods of sharp swings. Crypto assets are not a special case in this respect; they are the area in which the problem becomes visible fastest.
The ban is not absolute. The order names exceptions, and it is precisely at those exceptions that it is decided whether you get a Bitcoin Cash contract into your account from October 19.
Additional margin or hedging declaration: the two routes for retail clients
The first route, and the one that matters most in practice: the investment firm contractually excludes the obligation to post additional margin. Your loss is then limited to what you have posted as margin. In technical language this commitment is called negative balance protection, the contractual safeguard against a negative account balance. If your broker offers the contracts on that basis, you are allowed to trade them as a retail client.
The second route is aimed at investors with a concrete hedging need. Here the retail client confirms in writing before each individual transaction that the contract is being acquired exclusively for hedging purposes. If you want to protect an existing Bitcoin Cash position against a price decline, you fall under it; if you want to speculate on rising prices, you do not. The declaration is not a formality but a precondition, and the investor is bound by its truthfulness.
As a third case, the order names the acquisition of futures to close existing positions opened before the order took effect. That plays no role for the new contracts.
In practice this leads to a simple order of checks before October 19. Ask your broker whether it offers the CME crypto futures at all, whether the obligation to post additional margin is excluded, and what margin it requires. The answers differ widely, because the houses have tailored their offering for German retail clients in different ways. An assessment of the providers active here and their terms can be found in our broker overview.
250 BCH per contract: why the micro future is the realistic size
Contract size decides whether a product is suitable for a private account at all. A standard Bitcoin Cash contract represents 250 BCH. At the price of $327.15 on September 22, that corresponds to a notional value of roughly $81,800 per contract. The micro contract covering 25 BCH comes to about $8,180.
For Uniswap the difference is similar: 10,000 UNI in the standard contract works out at roughly $92,900 notional at a price of $9.29, with the micro contract of 1,000 UNI at about $9,290. These figures are snapshots of September 22 and shift with every move in the price.
What you have to post is not the notional value but the collateral, known as margin in derivatives trading. For crypto futures it typically sits in the double-digit percentage range of the notional value, depending on exchange and broker, and is set by the derivatives exchange in line with volatility. The specific rates for the new contracts are still outstanding at the time of writing; they are usually published only shortly before trading starts.
Margin and liquidation: what actually ends a leveraged position
Liquidation is the forced closure of a position by the trading venue once the posted margin falls below a defined threshold. It is the mechanism on which most leveraged positions end, and it does not ask whether the investor's view of the market was right over a horizon of weeks.
With an asset that gains 24 percent in a day, the counter-move is just as possible. Bitcoin Cash has shown double-digit daily moves in both directions several times this year. A position with five times leverage is arithmetically wiped out by a 20 percent decline, before the question of additional margin even comes up.
Why liquidations rarely happen one at a time
There is a further point that is often underestimated in crypto trading: liquidations cluster. When many similarly positioned trades are closed out at the same time, the resulting sales create further pressure that reaches the next group. That is precisely why price swings on such days are larger than the news that triggered them.
Tax on derivatives: the 20,000-euro cap is gone since the 2024 Annual Tax Act
For investors who trade derivatives, the tax situation has improved noticeably over the past two years. Until then, Section 20 (6) sentences 5 and 6 of the German Income Tax Act created a separate loss-offsetting pool: losses from derivatives could only be set against gains from derivatives, and only up to 20,000 euros a year.
The Annual Tax Act 2024 of December 2, 2024, promulgated in the Federal Law Gazette on December 5, 2024, deleted those two sentences without replacement. The background was constitutional concerns raised by the Federal Fiscal Court in its decision of June 7, 2024 (case number VIII B 113/23) in proceedings on the suspension of enforcement. Under Section 52 (28) of the Income Tax Act, the deletion applies retroactively to 2024 and to all open cases.
For you this means: losses from a crypto future can be set against all investment income, including interest or dividends, and the annual cap is gone. Implementation by custodian institutions in the withholding of capital gains tax became mandatory on January 1, 2026. Whether your institution reflects this properly is visible in your tax certificate; for older loss carry-forwards it is worth looking at the income statement. For ongoing documentation of your positions, a portfolio tracker helps, of the kind we compare in our overview of crypto tax tools.
Future or coin in the wallet: two separate tax worlds
The distinction from a directly held coin matters. A future is an investment product and falls under the flat-rate withholding tax. A Bitcoin Cash held in your own wallet is by contrast another asset within the meaning of Section 23 of the Income Tax Act, for which the one-year holding period applies. These two worlds cannot be offset against each other for tax purposes. Which legal consequence applies in an individual case belongs in the hands of a tax adviser.
Spot instead of leverage: holding period, custody and the route through a licensed exchange
For most retail investors, buying directly remains the obvious route, especially with an asset whose news flow turns within hours. Since the end of 2024, the EU Markets in Crypto-Assets Regulation, MiCA for short, has been in force; it requires trading venues to hold a licence and governs obligations on custody, own funds and client information. We have set out which obligations those are in detail, and by when they apply, in our overview of the MiCA licensing requirements.
Three checks before the buy order
With a spot purchase, you check three things before the order goes out: whether the trading venue runs its own order book for euro trading or routes through an intermediate currency, how deep that order book is at your order size, and how custody is arranged. A list of the venues licensed here can be found in our exchange overview.
The tax difference is substantial. If you hold Bitcoin Cash in your own possession for more than a year, a disposal gain is tax-free under current law. That option does not exist with a future, because it counts as an investment subject to the flat-rate withholding tax and ends at its expiry date in any case.
Levels above and below: how to measure the next move in BCH and UNI
October 19 is a scheduled event date, and such dates are regularly anticipated in crypto markets. Experience with earlier CME listings shows two patterns that can rule each other out: part of the move runs ahead of the launch, and the launch day itself can come with profit-taking. Which pattern applies cannot be predicted, and any figure attached to it would be invented.
Three measures are observable, though. First, open interest in CME's existing crypto contracts, which the exchange publishes daily and which shows whether institutional money is actually flowing into the segment. Second, trading volume in Bitcoin Cash, which with the reported jump of 153.8 percent currently sits far above its normal level and whose return to that level would mark the end of the impulse. Third, whether the regulatory review the listing is subject to is completed on schedule.
On the price side, the round numbers are the reference points where orders gather: for Bitcoin Cash the area around $300 on the downside, which served as the starting point before the news, and for Uniswap the nine-dollar mark reclaimed over the past week. If the price falls back below those starting points, the market has digested the news.
What is still open on October 19
Three points are not settled at the time of writing and cannot be anticipated seriously. The exchange has not yet published margin requirements for the new contracts. Whether and which brokers active in Germany will offer the contracts to retail clients with the obligation to post additional margin excluded is equally open. And the regulatory review the announcement is subject to has not been completed.
Anyone who wants to act now therefore works with what is documented: the announcement itself, the contract sizes and the law as it stands for retail clients in Germany.
Checking CME futures on Bitcoin Cash: what to take away
- Sort out your access before trading starts. Ask your broker whether it carries the new CME contracts for retail clients and whether the obligation to post additional margin is contractually excluded. Without that exclusion, all that remains is the route via the written hedging declaration, and that presupposes an existing position you are hedging. Which houses come into question for leveraged trading at all is shown in the broker overview.
- Convert the contract size into euros before you look at the margin. 250 BCH in the standard contract are worth roughly $81,800 notional at the current price; the micro contract over 25 BCH is the only realistic size for a private account. If the leverage is too much for you, buying directly through a licensed crypto exchange with the one-year holding period remains an option.
- Check your loss carry-forwards from derivatives. Since the deletion by the Annual Tax Act 2024 they can be set against all investment income, and banks have had to reflect this in withholding since January 1, 2026. A look at your tax certificate is worth it; the ongoing documentation is handled by a tax and portfolio tool.
Sources: The announcement in full is in the CME Group press release of September 22, 2026. The conditions for selling futures to retail clients in Germany are set out in the BaFin general order of September 30, 2022.
(As of September 22, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
$XRP spent three weeks getting rejected by the same falling line. Today it stopped asking politely. The daily candle opened at $1.5361, ran to $1.5955 and is holding $1.5699 at the time of writing, up 2.20% on the session. More importantly, it did that by closing above the descending trendline that has capped every rally attempt since the late August spike to $1.70.
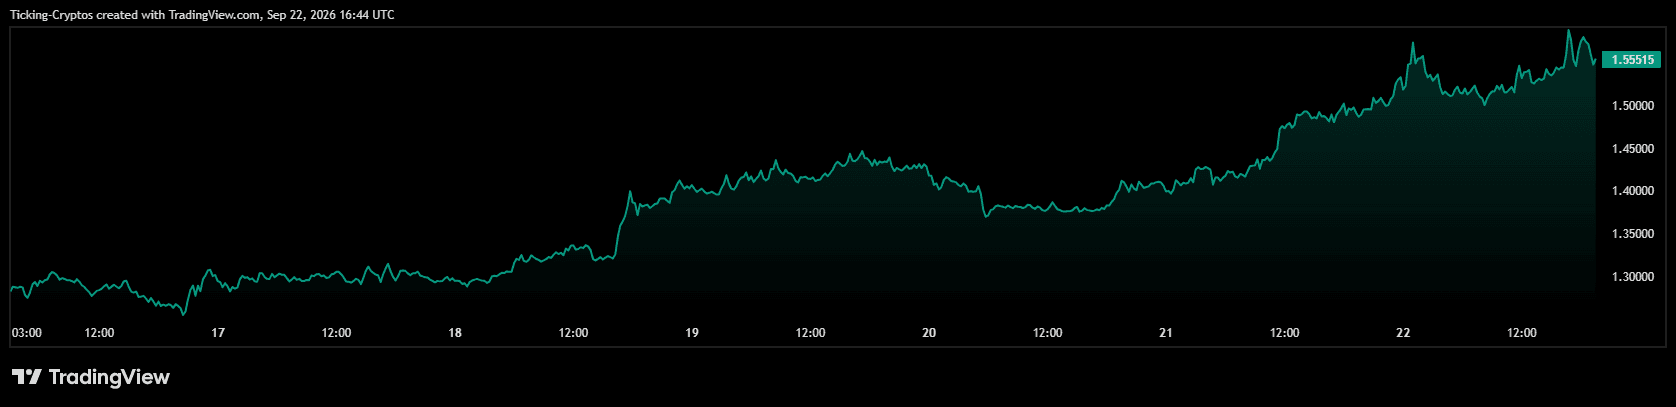
Why Did The XRP Price Break Out Today?
Three things lined up on the daily.
- The descending trendline drawn from the August high finally gave way. Price had been compressing against it since early September, with each rejection landing a little higher. That is textbook coiling, and coils resolve.
- The $1.50 level flipped. It acted as resistance through the entire September range, capping the mid-month push. XRP is now trading above it with room to spare, which turns the old ceiling into the first line of defence.
- The 200 EMA at $1.3589 sits well below price and is flattening out after months of decline. XRP reclaimed it during the August move and has not lost it since, including on the dip to $1.30 in mid-September. A rising market above a flattening 200 EMA is a different animal to a bounce inside a downtrend.
The backdrop helps. Large holders added roughly 1.54 billion tokens during the recent rally, worth around $2.2 billion, although some of that flow also moved toward exchanges. US spot XRP funds also pulled in $153.55 million during August according to SoSoValue data, with the vast majority of that arriving in the final two weeks of the month. Flows do not move an asset of this size on their own, but they do explain why every dip since $1.00 has been bought quickly.
What Is The Next XRP Price Target?
The first real obstacle is $1.80.
There is nothing meaningful between current price and that level, which is exactly why the move can be fast if momentum holds. The August spike stalled at $1.70, so expect some friction there, but $1.70 is a wick level rather than a zone with volume behind it. $1.80 is the horizontal that has actually been defended.
Above $1.80, the chart opens into the $1.80 to $1.95 band highlighted on the daily. That is the pocket where the previous distribution happened, and it is the logical destination if XRP clears the breakout with conviction into October.
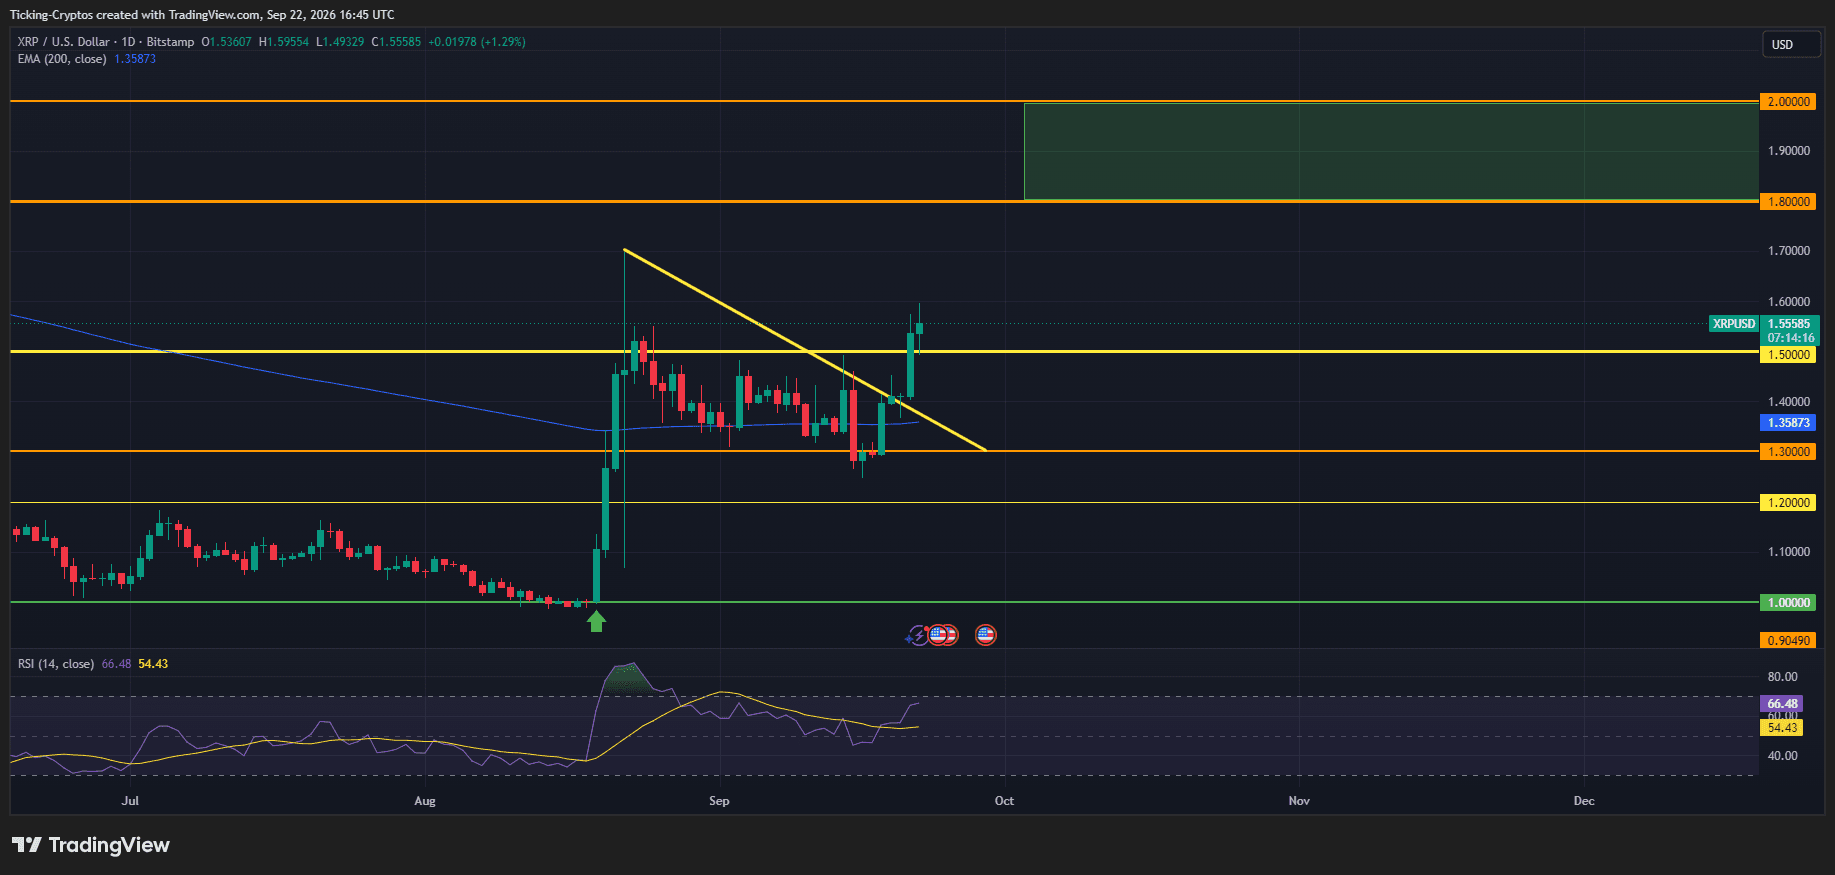
RSI backs the setup without screaming at anyone. It sits at 67.25 with its moving average at 54.49, so momentum is expanding but has not tipped into the overbought exhaustion that marked the top of the August candle. There is room to run before the indicator becomes a problem.
Where Is XRP Support If The Breakout Fails?
This is where discipline matters, because breakouts fail all the time.
The immediate line is $1.50. A daily close back below it would put this move firmly in the failed-breakout bucket, and the natural target from there is the $1.40 shelf where September spent most of its time.
Below that, $1.30 is the one that counts. It has held as support twice in the last month and lines up closely with the 200 EMA at $1.3589. Losing $1.30 on a daily close would hand the trend back to the sellers and reopen $1.20, with $1.00 as the structural floor that produced the entire August rally.
Track the levels live on the CryptoTicker XRP chart.
XRP Price Prediction: What Happens Into October?
Three scenarios, ranked by what the chart currently supports.
- Bullish (most likely while above $1.50): XRP consolidates between $1.55 and $1.60 for a few sessions, absorbs the profit taking, then pushes into $1.70. A clean break of $1.70 puts $1.80 on the table within weeks, with $1.90 to $1.95 as the extended target into late October.
- Neutral: The breakout stalls and XRP chops between $1.50 and $1.60 while RSI cools off. Frustrating, but healthy, and it builds the base for a second attempt at $1.80.
- Bearish: A daily close back under $1.50 traps the breakout buyers. Price slides to $1.40, then tests $1.30 and the 200 EMA together. That level decides whether the August recovery was a trend change or a relief rally.
The line to watch is simple. As long as XRP closes days above $1.50, the path of least resistance points at $1.80.
Of the 25 largest cryptocurrencies, on September 22, 2026 there are three you cannot buy directly against euros at any of the five trading venues we checked, and four more at exactly one. Anyone chasing a riser during the current rally therefore runs into a wall at a point that appears nowhere in the price rankings: the coin sits at number nine or number fourteen, but your euro cannot reach it.
cryptoticker.io compiled this analysis itself on September 22, 2026. What it means for your next order, which detours exist and what they cost is set out in this article.
What We Measured on September 22, 2026: Method, Sample and Limits
The method in one sentence: on September 22, 2026, between 09:48 and 09:52 UTC, we pulled the public trading pair directories of five trading venues active in the EU and checked, for each of the 25 largest cryptocurrencies, whether an active pair against the euro exists there.
We checked 25 coins against 5 trading venues, so 125 individual checks. The ranking of the 25 largest coins comes from CoinGecko's public market overview, retrieved on September 22, 2026 at 09:48 UTC. As trading venues we took Kraken, Bitvavo, Coinbase, Bitstamp and Bitpanda, because all five serve German customers and settle in euros.
A coin only counts as tradable if the directory lists a pair with the euro as the counter currency and that pair is flagged as active. A coin you can only buy against US dollars, against Tether or against bitcoin does not count as tradable in this analysis. That distinction is precisely the point, because it reflects what the euro in your bank account can reach without you swapping first.
What we could not check
Three gaps come with this, and we would rather name them ourselves. First, neobrokers such as Trade Republic, Scalable Capital or Bison have no public directory of their tradable assets that can be retrieved automatically; they are therefore missing from the sample, even though many investors in Germany buy precisely there. Second, at Coinbase we queried the public directory of the trading platform, not the offering in the retail app: in the app a purchase can run through an intermediate currency that does not appear in the order book directory. Third, Bitpanda's price directory lists precious metals and other assets alongside cryptocurrencies, which is why we only looked up the 25 coins on our list individually there and did not form an overall figure.
All the numbers in this article refer to this one retrieval moment. Trading venues add pairs and drop them again continuously; a finding from this morning may be out of date in two weeks.
The Result: Three of the 25 Largest Coins Have a Euro Pair at No Venue at All
Twelve of the 25 coins are available against euros at all five trading venues. They are the names you would expect: bitcoin, ethereum, XRP, Solana, Dogecoin, Cardano, Chainlink, Stellar, Uniswap, Bitcoin Cash, Avalanche and the stablecoin USDC. At the other end stands a group that ranks high in the table and barely features in euro trading at all.
| Euro trading venues in the sample | Coins |
|---|---|
| 5 of 5 | Bitcoin, Ethereum, XRP, USDC, Solana, Dogecoin, Chainlink, Cardano, Stellar, Uniswap, Bitcoin Cash, Avalanche |
| 4 of 5 | Tether, BNB, TRON, Hyperliquid, NEAR Protocol |
| 2 of 5 | Zcash |
| 1 of 5 | Monero, WhiteBIT Coin, USDS, Ethena USDe |
| 0 of 5 | Figure Heloc, Rain, LEO Token |
Seven of the 25 largest coins therefore have at most a single euro trading venue in this sample. Figure Heloc at number ten, Rain at number sixteen and LEO Token at number nineteen have none at all. For an investor in Germany, that means the purchase is not impossible, but it runs via a detour, and every detour has a price.
How the individual venues compare
Across the top 25, Kraken lists 22 coins with a euro pair, Bitpanda 18, Bitstamp 17, Bitvavo 16 and Coinbase 13. The spread between the broadest and the narrowest offering is thus nine coins, and it does not run along the lines of how well known the providers are.
Zcash, Monero and WhiteBIT Coin: Why It Is the Rally's Risers That Are Missing
Zcash sits at number nine on the survey date at $1,504, up 31.5 percent over the week (CoinGecko, September 22, 2026, 09:48 UTC). A coin of that size would normally be available everywhere. In our sample, two of five trading venues list it against euros.
Monero, at number thirteen, stands at $569.75 and has exactly one euro trading venue. Both are so-called privacy coins, cryptocurrencies whose protocol obscures the sender, the recipient or the amount of a transfer. The connection to the trading offering is no coincidence, and there is more on that shortly in the section on anti-money-laundering law. How the situation for Zcash is developing in concrete terms we set out in our article on buying Zcash despite the EU trading ban.
WhiteBIT Coin sits at number fourteen at $86.50 and likewise has only one euro trading venue in the sample. Here the explanation is a different one: WBT is a trading platform's own token, and such tokens are rarely quoted widely outside their own platform. The same pattern shows in LEO Token at number nineteen, which has no euro pair at any of the five venues checked.
Hyperliquid is the counter-example and shows that a young riser can indeed arrive: HYPE sits at number eleven and has four of the five euro trading venues. Anyone wanting to buy there should nonetheless know what applies at a trading venue without European authorisation; we described that in our piece on how Hyperliquid can be used from Germany.
Euro Pair, Quoting and the Broker Model: What Tradable Means Technically
A euro pair is an order book in which buyers and sellers of a cryptocurrency place their bids directly in euros. If it is missing, that does not automatically mean you cannot get the coin at that provider. It means your euro has to be turned into something else first.
There are two designs here that you should keep apart. A trading platform with an order book matches you against other customers; the price arises from their bids, and you see bid and ask separately. A broker, by contrast, quotes you a price itself and earns on the spread in between. Broker models often list a great many assets, because they do not need an order book per asset, only a source for the price.
For you that has one practical consequence. At a broker you will find more exotic names more often, but you pay a spread that you rarely see itemised. On a trading platform with a thin order book, by contrast, the mark-up is visible, sitting right in front of you as the gap between the bids. Which design your provider uses is set out in its fee overview; we have put the common models side by side in our crypto exchange comparison.
Coinbase Lists Only 13 of the Top 25 With a Euro Order Book: What That Means for Your Order
The most striking single finding of our survey concerns Coinbase. On September 22, 2026, the trading platform's public directory held exactly 33 base assets with an active euro order book, and 13 of them belong to the 25 largest coins. At Kraken, the same directory query returned 499 base assets with a euro pair, at Bitvavo 426 and at Bitstamp 111.
That figure needs explaining, and we do not want to make it bigger than it is. The number describes the order book offering of the trading platform, which is aimed above all at professional users. In the retail app the same provider can offer more coins, by having the purchase run internally through an intermediate currency. What is incurred in conversion along the way is usually not itemised separately for you as a retail client, and that is exactly why it is worth a look at the order book before you move a larger sum.
The action that follows is simple: look up the coin you want to buy in your preferred provider's directory before you open an account, and check whether the euro really is listed there as the counter currency. At many providers you will find this list on a public price page, for instance in Kraken's price overview.
The Detour via USDT or USDC: Fee, Spread and an Extra Taxable Event
If no euro pair exists, the usual route is a two-stage purchase. You first buy a stablecoin, a cryptocurrency whose price is pegged to a currency such as the US dollar, and then swap it into the coin you actually want. Technically that works reliably. It becomes expensive in three places at once.
What the detour costs
First, you pay a trading fee twice instead of once, because one order becomes two. Second, you pay the gap between the bid and the ask twice, and in the second step often in a thinner market. Third, the exchange rate shifts between the two steps if the stablecoin is pegged to the dollar and you started in euros. You bear that exchange rate movement without ever seeing it as a line item on a statement.
The fourth point is a tax one and is the most frequently overlooked. In Germany, swapping one cryptocurrency for another counts as a disposal of the first. The intermediate step via a stablecoin is therefore a taxable event in its own right that needs documenting, even if hardly any gain arises in arithmetic terms. We dealt with this point in more detail on May 25, 2026 in our article on stablecoins and tax; for day-to-day record keeping, one of the tools from our overview of crypto tax tools helps.
MiCA Authorisation and Anti-Money-Laundering Law: Why a Coin Disappears From Euro Trading
That it is privacy coins of all things that are thinly represented in euro trading has a legal background. Providers offering crypto asset services in the EU have needed authorisation under the European regulation on markets in crypto assets, MiCA for short, since the end of 2024. Which activities fall under it and who supervises them is described by BaFin on its page on crypto asset services.
With the authorisation come obligations to make transfers traceable. With a cryptocurrency whose protocol obscures amounts or addresses, those obligations are hard to meet, and several providers have therefore removed the affected pairs from their European offering. What else follows from MiCA authorisation we set out in our overview of the MiCA obligations for crypto companies.
The distinction between trading and holding matters here. The fact that a coin is no longer tradable against euros at one provider forbids you neither from holding it nor from selling it elsewhere. It narrows the route, and it narrows it more for the future than for today.
Checking Liquidity and Spread: How to Spot a Thin Euro Market
Having a euro pair is one question, having a usable euro pair is another. Liquidity here means a market's ability to absorb an order without the price running away noticeably. There are three signs you can read yourself before buying.
First, look at the gap between the highest bid and the lowest offer, the spread. If it is well above half a percent for a large coin, the market is thin. Second, look at the depth of the order book, that is how much volume sits in the next price levels; if your planned order size clears several levels at once, you pay a mark-up that appears in no fee table. Third, check the turnover of the past 24 hours specifically in the euro pair and not in the dollar pair of the same coin, because the two can differ widely.
As a practical cross-check, a small test order helps before you move the actual sum. If the executed price deviates noticeably from the one displayed, you have your answer. Providers with European authorisation and a euro account we have compiled in our overview of regulated crypto exchanges.
Delisting Risk: What Happens if Your Venue Drops the Euro Pair
A coin with only one euro trading venue has no cushion. If that single provider drops the pair, nothing is left for you in euros, and in our sample that affects Monero, WhiteBIT Coin, USDS and Ethena USDe. A delisting, that is the removal of a trading pair, usually follows a fixed pattern: the provider announces it, halts trading on a cut-off date and then sets a deadline by which you can still withdraw your balance.
That second deadline is the more important one, and it is missed regularly. What happens technically in the process and which routes remain to you after trading stops we described in our article on what happens to your tokens in a delisting.
The precaution against it is unspectacular. If you hold a coin that hangs on a single euro pair in Europe, set up that provider's notifications and check in advance whether you could withdraw the coin to your own wallet. Both cost you ten minutes once and spare you, in an emergency, a deadline you only learn about afterwards.
Four Metrics Before the Order: The Short Version
Before you chase a name in a rally that has just appeared in the top 25, four checks are worth it. First: does your provider offer a pair against euros at all, or only against dollars and stablecoins? Second: how many providers list this euro pair, and what happens if one of them steps out? Third: how wide is the spread in precisely that pair at the time of day when you want to trade? And fourth: does your purchase run via an intermediate swap that you have to record for tax purposes?
None of these questions is hard to answer. All four are readily skipped, because the price is running and opening an account is quicker than checking.
Checking Your Buying Route: What to Take Away
- Look the coin up before you open an account. Check in your preferred provider's public price directory whether a euro pair really is listed there. If the provider does not suit your selection, you will find alternatives with a euro account in our crypto exchange comparison.
- Count how many euro pairs your coin hangs on. With a single trading venue, a fallback plan belongs in place before you buy, not after. Which providers are authorised in Europe and settle in euros is set out in our overview of regulated crypto exchanges.
- Record the intermediate swap from the start. If your purchase runs via a stablecoin, log both steps with date, quantity and price. A tool from our overview of crypto tax tools takes that off your hands, as long as you set it up before the first swap.
(As of September 22, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
The information provided in this article is for informational purposes only and does not constitute financial advice. Investing in cryptocurrencies carries a high level of risk.
A trading demo account is a trading account with play money: you place orders at real prices, but no money moves and no trade reaches an exchange. The point is not to practise making profits, but to make mistakes where they cost nothing. European regulators have put a figure on how expensive the alternative is: when ESMA adopted restrictions on CFD trading with retail clients on March 27, 2018, it cited analyses by national authorities finding that 74 to 89 percent of retail client accounts lost money, on average between 1,600 and 29,000 euros per client. This article explains what a demo account can do, how a broker's demo account differs from an independent simulator, and how you can start with 10,000 euros of play money at real prices without signing up.
What Demo Trading Is and What It Is Not
Demo trading means the prices are real and the execution is simulated. You see the same charts as a trader using real money, you place the same order types, and the account calculates profit, loss, fees and, with leveraged products, liquidation too. The difference lies in three points:
- No market contact. Your order moves no price, because it never reaches an exchange. In liquid markets such as bitcoin or ethereum that is no problem for retail position sizes; in thin markets it is.
- No pain. A 20 percent drawdown in play money is a number; in a real account it is a feeling. That is why demo accounts train discipline only in part.
- No barrier to starting over. A demo account can be reset, a real-money account cannot. Anyone who starts again after every loss learns how to start again, not how to handle a loss.
What a demo account does do very well, on the other hand, is test your rule set. Setting a stop loss before entering, calculating position size from your risk, keeping to a daily limit. Whether those rules hold shows up after two weeks with play money just as reliably as with real money, only without the bill.
Trading Demo Account Without Signing Up: How to Start
Most demo accounts require registration first. The CryptoTicker Trading Hub takes the other route, as of September 22, 2026:
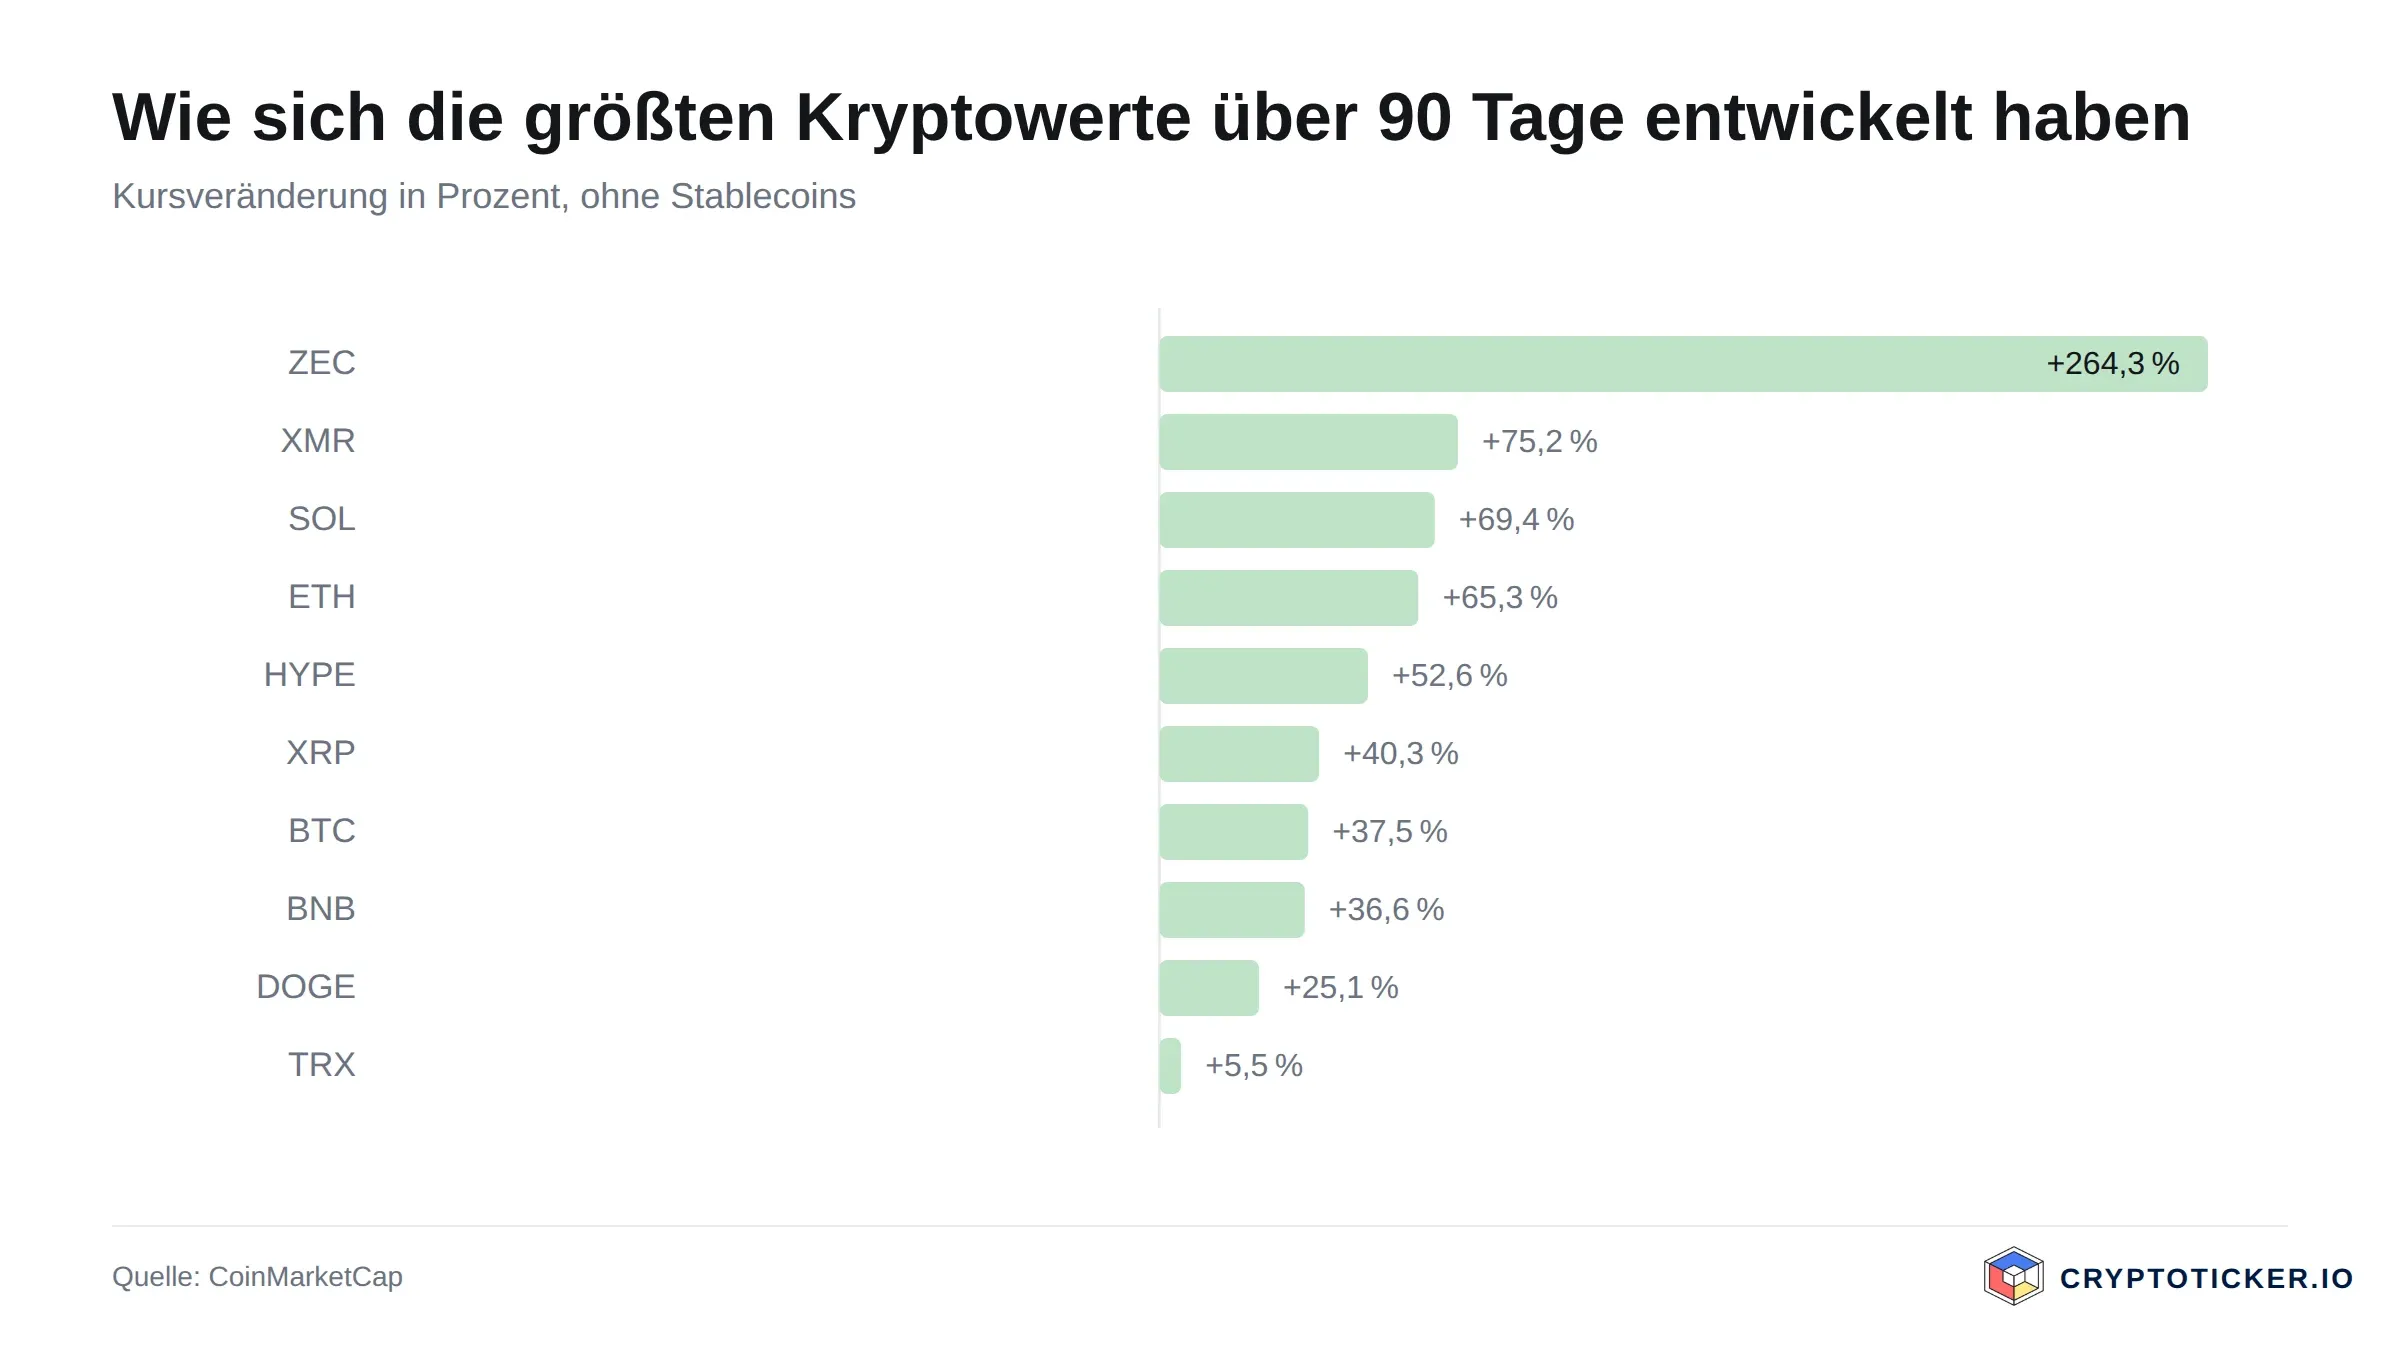
- Open the cockpit. No account, no email address, no payment details. 10,000 euros of play money are ready and the prices of 50 coins come in live from the exchange.
- Place your first three trades without an account. An order ticket with stop loss and take profit, a chart with indicators, long or short, selectable leverage. Fees are calculated and reduce your result, so that you do not learn a strategy that only works without costs.
- Create an account if you want to continue. After the third trade, one click creates the account, without an email address and password; you can add a mail address or Google sign-in later so that you find your progress again on a second device. There are no payment details.
- Choose ranked or practice mode. Ranked, you trade in one of two leagues, up to 10x or up to 100x leverage, and appear under your pseudonym on the leaderboard as soon as you make your profile public. Unranked, you practise without elimination for as long as you like.
All of it runs in the browser, on a phone as on a computer, and can be added to the home screen as a web app. An app from the store is not needed.
Broker Demo Account or Independent Simulator?
Both simulate trades at real prices. The difference lies in whom the demo account serves. The statements about broker demo accounts apply to the market as a whole, not to any particular provider; individual brokers handle it differently.
| Feature | Broker demo account (typical) | Independent simulator, such as the Trading Hub |
|---|---|---|
| Sign-up | usually registration with an email address, often a phone number too | first three trades without an account, then one click; mail address optional |
| Duration | frequently time-limited, around 30 days, sometimes extendable | no expiry date; ranking in monthly periods, progress kept until the account is deleted |
| Starting capital | often 10,000 to 100,000 euros virtual, sometimes freely selectable | 10,000 euros, so that position sizes stay realistic |
| Prices | the broker's real prices, in part with the broker's spreads | real exchange prices, fees are calculated |
| Purpose | getting to know the platform, then moving to a real-money account | practising, measuring on the leaderboard, no move to real money needed |
| Products | the broker's: CFDs, forex, equities, crypto | 50 coins, long and short, leverage up to 100x |
| After the demo | advertising for the real-money account, often with a deposit bonus | no real-money account exists |
A broker demo account is the right choice if you have already settled on a provider and want to get to know its interface. An independent simulator is the right choice if you want to learn the craft before you settle on a provider. Anyone who uses both in that order arrives at the broker with routine rather than with hope.
What to Look For in Any Demo Account
- Realistic starting capital. Anyone practising with 100,000 euros of play money who later deposits 2,000 euros has learned position sizes they will never trade. Set the demo account to the amount you would actually commit later, or convert every position to that amount.
- Real prices, not delayed ones. A demo account with a 15-minute price delay trains the wrong reflex. Ask whether the prices are live.
- Fees and spread in the demo. A demo account without fees makes every strategy more profitable than it is. At 20 trades a day, 0.1 percent per execution decides between profit and loss.
- No time pressure. A demo account that expires after 30 days pushes you towards a real-money account before the rules have settled. Four weeks are the beginning, not the end.
- The same rules as later. One percent risk per trade, stop before entry, daily limit. Anyone who trades differently in the demo account than planned is measuring nothing.
Crypto Demo Account: Three Differences From Equities and Forex
A crypto demo account differs in three respects from a demo account for equities or currencies, and all three are worth experiencing with play money before they cost money:
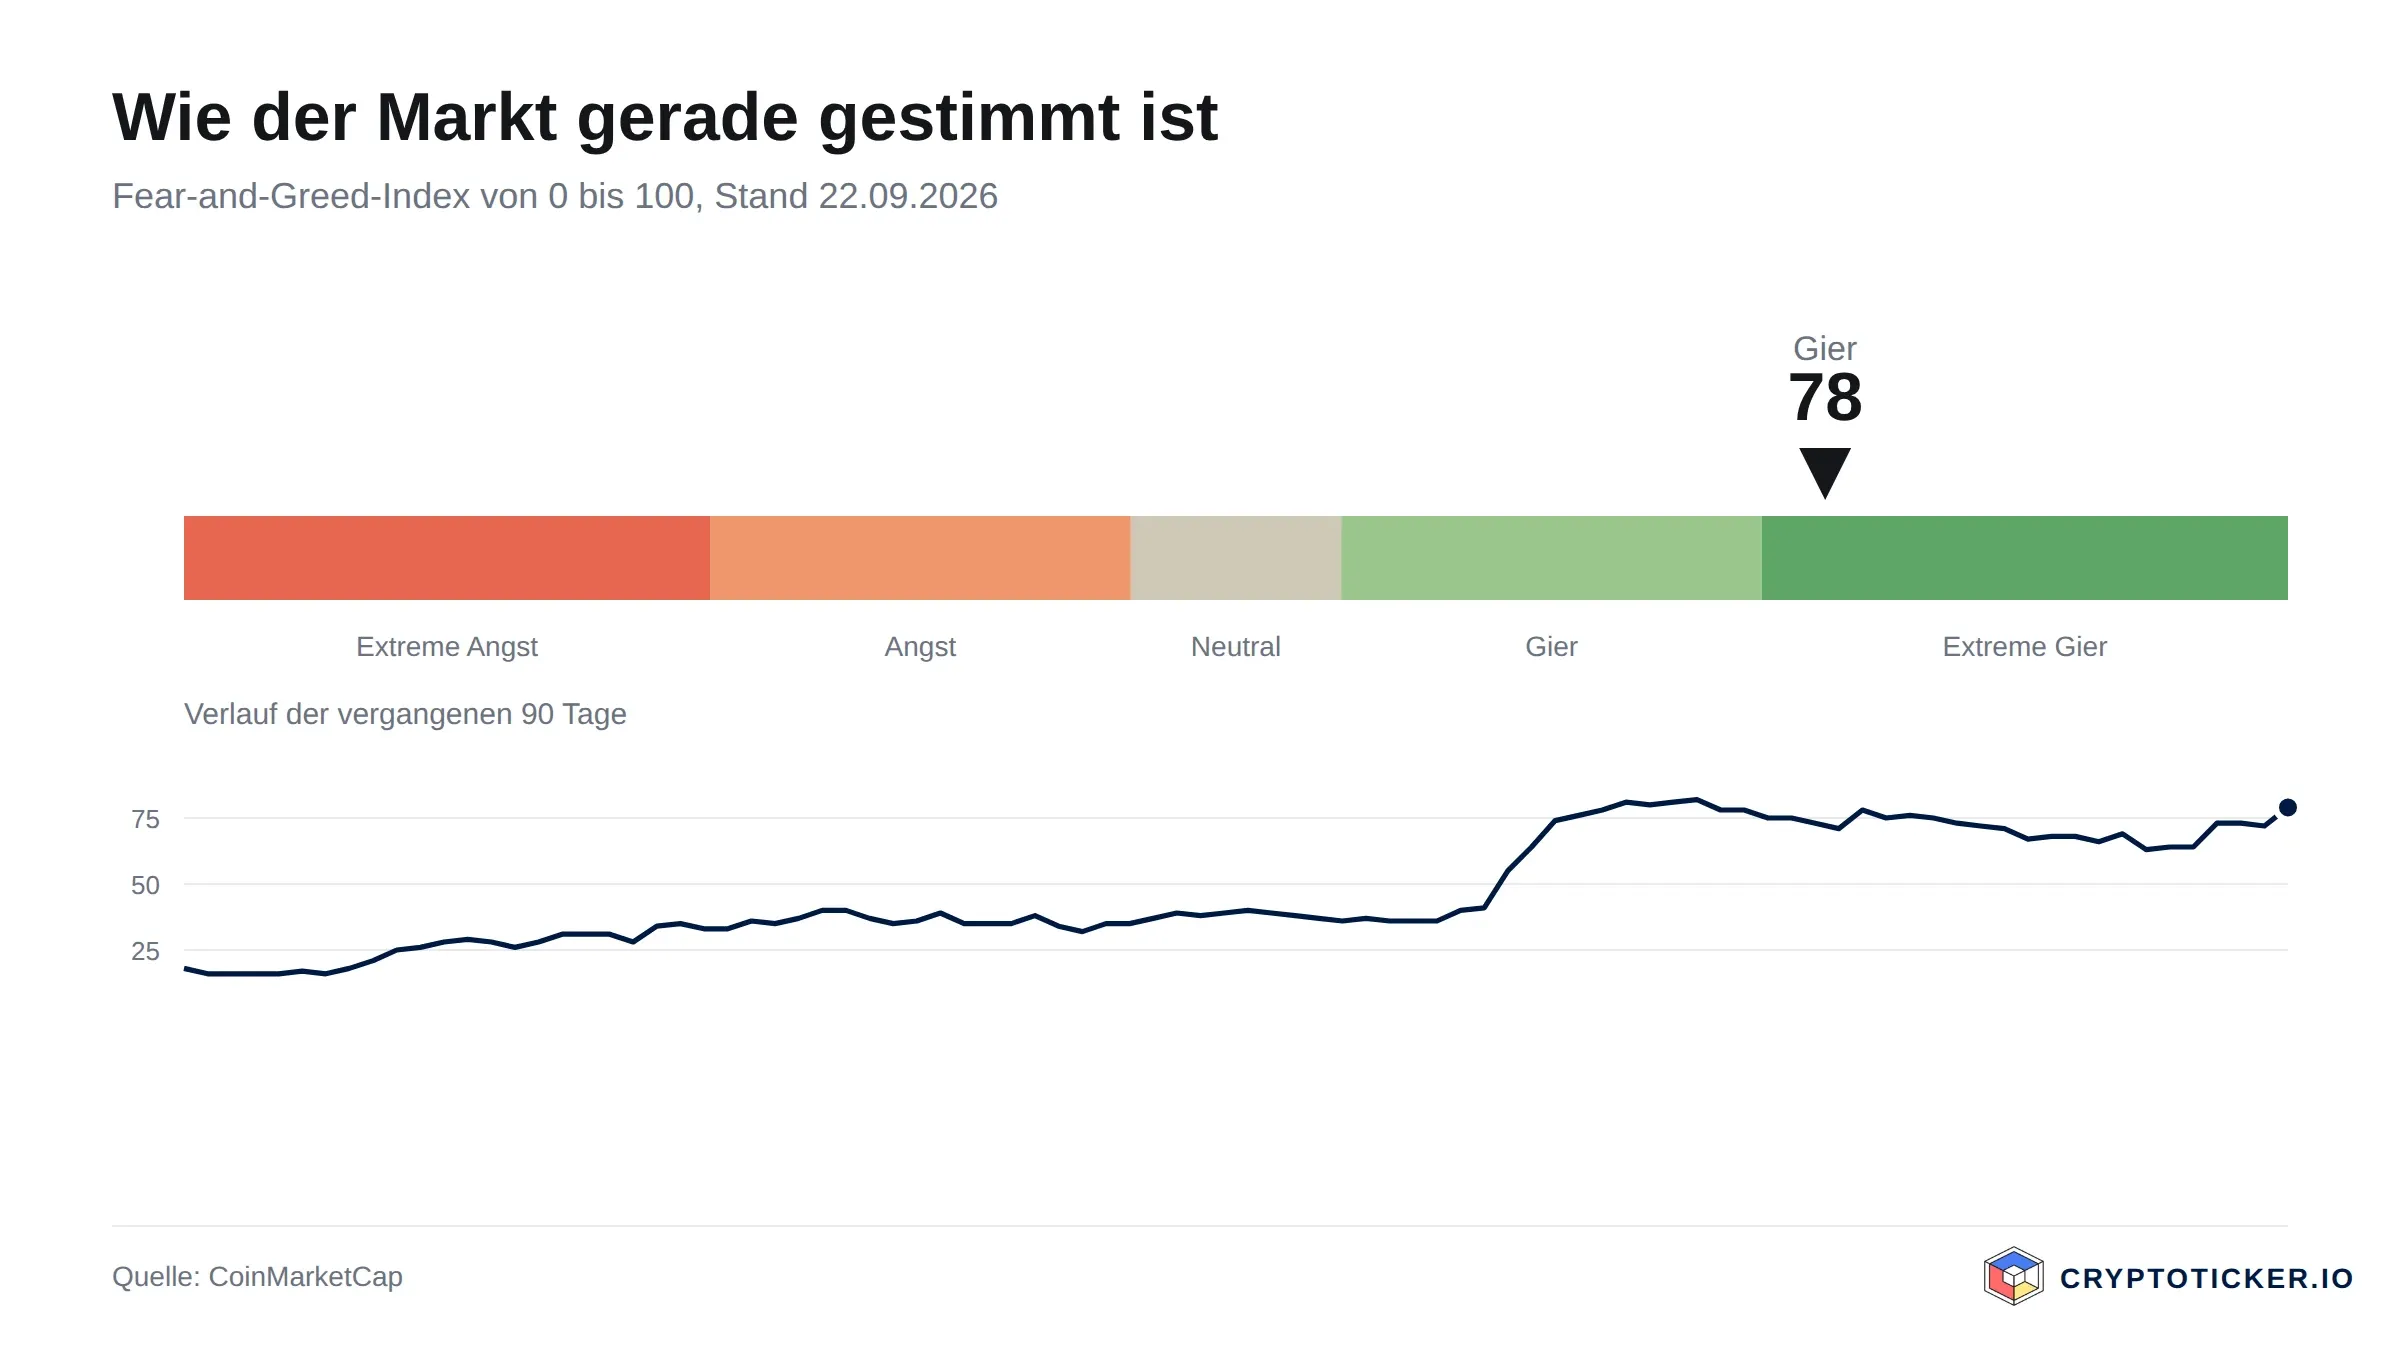
- No close of trading. Bitcoin trades around the clock, seven days a week. A stop that is not triggered overnight is a bigger problem than on Xetra, where trading ends at 5:30 pm on weekdays.
- Leverage up to 100x. Perpetual futures on crypto allow leverage that does not exist for retail clients in equities. Tenfold leverage means that roughly ten percent of adverse movement is enough to liquidate the position, before fees are even counted. How perpetuals work is set out in the comparison of the best perp DEXs.
- Swings of ten percent in a day. They are normal with smaller coins. A stop that would be generous with equities is triggered constantly here; the position size has to be correspondingly smaller.
From the Demo Account to a Real Account
The switch is only worth it once three numbers hold up over several weeks: the number of rule breaches (zero), the largest drawdown (known and endured) and the result in relation to it (the Trading Hub calculates this as the CT score). Then the question is not which provider is the best, but which suits your style: a regulated exchange for spot without leverage, a broker or perp DEX for derivatives. Fees, regulation and test reports are in the comparison of the best crypto brokers and in the comparison of the best crypto exchanges. Your first real commitment should be smaller than the play money, not larger.
Frequently Asked Questions
What is a trading demo account?
A trading account with play money: real prices, simulated execution, no money moving. It serves to test the platform and your rule set before real capital is in the market.
Is there a trading demo account without signing up?
Yes. In the CryptoTicker Trading Hub the first three trades work without an account, with 10,000 euros of play money at real prices. After that an email address secures your progress, as of September 2026.
Are demo accounts free?
As a rule, yes. Brokers finance them as a route to the real-money account. The Trading Hub is free during the current trial month. Everything is free to play until the first ranked season starts; after that, taking part in the ranking costs from 29 euros a month according to the terms of participation, while practising without a ranking stays free (as of September 22, 2026). A prize pool has been announced for the ranked seasons.
How long should I practise in a demo account?
Until you keep to your rules for several weeks without a breach and know your largest drawdown. A demo account that expires after 30 days is often too short for that.
Which demo account is suitable for crypto?
One with real prices around the clock, selectable leverage and calculated fees, so that liquidation and costs are realistic. The Trading Hub offers 50 coins, long and short, and two leagues up to 10x and up to 100x leverage.
Do gains in a demo account count anywhere?
Not as money. In the Trading Hub they count on the leaderboard, scored as the CT score, the result in relation to the largest drawdown.
The basic terms, the position-size calculation and the four-week practice plan are in our guide to learning to trade; anyone planning a first real trade after the demo account will find fees, regulation and leverage limits in the comparison of the best crypto brokers.
Sources
- ESMA, press release of 27.03.2018: "ESMA agrees to prohibit binary options and restrict CFDs to protect retail investors", https://www.esma.europa.eu/press-news/esma-news/esma-agrees-prohibit-binary-options-and-restrict-cfds-protect-retail-investors
- Deutsche Börse, Xetra trading calendar and trading hours, https://www.cashmarket.deutsche-boerse.com/cash-de/Handel/handelskalender-und-zeiten
- CryptoTicker Trading Hub, home page and terms of participation, https://trading.cryptoticker.io/ and https://trading.cryptoticker.io/agb (accessed on 22.09.2026)
Decrypt
Head of cryptography Yehuda Lindell says the exchange is designing custody that can adapt to whatever post-quantum signing scheme Bitcoin adopts.
Galaxy Research says white-hat actors consolidated coins tied to the exploit into a fresh address tagged for a "Crypto Recovery Trust," though the funds represent just 2.8% of the total haul.
OpenAI cut prices 50% on its mid-tier models the same day Anthropic shipped a cheaper flagship, escalating a rivalry now measured in minutes.
A stretched but firmly bullish Bitcoin chart is riding the same tailwind lifting stocks: falling oil, a record Nasdaq, and a Fed that hiked rates while quietly pumping liquidity into the system.
Bernstein now projects prediction markets will handle $10 trillion a year by 2035, up from its own $1 trillion by 2030 forecast made just five months ago.
U.Today - IT, AI and Fintech Daily News for You Today
Bitcoin is having its best September in 14 years, defying the cryptocurrency’s historically weak seasonal trend as its powerful recovery pushes the price toward the $90,000 level.
Elon Musk has revived one of the strangest moments of the NFT boom, laughing at a throwback to his brief 2022 stint with a Bored Ape Yacht Club profile picture that sent ApeCoin soaring.
For the first time in 3 years, Bitcoin breaks above $80,500, flashing the rare long-term on-chain signal behind the 2019 and 2023 bull markets.
XRP has recovered sharply from its September low, while renewed ETF flows and improving technical momentum have brought the "Uptober" narrative back into focus.
Bitcoin holders are showing little appetite for profit-taking even after BTC surged 47% from its July low.
Blockonomi
TLDR
- Ionis shares rise 2.58% after positive Phase 3 ulefnersen trial results emerge.
- Ulefnersen meets the FUSION primary endpoint with strong statistical significance.
- The FUS-ALS study also records improvements across several key secondary endpoints.
- Otsuka plans FDA discussions and explores expedited regulatory approval pathways.
- Ionis remains eligible for milestone payments and royalties under the Otsuka deal.
Ionis Pharmaceuticals shares rose 2.58% to $46.06 after the company announced positive Phase 3 results for ulefnersen. The experimental medicine met its primary endpoint in patients with a rare genetic form of amyotrophic lateral sclerosis. The outcome strengthens Ionis’ neurological pipeline and supports the next regulatory steps for the treatment.
Ionis Pharmaceuticals, Inc., IONS
Phase 3 FUSION Trial Meets Primary Endpoint
Ionis and Otsuka Pharmaceutical reported positive topline results from the Phase 3 FUSION study evaluating ulefnersen. The trial involved patients with ALS caused by mutations in the fused in sarcoma gene, known as FUS-ALS. Researchers developed ulefnersen to target the genetic cause of this rare and rapidly progressing form of ALS.
The study met its primary endpoint after showing statistically significant improvements against placebo across function and survival measures. Researchers assessed death, permanent ventilation, rescue treatment, and changes in the ALS Functional Rating Scale Revised. The primary analysis produced a p-value of 0.0005, supporting the statistical significance of the findings.
Ulefnersen also delivered statistically significant improvements across several important secondary endpoints included in the trial. These measures included serum neurofilament light chain levels and time to death, ventilation, rescue, or disease-related withdrawal. The companies also reported favorable safety and tolerability, while most adverse events remained mild or moderate.
Positive Results Advance Ulefnersen Toward Regulatory Review
The successful trial gives Ionis and Otsuka important clinical evidence as they prepare for discussions with global regulators. Otsuka plans to review the FUSION findings with the U.S. Food and Drug Administration. The company will also discuss possible expedited submission pathways with other health authorities.
Both companies plan to present detailed FUSION results at a future medical meeting. They also intend to submit the complete findings for publication in a peer-reviewed medical journal. Additional prespecified and exploratory analyses will further examine ulefnersen’s effects across the study population.
Ionis licensed ulefnersen to Otsuka in 2024 through a collaborative development and licensing agreement. Ionis received an upfront payment and remains eligible for additional regulatory and commercial milestone payments. The agreement also gives Ionis tiered royalties on future net sales if the treatment reaches the market.
FUSION Expands Ionis’ Genetic ALS Program
FUSION used a global, randomized, double-blind, placebo-controlled design to assess ulefnersen’s safety and effectiveness in FUS-ALS. Participants received either ulefnersen or placebo during a 72-week blinded treatment period. They later entered an open-label extension where all participants received ulefnersen.
The primary analysis included 73 participants and combined clinical function with several survival-related outcomes. Researchers also evaluated respiratory function, muscle strength, quality of life, and key biological markers. These additional measures will help define the treatment’s wider clinical profile during further analysis.
The program expands Ionis’ work in genetically targeted treatments for rare forms of ALS. Its earlier neurological development work also included QALSODY, which targets a different genetic cause of the disease. Ulefnersen now adds a successful Phase 3 program focused specifically on patients with FUS-related ALS.
The post Ionis Pharmaceuticals, Inc. (IONS) Stock: Surges as Phase 3 ALS Trial Delivers Positive Results appeared first on Blockonomi.
TLDR
- White hats rescued 52.37 BTC worth more than $4.5 million from the Coldcard exploit.
- Crypto Recovery Trust now holds the rescued Bitcoin for verified victims to reclaim.
- Galaxy Digital tracked 1,789.28 BTC, worth about $154.1 million, lost in the attacks.
- Coinkite linked the exploit to weak seed generation caused by a firmware flaw.
- Coldcard advised users to update their firmware or move funds from vulnerable devices.
The Coldcard hack has entered a recovery phase after white-hat researchers secured 52.37 Bitcoin in a Wyoming trust. Galaxy Digital researcher Alex Thorn said the funds exceed $4.5 million. Crypto Recovery Trust now controls the address and plans to return claims.
COLDCARD WHITE HAT MOVES FUNDS TO TRUST
52.37 BTC comprised of coins from Wave 2, Footprints AA, AU, AX consolidated into a fresh address with an OP_RETURN "claim:cryptorecoverytrust dot com" in block 967,948
these white hatted funds represent 2.8% of the coldcard exploit pic.twitter.com/c5eYeQMxHQ
— Alex Thorn (@intangiblecoins) September 21, 2026

Coldcard Hack Funds Enter Recovery Trust
Thorn said the rescued Bitcoin represents about 2.8% of funds connected to the exploit. Nick Bax of Ump Labs confirmed he helped protect about 50 BTC. He said thieves were close to taking the funds.
The transfer gives affected Coldcard users a route to recover losses. Another security case saw an MEV bot stop an Ethereum wallet exploit before an attacker could drain $7.8 million. KelpDAO froze the destination address for 24 hours.
Firmware Bug Exposed Wallet Seeds
The attacks began on July 31 and targeted Bitcoin held through Coinkite’s Coldcard hardware wallets. CoinKite traced the weakness to a firmware bug affecting seed generation. The flaw forced some devices to rely on a software random generator.
Attackers could use predictable seed data to identify wallet credentials and access funds. Galaxy Digital tracked 1,789.28 BTC lost during the attacks. That amount equals about $154.1 million at Bitcoin prices.
Users Shift Bitcoin After Attacks
CoinKite urged users to update affected software or transfer funds away from vulnerable devices. Some users moved Bitcoin to other storage services, including exchanges. The company said the bug remained unnoticed as more product releases carried the faulty code.
Crypto firms have faced other security cases this month. A Revolut customer data breach exposed information from 680 customers after fraudulent requests bypassed verification checks. The company reported the incident to regulators during a security review.
Trust Starts Victim Recovery Process
Crypto Recovery Trust now holds the rescued assets while it verifies ownership claims from affected users. The Wyoming structure provides a legal process for safeguarding funds during recovery. White hats can use that process while investigators continue tracing stolen Bitcoin.
Security threats also continue across the wider crypto market. A North Korean crypto theft campaign used fake job offers to compromise more than 30,000 devices. Researchers linked the operation to theft from over 7,000 cryptocurrency wallets.
Investigators continue reviewing the Coldcard hack and tracing addresses tied to stolen funds. CoinKite has urged affected users to follow security guidance. The recovery trust may return rescued Bitcoin after it confirms rightful ownership.
The post White Hats Rescue $4.5M Bitcoin From Coldcard Exploit appeared first on Blockonomi.
TLDR
- Dogecoin gained nearly 20% over the past week and briefly touched the $0.10 level.
- Analysts are watching $0.10 as a key resistance zone before targets near $0.1175 and $0.15.
- Some market analysts have issued much higher DOGE targets between $1 and $3.
- Whales bought more than 240 million DOGE earlier this month, adding to bullish market activity.
- Rising exchange inflows could increase short-term selling pressure and weaken DOGE’s recent recovery.
Dogecoin has climbed nearly 20% over the past week and briefly touched $0.10, a level last seen in early June. The interbank Dogecoin price trend has drawn attention as traders watch whether DOGE can hold recent gains. Its market value has also risen to about $15.2 billion, placing it among the largest cryptocurrencies.
DOGE now trades close to the $0.10 level after recovering from weaker prices earlier this month. Several market analysts see the area as an important test. Their forecasts vary widely, ranging from modest gains above current resistance to much larger long-term targets. Trading volume has also increased, giving market participants more activity to assess as DOGE approaches levels that previously limited gains.
Analysts Map Dogecoin Resistance Levels
Analyst Cyriptoman4 said a clear move above $0.10 could open a path toward $0.1175 and $0.15. Recent Blockonomi coverage also tracked Dogecoin whale accumulation, reporting that large wallets bought more than 240 million DOGE during a recent pullback.
BSC Gems Alert pointed to a higher-low price structure and said DOGE is pressing against the top of a descending pattern. The analyst said a break and hold above $0.22 could support a move toward higher resistance. A loss of support, however, would weaken that setup.
$1 Dogecoin Targets Remain Speculative
Other analysts have published much higher targets. X user Bark said Dogecoin has started a move toward $1. MikybullCrypto also expects a stronger advance and cited a possible $1 to $3 range. These projections remain analyst forecasts rather than confirmed price outcomes.
Recent market data provides a more measured reference point. As reported earlier, DOGE resistance near $0.09 remained a key hurdle last week, while buyers repeatedly defended the $0.08 area. DOGE later moved above that resistance as market demand improved.
Whale Buying Meets Exchange Selling Risk
Large holders bought more than 240 million DOGE earlier this month. That activity reduced the amount held outside major whale wallets and attracted attention from traders. Moreover, a Dogecoin breakout setup near $0.0885 to $0.09 is forming as buying activity strengthens.
Selling risk remains present. CoinGlass data shows exchange inflows exceeded outflows during recent sessions. Transfers to centralized exchanges can increase the amount of DOGE available for sale. Traders are therefore watching whether the interbank Dogecoin price can stay near $0.10 while buying demand absorbs any added supply.
The post Dogecoin Price Nears $0.10, Can Bulls Push Higher? appeared first on Blockonomi.
TLDR:
- Tether says MiCA’s 60% bank-deposit rule was a key reason it declined to seek authorization in the EU.
- MiCA requires significant stablecoins to keep at least 60% of reserve funds in commercial bank deposits.
- Tether reported $184.6B in USDT outstanding, with assets exceeding liabilities by about $4.11B in Q2.
- EU central banks now want fixed deposit thresholds replaced with one- and five-day liquidity requirements.
Tether’s refusal to seek European authorization is gaining renewed attention after central banks questioned one of the rules behind the company’s decision. CEO Paolo Ardoino said the issuer avoided licensing under MiCA because significant stablecoins must place at least 60% of reserves in commercial bank deposits.
He has argued that such concentration introduces counterparty risk instead of strengthening reserve safety. That position now overlaps partly with concerns raised by the ECB and national central banks across the EU. They recommended removing fixed deposit thresholds, although existing requirements remain unchanged.
Tether MiCA Exit Centers on 60% Bank Reserve Rule
MiCA requires e-money token issuers to hold at least 30% of backing funds in deposits with credit institutions. However, the threshold increases to 60% once a stablecoin receives significant status.
The remaining reserves can include secure and highly liquid assets, giving issuers some flexibility outside the banking system. Still, Ardoino has opposed mandatory concentration in commercial deposits.
His argument centers on the possibility that a bank failure could temporarily trap reserves needed to process stablecoin redemptions. The 2023 collapse of Silicon Valley Bank provided a prominent example of that exposure.
Circle disclosed that $3.3 billion backing USDC was held at the failed lender when regulators closed the bank. The episode briefly intensified concerns over reserve access and stablecoin liquidity.
The ECB has also cited that event while assessing the risks created by deposit requirements. It said bank defaults could expose issuers to losses while strengthening links between crypto markets and lenders. Tether, however, follows a different reserve structure.
At the end of June, the company reported $184.6 billion of USDT outstanding. Its reserves were concentrated mainly in U.S. government-backed instruments and short-term liquidity facilities. Meanwhile, reported assets exceeded liabilities by approximately $4.11 billion.
ECB and EU Central Banks Push for Liquidity-Based Rules
The European System of Central Banks has now recommended dropping fixed minimum percentages for stablecoin reserves held as commercial bank deposits. Instead, it proposed liquidity requirements based on assets capable of maturing within one working day and five working days.
However, the central banks reached that position through a broader financial-stability concern. They warned that stablecoin growth could change the composition of funding held by European lenders. Stable retail deposits could increasingly be replaced by larger deposits from issuers.
Those balances could also prove more volatile during periods of heavy redemptions. A widespread stablecoin run could therefore force issuers to withdraw substantial bank deposits quickly, potentially adding liquidity pressure to exposed institutions.
Regardless, the recommendation does not change MiCA immediately. Any revision would still require the EU’s regulatory process to amend the existing framework.
Consequently, the 30% and 60% deposit thresholds remain effective. Tether also remains without MiCA authorization for USDT despite growing official scrutiny of the rule behind its decision.
The post Tether Says MiCA’s 60% Reserve Rule Drove EU Exit as ECB Seeks Change appeared first on Blockonomi.
TLDR
- Canada’s Big Six banks are exploring a shared interbank tokenized deposit system for faster money transfers.
- The first phase will test tokenized deposit movement between participating Canadian financial institutions.
- The system could support 24/7 programmable payments while keeping customer funds within regulated banks.
- Bank of Montreal, CIBC, National Bank, RBC, Scotiabank, and TD Bank Group are part of the joint venture.
- The project remains exploratory, with no confirmed launch date or final commitment to issue tokenized deposits.
Canada’s six largest banks are exploring an interbank tokenized deposit system that could move Canadian dollars faster between financial institutions. The project brings Bank of Montreal, CIBC, National Bank, RBC, Scotiabank, and TD Bank Group into one joint venture.
The banks plan to test transfers of tokenized deposits before connecting the system with other digital asset projects. They said the model could support faster, programmable payments while keeping customer funds inside the regulated banking system.
Interbank Tokenized Deposit Plan Takes Shape
The first phase will focus on moving tokenized deposits between participating banks. More Canadian lenders could join later. The banks have not committed to issuing a tokenized deposit, and they have not announced a launch date.
Tokenized deposits represent money that customers already hold at banks. They differ from stablecoins issued by crypto companies. A shared network could allow banks to process payments around the clock while retaining existing banking controls and oversight.
Banks Test Digital Payment Networks
The Canadian project follows similar work in other markets. A recent U.S. Bank stablecoin pilot used Stellar for a live cross-border payment between bank entities in North America and Europe.
Canada has also tested tokenized settlement through Project Samara. In March, the Bank of Canada, RBC, and TD issued, traded, and settled a C$100 million bond using tokenized wholesale Canadian dollars on distributed-ledger infrastructure. The test showed how regulated institutions can pair digital settlement with financial controls and processes.
Tokenization Efforts Extend Across Markets
The new bank venture adds another route for Canadian-dollar activity on blockchain networks. It also places commercial banks directly beside stablecoin issuers as both groups develop new digital payment and settlement systems.
Europe is moving on a related track. The European Central Bank recently introduced Pontes for tokenized asset settlement using central bank money. The platform connects distributed-ledger networks with the Eurosystem’s existing TARGET payment infrastructure.
Canada is also building a domestic stablecoin market. Shopify and National Bank of Canada backed a regulated digital Canadian dollar in May. Meanwhile, Coinbase and Stablecore expanded digital asset services for community banks and credit unions in the United States.
The six-bank effort remains exploratory. Its next steps will depend on testing, technical design, regulatory requirements, and whether participating banks decide to move from trials to a common interbank tokenized deposit network.
The post Canada’s Largest Banks Eye Shared Tokenized Deposit Network appeared first on Blockonomi.
CryptoPotato
Bitcoin (BTC) slipped toward $85,000 on Tuesday after briefly climbing above $87,000, putting its latest recovery under pressure. The move came after a sharp rebound from last week’s low near $75,000, when BTC fell below its September trading range.
That recovery followed a period of weakness. According to the latest Bitfinex Alpha report, Bitcoin had spent much of September between roughly $77,100 and $81,300 before breaking lower. The market then reversed sharply, with Bitcoin gaining 5.9% on September 18 as strong buying and ETF inflows pushed prices higher.
Spot Buying Supports Rally
The rebound carried BTC above the previous range and brought $85,000 into focus as an important level. Bitfinex analysts had identified that price as the first major test for the recovery.
Bitcoin later moved toward $87,000 before giving back some of its gains. Spot buying drove much of the move, but several indicators linked to sustained rallies remain weak. Trading volume has yet to show strong follow-through, while open interest remains relatively subdued.
Short covering also contributed to the rally as traders who had bet on lower prices bought Bitcoin back. Such buying can accelerate a recovery, but its effect may fade if fresh demand does not continue.
Corporate Demand Adds to Bitcoin’s Recovery
Corporate Bitcoin holdings are also receiving attention as the price moves above the estimated average purchase cost of about $80,500. Recent disclosures from Strategy and Strive showed additional Bitcoin purchases. This suggests corporate demand could become more active after slowing earlier this year.
Beyond corporate buying, investors are watching whether broader demand can support the recovery. Coin-denominated open interest remains subdued, while short-term holder exchange transfers stay below roughly 20,000 BTC daily. A sustained level below that threshold could point to lower selling pressure.
The next major test comes on September 25, when a large options expiry could add volatility and selling pressure. A sustained move above $85,000 would keep the recovery in focus, while a drop below $81,300 could return BTC to its previous range.
If selling intensifies, $77,100 remains an important lower boundary. Higher U.S. real yields also remain a challenge, with the yield recently near 2.68%. This keeps broader financial conditions relevant as the apex coin attempts to hold its recovery.
The post Bitcoin’s Rally Above $87,000 Faces Fresh Tests: Bitfinex Alpha appeared first on CryptoPotato.
Cardano has joined the x402 payment standard through an official SDK integration, allowing applications and AI agents to pay for API calls and other online services using ADA or Cardano native tokens.
The rollout puts the network alongside Solana and XRP Ledger in the emerging market for automated internet payments, while ADA’s price has climbed about 6% in 24 hours.
Cardano Adds x402 Support for AI Agent Payments
The Cardano Foundation announced on September 21 that the x402 integration was available through npm, giving developers a way to build applications and AI agents that send and receive ADA or Cardano native tokens over HTTP.
The integration makes Cardano part of the official x402 SDK, allowing an application or agent to pay for an API request without creating an account, obtaining an API key, or using a checkout page.
According to the foundation, Cardano’s specification was merged in June. Its engineers subsequently developed the client, server, and facilitator components. Working with the Masumi Network team, they also added Masumi as a transfer method and completed a three-month review.
Developers can install the package using npm install @x402/cardano. The demo and facilitator are open source, and TypeScript is the first supported language, with Python support planned next.
The x42 standard uses HTTP’s existing “402 Payment Required” status code to initiate payments. When a request arrives without payment, a server can return a 402 response, prompting the client to pay and retry.
ADA Rises as x402 Adoption Expands
Cardano’s jump onto the x402 bandwagon follows Ripple’s joining of the Linux Foundation-hosted x402 Foundation in July, alongside other companies working on the protocol, including Coinbase and Circle. The XRP Ledger already supports x402, with XRP and RLUSD available for agent transactions.
However, in August, analyst Jamie Coutts measured x402 settlement volume as down 93% from the beginning of the year to that point, with its seven-day average having fallen to around $41,800, despite continued development of infrastructure for automated payments.
But at the time of writing, the x402 website reported 75.41 million transactions and $24.24 million in volume over the previous 30 days, with 94,060 buyers and 22,000 sellers.
ADA, meanwhile, was trading around $0.24, up nearly 6% in 24 hours and over 20% in the last seven days, as the broader crypto sector turned green, with several large altcoins marking huge gains, including XRP (6.8%), SOL (4.9%), and DOGE (13.5%).
The post Cardano Joins Solana, XRPL in AI Agent Payments Race as ADA Gains 6% appeared first on CryptoPotato.
[PRESS RELEASE – Miami, FL, USA, September 22nd, 2026]
Kaplan Rothstein Prüss Peraza (KRP2), a prominent cybersecurity and data privacy litigation firm, has announced the expansion of its specialized legal practice focused on recovering digital assets lost to SIM swap fraud. The firm is scaling its plaintiff-side litigation efforts across Florida, New York, and California to pursue civil recovery claims against major telecommunications carriers and cryptocurrency exchanges that fail to protect user accounts from preventable security breaches.
SIM swap attacks occur when malicious actors exploit vulnerabilities in mobile carrier verification processes to hijack a victim’s phone number, allowing them to bypass SMS-based two-factor authentication (2FA). According to the FBI Internet Crime Complaint Center (IC3) annual report, US victims suffered nearly $21 million in losses from SIM swapping in 2025. Furthermore, blockchain analyst ZachXBT documented the theft of over $82 million in SIM swap incidents in 2024, underscoring the severe risk facing retail and institutional investors alike.
As a result of these institutional vulnerabilities, KRP2’s expanded practice provides a direct civil litigation route for victims who have lost cryptocurrency due to a SIM swap attack. Rather than focusing solely on anonymous hackers, the firm targets the corporate entities whose weak identity verification or inadequate account recovery protocols enabled the theft. This litigation model asserts that both telecom providers and cryptocurrency platforms can be held legally accountable under consumer protection, negligence, and data privacy laws when their systemic failures lead to user asset depletion.
Legal precedents increasingly support this institutional liability approach. In a landmark March 2025 arbitration ruling, T-Mobile was ordered to pay $33 million to a customer whose high-security account was breached via a fraudulent SIM transfer, resulting in a massive crypto theft. Globally, judicial bodies are mirroring this stance; India’s Karnataka High Court recently held a major telecom provider liable for negligence following a similar mobile-enabled cybercrime.
To protect claims and ensure evidence preservation immediately following an attack, KRP2 advises victims to take swift action:
- Immediate Carrier Escalation: Report the fraudulent transfer to the mobile carrier to freeze the number and document port-out logs.
- Exchange Lockdown: Notify affected cryptocurrency exchanges to freeze remaining assets, change credentials, and remove SMS-based 2FA.
- Data Preservation: Request and secure all transaction hashes, IP login records, and communication transcripts from both telecom and crypto platforms.
By standardizing recovery protocols across its Miami, New York, and Los Angeles offices, KRP2 aims to bridge the gap between complex blockchain forensics and civil litigation, ensuring that corporations are held financially accountable for infrastructure-level security gaps.
About Kaplan Rothstein Prüss Peraza (KRP2)
Kaplan Rothstein Prüss Peraza (KRP2) is a premier litigation law firm specializing in data privacy, cybersecurity breaches, and digital asset recovery. Operating out of Miami, New York City, and Los Angeles, the firm champions consumer rights by holding major corporations accountable for systemic technical vulnerabilities.
The post KRP2 Law Firm Expands Specialized SIM Swap Crypto Recovery Litigation Across Major US Jurisdictions appeared first on CryptoPotato.
The OG meme coin has been on a tear lately, with its price tapping $0.10 for the first time since the beginning of June.
Analysts have spotted highly bullish signals, and some think the token could be gearing up for a rally to a new all-time high.
Realistic and Wild Predictions
DOGE has risen by almost 20% over the past week, with its market capitalization surging to roughly $15.2 billion and making it the 12th-largest cryptocurrency.
Currently, it trades just below the $0.10 psychological mark, but according to X user Cyriptoman4, it seems well positioned to attack higher levels. The analyst claimed that if DOGE decisively breaks above that zone, the upward move could continue toward the $0.1175-$0.15 region.
For their part, BSC Gems Alert claimed that the price has started forming a higher-low structure and is pushing against the upper boundary of the latest descending pattern.
“If DOGE can break and hold above $0.22, momentum could accelerate toward the higher resistance zones. The setup is simple: Breakout → Retest → Continuation,” they said.
At the same time, the analyst warned that a loss of support would invalidate the bullish setup and could trigger a pullback.
Others, like X user Bark, are much more optimistic. The analyst argued that the breakout to $1 has begun, expecting the potential explosion to happen faster than most people think.
MikybullCrypto issued a similar forecast, maintaining that the bullish move is about to kick off and setting the $1-$3 range as the bullish target.
Key Factors to Consider
Earlier this month, whales purchased more than 240 million DOGE in about a week. Many interpret such accumulations as bullish for several reasons.
First, the development reduces the tokens available on the open market, which, combined with steady or rising demand, is supposed to trigger a price pump.
Second, whales are experienced investors who make calculated moves and usually aren’t driven by pure instinct. Smaller players closely monitor their moves and might get encouraged to jump on the bandwagon, too, thus distributing fresh capital into the ecosystem.
However, some elements suggest that DOGE may be gearing up for a short-term correction. CoinGlass data shows exchange inflows have surpassed outflows over the past few days, suggesting some investors have moved from self-custody to centralized platforms. This, in turn, increases immediate selling pressure.

The post Dogecoin (DOGE) Rises to a 3-Month High: The Breakout to $1 Has Begun? appeared first on CryptoPotato.
Binance is facing a new investigation in the United States over possible violations of sanctions on Iran, Bloomberg News reported on Monday.
Investigators are examining whether Binance allowed certain trading activity linked to Iran on its platform. Authorities are also looking into whether the crypto exchange knowingly allowed the activity to take place, Bloomberg reported.
Another Probe
Binance maintained that it has a zero-tolerance policy toward sanctions violations. The company also asserted that it works closely with law enforcement agencies and remains focused on identifying and removing bad actors from its platform.
This isn’t the first time Binance has faced major scrutiny from US authorities. Its former CEO, Changpeng Zhao, stepped down in November 2023 after the Justice Department accused him of violating US financial laws, including the Bank Secrecy Act and the International Emergency Economic Powers Act. Zhao pleaded guilty and was sentenced to four months in prison in April 2024. He also paid a $50 million fine.
Binance agreed to plead guilty and pay $4.3 billion in penalties as part of the case. Zhao completed his sentence in September 2024. The following year, US President Donald Trump granted him a presidential pardon.
Iran Crypto Crackdown
The latest investigation comes as Washington continues to increase pressure on Iran. The US sanctioned firms and individuals it accused of supporting Hezbollah and other Iranian-backed groups in the Middle East.
Just last week, the Treasury Department added BitBank to its sanctions list. The Office of Foreign Assets Control (OFAC) said that the crypto exchange is controlled by Iranian financier Babak Zanjani, who is already under US sanctions. It was accused of helping move money connected to sanctioned Iranian entities. OFAC said BitBank transferred payments received by the Hormuz Safe Marine Services Authority, which was previously designated by the US.
The platform also allegedly moved hundreds of millions of dollars in Bitcoin to the Islamic Revolutionary Guard Corps between June and July. The sanctions cover BitBank’s developer, Pishtaz Simorgh Electronic Trade Company, and three executives linked to Zanjani.
The post Binance Under US Investigation as Prosecutors Examine Iran-Linked Trading appeared first on CryptoPotato.