Cryptocurrency Posts
Crypto Briefing
Mbapp's move to On could disrupt the football boot market, challenging established brands and reshaping athlete-brand partnerships.
The post Kylian Mbappé leaves Nike to become face of On’s football boots expansion appeared first on Crypto Briefing.
The increasing involvement of banks in the EU's crypto market could accelerate mainstream adoption and reshape financial landscapes.
The post Banks represent 23% of crypto providers on EU’s MiCA register appeared first on Crypto Briefing.
Oklo's microreactor deployment could revolutionize energy supply for data centers, but hinges on securing binding agreements and fuel scalability.
The post Oklo plans to deploy first Aurora microreactors by 2028 appeared first on Crypto Briefing.
Kalshi's rapid valuation growth highlights the increasing investor confidence in prediction markets, potentially reshaping financial and regulatory landscapes.
The post Kalshi eyes $750M funding round that would nearly double its valuation to $40B appeared first on Crypto Briefing.
The exposure of UK police data on Microsoft's cloud highlights urgent data sovereignty and compliance challenges, necessitating sovereign cloud solutions.
The post Microsoft cloud platform exposes UK police data to US government access risks appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Bitcoin Price Surges Over $81,000 Despite Clarity Act Fail and Interest Rate Hike
Bitcoin’s price on Friday shot above $81,000 — despite a week of setbacks for the crypto industry.
The biggest coin was recently trading for $80,982, after jumping as high as $81,055 at one point Friday morning in New York. Over the past 24 hours, it has risen by nearly 6%.
Its surge comes after lawmakers on Tuesday blocked long-awaited crypto legislation, the Clarity Act, and the Federal Reserve on Wednesday hiked interest rates.
JUST IN: Bitcoin surges to $81,000
— Bitcoin Magazine (@BitcoinMagazine) September 18, 2026pic.twitter.com/EQi5apUlxU
Digital asset industry bigwigs had long called for clear rules to regulate the crypto space and the Clarity Act — which wants to divide oversight between regulators — aimed to do that. But lawmakers blocked the landmark digital asset market structure bill in a procedural vote.
And the Federal Reserve increased borrowing costs for the first time due to skyrocketing inflation in the U.S. The central bank’s chair, Kevin Warsh, said that price stability in the U.S. was the Fed’s number one priority.
“The plain fact is that inflation is too high, and has been for too long,” Warsh said. “This summer’s inflation readings do not tell me that underlying trends have meaningfully improved.”
Bitcoin has in the past done well in a low interest rate environment because it means there is more liquidity to trade the asset.
While Bitcoin’s price dipped initially news of the Clarity Act blockage and Fed’s move, it shot up on Friday.
Bitcoin exchange-traded funds in the U.S. have so far this week experienced net negative flows, with investors cashing out nearly $427 million from the vehicles, according to Farside Investors data.
Flows on Thursday turned positive, with investors chucking nearly $160 million at the funds following two days of consecutive outflows.
In a research note Thursday, asset manager Grayscale said that it didn’t expect bitcoin’s price to be hurt by the Fed’s decision because the move reflects a mid-cycle adjustment, not a cyclical change.
And despite lawmakers blocking the Clarity Act, regulators like the SEC are already pushing ahead with pro-crypto regulation.
This post Bitcoin Price Surges Over $81,000 Despite Clarity Act Fail and Interest Rate Hike first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Bitcoin Community Recognizes Quantum Computing Risk: VanEck
Quantum computing is a risk to Bitcoin but the community recognizes the issue, according to asset manager VanEck’s Head of Digital Assets Research.
Speaking to CNBC on Friday, Matthew Sigel said that while progress on addressing the issue may be slow because of the crypto network’s decentralized nature, the community was working on it.
The crypto community has sounded the alarm about hypothetical advancements in quantum computers that could in the future be able to break Bitcoin’s cryptography.
Some in the space — including Bitcoin developers — have started preparing for a post-quantum future by testing quantum-resistant signatures on live sidechains.
“It’s a risk,” he said. “But the community has recognized the scope of the issue. There’s a lot of talent that’s now come together with a framework of how to upgrade the system.”
He added: “The upgrades don’t happen as fast because there’s no CEO who can tell the devs, ‘hey, do it now.’ There’s a governance process — it takes more time, it’s a little bit messier, but there are technological paths for quantum resistance, and I think you’ll see more of that over the next couple of years.”
Quantum computers do exist but make mistakes and a machine that can break Bitcoin’s cryptography currently does not exist. Bitcoin currently is the biggest computer network in existence.
Major companies in the space — including America’s biggest crypto exchange, Coinbase, and Bitcoin infrastructure firm, Blockstream — are already working on solutions.
Back in July, Coinbase said it plans to deliver a post-quantum signing pipeline using secure enclaves and threshold cryptography.
A Bitcoin Security Consortium — made up of BlackRock, Fidelity Digital Assets, Block, and others — formed in July and donates funds and dedicates engineers to open-source work supporting proposals like BIP-360, which aims to introduce a new transaction output type to reduce long-exposure quantum computing risks.
This post Bitcoin Community Recognizes Quantum Computing Risk: VanEck first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
The Next 3-5 Years of Bitcoin Lending
SALT Lending CRO Hunter Albright says a growing number of Bitcoin holders may eventually borrow against their bitcoin rather than sell it, creating a new relationship between bitcoin, credit and stablecoins.
Bitcoin-backed lending could become an increasingly important part of how holders access the value of their bitcoin without selling it, according to Hunter Albright, Chief Revenue Officer of SALT Lending.
Speaking on BMTV, Albright said he expects borrowing against bitcoin to become more common as the market matures and holders become more comfortable using bitcoin as collateral.
“I’d like to think we will see a growing percentage of the population of bitcoin holders borrow against it,” Albright said.
For Albright, that shift could also change how bitcoin and stablecoins function alongside one another.
“I do believe people borrowing against their bitcoin and leveraging stables is the difference between money in motion and money at rest,” he said. “The speed of conversion really creates a utility and advantage for people willing to operate in that ecosystem.”
In that framework, bitcoin increasingly becomes “money at rest” – an asset held for the long term – while stablecoins serve as “money in motion,” providing liquidity that can be transferred and used more easily without requiring holders to sell their bitcoin.
A Behavioral Shift for Bitcoin Holders
Getting there, however, will require more than simply building lending products.
Albright said greater education around both Bitcoin itself and the mechanics of borrowing against bitcoin will be necessary before the behavior becomes mainstream – something SALT Lending has made part of its own efforts in the market.
It also requires a change in how Bitcoin holders think about the value stored in their assets.
Instead of viewing bitcoin only as something to accumulate and eventually sell, holders can potentially use it as collateral to access liquidity while maintaining their bitcoin exposure.
That model is already common elsewhere in finance, where owners of real estate, equities and other assets regularly borrow against their holdings rather than liquidating them.
For Bitcoin holders, there can also be tax advantages. In the U.S., borrowing against an asset generally does not itself constitute a taxable sale, whereas selling appreciated bitcoin can trigger capital gains taxes. Individual tax consequences depend on the structure of the transaction and the borrower’s circumstances, readers should consult a tax advisor.
Albright sees that combination – long-term bitcoin holdings, growing stablecoin adoption and easier access to credit – as part of a broader shift in how Bitcoin holders may eventually use their wealth.
Rather than bitcoin needing to move every time its value is put to use, bitcoin can remain at rest while liquidity moves around it.
SALT Lending is the Official Liquidity Sponsor of BMTV. Learn more about borrowing against your bitcoin and explore SALT’s BMTV offer at https://saltlending.com/bmtv/?utm_source=bmtv&utm_medium=article&utm_campaign=52783658-BMTV%20article&utm_term=BMTV
Disclaimer: SALT Lending is a paid sponsor of BMTV and serves as BMTV’s Official Liquidity Sponsor. This article is sponsored content and does not necessarily reflect the views or opinions of Bitcoin Magazine. The information provided is for promotional purposes and should not be considered financial advice. Readers are encouraged to conduct their own research before making any investment decisions related to Bitcoin or other financial products mentioned herein.
This post The Next 3-5 Years of Bitcoin Lending first appeared on Bitcoin Magazine and is written by Josh Plischke.
Bitcoin Magazine
Dan Hillery: Digital Credit Could Rival BTC’s $1.5 Trillion Market Cap
Two years ago, Bitcoin-backed digital credit barely existed. Today it’s a roughly $16 billion market and Dan Hillery of UXTO thinks the financialization layer on top of Bitcoin could one day rival the network itself. In the debut episode of The Allocators Edge, Hillery breaks down how variable-rate preferred securities like STRC and SATA are priced, why buybacks keep them anchored near $100 par, and what separates digital credit risk from digital equity risk. He also walks through the structured credit fund he’s building, including its senior and junior tranches.
0:00 — Digital Credit Is the Fastest-Growing Part of Bitcoin’s Capital Structure
1:18 — Why STRC’s Variable Rate Design Has No Precedent in Market History
2:59 — What Flat or Falling Bitcoin Prices Mean for Strategy and Strive
4:17 — Short-Duration Bitcoin-Backed Notes and the Next Five Years of Products
5:45 — The Biggest Misconceptions Investors Have About Preferred Securities
6:58 — How Buybacks and Capital Markets Activity Anchor STRC Near $100 Par
8:09 — Why Major Fund Classes Still Can’t Touch Digital Credit Today
9:10 — Inside the UXTO Credit Fund: Senior and Junior Tranche Structure
10:35 — Where the Leverage Comes From and How Volatility Risk Gets Transferred
11:50 — Liquidity, Redemptions, and Digital Credit in a 60/40 Portfolio
This video is for informational purposes only and does not constitute an offer to sell or a solicitation of an offer to buy any securities. Past performance is not indicative of future results. Investments in digital assets involve significant risk and may result in loss of capital. Both UTXO Management and BTC Inc., producer of BMTV, are owned by Nakamoto Inc. (NASDAQ: NAKA)
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Dan Hillery: Digital Credit Could Rival BTC’s $1.5 Trillion Market Cap first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Treasury Sanctions Iranian Crypto Exchange BitBank Over Bitcoin Transfers to IRGC
The U.S. is continuing to target Iran’s use of bitcoin.
In a Thursday statement, the U.S. Department of the Treasury designated BitBank, an Iranian crypto exchange, as part of Operation Economic Outcast — the Trump Administration’s whole-of-government economic campaign against the Islamic Republic of Iran and its enablers.
The U.S. has sanctioned Iran for decades. This year, the Middle Eastern country has stepped up its use of cryptocurrencies — including bitcoin — in order to skirt around economic penalties.
“Today’s designations of Iranian digital asset infrastructure make perfectly clear that efforts to finance the Iranian regime using cryptocurrencies are not beyond OFAC’s reach,” Secretary of the Treasury Scott Bessent said in a statement.
“If you support the Iranian regime, the Department of the Treasury will sanction you.”
The sanctions target designated Iranian financier Babak Zanjani, along with its software developer, Pishtaz Simorgh Electronic Trade Company, and three of Zanjani’s associates: Hossein Ali Zaker Hossein, Mohammad Mahdi Zaker Hossein, and Seyed Adel Heidari.
Since June, the Iranian Hormuz Safe Marine Services Authority has used BitBank to move bitcoin to the Iranian regime, according to the Treasury.
Thursday’s sanctions aim to hit the “architecture Zanjani built to launder funds,” it added.
“The Department of the Treasury will continue to not only target the Iranian digital asset ecosystem, but also international entities and actors which help facilitate it,” the statement continued.
Iran started a bitcoin-backed insurance service for its counties shipping companies earlier this year.
The U.S. in July said that it had frozen crypto linked to the Iranian regime, mostly in the form of Tether’s stablecoin.
Stablecoins like Tether’s USDT can be frozen by the company that issues the asset. But bitcoin, being decentralized and having no single issuer, cannot.
The U.S. Treasury’s Office of Foreign Assets Control in July said Iran had been dodging sanctions by accepting pay in bitcoin from ships passing through the Strait of Hormuz.
OFAC said at the time that Hormuz Safe, developed by Iran’s Ministry of Economy, “accepts payment in Bitcoin and other digital assets” so it can bypass sanctions.
This post Treasury Sanctions Iranian Crypto Exchange BitBank Over Bitcoin Transfers to IRGC first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
CryptoSlate
The US sanctioned Iranian crypto exchange BitBank, widening its campaign against digital-asset infrastructure allegedly used to finance the Islamic Revolutionary Guard Corps (IRGC).
On Sept. 17, the Treasury Department’s Office of Foreign Assets Control (OFAC) said that the sanctioned Iranian financier Babak Zanjani used BitBank between June and July to facilitate hundreds of millions of dollars in Bitcoin transfers to the IRGC.
Treasury also said Hormuz Safe Marine Services Authority, previously sanctioned over an alleged maritime-payment scheme in the Strait of Hormuz, had used the exchange since June to move receipts to the Iranian government.
The action reaches beyond BitBank to Pishtaz Simorgh Electronic Trade Company, which developed the exchange’s software, and three people tied to Zanjani’s broader corporate network. OFAC described the group as part of Iran’s digital-asset sanctions-evasion infrastructure and designated them under Executive Order 13902, which Treasury has expanded to cover Iran’s digital-asset sector.
Treasury Secretary Scott Bessent said the move demonstrates that crypto-based financing is “not beyond OFAC’s reach,” warning that parties supporting the Iranian government could also become sanctions targets.
The designations deepen Operation Economic Outcast, a campaign Treasury launched Aug. 24 to cut Iran off from financial channels used to move oil revenue, evade sanctions and fund the IRGC. The program also widened secondary-sanctions exposure for companies outside the US that continue doing business with targeted Iranian entities.
BitBank is the latest Iranian crypto platform swept into that effort. In June, OFAC sanctioned Nobitex, Wallex, Bitpin and Ramzinex as part of its earlier Economic Fury campaign. The pressure expanded again in August when OFAC designated Shelbit and Aban Tether.
The accumulating designations show Washington increasingly treating Iranian crypto venues as parts of interconnected financing networks rather than isolated trading businesses.
Treasury follows Zanjani’s crypto network beyond the exchange
The BitBank action pushes that strategy further by targeting the developers, executives, and corporate infrastructure Treasury says allowed Zanjani’s network to move funds.
Zanjani, a longtime Iranian businessman already under US sanctions, publicly promoted BitBank beginning in at least 2024, Treasury said. Several other companies tied to his sanctions-evasion network also listed the exchange as a partner.
Pishtaz Simorgh, BitBank’s software developer, is a subsidiary of Dot One Value Creation Group, which OFAC sanctioned in July as part of another action against Zanjani’s commercial network. Treasury said Dot One sits within a portfolio spanning financial services, digital assets, transportation and infrastructure that Zanjani used to obscure ownership and move money.
TRM Labs said the latest designations extend an investigation it began around Zedcex and Zedxion, two crypto exchanges sanctioned with Zanjani in January. The blockchain-intelligence firm said it initially identified about $1 billion in IRGC-linked activity tied to those platforms before broadening its analysis into the companies, payment systems and digital infrastructure surrounding them.
That work eventually mapped a wider ecosystem that included Dot One, ZedPay, transportation companies and other businesses subsequently targeted by Treasury in July. TRM said BitBank and Pishtaz Simorgh sit within that same network, alongside the MyDot social platform, DOTO digital asset and Dot One Smart Chain.
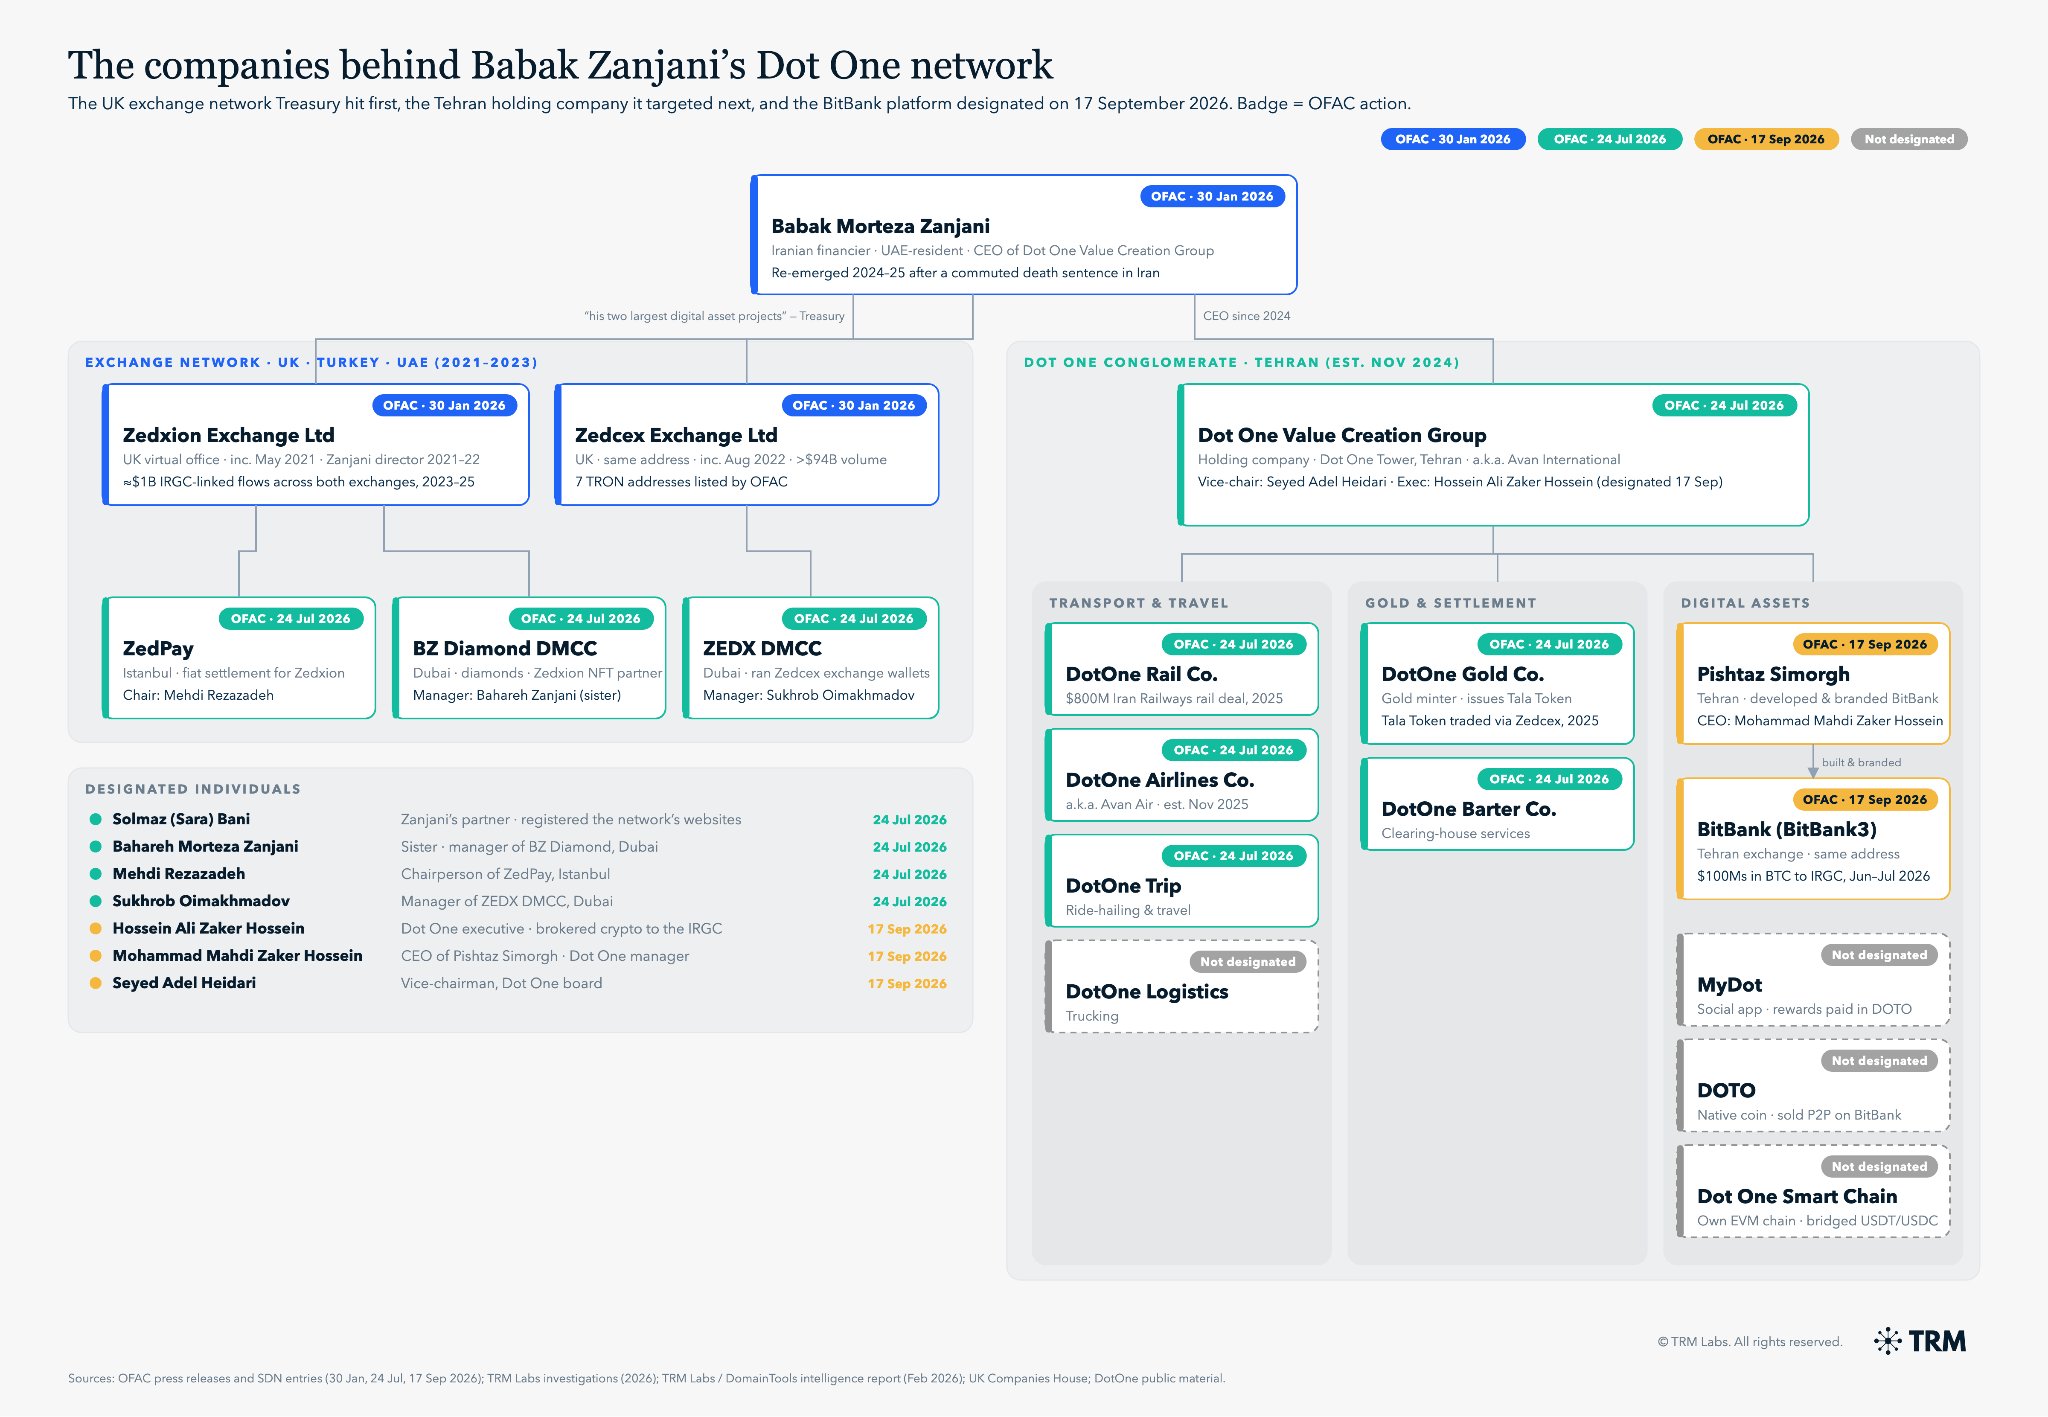
The pattern gives investigators more targets than blockchain addresses alone. Corporate ownership, software development, payment relationships and executive control can connect entities that may otherwise appear separate on-chain.
Treasury’s inclusion of BitBank’s software company reflects that broader approach.
Mohammad Mahdi Zaker Hossein, chief executive of Pishtaz Simorgh and a Dot One manager, was sanctioned for acting on behalf of the software company. Seyed Adel Heidari, vice chairman of Dot One’s board, was designated for acting on behalf of Dot One.
Hossein Ali Zaker Hossein was sanctioned for acting for Zanjani. Treasury alleged he participated in much of Zanjani’s sanctions-evasion activity, including Iranian oil exports and digital-asset transactions, and brokered crypto transfers that ultimately reached the IRGC.
The post US sanctions Iranian crypto exchange and its software developer over alleged IRGC Bitcoin transfers appeared first on CryptoSlate.
Bitcoin’s rebound above $80,000 on Sept. 18 extended a technology-led relief rally. The move coincided with yen weakness and followed a return to Bitcoin ETF inflows the previous day. The advance was already underway in European trading, hours before weak US economic figures offered a possible argument against further monetary tightening.
At press time, Bitcoin traded at $80,856, up 5.60% over 24 hours. The clearest explanation is a broader relief rally with an improving, but still tentative, demand signal. The timing points to a recovery in risk appetite, although it does not identify one decisive trigger.
Dow Jones reported Bitcoin at $78,309, up 2.3%, in early European trading, linking the rebound to Thursday’s technology-led recovery. The 10:54 a.m. BST dispatch described prices earlier that morning.
The equity backdrop was already firmer. Reuters reported Nasdaq 100 E-mini futures up 0.56% at 9:50 a.m. BST as lower oil prices eased inflation concerns. That supports the interpretation of Bitcoin participating in renewed appetite for risk, rather than reacting solely to an afternoon US announcement.
By the opening minutes of US stock trading, Bitcoin was above $79,000 with a gain of more than 4%, according to a Yahoo Finance report published at 3:13 p.m. BST.
The Bank of Japan announced its decision at 3:54 a.m. BST. A 7–2 majority approved a 1.25% overnight call-rate target, up from 1% and in line with expectations. The new setting takes effect Sept. 24.
The yen’s decline was consistent with relief rather than a shock from unexpectedly aggressive tightening. The BoJ’s daily observations showed the dollar buying 156.15–17 yen at 1 a.m. BST and 157.48–50 yen at 9 a.m. BST. The yen therefore weakened across the announcement window.
Reuters attributed that weakness to the two dissenters and guidance that disappointed traders expecting a more hawkish message. A weaker yen is consistent with relief over pressure on yen-funded positions. That remains a possible supporting mechanism, not evidence of money moving from those positions into Bitcoin.
The US policy backdrop also remained restrictive: Wednesday’s Federal Reserve decision was a quarter-point rate hike, as Dow Jones reported.
What supported the move, and what remains uncertain
US spot Bitcoin ETFs recorded net inflows of USD 159.5 million on Sept. 17, according to Farside Investors. BlackRock’s IBIT led the inflows, while withdrawals from other funds reduced the overall total.
That followed net outflows on Sept. 15 and 16. The positive session is evidence that demand through the funds improved before Friday’s advance, but one day does not establish a durable reversal.
The funds provide a concrete demand signal, but daily totals do not reveal when purchases occurred or establish the source of Friday’s buying.
At 2 p.m. BST US industrial production was reported unchanged for August, and manufacturing output fell 0.3%. The Federal Reserve release confirmed those results, while Trading Economics listed expectations for a 0.3% increase in each. At 3 p.m., the leading economic index fell 0.1%, against expectations for a 0.1% rise.
Weaker activity could reduce the case for additional tightening. But these releases cannot explain an advance already visible that morning. Nor was Friday simply a falling-yields story: Reuters reported the 10-year Treasury yield up 2.9 basis points to 4.976% before the US open.
Forced buying may have amplified the move, but the available measurements do not establish its contribution. CoinGlass showed about $230.6 million in total Bitcoin futures liquidations over 24 hours and $56.36 billion in open interest.
The liquidation total includes both sides of the market. A short squeeze would involve bearish positions being forcibly closed as prices rise. The available total, without a short-side breakdown or matching funding and open-interest changes, cannot show how much of Friday’s advance came from that process.
Thursday’s SEC tokenized-stock exemption also offered broader regulatory context. Its conditional relief concerns certain stock-trading venues and liquidity providers, rather than a Bitcoin-specific approval.
For the rally’s durability, repeated ETF inflows would be a clearer demand signal than a one-day rebound, while directional liquidation data could show whether forced buying is playing a substantial role. Friday’s sequence supports a relief rally; it leaves the balance between fresh demand and short covering unresolved.
The post Why Bitcoin hit $80k today hours before bad US data even landed appeared first on CryptoSlate.
XRP Ledger (XRPL) developers are using mathematical proofs to test whether the network’s forthcoming lending market can be drained or become insolvent.
On Sept. 17, protocol research firm Common Prefix said it is formally verifying XRPL’s Lending Protocol with Lean 4, a theorem-proving language designed to establish whether software satisfies defined mathematical properties across possible system states.
The firm said the work is intended to show that the protocol cannot enter states that violate its accounting and safety rules.
The work has taken on greater significance after xrpld version 3.4.0 shipped this week with LendingProtocolV1_1, an amendment that introduces closed-ended lending vaults and cash-basis accounting. The amendment is included in the server software but still requires approval through the XRP Ledger’s amendment process before taking effect.
XRPL’s lending design would allow depositors to pool assets that loan brokers can deploy into fixed-term, uncollateralized loans. Borrower underwriting and credit assessment happen off-chain, while the ledger records loan origination, repayments, and accounting.
That puts a premium on getting the protocol’s internal bookkeeping right. Errors involving vault balances, loan payments, or share calculations could affect pooled depositor funds rather than an isolated application.
Locked capital raises the stakes for XRPL lending
LendingProtocolV1_1 increases the consequences of accounting failures because depositor assets can remain committed through a predetermined investment period.
Closed-ended vaults move through three stages: subscription, investment, and redemption. Depositors can add or withdraw assets during the subscription phase, but both actions are blocked once the vault enters its investment period and the capital becomes available for lending. Withdrawals resume when the vault reaches redemption.
The timetable is set when the vault is created and cannot be changed later, giving participants advance visibility into how long their capital may remain committed.
Version 3.4.0 also changes how new vaults recognize interest income.
Under the earlier design, scheduled interest could be recorded as income when a loan was originated, even before the borrower made those payments. Cash-basis accounting instead recognizes interest only as payments arrive, reducing the risk that vault-share values reflect income not yet received.
Those changes add more states and transitions that must remain consistent as deposits are accepted, loans are issued, repayments arrive, borrowers default, and vaults eventually reopen for withdrawals.
Common Prefix is using formal verification to test those relationships beyond the scenarios engineers might anticipate in a conventional test suite.
Researchers are not attempting to mathematically verify the entire xrpld C++ codebase. They instead recreate the relevant protocol logic in Lean 4 and define the properties the system is expected to preserve.
An oracle can then run equivalent inputs against the mathematical model and the production implementation, helping identify cases where the two behave differently.
That distinction matters because a mathematical proof is only as strong as the model and assumptions behind it. The process can establish that defined properties hold across the modeled state space, while comparisons with the implementation help test whether the production code continues to match those assumptions.
Earlier proofs already exposed XRPL failures
The approach has already uncovered edge cases that conventional testing missed.
During an exploratory verification phase between February and April, Common Prefix modeled parts of the Lending Protocol and defined invariants the system was expected to maintain.
RippleX said the work uncovered vault invariant violations, loan-payment assertion failures, arithmetic rounding errors, and differences between written XLS specifications and their implementation.
The identified issues were subsequently addressed across xrpld versions 3.1.3 and 3.2.0.
That record gives the current verification effort a practical role before significant depositor capital is placed behind the protocol. Formal methods can challenge assumptions embedded in the lending logic, while developers can still change the implementation before broader adoption.
The problem becomes more complex as native lending interacts with existing ledger functions, including asset transfers, freezes and clawbacks. Each additional interaction expands the number of system states developers must account for.
RippleX has previously argued that this complexity raises the limits of relying solely on functional tests, audits, bug bounties and validator testing.
The stakes are also becoming commercial.
RippleX has identified Evernorth, which is preparing to become a Nasdaq-listed XRP treasury company, and VS1.Finance as among the companies preparing to use or build around Single Asset Vaults and the Lending Protocol, putting more pressure on the underlying accounting rules to behave predictably before institutional capital arrives.
Mathematical proofs still leave credit risk outside the ledger
Even successful verification would leave one of XRPL lending’s largest risks outside the mathematical model: whether borrowers repay.
The protocol relies on off-chain underwriting to determine borrower creditworthiness and does not currently depend on automated on-chain collateral and liquidation mechanisms commonly used in decentralized lending markets.
Loan brokers can supply first-loss capital intended to absorb part of a default before losses reach depositors, but XRPL’s documentation notes that the mechanism does not eliminate credit risk.
Formal verification also cannot prove that every external integration, operational process, or underwriting decision will behave safely. Its guarantees extend only to the properties developers define and the assumptions represented in the model.
That creates two separate layers of assurance for depositors.
The first is whether XRPL’s own accounting machinery behaves consistently across deposits, lending, repayments, and withdrawals. The second is whether loan brokers correctly price and manage borrowers whose obligations remain subject to real-world credit risk.
Common Prefix’s work is focused on strengthening the first. With LendingProtocolV1_1 now distributed in xrpld 3.4.0, validators will ultimately determine whether the amendment becomes active.
Before that happens, developers are trying to establish stronger evidence that the lending machinery itself behaves as specified when real capital, loan brokers, and off-chain credit decisions begin interacting with it.
The post XRPL tries to mathematically prove its new lending market cannot be drained appeared first on CryptoSlate.
Hyperliquid has launched native manual borrowing, extending its trading infrastructure into credit as HYPE climbed to a fresh all-time high above $90.
The Sept. 18 rollout lets users pledge HYPE or Bitcoin as collateral to borrow USDC or USDT directly through HyperCore. Hyperliquid said $269 million in assets were borrowed Friday, giving the new product immediate scale.
The launch comes as Hyperliquid broadens the financial functions available inside its core infrastructure, allowing users to move between trading, collateral and credit without relying on separate lending protocols.
HYPE has risen roughly 15% this week and traded above $90 on Friday, with CryptoSlate's data recording an intraday high of about $91.06. That surpassed the token’s previous record near $89.60 and extended a rally from roughly $77 earlier in the week.
Manual borrowing opens HyperCore’s existing credit engine
The new product exposes lending infrastructure that had largely operated beneath Hyperliquid’s portfolio-margin system.
Founder Jeff Yan said Hyperliquid built borrowing and lending as a separate HyperCore primitive rather than embedding credit directly into margin accounts. Every borrowed asset comes from supplied liquidity, allowing other products to tap the same market while keeping lending risk separate from derivatives exposure.
Portfolio margin then operates as an orchestration layer, combining borrowing with perpetuals, spot markets and other HyperCore products.
That design meant Hyperliquid did not need to create a lending market from scratch for Friday’s launch. Yan said borrowers had access to more than $400 million of supplied liquidity from the outset because the same pools were already supporting portfolio-margin activity.
The $269 million reported as borrowed on Friday indicates the scale of the underlying credit market.
HYPE carries a 65% loan-to-value ratio, while Bitcoin has a 50% LTV. Liquidation thresholds are 82.5% for HYPE and 75% for Bitcoin. Stablecoin suppliers earn variable interest based on utilization, while borrowers pay interest on USDC and USDT.
Portfolio-margin users can also earn interest on idle stablecoin balances because those assets feed the same pools borrowers use.
Yan compared the architecture with Amazon’s decision to separate its computing infrastructure into Amazon Web Services, allowing one underlying system to support products beyond its original retail business.
“Do one thing and do it well,” Yan said, invoking the Unix design principle.
Hyperliquid argues that separating lending from perpetual-margin risk makes the system easier to manage because each financial primitive retains its own risk parameters even when users access them through the same platform.
Lending lands as HYPE and US access expand
The lending rollout comes as Hyperliquid gains broader distribution and accumulates a larger pool of dollar liquidity across its ecosystem.
Two days before the launch, Payward, Kraken’s parent company, announced plans to deploy on-chain perpetual futures markets for US clients, starting with Hyperliquid’s HIP-3 framework.
That push would give Hyperliquid another route into a market where perpetual futures have historically faced tighter restrictions than offshore crypto derivatives, potentially widening access to its ecosystem-tied products.
Hyperliquid is also drawing a growing pool of stablecoin liquidity, with total stablecoin supply on the network approaching $7 billion. DeFiLlama data show the blockchain network's circulating USDC supply at about $6.77 billion, slightly above Solana’s roughly $6.72 billion and leaving Hyperliquid behind only Ethereum in USDC supply.
The ranking can shift as balances move between networks, but the size of Hyperliquid’s stablecoin base gives its expanding credit markets a substantial pool of potential collateral and supplied liquidity.
USDC already serves as a core settlement and collateral asset across Hyperliquid’s trading markets. Native borrowing extends that capital's role by letting suppliers earn yield while traders borrow stablecoins against HYPE or Bitcoin.
For HYPE holders, the product also creates a way to access dollar liquidity without selling their tokens, adding another use for the asset within HyperCore.
Meanwhile, the lending rollout expands a set of financial primitives that increasingly resembles the product stack normally spread across several DeFi protocols.
Ryan Watkins, co-founder of Syncracy Capital, pointed to HyperCore’s combination of perpetuals, spot trading, prediction markets, lending and vaults as evidence of that expansion.
HyperCore is integrating those products rather than developing them as separate applications around the network, allowing collateral, liquidity, and trading activity to move more directly between them.
That gives Hyperliquid a broader strategic objective beyond adding individual products: building a financial system where trading, credit and liquidity increasingly operate through the same underlying infrastructure.
The post Hyperliquid opens native lending as HYPE hits new ATH above $90 appeared first on CryptoSlate.
Participating Zcash coinholders have overwhelmingly favored keeping scheduled halvings and waiting until February 2031 to begin returning ZEC collected by the Network Sustainability Mechanism to future block rewards.
The choices were part of a five-question poll on NU7, Zcash's next network upgrade. Between 2.399 million and 2.404 million ZEC participated in each question. All five cleared 1 million ZEC, although the poll rules required only one question to reach that threshold for the overall poll to be considered representative.
The result gives implementers a strong signal from participating economic stake. It does not activate any change, schedule NU7 or guarantee that every preferred feature will ship.
ZEC poll favors halvings over smoother issuance
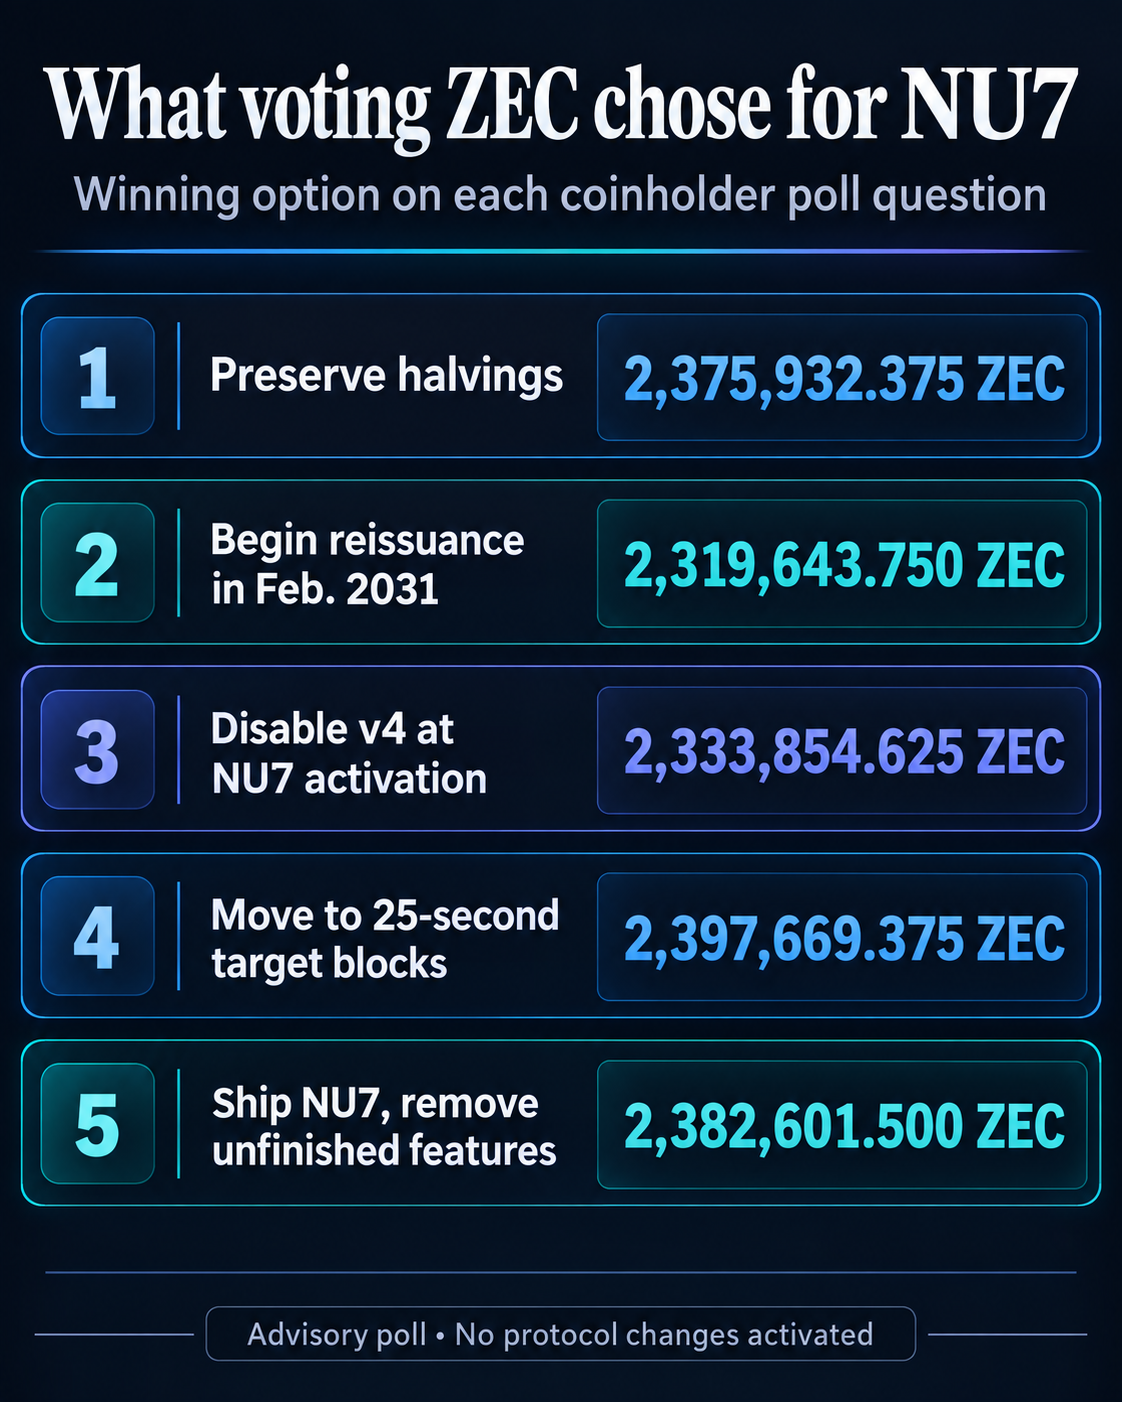
The largest monetary-policy result came on whether the Network Sustainability Mechanism should replace periodic halvings with a smoother issuance curve. The final tally put 2,375,932.375 ZEC behind preserving halvings, compared with 22,384.875 ZEC for smoothing issuance.
A separate timing question put 2,319,643.75 ZEC behind February 2031 as the date to begin recycling funds that the mechanism removes from circulation. Starting as soon as possible drew 70,239.625 ZEC, while February 2027 received 6,283 ZEC. That preference selects a timetable, but the advisory poll neither encodes the date nor commits the network to activating it.
The remaining questions also produced clear results. About 2.33 million ZEC supported disabling Sprout-era v4 transactions at NU7 activation. Nearly 2.4 million ZEC favored cutting target block spacing from 75 seconds to 25 seconds alongside per-pool action limits. Another 2.38 million ZEC supported shipping NU7 without any applicable feature that misses a Sept. 30 implementation deadline.
Other Zcash constituencies showed less unanimity on the monetary questions. The Zcash Community Advisory Panel, a group that provides community input to the Zcash Foundation, drew 135 of 198 eligible members for a 68% response rate. A community-authored recap characterized ZCAP as narrowly favoring smoother issuance and other panels collectively as preferring recycled issuance to begin as soon as possible. Those signals differ from the ZEC-weighted poll and remain separate advisory inputs.
On Sept. 15, a public post in the results discussion said Shielded Labs, Project Tachyon, ZODL, the Zcash Foundation and Valar Group had aligned on February 2031 as the most conservative interpretation of the outcome. It added that another poll could revisit the timing if conditions change.
As of Sept. 17, Zcash's official NU7 page said the upgrade's activation height had not been set. The preserve-halvings specification work also remained open, with relevant deployment values unassigned.
The next consequential step is therefore implementation rather than another tally. Specifications, code, review, testing and a final activation decision will determine which preferences reach mainnet and when.
The post Zcash holders vote to preserve halvings and defer recycled ZEC until 2031 appeared first on CryptoSlate.
CryptoTicker.io
$Bitcoin has punched back through $80,000. BTC is trading at $81,006, up 5.75% over the past 24 hours, pushing its market cap back to $1.62 trillion on roughly $35.5 billion in daily volume. It is the cleanest green day the market has had in weeks, and this time the altcoins came along for the ride.
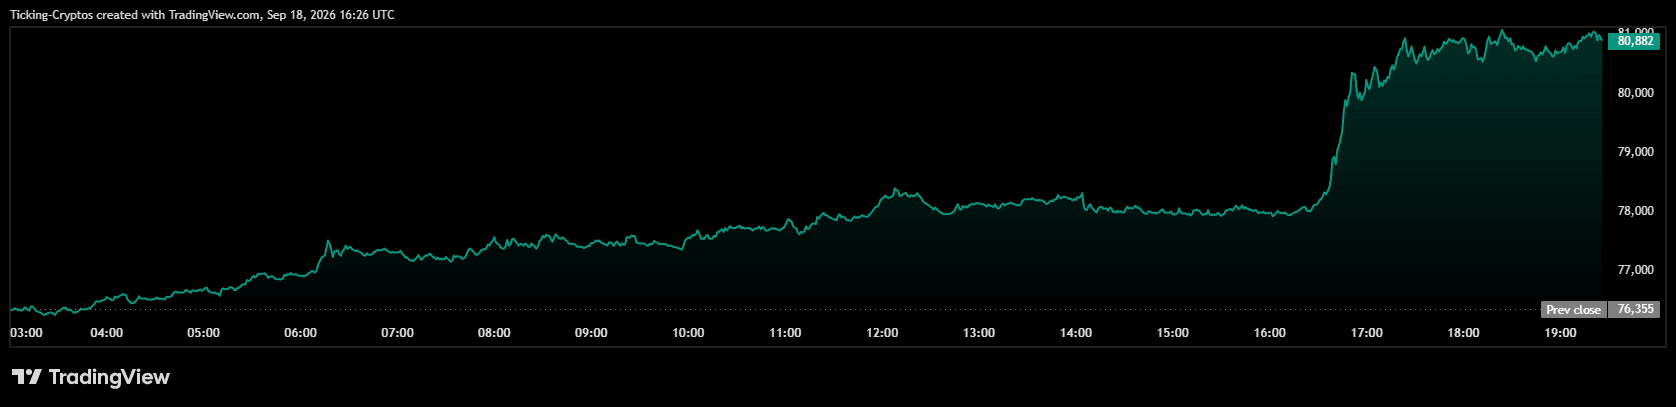
Why Did the Bitcoin Price Break Back Above $80,000?
There is no single smoking gun. The rebound above $80,000 extended a technology-led relief rally, coinciding with yen weakness and following a return to Bitcoin ETF inflows the previous day. The advance was already underway during European trading hours, before weak US economic figures gave markets a fresh argument against further monetary tightening.
In other words: risk appetite is recovering, and Bitcoin is the highest-beta expression of that. Repeated ETF inflows would be a far more convincing demand signal than a single day of buying, so treat this as a relief bounce until proven otherwise. $BTC is still down 7.43% on the year.
Which Altcoins Are Leading the Crypto Rally?
$Solana is the standout among the majors at $111.53, up 10.28% on the day and 9.66% on the week. $Ethereum added 5.37% to $2,596, $XRP gained 5.94% to $1.38, and $BNB climbed 4.54% to $759. $Dogecoin tacked on 6.91%, Chainlink 7.09%.
Are Privacy Coins Quietly Winning 2026?
This is the trade nobody wants to talk about at dinner parties. $Monero jumped 17.33% to $598, the biggest 24-hour move in the top 15, and is up 38.25% year to date. $Zcash is at $1,474 after a 26.44% weekly run and an eye-watering 187.77% YTD gain. $Hyperliquid is the other outlier, up 11.22% on the day and 259.38% on the year.
While Bitcoin fights to stay above a level it first cleared long ago, privacy coins and a handful of newer names are the only assets on the board with genuinely strong annual numbers.
What Happens Next for BTC Price?
$80,000 was resistance yesterday. If it holds as support into the weekend, the case for a proper reversal gets much stronger. If ETF flows stall and BTC slips back under, this goes down as another bounce in a choppy year.
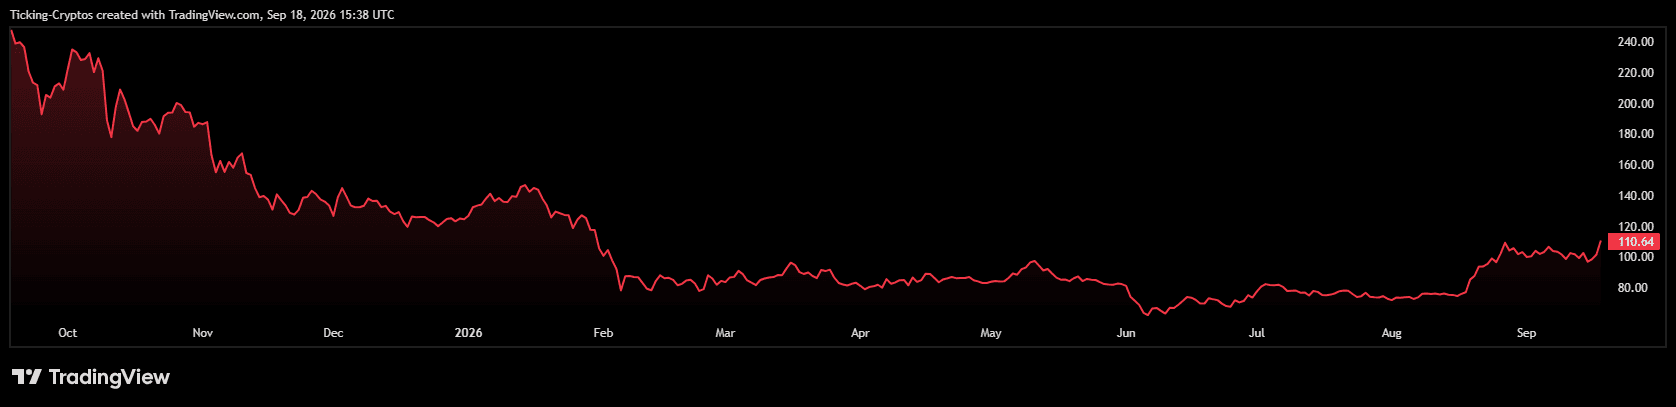
For most of the past year, Solana was a chart nobody wanted to open. From roughly $240 last October it bled almost without pause into a June low near $62. Then in mid-August the whole thing changed in about three sessions, and $SOL has spent the last month doing something it had not done all year: holding above $100.
Where is the SOL price right now?
$Solana has just tagged $110. That is the top of the range it has traded in since the August breakout, and it is the level this entire setup has been building toward. The session opened at $101.52 with a low of $100.80, so SOL has swung close to 10% inside a single day.
The floor is the other half of the story. $100 was the ceiling that capped every rally from February through August. It is now acting as the floor. A level that flips from resistance to support is the single most reliable signal in technical analysis, and SOL has now defended it repeatedly, including a drop to around $95.84 earlier this week when the US Senate failed to advance the CLARITY Act. Even that scare got bought back inside two sessions.
Zoom out and the damage is still obvious. SOL is roughly 56% below its October 2025 high. But the shape of the chart has changed completely since August.
What does the SOL chart analysis say about $120?
Look at what happened in mid-August. Solana had been grinding in a tight band between $72 and $85 for six weeks, compressing to barely $75 to $78 by the end of the month. Then it went vertical: through $76, through the 200 EMA, through $90.21, and straight into the $100 handle. Early September printed a high near $110.
The weeks since were spent digesting between roughly $95 and that level rather than giving the move back, which is exactly what a healthy market does after an expansion.
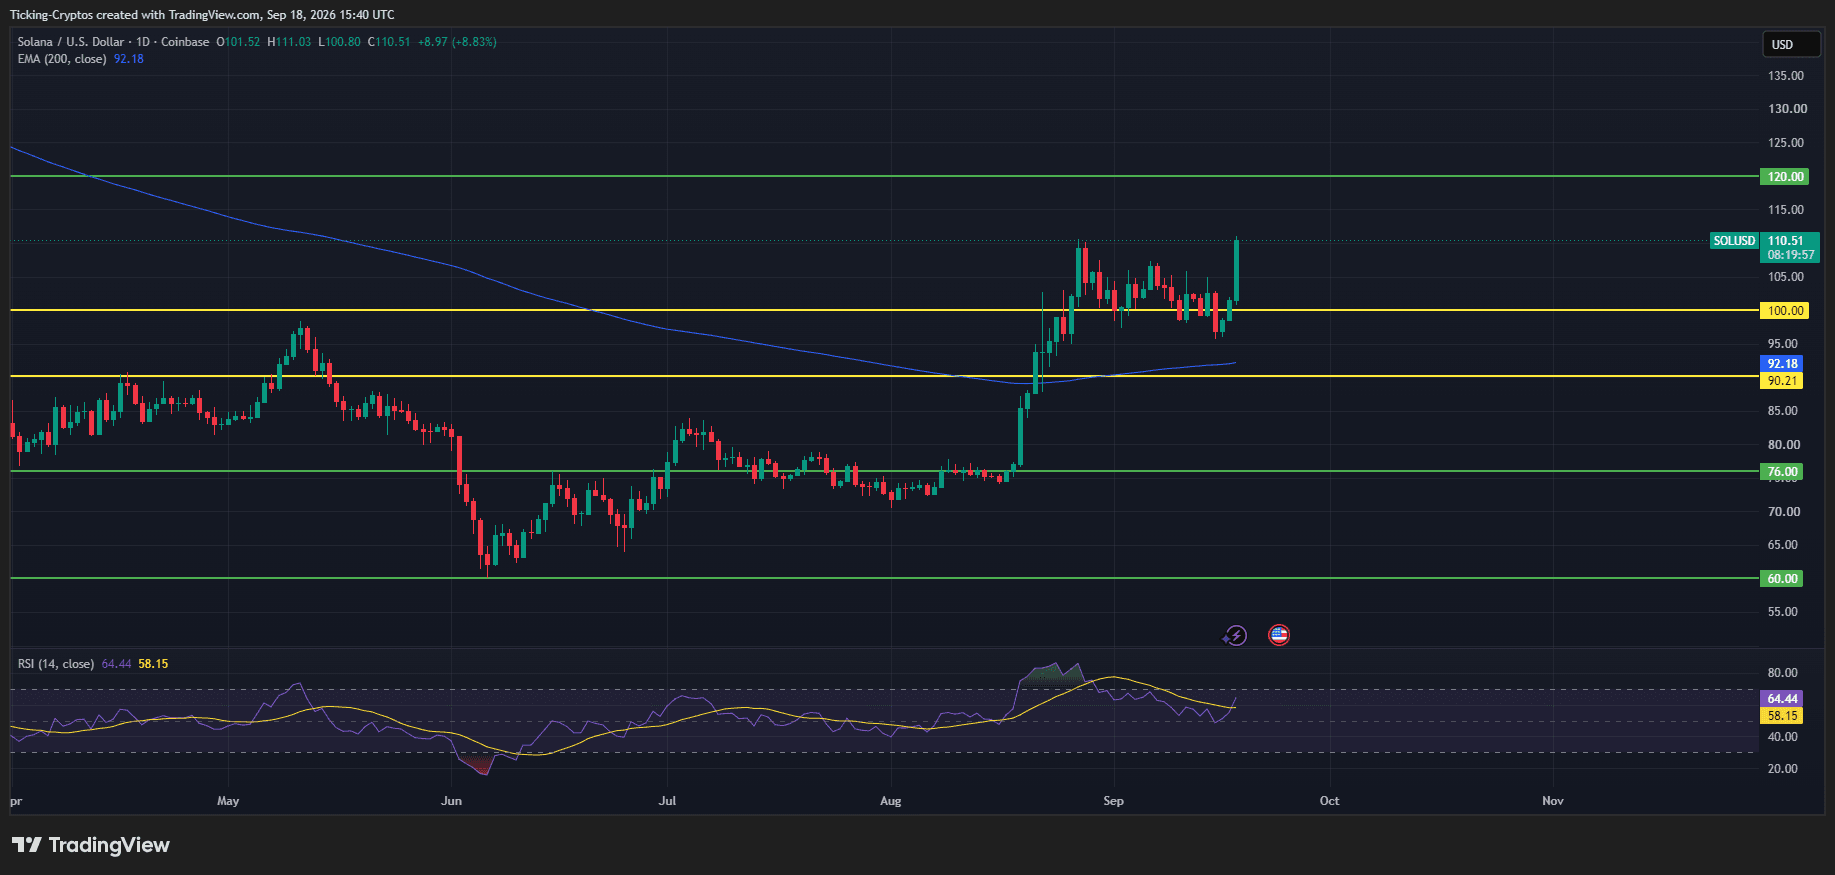
SOL is now back at the top of that range. Second tests of a range high tend to work far more often than first ones, because the sellers who defended the level in early September have had four weeks to get filled. That is the situation on the screen right now.
The measured move math points at the next target. The multi-month base between $76 and $100 was 24 points wide. A confirmed break above $100 projects roughly $124, which sits right on top of the $120 level drawn on the chart. That is the first real objective, not a stretch goal.
Above $120, the chart thins out fast. The next marked levels are $144.04 and then $160, both of which come from the early-2026 breakdown structure. There is very little traded volume between them, which is why moves through this zone tend to be quick when they come.
Is the 200 EMA finally working for Solana instead of against it?
This is the piece most people are missing.
The 200-day EMA sits at $92.13. For the entire first half of the year it sloped down, and it rejected SOL on every single attempt to recover. Solana is now trading about 15% above it, and the line itself has flattened and started to curl upward for the first time in 2026.
That is the difference between a relief bounce and a structural change. A rising long-term average underneath price turns pullbacks into entries rather than exits.
RSI supports the setup without overheating. The 14-period reading is 60.18, sitting above its own signal line at 57.84. That is firmly in bullish territory with no overbought condition, meaning there is room for another leg before momentum needs a rest.
Are ETF flows and the network upgrades enough to get SOL there?
The fundamental backdrop has improved more quietly than the price.
US spot Solana ETFs have now recorded nine consecutive weeks of net inflows, with more than $200 million arriving in the past month alone. The latest reading put the 30-day total at $220.1 million and cumulative net inflows at roughly $1.37 billion. The nine products tracked by SoSoValue held about $1.41 billion in net assets in early September. Flows are not explosive, but they are persistent, and they held up through the CLARITY Act disappointment.
Regulatory positioning also improved. On 5 September the SEC formally named SOL a core ETF asset alongside Bitcoin and Ether for commodity-based trusts, which matters far more for future product launches than for today's candle.
On the technical side, the roadmap is dense. Transaction V1 went live on 9 September, raising the maximum serialized transaction size from 1,232 to 4,096 bytes and opening the door to ZK proofs and more complex on-chain operations. A phased rent reduction started on 31 August, targeting roughly 90% lower on-chain storage costs across five stages.
The big one is Alpenglow, the largest consensus overhaul in Solana's history. It retires Proof of History and Tower BFT in favour of Votor and Rotor, cutting transaction finality from about 12.8 seconds to roughly 150 milliseconds and freeing up around three quarters of block space currently consumed by validator votes. Mainnet activation is targeted for October 2026 with the Agave 4.3 release.
An October catalyst landing while price sits just under a breakout level is a setup worth respecting. If you are positioning for it, it is worth checking fees and SOL spreads first, since the difference between venues eats into a 20% move faster than most people expect. Our updated table lets you compare the best crypto exchanges side by side.
What would invalidate this Solana price prediction?
First, a rejection at $110 is not a failure. It simply resets the range and sends SOL back toward the middle of it. Range highs are rarely taken on the first or second attempt.
The level that actually breaks the thesis is $100. That is the whole case in one number: the breakout level, the flipped resistance, and the line that has now been defended more than once.
A daily close back below $100 puts the 200 EMA at $92.13 in play, immediately followed by the $90.21 shelf. Lose both and the August breakout starts to look like a liquidity grab rather than a trend change, with $76 as the next structural support underneath.
The risks are not only technical. SOL inflation still runs near 3.7%, the active validator count has fallen to roughly 800, which raises fair questions about centralisation, and Alpenglow has already slipped once from September to October. Upgrades that slip tend to slip again.
Solana price prediction: how realistic is $120?
Analyst views are spread wide. Chart-based targets cluster around $140 if the current bull flag resolves upward, while long-horizon models put SOL's base case far higher and are therefore close to useless for a September or October decision.
The chart gives the cleaner answer, and it is no longer hypothetical. Solana does not need a new narrative to reach $120. It needs a daily close above $110 rather than a wick through it, and then the measured move, the rising 200 EMA, the RSI position and the October upgrade catalyst all point the same way. Tagging the level was the easy part. Closing above it on real volume is the confirmation, and that is what to watch into the weekly close.
Fail to hold $100 and none of that matters. Ranges resolve in both directions, and this one has not resolved yet.
Ethereum spent most of this year looking like the coin everybody had given up on. Then one candle in August changed the entire picture, and ETH has been quietly building a launchpad ever since. The $3,000 level is no longer a fantasy number. It is roughly 19% away, and the chart is doing exactly what it needs to do to get there.
Where Is the ETH Price Right Now?
$Ethereum is trading at $2,510 on the daily, up 2.65% on the session, after opening at $2,445 and tagging $2,518 intraday. The low of the day was $2,435, which is the important part, because that is the third time in a month buyers have shown up in that exact zone.
Step back and the year looks brutal. ETH ground sideways through April near $2,400, rolled over in May, and collapsed through June into a low around $1,550. That is a drawdown of more than 65% from the August 2025 all-time high near $4,946. July was a slow repair job above $1,600. August was a boring drift between $1,900 and $2,050.
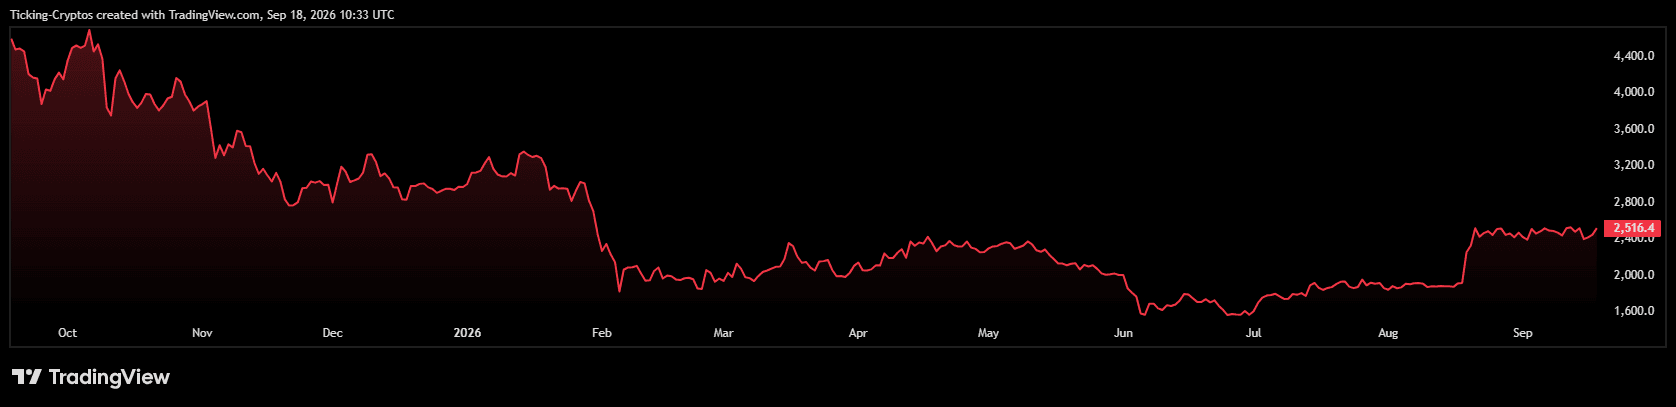
Then came the candle. In mid-August, Ethereum went vertical in a single daily session, ripping from roughly $1,950 through $2,000, through the 200 EMA, through $2,400, and closing near $2,500. That is a 28% expansion move in one bar, and it did not retrace. Everything since has been consolidation, not distribution.
What Does the ETH Chart Say About $3,000?
The structure right now is a textbook range. $2,400 is the floor. $2,600 is the ceiling. Ethereum has been locked between them for a full month, and neither side has broken.
That matters more than it sounds. When a market makes a violent vertical move and then goes sideways at the highs instead of giving the move back, it is usually absorbing supply rather than topping out. Sellers who wanted out at $2,400 have been getting filled for four weeks, and price has not cracked.
The measured move math is clean. The $1,600 to $2,000 base was 400 points wide, and the breakout above $2,000 projected $2,400. That target was hit almost exactly. The current $2,400 to $2,600 range is 200 points wide, so a clean daily close above $2,600 projects $2,800. From there, $3,000 is the next horizontal level on the chart, and it is the level that was acting as resistance through the entire first half of the year.
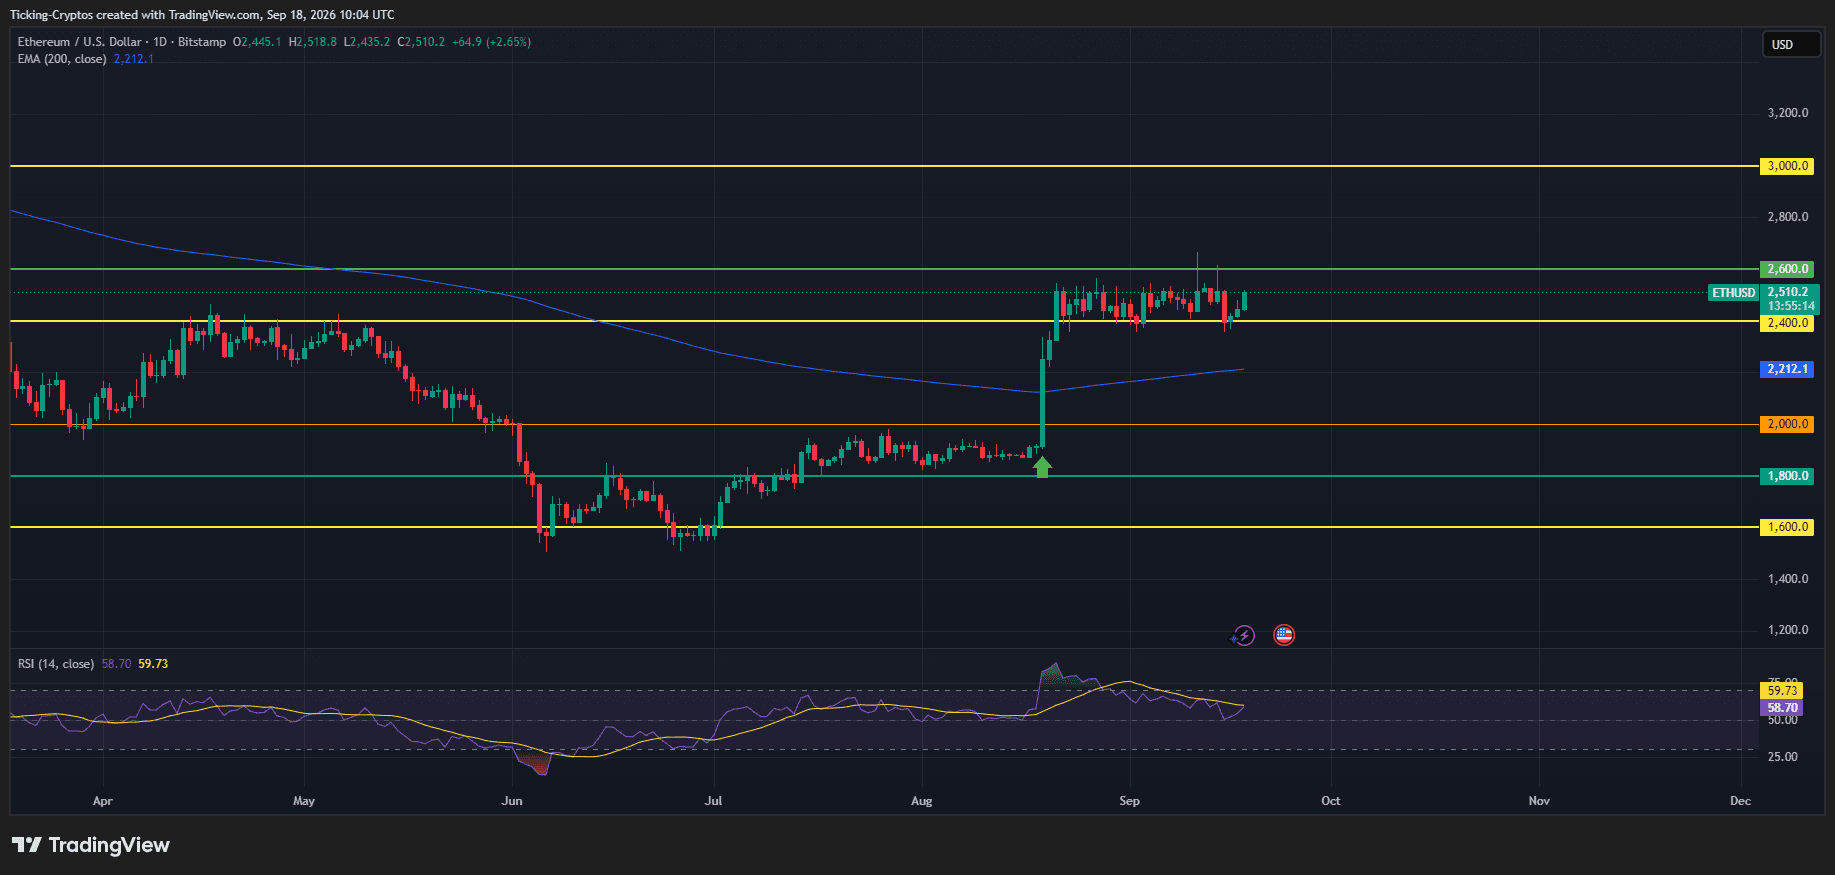
So the path is not a single leap. It is two steps: reclaim and hold $2,600, then run the gap to $2,800 where there is almost no historical resistance, then attack $3,000.
Is the 200 EMA Turning Bullish for Ethereum?
The 200-day EMA sits at $2,212. For eight straight months it pointed down, and every rally in spring and summer died against it. Ethereum is now trading roughly 13% above it, and more importantly, the line itself has flattened and hooked upward for the first time this year.
A rising 200 EMA underneath price is what separates a dead-cat bounce from a trend reversal. As long as ETH stays above it, the medium-term bias flips from bearish to constructive, and pullbacks become buyable instead of terrifying.
RSI backs this up without screaming. The 14-period reading is 59.73, sitting just above its own signal line at 58.70. That is the bullish half of the range with no overbought condition anywhere in sight. Ethereum can rally another 15% before RSI even starts flashing warnings, which is exactly the kind of fuel tank you want before a breakout attempt.
Are ETF Inflows Strong Enough to Push ETH to $3,000?
The chart is not moving in a vacuum. Institutional flow has flipped hard in Ethereum's favor.
US spot Ethereum ETFs pulled in roughly $1.75 billion to $1.85 billion in August 2026, their best month since August 2025, after more than $1 billion had left the funds in May and June. The week ending September 11 added another $197 million, a fourth consecutive positive week, while Bitcoin ETFs bled $463 million over the same stretch. A single session on September 11 brought in $216 million, the largest daily total of that week.
That divergence is the story. Money is not leaving crypto, it is rotating from Bitcoin into Ethereum, and the staking yield inside the newer ETH products is a large part of why. Ethereum spot ETFs now hold $16.31 billion in total net assets, around 5.28% of Ethereum's entire market capitalization.
One caveat worth being honest about: the buying is heavily concentrated, with BlackRock's ETHA accounting for roughly 72% of the inflow streak that began in mid-August. A trend carried by one issuer is a trend with a single point of failure.
The other catalyst is on the roadmap. The Glamsterdam upgrade has slipped to Q4 2026, with the Sepolia testnet fork scheduled for 28 September. A delayed catalyst is still a catalyst, and it lands right in the seasonal window where crypto tends to get interesting.
What Would Invalidate This Ethereum Price Prediction?
$2,400 is the line. It is the breakout level, it is the range floor, and it has now been defended three separate times. Bitfinex analysts also flagged the September 11 daily low near $2,432 as the level to watch on pullbacks.
A daily close below $2,400 kills the range and puts the $2,212 EMA directly in play. Lose that, and the August candle starts looking like a liquidity event rather than a trend change, with $2,000 the next real shelf underneath.
The bearish case is not just technical. ETF flows can stop as fast as they started, and the macro backdrop around Fed policy has been the single biggest driver of crypto beta all year.
Ethereum Price Prediction: How Soon Can ETH Hit $3,000?
Analyst targets are scattered across a wide band, which tells you the market genuinely does not know. CoinDCX puts September at a $2,800 target with a $2,405 to $2,950 range. LongForecast is far more aggressive, modelling a September close near $2,959 and October at $3,432. Messari's base case is $3,200 to $3,800 by December, with VanEck pointing to $4,500 if macro conditions improve. Prediction markets are more sober, giving roughly a 31% chance of a $3,500 touch before year end.
Strip out the noise and the chart gives a cleaner answer. Ethereum does not need a miracle to see $3,000. It needs one daily close above $2,600 with volume, and the structure opens up. Given the range has already compressed for four weeks with a rising 200 EMA underneath and RSI holding the bullish band, a breakout attempt in October is the base case, not the moonshot case.
Fail at $2,600 again and $ETH simply keeps grinding between $2,400 and $2,600 until something forces a decision. Ranges do not last forever.
This week was supposed to be the one that ended the rally. The Senate killed the crypto industry's biggest legislative push in years on Tuesday. The Federal Reserve raised interest rates for the first time since 2023 on Wednesday. Two catalysts, 24 hours apart, both pointing down.
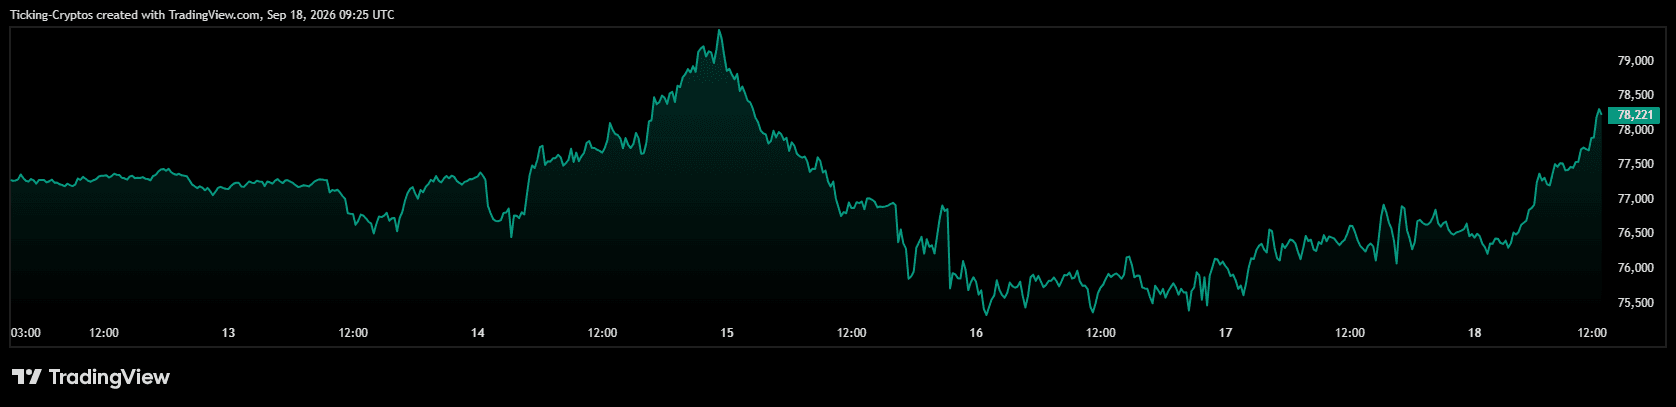
$Bitcoin is trading near $77,900 as of Friday, after a previous close of $76,559 and a day range between $76,289 and $78,051. It gave up ground, took it back, and is now sitting almost exactly where it started the week. That is not weakness. That is consolidation, and there are three solid reasons behind it.
What Is Actually Happening in the Crypto Market Right Now?
Over the past 30 days Bitcoin is up 20.5%, having run from roughly $64,000 in mid-August to the high $70,000s, with an average price of $77,286 across the period. August alone delivered a 25% gain.
A market that has just added a fifth of its value in a month does not usually push straight through. It ranges, it shakes out leverage, and it waits for the next input. That is exactly what the $75,000 to $78,000 band has been doing.
Reason 1: The Bad News Was Already in the Price
The Fed hike was priced at roughly 93% odds in futures markets going into the meeting. When the 12-0 decision landed, Bitcoin spiked to about $76,500 within five minutes and gave the move back within half an hour. A market that barely reacts to a confirmed hawkish event has already absorbed it.
The CLARITY Act was a similar story. Bitwise's CIO had already revised his outlook on the bill and argued the bull market can continue without legislation, pointing out that Bitcoin climbed above $80,000 in early September even as the odds of passage were falling. Traders had been repricing the legislative path for weeks before the vote.
Reason 2: Institutional Demand Has Not Left the Table
This is the strongest leg of the argument. Total Bitcoin ETF assets sit above $103 billion after August pulled in $3.52 billion, the best month of 2026.
The altcoin funds tell the same story. On days when spot prices fell, $Ethereum, $Solana and XRP ETFs still posted net inflows of $10.95 million, $10.19 million and $14.38 million, and $XRP funds ran 11 consecutive days of net buying worth roughly $170 million. Nasdaq put $100 million into Payward, Kraken's parent, on September 10 at a $21 billion valuation, and the Canary staked TRX ETF launched on September 9 as the first spot staked crypto fund in the US.
Positioning adds to the case. JPMorgan noted on September 16 that gold ETFs have recovered all of their 2026 outflows while Bitcoin ETFs have recovered only about half, and that short interest in BlackRock's IBIT remains near its highest level of the year. If that hedging pressure unwinds, it becomes fuel rather than drag.
Reason 3: Regulation Is Moving Without Congress
The CLARITY Act failing 49-50 looked like a wall. It is closer to a detour.
The SEC put Regulation Crypto Assets out for comment in August and has since opened a five-year pathway for tokenized US stock trading. The CFTC chair had already instructed staff to build a market-structure regime under existing Commodity Exchange Act authority. Neither depended on the Senate.
Congress has not gone quiet either. The House Financial Services Committee advanced the American Reserve Modernization Act, H.R. 8957, by 28-21, keeping the US Bitcoin reserve idea alive. Outside the US, Canada's financial regulator clarified that tokenized bank deposits are legally equivalent to traditional deposits. The direction of travel has not reversed, only the vehicle has changed.
What Could Still Break the Bull Case?
Being honest about the other side matters. Bitcoin remains roughly 39% below its October 2025 all-time high of $128,198, and the 52-week range runs from $57,833 to $126,186, so this is still a recovery, not a breakout.
The Fed is the real risk. Sixteen of eighteen officials project at least one more hike this year and four expect two, which puts December in play. With the 10-year Treasury yield near 5% and Bitcoin carrying a 0.89 correlation to the S&P 500 and 0.91 to the Nasdaq, crypto is trading as a risk asset right now, not as a hedge. If equities crack, crypto follows.
The short answer first: if you hold Bitcoin privately and move away from Germany, the move itself triggers no tax on your capital gains. There is no deemed sale on the day you deregister and no taxation of unrealised gains on your wallet balance. The exit tax that so many emigrants warn about catches something other than crypto assets.
The move can still become expensive if you overlook the four places where German tax law reaches you even after departure: the moment your tax residence genuinely ends, the one-year holding period that keeps running when you sell, the legal form of your crypto investment, and the question of what your tax office will learn automatically from the 2026 reporting year onwards. This article works through those points in order, under German law, with the statutory references you can put in front of your tax adviser if in doubt.
Does the exit tax under Section 6 AStG apply to Bitcoin held privately?
Exit taxation means the state treats an asset as if you had sold it on the day you left and taxes the increase in value, although not a single euro has reached you. That is a hard intervention, and it is precisely why the legislator drew the scope narrowly.
Section 6 of the Foreign Transactions Tax Act attaches to shareholdings within the meaning of Section 17(1) sentence 1 EStG, meaning holdings in corporations from a stake of one percent upwards. Shares in a German GmbH fall under it, and so do equity blocks above that threshold. A Bitcoin, an Ether or a stablecoin in your own wallet is not a holding in a corporation. The wording of the provision leaves no room here, and that is why there is no German exit tax on directly held crypto assets in private hands. You can read the statute yourself if you want to: Section 6 AStG on the portal of the Federal Ministry of Justice.
The distinction matters in both directions. Anyone holding their coins through their own GmbH is not safe merely because the underlying asset is crypto. In that case the GmbH share is the asset that triggers the exit tax, and the value of the coins inside it helps determine how much tax falls due. The structure is widespread among German investors, and it turns the outcome on its head. Readers interested in the motives behind such departures will find the reasons and the destination countries set out in our survey of why crypto investors emigrate.
When does your unlimited tax liability end: residence under Section 8 AO and habitual abode under Section 9 AO
The decisive question when you leave is not when you boarded the plane but when your unlimited tax liability ends. You are subject to unlimited tax liability for as long as you have a residence or your habitual abode in Germany. The German tax authorities then capture your worldwide income, including gains made on a crypto exchange in Singapore.
Residence: the key counts, not the deregistration certificate
Section 8 of the Fiscal Code defines residence by the facts on the ground: you keep a dwelling under circumstances suggesting that you will retain and use it. Deregistering at the residents' registration office is evidence of that and nothing more. Anyone who leaves the old flat standing empty, who keeps a room in the family home available at any time, or who has held on to the key to a shared flat risks the tax office treating the residence, and with it full tax liability, as continuing. A genuine tenancy agreement solves the problem. An accommodation arranged as a favour among relatives usually does not.
Habitual abode: the six-month line
Section 9 of the Fiscal Code adds the habitual abode: anyone staying in Germany for more than six consecutive months is subject to unlimited tax liability even without a dwelling, and short interruptions count towards the period. For emigrants with a German client base this is the most common trap. Spend every summer in Germany without ever documenting the days and you will have nothing to set against a tax audit later. Keep a plain travel log from day one, with dates, border crossings and evidence.
If your unlimited tax liability ends mid-year, you also need a tax report that separates the periods cleanly. Many portfolio tools default to full calendar years. Which programs handle partial periods and several tax jurisdictions is set out in our comparison of crypto tax software and portfolio trackers.
The one-year holding period under Section 23 EStG keeps running when you leave
For as long as you are subject to unlimited tax liability in Germany, gains on the sale of crypto assets are private disposal transactions under Section 23(1) sentence 1 no. 2 EStG. If more than a year lies between acquisition and sale, the gain stays tax-free. Below that it counts as taxable income and is charged at your personal rate. An exemption limit of 1,000 euros applies to all private disposal transactions of a year taken together. An exemption limit is not an allowance: one euro above it makes the entire gain taxable.
Leaving the country does not interrupt that period, it only shifts who taxes at the end. What counts is the actual sale or swap, and where you are tax resident at that moment. From this follows the most practical rule in this article: do not sell while your change of residence is still incomplete. Cash in coins inside the one-year period two weeks before you deregister and you pay the full German rate on the entire gain.
The reverse holds as well. Your acquisition data does not disappear because you leave the country. Your new country of residence will ask, by its own rules, when you bought and at what price, and some states use the value at the time of arrival. Which records support a German holding period is something we have written up in detail elsewhere, and the same paperwork will serve you abroad.
Crypto ETPs, ETFs and fund units: where the exit tax under Section 19 InvStG does bite
This is where matters turn unexpectedly serious for many German investors. Since 1 January 2025 the Investment Tax Act has had its own exit tax for fund units held privately. Under Section 19(3) InvStG, the end of unlimited tax liability through giving up a residence or a habitual abode is treated as a disposal at fair market value. The tax authorities therefore act as though you had sold your fund units on the day you left.
That is triggered only above two thresholds, either of which suffices: you held at least one percent of a fund's issued units at some point in the past five years, or your units in that fund carry acquisition costs of at least 500,000 euros. Anyone with a larger portfolio of broad equity ETFs alongside a crypto allocation breaches the second threshold sooner than they would like.
Whether your crypto position itself falls under this depends purely on the legal form of the product. An investment unit is a unit in an investment fund within the meaning of the Investment Tax Act. The crypto ETPs common in Europe, by contrast, are mostly structured as debt securities, meaning ETNs, and therefore precisely not fund units. A US spot ETF on Bitcoin, on the other hand, is a fund. Check each position individually for what you actually hold, and use the terms of issue or the key information document for that, not the product name on your brokerage statement. On departure this distinction decides a five-figure tax bill.
Extended limited tax liability under Section 2 AStG: when a low-tax country holds you for ten years
Extended limited tax liability is a run-on. Germany continues to tax you after you leave, though only on certain categories of income and only under narrow conditions. It is governed by Section 2 AStG and catches only those who meet every criterion at once.
First, in the ten years before the end of your unlimited tax liability you must have been subject to unlimited income tax as a German national for at least five years in total. Second, you must be resident in a low-tax territory or in no state at all; the law measures this against a comparative income of 77,000 euros and a burden of less than two thirds of the German income tax. Third, you need substantial economic interests in Germany, which Section 2(3) AStG assumes among other things where domestic income exceeds 62,000 euros or domestic assets exceed 154,000 euros. Where all of that applies, the run-on lasts until ten years after the end of the year of departure, and it takes effect only above 16,500 euros of income subject to limited tax liability in an assessment period.
For crypto investors the point is delicate, because Section 2 AStG captures all income that does not constitute foreign income within the meaning of Section 34d EStG. A gain on the sale of coins can be allocated neither to foreign real estate nor to a foreign permanent establishment, so the classification has to be settled case by case. Anyone moving to Dubai, Paraguay or a similarly taxing country while keeping German rental income or a stake in a German company should settle that question with a tax adviser before the move rather than after it.
Commercial trading and business assets: deemed disposal instead of exit tax
If you hold your crypto assets as business assets, a different system applies. Deemed disposal means that Germany treats an asset as withdrawn as soon as the German right of taxation over it is excluded or restricted; the legal basis is Section 4(1) sentence 3 EStG. Move your business abroad and cessation of business under Section 16(3a) EStG comes into play on top.
So anyone trading commercially, mining commercially or running a trading structure can well trigger taxation of unrealised gains on departure, and that without Section 6 AStG being needed at all. The line between private asset management and a trade depends on scale, external financing, organisation and outward appearance. If that question gives you pause, that in itself is a sign that a case-by-case review is needed.
Double tax treaties: who taxes when both states see you as resident
In the first months after a move it often happens that two states treat you as tax resident at the same time. German double tax treaties provide an order of precedence for this, modelled on Article 4 of the OECD Model Convention: first the permanent home, then the centre of vital interests, then the habitual abode, and finally nationality.
The centre of vital interests is where most emigrants come unstuck, and it is measured by mundane things. Where does your family live, where is your doctor, where is the sports club, where is the current account that pays the running costs. You do not change country with a passport alone. Most treaties, incidentally, allocate gains on the sale of crypto assets to the state of residence, because they fall under the catch-all clause for other property. That too is what makes a clean determination of residence so important.
Where your coins sit: self-custody, exchange accounts and the duty to cooperate under Section 90 AO
The location of your coins is irrelevant for tax purposes; the location of your records is not. The Federal Ministry of Finance circular of 6 March 2025 on individual questions of the income tax treatment of certain crypto assets regulated the duties to cooperate and to keep records explicitly for the first time, and it replaces the older circular of 10 May 2022. Anyone buying or selling through centralised trading platforms run by foreign operators is subject to the extended duty to cooperate in cross-border matters under Section 90(2) AO. In plain terms, you have to establish the facts and obtain the evidence yourself, and the tax office may estimate if you cannot. The full text is available as a PDF from the Federal Ministry of Finance.
That creates a practical difference between the forms of custody. An exchange account is tied to an identity and to a country: many providers block or restrict accounts when the registered address changes to a country they do not serve, and exporting the trading history then becomes difficult. A self-custody wallet moves with you and needs nobody's consent. The price is that nobody else keeps your records. If you are switching to self-custody, do it before you leave rather than after, and download every transaction history first. Which device suits you is covered in our hardware wallet comparison.
What the tax office learns about your crypto accounts from 2026: DAC8 and the KStTG
DAC8 is EU Directive 2023/2226 on cooperation between tax administrations, which obliges providers of crypto services to report on their customers. Germany implemented it through the Crypto Asset Tax Transparency Act, which came into force on 1 January 2026. The first reporting period is the 2026 calendar year; providers transmit the data by 31 July 2027 to the Federal Central Tax Office, which exchanges it with partner states.
For a departure that has two consequences. First, your master data and aggregated transactions for 2026 are reported even if you move away in the course of that year, and the comparison with your final German tax return does take place. Second, the report follows the country of residence that you give your provider. An out-of-date address in your customer account therefore generates reports to the wrong country, and untangling that costs more time than updating it in good time. How the reported amount is arrived at, and why it does not correspond to your gain, is explained in our piece on crypto reporting duties and the difference between the gross amount and the gain.
The misconceptions that get expensive when you emigrate with Bitcoin
“I have deregistered, so I am out.” Deregistration is registration law, not tax law. What counts is dwelling and abode under Sections 8 and 9 AO.
“Crypto falls under the exit tax.” For directly held coins in private assets it does not arise. For fund units above the thresholds of Section 19 InvStG, and for shares in corporations, the picture is different.
“After the move I can sell tax-free.” That holds only if your unlimited tax liability had genuinely ended at the time of sale, no run-on under Section 2 AStG applies, and your new country of residence does not tax the transaction itself.
“My exchange is abroad, so nobody finds out.” Since the 2026 reporting year that is a mistaken assumption made with fair warning, and the cross-border element triggers the stricter duty to cooperate on top.
“I will sort that out after the move.” Almost every planning option in this article requires you to use it before the cut-off date. After that, all you are doing is documenting.
Which records to secure before you move
The burden of proof for the date and the cost of acquisition lies with you, and it does not lapse with your residence. Before you leave, download the complete transaction export as a CSV from every platform, along with the annual statements, the bank's deposit and withdrawal receipts, and the account statements showing the euro inflows.
What is usually missing once it is needed
Records from trading venues that have since closed. Wallet addresses you never wrote down and whose link to you only you know. Documentation of swaps between two coins that never touched a euro account and are therefore absent from the bank statement. Evidence of staking and lending income, which many platforms keep for only twelve months. And the record of which units were disposed of in a partial sale, which you have to keep per wallet anyway once you use more than one.
Put the export on a medium that survives the move and keep a second copy separately. A tax report that cleanly closes out your German period is the best investment of this move.
Bitcoin and moving abroad: what to take away
- Settle the cut-off date first, not the tax. Determine the date on which your dwelling and abode in Germany demonstrably end, and place every sale deliberately before or after it. Keep your position data cleanly separated as you go; the tools that handle partial periods are in the comparison of crypto tax software.
- Check every position for its legal form. Directly held coins are not caught by the exit tax, while fund units from 500,000 euros of acquisition costs and holdings in corporations are. At the same time, move your custody into a form that travels with you: the options are in the hardware wallet comparison.
- Secure the records before you go. Complete transaction export, bank records, wallet addresses and a closing report for your German period. If you notice that a year has gaps, close it now with one of the portfolio trackers and not when the tax office asks.
This article sets out the legal position and does not replace tax advice in an individual case. On departure in particular the outcome turns on details that only someone who knows your paperwork can judge.
(As of September 18, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
XRP is roaring back as Bitcoin claws its way above $800,000 again, but the charts continue to give traders mixed signals.
The agency submitted a prerule on crypto asset transactions and markets to the White House for review, signaling it will build a derivatives framework on its own authority after the Clarity Act's collapse.
Bitcoin just ripped 5.88% higher in a single session, tearing back toward its 2026 highs. The charts say the move is real, but they also say it's gotten ahead of itself.
Internal memos warned of a "doom loop" threatening the quality of the very models it was building with OpenAI.
It came just hours after S&P Global announced its acquisition of OpenZeppelin, as everything TradFi moves onchain.
U.Today - IT, AI and Fintech Daily News for You Today
Barry Silbert mirrors his early BTC and Zcash strategies, shifting institutional DCG capital to back Bittensor (TAO) as the next major AI scarcity play.
XRP gains spotlight in South Korea after its largest treasury firm, Evernorth, secured a massive $30 million funding from South Korean investment firm NH Investment & Securities through convertible notes.
XRP whales moving big with Binance inflows reaching 1.6 billion tokens.
Following a record ATH, Hyperliquid hits the top 10 as analyst Aksel Kibar predicts a 3-digit price tag.
XRP Ledger payment volume has surged above 1.1 billion XRP, more than twice the 30-day average, as XRP attempts to recover from its latest decline.
Blockonomi
TLDR
- Amazon’s air cargo network prepares for a major Airbus A330 fleet expansion
- ATSG receives its first Amazon-ready A330 and targets operations in 2027
- ABX Air plans new pilots and maintenance staff for the expanding A330 fleet
- Amazon has committed to multi-year leases covering four Airbus A330 freighters
- ATSG expands beyond Amazon through new Latin American cargo operations
Amazon (AMZN) stock traded at $253.20 as its air cargo network prepared for a wider Airbus A330 rollout. The expansion will gradually reduce reliance on Boeing 767 aircraft across Amazon’s cargo operations. Meanwhile, Air Transport Services Group is preparing its first A330 for Amazon service in 2027.
Amazon.com, Inc., AMZN
Amazon Prepares for A330 Expansion
ATSG received its first A330 freighter modified from a passenger aircraft for Amazon’s cargo network. The company expects ABX Air to begin operating the aircraft during the first quarter of 2027. Meanwhile, Amazon has committed to multi-year operating leases covering four A330 aircraft.
ABX Air must complete Federal Aviation Administration programs before adding the A330 to its operating certificate. These programs cover pilot training, aircraft operations, and maintenance procedures for the new type. Therefore, ATSG plans to hire additional pilots and maintenance workers as A330 capacity increases.
ATSG currently operates 56 aircraft within Amazon’s fleet of more than 100 planes. The company has supported Amazon since 2016 using Boeing 767-200 and 767-300 freighters. Meanwhile, Alaska Airlines operates 11 Airbus A330 freighters for Amazon.
ATSG Builds a New Freighter Fleet
The A330 expansion reflects the declining supply of mid-life Boeing 767 passenger aircraft available for cargo conversions. Boeing no longer produces the 767, while older passenger aircraft continue to leave commercial service. As a result, ATSG has pursued the A330 as its next medium-widebody freighter platform.
ATSG plans to acquire and convert 30 A330 aircraft as part of its broader cargo fleet strategy. Airbus aftermarket affiliate Elbe Flugzeugwerke performs the passenger-to-freighter conversion work. However, supply chain problems have slowed the conversion program and delayed some planned deliveries.
EFW has delivered two converted A330 freighters to Turkey-based ULS Airlines Cargo so far. ATSG also plans to support its new aircraft through maintenance operations in Ohio and Florida. The company is developing an Airbus maintenance program at Wilmington Air Park and in Tampa.
Amazon Cargo Network Expands
ABX Air has also added a new cargo customer as ATSG expands its business beyond Amazon and DHL Express. Miami-based Global Aviation Link hired ABX Air to operate a Boeing 767-300 to Latin America. Under the one-year agreement, ABX Air provides the aircraft and operates the service.
The service began flights between Miami and Quito on September 2 and operates six days each week. Global Aviation Link plans to expand service toward Venezuela and Peru, which export flowers and fruit. The company already provides scheduled cargo service between Miami and Bogota using Boeing 767 aircraft.
ATSG also announced three executive appointments as it continues changes following its 2025 acquisition by Stonepeak. Mike Hough became group president for airlines and services, while Tim Schulze joined as chief risk officer. Doug Belding also joined as vice president for enterprise performance and operating systems.
The post Amazon (AMZN) Stock: Air Cargo Network Prepares for Airbus A330 Expansion appeared first on Blockonomi.
TLDR
- HSBC stock falls 1.56% as the bank expands Premier services across the US market.
- Premier now combines wealth, health, travel and cross-border banking services.
- New mobile tools let customers open brokerage accounts and manage investments.
- HSBC adds telemedicine, wellness benefits and enhanced travel support for clients.
- The bank strengthens its US wealth corridor with 21 Wealth Centers nationwide.
HSBC Holdings (HSBC) shares fell 1.56% to $101.24 as the bank expanded its Premier offering across the United States. The upgrade targets affluent customers seeking wealth, health, travel, and international banking services. The move supports HSBC’s broader plan to deepen its global wealth business.
HSBC Holdings plc, HSBC
HSBC Stock Slides as Premier Upgrade Reaches US Market
HSBC launched the enhanced Premier service as affluent customers increasingly manage money across several markets. The bank said the United States remains a leading destination for international investment. Its 2026 research found many wealthy clients plan to maintain or increase exposure to US assets.
The new service combines banking tools with support for customers who travel, relocate, or invest internationally. HSBC also wants to simplify access to financial services across different countries. The bank is positioning Premier as a wider relationship offering for globally connected customers.
HSBC shares still moved lower during the session despite the service expansion. The stock traded at $101.24 after falling 1.56% during the day. The decline came as HSBC promoted its larger US wealth strategy.
HSBC Expands Wealth Health and Travel Services
HSBC added new investment tools to its US mobile application for eligible Premier customers. Clients can open brokerage accounts, review holdings, and trade mutual funds through the platform. Wealth Relationship Managers will also continue providing financial planning and personalized support.
The health package includes third-party telemedicine services and wellness support for members. Customers can access doctors by phone or video for primary, urgent, and mental healthcare needs. The package also includes selected discounts on fitness, nutrition, massage, acupuncture, and other wellness services.
HSBC expanded travel benefits through global support, merchant partnerships, and credit card rewards. Premier customers can receive selected hotel and dining savings alongside points on qualifying travel purchases. Eligible cards also carry no foreign transaction fees for overseas spending.
US Wealth Strategy Targets Cross-Border Banking Demand
HSBC strengthened international banking features for customers moving money or relocating across borders. The service includes competitive foreign exchange rates and no HSBC fees on international transfers. Customers moving to the United States can also open accounts before arriving.
The Premier expansion forms part of HSBC’s wider strategy for the United States. The bank is combining digital services with physical wealth centers in major financial markets. HSBC currently operates 21 Wealth Centers across the country, including locations in New York and California.
HSBC relaunched its Park Avenue Wealth Center earlier this year and plans another relaunch in Cupertino this month. Its network also covers South Florida, Washington, Los Angeles, San Francisco, and Seattle. HSBC expects these centers to support affluent customers with international banking and wealth needs.
The post HSBC Holdings (HSBC) Stock: Plunge as Global Banking Push Expands With Premier Upgrade appeared first on Blockonomi.
Quick Overview
- Bitcoin pushed past the $80,000 threshold with approximately 5.5% gains in one day, shrugging off Federal Reserve rate increases and congressional setbacks on crypto rules
- Cryptocurrency-linked equities saw strong gains: Strategy jumped 12%, Coinbase climbed 10%, and Robinhood rose 8%
- Nvidia’s chief executive indicated potential for chip sales to double from 2026 to 2027
- Ten-year Treasury yields reached the 5% mark, creating headwinds for equities with nine of eleven S&P 500 sectors declining
- Congressional efforts to pass the Clarity Act stalled, leaving digital asset oversight with existing regulatory agencies
Digital currency markets witnessed significant upward momentum with Bitcoin crossing $80,000, while chip manufacturer Nvidia outlined ambitious growth projections and bond markets saw yields climb to levels that created pressure across equity sectors. Here’s a breakdown of the week’s major market developments.
Digital Currency and Related Equities Experience Strong Gains
Bitcoin’s price climbed approximately 5.5% within a 24-hour period, reaching around $80,940. This upward movement occurred even as the Federal Reserve implemented a 25-basis-point rate increase, bringing rates to a 3.75%-4.00% range, and as lawmakers failed to advance crucial digital asset legislation.
Market participants had broadly anticipated the central bank’s decision, which helped mitigate potential negative sentiment. The cryptocurrency’s strength provided momentum across the digital asset sector, with capital flowing back into this asset class.
Equities with cryptocurrency exposure demonstrated similar strength. Strategy’s shares increased approximately 12%, Coinbase recorded gains near 10%, and Robinhood advanced roughly 8%.
Strategy maintains substantial Bitcoin holdings on its corporate balance sheet, creating direct exposure to cryptocurrency price fluctuations. Coinbase sees immediate benefits from increased trading activity in digital assets. These three stocks had experienced declines earlier in the week due to rate concerns and legislative disappointments, making the subsequent bounce particularly notable.
Digital Asset Oversight Returns to Regulatory Agencies
Congressional efforts to move forward with the Clarity Act encountered a roadblock this week. The proposed legislation aimed to establish more definitive regulatory boundaries for digital assets and clarify jurisdictional responsibilities between the SEC and CFTC.
The legislative failure doesn’t signal an end to regulatory development. According to industry sources speaking with CoinDesk, both regulatory bodies are anticipated to continue crafting rules using their current statutory powers, even without fresh congressional mandates.
This situation leaves the digital asset sector navigating an environment without unified federal legislation, with agencies expected to exercise existing regulatory authority to address emerging issues.
Nvidia Executive Projects Dramatic Sales Growth by 2027
Jensen Huang, Nvidia’s chief executive, projected that the company’s chip sales volume could approximately double between 2026 and 2027.
According to projections referenced by Barron’s, Nvidia’s 2026 sales could reach approximately 5.09 million AI GPUs, plus tens of thousands of fully integrated AI server systems. The anticipated expansion is expected to be driven by the upcoming Vera Rubin architecture generation, central processing units, networking solutions, and additional AI infrastructure offerings.
The company previously indicated that revenue potential for its artificial intelligence chips could exceed $1 trillion cumulatively through 2027, illustrating the enormous investment levels directed toward AI computing infrastructure.
Bond Yields Reach 5%, Creating Equity Market Headwinds
The ten-year United States Treasury yield climbed back to approximately 5% on Friday, enhancing bonds’ relative attractiveness versus equities and compressing stock valuations.
Nine out of eleven sectors in the S&P 500 experienced declines during trading. Markets also navigated quarterly triple witching—the concurrent expiration of equity options, index options, and futures contracts—a phenomenon that typically amplifies market volatility.
Elevated yields disproportionately affect growth-oriented stocks because they increase discount rates applied to projected future earnings, reducing their present-day valuation.
The post Market Roundup: Bitcoin (BTC) Soars Past $80K, Nvidia (NVDA) Projects Chip Surge, Treasuries Touch 5% appeared first on Blockonomi.
Key Highlights
- BitMine (BMNR) shares climbed approximately 8% during Friday’s session, reaching $25.77 at the time of writing
- Ethereum’s robust 4.62% recovery to approximately $2,558 provided the primary catalyst for the rally
- Short-dated call options with strikes above $25 saw heavy volume as implied volatility spiked
- Eightco Holdings, supported by BitMine, revealed approximately $380 million in total assets, including a $90 million indirect stake in OpenAI
- BMNR currently trades above its 20-day, 50-day, 100-day, and 200-day simple moving averages, despite a January death cross that remains unresolved
BitMine Immersion Technologies (BMNR) delivered a robust Friday performance, climbing roughly 8% to $25.77, even as broader equity indices struggled. The S&P 500 declined 0.44% while the Nasdaq remained essentially unchanged.
Bitmine Immersion Technologies, Inc., BMNR
Ethereum’s resurgence served as the primary catalyst. ETH advanced 4.62% during the previous 24-hour period to approximately $2,558, providing substantial support to BitMine, whose operations and financial position are deeply intertwined with cryptocurrency performance.
This relationship carries significant weight. BitMine maintains substantial Ethereum holdings that generate staking rewards, creating a steady passive revenue channel that complements its core mining activities.
Eightco Holdings, which receives backing from BitMine, released a Thursday disclosure that attracted market attention. The entity reported approximately $380 million in total assets.
Within that portfolio sits a $90 million indirect OpenAI position, an $18 million Beast Industries stake, a $1 million Mythical Games investment, and more than 301 million Worldcoin tokens priced at 37 cents apiece.
Additionally, Eightco maintains 16,278 Ethereum tokens and approximately $120 million in cash and stablecoin holdings. The company also executed share repurchases exceeding 26 million common shares during the current quarter.
Derivatives Market Provides Additional Momentum
Options trading activity amplified the stock’s upward trajectory. Market participants aggressively purchased near-term call contracts, particularly September expiration calls struck above $25. Implied volatility expanded in tandem with the increased activity.
Such derivatives enthusiasm typically attracts momentum-focused traders seeking to capitalize on short-term price action. While no official price projections were announced, the options market is essentially forecasting additional near-term appreciation.
Technical Analysis and Chart Positioning
BMNR currently trades above every significant moving average. The stock sits above its 20-day SMA at $24.46, its 50-day at $20.28, its 100-day at $19.13, and its 200-day at $22.08.
Near-term technicals show improvement. The 20-day SMA has crossed above the 50-day, representing a constructive development. However, the 50-day remains beneath the 200-day, reflecting the death cross that materialized in January.
Resistance emerges around the $27 level, a psychological round number where upward momentum could face challenges. Support appears near $23, aligned with the 20-day EMA at $23.64.
BitMine maintains meaningful representation across multiple cryptocurrency-focused ETFs. The stock comprises 9.97% of the Global X Blockchain ETF (BKCH), 7.00% of the Bitwise Crypto Industry Innovators ETF (BITQ), and 5.87% of the Corgi Crypto Infrastructure ETF (BLCK). Significant ETF fund flows could create additional stock price volatility.
Important consideration: BitMine continues to operate at a cash deficit and report losses. This fundamental challenge persists regardless of positive trading days. The company’s financial performance remains closely correlated with cryptocurrency valuations, and any substantial digital asset correction would create significant headwinds.
BMNR’s year-to-date return stands at negative 12.01%, with average daily volume reaching 39.15 million shares. The company’s market capitalization totals $13.76 billion.
The post BitMine (BMNR) Stock Rallies 8% Friday Amid Ethereum Recovery and Bullish Options Activity appeared first on Blockonomi.
Key Highlights
- On September 17, the CFTC forwarded a comprehensive crypto market regulation framework to the White House Office of Management and Budget
- Congressional efforts to pass the Clarity Act collapsed earlier that week, prompting federal agencies to utilize their existing regulatory powers
- The SEC introduced an “innovation exemption” providing qualified platforms a five-year runway for onchain tokenized equity trading
- A CFTC no-action letter now permits technology providers to link users with derivatives platforms without broker registration requirements
- Brian Armstrong, CEO of Coinbase, declared that regulatory clarity would arrive “regardless” of the Senate’s decision
Following the Senate’s inability to move forward with the Clarity Act, the CFTC has submitted a comprehensive crypto regulatory framework to the White House for consideration. The submission, documented on September 17, remains in the “prerule” phase—an indication that substantial development work lies ahead. Specifics regarding the regulatory framework remain undisclosed at this time.
Officially designated as “Regulation Crypto Asset Transactions and Regulation Crypto Asset Markets,” the proposal’s scope regarding covered assets and compliance obligations for trading platforms has not been revealed.
Following White House Office of Management and Budget examination, the framework will return to the CFTC for an initial vote alongside a public commentary period. Implementation would require an additional approval vote.
Congressional Legislative Effort Stalls
Designed to establish nationwide standards for digital asset markets, the Clarity Act failed to gain sufficient support during the September 15 Senate proceedings.
Within 24 hours of the legislative setback, CFTC Chair Michael Selig declared via X that his agency remained “locked in and ready to ship” regulations leveraging current statutory powers. SEC Chair Paul Atkins echoed this commitment, stating his commission would proceed “with or without legislation.”
Selig had telegraphed this approach weeks earlier. During an Innovation Advisory Committee gathering on August 20, he indicated the CFTC stood ready to implement regulations should congressional action falter.
Additionally, he revealed having instructed agency personnel to develop frameworks enabling both registered and unregistered crypto trading venues to achieve “crypto asset market” designation—a specialized contract market category permitting leveraged cryptocurrency trading under CFTC supervision.
SEC Establishes Framework for Tokenized Equity Trading
Coinciding with the CFTC’s White House submission, the SEC unveiled an “innovation exemption” initiative. This provision grants eligible platforms a five-year authorization period for facilitating onchain trading of specified tokenized equities without formal securities exchange registration.
Both regulatory bodies emphasize their collaborative approach to establishing transparent guidelines for the cryptocurrency sector within existing statutory frameworks.
The CFTC simultaneously released a no-action letter on Friday, enabling designated software platforms to facilitate user access to regulated derivatives marketplaces without introducing broker registration.
These platforms may promote particular contracts and receive transaction-dependent compensation. However, they are prohibited from maintaining customer assets, generating trade recommendations, or controlling order execution pathways.
The exemption incorporates requirements including risk disclosure statements and documentation protocols. It remains effective until the CFTC establishes permanent regulations governing software developer activities.
Following the Senate vote, Coinbase CEO Brian Armstrong emphasized that regulatory agencies possess sufficient authority to act independently. “So clarity is coming to crypto regardless,” he posted on X on September 15.
The post CFTC Forwards Crypto Regulation Framework to White House Following Clarity Act Setback appeared first on Blockonomi.
CryptoPotato
ETH witnessed a notable recovery after briefly plunging near $2,350 this week. The leading altcoin has since climbed over $2,480. At the same time, its transaction fees have fallen sharply, making the network cheaper to use.
The average cost per ETH transfer has dropped to around $0.095 from this year’s peak of $0.72 on April 21, according to Santiment’s findings.
Ethereum Gets Cheaper
The decline comes as mainnet demand softened during the bearish summer. However, network upgrades have also increased Ethereum’s capacity. Fusaka, higher blob throughput, and a 60 million gas limit have helped the network handle more activity. At the same time, Layer 2 solutions are processing large amounts of transactions that previously competed for Ethereum’s mainnet blockspace.
Lower fees could make Ethereum more accessible for users and developers, according to Santiment. Swaps, transfers, DeFi activity, stablecoin movements, and ERC-20 transactions can now be completed at a lower cost.
The analytics platform said that cheap transactions do not necessarily mean demand is recovering. But it is important to note that lower costs remove one of Ethereum’s long-standing barriers. With ETH prices having recovered, cheaper network activity could provide a more favorable environment for Ethereum-based projects.
Meanwhile, Ali Martinez observed that the asset is trading within a defined 4-hour channel despite recent market volatility. ETH has reached the lower boundary of the range, following which the $2,570 level has come into focus. Martinez expects a potential rebound toward the middle and upper end of the channel. A strong 4-hour close above $2,570, supported by higher trading volume, could signal a breakout. He added that the next stops would be $2,700 and then $3,000.
The Long Investor believes Ethereum remains a buy despite an almost 45% rise over the past three months. The investor said buying before ETH moves above $3,000 may put investors ahead of late buyers. They also pointed to the 200-week moving average as a strong long-term reference.
Supply Drain
Less ETH on exchanges is helping the recovery. Recent estimates revealed that only 6.06 million units now sit on exchanges, down from 22.9 million at the June 2020 peak. That is a 73% decline in readily available supply. The drop reflects more ETH moving into staking, ETFs, treasury holdings, and long-term custody.
Validators are also locking ETH to help secure the network. Lower liquid supply may increase the impact of buying activity. Even without a major rise in demand, smaller waves of buying can have a stronger effect when fewer coins are available on exchanges.
The post Ethereum Gets Cheaper: Network Fees Collapse Over 85% as ETH Price Rebounds appeared first on CryptoPotato.
Ethereum has recovered sharply from its mid-year lows and jumped past the key $2.5K level on Friday. The charts show a constructive improvement in the broader market structure, although ETH remains below several important higher-timeframe resistance levels.
Meanwhile, the Coinbase Premium Index is once again negative, suggesting that the recent recovery has not been accompanied by consistently strong spot demand from U.S. investors.
Ethereum Price Analysis: The Daily Chart
On the daily timeframe, ETH has undergone a significant structural recovery from the $1.5K support area. The rebound has pushed price back above both the 100-day and 200-day major moving averages shown on the chart, with the 100-day yellow average aggressively pushing toward the 200-day one from below, likely to form a bullish crossover around $2K.
ETH is currently trading around $2.5K, directly inside a key resistance zone. This area has repeatedly contained price during the recent consolidation. Yet, a valid daily breakout above it can lead to continuation of the recovery.
A successful move above the $2.5K area could expose the next major resistance around $3.0K. Beyond that, the larger daily resistance zone sits around $3.3K-$3.4K, which coincides with the broader structure established earlier in the year.
On the downside, the first important support is around $2.1K, where the moving averages are also currently clustered. Below this area, the $1.9K zone becomes the next notable support. Still, the daily RSI is around the mid-to-upper 50s, meaning momentum is still bullish but not showing an overbought reading anymore. Therefore, there could still be room to the upside if sufficient demand emerges.
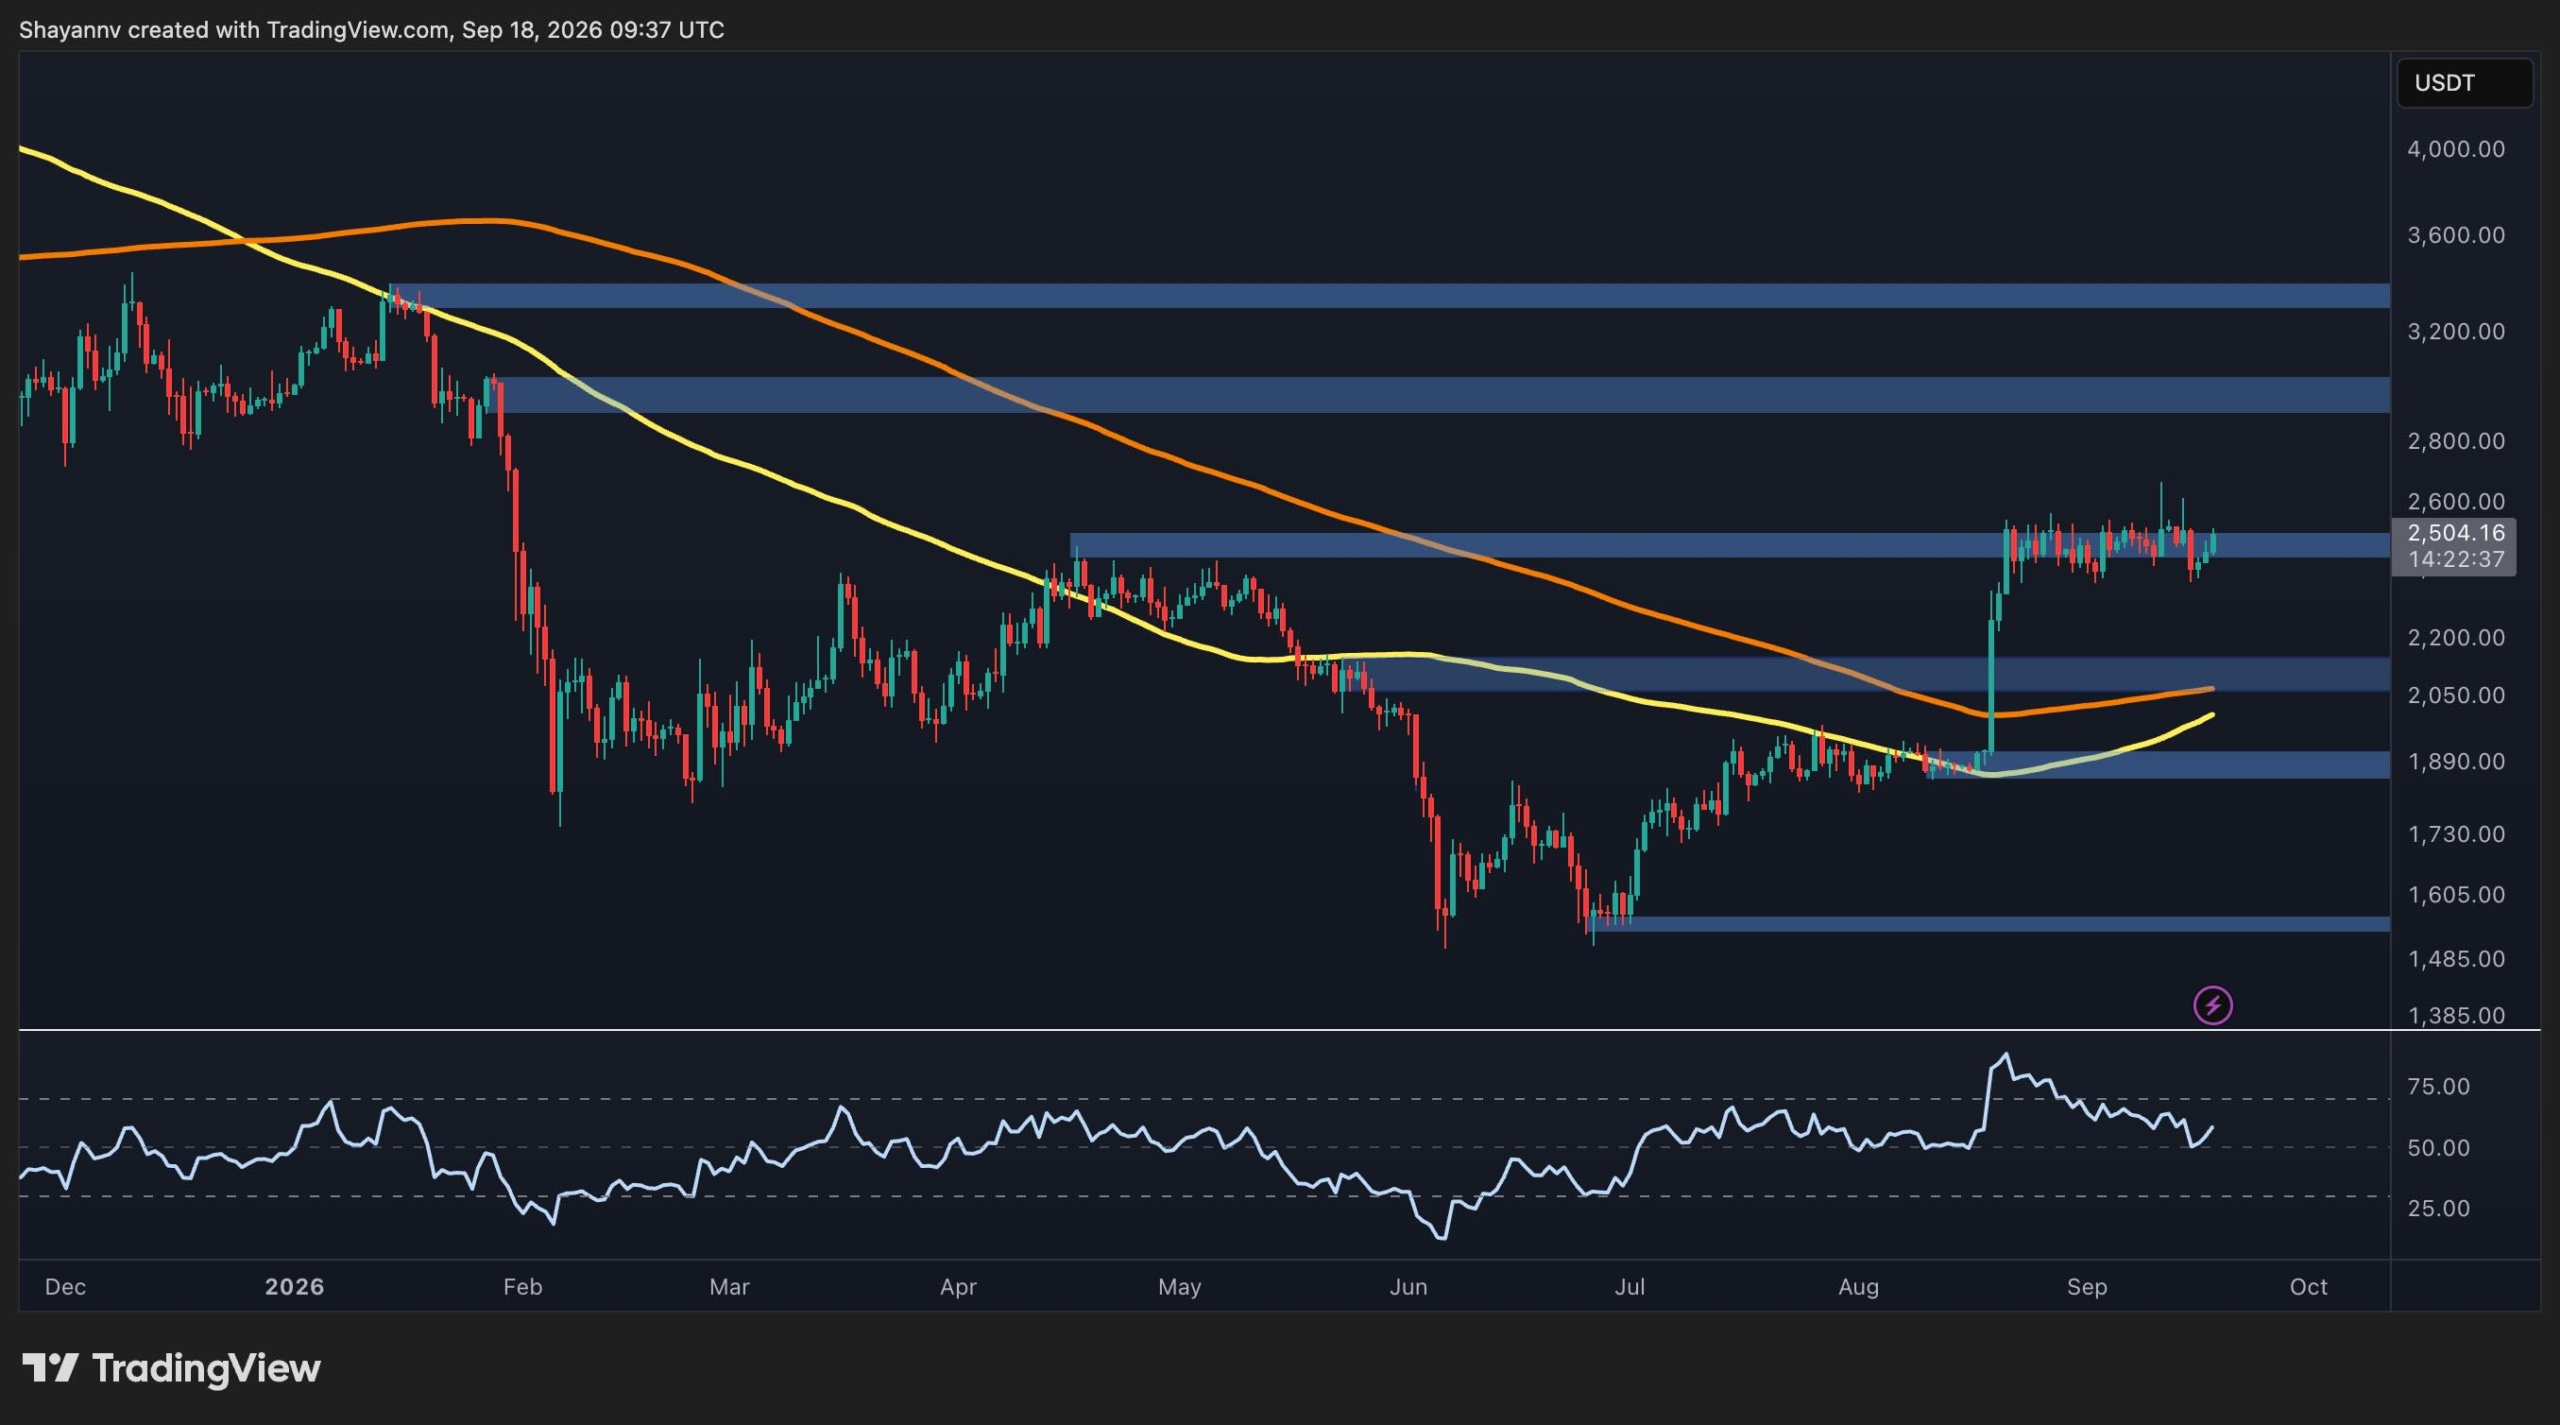
ETH/USDT 4-Hour Chart
The 4-hour chart provides a clearer picture of the current consolidation. ETH has been trading inside a broad range roughly between $2.35K and $2.65K since the sharp late-August advance.
The latest price action shows ETH recovering from the lower portion of the range and returning toward the $2.5K area. The repeated reactions around the range boundaries suggest that the market is still in consolidation rather than an established directional breakout.
The immediate resistance is around $2.5K, followed by the upper range boundary near $2.65K. A decisive 4-hour breakout above the latter would provide a clearer structural shift and could open the way toward the higher daily resistance zones.
Conversely, rejection around the current resistance and a move back below $2.35K would weaken the short-term structure. Losing that zone would invalidate much of the current range-based bullish setup and bring the next major support into consideration, as a deeper retracement would be probable.
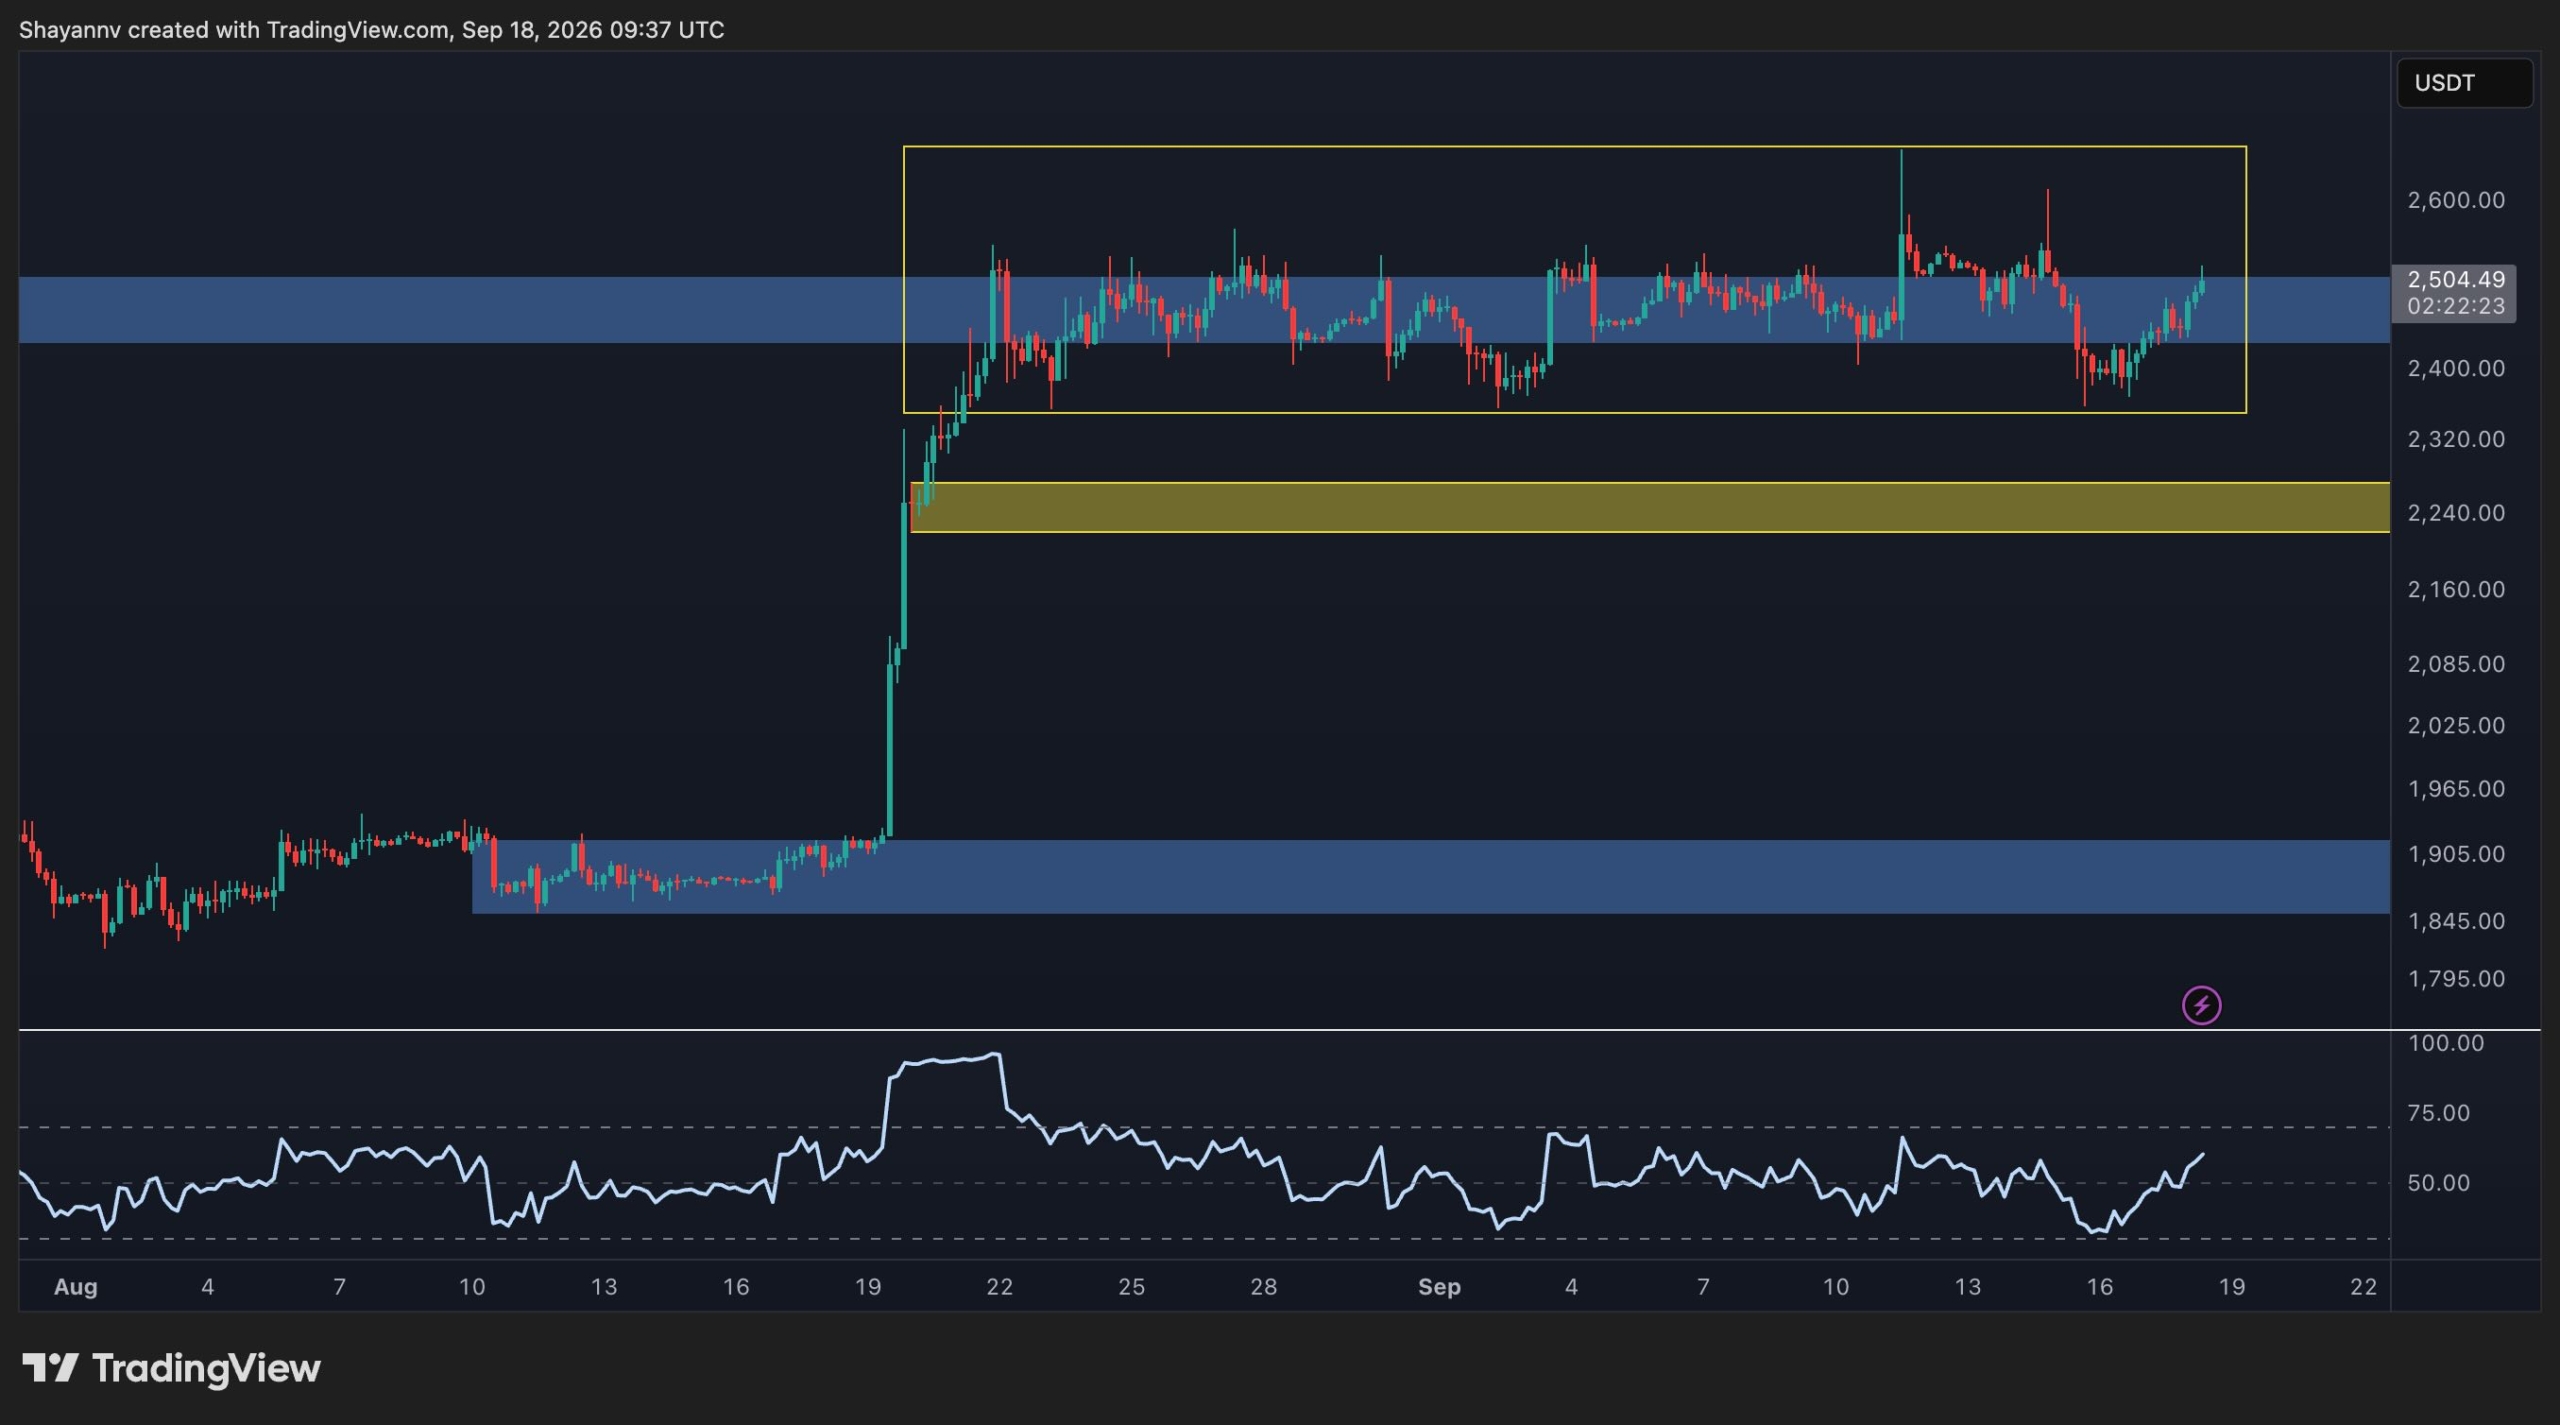
On-Chain Analysis
The Coinbase Premium Index is currently around -0.07, with the indicator spending much of the recent period below the zero line. The metric compares ETH prices on Coinbase with those on other major exchanges and is commonly used as an indication of relative buying or selling pressure from Coinbase’s predominantly U.S.-based market.
The notable point is the divergence between price and the premium index. ETH has recovered from roughly $1.5K to around $2.5K, yet the Coinbase Premium has generally remained negative during much of that advance. This suggests that the recovery visible on the price chart has not been accompanied by consistently strong US-based spot demand.
There have been brief positive spikes, particularly during parts of the summer, but they have not developed into a sustained positive trend. The latest reading has also returned firmly below zero.
This does not necessarily invalidate the broader recovery, since ETH can rise through demand from other venues and derivatives markets. However, a sustained move back above the zero line in the Coinbase Premium Index, particularly alongside a breakout above $2.5K, would provide additional confirmation that spot demand is strengthening, and that the recovery is likely to continue.
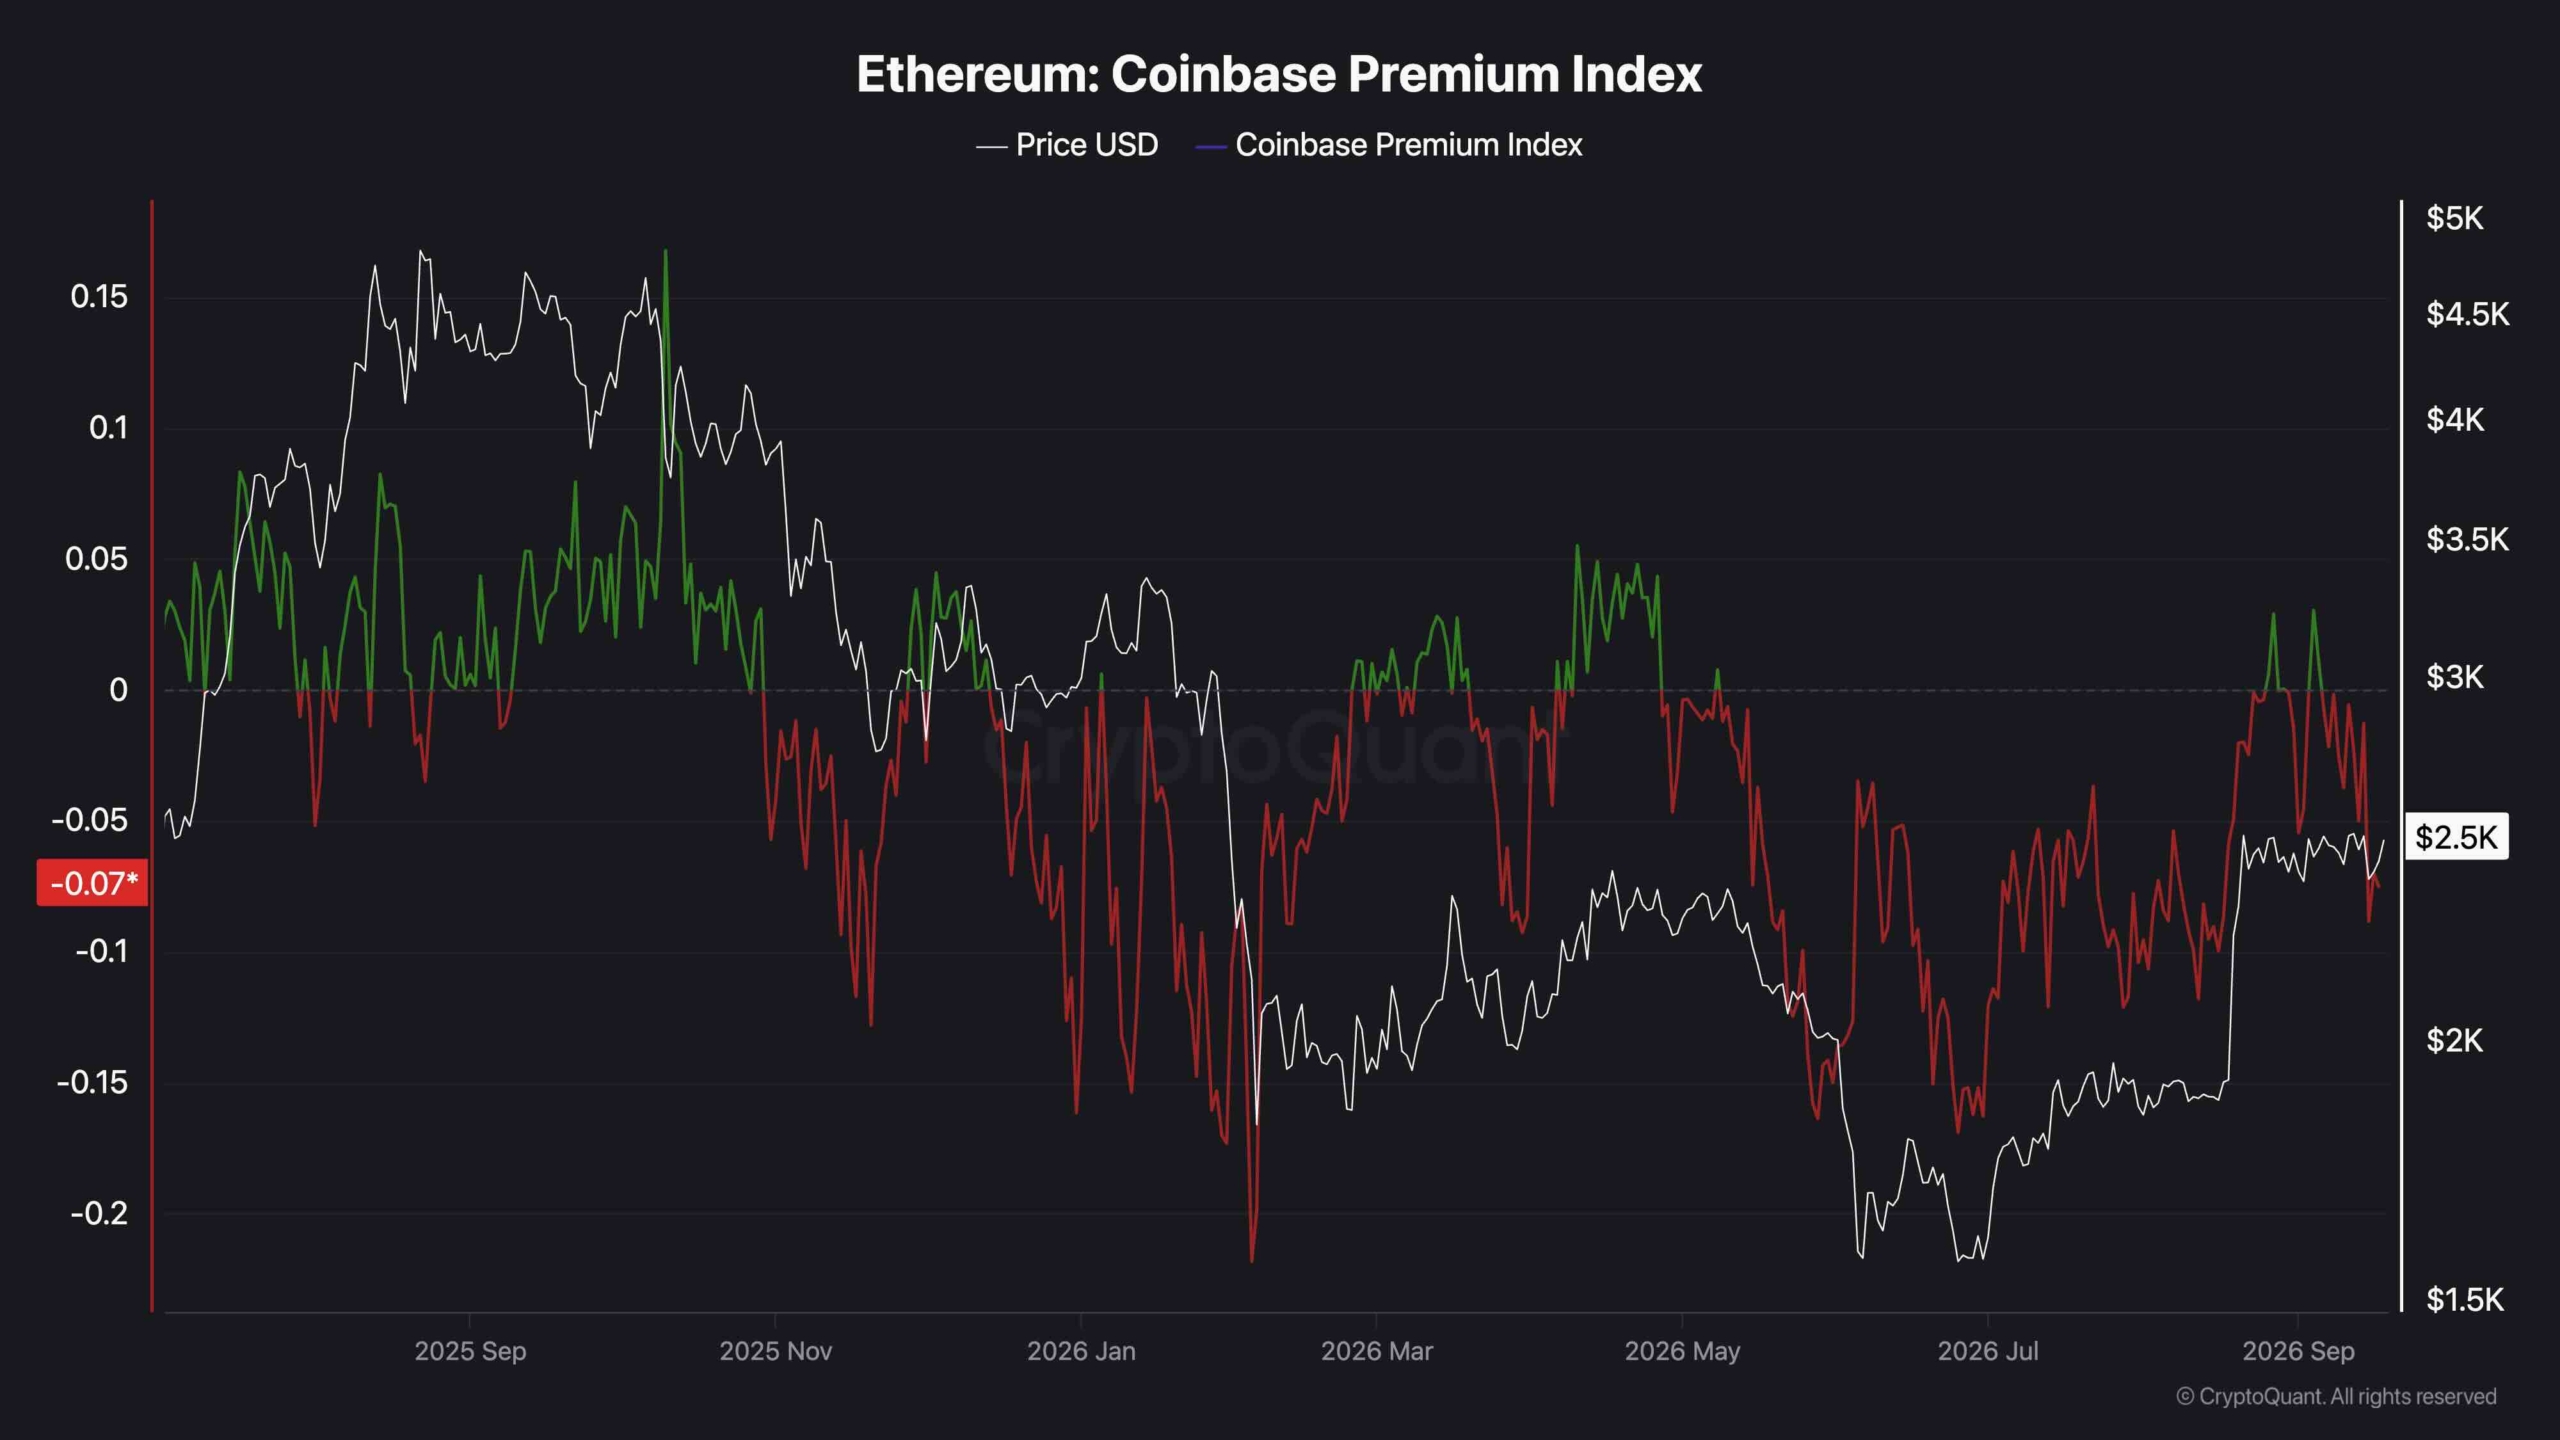
The post Ethereum Price Analysis: ETH Jumps Past $2.5K as Moving Averages Eye Bullish Cross appeared first on CryptoPotato.
XRP is consolidating after a sharp recovery from the sub-$1 area, with the price now attempting to stabilize around $1.35. The daily chart shows a major structural improvement following the recent rally, while the 4-hour timeframe suggests that the asset is still trading inside a descending channel that is guiding a corrective price action.
Ripple Price Analysis: The USDT Pair
On the daily timeframe, XRP staged a strong impulsive move from the $1.00 support area to roughly $1.70 before entering a prolonged consolidation. The rally also pushed the RSI sharply into overbought territory, but the subsequent cooling-off phase has brought the indicator back toward the neutral 50 area.
The price is currently around $1.35, sitting just above the 200-day moving average at approximately $1.30. This is an important near-term area because holding above this zone would keep the recent structural recovery intact. The yellow 100-day moving average is also located lower, around $1.18, providing a deeper dynamic support area if the correction extends.
On the upside, the most visible resistance is the $1.60-$1.70 zone, marked by the recent swing high. A successful move through this region would put the larger $1.90 resistance zone back into focus.
On the downside, the chart’s major structural support remains around $1.00. This is substantially below the current market and therefore represents a broader invalidation area rather than an immediate support level.
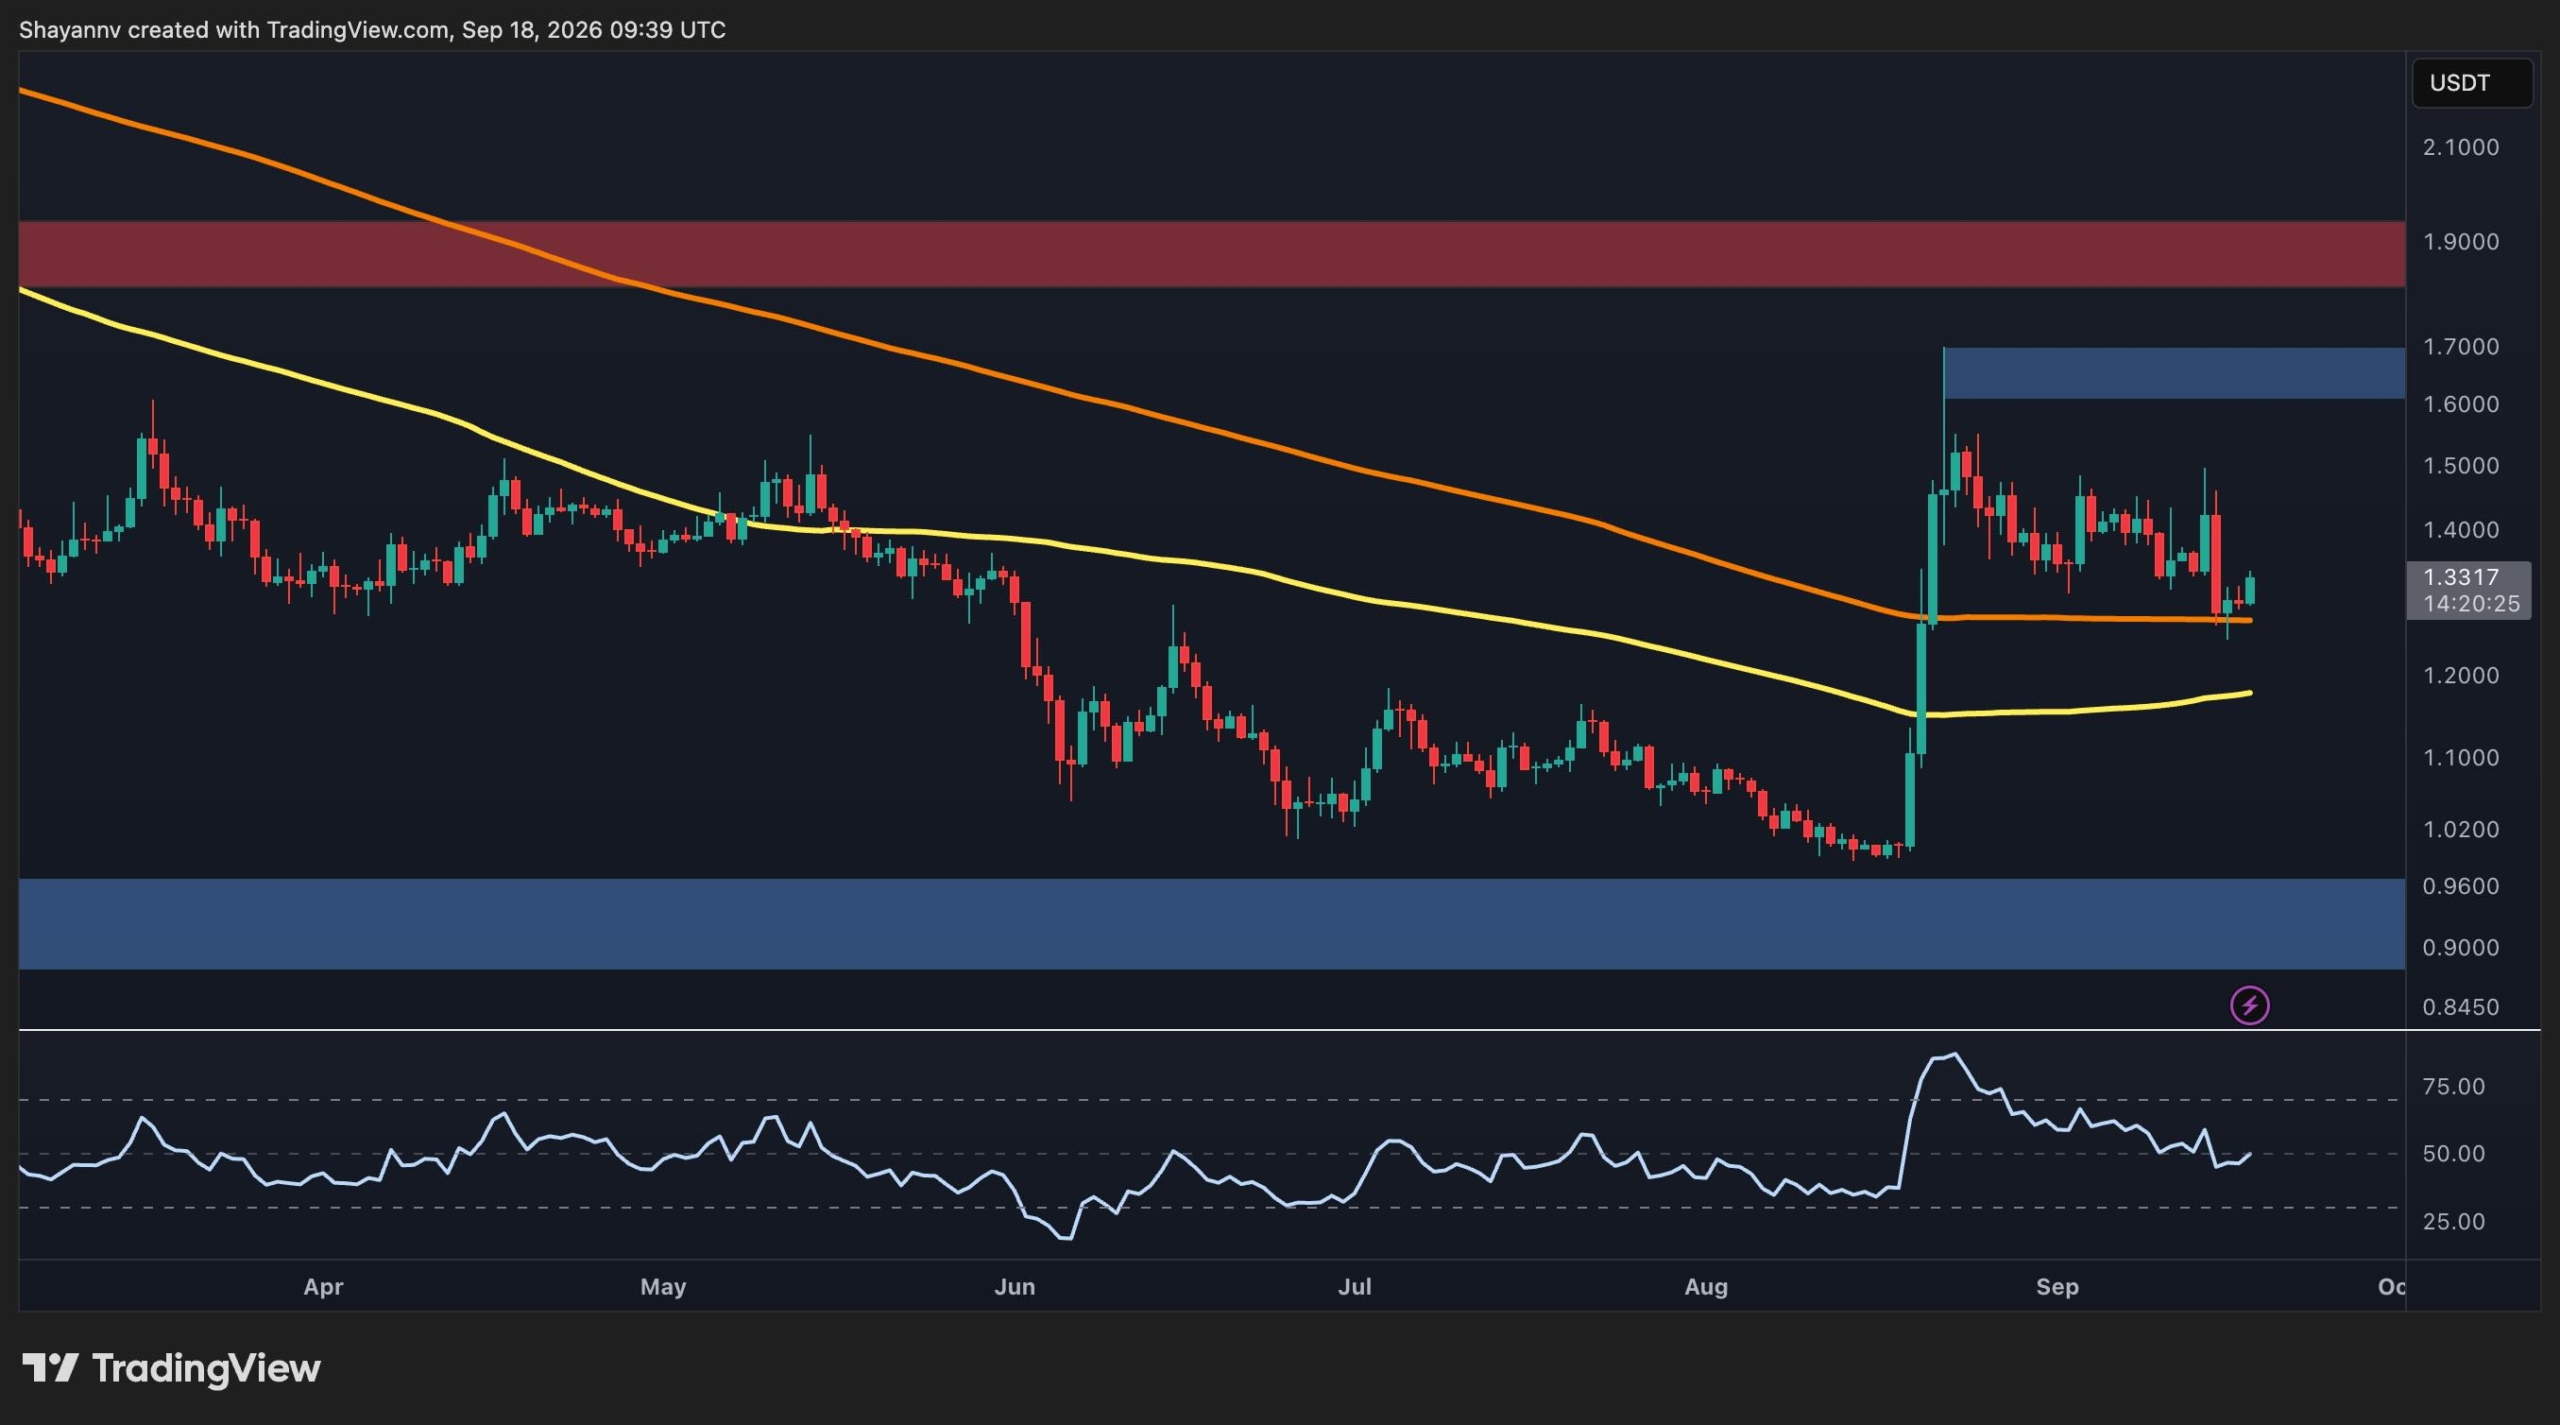
The 4-Hour Chart
The 4-hour chart provides a more cautious picture. XRP has been moving inside a descending channel, with both the upper and lower trendlines sloping downward. The latest rejection from approximately $1.48 resulted in a sharp decline toward the $1.25 support zone and the lower boundary of the channel.
That support area has so far held, and XRP has started to recover toward $1.35. The immediate obstacle, however, is the $1.33-$1.37 resistance zone, which is currently being approached from below. A clean breakout and hold above this area would improve the short-term structure and could open the way toward the channel’s upper boundary around $1.40-$1.45.
Conversely, a rejection around this resistance area could lead to a move back toward the $1.25 support zone again. The lower channel trendline is also located in this area, making it an important level for the current consolidation and for investors, as losing it could lead to a much deeper correction in the coming weeks.

The post Ripple Price Analysis: What’s Next for XRP After an 8% Daily Surge? appeared first on CryptoPotato.
It was expected to be a massively eventful week for the entire cryptocurrency industry, and it was.
But first, let’s see what happened precisely seven days ago. The US CPI data had just come out, confirming that inflation is still persistent. As such, the US Federal Reserve had all the missing pieces to its monetary puzzle, and experts predicted a rate hike on September 16.
BTC went wild after the CPI data was announced, going from $77,000 to $76,000 before it suddenly exploded to $79,800, where it was violently rejected and driven south to its starting point. All of this took place within an hour or so. After this enhanced volatility, the market calmed during the weekend, with BTC trading sideways at around $77,000.
It dipped to $76,400 on Monday before the bulls took control and drove it to $79,600 ahead of the key CLARITY Act vote a day later. BTC had already retreated to $77,000 when it became official that the Senate rejected cloture to advance the bill, and bitcoin plunged to a three-week low of $75,000.
The bulls managed to defend that level, but the next day was anticipated to be just as eventful with the conclusion of the FOMC meeting. The Fed indeed hiked the rates for the first time in over three years, but BTC’s reaction was more modest and somewhat surprising. The asset slipped to $75,000 once again initially, but rocketed to over $76,000 within minutes.
It kept climbing gradually on Thursday and especially on Friday. Although the BOJ also increased the rates by 25 bps to a 31-year high, BTC actually reclaimed $78,000 during the morning trading session. It stood there for a while, but initiated another leg up as US trading hours began and rocketed to a two-week peak of $81,000, where it was stopped, at least for now.
This means that BTC is actually in the green during the week in which all major events went against it. Meanwhile, ZEC continues its massive rally, while NEAR has rocketed by 35%. UNI is up by over 30% as well, followed by HYPE, BCH, and a few others. RAIN has plummeted by 22%.
Market Data

Market Cap: $2.770T | 24H Vol: $96B | BTC Dominance: 58.6%
BTC: $80,600 (+0.9%) | ETH: $2,570 (-3%) | XRP: $1.37 (-4%)
This Week’s Crypto Headlines You Can’t Miss
Strategy Stays on the Sidelines Again, but Strive Buys More Bitcoin. The week began with a familiar announcement: Strategy refused to buy more BTC while it continues to focus on rebuilding its USD stash. At the same time, Strive keeps accumulating more BTC, adding another 469 units.
Bitcoin Could Get More Support Than Gold as ETF Hedging Eases: JPMorgan. Analysts at the Wall Street behemoth said BTC may gain more price support than the precious metal amid easing ETF hedging demand, with BlackRock’s iShares Bitcoin Trust showing high short interest.
From Bear to Bull: Analyst Says Bitcoin UTXO Data Points to a Cycle Shift. Bitcoin’s share of addresses sitting at a loss has dropped sharply, and an on-chain analyst said moves of that size have historically ended bear markets and are not just producing a short bounce.
SEC Opens Door to Onchain Stock Trading With New ‘Innovation Exemption’. The regulator has launched an “Innovation Exemption” to promote secondary trading of tokenized stocks on blockchain platforms, easing regulatory burdens for Tokenized Securities Venues.
Seven Democrats Refuse to Give Up on CLARITY Act After Senate Setback. Despite the latest developments on the matter, several Democrats stated that this is not the end, pledging to continue bipartisan efforts for crypto regulatory clarity.
CoinEx Calls Time After Nearly Nine Years as Crypto Market Pressure Mounts. After nine years in existence, CoinEx has decided to shut down its platform by the end of the year due to declining crypto market conditions and increased regulatory pressures. As such, the exchange joins other major names that fell during the 2026 bear market, such as BitMart and BitMEX.
Charts
This week, we have a chart analysis of Ethereum, Ripple, Cardano, Binance Coin, and Hyperliquid – click here for the complete price analysis.
The post Bitcoin Hits 14-Day High Despite CLARITY Setback, Fed and BOJ Rate Hikes: Weekly Recap appeared first on CryptoPotato.
Just a few days after receiving major blows from the US Federal Reserve and the Senate, bitcoin’s price suddenly skyrocketed by a few grand and topped $80,000 for the first time in over ten days.
The altcoins have followed suit, with ETH surging past $2,550, while XRP has rocketed to over $1.35. Naturally, the liquidations are on the rise.
Recall that the primary cryptocurrency slumped to $75,000 on Tuesday evening after the CLARITY Act setback in the US Senate. Although the asset defended that zone, more volatility ensued a day later when the Fed hiked rates for the first time since July 2023.
However, BTC rebounded almost immediately after the initial shock and went past $76,000. It kept fluctuating in the following days, but the bulls appeared to be in control. Today’s decision by the Bank of Japan to increase the rates to a 31-year high was well received by the cryptocurrency, which jumped to just over $78,000.
It remained there for hours before it went on the offensive minutes ago, skyrocketing to over $80,000. This level was last breached on September 7.
Most altcoins have marked substantial 2-3% gains over the past hours as well. Ethereum has seemingly reclaimed the $2,550 level after a 2.3% hourly jump, while XRP is above $1.35 after a 3% increase. SOL and BNB have marked slightly more modest gains.
Data from CoinGlass shows that $192 million worth of over-leveraged positions were wrecked in the past hour, with shorts responsible for more than $183 million. BTC holds the lion’s share ($119 million), followed by ETH ($36 million).
On a daily scale, the numbers are even higher, with $450 million wrecked. $390 million was from shorts. In total, more than 100,000 traders have been wiped out within this timeframe.
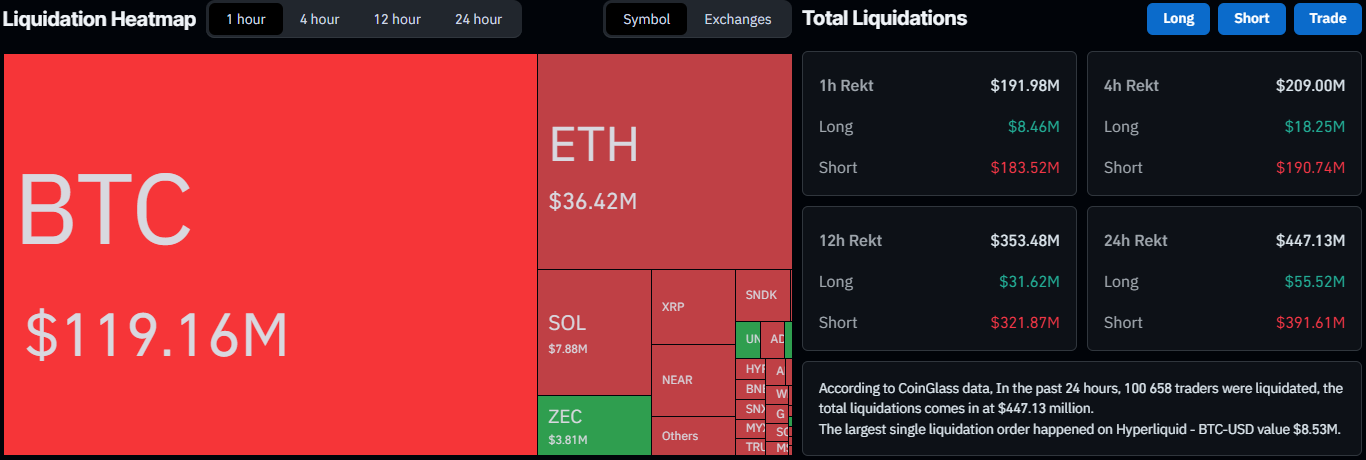
The post Bitcoin Price Suddenly Rockets Past $80K Leaving $180M in Shorts Liquidated appeared first on CryptoPotato.


