Cryptocurrency Posts
Crypto Briefing
These dividend hikes reflect robust financial health and strategic positioning in AI, potentially attracting more investor interest and confidence.
The post Nvidia, Micron Technology, and OTC Markets declare dividend raises of 30% or more appeared first on Crypto Briefing.
Despite AI development concerns, tech fundraising remains robust, but potential future capex deceleration could impact US economic growth.
The post AllianceBernstein says AI development slowdown won’t derail tech fundraising appeared first on Crypto Briefing.
Barclays' fintech classification of Strategy Inc. highlights its evolving identity, balancing software growth with Bitcoin volatility risks.
The post Barclays reiterates buy rating on Strategy, sets price target at $160 appeared first on Crypto Briefing.
MediaTek's aggressive entry into the premium segment could intensify competition, potentially driving innovation and price shifts in the market.
The post MediaTek launches Dimensity 9600 Pro on TSMC’s 2nm process, taking direct aim at Qualcomm appeared first on Crypto Briefing.
The trillion-dollar AI investment gamble could lead to a major economic shift or a historic capital misallocation, impacting global markets.
The post AI hyperscalers face trillion-dollar gamble as spending outpaces revenues appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Swiss Bitcoin Pay Shuts Down Servers After Data Breach
Another day, another data breach.
Swiss Bitcoin Pay, a non-custodial bitcoin payment processor, said that it had to temporarily shut down its servers following a data breach on Monday.
The Neuchâtel, Switzerland-based company said that user funds were safe but customer email addresses, bitcoin addresses and IBANs, transaction history, and hashed passwords were believed to be breached.
A malicious user has likely gained access to Swiss Bitcoin Pay’s internal systems. As a precaution, we are temporarily shutting down our servers while we investigate and secure our infrastructure.
—
At this stage, we believe they may have accessed customer email addresses, Bitcoin…Swiss Bitcoin Pay (@SwissBitcoinPay) September 14, 2026
The announcement comes amid a run of breaches hitting bitcoin and fintech firms. Revolut confirmed last week that it handed customer passports, driver’s licenses, verification selfies and transaction histories to an unauthorized party that sent fraudulent requests from a legitimate government agency’s email domain.
And top hardware wallet manufacturer Trezor last week warned that a data breach at the third-party marketing platform it uses for sending newsletters was leading criminals to target customers with phishing attacks.
“A malicious user has likely gained access to Swiss Bitcoin Pay’s internal systems …As a precaution, we are temporarily shutting down our servers while we investigate and secure our infrastructure.” Swiss Bitcoin Pay said on Monday.
The company added that; “User funds are safe, and any amounts owed to users will be fully returned.”
Swiss Bitcoin Pay did not immediately respond to Bitcoin Magazine’s request for comment.
The company lets businesses accept Bitcoin payments quickly and easily using both on-chain transactions and the Lightning Network.
Criminals have increasingly been targeting data in 2026. Scammers in January were able to get hold of customer information via crypto wallet Ledger’s payment processor Global-e to send phishing emails.
Crypto wallet provider SafePal last month also announced a data breach that involved unauthorized access to about 39,798 customers’ order information, including personal details such as names, addresses and purchase data.
This post Swiss Bitcoin Pay Shuts Down Servers After Data Breach first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
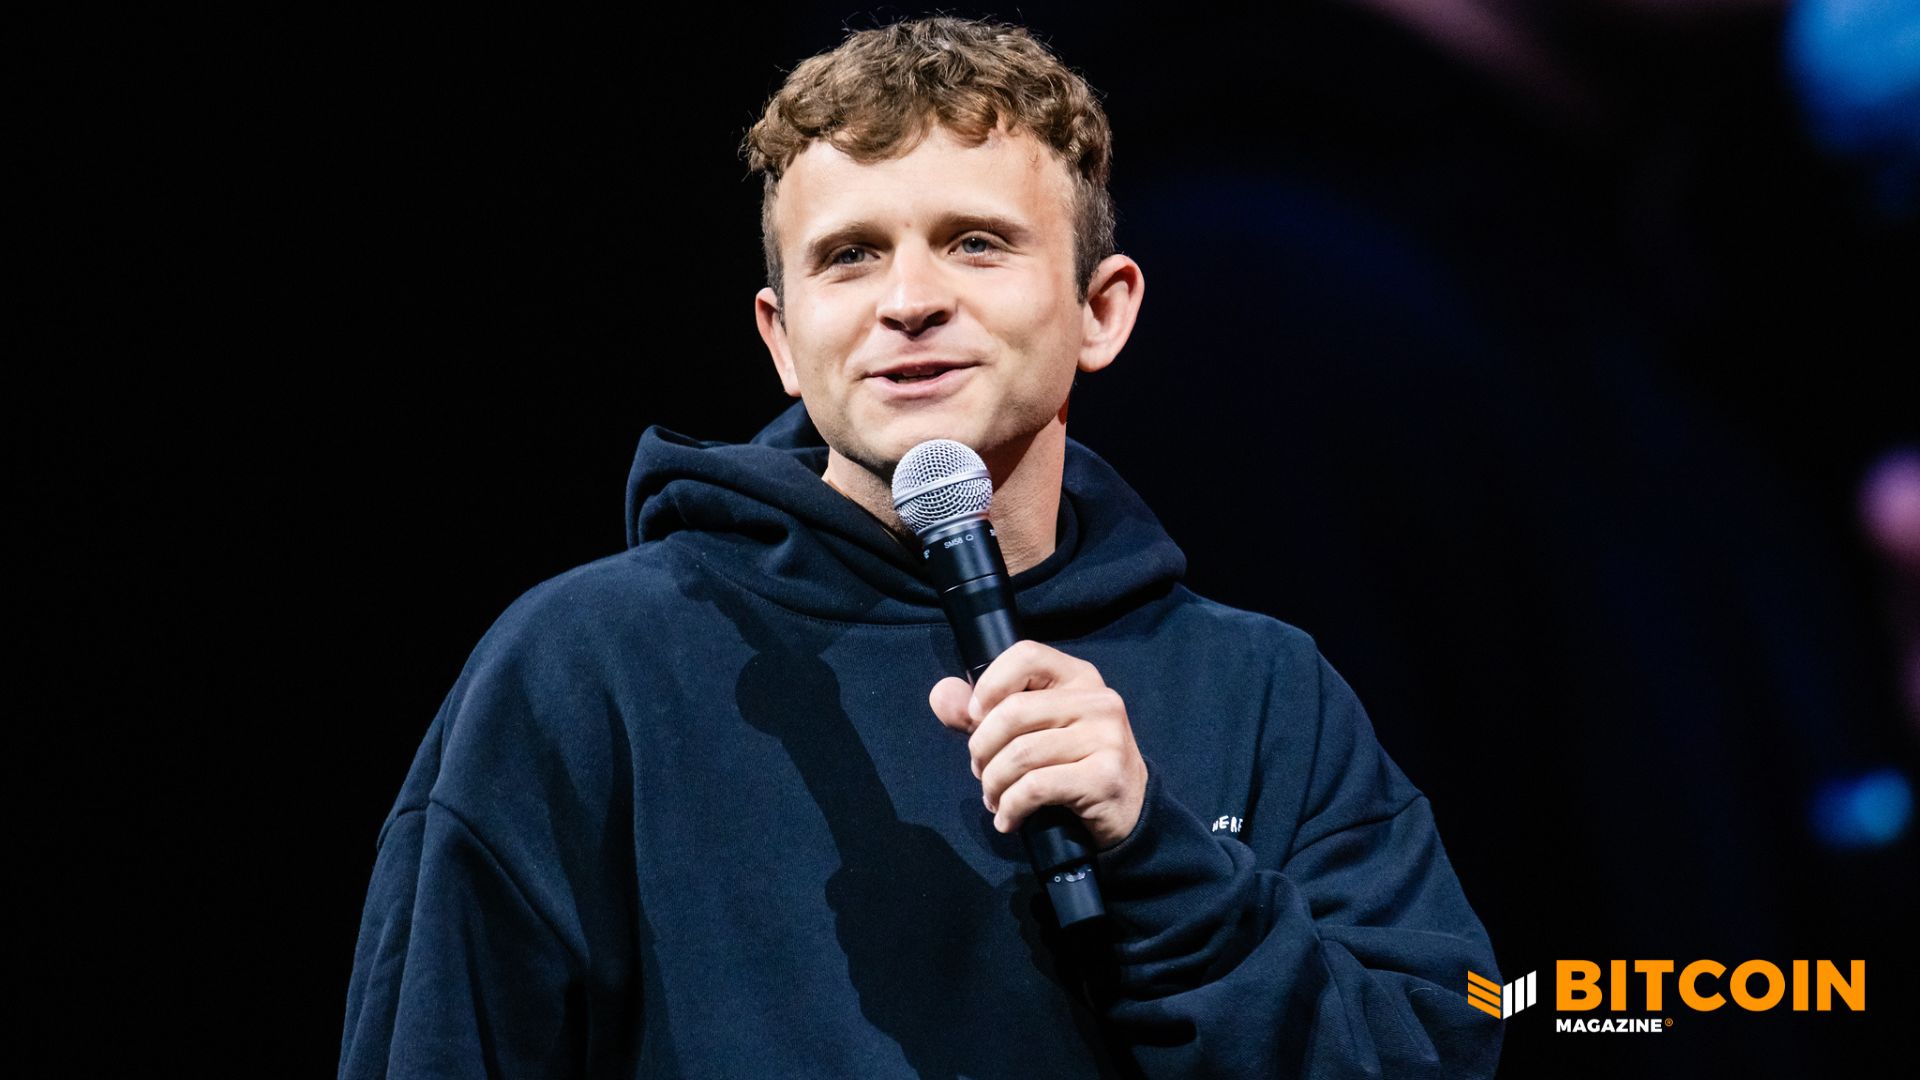
Mallers: Bitcoin and AI Could Give Humans Back Their Time
Bitcoin — along with artificial intelligence — could help humans get their time back to create again, according to Strike CEO Jack Mallers.
The reason: hard money doesn’t rob people of their time and energy and truly rewards people time and energy well spent, Mallers argued on Bitcoin Magazine’s debut TV show on Monday.
“Money broadly is our time and energy in an abstracted form — it is the market good that represents the effort, the labor,” Mallers said.
“If the money is bad, it’s very destructive to our time and energy: It robs us of our time and energy. You have to work longer and harder to get a house; you have to work longer and harder to get a vacation. You have to work longer and harder to have hours to pursue your artistic interests.”
“And if the money is good, it actually gives you and rewards back time and energy,” he continued, adding that Bitcoin and AI could free humans from the “drudgery” of bad money.
Mallers went on to cite the example of the creators of the airplane, the Wright brothers, who came up with their invention when the U.S. was on a gold standard.
Mallers’ comments come following Bitcoin’s best run in years. Bitcoin gained about 25% in August, its strongest month of 2026 and its first positive August since 2021, closing the month near $78,000.
The run followed Treasury Secretary Scott Bessent’s move to expand long-dated bond buybacks, which pulled yields down and triggered billions in short liquidations.
Since the news, the so-called debasement trade has been back in the headlines again: when traders buy assets like gold or bitcoin to hedge against a currency losing its value.
The dollar slid on the Treasury buyback news and an announcement the same week that U.S. debt had hit the $40 trillion mark.
Speaking about the state of the U.S. economy, Mallers added: “This level of debt is unsustainable, so when people debate, oh well, what if they hike rates? What if they cut rates? It doesn’t matter: it’s all inflationary and it’s all untenable.”
Data on Friday revealed that the consumer price index, excluding food and energy, climbed 0.3% in August from a month earlier — higher than expected.
The U.S. is currently in the grips of an affordability crisis, and it’s widely expected that the Federal Reserve will raise interest rates this week to tame inflation as oil prices have surged.
This post Mallers: Bitcoin and AI Could Give Humans Back Their Time first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
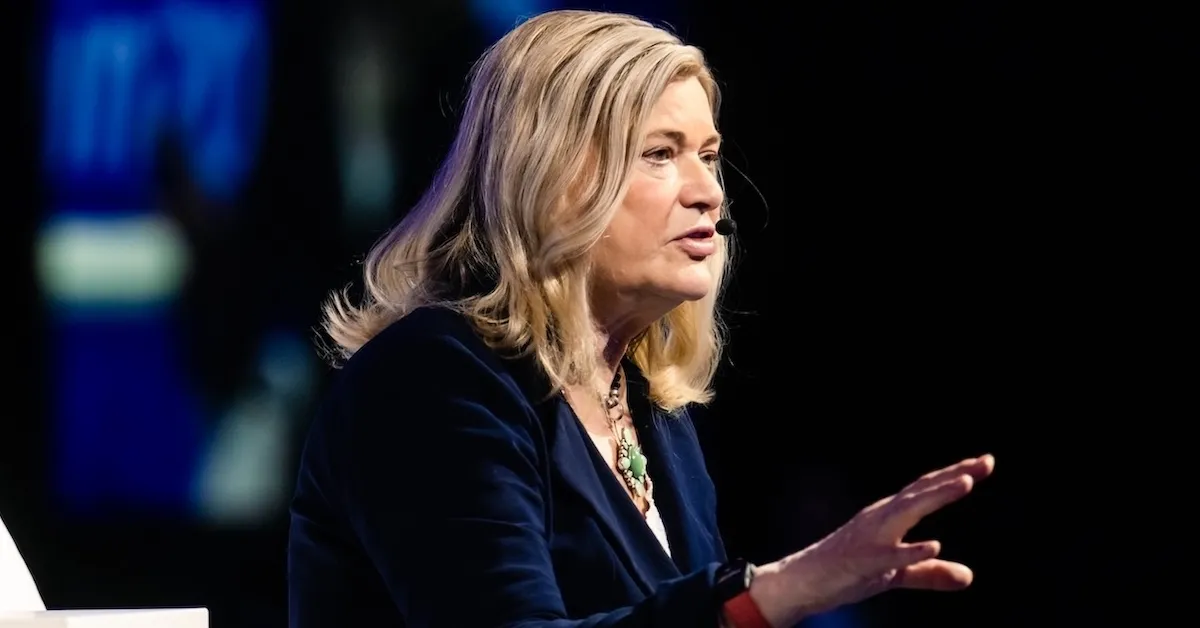
Lummis Credits Trump for Ethics Deal as Clarity Act Faces Tuesday Vote
Republican senator Cynthia Lummis has praised U.S. President Donald Trump for agreeing “to the toughest ethics restrictions” in order to get the Clarity Act over the line.
The pro-crypto senator wrote on X Monday that Trump had agreed to tighter laws which give state attorneys generals standing to sue to enforce the conflict-of-interest rules on federal officials.
Lawmakers will vote on the Clarity Act tomorrow. The bill aims to formally divide oversight between regulators, distinguishing which digital assets are securities, commodities or stablecoins — rules crypto industry executives have long called for.
JUST IN:
— Bitcoin Magazine (@BitcoinMagazine) September 14, 2026Senator Lummis on the Clarity Act: "President Trump had already agreed to the toughest ethics restrictions on federal officials in American history to get this bill done."
"Time for Democrats to take yes for an answer." pic.twitter.com/3VLn6y4fph
“Back in July, Trump voluntarily put himself, the VP, every federally elected official, judges, and their spouses under the strictest ethics rules this country has ever seen. Most people in Washington never would’ve offered that. Democrats still wanted independent, outside enforcement, not DOJ alone — so Trump went back to the table and gave more,” Lummis said.
She added: “A no vote tomorrow kills the toughest ethics reform this country has ever put on the books, kills consumer protections for every American holding digital assets, and hands the future of this industry to our foreign competitors.”
Alongside senators John Boozman and Tim Scott, Lummis released a new draft of the Clarity Act on Sunday night that gives attorneys enforcement new powers.
An updated draft of the Clarity Act banning government officials from promoting or making money from crypto started circulating in July but Democrats wanted more work on it.
President Donald Trump campaigned on a ticket to help the crypto space but some Washington lawmakers have criticized the way the Trump family has profited from digital asset ventures, such as the President’s memecoin, $TRUMP, and World Liberty Financial project.
Trump and the White House have always denied any conflicts of interest.
Speaking in an interview with Punchbowl News in August, about the Clarity Act and ethics, President Trump pointed out the Democrats have also made money from stock trading.
Though passed by the House of Representatives last year, the Clarity Act has been stalled this year, mostly because the banking lobby clashed with crypto companies over paying customers stablecoin yield.
Republicans like Lummis have accused Democrats of deliberately holding back the bill.
This post Lummis Credits Trump for Ethics Deal as Clarity Act Faces Tuesday Vote first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
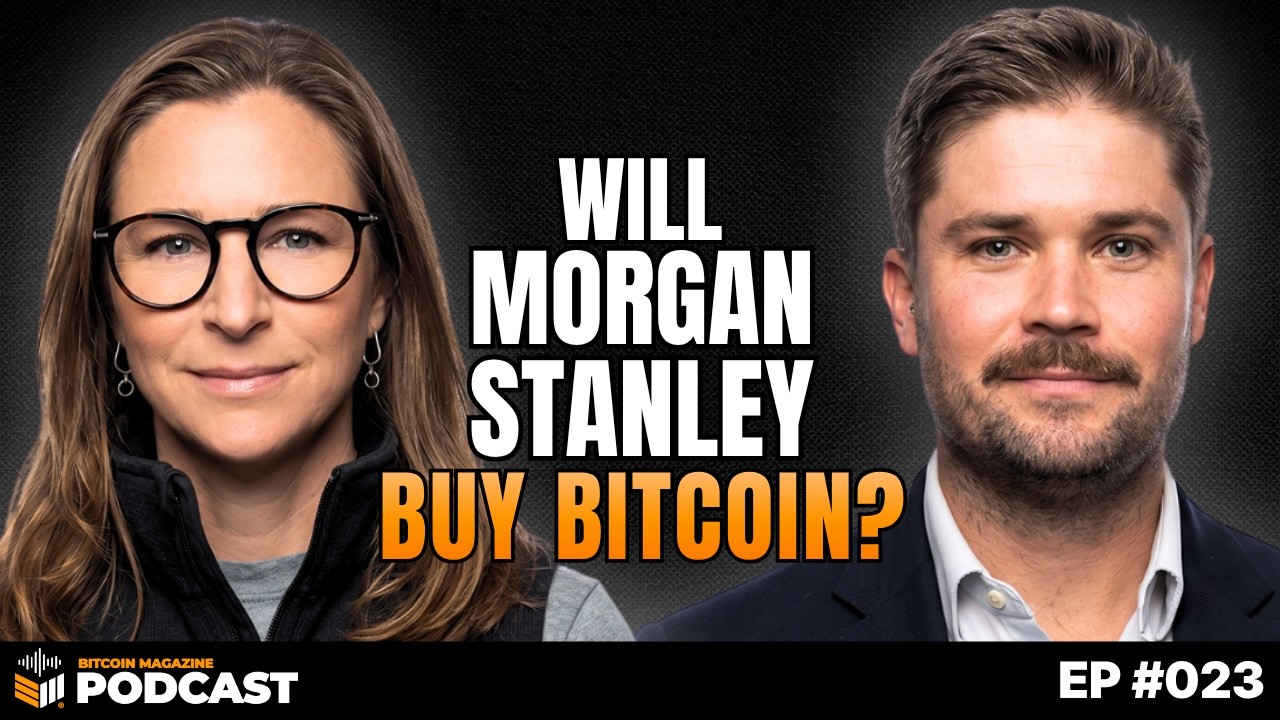
Morgan Stanley’s Bitcoin Investment Recommendation Explained w/ Amy Oldenburg
Morgan Stanley became the first global systemically important bank to launch a spot Bitcoin ETP and it crossed $600 million within months of its April debut. Amy Oldenburg, Head of Digital Assets at Morgan Stanley, joins host Spencer Nichols to explain how that product came together, why it was priced below competing spot Bitcoin ETFs, and what still stands between clients and their first Bitcoin allocation. She also details the firm’s 0–4% allocation framework across three investor risk profiles and why Morgan Stanley has no equivalent gold allocation. Plus: whether Bitcoin could land on Morgan Stanley’s own balance sheet.
 Host: Spencer Nichols — Bitcoin Magazine Amy Oldenburg, Head of Digital Assets at Morgan Stanley
Chapters:
0:00 — Morgan Stanley on Putting Bitcoin on Its Own Balance Sheet
1:14 — 26 Years at Morgan Stanley: Emerging Markets to Head of Digital Assets
2:10 — First Major Bank to Launch a Spot Bitcoin ETP Tops $600 Million
3:14 — Education, E-Trade Spot Crypto, and What Clients Actually Own
4:49 — Why Morgan Stanley Priced Its Bitcoin ETP So Low
6:40 — The 0–4% Allocation Framework and the Digital Gold Thesis
8:52 — Correlation Regimes: Digital Gold, High Beta Tech, and Volatility
11:41 — Gold 2.0, Market Cap, and Bitcoin on the Balance Sheet
14:37 — Institutional Market Structure, Quantum Risk, and Client Trust
18:02 — Global Off-Ramps, Tokenization, Stablecoins, and Morgan Stanley Research
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Morgan Stanley’s Bitcoin Investment Recommendation Explained w/ Amy Oldenburg first appeared on Bitcoin Magazine and is written by Mark Mason.
Bitcoin Magazine
Strive Snaps Up More Bitcoin, Brings Holdings to 25,000 BTC
Nasdaq-listed bitcoin treasury Strive now holds 25,000 BTC — worth nearly $2 billion — following its latest buy.
The company said Monday that it bought 469 bitcoins at an average price of approximately $77,954. It is still the fifth biggest publicly traded bitcoin company, according to Bitcoin Treasuries. Strategy, Twenty One, Metaplanet, and MARA all hold more bitcoin than Strive.
CEO Matt Cole wrote on X Monday that 100% of the capital raised during the week came through sales of SATA, Strive’s perpetual preferred stock.
Dallas, Texas-based Strive’s stock (ASST) was trading more than 6% higher following the news.
Strive debuted as an official bitcoin treasury last year. The company was founded by former Ohio gubernatorial candidate and tech entrepreneur Vivek Ramaswamy.
In January 2026, it completed the acquisition of Semler Scientific in an all-stock deal — the first instance of a publicly traded Bitcoin treasury company acquiring another such company.
Like with other digital asset treasuries, the idea is that investors can get amplified returns from Strive’s stock. The company buys bitcoin with equity, and maintains a debt-free balance sheet: no bonds, no credit lines, and no leveraged positions that could trigger forced liquidation in a downturn.
The company is different to other major bitcoin treasuries because it has no debt.
Other major bitcoin treasuries — like the biggest, Strategy — have used leverage to buy the leading cryptocurrency.
Strive CEO Matt Cole has described the company as debt-free with zero margin requirements and zero encumbered bitcoin.
This post Strive Snaps Up More Bitcoin, Brings Holdings to 25,000 BTC first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
CryptoSlate
Glassnode reported that altcoin market capitalization climbed 21% over the past month, while altcoins' share of the combined Bitcoin-and-altcoin market fell 0.9 percentage points over 90 days, based on data as of Sept. 7.
Capital has moved up the entire crypto ladder together, with Bitcoin absorbing most of the gain while higher-beta tokens held their ground without gaining. That divergence sets up an unusually clean test this week, running through both the Federal Reserve and the US Senate.
| Market signal | Current reading | What it says |
|---|---|---|
| Altcoin market cap | +21% over one month | Altcoins have participated in the rebound |
| Altcoin share of BTC + alt market | -0.9 percentage point over 90 days | Alts are rising, but not outperforming Bitcoin |
| Glassnode historical late-cycle signal | +2.8 percentage points over 90 days near BTC highs | Historical late-cycle rotation signal is absent |
| Bitcoin recovery | ~27% from August lows | BTC remains the market leader |
The Fed decides how Bitcoin's recovery can hold
Bitcoin recovered roughly 27% from the August lows near $62,000, trading close to $79,000 as of Sept. 15. Yet, BTC remains well below the $83,000 to $86,000 band Glassnode identifies as a genuine cost-basis wall.
Roughly 1.07 million BTC was acquired inside that range, almost entirely by long-term holders, with the heaviest concentration near $85,000. Sellers positioned there are defending their cost basis, well beyond simply chasing a round number.
Below current price, Glassnode's True Market Mean sits near $76,600, functioning as the rough floor beneath this recovery.
Reports noted that 85% of economists expect the Fed to raise rates 25 basis points to 3.75%-4% at the Sept. 16 meeting. Futures markets have priced roughly 90% odds of a hike alongside several more increases through mid-2027.
Major banks, including Goldman Sachs, JPMorgan, HSBC, and Deutsche Bank, have shifted toward expecting the move after last week's inflation surprise landed. The 10-year Treasury yield briefly touched 5% intraday on Sept. 14, its first such move since 2023, adding a materially higher global hurdle rate to a market already testing its own supply wall.
Spot Bitcoin ETFs posted four straight days of outflows totaling roughly $463 million from Sept. 8 to 11, snapping a three-week run of inflows. Farside data show flows turned positive on Sept. 14, with $159.9 million of net inflows.
The Sept. 16 surprise hinges on whether the Fed points to a single adjustment or the start of a longer tightening run, since futures already price something closer to a cycle than a one-off move.
| Level / signal | Current zone | Why it matters |
|---|---|---|
| August low | ~$62,000 | Starting point for the recovery |
| Glassnode True Market Mean | ~$76,600 | Rough floor beneath the rebound |
| Current BTC price | ~$79,000 | Market is above recovery floor but below breakout zone |
| Cost-basis wall | $83,000-$86,000 | Roughly 1.07M BTC acquired in this band |
| 10-year Treasury yield | Briefly touched 5% | Raises the hurdle rate for risk assets |
| Spot BTC ETF flows | -$463M Sept. 8-11; +$159.9M Sept. 14 | Inflows resumed after four days of outflows |
Congress tests how far the rally can stretch
The Senate faces a cloture vote on the motion to proceed to the CLARITY Act on Sept. 15, requiring 60 votes to advance consideration. Republicans say their proposed substitute incorporates 126 substantive changes Democrats requested.
The bill's core function is establishing clearer SEC and CFTC boundaries across digital asset markets, expanding CFTC authority over digital commodities while leaving SEC jurisdiction over parts of primary-market activity intact.
Bitcoin already has most of the institutional infrastructure that clarity would extend to other assets: spot ETFs, regulated derivatives, established custody, and a comparatively settled regulatory identity.
CLARITY's marginal benefit falls more heavily on everything sitting behind Bitcoin in that build-out, such as exchanges, token markets, custody providers, and DeFi platforms still operating under an unresolved American regulatory discount.
Passing cloture would remove one reason capital has stayed concentrated at the top of the crypto ladder, though it offers no guarantee of an altcoin rally.
Two different levers for Q4
Easier monetary policy can lift Bitcoin's price without touching crypto's underlying regulatory bottleneck. Statutory clarity can resolve part of that bottleneck without making money any cheaper.
A genuinely broad rally in the fourth quarter, the kind that moves altcoin market share alongside altcoin prices, plausibly needs both conditions landing together to have a real chance.
Bitcoin trading above or below any single round number matters less than four relative measures once both events resolve. Whether the pair ETH/BTC strengthens and whether altcoin market share, which has slipped for months, finally starts climbing are indicators to watch.
| Fed outcome | CLARITY outcome | Bitcoin implication | Broader crypto implication |
|---|---|---|---|
| Softer one-and-done hike | Cloture advances | Best chance to clear $83K-$86K | Strongest setup for ETH/BTC and altcoin share to improve |
| Hawkish hiking-cycle signal | Cloture advances | Resistance remains harder to clear | Regulatory discount narrows, but liquidity stays expensive |
| Softer Fed | CLARITY stalls | Bitcoin can rally on rates alone | Altcoins remain burdened by policy uncertainty |
| Hawkish Fed | CLARITY stalls | $76.6K floor comes under pressure | High-beta crypto likely underperforms hardest |
Another key point to watch is whether ETF inflows continue while funding rates and leverage stay contained, and whether high-beta tokens outperform Bitcoin on good news well beyond simply tracking it.
Glassnode's historical comparison shows a 90-day altcoin-share gain of at least 2.8 percentage points near three of four past Bitcoin peaks. The Sept. 7 reading was negative 0.9 percentage points, so that late-cycle rotation signal was absent.
Where this Bitcoin recovery could go
The bull case has cloture clearing on Sept. 15 and the Fed delivering its hike alongside language pointing to a single adjustment, well short of an opening move in a longer campaign.
Under that path, Bitcoin gets its best shot at clearing $83,000 to $86,000 and testing the options market's next real cluster of interest near $100,000. ETH/BTC and altcoins both have room to turn higher for the first time in months.
That combination would be the clearest evidence that August's bounce marked the start of a genuine cycle.
The bear case has CLARITY stalling in the Senate while the Fed points toward the first move in a longer tightening run. In that scenario, the mid-$76,000s floor comes under real strain, and Glassnode's deeper accumulation zone near $62,000 to $65,000 turns from background context into an active downside target.
Higher-beta crypto absorbs the brunt of any selloff, as it has each time hike odds have hardened this cycle. Bitcoin's relative resilience would persist, but resilience within a falling market carries much less weight than resilience within a climbing one.
This week tests if anything can convince the rest of the market to follow Bitcoin's recovery.
The post Altcoins gained 21% and still lost ground to Bitcoin. What would finally turn the tables? appeared first on CryptoSlate.
The American Reserve Modernization Act (ARMA) would put the federal government's Bitcoin reserve into law for the first time. But ahead of its first House committee vote on Sept. 16, the bill has attracted just one Democratic cosponsor, and he does not sit on the committee considering it.
That goes against Congress's broader crypto push. Seventy-eight House Democrats voted for the CLARITY Act in 2025 after the crypto market structure bill advanced through the House Financial Services Committee on a bipartisan 32-19 vote.
The difference is what lawmakers are being asked to support now.
CLARITY establishes rules for private crypto markets. ARMA asks Congress to make Bitcoin a formal Federal Reserve asset and make the existing reserve harder for a future president to reverse unilaterally.
H.R. 8957 enters Wednesday's House Financial Services markup with 23 cosponsors, according to the committee materials. Twenty-two are Republicans. The only Democrat is Maine Rep. Jared Golden, who does not sit on Financial Services.
Cross-referencing the cosponsor list with the committee roster shows six Republican committee members backing the bill and none of the panel's 23 Democrats.
That sets up a straightforward test on Sept. 16: does the bipartisan coalition that supported rules for crypto markets extend to putting Bitcoin on the federal government's balance sheet?
| Measure | Policy question | Democratic support cited in article | Committee signal |
|---|---|---|---|
| CLARITY Act | How should private crypto markets be regulated? | 78 House Democrats voted yes | Advanced through Financial Services 32-19 |
| ARMA / H.R. 8957 | Should the US government hold Bitcoin as a reserve asset? | 1 Democratic cosponsor | 0 active Financial Services Democrats currently cosponsor |
| Committee screen | Does reserve policy have bipartisan support where it must advance? | 23 active committee Democrats | 0 Democratic cosponsors on the panel |
ARMA is a considerably more restrained proposal than the earlier BITCOIN Act framework it descends from. The bill centers on consolidating qualifying government-held Bitcoin at the Treasury and creating a formal Strategic Bitcoin Reserve alongside a separate Digital Asset Stockpile for non-Bitcoin assets.
An amendment posted ahead of the Sept. 16 markup retains a minimum 20-year holding period for Bitcoin placed in the reserve. It also requires an annual public proof-of-reserve report covering holdings, transactions, and control of private keys, with verification by an independent third-party auditor.
The updated text also calls for a 180-day study of whether the government could acquire additional Bitcoin through budget-neutral methods. It does not authorize borrowing, new taxes, deficit spending or pledging government assets as collateral to fund those purchases.
That restraint was meant to broaden the bill's appeal, yet the cosponsor list shows a more institutionally conservative reserve has so far failed to translate into more bipartisan support.
Statute changes what a Bitcoin reserve is
President Donald Trump created the Strategic Bitcoin Reserve and U.S. Digital Asset Stockpile through an executive order in March 2025.
That means the current reserve rests on presidential authority and could be changed by a future administration.
ARMA would instead establish the reserve through an act of Congress. A future Congress could still change or repeal the law, but a future president could not simply reverse the statutory reserve through another executive order.
That is what makes the Sept. 16 committee vote more consequential than another congressional vote on crypto regulation.
Bitcoin has recovered from a late-August two-year low near $60,000 to trade around $79,000 heading into the markup. Third-party trackers estimate US government-linked holdings at roughly 324,000 to 328,000 BTC, although those figures remain estimates rather than a confirmed Treasury balance.
At today's price, roughly 328,000 BTC would be worth about $26 billion. The same holding would have been worth closer to $19.7 billion at August's low and $41.4 billion at last October's peak of $126,000.
That swing is large enough to make Bitcoin's volatility one of the most important parts of the policy debate.
| Bitcoin price reference | Implied value of 328,000 BTC | Policy relevance |
|---|---|---|
| ~$60,000 late-August low | ~$19.7 billion | Shows downside volatility risk if BTC sits on the federal balance sheet |
| ~$79,000 current level | ~$25.9 billion | Approximate value heading into the Sept. 16 markup |
| ~$126,000 prior peak | ~$41.3 billion | Shows upside case proponents can cite as reserve optionality |
The Congressional Budget Office projects the federal deficit climbing from $1.9 trillion this year to $3.1 trillion by 2036. Debt held by the public would climb from 101% to 120% of GDP over the same period..
Supporters can argue that holding Bitcoin gives the government exposure to an asset that could appreciate while federal debt continues to rise.
Opponents can argue that it puts a highly volatile asset onto a federal balance sheet already facing growing fiscal pressure.
Similar concerns have surfaced outside the United States. European Central Bank President Christine Lagarde has argued that reserve assets need to remain liquid and secure. World Bank research has separately concluded that crypto assets are not yet suited to central bank reserve portfolios because they fall short on measures including safety, liquidity and market maturity.
The vote will show where bipartisan crypto support stops
Republicans hold a 30-23 majority on the House Financial Services Committee, giving ARMA a path to advance without Democratic support.
But the more revealing question is whether any Democrats vote for it.
A party-line vote would show that the bipartisan coalition behind private-market crypto legislation does not currently extend to federal Bitcoin ownership.
Even one or two Democratic votes would tell a different story. It would suggest that some lawmakers who crossed party lines to establish rules for private crypto markets are also willing to consider Bitcoin as an asset held by the federal government.
Democratic amendments could provide another signal. A member could oppose ARMA as written while proposing changes to custody, reporting, acquisition rules, or Treasury authority that leave the underlying reserve intact.
| Committee outcome | Political signal | What it would mean for the Bitcoin reserve |
|---|---|---|
| Zero Democratic yes votes | Reserve policy remains partisan | ARMA can advance, but the bipartisan crypto coalition stops at government ownership |
| One Democratic yes vote | First crack in the line | Bitcoin reserve policy gains a foothold, but not yet a durable coalition |
| Two or more Democratic yes votes | Coalition starts to stretch | ARMA begins to look less like a Trump-only executive policy and more like an institutional project |
| Democratic amendments accepting the reserve concept | Constructive opposition | Democrats may oppose the bill text while leaving room for a revised reserve framework |
| GOP defections | Republican ceiling emerges | The issue becomes not only bipartisan viability, but whether Republicans are fully aligned |
The strongest outcome for supporters would be Democratic votes or amendments that accept the reserve itself while seeking changes to how it is managed. That would move the debate beyond whether Bitcoin should be held by the federal government and toward how such a reserve should operate.
The opposite outcome would be a party-line vote, with Democrats rejecting the reserve over concerns such as volatility, fiscal governance, or Treasury authority.
ARMA could still advance under that scenario, but the political message would be different.
The 78 Democrats who supported CLARITY showed that regulating crypto markets can attract substantial bipartisan support. ARMA asks lawmakers to cross a different line: not how Washington should regulate Bitcoin, but whether it should hold it at all.
Wednesday's markup will provide the first clear indication of how many Democrats are willing to cross that line.
The post The US Bitcoin reserve faces a crucial bipartisan test Wednesday appeared first on CryptoSlate.
A Bitcoin investor can withdraw coins from an exchange, return them to the same account, and still fall outside mandatory cost-basis reporting when those coins are sold.
For the 2026 US reporting year, the broker can still be required to report sale proceeds, while reporting the acquisition cost remains voluntary.
Cost basis, the acquisition cost used to calculate a gain, only changes the broker's obligation to supply an ordinary transfer between the investor's own accounts. That creates a practical divide between a record showing how much a sale brought in and one that supports the gain calculation.
The IRS's 2026 Form 1099-DA instructions make that divide explicit. Covered digital assets generally must have been acquired after 2025 in the reporting broker's custodial account and held there until disposal. Assets bought before 2026 or transferred into the broker are noncovered, with basis reporting voluntary.
The distinction runs through the current reporting year as international reporting develops and blockchain analytics providers offer tax authorities a wider view of activity.
Three routes, the same gain
Consider a deliberately simplified hypothetical US investment: 0.1 Bitcoin bought for $5,000 in February 2026 and sold for $7,000 in September. Assume one purchase lot, unchanged ownership, no intervening trades, no fees, and no other basis adjustments.
The purchase and sale stay identical across three paths, only the custody route changes.
| Custody route | 2026 reporting classification | Basis and gain in this example |
|---|---|---|
| Bought and continuously held with the selling broker | Covered; mandatory basis reporting | $5,000 basis; $2,000 gain |
| Bought with one broker, transferred to another and sold | Noncovered; basis reporting voluntary | $5,000 basis; $2,000 gain |
| Bought with a broker, withdrawn to an owned wallet, returned and sold | Noncovered; basis reporting voluntary | $5,000 basis; $2,000 gain |
The third path is the easiest to miss. Returning to the original account does not satisfy the continuous-custody condition. A broker may have recorded the original purchase, but that does not make returned coins continuously held assets under the reporting definition.
For the investor, each hypothetical sale still produces the same $2,000 gain. A blank basis field cannot be read as a $7,000 gain, so the missing information on the form does not determine that the acquisition cost was zero.
The IRS's digital-asset FAQs explain why the wallet movement itself does not change that result: transferring assets between accounts or wallets belonging to the same taxpayer is nontaxable, except for digital assets used or withheld to pay for transfer services.
Fee coins can create a separate disposal, which is why the comparison deliberately excludes fees.
Outside applicable optional reporting methods, the form includes fields for transferred units subsequently disposed of and their transfer-in date, with a date exception for transfers on varied dates. Sale proceeds can be reportable even when basis is not mandatory.
Coinbase's current guidance distinguishes its proceeds-only 2025 forms from basis information beginning in tax year 2026 for certain assets. It also tells customers to retain records from other accounts and wallets. That qualification matters: the change does not promise a completed basis record for every sale.
Kraken's guide to its 2025 combined forms, updated March 30, describes a more specific split. Customer copies showed estimated basis and gains or losses using FIFO, or first in, first out. What was sent to the IRS was the gross proceeds.
The same guide says Kraken tracks basis for activity within the same account, does not track what happens outside it, and treats returning assets as a new deposit without automatically restoring their previous basis.
For the unchanged lot in this hypothetical, recording its return as a new deposit does not create a new acquisition cost. The original purchase record remains relevant even if the returning deposit lacks an automatically attached basis.
This distinction gives investors three separate questions to resolve: what the platform displays, what it reports to the authority, and what their full transaction history supports. A convenient gain estimate may answer only the first.
Why a wider Bitcoin transaction trail still needs acquisition records
International reporting addresses a different part of the problem. The OECD's Crypto-Asset Reporting Framework (CARF) provides for annual exchange of crypto-transaction information with taxpayers' residence jurisdictions through domestic rules and exchange arrangements. It is separate from US Form 1099-DA and does not create a single worldwide crypto tax bill.
The UK offers a concrete timetable. HMRC's guidance calls for user details and transaction summaries, with the first provider report due between Jan. 1 and May 31, 2027, covering calendar 2026.
That reporting can reveal transactions without attaching the acquisition history needed for every investor's gain.
Blockchain analytics extends the question beyond broker submissions. In an Aug. 26 research preview, Chainalysis estimated more than $457 billion in potentially taxable on-chain activity during 2025, including approximately $112.6 billion attributed to the US.
The commercial analytics provider says it covers Bitcoin, Ethereum, Solana, Tron, BNB Smart Chain and Base, assigning countries through direct location signals and proportional allocation based on service activity.
Its estimate excludes trading, staking, and lending conducted inside centralized exchanges and does not apply some countries' transaction or income exemptions. Missing activity restricts coverage, while unapplied exemptions prevent treating every estimated dollar as taxable in its assigned jurisdiction.
Address tracing can help connect movements. However, a path between addresses does not establish an investor's purchase price, unchanged ownership, chosen acquisition lot or subsequent adjustments.
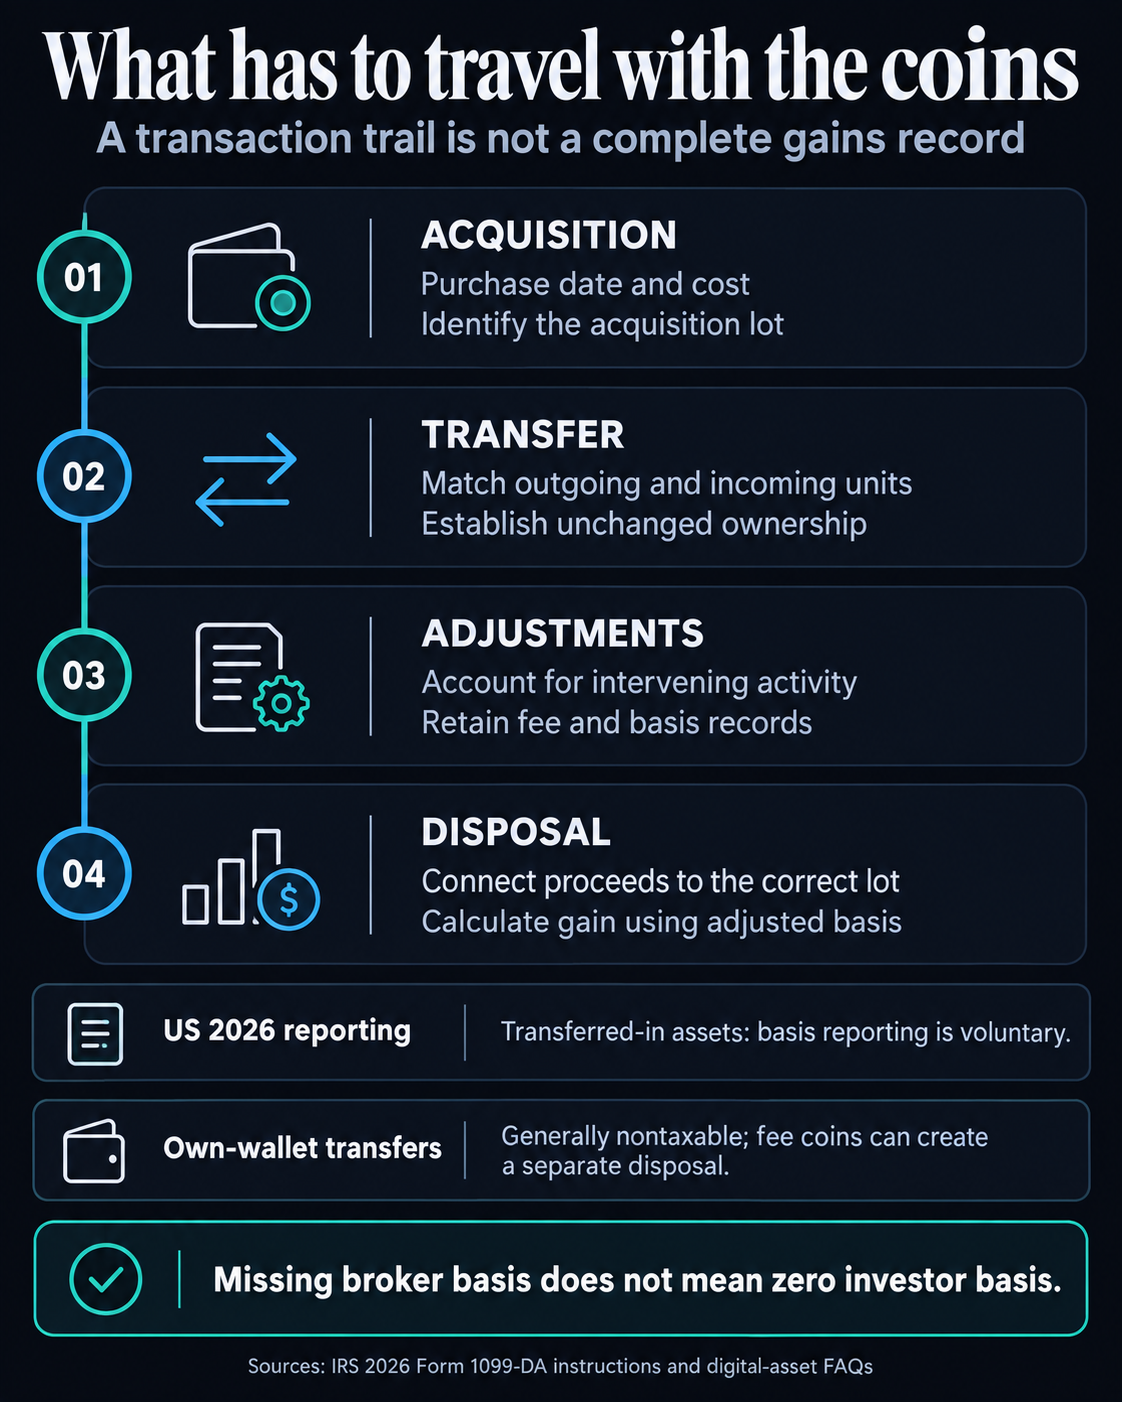
For the US investor in the three-route comparison, a usable gains record needs continuity of information and continuity of ownership. In the three-route example, the crucial connection is between the original $5,000 purchase and the eventual disposal. An incoming transfer's date and quantity alone do not make that connection.
Better interoperability would need to preserve acquisition details, match outgoing and incoming transfers, and account for intervening disposals and adjustments. That could reduce reconstruction work without requiring every investor to remain in one account. Sharing those records would not make the transferred lots continuously held assets under the current rule.
For relevant partial disposals after 2025, IRS FAQ 85 requires investors using specific identification to identify units to the custodial broker by transaction time using its designated identifiers and retain substantiating records. A later spreadsheet choice does not substitute for timely identification.
The reporting rules also contain exceptions: eligible optional methods for qualifying stablecoins and specified NFTs can omit basis even for covered assets, and certain categories have reporting thresholds. Assess a form's completeness based on the method used.
The available disclosures establish why more reporting can coexist with unfinished records. For a transferred holding, calculating the gain still means connecting the sale to the original acquisition, the correct lot, and any subsequent adjustments.
The post Bitcoin self-custody creates a massive cost-basis blind spot on your 2026 crypto tax forms appeared first on CryptoSlate.
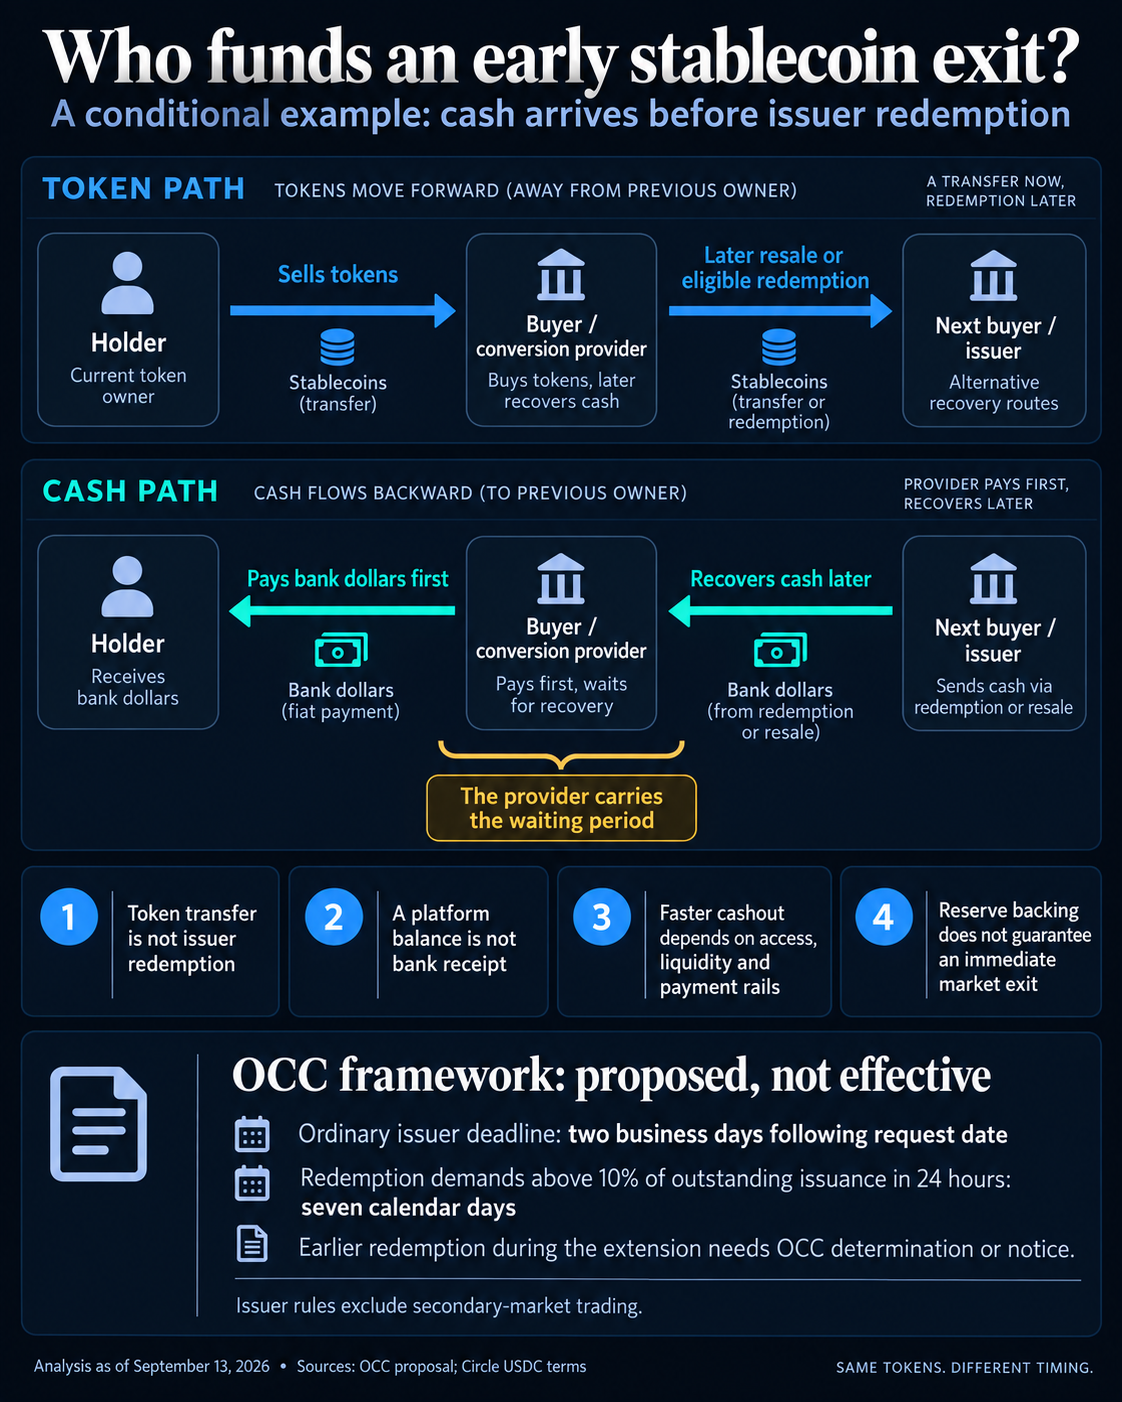
When a stablecoin holder receives spendable bank dollars before the issuer redeems the token, a buyer or conversion provider has funded the early exit. If that party keeps the token, it must wait until resale or redemption to get its cash back.
The Office of the Comptroller of the Currency's proposed redemption framework could give an issuer time to sell reserves in an orderly way while allowing secondary-market trading to continue.
A Sept. 4 Federal Reserve staff analysis clarifies the issue by separating round-the-clock blockchain payment functionality from conversion into bank dollars. Its authors describe redemption timeframes as unsettled.
The practical question for households and businesses is what happens between transferring a token and receiving money they can spend through their bank.
A longer redemption window leaves trading open
The OCC's proposed section 15.12 would set an ordinary redemption deadline of two business days following the request date, keeping faster redemption possible.
However, demands exceeding 10% of outstanding issuance value in one 24-hour period would automatically extend the period to seven calendar days for outstanding and subsequent requests.
During that extension, earlier redemption would require an OCC determination that it could proceed in an orderly, fair and transparent way, or notice that the extension no longer applied. The OCC could also extend the period for specified safety, stability or public-interest reasons.
The agency says the provisions cover issuer redemption, including entities acting on an issuer's behalf, but exclude secondary-market trading. The proposal applies to entities within OCC jurisdiction, and its stated rationale is orderly reserve liquidation with less price disruption from sudden sales.
As of Sept. 13, the measure remained on the OCC's proposed-issuance list, with a March 2 opening and a May 1 comment deadline. No corresponding rule appeared on its 2026 final-issuance list.
For a holder selling before issuer redemption, the immediate source of cash is the buyer or service completing the conversion. The issuer's reserves remain separate from the transaction chain, so a sale changes who holds the token.
If a provider uses available dollars to pay a departing holder and retains the acquired tokens, it has exchanged cash for an asset it must either hold, resell, or redeem. If it resells to another willing buyer, the exposure moves again. If it waits for issuer redemption, its cash remains committed through that interval.
This is why an issuer delay need not translate into an equally long customer delay. A provider with available cash and willing counterparties could continue offering conversion. For the customer, the bridge may be almost invisible: the token leaves, and the bank payment arrives before the issuer pays the provider.
A longer interval could require more funding for the same pace of payouts, or reduce a provider's willingness to hold additional tokens, and quotes and fees could respond.
That mechanism explains where the waiting exposure goes when an earlier exit succeeds.
A redemption right still needs an access route
Circle's USDC terms for holders outside the European Economic Area distinguish token ownership from direct redemption access. The terms require an eligible Circle Mint account in good standing. A holder receiving USDC acquires a conditional redemption right, but holding the token alone does not make that direct route immediately available.
The same terms commit to one dollar per USDC on redemption, subject to the terms, applicable law, and fees. They do not guarantee that third-party platforms will quote USDC at one dollar.
An issuer's contractual conversion value and a buyer's executable price answer different questions.
For a holder using a platform, the relevant sequence includes access to that platform, a conversion at the available price, and a final payment into the bank account. Success at one step does not establish the timing of the next. A completed token trade can leave the customer with a platform balance while the cashout process is still under way.
These particular Circle terms expressly exclude EEA holders, and they support an analysis of the specified non-EEA route.
Existing service descriptions give reasons an issuer's ordinary processing interval may not dictate a customer's experience.
Circle's 2025 Form 10-K described institutional onboarding and two redemption options: basic redemption initiated within two business days and standard redemption initiated nearly instantly. It also described banking infrastructure with multiple rails, including round-the-clock funds-flow capabilities where available.
Coinbase's instant-cashout guidance describes US customers withdrawing from US dollars or USDC balances to eligible US bank accounts connected to Real Time Payments. It specifies a $100,000 limit per transaction for instant bank cashouts and requires an eligible, verified payment method.
Its general guidance says instant cashouts typically take around 30 minutes but can take up to 24 hours depending on the bank or card provider. That broader timing guidance should not be read as a separate guaranteed delivery time for every RTP transaction.
These routes weaken any blanket claim that stablecoin holders must always wait for an issuer's full redemption window. They also make the limits concrete: eligibility, transaction size, and payment arrangements matter. A documented service can provide a usable exit without establishing unlimited capacity during a surge in demand.
Stablecoin reserve liquidity and market liquidity do different jobs
The proposal also contemplates qualifying Treasury-bill repo borrowing to support redemptions. That provides a potential source of issuer liquidity alongside liquid reserves, while permission to borrow does not establish an actual counterparty commitment, nor does a funding mechanism by itself remove the proposed conditions for redeeming early during the seven-day extension.
Circle's terms say that affiliate trading activity supporting USDC is optional and may stop. That qualification concerns those activities, and leaves a meaningful difference between a functioning secondary market and an obligation to keep buying tokens under all conditions.
For a business that needs bank money before an issuer pays, the useful distinction is whether its conversion route has both an executable price and a payment arrangement that meets its deadline. Reserve backing alone cannot answer that operational question, nor can the speed at which the token changes blockchain addresses.
The Fed staff note offers a reason to keep these functions separate: transferring value and converting it into dollars can follow different timelines.
As the OCC framework develops, the terms of any final redemption extension will determine the issuer's permitted timetable. An earlier customer exit will depend on a provider's willingness, available liquidity, eligibility rules, and payment settlement.
When that bridge works, the holder exits and another party carries the interval. When it is unavailable, sound backing alone does not bring the bank payment forward.
The post Proposed stablecoin rules might guarantee your dollar while making you wait a week to spend it appeared first on CryptoSlate.
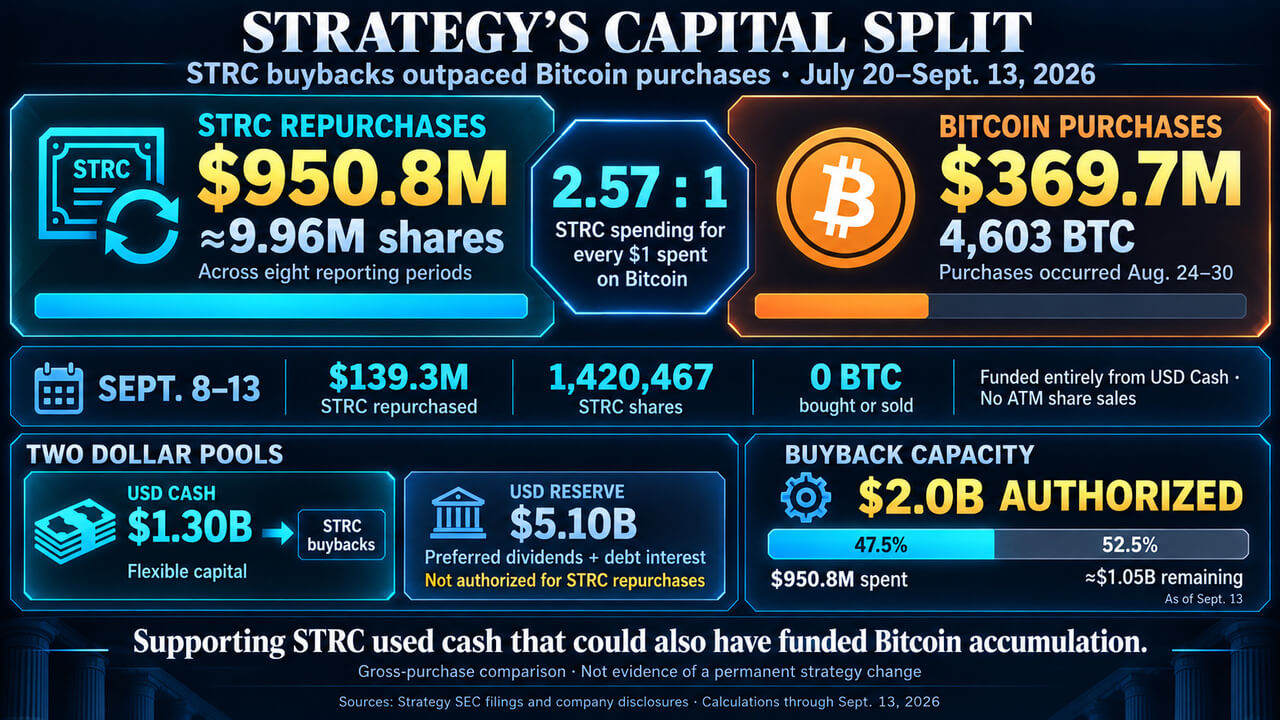
Strategy’s latest $139.3 million repurchase of STRC variable-rate preferred shares has brought its spending on buybacks to about $950.8 million since July 20, more than twice what it spent acquiring Bitcoin over the same period.
The company’s Sept. 14 filing disclosed purchases of 1,420,467 STRC shares between Sept. 8 and Sept. 13, funded entirely from its USD Cash balance. Strategy neither bought nor sold Bitcoin and sold no shares through its at-the-market program during that reporting period.
Across eight reporting periods spanning July 20 to Sept. 13, Strategy repurchased approximately 9.96 million STRC shares. Its reported Bitcoin purchases were confined to Aug. 24-30, when it acquired 4,603 BTC for $369.7 million.
That puts STRC repurchase spending at roughly $2.57 for every $1 spent buying Bitcoin during the window.
Cash goes toward preferred shares
The latest purchases extend a pattern, when cumulative STRC spending stood at $811.5 million. Supporting the preferred shares draws on money that could also fund Bitcoin accumulation.
In its July 27 buyback policy, the company said repurchasing shares below their $100 stated amount could reduce future preferred-dividend requirements at a discount.
Management expected purchases generally to taper as STRC approached $100, although timing and amounts remain discretionary. The policy gives Strategy a reason to spend on its own securities even when that spending does not add Bitcoin to its treasury.
Earlier in the campaign, Bitcoin sales helped finance those obligations. During July 27-Aug. 2, Strategy sold 1,638 BTC, using $52.4 million of proceeds for preferred dividends and $52.3 million for STRC repurchases.
The following week, it sold another 1,690 BTC for $108.6 million, using those proceeds to fund STRC buybacks.
The distinction between Strategy’s two dollar pools matters. As of Sept. 13, its flexible USD Cash stood at $1.3 billion. Its separate USD Reserve was $5.10 billion and designated for preferred dividends and debt interest.
Under the July 27 policy, that reserve was not authorized to fund STRC repurchases.
Strategy still held 845,050 BTC as of Sept. 13. The buybacks compete with further accumulation, but the eight-week comparison does not establish a permanent change in its Bitcoin strategy.
The board doubled the preferred-security repurchase authorization to $2 billion on Sept. 8, including earlier purchases. About $1 billion remained available as of Sept. 13, giving Strategy room to continue supporting its preferred shares while Bitcoin purchases remain intermittent.
The post Strategy prioritizes $950 million STRC buyback over expanding its Bitcoin treasury appeared first on CryptoSlate.
CryptoTicker.io
The first release candidate for Bitcoin Core 32.0 has been available since September 14, 2026. For you as the operator of your own node that means two things: the feature set of the coming major version is settled, and when it ships the 29 series drops out of the project's maintenance window. Anyone still running 29.x today will get no more security fixes after the planned date of October 10. The check takes two minutes; the update costs half an hour depending on your setup.
Our own count of reachable nodes worldwide, which we carried out for this article on the morning of September 15, shows how large the affected group is: roughly six in ten reachable Bitcoin nodes run a version that will no longer be a maintained one once 32.0 appears. The figures and the method are further down.
Bitcoin Core 32.0: what happened on September 14
Bitcoin Core is the reference software of the Bitcoin network. It checks blocks and transactions against the consensus rules, keeps its own copy of the blockchain and is therefore the foundation for anyone who does not leave their payments to somebody else's infrastructure. By its own schedule, the project publishes a major version roughly every six months.
On September 14, 2026, the tag v32.0rc1 appeared in the project's source repository, the first release candidate of the coming major version. The industry outlet TFTC puts this at 12:58 UTC and gives October 10, 2026 as the planned date for the final tag. That leaves a test window of around four weeks between candidate and release. For comparison: the most recently released major version, 31.0, dates from April 19, 2026 according to the project's lifecycle schedule, and the corresponding maintenance build 31.1 carries the date July 7, 2026 in the download directory.
A release candidate is not a preview in the sense of a beta. The code is considered functionally complete. What still goes in now are fixes for bugs noticed during the test window, and nothing else. For you as an operator that means the content of the coming version is known, and you can check your configuration against it now rather than being surprised on release day.
Release candidate, feature freeze, maintenance window: three terms for this article
Release candidate
A release candidate is a build the project considers ready for publication and puts through broad testing before the final release. It carries the suffix rc1, rc2 and so on, and is withdrawn or replaced if a serious bug turns up.
Feature freeze
A feature freeze is the point from which no new functions are taken into a version. It comes before the first release candidate and is the reason the feature set of 32.0 can already be described.
Maintenance window
The maintenance window is the period in which a major version still receives bug and security fixes. Under its own lifecycle schedule, Bitcoin Core maintains the three most recent major versions at any time. As soon as a new major version appears, the oldest of those three slips out and is considered end of life. Versions in the end-of-life state generally receive no further security fixes either.
Our own analysis: 60 percent of reachable nodes lose maintenance with 32.0
This analysis was carried out by cryptoticker.io on September 15, 2026. The method in one sentence: at 06:35 UTC we retrieved the public snapshot from the node counter btcnodes.io (formerly bitnodes.io) and counted the version identifier each node reports about itself, grouped by major version.
We examined 26,516 nodes from that snapshot. Of those, 25,902 carry an identifier in the usual form with a version number; the remaining 614 report different software, 556 of them a library implementation with no version relation to Bitcoin Core. The count refers to those 25,902 nodes.
- 29.x: 8,629 nodes (33.31 percent) – precisely the series that drops out of maintenance when 32.0 appears.
- 28.x and older: 7,017 nodes (27.09 percent) – already unmaintained today. The 28 series has been end of life since April 19, 2026.
- 30.x: 1,732 nodes (6.69 percent) and 31.x: 8,512 nodes (32.86 percent) – the two series that will continue to be maintained alongside 32.x after the release.
- 32.x: 12 nodes (0.05 percent) – presumably test systems already running the candidate.
Adding the 29 series and everything older gives 15,646 nodes, or 60.40 percent. That majority will be left without maintained software the day after the release. A side finding from the same count: 4,459 nodes (17.2 percent) additionally report the identifier of the divergent implementation Bitcoin Knots, which has its own release rhythm and is untouched by this maintenance schedule.
What this survey cannot do belongs here too. The snapshot contains no country field, so a separate figure for any one country cannot be derived from it. The version identifier is self-reported and technically forgeable. And only nodes reachable from outside are counted. Anyone running their node behind a firewall or reachable exclusively over Tor does not appear in these statistics. The actual number of outdated installations is therefore likely to be higher than shown here.
The Bitcoin Core maintenance window: which version drops out when
The project's lifecycle schedule is a public table and can be read line by line. The entries that matter for you:
- 29.x, released April 14, 2025: end of life when 32.0 appears, so on current plans October 10, 2026.
- 30.x, released October 10, 2025: end of life only with 33.0.
- 31.x, released April 19, 2026: end of life only with 34.0.
- 28.x: end of life since April 19, 2026.
The project explicitly recommends running the most recent maintenance build of the highest major version you can move to. There is one particularity here that argues for a calm upgrade path: the project ships proposals for changes to the consensus rules in maintenance versions first, not in major versions. Anyone updating conservatively therefore still stays compatible, as long as their own major version is maintained. That compatibility is exactly what ends for the 29 series in October.
Reading your Core version: how to find out what your node runs
Before you download anything, establish where you stand. Three routes, depending on your setup.
Command line
On a server or single-board computer, bitcoind --version gives the version number directly in the first line. With the service running it also works via bitcoin-cli --version or, if you are talking to the node anyway, via the call bitcoin-cli getnetworkinfo; there the identifier sits in the subversion field, in the same form our count above used.
Graphical interface
In the desktop application you find the version number under the Help menu item, in the window with the information about the application. It also appears in the debug information window that the application offers under the Window menu item.
Prebuilt node package
Anyone running a turnkey solution, meaning a preconfigured operating system for a home node, usually reads the Core version in the detail view of the respective application. What matters here is the version of Bitcoin Core itself, not the version number of the interface around it. The two figures almost always differ, and only the first decides on maintenance.
Note the number down. If it says 29 or anything lower, you have a task for the coming weeks. If it says 30 or 31, you are on the safe side for now and can plan the update at your leisure.
What changes in Bitcoin Core 32.0: fee estimation, index, interface
The draft release notes for 32.0 sit in the project's development wiki. It is explicitly a draft and may still change before the final tag; the following points should therefore be read as a direction of travel, not as final wording.
What stands out is the emphasis on operation rather than on visible features. Fee estimation will in future combine the block-based estimator with the estimator from the mempool and comes out more cautious as a result. According to the draft, the transaction index takes up less than half the disk space it used to, though only after a rebuild of the index. Block validation gains a parallel prefetch of input data with its own setting for the number of worker threads, preset to eight and capped at sixteen.
At the network layer, the draft has a global rather than a per-connection limit on transaction relay, plus proof protection for Tor services where the counterparty supports it. The outdated encryption of the I2P network is being retired; anyone running their node over it should plan the switch before version 34. The interface gains new calls for handling keys and for exporting a watch-only wallet, and the built-in HTTP server has been rewritten, including a new cap on simultaneous connections.
None of this forces you to act on release day. Two points are still worth noting: the rebuild of the index, if disk space is getting tight, and the removed settings covered in the next section.
Removed options in bitcoin.conf: why your node warns after the update
The most common trouble after a major version jump comes not from the program but from your own configuration file. According to the draft, several settings that stood in guides for years are dropped in 32.0. Among them are a setting for full replaceability of transactions in the mempool and an older network option. Two keys also disappear from the responses of the mempool calls, unless you explicitly switch them back on through the setting for deprecated interfaces.
In practice that means: open your bitcoin.conf before you update and check every line against the release notes. A node that will not start because of an unknown setting, or that comes up with warnings, is an unnecessary night shift. Anyone who has hung their own scripts or accounting software off the interface should additionally check whether one of the disappearing keys is read there.
Testing the release candidate without risking your production node
Four weeks of test window is an invitation, and it applies to operators without a developer background too. The more different setups run the candidate, the sooner bugs surface before they land in the released build. Three rules make testing harmless.
First, a release candidate does not belong on the node your wallet hangs off. A separate device, a virtual machine or a test run on testnet is entirely sufficient. Second, before starting you verify the signature of the downloaded files against the published checksums; that is as mandatory for a pre-release build as for a regular release. Third, you report anything odd while the window is still open. After the final tag, the route for fixes is considerably longer.
Anyone wanting to be sure makes a backup of the wallet file and the configuration file before every version jump and keeps it separate from the node. That applies to the candidate as much as to the later release. How strictly the same discipline applies to hardware devices was demonstrated this year by the case of a manufacturer whose firmware bug affected an entire device generation.
No node of your own? What this update says about your custody
The larger part of the readership runs no node of their own, and that is a legitimate decision. This release still has something to say to you. Anyone leaving their holdings at an exchange or a broker is relying on somebody there keeping an eye on this maintenance window. Anyone self-custodying but reaching a third-party server through a wallet application is relying on the same unknown third party, just one layer down.
The practical middle route for most people is separating keys from software: the keys sit on a device that never touches the network, the software stays replaceable. Which devices are suitable and how they differ is in our hardware wallet comparison. Your own node comes as a second step after that, and the version question from this article becomes yours from then on.
Two cases from recent weeks show that maintenance is no marginal topic: a vulnerability in a Lightning implementation and a critical hole in a widely used wallet interface where only reachability from the internet decided the risk. In both cases the remedy was an update that was already available.
What this release is not: no consensus change and no price event
A word against the obvious wrong conclusions. On the draft as it stands, Bitcoin Core 32.0 changes no consensus rules. There is no vote, no signalling deadline and no point at which a node that has not updated falls out of the network. A node on version 29 will keep validating correctly after October 10. What it lacks are fixes for bugs found after that.
Nor is a release a price event. Anyone drawing a connection between version numbers and price moves is claiming something that cannot be demonstrated. The relevance of this date lies purely in operations: in the question of whether the software checking your payments is still maintained.
That leaves the question of timing. A jump to 32.0 on release day is no mistake for a private node, but no obligation either. Anyone on 30.x or 31.x has months. Anyone on 29.x or below should plan the switch for October, and specifically to the most recent maintenance build of the highest major version their setup allows. For setups where a full node demands too much disk space, pruned mode remains an option; the node does the validation work unchanged either way.
Checking Bitcoin Core 32: what to take away
- Read your version and note it down. Via
bitcoind --version, via the information window of the desktop application, or in the detail view of your turnkey solution. If it says 29 or less, put a date in October in your calendar. Anyone not yet self-custodying should settle the key question first and look at the hardware wallet comparison for that. - Prepare your configuration file and a backup. Check every line of your
bitcoin.confagainst the release notes, and back up the wallet file and the configuration separately. Anyone keeping their keys in an application on their computer should check its update situation in parallel through our software wallet comparison. - Test on a separate device, then move over calmly. Never run the candidate on the node your wallet hangs off. And if you conclude that you do not want to run a node of your own at all, then choosing the custodian is the decision that counts at this point, and the exchange comparison is worth a look for that.
The sources for this article: the Bitcoin Core lifecycle schedule with the maintenance table and the tag list of the source repository, where the candidate v32.0rc1 appears with its date.
(As of September 15, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
When your Core Lightning node prints v26.06.7 at startup, that is no proof that the security fixes in this version are actually running. Anyone who pulled their update via Docker between August 28, 2026, 16:04 UTC, and September 1 may be running an image that reports itself correctly and still does not contain the fixes. The reliable evidence is the image digest, not the version output. This piece walks you through the check that requires, and through what to do afterwards.
The situation has changed in two places since our article of August 30: the faulty Docker window is now documented in the release note, and the embargo on the source code expired on September 11. Both change what you as an operator need to do.
What Core Lightning is and why this update concerns you
Core Lightning (formerly c-lightning) is one of three widely used implementations of the Lightning protocol, written in C and maintained in the ElementsProject/lightning repository. An implementation here is simply a standalone program that applies the same network rules as the competing programs but has its own code and therefore its own bugs.
The Lightning network itself is a second layer on top of the Bitcoin blockchain: two parties jointly lock funds in a payment channel and then settle any number of payments between them without writing every single one to the chain. Whoever runs such a node holds the keys to those locked funds themselves. That is what makes this serious: a bug in the node software directly affects Bitcoin that belongs to you and that nobody else is watching over.
Self-custody means taking responsibility, and that does not end with storing the key. It also covers the question of whether the software using that key matches the state you believe you have installed. If you would rather hold your assets without running a server service, you will find the devices for that in our hardware wallet comparison. For a Lightning node, though, there is no way around keeping running software current.
What went wrong with the Docker image of version 26.06.7
Version 26.06.7 was released on August 28, 2026 as a maintenance release. The project's announcement is terse: it is a point release fixing confirmed vulnerabilities that had been reported to the team over the preceding three weeks. A point release is an interim version containing fixes only and no new features.
For Docker users, something went wrong in the process. The release note was subsequently extended with a section that names the error outright: between August 28 at 16:04 UTC and September 1, four tags served images that reported v26.06.7 at startup but did not contain that version's fixes. The affected tags were v26.06.7, latest, v26.06.7-vls and latest-vls.
The project names the cause itself: an automated build process had published the images from a placeholder tag. They have since been replaced, and the wrong manifests are no longer referenced by any tag. A manifest is the descriptor file that defines which individual parts make up a container image. Anyone still holding the wrong version locally will notice nothing of this correction, however: what you downloaded back then stays on your machine.
One point clears a group of operators entirely. Anyone pinned to v26.06.6 or older was never affected at any point, according to the project. The problem only hits those who pulled 26.06.7 or latest during the window described.
Why the version number at startup is no proof of the patch level
The obvious check is also the useless one. A call that prints the running version merely reads out a string written into the program at build time. If that string comes from a placeholder tag, then an unpatched program truthfully reports the number it was handed and tells you nothing about the actual code.
That is the awkward part of our own article of August 30: there we had you check the version. For Docker operators inside the affected window, that check was worthless, without any way of telling at the time. Hence this follow-up, and hence a different check from here on.
The digest is the check value that uniquely identifies a container image. It is a cryptographic hash over the manifest, and therefore over the actual content of the image. A tag such as latest is a moving pointer that can point at one image today and another tomorrow. The digest cannot do that: change a single byte of the content and the value changes. It is therefore the only piece of information that tells you what you are really running.
Are you affected? The window, the tags and the three platforms
Three questions settle the case. First: did you obtain the software as a container at all? Anyone who installed the tarballs from the release page was never affected, because those archives were the right ones from the start. Second: did your download fall inside the window between August 28 at 16:04 UTC and September 1? The release note gives no exact time for the end of that window, so a degree of fuzziness remains, and in case of doubt it is better to check once too often. Third: did you use one of the four tags named?
Anyone unsure about all three questions is always right to run the digest check. That check costs you a single command and answers the question conclusively, no matter when and how you obtained the image.
There are three platforms for this version's images: linux/amd64, linux/arm64 and linux/arm/v7. The third has a peculiarity that concerns operators of small single-board computers: there is no release tarball for linux/arm/v7. The binaries for that platform are compiled separately and are covered by no signed manifest. Anyone working on that architecture therefore starts out with a weaker chain of evidence than on the other two. On top of that, according to the project the images carry neither provenance nor SBOM attestations, meaning no machine-readable proof of origin.
How to check the image digest of your Lightning node
The command named in the release note reads out the digest of the image held locally. It looks like this:
docker image inspect --format '{{index .RepoDigests 0}}' elementsproject/lightningd:v26.06.7The output is the value you have to compare. The project names two target values for the corrected images. For the tags v26.06.7 and latest it reads sha256:0421a5f0d1b2e1ad639edfa17d777816040e3850d91bae7f2d32186d9c1e6da4. For the signer variant under v26.06.7-vls and latest-vls it reads sha256:6a5e05c13a65613f8c0fe3830c60248a6724e7206c1c23dd26ac2e98a3e72c1f.
Two notes on running it. The command queries your local store only, downloads nothing and changes nothing. And it refers to the tag you give it: if you work with latest, use latest; if you run the signer variant, use the respective -vls tag. If the value printed matches the target value character for character, you are done and running the corrected build.
What matters is comparing the full length. A quick glance at the first and last four characters is not enough, because that is precisely the part a human waves through as "close enough" when in doubt. Copy both values next to one another and compare them mechanically, for instance by writing the target value into a file and checking the output against it.
Digest does not match: how to pull the corrected image
If the value differs, the remedy is unspectacular. You pull the image again, for every tag you actually use:
docker pull elementsproject/lightningd:v26.06.7
docker pull elementsproject/lightningd:latest
Then check the digest again with the same command as above. Only once the new value matches the target value do you restart the container, so that the running process actually uses the fresh image. A pull on its own does not replace a running container; your node keeps running on the old state until it restarts.
Anyone running containers through a Compose file or an orchestrator should make sure the configuration does not fall back on a cached local state. The cleanest approach is to pin the verified digest itself afterwards instead of the moving tag. The same mix-up then cannot happen to you a second time, because the reference is bound to the content rather than to a name.
One change at the margin may show up on restart: in the current images, Core Lightning is installed to /usr/bin and /usr/libexec/c-lightning, whereas earlier images used /usr/local. Symlinks from the old locations are included, so hard-wired paths continue to work. Anyone running their own scripts with absolute paths should still give them a once-over.
VLS operators: why the signer has to match the node version
VLS stands for Validating Lightning Signer and denotes a separated signing service that holds the node's keys and checks every signature against its own rules before issuing it. The point of it: even if the node is compromised, an attacker cannot talk the signer into arbitrary payouts.
For these operators there is a hard edge when moving to 26.06.7. According to the project, the v26.06.7-vls variant contains the same signer as v26.06.6-vls, namely VLS v0.14.0, which this release leaves untouched. The signer does, however, require the VLS_CLN_VERSION variable to match the node it talks to. If it still reads v26.06.6 while the node runs v26.06.7, remote_hsmd_socket refuses to start.
That is inconvenient but benign in effect: the service does not start at all rather than carrying on in a half-matching state. Set the variable during the upgrade and the signer stays reachable. Anyone who misreads the message and rolls the node back to the old version to get the signer running undoes precisely the fix this is all about.
The embargo has ended: what that means for unpatched nodes
The project had deliberately withheld the source code for this version. The reasoning is in the release note: a patch shows which code it changes, and the delay was meant to lower the likelihood of attackers reverse-engineering the fixes and exploiting them before the network had updated.
That period is over. The release note now says so in as many words: "The embargo has ended. The source for this release was published on 2026-09-11T11:42Z." The v26.06.7 tag has since pointed at the commit the binaries were built from, and the source archive is attached to the release.
For you as an operator, that reverses the risk picture. Until September 11, an unpatched node was also protected by the fact that attackers did not know the details. That protection has fallen away with nothing to replace it, because the changes have been publicly readable ever since. Anyone who has not caught up by today is running software whose vulnerabilities are documented and open to inspection by anyone. The project also states that versions before 26.06.7 are no longer supported.
Notable on the side, and readable from the release metadata itself: the signature file for the amd64 checksums was not uploaded until September 12, 2026 at 06:02 UTC. Anyone wanting to verify the signature before that found none for this architecture. The checksum file itself, by contrast, had been available since August 28.
Why the --offline stopgap is no substitute for the update
The project announcement of August 28 included an interim step for everyone unable to update straight away. A restart with the --offline flag cuts the node off from incoming messages and thereby denies attackers any way of addressing it at all. The service keeps running and processes the blockchain, so it can still detect a cheating attempt by the channel partner. The project writes that the flag should be removed again after the upgrade and the node restarted.
This stopgap was intended for the period without public details. Since September 11 it is no longer a substitute for the update, only a bridge covering the hours you need to catch up. A sealed-off node forwards no payments, earns no fees and is unreachable for counterparties. As a permanent state, that is expensive downtime.
The same check routine is worth applying to other building blocks in your own setup. If you put a management interface in front of the node, you should know how reachable it is from the network as well; we described that route for Alby Hub on September 11. The starting point for this series of vulnerabilities is in our article of August 30, Core Lightning: what node operators have to do now.
Installed without Docker? How to verify checksums and signatures
Anyone obtaining the tarballs from the release page has the better chain of evidence but also has to walk it. Every binary is covered by a signed manifest. First you check the checksums:
sha256sum -c SHA256SUMS-v26.06.7 --ignore-missingThen the signature over that checksum file:
gpg --verify SHA256SUMS-v26.06.7.asc SHA256SUMS-v26.06.7The file SHA256SUMS-v26.06.7 covers the amd64 archives; for arm64 there is a separate file with its own signature. Four maintainers of the project signed, and the release note lists their fingerprints individually. One detail spares you a false alarm: a signature can report a fingerprint that differs from the one listed, because the signers use subkeys. Once the primary key is imported, gpg --verify resolves this itself, and the discrepancy is not a failed check.
There is a second, faster piece of evidence, and it is the genuinely elegant part of this release. The checksum file contained a line for the source archive clightning-v26.06.7.zip from the start, even though that archive was not yet public on August 28. Because the file was signed back then, it amounts to a commitment made in advance to exactly the bytes that are published now. That makes it possible to show in minutes and without a compiler that the source code visible today is the same one signed in August, and that nothing was altered during the embargo.
Reproducible builds: where the chain of evidence for this version ends
A reproducible build is a build process that produces the same binary byte for byte from the same source code. It allows third parties to demonstrate independently that a published file really does come from the published source. For this version that holds only in part, and the project names the limitations itself.
First, the archives were not built at the default optimisation level. The configuration uses -Og by default, while the published binaries were produced with -O3. Anyone checking out the tag and building normally gets files that do not match the checksums; COPTFLAGS=-O3 has to be passed explicitly. Second, the arm64 archives cannot be rebuilt from this state, because the tooling required for it is not in this version's source tree. Those files remain verifiable through the signature but not independently reproducible. Third, the project points out that the Fedora rebuild may differ, because the build image there is freshly updated on every run and two people on different days can end up with different tool versions.
This reads as an honest description of a chain of evidence with gaps, not as criticism of the people involved. For you as an operator it means, in practice: rely on the signature and the checksum, and treat a full rebuild as a job for specialists rather than a step in your maintenance routine.
What this incident shows about supply chains in crypto software
The real lesson lies in the delivery and not in the vulnerability itself. The error arose in an automated build process that published an image from a placeholder. Nobody had to be attacked for it, and yet a file that did the wrong thing while claiming the right one sat there ready for days.
The project itself names a reason in the release note why such maintenance releases are likely to become more frequent: ever more capable AI models are being deployed to hunt for possible vulnerabilities in open-source code, which markedly increases both the number and the pace of reports. Anyone running infrastructure will therefore have to update more often, which makes the question of how you verify an update more important than the question of whether you carried one out.
Three habits follow from this, and they cost little time. Pin containers to digests rather than to moving tags. After every update, check the content and not the label. And keep a record of which version with which check value you rolled out when, so that at the next advisory you know within minutes whether it affects you. Anyone unwilling to put that effort into a running server service should honestly consider whether a leaner custody arrangement fits their daily routine better.
Checking your Core Lightning update: what to take away
- Check the digest today, not the version number. One command, one comparison against the target value from the release note, and the question is answered. If you find in the process that running your own node is becoming too much work, our hardware wallet comparison gives you an overview of the alternatives to pure self-custody via a server.
- Pull again and restart if the value differs. Pull, check the digest again, swap the container, and only then remove the
--offlineflag. For everything else you run in software on the node afterwards, the software wallet comparison is worth a look, because the same question of update routes and proof of origin applies there. - Build your maintenance around check values. Pin the digest, verify checksums and signatures after every download, document the state. And if you want to top up channels, you will find the routes in our overview of how to buy Bitcoin.
(As of September 15, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Primary sources: the release note for Core Lightning v26.06.7 in the project's repository and the Blockstream project announcement for the release.
Crypto exchange CoinEx is closing down. Anyone still holding a balance there has to withdraw it by December 22, 2026; after that the withdrawal channel shuts. The wind-down starts today, September 15, and the key interim date is September 29, because spot trading ends that day. From then on you can only withdraw a balance in whatever currency it already sits in.
On the day of the first wind-down stage we measured what is still technically possible on the exchange. The headline finding: of 992 listed currencies, 37 could not be withdrawn at the time of measurement, deposits had already been switched off for 465, and there was no euro trading pair anywhere on the exchange. This analysis was carried out by cryptoticker.io on September 15, 2026.
CoinEx is shutting down: the deadlines that apply from September 15
CoinEx has announced the closure as an orderly wind-down and attributes it to the prolonged market downturn, to falling trading volume and to supervisory and compliance costs the company describes as no longer sustainable. The exchange had been on the market for nine years. The wind-down runs in four stages, and each stage takes an option away from you:
- September 15, 2026: no new registrations, no referral rewards, and futures trading moves into reduce only mode. That means you can shrink or close existing positions but can no longer open new ones.
- September 22, 2026: all services outside the spot market are switched off. Anyone still running a leveraged position or an interest-bearing product has to unwind it before then.
- September 29, 2026: spot trading ends. From that day you can no longer swap a balance into another currency. The exchange says its in-house token CET will be bought back at 0.005 USDT per unit.
- December 22, 2026, 02:00 UTC: the withdrawal channel closes and operations end.
Between September 29 and December 22 the platform is therefore a pure withdrawal counter for just under three months. That sounds like plenty of time, but it pulls the decisive work forward: whatever you have not swapped into a withdrawable currency during the last week of September will sit there in exactly that form until the end. The exchange publishes its notices in its public announcements section; CryptoBriefing and the Asian industry service PANews, among others, reported on the wind-down independently of one another.
Why an orderly wind-down is different from an insolvency
An orderly wind-down is a process in which a company ends its operations by its own decision and returns customer holdings according to plan. That sets it apart from an insolvency, where an administrator takes control and payouts stop immediately. CoinEx states that it holds a reserve ratio above 100 percent and can pay out all customer holdings in full. That is a company statement, not an externally audited fact. How to handle such a statement is covered further down.
CoinEx and European users: why the July exit from the EEA makes the situation worse
For investors in Germany this is not fresh news but the second half of an old story. CoinEx already left the European Economic Area on July 1, 2026, and has listed the EU as an excluded region ever since. The exchange holds no authorisation as a crypto-asset service provider under the EU regulation MiCA, and without that permission it has not been allowed to serve EU customers since the transition period ended. Germany's BaFin has granted most of these authorisations across the entire Union to date and has visibly moved against providers operating without a licence.
In practice that means this: if you are a German user still holding a residual balance at CoinEx, it dates from before July, and you have already been asked once to act. Residual holdings of exactly that kind tend to be left lying around, because they are small and the effort looks larger than the amount. This time that is an expensive misjudgement, for two reasons, both backed by figures below: the withdrawal fee eats a double-digit percentage of small holdings, and the exchange has announced a monthly custody fee for USDT that is not collected.
If you are reorganising your holdings anyway, it is worth looking at exchanges with a European licence, because with them this particular risk disappears: a provider with MiCA authorisation does not have to clear out of the European market overnight. We have described the general order of steps during a closure in a separate piece that explains what you need to do before a deadline expires.
Our own measurement: how many coins can actually be withdrawn from CoinEx right now
Whether a balance can be moved out is decided not by the date in the calendar but by a switch in the exchange software. CoinEx publishes that state through an open interface that can be queried without an account. We called it three times on September 15, 2026, at 03:50, 03:51 and 03:54 UTC, and evaluated the full response each time.
We checked 992 currencies with 1,011 currency-network combinations between them, plus 851 spot markets and 221 futures markets. The method is plain: for each currency and each network, the interface states whether deposits and withdrawals are enabled, what minimum amount applies and what fee is charged. We counted those fields and set them in relation to one another.
The three measurement windows returned identical values, which suggests a configured state rather than a brief outage:
- 37 of 992 currencies could not be withdrawn, which is 3.7 percent.
- 465 of 992 currencies no longer accepted deposits. Just under half of the inflow is therefore already closed.
- At network level, 38 of 1,011 combinations were blocked for withdrawals.
- 8 spot markets already carried a stored delisting date.
The number of blocked withdrawals is lower than you would expect during a wind-down. That is the good news in this measurement. The bad news is in the next section, because there it is about the selection rather than the quantity.
37 blocked coins: which balances cannot leave the exchange right now
Among the 37 currencies without withdrawals are several that do turn up in European portfolios. In full, and in the exchange's own spelling, they were: ARRR, AVAIL, BABY, CELO, CRO, DAG, DERO, DYDX, EGLD, ETC, ETHW, EURR, GLMR, HFUN, HYPE, ICX, KAT, LYX, MANTRA, MODE, MOVR, NEOX, OCTA, ONE, ONG, ONT, PI, PUMPBTC, PURR, REEF, SAL, USDR, VENOM, WING, XNO, XRD and ZIL.
Three entries stand out. ETC is Ethereum Classic, one of the older large currencies. CRO belongs to the ecosystem of a major competing exchange. EURR is a euro-denominated stablecoin, which is precisely the entry a European user might need as an exit into their own currency. The exchange does not communicate through the interface why these blocks are in place, and we claim no reason for them. Blocks of this kind can have technical causes, such as maintenance on the network concerned.
The finding still has a practical bearing, and an uncomfortably concrete one: if your currency is on this list, the December 22 deadline is no help to you while the switch stays shut. Your only route then runs through the spot market, and that ends as early as September 29. You would have to swap the affected holding into a withdrawable currency before then. So check the withdrawal switch for your currency now, not in December.
Withdrawal fees by chain: why USDT on TRC20 costs almost a thousand times more
The second finding of the measurement is the most expensive one, and it affects practically anyone holding a balance in stablecoins. A withdrawal at CoinEx costs a fixed fee, and that fee depends solely on which network you withdraw through. The same USDT, the same amount, the same moment, nine possible routes at nine very different prices. This is how they looked on the day of measurement:
- Plasma: 0.000043 USDT
- CSC: 0.0016 USDT
- Polkadot Asset Hub: 0.0036 USDT
- BNB Smart Chain: 0.0079 USDT
- Avalanche C-Chain: 0.021 USDT
- Ethereum (ERC20): 0.071 USDT
- TON: 0.22 USDT
- Solana: 0.48 USDT
- Tron (TRC20): 7.50 USDT
Between the cheapest and the most expensive chain, Plasma against Tron, sits a factor of 174,000, and even between the two most widely used routes, BNB Smart Chain and Tron, the factor is 949. Tron is the standard recommendation for USDT transfers in many guides, because the chain was long considered cheap. At this exchange, on this day, it is by some distance the most expensive way out.
The effect turns brutal as soon as the residual holding is small. On a balance of 20 USDT, a withdrawal via Tron costs 7.50 USDT, which is 37.5 percent. Via BNB Smart Chain it would be 0.04 percent. A fee exceeding the minimum amount is no isolated case at CoinEx: in 78 of the 1,011 currency-network combinations, the withdrawal fee came to at least half of the respective minimum withdrawal amount. For Tron USDT the minimum amount was 1 USDT and the fee 7.50 USDT.
What this means for Bitcoin and Ethereum
For Bitcoin there was only one withdrawal route, the Bitcoin network itself, with a fee of 0.0001 BTC and a minimum amount of 0.001 BTC. At the measured price of around 77,742 USDT per Bitcoin, the fee works out at roughly 7.80 USDT and therefore a tenth of the smallest possible withdrawal amount. Ether cost 0.000011 ETH on a minimum amount of 0.005 ETH, a ratio of around 0.2 percent. The difference between the two is no coincidence and follows the usual transaction costs of each chain.
The practical consequence for you: pool your holdings into a currency with a cheap withdrawal before September 29, and check every chain on offer individually when you withdraw. Make sure the destination address supports the same chain. A withdrawal to an address on the wrong network is the most common way to lose a balance for good; a hardware wallet with a clear network display largely takes that mistake off your hands.
No euro pair on CoinEx: how to get out of the exchange without a fiat exit
Among the exchange's 851 spot markets there was not a single euro pair on the day of measurement. Trading ran against USDT in 645 markets, against Bitcoin in 134 and against USDC in 72. A direct route from your CoinEx account to your bank account therefore does not exist, and none will appear before December 22 either.
The exit consequently runs through two steps. First you withdraw your balance as crypto assets, either to your own wallet or to an account with a provider authorised in the EU. Only there do you swap into euros and cash out. Anyone planning the second step anyway should set up the destination account before withdrawing, so that no waiting period opens up between payout and sale in which the price runs against you. We have worked through the trading costs elsewhere to show that a missing euro order book is more than an inconvenience.
The CET buyback at 0.005 USDT: what the price said on the day of measurement
According to CoinEx, the exchange's own token CET will be bought back out of user accounts at 0.005 USDT per unit on September 29. A buyback at a fixed price acts like a floor that the market orients itself around. That is exactly what the measurement showed: CET traded in all three windows at 0.005 and 0.005001 USDT respectively, so practically exactly at the announced buyback price.
The remaining daily figures show how the market found its way there. It opened at 0.004826 USDT, fell to a low of 0.0045 and rose to a high of 0.005043. Trading volume over the past 24 hours came to around 75.5 million CET, with the sell side at about 52.3 million clearly above the buy side at around 2.5 million.
From this follows a plain calculation for CET holders. Anyone selling on the market before September 29 currently gets roughly the same price as in the buyback, but carries the trading fee and the risk that the price slips before the sale goes through. Anyone who waits is relying on the exchange carrying out the buyback as announced. Both are defensible, and both hang on the same question: how reliable you consider the company's commitments to be. We are not making a recommendation here.
A custody fee of 5 percent a month: what happens to USDT you do not withdraw
For the case that a balance is still sitting in the account on December 22, CoinEx has announced an arrangement that is unusual and that you should know about. USDT not withdrawn by the cut-off date is to be transferred into separate custody. For this the company names a monthly custody fee amounting to 5 percent of the original holding.
Work that through, because the basis of assessment makes the difference. A fee of 5 percent on the original amount is not a proportional shrinkage that approaches zero asymptotically, but a constant deduction. On 500 USDT that would be 25 USDT a month. After twenty months the holding would be used up on paper. A balance you simply leave alone is therefore gone after just under two years, without anyone having taken it from you.
This construction is no isolated case in wind-downs; we have described it in earlier cases and shown what happens to residual balances after an exchange closes. What is new is the level. So set yourself a reminder for the start of December in case you have to postpone the withdrawal for any reason.
Reserves above 100 percent: what CoinEx commits to and what follows from it
CoinEx states that it holds a reserve ratio of more than 100 percent, so that all customer holdings can be paid out in full. That figure comes from the company itself. We can neither confirm nor refute it, and we expressly imply nothing else about the company.
As an investor you need the distinction all the same. A reserve ratio describes a state at a point in time, not a promise for the coming three months. Nor does it replace deposit insurance: there is no statutory protection for crypto assets on an exchange of the kind you know from bank deposits. The sober way to handle this is to take the order of events seriously. As long as the withdrawal channel is open, moving your money out is a decision you make. Once it is no longer open, you no longer make it.
Withdrawing your balance: which steps count before September 29
The order follows from the dates. Anything that needs a working spot market belongs before September 29. Everything else can wait, though it should not.
- Review your holdings. Note every currency in your account and check for each one individually whether withdrawals are enabled. If it is on the blocked list above, you only have until September 29 to swap it.
- Close futures positions. Futures trading has been running in reduce only mode since today and will be switched off entirely from September 22. Unwind open positions yourself by then rather than leaving it to the wind-down.
- Pool into a cheap currency. Withdrawing small holdings one by one is expensive because of the fixed fees. Swap them together before trading ends and withdraw once.
- Choose the chain deliberately. When withdrawing, compare the networks on offer and take the one with the lowest fee that your destination address also supports.
- Test with a small amount. Send a small sum to the destination address first and check it arrives before you transfer the rest.
- Secure your records. Download your transaction history before December 22. Once the exchange is switched off you cannot reach this data any more, and the tax office will ask for it later.
Tax on withdrawal: when moving to your own wallet counts
A pure transfer from the exchange to your own wallet is not a disposal in Germany and does not by itself trigger any tax. Nor does it interrupt the one-year holding period under section 23 of the German Income Tax Act, because the beneficial owner does not change in the process.
The swaps this wind-down forces on you are a different matter. Anyone swapping a blocked coin into USDT before September 29 disposes of it for tax purposes. If the purchase was less than a year ago, the gain counts as a private disposal transaction. The same applies to the CET buyback. That is no reason to postpone the withdrawal, but it is a reason to secure your acquisition data while the history can still be retrieved. A tax and portfolio tool reads such statements in and classifies the transactions before the data source disappears.
Limits of this measurement: what three queries do not show
The survey describes a state on the morning of September 15, 2026 and nothing beyond that. It does not say how the blocks will develop by December; the number of currencies that cannot be withdrawn may rise or fall. Nor does it say anything about why an individual currency is blocked, because the interface gives no reason for it.
We were also unable to check whether withdrawals run as promptly in practice as their enabled status suggests. That would require an account on the exchange, and we do not have one. The fees named are the fixed amounts published by the exchange; whether further costs arise in an individual case was beyond our measurement. The wind-down dates come from the company's announcement and from reporting on it, among others at CryptoBriefing, and therefore not from our measurement.
Withdrawing your CoinEx balance: what to take away
- Check this week whether your currency can be withdrawn. 37 of 992 currencies could not be on the day of measurement, among them ETC, CRO and the euro stablecoin EURR. If yours is among them, you have to swap it before September 29. If you are changing exchange anyway, start with the trading venues authorised in the EU, so the same retreat does not happen to you a second time.
- Choose the chain by the fee, not by habit. USDT via Tron cost 7.50 USDT, via BNB Smart Chain 0.0079 USDT. On small residual holdings that choice decides whether anything arrives at all. The withdrawal should target an address you control yourself; we have compared which hardware wallets are suited to it.
- Secure the history before December 22. After the shutdown it is gone, and the forced swaps are relevant for tax. Download the statements and read them into a tax tool while you can still reach them.
(As of September 15, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
The crypto market is doing the thing it always does before a binary event: almost nothing. Bitcoin sits at $77,095, down 0.82% on the day. Ethereum is at $2,477. Solana is clinging to the $100 handle. Nine of the top fourteen assets are red over 24 hours, and none of them are red by much. That flatness is not calm. It is two very large question marks stacked on top of each other, and both get answered within roughly 24 hours.
Why Is the Crypto Price Frozen Before the Fed Decision?
The first question mark is monetary. The FOMC meets on 15 and 16 September, and this is not a "will they cut" meeting. Futures and prediction markets are pricing an 85% to 91% chance of a 25 basis point hike, which would lift the federal funds range off the 3.50% to 3.75% level that has held all year. Hotter than expected August core CPI, a resilient labour market with unemployment around 4.1%, and energy prices pushed higher by the ongoing conflict since February have all pointed the same direction. Goldman Sachs and J.P. Morgan both moved to expect the hike.
Rate hikes are the opposite of what crypto rallied on for the last two years. Bitcoin's 24% run from mid August to early September was built on $3.34 billion of US spot ETF inflows between 19 August and 4 September. That bid has now cooled: the last four sessions before 14 September produced $462.7 million of combined Bitcoin ETF outflows, ending a three week inflow streak. Institutional appetite did not vanish. It just stopped chasing.
The mitigating detail is that long term holders are not the ones selling. Glassnode's Sell-Side Risk Ratio has dropped to 7 basis points per day from 16 at August's peak, and long term holders accounted for only 47% of realised profits versus 88% in August. The old coins are staying put. What is missing is new money.
What Does the CLARITY Act Vote Mean for Crypto Prices Today?
The second question mark is regulatory, and it is arguably the bigger one. At 2:15 pm ET today the US Senate holds a cloture vote on the motion to proceed to H.R. 3633, the Digital Asset Market Clarity Act. Sixty votes are needed. The bill splits oversight of digital assets between the SEC, which keeps securities, and the CFTC, which would gain exclusive jurisdiction over digital commodity spot markets.
It passed the House 294 to 134 back in July 2025 and cleared the Senate Banking Committee 15 to 9 in May 2026. Then it stalled, over ethics provisions, stablecoin rewards, and illicit finance language. Seven Democratic senators publicly called the current draft insufficient. Prediction market odds for the bill being signed into law in 2026 have collapsed from 82% in February to the high teens and low twenties. Galaxy Digital has it at 10%.
Here is the asymmetry that matters for traders. A successful cloture vote does not make anything law. It merely allows debate. A failed vote, on the other hand, effectively ends comprehensive market structure legislation before the November midterms and hands the industry another three years of regulation by enforcement. One analysis puts the near term Bitcoin downside from a failed vote at 10% to 25%. The upside of a procedural win is a sentiment bump. The downside of a loss is structural. That is why nobody is positioning aggressively in either direction right now.
Trading the volatility rather than holding through it? An account with a regulated broker is the cleaner route for CFD exposure around macro events. Compare XTB here
Bitcoin Price Today: Why Is BTC Down 12% Year to Date?
$Bitcoin trades at $77,095, down 0.82% over 24 hours, 1.79% over seven days, and 11.90% year to date. Market cap is $1.54 trillion. It remains roughly 38% below the October 2025 all time high near $126,000.
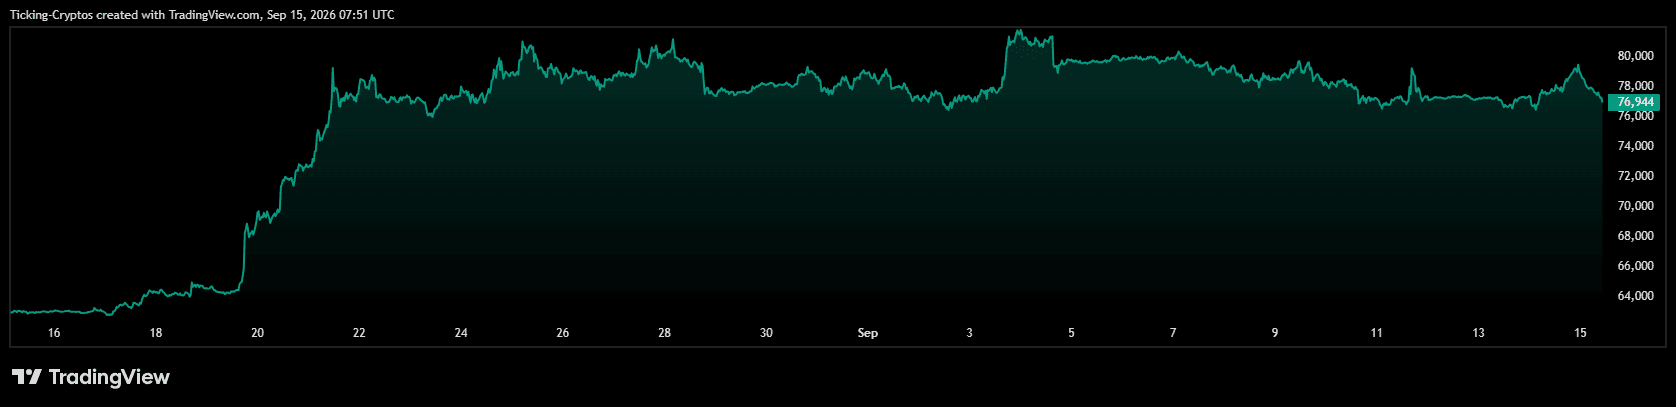
The structure is still technically constructive. $BTC holds above its major daily moving averages and dominance has climbed to around 58.9%, which tells you capital is rotating into Bitcoin from altcoins rather than out of crypto entirely. But the daily MACD histogram has turned negative and the ATR is elevated near $2,077, so a $2,000 candle in either direction on the Fed print would be ordinary, not dramatic.
The level that matters is $80,000. Bitcoin has not reclaimed it since the ETF bid softened, and every rally attempt since has been capped below it. Below, the August base around $73,000 is the first serious test.
Ethereum Price: Flat on the Week, Down 16% on the Year
$ETH at $2,477 is the strange one. It is down 1.71% on the day and 16.51% year to date, yet essentially flat over seven days at negative 0.12%, and its ETFs are on a four week inflow streak. Last week alone Ether products pulled in $197.11 million, including a single Friday session of $216.41 million that erased the whole week's earlier weakness. $Ether ETF turnover jumped about 54% week over week while Bitcoin ETF turnover fell 28%.
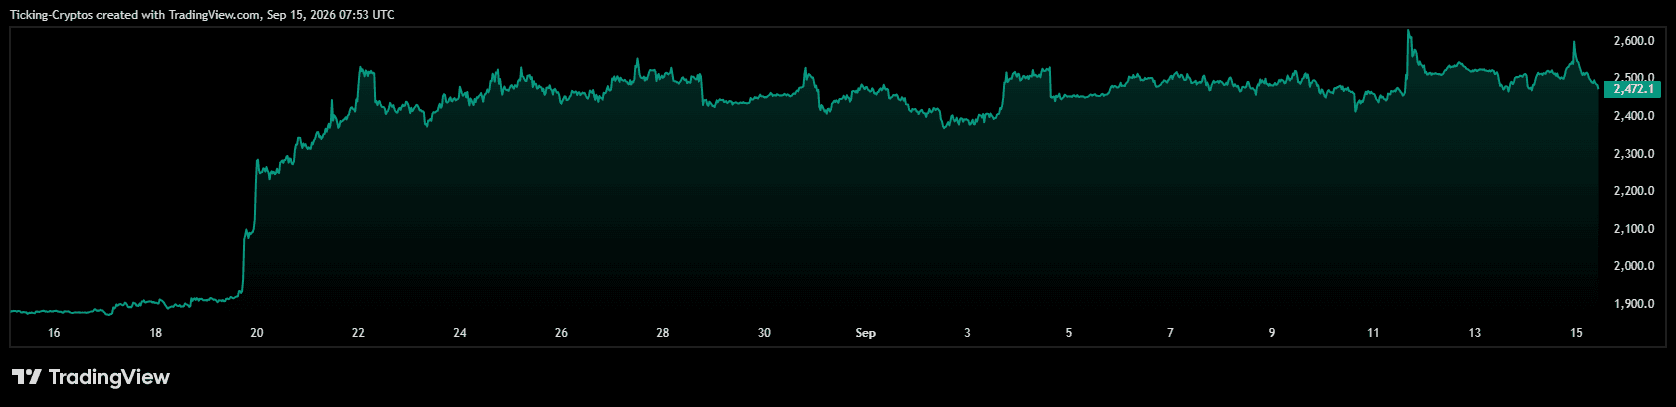
So institutions are buying ETH while the price refuses to move. Either the spot bid is being absorbed by sellers elsewhere, or the market is waiting for the same macro answer as everyone else. The $2,400 area has held repeatedly. That is the line to watch.
XRP Price: The Worst Major of 2026, and the Only ETF Still Attracting Money
$XRP at $1.40 is up 0.98% on the day and 0.74% on the week, but down 23.91% year to date. That is the worst year to date performance of any top ten asset in this table, and it sits next to a genuinely interesting flow story: on several recent sessions XRP was the only major crypto ETF category attracting inflows while Bitcoin, Ether and Solana funds bled.
Why? The most plausible explanation is the CLARITY Act itself. XRP is the asset whose regulatory status has been most explicitly contested, so a statutory commodity framework is worth more to XRP than to almost anything else on the board. XRP ETF net assets are only $1.45 billion, or about 1.7% of market cap, so there is a lot of room to fill if clarity arrives. This is the highest beta name to today's 2:15 pm vote in both directions.
Solana Price: Can SOL Defend $100?
$Solana at $100.62 is down 0.80% on the day, 2.30% on the week, and 19.16% year to date. The round number is doing a lot of psychological work here. SOL ETFs brought in over $170 million in August with total assets approaching $1.5 billion, but September flows have turned choppy, with four outflow sessions this month, all small.
Nothing in the Solana story has broken. The problem is that $SOL is a high beta asset heading into a rate hike, and high beta assets are exactly what gets sold when Bitcoin dominance is rising toward 59%. A clean loss of $100 opens air down to the low nineties.
Zcash Price: Up 119% This Year While Everything Else Bleeds
Now the actual story of 2026. $Zcash at $1,147.97 is up 0.66% on the day, 2.00% on the week, and 118.68% year to date, with a $19.36 billion market cap that has taken it from the 82nd largest crypto a year ago to the top ten.
The catalyst was Grayscale's ZCSH spot ETF, which began trading on NYSE Arca on 25 August as the first US spot ETF for a privacy coin. It gathered roughly $463 million in net assets within ten days. $ZEC crossed $1,000 on 5 September for the first time since 2016, briefly touched $1,249, and a $212 million liquidation cascade weighted 75% toward shorts did the rest.
The sector context is remarkable. Privacy coins hit a combined $33.6 billion market cap in early September, up from $7.1 billion a year earlier, and privacy is the only crypto sector trading above its October 2025 cycle high, up 213%, while the median top 200 asset sits 58% below it.
Two risks deserve naming. Futures open interest around $2.3 billion means this is a leveraged move that cuts both ways. And the EU's AMLR Article 79 takes effect on 10 July 2027, banning custodial support for anonymity enhancing coins including ZEC and XMR across the bloc. Over 40 privacy tokens have already been pulled from EU regulated venues.
Monero Price: The Catch-Up Trade That Has Not Broken Yet
$Monero at $514.35 is up 1.72% on the day and 22.59% year to date, and it is one of only two green 24 hour prints in the top twelve alongside Zcash. That is not a coincidence. XMR broke a descending trendline in late August that had capped every rally since January's $757 high, and it has held above it since.
The honest read is that Monero did not start this rally, it is riding one. Traders who missed Zcash rotated into the privacy asset that had not gone parabolic yet, which is why the move looks calmer and more spot driven than ZEC's. The 20 day EMA near $469 is the first real support. Reclaiming $600 puts January's $757 back in play. Losing $469 would say the rotation faded faster than it built.
Hyperliquid Price: Best Performer of the Year, Worst Week in the Top Ten
$HYPE at $79.19 is up 227.26% year to date, by far the strongest number on this screen, and down 5.73% over the last seven days, which is the worst weekly print of any top ten asset. Both facts are true and both matter.
The bull case is fundamental rather than narrative. Open interest on the platform recovered toward $3.5 billion, the fee driven buyback mechanism gives the token a real revenue link, and a reported arrangement with Payward, Kraken's parent, could open a US path. HYPE printed an all time high near $89.60 on 6 September.
The bear case is mechanical. A 9.92 million token unlock landed on 6 September, roughly a quarter of total supply is circulating against a fully diluted count near 952 million, and HYPE ETF products have started seeing outflows. At $79 the token is about 12% off its high with $86.55 as first resistance and the high seventies as the level bulls need to defend.
What to Watch Next
Three things, in order of importance:
- 2:15 pm ET today. The CLARITY Act cloture vote. Sixty votes or the 2026 legislative path closes. XRP and the broader altcoin complex are the most exposed.
- Wednesday, 16 September. The FOMC decision. A 25 basis point hike is largely priced, so the reaction will come from the statement and from Chair Warsh's tone on what comes after.
- The privacy sector. Zcash and Monero are the only large caps going up while the market goes sideways. If that holds through both events, the rotation is real rather than a leveraged squeeze.
The flat tape today is not a forecast. It is a market that has priced in uncertainty and is waiting to be told which way to resolve it.
The short answer first: if you trade on Hyperliquid as a private individual in Germany, you are not committing an offence. The EU's authorisation requirement is addressed to firms that offer services, not to the users who take them up. The price is still yours to pay. Where there is no authorisation, none of the safeguards that European crypto law attaches to one apply to your funds either. This article shows you what you can look up for yourself, what the law actually says, and what the tax office expects from you.
Is Hyperliquid legal in Germany? The answer separates users from providers
The question is almost always framed the wrong way. What matters is not whether you are allowed to use a trading venue, but whether a firm is allowed to offer it to you in the EU. The law treats those two sides separately.
The text that governs this is Regulation (EU) 2023/1114, better known as MiCA. Article 59(1) reads: "A person shall not provide crypto-asset services within the Union unless that person has been authorised […] as a crypto-asset service provider", or belongs to one of the financial undertakings expressly named, such as credit institutions and investment firms. Paragraph 2 adds a registered office in a member state, a place of effective management in the Union and at least one director resident in the Union.
That is an obligation on the provider. For you as an investor, MiCA contains no prohibition that makes trading on an unauthorised venue a punishable act. What is missing is something else: the entire protective apparatus that authorisation triggers in the first place. That is what the sections below are about.
Crypto-asset service is a defined legal term here. MiCA counts among them the custody and administration of crypto-assets on behalf of clients, the operation of a trading platform for crypto-assets and the exchange of crypto-assets for funds. Anyone carrying out one of these activities commercially for clients in the Union needs the authorisation under Article 59.
What a MiCA licence covers, and why perpetual futures fall outside it
Here is the point that hardly any German-language text separates cleanly. Hyperliquid is not primarily a spot exchange but a marketplace for perpetual futures. These are derivatives with no expiry date: you are not buying the coin, you are entering into a contract whose value is derived from the price of an underlying asset and which is settled in cash. To stop such a contract drifting away from the spot price for good, long and short positions pay each other the funding rate at fixed intervals, a balancing payment between the two sides of the market.
And contracts of exactly that kind are carved out of MiCA by MiCA itself. Article 2(4)(a) states: "This Regulation does not apply to crypto-assets that qualify as one or more of the following: (a) financial instruments". Derivatives on an underlying are financial instruments within the meaning of MiFID II, the European markets in financial instruments directive. In its guidance note on financial instruments, the German supervisor BaFin describes derivatives as forward or option transactions to be settled with a time delay and whose value is derived directly or indirectly from the price of an underlying; the definition applies equally under the German Banking Act and the Securities Institutions Act.
The practical consequence is inconvenient: a MiCA authorisation would not be the right paperwork for perpetual futures trading at all. Anyone who commercially arranges or deals in derivatives for clients in Germany operates under the licensing regime for securities institutions, not under the crypto-asset regime. Searching for a MiCA entry therefore comes up empty even when you do it correctly. This classification is a legal assessment, not investment advice and not legal advice; which permission a specific offering needs is for the supervisor to decide case by case on the full contractual documentation.
What you can take from this: two different rulebooks, two different registers, two different answers. If all you have in mind is buying the HYPE token on the spot market, MiCA is the right rulebook. As soon as leverage is involved, it is the wrong one.
Looking up the ESMA register yourself: 346 authorised crypto-asset service providers, 89 of them German
You do not have to rely on anyone's summary, including this one. ESMA, the European Securities and Markets Authority, maintains a public register of all authorised crypto-asset service providers and publishes it as a freely downloadable CSV file. We pulled it for this article on September 15, 2026 and counted it ourselves.
The position on that day: 346 authorised providers across the EU. The authorisations run up to August 31, 2026, so the list is being kept current. By home member state they break down as follows:
- Germany: 89 providers — by some distance the largest home state, among them institutions such as Trade Republic Bank, flatexDEGIRO and Börse Stuttgart Digital Custody.
- France: 35, the Netherlands: 29, Cyprus: 25, Malta: 22, Spain: 15.
No entry in that list contains the string "Hyperliquid". Nor does the platform appear on the second list ESMA maintains alongside it, the register of non-compliant entities, which held 167 entries that day. Both findings are register positions, no more and no less, and in light of the previous section they are hardly surprising, because a derivatives market does not belong in a crypto-asset register. When we last went through the register in the summer, it held only 21 trading platforms with that permission, so the numbers are growing quickly.
Here is how to go about it yourself if you want to check any platform. The register files are published openly on ESMA's crypto regulation pages; for firms authorised in Germany, BaFin additionally runs its company database with a "crypto-asset service provider" category. Always check the name of the legal entity, not the brand name of the app, because the two come apart routinely.
Article 61 MiCA: why the own-initiative exemption gives you no protection
At this point a reassuring-sounding term turns up in forums with some regularity: reverse solicitation. What is meant is the exemption in Article 61 MiCA, which provides that the authorisation requirement under Article 59 does not bite where a client established or situated in the Union initiates "at its own exclusive initiative" the provision of a crypto-asset service by a third-country firm.
Anyone reading that as a general permission has not read the provision to the end. The second subparagraph immediately narrows the exemption again: a service is not deemed to be provided at the client's own initiative where the third-country firm solicits clients or prospective clients in the Union, and that applies "regardless of any communication means used for solicitation, promotion or advertising in the Union", and also where another entity acts on the firm's behalf. Advertising, affiliate programmes and outreach through social networks all count.
The third subparagraph is blunter still. It states expressly that contractual and disclaimer clauses change nothing about this, including clauses stipulating that the service is to be regarded as provided at the client's own initiative. A tick box in the terms of use, in other words, does not turn a solicited client relationship into one you sought out. And paragraph 2 makes clear that a single request does not entitle the firm to market new types of crypto-assets or services to you.
For you as an investor the decisive insight is that Article 61 is not a client protection provision at all. The rule relieves the firm of the authorisation requirement in an individual case and gives you not a single claim, no compensation and no supervision in return. You can read the full wording in the Official Journal: Regulation (EU) 2023/1114 on EUR-Lex.
Without a MiCA licence you have no route of complaint: what applies to your funds in practice
What you actually give up by trading on a venue that is not authorised in the EU can be set out concretely. None of these points is a supposition about any particular firm; they are the legal consequences that a missing authorisation carries in general.
- No deposit guarantee. The statutory deposit guarantee of 100,000 euros covers bank deposits, not crypto-assets and not margin balances on a trading venue. It does not apply at authorised providers either, and the difference lies in the obligations that apply instead.
- No supervised segregation of your assets. Authorised providers have to hold client funds and client crypto-assets separately from their own holdings and to account for them. Without authorisation there is no authority checking that.
- No complaints procedure and no supervision. With an authorised provider you can turn to the competent supervisor, in Germany BaFin. Against a firm with no authorisation in the EU, that route does not exist.
- Enforcement is difficult. With no registered office and no management in the Union, the question of which court has jurisdiction and how a judgment would be enforced is close to unanswerable in practice.
- No tax withheld at source. A foreign platform withholds no capital gains tax. The declaration is entirely down to you, and there is more on that below.
If that catalogue feels too abstract, a comparison helps: our overview of regulated crypto exchanges with EU authorisation shows which providers actually meet the obligations listed.
Who holds the keys: self-custody, the bridge and the on-chain order book
One objection comes up regularly at this point, and it is a fair one. If everything runs fully on chain, why would you need a custodian at all? The answer is more nuanced than either camp would like.
Hyperliquid runs its own layer 1 blockchain with an on-chain order book. That is a technical departure from most first-generation decentralised exchanges: there, an automated market maker derives the price arithmetically from liquidity pools, while here a matching engine runs a classic limit order book whose orders and fills sit in the network as transactions. What such a marketplace actually is and how it differs from a centralised exchange is explained in our primer What is a perp DEX?.
To use it you connect a crypto wallet and keep your private keys yourself; you do not go through a classic KYC procedure with identity checks. That is the honest advantage of this design. The catch is that to trade at all you have to deposit funds into the network across a bridge, and your margin then sits in the protocol. Self-custody protects you from the failure of a custodian, but not from a flaw in the protocol, not from a hole in the bridge, and not from a leveraged position being liquidated while you sleep.
Technical transparency and regulatory safety are two different things. Having every order publicly visible is no substitute for a capital requirement or a complaints body. Confusing those two levels draws the wrong conclusion from a genuine merit.
Leverage, funding rate and liquidation: what the trading venue actually offers today
Rather than passing on market reports, we queried the platform's public programming interface ourselves on September 15, 2026. These are the figures from that call, and they describe a snapshot, not a Hyperliquid price forecast.
- 234 perpetual markets were tradable.
- Total open interest, meaning the sum of all open positions, stood at around $10.4 billion.
- Trading volume over the preceding 24 hours added up to roughly $6.5 billion.
- The largest single market was the BTC contract at around $2.8 billion of open interest, followed by the ETH contract at $2.6 billion and the HYPE contract at $1.7 billion.
More revealing than the size is the leverage the protocol allows on each market. That sits in the same interface: the BTC contract permitted up to 40 times leverage, the ETH contract up to 25 times. Four further markets reached 20 times, 35 markets 10 times, 63 markets 5 times, and at 130 of the 234 markets, meaning the majority, the ceiling was 3 times.
That tiering is not accidental but risk management by the protocol: the thinner a market, the lower the leverage allowed. For you it means the reverse, that the spectacular leverage figures from the advertising are not available at all on niche markets. And at every level of leverage the same mechanics apply. A move of a few percent against a position geared 20 times wipes out the stake. Order types such as a stop-loss are meant to cap that in principle, but in a price gap they may only trigger below your mark. For comparing providers in this segment we keep a separate overview of perp DEX platforms with their fees and leverage tiers.
Crypto tax in Germany: perpetual futures are forward transactions under Section 20 EStG
This is the part that costs the most money in practice, and it has nothing to do with the authorisation question. The tax office is not interested in where a platform is based, but in what kind of contract you have entered into.
A forward transaction is a transaction under which you obtain a cash settlement or a sum of money determined by the value of a variable reference figure. That is precisely the wording of Section 20(2) sentence 1 no. 3(a) of the German Income Tax Act. On that definition, perpetual futures are routinely classified as forward transactions by the tax authorities and by tax advisers, because they are settled in cash and never lead to delivery of a coin.
The difference from a spot purchase is severe, and it usually works against you:
- On a spot purchase of a coin, Section 23 EStG applies. After a holding period of one year the gain is tax free.
- On a forward transaction, Section 20 EStG applies. There is no holding period and no tax exemption after a year, but the flat withholding rate of 25 percent plus solidarity surcharge and, where applicable, church tax, regardless of whether you held the position for a minute or for two years.
Because a foreign platform withholds no capital gains tax, you have to declare this income yourself in the Anlage KAP annex to your tax return. That is not a formality: anyone who fails to declare gains from forward transactions risks criminal tax proceedings. How funding payments are to be classified in detail has not been settled conclusively, and where meaningful sums are involved that is a case for a tax adviser. For gathering your records, the tools in our comparison of crypto tax software and portfolio trackers will help.
Loss offsetting: the 20,000 euro cap on forward transactions has been scrapped
One rule that still appears in many older guides no longer applies, and that is in your favour. Until the 2024 Annual Tax Act, losses from forward transactions formed their own offsetting pot: they could be set only against gains from transactions of the same kind, and then only up to 20,000 euros a year. Someone who made 100,000 euros and lost 90,000 euros in the same year could end up with a tax assessment on a gain they had never economically made.
The legislature struck those sentences after the Federal Fiscal Court expressed serious constitutional doubts. In the current wording of Section 20 EStG, paragraph 6 no longer contains a separate offsetting pot for forward transactions; the restriction that remains in sentence 4 concerns only losses on the disposal of shares. Losses from forward transactions can therefore once again be set against all investment income.
For you that means two things. First, old loss carry-forwards from forward transactions are worth more than you may think. Second, offsettable does not mean harmless. The losses stay trapped in the pot of investment income and still reduce no income from any other category.
What regulated alternatives deliver, and where their limit lies
If you are not willing to carry the drawbacks listed, the question is what an authorised provider in Germany offers instead. Answered honestly: protection, but less choice.
Authorised firms are subject to ongoing supervision, have to segregate client assets, handle complaints and meet disclosure obligations. On spot trading and savings plans you get the same product there as anywhere else, only with a supervisor behind it. Coins bought in spot trading also fall under the one-year rule in Section 23 EStG.
Where the limit lies: you will not find highly leveraged perpetual futures in this form at a German provider serving retail clients. That is not an oversight but the intention of European investor protection, which has capped retail leverage on contracts for difference sharply for years. Anyone looking for these products is leaving the protected space. That is a deliberate decision and should be taken as one, rather than out of ignorance. How quickly the terms in this segment can change was shown most recently by our analysis of the dilution from the HYPE unlocks.
Using Hyperliquid from Germany: what to take away
- Check the legal entity before you deposit money. Look the name up in the ESMA register and in BaFin's company database, and accept no brand name as evidence. Which providers pass that check is set out in our overview of regulated crypto exchanges.
- Decide deliberately between protection and product range. If spot buying and savings plans are what you are after, there is no reason to leave the protected space. If derivatives are what you are after, compare the terms soberly using our overview of perp DEX platforms, and commit only capital whose total loss you can absorb.
- Collect your records from the first position onwards. Forward transactions belong in the Anlage KAP, and a foreign platform reports nothing to the tax office. Set up a complete record from your first trade, for instance with a tool from our comparison of crypto tax software.
(As of September 15, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
The asset manager funded the entire purchase through preferred stock, pushing SATA's notional value past $1 billion for the first time.
Eight trade associations say exceptions for interest-like rewards could pull deposits from banks and reduce lending.
The OpenAI chief called for safeguards during training and shared industry standards, saying developers can act before legislation arrives.
Aboard Air Force One, the president threw his support behind the AI-powered license plate readers that have drawn a Senate investigation and a pledged bill from Bernie Sanders.
Mustafa Suleyman's AI unit wants feedback for six weeks before the document guides model training in 2027.
U.Today - IT, AI and Fintech Daily News for You Today
Zcash could be extremely close to overtaking Hyperliquid and entering crypto market's top-10 further.
The man behind XRP and Ripple, David Schwartz, admits early blockchain mistakes and explains why stablecoin payments remain fundamentally broken in 2026.
Major exchange announces the end of their operations following the industry-wide decline.
Ripple CEO Brad Garlinghouse is urging senators to back the Clarity Act ahead of a crucial procedural vote.
Coinbase is removing eight non-USD crypto trading pairs on Sept. 15 as part of its continuing push to consolidate liquidity into more active markets.
Blockonomi
TLDR
- Firelight plans to use deposited FXRP as collateral to back DeFi coverage, letting XRP holders earn premiums as yield.
- Withdrawal times could stretch from today’s 1-2 days to roughly 30-60 days once 30-day coverage periods begin.
- Rewards stop the moment a holder starts unstaking, even though the exit process can take weeks to finish.
- A claim tied to an earlier coverage period can still lower the amount of FXRP a holder receives back.
- Firelight has attracted about $72 million in deposits, but it’s unclear how much paid coverage it has actually sold.
Firelight, a protocol built on the Flare network, is preparing a system that lets XRP holders earn yield by backing coverage for DeFi users. Holders deposit an XRP-linked asset and get paid when customers buy protection.
But the plan comes with a tradeoff. Getting that money back out could take far longer than it does today.
How The Vault Works
Holders deposit FXRP, an XRP-linked asset on Flare, into a Firelight vault. In return, they receive stXRP, a token that represents their position in the vault.
In the next phase of the protocol, Firelight plans to use that deposited FXRP as collateral to back coverage sold to DeFi protocols. Customers who buy this protection pay premiums, and that money becomes income for the people supplying the collateral.
Right now, Firelight uses one-day coverage periods. That keeps withdrawal times short, at about one to two days.
Once the protocol moves to 30-day coverage periods, the same process will stretch withdrawal times out. A holder who exits near the end of a period could wait just over 30 days. Someone who exits near the start of a period could wait closer to 60 days.
Firelight has not confirmed an exact launch date for this next phase. A funding announcement from September 1 pointed to a September rollout of the protocol and its first coverage deals, without naming a specific day.
What Happens During The Wait
Once a holder starts the unstaking process, rewards stop right away. The stXRP is redeemed at that moment, and its value is recorded.
But the FXRP is not free of risk yet. For the rest of that coverage period, it still backs active coverage and can be reduced if a claim occurs.
After that period ends, the FXRP no longer backs new coverage. However, a claim tied to an earlier period can still lower the final amount the holder receives.
That means the value recorded when a holder begins unstaking is not a guarantee. The final payout can end up lower than expected.
After the waiting period ends, holders must submit a separate transaction to withdraw their funds. Until they do, the assets stay in the vault.
Firelight has already attracted a large amount of deposits ahead of this change. DefiLlama recorded $71.74 million in total value locked in a September 13 snapshot.
That figure reflects deposits only. It does not show how much coverage Firelight has actually sold or how much premium income it has collected so far.
To limit losses for depositors, Firelight has a separate reserve called the First-Loss Buffer. This stablecoin reserve pays out validated claims first, before any loss reaches staked FXRP.
If a loss is larger than the buffer, the remaining amount is spread across vault positions. Holders would then keep the same number of shares, but each share would be worth less FXRP.
Firelight also limits how much coverage it can sell based on how much capital is available to cover losses. The protocol is designed to stop offering new coverage if that ratio drops too low.
For now, XRP holders have shown willingness to deposit collateral. Whether the coverage business can generate enough paid premiums to make the yield worth the wait and the risk remains to be seen.
The post XRP Holders May Earn New Yield From Firelight DeFi Coverage appeared first on Blockonomi.
TLDR
- House of Lords voted 194-138 to require the Treasury to draft a national digital-assets strategy.
- The amendment covers cryptoassets, stablecoins, central bank digital currencies, and tokenized securities.
- The bill faces a Lords third reading on Sept. 15 before moving to the Commons.
- The FCA’s crypto authorization gateway opens Sept. 30, 2026, with the full regime effective Oct. 25, 2027.
- The EU and US already have crypto frameworks in place, adding pressure on the UK to act.
The UK government lost a vote in the House of Lords this week over its approach to digital assets.
Peers voted 194 to 138 in favor of an amendment that would force the Treasury to produce a national strategy for crypto and related technologies.
The amendment was introduced by Conservative peer Baroness Neville-Rolfe, a former Treasury minister. It passed with support from 138 Conservative peers and 48 Liberal Democrats. 127 Labour peers voted against it.
What the Amendment Requires
The amendment adds a clause to the Financial Services and Markets Bill. It would require the Treasury to prepare, publish, and consult on a digital-assets strategy within 12 months of the bill becoming law.
The strategy would need to cover several types of digital assets. This includes cryptoassets, qualifying stablecoins, central bank digital currencies, and tokenized securities.
It would also require the Treasury to look at how banks and payment providers treat crypto businesses. This includes cases where financial services are withdrawn from crypto firms.
The vote comes shortly after the UK government approved a plan for the Bank of England to support new forms of digital payments, including stablecoins.
The bill has not become law yet. It still needs to pass its third reading in the Lords, scheduled for Sept. 15, before heading to the House of Commons.
How the UK Compares to Other Regions
The UK already has some crypto rules in motion, separate from this amendment.
The Financial Conduct Authority finalized rules for its new cryptoasset regime on June 30. The authorization gateway for firms opens on Sept. 30, 2026.
The full regime does not take effect until Oct. 25, 2027. That gives firms over a year between applying and full enforcement.
The Lords amendment is different. It calls for a wider strategy that ties together regulation, tokenized finance, payments systems, and how the UK competes globally in this space.
Other regions have already moved forward with their own rules. The European Union’s MiCA framework became fully applicable on Dec. 30, 2024.
In the United States, the GENIUS Act created a federal framework for payment stablecoins in July 2025. A separate bill, the CLARITY Act, is still being debated in the Senate.
Supporters of the amendment argue the UK risks falling behind these markets without a clear plan.
The bill’s next step is the Lords third reading on Sept. 15. After that, it moves to the Commons for further debate.
The post UK Lords Vote 194-138 to Force Government Crypto Strategy appeared first on Blockonomi.
TLDR
- Bitmine Immersion Technologies raised its Ethereum holdings to 5.96 million ETH, worth close to $15 billion.
- The company now owns about 4.9% of Ethereum’s total supply and is 98% of the way to its 5% target.
- Bitmine has staked over 5 million ETH through its MAVAN platform, projecting $334 million in yearly staking income.
- Ethereum outperformed the S&P 500 by 5,866 basis points in the third quarter of 2026.
- Bitmine’s total crypto and cash holdings now stand at $15.8 billion.
Bitmine Immersion Technologies has grown its Ethereum treasury to 5.96 million ETH. The company announced the update on September 14, 2026.
The purchase brings Bitmine’s total holdings to about 4.9% of Ethereum’s supply. Based on 122 million ETH in circulation, the firm is now 98% of the way toward its stated goal of owning 5% of all Ethereum.
Bitmine calls this goal the “Alchemy of 5%.” The company has been buying ETH every week since starting its treasury strategy on June 30, 2025.
Over the past week, Bitmine added 27,180 ETH to its holdings. At a price of $2,513 per ETH, the company’s Ethereum alone is worth close to $15 billion.
Staking Makes Up Most of the Holdings
Bitmine has staked 5,067,309 ETH through MAVAN, its own institutional staking platform. That figure represents about 85% of the company’s total Ethereum holdings.
The staked position is worth approximately $12.7 billion. MAVAN was built to support Bitmine’s own treasury but has since expanded to serve outside institutional investors.
The current seven-day staking yield is 2.62%. Based on that rate, Bitmine projects roughly $334 million in annual staking income from its current holdings.
If the company reaches its full 5% target, it expects staking income to rise to about $392 million per year.
Bitmine’s broader portfolio includes more than Ethereum. The company reported $549 million in cash and marketable securities, along with 212 Bitcoin.
It also holds a $180 million stake in Beast Industries and about $98 million in Eightco Holdings. Bitmine describes the Eightco position as indirect exposure to OpenAI.
Combined, these assets bring Bitmine’s total crypto, cash, and investment holdings to $15.8 billion.
Ethereum Outperforms Other Assets in 2026
Ethereum has been the top performing major asset in the third quarter of 2026. The cryptocurrency beat the S&P 500 by 5,866 basis points during that period.
Bitmine Chairman Tom Lee said the ETH to BTC price ratio reached its highest level since January 30, 2026. He described this as a new uptrend for Ethereum relative to Bitcoin.
Lee pointed to Ethereum’s growing role in Wall Street tokenization and agentic AI applications as factors behind the move. Technical analyst Tom DeMark also forecast a sharp upward price move for Ethereum in the coming weeks, based on the asset’s trading pattern in August.
Bitmine pointed to several factors that could shape the crypto market later in 2026. These include a scheduled vote on the CLARITY Act and renewed buying from Korean investors.
Bitmine holds the largest Ethereum treasury in the world. It ranks as the second largest crypto treasury overall, behind Strategy Inc, which holds 845,080 Bitcoin valued at roughly $71 billion.
Bitmine stock also trades under a large volume. The company reported an average daily dollar volume of $924 million, ranking 98th among all US listed stocks.
Tom Lee is scheduled to deliver a keynote address at Korea Blockchain Week on September 30, 2026, in Seoul. The talk will focus on Ethereum’s role in the current market cycle.
The post Bitmine Nears 5% Ethereum Supply Target With Latest ETH Purchase appeared first on Blockonomi.
Key Highlights
- The greenback reached its strongest position in over a week during Tuesday’s trading session
- Fed rate hike probability for Wednesday’s meeting stands at 92.1%
- The Dollar Index advanced approximately 0.24% to trade around the 99.60 level
- Brent crude jumped above $113 per barrel following attacks on Saudi energy infrastructure
- The euro declined to one-month lows around $1.1539, with the yen dropping to more than one-week lows
The U.S. dollar gained momentum on Tuesday, reaching its most robust level in over seven days as market participants dramatically raised their expectations for a Federal Reserve rate increase during the upcoming policy announcement.
The Dollar Index, tracking the U.S. currency against a basket of six major rivals, advanced roughly 0.24% to hover around 99.60. A day earlier, the index had already climbed to a monthly peak of 99.736.
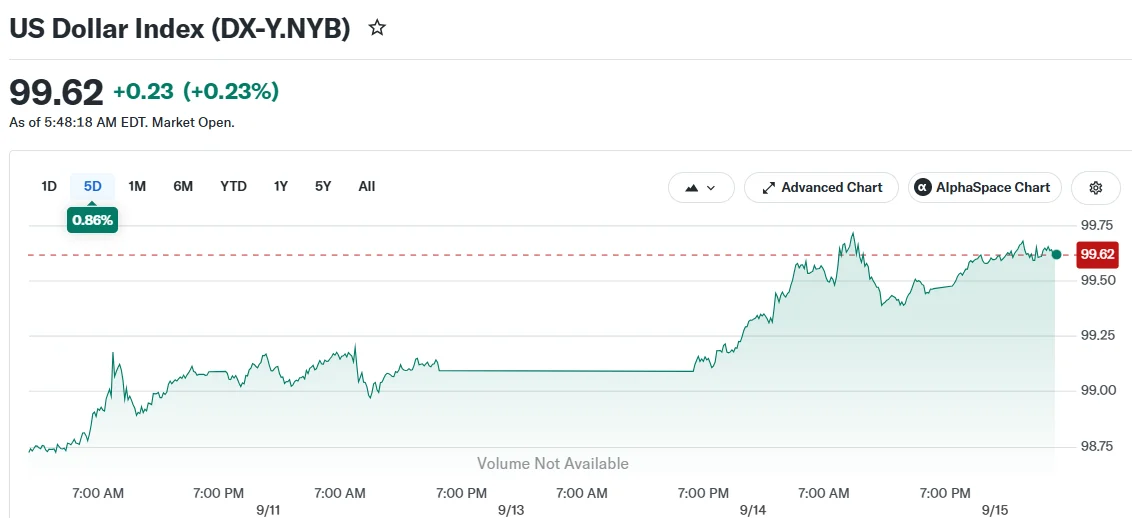
Financial markets are now viewing a Fed rate move as virtually guaranteed. According to CME FedWatch data, there’s a 92.1% likelihood of a 25-basis-point increase to the 3.75%-4.00% target range, a substantial jump from approximately 60% recorded a week earlier. Money market pricing also indicates a 53.4% probability of an additional hike coming in October.
Energy Market Volatility Bolsters Dollar
Crude oil prices provided additional momentum to the dollar’s advance. Brent crude surged beyond $113 per barrel following renewed attacks targeting Saudi Arabian pipeline facilities and Houthi operations in the Red Sea region.
Elevated oil prices are intensifying inflation worries, which consequently drive Treasury yields upward. The benchmark U.S. 10-year Treasury yield broke through the 5% threshold on Tuesday, marking its first such breach since 2007.
Given that the U.S. functions as an oil exporter, elevated energy costs typically support the dollar. John Velis from BNY noted that monetary policy must maintain control over inflationary expectations, despite not being ideally designed to counteract supply-side disruptions.
DBS analysts cautioned against aggressively pursuing the dollar’s upward movement ahead of the Fed announcement, pointing out that two high-ranking Fed officials had indicated openness to maintaining current rates before their pre-meeting communications blackout began.
European and Japanese Currencies Face Headwinds
The euro declined 0.1% during the session to hover near $1.1539, representing its weakest level in four weeks. Market participants are balancing stagflation concerns across the euro area against dollar strength, despite the European Central Bank’s quarter-point rate increase to 2.50% during last week’s meeting.
The Japanese yen weakened 0.3% to reach an over one-week low at 154.82 against the dollar. This represents a retreat from the seven-month peak of 152.89 achieved the previous week.
The Bank of Japan faces its own rate decision on Friday. Market observers are closely monitoring whether the BOJ will indicate an accelerated tightening timeline following an anticipated increase to 1.25%.
The yen has appreciated approximately 4% throughout this month, supported by capital repatriation flows and Japan’s 10-year government bond yield surging to a three-decade high of 3.025%.
This week features a concentrated schedule of major central bank policy decisions, with the Fed’s two-day gathering commencing Tuesday and the BOJ’s meeting scheduled for Friday.
The post Greenback Surges to Weekly Peak as Fed Hike Probability Reaches 92% appeared first on Blockonomi.
Key Takeaways
- Berenberg elevated GSK to “buy” from “hold” and increased the price objective to £22 from £20
- Shares advanced 0.4% to £18.62 during early London market hours
- The pharmaceutical company trades at a 23% valuation discount compared to European drugmaker peers
- GSK secured rights to a trispecific T cell-engager from Chimagen Biosciences in a transaction worth as much as $750 million
- The acquired Chimagen asset targets multiple myeloma and is projected to begin Phase 1 clinical trials in 2027
Shares of GSK increased 0.4% to £18.62 during early trading hours in London on Tuesday following Berenberg’s decision to raise the pharmaceutical manufacturer from “hold” to “buy” while lifting the price objective to £22 from £20.
GSK plc, GSK
The rating enhancement arrives as Berenberg highlighted a more robust late-stage development portfolio and increased business development activity as justification that the existing valuation gap is unjustified.
The company trades at 9.6 times projected 2027 adjusted earnings. This represents a 23% markdown versus European pharmaceutical competitors, which command a 12.4 times multiple. Berenberg contends this disparity has grown excessive.
The investment firm observed that 10 of GSK’s 11 innovative Phase 3 programs were obtained through external partnerships. Six of these advanced-stage candidates are projected to deliver peak yearly revenues of at least £2 billion each.
Berenberg projects GSK revenues approaching £39 billion by 2031. This estimate exceeds the Street consensus of approximately £36 billion and approaches GSK’s internal target of exceeding £40 billion.
Upcoming Pipeline Milestones
Recently introduced therapies Exdensur and Blenrep are anticipated to drive revenue expansion. Berenberg identifies additional growth opportunities from bepirovirsen, Nuvalent’s pulmonary cancer programs, and GSK’s oncology antibody-drug conjugates developed with Hansoh.
The investment firm highlighted two imminent regulatory milestones. A U.S. regulatory determination on bepirovirsen for hepatitis B treatment is anticipated by October 26, while a decision on neladalkib for second-line ALK-positive lung cancer is scheduled for November 27.
Phase 3 results and proof-of-concept information are expected within the coming 12 months spanning small-cell lung cancer, HIV, asthma, food allergy, and bronchiectasis treatment programs.
GSK’s efficiency initiative aims for £1.9 billion in yearly savings by 2029. Berenberg indicated this should safeguard research investment and maintain margin stability despite anticipated erosion of high-margin oral HIV therapies beginning in 2028.
Patent expiration on dolutegravir represents a recognized challenge. Berenberg’s above-consensus projections indicate confidence that pipeline candidates and operational discipline can offset this pressure.
GSK Expands Multiple Myeloma Portfolio Through Chimagen Transaction
In a separate announcement, GSK revealed it has entered an agreement to obtain a trispecific T cell-engager from Chimagen Biosciences. The arrangement includes complete worldwide rights and represents a total potential consideration of up to $750 million, encompassing development and commercialization milestone payments.
The T cell-engager concurrently engages T cells while targeting two tumor-associated antigens. The candidate is anticipated to commence Phase 1 clinical studies in 2027.
Multiple myeloma ranks as the third most prevalent blood cancer worldwide, with approximately 180,000 new diagnoses reported annually. The condition is manageable but remains incurable with current treatment options.
Hesham Abdullah, GSK’s Global Head of Oncology R&D, stated the transaction “advances GSK’s leadership goals in blood cancer” and introduces a new prospective treatment alternative for patients.
The Chimagen transaction expands upon an established collaboration between both organizations. GSK previously committed to acquiring CMG1A46, a dual CD19 and CD20-targeted T cell-engager presently undergoing Phase 1 evaluation for B-cell malignancies.
The post GSK (GSK) Stock Gains Following Berenberg Analyst Upgrade and $750M Chimagen Acquisition appeared first on Blockonomi.
CryptoPotato
The controversial crypto project has unveiled multiple updates over the past few weeks, yet the price of the native token has failed to capitalize on these developments significantly, though it’s still in the green monthly.
A major development scheduled for today (September 15) may finally benefit PI’s valuation, yet a delay is also possible.
Big Day for Pioneers or Another Disappointment?
The Core Team started the long process of protocol updates at the beginning of 2026. First, it implemented version 19.6, followed by many others, including v20.2, which laid the foundation for smart contract capabilities.
During the summer, it introduced versions 25 and 26, which actually surpassed their initial deadlines. Now all eyes are on v27, which is supposed to add more flexible and secure smart-contract authentication, giving accounts and apps better ways to authorize transactions. It will be the last update on that list and should be deployed later today (September 15).
Pioneers and community members have shared their enthusiasm for the upcoming development. X user drealFx, for instance, claimed the date is one of those “Pi watchers will remember.”
“Whatever happens after the upgrade, the real test begins when developers start turning the infrastructure into products people actually use,” they added.
Of course, a delay is also plausible because, as we mentioned above, Pi Network’s team has the habit of postponing important upgrades.
Other Dates to Monitor
Besides the protocol v27, set for today, the Pi Network community has also shifted its focus to September 24 and October 7-8. Some X users, including sunday peter, suggested that the project may unveil an announcement this month.
“The community is speculating because the Pi Core Team sometimes drops updates mid-month. No confirmation from Pi News or the Core Team so far. Treat it as rumor until they post,” they explained.
Meanwhile, rumors are circulating that Pi Network may have some form of presence at the crypto conference TOKEN2049 in Singapore, scheduled for October 7-8. Again, this is far from guaranteed and is likely speculation, given that the project served as a Gold Sponsor of the event last year.
PI Price Outlook
The project’s native token has posted an 11% monthly increase, following the broader crypto market’s resurgence during that period. Nonetheless, it remains 97% down from its all-time high of around $3 and currently trades at roughly $0.09 (according to CoinGecko).
Some analysts believe a further rebound could be in the cards. X user Crypto With Gopal claimed that the price is compressing between support and descending resistance, with volatility tightening and setting the stage for a decisive move.
“A breakout above the $0.096-$0.098 zone could push toward $0.103, while a breakdown risks the lower target near $0.086. Bullish bias — watching for the breakout,” he added.
Meanwhile, certain industry participants have floated the idea that Pi Network is about to introduce a burning mechanism that could positively impact PI’s price. However, the X account BSCN and others have rejected the development.
The post Important Pi Network News and PI Price Update: September 15 appeared first on CryptoPotato.
Crypto traders have always loved a shrinking supply story. The logic is brutally simple: if demand holds while fewer tokens remain available, the setup can become more attractive. That is why burns, buybacks, and supply reduction mechanics still grab attention even after years of tokenomics experiments.
The numbers can be dramatic. In July 2026, BNB Chain completed its 36th quarterly burn, removing more than 1.6 million BNB valued at roughly $932 million at the time. BNB’s Auto-Burn is designed to keep reducing supply toward 100 million tokens.
That kind of headline gets traders interested because scarcity is easy to understand. But the next evolution of the burn narrative may be more important than the burn itself: where does the money that removes the tokens actually come from?
Semrush currently estimates about 40 monthly U.S. searches for “token burn,” with a relatively approachable keyword difficulty of 24. The direct search volume is small, but burn mechanics remain one of crypto’s most recognizable supply narratives. The higher-upside version is a model where growing business activity creates the funds used to buy and burn tokens.
That turns a token burn from a scheduled event into a potential demand loop.

A Burn Is Only as Powerful as the Economy Behind It
Burning tokens sounds bullish because the visible number goes down. That alone does not create value. A project can destroy half of an irrelevant supply and still have an irrelevant token. If nobody needs the asset, scarcity does not magically create demand.
This is where traders sometimes confuse tokenomics with economics. Tokenomics can control supply. Economics decides whether anyone actually wants what is being supplied. The strongest burn stories combine both sides.
BNB is a useful example because the asset sits inside a functioning blockchain ecosystem. It is used across BNB Chain for transaction fees, governance and other network activity, while the Auto-Burn steadily reduces total supply. The burn is not the entire story — it exists beside a network that people already use.
That distinction matters for smaller tokens chasing much larger upside. If an early-stage project can create real demand first and then connect part of its revenue or activity to token purchases and burns, the burn becomes a multiplier on a growing economy rather than a substitute for one. That is a much more interesting speculative setup.
Revenue-Linked Burns Create a Different Kind of Flywheel
Imagine two projects with identical token supplies. Project A burns a fixed amount every quarter regardless of whether anyone uses the product. Project B takes a portion of revenue generated by real customers, uses that economic activity to purchase tokens, and then removes those tokens from circulation.
If both businesses remain small, the difference may barely matter. But if Project B grows from $100,000 in annual commercial volume to $1 million, then $10 million or $100 million, the amount of economic activity feeding the token mechanism can grow alongside the company.
That is where speculative buyers start doing the math. A token that looks insignificant while the business is early can become much more interesting if the mechanism scales with adoption. The buyer is no longer betting only on a shrinking denominator. They are betting that commercial growth can create recurring buy-side pressure while supply is simultaneously reduced.
There are still no guarantees. Liquidity, unlocks, emissions, market conditions and execution can overwhelm even a well-designed burn model. But the upside thesis is easy to understand: more product usage could mean more economic fuel for the token.
Crypto Traders Love Simple Stories — Revenue Makes Them Stronger
The best token narratives can usually be explained in one sentence. Bitcoin has fixed scarcity. Ethereum burns part of transaction fees. BNB has a long-running supply-reduction program. The reason those mechanisms attract attention is not because traders enjoy reading tokenomics diagrams. It is because the economic story is intuitive.
Supply matters. Demand matters. When a project can show how the two interact, the speculative thesis becomes much easier to evaluate. This is especially important for presale and low-cap buyers. Early investors are usually accepting substantial risk because they want substantial upside. They are trying to find a small system before it becomes a large one. A burn that is tied to growth gives them something concrete to watch.
Is revenue increasing? Is token purchasing increasing? Are more tokens being removed? Is the product attracting real users or businesses?
Those questions are far more useful than staring at a countdown timer and hoping scarcity alone creates wealth.

Where Wanted Network Fits
Wanted Network’s WNTD model includes a version of this revenue-linked idea. The platform is being built around creator Missions and Bounties. Creators complete structured campaign work and can earn WNTD-powered rewards while building Heat reputation. Advertisers are the commercial demand side of the network.
Wanted Network’s documented Sponsor Campaign Economy is designed so qualifying outside advertiser revenue can be divided through a 60/20/15/5 model that includes an allocation for open-market WNTD purchases followed by burns.
The important part is not the burn in isolation. The important part is the sequence:
Brands want creator campaigns → campaigns generate revenue → part of that activity can create open-market WNTD buying → purchased tokens can be burned.
If advertiser demand remains small, the burn mechanism remains small. If campaign volume grows materially, the mechanism has more fuel.
That creates a speculative thesis buyers can actually test against business performance instead of treating the burn as financial magic. For an early-stage token, that is the kind of leverage traders look for. A small economic loop today can become much more meaningful if the product scales.
The Bigger Prize Is a Burn That Earns Its Fuel
Crypto will probably never stop loving token burns. They are visual, measurable and easy to market. A transaction sends tokens somewhere they cannot return, and the supply number drops.
But the market is becoming more sophisticated about what that actually means. The stronger question is no longer simply “How many tokens will be burned?” It is “What creates the money that buys or removes them?”
A burn funded by real network fees, marketplace activity, advertiser spending or another commercial engine has a different economic character from a burn scheduled mainly to create headlines.
For buyers hunting the next high-upside token, that difference could matter enormously. The dream is still the same: get positioned while the system is small, then benefit if the system becomes much larger. The burn does not create that growth. But if growth creates the burn, the tokenomics suddenly become much more interesting.
More about Wanted Network:
Website — https://wantednetwork.io
Discord — https://discord.gg/wantednetwork
X — https://x.com/Wanted_Network
Disclaimer: The above article is sponsored content; it’s written by a third party. CryptoPotato doesn’t endorse or assume responsibility for the content, advertising, products, quality, accuracy, or other materials on this page. Nothing in it should be construed as financial advice. Readers are strongly advised to verify the information independently and carefully before engaging with any company or project mentioned and to do their own research. Investing in cryptocurrencies carries a risk of capital loss, and readers are also advised to consult a professional before making any decisions that may or may not be based on the above-sponsored content.
Readers are also advised to read CryptoPotato’s full disclaimer.
The post Token Burns Still Make Crypto Traders Pay Attention — Revenue-Linked Burns Could Be the Bigger Upside Play. Where Does Wanted Network Fit? appeared first on CryptoPotato.
Somewhat surprisingly, bitcoin’s price jumped quite hard on Monday, reaching a multi-day peak of almost $80,000 before it was halted once again and pushed below $77,000 ahead of today’s crucial CLARITY Act vote in the US Senate.
Most altcoins tried to follow suit but were rejected at their local peaks. Still, some, such as XRP, XLM, and UNI, are still in the green on a daily scale.
BTC Braces for CLARITY Vote
The primary cryptocurrency experienced some intense volatility at the end of the previous business week as all eyes had turned to the US Consumer Price Index numbers. Once they came out, which were actually in line with expectations, BTC first dumped from $77,000 to $76,000 before it suddenly skyrocketed to $79,800, where its progress came to a screeching halt and dropped back to its starting point.
The weekend, as most previous ones, was quite sluggish, with BTC trading sideways at around $77,000. It dipped again on Monday twice to $76,500, where the bulls finally stepped up and didn’t allow another leg down.
Just the opposite; the cryptocurrency started to gain traction, especially during the early US trading hours, and jumped to over $79,500. However, the Friday scenario repeated, and the bears pushed it south hard, with BTC currently struggling at $77,000 once again. More volatility is expected today, with the CLARITY Act vote in the US Senate, and tomorrow when the US Fed will announce its interest rate decision.
For now, bitcoin’s market cap remains at $1.540 trillion on CMC, while its dominance over the alts has retreated slightly to 58.85%

ETH Below $2.5K Again
The leading altcoin exploded on Friday to an eight-month peak of $2,670, where it was rejected and slipped back to $2,500 almost immediately. It has dipped below that level now, after another 1.5% daily decline. XRP pumped to $1.46 yesterday, but it was stopped there, and now it fights for the $1.40 level. BNB, SOL, TRX, HYPE, and DOGE are slightly in the red, while RAIN has plummeted by over 11%.
In contrast, ZEC, XMR, and LINK have marked minor gains, while XLM and UNI are up by around 4%-5% to $0.19 and $6.55, respectively.
The total crypto market cap has remained essentially the same as yesterday, at $2.650 trillion on CMC.

The post Bitcoin Rejected at $80K Again Ahead of Crucial CLARITY Act Senate Vote: Market Watch appeared first on CryptoPotato.
World Liberty Financial has put a new governance proposal up for a vote on its forum, offering rewards for holders of its native WLFI token who lock them and actually vote instead of just sitting on them.
The plan sets a target launch date of October 1, and it changes how the Trump-linked project wants its token used, tying payouts to active participation.
The Proposal, In Plain Terms
The WLFI Governance Engagement Incentive Program calls for a minimum 180-day lock through a non-custodial, on-chain protocol. But locking alone isn’t enough. Holders will have to vote on at least one governance proposal every 90 days to stay eligible for rewards, and World Liberty has committed to putting up at least one vote per quarter, so there’s always something to vote on.
Rewards would come from a dynamic pool funded by ecosystem sources, including fees from World Liberty Markets and Dolomite. That pool tops up every two weeks as the project grows, and if fewer tokens lock early, the early participants could capture a larger share.
A 5% cap on voting-power concentration through the staking protocol keeps any single position from dominating votes, and every WLFI holder will keep their governance rights whether or not they lock anything.
The proposal has so far drawn dozens of replies on the forum, most of them being brief endorsements. It was largely the same on X, with trader Elja calling the plan “one of the more interesting developments for $WLFI holders,” framing it as a way to reward commitment rather than passive holding.
New Incentive Follows Earlier Staking Plans
This isn’t WLFI’s first attempt at tying governance to staking. The project floated a tiered Node and Super Node staking system back in March, one built around bigger lockups unlocking OTC access and partnership perks. But this new one is narrower and centers on voting instead of tiers.
It has also come at a time when World Liberty is still dealing with Justin Sun’s lawsuit over frozen tokens and governance rights, a case that stayed in open court after a ruling against the company last month.
The news has barely stirred the WLFI token itself, with data from CoinGecko at the time of writing showing it trading just below $0.060, down about 1.4% in 24 hours, although it was 2% higher than where it had been a week ago. It is also sitting more than 70% below its price from one year ago, and it even touched a new all-time low near $0.048 just four days ago, a steep drop from the $0.33 high it hit last September.
The post World Liberty Financial Unveils Token-Lock Rewards to Boost Governance Turnout appeared first on CryptoPotato.
The latest stage of negotiations over the CLARITY Act has moved the bill toward a key vote while major disagreements remain. Senate Democrats sent Republicans their counterproposal late Monday after reviewing the newest Republican draft released a day earlier.
The timing came just before the legislation’s first scheduled Senate vote on Tuesday afternoon.
CLARITY Act Negotiations Heat Up
The counterproposal’s details were not disclosed. Much of the disagreement centers on its revised ethics language. Concerns were raised about a provision involving the Office of Government Ethics that could allow senior government officials to keep their existing crypto business connections.
Senator Cynthia Lummis, who is one of the Republicans leading the negotiations, said Monday that Democrats were continuing to seek additional concessions. She maintained that the legislation was still ready to move to a vote.
The White House has also defended the latest version. Patrick Witt, the White House’s top crypto advisor, spoke at a Solana Policy Institute summit in Washington and said the administration had worked to address the concerns that emerged during negotiations.
While expressing confidence about the Senate beginning its consideration of the highly anticipated cryptocurrency regulation, he said that the question of securing 60 votes would ultimately be political rather than a matter of policy since he viewed the bill as genuinely bipartisan and deserving of support.
His remarks come a day after a 635-page Republican draft that made changes to several provisions that had become contentious.
Banking Groups and States Raise Alarms
The changes have drawn complaints from different groups. For instance, banking groups are mainly focused on the rules for stablecoin rewards. Eight trade associations sent their concerns to Senate leaders John Thune and Chuck Schumer on Monday. The groups also asked lawmakers to make several changes to the bill.
Separately, New York Attorney General Letitia James and 17 other attorneys general urged senators to reject the legislation. They warned that federal preemption could weaken state anti-fraud, investigative, and enforcement authority, including administrative, civil, and criminal powers that form the basis of state police powers. They also claimed that it could leave the SEC with “broad preemptive power” to decide where the rules apply.
Despite those reactions, Witt said that it was the “best and final offer.”
The post CLARITY Act Hits Final Stretch as Democrats Push Back Before Senate Vote appeared first on CryptoPotato.


