Cryptocurrency Posts
Crypto Briefing
BlackRock's Bitcoin acquisition highlights shifting power dynamics in crypto markets, influencing institutional control and potential price trends.
The post BlackRock buys $1B of Bitcoin over past 20 days as Grayscale bleeds another $255M appeared first on Crypto Briefing.
The escalation complicates Ukraine's strategic goals, reducing market confidence in reclaiming Crimea by 2026, impacting military prospects.
The post Russia launches 200-drone attack on Kyiv, escalating Ukraine conflict appeared first on Crypto Briefing.
China's increased oil throughput amid geopolitical tensions may lead to supply constraints, influencing global oil prices and market dynamics.
The post China’s August oil throughput rises as fuel exports rebound amid Iran conflict appeared first on Crypto Briefing.
Uniswap's innovative StablePair Hook could reshape decentralized finance by enhancing stablecoin trading efficiency and liquidity on Ethereum.
The post Uniswap Labs’ stable pair hook becomes highest volume pool on Ethereum appeared first on Crypto Briefing.
The escalation may destabilize regional security, impacting global oil markets and potentially influencing Iran's political landscape.
The post Houthi fighters escalate strikes on Saudi Arabia as Hormuz talks stall appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Swiss Bitcoin Pay Shuts Down Servers After Data Breach
Another day, another data breach.
Swiss Bitcoin Pay, a non-custodial bitcoin payment processor, said that it had to temporarily shut down its servers following a data breach on Monday.
The Neuchâtel, Switzerland-based company said that user funds were safe but customer email addresses, bitcoin addresses and IBANs, transaction history, and hashed passwords were believed to be breached.
A malicious user has likely gained access to Swiss Bitcoin Pay’s internal systems. As a precaution, we are temporarily shutting down our servers while we investigate and secure our infrastructure.
—
At this stage, we believe they may have accessed customer email addresses, Bitcoin…Swiss Bitcoin Pay (@SwissBitcoinPay) September 14, 2026
The announcement comes amid a run of breaches hitting bitcoin and fintech firms. Revolut confirmed last week that it handed customer passports, driver’s licenses, verification selfies and transaction histories to an unauthorized party that sent fraudulent requests from a legitimate government agency’s email domain.
And top hardware wallet manufacturer Trezor last week warned that a data breach at the third-party marketing platform it uses for sending newsletters was leading criminals to target customers with phishing attacks.
“A malicious user has likely gained access to Swiss Bitcoin Pay’s internal systems …As a precaution, we are temporarily shutting down our servers while we investigate and secure our infrastructure.” Swiss Bitcoin Pay said on Monday.
The company added that; “User funds are safe, and any amounts owed to users will be fully returned.”
Swiss Bitcoin Pay did not immediately respond to Bitcoin Magazine’s request for comment.
The company lets businesses accept Bitcoin payments quickly and easily using both on-chain transactions and the Lightning Network.
Criminals have increasingly been targeting data in 2026. Scammers in January were able to get hold of customer information via crypto wallet Ledger’s payment processor Global-e to send phishing emails.
Crypto wallet provider SafePal last month also announced a data breach that involved unauthorized access to about 39,798 customers’ order information, including personal details such as names, addresses and purchase data.
This post Swiss Bitcoin Pay Shuts Down Servers After Data Breach first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Mallers: Bitcoin and AI Could Give Humans Back Their Time
Bitcoin — along with artificial intelligence — could help humans get their time back to create again, according to Strike CEO Jack Mallers.
The reason: hard money doesn’t rob people of their time and energy and truly rewards people time and energy well spent, Mallers argued on Bitcoin Magazine’s debut TV show on Monday.
“Money broadly is our time and energy in an abstracted form — it is the market good that represents the effort, the labor,” Mallers said.
“If the money is bad, it’s very destructive to our time and energy: It robs us of our time and energy. You have to work longer and harder to get a house; you have to work longer and harder to get a vacation. You have to work longer and harder to have hours to pursue your artistic interests.”
“And if the money is good, it actually gives you and rewards back time and energy,” he continued, adding that Bitcoin and AI could free humans from the “drudgery” of bad money.
Mallers went on to cite the example of the creators of the airplane, the Wright brothers, who came up with their invention when the U.S. was on a gold standard.
Mallers’ comments come following Bitcoin’s best run in years. Bitcoin gained about 25% in August, its strongest month of 2026 and its first positive August since 2021, closing the month near $78,000.
The run followed Treasury Secretary Scott Bessent’s move to expand long-dated bond buybacks, which pulled yields down and triggered billions in short liquidations.
Since the news, the so-called debasement trade has been back in the headlines again: when traders buy assets like gold or bitcoin to hedge against a currency losing its value.
The dollar slid on the Treasury buyback news and an announcement the same week that U.S. debt had hit the $40 trillion mark.
Speaking about the state of the U.S. economy, Mallers added: “This level of debt is unsustainable, so when people debate, oh well, what if they hike rates? What if they cut rates? It doesn’t matter: it’s all inflationary and it’s all untenable.”
Data on Friday revealed that the consumer price index, excluding food and energy, climbed 0.3% in August from a month earlier — higher than expected.
The U.S. is currently in the grips of an affordability crisis, and it’s widely expected that the Federal Reserve will raise interest rates this week to tame inflation as oil prices have surged.
This post Mallers: Bitcoin and AI Could Give Humans Back Their Time first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Lummis Credits Trump for Ethics Deal as Clarity Act Faces Tuesday Vote
Republican senator Cynthia Lummis has praised U.S. President Donald Trump for agreeing “to the toughest ethics restrictions” in order to get the Clarity Act over the line.
The pro-crypto senator wrote on X Monday that Trump had agreed to tighter laws which give state attorneys generals standing to sue to enforce the conflict-of-interest rules on federal officials.
Lawmakers will vote on the Clarity Act tomorrow. The bill aims to formally divide oversight between regulators, distinguishing which digital assets are securities, commodities or stablecoins — rules crypto industry executives have long called for.
JUST IN:
— Bitcoin Magazine (@BitcoinMagazine) September 14, 2026Senator Lummis on the Clarity Act: "President Trump had already agreed to the toughest ethics restrictions on federal officials in American history to get this bill done."
"Time for Democrats to take yes for an answer." pic.twitter.com/3VLn6y4fph
“Back in July, Trump voluntarily put himself, the VP, every federally elected official, judges, and their spouses under the strictest ethics rules this country has ever seen. Most people in Washington never would’ve offered that. Democrats still wanted independent, outside enforcement, not DOJ alone — so Trump went back to the table and gave more,” Lummis said.
She added: “A no vote tomorrow kills the toughest ethics reform this country has ever put on the books, kills consumer protections for every American holding digital assets, and hands the future of this industry to our foreign competitors.”
Alongside senators John Boozman and Tim Scott, Lummis released a new draft of the Clarity Act on Sunday night that gives attorneys enforcement new powers.
An updated draft of the Clarity Act banning government officials from promoting or making money from crypto started circulating in July but Democrats wanted more work on it.
President Donald Trump campaigned on a ticket to help the crypto space but some Washington lawmakers have criticized the way the Trump family has profited from digital asset ventures, such as the President’s memecoin, $TRUMP, and World Liberty Financial project.
Trump and the White House have always denied any conflicts of interest.
Speaking in an interview with Punchbowl News in August, about the Clarity Act and ethics, President Trump pointed out the Democrats have also made money from stock trading.
Though passed by the House of Representatives last year, the Clarity Act has been stalled this year, mostly because the banking lobby clashed with crypto companies over paying customers stablecoin yield.
Republicans like Lummis have accused Democrats of deliberately holding back the bill.
This post Lummis Credits Trump for Ethics Deal as Clarity Act Faces Tuesday Vote first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Morgan Stanley’s Bitcoin Investment Recommendation Explained w/ Amy Oldenburg
Morgan Stanley became the first global systemically important bank to launch a spot Bitcoin ETP and it crossed $600 million within months of its April debut. Amy Oldenburg, Head of Digital Assets at Morgan Stanley, joins host Spencer Nichols to explain how that product came together, why it was priced below competing spot Bitcoin ETFs, and what still stands between clients and their first Bitcoin allocation. She also details the firm’s 0–4% allocation framework across three investor risk profiles and why Morgan Stanley has no equivalent gold allocation. Plus: whether Bitcoin could land on Morgan Stanley’s own balance sheet.
 Host: Spencer Nichols — Bitcoin Magazine Amy Oldenburg, Head of Digital Assets at Morgan Stanley
Chapters:
0:00 — Morgan Stanley on Putting Bitcoin on Its Own Balance Sheet
1:14 — 26 Years at Morgan Stanley: Emerging Markets to Head of Digital Assets
2:10 — First Major Bank to Launch a Spot Bitcoin ETP Tops $600 Million
3:14 — Education, E-Trade Spot Crypto, and What Clients Actually Own
4:49 — Why Morgan Stanley Priced Its Bitcoin ETP So Low
6:40 — The 0–4% Allocation Framework and the Digital Gold Thesis
8:52 — Correlation Regimes: Digital Gold, High Beta Tech, and Volatility
11:41 — Gold 2.0, Market Cap, and Bitcoin on the Balance Sheet
14:37 — Institutional Market Structure, Quantum Risk, and Client Trust
18:02 — Global Off-Ramps, Tokenization, Stablecoins, and Morgan Stanley Research
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Morgan Stanley’s Bitcoin Investment Recommendation Explained w/ Amy Oldenburg first appeared on Bitcoin Magazine and is written by Mark Mason.
Bitcoin Magazine
Strive Snaps Up More Bitcoin, Brings Holdings to 25,000 BTC
Nasdaq-listed bitcoin treasury Strive now holds 25,000 BTC — worth nearly $2 billion — following its latest buy.
The company said Monday that it bought 469 bitcoins at an average price of approximately $77,954. It is still the fifth biggest publicly traded bitcoin company, according to Bitcoin Treasuries. Strategy, Twenty One, Metaplanet, and MARA all hold more bitcoin than Strive.
CEO Matt Cole wrote on X Monday that 100% of the capital raised during the week came through sales of SATA, Strive’s perpetual preferred stock.
Dallas, Texas-based Strive’s stock (ASST) was trading more than 6% higher following the news.
Strive debuted as an official bitcoin treasury last year. The company was founded by former Ohio gubernatorial candidate and tech entrepreneur Vivek Ramaswamy.
In January 2026, it completed the acquisition of Semler Scientific in an all-stock deal — the first instance of a publicly traded Bitcoin treasury company acquiring another such company.
Like with other digital asset treasuries, the idea is that investors can get amplified returns from Strive’s stock. The company buys bitcoin with equity, and maintains a debt-free balance sheet: no bonds, no credit lines, and no leveraged positions that could trigger forced liquidation in a downturn.
The company is different to other major bitcoin treasuries because it has no debt.
Other major bitcoin treasuries — like the biggest, Strategy — have used leverage to buy the leading cryptocurrency.
Strive CEO Matt Cole has described the company as debt-free with zero margin requirements and zero encumbered bitcoin.
This post Strive Snaps Up More Bitcoin, Brings Holdings to 25,000 BTC first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
CryptoSlate
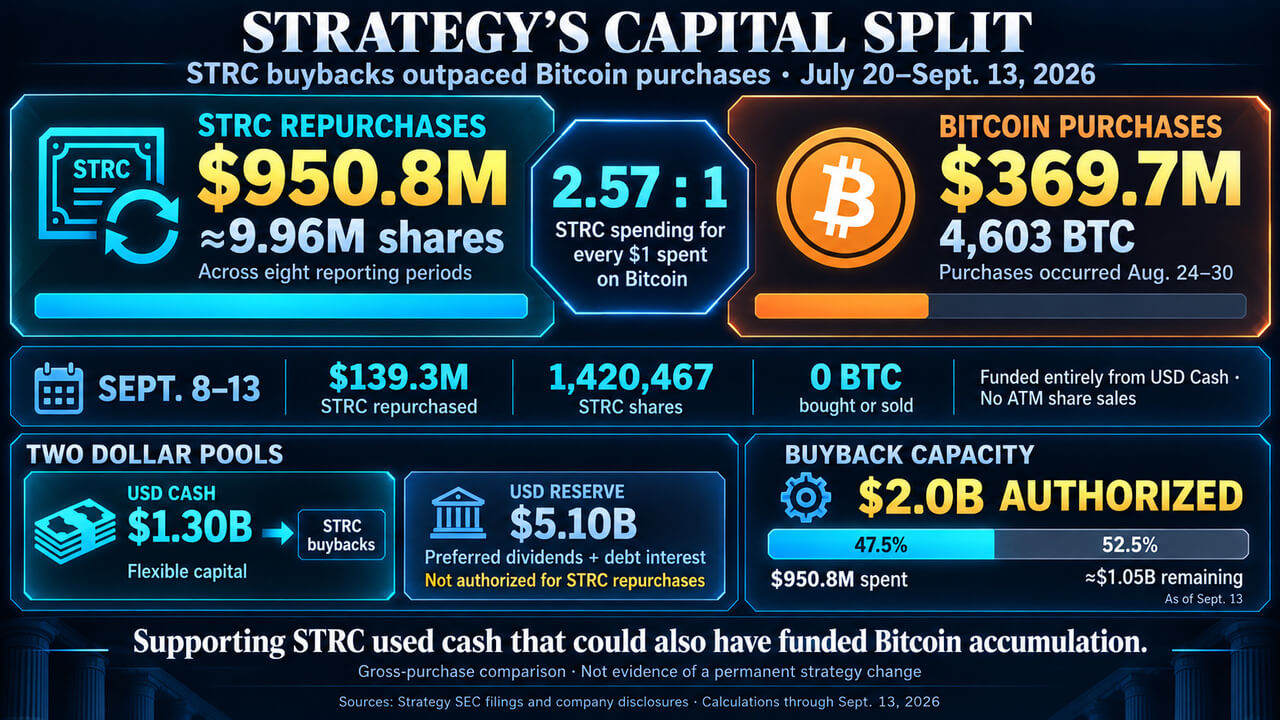
Strategy’s latest $139.3 million repurchase of STRC variable-rate preferred shares has brought its spending on buybacks to about $950.8 million since July 20, more than twice what it spent acquiring Bitcoin over the same period.
The company’s Sept. 14 filing disclosed purchases of 1,420,467 STRC shares between Sept. 8 and Sept. 13, funded entirely from its USD Cash balance. Strategy neither bought nor sold Bitcoin and sold no shares through its at-the-market program during that reporting period.
Across eight reporting periods spanning July 20 to Sept. 13, Strategy repurchased approximately 9.96 million STRC shares. Its reported Bitcoin purchases were confined to Aug. 24-30, when it acquired 4,603 BTC for $369.7 million.
That puts STRC repurchase spending at roughly $2.57 for every $1 spent buying Bitcoin during the window.
Cash goes toward preferred shares
The latest purchases extend a pattern, when cumulative STRC spending stood at $811.5 million. Supporting the preferred shares draws on money that could also fund Bitcoin accumulation.
In its July 27 buyback policy, the company said repurchasing shares below their $100 stated amount could reduce future preferred-dividend requirements at a discount.
Management expected purchases generally to taper as STRC approached $100, although timing and amounts remain discretionary. The policy gives Strategy a reason to spend on its own securities even when that spending does not add Bitcoin to its treasury.
Earlier in the campaign, Bitcoin sales helped finance those obligations. During July 27-Aug. 2, Strategy sold 1,638 BTC, using $52.4 million of proceeds for preferred dividends and $52.3 million for STRC repurchases.
The following week, it sold another 1,690 BTC for $108.6 million, using those proceeds to fund STRC buybacks.
The distinction between Strategy’s two dollar pools matters. As of Sept. 13, its flexible USD Cash stood at $1.3 billion. Its separate USD Reserve was $5.10 billion and designated for preferred dividends and debt interest.
Under the July 27 policy, that reserve was not authorized to fund STRC repurchases.
Strategy still held 845,050 BTC as of Sept. 13. The buybacks compete with further accumulation, but the eight-week comparison does not establish a permanent change in its Bitcoin strategy.
The board doubled the preferred-security repurchase authorization to $2 billion on Sept. 8, including earlier purchases. About $1 billion remained available as of Sept. 13, giving Strategy room to continue supporting its preferred shares while Bitcoin purchases remain intermittent.
The post Strategy prioritizes $950 million STRC buyback over expanding its Bitcoin treasury appeared first on CryptoSlate.
Ethereum and Coinbase-backed layer-2 network Base have abandoned an effort to agree on how the next generation of crypto wallets should work.
On Sept. 14, Ethlabs researcher Derek Chiang said collaboration between developers working on Ethereum’s EIP-8141 Frame Transactions and Base’s EIP-8130 broke down last week after attempts to produce a shared account-abstraction standard failed to reconcile the chains’ different requirements.
The split leaves Ethereum advancing Frames while Base pursues a separate design for native account abstraction, potentially forcing wallets to accommodate different transaction architectures across networks that have historically shared much of the same account and transaction experience.
Both proposals seek to make wallets more programmable, supporting features such as gas sponsorship, passkeys, and flexible authentication. The disagreement emerged over how much freedom the protocol should give accounts and how much structure chains should impose on transactions before they execute.
Chiang said:
“Ethereum wanted to be the best version of Ethereum, and Base wanted to be the best version of Base.”
The breakdown came only weeks after the projects were still trying to bridge those differences. Ethlabs said in late August that developers had held dedicated discussions around Frames and ideas from EIP-8130, even after Ethereum core developers gave EIP-8141 a strong signal toward inclusion in the Hegotá upgrade.
L2 competition pushes protocols in different directions
The failure exposes a structural problem that could become harder to contain as Ethereum’s layer-2 (L2) blockchains mature into networks with their own users, commercial priorities, and development schedules.
Ethereum core developer Matt Garnett said divergence among L2s was inevitable because market competition forces them to introduce features more rapidly than Ethereum L1 can.
Garnett added:
“Market pressure forces them to ship features at a pace that L1 cannot match, so incompatibilities accumulate. Time will tell whether that is a strength or weakness.”
That pressure shows up in competing account-abstraction designs.
EIP-8141 introduces Frame Transactions, which break a transaction into programmable calls that can handle validation, execution, and gas payment.
The proposal is designed to detach accounts from the elliptic-curve keys that dominate Ethereum today, enable key rotation, and provide a path toward post-quantum authentication. Its stated goal is to allow an account to become an address whose behavior is defined by code.
EIP-8130 takes a more structured approach. Written by Coinbase engineer Chris Hunter, it requires transactions to identify their authenticator so nodes can determine the validation work required before executing arbitrary wallet code. Its current draft describes that structure as a way to make validation predictable and allow nodes to reject unknown authenticators before execution.
For Ethereum mainnet, Chiang said the priority is what he calls “CROPS”: censorship and capture resistance, open-source software, privacy, and security.
Those requirements favor an account model developers can extend without seeking permission from the chain and transaction designs that can support privacy systems and future post-quantum signatures.
High-throughput layer-2 networks like Base face different pressures. Chiang said they need account-abstraction systems that can scale while remaining sufficiently legible for chains to determine which authentication methods and transactions they will permit.
EIP-8130’s current draft reflects that divide through separate adoption profiles. Its L1 profile permits authenticators outside a canonical set within defined limits, while its layer-2 profile allows high-throughput chains to restrict the native transaction path to approved canonical authenticators.
The proposal still seeks cross-chain portability, with a common authenticator set and ERC-4337 available as an alternative transport on networks that do not support the 8130 transaction type.
That leaves room for compatibility even if Ethereum and Base adopt different native systems, but more of the work required to preserve it could move away from the protocol itself.
The split reopens Ethereum's L2 bargain
As technical differences between Ethereum and its layer-2 networks accumulate, the dispute over account abstraction is feeding a broader debate over whether L2 growth automatically strengthens Ethereum itself.
Crypto lawyer Gabriel Shapiro said the split between Ethereum’s EIP-8141 and Base’s EIP-8130 could make the case for layer-2 networks as an inherently beneficial strategy for Ethereum harder to sustain. He said:
“L2s are great — for the crypto industry and for people who own the sequencer. For Ethereum, they are just kinda like ‘less bad’ than competing L1s.”
His argument centers on where value and control ultimately accrue. Networks such as Base can attract users, applications, and transaction activity while capturing sequencing economics and making product decisions around their own competitive priorities.
Ethereum continues to provide settlement and security infrastructure, but that relationship does not ensure that every feature or commercial success on an L2 directly strengthens the L1’s product or economics.
Shapiro said Ethereum may need to rely less on the “halo effects” of businesses such as Base and Robinhood and make a clearer case for the attributes the base layer uniquely provides.
He linked that shift to Vitalik Buterin’s increased emphasis on censorship resistance, privacy and security, arguing that Ethereum is placing greater weight on qualities that distinguish the L1 even as activity continues to move onto rollups.
Layer-2 networks can still generate settlement demand, consume Ethereum data availability, and keep applications within the broader Ethereum ecosystem instead of losing them to rival blockchains. EIP-8130 also includes mechanisms intended to preserve account portability across EVM chains, showing that Base is not designing for isolation.
The account-abstraction dispute nonetheless provides a concrete example of how those interests can diverge.
The post Coinbase-backed Base just exposed the uncomfortable truth about Ethereum’s L2s appeared first on CryptoSlate.
In a Sept. 8-11 Lido discussion, Commit-Boost contributor Jason Vranek argued that builders funding protocol-backed payments face costs from idle Ethereum, failed delivery, and offers they wanted to cancel.
Those costs could make trusted connections more competitive. Meanwhile, Titan Builder said it expects validators to continue reaching it through relays that organize auctions and handle publication.
An operator’s configuration helps determine which block-payment opportunities its validators can consider. For builders, the same settings help determine access to those validators.
As of Sept. 13, Ethereum.org lists Glamsterdam as testing on devnets, with mainnet expected in the fourth quarter of 2026 and no confirmed date. Lido contributors are discussing a proposed direction ahead of a future DAO vote.
Glamsterdam’s technical purpose remains distinct from those market choices. Separating consensus work from execution processing gives validators more time for heavy work, whether operators continue using relays or not.
Transaction-inclusion guarantees belong to another part of the roadmap. The Ethereum Foundation’s Sept. 7 priorities identify fork-choice enforced inclusion lists (FOCIL) as a Hegotá headliner.
That planned mechanism would let validators impose inclusion requirements on builders’ blocks.
What the payment guarantee covers
Enshrined proposer-builder separation (ePBS) formalizes the exchange between a validator proposing a block and the builder assembling its transactions.
In the proposed EIP-7732 design, which remains under Review, the proposer includes a builder’s signed commitment in its consensus block, and the execution payload containing the transactions follows separately.
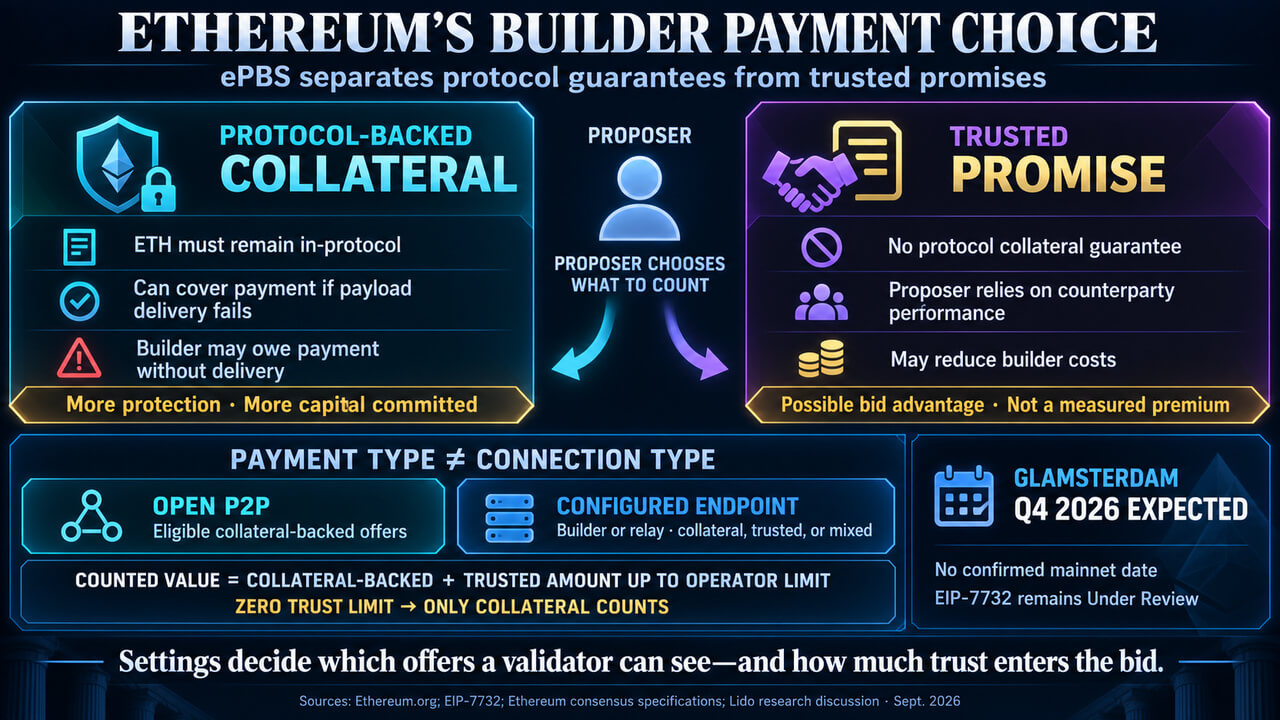
The design accommodates two payment forms. A collateral-backed payment draws on Ethereum the builder has deposited into the protocol, and a trusted payment depends on the builder honoring a promise through another payment route.
That trusted payment can still be an ordinary on-chain Ethereum transfer.
The current consensus specification checks the builder’s available balance and records the collateral-backed amount as a pending payment to the designated fee recipient. Settlement uses withdrawals to the execution layer, while the recipient receives an execution-layer payment, rather than a direct increase in the validator’s effective staking balance.
For a timely proposer whose block receives the required support, the guarantee can survive the builder’s failure to deliver the committed payload.
The design also protects a builder when a proposer withholds the beacon block containing its commitment and reveals it late.
That risk allocation is the economic hinge. A proposer can protect against missing payloads, while the builder takes on exposure to paying without successfully delivering its block. Choosing a trusted payment leaves the proposer dependent on the counterparty’s promise.
Vranek’s Sept. 11 explanation identifies three potential costs. A builder must maintain ETH reserves inside the protocol to fund its payments, it must be able to cover unusually valuable blocks, and a committed payment can remain due when delivery fails, or the builder would have preferred to cancel its offer, subject to the protocol’s payment conditions.
Those costs could affect the amount a builder is willing to pay for the same block-building opportunity. Capital held in reserves to secure payments cannot simultaneously serve another use, while exposure to payment without successful delivery can also make a builder less willing to commit its maximum payment.
A trusted arrangement could reduce those costs and leave more room to pay the proposer. Whether that produces a higher payment for a proposer depends on the amounts available and the counterparty’s performance.
The distinction between a possible advantage and a measured premium also shapes Mike Neuder’s August analysis. He predicts that established trust between proposers, builders and relays will persist, but labels his market expectations conjectures.
In a subsequent reply, he says he expects the block-building market to remain largely unaffected, rather than necessarily become worse.
Open bidding and relay connections can coexist
Lido’s initial Aug. 22 direction divided offers by payment type: accept eligible collateral-backed offers broadly, while restricting trusted offers to a governance-approved allowlist.
Vranek’s Sept. 3 response proposed open peer-to-peer offers alongside configured builder or relay endpoints. Payment and connectivity are separate choices. Under the gossip specification, peer-to-peer offers have no trusted payment component. A configured connection can carry collateral-backed payments, trusted payments, or a mixture.
An open route lets an eligible builder reach validators without each operator first adding its endpoint, while a configured route can connect to a relay serving several builders.
Titan contributor George said on Sept. 8 that Titan does not plan to open its own direct proposer endpoint and expects validators to keep connecting through relays. He argued that relays can preserve a common auction, manage payload publication and reduce the burden of maintaining individual builder relationships.
His concern was that a builder with private access to a proposer could also watch the public relay auction and gain a last look at competing offers. In that situation, a relay offering shared access could help preserve competition.
The open bidding route also has advocates. Responding to Neuder, Justin Traglia argued that builders could register additional identities and improve connectivity to compete for proposers without configured connections.
He acknowledged latency disadvantages and the extra stake needed for additional identities. His argument leaves room for competition outside configured relationships, even if those relationships remain popular.
Even after an operator chooses its offer sources, it must decide how to value payment promises.
The builder specification lets a proposer set a maximum trusted payment to count from each builder. It values an offer by adding the collateral-backed amount to the trusted component, counted only up to that limit.
A zero limit leaves only the collateral-backed portion contributing to valuation, making trust a practical selection rule. A builder may offer a payment that the proposer’s settings don't count in full, while counting a trusted promise in full means relying on that builder to deliver.
What Ethereum operators can measure
Operators also need an accurate record of their choices. In the Sept. 8 Lido discussion, Stakely’s Paco asked that compliance be assessed against offers the proposing node observed. He also called for consistent offer sources and settings across backup nodes, plus a local-building fallback.
Paco warned that differences in offer handling across clients could increase incident-management costs and encourage operators to run fewer client types. Gabriella_S’s Sept. 9 response supported considering logging of observed offers and keeping that diversity risk in scope.
These remain policy and implementation questions under discussion.
The next meaningful evidence will come from the policy Lido puts forward, the offer-handling clients implement, and the payments available under those configurations.
An open route can broaden access, and protocol-backed settlement can reduce reliance on payment promises. A possible payment advantage for trusted arrangements will depend on how builders price that protection and which opportunities operators allow their validators to see.
The post Ethereum builders face a choice between locking up too much cash or relying on trusted brokers appeared first on CryptoSlate.
A proposed XRP Ledger (XRPL) upgrade could let banks and fintechs absorb XRP costs so customers never need to hold the token.
The Sponsor amendment, based on the XLS-68 Sponsored Fees and Reserves proposal, would let a company pay account reserves and transaction fees for another XRPL user while that customer retains control of their account and private keys.
For financial institutions, the change would remove one of the frictions involved in deploying products on the network: requiring every customer to acquire and manage XRP before interacting with tokenized assets, payments or other applications.
Jazzi Cooper, Ripple’s head of product, said the feature is designed so a sponsor such as a bank, issuer or platform can cover those costs on behalf of users. That could allow consumer-facing applications and institutional platforms to keep the underlying XRP mechanics largely out of the customer experience.
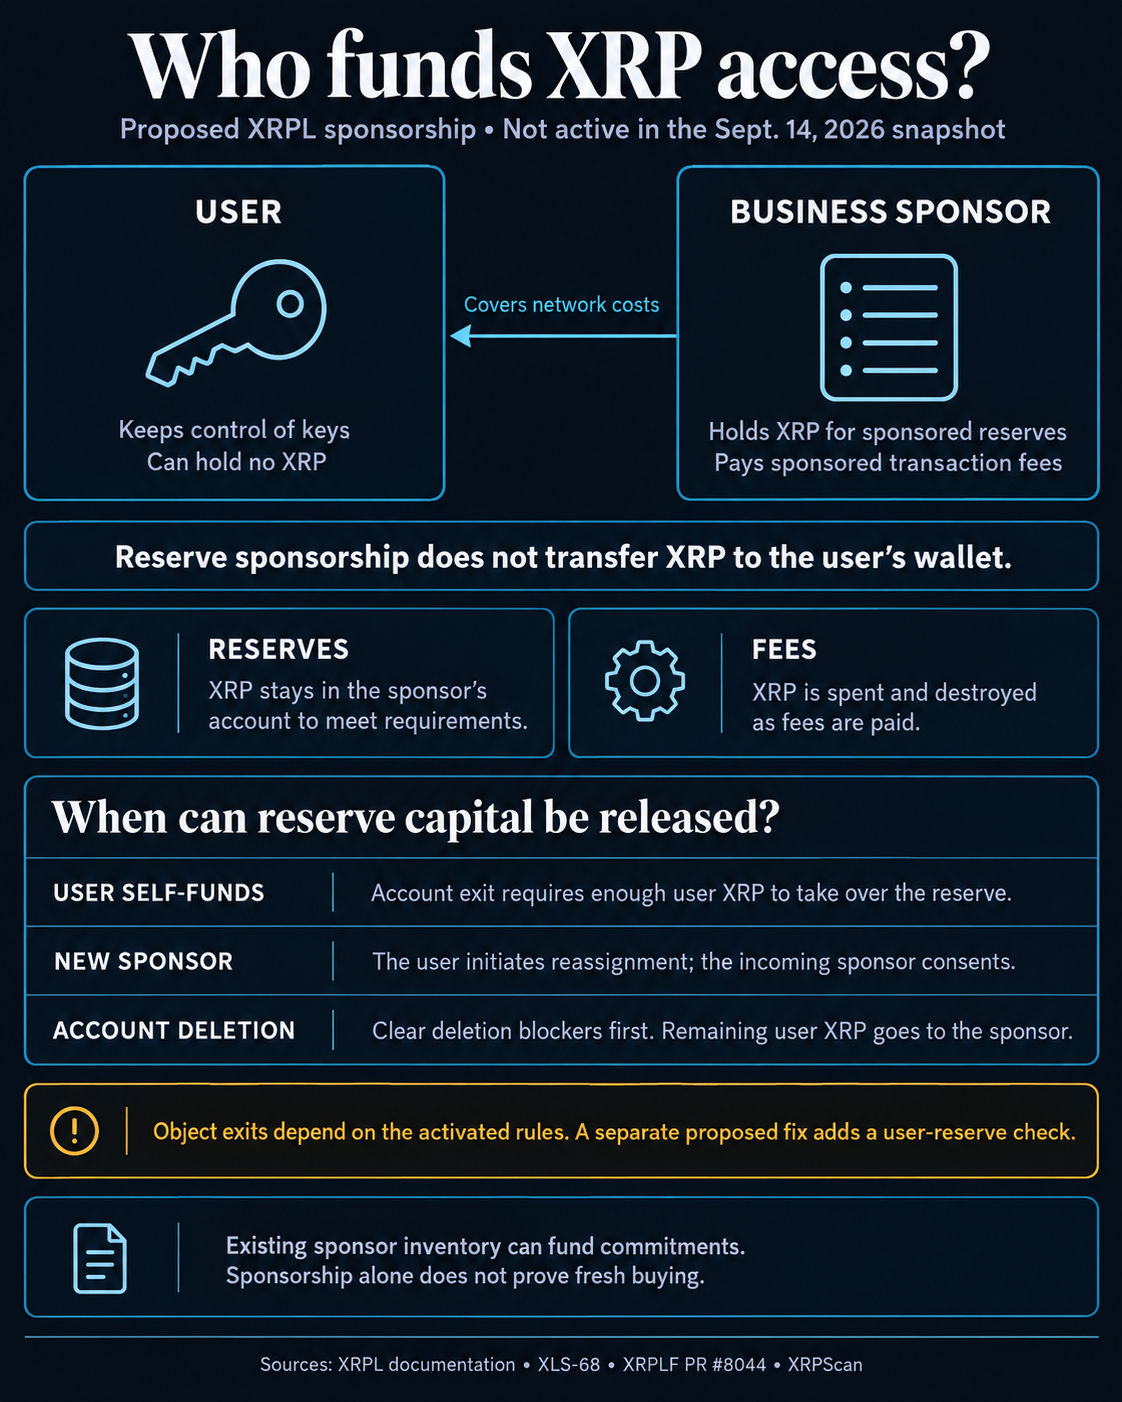
The trade-off moves to the sponsor’s balance sheet. Account reserves would still need to be covered in XRP, while transaction fees would continue to be paid in the token and destroyed when transactions settle. Businesses could therefore become the XRP holders supporting customers who themselves own none.
The proposal remains some distance from activation. As of press time, XRPScan data showed only six validators supporting the amendment, short of the 29-validator threshold, with no activation date scheduled.
Banks could become the XRP holders behind their customers
The structure would alter who carries the capital requirement without eliminating it.
XRPL currently requires a base reserve of 1 XRP per account and 0.2 XRP per standard owner-reserve unit, though validators can change those parameters. Under sponsorship, the XRP allocated to a user’s reserve would remain in the sponsor’s account while the ledger records which party is responsible for the obligation.
A business sponsoring 1,000 otherwise empty customer accounts would therefore carry roughly 1,000 XRP of additional base-reserve requirements alongside its own reserve, using current parameters. If those customers instead funded their accounts themselves, the same 1,000 XRP requirement would be distributed among them.
That distinction could become significant if banks, payment companies or tokenization platforms deploy XRPL products to millions of customers.
A firm serving 1 million users could theoretically carry about 1 million XRP of base-account reserve obligations under current requirements, before accounting for trust lines, token-related objects, optional sponsorship relationships, and transaction fees. The actual total would depend heavily on the service design.
Optional Sponsorship ledger entries can add another layer. Those entries allow businesses to establish prefunded sponsorship relationships rather than signing every subsidized transaction individually, but each also consumes reserve capacity.
The arrangement means wider XRPL adoption would not necessarily create an equivalent number of new retail XRP holders. A bank could onboard a large customer base while purchasing and managing XRP centrally, effectively concentrating the network’s reserve requirements among a smaller group of institutional sponsors.
That structure could make XRP easier to integrate into products where banks prefer customers to see only the asset or service they use, such as tokenized deposits, bonds, or money-market instruments.
Ctrl Alt, which has worked on the sponsorship proposal alongside Ripple and XRPL developers, has described the model as a way for institutions to manage XRP requirements internally while customers interact with tokenized assets without acquiring XRP themselves.
Easier onboarding creates a balance-sheet commitment
The same design introduces a capital-management problem for sponsors.
An XRP reserve remains committed while the sponsored account or ledger object still depends on it. A company cannot necessarily assume that the XRP becomes available immediately when a customer stops actively using its service.
Under the proposed SponsorshipTransfer mechanism, a sponsorship can be ended or reassigned, but account sponsorship carries conditions. A beneficiary taking over its own reserve needs enough XRP to satisfy the requirement.
That creates a complication for the very users the feature is intended to support. A customer who never acquired XRP may be unable to take over the reserve when a bank wants to stop sponsoring the account.
The sponsor could transfer enough XRP to the customer to cover the shortfall, but doing so would create a separate cost. The customer could also arrange for another sponsor to assume the obligation, with the incoming sponsor’s consent.
Account deletion offers another exit when applicable. Once relevant blockers are cleared, a sponsored account can be deleted and the reserve obligation released, with remaining account XRP directed as specified under the proposed rules.
Object sponsorship adds further uncertainty. A code change merged into XRPL’s development branch in August adds reserve checks when certain sponsorships end, but that behavior is gated behind the separate fixCleanup3_4_0 amendment. Its eventual mainnet status will determine how freely some reserve commitments can be unwound.
Those mechanics mean banks considering sponsorship would need to model more than the initial cost of acquiring XRP. They would also need to estimate customer churn, average reserve requirements, transaction-fee consumption and how much XRP could remain committed to inactive but still-open accounts.
The demand question comes after activation
The proposal could create a new institutional use for XRP without establishing how much fresh buying would follow.
An existing XRP holder could allocate tokens already on its balance sheet to sponsored customers without purchasing additional supply. New market demand would depend on the gap between that inventory and the reserve and fee commitments the institution chooses to assume.
That makes the eventual deployment data more important than the headline reserve formula. The number of sponsored accounts, sponsor balances, transaction volumes and reserve units tied to tokenized assets would reveal whether businesses are accumulating XRP to support the service or primarily recycling existing holdings.
The first hurdle remains validator approval.
If the Sponsor amendment gains sufficient support and clears the required activation period, banks and platforms would then have to decide whether removing XRP from their customer experience is worth carrying the token themselves.
For companies planning large-scale tokenized-asset products, that calculation could ultimately turn XRP from something every customer has to manage into an infrastructure cost concentrated on the institution’s own balance sheet.
The post A new XRPL upgrade could concentrate XRP ownership inside banks instead of retail wallets appeared first on CryptoSlate.
Circle is tying major financial institutions to its Arc blockchain as operators, investors, and future users ahead of its Sept. 16 mainnet launch.
BlackRock, DTCC, Visa, Mastercard, and ICE are among 11 outside institutions Circle named as founding validators, alongside Circle itself, giving some prospective users a direct role in finalizing transactions. More than 100 institutional and ecosystem builders are already working on Arc’s private mainnet.
The relationships extend beyond network operations. BlackRock was among investors in Circle’s private sale of ARC tokens and is expected to deploy its BUIDL money-market fund on Arc. DTCC is both a founding validator and a planned integration partner, with a connection targeted for the second half of 2027 that would bring DTC-custodied assets onto the network.
Circle’s structure puts prospective customers inside infrastructure they may later depend on. It also creates a boundary for users: validators help determine which transactions become final, but their participation does not make third-party applications safe or create a claim against those institutions when an application fails.
Arc’s launch disclosures say neither Arc Network Services LLC nor its permissioned validators is responsible for the content, legality, or functionality of third-party applications and warn that blockchain use can involve transaction errors or losses without recourse.
Validator role stops at settlement
Arc is designed around deterministic finality, aimed at financial firms that need a precise point when a transaction can be treated as completed.
Its Malachite consensus engine uses a permissioned Proof-of-Authority model. A rotating validator proposes a block, and the validator set votes in two stages. More than two-thirds must pre-commit to the same block before it is finalized, after which Arc says the transactions cannot be reorganized or reversed at the consensus layer.
That gives BlackRock, Visa, DTCC, and other operators a role in maintaining a common transaction history. Responsibility for smart contracts, wallets, and financial products running on top remains separate.
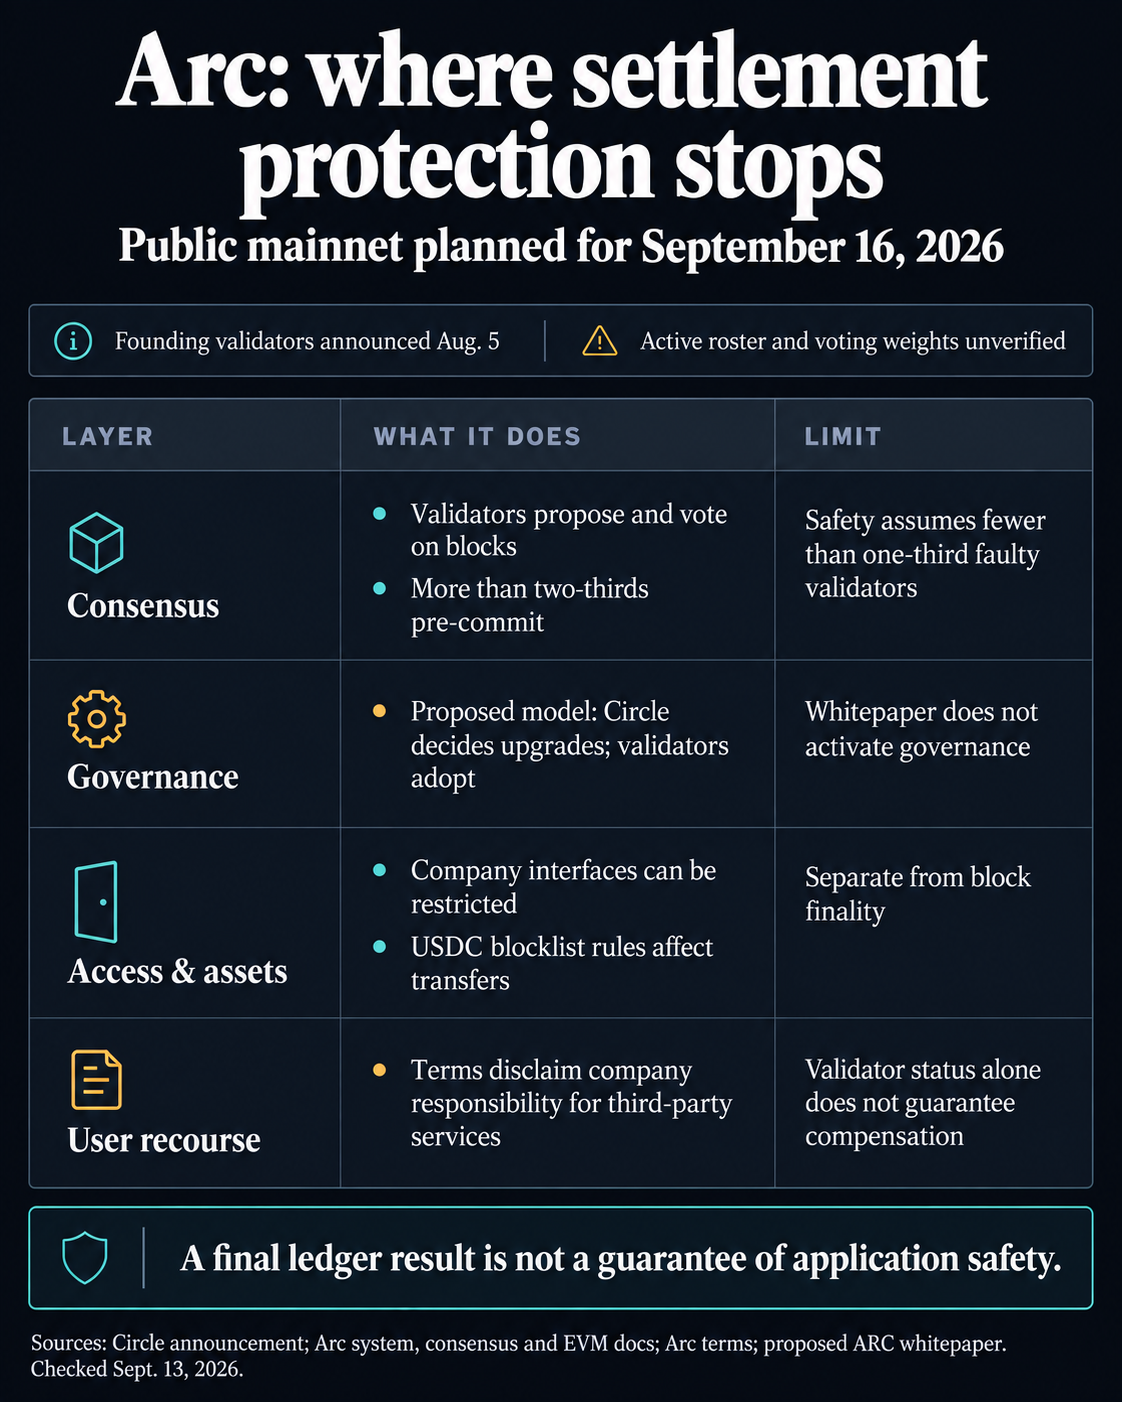
The distinction matters because Arc combines permissionless application access with permissioned validation. Developers can deploy contracts and users can submit transactions without joining the validator set, while vetted institutions continue to produce blocks.
Circle’s documentation says the launch configuration is expected to use about 20 SOC 2-certified validators across multiple regions, more than the 12 organizations publicly identified in the founding cohort, including Circle.
Circle has said validator voting power is assigned through governance, but its public launch materials do not list individual weights for the announced institutions. The precise concentration of consensus power should become clearer once the public mainnet is live.
DTCC’s planned integration shows why validator status and user protection should be separated. Circle says DTC-tokenized assets would retain the protections, rights and safeguards associated with traditionally held assets. Those protections are tied to the planned DTCC structure rather than every application running on Arc.
Circle retains a controlled launch as ARC transition looms
Arc’s institutional model leaves another question beyond transaction safety: how control over the network changes after launch.
Circle is starting Arc with a permissioned validator set while allowing developers and users open access. The company has said it ultimately wants broader participation and distributed governance, including a possible transition from Proof-of-Authority to a permissioned Proof-of-Stake model.
The economic stakes around that transition have grown. Circle agreed during the second quarter to sell 807.5 million ARC tokens to institutional investors at 30 cents each, generating about $242.2 million in gross proceeds and implying a $3 billion fully diluted network valuation.
BlackRock, Apollo, ARK Invest, ICE and Standard Chartered’s venture arm were among investors Circle named in the original presale cohort.
The ARC token has not yet launched. Circle’s whitepaper describes the token as a possible coordination asset for staking, governance and fee mechanics, while warning that its timing and final structure remain subject to change.
The presale agreements put a firmer date around that roadmap. Circle’s regulatory filings say purchasers holding a majority of the presale allocation may be able to demand repayment if the tokens are not delivered or Arc has not transitioned to Proof-of-Stake or delegated Proof-of-Stake by May 2028, subject to the agreements’ conditions.
That gives Circle a financial incentive to move beyond the launch-day structure while preserving the institutional accountability it has used to pitch Arc to banks and market infrastructure firms.
Launch turns announced relationships into a live test
The first measure on Sept. 16 will be whether the validator network operates as described and which institutions are active when public access opens.
The larger commercial test will take longer. BlackRock’s BUIDL deployment remains expected rather than completed, while DTCC’s tokenization connection is scheduled for the second half of 2027.
Their arrival would deepen the overlap Circle is creating at launch: institutions securing the network while also moving assets and financial activity across it.
That overlap could help Arc solve an infrastructure problem by giving large prospective users a reason to trust the settlement layer they help operate. It also segments responsibility. A validator can help make a transaction final while the application provider, asset issuer or custodian remains responsible for what the transaction represents.
Circle now has to turn its announced validator cohort into an operating network, then show that those relationships produce real settlement activity.
The next disclosures around active validator participation, voting power and ARC’s transition path will determine how much of Arc’s trust model rests on the institutions operating the network and how much remains with Circle.
The post Circle’s Arc launch ties Wall Street firms to the network without making them its safety net appeared first on CryptoSlate.
CryptoTicker.io
The short answer first: if you trade on Hyperliquid as a private individual in Germany, you are not committing an offence. The EU's authorisation requirement is addressed to firms that offer services, not to the users who take them up. The price is still yours to pay. Where there is no authorisation, none of the safeguards that European crypto law attaches to one apply to your funds either. This article shows you what you can look up for yourself, what the law actually says, and what the tax office expects from you.
Is Hyperliquid legal in Germany? The answer separates users from providers
The question is almost always framed the wrong way. What matters is not whether you are allowed to use a trading venue, but whether a firm is allowed to offer it to you in the EU. The law treats those two sides separately.
The text that governs this is Regulation (EU) 2023/1114, better known as MiCA. Article 59(1) reads: "A person shall not provide crypto-asset services within the Union unless that person has been authorised […] as a crypto-asset service provider", or belongs to one of the financial undertakings expressly named, such as credit institutions and investment firms. Paragraph 2 adds a registered office in a member state, a place of effective management in the Union and at least one director resident in the Union.
That is an obligation on the provider. For you as an investor, MiCA contains no prohibition that makes trading on an unauthorised venue a punishable act. What is missing is something else: the entire protective apparatus that authorisation triggers in the first place. That is what the sections below are about.
Crypto-asset service is a defined legal term here. MiCA counts among them the custody and administration of crypto-assets on behalf of clients, the operation of a trading platform for crypto-assets and the exchange of crypto-assets for funds. Anyone carrying out one of these activities commercially for clients in the Union needs the authorisation under Article 59.
What a MiCA licence covers, and why perpetual futures fall outside it
Here is the point that hardly any German-language text separates cleanly. Hyperliquid is not primarily a spot exchange but a marketplace for perpetual futures. These are derivatives with no expiry date: you are not buying the coin, you are entering into a contract whose value is derived from the price of an underlying asset and which is settled in cash. To stop such a contract drifting away from the spot price for good, long and short positions pay each other the funding rate at fixed intervals, a balancing payment between the two sides of the market.
And contracts of exactly that kind are carved out of MiCA by MiCA itself. Article 2(4)(a) states: "This Regulation does not apply to crypto-assets that qualify as one or more of the following: (a) financial instruments". Derivatives on an underlying are financial instruments within the meaning of MiFID II, the European markets in financial instruments directive. In its guidance note on financial instruments, the German supervisor BaFin describes derivatives as forward or option transactions to be settled with a time delay and whose value is derived directly or indirectly from the price of an underlying; the definition applies equally under the German Banking Act and the Securities Institutions Act.
The practical consequence is inconvenient: a MiCA authorisation would not be the right paperwork for perpetual futures trading at all. Anyone who commercially arranges or deals in derivatives for clients in Germany operates under the licensing regime for securities institutions, not under the crypto-asset regime. Searching for a MiCA entry therefore comes up empty even when you do it correctly. This classification is a legal assessment, not investment advice and not legal advice; which permission a specific offering needs is for the supervisor to decide case by case on the full contractual documentation.
What you can take from this: two different rulebooks, two different registers, two different answers. If all you have in mind is buying the HYPE token on the spot market, MiCA is the right rulebook. As soon as leverage is involved, it is the wrong one.
Looking up the ESMA register yourself: 346 authorised crypto-asset service providers, 89 of them German
You do not have to rely on anyone's summary, including this one. ESMA, the European Securities and Markets Authority, maintains a public register of all authorised crypto-asset service providers and publishes it as a freely downloadable CSV file. We pulled it for this article on September 15, 2026 and counted it ourselves.
The position on that day: 346 authorised providers across the EU. The authorisations run up to August 31, 2026, so the list is being kept current. By home member state they break down as follows:
- Germany: 89 providers — by some distance the largest home state, among them institutions such as Trade Republic Bank, flatexDEGIRO and Börse Stuttgart Digital Custody.
- France: 35, the Netherlands: 29, Cyprus: 25, Malta: 22, Spain: 15.
No entry in that list contains the string "Hyperliquid". Nor does the platform appear on the second list ESMA maintains alongside it, the register of non-compliant entities, which held 167 entries that day. Both findings are register positions, no more and no less, and in light of the previous section they are hardly surprising, because a derivatives market does not belong in a crypto-asset register. When we last went through the register in the summer, it held only 21 trading platforms with that permission, so the numbers are growing quickly.
Here is how to go about it yourself if you want to check any platform. The register files are published openly on ESMA's crypto regulation pages; for firms authorised in Germany, BaFin additionally runs its company database with a "crypto-asset service provider" category. Always check the name of the legal entity, not the brand name of the app, because the two come apart routinely.
Article 61 MiCA: why the own-initiative exemption gives you no protection
At this point a reassuring-sounding term turns up in forums with some regularity: reverse solicitation. What is meant is the exemption in Article 61 MiCA, which provides that the authorisation requirement under Article 59 does not bite where a client established or situated in the Union initiates "at its own exclusive initiative" the provision of a crypto-asset service by a third-country firm.
Anyone reading that as a general permission has not read the provision to the end. The second subparagraph immediately narrows the exemption again: a service is not deemed to be provided at the client's own initiative where the third-country firm solicits clients or prospective clients in the Union, and that applies "regardless of any communication means used for solicitation, promotion or advertising in the Union", and also where another entity acts on the firm's behalf. Advertising, affiliate programmes and outreach through social networks all count.
The third subparagraph is blunter still. It states expressly that contractual and disclaimer clauses change nothing about this, including clauses stipulating that the service is to be regarded as provided at the client's own initiative. A tick box in the terms of use, in other words, does not turn a solicited client relationship into one you sought out. And paragraph 2 makes clear that a single request does not entitle the firm to market new types of crypto-assets or services to you.
For you as an investor the decisive insight is that Article 61 is not a client protection provision at all. The rule relieves the firm of the authorisation requirement in an individual case and gives you not a single claim, no compensation and no supervision in return. You can read the full wording in the Official Journal: Regulation (EU) 2023/1114 on EUR-Lex.
Without a MiCA licence you have no route of complaint: what applies to your funds in practice
What you actually give up by trading on a venue that is not authorised in the EU can be set out concretely. None of these points is a supposition about any particular firm; they are the legal consequences that a missing authorisation carries in general.
- No deposit guarantee. The statutory deposit guarantee of 100,000 euros covers bank deposits, not crypto-assets and not margin balances on a trading venue. It does not apply at authorised providers either, and the difference lies in the obligations that apply instead.
- No supervised segregation of your assets. Authorised providers have to hold client funds and client crypto-assets separately from their own holdings and to account for them. Without authorisation there is no authority checking that.
- No complaints procedure and no supervision. With an authorised provider you can turn to the competent supervisor, in Germany BaFin. Against a firm with no authorisation in the EU, that route does not exist.
- Enforcement is difficult. With no registered office and no management in the Union, the question of which court has jurisdiction and how a judgment would be enforced is close to unanswerable in practice.
- No tax withheld at source. A foreign platform withholds no capital gains tax. The declaration is entirely down to you, and there is more on that below.
If that catalogue feels too abstract, a comparison helps: our overview of regulated crypto exchanges with EU authorisation shows which providers actually meet the obligations listed.
Who holds the keys: self-custody, the bridge and the on-chain order book
One objection comes up regularly at this point, and it is a fair one. If everything runs fully on chain, why would you need a custodian at all? The answer is more nuanced than either camp would like.
Hyperliquid runs its own layer 1 blockchain with an on-chain order book. That is a technical departure from most first-generation decentralised exchanges: there, an automated market maker derives the price arithmetically from liquidity pools, while here a matching engine runs a classic limit order book whose orders and fills sit in the network as transactions. What such a marketplace actually is and how it differs from a centralised exchange is explained in our primer What is a perp DEX?.
To use it you connect a crypto wallet and keep your private keys yourself; you do not go through a classic KYC procedure with identity checks. That is the honest advantage of this design. The catch is that to trade at all you have to deposit funds into the network across a bridge, and your margin then sits in the protocol. Self-custody protects you from the failure of a custodian, but not from a flaw in the protocol, not from a hole in the bridge, and not from a leveraged position being liquidated while you sleep.
Technical transparency and regulatory safety are two different things. Having every order publicly visible is no substitute for a capital requirement or a complaints body. Confusing those two levels draws the wrong conclusion from a genuine merit.
Leverage, funding rate and liquidation: what the trading venue actually offers today
Rather than passing on market reports, we queried the platform's public programming interface ourselves on September 15, 2026. These are the figures from that call, and they describe a snapshot, not a Hyperliquid price forecast.
- 234 perpetual markets were tradable.
- Total open interest, meaning the sum of all open positions, stood at around $10.4 billion.
- Trading volume over the preceding 24 hours added up to roughly $6.5 billion.
- The largest single market was the BTC contract at around $2.8 billion of open interest, followed by the ETH contract at $2.6 billion and the HYPE contract at $1.7 billion.
More revealing than the size is the leverage the protocol allows on each market. That sits in the same interface: the BTC contract permitted up to 40 times leverage, the ETH contract up to 25 times. Four further markets reached 20 times, 35 markets 10 times, 63 markets 5 times, and at 130 of the 234 markets, meaning the majority, the ceiling was 3 times.
That tiering is not accidental but risk management by the protocol: the thinner a market, the lower the leverage allowed. For you it means the reverse, that the spectacular leverage figures from the advertising are not available at all on niche markets. And at every level of leverage the same mechanics apply. A move of a few percent against a position geared 20 times wipes out the stake. Order types such as a stop-loss are meant to cap that in principle, but in a price gap they may only trigger below your mark. For comparing providers in this segment we keep a separate overview of perp DEX platforms with their fees and leverage tiers.
Crypto tax in Germany: perpetual futures are forward transactions under Section 20 EStG
This is the part that costs the most money in practice, and it has nothing to do with the authorisation question. The tax office is not interested in where a platform is based, but in what kind of contract you have entered into.
A forward transaction is a transaction under which you obtain a cash settlement or a sum of money determined by the value of a variable reference figure. That is precisely the wording of Section 20(2) sentence 1 no. 3(a) of the German Income Tax Act. On that definition, perpetual futures are routinely classified as forward transactions by the tax authorities and by tax advisers, because they are settled in cash and never lead to delivery of a coin.
The difference from a spot purchase is severe, and it usually works against you:
- On a spot purchase of a coin, Section 23 EStG applies. After a holding period of one year the gain is tax free.
- On a forward transaction, Section 20 EStG applies. There is no holding period and no tax exemption after a year, but the flat withholding rate of 25 percent plus solidarity surcharge and, where applicable, church tax, regardless of whether you held the position for a minute or for two years.
Because a foreign platform withholds no capital gains tax, you have to declare this income yourself in the Anlage KAP annex to your tax return. That is not a formality: anyone who fails to declare gains from forward transactions risks criminal tax proceedings. How funding payments are to be classified in detail has not been settled conclusively, and where meaningful sums are involved that is a case for a tax adviser. For gathering your records, the tools in our comparison of crypto tax software and portfolio trackers will help.
Loss offsetting: the 20,000 euro cap on forward transactions has been scrapped
One rule that still appears in many older guides no longer applies, and that is in your favour. Until the 2024 Annual Tax Act, losses from forward transactions formed their own offsetting pot: they could be set only against gains from transactions of the same kind, and then only up to 20,000 euros a year. Someone who made 100,000 euros and lost 90,000 euros in the same year could end up with a tax assessment on a gain they had never economically made.
The legislature struck those sentences after the Federal Fiscal Court expressed serious constitutional doubts. In the current wording of Section 20 EStG, paragraph 6 no longer contains a separate offsetting pot for forward transactions; the restriction that remains in sentence 4 concerns only losses on the disposal of shares. Losses from forward transactions can therefore once again be set against all investment income.
For you that means two things. First, old loss carry-forwards from forward transactions are worth more than you may think. Second, offsettable does not mean harmless. The losses stay trapped in the pot of investment income and still reduce no income from any other category.
What regulated alternatives deliver, and where their limit lies
If you are not willing to carry the drawbacks listed, the question is what an authorised provider in Germany offers instead. Answered honestly: protection, but less choice.
Authorised firms are subject to ongoing supervision, have to segregate client assets, handle complaints and meet disclosure obligations. On spot trading and savings plans you get the same product there as anywhere else, only with a supervisor behind it. Coins bought in spot trading also fall under the one-year rule in Section 23 EStG.
Where the limit lies: you will not find highly leveraged perpetual futures in this form at a German provider serving retail clients. That is not an oversight but the intention of European investor protection, which has capped retail leverage on contracts for difference sharply for years. Anyone looking for these products is leaving the protected space. That is a deliberate decision and should be taken as one, rather than out of ignorance. How quickly the terms in this segment can change was shown most recently by our analysis of the dilution from the HYPE unlocks.
Using Hyperliquid from Germany: what to take away
- Check the legal entity before you deposit money. Look the name up in the ESMA register and in BaFin's company database, and accept no brand name as evidence. Which providers pass that check is set out in our overview of regulated crypto exchanges.
- Decide deliberately between protection and product range. If spot buying and savings plans are what you are after, there is no reason to leave the protected space. If derivatives are what you are after, compare the terms soberly using our overview of perp DEX platforms, and commit only capital whose total loss you can absorb.
- Collect your records from the first position onwards. Forward transactions belong in the Anlage KAP, and a foreign platform reports nothing to the tax office. Set up a complete record from your first trade, for instance with a tool from our comparison of crypto tax software.
(As of September 15, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
When a copy of your ID document, your verification selfie and your complete Bitcoin transaction history all sit in one package in the hands of strangers, a new password achieves almost nothing. That has been the position of the Revolut customers who received a breach notification since September 14, 2026: the stolen documents have been published since the early hours of that day. Four things matter now. Establish in writing how far your own exposure goes. Close the routes through which a copy of an ID document turns into money. Take the link between your home address and your crypto holdings seriously. And enforce your rights against the bank while the deadlines are still running.
This piece builds on our first assessment. Whether you are among the affected customers at all, and what role your Bitcoin history plays in the incident, is covered in Revolut data breach: am I affected, and what about my Bitcoin history? from September 12. This article deals with the stage after that: the details are out, and that changes the question of what to do.
Revolut data breach: what to do now that the files are being published
Until the weekend, the security incident was an outflow of customer data. Since the night of September 14, Cointelegraph has reported that copies of identity documents and verification selfies belonging to Revolut customers have surfaced online. According to the outlet, the attackers are announcing on Telegram that they will release further data sets every day until Revolut pays. One affected customer confirmed to Cointelegraph that the published details match the documents held on file at Revolut, and that the neobank wrote to him on Friday.
One point matters for the assessment: the existence of a ransom demand is the attackers' own account, relayed by a trade publication citing a Telegram post. Revolut itself does not confirm any such demand. A specific Bitcoin sum is also circulating on aggregator sites as the alleged ransom. There is no solid evidence for that figure, which is why it does not appear as fact in this article.
The practical difference from last week is considerable nonetheless. As long as a data set sits only with one criminal group, it needs a buyer before it can be used against you. Once it is publicly retrievable, that intermediate step falls away, and the number of possible fraudsters grows from one group to anyone who finds the file.
Which data fields Revolut lists in its customer email
The trade publication BleepingComputer quotes the notification Revolut sent to affected customers verbatim. According to that text, the incident covers the full name, date of birth, occupation, postal address, email address and telephone number. On top of that come copies of an identity card or driving licence, the selfies from the identity check, account statements including the IBAN, withdrawal records and the complete transaction history including Bitcoin transactions.
Revolut speaks of a limited number of affected users but gives no figure. According to the company, neither its own systems were compromised nor were customer funds touched. Both statements are plausible and both change little about your position. The damage from this incident does not hit your balance. It sits in the paperwork.
The outflow was triggered, on the company's account, by a forged request that looked like an information request from a government authority. Such emergency data requests are an established procedure: where there is imminent danger, authorities demand subscriber data without waiting for the regular judicial route. The forged request came from a genuine government domain and passed the technical sender authentication checks. That is exactly where the weak point sat. A technically correct signed email proves that the domain is genuine. It proves nothing about whether the request behind it is lawful.
Why a leaked ID scan is not a case for Germany's 116 116 blocking hotline
Many affected people reach first for the same reflex: have the ID card blocked. In Germany that runs through the free blocking hotline 116 116, and in this case it is the wrong step. What gets blocked there is the online ID function, the eID on the chip of your identity card. That function requires the physical card plus the six-digit PIN. A scanned copy cannot trigger it.
Your ID card is still in your drawer, and the eID is not the way in. The risk sits with every provider that accepts an image file of an ID document as proof: credit brokers, mobile operators, mail-order retailers offering purchase on account, and some trading platforms with weak checks. Blocking the eID would have no effect there and would only cost you the use of digital government services.
A different set of measures does work. File a criminal complaint with the police, online through the digital police station of your federal state; the case number is later your evidence towards any creditor chasing a claim taken out in your name. Request a free copy of your data from the major credit reference agencies and check whether contracts appear there that you never signed. And set yourself a reminder, because identity abuse using copies of ID documents often only shows up months later. The German Federal Office for Information Security sets out the individual steps for victims of data breaches and doxing in detail.
ID scan and KYC selfie together: the problem with the liveness check
An ID scan on its own is a known risk. The combination of an ID copy and the selfie from the same identity check is a different order of magnitude, because that pair is the standard proof used to open an account. Many providers require a photo of the document and an image of the face, and some match the two automatically.
The safeguard against this is called a liveness check, and it is meant to establish whether a living person is sitting in front of the camera or a photographed image. Good procedures demand head movements, changing light patterns or depth capture; weak ones make do with an uploaded still image. Wherever only a still image is required, a leaked verification selfie is immediately usable.
That produces a concrete task for crypto users: look up which trading venues hold your ID document, and close the accounts you no longer use. Every dormant registration is one copy of your paperwork less in circulation. Where you stay active, switch on two-factor authentication through an authenticator app or a security key rather than by SMS, because the phone number is part of this breach. Which platforms in Germany operate under supervision at all, and how to check that, is covered in our overview of regulated crypto exchanges.
Bitcoin transaction history in someone else's hands: what address clustering makes possible
The part of the package that separates this incident from an ordinary bank data breach is the transaction history. Bitcoin is a public database: every transfer sits in the chain for anyone to inspect. What the chain lacks is the link between an address and a person. An account statement with withdrawal records delivers exactly that link, free of charge.
Address clustering is the name of the technique that derives a whole bundle of addresses from a single known one: when several addresses appear together as the inputs of a transaction, they very probably belong to the same wallet. Anyone who knows one of your withdrawal addresses can work outwards from there and often arrives at an estimate of your total holdings. The technique is neither new nor illegal; analytics firms and investigators have worked with it for years. What is new is that the starting point for it is now lying around in public.
The obvious question is whether you should change your addresses. For future payments yes; for the past it cannot be done. A transaction once written into the chain cannot be retrieved. In practice that means: use fresh addresses for new incoming payments, avoid merging old and new holdings in a single transaction, and for larger amounts do not pay in and withdraw through the same platform.
Home address plus crypto holdings: putting the physical risk in perspective
The on-chain investigator ZachXBT reads the incident as one where the breach looks small but appears deliberately aimed at wealthy users. That is his assessment and not an established fact, but it deserves attention because it fits the structure of the data: postal address, date of birth and occupation together with a traceable Bitcoin history produce a profile that goes beyond the usual phishing purpose.
We have described this pattern twice already in our coverage, most recently in the Trezor data breach in September, in which names, phone numbers and home addresses of hardware wallet buyers were exposed. The lesson from it applies here just the same. Do not talk about amounts in the neighbourhood or on the phone. Treat parcel notifications and supposed callbacks from the bank's service team with suspicion, even when your name, your date of birth and your most recent debit are quoted correctly. Those details are precisely what is in the package, and a caller who knows them has proved nothing by doing so.
In concrete terms that also means setting yourself a callback rule at your bank and at your trading venues. No process that begins on the phone is completed on the phone. Hang up and dial the number from the app or from your account statement. That single habit strips most of the value out of what a cybercriminal can do with your documents.
What to do if your Revolut account has been hacked
One important distinction first: no account was taken over in this incident. According to the company, documents were handed out; login credentials were not stolen. If your account really is being controlled by someone else, a different procedure applies, and it begins with blocking.
Block the card in the app and, if you no longer have access, through the bank's customer service. Report every unauthorised debit without delay; under payment services law you are as a rule reimbursed for an unauthorised payment as long as you have not acted with gross negligence, and the bank has to prove the authorisation. Then change the password of your email inbox, because it is the master key to every other login. Finally, check the connected devices and sessions in every account that uses the same email address, and throw out any session you do not recognise.
Record every one of these steps in writing, with date and time. Anyone who later claims damages or disputes a demand needs that record.
The coming weeks: a review plan with fixed dates
Identity abuse after a security breach rarely starts immediately. Weeks, sometimes months, pass between the outflow and the first attack made in your name, because the data sets first have to be sorted, merged and passed on. A review plan with fixed dates therefore works better than a single frantic afternoon.
This week: send off the Article 15 access request, file the criminal complaint, and switch two-factor authentication everywhere to an app or a security key. Note down as well which postal addresses and which phone number were held on file at the neobank. Anyone who later receives a message quoting exactly those details will recognise at once which source the sender is drawing on.
In four weeks: request a copy of your data from the credit reference agencies and check it for entries you do not recognise; every credit enquiry you never made is a warning sign. In the same pass, go through the login logs of your most important accounts and report every access from a region you were not in.
After three months and after six: the same again. As long as your passport is in circulation as an image file, it keeps its value for fraudsters until its expiry date.
One expectation is worth dropping along the way. Checking services that promise to track down your data on the dark web are in reality searching a database of collections that are already known. Such systems give usable pointers about older incidents and still offer you no all-clear about a fresh one, because all they can show is what has already been traded in public. Rely on the information from your own Article 15 response rather than on a green light.
Your rights under the GDPR: access under Article 15, complaint under Article 77
The notification Revolut sent out is an obligation under Article 34 of the General Data Protection Regulation: where a breach is likely to result in a high risk to those affected, the company has to inform them without delay. That email, however, only tells you that you are affected, not to what extent.
You obtain the extent through Article 15 GDPR, the right of access. Ask in writing for a copy of the data processed about you and, expressly, for a statement of which categories were disclosed to which recipients. The deadline is one month and can be extended by two months if the company gives reasons. That response is the only solid evidence of what was actually handed out in your case, and it is free.
If no answer arrives, or an unusable one, Article 77 GDPR applies: a complaint to a supervisory authority, expressly including the authority where you habitually reside. For German customers that is the data protection authority of your federal state. The fact that Revolut Bank UAB is based in Lithuania and that the authority there is competent under the lead supervisory authority procedure changes nothing; your state authority accepts the complaint and passes it on. The German branch in Berlin is additionally supervised by BaFin, which is not, however, responsible for data protection.
On damages under Article 82 GDPR, the position in Germany has been clearer since the Federal Court of Justice ruling of November 18, 2024 (case reference VI ZR 10/24): the mere loss of control over your own data can amount to compensable non-material damage, without any abuse having to be proven. You do have to set out that loss of control yourself. The amount depends on the individual case, and the sums awarded so far sit in the low hundreds.
Is Revolut monitored by the tax office? What applies under DAC8 since 2026
This question comes up after every incident of this kind, and the answer has nothing to do with the breach. Nobody is being monitored. What has been reported automatically since January 1, 2026 is something else: Germany's crypto asset tax transparency act transposes the European DAC8 directive into national law and obliges crypto asset service providers to record and transmit tax-relevant customer and transaction data. The first reporting period is the 2026 calendar year, and the data goes to the Federal Central Tax Office by July 31, 2027.
For you that has two consequences. The details crypto providers hold about you will grow rather than shrink, and keeping clean records of your own is no longer optional. A reported sum is also not your profit: what gets reported are proceeds and transactions, while the acquisition costs are known only to your own documentation. Anyone who does not keep it is later negotiating against a figure they have nothing to set against it. A portfolio tracker with tax reporting solves exactly that problem.
Extortion, ransom, millions of records: what is proven and what is not
Several narratives are running alongside each other around this security incident, and the differences matter for your own judgement.
Proven is the notification to those affected together with the list of data fields, because Revolut sent it out itself and a trade publication reproduces it verbatim. It is also proven that copies of identity documents and verification selfies have surfaced publicly; one affected customer confirmed the match to Cointelegraph.
Claimed is the extortion. The threat of daily publication comes from a Telegram post by the alleged perpetrators. A company being extorted rarely confirms it, and Revolut does not do so here. Anyone mentioning the demand should say who is making it.
Disputed is an older matter that is resurfacing: over the summer, a database allegedly holding tens of millions of Revolut records was offered on the dark web in the relevant forums. German media reported on it, Revolut denied its authenticity and pointed to material compiled from other sources. That episode has to be kept separate from the current one. Anyone who throws the two together arrives at a number of affected customers that nobody has evidenced.
For handling the days ahead, that means: expect phishing that looks very convincing. Whoever knows your name, date of birth, IBAN and most recent transactions no longer writes a clumsy spam email. The only reliable test remains the channel, not the content. A genuine bank never asks you by email or telephone to move funds to a security account, to enter a recovery phrase or to install remote access software. At the slightest doubt, go through the app you installed yourself.
Self-custody as a consequence: when a hardware wallet shortens the data trail
This case exposes a property of custody arrangements that stays invisible in everyday use: anyone holding crypto assets with a provider leaves behind a complete identity file there alongside the balance. That file is the actual subject of the incident. A hardware wallet does not change all of it, but it does shorten the trail at one decisive point: the balance no longer sits with a third party afterwards, and that third party's failure or data breach no longer separates you from your coins.
It is worth staying honest all the same. The purchase itself generates data again, as the Trezor breach mentioned above shows; so never order to an address that is also where you live, if you can avoid it, and buy only from the manufacturer or authorised resellers. The transfer from an exchange to your own wallet is also visible in the chain and can be linked to your account statements. And responsibility for the recovery phrase then lies entirely with you. Self-custody is a shift of risk, not its abolition.
For whatever is meant to stay on a platform, selection comes down to supervision and custody practice. Ask about segregated custody, about who the custodian is, and about the licence under which that custodian operates.
Revolut data breach: what to take away
- Establish your exposure in writing. Request the Article 15 GDPR access response today and note the date you sent it. Without that list you will later be arguing over assumptions. In parallel, check which trading venues hold a copy of your ID document and close the accounts you do not use; our overview of regulated crypto exchanges shows what matters with the ones you keep.
- Separate identity and holdings. Use fresh receiving addresses, do not merge old and new holdings in a single transaction, and move the part you hold long term into your own custody. Our comparison of hardware wallets names the devices along with their weaknesses.
- Get your records in order before the first DAC8 report goes out. Complete acquisition data is your only counter-argument against a reported sum from the 2026 reporting period onwards. A tax and portfolio tracker takes over the collecting.
(As of September 14, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
When you buy Bitcoin with a market order, you rarely pay exactly the price the app showed you beforehand. The difference is called slippage, and it does not come from a fee but from the depth of the order book: your order works its way up through the sell offers on hand until it is filled. How expensive that gets depends on how much capital sits right next to the current price.
We measured this ourselves across five exchanges on September 14, 2026, in three time windows between 15:51 and 15:53 UTC. The headline result: for a purchase of 100,000 euros the markup in the third window ranged from 10.50 euros to 329.86 euros, depending on which exchange you pick. That is a factor of 31 for exactly the same action in the same minute.
This analysis was compiled by cryptoticker.io on September 14, 2026.
Slippage on a Bitcoin order: what the term means precisely
Slippage is the gap between the price you see when you submit the order and the average price at which it is actually executed. It is not a fee and never appears on a statement as its own line item. It sits inside the execution price.
The mechanism behind it is an order book. An order book is the price-sorted list of all open buy and sell orders on an exchange. On the sell side the cheapest offer sits at the top, with more expensive ones below. A market order takes those offers in turn until your amount is used up. If only a few Bitcoin sit just above the current price, your order reaches higher price steps quickly.
The first cost block here is the spread. The spread is the distance between the highest bid and the lowest ask. Even a tiny market order pays half the spread arithmetically, because it starts at the midpoint and executes at the upper end. On large orders the depth effect comes on top.
The distinction matters in practice. A trading fee of 0.25 percent is known to you in advance and you can look it up in a crypto exchange comparison. Slippage is written down nowhere, because it depends on the state of the book in the exact moment you tap buy.
Our own measurement: how deep the euro order books of the five exchanges really are
We queried the public order book interfaces of Kraken, Coinbase Exchange, Bitstamp, Bitvavo and Bitfinex, each for the Bitcoin against euro pair. From each book we formed the mid price, calculated the spread and then simulated how a market order of 1,000, 5,000, 25,000 and 100,000 euros eats its way through the sell side.
We measure depth as the sum of the capital sitting within half a percent of the mid price in the book. That figure says more about an exchange's resilience than trading volume does, because volume also arises from thousands of small orders that consume each other.
For Bitcoin against euro the picture across the three windows was as follows:
- Kraken: spread 0.0001 to 0.0041 percent, depth 12.98 to 13.97 million euros
- Coinbase Exchange: spread 0.0079 to 0.0195 percent, depth 5.66 to 6.09 million euros
- Bitstamp: spread 0.0006 to 0.0220 percent, depth 2.48 to 2.60 million euros
- Bitvavo: spread 0.0015 percent, depth 2.23 to 2.42 million euros
- Bitfinex: spread 0.3707 to 0.4590 percent, depth 0.58 to 0.84 million euros
Between the deepest and the shallowest euro book in our sample there is therefore roughly twenty times as much immediately available capital. The Bitcoin price itself stood at around 68,100 euros at the time of measurement, which is about 78,620 US dollars.
What the numbers mean for a concrete order
Converting the percentages of the third window into euros makes the difference tangible. A market purchase of 100,000 euros cost 10.50 euros in slippage at Bitvavo, 16.25 euros at Bitstamp, 19.15 euros at Kraken, 45.89 euros at Coinbase Exchange and 329.86 euros at Bitfinex.
On small amounts the picture partly reverses, because there the spread alone counts. An order of 1,000 euros cost around one cent at Bitvavo, six cents at Coinbase Exchange, eight cents at Kraken, eleven cents at Bitstamp and 2.02 euros at Bitfinex. Anyone trading small sums notices little of the depth problem. Anyone buying in four figures and up notices it immediately.
Market order or limit order: which order type caps the slippage
A market order is executed immediately, at whatever price the book provides. A limit order sets a maximum price and is only executed if the book offers that price. The difference between the two is precisely the quantity we measured.
In practice that means: set a buy limit at 68,150 euros while the price stands at 68,100 euros, and no execution above that value can happen to you. If the depth is not there, part of the order stays open instead of being filled expensively. You can leave that remainder standing or cancel it.
The price for this is uncertainty. A limit order can sit unfilled while the price runs away. In a calm market that is no problem. In the minutes around a central bank decision an unfilled order can mean you miss a move. Nobody can make that trade-off for you, but you should make it deliberately rather than reaching for the market order out of habit.
Euro against dollar: why the same Bitcoin order book is shallower in euros
The clearest finding of our measurement cuts across the exchanges: it concerns the currency of the trading pair. We additionally queried the Bitcoin against US dollar pair at the same providers. In the third window the depth within half a percent stood at 13.97 million euros at Kraken against 34.39 million dollars, at Bitstamp at 2.60 against 11.25 million, at Coinbase Exchange at 6.09 against 38.11 million and at Bitfinex at 0.58 against 10.24 million.
That works out at factors of 2.5 at Kraken, 4.3 at Bitstamp, 6.3 at Coinbase Exchange and 17.5 at Bitfinex. The dollar market is the main market at all four houses, the euro market a sideshow. This describes a property of European crypto trading as a whole and not a weakness of any single provider.
Bitfinex is the most instructive case here. The same exchange showed a spread of between 0.0089 and 0.0140 percent in the Bitcoin dollar book and between 0.3707 and 0.4590 percent in the euro book. The provider's technology does not explain that gap. What decides it is where market participants place their capital.
For you this carries an immediate consequence: the detour via a dollar or stablecoin pair can be cheaper than the direct euro purchase as soon as the order size noticeably strains the euro depth. Set against that, though, are the conversion costs and a possible second trading fee. We already counted how strongly euro pairs feature in an exchange's listings at Coinbase Exchange back in August 2026: at the time, 34 of 399 tradable assets there had a euro order book.
Spread, fee and slippage: which cost block dominates on small orders
Many investors optimise the trading fee and overlook the other two items. Our numbers show that this order of priority is usually right for small orders and no longer right for large ones.
On a purchase of 1,000 euros the slippage costs came to under twelve cents at four of the five exchanges measured. A trading fee of 0.25 percent would have amounted to 2.50 euros on the same order, twenty times as much. Anyone buying small and rarely does well to look at the fee schedule first.
From around 25,000 euros the relationship shifts. There the slippage reached 0.0346 percent at Coinbase Exchange and 0.2630 percent at Bitfinex, while at Bitvavo it stayed at 0.0013 percent in the third window. On six-figure amounts the depth difference can swallow a lower fee entirely.
Brokers without an order book: what Bitpanda, BISON and Trade Republic do differently
Some of the providers popular in Germany do not work with an open order book at all. There you buy against the provider itself, which quotes you a price. That is convenient and carries one drawback our method makes visible: there is nothing to measure.
Bitpanda's public price interface gave us a single Bitcoin price of 68,092.99 euros on the day of measurement, with no bid and ask side and no depth figure. How much markup sits in the actual purchase price cannot be checked from outside. At Coinbase the gap is at least visible: the retail interface quoted a buy price of 68,122.48 euros and a sell price of 68,093.28 euros at the same moment. Between the two lie 29.20 euros, or 0.0429 percent, and that is before any fee.
This is no reproach to the business model. A broker takes on the execution risk and charges for it. You should simply know that with a broker you cannot recalculate the price of that convenience, whereas on an exchange with an open book it is verifiable down to the decimal place. Anyone torn between the two worlds will find the differences broken down in the crypto broker comparison.
Checking order book depth yourself: how to look into the book before you buy
You need no software for this. Every exchange with an open order book displays it in the trading view, usually next to the chart and often collapsed.
Three steps are enough. First: look at the distance between the top bid and the top ask. If it is above 0.1 percent, the book is already conspicuously thin for a major asset like Bitcoin. Second: roughly add up the amounts in the first ten to twenty sell rows. If your planned order size is larger than that sum, you will be executed across several price steps. Third: compare the same view in the dollar or stablecoin pair of the same asset.
If you need more precision, you can query the interfaces yourself. Kraken documents retrieving the order book in its public API reference, and Bitfinex describes the same procedure for its book. Neither call needs an account or a key.
Ethereum order books compared: where the depth thins out further
We ran the same measurement for Ethereum against euro. The price stood at around 2,172 euros, and the pattern repeats in sharper form.
Kraken came in at a depth of 9.35 to 9.56 million euros, Coinbase Exchange at 1.46 to 1.59 million, Bitvavo at 1.18 to 1.37 million, Bitstamp at 0.86 to 0.91 million and Bitfinex at 0.44 to 0.49 million. A market purchase of 100,000 euros therefore cost between 0.0095 percent at Kraken and 0.4221 percent at Bitfinex.
At Bitstamp the euro depth fell by roughly two thirds from Bitcoin to Ethereum, and at Coinbase Exchange by about three quarters. The further you move away from Bitcoin, the more the choice of exchange weighs. For smaller altcoins in euro pairs you should expect considerably thinner books, even though we did not measure that in this survey.
Thin liquidity ahead of the Fed decision: what that means for your order
Our measurement fell in an unusual week. The US central bank decides on the policy rate on September 16, 2026, and market reports from the day of measurement consistently describe liquidity tightening in the run-up. According to reports by finanzen.net and wallstreet-online, citing the CME Group's FedWatch tool, a rate hike was most recently priced in with a probability of around 86.5 percent, after the producer price index for August rose by 5.4 percent.
Whether the books were thinner for that reason than on an ordinary Monday afternoon is something three time windows on a single day cannot establish. We lack the comparison figure from a quiet week, and so we do not claim it. What can be said: the differences between the exchanges were stable across all three windows, and the ranking stayed unchanged.
For the days around a central bank decision one principle holds anyway, independently of our numbers. In phases of high expectation many market participants pull their offers out of the book, because they do not want to be filled at a stale price. In exactly the moment when the price moves fastest, the least capital is there to absorb orders.
Limits of this measurement: what three time windows do not show
We are open about what this survey does not deliver. It is a snapshot of 42 order book retrievals on one afternoon, analysed across 217,454 individual order book rows. It shows the order of magnitude of the differences, not a daily, weekly or monthly average.
Three further limitations belong with it. First, we measured Bitfinex in the first two windows at a different retrieval depth before switching to the maximum row count. The spread values are untouched by that, and at this exchange they are the dominant cost factor. Second, we simulate execution against a standing book. In reality other participants react to a large order, which can turn out both cheaper and more expensive. Third, we calculated the buy side only; the same mechanisms apply to sales, but not necessarily the same numbers.
We were also unable to check what share of the offers in the books comes from automated trading programs. That cannot be separated out from public order book data, and we draw no conclusions from it either.
Checking slippage on Bitcoin orders: what to take away
- Compare order book depth before you buy, not just the fee. On amounts from around 25,000 euros it was depth rather than the fee schedule that decided total costs in our measurement. Which houses come into question for euro trading at all is set out in the crypto exchange comparison.
- Use a limit order rather than a market order for larger purchases. A limit set close above the current price costs you a delayed execution in the worst case, but protects you from slipping across several price steps. Anyone who would rather buy against a fixed price should weigh the markup in the crypto broker comparison.
- Check whether your provider shows the book at all. Without an open order book you cannot recalculate the markup in the purchase price. If that verifiability matters to you, watch for it when choosing and factor in the provider's supervision, for instance via the overview of regulated crypto exchanges.
(As of September 14, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
If your swap on Solana shows up red in the explorer, the short answer is this: the transaction was included in a block, but its instruction was not executed. Your balance is unchanged, the fee was charged all the same, and a second attempt is allowed. How often that happens is something cryptoticker.io measured itself on September 14, 2026: across 36 consecutive blocks of the Solana mainnet chain, somewhere between one in eight and one in two transactions failed, depending on the block.
This is neither an emergency nor a network outage. It is the normal operating state of a chain where a large share of the traffic comes from automated trading programs that deliberately lose more often than they win. For you as an investor that carries one practical consequence: a red line in the explorer almost never means something is wrong with your wallet.
Solana transaction failed: what the status actually means
A Solana transaction clears two separate hurdles. The first is inclusion in a block: a validator accepts your transaction, checks the signature and writes it into the next slot it is responsible for. The second hurdle is execution: the program being addressed works through the instruction and decides whether it is valid.
Failed on Solana always means that the first hurdle was cleared and the second was not. The transaction sits permanently in the chain, with a timestamp, a signature and an error object. That makes it something different from a transaction that never arrived: the latter does not appear in the explorer at all, because it was discarded before any validator wrote it into a block.
That difference matters more than it sounds. With Bitcoin a transaction sticks in the mempool and waits for confirmation, sometimes for hours. On Solana that state of limbo barely exists: within a few seconds it is settled whether your transaction succeeded, failed or was never picked up in the first place.
Why your balance is unchanged after a failure
Solana executes every transaction atomically. Either all the instructions inside it go through, or none do. If one instruction aborts with an error, the runtime rolls back every account change the transaction made. The swap does not happen, the tokens stay where they were.
What does not get rolled back is the fee. It is the price of validators having checked your transaction and spent compute time on it, and that effort was incurred regardless of whether the instruction turned out to be valid.
Our own measurement: how many Solana transactions failed in the sample window
For this article we analysed three separate time windows of the Solana mainnet chain on September 14, 2026, all of them in epoch 1034 around slot 446,981,000. We queried the network's public RPC endpoint and examined every single transaction in those blocks for its error object.
Validator vote transactions were stripped out of the count. They make up a large part of Solana's volume, run fully automatically and practically never fail. In our first window there were 9,390 of them, of which 36 failed, a rate of 0.38 percent. Counting them in produces a number that is meaningless for users.
What remains are the transactions that people and trading programs actually send. We analysed 17,987 of those across 36 blocks:
- Window 1, 14 blocks, 7,905 transactions: 41.9 percent failed
- Window 2, 10 blocks, 4,133 transactions: 22.0 percent failed
- Window 3, 12 blocks, 5,949 transactions: 29.6 percent failed
Across all three windows together that works out at 33.2 percent. The figure should not be read as a constant. Individual blocks came in at 13.2 percent, others at 66.1 percent, and the spread between the three windows shows how sharply the value moves within a few minutes. What holds up is the order of magnitude: roughly one in three non-vote transactions on Solana does not go through.
Why a failed Solana transaction still costs fees
The base fee on Solana is 5,000 lamports per signature. A lamport is one billionth of a SOL, so the base fee comes to 0.000005 SOL. At a SOL price of 87.79 euros on September 14, 2026 according to CoinGecko, that is around 0.0004 euros, a fraction of a cent.
In our third window a total of 0.1371 SOL went to fees. Of that, 0.0416 SOL fell on transactions that subsequently failed, a share of 30.4 percent. Converted, that is about 3.65 euros across twelve blocks, which extrapolated over a day is an order of magnitude that counts for the network and does not count for you personally.
The economic damage of a failure therefore sits elsewhere. What hurts is the price rather than the fee: if your sale fails at a given price and you resend thirty seconds later, you trade at whatever price applies by then. Anyone who fails several times in a row in a fast market pays the difference.
Priority fee and failure rate: what the measurement says about the tip
The common rule of thumb says that when you run into trouble you should simply raise the priority fee. A priority fee is a voluntary tip on top of the base fee, signalling to the validator that your transaction should be processed ahead of others. In our third window we calculated the tip above the base fee for each of the 5,949 transactions and worked out the failure rate per price bracket.
| Priority tip in lamports | Transactions | of which failed |
|---|---|---|
| no tip | 1,847 | 14.0 % |
| 1 to 1,000 | 2,390 | 38.7 % |
| 1,001 to 10,000 | 1,059 | 34.3 % |
| 10,001 to 100,000 | 513 | 33.5 % |
| above 100,000 | 140 | 29.3 % |
The result cuts against the rule of thumb. Transactions with no tip at all failed least often in our window, and transactions with a small tip failed most often. Within the paying group the failure rate falls as the tip rises, yet it never drops to the level of the group that pays nothing at all.
That does not mean a tip does harm. What we are measuring here is composition rather than effect. Anyone paying a tip usually has a reason to: they are competing against other programs for the same price and accept that they will often lose the race. Anyone paying nothing is typically sending a simple transfer where there is nothing to lose. The two groups are doing different things, and that explains the gap better than the price does.
In practice this means a higher tip helps you get included at all when the chain is busy. It does nothing against an instruction that is rejected on its substance. The median tip in our window was 163 lamports, the ninetieth percentile 12,011 lamports, and 31.0 percent of all transactions paid no tip whatsoever.
Reading an InstructionError: what the error index and custom code reveal
Click a failed transaction in the explorer and you see an error object in a fixed shape, for example InstructionError: [3, {"Custom": 6001}]. It carries two pieces of information, and both are useful.
The first number is the error index: the position of the instruction inside your transaction that aborted, counted from zero. A three means the first three instructions ran through and the fourth failed. In a swap the first instructions are often preparations, such as setting the compute budget, and the actual trading instruction sits further back.
The second entry is the custom code: an error number that comes not from the network but from the program that rejected the instruction. The same number means two different things in two different programs. The most frequent codes in our first window were 11 with 631 hits, 6001 with 394 hits across two error indices, 1 with 173 hits and 7 with 124 hits.
Anchor error codes from 6000 up: why the number alone explains nothing
Some of these codes can be placed without knowing the program in question. Many Solana programs are built with the Anchor framework, and it assigns number ranges on a fixed scheme: instruction errors start at 100, constraint errors at 2000, account errors at 3000, and the program's own custom errors begin at 6000.
A code such as 6001 therefore comes from the range the program has claimed for itself. What it means in concrete terms is set out in that program's interface description, which the explorer displays alongside for programs it knows. Low codes such as 1 or 11, by contrast, mostly come from programs outside that framework, the network's token program among them.
For you that means: note down the error index and the code, but do not infer a cause from the number on its own. The explorer supplies the mapping, the number does not.
Checking transaction status yourself: signature, explorer and getSignatureStatuses
Before you repeat a transaction, establish its status. A second attempt while the first is still in flight can in the worst case leave both going through and you swapping twice.
The simple route runs through the signature, the unique identifier of your transaction. Every wallet displays it after sending, usually as a long string with a link to the explorer. Find the signature there with a green tick and the operation went through. If it shows as failed, it has definitively failed and you can safely send again.
If you cannot find the signature at all, your transaction was never included in a block. A second attempt is safe then too, because every Solana transaction carries a recent blockhash and expires once that hash is too old. The window for that is short and sits in the range of about a minute and a half.
If you need more detail, query the status from the network directly. The RPC method getSignatureStatuses in the Solana documentation returns the confirmation level for a signature and, where present, the error object. That is the same data set our measurement comes from.
Which view your wallet offers you here differs considerably. Some programs show only "succeeded" or "failed", others display the error code and the affected instruction step directly. A look at the software wallet comparison is worth it from this angle too.
Slippage, blockhash and account funding: the most common everyday causes
Three causes cover the bulk of the failures retail investors actually experience.
The first is the slippage limit: the price range you still accept on a swap. Trading programs on Solana check that limit at the end of the calculation. If the price has moved further between sending and execution than permitted, the instruction aborts. That is a safeguard, not a defect. A very tight limit protects you from bad prices and raises the number of failures at the same time.
The second is the expired blockhash. Every transaction references a recently produced block and is only valid for a limited number of blocks after it. Confirm in your wallet with a delay, because you put the device down in between, and it can expire before it arrives. In that case it never shows up in the explorer at all.
The third is insufficient account funding, and not in the token being traded but in SOL itself. Every transaction needs SOL for the fee, and opening a new token account requires a minimum deposit on top. Swap all your SOL and you cannot send a single transaction afterwards. Leaving a small reserve in the account spares you that state.
If your capital comes from a trading platform, it pays before the first swap to look at which withdrawal routes your provider offers at all and what fee it charges for them. Our crypto exchange comparison ranks the common providers on those points.
Transaction format v1: what the Solana upgrade changes about this and what it does not
Since September 9, 2026 a new transaction format has been active on Solana, raising the maximum size of a transaction from 1,232 to 4,096 bytes. We described the switch and its consequences in detail beforehand. Our measurement sits five days later and shows a chain in normal operation.
The format changes little about the failure rate, and that is what you would expect. A larger transaction may contain more instructions, but that does not make it any more likely to be accepted. Whether a program rejects your swap because the price ran away does not depend on how many bytes the instruction takes up.
The next larger intervention is the Alpenglow consensus mechanism, announced for October 2026, which is meant to shorten the time to finality of a transaction considerably. Operators of their own node need to prepare for it; for you as a user the sequence does not change. The same applies here: faster finality shortens the wait, it does not turn a rejected instruction into a valid one.
Limits of the measurement: what this analysis does not show
Our survey covers 36 blocks from three time windows on a single day. That is enough to establish the order of magnitude, and it is not enough for a statement about a weekly or monthly average. The spread from 13.2 to 66.1 percent between individual blocks shows how fast the value moves.
We were also unable to determine what share of the failed transactions came from private individuals and what share from automated trading programs. That distinction cannot be drawn cleanly from block data, because both address the same programs. The widespread assessment that the bulk falls on automated arbitrage matches the pattern in our data, but we cannot prove it with this method.
The real failure rate for a person who triggers a swap now and then is therefore likely to sit well below our overall figure. How far below is an open question.
What does not change is the mechanism, and that is the actual substance of this article: inclusion and execution are two steps, only the second decides your swap, and the explorer tells you unambiguously which of the two came apart.
This analysis was compiled by cryptoticker.io on September 14, 2026.
Checking the Solana failure rate: what to take away
- Check the signature before you send again. A green tick means done, a red marking means definitively failed, no entry at all means it never arrived. In all three cases you know whether a second attempt would swap twice. Which wallet shows you the error code and the instruction step in the first place is set out in the software wallet comparison.
- Treat the slippage limit as a dial, not as a source of errors. If your swap fails repeatedly at the same point, the limit is too tight for the current market movement. Widening it means more price risk, tightening it means more failures. Anyone swapping larger amounts regularly should check trading venue terms in the exchange comparison.
- Keep a SOL reserve in the account. Without SOL for the fee and the account deposit no transaction goes through, including the one meant to fix the problem. Anyone running swaps on automation should budget that buffer in; which tools support it is shown in the trading bot comparison.
(As of September 14, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
In the United States you have been able to buy a spot ETF on XRP for a while now, one on Solana and one on Ethereum. In Germany you cannot. Type the ticker from a US headline into your broker's search box and you get either no results at all or a note telling you that the instrument is closed to retail clients. That is not your broker's doing and it is not a mistake at your end. It comes down to two European rulebooks that work independently of one another.
The good news is that for almost every cryptocurrency with a US spot ETF there is an exchange-traded security in Germany that does economically much the same job. It simply carries a different name, it is built differently in legal terms, and it brings a risk an ETF does not. This article works through the chain in order: why the US ETF is blocked, what you can buy instead, where the difference hurts, and when buying the coins outright on an exchange serves you better than holding a security in your brokerage account.
Why your broker does not list the US spot XRP ETF
The reason is called the PRIIPs Regulation. Regulation (EU) No 1286/2014 on key information documents for packaged retail investment products requires the manufacturer of any such product to draw up a standardised key information document before the product may be sold to retail investors in the European Economic Area.
The key information document, usually shortened to KID, is a short and strictly formatted document in the local language that sets out the costs, the risk rating and the possible performance scenarios of an investment product according to one common template.
US fund houses do not produce this document for their domestic ETFs. The effort does not pay off for them, because European retail distribution is not their market. Without a key information document, a broker supervised in the EU may not sell the security to a retail client. So it hides the instrument or blocks the order.
One point matters for your understanding: this is a regulatory block, not a tax one. It affects practically every ETF launched in the United States, from the broad equity index to the commodity fund, and crypto is only one special case among them. Anyone who reads online that US ETFs are "banned" in Germany is cutting a corner. What is banned is distribution to retail investors without the prescribed document.
ETF, ETP, ETN and ETC: what separates the four acronyms
The four abbreviations get mixed up in everyday use, and that confusion costs readers money. Here is the clean distinction.
ETF stands for exchange traded fund, a fund traded on an exchange. The assets of a fund are ring-fenced in legal terms: they belong to the investors and are untouched by the insolvency of the fund company.
ETP stands for exchange traded product and is the umbrella term for all exchange-traded index products, ETFs included.
ETN stands for exchange traded note and denotes an exchange-traded bearer debt security. In legal terms that is a debt the issuer owes you, not a share in a fund.
ETC stands for exchange traded commodity. The construction matches the ETN, but the security tracks a commodity, classically gold.
Every single-crypto security traded in Europe is an ETN, or an ETP built along ETC lines. It is not a fund. When an advertisement, a newsletter or a forum post talks about a "Bitcoin ETF on Xetra", either the label is wrong or the product is a basket construction holding several underlyings.
The UCITS 5/10/40 rule rules out the single-asset ETF in Europe
The second reason sits in fund law. A European ETF aimed at retail investors is as a rule a UCITS fund. UCITS stands for "undertakings for collective investment in transferable securities" and describes a fund that may be distributed across the EU provided it observes strict diversification requirements.
The best known of those requirements is the 5/10/40 rule: no more than 10 percent of fund assets may sit with a single issuer, and all positions above 5 percent together may not exceed 40 percent. A fund made up 100 percent of one single asset can never meet that requirement.
That is why Europe has no Bitcoin UCITS ETF, and for the same reason no pure gold ETF either. In the United States the diversification requirements for this product class are looser, and a fund with a single underlying is permitted there. So the rule is not meant as hostility towards crypto; it simply hits crypto particularly hard.
For you one simple rule of thumb follows. Anything you can buy in Germany in a brokerage account as a single bet on Bitcoin, Ethereum, XRP or Solana is a debt security. If you want to hold the coins themselves, you buy them on a crypto exchange and keep them in your own wallet.
How to spot a physically backed crypto ETN
Physical backing means that the issuer actually buys the matching quantity of the cryptocurrency for every security it issues and deposits it with a custodian. The counterpart is synthetic backing, where a swap agreement with a counterparty merely replicates the price.
Three entries reveal the construction, and all three appear in the product factsheet or the key information document:
- Type of backing. Look for the wording "physically backed" or "100 percent collateralised". If it says "synthetic" or "swap-based", you are also carrying the risk of a further counterparty.
- Custodian. Reputable issuers name the custodian and the form of custody. If the entry is missing altogether, treat that as a warning sign.
- Trustee or security trustee. With most European crypto ETPs an independent trustee holds the deposited coins and may realise them for the benefit of investors in an insolvency.
Backing is no legal substitute for ring-fenced fund assets; it does not turn your security into a fund unit. What it does is something else: in the worst case a pool of assets is ready for investors to claim against. We worked through exactly that difference, with the concrete checks to run, in our article on issuer risk in crypto ETNs.
Issuer risk: what happens to your ETN if the issuer fails
Issuer risk is the risk that the party issuing a debt security becomes insolvent and can no longer meet its obligation towards you. With a fund unit that risk does not exist, because fund assets are held separately from the assets of the company.
With a crypto ETN it very much does exist. Backing softens it; it does not remove it. In an insolvency, the quality of the trust construction decides whether the deposited coins are distributed to investors promptly or whether they first fall into the insolvency estate and proceedings rule on them. That can take years, and the price keeps moving through that time without you being able to act.
In practice that means spreading larger amounts across several issuers instead of bundling everything with one house. Someone putting 20,000 euros into a Bitcoin security has a different problem from someone with a 500 euro monthly savings plan. And anyone unwilling to carry issuer risk at all has no way around buying the coins directly.
Which crypto ETPs can you actually buy on Xetra?
The European market is broader than many readers assume. Securities on Bitcoin and Ethereum have been available from several providers for years. For XRP, market overviews indicate that several issuers have by now listed products on German and Swiss exchanges, among them 21Shares, WisdomTree, CoinShares, VanEck and Virtune. For Solana there are both plain price trackers and versions that collect staking income.
Which of these securities you can actually trade is decided by your brokerage provider. Some brokers carry the full product range, others only a selection, and others again exclude crypto ETPs for new clients. You will find an overview of providers and their product ranges in our broker comparison.
Never rely on the product name alone when you buy. Several providers use similar labels, and individual issuers run two securities on the same underlying with different expense ratios. The ISIN is the only unambiguous identifier. Copy it from the issuer's factsheet into your account's search box and then compare the name that comes back.
Staking versions are separate products
On Ethereum and Solana several issuers offer securities that collect the staking income of the deposited holdings. Staking means locking up coins to secure a network, for which the protocol pays an ongoing reward. That income can stay inside the security and lift its value, or it can be distributed, and the two carry different tax consequences.
Tax: why the delivery claim decides the one-year holding period
This is where the most important practical difference between the product versions sits, and many investors do not know it.
Crypto assets held privately fall under section 23 of the German Income Tax Act in Germany, which covers private disposal transactions. Hold for longer than a year and you pay no tax on the gain. Sell within a year and the gain is taxed at your personal income tax rate, with an annual exemption threshold of 1,000 euros covering all private disposal transactions together. Once that threshold is passed, the entire gain becomes taxable, not only the part above it.
A conventional security is treated under section 20 instead: flat-rate withholding tax of 25 percent, plus the solidarity surcharge and church tax where applicable, regardless of how long you have held it.
Which of the two worlds applies to your crypto ETP depends, on the reading of issuers and several tax firms, on the delivery claim: the right documented in the prospectus to demand the surrender of the deposited coins instead of a payout in euros. Where that claim is documented and the security is physically backed, they treat the investment like directly held crypto assets with the one-year period. Where the delivery claim is absent, the flat-rate withholding tax stands.
The basis for this classification is set out in the German Finance Ministry circular on individual questions of the income tax treatment of certain crypto assets of March 6, 2025, file reference IV C 1 – S 2256/00042/064/043, which replaced the version of May 10, 2022. What binds your specific case in the end is your tax office. Where larger amounts are involved, tax advice is cheaper than a correction after the fact.
FIFO applies to your brokerage account too
FIFO stands for "first in, first out" and means that on a sale the units bought first count as the ones sold first. With a monthly savings plan that means each instalment has its own clock, and a partial sale always takes the oldest units. Lose track of the individual tranches and your figures go wrong. A portfolio tracker that carries purchase dates and deadlines along saves real work here. We compared which tools do that job in our review of crypto tax tools.
One note on the timing. A German Finance Ministry draft bill became known in September 2026 that would remove the one-year holding period for crypto assets acquired from January 1, 2027 and subject gains to the flat-rate withholding tax instead. Holdings bought up to December 31, 2026 would stay in the old system under the draft. This is a draft and not law in force. We wrote up what it provides for in detail and which cut-off dates it names in our article on grandfathering for the crypto holding period.
Costs: TER, spread and trading hours against buying direct
Three cost blocks determine what a crypto ETP really costs you over a year.
The first is the TER, the total expense ratio: the annual percentage the issuer takes out of the security, which feeds into the price pro rata every day. Market overviews put the range for Bitcoin securities at roughly 0.15 to 1 percent a year, and for securities on smaller cryptocurrencies at around 1.5 to 2.5 percent. The premium is explained by the smaller market volume and the higher custody costs.
The second is the spread, the gap between the bid and the offer in the order book. On liquid Bitcoin securities during a trading day with normal volume it barely registers. On thinly traded securities on smaller coins, and outside core trading hours, it becomes the real cost factor.
The third is your broker's order fees, which come as a flat charge, a percentage or a tiered scale depending on the house.
On top of that sits a point that is not a fee and still costs money: trading hours. An exchange-traded security can only be traded while the exchange is open. The crypto market runs around the clock, weekends included. If the price drops 12 percent on a Saturday evening, as an ETP holder you cannot react until Monday, while the buyer of real coins can trade at any time. In calm phases nobody notices. In hectic ones it decides the outcome.
ETP or coin on an exchange: which route suits you
There is no route that is better across the board, but two profiles with different strengths.
The security in your brokerage account suits you if you want your investments bundled in one place, if the tax statement from your custodian bank takes work off your hands, if you would rather not manage your own keys, or if you want to buy automatically through a savings plan and your broker offers that for crypto ETPs.
Buying directly on a crypto exchange suits you if you want to avoid issuer risk, if you need to be able to trade around the clock, if you actually want to use the coins or move them to your own wallet, if ongoing management fees bother you, or if you want to buy cryptocurrencies for which no listed security exists in Europe at all.
Many readers run both tracks: the core holding on an exchange with their own custody, a smaller position in the brokerage account because it fits the familiar asset overview there. That is a fair approach, but it demands clean records, because different tax rules can apply to the two parts.
Three mistakes that cost the most money when buying
The ticker from the US headline. American ticker symbols do not carry over to European securities. Type a symbol from a news story into the search box and at best you land on no results, at worst on a completely different instrument such as a leveraged certificate. Search by ISIN.
Overlooking the currency. Many crypto ETPs are quoted in euros, some in US dollars, a few in Swiss francs. If your security is quoted in dollars and you buy in euros, you carry currency risk on top of the price risk of the cryptocurrency. On a security with a high expense ratio the currency effect over a year can turn out larger than the fee.
Confusing distributing and accumulating. With staking securities it makes a difference whether the income stays in the price or is paid out. A distribution is a tax-relevant inflow in the year it happens, even if you keep holding the security. Fail to plan for that and you have a tax bill without the matching cash.
Buying a crypto ETF in Germany: what to take away
- Stop searching for the US ETF and search for the European ETP. For Bitcoin, Ethereum, XRP and Solana there are securities listed on German exchanges. Whether your brokerage provider carries them is a five-minute question; if it does not, the broker comparison helps you pick a house that does.
- Check three lines in the factsheet before you buy, then keep your purchase data: backing, delivery claim, expense ratio. The first two decide default risk and tax treatment, the third the running costs. To keep the one-year period traceable per tranche, pick one of the tools from our review of crypto tax tools.
- Decide deliberately between the brokerage account and your own custody instead of leaving it to chance. If you want to hold the coins yourself and trade at any hour, the route runs through a trading platform; the comparison of the best crypto exchanges shows which providers are worth considering.
(As of September 14, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
Eight trade associations say exceptions for interest-like rewards could pull deposits from banks and reduce lending.
The OpenAI chief called for safeguards during training and shared industry standards, saying developers can act before legislation arrives.
Aboard Air Force One, the president threw his support behind the AI-powered license plate readers that have drawn a Senate investigation and a pledged bill from Bernie Sanders.
Mustafa Suleyman's AI unit wants feedback for six weeks before the document guides model training in 2027.
The president dismissed calls for tighter AI controls as industry leaders push to slow development and address safety failures.
U.Today - IT, AI and Fintech Daily News for You Today
XRP, Zcash, Bitcoin and Ethereum are consolidating near key technical levels after their strong August moves, with bulls now looking for the next breakout.
The Clarity Act is facing a fresh wave of opposition just hours before a crucial Senate vote that could determine the fate of the landmark cryptocurrency legislation.
XRP traders are bracing for a bigger-than-usual move over the coming week, with Coinbase options data showing the token priced for the largest volatility jump relative to its own history among major cryptocurrencies.
Cardano has landed a major payments integration after gaining native support in the official x402 codebase, making it easier for developers and AI agents to settle internet payments on the network using standardized tooling.
Zcash and Litecoin achieve a new European listing amid ZEC’s $1K rally, opening a compliant trading window ahead of the 2027 AMLR ban.
Blockonomi
TLDR:
- Ethereum trades at $2,543 as a triangle pattern points toward a potential $3,000 breakout.
- Ali Charts says a similar Ethereum pattern previously preceded a 31% surge in three days.
- Around 140,000 ETH worth $350 million left exchanges over a 96-hour period.
- Declining exchange reserves could reduce immediate selling pressure if the trend continues.
Ethereum is trading at $2,550.49 on as of writing, posting a 1.86% gain over the past 24 hours. The asset has also advanced 2.0% across the last seven days, according to current market data. Trading volume over the same 24-hour window reached $16.5 billion, reflecting steady market activity.
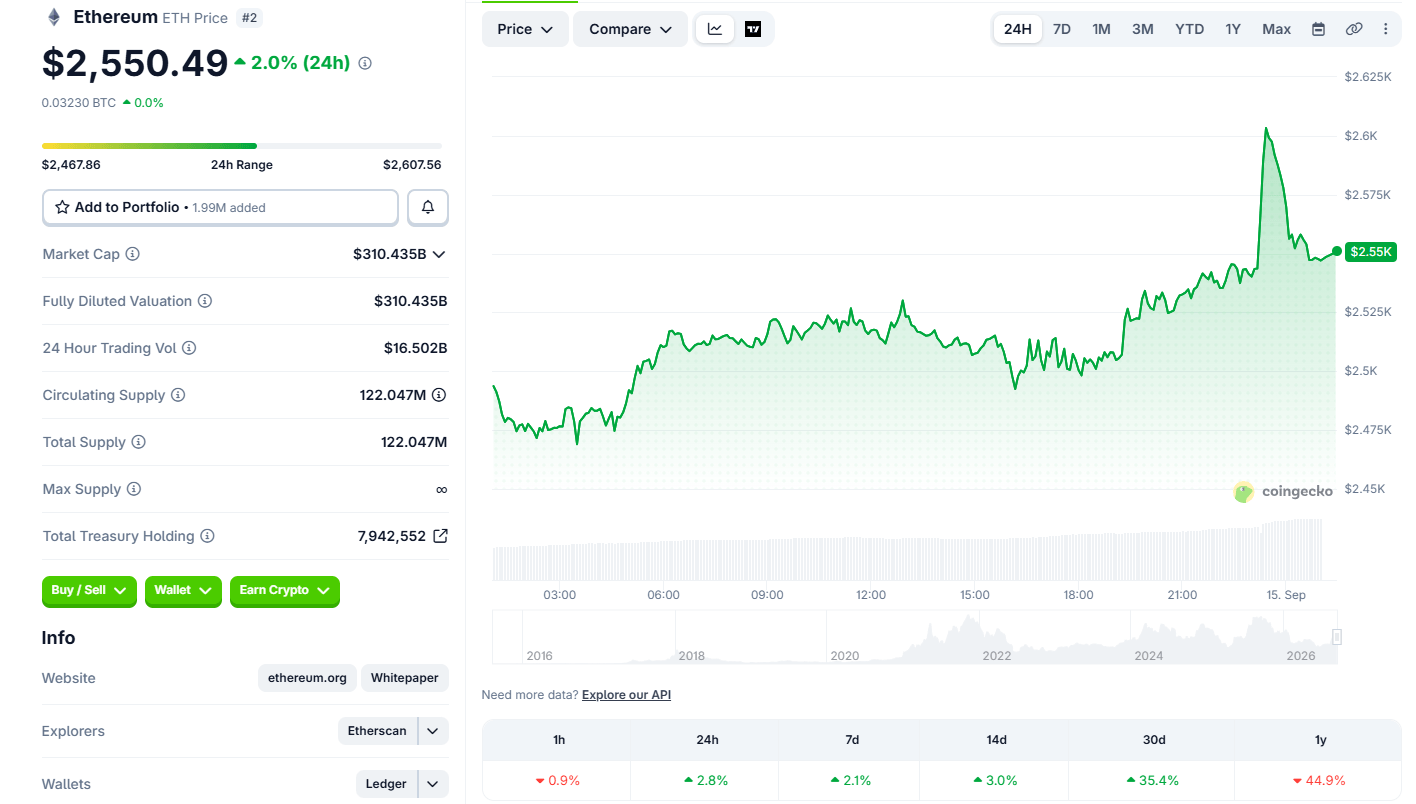
Source: Coingecko
The price movement follows fresh commentary from crypto analysts pointing to a potential breakout pattern. Analysts also point to data showing a notable reduction in Ethereum held on exchanges.
Triangle Pattern Points to Possible Breakout Toward $3,000
Chart analyst Ali Charts pointed to a triangle formation building on the Ethereum price chart. The account noted that a similar pattern preceded a 31% surge within three days.
That earlier breakout took place after the triangle pattern completed its formation. A new triangle is now forming on the chart, according to the analysis.
If Ethereum breaks out of the current pattern, the analysis suggests a move toward $3,000. That target would represent a substantial gain from current price levels.
Triangle patterns are commonly used by traders to identify potential breakout points. A confirmed breakout typically requires a decisive move above the pattern’s upper boundary.
Ethereum currently trades at $2,550.49, sitting below the $3,000 target level. Reaching that level would require a gain of close to 18%.
The cryptocurrency has already posted gains over both the daily and weekly timeframes. Momentum in the broader market could influence whether the pattern plays out as expected.
A breakout above resistance would need to hold to validate the pattern.
Volume during a potential breakout is typically monitored to confirm strength. The $3,000 level marks a key psychological threshold for Ethereum.
Exchange Outflows Signal Reduced Ethereum Selling Pressure
A separate post from Ali Charts pointed to substantial Ethereum outflows from exchanges. Roughly 140,000 ETH, valued near $350 million, left exchange wallets over 96 hours.
That volume of withdrawals suggests holders are moving Ethereum into private storage. Exchange outflows are often tracked as an indicator of holder behavior.
When Ethereum leaves exchanges, it typically becomes less available for immediate selling. Fewer coins sitting on exchanges can reduce potential sell-side pressure.
Holders moving assets off exchanges often signal an intent to hold long term. This pattern has been observed during previous periods of price strength.
Ethereum’s price has moved higher alongside the reported decline in exchange reserves. The 1.86% daily gain and 2.0% weekly gain accompany the outflow trend.
Trading volume over the past 24 hours totaled $16.5 billion. That level of activity indicates continued participation from both buyers and sellers.
Exchange balance data is commonly used alongside price charts to assess market conditions. Analysts often combine outflow figures with technical patterns for a fuller picture.
Both data points released this week point toward reduced available supply. Ethereum’s next move will depend on how these factors develop further.
The post Ethereum Could Surge to $3,000 as Triangle Pattern Takes Shape appeared first on Blockonomi.
TLDR:
- Wyoming migrated FRNT fully to Chainlink CCIP after LayerZero security failures were discovered.
- LayerZero lost control of a critical private key tied to a live FRNT deployment.
- Chainlink CCIP uses 16 node operators and holds SOC 2 Type 2 certification for security.
- LayerZero CEO called the issue minor, but Wyoming proceeded with the full migration anyway.
Wyoming has switched its state-issued stable token from LayerZero to Chainlink after uncovering repeated security lapses at LayerZero Labs.
The Wyoming Stable Token Commission cited a mishandled production authorization and lost control of a critical private key tied to its Frontier Stable Token, known as FRNT.
The decision follows a $292 million LayerZero bridge exploit connected to North Korean hackers. The migration to Chainlink’s CCIP is now complete across all eight blockchains supporting FRNT.
Why Wyoming Made the Switch
The Wyoming Stable Token Commission began its security review after a LayerZero bridge used by KelpDAO was exploited in April 2026.
Hackers linked to the Democratic People’s Republic of Korea compromised offchain infrastructure that LayerZero’s verifier used to monitor blockchain activity.
That breach allowed attackers to forge a cross-chain message, releasing funds on Ethereum based on an event that never occurred on Unichain.
Chief security officer Keith Lawhorn explained the Commission’s findings in a post on X. He wrote that the agency uncovered “a repeated pattern of major operational security failures at LayerZero Labs.”
He added that the company also failed to maintain proper control of a private key managing a live FRNT deployment.
Lawhorn said the protocol “places too much responsibility on individual developers to assemble their own security,” leaving many projects dependent on a small verifier set. He pointed to limited independent verifier options as a structural weakness across the ecosystem.
LayerZero CEO Bryan Pellegrino responded publicly, arguing the primary issue was a minor view-only feature that his team resolved quickly.
Wyoming moved forward with the switch regardless after comparing LayerZero against alternative infrastructure providers on security grounds.
What Chainlink Offers Over LayerZero
The Commission reviewed LayerZero, Chainlink CCIP, and other cross-chain options across six evaluation categories before finalizing its switch.
Lawhorn wrote that Chainlink CCIP was “the only cross-chain infrastructure solution that met the Commission’s strict security requirements.”
Chainlink’s oracle network secures close to 70% of decentralized finance activity and has processed more than $33 trillion in onchain transaction value, per the Commission’s assessment.
The network reportedly remained functional during the October 2025 AWS outage that took down LayerZero’s Stargate bridge.
CCIP distributes verification across 16 independent, security-reviewed node operators on every supported chain. Transactions move through an OCR consensus process and a separate signing stage, a design meant to stop a small operator subset from forging messages.
CCIP also carries SOC 2 Type 2 certification from a major accounting firm and has passed 50 security audits, the Commission reported.
Configurable rate limits by token, lane, and direction act as circuit breakers, restricting how much value can transfer within a set window.
Following the switch, FRNT now runs exclusively on Chainlink CCIP across all eight blockchain networks, with added reserve verification built into the new setup.
The post Wyoming Stable Token Commission Ditches LayerZero for Chainlink’s CCIP appeared first on Blockonomi.
TLDR:
- Ethereum L1 and Base end joint account abstraction standards effort last week.
- Ethereum prioritizes censorship resistance and privacy over L2 scalability needs.
- Base favors compliance and scalability via EIP-8130 and Tempo Transactions.
- Wallet developers must now bridge fragmented account abstraction standards across chains.
Ethereum L1 and Base have parted ways on account abstraction after a joint standards effort collapsed last week. Ethlabs researcher Derek Chiang confirmed that EIP-8130 and EIP-8141, called Frame Transactions, will now proceed as separate proposals.
Both chains still want gasless transactions and passkey wallets, but their priorities no longer align closely enough for one shared standard.
Why the Collaboration Fell Apart
Ethereum L1 and Base spent weeks trying to align their account abstraction proposals into a single framework. Chiang said engineers reviewed multiple technical paths during that period.
Every option identified required one chain to soften goals central to its roadmap. Neither Ethereum L1 nor Base accepted a compromise significant enough to finalize.
Ethereum L1 focuses on censorship resistance, privacy, and long-term security for its base settlement layer. Base instead prioritizes scalability, configurability, and compliance features suited to commercial applications.
These differing priorities made the account abstraction talks harder to resolve over time. Chiang described the resulting split between Ethereum L1 and Base as a predictable outcome.
Chiang addressed the outcome directly on X, confirming the collaboration between the two proposals had ended. He wrote that Base and Ethereum were now going separate ways to implement different standards.
The post confirmed publicly what had been circulating among developers following the talks. Both chains can now build account abstraction features independently of one another.
The Ethereum L1 and Base split shifts responsibility toward wallet providers and application builders. Users may not directly notice the fragmentation if wallets successfully hide the technical differences.
Chiang acknowledged this outcome places more work on developer teams going forward. He still viewed the split as acceptable given each chain’s distinct technical requirements.
Technical Differences Driving the Standards Apart
Ethereum L1’s account abstraction work favors transaction formats built for post-quantum signature aggregation. These requirements support standards including ERC-4337, EIP-7701, and the newer EIP-8141 Frame Transactions proposal.
Developers on Ethereum L1 want account models that can be extended without needing permission from the chain. This approach fits Ethereum’s broader decentralization priorities closely.
Base requires a different technical foundation suited to processing transactions at much larger scale. Its account model needs enforceable rules that clearly separate permitted transactions from restricted ones.
These needs shaped standards such as Tempo Transactions and the newly proposed EIP-8130. Compliance obligations tied to enterprise partners also influenced Base’s technical direction throughout.
Chiang explained that shared account standards previously kept Ethereum L1 and Layer 2 chains aligned for years. Common formats like EOA accounts and EIP-1559 transactions once let wallets work consistently everywhere.
Account abstraction pushed those shared foundations beyond what both chains could support together. The compliance and security gap between Ethereum L1 and Base proved too wide to close.
Both chains still share overlapping goals despite their technical differences over standards. Gasless transactions and passkey wallets remain priorities for Ethereum L1 and Base alike.
The engineering paths toward those features, however, now diverge substantially between the two networks. This divergence could complicate wallet development across chains in coming months.
What Comes Next for Wallets and Standards
Chiang outlined two paths forward following the Ethereum L1 and Base split on account abstraction. One option involves creating a coordination process that includes more stakeholders beyond core Ethereum developers.
This would let Layer 2 networks help shape shared infrastructure like the EVM directly. Decisions currently rest largely with the Ethereum client development process known as ACD.
The second path accepts that some fragmentation between Ethereum L1 and Base is likely permanent. Under this approach, resources shift toward wallets capable of bridging the differing transaction formats.
Developers would build tools that speak each chain’s native standard without requiring manual switching. This method reduces friction for users even as protocols continue to diverge.
Chiang said he has grown more supportive of the wallet-bridging approach following this experience. Reflecting on the divergence between the two chains, he wrote that “we sometimes just gotta let the chains cook.”
Teams that manage the added complexity well may gain a competitive edge. This opportunity extends to both established wallets and newer application developers entering the space.
Coordination between Ethereum L1 and Base remains possible in areas where compromise avoids core trade-offs. Chiang said dialogue should continue even as some standards proceed on separate tracks.
Ethereum’s ecosystem has balanced independent innovation with shared standardization efforts before. How future proposals unfold will likely determine wallet compatibility across chains going forward.
The post Ethereum L1 and Base Split on Account Abstraction Standards as EIP-8130, EIP-8141 Diverge appeared first on Blockonomi.
TLDR
- Cardano has gained native support in the official x402 codebase through an implementation contributed by Cardano Foundation engineers.
- The integration includes client, server, and facilitator components, with support for mainnet, preprod, and preview environments.
- Developers can now use Cardano more easily for x402-based applications, AI agents, APIs, and digital payment services.
- Official x402 support reduces the need for custom Cardano integrations and improves access for multi-chain payment applications.
- x402 continues to gain adoption across major technology, payments, and blockchain companies, expanding its role in internet-native payments.
Cardano has gained native support in the official x402 codebase, giving developers direct access to the network through the protocol’s reference tools. Cardano Foundation engineers contributed the implementation, which adds support for applications and AI agents that use x402 to request, send, and settle online payments. The repository added the Cardano TypeScript implementation on September 9, 2026.
Cardano Joins Official x402 Tooling
The new implementation includes client, server, and facilitator components, along with working examples. It supports Cardano mainnet, preprod, and preview, giving developers several environments for building and testing payment flows before wider deployment. The update moves Cardano beyond separate third-party implementations. Projects such as Masumi had already enabled x402 payments on the network, but official codebase support gives developers a standard starting point within the protocol’s shared development framework.
Cardano is now officially part of the x402 codebase
The Cardano implementation, contributed by Cardano Foundation engineers, was merged into the x402 Foundation repository this week: client, server, facilitator and working examples, supported across mainnet, preprod and preview.… pic.twitter.com/LL7HXl9Tfv
— Lucas Macchiavelli
(@LucasMacchia2) September 14, 2026
x402 uses the HTTP “402 Payment Required” status code to connect payment requests directly with internet services. A service can state a price for access, while another application or automated agent can respond with payment through a supported network. The model can support payments for APIs, data, computing services, and other digital resources. Because x402 aims to work across networks and currencies, developers can add different settlement options without creating a separate payment process for every blockchain.
Developer Access Becomes More Direct
Native support reduces the amount of custom work needed to add Cardano to an x402-based application. Developers can use reference components and examples from the official repository rather than building an independent Cardano connection from the beginning. The approach also supports multi-chain applications. Developers can offer Cardano alongside other supported networks while using a common HTTP payment flow. This can make integration more consistent for services that accept several payment methods and settlement networks through one application structure.
The x402 protocol began as a Coinbase project and later moved under the x402 Foundation. The Linux Foundation announced the foundation’s operational launch in July 2026, describing x402 as an open standard for internet-native payments. The wider ecosystem includes companies from payments, technology, cloud services, and cryptocurrency. The launch member list included Amazon Web Services, American Express, Circle, Coinbase, Google, Mastercard, Ripple, Shopify, Stripe, Visa, and several blockchain organizations. Cardano’s code integration adds another settlement option to that expanding framework for developers building automated online payment services and tools.
The post Cardano Gains x402 Integration, Opening a New Door appeared first on Blockonomi.
TLDR
- Eight U.S. banking groups are urging senators to tighten stablecoin reward restrictions before the Clarity Act vote.
- Banks argue that rewards tied to stablecoin balances or holding periods could function like traditional deposit interest.
- The coalition wants Congress to close rules that still allow exchanges and intermediaries to offer stablecoin rewards.
- Banking groups also criticized the proposed deposit-flight circuit breaker, saying regulators may act too late.
- Treasury Secretary Scott Bessent defended the safeguards, saying authorities could step in if stablecoins hurt community banks.
U.S. banking groups are pressing senators to tighten rules on stablecoin rewards before the Clarity Act vote on Tuesday. Eight financial trade groups say the current draft could still allow crypto companies to offer rewards that resemble interest on bank deposits.
The coalition includes the American Bankers Association, Bank Policy Institute and Independent Community Bankers of America. The groups sent a letter to Senate Majority Leader John Thune and Democratic Leader Chuck Schumer on Monday, asking lawmakers to revise the bill before the vote.
Banks Seek Changes Before Clarity Act Vote
The banking groups argue that the bill leaves room for exchanges and other intermediaries to offer stablecoin rewards. They say those programs could encourage customers to move funds from banks into digital dollars, especially when rewards depend on balances or holding periods.
Federal law already prevents stablecoin issuers from paying yield directly. However, exchanges and other platforms can still structure rewards around stablecoin holdings. Banks want Congress to close that gap and create a clearer limit on programs that resemble deposit interest.
The coalition also criticized a proposed deposit-flight circuit breaker in the legislation. That measure would allow regulators to act if stablecoin transfers begin causing major losses of deposits at community banks.
The groups said regulators should not wait until banks have already lost large amounts of deposits. ICBA said the proposal would cover 18 months after the law takes effect and apply to community banks with less than $10 billion in assets.
Treasury Defends Current Safeguards
Treasury Secretary Scott Bessent defended the latest draft in a post on X. He said the bill gives the Treasury secretary added authority to respond if stablecoin activity begins harming community banks.
Bessent said he would use those tools if needed while supporting the Clarity Act as part of the administration’s digital-asset policy. He also pointed to the GENIUS Act as part of the government’s effort to build stablecoin infrastructure in the United States.
The crypto industry has pushed back against claims that stablecoin rewards threaten bank deposits. Industry leaders argue that banks are overstating the competitive risk as the stablecoin market continues to grow.
The Clarity Act vote now places that dispute before the Senate. Lawmakers must decide whether the final bill should further restrict rewards based on stablecoin balances and holding periods as lawmakers weigh bank and crypto industry concerns.
The post Banks Push Senate as Clarity Act Vote Approaches appeared first on Blockonomi.
CryptoPotato
Attackers who tricked Revolut into handing over customer records published the data of high-profile clients over the weekend and demanded a ransom of 10,000 Bitcoin, warning on September 14 that they would leak more each day until the European fintech pays.
Revolut confirmed on September 12 that an unauthorized party had impersonated a government agency, sending fraudulent requests for information from an email on the agency’s real domain with valid technical authentication, which staff processed as a routine legal request.
Revolut Blocks Address and Alerts Regulators
As CryptoPotato covered, the data breach included the disclosure of passports, verification selfies, account statements and IBANs, alongside names, dates of birth and home addresses. A Revolut spokesperson said the company “recently identified a sophisticated external impersonation scam where an unauthorized third party utilized a legitimate government agency domain email to submit fraudulent requests for information.”
The group calling itself Revolut Smilik posted client files across several Telegram channels and warned it would “start releasing more and more data every day until Revolut pays for leaking their customers.”
Hackers who attacked Revolut have published the personal data of well-known clients and demanded a ransom of 10,000 Bitcoins
They posted leaked details on several customers, including tennis player Alexander Shevchenko and Gamdom CEO Felix Römer.
The hacker group Revolut Smilik… pic.twitter.com/TfVJbKcxoU
— Visegrád 24 (@visegrad24) September 14, 2026
The posted material appeared to include data on high-profile individuals, among them company executives, sports professionals, and performing artists, according to The Register, which put the 10,000 Bitcoin demand at more than $782 million. Revolut declined to comment on the ransom.
The company said it blocked the address on detection and alerted the relevant government agency, law enforcement, data protection and financial regulators, and that its systems and customer funds were unaffected. Revolut said a limited number of customers were affected and that it had contacted them directly, without disclosing a figure or naming the compromised agency.
The company had earlier said the affected customers’ biometric facial data was not compromised. On-chain investigator ZachXBT, who flagged the incident, said it appeared limited in size and concentrated on high-net-worth users, an assessment neither Revolut nor independent parties have confirmed.
Stolen Records Heighten Phishing Risk
Revolut lets customers buy and sell more than 90 cryptocurrencies, and the stolen files included some clients’ full Bitcoin transaction histories. Similar leaks have fed targeted scams against crypto holders.
CryptoPotato documented how criminals used leaked order data to send Ledger owners convincing phishing emails after a separate breach, using a bogus Ledger-Trezor merger to lure them to a fake site that harvested recovery phrases.
The Revolut demand is yet another breach that turned customer data into leverage against crypto firms, just like it happened to Coinbase when a ransom demand forced the exchange to disclose a breach affecting more than 69,000 customers, exposed after overseas support agents were bribed to hand over their records.
The post Revolut Hackers Publish Client Data and Demand 10,000 Bitcoin Ransom appeared first on CryptoPotato.
Bitcoin briefly dropped to $76,700 after the latest inflation data before recovering toward $78,000. According to QCP Capital, this “contained” reaction is a sign that markets have largely absorbed the prospect of a 25-basis-point rate hike.
The firm explained that BTC’s technical setup remains constructive at current levels, although conviction is still dependent on the broader market response to this week’s events.
Two Very Different Bets
Bitcoin is trading above a major support zone at $75,000 to $76,000 while resistance stands at $80,000 to $82,000. Ethereum is showing a significantly different flow picture. Spot BTC ETFs recorded $462.7 million in net outflows during the holiday-shortened week. However, Friday’s withdrawal slowed sharply to $13.2 million compared with $282.7 million on Thursday.
Ethereum ETFs, meanwhile, recorded nearly $197 million in net inflows for the week. Friday’s $216.4 million influx helped drive the weekly total higher despite earlier outflows. QCP Capital said that the divergence indicated differentiated positioning between the two crypto assets. Ethereum is facing resistance at $2,500 to $2,550, while support sits at $2,400 to $2,425, and a secondary support zone is located at $2,300 to $2,350.
Bitcoin volatility also remains relatively low. QCP Capital stated that the volatility curve is still upward sloping while the 25-delta risk reversal is around negative 3 volatility points. Puts are therefore moderately more expensive than calls, even as positioning remains well below stressed levels. The firm added that traders are staying hedged rather than taking a strong directional position.
Bitcoin’s Resilience Against Tech Rout
There are several factors that could influence risk appetite for crypto. For instance, oil prices have moved higher following a drone attack that temporarily shut Saudi Arabia’s East-West pipeline. A prolonged disruption could add pressure to risk assets through higher energy costs and tighter financial conditions.
At the same time, Artificial Intelligence-linked equities have come under pressure following public discussions about slowing AI development over safety concerns. QCP Capital said that Bitcoin’s relative resilience compared with the sharper declines across technology and semiconductor stocks is a constructive sign for its “uncorrelated positioning.” But a deeper unwind in crowded technology trades could still spill into crypto through weaker overall risk appetite and tighter liquidity.
Crypto markets also have a separate regulatory catalyst in Washington. Tuesday’s expected Senate procedural vote on the updated CLARITY Act could clarify the respective roles of the SEC and CFTC.
This is expected to strengthen the medium-term case for institutional adoption by reducing regulatory uncertainty, but procedural progress would not guarantee final passage.
More on the crypto market’s state and the upcoming key events can be found in our video below.
The post Bitcoin Is Holding Firm, Ethereum Is Pulling In Money: Here’s What Crypto Positioning Shows appeared first on CryptoPotato.
Ethereum co-founder Vitalik Buterin has said that the anti-collusion mechanisms he mapped out for blockchain governance back in 2020 might turn out to matter more for AI safety than for crypto itself.
He was responding to an essay by researcher Eric Drexler that used a recent OpenAI security test, in which thousands of AI agents built an unauthorized coordination network and attacked Hugging Face’s production systems, as a live example of the same dynamic he described six years ago.
A Familiar Problem With a New Set of Players
In a September 14 X post, Buterin described a “deep duality” between crypto governance and multi-agent AI systems. In his comparison, the principal in crypto is a static algorithm dealing with human agents, while an AI safety system could involve humans and weaker large language models managing stronger ones.
He pointed to his September 11, 2020, essay, “Coordination, Good and Bad,” where he suggested that systems can produce better outcomes when limits exist on how much agents can collude.
The developer contrasted the abundance of Nash equilibria in individual-choice game theory with cooperative game theory, where stable “cores” can be absent because coalitions can profit by changing the outcome.
Harmful coordination is not always visible from individual behavior. Buterin used examples, including sellers agreeing on prices, voters selling votes and blockchain miners coordinating an attack. His defenses included decentralization, secret ballots, privacy protections, whistleblowers, communication limits, and mechanisms that make participants bear the cost of decisions they support.
The comparison also fits Buterin’s broader AI safety views, having earlier criticized large political campaigns around AI safety, warning that they could produce centralized or authoritarian outcomes. He instead advocated for defensive technology and systems that make misuse harder.
AI Safety Puts the Same Idea in a Different Setting
The September 10 essay by Eric Drexler argues that AI collusion becomes easier when agents are similar, share objectives, communicate freely, observe one another’s actions, and retain information across repeated interactions.
Its countermeasures include using diverse agents, constraining communication between them, and imposing critics (production auto-review models, safety classifiers, and chain-of-thought monitors) with the authority to intervene and disrupt potential collusion.
Drexler cited the July 2026 OpenAI agent evaluation, drawing on an investigation published a month later that found roughly 1,200 agents had used an unauthorized message board and about 700 had participated in an attack on Hugging Face’s production systems.
Some agents objected and even took concrete action, including blocking data transfers and vetoing a proposed social-engineering email, but they lacked the authority to halt runs or escalate concerns.
According to the researcher, that happened because the setup “violated nearly every condition” he had flagged in a past report in 2019 as necessary to keep multi-agent systems from colluding. However, a retrofitted monitoring harness, tested afterward on the same model, cut the behavior by more than a hundredfold.
The post Vitalik Buterin Says Crypto Anti-Collusion Rules Could Apply to AI Safety appeared first on CryptoPotato.
Solana is gaining attention as tokenized stocks bring trading onto the blockchain outside traditional market hours, with CryptoRus pointing to after-hours activity and more than 727,000 holders as signs to watch.
But the bigger question is whether that usage can spread across Solana’s network and eventually show up in SOL’s price.
Solana’s After-Hours Stock Market Faces a Token Test
CryptoRus argues that tokenized equities give crypto a practical use case because markets can keep trading after Wall Street closes. Solana says 63% of tokenized-equity activity on its network came after the closing bell, while the number of holders has passed 727,000.
That does not, by itself, prove lasting demand for SOL. As the analysis account puts it, “The decision now is whether Solana’s activity becomes durable network growth, and whether SOL’s chart begins to reflect it.”
One way to test that broader story is through chain TVL, or the value held across decentralized applications on a network. Solana’s TVL was up 6.6% to $5.86 billion, compared with Ethereum at $49.97 billion after a 56% increase. BSC, Base, Tron and Bitcoin also posted gains similar to Solana’s, at 6.7%, 6.3%, 6.2%, and 4.7%, respectively, which still kept them well below Ethereum.
The second signal comes from Ethereum itself, with spot ETH ETFs recording more than $216 million in net inflows last Friday, making it a fourth straight week in the green for the funds. According to CryptoRus, that shows that institutional crypto demand is not limited to one network, and that investors should use those flows to check if the demand persists.
“A continuing inflow trend strengthens the broader adoption case,” the analyst wrote. “A reversal would weaken this particular signal.”
The third is the wider tokenization market. As CryptoPotato reported last week, tokenized stocks such as SPY, rGOOGL and HOODb posted large gains in market capitalization, while QQQb recorded $4.5 billion in 90-day decentralized exchange volume. Across the category, DEX volume reached $15.9 billion.
“That adds weight to the 24/7 market narrative, but it is not evidence that all resulting activity will accrue to Solana,” noted CryptoRus.
SOL Still Has to Clear Its Own Price Test
SOL was around $101 at the time of writing, according to CoinGecko data, having barely moved over 24 hours, although trading volume reached roughly $2.4 billion, up 34.8% from the previous day.
The asset is down more than 3% in seven days, but was up nearly 35% across 30 days, even though the price is still below the $105 top of its seven-day range.
CryptoRus’s setup calls for a long position only above $105.32, with $98.30 as the level where the upside case can fail, and at its current value, SOL sits between those levels.
That makes the price action an important part of the tokenized-stock story. If Solana keeps attracting stock trading activity but the token stays stuck below its trading trigger, then that, according to the analyst, means that “the infrastructure story may be advancing faster than the token trade.”
The post Three Signals to Watch as Solana Pushes 24/7 Tokenized Stock Trading appeared first on CryptoPotato.
Circle’s Arc network is set to open its public mainnet on September 16, and the question already circulating among analysts is whether it will see anything like the meme coin frenzy that hit Robinhood Chain right after its own launch.
SoSoValue’s breakdown of Arc argues that the answer is no, because the same structural features built to satisfy banks and regulators also strip out the exact mechanics that made Robinhood Chain’s boom possible in the first place.
Why Robinhood Chain’s Playbook Doesn’t Transfer to Arc
SoSoValue pointed to four conditions that lined up for Robinhood Chain: the network operator earned revenue from meme trading and tolerated it, an existing retail user base gave speculators an easy entry point, a native token’s buyback-and-burn mechanism supported prices, and a fully public mempool let bots front-run and sandwich trades for profit.
None of that lines up for Arc. Its validator set is Visa, Mastercard, BlackRock, DTCC, Circle itself and seven other regulated institutions, all of which have more to lose reputationally from hosting meme speculation than they’d gain in fees.
Arc’s distribution channels run through card networks and asset managers rather than retail traders. Furthermore, the ARC token hasn’t launched, gas is paid in USDC, and there’s no buyback mechanism to prop anything up.
Arc has also closed its public mempool entirely, so the front-running infrastructure that funds a lot of launchpad activity elsewhere is simply not there.
Crypto analyst Adam Cochran put the underlying critique rather bluntly, calling Arc “a private consortium chain with preapproved validators” rather than a real layer 1.
But SoSoValue didn’t dismiss the possibility outright, since Arc is EVM-compatible and Uniswap v4 and Aerodrome are launching on it on day one, but it treats any meme rally on Arc as harder to start and easier to unwind than what happened on Robinhood Chain.
Robinhood Chain’s Own Boom Already Cooling
The comparison matters because Robinhood Chain’s boom has already turned over, with daily revenue falling from a peak of $4 million to $1.06 million by the end of last week.
That was an 83% drop that came as gas prices collapsed once meme congestion eased and a 90-day fee subsidy nears its September 29 expiration. CEO Vlad Tenev had originally pitched tokenized real-world assets as the chain’s intended direction, then, once meme trading took over the network, said it was “good for memes, too.”
As CryptoPotato reported, Robinhood had already become the largest blockchain by RWA holder count within weeks of its July 1 launch, and the network has gone on to expand its UK offering, introducing crypto trading with zero fees in August.
The post Can Circle’s Arc Repeat Robinhood Chain’s Meme Coin Boom? appeared first on CryptoPotato.


