Cryptocurrency Posts
Crypto Briefing
The merger could reshape media landscapes, influencing content diversity, market competition, and the future of media conglomerates globally.
The post Paramount settles lawsuits, clears path for $110B Warner Bros. acquisition appeared first on Crypto Briefing.
OpenAI's advisory group initiative highlights the need for rigorous AI research standards and collaboration to maintain trust in scientific advancements.
The post OpenAI forms independent advisory group for AI and mathematics after backlash from hundreds of mathematicians appeared first on Crypto Briefing.
AMD's market surge underscores the growing importance of AI-driven data-center solutions, intensifying competition in the semiconductor industry.
The post Advanced Micro Devices shares surge, poised to hit $1T market value appeared first on Crypto Briefing.
Benchmark initiates Securitize coverage with a Buy rating and $16 target, citing its 70% US tokenization market share and BlackRock BUIDL
The post Securitize stock surges as Benchmark initiates coverage with buy rating and $16 target appeared first on Crypto Briefing.
The widening fraud probe into Radiant World could reshape trade finance norms, impacting creditor trust and regulatory scrutiny globally.
The post Radiant World discloses $870M exposure to six lenders as commodity fraud probe widens appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Russian Crypto Industry Could Be Operating Legally by Year-End: Central Bank
Russia’s crypto industry may have all it needs to start legally functioning by year-end, according to reports.
The deputy governor of the country’s central bank, Vladimir Chistyukhin, said that regulations were moving ahead as scheduled, Interfax reported on Monday.
Russia this year has pressed ahead with crypto legislation. President Vladimir Putin in August signed a law to set in stone the regulation of digital currencies and digital rights in the country — although using bitcoin for payments is still banned.
JUST IN:
— Bitcoin Magazine (@BitcoinMagazine) September 21, 2026The Russian Bitcoin and crypto industry may begin functioning within a legal framework before the end of this year, Central Bank Deputy Governor says. pic.twitter.com/Kp1ICUgDrg
“Right now we are talking about creating subordinate regulation; it is very large and significant,” Chistyukhin was quoted saying, adding that the “fine-tuning” of internal rules could be carried out before the end of 2026.
Russia’s central bank has approved Bitcoin trading for the public on the country’s crypto exchanges. Law currency states that unqualified investors can buy 300,000 rubles ($3,582) worth of bitcoin and other assets through one intermediary; qualified investors have no limits.
Sberbank, the biggest bank in Russia, plans to debut a Bitcoin and crypto wallet as well as digital asset custody by December. The bank in August said it expected trading volume with its new crypto rollout to hit 4 trillion rubles ($47 bln) in the first year.
Using digital assets as a means of payment or legal tender within Russia has been prohibited in Russia since 2022.
Despite Putin appearing to praise Bitcoin in the past, its use as a medium of exchange and currency has been banned for years.
Russian lawmakers have made an exception for international payments — but most likely as a way to dodge Western sanctions.
The U.S. and European governments cut Russia off from the SWIFT payments system after it invaded Ukraine in 2022 and Russian companies have been using Bitcoin to skirt around the penalties, according to the country’s finance minister.
This post Russian Crypto Industry Could Be Operating Legally by Year-End: Central Bank first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Bitcoin Price Shrugs Off Clarity Act Fail, Blasts Past $86,000
Long-awaited crypto legislation failed last week — but Bitcoin buyers don’t seem to care.
The price of the leading cryptocurrency shot up Monday by nearly 7% over a 24-hour period, six days after lawmakers blocked the Clarity Act.
Digital asset industry bigwigs have been calling for clear rules to be put in place to regulate the fast-moving space. But the key legislation aiming to do so in the form of the crypto market structure bill didn’t progress last week after Democrats mostly disagreed with the ethics side of the bill.
JUST IN: Bitcoin surges to $86,030
— Bitcoin Magazine (@BitcoinMagazine) September 21, 2026pic.twitter.com/3Z0RvIVvJ3
Bitcoin’s price has shrugged off the bill’s collapse, and recently stood at $86,225 after touching as high as $86,247 Monday morning in New York.
Over a 30-day period, the coin is up 10%. Bitcoin started a phenomenal run in August — its best in years — after the U.S. Treasury announced it would at least double the size of its liquidity-support buyback operations.
The asset’s price further benefited after U.S. President Donald Trump the same week hosted a meeting at the White House with crypto industry leaders and urged lawmakers to get what he called the “powerful” Clarity Act over the line.
Both Republicans and Democrats blocked the bill but Democrats had mostly been accused of trying to deliberately stall it by pro-crypto lawmakers for months.
The central sticking point for Democratic lawmakers was the conflict of interest posed by the Trump family’s crypto holdings. Beginning in the run-up to his return to office, the president and his sons launched a series of digital asset ventures, and Trump’s own financial disclosure reported roughly $1.4 billion in crypto-related income.
The White House says his assets sit in a trust managed by his children and that no conflict exists.
Democratic Senator Elizabeth Warren, of the crypto industry’s loudest critics, told congress ahead of the vote that the bill “posed a massive risk to families.”
Though despite the bill not advancing, the Securities and Exchange Commission and Commodity Futures Trading Commission are pushing ahead with rulemaking.
Bitcoin exchange-traded funds in the U.S. experienced positive net flows last week after having started the week with investors cashing out.
On Thursday and Friday, investors bought nearly $593 million in shares in the products managed by BlackRock, Fidelity, and Grayscale, according to Farside Investors data.
The Federal Reserve also last week raised interest rates — as expected — but the price of bitcoin hasn’t been affected by the central bank’s decision. Bitcoin has performed well in the past in a low interest rate environment.
This post Bitcoin Price Shrugs Off Clarity Act Fail, Blasts Past $86,000 first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
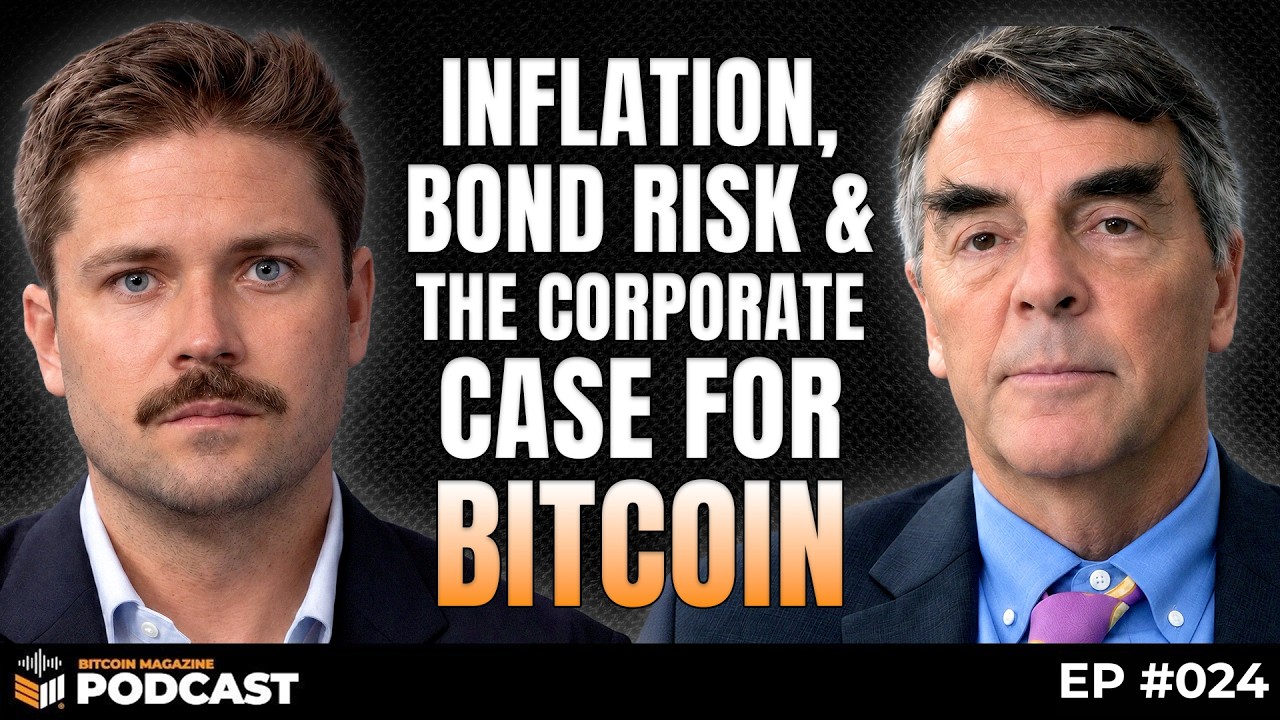
Billionaire Investor Tim Draper: “Irresponsible” for Apple & Meta NOT to Hold BTC
Government spending hasn’t slowed, and Tim Draper says that leaves only two real outcomes: hyperinflation or interest rates high enough to break banks. In this Bitcoin Magazine Podcast conversation with host Spencer Nichols, the Draper Associates founder makes the case that every business should hold at least four weeks of operating expenses in Bitcoin, every individual about six months, and every government a Bitcoin hedge. He explains why he considers boards that hold zero Bitcoin to be exposed — legally and financially — when a bank holding their cash goes under. Draper also maps his $250,000 Bitcoin price target to the next halving and the supply shock that follows.
 Host: Spencer Nichols — Bitcoin Magazine Tim Draper — Draper Associates
Chapters:
00:00 — Why Apple and Facebook Should Hold Bitcoin on the Balance Sheet
01:56 — Decentralization and the Speed of Innovation
04:06 — Is AI a Centralizing or Decentralizing Force?
06:31 — AI Versus Big Law, Big Banks, and the Bureaucracy
09:05 — Government Spending, Hyperinflation, and Bitcoin as a Safe Harbor
11:21 — The Confederate Million Dollar Bill and Three Paths for the Dollar
13:58 — Open Borders, Pandemic Fear, and the Marketplace of Governments
16:56 — Governance as a Service and Governments That Compete for You
20:00 — Voting on Phones, Estonia, and Bitcoin’s Road to Retail
23:28 — The $250K Target, Two More Halvings, and an All-Bitcoin Fund
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Billionaire Investor Tim Draper: “Irresponsible” for Apple & Meta NOT to Hold BTC first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Strategy Founder Michael Saylor Argues Clarity Act Collapse Is a Win
Bitcoin treasury founder and pioneer Michael Saylor has said that the blockage of the Clarity Act is actually good for the digital asset space.
Writing on X on Saturday, the Strategy founder and chair said that legislation can make restrictions permanent just as easily as rights.
Lawmakers this week blocked long-awaited crypto legislation, the Clarity Act, which aims to formally divide oversight between regulators. The digital asset industry had long called for such rules to be in place.
Despite the hurdle, regulators like the Securities and Exchange Commission and the Commodity Futures Trading Commission are pushing ahead with rulemaking.
“We have an administration willing to modernize financial markets. We should use the next two years to put better financial products into people’s hands,” Saylor wrote.
He continued: “Let the Digital Assets industry innovate rapidly in a free market and create the greatest possible value for the U.S. and global economy.”
Saylor, whose company Strategy started buying bitcoin in 2020, argued that watchdogs going ahead to make rules anyway — like the SEC’s conditional relief for onchain trading of certain tokenized stocks and the CFTC Chairman stated willingness to act without the bill — would give crypto companies the regulation they need.
Saylor went on to argue that proposals in the act — such as limits on paying customers for holding payment stablecoins — wouldn’t benefit the crypto space anyway.
Senators on Tuesday mostly voted against advancing the legislation — 49 for and 50 against — that the digital asset industry has long called for.
The bill aims to formally divide oversight between regulators, distinguishing which digital assets are securities, commodities or stablecoins.
President Donald Trump last month urged lawmakers to pass it, helping spur a bitcoin rally. But Republicans warned for months that Democrats were deliberately holding it back.
Crypto industry bigwigs had long called for rules to be in place after regulators during the Biden Administration penalized companies in the digital asset space with fines for allegedly selling unregistered securities.
This post Strategy Founder Michael Saylor Argues Clarity Act Collapse Is a Win first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
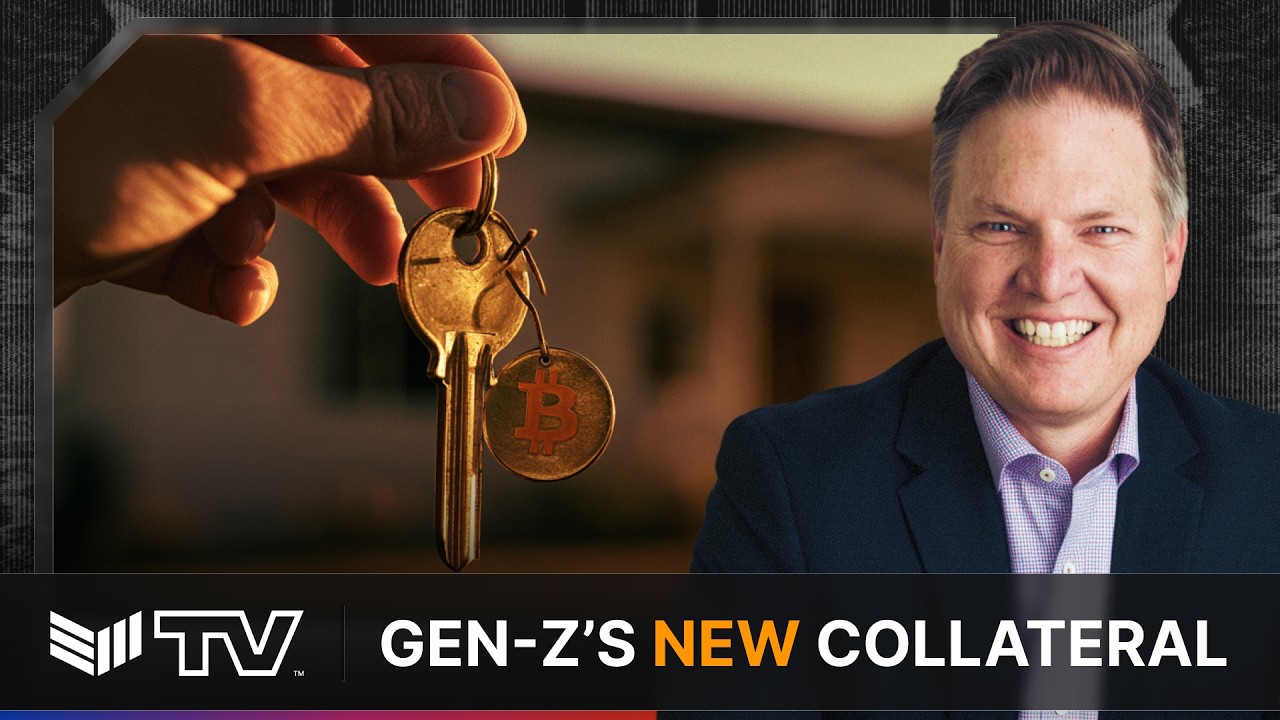
Move Over Housing – Bitcoin is Gen Z’s New Wealth Building Asset
Gen Z now makes up less than 5% of the new home market and Hunter Albright of SALT Lending thinks that changes what assets an entire generation chooses to build wealth with. In this conversation he connects housing affordability, Bitcoin as collateral, and the rise of borrowing against Bitcoin for down payments without locking your coins up for 30 years. Albright also covers Fannie Mae and Freddie Mac recognizing Bitcoin, SALT’s five-year loan terms, and what a Bitcoin-powered life actually looks like in practice.
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Move Over Housing – Bitcoin is Gen Z’s New Wealth Building Asset first appeared on Bitcoin Magazine and is written by Patrick Green.
CryptoSlate
Bitcoin’s rally toward $86,000 has pushed US spot exchange-traded fund (ETF) investors back into profit after months underwater.
Data from CryptoSlate showed Bitcoin gained about 6% over the past 24 hours, extending its September rebound and briefly trading near $86,000.
Bloomberg Intelligence ETF analyst James Seyffart said the move put the average US Bitcoin ETF holder above water for the first time since January. The funds’ estimated buys-only cost basis stands at about $81,722 per Bitcoin, while their net cost basis sits closer to current prices.
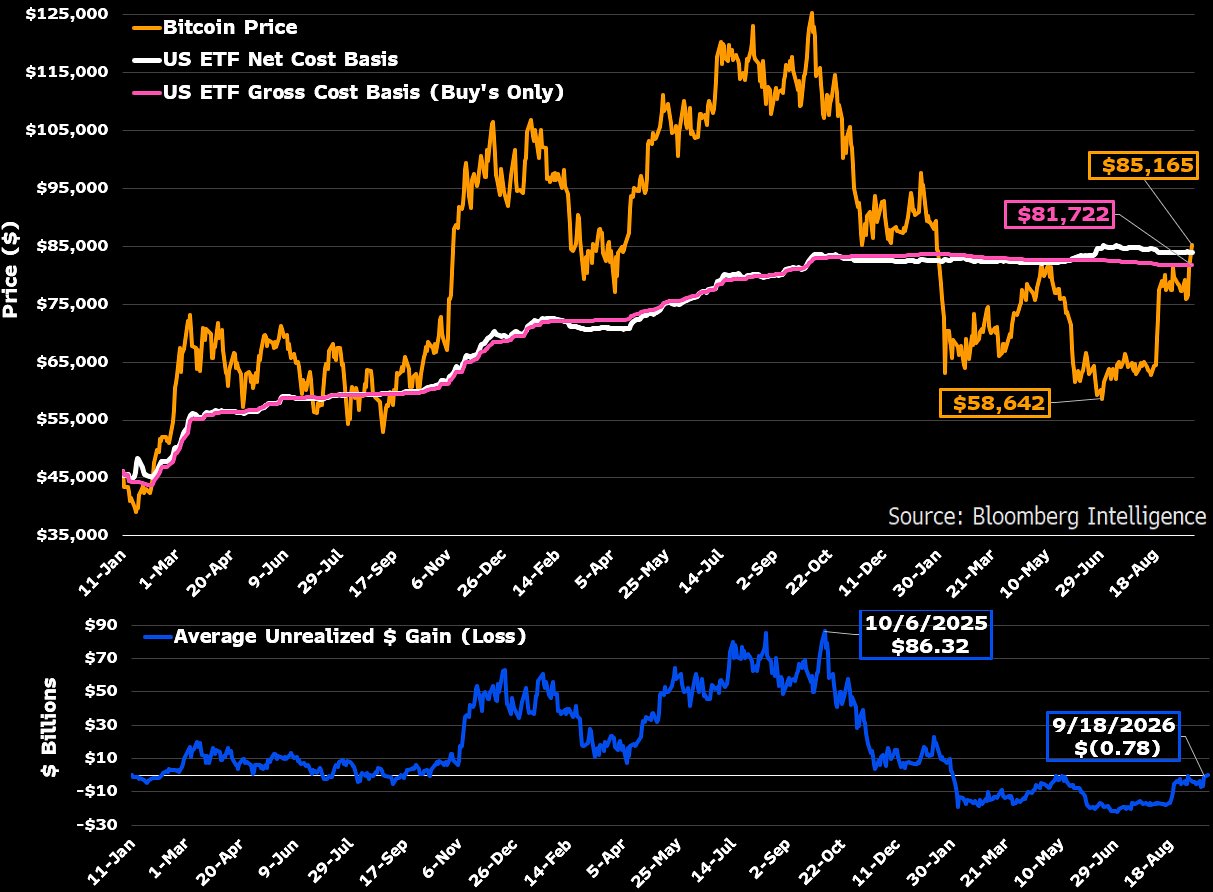
Bitcoin traded around $85,165 in Bloomberg Intelligence’s latest reading, clearing both levels and reversing much of the damage inflicted on ETF investors during this year’s downturn.
The turnaround has been dramatic. US Bitcoin ETF investors held about $86.32 billion in unrealized gains on Oct. 6, 2025, before the subsequent selloff erased that entire cushion. By Sept. 18, the cohort was sitting on an estimated $780 million unrealized loss.
Bitcoin’s latest advance has effectively repaired that drawdown. Capital flows have recovered more slowly, leaving ETF investors profitable again even as cumulative inflows remain well below their 2025 peak.
BTC's price recovery outruns ETF demand
The return to profitability has come well before a full recovery in ETF demand.
SoSoValue data show cumulative net inflows into US spot Bitcoin ETFs peaked at about $61.19 billion in October 2025 before falling to roughly $55.16 billion, leaving the products about $6.03 billion below their high-water mark.
The fund has recorded about $1.46 billion in net outflows so far in 2026. January accounted for roughly $1.61 billion of withdrawals and February another $206.5 million. March and April then brought a combined $3.29 billion of inflows before May and June reversed the improvement with about $6.94 billion of net withdrawals.
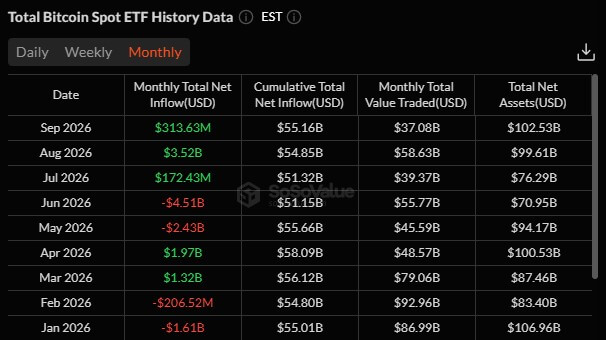
Demand strengthened again in the third quarter. July attracted about $172 million, followed by roughly $3.52 billion in August and another $314 million so far in September. Those inflows have steadied the cumulative total but have yet to replace the capital that left after last October’s peak.
Meanwhile, Bitcoin's price has recovered much faster.
Bloomberg Intelligence’s data show the cryptocurrency fell as low as about $58,642 during the downturn, leaving ETF investors well below both estimated cost-basis measures. Its subsequent rebound of more than $26,000 has carried the market back through the roughly $81,722 buys-only cost basis and toward the higher net measure.
That price appreciation has restored the value of Bitcoin already held inside the funds even as cumulative net inflows remain almost 10% below their October 2025 peak.
The setup differs from last year, when rising Bitcoin prices were accompanied by expanding ETF inflows and a growing pool of unrealized profits. This time, existing holders have moved back into profit while the cumulative capital committed to the products remains smaller.
The recovery is also uneven across the investor base. Bloomberg Intelligence’s buys-only cost basis sits near $81,722, giving those holders a wider cushion at current prices, while the net cost basis remains closer to Bitcoin’s market price and leaves that group nearer breakeven.
ETF breakeven will test investor conviction
That narrow cushion above breakeven is already being tested by volatile ETF flows, even though last week’s headline total looked almost unchanged.
US spot Bitcoin ETFs ended the week with just $6.21 million of net inflows, SoSoValue data show. Beneath that figure, however, investors moved sharply in and out of the products across individual sessions.
About $160 million entered the funds last Monday before roughly $450 million was withdrawn Tuesday and another $296 million Wednesday. The selling then reversed, with about $160 million returning Thursday and $433 million flowing in Friday, the strongest daily inflow since Sept. 3. Fidelity’s FBTC accounted for roughly $311 million of Friday’s total.
That left the funds almost flat for the week despite nearly $1.5 billion of gross daily inflows and outflows. Bitcoin ETF trading volume totaled about $16.17 billion, making the $6.21 million net subscription equivalent to roughly 0.04% of turnover.
The weekly result nevertheless marked an improvement from the previous period, when the funds recorded about $463 million of net outflows. More importantly, the sequence showed that heavy midweek selling did not develop into a sustained exit, with buyers rebuilding exposure rapidly over the final two sessions.
Moving ETF investors back into profit could now determine whether that re-risking continues. Holders who stayed through Bitcoin’s downturn can reduce exposure near or above their average entry levels without realizing the losses they faced earlier this year, creating the possibility of renewed selling as more positions move back into the black.
The next test is whether crossing above the ETF cost basis draws sustained new money into the products or gives investors who endured the downturn an opportunity to leave. Continued inflows would put fresh capital behind Bitcoin’s recovery, while another round of redemptions would show that the return to breakeven has released holders who were waiting for prices to recover
The post Bitcoin hits $86,000 putting ETF investors back in profit after $86 billion wipeout appeared first on CryptoSlate.
Ethereum developers are weighing Ethereum Quick Slots for Hegotá, a proposed faster block rhythm that would reduce waiting without expanding the network's per-second capacity. EIP-8198, or Quick Slots, remains Proposed for Inclusion rather than scheduled, and neither its eight-second draft parameter nor the 10-second alternative has been adopted.
That makes validator performance the deciding issue. Shorter slots could refresh onchain prices sooner and accelerate confirmations and finality, but validators would have less time to receive, check and attest to each block. The proposal's market benefits are modeled; its effect on the slowest operators remains the evidence Ethereum still needs.
The Hegotá meta-EIP lists Quick Slots as Proposed for Inclusion, while Ethereum's official roadmap says most of the upgrade's scope remains undecided. Developers are choosing whether to spend performance headroom on lower latency while preserving the broad participation that gives Ethereum its decentralization.
Ethereum Quick Slots: a faster clock with the same per-second capacity
The canonical EIP-8198 draft uses eight seconds as a placeholder, down from Ethereum's current 12-second slot. It also says the exact target should follow performance characterization and may change before deployment.
Ethlabs favors a more conservative first move. Its updated Hegotá position advocates 10-second slots first, with later cuts only as evidence of safety accumulates. An open sponsor rewrite likewise proposes 10 seconds, but it has not been merged into the canonical EIP.
The possible outcomes therefore extend beyond an eight- versus 10-second choice. Hegotá could start at 10 seconds, retain the draft's eight-second parameter, or leave the 12-second schedule unchanged if testing shows that a cut would be unsafe.
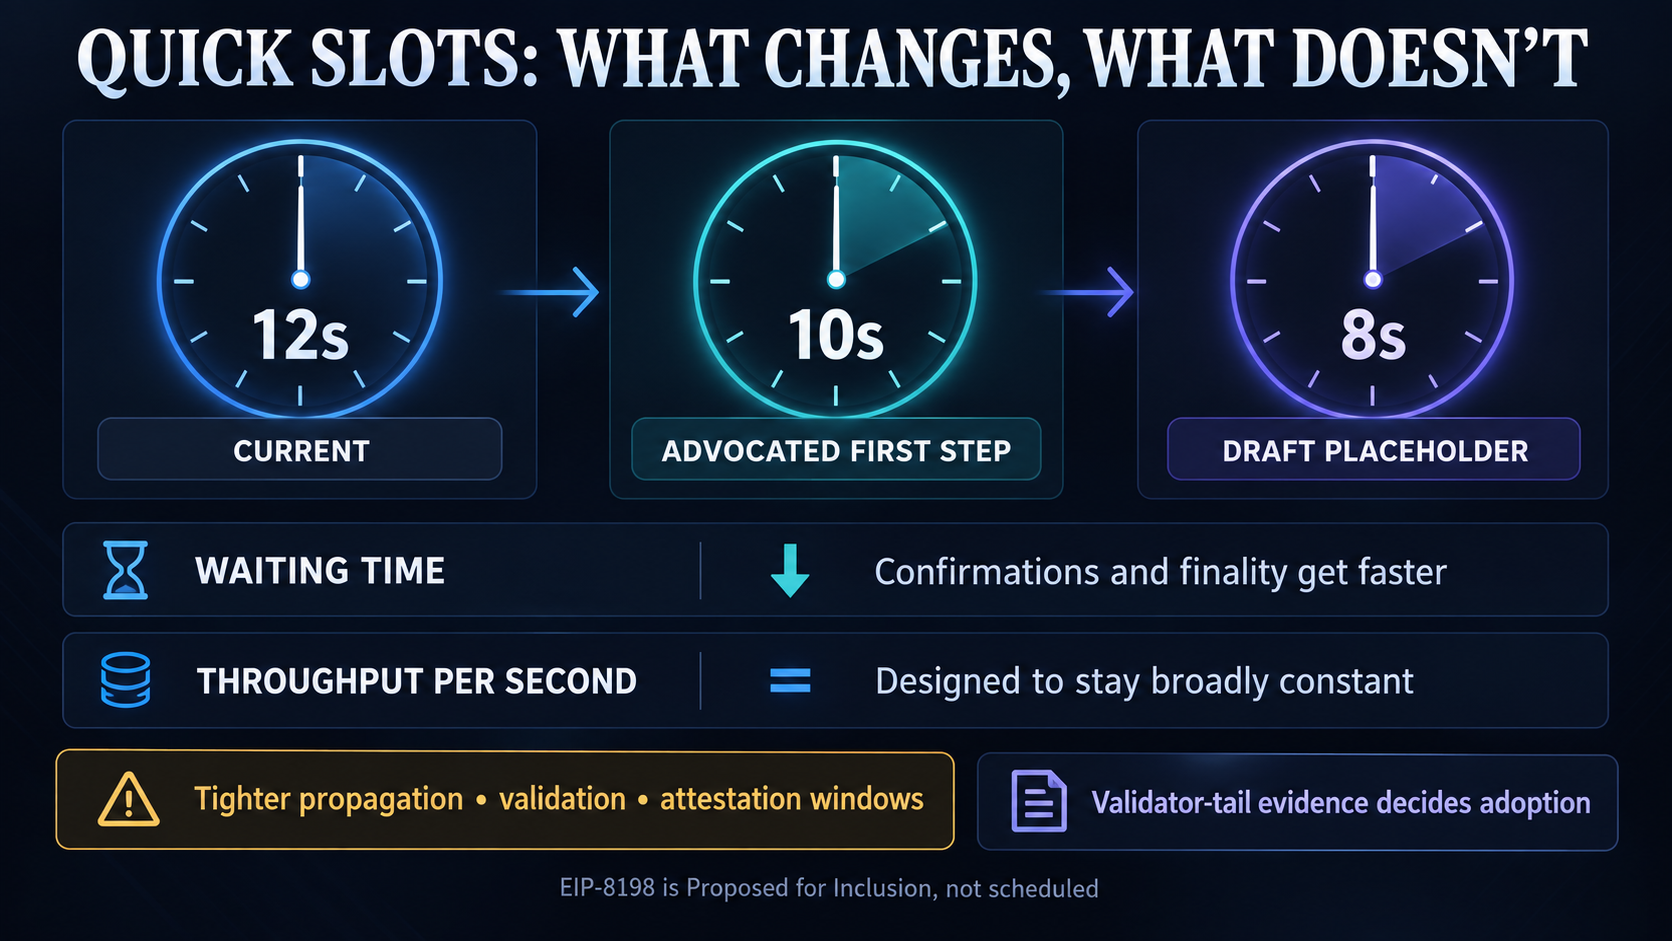
Under either shorter target, capacity per second stays broadly level only if the gas limit and maximum blob count per block fall in proportion to slot duration. Smaller blocks would arrive more frequently. Users could receive a first confirmation sooner, onchain markets could update more often, and systems that inherit Ethereum's cadence could react faster. Normal validator gas-limit voting would resume after the transition, and integer rounding could make blob capacity slightly lower rather than perfectly constant.
Keeping 32 slots in an epoch would also shorten epoch-based finality in wall-clock time. Under the draft's eight-second assumptions, EIP-8198 estimates finality falling from about 13 minutes to about 8.5 minutes. That is a proposal estimate, not an observed result from production Ethereum.
The same distinction applies to the draft's claim that a 12-to-eight-second change would reduce arbitrage losses by roughly 18%. The figure comes from a model in which those losses scale with the square root of the time between blocks. Ethereum has not operated an eight-second production regime that could demonstrate the result.
Independent work supports the direction more strongly than the exact magnitude. An empirical study of automated market maker losses found that faster blocks reduce losses to arbitrageurs, but the effect varied materially by trading pair. A newer jump-diffusion model found that sudden price jumps create a floor that shorter intervals do not eliminate.
Fresher prices could improve spreads and liquidity-provider economics while compressing some surplus available to searchers, builders and proposers. Yet fees, liquidity, volatility, jumps and burned base fees affect who captures the change. A separate Ethereum Research analysis shows why lower nominal arbitrage does not translate mechanically into a uniform 18% gain for users or liquidity providers.
Validator tails decide whether the trade works
Smaller blocks reduce peak payload size, but a faster cadence raises computational and bandwidth demands per second. Validators also face tighter absolute windows for propagation, validation and attestation aggregation. Average performance cannot settle the decentralization question because the network must remain usable for operators in slower regions, on weaker hardware and with varied client configurations.
An analysis of mainnet attestation timing found potential headroom for a shorter schedule alongside a meaningful tail. Some attestations in its sample arrived after the aggregation deadline contemplated for a six-second design, and timings differed across clients, operators and configurations. The study was exploratory and does not establish the safety of six, eight or 10 seconds.
Separate post-Pectra research found propagation delay strongly associated with reorg risk near the attestation boundary. Those observations support a distributional risk: reducing the timing margin could burden slower or poorly configured validators more than well-provisioned peers. They do not quantify validator reward losses under EIP-8198 or prove that either proposed target would centralize the network.
The proposal itself acknowledges incomplete knowledge about blob propagation, attestation aggregation, local block building and validator hardware. Developers have also linked Quick Slots to work on faster execution-payload broadcast, treating propagation improvements as part of the safety case rather than a later optimization.
The Ethereum Foundation Protocol cluster's Hegotá assessment placed Quick Slots in B tier after research teams offered stronger support than delivery-focused engineering teams. The practical requirements behind that split are clear: a complete specification, a full-spec prototype, a downstream-effects assessment and confirmation that Quick Slots will not complicate Ethereum's planned decoupled-consensus architecture.
Those requirements turn Hegotá's decision into an empirical test. A 10-second first step could deliver a measurable latency gain and defer a harder cut if client simulations and devnets show broad validator resilience. Eight seconds could remain the draft's ambition rather than the first deployment. If timing tails or reorg behavior worsen enough to favor larger operators, the market-quality benefit would carry a decentralization cost.
Ethereum Quick Slots could offer fresher markets, shorter transaction-inclusion waits and faster finality without increasing throughput. Broad validator resilience remains the condition that must be demonstrated before the faster clock is worth adopting.
The post Will proposed faster block times really fix Ethereum’s biggest market losses? appeared first on CryptoSlate.
Bitcoin treasury companies Strategy and Strive bought about $183 million of BTC last week as the cryptocurrency’s rebound helped corporate balance sheets recover losses.
Strategy Inc., the largest corporate holder of Bitcoin, acquired 950 BTC for $75.7 million between Sept. 14 and Sept. 20 at an average price of $79,670, according to a regulatory filing Monday. The purchase returned its holdings to 846,000 BTC, acquired for a total of $63.8 billion at an average cost of $75,416.
Strive Inc. separately bought 1,355 BTC for $107.7 million at an average price of $79,475 between Sept. 14 and Sept. 18, taking its treasury to 26,355 BTC. Cash and equivalents rose to $229.6 million over the same period.
Both purchases were made below Bitcoin’s latest market price. The token surged above $85,000 Monday, its highest level since January, extending a recovery of almost 30% from its August lows.
The buying stands out because the broader corporate treasury trade has slowed sharply. Listed companies added about 5,900 BTC over the past three months, Glassnode said in a report last week. That compares with roughly 89,000 BTC accumulated in July 2025 alone.
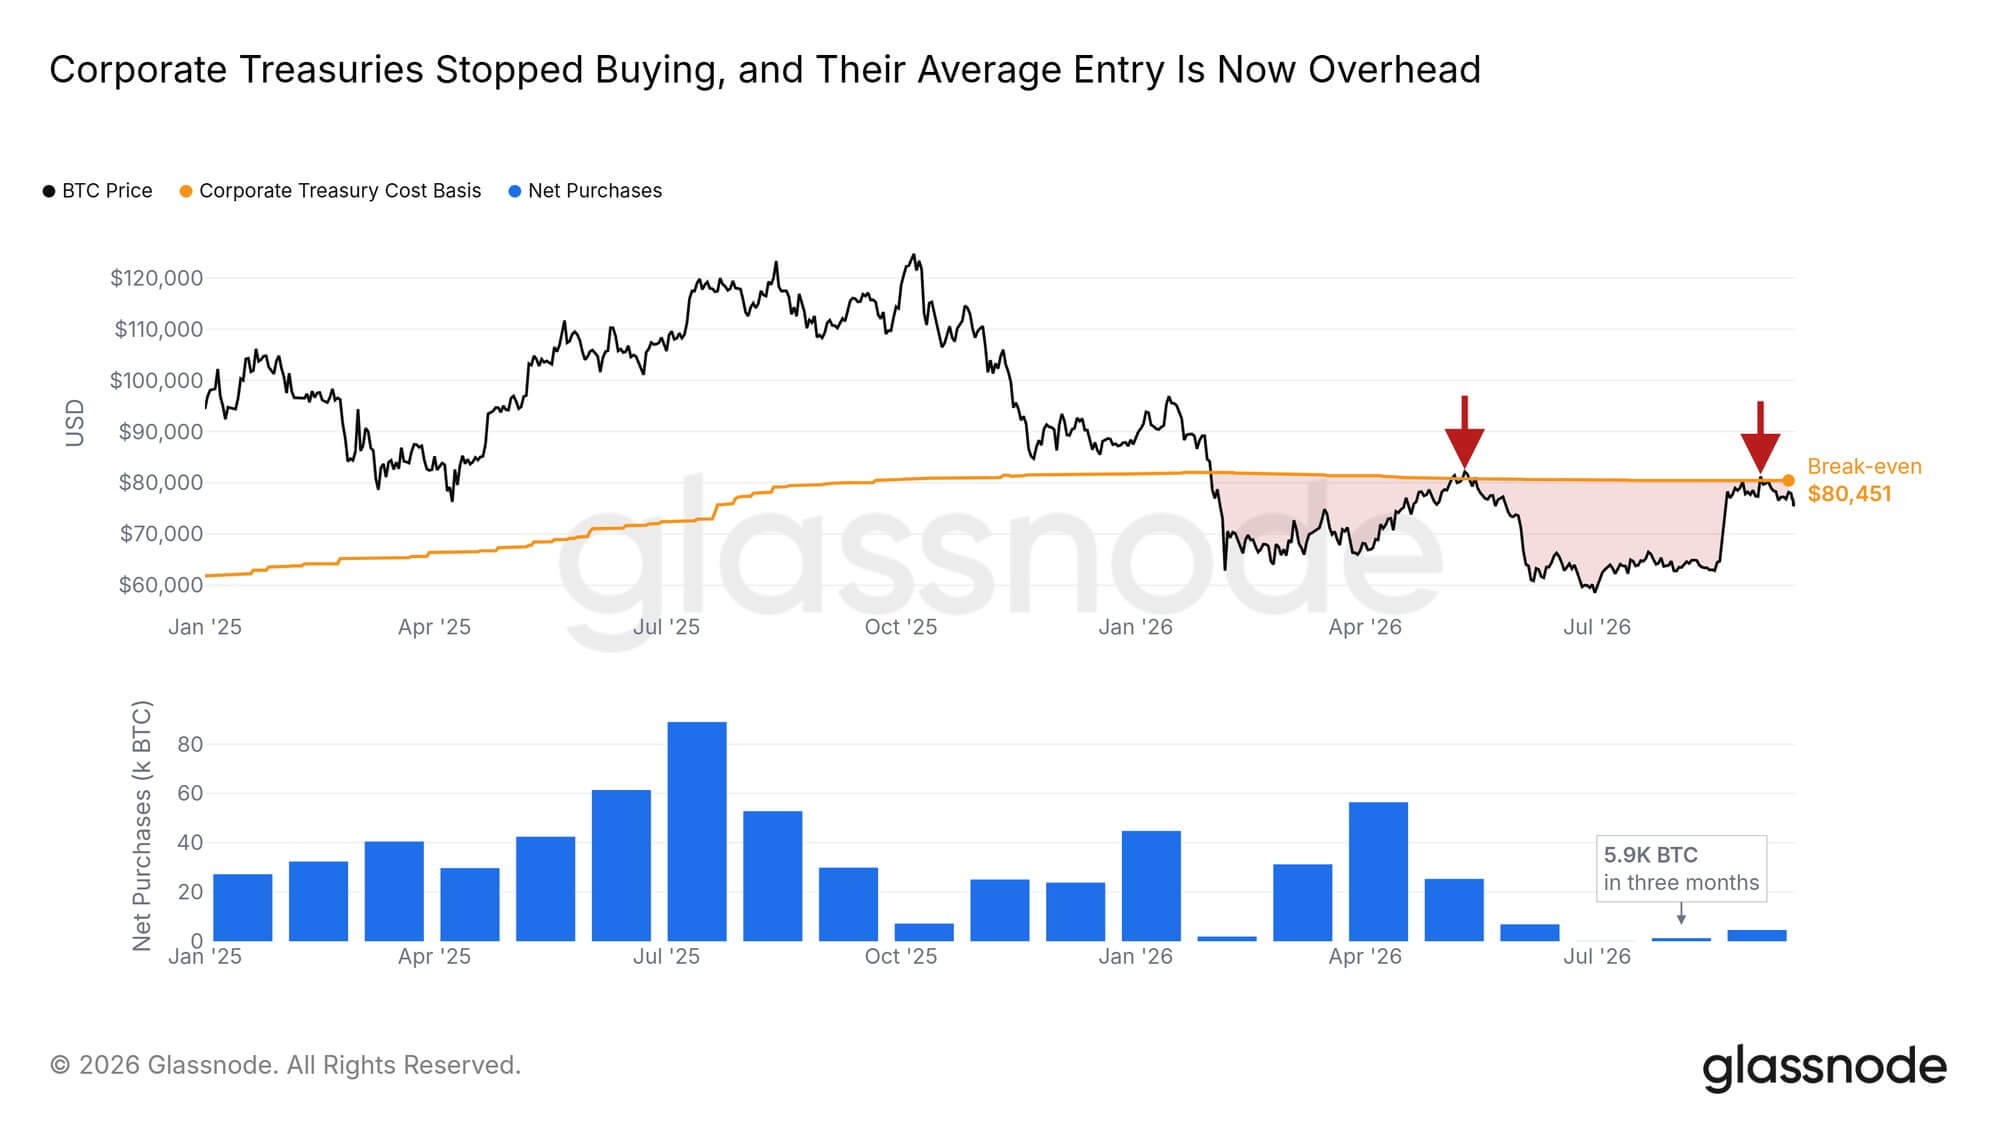
Glassnode estimated the sector’s average acquisition price at roughly $80,500. Bitcoin was still below that threshold when the firm published its report, leaving the aggregate corporate treasury cohort underwater. Monday’s move through $85,000 has reversed that position and pushed the group back above its estimated cost basis.
Strategy’s Bitcoin rebound collides with a capital-management pivot
For Strategy, the rally has particularly large accounting consequences.
Bitcoin ended the second quarter at $58,714, when Strategy held the same 846,000 BTC it does today. The decline contributed to an $8.32 billion loss on digital assets during the three months through June, including $8.31 billion of unrealized losses.
At $85,000, Strategy’s current Bitcoin holdings would be worth about $71.9 billion, roughly $8.1 billion above their aggregate acquisition cost. Their gross market value would also stand more than $22 billion above the value of 846,000 BTC at the June 30 closing price.
That comparison does not translate directly into Strategy’s eventual third-quarter accounting gain because the company bought and sold Bitcoin during the quarter and fair-value changes are recognized as they occur. Still, it illustrates the scale of the balance-sheet swing created by Bitcoin’s rebound.
Strategy has also been directing capital away from Bitcoin at times to manage the securities used to finance its treasury.
The company repurchased 1.77 million shares of its variable-rate STRC preferred stock for $174 million last week. It used another $57.4 million from its dollar reserve for preferred dividends and debt interest, leaving $5.04 billion in its reserve and $1.05 billion of separately designated cash as of Sept. 20.
Strategy has spent months trying to keep STRC near its $100 par value through buybacks and changes to its capital framework. Chief Executive Phong Le said in July that repurchasing the security below par can reduce future dividend obligations while supporting what the company considers a sustainable market for the preferred shares.
Since then, the firm has now spent roughly $1.1 billion on STRC buybacks.
The latest Bitcoin purchase therefore marks a return to accumulation alongside, rather than instead of, that balance-sheet management. Strategy had reported no Bitcoin purchases in the previous two weekly updates and held 845,050 BTC as recently as Sept. 13.
Strive leans on preferred stock to keep accumulating
Meanwhile, Strive has continued buying BTC more consistently while relying on its preferred stock.
Its latest purchase followed a 469-BTC acquisition the previous week and a 1,375-BTC purchase earlier in September, extending a strategy that has increasingly relied on its SATA preferred stock to raise capital.
Strive said warrant exercises also began generating fresh capital last week, producing about $21.2 million in gross proceeds. Including those funds, the company said SATA has accounted for about 57.7% of the total capital it has raised, reflecting how preferred equity has become central to financing its Bitcoin accumulation.
The latest filing showed SATA shares outstanding rose by 786,194 during the week to 11.18 million, while Strive’s Class A share count increased by about 2.07 million.
That financing model becomes easier to sustain when Bitcoin rises faster than the cost of the securities used to acquire it. Strive’s latest BTC was purchased almost $5,500 below Monday’s roughly $85,000 price, though its overall treasury remains closer to its historical acquisition cost than Strategy’s.
The broader question is whether other corporate buyers return now that Bitcoin has cleared the $80,500 sector cost basis.
Glassnode’s data suggest the treasury trade that absorbed tens of thousands of Bitcoin each month during 2025 has become increasingly concentrated among a smaller group of aggressive buyers. Strategy and Strive are adding again as prices recover, but matching last year’s corporate demand would require companies currently sitting on the sidelines to follow them.
The post Strategy and Strive buy $183 million in Bitcoin as $85,000 rally revives treasury trade appeared first on CryptoSlate.
The Balancer V1 recovery proposal would divide 296.401711 ETH returned after an Aug. 31 exploit among liquidity providers in 120 legacy pools, but it does not yet show what any address could claim.
The proposal says tokens worth about $1.39 million at attack-time prices were drained from the pools. It lists five ETH returns to the Balancer DAO Multisig between Sept. 8 and Sept. 16 from the main greyhat, three anonymous whitehats and block builder Ultrasound.money.
The 296.401711 ETH is the amount the proposal records as returned, not a promise of full reimbursement. The attack loss is expressed in dollars at historical prices while the recovery pool is denominated in ETH, and the proposal does not state a recovery percentage.
How Balancer would allocate the recovered ETH
Under the plan, Balancer would first allocate recovered ETH to each pool according to that pool’s share of the total dollar loss at the time of the attack. It would then divide each pool’s allocation among liquidity providers based on their pool-token holdings at Ethereum block 25,872,248.
That block immediately preceded the first exploit transaction at block 25,872,249. Using one pre-attack snapshot would cover all 120 pools, including those later targeted by copycat activity.
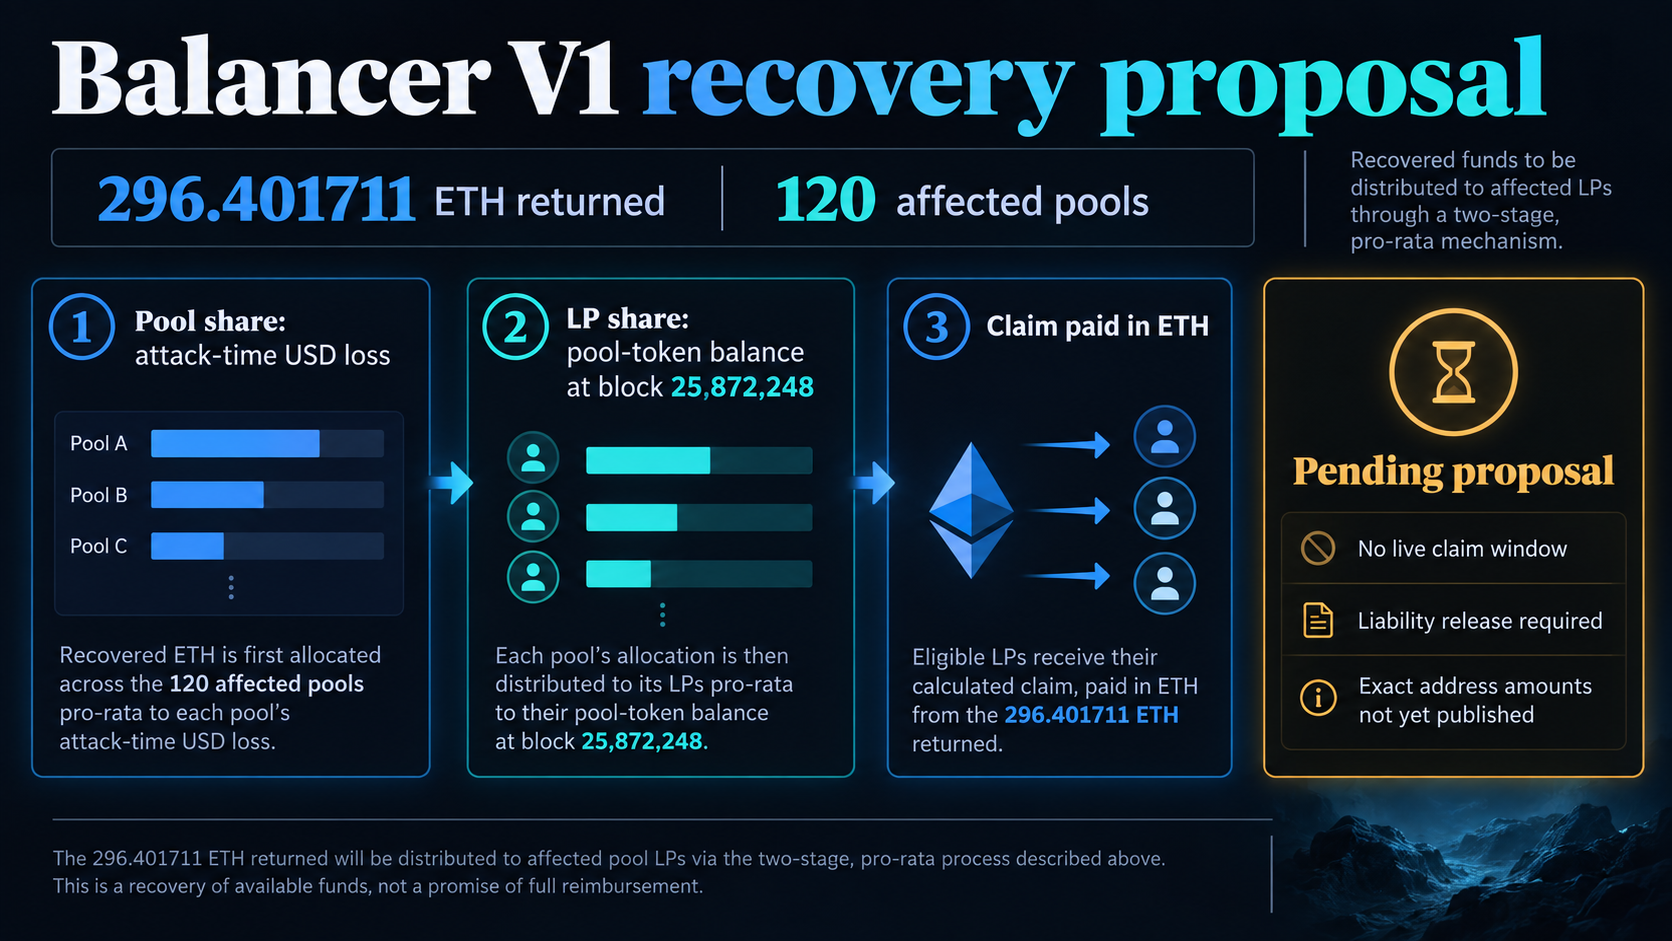
The formula determines the relative weighting of claims, but the Sept. 18 post does not include the per-pool allocation table, holder lists or per-address amounts. Until those files are published, an individual LP cannot calculate an exact ETH payout.
Claims await a vote and address-level data
Receiving the proposed payment would also carry a legal condition. Claimants would have to provide digital consent releasing Balancer Labs, Balancer DAO, Balancer Foundation, affiliated parties and service providers from liabilities related to the incident. Payments would be made in ETH, while contract and multisig claims would be handled case by case.
As of Sept. 20, the Sept. 18 forum post remained labeled BIP-XXX and contained no Snapshot vote link. It says claim data would be published and a claim mechanism deployed only if the proposal passes, leaving the V1 claim window unopened and without announced start or end dates.
The recovery pool is separate from the assets covered by Balancer’s proposed shutdown. Its wind-down proposal says funds recovered from protocol attacks belong to affected LPs and sit outside the treasury distribution intended for BAL holders, a distinction also noted in CryptoSlate’s earlier coverage.
That separation preserves recovered exploit funds for LPs, but the pending vote and unpublished allocation data mean the Balancer V1 recovery proposal defines a recovery route, not a confirmed payout.
The post Why Balancer’s $1.4M hack recovery won’t pay LPs anytime soon appeared first on CryptoSlate.
SEC Commissioner Hester Peirce drew a sharp line around decentralized finance on Sept. 17. She said investors need no exemption to use permissionless smart contracts for peer-to-peer trading. The SEC and CFTC actions examined here set separate limits on intermediary control.
The unresolved question is how much control a software provider can retain before it begins to resemble a regulated intermediary.
Peirce’s statement expressed her own position. A binding definition from the US Securities and Exchange Commission would require Commission action. The SEC’s tokenized-securities order and a separate staff statement leave her phrase “truly decentralized” undefined. Their specific provisions focus on custody, access, software parameters, fees, recommendations, routing and execution.
Each action operates under a different statute and carries a different legal effect. Together, they show how federal regulators are examining the authority that identifiable providers retain. A unified federal decentralization test remains absent.
The SEC traces control from the market to the frontend
The SEC’s Sept. 17 tokenized-securities order is an order of the Commission. It creates temporary, conditional relief for a defined Tokenized Securities Venue, or TSV, using automated market maker pools for permissioned trading in Tokenized NMS Stocks.
A TSV under the order performs two functions: It provides one or more AMM pools for permissioned participants, and it sets standards governing who may access those pools.
The order gives “provides” a functional meaning for that exemption. Selecting and designating a pool can count. Deploying its trading contract, changing its rules or parameters, setting its fees, or retaining authority to pause trading can also establish provision or control. Solely performing the administrative task of encoding a whitelist falls outside that definition.
Automation leaves several consequential choices in human hands. People may still choose the venue, set fees, pause activity or decide who gets in. Peirce placed the order outside decentralized finance and described genuinely permissionless software as a different model. The permissioned venue illustrates why operational powers matter even when smart contracts execute trades.
The interface creates another layer of control.
An April statement from the SEC’s Division of Trading and Markets describes when staff would refrain from objecting to certain crypto asset securities interface providers operating without broker-dealer registration under Section 15. Its legal effect is limited: The statement represents staff, has no legal force, creates no new obligations and will be considered withdrawn five years after April 13, 2026 absent intervening Commission action.
The covered interfaces help users prepare transactions through self-custodial wallets. The user holds the keys, chooses or customizes transaction parameters, signs the transaction and transmits the instructions. Multiple displayed execution routes must be filterable or sortable using objective factors. When an interface displays one route, users must be able to view alternatives when they exist. Software used to prepare instructions or display route information must operate on pre-disclosed, objective and independently verifiable parameters.
The staff position excludes functions that more closely resemble brokerage. It excludes a provider that solicits a specific crypto asset securities transaction, recommends an investment, holds or accesses user assets, executes or settles a transaction, or takes or routes an order.
How the provider is paid also matters. Staff says it would refrain from objecting when a user pays a flat fee or percentage transaction charge that is objectively determined, consistently applied and neutral among products, routes, venues and counterparties. Payments from another party based on the size, value or occurrence of a transaction fall outside the position.
These conditions make the frontend part of the regulatory analysis. Default settings, route rankings, preferred venues and fee incentives can steer users even when the user signs the final transaction from a self-custodial wallet.
The CFTC permits more promotion under a narrower registration position
The CFTC’s Sept. 17 announcement and Staff Letter 26-25 state a staff no-action position. The Market Participants Division said it would refrain from recommending enforcement against qualifying passive-software providers for failing to register as introducing brokers, or against relevant personnel for failing to register as associated persons.
The position applies when users transact on a designated contract market directly as members or indirectly through a futures commission merchant or introducing broker that is a DCM member. It is based on the presented facts, leaves Commission authority intact and may be changed, suspended or terminated by the Division.
Its covered activities allow more promotion and compensation than the SEC interface position. A provider may promote particular derivatives, direct users toward specific registered firms, charge users transaction-based fees and receive a share of a registrant’s revenue.
The provider must remain hands-off in several important respects. Users must be able to reach the registrant directly. The provider is barred from custody or control of customer property, explicit buy or sell signals, affirmative involvement in a particular order, and discretion over routing or execution.
The relief also depends on disclosures, marketing controls, written undertakings with registrants, recordkeeping and notices to the Division. These requirements preserve accountability while the software provider remains outside introducing-broker registration.
The main differences concern six forms of control.
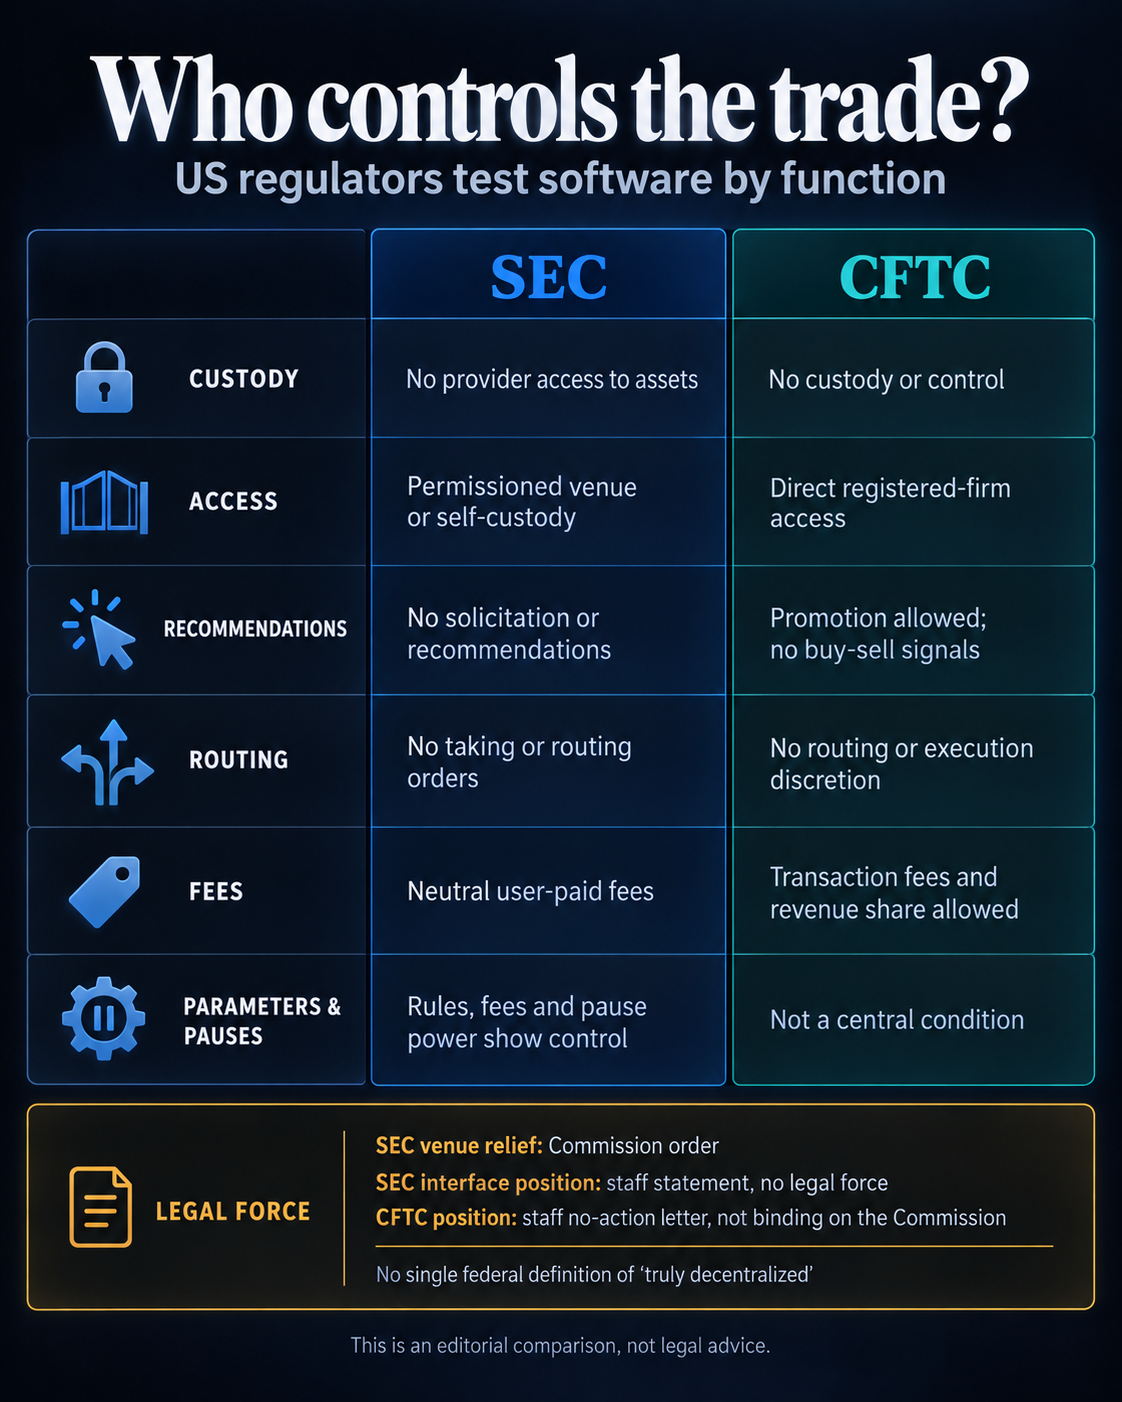
| Area of control | SEC order or staff position | CFTC staff position | Scope of the condition |
|---|---|---|---|
| Custody | The interface provider is barred from holding or accessing user assets | The provider is barred from custody or control of customer property | Each staff position requires separation from customer property |
| Access | A TSV sets participant standards; an interface discloses venue limits | Users trade on a DCM directly or through a member FCM or IB and retain direct access to the registrant | Each document specifies its own access structure |
| Recommendations | The interface position excludes specific-transaction solicitation and investment recommendations | Promotion may be allowed; explicit buy or sell signals are excluded | The staff positions draw different lines around steering |
| Routing | The interface provider is barred from taking or routing orders; displayed alternatives use objective parameters | User-directed transmission may occur; provider discretion over routing or execution is barred | The SEC position excludes order routing, while the CFTC position centers on discretion |
| Fees | User-paid charges must be objectively determined and neutral | Transaction fees and registrant revenue sharing may be allowed | Compensation is treated within each statutory setting |
| Parameters and pauses | Changing pool rules, parameters or fees, or pausing trading can mean a person provides the pool | The letter gives these powers no central role | The SEC factor belongs to the order’s specific venue exemption |
Every factor operates inside its source document’s narrow scope. The Commission order governs one securities-venue model. SEC staff states its Section 15 position for covered interfaces. CFTC staff offers conditional enforcement forbearance within the registered derivatives market.
Technical design matters alongside disclosures, access arrangements, marketing limits, recordkeeping and retained authority. The relevant mix changes across securities venues, crypto interfaces and derivatives software.
Who decides what counts as “truly decentralized”
Peirce supplies a principle: Removing the trusted intermediary weakens the regulatory rationale built around that intermediary. Her individual statement carries no power to establish a Commission category.
Authority is divided across the actions described here. The Commission defines the scope of its TSV order. The SEC’s Division of Trading and Markets applies its own nonbinding Section 15 position. The CFTC’s Market Participants Division decides whether presented facts fit its conditional enforcement posture. Each judgment answers a question arising under a particular statute and form of relief.
A protocol, its governance process and its frontend may occupy different points on the control spectrum. The core protocol may be difficult to alter while an interface remains curated, fee-taking and capable of steering users. Software may also connect users to regulated firms while leaving orders, assets and execution outside the provider’s discretion.
For builders and users, the practical inquiry begins with specific powers: Who controls access and assets? Who can recommend, route or execute a transaction? Who sets fees or changes software parameters? Who can pause the system? The governing statute and the actor exercising those powers then determine which regulator and legal standard apply.
“Truly decentralized” remains Peirce’s description. Federal law provides no matching legal category. These SEC and CFTC actions produce a fact-specific map of retained authority, with separate boundaries for the Commission order and each staff position.
The post Why truly decentralized DeFi needs no legal exemption according to SEC Commissioner Hester Peirce appeared first on CryptoSlate.
CryptoTicker.io
Render rose around 19 percent to $1.83 on Sunday, making it the second strongest asset in the upper market segment after Sui (CoinGecko, September 21, 2026, 12:50 UTC). Over the week it is up a good 27 percent, across 30 days just under 20 percent.
The advance is no isolated case. The whole group of AI-adjacent cryptocurrencies posted double-digit gains that day, Bittensor among them with just under 14 percent. For Render, though, figures from its own network come on top, and those can be checked independently of the price.
What The Render Network Actually Does
Render brokers computing power from graphics cards. Anyone wanting to render an elaborate 3D scene or train an AI model rents distributed GPU capacity through the network instead of buying their own hardware. Payment is in RENDER.
That sets the project apart from many other assets traded as AI cryptocurrencies. There is a service somebody draws on, and a number that can be tracked: the quantity of rendered images. That figure most recently stood at around 77 million frames.
Technically the token runs on Solana. That explains part of the move: Solana itself added 7.6 percent, and capital rotated visibly into applications of the Solana ecosystem that day.
Three Metrics That Support The Render Price
First, the expansion of the AI subnets through which specialised computing tasks are handled. Second, the burn of around 1.16 million RENDER, which permanently reduces supply. Third, the weighting by institutional providers: Grayscale most recently assigned Render a good 21 percent share in its fund for decentralised AI, which puts the project among the largest positions there.
None of these figures explains a single-day gain of 19 percent. Taken together they explain why capital lands here during a sector rotation and not with any other asset carrying AI in its name.
The Context That Gets Lost In The Rally
The distance to the all-time high sits at around 87 percent despite the rally. Render has therefore made up only a small part of the slump of recent months. Trading volume of around $162 million in 24 hours is solid for an asset of this size, but no outlier.
Anyone setting these figures side by side sees a recovery inside a long downtrend, not its end. That can change; so far it is not established.
Why AI Tokens Rise And Fall As A Block
The move on this Sunday follows a pattern that has been repeating for two years. When the overall market rises, and bitcoin reached its highest level since January at more than $85,000, freed-up capital looks for themes. AI is currently the strongest of them, and the associated tokens largely move together.
For investors that means picking a single AI token offers little protection from the sector's move. If the group falls, all of them fall, regardless of the quality of the individual network. The difference only shows over longer stretches, when projects without usage fall behind.
What To Watch On The Render Price Now
Three points are checkable and therefore more useful than any forecast. First, the number of rendered frames in the coming weeks: if it keeps rising, demand is genuinely growing. Second, the pace of the token burn. Third, the question of whether Render stays stronger relative to Solana. Applications run ahead in upward phases and lag in downward ones.
The current crypto prices give an overview of the move in the overall market. Anyone looking to acquire Render will find the terms in the comparison of the best crypto exchanges.
Solana added around 7.6 percent to $116.63 on Sunday. The move is considerably stronger among the applications running on Solana: Jupiter, the network's largest trading aggregator, rose around 13 percent to $0.305 (CoinGecko, September 21, 2026, 12:50 UTC). Over a month JUP is up just under 49 percent, Solana itself 25.5 percent.
That ratio is the actual finding. When application tokens rise faster than the chain they run on, capital is no longer just buying access to the ecosystem; it is reaching for leverage inside it.
Why Jupiter Amplifies The Solana Upswing
Jupiter bundles the liquidity of the trading venues on Solana and routes an order automatically to wherever it is filled most cheaply. A substantial share of trading on Solana therefore passes through this one application without users noticing.
How an aggregator differs from the individual trading venues is shown by the comparison of decentralised exchanges.
For the token that means a direct coupling: when trading volume on Solana rises, fees at Jupiter rise. Parts of that income flow into buybacks of its own token. Volume, fees and buybacks therefore move in lockstep, upwards as well as downwards.
That explains why JUP gains more than SOL in upward phases. It equally explains why the move in the opposite direction turns out sharper as soon as volume eases.
What Is Moving Capital Right Now
Three things are coming together. First the overall market: bitcoin stands above $85,000, as high as it has been since January, triggered by the liquidation of short positions in the hundreds of millions. That frees up capital which then looks for destinations.
Second, the reports of further filings for exchange traded Solana funds. Filings of that kind are not approvals, but they change what institutional investors expect of the chain.
Third, the rotation within the Solana ecosystem itself. Render, which runs its token on Solana, also added around 19 percent. Anyone invested in the ecosystem is currently shifting capital from the base chain into the applications.
The Metrics That Make The Difference
With application tokens it pays to look at the ratio of trading volume to market capitalisation. Jupiter reached around $116 million in volume over 24 hours. Measured against Solana with more than $5 billion that is little, but for an application token it is considerable.
The more important test runs over time: does the trading volume routed through Jupiter rise durably, or was it a one-day event? The answer will only be settled in a few days, and it decides whether the price rise has a foundation.
The Risk That Application Tokens Carry
A token like JUP carries two risks stacked on top of each other. The first belongs to the chain: if Solana goes down or loses traction, that hits every application on it. The second is its own: a competing aggregator, a flaw in the contracts or a change to the fee distribution acts on JUP alone.
The distance to the all-time high of around 85 percent shows how deep the move of recent months ran. A gain of 49 percent in a month sounds like a lot, yet it restores only a small part of that stretch.
What To Watch On The Jupiter Price Now
For Solana itself the $120 mark remains the next hurdle, a few dollars above the current level. If it is cleared and holds, the rotation into the applications should continue. If the attempt fails, the pullback hits the application tokens harder than the chain.
An overview of the overall market is given by the current crypto prices. Anyone interested specifically in how the chain develops will find the assessment of the $120 mark in the Solana price prediction.
Arbitrum is the strongest performer of the past four weeks. The ARB price stands at $0.246, a gain of around 17 percent within 24 hours, a good 82 percent over the week and around 151 percent across 30 days (CoinGecko, September 21, 2026, 13:12 UTC). No other asset in the top 60 has covered comparable ground over the same period.
Many of this week's price jumps trace back to a single rumour. This one rests on a measurable shift in activity instead. Two developments carry it, and both come with a catch.
Robinhood Builds On Arbitrum, And The ARB Price Feels It
The broker Robinhood runs its own second-layer network, Robinhood Chain, built on Arbitrum technology. That chain now generates a multiple of the fees accruing on the Arbitrum network itself. At peak times a factor on the order of 240 was mentioned.
For valuing ARB, that is the actual point. A layer 2 network earns from someone using it. When a regulated broker with millions of customers puts its settlement on it, the demand is of a different kind from the activity of a handful of DeFi users.
The catch: part of that activity ran on subsidised fees. Once the subsidy expires, how much volume stays is an open question. That is the first real stress test for the thesis.
Tokenised Assets Are Moving Onto The Chain
The second driver is the tokenisation of real assets, real world assets in the jargon. Arbitrum has grown into one of the largest venues for this and now sits within reach of Solana on the volume of tokenised assets.
That is notable because this segment works differently from the rest of the crypto market. Anyone bringing government bonds or credit funds onto a blockchain does not switch chains because of a price rise. Decisions of that kind have lead times of months and last correspondingly longer.
The ARB Price Breakout In The Chart
Technically ARB has cleared the downward line that had capped the recovery since spring. The price trades at its highest level since January. Trading volume came in at around $547 million in 24 hours, a multiple of the previous weeks' average.
At the same time the distance to the all-time high remains around 90 percent. Anyone taking the roughly 150 percent of the past 30 days as a yardstick should set that figure alongside it: ARB is working its way out of a very deep trough, and it is breaking no record.
The Two Dates Where The Rally Has To Prove Itself
Two events decide whether the advance holds. First, the release of around 92.6 million ARB on September 16. Releases like that increase supply, and in this case the market absorbed it without a visible drop. Whether that stays the case will only show once the released holdings are actually moved.
Second, the end of the fee subsidy on Robinhood Chain. If volume falls off sharply afterwards, part of the activity was bought. If it stays stable, Arbitrum has won a customer who brings revenue.
What That Means For Reading The ARB Price
Arbitrum is one of the few assets in this rally where the price rise can be tied to figures that exist independently of the price: fee income, volume of tokenised assets, number of transactions. That does not make the move safe, but it does make it verifiable.
The broader market is helping at the moment: bitcoin stands above $85,000, as high as it has been since January. Anyone wanting to place the overall picture will find the current crypto prices in the overview. If sentiment turns there, assets with a monthly gain of 150 percent are hit first. Which trading venues list ARB and at what fees is shown by the comparison of the best crypto exchanges.
Sui is the strongest asset among the 30 largest cryptocurrencies on Sunday. The price stands at $1.04, a gain of around 26 percent within 24 hours and of a good 40 percent over the week (CoinGecko, September 21, 2026, 12:50 UTC). That puts Sui well ahead of the wider market: bitcoin added 6 percent over the same period, ethereum 5.9 percent.
The jump did not come out of nowhere. It coincides with a broad risk-on day across the crypto market, but it lands on two pieces of news that concern Sui specifically. One at a time.
What Sets The Sui Price Apart From The Other Gainers
On a day when almost everything is rising, a gain on its own says little. It gets interesting at the trading volume: around $2.0 billion changed hands in 24 hours. For comparison, Avalanche, which also posted a double-digit gain, reached a fraction of that. Volume on that scale means real demand was in play, beyond the closing out of derivatives positions.
Open interest on the futures exchanges rose roughly 21 percent alongside it. A rising price with rising open interest is taken as a sign that new money is building positions rather than old positions being forced shut. The counter-test is still outstanding: whether those positions hold will only show up on the first pullback.
Reason One: Sui As A Bet On The AI Economy
The macro investor Raoul Pal has publicly described Sui as his highest-conviction position for the emerging economy of autonomous AI agents. His thesis: after Ethereum and Solana, Sui is the third smart contract network built for machine speed.
Technically that points to a Sui feature called programmable transaction blocks. Several working steps, say a swap, a deposit and a forwarding, can be settled in a single transaction. For a human that is convenient. For software working through thousands of such chains per hour, it is the difference between feasible and unaffordable.
An assessment from a prominent investor is not a fundamental. It does move capital, though, and that is exactly what happened here in measurable terms.
Reason Two: Bitcoin As Collateral On Sui
In parallel, Hashi went live, a protocol that makes bitcoin usable as programmable collateral on Sui without the coins leaving the bitcoin blockchain. The approach targets an old problem: bitcoin is by some distance the largest pool of capital in the crypto market, yet it largely sits idle. Any chain that pulls part of it into its own DeFi landscape gains liquidity without having to attract it first.
Whether the protocol holds up in operation remains open. Custody solutions for bitcoin on foreign chains have repeatedly failed at their bridges in the past. Anyone stepping in here should understand the construction before capital flows.
The Rotation Into Layer 1 Chains
The third driver is a market move rather than a Sui event. On September 21, capital rotated visibly into large layer 1 networks and into application tokens. Alongside Sui, Render added around 19 percent, Arbitrum a good 15 percent, Bittensor just under 14 percent. The trigger lies with bitcoin: the price reached its highest level since January at more than $85,000, carried by the liquidation of short positions in the hundreds of millions.
Rotations like this follow a familiar pattern. Bitcoin rises first, then the large alternatives follow, and the smaller application tokens come last. Anyone entering at the end of that chain is often buying the close of the move.
What To Watch On The Sui Price Now
Three levels decide how this develops. First the zone around $1.05, where Sui has been rejected several times in recent weeks. A daily close above it would be the first solid breakout in months. Second, open interest: if it falls while the price holds, speculators have reduced and the advance rests on spot demand. Third, the distance to the all-time high, which despite the rally sits at around 81 percent. Sui is not breaking a record right now; it is working its way back out of a deep trough.
For placing the wider market, it helps to look at the current crypto prices and at the question of whether the bitcoin advance carries or remains a squeeze spike. Anyone looking to acquire Sui will find the terms of the trading venues in the overview of the best crypto exchanges.
US funds holding ether lost a net $140 million in the week to September 18, 2026. It is the first week of outflows since mid-August, and it ends a run of four consecutive weeks of inflows. At the same time the Ethereum price stands at $2,703 on Monday morning, a good 5 percent above the previous day. Price and capital flows are pointing in different directions.
If you hold ether, this is less a question about the price than a question about the wrapper: which structure your ether sits in, what that means for tax, and which deadlines are currently running. This article puts the numbers in context and names the points you can check against your own holdings.
Ether ETFs: $140 Million of Outflows in One Week
The figure comes from The Block's weekly flow review published on September 19, 2026. It shows that US spot ETFs on ether recorded a net outflow of $140 million for the trading week to September 18. That is the first negative week since the one that ended on August 14.
What happened inside that week is worth noting. On Friday, September 18, ether funds still took in $143.8 million. The weekly loss was therefore built up on the days before it and was almost, though not quite, recovered on the final trading day. Anyone reading the Friday number alone gets a different picture from someone looking at the full week.
The four weeks before that looked very different. Taken together, ether funds gathered $1.94 billion over that run. Measured against it, an outflow of $140 million is a small amount; it marks an interruption, not a collapse.
One term that is often confused: net flow is the difference between fund shares created and shares redeemed over a period, converted into dollars. It measures how much fresh money goes into the wrapper or comes out of it, and it says nothing about how the value of the ether already held has developed.
Why the ETH Price Is Rising Despite the ETF Outflows
On Monday morning, September 21, 2026, ether trades at $2,703.62 according to CoinGecko. That is 5.10 percent more than 24 hours earlier and 5.80 percent more than a week ago. The price remains a good 45 percent below its all-time high of August 24, 2025.
The move is not confined to ether. Bitcoin stands at $83,650 over the same window, up 4.27 percent, XRP gains 7.30 percent and Solana 7.17 percent. When practically the entire top of the market rises at once, the cause usually lies not with any single asset but with general risk appetite.
That leads to a distinction worth keeping in mind. The previous week's ETF flows and this morning's price describe different periods. The flow data ends on Friday; the price is from today. A weekly outflow therefore does not explain what the price does on the following Monday.
Bitcoin ETFs for Comparison: $433 Million in a Day, $6.2 Million Over the Week
For the bitcoin funds the contrast in the same week was sharper still. On Friday, September 18, they took in $433 million. For the week as a whole, a net inflow of $6.2 million was left. The four days before it had therefore consumed almost all of the Friday inflow.
At fund level, Fidelity's FBTC led on Friday with $310.7 million, while BlackRock's IBIT reached $108.4 million. Over the full week the order reversed: IBIT took in $120.7 million, FBTC $79.9 million. Here too, a single strong day says little about where the money travels over longer stretches.
US Spot ETF or ETP: What You Can Actually Buy in Europe
This is the point at which many reports out of the United States mislead. The funds whose flows are described above are US spot ETFs. As a retail investor in Europe you generally cannot buy them. They are not set up under European law and do not provide a key information document under the PRIIPs regulation, which brokers in the EU must supply before selling to retail clients.
What you find instead on European exchanges are crypto ETPs, often structured as ETNs. An ETN is legally a debt security issued by the provider that tracks the price of the underlying asset and in practice is usually backed physically with real ether. Which of these products are tradable in Germany and how they differ is collected in our overview of crypto ETFs in Germany.
The third route is buying the coin directly on a trading platform, with custody either at the platform or in your own wallet. Which platforms are available on a regulated basis for this is shown in our crypto exchange comparison. All three routes lead to the same underlying asset, but they are treated differently for tax.
The Holding Period Under Section 23 EStG: Why the Wrapper Decides the Tax
When you buy and hold ether directly in Germany, Section 23 of the Income Tax Act applies, which governs private disposal transactions. If more than twelve months pass between acquisition and sale, the gain is tax free. Within the year there is an exemption threshold of 1,000 euros per year covering all private disposal transactions together. The text of the law is freely available from the Federal Office of Justice.
With an ETN the position is different and depends on how the paper is constructed. What matters is whether it grants you a claim to delivery of the actual coins. Papers carrying a delivery claim are in practice often treated as an asset under Section 23, while those without one count as a monetary claim subject to the 25 percent flat capital gains tax plus solidarity surcharge and, where applicable, church tax. In the second case there is no deadline after which the gain becomes tax free.
This is not an academic difference. On a gain of 10,000 euros after more than a year, one side carries a tax bill of zero and the other a burden of roughly 2,600 euros. Which case applies to your paper is set out in the issue terms and the key information document. Check that before you buy, not in the year you sell. Because the classification can be contested in an individual case, it belongs with your tax adviser and not in a forum.
Anyone who has bought at several different times also needs clean records of the acquisition dates in order to prove the deadline at all. Without that evidence the rule does you little good, because the burden of proof sits with you.
ETH Staking and the Holding Period: What Applies After the Ministry Guidance
Many ether holdings do not simply sit there but are committed to staking. Staking means putting up ether as security in the network and receiving rewards on an ongoing basis. For tax, those rewards are other income at the moment they accrue and are taxed at your personal rate, valued at the price on the day of receipt.
The once widespread worry that staking would extend the holding period of the staked balance to ten years has been cleared up by the German Federal Ministry of Finance. Twelve months continue to apply, even if the coins were staked in the meantime. The rewards received, however, start their own deadline from the day they accrue, which makes bookkeeping laborious where payouts are continuous.
If you invest through an ETP, the topic falls away for you, because staking there happens at most at the level of the issuer. Whether and how the issuer passes on the proceeds is set out in the product terms and differs from provider to provider.
Custody: Your Own Wallet, a Trading Platform or a Securities Account
The three routes also differ in who holds the keys. With your own wallet you carry the responsibility alone, with everything that follows: a lost access is final, a well secured one is hard to attack from outside. With a trading platform the counterparty risk sits with the provider, who in return takes on the technical security.
With an ETP your ether sits with the issuer's custodian and you hold a security in your bank's securities account. The practical advantage is settlement in the familiar account including a tax certificate, provided a German custodian bank is involved. The drawback is that in the end you hold a claim against an issuer rather than the coin itself.
Levels Above and Below: What the ETH Price Is Measured Against Now
To the upside the next notable zone is the area around $2,750 to $2,800, where ether has failed several times in recent weeks. Above that sits the round $3,000 mark, which the price has not seen since the spring.
To the downside the zone around $2,600 is the first reference point, because last week it turned from a barrier into a springboard. If the price falls back there, the breakout was a short-lived move. These levels are orientation points taken from the price history so far and expressly not a forecast.
For the tax question they are secondary in any case. Anyone close to the end of the twelve-month deadline has a different calculation to make from someone who holds for the long term regardless. Selling two weeks before the cut-off date can end up more expensive than a slightly worse price after it.
What Inflows and Outflows Are Really Worth as a Signal
ETF flows are one of the few robust figures published daily. They show how demand out of the regulated fund wrapper is developing. What they do not show is demand outside it, meaning on trading platforms, through European ETPs, or at companies buying directly.
A single week is therefore of little use as a direction indicator. The sequence says more: four weeks of inflows totalling $1.94 billion, then one week with $140 million of outflows, and on the final day of that week a clear inflow of $143.8 million again. That describes a pause whose continuation is open.
Anyone wanting to derive an action from it should tie that action to their own situation rather than to the weekly number. The questions that actually save or cost you money are those about wrapper, deadline and custody.
Checking Ethereum ETF Outflows: What to Take Away
- Establish which wrapper your ether sits in. Direct holding, ETN, or both side by side. If an ETN sits in your securities account, look in the key information document for the delivery claim, because the tax treatment depends on it. Which products are tradable in Germany is set out in the overview of crypto ETFs in Germany.
- Write down the acquisition dates of your direct holdings. Without evidence of acquisition, the twelve-month deadline cannot be demonstrated to the tax office. Anyone with many individual purchases is better served by a tool than by a spreadsheet; the common ones are in the crypto tax software comparison.
- Check your custody before you change anything. If you hold directly and are considering a move, first compare the terms and the licensing status of the platform in the exchange comparison. Moving coins between your own addresses is not a disposal; a sale followed by a repurchase certainly is.
The flow figures in this article come from the weekly review by The Block of September 19, 2026, the price data from CoinGecko, retrieved on September 21, 2026 at 08:49 UTC.
(As of September 21, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
The HashFly browser experiment uses a digital neural model for Bitcoin hashing and projects greater efficiency from a hypothetical biological version.
xAI says the new model is a "notable improvement" over Grok 4.6 at the same price. The benchmarks say it's still in second place.
Crypto advocates argue that NFTs can deliver real digital ownership, but privacy gaps and integration hurdles have held the tech back.
The senior roles cover Apple’s consumer payment products and Google Cloud’s institutional blockchain business in Asia.
The rally cleared an eight-month ceiling on a short squeeze and falling oil prices. The next three weeks will decide if it sticks.
U.Today - IT, AI and Fintech Daily News for You Today
Billionaire venture capitalist Tim Draper has taken aim at Apple, Meta and other tech giants for keeping Bitcoin off their balance sheets.
Solana’s 5-year chart pattern approaches resolution as the asset coils for a 106% run to the rim, according to veteran Peter Brandt.
Ethereum's open interest on Binance surges to its highest level on Binance in over nine months following a major breakout in its trading price.
An altcoin breakout led by XRP and NEAR triggered $666 million in crypto short position liquidations over the last 24 hours.
Dogecoin gathers momentum toward $0.10 as OI surges.
Blockonomi
Key Highlights
- Shares of Circle climbed approximately 6% on Monday amid a broader crypto market surge and the company’s institutional lending expansion.
- The stablecoin issuer introduced Digital Asset-Backed Borrowing, enabling qualified institutional clients to obtain USDC loans using Bitcoin collateral while maintaining BTC holdings.
- Users deposit Bitcoin, create cirBTC tokens, and leverage them as collateral via third-party lending platforms on Arc or Ethereum.
- Morpho protocol is initially supported, with plans to integrate Aave and additional protocols in the future.
- Users remain subject to fluctuating interest rates, collateral ratio adjustments, and liquidation risks set by the chosen lending platform.
Circle Internet Group (CRCL) shares advanced roughly 6% on Monday as Bitcoin surged past $85,000 and the stablecoin provider unveiled a new institutional borrowing solution. CRCL closed Friday at $91.78 and opened Monday trading at $98.09.
Circle Internet Group, CRCL
The newly introduced offering, dubbed Digital Asset-Backed Borrowing, enables qualified Circle Mint clients to leverage Bitcoin holdings as collateral for USDC loans without liquidating their BTC positions. The functionality is accessible via supported onchain lending venues on both Arc and Ethereum networks.
Clients deposit Bitcoin with Circle and generate Circle Wrapped Bitcoin tokens, known as cirBTC. These tokens can then be deployed as collateral through user-controlled wallets, with borrowed USDC transferred directly into their Circle Mint accounts.
This mechanism provides institutions with dollar-denominated capital access while preserving Bitcoin market exposure. Circle indicates the streamlined workflow aims to minimize the platforms and steps typically involved in crypto-collateralized lending.
Circle Broadens Bitcoin and USDC Functionality
Morpho serves as the inaugural third-party lending protocol integrated with the service. Circle has signaled that Aave and other lending infrastructure will be incorporated progressively.
The lending arrangements require overcollateralization rather than traditional credit assessment models. Clients can supplement collateral or repay USDC to retrieve their cirBTC holdings.
Circle does not directly provide the loans or establish borrowing parameters. Interest rate levels, collateral ratios, liquidation triggers, and capital availability are governed by the respective third-party marketplace.
The product debut aligns with cirBTC’s availability on Circle’s Arc blockchain network. Each cirBTC token maintains 1:1 backing by native Bitcoin custody through Circle National Trust, per company statements.
Circle initially rolled out cirBTC on Ethereum earlier this year. The Arc integration provides an additional blockchain environment where institutional participants can utilize Bitcoin collateral within Circle’s expanding stablecoin infrastructure.
Arc recently activated its mainnet and employs USDC as its native gas currency. Circle is strategically positioning the network around stablecoin transactions, asset tokenization, and institutional financial applications.
Cryptocurrency Market Upswing Provides Additional Momentum
Monday’s CRCL appreciation was not exclusively attributed to the borrowing product announcement. Bitcoin climbed to approximately $85,000, marking its strongest performance since January, which elevated optimism throughout crypto-related equities.
Circle stands to benefit if the product generates heightened institutional appetite for both USDC and cirBTC. The offering also creates another connection point between Circle Mint users and activities occurring on Arc.
Significant risks persist, however. A substantial Bitcoin price decline could force collateral positions toward liquidation thresholds, while borrowing expenses and collateral demands may shift based on prevailing market dynamics.
Circle is additionally dependent on third-party DeFi infrastructure, meaning participants face exposure to smart-contract vulnerabilities, liquidity constraints, and protocol risks beyond Circle’s direct oversight. New York-based customers are presently ineligible for the service.
From an investor perspective, the service introduces another potential driver of USDC utilization, though Circle has not revealed anticipated borrowing volumes or revenue projections tied to the product. Its financial impact will hinge on institutional client adoption rates.
For Monday’s session, the immediate catalyst combined strengthening cryptocurrency valuations with further expansion of Circle’s institutional offerings. Qualified Circle Mint participants can now establish Bitcoin-collateralized USDC borrowing arrangements through Morpho on Arc or Ethereum networks.
The post Circle (CRCL) Stock Surges 6% on Bitcoin-Collateralized USDC Lending Launch appeared first on Blockonomi.
Key Highlights
- Meta shares surged approximately 7% on Monday driven by strong reception of its Muse AI personal assistant.
- The Muse application climbed to the top position in Apple’s U.S. App Store free apps category, surpassing ChatGPT.
- Wells Fargo increased Meta’s price target from $640 to $796 while keeping its Overweight rating intact.
- The Meta Connect conference kicks off Wednesday, with expectations for additional Muse data and potential feature announcements.
- Meta faces challenges as Amazon has restricted Muse’s ability to conduct purchases on its platform.
Shares of Meta Platforms (META) climbed approximately 7% on Monday as market participants reacted positively to the swift uptake of its Muse personal AI assistant. The stock reached around $710 during trading hours following Friday’s close at $665.75.
Meta Platforms, Inc., META
The Muse application debuted in the United States on September 8 and has swiftly ascended to become the leading free download on Apple’s U.S. App Store. According to Sensor Tower estimates, the application accumulated over 730,000 U.S. downloads within its initial 10-day period.
Different from conventional chatbot interfaces, Muse functions as a task-completion agent for users. Its capabilities include arranging travel plans, dispatching emails, completing forms, conducting online shopping, and handling various multi-step operations.
The promising early performance is shifting investor sentiment regarding Meta’s substantial AI infrastructure investments. The company anticipates capital expenditures ranging from approximately $130 billion to $145 billion this year for AI infrastructure development.
Analyst Raises Meta Price Outlook to $796
Wells Fargo analyst Ken Gawrelski elevated the firm’s price target for Meta to $796 from the previous $640 while keeping an Overweight rating. The upgrade reflects positive momentum surrounding Muse and strengthening conviction in Meta’s AI development roadmap.
According to Wells Fargo, U.S. Muse downloads hit a peak of 264,000 on September 19. Sensor Tower data referenced by the firm indicated that daily active users had reached 448,000 one day prior.
The financial institution did not adjust its revenue projections upward, however. Additionally, it lowered its 2026 operating income forecast to reflect anticipated increases in legal expenses.
Muse represents a potential new revenue channel for Meta beyond its core advertising business. The platform features paid subscription options in addition to its free version, offering the company a direct monetization pathway for consumer AI engagement.
This opportunity holds particular significance given Meta’s existing reach through Facebook, Instagram, and WhatsApp, which collectively serve billions of users worldwide. The company could leverage this established user base to distribute Muse without requiring new audience development.
Upcoming Meta Connect Conference Takes Center Stage
Attention now shifts to Meta Connect, scheduled to commence Wednesday. Wells Fargo anticipates Meta will share more comprehensive Muse adoption metrics and may unveil additional functionality during the conference.
Challenges around third-party platform integration are already emerging. Amazon has prevented Muse from executing purchases on Amazon.com, stating that Meta’s agent was accessing its service without proper authorization.
Amazon emphasized that third-party agents must operate with transparency and honor platform decisions regarding participation. Meta has yet to publicly outline its approach to resolving Amazon’s concerns.
This development carries weight because Muse’s practical value hinges partially on its capacity to interface with various websites, e-commerce platforms, email systems, and other services. Should major technology companies impose access restrictions, several of Muse’s most valuable agent capabilities could face significant limitations.
User confidence presents another consideration, as a personal AI agent requires access to substantial quantities of sensitive personal data. Meta states that Muse operates within a protected virtual machine environment, mandates approval for sensitive operations, and empowers users to determine which services the agent can access.
The stock has already appreciated roughly 25% throughout September, elevating expectations entering the Connect conference. While initial download figures appear strong, questions remain about sustained user engagement, subscription conversion rates, and whether revenue generation will adequately support Meta’s escalating AI capital investments.
For Monday’s trading session, however, the driving force is evident. The combination of Muse’s impressive initial adoption metrics and Wells Fargo’s elevated $796 price target has provided investors with renewed confidence that Meta’s AI expenditures may yield a widely-appealing consumer product.
The post Meta Platforms (META) Stock Surges 7% on Muse AI Success and Analyst Upgrade appeared first on Blockonomi.
Key Highlights
- Arm shares jumped approximately 16% Monday amid renewed investor enthusiasm for AI and chip sector equities.
- Company CEO Rene Haas highlighted that demand for Arm’s technology reaches unprecedented levels, cautioning that semiconductor supply bottlenecks may persist for years.
- Customer orders for Arm’s latest AGI CPU have already surpassed $2 billion spanning fiscal years 2027 and 2028.
- Meta’s rapidly expanding Muse AI agent has reinforced market expectations that agentic AI applications will significantly boost CPU consumption.
- The challenge lies in valuation: ARM shares have already climbed substantially, and increased AI computing needs don’t necessarily convert directly into proportional royalty or chip sales growth.
Arm Holdings (ARM) shares climbed approximately 16% Monday, reaching around $319, as part of a broader rally across semiconductor and artificial intelligence stocks. The surge brought ARM’s gains to more than 27% across the previous five trading days.
Arm Holdings plc American Depositary Shares, ARM
The stock’s momentum reflects increasing market confidence in Arm’s positioning within AI data center infrastructure and central processing unit demand. Chief Executive Rene Haas recently emphasized that demand for the company’s technology has reached record levels as artificial intelligence applications drive requirements for processors, memory, and broader computing resources.
Haas expressed heightened optimism regarding revenue potential from Arm’s newest AGI CPU offering. The company has publicly disclosed that customer commitments have already topped $2 billion spanning fiscal 2027 and fiscal 2028.
This development provides Arm with a more direct pathway into data center hardware markets beyond its established licensing and royalty framework. Company leadership states that long-term objectives include transforming the AGI CPU segment into a substantially larger revenue contributor.
Agentic AI Applications Elevate CPU Importance
Additional momentum Monday came from Meta’s Muse AI agent, which has quickly ascended U.S. App Store rankings. Market participants increasingly anticipate that persistent AI agents will demand significantly greater CPU resources compared to conventional chatbot-style interactions.
Agentic frameworks extend beyond simple response generation. These systems browse content, invoke tools, execute code, handle data, and orchestrate background tasks, creating substantial additional CPU workload surrounding the AI model core.
Arm projects the server CPU market could approach approximately $120 billion by 2030, featuring annual growth exceeding 35%. This market segment gains importance as AI computing requirements expand beyond GPUs throughout the broader data center infrastructure.
Arm’s proprietary AGI CPU targets this transition toward agentic AI applications. Meta serves as lead partner and co-developer, while OpenAI, Cerebras, Positron, and Rebellions number among companies incorporating the processor into AI systems.
Arm also delivered record first-quarter fiscal 2027 revenue of $1.29 billion, representing 22% year-over-year growth. Data center royalty revenue more than doubled compared to the prior year period.
Rapid Rally Elevates Valuation Concerns
Broader market conditions contributed to Monday’s advance as well. Declining Treasury yields, falling oil prices, and renewed AI infrastructure optimism lifted semiconductor stocks generally, with AMD and Intel also recording substantial gains.
Arm has additionally benefited from industry commentary suggesting semiconductor supply constraints could extend several years. Limited supply can support pricing stability and strengthen demand for efficient computing designs.
However, investors should distinguish between AI compute expansion and Arm’s actual financial performance. Arm generates most revenue through licensing and royalties, meaning greater AI activity doesn’t automatically produce equivalent percentage increases in Arm’s top line.
The stock has also appreciated very rapidly. Monday’s move pushed ARM significantly above several recent valuation assessments, indicating investors are already incorporating substantial future growth from data centers and agentic AI applications.
Arm’s move into direct CPU sales also introduces execution challenges. Manufacturing capacity, customer acceptance, profit margins, and competitive dynamics will all influence how much of the stated $2 billion demand pipeline ultimately converts to recognized revenue.
For Monday’s session, the primary narrative centered on strengthened confidence in Arm’s AI infrastructure positioning. Enhanced CEO guidance, over $2 billion in AGI CPU commitments, and increasing excitement surrounding agentic AI converged to drive ARM substantially higher.
The post Arm Holdings (ARM) Stock Jumps 16% on Booming AI Processor Demand appeared first on Blockonomi.
TLDR
- AMD stock climbed 9.04% as broader compute demand strengthened market momentum.
- Data center revenue doubled as EPYC and Instinct products expanded AMD’s reach.
- Nebius pricing changes signaled strong demand for AMD-powered computing capacity.
- AMD could gain a 2027 gaming window if rival next-generation GPUs face delays.
- High valuation leaves future gains tied to stronger deployments and revenue growth.
Advanced Micro Devices shares surged 9.04% to $610.42 as stronger compute demand lifted the semiconductor stock on Monday. The move followed renewed interest in Meta’s Muse platform and expanding demand across global data center infrastructure. AMD also gains from its growing presence in server processors, accelerators, and future gaming hardware across major computing markets.
Advanced Micro Devices, Inc., AMD
AMD Broadens Its Data Center Opportunity
Meta’s Muse platform highlighted the heavy computing demands created by persistent software agents operating across large cloud environments. These workloads need graphics processing, but they also require general-purpose computing for coordination, applications, system management, and background tasks. That structure expands the market opportunity for AMD’s EPYC processors and Instinct accelerators across modern enterprise data centers.
AMD already serves major cloud and enterprise customers with products built for high-performance computing and accelerated workloads worldwide. The company now promotes a broader infrastructure strategy instead of depending on one processor category for future growth. This approach gives AMD exposure to multiple spending areas as cloud operators expand capacity for demanding software workloads globally.
Recent financial results also show how quickly AMD’s data center business has expanded during the current growth cycle. Second-quarter 2026 data center revenue reached $6.7 billion, representing 107% growth from the same period last year. Total company revenue rose 50% to $11.5 billion, giving the segment greater importance across AMD’s overall business mix.
Strong Demand Supports Pricing Power
Cloud provider Nebius added another demand signal after raising prices across several computing products in its infrastructure stack. Nebius increased rates for AMD EPYC Genoa capacity by 25% as demand strengthened and available resources tightened further. The company also raised Nvidia GPU prices, while memory-related services recorded even steeper increases during the latest adjustment.
Those price changes reinforce the role of central processors within large-scale computing systems, cloud platforms, and enterprise infrastructure. AMD has increasingly emphasized CPUs because they manage applications, move data, and support accelerator-heavy workloads across data centers. Stronger pricing for EPYC capacity suggests customers still value those processors despite intense competition across the global semiconductor market.
Forrest Norrod recently outlined AMD’s broader data center strategy and emphasized the company’s full-stack computing ambitions for large deployments. The strategy combines processors, accelerators, networking support, and software to address more parts of large infrastructure deployments. That mix gives AMD more ways to capture spending as cloud providers build larger computing environments for advanced applications.
Gaming Opportunity Meets High Valuation
Reports also suggest AMD could introduce a next-generation gaming graphics card during 2027 and gain a temporary timing advantage. A hardware leaker indicated that AMD may release a successor to the RX 9070 XT sometime next year. Other products from the same generation could arrive later, which would limit the scale of that potential advantage.
Separate industry reports suggest Nvidia may delay its next major gaming GPU generation until 2028 in the consumer market. If those reports prove accurate, AMD could become the only major vendor launching fresh gaming hardware during 2027. Steam’s August 2026 survey showed Nvidia with 72.88% GPU share, compared with 18.68% for AMD among surveyed users.
AMD’s sharp rally has also pushed valuation measures well above some fundamental benchmarks used by market analysts. At $607.30, shares traded 114.12% above a GF Value estimate of $283.63 during the recent market advance. Meta has not identified AMD as a Muse supplier, so stronger deployments must support future revenue growth across AMD’s portfolio.
The post Advanced Micro Devices, Inc. (AMD) Stock: AI Expansion Drives Investor Optimism appeared first on Blockonomi.
Key Highlights
- The Finnish smart ring manufacturer has kicked off its roadshow for a U.S. public offering aimed at securing up to $2.2 billion in capital.
- The health technology company intends to offer 50 million shares with a price band set at $40 to $44 per share.
- If priced at the upper end, the company would achieve a fully diluted market capitalization of roughly $15.6 billion.
- The firm’s revenues climbed approximately 74% compared to the prior year, reaching $1.21 billion for the nine-month period concluded June 30.
- Trading is scheduled to commence on the Nasdaq exchange next week under the symbol OURA, following final pricing.
The Finnish wearable technology company Oura has commenced its initial public offering roadshow, aiming to secure as much as $2.2 billion from American investors. The smart ring manufacturer is offering 50 million shares within a price range of $40 to $44 apiece.
Should the offering price at the maximum level, the company would command a fully diluted market value of nearly $15.62 billion. Oura has submitted its application to begin trading on the Nasdaq stock exchange using the ticker OURA.
Strong Revenue Performance Fuels Market Debut
The wearable health technology specialist recorded revenues of roughly $1.21 billion throughout the nine-month stretch ending June 30, marking an increase of approximately 74% versus the corresponding timeframe in the previous year. During that prior-year period, revenues stood at about $697 million.
The firm has also documented substantial expansion in hardware unit sales. According to filings with securities regulators, Oura distributed 3.6 million ring units during the twelve-month window ending June 30.
For the nine-month period concluded June 30, the company moved 4.1 million units, compared with 1.8 million rings in the equivalent period twelve months earlier. The manufacturer posted a net loss of $924 million across those nine months.
The latest generation device, the Oura Ring 5, carries a retail price ranging from $399 to $499. This wearable monitors various health indicators including sleep quality, physical activity levels, recovery readiness, stress markers, cardiovascular metrics and reproductive health data.
Distinguishing itself from conventional smartwatches, the Oura Ring features no display screen. This design choice enables the device to function for approximately seven days on a single charge while maintaining round-the-clock health monitoring capabilities.
Recurring Revenue Model Gains Traction
Beyond hardware sales, the company generates predictable income through its monthly subscription platform, priced at $5.99. As of June 2026, the service had accumulated 5 million paying subscribers.
Management forecasts that fiscal 2026 will conclude with roughly 5.7 million paid subscribers. Such growth would translate to an expansion rate of about 96% year-over-year.
The company’s membership base skews female, with approximately 72% of subscribers identifying as women, while 27% are aged 45 or older. Oura faces competition from wearable offerings by Apple, Fitbit, Samsung and Whoop.
Smart rings have carved out a distinct niche within the broader wearables industry by delivering compact, display-free health monitoring solutions. Samsung has recently joined this product category with its own smart ring offering.
Major Institutional Interest Emerges
The public offering has garnered attention from significant prospective investors. Pharmaceutical giant Eli Lilly has signaled potential interest in acquiring up to $100 million worth of shares during the IPO.
Dragoneer Investment Group has expressed interest in potentially purchasing as much as $300 million in stock. However, these indications of interest are non-binding and don’t guarantee actual purchase commitments.
This listing will also gauge investor appetite for consumer technology companies following a relatively quiet period for autumn public offerings. Financial markets have recently contended with rising government bond yields, shifting Federal Reserve policy expectations and questions surrounding technology sector valuations.
The company achieved an approximately $11 billion valuation during a private financing round conducted last year. A $15.62 billion IPO valuation would mark additional appreciation should the shares price at the range’s ceiling.
Goldman Sachs, Morgan Stanley and JPMorgan are serving as lead underwriters for the transaction. Final pricing is anticipated next week, with trading commencing shortly thereafter on the Nasdaq.
The post Oura Smart Ring Manufacturer Targets $15.6 Billion Valuation in Nasdaq Debut appeared first on Blockonomi.
CryptoPotato
Bitcoin is following a similar trajectory seen in 2022-2023, according to the latest observation by Doctor Profit.
The analyst said that the latest move above the 50-week moving average, in particular, set the stage for the breakout toward the $82,500-$83,000 area, which took place over the past several hours.
2022-2023 Structure Is Repeating
The MA50 Weekly is currently around $78,700. BTC recently pushed past that level and was trading near $85,000 at the time of writing after an explosive rally on Monday. Doctor Profit said a weekly close above the moving average would strengthen his bullish view. His observation stems from Bitcoin’s previous market structure in 2022-2023, when the crypto asset faced several rejections around the MA50 Weekly before eventually clearing it.
Bitcoin broke below the MA50 Weekly and then reclaimed it seven times. Five instances were followed by bull markets, while two became false signals. Those occurred once in 2011, when BTC had “virtually no liquidity,” and once in 2020 during the COVID-19 crash.
The current market is showing a similar pattern. The analyst explained,
“The recent bear trap adds another similarity to 2022-2023! Same rejections, for 3-4 Weeks followed by a shakeout, then a recovery above the moving average and breakout above the MA50 Weekly, exactly of what is happening right now! Bears interpreted weakness as confirmation of another collapse, but the market reversed. I see the same broader transition!”
The latest move puts the focus on the start of the next bull market phase, which analysts have been speculating about lately. Doctor Profit has identified $88,000 as the next target once the remaining resistance levels are cleared.
Even Bolder Target
Another market commentator believes that Bitcoin could be repeating a historical cycle. Crypto Patel flagged a 364-day gap between the crypto asset’s 2017 peak and 2018 bottom, followed by a similar 364-day gap between the 2021 peak and 2022 bottom. The analyst said the 2025-peak-to-2026-bottom also appears to follow the same timing.
Bitcoin is now retesting long-term trendline support after losing the major EC zone. If the historical pattern continues, Crypto Patel said the next major expansion could target $370,000. He stressed that price action must confirm the setup.
The post From Bear Trap to $88K: Analyst Reveals Why Bitcoin’s Rally Isn’t Over appeared first on CryptoPotato.
BitMine Immersion Technologies (BMNR) bought 27,562 Ethereum (ETH) over the week to September 20 and reported combined crypto, cash, and moonshot holdings of $17.1 billion in a press release and 8-K filed September 21.
Total holdings rose $1.3 billion from the $15.8 billion BitMine reported a week earlier, when it added 27,180 ETH. The company marked its Ether at $2,688 per token, per Coinbase, up from $2,513 a week earlier. That mark puts the week’s purchases at roughly $74 million, with the treasury at 5,983,940 ETH.
Staked Total Flat Since Late August
BitMine Chairman Thomas “Tom” Lee stated the company “has bought ETH each and every week since the inception of its ETH Treasury Strategy on June 30, 2025,” a track record he called “unmatched by any public company in the world.” The pace has swung this year; one July purchase fell to 7,430 ETH, down from more than 30,500, a slowdown Lee tied to share buybacks.
Holdings equal 4.9% of the 122.1 million ETH in supply, and BitMine puts itself 98% of the way to its target of owning 5% of all ETH, the plan it calls the Alchemy of 5%, 15 months after the strategy began.
BitMine stakes 5,067,309 ETH, worth $13.6 billion at its mark and 85% of the treasury, through MAVAN, its Made in America Validator Network. The staked count has held there for five consecutive weekly updates, even as the token total kept climbing.
Lee put projected annualized staking revenue at $357 million, up from $334 million a week earlier, rising to $421 million once the ether is fully staked, on a 2.62% seven-day yield.
Lee Sees Stronger Fourth Quarter
“We believe a crypto bull market is underway, having started in late June,” Lee said, citing “the rotation from AI back to crypto.”
He put Ether’s quarter-to-date lead over the S&P 500 at 6,519 basis points, called the run “a prelude to a potentially stronger up move in the 4th quarter of 2026,” and said the company expects institutions “to substantially increase their exposure in the final 3 months of 2026.”
Cash and marketable securities rose to $714 million from $549 million a week earlier. The release gave no reason for the increase. Alongside the ether, BitMine held 212 Bitcoin (BTC), a $180 million stake in Beast Industries and a $105 million position in Eightco Holdings (ORBS), up from $98 million.
BMNR traded $1.2 billion in average daily dollar volume over the five days to September 18, ranking 100th of 5,704 US-listed stocks, according to Fundstrat, Lee’s research firm. The release ranks BitMine first among ether treasuries and second among crypto treasuries overall, behind Strategy (MSTR), which the release said owns 845,080 Bitcoin worth about $75 billion.
The post BitMine Buys 27,562 ETH in a Week as Holdings Reach $17.1 Billion appeared first on CryptoPotato.
The cryptocurrency market has been on fire over the last few days despite negative news such as the CLARITY Act failure, rising interest rates in the United States, and escalating global geopolitical tensions.
The past 24 hours have delivered even more gains, with Bitcoin (BTC) climbing past $85,000 for the first time since January, while Ethereum (ETH) hit a nine-month high of roughly $2,750. Many analysts believe the second-largest cryptocurrency is poised for a further rally in the near future, but some describe the current setup as a classic bull trap.
Don’t Pop the Champagne Yet?
At first glance, it seems like ETH’s cycle bottom is behind us and might be gearing up for a shift toward a bull run. X user DANNY, though, doesn’t support that thesis, claiming that the asset is setting up “a huge trap.”
The analyst argued that if ETH pumps to $2,670 (as it happened), sentiment will flip fast, and then people will start projecting further pumps to $4,000 and $5,000. For the X user, that level is the area where the market can trap late buyers before the real flush starts.
DANNY envisioned a slip toward $1,800, which could trigger the first real panic, followed by $1,500 and capitulation that may occur in the final months of the year. The analyst then sees an incoming reversal and a jump above $3,250 in the second or third quarter of 2027.
X user Midas also shared a pessimistic bet, maintaining that ETH has formed “a huge bearish setup.” The analyst doesn’t expect the upward move to last in the short term and forecasts a retest of the $1,700-$1,800 range.
“And if that liquidity gets swept, ETH can extend lower toward $1.4K-$1.5K. But I still don’t expect ETH to make the same kind of new cycle lows as BTC. ETH has been showing much stronger relative structure, and I still think it will outperform once this correction is finished. There is just one major downside target left to clear before the real expansion starts. So, short-term, I’m bearish on ETH. Long term this setup can become one of the strongest opportunities of the cycle ” they added.
Ted also predicted a potential correction ahead, but expects it to come once Ethereum’s price taps the $2,900-$3,000 area.
These Factors Favor the Bulls
The combination of multiple positive elements suggests ETH’s price may keep surging in the short term. As CryptoPotato recently reported, whale transactions have been climbing, showing that large holders have become increasingly active.
Ethereum’s non-empty wallets have risen to 207.17 million, with staking remaining a major reason why ETH stays parked in the long run. Just hours ago, Lookonchain revealed that a mysterious whale has sold 1,107 BTC (worth over $86 million) over the past five days, bought 34,422 ETH, and staked it all.
The solid institutional interest is another bullish factor. Although they finally registered a red week, spot ETH ETFs have attracted a lot of capital over the past few months, which could support a more substantial price rally ahead.
Not long ago, renowned analyst Ali Martinez highlighted the $2,570 level, saying a decisive breakout could open the door to a jump toward $2,700 and even $3,000. For more ETH price forecasts, check out our article here.
The post Ethereum Crosses $2,700: Bull Trap or the Start of a Major Rally? appeared first on CryptoPotato.
[PRESS RELEASE – Tallinn, Estonia, September 21st, 2026]
NOWPayments today published new empirical data analyzing six months of enterprise payout activity, offering a comparative performance benchmark across TRON, BNB Smart Chain, Solana, Bitcoin, and Ethereum to help businesses select optimal blockchain rails based on speed, transaction volume, and cost efficiency.
The dataset reveals distinct operational advantages depending on transfer priorities: Solana recorded the fastest average payout speed at 1 minute and 45 seconds while accounting for 3.08% of volume and 3.86% of transactions. TRON led in total monetary volume at 43.69%, and BNB Smart Chain handled the largest share of individual payout transactions at 48.23%.
High-Frequency Payouts Put BNB Smart Chain in the Lead
Together, TRON, BNB Smart Chain, Ethereum, Bitcoin, and Solana accounted for 94.04% of payout volume and 77.84% of payout transactions during the period analyzed.
BNB Smart Chain accounted for 48.23% of transactions, compared with 15.73% for TRON. Its share of payout volume was lower at 21.75%.
The network handled far more individual transfers without carrying the largest share of value, a pattern consistent with higher-frequency, lower-value payouts in the NOWPayments dataset.
Higher-Value Payouts Put TRON in the Lead
TRON moved 43.69% of payout volume, more than twice BNB Smart Chain’s 21.75% share, despite accounting for a much smaller share of transactions.
Based on those shares, the average TRON payout was approximately 6.2 times larger than the average BNB Smart Chain payout during the period. The networks served different payout patterns: TRON carried more value, while BNB Smart Chain handled far more individual transfers.
Ethereum ranked third by volume at 18.84% and represented 7.42% of transactions. Bitcoin accounted for 6.68% of volume and 2.60% of transactions, while Solana represented 3.08% of volume and 3.86% of transactions.

The data suggests a practical framework for matching the network to the payout flow:
 The data offers a starting point, not a universal network recommendation.
When Speed Matters, Solana Leads
Solana led on speed with an average payout time of 1:45. Bitcoin followed at 2:53, ahead of TRON at 3:08 and BNB Smart Chain at 3:13. Ethereum recorded the longest average at 5:56.
The gap between the fastest and slowest networks was 4 minutes and 11 seconds. Every network in the comparison still averaged less than six minutes, while TRON and BNB Smart Chain were separated by only five seconds.
The fastest network was not the most widely used. That points to a broader principle: crypto infrastructure should be evaluated across the full movement of funds, not by a single headline metric.
Kate Lifshits, Commercial Director at NOWPayments, applies the same data-first approach in Crypto That Works for Business, her Cryptopolitan series on the commercial impact of crypto payments. The first column, the 22% Sales Boost Hiding in Your Crypto Checkout, examined checkout performance; future editions will cover other points where payment infrastructure affects revenue, costs, and growth.
“The useful question is not which network tops a leaderboard. It is what a specific payout flow needs to optimize: value, frequency, speed, or cost,” said Kate Lifshits, Commercial Director at NOWPayments.
When Cost Matters, The Best Route May Not Be a Blockchain Network
When minimizing payout costs is the priority, comparing blockchain networks may be the wrong place to start.
NOWPayments allows businesses to send payouts to ChangeNOW Pro wallets with no network or service fees within the ecosystem. Creator Andy Tries Coding publicly tested the route and reported receiving a fee-free payout in under five seconds.
Recipients are identified by email and confirm the transfer before funds move, so businesses do not need to collect wallet addresses at the beginning of the payout process. An interactive guide walks through the process from payout creation to recipient access.
The takeaway is simple: define the payout flow first, then select the network or route. Value, frequency, speed, and cost will not point every business to the same answer.
About NOWPayments
NOWPayments is a crypto business ecosystem designed to help companies accept payments, automate mass payouts, manage stablecoin treasury, and scale global digital asset operations through a single infrastructure. The platform supports more than 350 cryptocurrencies, over 30 stablecoins, flexible settlement options, and enterprise-grade APIs.
The post NOWPayments Releases Cross-Chain Payout Data Revealing Key Performance Benchmarks Across TRON, BNB Chain, and Solana appeared first on CryptoPotato.
Bitcoin pushed through $85,000 on Monday as the latest leg higher took it to levels last seen in late January. The crypto asset has gained 6% over the past 24 hours.
But data suggests that this recovery has yet to receive strong confirmation from US spot demand.
Recovery Has a Missing Piece
According to the latest data shared by CryptoQuant, the Coinbase Premium Index has turned negative again. The index measures the price difference between Bitcoin on Coinbase’s USD market and Binance’s USDT market. A positive reading usually means stronger buying activity from US investors. A negative reading, on the other hand, suggests weaker demand or relatively stronger selling pressure on Coinbase.
It’s worth noting that the data came earlier today when BTC stood at around $81,500, and the index was at -0.02. The premium had briefly moved above zero but has now slipped back into negative territory. This means the recent Bitcoin recovery is not being matched by consistently stronger demand on Coinbase.
In previous cases, steady positive Coinbase premiums have often appeared during periods when US spot demand was supporting BTC’s price gains. CryptoQuant stated that traders should watch whether the premium can move back above zero, remain positive, and rise alongside Bitcoin’s price. Such a move would provide stronger evidence that US-based spot buyers are taking part in the recovery.
However, the current negative reading does not necessarily signal a bearish reversal. The index is only slightly below zero and is not showing an extreme reading.
Experts are increasingly debating whether crypto winter has finally ended. Bitwise CIO Matt Hougan, meanwhile, believes the market has entered “crypto spring.” Speaking to CNBC, the exec said the downturn after BTC’s all-time high above $126,000 in October 2025 is now over. He expects the current cycle to develop into the “strongest and longest-running” bull market in the industry’s history.
Strategy’s Comeback
Adding to the bullish backdrop, Strategy resumed its Bitcoin purchases after a three-week pause. The company bought 950 BTC for $75.7 million at an average price of $79,670, co-founder Michael Saylor announced.
The latest purchase takes its total Bitcoin holdings to 846,000 BTC, acquired for $63.8 billion. At current prices, the stash is worth about $72 billion.
The post Bitcoin (BTC) Just Reached $86K: There’s Just One Problem appeared first on CryptoPotato.