Cryptocurrency Posts
Crypto Briefing
Iran's precarious situation amid US tensions could lead to increased political instability and shifts in leadership dynamics.
The post Iran’s Pezeshkian warns of precarious situation amid US tensions appeared first on Crypto Briefing.
The partnership could enhance AI security confidence, potentially boosting Anthropic's market position and influencing industry standards.
The post Nvidia and Anthropic partner to enhance AI security with OpenShell integration appeared first on Crypto Briefing.
Countries developing sovereign AI could reduce reliance on foreign tech, but still depend on Nvidia, highlighting complex tech sovereignty.
The post Nvidia CEO Jensen Huang urges countries to build their own sovereign AI appeared first on Crypto Briefing.
Google's Gemini 4 Argon's rapid adoption highlights potential scalability challenges, impacting Google's ability to meet growing AI demand.
The post Google’s Gemini 4 Argon processes nearly 25 trillion tokens in its first 72 hours appeared first on Crypto Briefing.
Nvidia's push for physical AI in Europe could accelerate industrial digitalization, fostering regional autonomy and strategic tech partnerships.
The post Nvidia CEO Jensen Huang takes the stage at GTC Berlin with physical AI in focus appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Liquid Network Announces Final Stages of Recovery Following Massive Hack
The Liquid Network on Tuesday said that things were up and running again, over one month after hackers stole 4,000 bitcoin, worth about $320 million at the time, from the network’s federation wallet before returning most of it in a “white hat” operation.
Writing in a blog post, the Liquid Network said that it was entering “the final stages of recovery with enhanced security.”
Hackers in September stole 4,000 bitcoins from the federation wallet that backs the Blockstream sidechain. Blockstream was able to negotiate to get back most of the funds.
“The final phase of restoration involves reestablishing the network’s full 1:1 bitcoin backing, followed by the controlled reactivation of Federation peg-outs for authorized PAK key holders,” the Liquid blog post read.
“The Federation, Blockstream, and independent security experts have made substantial progress toward this objective, with the necessary technical infrastructure and safeguards now in place.”
The post added that it had introduced phased swaps again. Blockstream CEO Adam Back wrote on X on Tuesday that swaps were working again.
Liquid is a layer-2 created by Blockstream that allows users to quickly move assets backed 1:1 with bitcoin. People can swap stablecoins for bitcoin and bitcoin on the Lightning Network on apps that support the Liquid Network.
Hackers were able to get 4,000 bitcoins by exploiting an inflation bug on the Liquid sidechain to create over 4,000 LBTC — a token supposedly backed by bitcoin — that did not exist before and cash them out for real on-chain BTC.
The hackers claimed to be white hat hackers who then had an exchange with Blockstream via messages written into Bitcoin blocks. Though critics argue they were not so ‘white’ since they kept 15% of the stolen funds, worth millions.
In one message, the hackers slammed Blockstream as “delusional, greedy, and arrogant,” and threatened to reveal all of Blockstream’s encrypted messages in the exchange unless the company paid the hackers 10% of the bitcoins as an official bounty.
“You SHALL pay 10% using your own money as bug bounty or you will cause all your holders a 15% loss for your irresponsibility and stinginess,” the message read.
The hackers are still holding onto around 600 bitcoins — or 15% of the total funds — worth close to $50 million at today’s prices as per the latest public knowledge.
It is not clear if Blockstream reached a settlement with the hackers in private.
This post Liquid Network Announces Final Stages of Recovery Following Massive Hack first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Swiss Financial Regulator Gives Green Light to Country’s First Bitcoin ETF
Swiss financial regulator FINMA has approved the country’s first bitcoin exchange-traded fund for retail investors.
The watchdog said Tuesday that the approval comes as people in Switzerland express a growing interest in crypto — particularly bitcoin.
Bitcoin ETFs — particularly in the U.S. — have widened the scope of investors who can buy and sell the leading cryptocurrency. Via shares that trade on the stock exchange, investors can buy exposure to the biggest cryptocurrency in a safe and regulated way.
“As early as 2021, FINMA authorised a fund for qualified investors that invests primarily in a basket of cryptocurrencies,” the announcement read.
JUST IN:
— Bitcoin Magazine (@BitcoinMagazine) October 20, 2026Switzerland's Financial Market Supervisory Authority has approved the country's first Bitcoin ETF
pic.twitter.com/AOVLGqTa5H
“As Bitcoin has a long trading history and a particularly high trading volume compared with other cryptocurrencies, FINMA has approved an exemption from the applicable risk diversification rules in this case.”
It added: “At the same time, FINMA emphasises that investments in Bitcoin — even through an approved ETF — remain highly risky.”
The announcement did not reveal which asset manager or bank would debut the product. Switzerland already has crypto ETFs limited to institutional or qualified investors on the market.
In the U.S., bitcoin ETFs had the most successful debut in the history of investment vehicles when approved in 2024.
Now, traders, institutions, and retail investors can quickly buy shares that track the price of the leading cryptocurrency and not worry about exchanges or storage of the digital coin.
The funds, managed by Wall Street giants like BlackRock, Fidelity, and Morgan Stanley, manage over $97 billion in assets, according to CoinGlass data.
This post Swiss Financial Regulator Gives Green Light to Country’s First Bitcoin ETF first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Bitcoin Treasury Strive Debuts New Preferred Stock With 15% Dividend
Bitcoin treasury Strive’s preferred stock, SATS, is now trading on the Nasdaq, according to the company.
The stock debuted Tuesday and will pay a 15% dividend every business day, according to an announcement.
Nasdaq-listed Strive said it closed its upsized initial public offering of 7,000,000 shares of SATS at a public offering price of $90 per share.
JUST IN:
— Bitcoin Magazine (@BitcoinMagazine) October 20, 2026Strive’s 'SATS' has officially IPO’d on the Nasdaq, and is raising $630 million to buy more Bitcoin and income-generating assets
It comes as public companies work to financialize bitcoin via different products. OG bitcoin treasury Strategy, which has five different preferred stocks, proposed daily dividends for its products last month.
“The successful, upsized IPO of SATS marks a critical milestone in our strategy to maximize long-term total returns for our common equity investors,” Matt Cole, Chairman and CEO of Strive, said in a statement.
The Nasdaq-listed Strive also has SATA, another preferred stock, which pays a variable dividend.
Strive debuted as an official bitcoin treasury last year and is now the fourth biggest company in the space.
Founded by former Ohio gubernatorial candidate and tech entrepreneur Vivek Ramaswamy, the company holds 36,818 BTC worth over $3 billion at today’s prices. The company on Monday announced another bitcoin buy of 4,045 BTC between October 12 and 16.
In January 2026, it completed the acquisition of Semler Scientific in an all-stock deal — the first instance of a publicly traded Bitcoin treasury company acquiring another such company.
Like with other digital asset treasuries, the idea is that investors can get amplified returns from Strive’s stock. The company buys bitcoin with equity, and maintains a debt-free balance sheet: no bonds, no credit lines, and no leveraged positions that could trigger forced liquidation in a downturn.
Strive is following in the footsteps of software company Strategy, which started buying bitcoin in 2020. Strategy is now the largest corporate holder of bitcoin, with 848,517 coins worth over $60 billion.
Its five preferred stocks are STRF, STRC, STRK, STRD, and STRE.
Strive’s stock, ASST, was trading 4% higher on Tuesday.
This post Bitcoin Treasury Strive Debuts New Preferred Stock With 15% Dividend first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Bitcoin Could Outperform Most Assets, JPMorgan Says — But the Bank Still Won’t Recommend It
JPMorganChase’s asset management division has said that while bitcoin is still too volatile to be recommended for strategic investors’ portfolios, the cryptocurrency could outperform most asset classes over the next 10 years.
In its 2027 “Long-Term Capital Market Assumptions” report, the bank said that while volatility in the biggest cryptocurrency’s price has dampened, it is “premature to consider BTC as a diversifier in a balanced portfolio.”
JPMorgan, one of the world’s biggest banks, has utilized Bitcoin’s underlying tech — the blockchain — to debut its own products. But the multinational’s CEO, Jamie Dimon, has long been a Bitcoin skeptic.
JUST IN: The largest bank in the U.S. JPMorgan is forecasting Bitcoin to outperform every major asset over the next decade.
— Bitcoin Magazine (@BitcoinMagazine) October 20, 2026
You are not bullish enough
“BTC currently lacks a clear role as a diversifier in balanced portfolios due to unstable correlations to other asset classes,” the report read.
It added: “We see bitcoin as a speculative asset and a hedge against monetary easing.”
The report went on to show a graph with a base case for bitcoin returns beating stocks, bonds and gold. But it did add that the coin’s volatility could harm its role in portfolios.
“But should volatility continue to decline and correlations to other asset stabilize, this may evolve in the future, particularly as regulation becomes clearer and liquidity and price discovery continue to improve,” it noted.
For now, the report added, bitcoin “mostly trades like a high beta risk asset that tracks global money supply growth.”
Bitcoin has become more popular on Wall Street, especially since the Securities and Exchange Commission green lighted exchange-traded funds to trade in 2024.
President Donald Trump’s pro-crypto stance has also helped: regulators under the U.S. leader have taken a far more open approach to watchdogging the space since 2025.
JPMorganChase boss Jamie Dimon has famously blasted Bitcoin, calling it a “hyper up fraud” and “pet rock” — adding that its only value is to criminals.
Still, he has praised the coin’s underlying technology, and lauded crypto products like stablecoins.
This post Bitcoin Could Outperform Most Assets, JPMorgan Says — But the Bank Still Won’t Recommend It first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
BlackRock Files for Bitcoin ETF With Downside Buffer and Capped Upside
BlackRock has filed for a new bitcoin exchange-traded fund which, if approved, would cap investors’ upside while limiting their losses.
The iShares Bitcoin Managed Protection ETF, or PBIT, would aim “to create and manage bitcoin exposure,” according to a Monday filing with the Securities and Exchange Commission.
It would work buying options and fixed-income strategies to give investors regulated bitcoin exposure with capped upside and some downside protection — but not direct bitcoin ownership.
The fund would suit investors who want to invest in bitcoin but not experience all the volatility that comes with the top cryptocurrency.
Bitcoin has attracted attention for its wild price swings over the years but its volatility has dampened as more investors have bought into the space.
But 2025 was the least volatile year for the asset and the bear market of 2026 has been its most shallow on record: in past cycles, bitcoin’s price has dropped as low as 80% from its all-time high; this year it shed just 50% of its value.
BlackRock’s iShares Bitcoin Trust — IBIT — started trading in 2024 after the SEC gave the green light to 11 spot bitcoin ETFs.
The most successful of the ETFs in terms of flows, the investment vehicle has helped bring bitcoin to Wall Street. Now traders, institutions and retail investors can quickly buy shares that track the price of the leading cryptocurrency.
They don’t need to worry about exchanges or storage of the digital coin, rather, BlackRock buys and holds the bitcoin while investors simply hit the buy or sell button via their brokerage account.
IBIT has the most assets under management out of the bitcoin ETFs, currently handling $65.7 billion.
On Monday, the fund received $665.2 million in fresh investment as bitcoin buyers flooded back into the market.
That’s the biggest number of shares bought in the product since October 2025, when bitcoin notched a new all-time high, according to Farside Investors data.
This post BlackRock Files for Bitcoin ETF With Downside Buffer and Capped Upside first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
CryptoSlate
About 1.3 billion SpaceX shares become eligible for sale on Oct. 22, worth roughly $194.3 billion at the Oct. 20 close of $147.89. A week earlier, Aave Labs proposed accepting tokenized SpaceX shares (SPCXc) as collateral on its V4 Equities Hub on Base. Aave's risk adviser LlamaRisk published its assessment of the listing on Oct.…
Read the full story on CryptoSlate
Understand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
SHRINCS keeps a larger signing path for recovery, while compact signatures require reliable counters and tighter custody coordination.
Read the full story on CryptoSlate
Understand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
Deka’s launch brings crypto trading to participating savings banks, with a €0.99 order fee plus a spread and restricted transfers.
Read the full story on CryptoSlate
Understand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
FINMA permits a Swiss-law retail fund to concentrate on Bitcoin while keeping custody safeguards, risk disclosures and sales duties.
Read the full story on CryptoSlate
Understand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
September orders bind Apple and Google upon service and target unauthorized services in the AIFC; implementation remains unconfirmed.
Read the full story on CryptoSlate
Understand the crypto stories that matter and what to watch next. Get The Catalyst in your inbox
CryptoTicker.io
If you hold LEO Token and want to sell, the figure that decides is not the price but daily turnover. LEO ranks 18th among all crypto assets by market capitalisation, at around $8.32 billion. Of that, about $150,000 was traded in the past 24 hours. That is a ratio of roughly 1 to 55,000, and for you it means the price on the overview page says little about the price at which you would actually get out of a larger position.
This analysis was compiled by cryptoticker.io itself on October 21, 2026, on the basis of CoinGecko's public market data on LEO Token and its nine listed trading pairs. The figures below each state when they were taken, because with an order book this thin even individual orders make themselves felt.
LEO Token over the week: $9.04 and a range of 0.35 percent
LEO trades at $9.04, or €8.06, as of Wednesday 07:00 German time. Over seven days that makes a gain of 0.37 percent. The weekly high was $9.0451, the weekly low $9.0132. Between high and low lie around 0.35 percent.
That narrowness is no outlier for LEO but the normal picture. Over 30 days there is a gain of 1.40 percent, over a year a gain of 0.73 percent. A look at the daily range shows the same pattern: daily high $9.05, daily low $9.01. If you hold LEO as a bet on price movement, you hold an instrument that barely moves.
For context the other direction belongs here too. LEO reached its all-time high on May 4, 2026 at $10.61. From today's price that is 14.8 percent away. Downwards the distance is greater: the all-time low of $0.7999 dates from December 24, 2019.
Market capitalisation against daily turnover: $8.32 billion meets $150,000
Market capitalisation is the number of circulating tokens multiplied by the last price. It describes a book value, not an amount that is available. With daily turnover it becomes a practical question: how much money really changes sides in a day?
With LEO, between around $92,000 and $265,000 a day passed through the books in the seven days to October 21, 2026, measured against CoinGecko's daily data. The most recent value is about $150,000. For a sense of scale: with 919.86 million circulating tokens, a daily turnover of $150,000 corresponds to just under 16,600 tokens, or 0.0018 percent of the supply in circulation.
One figure belongs honestly alongside it, because it points the other way. Add up the turnover of the nine individual trading pairs CoinGecko lists for LEO and you arrive at around $1.76 million. That sum and the $150,000 figure at coin level arise from different methods, and the gap between them is explained in the next section. Only together are the two reliable.
Nine trading pairs, one venue: the concentration risk in the order book
According to the data compiled, LEO is listed on seven exchanges in nine pairs. Of the roughly $1.76 million in gross turnover, about $1.59 million falls on a single pair at a single venue, CoinUp.io. That is around 90 percent. The remaining $170,000 or so spreads across eight pairs.
The breakdown, as of October 21, 2026: Bitfinex lists LEO against the dollar with about $122,069 in turnover and against USDT with about $26,788. GroveX comes to around $22,048, OKX against USDT to $728, Gate to $288, and Indodax against the Indonesian rupiah to $18. On Uniswap V3 on Ethereum, $12 was traded. And OKX against the euro, the only euro pair on the entire list, came to $117.
That gives the sentence that counts for you: strip out the dominant venue and what remains at the home exchange, Bitfinex, is turnover of just under $149,000 a day. The coin-level figure sits in exactly that order of magnitude. If you want to sell LEO, you are in practice selling on one market, not on one of seven. How such concentration affects the exit can be read up on with other exchange tokens, for instance in our analysis of OKB and its trading venues from October 19, 2026. To see which venues carry euro pairs across the board, look at the comparison of crypto exchanges.
The euro pair and the term slippage
Slippage is the difference between the price you see when you submit an order and the price at which it is finally executed. It arises when there is not enough volume on the other side of the order book at the price you want, and the order eats its way through several, ever worse price levels.
At a pair with $117 in daily turnover that is not a fine point for professionals. A sell order of €2,000 would be a multiple of the entire daily volume at that euro pair. What happens then depends on the order type. A market order is executed at whatever price the book provides. A limit order protects the price but may be filled only in part, or not at all, possibly over days.
In practical terms: a larger exit from LEO runs either through the dollar or USDT pair at the home exchange, with an extra currency step back into euros, or through partial sales in small slices. Both cost fees and time, and both belong in the calculation before the sale, not after.
iFinex's burn mechanism: 27 percent of gross revenue
A token burn is the permanent removal of tokens from circulation by sending them to an address from which nobody can move them again. With LEO that process is the core of the construction. Under the token's whitepaper, Bitfinex's parent iFinex commits to buying LEO on the market each month to the value of at least 27 percent of its consolidated gross revenue from the previous month, and burning it. Cointelegraph reported on that commitment and its extension to earlier revenue when the mechanism was introduced. The exchange keeps its own public transparency report on it.
That mechanic explains the calm in the price better than any market sentiment. On the demand side stands a buyer who buys to a formula rather than to an opinion. On the supply side stands a circulating supply that shrinks as a result. An instrument whose price is tied to a buyback out of revenue behaves more like a stake in the exchange's business than like a freely traded altcoin. That is the assessment the figures support; it is not a guarantee for the price.
65.4 million LEO burned: the difference between circulating and total supply
The data compiled give 919.857 million LEO in circulation against a total supply of 985.240 million. The difference comes to around 65.38 million tokens, or about 6.6 percent of total supply. LEO was issued in 2019 as one billion tokens.
No upper limit on supply is set in the data, and with LEO that is not the point either: the direction is designed to run downwards over time, until, under the commitment, no token remains in commercial circulation. For holders, the difference is the one figure by which you can verify the mechanism month after month without having to believe an announcement.
Reimbursement from the Bitfinex hack: Recovery Right Tokens come first
Alongside the running buyback out of revenue there is a second, irregular route by which LEO is to be burned: funds recovered from the 2016 Bitfinex hack. We described that process on October 9, 2026 in our piece on the return of 264 bitcoin to Bitfinex, including the sequence that matters.
That sequence often gets skipped. Recovery Right Tokens are redeemed first, meaning the claims of those harmed in 2016, and further deductions follow for legal costs among other things. Only the remaining net balance is covered by the commitment of at least 80 percent for buyback and burning. A sum of transferred bitcoin is therefore never the same as a burn amount, and no figure for LEO can be derived from a transfer. If you read such a calculation in an article, ask about the intermediate step.
Buying from Germany: how to check the MiCA register
Since July 1, 2026, providers serving retail clients in the EU need a granted authorisation under the Markets in Crypto-Assets Regulation, MiCA for short. A pending application is not enough. Before buying or selling LEO that is your first check, and it comes before any look at the fee: which of the venues that list LEO at all is allowed to serve you as a client in Germany?
That can be looked up in BaFin's company database and in ESMA's public register, not in the provider's advertising. Which exchanges can show a granted authorisation is something we track continuously in our overview of regulated crypto exchanges. Mind the combination of the two: an authorised exchange is of use to you with LEO only if it also lists the token, and a venue with plenty of LEO turnover is of no use if you are not allowed to hold an account there as a German retail client. That is precisely the vice LEO is caught in.
A second point concerns custody. LEO runs as an ERC-20 token on Ethereum, with a contract address beginning 0x2af5d2ad. You can therefore withdraw the token from the exchange and hold it yourself, in a hardware or software wallet. That solves counterparty risk but not the liquidity problem: in the end you have to sell again where an order book stands.
A twelve-month holding period: why the timing of a sale counts twice with LEO
In Germany, crypto assets held privately fall under private disposals pursuant to section 23 of the Income Tax Act. Sell within twelve months of buying and a gain is taxable at your personal rate. After twelve months have elapsed, the gain from the sale is tax-free. For gains inside the period an exemption threshold of €1,000 per calendar year applies, covering all private disposals together. Exceed it and the entire gain is taxable, not just the portion above.
With a token that has gained 0.73 percent in a year, the taxable gain is usually small. The timing nonetheless counts twice here, and the reason is liquidity: if you sell in small slices over days or weeks because the order book provides no more, each partial disposal creates its own date and its own allocation to the purchase. Fail to document the sequence and you will be reconstructing it later from exchange exports. There are tools that allocate purchases and sales automatically. The tax treatment of your individual case remains a matter for your tax adviser.
Levels above and below: $9.01, $9.05 and the all-time high at $10.61
As an observation, not a price target: upwards the next bearings are the daily high of $9.05 and the weekly high of $9.0451, above them the round $9.50 mark and the all-time high of $10.61 from May 4, 2026. Downwards the weekly low of $9.0132 and the round $9.00 mark set the first step.
With LEO, however, such levels carry less meaning than with liquid coins, and that follows directly from the figures above. Where a single pair carries 90 percent of turnover and the rest sits in the range of a few hundred dollars a day, one larger order can break a level without anything fundamental having changed in supply or demand. With this token, a breakout on thin volume is above all an indication about volume, not about direction.
LEO Token: without euro liquidity the venue decides
LEO is not a token for which the price question is the most important one. The mechanism keeps the price calm, and the buybacks out of revenue give it a foundation many altcoins do not have. The price for that is a market you cannot get out of at any time in any size. Holding or selling therefore turns less on the percentage figure than on whether your venue carries you on the way out. Three steps to settle that for yourself:
- Check the venue and the pair. Look up which pair your position can actually be sold through and what daily turnover that pair carries. If your position is in the order of magnitude of the daily volume, plan for partial sales. Which venues carry euro pairs across the board is set out in the comparison of crypto exchanges.
- Match the authorisation. Check in BaFin's company database or ESMA's register whether your provider has a granted MiCA authorisation, and hold that against the question of whether it lists LEO. The overview is available at the regulated crypto exchanges.
- Sort out the period and the records. Fix the purchase date and purchase price for every tranche before you sell in slices, and secure the exchange exports. For allocating purchases and sales, crypto tax software helps.
(As of October 21, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Solana is replacing its consensus today. The switch from TowerBFT to Alpenglow is set for October 21, at around 14:50 UTC according to the developer house Anza, which is around 16:50 German time. The Solana Foundation most recently projected the corresponding epoch start at about 15:00 UTC; an earlier estimate named 13:20 UTC. Expect a window of roughly two hours, then, not a button press to the minute. What changes, by contrast, can be stated precisely: the time to irreversibility of a payment falls from around 12.8 seconds to a target of 100 to 150 milliseconds.
The price has been unmoved by it so far. SOL traded at $106.54 on Wednesday morning, 2.3 percent above the previous day, after a daily low of $103.72 and a high of $107.93 (data from CoinGecko, as of October 21). Where the price can point over a horizon of months is set out in our Solana price prediction. For today something else counts: for investors, a protocol switch is first a risk date and only then an argument.
Alpenglow replaces TowerBFT: what happens on mainnet today
TowerBFT is the procedure by which Solana's validators have until now agreed on which block holds. Each of those votes ran across the blockchain as a transaction of its own. Alpenglow takes the votes off the blockchain: validators will sign them as BLS messages, which can be bundled into a single certificate. A BLS signature scheme is one in which many individual signatures can be combined mathematically into a single one that can be verified in one step.
The changeover does not run over days. According to Unchained's report on Anza's schedule, a feature gate with the identifier SIMD-0384 flips at an epoch boundary. A counter then runs over 5,000 slots in which the blocks contain validator votes and nothing else. That sounds like a standstill and is a safeguard: because no user transactions sit in the blocks during that window, the section can be rolled back without anyone losing a payment. At the end of the counter the validators certify an Alpenglow genesis block carried by 82 percent of staked capital. Anza expects that final step to take hundreds of milliseconds. TowerBFT is then retired.
From 12.8 seconds to 150 milliseconds: how Votor works
The new voting component is called Votor, and it knows two routes to completion. On the fast route, 80 percent of staked capital votes for a block and the process is finished after one round. Where that is not enough, a fallback route with a threshold of 60 percent kicks in, which needs two rounds. Both figures appear on the Solana Foundation's Alpenglow overview page. The fault tolerance is there too: Alpenglow tolerates 20 percent malicious capital plus a further 20 percent offline. By the same source, TowerBFT tolerates less than 33 percent hostile capital.
Finality is the point from which an entry can no longer be reversed. At an exchange, that is the time a deposit needs before it counts as credited. If it falls from just under 13 seconds to a tenth of a second, a waiting period disappears that card payments do not have. Whether the 150 milliseconds actually hold under load is a target, though, and not yet a measurement. The target also applies in the first instance to admitted validators, not to every route by which a wallet obtains its information.
98.27 percent approval and nine rehearsals: how well the procedure has been tested
The validators voted on Alpenglow in September 2025. Approval came from 98.27 percent of the votes cast, with 52 percent of all staked SOL participating. The second figure is the more interesting one: almost half the capital did not vote at all.
Testing then ran for months. Anza cites a bug bounty of more than 25,000 SOL, 115 participating security researchers, a simulation across 1,500 nodes and nine full-scale migrations. On testnet Alpenglow took over consensus on September 24, on devnet a day later. The testnet was restarted from scratch several times from the beginning of May, and one migration attempt failed network-wide and was rolled back before a later one succeeded. A network-wide failed attempt in testing is therefore part of the backstory to this date.
0.8 SOL per epoch instead of 2 SOL a day: the new admission fee
For validators the cost side changes fundamentally. Until now they paid a transaction fee for every single vote, together around 2 SOL a day. That amount had doubled after slot times were shortened to about 200 milliseconds. Alpenglow replaces the individual fees with a flat admission fee of 0.8 SOL per epoch. An epoch lasts about 24 hours. The fee is paid from the vote account one epoch in advance, and it is burned.
Work it through yourself: 2 SOL against 0.8 SOL a day is a saving of 1.2 SOL per validator, or around $128 a day at Wednesday morning's price. The 60 percent cost reduction being cited is therefore documented. The second part of the calculation is mentioned less often and matters more for the token supply: the old vote fees mostly passed on to other validators, whereas the new admission fee accrues to nobody. The amount leaves circulation. At roughly 1,000 active vote accounts that would be 800 SOL a day withdrawn from supply. That extrapolation is our own and depends on the number of validators that actually remain admitted after the switch.
75 percent of block space falls away: why reported TPS will decline
Vote transactions historically took up around 75 percent of the room in Solana's blocks. Once they disappear from the blockchain, every statistic that simply counts transactions per second falls with them. You will see that in rankings over the coming days, and it does not mean a decline in economic activity. It means the count has until now included something no user triggered.
When reading metrics that means: from today, stop comparing Solana's TPS with the figure from two days ago. What remains reliable is the number of active addresses, trading volume on the decentralised exchanges and fee revenue. If you read a headline in the coming weeks about a collapse in Solana transactions, check whether the figure was gathered before or after October 21.
Firedancer stays out of the handover window
One detail that gets lost in the short reports: Firedancer and Frankendancer, the alternative validator clients, are not active during the handover window. For Alpenglow, validators have to register a public BLS key and run Agave version 4.3; version 4.3.2 is named for Agave, Jito-Solana and Harmonic Salsa. If you run your own node today and do not meet those requirements, you simply do not take part in the new consensus.
There is also a limitation that affects wallet users: some RPC providers are likely to report finality with small delays against the 150-millisecond mark. The clock on the blockchain keeps its accuracy of one second, and transaction timestamps remain approximations. The tenth of a second therefore describes the consensus and not automatically what your app displays.
Fund flows are running against the upgrade
While work went on at the protocol, money flowed out. The US spot funds on Solana saw net withdrawals of $6.72 million on October 19, the largest single item being the Bitwise Solana Staking ETF at $4.8816 million, with Fidelity's FSOL accounting for around $1.84 million (data from SoSoValue). How long the run now is depends on the analysis: one counts eleven consecutive trading days of net outflows, another describes the run from October 5 to 16 and so arrives at ten. The funds have lost more than $60 million in October.
September ran the other way: inflows there came to around $272 million. Since launch, net inflows add up to about $1.55 billion, and the net assets of the spot funds stand at around $1.625 billion. October has therefore undone just under a quarter of September without seriously denting the stock. If you are considering a fund route yourself, it is worth looking at crypto ETFs in Germany and the cost structures there.
Solana price at $106: the levels the switchover day sets
On the downside the daily low of $103.72 is the first line, with the round $100 mark below it, which the price has defended several times in October. On the upside the daily high of $107.93 comes first. Between them lies a level from our article yesterday on the treasury sale: $107.51, the line at which a listed treasury holder's sale was pinned yesterday. That line has held since, with the price running back from $103 to $106.54 and sitting just under a dollar below it.
That is the real difference from yesterday. Twenty-four hours ago the question was whether a single seller was pressing the market. Today the question is whether a technical date attracts buyers. Historically, upgrades to crypto networks have tended to be a reason to sell, because the date was known well in advance. For Alpenglow that can only be demonstrated in the days afterwards.
Our assessment: the upgrade does not fix a capital problem
From this desk, Alpenglow is technically the biggest step in years and still secondary to this week's price question. Three figures from this article argue for that: ten to eleven trading days of outflows, more than $60 million out of the spot funds in October, and a price that at $106.54 sits around 64 percent below its all-time high of $293.31. Faster finality creates no buyer; it lowers friction for applications that are being built anyway.
One point argues against that, and we take it seriously: payment settlement with a tenth of a second of finality is an argument Solana can make against card networks and hardly any other blockchain can. If the 150 milliseconds hold in operation, that shifts the outlook for payment applications in 2027, not the outlook for the price in October 2026. Dissent comes from inside the project: Solana co-founder Anatoly Yakovenko wrote, "Alpenglow would have shipped in half the time if they just changed the vote program to the ag state machine", questioning the effort rather than the goal. A response from Anza is not available.
Holding period and staking: the tax position in Germany on switchover day
For holders in Germany the most important news is a non-event. A consensus switch is neither a sale nor a swap. Your SOL remain the same units, the holding period under section 23 of the Income Tax Act continues to run, and the day triggers no disposal. If you hold your SOL for more than a year, you still sell gains tax-free; within the year the €1,000 exemption threshold for private disposals applies. If your acquisition dates are not cleanly in order, crypto tax software helps you catch up.
With staking the case is different and has nothing to do with today: rewards from delegating are other income and must be recognised in the year they accrue. What changes for delegators is their validator's cost side, not their own tax liability. If its vote fees fall by 1.2 SOL a day, more yield stays in the pool. Whether the validator passes that on depends on its commission, which you will find in the comparisons of staking providers under review.
What actually affects delegators and exchange customers today
For users, no action is required according to the Solana Foundation. Signing, sending and approving remain unchanged; finality simply arrives earlier. That applies to you whether your SOL sit in your own wallet or are delegated to a validator. Three points are still worth a look.
First, trading venues routinely pause deposits and withdrawals during protocol switches, even when nothing goes wrong. If you are planning a transfer today between 1pm and 5pm German time, check your exchange's status page beforehand; an overview of providers is available at the crypto exchanges under review. Second, your wallet may show the new speed only with a delay, because the RPC provider sits behind it. A slow display in the first few hours is not yet evidence of a problem in the network. Third, version 4.3.2 concerns you only if you run a validator yourself.
You can put it to the test yourself this evening: send a small amount from your wallet to your exchange address and measure how long the credit takes. If it comes in well under the familiar twelve-plus seconds, the switch has reached your provider. If it comes in above that, the cause is the exchange's processing, no longer the consensus.
Alpenglow day: prove the finality first, then the $100 mark
October 21 does not decide the price; it decides a claim. Three steps make sense today and tomorrow:
- Check your trading venue's status page this evening before you initiate deposits or withdrawals. Which providers reopen how quickly can be seen in the comparison of crypto exchanges under review.
- Note the time of your next SOL credit. That time is your own measurement of the 150-millisecond claim, independent of any announcement.
- If you delegate, check over the coming two weeks whether your validator passes the saved vote fees on to the yield. Provider commissions are listed in the comparison of staking providers under review.
If the price holds $103.72 and runs above $107.93, the upgrade has given the market something. If it falls below $100, it was a technical date with no price effect, and the fund flows remain the story of the month.
(As of October 21, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Nine blockchain companies founded the Quantum Alliance on October 15, 2026, an open standards body for post-quantum security. Three things about it are documented so far: the launch itself, the alliance's count of roughly 6.04 million bitcoin, about 30 percent of the circulating supply, held in addresses whose public key is permanently exposed, and a model run by two contributors that names March 2028 as the earliest window for a cryptographically relevant quantum computer. Everything beyond that is assessment, not evidence: when such a machine will actually exist, whether it will be built at all, and whose hands it will be in by then. This piece keeps the two apart and says which address in your own holdings falls into the risk group and which does not.
What the Quantum Alliance is and who founded it on October 15
The Quantum Alliance is a standards body, not a product and not a blockchain. Its purpose is a common definition of what "quantum-ready" actually means for a blockchain, a wallet and a custodian, plus a test procedure that allows such claims to be checked. According to the report by Decrypt, the named contributors include Quantus, Postquant Labs, the Midnight Foundation, Keystone, Abelian and Hacken; the industry outlet TFTC adds American Fortress, Intmax and The Vault. The line-up therefore runs from base protocols through rollups and privacy networks to a hardware wallet maker and an audit firm.
The model is explicitly the Internet Engineering Task Force: proposals win on publicly verifiable evidence and running implementations rather than on company size or token holdings, and all results are published openly. One point matters for expectations. The alliance cannot force anyone to migrate. What it supplies is a yardstick against which providers will have to measure themselves. Sources differ slightly on the founding date, with one aggregator putting the start at October 16; the detailed reports name October 15, a Thursday.
6.04 million bitcoin: where the figure comes from and what it counts
The widely quoted number comes from a count of the blockchain as it stands today and is not a forecast. What it counts are bitcoin sitting in outputs whose public key is already permanently recorded on the blockchain. TFTC traces the figure to Glassnode data and gives 6.04 million BTC, or 30.2 percent of the circulating supply. Decrypt attributes the same order of magnitude to the alliance's own count and speaks of around 30 percent. Both values therefore come from the same measurement; no independent third survey exists so far.
A large share of that stock is old. Early balances from 2009 sit in pay-to-public-key outputs, the first bitcoin output type, in which the public key appears directly in the output. Those coins have not moved for years and some will never move again because the keys are lost. For risk purposes that means the 6.04 million describe an upper bound on the exposed stock. How much of it belongs to active holders who reuse their addresses carelessly today is something the figure does not say.
The public key is the risk, not the bitcoin address
This is the mechanism missing from most of the coverage. A bitcoin address is a hash value, a one-way function over the public key. As long as only the address is known, the public key itself is not on the blockchain, and a quantum computer would have nothing to run Shor's algorithm against. Shor's algorithm is the method by which a sufficiently large quantum computer could derive the private key from a public one.
The public key is exposed the moment funds are first spent from an address, because the signature in the input contains it. From that comes the practical rule that holds regardless of any timetable: an address that has never had anything leave it keeps its public key hidden. An address that is used repeatedly, and that retains a remaining balance after a spend, has published it permanently. Which output types expose their key is something we have broken down in our analysis of the subject.
For self-custody this is the distinction that counts. If you use a modern wallet that generates a fresh receiving address for every incoming payment and sends the change to a new change address, you are already working the way the migration debate demands. Which devices do this reliably is shown in our overview of hardware wallets.
Four alliance working groups, from migration to wallet security
The work starts in four groups. The first deals with migrating existing blockchains, that is, the question of how a live network adopts new signature schemes without devaluing old balances. The second takes on post-quantum zero-knowledge methods; a zero-knowledge proof establishes a statement without revealing the underlying data, and many of these methods today rest on the same mathematics as the vulnerable signatures. The third group works on wallet security, the fourth on cross-blockchain compatibility, so that a migrated network can keep working with one that has not migrated.
That division says more about the time required than any forecast does. Three of the four areas concern software running at third parties: exchanges, custodians, wallet makers and bridge operators. That is precisely why Coinbase has been pressing since mid-October for an early start to the switch and talks about a lead time of years.
Google's March 30, 2026 paper cuts the estimate to under 500,000 qubits
Behind the urgency sits a calculation. No working machine exists to this day. A paper from Google Quantum AI dated March 30, 2026 lowered the estimated number of physical qubits needed to break secp256k1, the curve bitcoin uses, to under 500,000. A physical qubit is a single computing element of the machine; many of them together make up one error-corrected logical qubit, which is what an algorithm actually computes with. Earlier estimates, according to the coverage of the alliance, stood at a multiple of that figure; TFTC puts the improvement at roughly one twentieth of the previous assumption.
That number describes the size of a hypothetical machine, not its delivery date. Nothing in the paper says such a machine exists; both reports examined here state explicitly that it does not. The figure is nonetheless the hardest reference point the debate has, because it replaces a moving estimate with an upper bound that can be checked.
March 2028 in the Quantum Doom Clock is an early-warning window, not a deadline
Two alliance contributors run a model that derives a date from progress in qubit counts, and according to Decrypt that model names March 2028 as the earliest window. It is a model calculation. Anyone working with it reads it as an early warning: before then, no attack is to be expected given the current state of the technology, and after it begins the range in which the model's assumptions are no longer backed by reality.
For your own planning the interval matters more than the date. Roughly 17 months lie between today and March 2028. A soft fork in bitcoin has historically taken longer than that from a mature specification to activation, and the switch at custodians and exchanges comes after. That calculation is exactly the alliance's argument for an early start, and it stands whether or not you believe the date.
BIP-360 and pay-to-merkle-root: bitcoin needs a soft fork to make the switch
Inside bitcoin the work runs separately from the alliance. The concrete proposal is called BIP-360; a BIP is a Bitcoin Improvement Proposal, the public drafting route for protocol changes. According to TFTC, BIP-360 describes an output type called pay-to-merkle-root that keeps the public key out of the blockchain for longer by having the output contain only a commitment to a quantum-resistant key hash. A revision dated July 24, 2026 added Python examples and test vectors, which makes the draft testable.
Implementation would come as a soft fork, a backward-compatible rule change under which old nodes continue to accept the new transactions. A soft fork is easier to push through than a hard split, but it needs agreement among miners, node operators and wallet makers. That the majority of the alliance's founding members do not come from bitcoin core development is the central criticism of it, and TFTC frames that as an opinion piece. For context, that means the alliance sets standards for the whole field; it does not decide bitcoin's path.
Christopher Smith, founder and chief executive of member firm Quantus, sums up the expectation: "In the future, post-quantum cryptography will simply be called cryptography, and everything else will be in a museum." The quote appears in that form in both reports examined here.
Address reuse is the point holders in Germany control themselves
Of all the areas named, exactly one is reachable without a protocol change: address reuse. Address reuse means using the same receiving address more than once, for instance as a fixed withdrawal address at an exchange or as a donation address. After the first spend from that address its public key is exposed, and every further incoming payment lands on a key that is already public.
The wallet setting comes first: does the wallet generate a new address for every incoming payment, or has it been showing the same one for months? Then there are the withdrawal addresses stored at exchanges and payment services, which often sit unchanged for years and hit the same exposed key with every deposit. And then there is the output type of old holdings: balances in very early output types belong to the group the alliance is talking about.
A word on the caution this debate requires: a demand to move funds to a supposedly "quantum-safe" address is not a step in the migration. Changes of that kind run through software updates and through your own wallet, never through an address that arrives in a message.
$15 million from BlackRock, Strategy and Coinbase for the quantum problem
The alliance is not the only answer to Google's calculation. According to Decrypt, a consortium backed by BlackRock, Strategy and Coinbase has committed $15 million to work on quantum risk. Measured against the holdings of those three houses it is a small sum, and it says nothing about success. It does say something about direction: the large custodians now treat the subject as an operational risk with a budget rather than a debate about the future.
For investors in Germany that is the more important observation. If you hold bitcoin through a security or leave it with a custodian, your exposure to the switch depends on their schedule. If you hold it yourself, you decide yourself, but you also pay for the switch yourself.
Custody at a regulated exchange shifts the switch onto the provider
If the coins sit at an exchange or a custodian, migration belongs on their list of duties. The addresses holding the balances belong to the provider, and the decision on output types and signature schemes is theirs. The useful question to put to a provider is therefore not whether it is "quantum-safe" but whether it has a published roadmap for the switch and who audits it. That is exactly what the alliance's yardstick is being built for. Which providers operate with authorisation in the EU and how their custody is structured is set out in our overview of regulated crypto exchanges.
If you hold your coins yourself, you carry the migration yourself, but you can also start immediately. The order is always the same: first secure and verify the recovery phrase, then update the software, and move balances after that. Reverse the order and start by moving, and you risk losing the funds at a point where no quantum computer is needed at all.
Holding period and records: why the wallet counts for FIFO allocation
Moving to fresh addresses creates transactions, and those have to remain traceable. The German finance ministry's letter of March 6, 2025 on individual questions of the income tax treatment of crypto assets takes individual identification as the basis for the sequence of disposals of privately held assets and, where that is not possible, permits the FIFO method as a simplification, applied per wallet. Which holdings sit in which wallet therefore forms part of the calculation.
In practice that means: if you move holdings to new addresses, record the times, addresses, amounts and prices so that acquisition and allocation can be evidenced later. A transfer between two of your own addresses is not a sale on the market, because there is no consideration and no buyer; how the transaction is to be treated in your own return is something to settle against the letter, and with a tax adviser for larger holdings. The usual tools collect the records as you go.
Our assessment: the timetable is contested, address hygiene is not
From this desk, what carries this story is the mechanics, not the date. Three documented points argue for that: the 6.04 million exposed bitcoin come from a single measurement, the qubit estimate of under 500,000 describes a machine that does not exist, and March 2028 comes out of a model run by two parties who make their living from the subject. Nothing argues against the practical consequence: a fresh receiving address per incoming payment costs nothing, requires no protocol change, and works whether or not the model is right. Selling in panic today, or moving holdings in haste, means taking on a real risk to avoid a hypothetical one. Crypto assets can swing sharply and can lead to a total loss.
Quantum Alliance: before March 2028 your choice of address decides alone
Three steps, in this order:
- Check the wallet. Open your wallet and see whether it offers a new address when you receive. If it does not, a change is due; which programs get it right is shown in our comparison of software wallets.
- Renew withdrawal addresses. Review the addresses stored permanently at exchanges and services and replace reused ones with fresh addresses. If you use a custodian, ask there about the published roadmap; the market overview is provided by the major crypto exchanges compared.
- Secure the records. Before every move, note the time, address, amount and price so the allocation holds up later; tax software and portfolio trackers help with this.
(As of October 21, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Canary’s Litecoin ETF took in a net $581,140 on Monday. That was the first inflow after seven trading days in which the fund moved nothing at all, and it lands in a week when most large coins have lost ground. Litecoin costs $61.47 on Wednesday morning and is up 0.33 percent over seven days.
That sounds like a small number, and it is one. On a normal trading day, $581,140 is less than Bitcoin funds turn over in a minute. The figure is interesting not for its size but for its direction: money flowed out of the Solana and Zcash funds the same day. If you invest from Germany, though, a quite different question hangs on it, namely whether you can buy this fund at all. The answer comes further down, and it is no.
$581,140 flows into Canary's Litecoin ETF after seven flat trading days
The fund, ticker LTCC, is a US spot ETF on Litecoin. Spot ETF means the fund holds the coins itself rather than taking futures positions. On Monday, October 19, 2026, it booked a net inflow of $581,140, after seven trading days in which nothing went in and nothing came out. Since launch, net inflows add up to $16.88 million. The figures come from TokenPost’s flow review of October 19.
A net inflow arises when a fund issues new shares because investors are buying. The fund then has to buy Litecoin in the market. Conversely, it sells coins when shares are redeemed. That is why many investors read fund flows as a demand signal: they contain buying pressure that comes from portfolios rather than from short-term trading.
Seven flat days in a row say just as much as the inflow itself. A fund where no money moves in or out for days on end has no audience trading it daily. For a spot ETF, $16.88 million of capital raised is a small sum. Read this fund’s flows as evidence of institutional interest in Litecoin and you are stretching a thin set of data.
Litecoin's week: $61.47 between $58.78 and $61.52
Litecoin trades at $61.47 on Wednesday morning, up 2.96 percent on the previous day. Over seven days it is up 0.33 percent, over thirty days 5.33 percent. The weekly high of $61.52 was reached overnight into Wednesday, the weekly low of $58.78 last Sunday. Market value is $4.78 billion, which puts it 23rd, with turnover of around $279 million in a day. All price figures in this article refer to CoinGecko, as of Wednesday around 6 a.m. German time.
It sits 85 percent below its all-time high of $410.26 from May 2021. There are 77.74 million LTC in circulation out of a maximum 84 million that will ever exist. That makes Litecoin one of the oldest blockchains in existence, running since October 2011; the network turned fifteen this month.
A week with a gain of 0.33 percent is no news in itself. The gain only becomes news next to the other large coins.
Thirteen of twenty large coins are down over the week, Litecoin up 0.33 percent
We counted through the twenty-five largest crypto assets by market value and took out the five that are pegged to the dollar or represent a tokenised financial product, namely Tether, USDC, USDS, Ethena USDe and Figure Heloc. That leaves twenty genuine coins. Thirteen of them are down over seven days. Only four sit ahead of Litecoin: TRON, Monero, Bitcoin Cash and Uniswap. Litecoin therefore takes fifth place out of twenty over the week. Cryptoticker.io compiled this review itself on October 21, 2026, based on CoinGecko price and market value data for twenty verified coins.
That puts the fund inflow in context. Litecoin is holding up better than average in a weak week, and at the same time the associated fund is taking in money again. Together the two make for a quiet picture, not a turning point. If you want to assess the coming week, our running price analysis is in the Litecoin price prediction.
The same day, the Solana and Zcash funds lose $6.72 million and $10.45 million
October 19 was not a uniform day for altcoin funds. The Solana spot ETFs saw $6.72 million flow out, the eleventh day of outflows in a row. The Grayscale Zcash ETF lost $10.45 million, its third consecutive day. Alongside Litecoin, Bitwise’s NEAR fund booked inflows of $5.42 million. These figures also appear in the TokenPost review cited above.
That money is leaving the Zcash funds while Litecoin takes some in is notable for investors watching the privacy assets. Zcash has a rally behind it that carried the price above $1,200 this year, and a sharp counter-move since September. Litecoin has experienced neither.
Grayscale's conversion filing for NYSE Arca has sat with the SEC since January 2025
Beside the Canary fund there is a second route by which Litecoin is meant to reach ordinary securities accounts. Grayscale has run the Grayscale Litecoin Trust, a closed-end vehicle with the ticker LTCN, for years, and wants to convert it into an exchange-traded fund. On September 11, 2026, the firm filed an amended registration statement to that end, renaming the trust Grayscale Litecoin Trust ETF and providing for a listing on NYSE Arca. The document is on file as Form S-3/A in the SEC archive.
One sentence in that filing is decisive: the trust will not seek effectiveness of the registration, and will issue no shares, as long as the exchange listing approval is not in place. The corresponding NYSE Arca rule filing is dated January 24, 2025 and remains open. The regulator has named no decision date, and neither does Grayscale.
Bloomberg Intelligence analysts, specifically James Seyffart and Eric Balchunas, put the approval probability for Litecoin, Solana and XRP products at 90 to 100 percent. That is an assessment by market observers, not a commitment from an authority. It changes nothing on your statement as long as there is no decision.
Spot ETF in the US, ETN in Germany: the LTCC fund is not approved for your account
Here is the point where the American fund story becomes practical for you. A US spot ETF on a cryptocurrency is not approved for distribution to retail investors in the European Union. That comes down to the product wrapper. An ETF under European law has to be a security with risk diversification, and a fund holding only a single asset does not meet that test. That is why the European Litecoin products are called exchange-traded notes, ETN or ETP for short.
An ETN is legally a bearer debt instrument, that is, a claim on the issuer. Most crypto ETNs tradable in Germany are physically backed with coins and held separately at a custodian. Issuer risk does not disappear entirely; it gets smaller. Which of that applies to which product is set out in the key information document your broker has to show you before you buy. Which providers offer crypto ETNs and what trading costs is in our overview of crypto ETFs and ETNs for German investors.
In practice, you can reach Litecoin two ways. Either through a broker with a securities account, in which case you buy an ETN on Litecoin and hold a security. Or through a crypto exchange, in which case you buy the coin itself and decide who holds it. In both cases the flows of the Canary fund in New York reach you only as news, never as a product on your statement.
The one-year holding period applies to the coin; with an ETN, withholding tax decides
The tax difference between the two routes is larger than the price difference. Hold Litecoin as a coin and section 23 of the German Income Tax Act applies. Sell within a year of buying and the gain is taxed at your personal rate, with a 1,000 euro exemption threshold covering all private disposals in a year together. Sell after more than a year and the gain is tax-free. That one-year period is why many holders keep records of their purchase dates.
An ETN, by contrast, is a security. Gains on it are subject to withholding tax of 25 percent plus the solidarity surcharge and, where applicable, church tax, regardless of how long you held it. There is no tax-free holding period there; in return, the account-holding institution withholds the tax directly in many cases. Which route works out cheaper depends on your tax rate and your time horizon, and over a long holding period the sums turn clearly in favour of the coin. Anyone pulling together many purchases over the years cannot avoid a schedule; the common tax and portfolio tools work out the periods on a first-in, first-out basis.
MWEB and the EU anti-money-laundering regulation from July 1, 2027: the open point for LTC holders
Litecoin has carried a feature called MWEB, short for MimbleWimble Extension Blocks, since 2022. It allows the amounts and addresses of a transfer to be hidden, and its use is voluntary: skip it and you keep transacting on an openly readable blockchain. That very option makes Litecoin a borderline case in a question that affects every holder in the EU.
The European anti-money-laundering regulation provides that from July 1, 2027, supervised crypto service providers may not maintain anonymous accounts or offer crypto assets that obscure transactions. For pure privacy coins such as Monero the consequence is clear, and several trading venues have already delisted such assets. For a blockchain with switchable obfuscation it is not settled. How the supervisors classify Litecoin has not been publicly determined, and we assert no outcome here. Cryptoticker.io described the position of privacy assets under this legal framework in its own analysis of the ban from July 2027 on August 16, 2026.
What is tangible in this for you: a venue that delists an asset announces it with notice and sets a last trading day plus a withdrawal deadline. Switch off your notifications at a provider and you will be the last to hear. Quite apart from Litecoin, that is the most common reason balances get force-sold in such cases.
Leverage and liquidation: with Litecoin futures, the distance to your entry price decides
A weekly gain of 0.33 percent with a daily range between $58.27 and $62.10 describes a market moving sideways while swinging several percent a day. For leveraged positions that combination is the most awkward of all. At fivefold leverage a counter-move of around twenty percent is enough to consume the margin; at twentyfold leverage it is about five percent, and five percent sits inside Litecoin’s normal daily move. Liquidation happens automatically and does not ask whether the price comes back afterwards.
For retail investors in the EU, leverage on crypto contracts for difference is capped at twofold. Offers with forty or a hundred times leverage are aimed at customers outside that framework, and a provider that still shows them to you is saying something about its licensing.
Levels above and below: $61.52 as the weekly high, $58.78 as the weekly low
The two numbers that decided the week sit close together. On the upside, the weekly high of $61.52 is the next level, and the price is practically on it. Above that begins the area around $64, where the price last turned in early October. On the downside, the weekly low of $58.78 is the first level, then the round number of $55.
These are observation points from this week’s price series, not price targets and not a recommendation. Use them as triggers and you set them in advance, not in the middle of the move.
Litecoin at $61.47: what the fund inflow does not answer
The inflow of $581,140 shows that the Litecoin fund in New York is being traded again. It does not show that Litecoin is treated any differently in your account than before, and it says nothing about the open approval question at Grayscale. Three things are independent of all that and can be settled today:
- Settle the wrapper. Decide whether you want to hold Litecoin as a security or as a coin, because tax and custody hang on that. For the securities route, compare account costs at the crypto brokers.
- Look at your venue's licensing. A provider without a European permission can close your access at short notice. Which houses hold the licence is set out in the overview of crypto exchanges.
- Decide on custody. Hold the coin yourself and you carry the key management. The differences between the devices are in the hardware wallet comparison.
(As of October 21, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
A Bitcoin costs $82,708 on Wednesday morning, or 73,652 euros. On Monday, $526.7 million flowed into the US spot ETFs, the strongest day since September, and yet October is still negative for those funds. Two lines frame the market until the Federal Reserve decides on rates on October 28: the 50-day moving average at $81,679 below, and the 20-day average at $83,117 above.
Overnight trading: the $81,273 low sat below the 50-day average
Between Tuesday morning and Wednesday morning the price moved between $81,273 and $83,249. That is a range of $1,976, or 2.39 percent measured against the current level. The night was therefore far livelier than the three days before it, which we covered on Tuesday.
Where the low sat matters more than the range itself. In our Tuesday morning piece, the 50-day average at $81,481 was the next level on the downside. That line has since risen to $81,679, an increase of $198. The overnight low of $81,273 sat $406 below it. The price broke the line and had worked its way back $1,029 above it by the morning.
In practice, that means a single breach has triggered no follow-on selling in this phase. Only a daily close below the line would be a signal that trading systems built on moving averages react to, and that did not happen overnight.
We calculated the moving averages in this piece ourselves, from CoinGecko daily closes over the past 200 days, as of Wednesday morning. Such lines differ by a few dollars between providers and data sources, because exchanges use different closing times.
$526.7 million into the US Bitcoin ETFs, the strongest day since September
According to Farside Investors data, the US spot Bitcoin ETFs took in $526.7 million net on Monday. That is the largest inflow on a single trading day since September. A spot ETF holds the coins itself rather than tracking the price through a futures position. Every dollar of inflow therefore leads to an actual purchase in the market.
The Ethereum ETFs ran the other way the same day and gave up $103.3 million, $95.4 million of it at BlackRock’s ETHA alone. So the money did not move broadly into crypto; it went into Bitcoin specifically.
BlackRock’s IBIT brought in $665.2 million, Fidelity’s FBTC lost $83.6 million
The net figure hides how uneven the day was. BlackRock’s IBIT alone took in $665.2 million, more than the entire net inflow for the day. Fidelity’s FBTC gave up $83.6 million over the same period.
A single provider carried the day, then, while at least one other lost money. Read the net figure as a broad return of institutional buyers and you are reading in more than the breakdown supports. For the price effect that is secondary: the coins have to be bought in the market, whichever provider receives the money.
October stays around $88 million in the red despite Monday
One strong day does not turn the monthly balance. On the daily Farside Investors figures, which the financial service FXStreet reviewed on Tuesday, the US spot Bitcoin ETFs remain around $88 million in the red for October. Monday almost evened out the month, no more than that.
That fits the price picture. Bitcoin is down 1.16 percent over seven days and up 1.56 percent over 30 days. It sits 34.4 percent below the all-time high of $126,080 from October 6, 2025. The market has been moving sideways for weeks, and the fund flows are doing the same.
The 200-day average at $72,723 and a gap of 13.73 percent
The short averages sit close to the price, but the distance to the downside is wide. On our calculation the 200-day average stands at $72,723, with the price 13.73 percent above it. The 100-day average sits at $74,780, 10.60 percent below the current level.
That spread is the real state of the market: everything is tight in the short term, while there is plenty of room below before any of the long averages even comes into play. The 20-day average at $83,117 is $409 above the price, the 50-day average $1,029 below it. This week’s trading plays out between those two values.
Bitcoin’s share of the entire crypto market stands at 59.52 percent, with $26.74 billion of turnover in 24 hours. Both readings suggest the money in the market is staying with Bitcoin rather than rotating into smaller coins.
Fed meeting on October 28: the target range stands at 3.75 to 4.00 percent
The Federal Open Market Committee meets on October 27 and 28, with the decision due at 2 p.m. local time in Washington on the Wednesday, 7 p.m. in Germany. The date appears in the Federal Reserve meeting calendar. A fresh round of projections with members’ rate forecasts is not part of it; a press conference by chair Kevin Warsh is.
The target range stands at 3.75 to 4.00 percent. The Fed raised it by a quarter point in September, the first increase in more than three years. On prediction markets the probability of an unchanged range sat between 84 and 88 percent on Tuesday, and between 12 and 13 percent for a further increase. For the December meeting, an increase is priced at around 78 percent.
Phil Camporeale, chief global investment strategist at J.P. Morgan Wealth Management, writes that his team expects no move at the October meeting. His firm looks for around 50 basis points of further increases, spread out into 2027. From inside the central bank, New York Fed president John Williams set out the line that there is no rush.
How a rate-hiking cycle works on the Bitcoin price
Bitcoin has lived through falling or flat rates for most of its existence. A hiking cycle is new for this market, and it works through three channels.
First, the alternative: as the risk-free rate rises, a term deposit pays more, and an asset with no running yield has to make up that head start through its price. Second, financing: anyone invested on credit or with leverage pays more for it, and some of those positions get closed. Third, the dollar: higher rates usually support the US currency, and a strong dollar weighs on the dollar-denominated Bitcoin price.
That third channel hits euro-based holders twice. You pay in euros but convert a dollar price. If the dollar rises against the euro, your loss in euros is smaller than the dollar loss, and the other way round. At $82,708 and 73,652 euros, the implied rate is currently just under $1.123 per euro.
Funding of 0.0034 percent per eight hours equals 3.75 percent a year
The financing rate, known in trading as funding, is the payment that holders of perpetual futures make to each other every eight hours. When it is positive, buyers pay sellers, and the futures market trades above spot.
On the OKX exchange the rate for the Bitcoin perpetual stood at 0.00343 percent per eight hours on Wednesday morning. Annualised, that is around 3.75 percent. The number is notable because it sits almost exactly at the upper edge of the Fed’s target range. A leveraged long currently costs about as much as the risk-free rate in dollars, before the price has moved at all.
That leads to a calculation anyone can run: hold a long position for a year and you need roughly 3.75 percent of price gains just to pay the financing. Over a week that is 0.072 percent, over a month 0.31 percent. For a position meant to run to October 28, it is about 0.07 percent, or $58 per Bitcoin held.
Spot, ETN or perpetual: what makes the difference before October 28
There are three common routes into Bitcoin for European investors, and they behave differently ahead of a central bank date.
Buying real coins on an exchange licensed under the European MiCA regulation costs a one-off order fee and nothing after that. There is no liquidation price, and a ten percent move costs ten percent. Which providers hold a licence and what they charge per order is set out in our comparison of crypto exchanges.
An exchange-traded note, or ETN, tracks the price through a securities account and carries a running management fee. What counts is whether the paper is physically backed with coins or merely replicates the performance. That distinction, and the fee levels of the papers tradable in Europe, are set out in our overview of crypto ETFs and ETNs in Germany.
A leveraged perpetual future costs the financing described in the previous section and comes with a liquidation price. At tenfold leverage and an entry at $82,708, that price sits roughly ten percent away, around $74,400 before fees. Last night’s range was 2.39 percent. Four such nights in the same direction would be enough. What the individual platforms charge in financing is shown in our comparison of perp exchanges.
Our assessment: the inflow came from one provider, not from the market
From the newsroom’s point of view, Monday was weaker than the $526.7 million headline suggests. The evidence is above: IBIT took in $665.2 million, more than the entire net amount, FBTC gave up $83.6 million, and the month remains around $88 million in the red. The Ethereum funds lost $103.3 million the same day. A market buying broadly looks different.
Against that, the origin of the money does not matter for the price effect. A fund taking in $665 million has to buy coins, and that purchase meets the same order book as any other. The price responded with only 0.80 percent in 24 hours, and that says more about the state of the market than the inflow figure itself: there is enough supply on offer to absorb sums like these.
For the week up to the Fed meeting, that suggests fund flows are unlikely to lift the price out of its range. The October 28 decision is the date that can change it, and prediction markets expect no change there. The setback risk therefore lies less in the decision itself than in what Kevin Warsh says about December at the press conference.
Bitcoin before October 28: the line sits at $81,679
Three steps worth taking ahead of the central bank date:
- Identify the form of your position. Are you holding real coins, a security or a leveraged contract? Only the third route has a liquidation price, and only there does holding cost money on an ongoing basis. The fee models of licensed venues are set out in our comparison of crypto exchanges.
- Recalculate the distance to your liquidation price. Divide your entry price by the leverage, and you get roughly the move that wipes out your position. At tenfold leverage that is ten percent, at fivefold twenty. Platform financing rates are set out in our comparison of perp exchanges.
- Record your acquisition data. Purchase and sale dates determine how your gains are treated for tax in Germany. Use several venues and you lose track quickly; which tools take that over is shown in our comparison of tax tools.
On the downside, the 50-day average at $81,679 remains the level that decides whether the sideways phase holds. On the upside sits the 20-day average at $83,117. As long as the price stands between the two, any directional call is a bet on October 28.
(As of October 21, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
A viral Claude Code prompt lets Android TV owners switch off sponsored rows and tracking software and build their own home screens, with no root access and every change reversible.
The ChatGPT maker is folding Orchestra’s drug-program agents into Rosalind, its life sciences suite, betting AI can shave time off the decade-plus it takes to bring a medicine to patients.
J.P. Morgan Asset Management’s 2027 Long-Term Capital Market Assumptions project a 10% annual return for Bitcoin over 10 to 15 years, though the firm isn’t adding it to its main portfolio models.
The North Korea-linked attacker behind April's $295 million Drift heist pushed 25,700 ETH through the mixer in two hours, and still controls roughly $198 million more.
Sixteen companies have now objected to having their shares traded on the planned OKX-ICE tokenized stock venue, up from nine just four days earlier, according to an updated public notice.
U.Today - IT, AI and Fintech Daily News for You Today
Following a severe validator lag, Ripple's David Schwartz details critical flaws in XRP Ledger architecture and its network safety margins.
Veteran trader Peter Brandt has spotted a striking similarity between Monero's (XMR) long-term chart and silver's explosive rally to nearly $125, potentially hinting at a major breakout for the privacy coin.
The market and XRP in particular is yet to decide the direction in which it's going to move.
Ripple has officially backed the SEC's proposed Regulation Crypto Assets, urging the regulator to abandon its controversial enforcement-driven approach in favor of clearer rules for the cryptocurrency industry.
The market headliners are yet to catch up wi the market growth, despite the relatively weak pressure that is coming from bears right now.
Blockonomi
TLDR
- Bitcoin briefly rose above $83,000 on Tuesday before slipping back toward $82,600.
- U.S. stocks rose as oil prices fell, and healthcare shares hit a record high.
- Trader Ardi said Bitcoin needs to clear $84,200 to break its local bearish structure.
- Glassnode found selling pressure has eased, but spot and ETF demand remain weak.
- Analysts named $82,000 as a key support level, with $80,000 as the next downside target.
Bitcoin climbed back above $83,000 on Tuesday as U.S. stocks rallied. The gains faded later, and the price slipped toward $82,600.
CoinGecko data showed Bitcoin at $82,601.56, up 0.8% over 24 hours. Its daily range ran from $81,155.23 to $83,249.46.
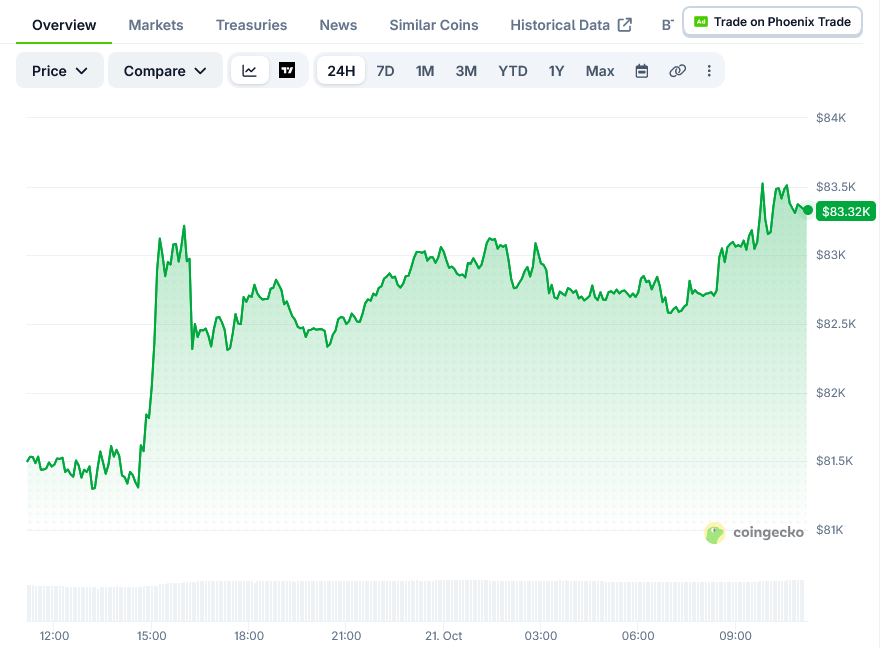
Ether also moved higher. ETH traded at $2,437.55, a daily gain of 1.6%, after reaching a high of $2,471.63.
Stocks Rise as Oil Prices Fall
The S&P 500 rose 0.70% to 7,744.72 in Tuesday morning trading. The Nasdaq Composite gained 0.59% to 26,585.47.
Healthcare stocks hit a record high as oil prices dropped. More than 400 S&P 500 stocks traded higher, according to MarketWatch, with hopes for peace talks helping push oil lower.
The move followed a Monday rebound in technology shares. Concerns about CoreWeave’s debt and the cost of funding AI infrastructure had weighed on the sector last week.
Zaye Capital Markets analyst Naeem Aslam linked Bitcoin’s recovery to better liquidity expectations. He also pointed to lower expectations of a near-term Federal Reserve rate hike.
Aslam said the rebound did not yet confirm a lasting reversal. He noted that high inflation, tight borrowing conditions and unclear monetary policy still affect demand for risky assets.
Bitcoin Stays Below Key Resistance
Trader Ardi named $84,200 as the level Bitcoin must clear to break its local bearish structure. He made the call on Oct. 16, after Bitcoin bounced from a weekly low near $79,800.
Ardi said he would consider long positions after a break above that level. Tuesday’s high of $83,249.46 left Bitcoin about 1.14% short of the mark.
A CoinGlass liquidation heatmap cited in his analysis showed clusters around $83,300–$83,700 and $84,300–$84,700. These were estimates of possible forced closures, not confirmed liquidations.
Glassnode’s Oct. 19 report said selling had slowed. “The heavy selling behind that slide has faded, but fresh demand has not replaced it,” the firm wrote.
In the week to Oct. 18, ETF outflows narrowed to about $230 million. Spot cumulative volume delta fell to negative $83.6 million, from negative $67 million a week earlier.
Options traders kept paying for downside protection. On-chain fees and transfer volume each fell about 10%, while active addresses held steady.
Earlier in October, Bitget Wallet research lead Lacie Zhang and ViaBTC chief analyst Jeff Ko named $82,000 as an important support level. Zhang said losing the $82,000–$82,500 zone could speed a drop toward $80,000.
Zhang set an October range of $78,000 to $95,000. She said Bitcoin would need to recover above $87,500 for her bullish scenario to play out.
Bitcoin now trades near $82,600, just above that $82,000 support. Reaching Ardi’s $84,200 threshold would require a gain of about 1.94%.
The post Bitcoin (BTC) Price: Analysts Watch $82,000 Support and $84,200 Resistance appeared first on Blockonomi.
TLDR
- J.P. Morgan Asset Management projects a 10% compound annual return for Bitcoin over the next 10 to 15 years.
- The forecast is higher than the firm’s outlook for U.S. large-cap stocks (7.5%), gold (5.5%) and a 60/40 portfolio (7%).
- The report puts Bitcoin’s annualized volatility at 55%, compared with about 17% for gold.
- JPMorgan left Bitcoin out of its main portfolio models, citing volatility and unstable correlations.
- U.S. spot Bitcoin ETFs drew $526.7 million on Monday, their best day since Sept. 22.
J.P. Morgan Asset Management has published its first long-term return forecast for Bitcoin. The firm expects the cryptocurrency to deliver a 10% compound annual return over the next 10 to 15 years.
The projection appears in the firm’s 2027 Long-Term Capital Market Assumptions, released Monday. This is the 31st annual edition of the report and the first to include Bitcoin.
The 10% figure is higher than the firm’s forecasts for several traditional assets. JPMorgan projects 7.5% for U.S. large-cap stocks, 5.5% for gold and 7% for a classic 60/40 stock and bond portfolio.
How Volatility Shapes the Forecast
The report places Bitcoin’s annualized volatility at 55%. By comparison, gold’s volatility is about 17%.
Because of these large price swings, Bitcoin’s arithmetic average return comes in at 20.9%. That figure is a simple average of yearly gains and is more than double the compound return investors would actually keep.
JPMorgan did not add Bitcoin to its main covariance matrices, the models it uses to track how assets move together. “For the first time, we put a range on bitcoin returns, though we do not yet include bitcoin in our main covariance matrices,” the report says.
The firm instead built a separate, smaller matrix comparing Bitcoin with a subset of assets. It cited the cryptocurrency’s volatility and unstable correlations as obstacles to wider portfolio inclusion.
JPMorgan also disputed a popular argument for Bitcoin. The report called the idea that currency debasement will drive a rush into crypto “wide of the mark.”
Industry Reaction and ETF Flows
Bitwise Chief Investment Officer Matt Hougan responded to the forecast on X. “First they ignore you, then they laugh at you, then they fight at you, then they add you to their Long-Term Capital Markets Assumptions paper and predict you’ll be the best-performing asset of the next decade,” he wrote.
Hougan said JPMorgan’s 55% volatility assumption is too high, which makes the return forecast too conservative. Bitwise manages crypto index funds and ETFs, so it has a stake in that view.
The report arrives as JPMorgan expands its own blockchain work. The bank is bringing JPM Coin, a token representing dollar deposits, to the Ethereum network.
JPMorgan has also joined BlackRock, Goldman Sachs and the DTCC in efforts to tokenize stocks.
U.S. spot Bitcoin ETFs drew $526.7 million in inflows on Monday. That was their best day since Sept. 22.
BlackRock’s iShares Bitcoin Trust took in $665.2 million on the day. The inflows cut October’s net outflows to about $88 million.
The 10-year Treasury yield held above 5%, offering a competing return with far less volatility. JPMorgan’s own global bond forecasts are at their highest level in two decades.
Bitcoin hovered around $82,000 after the report’s release. By Wednesday, it was trading near $83,470, up 0.22% over 24 hours.
The post JPMorgan Forecasts 10% Annual Bitcoin Return in First Long-Term Outlook appeared first on Blockonomi.
TLDR
- A wallet tied to the April Drift hack sent 25,710 ETH, worth about $63.1 million, into Tornado Cash on Oct. 20.
- The wallet made 258 deposits over two hours and 13 minutes, leaving about 3.98 ETH behind.
- Drift estimated about $280 million was taken in the April 1 attack, which Mandiant linked to North Korean group UNC6862.
- Drift opened DFX token claims on Oct. 1, giving users one DFX for each USDT of verified loss.
- As of Oct. 4, the redemption quote was about 0.0104 USDT per DFX, close to one cent per USDT lost.
A wallet tied to the April hack of crypto trading protocol Drift sent 25,710 ETH into the Tornado Cash mixer on Oct. 20. The transfers were worth about $63.1 million.
The address is labeled “Drift Exploiter 5” on the blockchain explorer Etherscan. The deposits were the wallet’s first outgoing Ethereum transactions, and they left it nearly empty.
How the Transfers Happened
The wallet made 258 deposits to the Tornado Cash router. It sent 257 deposits of 100 ETH each, followed by one final deposit of 10 ETH.
The first deposit was confirmed at 07:08:35 UTC in block 26,232,203. The last came at 09:21:35 UTC in block 26,232,865. The full sequence took two hours and 13 minutes.
After the transfers, the address held about 3.98 ETH. The dollar value of the deposits is based on an average Ethereum price of $2,450 on Oct. 20.
On-chain analysis account Lookonchain separately reported that the exploiter wallets it tracks hold a combined 81,864 ETH.
Drift was attacked on April 1, more than six months before these transfers. In an April 2 disclosure, the protocol estimated that about $280 million had been withdrawn.
Drift said the attacker took over the administrative powers of its Security Council. The attacker used durable nonce accounts to pre-sign transactions and delay when they were carried out.
According to Drift, this allowed the attacker to get unauthorized or misrepresented transaction approvals in advance. At the time, the protocol said it had not found a bug in its programs or smart contracts.
In a June 4 update, Drift said the investigation it hired Mandiant to carry out linked the attack to UNC6862. That is a North Korean threat group.
How Drift Plans to Repay Users
Drift has set up a Recovery Pool to return funds to affected users. Money recovered through freezes, a bounty, or law enforcement goes into the pool. A share of the platform’s net protocol revenue is also added.
The protocol opened claims and redemptions for its DFX token on Oct. 1. Users receive one DFX for each USDT of verified loss.
Holders can trade their DFX for USDT at the quoted redemption amount. The tokens they submit are burned in the same transaction.
Users who redeem give up their share of future pool deposits for those tokens. Those who redeem only part of their holdings keep that share for the DFX they hold onto.
As of Oct. 4, the quote was about 0.0104 USDT per DFX. That is close to one cent per USDT lost.
In an April 16 update, Drift proposed up to $127.5 million from Tether and $20 million from other partners. The plan included a revenue-linked credit facility, an ecosystem grant, and market-maker loans.
The Oct. 20 deposits show where this wallet’s ETH went. How much of the stolen money will return to the Recovery Pool is still unknown. Ethereum was last trading at $2,462.20, up 3.55% over the past 24 hours.
The post Drift Hacker Moves $63 Million in Ethereum Through Tornado Cash appeared first on Blockonomi.
TLDR
- A developer used Claude Code to switch off 25 Xiaomi software packages on his parents’ TV and build a new home screen.
- His open-source project, cleanyourtv, lists tested setups for 107 TV models from 37 brands.
- The tool disables apps through Android’s debugging bridge instead of deleting them, so every change can be undone.
- Texas sued Sony, Samsung, LG, Hisense and TCL in December 2025 over TV viewing data collection.
- Some users reported broken TVs, and the project warns that network debugging is unencrypted.
Smart TV owners are using AI coding agents to remove sponsored ads, tracking software and slow home screens from their sets. The trend spread on X over the weekend, where users call it “vibe coding” their TVs.
Vibe coding means describing what you want in plain language and letting an AI write and run the code. OpenAI co-founder Andrej Karpathy gave the practice its name in 2025.
How the Xiaomi TV Cleanup Worked
The most shared example came from a developer named Gathin T. He posted on Saturday that his parents’ Xiaomi TV showed a sponsored ad before anyone could reach Netflix.
He gave Claude Code, Anthropic’s coding agent, the TV’s model number. The agent found the set on his home Wi-Fi, switched off 25 Xiaomi software packages and wrote a new home screen.
The method relies on the Android Debug Bridge, or ADB, a maintenance tool built into Android TVs. Once developer mode is unlocked, a computer on the same network can control the set and list every installed app.
Gathin turned his prompt into cleanyourtv, an open-source project. It switches unwanted apps off instead of deleting them, so one restore script can undo every change. It does not require root access.
As of Tuesday, the project listed tested setups for 107 TV models from 37 brands. It had collected 10,700 stars on GitHub. Gathin wrote that a few thousand people cleaned their own TVs within two days.
Other users went further. Mihir Gupta replaced a 192 MB stock launcher with an 83 MB custom one. Ansub Khan said free memory on his parents’ old Android TV rose about 90%.
A rival project called dumbtv targets the Amazon Fire TV. It disables about 65 packages, including tracking software, and installs a 41 KB launcher with no internet permission.
Why TV Makers Collect Viewing Data
Many TVs run Automatic Content Recognition, or ACR. This software identifies what is on screen, including cable and HDMI devices, and reports it back so makers can sell targeted ads.
Texas sued Sony, Samsung, LG, Hisense and TCL in December 2025. The state alleged their TVs can capture a screenshot of the display every 500 milliseconds.
In 2017, Vizio paid $2.2 million to settle charges that it collected viewing data from 11 million TVs without consent. Walmart bought Vizio for about $2.3 billion in 2024, and its executives pointed to Vizio’s ad business as part of the appeal.
Cleanyourtv fully works only on Android TV and Google TV sets from brands such as Sony, TCL, Hisense, Philips and Xiaomi. Samsung and LG TVs use different operating systems, and Fire TV supports only the cleanup step.
Not every attempt worked. One user said he bricked his TV, and another got stuck partway through a Fire TV job.
The project’s readme warns that network ADB is unencrypted. On some firmware, any device on the same Wi-Fi can take control of the TV, so users should turn debugging off afterward.
Microsoft also found this year that hidden instructions could push Claude Code into exposing credentials. Anthropic patched that flaw in May.
As of Tuesday, the cleanyourtv repository had been forked 1,200 times. It had 85 open pull requests from volunteers.
The post Smart TV Owners Use Claude Code to Remove Ads and Tracking Software appeared first on Blockonomi.
TLDR
- Hackers hijacked a third-party notification provider for Ngrave’s LIQUID app and sent fake security alerts on Oct. 17.
- About $2.56 million was stolen from 70 wallet addresses across four blockchain networks.
- Bitcoin made up $1.77 million of the losses, followed by XRP, Ethereum-based assets and Stellar.
- Ngrave says its ZERO hardware wallets were not breached. Victims entered their recovery phrases on a fake website.
- The CEO said the company “absolutely and utterly failed” and has added new security controls.
Belgian hardware wallet maker Ngrave says thieves stole about $2.56 million from its customers after hijacking a system used to send app alerts. The company disclosed the attack on Oct. 19.
Attackers gained control of a third-party notification provider used by Ngrave’s LIQUID companion app. On Oct. 17, they used it to send fake security warnings straight to users.
The message said a user’s portfolio had been synced with a Pixel 9 device in Moscow. Tapping the alert opened a fake Ngrave website with a countdown timer and buttons to approve or deny the activity.
Both buttons led to the same trap. Users were asked to enter their 24-word recovery phrase or their Perfect Key, which gave attackers full access to their wallets.
Automated scripts then emptied the accounts within minutes. Ngrave traced the losses to 70 wallet addresses across four networks.
Bitcoin made up most of the stolen funds at $1.77 million. Thieves also took $454,000 in XRP, $316,000 in Ethereum-based assets and $18,000 in Stellar.
How the Attack Unfolded
Ngrave’s incident report says unauthorized access may have started on Oct. 11, six days before the fake alerts went out. Attackers got one access key and used it to obtain a second key with wider permissions, including access to some analytics data.
The company spotted the fake alerts within a minute of their appearance at 9:30 p.m. UTC on Oct. 17. Even so, the first wallet was drained six minutes later.
Ngrave shut off its notification system by 10:45 p.m. Thefts from wallets that were already compromised continued until 3:51 a.m. the next morning.
The company says its ZERO hardware wallets and private keys were never breached. Instead, attackers tricked customers into handing over their own recovery details.
The stolen funds moved through exchanges, blockchain bridges and new addresses. Ngrave traced bitcoin into 12 addresses, while XRP moved through 54 transfers.
Analytics firm Bitquery said in its own report that “most of it now sits on Hyperliquid as a Monero token.” It estimated about 81% of the funds ended up on the decentralized perpetuals exchange.
Ngrave CEO Admits Failure
Ngrave’s CEO gave a direct statement in the incident report. “In my humble opinion, the first duty of a crypto security company is to provide exactly that: security. In this, we have absolutely and utterly failed,” he said.
He said the company’s security was not strong enough when he took over as leader months earlier. Ngrave also said device information, wallet activity, IP addresses and approximate locations may have been exposed.
The incident adds to a difficult year for hardware wallet makers. Nearly a dozen security incidents in 2026 have involved brands such as Ledger, Trezor, Tangem, Safepal, Bitbox02 and Coldcard, with reported losses topping $180 million across two incidents.
Ngrave has replaced the compromised keys and plans tighter notification controls. These include two-person approvals, restricted domains and an emergency shutdown option.
The company is urging affected customers to set up new wallets and contact support. Its investigation is ongoing.
The post Ngrave Wallet Users Lose $2.56M in Bitcoin and XRP After Fake Security Alerts appeared first on Blockonomi.
CryptoPotato
Demand for the spot XRP ETFs remains far below their recent peaks, with the funds attracting zero net inflows in the past couple of days. Moreover, they were in the red before that.
However, this hasn’t prevented the underlying asset from staging a notable comeback that pushed it above a key resistance area. The question is, what’s next for XRP?
ETFs Disappoint, but XRP Rebounds
CryptoPotato reported over the weekend the end of a major XRP ETF streak that lasted roughly three months in which they didn’t see a single week in the red. This finally changed during the week that ended on October 16, with net outflows slightly higher than inflows at $1.84 million.
Although that was a relatively modest number, the following two business days have been quite lackluster as well. Data from SoSoValue shows that there were no reportable inflows on October 19 and 20, which continues the disappointing trend that began on October 15 with $104,510 in net withdrawals, and another $2.47 million on October 16.
This means that the ETFs have not been in the green for a week now. As such, it’s safe to conclude that they are not behind XRP’s notable price pump over the past 24 hours. The asset jumped by 5% daily to $1.37 minutes ago, which became a weekly peak. Moreover, it’s up by almost 10% since the weekend, when it plunged to $1.25 and popular analyst Ali Martinez declared the bottom was in.
Nothing But Green?
The substantial uptick over the past few days didn’t go unnoticed by other analysts, including Dark Defender, who argued that the sky above the XRP chart has turned green. The chart in question claims that the token has just bottomed on its macro Wave 2 formation and outlines some massive targets ahead, up to $10.
In a more modest post from yesterday, the analyst confirmed the completion of the correction in Wave 2 and noted that XRP is heading toward $1.44-$1.56 as long as it holds the $1.29 support, which it has so far. Once it reclaims the $1.56 resistance, Dark Defender predicted that “double digits will be instant.”
Meanwhile, fellow analyst CW joined the bullish bandwagon, indicating that XRP has reclaimed a key resistance at $1.3464, which means that it has shifted back into a “bullish trend.”
The post XRP ETFs Disappoint Again but XRP Price Rockets 5% to Weekly High appeared first on CryptoPotato.
Bitcoin’s price reacted well to the recent macro pressure and rebounded from the $81,000 range to over $83,000 as of now, charting a weekly high.
The larger-cap alts have followed suit with notable recovery sessions today, including ETH’s 3.4% rise to over $2,450 and XRP’s strong rebound to $1.35.
BTC Back Above $83K
Bitcoin’s troubles intensified precisely a week ago when the US CPI numbers came out and showed inflation was still persistent and slightly higher than expected. A day later, the PPI reading confirmed this, and BTC nosedived once again. In total, the asset fell from over $84,000 to a monthly low of just under $80,000 all within 24 hours or so.
The bulls finally intervened at this point and didn’t allow another leg down. Instead, BTC bounced off to $82,500, where it stood for a day, before its breakout attempt was halted at $83,000 and it slipped to under $81,000.
The weekend was rather weird, including a $1,000 flash crash on Saturday evening. Another dip followed to $80,750 before the asset finally showed some strength and surged to $83,000 on Monday despite expectations for a Black Monday crash. However, this was a short-term relief rally, and BTC quickly dipped toward $81,000 on Tuesday.
Another major rebound took place in the evening, taking bitcoin to $83,000. Earlier today, the asset climbed above that level and tapped $83,600 for the first time since last Wednesday’s pullback began. Although it was stopped there for now, it still trades above $83,000.
Its market cap has recovered to $1.670 trillion, while its dominance over the alts is shaky at 60% on CMC.

ZEC, NEAR Pump
Today’s major altcoin rally is led by ZEC’s impressive 13% surge to $1,267. NEAR Protocol’s 11% pump and RAIN’s 13% follow suit among the mid-cap alts. Naturally, BTW is also here, with a 41% surge today, after it nosedived by a similar percentage yesterday.
Other notable price gainers on October 21 include BCH, ENA, PUMP, WLD, SUI, AAVE, PEPE, UNI, and SKY.
Ethereum is above $2,450 after a 3.4% increase; XRP is back at $1.35 following an even more impressive 4.5% jump, while SOL defended the $100 support and now sits at $106. ADA, DOGE, HYPE, LINK, and BNB are also in the green today.
The total crypto market cap is up by just over 2% since yesterday to $2.780 trillion on CMC.

The post ZEC Skyrockets by 13% in 24 Hours, BTC Price Reclaims $83K: Market Watch appeared first on CryptoPotato.
France’s National Assembly voted 38 to 37 on Friday to end the tax deferral on swaps from crypto into stablecoins, starting January 1, 2027.
That vote adopted amendment I-3898 to the 2027 budget bill, with 25 abstentions among 100 votes cast. The amendment targets the deferral that lets a crypto-to-crypto trade postpone any gain until the investor sells for euros or spends the coins.
It removes that deferral when the investor receives an e-money token, as defined in Article 3 of the Markets in Crypto-Assets Regulation (MiCA). Gains on those swaps would then fall under the 31.4% flat tax France has applied to crypto disposals since January.
That definition covers a token pegged to one official currency and says nothing about whether the issuer holds an EU authorization. Circle’s USDC is the first such token classified as significant under MiCA.
Government Asked for Withdrawal
Nicolas Sansu, a deputy from the Democratic and Republican Left group, filed the amendment on October 10, after the finance committee backed the same text on October 7. Sansu told the chamber that converting crypto into euros triggers the flat tax while converting into a stablecoin does not, and called that a gap in the law.
David Amiel, Minister for Public Action and Accounts, asked Sansu to withdraw the amendment and opposed it when he refused. Amiel said France would first need to define stablecoins, then build the ability to trace reallocations inside a portfolio.
Philippe Juvin, the finance committee’s rapporteur general, said the committee backed the amendment but he personally favored keeping the deferral because of crypto’s volatility.
Deputy Charles de Courson backed the principle and cited figures from a parliamentary inquiry he co-wrote. He said 20,000 taxpayers declared 400 million euros in taxable crypto gains for 2021, against an estimated 3.5 billion euros realized.
Cost Basis Changes Too
The amendment also rewrites how French investors compute a gain. Today that gain runs off the whole portfolio’s value and its total acquisition cost at each sale. The new method takes the sale price minus the acquisition cost of the specific assets sold, with a weighted average for units bought at different prices. Holders of pre-2027 coins would choose once, irrevocably, between actual cost per asset and a pro-rata share of portfolio cost at December 31, 2026.
In the same sitting, deputies rejected a 10-year carryforward of crypto losses by 75 votes to 18. The amendment is not law yet. It sits in the budget’s revenue section, which was due for a floor vote on Tuesday. That vote was postponed with 2,828 of 3,396 amendments still unexamined, according to parliamentary channel LCP.
The amendment’s start date falls in the same month licensed EU firms must finish winding down non-MiCA stablecoins under ESMA’s October opinion.
The post France’s National Assembly Votes 38 to 37 to Tax Crypto-to-Stablecoin Swaps From 2027 appeared first on CryptoPotato.
Ripple filed a comment letter with the SEC, voicing support for the agency’s proposed Regulation Crypto Assets and urging it to finalize the rule.
As per the company, the proposal allows replacing years of regulatory uncertainty that worked on a case-by-case basis with an established framework of laws, all the while maintaining protection for investors under existing regulations.
What Ripple Wants the SEC to Keep and Change
The proposal’s core idea is that the investment contract, not the token, is the security. Stuart Alderoty, Ripple’s chief legal officer, called that faithful to Howey, the 1946 Supreme Court case that defines an investment contract, and wrote:
“What matters is what an issuer actually promised and when those promises end, not a subjective ‘decentralized’ test.”
Rule 400, a proposed safe harbor, would let an issuer file a public Form TR certifying that the work it promised buyers is finished or abandoned. Ripple opposes an SEC suggestion to limit it to issuers that fulfilled their promises, arguing that buyers can no longer expect profits from abandoned work either.
The letter also rejects sorting tokens into “company-backed” and “network” camps, warning that the split would revive the “implicit” promise standard the SEC dropped in its 2026 interpretation.
In one example, a company sending 5% of each sale to buy and burn its own token creates an investment contract, Ripple says, because the code automates a promise to return revenue to holders.
On authority, the letter points to Section 28 of the Securities Act and Section 36 of the Exchange Act, which let the SEC exempt “class or classes” of securities. A failed 49-50 Senate vote on September 15 to advance the Digital Asset Market Clarity Act removes none of that power, according to the filing.
Ripple also wants a new Rule 400 clause stating that skipping Form TR creates no presumption that a token is tied to an investment contract, since filing could become a litmus test for a future commission. Another fix targets Rule 500(b), which overrides state law for secondary-market trades but excludes dealers with no end date, leaving registered dealers to seek state-by-state exemptions.
XRP’s Legal Fight Shows the Cost of Regulatory Uncertainty
Ripple’s argument drew heavily on its own legal dispute with the SEC. According to it, after the SEC sued in December 2020 alleging XRP was itself a security, the token fell roughly 70% within days and about $15 billion in market value disappeared, with nearly every exchange open to US customers delisting it or blocking access.
A July 2023 district court ruling that XRP is not in itself a security then added about $21 billion to its market cap, and Coinbase and Kraken restored US trading the same day, with Alderoty pointing to the financial burden of obtaining that legal clarity on X.
“Ripple spent more than $150 million to get clarity. No company should have to do that to learn what the law requires,” he wrote.
The letter also cited a National Cryptocurrency Association study that estimates that having clearer rules in place from 2022 to October 2026 would have brought 382 to 1,518 more US token offerings and $325 million to $1.117 billion in capital, mostly from projects that otherwise raised money abroad.
The post Ripple Backs SEC’s Proposed Crypto Regulation, Calls for End to Case-by-Case Enforcement appeared first on CryptoPotato.
The popular meme coin has had a tough year so far, with its price collapsing by nearly 30% since January 1. At the same time, investor interest in the token has cooled significantly, which could weigh on any potential rebound.
The resurgence of Shiba Inu’s burning mechanism is one of the few rays of hope, but it may not be as bullish as it appears at first glance.
The Burns and More
According to the X account Shibburn, the team and community have scorched almost 2.7 million SHIB in the past 24 hours, a 492% increase from the previous day. The burning program is a vital part of Shiba Inu’s ecosystem, designed to gradually reduce the token’s vast supply and potentially increase its value through scarcity.
Nearly 2.7 million coins may sound impressive, yet the USD valuation of the stash is negligible at around $13. That said, far more aggressive burns will likely be needed to meaningfully affect SHIB’s supply dynamics.
The team introduced the mechanism in 2022, and over 410.8 trillion tokens have already been sent to a null address, with Vitalik Buterin contributing a significant portion of that figure.
Another factor that could help SHIB recover some of its losses is a potential uptick in Shibarium’s activity. Daily transactions processed on the layer-2 scaling solution have exploded by roughly 370% in the past 24 hours, reaching 7,300. Still, this is nowhere near the levels seen months ago and is unlikely to be a major bullish catalyst.

Price Prediction
There has been little commentary on SHIB lately, with Crypto With Gopal emerging as one of the few analysts to offer a forecast. The X user suggested the meme coin has printed a falling Wedge formation as the price consolidates near $0.00000502, while buyers look to defend support.
The analyst said a breakout above the descending resistance could spark a bullish momentum shift, setting $0.0000060 as an upside target and identifying $0.0000047-$0.0000048 as a support zone.
“SHIB bulls are watching for a breakout – meme coin momentum could return,” he concluded.
Meanwhile, the amount of Shiba Inu stored on crypto exchanges remains relatively low at just north of 87 trillion coins, which supports the bullish perspective since it reduces immediate selling pressure.

The post Shiba Inu (SHIB) Burn Rate Explodes Nearly 500% in a Day, But There Is a Catch appeared first on CryptoPotato.