Cryptocurrency Posts
Crypto Briefing
The anticipated crypto bull cycle could reshape investment strategies, driven by tokenization, wealth transfers, and AI-driven demand.
The post Bitmine adds 12,532 ETH as Tom Lee predicts record crypto bull cycle appeared first on Crypto Briefing.
Microsoft's deployment of Maia 300 AI chips could enhance efficiency and cost-effectiveness, impacting the AI hardware market dynamics.
The post Microsoft prepares to deploy its Maia 300 AI chips in Azure data centers appeared first on Crypto Briefing.
Persistent inflation above the Fed's target could challenge monetary policy, impacting economic stability and investor confidence.
The post Kalshi traders bet inflation has peaked for 2026 but will stay sticky appeared first on Crypto Briefing.
Allora's Forge's dynamic market approach and stringent accuracy criteria could redefine AI model credibility and strategic forecasting in trading.
The post Allora’s Forge launches Hyperliquid log return topic for AI price predictions appeared first on Crypto Briefing.
The incident underscores the critical need for stringent supply chain security and transparency in the cryptocurrency hardware wallet industry.
The post OneKey drops CryptoBilis and offers replacements after $86 million Ledger wallet incident appeared first on Crypto Briefing.
Bitcoin Magazine
Bitcoin Magazine
Strategy Smash Buys $21.5M in Bitcoin as It Continues BTC Accumulation
Bitcoin juggernaut Strategy has bought more BTC as it pivots back to accumulating on a weekly basis.
The Nasdaq-listed bitcoin treasury spent $21.5 million on 250 bitcoins from October 5 and October 11, according to a Monday filing.
It added that it also spent $192.4 million repurchasing its STRC preferred stock.
Strategy now holds 848,250 bitcoins worth $70.2 billion at today’s prices. Its stock (MSTR) on Monday was trading nearly 2% higher.
The company — formerly MicroStrategy — has spent the past four weeks buying bitcoins after months of more sporadic buys or sometimes halting purchases for months altogether in order to build a bigger cash buffer.
Monday’s filing also shows that the company bought last week’s bitcoin using net proceeds from MSTR Stock sales with its USD Cash buffer. Strategy has two cash reserves: “USD Reserve”, used to support the payment of dividends on the company’s preferred stock offerings and interest on its outstanding indebtedness, and “USD Cash”, which it uses to buy bitcoin.
It first bought the cryptocurrency in 2020 to protect its shareholders from inflation. Since then, it has aggressively bought the asset and pivoted to being a bitcoin treasury.
Investors can now buy its shares to get heightened exposure to the cryptocurrency, or get paid a yield via its digital credit products.
The company is now focusing on products that pay investors yield via its STRF, STRC, STRK, and STRD preferred shares.
Its Nasdaq-listed stock is down over 50% over the past year after the price of bitcoin took a hit.
But since the company started buying bitcoin in August 2020, MSTR has appreciated by nearly 1,000%.
This post Strategy Smash Buys $21.5M in Bitcoin as It Continues BTC Accumulation first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
Bitcoin Magazine
Congressman Warren Davidson: The Future of Money Will Decide Western Civilization
America is carrying $40 trillion in debt, and the dollar has lost about 30% of its purchasing power since 2020. Rep. Warren Davidson, founder of the Sound Money Caucus, explains why rising default risk and inflation are pushing rates higher, and why he believes people without real assets will lose purchasing power. He also warns that the future of Western civilization is centrally tied to the future of money.
Chapters:
0:00 – Why the Future of Western Civilization Is Tied to the Future of Money
0:40 – Clarity Act Cloture Vote Fallout and Section 305’s Threat to Self-Custody
3:48 – Will the Clarity Act Return After the Midterms?
6:22 – Open-Source Developer Protections and Trump Family Ethics Provisions
9:46 – The American Reserve Modernization Act and U.S. Government Bitcoin
13:58 – Has Bitcoin Become a Partisan Issue?
16:31 – CBDCs, Financial Surveillance and Bank Secrecy Act Reform
21:34 – Stablecoins as a “Hydra” CBDC and the GENIUS Act
25:02 – Bitcoin, $40 Trillion in Debt and the Dollar’s Reserve Status
29:37 – Why Bitcoiners Should Defend Freedom in the Midterms
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Congressman Warren Davidson: The Future of Money Will Decide Western Civilization first appeared on Bitcoin Magazine and is written by Mark Mason.
Bitcoin Magazine
Ark Invest’s Lorenzo Valente: Bitcoin’s 5-Year Forecast – Stablecoin & Gold Impacts
Bitcoin has been flat to down this year, but ARK Invest isn’t changing its view. Lorenzo Valente, Director of Research for Digital Assets at ARK Invest, explains why the firm looks at Bitcoin on a five-year horizon and still believes it’s very early in the Bitcoin journey. He discusses ARK’s Big Ideas report, Bitcoin’s role as digital gold and permissionless money, and what still keeps institutional money on the sidelines.
Chapters:
0:00 – ARK Invest’s Lorenzo Valente on How Wall Street Sees Bitcoin Now
1:36 – ARK’s Big Ideas Bitcoin Price Target for 2030
2:51 – How Stablecoins Changed ARK’s Emerging Market Bitcoin Thesis
4:53 – The Rise of Tokenized Stocks and Real-World Assets
7:13 – What Tokenized Stocks Can Do That Brokerage Accounts Can’t
9:35 – Higher Rates, Inflation, AI and Bitcoin’s Macro Outlook
12:49 – Which Tokenization Business Models Will Win?
15:41 – Exporting U.S. Assets Offshore Through Tokenization
17:34 – ARK’s Bitcoin Outlook for the Next 12 to 18 Months
18:29 – The Four-Year Cycle and What to Watch Next
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Ark Invest’s Lorenzo Valente: Bitcoin’s 5-Year Forecast – Stablecoin & Gold Impacts first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Willem Middelkoop: Bitcoin is the Fastest Horse – Why the Debasement Trade Takes it to $1M
Central banks are buying gold at a record pace, so why won’t they touch Bitcoin? Willem Middelkoop, founder of the Commodity Discovery Fund and author of The Big Reset, explains that central banks want assets they can control. Bitcoin’s price, supply, and market are beyond their reach. He also shares why institutional investors, including his own fund, have embraced Bitcoin through ETFs.
Chapters:
0:00 – Willem Middelkoop on Oil Prices, Iran and the Gulf
1:19 – The Debasement Trade: Bitcoin, Gold and the Commodity Bull Market
2:20 – The Big Reset: Is the Dollar System in Its Last Inning?
3:58 – BRICS, De-Dollarization and Falling Demand for U.S. Treasuries
5:15 – Central Bank Gold Buying and China’s Accumulation
6:14 – The 25% Portfolio Model: Real Estate, Gold, Equities and Bitcoin
7:49 – Why Central Banks Won’t Hold Bitcoin They Can’t Control
9:29 – Bitcoin vs. Gold: Is Bitcoin’s Correction Over?
11:57 – Bitcoin Amsterdam and the “Mad Max” Bitcoin Scenario
13:30 – Why Willem Middelkoop Targets $1 Million Bitcoin by 2030
DISCLAIMER: The views and opinions expressed in this show are those of the participants and do not necessarily reflect the official policy or position of BTC Inc., Bitcoin Magazine, or any affiliated entities. This content is provided for informational and educational purposes only and should not be construed as investment, legal, tax, or accounting advice. Nothing contained in this show constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Viewers should consult their own advisors before making financial or business decisions.
This post Willem Middelkoop: Bitcoin is the Fastest Horse – Why the Debasement Trade Takes it to $1M first appeared on Bitcoin Magazine and is written by Patrick Green.
Bitcoin Magazine
Bitcoin Life Insurer Meanwhile Raises $37.5M as Wealthy Families Look to Pass On Their BTC
Meanwhile, the first life insurer licensed to operate entirely in Bitcoin, has raised $37.5 million in new funding from its existing investors, the company announced.
Bain Capital Crypto led the round, with participation from Haun Ventures, Framework Ventures, Pantera Capital, Apollo, Northwestern Mutual Future Ventures and Morgan Creek Digital. The raise brings Meanwhile’s total funding to more than $180 million. Sam Altman is also among its backers.
The company said the round follows a surge in demand for its Bitcoin life insurance policies outside the US, particularly in Asia, Europe and the Middle East, amid broader macroeconomic instability.
“Wealthy families around the world already hold Bitcoin. What they haven’t had is a regulated way to pass it on,” Zac Townsend, Meanwhile’s co-founder and CEO, said in a statement.
“Brokers came to us because their clients kept asking. This round lets us keep up with them.”
In early 2026, Meanwhile launched BTC Life 1-Pay, a single-premium whole life policy aimed at high-net-worth clients outside the US. It is the company’s second product line, after BTC 10-Pay, which is designed for US taxpayers.
Under BTC Life 1-Pay, a client pays one premium in Bitcoin and receives a guaranteed death benefit in Bitcoin for life. The policy’s value grows in Bitcoin, and after the first year the owner can borrow up to 90% of it, with no repayment schedule and no margin calls.
Policies can be owned by individuals, trusts or companies, which the company says makes them suited to succession and estate planning.
Since launch, Meanwhile has signed 15 brokers serving wealthy families, including in Singapore, Hong Kong, the UAE and Switzerland. Partners include Lioner, an insurance, trust and family office group with offices in Hong Kong, Singapore and Zurich, and Apeiron Group, a marketplace for high-net-worth life insurance.
“We’re reaching a turning point where more high-net-worth clients are asking not just how to hold Bitcoin and digital assets, but how to plan around them and ultimately transfer that wealth to the next generation,” said Justin Man, CEO of Apeiron Group. Digital assets.
Meanwhile said its net long-term underwriting income has already passed last year’s total and is on track to more than double in 2026. The company did not disclose specific figures.
“Meanwhile owns every layer of a regulated life insurer and builds it like an AI-enabled startup,” said Stefan Cohen, partner at Bain Capital Crypto. “The growth this year proves the model, and we’re glad to back them again.”
The company’s operating entity, Meanwhile Insurance Bitcoin (Bermuda) Limited, holds the first Class IILT license granted by the Bermuda Monetary Authority. It received the license in July 2024 after two years in the regulator’s sandbox.
The insurer’s balance sheet, reserves and audited financial statements are all denominated in Bitcoin. Policyholder Bitcoin is held with regulated institutional custodians.
This post Bitcoin Life Insurer Meanwhile Raises $37.5M as Wealthy Families Look to Pass On Their BTC first appeared on Bitcoin Magazine and is written by Mathew Di Salvo.
CryptoSlate
France’s proposed crypto tax changes would make a move from Bitcoin or Ether into certain stablecoins a taxable disposal, even if the investor never withdraws cash.
The National Assembly’s Finance Committee adopted amendment I-CF1826 on Oct. 7, adding that proposed exception to a broader overhaul of how private crypto gains are calculated. The provision would apply to disposals and exchanges from Jan. 1, 2027 if enacted.
For an investor selling Bitcoin exposure into USDC, the consequence would be a change in the tax timing of a risk-reduction trade. A gain could become reportable while the proceeds remain in a crypto wallet or exchange account. But the proposal also changes the cost deducted from those proceeds, and gives older holdings a transition choice.
Under French tax authority guidance, covered crypto-to-crypto exchanges without a cash balancing payment receive tax deferral. Converting into fiat or using crypto to obtain other goods or services can already be taxable under the private-disposal regime, subject to its applicable exemption.
CF1826 would remove the exchange deferral when the investor receives e-money tokens as defined by the EU’s Markets in Crypto-Assets regulation, or related rights. The operative wording targets the asset received. A swap out of Bitcoin into a qualifying token could therefore recognize a gain before any later cash withdrawal.
MiCA’s definition describes a crypto-asset that seeks to maintain stable value by reference to one official currency. That legal definition sets the exception’s scope. The amendment invokes it without an express issuer-licensing condition.
USDC provides a concrete example: Circle’s European white paper identifies it as an e-money token under the same MiCA provision. The illustrations below use native USDC, with transactions measured in euros.
The amendment’s sponsors justify the change by describing deferral on fiat-backed stablecoin conversions as a legislative loophole. For an investor using a swap to reduce market exposure, the practical effect would be earlier recognition of any gain.
The proposed tax calculation concerns the gain above cost. It subtracts the acquisition basis of the assets surrendered from the disposal price. That basis is the cost recognized for tax purposes; a transaction can produce a gain, no gain or a loss.
Two ways to value older holdings
France’s existing portfolio-based calculation allocates part of the acquisition price of the entire crypto portfolio to each taxable disposal. Current guidance deducts total portfolio acquisition price multiplied by the ratio of disposal price to portfolio value immediately before the transaction.
The proposed replacement would focus on the crypto-assets actually disposed of. For assets of the same nature purchased at different prices, it specifies weighted-average acquisition value.
For holdings acquired before 2027, the amendment offers two routes. An investor could use evidenced actual acquisition costs, determined under the new basis rules. Alternatively, the investor could allocate the portfolio acquisition price calculated under the old rules at Dec. 31, 2026 among the assets held then, in proportion to their values on that date.
The allocation option preserves a pool of acquisition cost and distributes it among holdings. The available cost pool remains the acquisition price calculated under the old rules, rather than the portfolio’s full market value. The text makes that choice irrevocable for the entire portfolio when the first return reporting a taxable disposal after Jan. 1, 2027 is filed.
Consider a hypothetical investor whose Bitcoin cost €20,000 and is worth €60,000, while their Ether cost €40,000 and is worth €40,000 at the transition date. The portfolio has €60,000 of acquisition cost and a €100,000 value. Assume no prior disposals, fees or cash balancing payments, no other holdings of the same tokens, and unchanged euro values through the transactions.
Under the allocation option, Bitcoin represents 60% of the portfolio value and receives €36,000 of basis. Ether receives the remaining €24,000. Using actual costs instead would leave their bases at €20,000 and €40,000, respectively.
The same Bitcoin-to-USDC transaction would then produce different first-disposal gains:
| Hypothetical transaction or basis | Proposed actual-cost route | Proposed allocation route |
|---|---|---|
| Bitcoin basis before the swap | €20,000 | €36,000 |
| Gain on swap into €60,000 of native USDC | €40,000 | €24,000 |
| Basis of the USDC received | €60,000 | €60,000 |
| Gain on later Ether disposal for €40,000 | €0 | €16,000 |
The table compares hypothetical gross gains under the proposal. Under the current rules, the qualifying swap itself would receive deferral. Under either proposed transition route, the Bitcoin-to-USDC swap would become a taxable event.
Changing only the historical costs to €50,000 for Bitcoin and €10,000 for Ether reverses the first-disposal comparison: actual cost would produce a €10,000 Bitcoin gain against allocation’s €24,000. The remaining Ether gain at unchanged values would be €30,000 under actual cost or €16,000 under allocation. Historical costs determine which method recognizes more gain first.
Basis resets and the cost of loss timing
The proposal expressly distinguishes exchanges that retain deferral from exchanges that become taxable. A deferred exchange carries the surrendered assets’ basis into the assets received. A taxable exchange gives the received crypto-assets a basis based on the consideration value already used to calculate the gain, adjusted for any cash balancing payment.
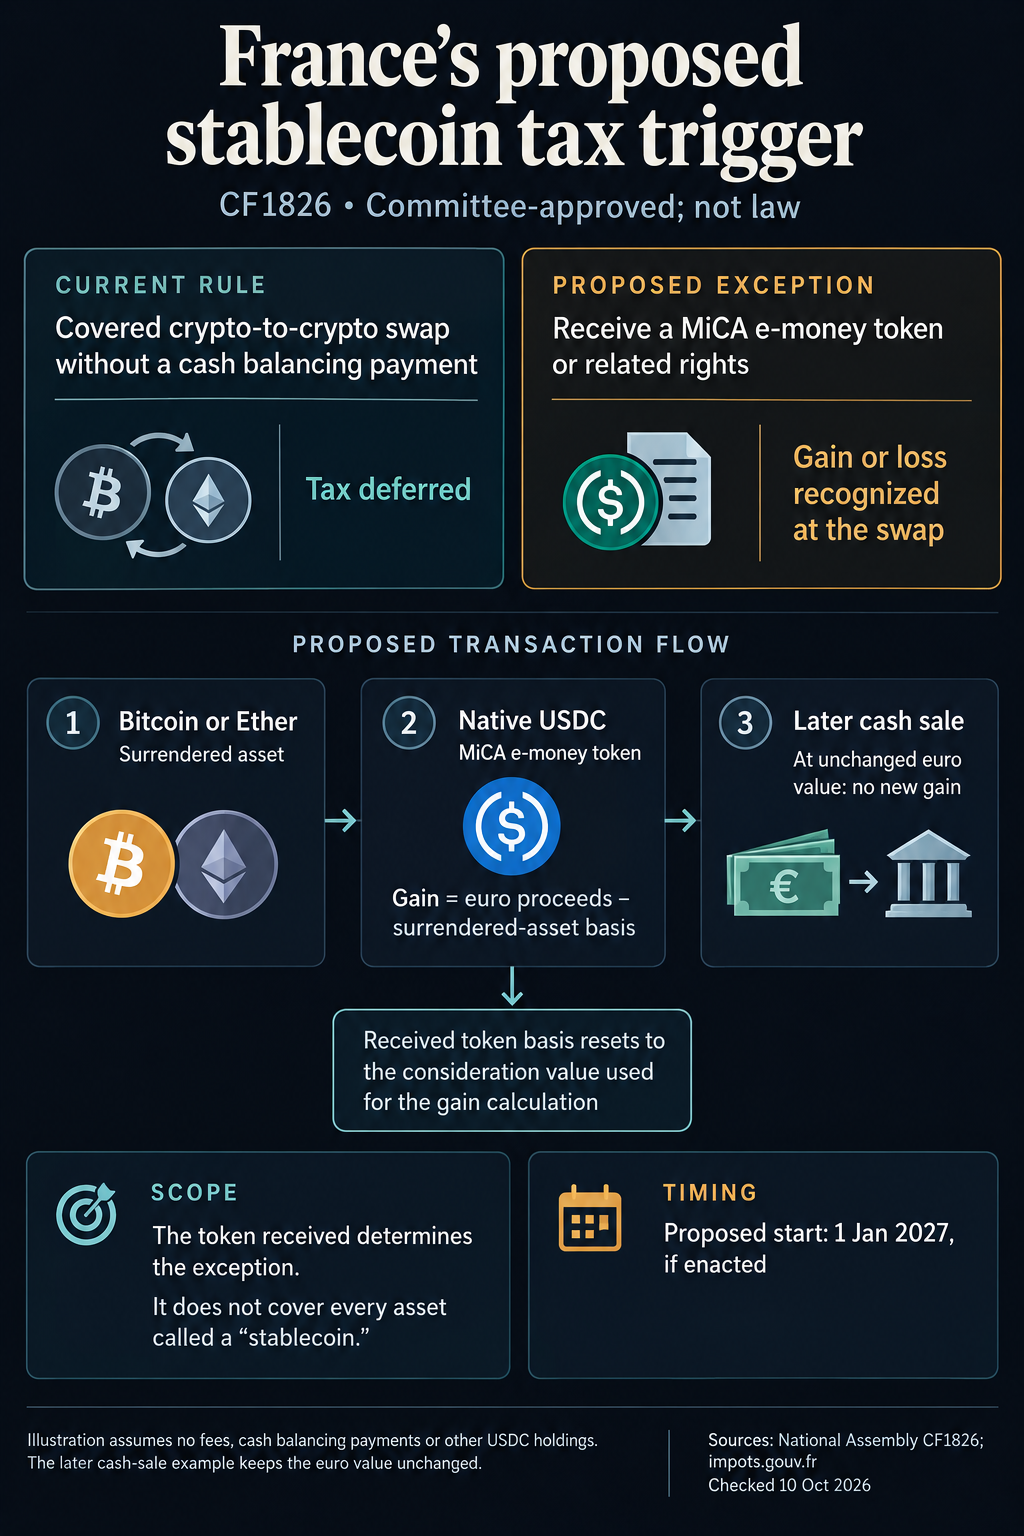
For the Bitcoin-to-USDC swap in the first example, the reset rule would give the USDC received €60,000 of basis under either transition route. Selling it later for the same €60,000 would produce no further gain. That reset would prevent repeat recognition of the original Bitcoin gain when the unchanged-value proceeds finally reached a bank account.
USDC references the dollar, so the unchanged-euro-value assumption is essential. A later disposal at a different euro value would require its own gain or loss calculation.
If the investor also sold the remaining Ether for €40,000, the first example would produce aggregate realized gains of €40,000 under either proposed transition route. Actual cost recognizes all of that in Bitcoin; allocation splits it between Bitcoin and Ether.
The amendment would change the swap exception and basis rules without rewriting the existing crypto loss restriction. The tax authority says crypto gains and losses offset within the same tax year, while a net crypto loss cannot be carried into later years or used against gains on other assets.
A separate hypothetical shows the effect of recognizing losses and gains in different years. Under the proposed actual-basis rules, a sole Bitcoin holding bought for €30,000 and swapped into €20,000 of native USDC would recognize a €10,000 loss. The USDC would receive €20,000 of basis.
If that USDC were later exchanged into Bitcoin without a cash balancing payment, the swap would retain deferral because Bitcoin is outside the received e-money-token exception. It would carry the €20,000 basis into Bitcoin. A subsequent taxable Bitcoin sale for €30,000 would recognize a €10,000 gain. Assume no fees, other token pools, cash adjustments or other gains and losses.
Those amounts could offset if realized in the same tax year. If the net loss arose in one year and the gain in a later year, the earlier loss would not shelter that later gain under the existing rule. Recognition in different years can therefore change the taxable result even when the transaction sequence returns the holding to its original value.
The reporting trade-off follows from the same mechanics. Asset-specific basis would remove the portfolio-wide allocation formula for new disposals, but investors would need to preserve acquisition evidence, weighted averages and the basis carried or reset through swaps. For older holdings, the proposed allocation route would also require a Dec. 31 valuation and a whole-portfolio decision that the text makes irrevocable.
The next legislative test remains ahead. The 2027 budget dossier, checked Oct. 12, lists National Assembly plenary discussion for Oct. 13.
The post France’s tax proposal would tax Bitcoin-to-USDC swaps before investors cash out appeared first on CryptoSlate.
Bitcoin and Ethereum extended their weekend recovery, although on-chain indicators and derivatives positioning suggest the rebound faces significant obstacles.
Data from CryptoSlate showed that Bitcoin briefly climbed above $84,000 after falling toward $80,000 during last week's selloff. Ethereum also recovered above $2,500, reversing part of its recent losses as buying activity returned to the cryptocurrency market.
However, Bitcoin's advance has brought it closer to a major concentration of investor acquisition costs between $84,000 and $85,000, where selling pressure could intensify. Meanwhile, Ethereum's recovery comes as larger derivatives traders appear to be reducing their bullish exposure despite substantial outstanding positions.
Bitcoin's $85,000 resistance threatens to stall recovery
Bitcoin's recovery gained momentum during Sunday's trading session as traders appeared to capitalize on a liquidity concentration above the prevailing market price.
CryptoQuant analyst J.A. Maartunn said on Oct. 11 that a liquidity cluster formed just above Bitcoin's trading level, giving traders an opportunity to push prices higher.
According to Maartunn, traders appeared to establish a substantial wall of buy orders beneath the market, providing support as Bitcoin advanced toward the overhead liquidity.
The spot Bid/Ask Ratio, which measures buying and selling liquidity within 1% of the prevailing price, rose to 0.3.
The increase indicated that visible buying interest had strengthened relative to selling orders. Such liquidity can also disappear if traders cancel their orders.
Checkonchain data highlighted by analyst Darkfost on Oct. 11 showed that approximately 53% of Bitcoin's invested capital had an estimated acquisition price above $83,000 when the cryptocurrency traded around that level.
The measure weights acquisition prices by invested capital, so larger positions carry more weight.
More importantly, the largest concentration of acquisition costs sits between $84,000 and $85,000, making the region a potential obstacle to further gains.
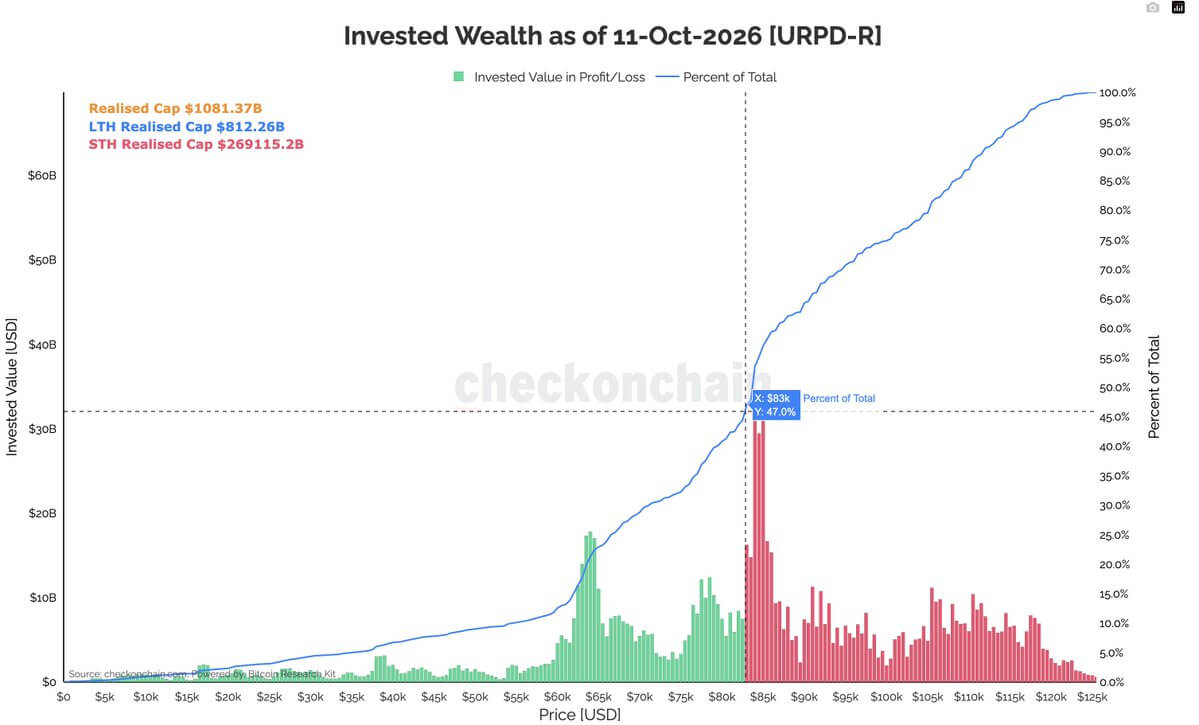
Investors who acquired Bitcoin around those levels could become more willing to sell as prices approach their estimated cost basis, increasing the supply that buyers must absorb.
A sustained move through the region would suggest buying demand is strong enough to overcome that potential selling pressure. If it fails to do so, Bitcoin could be vulnerable to another decline, with Darkfost identifying the $77,000 to $79,000 range as a possible support area.
Ethereum's $2,500 rebound faces risk from leveraged traders
Ethereum's recovery faces another challenge as derivatives positioning among larger market participants continues to deteriorate.
Alphractal CEO Joao Wedson noted on Oct. 10 that Ethereum's 30-day and 180-day open-interest deltas were both negative, along with weakening readings in its Whale vs. Retail Delta indicator.
He interpreted the combination as evidence that major traders have reduced their bullish exposure while increasingly favoring defensive or short positions.
The negative open-interest readings indicate that outstanding derivatives positions have contracted over the measured periods.
Despite the contraction, Ethereum's total futures open interest remained substantial at approximately 10.58 million ETH, indicating that considerable derivatives exposure was still outstanding.
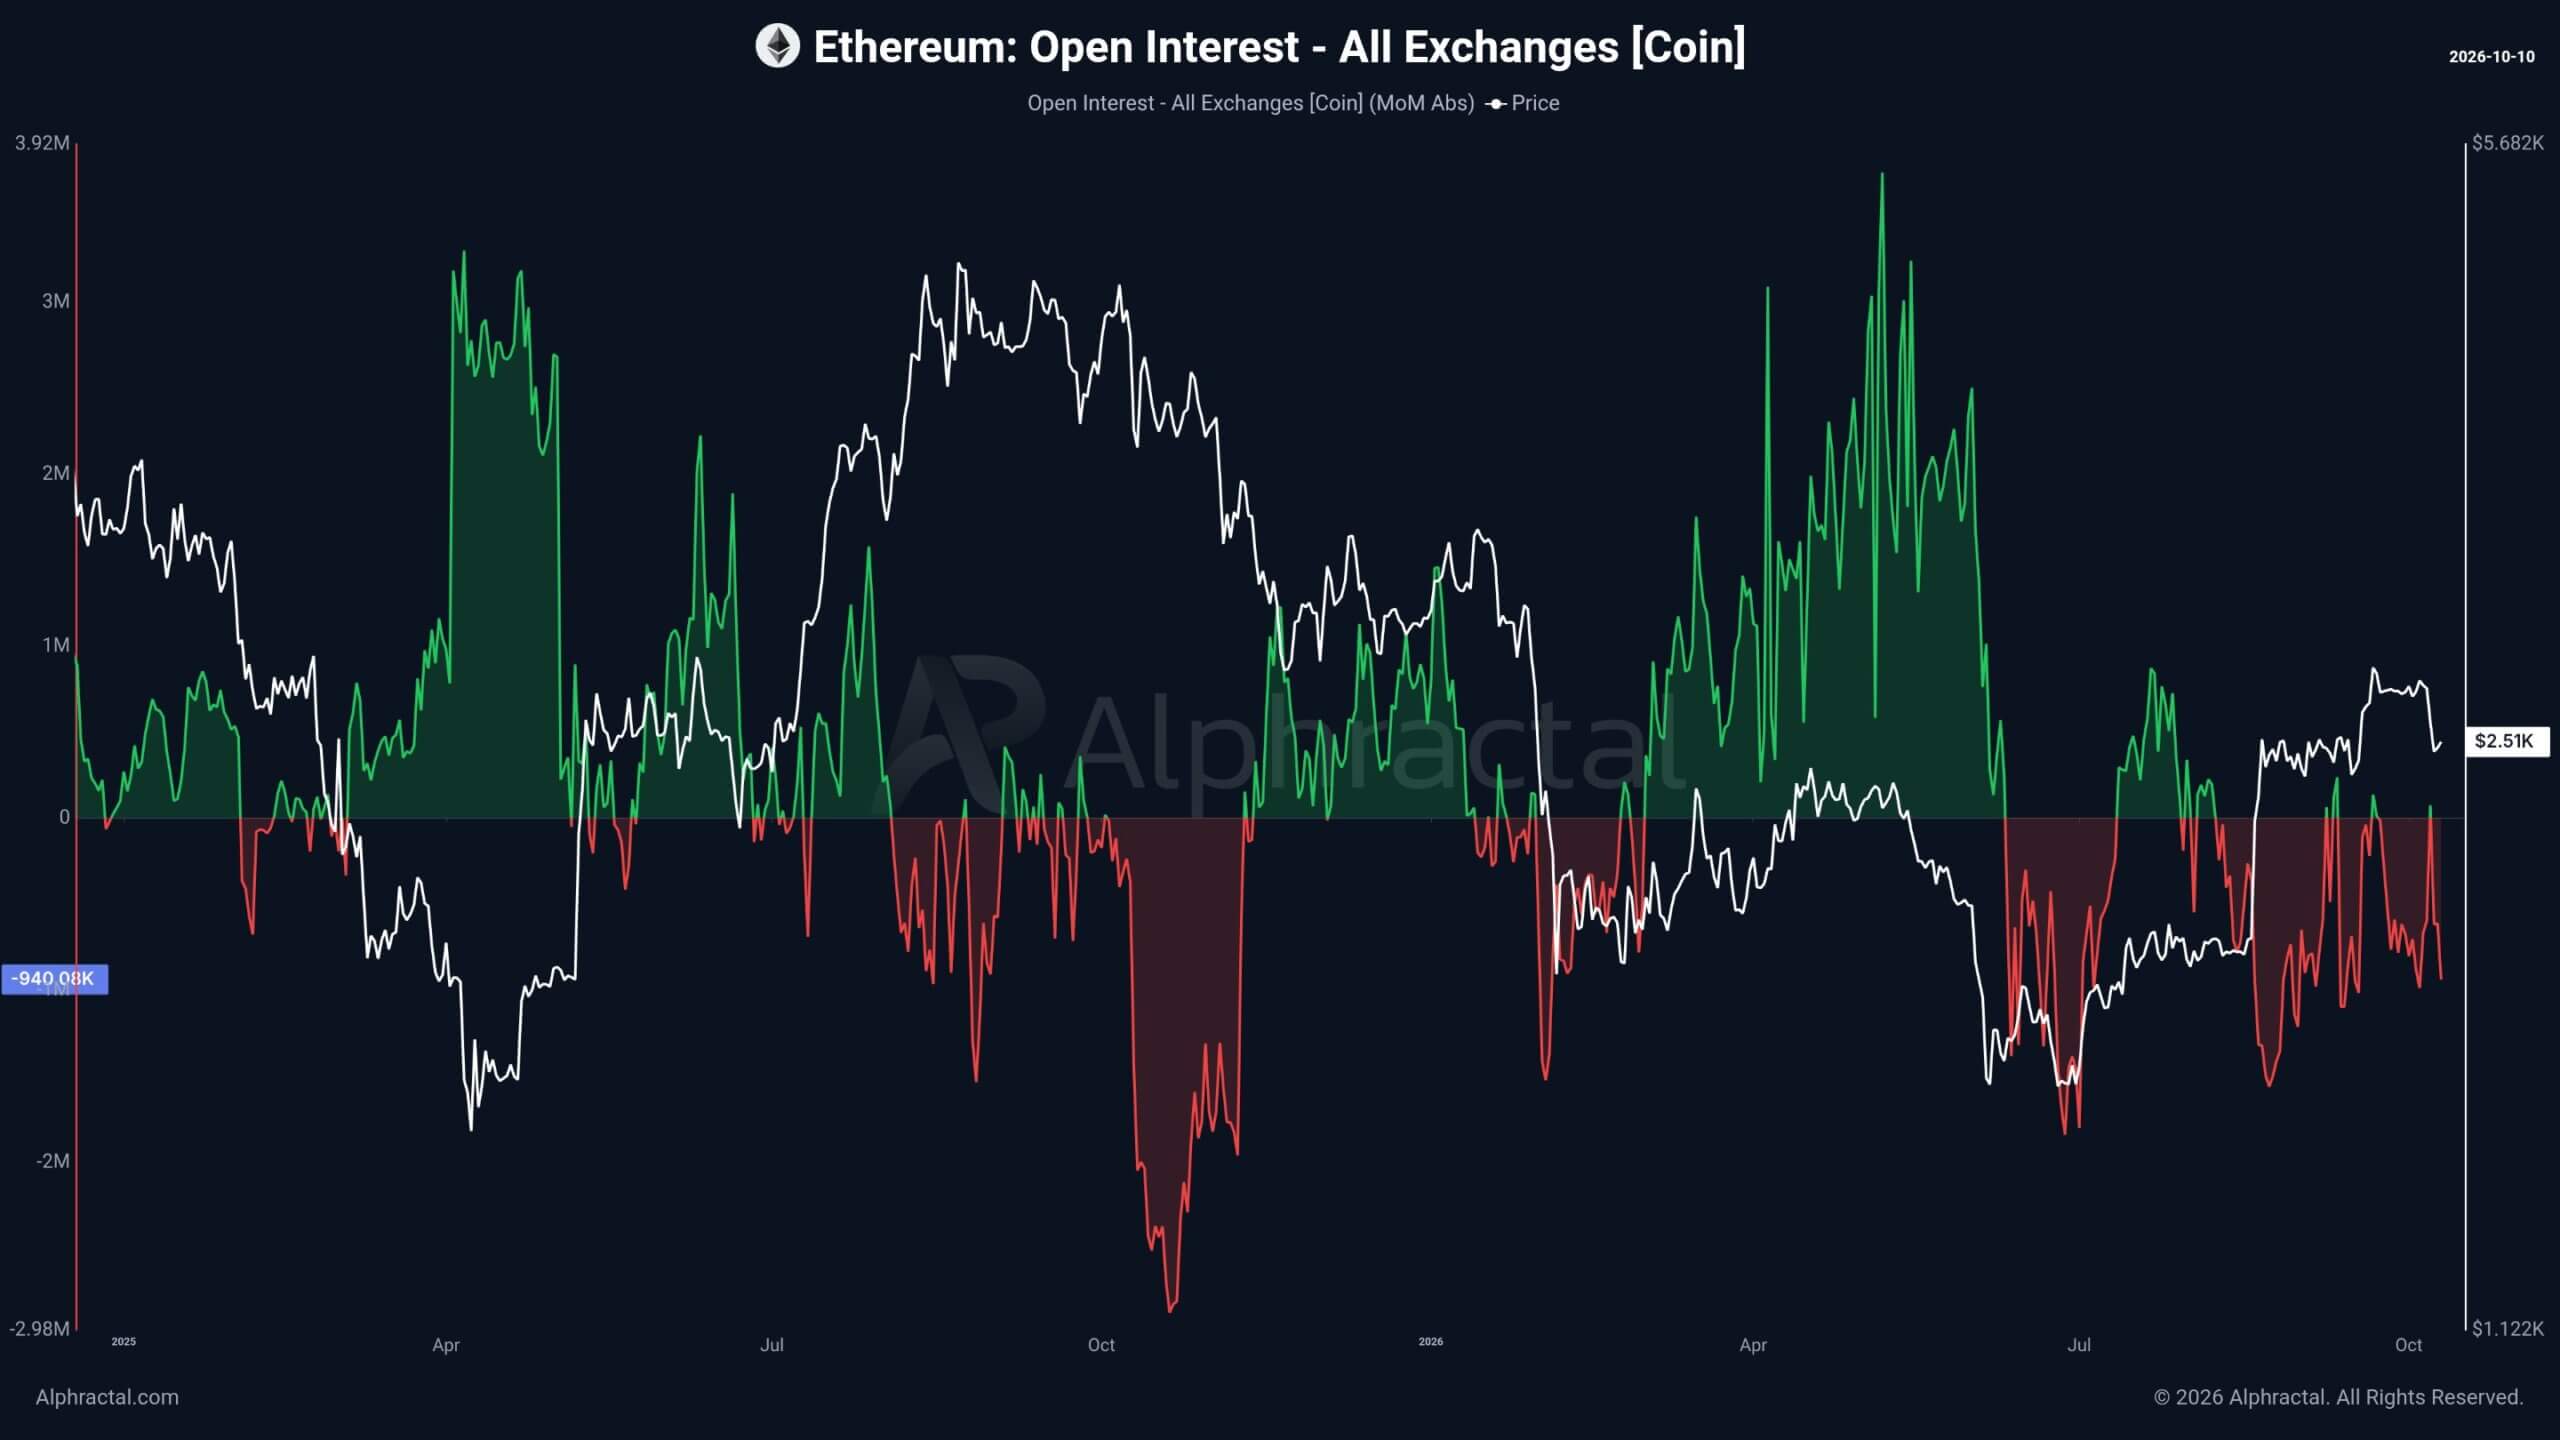
Valued at $2,500 per ETH, that represents roughly $26.5 billion in notional exposure.
The combination of weakening bullish positioning and substantial remaining exposure increases the potential for sharp price movements if volatility returns.
A renewed decline could push leveraged long positions toward forced liquidation, potentially adding selling pressure and accelerating losses. Conversely, a sustained recovery could force short sellers to close positions, contributing to further upward momentum.
Wedson warned that Ethereum's derivatives market remains vulnerable to further liquidations despite the recent reduction in outstanding positions.
The post Bitcoin’s rebound approaches the $85,000 zone where past buyers may sell appeared first on CryptoSlate.
EU finance ministers agreed to shift oversight of major crypto companies to a central watchdog, reshaping supervision under MiCA.
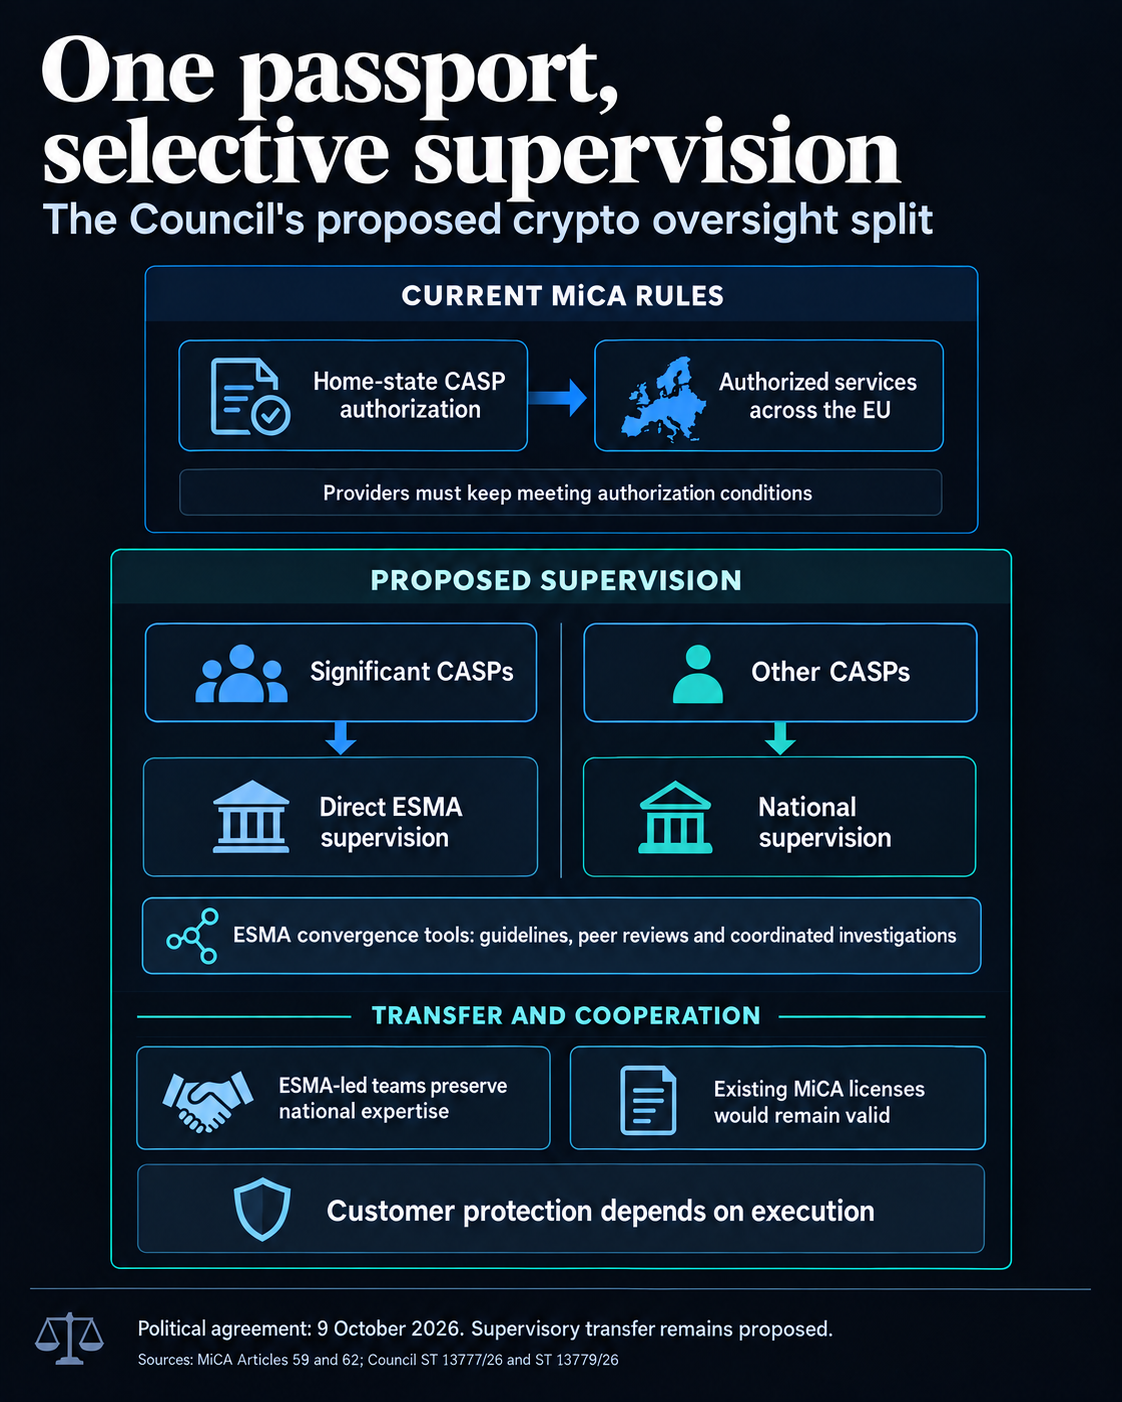
The Council of the European Union reached a political agreement on Oct. 9 to give the European Securities and Markets Authority (ESMA) direct responsibility for the bloc's most significant crypto-asset service providers, as part of a wider package to integrate European financial markets.
The proposed overhaul addresses a weakness in the Markets in Crypto-Assets Regulation (MiCA), which allows firms licensed in one member state to serve customers across the 27-country bloc while remaining primarily supervised by their home-country regulator.
The compromise, however, is considerably narrower than the European Commission's original plan to move all crypto service providers under ESMA. Officials estimate that only 10 to 15 of roughly 360 providers would qualify for centralized supervision, Reuters reported.
The agreement sets the Council's negotiating position rather than changing the law immediately. The Council must still negotiate the proposal with the European Parliament.
National licenses expose gap in EU-wide oversight
MiCA's passporting system was designed to provide crypto firms with a single route into the European market. Under the regulation, a provider authorized in one member state can offer approved services elsewhere in the EU without establishing a physical presence in every country it serves.
That arrangement reduces duplication for firms expanding across borders, but it also places considerable responsibility on the national authority issuing the initial approval. This is because a company's operations, client assets, and technology systems can grow well beyond the market where it was licensed.
The consequences emerged in a July 2025 ESMA review of the Malta Financial Services Authority's authorization of an unnamed crypto provider.
ESMA questioned why the company received approval while material issues remained unresolved. Its reviewers found insufficient evidence that the licensing assessment adequately addressed governance, potential conflicts of interest, technology infrastructure, custody arrangements and certain anti-money-laundering risks.
The review did not establish that every Maltese license was deficient. It also credited the Maltese regulator with sector expertise and sufficient supervisory resources, while recommending improvements to its authorization process.
Malta subsequently said it was implementing the recommendations but opposed transferring supervision to ESMA, arguing in September 2025 that MiCA was too new to justify an additional regulatory layer. The authority warned that centralization could introduce bureaucracy and hamper competitiveness.
The dispute highlighted a broader tension: one regulator's authorization decision can affect crypto customers across Europe, even when other national watchdogs view the required level of scrutiny differently.
Largest crypto providers face new thresholds and EU enforcement
In response, EU regulators are proposing a new framework to address these issues.
Under the Council's draft, ESMA would take direct oversight of crypto providers with at least 15 million active EU users, or those meeting three of five additional significance criteria covering their customer base, custody assets, transaction volumes and financial interconnectedness.
Those criteria include more than 1 million active users, over €1 billion in crypto assets under custody and more than €4 billion in annual client transactions.
Together, these factors mean a provider's overall scale and connections to the financial system, rather than its place of incorporation alone, would determine whether supervision moves to ESMA.
The agency would gain powers to request information from directly supervised firms, conduct inspections, investigate breaches, and impose financial penalties. The draft also envisages the authority to restrict services or withdraw authorization where firms do not meet regulatory requirements.
While most crypto service providers would remain under national regulators, ESMA would use guidelines, peer reviews, coordinated investigations, and certain intervention powers to address uneven enforcement across jurisdictions.
The overhaul would also create a full-time ESMA executive board, including a chair and five independent members, to handle operational and company-specific decisions. National regulators would continue participating in broader policy and supervisory coordination.
The Council envisages a two-year transition in which joint teams transfer information, operational responsibilities and expertise to ESMA. Existing MiCA licenses for companies brought under direct supervision would remain valid, avoiding the automatic need to seek new authorization.
The proposed structure would bring greater supervisory scrutiny to a small group of large firms while leaving the majority of the market within the current national model. The decisive questions now concern the final thresholds, ESMA's available resources, and how providers near the boundary are treated.
The Council must formally adopt its negotiating position before talks can begin once the European Parliament establishes its own. Those negotiations will determine how many crypto companies ultimately move from national to EU-level supervision and when the transfer can begin.
The post EU targets MiCA loophole that lets crypto exchanges serve 27 countries with one license appeared first on CryptoSlate.
Thailand has finalized rules allowing domestic Bitcoin and Ethereum ETFs while restricting retail access to competing overseas investment products.
The Securities and Exchange Commission (SEC) announced on Oct. 8 that 11 regulatory notifications will take effect on Oct. 16, establishing a framework for cryptocurrency exchange-traded funds listed exclusively on the Stock Exchange of Thailand.
Thailand's move follows the success of spot Bitcoin and Ethereum ETFs in the United States, which have attracted about $70.37 billion in combined cumulative net inflows since their launches.
According to SoSoValue data, the funds held about $121 billion in combined net assets as of Oct. 12, illustrating the scale of the market Thailand seeks to enter.
Thailand prioritizes domestic ETFs over foreign competitors
Under the new framework, Thailand will initially prohibit the issuance and offering of investment products linked to foreign crypto ETFs, including depositary receipts that would otherwise allow local investors to gain exposure to overseas funds through domestic securities markets.
Securities companies will also be restricted from facilitating investments in foreign crypto ETFs for clients who do not qualify as institutional or ultra-high-net-worth investors.
The restrictions are targeted rather than a comprehensive prohibition on overseas crypto investments. They primarily affect specified investment products and brokerage services available to ordinary investors.
The SEC said the measures aim to support the development of Thailand's domestic crypto ETF ecosystem and strengthen local financial institutions' capabilities.
The regulator has also expanded the investment options available to existing asset managers.
Previously, Thai mutual funds and private funds could invest in foreign crypto ETFs but not domestic equivalents. Under the revised rules, they may invest in Thai-listed crypto ETFs, subject to existing investment limits.
Together, these changes could establish an additional source of demand for domestic products while reducing the availability of some foreign alternatives.
The framework may also create opportunities for Thai asset managers, custodians and other licensed digital asset businesses to participate in the emerging market.
However, the restrictions could leave retail investors with fewer competing products, making the fees, liquidity and tracking performance of domestically listed funds particularly important once trading begins.
Thailand imposes margin restrictions and investor safeguards
Beyond restrictions on foreign products, Thailand's framework sets operating requirements to limit risk and ensure crypto ETFs function within the country's existing securities market.
Initially, only Bitcoin and Ethereum will qualify as underlying assets, with each ETF required to passively track a single cryptocurrency.
Funds must maintain average net exposure of at least 80% of their net asset value to the chosen asset over each accounting year.
Asset managers must demonstrate adequate personnel, operational systems and service-provider arrangements before establishing a fund. Digital assets held by the ETFs must also be safeguarded by custodians regulated by Thailand's SEC.
Investor protections extend to trading activities.
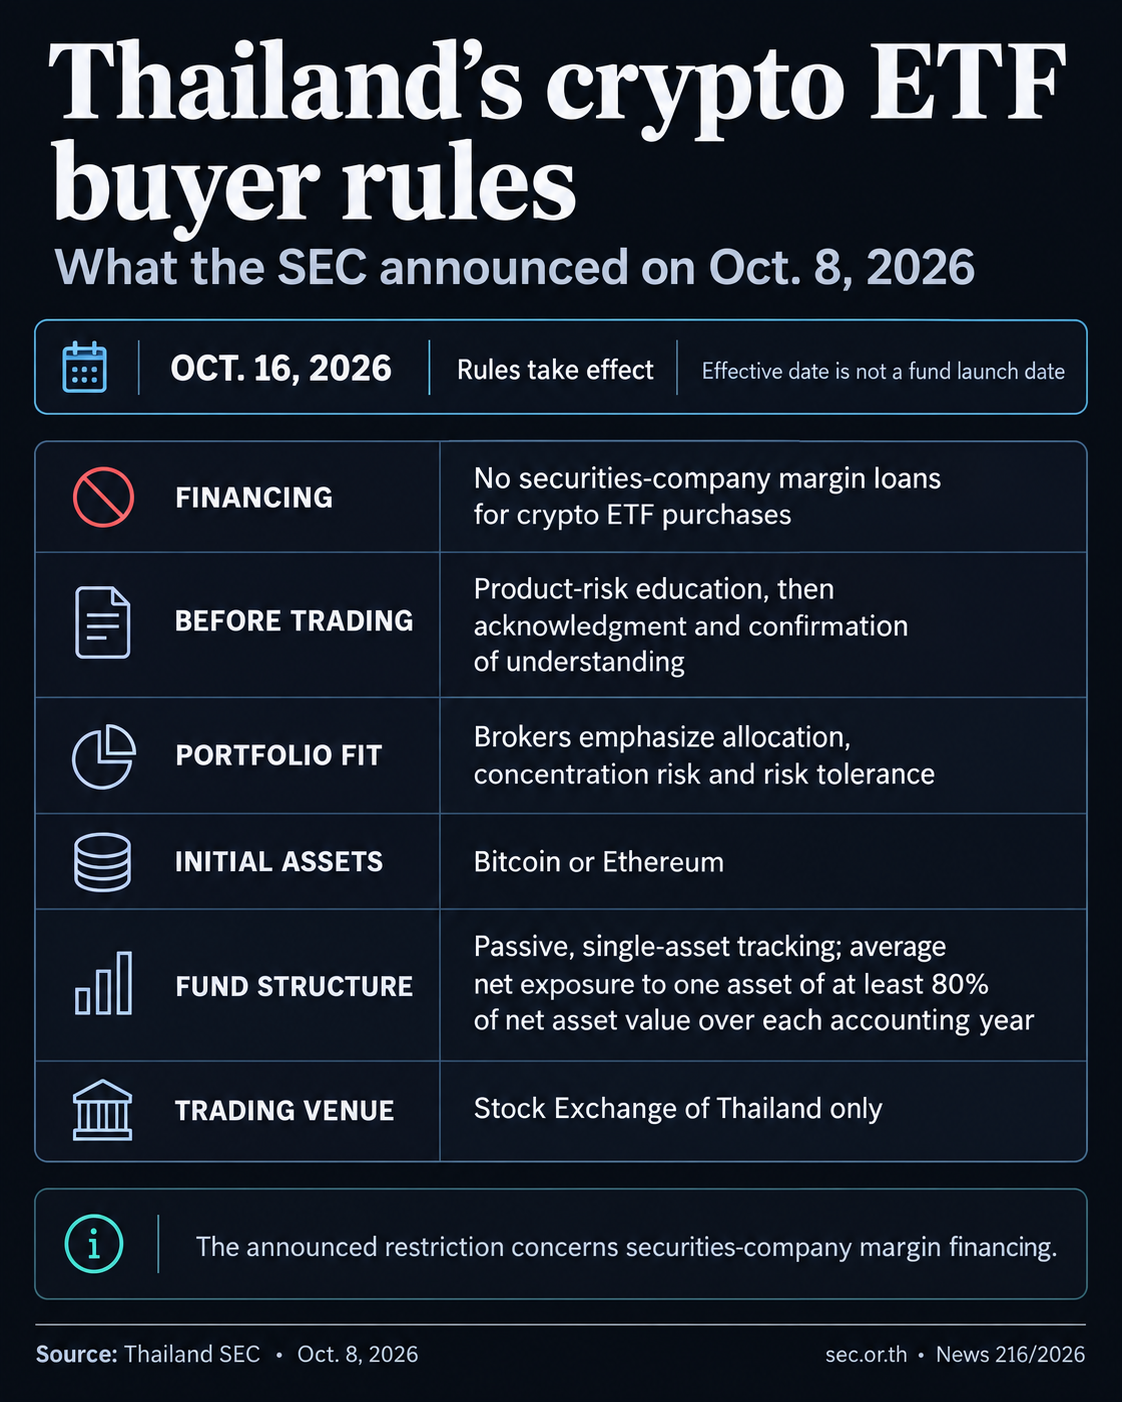
Securities companies will be prohibited from providing margin loans for crypto ETF purchases, preventing investors from using that form of broker financing to increase their exposure.
Before trading, investors must receive education about the products' characteristics and risks and formally acknowledge their understanding.
Brokers must also emphasize portfolio diversification and investment decisions consistent with individual risk tolerance.
The regulator has separately permitted licensed digital asset fund managers to undertake outsourced investment management functions, while qualified digital asset businesses may apply to serve as mutual fund supervisors.
The final regulations follow consultations conducted between April and September, during which the SEC said most respondents supported the proposals.
The next milestone is Oct. 16, when the regulatory framework becomes effective. The SEC has not yet approved a Bitcoin or Ethereum ETF or announced when either product will begin trading on Thailand's stock exchange.
The post Thailand wants a piece of the $120 billion Bitcoin and Ethereum ETF market, but on its own terms appeared first on CryptoSlate.
Lookalike payment addresses targeted nearly 4.5 million Solana wallets over 11 months, according to blockchain-data firm Bitquery’s Oct. 9, 2026 findings. The findings show why a successful small test transfer can still precede a much larger payment to a scammer.
The technique, known as address poisoning, plants a misleading entry in a wallet’s payment history. A tiny incoming transfer puts the sender’s lookalike address near a legitimate payment. If the user later copies that address, they can send money to the wrong recipient.
A Solana test transfer can reach the wrong address
Bitquery describes a Nov. 17, 2025 case in which a wallet first paid $10 in USDT to its Gate.io deposit address. A lookalike sent dust 12 seconds later. The wallet then sent a second $10 test to the fake, followed by 30,749.80 USDT to that same address.
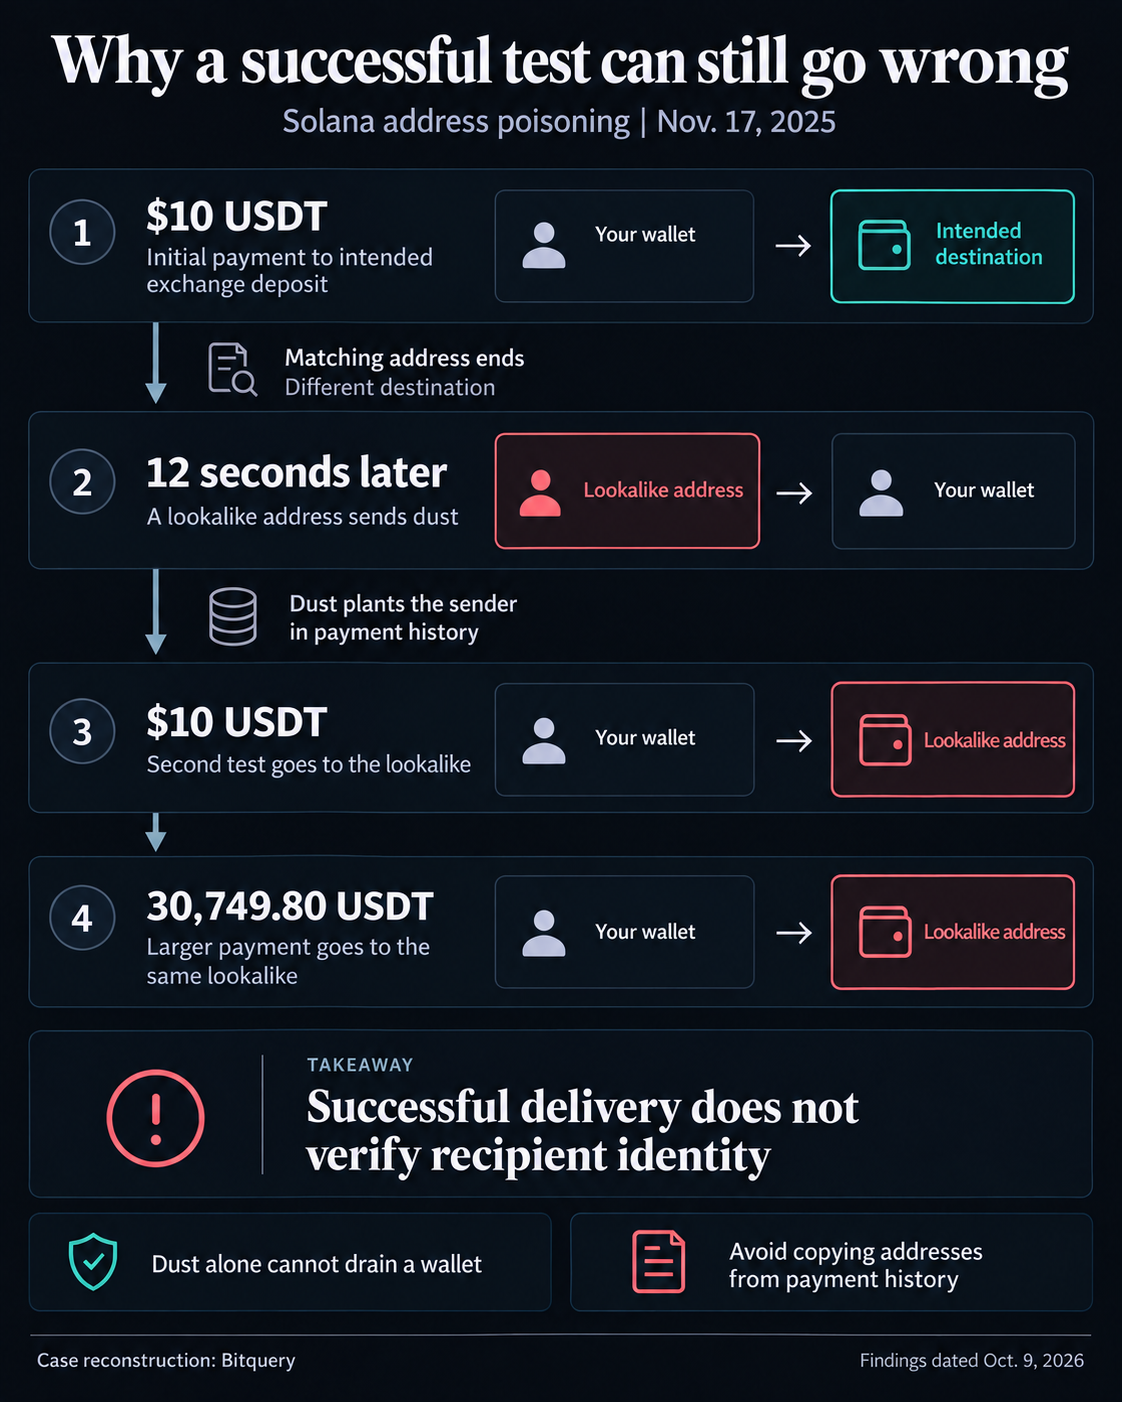
The implication is that a successful test confirms delivery to the selected address, but cannot establish who controls it. If the destination was copied incorrectly, repeating the payment repeats the mistake.
Receiving dust does not itself drain a wallet in this mechanism. The loss occurs when its owner subsequently authorizes a payment to the lookalike.
Bitquery counted 4,497,798 targeted wallets from Oct. 30, 2025, through Oct. 7, 2026. Its rule required a same-day payment of at least $1 in SOL, USDC or USDT, followed by dust or a fake stablecoin token from a different address matching at least three characters at each end of the payee.
The loss analysis used a smaller subset: approximately 3.0 million wallets poisoned through July 9, 2026. Of those, 1,104 made qualifying payments totaling $940,106. The wider targeting count does not mean 4.5 million wallets lost money.
The loss total is a floor. It counts payments of at least $1 within 90 days of the first dust. Beyond that window, a payment could qualify if more dust arrived that day. Wallets poisoned after July 9 and payments outside those rules were excluded. Bitquery also removed likely existing relationships, such as pairs with earlier payments or repayments; some genuine thefts may have been excluded.
Phantom’s address-poisoning guidance advises avoiding addresses copied from transaction history and verifying the address before sending.
Its receiving-payment instructions separate the checks: first confirm the exact recipient address and network, then look up the transaction status on an explorer. Phantom also says it cannot recover tokens sent to the wrong address.
The post A Solana wallet tested a fake address with $10, then sent it $30,750 appeared first on CryptoSlate.
CryptoTicker.io
The American spot funds holding XRP together manage around $1.57 billion, the comparable Solana funds around $1.73 billion. Some $160 million still separates the two groups, and the gap has been shrinking for weeks. That is the real story behind the XRP price this Monday, because the price sheet itself does not show it: XRP traded at $1.38 at midday on Monday, a good 9 percent below where it stood a week earlier.
This contradiction is the heart of the forecast. Money has flowed into the XRP funds for thirteen consecutive weeks, most recently $11.31 million in the week to October 9. Over the same stretch the funds holding Bitcoin, Ethereum and Solana lost a combined $1.248 billion. Even so, the assets of the XRP funds fell from $1.66 billion to $1.57 billion. To see where the price can run by year end, start with why inflows and fund assets are pointing in opposite directions here.
Where the XRP price stands on October 12
XRP traded at $1.38 at midday on Monday. The day's low sits at exactly that level and the high at $1.42. Over 24 hours the move is a loss of 1.45 percent, over seven days a loss of 9.02 percent. A week ago, then, the price was still around $1.52.
Over 30 days the gain is 0.78 percent; over twelve months the loss is 42.11 percent. The price sits 62.2 percent below its record high of $3.65. Market capitalisation stands at roughly $87 billion, turnover over the past 24 hours at about $1.52 billion, and circulating supply at 63.13 billion XRP. All figures come from CoinGecko, as of around midday on October 12.
What stands out on this price sheet is that the day's low and the current price coincide. XRP is trading at the bottom of its daily range, and without any single piece of news to explain the slide. That is precisely why the fund flows are worth a look.
The ETF gap to Solana: $1.57 billion against $1.73 billion
According to data from the research firm SoSoValue, reported by 24/7 Wall St. on October 12, the American Solana funds hold around $1.73 billion and the XRP funds around $1.57 billion. The difference of some $160 million amounts to just under 10 percent of the XRP funds' assets.
The direction this convergence comes from is the interesting part. The Solana funds recorded outflows on six of seven trading days in October, with only October 2 adding money. The XRP funds, by contrast, took in fresh capital over the same period. The gap is closing not because XRP is surging, but because money is being pulled out on the other side.
That matters for how to read it. A product taking in money month after month builds demand that is independent of the day's business on the spot market. Fund providers have to buy and hold the underlying coins, and that holding is locked away. The larger it grows, the smaller the freely tradable share of supply becomes.
Thirteen weeks of inflows and a smaller fund base all the same
In the week to October 9 the XRP funds took in a net $11.31 million. It was the thirteenth consecutive week of inflows. Cumulatively, inflows since launch add up to around $1.80 billion, as CryptoSlate reports, citing SoSoValue.
The same report carries the second figure that matters: net assets of the XRP funds fell over that week from $1.66 billion to $1.57 billion, a drop of 5.4 percent. The funds took in money and shrank regardless.
Why $1.80 billion of inflows leaves only $1.57 billion in assets
A spot ETF is a container, and its value rests on two quantities: how many coins sit inside, and what a coin costs. Inflows change only the first. The price changes the second, and it acts on the entire holding, not just on the money newly paid in.
Set cumulative inflows of around $1.80 billion against today's fund assets of around $1.57 billion and a difference of about $230 million remains. That sum comes from the two figures above and shows the order of magnitude by which the fall in the price has eaten into investors' contributions. Every new dollar flowing into the funds meets a holding that is losing value.
That leads to a sober conclusion for the forecast: fund inflows signal demand, but they are no lever that automatically carries the price. Weekly inflows of $11.31 million stand against daily turnover of around $1.52 billion. The weekly inflow therefore amounts to less than one percent of what trades in a single day. Read the inflow streak as a driver of the price and you overstate its size many times over.
The value of the streak lies elsewhere. Thirteen weeks show that one group of buyers has not sold across three months, while Bitcoin and Ethereum saw $681.1 million and $542.07 million withdrawn in that same week. That persistence says something about those buyers' time horizon, not about next week's price.
What has changed since the last XRP article
On Sunday the focus here was the state of voting in the XRP Ledger, when the lending function stood at 17 of the 25 votes required and the price was $1.39. Little has happened to the price since; it sits one cent lower at $1.38.
On the ledger itself the position is unchanged: the LendingProtocol amendment still stands at 17 votes. An amendment needs more than 80 percent of the trusted validators and must hold that majority for two full weeks before it goes live. If support drops below the line in between, the clock restarts. An activation date for the lending function therefore remains out of sight.
What is new is a different amendment: fixCleanup3_4_0 has reached the required majority and stands at 26 of 32 validators. It goes live on October 23. Confuse the two and a housekeeping update looks like the launch of the lending business. For the price, fixCleanup3_4_0 is immaterial; for market expectations it is not, because it shows the voting process working.
The levels the price is carrying today
On the downside, $1.38 is the level of the day, because the daily low and the current price meet there. If the price gives up that area during the session, there is no intermediate step from recent trading days before the next round number at $1.30.
On the upside the first hurdle is $1.42, the day's high. Above it comes last week's level at around $1.52. That second mark is the more telling of the two, because it marks the starting point of the current decline. Only once the price takes it back is the move of the past seven days undone.
Higher still sits $2.80, and that level deserves an assessment of its own.
Standard Chartered's target and the case against it
Geoffrey Kendrick, head of digital asset research at Standard Chartered, cut his year-end 2026 target for XRP from $8 to $2.80 back in February, a reduction of 65 percent. He cited outflows from crypto funds, the high level of interest rates and geopolitical uncertainty. His longer-term target of $28 by 2030 he left unchanged.
From today's level that target demands a rise of 102.9 percent. Eighty days remain until December 31. XRP has managed to double in less than three months several times in its history, most recently in the upswing after the turn of 2024 into 2025. Those moves each needed an external trigger, however, and no such trigger is visible in the calendar before year end.
The case against the target is also the development Kendrick himself gave as his reason for cutting it. Fund inflows have not accelerated; at $11.31 million a week they have stayed small, and fund assets have fallen of late. The grounds for the cut therefore still hold.
Two dates that can move the price in the coming weeks
On Wednesday, October 14, the US Department of Labor publishes the consumer price index for September, at 8:30 a.m. New York time and so 2:30 p.m. in Germany. The inflation reading helps decide how the market prices the next rate decision.
That decision comes on October 28, the second day of the Federal Reserve's Open Market Committee meeting. For crypto assets the path of rates counts twice over: it sets how attractive interest-bearing investments look by comparison, and it steers the risk appetite of institutional investors, which is precisely the group buying through the funds.
Both dates fall before year end and therefore inside the period the $2.80 target refers to. Anyone following the forecast for XRP has in those two dates the most important junctions in the calendar.
What the US fund inflows mean for investors in Germany
The funds this article is about are American products. As a retail investor in Germany you cannot buy them, for a regulatory reason: the EU regulation on key information documents, PRIIPs Regulation (EU) No 1286/2014, requires a key information document in an official language of the relevant country before any sale to retail clients. Most American fund providers do not produce one, because they largely serve their home market. A broker supervised in the EU may then not sell the security to retail clients and either hides it or rejects the order. This block has applied since 2018.
Anyone already holding such a security may keep it and sell it, but not buy more. For everyone else two routes remain, and they differ considerably in tax terms. More on the products approved in Germany is in our overview of crypto ETFs in Germany.
The first route is buying the coins directly on a trading platform. Which platforms are licensed under the European crypto regulation MiCA and what they cost is set out in our comparison of crypto exchanges. The second route runs through exchange-traded debt securities, which in Europe trade as ETNs or ETPs and are available through any securities broker.
Holding period, ETNs and the December 31, 2026 cut-off
A direct purchase falls under section 23 of the German Income Tax Act. Sell your coins after a holding period of more than one year and the gain stays tax free. Sell within the year and the gain counts as other income and is taxed at your personal rate, with an exemption threshold of €1,000 a year.
With debt securities it depends on the product terms. If the security grants a genuine right to delivery of the coins, the tax authorities treat it like a direct investment under the Federal Ministry of Finance circular of May 10, 2022, because a claim to delivery in kind exists rather than a monetary claim. The one-year rule then applies. Without that right to delivery, the security falls under section 20 of the Income Tax Act and the 25 percent withholding tax applies plus the solidarity surcharge, regardless of how long you have held it. Which of the two regimes applies to your security is in the product terms and nowhere else. A tax tool with a portfolio tracker assigns the positions automatically after purchase.
There is also a date that matters directly for the forecast to year end. In early September 2026 the Federal Ministry of Finance published a draft bill under which gains on crypto assets would be taxed from 2027 as investment income at 25 percent regardless of the holding period, or 26.375 percent including the solidarity surcharge. The draft provides that holdings acquired up to December 31, 2026, remain under today's system and so keep the one-year rule.
A draft bill is not a law. It can still change in cabinet and in the parliamentary process, and the cut-off date for existing holdings is itself among the open points. That is exactly why this point is a reason to review your own timetable rather than postpone it.
Our assessment of the XRP price to year end
In the view of this desk, the $2.80 target for December 31, 2026, is not plausible on today's data. The evidence is above: weekly inflows into the funds come to $11.31 million, less than one percent of daily turnover of $1.52 billion. Fund assets fell 5.4 percent in that same week. And the path from $1.38 to $2.80 demands a doubling in 80 days for which no trigger is visible in the calendar.
Against that, crypto markets have regularly begun their largest moves with no visible cause beforehand, and the rate decision on October 28 could be such a turning point. The thirteen weeks of inflows also show a group of buyers that did not sell into falling prices. Anyone betting on that should adopt that group's time horizon rather than the horizon of a year-end target.
This assessment judges the situation and is not a recommendation to buy or sell XRP. With crypto assets, a total loss of the capital employed is possible.
XRP forecast: $2.80 demands 102.9 percent in 80 days
The inflow streak of the XRP funds is documented; its effect on the price is smaller than the headline suggests. To draw something from it for your own portfolio, work through it in this order:
- Settle the product type. Decide whether you want to hold the coins directly or hold a debt security. On a direct purchase the one-year rule under section 23 of the Income Tax Act applies. Which MiCA-licensed platform suits your plan and what trading costs there is in the comparison of crypto exchanges.
- With securities, read up on the right to delivery. Only a genuine right to delivery brings the one-year rule into play; otherwise it is the withholding tax. Which provider carries which securities and at what order fees is shown in the comparison of crypto brokers.
- Document the purchase date. Record the date, quantity and price of every position, because the one-year rule hangs on it, and possibly the classification as an existing holding too. A tax tool with a portfolio tracker takes that from your trading data.
(As of October 12, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
The largest remaining Dogecoin fund in the United States no longer keeps its coins in a single place. In a supplement to its prospectus dated October 5, 2026, Grayscale told the US Securities and Exchange Commission that Anchorage Digital Bank N.A. may serve as an additional custodian for the trust's DOGE holdings. Coinbase Custody remains the primary custodian. Two days earlier the same issuer had switched on in-kind creations, and the day after tomorrow its competitor Bitwise closes its Dogecoin fund for good. For investors in Europe this is not an American footnote, because the question underneath it applies to every German Dogecoin product in exactly the same way: who holds the keys, and what happens if that one custodian fails?
DOGE traded at $0.086 on Monday midday, up 0.9 percent over 24 hours and down 9.5 percent over the week (CoinGecko, as of October 12). Market capitalisation stands at $13.4 billion, with $522 million changing hands in the most recent trading day. The price here is only the frame. The subject of the day is the custody chain, and unlike the price, that can actually be checked.
Grayscale adds Anchorage Digital as a second custodian
The filing is titled Prospectus Supplement No. 1 and amends the prospectus of April 16, 2026. Its operative wording states that Anchorage Digital may serve as an additional custodian for the trust's DOGE holdings (SEC filing on Form 424B3). Coinbase Custody Trust Company, LLC expressly remains the trust's primary custodian, and Coinbase, Inc. remains prime broker. The fund trades on NYSE Arca under the ticker GDOG.
A custodian is the entity that holds the private keys to a fund's coins and moves those coins on instruction. Adding a second one spreads the failure risk: if one entity drops out, through a hack, an insolvency or an order from a regulator, the entire holding no longer hangs on it. How much of the DOGE will actually move is left open. The document says the sponsor has not currently determined the aggregate amount of the trust's DOGE it will transfer to Anchorage Digital.
144,871,236 DOGE in the fund, 117.33 per share
The size of the holding is what makes the filing interesting. As of October 5, 2026, Grayscale reported 144,871,236.7167 Dogecoin for the trust, equal to 117.33314709 DOGE per share at a net asset value of $11.20 per share and assets under management of roughly $13.8 million. The issuer's own overview from October 7 shows $10.38 per share and $12.81 million, which reflects last week's weakness in the price.
Set against the open market: 144.9 million DOGE are worth around $12.5 million at the current price, roughly 2.4 percent of the daily turnover CoinGecko reports for Dogecoin. The fund is therefore no driver of the price, but it is a useful lesson in how professional custody is built.
The sixth amendment to the custody agreement, signed September 29
Legally, the addition rests on a change of contract. The sixth amendment to the Master Custody Service Agreement was signed on September 29, 2026; the original agreement dates from August 8, 2025. Only that amendment creates the framework in which a second custodian can stand alongside Coinbase at all.
The timing next to the second change of the same date is striking. Also with effect from September 29, 2026, the trust may create and redeem shares in kind, that is against delivery of DOGE rather than cash. The authorised participants for this are Virtu Americas LLC and Macquarie Capital (USA) Inc. In-kind settlement means more coin movement between market participants and the fund, and more movement demands more custody capacity. Splitting across two institutions fits that rebuild.
A $5 million liability cap for the additional custodian
To understand what such a split is worth, read the liability clause. For the additional custodian, liability under the contract is capped at the greater of $5 million or twelve months of fees. Measured against trust assets of $12.81 million, that cap covers a substantial share, but not the entire holding, and certainly not every loss automatically.
Two further figures from the same filing set the frame. The custodian must maintain crime insurance or fidelity coverage of at least $100 million in aggregate, and a threshold of $100 million applies per cold storage address. Cold storage means keys that have never touched the internet. The threshold limits how much value may sit at a single address, and is thus the technical counterpart to splitting across two institutions.
Trading in the Bitwise fund ends on October 14
While one issuer builds out its custody, the other withdraws. Bitwise announced the liquidation of its Dogecoin fund on September 10, 2026. According to the issuer, Wednesday, October 14, 2026, is the last trading day on NYSE Arca. On that day the fund's DOGE will be converted into cash, and no new shares will be created from before the market open on October 15.
Remaining shareholders will be paid the net asset value of their shares as of October 21 in cash, on October 22 according to the issuer. The filing on Form 8-K is more cautious and speaks of the holdings being liquidated on or shortly after October 22, 2026. The date is therefore expected, not promised. Bitwise says shareholders need take no action in the process. The fund had become tiny: Decrypt put its net assets at around $722,000 as of September 8.
In our October 10 piece on the wind-down of the Bitwise fund, DOGE stood at $0.0862; a day later, at the $57.2 million exchange outflow, it was $0.0868. Today it is $0.086. The announced closure has therefore moved the price by less than one percent over those two days, which should surprise nobody given a fund size of $722,000. What is new since October 10 is not the price reaction but the custody question on the other side of the market.
The German Dogecoin ETP rests on a single custodian
In Germany nobody gets at a US fund such as GDOG without further ado. Anyone who wants DOGE in a brokerage account buys an exchange-traded product, an ETP, which here is a bearer debt security with assets deposited behind it. The best known is the 21Shares Dogecoin ETP with ISIN CH1431521033 and German security number A4A5WJ, tradable in euros on Deutsche Boerse. The issuer describes it as 100 percent physically backed, with custody handled by BitGo Europe GmbH. A second product came to the Frankfurt exchange from Valour, security number A4AK2K.
The difference from the American filing sits precisely here: the German product names one custodian, not two. That is no weakness of the house but the usual construction of European crypto ETPs, and it has worked for years. It does mean, though, that the question of spreading the risk stays open for German holders while the American competitor is answering it right now.
In-kind instead of cash: the rebuild since September 29
The mechanism behind in-kind settlement is worth two sentences, because it works the same way at an ETP. If new shares are created against cash, somebody has to buy DOGE on the market, and that purchase leaves a trace in the order book. If they are created against delivery of coins, the DOGE move straight from the trading firm into custody without a market order ever appearing. For the price that means less visible pressure in either direction; for custody it means more deliveries in and out each day.
The same filing names the practical limits: the order cut-off is 3:59:59 p.m. New York time, and settlement runs T+1 or T+2, one or two trading days later. A German investor holding an ETP will find the equivalent deadlines in the key information document for that product, and they are rarely identical.
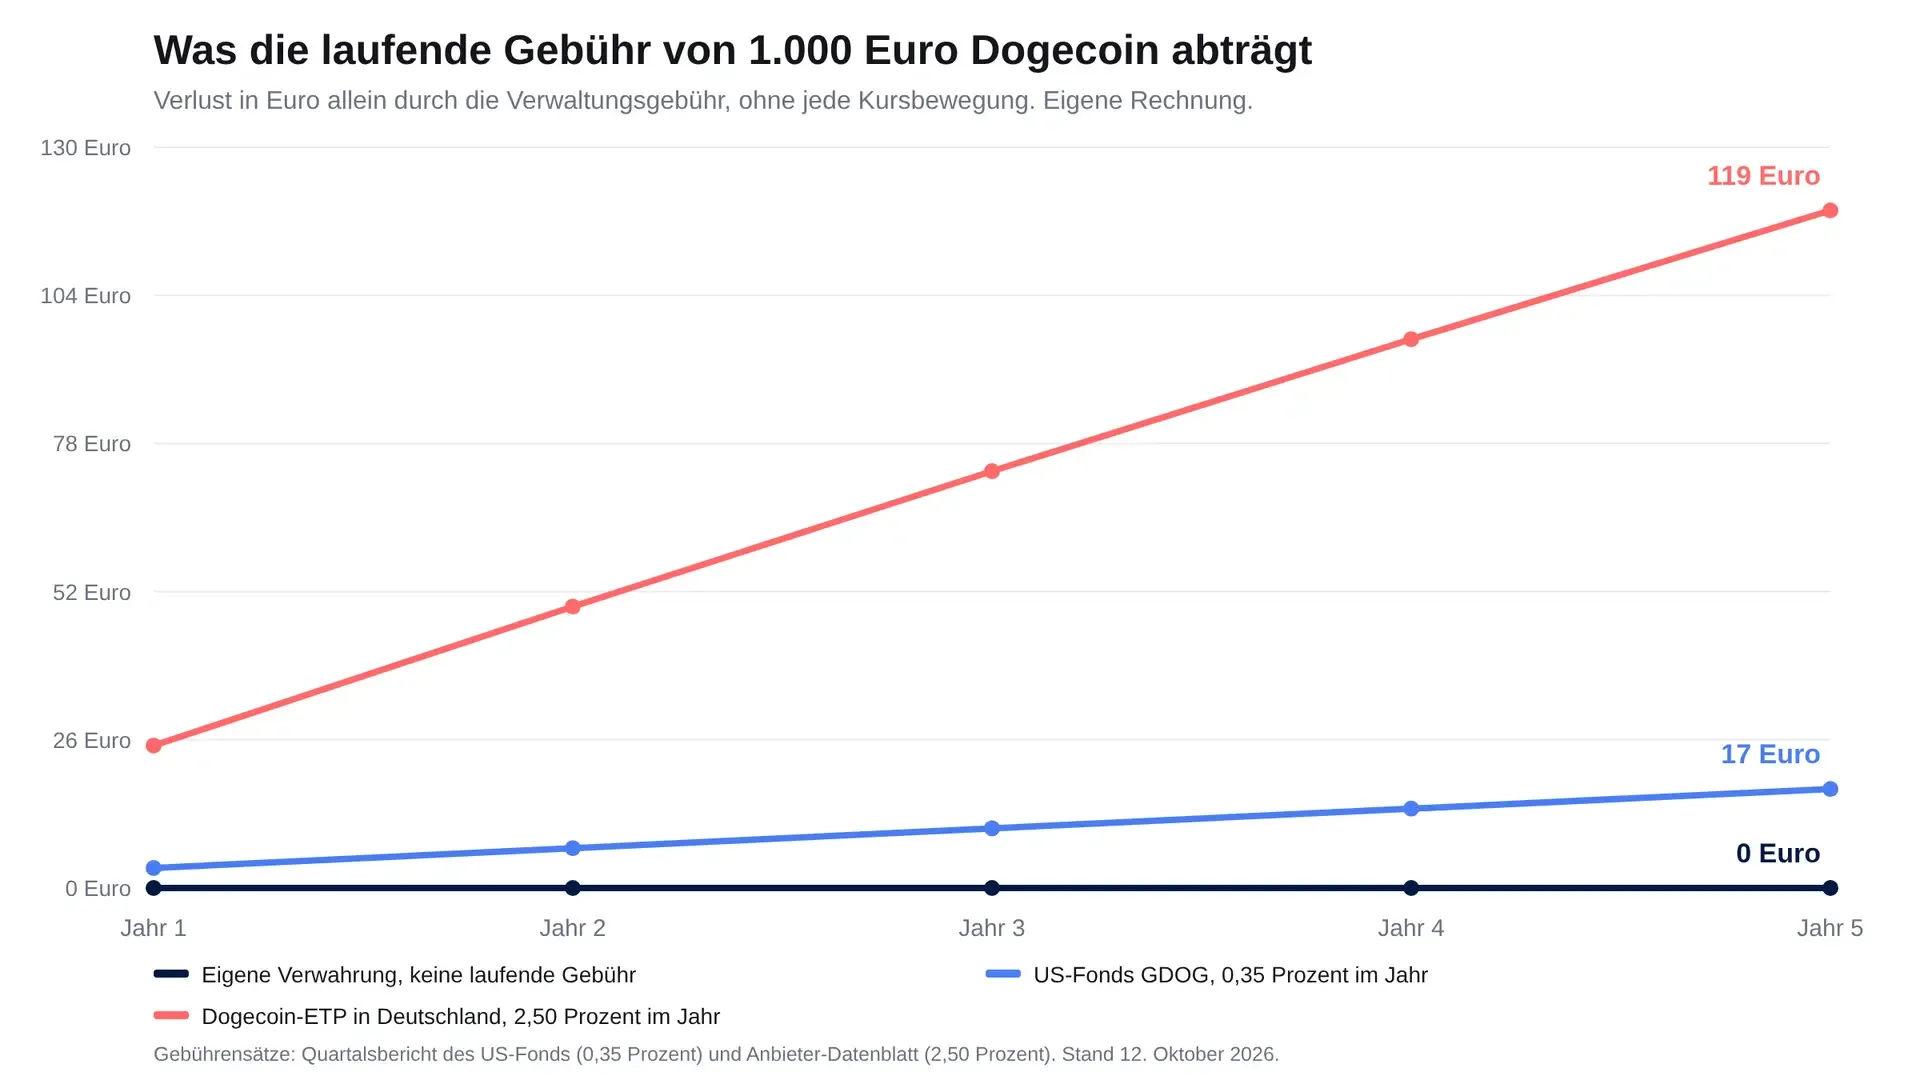
What custody costs per year, counted in euros
The convenience of a fund wrapper is paid for through the ongoing fee, and the spread between the routes is wide. For GDOG, the first-quarter 2026 report shows a sponsor fee of 0.35 percent annualised, once a temporary waiver has run out. The German 21Shares Dogecoin ETP costs 2.50 percent a year according to the issuer. Self-custody carries no ongoing fee, but a one-off cost for hardware and your own effort.
On a €1,000 stake, and with no price movement whatsoever, five years cost €0 under self-custody, around €17 in the US fund and around €119 in the German ETP. The fee is taken from the holding daily, so the share of coins behind each security keeps shrinking. GDOG makes that legible directly: 117.33314709 DOGE per share is a snapshot that gets smaller with every day.
Four entries in the key information document that put a number on your risk
The details that matter here are public in every product, just rarely in a prominent place. In the key information document and the prospectus for your ETP you will find four points that take minutes to look up: the name of the custodian and its domicile, whether there is one or several, the size of the insurance or of a liability cap, and whether there is a right to delivery of the coins. In a product with a single custodian, that custodian's creditworthiness decides your counterparty risk; with several, the risk is spread.
The benchmark from the American filing serves as a yardstick: insurance of at least $100 million, a cap per cold storage address, a quantified liability for the custodian. If your documents carry no figure for any of those points, that absence is the real information. If you are weighing the alternative and want to hold the keys yourself, the devices and their differences are in our hardware wallet comparison; the price of that route is that you secure the recovery phrase yourself and nobody can replace it for you.
Holding period for self-custody, withholding tax for the ETP
In tax terms the two routes diverge in Germany, and for most holders that difference is larger than any fee. Buying Dogecoin directly and holding it yourself falls under section 23 of the German Income Tax Act: after a holding period of more than one year, the gain from the private disposal is tax free, and within the year an exemption threshold of €1,000 applies.
For an ETP the classification is disputed. Because these are bearer debt securities, treatment as a capital investment under section 20 of the Income Tax Act is the obvious reading, which would mean 25 percent withholding tax regardless of the holding period. For physically backed products carrying a right to delivery of the coins, the specialist literature also argues for section 23. There is no ruling from the Federal Fiscal Court specifically on crypto ETPs. Anyone counting on the holding period should therefore ask the issuer or a tax adviser about the treatment before buying and document their acquisition data cleanly, for which the tools in our overview of tax software and portfolio trackers are suited.
What the switch says about the state of the Dogecoin market
Two filings within a few days draw the same picture from two directions. One issuer gives up because, after a good eleven months, barely any money sits in the product; another builds out its custody and opens share creation to in-kind delivery. That says nothing about the price, but something about the infrastructure: the number of products is falling, the quality of those left is rising.
For the price itself the picture stays thin. Dogecoin has lost 9.5 percent over the week and, at a market capitalisation of $13.4 billion, sits well below the large names. A change of custody creates no demand. It only lowers the probability that a technical or legal incident at a single service provider drags an entire fund down with it.
Our assessment of the split across two custodians
In the view of this desk, adding a second custodian is the more useful of the week's two events, for a reason that can be checked: the additional custodian's liability is quantified at a minimum of $5 million, the insurance requirement at $100 million, and the cold storage threshold caps concentration per address at $100 million. Three quantified figures an investor can hold up against their own product are worth more than any announcement without a number.
Against that stands the sponsor leaving open how much it will actually move. As long as the transferred share is not quantified, the split remains a possibility rather than a measured fact, and at assets under management of $12.81 million even a complete transfer would be a small matter financially. We therefore read the filing as a sign of the segment maturing, not as a reason to buy. Which route somebody picks depends on the holding period and on the willingness to secure keys personally, not on where the fund wrapper comes from.
Dogecoin custody: two addresses only lower custodian risk
Splitting across Coinbase Custody and Anchorage Digital changes a fund's counterparty risk, not the price risk of Dogecoin. If you want to take something from it for your own portfolio, work through it in this order. First: look up in the key information document for your product how many custodians are entered and whether a liability sum is quantified. Second: project the ongoing fee onto your intended holding period, because at 2.50 percent a year, five years take around €119 of €1,000 before the price has moved at all; the devices for the route without an ongoing fee are in the hardware wallet comparison. Third: settle the tax treatment of your route before you buy, and document the purchase date and acquisition cost from the outset, for instance with a tool from the overview of tax software and portfolio trackers.
(As of October 12, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy. Crypto investments can lead to a total loss.)
Avalanche costs around $11.09, or €9.92, on October 12, 2026, which is 7.2 percent more than the day before. That is the high of the day: the range over the past 24 hours ran from $10.32 to $11.09. The contrast with the rest of the market is the striking part. Bitcoin lost 3.2 percent over the week, ether 6.0 percent, Solana 7.8 percent and XRP 7.3 percent, while AVAX stayed 1.1 percent up over the same week.
Across 30 days the gap is considerably wider. The AVAX price rose 48.9 percent over that period and 70.7 percent over 60 days. From the monthly low of $7.27 on September 16 to today it is 52.5 percent. Look at the chart alone and you see one of the strongest moves among the 25 largest cryptocurrencies.
This is precisely where a second look pays off. A price rises because buyers pay more than sellers ask, and that may or may not have anything to do with the use of a blockchain. So we looked not only at the price but at the capital actually working on the Avalanche chain. The result carries this article: both are growing, but not at the same pace.
Avalanche price today: $11.09, rank 25 and a $4.92bn market value
Avalanche is a layer-1 blockchain, meaning a self-contained network with its own consensus on which applications and tokens run. AVAX is the associated token, used to pay fees and to collateralise validators. With a market capitalisation of $4.92bn, Avalanche sits at rank 25 among the largest cryptocurrencies. Of a maximum 470.02 million AVAX, 443.35 million are in circulation, or 94.3 percent of the total supply.
Trading volume over the past 24 hours comes to $388.8m. Measured against the market value, that is turnover of roughly eight percent a day, a figure that indicates normal liquidity for a token of this size. For you that means an order of a few hundred or a few thousand euros will not move the price on a liquid exchange.
The distance to the all-time high remains large. On November 21, 2021 AVAX stood at $144.96. From that level it is 92.4 percent short. Over twelve months the books also show a loss of 47.7 percent. The rally of recent weeks is therefore recovering part of a multi-year decline rather than breaking new ground.
The counter-move in figures: AVAX up 7.2 percent, Solana down 7.8 percent
An altcoin running against the broader market does happen, but it rarely lasts. That makes a comparison of the time windows all the more worthwhile, because it shows when the move began. Over 14 days AVAX is 7.0 percent up, and over seven days only 1.1 percent. The bulk of the increase therefore falls in the second half of September and the first week of October rather than the past few days.
The price has in fact already left its monthly high behind. On October 7 AVAX traded at $11.60, then fell back to $10.07 by October 9. Today’s jump to $11.09 therefore returns the price to the top of the range without exceeding it. That $11.60 is the first level against which the move has to be measured.
Two documented developments from September sit in the background. First, the Helicon upgrade went live on September 22, shortening among other things the lock-up period for validators; what that changes for delegators is something we set out on September 17 in a separate piece on the Helicon upgrade and the staking lock-up. Second, the business in tokenised assets on the chain is growing, which we described on October 3 with an increase of $266m over 30 days in tokenised assets on Avalanche.
Total value locked: $643m is working on the Avalanche chain
Total value locked, or TVL, describes the sum of all deposits held in the applications of a blockchain, for instance in lending protocols, trading venues and staking services. What gets measured is the capital users entrust to the network, not the value of a token. The metric therefore provides the obvious cross-check on a rising price.
Avalanche currently holds $643.1m. Thirty days ago it was $471.7m and 60 days ago $416.3m. Chain capital has thus grown 36.3 percent within a month and 54.5 percent within two. The chain is in better shape than it was in the summer, and anyone claiming that only the price is moving here is wrong.
The swing within October is notable. On October 5 the chain held $648.6m, on October 9 only $599.6m, and today $643.1m again. A fall of 7.6 percent in four days and a recovery in three: the capital on Avalanche reacts sensitively to price moves, because part of the deposits are themselves valued in AVAX.
The gap: price up 48.9 percent, chain capital up 36.3 percent in 30 days
Lay the two series on top of each other and a gap of 12.6 percentage points remains over 30 days, and of 16.2 points over 60 days. In both windows the price rose faster than the capital working on the chain. The valuation is running ahead of the usage, not dramatically, but measurably.
Placing that in context requires a comparison with other chains, because an absolute figure says little. According to chain data from October 12, DeFi capital is distributed as follows: Ethereum leads with $51.87bn, followed by Solana with $6.27bn, Base with $6.26bn and Arbitrum with $1.38bn. Avalanche trails with $643m, or roughly a tenth of the Solana figure.
On market value the gap is smaller. Avalanche comes to $4.92bn and Solana to around $49.6bn. Avalanche’s market value therefore amounts to about a tenth of Solana’s, as does its chain capital. On that relation AVAX is not conspicuously expensive, measured by what sits on the chain.
Stablecoins as a second cross-check: $1.39bn on Avalanche
The second metric we examined is stablecoins. These are tokens whose value is pegged to a currency, usually the dollar. For money ready to be deployed on a chain they are a usable gauge, because nobody holds stablecoins waiting for price gains; they sit where trading, lending and paying happen.
Dollar stablecoins worth $1.39bn are in circulation on Avalanche. Solana carries $15.91bn and Ethereum $145.36bn. Avalanche therefore holds just under nine percent of the Solana stock and under one percent of the Ethereum stock. Euro stablecoins are practically absent on Avalanche at $6.7m, which for an investor in Germany means the route onto the chain runs via the dollar or via a swap on an exchange.
This analysis was compiled by cryptoticker.io itself on October 12, 2026. It is based on the public market data of the 25 largest cryptocurrencies, the chain data of five blockchains and 31 daily readings of the capital deposited on Avalanche.
Helicon and the 48-hour lock-up: what applies to AVAX staking since September 22
Staking on Avalanche means depositing AVAX in order to run a validator or to delegate to one, and receiving a share of the network rewards in return. The deposited capital is tied up for the duration of the chosen period. The Helicon upgrade of September 22 shortened that commitment, which speeds up both re-entry and exit.
In practice that changes two things. The lock-up period decides how quickly you can sell again in a falling market, and it decides how often you can reinvest rewards. Both affect the return more than a percentage point more or less in the advertised rate. If you use staking through a provider rather than your own validator, you will find the terms and the minimum amounts in our comparison of staking platforms.
For tax purposes staking has to be treated separately in Germany and should not be confused with a straightforward purchase. The rewards and the later sale of the coins follow different rules, and the documentation is down to you. So record from the very first reward when it arrived, in what quantity and at what price.
Our assessment: the rally is documented, its broadening is not yet
From this newsroom’s point of view the move rests on a real foundation, though a narrower one than the chart suggests. Three figures support it: 36.3 percent more chain capital in 30 days, an upgrade with a concrete effect on lock-up periods since September 22, and a growing business in tokenised assets. Three others cut the other way: the capital on the chain amounts to a tenth of the Solana figure, the stablecoin stock to just under nine percent of it, and the price has yet to regain its monthly high of $11.60 from October 7.
What follows is a reading, not a buying decision: Avalanche is winning institutional applications but broadening its user base more slowly than its price. As long as the gap between the two series widens, the rally carries more expectation than usage. If it narrows, the move becomes more durable. Total loss remains possible with any crypto token.
The buying route in Germany: MiCA exchange, holding period and self-custody
If you want to buy AVAX, the venue is the first decision. Since the European MiCA regulation took effect, providers that hold or broker crypto assets in the EU need an authorisation. A licensed exchange gives you a clear point of contact, regulated complaint channels and the duty to segregate client funds. Which venues list AVAX and what trading costs there is shown by our comparison of the best crypto exchanges.
On price it is worth looking at the difference between instant buy and the order book. The convenient instant buy costs around one percent at many providers, while trading through the order book costs considerably less. At a price of $11.09 and an order of €1,000 that is a difference of roughly ten euros, incurred regardless of how the price moves.
For custody you have two routes. Leave the coins on the exchange and you carry the provider’s risk. Transfer them to your own wallet and you carry responsibility for the access key. Before any transfer, check that you can select the right network, because AVAX exists on several Avalanche chains and a transfer to the wrong one is laborious to correct.
On the holding period: in Germany, gains from selling crypto assets are taxable as a private disposal if less than a year lies between purchase and sale. Buy into a rally and sell soon after and you will regularly land in taxable territory. That is no argument against buying, but it is a reason to record the purchase date and purchase price from the outset.
Levels up and down: $11.60 as the ceiling, $10.07 as the last floor
On the upside the first relevant level is the monthly high of $11.60 from October 7. As long as AVAX stays below it, the price is moving inside the known range, even on a daily gain of seven percent. A close above it would open the range to the upside.
On the downside, October 9 supplies the last interim floor at $10.07. Below that, the area around the level at the start of the month serves as a second reference. The monthly low of $7.27 from September 16 shows how far away the price was before the rally; it is not a forecast but the starting point of the current move.
More important than any of these levels over the coming weeks is the gap between the price and chain capital. Both series can be traced publicly, and anyone laying them side by side regularly will see sooner than from the chart alone whether a move is gaining substance or losing it.
AVAX at $11.09: chain capital trails by 12 points
- Note both series for your observation window: today’s price level of $11.09 and chain capital of $643.1m. Compare them again in four weeks. If the gap of 12.6 percentage points keeps widening, the move carries more expectation than usage. A venue that lists AVAX can be found in our comparison of the best crypto exchanges.
- Settle the fee question before buying: instant buy or order book, and at what rate. On an order size of €1,000 there are roughly ten euros between them, which you pay for certain while the price gain stays open.
- If you are considering staking, check the lock-up period first and the advertised rate only after that. Providers’ terms and minimum amounts are set out in our comparison of staking platforms.
You can review the full chain data yourself on the Avalanche overview at DefiLlama, and technical details of the network are in the developer documentation of the Avalanche project.
(As of October 12, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Anyone holding an Otherdeed has owned a plot of land in the Otherside metaverse built by Yuga Labs, the company behind the Bored Ape Yacht Club (BAYC), since the spring of 2022. Since September 9, 2026, it has been clear what is eventually meant to happen on that land: Yuga has announced an on-chain resource economy of 74 goods in which ApeCoin is the only route for moving value in and back out again. There is no launch date. This piece collects what is documented, what Yuga has left open, and what a holder in Germany should take from it for their tax return.
The short answer first: what has been announced is a design, not a product. Testing will begin only on plots that Yuga owns itself, and only with a narrow slice of the resources. Nothing measurable changes today for the ApeCoin price, and nothing changes for landowners until the contracts are running on chain.
What Yuga Labs announced about the resource economy on September 9
The announcement came as a post on X and describes an economic system rather than a game. In that post Yuga calls the step “the kickoff of one of the most sophisticated game economies ever built on blockchain” and states explicitly that this is not an ordinary product launch. The trade publication BlockchainGamer.biz broke down the mechanics two days later.
Three things are established. The system is meant to cover 74 resources held directly on the blockchain. Harvesting on someone else’s land means paying the owner a fee, and the owner alone sets how high it is. And ApeCoin is the single channel through which value flows into the economy and out of it.
Almost everything a holder would need in order to do the arithmetic was left open: no launch date, no sign-up route, no participation terms, no cap on the harvest fee, and no word on how payment is handled technically. Yuga says it has already simulated the economic systems internally; the next step is to switch on the contracts on chain.
74 resources on chain: harvesting and crafting in the design
On-chain resource means this: each of the 74 goods is a separate entry in a contract on the Ethereum blockchain, not a row in the operator’s database. Whoever owns one can in theory pass it on without the operator having to agree. That distinction is exactly what makes the resources interesting for tax purposes, and there is more on that below.
Items are meant to be craftable from the resources. One restriction applies in the first test round, and Yuga names it openly: resources can be reset, whereas crafted items stay with the players. Some items are meant to exist only during the test phase. Nowhere does it yet say what triggers a reset or how players would learn about one.
A second layer is formed by the Kodas, an older NFT collection from the Otherside universe. Koda owners are meant to receive gameplay advantages, and MegaKodas are meant to grant further benefits in return for a tribute. Yuga has not spelled out what those advantages consist of, what a tribute costs, or how either feeds into harvesting and crafting.
ApeCoin as the only way in and out: what that means for the price
A game economy with a single token as its gateway is good news for that token at first glance: every euro that wants in or out has to pass through ApeCoin. Whether that turns into noticeable demand depends on two figures, and both are small today.
The first is the price itself. ApeCoin traded on Monday morning at roughly $0.157, or €0.140. Daily turnover runs at $13m to $16m and market capitalisation at somewhere between $118m and $157m depending on the data provider, because providers assume different circulating supplies. The price sits about 99.4 percent below the all-time high of $26.84 set on April 28, 2022. Maximum supply is one billion tokens.
The second figure is the comparison with the 2022 land sale. Yuga issued 100,000 Otherdeeds at the time, 55,000 of them in a public sale at 305 ApeCoin each; the remaining 45,000 could be claimed within 21 days by holders from the Bored Ape Yacht Club and the Mutant Ape Yacht Club (MAYC). Those 55,000 plots therefore brought in 16,775,000 ApeCoin, worth roughly $2.64m at today’s price. Reports from the spring of 2022 put the proceeds at more than $320m. The same token amount, two orders of magnitude apart. How the wider ecosystem around the token and its own chain has fared since then is something we gathered in September in our overview of ApeCoin and ApeChain.
The harvest fee: why the landowner sets the price
The sentence that offers Otherdeed owners the most in economic terms is the shortest in the whole announcement: harvest on someone else’s ground and you owe the owner a fee, with the owner setting the level. That turns a collectible into a plot of land with the prospect of income, on paper at least.
On paper, because three conditions are missing without which no income can be estimated. There is no cap on the fee, and therefore no reference point for a market price. The payment route is not described, so it is unclear whether the fee is settled automatically on chain. And the first test round runs exclusively on plots that Yuga owns itself, where the fee does not arise at all.
Otherdeed and Otherdeed Expanded: the land sits in two collections
Here comes a point that coverage of the announcement has consistently left out, and which affects everyone who wants to buy or sell a plot today. Otherside land no longer sits in a single collection but in two. Yuga had offered holders the chance to burn their original Otherdeed in exchange for an Otherdeed Expanded, which opens access to gaming experiences outside Otherside as well. The fan outlet The Bored Ape Gazette reported some time ago that more than half of the original Otherdeeds had been swapped.
The holdings on OpenSea bear that out as of October 12, 2026: the original “Otherdeed for Otherside” collection still lists 32,860 items across 13,792 owners, while “Otherdeed Expanded” lists 70,311 items across 11,655 owners. Together that comes to 103,171 plots, roughly the 100,000 from the first wave. Looking for a plot therefore means looking at two sets of listings with two different floor prices, and not only on the largest NFT marketplace.
Floor price of 0.075 to 0.084 ETH: what the market pays for the plots
The floor price stands at 0.0840 ether for the original collection and 0.075 ether for Otherdeed Expanded. At an ether price of around $2,562 that works out at roughly $215 and $192 per plot respectively. For comparison: the public sale cost 305 ApeCoin each in 2022.
Turnover says more than the floor price. In the seven days to October 12, plots in the original collection changed hands for roughly $9,140, and for roughly $21,220 in Otherdeed Expanded. Across both collections that is a little over $30,000 in a week, spread across more than 103,000 plots. A venue where fewer than one plot in three hundred trades over seven days has a pricing problem: single sales move the floor sharply, and sellers looking to offload larger numbers find no counterparty. Which venues still exist at all for collections like these is something we set down in our stocktake of NFT marketplaces.
Our assessment: $30,000 of weekly turnover cannot carry an economy
From this newsroom’s point of view, the announcement stands in disproportion to the market it is meant to land in. In favour of the billing as “one of the most sophisticated game economies ever built on blockchain” is the sheer scope of the design: 74 resources, a fee layer between landowners and players, and a single token as the gateway are more than most Web3 games have ever implemented. Against it stand three documented figures from this article: a little over $30,000 in weekly turnover across both land collections, an ApeCoin price 99.4 percent below its high, and a timetable that since September 9 has consisted of exactly one sentence, namely that testing begins on Yuga’s own plots.
Buy an Otherdeed today and you are therefore not buying a source of income but a bet that the contracts arrive and that somebody then harvests on the plot. Both may happen. Total loss is equally possible with a collectible at this level of turnover, and that holds even if the game does ship. We described the same tension between announcement and market reality across four companies in early October, in our overview of Web3 gaming in 2026.
Koda Nexus in the browser: who gets in without a wallet
The metaverse itself has been open to visitors since November 12, 2025. Yuga launched the Otherside metaverse with Koda Nexus as its central world, and did so in the browser: an email address is enough to enter, and a crypto wallet can be connected but is not a requirement. Michael Figge, responsible for the product as chief product officer, justified that with a low barrier to entry: “We think that there should be a very low barrier to entry for somebody to try out Otherside.”
The practical upshot: anyone can look around Otherside without a wallet and without an NFT. Earning from the planned resource economy, by contrast, requires owning land or Kodas. The Voyagers, which Yuga wants to bring into Starpods as playable avatars over the course of 2026, are described by Figge as a “skin” in the sense familiar from conventional games; the company has named no price for them. How the German-speaking community around the project is holding up is something we counted up ahead of this year’s ApeFest.
Tax in Germany: the finance ministry letter is silent on NFTs
Now to the part that appears in no international report and that decides the return in Germany. The authoritative document from the tax administration is the finance ministry letter of March 6, 2025, titled “Einzelfragen zur ertragsteuerrechtlichen Behandlung bestimmter Kryptowerte”, file reference IV C 1 – S 2256/00042/064/043. It replaces the older letter of May 10, 2022, and its most important addition is a dedicated part on filing, cooperation and record-keeping duties.
And the decisive gap sits precisely there. In margin number 5 the ministry, on the reading of the law firm Minoggio Grezesch Bachmann, “explicitly does not” take a position on the income tax treatment of non-fungible crypto assets (non-fungible tokens, NFTs). For Otherdeeds, Kodas and the 74 resources there is therefore no internal administrative guidance that a tax office would have to follow. Anyone who needs a binding ruling gets it from a tax adviser, not from a guide.
Holding period, tax-free threshold and the open question on harvested resources
What can still be said follows from the statute. Sell an Otherdeed at a profit within a year of buying it and that is a private disposal under section 23 of the Income Tax Act. Since the 2024 Annual Tax Act such gains stay tax free up to €1,000 a year, against €600 before. This is a threshold and not an allowance: one euro above it makes the entire gain taxable, and the limit applies to all private disposals in a year taken together, not to crypto alone. After a year has elapsed, the sale is tax free.
It gets harder with the resources and the crafted items. If they are issued as tradable tokens on chain and you sell them on, the same section 23 is the obvious fit. Running income from the harvest fee would sit closer to other income under section 22 number 3 of the Income Tax Act, where a separate threshold of €256 a year applies. One note of caution: for assets that have generated income in at least one calendar year, the section 23 period can extend to ten years. Whether that rule catches a plot of land throwing off fees has not been settled for NFTs, and the finance ministry has precisely not commented on it.
In practice that means one thing above all: anyone wanting to take part needs complete records from day one. The ministry letter demands less for private holdings than for business assets and provides a non-objection rule for assessment periods up to and including 2024, but it does expressly accept tax reports as evidence where they are plausible. Where the tax base cannot be established, the tax office may estimate it. A tax tool with a portfolio tracker takes that work off your hands, provided you record the additions from the start.
Otherside: 74 resources, but no start date for the economy
The September 9 announcement describes a complete economic model and names no day on which it begins. Until the contracts are live on chain, the income from an Otherdeed remains an expectation. Three steps help you judge the situation yourself:
- Look at both collections side by side. Floor price and weekly turnover differ markedly between “Otherdeed for Otherside” and “Otherdeed Expanded”. Which venues come into question is set out in our comparison of NFT marketplaces.
- Set up the records before the first purchase. Purchase date, price in euros and fees belong in a list from the first addition onwards, because the one-year period and the €1,000 limit cannot otherwise be evidenced. You will find the providers for that in our overview of crypto tax tools.
- Settle the route to ApeCoin separately. Using the economy later requires APE, and the buying route decides the fee and the custody. Which venues are licensed in the EU is shown by our exchange comparison.
(As of October 12, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy. Statements on tax are no substitute for advice from a tax adviser.)
Solana trades at $111.84 on Monday midday, or 99.94 euros, up 2.2 percent over 24 hours. The real news of the day, though, is not in the price but in the chain's revenue: over the past seven days the applications on Solana took in $99.6 million in fees, 35.3 percent less than in the week before. The price lost only 7.3 percent over the same period. This gap between willingness to pay and valuation is the subject of this forecast, and it decides whether the 20-day line at $117.05 stays within reach this week.
For holders in Germany one concrete consequence follows: anyone with SOL in the portfolio can use the two levels of $109.21 and $117.05 as a frame for limit orders today instead of waiting for a decision on direction. Which of the two gives way first hangs on numbers anyone can look up.
Solana price at $111.84: the day's numbers
The daily high stood at $113.22, the daily low at $109.17. Trading volume across all exchanges added up to $2.43 billion and market capitalisation to $65.90 billion. Solana therefore sits 7.3 percent below where it stood a week ago, but 10.0 percent above the level of 30 days ago. The figures come from CoinGecko, as of October 12, shortly before 9 a.m. UTC.
More interesting than the daily reading is the position between the moving averages. From the daily closes of the past 90 days, three levels emerge that recur throughout this forecast:
- 7-day line: $112.67. The price sits just below it, so the short-term tendency has not turned yet.
- 20-day line: $117.05. That is the lid on which the recovery of the last two days hangs.
- 50-day line: $109.21. This line caught Friday's daily low and is carrying the price at present.
The 30-day high stands at $122.08, the 30-day low at $96.87. Over 90 days the range runs from $71.89 to $122.08. Solana is therefore moving in the upper third of its quarterly range, but below the monthly high.
Network fees on Solana: $99.6 million in seven days
On a blockchain, fees are what revenue is in a set of accounts, and they show what users are actually willing to pay. According to data from DefiLlama, the applications on Solana took in $11.24 million over the past 24 hours, $99.6 million over seven days and $467.3 million over 30 days. The weekly figure is 35.3 percent below the previous week, the daily figure 5.8 percent below the day before.
The daily series makes the path clearer than any percentage:
| Day | Fees across all applications on Solana |
|---|---|
| October 2 | $18.75 million |
| October 5 | $16.75 million |
| October 7 | $14.31 million |
| October 9 | $13.91 million |
| October 10 | $11.94 million |
| October 11 | $10.75 million |
From $18.75 million to $10.75 million in nine days is 42.7 percent less. To be looked at separately are the chain's own pure transaction fees, meaning what users pay for a transaction to be included in a block. That item stood at $753,342 over 24 hours, 13.7 percent below the comparable figure of the previous week. The two numbers measure different things: the large item contains the revenue of trading venues and token platforms, the small one only the fee for block space.
How fees and MEV work on the SOL price
The connection is more technical than it sounds, and it can be explained in three sentences. On Solana, 50 percent of every transaction fee is burned and the other half goes to the validator that built the block. Added to that are priority fees, which users pay voluntarily to stand at the front of a crowded block, as well as payments from trading around the ordering of transactions, known in the industry as MEV.
These three items together are the pay from which validators fund their servers and from which stakers receive their yield. If they fall by a third, the part of the staking yield that does not come from newly created tokens but from real demand shrinks. That is the link to the price: the smaller the share of real revenue in the yield, the more the appeal of staking hangs on the chain's inflation, and inflation dilutes existing holders.
The supply provides the yardstick. According to a direct query of the Solana network, 635.66 million SOL exist in total, of which 589.11 million circulate freely. The chain stands in epoch 1,055 and has processed 559.08 billion transactions so far. A fall in fees of $8 million a day corresponds, at this supply, to roughly $0.0000136 of lost revenue per circulating SOL per day, or about $0.005 a year. The number is small, but it works through expectations: anyone valuing Solana as payment infrastructure calculates with fee revenue, not with daily closing prices.
The 50-day line at $109.21 is carrying the price
The daily low of $109.17 came in four cents below the 50-day line. The price therefore touched it and left it upwards immediately, and that is exactly what makes it the reliable level for this week. As long as daily closes stay above $109.21, last week's slide is a correction inside the uptrend that began at the quarterly low of $71.89.
Below it a zone without support begins, running to the 30-day low at $96.87. Between those two values there is no moving average and no multiple high of the past three months, and therefore no chart-based reason for a decline to slow. Anyone working with a stop order has a gap of 11.3 percent ahead of them below $109.
The $117 level from the October 6 article has given way
On October 6 the question in this slot was whether the level at $117 would hold. SOL traded at around $120 at the time, the 20-day line sat at $117 and counted as support. Six days later the answer is unambiguous: the level has given way, the price fell as far as $109.17, and the same $117 line now lies above the price. Support has turned into resistance, at a nearly identical value of $117.05.
In between came two pieces of news that explain the decline. Stablecoin reserves on Solana fell by 6.4 percent, and the inflow streak of the Solana ETFs ended after 14 weeks with an outflow of $24.8 million. Both pull out capital that would have generated fees. The collapse in fees is therefore not an isolated event but the trace of those outflows in the chain's numbers.
DEX volume of $1.25 billion: the second point of entry
Beyond the chart, what is traded on the chain is worth a look. The volume of decentralised trading venues on Solana stood at $1.25 billion over the past 24 hours and $12.88 billion over seven days. The weekly figure is 27.0 percent below the previous week. The capital locked in Solana applications, known in the industry as total value locked, amounts to $6.29 billion; seven days ago it was $6.73 billion, 30 days ago $5.90 billion.
That produces a differentiated picture. On a monthly view there is more capital on the chain than at the start of September, on a weekly view 6.5 percent less. Trading cools faster than locked capital flows out, and fees fall faster than both. The order holds the clue: speculative activity disappears first, then the capital.
Our assessment: the price holds, the revenue does not
From the newsroom's point of view, the situation at Solana is split in two, and the evidence points in different directions. In favour of stability: the 50-day line at $109.21 held to the cent on Friday, locked capital at $6.29 billion sits above the level of early September, and the price at $111.84 is 10 percent above where it stood a month ago. Against a quick return above $117 stands the fee series: 42.7 percent less revenue in nine days, alongside trading volume 27 percent lower. A price that holds while the chain's revenue falls by more than a third is becoming more expensive, measured against what is actually earned on the chain.
What follows from that: the most likely development of the coming days is a sideways move between $109 and $117, until fees either rise again or the 50-day line breaks. What argues against it: if new inflows into the Solana ETFs arrive, the price can take the $117 without anything changing in the fees, because ETF purchases happen on the spot market and generate no transactions on the chain. This is not a buy or sell recommendation but a placing of the levels. A total loss is possible at any time with crypto-assets.
Bull case and bear case: which levels carry the scenarios
Both directions can be pinned to verifiable values rather than to the price targets of outside research houses:
- Upside: a daily close above $112.67 brings the price back above the 7-day line. The next hurdle is the 20-day line at $117.05, after that the 30-day high at $122.08. The precondition would be rising fee revenue, meaning daily figures back above $14 million.
- Downside: a daily close below $109.21 opens the gap to $96.87. A trigger for that would be further ETF outflows on the scale of the $24.8 million from the weekend, or fee figures below $10 million a day.
Long-term price targets from investment houses sit considerably higher, but they are no yardstick in this situation, because such targets describe years rather than weeks and were set at different fee levels. Anyone quoting them has to name the date and the author as well.
Buying Solana in Germany: a MiCA exchange, fees and custody
Since the European crypto regulation MiCA, trading venues need authorisation to serve retail clients in the EU. For buying SOL that means in practice: an authorised exchange states its licence and its supervisory state, keeps client money separate and publishes a fee schedule. The spread between buying and selling price is the item many underestimate; at $111.84 per SOL, a spread of half a percent already costs 56 cents per unit. Anyone buying regularly therefore compares not only the order fee but also the spread and withdrawal costs. Which providers charge what is shown by our comparison of the best crypto exchanges.
After the purchase comes the question of custody. SOL on an exchange sits in the exchange's name, SOL in your own wallet in your own name, with the key as your responsibility. For amounts beyond a few hundred euros a hardware wallet is the more robust route, not least because it supports staking directly.
SOL staking and tax: a 1,000 euro threshold and the one-year rule
Solana is secured by validators, and anyone who deposits SOL receives a share of their revenue. This is exactly where the fee decline bites: the part of the yield that comes from transaction fees and MEV shrinks with the 35.3 percent from the weekly tally, while the part from newly created tokens remains. Anyone comparing returns therefore looks at the composition, not only at the percentage. The providers' terms are in the comparison of staking providers.
On tax, the one-year holding period under Paragraph 23 of the German Income Tax Act applies in Germany to the sale of crypto-assets: hold SOL for longer than a year and you pay no income tax on the gain. Within the year gains are taxable, but stay tax-free up to the threshold of 1,000 euros per calendar year; once it is exceeded, the entire amount is taxable. Staking income counts separately as other income with a threshold of its own, 256 euros. The details on the treatment of crypto-assets, including the duties to cooperate and keep records, are set out in the letter from the German Federal Ministry of Finance of March 6, 2025.
Practical consequence for today: anyone who bought in October 2025 at considerably lower prices reaches the one-year mark in the coming weeks. The purchase date for each position is therefore a number that matters more on a sale between $109 and $117 than the level itself.
Solana at $112: without a fee recovery the $117 line stays the ceiling
The situation can be worked through in three steps, each with a concrete number:
- Note the two levels. $109.21 as the 50-day line on the downside, $117.05 as the 20-day line on the upside. Limit and stop orders belong at these values, not at round numbers. Where that is possible at what cost is in the exchange comparison.
- Follow the fee series. Daily figures above $14 million argue for the upside variant, figures below $10 million for the downside variant. The series is public daily at DefiLlama.
- Check the purchase date. If the purchase is almost a year old, the one-year rule decides the tax burden; if staking income is due, the 256 euro threshold counts separately. Returns and provider terms are compared in the staking comparison.
(As of October 12, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Decrypt
An integer overflow in the payment engine, dormant since 2015, could have let an attacker mint spendable XRP beyond the token’s total supply.
The Ethereum treasury firm now holds 6.03 million ETH, 4.9% of supply, as Lee predicts the biggest crypto bull market yet.
The purchase lifts Strategy's holdings to 848,250 BTC and follows a $176 million repurchase of STRC preferred stock the week before.
October rate-hike odds have slumped, but analysts say Treasury yields at two-decade highs are still keeping a lid on risk appetite.
Thet Li is accused of running the finances of a scam empire tied to $14 billion in Bitcoin the U.S. has moved to seize.
U.Today - IT, AI and Fintech Daily News for You Today
Near Protocol's recovery might be complicated.
473 million XRP meets public markets as Evernorth makes Nasdaq debut.
Crypto news this morning, Oct 12: Bitcoin holds $83,300 after a $229 million short squeeze while Standard Chartered launches XRPL custody.
Solana is preparing to launch its second ETF in Hong Kong as Pando schedules the listing of its Solana fund for this month.
The critical bug that was found is apparently not that big of a deal, according to the relatively small bounty issued by the foundation.
Blockonomi
FUNToken has announced the addition of ENA to its growing list of supported tokens, further strengthening its commitment to improving token accessibility and simplifying participation across its ecosystem.
With this latest integration, users holding ENA can now deposit their tokens directly into the FUNToken platform, where they are automatically converted into $FUN with 0% conversion fees. The process eliminates the need for manual token swaps, offering users a straightforward way to access $FUN and explore its expanding range of utilities.
Making $FUN More Accessible Through Token Integration
As the digital asset landscape continues to evolve, users increasingly hold multiple tokens across different networks. FUNToken aims to simplify the experience of accessing its ecosystem by supporting a growing selection of tokens that can be converted into $FUN.
The addition of ENA (ERC-20) introduces another option for users looking to put their existing digital assets to use without navigating multiple conversion platforms.
Through FUNToken’s automatic conversion system, ENA holders can deposit their tokens and receive $FUN without incurring additional conversion fees.
This streamlined approach is part of FUNToken’s broader effort to reduce unnecessary steps, improve accessibility, and create a more connected experience for its users.
Expanding Utility Beyond Token Conversion
The integration of ENA goes beyond simply adding another supported asset. It creates an additional entry point into FUNToken’s growing ecosystem of gaming experiences, staking opportunities, and token-based rewards.
Once ENA is converted into $FUN, users can explore the different utilities available within the ecosystem.
FUNToken’s expanding Android gaming portfolio features nine titles designed around accessible, engaging gameplay, with no ads, no paywalls, and real $FUN rewards. The ecosystem also includes browser-based gaming experiences, staking features, and referral reward opportunities.
By connecting these experiences through a common token, FUNToken continues to build an environment where $FUN serves multiple purposes across different products and activities.
A Growing List of Supported Tokens
The addition of ENA reflects FUNToken’s ongoing strategy to expand the range of digital assets supported by its automatic conversion system.
Recent integrations have included ONDO, TRUMP, FARTCOIN, and JTO, alongside previously supported tokens such as USDT, USDC, SOL, LINK, UNI, AAVE, and others.
Each new integration provides users with additional flexibility in accessing $FUN while supporting the platform’s objective of making token conversion more convenient.
With 0% conversion fees remaining a central feature of the supported token system, FUNToken continues to focus on simplifying the transition from existing token holdings into its connected gaming and rewards ecosystem.
Continuing to Build a More Connected $FUN Ecosystem
The ENA integration represents another step in FUNToken’s ongoing ecosystem expansion.
Alongside its growing supported token list, FUNToken continues to develop new gaming experiences, expand token utility, and introduce additional opportunities for users to participate.
By combining accessible token conversion with an expanding range of products, FUNToken is working toward an ecosystem where users have greater flexibility in how they access, earn, hold, and use $FUN.
As further integrations and platform developments are introduced, the project remains focused on making participation simpler and creating more practical uses for $FUN.
About FUNToken
FUNToken is a blockchain-powered ecosystem built around $FUN, combining gaming, rewards, staking, and growing token utility within a connected experience.
With an expanding portfolio of Android and browser-based games, supported token integrations, multi-chain accessibility, and reward opportunities, FUNToken is focused on creating more ways for users to access, earn, hold, and use $FUN.
The ecosystem emphasizes accessible gaming experiences, including a growing selection of Android titles featuring no ads, no paywalls, and $FUN rewards.
Through continued product development and ecosystem expansion, FUNToken aims to strengthen the role of $FUN as a common token connecting its growing range of digital experiences.
Website: https://funtoken.io
The post FUNToken Expands Token Accessibility With ENA Integration and 0% Conversion Fees appeared first on Blockonomi.
TLDR:
- Bitcoin whales added 16,010 BTC over five days while the price fell from $87,000 toward $80,000.
- Whale holdings rose from 5,247,316 BTC to 5,263,326 BTC, a 0.305% increase, per Santiment data.
- Nearly 800,000 BTC were previously traded near $84,569, a supply zone Bitcoin must clear first.
- If support holds and $84,569 breaks, Ali Charts eyes $89,000, then $94,000, as Bitcoin upside targets.
Bitcoin whales added 16,010 BTC over five days while the asset fell from $87,000 toward $80,000, according to Santiment data.
Their combined holdings rose from 5,247,316 BTC to 5,263,326 BTC. That marks a 0.305% increase during a period of declining prices.
Bitcoin traded at $83,341.34 as of this writing, up 0.56% in 24 hours. However, the price is still down 3.19% over the past week. Analysts are now watching whether the buying can support a rebound toward higher resistance levels.
Bitcoin Whales Buy as Prices Decline
Ali Charts shared the findings in a five part thread on X. The opening post stated that whales bought the dip. It also said the next leg higher starts now. The thread contains five posts and combines on-chain data with technical chart analysis.
The thread cited Santiment data to support the claim. Bitcoin whales kept adding coins while the market moved lower. Their holdings grew even as the price fell. Santiment provided the holdings figures that Ali Charts used in the second post of the thread.
Market data provides further context for the move. Daily trading volume stands at $22,486,836,062. Trading volume reflects the amount of Bitcoin exchanged across markets over the previous 24 hours.
The 0.56% daily gain follows a 3.19% decline over seven days. These figures reflect the latest price data available at the time of writing.
Ali Charts closed the thread by saying the price now needs to confirm the buying by Bitcoin whales. The analyst listed three levels to monitor.
These levels connect to supply data and a rising channel. They range from a breakout point to two upside targets.
Resistance Near $84,569 Draws Attention
Glassnode data shows nearly 800,000 BTC were previously traded around $84,569. Ali Charts described this area as a supply zone.
Bitcoin must clear it before a move higher gains strength. Glassnode supplied the on-chain data in the third post, which focused on supply near that price.
A break above this level would strengthen the case for a rally, according to the thread. Until then, the zone remains a hurdle for buyers. Bitcoin currently trades just below it. The analyst presented this break as the first condition for the upside move.
Bitcoin is also testing the lower boundary of a rising channel. Support at this boundary needs to hold. A hold at that boundary would keep the rising channel structure intact.
Ali Charts tied the setup to the potential rebound. The fourth post of the thread presents this channel as part of the technical outlook.
If support holds and Bitcoin clears $84,569, the analyst is watching for a rally toward $89,000. That level sits near the channel’s mid-range.
The upper boundary around $94,000 serves as the next target. Ali Charts repeated these three levels in the final post as the key targets for the move.
The post Bitcoin Whales Accumulate 16,010 BTC During Pullback From $87,000 appeared first on Blockonomi.
TLDR:
- Hyperliquid matches orders block by block and prioritizes cancellations within each block, says Xu.
- Xu links Hyperliquid’s order book depth to its market maker friendly design versus many exchanges.
- Xu says the design offers another approach for long-tail assets that have limited liquidity.
- Xu blames the October 10 liquidations partly on USDe being treated like a stablecoin as collateral.
Star Xu says the Hyperliquid matching engine is more market maker friendly than the systems used by centralized exchanges. The OKX founder shared the view on the New Era Finance Podcast with host Michael.
He said Hyperliquid matches orders block by block and gives cancellations priority within each block. Market makers can therefore cancel orders ahead of takers. Xu also covered MiCA, customer protection, and the October 10 market turmoil during the discussion.
How the Hyperliquid Matching Engine Works
Xu said the Hyperliquid matching engine differs fundamentally from centralized order book exchanges in its technical design. Centralized exchanges process orders individually. Hyperliquid, by contrast, matches orders in blocks.
Within each block, the system prioritizes cancellations. Under the Hyperliquid matching engine, market makers can therefore cancel orders ahead of takers. Xu called this design market maker friendly.
Xu believes this design explains why Hyperliquid’s order book depth appears better than that of many centralized exchanges. He added that the Hyperliquid matching engine offers another approach for long-tail assets with limited liquidity.
Xu made the comments while discussing crypto’s evolution. He said repeated crises, from early Bitcoin attacks and Mt. Gox to FTX, tested the sector.
Each episode also prompted improvements, in his view. He sees blockchain as a base for more efficient finance through self-custody, stablecoins, and tokenized assets.
Trust, Risk Controls, and the October 10 Turmoil
Xu described MiCA as an important step toward consistent crypto regulation across Europe. He noted the compliance challenges OKX faced while entering the market.
He said international growth depends on earning customer and regulator trust through transparent operations and stronger governance.
He pointed to board oversight, compliance and risk functions, monthly proof-of-reserves reports, and external auditing. OKX also plans to pursue a public listing. Xu said these steps increase accountability.
Xu said safeguarding customer funds matters more than aggressive growth. Exchanges, he added, should follow financial rules and earn money from technology and services.
He recommends self-custody for users who can manage keys securely, though wallets can be vulnerable. He also warns against unusually high yields and demands to “just trust” an exchange.
Xu attributed the cascading October 10 liquidations partly to USDe being treated like a stablecoin and accepted as derivatives collateral. He described USDe as a higher-risk, hedge-fund-like product.
Leveraged borrowing against it could magnify returns but also amplify losses when prices moved. Xu argued that tighter risk controls and regulated derivatives venues could help prevent such episodes.
Looking ahead, Xu expects crypto to expand beyond trading into everyday financial services. These include wallets for holding money, blockchain payments, and tokenized equities.
He also expects on-chain asset-management tools that let users keep control of their funds. He is optimistic these technologies could become widely used financial infrastructure.
The post OKX founder Star Xu Says Hyperliquid’s Matching Engine Favors Market Makers appeared first on Blockonomi.
TLDR:
- Payward received Full Market Approval from VARA, the final stage of Dubai’s licensing process.
- Kraken will offer AED-denominated spot and margin trading, with direct dirham deposits and withdrawals.
- Institutional clients will receive OTC spot trading and Kraken Prime access when the service goes live.
- Crypto derivatives and new yield products are expected later in 2026 and into 2027, subject to approval.
Kraken UAE launch plans are moving ahead after Payward received Full Market Approval from Dubai’s VARA. Payward is the parent company of Kraken.
The approval permits it to operate as a regulated Virtual Asset Service Provider. It can serve retail, professional, and institutional investors.
Kraken expects to go live for UAE clients within the coming weeks. Payward announced the news through a Business Wire release from Cheyenne, Wyoming. The company said it will begin regulated activity in Dubai.
Kraken UAE Launch Products for Clients
The Kraken UAE launch will include spot and margin markets with AED-denominated pairs. Additionally, clients can fund accounts and withdraw directly in dirhams. The company has not given an exact launch date in the announcement.
Beyond trading, the platform will offer on-chain staking and tokenized stocks through xStocks. Krak will also be available for crypto transfers. Together, these products sit alongside spot and margin trading in the launch lineup.
Institutional clients will receive additional services at launch. These include OTC spot trading and access to Kraken Prime. Therefore, the launch covers retail, professional, and institutional investors.
Arjun Sethi, Co-CEO of Payward and Kraken, commented on the offering in a statement. Sethi said clients get “the same order book and multi-asset coverage we run in every other market.”
He added that this operates “under one of the clearest regulatory frameworks in the world.” “Payward’s regulatory infrastructure now connects them directly to Kraken’s market-leading liquidity,” Sethi continued. The statement also referenced “a growing range of opportunities across digital assets.”
VARA Approval and Expansion Plans
VARA regulates virtual asset activity in Dubai. Full Market Approval is the final stage of VARA’s licensing process. It authorizes Payward to commence regulated activity in Dubai. The decision follows preliminary approval granted in May 2026.
That earlier approval allowed the entity to complete operational set-up ahead of client onboarding. Therefore, the Kraken UAE launch now has its final regulatory approval in place.
Further products will follow the Kraken UAE launch later in 2026 and into 2027. These include crypto derivatives and an expanded range of new yield opportunities.
Each of these remains subject to regulatory approval. In addition, Payward will make its infrastructure available to regional partners through embedded trading as a service.
Embedded trading lets partners offer trading inside their own platforms. The company did not provide product-specific dates in its announcement.
Payward describes itself as a unified financial infrastructure platform. The launch forms part of Payward’s effort to build regulated, on-the-ground operations across key financial centers.
Kraken connects new markets to its core trading network for premium execution and deep liquidity. Clients also receive a consistent standard of service.
Payward currently holds more than 100 licences and registrations worldwide. These span Europe, the Americas, Asia-Pacific, and the Middle East.
The post Kraken UAE Launch Nears as Payward Secures Full VARA Approval appeared first on Blockonomi.
The power of combining interactive community engagement with a utility-driven rewards layer has been unleashed during the initial stage of a partnership between Predictfully, a free-to-play sports fan engagement platform built on the Avalanche blockchain, and the nGRND Gold Protocol, an ecosystem designed to bridge the legacy gold industry with the emerging digital economy.
Launched on September 17, 2026, the joint Participation Stream Partnership integrated Predictfully’s white-label capable fan engagement platform with the nGRND Gold Protocol Staking & Rewards Ecosystem using a custom Predictfully Dynamic Soulbound Token (DSBT). By October 6, 2026, just nine days into the rollout, the initiative sparked explosive growth across all primary user metrics. New account growth skyrocketed by 472%, active players increased by 465%, and market predictions grew by 299%, driving a 56% increase in total accounts overall.
The integration proved highly effective at converting passive sports fans into verified web3 participants without the friction of stakes, odds, or a traditional house. The custom Predictfully nGRND DSBT program rapidly scaled to 35,589 total users, maintaining exceptionally high data and identity verification standards across the board. Digital wallet verification reached a flawless 100%, while email and Telegram verification levels hit 92% and 95% respectively.
Rather than creating “empty” accounts, the campaign prioritized deep, protocol-level engagement, encouraging fans to climb the leaderboards to win rewards funded by clubs and sponsors, ranging from merchandise to matchday experiences. Within the first twenty days, 32,834 users successfully completed the Predictfully DSBT process to activate their profiles, earn their first virtual NGRND, and enter the broader staking ecosystem.
Acting as a digital passport, the DSBT provides exclusive access to participation streams and dynamically tracks on-chain activity and credentials. To date, these activated participants have completed 294,502 micro-tasks to earn Reward Points, validating the partnership’s focus on sticky, repeatable user behavior over short-term speculation.
The early performance of this joint case study underscores a larger shift in decentralized growth strategies, blending sports engagement with participation-driven opportunities backed by Preserved Gold and network engagement.
By offering a plug-and-play rewards infrastructure, the nGRND Gold Protocol allows ecosystem partners to boost user acquisition and retention without exhausting internal development resources. For Predictfully, which licenses its platform to professional clubs and rights holders, the collaboration provides a continuous loop of player activation, while the nGRND Gold Protocol successfully expands its footprint of verified, high-intent network participants. Users can find out more or get started by visiting predictfully.app and nGRND.io.
The post Predictfully and nGRND Gold Protocol Secure Massive Engagement Surge in 20-Day Campaign appeared first on Blockonomi.
CryptoPotato
Ethereum is recovering toward $2.55K after buyers responded to the latest selloff near a key demand area. The rebound preserves the broader ascending structure, but ETH still needs to reclaim overhead supply to demonstrate a more durable recovery.
Ethereum Price Analysis: The Daily Chart
On the daily timeframe, Ethereum’s correction extended into the $2.36K–$2.42K demand zone before producing a notable lower wick and several recovery candles. The price has since climbed toward $2.55K, suggesting that buyers are defending the region following the sharp decline from the recent consolidation.
ETH also remains within the broader ascending channel and above both major moving averages. The 100-day average sits near $2.24K, above the 200-day average around $2.14K, maintaining the bullish crossover established earlier. However, this supportive backdrop has yet to translate into a recovery of the lost resistance levels.
The highlighted $2.66K–$2.74K supply zone represents the main nearby barrier. Reclaiming this area would strengthen the recovery scenario and allow another challenge of the recent $2.8K high, followed by the $2.9K–$3K resistance region.
Conversely, renewed selling would bring the $2.36K–$2.42K demand zone and nearby channel support back into focus. A sustained break below this confluence would weaken the broader structure and expose the moving-average region around $2.14K–$2.24K.
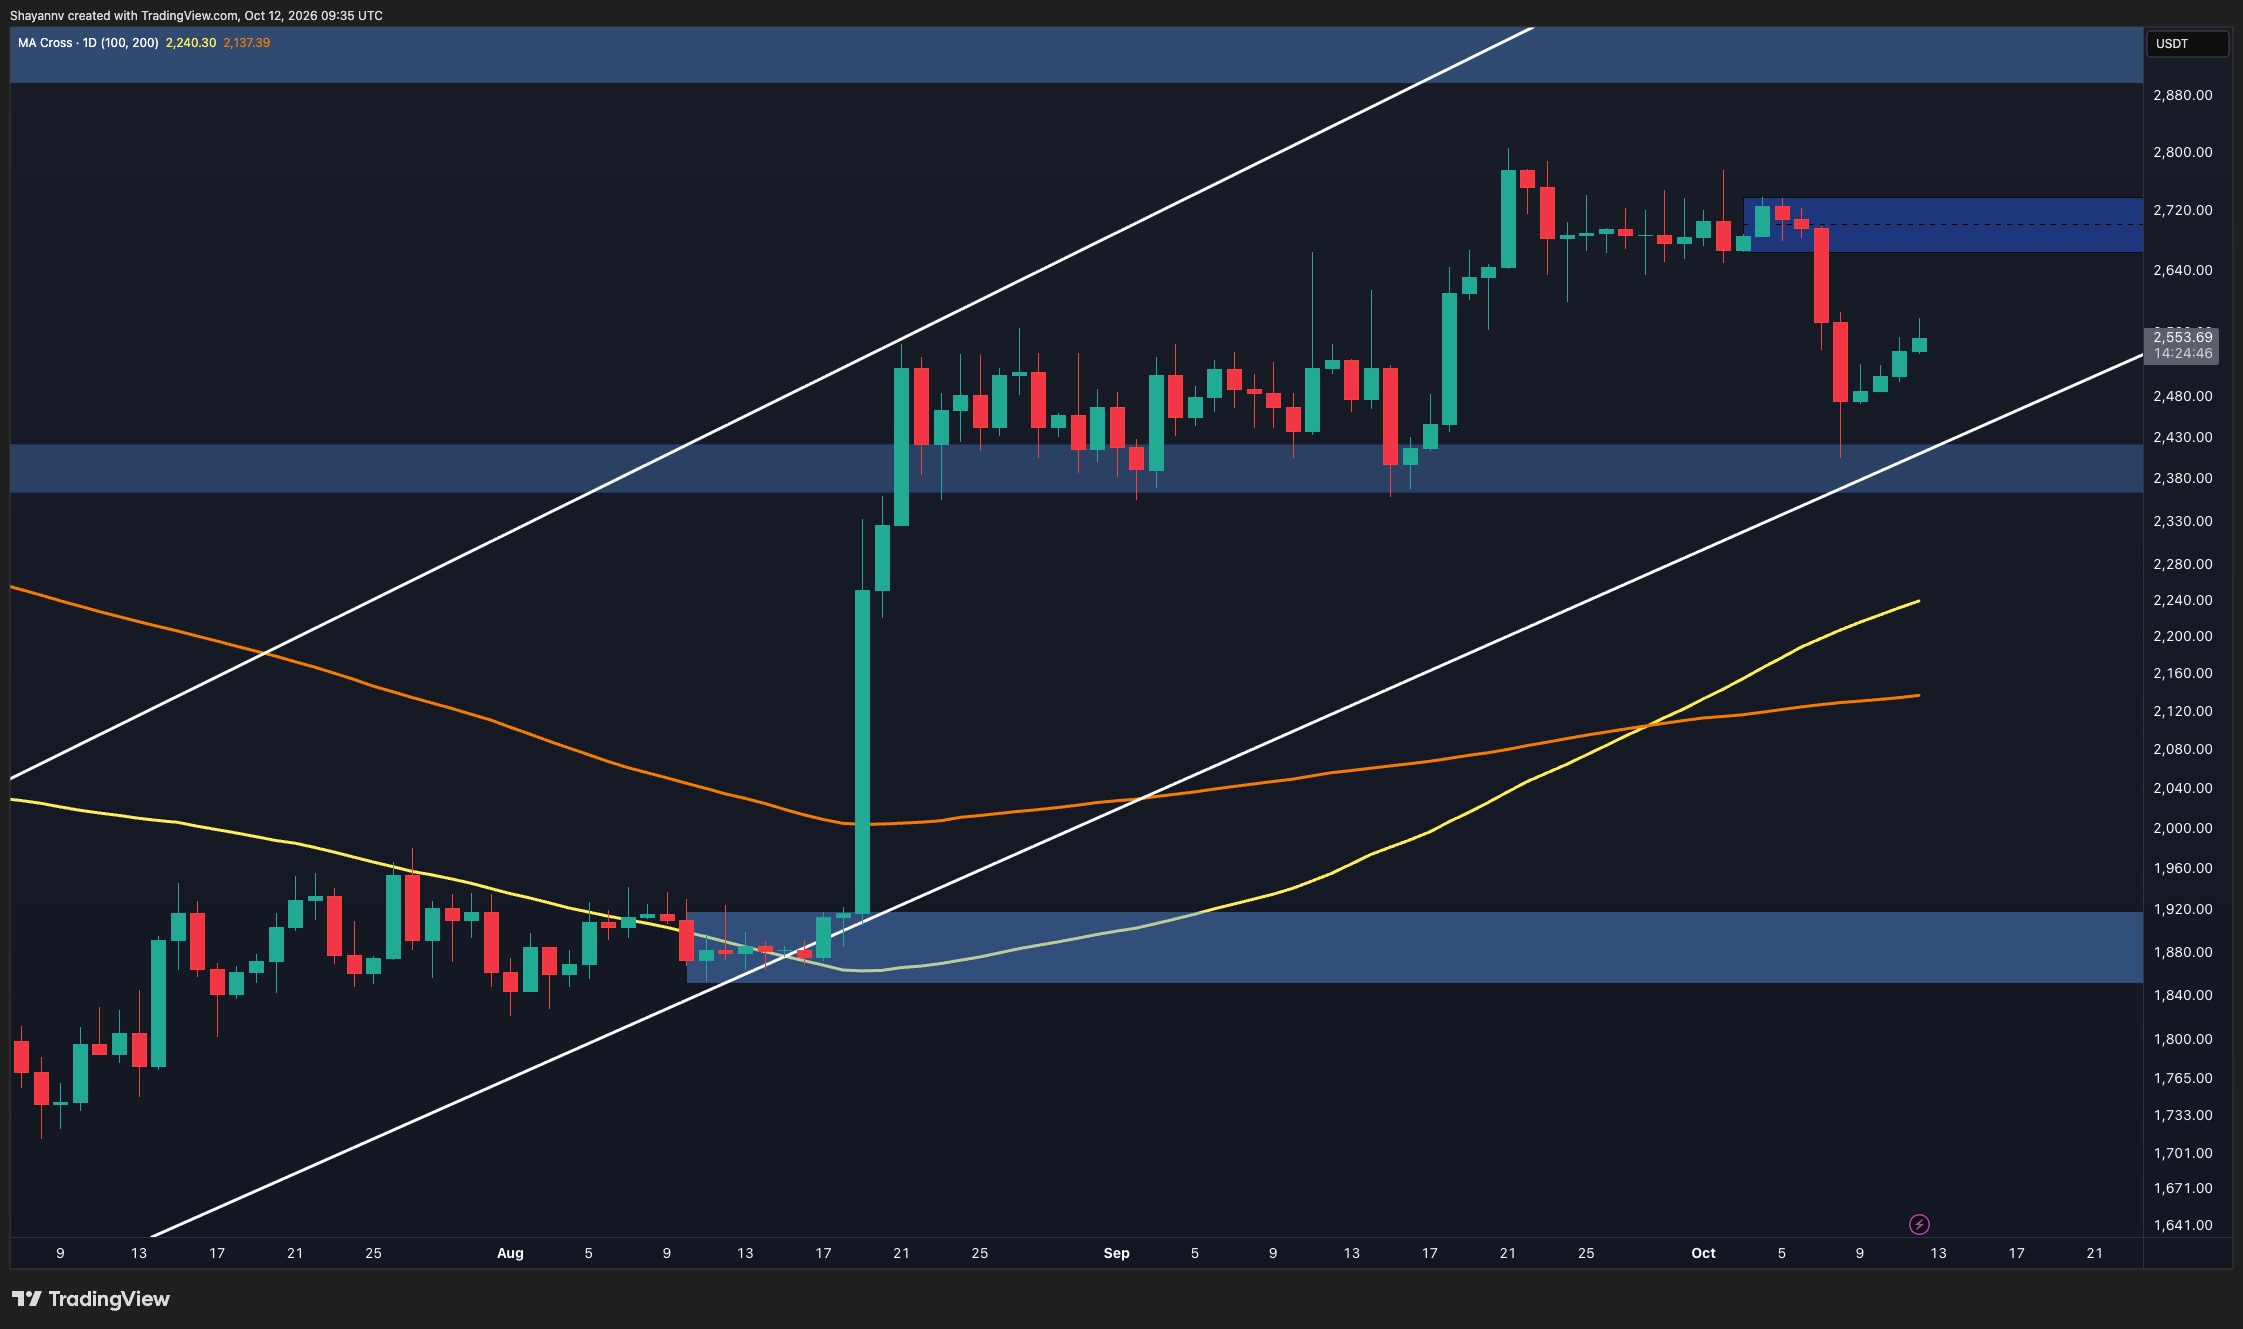
ETH/USDT 4-Hour Chart
The 4-hour chart shows Ethereum rebounding after briefly piercing the $2.43K–$2.48K demand zone and the lower ascending trendline. The subsequent recovery above both suggests rejection of lower prices, although the earlier selloff has left ETH trading beneath the rising structure’s middle trendline.
Holding the reclaimed trendline around $2.49K–$2.5K would support a continuation of the rebound toward the $2.6K area. Beyond that, the $2.66K–$2.74K supply zone overlaps with the broken middle trendline, creating an important resistance confluence where sellers could reappear.
Until Ethereum clears that region, the advance remains a recovery within a weakened short-term structure. Losing $2.49K would increase the likelihood of another test of the $2.43K–$2.48K demand zone. A decisive breakdown below the recent wick low around $2.4K could then expose the next highlighted support area at $2.22K–$2.28K.

Sentiment Analysis
The Ethereum Spot Average Order Size chart classifies spot activity by average trade size, distinguishing normal orders from retail-sized and whale-sized activity. It provides context for participant size, although it does not independently identify whether larger traders are buying or selling.
The latest observations remain predominantly in the normal-order category, including the recent advance toward $2.7K and the subsequent correction toward $2.5K. This contrasts with the frequent whale-sized readings visible during earlier periods, particularly around the June–August price base.
Consequently, the current rebound is not accompanied by a visible return of whale-sized average orders. This does not establish that large investors are absent or that the recovery must fail, but the metric offers limited confirmation of renewed large-order participation. A shift toward whale-sized readings alongside a sustained price recovery would provide additional context, while buying direction would still need confirmation from other data.

The post Ethereum Price Prediction: Relief Rally or Another ETH Dump Next? appeared first on CryptoPotato.
Bitcoin has closed above its 50-week moving average for four weeks in a row.
Analyst Ash Crypto sees that as a sign the bottom is in, yet the average still slopes down, and Bitcoin sits about a third below its all-time high.
Bitcoin Holds Above a Falling 50-Week Average
“Historically, this means the bottom is in and the new bull market has started,” Ash Crypto wrote in a post on X.
The weekly chart attached to the post showed BTC near $84,000 against a 50-week average of roughly $77,000, after a low near $58,000 and a strong green weekly candle that carried price back above the line. That average is the mean of the last 50 weekly closes, which is about a year of trading.
As CryptoPotato reported earlier, Bitcoin topped out near $87,000 on October 2, slid to around $80,000 last Thursday, and had been trading near $83,000 since a Friday rebound. But the latest CoinGecko data shows it passing $84,000, up about 1% in the last 24 hours and 9% on the month, but down 2% across seven days and 24% lower than where it was a year ago.
A CryptoRus note on X reminded that an earlier short-lived push through $84,000 forced out nearly $83 million in short positions, bets on falling price that traders must close when it climbs. That forced buying can speed up a move but cannot sustain one alone, according to the note, which puts the market at “a decision point rather than a confirmed breakout.”
Fund flows have not helped. Spot Bitcoin ETFs recorded $681 million in net outflows last week, the most since late June, including $487 million on Wednesday as the price dropped.
Confirmation Still Depends on Demand
Meanwhile, XWIN Japan sees conditions for a bottom improving but ties confirmation to sustained ETF inflows, stronger US spot buying and a continued recovery in demand.
Its on-chain charts show exchange BTC reserves still low and whale holdings around 3 million BTC, while its Apparent Demand measure has climbed from deeply negative levels but remains below zero.
The firm noted that markets have priced in roughly an 18% chance of an October Fed rate hike, with the November 3 midterms approaching. In XWIN’s words, “A correction can build the foundation for the next advance.”
CryptoRus wants repeated four-hour closes above $84,000 on rising volume and says another rejection there would show positioning did more of the work than conviction. Furthermore, it said releases such as inflation data (CPI and PPI), retail sales, and jobless claims could change market liquidity quickly.
The post Bitcoin Bull Market Signal Emerges Even as BTC Struggles to Break $84K appeared first on CryptoPotato.
The second-largest cryptocurrency has retraced 6% over the past week, yet an important development suggests the bullish setup remains intact.
Many market observers believe ETH could soon reach a new all-time high, while one mysterious trader spent millions to open an extremely risky long position in the asset.
The Bullish Perspective
Popular X user Ash Crypto revealed that ETH closed its fourth consecutive week above the 50-week moving average (MA) after bouncing off multi-month support at $2,405. This is considered a major long-term trend indicator and suggests momentum remains on the bulls’ side (despite recent volatility).
“Four consecutive weekly closes above the 50-week MA is an encouraging signal for ETH. Holding this level could strengthen the bullish outlook, but confirmation on the next few candles will be key,” one X user commented on the post.
Many analysts think the asset could be on the verge of an imminent surge. Ali Martinez recently noted that ETH has formed an “Adam and Eve” bottoming pattern, outlining the neckline at $2,520 as the key zone.
“A sustained close above this level could confirm a bullish breakout and open the door for ETH to rally toward $2,640.”
For his part, Ted said ETH is currently facing resistance around the $2,560-$2,570 range. He believes that reclaiming this zone could set the stage for a pump to $2,700. X user BLADE noted the recent price correction but reminded that the asset has historically rallied after such dips.
“It’s a simple dynamic that keeps repeating. Same base as the 2025 bottom, so naturally I’d expect the same run over the months ahead. My target: $5K,” they said.
Meanwhile, investors have become increasingly aggressive on ETH. X user Gerla disclosed that Ethereum longs on Bitfinex have spiked by 266% in just a few weeks, reaching their highest level since 2022. Ash Crypto revealed that an anonymous whale opened a $50 million long position on ETH with 25x leverage and is currently less than $50 away from liquidation.
The Bearish Signals
Despite analysts’ predominant optimism, two key developments suggest the asset could underperform in the near future. The first is the recent performance of the spot ETH ETFs.
As CryptoPotato reported, the investment vehicles recorded total outflows of more than $540 million last week, signaling that pension funds, hedge funds, and other conservative investors have reduced their exposure to the cryptocurrency. More concerning, spot ETH ETFs have posted nine consecutive red days, with September 28 as the last day inflows exceeded outflows.
Next is the rising amount of coins stored on crypto exchanges. According to CryptoQuant, the figure has risen to a one-month high of about 14.9 million units, which doesn’t guarantee a price collapse but increases immediate selling pressure.

The post Ethereum (ETH) Flashes a Major Bullish Signal: The Beginning of a Massive Rally? appeared first on CryptoPotato.
Standard Chartered has launched institutional custody support for Ripple’s native stablecoin and is working with the company and LMAX Group on a broader collateral integration aimed at bringing the asset deeper into institutional trading.
The service is now live through the bank’s DIFC Branch in Dubai, which is regulated by the Dubai Financial Services Authority, and allows eligible clients access to Standard Chartered’s digital asset custody infrastructure.
The banking behemoth wants to make RLUSD eligible collateral for selected LMAX products and services, and the current planned structure indicates that Standard Chartered would extend its mirroring model to the latter.
If successful, this would allow the value of the stablecoin held in custody to be reflected at the trading venue without requiring the underlying assets themselves to be transferred there.
The parties involved in the new collaboration argued that this setup could reduce transfer-related operational risk, improve counterparty exposure management, and make institutional capital more efficient.
“RLUSD was built for exactly this kind of institutional use case. Our customers want the efficiency of a regulated stablecoin without giving up the custody standards they already trust. Bringing together RLUSD on the XRP Ledger, Standard Chartered’s custody capabilities and LMAX Group’s institutional trading infrastructure creates a practical path for institutions to put stablecoins to work across global markets,” said Jack McDonald, SVP, Stablecoins, Ripple.
Importantly, the planned collateral integration is not live yet, but Standard Chartered said it remains subject to final documentation, testing, regulatory requirements, internal approvals, and jurisdictional readiness.
Nevertheless, this is another major adoption win for Ripple and its native assets. The stablecoin alone recently reached a market cap of over $2.5 billion, less than two years after its debut.
The post Big Ripple (XRP) Development as Standard Chartered Goes Live With RLUSD Custody appeared first on CryptoPotato.
After hinting on X yesterday that the company he co-founded decades ago has completed another BTC purchase, Michael Saylor announced the development minutes ago, indicating that Strategy has indeed upped its bitcoin reserve.
Although the latest buy was relatively modest compared with some of the previous ones, Strategy’s BTC holdings still reached a new all-time high of 848,250 units.
Aside from spending $21.5 million to acquire 250 BTC at an average price of $86,194, Strategy repurchased another $192 million in preferred stock (STRC). Its USD stash has slipped to $5.5 billion after the latest accumulations, down from over $6 billion just a few weeks ago.
Strategy has acquired 250 $BTC and repurchased $192M of $STRC. As of 10/11/26, we hold 848,250 BTC and $5.5B of USD Assets. $MSTR https://t.co/hhxR6N95mq
— Michael Saylor (@saylor) October 12, 2026
Strategy resumed its BTC accumulation spree in the middle of September after the summer hiatus, during which it even sold on several occasions. The current streak now extends to four weeks in a row with consecutive purchases.
Meanwhile, STRC’s price continues to recover from the summer lows. Recall that the asset tumbled far below its par level of $100 to under $75 during its darkest hour. However, Strategy’s decision to halt its BTC accumulation in order to rebuild investors’ trust in STRC, as well as its USD stash, turned out to be quite beneficial for the preferred stock, which closed on Friday at $99.66.
The post Strategy Buys Another $21M in Bitcoin as Accumulation Streak Rolls On appeared first on CryptoPotato.